3Q 2026 Earnings Presentation October 22, 2026 Exhibit 99.2
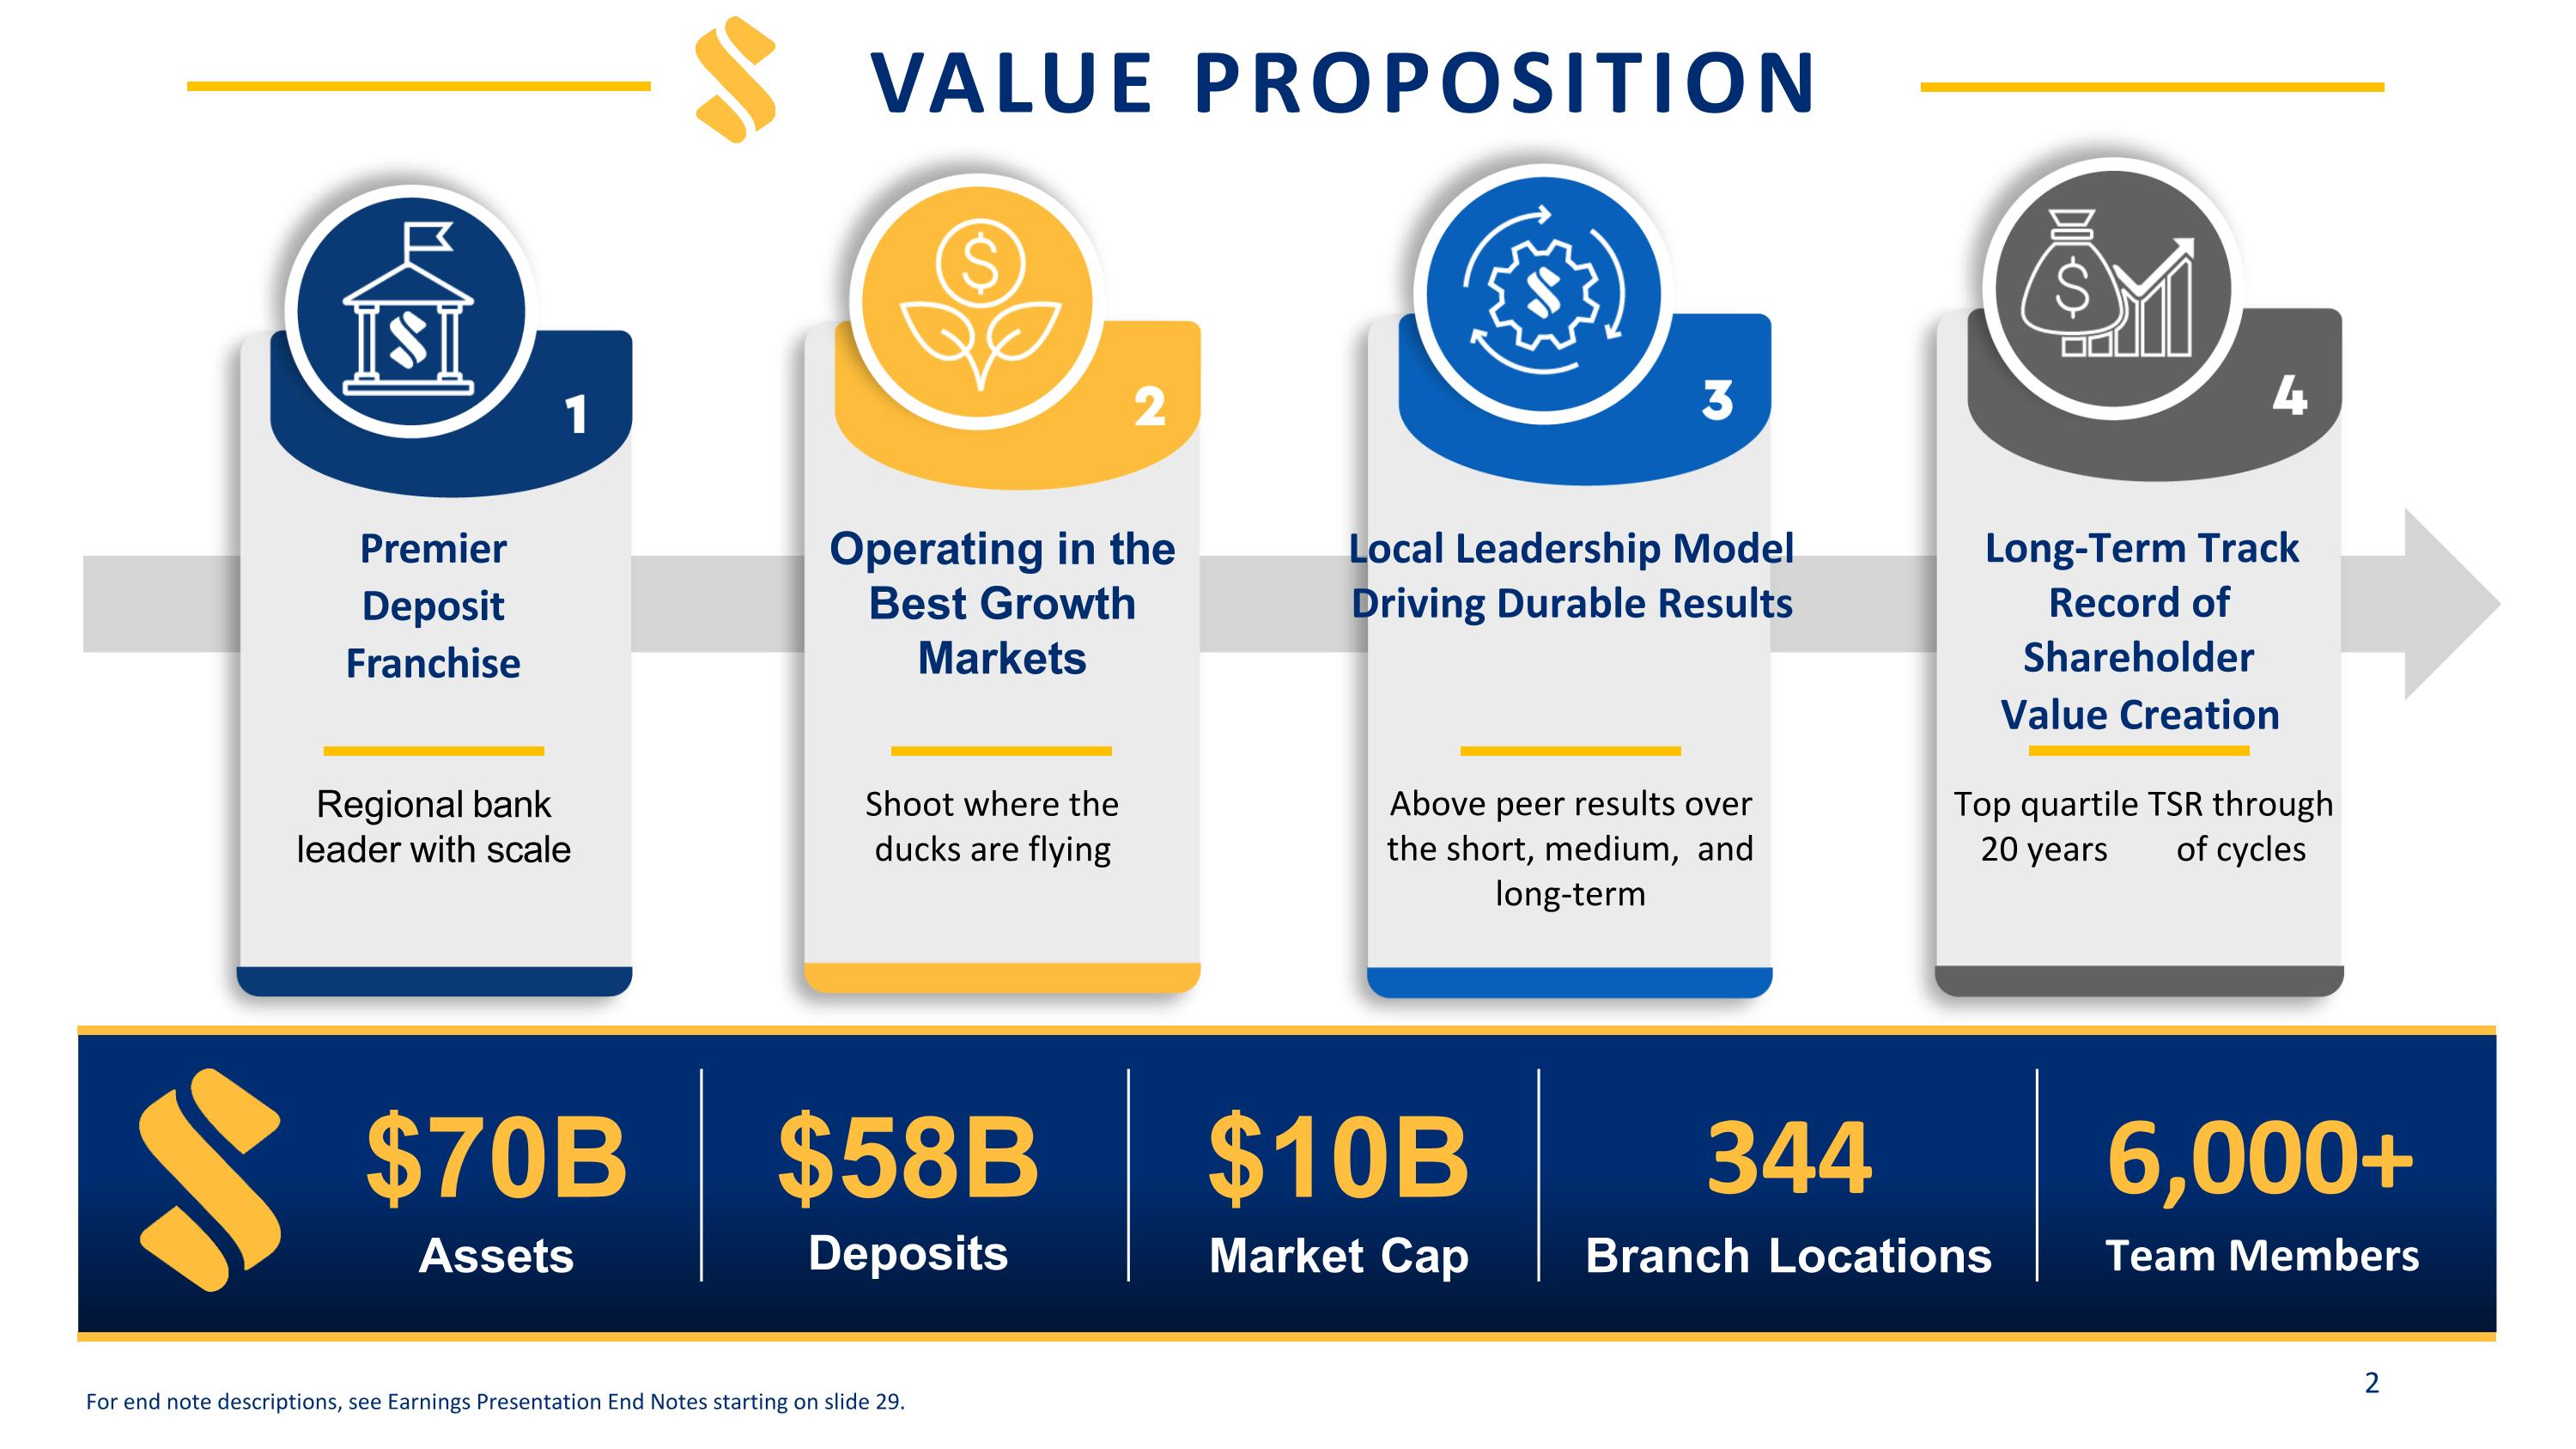
VALUE PROPOSITION 2 For end note descriptions, see Earnings Presentation End Notes starting on slide 29. 344 Branch Locations $70B Assets $58BDeposits $10B Market Cap 6,000+ Team Members Local Leadership Model Driving Durable Results Long-Term Track Record of Shareholder Value Creation Premier Deposit Franchise Regional bank leader with scale Operating in the Best Growth Markets Top quartile TSR through 20 years of cycles Shoot where the ducks are flying VALUE PROPOSITION Above peer results over the short, medium, and long-term
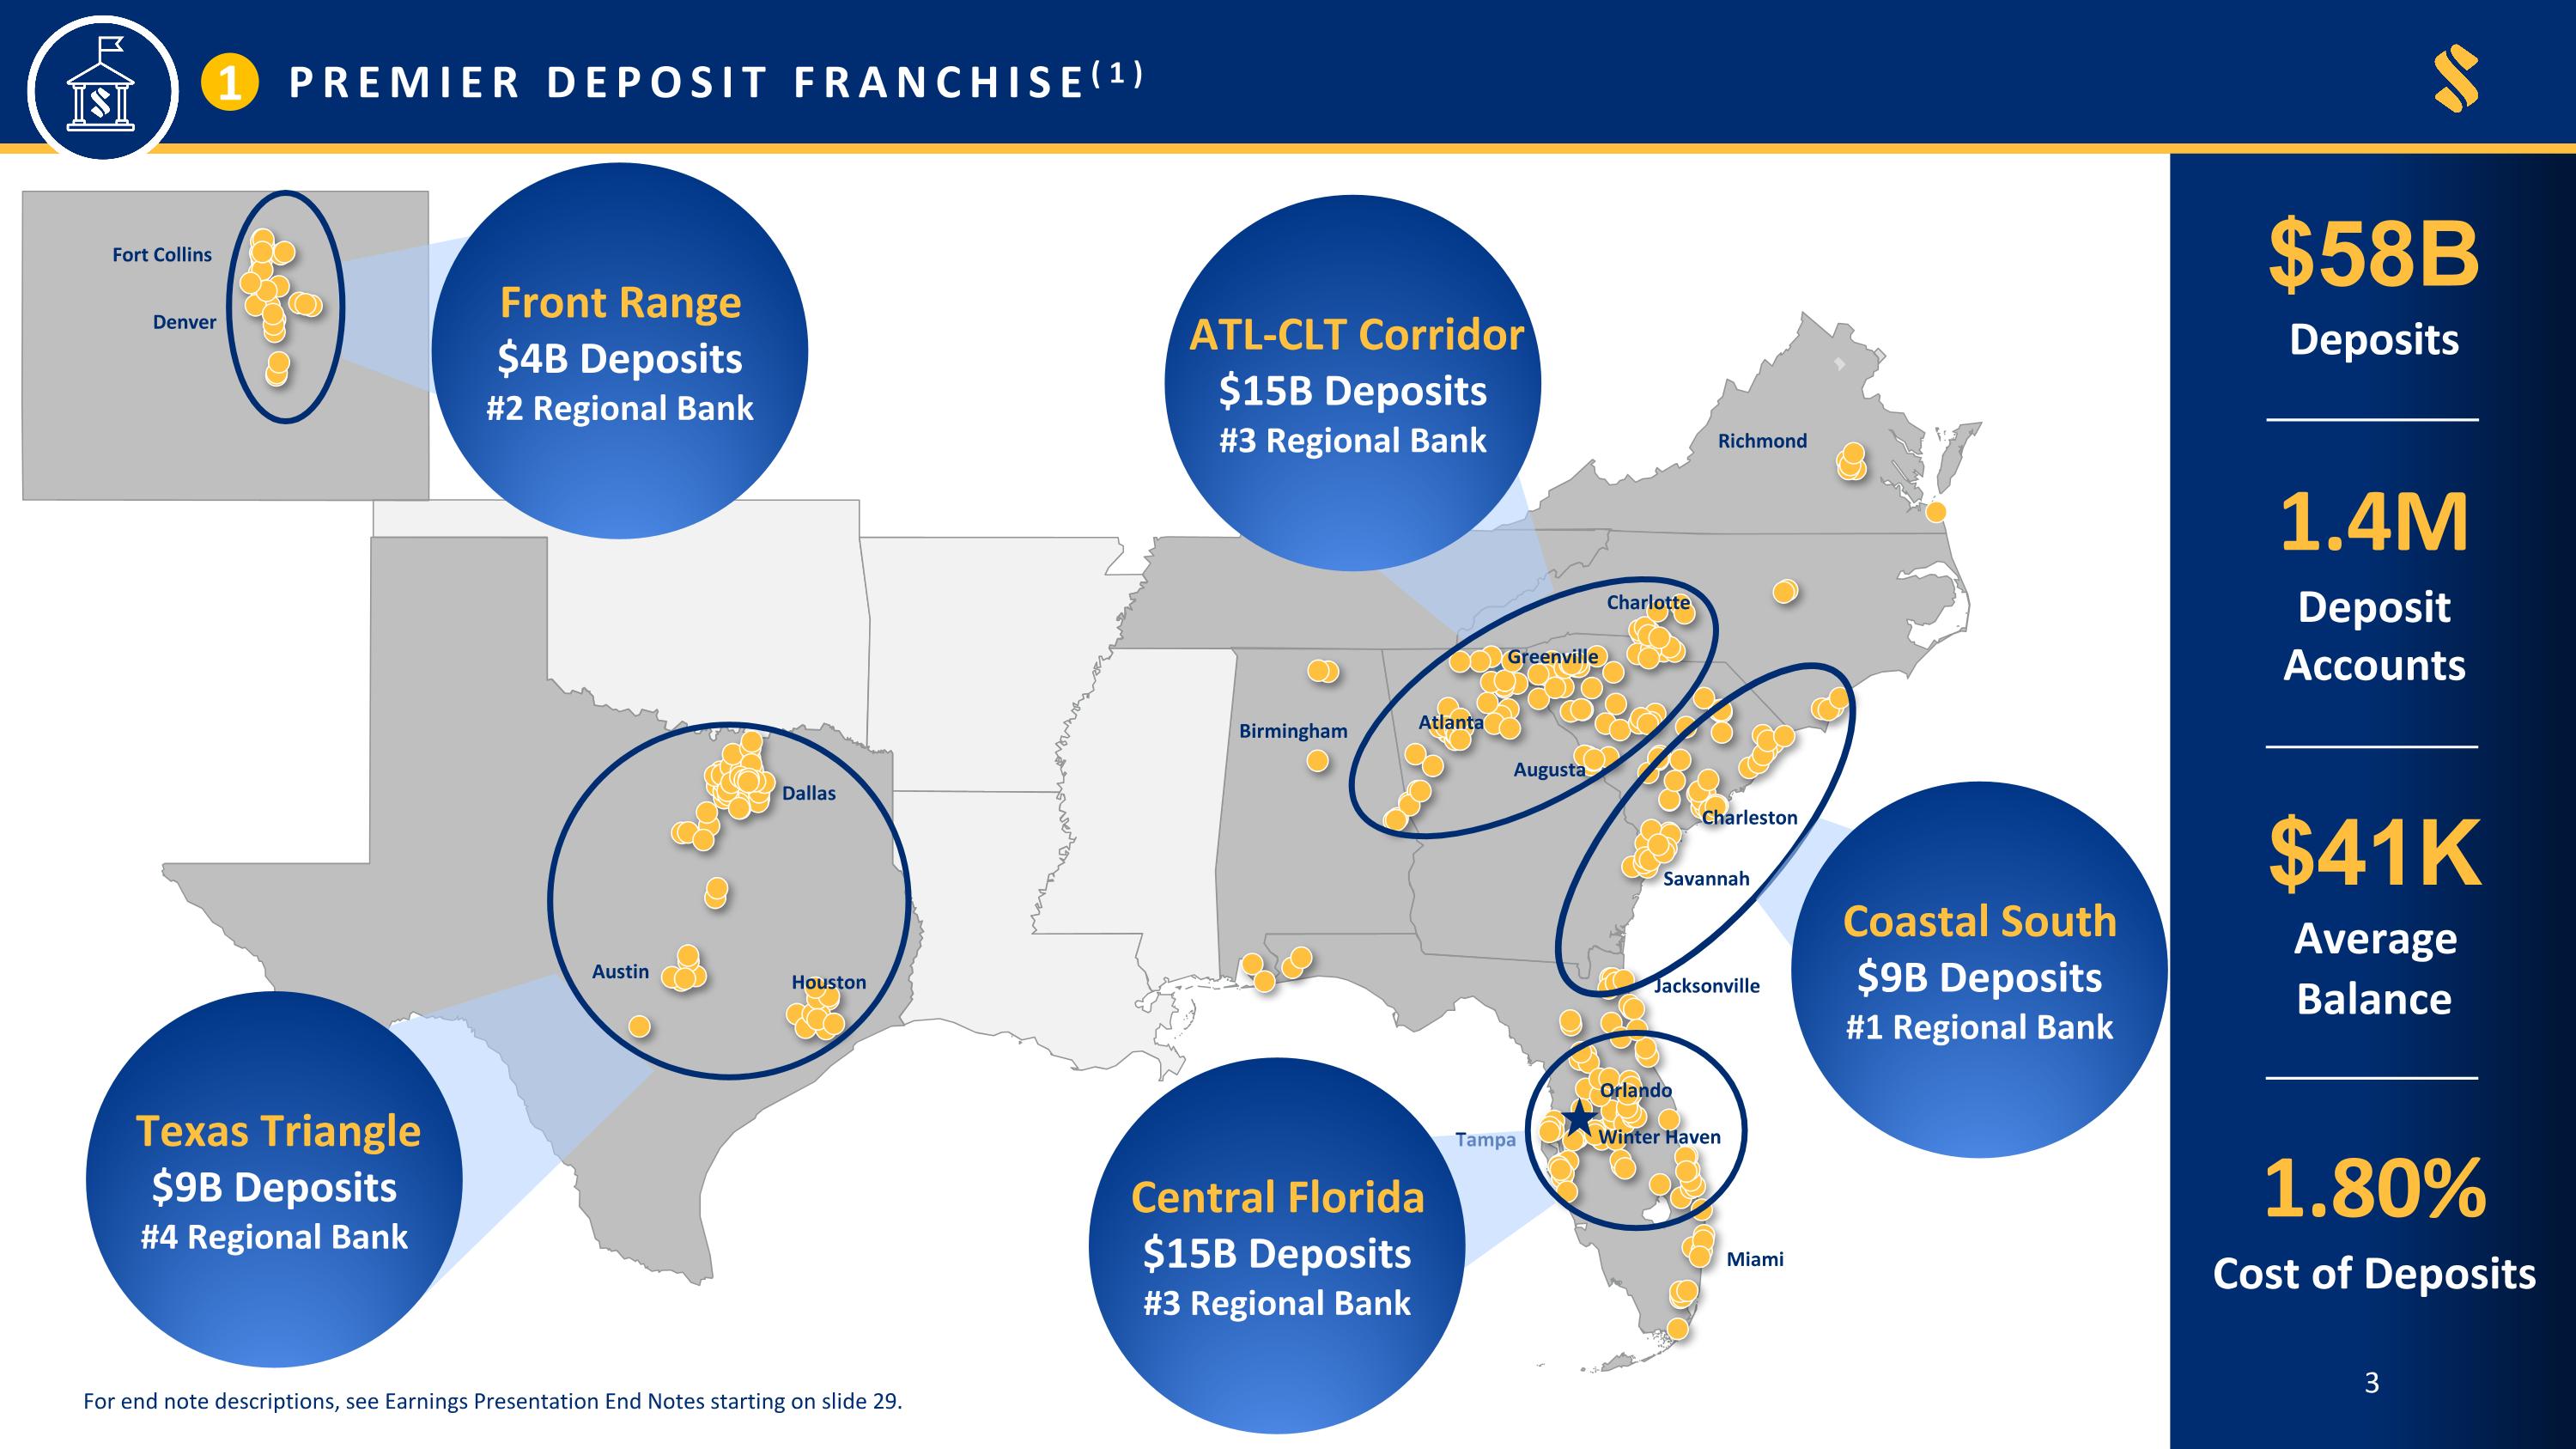
Fort Collins Denver Dallas Austin Houston Birmingham Richmond Charleston Atlanta Augusta Savannah Jacksonville Miami Orlando Winter Haven Tampa Greenville Charlotte PREMIER DEPOSIT FRANCHISE(1) 1.80% Cost of Deposits $58B Deposits $41K Average Balance 1.4M Deposit Accounts 1 3 For end note descriptions, see Earnings Presentation End Notes starting on slide 29. Texas Triangle $9B Deposits #4 Regional Bank ATL-CLT Corridor $15B Deposits #3 Regional Bank Coastal South $9B Deposits #1 Regional Bank Central Florida $15B Deposits #3 Regional Bank Front Range $4B Deposits #2 Regional Bank
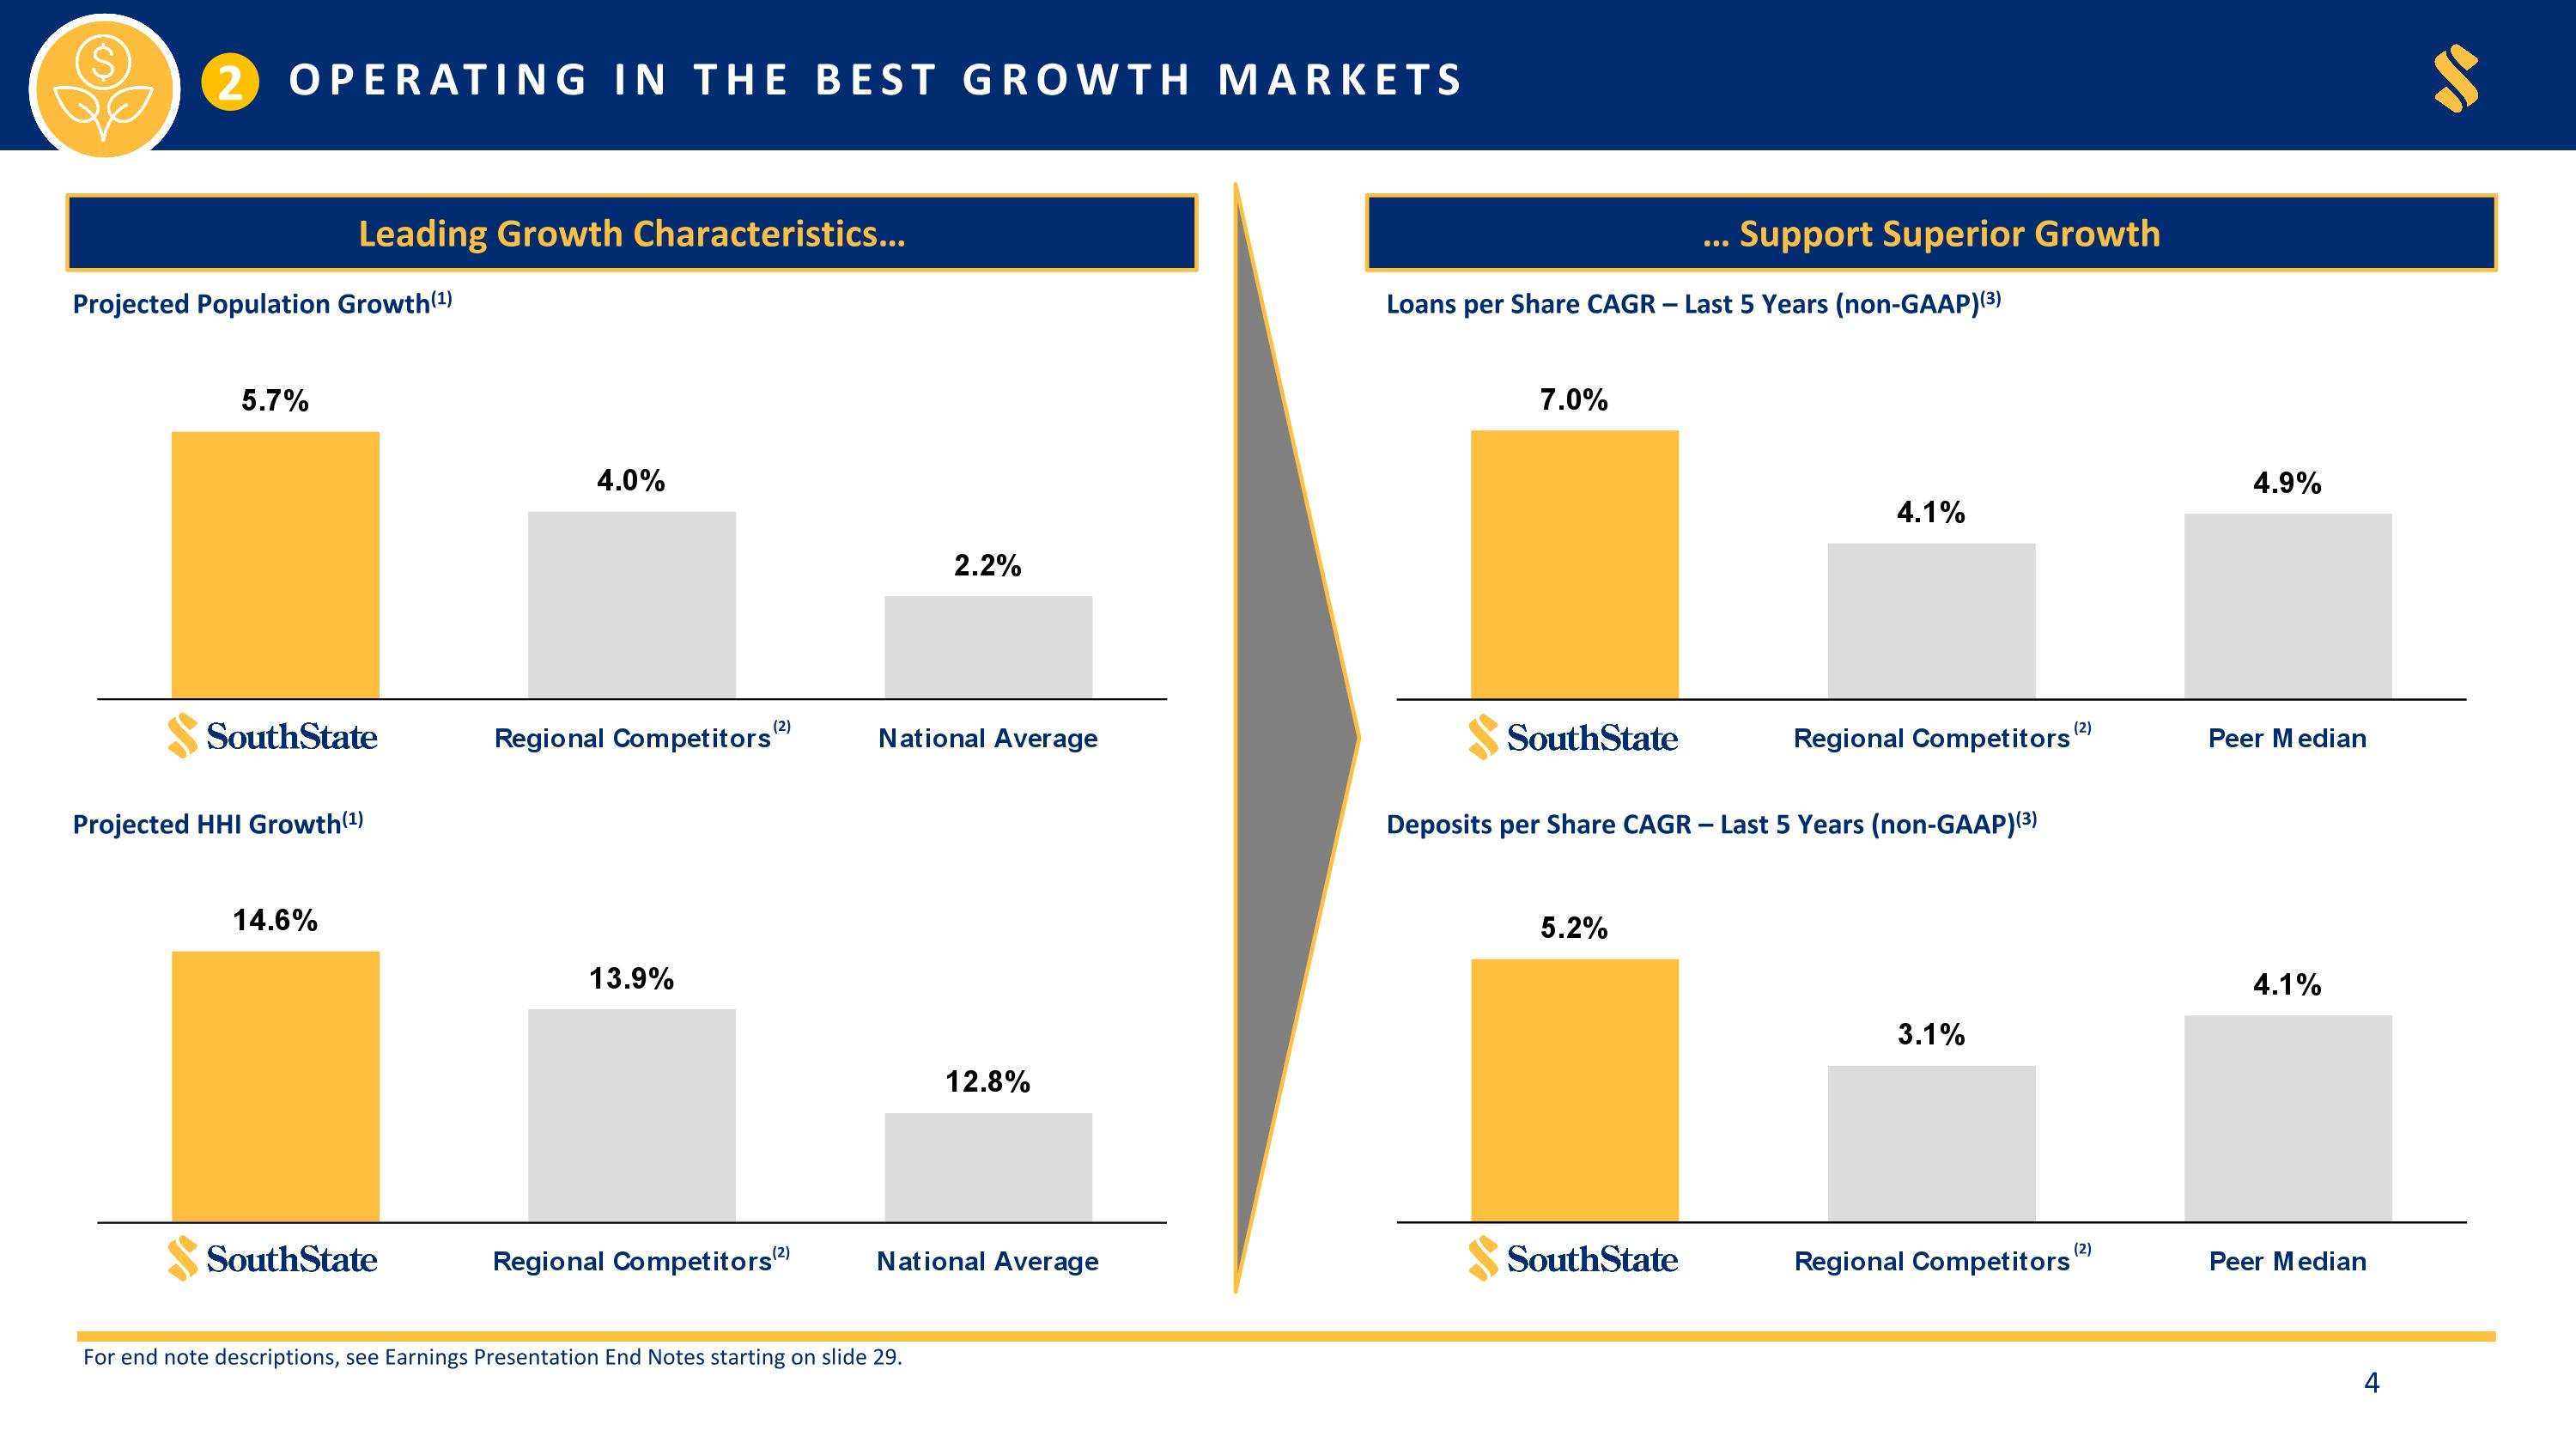
OPERATING IN THE BEST GROWTH MARKETS 4 2 Leading Growth Characteristics… … Support Superior Growth Projected HHI Growth(1) Projected Population Growth(1) Deposits per Share CAGR – Last 5 Years (non-GAAP)(3) Loans per Share CAGR – Last 5 Years (non-GAAP)(3) For end note descriptions, see Earnings Presentation End Notes starting on slide 29. (2) (2) (2) (2)
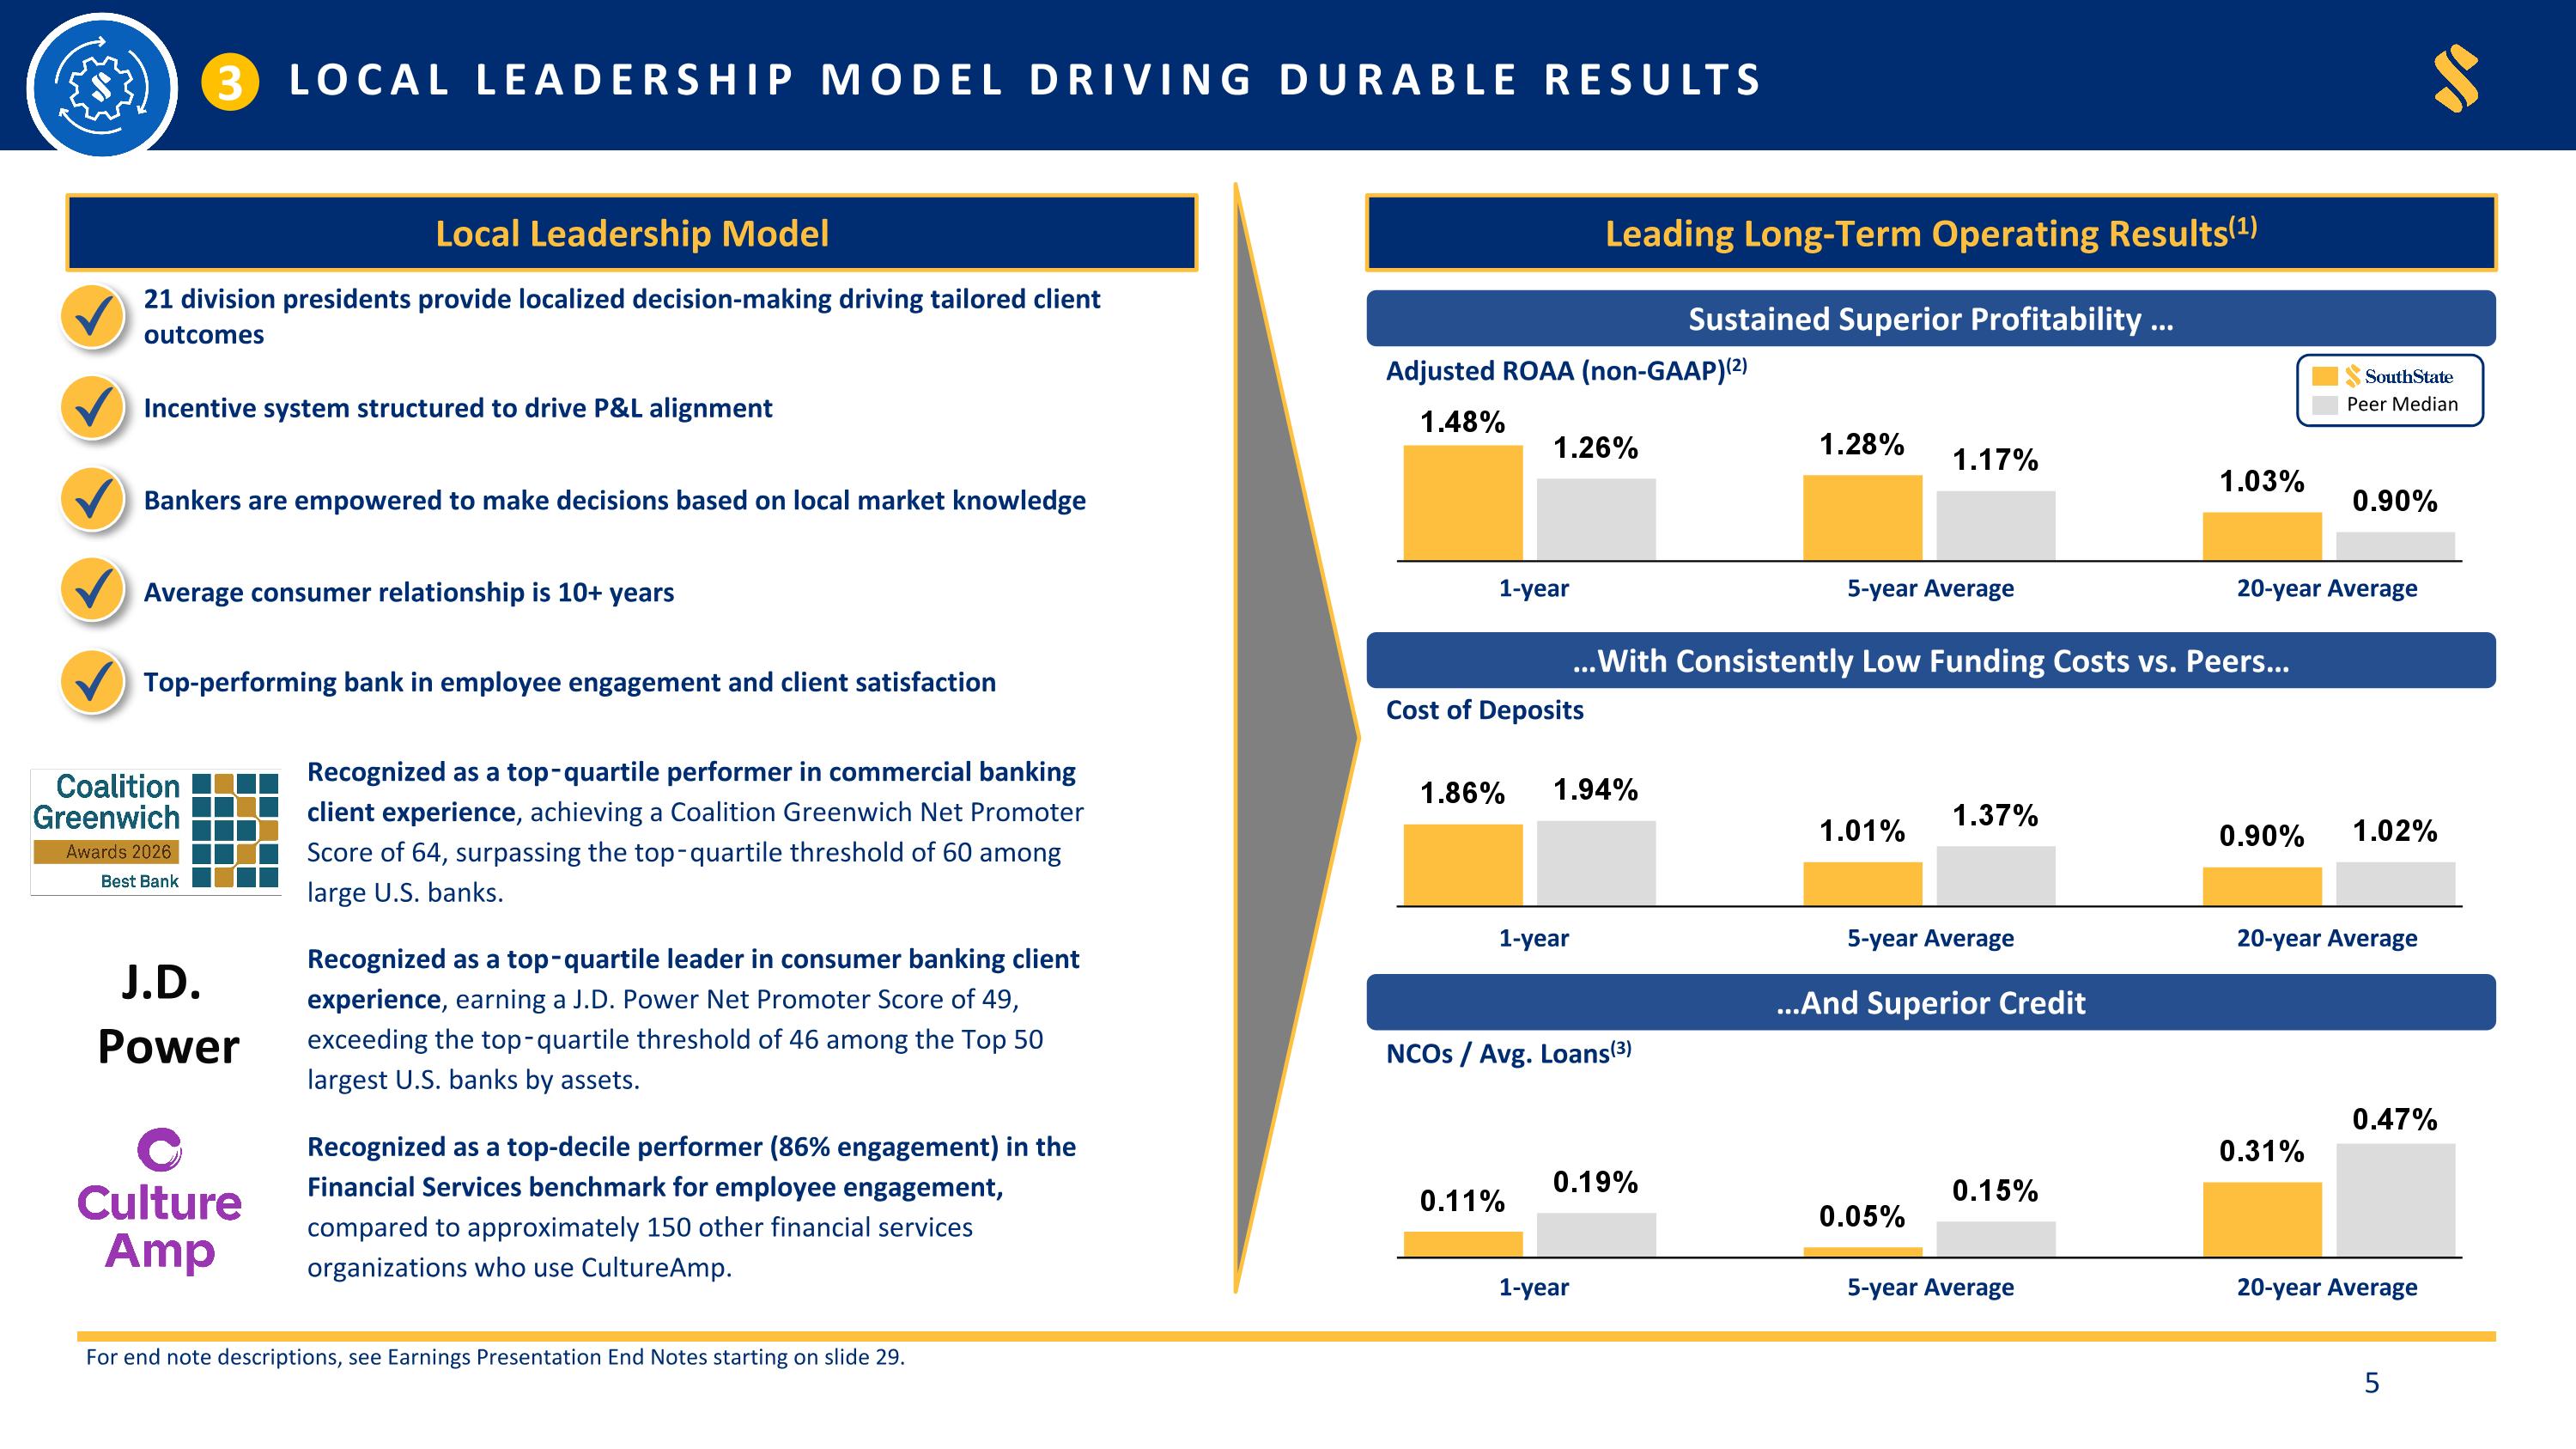
Local Leadership Model Driving Durable Results 5 3 Local Leadership Model Leading Long-Term Operating Results(1) Top-performing bank in employee engagement and client satisfaction Average consumer relationship is 10+ years Bankers are empowered to make decisions based on local market knowledge Incentive system structured to drive P&L alignment 21 division presidents provide localized decision-making driving tailored client outcomes Cost of Deposits Adjusted ROAA (non-GAAP)(2) NCOs / Avg. Loans(3) Sustained Superior Profitability … …With Consistently Low Funding Costs vs. Peers… …And Superior Credit Peer Median For end note descriptions, see Earnings Presentation End Notes starting on slide 29. Recognized as a top‑quartile leader in consumer banking client experience, earning a J.D. Power Net Promoter Score of 49, exceeding the top‑quartile threshold of 46 among the Top 50 largest U.S. banks by assets. Recognized as a top‑quartile performer in commercial banking client experience, achieving a Coalition Greenwich Net Promoter Score of 64, surpassing the top‑quartile threshold of 60 among large U.S. banks. Recognized as a top-decile performer (86% engagement) in the Financial Services benchmark for employee engagement, compared to approximately 150 other financial services organizations who use CultureAmp. J.D. Power 1-year 5-year Average 20-year Average 1-year 5-year Average 20-year Average 1-year 5-year Average 20-year Average
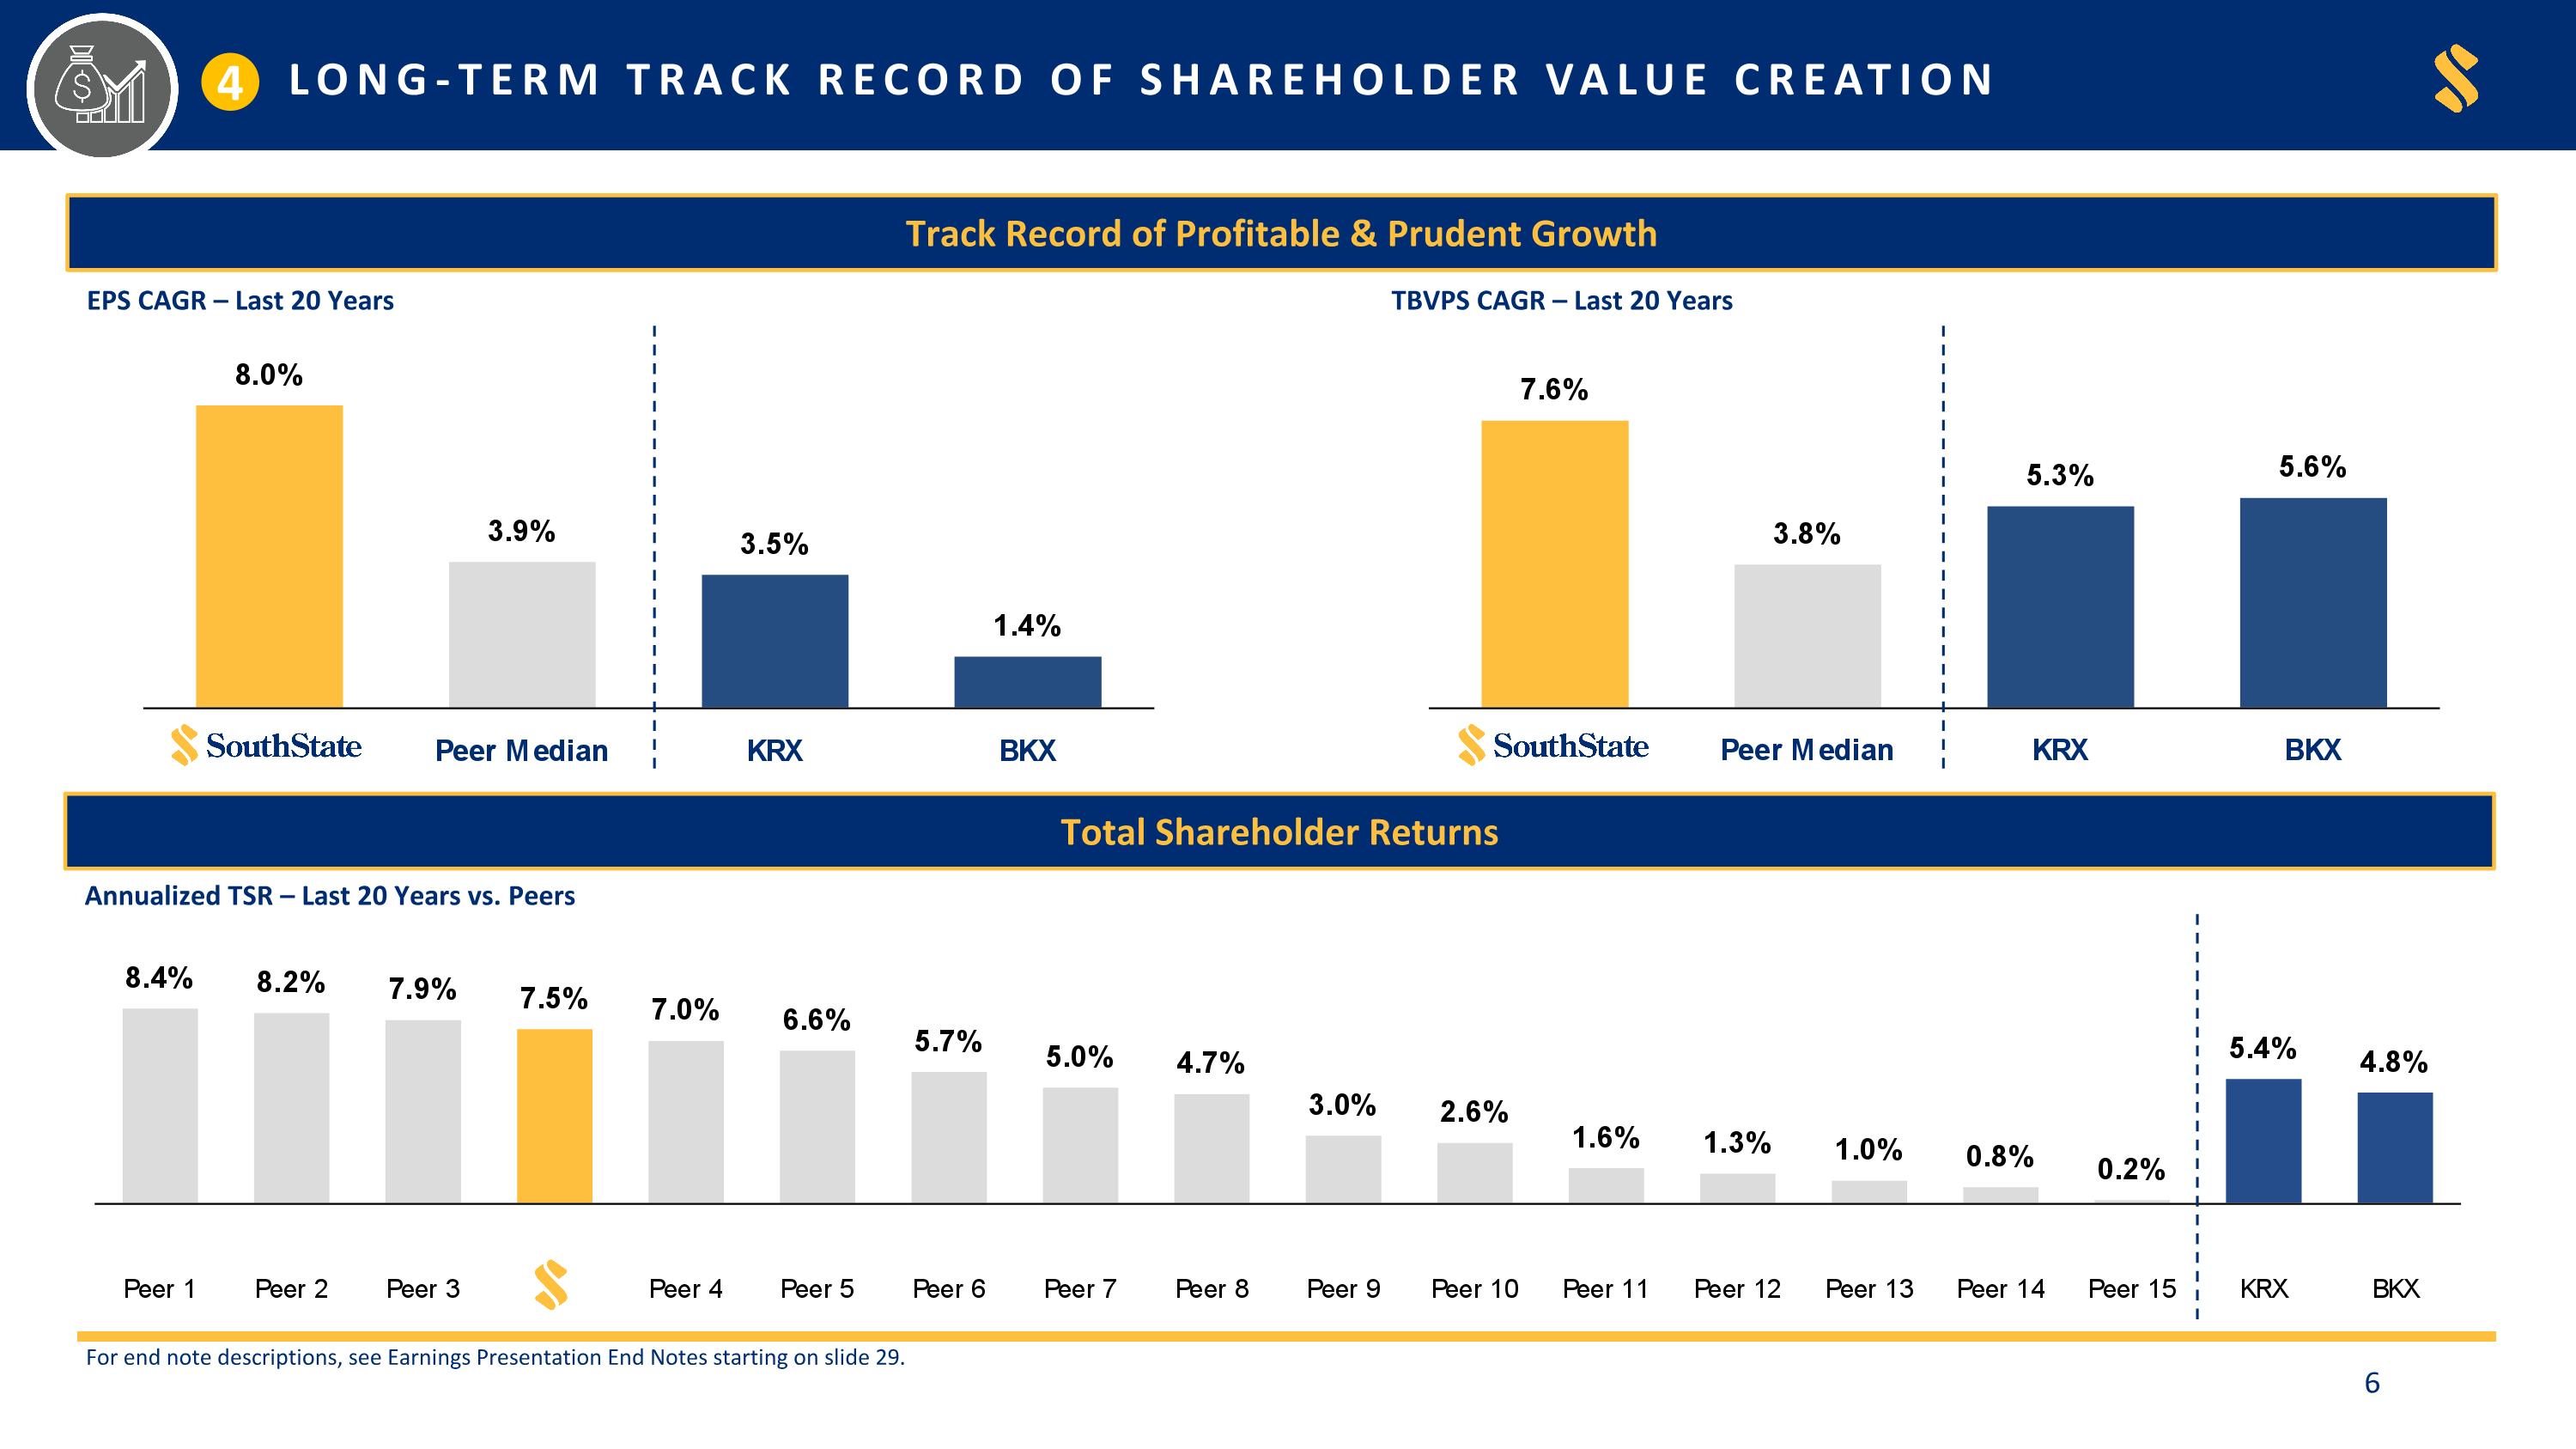
LONG-TERM TRACK RECORD OF SHAREHOLDER VALUE CREATION 6 4 Track Record of Profitable & Prudent Growth TBVPS CAGR – Last 20 Years EPS CAGR – Last 20 Years Total Shareholder Returns Annualized TSR – Last 20 Years vs. Peers For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
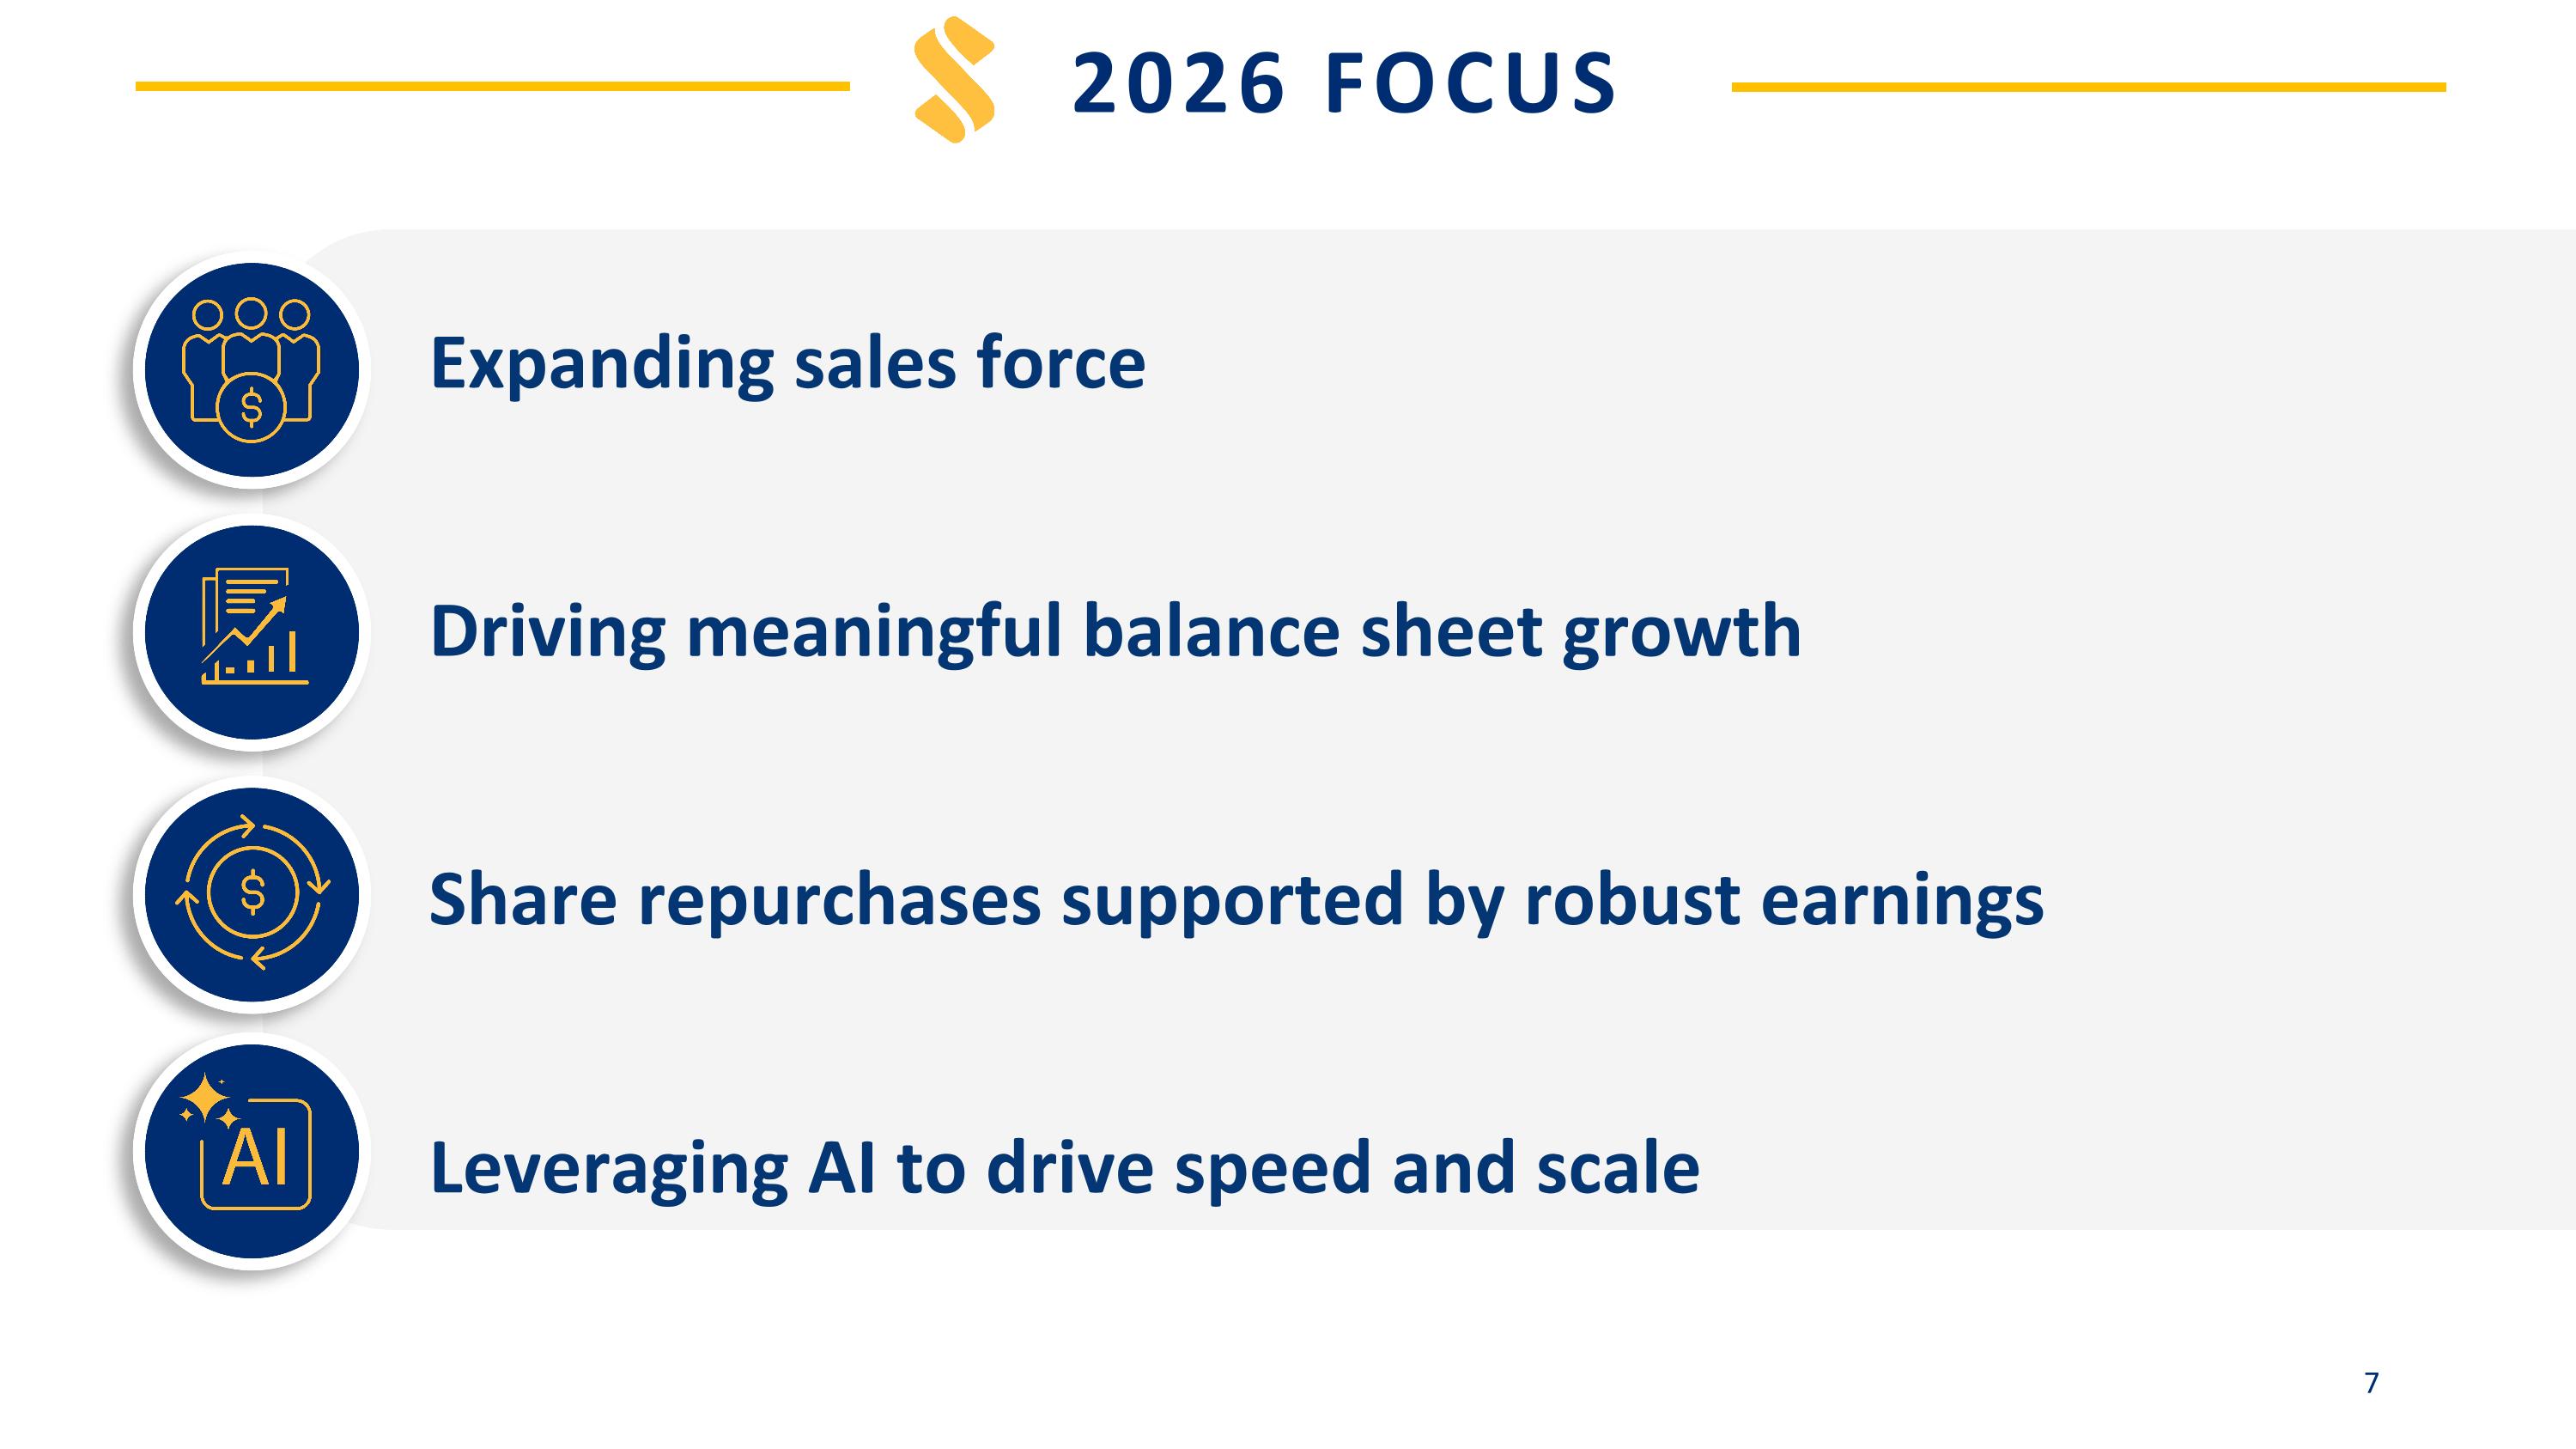
2026 FOCUS Expanding sales force Driving meaningful balance sheet growth Share repurchases supported by robust earnings Leveraging AI to drive speed and scale 2026 FOCUS
Quarterly Results
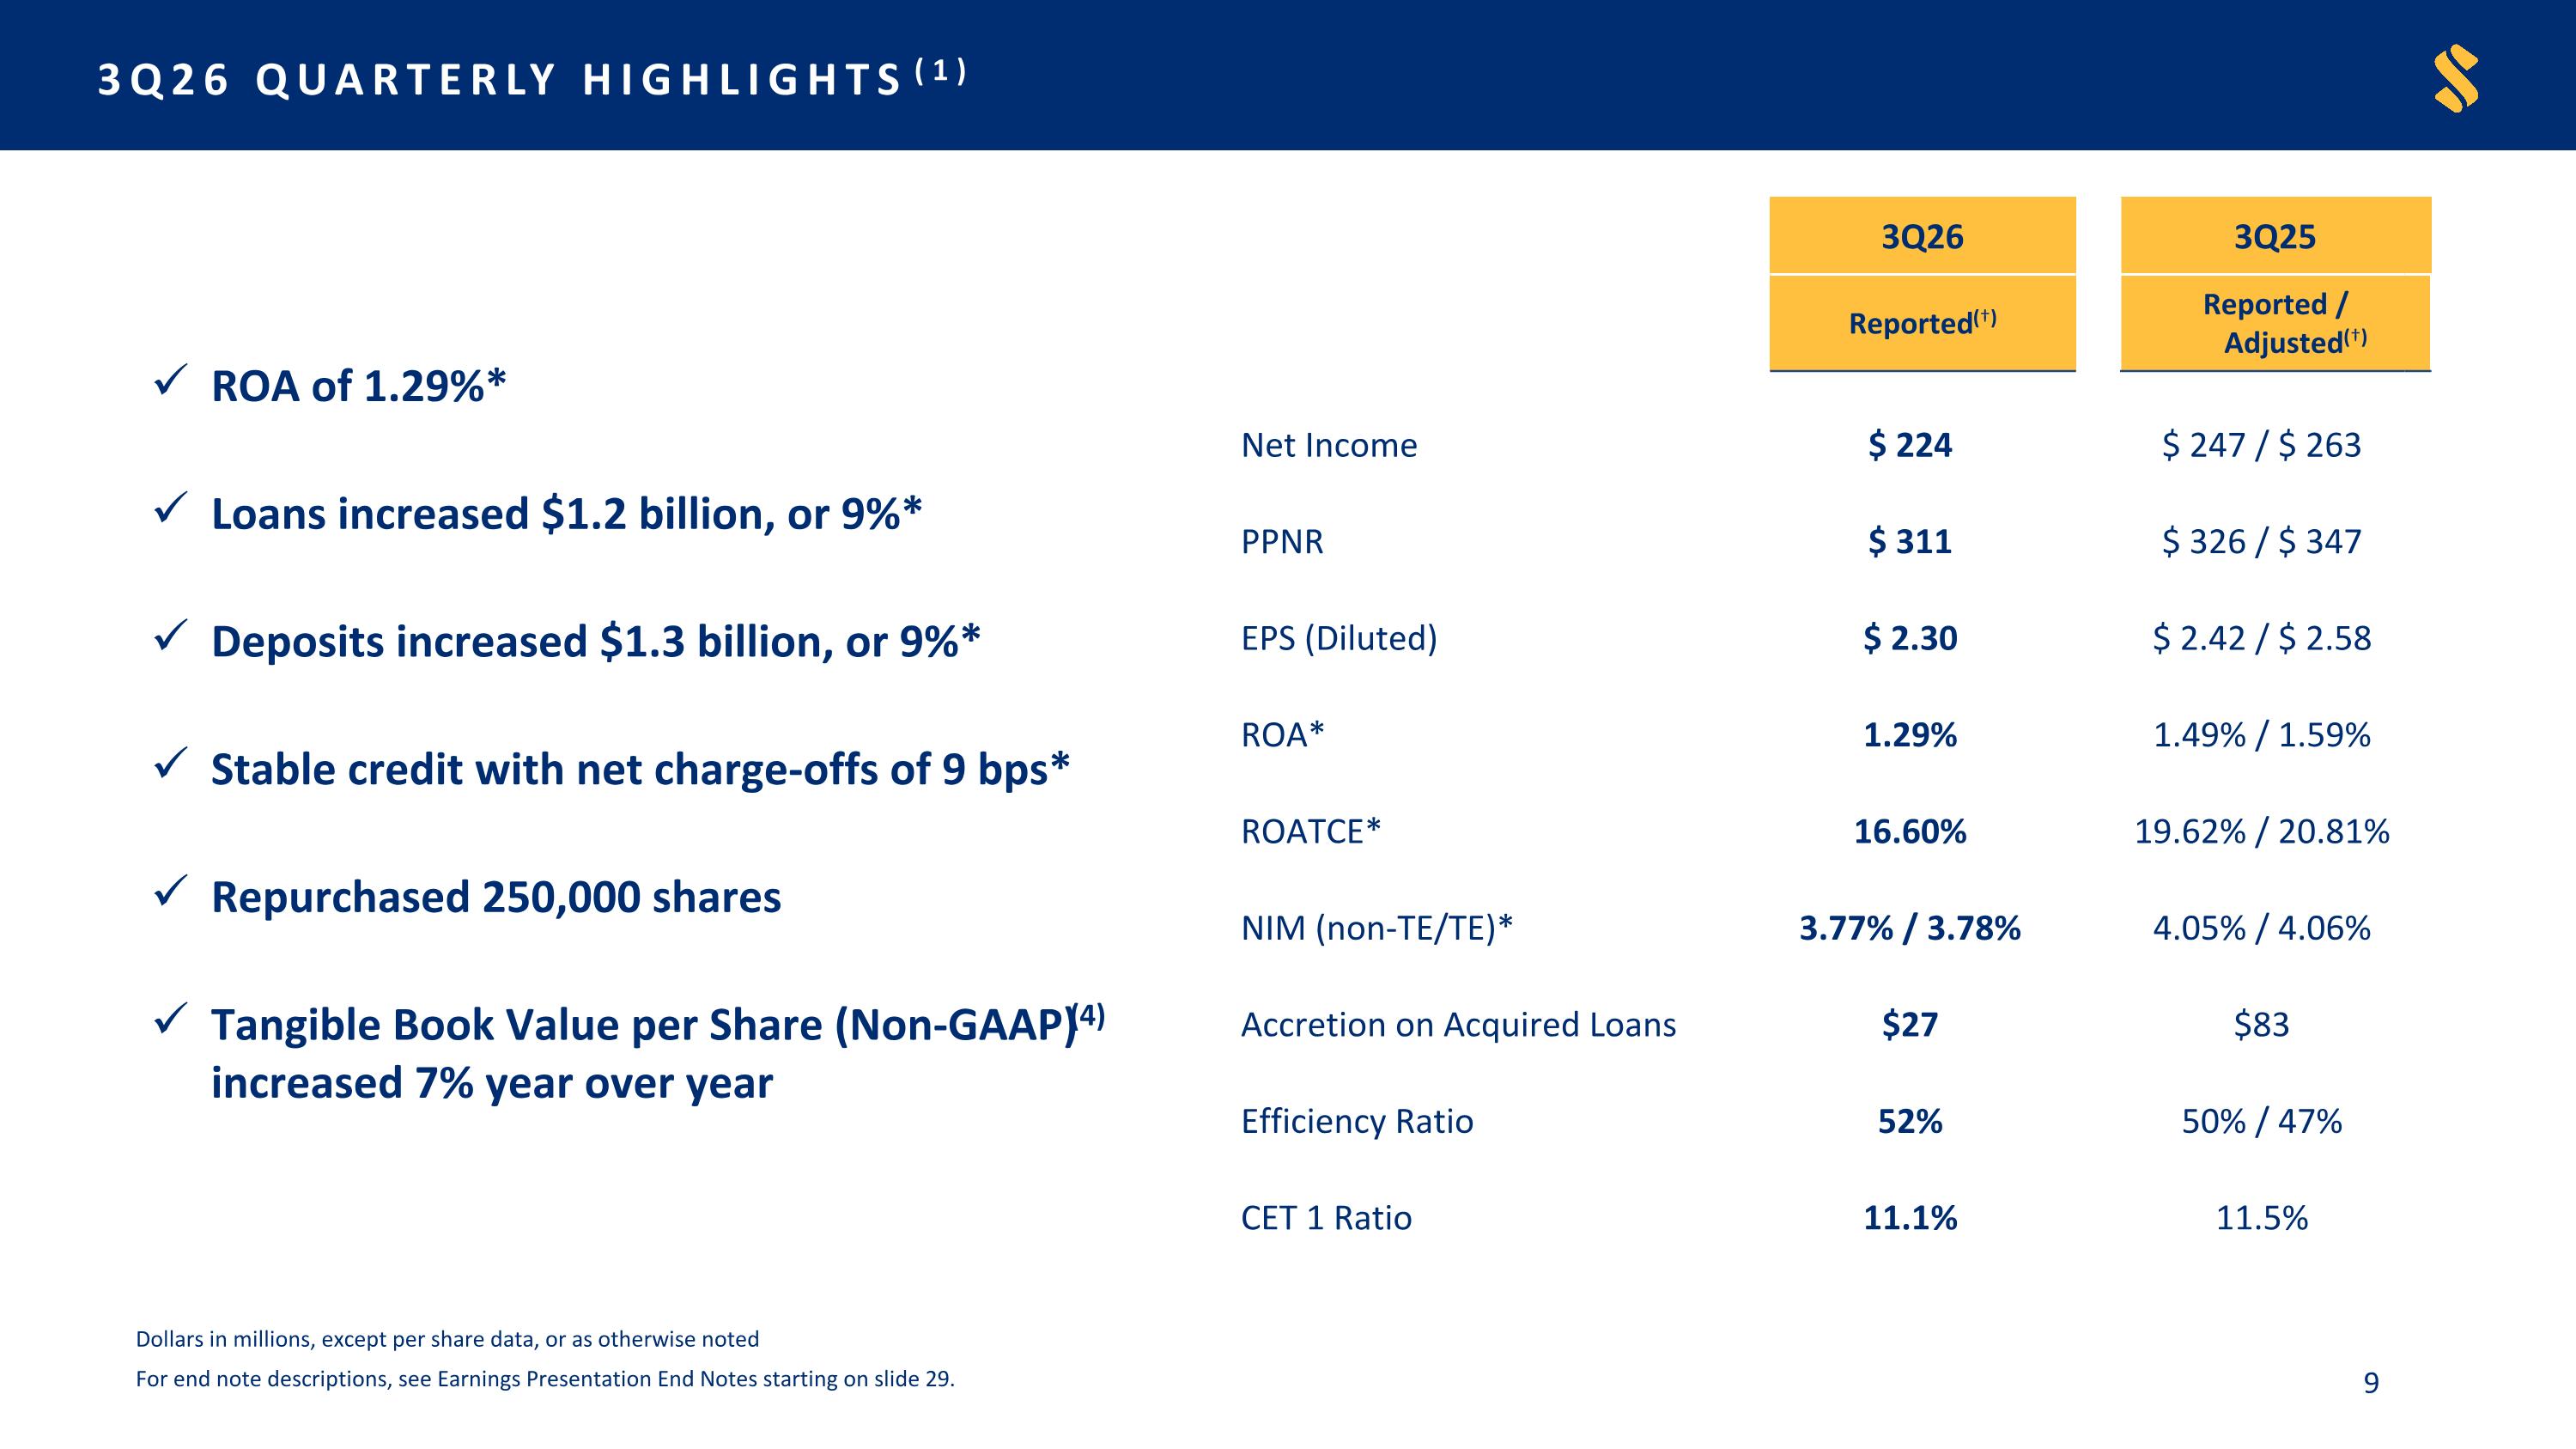
3Q26 QUARTERLY HIGHLIGHTS(1) Dollars in millions, except per share data, or as otherwise noted For end note descriptions, see Earnings Presentation End Notes starting on slide 29. 3Q26 3Q25 Reported(†) Reported / Adjusted(†) Net Income $ 224 $ 247 / $ 263 PPNR $ 311 $ 326 / $ 347 EPS (Diluted) $ 2.30 $ 2.42 / $ 2.58 ROA* 1.29% 1.49% / 1.59% ROATCE* 16.60% 19.62% / 20.81% NIM (non-TE/TE)* 3.77% / 3.78% 4.05% / 4.06% Accretion on Acquired Loans $27 $83 Efficiency Ratio 52% 50% / 47% CET 1 Ratio 11.1% 11.5% ROA of 1.29%* Loans increased $1.2 billion, or 9%* Deposits increased $1.3 billion, or 9%* Stable credit with net charge-offs of 9 bps* Repurchased 250,000 shares Tangible Book Value per Share (Non-GAAP)(4) increased 7% year over year
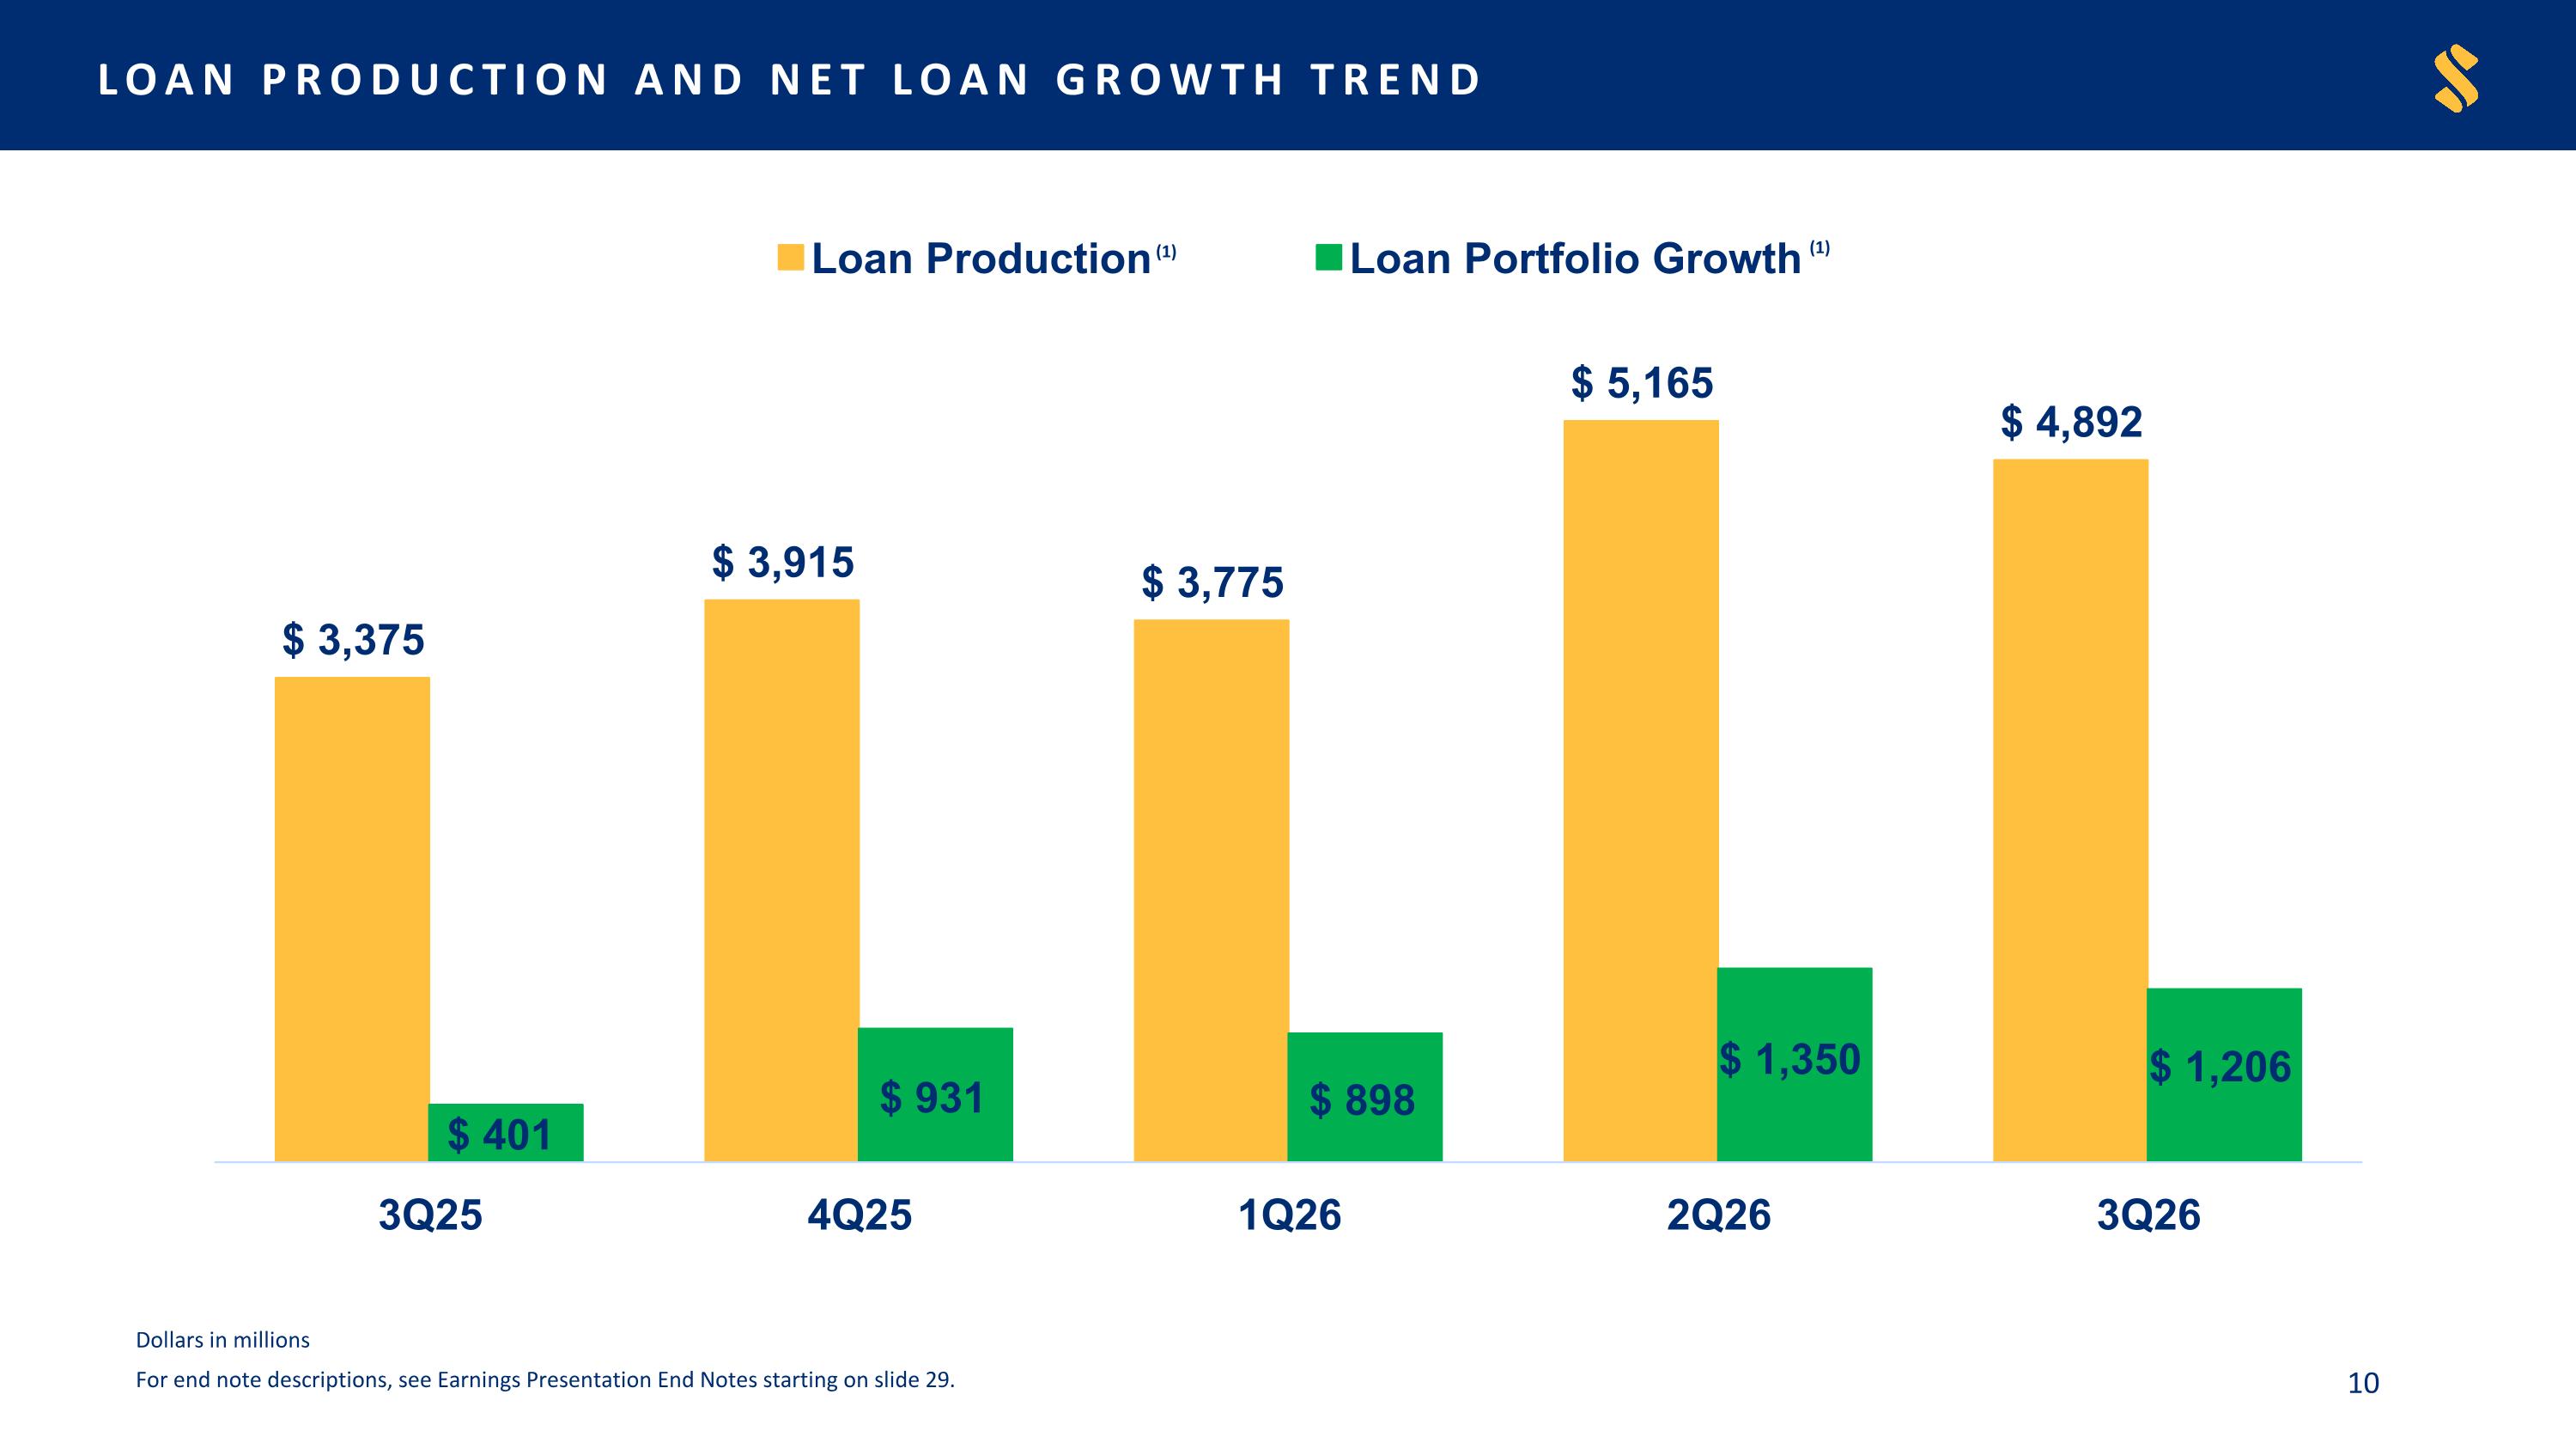
LOAN PRODUCTION AND NET LOAN GROWTH TREND Dollars in millions For end note descriptions, see Earnings Presentation End Notes starting on slide 29. (1) (1)
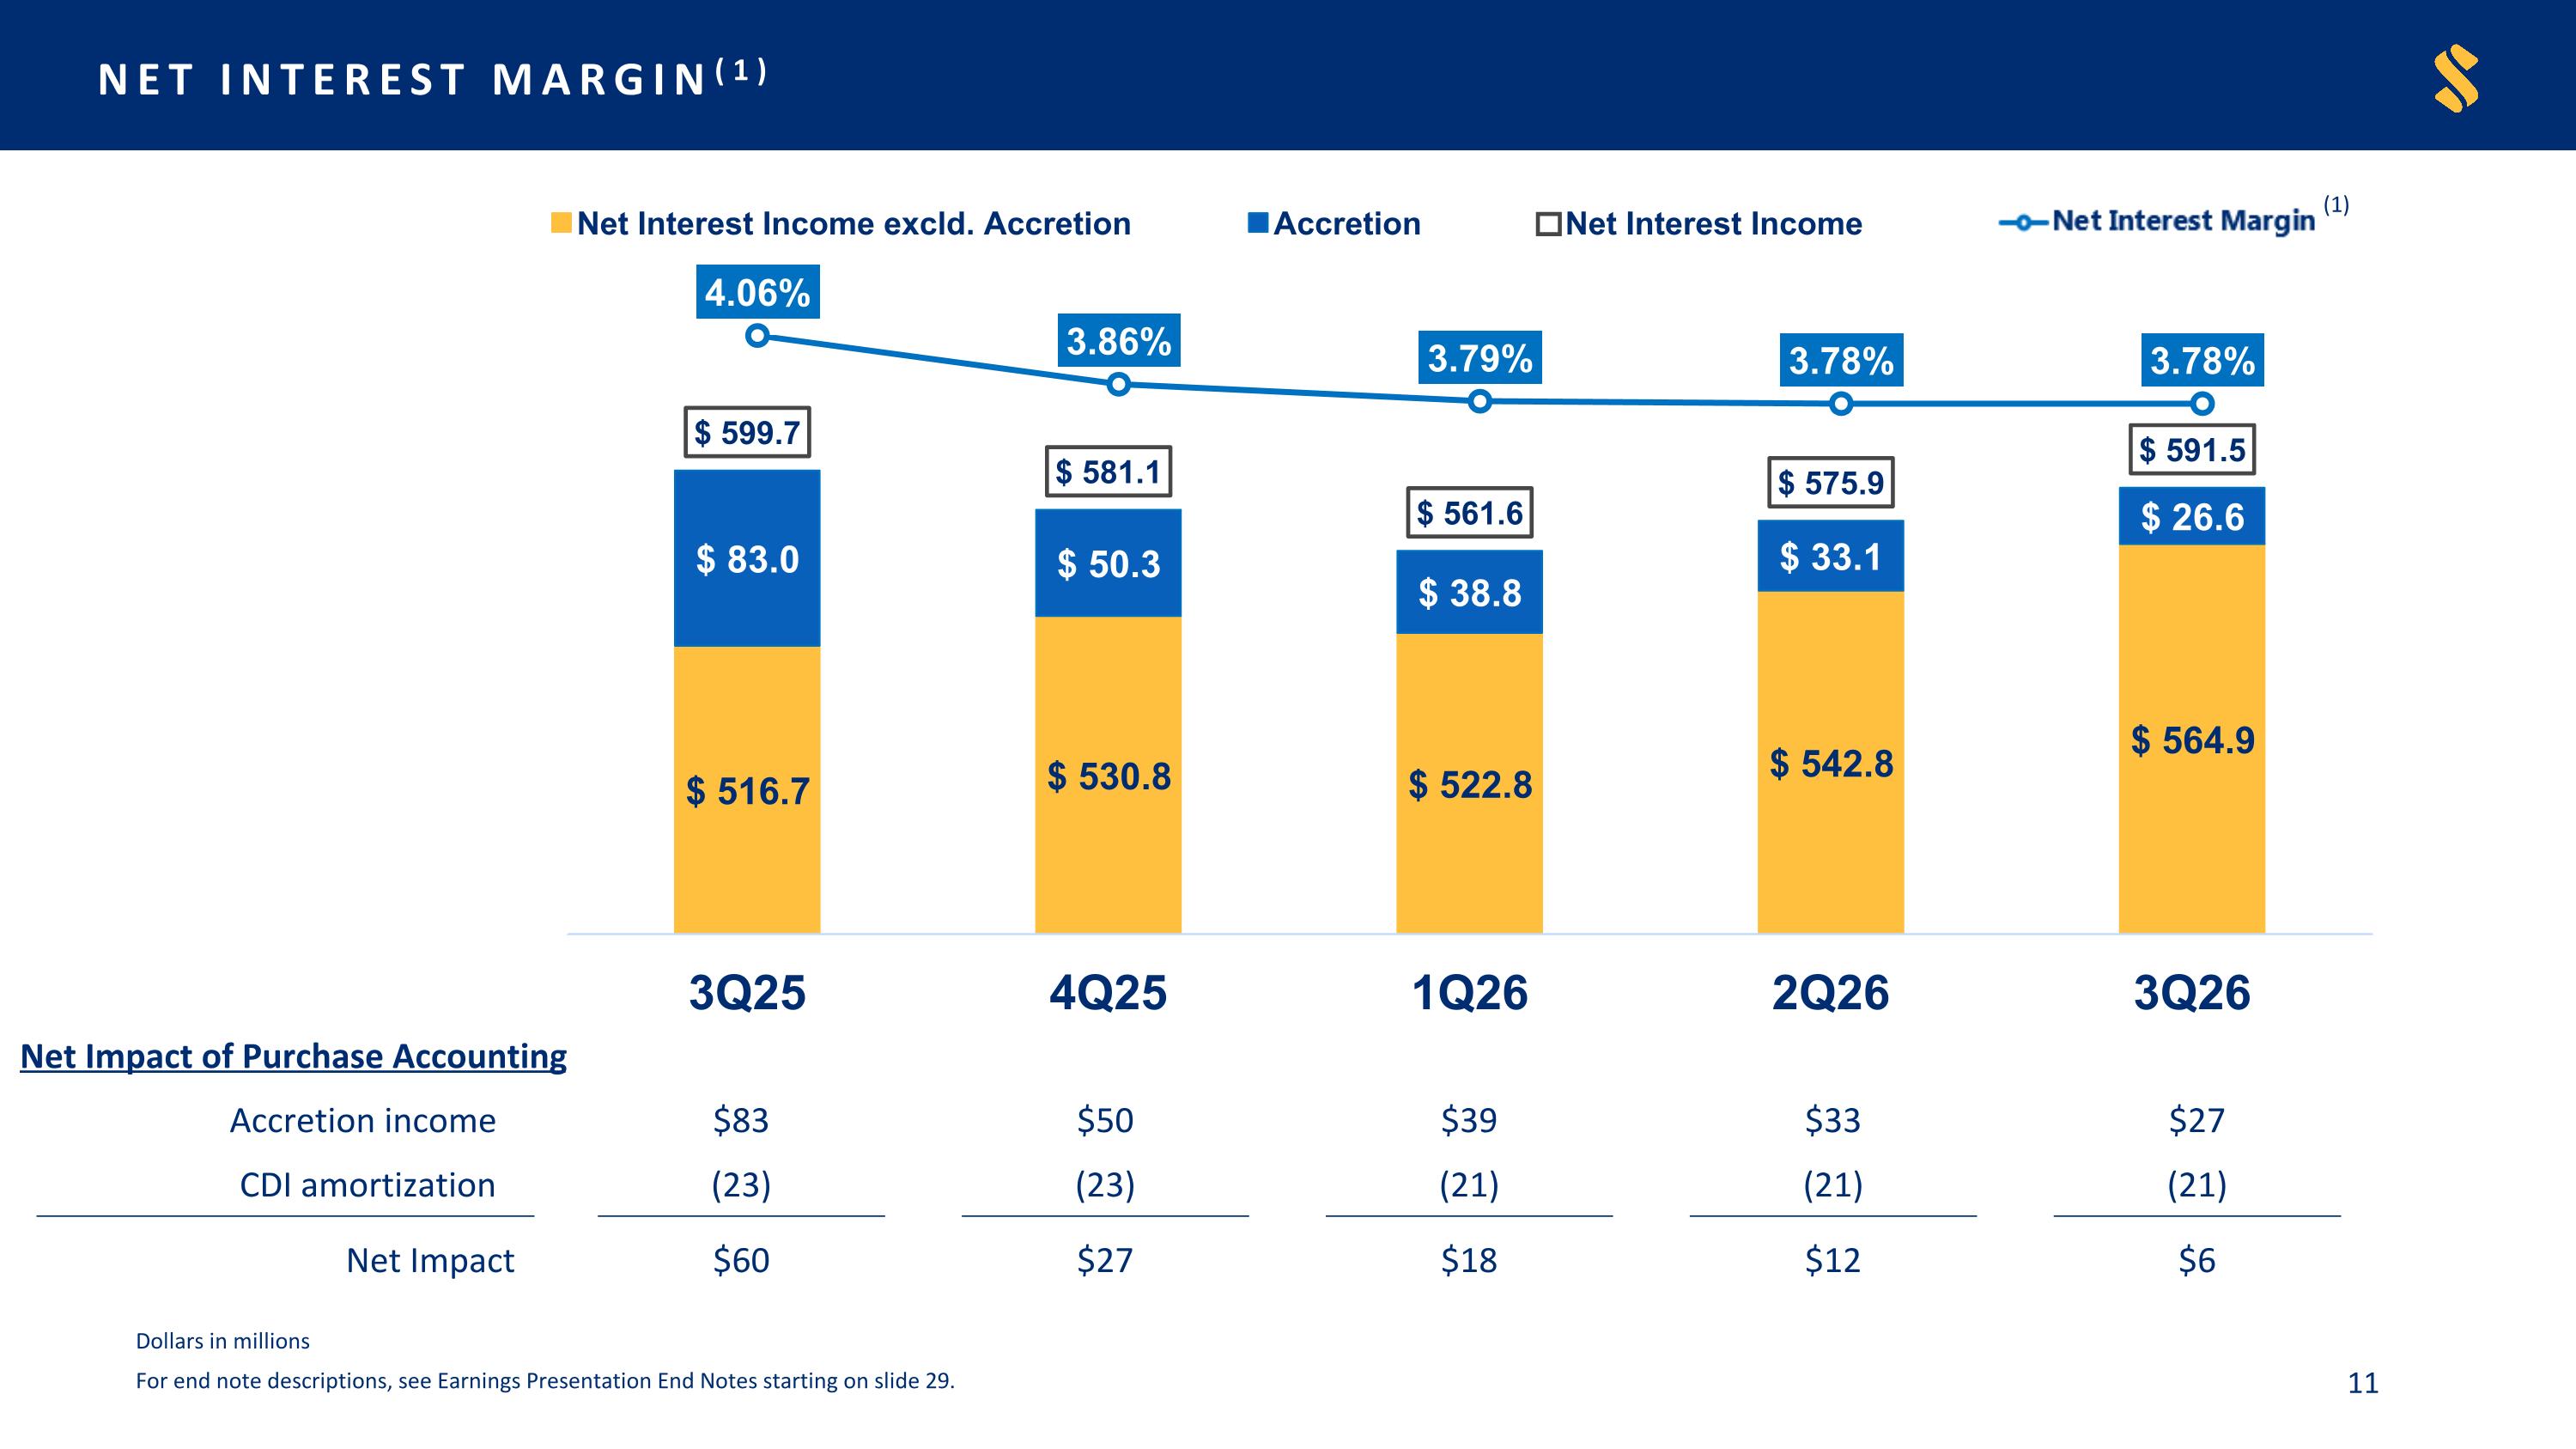
NET INTEREST MARGIN(1) Dollars in millions For end note descriptions, see Earnings Presentation End Notes starting on slide 29. Accretion income $83 $50 $39 $33 $27 CDI amortization (23) (23) (21) (21) (21) Net Impact $60 $27 $18 $12 $6 Net Impact of Purchase Accounting (1)
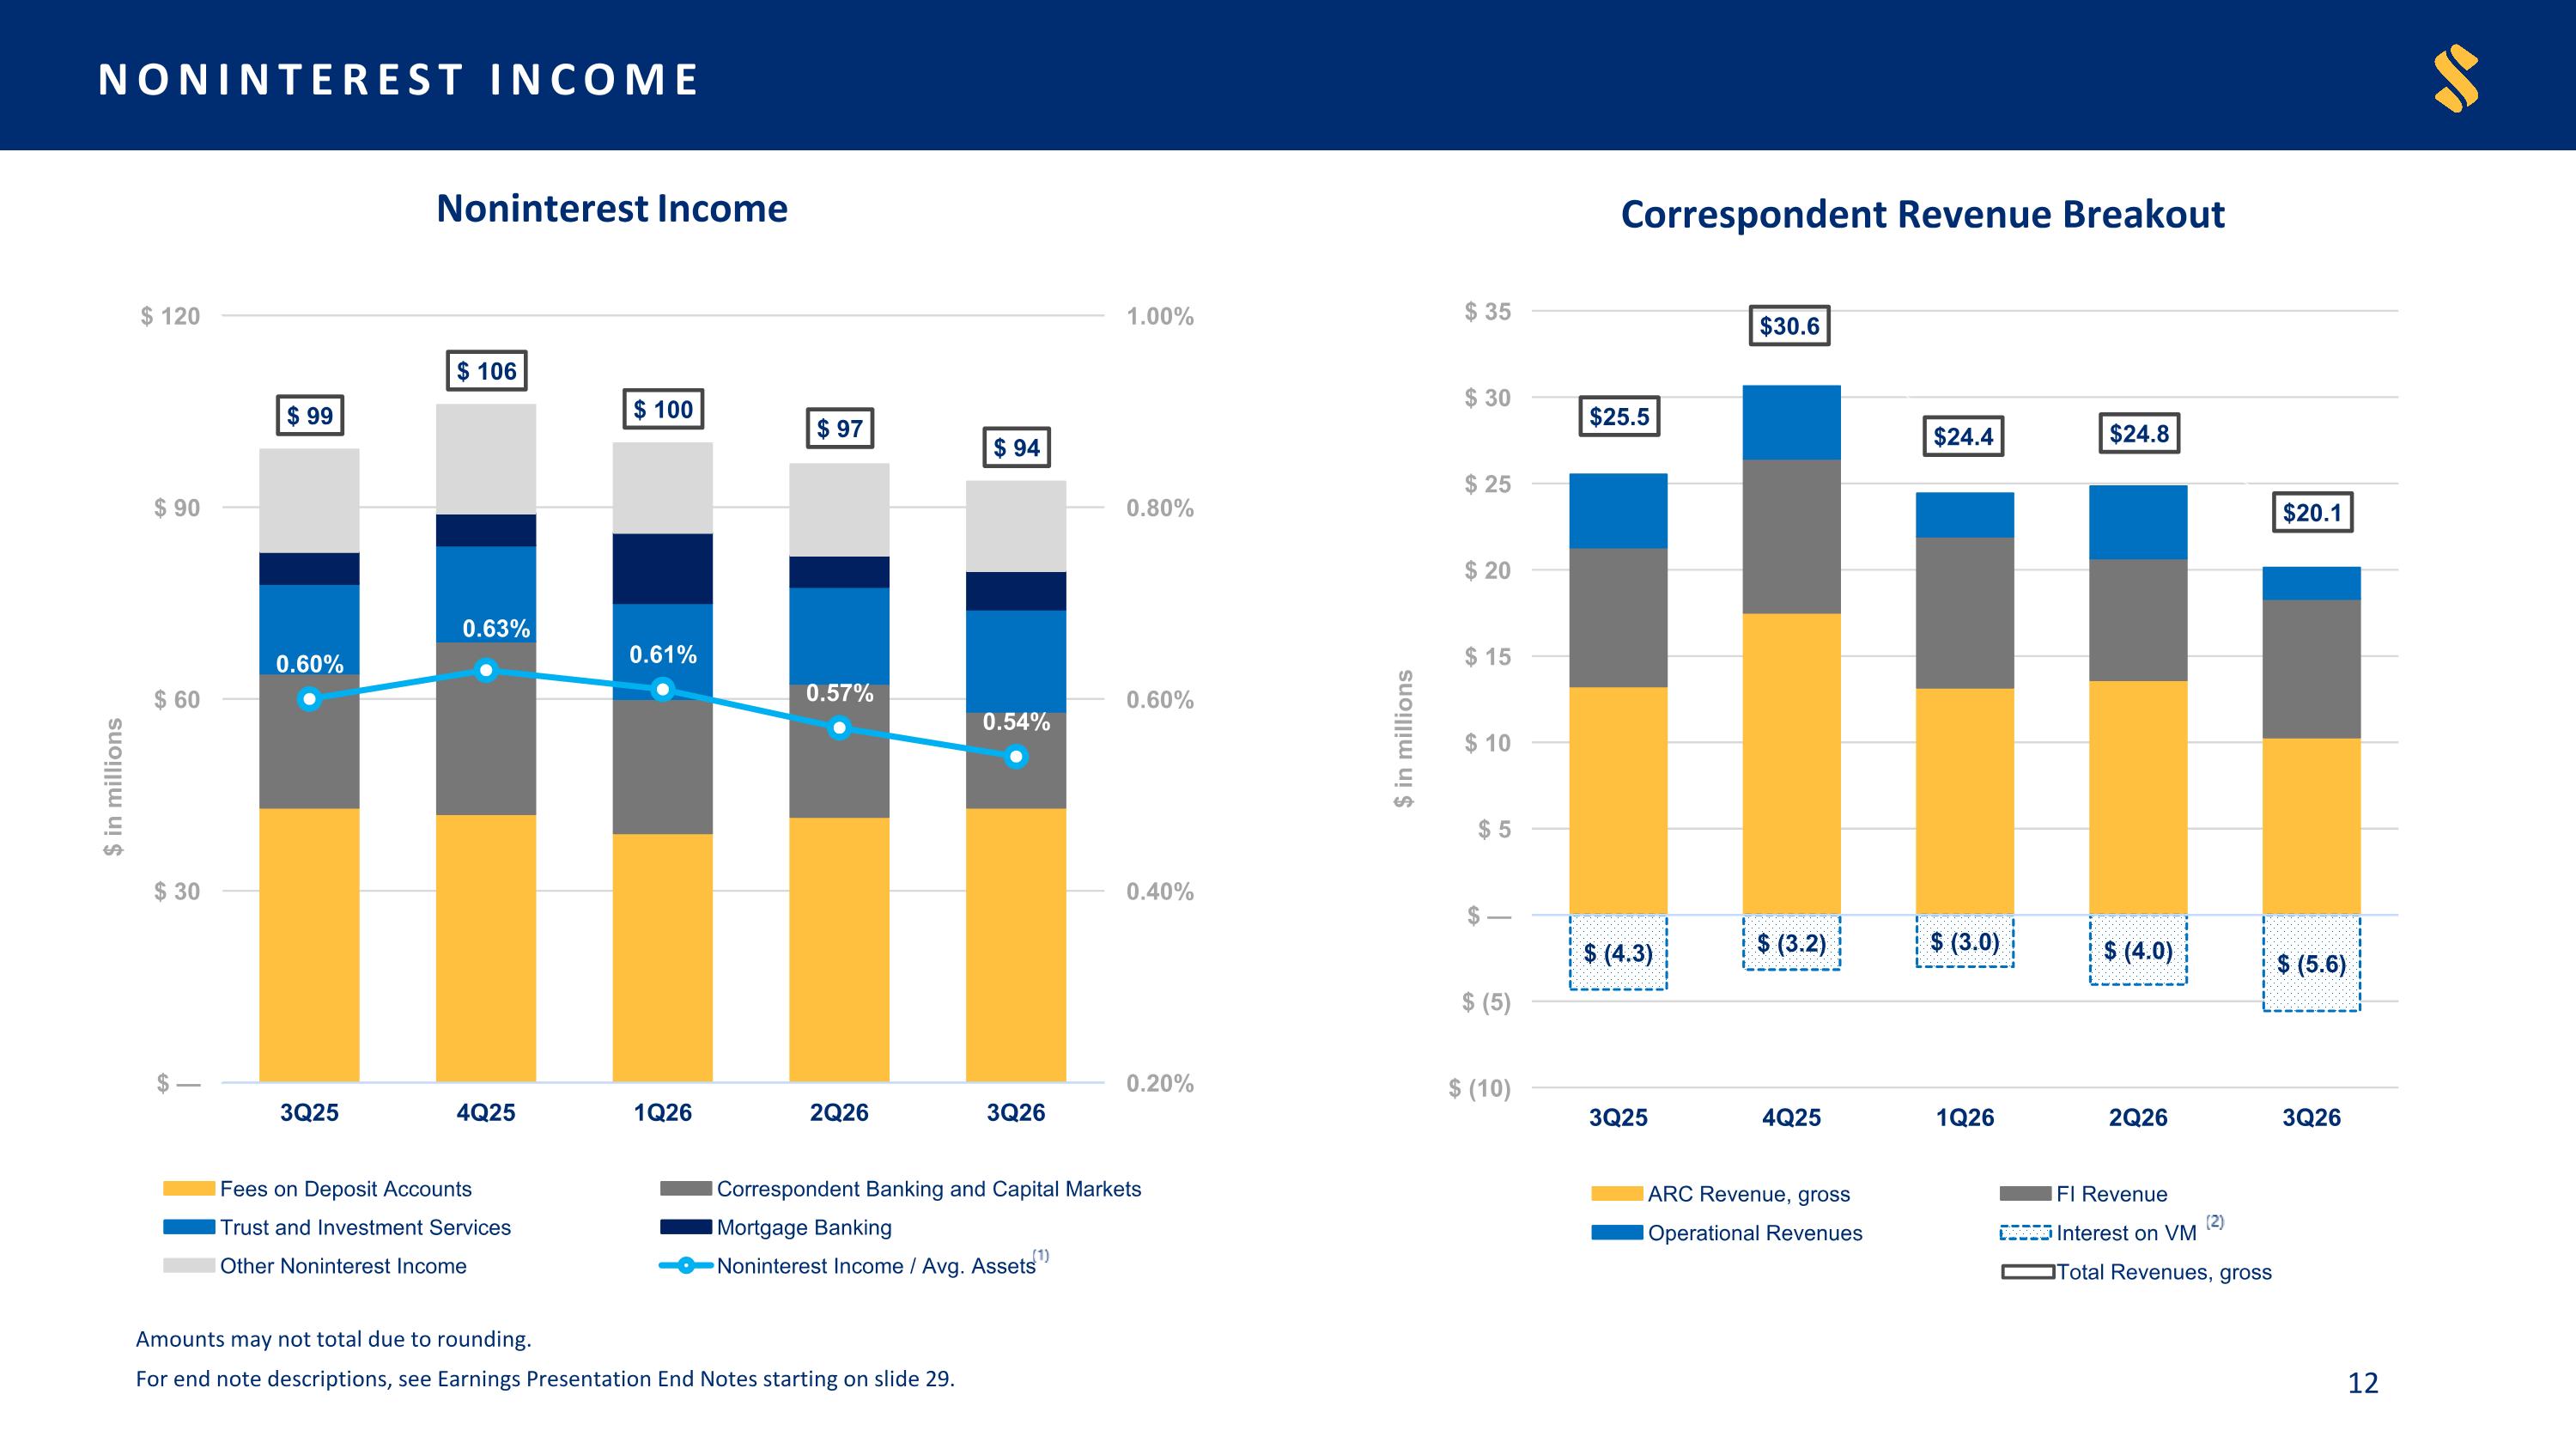
NONINTEREST INCOME Amounts may not total due to rounding. For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
Balance Sheet
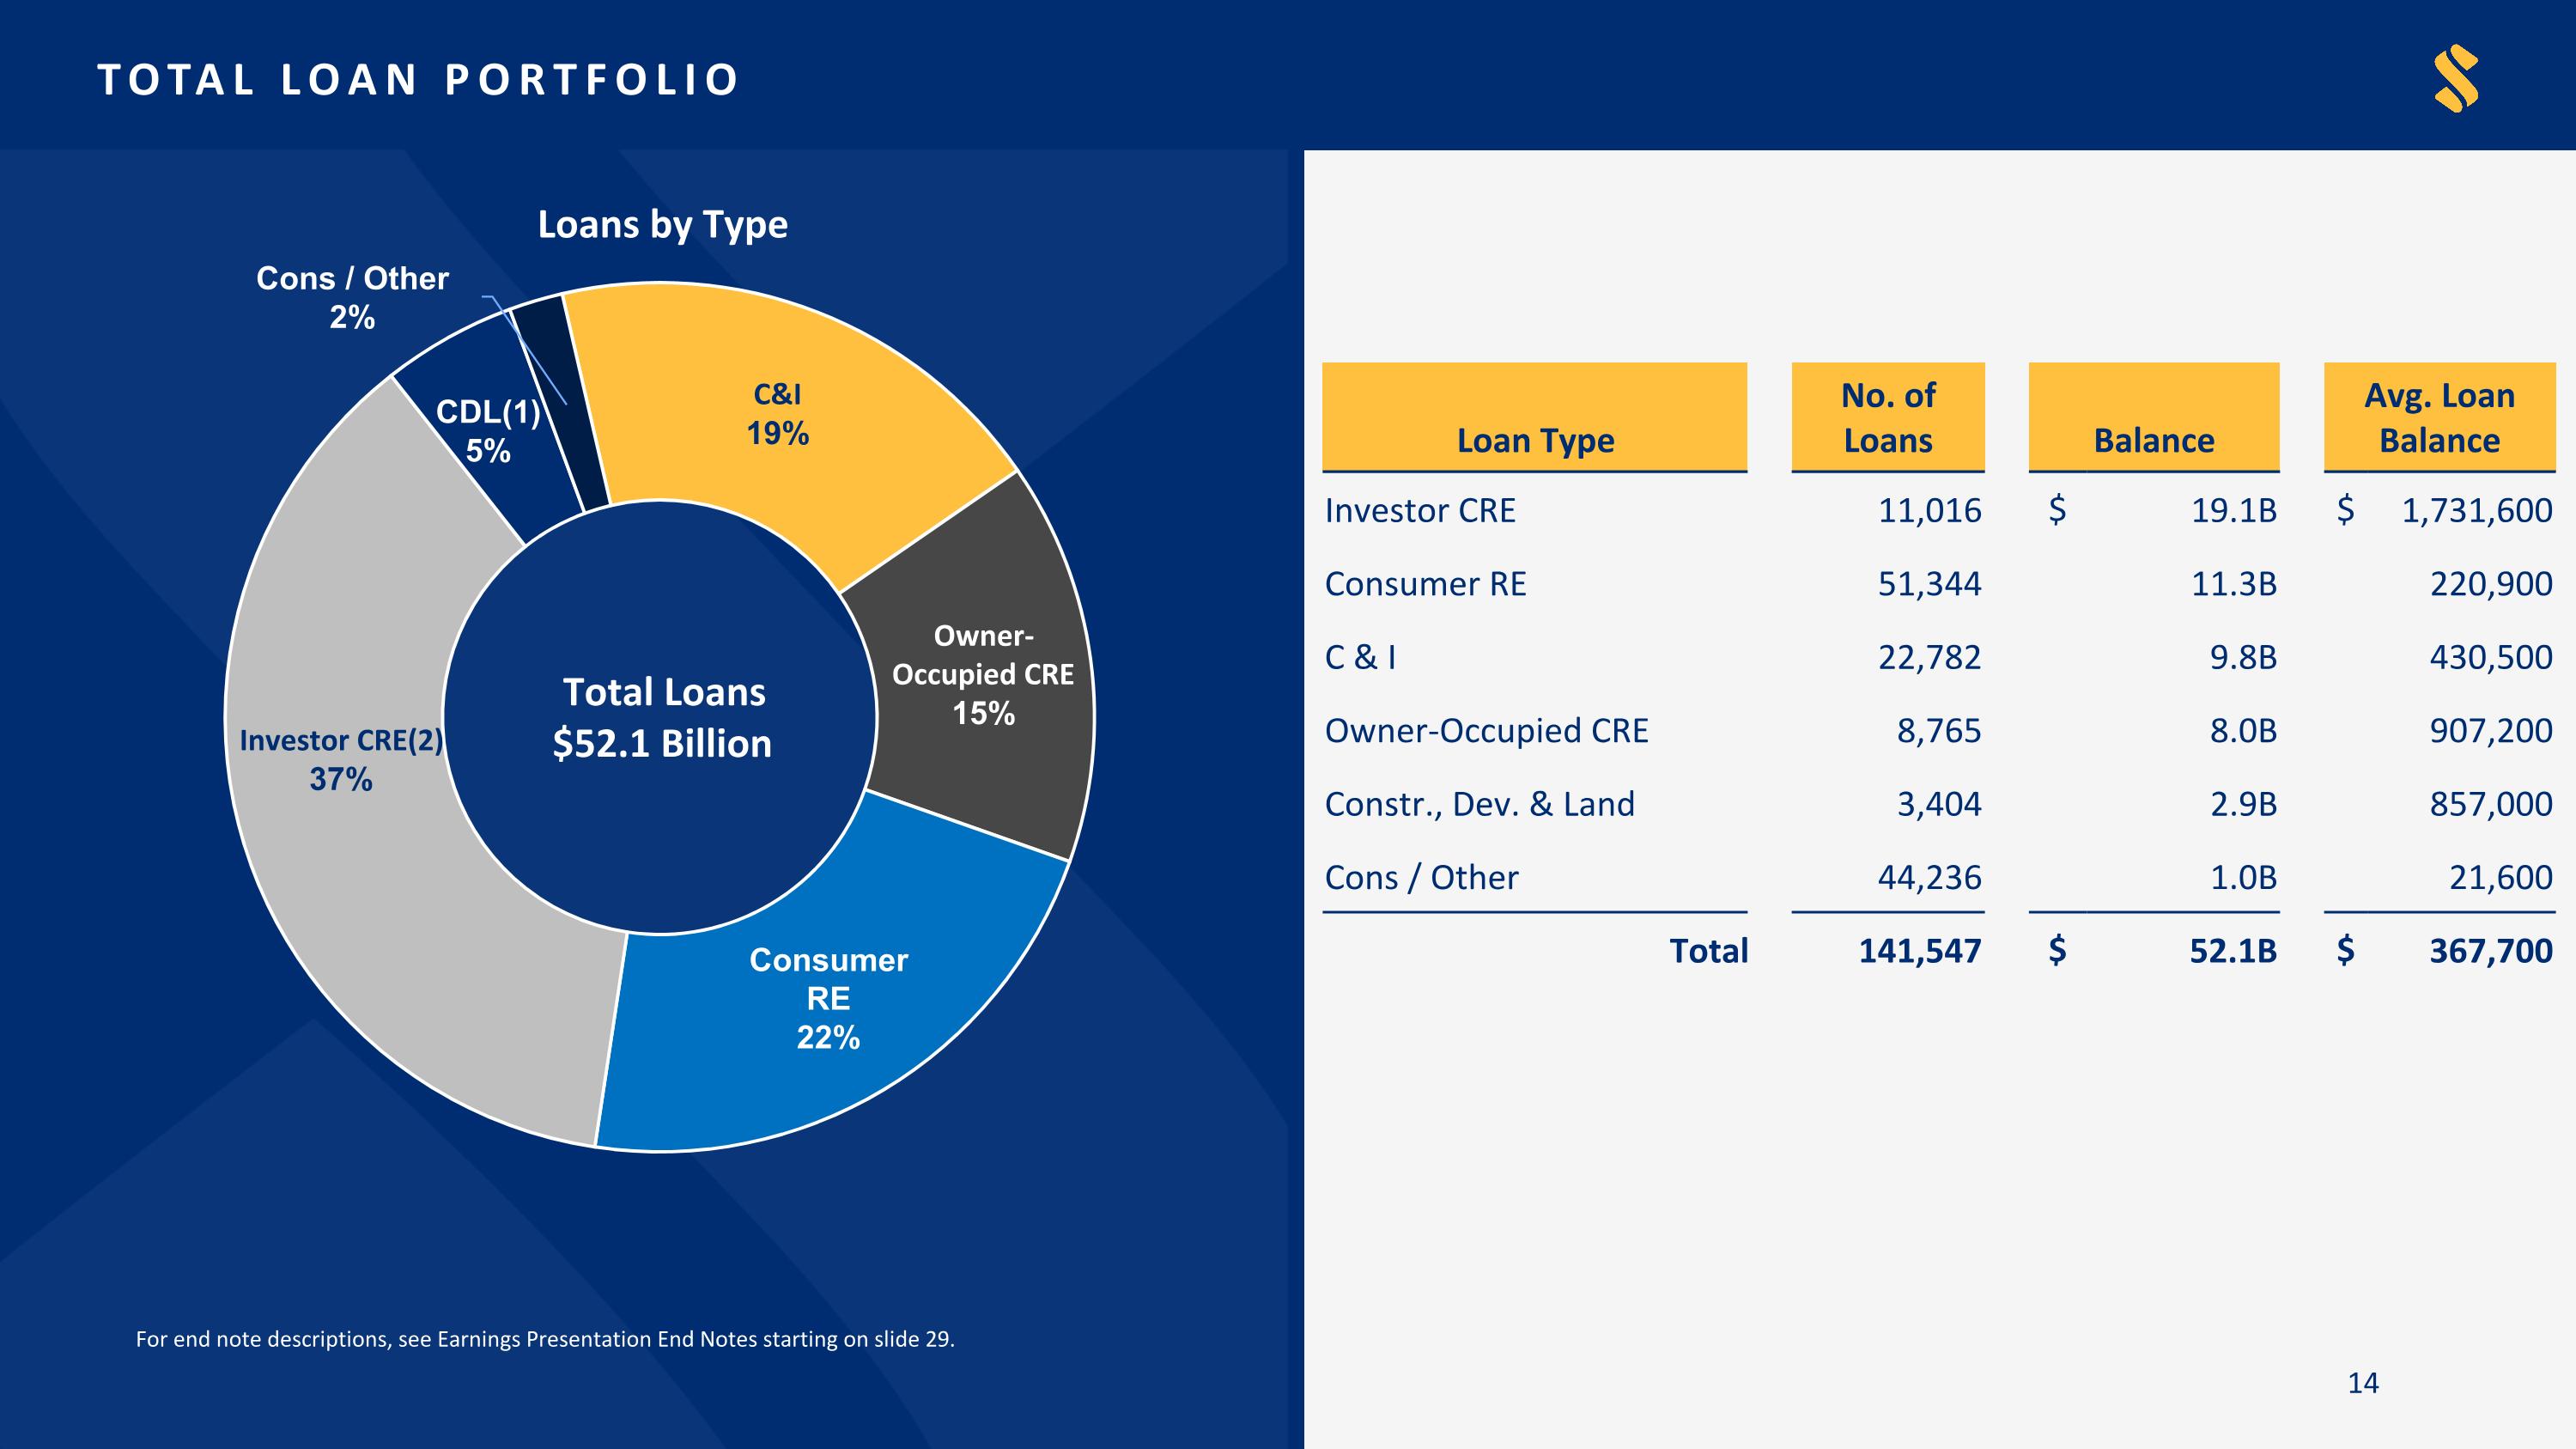
TOTAL LOAN PORTFOLIO For end note descriptions, see Earnings Presentation End Notes starting on slide 29. Loan Type No. of Loans Balance Avg. Loan Balance Investor CRE 11,016 $ 19.1B $ 1,731,600 Consumer RE 51,344 11.3B 220,900 C & I 22,782 9.8B 430,500 Owner-Occupied CRE 8,765 8.0B 907,200 Constr., Dev. & Land 3,404 2.9B 857,000 Cons / Other 44,236 1.0B 21,600 Total 141,547 $ 52.1B $ 367,700 Loans by Type Total Loans $52.1 Billion
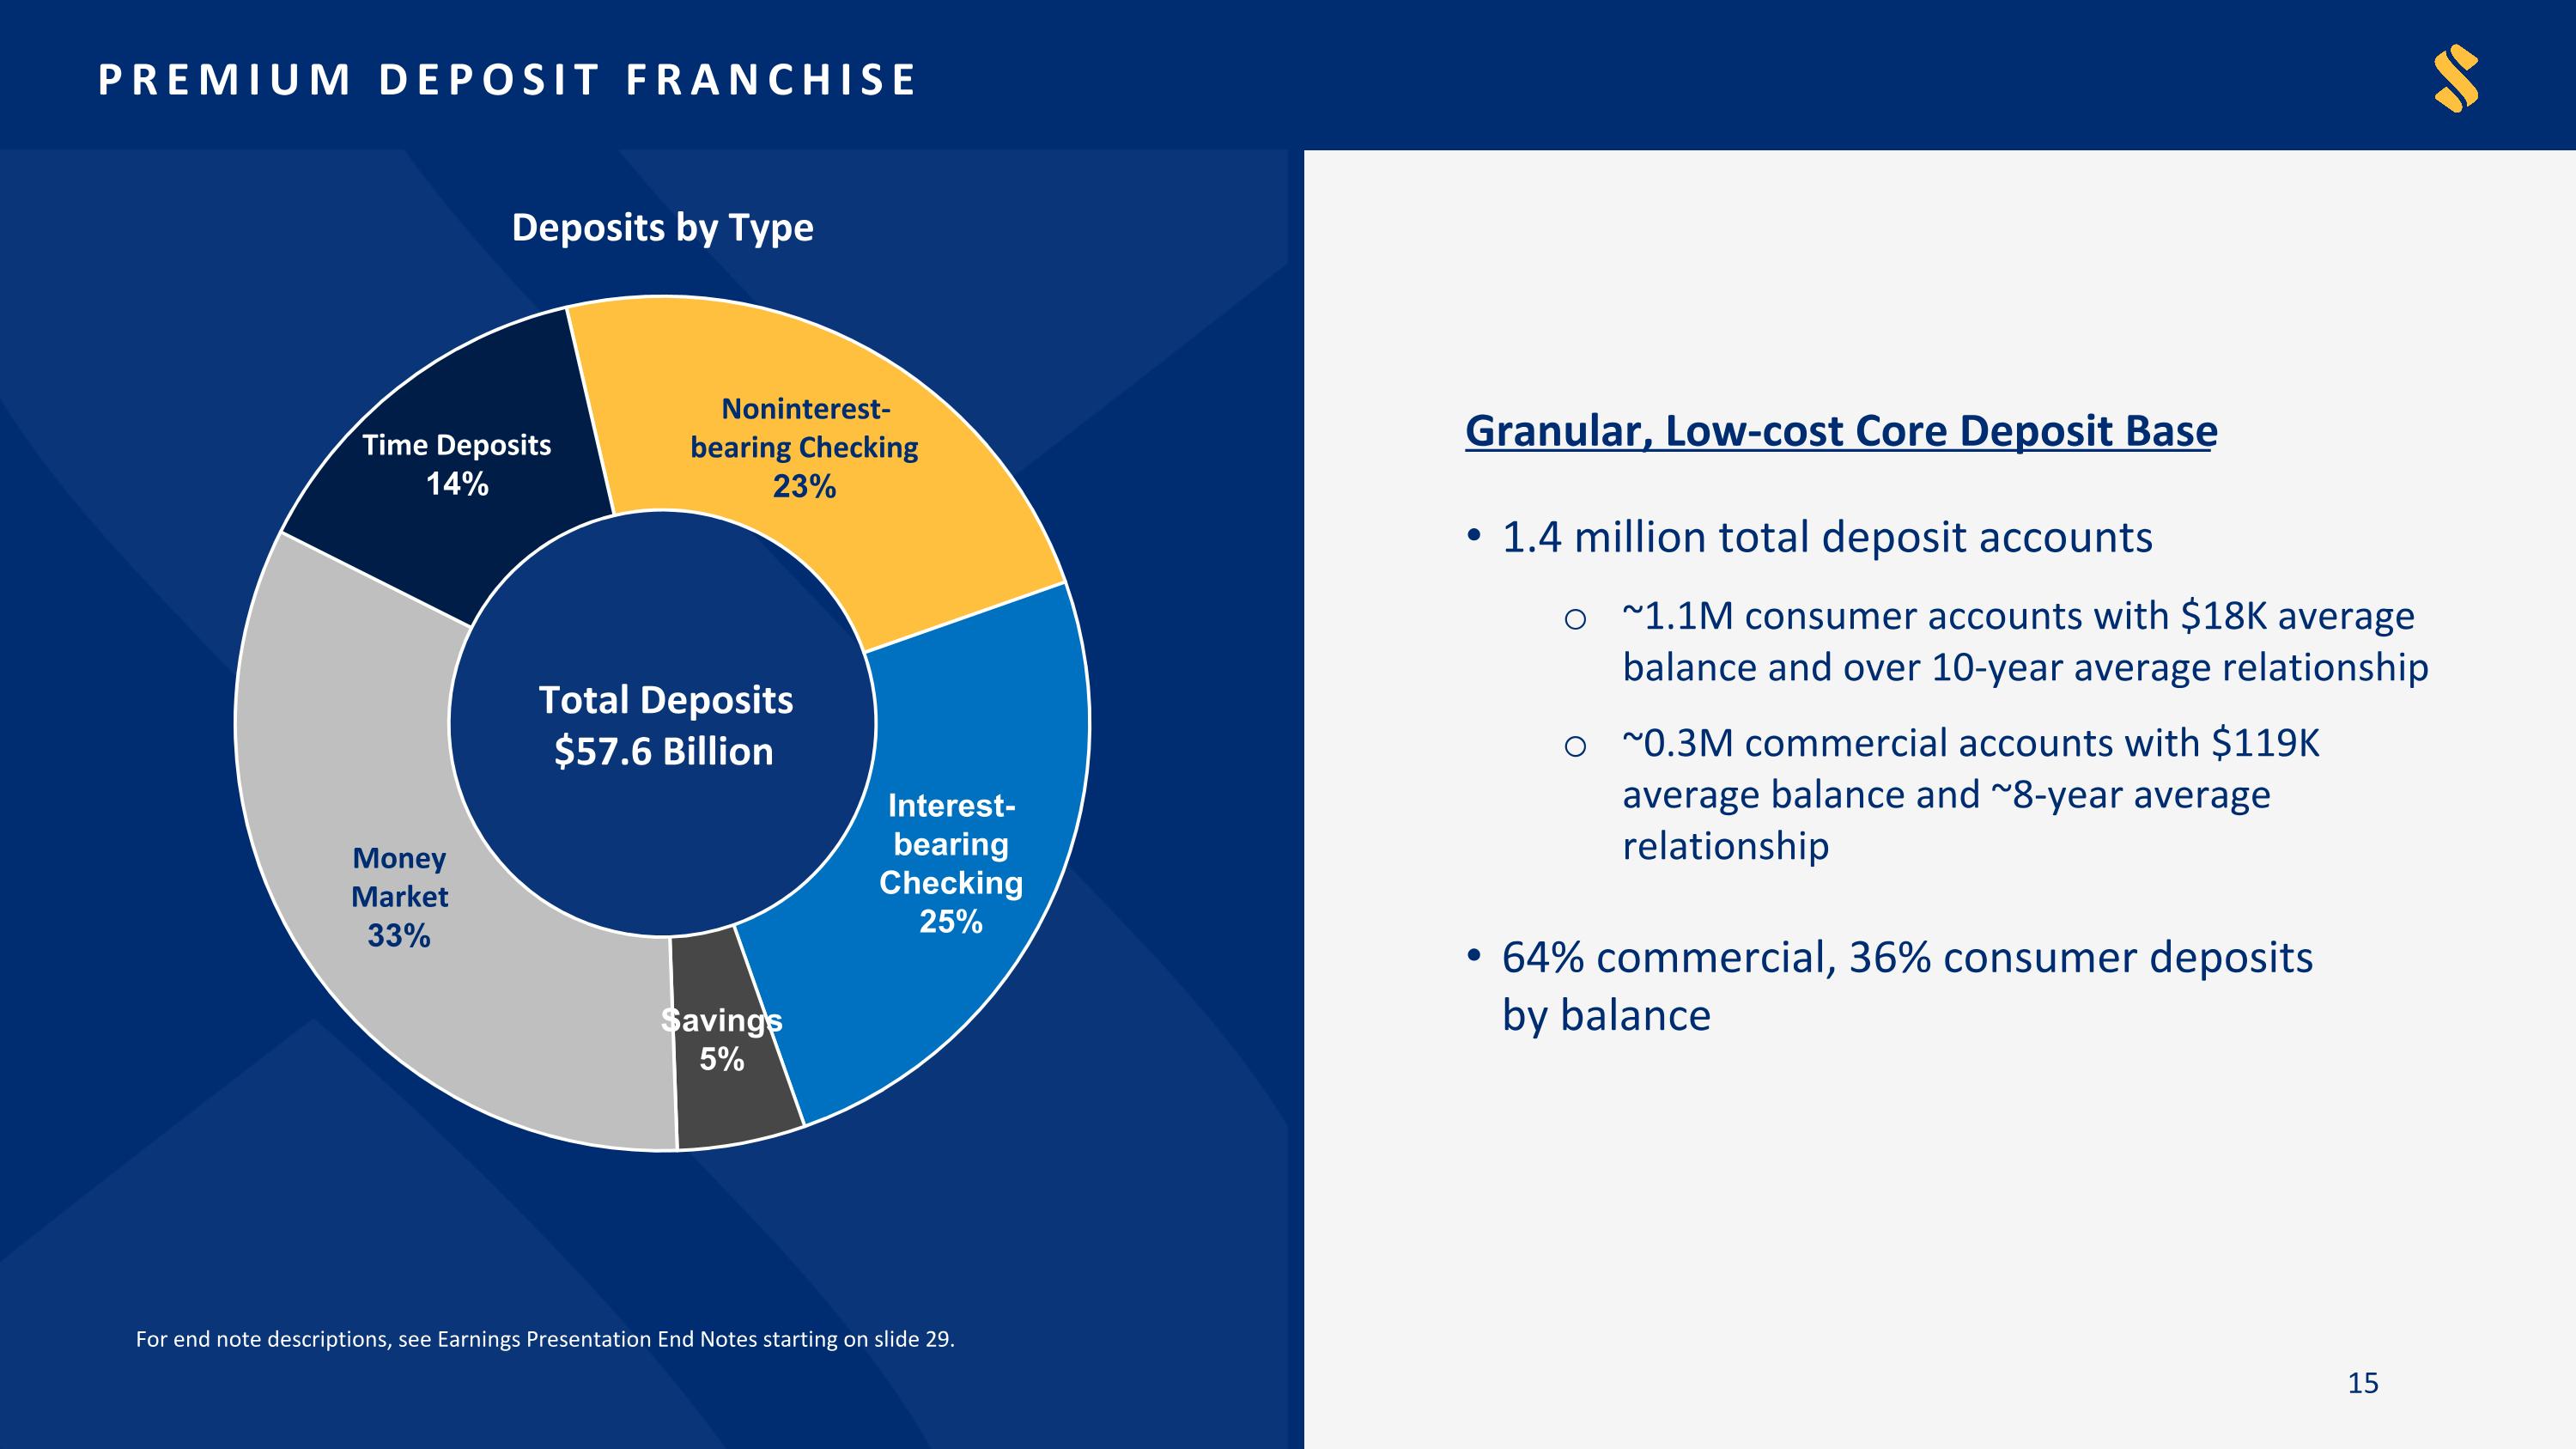
PREMIUM DEPOSIT FRANCHISE Total Deposits $57.6 Billion Deposits by Type Granular, Low-cost Core Deposit Base 1.4 million total deposit accounts ~1.1M consumer accounts with $18K average balance and over 10-year average relationship ~0.3M commercial accounts with $119K average balance and ~8-year average relationship 64% commercial, 36% consumer deposits by balance For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
Credit
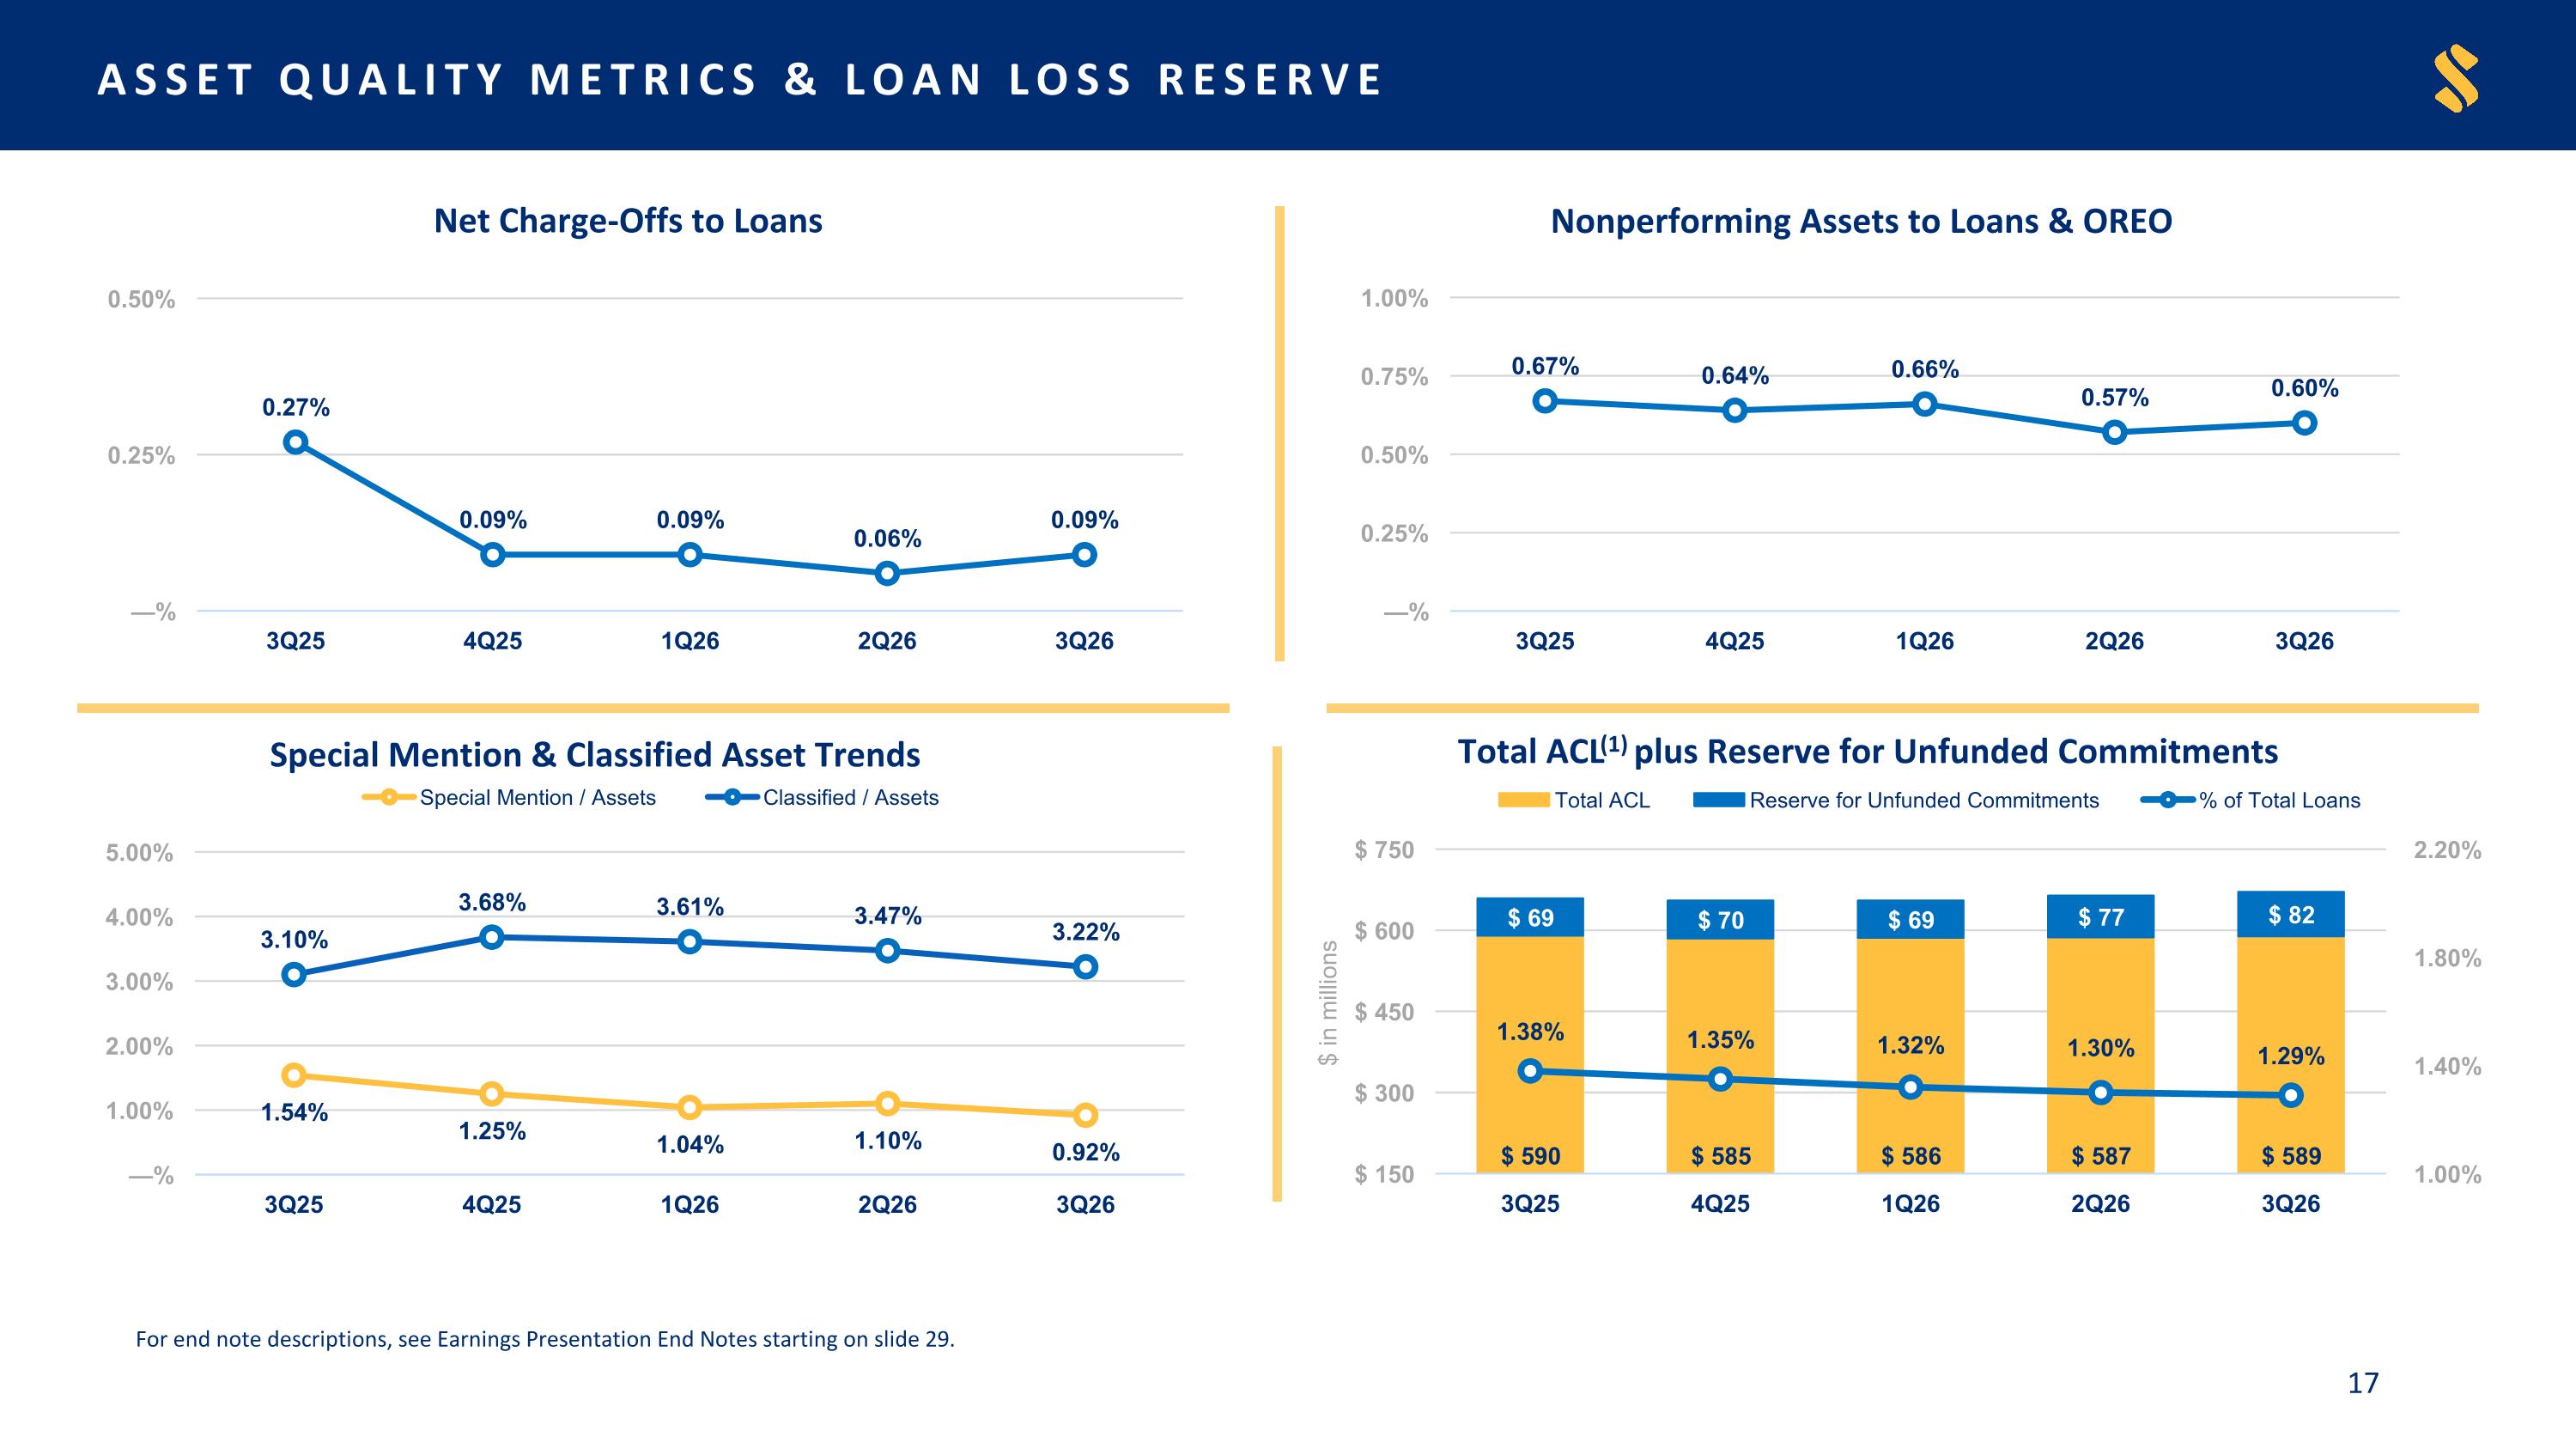
ASSET QUALITY METRICS & LOAN LOSS RESERVE For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
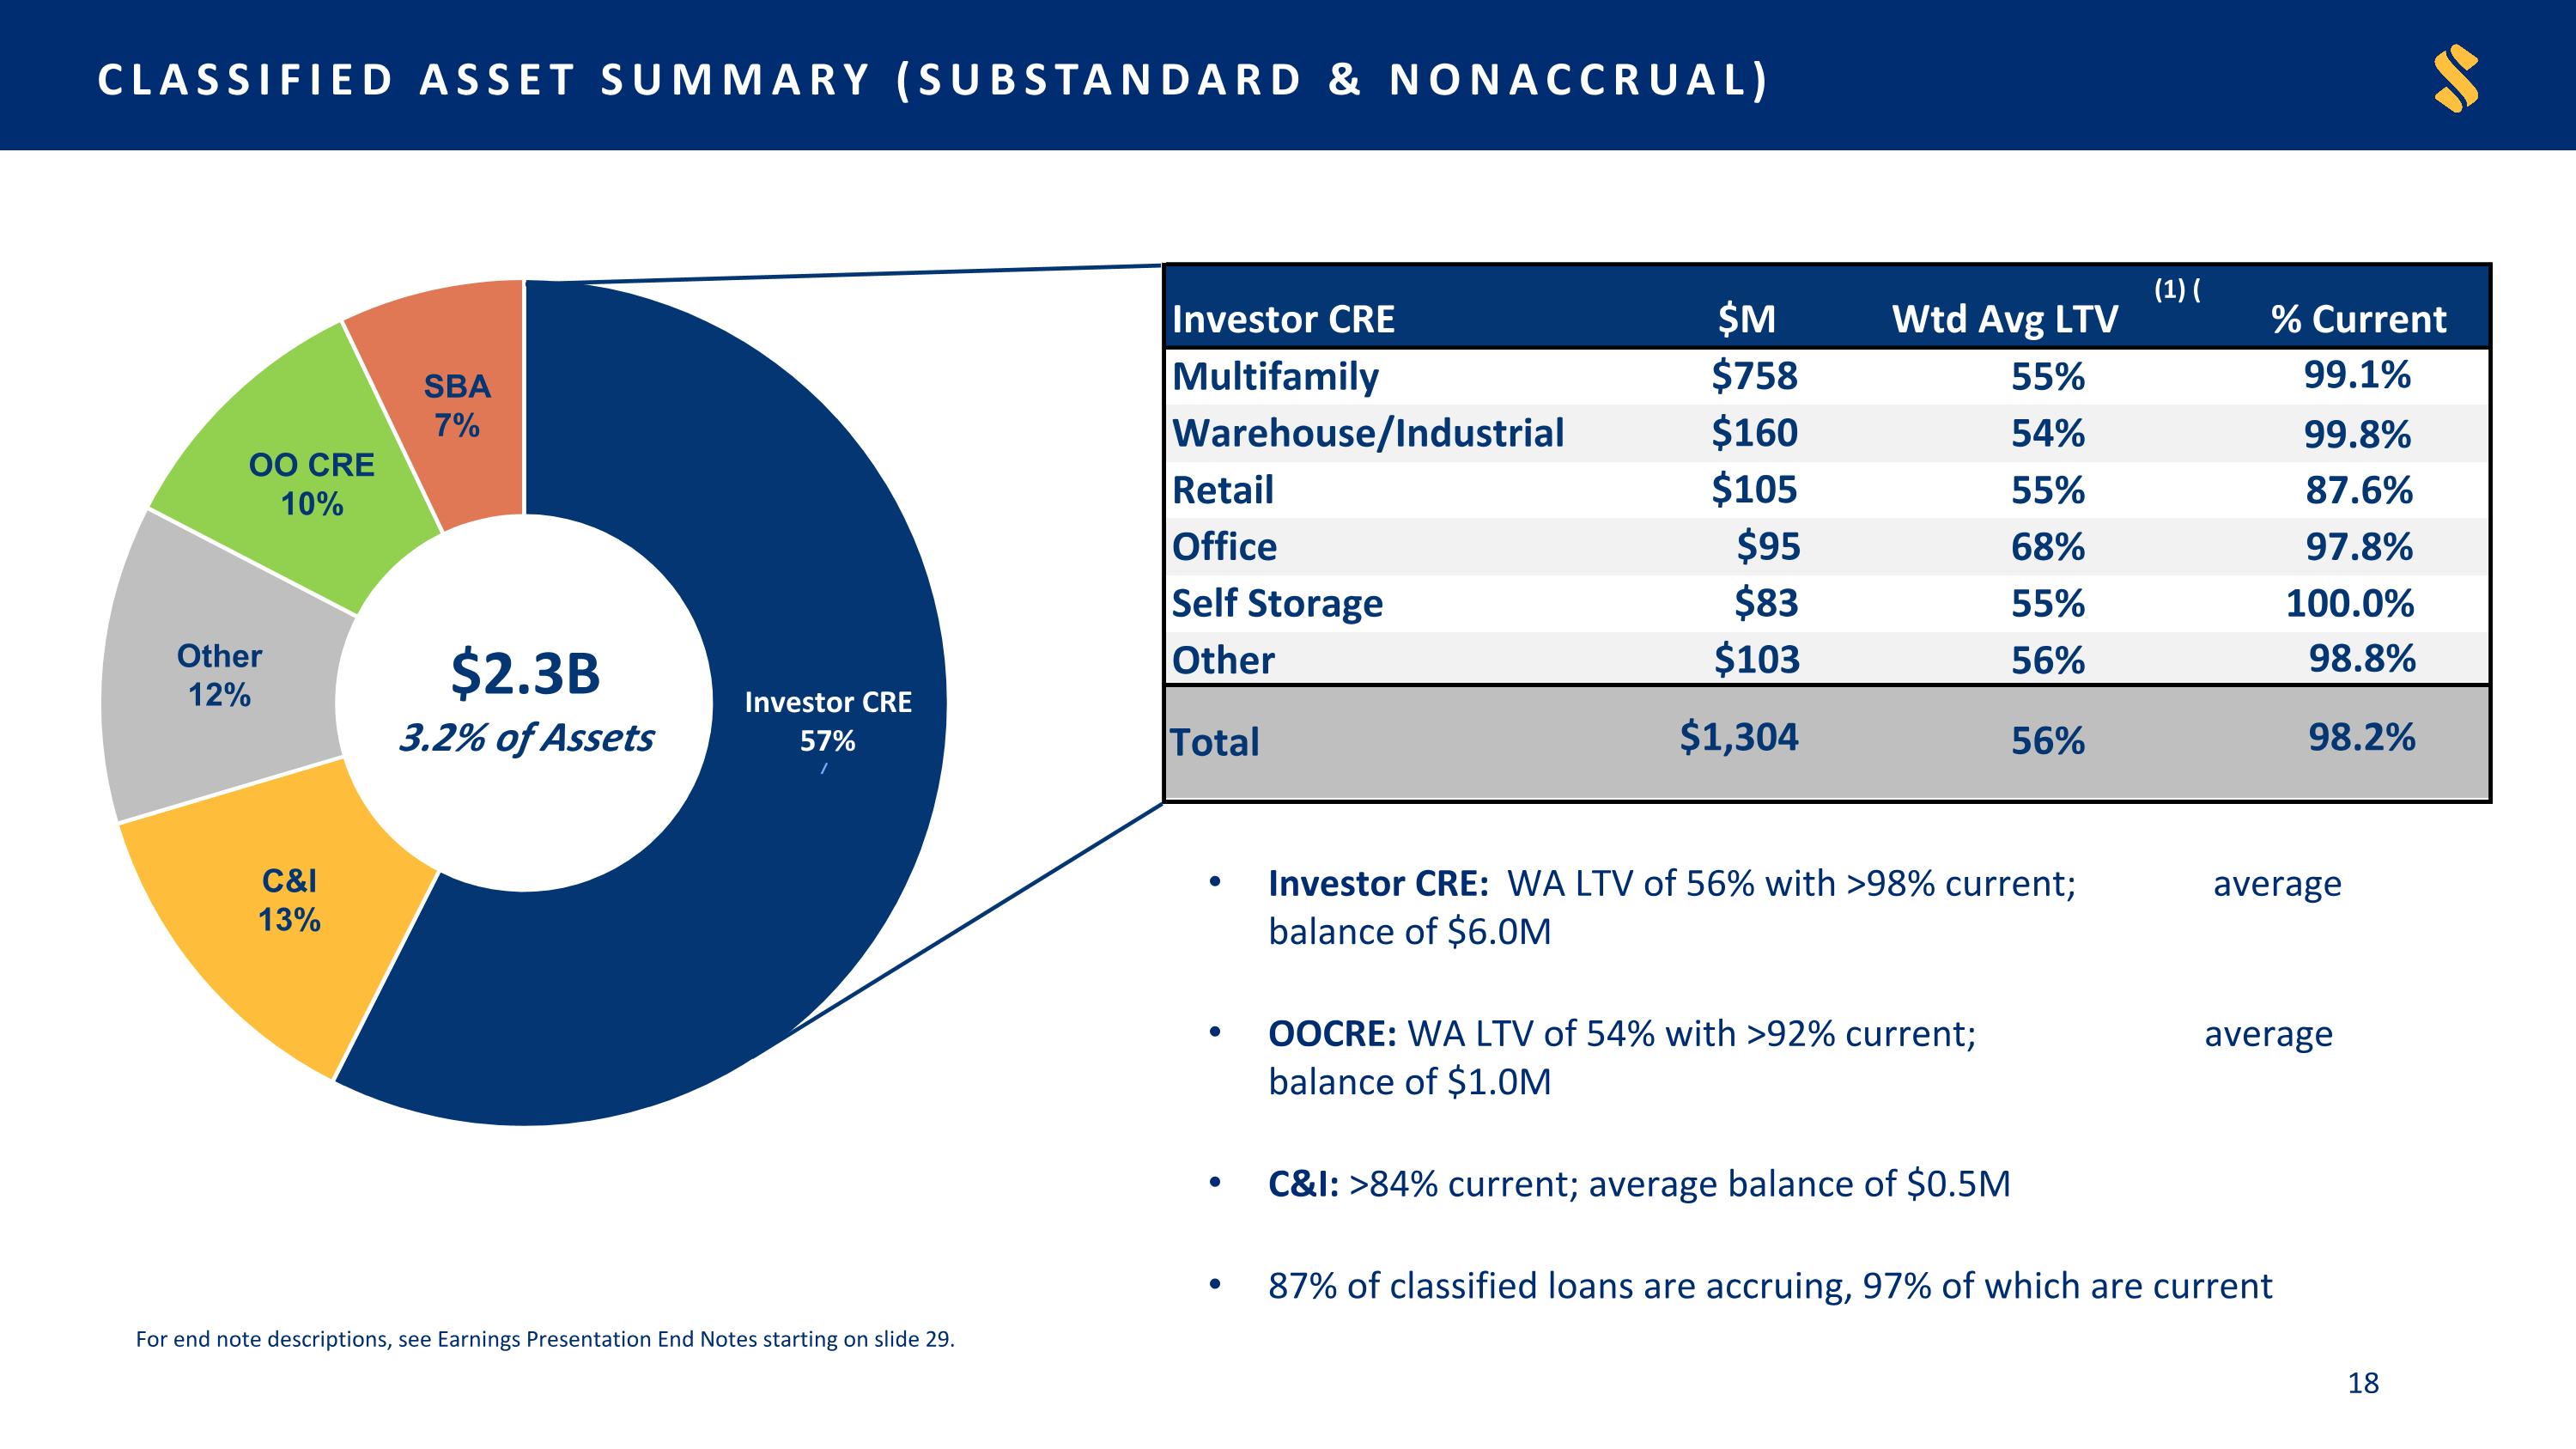
$2.3B 3.2% of Assets CLASSIFIED ASSET SUMMARY (SUBSTANDARD & NONACCRUAL) For end note descriptions, see Earnings Presentation End Notes starting on slide 29. Investor CRE: WA LTV of 56% with >98% current; average balance of $6.0M OOCRE: WA LTV of 54% with >92% current; average balance of $1.0M C&I: >84% current; average balance of $0.5M 87% of classified loans are accruing, 97% of which are current Investor CRE $M Wtd Avg LTV (1) (2) % Current Multifamily $758 55% 99.1% Warehouse/Industrial $160 54% Retail $105 55% 87.6% Office $95 68% 97.8% Self Storage $83 55% 100.0% Other $103 56% 98.8% Total $1,304 56% 98.2% 99.8%
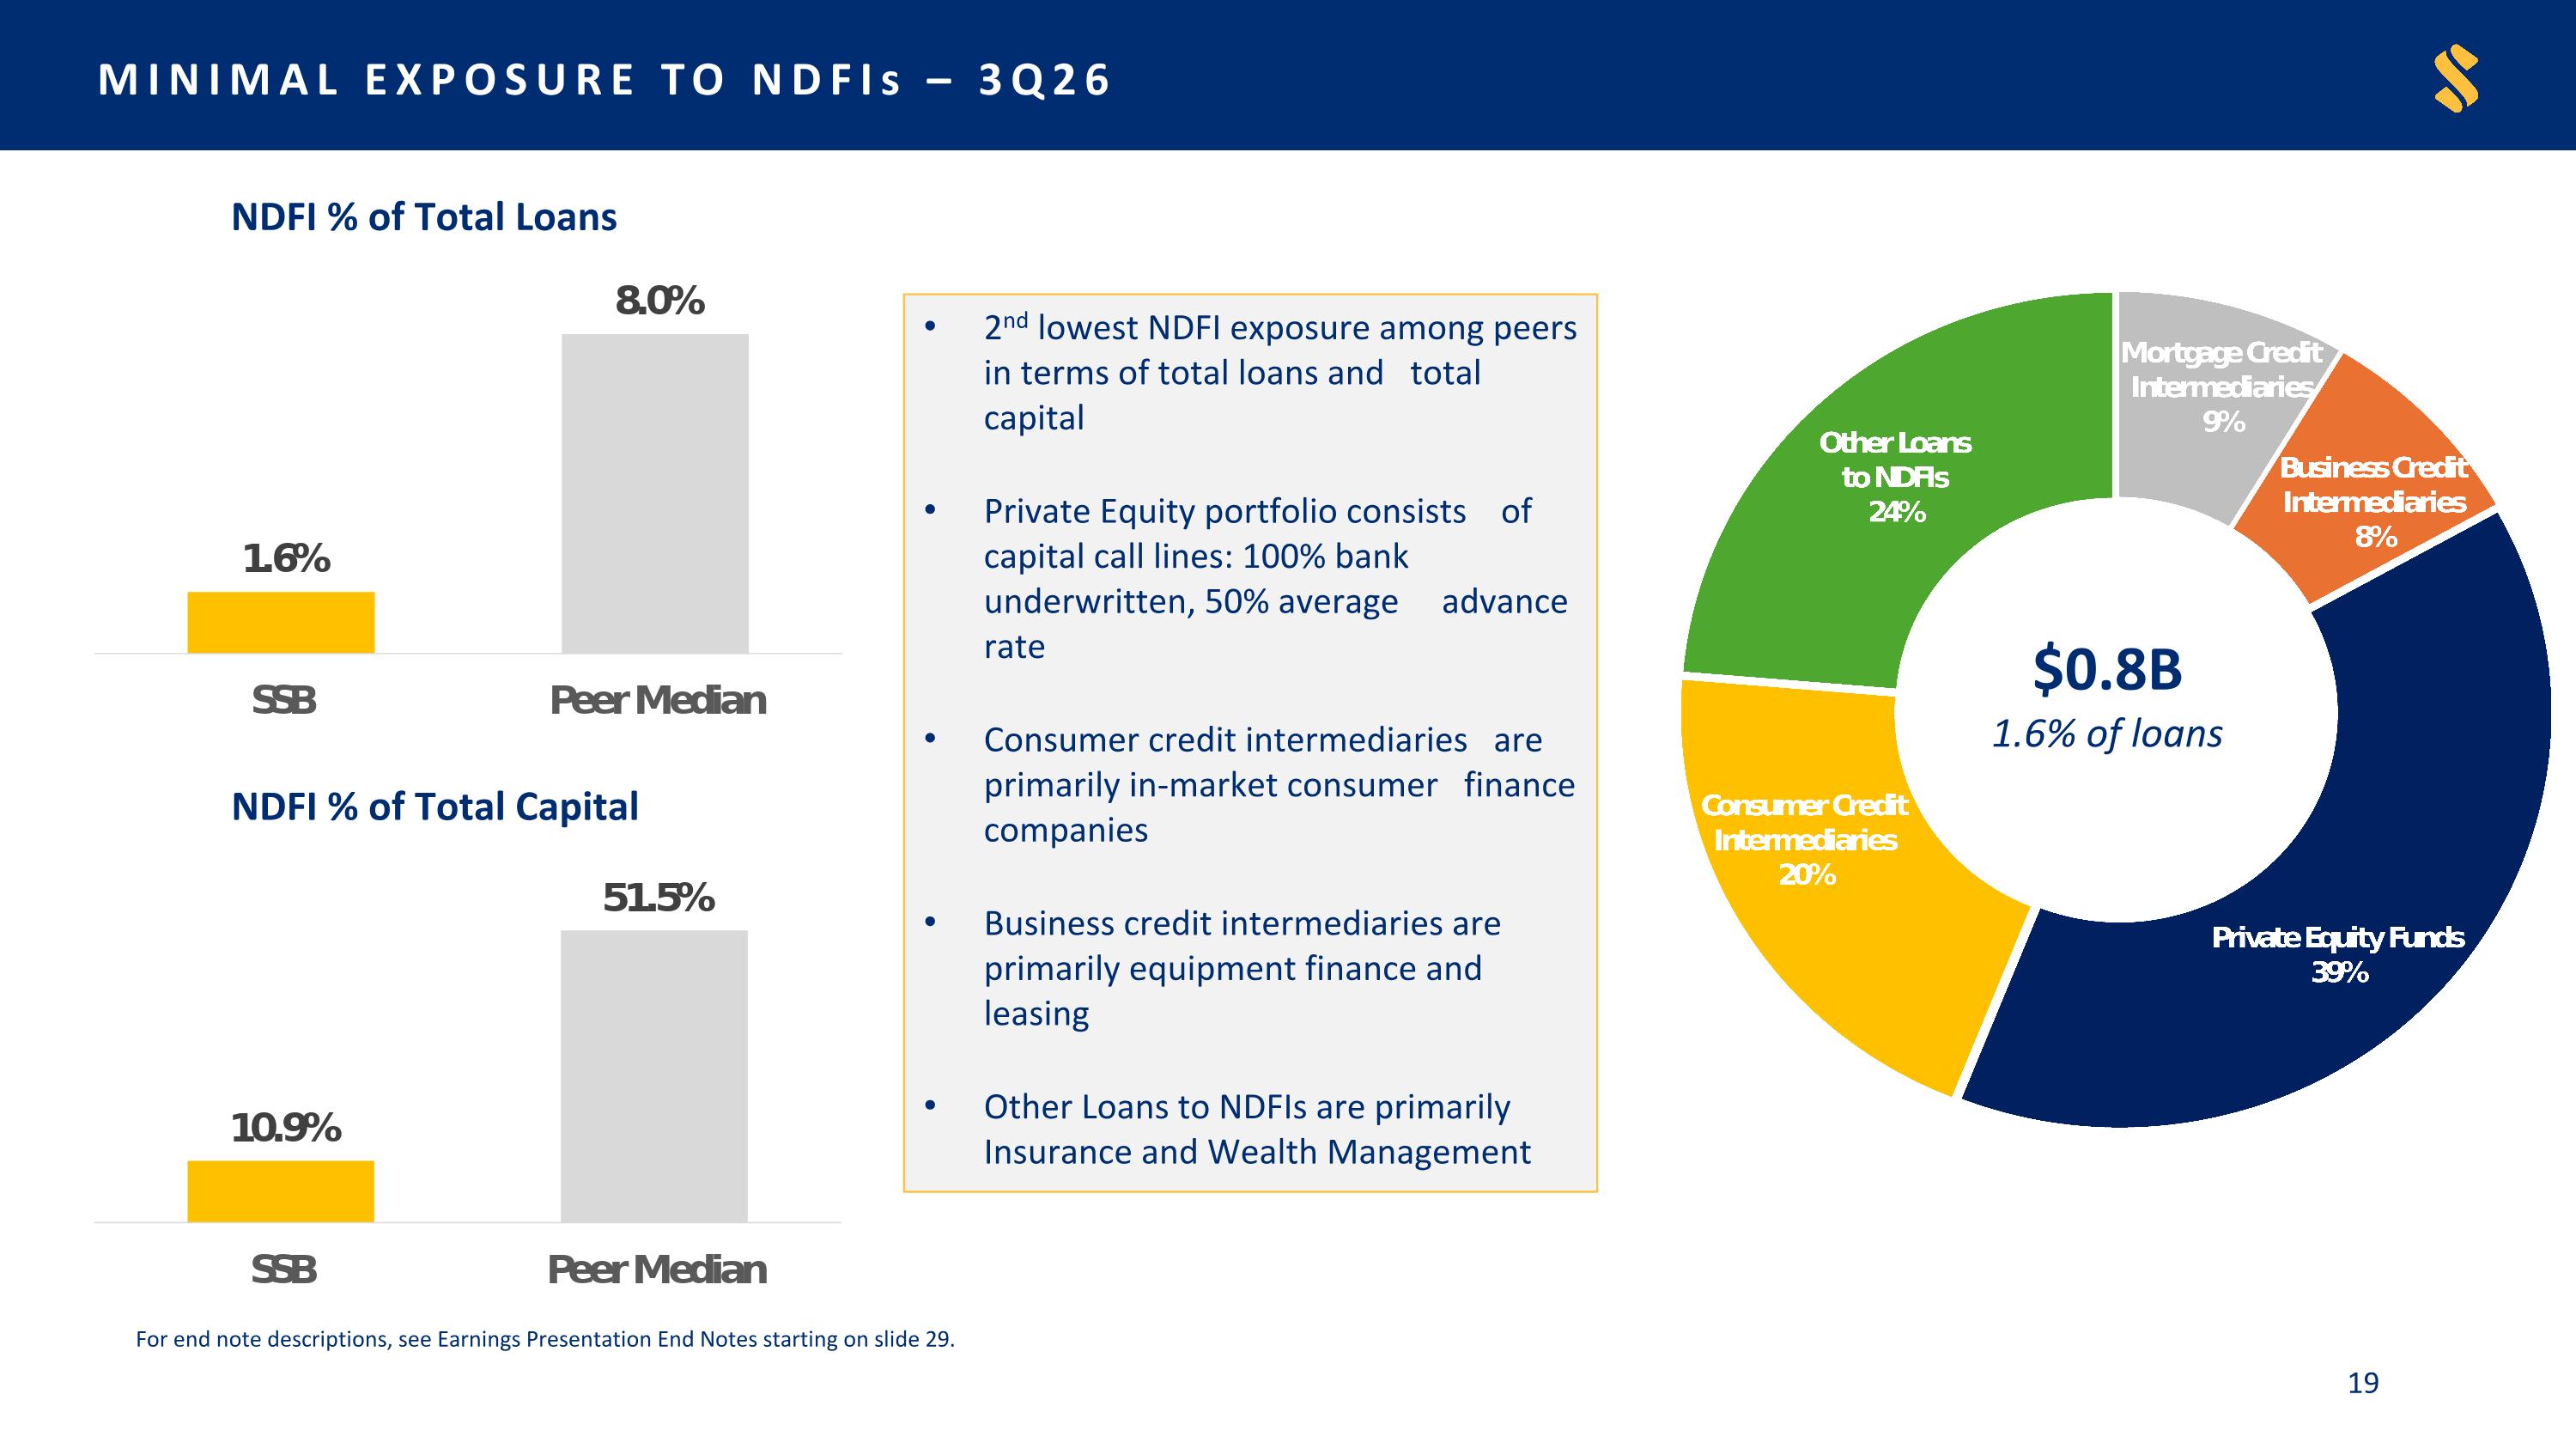
MINIMAL EXPOSURE TO NDFIs – 3Q26 $0.8B 1.6% of loans NDFI % of Total Loans NDFI % of Total Capital 2nd lowest NDFI exposure among peers in terms of total loans and total capital Private Equity portfolio consists of capital call lines: 100% bank underwritten, 50% average advance rate Consumer credit intermediaries are primarily in-market consumer finance companies Business credit intermediaries are primarily equipment finance and leasing Other Loans to NDFIs are primarily Insurance and Wealth Management For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
Capital
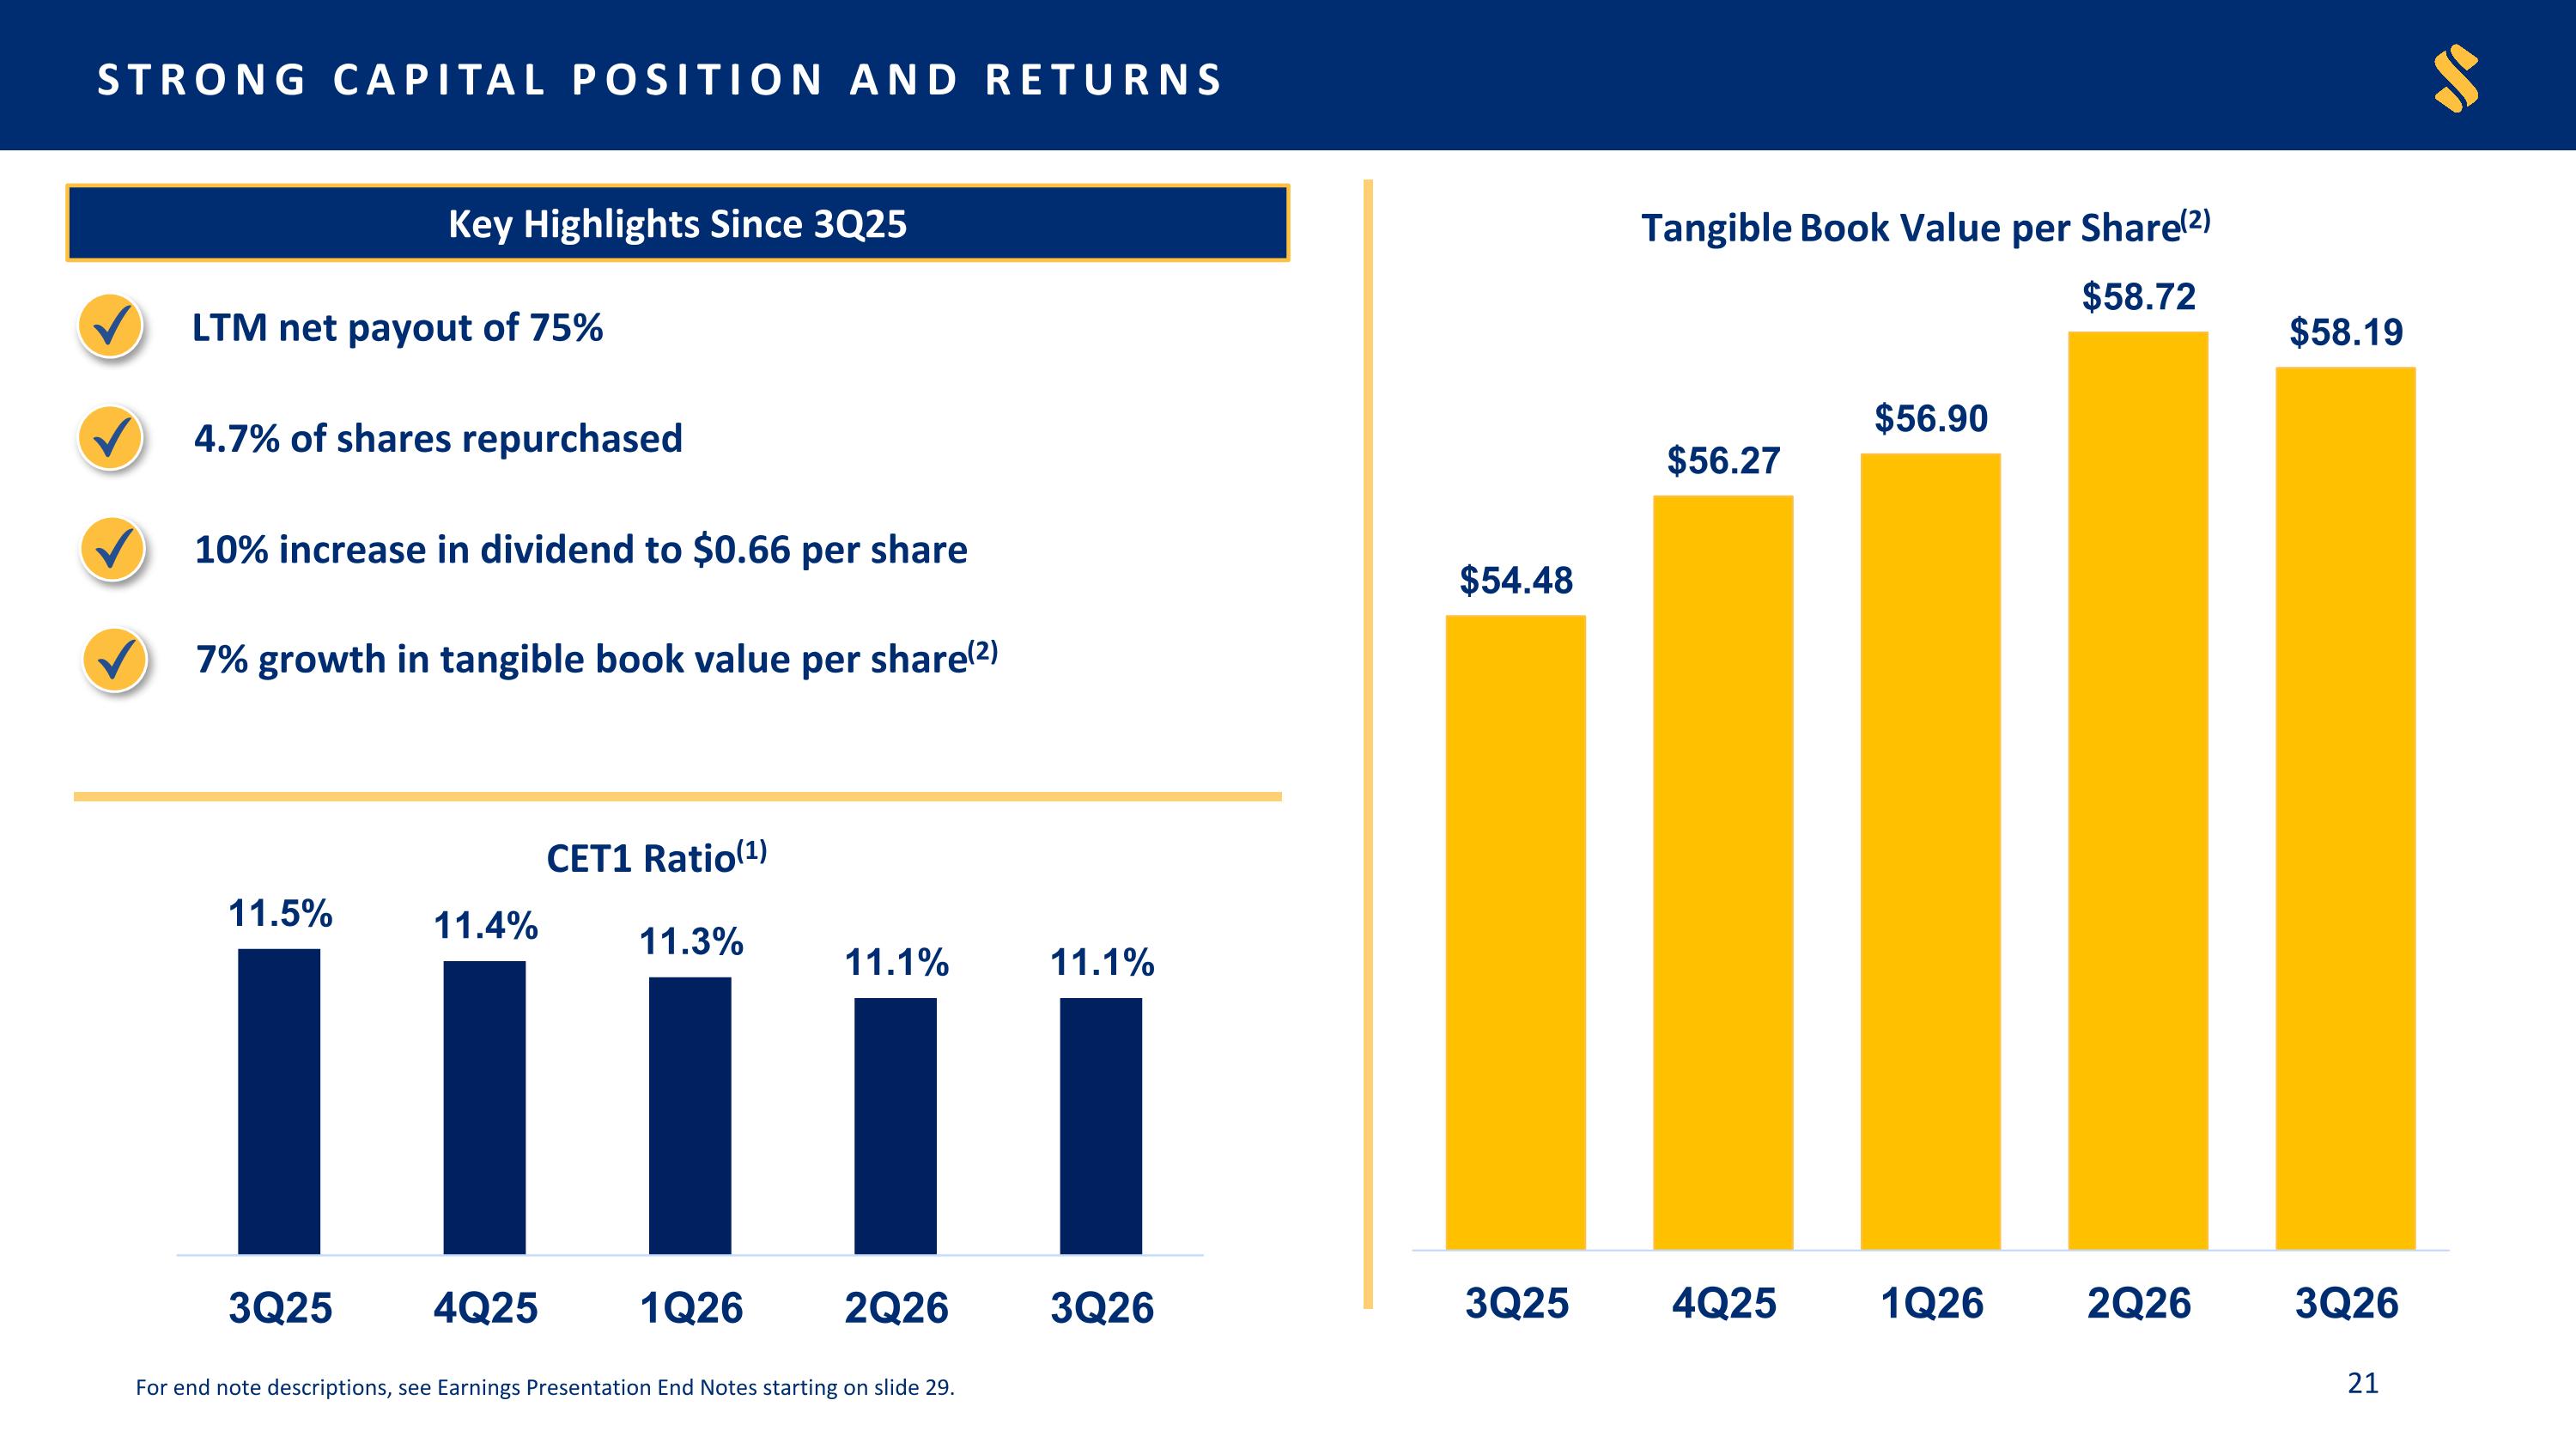
STRONG CAPITAL POSITION AND RETURNS For end note descriptions, see Earnings Presentation End Notes starting on slide 29. LTM net payout of 75% Key Highlights Since 3Q25 4.7% of shares repurchased 10% increase in dividend to $0.66 per share 7% growth in tangible book value per share(2)
Appendix
23
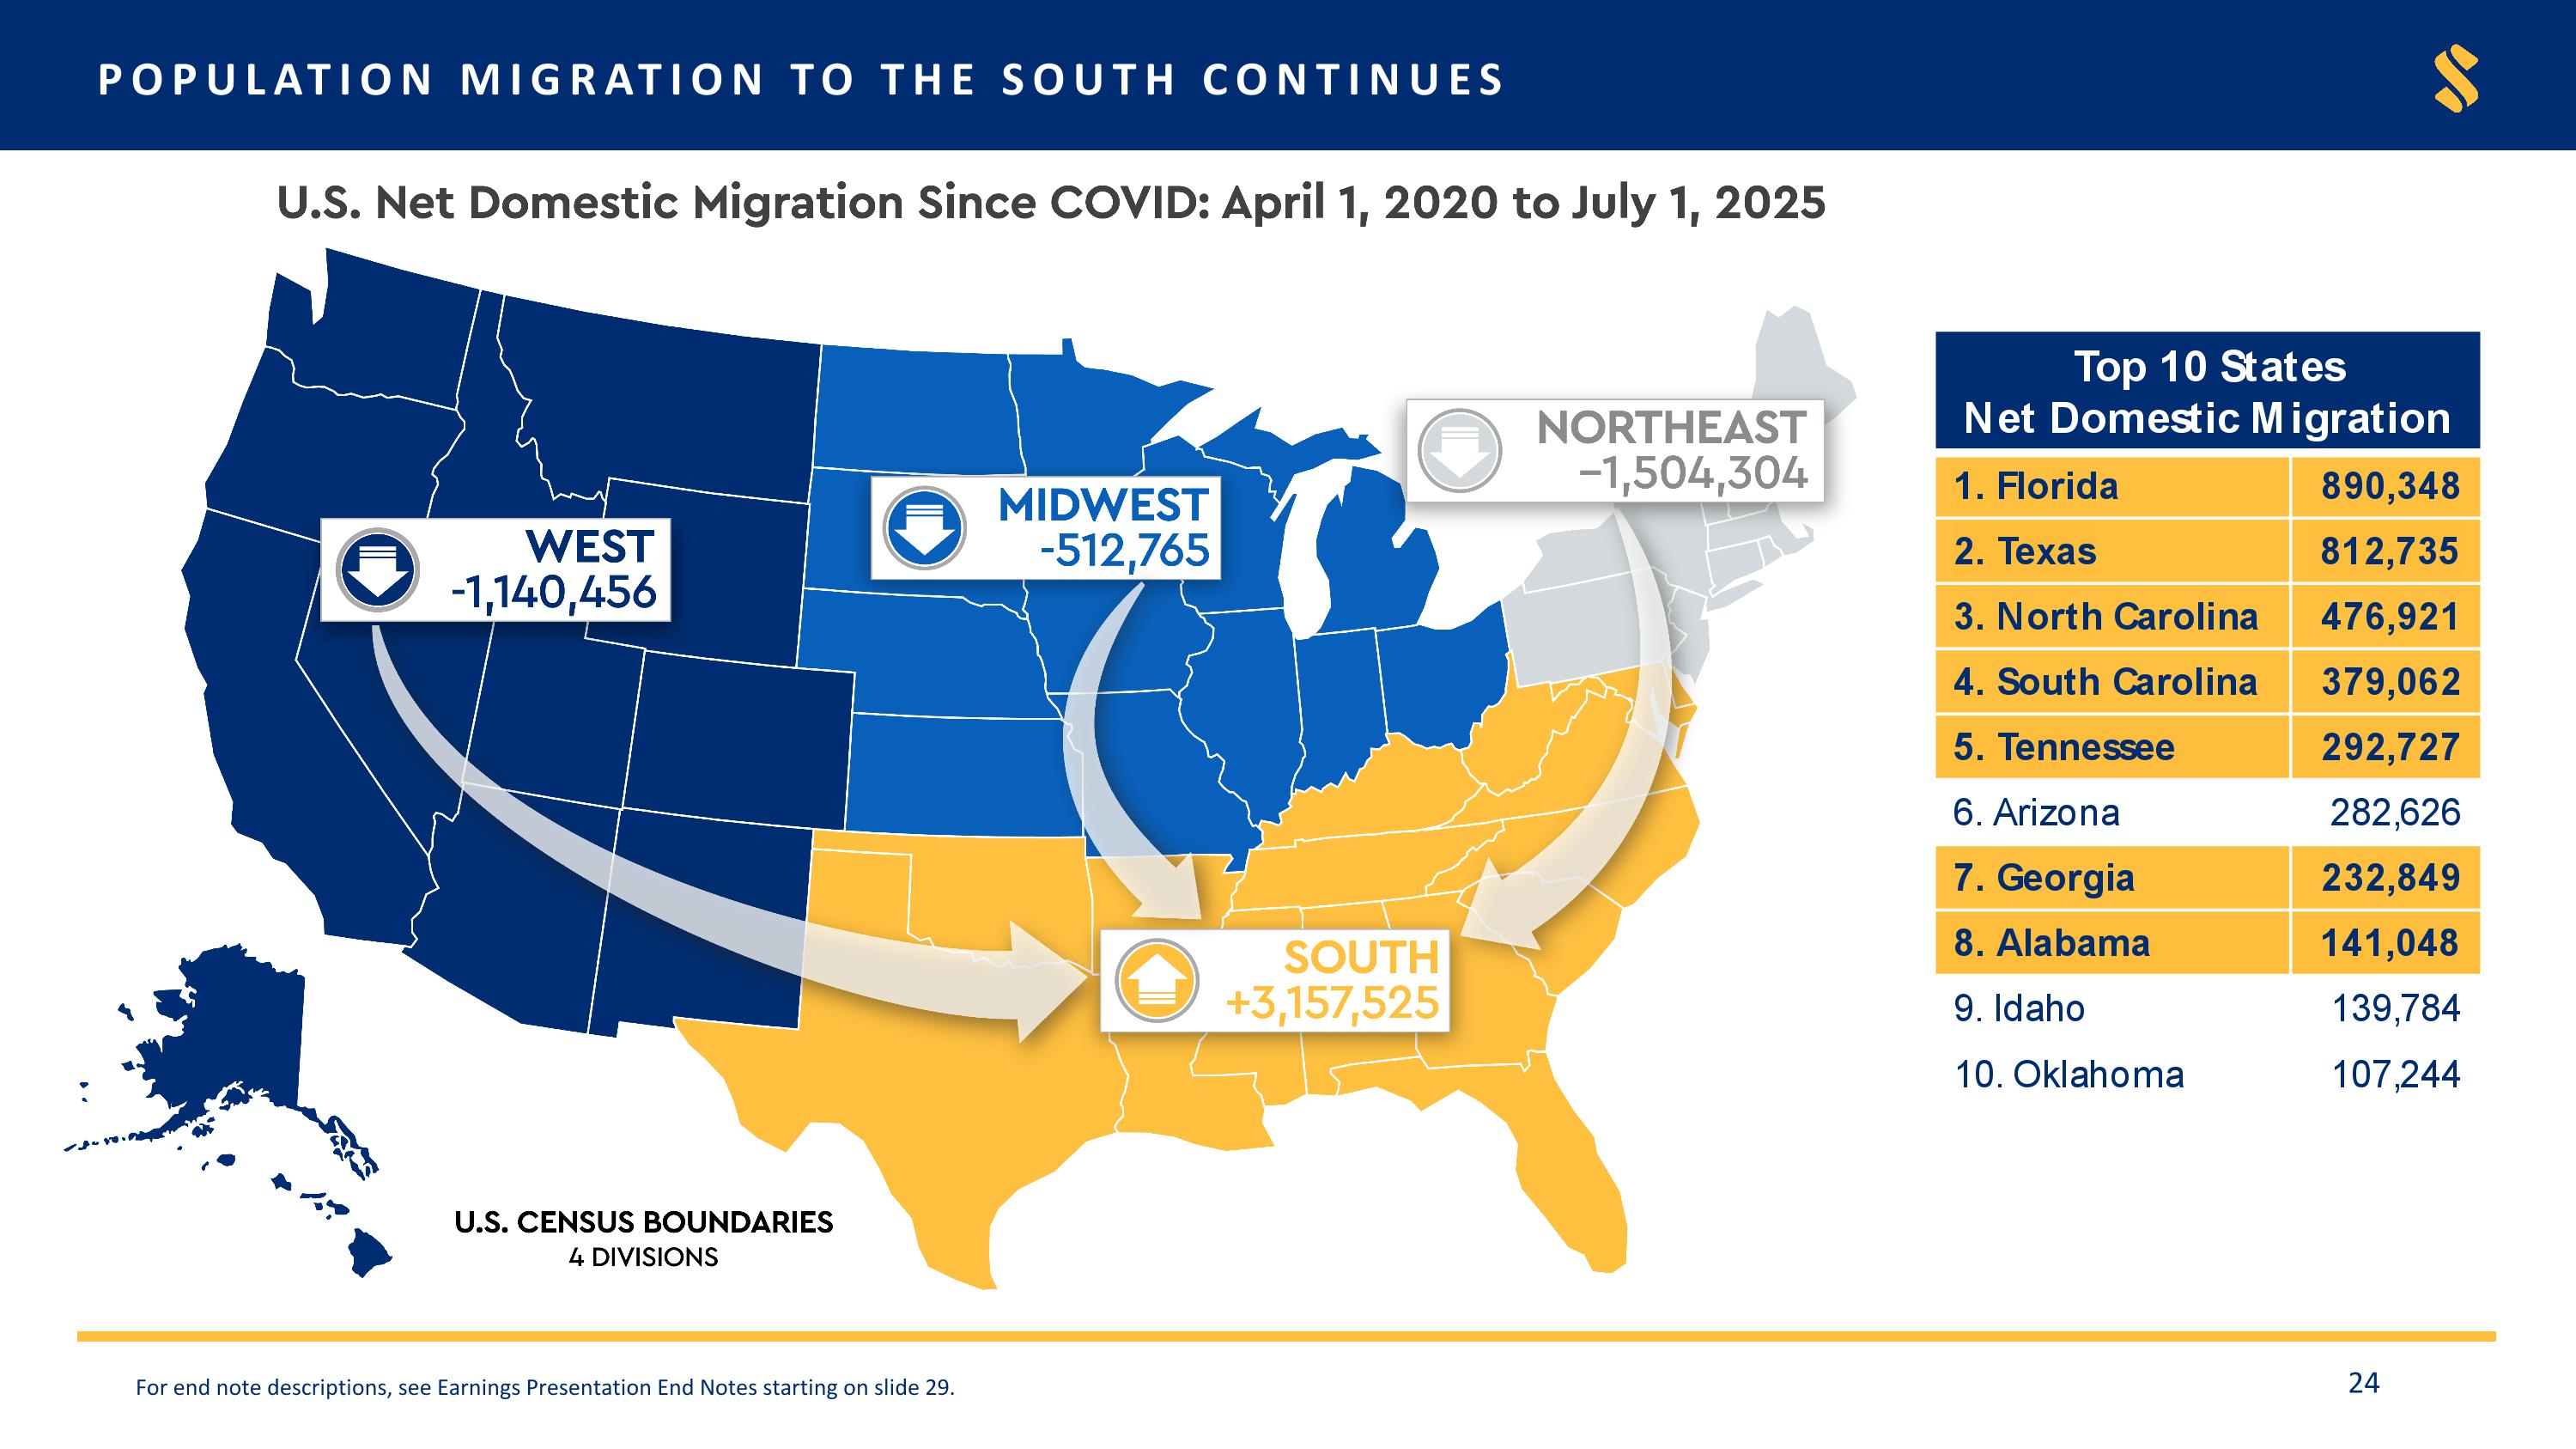
POPULATION MIGRATION TO THE SOUTH CONTINUES 24 For end note descriptions, see Earnings Presentation End Notes starting on slide 29.
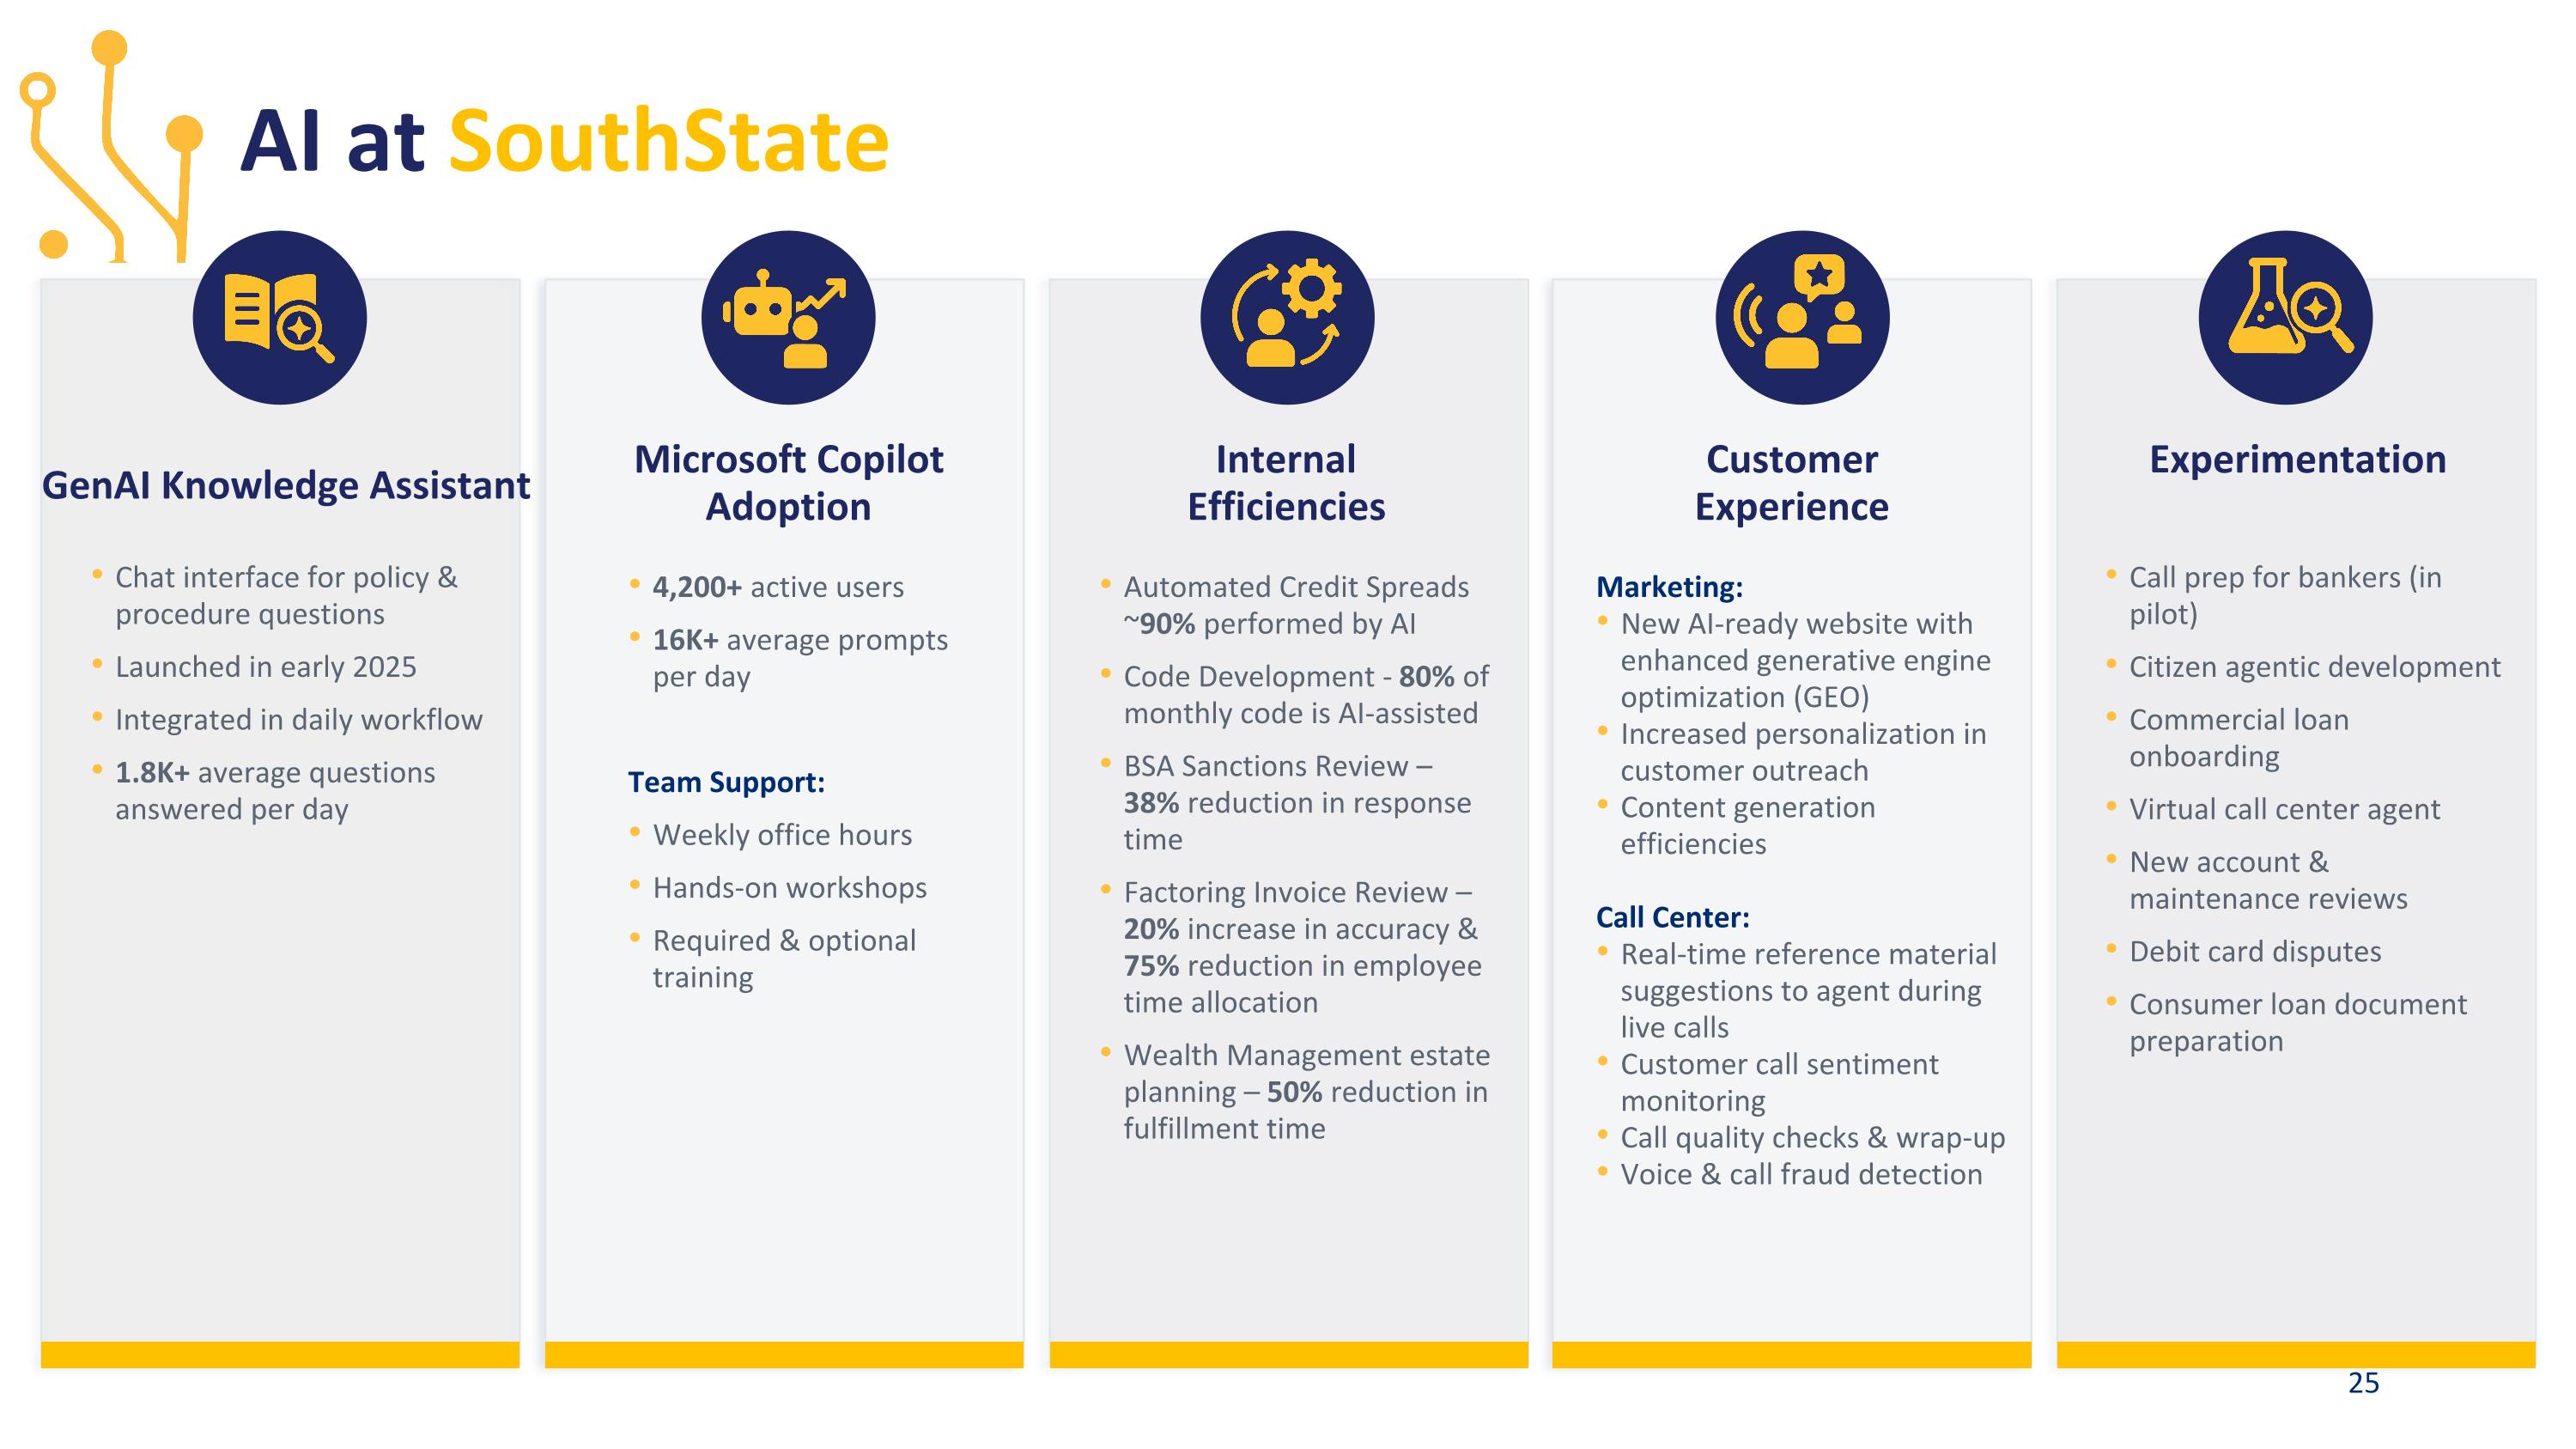
GenAI Knowledge Assistant AI at SouthState Microsoft Copilot Adoption Internal Efficiencies Customer Experience Experimentation Chat interface for policy & procedure questions Launched in early 2025 Integrated in daily workflow 1.8K+ average questions answered per day Call prep for bankers (in pilot) Citizen agentic development Commercial loan onboarding Virtual call center agent New account & maintenance reviews Debit card disputes Consumer loan document preparation Marketing: New AI-ready website with enhanced generative engine optimization (GEO) Increased personalization in customer outreach Content generation efficiencies Call Center: Real-time reference material suggestions to agent during live calls Customer call sentiment monitoring Call quality checks & wrap-up Voice & call fraud detection Automated Credit Spreads ~90% performed by AI Code Development - 80% of monthly code is AI-assisted BSA Sanctions Review – 38% reduction in response time Factoring Invoice Review – 20% increase in accuracy & 75% reduction in employee time allocation Wealth Management estate planning – 50% reduction in fulfillment time 4,200+ active users 16K+ average prompts per day Team Support: Weekly office hours Hands-on workshops Required & optional training 25
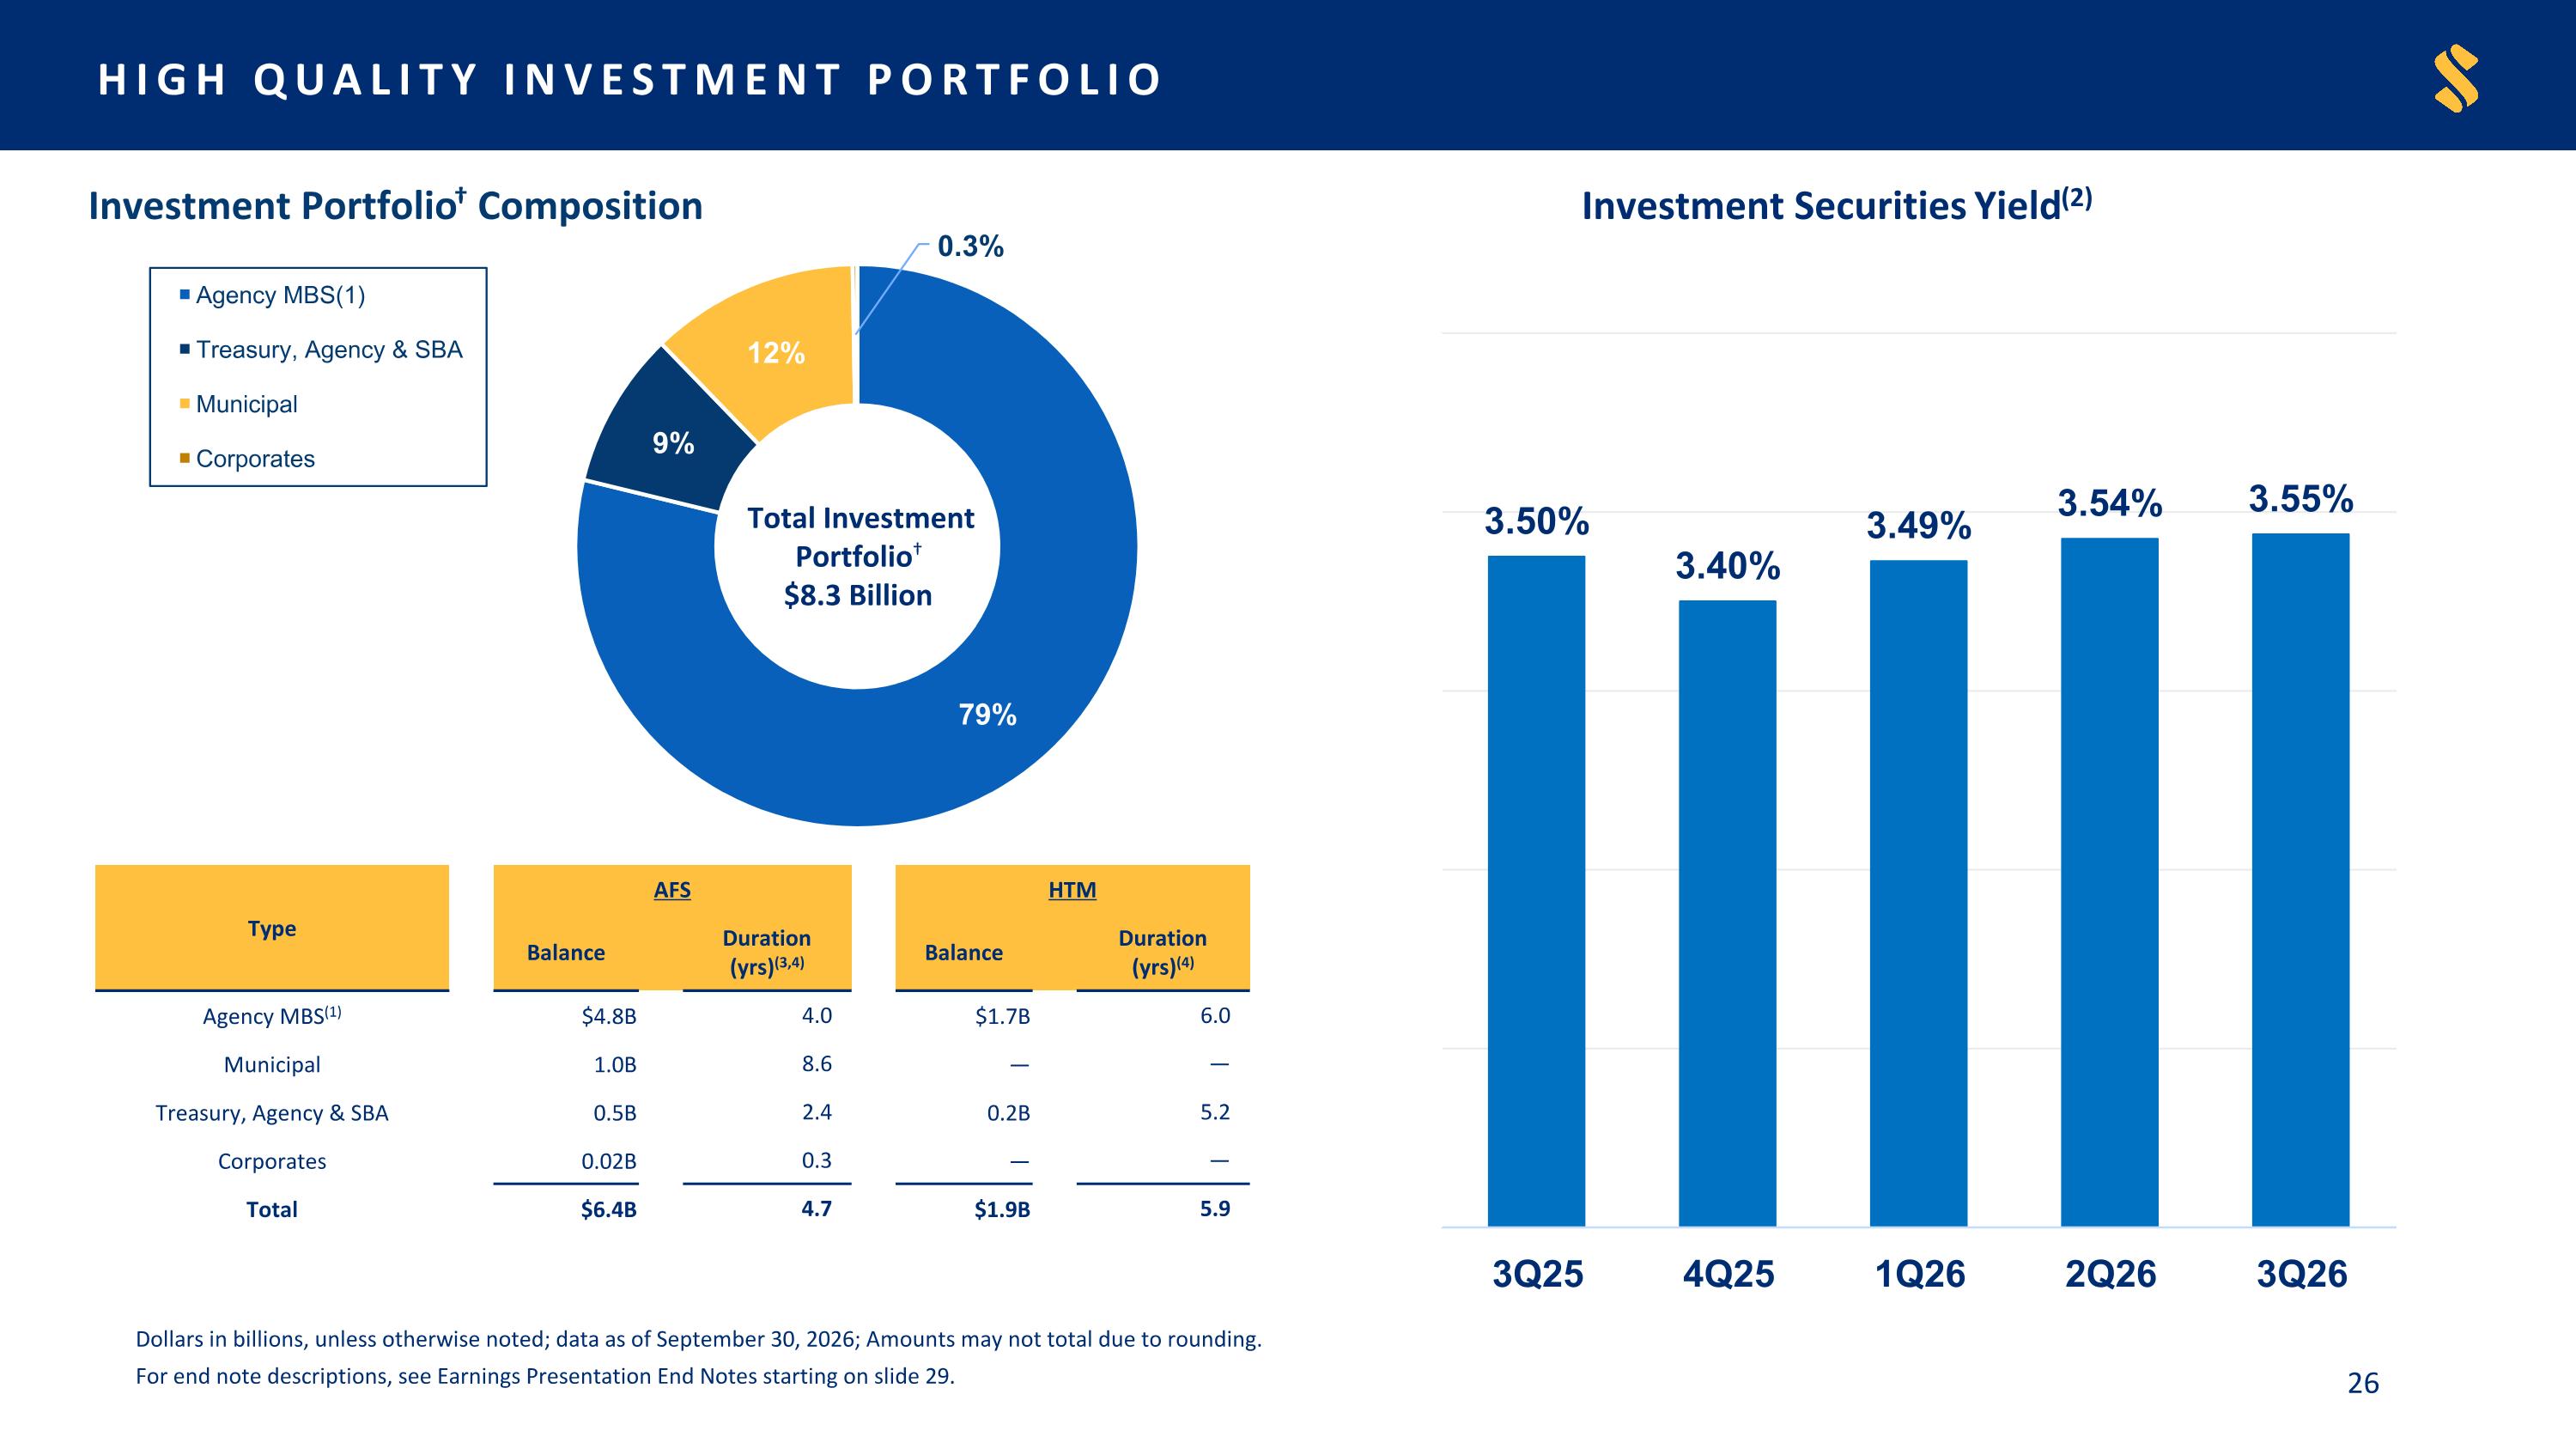
Dollars in billions, unless otherwise noted; data as of September 30, 2026; Amounts may not total due to rounding. For end note descriptions, see Earnings Presentation End Notes starting on slide 29. HIGH QUALITY INVESTMENT PORTFOLIO Type AFS HTM Type Balance Duration (yrs)(3,4) Balance Duration (yrs)(4) Agency MBS(1) $4.8B 4.0 $1.7B 6.0 Municipal 1.0B 8.6 — — Treasury, Agency & SBA 0.5B 2.4 0.2B 5.2 Corporates 0.02B 0.3 — — Total $6.4B 4.7 $1.9B 5.9 Total Investment Portfolio† $8.3 Billion
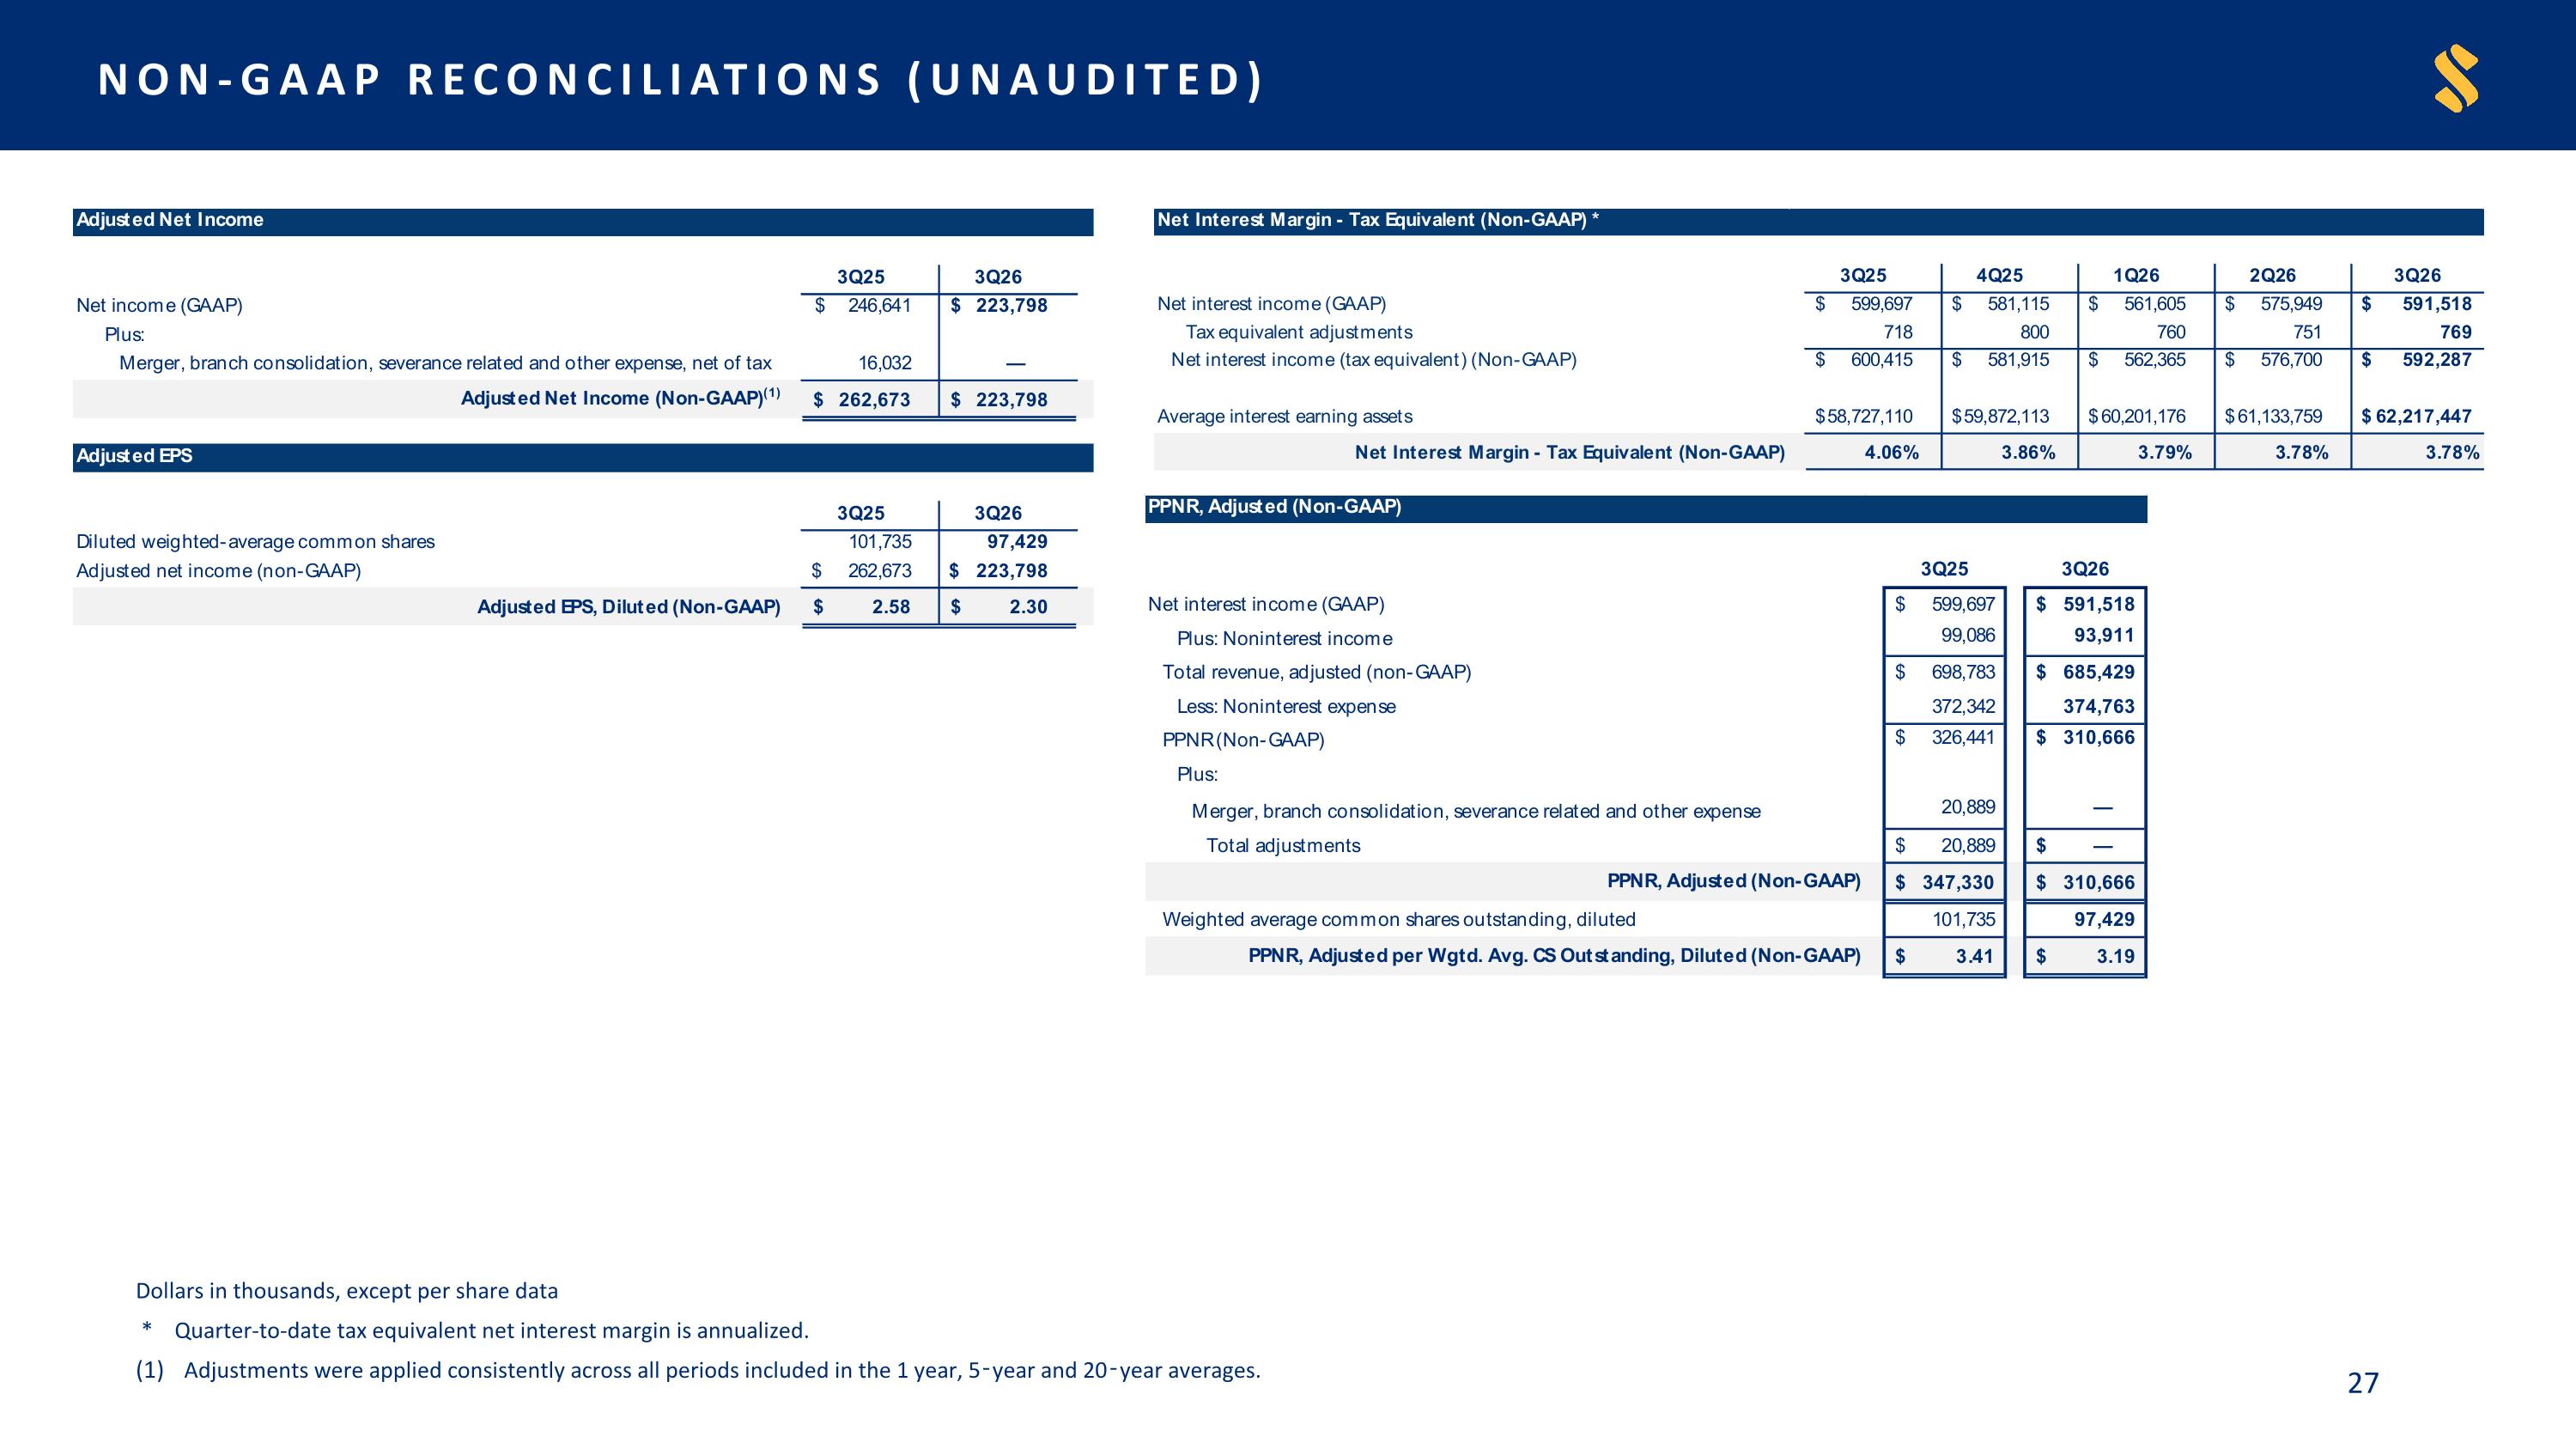
NON-GAAP RECONCILIATIONS (UNAUDITED) Dollars in thousands, except per share data * Quarter-to-date tax equivalent net interest margin is annualized. Adjustments were applied consistently across all periods included in the 1 year, 5‑year and 20‑year averages.
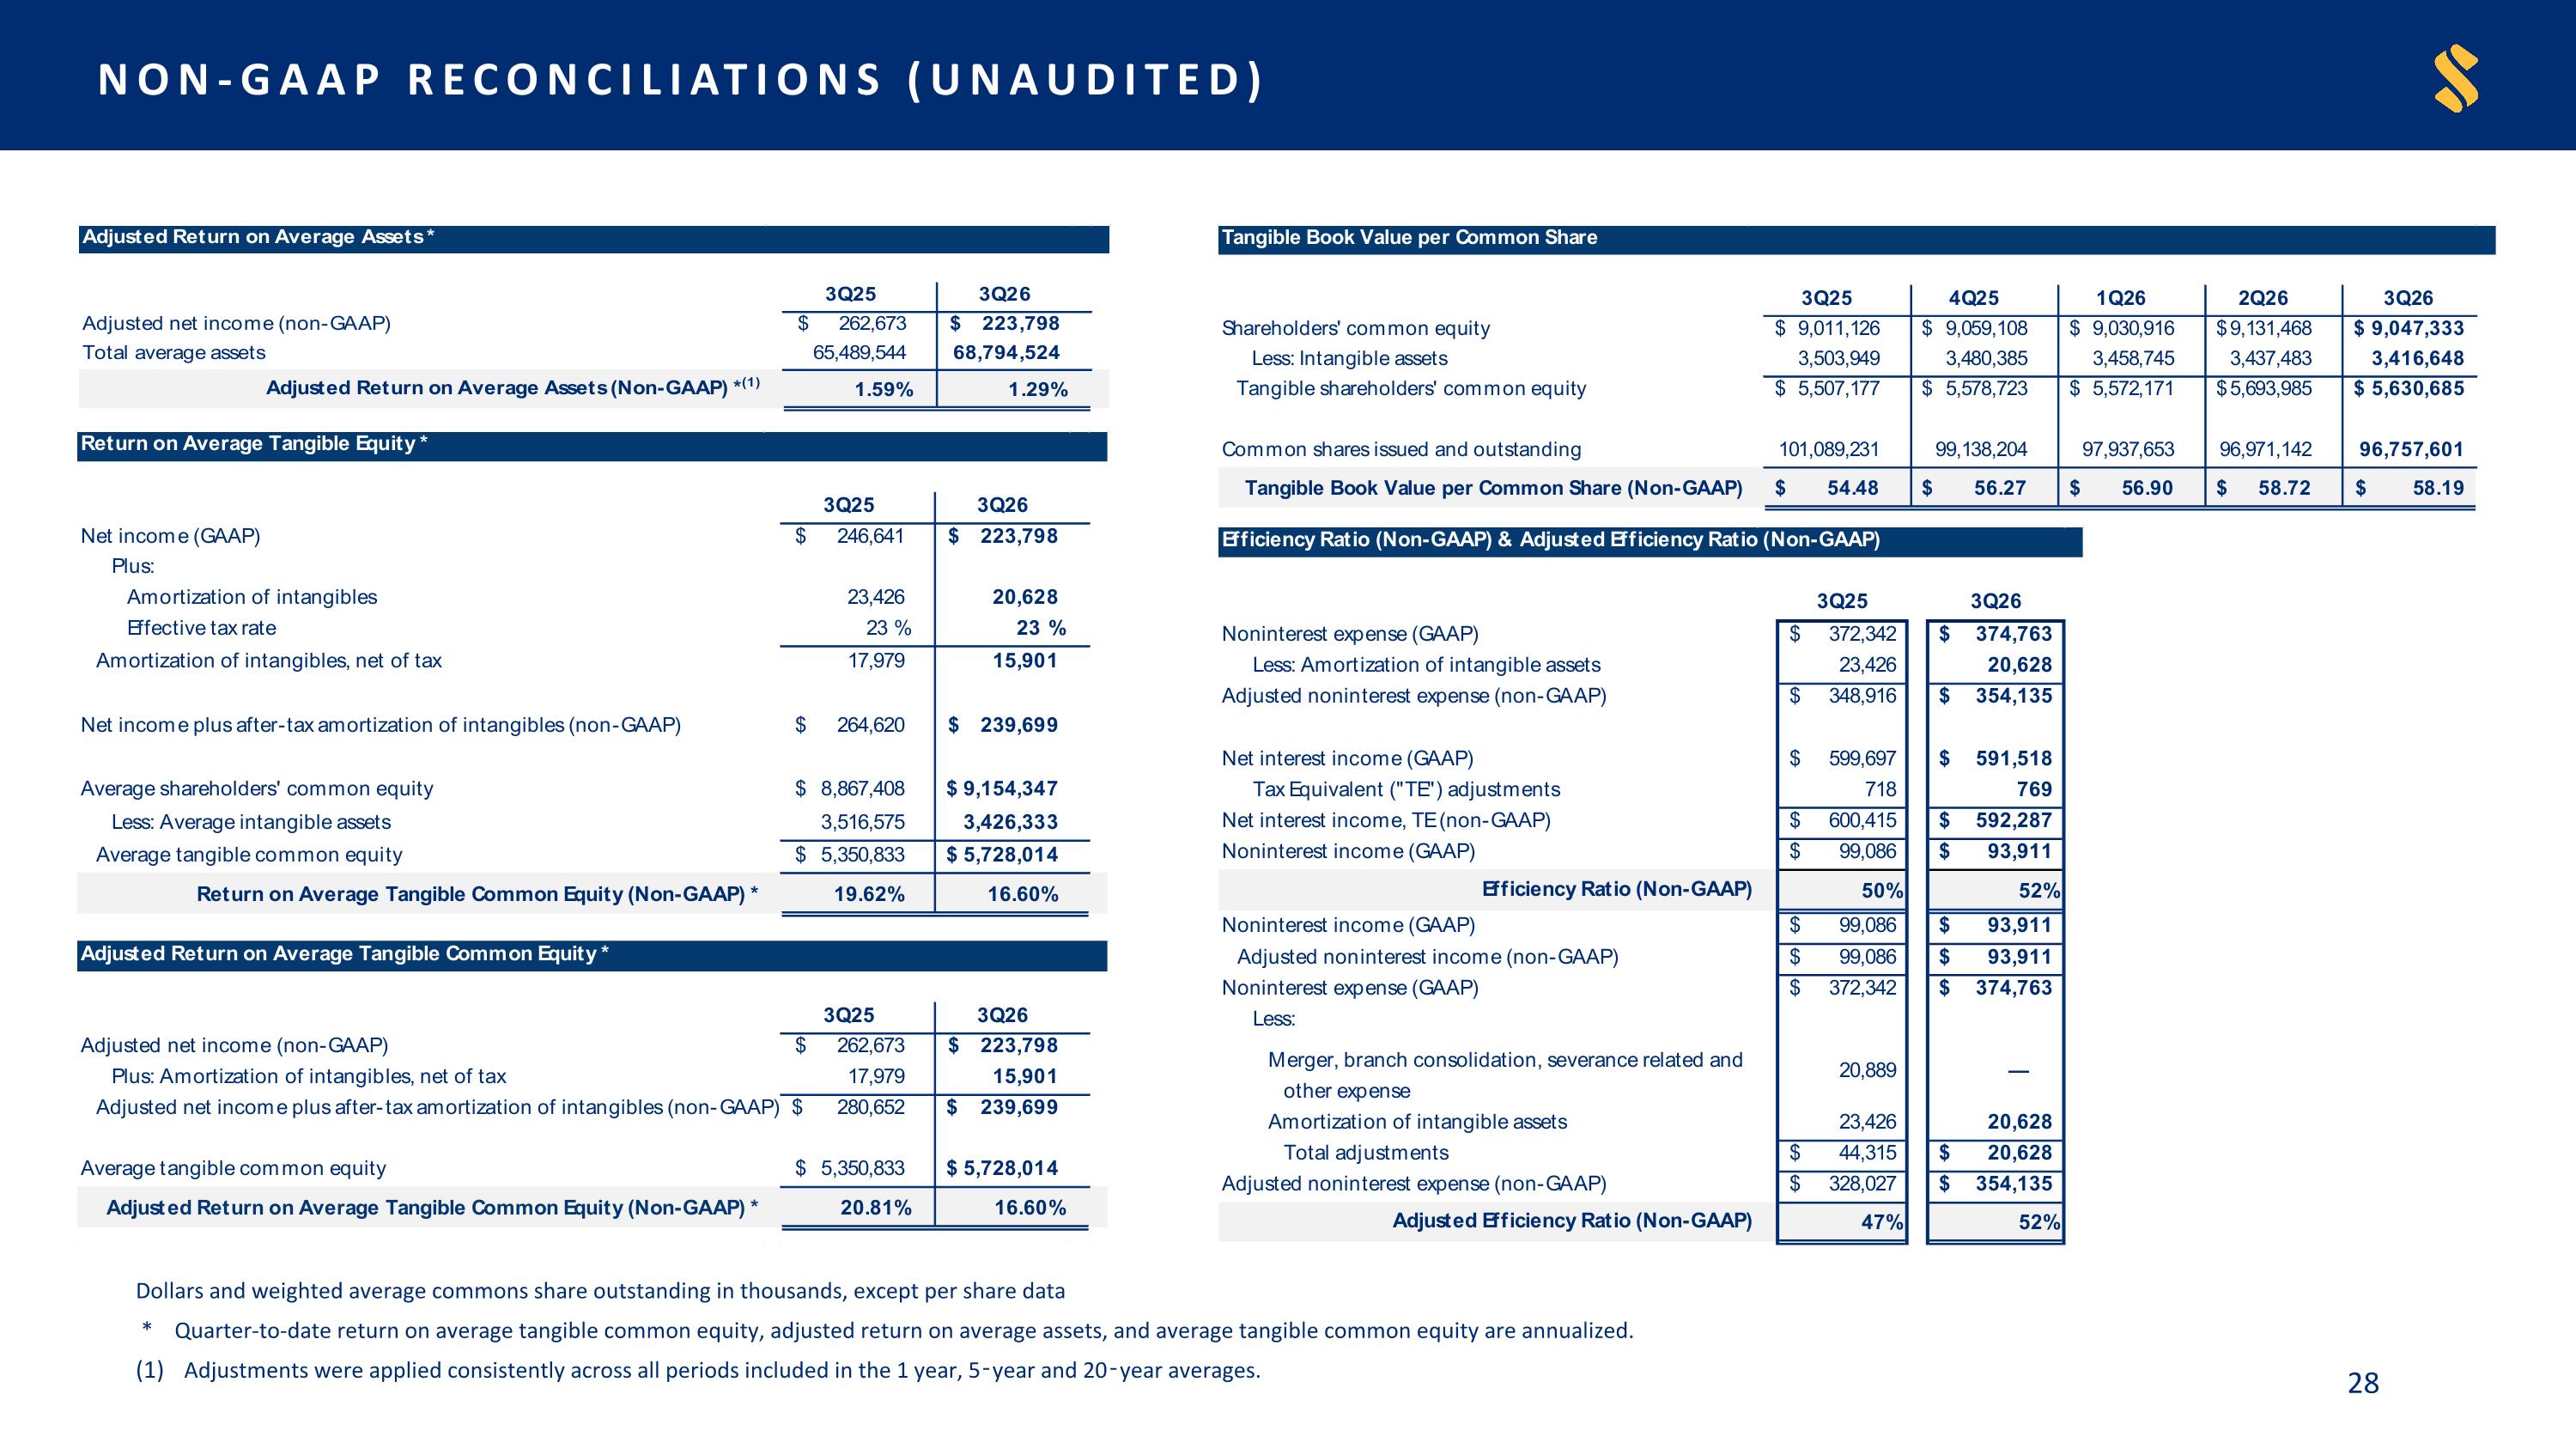
NON-GAAP RECONCILIATIONS (UNAUDITED) Dollars and weighted average commons share outstanding in thousands, except per share data * Quarter-to-date return on average tangible common equity, adjusted return on average assets, and average tangible common equity are annualized. Adjustments were applied consistently across all periods included in the 1 year, 5‑year and 20‑year averages.
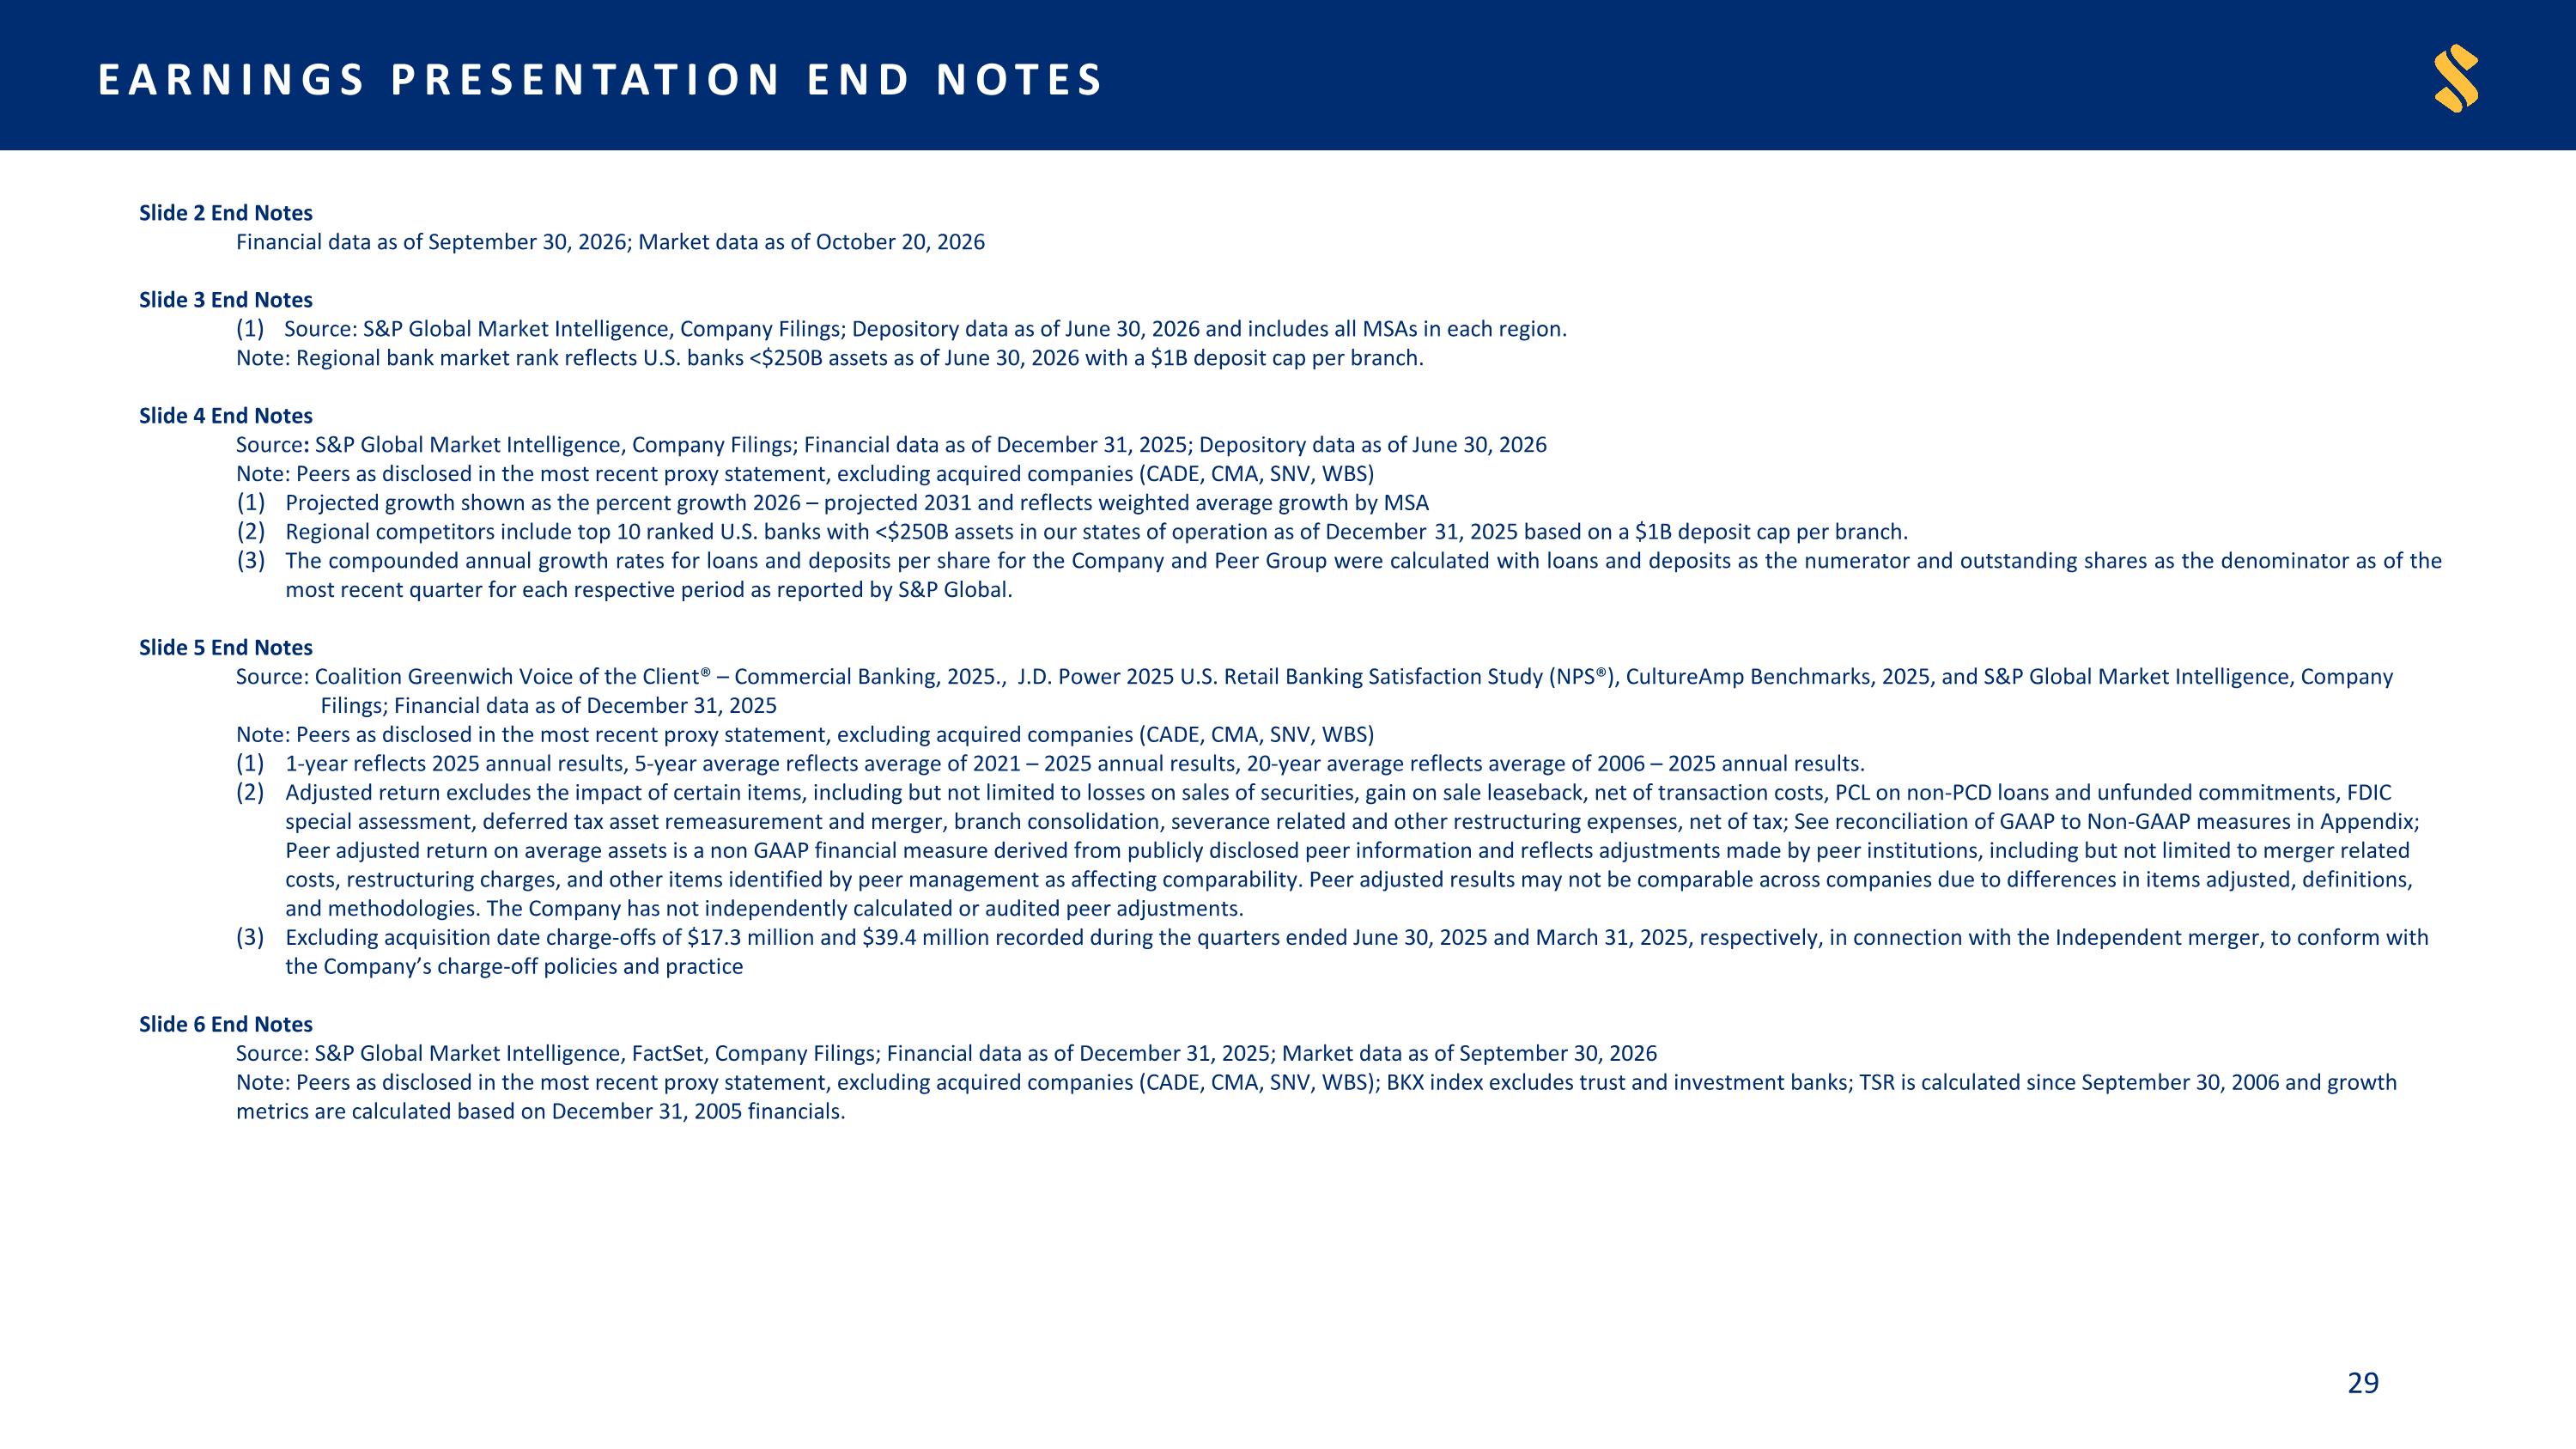
EARNINGS PRESENTATION END NOTES Slide 2 End Notes Financial data as of September 30, 2026; Market data as of October 20, 2026 Slide 3 End Notes Source: S&P Global Market Intelligence, Company Filings; Depository data as of June 30, 2026 and includes all MSAs in each region. Note: Regional bank market rank reflects U.S. banks <$250B assets as of June 30, 2026 with a $1B deposit cap per branch. Slide 4 End Notes Source: S&P Global Market Intelligence, Company Filings; Financial data as of December 31, 2025; Depository data as of June 30, 2026 Note: Peers as disclosed in the most recent proxy statement, excluding acquired companies (CADE, CMA, SNV, WBS) Projected growth shown as the percent growth 2026 – projected 2031 and reflects weighted average growth by MSA Regional competitors include top 10 ranked U.S. banks with <$250B assets in our states of operation as of December 31, 2025 based on a $1B deposit cap per branch. The compounded annual growth rates for loans and deposits per share for the Company and Peer Group were calculated with loans and deposits as the numerator and outstanding shares as the denominator as of the most recent quarter for each respective period as reported by S&P Global. Slide 5 End Notes Source: Coalition Greenwich Voice of the Client® – Commercial Banking, 2025., J.D. Power 2025 U.S. Retail Banking Satisfaction Study (NPS®), CultureAmp Benchmarks, 2025, and S&P Global Market Intelligence, Company Filings; Financial data as of December 31, 2025 Note: Peers as disclosed in the most recent proxy statement, excluding acquired companies (CADE, CMA, SNV, WBS) 1-year reflects 2025 annual results, 5-year average reflects average of 2021 – 2025 annual results, 20-year average reflects average of 2006 – 2025 annual results. Adjusted return excludes the impact of certain items, including but not limited to losses on sales of securities, gain on sale leaseback, net of transaction costs, PCL on non-PCD loans and unfunded commitments, FDIC special assessment, deferred tax asset remeasurement and merger, branch consolidation, severance related and other restructuring expenses, net of tax; See reconciliation of GAAP to Non-GAAP measures in Appendix; Peer adjusted return on average assets is a non GAAP financial measure derived from publicly disclosed peer information and reflects adjustments made by peer institutions, including but not limited to merger related costs, restructuring charges, and other items identified by peer management as affecting comparability. Peer adjusted results may not be comparable across companies due to differences in items adjusted, definitions, and methodologies. The Company has not independently calculated or audited peer adjustments. Excluding acquisition date charge-offs of $17.3 million and $39.4 million recorded during the quarters ended June 30, 2025 and March 31, 2025, respectively, in connection with the Independent merger, to conform with the Company’s charge-off policies and practice Slide 6 End Notes Source: S&P Global Market Intelligence, FactSet, Company Filings; Financial data as of December 31, 2025; Market data as of September 30, 2026 Note: Peers as disclosed in the most recent proxy statement, excluding acquired companies (CADE, CMA, SNV, WBS); BKX index excludes trust and investment banks; TSR is calculated since September 30, 2006 and growth metrics are calculated based on December 31, 2005 financials.
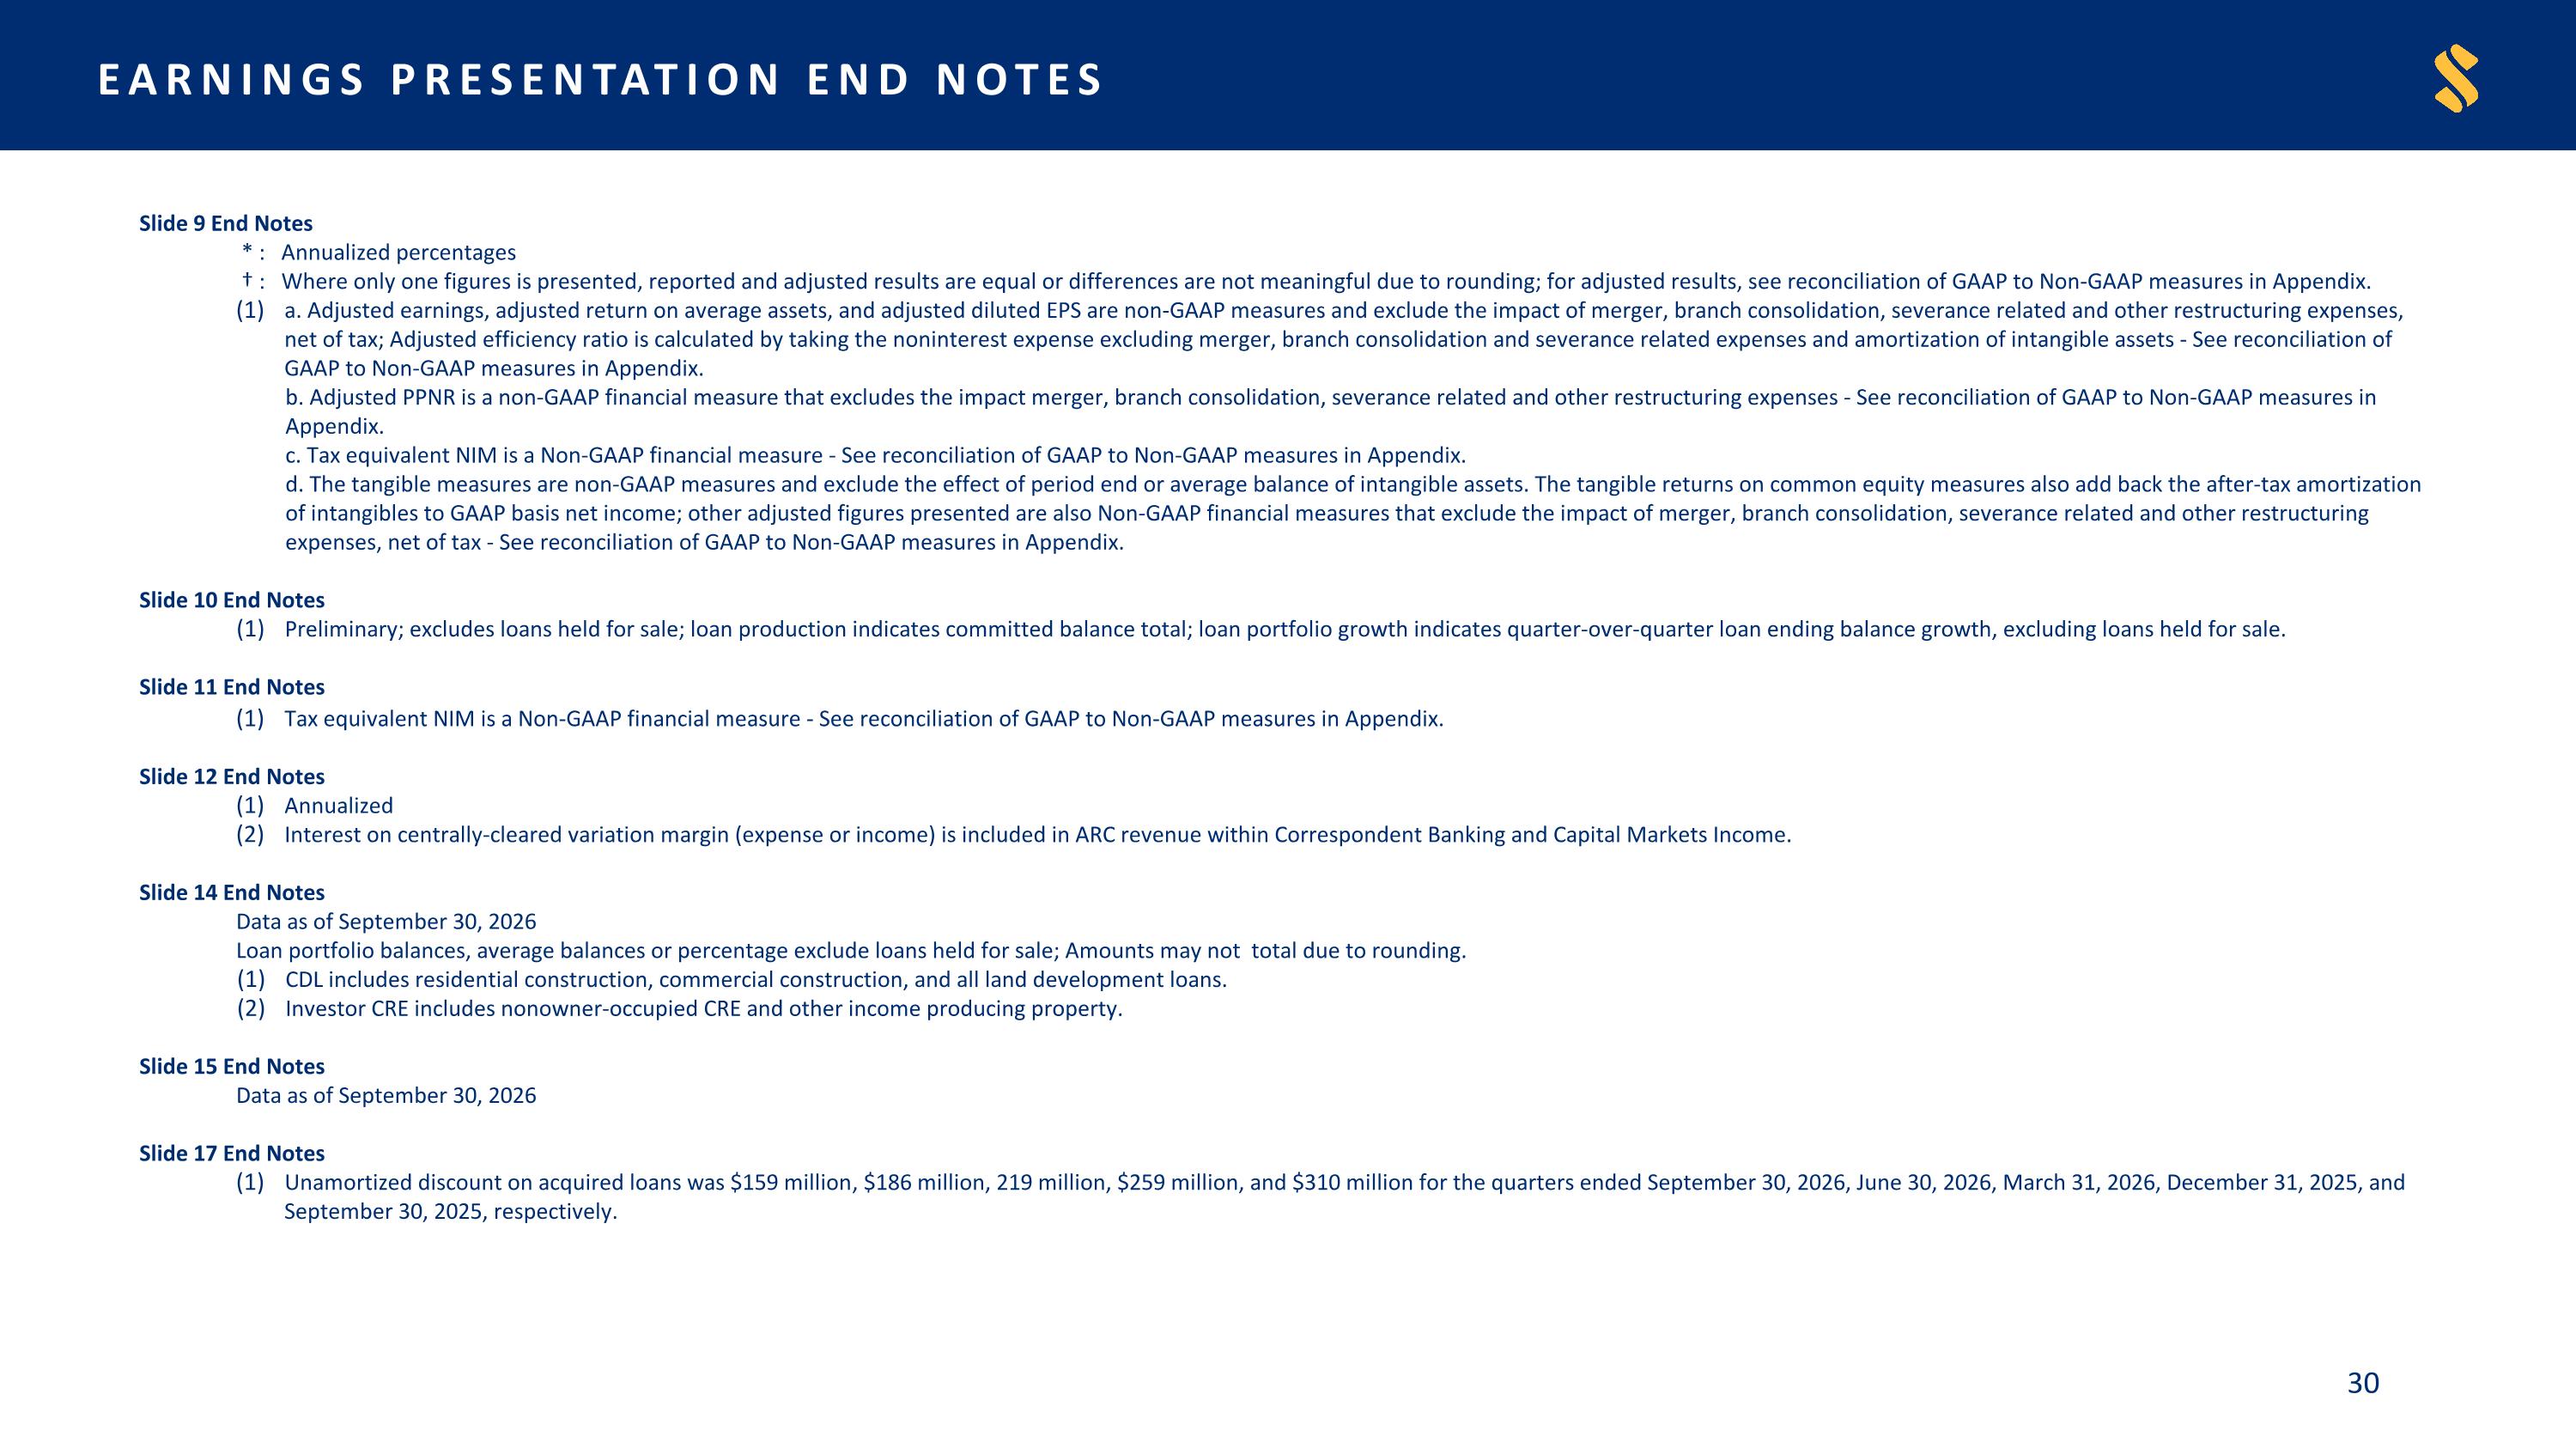
EARNINGS PRESENTATION END NOTES Slide 9 End Notes * : Annualized percentages † : Where only one figures is presented, reported and adjusted results are equal or differences are not meaningful due to rounding; for adjusted results, see reconciliation of GAAP to Non-GAAP measures in Appendix. a. Adjusted earnings, adjusted return on average assets, and adjusted diluted EPS are non-GAAP measures and exclude the impact of merger, branch consolidation, severance related and other restructuring expenses, net of tax; Adjusted efficiency ratio is calculated by taking the noninterest expense excluding merger, branch consolidation and severance related expenses and amortization of intangible assets - See reconciliation of GAAP to Non-GAAP measures in Appendix. b. Adjusted PPNR is a non-GAAP financial measure that excludes the impact merger, branch consolidation, severance related and other restructuring expenses - See reconciliation of GAAP to Non-GAAP measures in Appendix. c. Tax equivalent NIM is a Non-GAAP financial measure - See reconciliation of GAAP to Non-GAAP measures in Appendix. d. The tangible measures are non-GAAP measures and exclude the effect of period end or average balance of intangible assets. The tangible returns on common equity measures also add back the after-tax amortization of intangibles to GAAP basis net income; other adjusted figures presented are also Non-GAAP financial measures that exclude the impact of merger, branch consolidation, severance related and other restructuring expenses, net of tax - See reconciliation of GAAP to Non-GAAP measures in Appendix. Slide 10 End Notes Preliminary; excludes loans held for sale; loan production indicates committed balance total; loan portfolio growth indicates quarter-over-quarter loan ending balance growth, excluding loans held for sale. Slide 11 End Notes Tax equivalent NIM is a Non-GAAP financial measure - See reconciliation of GAAP to Non-GAAP measures in Appendix. Slide 12 End Notes Annualized Interest on centrally-cleared variation margin (expense or income) is included in ARC revenue within Correspondent Banking and Capital Markets Income. Slide 14 End Notes Data as of September 30, 2026 Loan portfolio balances, average balances or percentage exclude loans held for sale; Amounts may not total due to rounding. CDL includes residential construction, commercial construction, and all land development loans. Investor CRE includes nonowner-occupied CRE and other income producing property. Slide 15 End Notes Data as of September 30, 2026 Slide 17 End Notes Unamortized discount on acquired loans was $159 million, $186 million, 219 million, $259 million, and $310 million for the quarters ended September 30, 2026, June 30, 2026, March 31, 2026, December 31, 2025, and September 30, 2025, respectively.
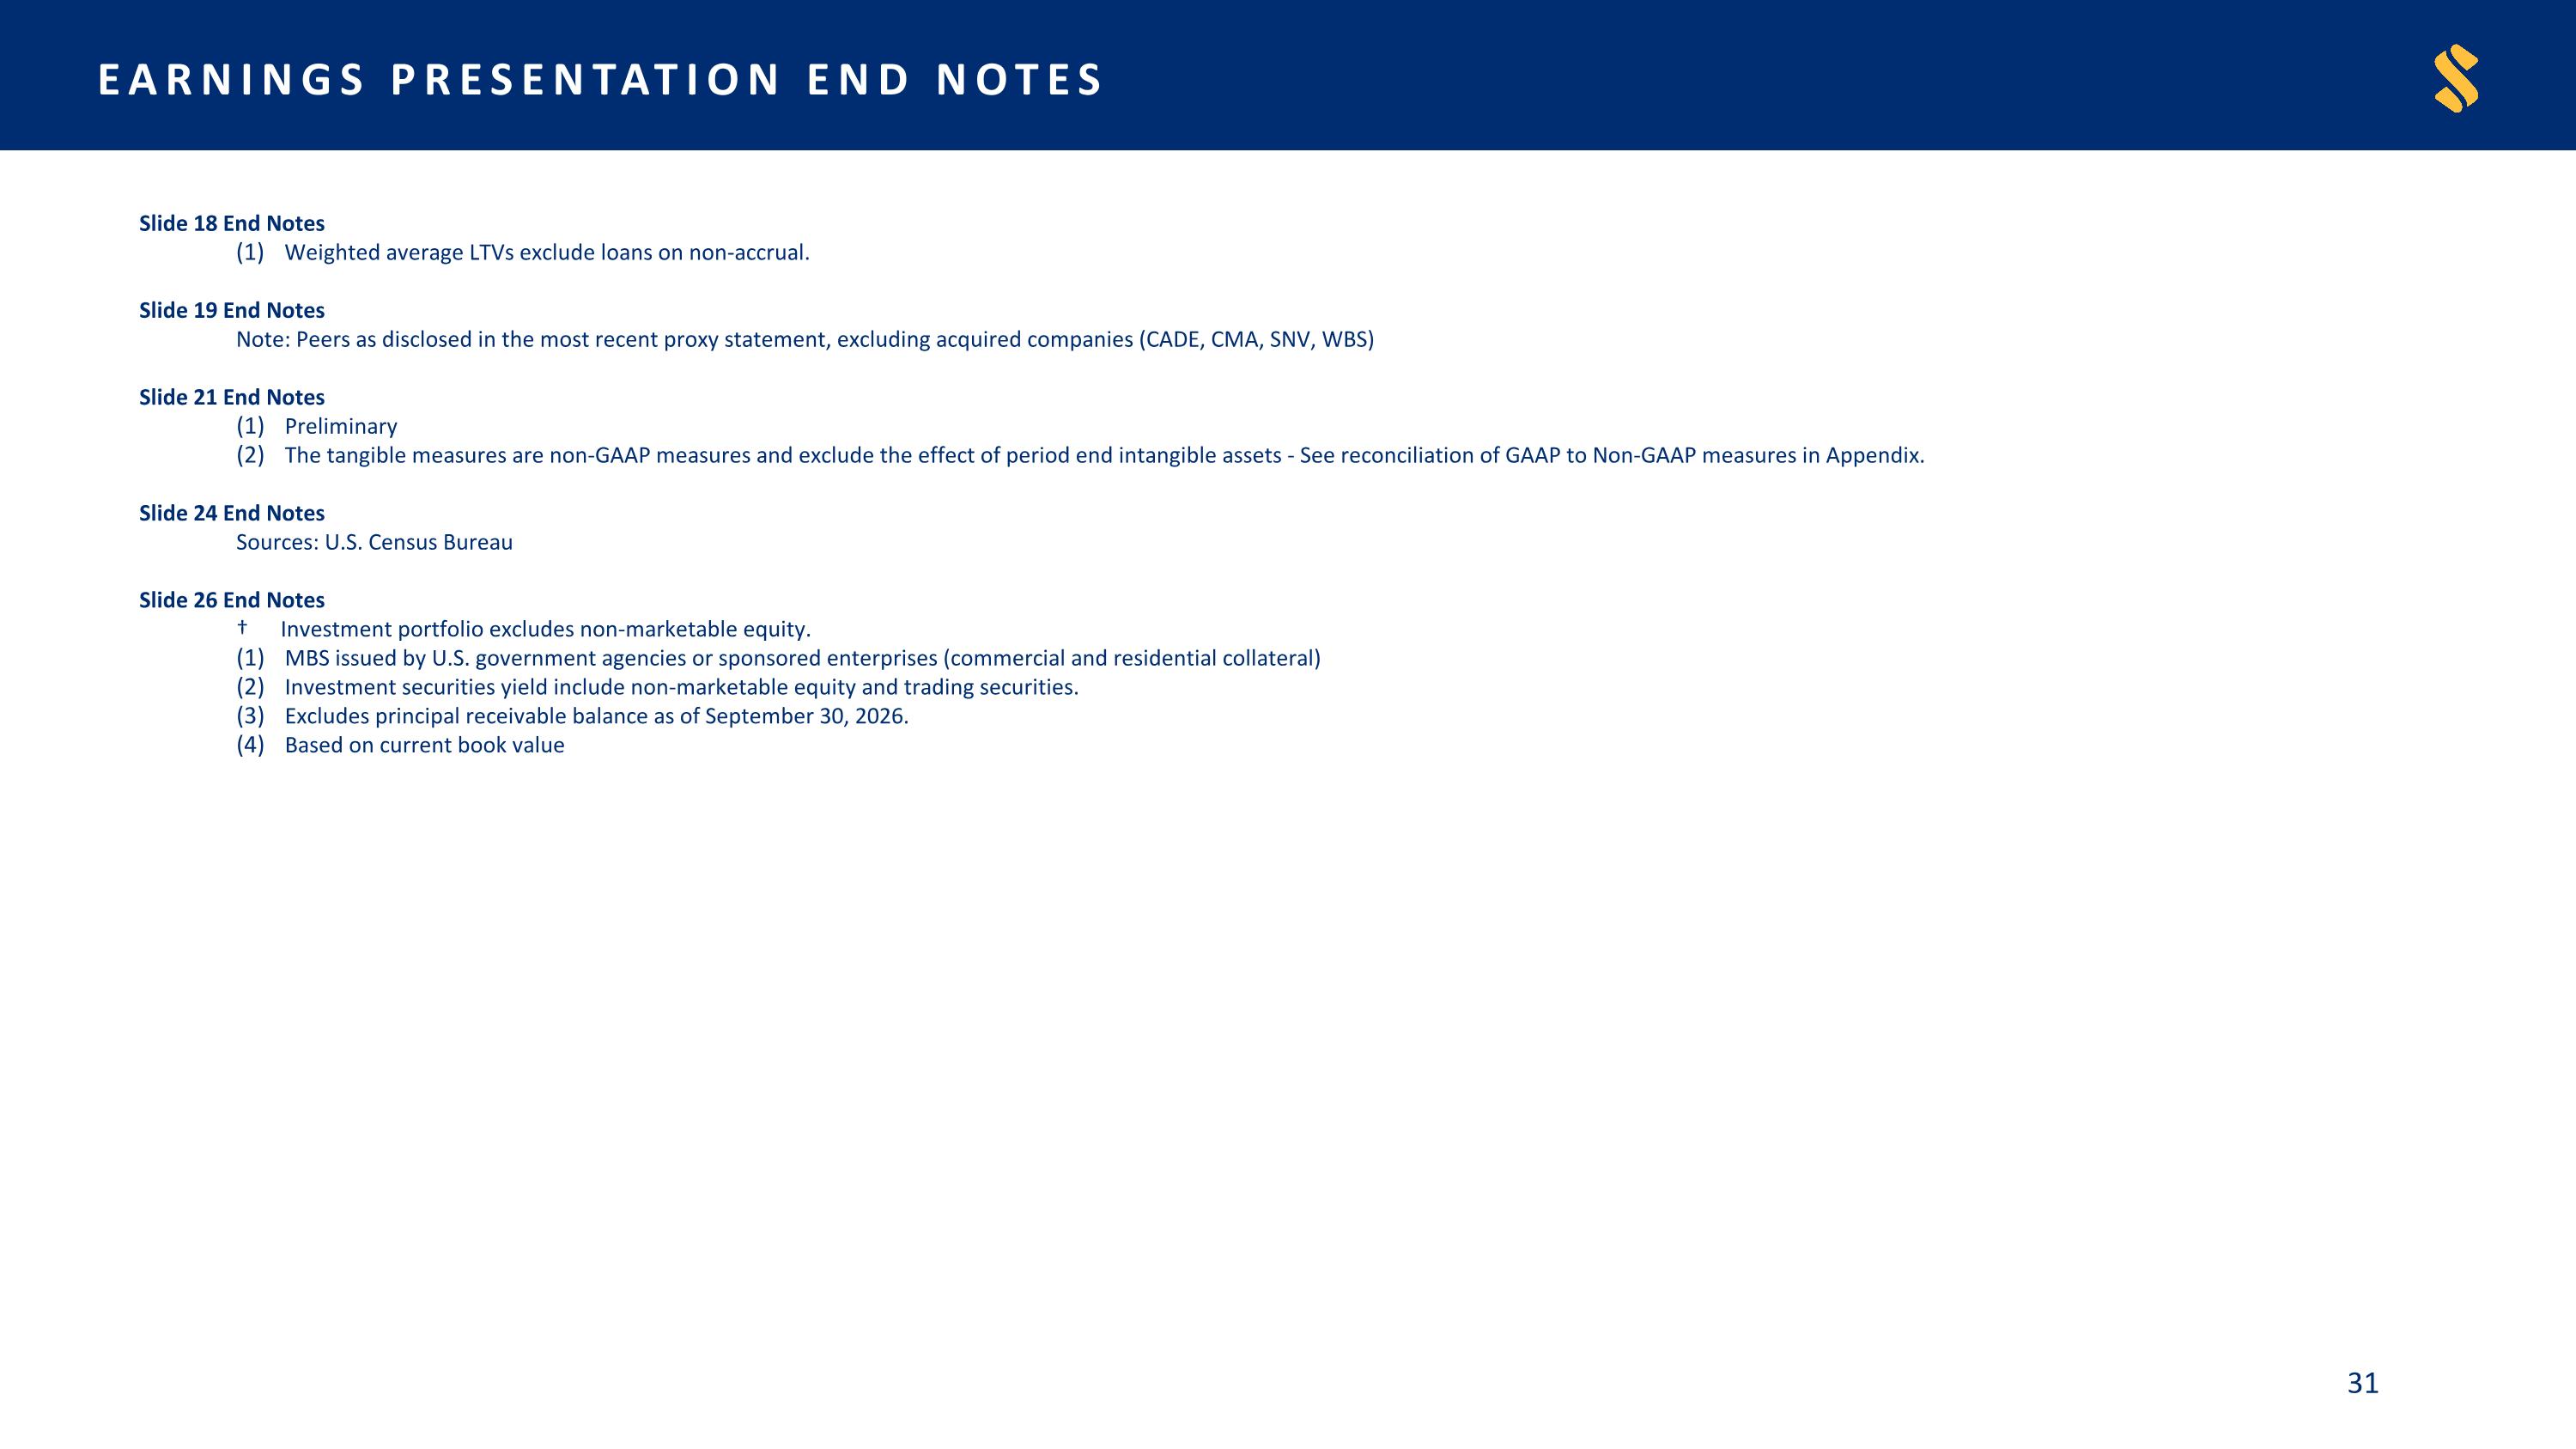
EARNINGS PRESENTATION END NOTES Slide 18 End Notes Weighted average LTVs exclude loans on non-accrual. Slide 19 End Notes Note: Peers as disclosed in the most recent proxy statement, excluding acquired companies (CADE, CMA, SNV, WBS) Slide 21 End Notes Preliminary The tangible measures are non-GAAP measures and exclude the effect of period end intangible assets - See reconciliation of GAAP to Non-GAAP measures in Appendix. Slide 24 End Notes Sources: U.S. Census Bureau Slide 26 End Notes † Investment portfolio excludes non-marketable equity. MBS issued by U.S. government agencies or sponsored enterprises (commercial and residential collateral) Investment securities yield include non-marketable equity and trading securities. Excludes principal receivable balance as of September 30, 2026. Based on current book value
This presentation contains forward looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements are based on the current beliefs and expectations of management of SouthState Bank Corporation (“SouthState”) and are subject to significant risks and uncertainties. Actual results may differ materially from those set forth in the forward looking statements. Factors that could cause SouthState’s actual results to differ materially from those described in the forward looking statements are discussed in SouthState’s Annual Report on Form 10 K for the year ended December 31, 2025, filed with the Securities and Exchange Commission and available on SouthState’s website (https://southstatecorporation.q4ir.com/SEC-Filings/Documents/default.aspx), and on the Securities and Exchange Commission's website (www.sec.gov). SouthState undertakes no obligation to update any forward looking statements. CAUTIONARY NOTE REGARDING FORWARD LOOKING STATEMENTS