Q 3 2 0 2 6
2© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Agree Realty Overview (NYSE: ADC) OUR COMPANY NET LEASE REIT FOCUSED ON THE ACQUISITION & DEVELOPMENT OF HIGH-QUALITY RETAIL PROPERTIES Founded in 1971 by Executive Chairman, Richard Agree Public on the NYSE since 1994 $12.6 billion(1) retail net lease REIT headquartered in Royal Oak, Michigan 2,888 retail properties totaling 61.1 million square feet in all 50 states and the District of Columbia Investment grade issuer ratings of A- from Fitch, Baa1 from Moody’s, and BBB+ from S&P RETHINK RETAIL Capitalize on distinct market positioning in the retail net lease space Focus on industry- leading retailers through our three unique external growth platforms Leverage our real estate acumen and relationships to identify superior risk- adjusted opportunities Maintain a conservative and flexible capital structure that enables our growth trajectory Provide consistent, high-quality earnings growth and a well-covered, growing dividend A s o f S e p te m b e r 3 0, 2 02 6. ( 1) S e e G lo ss a ry b e g in n in g o n p a g e 4 4 fo r t h e d e fin iti o n o f E n te rp ris e V a lu e .
3© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. consistency noun steadfast adherence to the same principles, course, or form [ kuh n-sis-tuh n-see ]
4© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. As of September 30, 2026, unless otherwise noted. (1) Reflects full-year 2026 guidance provided by the Company on October 20, 2026. (2) Reflects total capital committed for the 26 projects. (3) See Glossary beginning on page 44 for the definition of Recapture Rate. (4) Proforma for the settlement of the Company’s outstanding forward equity as of September 30, 2026. (5) Declared by the Company on October 13, 2026. Note: this presentation includes non-GAAP financial measures, and reconciliations of these non-GAAP financial measures to the most directly comparable GAAP measures are included in the Appendix herewith. Recent Highlights Issued $400 million of 10-year senior unsecured notes at an all-in interest rate of 5.36% 26 development or DFP projects completed or under construction year to date for $257 million(2) Declared a monthly cash dividend of $0.271 per common share for October, a 3.4% year-over-year increase(5) Increased 2026 AFFO per share guidance to $4.58 to $4.59, representing nearly 6% year- over-year growth at the midpoint(1) Updated 2026 investment volume guidance to approximately $1.6 billion(1) 3.9x Proforma Net Debt to Recurring EBITDA as of quarter end(4) 2.5 million square feet of leasing activity through the first nine months with a recapture rate of approximately 105%(3) Fortress balance sheet with liquidity of approximately $2.0 billion(4) Increased 2026 disposition guidance to a new range of $100 to $150 million(1) Acquired approximately $1.2 billion of high-quality retail net lease assets year to date at a weighted-average cap rate of 7.1% No short-term or variable-rate debt outstanding at quarter end; no material debt maturities until 2028
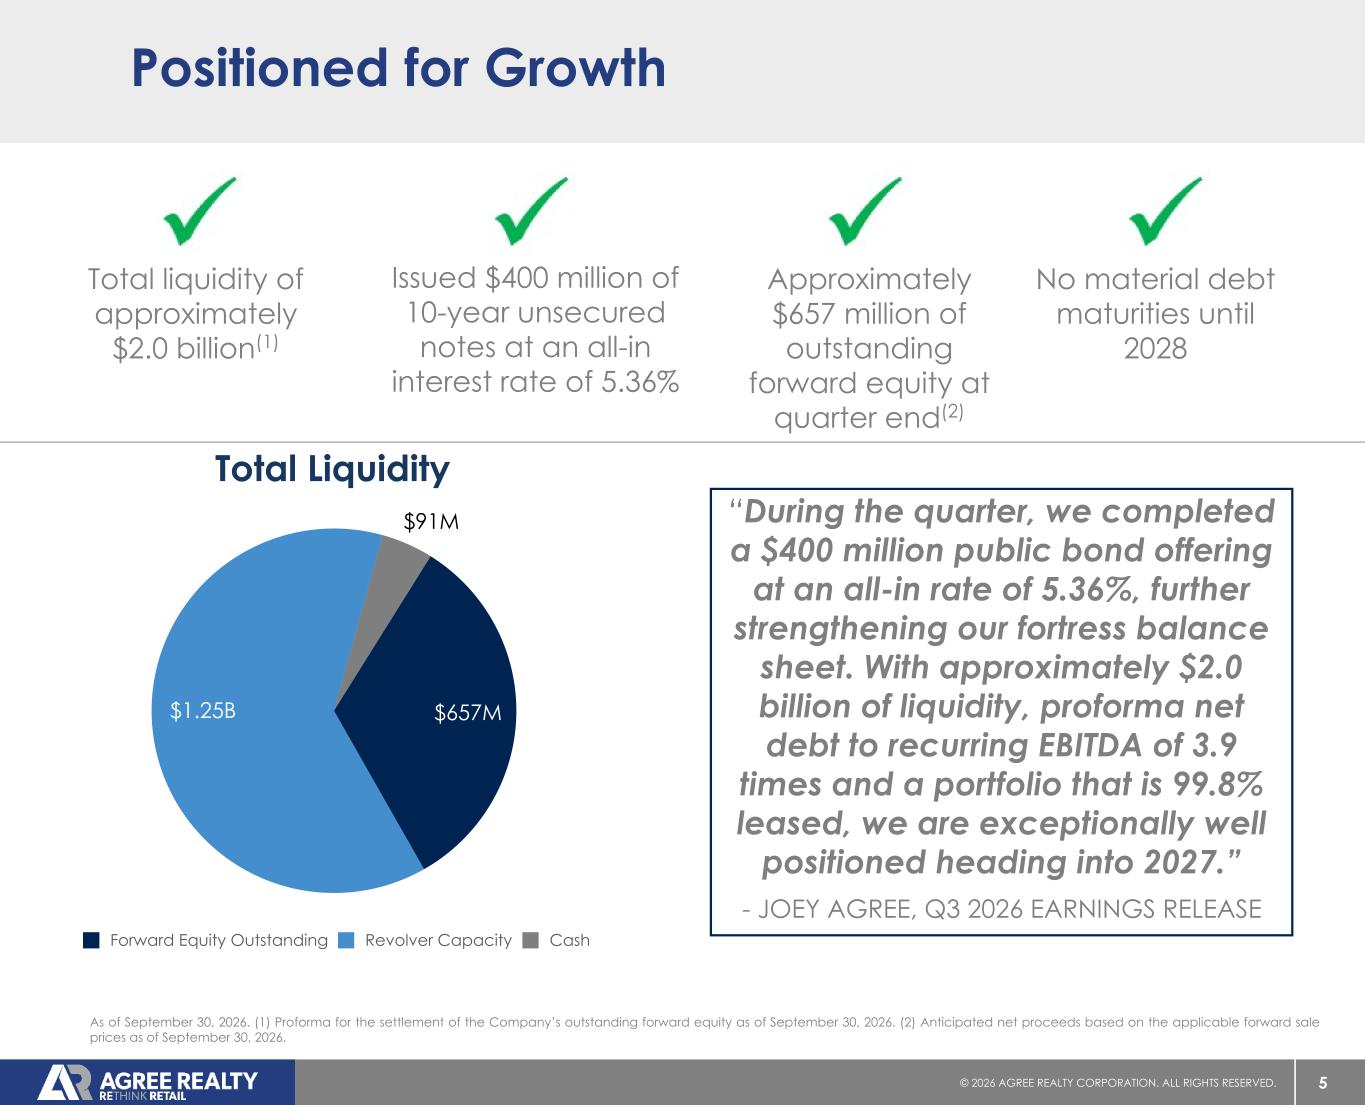
5© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Total liquidity of approximately $2.0 billion(1) Issued $400 million of 10-year unsecured notes at an all-in interest rate of 5.36% No material debt maturities until 2028 Positioned for Growth “During the quarter, we completed a $400 million public bond offering at an all-in rate of 5.36%, further strengthening our fortress balance sheet. With approximately $2.0 billion of liquidity, proforma net debt to recurring EBITDA of 3.9 times and a portfolio that is 99.8% leased, we are exceptionally well positioned heading into 2027.” - JOEY AGREE, Q3 2026 EARNINGS RELEASE Total Liquidity $657M$1.25B $91M Forward Equity Outstanding Revolver Capacity Cash As of September 30, 2026. (1) Proforma for the settlement of the Company’s outstanding forward equity as of September 30, 2026. (2) Anticipated net proceeds based on the applicable forward sale prices as of September 30, 2026. Approximately $657 million of outstanding forward equity at quarter end(2)
6© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. ADC’s Retail Thought Leadership Launched acquisition platform in 2010 with a focus on e-commerce resistance Launched RETHINK RETAIL campaign to challenge misperceptions about the future of brick & mortar Published proprietary ADC White Papers highlighting omni-channel retail trends Avoided or actively disposed of troubled retail sectors including theaters, pharmacy, car washes, health & fitness and entertainment retail Early identification of promising retailers:
7© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Omni-Channel Vision IDENTIFIED CRITICAL ROLE OF NET LEASE IN DRIVING OMNI-CHANNEL STRATEGY “The strongest and most resilient retailers in today’s omni- channel world have embraced a comprehensive approach that blurs the historical lines between e- commerce distribution and brick & mortar operations.” - Agree Knowledge Base: Omni-Channel 101 “Every retailer in the country is going to [have to] have billions of dollars, national retailers, to experiment, to test and eventually effectuate a true omni-channel experience because you can't be an e-commerce-based retailer or just a brick-and-mortar-based retailer today, it doesn't work.” - Joey Agree “So, I think as retailers look forward in 2016 and beyond and they're looking in the omni-channel world, how is their e-commerce presence, online ordering, physical pick up, more and more retailers are going to realize the benefit of net leased retail.” - Joey Agree, Q1 2016 Earnings Call “COVID reaffirmed our belief that, one, we're heading toward a world where all retailers are omni- channel. Brick-and-mortar is an integral part of that omni-channel overall experience.” - Joey Agree, 2022 Citi Conference
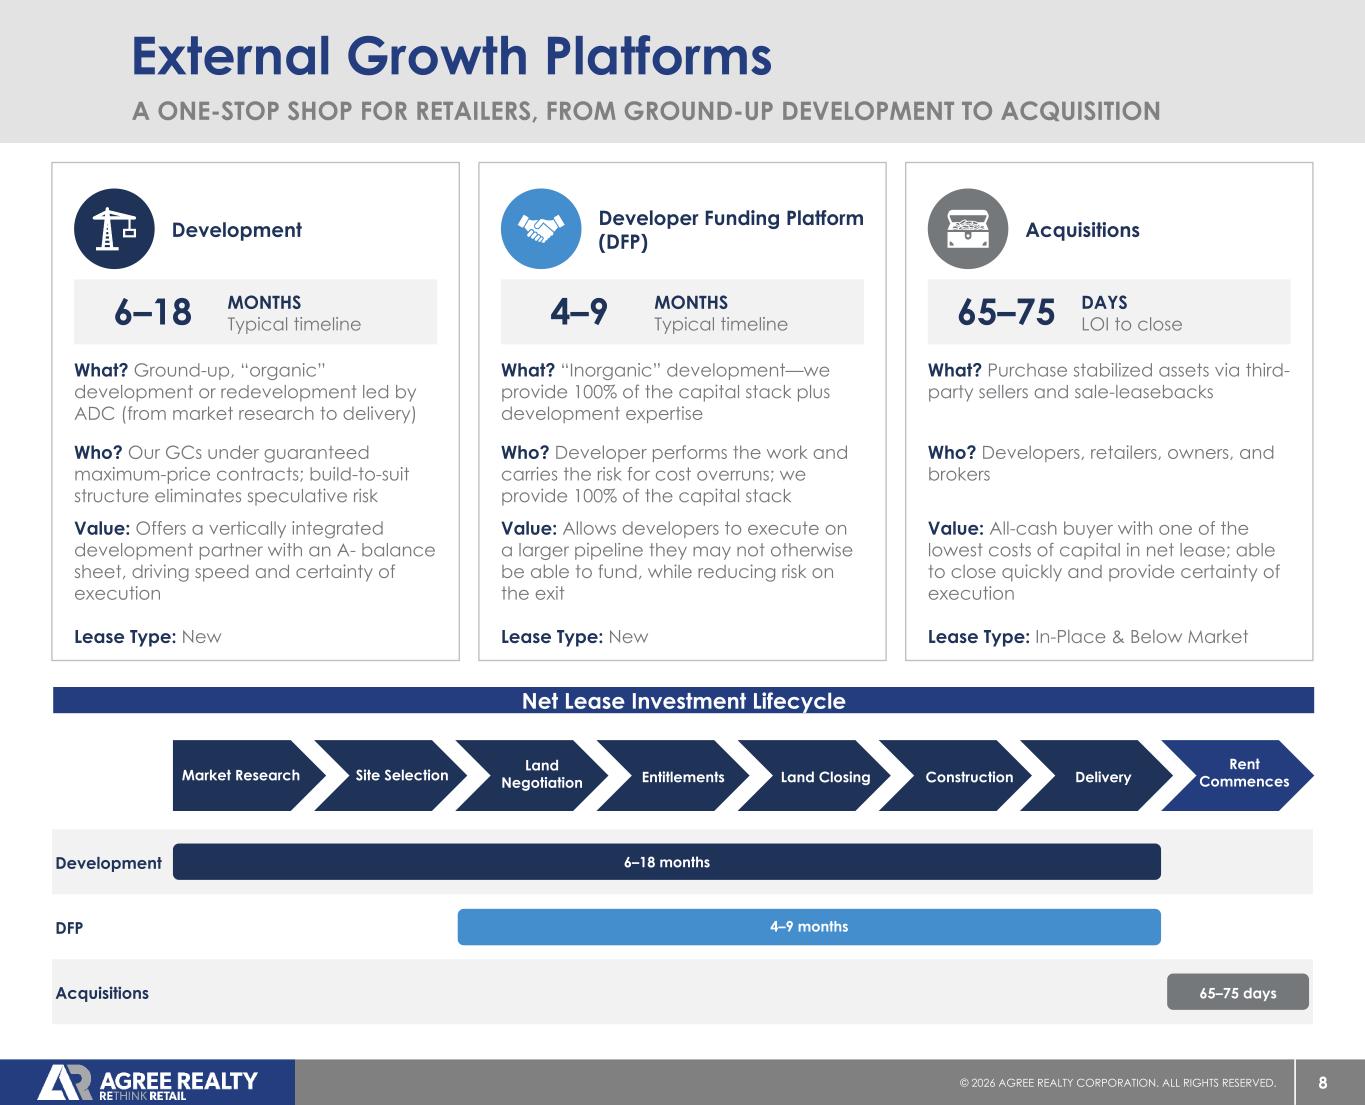
8© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. External Growth Platforms A ONE-STOP SHOP FOR RETAILERS, FROM GROUND-UP DEVELOPMENT TO ACQUISITION Development 6–18 MONTHS Typical timeline What? Ground-up, “organic” development or redevelopment led by ADC (from market research to delivery) Who? Our GCs under guaranteed maximum-price contracts; build-to-suit structure eliminates speculative risk Value: Offers a vertically integrated development partner with an A- balance sheet, driving speed and certainty of execution Lease Type: New Developer Funding Platform (DFP) 4–9 MONTHS Typical timeline What? “Inorganic” development—we provide 100% of the capital stack plus development expertise Who? Developer performs the work and carries the risk for cost overruns; we provide 100% of the capital stack Value: Allows developers to execute on a larger pipeline they may not otherwise be able to fund, while reducing risk on the exit Lease Type: New Acquisitions 65–75 DAYS LOI to close What? Purchase stabilized assets via third- party sellers and sale-leasebacks Who? Developers, retailers, owners, and brokers Value: All-cash buyer with one of the lowest costs of capital in net lease; able to close quickly and provide certainty of execution Lease Type: In-Place & Below Market Net Lease Investment Lifecycle Land Negotiation Entitlements Land Closing Construction Delivery Rent Commences Development 6–18 months DFP 4–9 months Acquisitions 65–75 days Site SelectionMarket Research
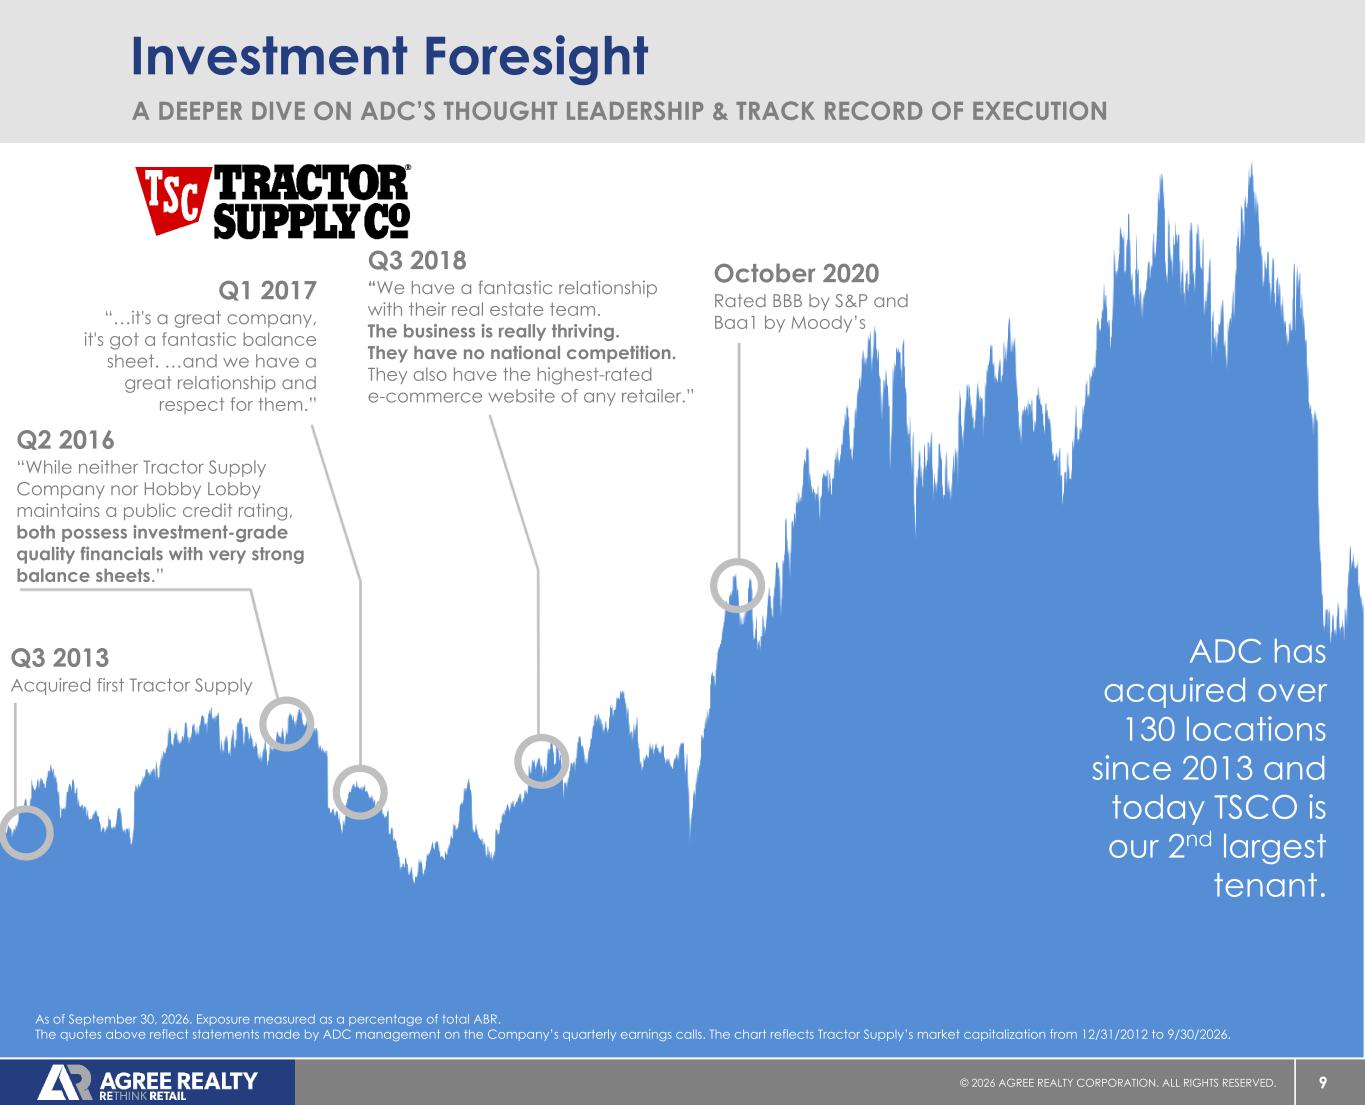
9© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. A DEEPER DIVE ON ADC’S THOUGHT LEADERSHIP & TRACK RECORD OF EXECUTION October 2020 Rated BBB by S&P and Baa1 by Moody’s Q2 2016 “While neither Tractor Supply Company nor Hobby Lobby maintains a public credit rating, both possess investment-grade quality financials with very strong balance sheets.” Q1 2017 “…it's a great company, it's got a fantastic balance sheet. …and we have a great relationship and respect for them.” Q3 2018 “We have a fantastic relationship with their real estate team. The business is really thriving. They have no national competition. They also have the highest-rated e-commerce website of any retailer.” Investment Foresight As of September 30, 2026. Exposure measured as a percentage of total ABR. The quotes above reflect statements made by ADC management on the Company’s quarterly earnings calls. The chart reflects Tractor Supply’s market capitalization from 12/31/2012 to 9/30/2026. ADC has acquired over 130 locations since 2013 and today TSCO is our 2nd largest tenant. Q3 2013 Acquired first Tractor Supply
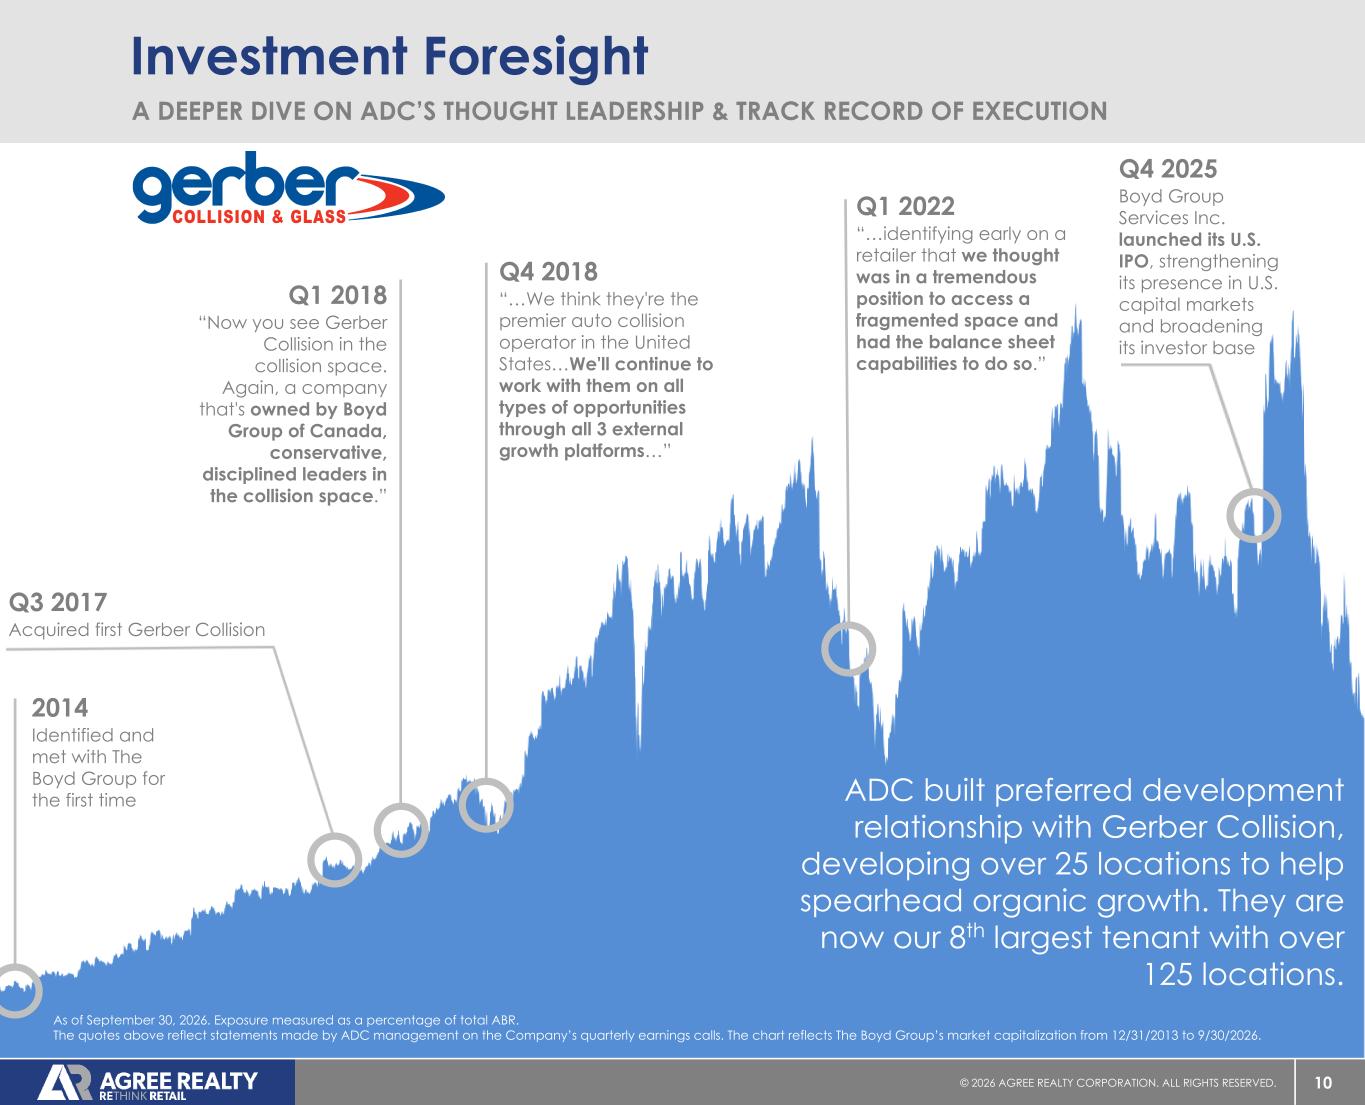
10© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Investment Foresight A DEEPER DIVE ON ADC’S THOUGHT LEADERSHIP & TRACK RECORD OF EXECUTION Q3 2017 Acquired first Gerber Collision Q4 2018 “…We think they're the premier auto collision operator in the United States…We'll continue to work with them on all types of opportunities through all 3 external growth platforms…” Q1 2022 “…identifying early on a retailer that we thought was in a tremendous position to access a fragmented space and had the balance sheet capabilities to do so.” ADC built preferred development relationship with Gerber Collision, developing over 25 locations to help spearhead organic growth. They are now our 8th largest tenant with over 125 locations. As of September 30, 2026. Exposure measured as a percentage of total ABR. The quotes above reflect statements made by ADC management on the Company’s quarterly earnings calls. The chart reflects The Boyd Group’s market capitalization from 12/31/2013 to 9/30/2026. Q1 2018 “Now you see Gerber Collision in the collision space. Again, a company that's owned by Boyd Group of Canada, conservative, disciplined leaders in the collision space.” 2014 Identified and met with The Boyd Group for the first time Q4 2025 Boyd Group Services Inc. launched its U.S. IPO, strengthening its presence in U.S. capital markets and broadening its investor base
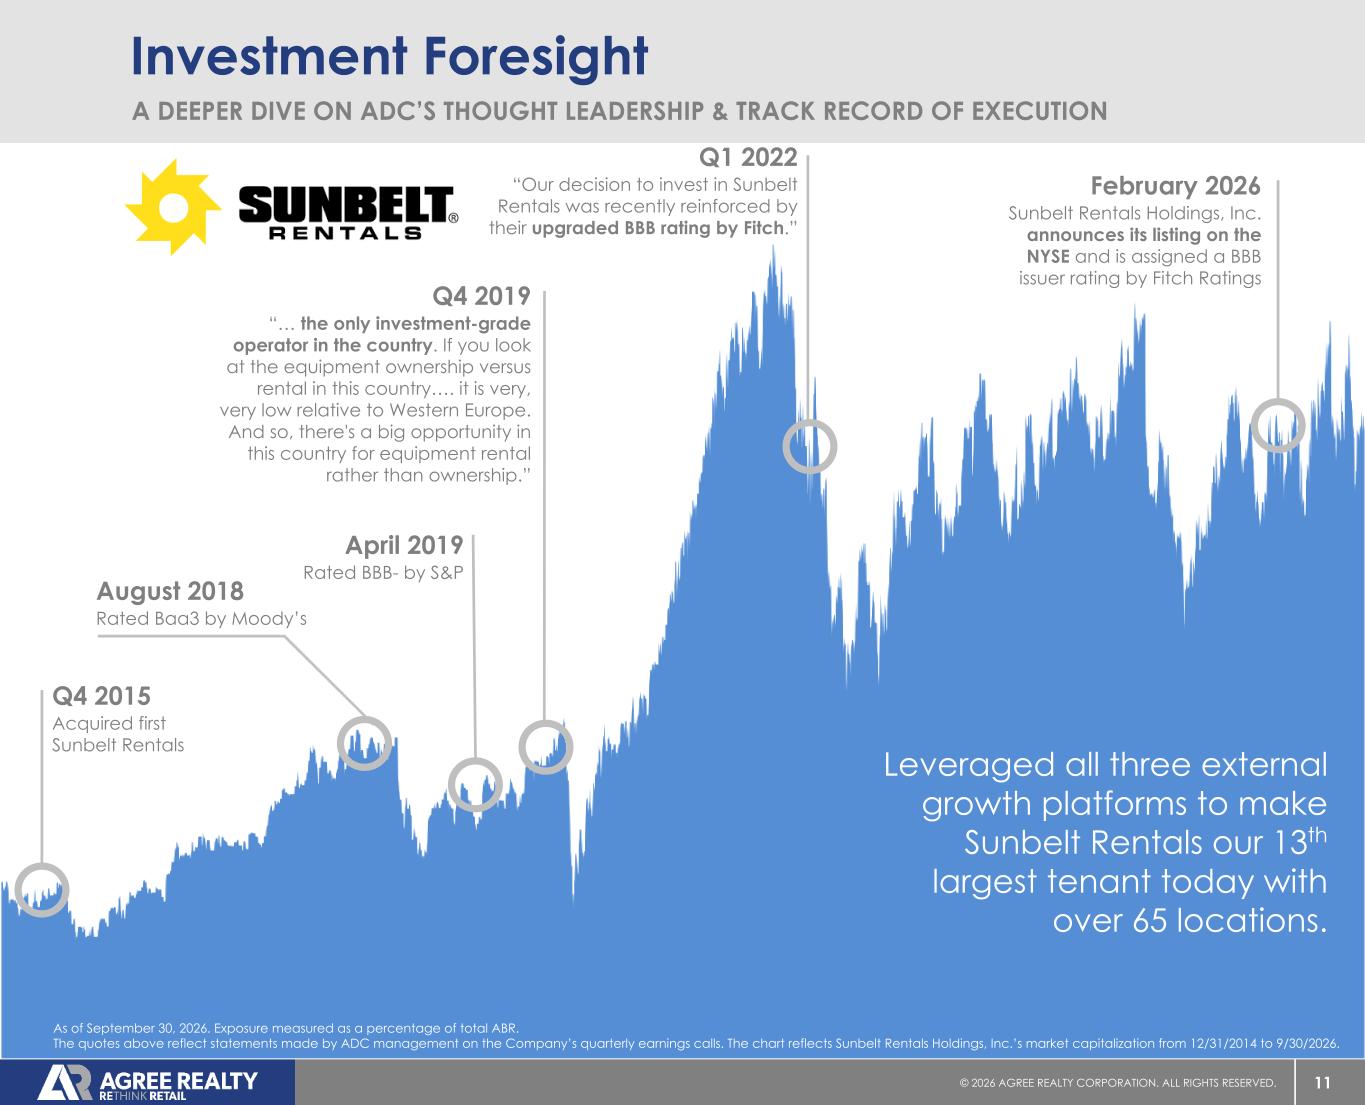
11© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Investment Foresight A DEEPER DIVE ON ADC’S THOUGHT LEADERSHIP & TRACK RECORD OF EXECUTION Leveraged all three external growth platforms to make Sunbelt Rentals our 13th largest tenant today with over 65 locations. As of September 30, 2026. Exposure measured as a percentage of total ABR. The quotes above reflect statements made by ADC management on the Company’s quarterly earnings calls. The chart reflects Sunbelt Rentals Holdings, Inc.’s market capitalization from 12/31/2014 to 9/30/2026. Q4 2015 Acquired first Sunbelt Rentals Q4 2019 “… the only investment-grade operator in the country. If you look at the equipment ownership versus rental in this country…. it is very, very low relative to Western Europe. And so, there's a big opportunity in this country for equipment rental rather than ownership.” April 2019 Rated BBB- by S&P August 2018 Rated Baa3 by Moody’s Q1 2022 “Our decision to invest in Sunbelt Rentals was recently reinforced by their upgraded BBB rating by Fitch.” February 2026 Sunbelt Rentals Holdings, Inc. announces its listing on the NYSE and is assigned a BBB issuer rating by Fitch Ratings
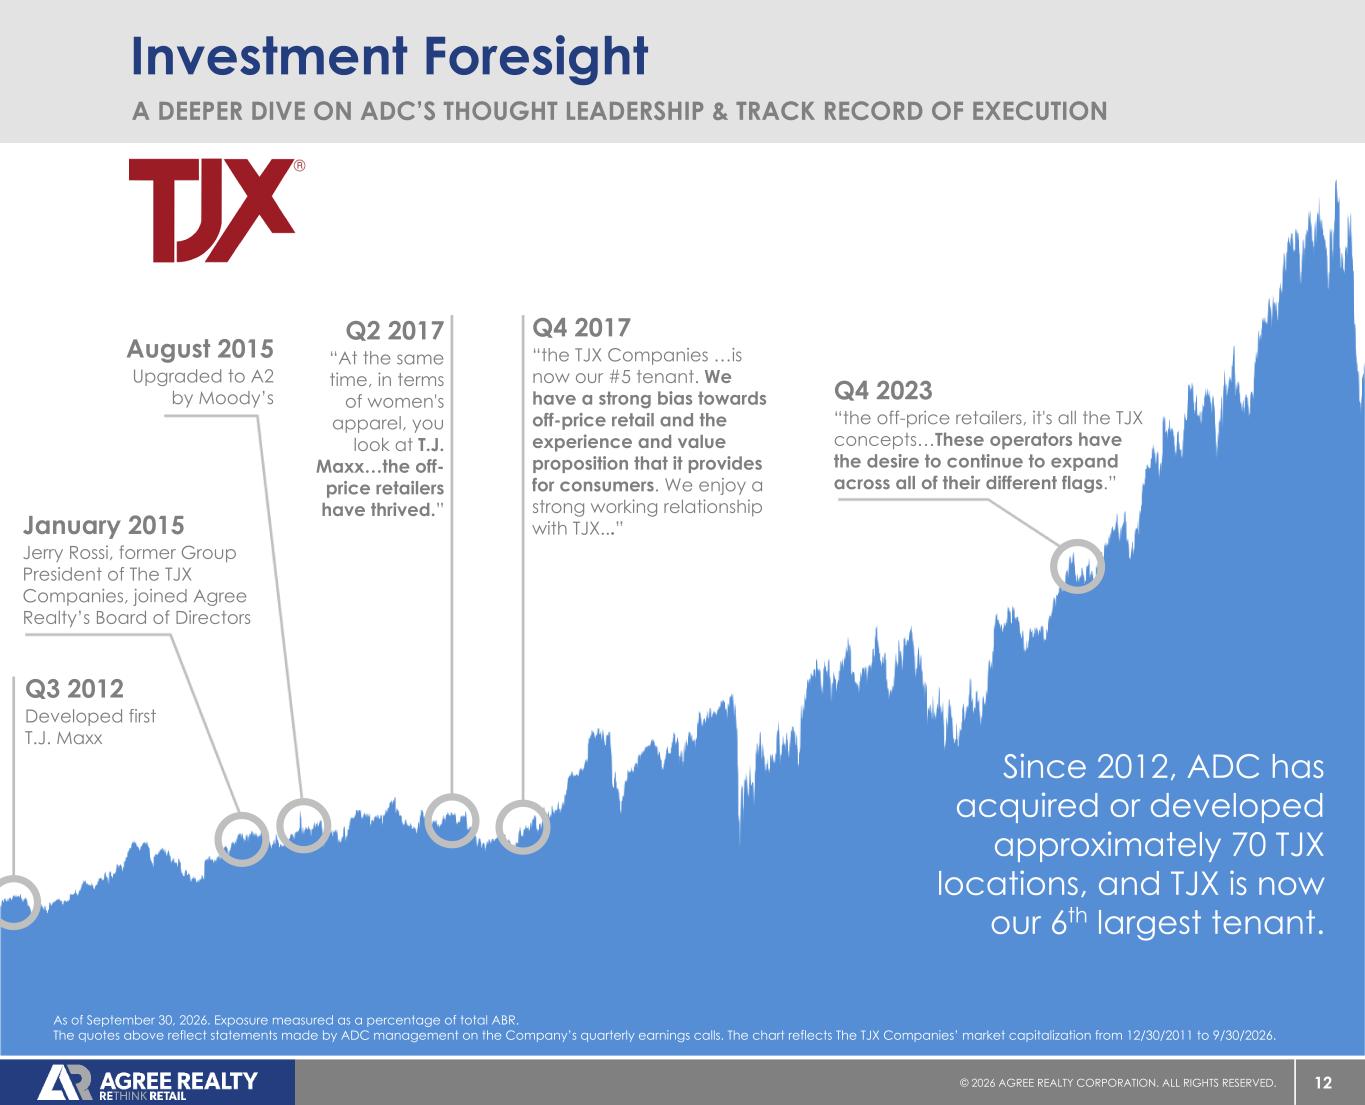
12© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Investment Foresight A DEEPER DIVE ON ADC’S THOUGHT LEADERSHIP & TRACK RECORD OF EXECUTION Since 2012, ADC has acquired or developed approximately 70 TJX locations, and TJX is now our 6th largest tenant. As of September 30, 2026. Exposure measured as a percentage of total ABR. The quotes above reflect statements made by ADC management on the Company’s quarterly earnings calls. The chart reflects The TJX Companies’ market capitalization from 12/30/2011 to 9/30/2026. Q3 2012 Developed first T.J. Maxx Q4 2023 “the off-price retailers, it's all the TJX concepts…These operators have the desire to continue to expand across all of their different flags.” August 2015 Upgraded to A2 by Moody’s Q2 2017 “At the same time, in terms of women's apparel, you look at T.J. Maxx…the off- price retailers have thrived.” Q4 2017 “the TJX Companies …is now our #5 tenant. We have a strong bias towards off-price retail and the experience and value proposition that it provides for consumers. We enjoy a strong working relationship with TJX...” January 2015 Jerry Rossi, former Group President of The TJX Companies, joined Agree Realty’s Board of Directors
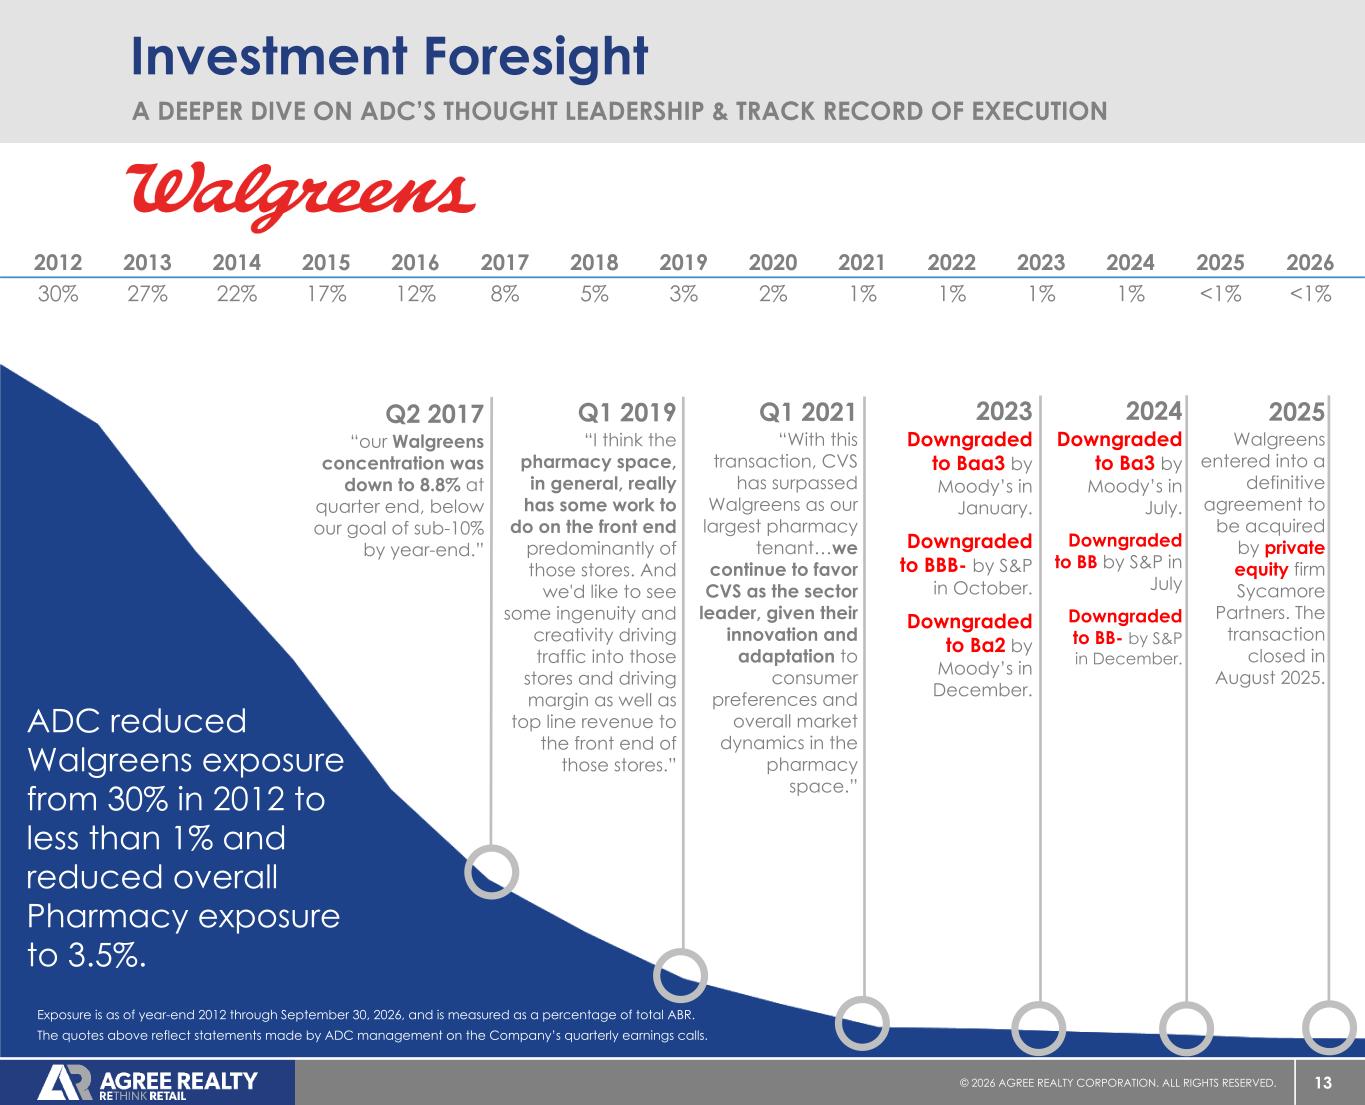
13© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Investment Foresight A DEEPER DIVE ON ADC’S THOUGHT LEADERSHIP & TRACK RECORD OF EXECUTION 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 30% 27% 22% 17% 12% 8% 5% 3% 2% 1% 1% 1% 1% <1% <1% Q2 2017 “our Walgreens concentration was down to 8.8% at quarter end, below our goal of sub-10% by year-end.” Q1 2021 “With this transaction, CVS has surpassed Walgreens as our largest pharmacy tenant…we continue to favor CVS as the sector leader, given their innovation and adaptation to consumer preferences and overall market dynamics in the pharmacy space.” Q1 2019 “I think the pharmacy space, in general, really has some work to do on the front end predominantly of those stores. And we'd like to see some ingenuity and creativity driving traffic into those stores and driving margin as well as top line revenue to the front end of those stores.” ADC reduced Walgreens exposure from 30% in 2012 to less than 1% and reduced overall Pharmacy exposure to 3.5%. Exposure is as of year-end 2012 through September 30, 2026, and is measured as a percentage of total ABR. The quotes above reflect statements made by ADC management on the Company’s quarterly earnings calls. 2023 Downgraded to Baa3 by Moody’s in January. Downgraded to BBB- by S&P in October. Downgraded to Ba2 by Moody’s in December. 2024 Downgraded to Ba3 by Moody’s in July. Downgraded to BB by S&P in July Downgraded to BB- by S&P in December. 2025 Walgreens entered into a definitive agreement to be acquired by private equity firm Sycamore Partners. The transaction closed in August 2025.
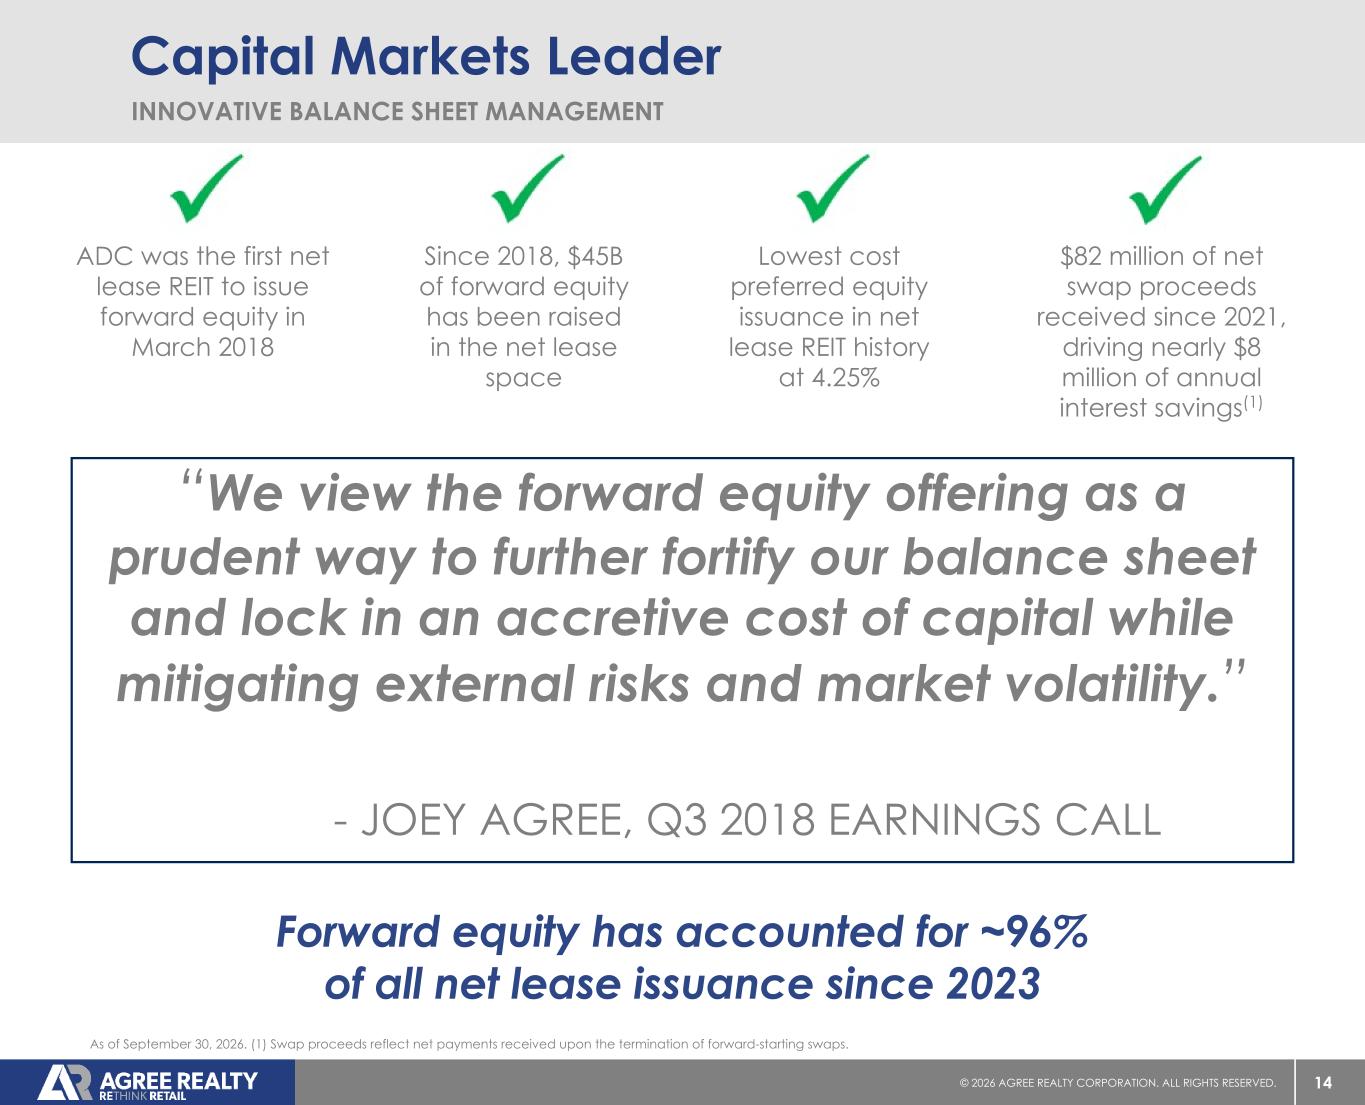
14© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Capital Markets Leader INNOVATIVE BALANCE SHEET MANAGEMENT “We view the forward equity offering as a prudent way to further fortify our balance sheet and lock in an accretive cost of capital while mitigating external risks and market volatility.” - JOEY AGREE, Q3 2018 EARNINGS CALL ADC was the first net lease REIT to issue forward equity in March 2018 Since 2018, $45B of forward equity has been raised in the net lease space Lowest cost preferred equity issuance in net lease REIT history at 4.25% $82 million of net swap proceeds received since 2021, driving nearly $8 million of annual interest savings(1) Forward equity has accounted for ~96% of all net lease issuance since 2023 As of September 30, 2026. (1) Swap proceeds reflect net payments received upon the termination of forward-starting swaps.
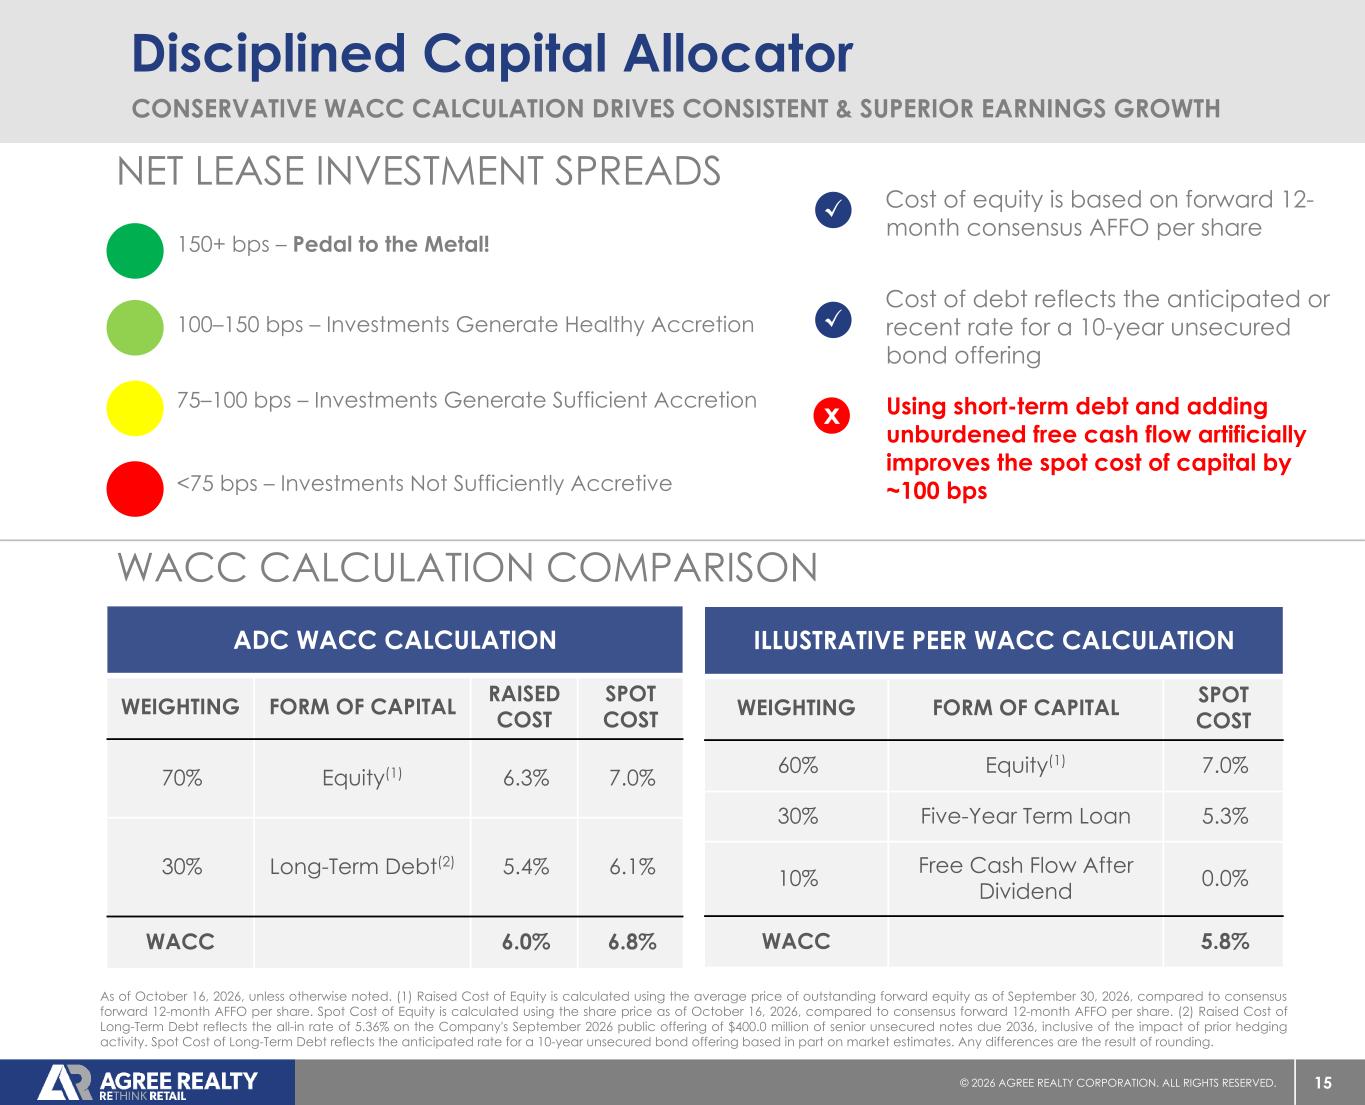
15© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Disciplined Capital Allocator CONSERVATIVE WACC CALCULATION DRIVES CONSISTENT & SUPERIOR EARNINGS GROWTH ADC WACC CALCULATION WEIGHTING FORM OF CAPITAL RAISED COST SPOT COST 70% Equity(1) 6.3% 7.0% 30% Long-Term Debt(2) 5.4% 6.1% WACC 6.0% 6.8% ILLUSTRATIVE PEER WACC CALCULATION WEIGHTING FORM OF CAPITAL SPOT COST 60% Equity(1) 7.0% 30% Five-Year Term Loan 5.3% 10% Free Cash Flow After Dividend 0.0% WACC 5.8% 150+ bps – Pedal to the Metal! 100–150 bps – Investments Generate Healthy Accretion 75–100 bps – Investments Generate Sufficient Accretion <75 bps – Investments Not Sufficiently Accretive As of October 16, 2026, unless otherwise noted. (1) Raised Cost of Equity is calculated using the average price of outstanding forward equity as of September 30, 2026, compared to consensus forward 12-month AFFO per share. Spot Cost of Equity is calculated using the share price as of October 16, 2026, compared to consensus forward 12-month AFFO per share. (2) Raised Cost of Long-Term Debt reflects the all-in rate of 5.36% on the Company's September 2026 public offering of $400.0 million of senior unsecured notes due 2036, inclusive of the impact of prior hedging activity. Spot Cost of Long-Term Debt reflects the anticipated rate for a 10-year unsecured bond offering based in part on market estimates. Any differences are the result of rounding. Cost of equity is based on forward 12- month consensus AFFO per share Cost of debt reflects the anticipated or recent rate for a 10-year unsecured bond offering WACC CALCULATION COMPARISON NET LEASE INVESTMENT SPREADS Using short-term debt and adding unburdened free cash flow artificially improves the spot cost of capital by ~100 bps ✓ ✓ x
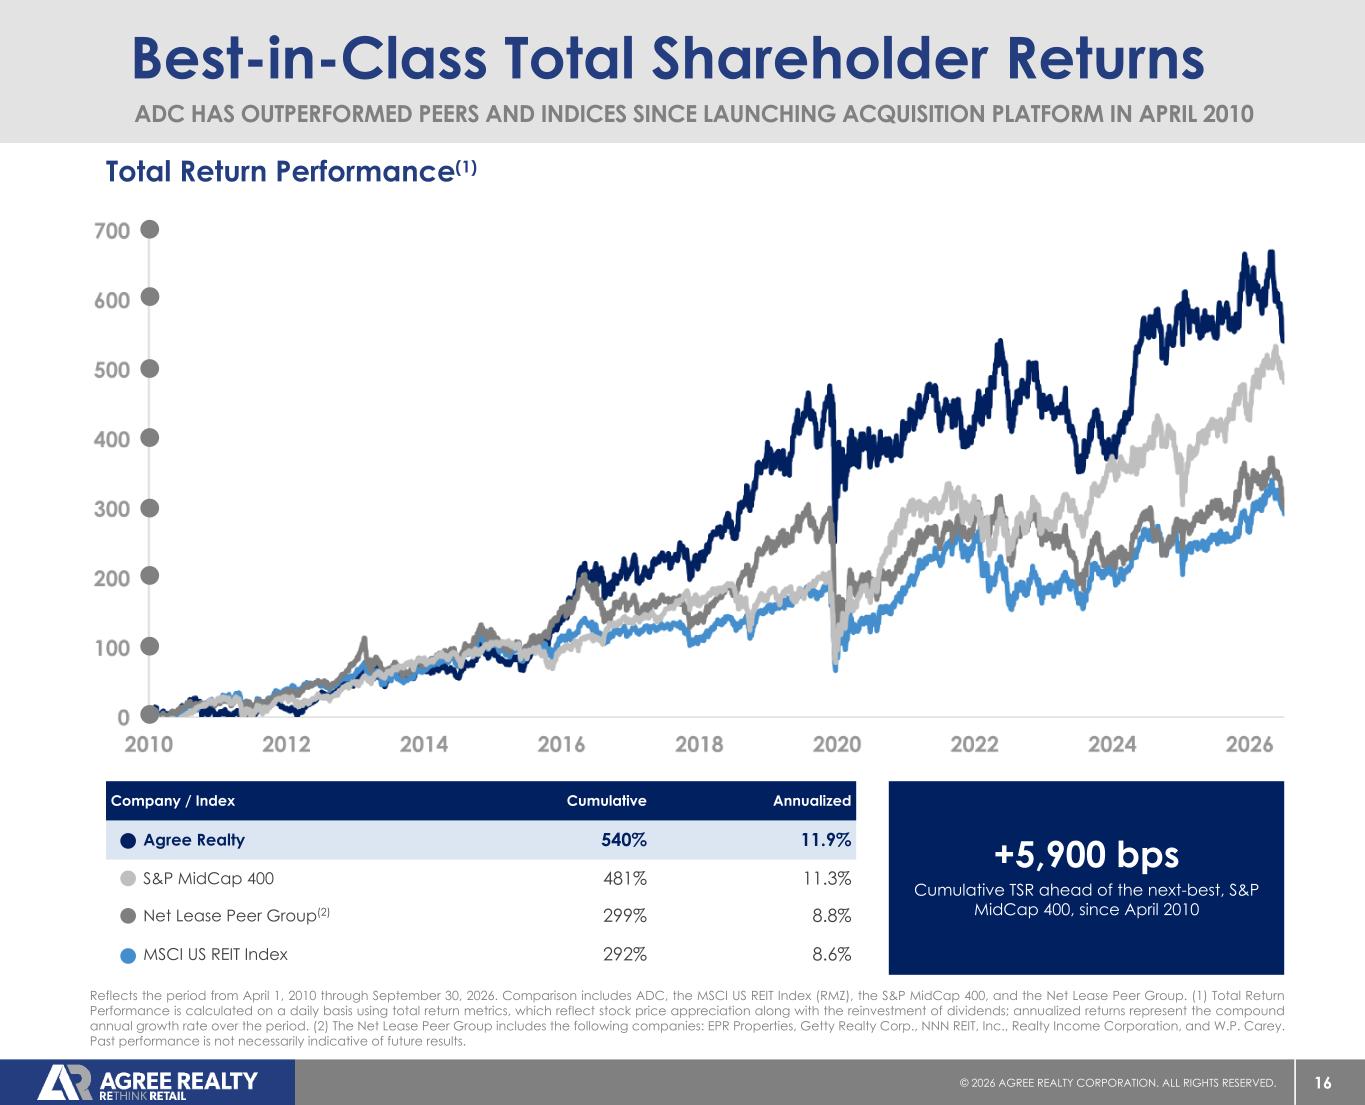
16© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Best-in-Class Total Shareholder Returns Reflects the period from April 1, 2010 through September 30, 2026. Comparison includes ADC, the MSCI US REIT Index (RMZ), the S&P MidCap 400, and the Net Lease Peer Group. (1) Total Return Performance is calculated on a daily basis using total return metrics, which reflect stock price appreciation along with the reinvestment of dividends; annualized returns represent the compound annual growth rate over the period. (2) The Net Lease Peer Group includes the following companies: EPR Properties, Getty Realty Corp., NNN REIT, Inc., Realty Income Corporation, and W.P. Carey. Past performance is not necessarily indicative of future results. Total Return Performance(1) 1 c ADC HAS OUTPERFORMED PEERS AND INDICES SINCE LAUNCHING ACQUISITION PLATFORM IN APRIL 2010 Company / Index Cumulative Annualized Agree Realty 540% 11.9% S&P MidCap 400 481% 11.3% Net Lease Peer Group(2) 299% 8.8% MSCI US REIT Index 292% 8.6% +5,900 bps Cumulative TSR ahead of the next-best, S&P MidCap 400, since April 2010
The Country’s Leading Retail Portfolio
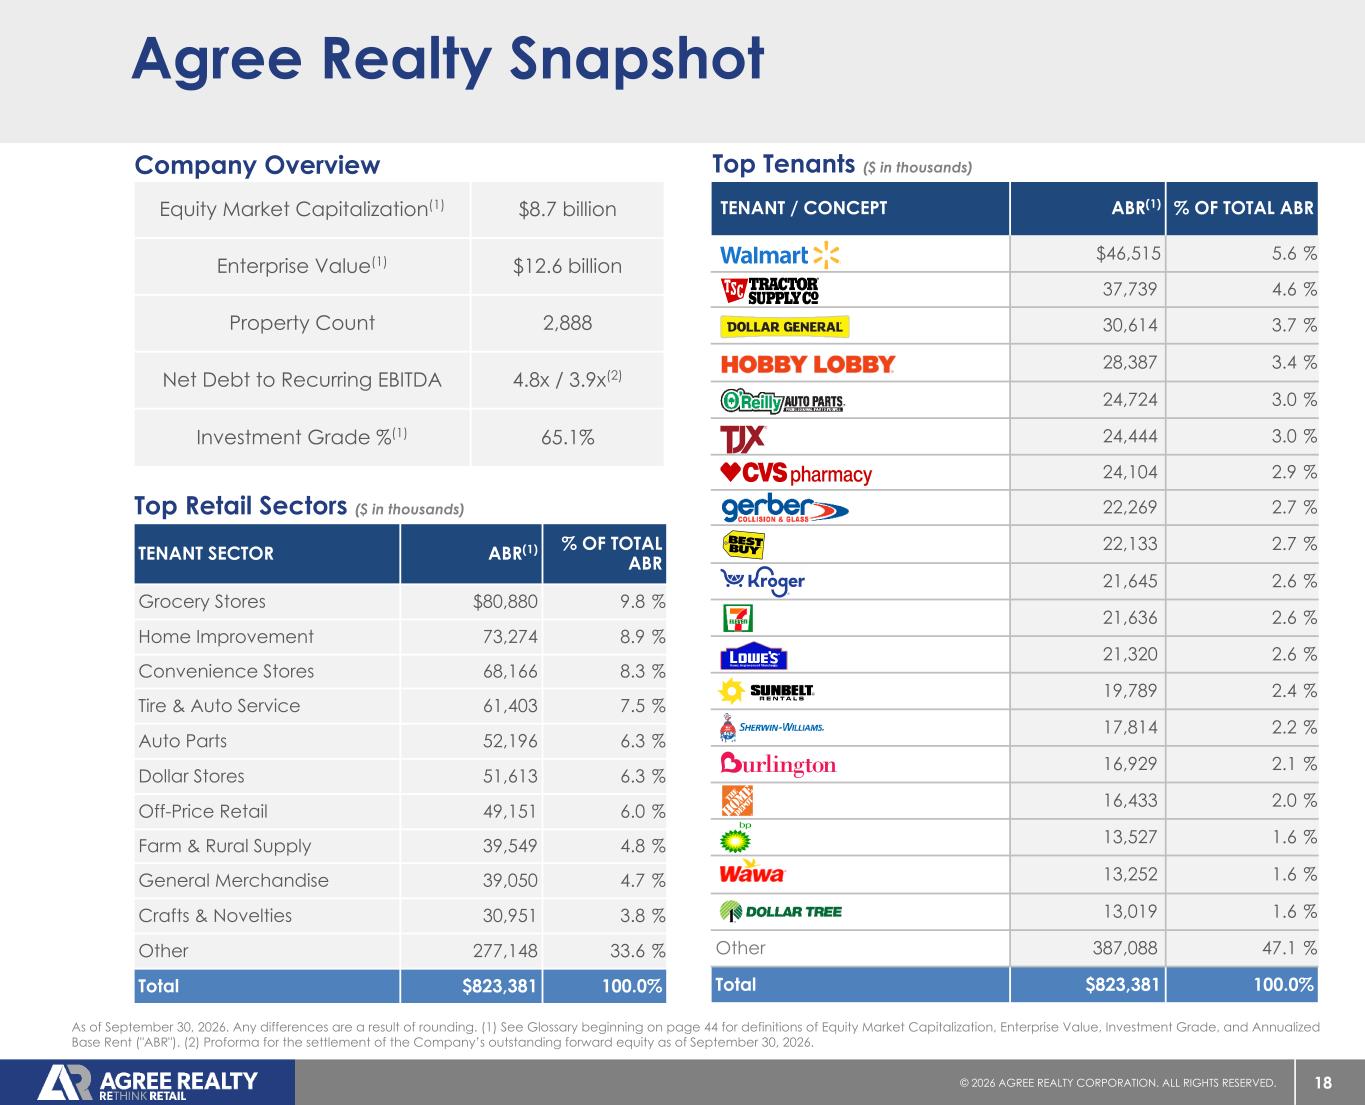
18© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. As of September 30, 2026. Any differences are a result of rounding. (1) See Glossary beginning on page 44 for definitions of Equity Market Capitalization, Enterprise Value, Investment Grade, and Annualized Base Rent ("ABR"). (2) Proforma for the settlement of the Company’s outstanding forward equity as of September 30, 2026. TENANT / CONCEPT ABR(1) % OF TOTAL ABR Walmart $46,515 5.6 % Tractor Supply 37,739 4.6 % Dollar General 30,614 3.7 % Hobby Lobby 28,387 3.4 % O'Reilly Auto Parts 24,724 3.0 % TJX Companies 24,444 3.0 % CVS 24,104 2.9 % Gerber Collision 22,269 2.7 % Best Buy 22,133 2.7 % Kroger 21,645 2.6 % 7-Eleven 21,636 2.6 % Lowe's 21,320 2.6 % Sunbelt Rentals 19,789 2.4 % Sherwin-Williams 17,814 2.2 % Burlington 16,929 2.1 % Home Depot 16,433 2.0 % BP 13,527 1.6 % Wawa 13,252 1.6 % Dollar Tree 13,019 1.6 % Other 387,088 47.1 % Total $823,381 100.0% Agree Realty Snapshot TENANT SECTOR ABR(1) % OF TOTAL ABR Grocery Stores $80,880 9.8 % Home Improvement 73,274 8.9 % Convenience Stores 68,166 8.3 % Tire & Auto Service 61,403 7.5 % Auto Parts 52,196 6.3 % Dollar Stores 51,613 6.3 % Off-Price Retail 49,151 6.0 % Farm & Rural Supply 39,549 4.8 % General Merchandise 39,050 4.7 % Crafts & Novelties 30,951 3.8 % Other 277,148 33.6 % Total $823,381 100.0% Equity Market Capitalization(1) $8.7 billion Enterprise Value(1) $12.6 billion Property Count 2,888 Net Debt to Recurring EBITDA 4.8x / 3.9x(2) Investment Grade %(1) 65.1% Company Overview Top Tenants ($ in thousands) Top Retail Sectors ($ in thousands)
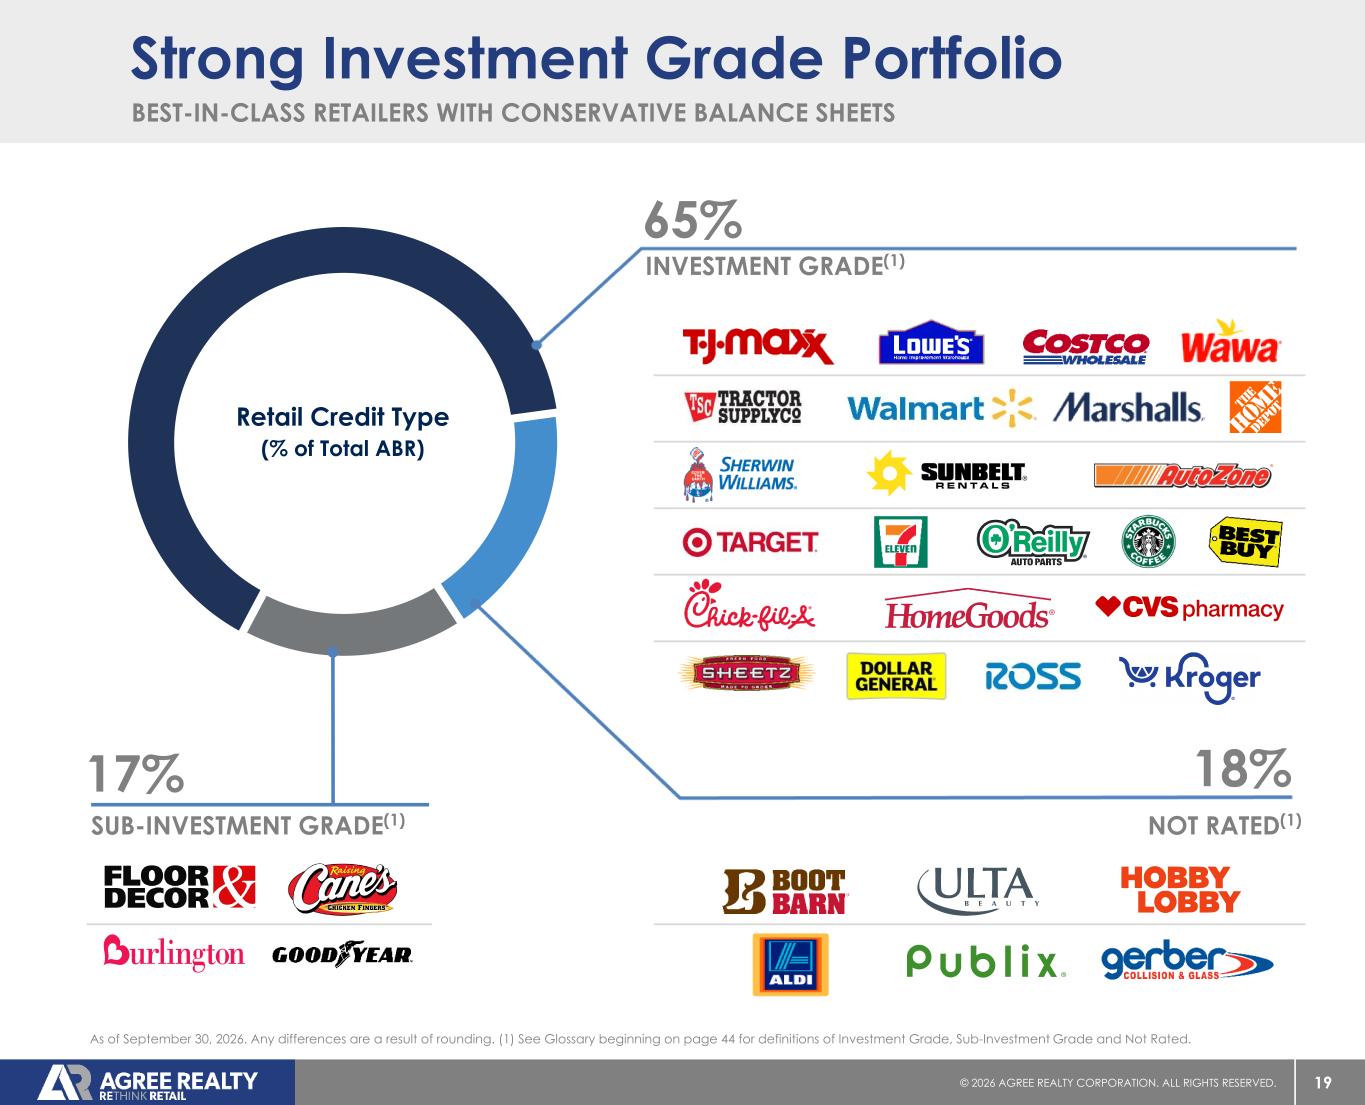
19© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. BEST-IN-CLASS RETAILERS WITH CONSERVATIVE BALANCE SHEETS Strong Investment Grade Portfolio 17% SUB-INVESTMENT GRADE(1) 18% NOT RATED(1) 65% INVESTMENT GRADE(1) As of September 30, 2026. Any differences are a result of rounding. (1) See Glossary beginning on page 44 for definitions of Investment Grade, Sub-Investment Grade and Not Rated. Retail Credit Type (% of Total ABR)
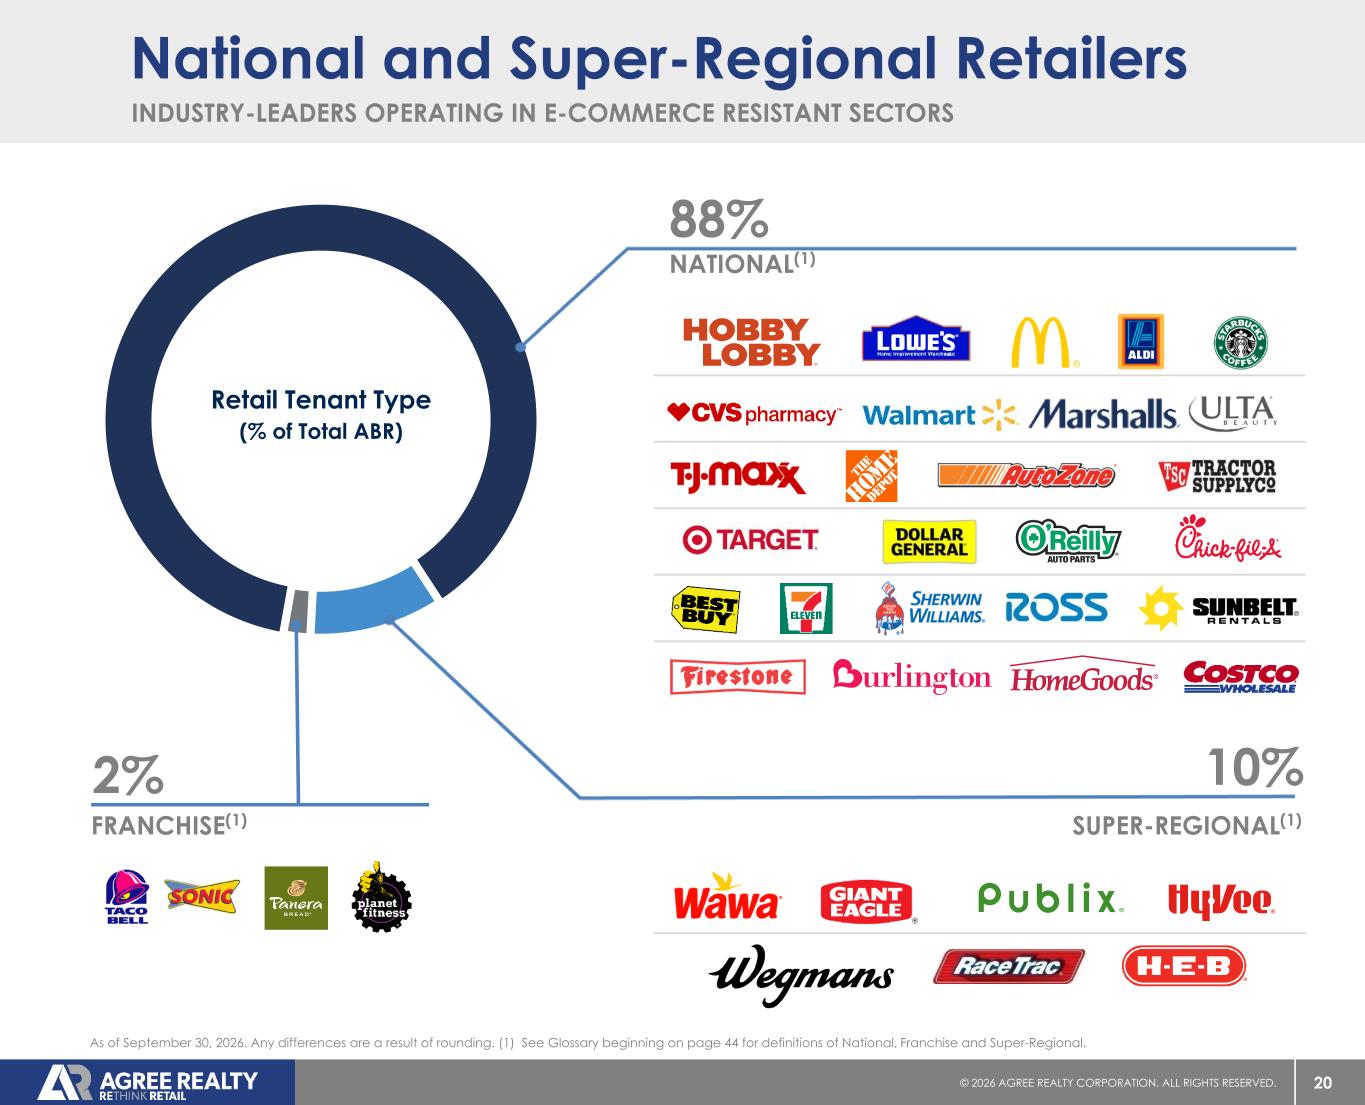
20© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. INDUSTRY-LEADERS OPERATING IN E-COMMERCE RESISTANT SECTORS National and Super-Regional Retailers 2% FRANCHISE(1) 10% SUPER-REGIONAL(1) 88% NATIONAL(1) As of September 30, 2026. Any differences are a result of rounding. (1) See Glossary beginning on page 44 for definitions of National, Franchise and Super-Regional. Retail Tenant Type (% of Total ABR)
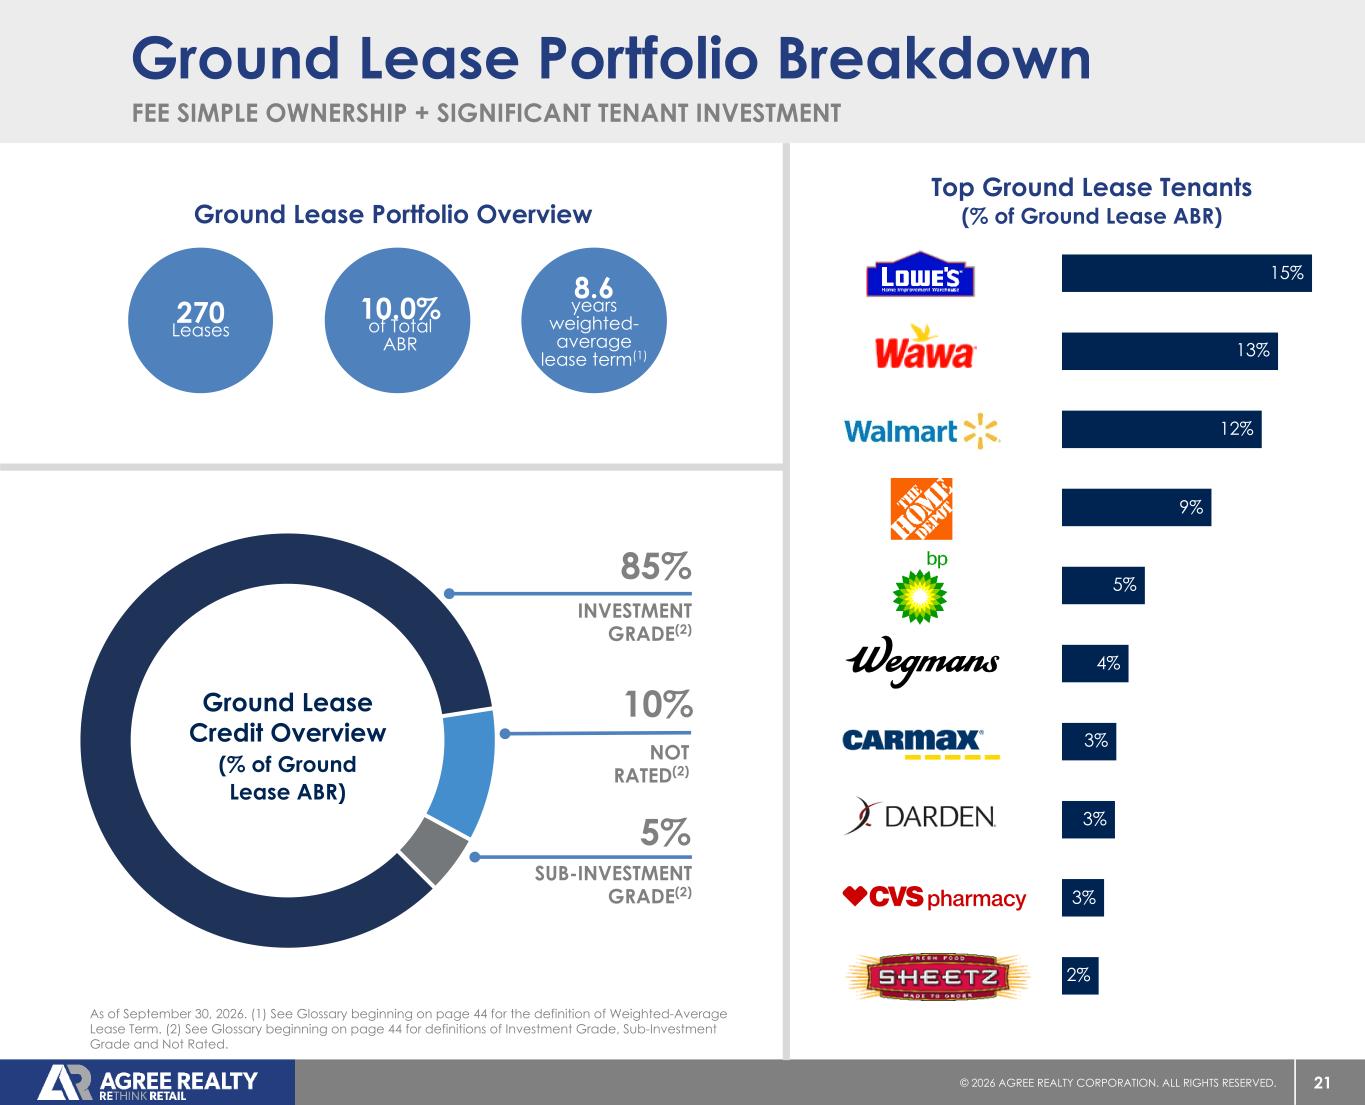
21© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. As of September 30, 2026. (1) See Glossary beginning on page 44 for the definition of Weighted-Average Lease Term. (2) See Glossary beginning on page 44 for definitions of Investment Grade, Sub-Investment Grade and Not Rated. FEE SIMPLE OWNERSHIP + SIGNIFICANT TENANT INVESTMENT Ground Lease Portfolio Breakdown Ground Lease Credit Overview (% of Ground Lease ABR) 85% INVESTMENT GRADE(2) 10% NOT RATED(2) 5% SUB-INVESTMENT GRADE(2) Ground Lease Portfolio Overview 270 Leases 10.0% of Total ABR 8.6 years weighted- average lease term(1) Top Ground Lease Tenants (% of Ground Lease ABR) 15% 13% 12% 9% 5% 4% 3% 3% 3% 2%
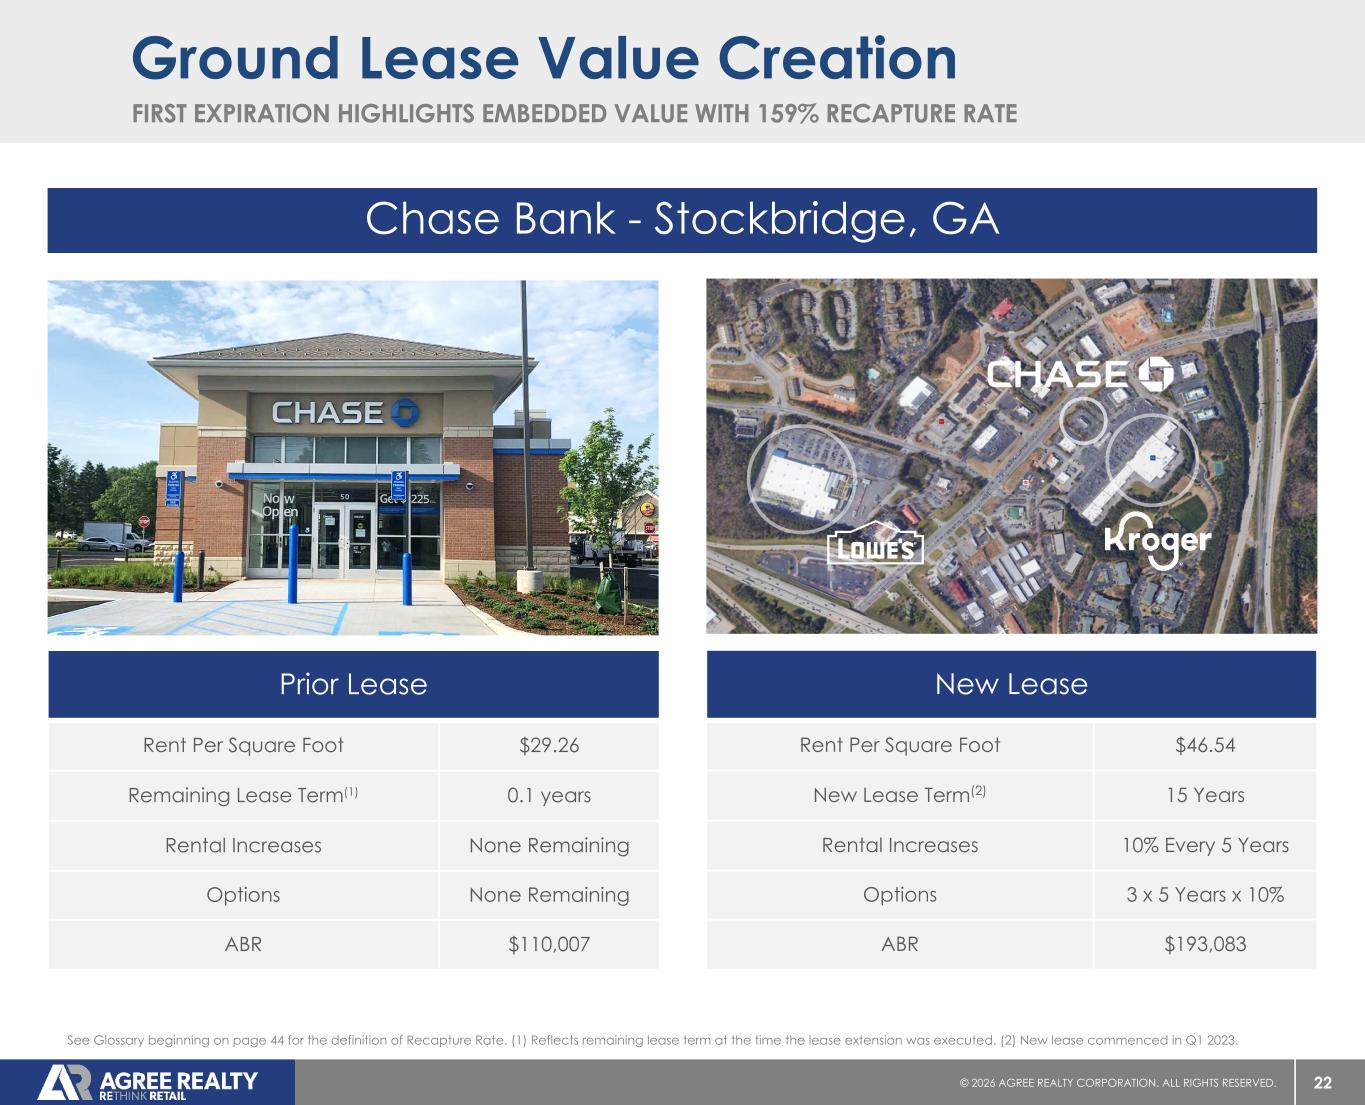
22© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. FIRST EXPIRATION HIGHLIGHTS EMBEDDED VALUE WITH 159% RECAPTURE RATE Ground Lease Value Creation Chase Bank - Stockbridge, GA New Lease Rent Per Square Foot $46.54 New Lease Term(2) 15 Years Rental Increases 10% Every 5 Years Options 3 x 5 Years x 10% ABR $193,083 Prior Lease Rent Per Square Foot $29.26 Remaining Lease Term(1) 0.1 years Rental Increases None Remaining Options None Remaining ABR $110,007 See Glossary beginning on page 44 for the definition of Recapture Rate. (1) Reflects remaining lease term at the time the lease extension was executed. (2) New lease commenced in Q1 2023.
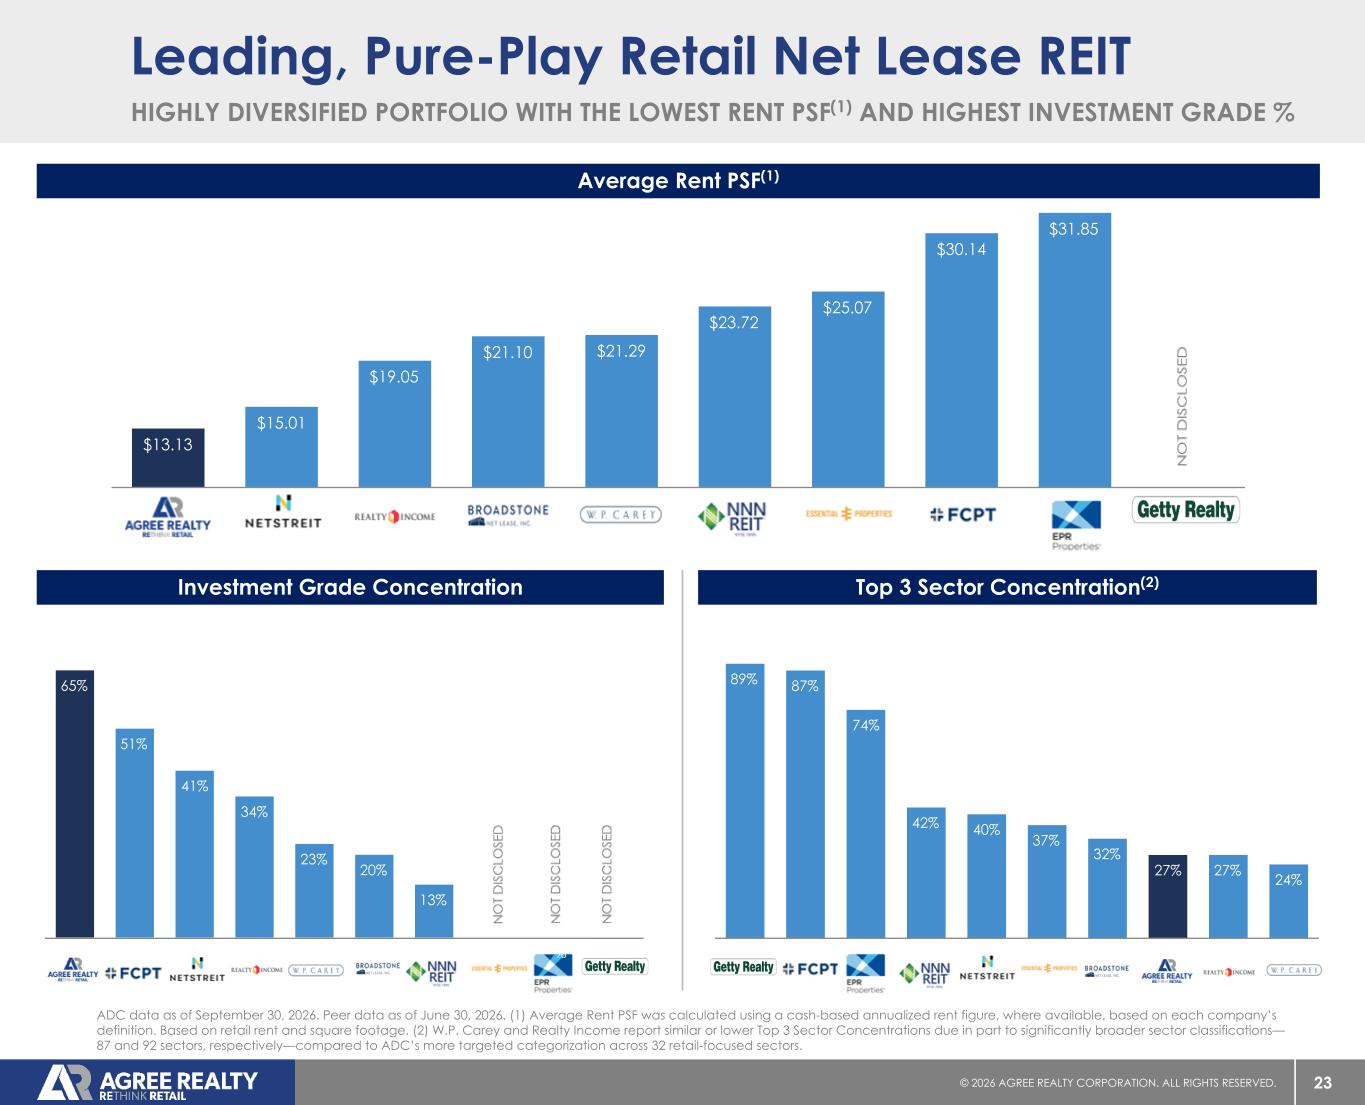
23© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. $13.13 $15.01 $19.05 $21.10 $21.29 $23.72 $25.07 $30.14 $31.85 65% 51% 41% 34% 23% 20% 13% —% —% —% Leading, Pure-Play Retail Net Lease REIT HIGHLY DIVERSIFIED PORTFOLIO WITH THE LOWEST RENT PSF(1) AND HIGHEST INVESTMENT GRADE % Average Rent PSF(1) Investment Grade Concentration Top 3 Sector Concentration(2) ADC data as of September 30, 2026. Peer data as of June 30, 2026. (1) Average Rent PSF was calculated using a cash-based annualized rent figure, where available, based on each company’s definition. Based on retail rent and square footage. (2) W.P. Carey and Realty Income report similar or lower Top 3 Sector Concentrations due in part to significantly broader sector classifications— 87 and 92 sectors, respectively—compared to ADC’s more targeted categorization across 32 retail-focused sectors. 89% 87% 74% 42% 40% 37% 32% 27% 27% 24%
Disciplined Investment Strategy & Active Portfolio Management
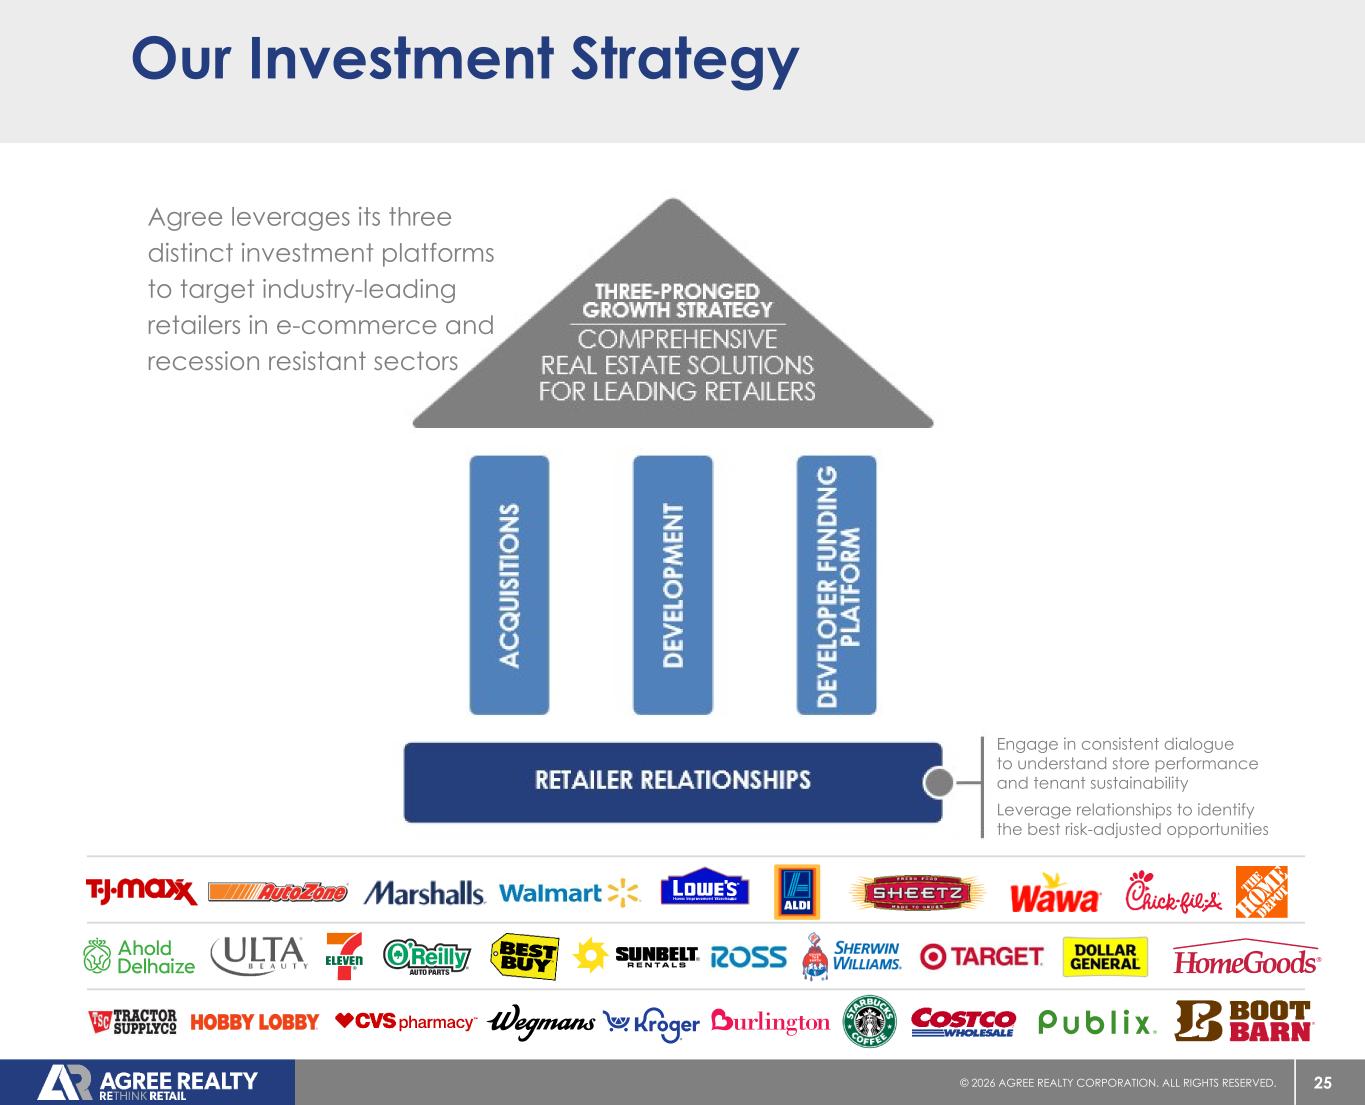
25© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Engage in consistent dialogue to understand store performance and tenant sustainability Leverage relationships to identify the best risk-adjusted opportunities Our Investment Strategy THREE-PRONGED GROWTH STRATEGY COMPREHENSIVE REAL ESTATE SOLUTIONS FOR LEADING RETAILERS A C Q U IS IT IO N S D EV EL O PM EN T D EV EL O PE R FU N D IN G PL A TF O RM RETAILER RELATIONSHIPS Agree leverages its three distinct investment platforms to target industry-leading retailers in e-commerce and recession resistant sectors
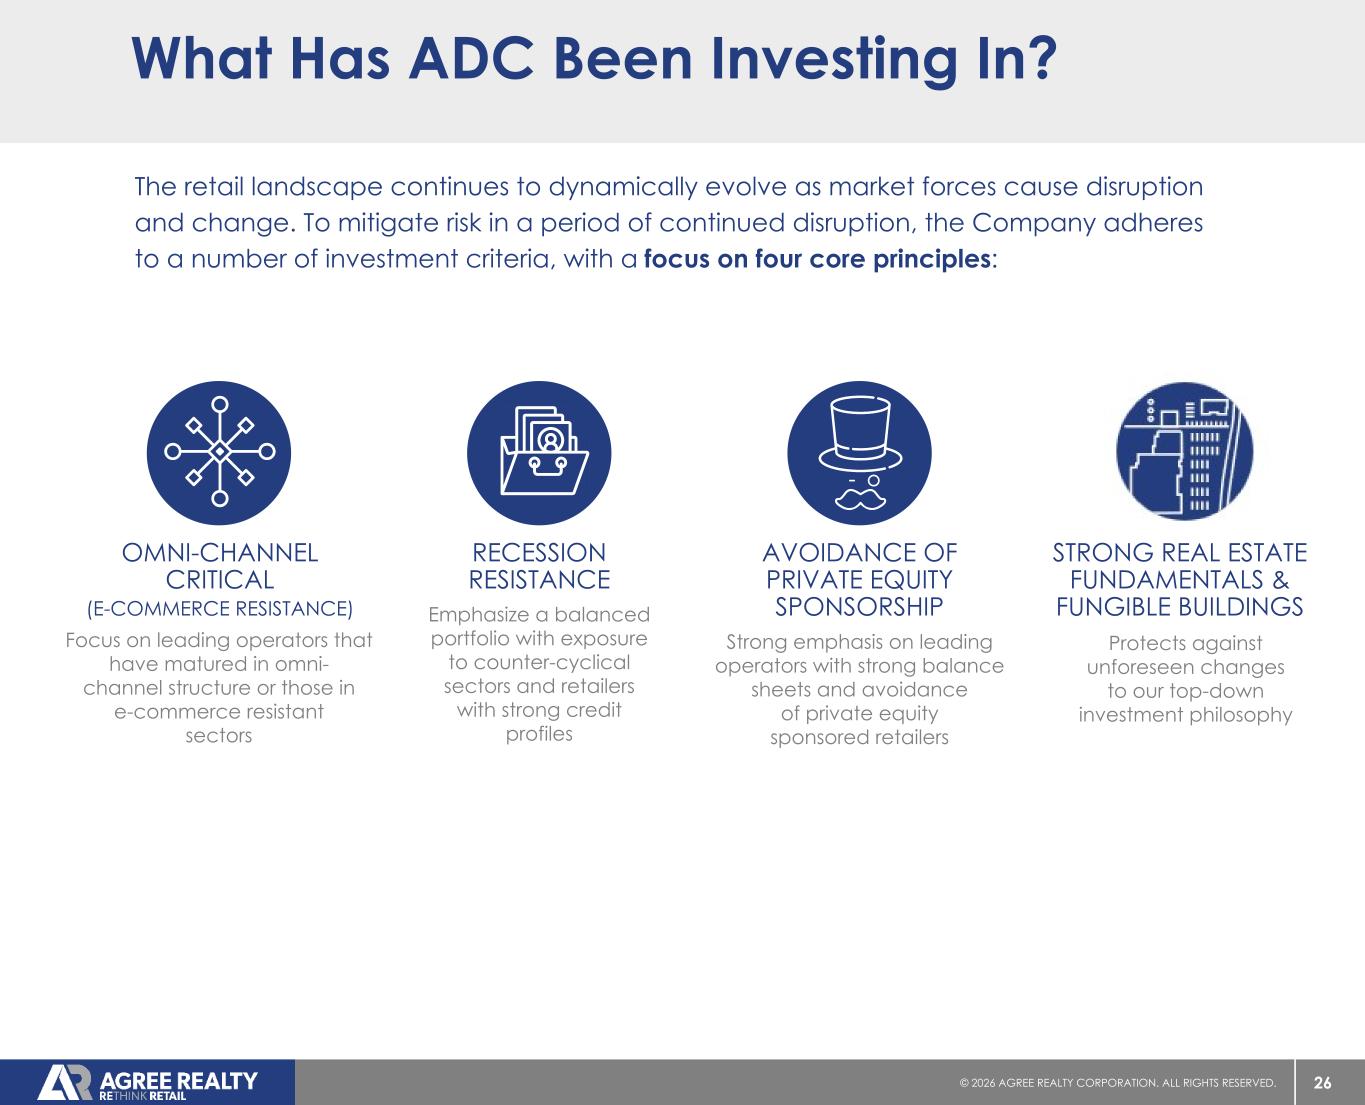
26© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. What Has ADC Been Investing In? The retail landscape continues to dynamically evolve as market forces cause disruption and change. To mitigate risk in a period of continued disruption, the Company adheres to a number of investment criteria, with a focus on four core principles: Focus on leading operators that have matured in omni- channel structure or those in e-commerce resistant sectors OMNI-CHANNEL CRITICAL (E-COMMERCE RESISTANCE) Emphasize a balanced portfolio with exposure to counter-cyclical sectors and retailers with strong credit profiles RECESSION RESISTANCE Strong emphasis on leading operators with strong balance sheets and avoidance of private equity sponsored retailers AVOIDANCE OF PRIVATE EQUITY SPONSORSHIP Protects against unforeseen changes to our top-down investment philosophy STRONG REAL ESTATE FUNDAMENTALS & FUNGIBLE BUILDINGS
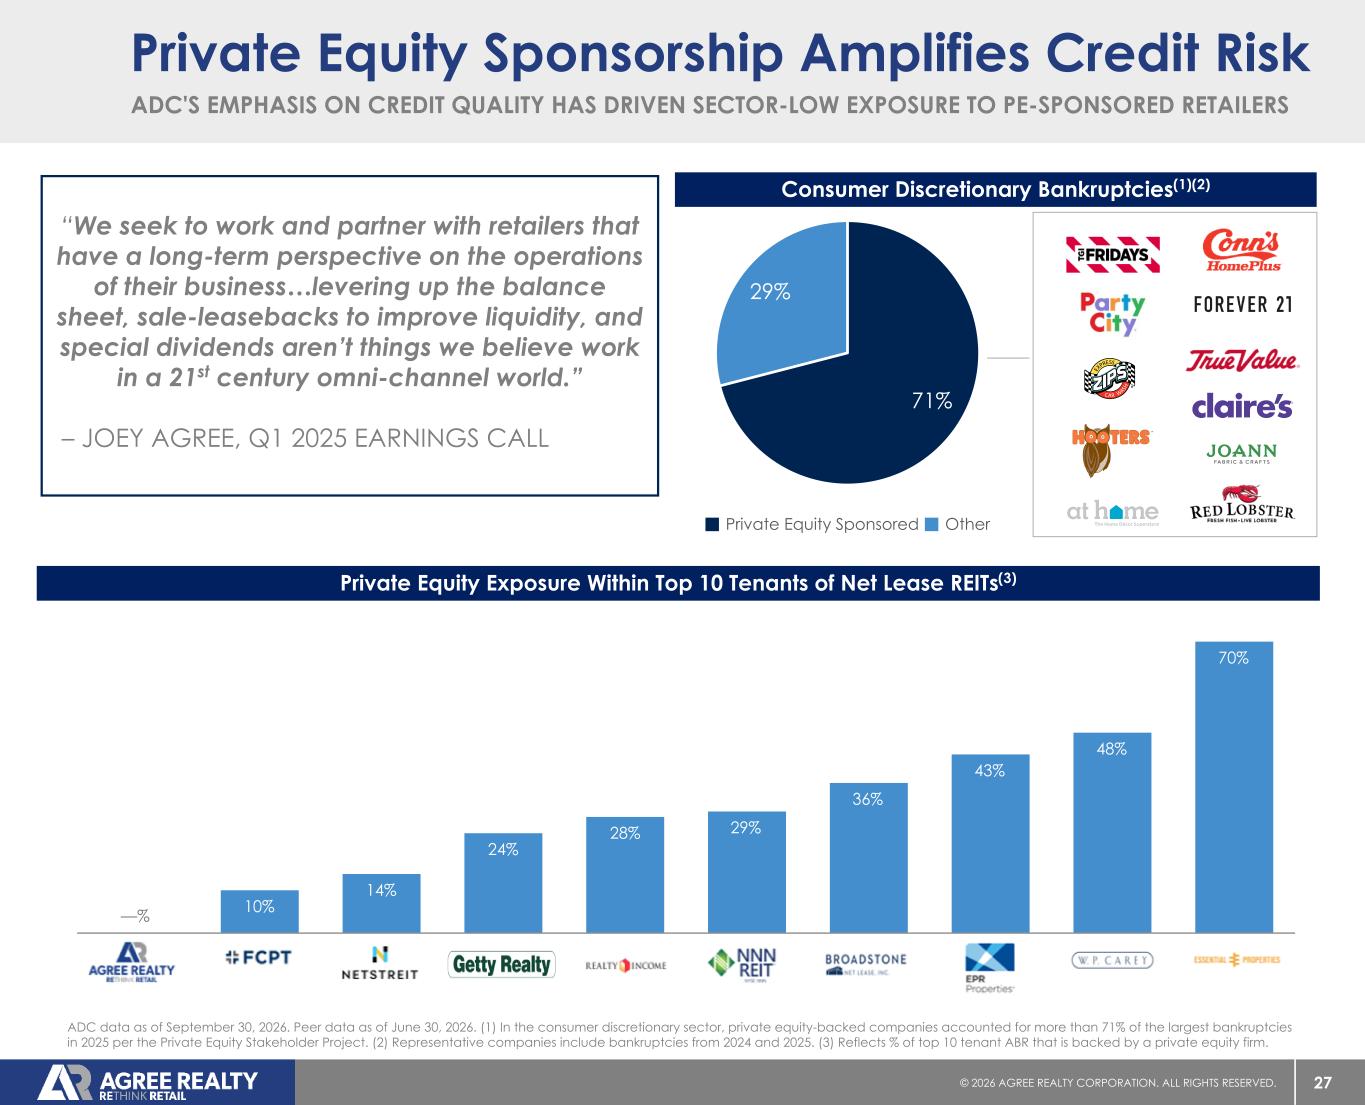
27© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Private Equity Sponsorship Amplifies Credit Risk “We seek to work and partner with retailers that have a long-term perspective on the operations of their business…levering up the balance sheet, sale-leasebacks to improve liquidity, and special dividends aren’t things we believe work in a 21st century omni-channel world.” – JOEY AGREE, Q1 2025 EARNINGS CALL ADC data as of September 30, 2026. Peer data as of June 30, 2026. (1) In the consumer discretionary sector, private equity-backed companies accounted for more than 71% of the largest bankruptcies in 2025 per the Private Equity Stakeholder Project. (2) Representative companies include bankruptcies from 2024 and 2025. (3) Reflects % of top 10 tenant ABR that is backed by a private equity firm. Private Equity Exposure Within Top 10 Tenants of Net Lease REITs(3) Consumer Discretionary Bankruptcies(1)(2) ADC'S EMPHASIS ON CREDIT QUALITY HAS DRIVEN SECTOR-LOW EXPOSURE TO PE-SPONSORED RETAILERS 71% 29% Private Equity Sponsored Other —% 10% 14% 24% 28% 29% 36% 43% 48% 70%
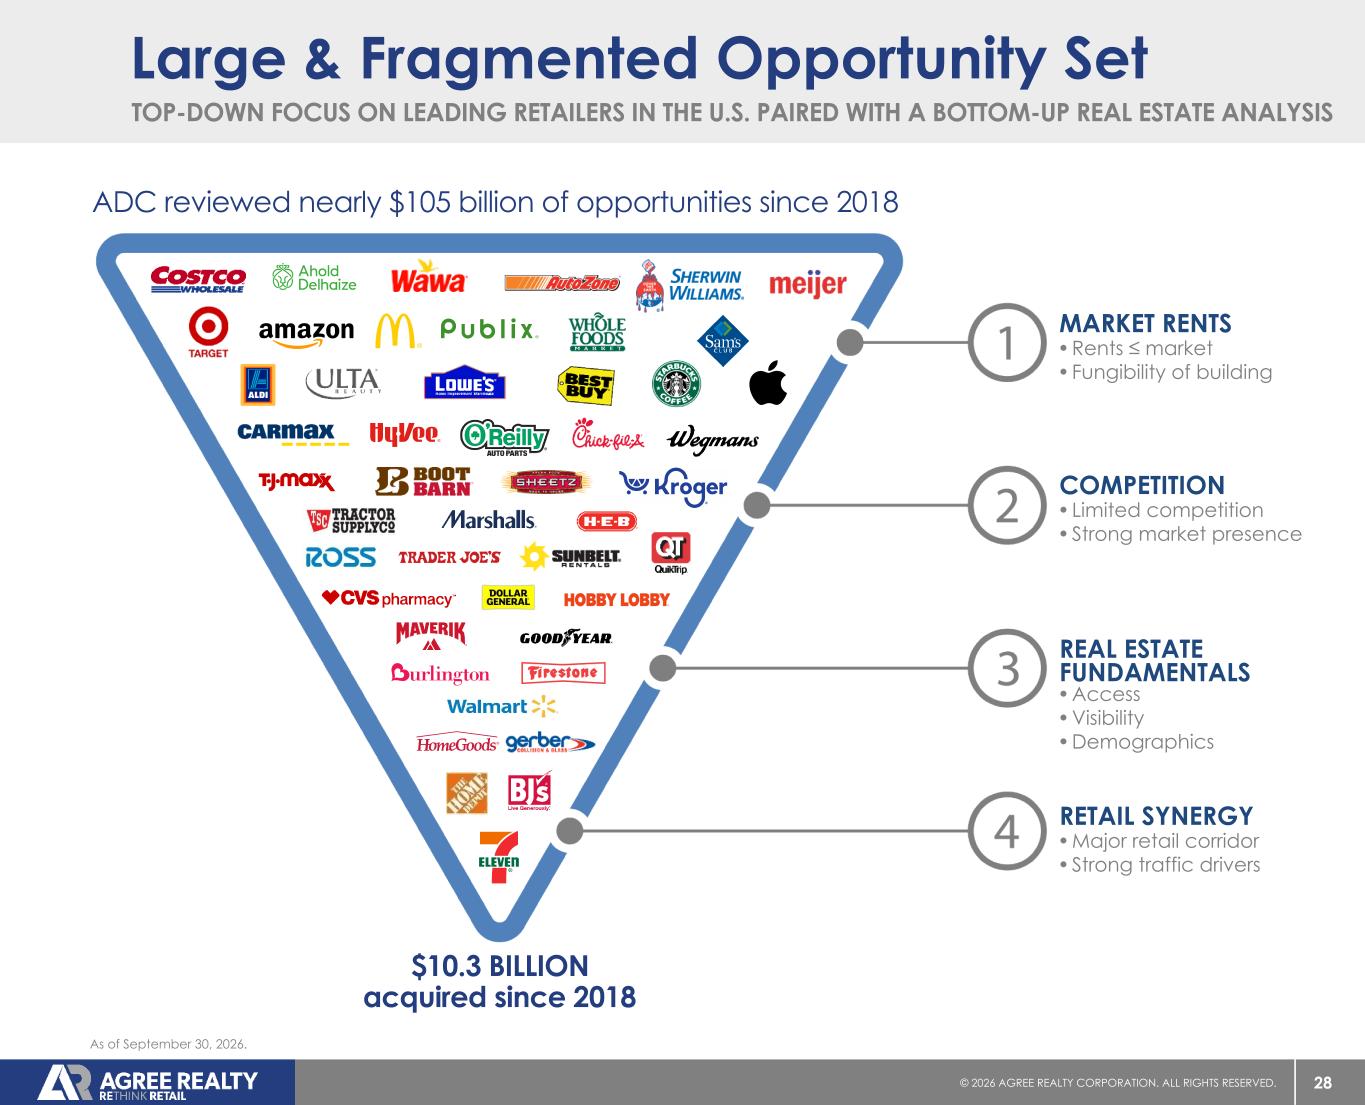
28© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. TOP-DOWN FOCUS ON LEADING RETAILERS IN THE U.S. PAIRED WITH A BOTTOM-UP REAL ESTATE ANALYSIS Large & Fragmented Opportunity Set REAL ESTATE FUNDAMENTALS •Rents ≤ market •Fungibility of building MARKET RENTS •Limited competition •Strong market presence COMPETITION •Access •Visibility •Demographics •Major retail corridor •Strong traffic drivers RETAIL SYNERGY ADC reviewed nearly $105 billion of opportunities since 2018 $10.3 BILLION acquired since 2018 As of September 30, 2026.
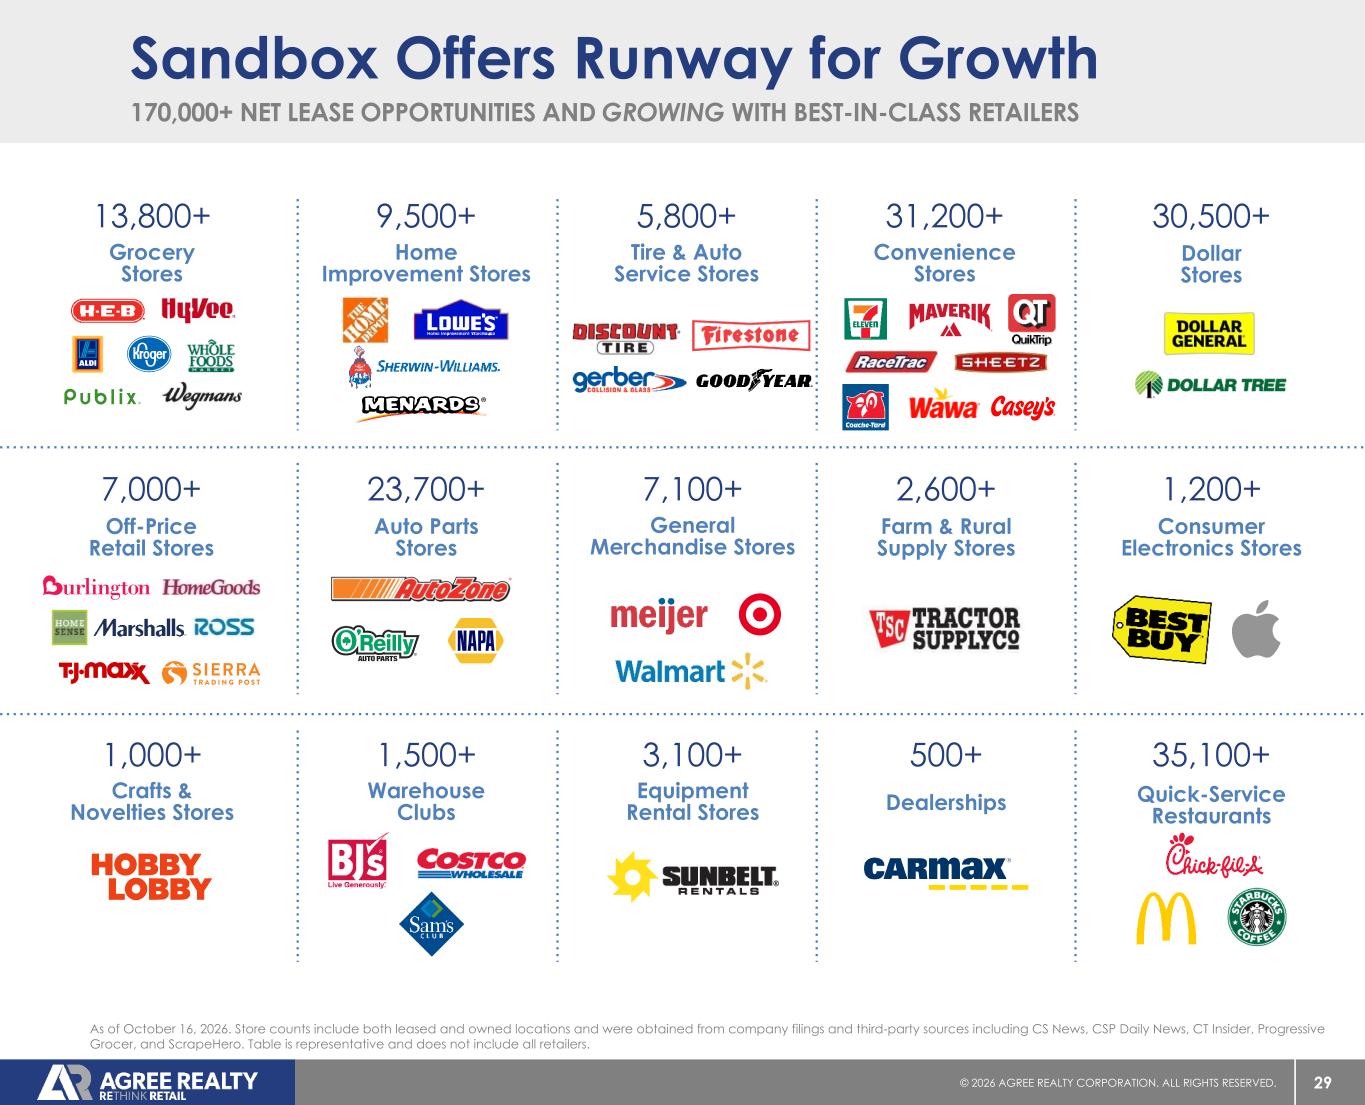
29© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. As of October 16, 2026. Store counts include both leased and owned locations and were obtained from company filings and third-party sources including CS News, CSP Daily News, CT Insider, Progressive Grocer, and ScrapeHero. Table is representative and does not include all retailers. 170,000+ NET LEASE OPPORTUNITIES AND GROWING WITH BEST-IN-CLASS RETAILERS Sandbox Offers Runway for Growth Auto Parts Stores 23,700+ Farm & Rural Supply Stores 2,600+ Crafts & Novelties Stores 1,000+ Quick-Service Restaurants 35,100+ Equipment Rental Stores 3,100+ Warehouse Clubs 1,500+ Home Improvement Stores 9,500+ Consumer Electronics Stores 1,200+ Grocery Stores 13,800+ Dealerships 500+ Convenience Stores 31,200+ Off-Price Retail Stores 7,000+ Tire & Auto Service Stores 5,800+ Dollar Stores 30,500+ General Merchandise Stores 7,100+
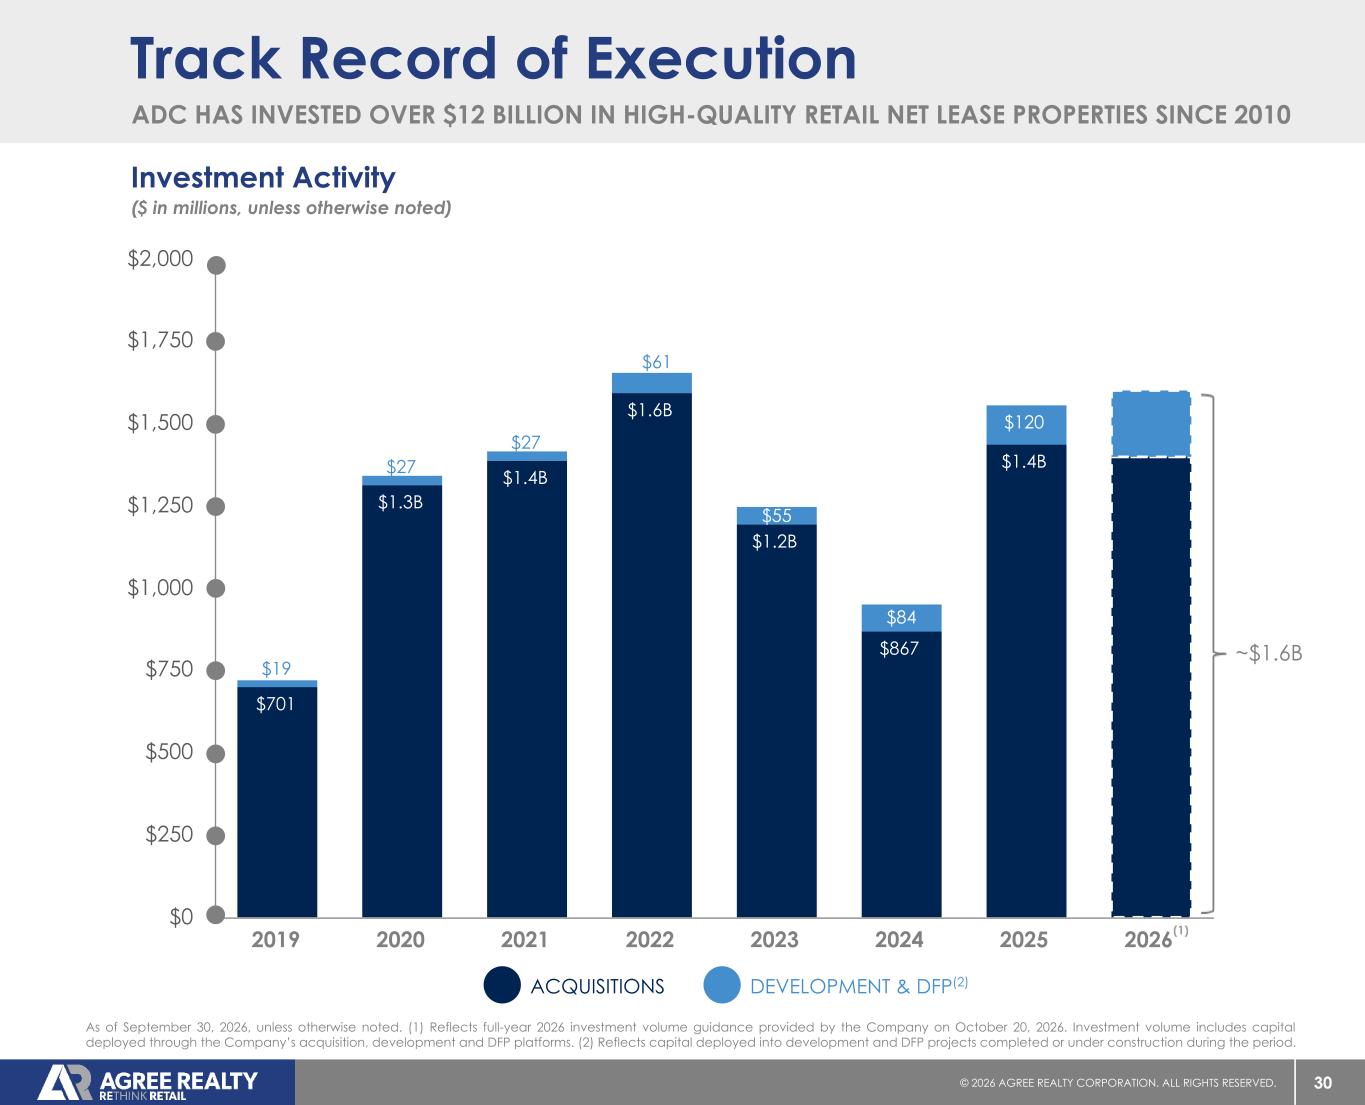
30© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. ~$1.6B $701 $1.3B $1.4B $1.6B $1.2B $867 $1.4B $19 $27 $27 $55 $84 $120 2019 2020 2021 2022 2023 2024 2025 2026 $0 $250 $500 $750 $1,000 $1,250 $1,500 $1,750 $2,000 ADC HAS INVESTED OVER $12 BILLION IN HIGH-QUALITY RETAIL NET LEASE PROPERTIES SINCE 2010 Track Record of Execution DEVELOPMENT & DFP(2)ACQUISITIONS Investment Activity ($ in millions, unless otherwise noted) As of September 30, 2026, unless otherwise noted. (1) Reflects full-year 2026 investment volume guidance provided by the Company on October 20, 2026. Investment volume includes capital deployed through the Company’s acquisition, development and DFP platforms. (2) Reflects capital deployed into development and DFP projects completed or under construction during the period. (1) $61
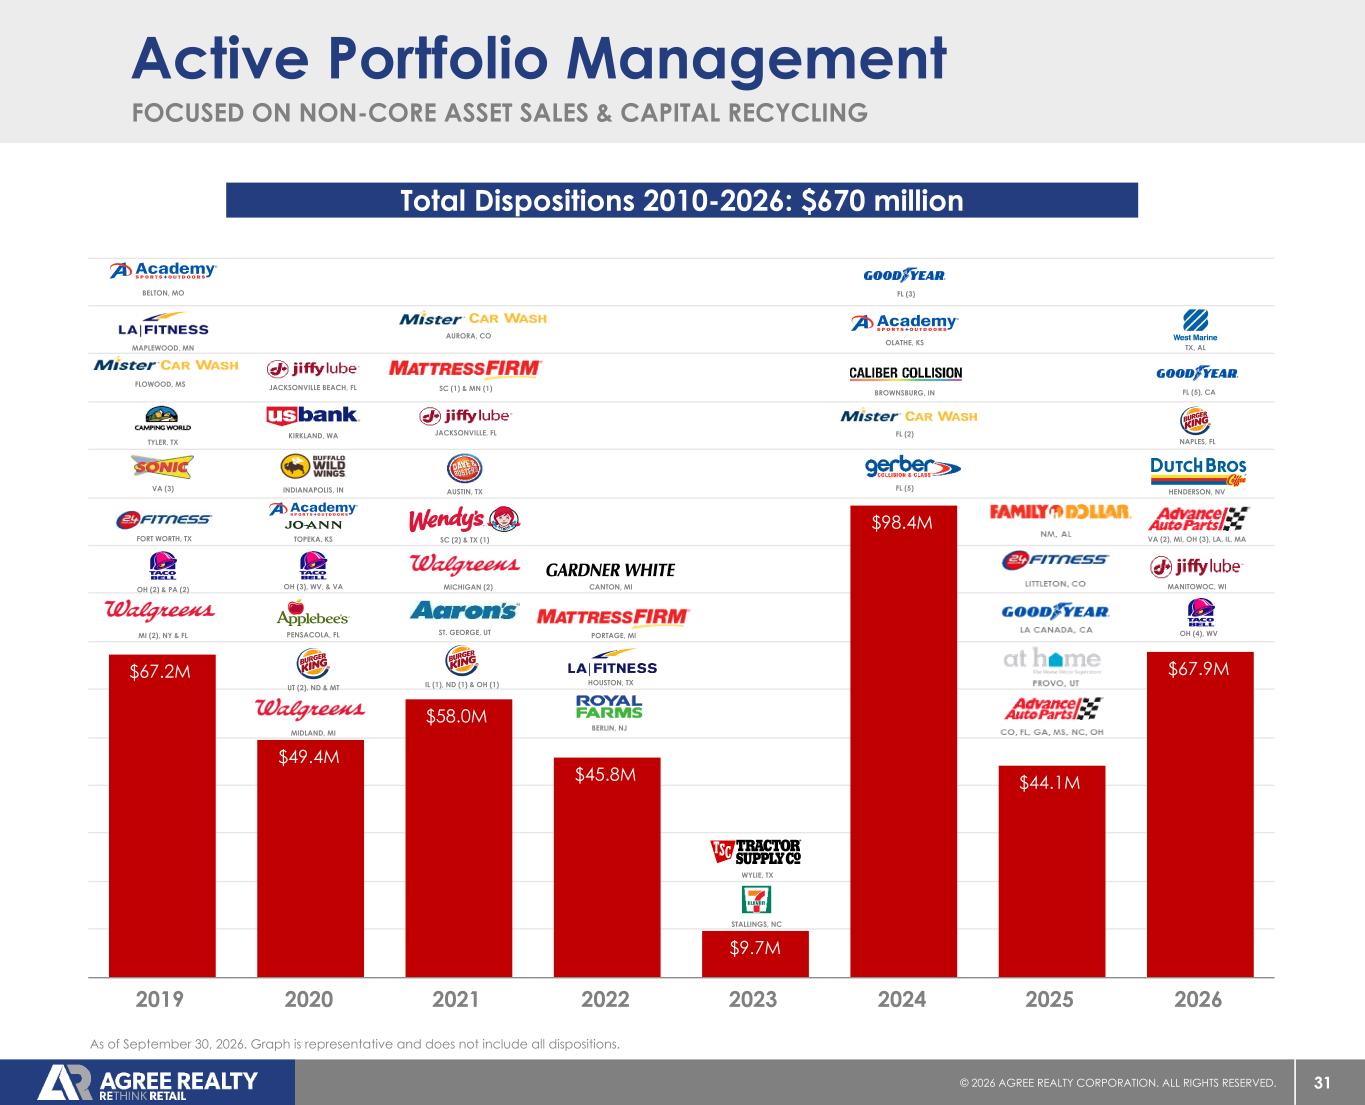
31© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. $67.2M $49.4M $58.0M $45.8M $9.7M $98.4M $44.1M $67.9M 2019 2020 2021 2022 2023 2024 2025 2026 BERLIN, NJ HOUSTON, TX PORTAGE, MI CANTON, MI FOCUSED ON NON-CORE ASSET SALES & CAPITAL RECYCLING Active Portfolio Management As of September 30, 2026. Graph is representative and does not include all dispositions. Total Dispositions 2010-2026: $670 million STALLINGS, NC FORT WORTH, TX OH (2) & PA (2) FLOWOOD, MS MAPLEWOOD, MN TYLER, TX BELTON, MO MI (2), NY & FL VA (3) MIDLAND, MI UT (2), ND & MT PENSACOLA, FL OH (3), WV, & VA TOPEKA, KS INDIANAPOLIS, IN KIRKLAND, WA JACKSONVILLE BEACH, FL IL (1), ND (1) & OH (1) MICHIGAN (2) ST. GEORGE, UT SC (2) & TX (1) AUSTIN, TX JACKSONVILLE, FL SC (1) & MN (1) AURORA, CO WYLIE, TX FL (5) FL (2) FL (3) OLATHE, KS BROWNSBURG, IN MANITOWOC, WI VA (2), MI, OH (3), LA, IL, MA HENDERSON, NV NAPLES, FL FL (5), CA TX, AL OH (4), WV
Fortified Balance Sheet
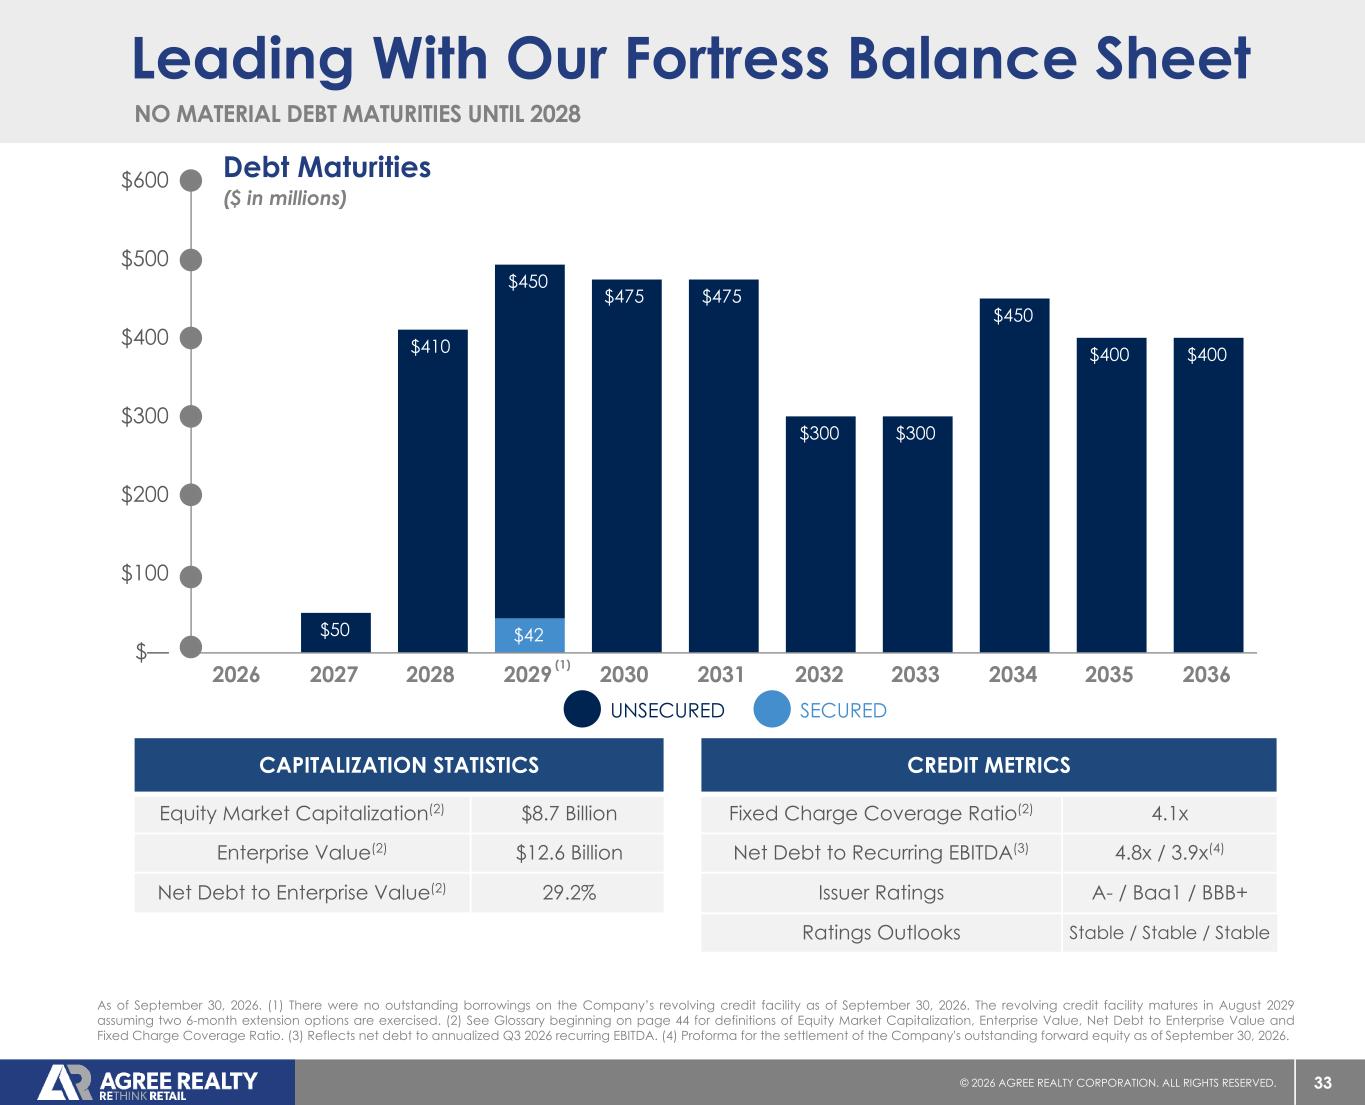
33© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. $42$50 $410 $450 $475 $475 $300 $300 $450 $400 $400 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035 2036 $— $100 $200 $300 $400 $500 $600 As of September 30, 2026. (1) There were no outstanding borrowings on the Company’s revolving credit facility as of September 30, 2026. The revolving credit facility matures in August 2029 assuming two 6-month extension options are exercised. (2) See Glossary beginning on page 44 for definitions of Equity Market Capitalization, Enterprise Value, Net Debt to Enterprise Value and Fixed Charge Coverage Ratio. (3) Reflects net debt to annualized Q3 2026 recurring EBITDA. (4) Proforma for the settlement of the Company's outstanding forward equity as of September 30, 2026. Leading With Our Fortress Balance Sheet CAPITALIZATION STATISTICS Equity Market Capitalization(2) $8.7 Billion Enterprise Value(2) $12.6 Billion Net Debt to Enterprise Value(2) 29.2% CREDIT METRICS Fixed Charge Coverage Ratio(2) 4.1x Net Debt to Recurring EBITDA(3) 4.8x / 3.9x(4) Issuer Ratings A- / Baa1 / BBB+ Ratings Outlooks Stable / Stable / Stable Debt Maturities ($ in millions) SECUREDUNSECURED NO MATERIAL DEBT MATURITIES UNTIL 2028 (1)
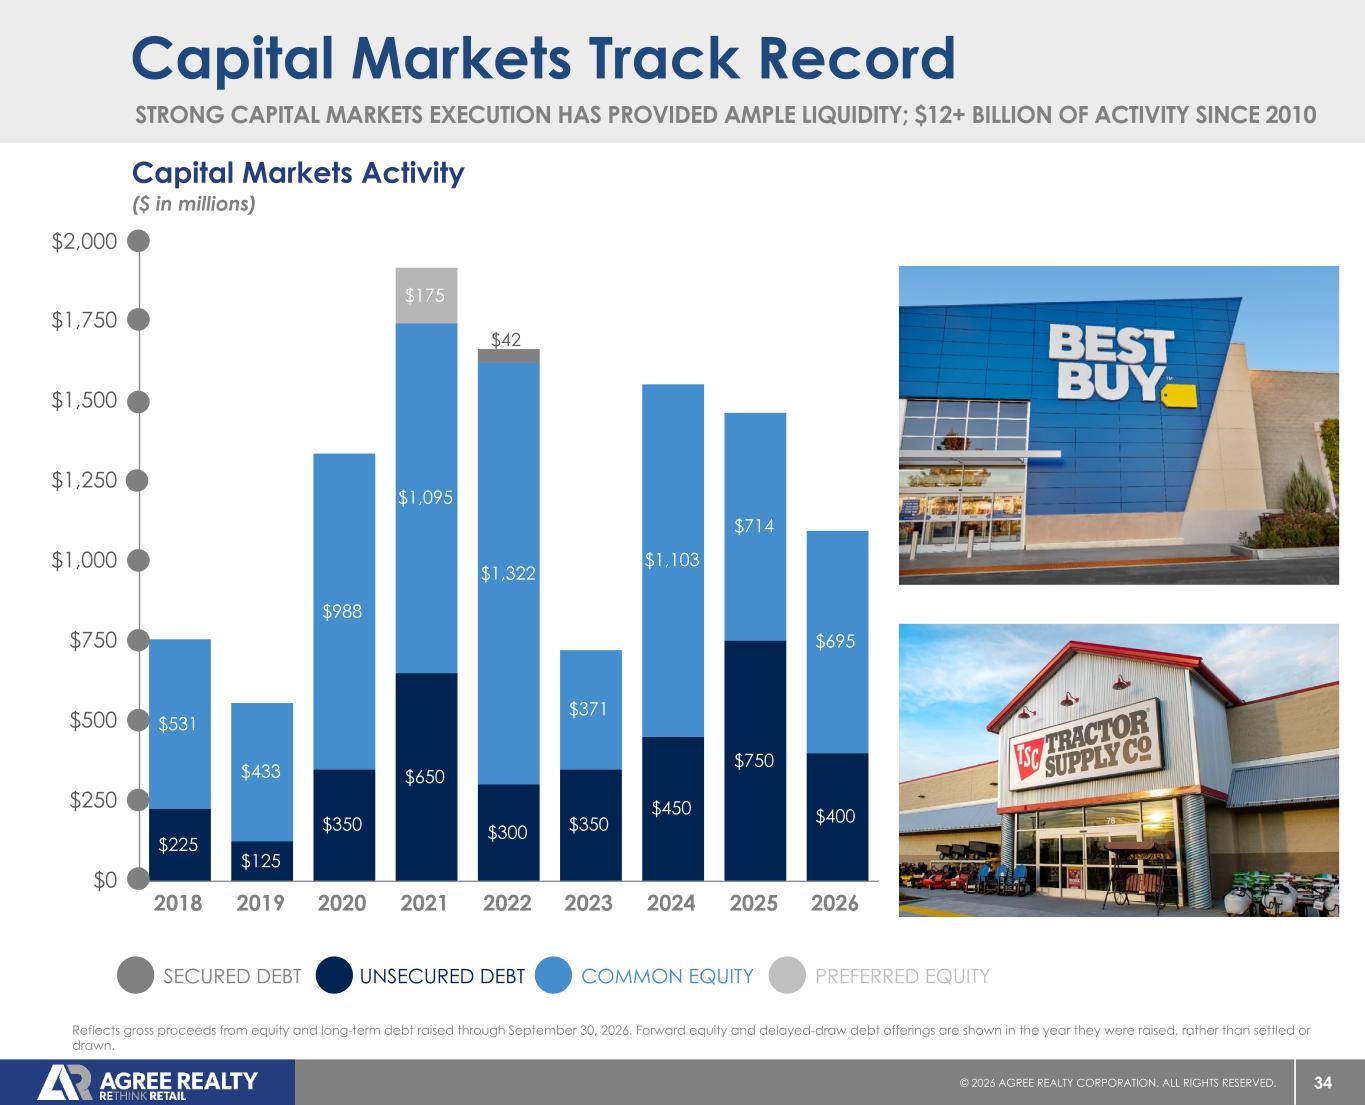
34© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. STRONG CAPITAL MARKETS EXECUTION HAS PROVIDED AMPLE LIQUIDITY; $12+ BILLION OF ACTIVITY SINCE 2010 Capital Markets Track Record Reflects gross proceeds from equity and long-term debt raised through September 30, 2026. Forward equity and delayed-draw debt offerings are shown in the year they were raised, rather than settled or drawn. Capital Markets Activity ($ in millions) COMMON EQUITYUNSECURED DEBTSECURED DEBT PREFERRED EQUITY $225 $125 $350 $650 $300 $350 $450 $750 $400 $531 $433 $988 $1,095 $1,322 $371 $1,103 $714 $695 $175 2018 2019 2020 2021 2022 2023 2024 2025 2026 $0 $250 $500 $750 $1,000 $1,250 $1,500 $1,750 $2,000 $42
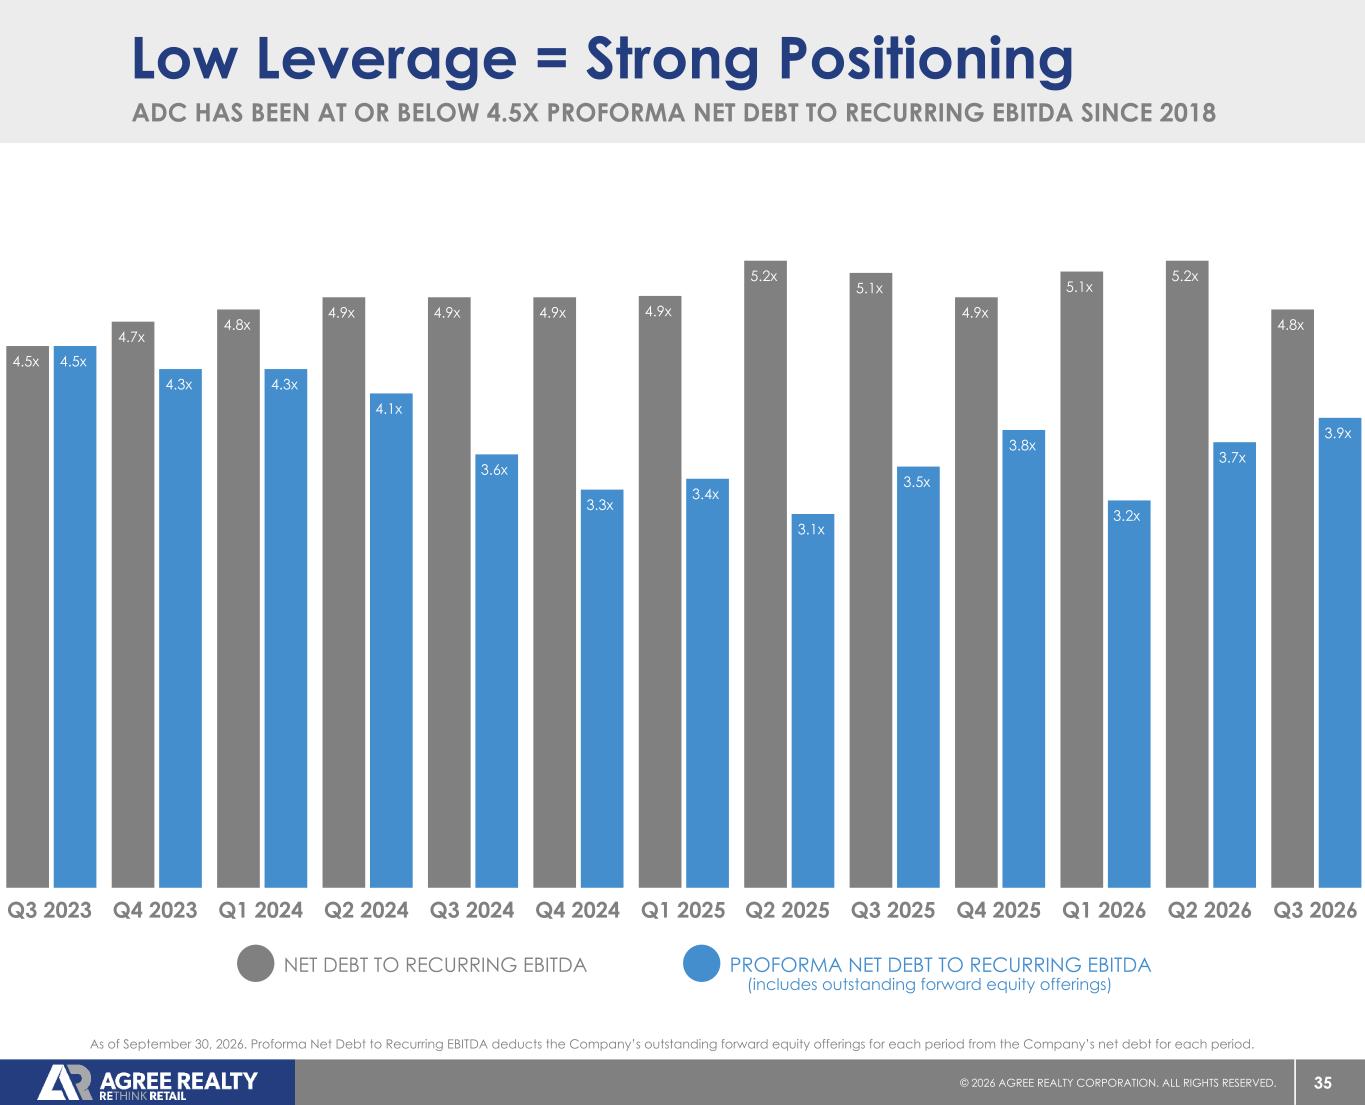
35© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. (includes outstanding forward equity offerings) ADC HAS BEEN AT OR BELOW 4.5X PROFORMA NET DEBT TO RECURRING EBITDA SINCE 2018 Low Leverage = Strong Positioning As of September 30, 2026. Proforma Net Debt to Recurring EBITDA deducts the Company’s outstanding forward equity offerings for each period from the Company’s net debt for each period. PROFORMA NET DEBT TO RECURRING EBITDANET DEBT TO RECURRING EBITDA 4.5x 4.7x 4.8x 4.9x 4.9x 4.9x 4.9x 5.2x 5.1x 4.9x 5.1x 5.2x 4.8x 4.5x 4.3x 4.3x 4.1x 3.6x 3.3x 3.4x 3.1x 3.5x 3.8x 3.2x 3.7x 3.9x Q3 2023 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026
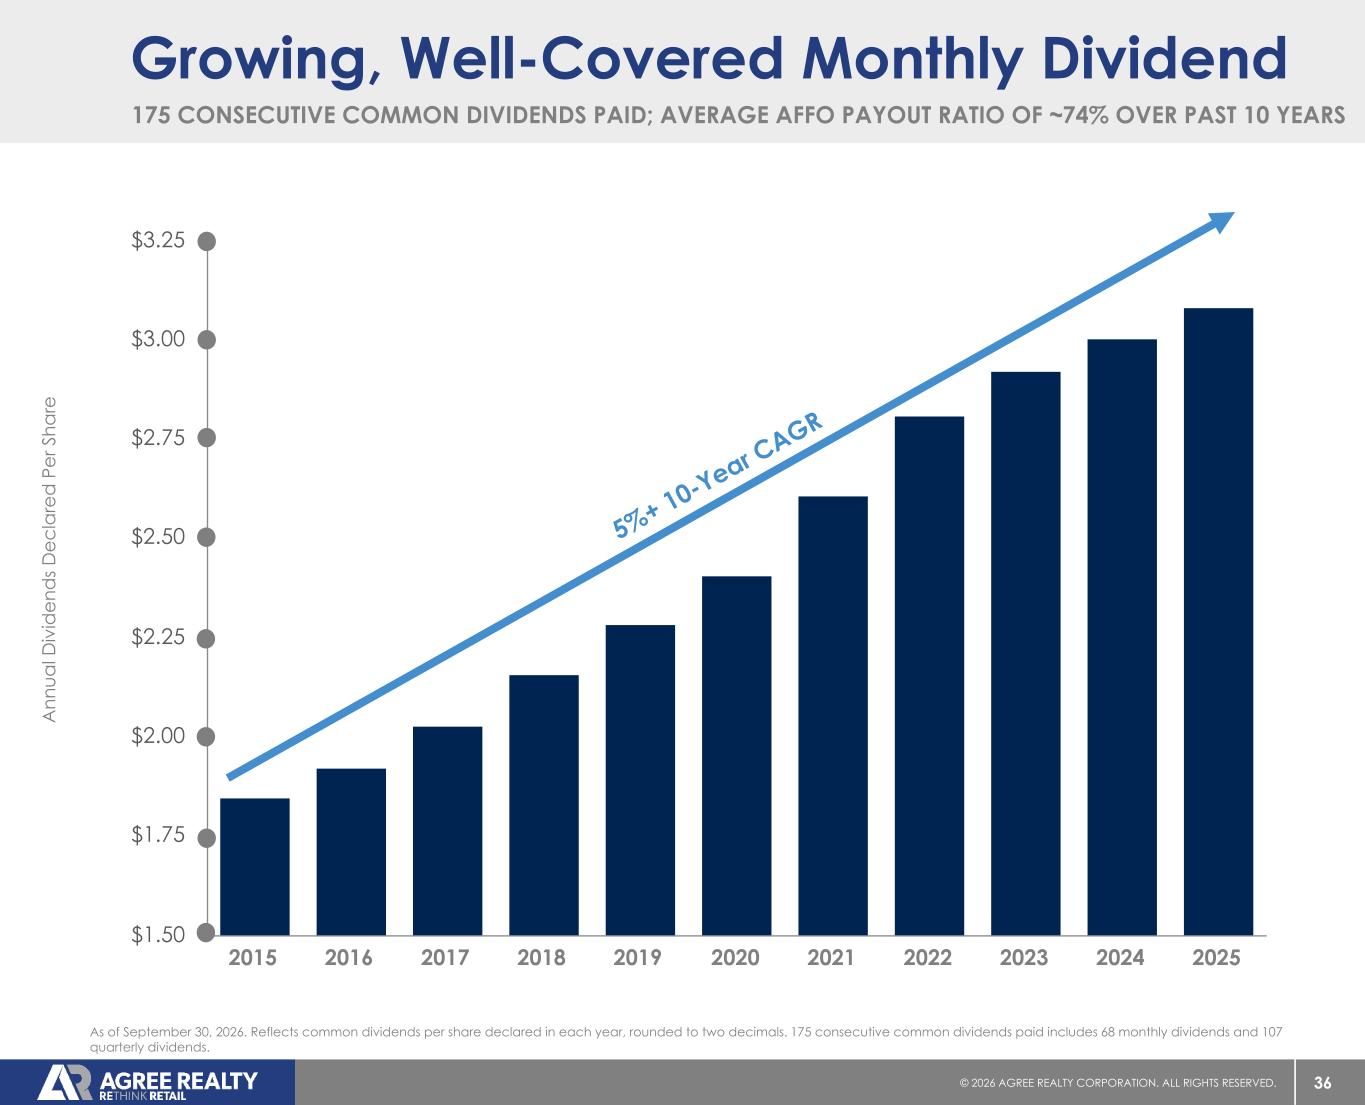
36© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 $1.50 $1.75 $2.00 $2.25 $2.50 $2.75 $3.00 $3.25 175 CONSECUTIVE COMMON DIVIDENDS PAID; AVERAGE AFFO PAYOUT RATIO OF ~74% OVER PAST 10 YEARS Growing, Well-Covered Monthly Dividend As of September 30, 2026. Reflects common dividends per share declared in each year, rounded to two decimals. 175 consecutive common dividends paid includes 68 monthly dividends and 107 quarterly dividends. 5%+ 10-Year C AGR A n n u a l D iv id e n d s D e c la re d P e r S h a re
37© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Investment Summary Highlights FORTIFIED BALANCE SHEET HIGHEST-QUALITY RETAIL REAL ESTATE INVESTMENT GRADE ISSUER RATINGS R o b u st g ro w th tr a je c to ry MULTI-YEAR TRACK RECORD OF EXECUTION Well-covered &consistent dividend
38© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED.
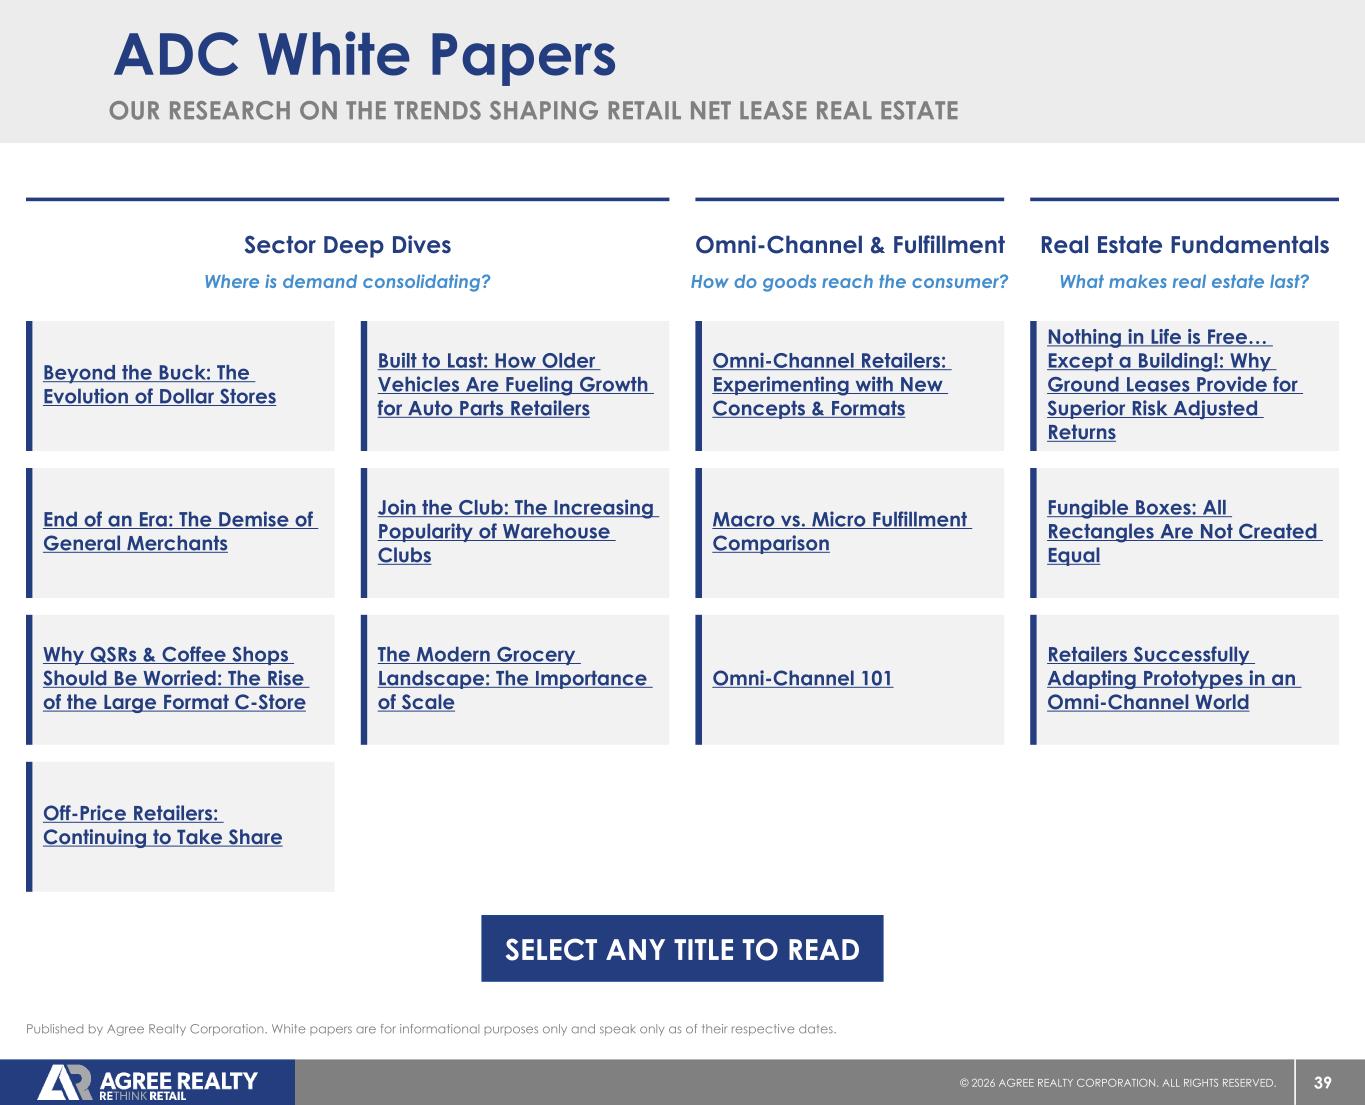
39© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. ADC White Papers OUR RESEARCH ON THE TRENDS SHAPING RETAIL NET LEASE REAL ESTATE Sector Deep Dives Where is demand consolidating? Beyond the Buck: The Evolution of Dollar Stores End of an Era: The Demise of General Merchants The Modern Grocery Landscape: The Importance of Scale Off-Price Retailers: Continuing to Take Share Built to Last: How Older Vehicles Are Fueling Growth for Auto Parts Retailers Join the Club: The Increasing Popularity of Warehouse Clubs Why QSRs & Coffee Shops Should Be Worried: The Rise of the Large Format C-Store Omni-Channel & Fulfillment How do goods reach the consumer? Omni-Channel Retailers: Experimenting with New Concepts & Formats Macro vs. Micro Fulfillment Comparison Omni-Channel 101 Real Estate Fundamentals What makes real estate last? Nothing in Life is Free… Except a Building!: Why Ground Leases Provide for Superior Risk Adjusted Returns Fungible Boxes: All Rectangles Are Not Created Equal Retailers Successfully Adapting Prototypes in an Omni-Channel World SELECT ANY TITLE TO READ Published by Agree Realty Corporation. White papers are for informational purposes only and speak only as of their respective dates.
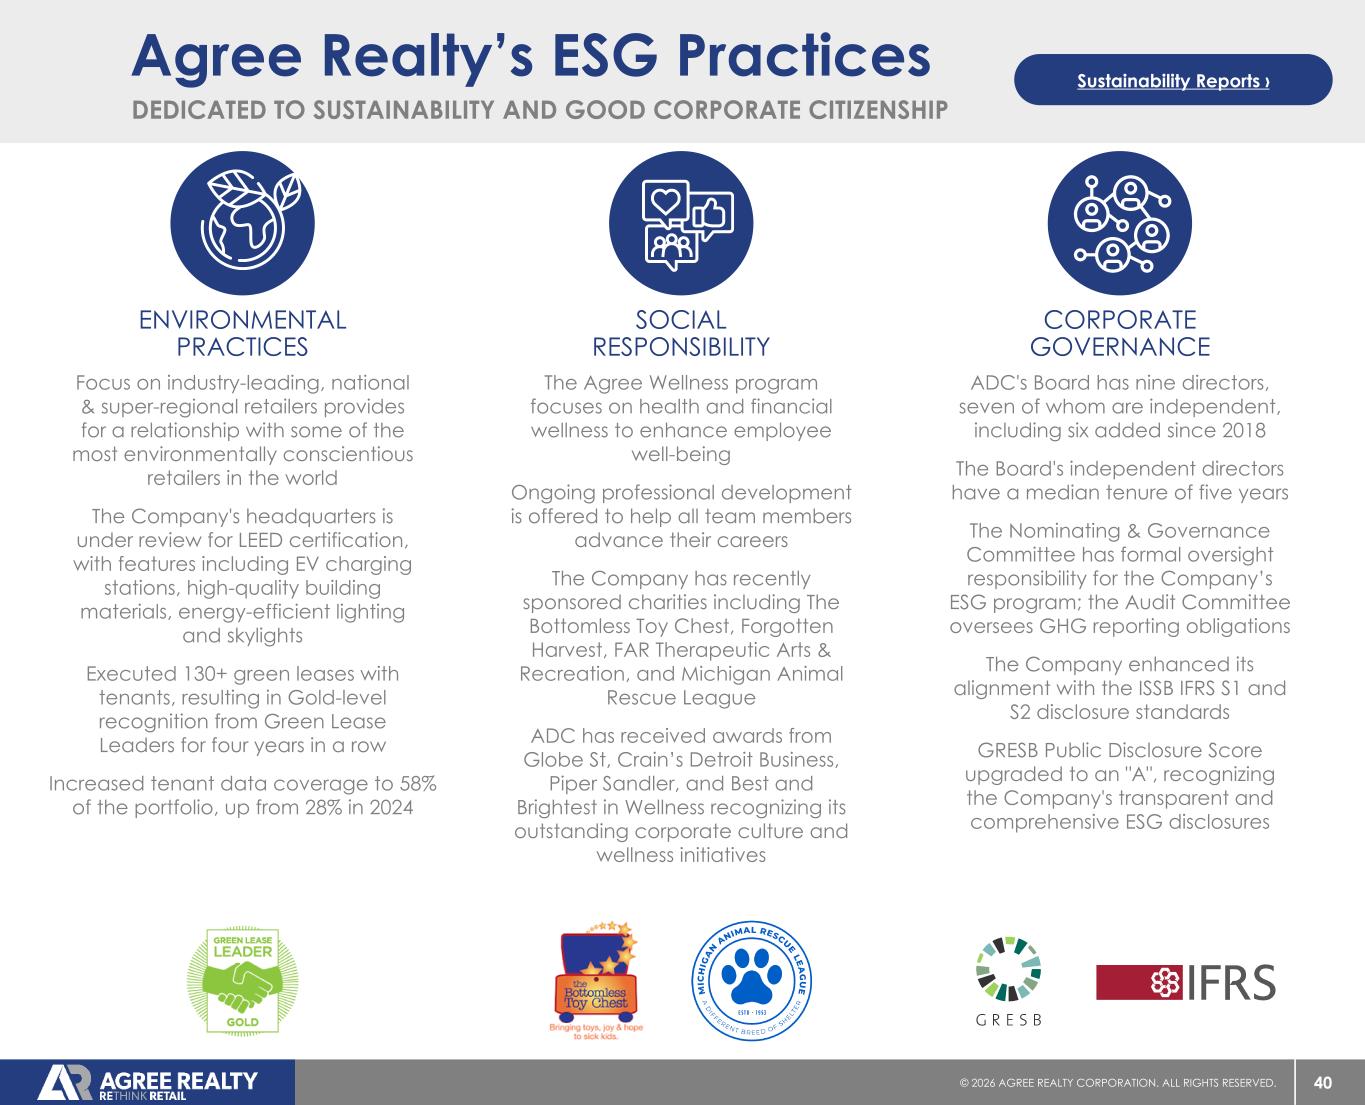
40© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. ADC's Board has nine directors, seven of whom are independent, including six added since 2018 The Board's independent directors have a median tenure of five years The Nominating & Governance Committee has formal oversight responsibility for the Company’s ESG program; the Audit Committee oversees GHG reporting obligations The Company enhanced its alignment with the ISSB IFRS S1 and S2 disclosure standards GRESB Public Disclosure Score upgraded to an "A", recognizing the Company's transparent and comprehensive ESG disclosures Focus on industry-leading, national & super-regional retailers provides for a relationship with some of the most environmentally conscientious retailers in the world The Company's headquarters is under review for LEED certification, with features including EV charging stations, high-quality building materials, energy-efficient lighting and skylights Executed 130+ green leases with tenants, resulting in Gold-level recognition from Green Lease Leaders for four years in a row Increased tenant data coverage to 58% of the portfolio, up from 28% in 2024 The Agree Wellness program focuses on health and financial wellness to enhance employee well-being Ongoing professional development is offered to help all team members advance their careers The Company has recently sponsored charities including The Bottomless Toy Chest, Forgotten Harvest, FAR Therapeutic Arts & Recreation, and Michigan Animal Rescue League ADC has received awards from Globe St, Crain’s Detroit Business, Piper Sandler, and Best and Brightest in Wellness recognizing its outstanding corporate culture and wellness initiatives SOCIAL RESPONSIBILITY DEDICATED TO SUSTAINABILITY AND GOOD CORPORATE CITIZENSHIP Agree Realty’s ESG Practices ENVIRONMENTAL PRACTICES CORPORATE GOVERNANCE Sustainability Reports ›
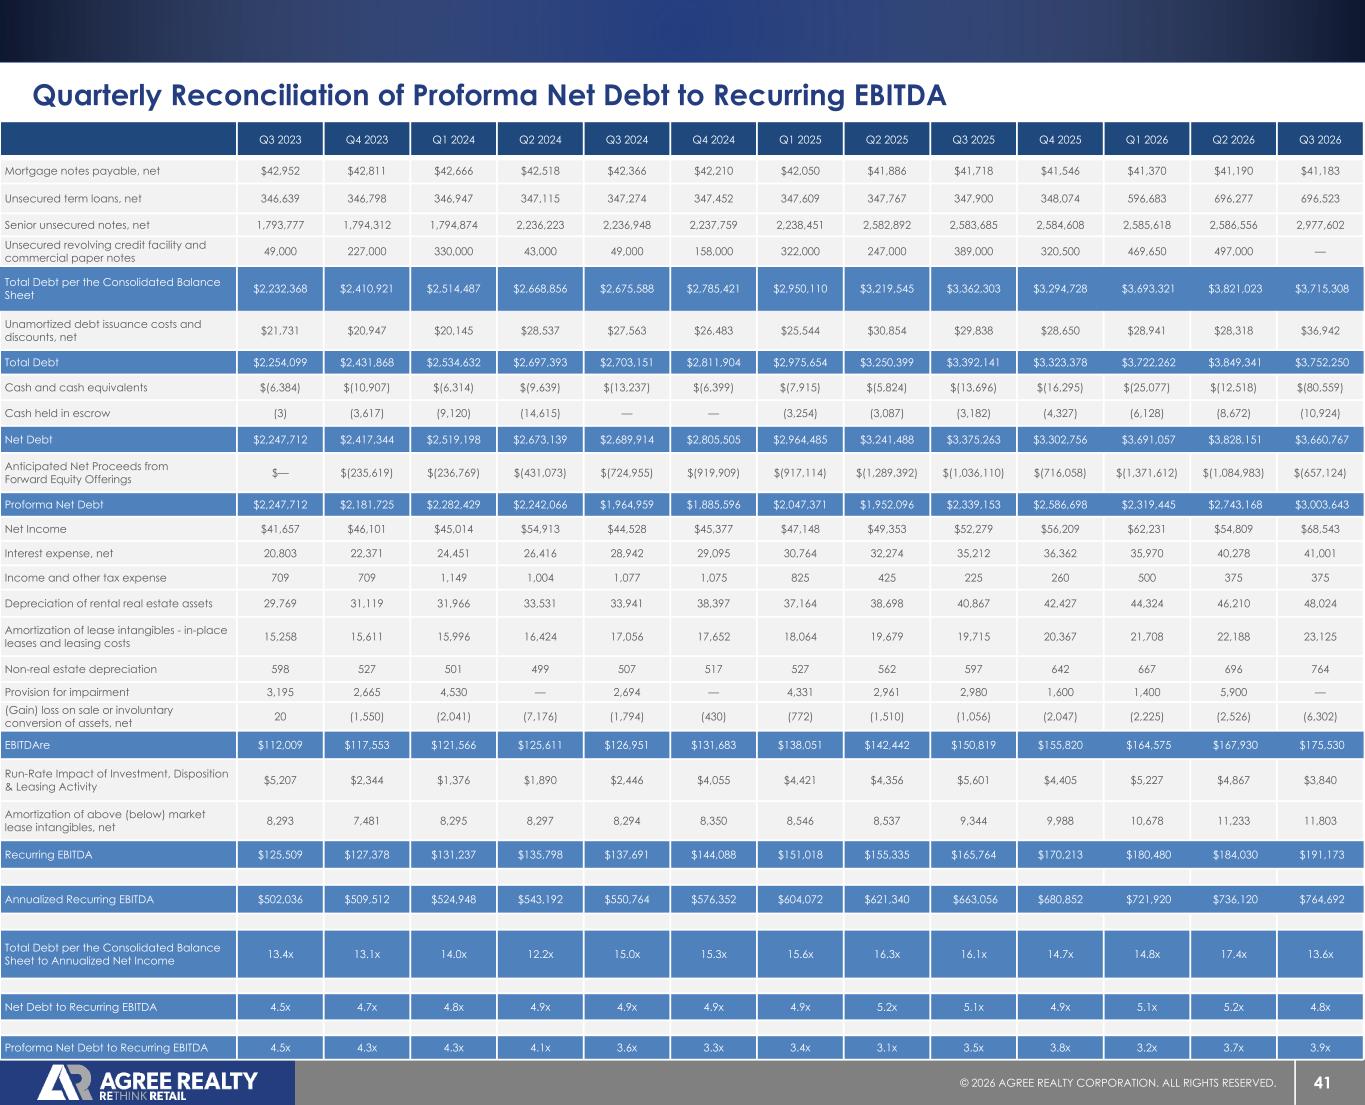
41© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Quarterly Reconciliation of Proforma Net Debt to Recurring EBITDA Q3 2023 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Mortgage notes payable, net $42,952 $42,811 $42,666 $42,518 $42,366 $42,210 $42,050 $41,886 $41,718 $41,546 $41,370 $41,190 $41,183 Unsecured term loans, net 346,639 346,798 346,947 347,115 347,274 347,452 347,609 347,767 347,900 348,074 596,683 696,277 696,523 Senior unsecured notes, net 1,793,777 1,794,312 1,794,874 2,236,223 2,236,948 2,237,759 2,238,451 2,582,892 2,583,685 2,584,608 2,585,618 2,586,556 2,977,602 Unsecured revolving credit facility and commercial paper notes 49,000 227,000 330,000 43,000 49,000 158,000 322,000 247,000 389,000 320,500 469,650 497,000 — Total Debt per the Consolidated Balance Sheet $2,232,368 $2,410,921 $2,514,487 $2,668,856 $2,675,588 $2,785,421 $2,950,110 $3,219,545 $3,362,303 $3,294,728 $3,693,321 $3,821,023 $3,715,308 Unamortized debt issuance costs and discounts, net $21,731 $20,947 $20,145 $28,537 $27,563 $26,483 $25,544 $30,854 $29,838 $28,650 $28,941 $28,318 $36,942 Total Debt $2,254,099 $2,431,868 $2,534,632 $2,697,393 $2,703,151 $2,811,904 $2,975,654 $3,250,399 $3,392,141 $3,323,378 $3,722,262 $3,849,341 $3,752,250 Cash and cash equivalents $(6,384) $(10,907) $(6,314) $(9,639) $(13,237) $(6,399) $(7,915) $(5,824) $(13,696) $(16,295) $(25,077) $(12,518) $(80,559) Cash held in escrow (3) (3,617) (9,120) (14,615) — — (3,254) (3,087) (3,182) (4,327) (6,128) (8,672) (10,924) Net Debt $2,247,712 $2,417,344 $2,519,198 $2,673,139 $2,689,914 $2,805,505 $2,964,485 $3,241,488 $3,375,263 $3,302,756 $3,691,057 $3,828,151 $3,660,767 Anticipated Net Proceeds from Forward Equity Offerings $— $(235,619) $(236,769) $(431,073) $(724,955) $(919,909) $(917,114) $(1,289,392) $(1,036,110) $(716,058) $(1,371,612) $(1,084,983) $(657,124) Proforma Net Debt $2,247,712 $2,181,725 $2,282,429 $2,242,066 $1,964,959 $1,885,596 $2,047,371 $1,952,096 $2,339,153 $2,586,698 $2,319,445 $2,743,168 $3,003,643 Net Income $41,657 $46,101 $45,014 $54,913 $44,528 $45,377 $47,148 $49,353 $52,279 $56,209 $62,231 $54,809 $68,543 Interest expense, net 20,803 22,371 24,451 26,416 28,942 29,095 30,764 32,274 35,212 36,362 35,970 40,278 41,001 Income and other tax expense 709 709 1,149 1,004 1,077 1,075 825 425 225 260 500 375 375 Depreciation of rental real estate assets 29,769 31,119 31,966 33,531 33,941 38,397 37,164 38,698 40,867 42,427 44,324 46,210 48,024 Amortization of lease intangibles - in-place leases and leasing costs 15,258 15,611 15,996 16,424 17,056 17,652 18,064 19,679 19,715 20,367 21,708 22,188 23,125 Non-real estate depreciation 598 527 501 499 507 517 527 562 597 642 667 696 764 Provision for impairment 3,195 2,665 4,530 — 2,694 — 4,331 2,961 2,980 1,600 1,400 5,900 — (Gain) loss on sale or involuntary conversion of assets, net 20 (1,550) (2,041) (7,176) (1,794) (430) (772) (1,510) (1,056) (2,047) (2,225) (2,526) (6,302) EBITDAre $112,009 $117,553 $121,566 $125,611 $126,951 $131,683 $138,051 $142,442 $150,819 $155,820 $164,575 $167,930 $175,530 Run-Rate Impact of Investment, Disposition & Leasing Activity $5,207 $2,344 $1,376 $1,890 $2,446 $4,055 $4,421 $4,356 $5,601 $4,405 $5,227 $4,867 $3,840 Amortization of above (below) market lease intangibles, net 8,293 7,481 8,295 8,297 8,294 8,350 8,546 8,537 9,344 9,988 10,678 11,233 11,803 Recurring EBITDA $125,509 $127,378 $131,237 $135,798 $137,691 $144,088 $151,018 $155,335 $165,764 $170,213 $180,480 $184,030 $191,173 Annualized Recurring EBITDA $502,036 $509,512 $524,948 $543,192 $550,764 $576,352 $604,072 $621,340 $663,056 $680,852 $721,920 $736,120 $764,692 Total Debt per the Consolidated Balance Sheet to Annualized Net Income 13.4x 13.1x 14.0x 12.2x 15.0x 15.3x 15.6x 16.3x 16.1x 14.7x 14.8x 17.4x 13.6x Net Debt to Recurring EBITDA 4.5x 4.7x 4.8x 4.9x 4.9x 4.9x 4.9x 5.2x 5.1x 4.9x 5.1x 5.2x 4.8x Proforma Net Debt to Recurring EBITDA 4.5x 4.3x 4.3x 4.1x 3.6x 3.3x 3.4x 3.1x 3.5x 3.8x 3.2x 3.7x 3.9x
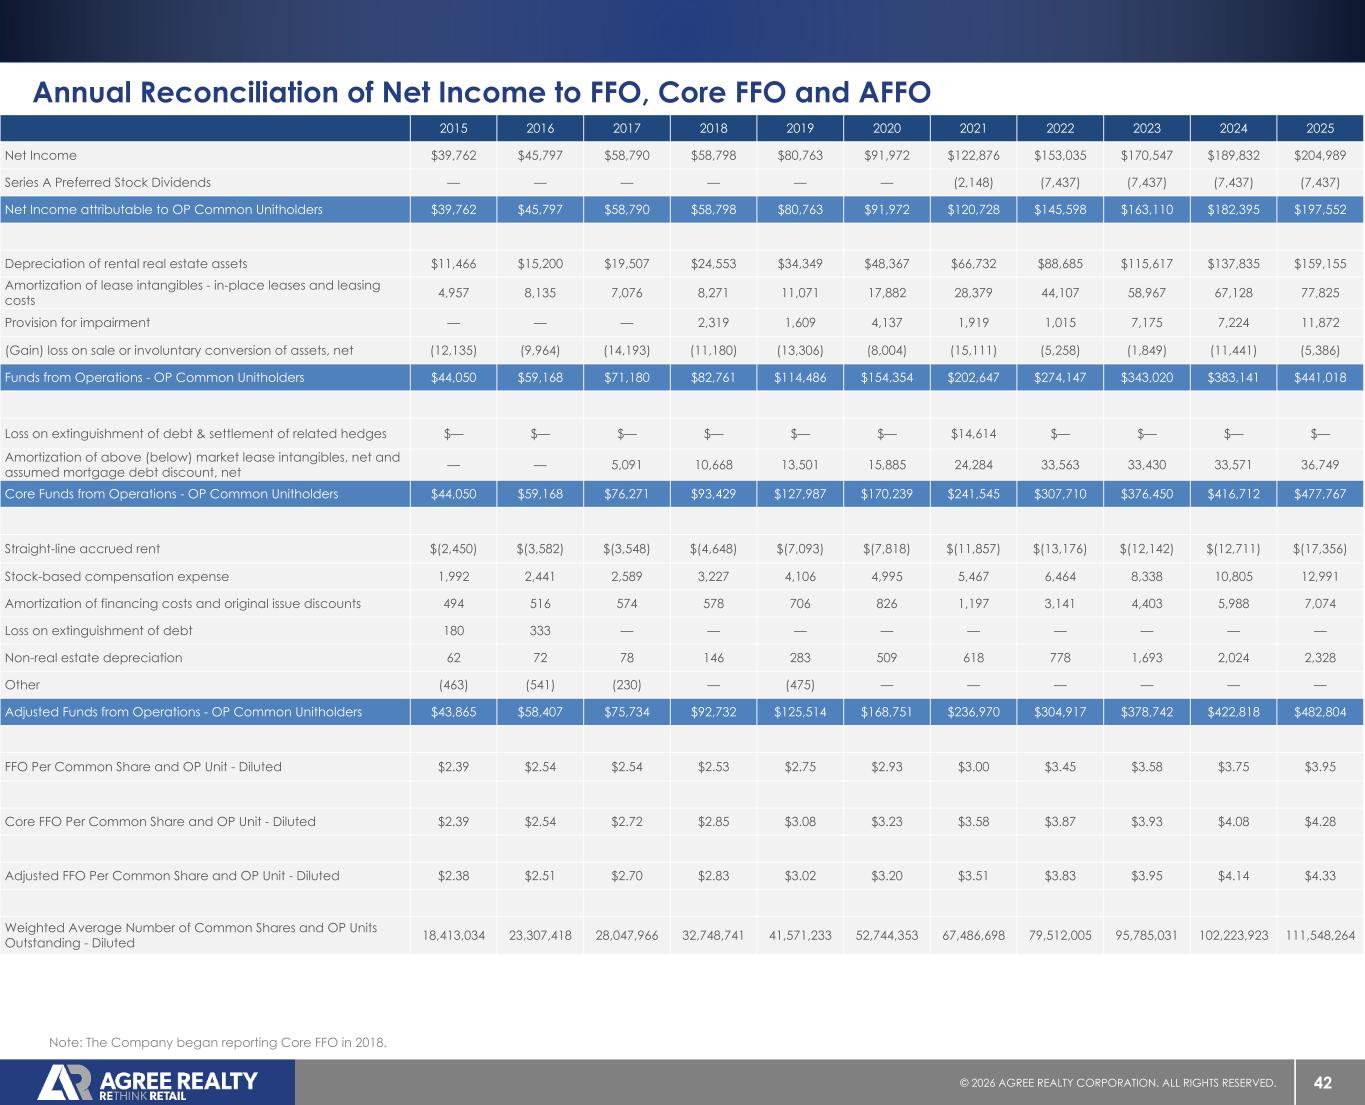
42© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 Net Income $39,762 $45,797 $58,790 $58,798 $80,763 $91,972 $122,876 $153,035 $170,547 $189,832 $204,989 Series A Preferred Stock Dividends — — — — — — (2,148) (7,437) (7,437) (7,437) (7,437) Net Income attributable to OP Common Unitholders $39,762 $45,797 $58,790 $58,798 $80,763 $91,972 $120,728 $145,598 $163,110 $182,395 $197,552 Depreciation of rental real estate assets $11,466 $15,200 $19,507 $24,553 $34,349 $48,367 $66,732 $88,685 $115,617 $137,835 $159,155 Amortization of lease intangibles - in-place leases and leasing costs 4,957 8,135 7,076 8,271 11,071 17,882 28,379 44,107 58,967 67,128 77,825 Provision for impairment — — — 2,319 1,609 4,137 1,919 1,015 7,175 7,224 11,872 (Gain) loss on sale or involuntary conversion of assets, net (12,135) (9,964) (14,193) (11,180) (13,306) (8,004) (15,111) (5,258) (1,849) (11,441) (5,386) Funds from Operations - OP Common Unitholders $44,050 $59,168 $71,180 $82,761 $114,486 $154,354 $202,647 $274,147 $343,020 $383,141 $441,018 Loss on extinguishment of debt & settlement of related hedges $— $— $— $— $— $— $14,614 $— $— $— $— Amortization of above (below) market lease intangibles, net and assumed mortgage debt discount, net — — 5,091 10,668 13,501 15,885 24,284 33,563 33,430 33,571 36,749 Core Funds from Operations - OP Common Unitholders $44,050 $59,168 $76,271 $93,429 $127,987 $170,239 $241,545 $307,710 $376,450 $416,712 $477,767 Straight-line accrued rent $(2,450) $(3,582) $(3,548) $(4,648) $(7,093) $(7,818) $(11,857) $(13,176) $(12,142) $(12,711) $(17,356) Stock-based compensation expense 1,992 2,441 2,589 3,227 4,106 4,995 5,467 6,464 8,338 10,805 12,991 Amortization of financing costs and original issue discounts 494 516 574 578 706 826 1,197 3,141 4,403 5,988 7,074 Loss on extinguishment of debt 180 333 — — — — — — — — — Non-real estate depreciation 62 72 78 146 283 509 618 778 1,693 2,024 2,328 Other (463) (541) (230) — (475) — — — — — — Adjusted Funds from Operations - OP Common Unitholders $43,865 $58,407 $75,734 $92,732 $125,514 $168,751 $236,970 $304,917 $378,742 $422,818 $482,804 FFO Per Common Share and OP Unit - Diluted $2.39 $2.54 $2.54 $2.53 $2.75 $2.93 $3.00 $3.45 $3.58 $3.75 $3.95 Core FFO Per Common Share and OP Unit - Diluted $2.39 $2.54 $2.72 $2.85 $3.08 $3.23 $3.58 $3.87 $3.93 $4.08 $4.28 Adjusted FFO Per Common Share and OP Unit - Diluted $2.38 $2.51 $2.70 $2.83 $3.02 $3.20 $3.51 $3.83 $3.95 $4.14 $4.33 Weighted Average Number of Common Shares and OP Units Outstanding - Diluted 18,413,034 23,307,418 28,047,966 32,748,741 41,571,233 52,744,353 67,486,698 79,512,005 95,785,031 102,223,923 111,548,264 Annual Reconciliation of Net Income to FFO, Core FFO and AFFO Note: The Company began reporting Core FFO in 2018.
43© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Forward-Looking Statements This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”) and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward- looking statements contained in the Private Securities Litigation Reform Act of 1995 and includes this statement for purposes of complying with these safe harbor provisions. Forward-looking statements are generally identifiable by use of forward-looking terminology such as “may,” “can,” “will,” “should,” “potential,” “intend,” “expect,” “seek,” “anticipate,” “estimate,” “approximately,” “believe,” “could,” “project,” “predict,” “forecast,” “continue,” “assume,” “plan,” references to “outlook” or other similar words or expressions. Forward-looking statements, including statements regarding our financial projections and operations, are based on certain assumptions and can include future expectations, future economic, competitive and market conditions, future plans and strategies, financial and operating projections and forecasts and other forward-looking information and estimates. These forward-looking statements are subject to various risks and uncertainties, many of which are beyond the Company’s control, which could cause actual results to differ materially from such statements. Certain factors could occur that might cause actual results to vary, including the potential adverse effect of ongoing worldwide economic uncertainties, disruptions in the banking system and financial markets, and increased inflation on the financial condition, results of operations, cash flows and performance of the Company and its tenants, the real estate market and the global economy and financial markets, the general deterioration in national economic conditions, tenant financial health, property acquisitions and the timing of these investments and acquisitions, weakening of real estate markets, decreases in the availability of credit, increases in interest rates, adverse changes in the retail industry, the Company’s continuing ability to qualify as a REIT and other risks and uncertainties as described in greater detail in the Company’s filings with the Securities and Exchange Commission (the “SEC”), including, without limitation, the Company’s Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q. Except as required by law, the Company disclaims any obligation to update any forward-looking statements, whether as a result of new information, future events or otherwise. For further information about the Company’s business and financial results, please refer to the “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and “Risk Factors” sections of the Company’s SEC filings, including, but not limited to, its Annual Report on Form 10-K and Quarterly Reports on Form 10-Q, copies of which may be obtained at the Investors section of the Company’s website at www.agreerealty.com. Most information in this presentation is as of September 30, 2026, unless otherwise noted. The Company undertakes no duty to update the statements in this presentation to conform the statements to actual results or changes in the Company’s expectations.
44© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Glossary This presentation includes certain non‑GAAP financial measures and other defined terms. These non‑GAAP measures are presented as supplemental information and should not be considered in isolation or as a substitute for financial measures prepared in accordance with GAAP. Definitions of non‑GAAP measures, as well as certain GAAP and other financial and operating terms, are presented alphabetically below. AFFO Payout Ratio is calculated as common dividends per share divided by AFFO per share for the same period. The Company believes this measure is a useful supplemental indicator of dividend coverage and the sustainability of its dividend policy. This measure is not a substitute for measures prepared in accordance with GAAP, and the Company’s calculation may differ from similarly titled measures used by other companies. Annualized Base Rent (“ABR”) represents the annualized amount of contractual minimum rent required by tenant lease agreements, computed on a straight-line basis. ABR is not, and is not intended to be, a presentation in accordance with GAAP. The Company believes annualized contractual minimum rent is useful to management, investors, and other interested parties in analyzing concentrations and leasing activity. Components of Funds From Operations, Core FFO, and AFFO Funds from Operations (“FFO” or “Nareit FFO”) is defined by the National Association of Real Estate Investment Trusts, Inc. (“Nareit”) to mean net income computed in accordance with GAAP, excluding gains (or losses) from sales of real estate assets and/or changes in control, plus real estate related depreciation and amortization and any impairment charges on depreciable real estate assets, and after adjustments for unconsolidated partnerships and joint ventures. Historical cost accounting for real estate assets in accordance with GAAP implicitly assumes that the value of real estate assets diminishes predictably over time. Since real estate values instead have historically risen or fallen with market conditions, most real estate industry investors consider FFO to be helpful in evaluating a real estate company’s operations. FFO should not be considered an alternative to net income as the primary indicator of the Company’s operating performance, or as an alternative to cash flow as a measure of liquidity. Further, while the Company adheres to the Nareit definition of FFO, its presentation of FFO is not necessarily comparable to similarly titled measures of other REITs due to the fact that all REITs may not use the same definition. Core Funds from Operations (“Core FFO”) the Company defines Core FFO as Nareit FFO with the add-back of (i) noncash amortization of acquisition purchase price related to above- and below-market lease intangibles and discount on assumed debt and (ii) certain infrequently occurring items that reduce or increase net income in accordance with GAAP. Management believes that its measure of Core FFO facilitates useful comparison of performance to its peers who predominantly transact in sale-leaseback transactions and are thereby not required by GAAP to allocate purchase price to lease intangibles. Unlike many of its peers, the Company has acquired the substantial majority of its net-leased properties through acquisitions of properties from third parties or in connection with the acquisitions of ground leases from third parties. Core FFO should not be considered an alternative to net income as the primary indicator of the Company’s operating performance, or as an alternative to cash flow as a measure of liquidity. Further, the Company’s presentation of Core FFO is not necessarily comparable to similarly titled measures of other REITs due to the fact that all REITs may not use the same definition. Adjusted Funds from Operations (“AFFO”) is a non-GAAP financial measure of operating performance used by many companies in the REIT industry. AFFO further adjusts FFO and Core FFO for certain non-cash items that reduce or increase net income computed in accordance with GAAP. Management considers AFFO a useful supplemental measure of the Company’s performance, however, AFFO should not be considered an alternative to net income as an indication of its performance, or to cash flow as a measure of liquidity or ability to make distributions. The Company’s computation of AFFO may differ from the methodology for calculating AFFO used by other equity REITs, and therefore may not be comparable to such other REITs.
45© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Glossary Components of Net Debt to Recurring EBITDA EBITDAre is defined by Nareit to mean net income computed in accordance with GAAP, plus interest expense, income tax expense, depreciation and amortization, any gains (or losses) from sales of real estate assets and/or changes in control, any impairment charges on depreciable real estate assets, and after adjustments for unconsolidated partnerships and joint ventures. The Company considers the non-GAAP measure of EBITDAre to be a key supplemental measure of the Company's performance and should be considered along with, but not as an alternative to, net income or loss as a measure of the Company's operating performance. The Company considers EBITDAre a key supplemental measure of the Company's operating performance because it provides an additional supplemental measure of the Company's performance and operating cash flow that is widely known by industry analysts, lenders and investors. The Company’s calculation of EBITDAre may not be comparable to EBITDAre reported by other REITs that interpret the Nareit definition differently than the Company. Recurring EBITDA The Company defines Recurring EBITDA as EBITDAre with the add-back of noncash amortization of above- and below-market lease intangibles, and after adjustments for the run-rate impact of the Company's investment and disposition activity for the period presented, as well as adjustments for non-recurring benefits or expenses. The Company considers the non-GAAP measure of Recurring EBITDA to be a key supplemental measure of the Company's performance and should be considered along with, but not as an alternative to, net income or loss as a measure of the Company's operating performance. The Company considers Recurring EBITDA a key supplemental measure of the Company's operating performance because it represents the Company's earnings run rate for the period presented and because it is widely followed by industry analysts, lenders and investors. Our Recurring EBITDA may not be comparable to Recurring EBITDA reported by other companies that have a different interpretation of the definition of Recurring EBITDA. Our ratio of net debt to Recurring EBITDA is used by management as a measure of leverage and may be useful to investors in understanding the Company’s ability to service its debt, as well as assess the borrowing capacity of the Company. Our ratio of net debt to Recurring EBITDA is calculated by taking our net debt and dividing it by annualized Recurring EBITDA. Total Debt and Net Debt The Company defines Total Debt as debt per the consolidated balance sheet excluding unamortized debt issuance costs, original issue discounts and debt discounts. Net Debt is defined as Total Debt less cash, cash equivalents and cash held in escrow. The Company considers the non-GAAP measures of Total Debt and Net Debt to be key supplemental measures of the Company's overall liquidity, capital structure and leverage because they provide industry analysts, lenders and investors useful information in understanding our financial condition. The Company's calculation of Total Debt and Net Debt may not be comparable to Total Debt and Net Debt reported by other REITs that interpret the definitions differently than the Company. The Company presents Net Debt on both an actual and proforma basis, assuming the net proceeds of the Forward Offerings (see below) are used to pay down debt. The Company believes the proforma measure may be useful to investors in understanding the potential effect of the Forward Offerings on the Company's capital structure, its future borrowing capacity, and its ability to service its debt. Anticipated Net Proceeds from Outstanding Forwards Since the first quarter of 2018, the Company has utilized forward sale agreements to sell shares of common stock. Selling common stock through forward sale agreements enables the Company to set the price of such shares upon pricing the offering (subject to certain adjustments) while delaying the issuance of such shares and the receipt of the net proceeds by the Company. Given the Company’s frequent use of forward sale agreements, the Company considers the non-GAAP measure of Anticipated Net Proceeds from Outstanding Forwards to be a key supplemental measure of the Company's overall liquidity, capital structure and leverage. The Company defines Anticipated Net Proceeds from Outstanding Forwards as the number of shares outstanding under forward sale agreements at the end of each quarter, multiplied by the applicable forward sale price for each agreement, respectively. This is also referred to as Outstanding Forward Equity. Enterprise Value is calculated as the sum of net debt, the liquidation value of the Company’s preferred stock, and the market value of the Company’s outstanding shares of common stock, assuming the conversion of Agree Limited Partnership common units into common stock. Equity Market Capitalization represents the market value of the Company’s outstanding shares of common stock, calculated based on the closing price of the Company’s common stock on the NYSE on the date specified, and assuming the conversion of Agree Limited Partnership common units into common stock.
46© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. Glossary Fixed Charge Coverage Ratio is calculated as Trailing Twelve Month (“TTM”) Fixed Charge EBITDA divided by TTM Fixed Charges. TTM Fixed Charge EBITDA represents TTM EBITDA adjusted for straight‑line rent and capital expenditure adjustments, and TTM Fixed Charges consist of interest expense, preferred share dividend payments, and scheduled principal payments. The Company believes this measure is a useful supplemental indicator of its ability to service fixed financial obligations, though it is not a substitute for measures prepared in accordance with GAAP and may not be comparable to similarly titled measures used by other companies. Investment Type Classifications Acquisitions refer to the purchase of individual properties or portfolios by the Company. Acquisitions generally involve the acquisition of stabilized assets and require limited tenant improvements relative to the overall investment. Developments refer to projects in which the Company directly controls the development process, typically including land acquisition, lease negotiation, due diligence, design, and construction. Development projects typically involve ground‑up construction or significant redevelopment. Developer Funding Platform (“DFP”) transactions involve the Company partnering with developers or retailers, typically on in‑process development projects, and providing capital and development expertise. In DFP transactions, the Company generally does not lead the development process, but supports execution through funding and oversight. The Company owns the asset outright upon completion. Net Debt to Enterprise Value represents the ratio of the Company’s net debt to its Enterprise Value and is used to evaluate the Company’s capital structure and balance sheet leverage. Recapture Rate measures the percentage of annualized cash rent (for the first year of the lease, excluding free rent periods) achieved on leasing activity relative to the expiring lease's annualized cash rent. Retail Credit Type Investment Grade (“IG”) refers to ABR derived from tenants, or parent or subsidiary entities thereof, that have an investment grade credit rating from S&P Global Ratings, Moody’s Investors Service, Fitch Ratings, or the National Association of Insurance Commissioners (“NAIC”). Not Rated (“NR”) refers to ABR derived from tenants, or parent or subsidiary entities thereof, that do not have a credit rating from S&P Global Ratings, Moody’s Investors Service, Fitch Ratings, or the NAIC. Sub‑Investment Grade (“SIG”) refers to ABR derived from tenants, or parent or subsidiary entities thereof, that have a credit rating below investment grade from S&P Global Ratings, Moody’s Investors Service, Fitch Ratings, or the NAIC. Retail Tenant Type Franchise refers to tenants whose locations are owned and operated by franchisees, rather than directly by a corporate entity. National refers to tenants that operate a nationwide store footprint across multiple regions of the United States and generate revenue from a broadly diversified geographic base. Super‑Regional refers to tenants that operate a large, multi‑state store footprint, but whose operations are concentrated in specific regions of the United States rather than nationwide. Weighted-Average Capitalization Rate for acquisitions and dispositions, it is defined as the sum of contractual fixed annual rents computed on a straight- line basis over the primary lease terms and anticipated annual net tenant recoveries, divided by the purchase and sale prices for occupied properties. Weighted-Average Lease Term (“WALT”) represents the remaining contractual lease term of in‑place leases, weighted by ABR, and excludes vacant properties and lease extension options.
47© 2026 AGREE REALTY CORPORATION. ALL RIGHTS RESERVED. CONTACT PETER COUGHENOUR Chief Financial Officer (248) 737-4190 investors@agreerealty.com