
Q3 2026 Update
Overview Financial Summary Technology Capacity Distribution Shares Outstanding Financial Statements Additional Information
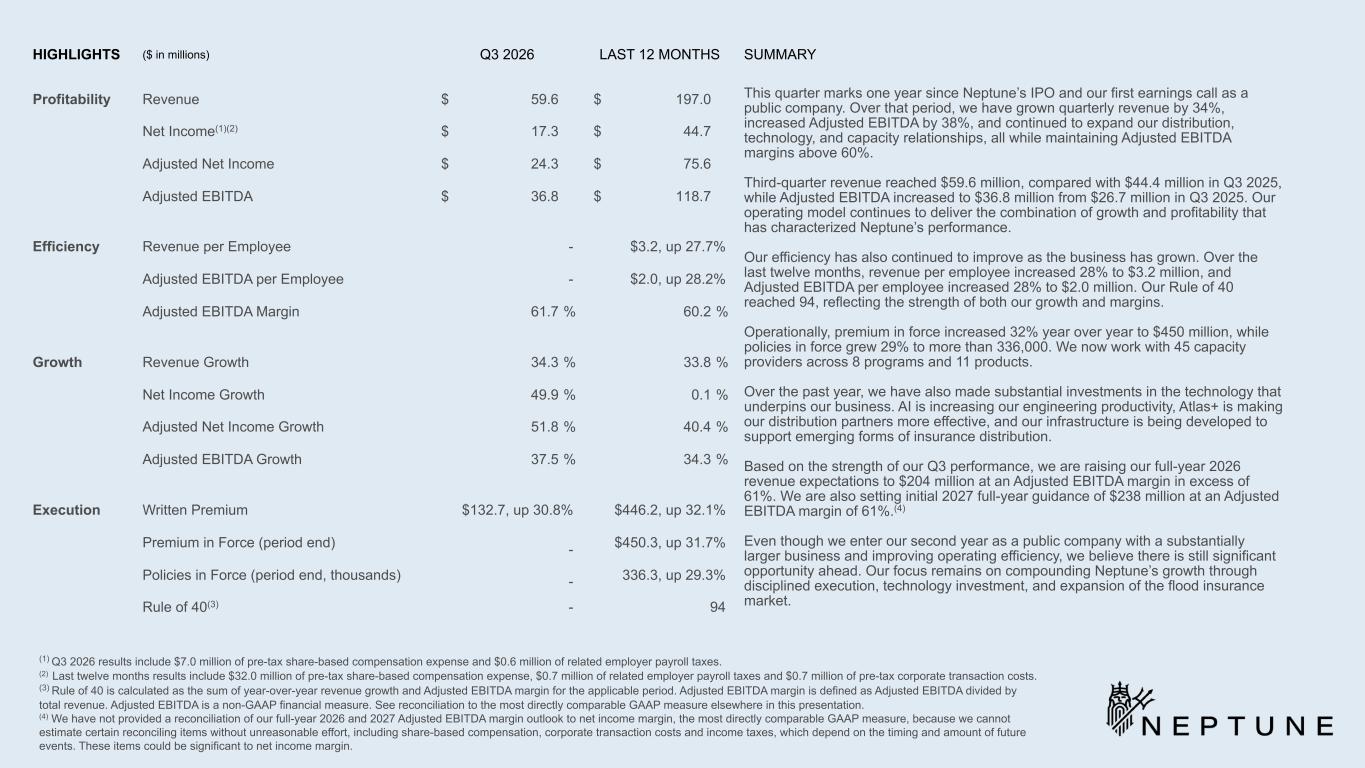
HIGHLIGHTS ($ in millions) Q3 2026 LAST 12 MONTHS SUMMARY Profitability Revenue $ 59.6 $ 197.0 This quarter marks one year since Neptune’s IPO and our first earnings call as a public company. Over that period, we have grown quarterly revenue by 34%, increased Adjusted EBITDA by 38%, and continued to expand our distribution, technology, and capacity relationships, all while maintaining Adjusted EBITDA margins above 60%. Third-quarter revenue reached $59.6 million, compared with $44.4 million in Q3 2025, while Adjusted EBITDA increased to $36.8 million from $26.7 million in Q3 2025. Our operating model continues to deliver the combination of growth and profitability that has characterized Neptune’s performance. Our efficiency has also continued to improve as the business has grown. Over the last twelve months, revenue per employee increased 28% to $3.2 million, and Adjusted EBITDA per employee increased 28% to $2.0 million. Our Rule of 40 reached 94, reflecting the strength of both our growth and margins. Operationally, premium in force increased 32% year over year to $450 million, while policies in force grew 29% to more than 336,000. We now work with 45 capacity providers across 8 programs and 11 products. Over the past year, we have also made substantial investments in the technology that underpins our business. AI is increasing our engineering productivity, Atlas+ is making our distribution partners more effective, and our infrastructure is being developed to support emerging forms of insurance distribution. Based on the strength of our Q3 performance, we are raising our full-year 2026 revenue expectations to $204 million at an Adjusted EBITDA margin in excess of 61%. We are also setting initial 2027 full-year guidance of $238 million at an Adjusted EBITDA margin of 61%.(4) Even though we enter our second year as a public company with a substantially larger business and improving operating efficiency, we believe there is still significant opportunity ahead. Our focus remains on compounding Neptune’s growth through disciplined execution, technology investment, and expansion of the flood insurance market. Net Income(1)(2) $ 17.3 $ 44.7 Adjusted Net Income $ 24.3 $ 75.6 Adjusted EBITDA $ 36.8 $ 118.7 Efficiency Revenue per Employee - $3.2, up 27.7% Adjusted EBITDA per Employee - $2.0, up 28.2% Adjusted EBITDA Margin 61.7 % 60.2 % Growth Revenue Growth 34.3 % 33.8 % Net Income Growth 49.9 % 0.1 % Adjusted Net Income Growth 51.8 % 40.4 % Adjusted EBITDA Growth 37.5 % 34.3 % Execution Written Premium $132.7, up 30.8% $446.2, up 32.1% Premium in Force (period end) - $450.3, up 31.7% Policies in Force (period end, thousands) - 336.3, up 29.3% Rule of 40(3) - 94 (1) Q3 2026 results include $7.0 million of pre-tax share-based compensation expense and $0.6 million of related employer payroll taxes. (2) Last twelve months results include $32.0 million of pre-tax share-based compensation expense, $0.7 million of related employer payroll taxes and $0.7 million of pre-tax corporate transaction costs. (3) Rule of 40 is calculated as the sum of year-over-year revenue growth and Adjusted EBITDA margin for the applicable period. Adjusted EBITDA margin is defined as Adjusted EBITDA divided by total revenue. Adjusted EBITDA is a non-GAAP financial measure. See reconciliation to the most directly comparable GAAP measure elsewhere in this presentation. (4) We have not provided a reconciliation of our full-year 2026 and 2027 Adjusted EBITDA margin outlook to net income margin, the most directly comparable GAAP measure, because we cannot estimate certain reconciling items without unreasonable effort, including share-based compensation, corporate transaction costs and income taxes, which depend on the timing and amount of future events. These items could be significant to net income margin.
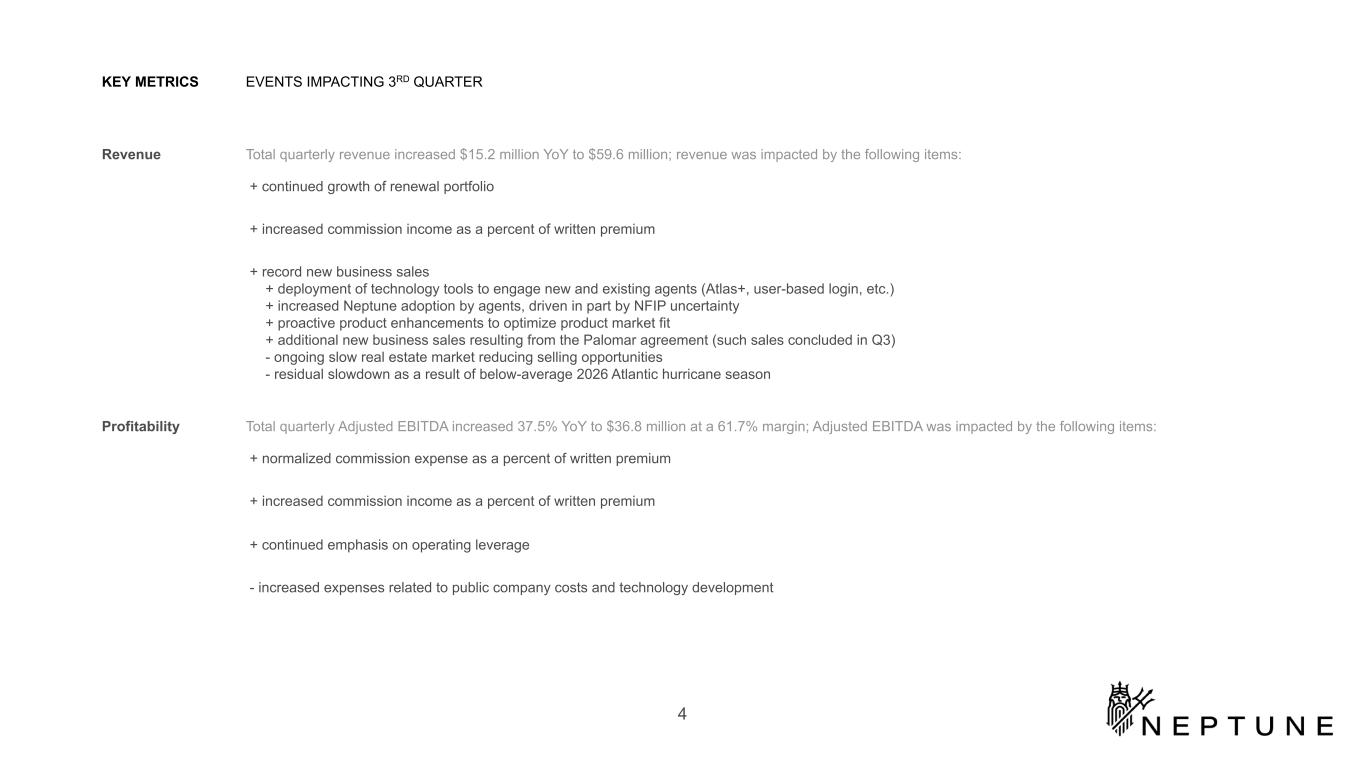
KEY METRICS EVENTS IMPACTING 3RD QUARTER Revenue Total quarterly revenue increased $15.2 million YoY to $59.6 million; revenue was impacted by the following items: + continued growth of renewal portfolio + increased commission income as a percent of written premium + record new business sales + deployment of technology tools to engage new and existing agents (Atlas+, user-based login, etc.) + increased Neptune adoption by agents, driven in part by NFIP uncertainty + proactive product enhancements to optimize product market fit + additional new business sales resulting from the Palomar agreement (such sales concluded in Q3) - ongoing slow real estate market reducing selling opportunities - residual slowdown as a result of below-average 2026 Atlantic hurricane season Profitability Total quarterly Adjusted EBITDA increased 37.5% YoY to $36.8 million at a 61.7% margin; Adjusted EBITDA was impacted by the following items: + normalized commission expense as a percent of written premium + increased commission income as a percent of written premium + continued emphasis on operating leverage - increased expenses related to public company costs and technology development 4
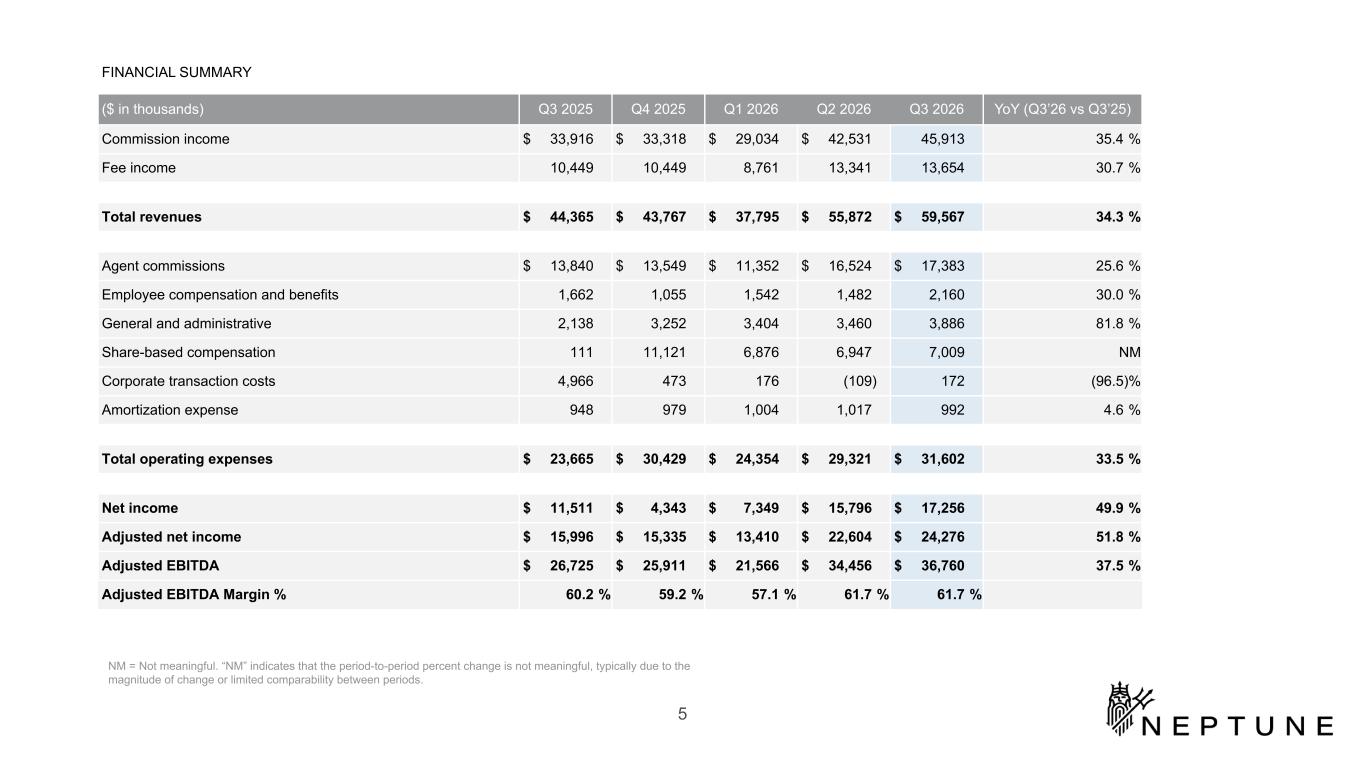
FINANCIAL SUMMARY ($ in thousands) Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 YoY (Q3’26 vs Q3’25) Commission income $ 33,916 $ 33,318 $ 29,034 $ 42,531 45,913 35.4 % Fee income 10,449 10,449 8,761 13,341 13,654 30.7 % Total revenues $ 44,365 $ 43,767 $ 37,795 $ 55,872 $ 59,567 34.3 % Agent commissions $ 13,840 $ 13,549 $ 11,352 $ 16,524 $ 17,383 25.6 % Employee compensation and benefits 1,662 1,055 1,542 1,482 2,160 30.0 % General and administrative 2,138 3,252 3,404 3,460 3,886 81.8 % Share-based compensation 111 11,121 6,876 6,947 7,009 NM Corporate transaction costs 4,966 473 176 (109) 172 (96.5) % Amortization expense 948 979 1,004 1,017 992 4.6 % Total operating expenses $ 23,665 $ 30,429 $ 24,354 $ 29,321 $ 31,602 33.5 % Net income $ 11,511 $ 4,343 $ 7,349 $ 15,796 $ 17,256 49.9 % Adjusted net income $ 15,996 $ 15,335 $ 13,410 $ 22,604 $ 24,276 51.8 % Adjusted EBITDA $ 26,725 $ 25,911 $ 21,566 $ 34,456 $ 36,760 37.5 % Adjusted EBITDA Margin % 60.2 % 59.2 % 57.1 % 61.7 % 61.7 % 5 NM = Not meaningful. “NM” indicates that the period-to-period percent change is not meaningful, typically due to the magnitude of change or limited comparability between periods.
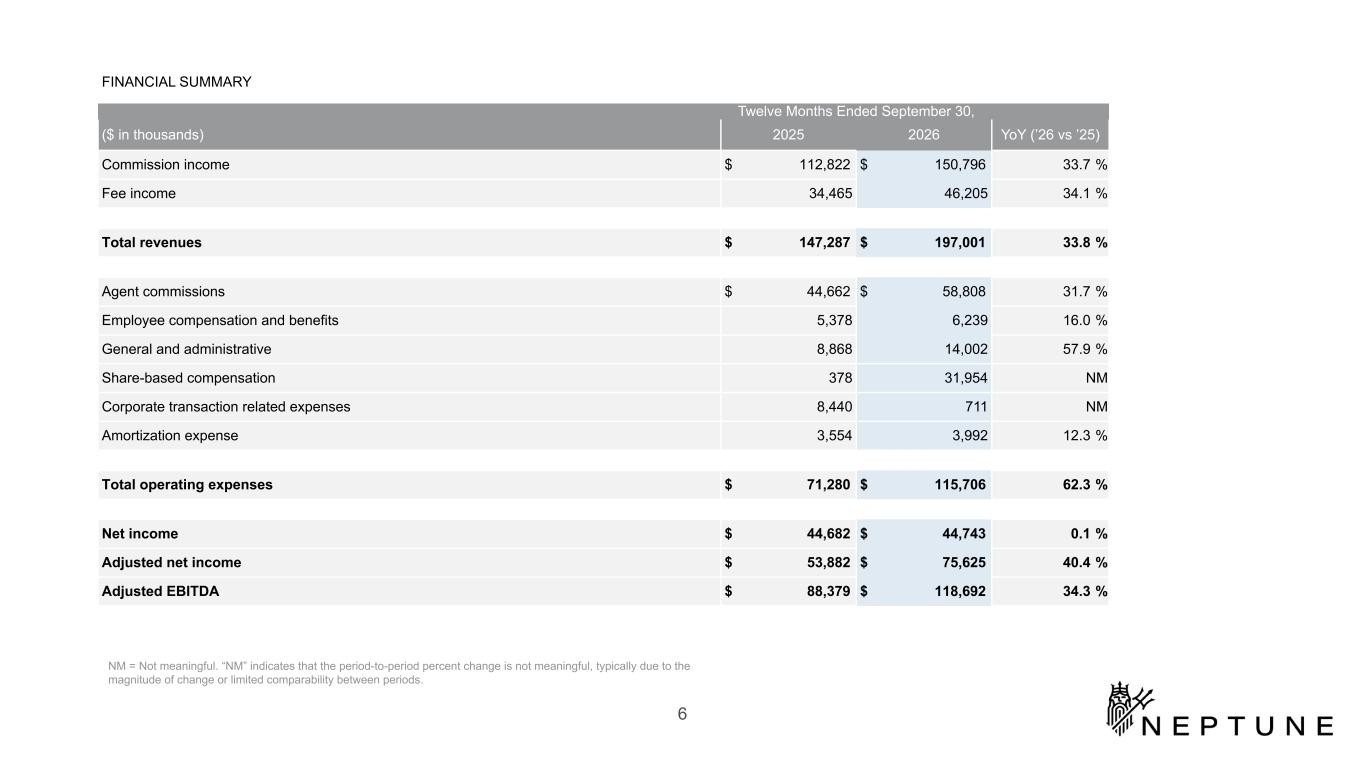
FINANCIAL SUMMARY Twelve Months Ended September 30, ($ in thousands) 2025 2026 YoY (’26 vs ’25) Commission income $ 112,822 $ 150,796 33.7 % Fee income 34,465 46,205 34.1 % Total revenues $ 147,287 $ 197,001 33.8 % Agent commissions $ 44,662 $ 58,808 31.7 % Employee compensation and benefits 5,378 6,239 16.0 % General and administrative 8,868 14,002 57.9 % Share-based compensation 378 31,954 NM Corporate transaction related expenses 8,440 711 NM Amortization expense 3,554 3,992 12.3 % Total operating expenses $ 71,280 $ 115,706 62.3 % Net income $ 44,682 $ 44,743 0.1 % Adjusted net income $ 53,882 $ 75,625 40.4 % Adjusted EBITDA $ 88,379 $ 118,692 34.3 % 6 NM = Not meaningful. “NM” indicates that the period-to-period percent change is not meaningful, typically due to the magnitude of change or limited comparability between periods.
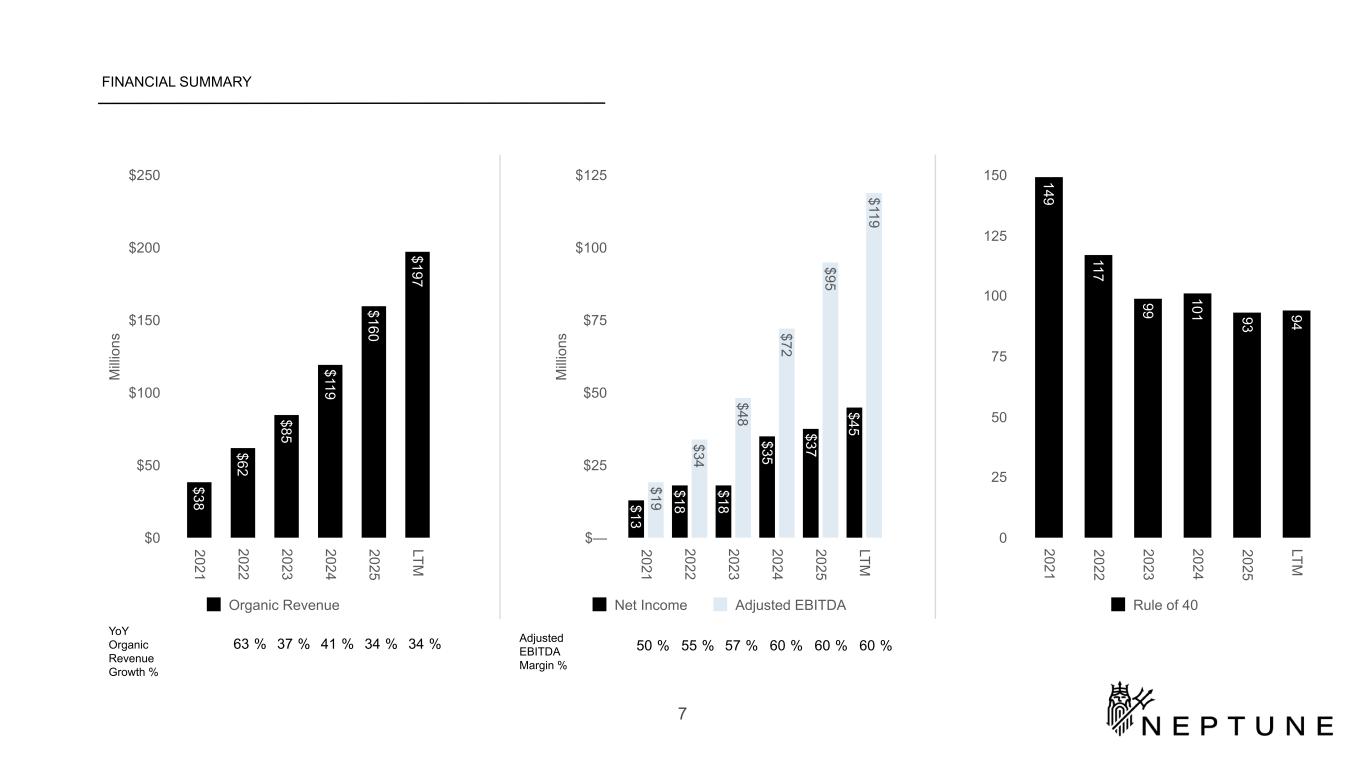
FINANCIAL SUMMARY M illi on s $13 $18 $18 $35 $37 $45 $19 $34 $48 $72 $95 $119 Net Income Adjusted EBITDA 2021 2022 2023 2024 2025 LTM $— $25 $50 $75 $100 $125 149 117 99 101 93 94 Rule of 40 2021 2022 2023 2024 2025 LTM 0 25 50 75 100 125 150 50 % 55 % 57 % 60 % 60 % 60 %Adjusted EBITDA Margin % YoY Organic Revenue Growth % 7 63 % 37 % 41 % 34 % 34 % M illi on s $38 $62 $85 $119 $160 $197 Organic Revenue 2021 2022 2023 2024 2025 LTM $0 $50 $100 $150 $200 $250
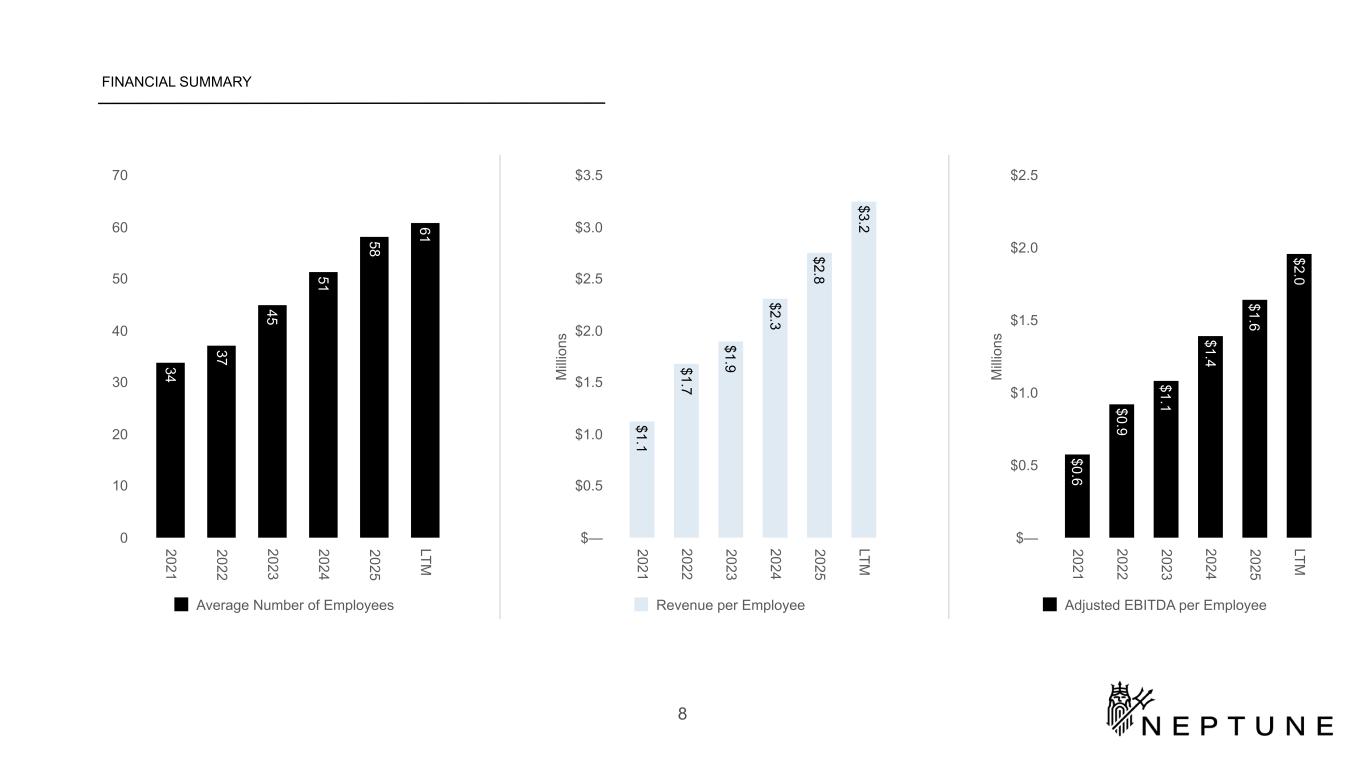
FINANCIAL SUMMARY 34 37 45 51 58 61 Average Number of Employees 2021 2022 2023 2024 2025 LTM 0 10 20 30 40 50 60 70 M illi on s $1.1 $1.7 $1.9 $2.3 $2.8 $3.2 Revenue per Employee 2021 2022 2023 2024 2025 LTM $— $0.5 $1.0 $1.5 $2.0 $2.5 $3.0 $3.5 M illi on s $0.6 $0.9 $1.1 $1.4 $1.6 $2.0 Adjusted EBITDA per Employee 2021 2022 2023 2024 2025 LTM $— $0.5 $1.0 $1.5 $2.0 $2.5 8
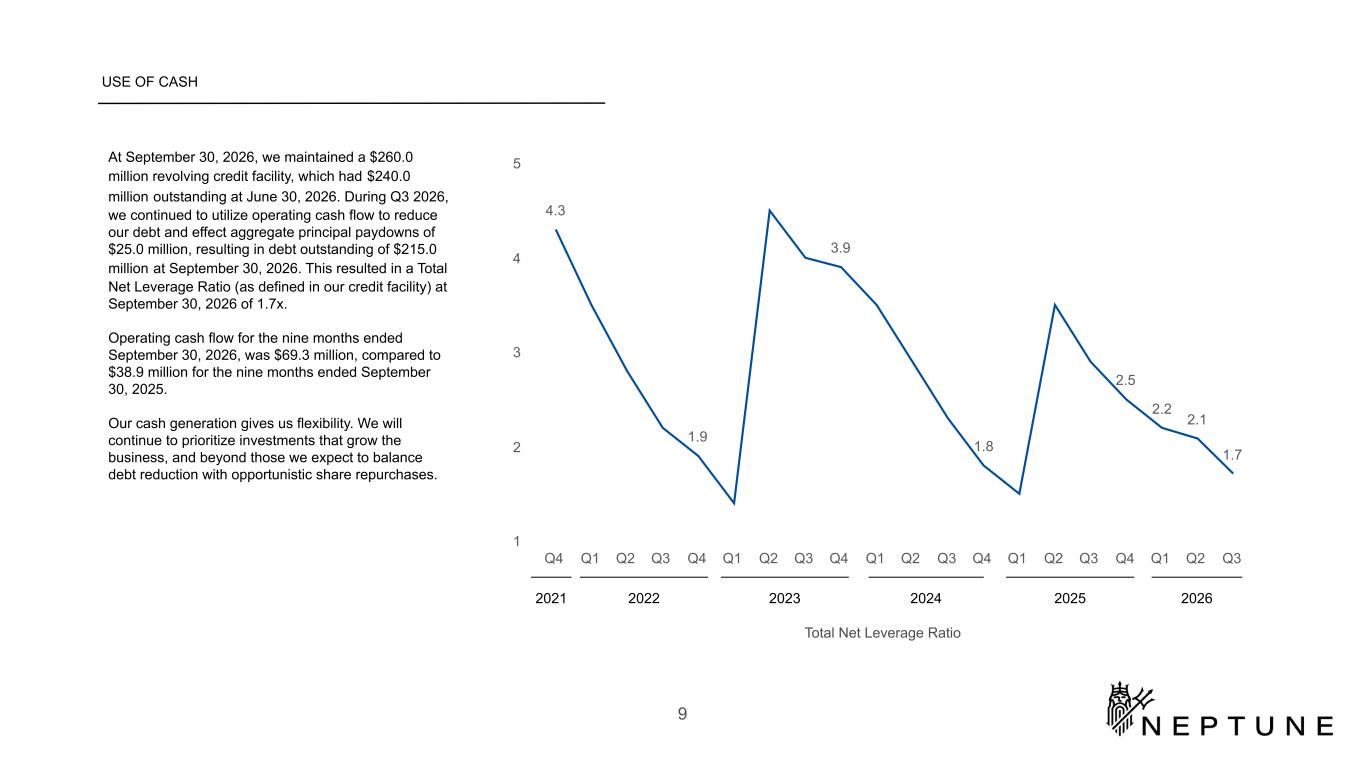
USE OF CASH At September 30, 2026, we maintained a $260.0 million revolving credit facility, which had $240.0 million outstanding at June 30, 2026. During Q3 2026, we continued to utilize operating cash flow to reduce our debt and effect aggregate principal paydowns of $25.0 million, resulting in debt outstanding of $215.0 million at September 30, 2026. This resulted in a Total Net Leverage Ratio (as defined in our credit facility) at September 30, 2026 of 1.7x. Operating cash flow for the nine months ended September 30, 2026, was $69.3 million, compared to $38.9 million for the nine months ended September 30, 2025. Our cash generation gives us flexibility. We will continue to prioritize investments that grow the business, and beyond those we expect to balance debt reduction with opportunistic share repurchases. 4.3 1.9 3.9 1.8 2.5 2.2 2.1 1.7 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 1 2 3 4 5 2021 2022 2023 2024 2025 Total Net Leverage Ratio 9 2026

Operations
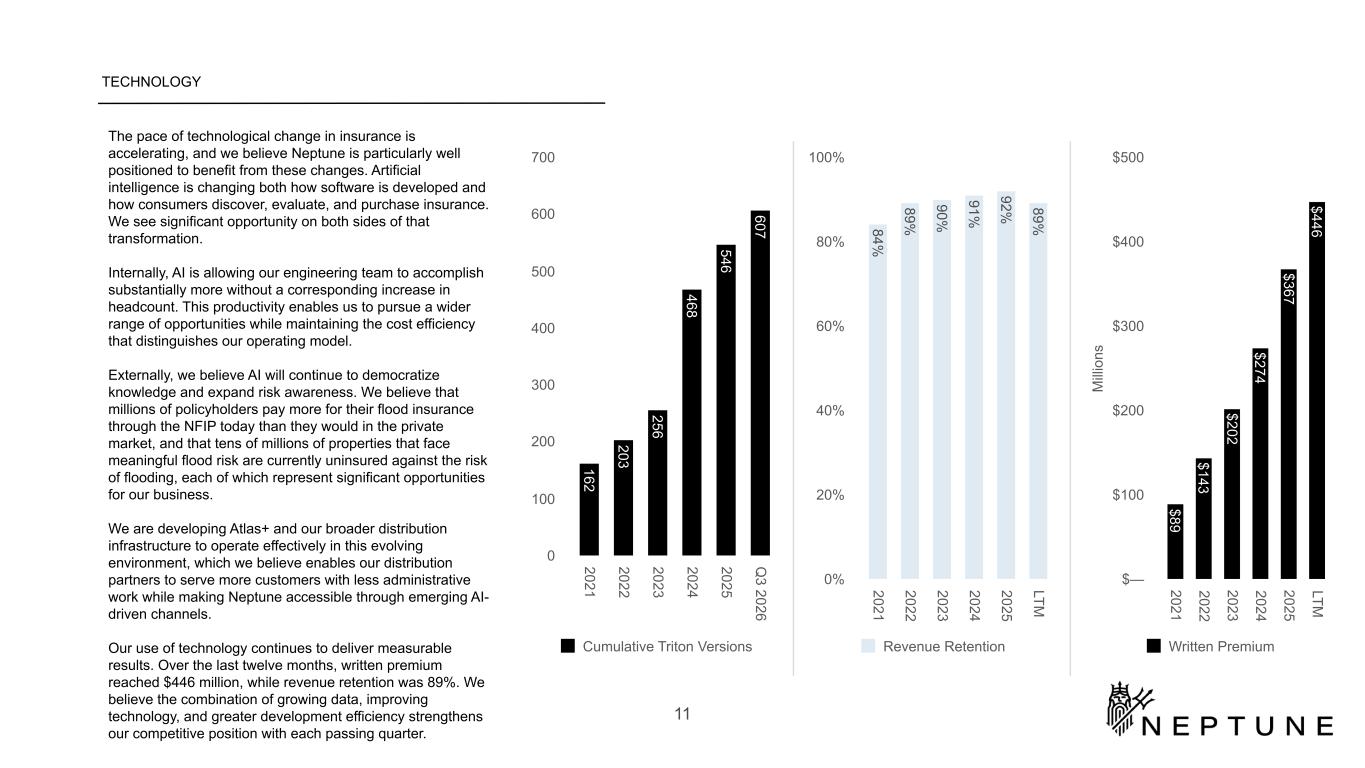
TECHNOLOGY The pace of technological change in insurance is accelerating, and we believe Neptune is particularly well positioned to benefit from these changes. Artificial intelligence is changing both how software is developed and how consumers discover, evaluate, and purchase insurance. We see significant opportunity on both sides of that transformation. Internally, AI is allowing our engineering team to accomplish substantially more without a corresponding increase in headcount. This productivity enables us to pursue a wider range of opportunities while maintaining the cost efficiency that distinguishes our operating model. Externally, we believe AI will continue to democratize knowledge and expand risk awareness. We believe that millions of policyholders pay more for their flood insurance through the NFIP today than they would in the private market, and that tens of millions of properties that face meaningful flood risk are currently uninsured against the risk of flooding, each of which represent significant opportunities for our business. We are developing Atlas+ and our broader distribution infrastructure to operate effectively in this evolving environment, which we believe enables our distribution partners to serve more customers with less administrative work while making Neptune accessible through emerging AI- driven channels. Our use of technology continues to deliver measurable results. Over the last twelve months, written premium reached $446 million, while revenue retention was 89%. We believe the combination of growing data, improving technology, and greater development efficiency strengthens our competitive position with each passing quarter. 162 203 256 468 546 607 Cumulative Triton Versions 2021 2022 2023 2024 2025 Q 3 2026 0 100 200 300 400 500 600 700 84% 89% 90% 91% 92% 89% Revenue Retention 2021 2022 2023 2024 2025 LTM 0% 20% 40% 60% 80% 100% M ill io ns $89 $143 $202 $274 $367 $446 Written Premium 2021 2022 2023 2024 2025 LTM $— $100 $200 $300 $400 $500 11
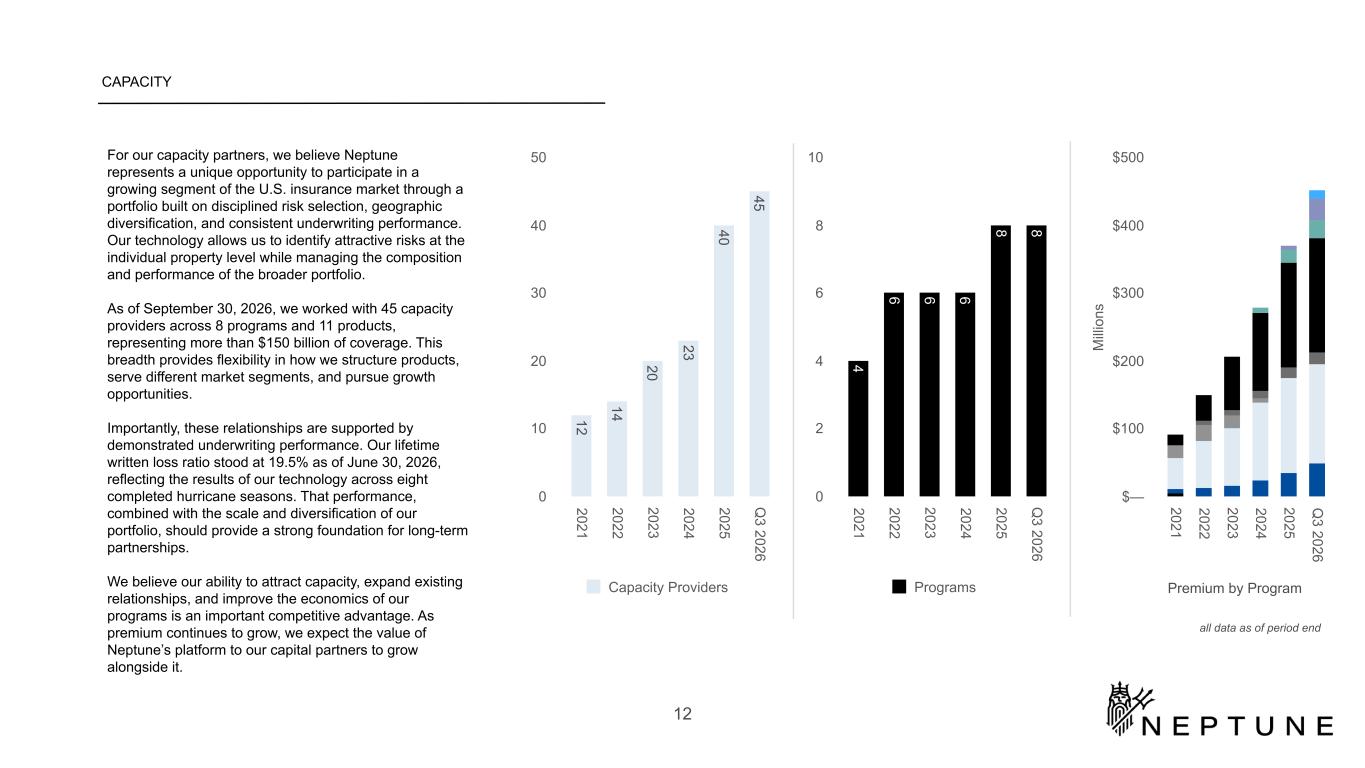
CAPACITY For our capacity partners, we believe Neptune represents a unique opportunity to participate in a growing segment of the U.S. insurance market through a portfolio built on disciplined risk selection, geographic diversification, and consistent underwriting performance. Our technology allows us to identify attractive risks at the individual property level while managing the composition and performance of the broader portfolio. As of September 30, 2026, we worked with 45 capacity providers across 8 programs and 11 products, representing more than $150 billion of coverage. This breadth provides flexibility in how we structure products, serve different market segments, and pursue growth opportunities. Importantly, these relationships are supported by demonstrated underwriting performance. Our lifetime written loss ratio stood at 19.5% as of June 30, 2026, reflecting the results of our technology across eight completed hurricane seasons. That performance, combined with the scale and diversification of our portfolio, should provide a strong foundation for long-term partnerships. We believe our ability to attract capacity, expand existing relationships, and improve the economics of our programs is an important competitive advantage. As premium continues to grow, we expect the value of Neptune’s platform to our capital partners to grow alongside it. Premium by Program 12 14 20 23 40 45 Capacity Providers 2021 2022 2023 2024 2025 Q 3 2026 0 10 20 30 40 50 4 6 6 6 8 8 Programs 2021 2022 2023 2024 2025 Q 3 2026 0 2 4 6 8 10 M illi on s $4 $— $—2021 2022 2023 2024 2025 Q 3 2026 $— $100 $200 $300 $400 $500 12 all data as of period end
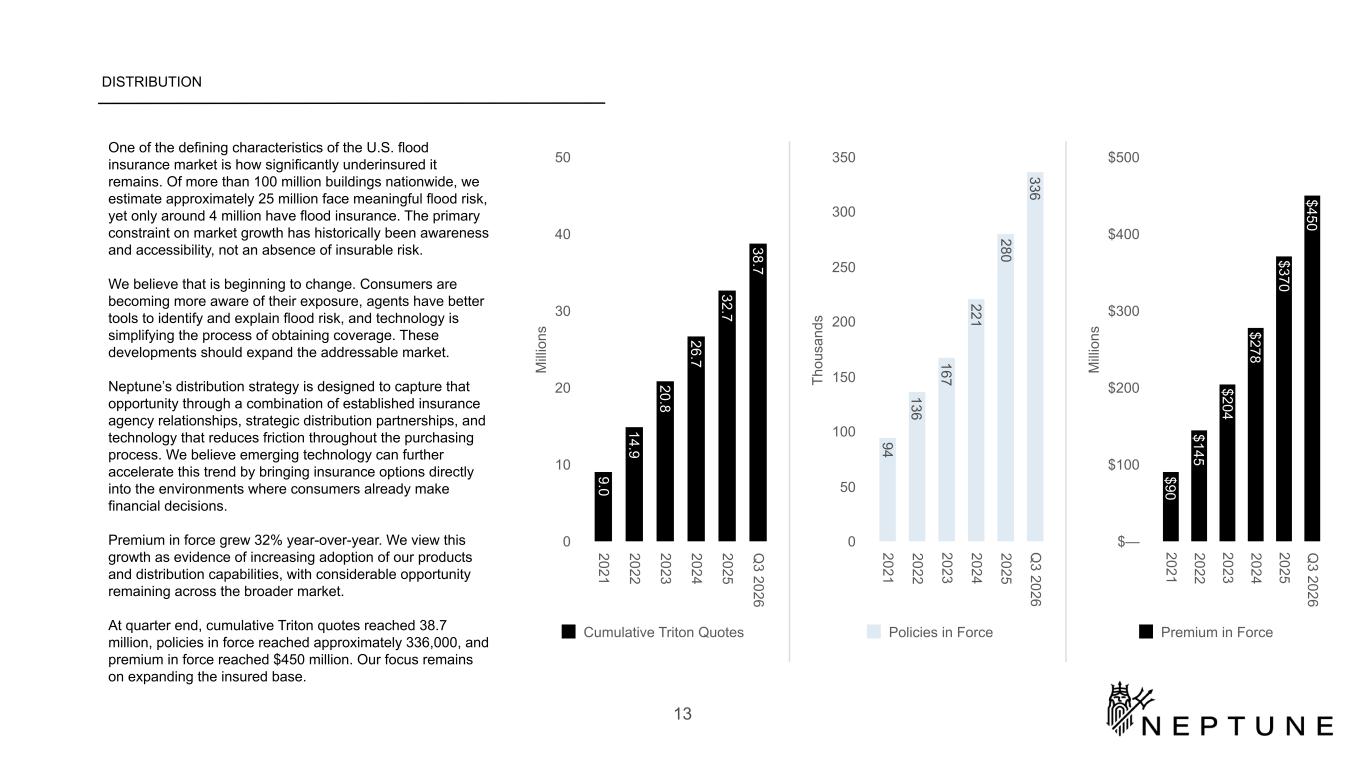
DISTRIBUTION One of the defining characteristics of the U.S. flood insurance market is how significantly underinsured it remains. Of more than 100 million buildings nationwide, we estimate approximately 25 million face meaningful flood risk, yet only around 4 million have flood insurance. The primary constraint on market growth has historically been awareness and accessibility, not an absence of insurable risk. We believe that is beginning to change. Consumers are becoming more aware of their exposure, agents have better tools to identify and explain flood risk, and technology is simplifying the process of obtaining coverage. These developments should expand the addressable market. Neptune’s distribution strategy is designed to capture that opportunity through a combination of established insurance agency relationships, strategic distribution partnerships, and technology that reduces friction throughout the purchasing process. We believe emerging technology can further accelerate this trend by bringing insurance options directly into the environments where consumers already make financial decisions. Premium in force grew 32% year-over-year. We view this growth as evidence of increasing adoption of our products and distribution capabilities, with considerable opportunity remaining across the broader market. At quarter end, cumulative Triton quotes reached 38.7 million, policies in force reached approximately 336,000, and premium in force reached $450 million. Our focus remains on expanding the insured base. M ill io ns $90 $145 $204 $278 $370 $450 Premium in Force 2021 2022 2023 2024 2025 Q 3 2026 $— $100 $200 $300 $400 $500 Th ou sa nd s 94 136 167 221 280 336 Policies in Force 2021 2022 2023 2024 2025 Q 3 2026 0 50 100 150 200 250 300 350 M ill io ns 9.0 14.9 20.8 26.7 32.7 38.7 Cumulative Triton Quotes 2021 2022 2023 2024 2025 Q 3 2026 0 10 20 30 40 50 13
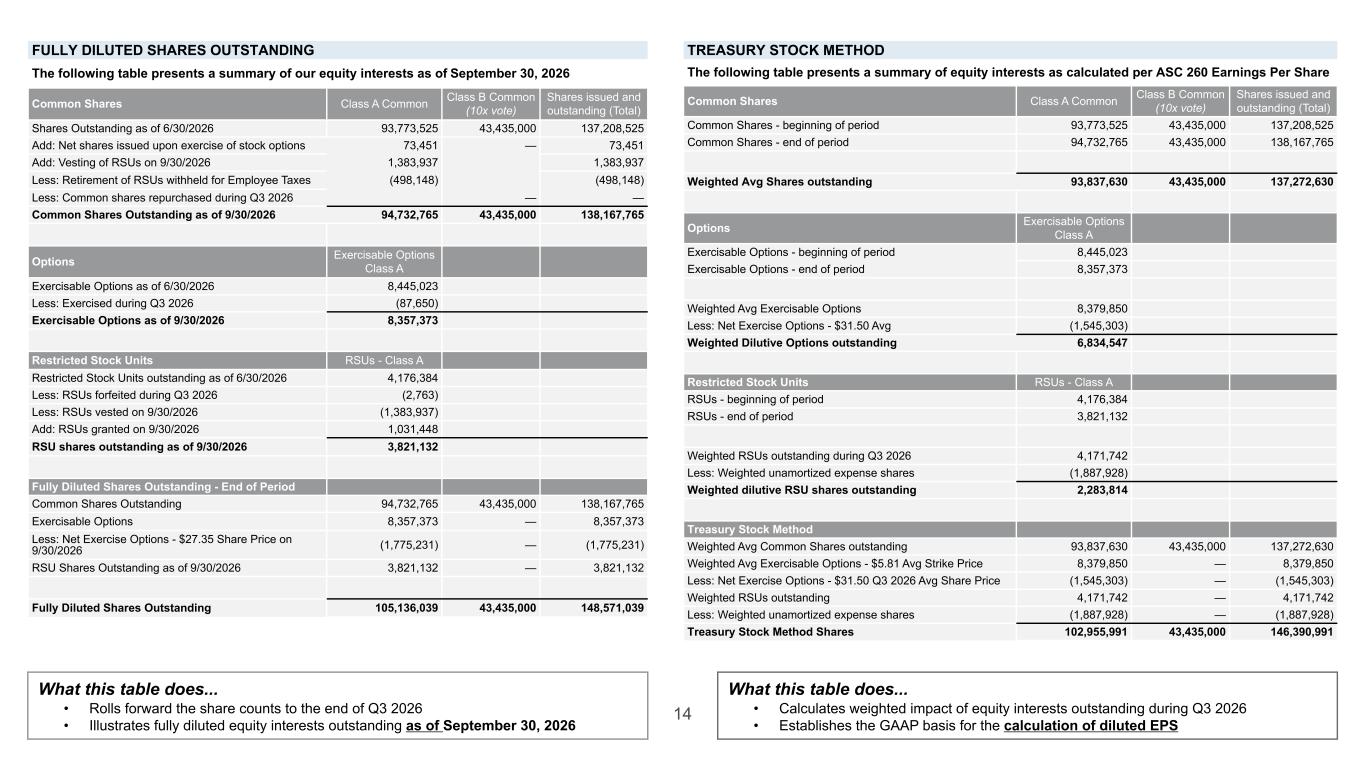
FULLY DILUTED SHARES OUTSTANDING The following table presents a summary of our equity interests as of September 30, 2026 Common Shares Class A Common Class B Common (10x vote) Shares issued and outstanding (Total) Shares Outstanding as of 6/30/2026 93,773,525 43,435,000 137,208,525 Add: Net shares issued upon exercise of stock options 73,451 — 73,451 Add: Vesting of RSUs on 9/30/2026 1,383,937 1,383,937 Less: Retirement of RSUs withheld for Employee Taxes (498,148) (498,148) Less: Common shares repurchased during Q3 2026 — — Common Shares Outstanding as of 9/30/2026 94,732,765 43,435,000 138,167,765 Options Exercisable Options Class A Exercisable Options as of 6/30/2026 8,445,023 Less: Exercised during Q3 2026 (87,650) Exercisable Options as of 9/30/2026 8,357,373 Restricted Stock Units RSUs - Class A Restricted Stock Units outstanding as of 6/30/2026 4,176,384 Less: RSUs forfeited during Q3 2026 (2,763) Less: RSUs vested on 9/30/2026 (1,383,937) Add: RSUs granted on 9/30/2026 1,031,448 RSU shares outstanding as of 9/30/2026 3,821,132 Fully Diluted Shares Outstanding - End of Period Common Shares Outstanding 94,732,765 43,435,000 138,167,765 Exercisable Options 8,357,373 — 8,357,373 Less: Net Exercise Options - $27.35 Share Price on 9/30/2026 (1,775,231) — (1,775,231) RSU Shares Outstanding as of 9/30/2026 3,821,132 — 3,821,132 Fully Diluted Shares Outstanding 105,136,039 43,435,000 148,571,039 14 What this table does... • Rolls forward the share counts to the end of Q3 2026 • Illustrates fully diluted equity interests outstanding as of September 30, 2026 What this table does... • Calculates weighted impact of equity interests outstanding during Q3 2026 • Establishes the GAAP basis for the calculation of diluted EPS TREASURY STOCK METHOD The following table presents a summary of equity interests as calculated per ASC 260 Earnings Per Share Common Shares Class A Common Class B Common (10x vote) Shares issued and outstanding (Total) Common Shares - beginning of period 93,773,525 43,435,000 137,208,525 Common Shares - end of period 94,732,765 43,435,000 138,167,765 Weighted Avg Shares outstanding 93,837,630 43,435,000 137,272,630 Options Exercisable Options Class A Exercisable Options - beginning of period 8,445,023 Exercisable Options - end of period 8,357,373 Weighted Avg Exercisable Options 8,379,850 Less: Net Exercise Options - $31.50 Avg (1,545,303) Weighted Dilutive Options outstanding 6,834,547 Restricted Stock Units RSUs - Class A RSUs - beginning of period 4,176,384 RSUs - end of period 3,821,132 Weighted RSUs outstanding during Q3 2026 4,171,742 Less: Weighted unamortized expense shares (1,887,928) Weighted dilutive RSU shares outstanding 2,283,814 Treasury Stock Method Weighted Avg Common Shares outstanding 93,837,630 43,435,000 137,272,630 Weighted Avg Exercisable Options - $5.81 Avg Strike Price 8,379,850 — 8,379,850 Less: Net Exercise Options - $31.50 Q3 2026 Avg Share Price (1,545,303) — (1,545,303) Weighted RSUs outstanding 4,171,742 — 4,171,742 Less: Weighted unamortized expense shares (1,887,928) — (1,887,928) Treasury Stock Method Shares 102,955,991 43,435,000 146,390,991

Financial Statements
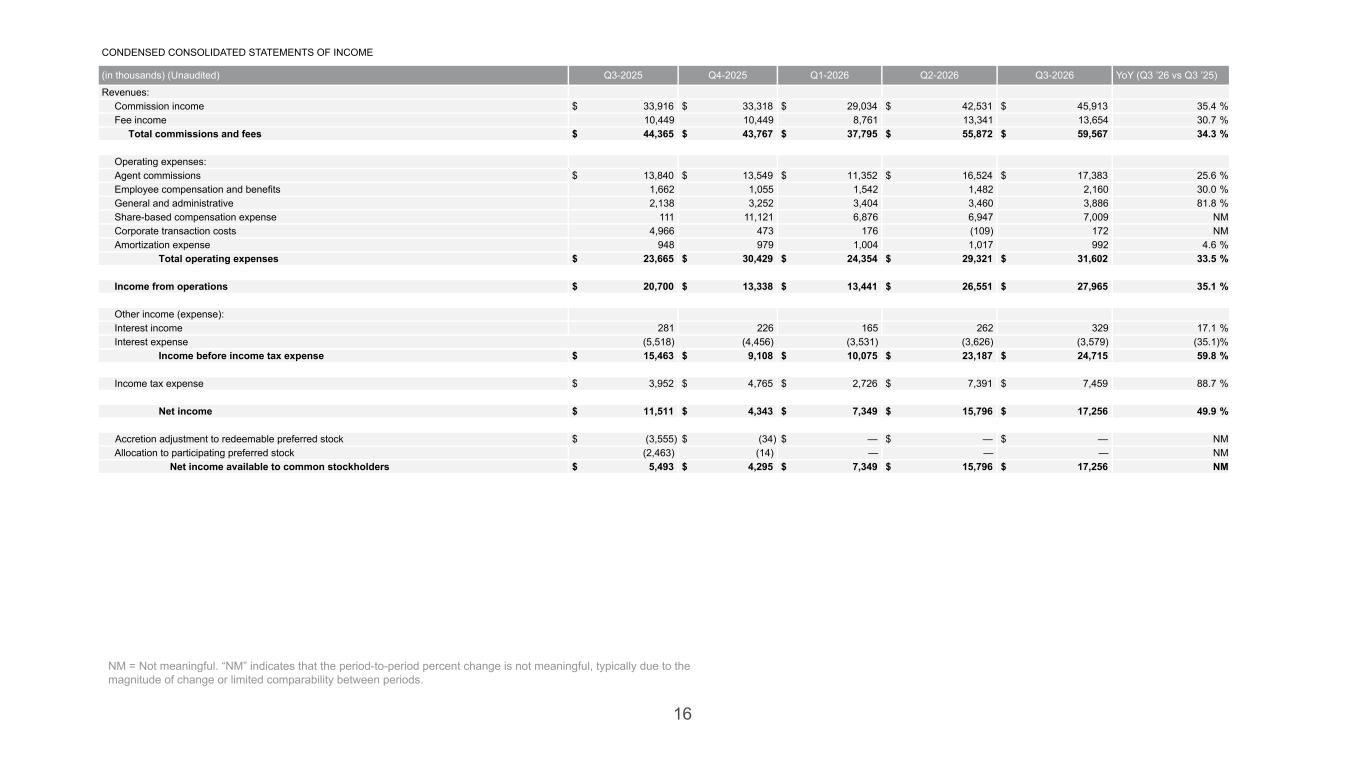
CONDENSED CONSOLIDATED STATEMENTS OF INCOME (in thousands) (Unaudited) Q3-2025 Q4-2025 Q1-2026 Q2-2026 Q3-2026 YoY (Q3 ’26 vs Q3 ’25) Revenues: Commission income $ 33,916 $ 33,318 $ 29,034 $ 42,531 $ 45,913 35.4 % Fee income 10,449 10,449 8,761 13,341 13,654 30.7 % Total commissions and fees $ 44,365 $ 43,767 $ 37,795 $ 55,872 $ 59,567 34.3 % Operating expenses: Agent commissions $ 13,840 $ 13,549 $ 11,352 $ 16,524 $ 17,383 25.6 % Employee compensation and benefits 1,662 1,055 1,542 1,482 2,160 30.0 % General and administrative 2,138 3,252 3,404 3,460 3,886 81.8 % Share-based compensation expense 111 11,121 6,876 6,947 7,009 NM Corporate transaction costs 4,966 473 176 (109) 172 NM Amortization expense 948 979 1,004 1,017 992 4.6 % Total operating expenses $ 23,665 $ 30,429 $ 24,354 $ 29,321 $ 31,602 33.5 % Income from operations $ 20,700 $ 13,338 $ 13,441 $ 26,551 $ 27,965 35.1 % Other income (expense): Interest income 281 226 165 262 329 17.1 % Interest expense (5,518) (4,456) (3,531) (3,626) (3,579) (35.1) % Income before income tax expense $ 15,463 $ 9,108 $ 10,075 $ 23,187 $ 24,715 59.8 % Income tax expense $ 3,952 $ 4,765 $ 2,726 $ 7,391 $ 7,459 88.7 % Net income $ 11,511 $ 4,343 $ 7,349 $ 15,796 $ 17,256 49.9 % Accretion adjustment to redeemable preferred stock $ (3,555) $ (34) $ — $ — $ — NM Allocation to participating preferred stock (2,463) (14) — — — NM Net income available to common stockholders $ 5,493 $ 4,295 $ 7,349 $ 15,796 $ 17,256 NM 16 NM = Not meaningful. “NM” indicates that the period-to-period percent change is not meaningful, typically due to the magnitude of change or limited comparability between periods.
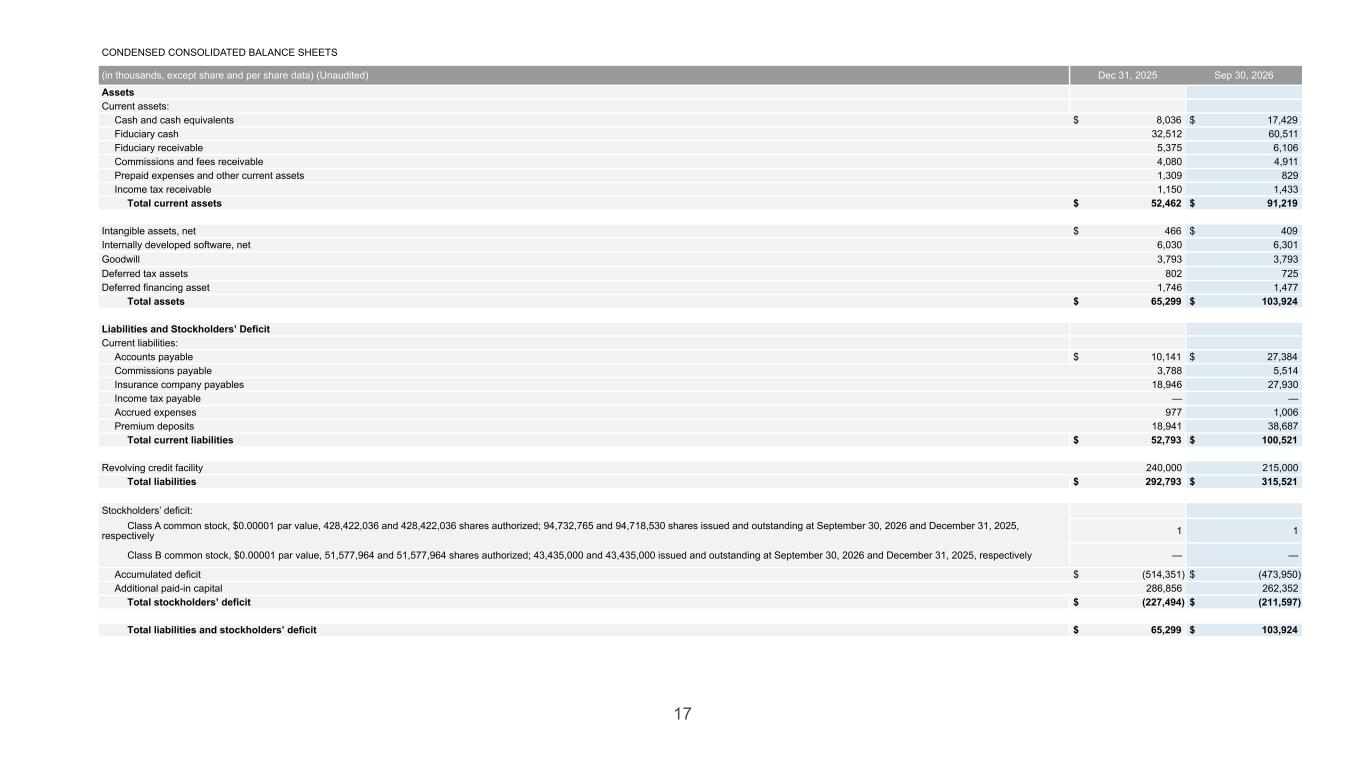
CONDENSED CONSOLIDATED BALANCE SHEETS (in thousands, except share and per share data) (Unaudited) Dec 31, 2025 Sep 30, 2026 Assets Current assets: Cash and cash equivalents $ 8,036 $ 17,429 Fiduciary cash 32,512 60,511 Fiduciary receivable 5,375 6,106 Commissions and fees receivable 4,080 4,911 Prepaid expenses and other current assets 1,309 829 Income tax receivable 1,150 1,433 Total current assets $ 52,462 $ 91,219 Intangible assets, net $ 466 $ 409 Internally developed software, net 6,030 6,301 Goodwill 3,793 3,793 Deferred tax assets 802 725 Deferred financing asset 1,746 1,477 Total assets $ 65,299 $ 103,924 Liabilities and Stockholders’ Deficit Current liabilities: Accounts payable $ 10,141 $ 27,384 Commissions payable 3,788 5,514 Insurance company payables 18,946 27,930 Income tax payable — — Accrued expenses 977 1,006 Premium deposits 18,941 38,687 Total current liabilities $ 52,793 $ 100,521 Revolving credit facility 240,000 215,000 Total liabilities $ 292,793 $ 315,521 Stockholders’ deficit: Class A common stock, $0.00001 par value, 428,422,036 and 428,422,036 shares authorized; 94,732,765 and 94,718,530 shares issued and outstanding at September 30, 2026 and December 31, 2025, respectively 1 1 Class B common stock, $0.00001 par value, 51,577,964 and 51,577,964 shares authorized; 43,435,000 and 43,435,000 issued and outstanding at September 30, 2026 and December 31, 2025, respectively — — Accumulated deficit $ (514,351) $ (473,950) Additional paid-in capital 286,856 262,352 Total stockholders’ deficit $ (227,494) $ (211,597) Total liabilities and stockholders’ deficit $ 65,299 $ 103,924 17
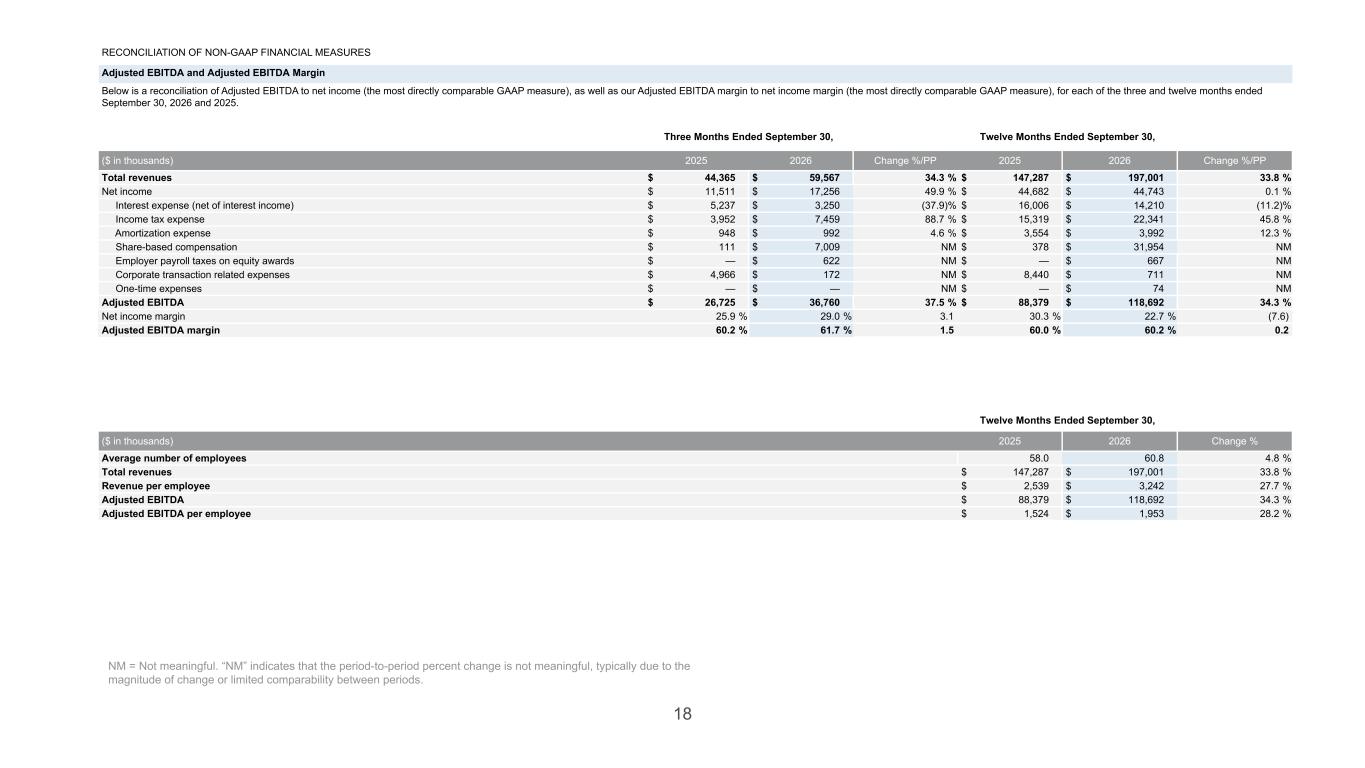
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES Adjusted EBITDA and Adjusted EBITDA Margin Below is a reconciliation of Adjusted EBITDA to net income (the most directly comparable GAAP measure), as well as our Adjusted EBITDA margin to net income margin (the most directly comparable GAAP measure), for each of the three and twelve months ended September 30, 2026 and 2025. Three Months Ended September 30, Twelve Months Ended September 30, ($ in thousands) 2025 2026 Change %/PP 2025 2026 Change %/PP Total revenues $ 44,365 $ 59,567 34.3 % $ 147,287 $ 197,001 33.8 % Net income $ 11,511 $ 17,256 49.9 % $ 44,682 $ 44,743 0.1 % Interest expense (net of interest income) $ 5,237 $ 3,250 (37.9) % $ 16,006 $ 14,210 (11.2) % Income tax expense $ 3,952 $ 7,459 88.7 % $ 15,319 $ 22,341 45.8 % Amortization expense $ 948 $ 992 4.6 % $ 3,554 $ 3,992 12.3 % Share-based compensation $ 111 $ 7,009 NM $ 378 $ 31,954 NM Employer payroll taxes on equity awards $ — $ 622 NM $ — $ 667 NM Corporate transaction related expenses $ 4,966 $ 172 NM $ 8,440 $ 711 NM One-time expenses $ — $ — NM $ — $ 74 NM Adjusted EBITDA $ 26,725 $ 36,760 37.5 % $ 88,379 $ 118,692 34.3 % Net income margin 25.9 % 29.0 % 3.1 30.3 % 22.7 % (7.6) Adjusted EBITDA margin 60.2 % 61.7 % 1.5 60.0 % 60.2 % 0.2 Twelve Months Ended September 30, ($ in thousands) 2025 2026 Change % Average number of employees 58.0 60.8 4.8 % Total revenues $ 147,287 $ 197,001 33.8 % Revenue per employee $ 2,539 $ 3,242 27.7 % Adjusted EBITDA $ 88,379 $ 118,692 34.3 % Adjusted EBITDA per employee $ 1,524 $ 1,953 28.2 % 18 NM = Not meaningful. “NM” indicates that the period-to-period percent change is not meaningful, typically due to the magnitude of change or limited comparability between periods.
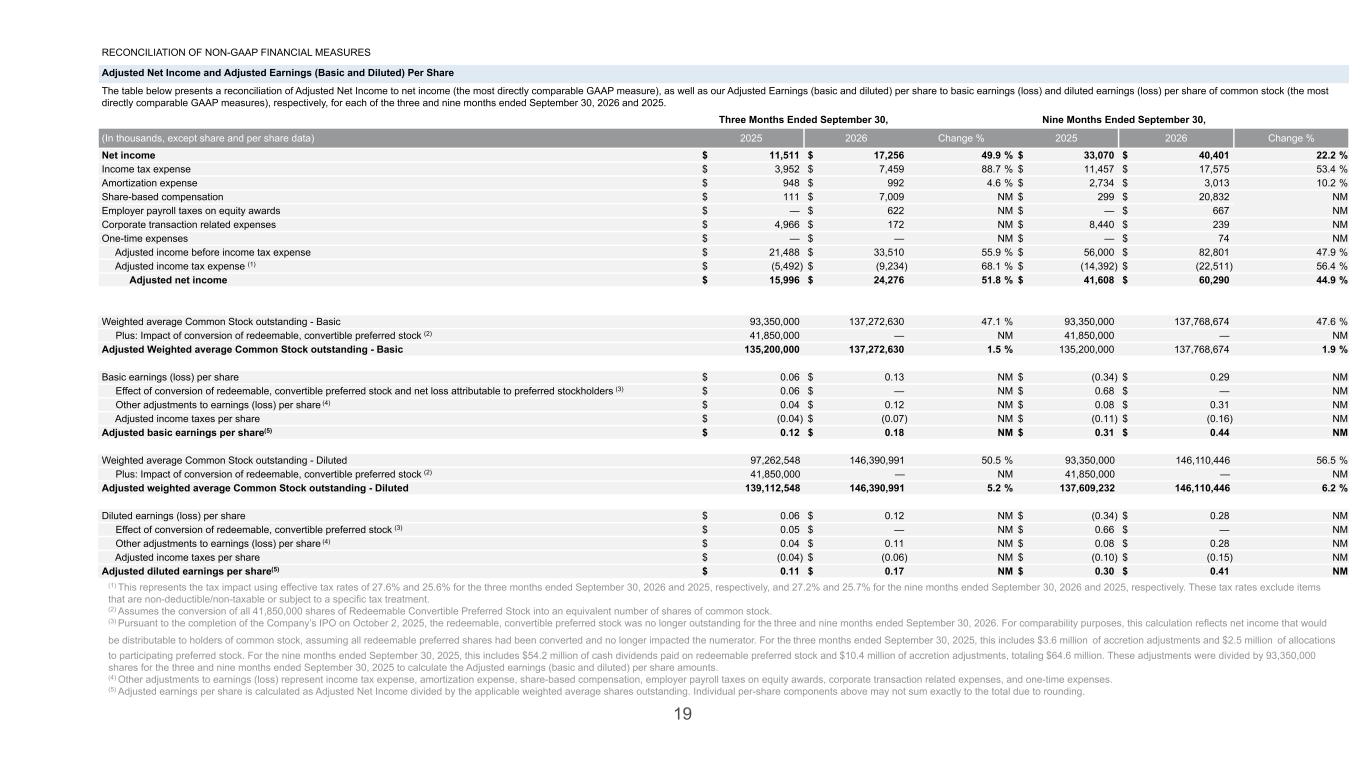
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES Adjusted Net Income and Adjusted Earnings (Basic and Diluted) Per Share The table below presents a reconciliation of Adjusted Net Income to net income (the most directly comparable GAAP measure), as well as our Adjusted Earnings (basic and diluted) per share to basic earnings (loss) and diluted earnings (loss) per share of common stock (the most directly comparable GAAP measures), respectively, for each of the three and nine months ended September 30, 2026 and 2025. Three Months Ended September 30, Nine Months Ended September 30, (In thousands, except share and per share data) 2025 2026 Change % 2025 2026 Change % Net income $ 11,511 $ 17,256 49.9 % $ 33,070 $ 40,401 22.2 % Income tax expense $ 3,952 $ 7,459 88.7 % $ 11,457 $ 17,575 53.4 % Amortization expense $ 948 $ 992 4.6 % $ 2,734 $ 3,013 10.2 % Share-based compensation $ 111 $ 7,009 NM $ 299 $ 20,832 NM Employer payroll taxes on equity awards $ — $ 622 NM $ — $ 667 NM Corporate transaction related expenses $ 4,966 $ 172 NM $ 8,440 $ 239 NM One-time expenses $ — $ — NM $ — $ 74 NM Adjusted income before income tax expense $ 21,488 $ 33,510 55.9 % $ 56,000 $ 82,801 47.9 % Adjusted income tax expense (1) $ (5,492) $ (9,234) 68.1 % $ (14,392) $ (22,511) 56.4 % Adjusted net income $ 15,996 $ 24,276 51.8 % $ 41,608 $ 60,290 44.9 % Weighted average Common Stock outstanding - Basic 93,350,000 137,272,630 47.1 % 93,350,000 137,768,674 47.6 % Plus: Impact of conversion of redeemable, convertible preferred stock (2) 41,850,000 — NM 41,850,000 — NM Adjusted Weighted average Common Stock outstanding - Basic 135,200,000 137,272,630 1.5 % 135,200,000 137,768,674 1.9 % Basic earnings (loss) per share $ 0.06 $ 0.13 NM $ (0.34) $ 0.29 NM Effect of conversion of redeemable, convertible preferred stock and net loss attributable to preferred stockholders (3) $ 0.06 $ — NM $ 0.68 $ — NM Other adjustments to earnings (loss) per share (4) $ 0.04 $ 0.12 NM $ 0.08 $ 0.31 NM Adjusted income taxes per share $ (0.04) $ (0.07) NM $ (0.11) $ (0.16) NM Adjusted basic earnings per share(5) $ 0.12 $ 0.18 NM $ 0.31 $ 0.44 NM Weighted average Common Stock outstanding - Diluted 97,262,548 146,390,991 50.5 % 93,350,000 146,110,446 56.5 % Plus: Impact of conversion of redeemable, convertible preferred stock (2) 41,850,000 — NM 41,850,000 — NM Adjusted weighted average Common Stock outstanding - Diluted 139,112,548 146,390,991 5.2 % 137,609,232 146,110,446 6.2 % Diluted earnings (loss) per share $ 0.06 $ 0.12 NM $ (0.34) $ 0.28 NM Effect of conversion of redeemable, convertible preferred stock (3) $ 0.05 $ — NM $ 0.66 $ — NM Other adjustments to earnings (loss) per share (4) $ 0.04 $ 0.11 NM $ 0.08 $ 0.28 NM Adjusted income taxes per share $ (0.04) $ (0.06) NM $ (0.10) $ (0.15) NM Adjusted diluted earnings per share(5) $ 0.11 $ 0.17 NM $ 0.30 $ 0.41 NM (1) This represents the tax impact using effective tax rates of 27.6% and 25.6% for the three months ended September 30, 2026 and 2025, respectively, and 27.2% and 25.7% for the nine months ended September 30, 2026 and 2025, respectively. These tax rates exclude items that are non-deductible/non-taxable or subject to a specific tax treatment. (2) Assumes the conversion of all 41,850,000 shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock. (3) Pursuant to the completion of the Company’s IPO on October 2, 2025, the redeemable, convertible preferred stock was no longer outstanding for the three and nine months ended September 30, 2026. For comparability purposes, this calculation reflects net income that would be distributable to holders of common stock, assuming all redeemable preferred shares had been converted and no longer impacted the numerator. For the three months ended September 30, 2025, this includes $3.6 million of accretion adjustments and $2.5 million of allocations to participating preferred stock. For the nine months ended September 30, 2025, this includes $54.2 million of cash dividends paid on redeemable preferred stock and $10.4 million of accretion adjustments, totaling $64.6 million. These adjustments were divided by 93,350,000 shares for the three and nine months ended September 30, 2025 to calculate the Adjusted earnings (basic and diluted) per share amounts. (4) Other adjustments to earnings (loss) represent income tax expense, amortization expense, share-based compensation, employer payroll taxes on equity awards, corporate transaction related expenses, and one-time expenses. (5) Adjusted earnings per share is calculated as Adjusted Net Income divided by the applicable weighted average shares outstanding. Individual per-share components above may not sum exactly to the total due to rounding. 19
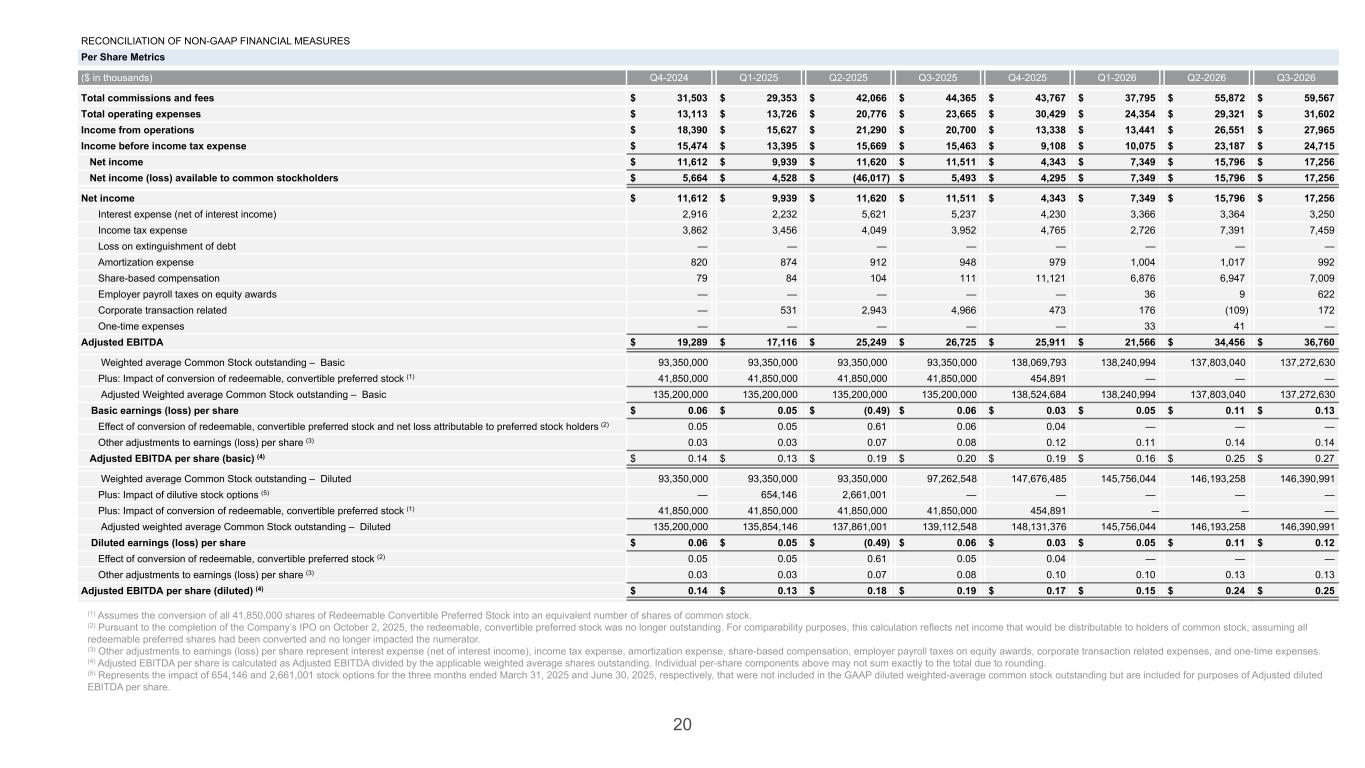
20 RECONCILIATION OF NON-GAAP FINANCIAL MEASURES Per Share Metrics ($ in thousands) Q4-2024 Q1-2025 Q2-2025 Q3-2025 Q4-2025 Q1-2026 Q2-2026 Q3-2026 Total commissions and fees $ 31,503 $ 29,353 $ 42,066 $ 44,365 $ 43,767 $ 37,795 $ 55,872 $ 59,567 Total operating expenses $ 13,113 $ 13,726 $ 20,776 $ 23,665 $ 30,429 $ 24,354 $ 29,321 $ 31,602 Income from operations $ 18,390 $ 15,627 $ 21,290 $ 20,700 $ 13,338 $ 13,441 $ 26,551 $ 27,965 Income before income tax expense $ 15,474 $ 13,395 $ 15,669 $ 15,463 $ 9,108 $ 10,075 $ 23,187 $ 24,715 Net income $ 11,612 $ 9,939 $ 11,620 $ 11,511 $ 4,343 $ 7,349 $ 15,796 $ 17,256 Net income (loss) available to common stockholders $ 5,664 $ 4,528 $ (46,017) $ 5,493 $ 4,295 $ 7,349 $ 15,796 $ 17,256 Net income $ 11,612 $ 9,939 $ 11,620 $ 11,511 $ 4,343 $ 7,349 $ 15,796 $ 17,256 Interest expense (net of interest income) 2,916 2,232 5,621 5,237 4,230 3,366 3,364 3,250 Income tax expense 3,862 3,456 4,049 3,952 4,765 2,726 7,391 7,459 Loss on extinguishment of debt — — — — — — — — Amortization expense 820 874 912 948 979 1,004 1,017 992 Share-based compensation 79 84 104 111 11,121 6,876 6,947 7,009 Employer payroll taxes on equity awards — — — — — 36 9 622 Corporate transaction related — 531 2,943 4,966 473 176 (109) 172 One-time expenses — — — — — 33 41 — Adjusted EBITDA $ 19,289 $ 17,116 $ 25,249 $ 26,725 $ 25,911 $ 21,566 $ 34,456 $ 36,760 Weighted average Common Stock outstanding – Basic 93,350,000 93,350,000 93,350,000 93,350,000 138,069,793 138,240,994 137,803,040 137,272,630 Plus: Impact of conversion of redeemable, convertible preferred stock (1) 41,850,000 41,850,000 41,850,000 41,850,000 454,891 — — — Adjusted Weighted average Common Stock outstanding – Basic 135,200,000 135,200,000 135,200,000 135,200,000 138,524,684 138,240,994 137,803,040 137,272,630 Basic earnings (loss) per share $ 0.06 $ 0.05 $ (0.49) $ 0.06 $ 0.03 $ 0.05 $ 0.11 $ 0.13 Effect of conversion of redeemable, convertible preferred stock and net loss attributable to preferred stock holders (2) 0.05 — 0.05 — 0.61 — 0.06 — 0.04 — — — Other adjustments to earnings (loss) per share (3) 0.03 0.03 0.07 0.08 0.12 0.11 0.14 0.14 Adjusted EBITDA per share (basic) (4) $ 0.14 $ 0.13 $ 0.19 $ 0.20 $ 0.19 $ 0.16 $ 0.25 $ 0.27 Weighted average Common Stock outstanding – Diluted 93,350,000 93,350,000 93,350,000 97,262,548 147,676,485 145,756,044 146,193,258 146,390,991 Plus: Impact of dilutive stock options (5) — 654,146 1 2,661,001 — — — — — Plus: Impact of conversion of redeemable, convertible preferred stock (1) 41,850,000 41,850,000 41,850,000 41,850,000 454,891 — — — Adjusted weighted average Common Stock outstanding – Diluted 135,200,000 135,854,146 137,861,001 139,112,548 148,131,376 145,756,044 146,193,258 146,390,991 Diluted earnings (loss) per share $ 0.06 $ 0.05 $ (0.49) $ 0.06 $ 0.03 $ 0.05 $ 0.11 $ 0.12 Effect of conversion of redeemable, convertible preferred stock (2) 0.05 — 0.05 — 0.61 — 0.05 — 0.04 — — — Other adjustments to earnings (loss) per share (3) 0.03 0.03 0.07 0.08 0.10 0.10 0.13 0.13 Adjusted EBITDA per share (diluted) (4) $ 0.14 $ 0.13 $ 0.18 $ 0.19 $ 0.17 $ 0.15 $ 0.24 $ 0.25 (1) Assumes the conversion of all 41,850,000 shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock. (2) Pursuant to the completion of the Company’s IPO on October 2, 2025, the redeemable, convertible preferred stock was no longer outstanding. For comparability purposes, this calculation reflects net income that would be distributable to holders of common stock, assuming all redeemable preferred shares had been converted and no longer impacted the numerator. (3) Other adjustments to earnings (loss) per share represent interest expense (net of interest income), income tax expense, amortization expense, share-based compensation, employer payroll taxes on equity awards, corporate transaction related expenses, and one-time expenses. (4) Adjusted EBITDA per share is calculated as Adjusted EBITDA divided by the applicable weighted average shares outstanding. Individual per-share components above may not sum exactly to the total due to rounding. (5) Represents the impact of 654,146 and 2,661,001 stock options for the three months ended March 31, 2025 and June 30, 2025, respectively, that were not included in the GAAP diluted weighted-average common stock outstanding but are included for purposes of Adjusted diluted EBITDA per share.
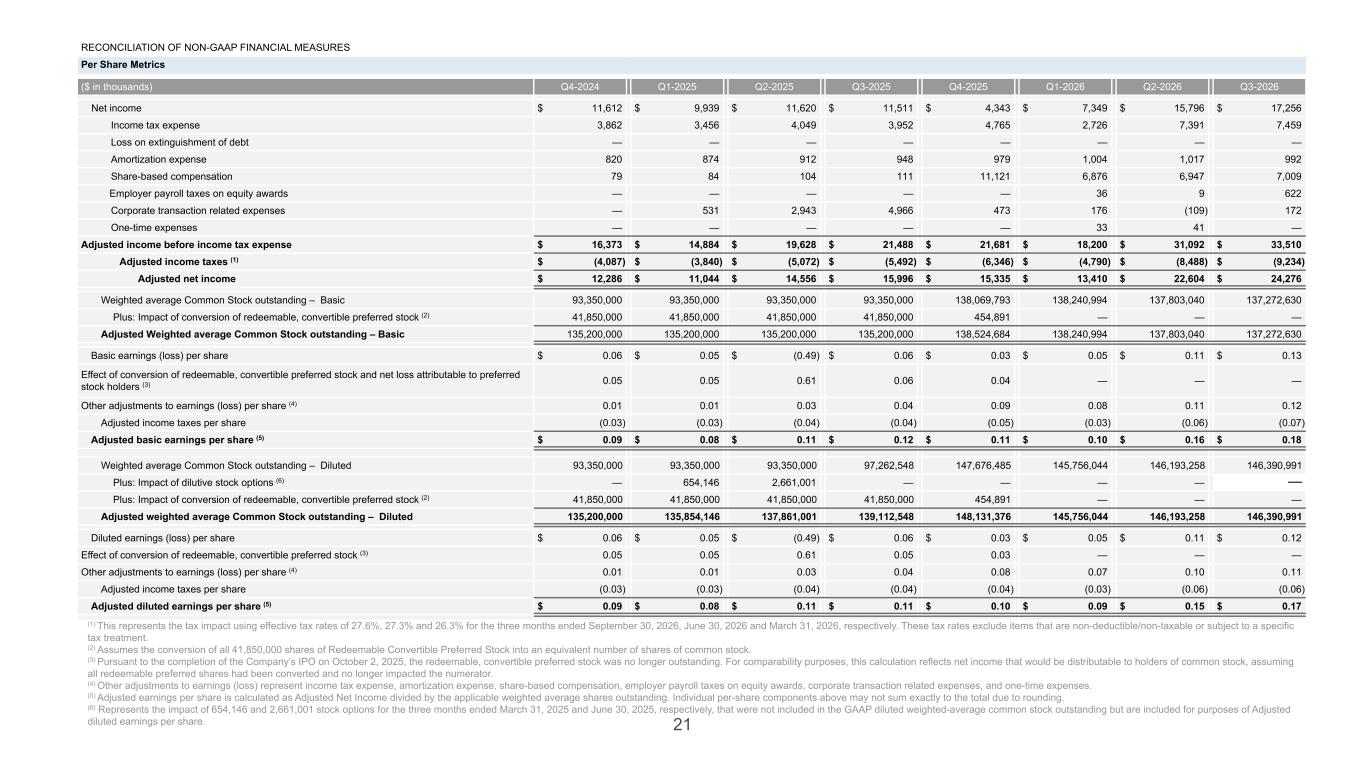
21 RECONCILIATION OF NON-GAAP FINANCIAL MEASURES Per Share Metrics ($ in thousands) Q4-2024 Q1-2025 Q2-2025 Q3-2025 Q4-2025 Q1-2026 Q2-2026 Q3-2026 Net income $ 11,612 $ 9,939 $ 11,620 $ 11,511 $ 4,343 $ 7,349 $ 15,796 $ 17,256 Income tax expense 3,862 3,456 4,049 3,952 4,765 2,726 7,391 7,459 Loss on extinguishment of debt — — — — — — — — Amortization expense 820 874 912 948 979 1,004 1,017 992 Share-based compensation 79 84 104 111 11,121 6,876 6,947 7,009 Employer payroll taxes on equity awards — — — — — 36 9 622 Corporate transaction related expenses — 531 2,943 4,966 473 176 (109) 172 One-time expenses — — — — — 33 41 — Adjusted income before income tax expense $ 16,373 $ 14,884 $ 19,628 $ 21,488 $ 21,681 $ 18,200 $ 31,092 $ 33,510 Adjusted income taxes (1) $ (4,087) $ (3,840) $ (5,072) $ (5,492) $ (6,346) $ (4,790) $ (8,488) $ (9,234) Adjusted net income $ 12,286 $ 11,044 $ 14,556 $ 15,996 $ 15,335 $ 13,410 $ 22,604 $ 24,276 Weighted average Common Stock outstanding – Basic 93,350,000 93,350,000 93,350,000 93,350,000 138,069,793 138,240,994 137,803,040 137,272,630 Plus: Impact of conversion of redeemable, convertible preferred stock (2) 41,850,000 41,850,000 41,850,000 41,850,000 454,891 — — — Adjusted Weighted average Common Stock outstanding – Basic 135,200,000 135,200,000 135,200,000 135,200,000 138,524,684 138,240,994 137,803,040 137,272,630 Basic earnings (loss) per share $ 0.06 $ 0.05 $ (0.49) $ 0.06 $ 0.03 $ 0.05 $ 0.11 $ 0.13 Effect of conversion of redeemable, convertible preferred stock and net loss attributable to preferred stock holders (3) 0.05 0.05 0.61 0.06 0.04 — — — Other adjustments to earnings (loss) per share (4) 0.01 0.01 0.03 0.04 0.09 0.08 0.11 0.12 Adjusted income taxes per share (0.03) (0.03) (0.04) (0.04) (0.05) (0.03) (0.06) (0.07) Adjusted basic earnings per share (5) $ 0.09 $ 0.08 $ 0.11 $ 0.12 $ 0.11 $ 0.10 $ 0.16 $ 0.18 Weighted average Common Stock outstanding – Diluted 93,350,000 93,350,000 93,350,000 97,262,548 147,676,485 145,756,044 146,193,258 146,390,991 Plus: Impact of dilutive stock options (6) — 654,146 2,661,001 — — — — — Plus: Impact of conversion of redeemable, convertible preferred stock (2) 41,850,000 41,850,000 41,850,000 41,850,000 454,891 — — — Adjusted weighted average Common Stock outstanding – Diluted 135,200,000 135,854,146 137,861,001 139,112,548 148,131,376 145,756,044 146,193,258 146,390,991 Diluted earnings (loss) per share $ 0.06 $ 0.05 $ (0.49) $ 0.06 $ 0.03 $ 0.05 $ 0.11 $ 0.12 Effect of conversion of redeemable, convertible preferred stock (3) 0.05 0.05 0.61 0.05 0.03 — — — Other adjustments to earnings (loss) per share (4) 0.01 0.01 0.03 0.04 0.08 0.07 0.10 0.11 Adjusted income taxes per share (0.03) (0.03) (0.04) (0.04) (0.04) (0.03) (0.06) (0.06) Adjusted diluted earnings per share (5) $ 0.09 $ 0.08 $ 0.11 $ 0.11 $ 0.10 $ 0.09 $ 0.15 $ 0.17 (1) This represents the tax impact using effective tax rates of 27.6%, 27.3% and 26.3% for the three months ended September 30, 2026, June 30, 2026 and March 31, 2026, respectively. These tax rates exclude items that are non-deductible/non-taxable or subject to a specific tax treatment. (2) Assumes the conversion of all 41,850,000 shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock. (3) Pursuant to the completion of the Company’s IPO on October 2, 2025, the redeemable, convertible preferred stock was no longer outstanding. For comparability purposes, this calculation reflects net income that would be distributable to holders of common stock, assuming all redeemable preferred shares had been converted and no longer impacted the numerator. (4) Other adjustments to earnings (loss) represent income tax expense, amortization expense, share-based compensation, employer payroll taxes on equity awards, corporate transaction related expenses, and one-time expenses. (5) Adjusted earnings per share is calculated as Adjusted Net Income divided by the applicable weighted average shares outstanding. Individual per-share components above may not sum exactly to the total due to rounding. (6) Represents the impact of 654,146 and 2,661,001 stock options for the three months ended March 31, 2025 and June 30, 2025, respectively, that were not included in the GAAP diluted weighted-average common stock outstanding but are included for purposes of Adjusted diluted earnings per share. 21
Additional Information
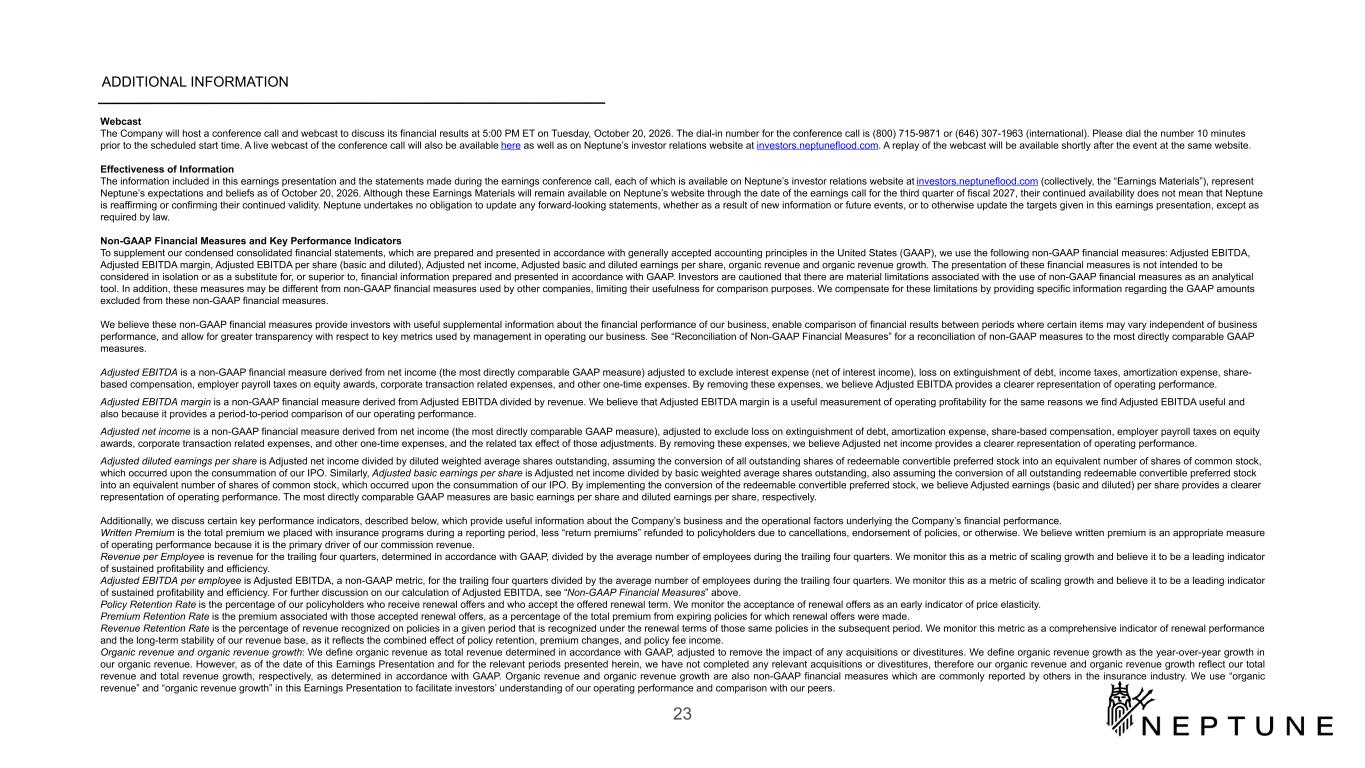
ADDITIONAL INFORMATION Webcast The Company will host a conference call and webcast to discuss its financial results at 5:00 PM ET on Tuesday, October 20, 2026. The dial-in number for the conference call is (800) 715-9871 or (646) 307-1963 (international). Please dial the number 10 minutes prior to the scheduled start time. A live webcast of the conference call will also be available here as well as on Neptune’s investor relations website at investors.neptuneflood.com. A replay of the webcast will be available shortly after the event at the same website. Effectiveness of Information The information included in this earnings presentation and the statements made during the earnings conference call, each of which is available on Neptune’s investor relations website at investors.neptuneflood.com (collectively, the “Earnings Materials”), represent Neptune’s expectations and beliefs as of October 20, 2026. Although these Earnings Materials will remain available on Neptune’s website through the date of the earnings call for the third quarter of fiscal 2027, their continued availability does not mean that Neptune is reaffirming or confirming their continued validity. Neptune undertakes no obligation to update any forward-looking statements, whether as a result of new information or future events, or to otherwise update the targets given in this earnings presentation, except as required by law. Non-GAAP Financial Measures and Key Performance Indicators To supplement our condensed consolidated financial statements, which are prepared and presented in accordance with generally accepted accounting principles in the United States (GAAP), we use the following non-GAAP financial measures: Adjusted EBITDA, Adjusted EBITDA margin, Adjusted EBITDA per share (basic and diluted), Adjusted net income, Adjusted basic and diluted earnings per share, organic revenue and organic revenue growth. The presentation of these financial measures is not intended to be considered in isolation or as a substitute for, or superior to, financial information prepared and presented in accordance with GAAP. Investors are cautioned that there are material limitations associated with the use of non-GAAP financial measures as an analytical tool. In addition, these measures may be different from non-GAAP financial measures used by other companies, limiting their usefulness for comparison purposes. We compensate for these limitations by providing specific information regarding the GAAP amounts excluded from these non-GAAP financial measures. We believe these non-GAAP financial measures provide investors with useful supplemental information about the financial performance of our business, enable comparison of financial results between periods where certain items may vary independent of business performance, and allow for greater transparency with respect to key metrics used by management in operating our business. See “Reconciliation of Non-GAAP Financial Measures” for a reconciliation of non-GAAP measures to the most directly comparable GAAP measures. Adjusted EBITDA is a non-GAAP financial measure derived from net income (the most directly comparable GAAP measure) adjusted to exclude interest expense (net of interest income), loss on extinguishment of debt, income taxes, amortization expense, share- based compensation, employer payroll taxes on equity awards, corporate transaction related expenses, and other one-time expenses. By removing these expenses, we believe Adjusted EBITDA provides a clearer representation of operating performance. Adjusted EBITDA margin is a non-GAAP financial measure derived from Adjusted EBITDA divided by revenue. We believe that Adjusted EBITDA margin is a useful measurement of operating profitability for the same reasons we find Adjusted EBITDA useful and also because it provides a period-to-period comparison of our operating performance. Adjusted net income is a non-GAAP financial measure derived from net income (the most directly comparable GAAP measure), adjusted to exclude loss on extinguishment of debt, amortization expense, share-based compensation, employer payroll taxes on equity awards, corporate transaction related expenses, and other one-time expenses, and the related tax effect of those adjustments. By removing these expenses, we believe Adjusted net income provides a clearer representation of operating performance. Adjusted diluted earnings per share is Adjusted net income divided by diluted weighted average shares outstanding, assuming the conversion of all outstanding shares of redeemable convertible preferred stock into an equivalent number of shares of common stock, which occurred upon the consummation of our IPO. Similarly, Adjusted basic earnings per share is Adjusted net income divided by basic weighted average shares outstanding, also assuming the conversion of all outstanding redeemable convertible preferred stock into an equivalent number of shares of common stock, which occurred upon the consummation of our IPO. By implementing the conversion of the redeemable convertible preferred stock, we believe Adjusted earnings (basic and diluted) per share provides a clearer representation of operating performance. The most directly comparable GAAP measures are basic earnings per share and diluted earnings per share, respectively. Additionally, we discuss certain key performance indicators, described below, which provide useful information about the Company’s business and the operational factors underlying the Company’s financial performance. Written Premium is the total premium we placed with insurance programs during a reporting period, less “return premiums” refunded to policyholders due to cancellations, endorsement of policies, or otherwise. We believe written premium is an appropriate measure of operating performance because it is the primary driver of our commission revenue. Revenue per Employee is revenue for the trailing four quarters, determined in accordance with GAAP, divided by the average number of employees during the trailing four quarters. We monitor this as a metric of scaling growth and believe it to be a leading indicator of sustained profitability and efficiency. Adjusted EBITDA per employee is Adjusted EBITDA, a non-GAAP metric, for the trailing four quarters divided by the average number of employees during the trailing four quarters. We monitor this as a metric of scaling growth and believe it to be a leading indicator of sustained profitability and efficiency. For further discussion on our calculation of Adjusted EBITDA, see “Non-GAAP Financial Measures” above. Policy Retention Rate is the percentage of our policyholders who receive renewal offers and who accept the offered renewal term. We monitor the acceptance of renewal offers as an early indicator of price elasticity. Premium Retention Rate is the premium associated with those accepted renewal offers, as a percentage of the total premium from expiring policies for which renewal offers were made. Revenue Retention Rate is the percentage of revenue recognized on policies in a given period that is recognized under the renewal terms of those same policies in the subsequent period. We monitor this metric as a comprehensive indicator of renewal performance and the long-term stability of our revenue base, as it reflects the combined effect of policy retention, premium changes, and policy fee income. Organic revenue and organic revenue growth: We define organic revenue as total revenue determined in accordance with GAAP, adjusted to remove the impact of any acquisitions or divestitures. We define organic revenue growth as the year-over-year growth in our organic revenue. However, as of the date of this Earnings Presentation and for the relevant periods presented herein, we have not completed any relevant acquisitions or divestitures, therefore our organic revenue and organic revenue growth reflect our total revenue and total revenue growth, respectively, as determined in accordance with GAAP. Organic revenue and organic revenue growth are also non-GAAP financial measures which are commonly reported by others in the insurance industry. We use “organic revenue” and “organic revenue growth” in this Earnings Presentation to facilitate investors’ understanding of our operating performance and comparison with our peers. 23
ADDITIONAL INFORMATION Safe Harbor Statement This earnings presentation, the press release, and the earnings conference call contain “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 that involve substantial risks and uncertainties. All statements, other than statements of historical fact included in this presentation, are forward-looking statements. Forward-looking statements give our current expectations relating to our financial condition, results of operations, plans, objectives, future performance, and business. You can identify forward-looking statements by the fact that they do not relate strictly to historical or current facts. In some cases, you can identify these statements by forward-looking words such as “may,” “might,” “will,” “should,” “expects,” “plans,” “anticipates,” “believes,” “estimates,” “outlook,” “predicts,” “potential,” or “continue,” the negative of these terms, and other comparable terminology. These forward-looking statements, which are subject to risks, uncertainties, and assumptions about us, include, among others, projections of our future financial performance, our anticipated growth and business strategies, anticipated trends in our business, capital allocation plans, technology initiatives, and other future events or developments. These statements are only predictions based on our current expectations and projections about future events. There are important factors that could cause our actual results, level of activity, performance, or achievements to differ materially from the results, level of activity, performance, or achievements expressed or implied by the forward-looking statements, including those factors discussed under the captions entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, the Company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2026, once filed, and the other documents that the Company files with the U.S. Securities and Exchange Commission, which are available free of charge on the SEC’s website at: www.sec.gov and on Neptune’s investor relations website at investors.neptuneflood.com. Although we believe the expectations reflected in the forward-looking statements are reasonable, we cannot guarantee future results, level of activity, performance, or achievements. Moreover, neither we nor any other person assumes responsibility for the accuracy and completeness of any of these forward-looking statements. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future developments, or otherwise, except as may be required by law. 24
