Exhibit 99.5
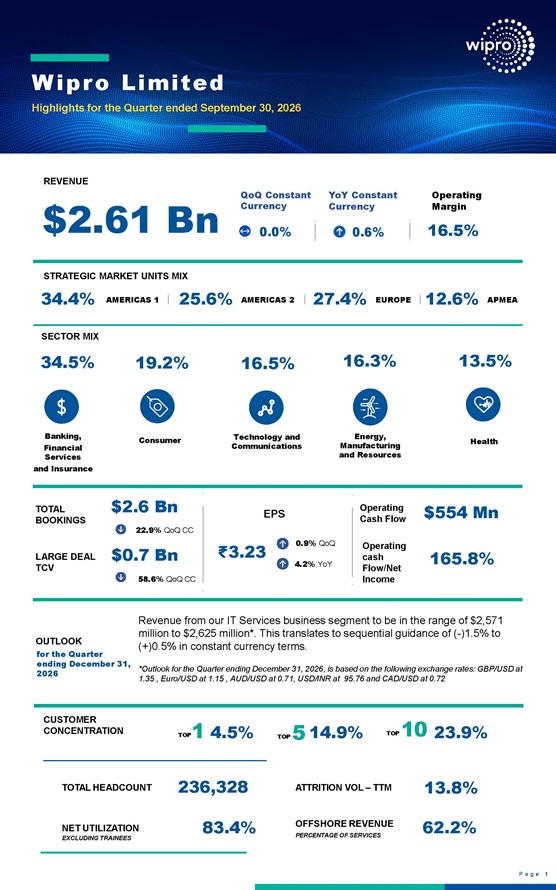
Wipro Limited Highlights for the Quarter ended September 30, 2026 CUSTOMER CONCENTRATION TOP1 4.5% TOP 5 14.9% TOP 10 23.9% TOTAL HEADCOUNT 236,328 ATTRITION VOL – TTM 13.8% NET UTILIZATION EXCLUDING TRAINEES 83.4% OFFSHORE REVENUE PERCENTAGE OF SERVICES 62.2% OUTLOOK for the Quarter ending December 31, 2026 Revenue from our IT Services business segment to be in the range of $2,571 million to $2,625 million*. This translates to sequential guidance of (-)1.5% to (+)0.5% in constant currency terms. *Outlook for the Quarter ending December 31, 2026, is based on the following exchange rates: GBP/USD at 1.35 , Euro/USD at 1.15 , AUD/USD at 0.71, USD/INR at 95.76 and CAD/USD at 0.72 REVENUE $2.61 Bn QoQ Constant Currency YoY Constant Currency Operating Margin STRATEGIC MARKET UNITS MIX 34.4% AMERICAS 1 25.6% AMERICAS 2 27.4% EUROPE 12.6% APMEA SECTOR MIX 34.5% Banking, Financial Services and Insurance TOTAL BOOKINGS 19.2% Consumer $2.6 Bn 22.9% QoQ CC 16.5% Technology and Communications EPS 16.3% Energy, Manufacturing and Resources Operating Cash Flow 13.5% Health $554 Mn LARGE DEAL TCV $0.7 Bn 58.6% QoQ CC 3.23 0.9% QoQ 4.2% YoY Operating cash Flow/Net Income 165.8%
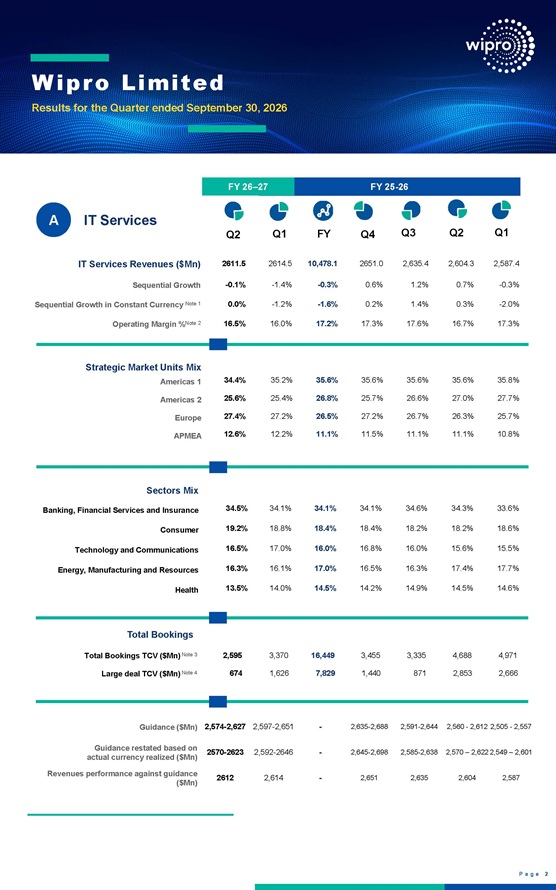
Q2 Q1 FY Q4 Q3 Q2 Q1 IT Services Revenues ($Mn) 2611.5 2614.5 10,478.1 2651.0 2,635.4 2,604.3 2,587.4 Sequential Growth -0.1% -1.4% -0.3% 0.6% 1.2% 0.7% -0.3% Sequential Growth in Constant Currency Note 1 0.0% -1.2% -1.6% 0.2% 1.4% 0.3% -2.0% Operating Margin %Note 2 16.5% 16.0% 17.2% 17.3% 17.6% 16.7% 17.3% IT Services Strategic Market Units Mix Americas 1 34.4% 35.2% 35.6% 35.6% 35.6% 35.6% 35.8% Americas 2 25.6% 25.4% 26.8% 25.7% 26.6% 27.0% 27.7% Europe 27.4% 27.2% 26.5% 27.2% 26.7% 26.3% 25.7% APMEA 12.6% 12.2% 11.1% 11.5% 11.1% 11.1% 10.8% Sectors Mix Banking, Financial Services and Insurance 34.5% 34.1% 34.1% 34.1% 34.6% 34.3% 33.6% Consumer 19.2% 18.8% 18.4% 18.4% 18.2% 18.2% 18.6% Technology and Communications 16.5% 17.0% 16.0% 16.8% 16.0% 15.6% 15.5% Energy, Manufacturing and Resources 16.3% 16.1% 17.0% 16.5% 16.3% 17.4% 17.7% Health 13.5% 14.0% 14.5% 14.2% 14.9% 14.5% 14.6% Total Bookings Total Bookings TCV ($Mn) Note 3 2,595 3,370 16,449 3,455 3,335 4,688 4,971 Large deal TCV ($Mn) Note 4 674 1,626 7,829 1,440 871 2,853 2,666 2,574-2,627 2,597-2,651 - 2,635-2,688 2,591-2,644 2,560 - 2,612 2,505 - 2,557 2570-2623 2,592-2646 - 2,645-2,698 2,585-2,638 2,570 – 2,622 2,549 – 2,601 2612 2,614 - 2,651 2,635 2,604 2,587 Guidance ($Mn) Guidance restated based on actual currency realized ($Mn) Revenues performance against guidance ($Mn)
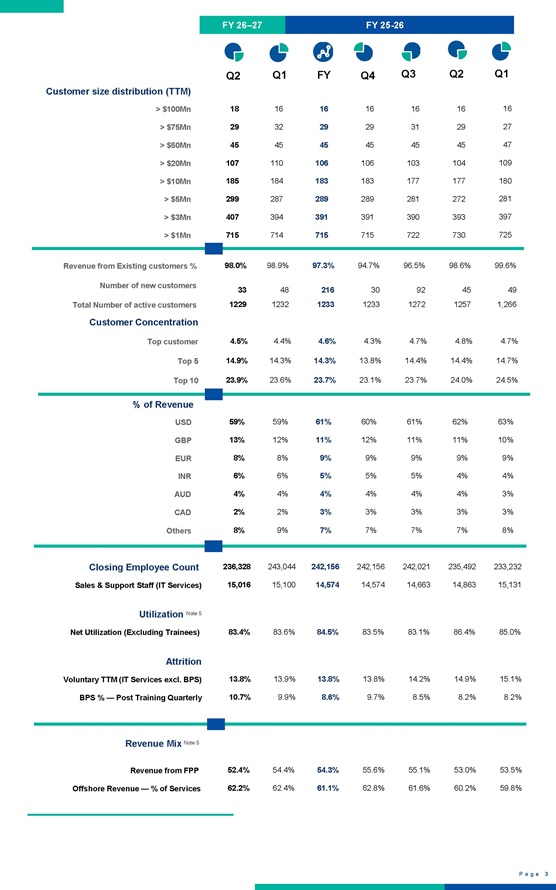
Q2 Q1 FY Q4 Q3 Q2 Q1 Customer size distribution (TTM) > $100Mn 18 16 16 16 16 16 16 > $75Mn 29 32 29 29 31 29 27 > $50Mn 45 45 45 45 45 45 47 > $20Mn 107 110 106 106 103 104 109 > $10Mn 185 184 183 183 177 177 180 > $5Mn 299 287 289 289 281 272 281 > $3Mn 407 394 391 391 390 393 397 > $1Mn 715 714 715 715 722 730 725 Revenue from Existing customers % 98.0% 98.9% 97.3% 94.7% 96.5% 98.6% 99.6% Number of new customers 33 48 216 30 92 45 49 Total Number of active customers 1229 1232 1233 1233 1272 1257 1,266 Customer Concentration Top customer 4.5% 4.4% 4.6% 4.3% 4.7% 4.8% 4.7% Top 5 14.9% 14.3% 14.3% 13.8% 14.4% 14.4% 14.7% Top 10 23.9% 23.6% 23.7% 23.1% 23.7% 24.0% 24.5% % of Revenue USD 59% 59% 61% 60% 61% 62% 63% GBP 13% 12% 11% 12% 11% 11% 10% EUR 8% 8% 9% 9% 9% 9% 9% INR 6% 6% 5% 5% 5% 4% 4% AUD 4% 4% 4% 4% 4% 4% 3% CAD 2% 2% 3% 3% 3% 3% 3% Others 8% 9% 7% 7% 7% 7% 8% Closing Employee Count Sales & Support Staff (IT Services) 15,016 15,100 14,574 14,574 14,663 14,863 15,131 Utilization Note 5 Net Utilization (Excluding Trainees) 83.4% 83.6% 84.5% 83.5% 83.1% 86.4% 85.0% Attrition Voluntary TTM (IT Services excl. BPS) 13.8% 13.9% 13.8% 13.8% 14.2% 14.9% 15.1% BPS % — Post Training Quarterly 10.7% 9.9% 8.6% 9.7% 8.5% 8.2% 8.2% Revenue Mix Note 5 Revenue from FPP 52.4% 54.4% 54.3% 55.6% 55.1% 53.0% 53.5% Offshore Revenue — % of Services 62.2% 62.4% 61.1% 62.8% 61.6% 60.2% 59.8% 236,328 243,044 242,156 242,156 242,021 235,492 233,232
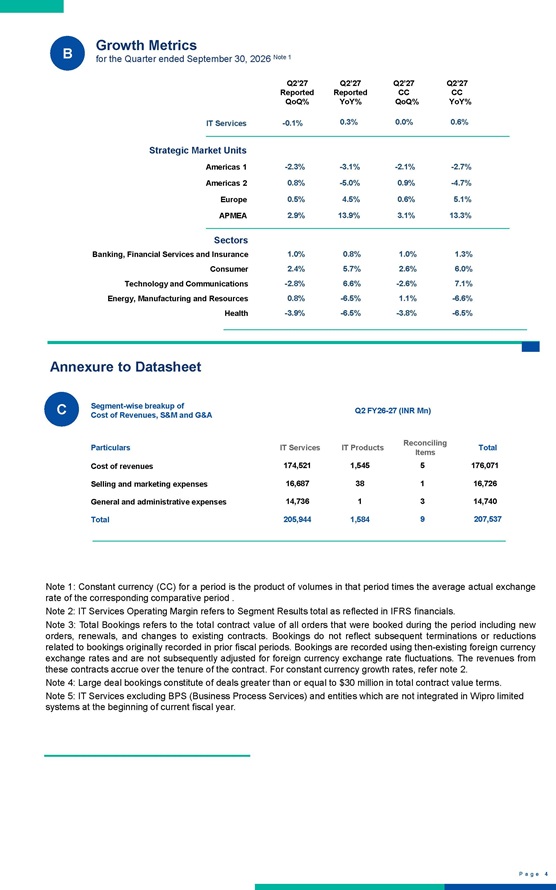
Growth Metrics for the Quarter ended September 30, 2026 Note 1 Q2’27 Reported QoQ% Q2’27 Reported YoY% Q2’27 CC QoQ% Q2’27 CC YoY% IT Services -0.1% 0.3% 0.0% 0.6% Strategic Market Units Americas 1 -2.3% -3.1% -2.1% -2.7% Americas 2 0.8% -5.0% 0.9% -4.7% Europe 0.5% 4.5% 0.6% 5.1% APMEA 2.9% 13.9% 3.1% 13.3% Sectors Banking, Financial Services and Insurance 1.0% 0.8% 1.0% 1.3% Consumer 2.4% 5.7% 2.6% 6.0% Technology and Communications -2.8% 6.6% -2.6% 7.1% Energy, Manufacturing and Resources 0.8% -6.5% 1.1% -6.6% Health -3.9% -6.5% -3.8% -6.5% Annexure to Datasheet Segment-wise breakup of Cost of Revenues, S&M and G&A Q2 FY26-27 (INR Mn) Particulars IT Services IT Products Reconciling Items Total Cost of revenues 174,521 1,545 5 176,071 Selling and marketing expenses 16,687 38 1 16,726 General and administrative expenses 14,736 1 3 14,740 Total 205,944 1,584 9 207,537 Note 1: Constant currency (CC) for a period is the product of volumes in that period times the average actual exchange rate of the corresponding comparative period . Note 2: IT Services Operating Margin refers to Segment Results total as reflected in IFRS financials. Note 3: Total Bookings refers to the total contract value of all orders that were booked during the period including new orders, renewals, and changes to existing contracts. Bookings do not reflect subsequent terminations or reductions related to bookings originally recorded in prior fiscal periods. Bookings are recorded using then-existing foreign currency exchange rates and are not subsequently adjusted for foreign currency exchange rate fluctuations. The revenues from these contracts accrue over the tenure of the contract. For constant currency growth rates, refer note 2. Note 4: Large deal bookings constitute of deals greater than or equal to $30 million in total contract value terms. Note 5: IT Services excluding BPS (Business Process Services) and entities which are not integrated in Wipro limited systems at the beginning of current fiscal year.