CoastalSouth Bancshares, Inc. Third Quarter 2025 Investor Presentation October 20, 2025 October 19, 2026 Third Quarter 2026 Investor Presentation Exhibit 99.2
Disclosures Forward Looking Statements Statements in this Investor Presentation regarding future events and our expectations and beliefs about our future financial performance and financial condition, as well as trends in our business and markets, constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are not historical in nature and may be identified by references to a future period or periods by the use of the words “believe,” “expect,” “anticipate,” “intend,” “plan,” “estimate,” “project,” “outlook,” or words of similar meaning, or future or conditional verbs such as “will,” “would,” “should,” “could,” or “may.” The forward-looking statements in this Investor Presentation should not be relied on because they are based on current information and on assumptions that we make about future events and circumstances that are subject to a number of known and unknown risks and uncertainties that are often difficult to predict and beyond our control. As a result of those risks and uncertainties, and other factors, our actual financial results in the future could differ, possibly materially, from those expressed in or implied by the forward-looking statements contained in this Investor Presentation and could cause us to make changes to our future plans. Factors that might cause such differences include, but are not limited to: the impact of current and future economic conditions, particularly those affecting the financial services industry, including the effects of declines in the real estate market, high unemployment rates, inflationary pressures, elevated interest rates and slowdowns in economic growth, as well as the financial stress on borrowers as a result of the foregoing; potential impacts of any adverse developments in the banking industry, including any impacts on customer confidence, deposit outflows, liquidity and the regulatory response thereto; changes in the interest rate environment, including changes to the federal funds rate; changes in prices, values and sales volumes of residential and commercial real estate; competition in our markets that may result in increased funding costs or reduced earning assets yields, thus reducing margins and net interest income; interest rate fluctuations, which could have an adverse effect on the Company’s profitability; a breach in security of our information systems, including the occurrence of cyber-attack incidents or deficiencies in cyber security; risks related to potential acquisitions; government actions or inactions, including a prolonged shutdown of the federal government, tariffs, or trade wars (including reduced consumer spending, lower economic growth or recession, reduced demand for U.S. exports, disruptions to supply chains, and decreased demand for other banking products and services), legislation or regulatory changes which could adversely affect the ability of the consolidated Company to conduct business combinations or new operations; changes in tax laws; significant turbulence or a disruption in the capital or financial markets and the effect of a fall in stock market prices on our investment securities; the effects of war or other conflicts, domestic civil unrest and tyranny, and changes in the overall geopolitical landscape; and adverse results from current or future litigation, regulatory examinations or other legal and/or regulatory actions, including as a result of the Company’s participation in and execution of government programs. Therefore, the Company can give no assurance that the results contemplated in the forward-looking statements will be realized. Additional information regarding these and other risks and uncertainties to which our business and future financial performance are subject is contained in the sections titled “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s 2025 Annual Report on Form 10-K under the Securities Act of 1933, as amended, filed with the Securities and Exchange Commission (the “SEC”) on March 12, 2026 and in other documents that we file with the SEC from time to time, which are available on the SEC’s website, http://www.sec.gov. In addition, our actual financial results in the future may differ from those currently expected due to additional risks and uncertainties of which we are not currently aware or which we do not currently view as, but in the future may become, material to our business or operating results. Due to these and other possible uncertainties and risks, readers are cautioned not to place undue reliance on the forward-looking statements contained in this Investor Presentation or to make predictions based solely on historical financial performance. Any forward-looking statement speaks only as of the date on which it is made, and we do not undertake any obligation to update or review any forward-looking statement, whether as a result of new information, future developments or otherwise, except as required by law. All forward-looking statements, express or implied, included in this Investor Presentation are qualified in their entirety by this cautionary statement.
Disclosures Non-GAAP Financial Measures In addition to results presented in accordance with U.S. generally accepted accounting principles (“GAAP”), this Investor Presentation contains certain non-GAAP financial measures. The Company believes that providing certain non-GAAP financial measures provides investors with information useful in understanding our financial performance, performance trends and financial position. Our management uses these measures for internal planning and forecasting purposes and we believe that our presentation and discussion, together with the accompanying reconciliations, allows investors, security analysts and other interested parties to view our performance and the factors and trends affecting our business in a manner similar to management. These non-GAAP measures should not be considered a substitute for GAAP measures and we strongly encourage investors to review our consolidated financial statements in their entirety and not to rely on any single financial measure to evaluate the Company. Non-GAAP financial measures have inherent limitations, are not uniformly applied and are not audited. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. The measures entitled return on average tangible common shareholders' equity, tangible book value per common share, tangible common equity, tangible assets, adjusted nonperforming assets to total assets, adjusted nonperforming assets, pre-tax pre-provision net revenue ("PPNR"), tangible common equity to tangible assets, core deposits and average core deposits are not measures recognized under accounting principles generally accepted in the United States of America (“GAAP”) and therefore are considered non-GAAP financial measures. The most comparable GAAP measures to these measures are return on average shareholders’ equity, book value per share, total shareholders’ equity, total assets, total nonperforming assets to total assets, total nonperforming assets, net income, total common equity to total assets, and total deposits, respectively. The delivery of this Investor Presentation will not, under any circumstances, create an implication that there has been no change in the affairs of the Company since the date of this Investor Presentation. The Company is not making any implied or express representation or warranty as to the accuracy or completeness of the information summarized herein or made available in connection with any further investigation of the Company. The Company expressly disclaims any and all liability which may be based on such information, errors therein or omission therefrom.
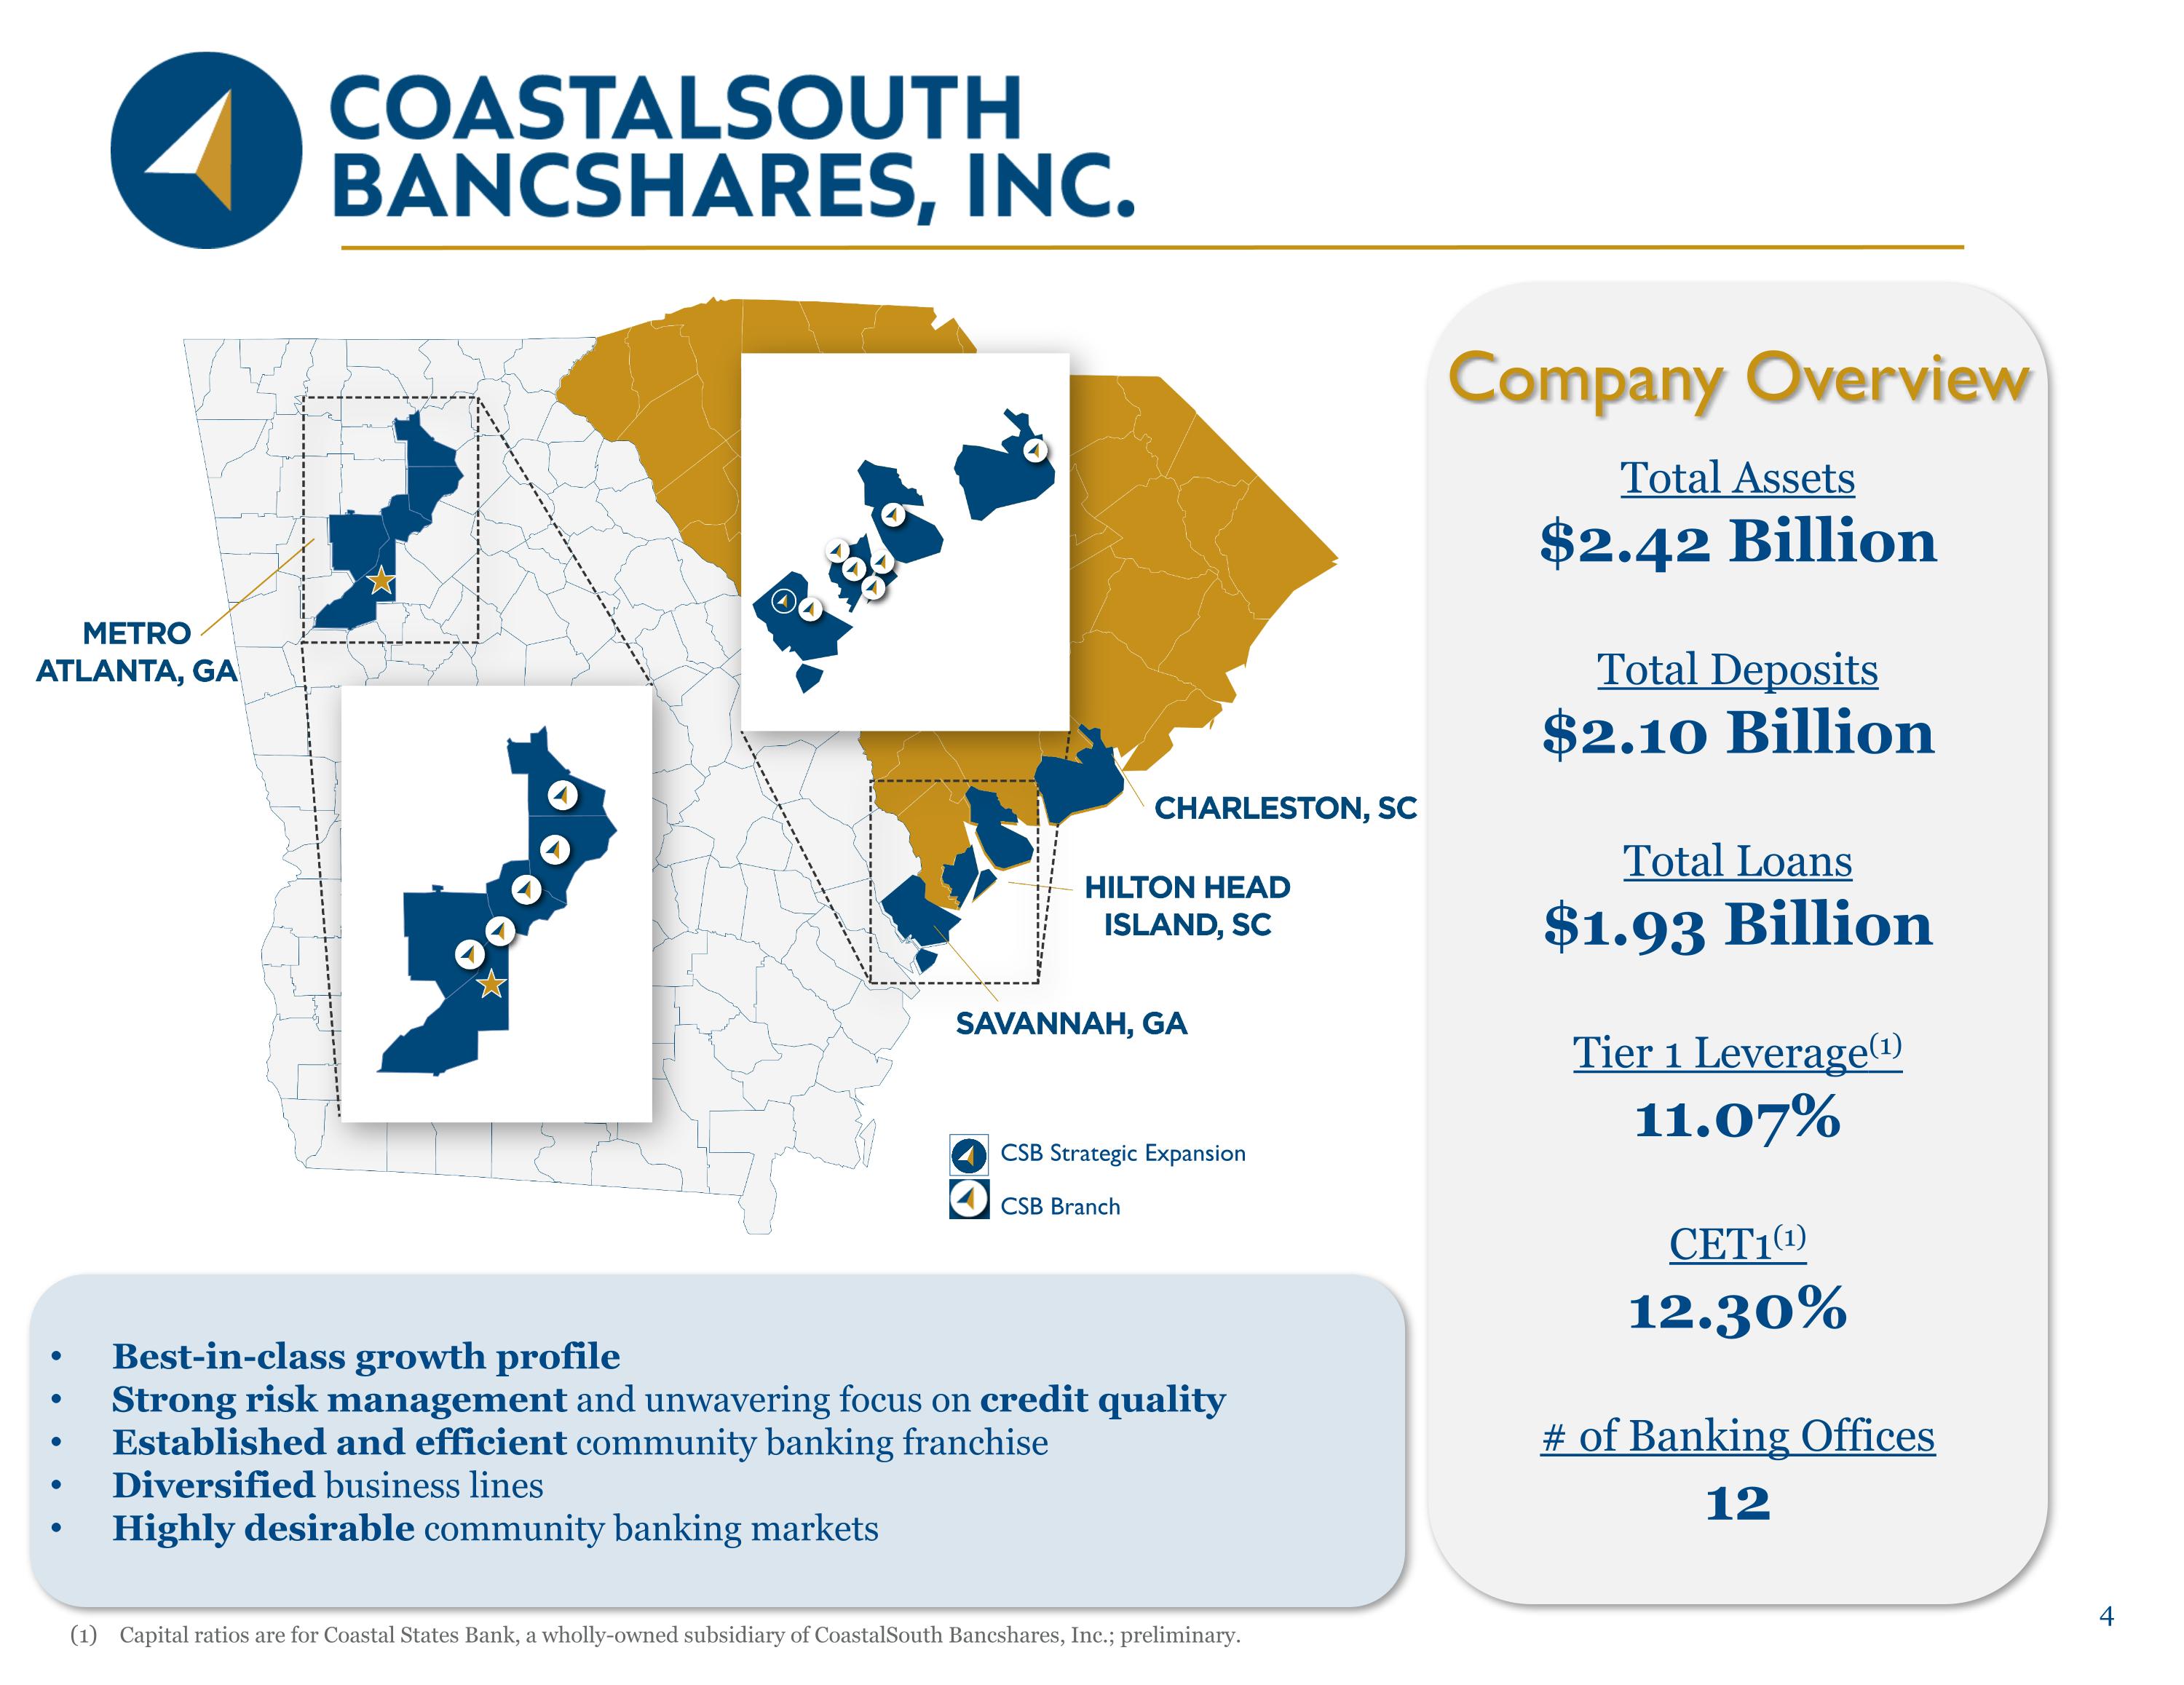
Company Overview Total Assets $2.42 Billion Total Deposits $2.10 Billion Total Loans $1.93 Billion Tier 1 Leverage(1) 11.07% CET1(1) 12.30% # of Banking Offices 12 Best-in-class growth profile Strong risk management and unwavering focus on credit quality Established and efficient community banking franchise Diversified business lines Highly desirable community banking markets Capital ratios are for Coastal States Bank, a wholly-owned subsidiary of CoastalSouth Bancshares, Inc.; preliminary. CSB Strategic Expansion CSB Branch
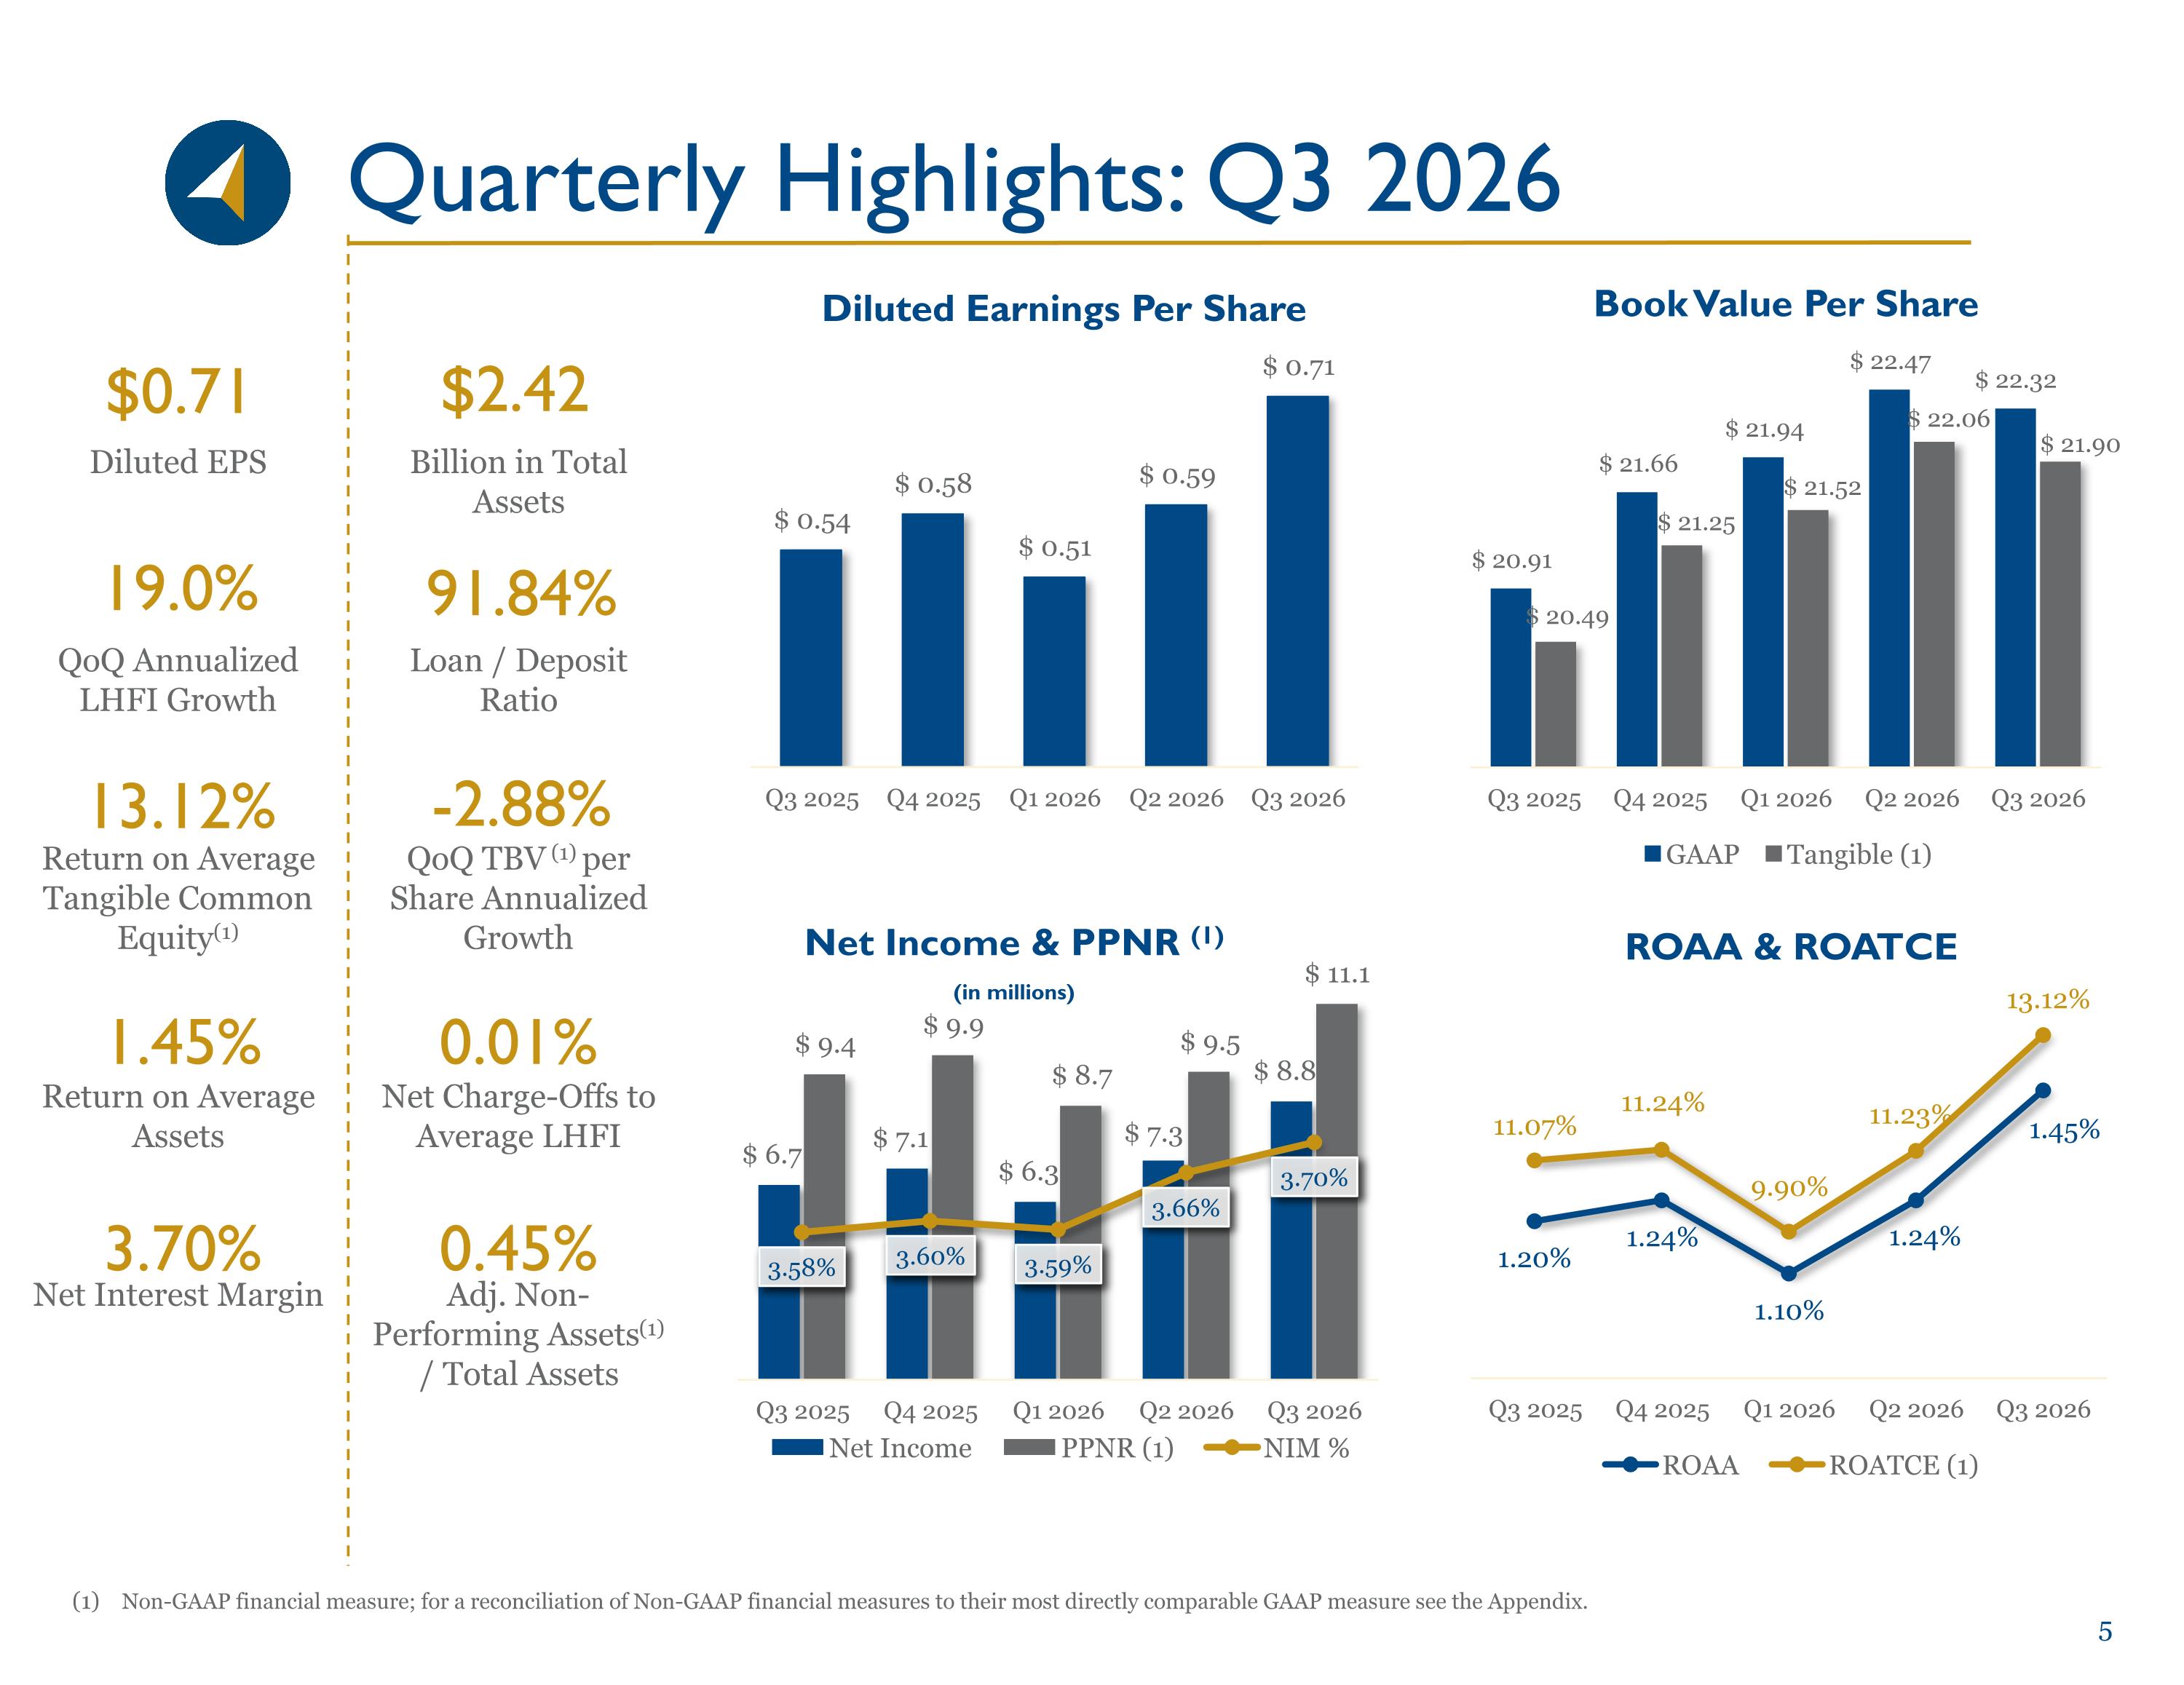
Diluted EPS QoQ Annualized LHFI Growth Return on Average Tangible Common Equity(1) Return on Average Assets Net Interest Margin Quarterly Highlights: Q3 2026 Non-GAAP financial measure; for a reconciliation of Non-GAAP financial measures to their most directly comparable GAAP measure see the Appendix. Billion in Total Assets Loan / Deposit Ratio QoQ TBV (1) per Share Annualized Growth Net Charge-Offs to Average LHFI Adj. Non-Performing Assets(1) / Total Assets $0.71 3.70% -2.88% $2.42 19.0% 91.84% 0.45% 13.12% 0.01% 1.45%
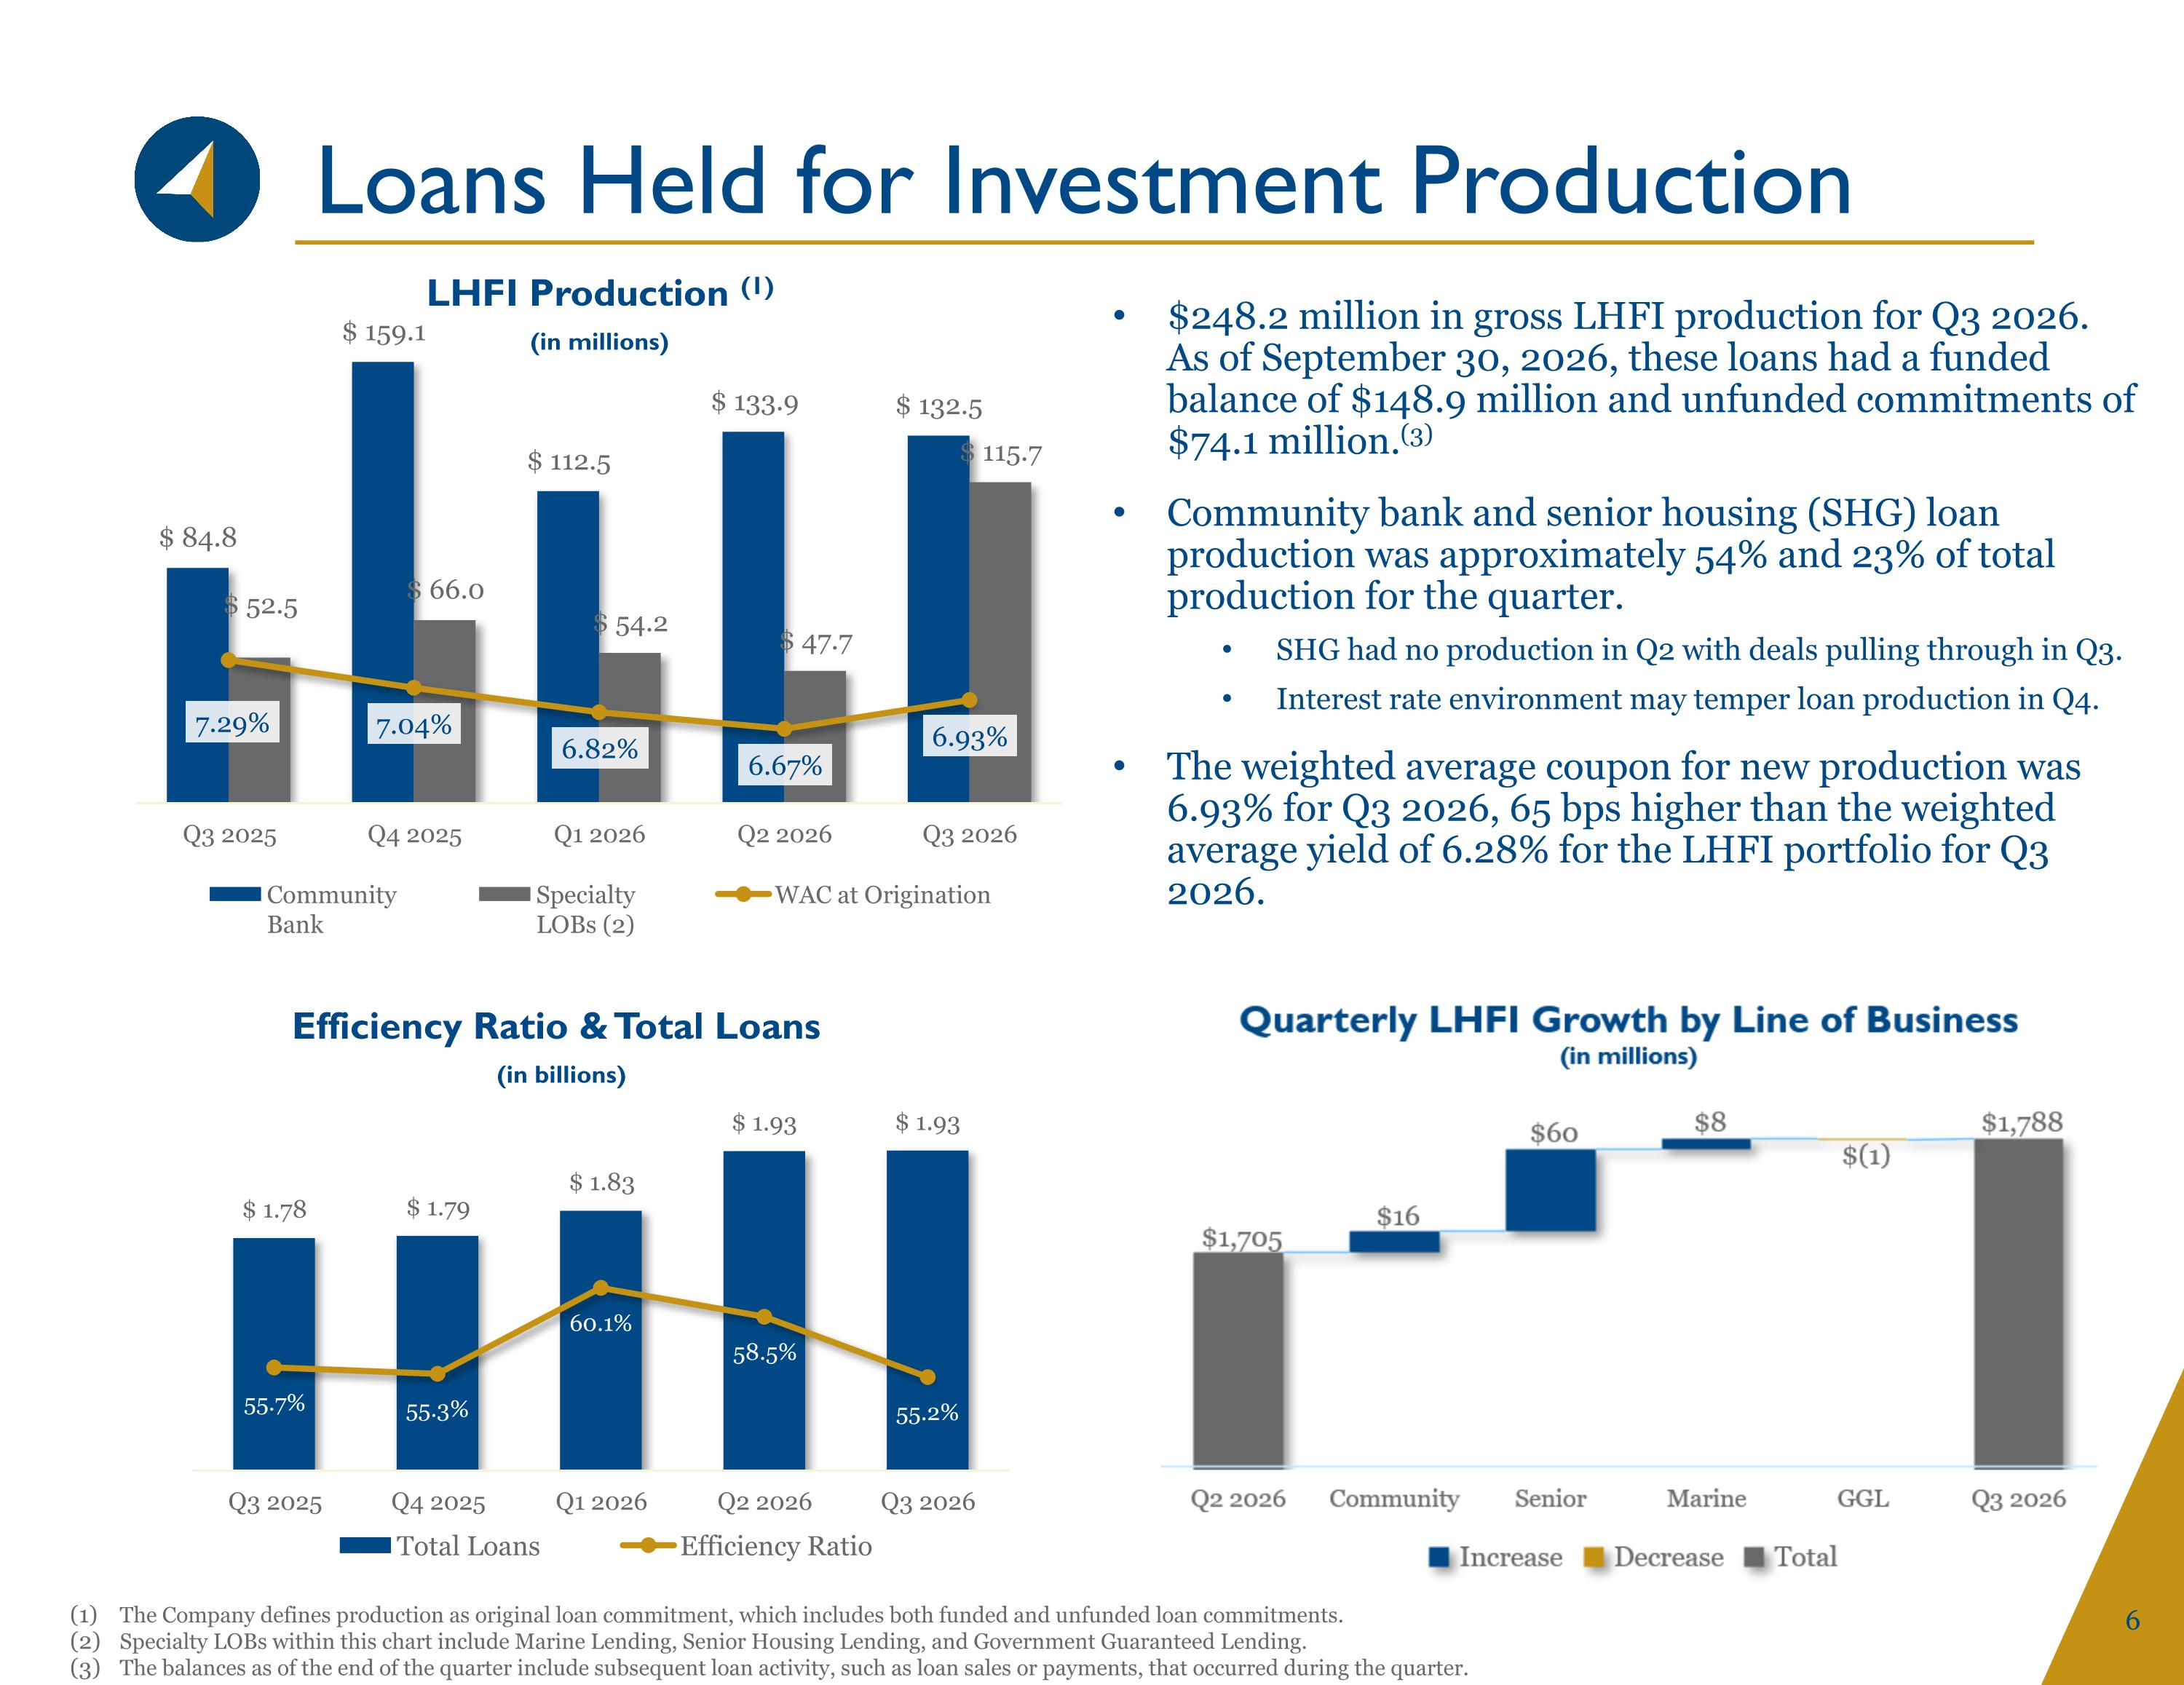
Loans Held for Investment Production $248.2 million in gross LHFI production for Q3 2026. As of September 30, 2026, these loans had a funded balance of $148.9 million and unfunded commitments of $74.1 million.(3) Community bank and senior housing (SHG) loan production was approximately 54% and 23% of total production for the quarter. SHG had no production in Q2 with deals pulling through in Q3. Interest rate environment may temper loan production in Q4. The weighted average coupon for new production was 6.93% for Q3 2026, 65 bps higher than the weighted average yield of 6.28% for the LHFI portfolio for Q3 2026. The Company defines production as original loan commitment, which includes both funded and unfunded loan commitments. Specialty LOBs within this chart include Marine Lending, Senior Housing Lending, and Government Guaranteed Lending. The balances as of the end of the quarter include subsequent loan activity, such as loan sales or payments, that occurred during the quarter.
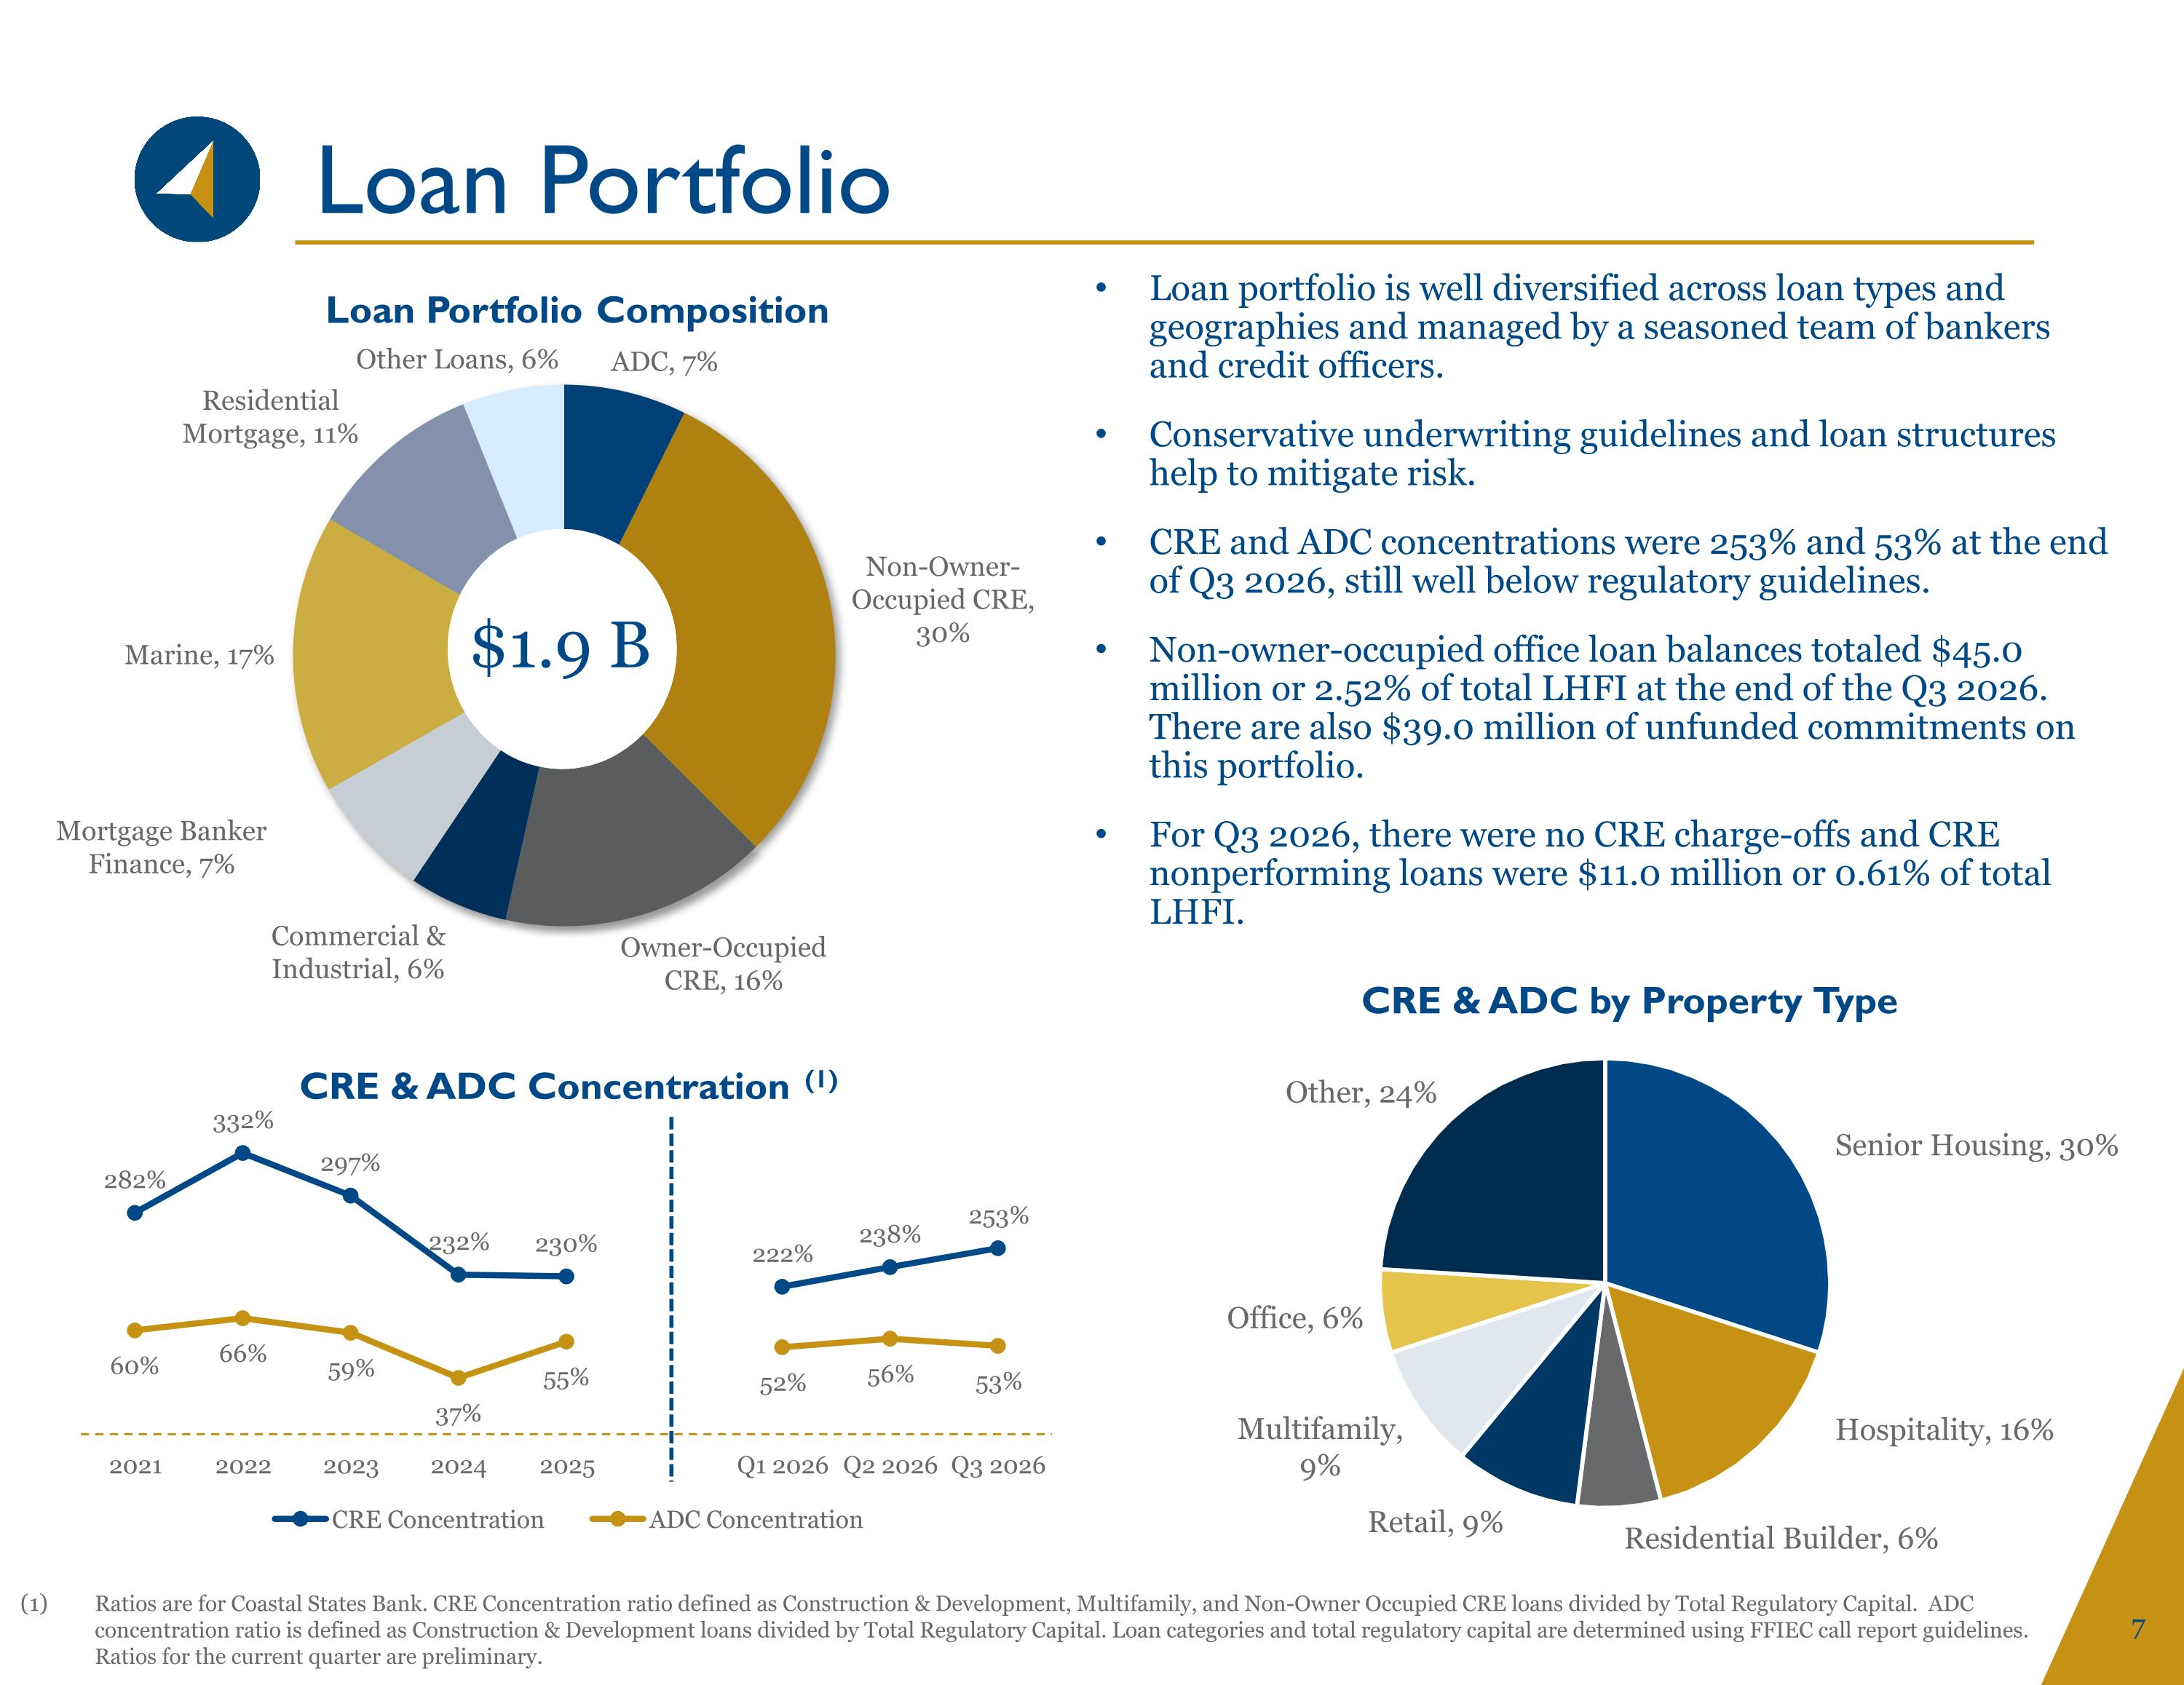
Loan Portfolio Loan portfolio is well diversified across loan types and geographies and managed by a seasoned team of bankers and credit officers. Conservative underwriting guidelines and loan structures help to mitigate risk. CRE and ADC concentrations were 253% and 53% at the end of Q3 2026, still well below regulatory guidelines. Non-owner-occupied office loan balances totaled $45.0 million or 2.52% of total LHFI at the end of the Q3 2026. There are also $39.0 million of unfunded commitments on this portfolio. For Q3 2026, there were no CRE charge-offs and CRE nonperforming loans were $11.0 million or 0.61% of total LHFI. Ratios are for Coastal States Bank. CRE Concentration ratio defined as Construction & Development, Multifamily, and Non-Owner Occupied CRE loans divided by Total Regulatory Capital. ADC concentration ratio is defined as Construction & Development loans divided by Total Regulatory Capital. Loan categories and total regulatory capital are determined using FFIEC call report guidelines. Ratios for the current quarter are preliminary. $1.9 B
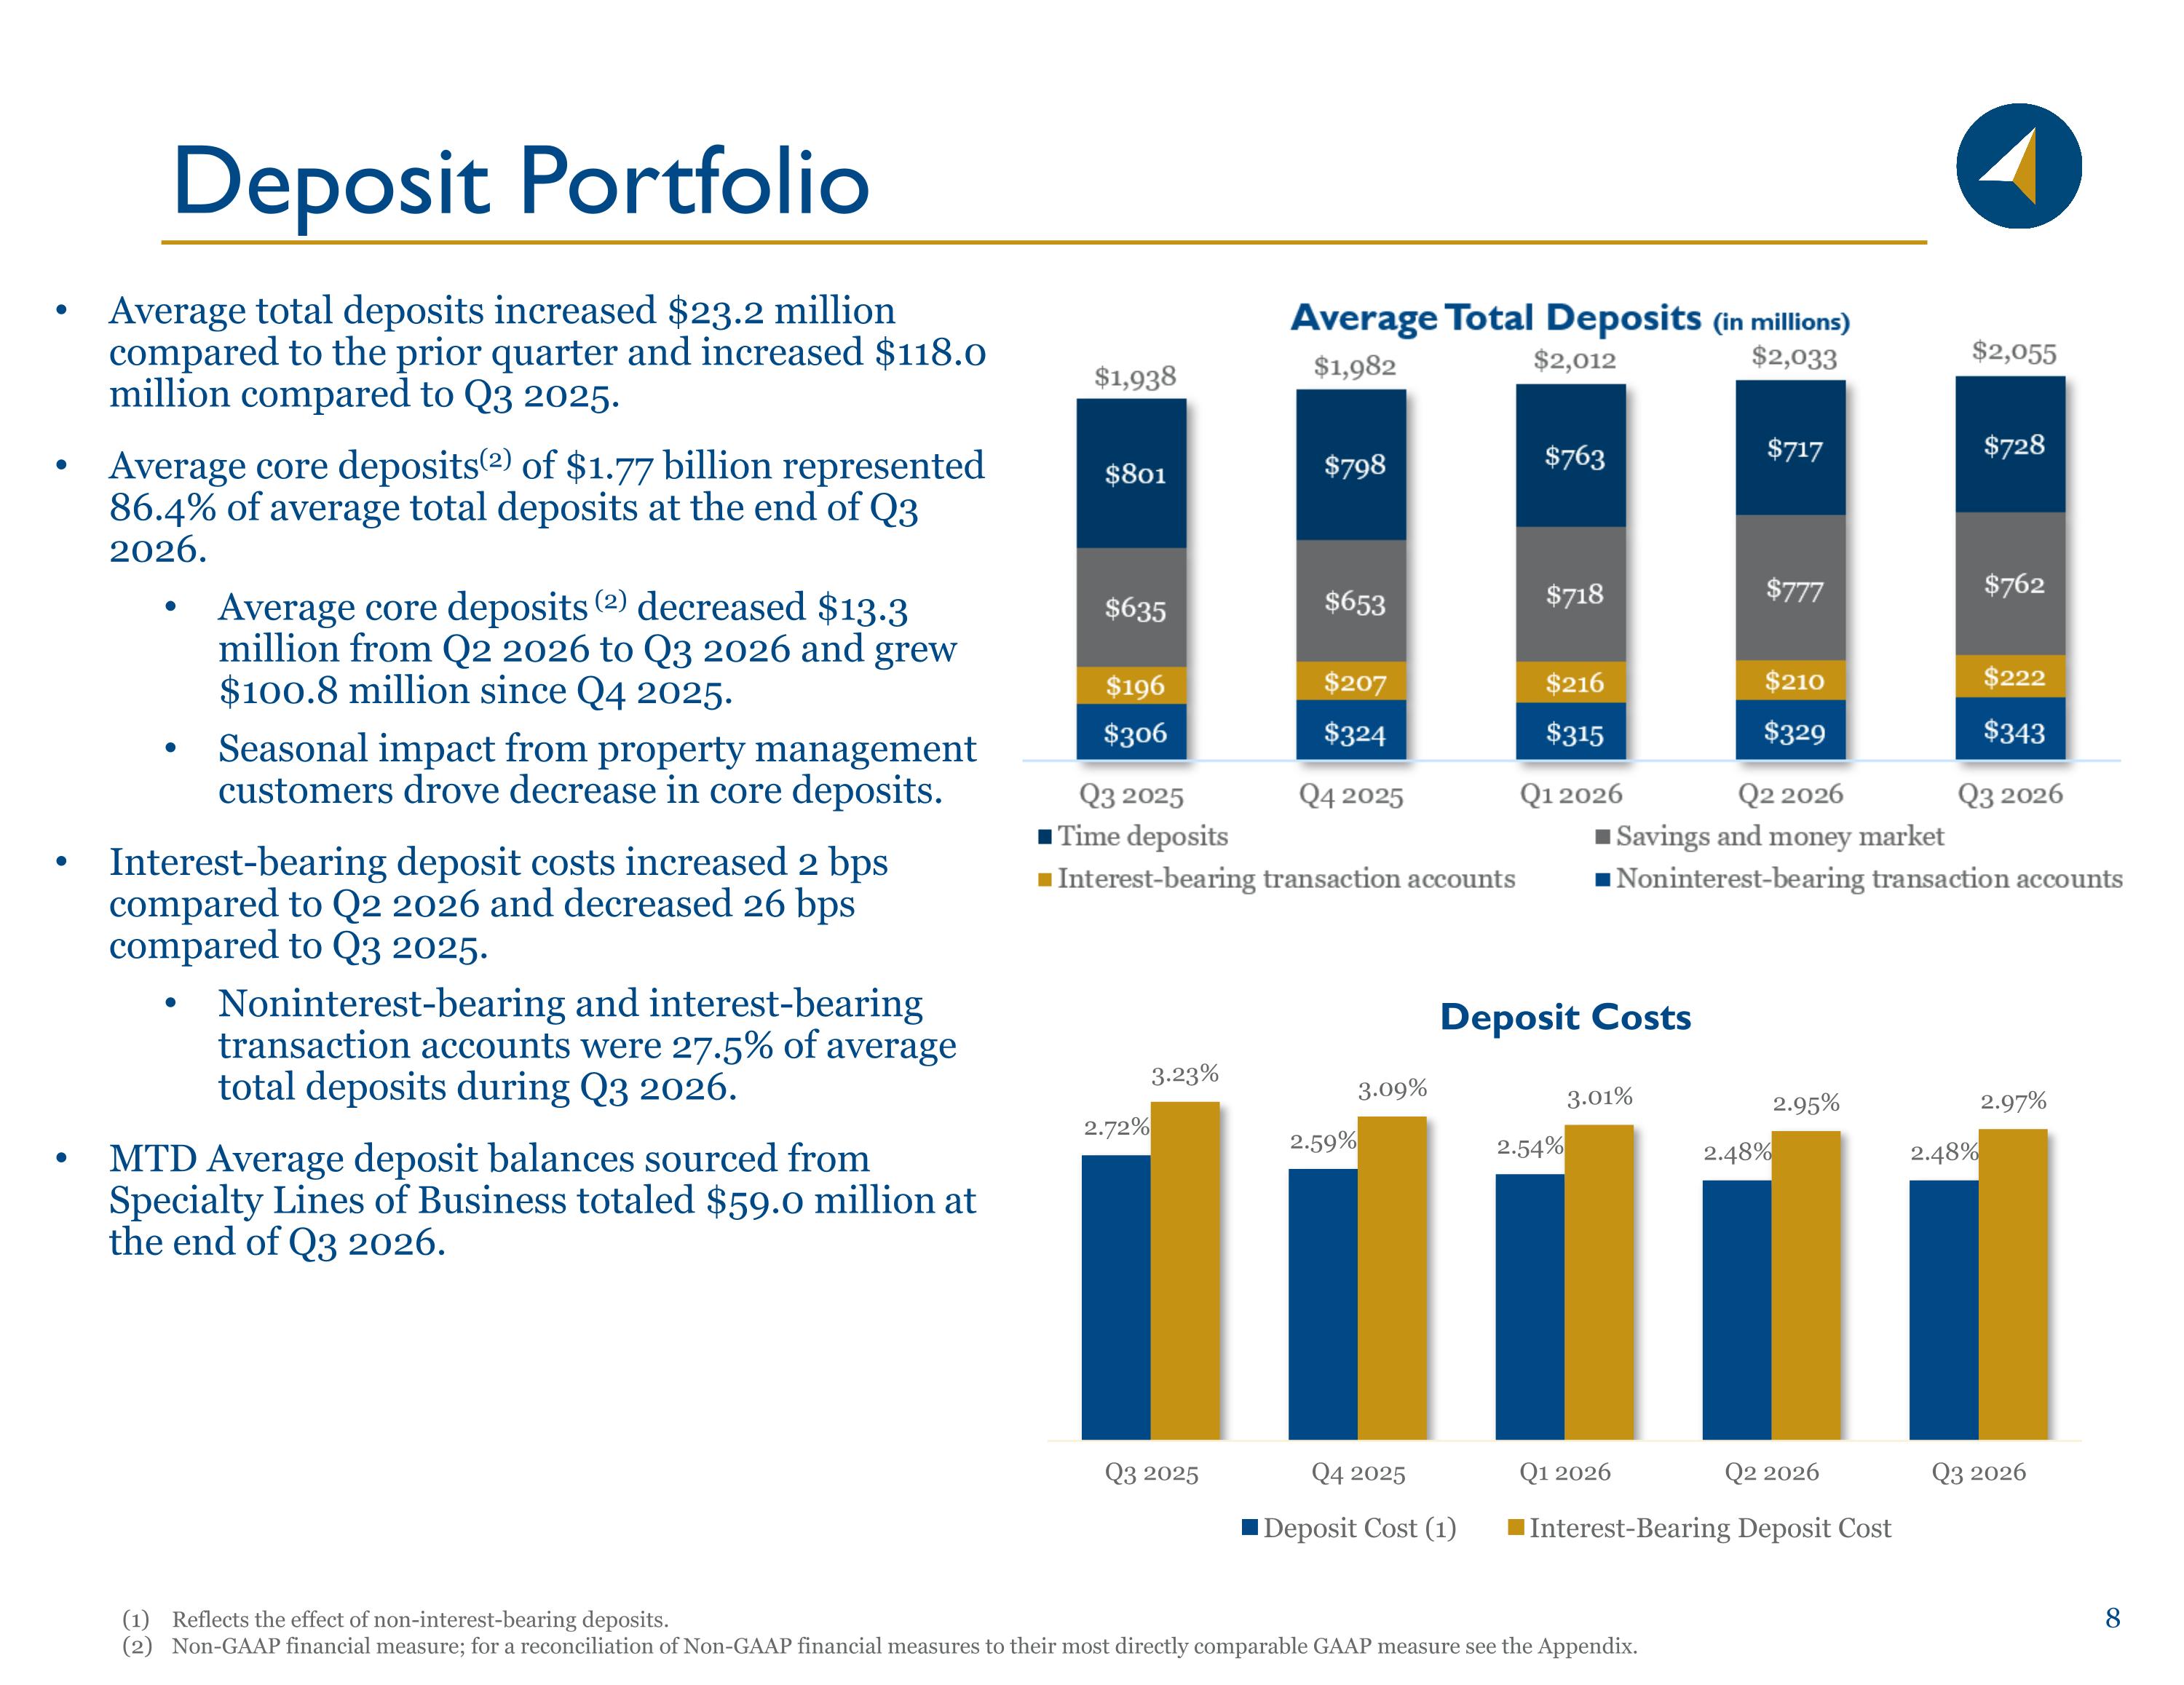
Deposit Portfolio Reflects the effect of non-interest-bearing deposits. Non-GAAP financial measure; for a reconciliation of Non-GAAP financial measures to their most directly comparable GAAP measure see the Appendix. Average total deposits increased $23.2 million compared to the prior quarter and increased $118.0 million compared to Q3 2025. Average core deposits(2) of $1.77 billion represented 86.4% of average total deposits at the end of Q3 2026. Average core deposits (2) decreased $13.3 million from Q2 2026 to Q3 2026 and grew $100.8 million since Q4 2025. Seasonal impact from property management customers drove decrease in core deposits. Interest-bearing deposit costs increased 2 bps compared to Q2 2026 and decreased 26 bps compared to Q3 2025. Noninterest-bearing and interest-bearing transaction accounts were 27.5% of average total deposits during Q3 2026. MTD Average deposit balances sourced from Specialty Lines of Business totaled $59.0 million at the end of Q3 2026.
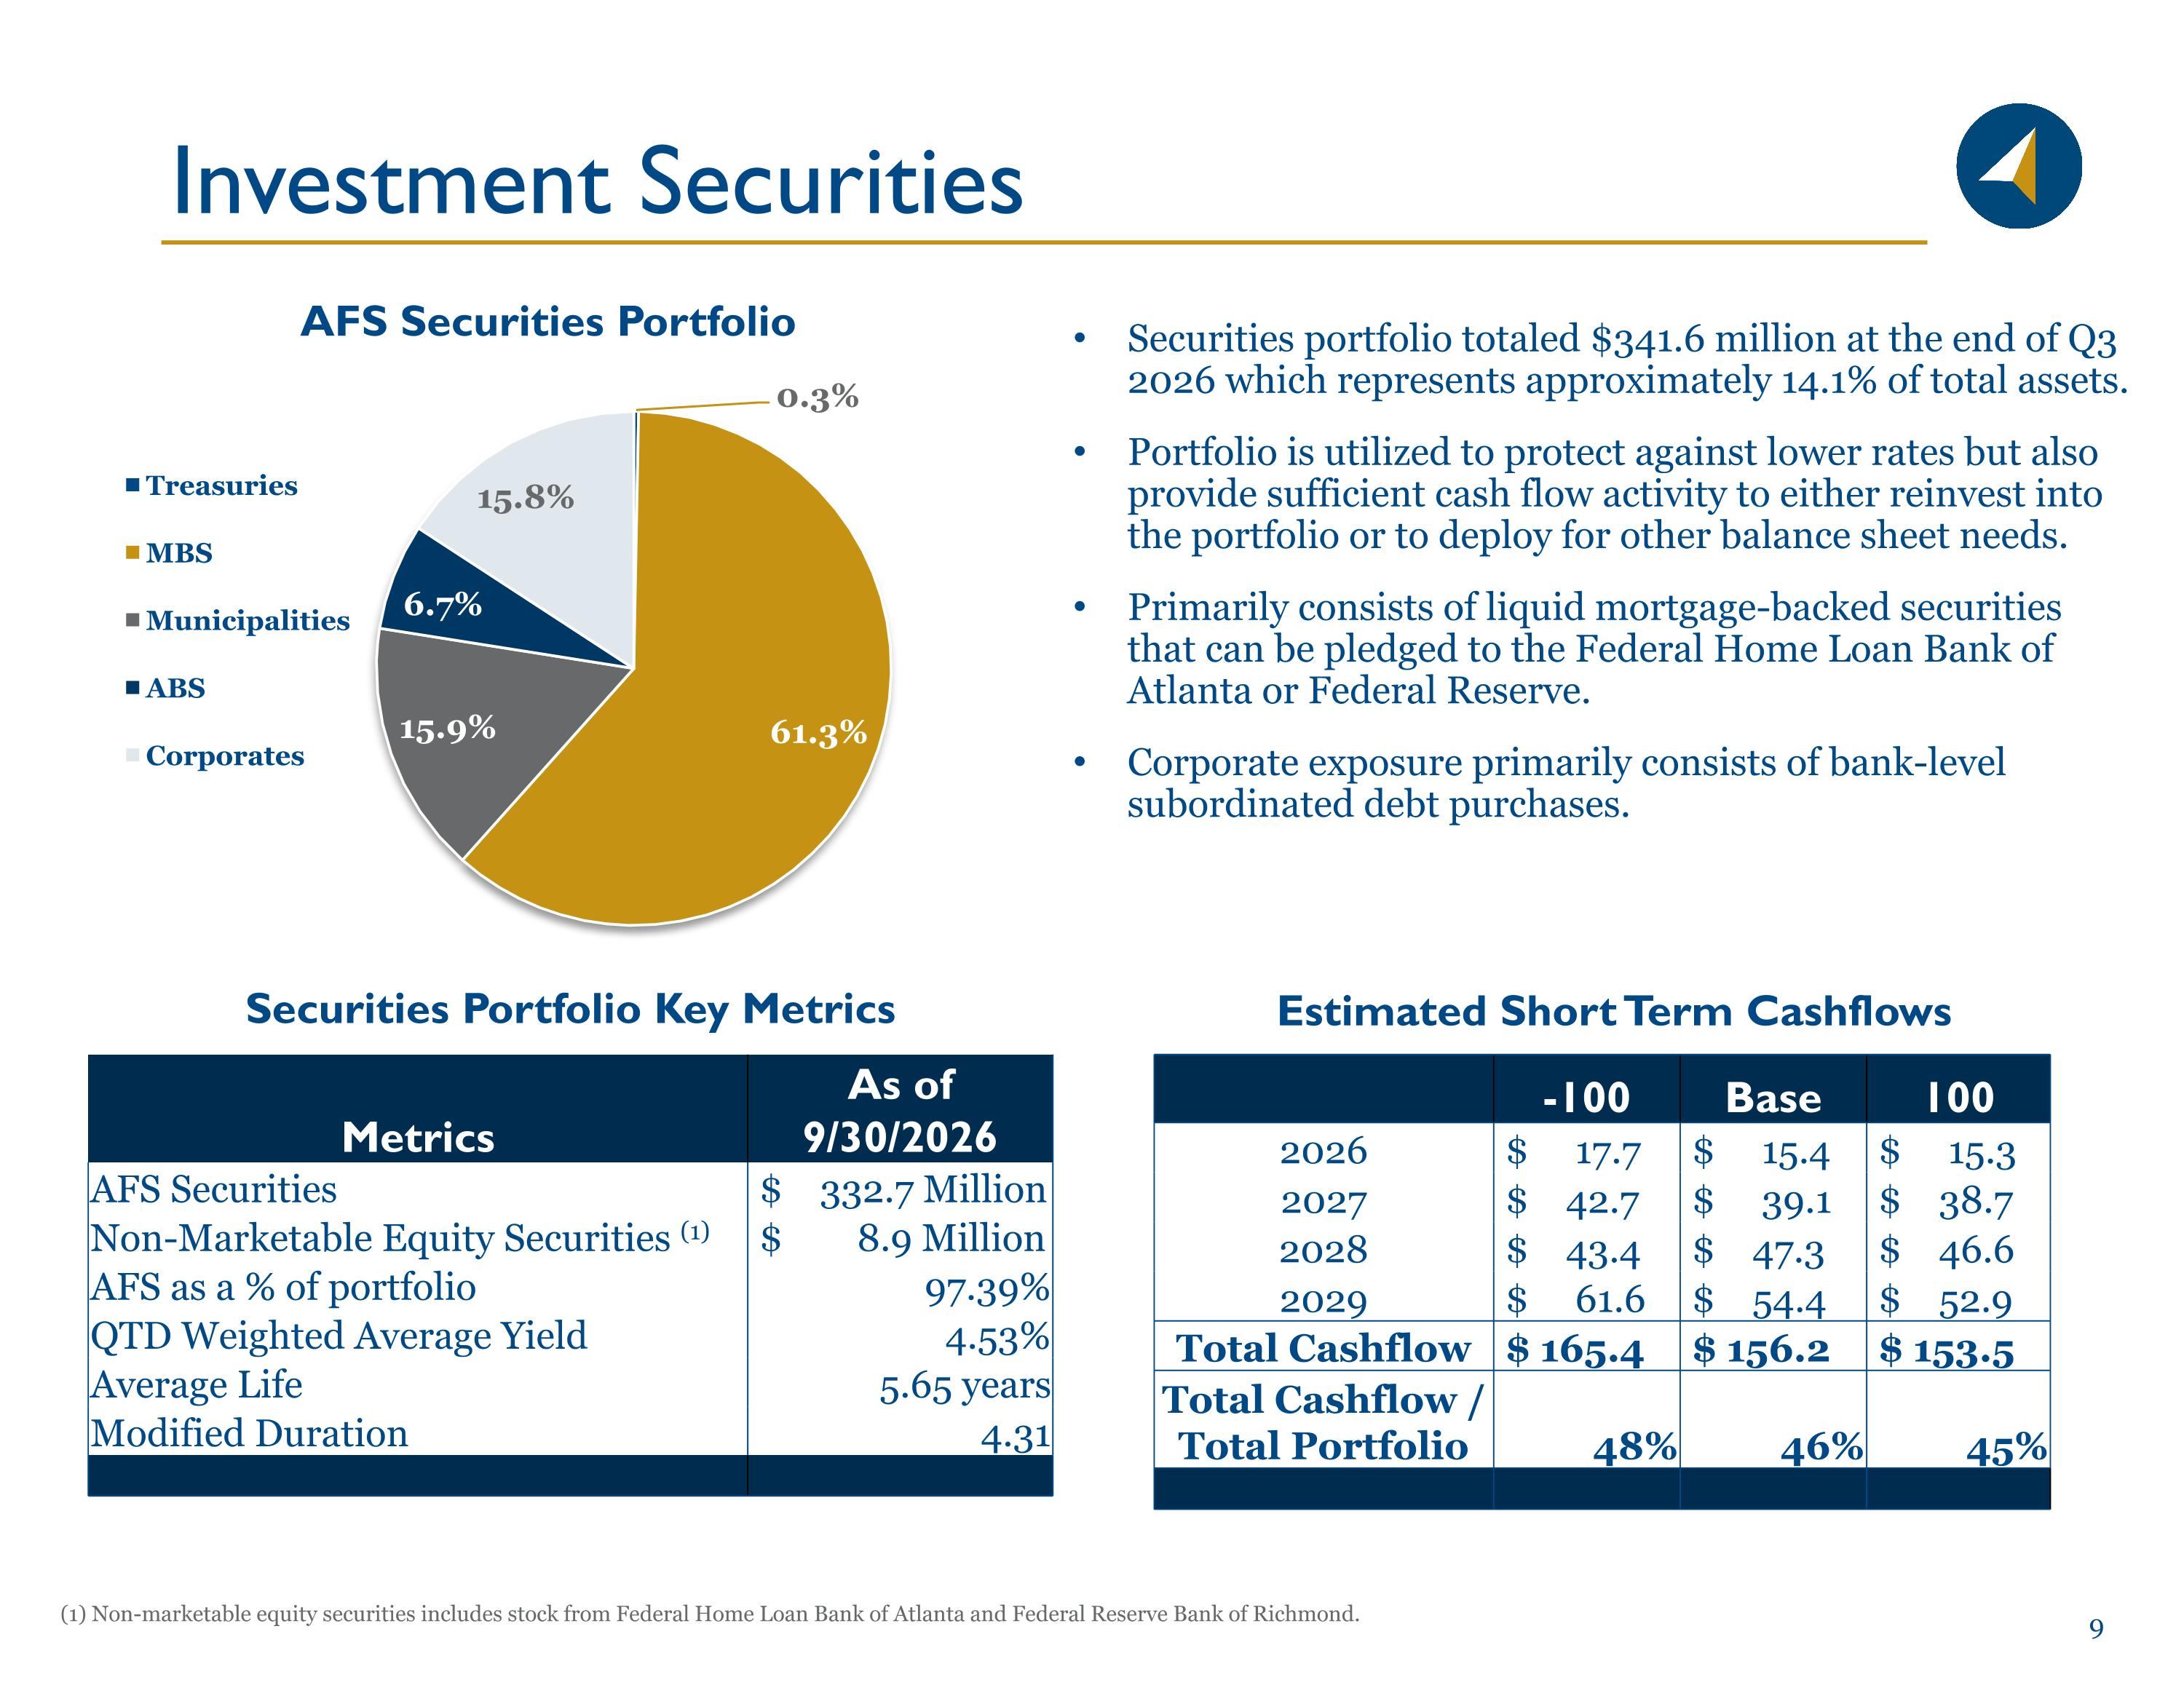
Investment Securities Metrics As of 9/30/2026 AFS Securities $ 332.7 Million Non-Marketable Equity Securities (1) $ 8.9 Million AFS as a % of portfolio 97.39% QTD Weighted Average Yield 4.53% Average Life 5.65 years Modified Duration 4.31 Securities Portfolio Key Metrics Estimated Short Term Cashflows -100 Base 100 2026 $ 17.7 $ 15.4 $ 15.3 2027 $ 42.7 $ 39.1 $ 38.7 2028 $ 43.4 $ 47.3 $ 46.6 2029 $ 61.6 $ 54.4 $ 52.9 Total Cashflow $ 165.4 $ 156.2 $ 153.5 Total Cashflow / Total Portfolio 48% 46% 45% Securities portfolio totaled $341.6 million at the end of Q3 2026 which represents approximately 14.1% of total assets. Portfolio is utilized to protect against lower rates but also provide sufficient cash flow activity to either reinvest into the portfolio or to deploy for other balance sheet needs. Primarily consists of liquid mortgage-backed securities that can be pledged to the Federal Home Loan Bank of Atlanta or Federal Reserve. Corporate exposure primarily consists of bank-level subordinated debt purchases. (1) Non-marketable equity securities includes stock from Federal Home Loan Bank of Atlanta and Federal Reserve Bank of Richmond.
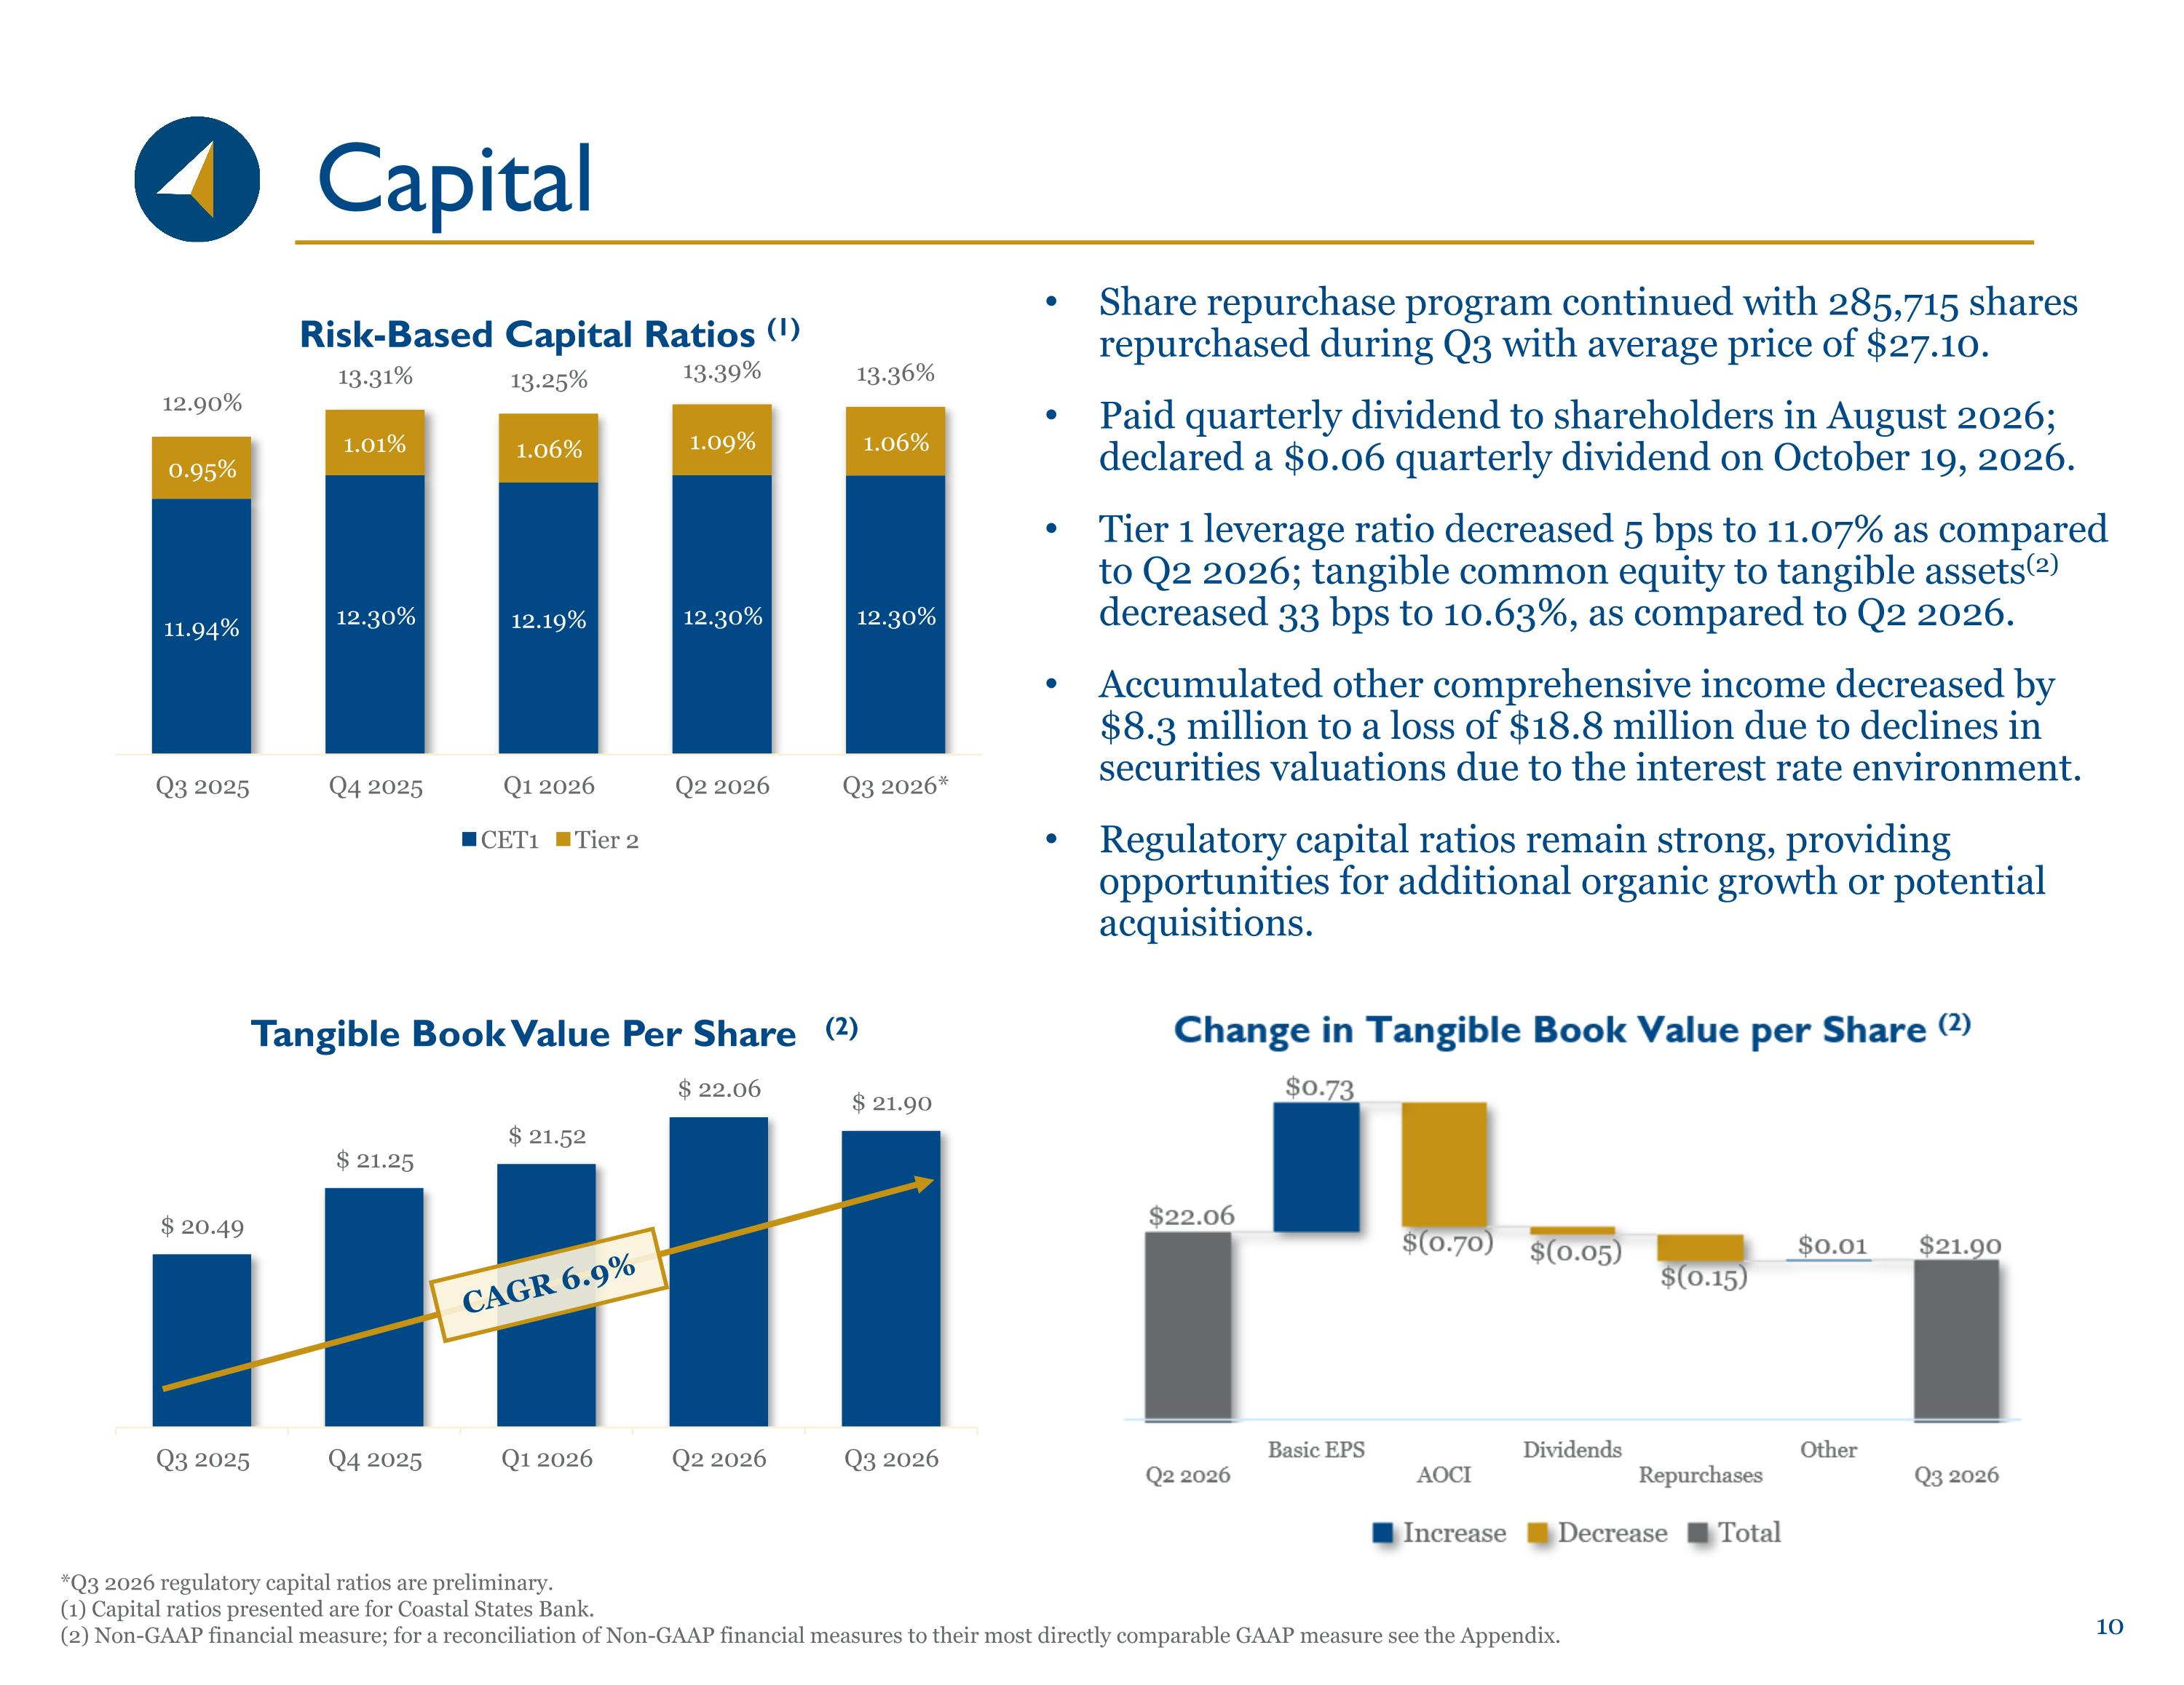
Capital *Q3 2026 regulatory capital ratios are preliminary. (1) Capital ratios presented are for Coastal States Bank. (2) Non-GAAP financial measure; for a reconciliation of Non-GAAP financial measures to their most directly comparable GAAP measure see the Appendix. Share repurchase program continued with 285,715 shares repurchased during Q3 with average price of $27.10. Paid quarterly dividend to shareholders in August 2026; declared a $0.06 quarterly dividend on October 19, 2026. Tier 1 leverage ratio decreased 5 bps to 11.07% as compared to Q2 2026; tangible common equity to tangible assets(2) decreased 33 bps to 10.63%, as compared to Q2 2026. Accumulated other comprehensive income decreased by $8.3 million to a loss of $18.8 million due to declines in securities valuations due to the interest rate environment. Regulatory capital ratios remain strong, providing opportunities for additional organic growth or potential acquisitions. CAGR 6.9%
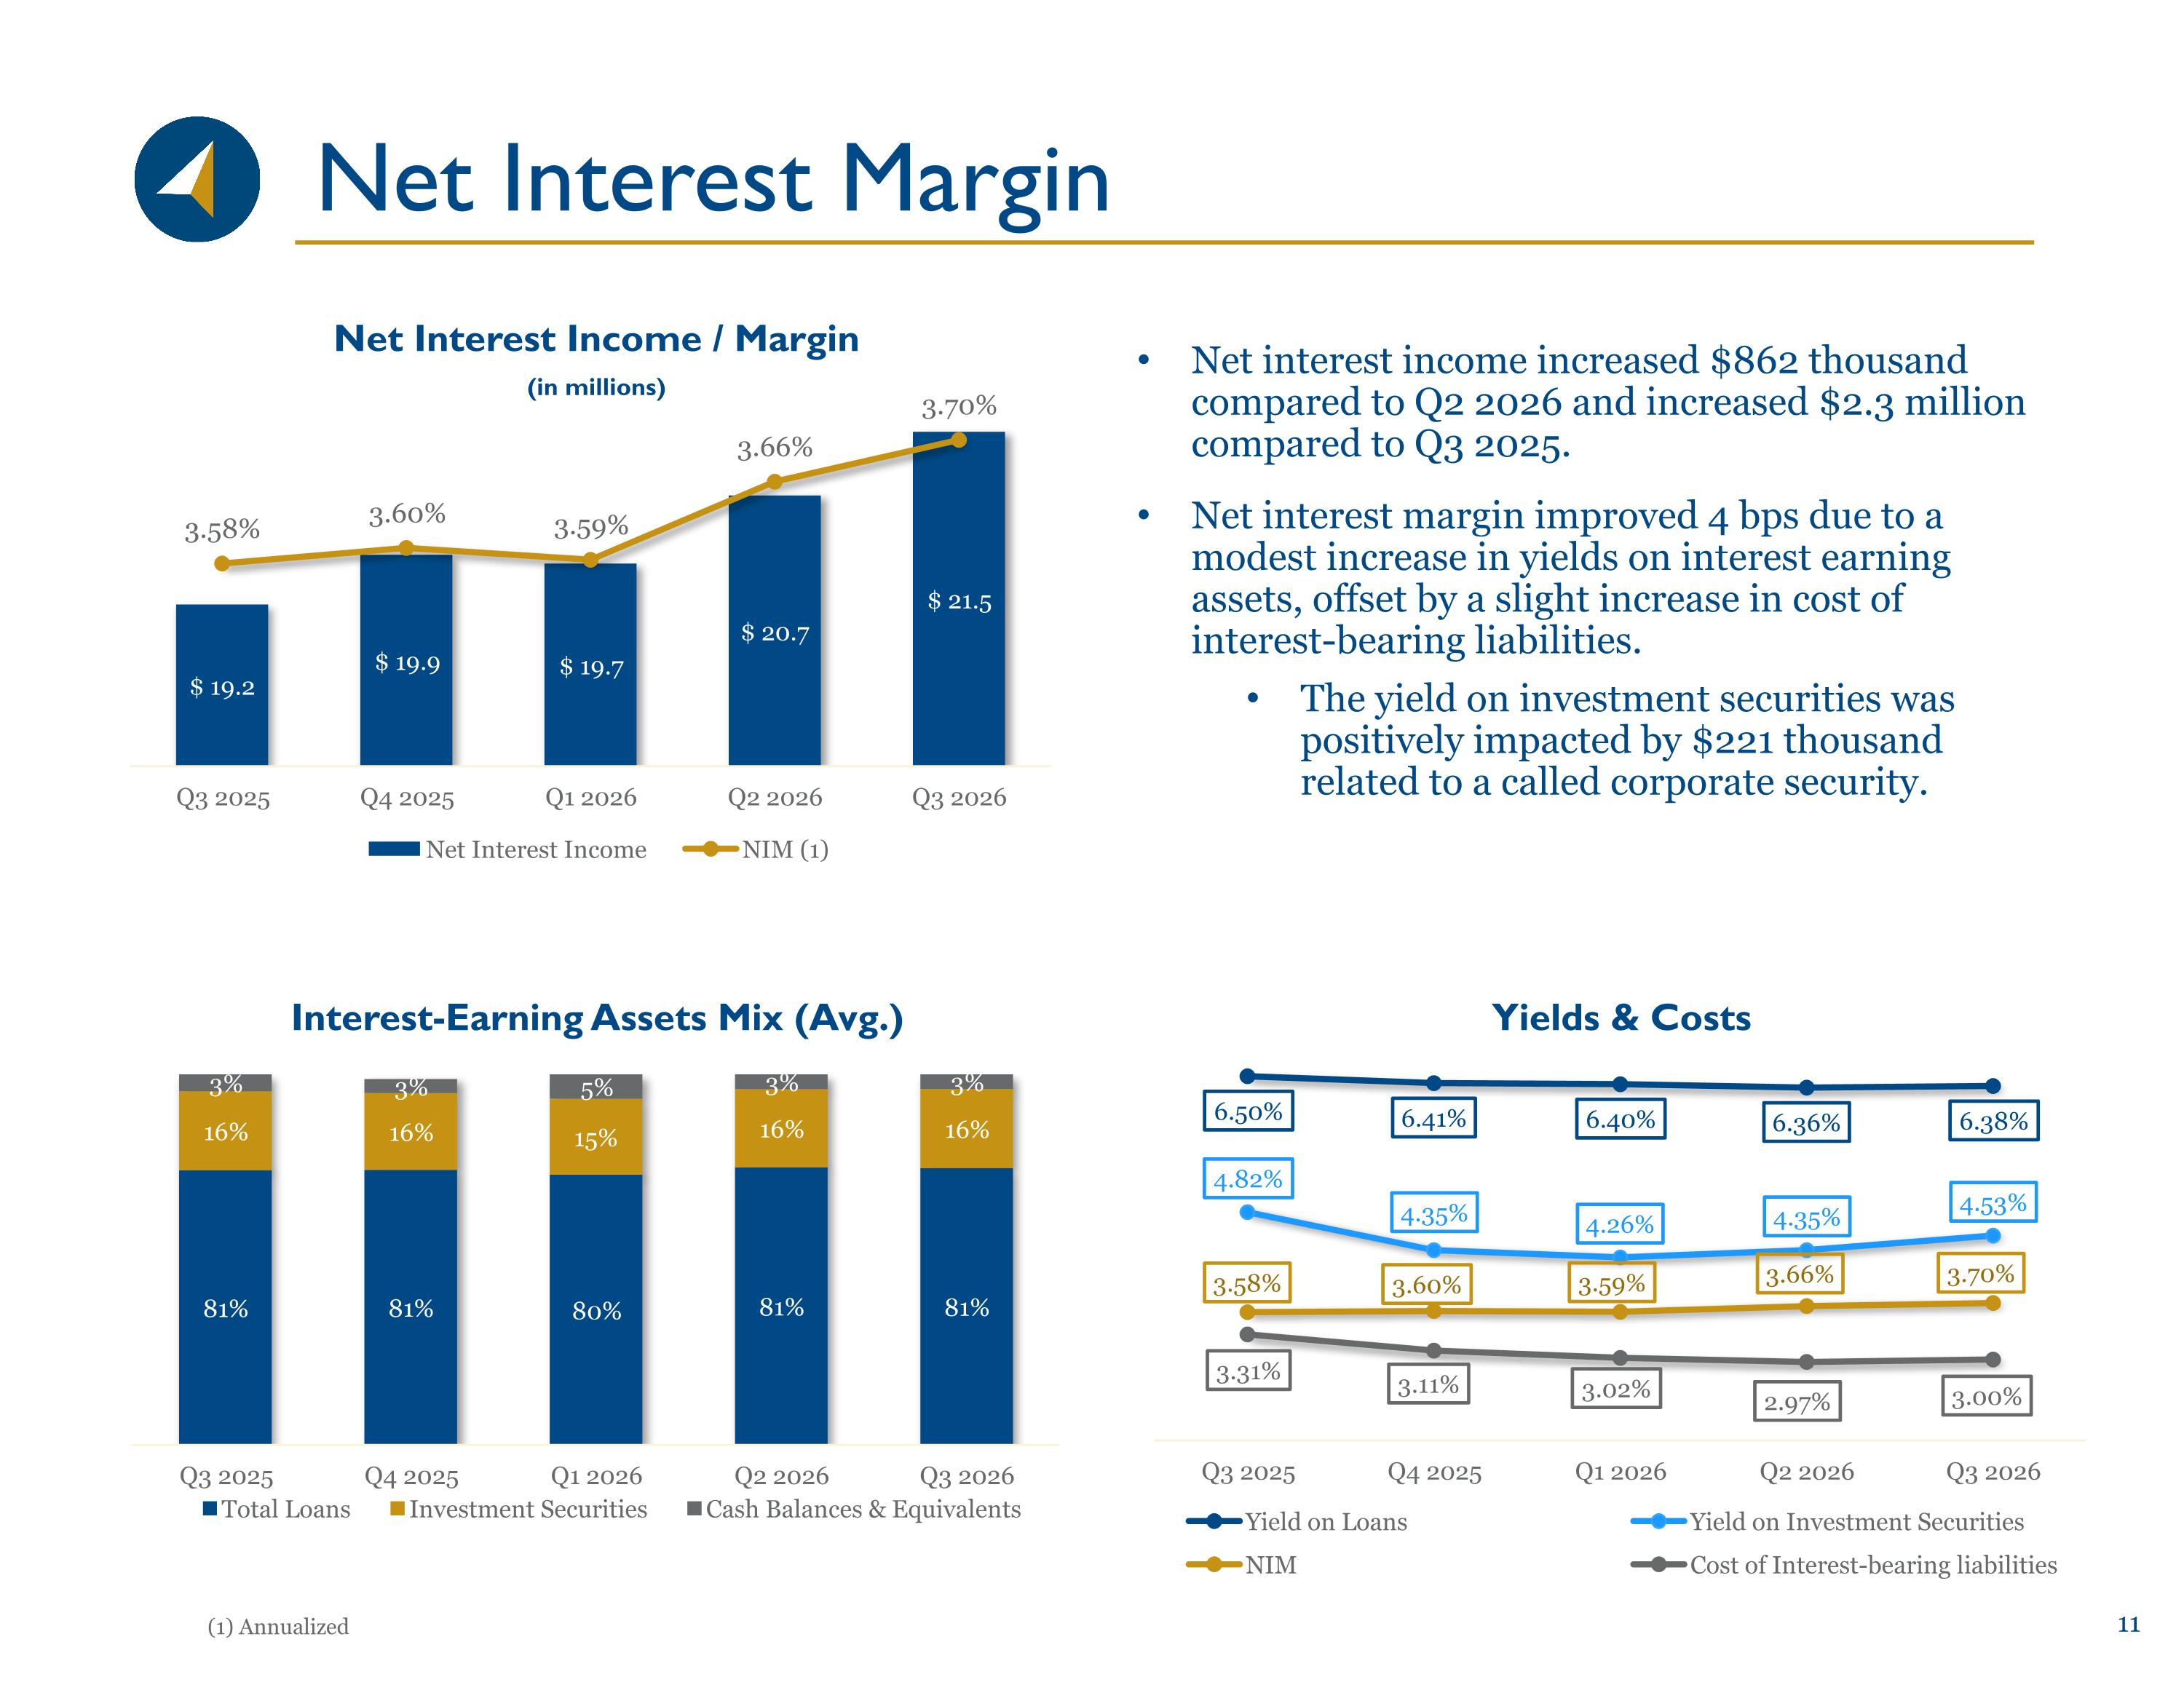
Net Interest Margin (1) Annualized Net interest income increased $862 thousand compared to Q2 2026 and increased $2.3 million compared to Q3 2025. Net interest margin improved 4 bps due to a modest increase in yields on interest earning assets, offset by a slight increase in cost of interest-bearing liabilities. The yield on investment securities was positively impacted by $221 thousand related to a called corporate security.
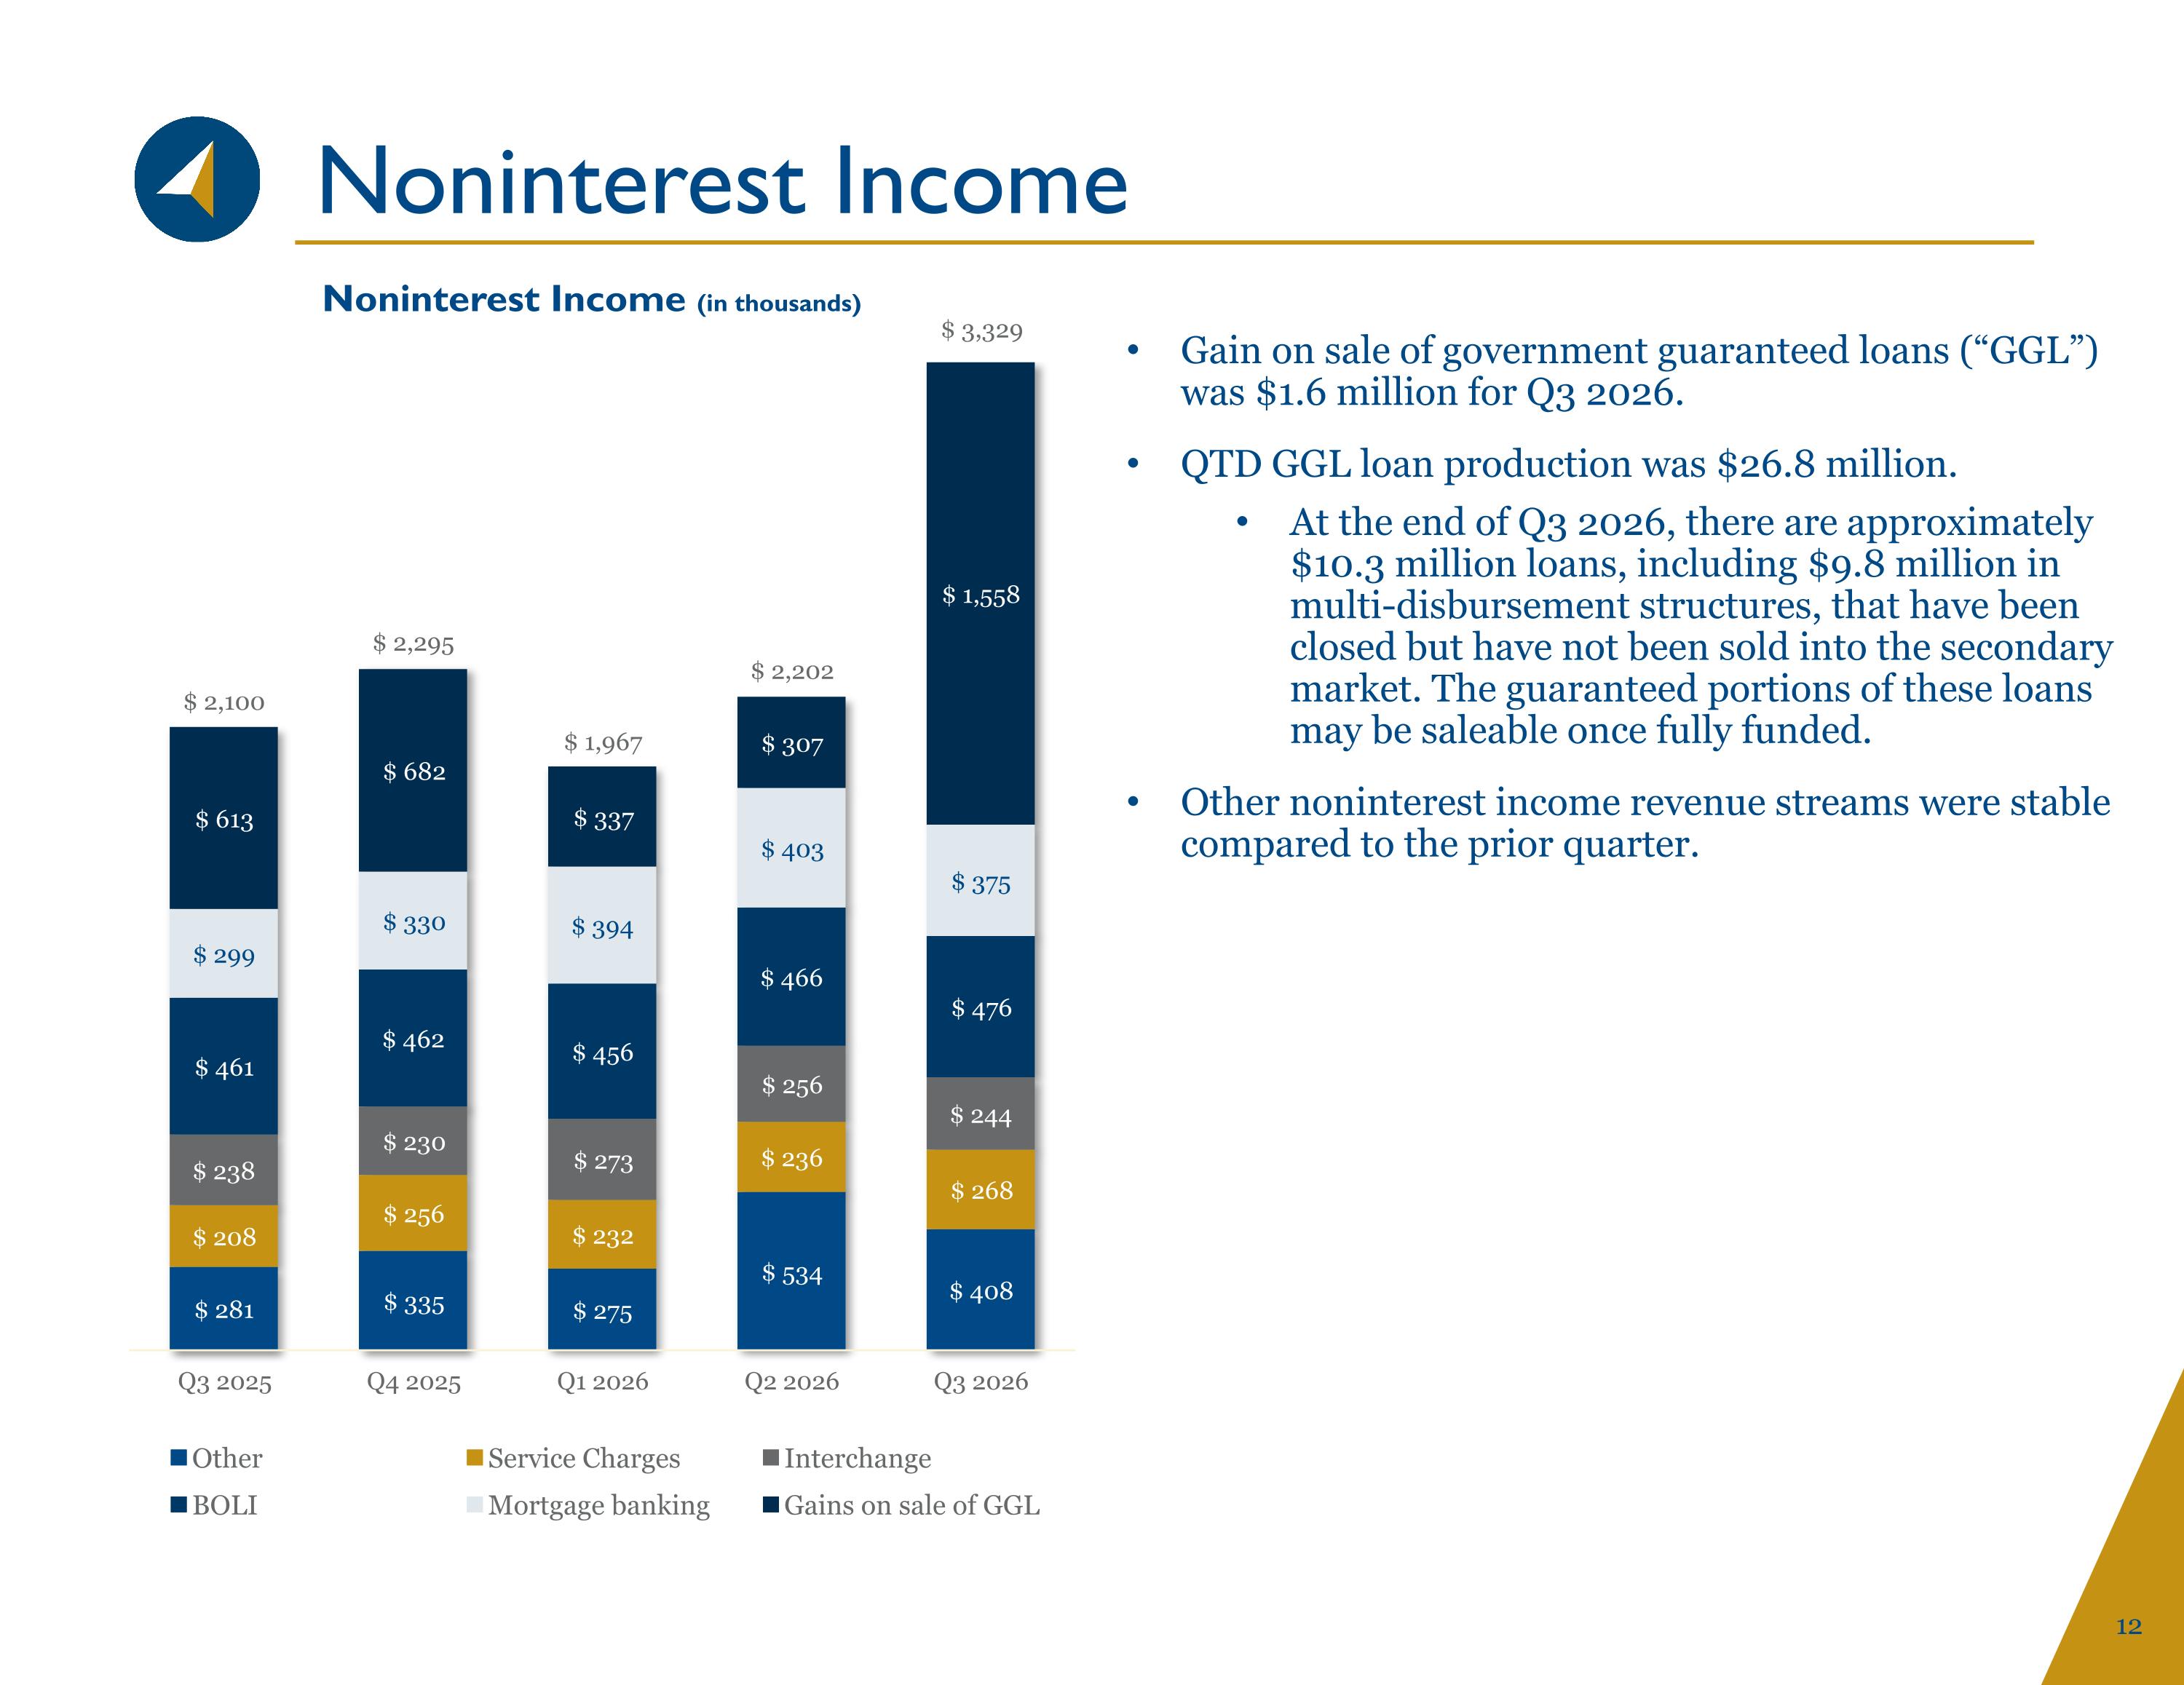
Noninterest Income Gain on sale of government guaranteed loans (“GGL”) was $1.6 million for Q3 2026. QTD GGL loan production was $26.8 million. At the end of Q3 2026, there are approximately $10.3 million loans, including $9.8 million in multi-disbursement structures, that have been closed but have not been sold into the secondary market. The guaranteed portions of these loans may be saleable once fully funded. Other noninterest income revenue streams were stable compared to the prior quarter.
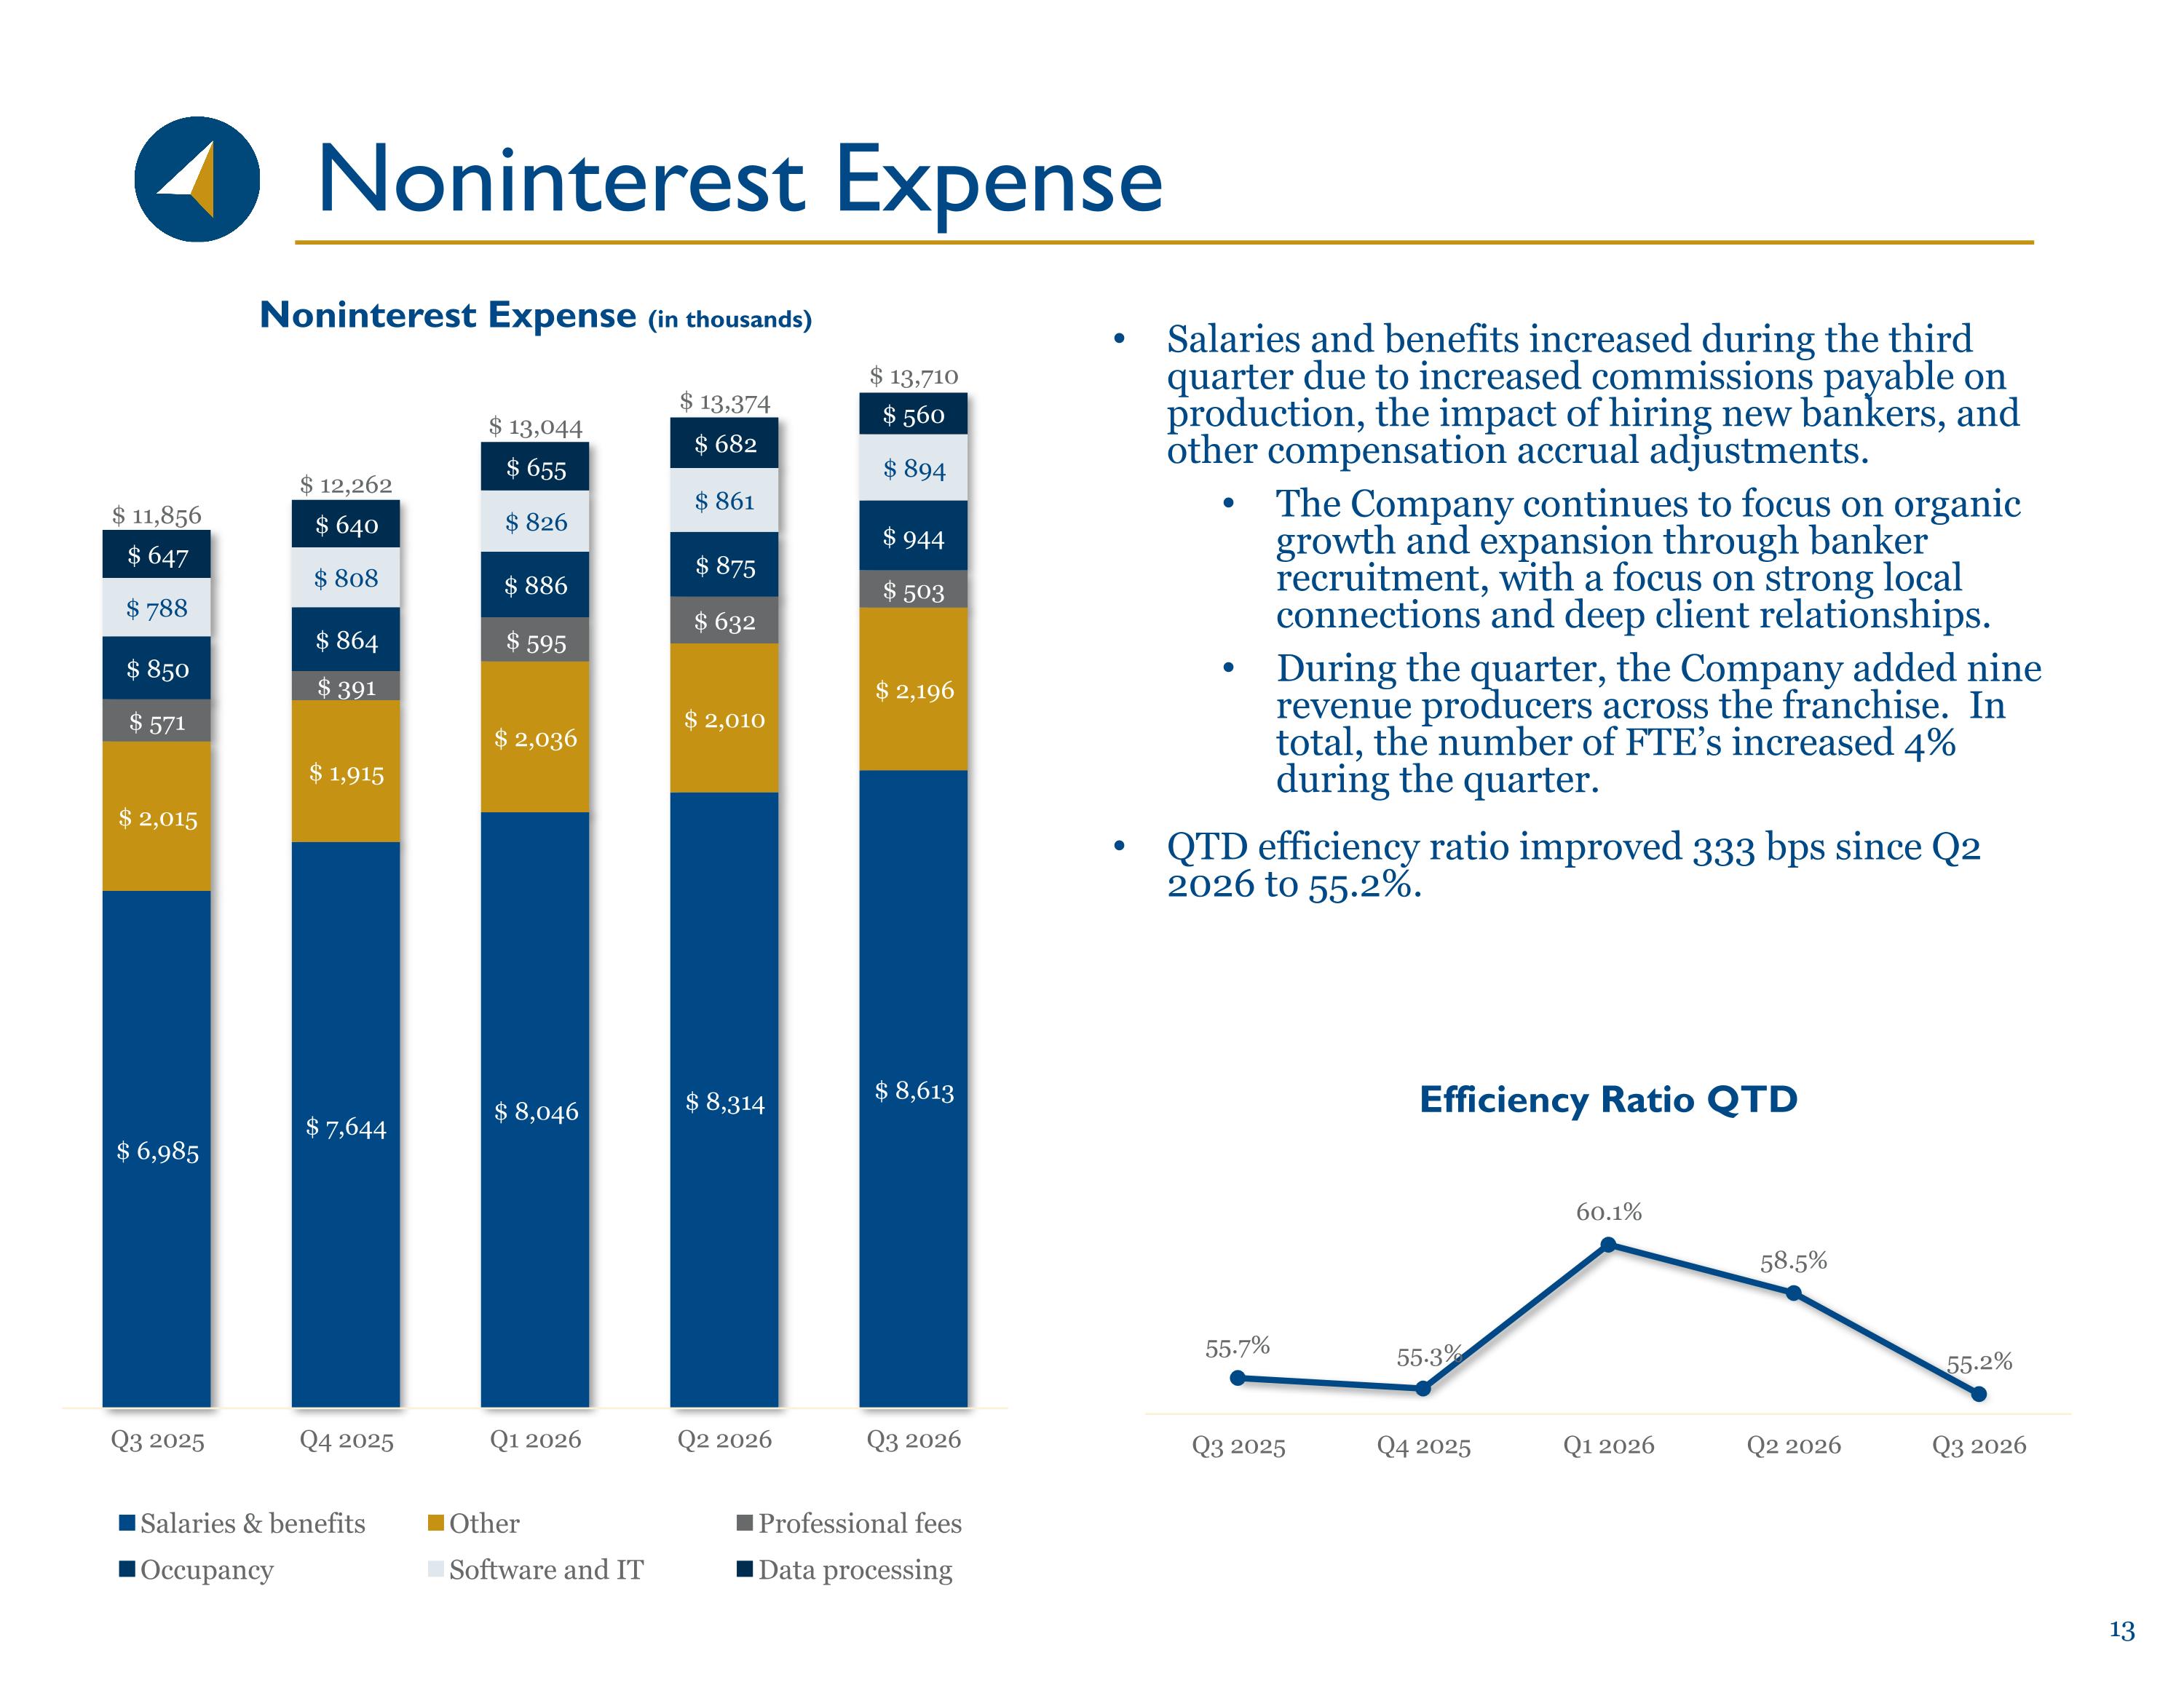
Noninterest Expense Salaries and benefits increased during the third quarter due to increased commissions payable on production, the impact of hiring new bankers, and other compensation accrual adjustments. The Company continues to focus on organic growth and expansion through banker recruitment, with a focus on strong local connections and deep client relationships. During the quarter, the Company added nine revenue producers across the franchise. In total, the number of FTE’s increased 4% during the quarter. QTD efficiency ratio improved 333 bps since Q2 2026 to 55.2%.
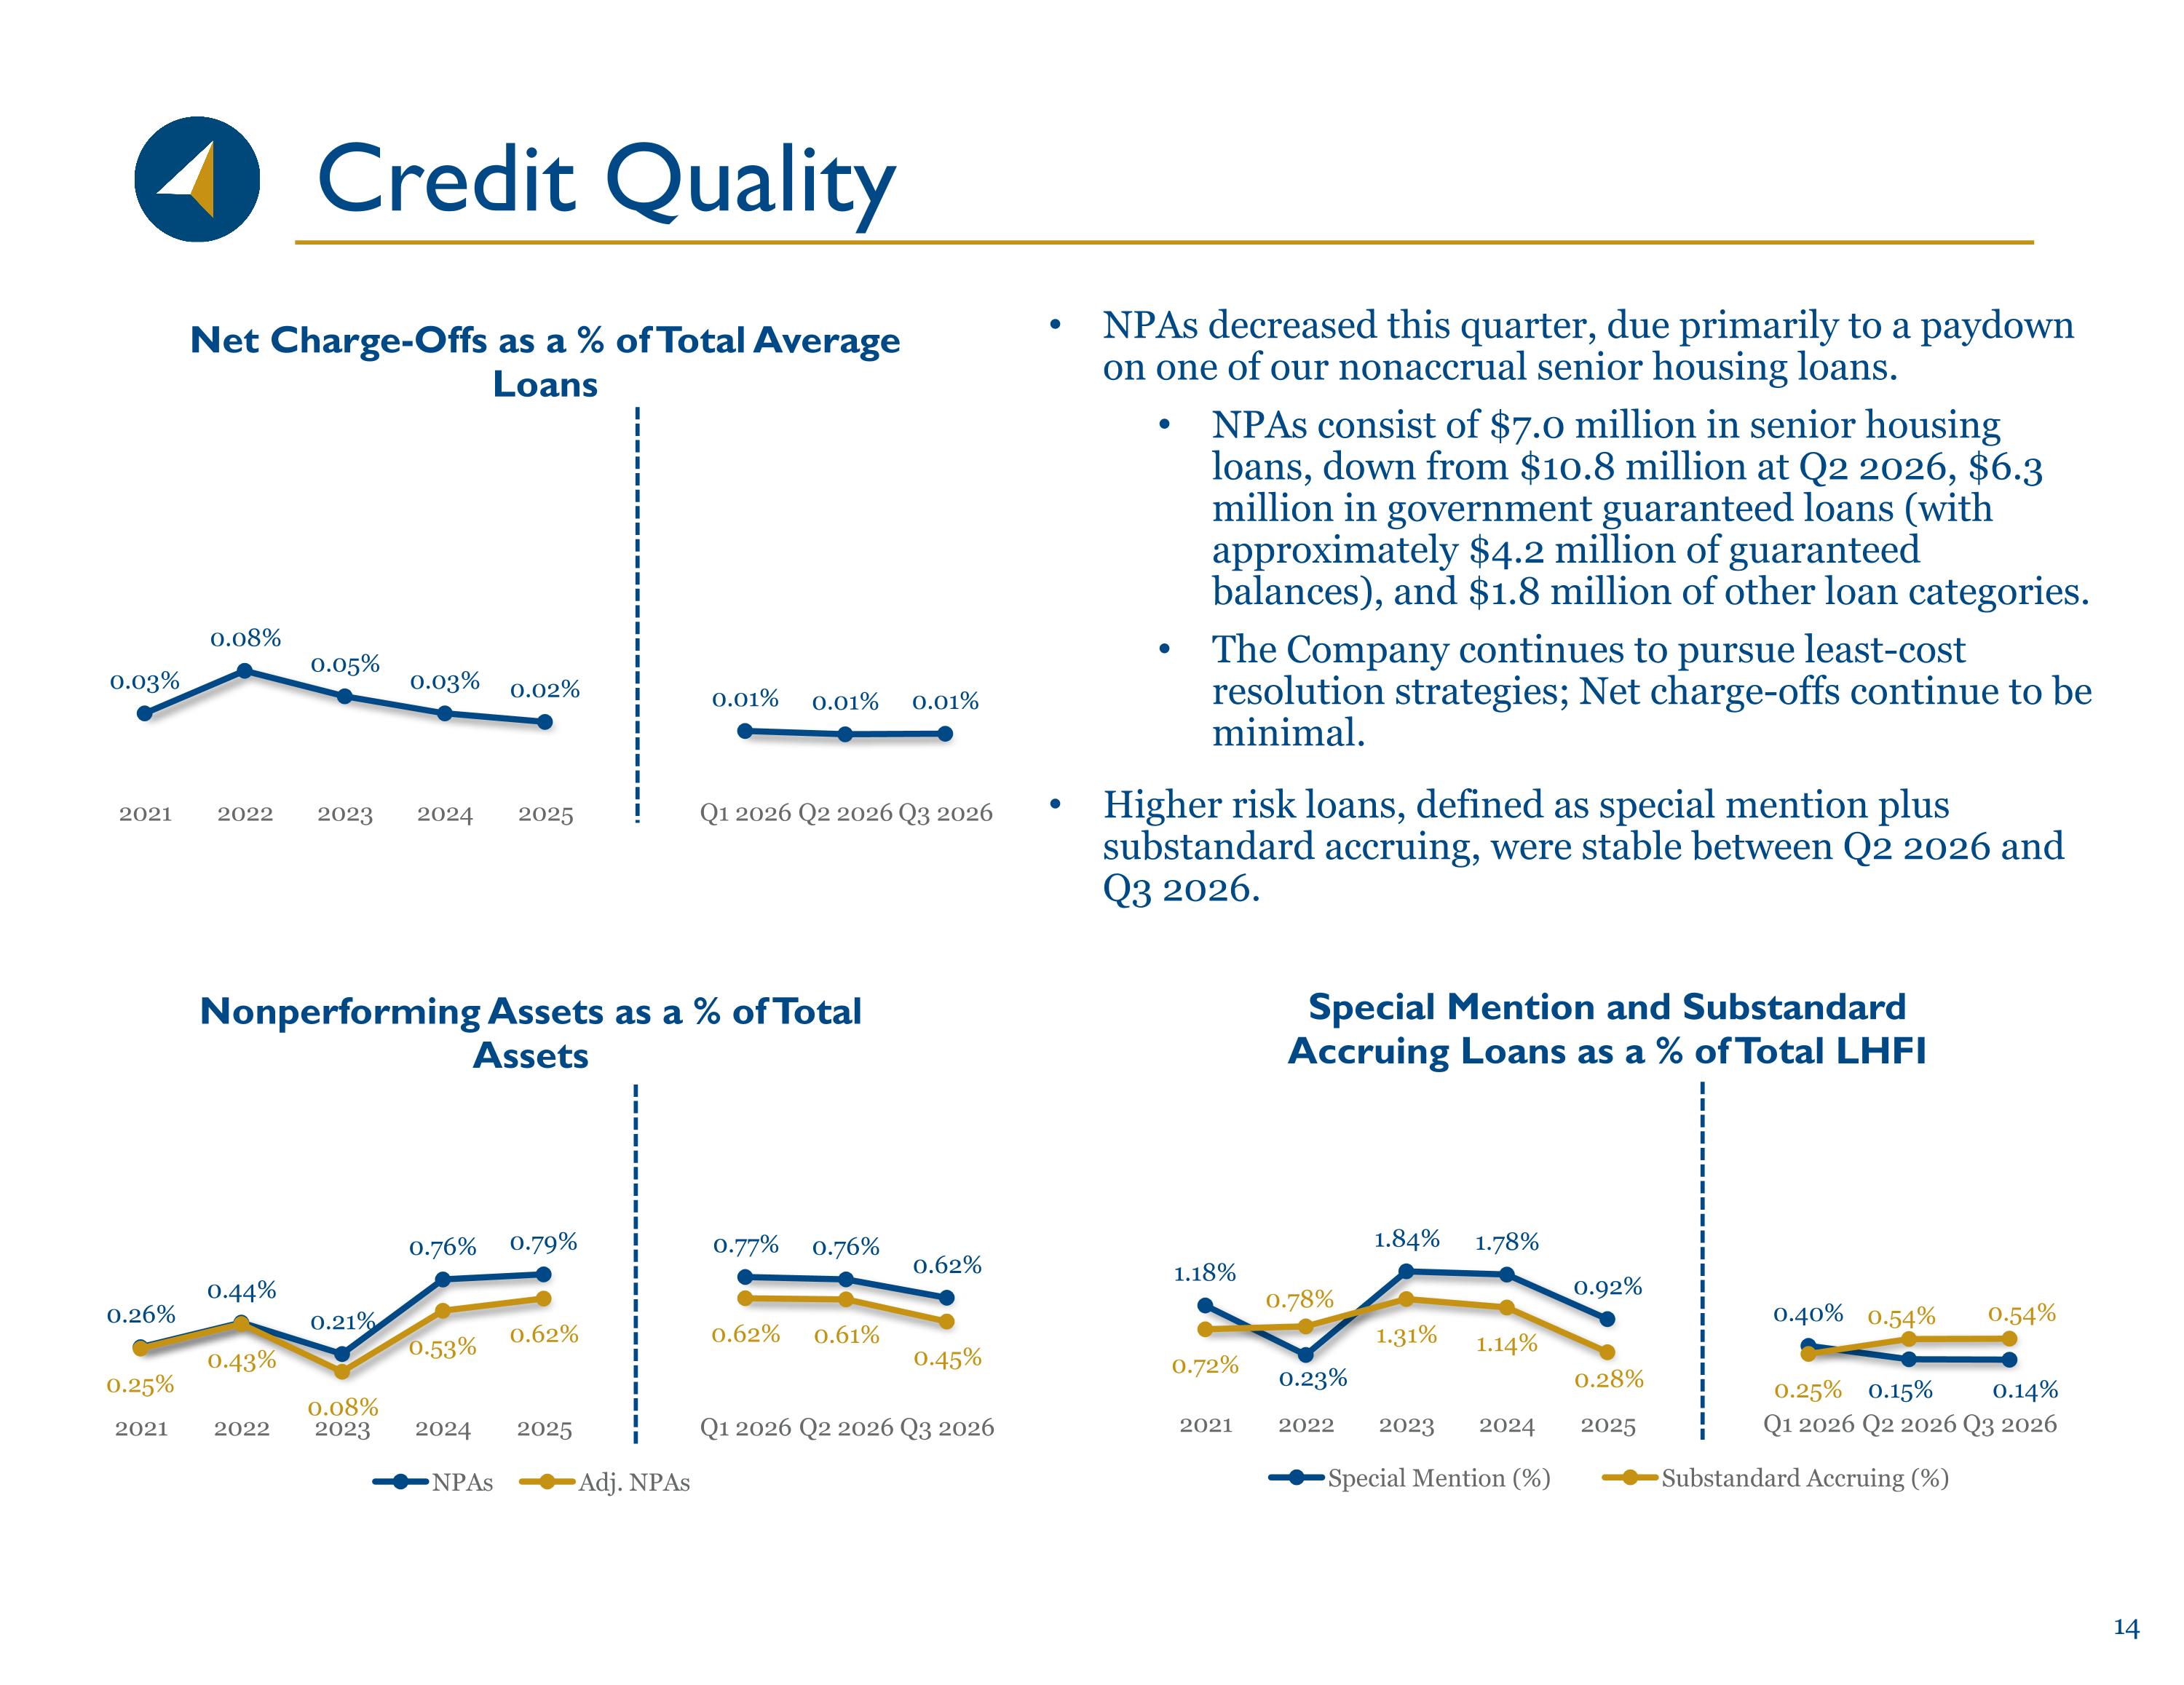
Credit Quality NPAs decreased this quarter, due primarily to a paydown on one of our nonaccrual senior housing loans. NPAs consist of $7.0 million in senior housing loans, down from $10.8 million at Q2 2026, $6.3 million in government guaranteed loans (with approximately $4.2 million of guaranteed balances), and $1.8 million of other loan categories. The Company continues to pursue least-cost resolution strategies; Net charge-offs continue to be minimal. Higher risk loans, defined as special mention plus substandard accruing, were stable between Q2 2026 and Q3 2026.
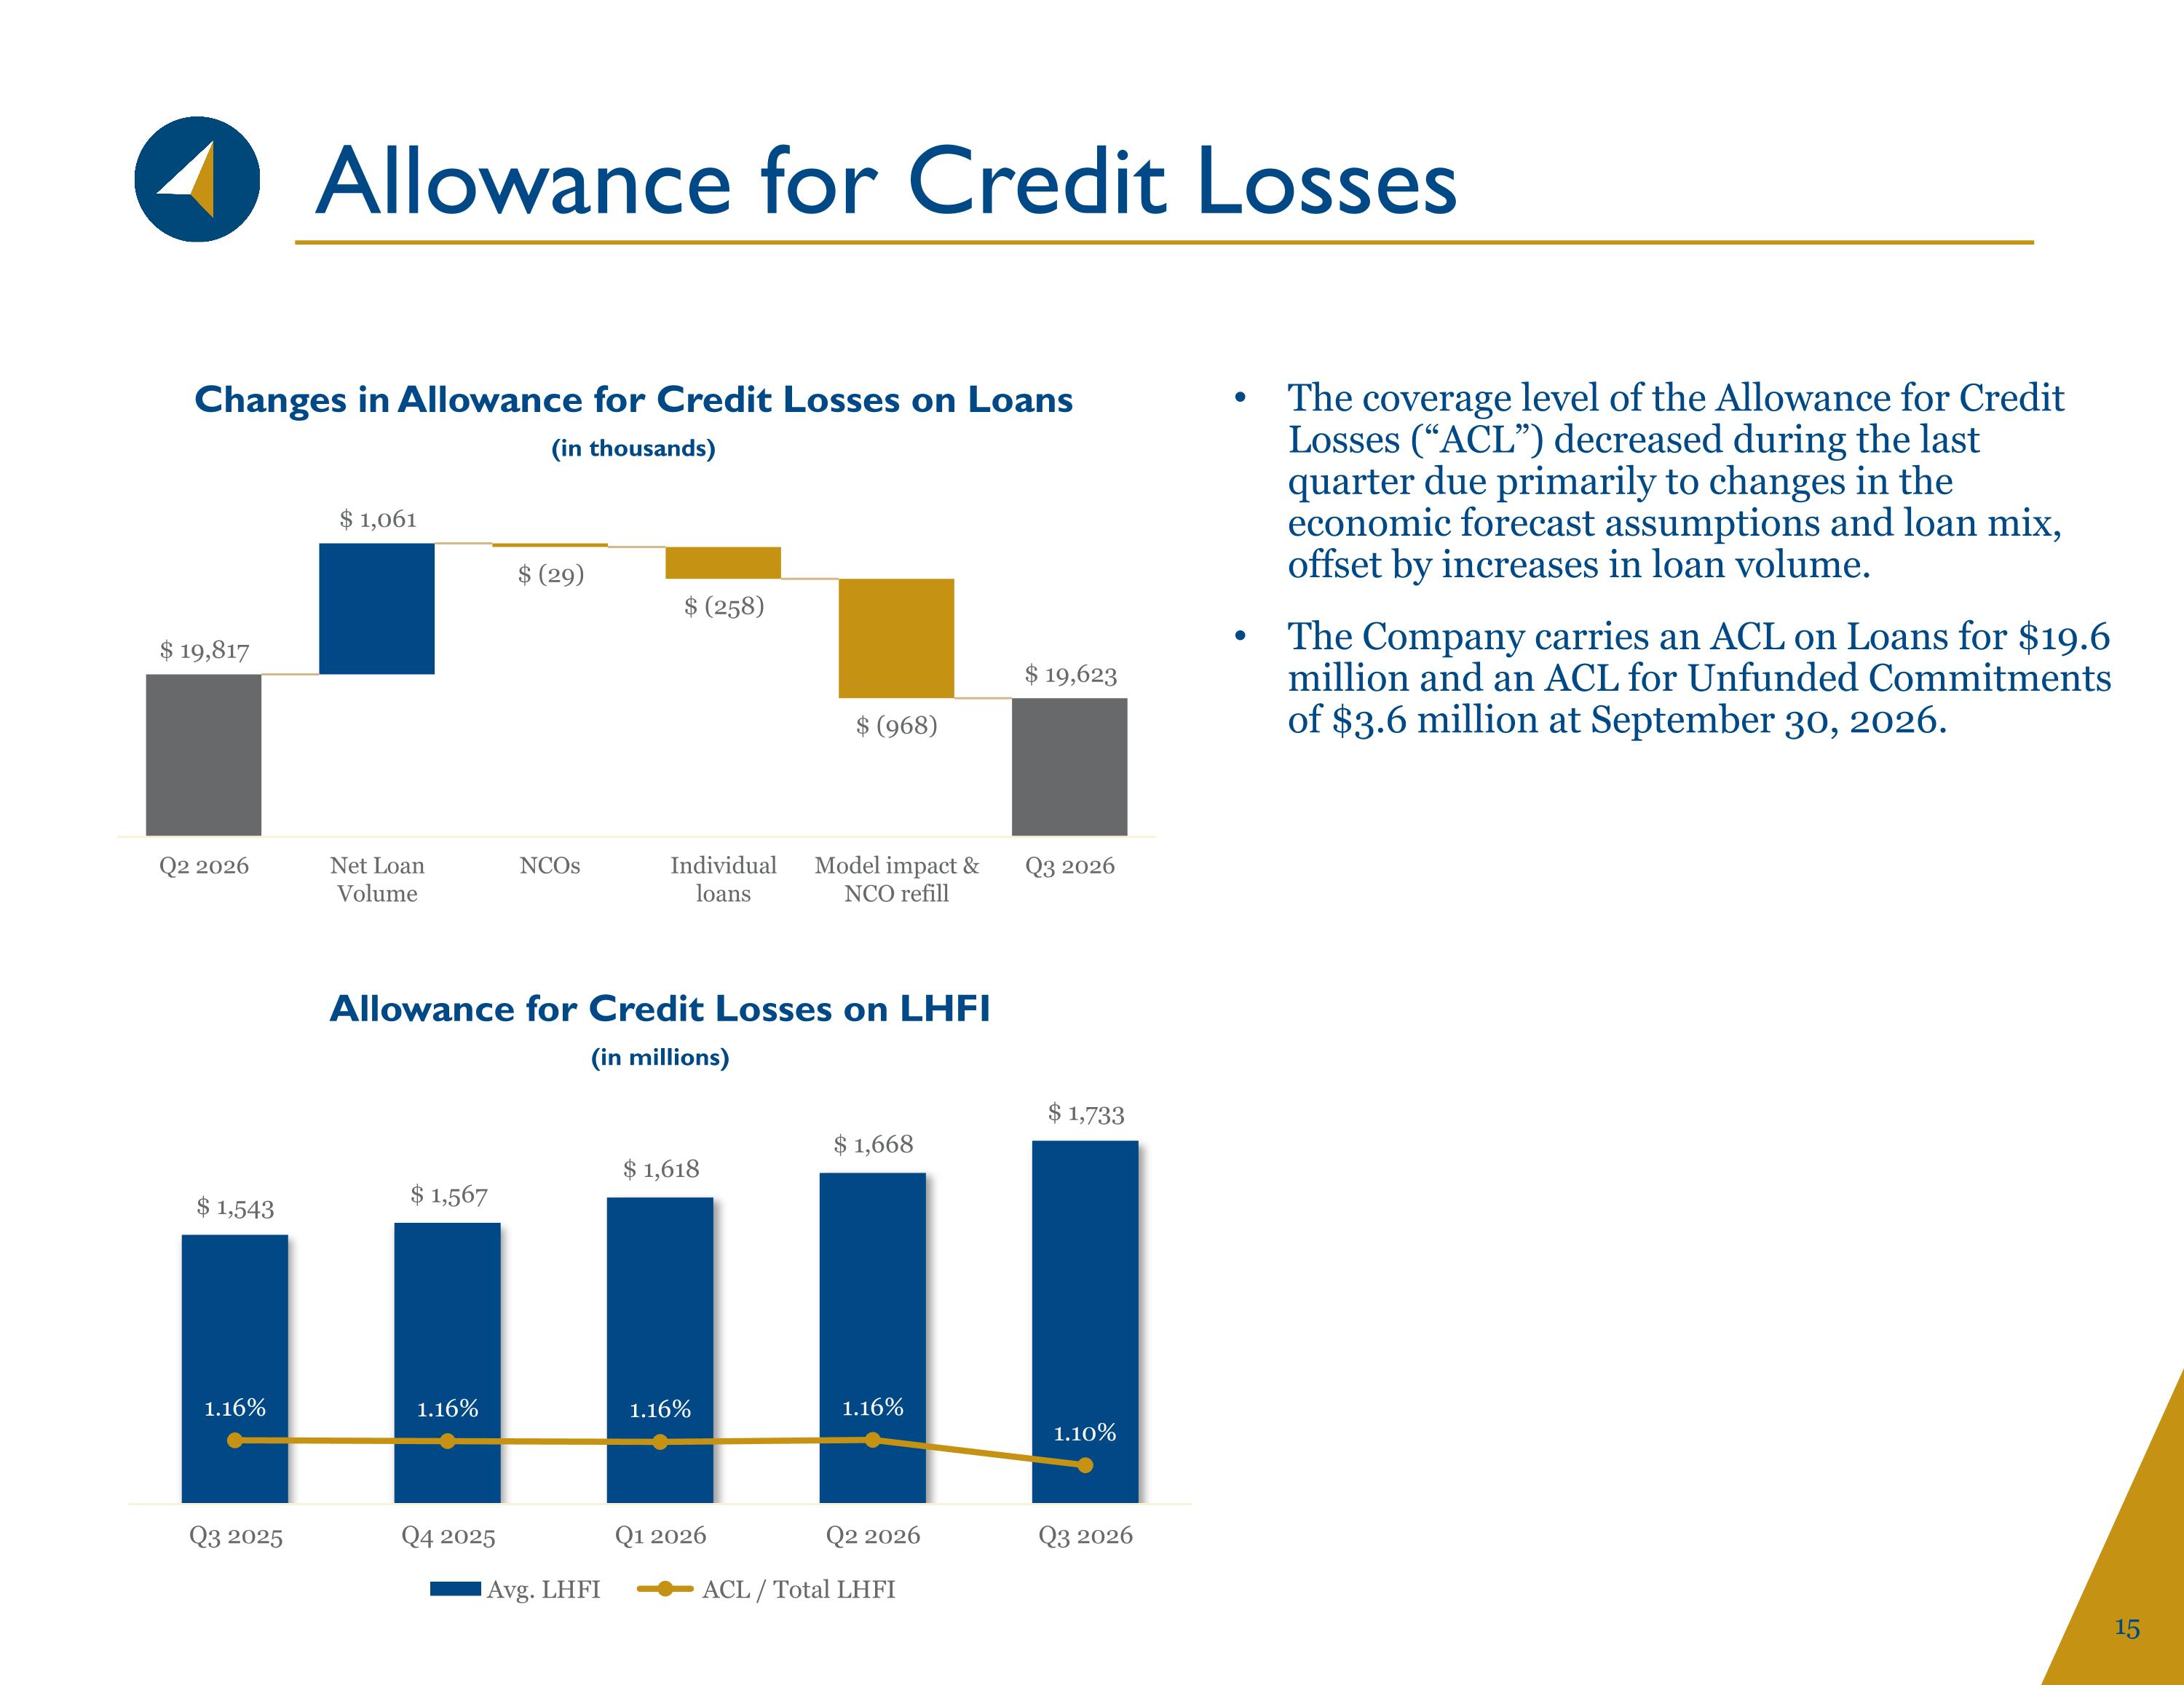
Allowance for Credit Losses The coverage level of the Allowance for Credit Losses (“ACL”) decreased during the last quarter due primarily to changes in the economic forecast assumptions and loan mix, offset by increases in loan volume. The Company carries an ACL on Loans for $19.6 million and an ACL for Unfunded Commitments of $3.6 million at September 30, 2026.
Appendix
Core Operating Principles We believe that by focusing on our five core values outlined below, we can create meaningful relationships between our Bank, team members, clients, and our communities Each of these relationships is critical to our financial success and supports our capacity to drive shareholder value. Key drivers of COSO’s success include: Unwavering commitment to hiring the best local bankers. Valuing our entrepreneurial culture and ensuring our daily actions are aligned with vision and values. Communicating clearly and candidly. Providing exceptional service and innovative solutions.
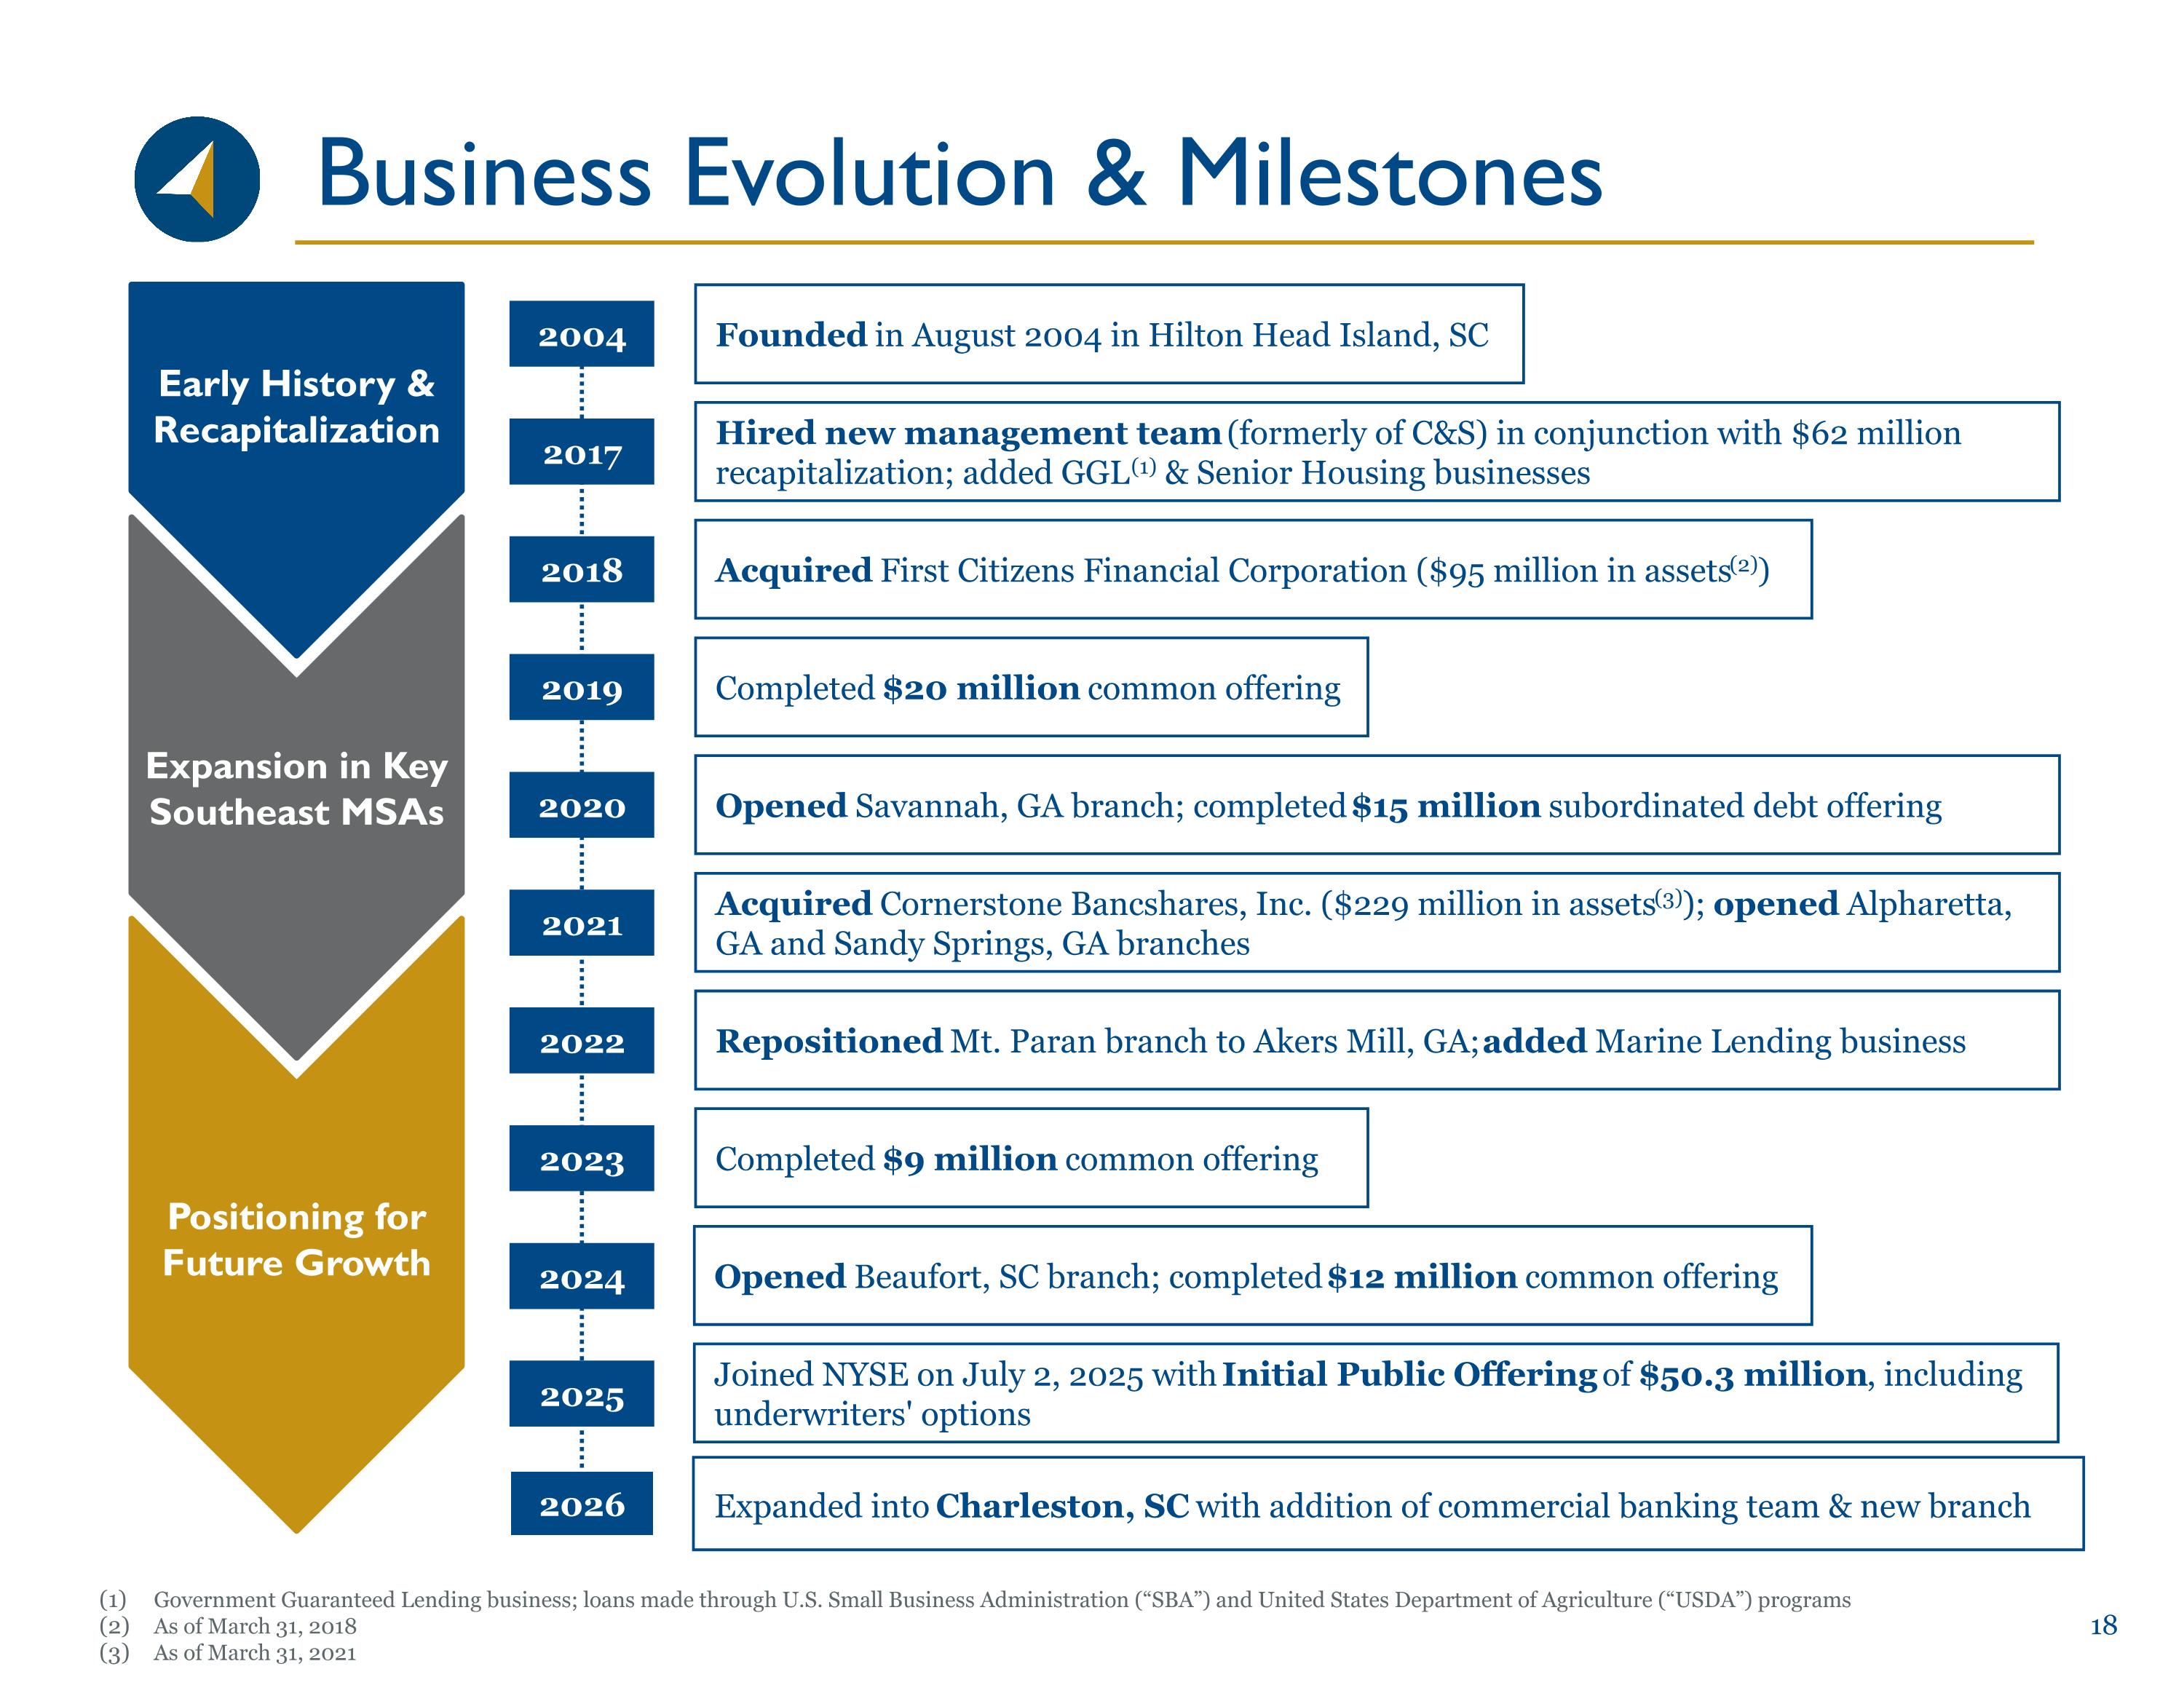
Business Evolution & Milestones Government Guaranteed Lending business; loans made through U.S. Small Business Administration (“SBA”) and United States Department of Agriculture (“USDA”) programs As of March 31, 2018 As of March 31, 2021 Early History & Recapitalization Expansion in Key Southeast MSAs Positioning for Future Growth Founded in August 2004 in Hilton Head Island, SC Opened Savannah, GA branch; completed $15 million subordinated debt offering Hired new management team (formerly of C&S) in conjunction with $62 million recapitalization; added GGL (1) & Senior Housing businesses Acquired First Citizens Financial Corporation ($95 million in assets (2)) Completed $20 million common offering 2004 2017 2018 2019 2020 Acquired Cornerstone Bancshares, Inc. ($229 million in assets (3)); opened Alpharetta, GA and Sandy Springs, GA branches Repositioned Mt. Paran branch to Akers Mill, GA; added Marine Lending business 2021 2022 Completed $9 million common offering 2023 Opened Beaufort, SC branch; completed $12 million common offering 2024 Joined NYSE on July 2, 2025 with Initial Public Offering of $50.3 million, including underwriters' options 2025 2026 Expanded into Charleston, SC with addition of commercial banking team & new branch
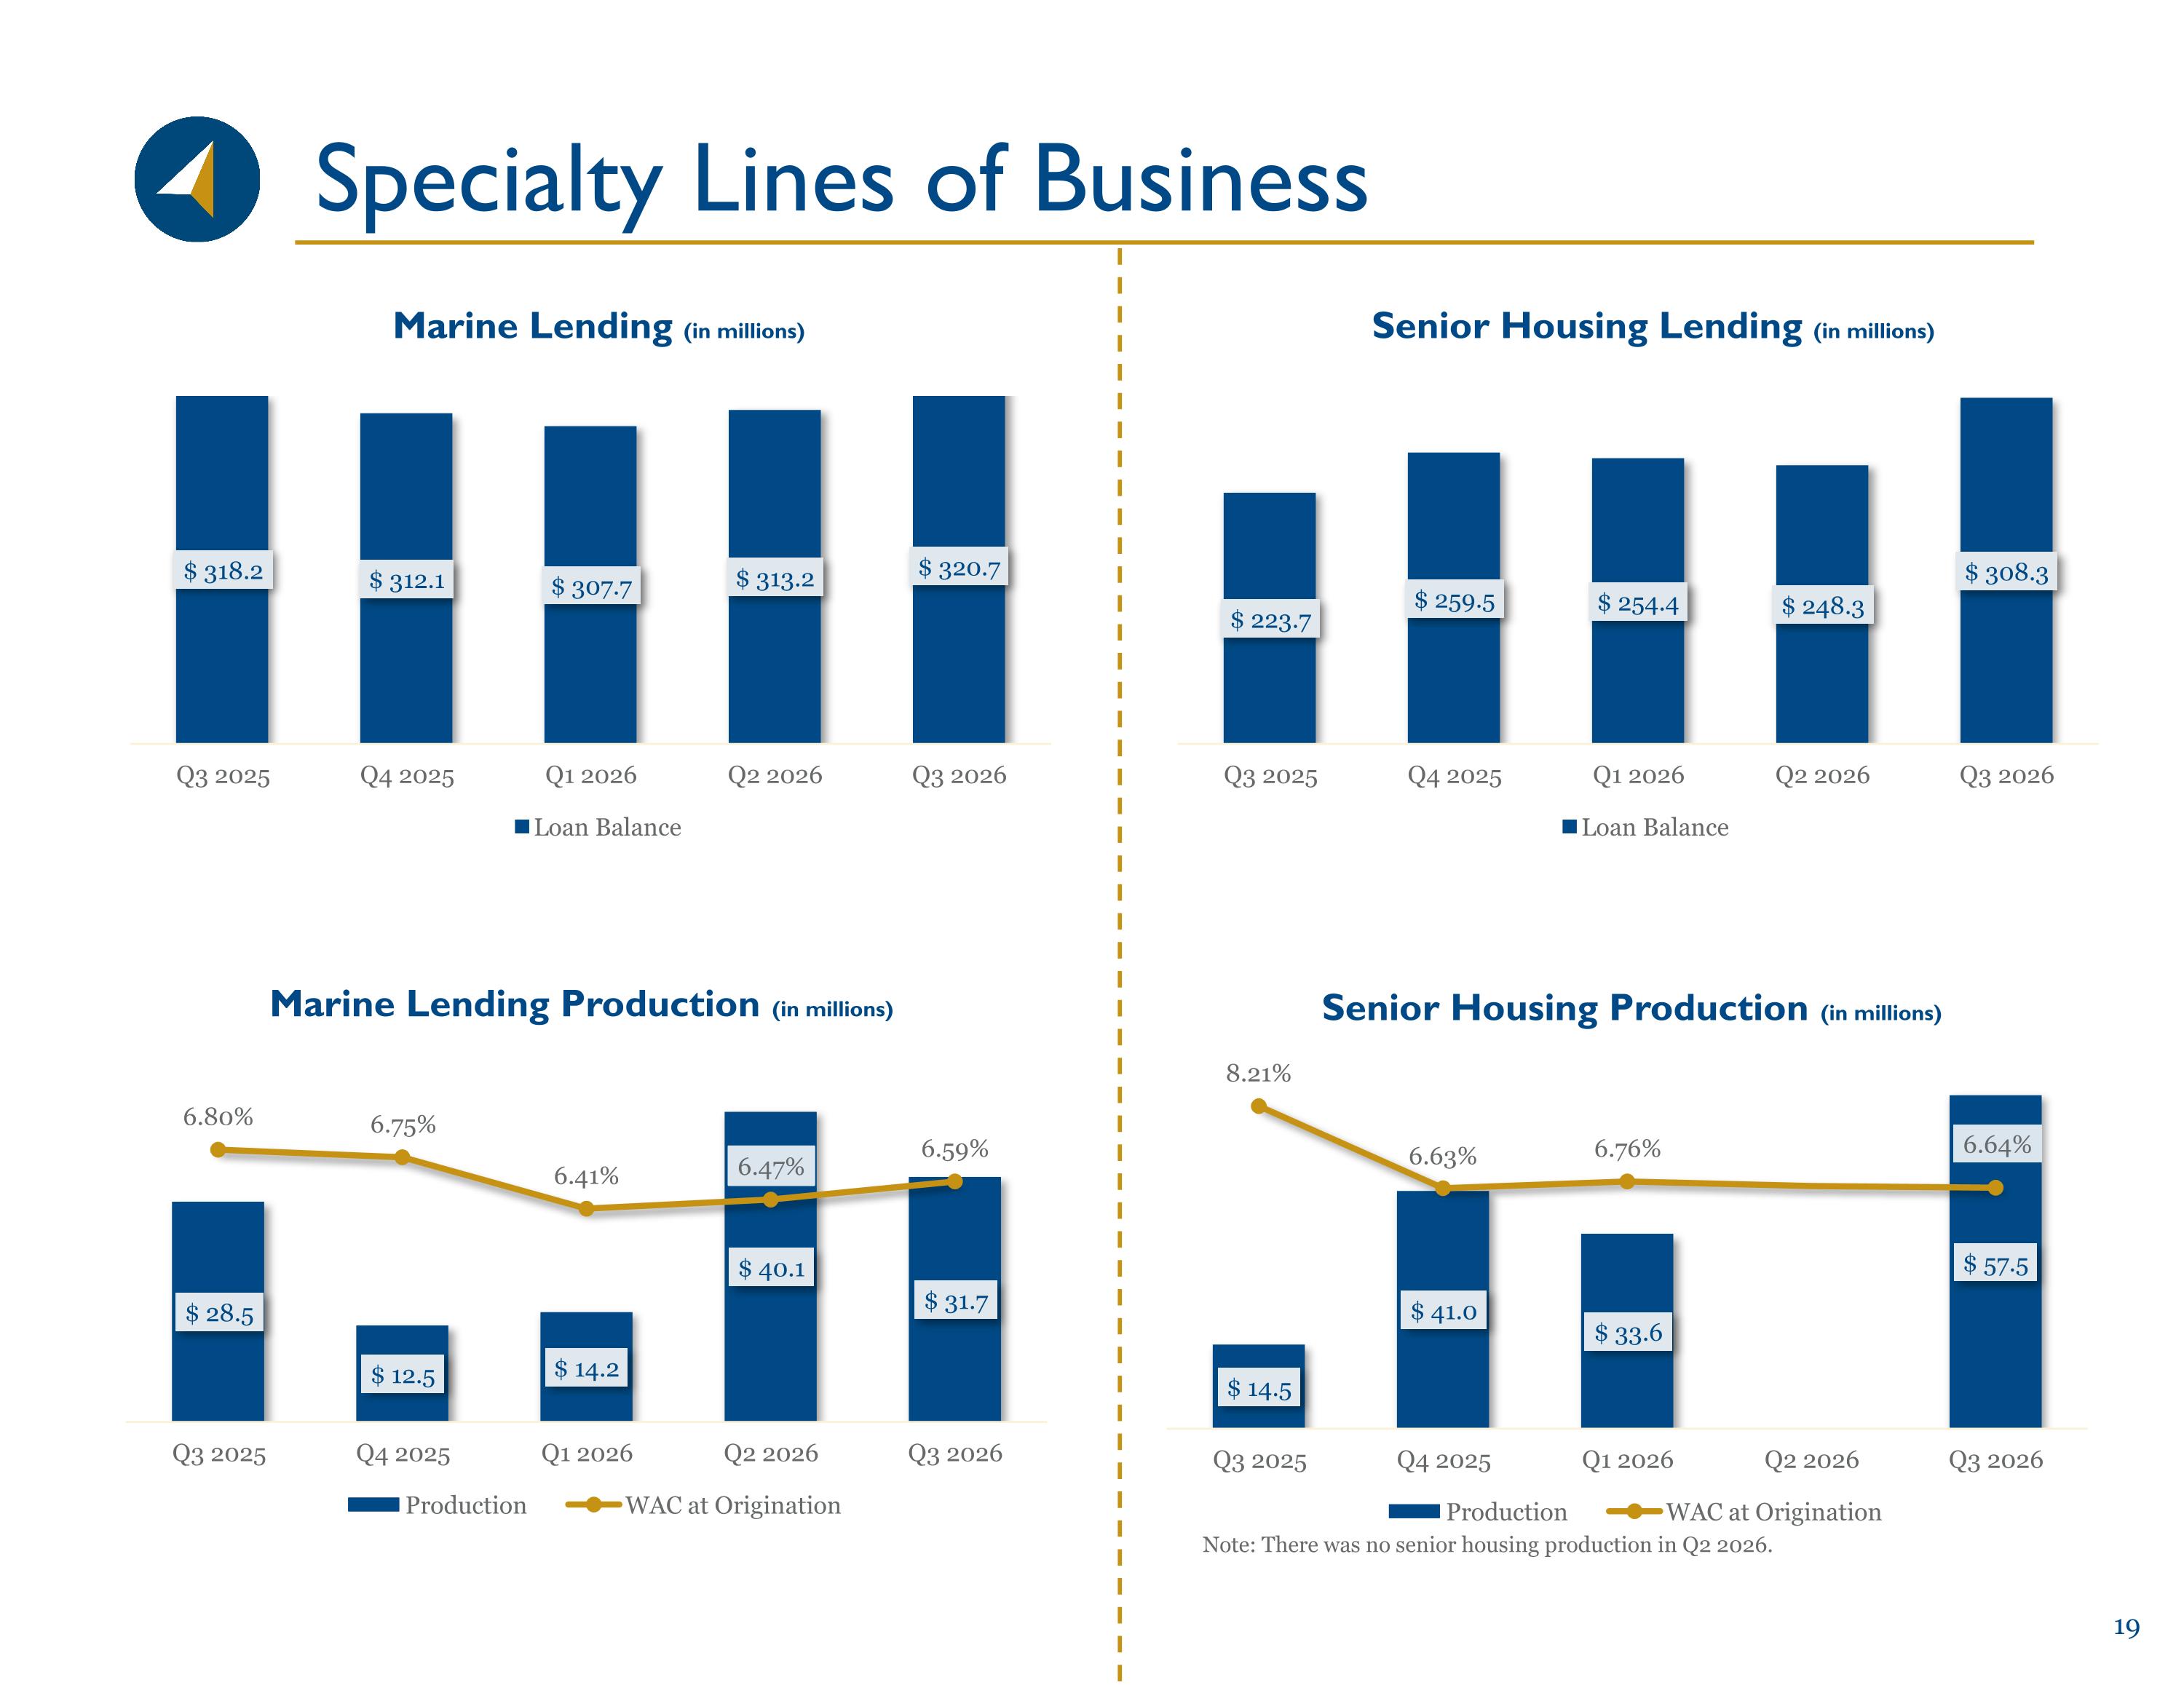
Specialty Lines of Business Note: There was no senior housing production in Q2 2026.
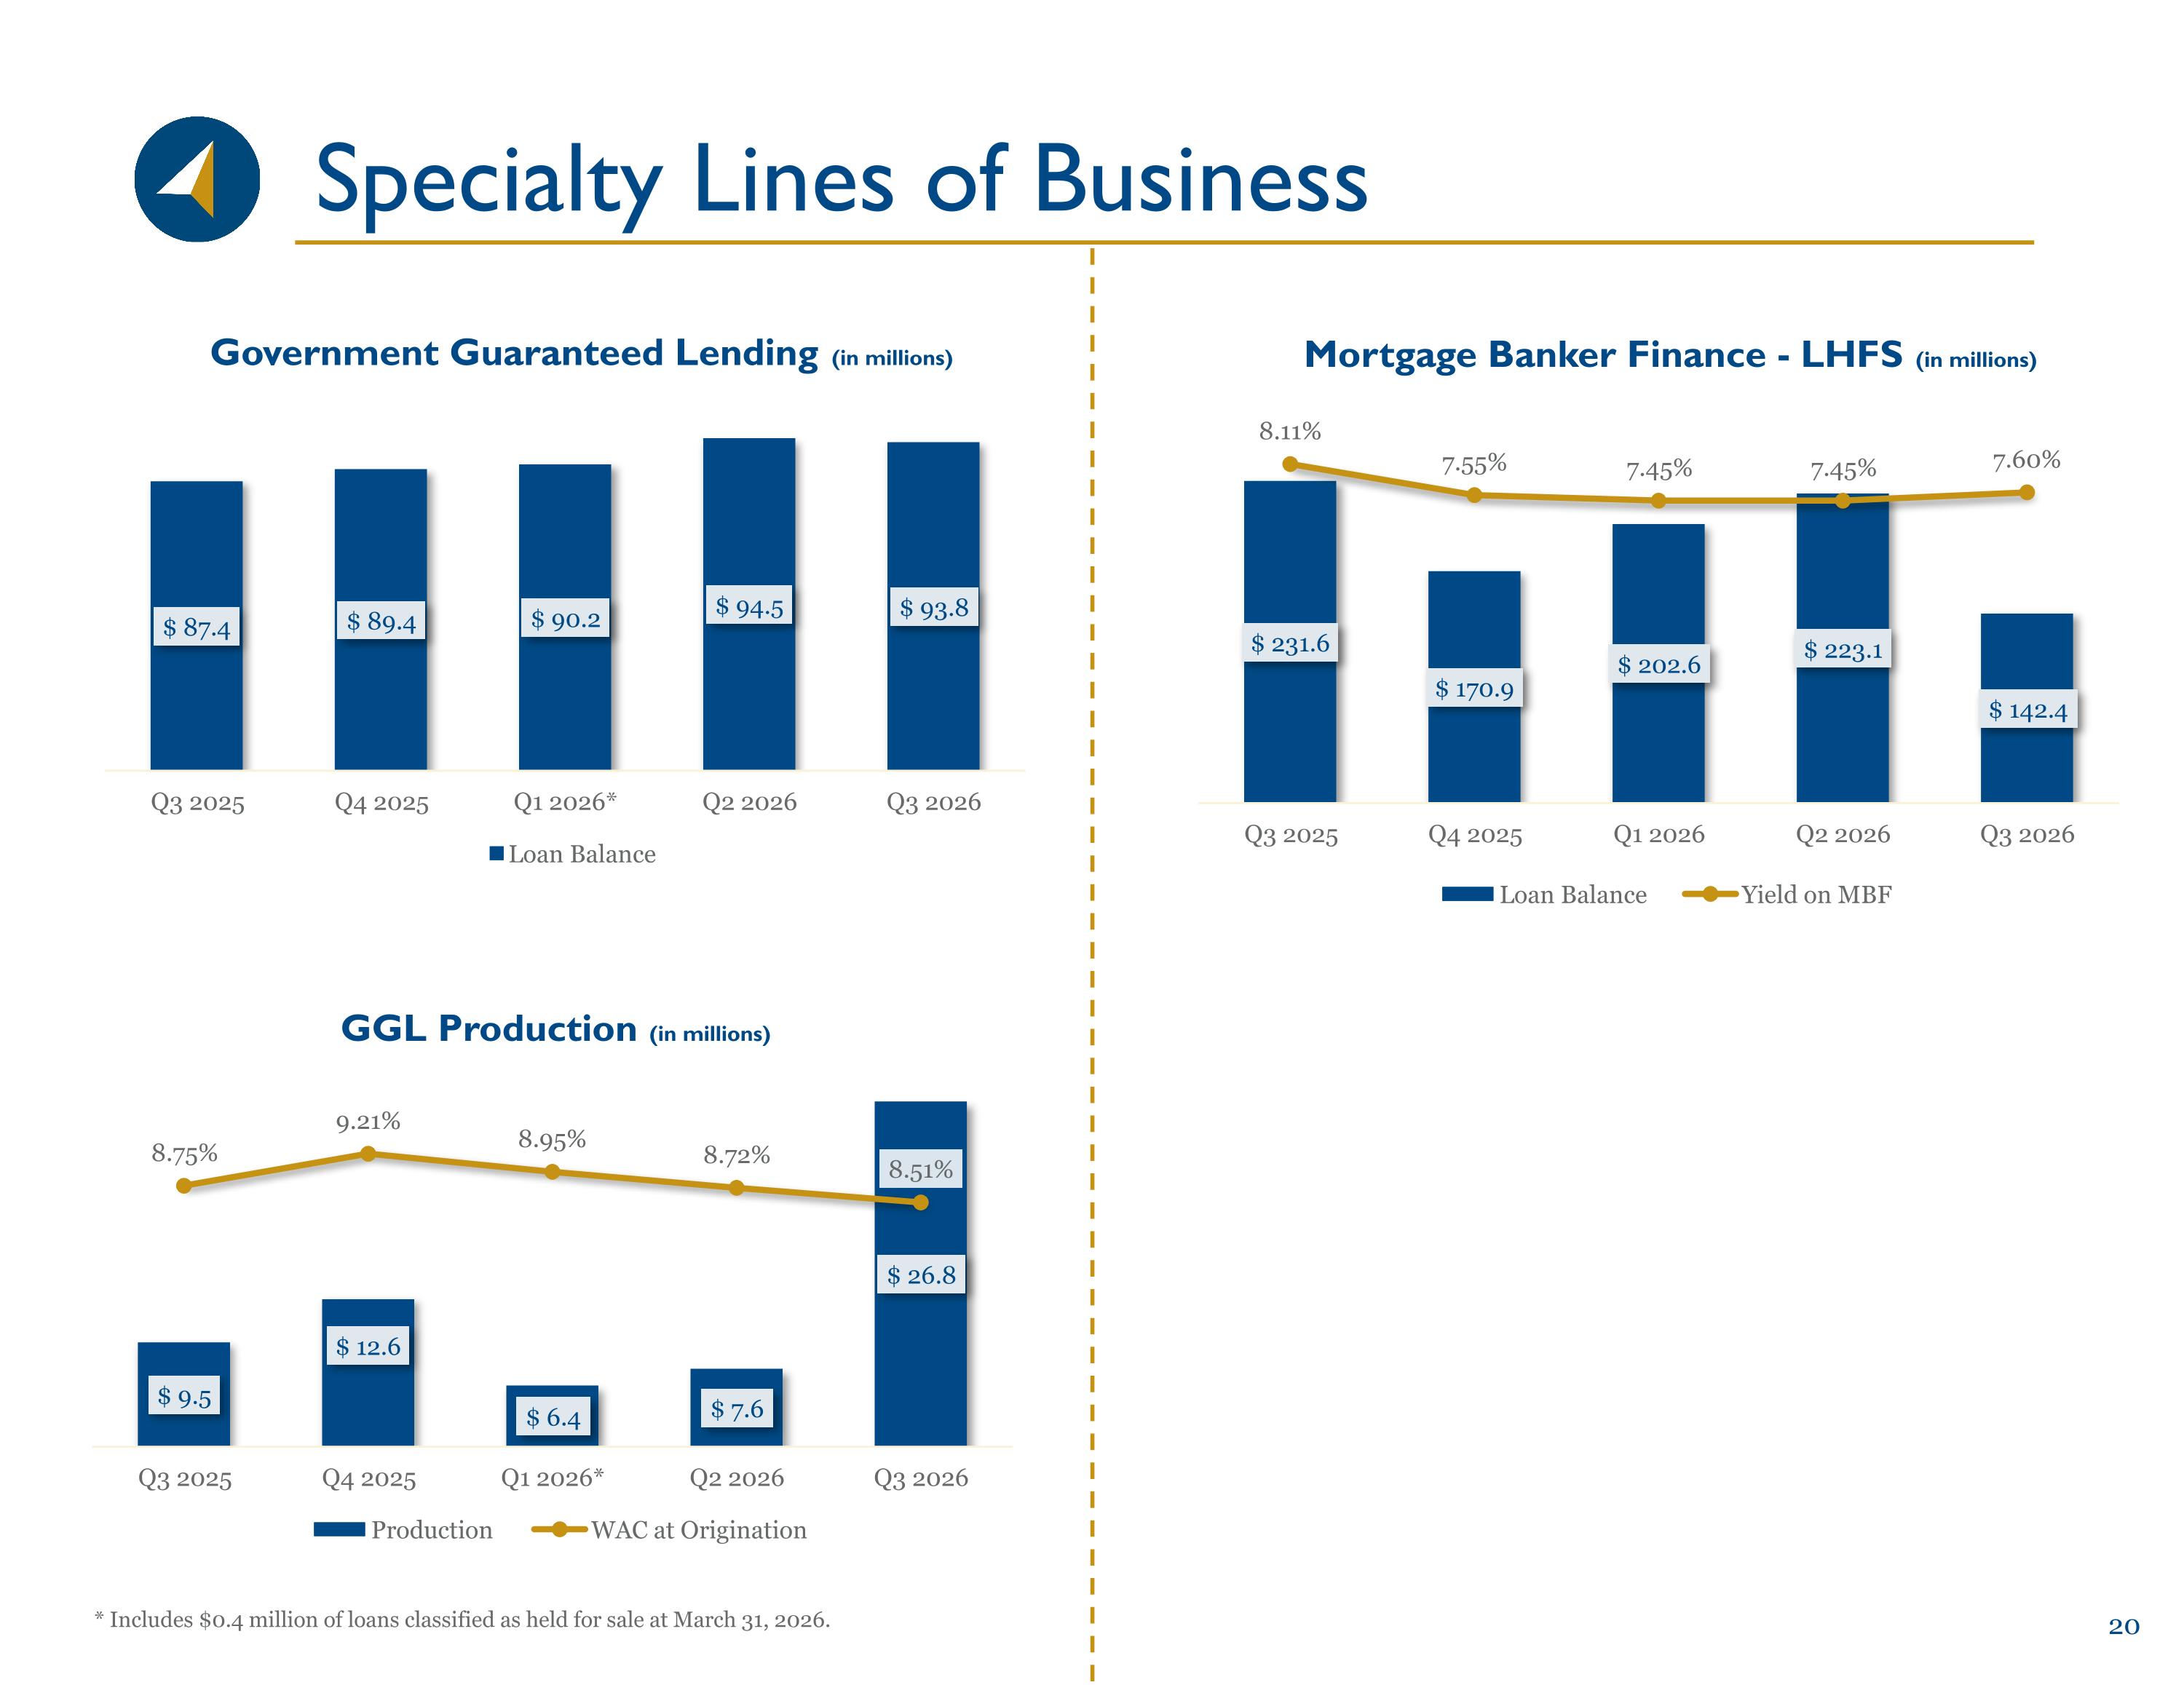
Specialty Lines of Business * Includes $0.4 million of loans classified as held for sale at March 31, 2026.
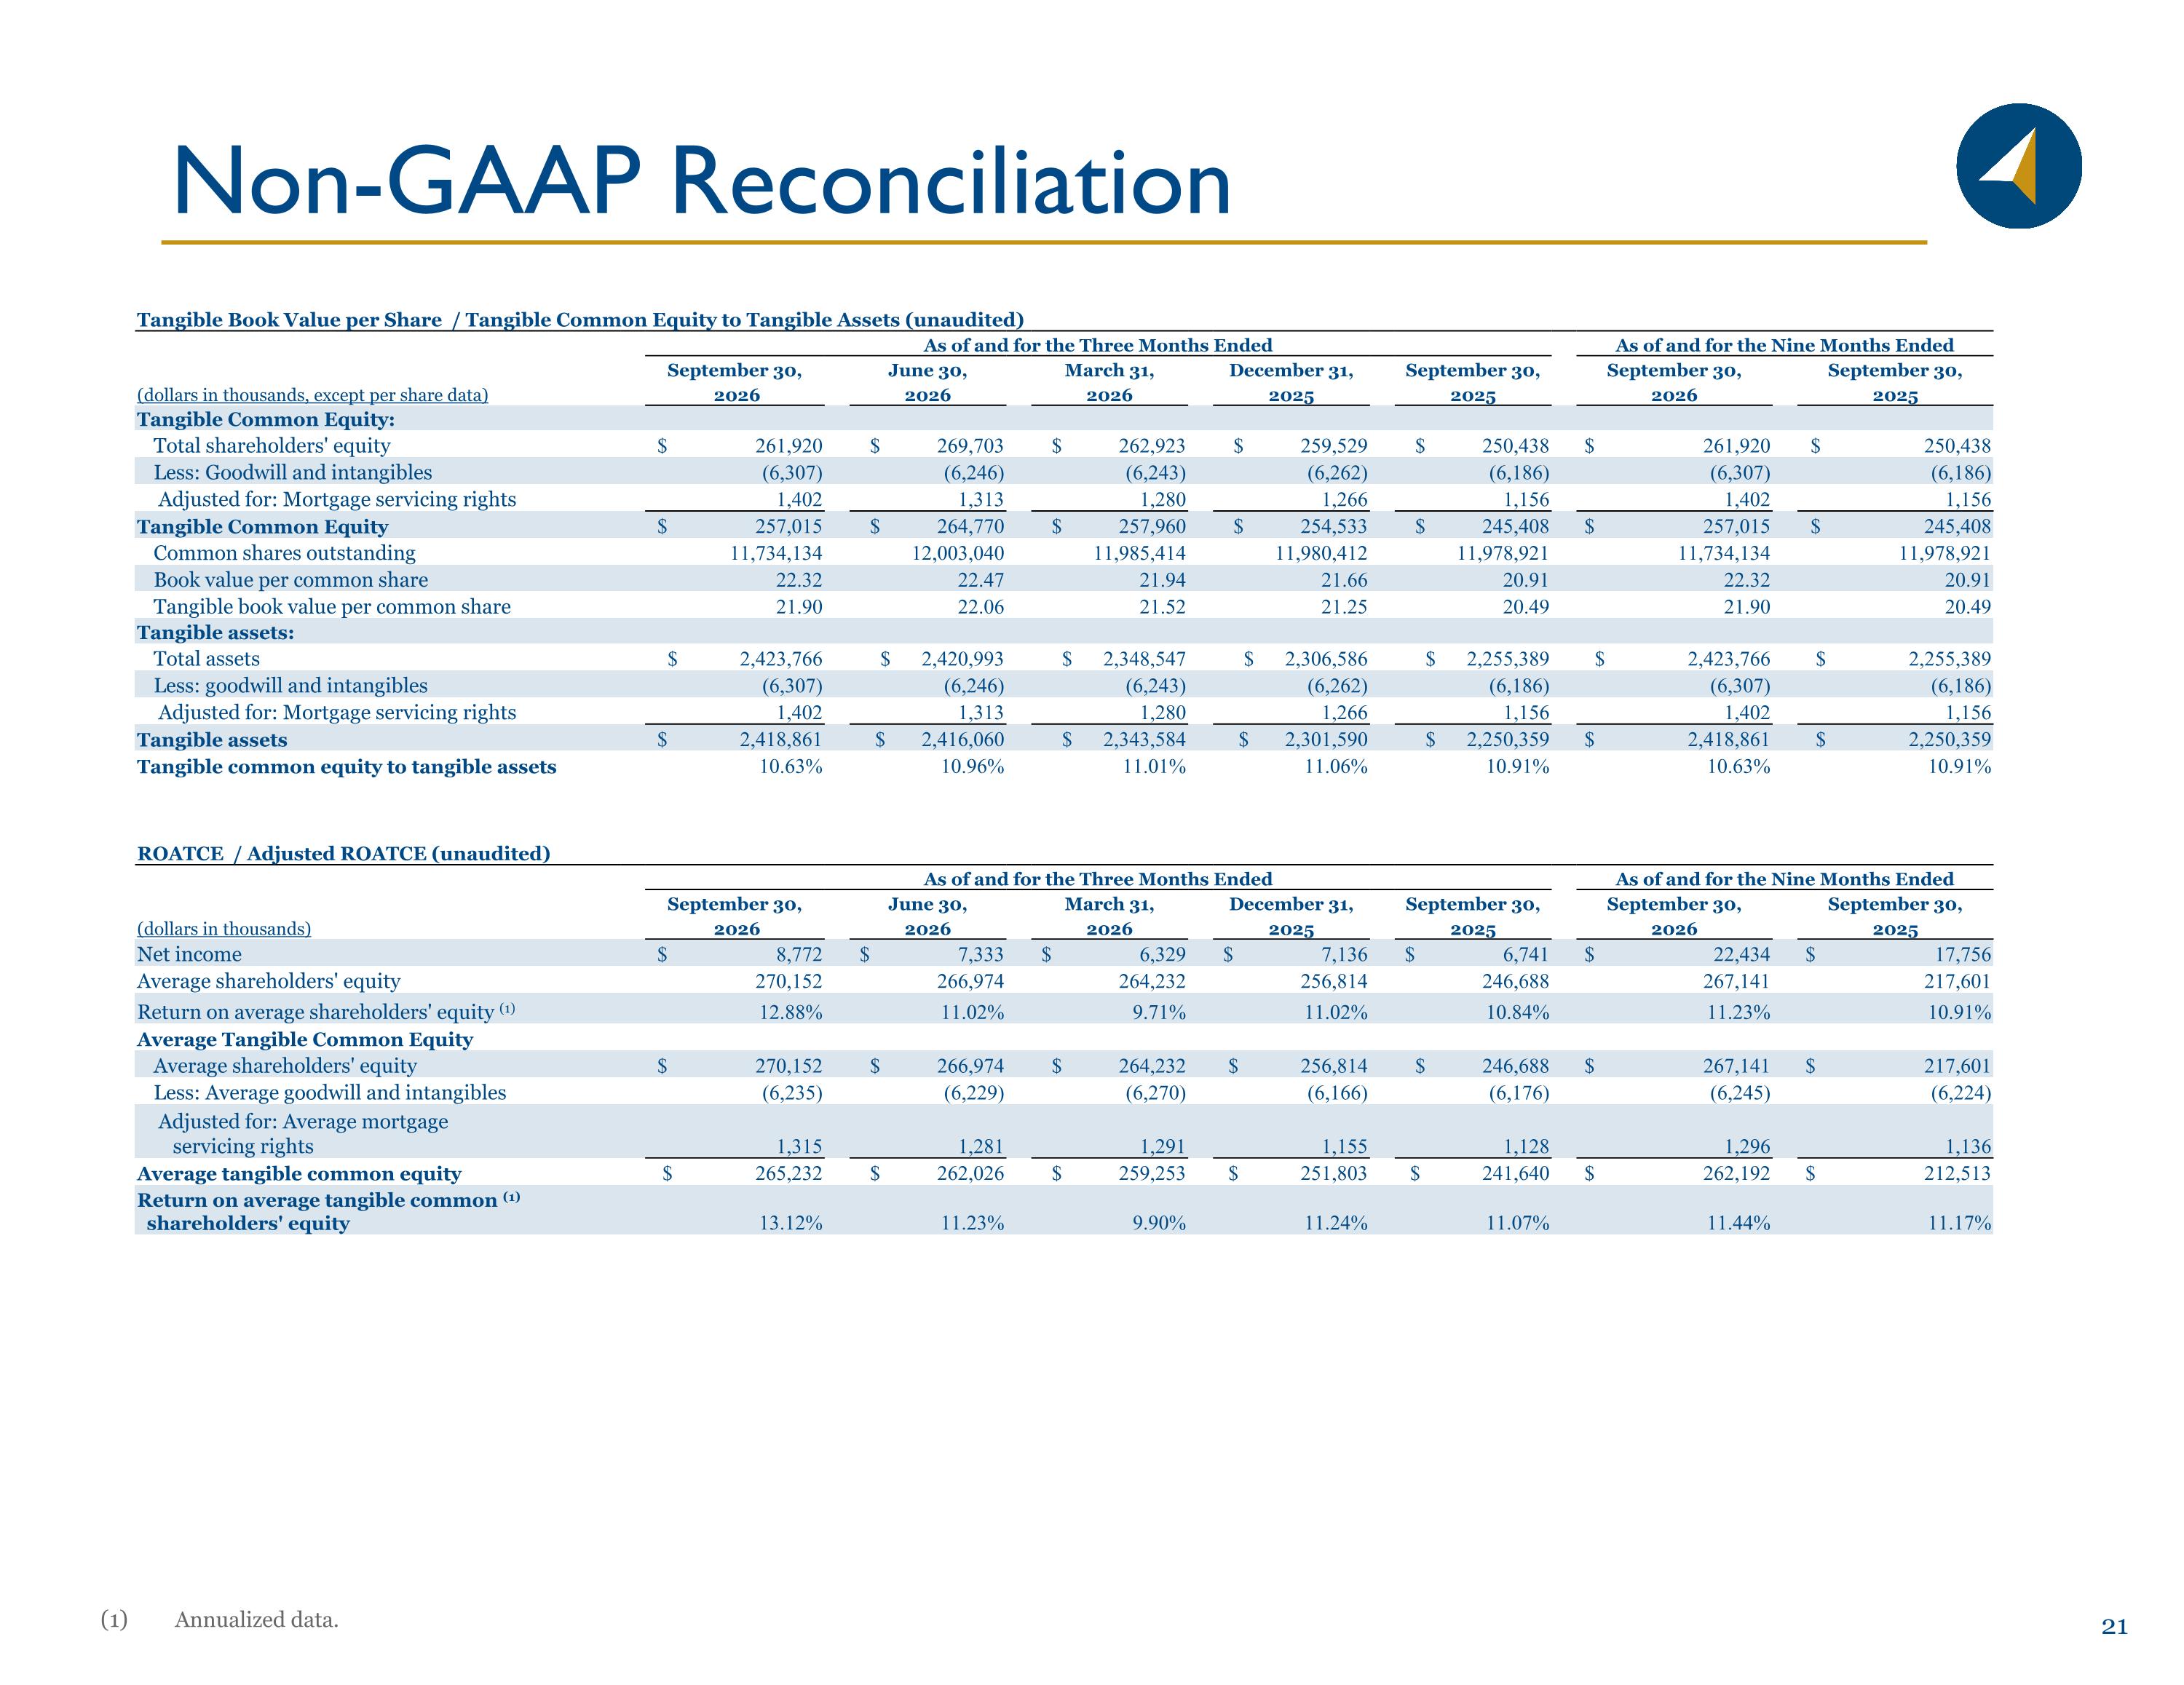
Non-GAAP Reconciliation Annualized data. Tangible Book Value per Share / Tangible Common Equity to Tangible Assets (unaudited) As of and for the Three Months Ended As of and for the Nine Months Ended September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands, except per share data) 2026 2026 2026 2025 2025 2026 2025 Tangible Common Equity: Total shareholders' equity $ 261,920 $ 269,703 $ 262,923 $ 259,529 $ 250,438 $ 261,920 $ 250,438 Less: Goodwill and intangibles (6,307) (6,246) (6,243) (6,262) (6,186) (6,307) (6,186) Adjusted for: Mortgage servicing rights 1,402 1,313 1,280 1,266 1,156 1,402 1,156 Tangible Common Equity $ 257,015 $ 264,770 $ 257,960 $ 254,533 $ 245,408 $ 257,015 $ 245,408 Common shares outstanding 11,734,134 12,003,040 11,985,414 11,980,412 11,978,921 11,734,134 11,978,921 Book value per common share 22.32 22.47 21.94 21.66 20.91 22.32 20.91 Tangible book value per common share 21.90 22.06 21.52 21.25 20.49 21.90 20.49 Tangible assets: Total assets $ 2,423,766 $ 2,420,993 $ 2,348,547 $ 2,306,586 $ 2,255,389 $ 2,423,766 $ 2,255,389 Less: goodwill and intangibles (6,307) (6,246) (6,243) (6,262) (6,186) (6,307) (6,186) Adjusted for: Mortgage servicing rights 1,402 1,313 1,280 1,266 1,156 1,402 1,156 Tangible assets $ 2,418,861 $ 2,416,060 $ 2,343,584 $ 2,301,590 $ 2,250,359 $ 2,418,861 $ 2,250,359 Tangible common equity to tangible assets 10.63% 10.96% 11.01% 11.06% 10.91% 10.63% 10.91% ROATCE / Adjusted ROATCE (unaudited) As of and for the Three Months Ended As of and for the Nine Months Ended September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands) 2026 2026 2026 2025 2025 2026 2025 Net income $ 8,772 $ 7,333 $ 6,329 $ 7,136 $ 6,741 $ 22,434 $ 17,756 Average shareholders' equity 270,152 266,974 264,232 256,814 246,688 267,141 217,601 Return on average shareholders' equity (1) 12.88% 11.02% 9.71% 11.02% 10.84% 11.23% 10.91% Average Tangible Common Equity Average shareholders' equity $ 270,152 $ 266,974 $ 264,232 $ 256,814 $ 246,688 $ 267,141 $ 217,601 Less: Average goodwill and intangibles (6,235) (6,229) (6,270) (6,166) (6,176) (6,245) (6,224) Adjusted for: Average mortgage servicing rights 1,315 1,281 1,291 1,155 1,128 1,296 1,136 Average tangible common equity $ 265,232 $ 262,026 $ 259,253 $ 251,803 $ 241,640 $ 262,192 $ 212,513 Return on average tangible common (1) shareholders' equity 13.12% 11.23% 9.90% 11.24% 11.07% 11.44% 11.17%
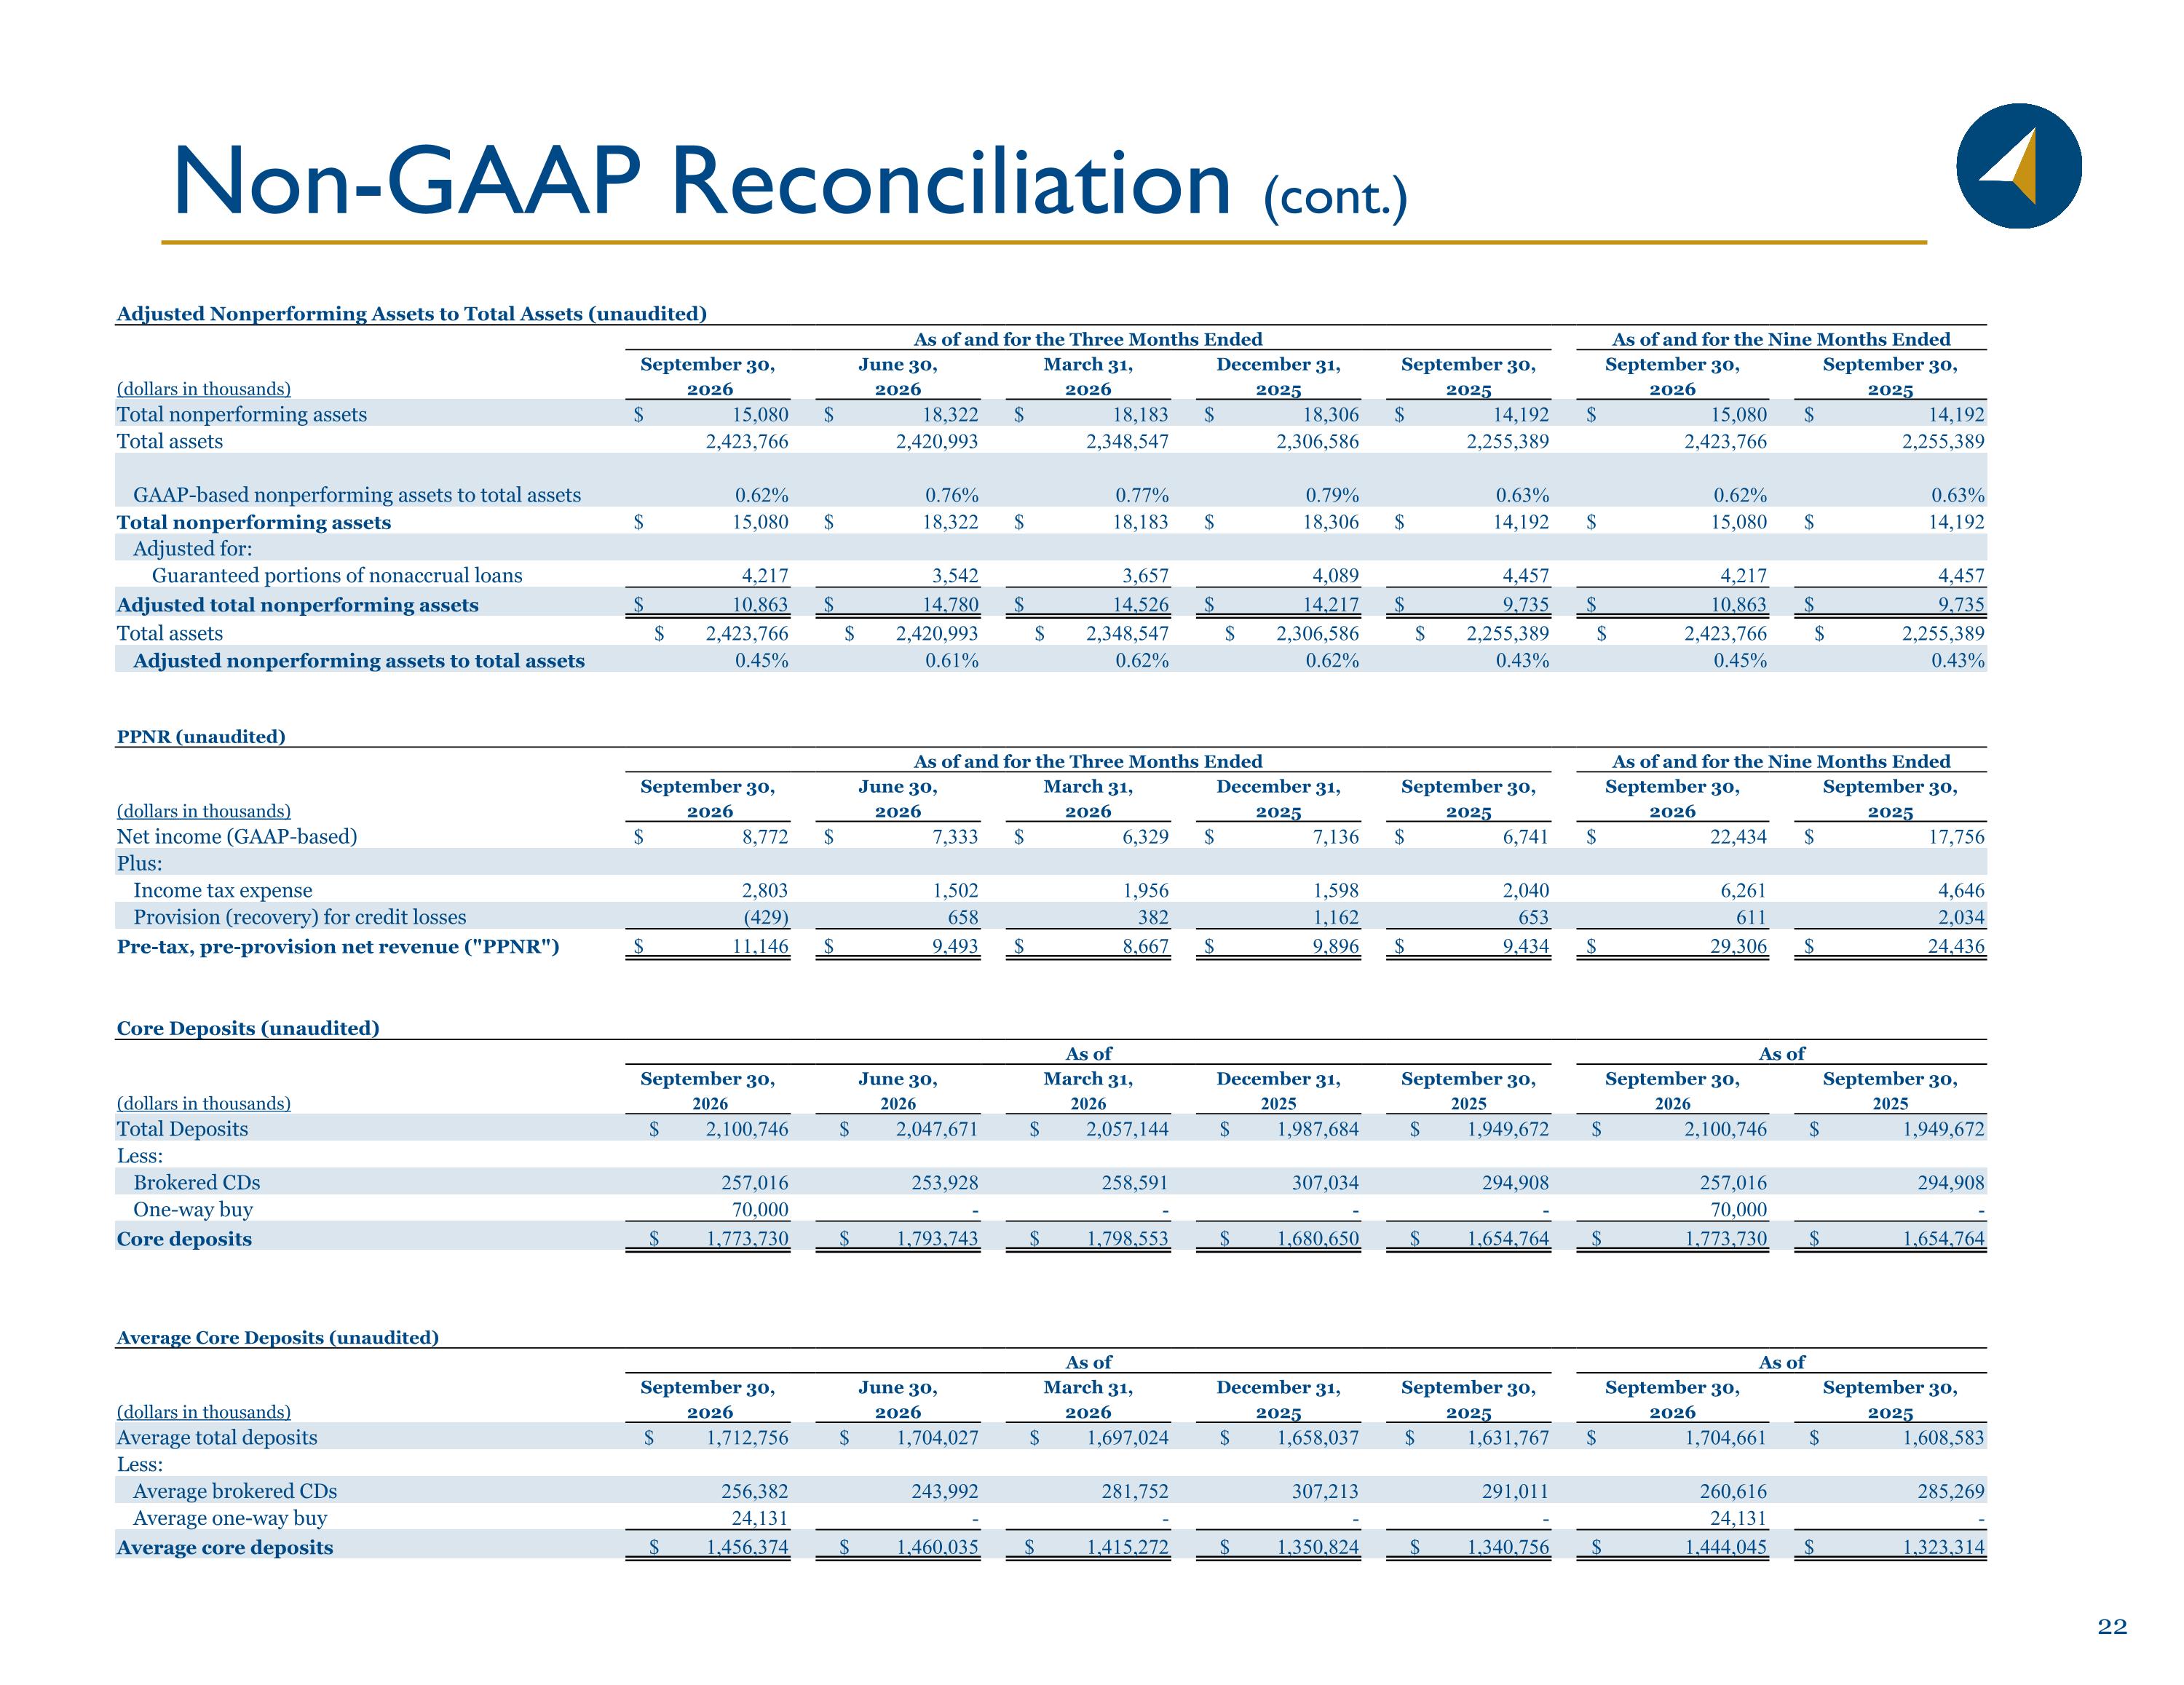
Non-GAAP Reconciliation (cont.) PPNR (unaudited) As of and for the Three Months Ended As of and for the Nine Months Ended September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands) 2026 2026 2026 2025 2025 2026 2025 Net income (GAAP-based) $ 8,772 $ 7,333 $ 6,329 $ 7,136 $ 6,741 $ 22,434 $ 17,756 Plus: Income tax expense 2,803 1,502 1,956 1,598 2,040 6,261 4,646 Provision (recovery) for credit losses (429) 658 382 1,162 653 611 2,034 Pre-tax, pre-provision net revenue ("PPNR") $ 11,146 $ 9,493 $ 8,667 $ 9,896 $ 9,434 $ 29,306 $ 24,436 Core Deposits (unaudited) As of As of September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands) 2026 2026 2026 2025 2025 2026 2025 Total Deposits $ 2,100,746 $ 2,047,671 $ 2,057,144 $ 1,987,684 $ 1,949,672 $ 2,100,746 $ 1,949,672 Less: Brokered CDs 257,016 253,928 258,591 307,034 294,908 257,016 294,908 One-way buy 70,000 - - - - 70,000 - Core deposits $ 1,773,730 $ 1,793,743 $ 1,798,553 $ 1,680,650 $ 1,654,764 $ 1,773,730 $ 1,654,764 Average Core Deposits (unaudited) As of As of September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands) 2026 2026 2026 2025 2025 2026 2025 Average total deposits $ 1,712,756 $ 1,704,027 $ 1,697,024 $ 1,658,037 $ 1,631,767 $ 1,704,661 $ 1,608,583 Less: Average brokered CDs 256,382 243,992 281,752 307,213 291,011 260,616 285,269 Average one-way buy 24,131 - - - - 24,131 - Average core deposits $ 1,456,374 $ 1,460,035 $ 1,415,272 $ 1,350,824 $ 1,340,756 $ 1,444,045 $ 1,323,314 Adjusted Nonperforming Assets to Total Assets (unaudited) As of and for the Three Months Ended As of and for the Nine Months Ended September 30, June 30, March 31, December 31, September 30, September 30, September 30, (dollars in thousands) 2026 2026 2026 2025 2025 2026 2025 Total nonperforming assets $ 15,080 $ 18,322 $ 18,183 $ 18,306 $ 14,192 $ 15,080 $ 14,192 Total assets 2,423,766 2,420,993 2,348,547 2,306,586 2,255,389 2,423,766 2,255,389 GAAP-based nonperforming assets to total assets 0.62% 0.76% 0.77% 0.79% 0.63% 0.62% 0.63% Total nonperforming assets $ 15,080 $ 18,322 $ 18,183 $ 18,306 $ 14,192 $ 15,080 $ 14,192 Adjusted for: Guaranteed portions of nonaccrual loans 4,217 3,542 3,657 4,089 4,457 4,217 4,457 Adjusted total nonperforming assets $ 10,863 $ 14,780 $ 14,526 $ 14,217 $ 9,735 $ 10,863 $ 9,735 Total assets $ 2,423,766 $ 2,420,993 $ 2,348,547 $ 2,306,586 $ 2,255,389 $ 2,423,766 $ 2,255,389 Adjusted nonperforming assets to total assets 0.45% 0.61% 0.62% 0.62% 0.43% 0.45% 0.43%