October 20, 2026 Q3 Earnings Conference Call
This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 that are based on management's beliefs, assumptions, current expectations, estimates and projections about BOK Financial Corporation, the financial services industry, and the economy generally. Words such as “anticipates,” “believes,” “estimates,” “expects,” “forecasts,” “plans,” "outlook," “projects,” “will,” “intends,” "may," "could," "should," "would," "potential," "continue," "seek," "target," variations of such words and similar expressions are intended to identify such forward-looking statements. Management judgments relating to and discussion of the provision and allowance for credit losses, allowance for uncertain tax positions, accruals for loss contingencies and valuation of mortgage servicing rights involve judgments as to expected events and are inherently forward-looking statements. Assessments that acquisitions and growth endeavors will be profitable are statements of belief as to the outcome of future events based in part on information provided by others which BOK Financial has not independently verified and for which BOK Financial assumes no responsibility for the accuracy or completeness. These various forward-looking statements are not guarantees of future performance and involve certain risks, uncertainties, and assumptions which are difficult to predict with regard to timing, extent, likelihood and degree of occurrence. All statements other than statements of historical fact are forward-looking statements. Therefore, actual results and outcomes may materially differ from what is expected, implied, or forecasted in such forward-looking statements. Internal and external factors that might cause such a difference include, but are not limited to changes in government, changes in governmental economic policy, including tariffs; changes in commodity prices; interest rates and interest rate relationships; inflation; demand for products and services; the degree of competition by traditional and nontraditional competitors; changes in banking regulations; tax laws; prices, levies and assessments; the impact of technological advances; trends in customer behavior as well as their ability to repay loans; credit quality deterioration; cybersecurity incidents and data breaches; operational failures or interruptions; liquidity risks; capital adequacy requirements; litigation and regulatory enforcement actions; and other risks detailed in BOK Financial Corporation's filings with the Securities and Exchange Commission. For a discussion of risk factors that may cause actual results to differ from expectations, please refer to BOK Financial Corporation’s most recent annual and quarterly reports. BOK Financial Corporation and its affiliates undertake no obligation to update, amend, or clarify forward-looking statements, whether as a result of new information, future events, or otherwise. Non-GAAP Financial Measures: This presentation may refer to non-GAAP financial measures. Additional information on these financial measures is available in BOK Financial’s Form 8-K filings furnished pursuant to Item 2.02, which can be accessed at bokf.com. All data is presented as of September 30, 2026 unless otherwise noted. Legal Disclaimers 2
Stacy Kymes Chief Executive Officer 3
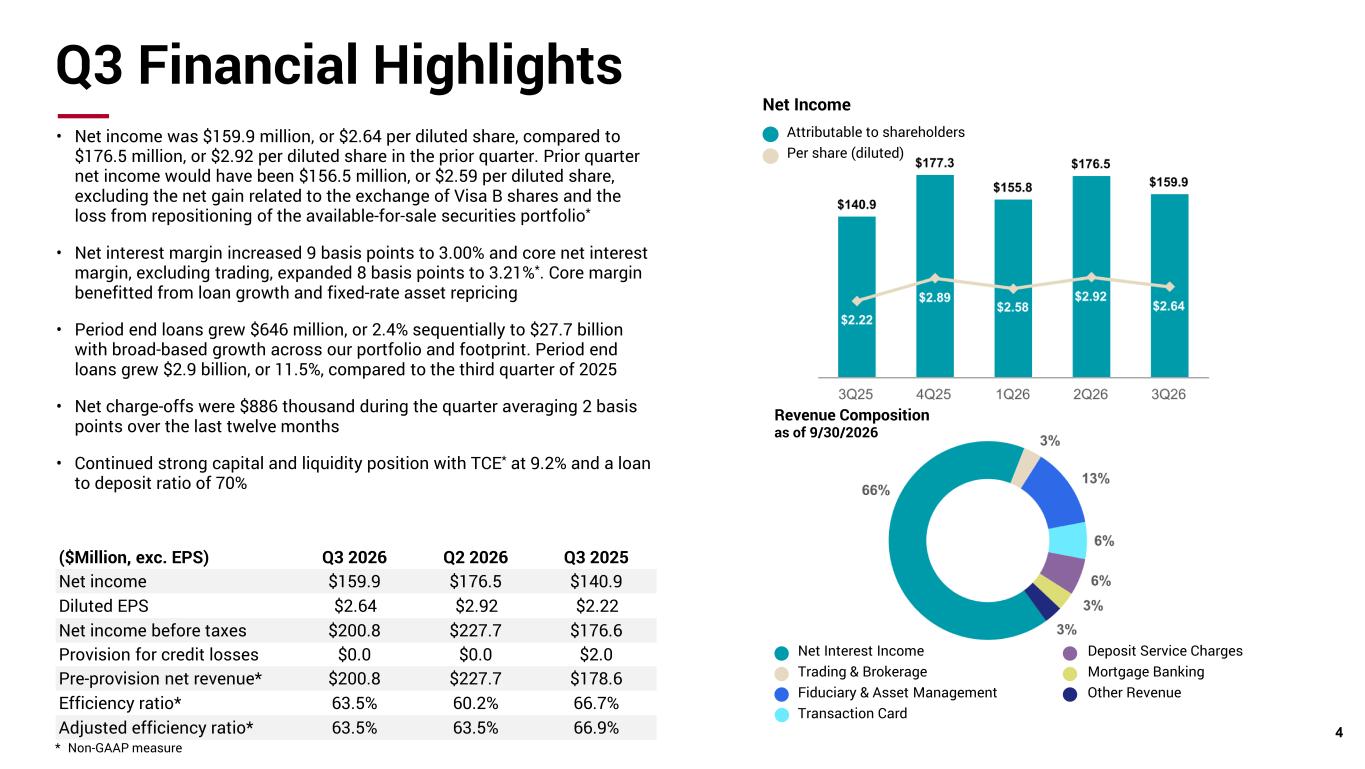
Q3 Financial Highlights * Non-GAAP measure Attributable to shareholders Per share (diluted) Net Income • Net income was $159.9 million, or $2.64 per diluted share, compared to $176.5 million, or $2.92 per diluted share in the prior quarter. Prior quarter net income would have been $156.5 million, or $2.59 per diluted share, excluding the net gain related to the exchange of Visa B shares and the loss from repositioning of the available-for-sale securities portfolio* • Net interest margin increased 9 basis points to 3.00% and core net interest margin, excluding trading, expanded 8 basis points to 3.21%*. Core margin benefitted from loan growth and fixed-rate asset repricing • Period end loans grew $646 million, or 2.4% sequentially to $27.7 billion with broad-based growth across our portfolio and footprint. Period end loans grew $2.9 billion, or 11.5%, compared to the third quarter of 2025 • Net charge-offs were $886 thousand during the quarter averaging 2 basis points over the last twelve months • Continued strong capital and liquidity position with TCE* at 9.2% and a loan to deposit ratio of 70% 4 ($Million, exc. EPS) Q3 2026 Q2 2026 Q3 2025 Net income $159.9 $176.5 $140.9 Diluted EPS $2.64 $2.92 $2.22 Net income before taxes $200.8 $227.7 $176.6 Provision for credit losses $0.0 $0.0 $2.0 Pre-provision net revenue* $200.8 $227.7 $178.6 Efficiency ratio* 63.5% 60.2% 66.7% Adjusted efficiency ratio* 63.5% 63.5% 66.9% Revenue Composition as of 9/30/2026 Net Interest Income Trading & Brokerage Fiduciary & Asset Management Transaction Card Deposit Service Charges Mortgage Banking Other Revenue
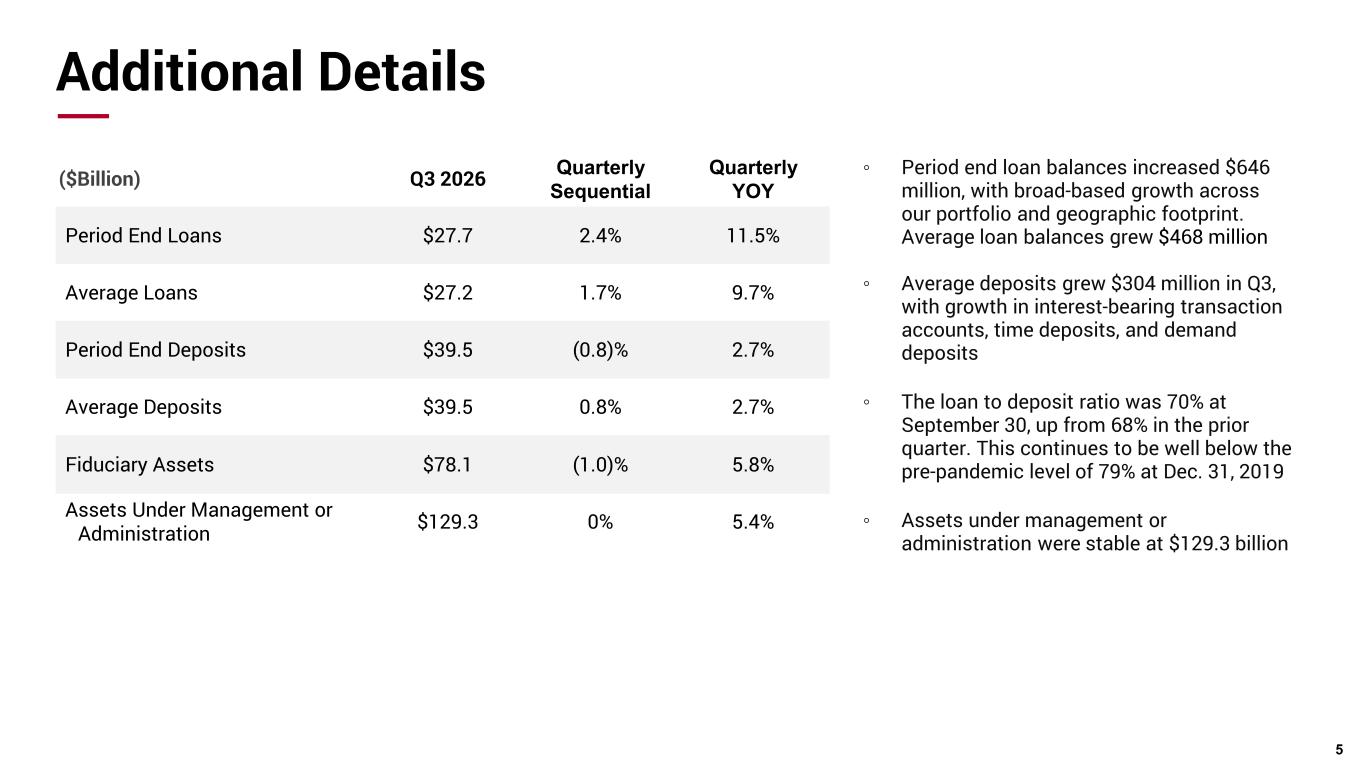
Additional Details 5 ◦ Period end loan balances increased $646 million, with broad-based growth across our portfolio and geographic footprint. Average loan balances grew $468 million ◦ Average deposits grew $304 million in Q3, with growth in interest-bearing transaction accounts, time deposits, and demand deposits ◦ The loan to deposit ratio was 70% at September 30, up from 68% in the prior quarter. This continues to be well below the pre-pandemic level of 79% at Dec. 31, 2019 ◦ Assets under management or administration were stable at $129.3 billion ($Billion) Q3 2026 Quarterly Sequential Quarterly YOY Period End Loans $27.7 2.4% 11.5% Average Loans $27.2 1.7% 9.7% Period End Deposits $39.5 (0.8)% 2.7% Average Deposits $39.5 0.8% 2.7% Fiduciary Assets $78.1 (1.0)% 5.8% Assets Under Management or Administration $129.3 0% 5.4%
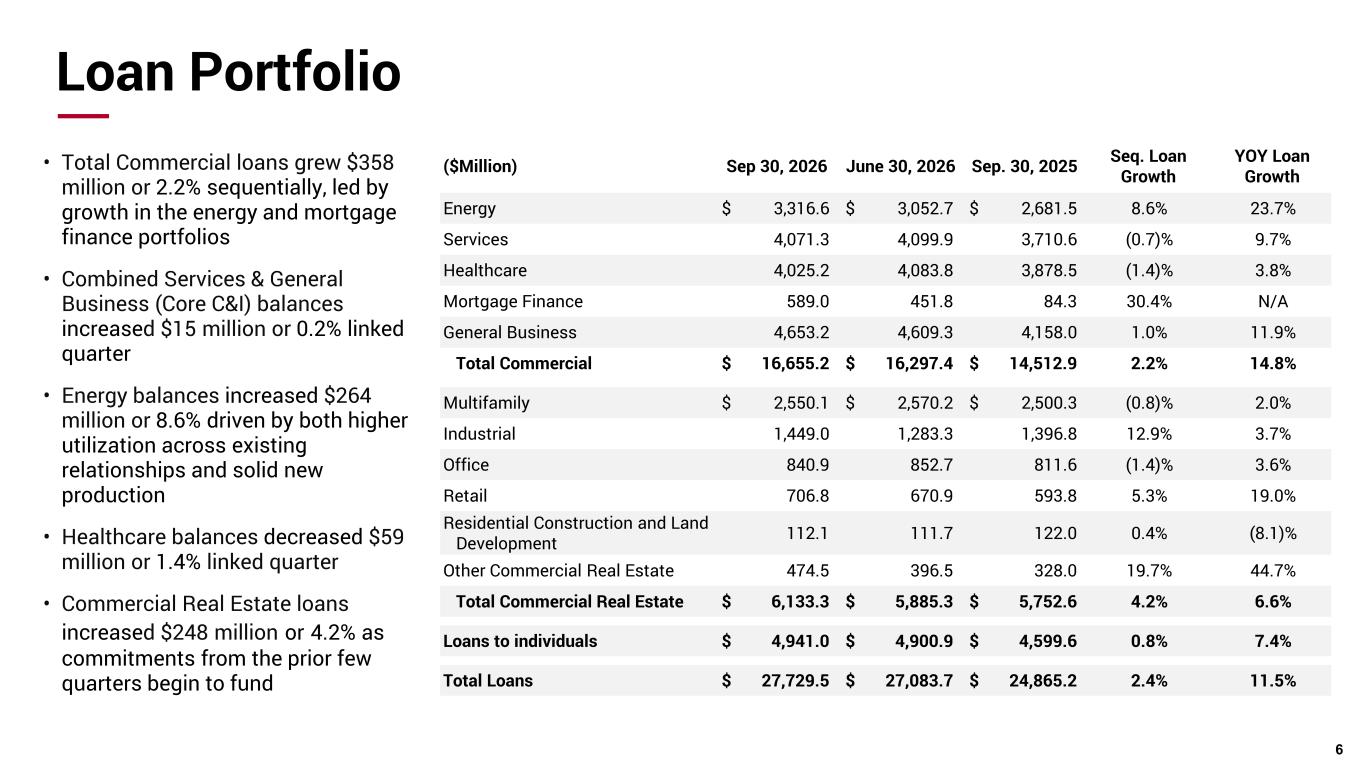
Loan Portfolio • Total Commercial loans grew $358 million or 2.2% sequentially, led by growth in the energy and mortgage finance portfolios • Combined Services & General Business (Core C&I) balances increased $15 million or 0.2% linked quarter • Energy balances increased $264 million or 8.6% driven by both higher utilization across existing relationships and solid new production • Healthcare balances decreased $59 million or 1.4% linked quarter • Commercial Real Estate loans increased $248 million or 4.2% as commitments from the prior few quarters begin to fund 6 ($Million) Sep 30, 2026 June 30, 2026 Sep. 30, 2025 Seq. Loan Growth YOY Loan Growth Energy $ 3,316.6 $ 3,052.7 $ 2,681.5 8.6% 23.7% Services 4,071.3 4,099.9 3,710.6 (0.7)% 9.7% Healthcare 4,025.2 4,083.8 3,878.5 (1.4)% 3.8% Mortgage Finance 589.0 451.8 84.3 30.4% N/A General Business 4,653.2 4,609.3 4,158.0 1.0% 11.9% Total Commercial $ 16,655.2 $ 16,297.4 $ 14,512.9 2.2% 14.8% Multifamily $ 2,550.1 $ 2,570.2 $ 2,500.3 (0.8)% 2.0% Industrial 1,449.0 1,283.3 1,396.8 12.9% 3.7% Office 840.9 852.7 811.6 (1.4)% 3.6% Retail 706.8 670.9 593.8 5.3% 19.0% Residential Construction and Land Development 112.1 111.7 122.0 0.4% (8.1)% Other Commercial Real Estate 474.5 396.5 328.0 19.7% 44.7% Total Commercial Real Estate $ 6,133.3 $ 5,885.3 $ 5,752.6 4.2% 6.6% Loans to individuals $ 4,941.0 $ 4,900.9 $ 4,599.6 0.8% 7.4% Total Loans $ 27,729.5 $ 27,083.7 $ 24,865.2 2.4% 11.5%
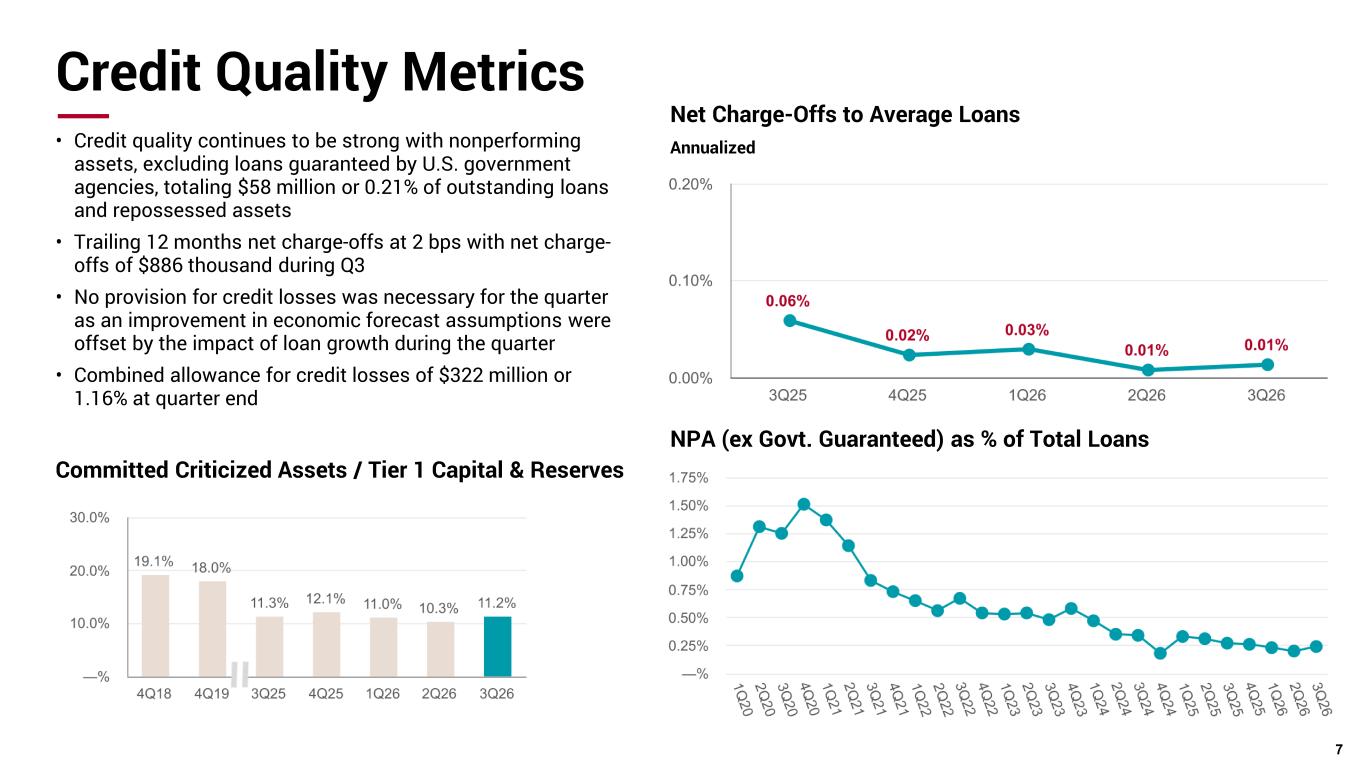
Credit Quality Metrics • Credit quality continues to be strong with nonperforming assets, excluding loans guaranteed by U.S. government agencies, totaling $58 million or 0.21% of outstanding loans and repossessed assets • Trailing 12 months net charge-offs at 2 bps with net charge- offs of $886 thousand during Q3 • No provision for credit losses was necessary for the quarter as an improvement in economic forecast assumptions were offset by the impact of loan growth during the quarter • Combined allowance for credit losses of $322 million or 1.16% at quarter end Net Charge-Offs to Average Loans NPA (ex Govt. Guaranteed) as % of Total Loans Annualized 7 Committed Criticized Assets / Tier 1 Capital & Reserves
Scott Grauer EVP, Wealth Management Executive 8
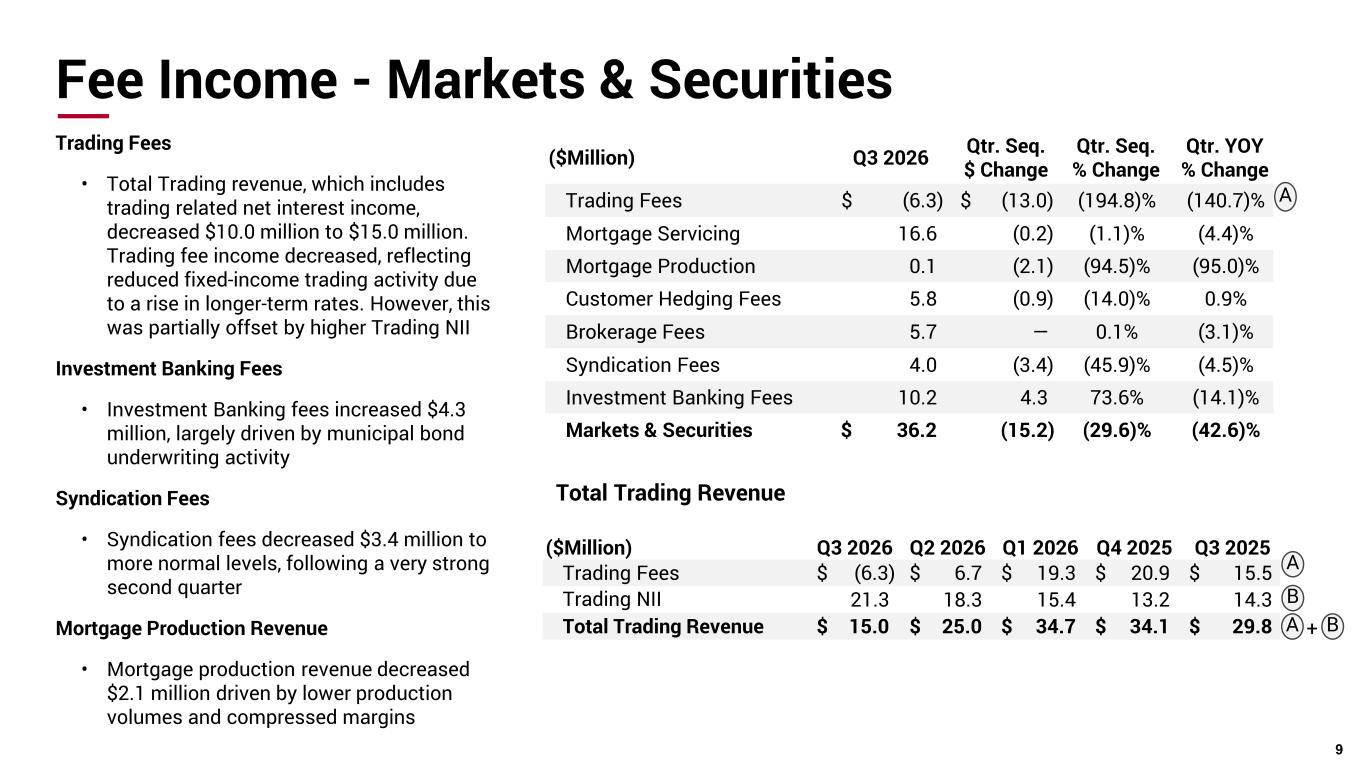
Fee Income - Markets & Securities Trading Fees • Total Trading revenue, which includes trading related net interest income, decreased $10.0 million to $15.0 million. Trading fee income decreased, reflecting reduced fixed-income trading activity due to a rise in longer-term rates. However, this was partially offset by higher Trading NII Investment Banking Fees • Investment Banking fees increased $4.3 million, largely driven by municipal bond underwriting activity Syndication Fees • Syndication fees decreased $3.4 million to more normal levels, following a very strong second quarter Mortgage Production Revenue • Mortgage production revenue decreased $2.1 million driven by lower production volumes and compressed margins 9 ($Million) Q3 2026 Qtr. Seq. $ Change Qtr. Seq. % Change Qtr. YOY % Change Trading Fees $ (6.3) $ (13.0) (194.8)% (140.7)% Mortgage Servicing 16.6 (0.2) (1.1)% (4.4)% Mortgage Production 0.1 (2.1) (94.5)% (95.0)% Customer Hedging Fees 5.8 (0.9) (14.0)% 0.9% Brokerage Fees 5.7 — 0.1% (3.1)% Syndication Fees 4.0 (3.4) (45.9)% (4.5)% Investment Banking Fees 10.2 4.3 73.6% (14.1)% Markets & Securities $ 36.2 (15.2) (29.6)% (42.6)% ($Million) Q3 2026 Q2 2026 Q1 2026 Q4 2025 Q3 2025 Trading Fees $ (6.3) $ 6.7 $ 19.3 $ 20.9 $ 15.5 Trading NII 21.3 18.3 15.4 13.2 14.3 Total Trading Revenue $ 15.0 $ 25.0 $ 34.7 $ 34.1 $ 29.8 A A Total Trading Revenue A + B B
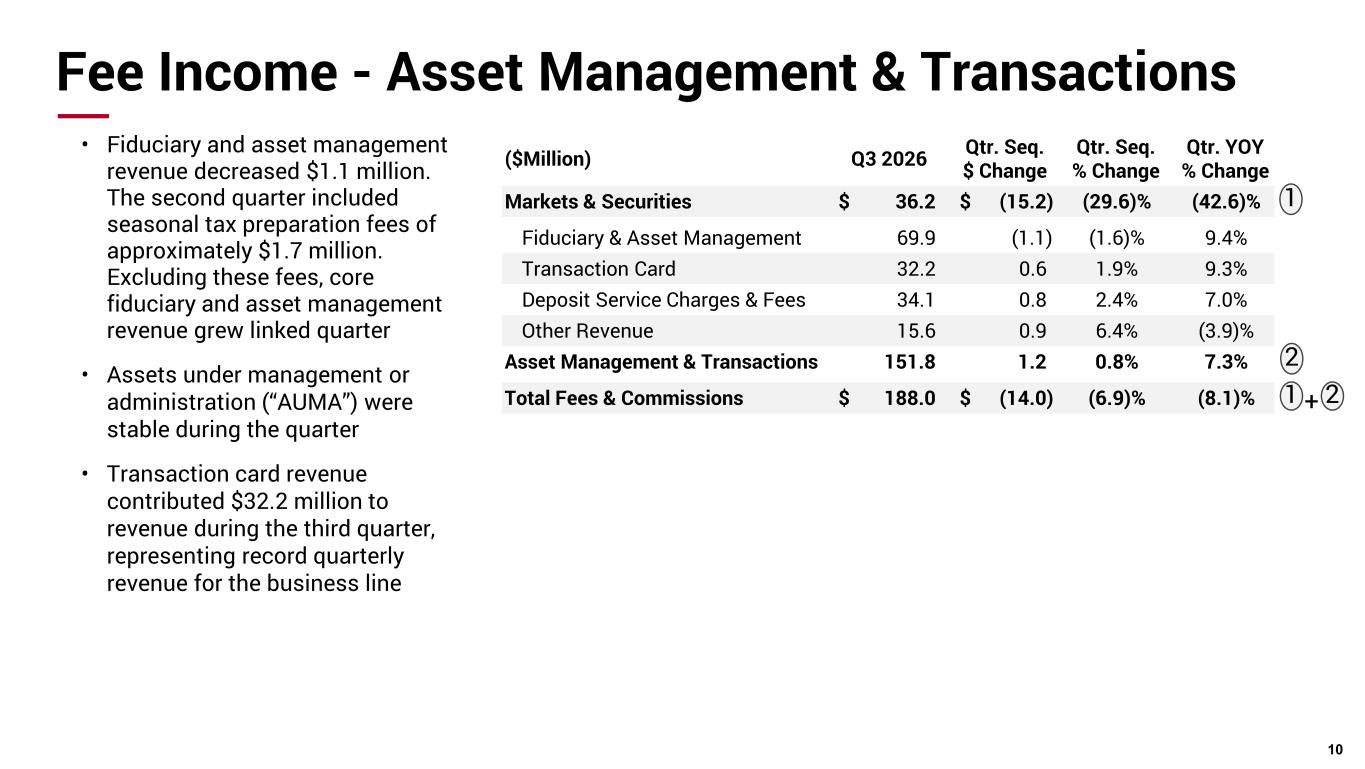
Fee Income - Asset Management & Transactions • Fiduciary and asset management revenue decreased $1.1 million. The second quarter included seasonal tax preparation fees of approximately $1.7 million. Excluding these fees, core fiduciary and asset management revenue grew linked quarter • Assets under management or administration (“AUMA”) were stable during the quarter • Transaction card revenue contributed $32.2 million to revenue during the third quarter, representing record quarterly revenue for the business line 10 ($Million) Q3 2026 Qtr. Seq. $ Change Qtr. Seq. % Change Qtr. YOY % Change Markets & Securities $ 36.2 $ (15.2) (29.6)% (42.6)% Fiduciary & Asset Management 69.9 (1.1) (1.6)% 9.4% Transaction Card 32.2 0.6 1.9% 9.3% Deposit Service Charges & Fees 34.1 0.8 2.4% 7.0% Other Revenue 15.6 0.9 6.4% (3.9)% Asset Management & Transactions 151.8 1.2 0.8% 7.3% Total Fees & Commissions $ 188.0 $ (14.0) (6.9)% (8.1)% 2+1 1 2
Marty Grunst EVP, Chief Financial Officer 11
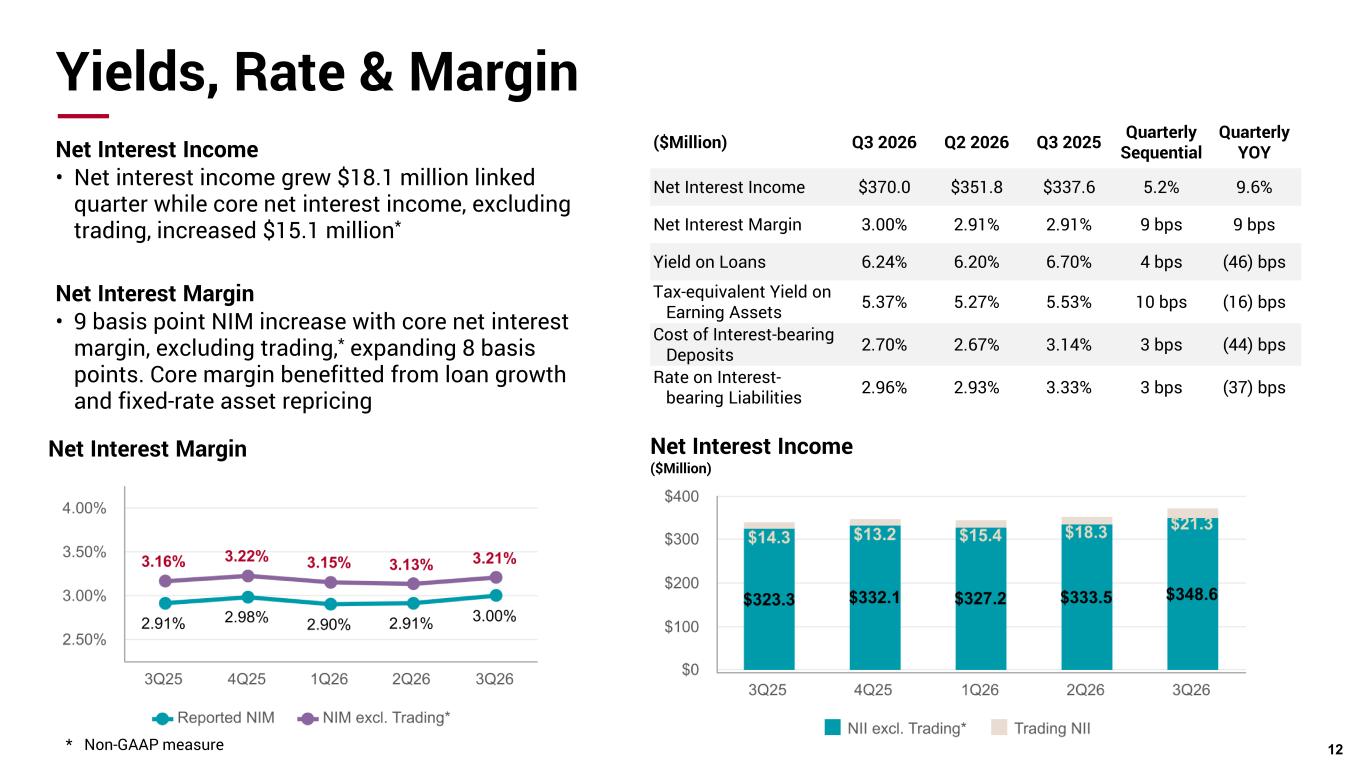
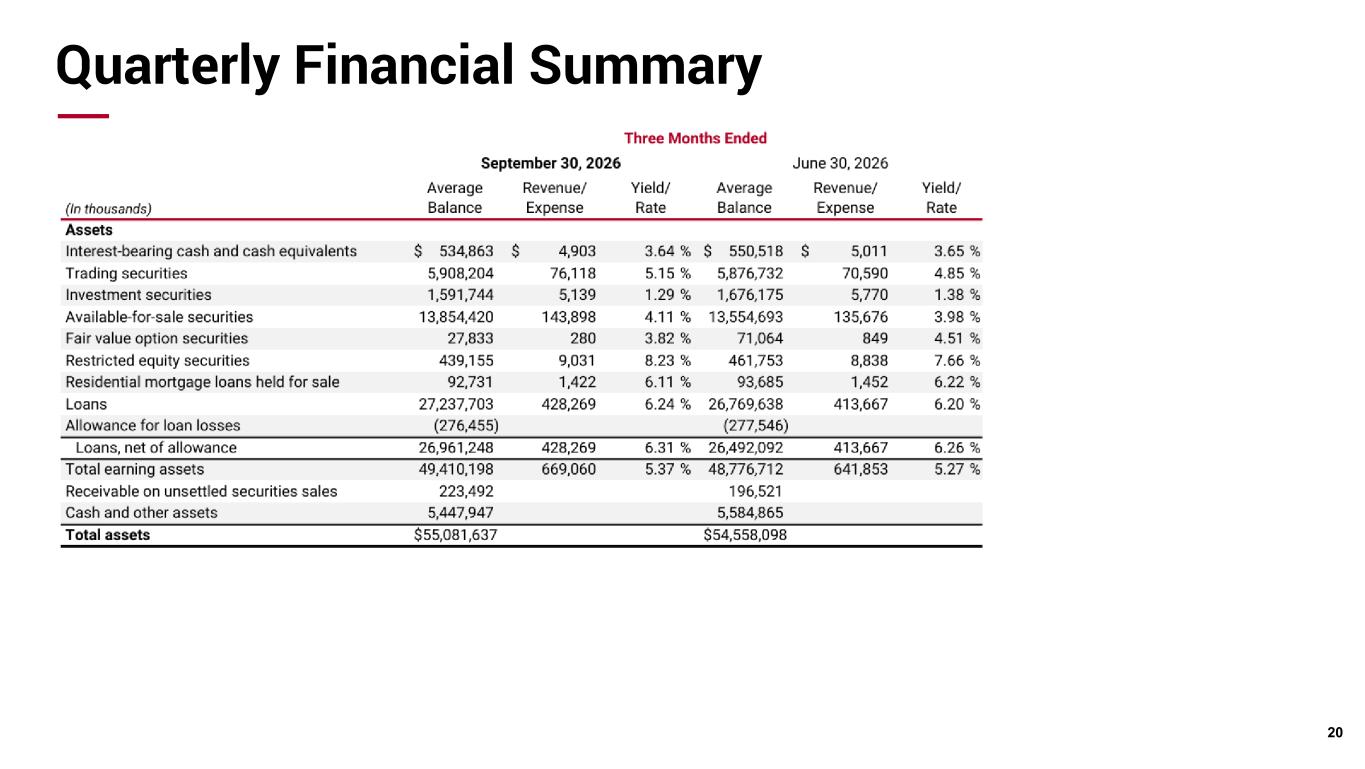
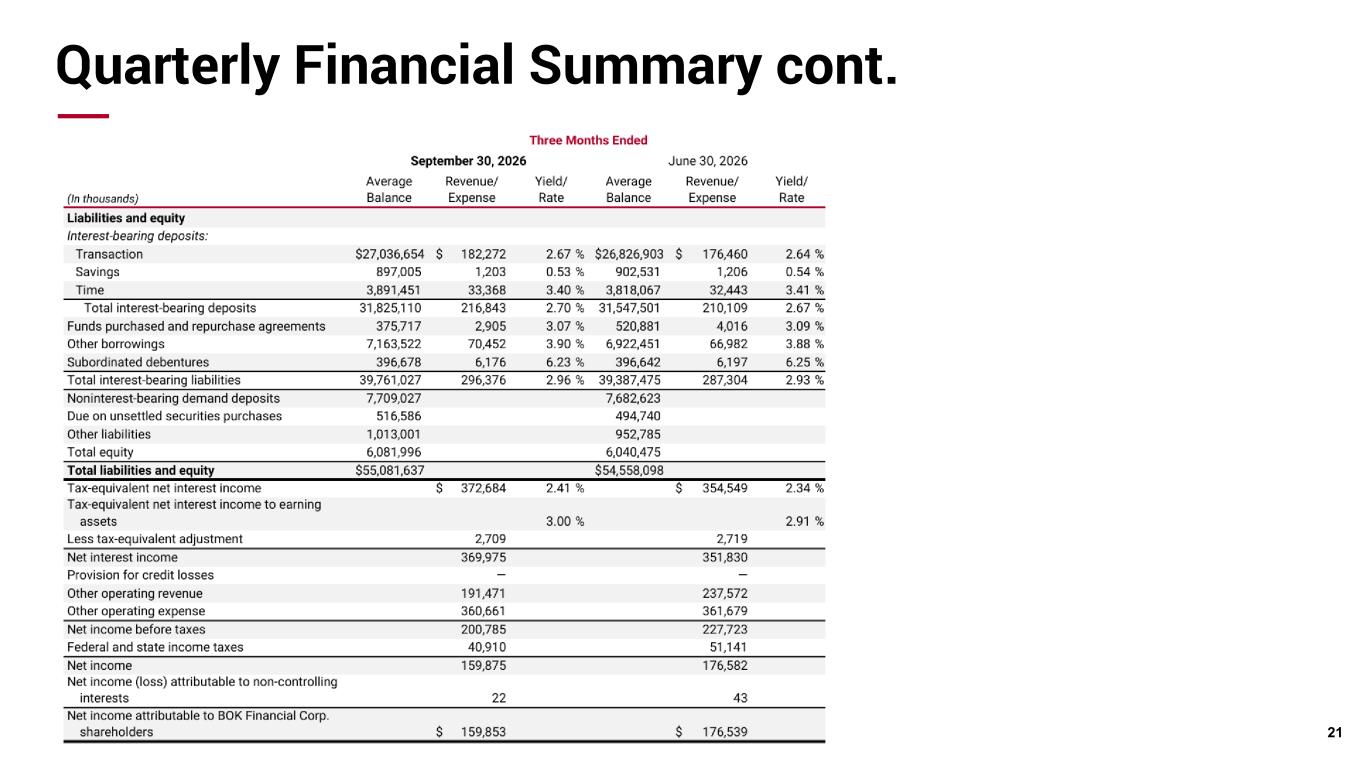
Yields, Rate & Margin Net Interest Income • Net interest income grew $18.1 million linked quarter while core net interest income, excluding trading, increased $15.1 million* Net Interest Margin • 9 basis point NIM increase with core net interest margin, excluding trading,* expanding 8 basis points. Core margin benefitted from loan growth and fixed-rate asset repricing 12 ($Million) Q3 2026 Q2 2026 Q3 2025 Quarterly Sequential Quarterly YOY Net Interest Income $370.0 $351.8 $337.6 5.2% 9.6% Net Interest Margin 3.00% 2.91% 2.91% 9 bps 9 bps Yield on Loans 6.24% 6.20% 6.70% 4 bps (46) bps Tax-equivalent Yield on Earning Assets 5.37% 5.27% 5.53% 10 bps (16) bps Cost of Interest-bearing Deposits 2.70% 2.67% 3.14% 3 bps (44) bps Rate on Interest- bearing Liabilities 2.96% 2.93% 3.33% 3 bps (37) bps Net Interest Income ($Million) Net Interest Margin * Non-GAAP measure
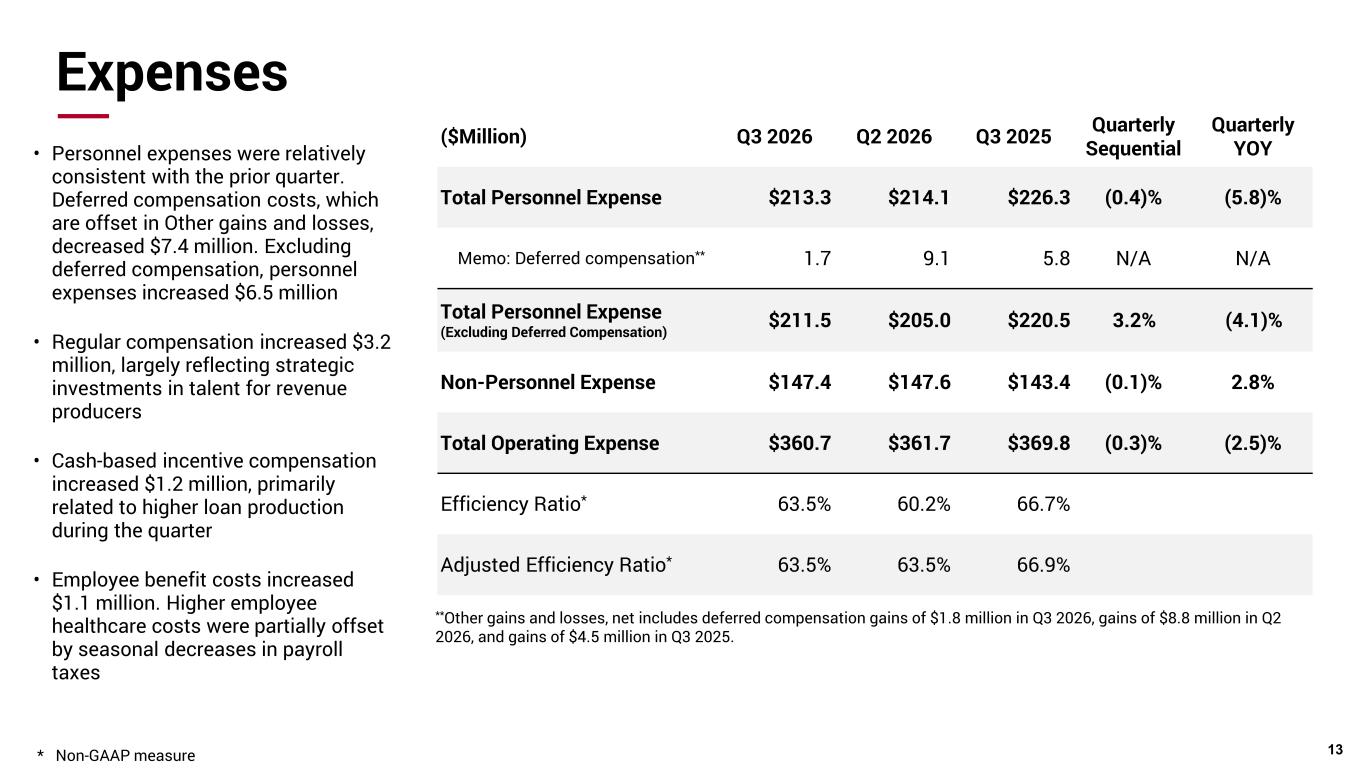
Expenses • Personnel expenses were relatively consistent with the prior quarter. Deferred compensation costs, which are offset in Other gains and losses, decreased $7.4 million. Excluding deferred compensation, personnel expenses increased $6.5 million • Regular compensation increased $3.2 million, largely reflecting strategic investments in talent for revenue producers • Cash-based incentive compensation increased $1.2 million, primarily related to higher loan production during the quarter • Employee benefit costs increased $1.1 million. Higher employee healthcare costs were partially offset by seasonal decreases in payroll taxes 13 ($Million) Q3 2026 Q2 2026 Q3 2025 Quarterly Sequential Quarterly YOY Total Personnel Expense $213.3 $214.1 $226.3 (0.4)% (5.8)% Memo: Deferred compensation** 1.7 9.1 5.8 N/A N/A Total Personnel Expense (Excluding Deferred Compensation) $211.5 $205.0 $220.5 3.2% (4.1)% Non-Personnel Expense $147.4 $147.6 $143.4 (0.1)% 2.8% Total Operating Expense $360.7 $361.7 $369.8 (0.3)% (2.5)% Efficiency Ratio* 63.5% 60.2% 66.7% Adjusted Efficiency Ratio* 63.5% 63.5% 66.9% * Non-GAAP measure **Other gains and losses, net includes deferred compensation gains of $1.8 million in Q3 2026, gains of $8.8 million in Q2 2026, and gains of $4.5 million in Q3 2025.
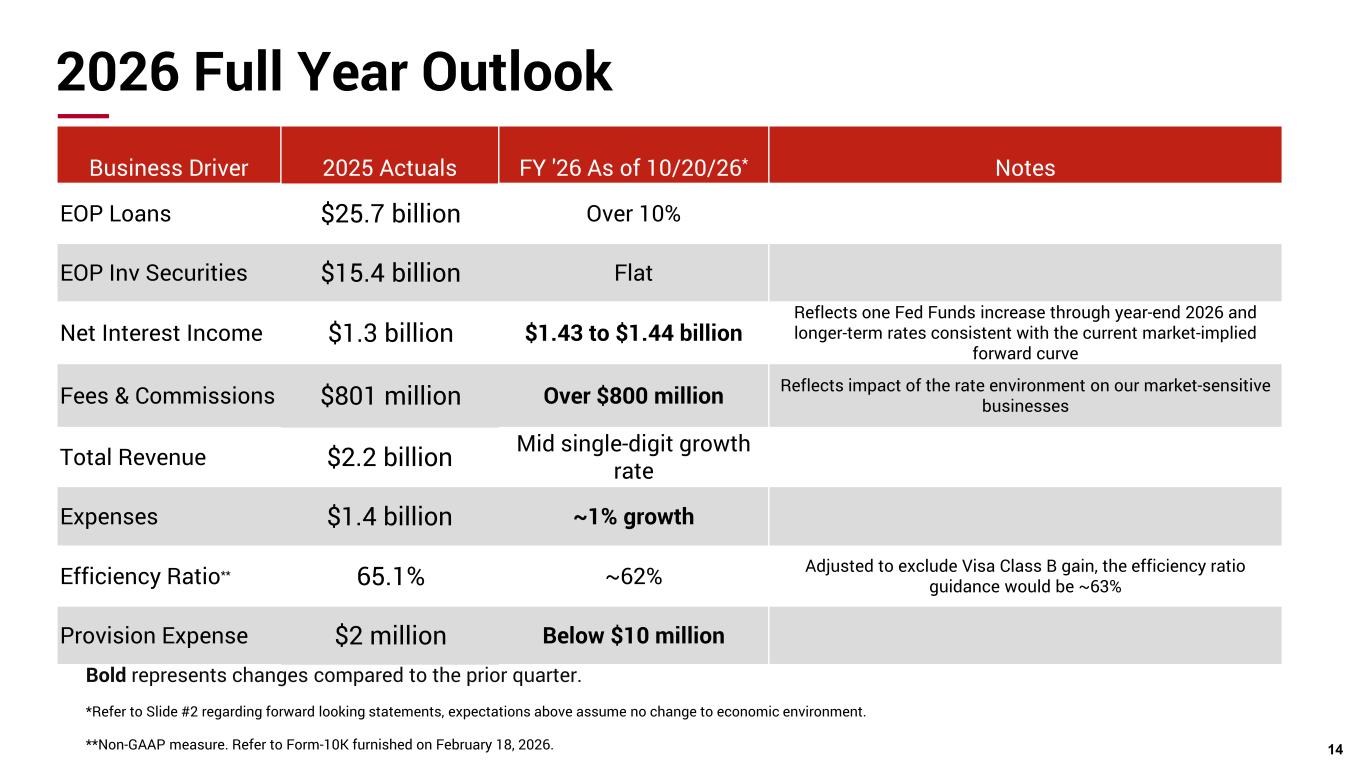
2026 Full Year Outlook 14 Bold represents changes compared to the prior quarter. *Refer to Slide #2 regarding forward looking statements, expectations above assume no change to economic environment. **Non-GAAP measure. Refer to Form-10K furnished on February 18, 2026. Business Driver 2025 Actuals FY '26 As of 10/20/26* Notes EOP Loans $25.7 billion Over 10% EOP Inv Securities $15.4 billion Flat Net Interest Income $1.3 billion $1.43 to $1.44 billion Reflects one Fed Funds increase through year-end 2026 and longer-term rates consistent with the current market-implied forward curve Fees & Commissions $801 million Over $800 million Reflects impact of the rate environment on our market-sensitive businesses Total Revenue $2.2 billion Mid single-digit growth rate Expenses $1.4 billion ~1% growth Efficiency Ratio** 65.1% ~62% Adjusted to exclude Visa Class B gain, the efficiency ratio guidance would be ~63% Provision Expense $2 million Below $10 million
Question & Answer Session 15
Stacy Kymes Chief Executive Officer 16
Appendix 17
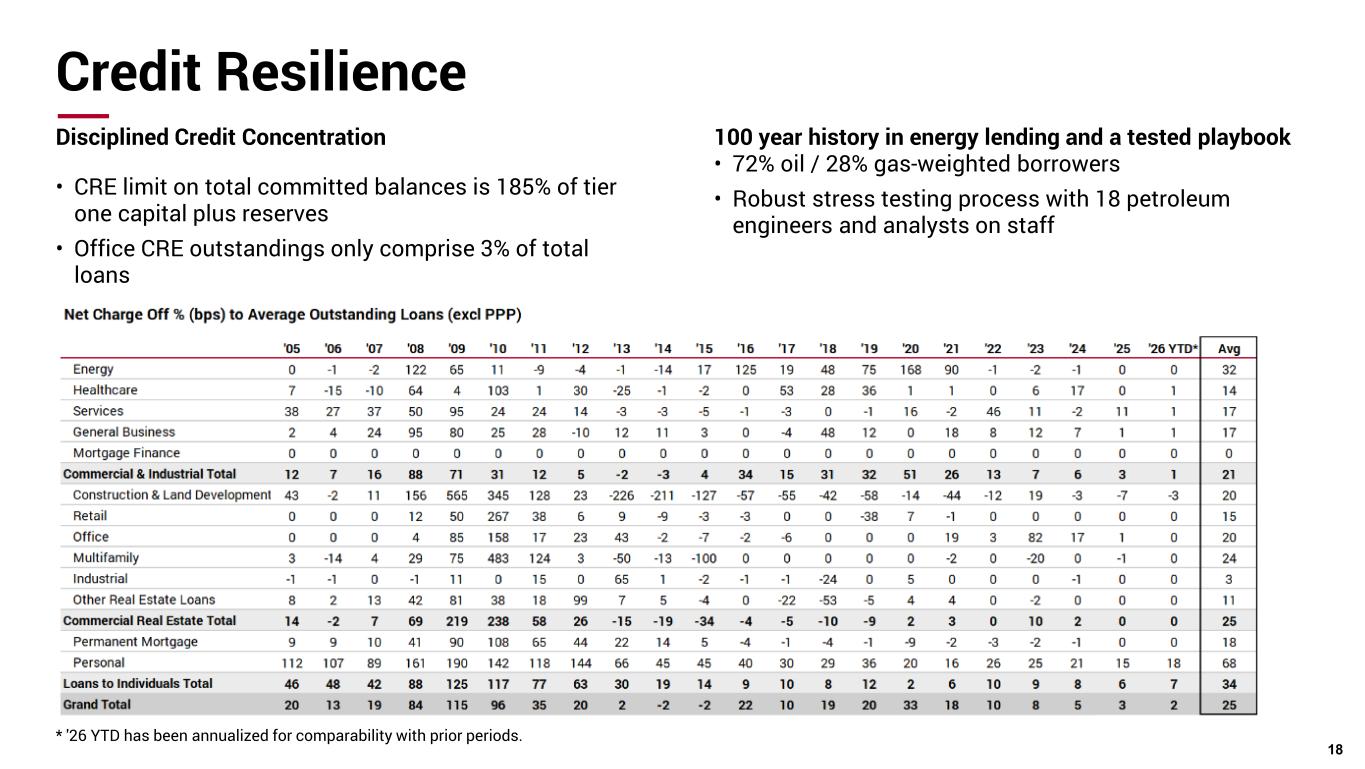
Credit Resilience Disciplined Credit Concentration • CRE limit on total committed balances is 185% of tier one capital plus reserves • Office CRE outstandings only comprise 3% of total loans 18 100 year history in energy lending and a tested playbook • 72% oil / 28% gas-weighted borrowers • Robust stress testing process with 18 petroleum engineers and analysts on staff * '26 YTD has been annualized for comparability with prior periods.
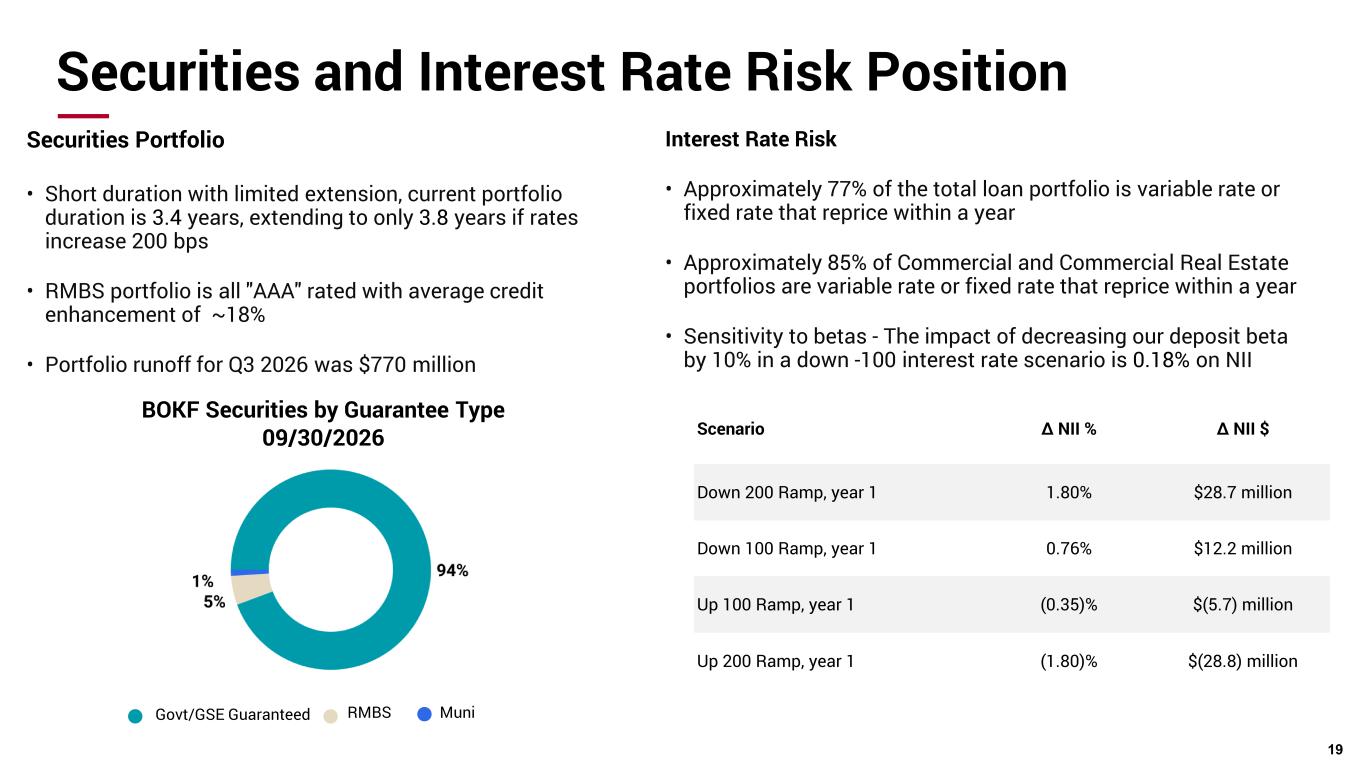
Securities and Interest Rate Risk Position Interest Rate Risk • Approximately 77% of the total loan portfolio is variable rate or fixed rate that reprice within a year • Approximately 85% of Commercial and Commercial Real Estate portfolios are variable rate or fixed rate that reprice within a year • Sensitivity to betas - The impact of decreasing our deposit beta by 10% in a down -100 interest rate scenario is 0.18% on NII 19 Scenario ∆ NII % ∆ NII $ Down 200 Ramp, year 1 1.80% $28.7 million Down 100 Ramp, year 1 0.76% $12.2 million Up 100 Ramp, year 1 (0.35)% $(5.7) million Up 200 Ramp, year 1 (1.80)% $(28.8) million Securities Portfolio • Short duration with limited extension, current portfolio duration is 3.4 years, extending to only 3.8 years if rates increase 200 bps • RMBS portfolio is all "AAA" rated with average credit enhancement of ~18% • Portfolio runoff for Q3 2026 was $770 million Govt/GSE Guaranteed RMBS Muni BOKF Securities by Guarantee Type 09/30/2026
Quarterly Financial Summary 20
Quarterly Financial Summary cont. 21