Exhibit 99.1
BUILDING THE WORLD’S LARGEST PUBLICLY TRADED BLOCKCHAIN, DIGITAL ASSET, AI, FINTECH INCUBATOR AND MERCHANT BANKING FIRM Investor Presentation · October 2026 DIGITAL ASSETS · FUTURE FINANCE · FRONTIER TECHNOLOGY
Disclaimer Confidentiality . This presentation has been prepared by Hawkeye Digital, Inc . (the "Company") solely for use by a limited number of prospective investors who have represented that they are "accredited investors" . It may not be copied, reproduced, or distributed, in whole or in part, to any other person without the Company's prior written consent . By accepting this presentation, the recipient agrees to keep its contents confidential . No Offer . This presentation is for informational purposes only and does not constitute an offer to sell, or a solicitation of an offer to buy, any securities . No representations or warranties, express or implied are given in, or in respect of, this Presentation . Investment Risk . An investment in the Company's securities involves a high degree of risk, including the possible loss of the entire investment, and is suitable only for investors who can bear that risk . Forward - Looking Statements . This presentation contains "forward - looking statements" within the meaning of Section 27 A of the Securities Act and Section 21 E of the Securities Exchange Act of 1934 , as amended, including statements regarding the Company's strategy, expected revenues, profitability, uplisting plans, market size and growth, and other future events . Words such as "anticipate," "believe," "could," "expect," "intend," "may," "plan," "potential," "project," "seek," "should," "target," "will," and "would" identify forward - looking statements . These statements are based on management's current expectations and assumptions and are subject to significant risks and uncertainties, many of which are beyond the Company's control, including : its limited operating history as an incubator and merchant bank and its ability to execute its strategy ; its need for additional capital ; risks associated with digital assets, blockchain, and frontier technology markets, including price volatility and regulatory change ; dependence on key personnel ; competition ; the illiquidity of, and limited trading market for, the Company's securities ; and the other risks described in the Company's filings with the U . S . Securities and Exchange Commission, including its Annual Report on form 10 - K for the fiscal year ended June 30 , 2026 . Actual results may differ materially . Forward - looking statements speak only as of the date hereof, and the Company undertakes no obligation to update them except as required by law . Projections and Third - Party Information . Any projections, targets, or illustrative scenarios are based on assumptions that may not prove correct and are not guarantees of future performance . Certain industry, market, and competitive data are derived from third - party sources the Company believes to be reliable but has not independently verified . References to public companies are for illustrative purposes only and are not a prediction of the Company's performance . Neither the SEC nor any state securities regulator has approved or disapproved of any securities or passed upon the accuracy or adequacy of this presentation . 2
Risk Factors 3 Strategy and execution risk The Company's strategy depends on sourcing, completing, and integrating investments and on its ability to raise additional capital on acceptable terms . If it cannot do so, the strategy described here may not be achievable . Integration and dependence on key personnel Realizing the flywheel depends on integrating advisory, incubator, and merchant banking activities and on the continued service of Mr . Sumichrast and other key personnel . Loss of key personnel or clients could materially harm the business . Limited operating history and need for capital Hawkeye has a limited operating history as an incubator and merchant bank, has not generated significant investment returns, and will need additional capital, which may be dilutive or unavailable . Investment and market risk Investments in early - stage digital asset and frontier technology companies are illiquid and speculative ; some may be lost entirely . Portfolio valuations may be volatile and affected by crypto asset prices . Regulatory risk Digital asset regulation is evolving in the U . S . and abroad ; changes could adversely affect the Company, its clients, and portfolio companies . Certain activities may require registrations or licenses . Related - party and governance considerations Certain officers, directors, and significant shareholders may have interests that differ from those of other investors . Securities and liquidity risk The Company's common stock trades on the OTC market with limited liquidity ; there is no assurance of an uplisting . Reliance on third - party information Market data is from third parties and has not been independently verified . * This summary is not complete. Investors should carefully review the risk factors in the Company's SEC filings before invest ing .
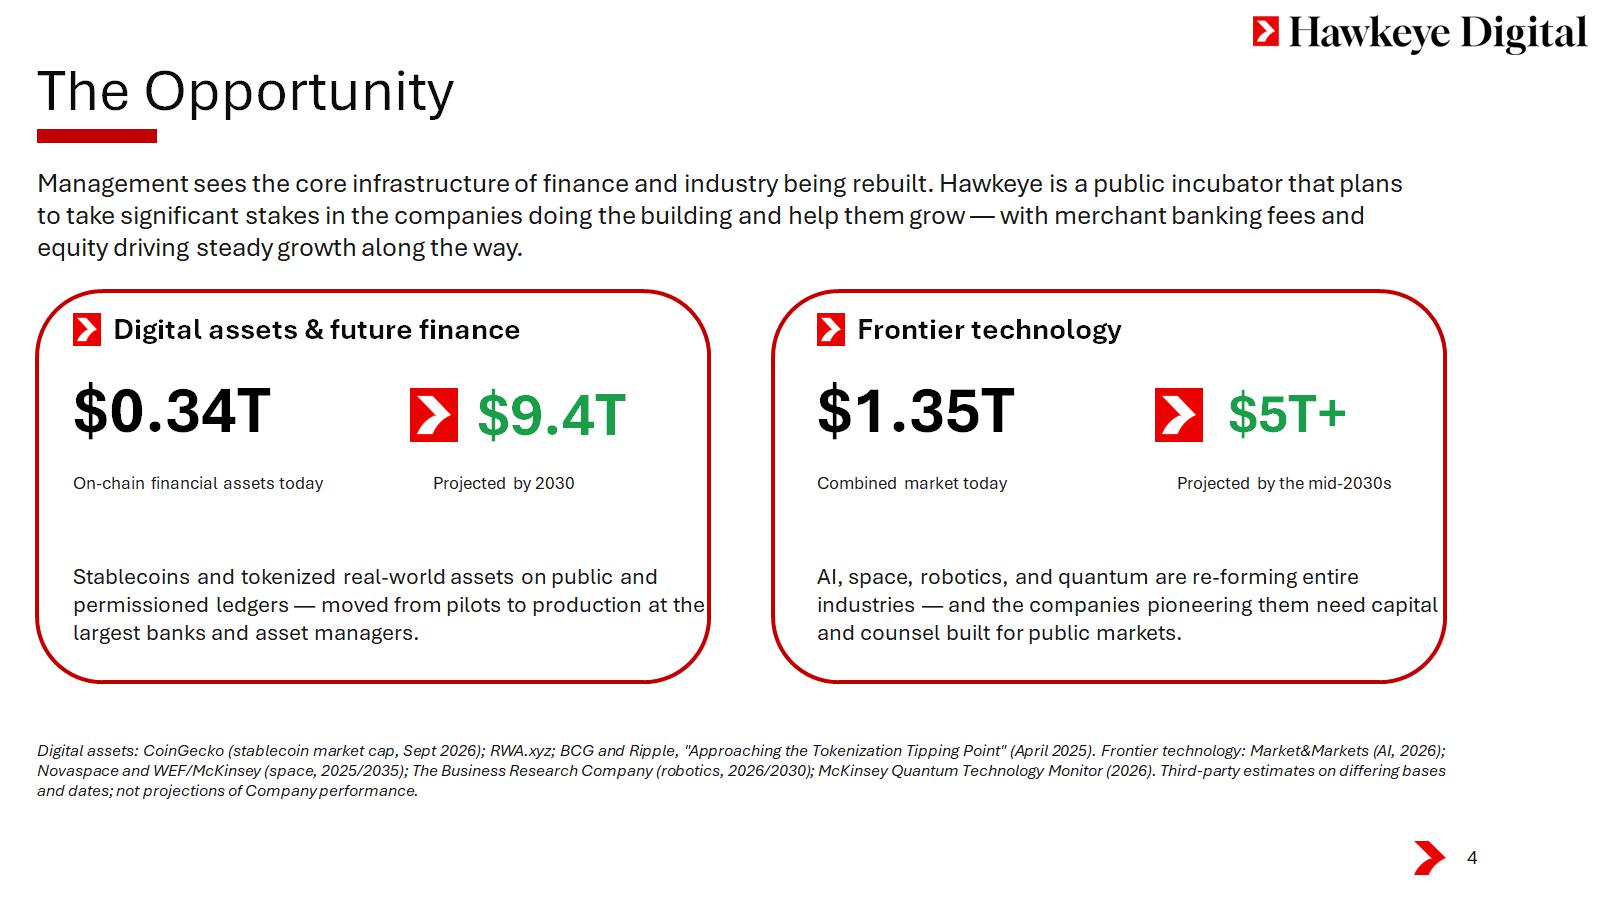
The Opportunity 4 Management sees the core infrastructure of finance and industry being rebuilt. Hawkeye is a public incubator that plans to take significant stakes in the companies doing the building and help them grow — with merchant banking fees and equity driving steady growth along the way. Digital assets & future finance $0.34T On - chain financial assets today $9.4T Projected by 2030 Stablecoins and tokenized real - world assets on public and permissioned ledgers — moved from pilots to production at the largest banks and asset managers. Frontier technology $1.35T Combined market today $5T+ Projected by the mid - 2030s AI, space, robotics, and quantum are re - forming entire industries — and the companies pioneering them need capital and counsel built for public markets. Digital assets : CoinGecko (stablecoin market cap, Sept 2026 ) ; RWA . xyz ; BCG and Ripple, "Approaching the Tokenization Tipping Point" (April 2025 ) . Frontier technology : Market&Markets (AI, 2026 ) ; Novaspace and WEF/McKinsey (space, 2025 / 2035 ) ; The Business Research Company (robotics, 2026 / 2030 ) ; McKinsey Quantum Technology Monitor ( 2026 ) . Third - party estimates on differing bases and dates ; not projections of Company performance .
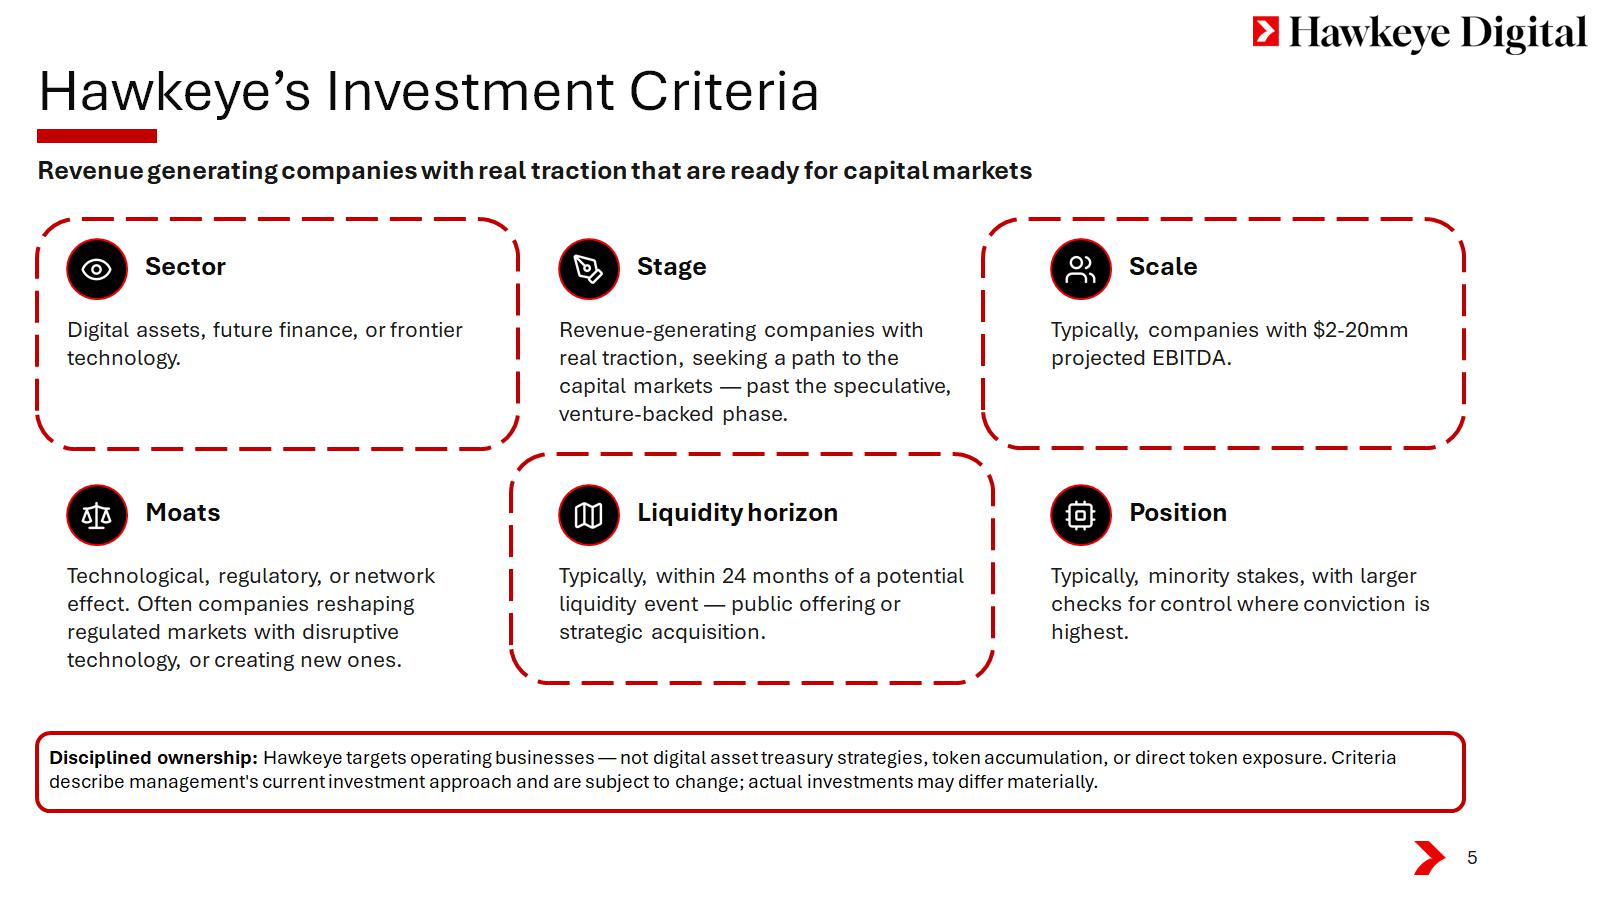
Hawkeye’s Investment Criteria 5 Revenue generating companies with real traction that are ready for capital markets Disciplined ownership: Hawkeye targets operating businesses — not digital asset treasury strategies, token accumulation, or direct token exposure. Cri teria describe management's current investment approach and are subject to change; actual investments may differ materially. Sector Digital assets, future finance, or frontier technology. Stage Revenue - generating companies with real traction, seeking a path to the capital markets — past the speculative, venture - backed phase. Scale Typically, companies with $2 - 20mm projected EBITDA. Moats Technological, regulatory, or network effect. Often companies reshaping regulated markets with disruptive technology, or creating new ones. Liquidity horizon Typically, within 24 months of a potential liquidity event — public offering or strategic acquisition. Position Typically, minority stakes, with larger checks for control where conviction is highest.
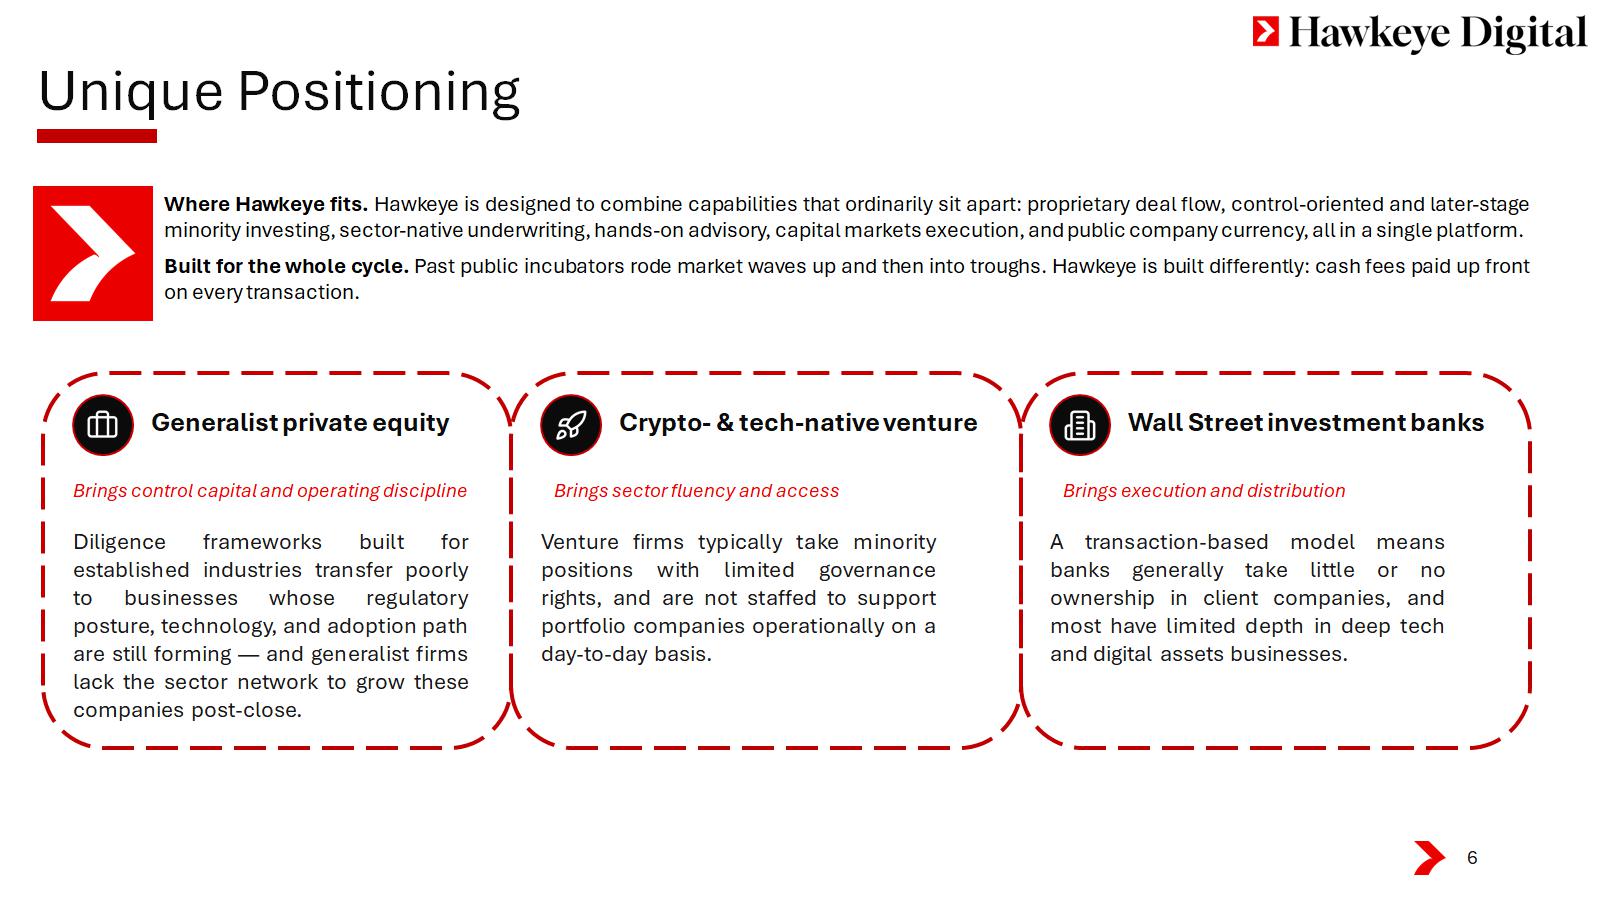
Unique Positioning 6 Where Hawkeye fits . Hawkeye is designed to combine capabilities that ordinarily sit apart : proprietary deal flow, control - oriented and later - stage minority investing, sector - native underwriting, hands - on advisory, capital markets execution, and public company currency, all in a single platform . Built for the whole cycle . Past public incubators rode market waves up and then into troughs . Hawkeye is built differently : cash fees paid up front on every transaction . Generalist private equity Brings control capital and operating discipline Diligence frameworks built for established industries transfer poorly to businesses whose regulatory posture, technology, and adoption path are still forming — and generalist firms lack the sector network to grow these companies post - close . Crypto - & tech - native venture Brings sector fluency and access Venture firms typically take minority positions with limited governance rights, and are not staffed to support portfolio companies operationally on a day - to - day basis . Wall Street investment banks Brings execution and distribution A transaction - based model means banks generally take little or no ownership in client companies, and most have limited depth in deep tech and digital assets businesses .
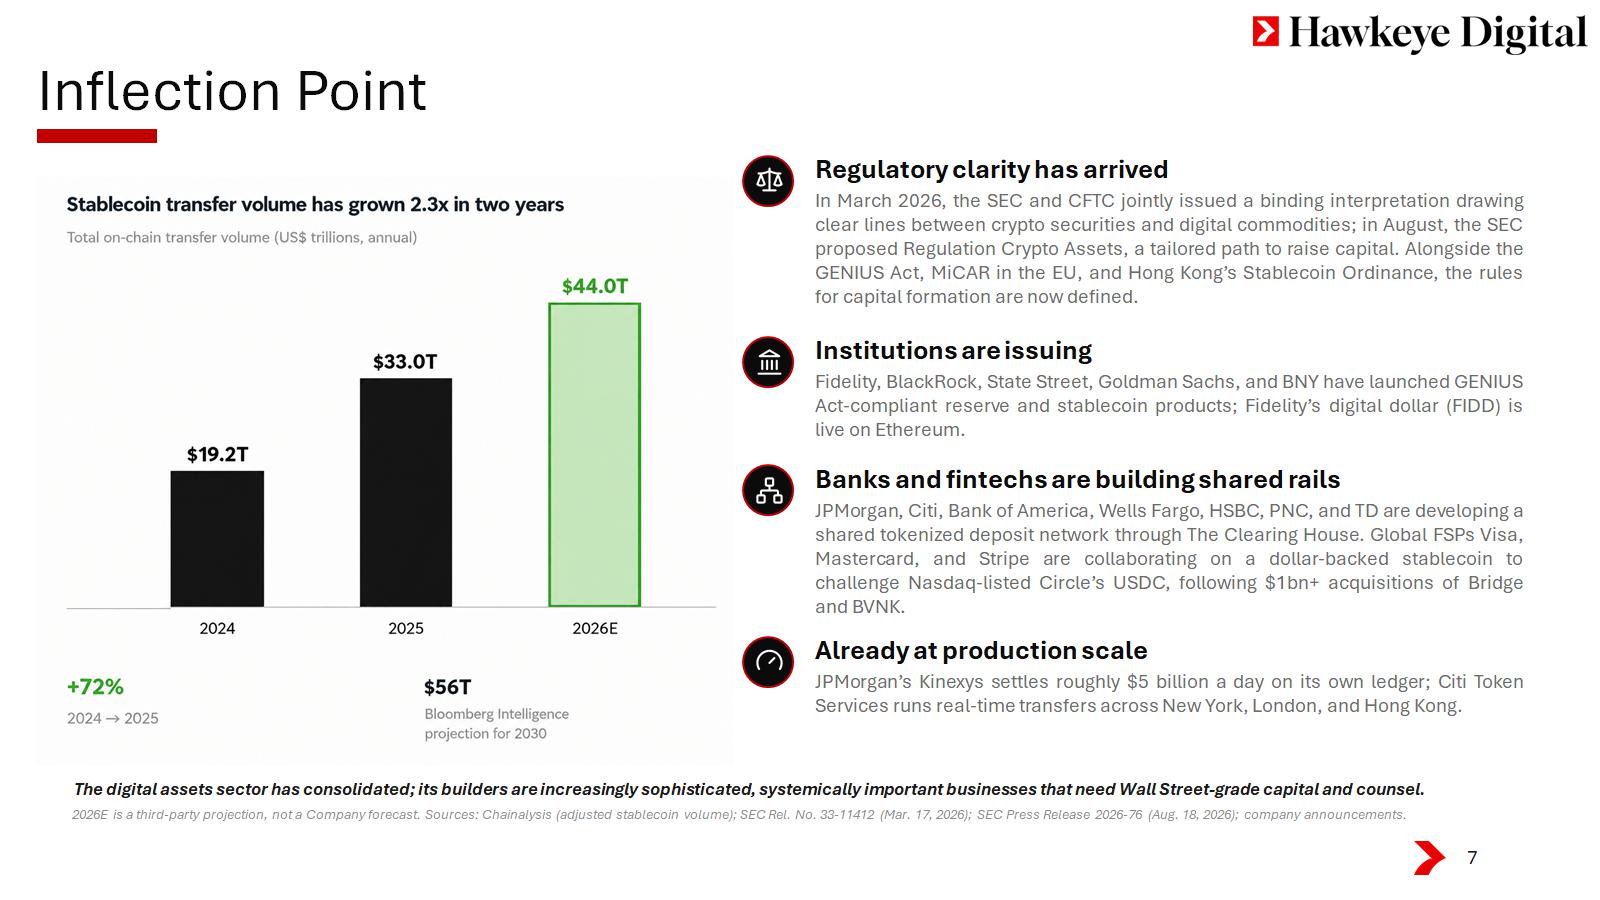
Inflection Point 7 Regulatory clarity has arrived In March 2026 , the SEC and CFTC jointly issued a binding interpretation drawing clear lines between crypto securities and digital commodities ; in August, the SEC proposed Regulation Crypto Assets, a tailored path to raise capital . Alongside the GENIUS Act, MiCAR in the EU, and Hong Kong’s Stablecoin Ordinance, the rules for capital formation are now defined . Institutions are issuing Fidelity, BlackRock, State Street, Goldman Sachs, and BNY have launched GENIUS Act - compliant reserve and stablecoin products ; Fidelity’s digital dollar (FIDD) is live on Ethereum . Banks and fintechs are building shared rails JPMorgan, Citi, Bank of America, Wells Fargo, HSBC, PNC, and TD are developing a shared tokenized deposit network through The Clearing House . Global FSPs Visa, Mastercard, and Stripe are collaborating on a dollar - backed stablecoin to challenge Nasdaq - listed Circle’s USDC, following $ 1 bn+ acquisitions of Bridge and BVNK . Already at production scale JPMorgan’s Kinexys settles roughly $ 5 billion a day on its own ledger ; Citi Token Services runs real - time transfers across New York, London, and Hong Kong . 2026E is a third - party projection, not a Company forecast. Sources: Chainalysis (adjusted stablecoin volume); SEC Rel. No. 33 - 11 412 (Mar. 17, 2026); SEC Press Release 2026 - 76 (Aug. 18, 2026); company announcements. The digital assets sector has consolidated; its builders are increasingly sophisticated, systemically important businesses th at need Wall Street - grade capital and counsel.
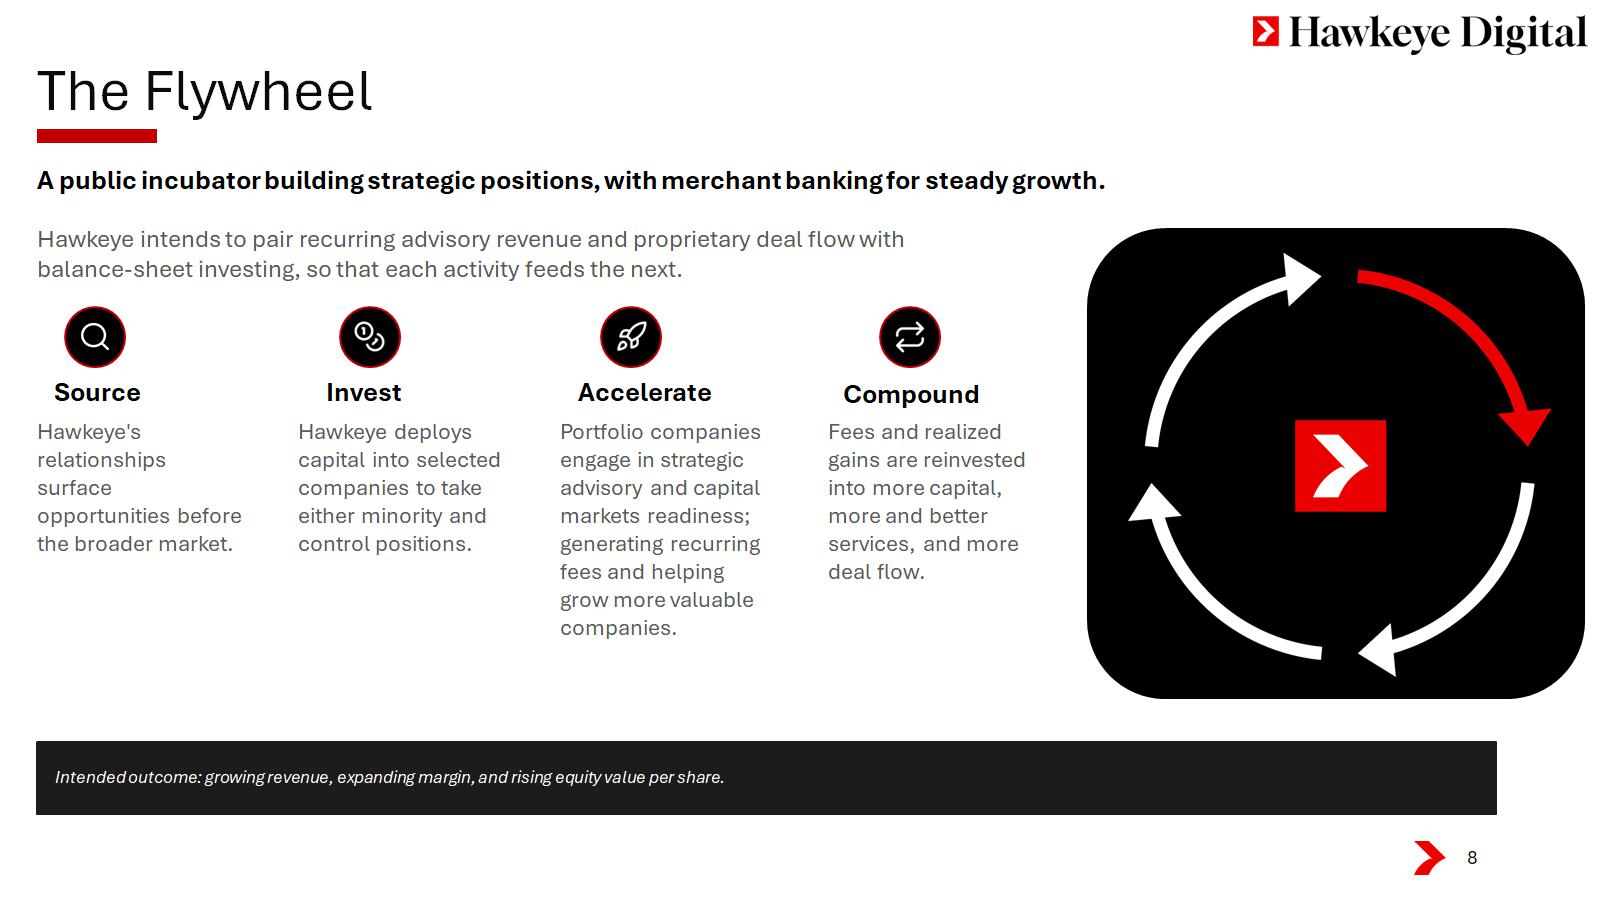
The Flywheel 8 A public incubator building strategic positions, with merchant banking for steady growth. Hawkeye intends to pair recurring advisory revenue and proprietary deal flow with balance - sheet investing, so that each activity feeds the next. Source Hawkeye's relationships surface opportunities before the broader market. Invest Hawkeye deploys capital into selected companies to take either minority and control positions. Accelerate Portfolio companies engage in strategic advisory and capital markets readiness; generating recurring fees and helping grow more valuable companies. Compound Fees and realized gains are reinvested into more capital, more and better services, and more deal flow. Intended outcome: growing revenue, expanding margin, and rising equity value per share.
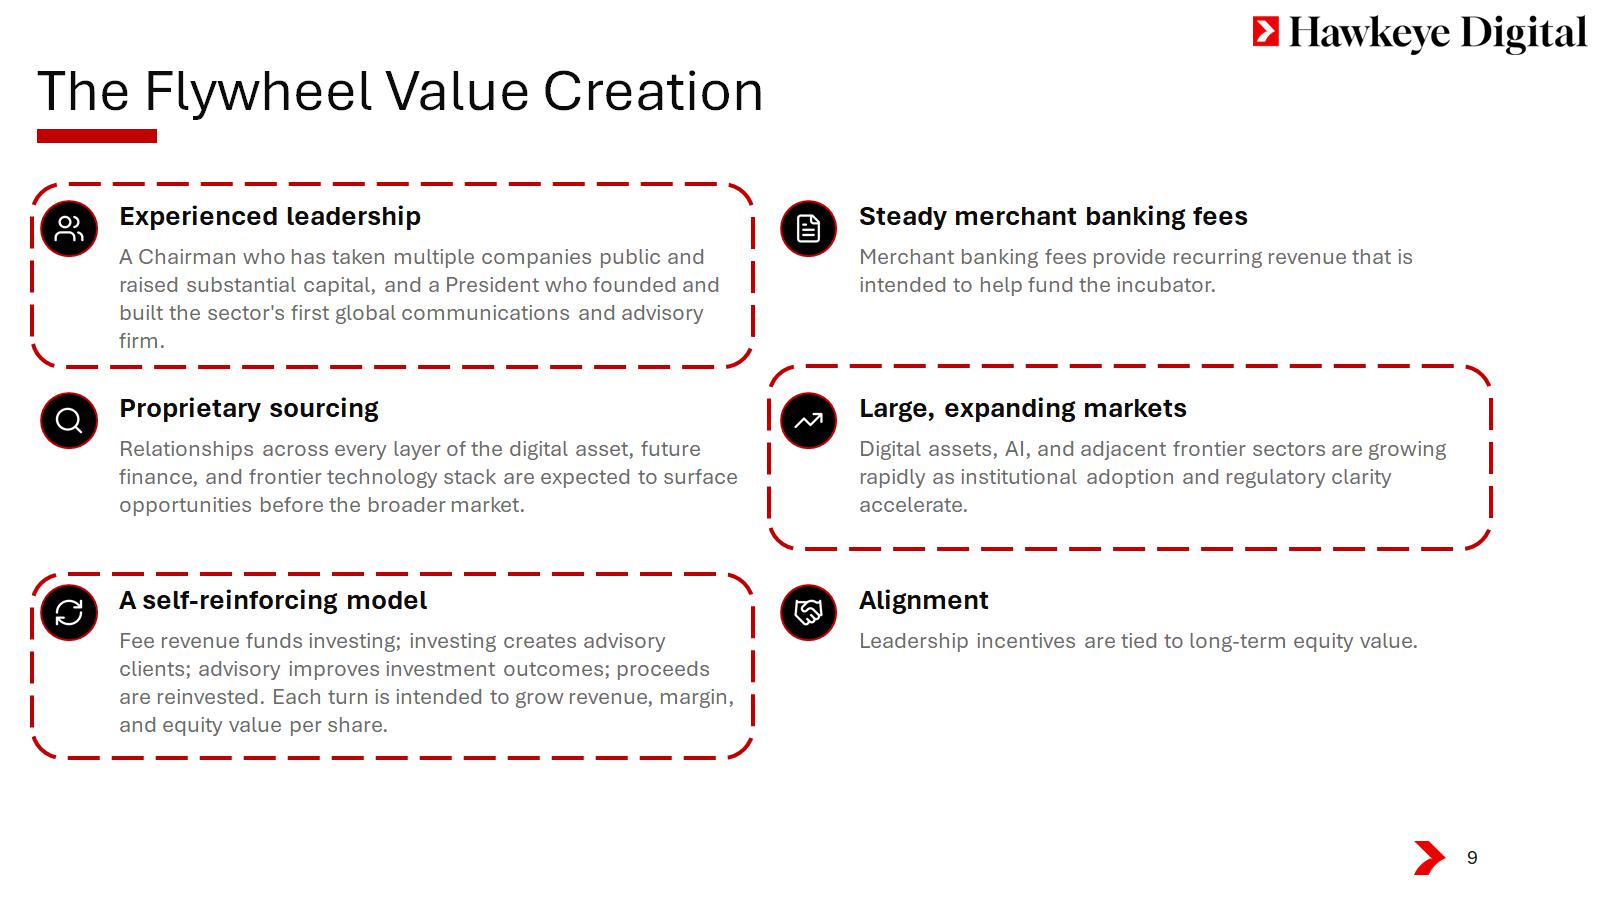
The Flywheel Value Creation 9 Experienced leadership A Chairman who has taken multiple companies public and raised substantial capital, and a President who founded and built the sector's first global communications and advisory firm. Steady merchant banking fees Merchant banking fees provide recurring revenue that is intended to help fund the incubator. Proprietary sourcing Relationships across every layer of the digital asset, future finance, and frontier technology stack are expected to surface opportunities before the broader market. Large, expanding markets Digital assets, AI, and adjacent frontier sectors are growing rapidly as institutional adoption and regulatory clarity accelerate. A self - reinforcing model Fee revenue funds investing; investing creates advisory clients; advisory improves investment outcomes; proceeds are reinvested. Each turn is intended to grow revenue, margin, and equity value per share. Alignment Leadership incentives are tied to long - term equity value.
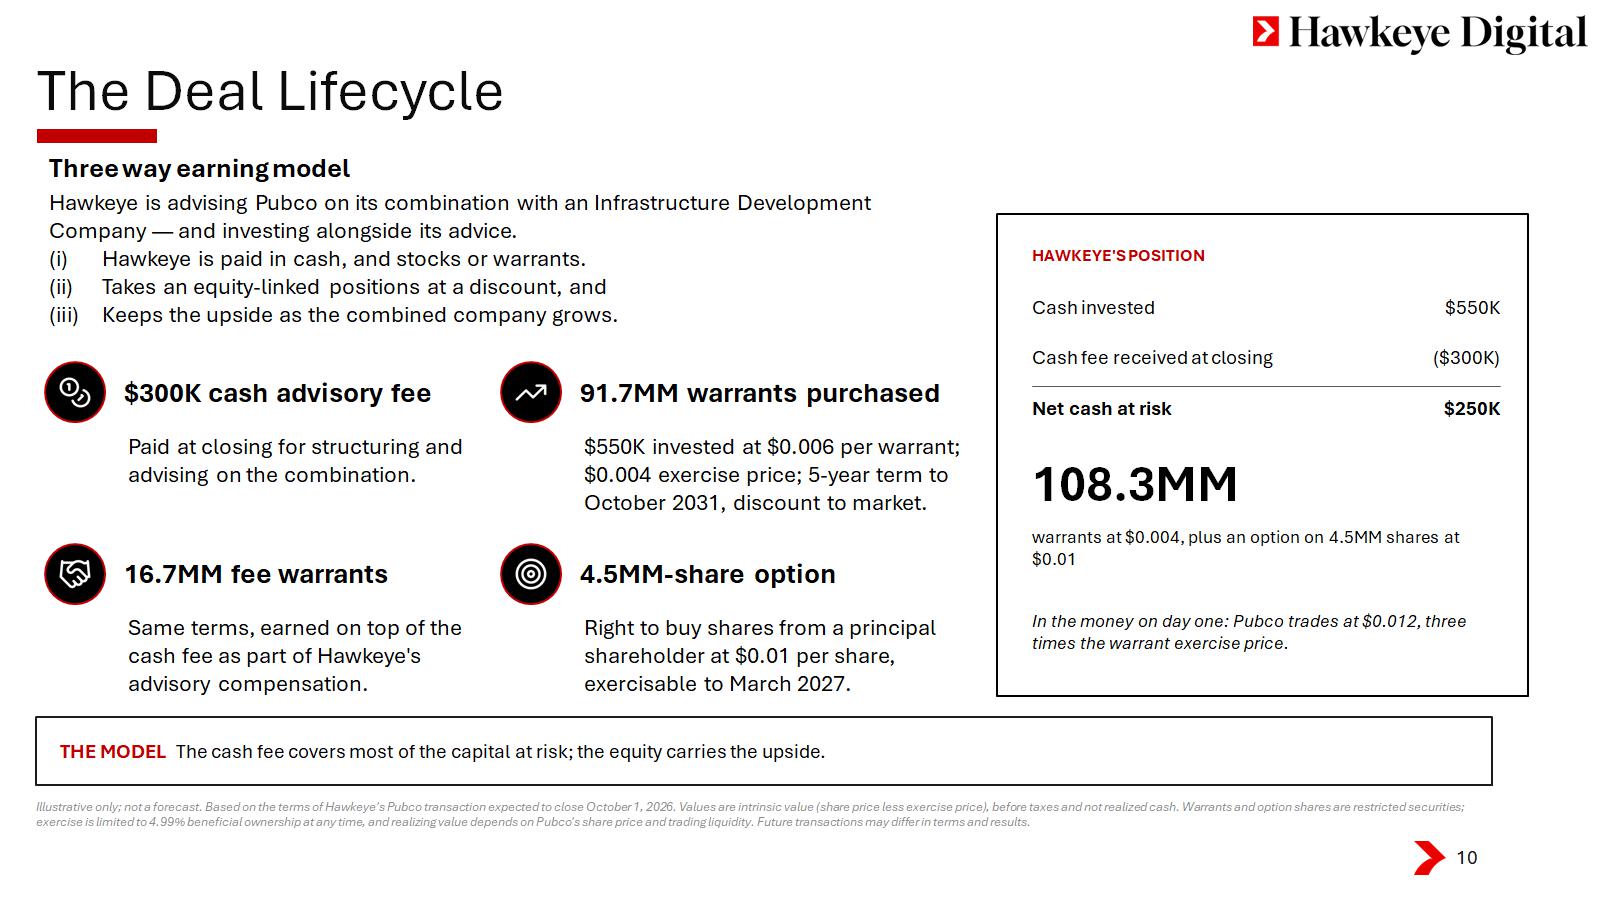
The Deal Lifecycle 10 Three way earning model Hawkeye is advising Pubco on its combination with Infrastructure Development Company — and investing alongside its advice. Hawkeye is paid in cash, takes equity - linked positions at a discount, and keeps the upside as the combined company grows. $300K cash advisory fee Paid at closing for structuring and advising on the combination. 91.7MM warrants purchased $550K invested at $0.006 per warrant; $0.004 exercise price; 5 - year term to October 2031. 16.7MM fee warrants Same terms, earned on top of the cash fee as part of Hawkeye's advisory compensation. 4.5MM - share option Right to buy shares from a principal shareholder at $0.01 per share, exercisable to March 2027. HAWKEYE'S POSITION Cash invested $550K Cash fee received at closing ($300K) Net cash at risk $250K 108.3MM warrants at $0.004, plus an option on 4.5MM shares at $0.01 In the money on day one: Pubco trades at $0.012, three times the warrant exercise price. THE MODEL The cash fee covers most of the capital at risk; the equity carries the upside. Illustrative only; not a forecast. Based on the terms of Hawkeye's Pubco transaction expected to close October 1, 2026. Value s a re intrinsic value (share price less exercise price), before taxes and not realized cash. Warrants and option shares are rest ric ted securities; exercise is limited to 4.99% beneficial ownership at any time, and realizing value depends on Pubco's share price and trading li quidity. Future transactions may differ in terms and results.
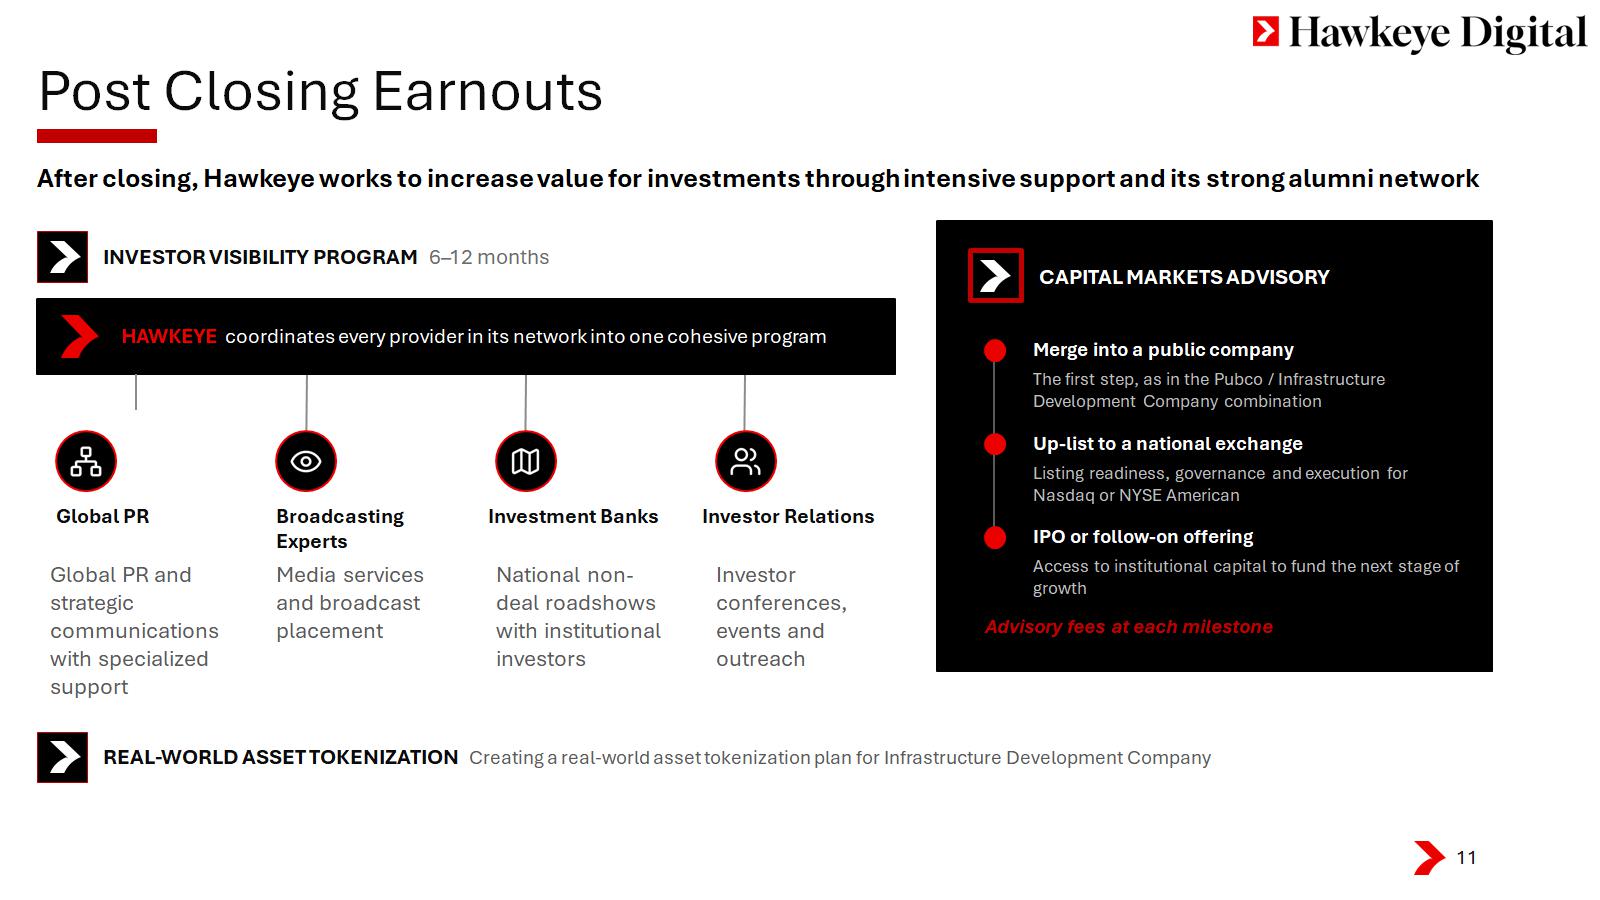
Post Closing Earnouts 11 4 INVESTOR VISIBILITY PROGRAM 6 – 12 months HAWKEYE coordinates every provider into one cohesive program Global PR Global PR and strategic communications across three continents HAWKEYE DIVISION Broadcasting Experts Media services and broadcast placement Investment Banks National non - deal roadshows with institutional investors Investor Relations Investor conferences, events and outreach 5 CAPITAL MARKETS ADVISORY Merge into a public company The first step, as in the Pubco / Infrastructure Development Company combination Up - list to a national exchange Listing readiness, governance and execution for Nasdaq or NYSE American IPO or follow - on offering Access to institutional capital to fund the next stage of growth Advisory fees at each milestone 6 REAL - WORLD ASSET TOKENIZATION Creating a real - world asset tokenization plan for Infrastructure Development Company After closing, Hawkeye works to increase value for investments through intensive support and its strong alumni network
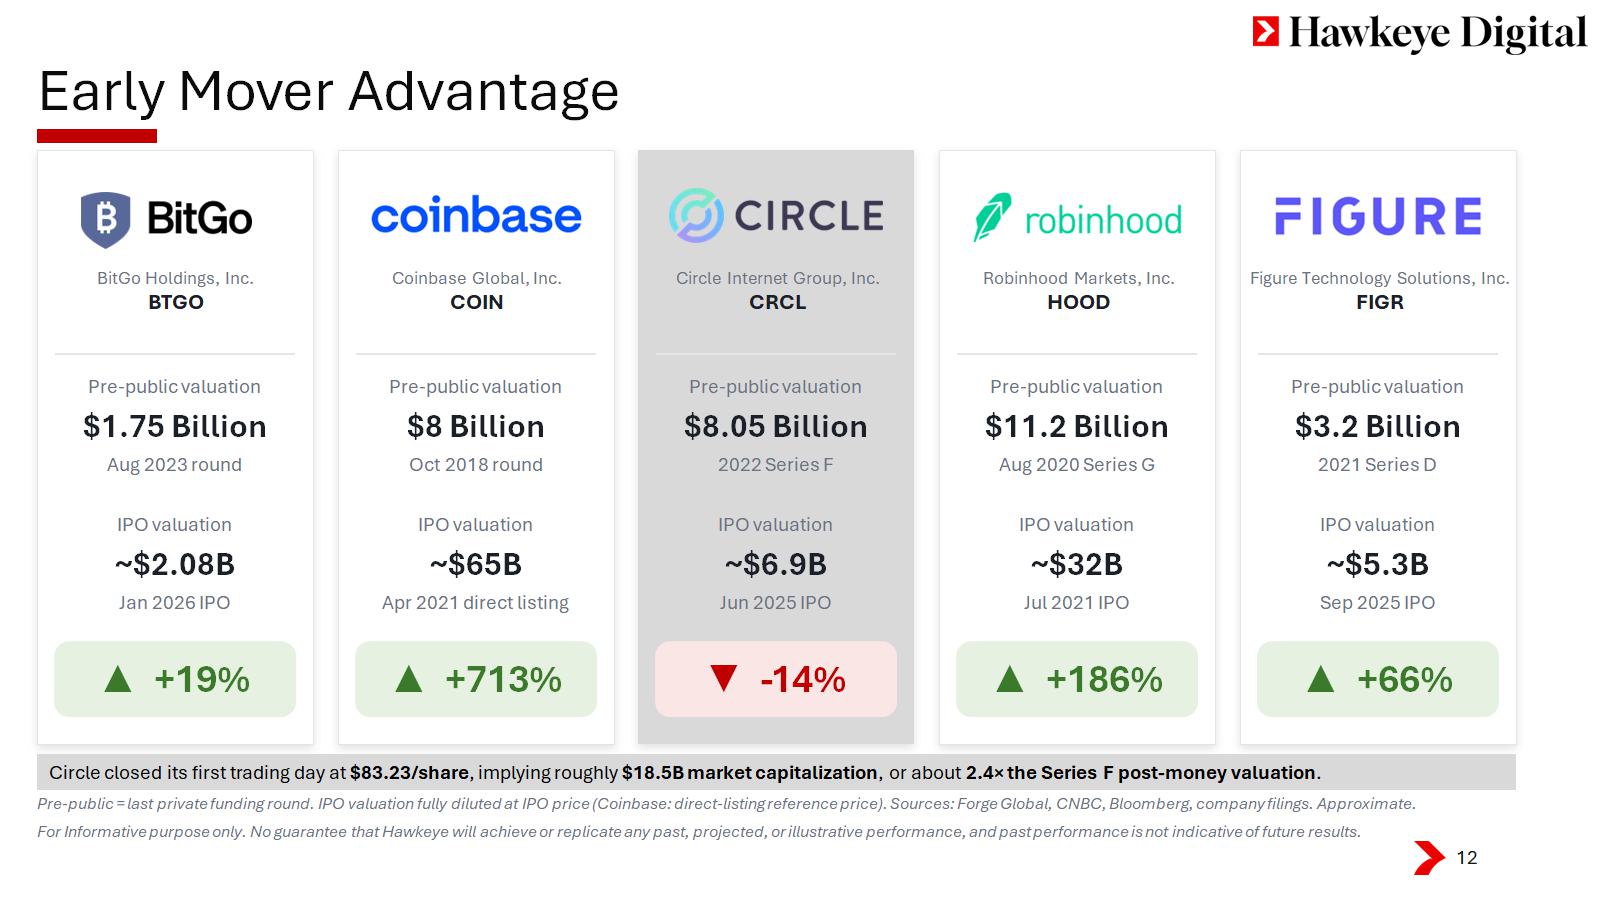
Early Mover Advantage 12 BitGo Holdings, Inc. BTGO ▲ +19% Coinbase Global, Inc. COIN Pre - public valuation $8 Billion Oct 2018 round IPO valuation ~$65B Apr 2021 direct listing ▲ +713% Circle Internet Group, Inc. CRCL Pre - public valuation $8.05 Billion 2022 Series F IPO valuation ~$6.9B Jun 2025 IPO ▼ - 14% Robinhood Markets, Inc. HOOD Pre - public valuation $11.2 Billion Aug 2020 Series G IPO valuation ~$32B Jul 2021 IPO ▲ +186% Figure Technology Solutions, Inc. FIGR Pre - public valuation $3.2 Billion 2021 Series D IPO valuation ~$5.3B Sep 2025 IPO ▲ +66% Pre - public = last private funding round. IPO valuation fully diluted at IPO price (Coinbase: direct - listing reference price). So urces: Forge Global, CNBC, Bloomberg, company filings. Approximate. Circle closed its first trading day at $83.23/share , implying roughly $18.5B market capitalization , or about 2.4 × the Series F post - money valuation . Pre - public valuation $1.75 Billion Aug 2023 round IPO valuation ~$2.08B Jan 2026 IPO For Informative purpose only. No guarantee that Hawkeye will achieve or replicate any past, projected, or illustrative perfor man ce, and past performance is not indicative of future results.
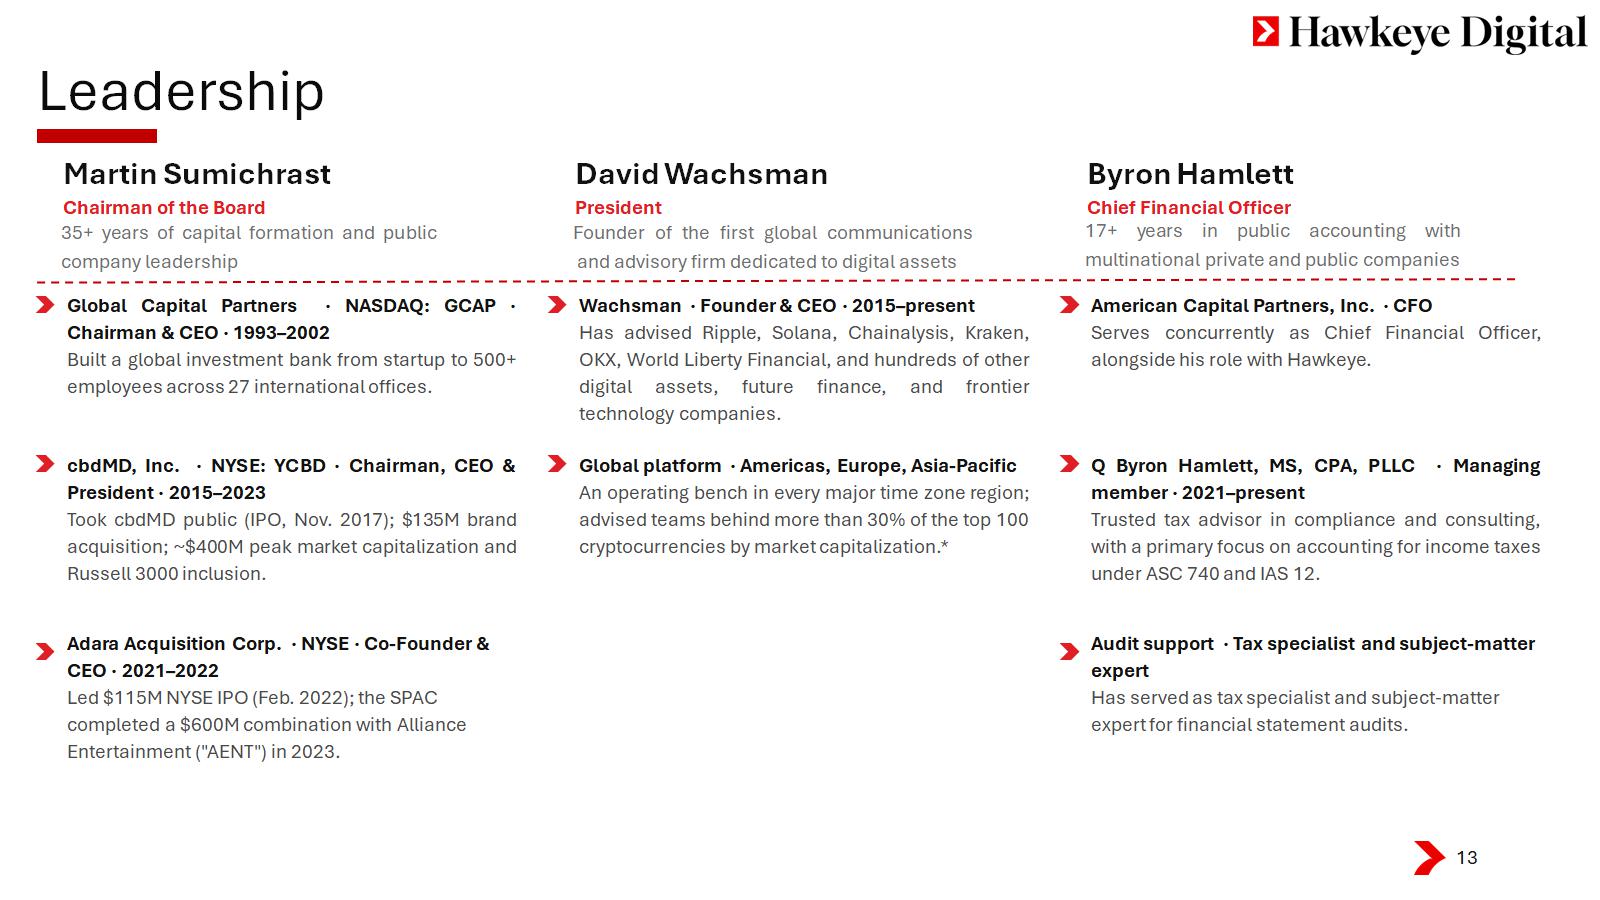
Leadership 13 Martin Sumichrast Chairman of the Board 35 + years of capital formation and public company leadership Global Capital Partners · NASDAQ : GCAP · Chairman & CEO · 1993 – 2002 Built a global investment bank from startup to 500 + employees across 27 international offices . cbdMD , Inc . · NYSE : YCBD · Chairman, CEO & President · 2015 – 2023 Took cbdMD public (IPO, Nov . 2017 ) ; $ 135 M brand acquisition ; ~ $ 400 M peak market capitalization and Russell 3000 inclusion . Adara Acquisition Corp. · NYSE · Co - Founder & CEO · 2021 – 2022 Led $115M NYSE IPO (Feb. 2022); the SPAC completed a $600M combination with Alliance Entertainment ("AENT") in 2023. David Wachsman President Founder of the first global communications and advisory firm dedicated to digital assets Wachsman · Founder & CEO · 2015 – present Has advised Ripple, Solana, Chainalysis, Kraken, OKX, World Liberty Financial, and hundreds of other digital assets, future finance, and frontier technology companies . Global platform · Americas, Europe, Asia - Pacific An operating bench in every major time zone region ; advised teams behind more than 30 % of the top 100 cryptocurrencies by market capitalization . * Byron Hamlett Chief Financial Officer 17 + years in public accounting with multinational private and public companies American Capital Partners, Inc . · CFO Serves concurrently as Chief Financial Officer, alongside his role with Hawkeye . Q Byron Hamlett, MS, CPA, PLLC · Managing member · 2021 – present Trusted tax advisor in compliance and consulting, with a primary focus on accounting for income taxes under ASC 740 and IAS 12 . Audit support · Tax specialist and subject - matter expert Has served as tax specialist and subject - matter expert for financial statement audits.
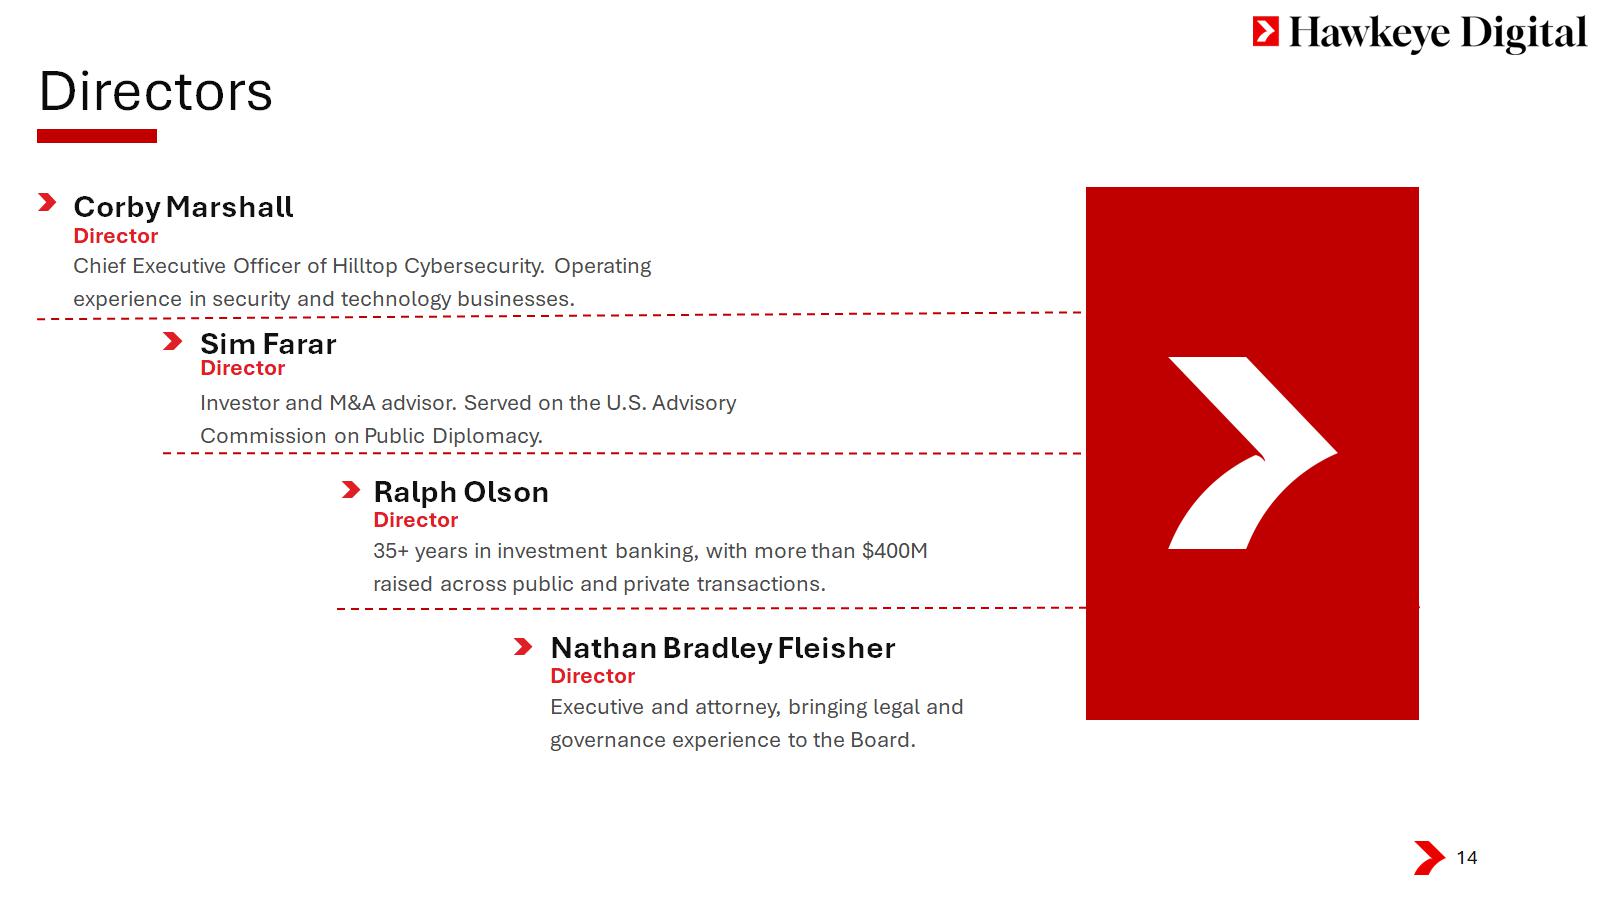
Directors 14 Corby Marshall Chief Executive Officer of Hilltop Cybersecurity. Operating experience in security and technology businesses. Director Investor and M&A advisor. Served on the U.S. Advisory Commission on Public Diplomacy. Ralph Olson 35+ years in investment banking, with more than $400M raised across public and private transactions. Nathan Bradley Fleisher Executive and attorney, bringing legal and governance experience to the Board. Sim Farar Director Director Director
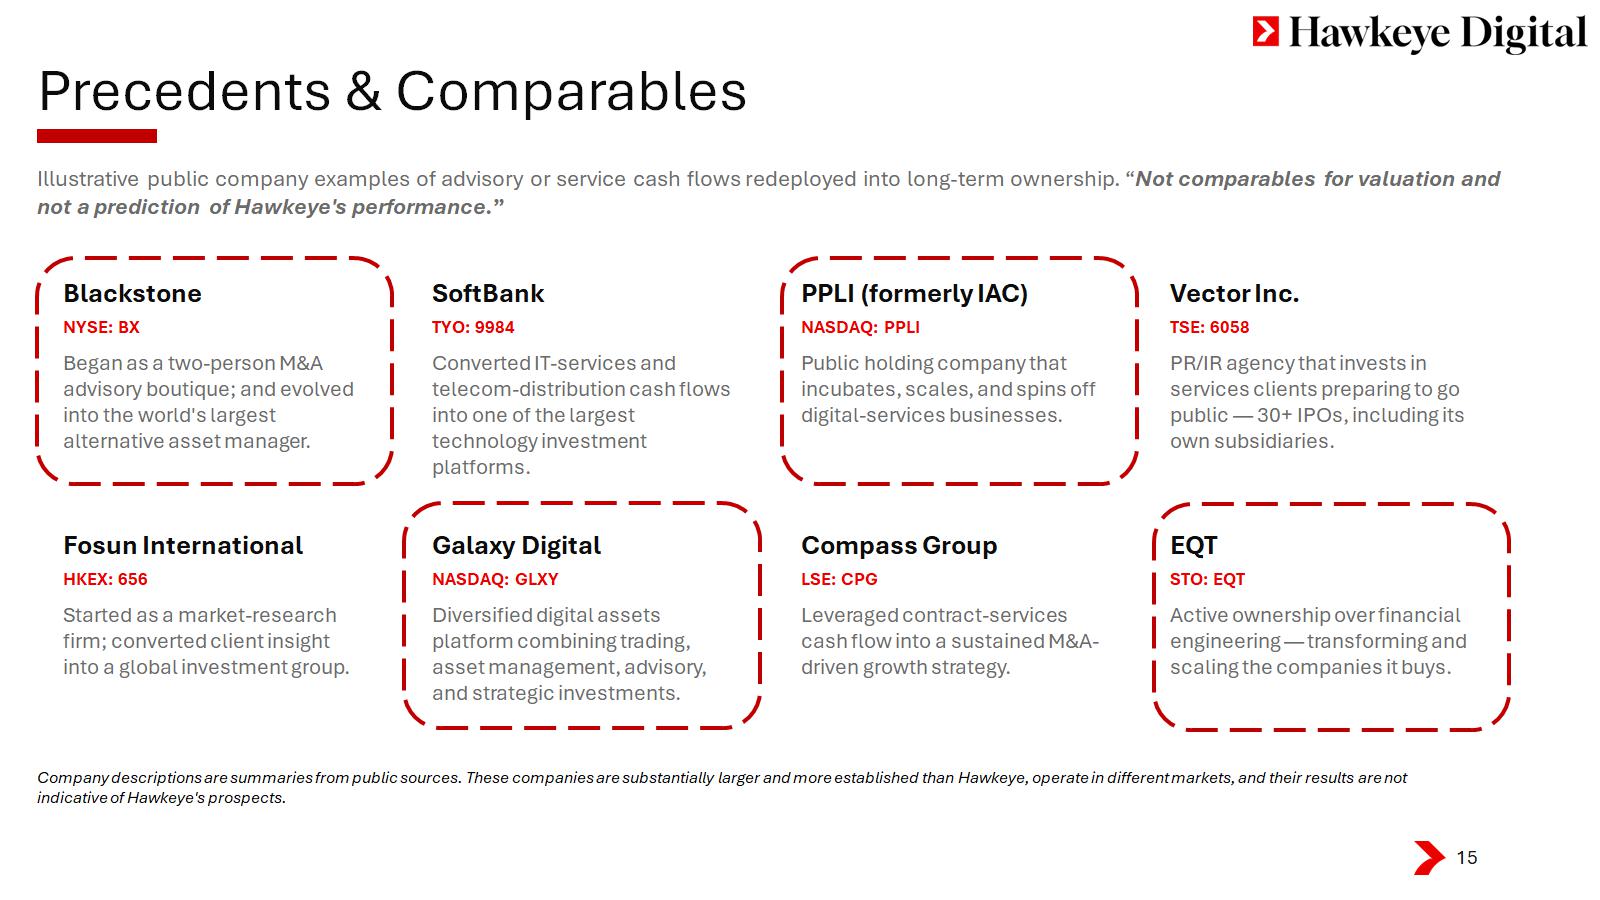
Precedents & Comparables 15 Illustrative public company examples of advisory or service cash flows redeployed into long - term ownership. “ Not comparables for valuation and not a prediction of Hawkeye's performance. ” Blackstone NYSE: BX Began as a two - person M&A advisory boutique; and evolved into the world's largest alternative asset manager. SoftBank TYO: 9984 Converted IT - services and telecom - distribution cash flows into one of the largest technology investment platforms. PPLI (formerly IAC) NASDAQ: PPLI Public holding company that incubates, scales, and spins off digital - services businesses. Vector Inc. TSE: 6058 PR/IR agency that invests in services clients preparing to go public — 30+ IPOs, including its own subsidiaries. Fosun International HKEX: 656 Started as a market - research firm; converted client insight into a global investment group. Galaxy Digital NASDAQ: GLXY Diversified digital assets platform combining trading, asset management, advisory, and strategic investments. Compass Group LSE: CPG Leveraged contract - services cash flow into a sustained M&A - driven growth strategy. EQT STO: EQT Active ownership over financial engineering — transforming and scaling the companies it buys. Company descriptions are summaries from public sources. These companies are substantially larger and more established than Ha wke ye, operate in different markets, and their results are not indicative of Hawkeye's prospects.
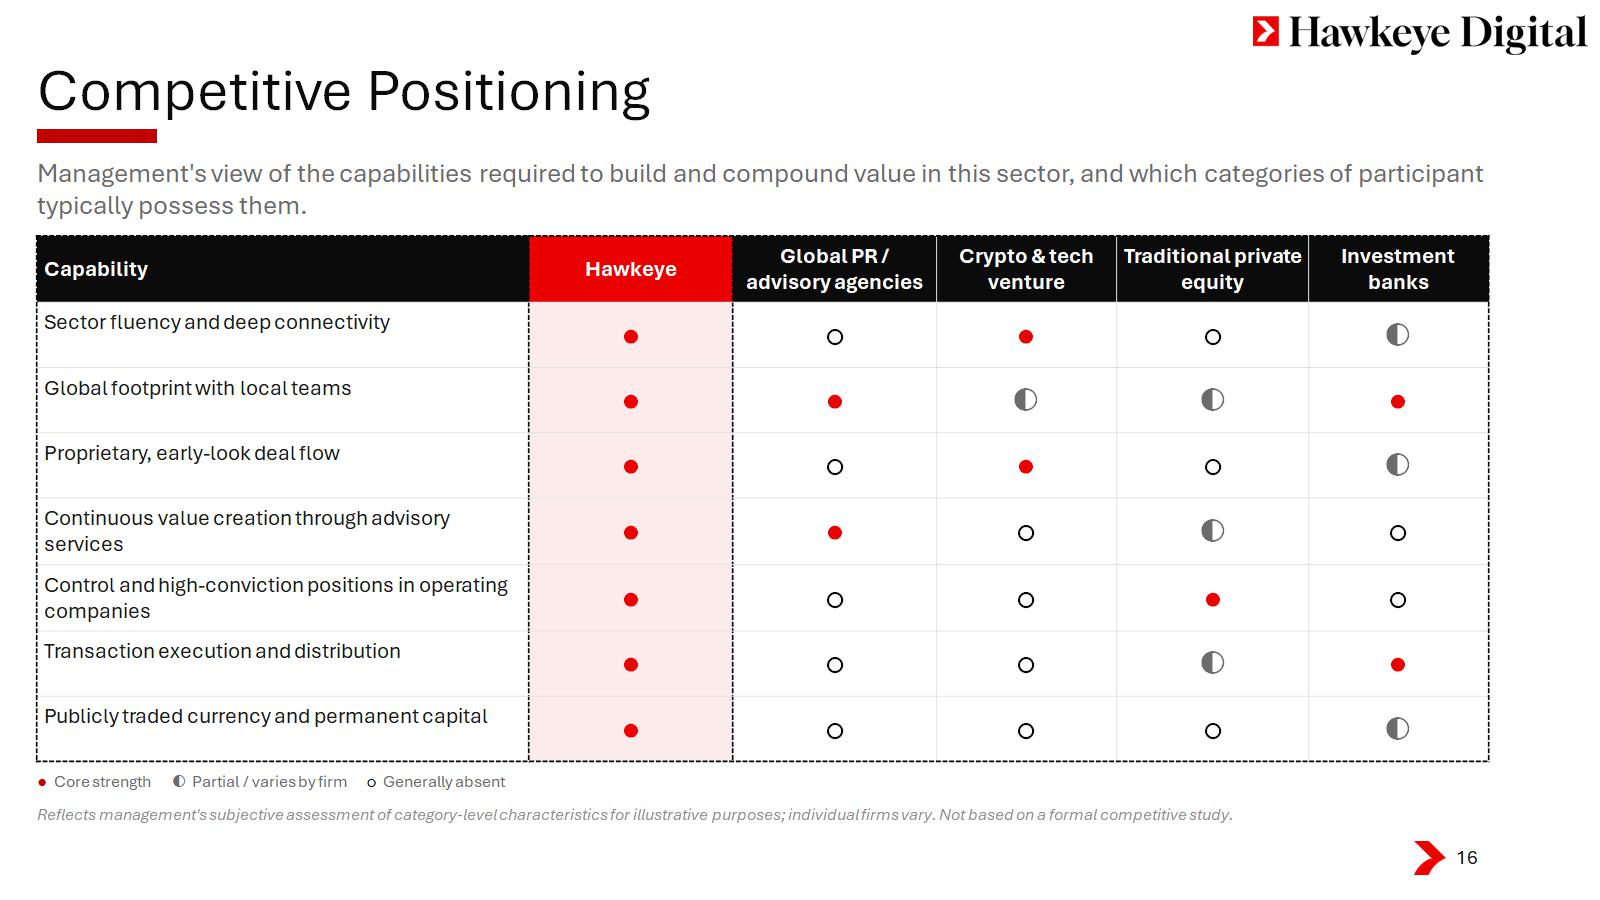
Competitive Positioning 16 Management's view of the capabilities required to build and compound value in this sector, and which categories of participan t typically possess them. Investment banks Traditional private equity Crypto & tech venture Global PR / advisory agencies Hawkeye Capability ◐ ○ ● ○ ● Sector fluency and deep connectivity ● ◐ ◐ ● ● Global footprint with local teams ◐ ○ ● ○ ● Proprietary, early - look deal flow ○ ◐ ○ ● ● Continuous value creation through advisory services ○ ● ○ ○ ● Control and high - conviction positions in operating companies ● ◐ ○ ○ ● Transaction execution and distribution ◐ ○ ○ ○ ● Publicly traded currency and permanent capital ● Core strength ◐ Partial / varies by firm ○ Generally absent Reflects management's subjective assessment of category - level characteristics for illustrative purposes; individual firms vary. Not based on a formal competitive study.
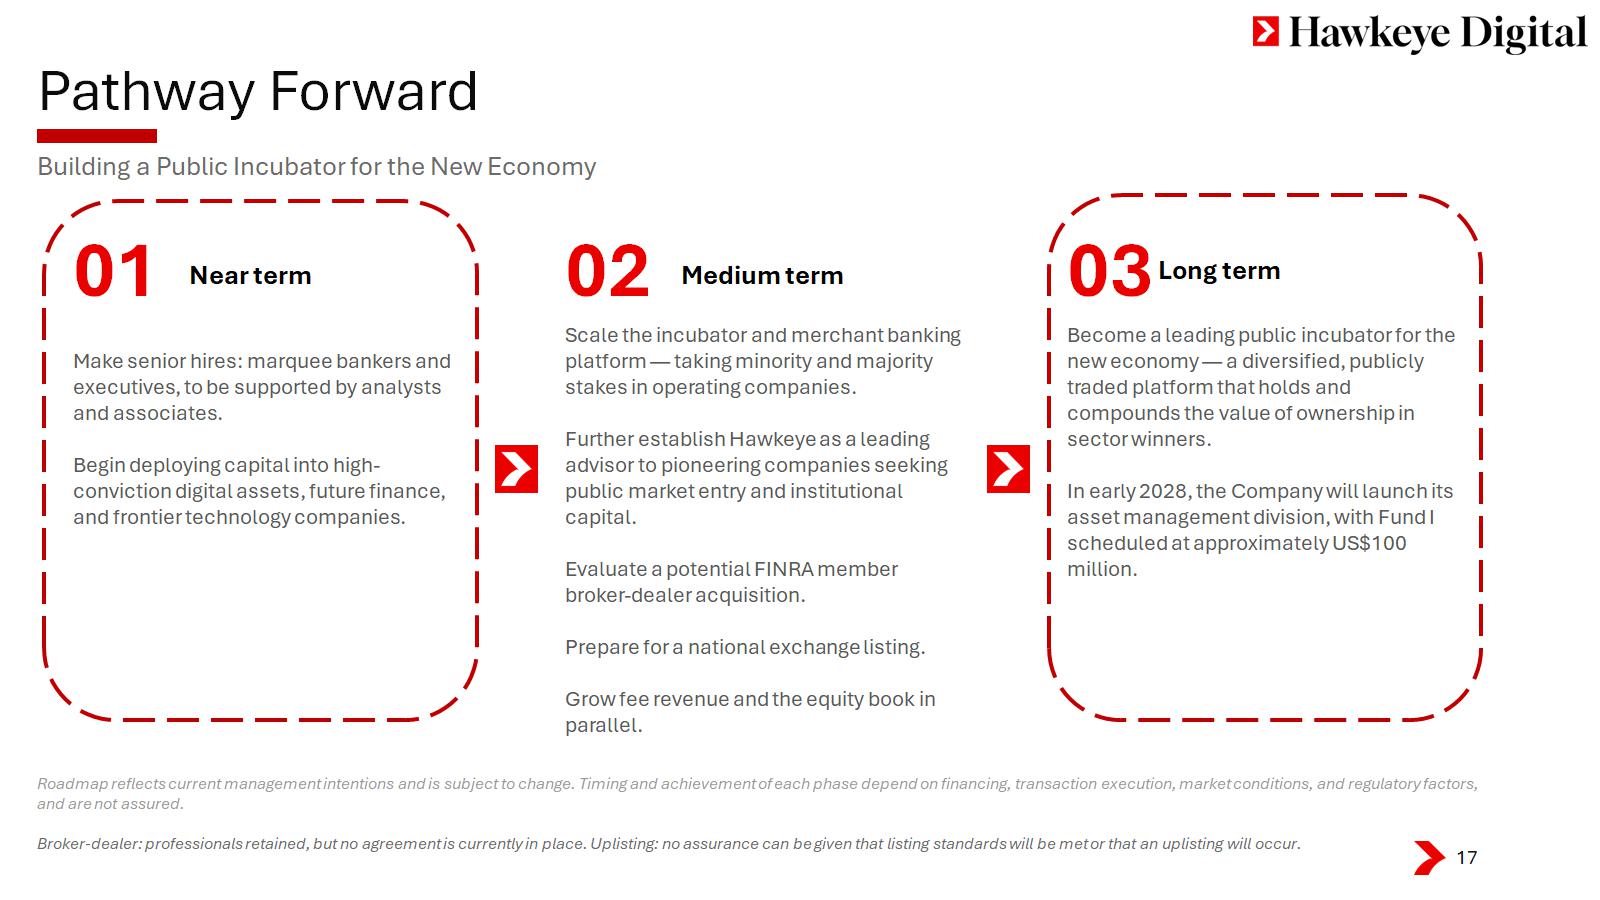
Pathway Forward 17 Building a Public Incubator for the New Economy 01 Near term Make senior hires: marquee bankers and executives, to be supported by analysts and associates. Begin deploying capital into high - conviction digital assets, future finance, and frontier technology companies. 02 Medium term Scale the incubator and merchant banking platform — taking minority and majority stakes in operating companies. Further establish Hawkeye as a leading advisor to pioneering companies seeking public market entry and institutional capital. Evaluate a potential FINRA member broker - dealer acquisition. Prepare for a national exchange listing. Grow fee revenue and the equity book in parallel. 03 Become a leading public incubator for the new economy — a diversified, publicly traded platform that holds and compounds the value of ownership in sector winners. In early 2028, the Company will launch its asset management division, with Fund I scheduled at approximately US$100 million. Roadmap reflects current management intentions and is subject to change. Timing and achievement of each phase depend on finan cin g, transaction execution, market conditions, and regulatory factors, and are not assured. Broker - dealer: professionals retained, but no agreement is currently in place. Uplisting: no assurance can be given that listing standards will be met or that an uplisting will occur. Long term
Thank You Investor Presentation · October 2026 DIGITAL ASSETS · FUTURE FINANCE · FRONTIER TECHNOLOGY 18