1©2025 U.S. Bank | Confidential U.S. Bancorp 3Q26 Earnings Conference Call O c t o b e r 1 5 , 2 0 2 6
2©2025 U.S. Bank | Confidential Forward-looking Statements and Additional Information The following information appears in accordance with the Private Securities Litigation Reform Act of 1995: This presentation contains forward-looking statements about U.S. Bancorp. Statements that are not historical or current facts, including statements about beliefs and expectations, are forward-looking statements and are based on the information available to, and assumptions and estimates made by, management as of the date hereof. These forward-looking statements cover, among other things, future economic conditions and the anticipated future revenue, expenses, financial condition, asset quality, capital and liquidity levels, plans, prospects, targets, initiatives and operations of U.S. Bancorp. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “projects,” “forecasts,” “intends,” “plans,” “goals,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements involve inherent risks and uncertainties that could cause actual results to differ materially from those set forth in forward-looking statements, including the following risks and uncertainties: deterioration in general business, political and economic conditions or turbulence in domestic or global financial markets, which could adversely affect U.S. Bancorp’s revenues and the values of its assets and liabilities, reduce the availability of funding to certain financial institutions, lead to a tightening of credit, and increase stock price volatility; changes to statutes, regulations, or regulatory policies or practices, including capital and liquidity requirements, and the enforcement and interpretation of such laws and regulations, and U.S. Bancorp’s ability to address or satisfy those requirements and other requirements or conditions imposed by regulatory entities; changes in trade policy, including the imposition of tariffs or the impacts of retaliatory tariffs, or the effects of related litigation; changes in interest rates; increases in unemployment rates; deterioration in the credit quality of U.S. Bancorp’s loan portfolios or in the value of the collateral securing those loans; changes in commercial real estate occupancy rates; increases in Federal Deposit Insurance Corporation (FDIC) assessments, including due to bank failures; actions taken by governmental agencies to stabilize or reform the financial system and the effectiveness of such actions; turmoil and volatility in the financial services industry; risks related to originating and selling mortgages, including repurchase and indemnity demands, and related to U.S. Bancorp’s role as a loan servicer; impacts of current, pending or future litigation and governmental proceedings; increased competitive pressure; changes in customer behavior and preferences and the ability to implement technological changes to respond to customer needs and meet competitive demands; failures or disruptions in or breaches of U.S. Bancorp’s operational, technology, data security or other security systems or infrastructure, or those of third parties, including as a result of cybersecurity incidents; failures to safeguard personal information; impacts of pandemics, natural disasters, terrorist activities, civil unrest, international hostilities and geopolitical events, including those arising from conflict in the Middle East; impacts of supply chain disruptions, rising inflation, slower growth or a recession; effects of climate change and related physical and transition risks; failure to execute on strategic or operational plans; effects of mergers and acquisitions, such as the acquisition of Condor Trading LP and its subsidiaries, including BTIG, LLC (collectively, “BTIG”), and related integration, including that the expected benefits may take longer than anticipated to achieve or may not be achieved in entirety or at all and the costs relating to the combination may be greater than expected; effects of critical accounting policies and judgments; effects of changes in or interpretations of tax laws and regulations; management’s ability to effectively manage credit risk, market risk, operational risk, compliance risk, strategic risk, interest rate risk and liquidity risk; and the risks and uncertainties more fully discussed in the section entitled “Risk Factors” of U.S. Bancorp’s Form 10-K for the year ended December 31, 2025, and subsequent filings with the Securities and Exchange Commission. Factors other than these risks also could adversely affect U.S. Bancorp’s results, and the reader should not consider these risks to be a complete set of all potential risks or uncertainties. Readers are cautioned not to place undue reliance on any forward-looking statements. Forward-looking statements speak only as of the date hereof, and U.S. Bancorp undertakes no obligation to update them in light of new information or future events. This presentation includes non-GAAP financial measures to describe U.S. Bancorp’s performance. The calculations of these measures are provided in the Appendix. These disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Management does not provide a reconciliation for forward-looking non-GAAP financial measures where it is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the difficulty forecasting the occurrence and the financial impact of various items that have not yet occurred, are out of U.S. Bancorp’s control or cannot be reasonably predicted. For the same reasons, U.S. Bancorp’s management is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures provided without the most directly comparable GAAP financial measures may vary materially from the corresponding GAAP financial measures.
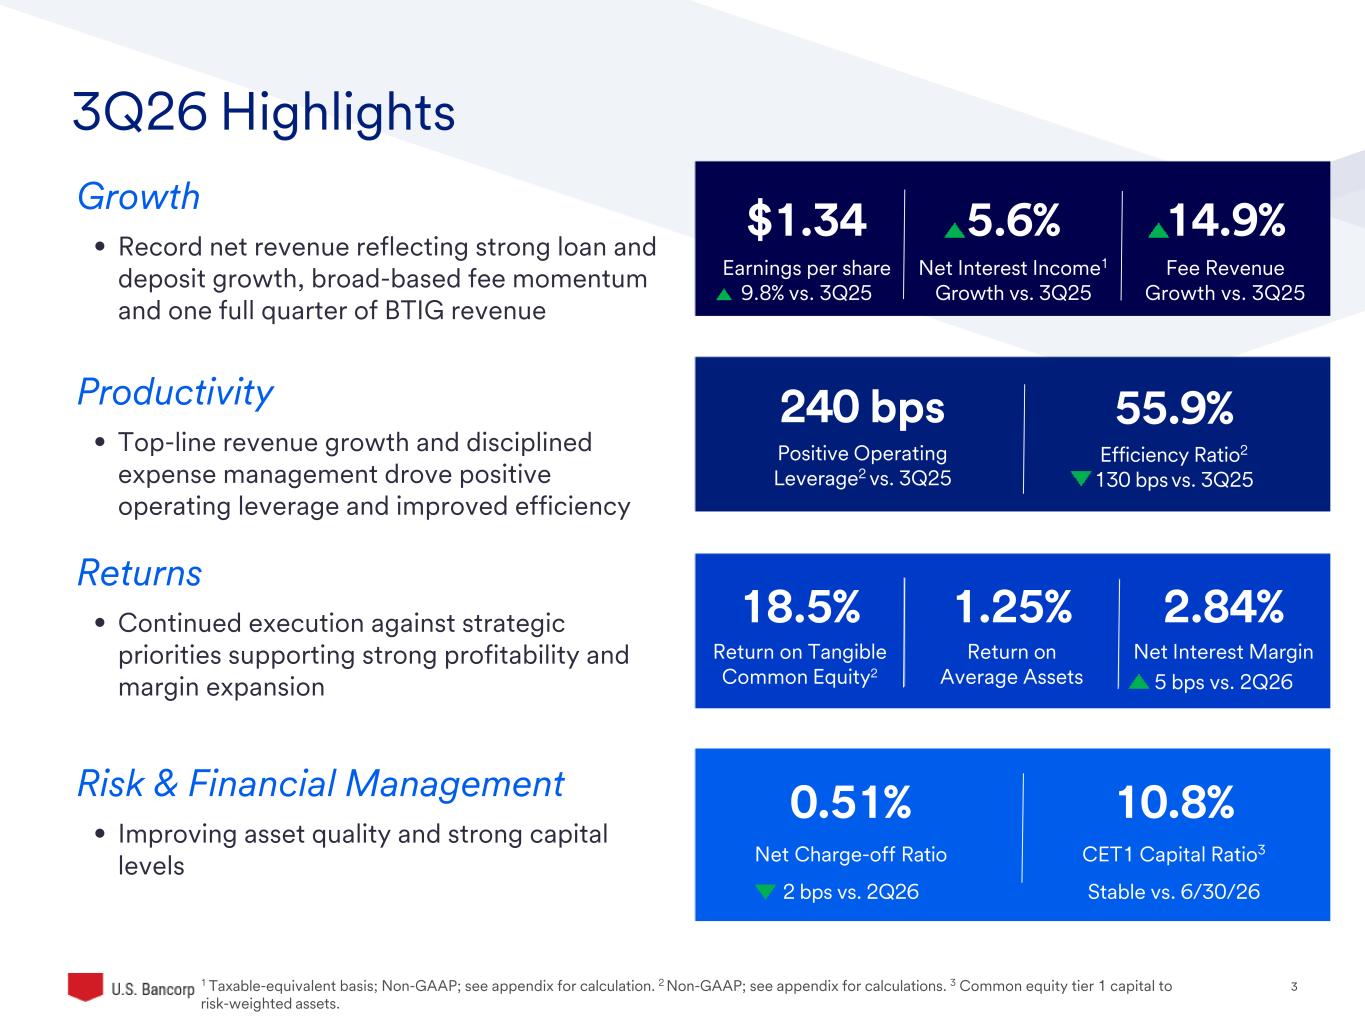
3©2025 U.S. Bank | Confidential Growth • Record net revenue reflecting strong loan and deposit growth, broad-based fee momentum and one full quarter of BTIG revenue 3Q26 Highlights Productivity • Top-line revenue growth and disciplined expense management drove positive operating leverage and improved efficiency Returns • Continued execution against strategic priorities supporting strong profitability and margin expansion Risk & Financial Management • Improving asset quality and strong capital levels 1 Taxable- quivalent basis; Non-GAAP; see appendix for calculation. 2 Non-GAAP; see appendix for calculations. 3 Common equity tier 1 capital to risk-weighted assets. 0.51% Net Charge-off Ratio 2 bps vs. 2Q26 5.6% Net Interest Income1 Growth vs. 3Q25 14.9% Fee Revenue Growth vs. 3Q25 240 bps Positive Operating Leverage2 vs. 3Q25 $1.34 Earnings per share 9.8% vs. 3Q25 18.5% Return on Tangible Common Equity2 1.25% Return on Average Assets 2.84% Net Interest Margin 5 bps vs. 2Q26 55.9% Efficiency Ratio2 130 bps vs. 3Q25 10.8% CET1 Capital Ratio3 Stable vs. 6/30/26
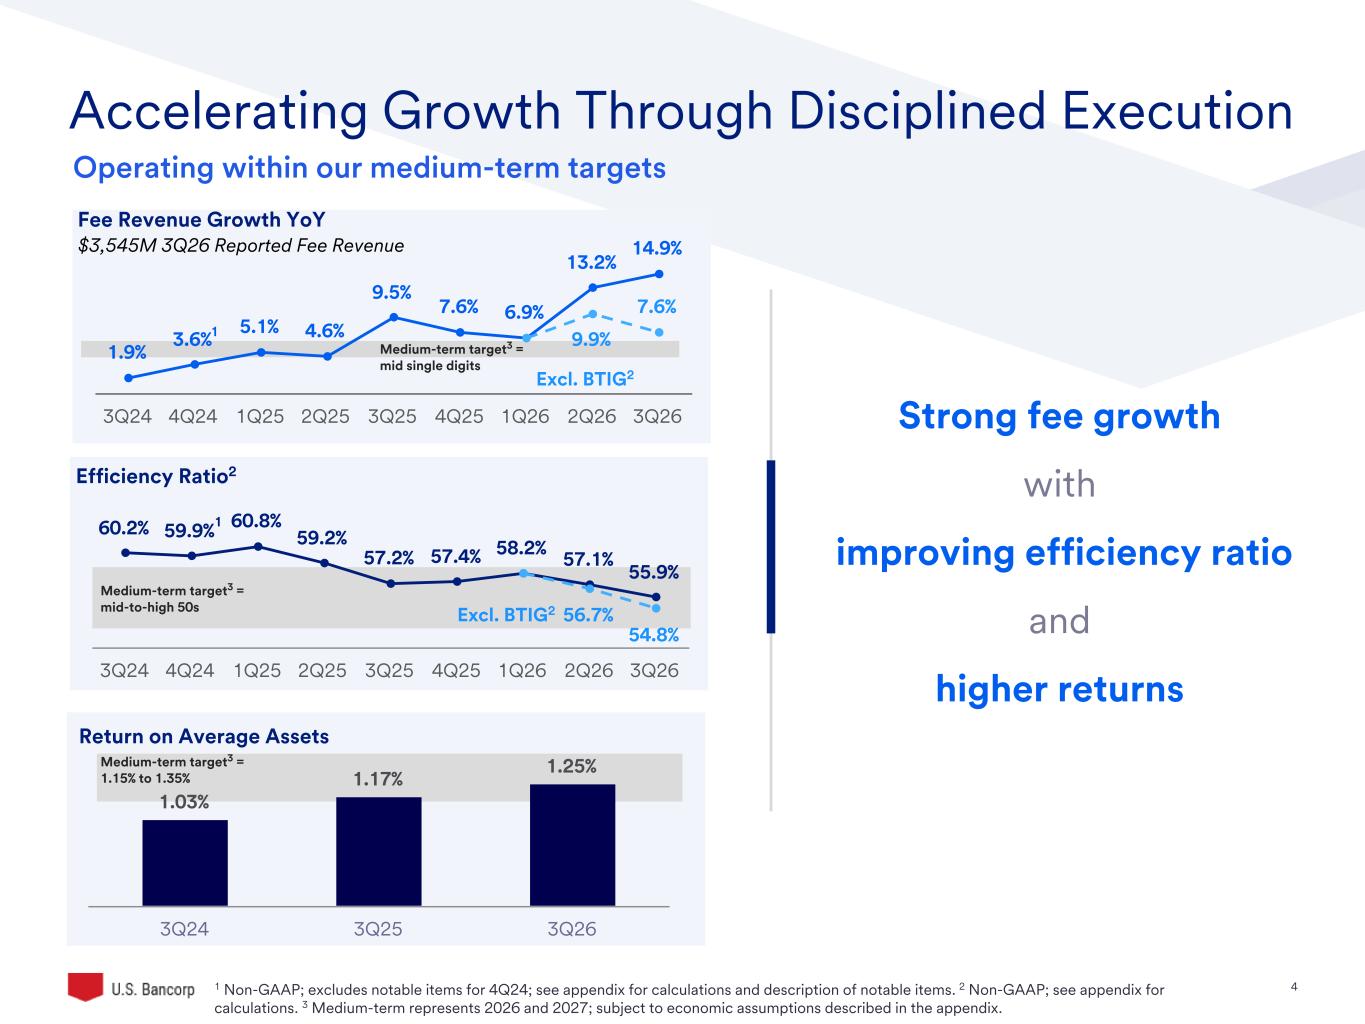
4©2026 U.S. Bank | Confidential Accelerating Growth Through Disciplined Execution Fee Revenue Growth YoY $3,545M 3Q26 Reported Fee Revenue Efficiency Ratio2 1 N -GAAP; excludes notable items for 4Q24; see appendix for calculations and description of notable items. 2 Non-GAAP; see appendix for calculations. 3 Medium-term represents 2026 and 2027; subject to economic assumptions described in the appendix. Strong fee growth with improving efficiency ratio and higher returns Return on Average Assets 1.9% 3.6% 5.1% 4.6% 9.5% 7.6% 6.9% 13.2% 14.9% 9.9% 7.6% 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 Excl. BTIG2 60.2% 59.9% 60.8% 59.2% 57.2% 57.4% 58.2% 57.1% 55.9% 56.7% 54.8% 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 Medium-term target3 = mid single digits Medium-term target3 = mid-to-high 50s Excl. BTIG2 1.03% 1.17% 1.25% 3Q24 3Q25 3Q26 Medium-term target3 = 1.15% to 1.35% Operating within our medium-term targets 1 1
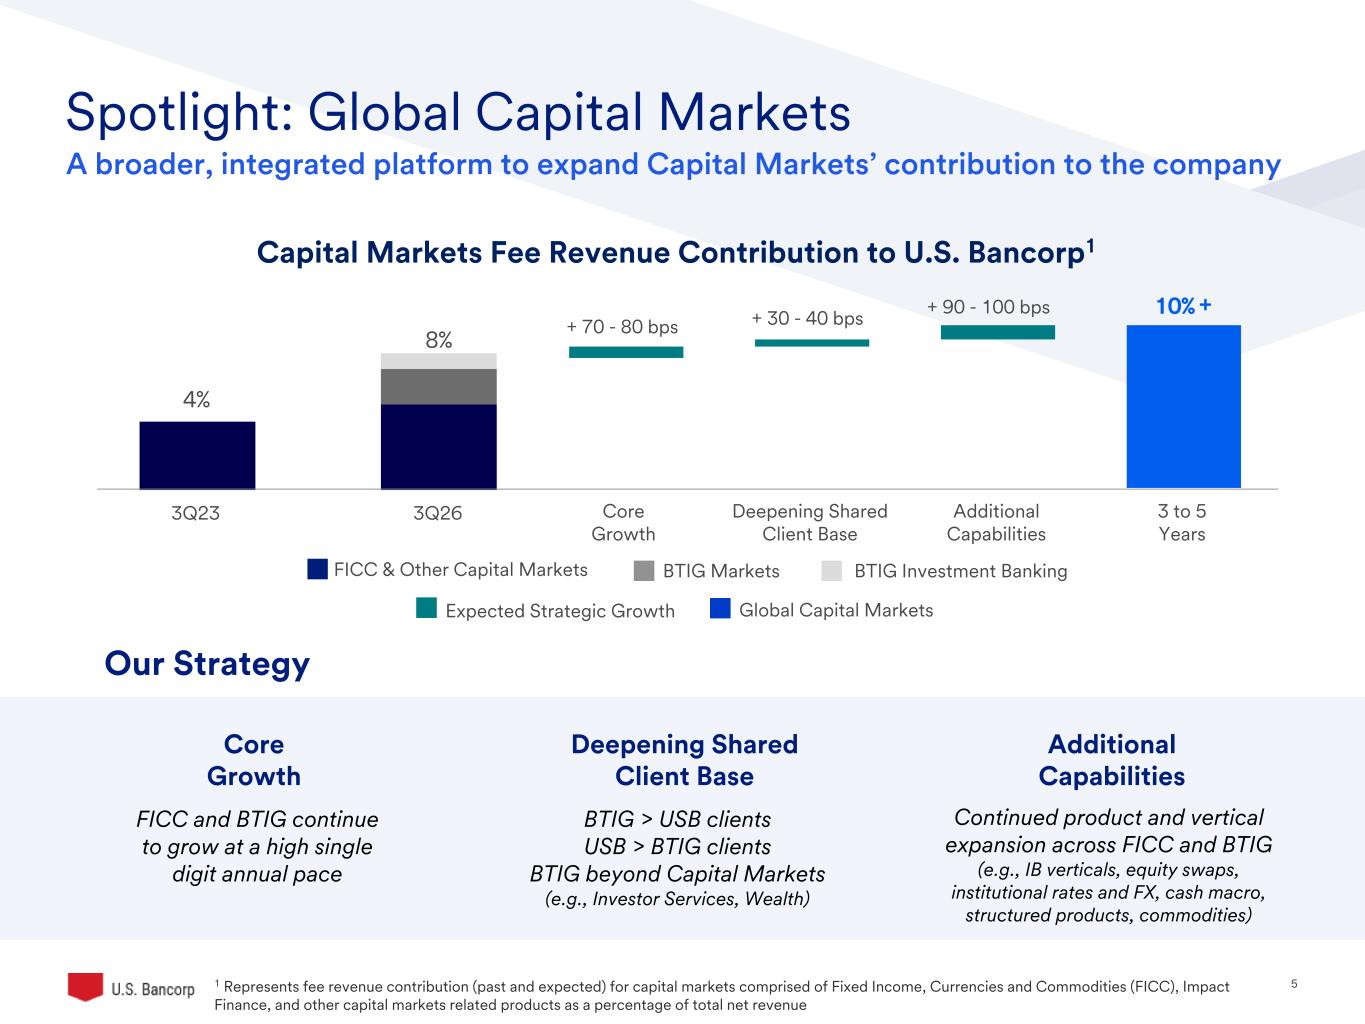
5©2026 U.S. Bank | Confidential 3Q23 3Q26 1 Repres ts fee revenue contribution (past and expected) for capital markets comprised of Fixed Income, Currencies and Commodities (FICC), Impact Finance, and other capital markets related products as a percentage of total net revenue Our Strategy Capital Markets Fee Revenue Contribution to U.S. Bancorp1 FICC & Other Capital Markets FICC and BTIG continue to grow at a high single digit annual pace BTIG > USB clients USB > BTIG clients BTIG beyond Capital Markets (e.g., Investor Services, Wealth) Continued product and vertical expansion across FICC and BTIG (e.g., IB verticals, equity swaps, institutional rates and FX, cash macro, structured products, commodities) BTIG Investment Banking + Global Capital Markets Spotlight: Global Capital Markets A broader, integrated platform to expand Capital Markets’ contribution to the company Core Growth Deepening Shared Client Base Additional Capabilities Core Growth Deepening Shared Client Base Additional Capabilities 3 to 5 Years 10% 8% 4% + 70 - 80 bps + 30 - 40 bps + 90 - 100 bps Expected Strategic Growth BTIG Markets
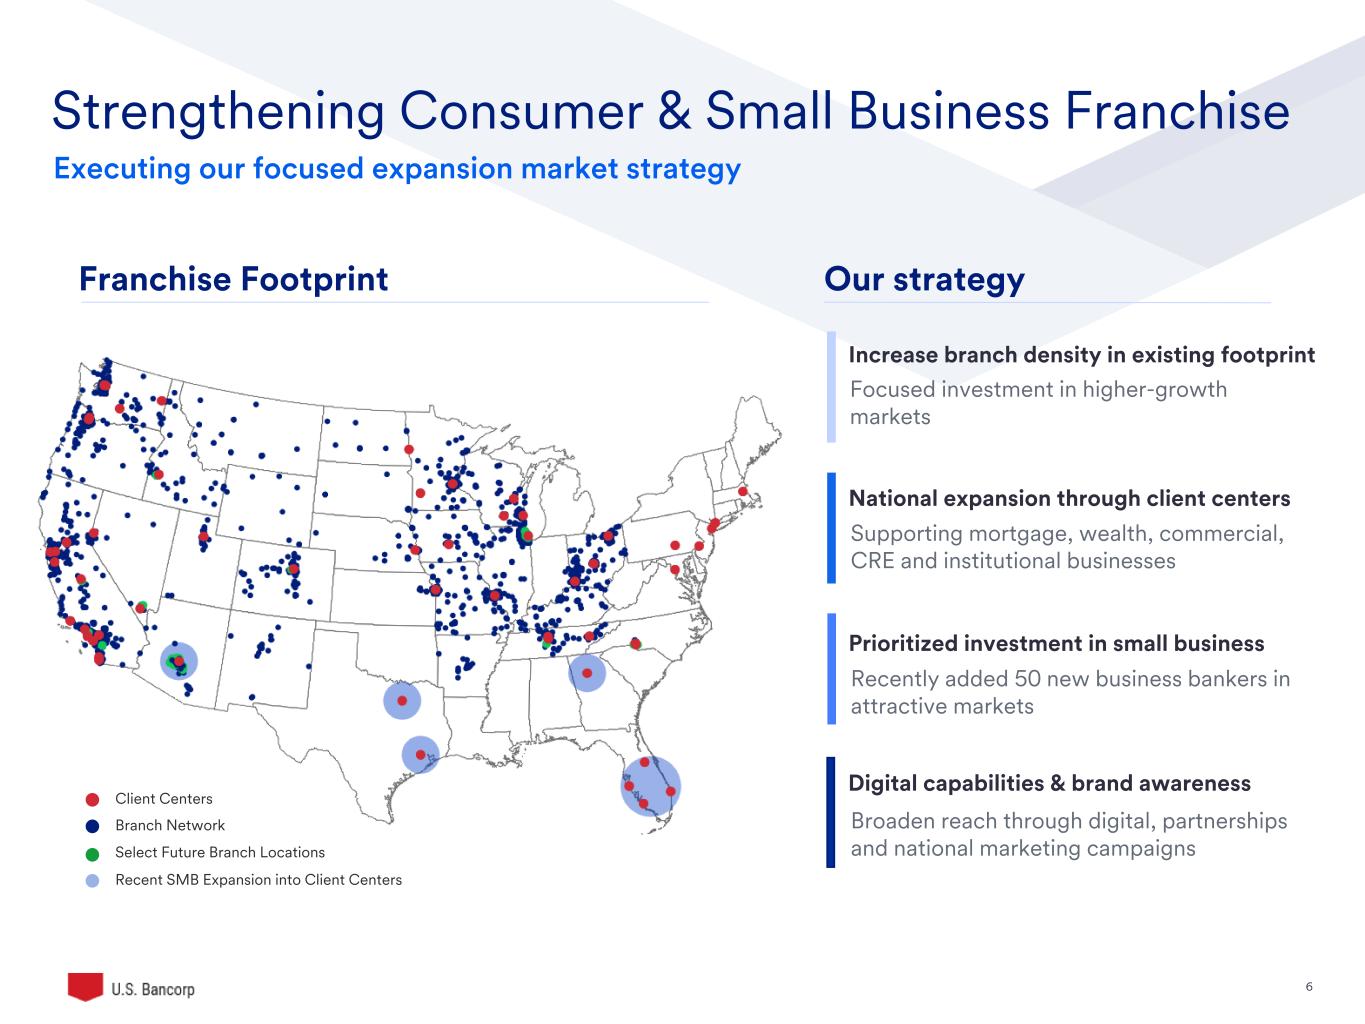
©2025 U.S. Bank | Confidential 6 Strengthening Consumer & Small Business Franchise Franchise Footprint Executing our focused expansion market strategy Our strategy Increase branch density in existing footprint National expansion through client centers Prioritized investment in small business Digital capabilities & brand awareness Focused investment in higher-growth markets Supporting mortgage, wealth, commercial, CRE and institutional businesses Recently added 50 new business bankers in attractive markets Broaden reach through digital, partnerships and national marketing campaigns Client Centers Branch Network Select Future Branch Locations Recent SMB Expansion into Client Centers
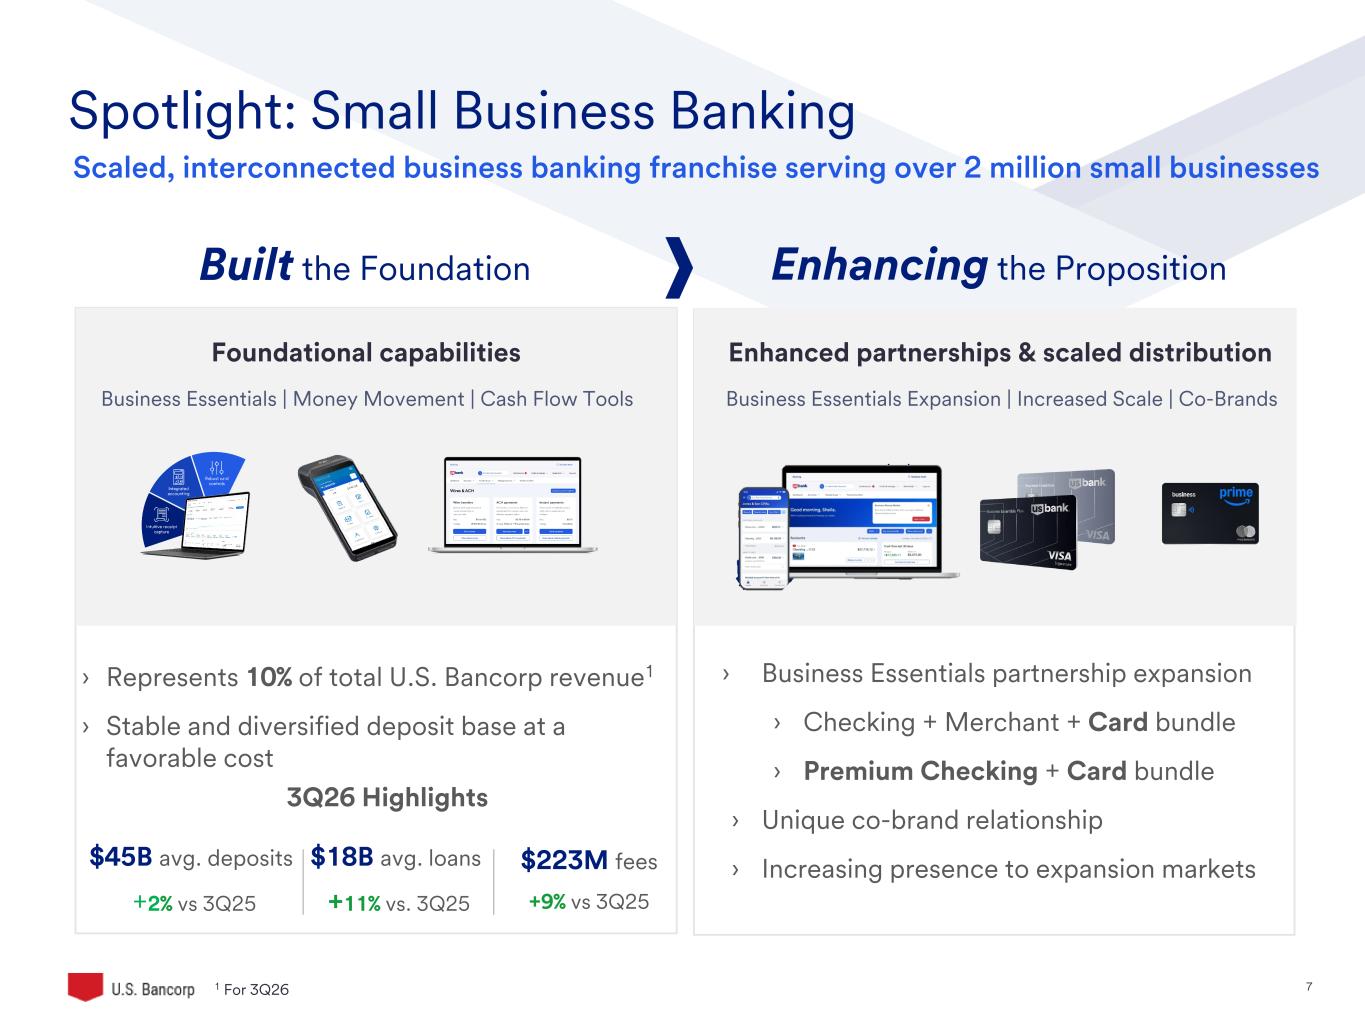
©2025 U.S. Bank | Confidential 7 Built the Foundation Enhancing the Proposition Foundational capabilities Business Essentials | Money Movement | Cash Flow Tools › Represents 10% of total U.S. Bancorp revenue1 › Stable and diversified deposit base at a favorable cost Enhanced partnerships & scaled distribution Business Essentials Expansion | Increased Scale | Co-Brands › Business Essentials partnership expansion › Checking + Merchant + Card bundle › Premium Checking + Card bundle › Unique co-brand relationship › Increasing presence to expansion markets Spotlight: Small Business Banking Scaled, interconnected business banking franchise serving over 2 million small businesses $45B avg. deposits +2% vs 3Q25 $18B avg. loans +11% vs. 3Q25 $223M fees +9% vs 3Q25 3Q26 Highlights 1 For 3Q26
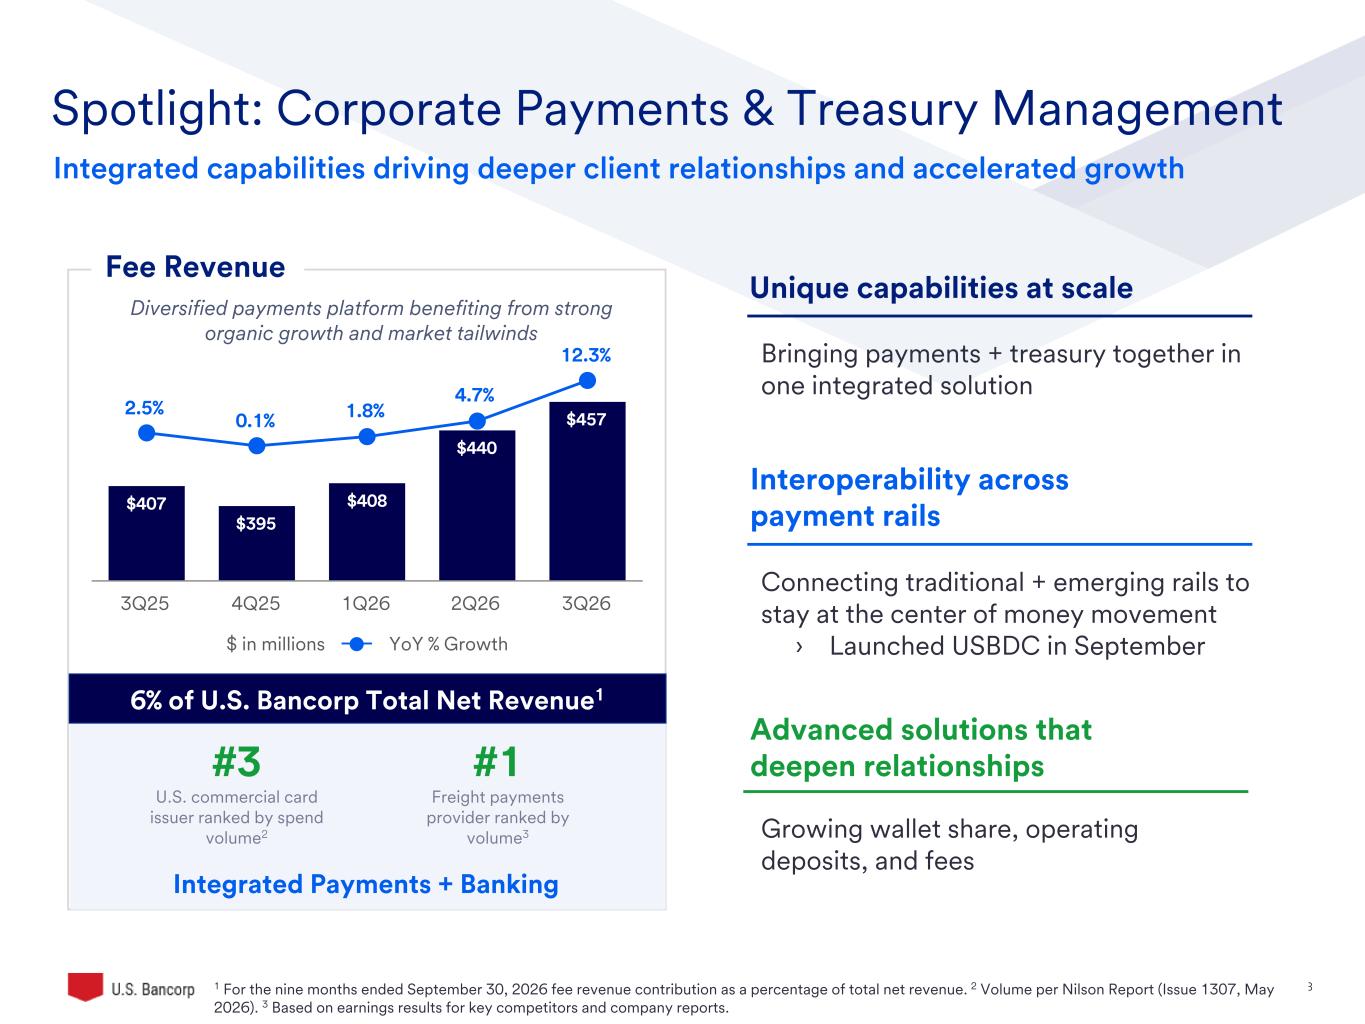
©2025 U.S. Bank | Confidential 8 Fee Revenue #3 U.S. commercial card issuer ranked by spend volume2 6% of U.S. Bancorp Total Net Revenue1 1 For the nine months ended September 30, 2026 fee revenue contribution as a percentage of total net revenue. 2 Volume per Nilson Report (Issue 1307, May 2026). 3 Based on earnings results for key competitors and company reports. Diversified payments platform benefiting from strong organic growth and market tailwinds Integrated Payments + Banking #1 Freight payments provider ranked by volume3 Spotlight: Corporate Payments & Treasury Management Integrated capabilities driving deeper client relationships and accelerated growth $407 $395 $408 $440 $4572.5% 0.1% 1.8% 4.7% 12.3% 3Q25 4Q25 1Q26 2Q26 3Q26 YoY % Growth Unique capabilities at scale Interoperability across payment rails Advanced solutions that deepen relationships Bringing payments + treasury together in one integrated solution Connecting traditional + emerging rails to stay at the center of money movement › Launched USBDC in September Growing wallet share, operating deposits, and fees $ in millions
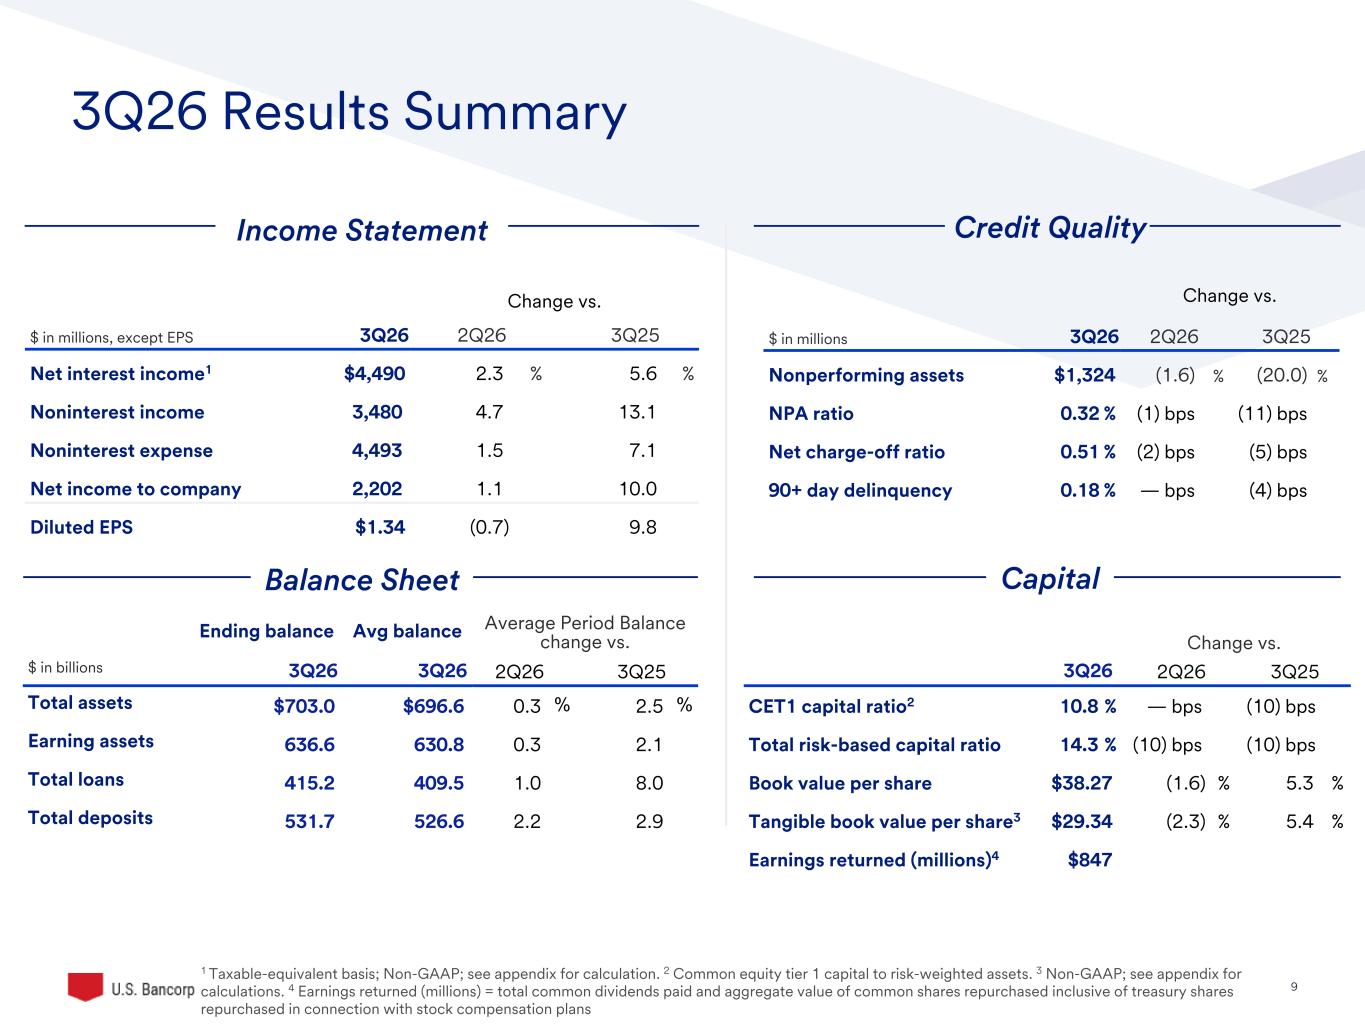
9©2025 U.S. Bank | Confidential 3Q26 Results Summary Income Statement Balance Sheet Capital 1 Taxable-equivalent basis; Non-GAAP; see appendix for calculation. 2 Common equity tier 1 capital to risk-weighted assets. 3 Non-GAAP; see appendix for calculations. 4 Earnings returned (millions) = total common dividends paid and aggregate value of common shares repurchased inclusive of treasury shares repurchased in connection with stock compensation plans Change vs. $ in millions, except EPS 3Q26 2Q26 3Q25 Net interest income1 $4,490 2.3 % 5.6 % Noninterest income 3,480 4.7 13.1 Noninterest expense 4,493 1.5 7.1 Net income to company 2,202 1.1 10.0 Diluted EPS $1.34 (0.7) 9.8 Change vs. $ in millions 3Q26 2Q26 3Q25 Nonperforming assets $1,324 (1.6) % (20.0) % NPA ratio 0.32 % (1) bps (11) bps Net charge-off ratio 0.51 % (2) bps (5) bps 90+ day delinquency 0.18 % — bps (4) bps Ending balance Avg balance Average Period Balance change vs. $ in billions 3Q26 3Q26 2Q26 3Q25 Total assets $703.0 $696.6 0.3 % 2.5 % Earning assets 636.6 630.8 0.3 2.1 Total loans 415.2 409.5 1.0 8.0 Total deposits 531.7 526.6 2.2 2.9 Change vs. 3Q26 2Q26 3Q25 CET1 capital ratio2 10.8 % — bps (10) bps Total risk-based capital ratio 14.3 % (10) bps (10) bps Book value per share $38.27 (1.6) % 5.3 % Tangible book value per share3 $29.34 (2.3) % 5.4 % Earnings returned (millions)4 $847 Credit Quality
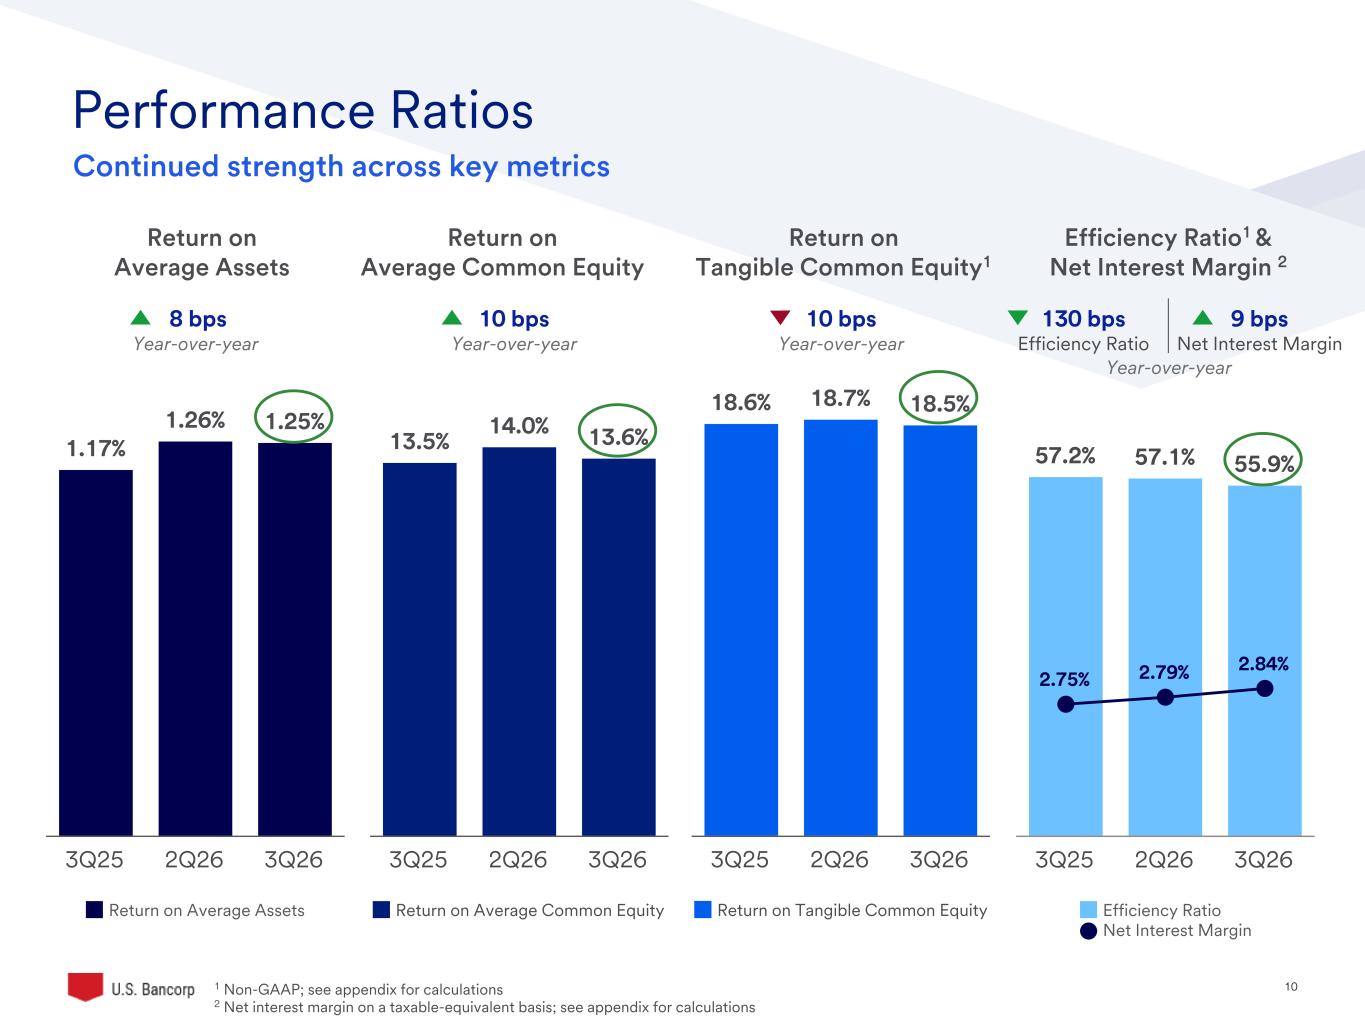
10©2025 U.S. Bank | Confidential 9 bps Net Interest Margin 130 bps Efficiency Ratio 1.17% 1.26% 1.25% Return on Average Assets 3Q25 2Q26 3Q26 57.2% 57.1% 55.9% 2.75% 2.79% 2.84% Efficiency Ratio Net Interest Margin 3Q25 2Q26 3Q26 Performance Ratios 13.5% 14.0% 13.6% Return on Average Common Equity 3Q25 2Q26 3Q26 18.6% 18.7% 18.5% Return on Tangible Common Equity 3Q25 2Q26 3Q26 Return on Average Assets Return on Average Common Equity Return on Tangible Common Equity1 Efficiency Ratio1 & Net Interest Margin 2 1 N -GAAP; see appendix for calculations 2 Net interest margin on a taxable-equivalent basis; see appendix for calculations 8 bps Year-over-year Continued strength across key metrics 10 bps Year-over-year 10 bps Year-over-year Year-over-year
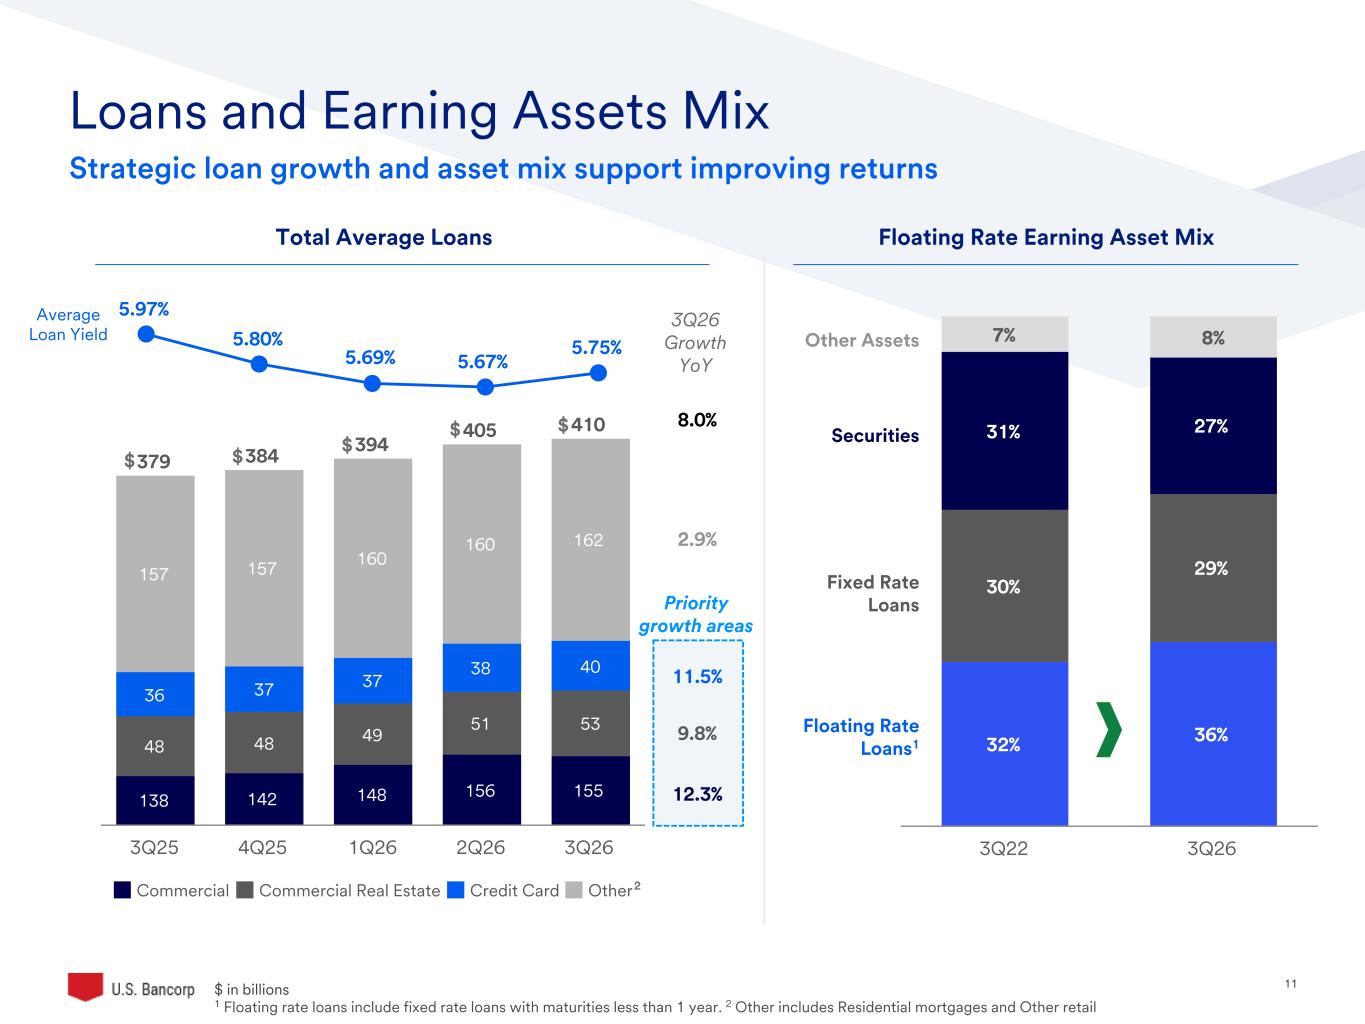
11©2026 U.S. Bank | Confidential Securities 5.97% 5.80% 5.69% 5.67% 5.75% Loans and Earning Assets Mix 379 384 394 405 410 138 142 148 156 155 48 48 49 51 53 36 37 37 38 40 157 157 160 160 162 Commercial Commercial Real Estate Credit Card Other 3Q25 4Q25 1Q26 2Q26 3Q26 32% 36% 30% 29% 31% 27% 7% 8% 3Q22 3Q26 Strategic loan growth and asset mix support improving returns 3Q26 Growth YoY 2.9% 11.5% 9.8% 12.3% Floating Rate Earning Asset MixTotal Average Loans Average Loan Yield Priority growth areas $ $ $ $ $ $ in billions 1 Floating rate loans include fixed rate loans with maturities less than 1 year. 2 Other includes Residential mortgages and Other retail 8.0% Floating Rate Loans1 Fixed Rate Loans Other Assets 2
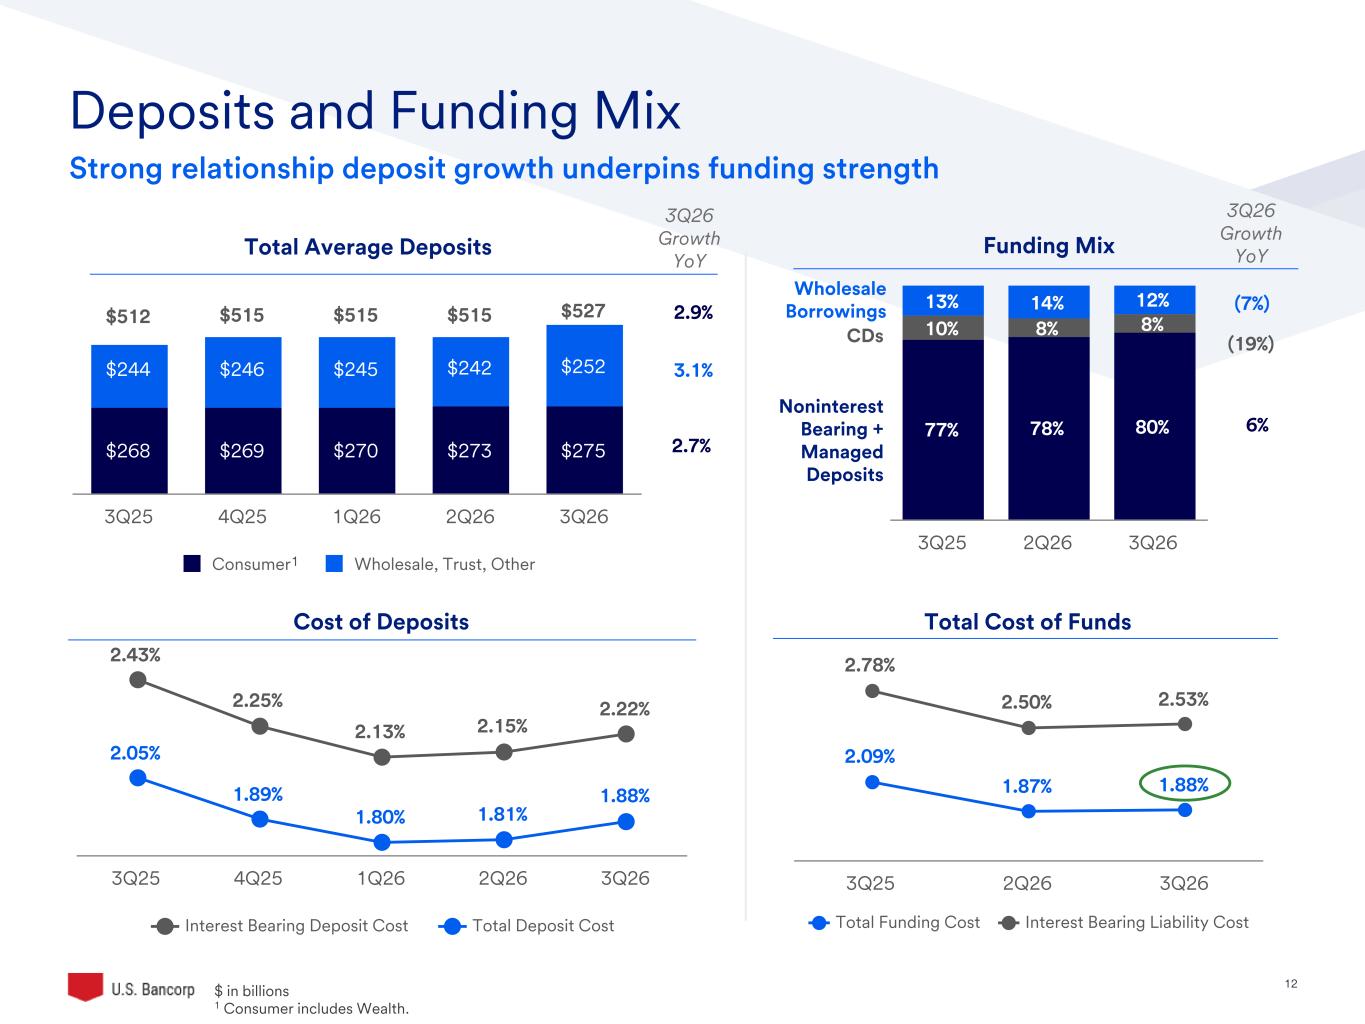
12©2026 U.S. Bank | Confidential Deposits and Funding Mix $512 $515 $515 $515 $527 $268 $269 $270 $273 $275 $244 $246 $245 $242 $252 Consumer Wholesale, Trust, Other 3Q25 4Q25 1Q26 2Q26 3Q26 Funding Mix 77% 78% 80% 10% 8% 8% 13% 14% 12% 3Q25 2Q26 3Q26 Wholesale Borrowings CDs Noninterest Bearing + Managed Deposits Cost of Deposits 2.43% 2.25% 2.13% 2.15% 2.22% 2.05% 1.89% 1.80% 1.81% 1.88% Interest Bearing Deposit Cost Total Deposit Cost 3Q25 4Q25 1Q26 2Q26 3Q26 Total Cost of Funds 2.09% 1.87% 1.88% 2.78% 2.50% 2.53% Total Funding Cost Interest Bearing Liability Cost 3Q25 2Q26 3Q26 Strong relationship deposit growth underpins funding strength 3Q26 Growth YoY Total Average Deposits 3.1% 2.7% (7%) 6% (19%) 2.9% $ in billions 1 Consumer includes Wealth. 3Q26 Growth YoY 1
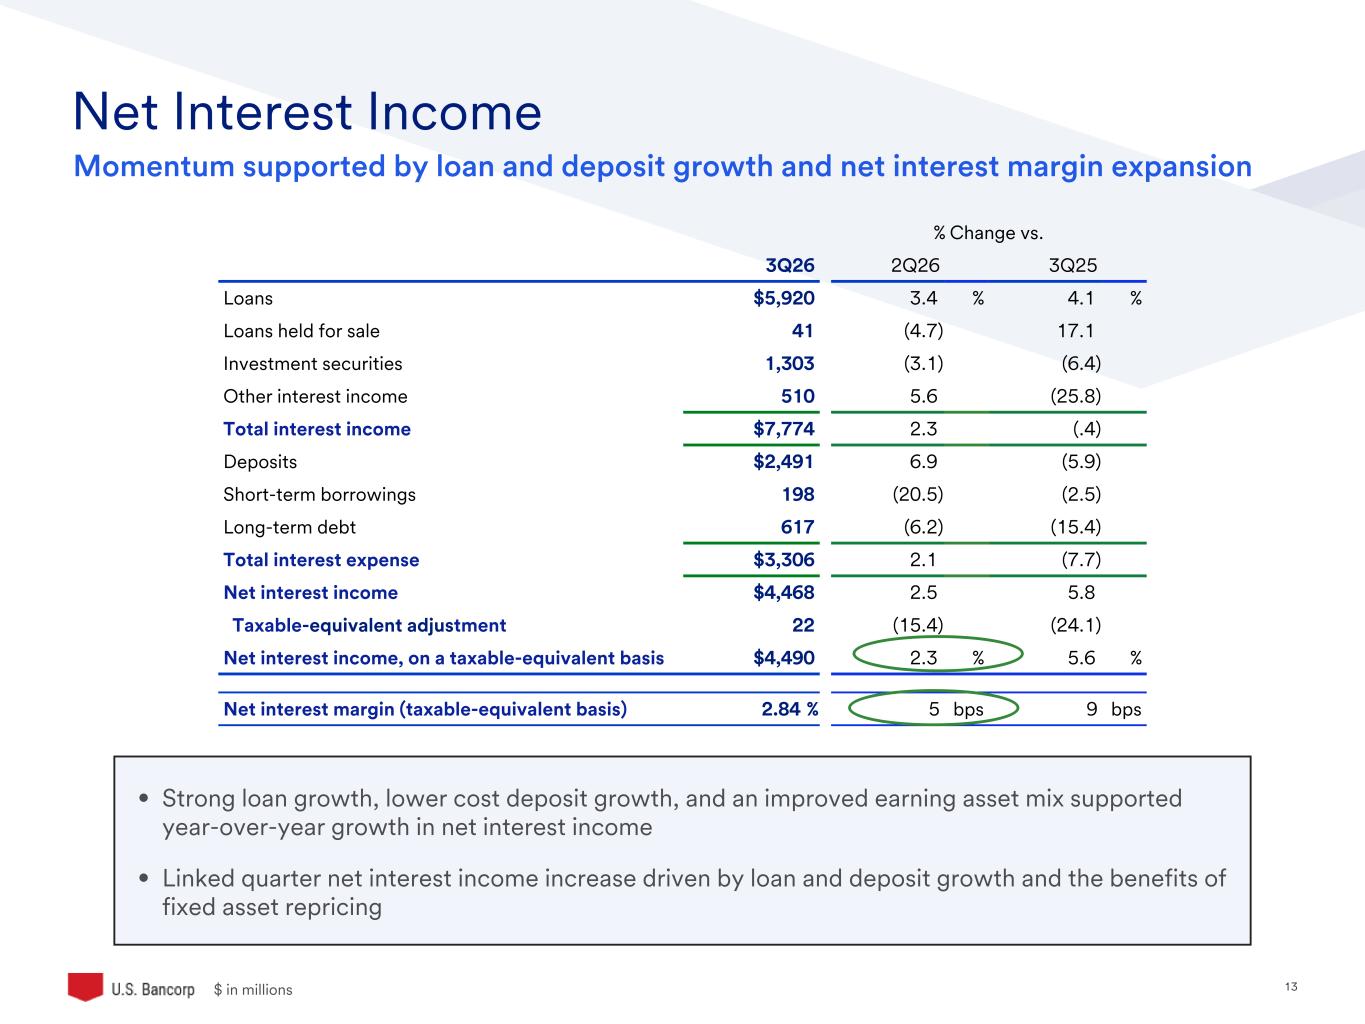
13©2025 U.S. Bank | Confidential • Strong loan growth, lower cost deposit growth, and an improved earning asset mix supported year-over-year growth in net interest income • Linked quarter net interest income increase driven by loan and deposit growth and the benefits of fixed asset repricing Net Interest Income % Change vs. 3Q26 2Q26 3Q25 Loans $5,920 3.4 % 4.1 % Loans held for sale 41 (4.7) 17.1 Investment securities 1,303 (3.1) (6.4) Other interest income 510 5.6 (25.8) Total interest income $7,774 2.3 (.4) Deposits $2,491 6.9 (5.9) Short-term borrowings 198 (20.5) (2.5) Long-term debt 617 (6.2) (15.4) Total interest expense $3,306 2.1 (7.7) Net interest income $4,468 2.5 5.8 Taxable-equivalent adjustment 22 (15.4) (24.1) Net interest income, on a taxable-equivalent basis $4,490 2.3 % 5.6 % Net interest margin (taxable-equivalent basis) 2.84 % 5 bps 9 bps Momentum supported by loan and deposit growth and net interest margin expansion $ in millio s
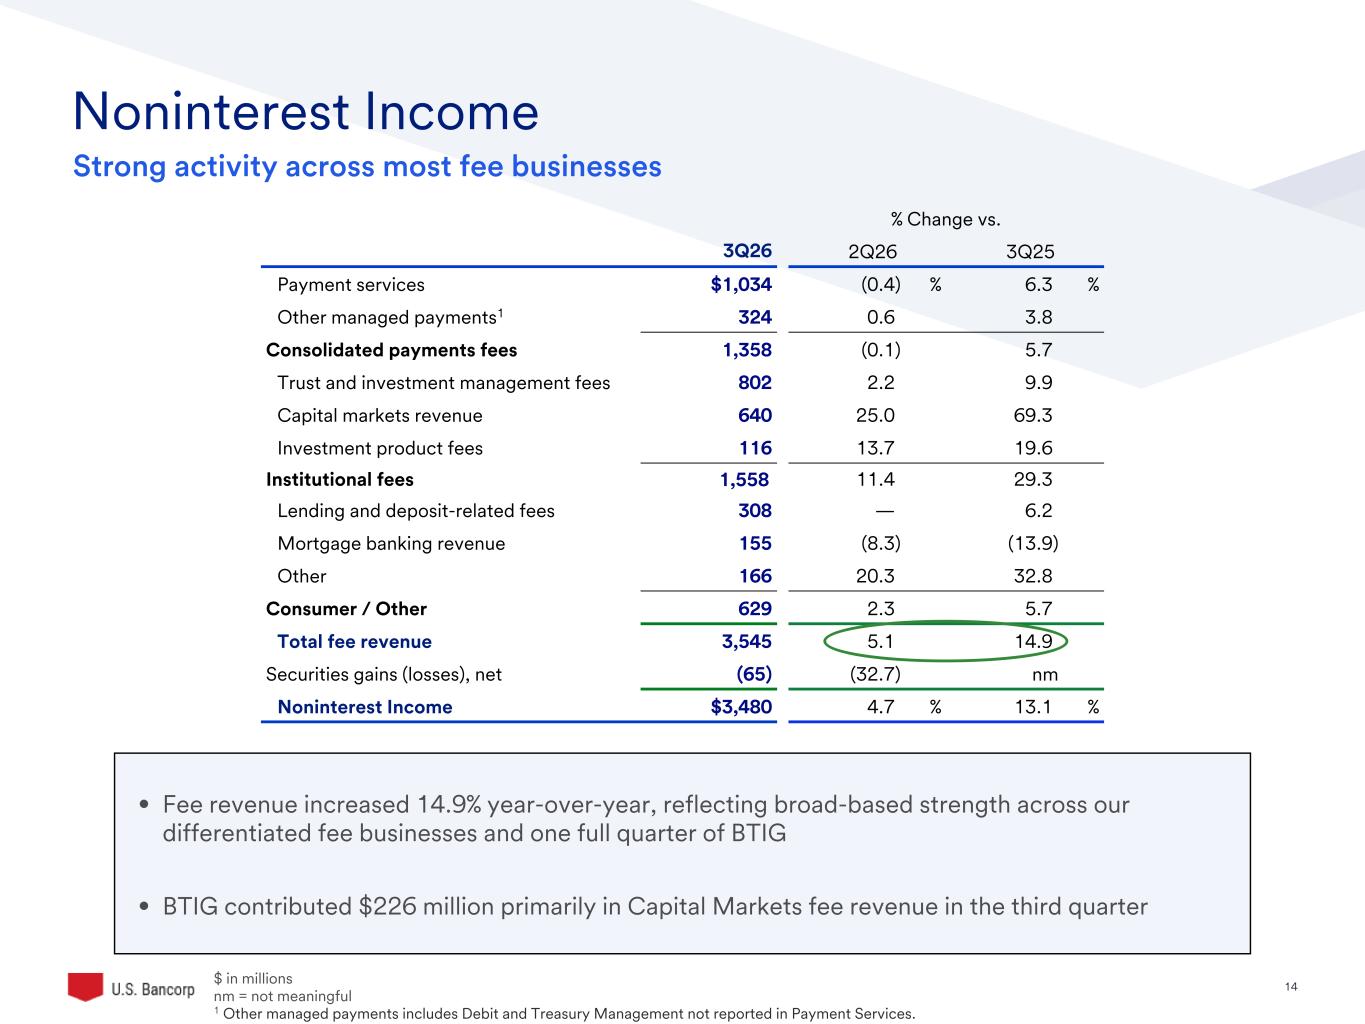
14©2025 U.S. Bank | Confidential Noninterest Income $ in millions nm = not meaningful 1 Other managed payments includes Debit and Treasury Management not reported in Payment Services. % Change vs. 3Q26 2Q26 3Q25 Payment services $1,034 (0.4) % 6.3 % Other managed payments1 324 0.6 3.8 Consolidated payments fees 1,358 (0.1) 5.7 Trust and investment management fees 802 2.2 9.9 Capital markets revenue 640 25.0 69.3 Investment product fees 116 13.7 19.6 Institutional fees 1,558 11.4 29.3 Lending and deposit-related fees 308 — 6.2 Mortgage banking revenue 155 (8.3) (13.9) Other 166 20.3 32.8 Consumer / Other 629 2.3 5.7 Total fee revenue 3,545 5.1 14.9 Securities gains (losses), net (65) (32.7) nm Noninterest Income $3,480 4.7 % 13.1 % Strong activity across most fee businesses • Fee revenue increased 14.9% year-over-year, reflecting broad-based strength across our differentiated fee businesses and one full quarter of BTIG • BTIG contributed $226 million primarily in Capital Markets fee revenue in the third quarter
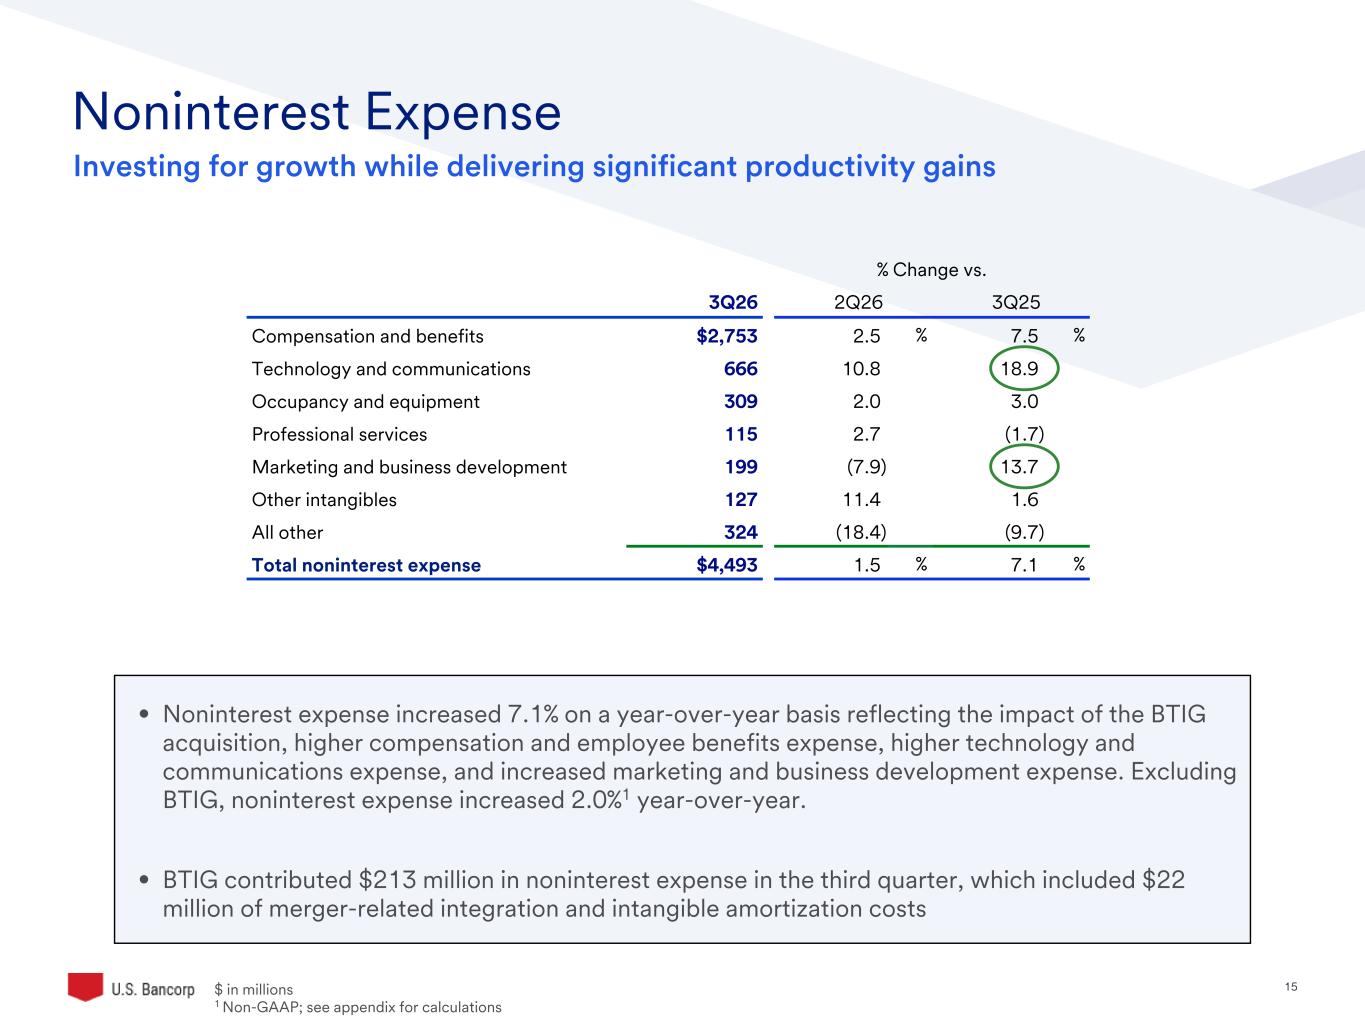
15©2025 U.S. Bank | Confidential Noninterest Expense $ in millio s 1 Non-GAAP; see appendix for calculations % Change vs. 3Q26 2Q26 3Q25 Compensation and benefits $2,753 2.5 % 7.5 % Technology and communications 666 10.8 18.9 Occupancy and equipment 309 2.0 3.0 Professional services 115 2.7 (1.7) Marketing and business development 199 (7.9) 13.7 Other intangibles 127 11.4 1.6 All other 324 (18.4) (9.7) Total noninterest expense $4,493 1.5 % 7.1 % Investing for growth while delivering significant productivity gains • Noninterest expense increased 7.1% on a year-over-year basis reflecting the impact of the BTIG acquisition, higher compensation and employee benefits expense, higher technology and communications expense, and increased marketing and business development expense. Excluding BTIG, noninterest expense increased 2.0%1 year-over-year. • BTIG contributed $213 million in noninterest expense in the third quarter, which included $22 million of merger-related integration and intangible amortization costs
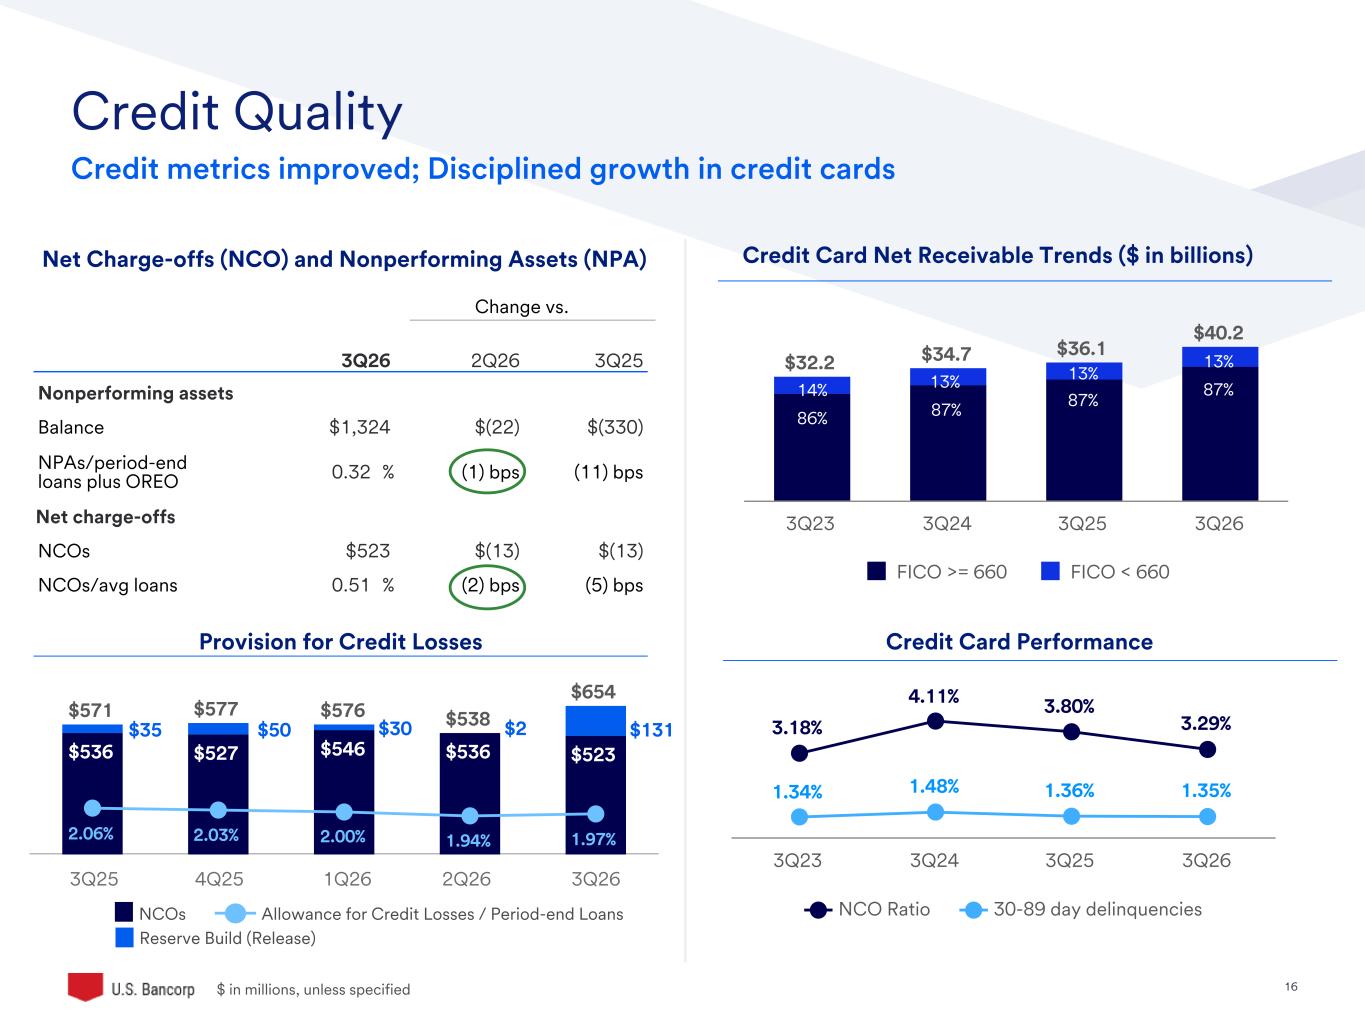
16©2025 U.S. Bank | Confidential $32.2 $34.7 $36.1 $40.2 FICO >= 660 FICO < 660 3Q23 3Q24 3Q25 3Q26 3.18% 4.11% 3.80% 3.29% 1.34% 1.48% 1.36% 1.35% NCO Ratio 30-89 day delinquencies 3Q23 3Q24 3Q25 3Q26 $571 $577 $576 $538 $654 $536 $527 $546 $536 $523 2.06% 2.03% 2.00% 1.94% 1.97% Credit Quality Change vs. 3Q26 2Q26 3Q25 Nonperforming assets Balance $1,324 $(22) $(330) NPAs/period-end loans plus OREO 0.32 % (1) bps (11) bps Net charge-offs NCOs $523 $(13) $(13) NCOs/avg loans 0.51 % (2) bps (5) bps Provision for Credit Losses Net Charge-offs (NCO) and Nonperforming Assets (NPA) NCOs Reserve Build (Release) Allowance for Credit Losses / Period-end Loans 3Q25 4Q25 1Q26 $35 2Q26 $50 $30 3Q26 $2 $131 Credit Card Net Receivable Trends ($ in billions) Credit metrics improved; Disciplined growth in credit cards Credit Card Performance 86% 14% 87% 13% 87% 13% 87% 13% $ in millions, unless specified
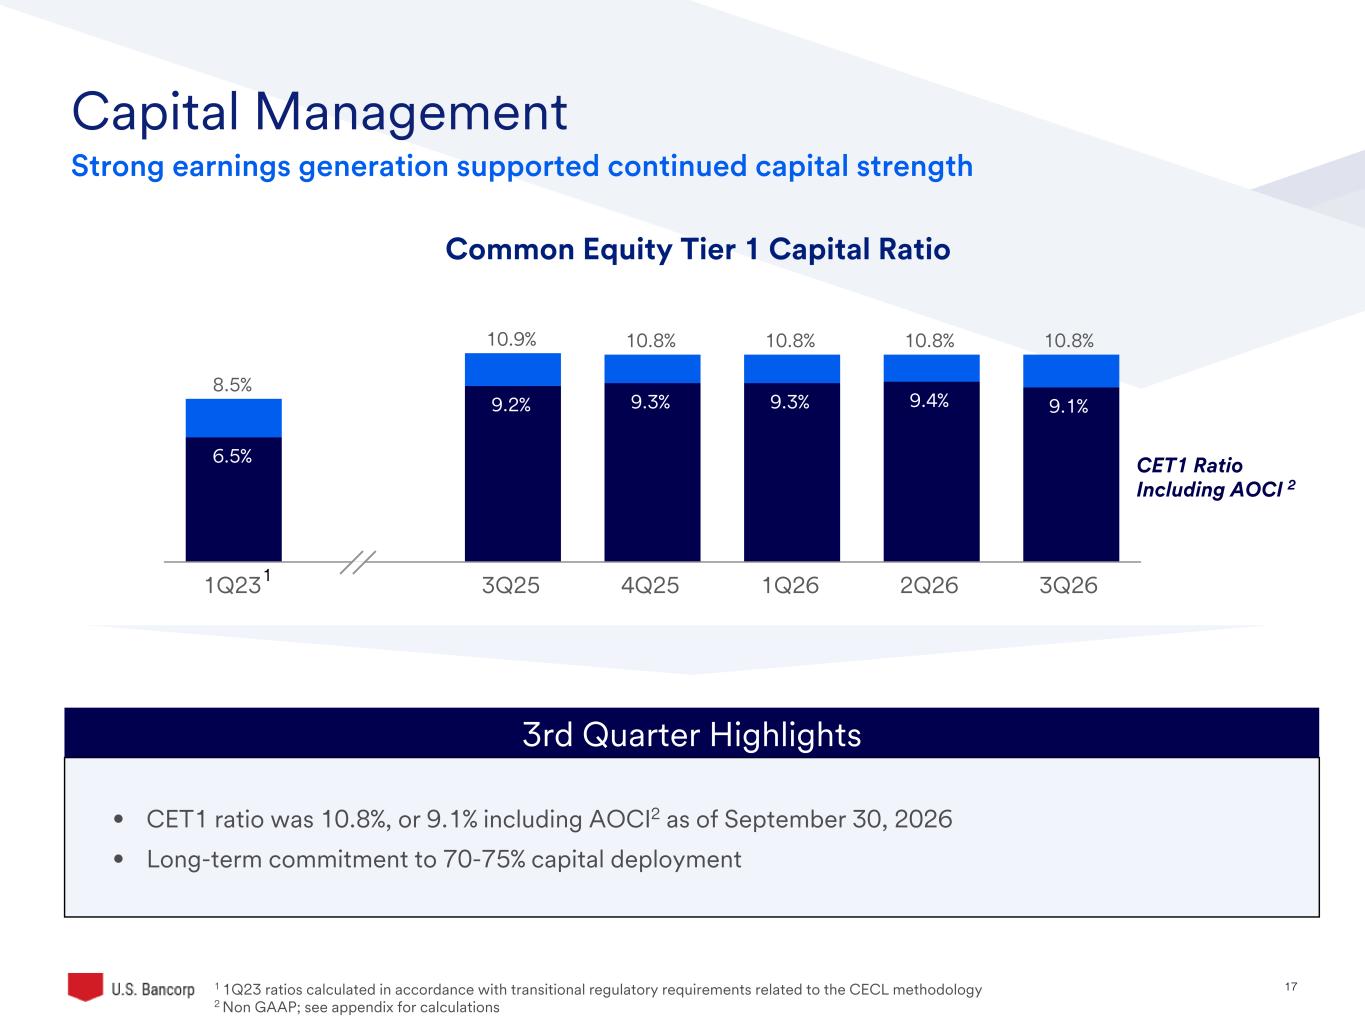
17©2025 U.S. Bank | Confidential • CET1 ratio was 10.8%, or 9.1% including AOCI2 as of September 30, 2026 • Long-term commitment to 70-75% capital deployment 8.5% 10.9% 10.8% 10.8% 10.8% 10.8% 6.5% 9.2% 9.3% 9.3% 9.4% 9.1% 1Q23 3Q25 4Q25 1Q26 2Q26 3Q26 Capital Management Strong earnings generation supported continued capital strength 1 1Q23 ratios calculated in accordance with transitional regulatory requirements related to the CECL methodology 2 Non GAAP; see appendix for calculations 3rd Quarter Highlights CET1 Ratio Including AOCI 2 Common Equity Tier 1 Capital Ratio 1
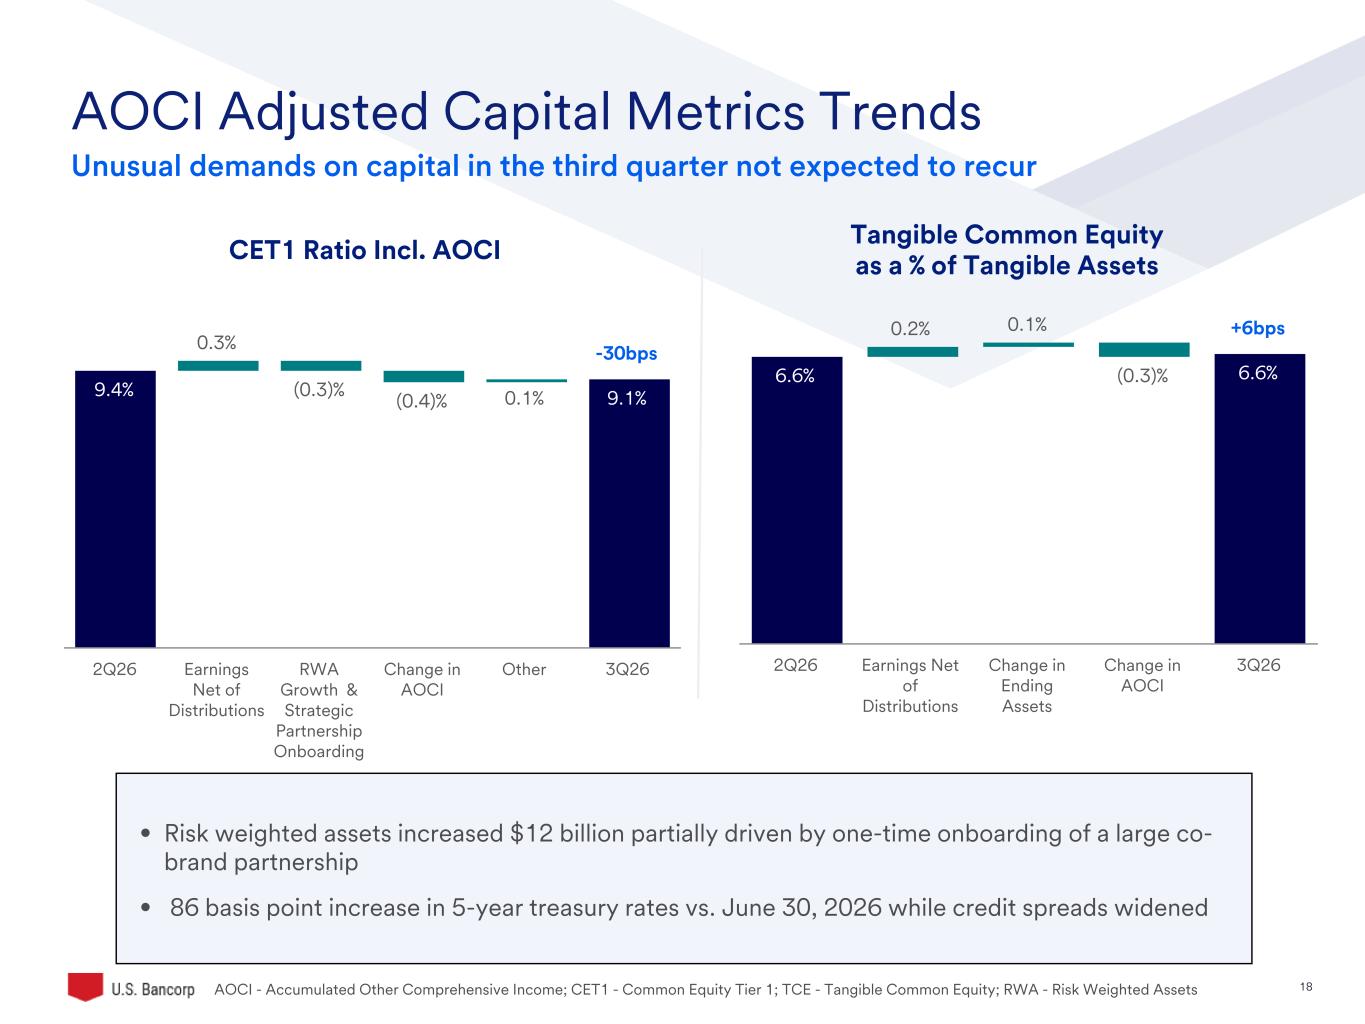
©2025 U.S. Bank | Confidential 18 AOCI Adjusted Capital Metrics Trends 9.4% 0.3% (0.3)% (0.4)% 0.1% 9.1% 2Q26 Earnings Net of Distributions RWA Growth & Strategic Partnership Onboarding Change in AOCI Other 3Q26 CET1 Ratio Incl. AOCI Tangible Common Equity as a % of Tangible Assets 6.6% 0.2% 0.1% (0.3)% 6.6% 2Q26 Earnings Net of Distributions Change in Ending Assets Change in AOCI 3Q26 -30bps +6bps Unusual demands on capital in the third quarter not expected to recur • Risk weighted assets increased $12 billion partially driven by one-time onboarding of a large co- brand partnership • 86 basis point increase in 5-year treasury rates vs. June 30, 2026 while credit spreads widened AOCI - Accumulated Other Comprehensive Income; CET1 - Common Equity Tier 1; TCE - Tangible Common Equity; RWA - Risk Weighted Assets
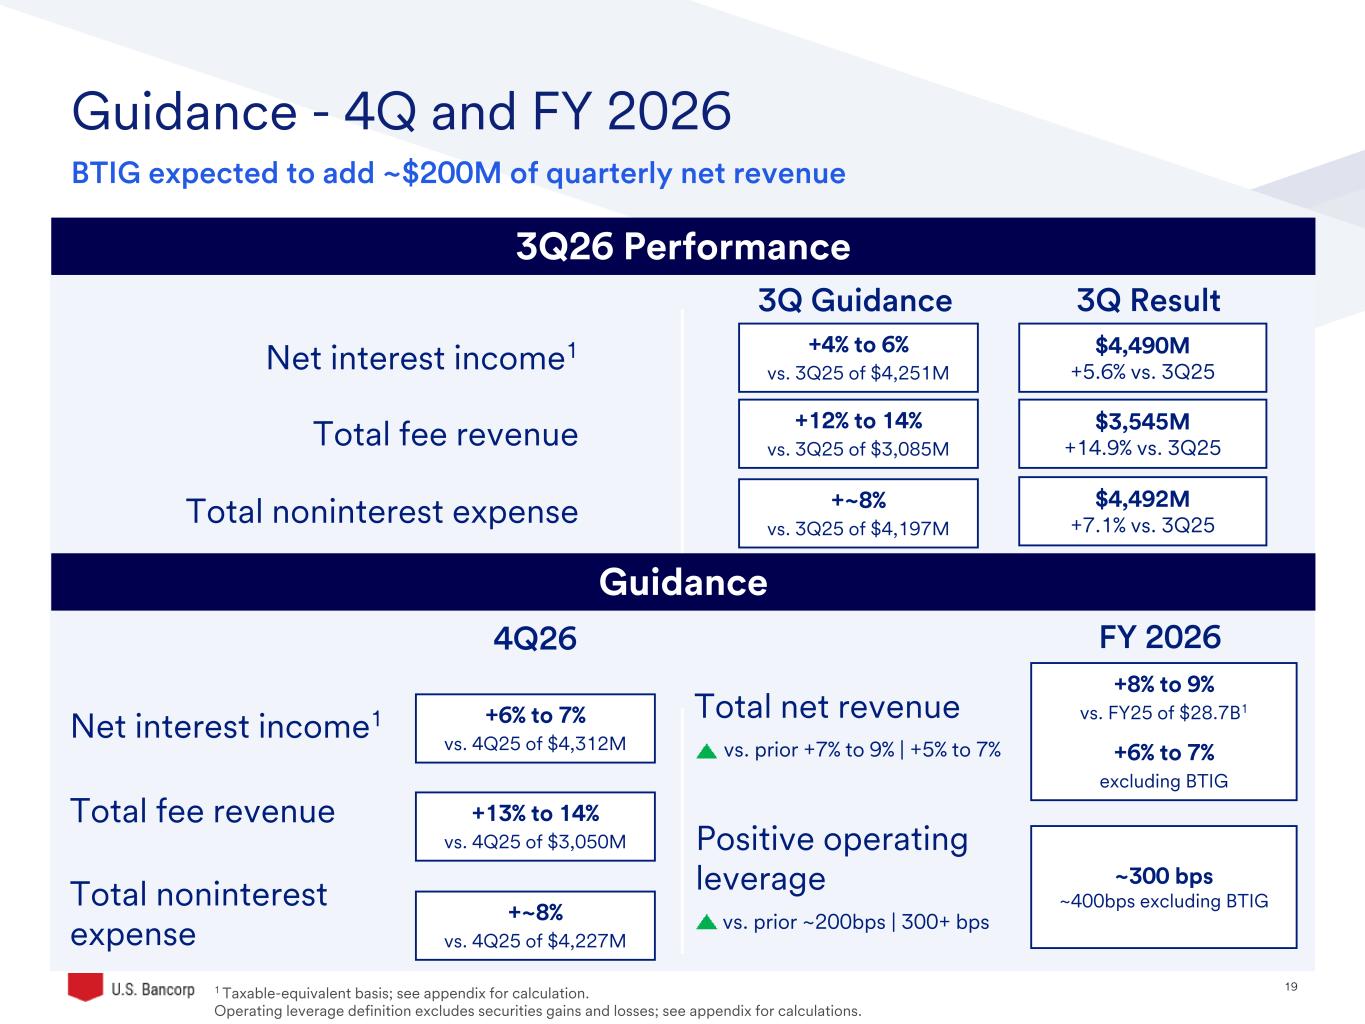
19©2025 U.S. Bank | Confidential +7% to 9% | +5% to 7% vs. prior guidance Guidance - 4Q and FY 2026 1 Taxable-equivalent basis; see appendix for calculation. Operating leverage definition excludes securities gains and losses; see appendix for calculations. 3Q26 Performance Net interest income1 Total noninterest expense 3Q Guidance 3Q Result $4,490M +5.6% vs. 3Q25 $4,492M +7.1% vs. 3Q25 Total fee revenue $3,545M +14.9% vs. 3Q25 4Q26 Net interest income1 Total noninterest expense Total fee revenue +4% to 6% vs. 3Q25 of $4,251M +12% to 14% vs. 3Q25 of $3,085M +~8% vs. 3Q25 of $4,197M Total net revenue Positive operating leverage ~300 bps ~400bps excluding BTIG +8% to 9% vs. FY25 of $28.7B1 +6% to 7% excluding BTIG BTIG expected to add ~$200M of quarterly net revenue +6% to 7% vs. 4Q25 of $4,312M +13% to 14% vs. 4Q25 of $3,050M +~8% vs. 4Q25 of $4,227M Guidance FY 2026 vs. prior ~200bps | 300+ bps vs. prior +7% to 9% | +5% to 7%
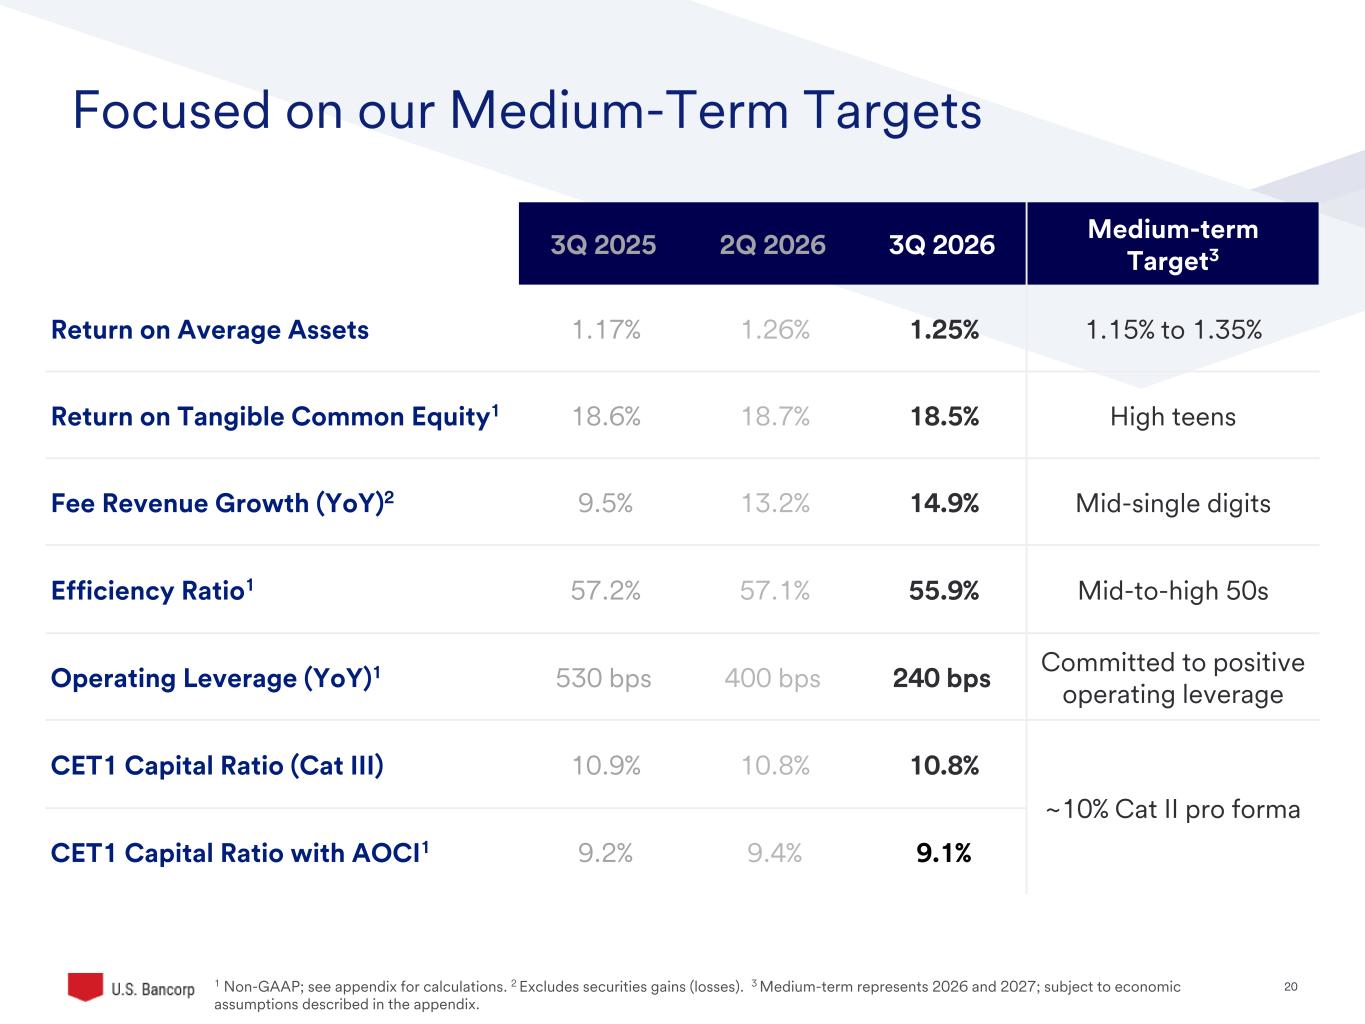
20©2025 U.S. Bank | Confidential Focused on our Medium-Term Targets 1 N -GAAP; see appendix for calculations. 2 Excludes securities gains (losses). 3 Medium-term represents 2026 and 2027; subject to economic assumptions described in the appendix. 3Q 2025 2Q 2026 3Q 2026 Medium-term Target3 Return on Average Assets 1.17% 1.26% 1.25% 1.15% to 1.35% Return on Tangible Common Equity1 18.6% 18.7% 18.5% High teens Fee Revenue Growth (YoY)2 9.5% 13.2% 14.9% Mid-single digits Efficiency Ratio1 57.2% 57.1% 55.9% Mid-to-high 50s Operating Leverage (YoY)1 530 bps 400 bps 240 bps Committed to positive operating leverage CET1 Capital Ratio (Cat III) 10.9% 10.8% 10.8% ~10% Cat II pro forma CET1 Capital Ratio with AOCI1 9.2% 9.4% 9.1%
21©2025 U.S. Bank | Confidential From Strength to Acceleration • Helping clients thrive with leading-edge products and services • Comfortably operating in medium-term target ranges • Sustaining high returns and productivity while accelerating EPS growth • Attractive, diversified fee complex, increasingly delivering scale and national presence
22©2025 U.S. Bank Appendix
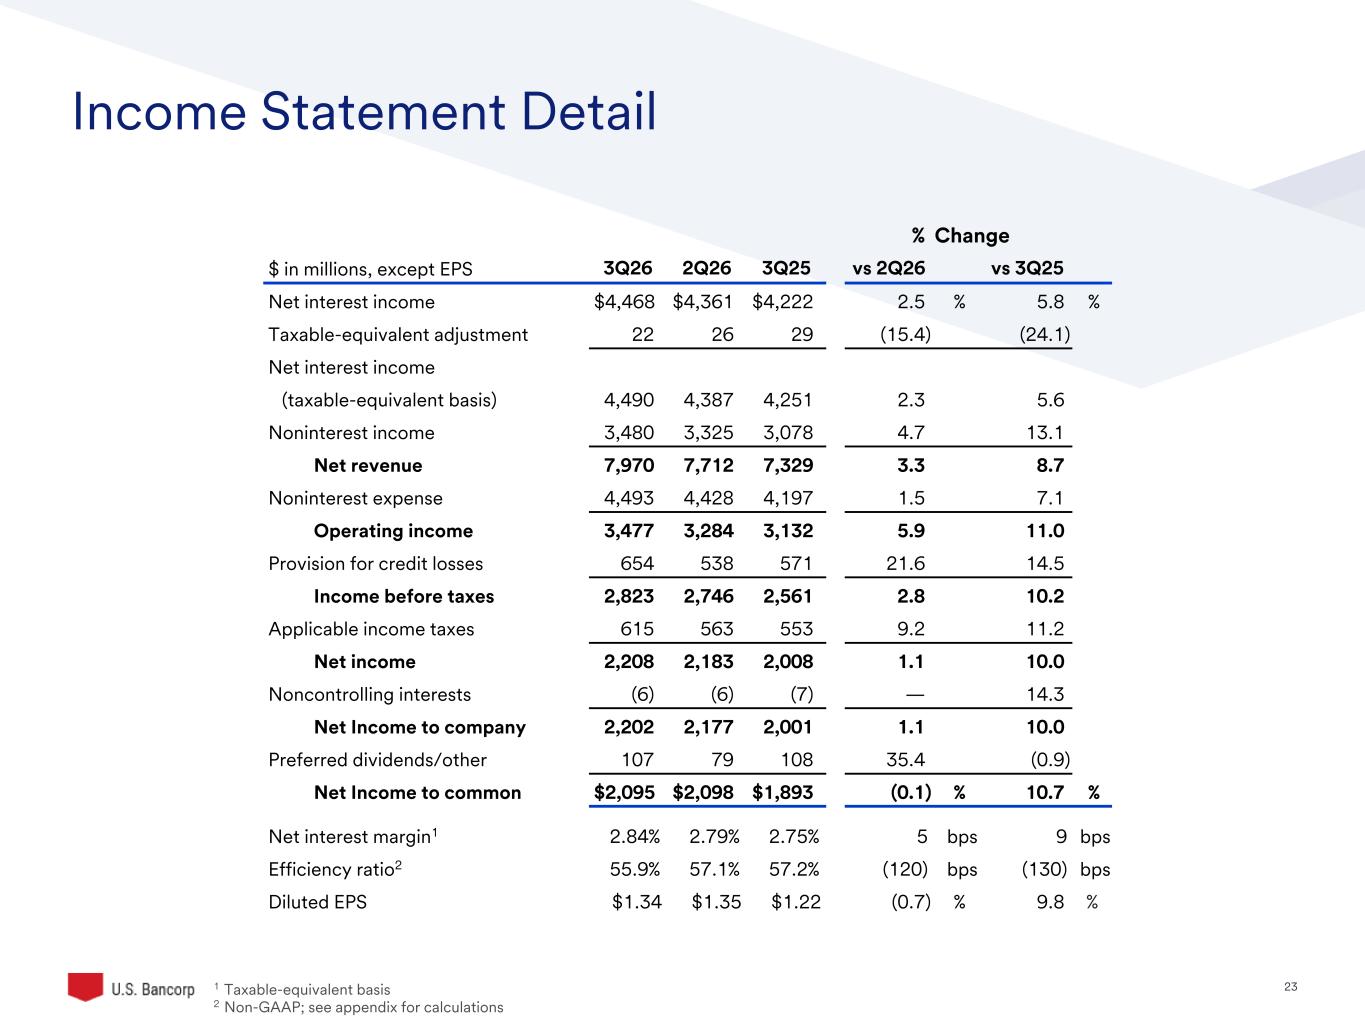
23©2025 U.S. Bank | Confidential Income Statement Detail 1 Taxabl -equivalent basis 2 Non-GAAP; see appendix for calculations % Change $ in millions, except EPS 3Q26 2Q26 3Q25 vs 2Q26 vs 3Q25 Net interest income $4,468 $4,361 $4,222 2.5 % 5.8 % Taxable-equivalent adjustment 22 26 29 (15.4) (24.1) Net interest income (taxable-equivalent basis) 4,490 4,387 4,251 2.3 5.6 Noninterest income 3,480 3,325 3,078 4.7 13.1 Net revenue 7,970 7,712 7,329 3.3 8.7 Noninterest expense 4,493 4,428 4,197 1.5 7.1 Operating income 3,477 3,284 3,132 5.9 11.0 Provision for credit losses 654 538 571 21.6 14.5 Income before taxes 2,823 2,746 2,561 2.8 10.2 Applicable income taxes 615 563 553 9.2 11.2 Net income 2,208 2,183 2,008 1.1 10.0 Noncontrolling interests (6) (6) (7) — 14.3 Net Income to company 2,202 2,177 2,001 1.1 10.0 Preferred dividends/other 107 79 108 35.4 (0.9) Net Income to common $2,095 $2,098 $1,893 (0.1) % 10.7 % Net interest margin1 2.84% 2.79% 2.75% 5 bps 9 bps Efficiency ratio2 55.9% 57.1% 57.2% (120) bps (130) bps Diluted EPS $1.34 $1.35 $1.22 (0.7) % 9.8 %
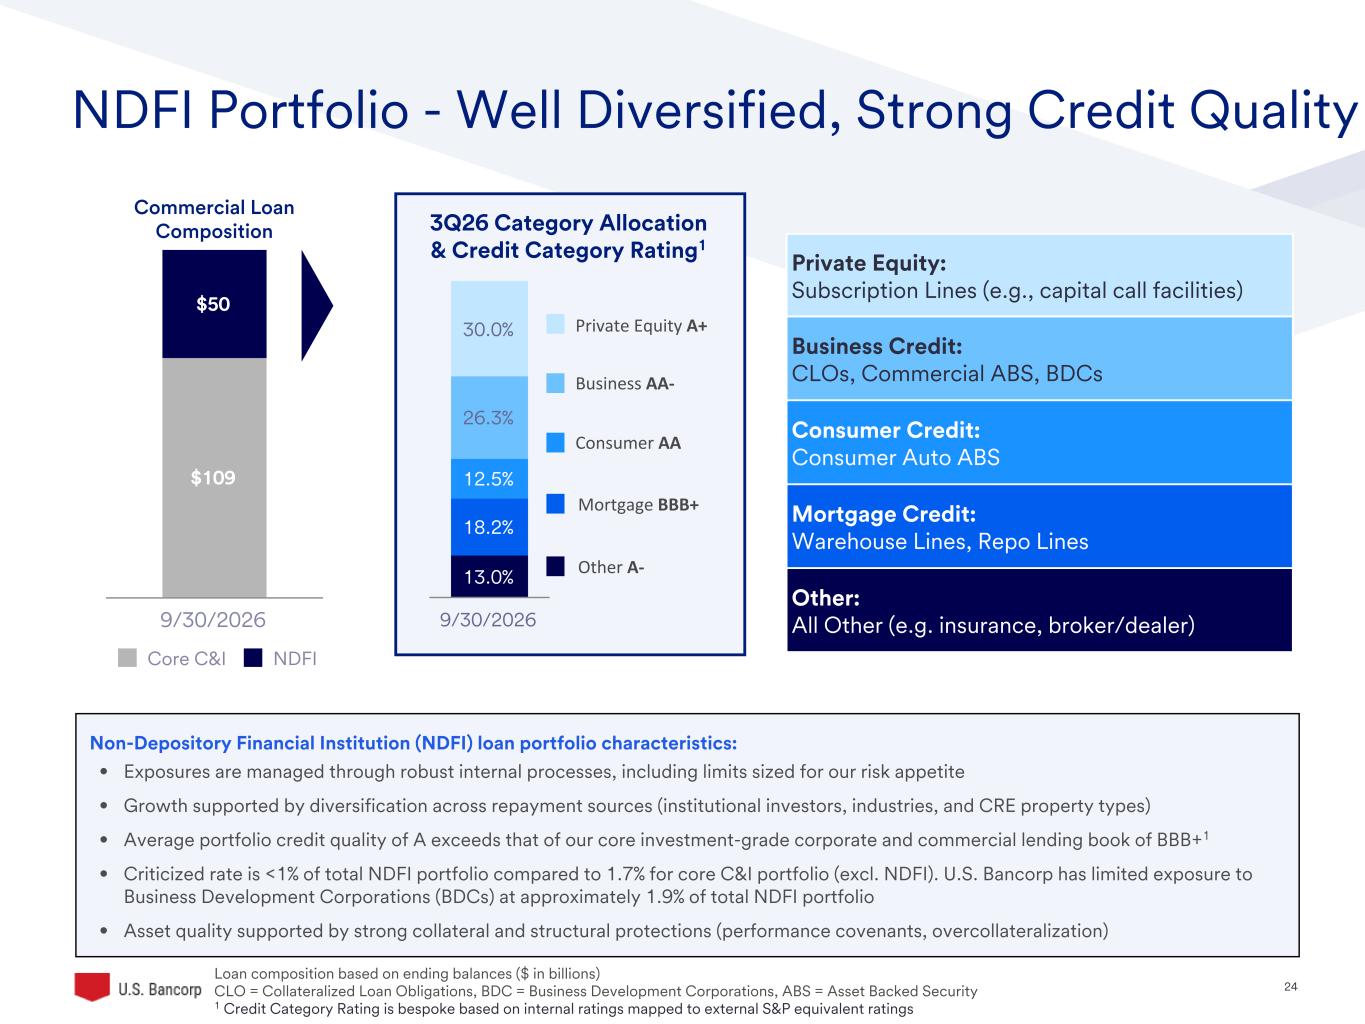
24©2025 U.S. Bank | Confidential $109 $50 Core C&I NDFI 9/30/2026 NDFI Portfolio - Well Diversified, Strong Credit Quality Loan composition based on ending balances ($ in billions) CLO = Collateralized Loan Obligations, BDC = Business Development Corporations, ABS = Asset Backed Security 1 Credit Category Rating is bespoke based on internal ratings mapped to external S&P equivalent ratings Private Equity: Subscription Lines (e.g., capital call facilities) Business Credit: CLOs, Commercial ABS, BDCs Consumer Credit: Consumer Auto ABS Mortgage Credit: Warehouse Lines, Repo Lines Other: All Other (e.g. insurance, broker/dealer) 3Q26 Category Allocation & Credit Category Rating1 Private Equity A+ Business AA- Consumer AA Mortgage BBB+ Other A-13.0% 18.2% 12.5% 26.3% 30.0% 9/30/2026 Commercial Loan Composition Non-Depository Financial Institution (NDFI) loan portfolio characteristics: • Exposures are managed through robust internal processes, including limits sized for our risk appetite • Growth supported by diversification across repayment sources (institutional investors, industries, and CRE property types) • Average portfolio credit quality of A exceeds that of our core investment-grade corporate and commercial lending book of BBB+1 • Criticized rate is <1% of total NDFI portfolio compared to 1.7% for core C&I portfolio (excl. NDFI). U.S. Bancorp has limited exposure to Business Development Corporations (BDCs) at approximately 1.9% of total NDFI portfolio • Asset quality supported by strong collateral and structural protections (performance covenants, overcollateralization)
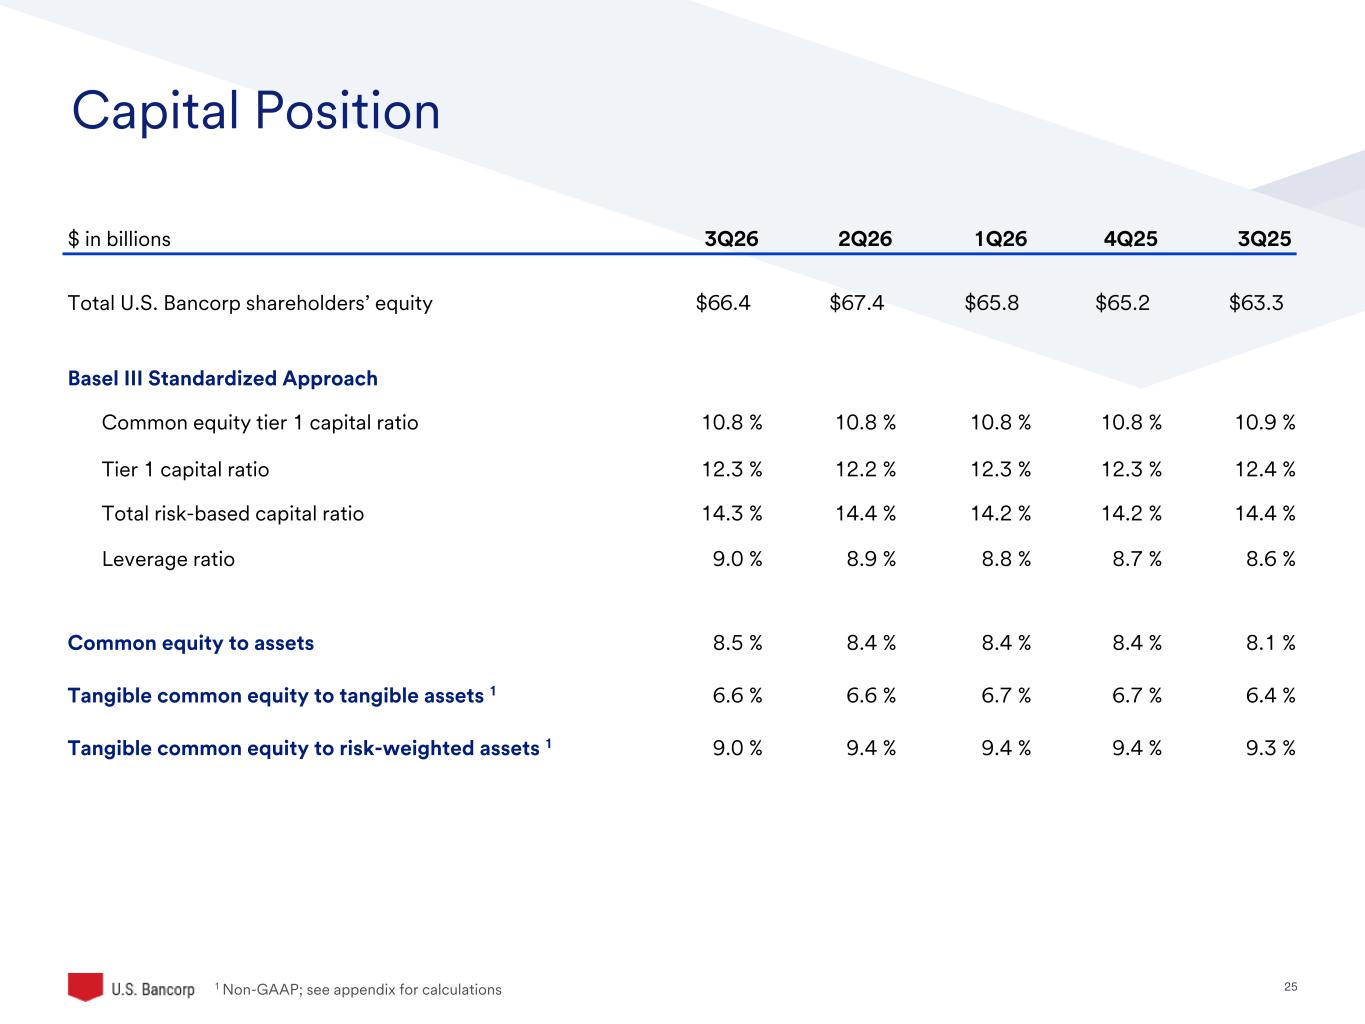
25©2025 U.S. Bank | Confidential Capital Position $ in billions 3Q26 2Q26 1Q26 4Q25 3Q25 Total U.S. Bancorp shareholders’ equity $66.4 $67.4 $65.8 $65.2 $63.3 Basel III Standardized Approach Common equity tier 1 capital ratio 10.8 % 10.8 % 10.8 % 10.8 % 10.9 % Tier 1 capital ratio 12.3 % 12.2 % 12.3 % 12.3 % 12.4 % Total risk-based capital ratio 14.3 % 14.4 % 14.2 % 14.2 % 14.4 % Leverage ratio 9.0 % 8.9 % 8.8 % 8.7 % 8.6 % Common equity to assets 8.5 % 8.4 % 8.4 % 8.4 % 8.1 % Tangible common equity to tangible assets 1 6.6 % 6.6 % 6.7 % 6.7 % 6.4 % Tangible common equity to risk-weighted assets 1 9.0 % 9.4 % 9.4 % 9.4 % 9.3 % 1 N -GAAP; see appendix for calculations
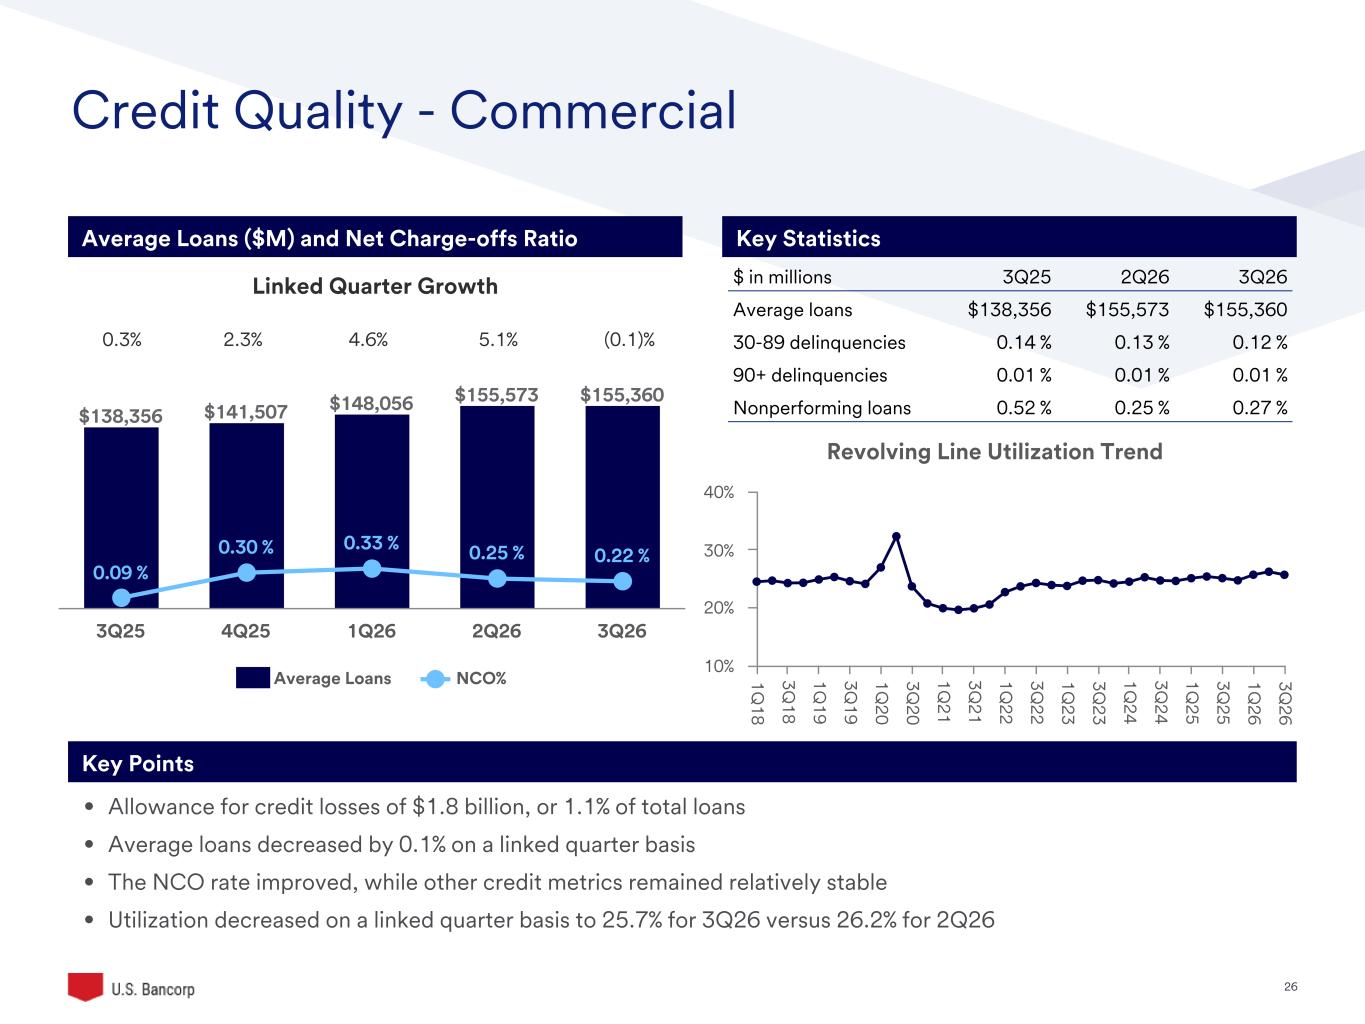
26©2025 U.S. Bank | Confidential Credit Quality - Commercial $138,356 $141,507 $148,056 $155,573 $155,360 0.09 % 0.30 % 0.33 % 0.25 % 0.22 % Average Loans NCO% 3Q25 4Q25 1Q26 2Q26 3Q26 Key StatisticsAverage Loans ($M) and Net Charge-offs Ratio 0.3% 2.3% 4.6% 5.1% (0.1)% Linked Quarter Growth Key Points • Allowance for credit losses of $1.8 billion, or 1.1% of total loans • Average loans decreased by 0.1% on a linked quarter basis • The NCO rate improved, while other credit metrics remained relatively stable • Utilization decreased on a linked quarter basis to 25.7% for 3Q26 versus 26.2% for 2Q26 $ in millions 3Q25 2Q26 3Q26 Average loans $138,356 $155,573 $155,360 30-89 delinquencies 0.14 % 0.13 % 0.12 % 90+ delinquencies 0.01 % 0.01 % 0.01 % Nonperforming loans 0.52 % 0.25 % 0.27 % Revolving Line Utilization Trend 1Q 18 3Q 18 1Q 19 3Q 19 1Q 20 3Q 20 1Q 21 3Q 21 1Q 22 3Q 22 1Q 23 3Q 23 1Q 24 3Q 24 1Q 25 3Q 25 1Q 26 3Q 26 10% 20% 30% 40%
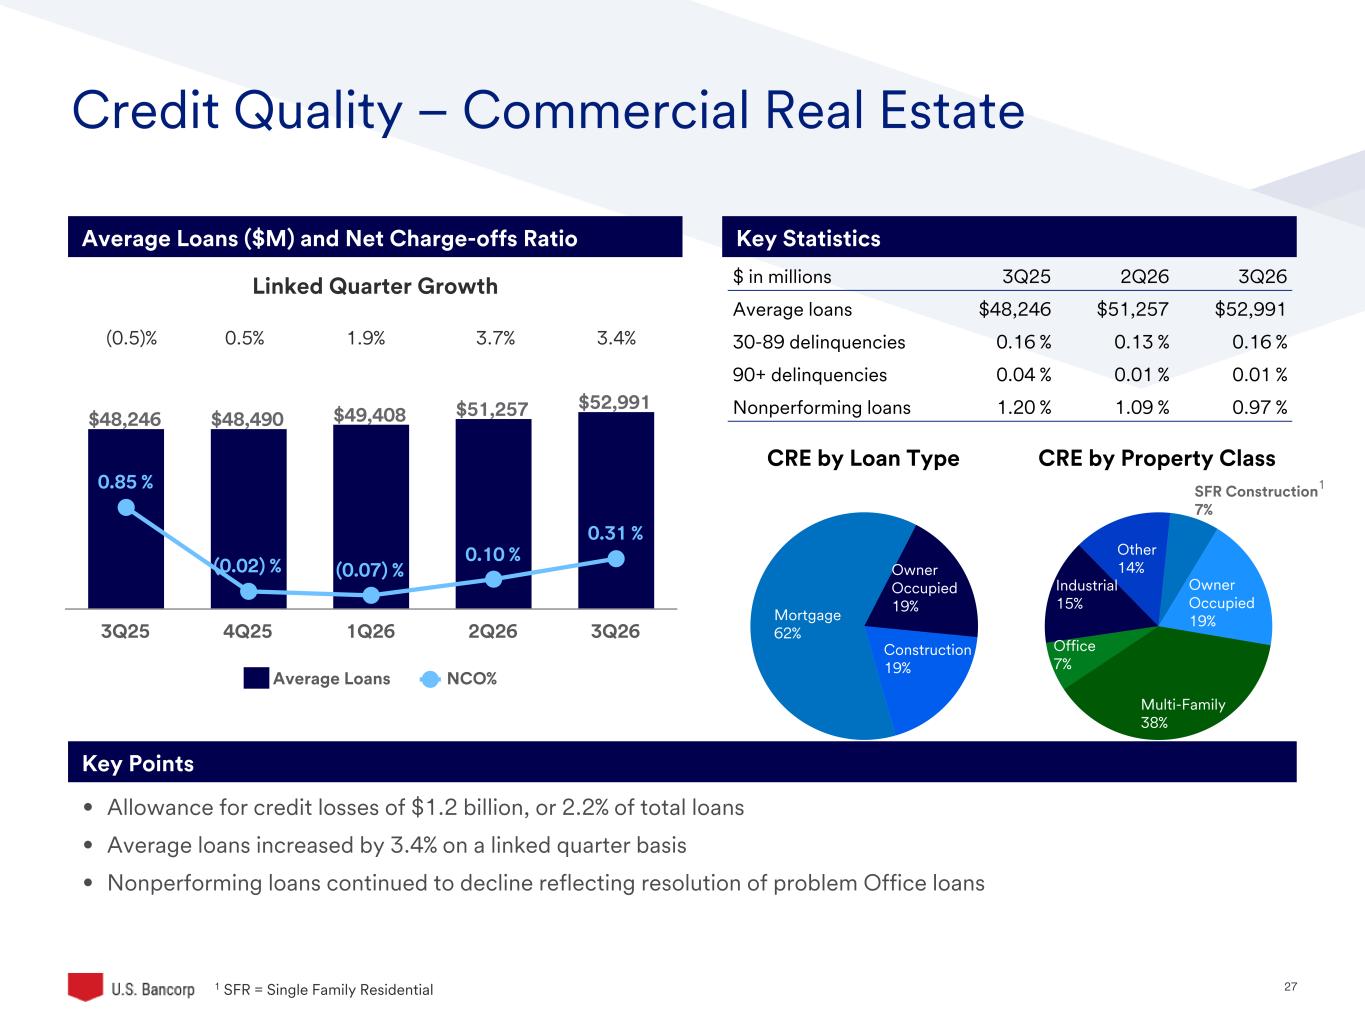
27©2025 U.S. Bank | Confidential CRE by Loan Type Mortgage 62% Owner Occupied 19% Construction 19% Credit Quality – Commercial Real Estate Key Points Average Loans ($M) and Net Charge-offs Ratio Key Statistics Linked Quarter Growth (0.5)% 0.5% 1.9% 3.7% 3.4% • Allowance for credit losses of $1.2 billion, or 2.2% of total loans • Average loans increased by 3.4% on a linked quarter basis • Nonperforming loans continued to decline reflecting resolution of problem Office loans $48,246 $48,490 $49,408 $51,257 $52,991 0.85 % (0.02) % (0.07) % 0.10 % 0.31 % Average Loans NCO% 3Q25 4Q25 1Q26 2Q26 3Q26 CRE by Property Class SFR Construction 7% Owner Occupied 19% Multi-Family 38% Office 7% Industrial 15% Other 14% $ in millions 3Q25 2Q26 3Q26 Average loans $48,246 $51,257 $52,991 30-89 delinquencies 0.16 % 0.13 % 0.16 % 90+ delinquencies 0.04 % 0.01 % 0.01 % Nonperforming loans 1.20 % 1.09 % 0.97 % 1 1 SFR = Si gle Family Residential
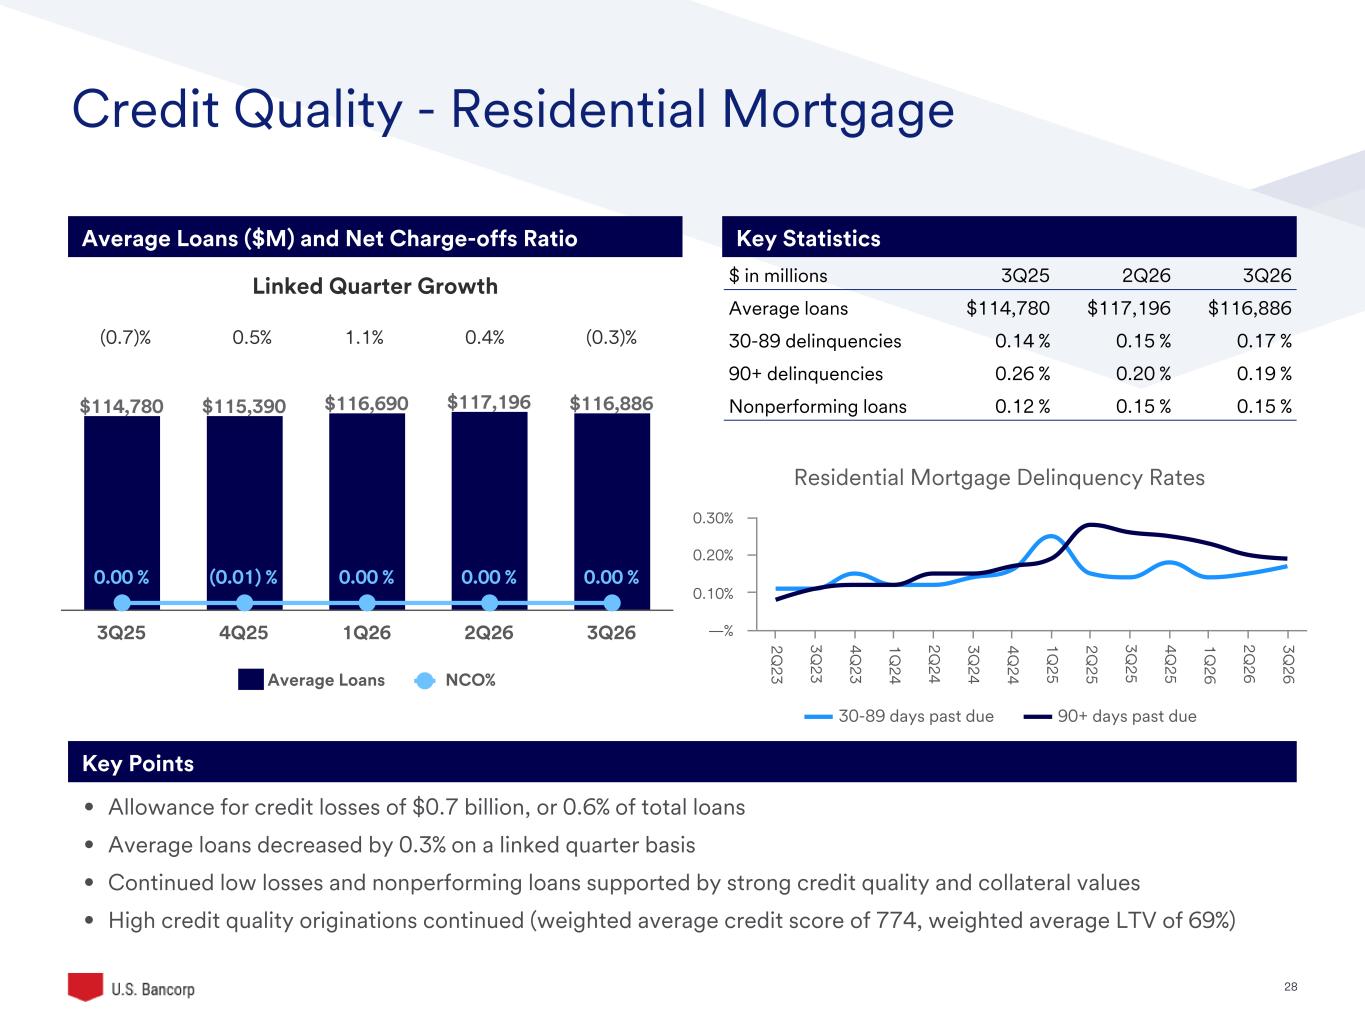
28©2025 U.S. Bank | Confidential Credit Quality - Residential Mortgage $114,780 $115,390 $116,690 $117,196 $116,886 0.00 % (0.01) % 0.00 % 0.00 % 0.00 % Average Loans NCO% 3Q25 4Q25 1Q26 2Q26 3Q26 Key Points • Allowance for credit losses of $0.7 billion, or 0.6% of total loans • Average loans decreased by 0.3% on a linked quarter basis • Continued low losses and nonperforming loans supported by strong credit quality and collateral values • High credit quality originations continued (weighted average credit score of 774, weighted average LTV of 69%) Linked Quarter Growth Average Loans ($M) and Net Charge-offs Ratio Key Statistics $ in millions 3Q25 2Q26 3Q26 Average loans $114,780 $117,196 $116,886 30-89 delinquencies 0.14 % 0.15 % 0.17 % 90+ delinquencies 0.26 % 0.20 % 0.19 % Nonperforming loans 0.12 % 0.15 % 0.15 % (0.7)% 0.5% 1.1% 0.4% (0.3)% Residential Mortgage Delinquency Rates 30-89 days past due 90+ days past due 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 2Q 25 3Q 25 4Q 25 1Q 26 2Q 26 3Q 26 —% 0.10% 0.20% 0.30%
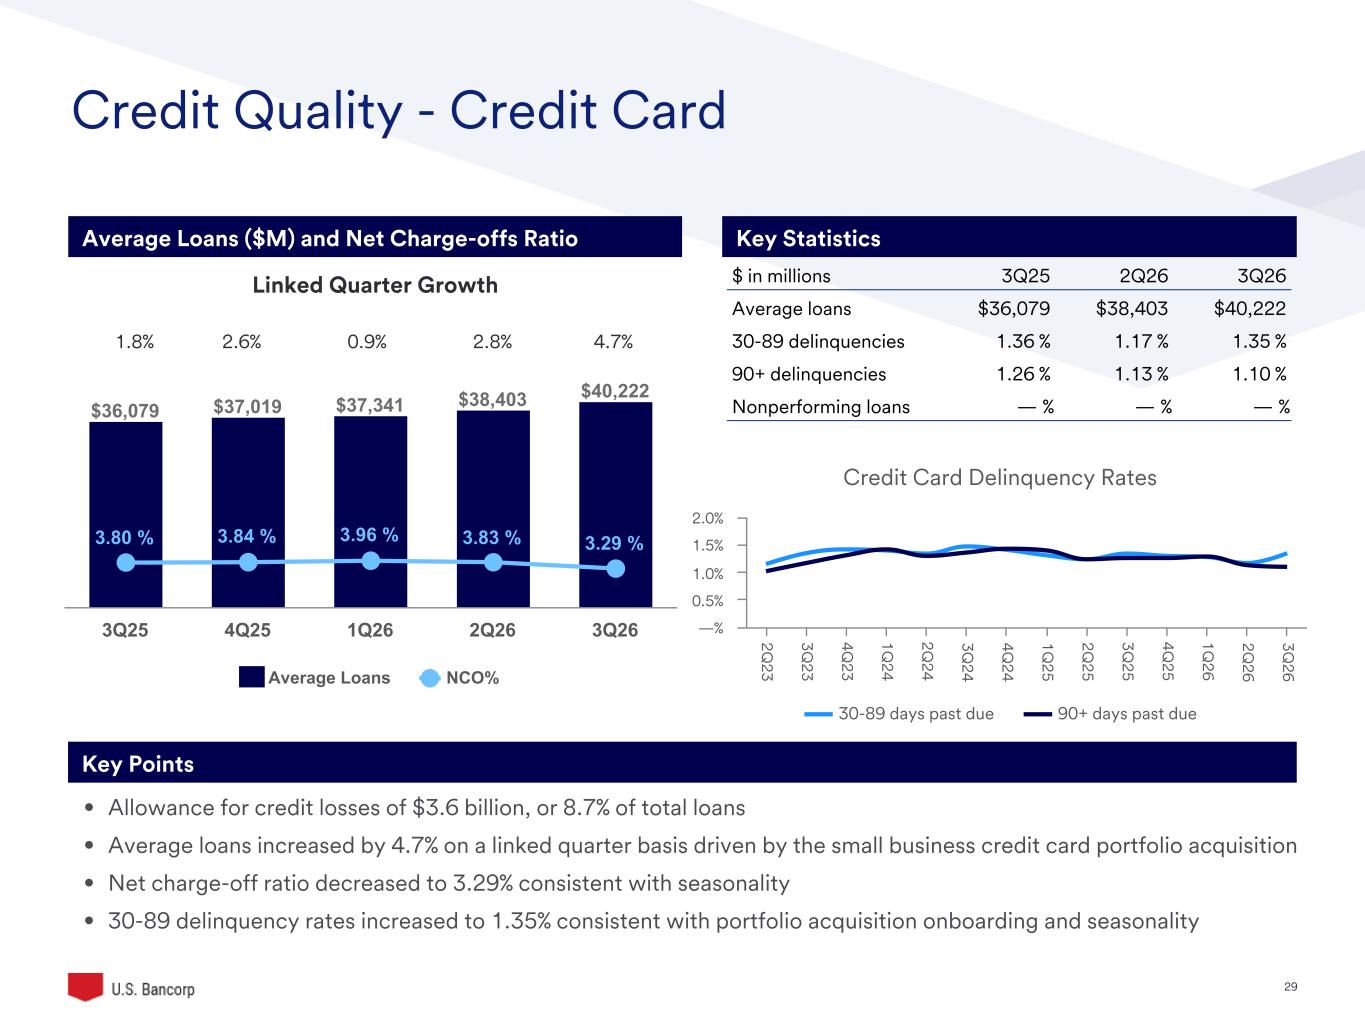
29©2025 U.S. Bank | Confidential Credit Quality - Credit Card $36,079 $37,019 $37,341 $38,403 $40,222 3.80 % 3.84 % 3.96 % 3.83 % 3.29 % Average Loans NCO% 3Q25 4Q25 1Q26 2Q26 3Q26 Key Points • Allowance for credit losses of $3.6 billion, or 8.7% of total loans • Average loans increased by 4.7% on a linked quarter basis driven by the small business credit card portfolio acquisition • Net charge-off ratio decreased to 3.29% consistent with seasonality • 30-89 delinquency rates increased to 1.35% consistent with portfolio acquisition onboarding and seasonality Average Loans ($M) and Net Charge-offs Ratio Key Statistics 1.8% 2.6% 0.9% 2.8% 4.7% Linked Quarter Growth $ in millions 3Q25 2Q26 3Q26 Average loans $36,079 $38,403 $40,222 30-89 delinquencies 1.36 % 1.17 % 1.35 % 90+ delinquencies 1.26 % 1.13 % 1.10 % Nonperforming loans — % — % — % Credit Card Delinquency Rates 30-89 days past due 90+ days past due 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 2Q 25 3Q 25 4Q 25 1Q 26 2Q 26 3Q 26 —% 0.5% 1.0% 1.5% 2.0%
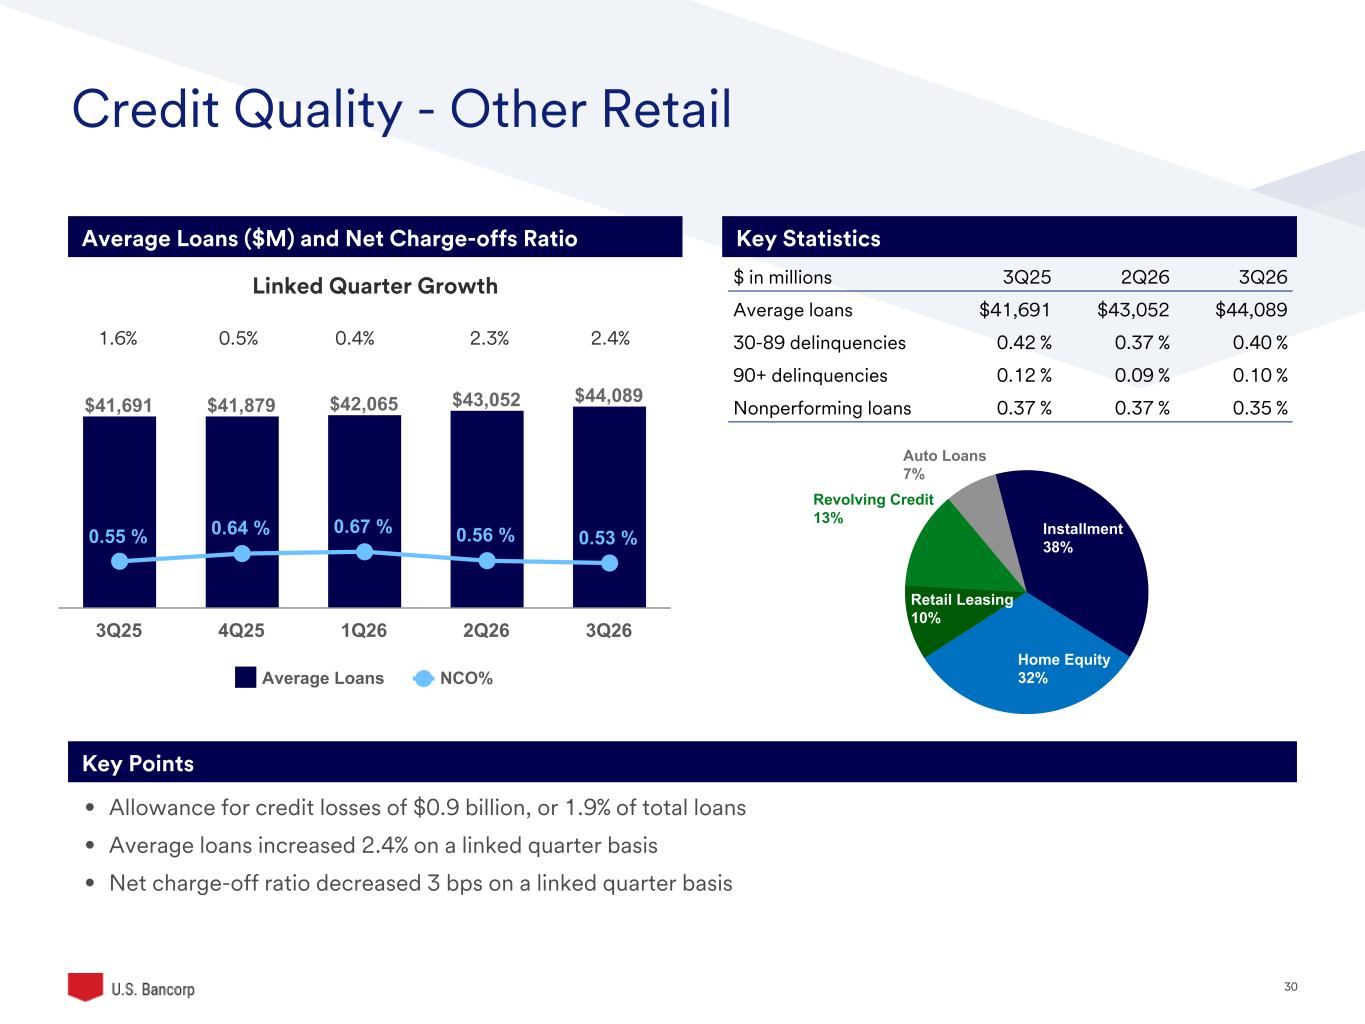
30©2025 U.S. Bank | Confidential Credit Quality - Other Retail Key Points • Allowance for credit losses of $0.9 billion, or 1.9% of total loans • Average loans increased 2.4% on a linked quarter basis • Net charge-off ratio decreased 3 bps on a linked quarter basis Average Loans ($M) and Net Charge-offs Ratio Key Statistics Linked Quarter Growth 1.6% 0.5% 0.4% 2.3% 2.4% $41,691 $41,879 $42,065 $43,052 $44,089 0.55 % 0.64 % 0.67 % 0.56 % 0.53 % Average Loans NCO% 3Q25 4Q25 1Q26 2Q26 3Q26 Auto Loans 7% Installment 38% Home Equity 32% Retail Leasing 10% Revolving Credit 13% $ in millions 3Q25 2Q26 3Q26 Average loans $41,691 $43,052 $44,089 30-89 delinquencies 0.42 % 0.37 % 0.40 % 90+ delinquencies 0.12 % 0.09 % 0.10 % Nonperforming loans 0.37 % 0.37 % 0.35 %
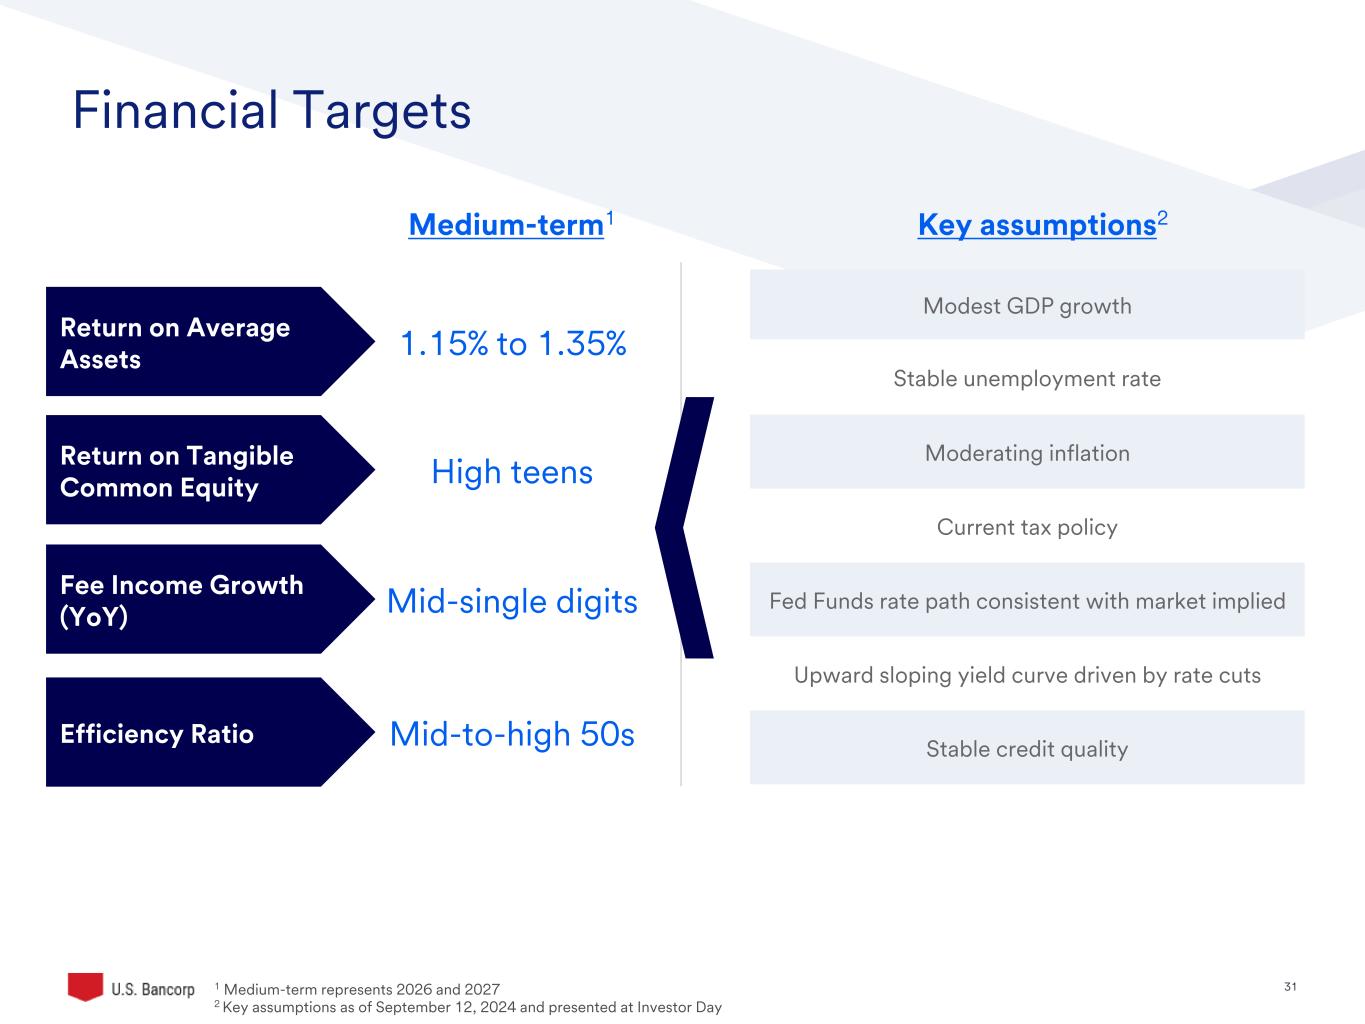
31©2025 U.S. Bank | Confidential Financial Targets Return on Average Assets Return on Tangible Common Equity Fee Income Growth (YoY) Efficiency Ratio 1.15% to 1.35% High teens Mid-single digits Mid-to-high 50s Medium-term1 Key assumptions2 Modest GDP growth Stable unemployment rate Moderating inflation Current tax policy Fed Funds rate path consistent with market implied Upward sloping yield curve driven by rate cuts Stable credit quality 1 Medium- erm represents 2026 and 2027 2 Key assumptions as of September 12, 2024 and presented at Investor Day
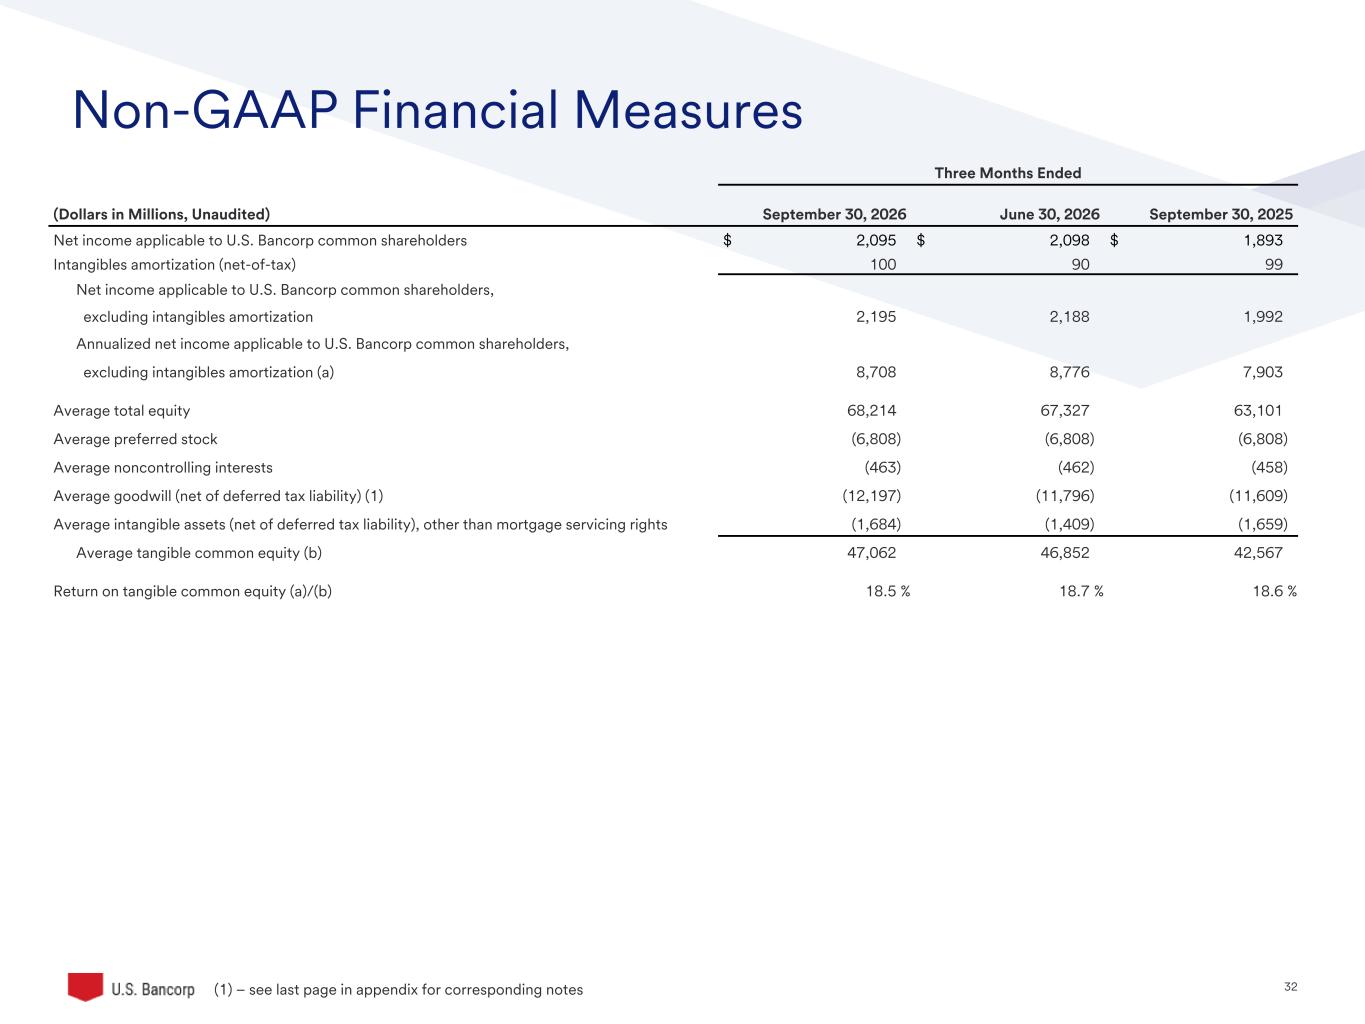
32©2025 U.S. Bank | Confidential Non-GAAP Financial Measures Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 June 30, 2026 September 30, 2025 Net income applicable to U.S. Bancorp common shareholders $ 2,095 $ 2,098 $ 1,893 Intangibles amortization (net-of-tax) 100 90 99 Net income applicable to U.S. Bancorp common shareholders, excluding intangibles amortization 2,195 2,188 1,992 Annualized net income applicable to U.S. Bancorp common shareholders, excluding intangibles amortization (a) 8,708 8,776 7,903 Average total equity 68,214 67,327 63,101 Average preferred stock (6,808) (6,808) (6,808) Average noncontrolling interests (463) (462) (458) Average goodwill (net of deferred tax liability) (1) (12,197) (11,796) (11,609) Average intangible assets (net of deferred tax liability), other than mortgage servicing rights (1,684) (1,409) (1,659) Average tangible common equity (b) 47,062 46,852 42,567 Return on tangible common equity (a)/(b) 18.5 % 18.7 % 18.6 % (1) – see last page in appendix for corresponding notes
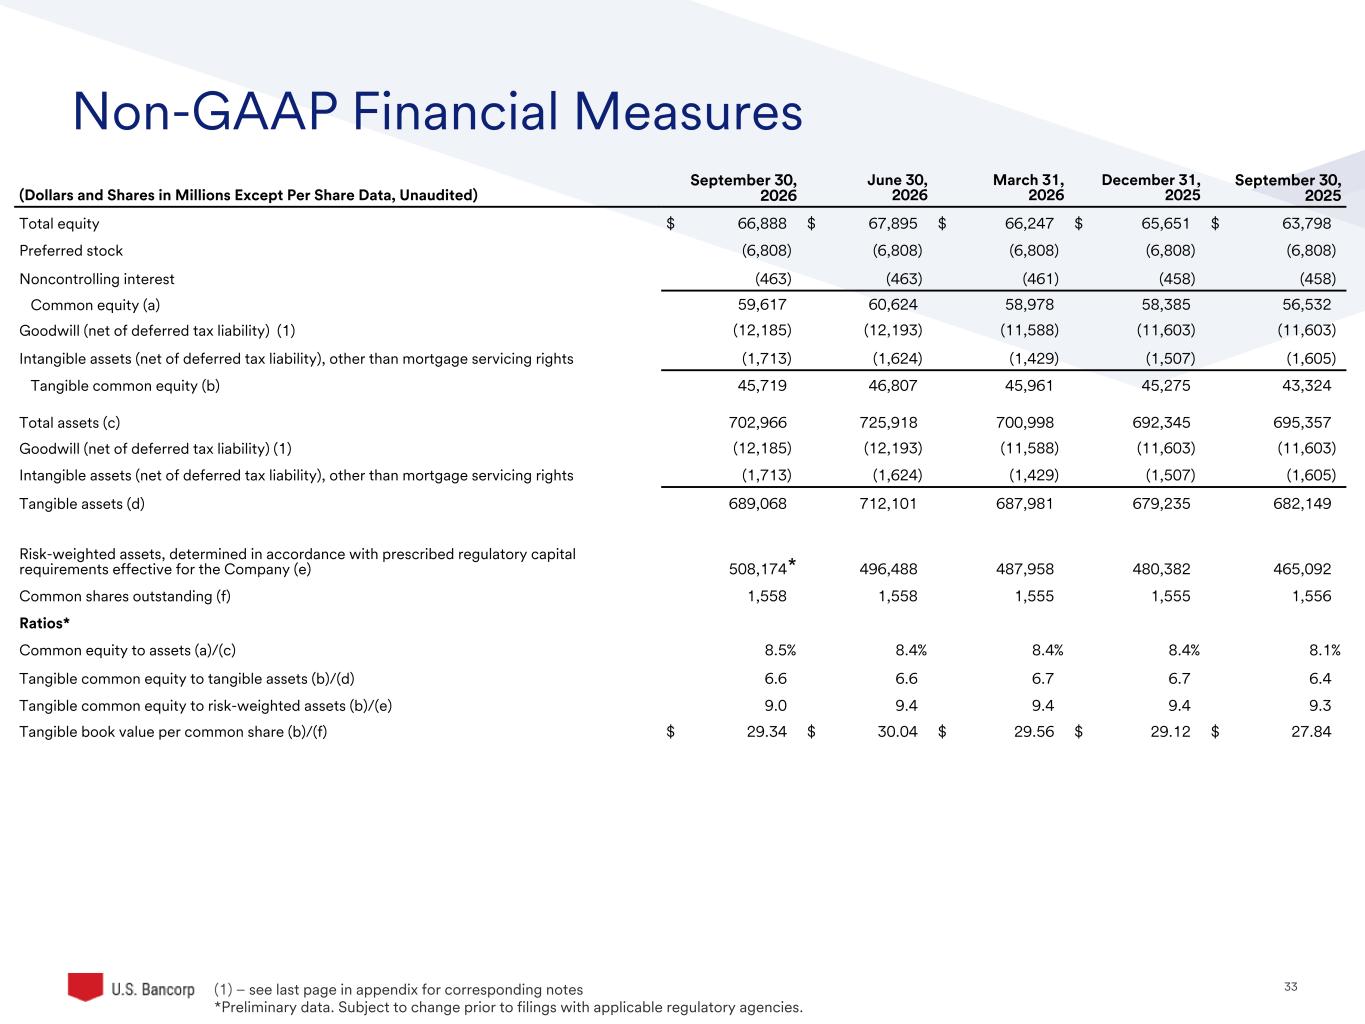
33©2025 U.S. Bank | Confidential Non-GAAP Financial Measures (Dollars and Shares in Millions Except Per Share Data, Unaudited) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Total equity $ 66,888 $ 67,895 $ 66,247 $ 65,651 $ 63,798 Preferred stock (6,808) (6,808) (6,808) (6,808) (6,808) Noncontrolling interest (463) (463) (461) (458) (458) Common equity (a) 59,617 60,624 58,978 58,385 56,532 Goodwill (net of deferred tax liability) (1) (12,185) (12,193) (11,588) (11,603) (11,603) Intangible assets (net of deferred tax liability), other than mortgage servicing rights (1,713) (1,624) (1,429) (1,507) (1,605) Tangible common equity (b) 45,719 46,807 45,961 45,275 43,324 Total assets (c) 702,966 725,918 700,998 692,345 695,357 Goodwill (net of deferred tax liability) (1) (12,185) (12,193) (11,588) (11,603) (11,603) Intangible assets (net of deferred tax liability), other than mortgage servicing rights (1,713) (1,624) (1,429) (1,507) (1,605) Tangible assets (d) 689,068 712,101 687,981 679,235 682,149 Risk-weighted assets, determined in accordance with prescribed regulatory capital requirements effective for the Company (e) 508,174 496,488 487,958 480,382 465,092 Common shares outstanding (f) 1,558 1,558 1,555 1,555 1,556 Ratios* Common equity to assets (a)/(c) 8.5% 8.4% 8.4% 8.4% 8.1% Tangible common equity to tangible assets (b)/(d) 6.6 6.6 6.7 6.7 6.4 Tangible common equity to risk-weighted assets (b)/(e) 9.0 9.4 9.4 9.4 9.3 Tangible book value per common share (b)/(f) $ 29.34 $ 30.04 $ 29.56 $ 29.12 $ 27.84 * (1) – see last page in appendix for corresponding notes *Preliminary data. Subject to change prior to filings with applicable regulatory agencies.
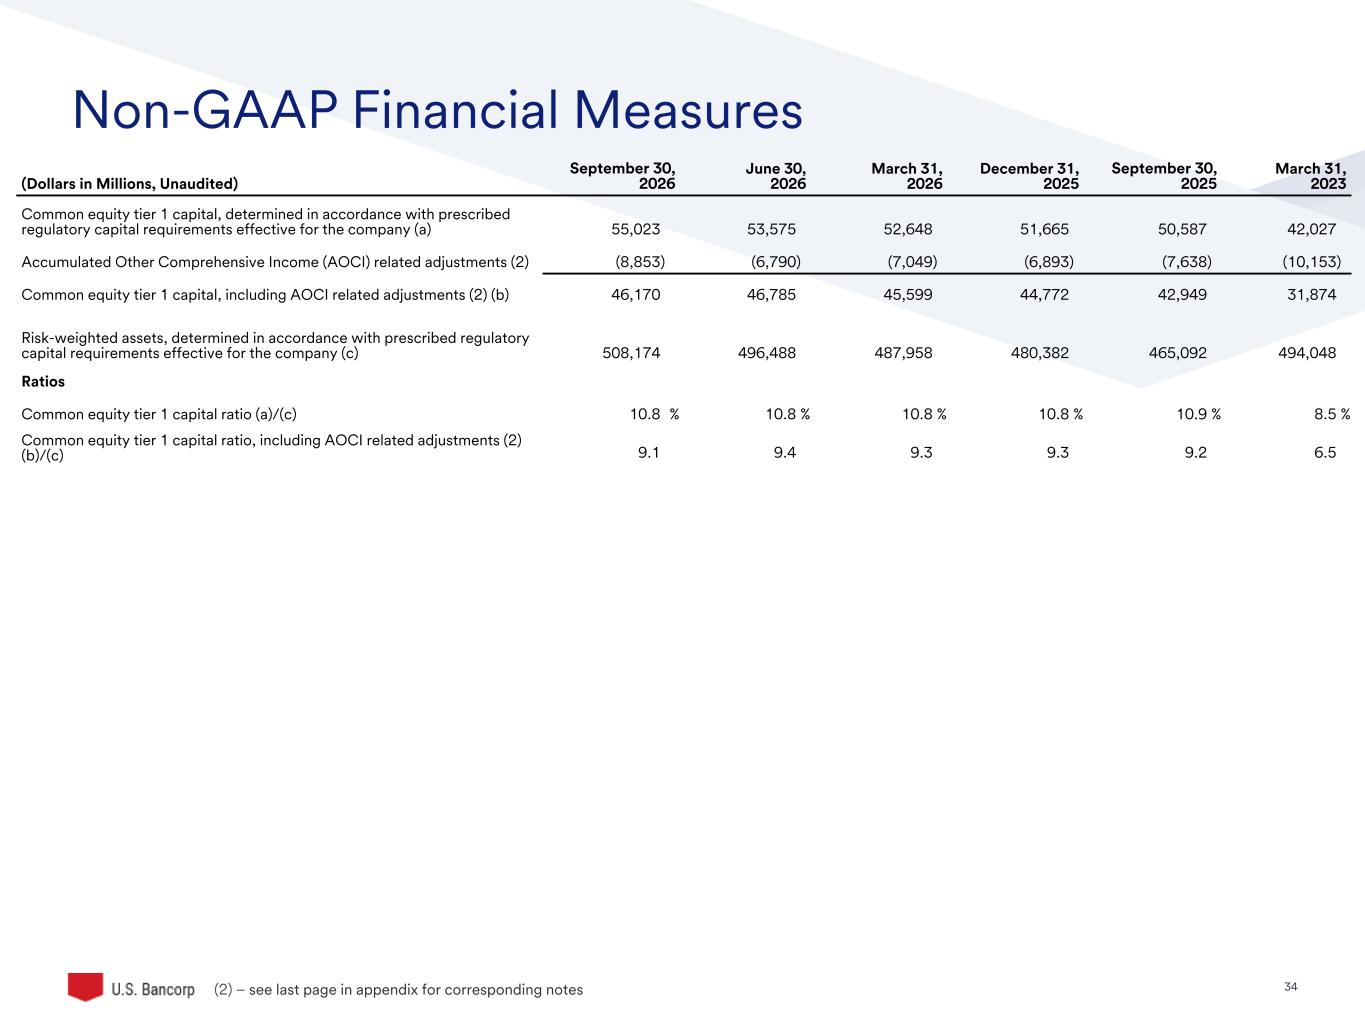
34©2025 U.S. Bank | Confidential Non-GAAP Financial Measures (Dollars in Millions, Unaudited) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 March 31, 2023 Common equity tier 1 capital, determined in accordance with prescribed regulatory capital requirements effective for the company (a) 55,023 53,575 52,648 51,665 50,587 42,027 Accumulated Other Comprehensive Income (AOCI) related adjustments (2) (8,853) (6,790) (7,049) (6,893) (7,638) (10,153) Common equity tier 1 capital, including AOCI related adjustments (2) (b) 46,170 46,785 45,599 44,772 42,949 31,874 Risk-weighted assets, determined in accordance with prescribed regulatory capital requirements effective for the company (c) 508,174 496,488 487,958 480,382 465,092 494,048 Ratios Common equity tier 1 capital ratio (a)/(c) 10.8 % 10.8 % 10.8 % 10.8 % 10.9 % 8.5 % Common equity tier 1 capital ratio, including AOCI related adjustments (2) (b)/(c) 9.1 9.4 9.3 9.3 9.2 6.5 (2) – see last page in appendix for corresponding notes
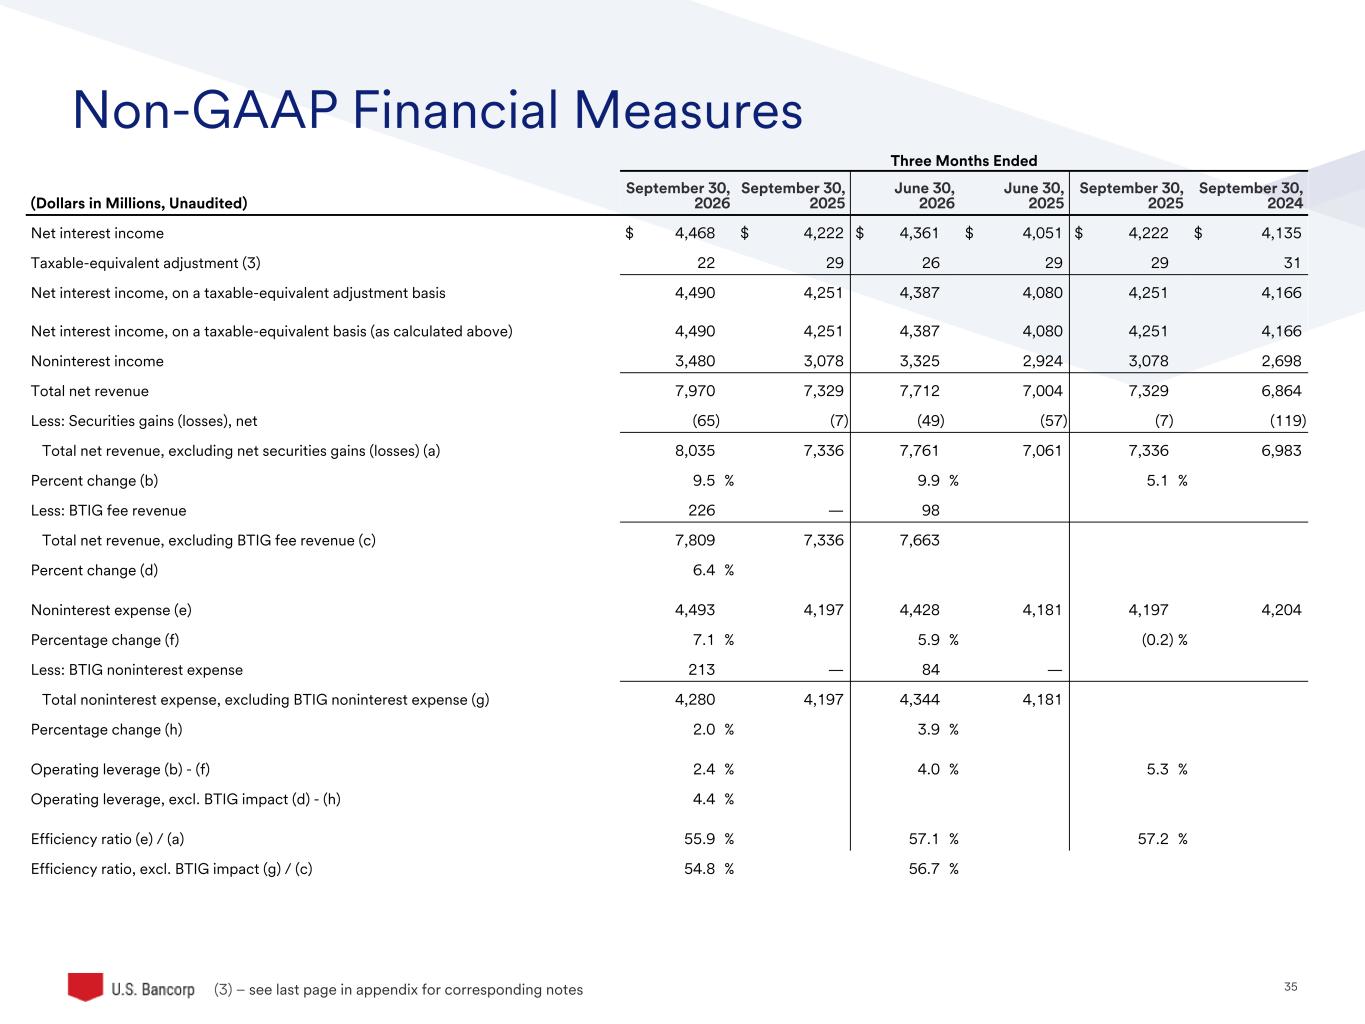
35©2025 U.S. Bank | Confidential Non-GAAP Financial Measures Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 September 30, 2025 June 30, 2026 June 30, 2025 September 30, 2025 September 30, 2024 Net interest income $ 4,468 $ 4,222 $ 4,361 $ 4,051 $ 4,222 $ 4,135 Taxable-equivalent adjustment (3) 22 29 26 29 29 31 Net interest income, on a taxable-equivalent adjustment basis 4,490 4,251 4,387 4,080 4,251 4,166 Net interest income, on a taxable-equivalent basis (as calculated above) 4,490 4,251 4,387 4,080 4,251 4,166 Noninterest income 3,480 3,078 3,325 2,924 3,078 2,698 Total net revenue 7,970 7,329 7,712 7,004 7,329 6,864 Less: Securities gains (losses), net (65) (7) (49) (57) (7) (119) Total net revenue, excluding net securities gains (losses) (a) 8,035 7,336 7,761 7,061 7,336 6,983 Percent change (b) 9.5 % 9.9 % 5.1 % Less: BTIG fee revenue 226 — 98 Total net revenue, excluding BTIG fee revenue (c) 7,809 7,336 7,663 Percent change (d) 6.4 % Noninterest expense (e) 4,493 4,197 4,428 4,181 4,197 4,204 Percentage change (f) 7.1 % 5.9 % (0.2) % Less: BTIG noninterest expense 213 — 84 — Total noninterest expense, excluding BTIG noninterest expense (g) 4,280 4,197 4,344 4,181 Percentage change (h) 2.0 % 3.9 % Operating leverage (b) - (f) 2.4 % 4.0 % 5.3 % Operating leverage, excl. BTIG impact (d) - (h) 4.4 % Efficiency ratio (e) / (a) 55.9 % 57.1 % 57.2 % Efficiency ratio, excl. BTIG impact (g) / (c) 54.8 % 56.7 % (3) – see last page in appendix for corresponding notes
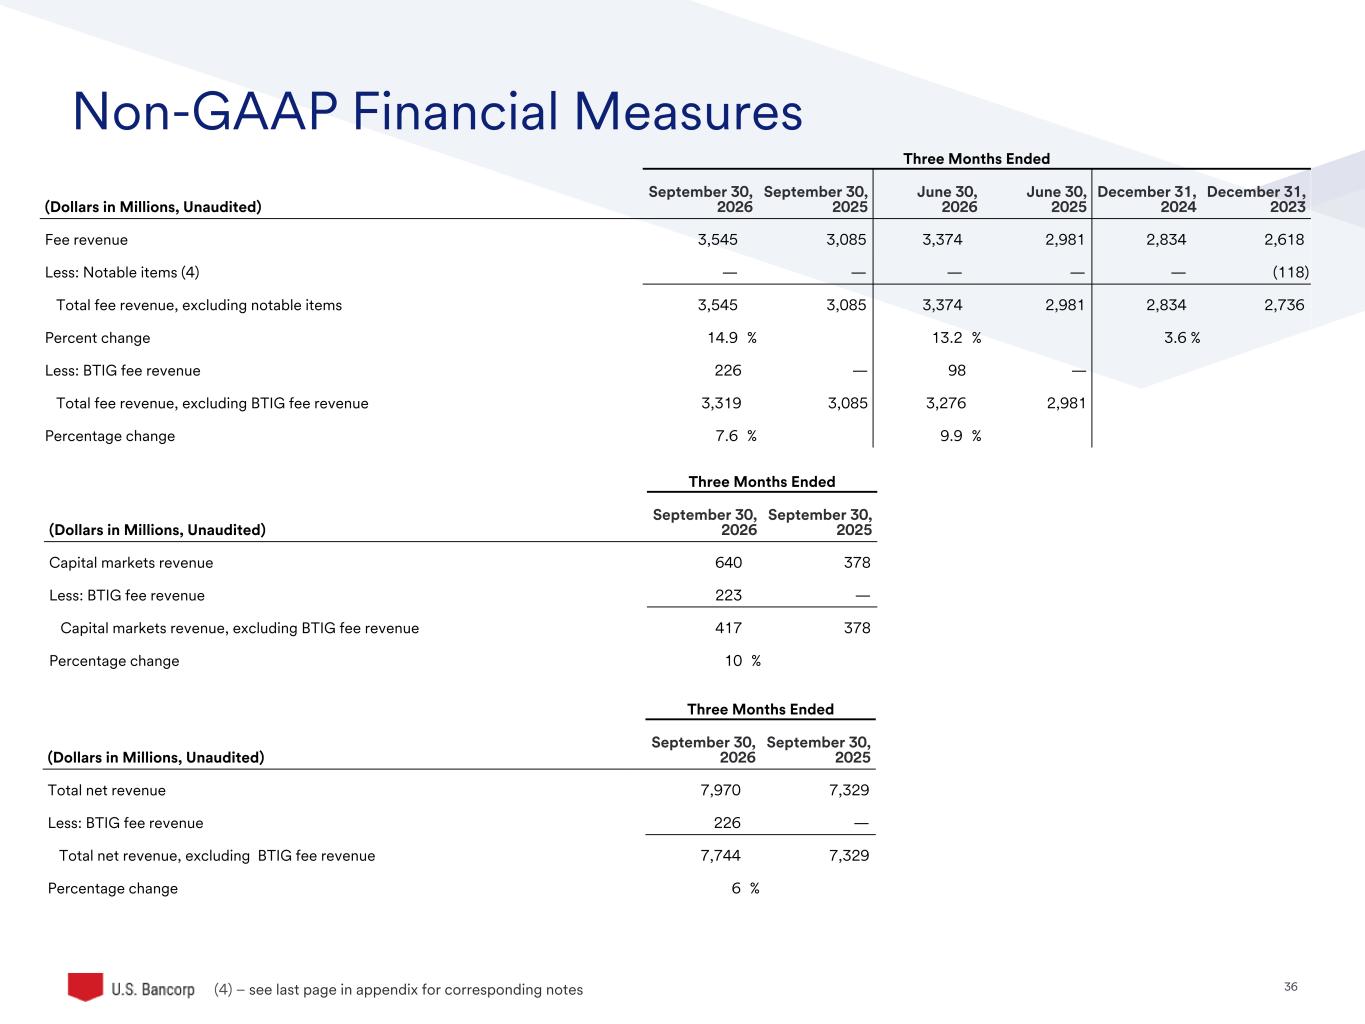
36©2025 U.S. Bank | Confidential Non-GAAP Financial Measures Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 September 30, 2025 June 30, 2026 June 30, 2025 December 31, 2024 December 31, 2023 Fee revenue 3,545 3,085 3,374 2,981 2,834 2,618 Less: Notable items (4) — — — — — (118) Total fee revenue, excluding notable items 3,545 3,085 3,374 2,981 2,834 2,736 Percent change 14.9 % 13.2 % 3.6 % Less: BTIG fee revenue 226 — 98 — Total fee revenue, excluding BTIG fee revenue 3,319 3,085 3,276 2,981 Percentage change 7.6 % 9.9 % (4) – see last page in appendix for corresponding notes Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 September 30, 2025 Capital markets revenue 640 378 Less: BTIG fee revenue 223 — Capital markets revenue, excluding BTIG fee revenue 417 378 Percentage change 10 % Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 September 30, 2025 Total net revenue 7,970 7,329 Less: BTIG fee revenue 226 — Total net revenue, excluding BTIG fee revenue 7,744 7,329 Percentage change 6 %
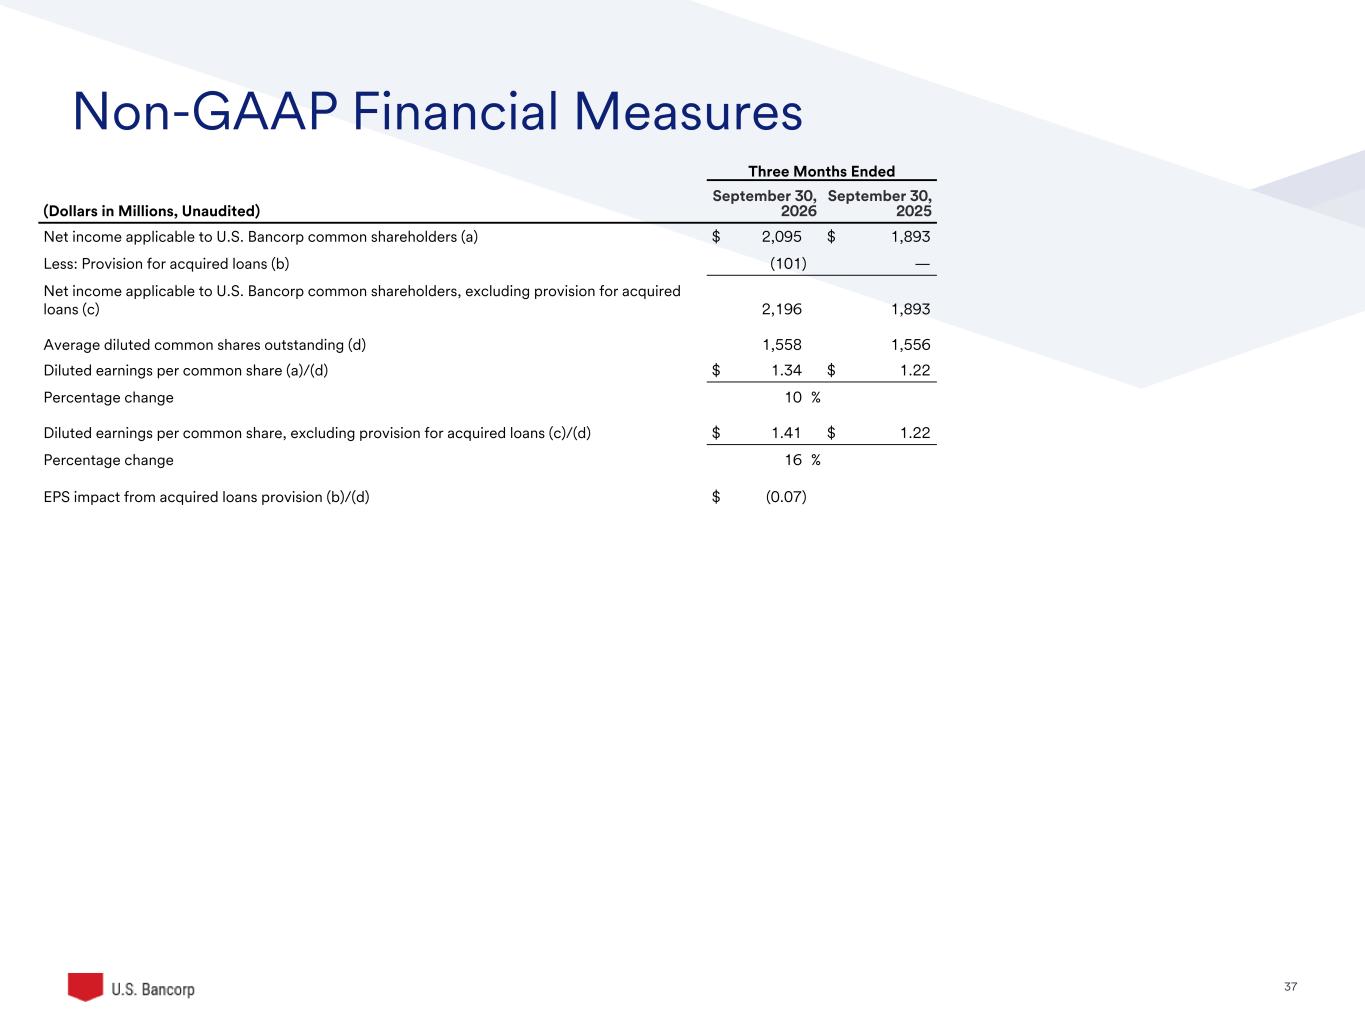
37 Non-GAAP Financial Measures Three Months Ended (Dollars in Millions, Unaudited) September 30, 2026 September 30, 2025 Net income applicable to U.S. Bancorp common shareholders (a) $ 2,095 $ 1,893 Less: Provision for acquired loans (b) (101) — Net income applicable to U.S. Bancorp common shareholders, excluding provision for acquired loans (c) 2,196 1,893 Average diluted common shares outstanding (d) 1,558 1,556 Diluted earnings per common share (a)/(d) $ 1.34 $ 1.22 Percentage change 10 % Diluted earnings per common share, excluding provision for acquired loans (c)/(d) $ 1.41 $ 1.22 Percentage change 16 % EPS impact from acquired loans provision (b)/(d) $ (0.07)
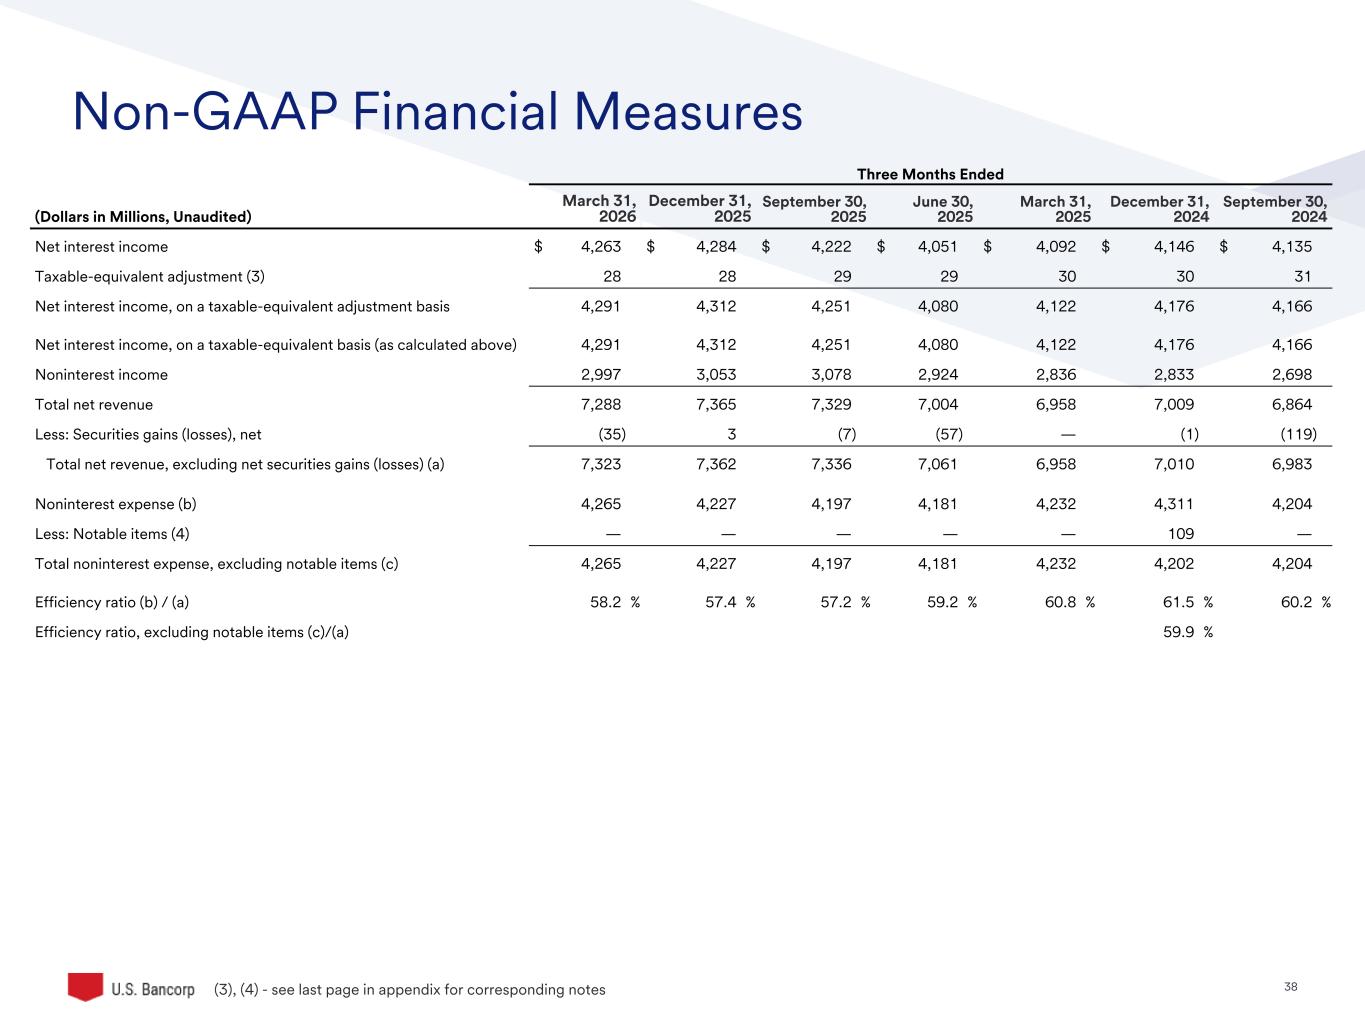
38©2025 U.S. Bank | Confidential Non-GAAP Financial Measures (3), (4) - see last page in appendix for corresponding notes Three Months Ended (Dollars in Millions, Unaudited) March 31, 2026 December 31, 2025 September 30, 2025 June 30, 2025 March 31, 2025 December 31, 2024 September 30, 2024 Net interest income $ 4,263 $ 4,284 $ 4,222 $ 4,051 $ 4,092 $ 4,146 $ 4,135 Taxable-equivalent adjustment (3) 28 28 29 29 30 30 31 Net interest income, on a taxable-equivalent adjustment basis 4,291 4,312 4,251 4,080 4,122 4,176 4,166 Net interest income, on a taxable-equivalent basis (as calculated above) 4,291 4,312 4,251 4,080 4,122 4,176 4,166 Noninterest income 2,997 3,053 3,078 2,924 2,836 2,833 2,698 Total net revenue 7,288 7,365 7,329 7,004 6,958 7,009 6,864 Less: Securities gains (losses), net (35) 3 (7) (57) — (1) (119) Total net revenue, excluding net securities gains (losses) (a) 7,323 7,362 7,336 7,061 6,958 7,010 6,983 Noninterest expense (b) 4,265 4,227 4,197 4,181 4,232 4,311 4,204 Less: Notable items (4) — — — — — 109 — Total noninterest expense, excluding notable items (c) 4,265 4,227 4,197 4,181 4,232 4,202 4,204 Efficiency ratio (b) / (a) 58.2 % 57.4 % 57.2 % 59.2 % 60.8 % 61.5 % 60.2 % Efficiency ratio, excluding notable items (c)/(a) 59.9 %
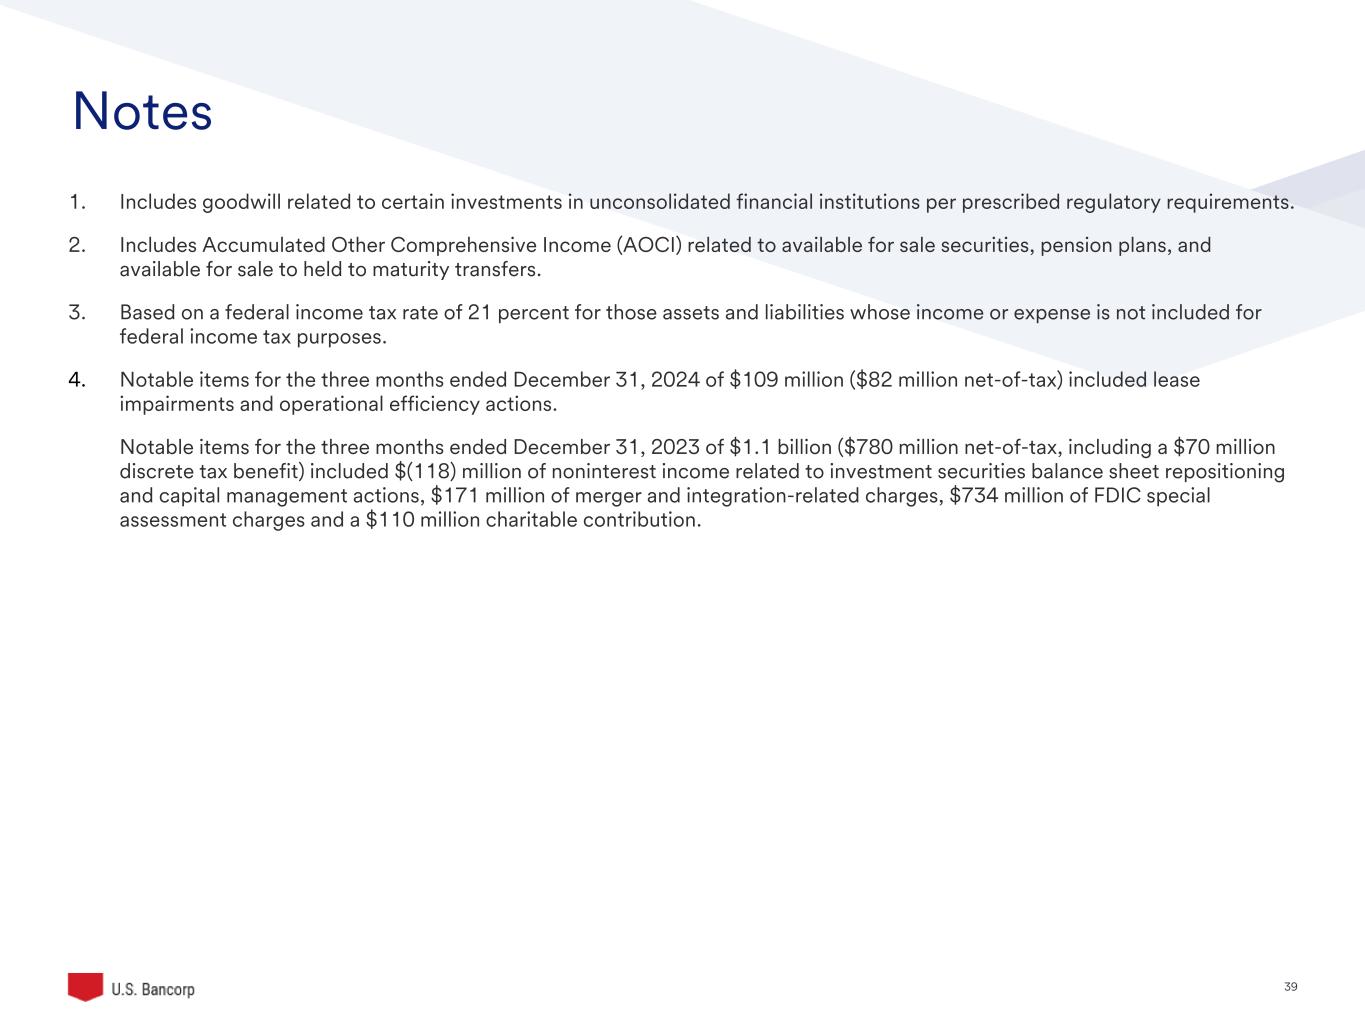
39©2025 U.S. Bank | Confidential Notes 1. Includes goodwill related to certain investments in unconsolidated financial institutions per prescribed regulatory requirements. 2. Includes Accumulated Other Comprehensive Income (AOCI) related to available for sale securities, pension plans, and available for sale to held to maturity transfers. 3. Based on a federal income tax rate of 21 percent for those assets and liabilities whose income or expense is not included for federal income tax purposes. 4. Notable items for the three months ended December 31, 2024 of $109 million ($82 million net-of-tax) included lease impairments and operational efficiency actions. Notable items for the three months ended December 31, 2023 of $1.1 billion ($780 million net-of-tax, including a $70 million discrete tax benefit) included $(118) million of noninterest income related to investment securities balance sheet repositioning and capital management actions, $171 million of merger and integration-related charges, $734 million of FDIC special assessment charges and a $110 million charitable contribution.
40©2025 U.S. Bank | Confidential Thank you