Third Quarter Results October 15, 2026 Exhibit 99.2
FORWARD-LOOKING STATEMENT This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Exchange Act of 1934, as amended, including statements regarding economic and geopolitical uncertainty, including uncertainty regarding trade policy developments, trends in labor demand and the future strengthening of such demand, the impact of AI on labor markets, financial outlook, outlook for our business in the regions in which we operate as well as key countries within those regions, the Company’s strategic initiatives and technology investments, including transformation programs and the use of AI to drive innovation, the ability of our PowerSuite platform to develop and deploy our AI capabilities at scale, and the positioning of future growth for our brands, that are forward-looking in nature and, accordingly, are subject to risks and uncertainties. The Company’s actual results may differ materially from those described or contemplated in the forward-looking statements due to numerous factors. These factors include those found in the Company’s reports filed with the SEC, including the information under the heading “Risk Factors” in its Annual Report on Form 10-K for the year ended December 31, 2025, which information is incorporated herein by reference. We caution that any forward-looking statement reflects only our belief at the time the statement is made. The Company assumes no obligation to update or revise any forward-looking statements. We reference certain non-GAAP financial measures, which we believe provide useful information for investors. We include a reconciliation of these measures, where appropriate, to GAAP on the Investor Relations section of our website at manpowergroup.com.
Third Quarter Highlights Momentum broadened across brands. Manpower delivered strong revenue growth driven by the U.S., Experis seeing improving trends and returned to growth in the U.S. representing a key milestone, and Talent Solutions growth improved sequentially in Q3. Continued business momentum. SG&A leverage improved year-over-year reflecting continued cost discipline. Year-to-date performance and expectations for Q4 reinforce 2026 as an inflection point. Delivered strong results, with ongoing revenue momentum in the quarter driving continued operating leverage. Performance reflects continued demand improvements, consistent execution, and benefits of the strategic actions taken. Global strategic transformation program progressing as planned, expanding to the U.K in Q3. Remain on track to deliver $200M cost savings target in 2028. Advanced AI strategy. Expanding AI-enabled talent screening to improve the candidate experience. Building go-to-market partnerships that combine technology, talent and services to deliver greater client value.
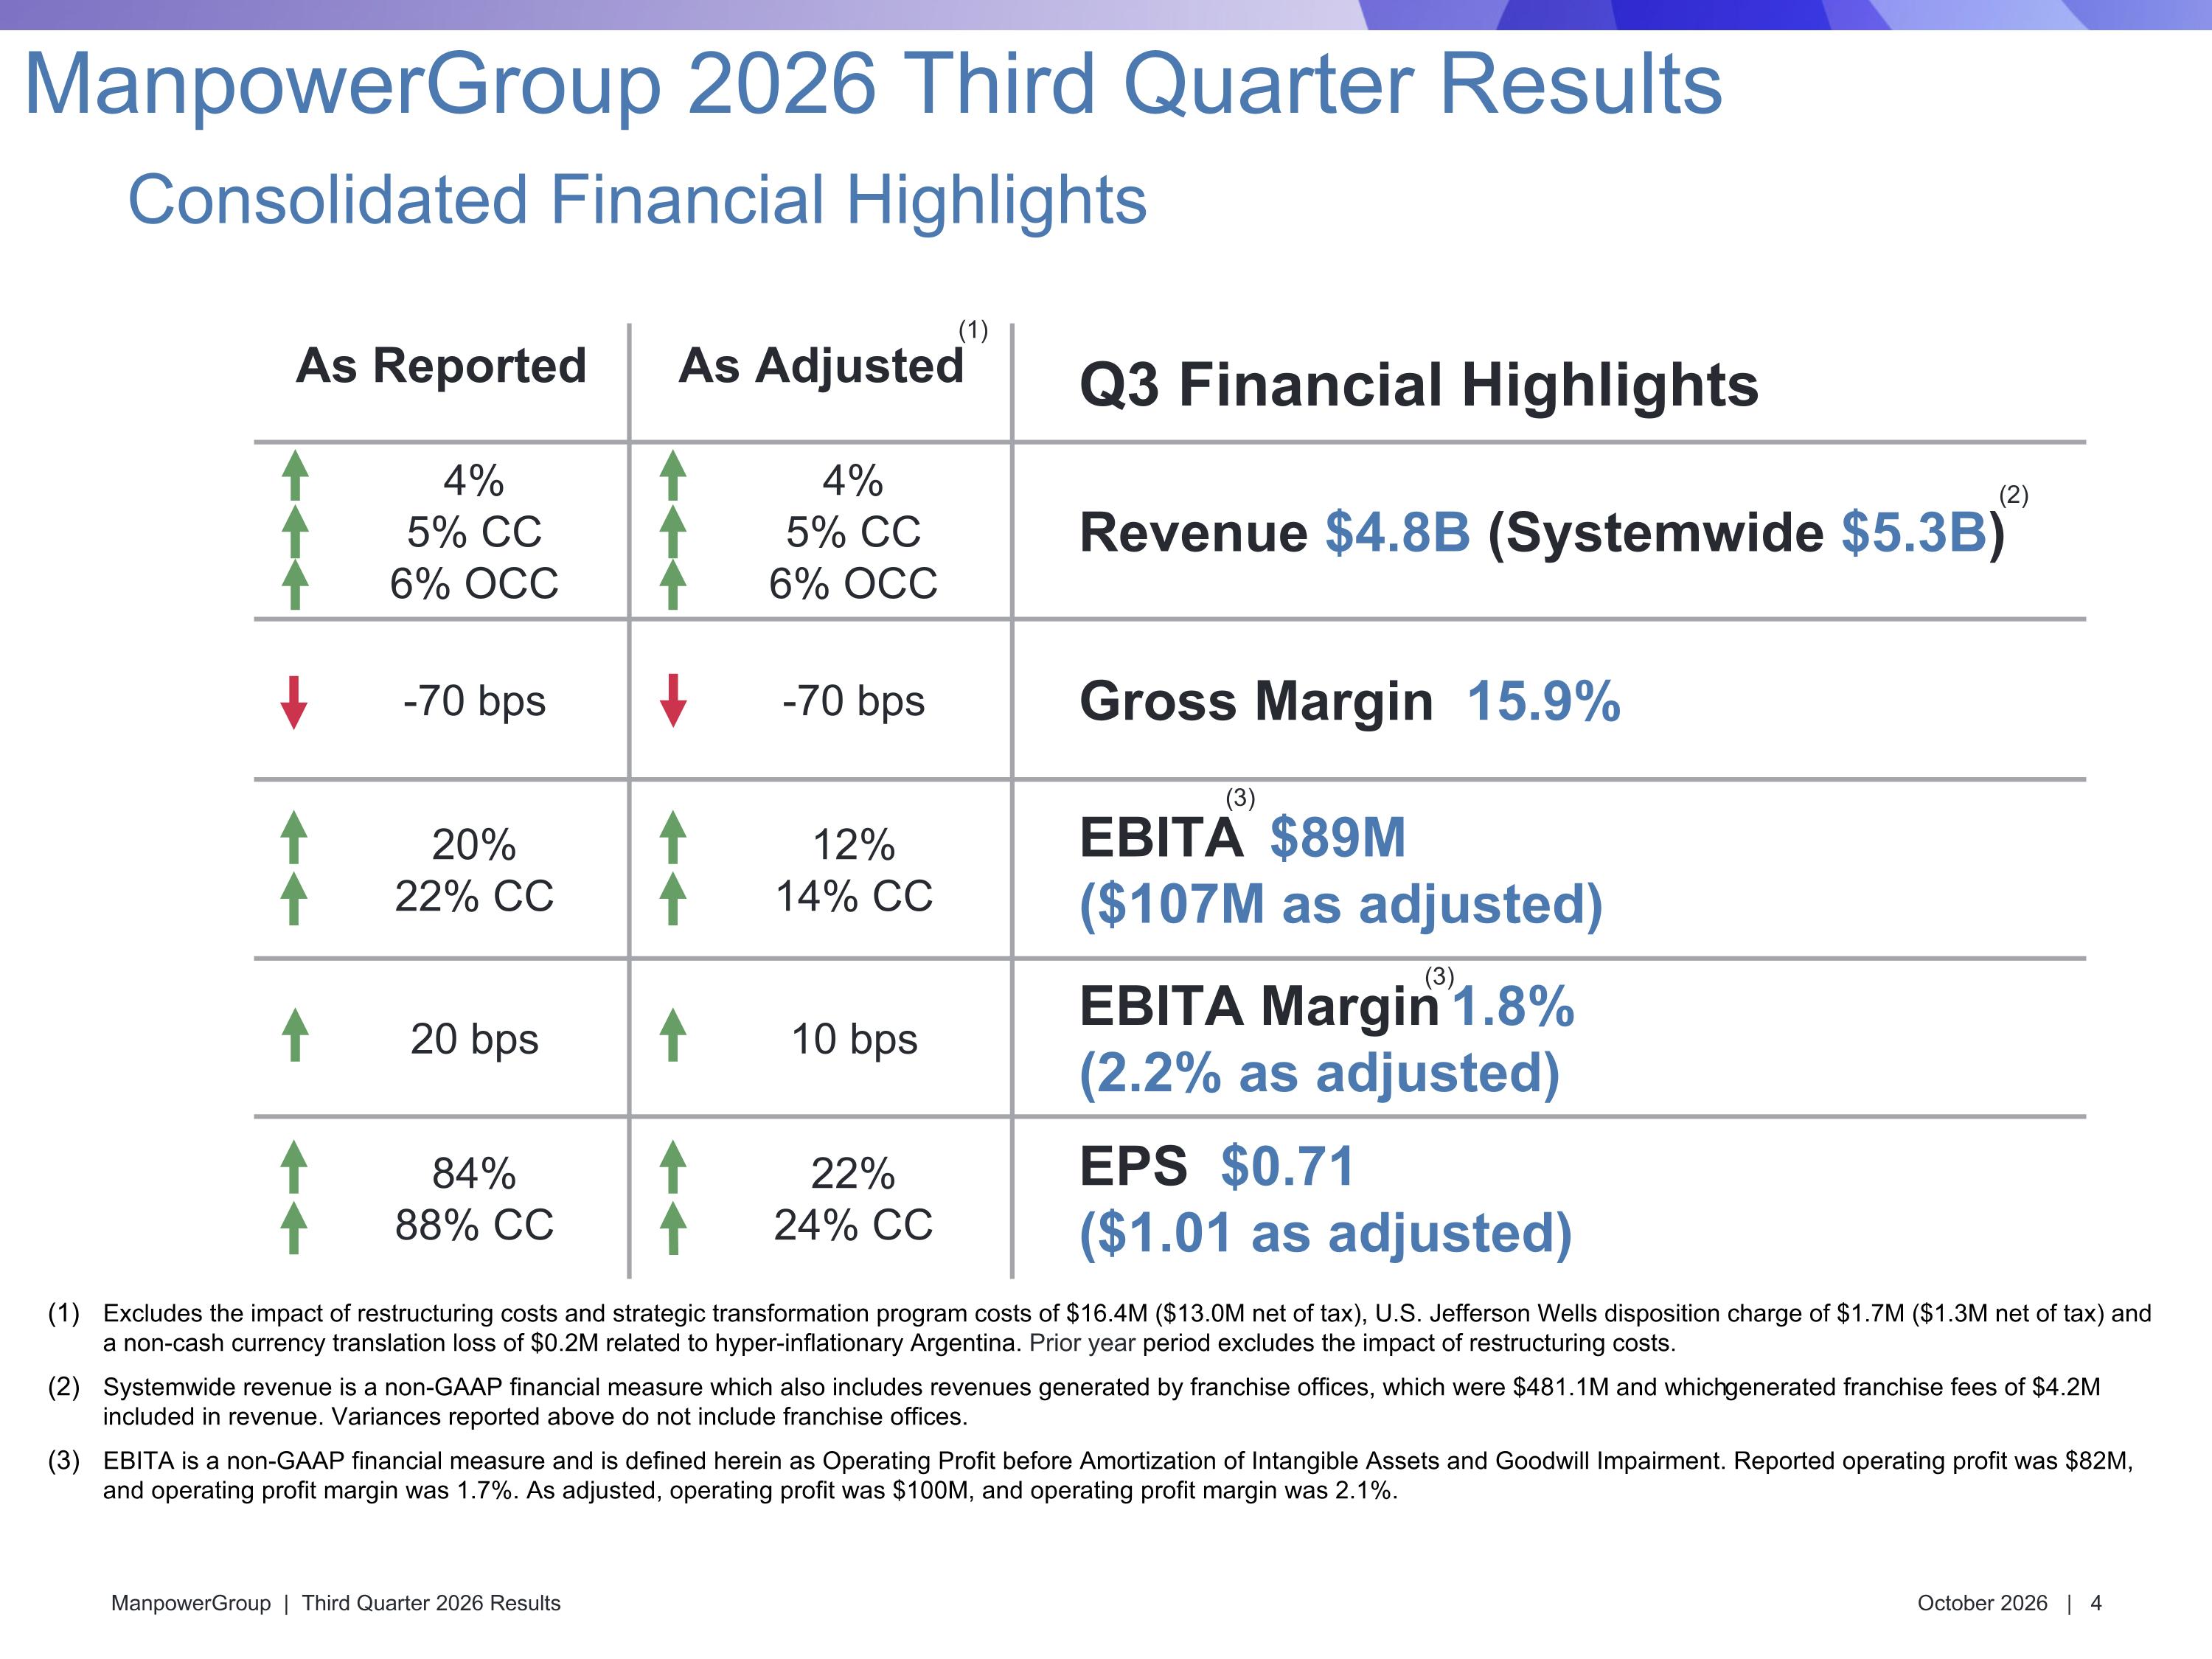
As Reported As Adjusted Q3 Financial Highlights 4% 5% CC 6% OCC 4% 5% CC 6% OCC Revenue $4.8B (Systemwide $5.3B) -70 bps -70 bps Gross Margin 15.9% 20% 22% CC 12% 14% CC EBITA $89M ($107M as adjusted) 20 bps 10 bps EBITA Margin 1.8% (2.2% as adjusted) 84% 88% CC 22% 24% CC EPS $0.71 ($1.01 as adjusted) Excludes the impact of restructuring costs and strategic transformation program costs of $16.4M ($13.0M net of tax), U.S. Jefferson Wells disposition charge of $1.7M ($1.3M net of tax) and a non-cash currency translation loss of $0.2M related to hyper-inflationary Argentina. Prior year period excludes the impact of restructuring costs. Systemwide revenue is a non-GAAP financial measure which also includes revenues generated by franchise offices, which were $481.1M and which generated franchise fees of $4.2M included in revenue. Variances reported above do not include franchise offices. EBITA is a non-GAAP financial measure and is defined herein as Operating Profit before Amortization of Intangible Assets and Goodwill Impairment. Reported operating profit was $82M, and operating profit margin was 1.7%. As adjusted, operating profit was $100M, and operating profit margin was 2.1%. (3) (3) Consolidated Financial Highlights ManpowerGroup 2026 Third Quarter Results (1) (2)
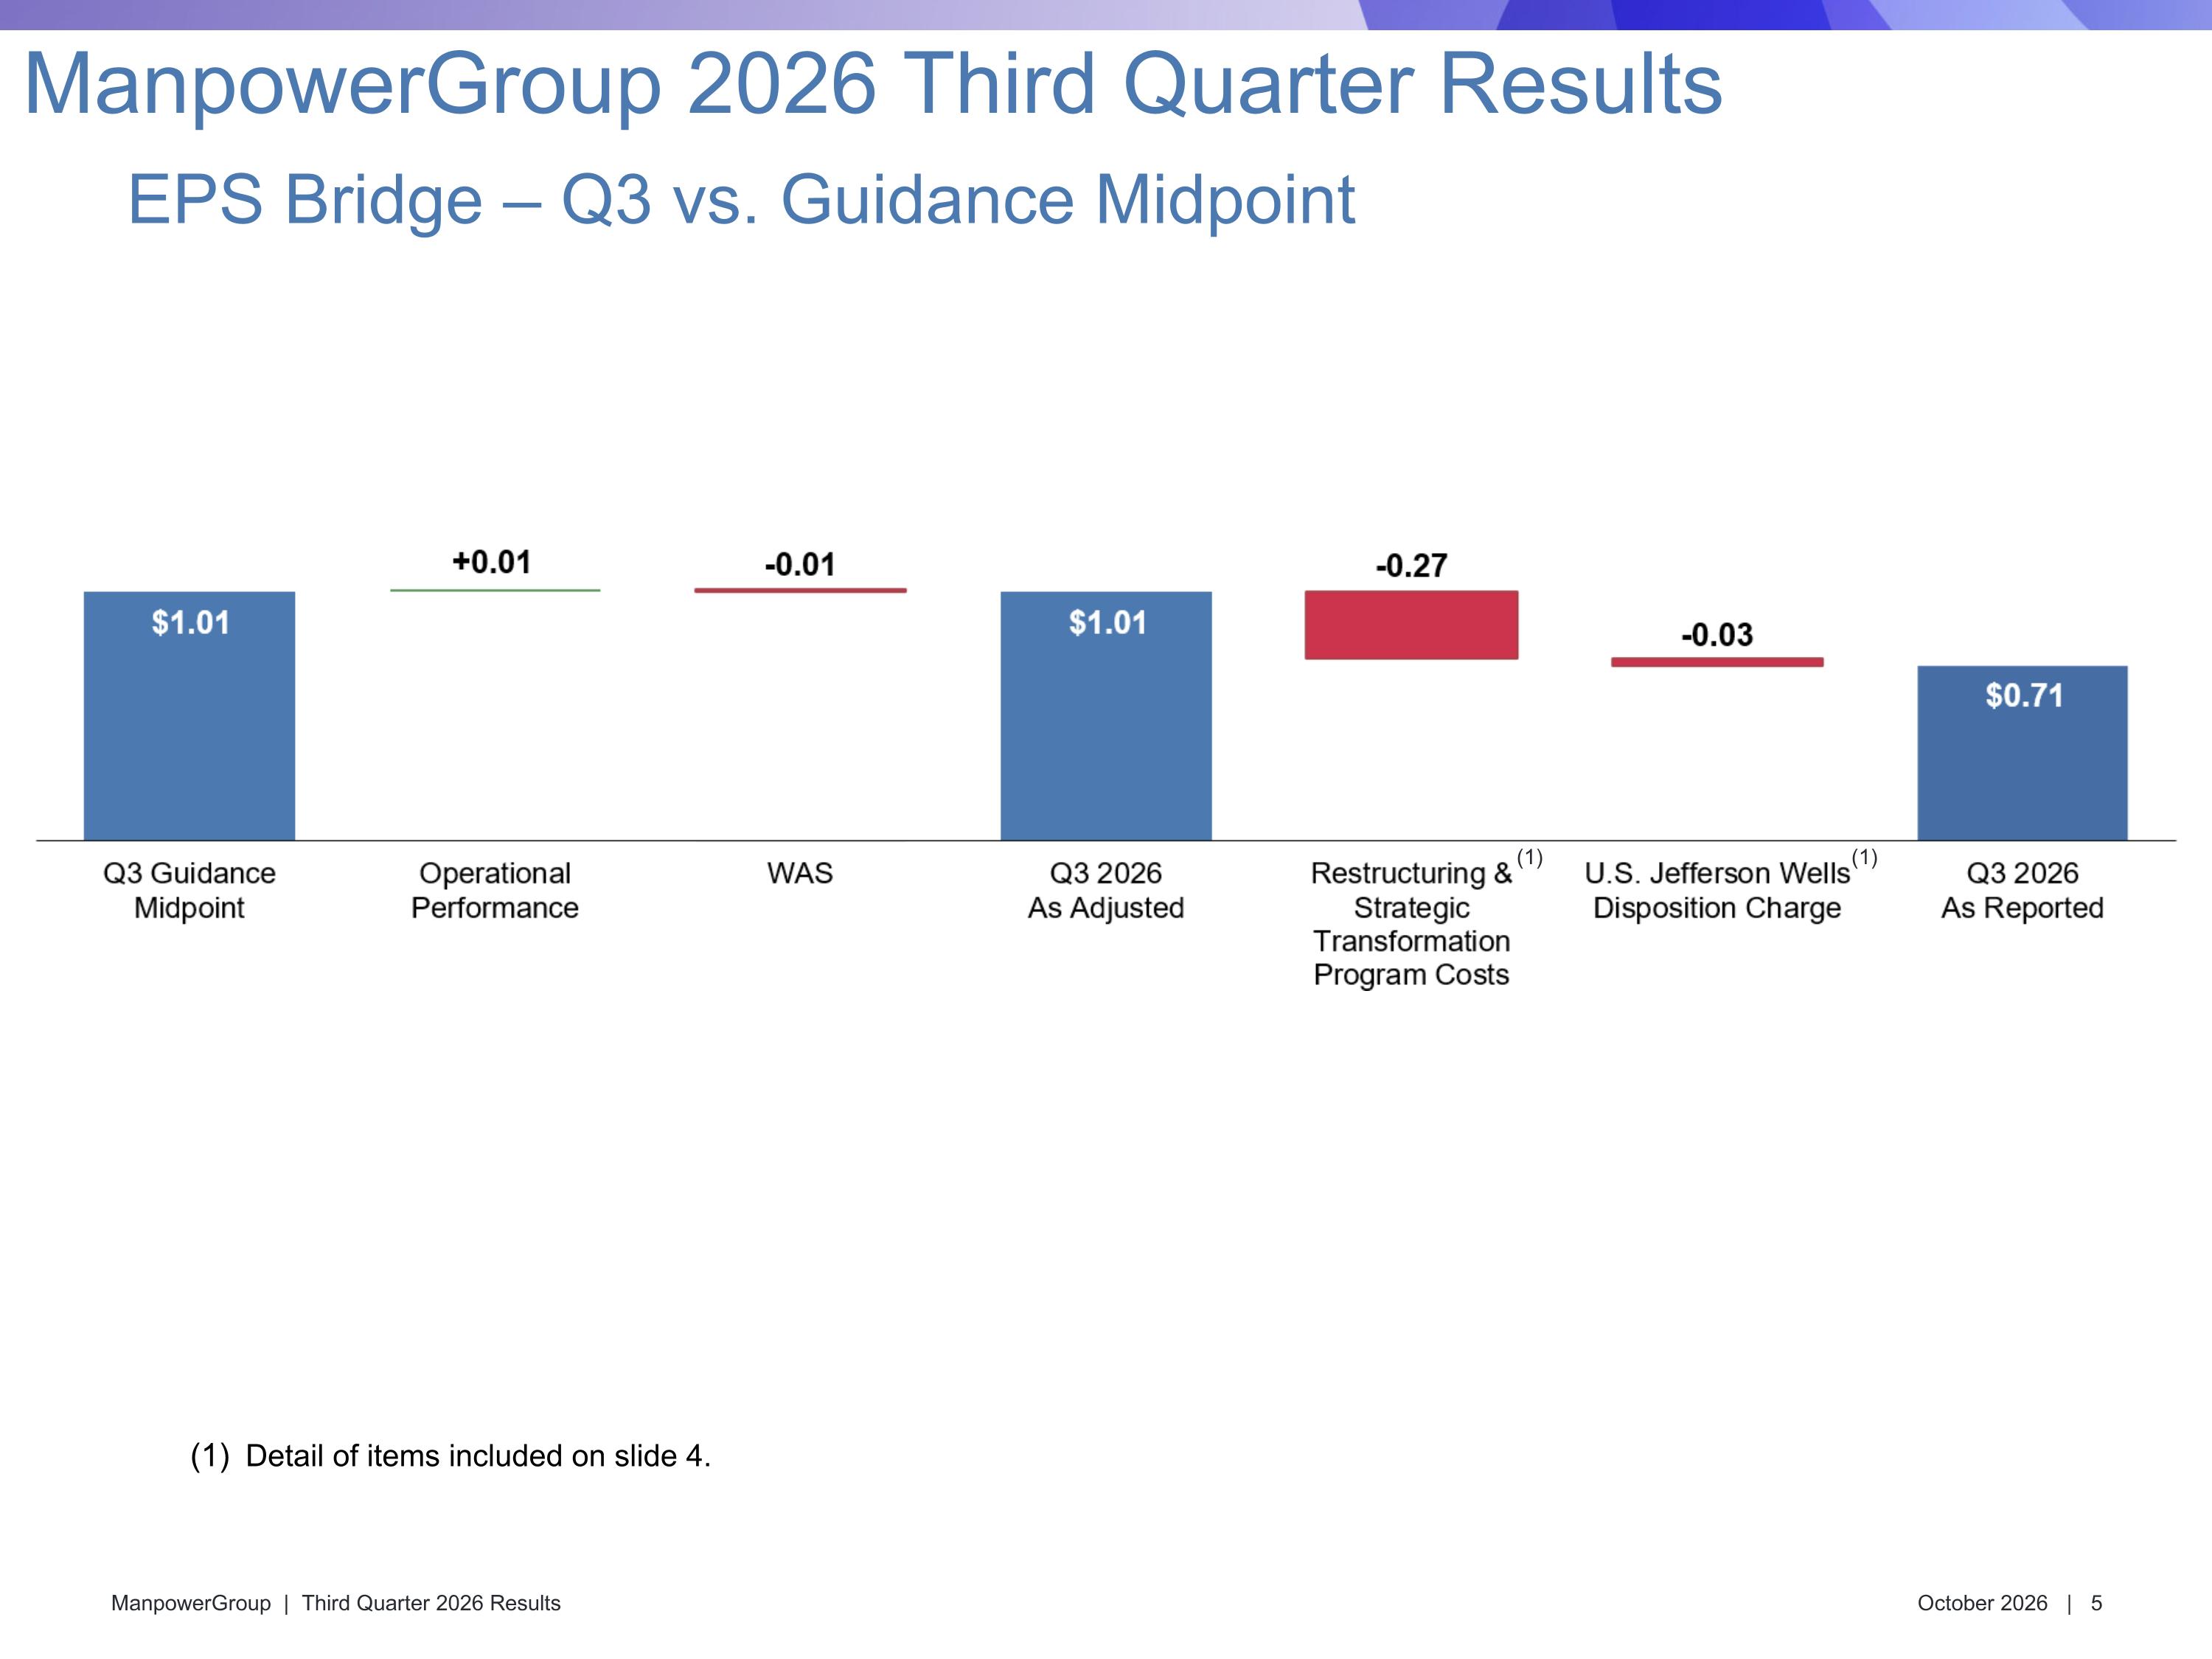
EPS Bridge – Q3 vs. Guidance Midpoint ManpowerGroup 2026 Third Quarter Results (1) Detail of items included on slide 4. (1)
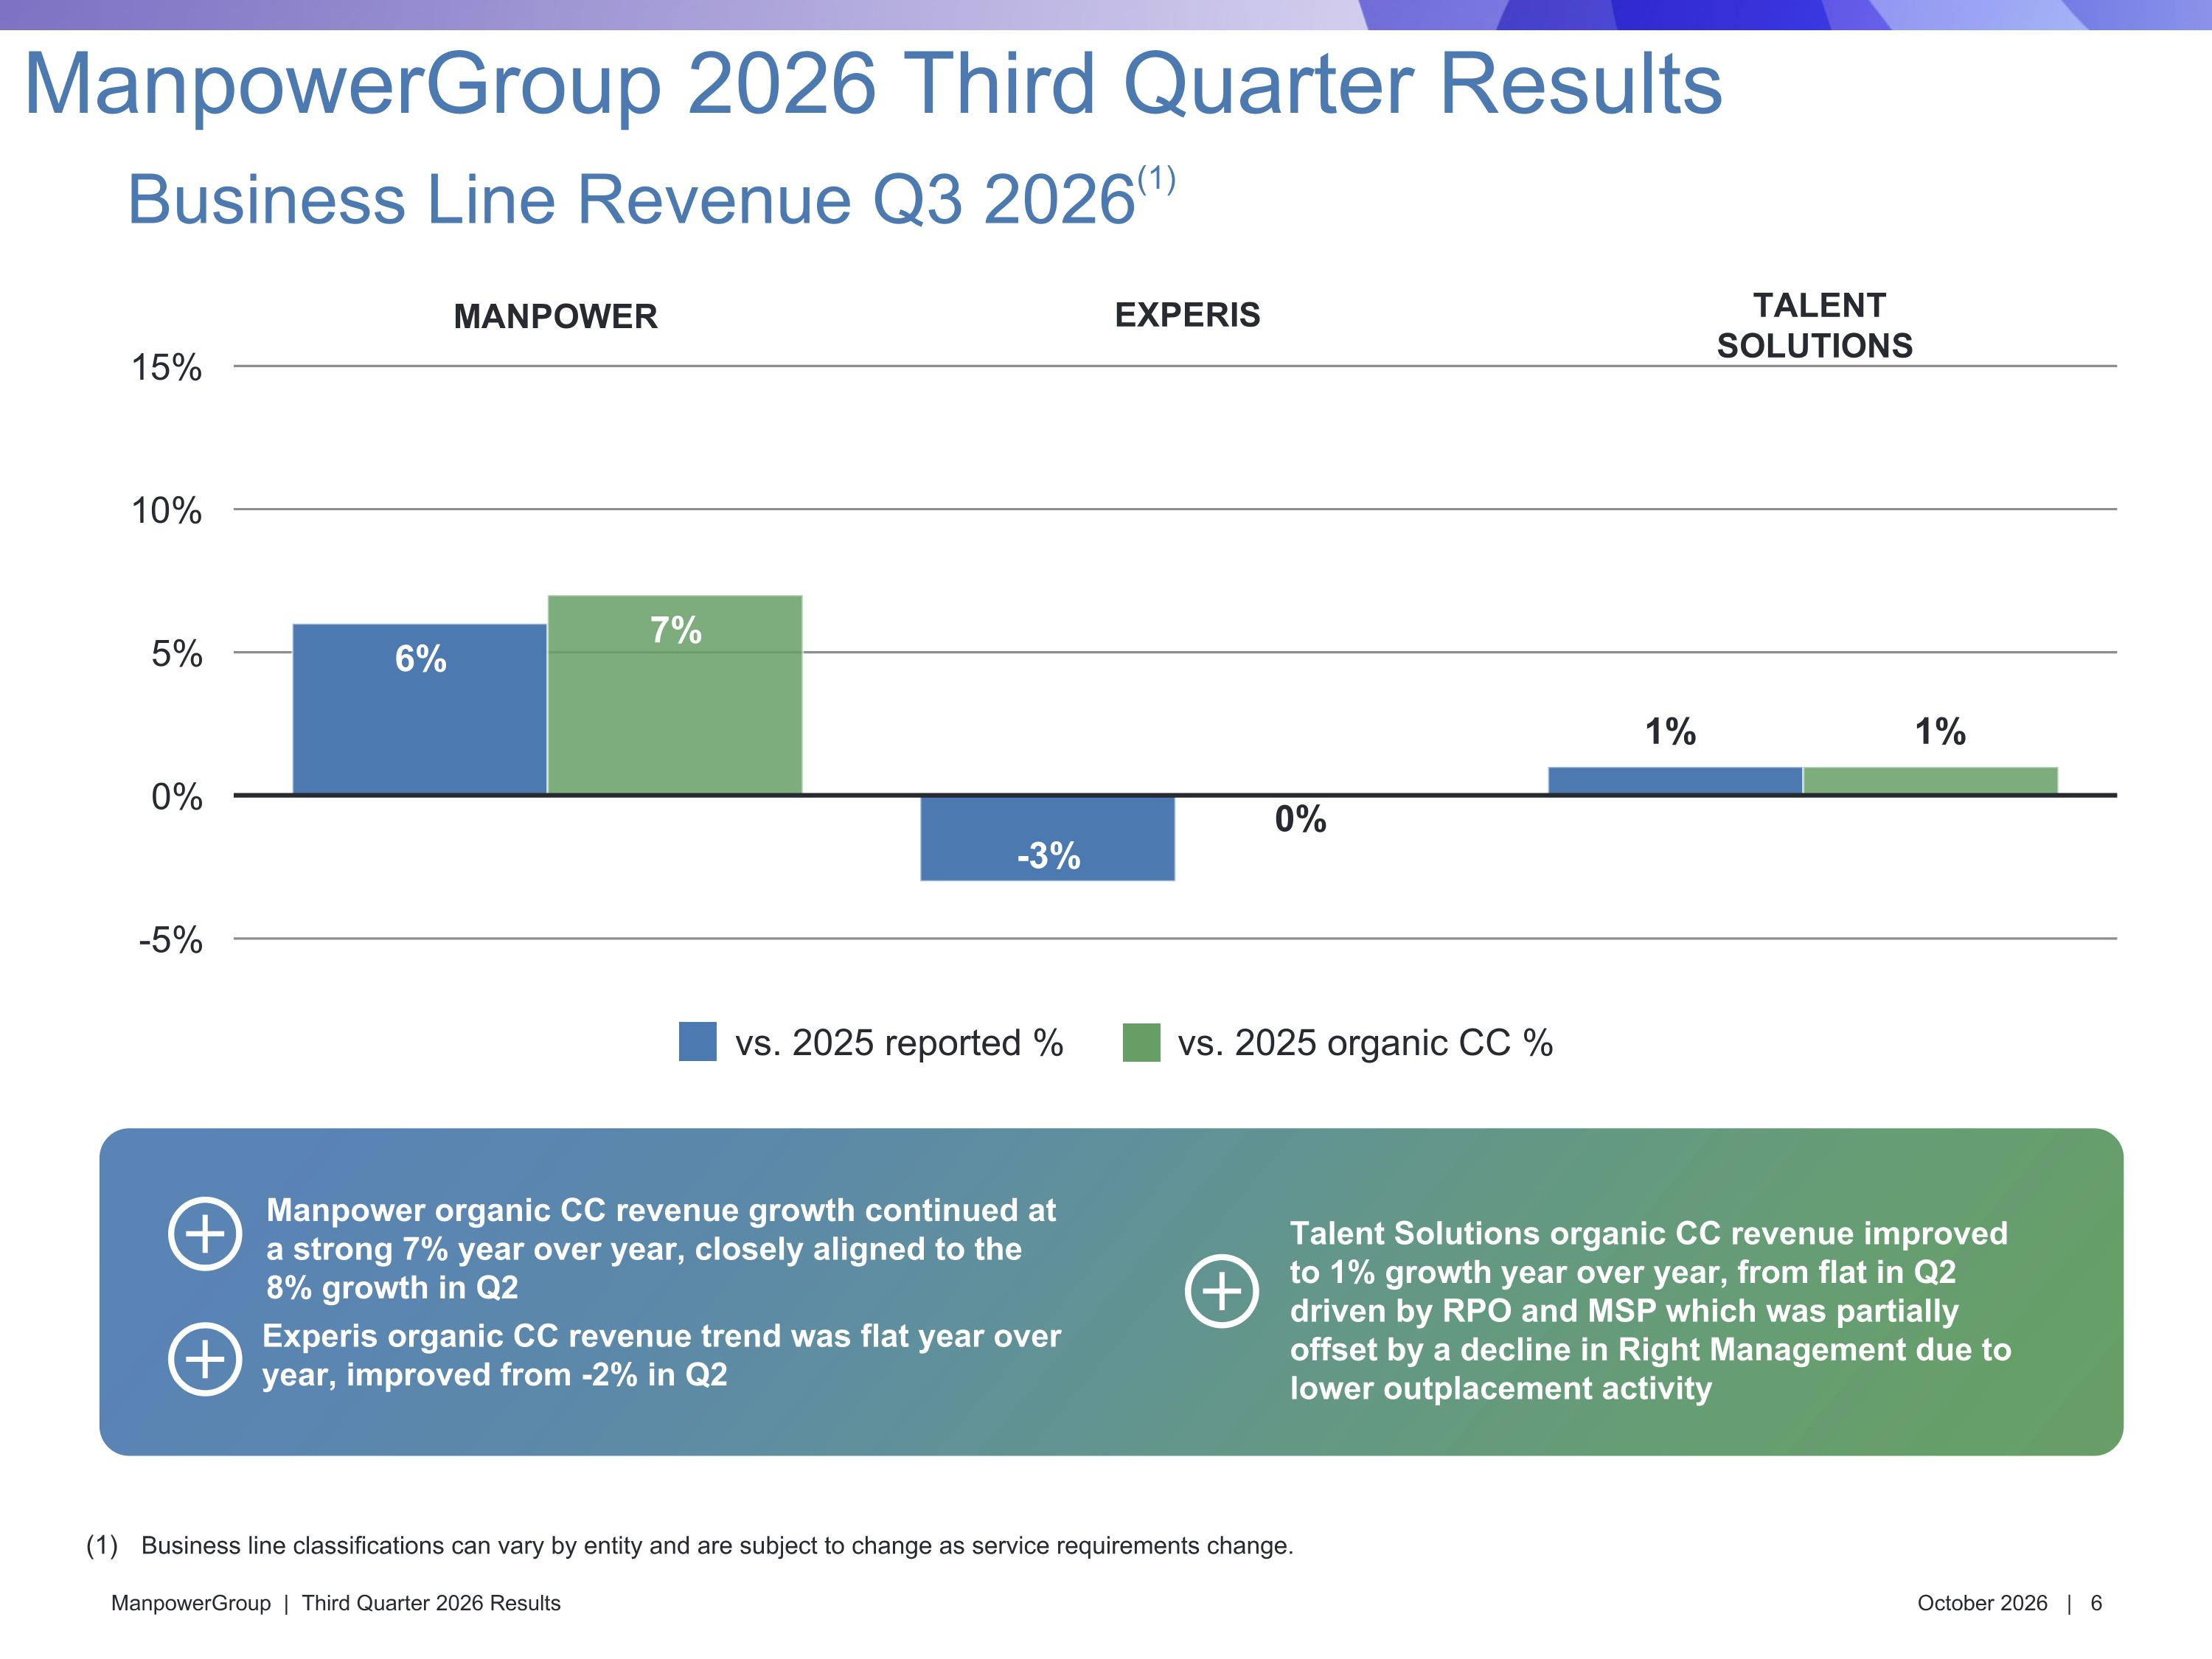
Manpower organic CC revenue growth continued at a strong 7% year over year, closely aligned to the 8% growth in Q2 Talent Solutions organic CC revenue improved to 1% growth year over year, from flat in Q2 driven by RPO and MSP which was partially offset by a decline in Right Management due to lower outplacement activity Experis organic CC revenue trend was flat year over year, improved from -2% in Q2 Business line classifications can vary by entity and are subject to change as service requirements change. Business Line Revenue Q3 2026(1) ManpowerGroup 2026 Third Quarter Results vs. 2025 reported % vs. 2025 organic CC % MANPOWER EXPERIS TALENT SOLUTIONS
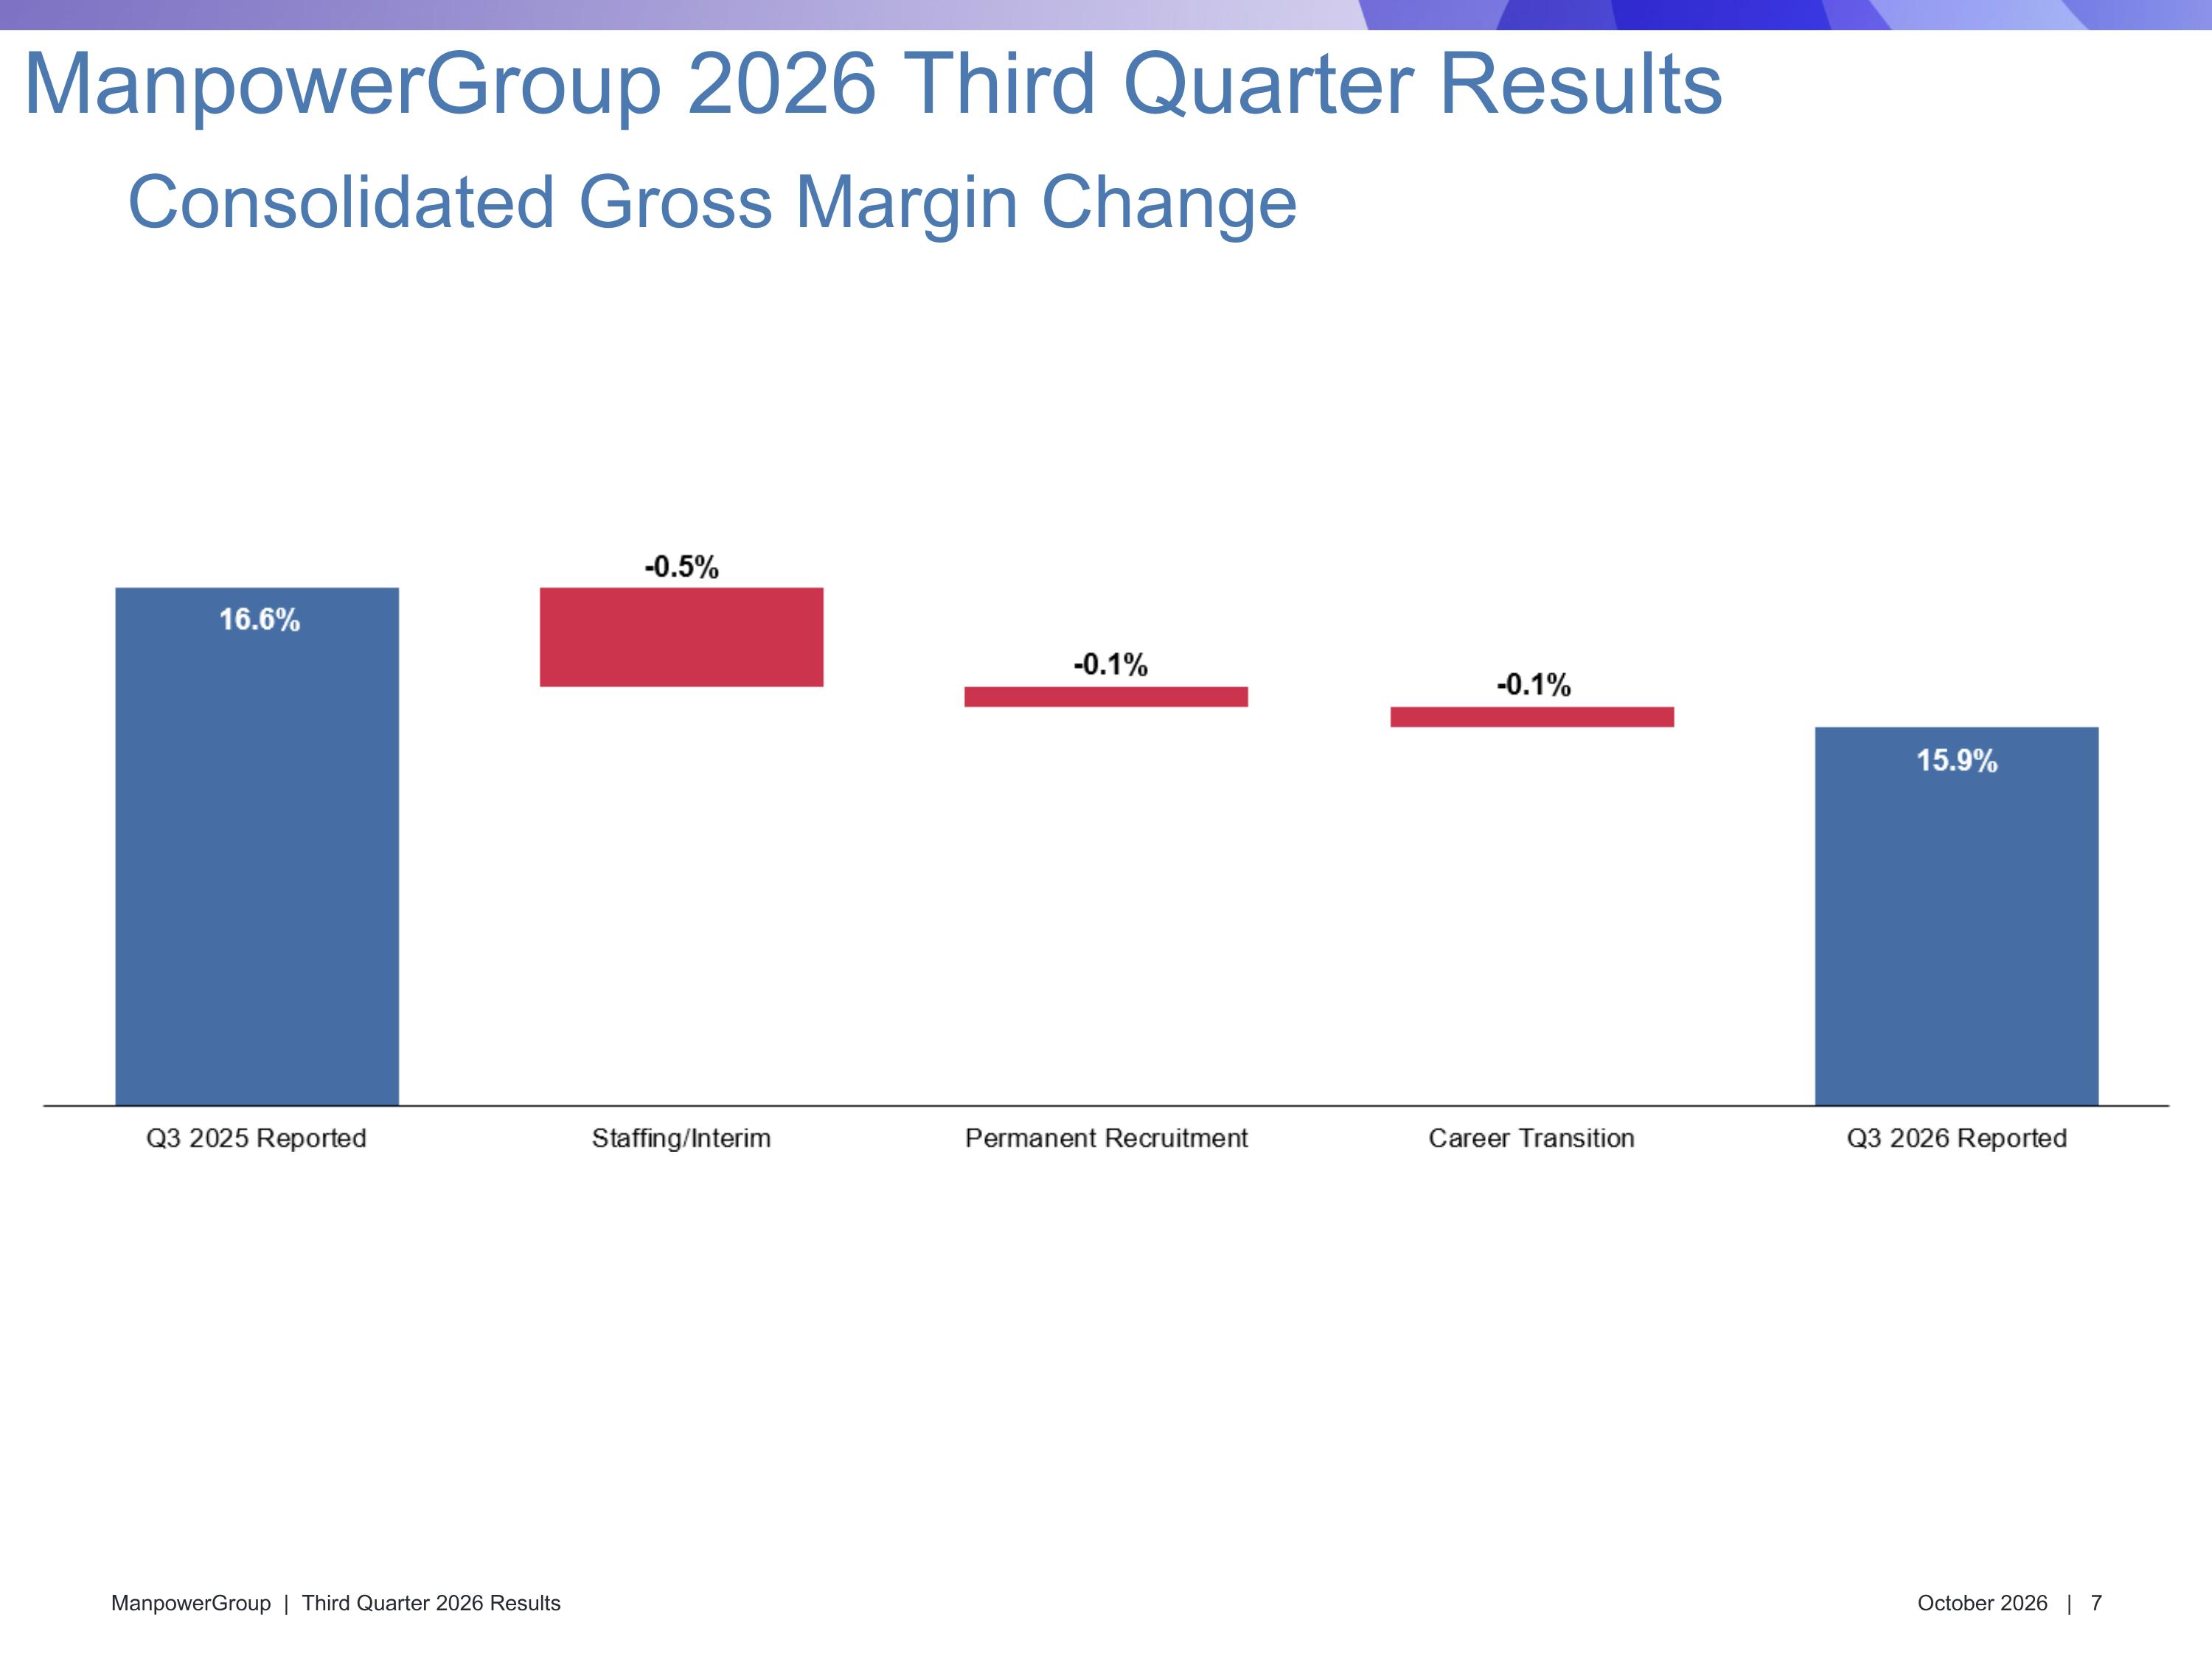
Consolidated Gross Margin Change ManpowerGroup 2026 Third Quarter Results
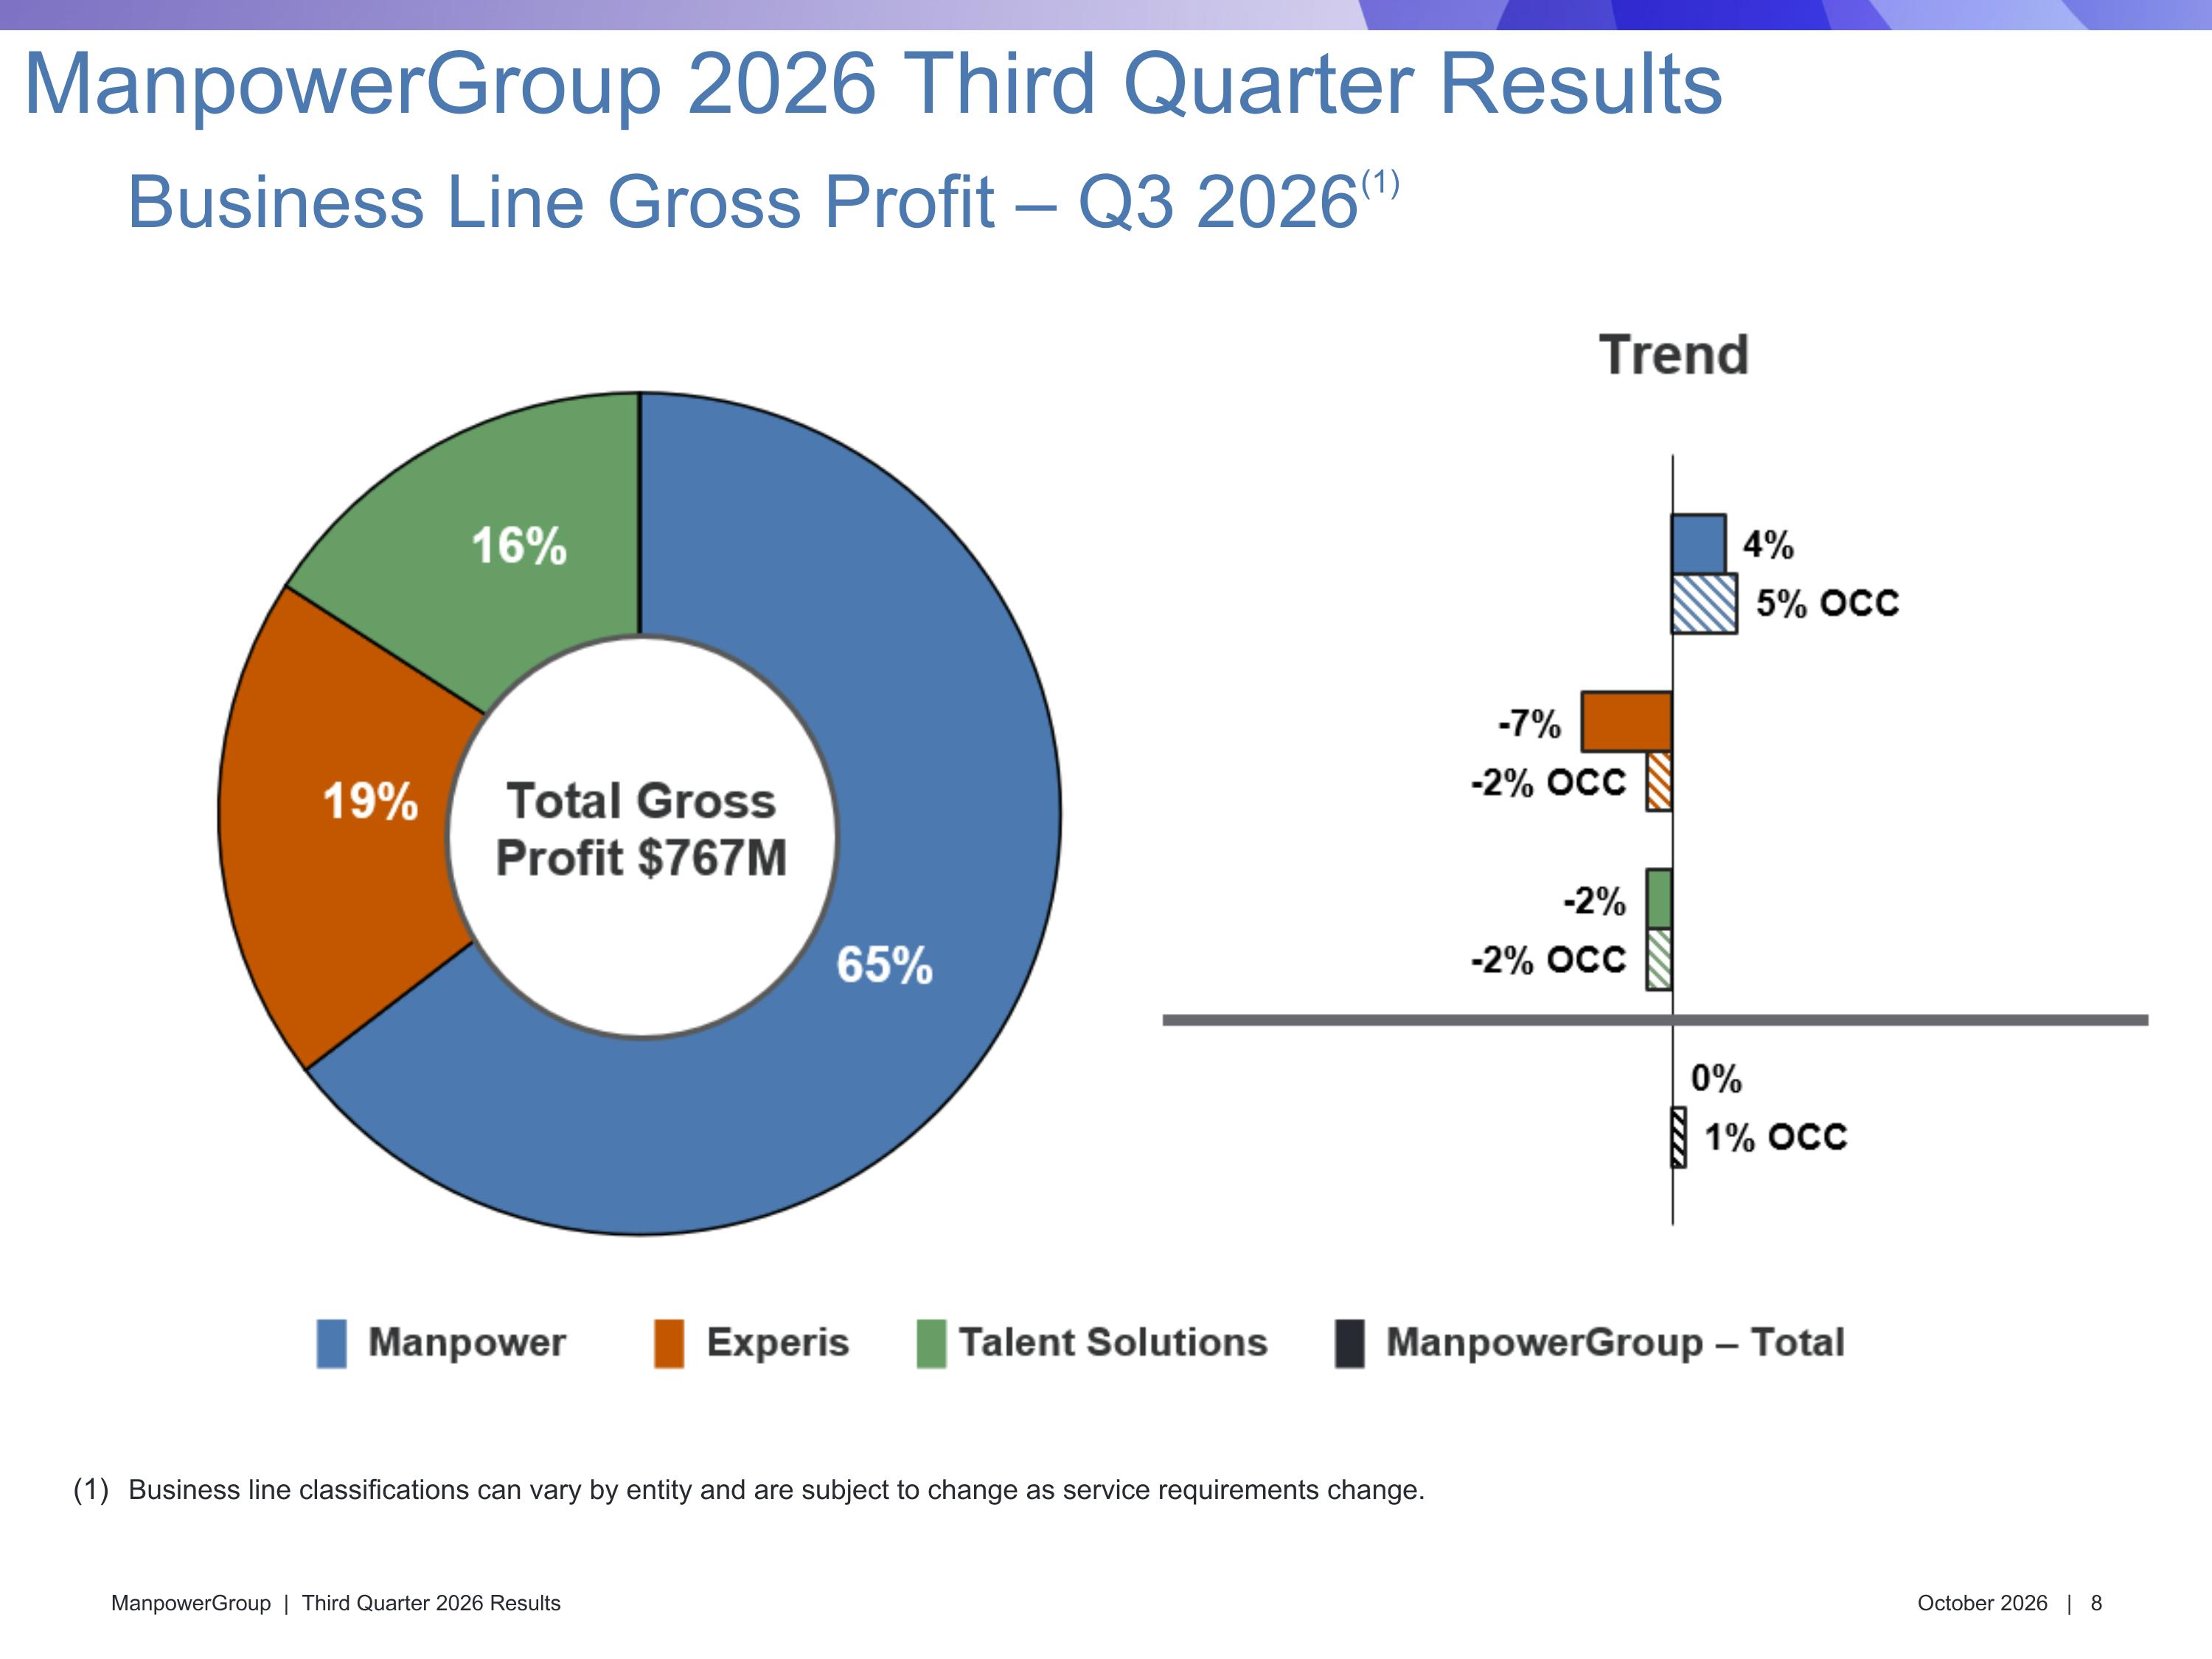
Business line classifications can vary by entity and are subject to change as service requirements change. Business Line Gross Profit – Q3 2026(1) ManpowerGroup 2026 Third Quarter Results
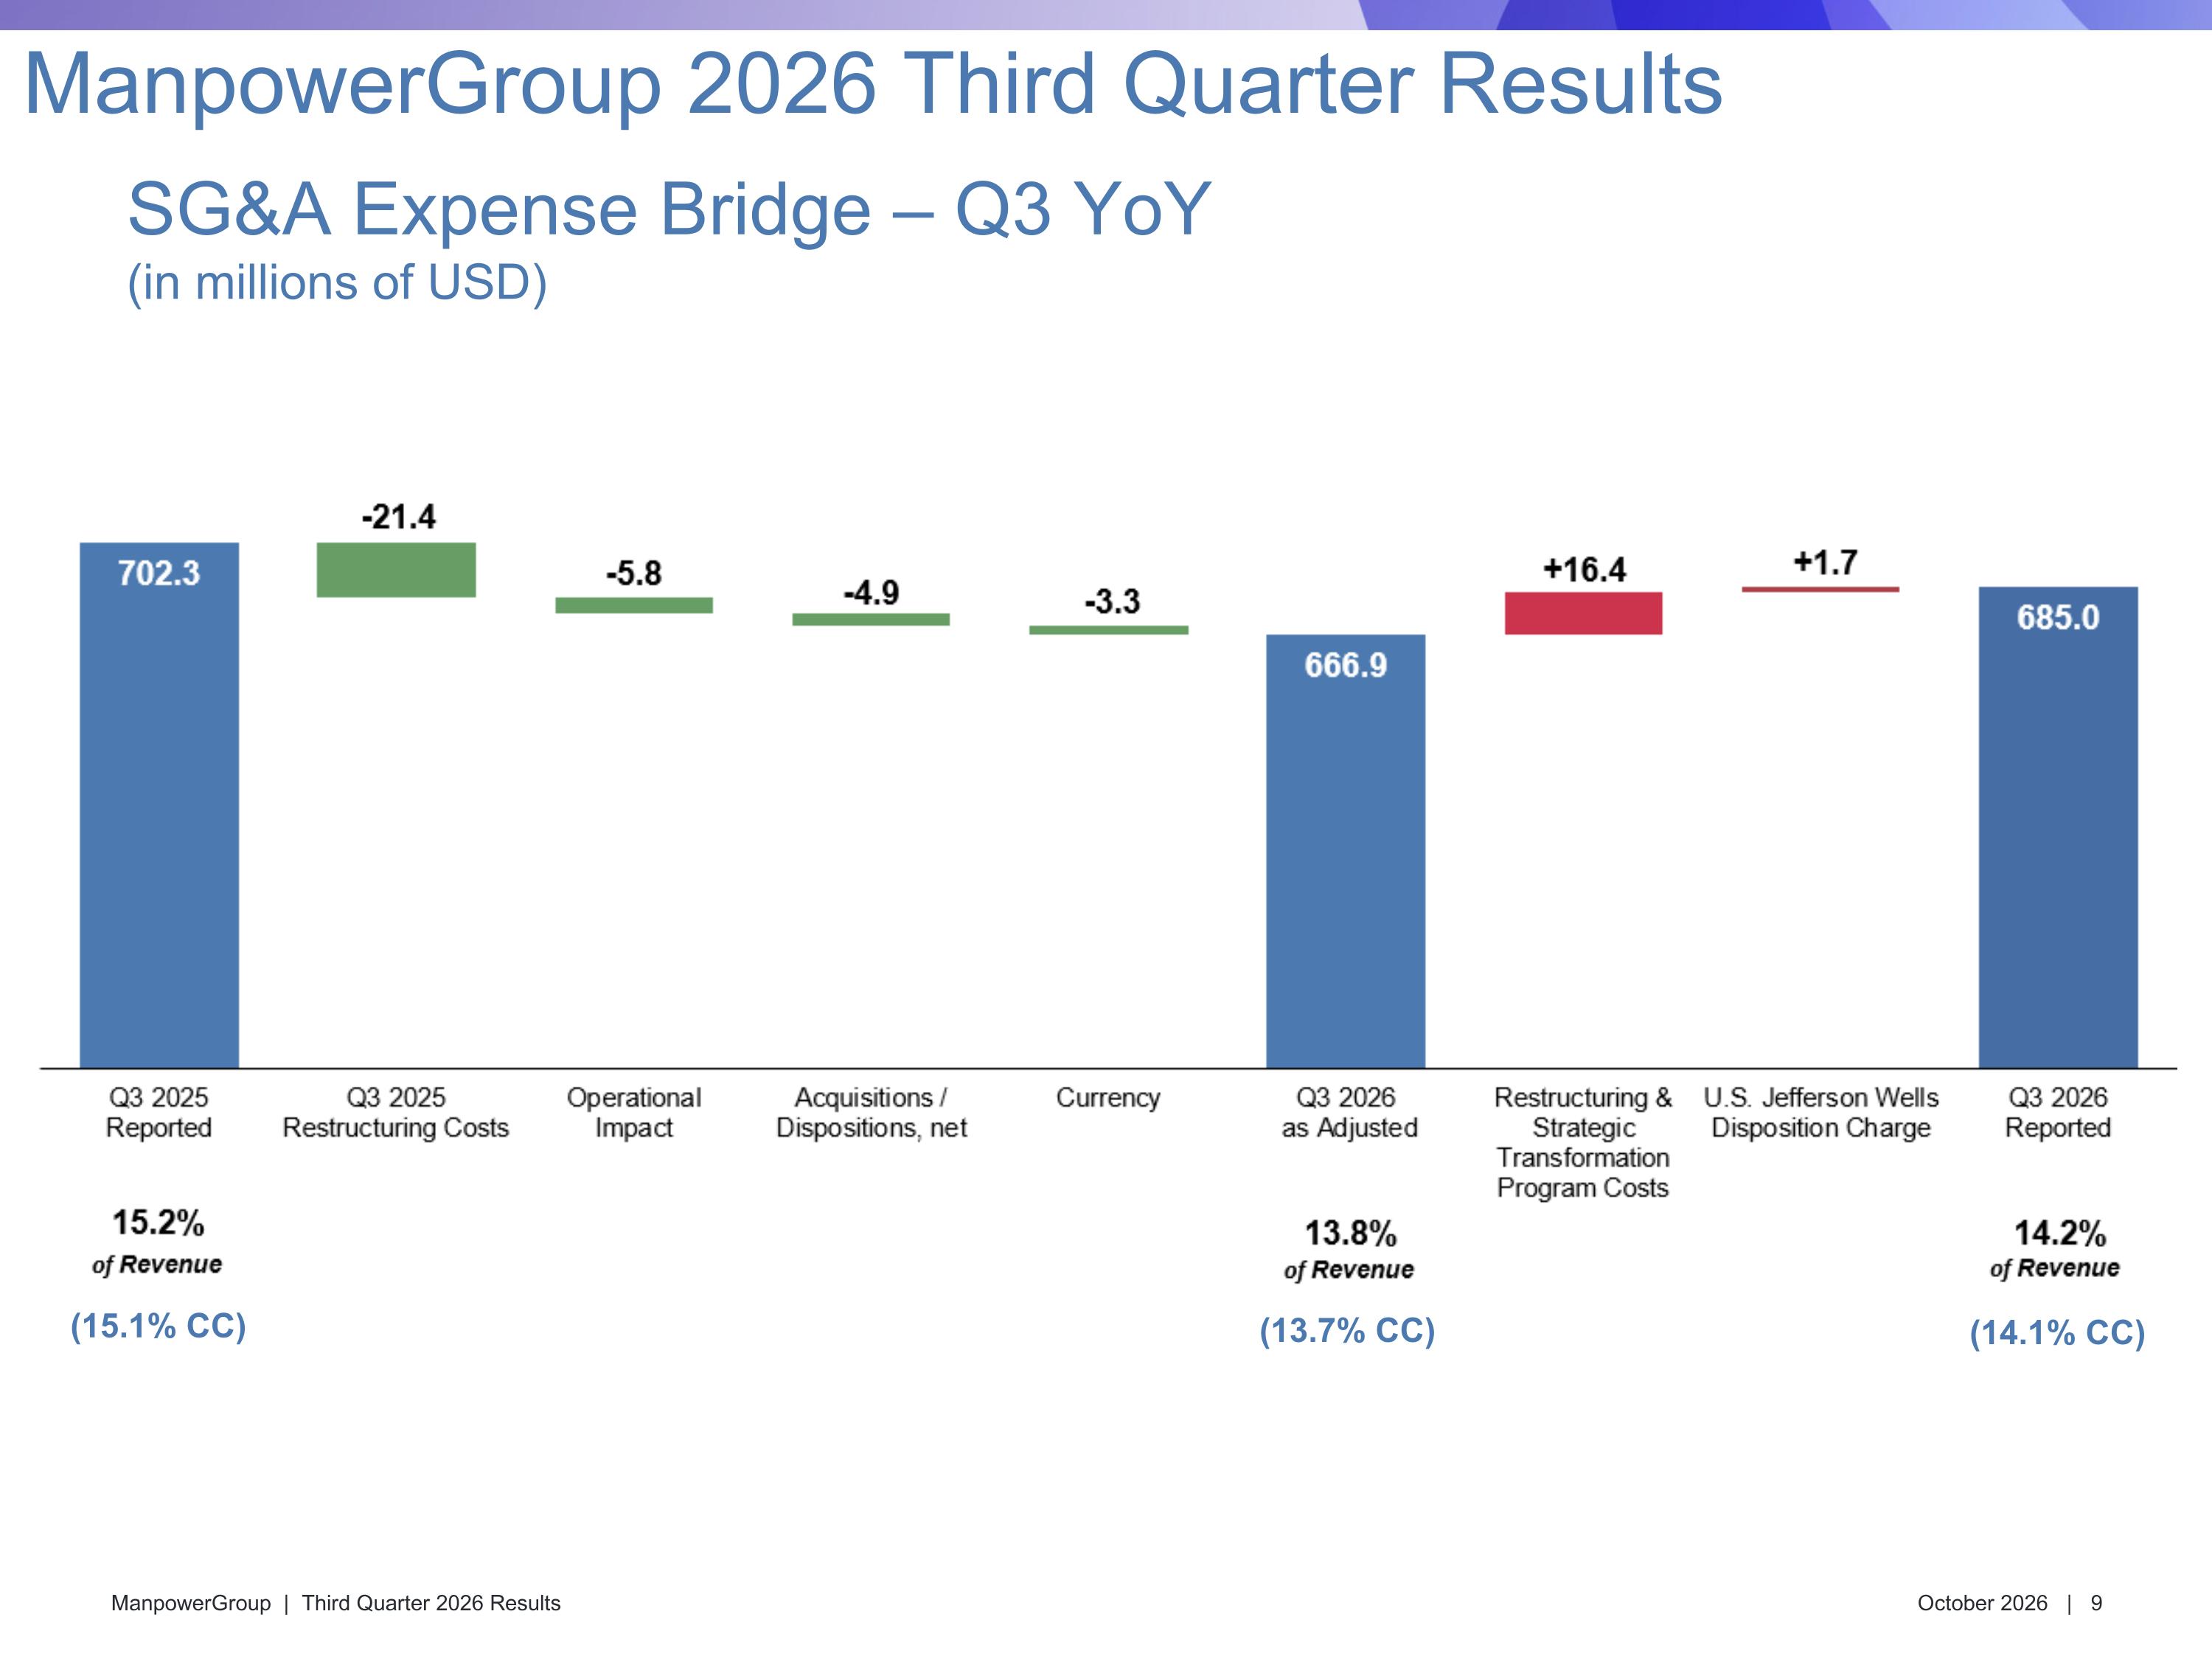
(14.1% CC) (15.1% CC) SG&A Expense Bridge – Q3 YoY (in millions of USD) ManpowerGroup 2026 Third Quarter Results (13.7% CC)
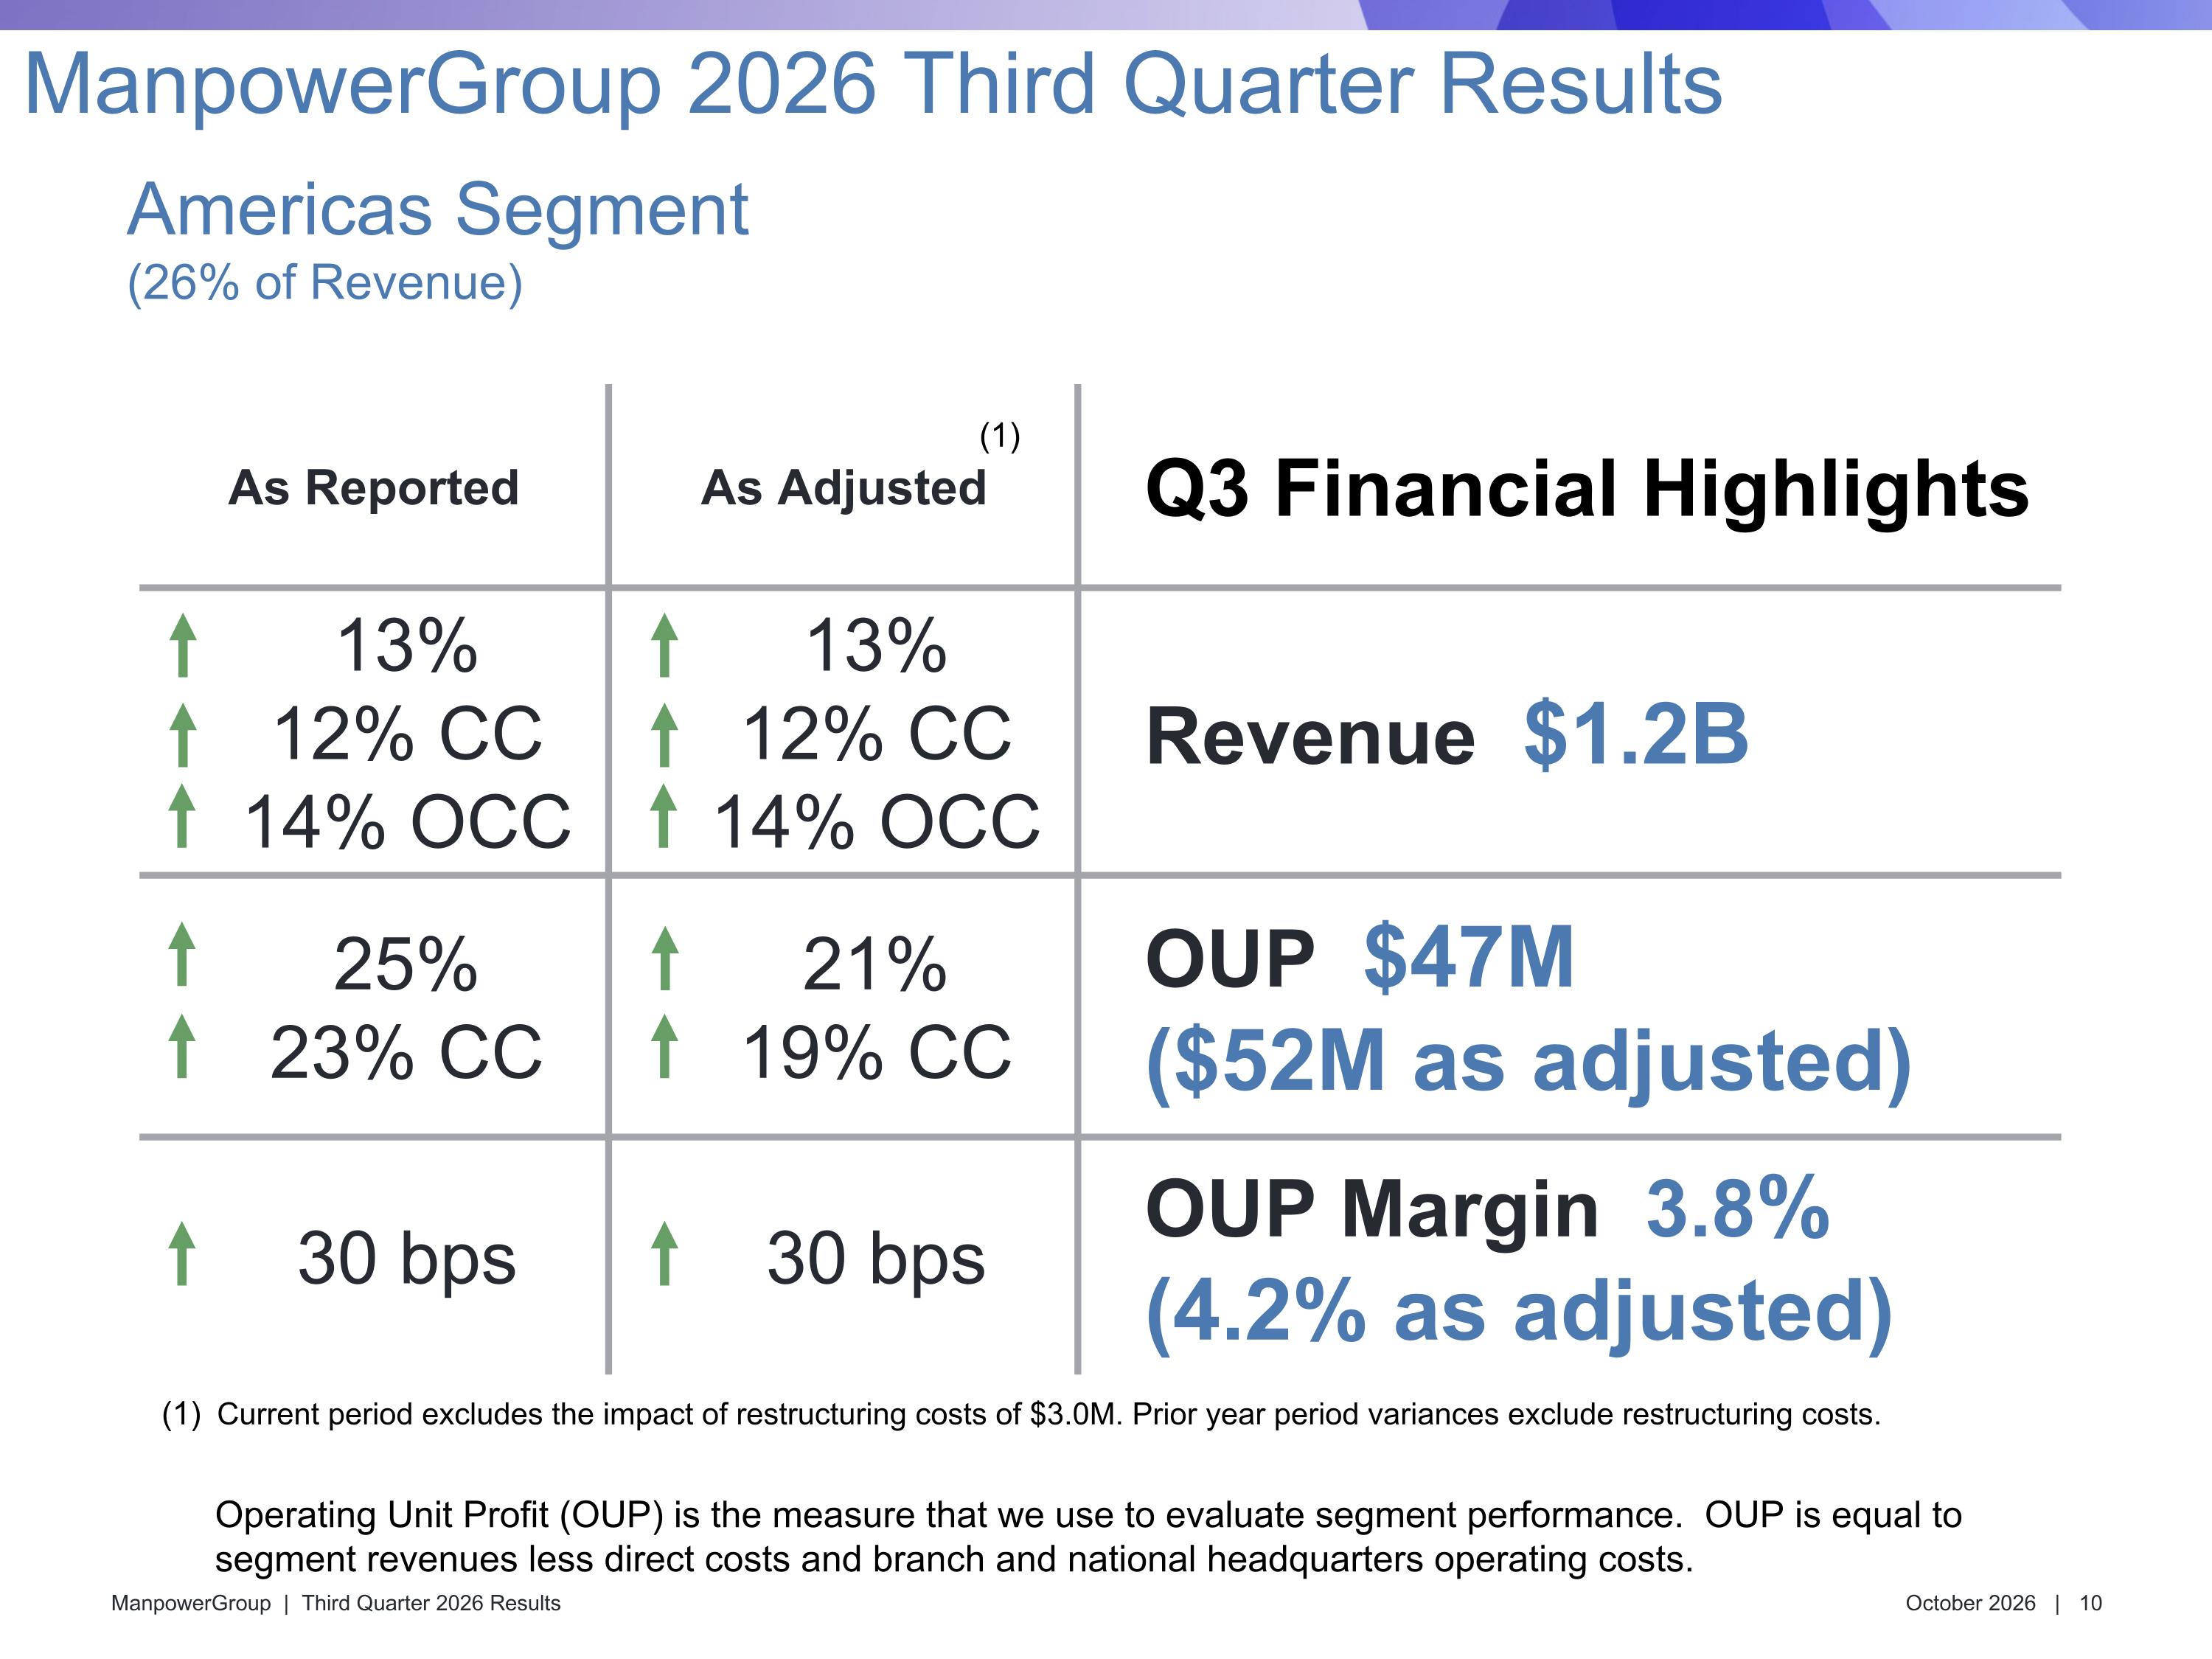
As Reported As Adjusted Q3 Financial Highlights 13% 12% CC 14% OCC 13% 12% CC 14% OCC Revenue $1.2B 25% 23% CC 21% 19% CC OUP $47M ($52M as adjusted) 30 bps 30 bps OUP Margin 3.8% (4.2% as adjusted) Americas Segment (26% of Revenue) ManpowerGroup 2026 Third Quarter Results Operating Unit Profit (OUP) is the measure that we use to evaluate segment performance. OUP is equal to segment revenues less direct costs and branch and national headquarters operating costs. Current period excludes the impact of restructuring costs of $3.0M. Prior year period variances exclude restructuring costs. (1)
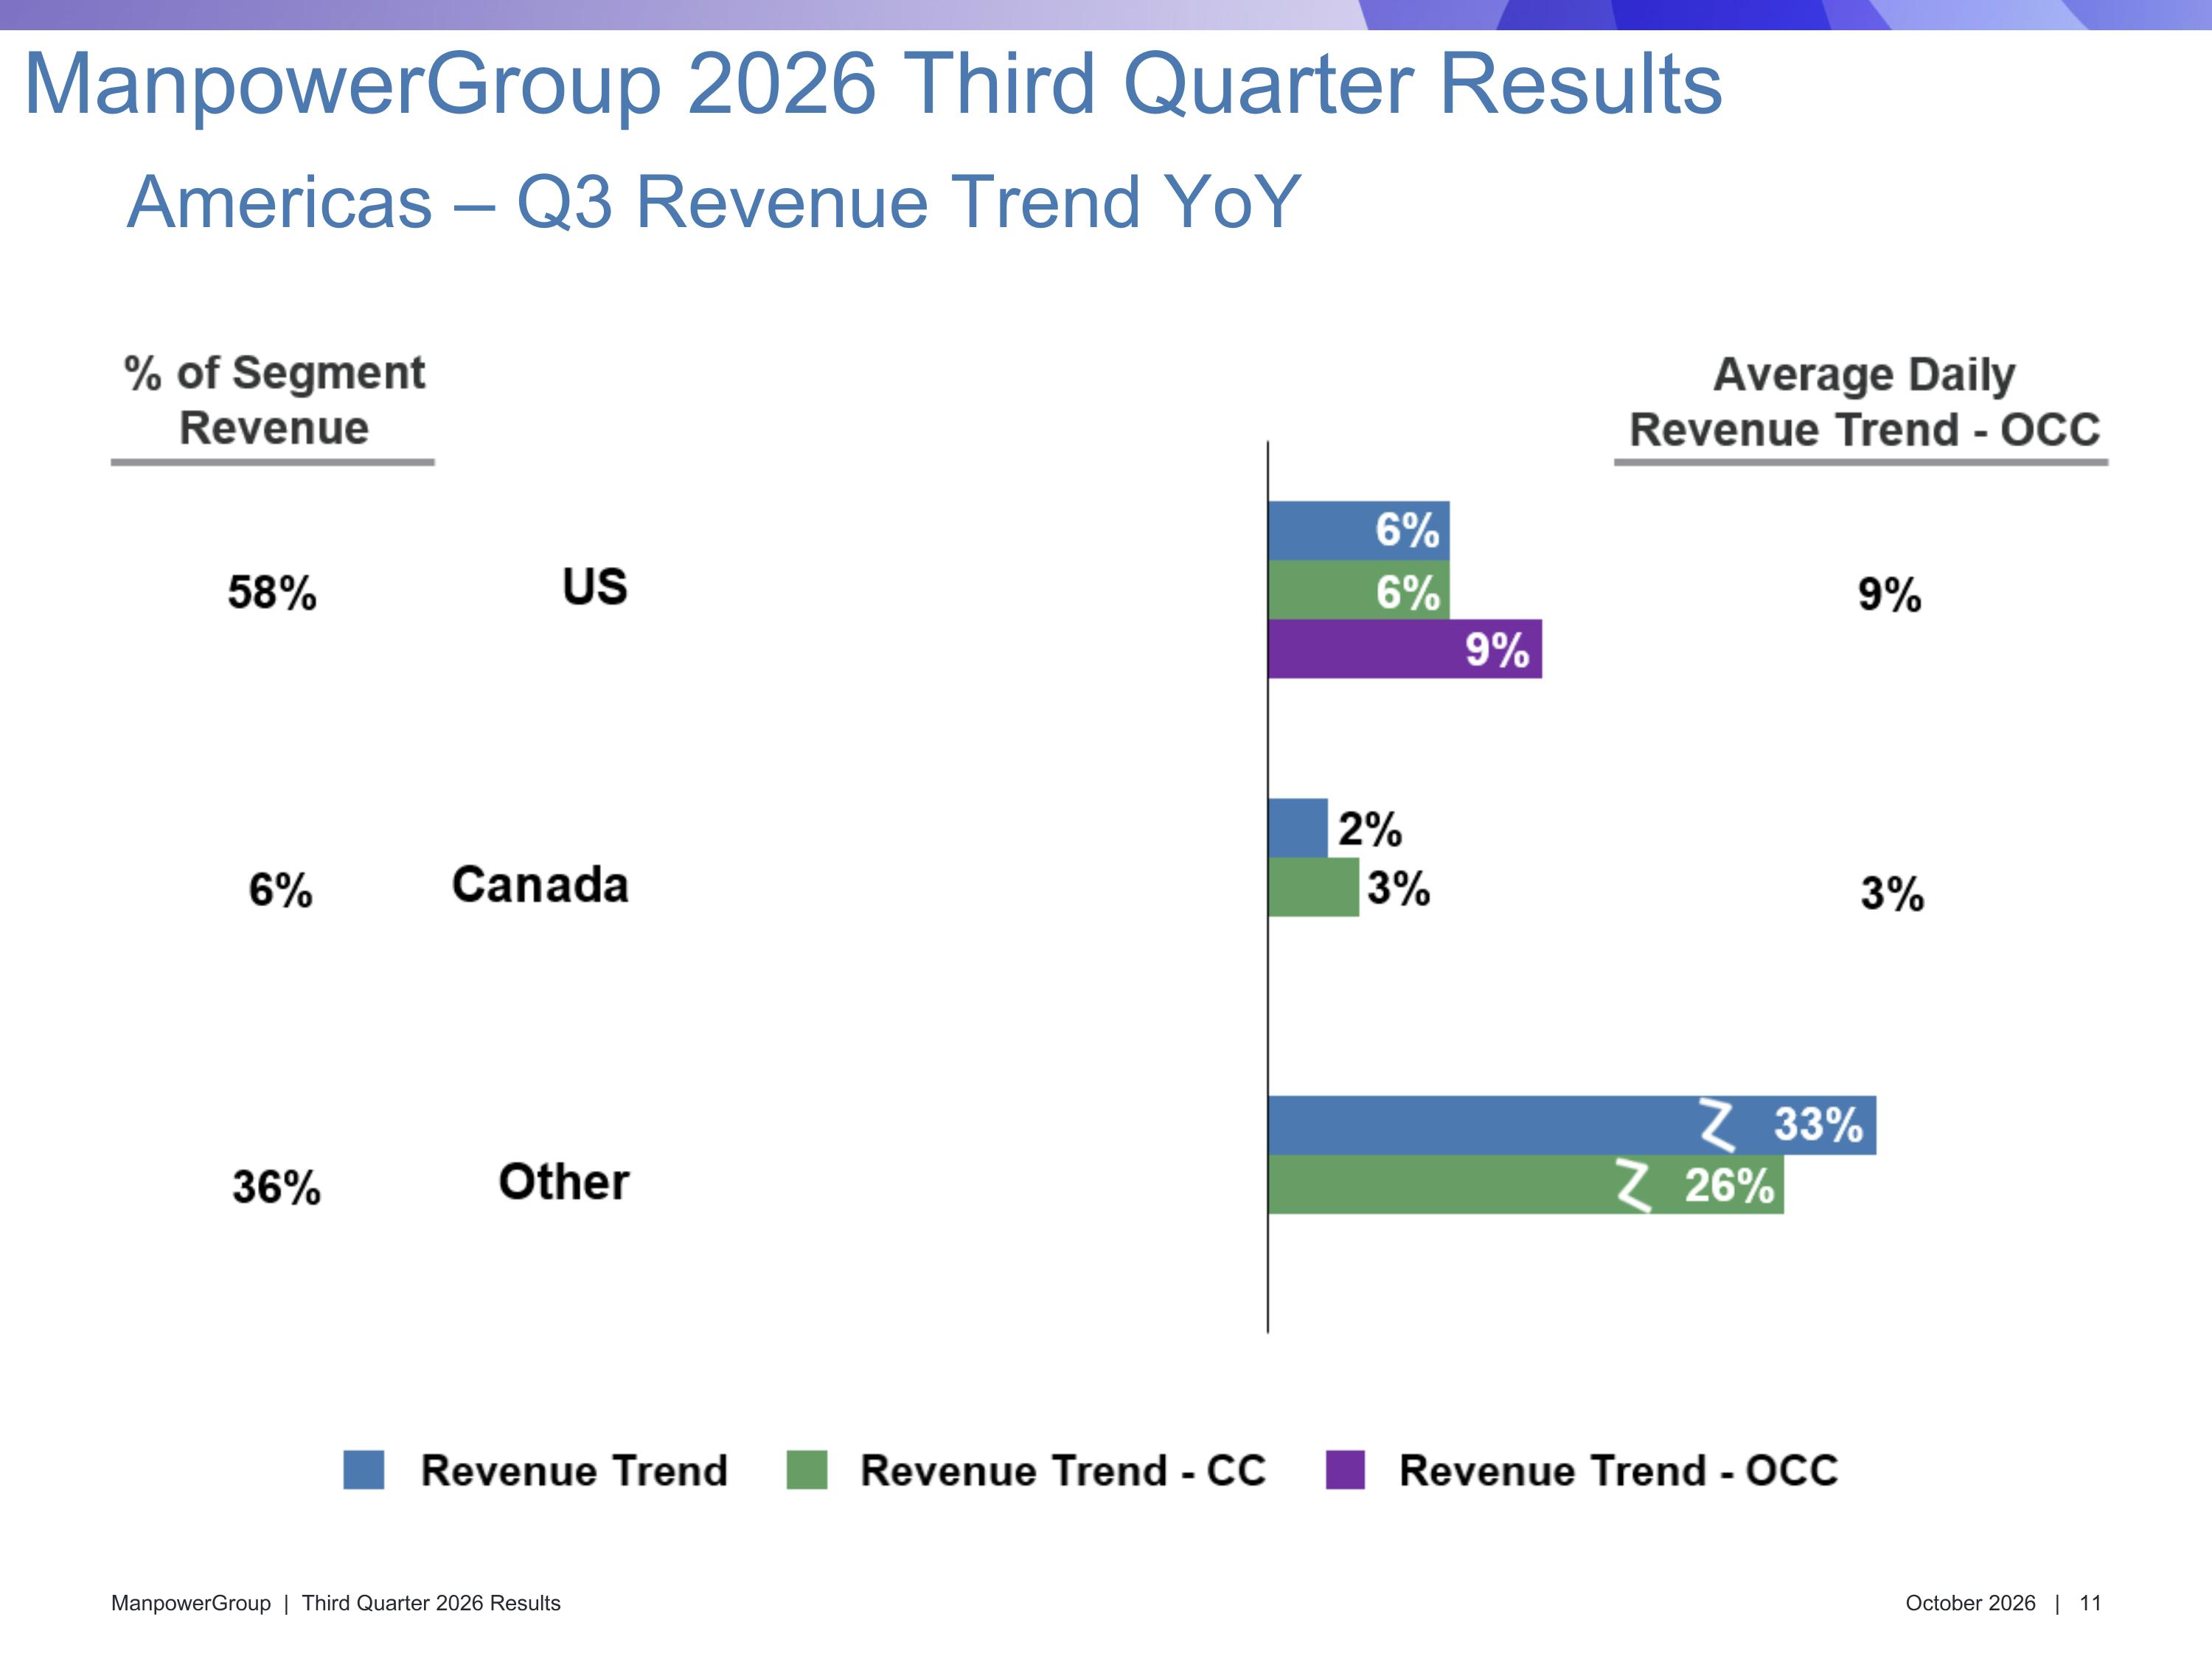
Americas – Q3 Revenue Trend YoY ManpowerGroup 2026 Third Quarter Results
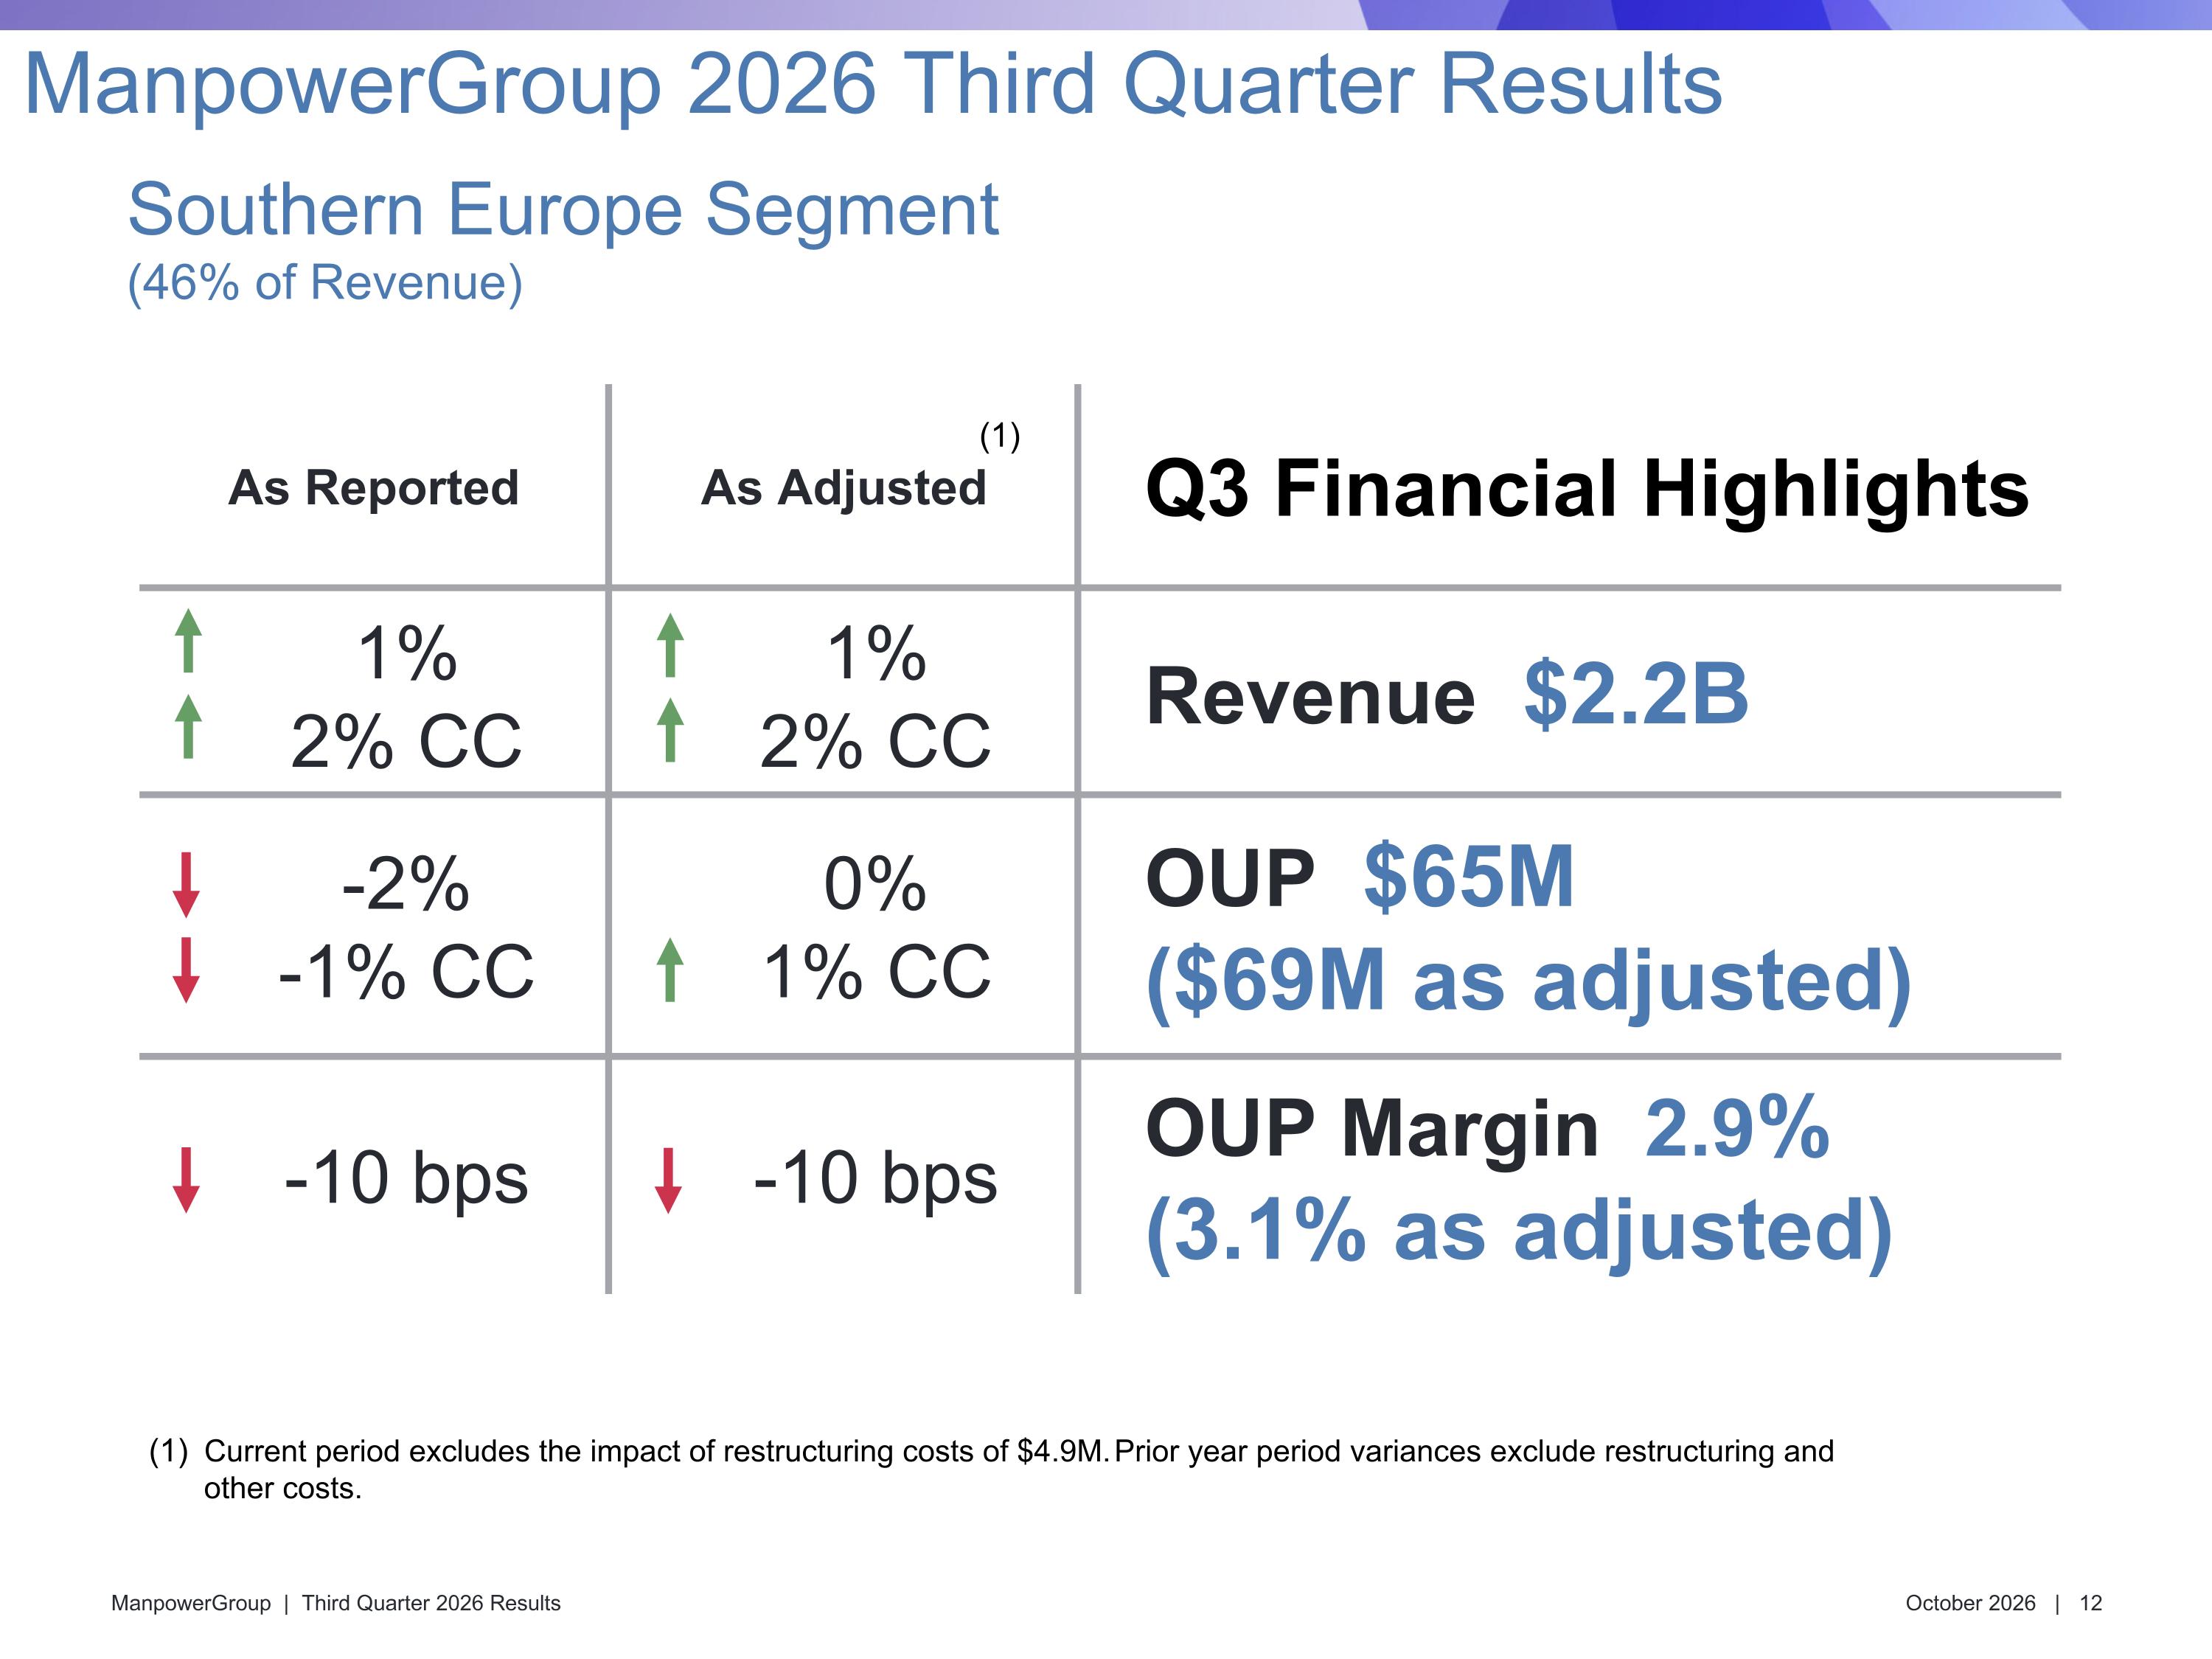
As Reported As Adjusted Q3 Financial Highlights 1% 2% CC 1% 2% CC Revenue $2.2B -2% -1% CC 0% 1% CC OUP $65M ($69M as adjusted) -10 bps -10 bps OUP Margin 2.9% (3.1% as adjusted) Southern Europe Segment (46% of Revenue) ManpowerGroup 2026 Third Quarter Results (1) Current period excludes the impact of restructuring costs of $4.9M. Prior year period variances exclude restructuring and other costs.
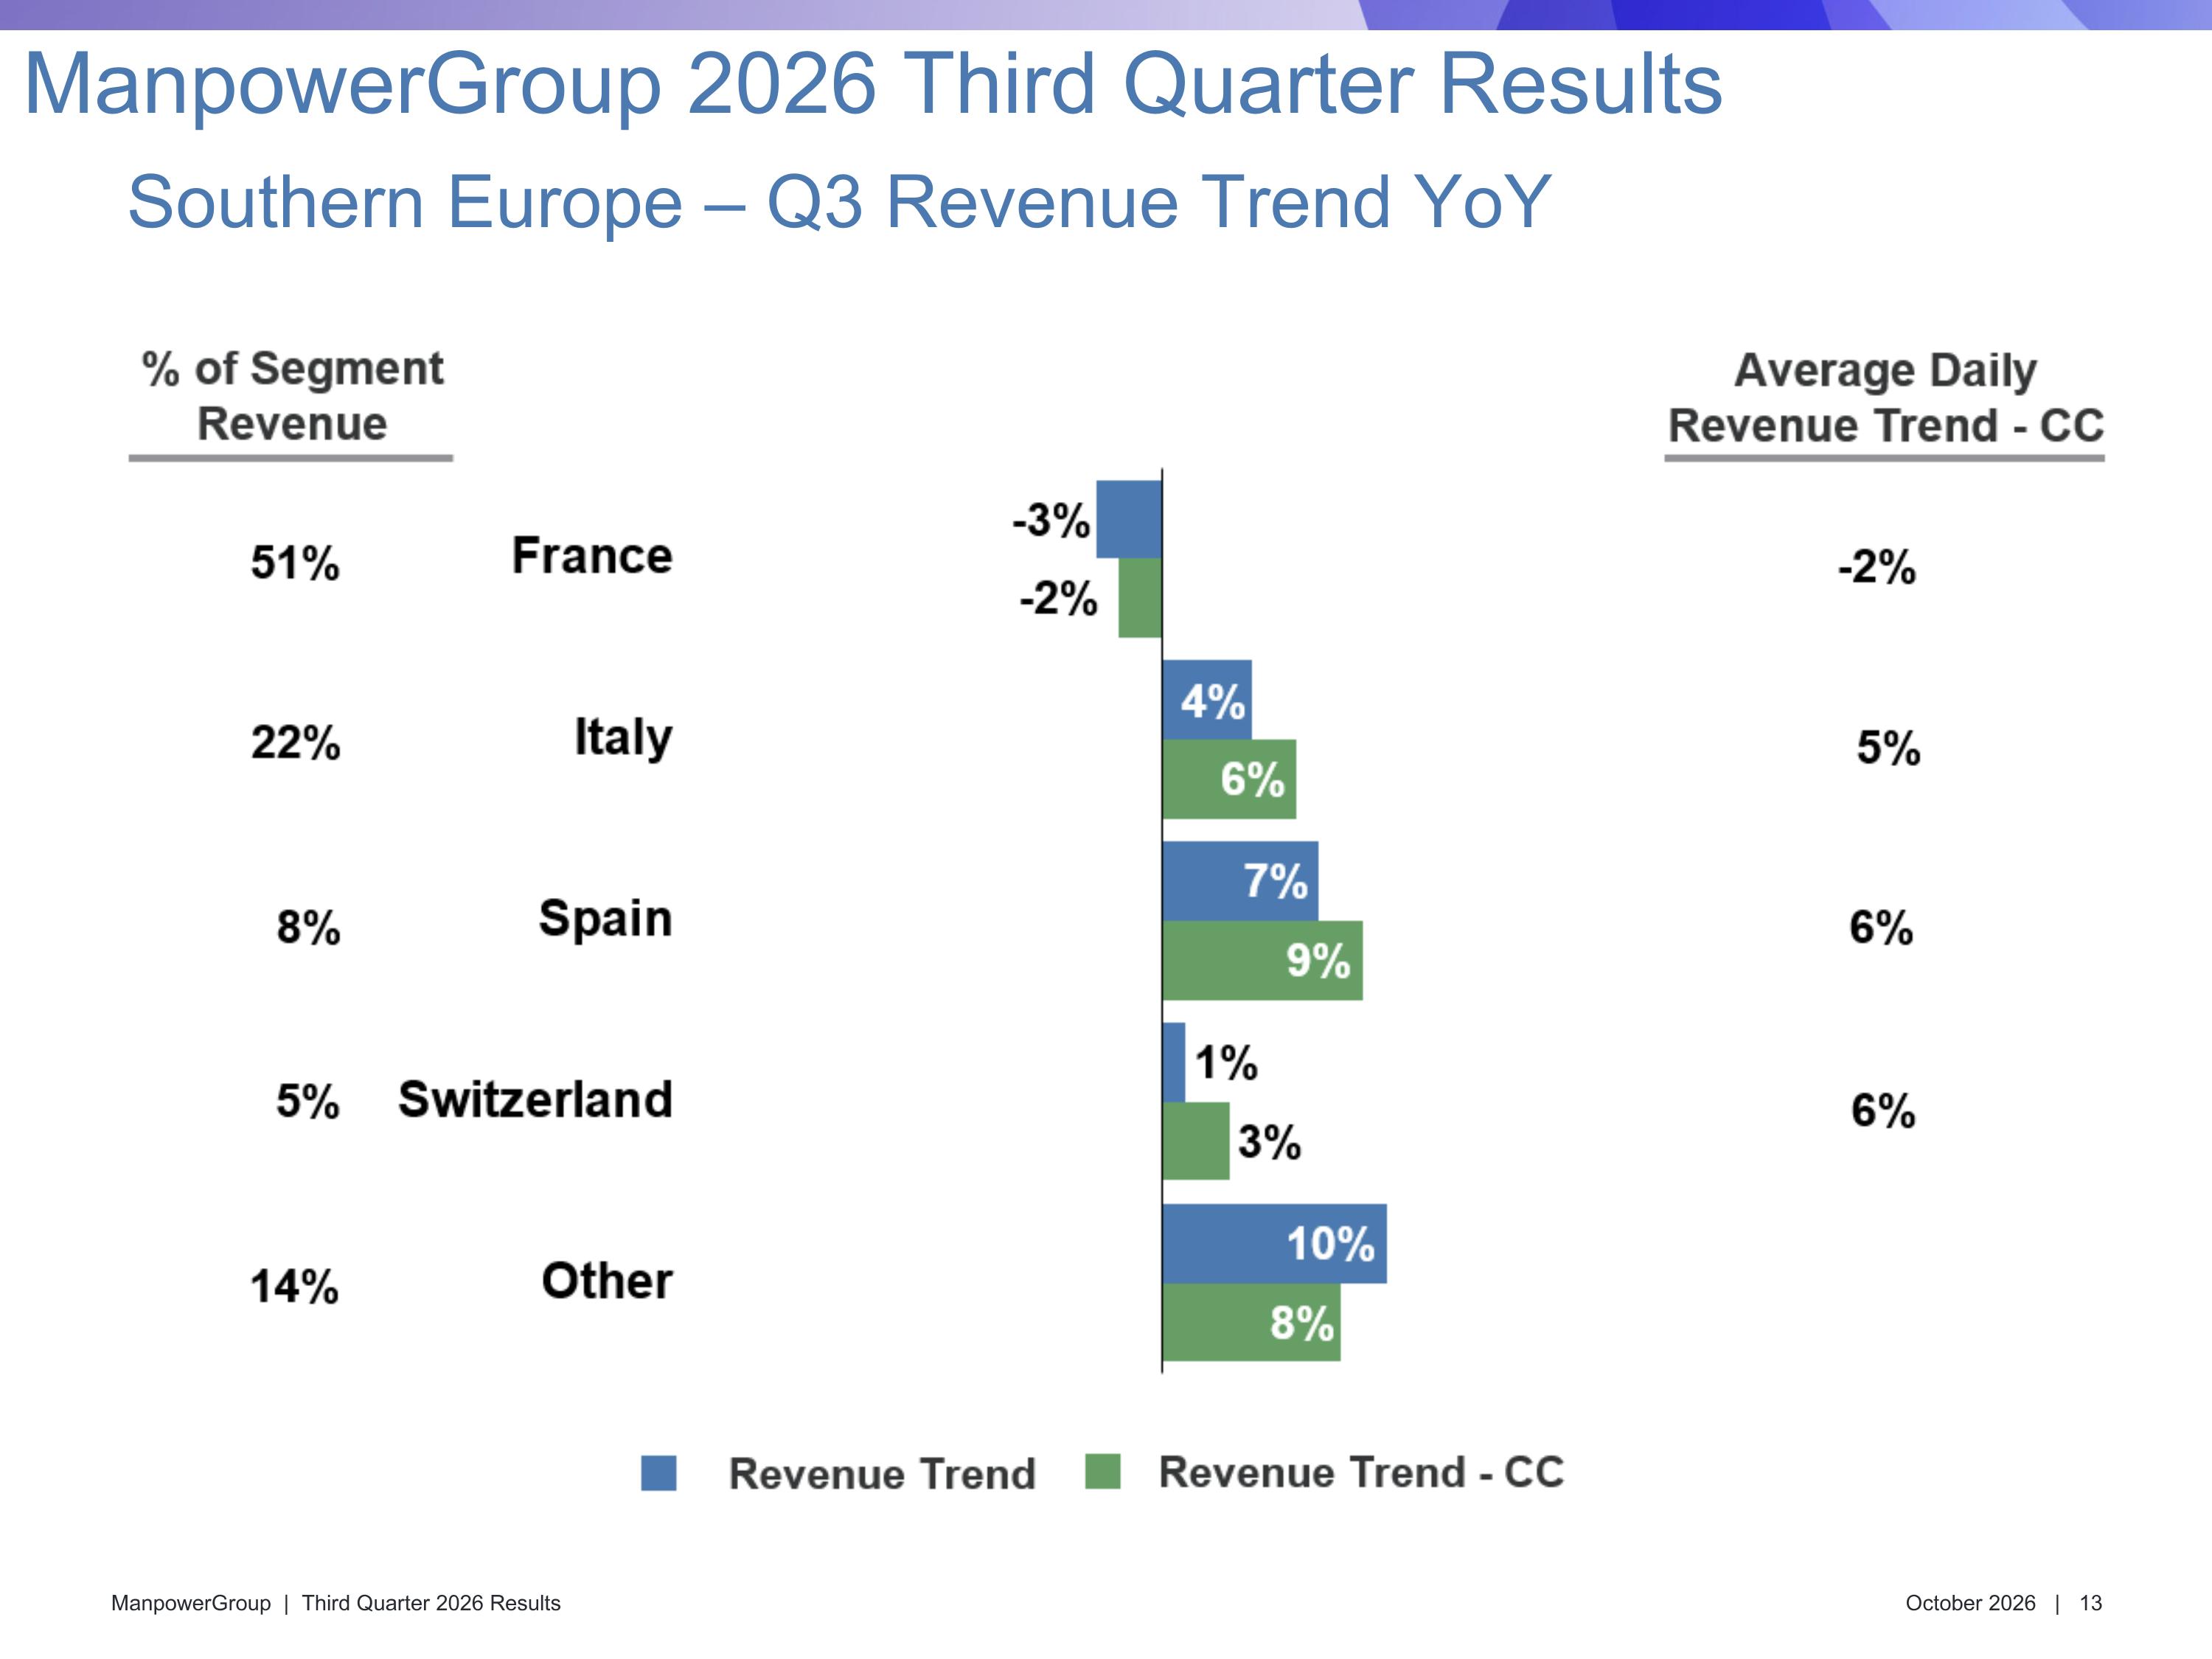
Southern Europe – Q3 Revenue Trend YoY ManpowerGroup 2026 Third Quarter Results
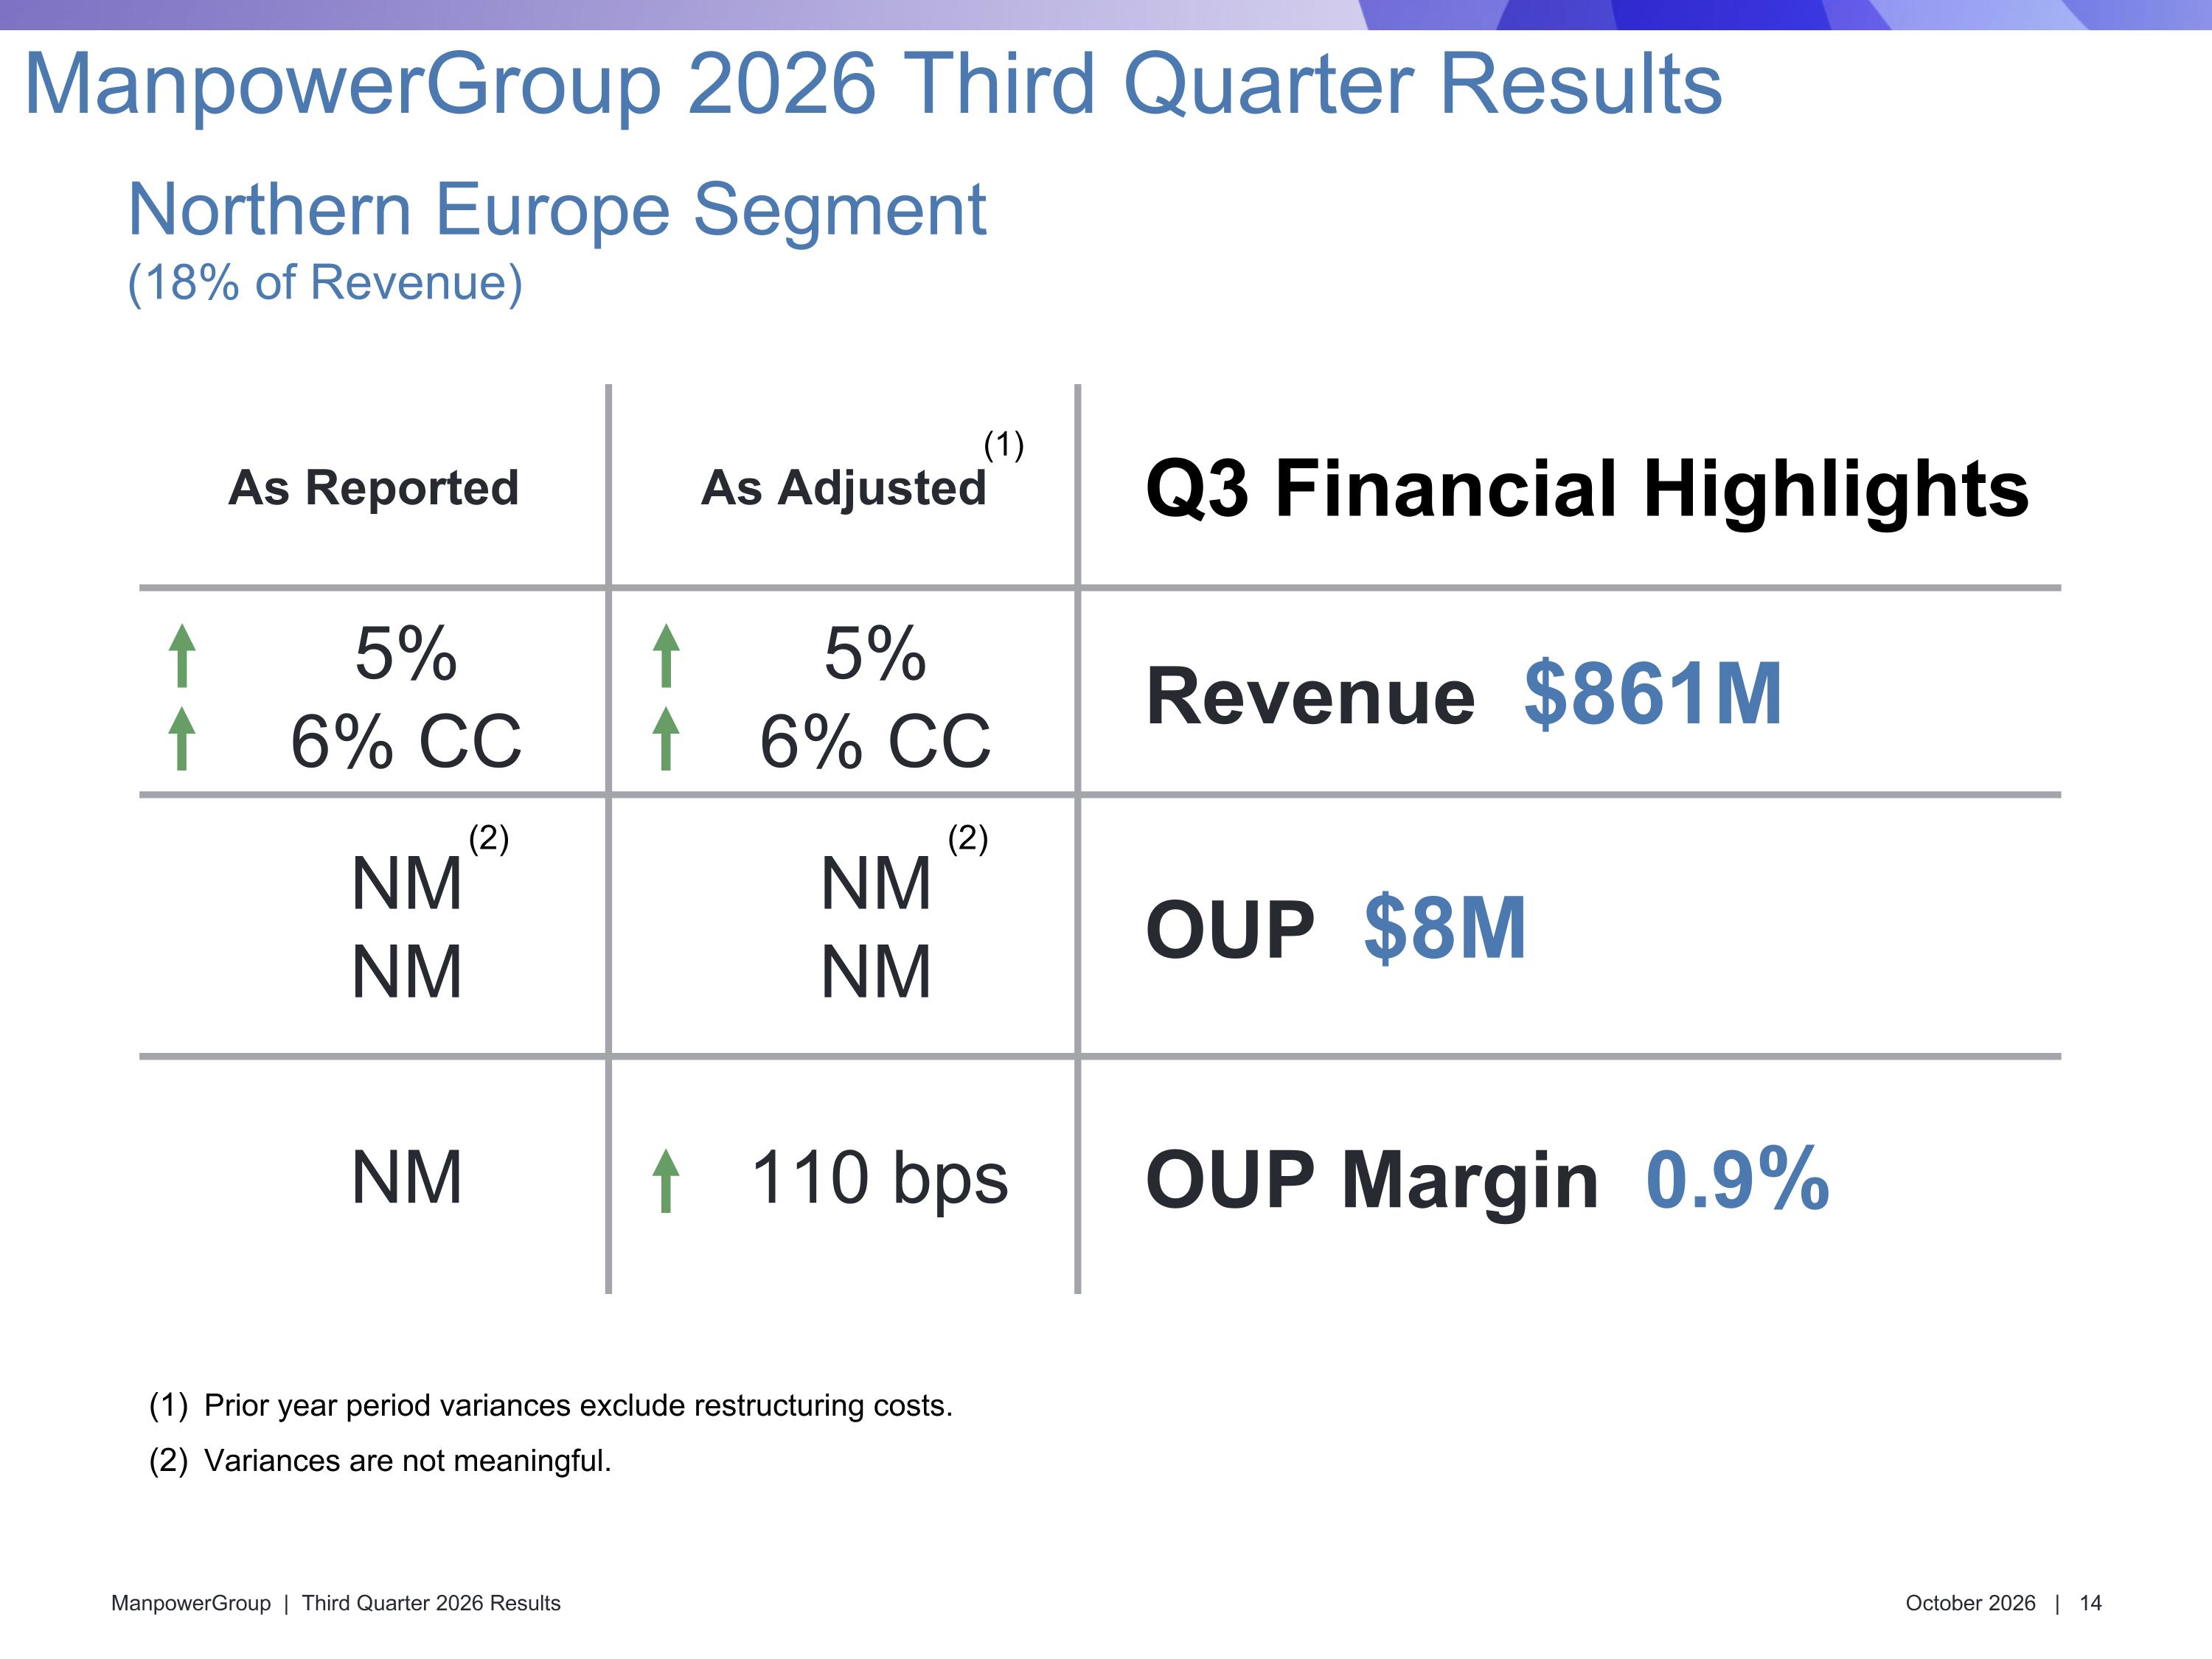
As Reported As Adjusted Q3 Financial Highlights 5% 6% CC 5% 6% CC Revenue $861M NM NM NM NM OUP $8M NM 110 bps OUP Margin 0.9% Northern Europe Segment (18% of Revenue) ManpowerGroup 2026 Third Quarter Results (1) Prior year period variances exclude restructuring costs. Variances are not meaningful. (2) (2)
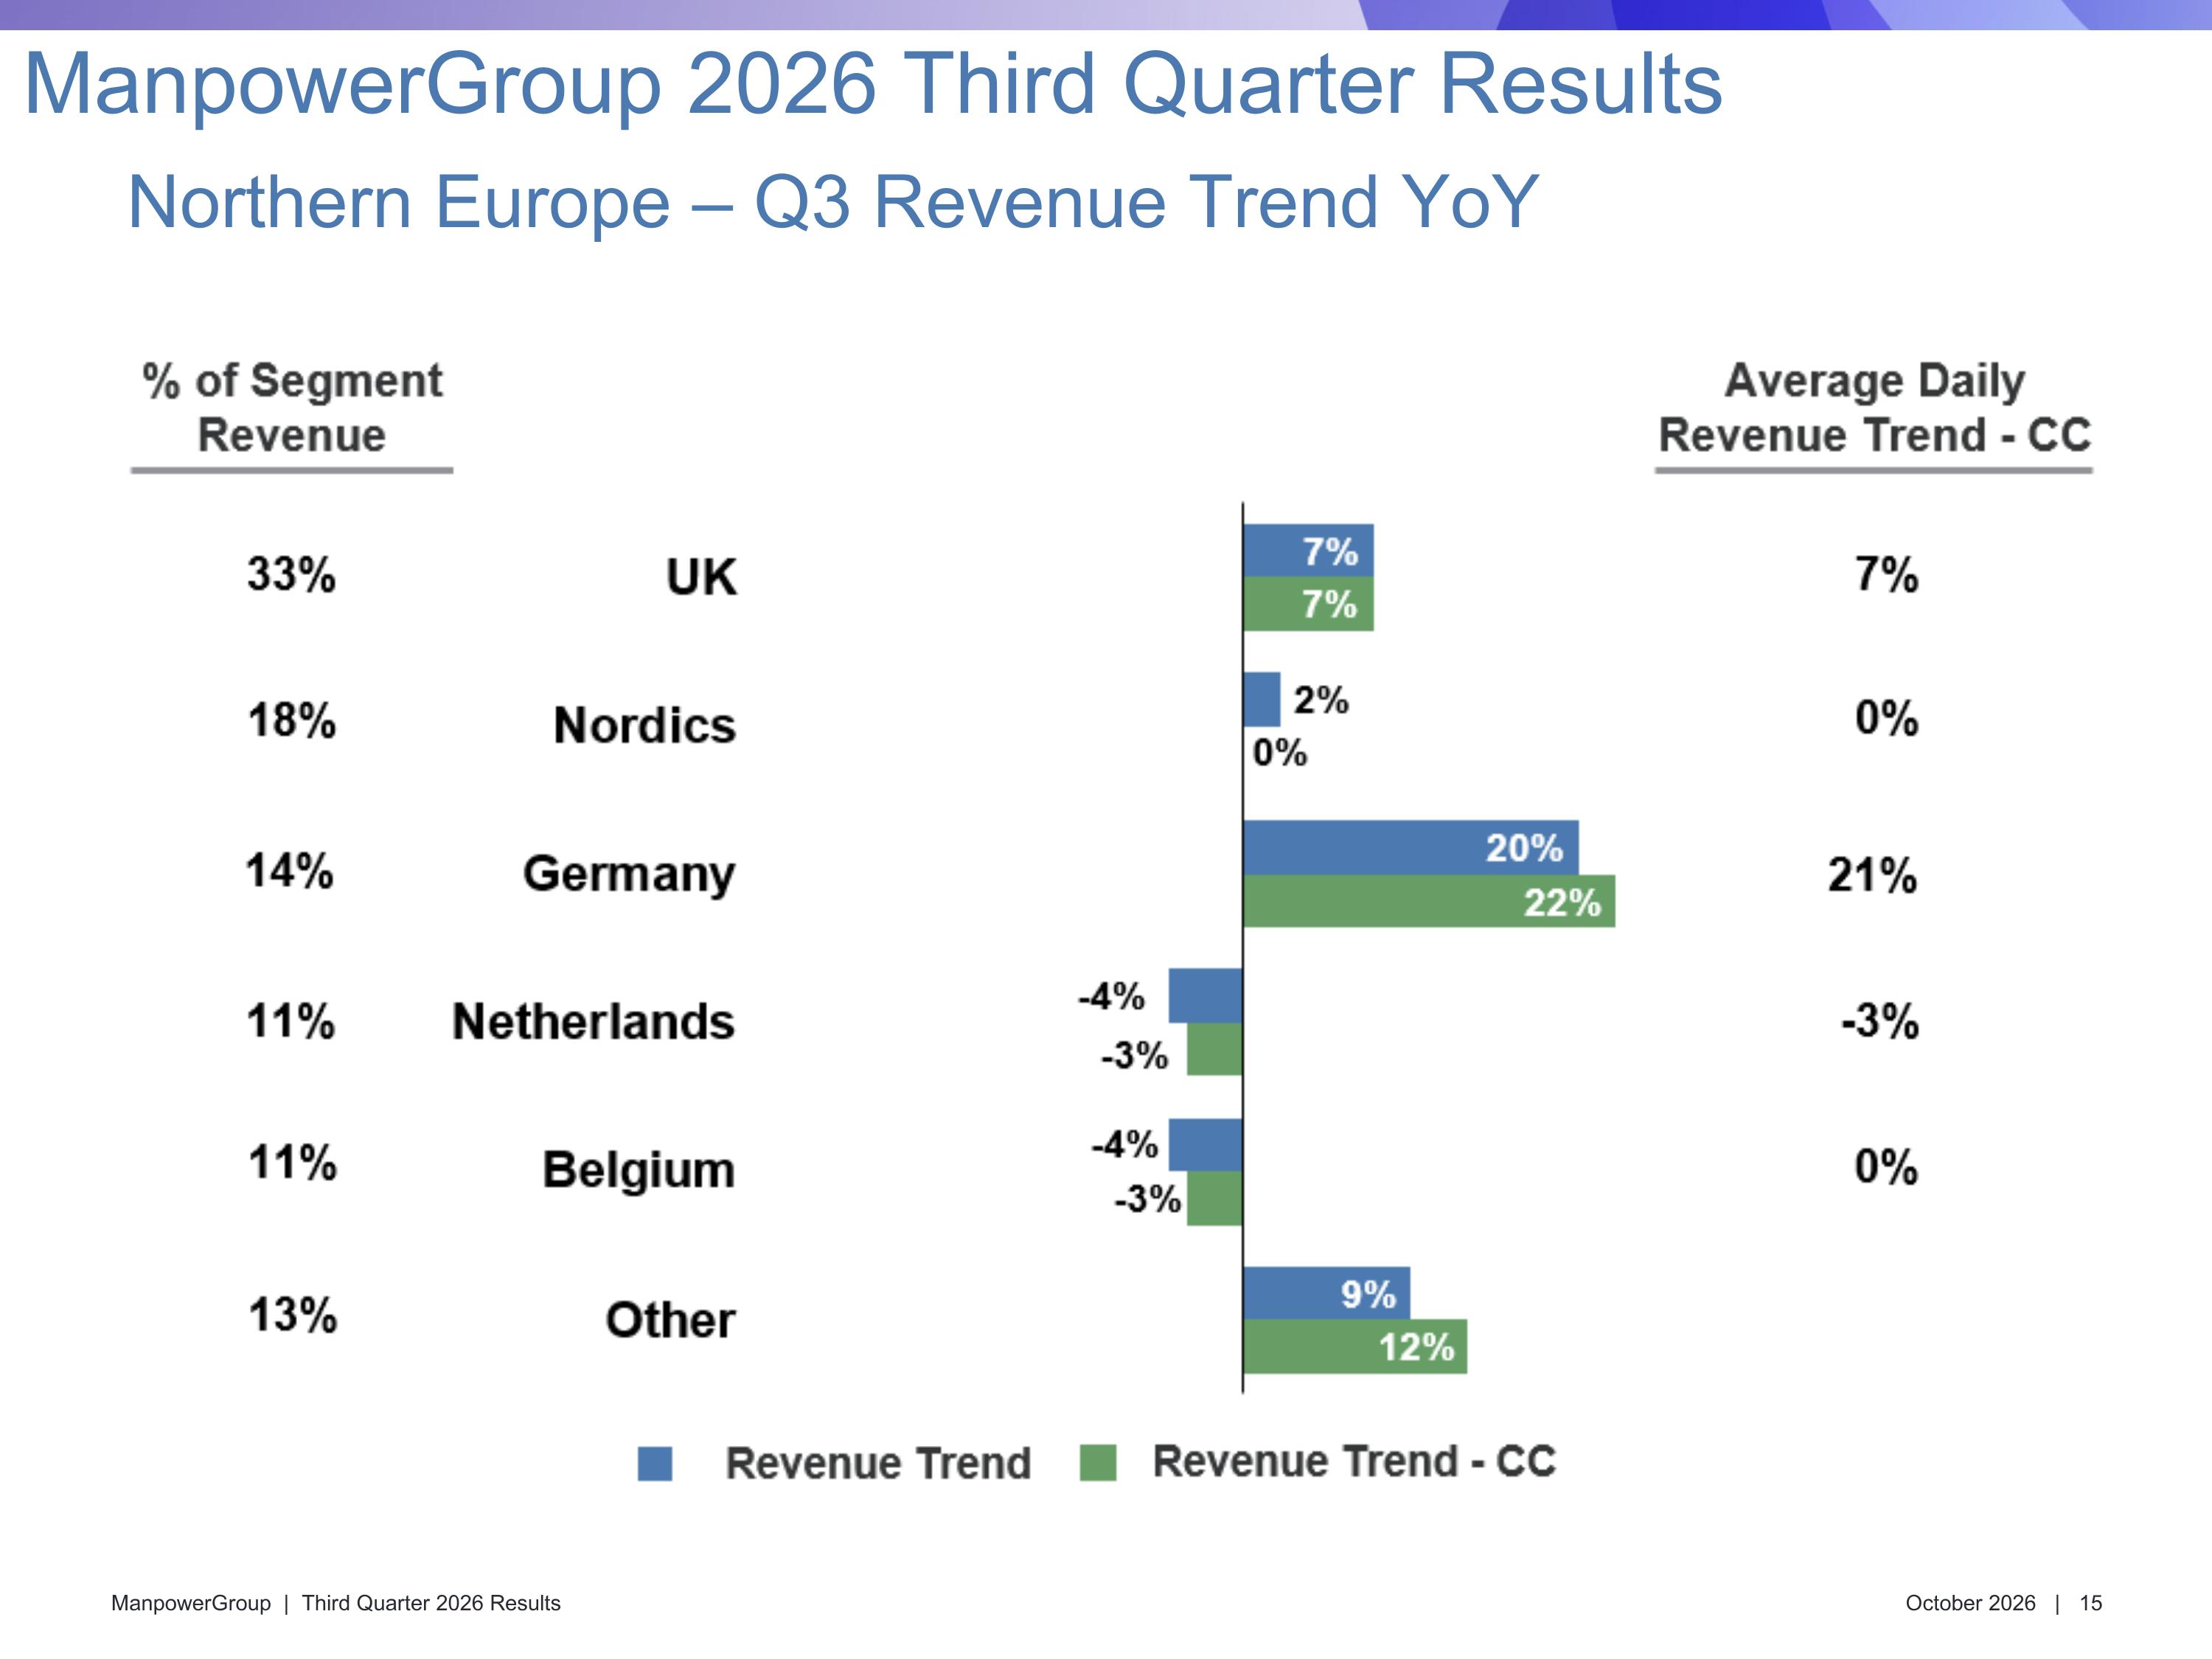
-28% Northern Europe – Q3 Revenue Trend YoY ManpowerGroup 2026 Third Quarter Results
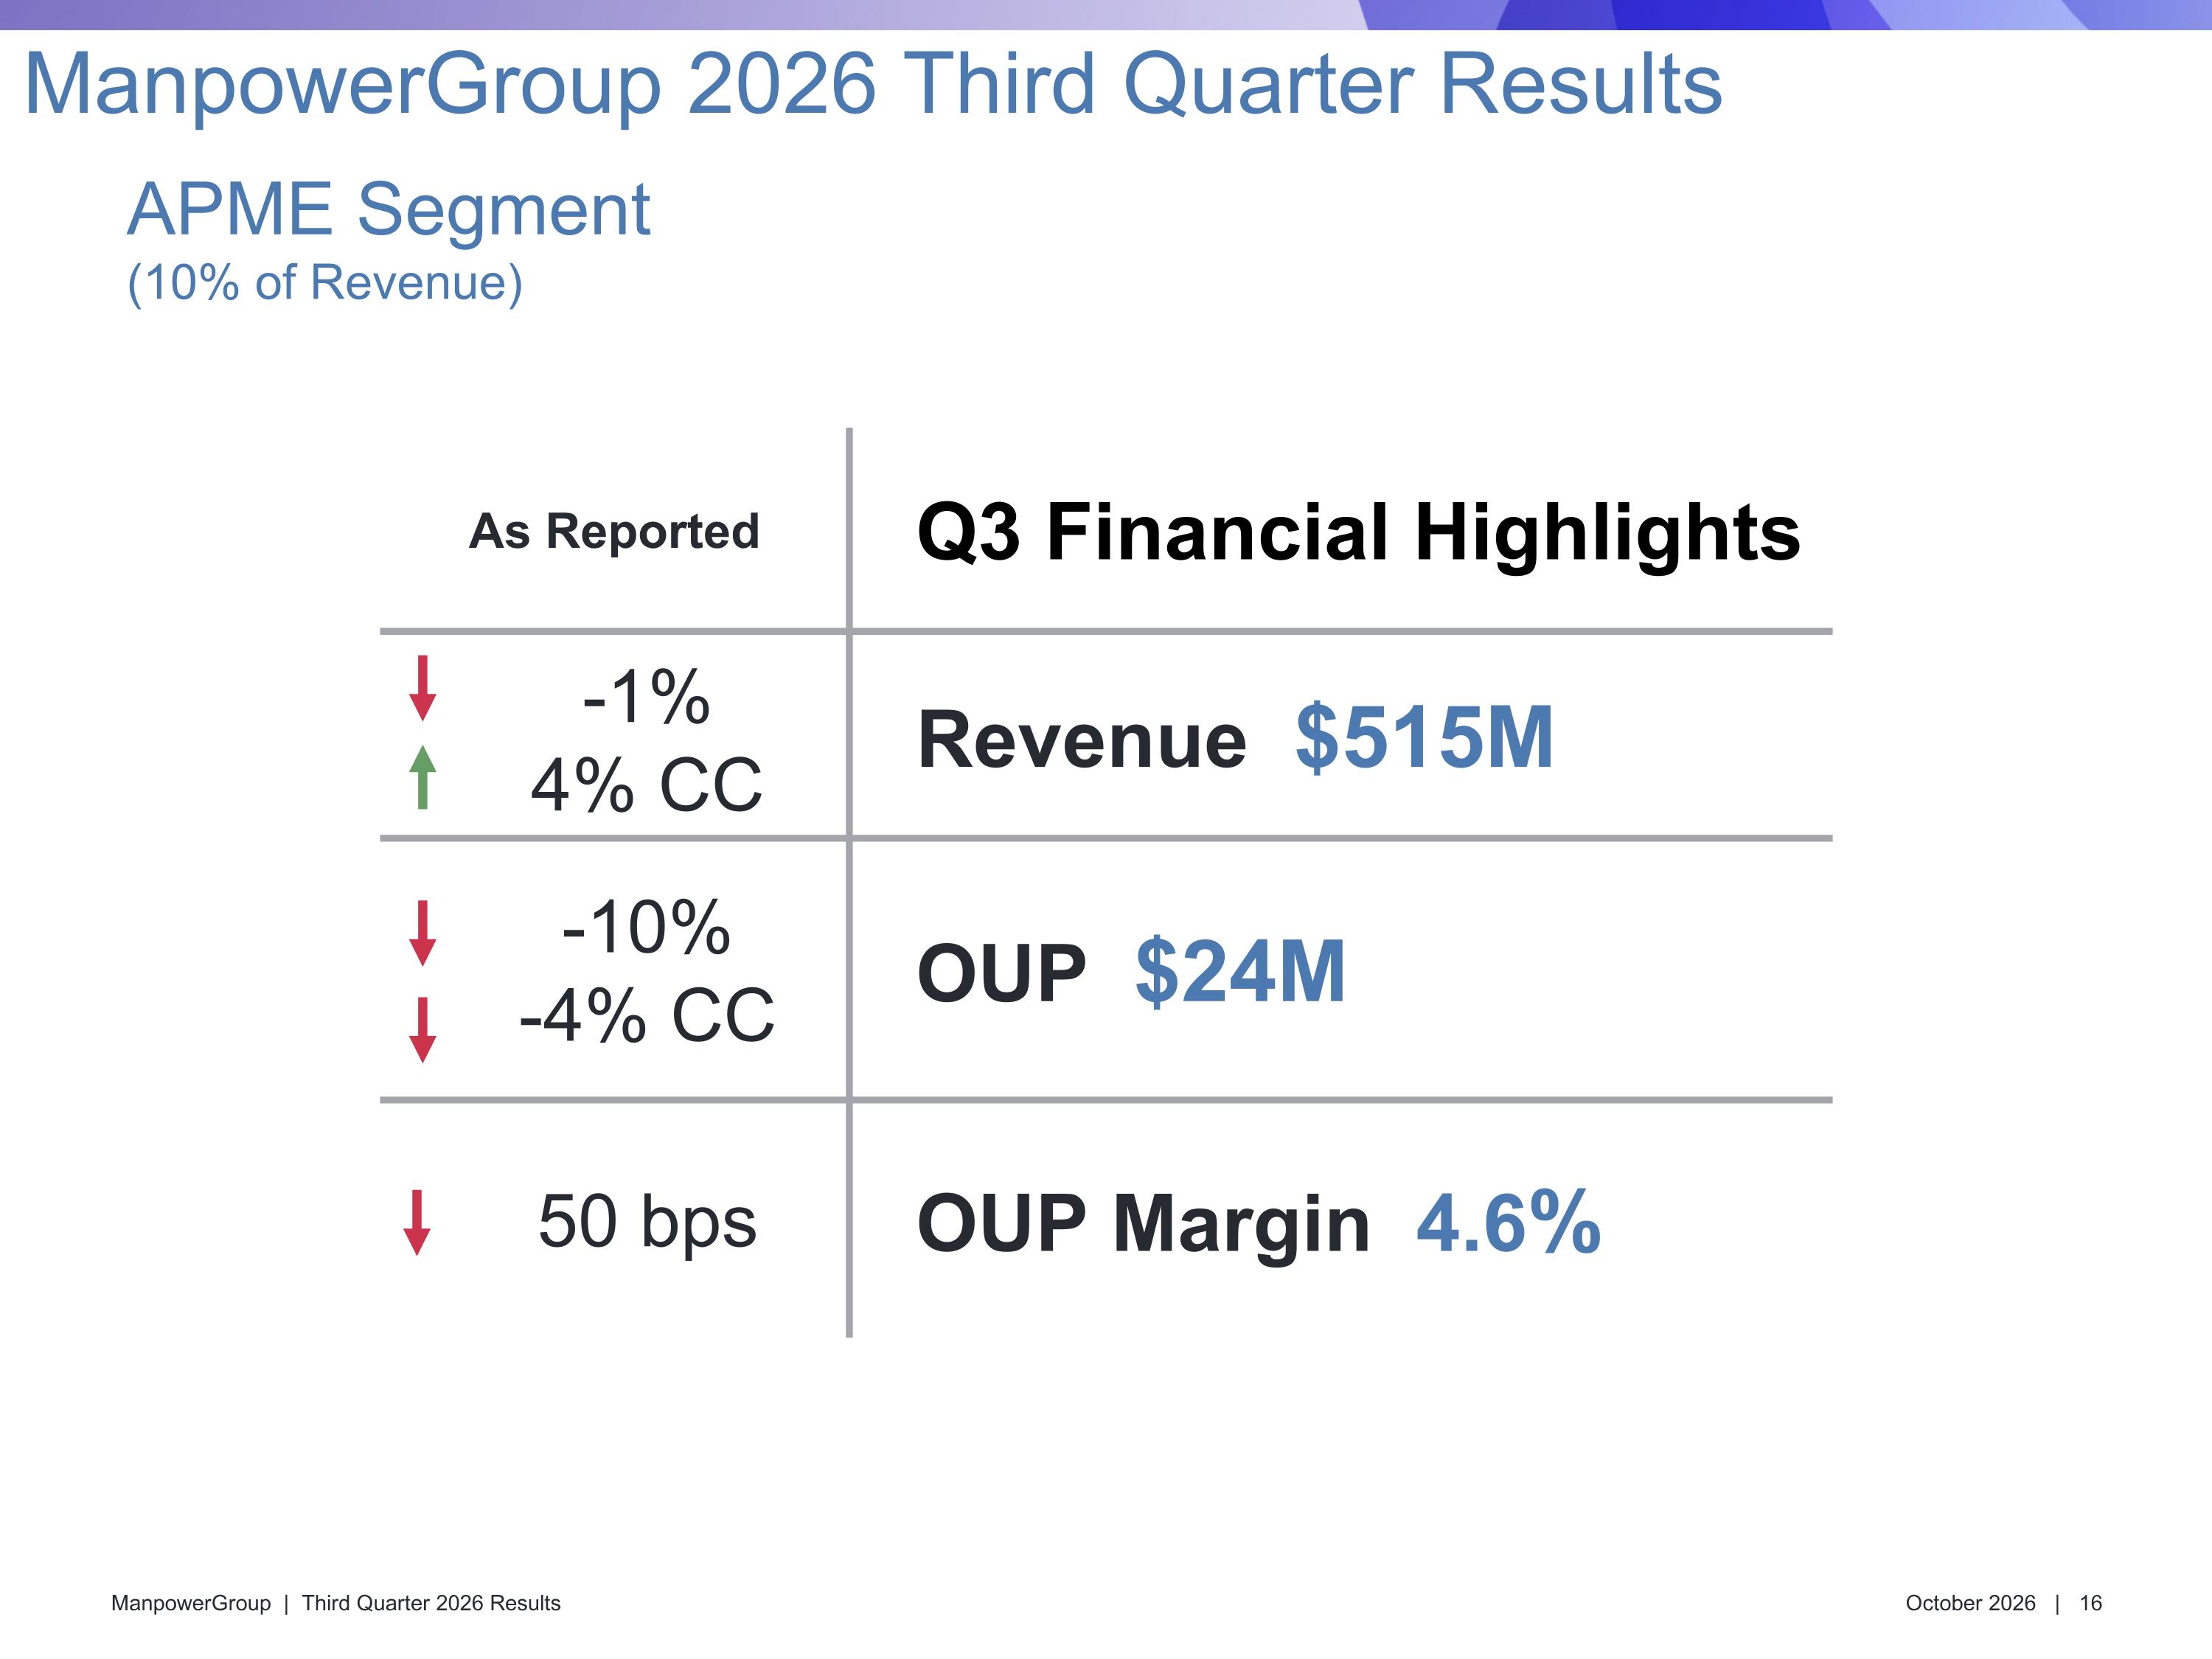
As Reported Q3 Financial Highlights -1% 4% CC Revenue $515M -10% -4% CC OUP $24M 50 bps OUP Margin 4.6% APME Segment (10% of Revenue) ManpowerGroup 2026 Third Quarter Results
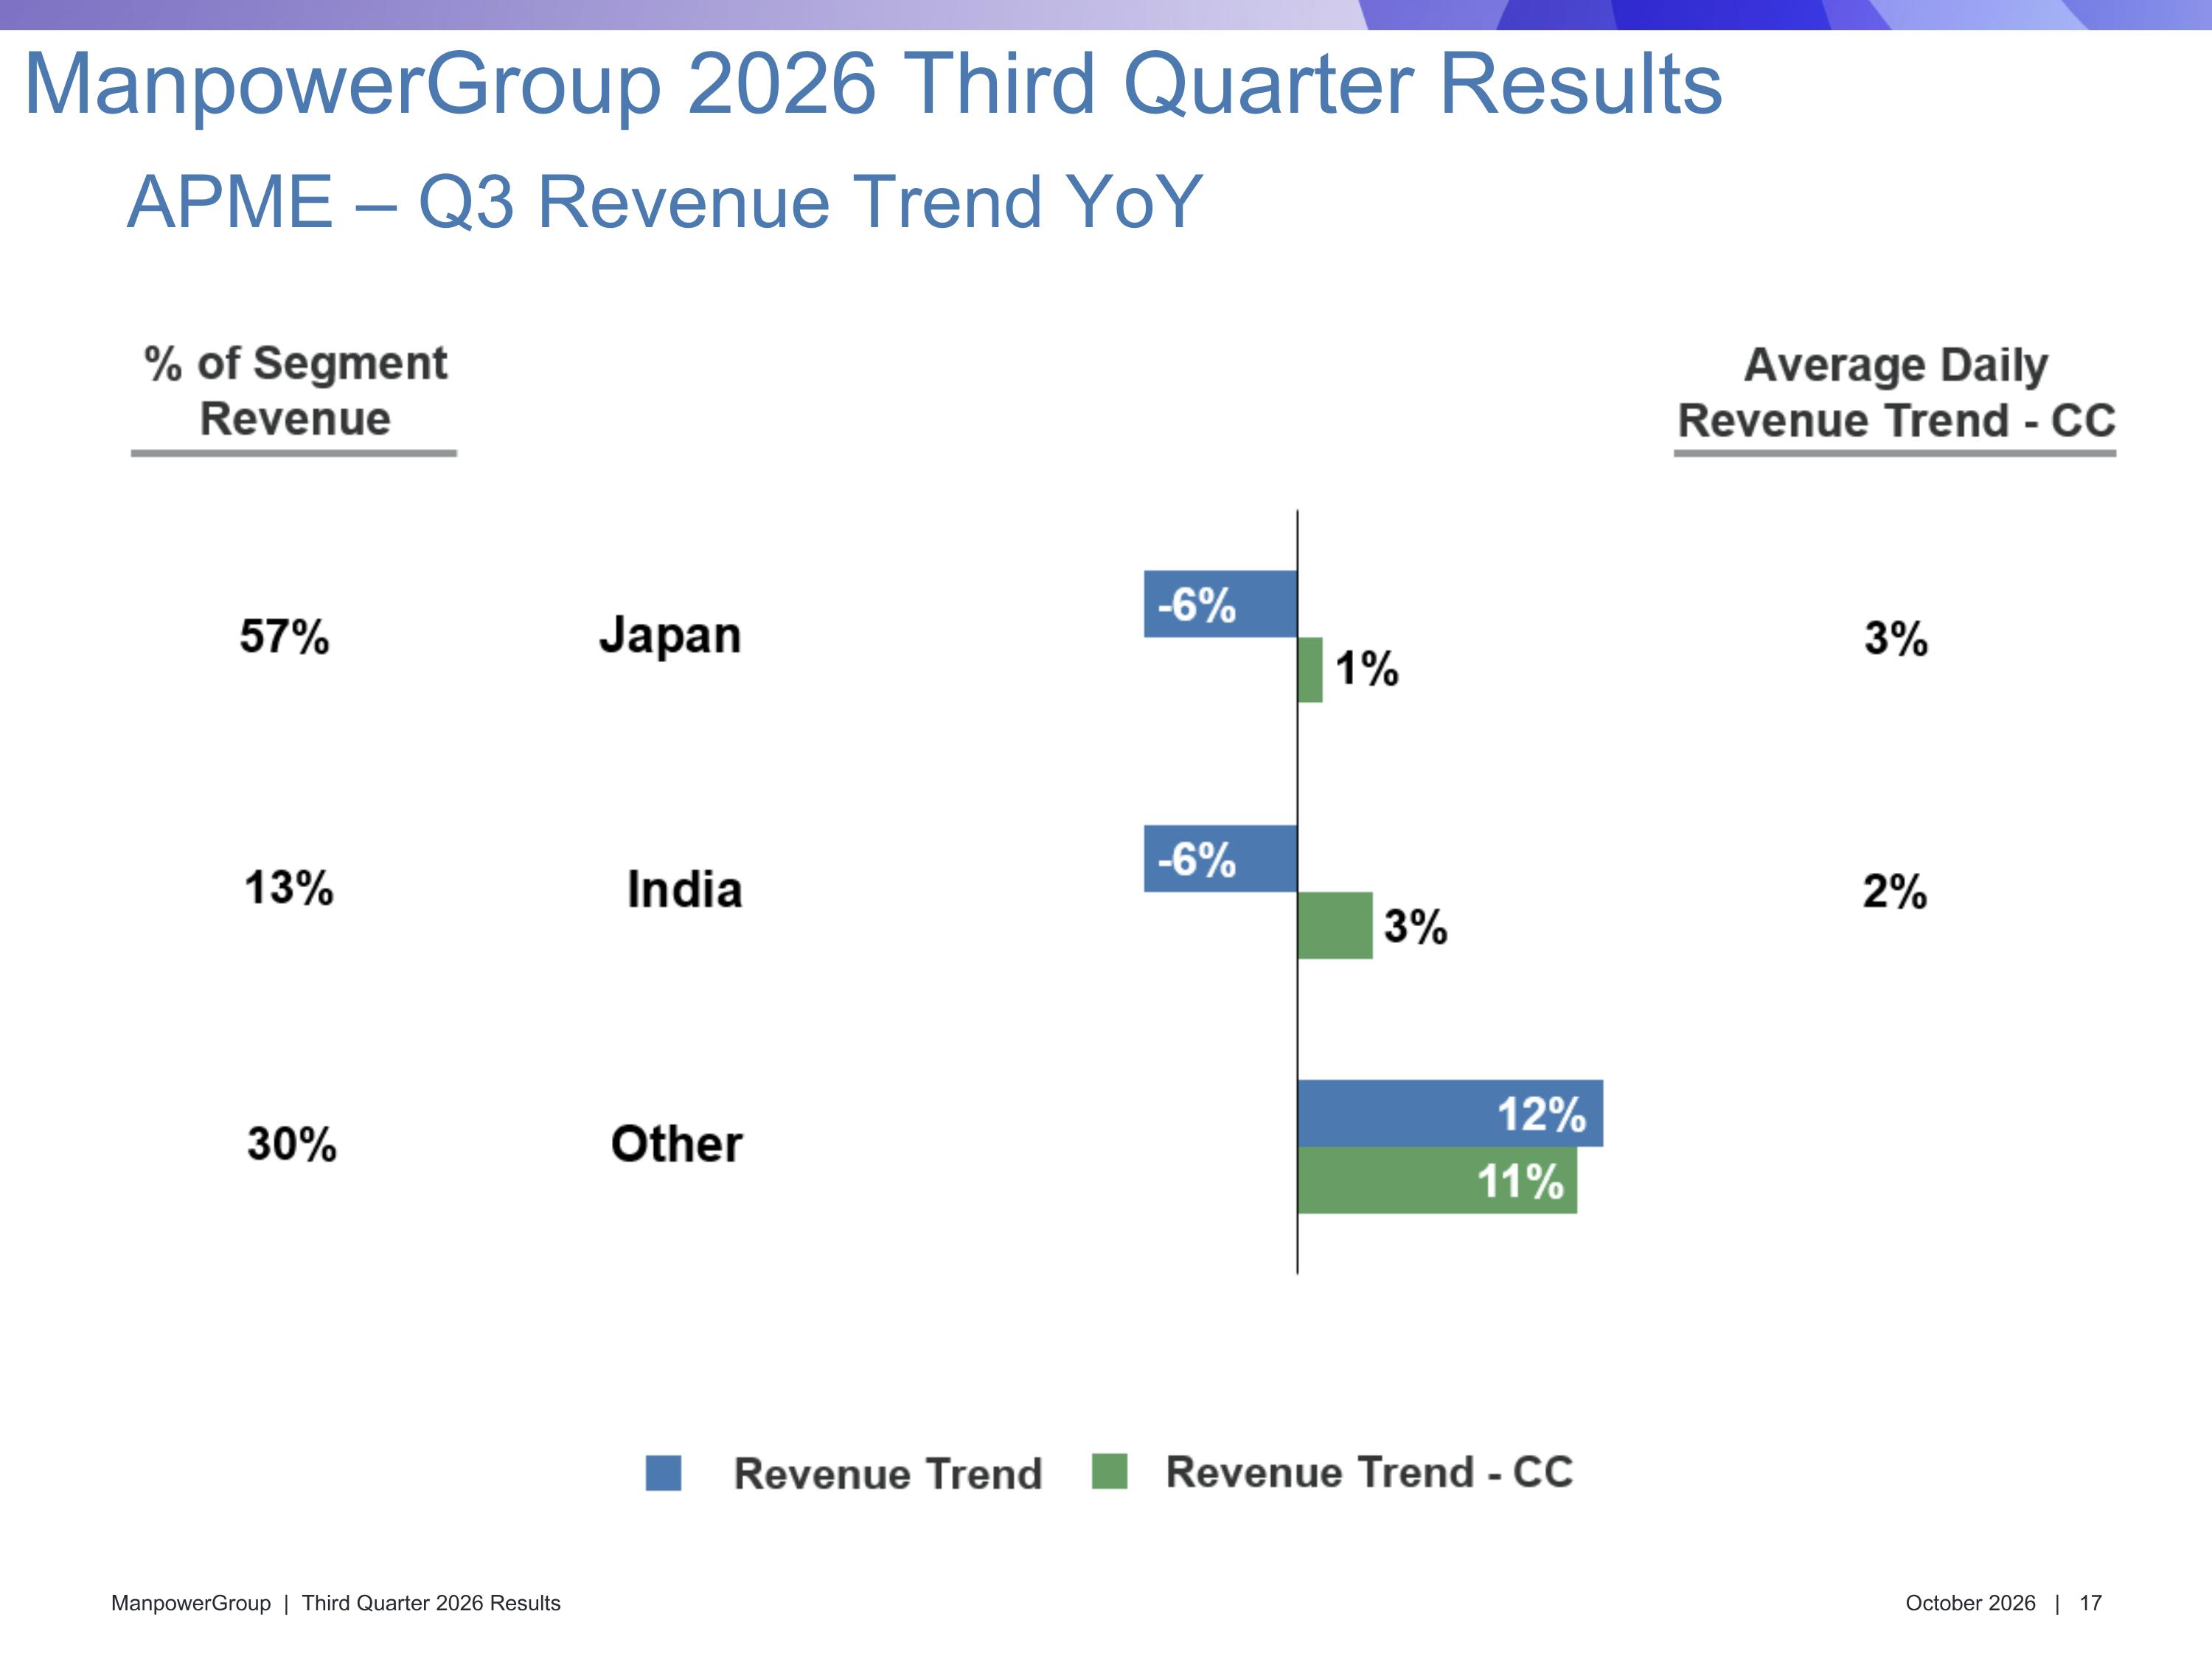
APME – Q3 Revenue Trend YoY ManpowerGroup 2026 Third Quarter Results
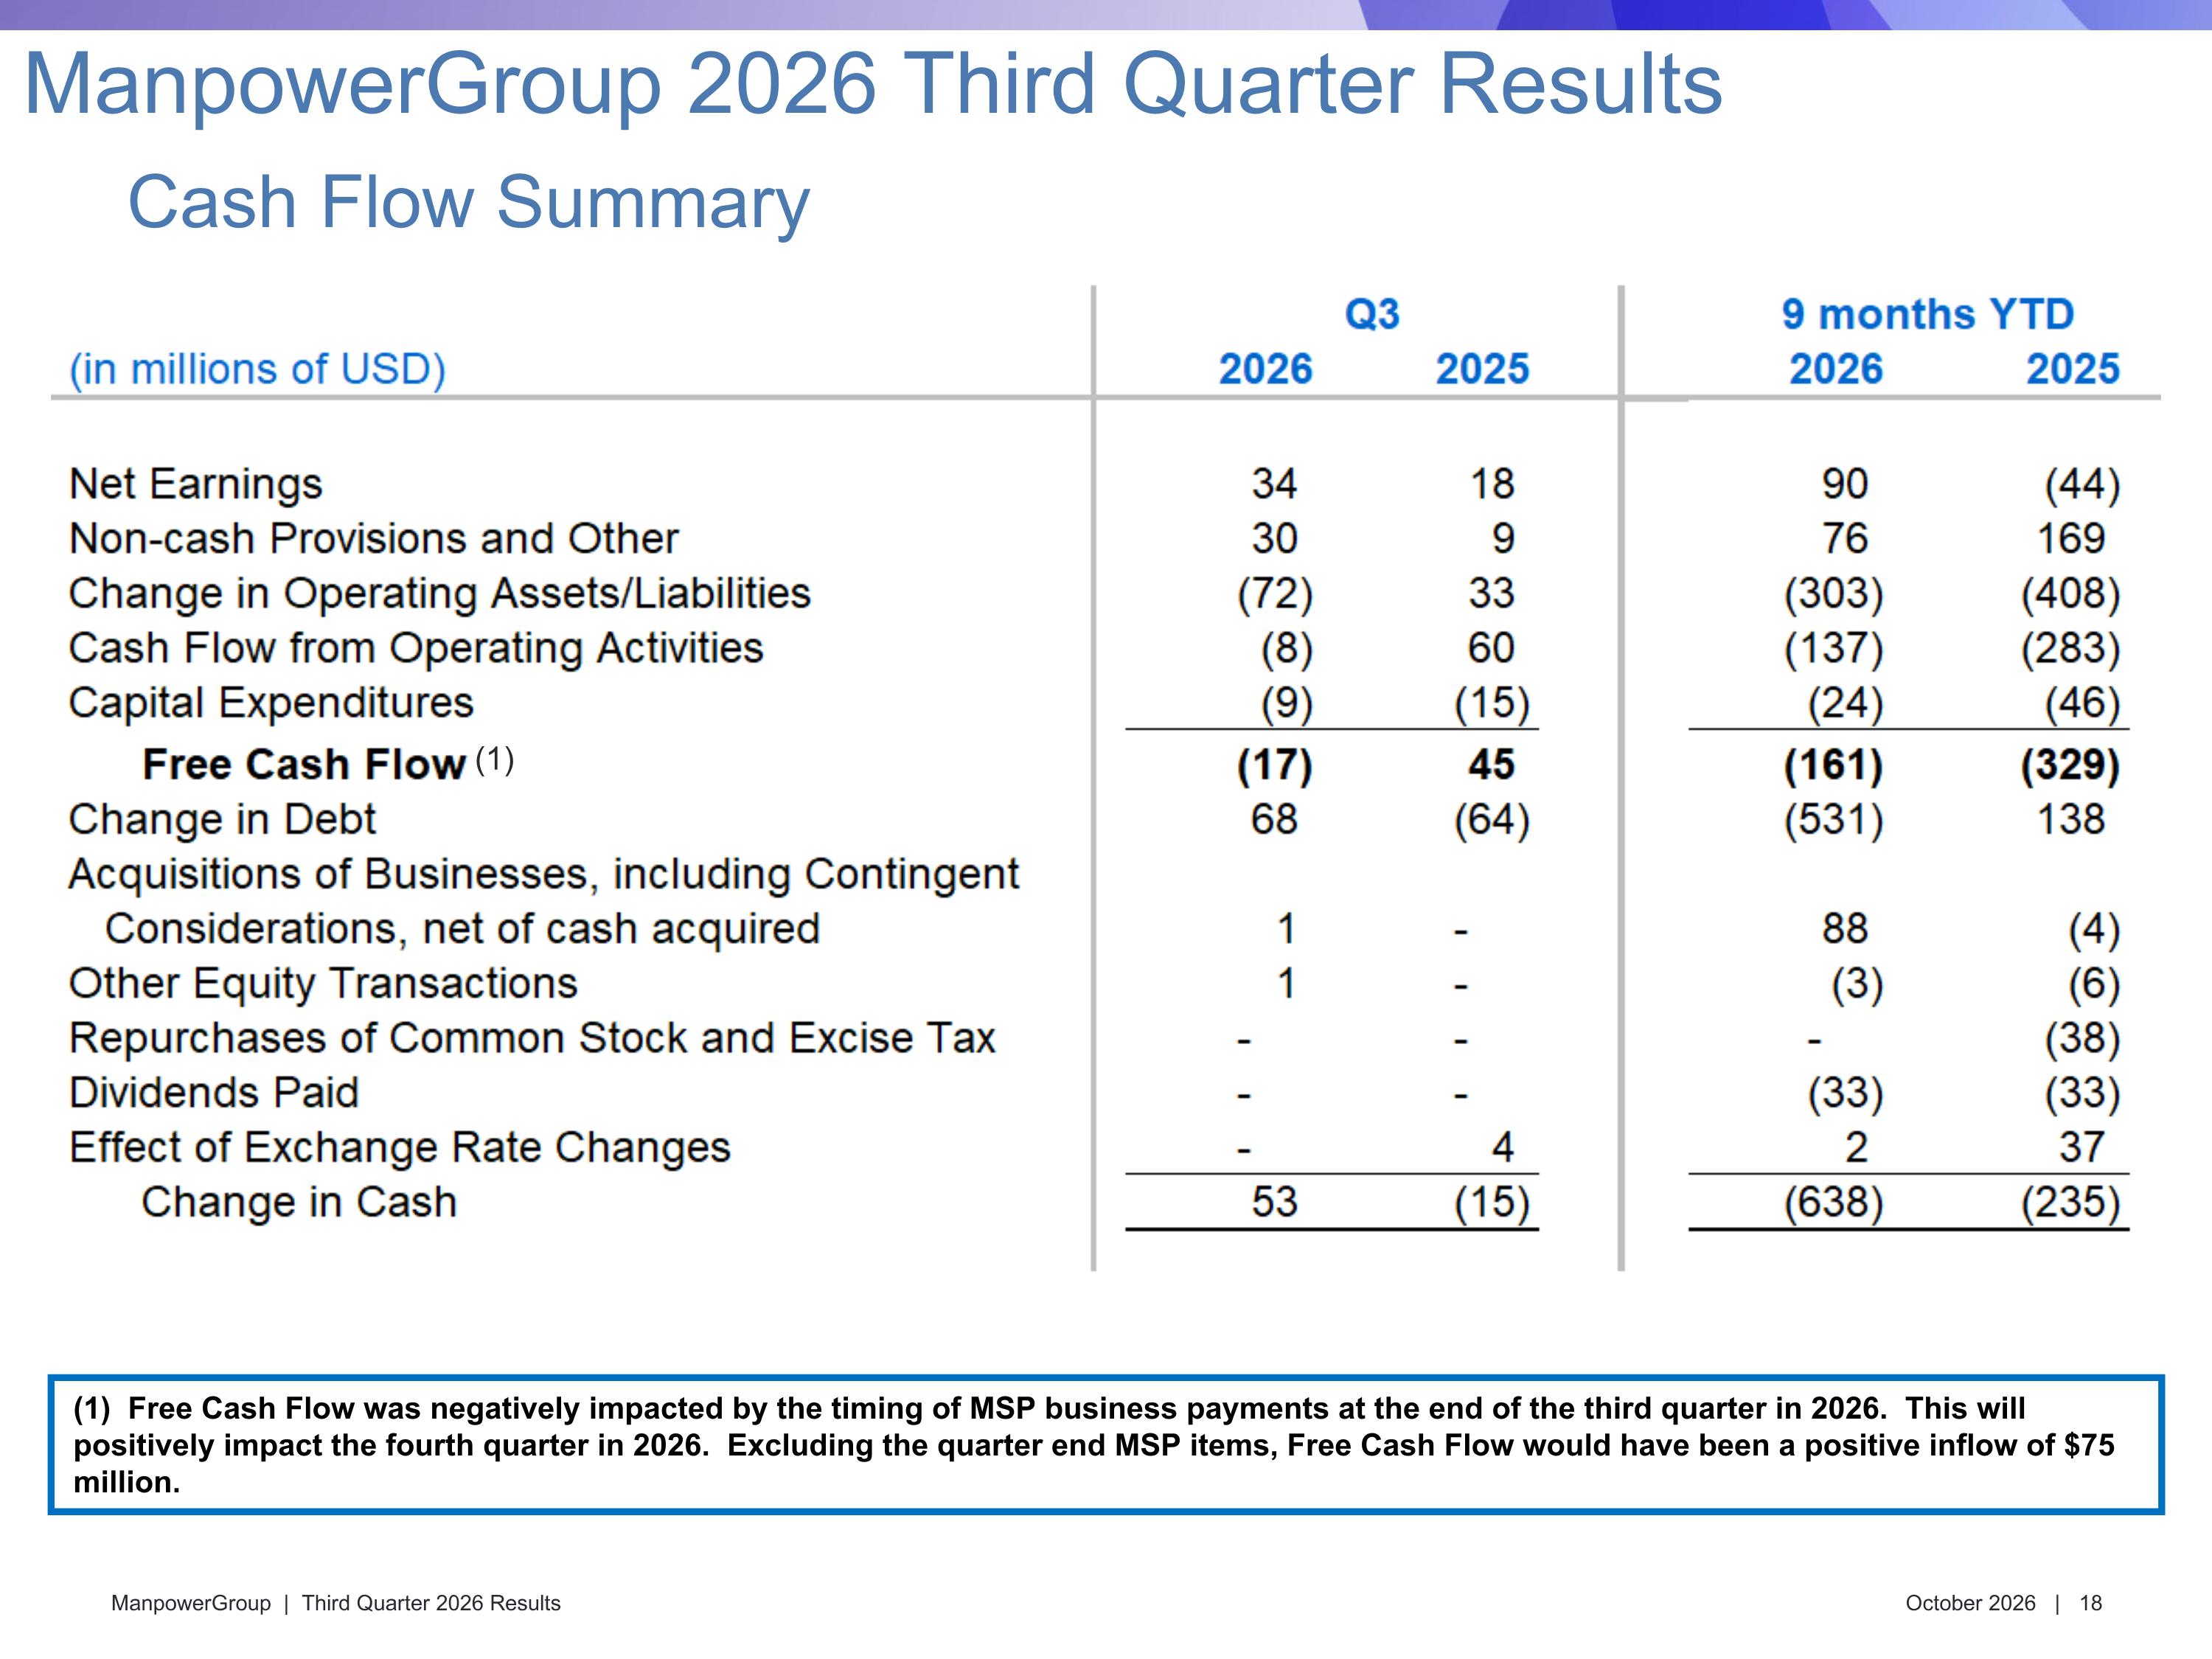
Cash Flow Summary ManpowerGroup 2026 Third Quarter Results (1) Free Cash Flow was negatively impacted by the timing of MSP business payments at the end of the third quarter in 2026. This will positively impact the fourth quarter in 2026. Excluding the quarter end MSP items, Free Cash Flow would have been a positive inflow of $75 million. (1)
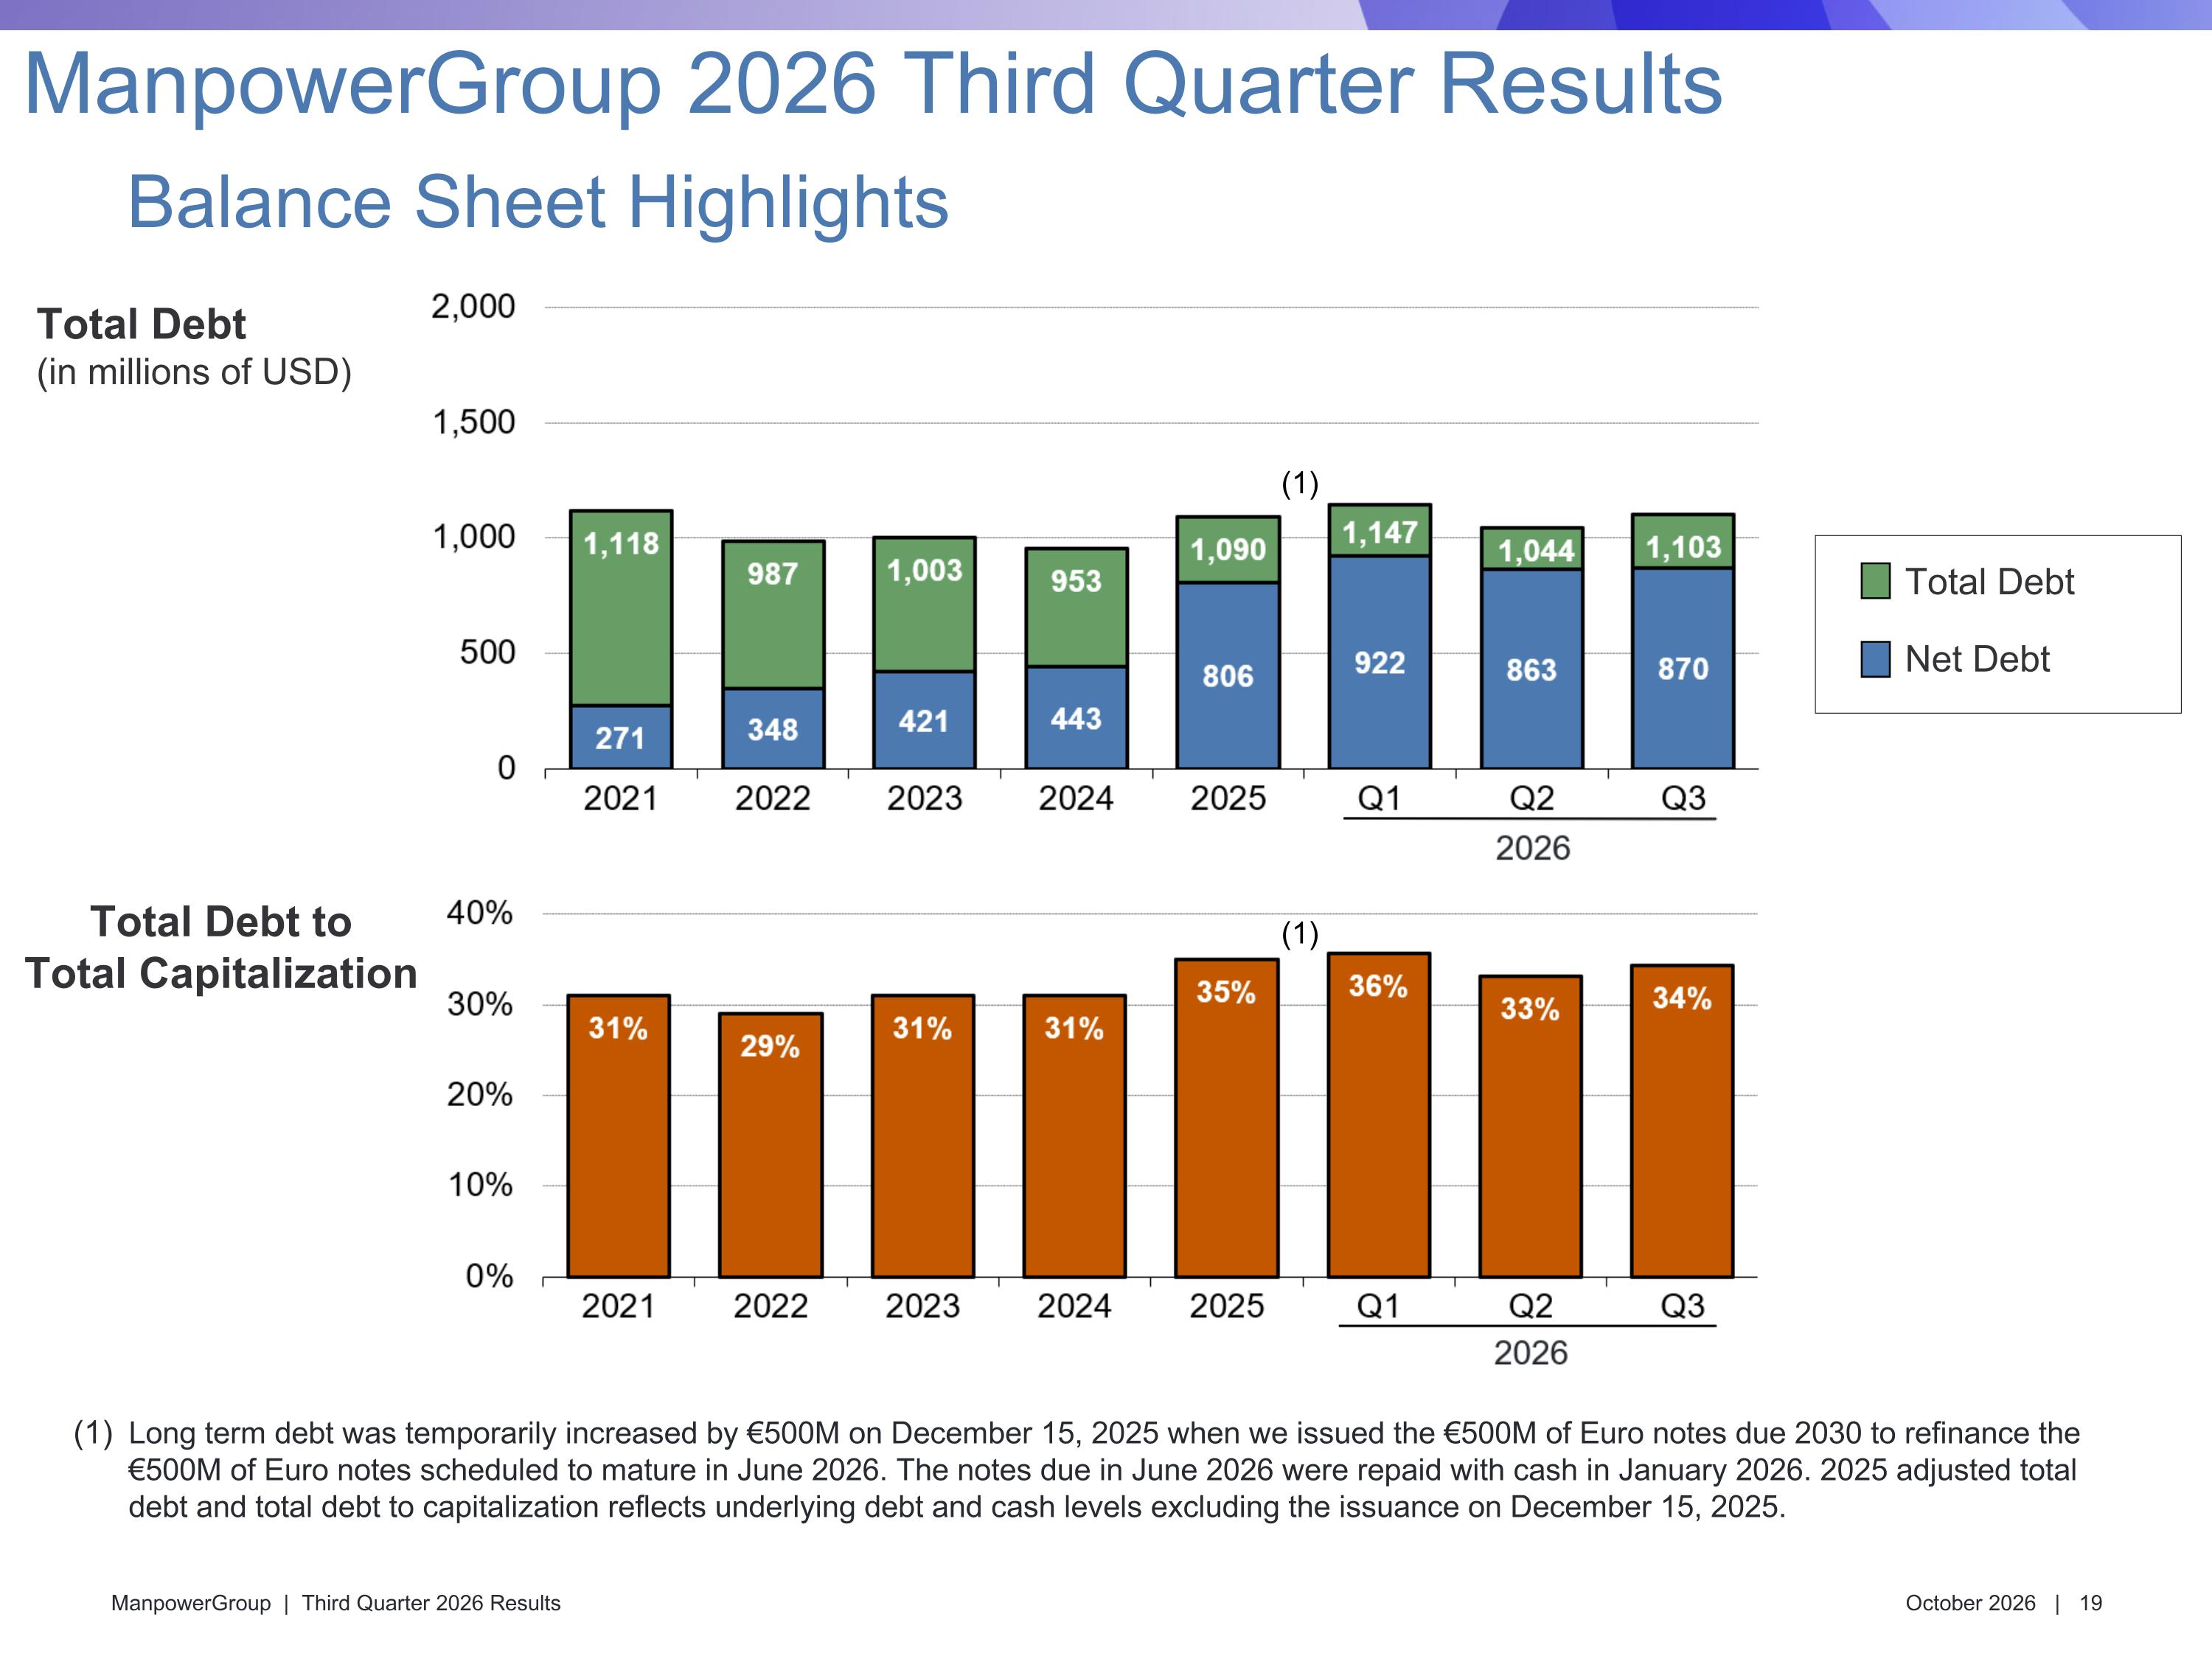
Total Debt (in millions of USD) Total Debt to Total Capitalization Total Debt Net Debt Balance Sheet Highlights ManpowerGroup 2026 Third Quarter Results Long term debt was temporarily increased by €500M on December 15, 2025 when we issued the €500M of Euro notes due 2030 to refinance the €500M of Euro notes scheduled to mature in June 2026. The notes due in June 2026 were repaid with cash in January 2026. 2025 adjusted total debt and total debt to capitalization reflects underlying debt and cash levels excluding the issuance on December 15, 2025. (1) (1)
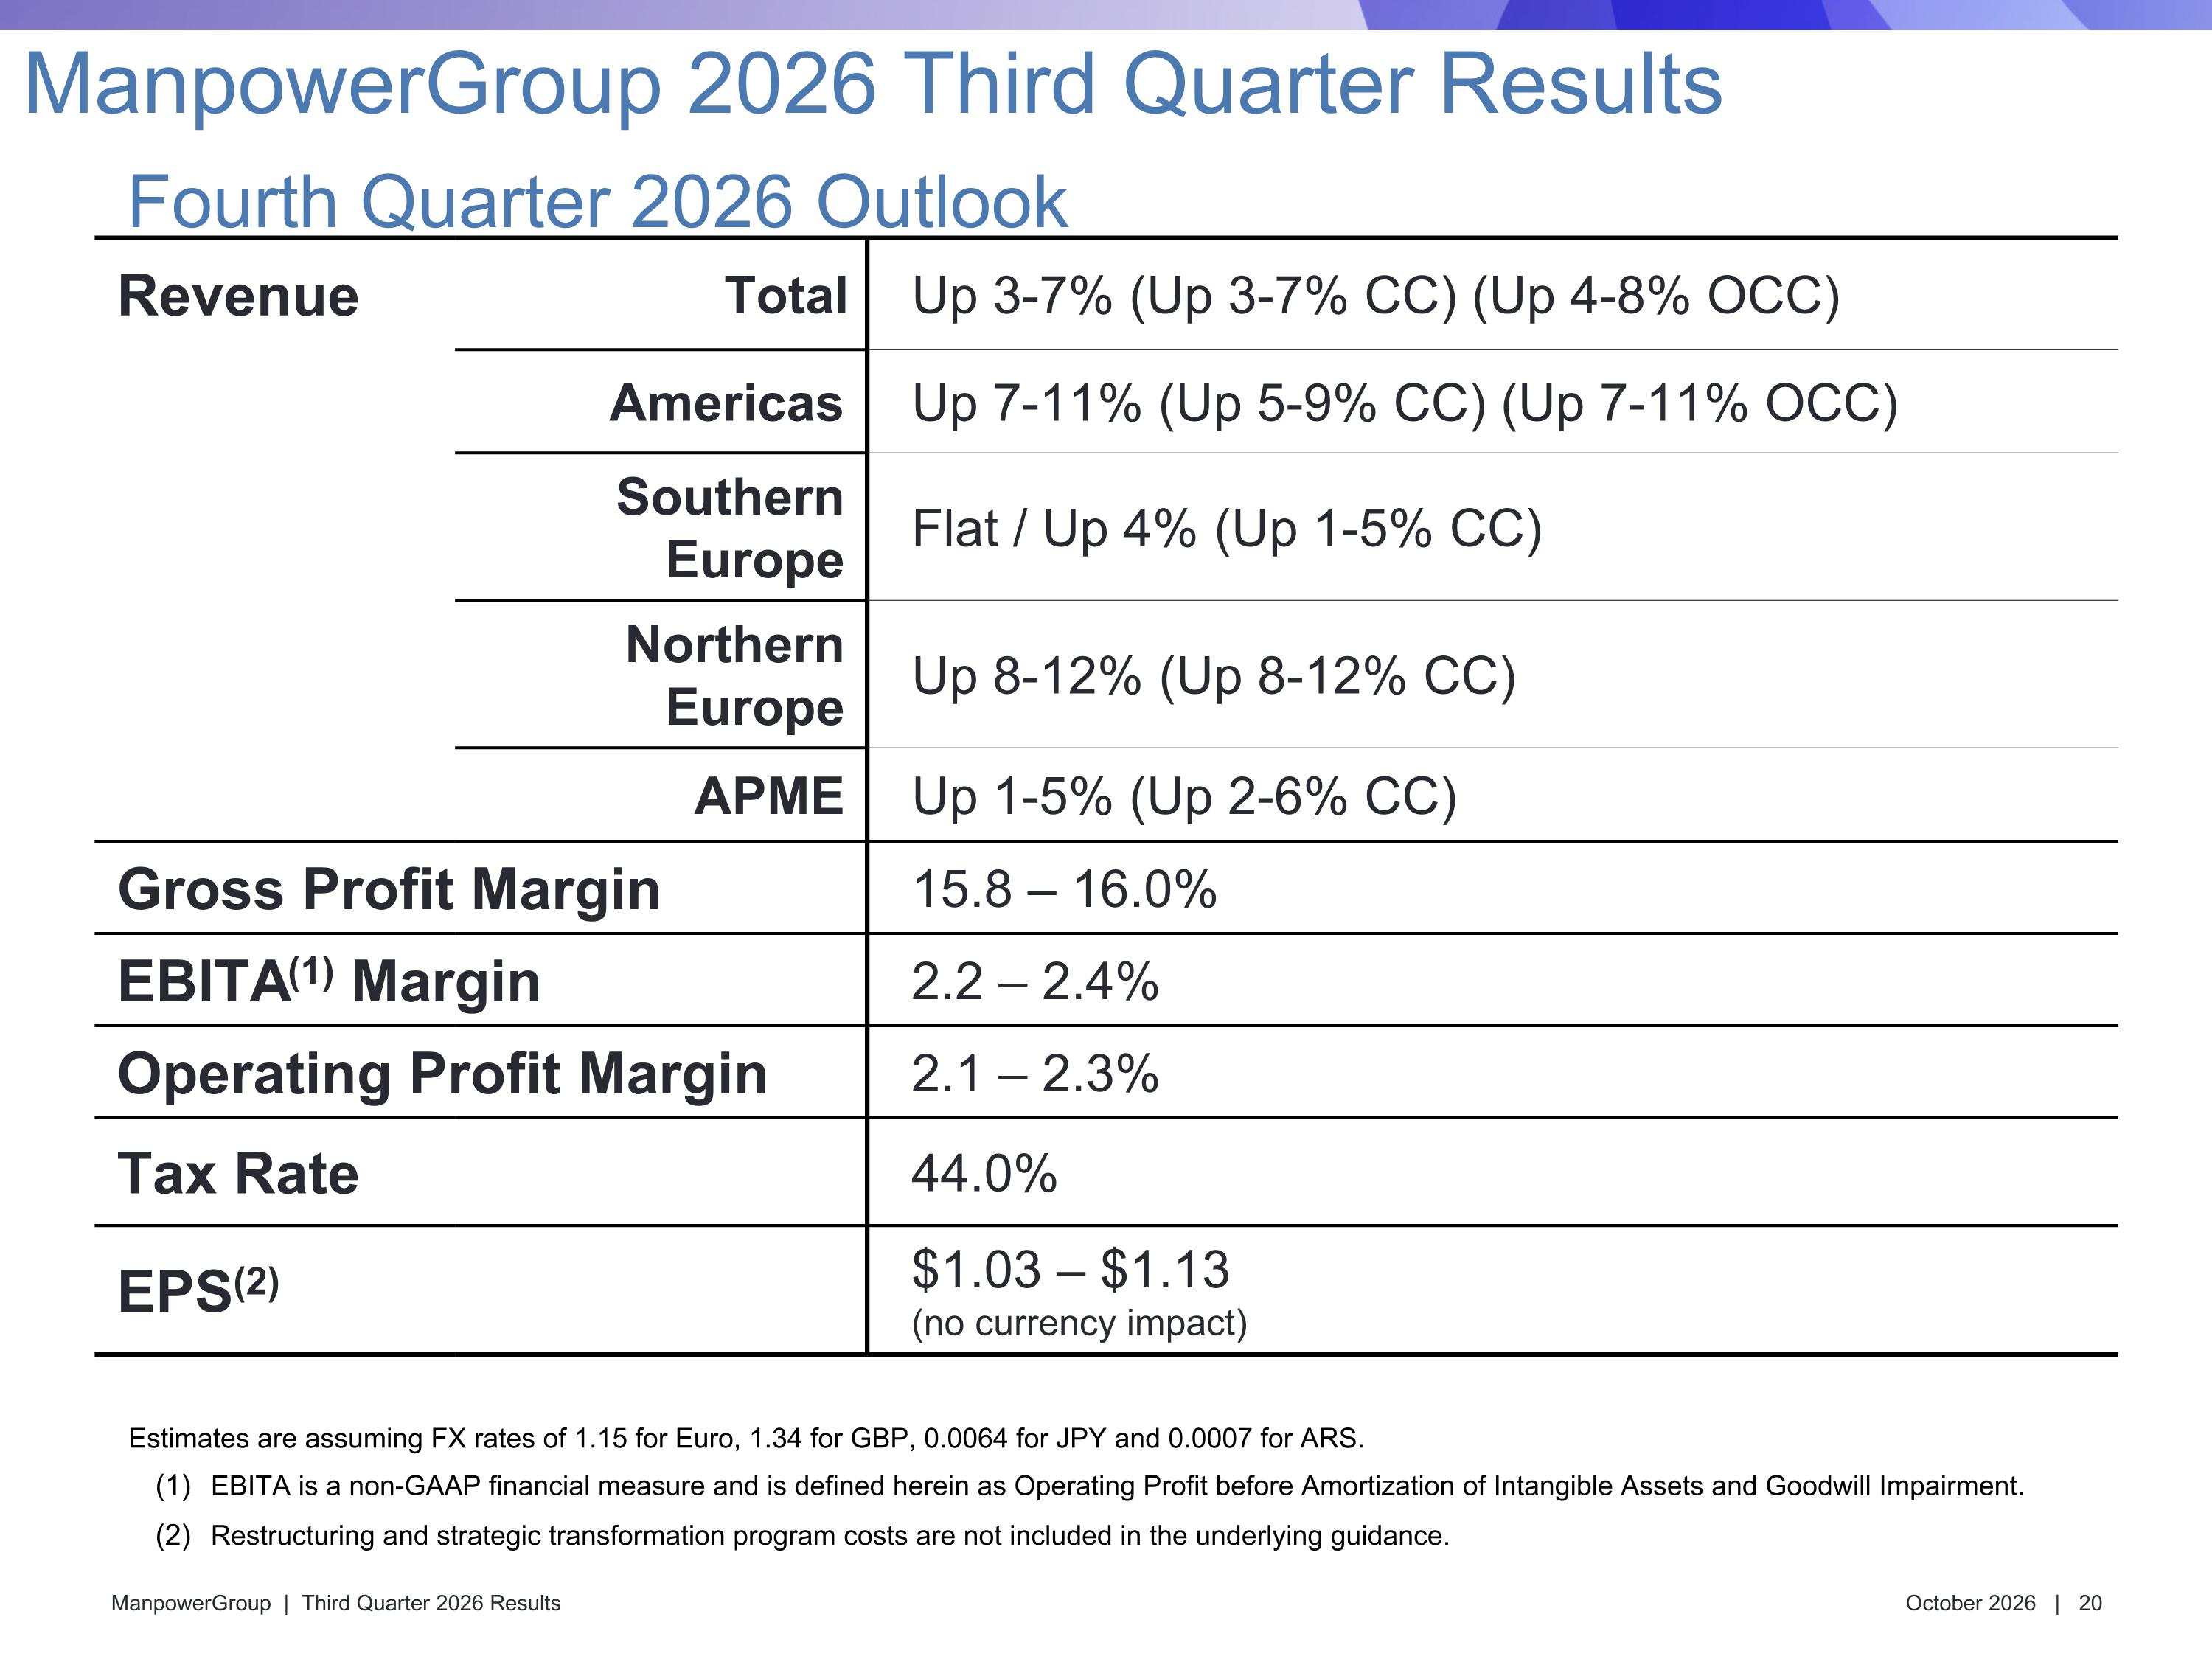
ManpowerGroup 2026 Third Quarter Results Fourth Quarter 2026 Outlook Revenue Total Up 3-7% (Up 3-7% CC) (Up 4-8% OCC) Americas Up 7-11% (Up 5-9% CC) (Up 7-11% OCC) Southern Europe Flat / Up 4% (Up 1-5% CC) Northern Europe Up 8-12% (Up 8-12% CC) APME Up 1-5% (Up 2-6% CC) Gross Profit Margin 15.8 – 16.0% EBITA(1) Margin 2.2 – 2.4% Operating Profit Margin 2.1 – 2.3% Tax Rate 44.0% EPS(2) $1.03 – $1.13 (no currency impact) Estimates are assuming FX rates of 1.15 for Euro, 1.34 for GBP, 0.0064 for JPY and 0.0007 for ARS. EBITA is a non-GAAP financial measure and is defined herein as Operating Profit before Amortization of Intangible Assets and Goodwill Impairment. Restructuring and strategic transformation program costs are not included in the underlying guidance.
Appendix
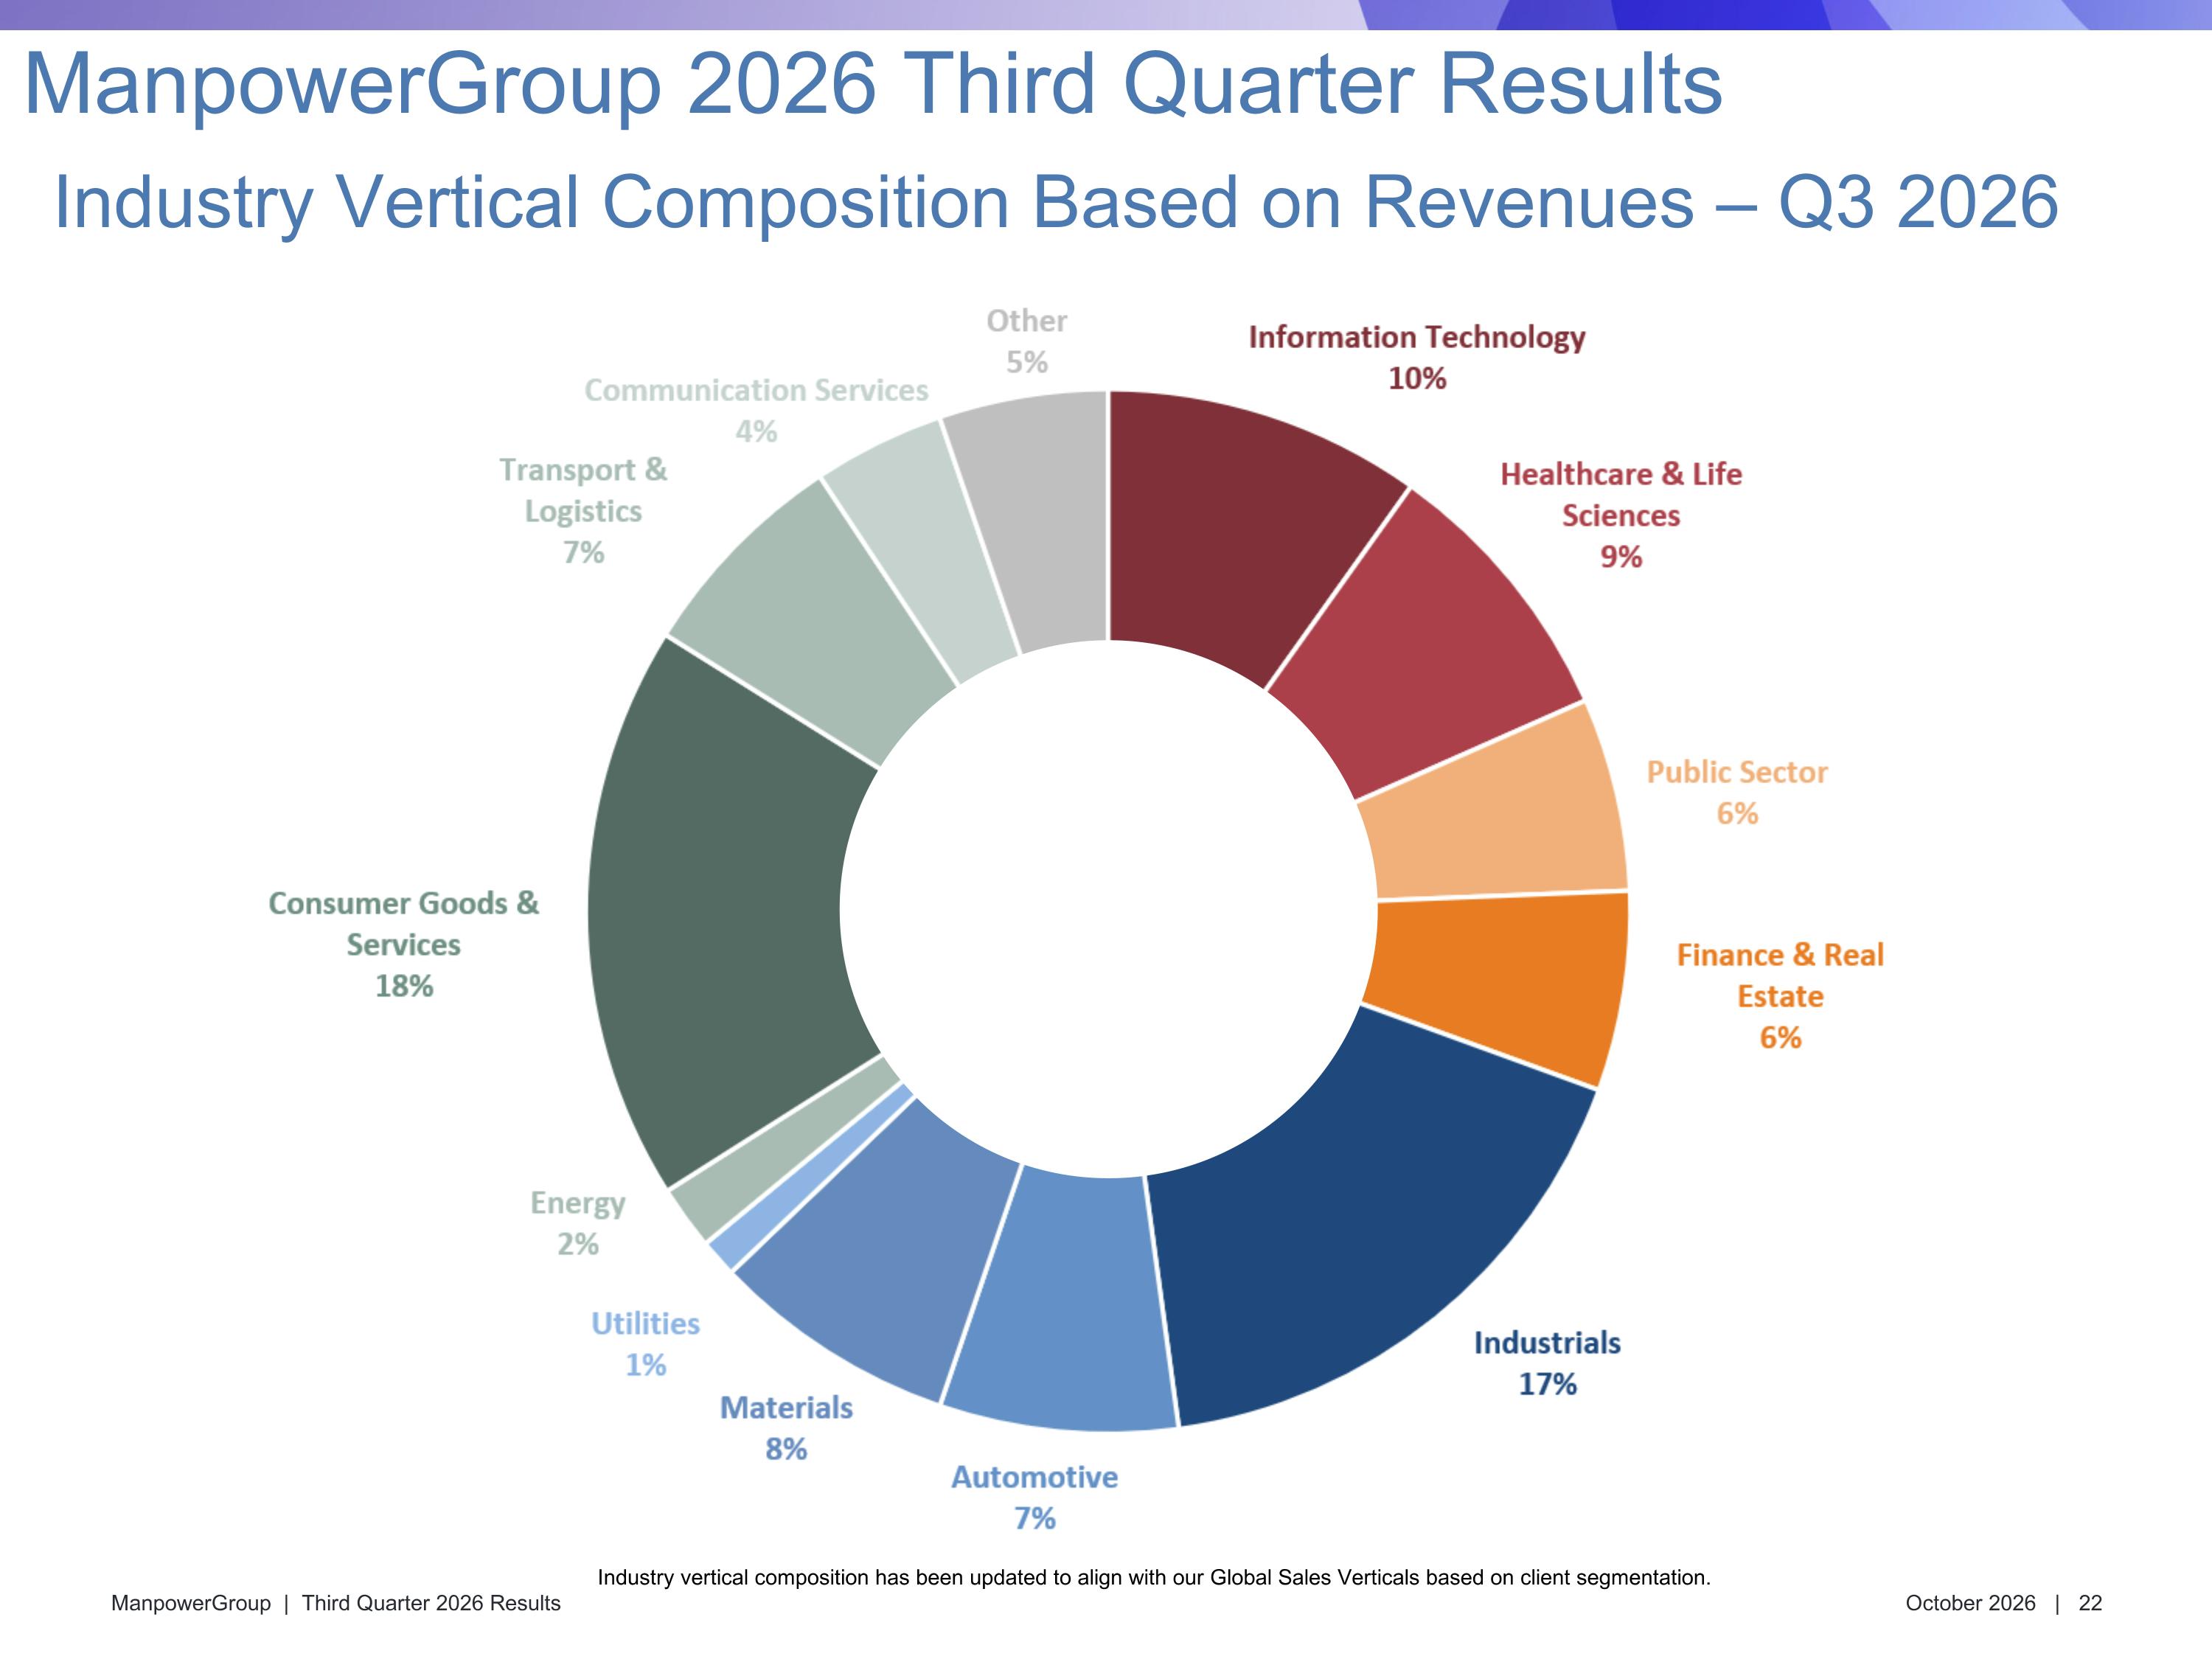
Industry Vertical Composition Based on Revenues – Q3 2026 ManpowerGroup 2026 Third Quarter Results Industry vertical composition has been updated to align with our Global Sales Verticals based on client segmentation.
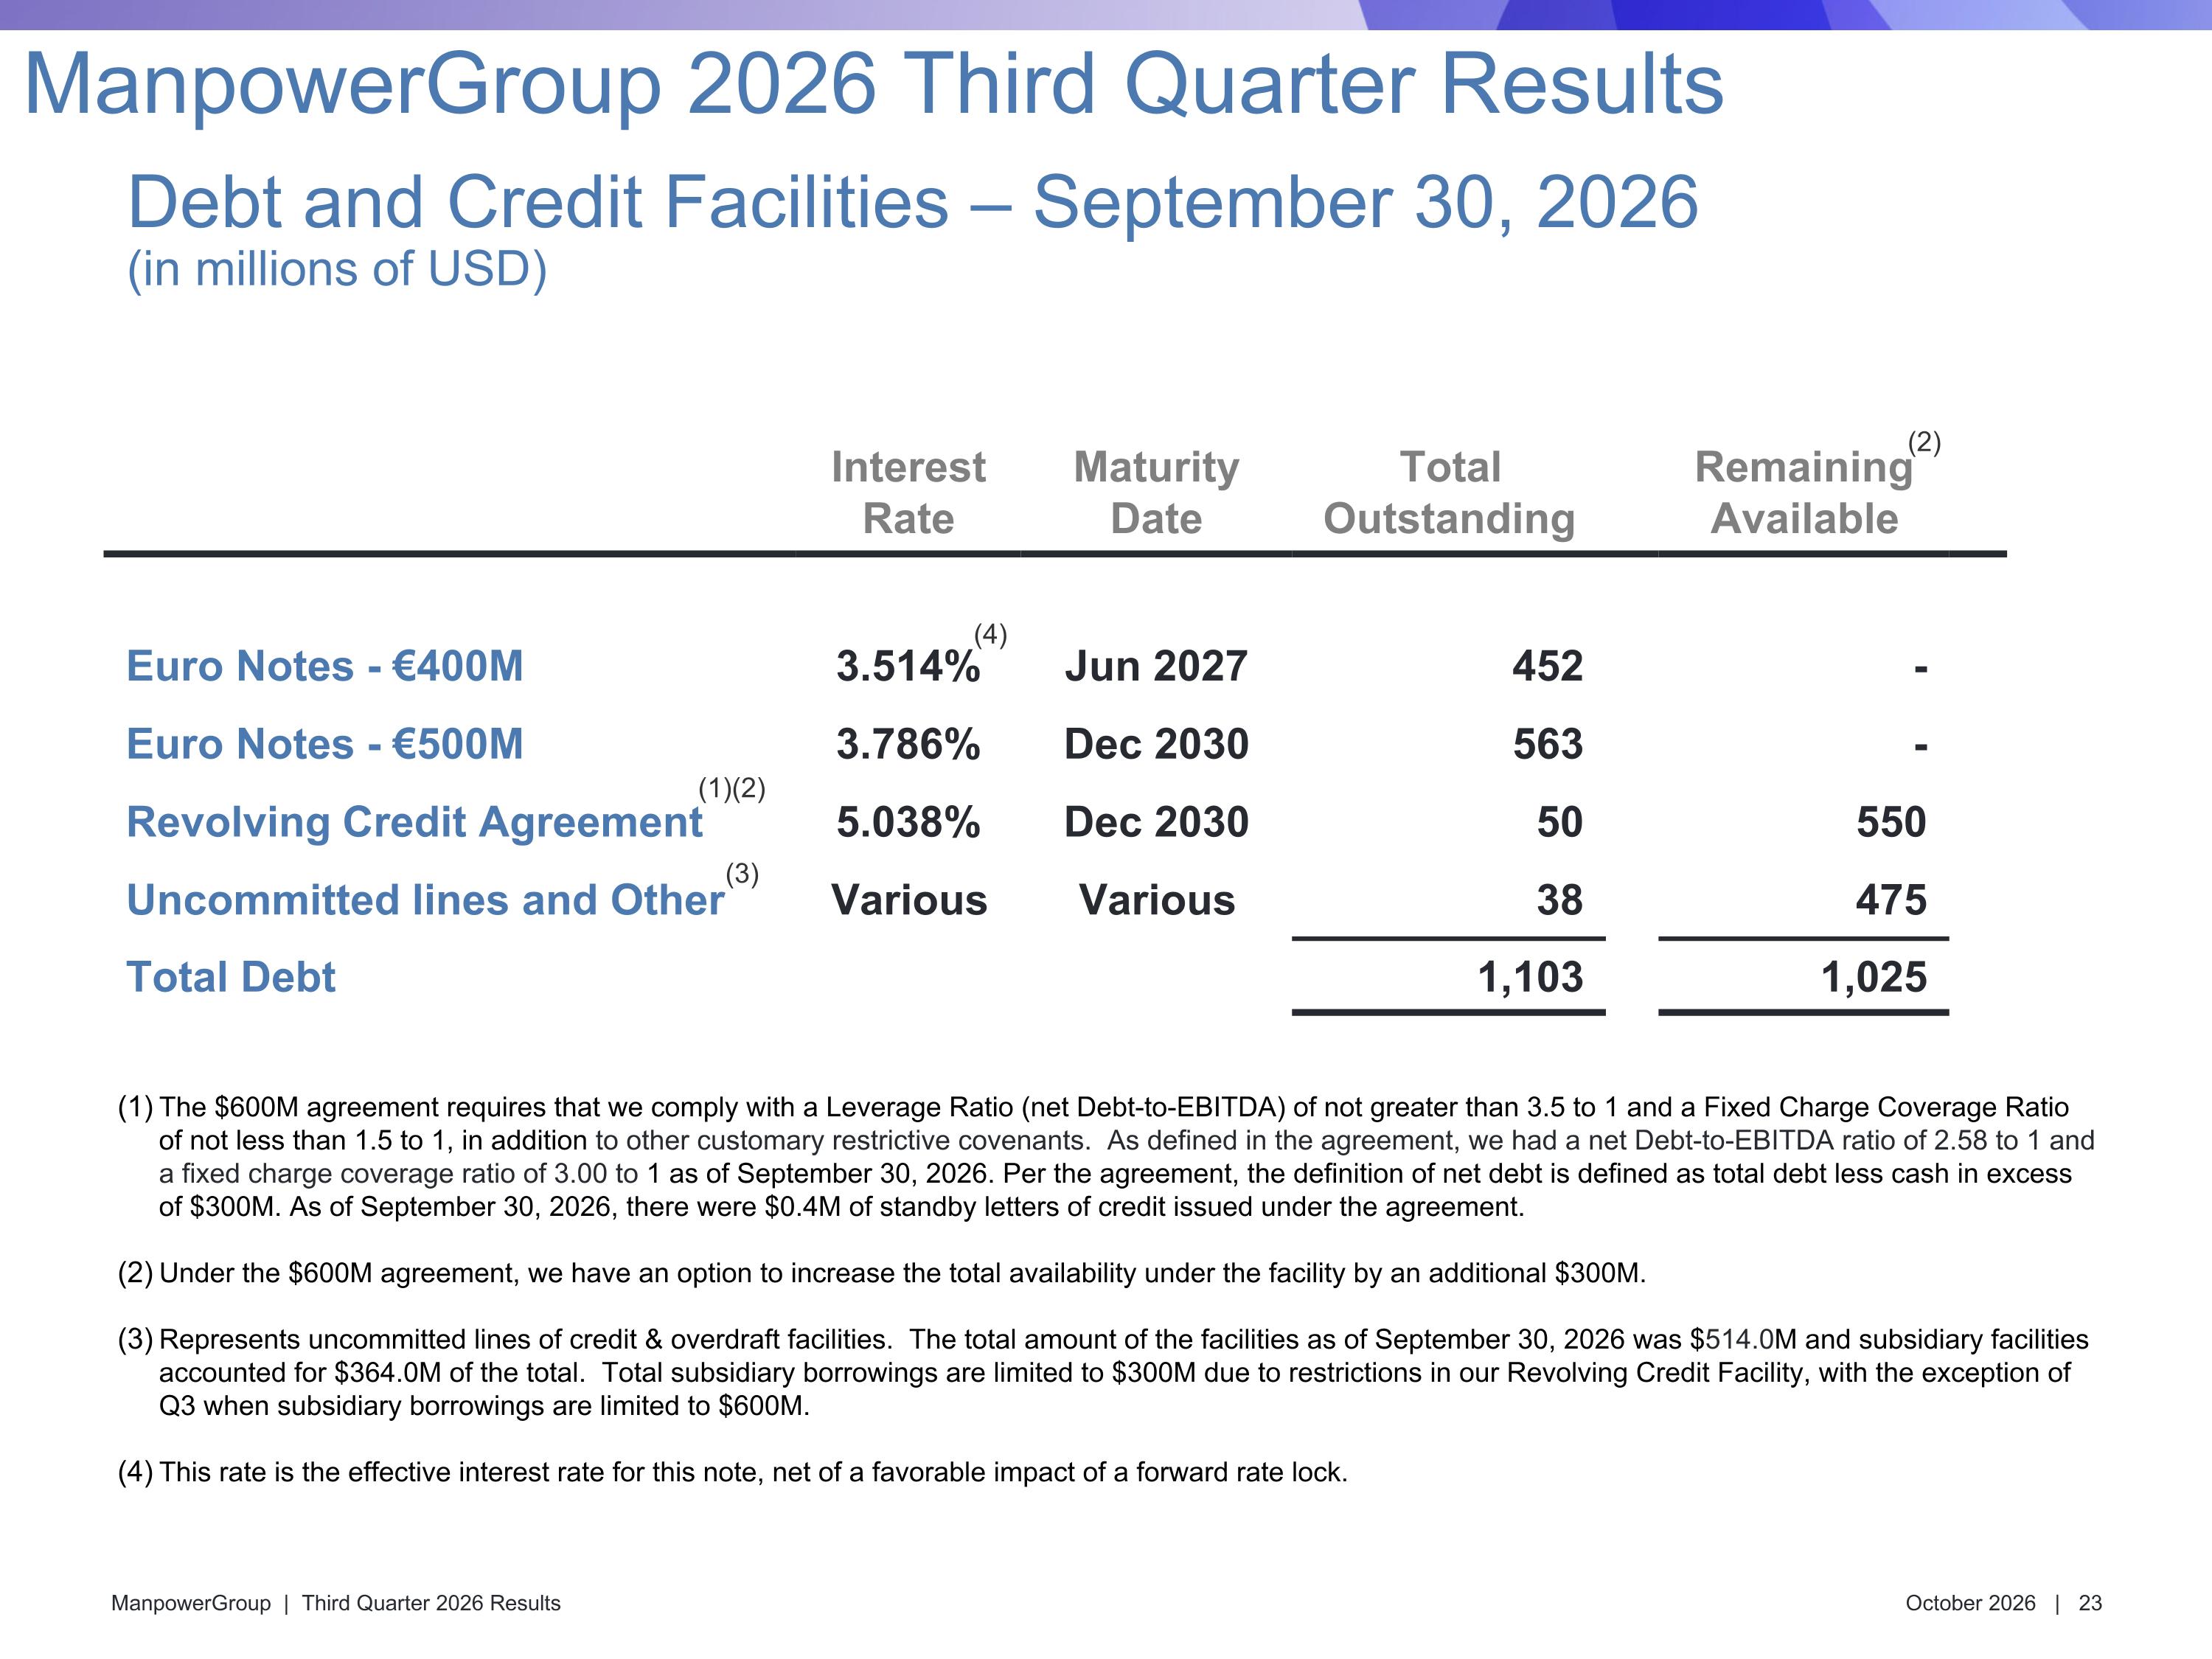
Interest Rate Maturity Date Total Outstanding Remaining Available Euro Notes - €400M 3.514% Jun 2027 452 - Euro Notes - €500M 3.786% Dec 2030 563 - Revolving Credit Agreement 5.038% Dec 2030 50 550 Uncommitted lines and Other Various Various 38 475 Total Debt 1,103 1,025 (3) (1)(2) (4) (2) Debt and Credit Facilities – September 30, 2026 (in millions of USD) ManpowerGroup 2026 Third Quarter Results The $600M agreement requires that we comply with a Leverage Ratio (net Debt-to-EBITDA) of not greater than 3.5 to 1 and a Fixed Charge Coverage Ratio of not less than 1.5 to 1, in addition to other customary restrictive covenants. As defined in the agreement, we had a net Debt-to-EBITDA ratio of 2.58 to 1 and a fixed charge coverage ratio of 3.00 to 1 as of September 30, 2026. Per the agreement, the definition of net debt is defined as total debt less cash in excess of $300M. As of September 30, 2026, there were $0.4M of standby letters of credit issued under the agreement. Under the $600M agreement, we have an option to increase the total availability under the facility by an additional $300M. Represents uncommitted lines of credit & overdraft facilities. The total amount of the facilities as of September 30, 2026 was $514.0M and subsidiary facilities accounted for $364.0M of the total. Total subsidiary borrowings are limited to $300M due to restrictions in our Revolving Credit Facility, with the exception of Q3 when subsidiary borrowings are limited to $600M. This rate is the effective interest rate for this note, net of a favorable impact of a forward rate lock.