Nasdaq SFNC Exhibit 99.2 rd 3 Quarter 2026 Earnings Presentation October 15, 2026
New York City I December 10 Join President and CEO Jay Brogdon, CFO Daniel Hobbs, and other members of the executive leadership team for an update on Simmons' strategy, financial performance and vision for the future. Attendance in person is for institutional investors and analysts, by invitation only. A live webcast of the event and presentation materials will be available on Simmons' Investor Relations website at https://ir.simmonsbank.com. For additional information, contact Ed Bilek at investorrelations@simmonsbank.com. 2
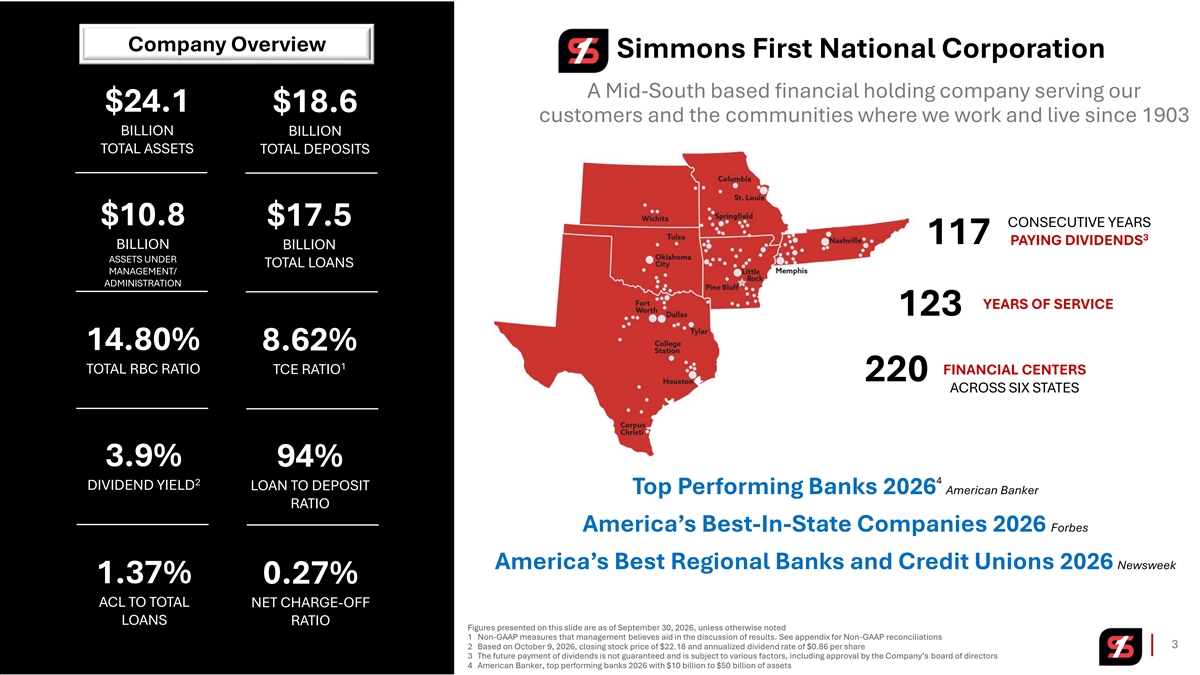
Company Overview Simmons First National Corporation A Mid-South based financial holding company serving our $24.1 $18.6 customers and the communities where we work and live since 1903 BILLION BILLION TOTAL ASSETS TOTAL DEPOSITS $10.8 $17.5 CONSECUTIVE YEARS 3 117 PAYING DIVIDENDS BILLION BILLION ASSETS UNDER TOTAL LOANS MANAGEMENT/ ADMINISTRATION YEARS OF SERVICE 123 14.80% 8.62% 1 TOTAL RBC RATIO TCE RATIO FINANCIAL CENTERS 220 ACROSS SIX STATES 3.9% 94% 4 2 DIVIDEND YIELD LOAN TO DEPOSIT Top Performing Banks 2026 American Banker RATIO America’s Best-In-State Companies 2026 Forbes America’s Best Regional Banks and Credit Unions 2026 Newsweek 1.37% 0.27% ACL TO TOTAL NET CHARGE-OFF LOANS RATIO Figures presented on this slide are as of September 30, 2026, unless otherwise noted 1 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations 3 2 Based on October 9, 2026, closing stock price of $22.18 and annualized dividend rate of $0.86 per share 3 The future payment of dividends is not guaranteed and is subject to various factors, including approval by the Company’s board of directors 4 American Banker, top performing banks 2026 with $10 billion to $50 billion of assets
3Q26 Financial Highlights 4
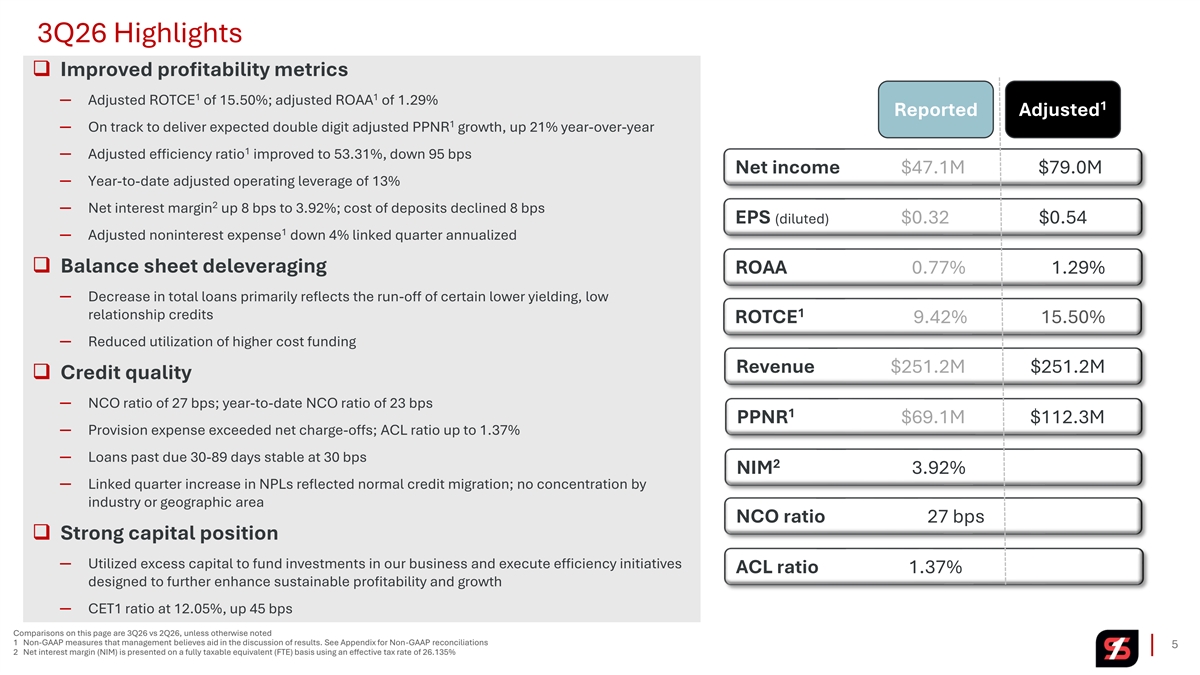
3Q26 Highlights ❑ Improved profitability metrics 1 1 ─ Adjusted ROTCE of 15.50%; adjusted ROAA of 1.29% 1 Reported Adjusted 1 ─ On track to deliver expected double digit adjusted PPNR growth, up 21% year-over-year 1 ─ Adjusted efficiency ratio improved to 53.31%, down 95 bps Net income $47.1M $79.0M ─ Year-to-date adjusted operating leverage of 13% 2 ─ Net interest margin up 8 bps to 3.92%; cost of deposits declined 8 bps EPS (diluted) $0.32 $0.54 1 ─ Adjusted noninterest expense down 4% linked quarter annualized ❑ Balance sheet deleveraging ROAA 0.77% 1.29% ─ Decrease in total loans primarily reflects the run-off of certain lower yielding, low 1 relationship credits ROTCE 9.42% 15.50% ─ Reduced utilization of higher cost funding Revenue $251.2M $251.2M ❑ Credit quality ─ NCO ratio of 27 bps; year-to-date NCO ratio of 23 bps 1 PPNR $69.1M $112.3M ─ Provision expense exceeded net charge-offs; ACL ratio up to 1.37% ─ Loans past due 30-89 days stable at 30 bps 2 NIM 3.92% ─ Linked quarter increase in NPLs reflected normal credit migration; no concentration by industry or geographic area NCO ratio 27 bps ❑ Strong capital position ─ Utilized excess capital to fund investments in our business and execute efficiency initiatives ACL ratio 1.37% designed to further enhance sustainable profitability and growth ─ CET1 ratio at 12.05%, up 45 bps Comparisons on this page are 3Q26 vs 2Q26, unless otherwise noted 1 Non-GAAP measures that management believes aid in the discussion of results. See Appendix for Non-GAAP reconciliations 5 2 Net interest margin (NIM) is presented on a fully taxable equivalent (FTE) basis using an effective tax rate of 26.135%
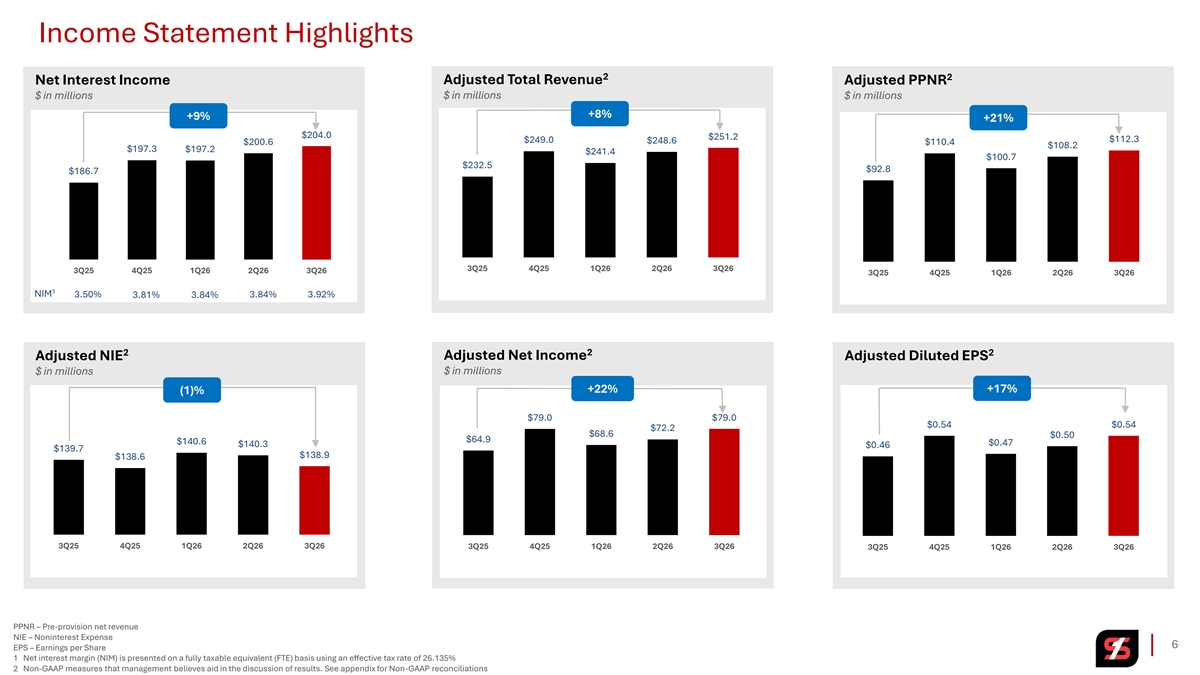
Income Statement Highlights 2 2 Net Interest Income Adjusted Total Revenue Adjusted PPNR $ in millions $ in millions $ in millions +8% +9% +21% $204.0 $251.2 $112.3 $249.0 $248.6 $200.6 $110.4 $108.2 $197.3 $197.2 $241.4 $100.7 $232.5 $92.8 $186.7 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 1 NIM 3.50% 3.84% 3.92% 3.81% 3.84% 2 2 2 Adjusted NIE Adjusted Net Income Adjusted Diluted EPS $ in millions $ in millions +22% +17% (1)% $79.0 $79.0 $0.54 $0.54 $72.2 $68.6 $0.50 $64.9 $140.6 $0.47 $140.3 $0.46 $139.7 $138.9 $138.6 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 PPNR – Pre-provision net revenue NIE – Noninterest Expense 6 EPS – Earnings per Share 1 Net interest margin (NIM) is presented on a fully taxable equivalent (FTE) basis using an effective tax rate of 26.135% 2 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations
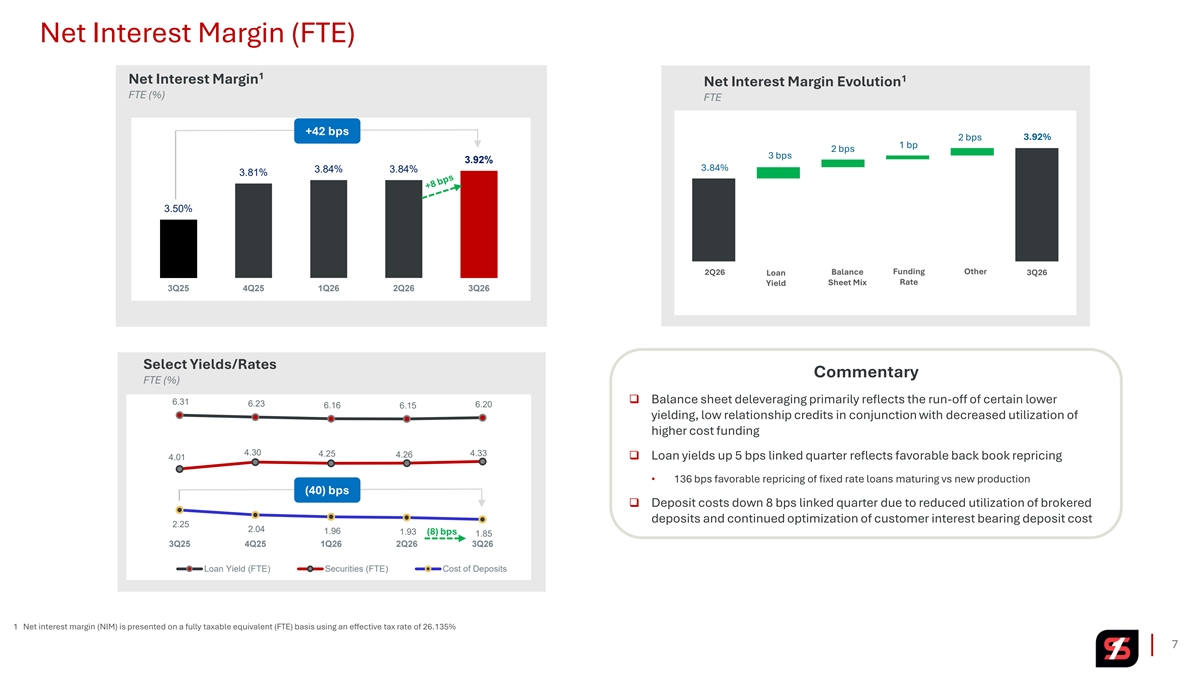
Net Interest Margin (FTE) 1 1 Net Interest Margin Net Interest Margin Evolution FTE (%) FTE +42 bps 3.92% 2 bps 1 bp 2 bps 3 bps 3.92% 3.84% 3.84% 3.84% 3.81% 3.50% 2Q26 Balance Funding Other 3Q26 Loan Sheet Mix Rate Yield 3Q25 4Q25 1Q26 2Q26 3Q26 Select Yields/Rates Commentary FTE (%) ❑ Balance sheet deleveraging primarily reflects the run-off of certain lower 6.31 6.23 6.20 6.16 6.15 yielding, low relationship credits in conjunction with decreased utilization of higher cost funding 4.30 4.25 4.33 4.26 4.01 ❑ Loan yields up 5 bps linked quarter reflects favorable back book repricing • 136 bps favorable repricing of fixed rate loans maturing vs new production (40) bps ❑ Deposit costs down 8 bps linked quarter due to reduced utilization of brokered deposits and continued optimization of customer interest bearing deposit cost 2.25 2.04 1.96 1.93 (8) bps 1.85 3Q25 4Q25 1Q26 2Q26 3Q26 Loan Yield (FTE) Securities (FTE) Cost of Deposits 1 Net interest margin (NIM) is presented on a fully taxable equivalent (FTE) basis using an effective tax rate of 26.135% 7
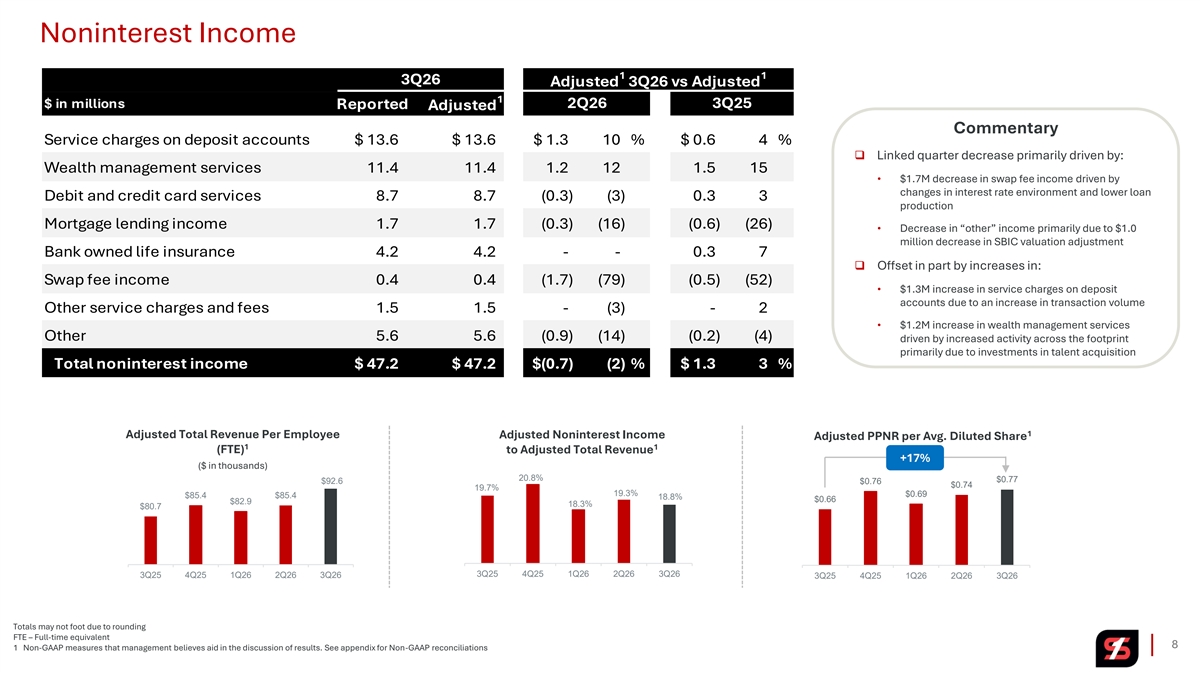
Noninterest Income 1 1 3Q26 Adjusted 3Q26 vs Adjusted 1 $ in millions Reported 2Q26 3Q25 Adjusted Commentary Service charges on deposit accounts $ 13.6 $ 13.6 $ 1.3 10 % $ 0.6 4 % ❑ Linked quarter decrease primarily driven by: Wealth management services 11.4 11.4 1.2 12 1.5 15 • $1.7M decrease in swap fee income driven by changes in interest rate environment and lower loan Debit and credit card services 8 .7 8.7 (0.3) (3) 0.3 3 production Mortgage lending income 1.7 1.7 (0.3) (16) ( 0.6) (26) • Decrease in “other” income primarily due to $1.0 million decrease in SBIC valuation adjustment Bank owned life insurance 4 .2 4.2 - - 0.3 7 ❑ Offset in part by increases in: Swap fee income 0 .4 0.4 ( 1.7) (79) (0.5) (52) • $1.3M increase in service charges on deposit accounts due to an increase in transaction volume Other service charges and fees 1.5 1.5 - ( 3) - 2 • $1.2M increase in wealth management services Other 5.6 5.6 (0.9) (14) ( 0.2) (4) driven by increased activity across the footprint primarily due to investments in talent acquisition Total noninterest income $ 47.2 $ 47.2 $(0.7) ( 2) % $ 1.3 3 % 1 Adjusted Total Revenue Per Employee Adjusted Noninterest Income Adjusted PPNR per Avg. Diluted Share 1 1 (FTE) to Adjusted Total Revenue +17% ($ in thousands) 20.8% $0.77 $92.6 $0.76 $0.74 19.7% 19.3% $0.69 $85.4 $85.4 18.8% $0.66 $82.9 18.3% $80.7 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 Totals may not foot due to rounding FTE – Full-time equivalent 8 1 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations
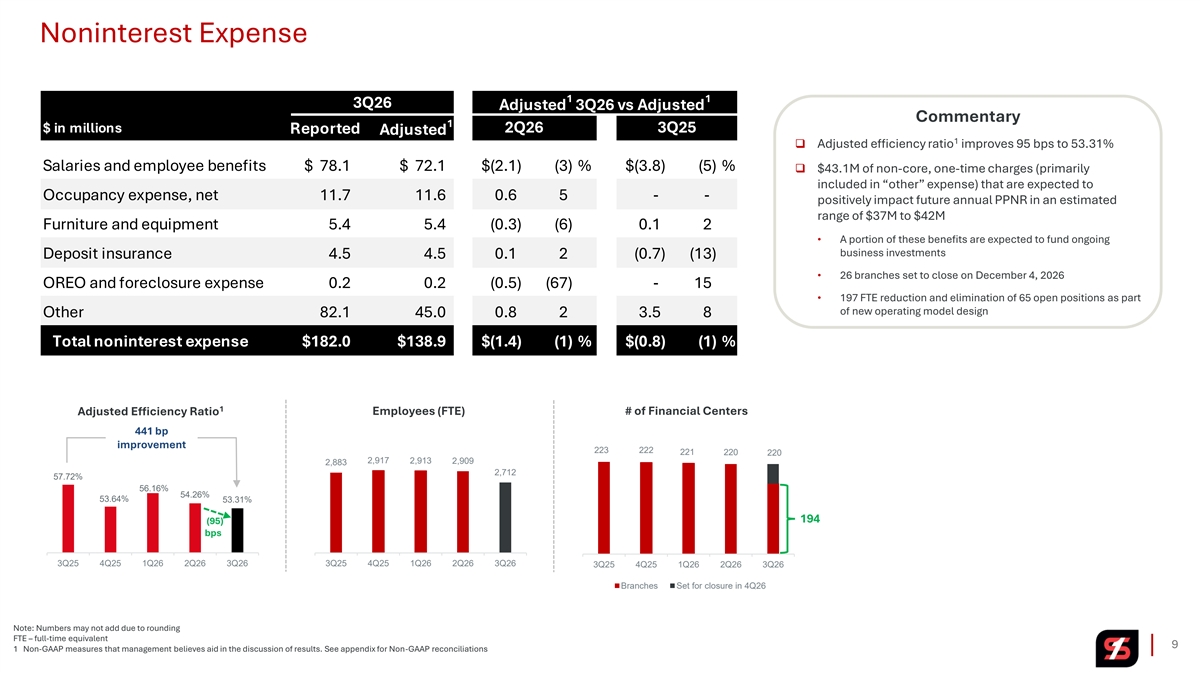
Noninterest Expense 1 1 3Q26 Adjusted 3Q26 vs Adjusted Commentary 1 $ in millions 2Q26 3Q25 Reported Adjusted 1 ❑ Adjusted efficiency ratio improves 95 bps to 53.31% Salaries and employee benefits $ 78.1 $ 72.1 $(2.1) (3) % $(3.8) (5) % ❑ $43.1M of non-core, one-time charges (primarily included in “other” expense) that are expected to Occupancy expense, net 11.7 11.6 0.6 5 - - positively impact future annual PPNR in an estimated range of $37M to $42M Furniture and equipment 5 .4 5.4 ( 0.3) (6) 0.1 2 • A portion of these benefits are expected to fund ongoing business investments Deposit insurance 4 .5 4.5 0.1 2 (0.7) (13) • 26 branches set to close on December 4, 2026 OREO and foreclosure expense 0.2 0.2 ( 0.5) (67) - 15 • 197 FTE reduction and elimination of 65 open positions as part of new operating model design Other 82.1 45.0 0.8 2 3.5 8 Total noninterest expense $182.0 $138.9 $(1.4) ( 1) % $(0.8) (1) % 1 Adjusted Efficiency Ratio Employees (FTE) # of Financial Centers 441 bp improvement 223 222 221 220 220 2,917 2,913 2,909 2,883 2,712 57.72% 56.16% 54.26% 53.64% 53.31% 194 (95) bps 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 Branches Set for closure in 4Q26 Note: Numbers may not add due to rounding FTE – full-time equivalent 9 1 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations
Deposits, Interest Rate Sensitivity, Hedging Program and Capital 10
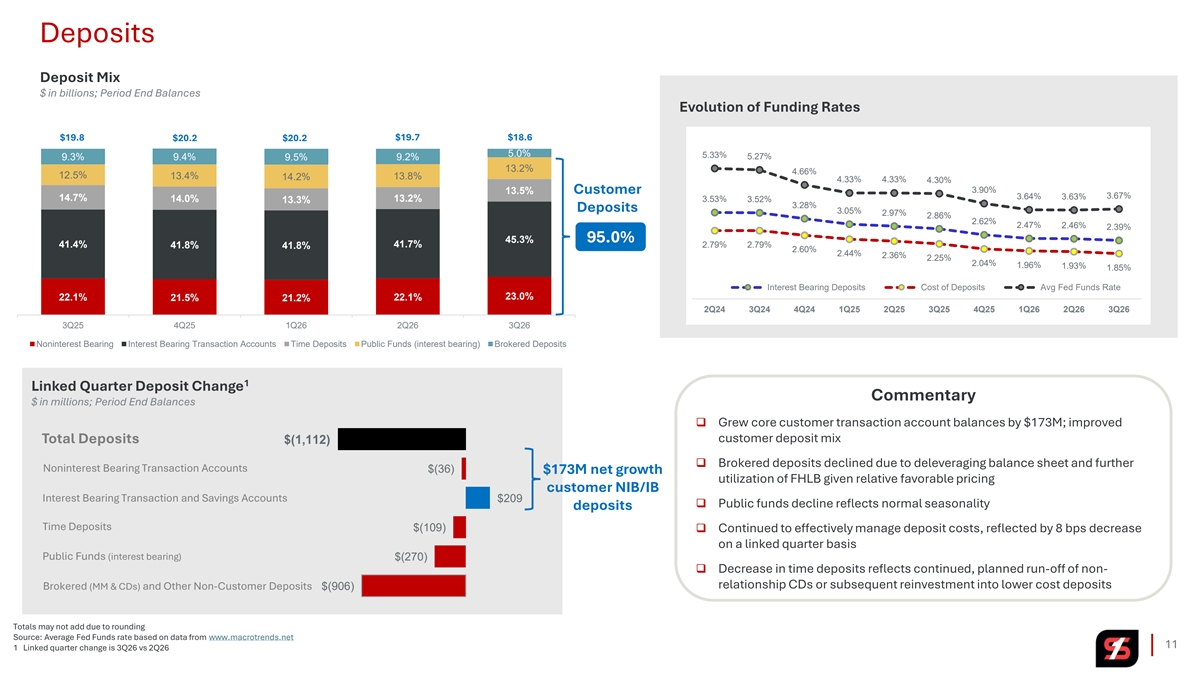
Deposits Deposit Mix $ in billions; Period End Balances Evolution of Funding Rates $19.8 $20.2 $20.2 $19.7 $18.6 5.0% 5.33% 9.3% 9.4% 9.2% 5.27% 9.5% 13.2% 4.66% 12.5% 13.4% 14.2% 13.8% 4.33% 4.33% 4.30% 13.5% Customer 3.90% 3.67% 3.64% 3.63% 14.7% 14.0% 13.2% 3.53% 3.52% 13.3% 3.28% Deposits 3.05% 2.97% 2.86% 2.62% 2.47% 2.46% 2.39% 95.0% 45.3% 41.4% 41.7% 2.79% 2.79% 41.8% 41.8% 2.60% 2.44% 2.36% 2.25% 2.04% 1.96% 1.93% 1.85% Interest Bearing Deposits Cost of Deposits Avg Fed Funds Rate 23.0% 22.1% 21.5% 21.2% 22.1% 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 Noninterest Bearing Interest Bearing Transaction Accounts Time Deposits Public Funds (interest bearing) Brokered Deposits 1 Linked Quarter Deposit Change Commentary $ in millions; Period End Balances ❑ Grew core customer transaction account balances by $173M; improved customer deposit mix Total Deposits $(1,112) ❑ Brokered deposits declined due to deleveraging balance sheet and further Noninterest Bearing Transaction Accounts $(36) $173M net growth utilization of FHLB given relative favorable pricing customer NIB/IB Interest Bearing Transaction and Savings Accounts $209 ❑ Public funds decline reflects normal seasonality deposits Time Deposits $(109) ❑ Continued to effectively manage deposit costs, reflected by 8 bps decrease on a linked quarter basis Public Funds (interest bearing) $(270) ❑ Decrease in time deposits reflects continued, planned run-off of non- relationship CDs or subsequent reinvestment into lower cost deposits Brokered (MM & CDs) and Other Non-Customer Deposits $(906) Totals may not add due to rounding Source: Average Fed Funds rate based on data from www.macrotrends.net 11 1 Linked quarter change is 3Q26 vs 2Q26
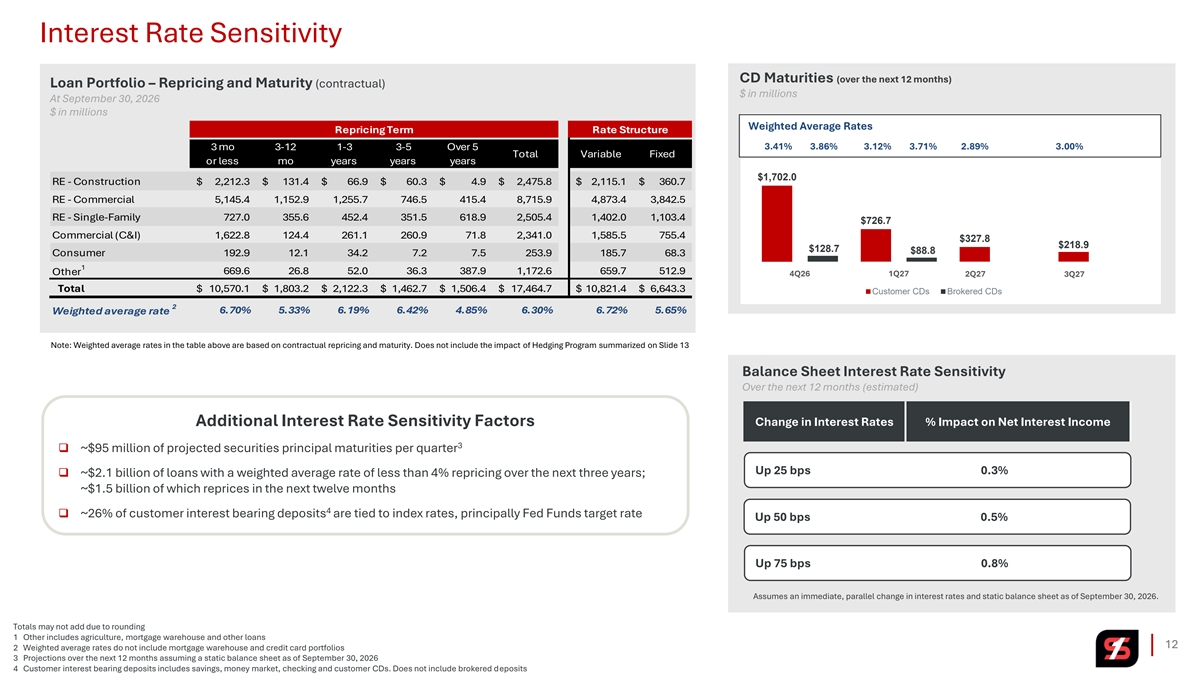
Interest Rate Sensitivity CD Maturities (over the next 12 months) Loan Portfolio – Repricing and Maturity (contractual) $ in millions At September 30, 2026 $ in millions Weighted Average Rates Repricing Term Rate Structure 3 mo 3-12 1-3 3-5 Over 5 3.41% 3.86% 3.12% 3.71% 2.89% 3.00% Total Variable Fixed or less mo years years years $1,702.0 RE - Construction $ 2,212.3 $ 131.4 $ 66.9 $ 60.3 $ 4.9 $ 2,475.8 $ 2,115.1 $ 360.7 RE - Commercial 5,145.4 1,152.9 1,255.7 746.5 415.4 8,715.9 4,873.4 3,842.5 RE - Single-Family 727.0 355.6 452.4 351.5 618.9 2,505.4 1,402.0 1,103.4 $726.7 Commercial (C&I) 1,622.8 124.4 261.1 260.9 71.8 2,341.0 1,585.5 755.4 $327.8 $218.9 $128.7 $88.8 Consumer 192.9 12.1 34.2 7.2 7.5 253.9 185.7 68.3 1 Other 669.6 26.8 52.0 36.3 387.9 1,172.6 659.7 512.9 4Q26 1Q27 2Q27 3Q27 Total $ 10,570.1 $ 1,803.2 $ 2,122.3 $ 1,462.7 $ 1,506.4 $ 17,464.7 $ 10,821.4 $ 6,643.3 Customer CDs Brokered CDs 2 6.70% 5.33% 6.19% 6.42% 4.85% 6.30% 6.72% 5.65% Weighted average rate Note: Weighted average rates in the table above are based on contractual repricing and maturity. Does not include the impact of Hedging Program summarized on Slide 13 Balance Sheet Interest Rate Sensitivity Over the next 12 months (estimated) Additional Interest Rate Sensitivity Factors Change in Interest Rates % Impact on Net Interest Income 3 ❑ ~$95 million of projected securities principal maturities per quarter Up 25 bps 0.3% ❑ ~$2.1 billion of loans with a weighted average rate of less than 4% repricing over the next three years; ~$1.5 billion of which reprices in the next twelve months 4 ❑ ~26% of customer interest bearing deposits are tied to index rates, principally Fed Funds target rate Up 50 bps 0.5% Up 75 bps 0.8% Assumes an immediate, parallel change in interest rates and static balance sheet as of September 30, 2026. Totals may not add due to rounding 1 Other includes agriculture, mortgage warehouse and other loans 12 2 Weighted average rates do not include mortgage warehouse and credit card portfolios 3 Projections over the next 12 months assuming a static balance sheet as of September 30, 2026 4 Customer interest bearing deposits includes savings, money market, checking and customer CDs. Does not include brokered deposits
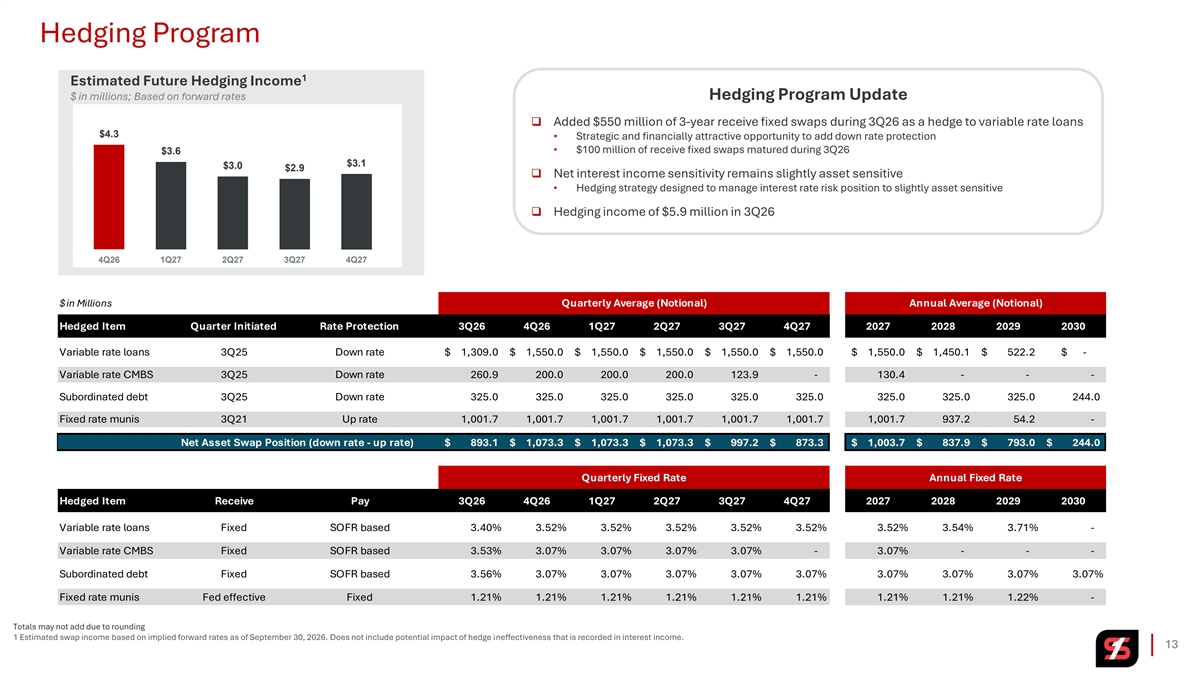
Hedging Program 1 Estimated Future Hedging Income $ in millions; Based on forward rates Hedging Program Update ❑ Added $550 million of 3-year receive fixed swaps during 3Q26 as a hedge to variable rate loans $4.3 • Strategic and financially attractive opportunity to add down rate protection • $100 million of receive fixed swaps matured during 3Q26 $3.6 $3.1 $3.0 $2.9 ❑ Net interest income sensitivity remains slightly asset sensitive • Hedging strategy designed to manage interest rate risk position to slightly asset sensitive ❑ Hedging income of $5.9 million in 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 $ in Millions Quarterly Average (Notional) Annual Average (Notional) Hedged Item Quarter Initiated Rate Protection 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 2027 2028 2029 2030 Variable rate loans 3Q25 Down rate $ 1 ,309.0 $ 1,550.0 $ 1,550.0 $ 1,550.0 $ 1 ,550.0 $ 1,550.0 $ 1 ,550.0 $ 1 ,450.1 $ 522.2 $ - Variable rate CMBS 3Q25 Down rate 260.9 200.0 200.0 200.0 123.9 - 130.4 - - - Subordinated debt 3Q25 Down rate 325.0 325.0 325.0 325.0 325.0 325.0 325.0 325.0 325.0 244.0 Fixed rate munis 3Q21 Up rate 1,001.7 1,001.7 1,001.7 1,001.7 1,001.7 1,001.7 1,001.7 937.2 54.2 - Net Asset Swap Position (down rate - up rate) $ 893.1 $ 1,073.3 $ 1,073.3 $ 1 ,073.3 $ 997.2 $ 873.3 $ 1 ,003.7 $ 837.9 $ 793.0 $ 244.0 Quarterly Fixed Rate Annual Fixed Rate Hedged Item Receive Pay 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 2027 2028 2029 2030 Variable rate loans Fixed SOFR based 3.40% 3.52% 3.52% 3.52% 3.52% 3.52% 3.52% 3.54% 3.71% - Variable rate CMBS Fixed SOFR based 3.53% 3.07% 3.07% 3.07% 3.07% - 3.07% - - - Subordinated debt Fixed SOFR based 3.56% 3.07% 3.07% 3.07% 3.07% 3.07% 3.07% 3.07% 3.07% 3.07% Fixed rate munis Fed effective Fixed 1.21% 1.21% 1.21% 1.21% 1.21% 1.21% 1.21% 1.21% 1.22% - Totals may not add due to rounding 1 Estimated swap income based on implied forward rates as of September 30, 2026. Does not include potential impact of hedge ineffectiveness that is recorded in interest income. 13
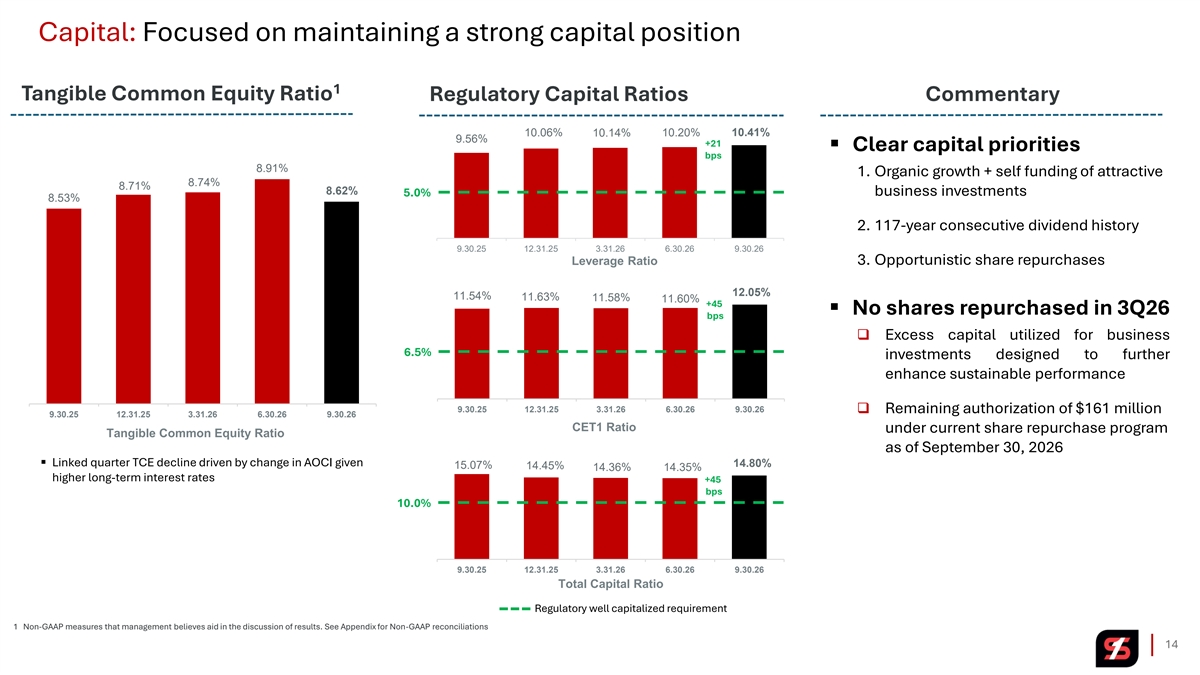
Capital: Focused on maintaining a strong capital position 1 Tangible Common Equity Ratio Regulatory Capital Ratios Commentary 10.06% 10.20% 10.41% 10.14% 9.56% +21 ▪ Clear capital priorities bps 8.91% 1. Organic growth + self funding of attractive 8.74% 8.71% 8.62% 5.0% business investments 8.53% 2. 117-year consecutive dividend history 9.30.25 12.31.25 3.31.26 6.30.26 9.30.26 Leverage Ratio 3. Opportunistic share repurchases 12.05% 11.54% 11.63% 11.58% 11.60% +45 ▪ No shares repurchased in 3Q26 bps ❑ Excess capital utilized for business 6.5% investments designed to further enhance sustainable performance 9.30.25 12.31.25 3.31.26 6.30.26 9.30.26 ❑ Remaining authorization of $161 million 9.30.25 12.31.25 3.31.26 6.30.26 9.30.26 CET1 Ratio under current share repurchase program Tangible Common Equity Ratio as of September 30, 2026 ▪ Linked quarter TCE decline driven by change in AOCI given 14.80% 15.07% 14.45% 14.36% 14.35% higher long-term interest rates +45 bps 10.0% 9.30.25 12.31.25 3.31.26 6.30.26 9.30.26 Total Capital Ratio Regulatory well capitalized requirement 1 Non-GAAP measures that management believes aid in the discussion of results. See Appendix for Non-GAAP reconciliations 14
Loan Portfolio and Credit Quality 15
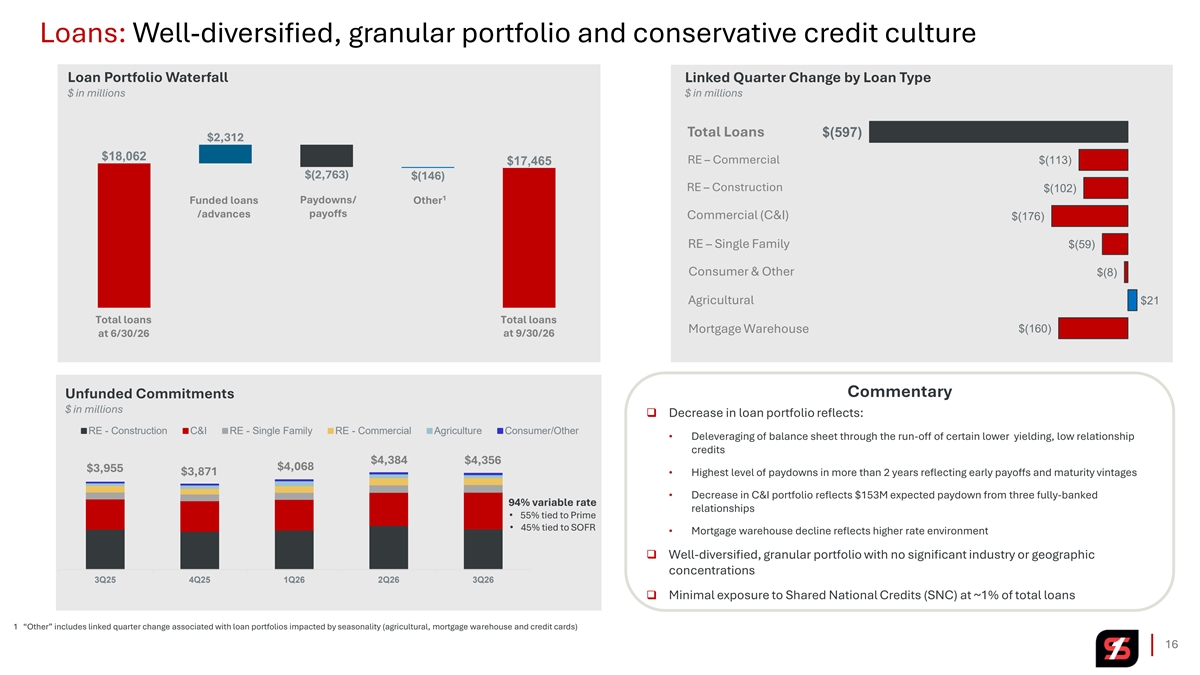
Loans: Well-diversified, granular portfolio and conservative credit culture Loan Portfolio Waterfall Linked Quarter Change by Loan Type $ in millions $ in millions Total Loans $(597) $2,312 $18,062 RE – Commercial $(113) $17,465 $(2,763) $(146) RE – Construction $(102) 1 Funded loans Paydowns/ Other /advances payoffs Commercial (C&I) $(176) RE – Single Family $(59) Consumer & Other $(8) Agricultural $21 Total loans Total loans Mortgage Warehouse $(160) at 6/30/26 at 9/30/26 Commentary Unfunded Commitments $ in millions ❑ Decrease in loan portfolio reflects: RE - Construction C&I RE - Single Family RE - Commercial Agriculture Consumer/Other • Deleveraging of balance sheet through the run-off of certain lower yielding, low relationship credits $4,384 $4,356 $4,068 $3,955 $3,871 • Highest level of paydowns in more than 2 years reflecting early payoffs and maturity vintages • Decrease in C&I portfolio reflects $153M expected paydown from three fully-banked 94% variable rate relationships • 55% tied to Prime • 45% tied to SOFR • Mortgage warehouse decline reflects higher rate environment ❑ Well-diversified, granular portfolio with no significant industry or geographic concentrations 3Q25 4Q25 1Q26 2Q26 3Q26 ❑ Minimal exposure to Shared National Credits (SNC) at ~1% of total loans 1 “Other” includes linked quarter change associated with loan portfolios impacted by seasonality (agricultural, mortgage warehouse and credit cards) 16
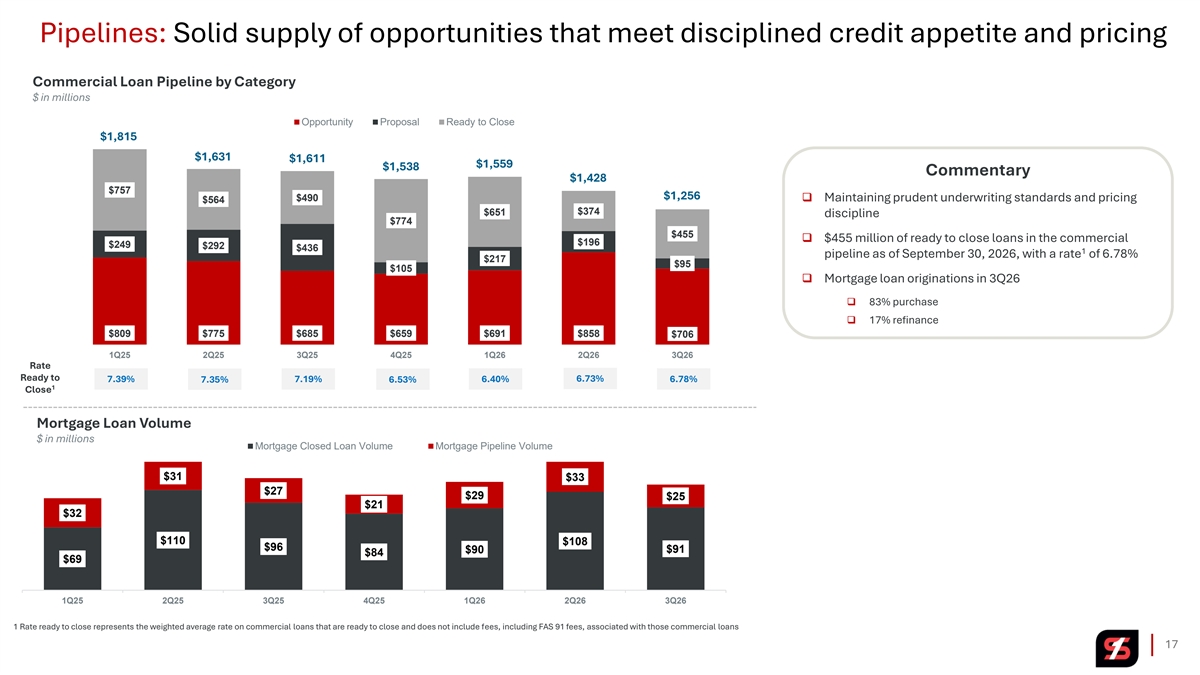
Pipelines: Solid supply of opportunities that meet disciplined credit appetite and pricing Commercial Loan Pipeline by Category $ in millions Opportunity Proposal Ready to Close $1,815 $1,631 $1,611 $1,559 $1,538 Commentary $1,428 $757 $1,256 $490 ❑ Maintaining prudent underwriting standards and pricing $564 $374 $651 discipline $774 $455 ❑ $455 million of ready to close loans in the commercial $196 $249 $292 $436 1 pipeline as of September 30, 2026, with a rate of 6.78% $217 $95 $105 ❑ Mortgage loan originations in 3Q26 ❑ 83% purchase ❑ 17% refinance $809 $775 $685 $659 $691 $858 $706 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 Rate Ready to 7.39% 7.35% 7.19% 6.53% 6.40% 6.73% 6.78% 1 Close Mortgage Loan Volume $ in millions Mortgage Closed Loan Volume Mortgage Pipeline Volume $31 $33 $27 $29 $25 $21 $32 $110 $108 $96 $90 $91 $84 $69 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 1 Rate ready to close represents the weighted average rate on commercial loans that are ready to close and does not include fees, including FAS 91 fees, associated with those commercial loans 17
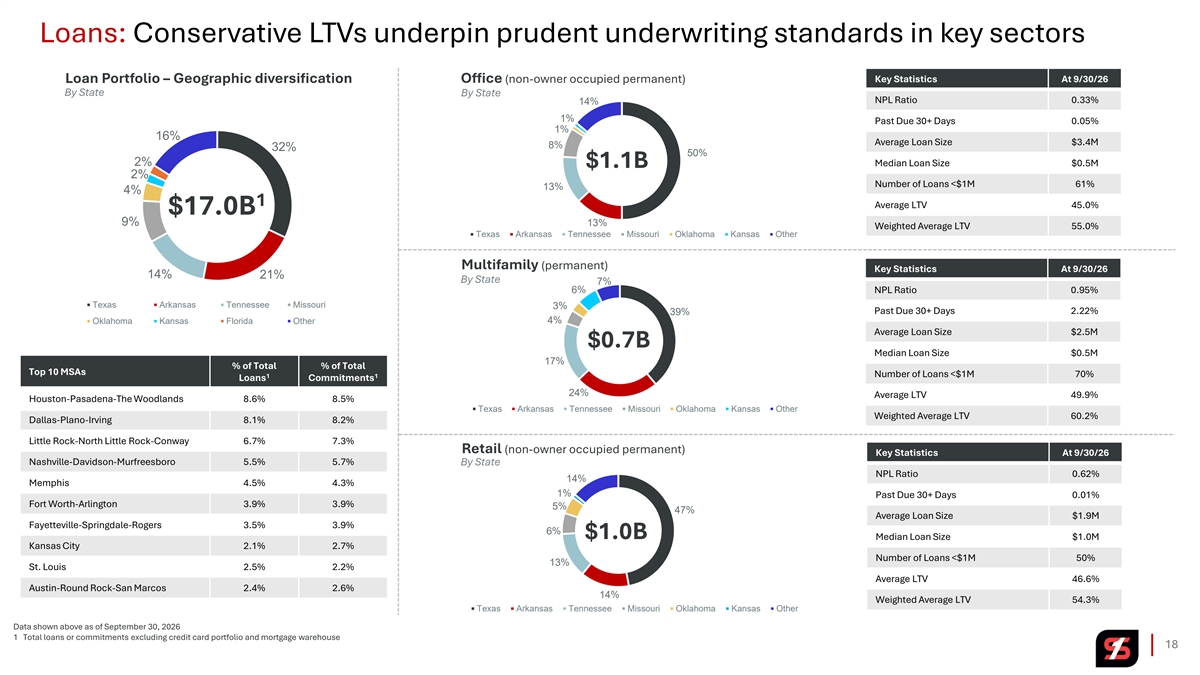
Loans: Conservative LTVs underpin prudent underwriting standards in key sectors Office (non-owner occupied permanent) Key Statistics At 9/30/26 Loan Portfolio – Geographic diversification By State By State NPL Ratio 0.33% 14% 1% Past Due 30+ Days 0.05% 1% 16% Average Loan Size $3.4M 8% 32% 50% 2% Median Loan Size $0.5M $1.1B 2% Number of Loans <$1M 61% 13% 4% 1 Average LTV 45.0% $17.0B 9% 13% Weighted Average LTV 55.0% Texas Arkansas Tennessee Missouri Oklahoma Kansas Other Multifamily (permanent) Key Statistics At 9/30/26 14% 21% By State 7% 6% NPL Ratio 0.95% Texas Arkansas Tennessee Missouri 3% Past Due 30+ Days 2.22% 39% Oklahoma Kansas Florida Other 4% Average Loan Size $2.5M $0.7B Median Loan Size $0.5M 17% % of Total % of Total Top 10 MSAs Number of Loans <$1M 70% 1 1 Loans Commitments 24% Average LTV 49.9% Houston-Pasadena-The Woodlands 8.6% 8.5% Texas Arkansas Tennessee Missouri Oklahoma Kansas Other Weighted Average LTV 60.2% Dallas-Plano-Irving 8.1% 8.2% Little Rock-North Little Rock-Conway 6.7% 7.3% Retail (non-owner occupied permanent) Key Statistics At 9/30/26 Nashville-Davidson-Murfreesboro 5.5% 5.7% By State NPL Ratio 0.62% 14% Memphis 4.5% 4.3% 1% Past Due 30+ Days 0.01% Fort Worth-Arlington 3.9% 3.9% 5% 47% Average Loan Size $1.9M Fayetteville-Springdale-Rogers 3.5% 3.9% 6% $1.0B Median Loan Size $1.0M Kansas City 2.1% 2.7% Number of Loans <$1M 50% 13% St. Louis 2.5% 2.2% Average LTV 46.6% Austin-Round Rock-San Marcos 2.4% 2.6% 14% Weighted Average LTV 54.3% Texas Arkansas Tennessee Missouri Oklahoma Kansas Other Data shown above as of September 30, 2026 1 Total loans or commitments excluding credit card portfolio and mortgage warehouse 18
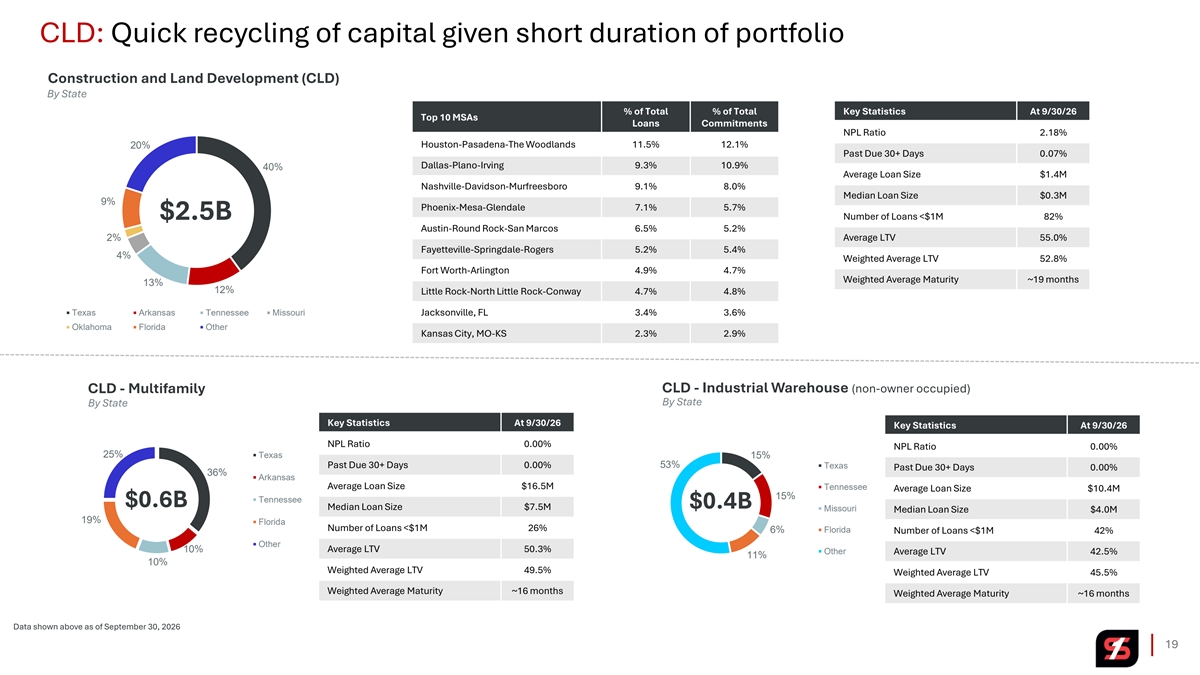
CLD: Quick recycling of capital given short duration of portfolio Construction and Land Development (CLD) By State % of Total % of Total Key Statistics At 9/30/26 Top 10 MSAs Loans Commitments NPL Ratio 2.18% Houston-Pasadena-The Woodlands 11.5% 12.1% 20% Past Due 30+ Days 0.07% Dallas-Plano-Irving 9.3% 10.9% 40% Average Loan Size $1.4M Nashville-Davidson-Murfreesboro 9.1% 8.0% Median Loan Size $0.3M 9% Phoenix-Mesa-Glendale 7.1% 5.7% $2.5B Number of Loans <$1M 82% Austin-Round Rock-San Marcos 6.5% 5.2% 2% Average LTV 55.0% Fayetteville-Springdale-Rogers 5.2% 5.4% 4% Weighted Average LTV 52.8% Fort Worth-Arlington 4.9% 4.7% Weighted Average Maturity ~19 months 13% 12% Little Rock-North Little Rock-Conway 4.7% 4.8% Texas Arkansas Tennessee Missouri Jacksonville, FL 3.4% 3.6% Oklahoma Florida Other Kansas City, MO-KS 2.3% 2.9% CLD - Industrial Warehouse (non-owner occupied) CLD - Multifamily By State By State Key Statistics At 9/30/26 Key Statistics At 9/30/26 NPL Ratio 0.00% NPL Ratio 0.00% 25% Texas 15% 53% Past Due 30+ Days 0.00% Texas Past Due 30+ Days 0.00% 36% Arkansas Average Loan Size $16.5M Tennessee Average Loan Size $10.4M 15% Tennessee $0.6B $0.4B Median Loan Size $7.5M Missouri Median Loan Size $4.0M 19% Florida Number of Loans <$1M 26% Florida 6% Number of Loans <$1M 42% Other 10% Average LTV 50.3% Other Average LTV 42.5% 11% 10% Weighted Average LTV 49.5% Weighted Average LTV 45.5% Weighted Average Maturity ~16 months Weighted Average Maturity ~16 months Data shown above as of September 30, 2026 19
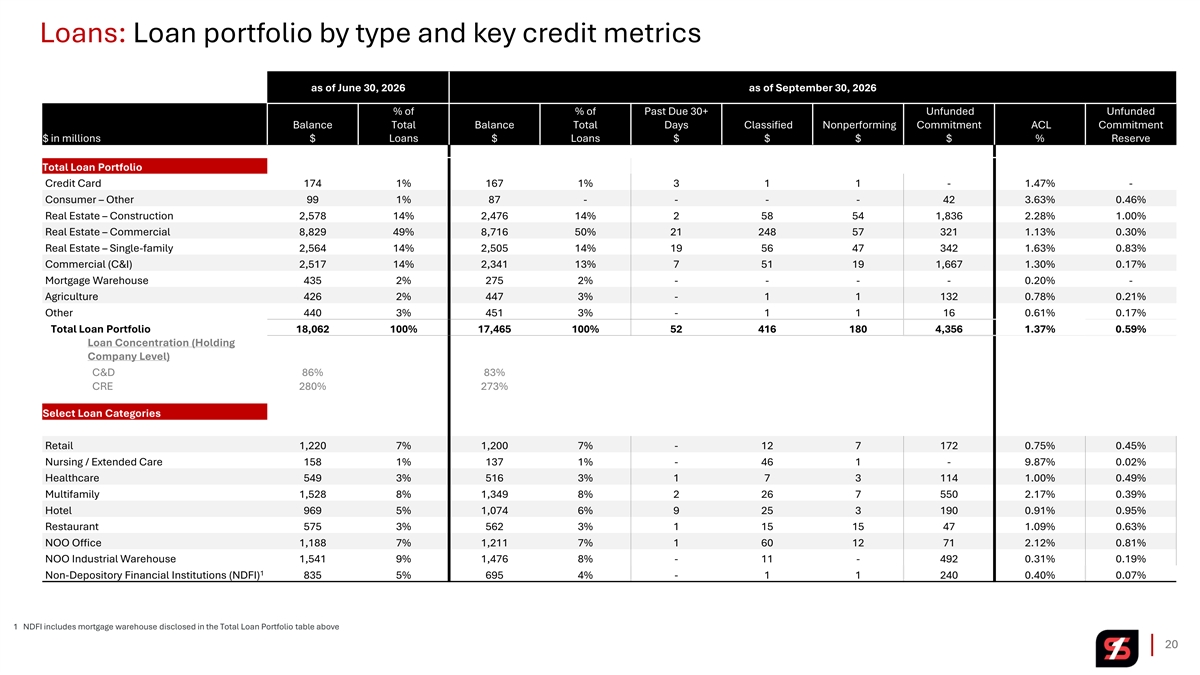
Loans: Loan portfolio by type and key credit metrics as of June 30, 2026 as of September 30, 2026 % of % of Past Due 30+ Unfunded Unfunded Balance Total Balance Total Days Classified Nonperforming Commitment ACL Commitment $ in millions $ Loans $ Loans $ $ $ $ % Reserve Total Loan Portfolio Credit Card 174 1% 167 1% 3 1 1 - 1.47% - Consumer – Other 99 1% 87 - - - - 42 3.63% 0.46% Real Estate – Construction 2,578 14% 2,476 14% 2 58 54 1,836 2.28% 1.00% Real Estate – Commercial 8,829 49% 8,716 50% 21 248 57 321 1.13% 0.30% Real Estate – Single-family 2,564 14% 2,505 14% 19 56 47 342 1.63% 0.83% Commercial (C&I) 2,517 14% 2,341 13% 7 51 19 1,667 1.30% 0.17% Mortgage Warehouse 435 2% 275 2% - - - - 0.20% - Agriculture 426 2% 447 3% - 1 1 132 0.78% 0.21% Other 440 3% 451 3% - 1 1 16 0.61% 0.17% Total Loan Portfolio 18,062 100% 17,465 100% 52 416 180 4,356 1.37% 0.59% Loan Concentration (Holding Company Level) C&D 86% 83% CRE 280% 273% Select Loan Categories Retail 1,220 7% 1,200 7% - 12 7 172 0.75% 0.45% Nursing / Extended Care 158 1% 137 1% - 46 1 - 9.87% 0.02% Healthcare 549 3% 516 3% 1 7 3 114 1.00% 0.49% Multifamily 1,528 8% 1,349 8% 2 26 7 550 2.17% 0.39% Hotel 969 5% 1,074 6% 9 25 3 190 0.91% 0.95% Restaurant 575 3% 562 3% 1 15 15 47 1.09% 0.63% NOO Office 1,188 7% 1,211 7% 1 60 12 71 2.12% 0.81% NOO Industrial Warehouse 1,541 9% 1,476 8% - 11 - 492 0.31% 0.19% 1 Non-Depository Financial Institutions (NDFI) 835 5% 695 4% - 1 1 240 0.40% 0.07% 1 NDFI includes mortgage warehouse disclosed in the Total Loan Portfolio table above 20
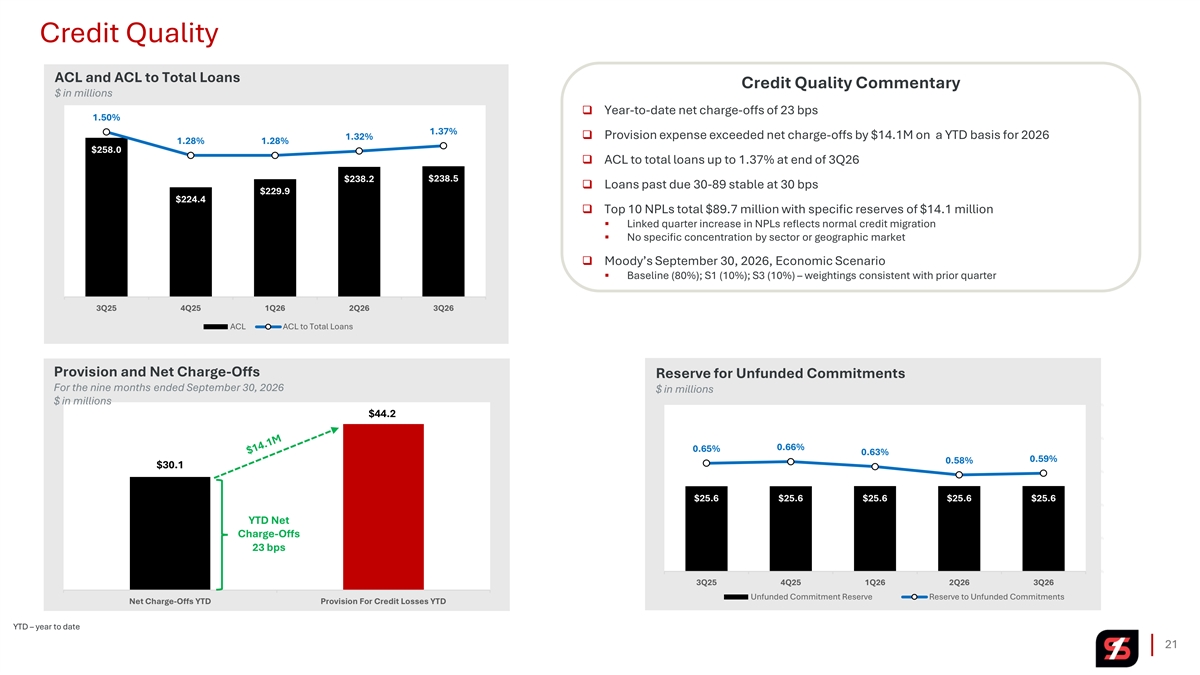
Credit Quality ACL and ACL to Total Loans Credit Quality Commentary $ in millions 1.75% $275.0 ❑ Year-to-date net charge-offs of 23 bps 1.50% 1.55% 1.37% ❑ Provision expense exceeded net charge-offs by $14.1M on a YTD basis for 2026 1.32% 1.28% 1.28% 1.35% $250.0 $258.0 ❑ ACL to total loans up to 1.37% at end of 3Q26 1.15% $238.5 $238.2 $225.0 ❑ Loans past due 30-89 stable at 30 bps 0.95% $229.9 $224.4 0.75%❑ Top 10 NPLs total $89.7 million with specific reserves of $14.1 million $200.0 ▪ Linked quarter increase in NPLs reflects normal credit migration 0.55% ▪ No specific concentration by sector or geographic market 0.35% $175.0 ❑ Moody’s September 30, 2026, Economic Scenario 0.15% ▪ Baseline (80%); S1 (10%); S3 (10%) – weightings consistent with prior quarter $150.0 -0.05% 3Q25 4Q25 1Q26 2Q26 3Q26 ACL ACL to Total Loans Provision and Net Charge-Offs Reserve for Unfunded Commitments For the nine months ended September 30, 2026 $ in millions $ in millions $50.0 1.00% $44.2 0.80% 0.66% 0.65% 0.63% 0.59% 0.58% $30.1 0.60% $25.0 $25.6 $25.6 $25.6 $25.6 $25.6 0.40% YTD Net Charge-Offs 0.20% 23 bps $0.0 0.00% 3Q25 4Q25 1Q26 2Q26 3Q26 Unfunded Commitment Reserve Reserve to Unfunded Commitments Net Charge-Offs YTD Provision For Credit Losses YTD YTD – year to date 21
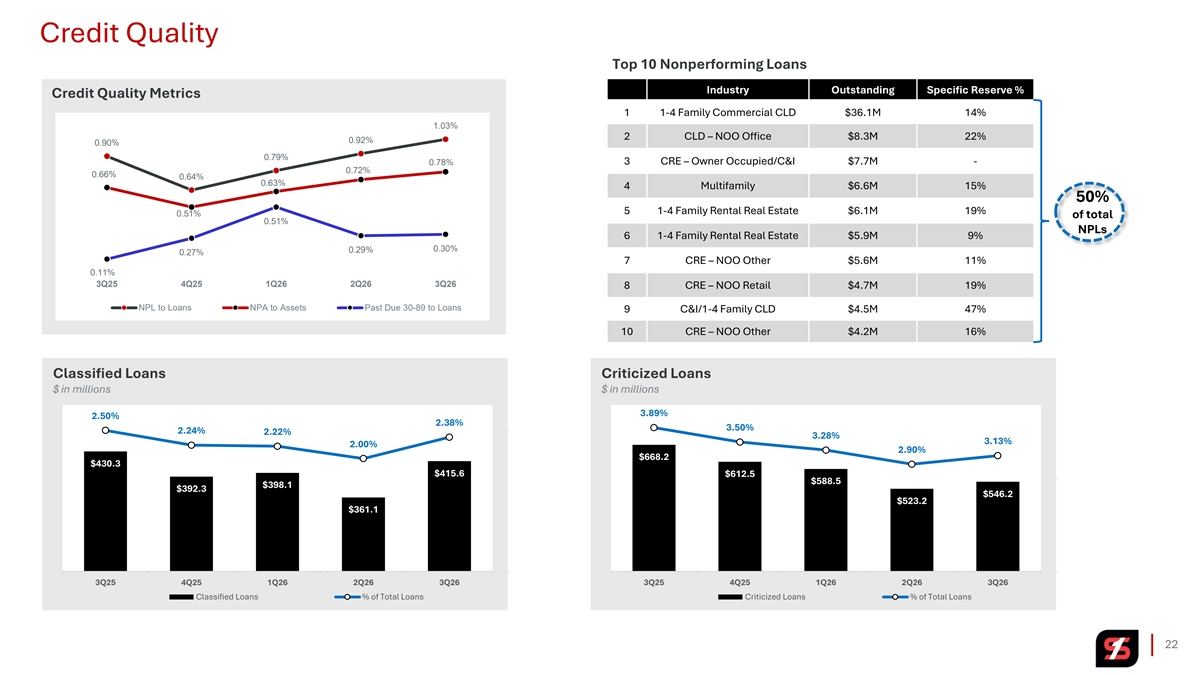
Credit Quality Top 10 Nonperforming Loans Industry Outstanding Specific Reserve % Credit Quality Metrics 1 1-4 Family Commercial CLD $36.1M 14% 1.03% 2 CLD – NOO Office $8.3M 22% 0.92% 0.90% 0.79% 3 CRE – Owner Occupied/C&I $7.7M - 0.78% 0.72% 0.66% 0.64% 0.63% 4 Multifamily $6.6M 15% 50% 5 1-4 Family Rental Real Estate $6.1M 19% 0.51% of total 0.51% NPLs 6 1-4 Family Rental Real Estate $5.9M 9% 0.30% 0.29% 0.27% 7 CRE – NOO Other $5.6M 11% 0.11% 3Q25 4Q25 1Q26 2Q26 3Q26 8 CRE – NOO Retail $4.7M 19% NPL to Loans NPA to Assets Past Due 30-89 to Loans 9 C&I/1-4 Family CLD $4.5M 47% 10 CRE – NOO Other $4.2M 16% Classified Loans Criticized Loans $ in millions $ in millions $500.0 $800.0 $775.0 3.89% 2.50% $750.0 $475.0 2.38% $725.0 3.50% 2.50% 2.24% 2.22% $700.0 3.28% $450.0 $675.0 3.13% 2.00% $650.0 2.90% $425.0 $625.0 $668.2 $430.3 $600.0 $400.0 $575.0 $415.6 $612.5 2.50% $550.0 $588.5 $398.1 $375.0 $525.0 $392.3 $500.0 $546.2 $523.2 $475.0 $350.0 $361.1 $450.0 $425.0 $325.0 $400.0 $375.0 $300.0 $350.0 $325.0 $275.0 $300.0 $275.0 $250.0 0.00% $250.0 0.00% 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 4Q25 1Q26 2Q26 3Q26 Classified Loans % of Total Loans Criticized Loans % of Total Loans 22
Forward-Looking Statements and Non-GAAP Financial Measures Forward-Looking Statements. Certain statements by Simmons First National Corporation (the “Company”, which where appropriate includes the Company’s wholly-owned banking subsidiary, Simmons Bank) contained in this presentation may not be based on historical facts and should be considered forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements may be identified by reference to a future period(s) or by the use of forward- looking terminology, such as anticipate, “believe,” “continue,” estimate, expect, foresee,“ “indicate,” “plan,” “potential,” “project,” “set,” “target,” may, might, will, would, could,“ “should,” “likely” or intend, future or conditional verb tenses, and variations or negatives of such terms or by similar expressions. These forward-looking statements include, without limitation, statements relating to the Company’s future growth (including, among other things, expected pre-provision net revenue growth during 2026); business strategies; product development; revenue; expenses (including interest expense and non-interest expenses); assets; loan demand (including loan growth, loan capacity, and other lending activity); deposit levels; dividends; asset quality; profitability; earnings; critical accounting policies; net interest margin; noninterest income; the Company's common stock repurchase program; adequacy of the allowance for credit losses; income tax deductions; credit quality; level of credit losses from lending commitments; interest rate sensitivity (including, among other things, the potential impact of rising rates); loan loss experience; liquidity; capital resources; future economic conditions and market risk; interest rates; the Company’s securities portfolio; legal and regulatory limitations and compliance and competition; anticipated loan principal reductions; projections regarding loan repricing; the estimated PPNR benefit, the closure of 26 branches on December 4, 2026, and the intended operating-model changes set forth on slide 9; the interest rate sensitivity estimates and projections set forth on slide 12; and the estimates related to the hedging program (including estimated future swap income) set forth on slide 13. Readers are cautioned not to place undue reliance on the forward-looking statements contained in this presentation in that actual results could differ materially from those indicated in or implied by such forward-looking statements due to a variety of factors. These factors include, but are not limited to, changes in the Company's operating or expansion strategy; the availability of and costs associated with obtaining adequate and timely sources of liquidity; changes in credit quality; changes in general market and economic conditions; increased unemployment; labor shortages; possible adverse rulings, judgments, fines, settlements and other outcomes of pending or future litigation; the ability of the Company to collect amounts due under loan agreements; significant increases in nonaccrual loan balances; changes in consumer preferences and loan demand; the effectiveness of the Company's interest rate risk management strategies; laws and regulations affecting financial institutions in general or relating to taxes; the effect of pending or future legislation; changes in governmental administrations; the ability of the Company to repurchase its common stock on favorable terms; the ability of the Company to successfully manage and implement its acquisition strategy and integrate acquired institutions; changes in tariff policies; difficulties and delays in integrating an acquired business or fully realizing cost savings and other benefits of mergers and acquisitions; changes in interest rates, deposit flows, real estate values, and capital markets; increased inflation; customer acceptance of the Company's products and services and changes in customer behaviors; changes or disruptions in technology and IT systems (including cyber or other information technology threats, attacks and events); emerging issues related to the development and use of artificial intelligence that could give rise to legal or regulatory action or increase cybersecurity threats; changes in accounting principles relating to loan loss recognition (current expected credit losses, or CECL); fraud that results in material losses or that we have not discovered yet that may result in material losses; the benefits associated with the Company’s early retirement program; pandemics or significant health hazards, severe weather conditions, natural disasters, terrorist activities, political crises, war, and other military conflicts (including the ongoing military conflicts in Iran and the Middle East and between Russia and Ukraine) or other major events, or the prospect of these events; increased competition in the markets in which the Company operates and from non-bank financial institutions; changes in governmental policies; the effects of a government shutdown; loss of key employees; reliance on third parties for key services; the soundness of other financial institutions and any indirect exposure related to the closings of other financial institutions and their impact on the broader market through other customers, suppliers and partners, or that the conditions which resulted in the liquidity concerns experienced by closed financial institutions may also adversely impact, directly or indirectly, other financial institutions and market participants with which the Company has commercial or deposit relationships; increased delinquency and foreclosure rates on commercial real estate and other loans; and other risk factors. Other relevant risk factors are detailed in the Company’s Form 10-K for the year ended December 31, 2025, Form 10-Qs for the quarters ended March 31, 2026 and June 30, 2026, and other reports that the Company has filed with or furnished to the U.S. Securities and Exchange Commission (the “SEC”), all of which are available from the SEC on its website, www.sec.gov. In addition, there can be no guarantee that the board of directors (“Board”) of the Company will approve a quarterly dividend in future quarters, and the timing, payment, and amount of future dividends (if any) is subject to, among other things, the discretion of the Board and may differ significantly from past dividends. Further, the timing, pricing and amount of any repurchases under the Company’s stock repurchase program will be determined by Simmons’ management at its discretion based on a variety of factors including, but not limited to, market conditions, trading volume and market price of Simmons’ common stock, Simmons’ capital needs, Simmons’ working capital and investment requirements, other corporate considerations, economic conditions, and legal requirements. The stock repurchase program does not obligate Simmons to repurchase any common stock and may be modified, discontinued or suspended at any time without prior notice. Any forward-looking statement speaks only as of the date of this presentation, and the Company undertakes no obligation to update these forward- looking statements to reflect events or circumstances that occur after the date of this presentation. Annualized, quarterized, pro forma, projected and estimated numbers are used for illustrative purpose only, are based on hypothetical assumptions that may not accurately reflect future incomes, are not forecasts and are not guaranteed and may differ significantly from actual results. The Company references certain market, industry, and demographic data and other statistical information in this presentation. The Company has obtained this data and information from various independent, third-party industry sources and publications. Nothing in the data or information used or derived from third-party sources should be construed as advice. We believe that these external sources and estimates are reliable but have not independently verified them. Non-GAAP Financial Measures. This presentation contains financial information determined by methods other than in accordance with U.S. generally accepted accounting principles (“GAAP”). The Company’s management uses these non-GAAP financial measures in their analysis of the Company’s performance and capital adequacy. These measures adjust GAAP performance measures to, among other things, include the tax benefit associated with revenue items that are tax-exempt, as well as exclude from net income (including on a per share diluted basis), pre-tax, pre-provision earnings, net charge-offs, income available to common shareholders, non-interest income, and non-interest expense certain income and expense items attributable to, for example, branch/real estate rightsizing costs, severance/early retirement program costs, certain professional services accelerated prepaid expenses, loss on sale of securities and loss on early extinguishment of debt. In addition, the Company also presents certain figures based on tangible common stockholders’ equity, tangible assets and tangible book value, which exclude goodwill and other intangible assets, and presents certain other figures to include the effect that accumulated other comprehensive income could have on the Company’s capital levels. The Company further presents certain figures that are exclusive of the impact of deposits and/or loans acquired through acquisitions, mortgage warehouse loans, and/or energy loans, or gains and/or losses on the sale of securities. The Company’s management believes that these non-GAAP financial measures are useful to investors because they, among other things, present the results of the Company’s ongoing operations without the effect of mergers or other items not central to the Company’s ongoing business, present the Company’s capital inclusive of the potential impact of AOCI (primarily comprised of unrealized losses on securities), as well as normalize for tax effects and certain other effects. Management, therefore, believes presentations of these non-GAAP financial measures provide useful supplemental information that is essential to a proper understanding of the operating results of the Company’s ongoing businesses, and management uses these non-GAAP financial measures to assess the performance of the Company’s ongoing businesses as related to prior financial periods. These non-GAAP disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Where non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found in the appendix to this presentation. 23
Appendix 24
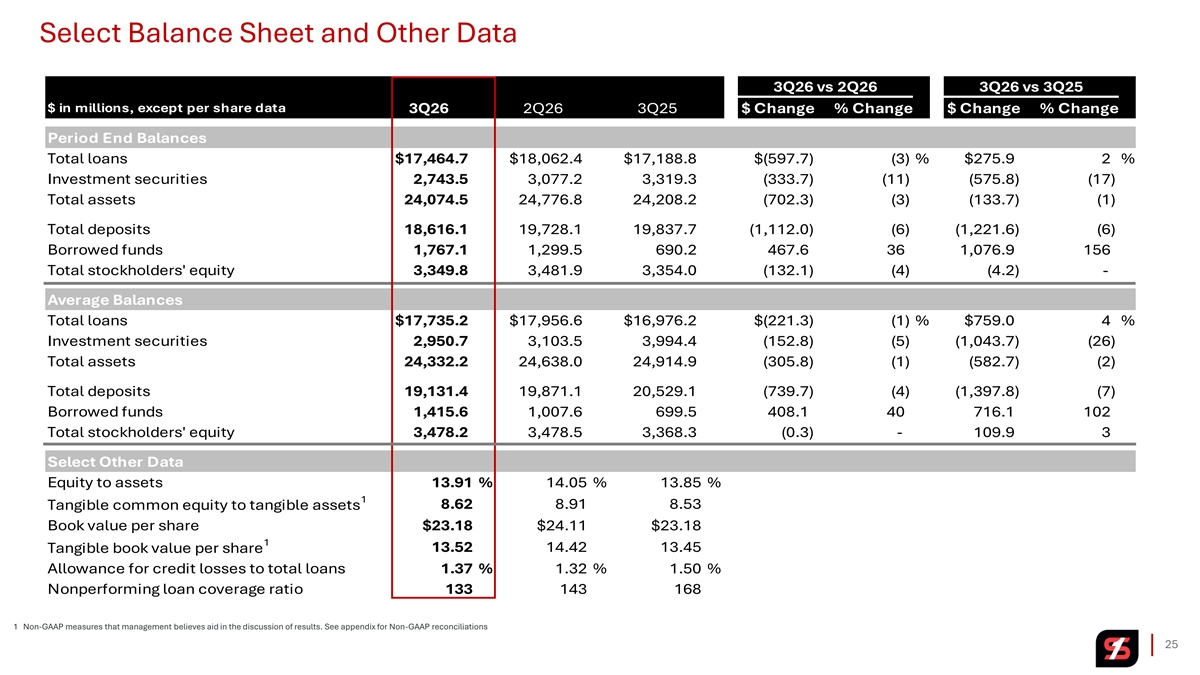
Select Balance Sheet and Other Data 3Q26 vs 2Q26 3Q26 vs 3Q25 $ in millions, except per share data 3Q26 2Q26 3Q25 $ Change % Change $ Change % Change Period End Balances Total loans $17,464.7 $18,062.4 $17,188.8 $(597.7) (3) % $275.9 2 % Investment securities 2, 743.5 3, 077.2 3, 319.3 ( 333.7) (11) ( 575.8) (17) Total assets 24,074.5 24,776.8 24,208.2 (702.3) (3) (133.7) (1) Total deposits 18,616.1 19,728.1 19,837.7 ( 1,112.0) (6) (1,221.6) (6) Borrowed funds 1, 767.1 1, 299.5 690.2 46 7.6 36 1,076.9 156 Total stockholders' equity 3,349.8 3, 481.9 3,354.0 (132.1) (4) (4.2) - Average Balances Total loans $17,735.2 $17,956.6 $16,976.2 $(221.3) (1) % $759.0 4 % Investment securities 2, 950.7 3,103.5 3,994.4 (152.8) (5) (1,043.7) (26) Total assets 24,332.2 24,638.0 24,914.9 (305.8) (1) (582.7) (2) Total deposits 19 ,131.4 19 ,871.1 20,529.1 (739.7) (4) (1,397.8) (7) Borrowed funds 1,415.6 1, 007.6 699.5 408.1 40 716.1 102 Total stockholders' equity 3,478.2 3,478.5 3,368.3 (0.3) - 109.9 3 Select Other Data Equity to assets 13.91 % 14.05 % 13.85 % 1 8.62 8.91 8.53 Tangible common equity to tangible assets Book value per share $23.18 $24.11 $23.18 1 13.52 14.42 13.45 Tangible book value per share Allowance for credit losses to total loans 1.37 % 1.32 % 1.50 % Nonperforming loan coverage ratio 133 143 168 1 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations 25
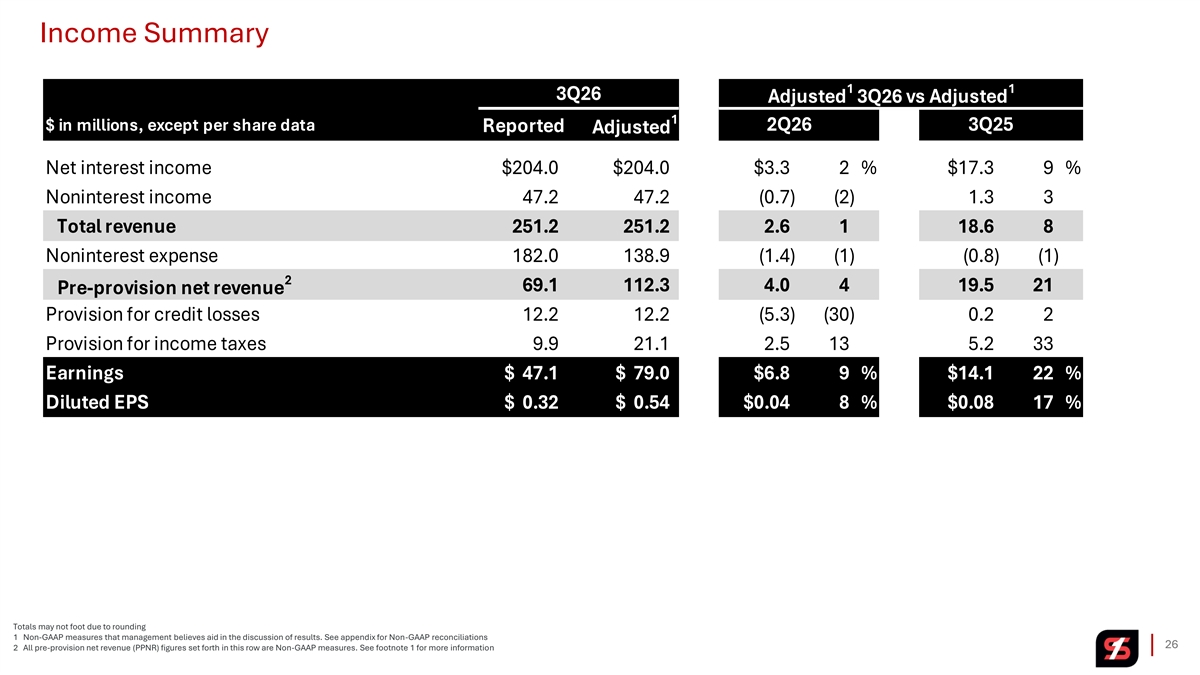
Income Summary 1 1 3Q26 Adjusted 3Q26 vs Adjusted 1 $ in millions, except per share data 2Q26 3Q25 Reported Adjusted Net interest income $204.0 $204.0 $3.3 2 % $17.3 9 % Noninterest income 47.2 4 7.2 (0.7) ( 2) 1.3 3 Total revenue 251.2 251.2 2.6 1 18.6 8 Noninterest expense 182.0 138.9 (1.4) (1) (0.8) (1) 2 6 9.1 112.3 4.0 4 19.5 21 Pre-provision net revenue Provision for credit losses 12.2 12.2 (5.3) (30) 0.2 2 Provision for income taxes 9.9 2 1.1 2.5 13 5.2 33 Earnings $ 47.1 $ 79.0 $6.8 9 % $14.1 22 % Diluted EPS $ 0.32 $ 0.54 $0.04 8 % $0.08 17 % Totals may not foot due to rounding 1 Non-GAAP measures that management believes aid in the discussion of results. See appendix for Non-GAAP reconciliations 26 2 All pre-provision net revenue (PPNR) figures set forth in this row are Non-GAAP measures. See footnote 1 for more information
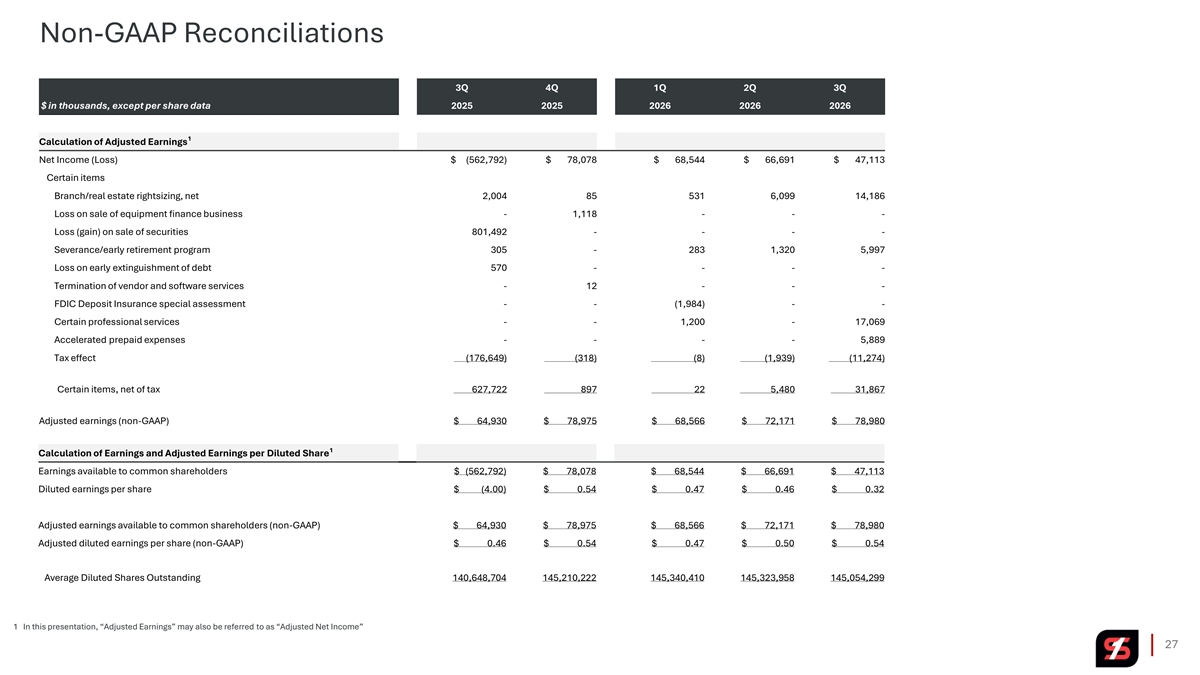
Non-GAAP Reconciliations 3Q 4Q 1Q 2Q 3Q $ in thousands, except per share data 2025 2025 2026 2026 2026 1 Calculation of Adjusted Earnings Net Income (Loss) $ (562,792) $ 78,078 $ 68,544 $ 66,691 $ 47,113 Certain items Branch/real estate rightsizing, net 2,004 85 531 6,099 14,186 Loss on sale of equipment finance business - 1,118 - - - Loss (gain) on sale of securities 801,492 - - - - Severance/early retirement program 305 - 283 1,320 5,997 Loss on early extinguishment of debt 570 - - - - Termination of vendor and software services - 12 - - - FDIC Deposit Insurance special assessment - - (1,984) - - Certain professional services - - 1,200 - 17,069 Accelerated prepaid expenses - - - - 5,889 Tax effect (176,649) (318) (8) (1,939) (11,274) Certain items, net of tax 627,722 897 22 5,480 31,867 Adjusted earnings (non-GAAP) $ 64,930 $ 78,975 $ 68,566 $ 72,171 $ 78,980 1 Calculation of Earnings and Adjusted Earnings per Diluted Share Earnings available to common shareholders $ (562,792) $ 78,078 $ 68,544 $ 66,691 $ 47,113 Diluted earnings per share $ (4.00) $ 0.54 $ 0.47 $ 0.46 $ 0.32 Adjusted earnings available to common shareholders (non-GAAP) $ 64,930 $ 78,975 $ 68,566 $ 72,171 $ 78,980 Adjusted diluted earnings per share (non-GAAP) $ 0.46 $ 0.54 $ 0.47 $ 0.50 $ 0.54 Average Diluted Shares Outstanding 140,648,704 145,210,222 145,340,410 145,323,958 145,054,299 1 In this presentation, “Adjusted Earnings” may also be referred to as “Adjusted Net Income” 27
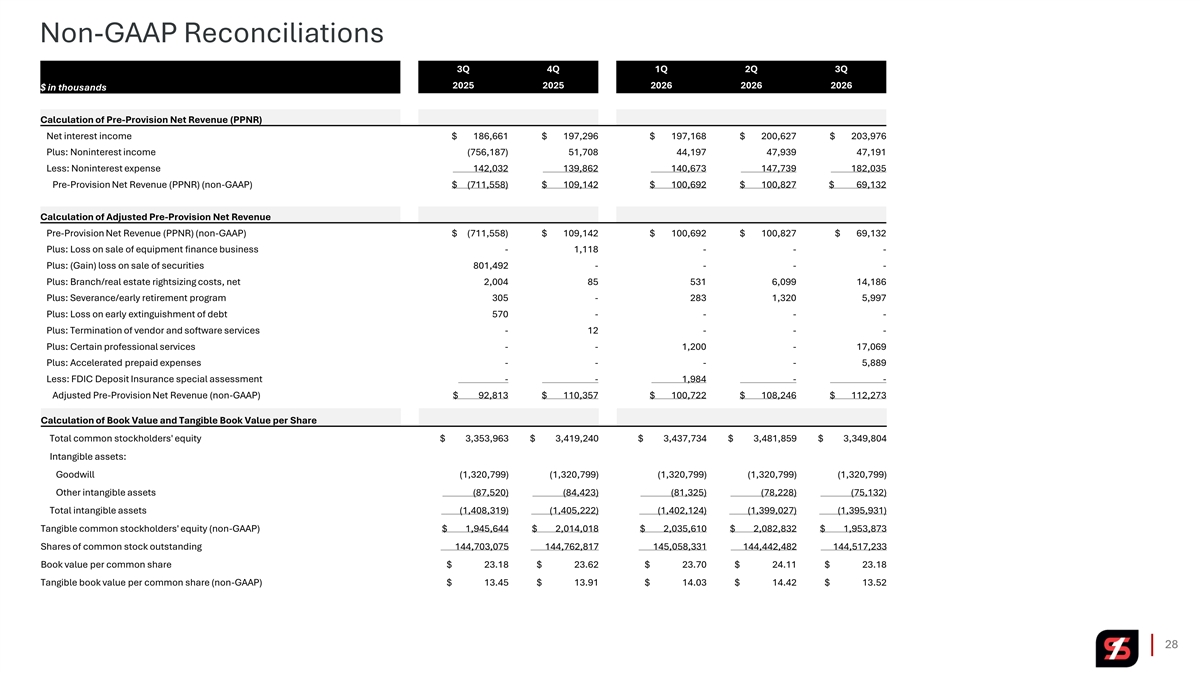
Non-GAAP Reconciliations 3Q 4Q 1Q 2Q 3Q 2025 2025 2026 2026 2026 $ in thousands Calculation of Pre-Provision Net Revenue (PPNR) Net interest income $ 186,661 $ 197,296 $ 197,168 $ 200,627 $ 203,976 Plus: Noninterest income (756,187) 51,708 44,197 47,939 47,191 Less: Noninterest expense 142,032 139,862 140,673 147,739 182,035 Pre-Provision Net Revenue (PPNR) (non-GAAP) $ (711,558) $ 109,142 $ 100,692 $ 100,827 $ 69,132 Calculation of Adjusted Pre-Provision Net Revenue Pre-Provision Net Revenue (PPNR) (non-GAAP) $ (711,558) $ 109,142 $ 100,692 $ 100,827 $ 69,132 Plus: Loss on sale of equipment finance business - 1,118 - - - Plus: (Gain) loss on sale of securities 801,492 - - - - Plus: Branch/real estate rightsizing costs, net 2,004 85 531 6,099 14,186 Plus: Severance/early retirement program 305 - 283 1,320 5,997 Plus: Loss on early extinguishment of debt 570 - - - - Plus: Termination of vendor and software services - 12 - - - Plus: Certain professional services - - 1,200 - 17,069 Plus: Accelerated prepaid expenses - - - - 5,889 Less: FDIC Deposit Insurance special assessment - - 1,984 - - Adjusted Pre-Provision Net Revenue (non-GAAP) $ 92,813 $ 110,357 $ 100,722 $ 108,246 $ 112,273 Calculation of Book Value and Tangible Book Value per Share Total common stockholders' equity $ 3,353,963 $ 3,419,240 $ 3,437,734 $ 3,481,859 $ 3,349,804 Intangible assets: Goodwill (1,320,799) (1,320,799) (1,320,799) (1,320,799) (1,320,799) Other intangible assets (87,520) (84,423) (81,325) (78,228) (75,132) Total intangible assets (1,408,319) (1,405,222) (1,402,124) (1,399,027) (1,395,931) Tangible common stockholders' equity (non-GAAP) $ 1,945,644 $ 2,014,018 $ 2,035,610 $ 2,082,832 $ 1,953,873 Shares of common stock outstanding 144,703,075 144,762,817 145,058,331 144,442,482 144,517,233 Book value per common share $ 23.18 $ 23.62 $ 23.70 $ 24.11 $ 23.18 Tangible book value per common share (non-GAAP) $ 13.45 $ 13.91 $ 14.03 $ 14.42 $ 13.52 28
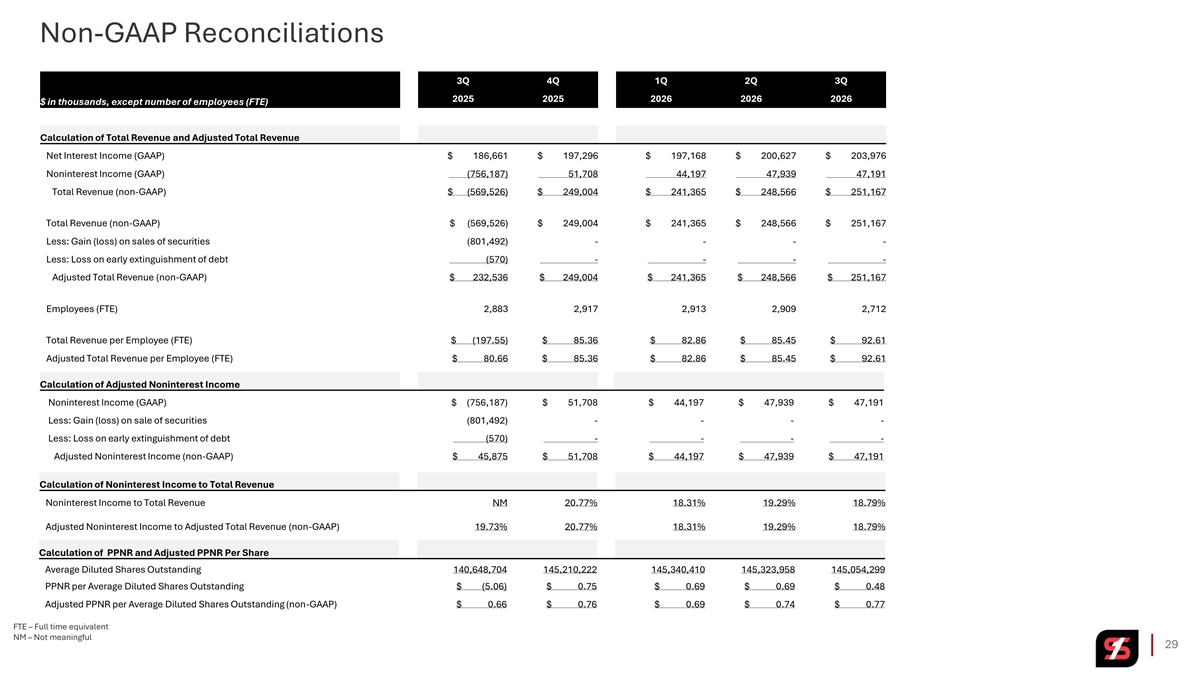
Non-GAAP Reconciliations 3Q 4Q 1Q 2Q 3Q 2025 2025 2026 2026 2026 $ in thousands, except number of employees (FTE) Calculation of Total Revenue and Adjusted Total Revenue Net Interest Income (GAAP) $ 186,661 $ 197,296 $ 197,168 $ 200,627 $ 203,976 Noninterest Income (GAAP) (756,187) 51,708 44,197 47,939 47,191 Total Revenue (non-GAAP) $ (569,526) $ 249,004 $ 241,365 $ 248,566 $ 251,167 Total Revenue (non-GAAP) $ (569,526) $ 249,004 $ 241,365 $ 248,566 $ 251,167 Less: Gain (loss) on sales of securities (801,492) - - - - Less: Loss on early extinguishment of debt (570) - - - - Adjusted Total Revenue (non-GAAP) $ 232,536 $ 249,004 $ 241,365 $ 248,566 $ 251,167 Employees (FTE) 2,883 2,917 2,913 2,909 2,712 Total Revenue per Employee (FTE) $ (197.55) $ 85.36 $ 82.86 $ 85.45 $ 92.61 Adjusted Total Revenue per Employee (FTE) $ 80.66 $ 85.36 $ 82.86 $ 85.45 $ 92.61 Calculation of Adjusted Noninterest Income Noninterest Income (GAAP) $ (756,187) $ 51,708 $ 44,197 $ 47,939 $ 47,191 Less: Gain (loss) on sale of securities (801,492) - - - - Less: Loss on early extinguishment of debt (570) - - - - Adjusted Noninterest Income (non-GAAP) $ 45,875 $ 51,708 $ 44,197 $ 47,939 $ 47,191 Calculation of Noninterest Income to Total Revenue Noninterest Income to Total Revenue NM 20.77% 18.31% 19.29% 18.79% Adjusted Noninterest Income to Adjusted Total Revenue (non-GAAP) 19.73% 20.77% 18.31% 19.29% 18.79% Calculation of PPNR and Adjusted PPNR Per Share Average Diluted Shares Outstanding 140,648,704 145,210,222 145,340,410 145,323,958 145,054,299 PPNR per Average Diluted Shares Outstanding $ (5.06) $ 0.75 $ 0.69 $ 0.69 $ 0.48 Adjusted PPNR per Average Diluted Shares Outstanding (non-GAAP) $ 0.66 $ 0.76 $ 0.69 $ 0.74 $ 0.77 FTE – Full time equivalent NM – Not meaningful 29
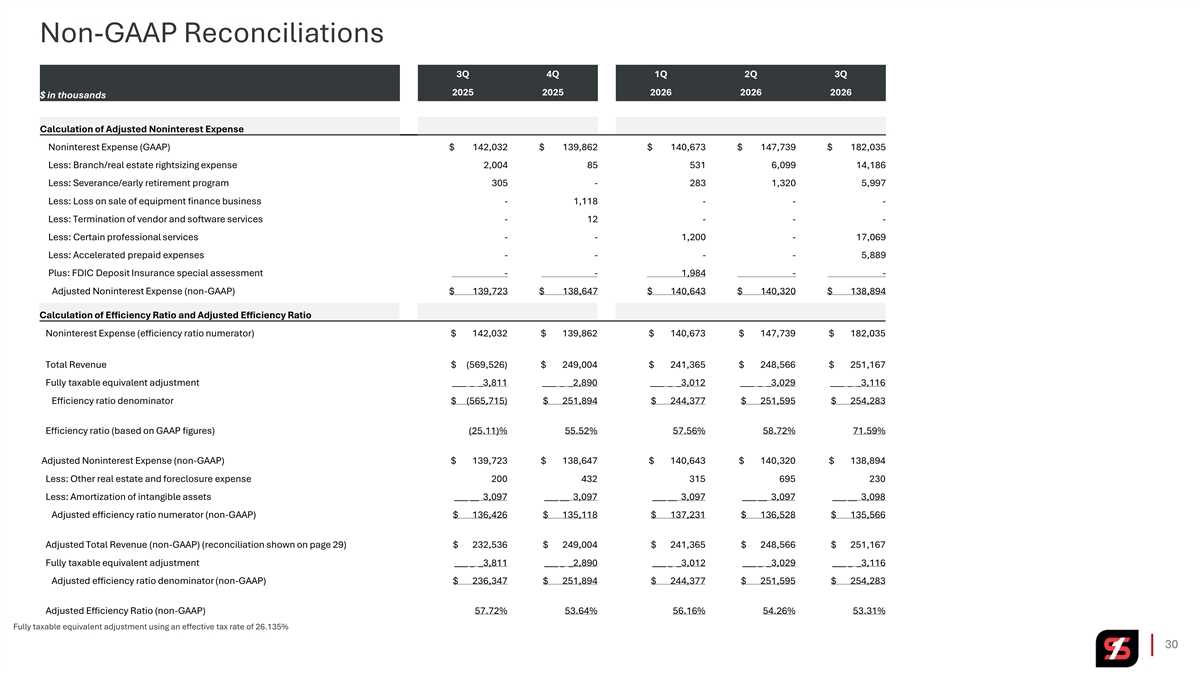
Non-GAAP Reconciliations 3Q 4Q 1Q 2Q 3Q 2025 2025 2026 2026 2026 $ in thousands Calculation of Adjusted Noninterest Expense Noninterest Expense (GAAP) $ 142,032 $ 139,862 $ 140,673 $ 147,739 $ 182,035 Less: Branch/real estate rightsizing expense 2,004 85 531 6,099 14,186 Less: Severance/early retirement program 305 - 283 1,320 5,997 Less: Loss on sale of equipment finance business - 1,118 - - - Less: Termination of vendor and software services - 12 - - - Less: Certain professional services - - 1,200 - 17,069 Less: Accelerated prepaid expenses - - - - 5,889 Plus: FDIC Deposit Insurance special assessment - - 1,984 - - Adjusted Noninterest Expense (non-GAAP) $ 139,723 $ 138,647 $ 140,643 $ 140,320 $ 138,894 Calculation of Efficiency Ratio and Adjusted Efficiency Ratio Noninterest Expense (efficiency ratio numerator) $ 142,032 $ 139,862 $ 140,673 $ 147,739 $ 182,035 Total Revenue $ (569,526) $ 249,004 $ 241,365 $ 248,566 $ 251,167 Fully taxable equivalent adjustment ___ _ _3,811 ___ _ _2,890 ___ _ _3,012 ___ _ _3,029 ___ _ _3,116 Efficiency ratio denominator $ (565,715) $ 251,894 $ 244,377 $ 251,595 $ 254,283 Efficiency ratio (based on GAAP figures) (25.11)% 55.52% 57.56% 58.72% 71.59% Adjusted Noninterest Expense (non-GAAP) $ 139,723 $ 138,647 $ 140,643 $ 140,320 $ 138,894 Less: Other real estate and foreclosure expense 200 432 315 695 230 Less: Amortization of intangible assets ___ __ 3,097 ___ __ 3,097 ___ __ 3,097 ___ __ 3,097 ___ __ 3,098 Adjusted efficiency ratio numerator (non-GAAP) $ 136,426 $ 135,118 $ 137,231 $ 136,528 $ 135,566 Adjusted Total Revenue (non-GAAP) (reconciliation shown on page 29) $ 232,536 $ 249,004 $ 241,365 $ 248,566 $ 251,167 Fully taxable equivalent adjustment ___ _ _3,811 ___ _ _2,890 ___ _ _3,012 ___ _ _3,029 ___ _ _3,116 Adjusted efficiency ratio denominator (non-GAAP) $ 236,347 $ 251,894 $ 244,377 $ 251,595 $ 254,283 Adjusted Efficiency Ratio (non-GAAP) 57.72% 53.64% 56.16% 54.26% 53.31% Fully taxable equivalent adjustment using an effective tax rate of 26.135% 30
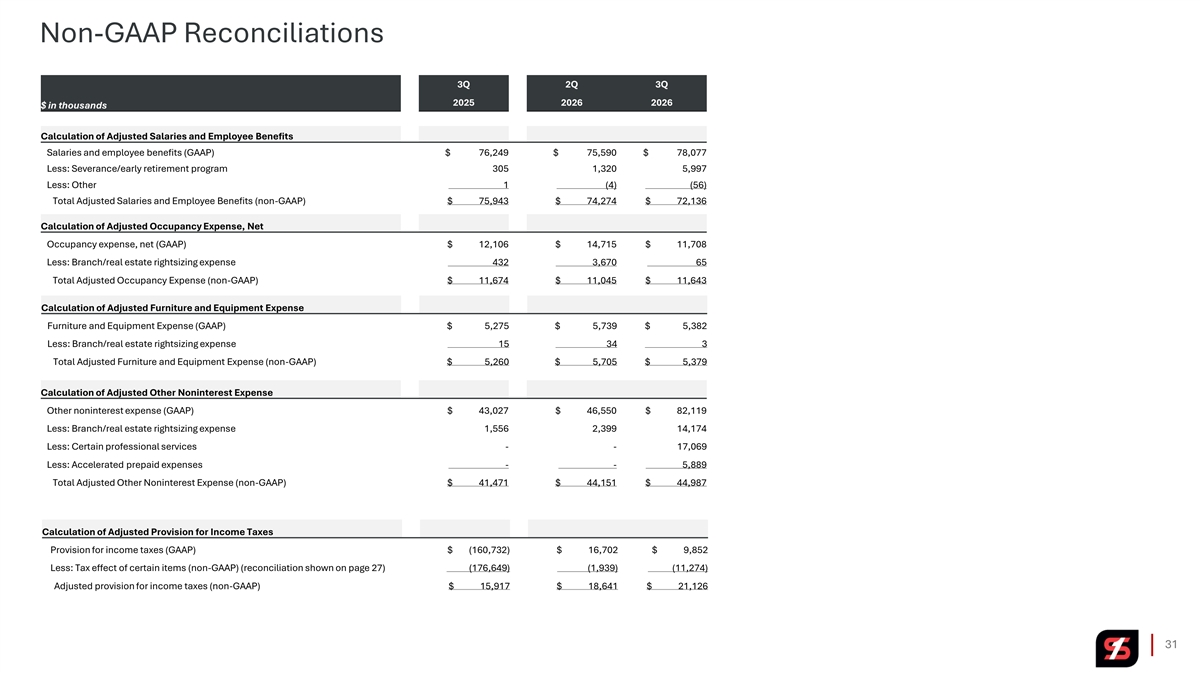
Non-GAAP Reconciliations 3Q 2Q 3Q 2025 2026 2026 $ in thousands Calculation of Adjusted Salaries and Employee Benefits Salaries and employee benefits (GAAP) $ 76,249 $ 75,590 $ 78,077 Less: Severance/early retirement program 305 1,320 5,997 Less: Other 1 (4) (56) Total Adjusted Salaries and Employee Benefits (non-GAAP) $ 75,943 $ 74,274 $ 72,136 Calculation of Adjusted Occupancy Expense, Net Occupancy expense, net (GAAP) $ 12,106 $ 14,715 $ 11,708 Less: Branch/real estate rightsizing expense 432 3,670 65 Total Adjusted Occupancy Expense (non-GAAP) $ 11,674 $ 11,045 $ 11,643 Calculation of Adjusted Furniture and Equipment Expense Furniture and Equipment Expense (GAAP) $ 5,275 $ 5,739 $ 5,382 Less: Branch/real estate rightsizing expense 15 34 3 Total Adjusted Furniture and Equipment Expense (non-GAAP) $ 5,260 $ 5,705 $ 5,379 Calculation of Adjusted Other Noninterest Expense Other noninterest expense (GAAP) $ 43,027 $ 46,550 $ 82,119 Less: Branch/real estate rightsizing expense 1,556 2,399 14,174 Less: Certain professional services - - 17,069 Less: Accelerated prepaid expenses - - 5,889 Total Adjusted Other Noninterest Expense (non-GAAP) $ 41,471 $ 44,151 $ 44,987 Calculation of Adjusted Provision for Income Taxes Provision for income taxes (GAAP) $ (160,732) $ 16,702 $ 9,852 Less: Tax effect of certain items (non-GAAP) (reconciliation shown on page 27) (176,649) (1,939) (11,274) Adjusted provision for income taxes (non-GAAP) $ 15,917 $ 18,641 $ 21,126 31
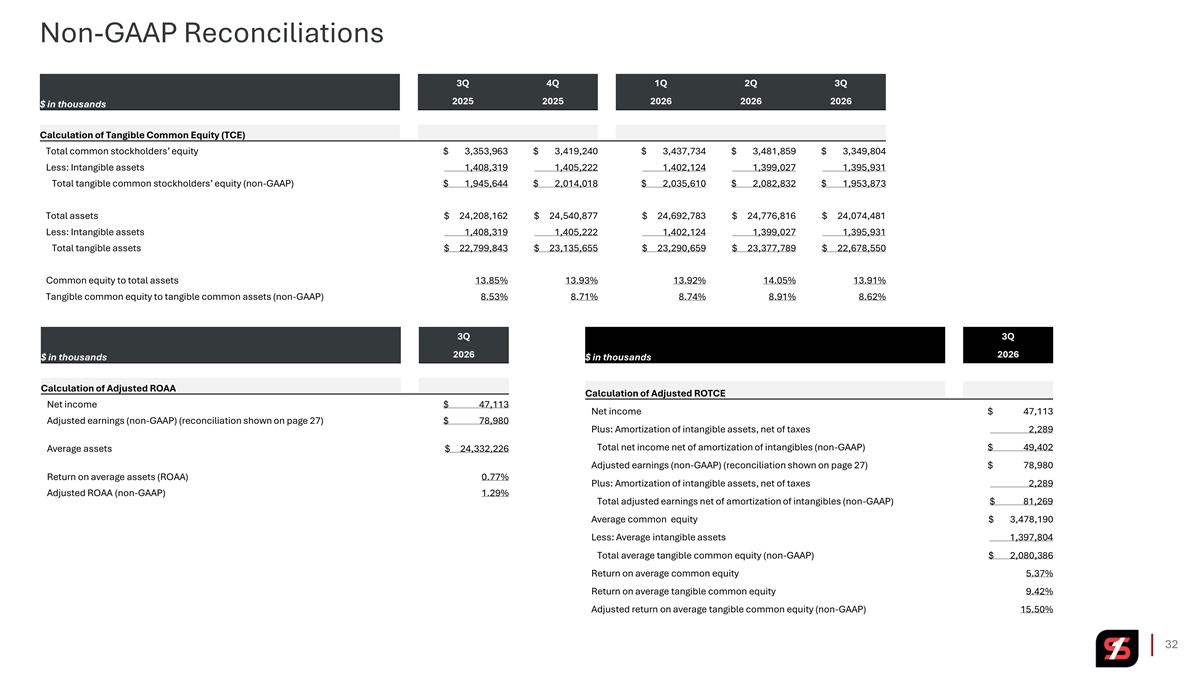
Non-GAAP Reconciliations 3Q 4Q 1Q 2Q 3Q 2025 2025 2026 2026 2026 $ in thousands Calculation of Tangible Common Equity (TCE) Total common stockholders’ equity $ 3,353,963 $ 3,419,240 $ 3,437,734 $ 3,481,859 $ 3,349,804 Less: Intangible assets 1,408,319 1,405,222 1,402,124 1,399,027 1,395,931 Total tangible common stockholders’ equity (non-GAAP) $ 1,945,644 $ 2,014,018 $ 2,035,610 $ 2,082,832 $ 1,953,873 Total assets $ 24,208,162 $ 24,540,877 $ 24,692,783 $ 24,776,816 $ 24,074,481 Less: Intangible assets 1,408,319 1,405,222 1,402,124 1,399,027 1,395,931 Total tangible assets $ 22,799,843 $ 23,135,655 $ 23,290,659 $ 23,377,789 $ 22,678,550 Common equity to total assets 13.85% 13.93% 13.92% 14.05% 13.91% Tangible common equity to tangible common assets (non-GAAP) 8.53% 8.71% 8.74% 8.91% 8.62% 3Q 3Q 2026 2026 $ in thousands $ in thousands Calculation of Adjusted ROAA Calculation of Adjusted ROTCE Net income $ 47,113 Net income $ 47,113 Adjusted earnings (non-GAAP) (reconciliation shown on page 27) $ 78,980 Plus: Amortization of intangible assets, net of taxes 2,289 Total net income net of amortization of intangibles (non-GAAP) $ 49,402 Average assets $ 24,332,226 Adjusted earnings (non-GAAP) (reconciliation shown on page 27) $ 78,980 Return on average assets (ROAA) 0.77% Plus: Amortization of intangible assets, net of taxes 2,289 Adjusted ROAA (non-GAAP) 1.29% Total adjusted earnings net of amortization of intangibles (non-GAAP) $ 81,269 Average common equity $ 3,478,190 Less: Average intangible assets 1,397,804 Total average tangible common equity (non-GAAP) $ 2,080,386 Return on average common equity 5.37% Return on average tangible common equity 9.42% Adjusted return on average tangible common equity (non-GAAP) 15.50% 32
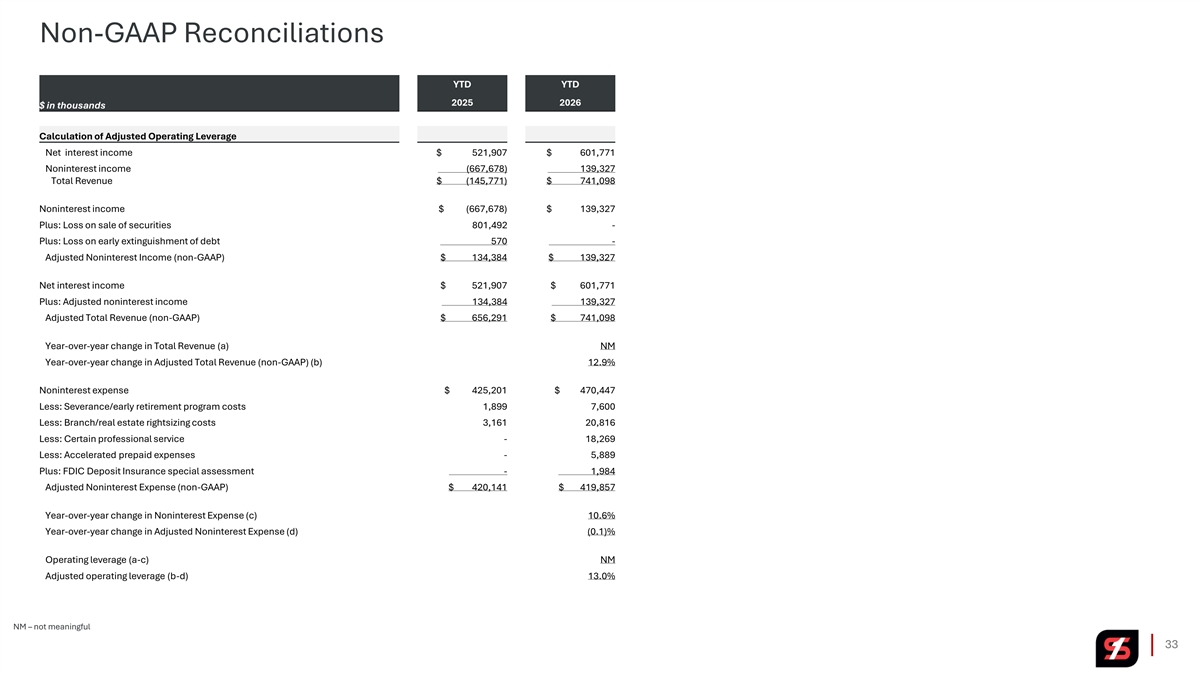
Non-GAAP Reconciliations YTD YTD 2025 2026 $ in thousands Calculation of Adjusted Operating Leverage Net interest income $ 521,907 $ 601,771 Noninterest income (667,678) 139,327 Total Revenue $ (145,771) $ 741,098 Noninterest income $ (667,678) $ 139,327 Plus: Loss on sale of securities 801,492 - Plus: Loss on early extinguishment of debt 570 - Adjusted Noninterest Income (non-GAAP) $ 134,384 $ 139,327 Net interest income $ 521,907 $ 601,771 Plus: Adjusted noninterest income 134,384 139,327 Adjusted Total Revenue (non-GAAP) $ 656,291 $ 741,098 Year-over-year change in Total Revenue (a) NM Year-over-year change in Adjusted Total Revenue (non-GAAP) (b) 12.9% Noninterest expense $ 425,201 $ 470,447 Less: Severance/early retirement program costs 1,899 7,600 Less: Branch/real estate rightsizing costs 3,161 20,816 Less: Certain professional service - 18,269 Less: Accelerated prepaid expenses - 5,889 Plus: FDIC Deposit Insurance special assessment - 1,984 Adjusted Noninterest Expense (non-GAAP) $ 420,141 $ 419,857 Year-over-year change in Noninterest Expense (c) 10.6% Year-over-year change in Adjusted Noninterest Expense (d) (0.1)% Operating leverage (a-c) NM Adjusted operating leverage (b-d) 13.0% NM – not meaningful 33
Nasdaq SFNC rd 3 Quarter 2026 Earnings Presentation October 15, 2026