Exhibit 99.1
Trasteel Holding S.A. People Behind Steel Steel & Metals Trading • Industrial Assets • Energy Investor Presentation | October 2026
Disclaimer ( 1/4 ) This Presentation (together with oral statements made in connection herewith, the “Presentation”) is for informational purposes only to assist interested parties in making their own evaluation with respect to a proposed business combination (the “Business Combination”) among Sizzle Acquisition Corp . II (“Sizzle II”), Trasteel Holding S . A . , a Luxembourg corporation (together with its subsidiaries, “Trasteel” or the “Company”), and a newly formed company, which will be the holding company of the Company and Sizzle II upon consummation of the Business Combination (“Pubco”), and the other parties thereto, and may be used in related transactions (including in connection with any proposed private placement of securities in connection with the Business Combination) . This Presentation does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation to purchase any equity, debt or other financial instruments or securities of Sizzle II or the Company or any affiliates thereof . The terms of the Business Combination set forth in this Presentation are indicative, non - binding and subject to further discussion, negotiation and change . You are hereby advised that the United States securities laws restrict persons with material non - public information about a company obtained directly or indirectly from that company from purchasing or selling securities of such company, or from communicating such information to any other person under circumstances in which it is reasonably foreseeable that such person is likely to purchase or sell such securities on the basis of such information . The information contained herein does not purport to be all - inclusive and none of Sizzle II, the Company, nor any of their respective subsidiaries, shareholders, affiliates, representatives, control persons, partners, members, managers, directors, officers, employees, advisers or agents make any representation or warranty, express or implied, as to the accuracy, completeness or reliability of the information contained in this Presentation, including any information based on studies, publications, surveys, or internal estimates . Prospective investors in the proposed private placement should consult with their own counsel and tax and financial advisors as to legal and related matters concerning the matters described herein, and, by accepting this Presentation, you confirm that you are not relying solely upon the information contained herein to make any investment decision . The recipient shall not rely upon any statement, representation or warranty made by any other person, organization, firm or corporation in making its investment decision to subscribe for securities of Pubco which is expected to be the holding company of Sizzle II and Trasteel upon consummation of the Business Combination (the “Combined Company”) . To the fullest extent permitted by law, in no circumstances will Sizzle II, the Company, Pubco or any of their respective subsidiaries, shareholders, affiliates, representatives, control persons, partners, members, managers, directors, officers, employees, advisers or agents be responsible or liable for any direct, indirect or consequential loss or loss of profit arising from the use of this Presentation, its contents, its omissions, reliance on the information contained within it, or relating to opinions communicated in relation thereto or otherwise arising in connection therewith . The general explanations included in this Presentation cannot address, and are not intended to address, your specific investment objectives, financial situations or financial needs . No Offer or Solicitation . This Presentation shall not constitute a “solicitation” as defined in Section 14 of the Securities Exchange Act of 1934 , as amended . This Presentation and any oral statement made in connection with this Presentation do not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation to purchase, any equity, debt or other financial instruments or securities of Sizzle II or the Company or any affiliates thereof . This Presentation also does not constitute any solicitation of any vote, consent, approval or proxy in connection with the Business Combination or of Sizzle II, Pubco or the Company or any of their affiliates, nor shall there be any sale of securities, investment or other specific product in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction . Neither Sizzle II, the Company nor Pubco is making any offer to sell, or soliciting any offer to buy securities, and cannot accept any securities for orders . Any offering of securities in any private placement will not be registered under the Securities Act of 1933 , as amended (the “Securities Act”), and such a private placement is expected to be offered to a limited number of institutional “accredited investors” as defined in Rule 501 (a)( 1 ), ( 2 ), ( 3 ) or ( 7 ) under the Act and “Institutional Accounts” as defined in FINRA Rule 4512 (c) . Prior to investment in any securities, any prospective investor should consult with their counsel as to the applicable requirements to avail itself of any exemption under the Securities Act and regarding the terms of any applicable subscription agreement . This Presentation does not constitute either advice or a recommendation regarding any securities . 2
Disclaimer ( 2/4 ) Sizzle II, the Company and Pubco and their respective directors and executive officers may be deemed participants in the solicitation of proxies from Sizzle II’s shareholders with respect to the potential Business Combination . A list of the names of Sizzle II’s directors and executive officers and a description of their interests in Sizzle II is contained in Sizzle II’s final prospectus relating to its initial public offering, which was filed with the Securities and Exchange Commission (the “SEC”) on April 2 , 2025 and is available free of charge at the SEC’s web site at www . sec . gov , or by directing a request to Sizzle II . Additional information regarding the interests of the participants in the solicitation of proxies from the shareholders of Sizzle II with respect to the proposed Business Combination will be contained in a registration statement on Form F - 4 , and accompanying proxy statement/prospectus, for the proposed Business Combination which is expected to be filed by Pubco with the SEC, and is available at the SEC’s web site referenced above, when available (the “Registration Statement”) . Additional Information and Where to Find It . In connection with the Business Combination, Pubco intends to file the Registration Statement, which will include a proxy statement to be sent to Sizzle II shareholders and a prospectus for the registration of Pubco securities in connection with the Proposed Business Combination . If and when the Registration Statement is declared effective by the SEC, its definitive proxy statement/prospectus and other relevant documents will be mailed to the shareholders of Sizzle II as of the record date to be established for voting on the Business Combination and will contain important information about the Business Combination and related matters . Shareholders of Sizzle II and other interested persons are advised to read, when available, these materials (including any amendments or supplements thereto) and any other relevant documents, because they will contain important information about Sizzle II, Trasteel, Pubco and the Business Combination . Shareholders and other interested persons will also be able to obtain copies of the Registration Statement, including its preliminary proxy statement/prospectus, its definitive proxy statement/prospectus, and other relevant materials in connection with the Proposed Business Combination, without charge, once available, at the SEC’s website at www . sec . gov or by directing a request to : Sizzle II Acquisition Corp . II, 4201 Georgia Avenue, NW, Washington, D . C . 20011 , Attn : Steve Salis, Chief Executive Officer . This Presentation is not a substitute for the Registration Statement or for any other document that Sizzle II or Pubco may file with the SEC in connection with the Business Combination . Interested persons are urged to read the documents filed with the SEC carefully and in their entirety when the become available because they will contain important information . Interested security holders and investors may obtain free copies of such documents, without charge, as described above . Forward - Looking Statements . Certain statements in this Presentation may be considered “forward - looking statements” . Forward - looking statements herein generally relate to future events or the future financial or operating performance of Sizzle II, the Company or the Combined Company . For example, projections of future financial performance of the Combined Company, the Business Combination, the Combined Company’s business plan, other projections concerning key performance metrics or milestones, the proceeds of the Business Combination and the Combined Company’s expected cash runway, and the potential effects of the Business Combination on Sizzle II, the Company and/or the Combined Company, are forward - looking statements . In some cases, you can identify forward - looking statements by terminology such as “may,” “should,” “expect,” “intend,” “will,” “estimate,” “anticipate,” “believe,” “predict,” “project,” “target,” “plan,” or “potentially” or the negatives of these terms or variations of them or similar terminology . Such forward - looking statements are subject to risks, uncertainties, and other factors which could cause actual results to differ materially from those expressed or implied by such forward - looking statements . Such forward - looking statements includes a projected financial information, which is for illustrative purposes only, is based on assumptions that may not materialize, and has not been audited or reviewed by any independent auditors . These forward - looking statements are based upon estimates and assumptions that, while considered reasonable by Sizzle II, the Company and their respective management, as the case may be, are inherently uncertain and subject to material change . New risks and uncertainties may emerge from time to time, and it is not possible to predict all risk and uncertainties . Factors that may cause actual results to differ materially from current expectations include, but are not limited to, factors beyond management’s control, including general economic conditions and other risks, uncertainties and factors set forth in the section entitled “Risk Factors” and “Cautionary Note Regarding Forward - Looking Statements” in Sizzle II’s final prospectus relating to its initial public offering, dated April 2 , 2025 , and other filings with the SEC, as well as factors associated with companies, such as the Company, including anticipated trends, growth rates, and challenges in their businesses and in the markets in which they operate, including the factors described in the summary risk factors that will accompany this Presentation . Nothing in this Presentation should be regarded as a representation by any person that the forward - looking statements set forth herein will be achieved or that any of the contemplated results of such forward - looking statements will be achieved . You should not place undue reliance on forward - looking statements in this Presentation, which speak only as of the date they are made and are qualified in their entirety by reference to the cautionary statements herein and referenced herein . 3
Disclaimer ( 3/4 ) Trademarks . This Presentation may contain trademarks, service marks, trade names and copyrights of other companies, which are the property of their respective owners . Solely for convenience, some of the trademarks, service marks, trade names and copyrights referred to in this Presentation may be listed without the TM, SM© or © symbols, but such references are not intended to indicate in any way that any of Sizzle II, the Company or Pubco or any third - party will not assert, to the fullest extent under applicable law, the rights of the applicable owners, if any, to these trademarks, service marks, trade names and copyrights . This Presentation also includes trademarks, trade names, and service marks that are the property of other organizations . We do not intend our use or display of other parties’ trademarks, trade names, or service marks to imply, and such use or display should not be construed to imply a relationship with, or endorsement or sponsorship of us by, these other parties . No Relationship or Joint Venture . Nothing contained in this Presentation will be deemed or construed to create the relationship of partnership, association, principal and agent or joint venture . This Presentation does not create any obligation on the part of the Company, Sizzle II or the recipient to enter into any further agreement or arrangement . Unless and until a definitive agreement has been fully executed and delivered, no contract or agreement providing for a transaction will be deemed to exist and none of Sizzle II, the Company or the recipient will be under any legal obligation of any kind whatsoever . Accordingly, this Presentation is not intended to create for any party a right of specific performance or a right to seek any payment or damages for failure, for any reason, to complete any proposed transactions contemplated herein . Third Party Information ; Information Sources . Certain information contained in this Presentation relates to or is based on studies, publications, surveys and the Company’s own internal estimates and research regarding the business or industry of the Company . All information contained in this Presentation regarding or relating to the Company have been supplied only by the Company . All information contained in this Presentation relating to Sizzle II have been supplied only by Sizzle II . In addition, all of the market data included in this Presentation involves a number of assumptions and limitations, and there can be no guarantee as to the accuracy or reliability of such assumptions . Finally, while the Company believes its internal research is reliable, such research has not been verified by any independent source, and the Company and Sizzle II cannot guarantee and make no representation or warranty, express or implied, as to its accuracy and completeness . Financial Information . The financial information and data of the Company and relating to the Business Combination contained in this Presentation is unaudited (or audited under non - U . S . accounting principles as noted below) and does not conform to Regulation S - X promulgated by the SEC . Accordingly, such information and data may not be included in, and may be adjusted in, or presented differently in, the Registration Statement . This Presentation includes financial information of the Company that is presented as of and for each of the years ended December 31 , 2025 , 2024 and 2023 (collectively, the “Annual Periods”), and unaudited interim financial information for the six months ended June 30 , 2026 , which information is preliminary, has not yet been audited by the Company’s independent registered public accounting firm and is subject to change . The Company’s actual results may differ materially from such financial information included in this Presentation due to the completion of the Company’s closing procedures, financial adjustments and other developments that may arise . This preliminary financial information is not a comprehensive statement of the Company’s financial results for any of the Annual Periods nor any period under review or presentation, and should not be viewed as a substitute for full financial statements prepared in accordance with International Financial Reporting Standards (“IFRS”), as issued by the International Accounting Standards Board . In addition, this preliminary financial information is not necessarily indicative of the results to be achieved in any future period . 4
Disclaimer ( 4/4 ) This Presentation also includes the Company’s historical consolidated financial information for the fiscal years ending December 31 , 2019 - 2022 which were prepared in accordance with accounting principles generally accepted in Switzerland (Fachempfehlungen zur Rechnungslegung / Accounting and Reporting Recommendations) (“Swiss GAAP FER” or “Swiss GAAP”) . Swiss GAAP FER differs in certain significant respects from IFRS, as issued by the International Accounting Standards Board . This financial information is solely based the Company’s management’s assessments of financial information for these periods, in all material respects, under Swiss GAAP FER and are unaudited in accordance with IFRS (or US GAAP), and does not conform to the requirements of Regulation S - X of the SEC . The Company has not prepared and does not intend to prepare financial information for any period preceding fiscal year ending December 31 , 2023 in accordance with IFRS (or US GAAP), and such information contained in this Presentation is solely based on such Swiss GAAP FER financial information . This Presentation also includes non - IFRS financial information of the Company, including EBIT, EBITDA, gross profit, adjusted net debt and adjusted equity, which should be considered supplemental to, not a substitute for, or superior to, the financial measures calculated in accordance with IFRS . The Company believes that these non - IFRS financial measures provide users of the Company’s financial information with useful supplemental information that enables a better comparison of the Company’s performance across periods . There are a number of limitations related to the use of these non - IFRS financial measures and their nearest IFRS equivalents . For example, the Company’s definitions of non - IFRS financial measures may differ from non - IFRS financial measures used by other companies . Accordingly, you should not place undue reliance on these preliminary financial results contained in this Presentation . Neither the Company’s (nor Sizzle II’s nor any of their affiliates’) independent registered public accounting firm has audited, reviewed, or performed any procedures with respect to the Company’s preliminary financial results or financial information contained in this Presentation or the accounting treatment thereof and any such firm does not express an opinion or any other form of assurance with respect thereto . Accordingly, the Company’s financial information and data contained in this Presentation may not be included in, may be adjusted in or may be presented differently in, any registration statement that the Company, Sizzle II or any of their affiliates submit to or file with the Securities and Exchange Commission . Use of Projections . The projections, estimates, and targets in this Presentation are forward - looking statements that are based on assumptions that are inherently subject to significant uncertainties and contingencies, many of which are beyond the control of each of the parties to the Business Combination . See “Forward - Looking Statements” above . The projections are for illustrative purposes only and should not be relied upon as being necessarily indicative of future results . The assumptions and estimates underlying the prospective information are inherently uncertain and are subject to a wide variety of significant business, economic and competitive risks and uncertainties that could cause actual results to differ materially from those contained in the prospective information . While all projections, estimates and targets are necessarily speculative, each of the parties to the Business Combination believe that the preparation of prospective information involves increasingly higher levels of uncertainty the further out the projection, estimate or target extends from the date of preparation . Accordingly, there can be no assurance that prospective results are indicative of future performance or that actual results will not differ materially from any results presented or indicated in the prospective information . 5
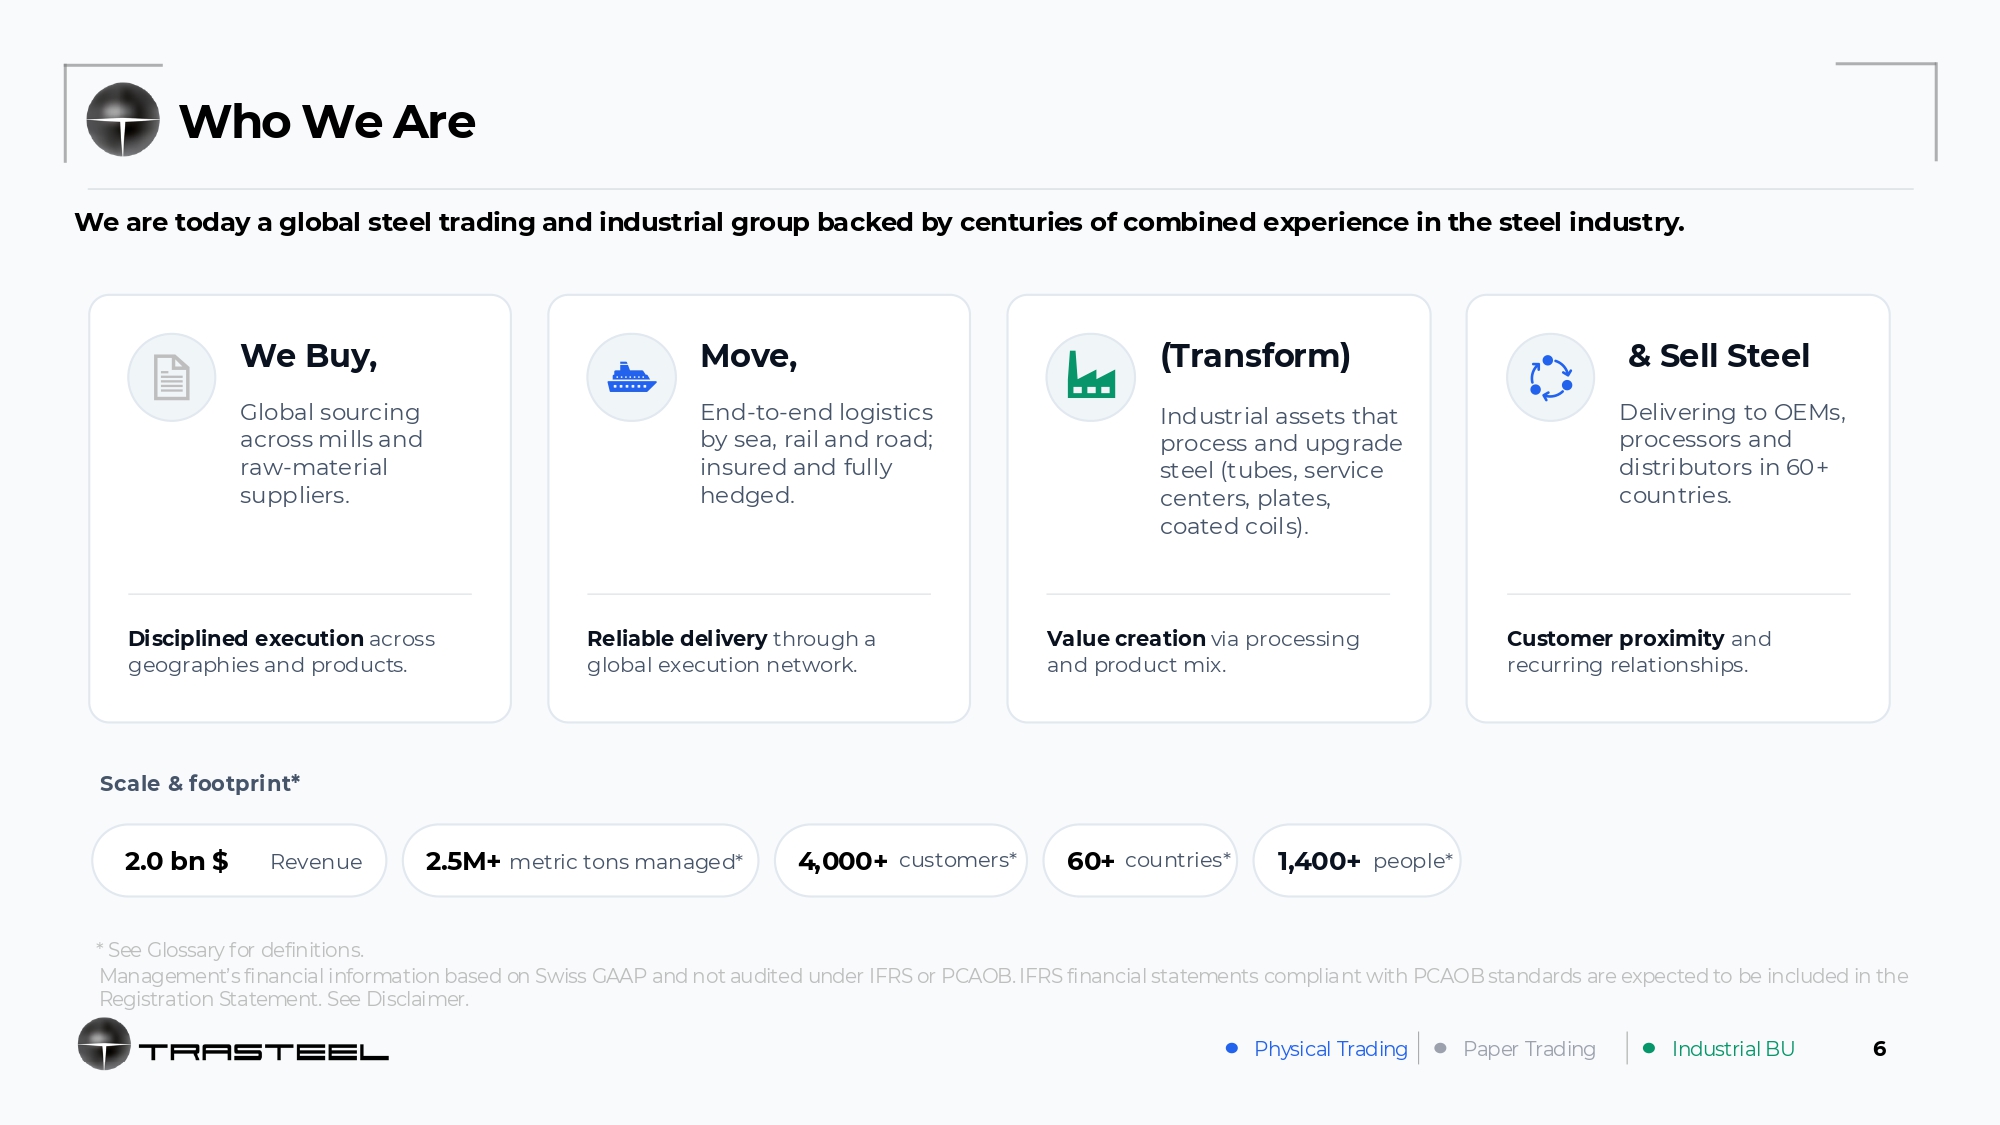
Who We Are We are today a global steel trading and industrial group backed by centuries of combined experience in the steel industry. We Buy, Global sourcing across mills and raw - material suppliers. Disciplined execution across geographies and products. Move, End - to - end logistics by sea, rail and road; insured and fully hedged. Reliable delivery through a global execution network. (Transform) Industrial assets that process and upgrade steel (tubes, service centers, plates, coated coils). Value creation via processing and product mix. & Sell Steel Delivering to OEMs, processors and distributors in 60+ countries. Customer proximity and recurring relationships. Scale & footprint* 2.0 bn $ Revenue 2.5M+ metric tons managed* 4,000+ customers* 60+ countries* 1,400+ people* * See Glossary for definitions. Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. Physical Trading Paper Trading 6 Industrial BU
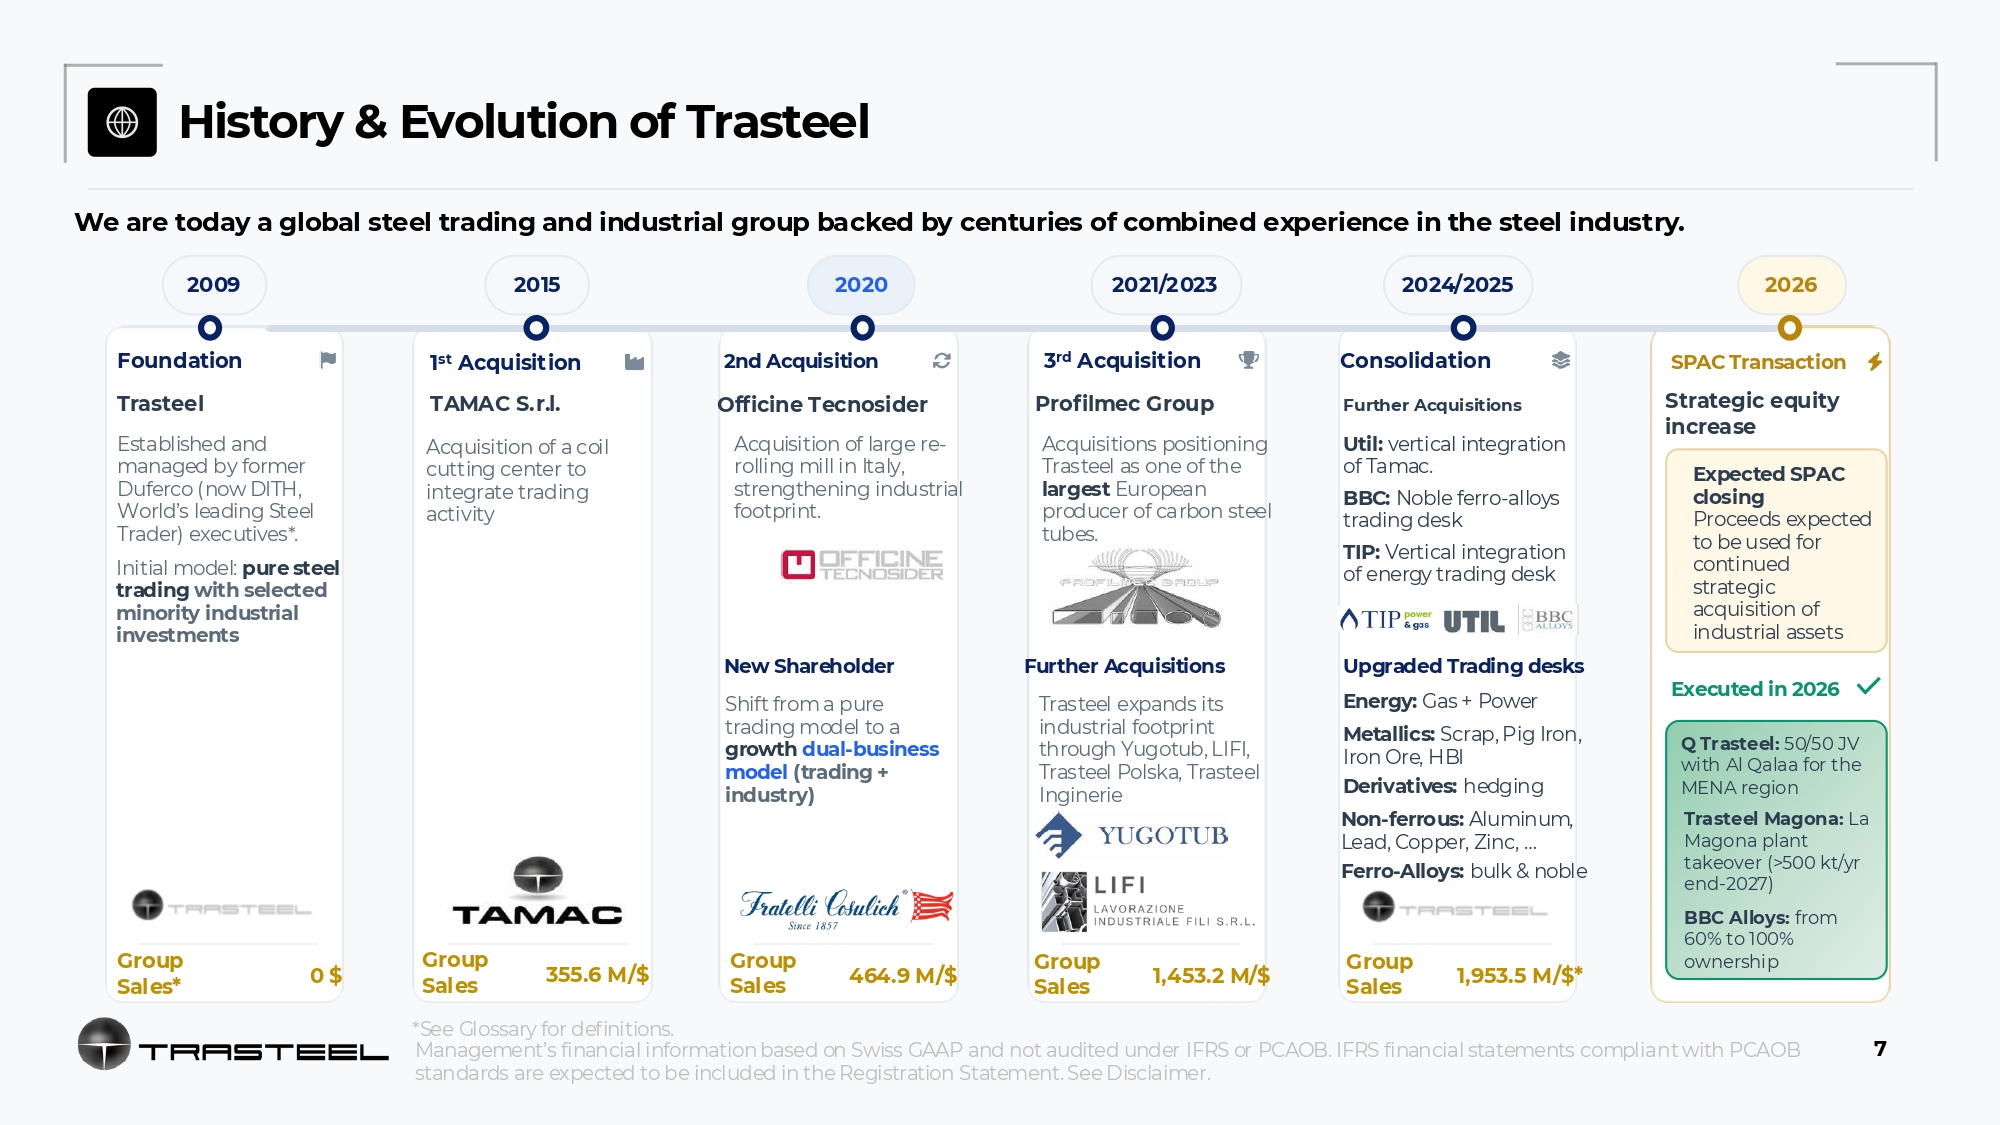
History & Evolution of Trasteel We are today a global steel trading and industrial group backed by centuries of combined experience in the steel industry. 2009 2015 2020 2021/2023 2024/2025 2026 Foundation Trasteel Established and managed by former Duferco (now DITH, World’s leading Steel Trader) executives*. Initial model: pure steel trading with selected minority industrial investments 1 st Acquisition TAMAC S.r.l. Acquisition of a coil cutting center to integrate trading activity 3 rd Acquisition Profilmec Group Acquisitions positioning Trasteel as one of the largest European producer of carbon steel tubes. Consolidation SPAC Transaction Strategic equity increase Expected SPAC closing Proceeds expected to be used for continued strategic acquisition of industrial assets 2nd Acquisition Officine Tecnosider Acquisition of large re - rolling mill in Italy, strengthening industrial footprint. Further Acquisitions Util: vertical integration of Tamac. BBC: Noble ferro - alloys trading desk TIP: Vertical integration of energy trading desk New Shareholder Shift from a pure trading model to a growth dual - business model (trading + industry) Further Acquisitions Trasteel expands its industrial footprint through Yugotub, LIFI, Trasteel Polska, Trasteel Inginerie Upgraded Trading desks Energy: Gas + Power Metallics: Scrap, Pig Iron, Iron Ore, HBI Derivatives: hedging Non - ferrous: Aluminum, Lead, Copper, Zinc, … Ferro - Alloys: bulk & noble Executed in 2026 Group Sales* 0 $ Group Sales 355.6 M/$ Group Sales 464.9 M/$ Q Trasteel : 50 / 50 JV with Al Qalaa for the MENA region Trasteel Magona: La Magona plant takeover (>500 kt/yr end - 2027) BBC Alloys: from 60% to 100% ownership Group Sales 1,453.2 M/$ Group Sales 1,953.5 M/$* *See Glossary for definitions. Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 7
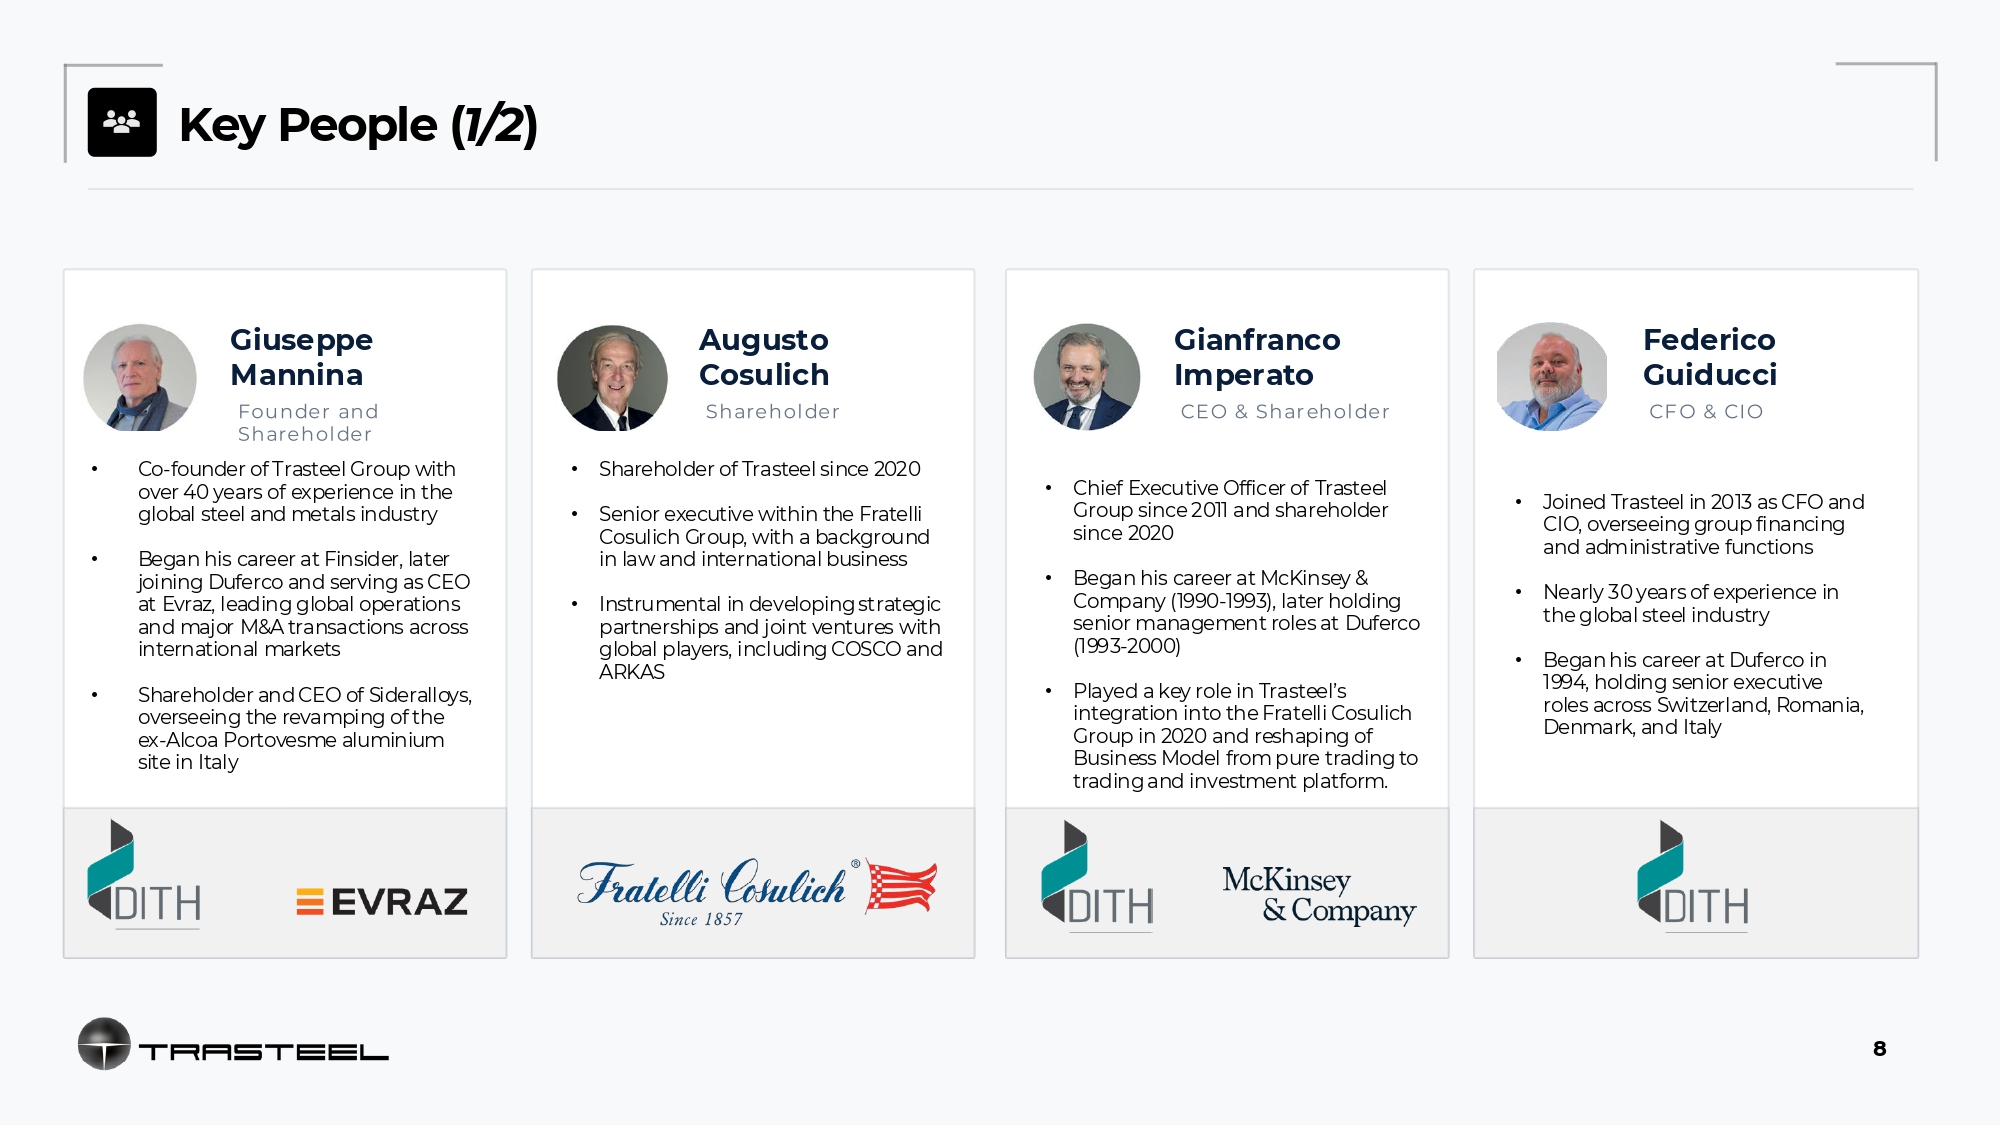
Key People ( 1/2 ) Giuseppe Mannina Augusto Cosulich Gianfranco Imperato Federico Guiducci • Co - founder of Trasteel Group with over 40 years of experience in the global steel and metals industry • Began his career at Finsider, later joining Duferco and serving as CEO at Evraz, leading global operations and major M&A transactions across international markets • Shareholder and CEO of Sideralloys, overseeing the revamping of the ex - Alcoa Portovesme aluminium site in Italy • Shareholder of Trasteel since 2020 • Senior executive within the Fratelli Cosulich Group, with a background in law and international business • Instrumental in developing strategic partnerships and joint ventures with global players, including COSCO and ARKAS • Chief Executive Officer of Trasteel Group since 2011 and shareholder since 2020 • Began his career at McKinsey & Company (1990 - 1993), later holding senior management roles at Duferco (1993 - 2000) • Played a key role in Trasteel’s integration into the Fratelli Cosulich Group in 2020 and reshaping of Business Model from pure trading to trading and investment platform. • Joined Trasteel in 2013 as CFO and CIO, overseeing group financing and administrative functions • Nearly 30 years of experience in the global steel industry • Began his career at Duferco in 1994, holding senior executive roles across Switzerland, Romania, Denmark, and Italy 8
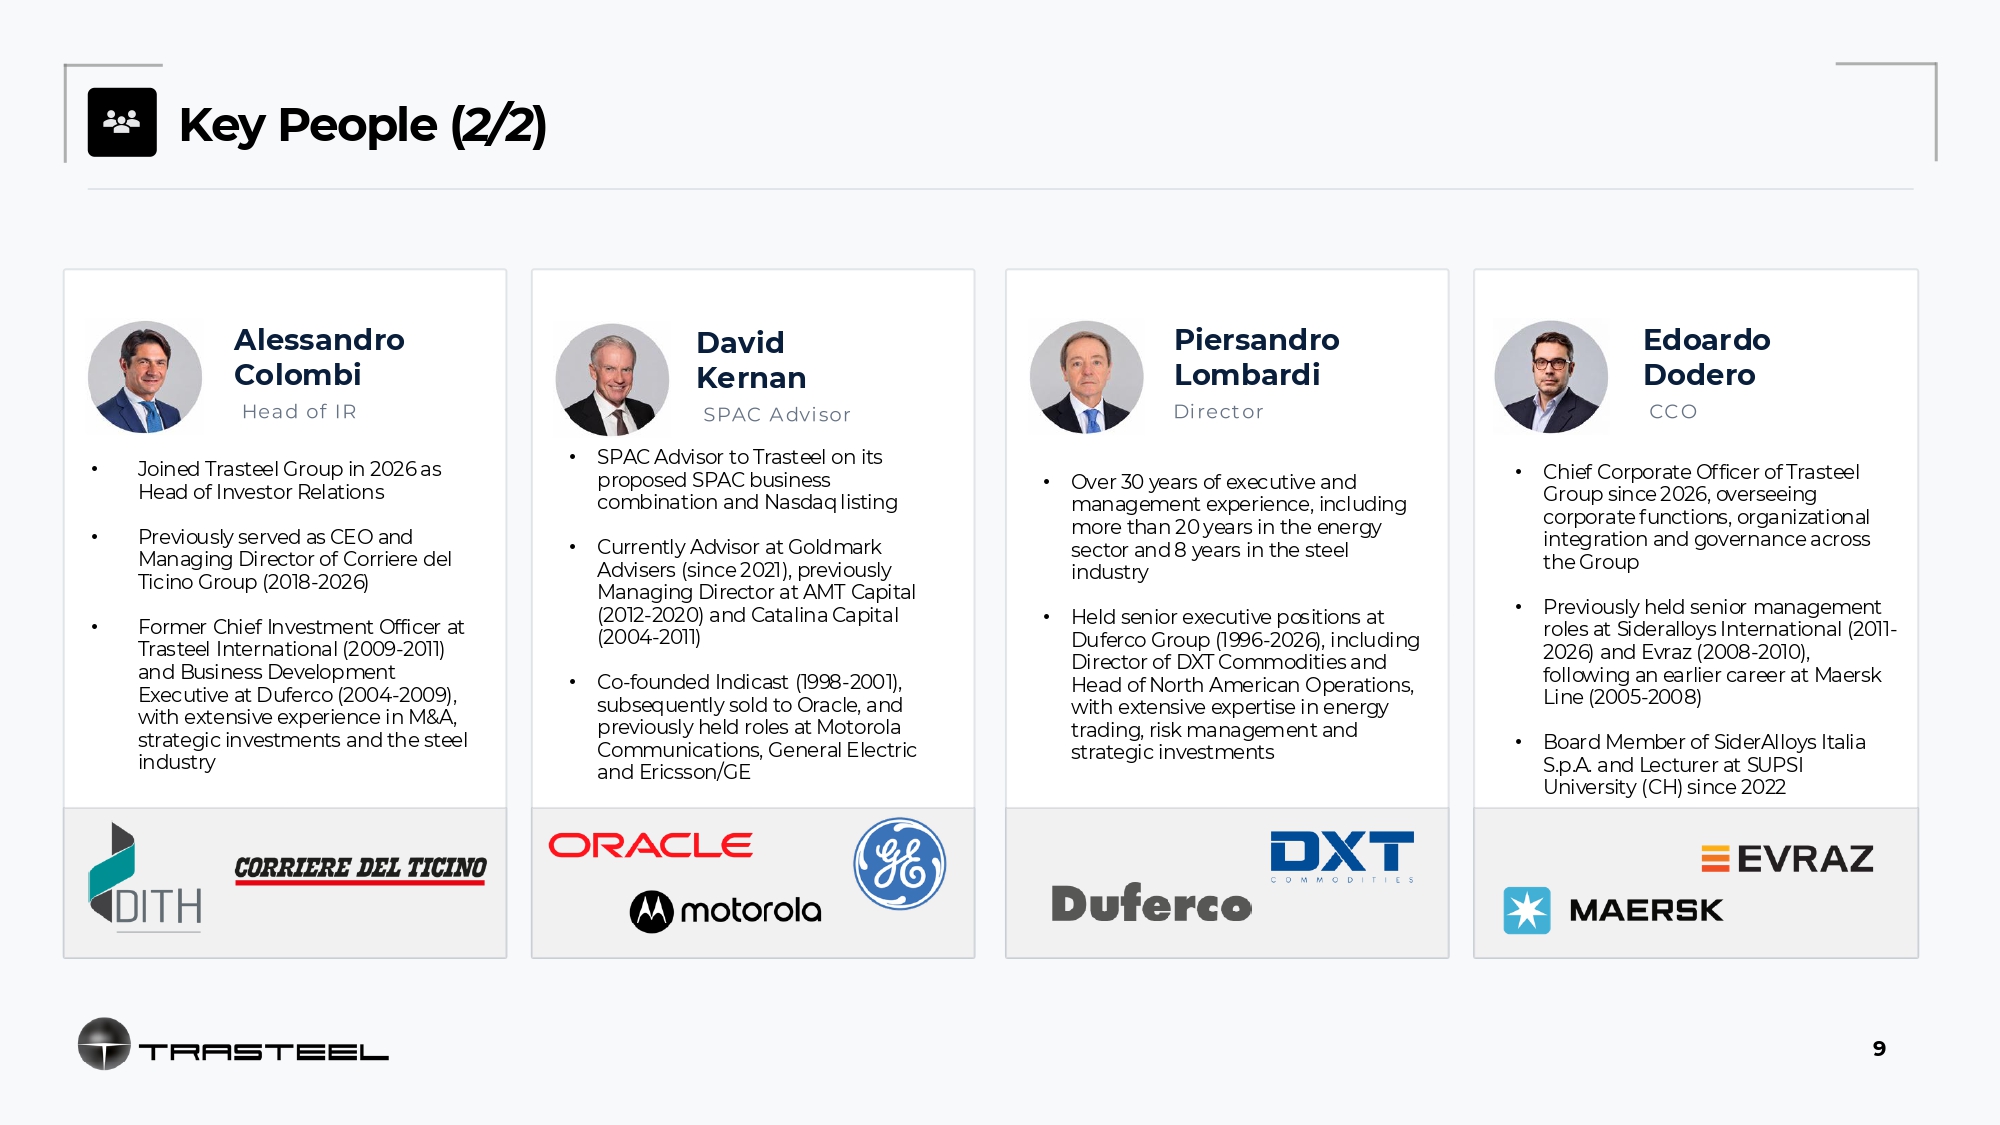
Key People ( 2/2 ) Edoardo Dodero • Joined Trasteel Group in 2026 as Head of Investor Relations • Previously served as CEO and Managing Director of Corriere del Ticino Group (2018 - 2026) • Former Chief Investment Officer at Trasteel International (2009 - 2011) and Business Development Executive at Duferco (2004 - 2009), with extensive experience in M&A, strategic investments and the steel industry Alessandro Colombi • SPAC Advisor to Trasteel on its proposed SPAC business combination and Nasdaq listing • Currently Advisor at Goldmark Advisers (since 2021), previously Managing Director at AMT Capital (2012 - 2020) and Catalina Capital (2004 - 2011) • Co - founded Indicast (1998 - 2001), subsequently sold to Oracle, and previously held roles at Motorola Communications, General Electric and Ericsson/GE David Kernan • Over 30 years of executive and management experience, including more than 20 years in the energy sector and 8 years in the steel industry • Held senior executive positions at Duferco Group (1996 - 2026), including Director of DXT Commodities and Head of North American Operations, with extensive expertise in energy trading, risk management and strategic investments Piersandro Lombardi • Chief Corporate Officer of Trasteel Group since 2026, overseeing corporate functions, organizational integration and governance across the Group • Previously held senior management roles at Sideralloys International (2011 - 2026) and Evraz (2008 - 2010), following an earlier career at Maersk Line (2005 - 2008) • Board Member of SiderAlloys Italia S.p.A. and Lecturer at SUPSI University (CH) since 2022 9
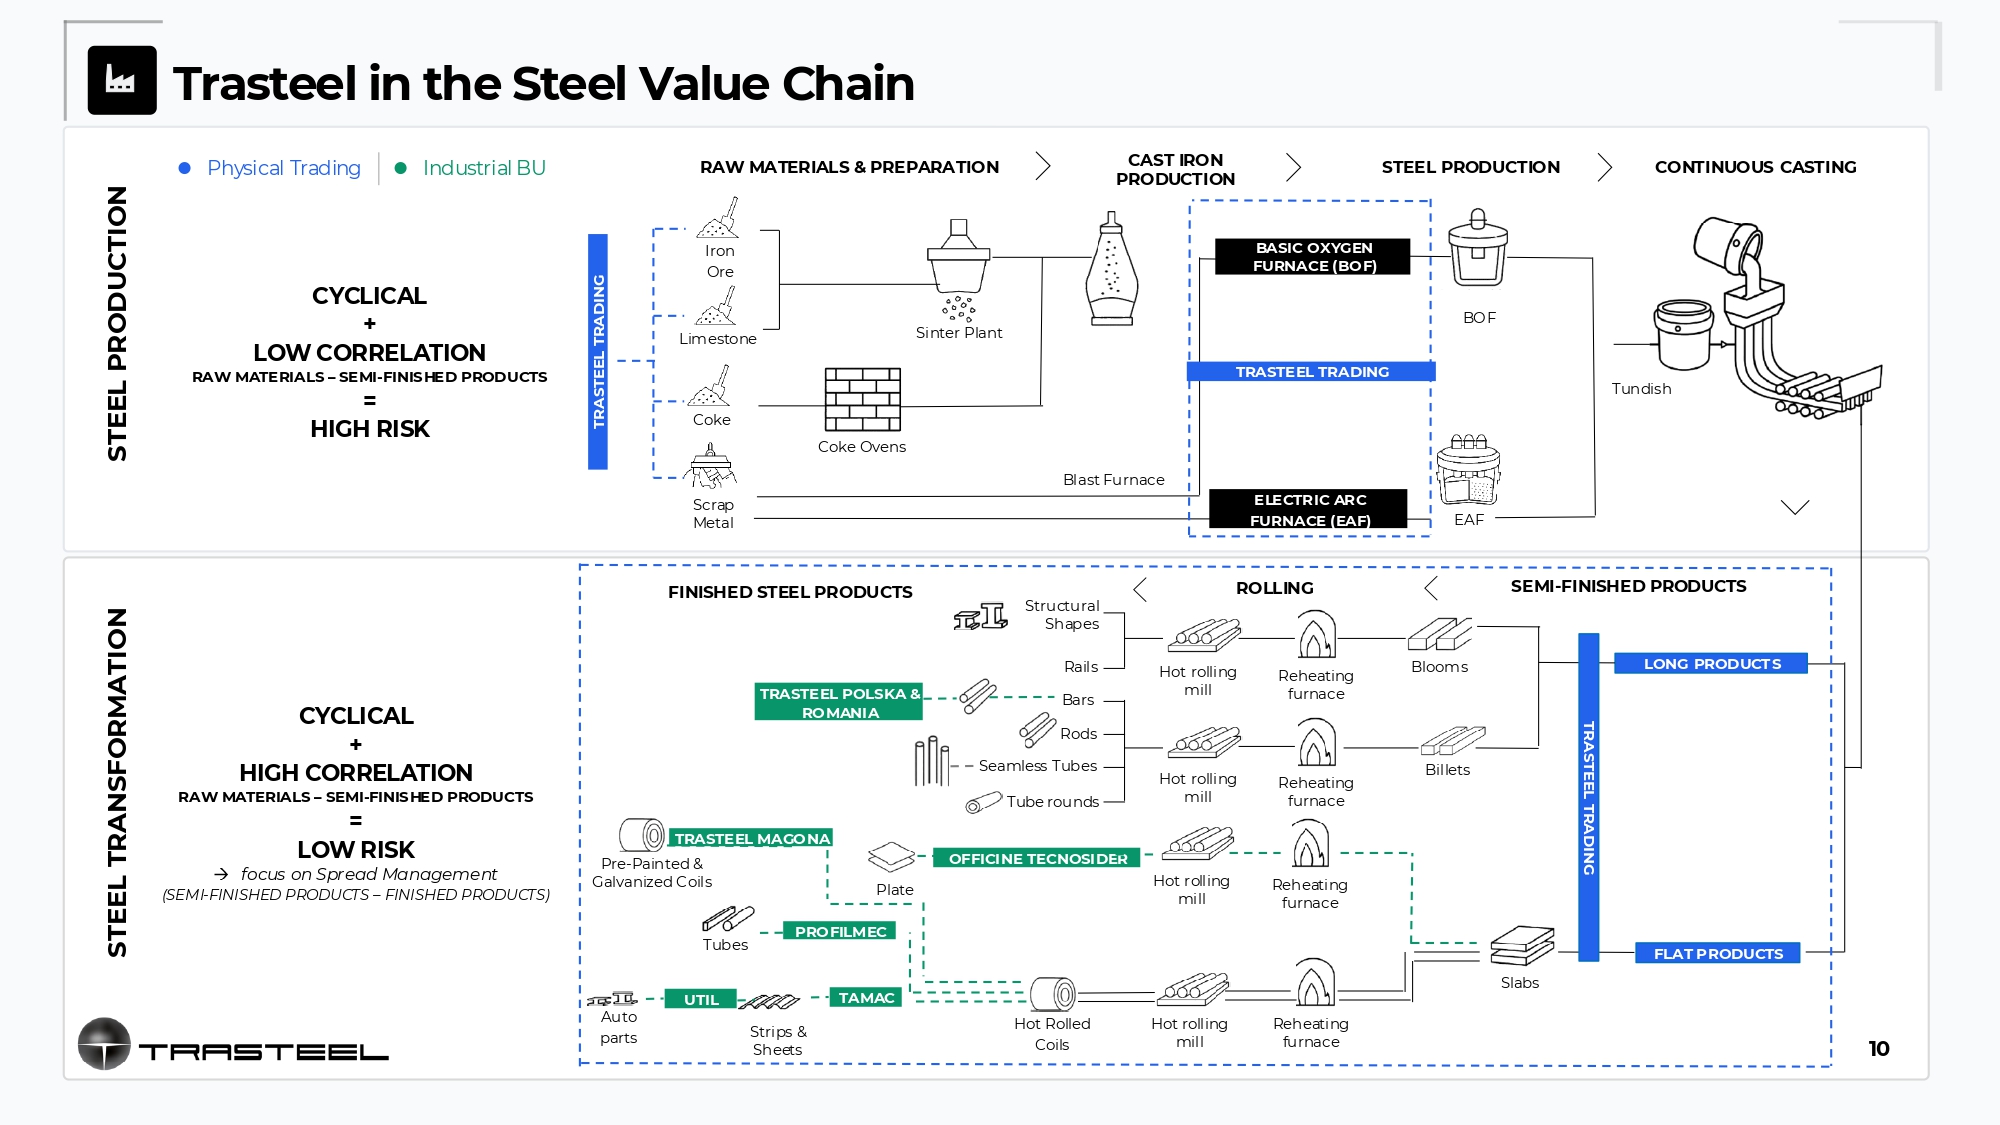
Trasteel in the Steel Value Chain RAW MATERIALS & PREPARATION CONTINUOUS CASTING STEEL PRODUCTION Sinter Plant Coke Ovens BASIC OXYGEN FURNACE (BOF) Tundish Blast Furnace Scrap Metal ELECTRIC ARC FURNACE (EAF) CAST IRON PRODUCTION STEEL PRODUCTION Iron Ore TRASTEEL TRADING Limestone Coke BOF TRASTEEL TRADING EAF FINISHED STEEL PRODUCTS ROLLING STEEL TRANSFORMATION Hot rolling mill Blooms Billets Slabs Reheating furnace Hot Rolled Coils SEMI - FINISHED PRODUCTS Structural Shapes LONG PRODUCTS Hot rolling mill Reheating furnace Tube rounds OFFICINE TECNOSIDER Hot rolling mill Reheating furnace TRASTEEL POLSKA & ROMANIA Pre - Painted & Galvanized Coils PROFILMEC Tubes FLAT PRODUCTS TAMAC Rails Bars Rods Seamless Tubes Plate Strips & Sheets Hot rolling mill Reheating furnace TRASTEEL TRADING CYCLICAL + LOW CORRELATION RAW MATERIALS – SEMI - FINISHED PRODUCTS = HIGH RISK CYCLICAL + HIGH CORRELATION RAW MATERIALS – SEMI - FINISHED PRODUCTS = LOW RISK focus on Spread Management (SEMI - FINISHED PRODUCTS – FINISHED PRODUCTS) Physical Trading Industrial BU TRASTEEL MAGONA UTIL Auto parts 10
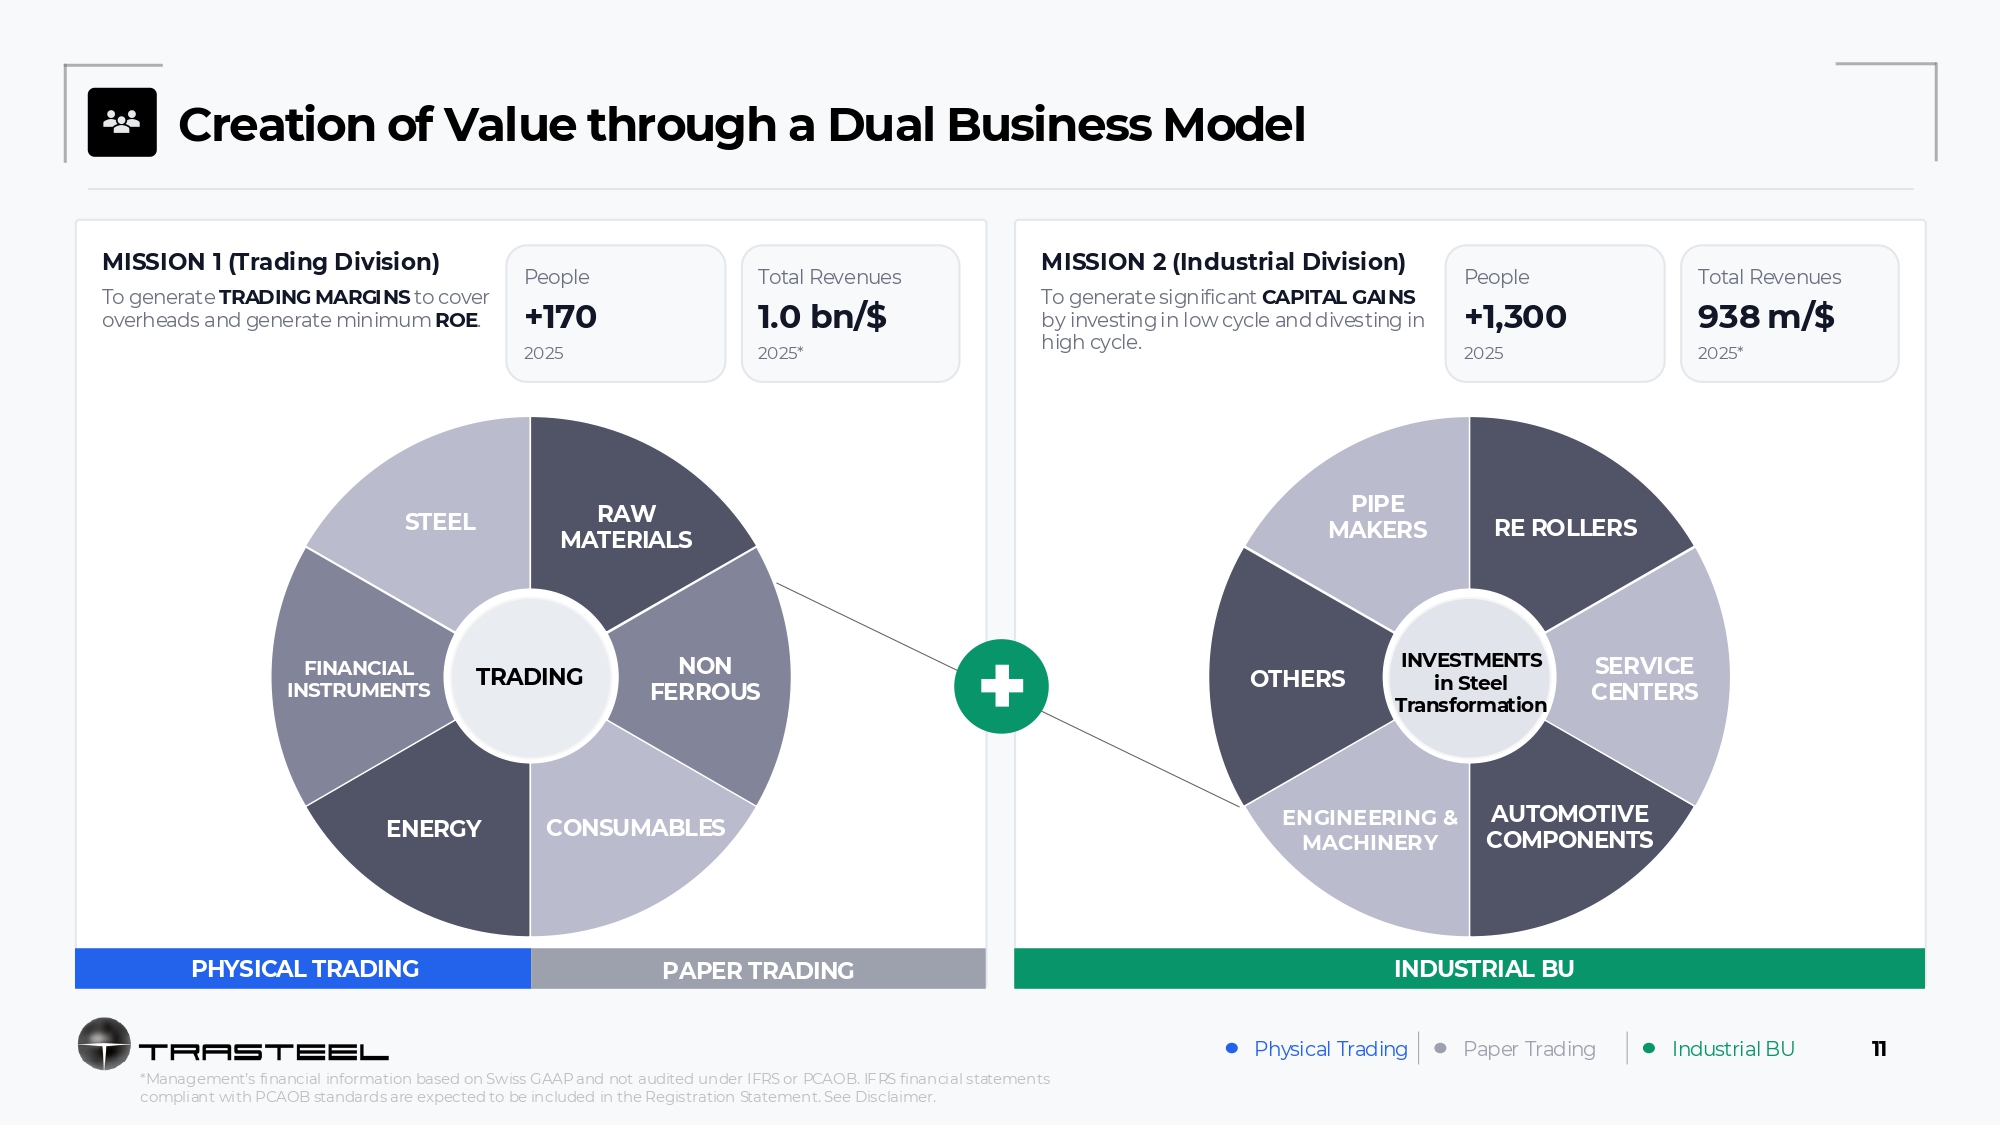
Creation of Value through a Dual Business Model MISSION 1 (Trading Division) To generate TRADING MARGINS to cover overheads and generate minimum ROE . People +170 2025 Total Revenues 1.0 bn/$ 2025* MISSION 2 (Industrial Division) To generate significant CAPITAL GAINS by investing in low cycle and divesting in high cycle. People +1,300 2025 Total Revenues 938 m/$ 2025* STEEL RAW MATERIALS PIPE MAKERS RE ROLLERS FINANCIAL INSTRUMENTS TRADING NON FERROUS OTHERS INVESTMENTS in Steel Transformation SERVICE CENTERS ENERGY CONSUMABLES ENGINEERING & MACHINERY AUTOMOTIVE COMPONENTS PHYSICAL TRADING PAPER TRADING INDUSTRIAL BU Physical Trading Paper Trading Industrial BU 11 *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer.
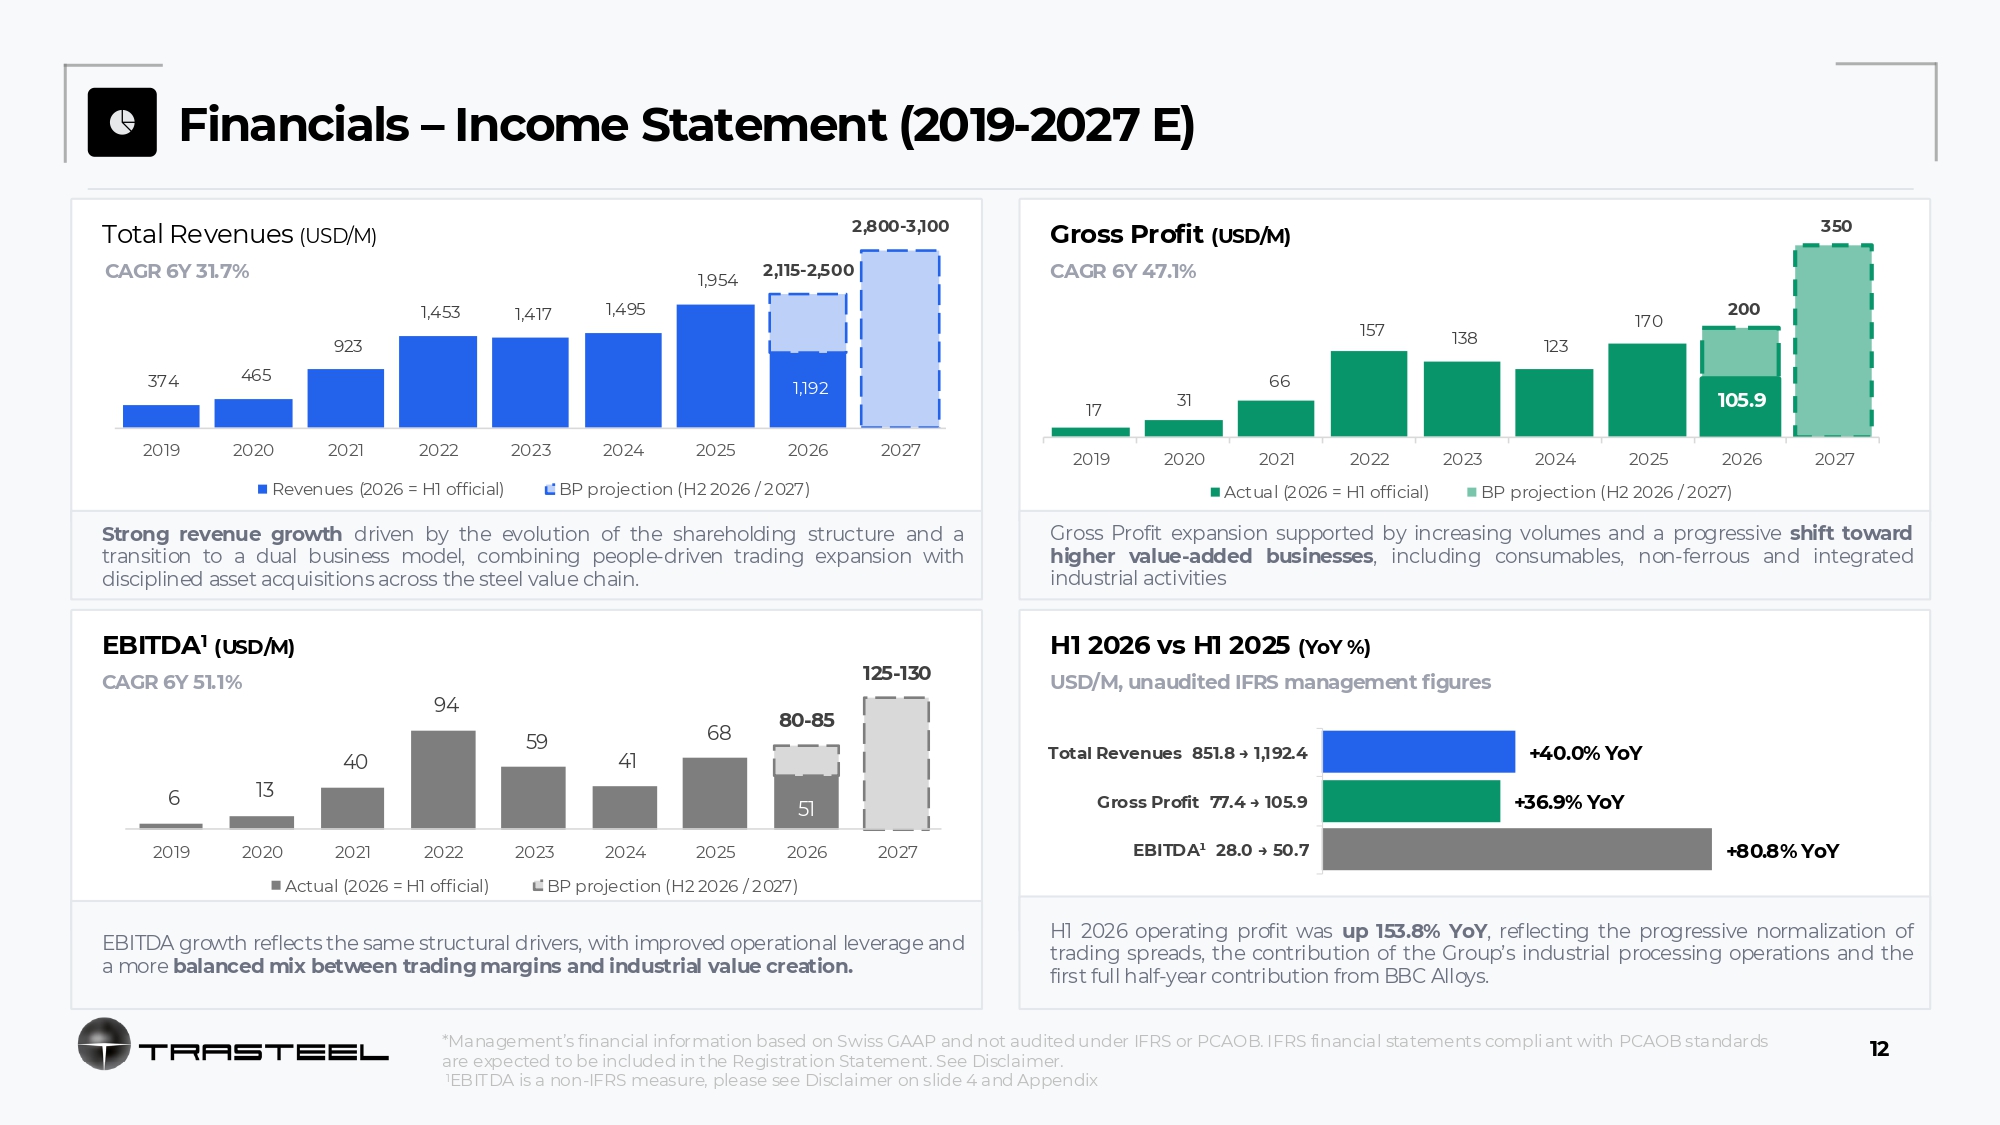
Financials – Income Statement (2019 - 2027 E) Total Revenues (USD/M) 2,800 - 3,100 Gross Profit (USD/M) 350 CAGR 6Y 31.7% 2,115 - 2,500 1,954 CAGR 6Y 47.1% 1,453 1,417 1,495 923 374 465 1,192 200 157 170 138 123 66 31 17 105.9 2019 2023 2027 2020 2021 2022 Revenues (2026 = H1 official) 2024 2025 2026 BP projection (H2 2026 / 2027) 2019 2020 2027 2021 2022 Actual (2026 = H1 official) 2023 2024 2025 2026 BP projection (H2 2026 / 2027) Strong revenue growth driven by the evolution of the shareholding structure and a transition to a dual business model, combining people - driven trading expansion with disciplined asset acquisitions across the steel value chain . Gross Profit expansion supported by increasing volumes and a progressive shift toward higher value - added businesses , including consumables, non - ferrous and integrated industrial activities EBITDA 1 (USD/M) CAGR 6Y 51.1% 125 - 130 EBITDA growth reflects the same structural drivers, with improved operational leverage and a more balanced mix between trading margins and industrial value creation. H1 2026 vs H1 2025 (YoY %) USD/M, unaudited IFRS management figures 94 80 - 85 59 68 40 41 Total Revenues 851.8 → 1,192.4 6 13 51 2019 2020 2027 2021 2022 Actual (2026 = H1 official) 2023 2024 2025 2026 BP projection (H2 2026 / 2027) +40.0% YoY Gross Profit 77.4 → 105.9 +36.9% YoY EBITDA¹ 28.0 → 50.7 +80.8% YoY H 1 2026 operating profit was up 153 . 8 % YoY , reflecting the progressive normalization of trading spreads, the contribution of the Group’s industrial processing operations and the first full half - year contribution from BBC Alloys . *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 1 EBITDA is a non - IFRS measure, please see Disclaimer on slide 4 and Appendix 12
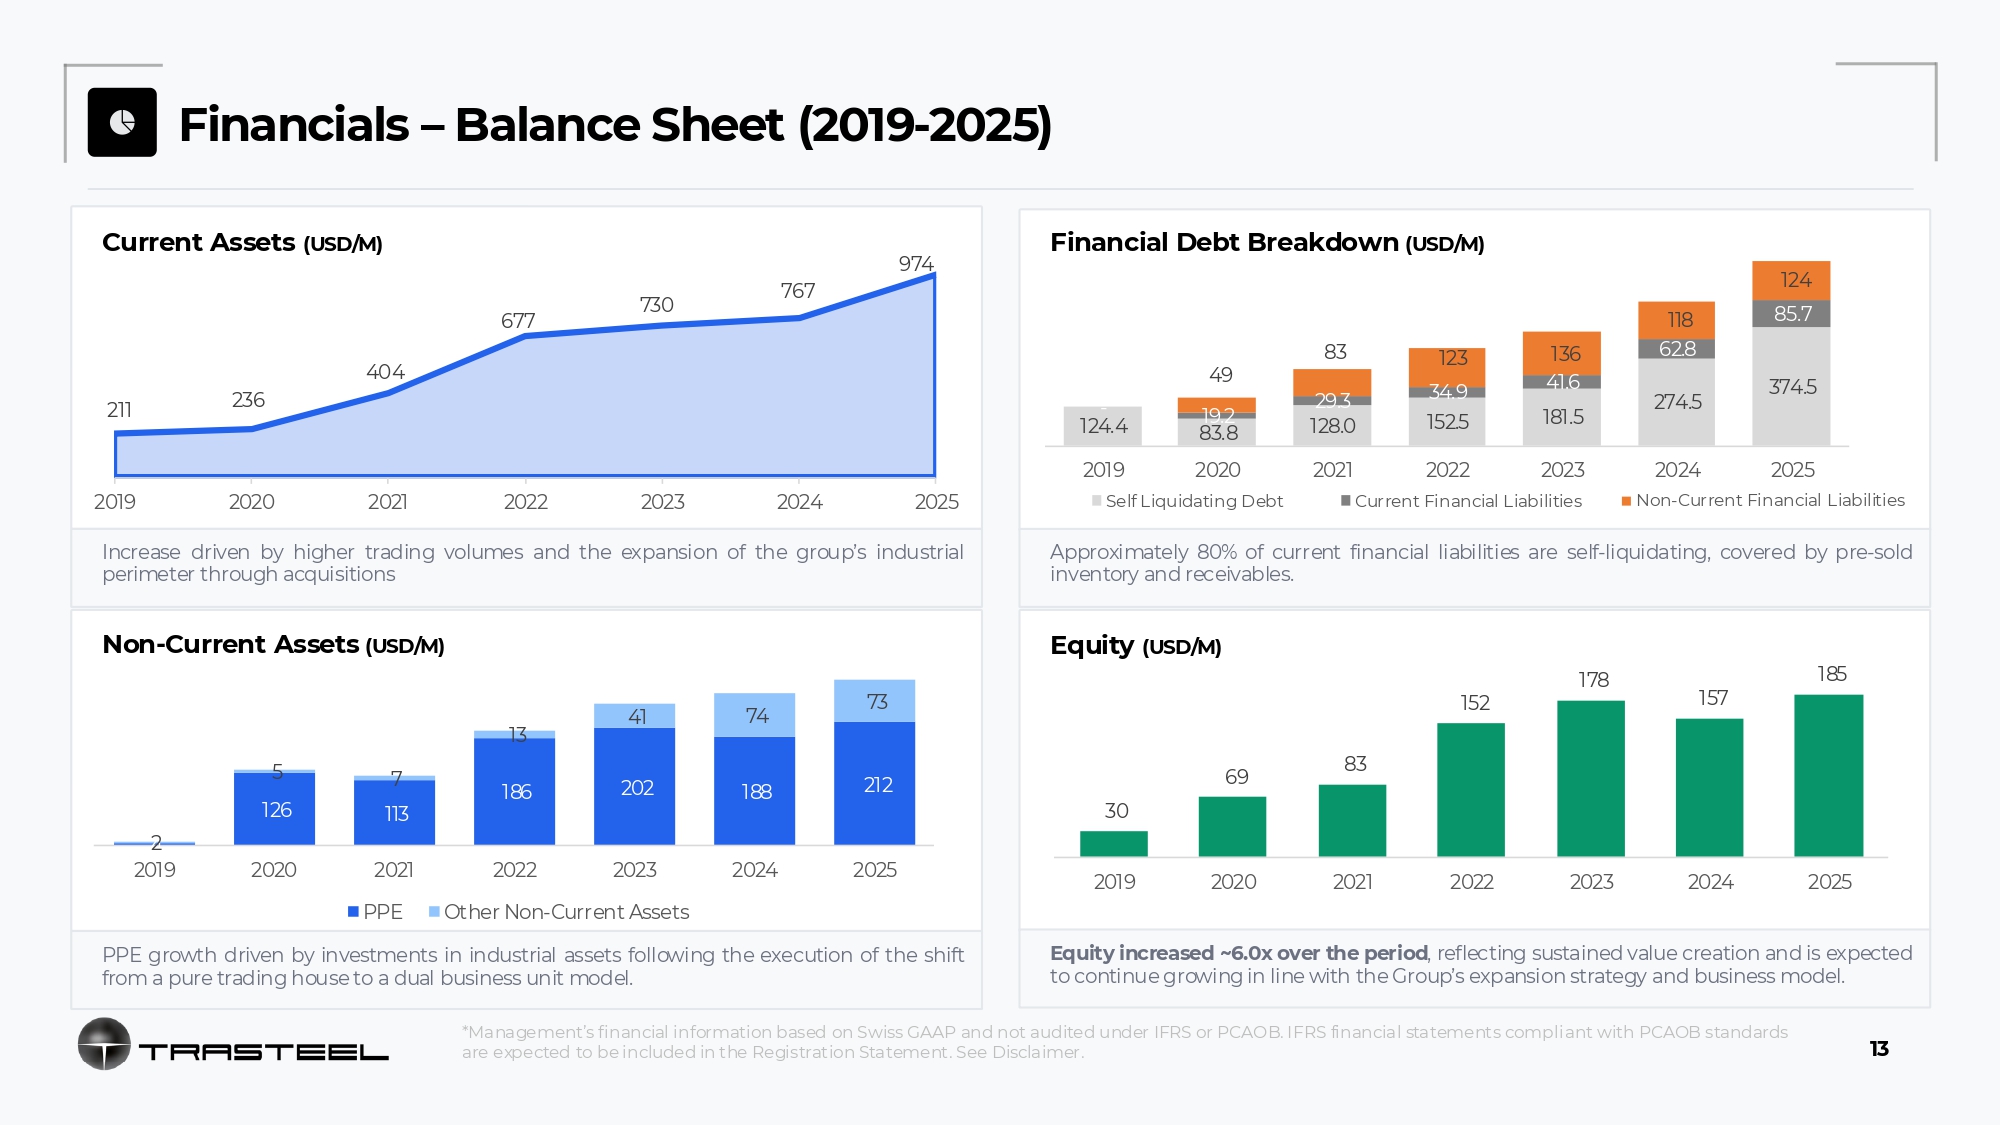
Financials – Balance Sheet (2019 - 2025) Current Assets (USD/M) 974 730 767 677 404 211 236 2019 2020 2021 2022 2023 2024 2025 Increase driven by higher trading volumes and the expansion of the group’s industrial perimeter through acquisitions Non - Current Assets (USD/M) 41 74 73 13 5 7 186 202 188 212 126 113 4 2 2019 2020 2021 2022 2023 2024 2025 PPE Other Non - Current Assets PPE growth driven by investments in industrial assets following the execution of the shift from a pure trading house to a dual business unit model. Financial Debt Breakdown (USD/M) 124 118 85.7 83 123 136 62.8 49 34.9 41.6 374.5 - 19.2 29.3 152.5 181.5 274.5 124.4 83.8 128.0 2019 2020 2021 2022 2023 2024 2025 Self Liquidating Debt Current Financial Liabilities Non - Current Financial Liabilities Approximately 80% of current financial liabilities are self - liquidating, covered by pre - sold inventory and receivables. Equity (USD/M) 178 185 152 157 69 83 30 2019 2020 2021 2022 2023 2024 2025 Equity increased ~6.0x over the period , reflecting sustained value creation and is expected to continue growing in line with the Group’s expansion strategy and business model. *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 13
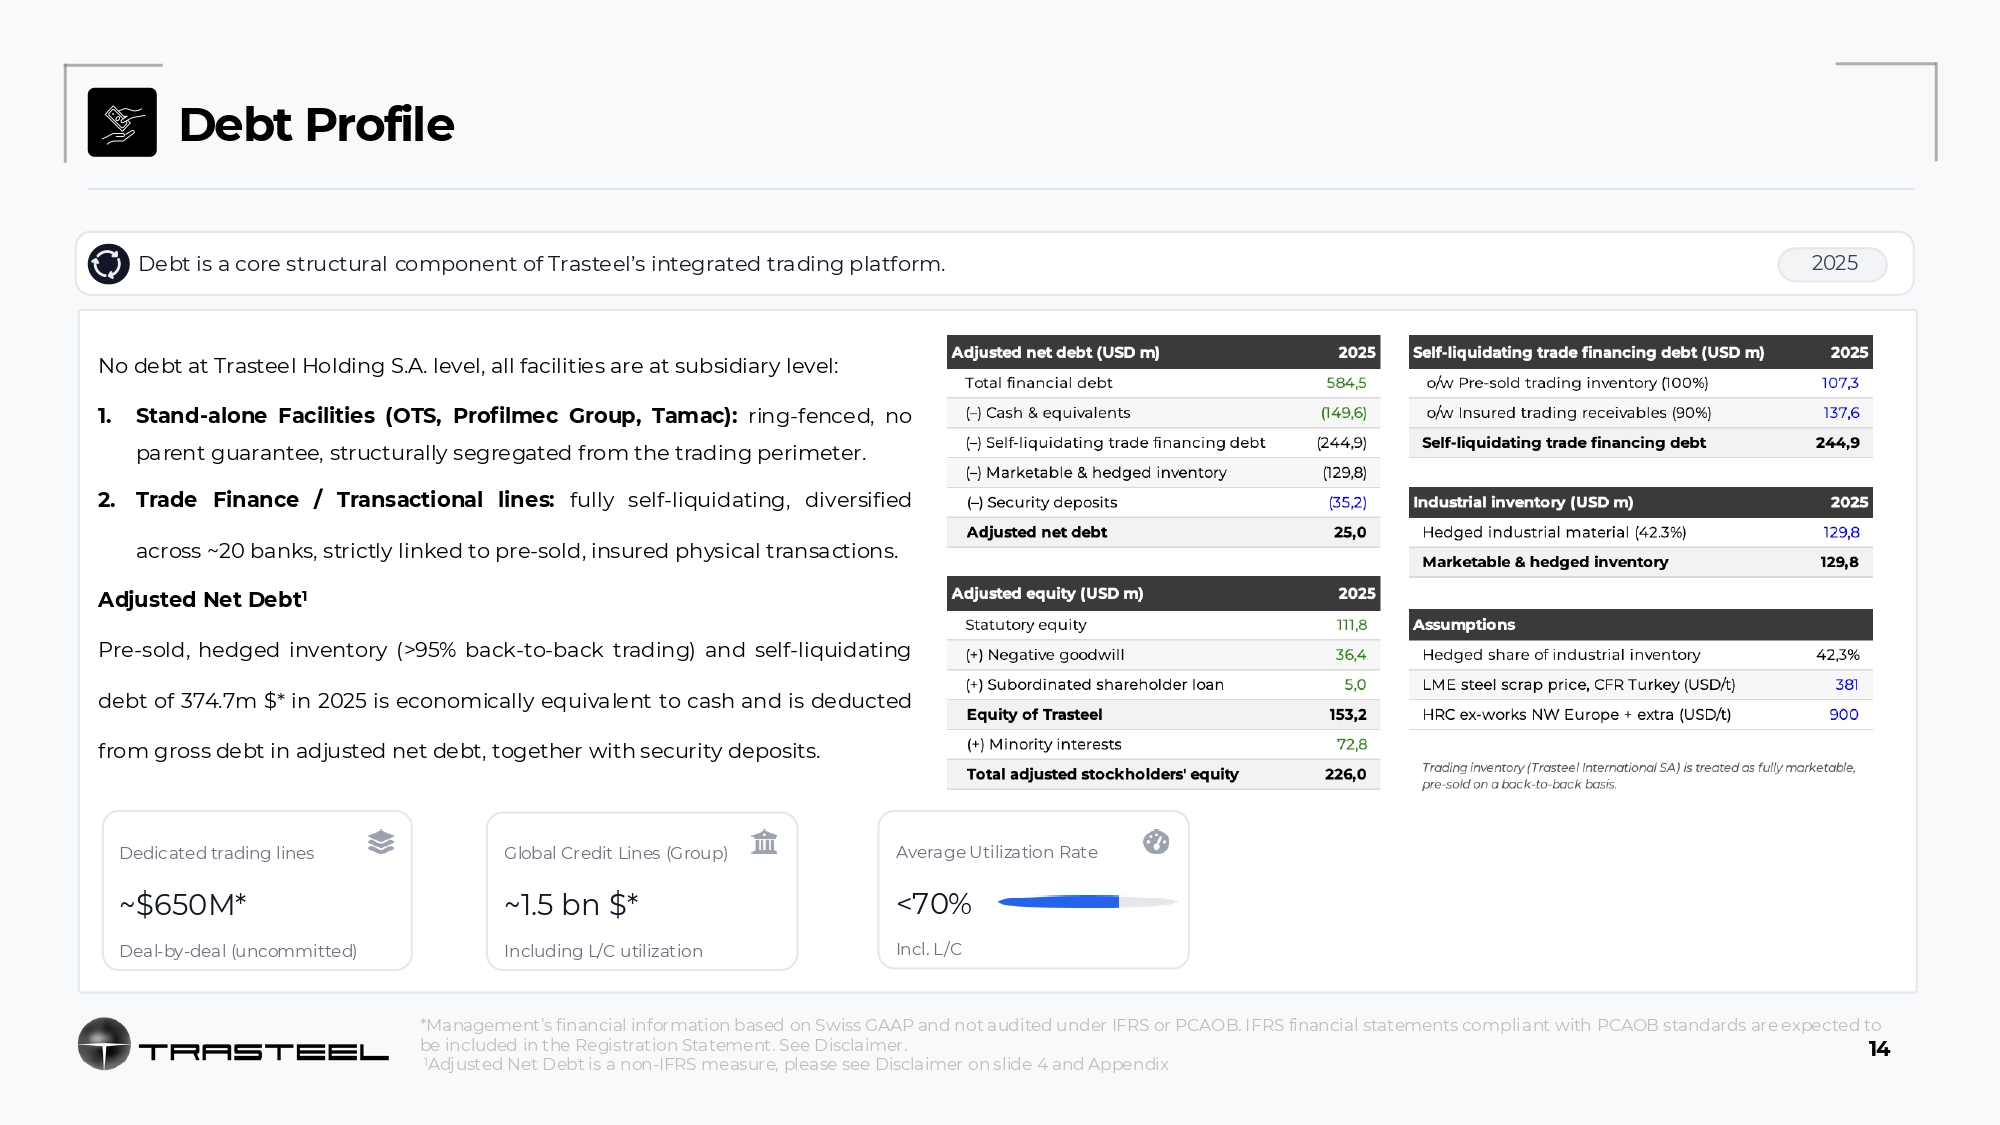
Debt Profile Debt is a core structural component of Trasteel’s integrated trading platform. 2025 No debt at Trasteel Holding S.A. level, all facilities are at subsidiary level: 1. Stand - alone Facilities (OTS, Profilmec Group, Tamac): ring - fenced, no parent guarantee, structurally segregated from the trading perimeter. 2. Trade Finance / Transactional lines: fully self - liquidating, diversified across ~20 banks, strictly linked to pre - sold, insured physical transactions. Adjusted Net Debt 1 Pre - sold, hedged inventory (>95% back - to - back trading) and self - liquidating debt of 374.7m $* in 2025 is economically equivalent to cash and is deducted from gross debt in adjusted net debt, together with security deposits. Dedicated trading lines ~$650M* Deal - by - deal (uncommitted) Global Credit Lines (Group) ~1.5 bn $* Including L/C utilization Average Utilization Rate <70% Incl. L/C 14 *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 1 Adjusted Net Debt is a non - IFRS measure, please see Disclaimer on slide 4 and Appendix
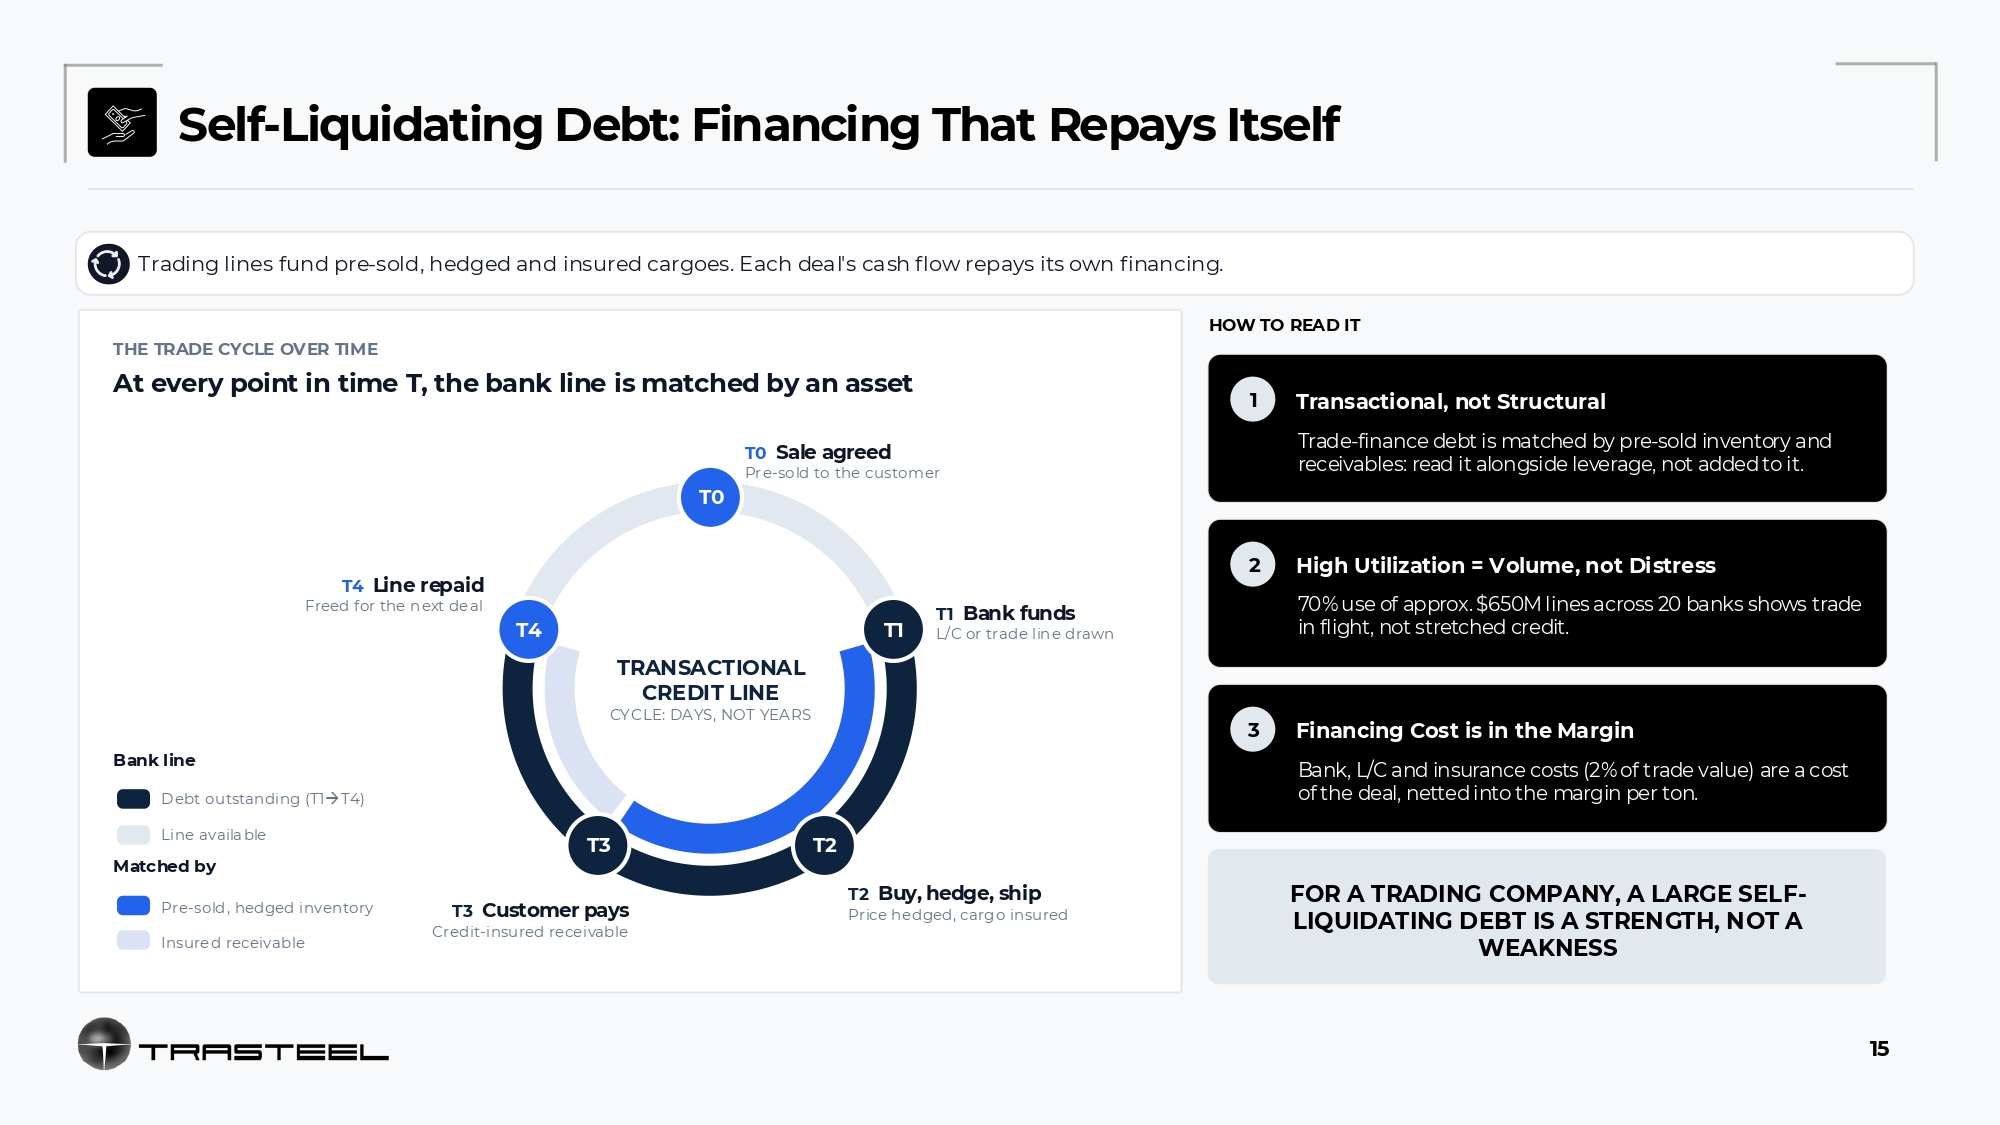
Self - Liquidating Debt: Financing That Repays Itself Trading lines fund pre - sold, hedged and insured cargoes. Each deal's cash flow repays its own financing. HOW TO READ IT 1 Transactional, not Structural Trade - finance debt is matched by pre - sold inventory and receivables: read it alongside leverage, not added to it. THE TRADE CYCLE OVER TIME At every point in time T, the bank line is matched by an asset T0 Sale agreed Pre - sold to the customer T0 T4 Line repaid Freed for the next deal T4 T1 Bank funds T1 L/C or trade line drawn 2 High Utilization = Volume, not Distress 70% use of approx. $650M lines across 20 banks shows trade in flight, not stretched credit. TRANSACTIONAL CREDIT LINE CYCLE: DAYS, NOT YEARS 3 Financing Cost is in the Margin Bank, L/C and insurance costs (2% of trade value) are a cost of the deal, netted into the margin per ton. Bank line Debt outstanding (T1 T4) Line available Matched by T3 T2 Pre - sold, hedged inventory Insure d receivable T3 Customer pays Credit - insured re ceivable T2 Buy, hedge, ship Price hedged, carg o insured FOR A TRADING COMPANY, A LARGE SELF - LIQUIDATING DEBT IS A STRENGTH, NOT A WEAKNESS 15
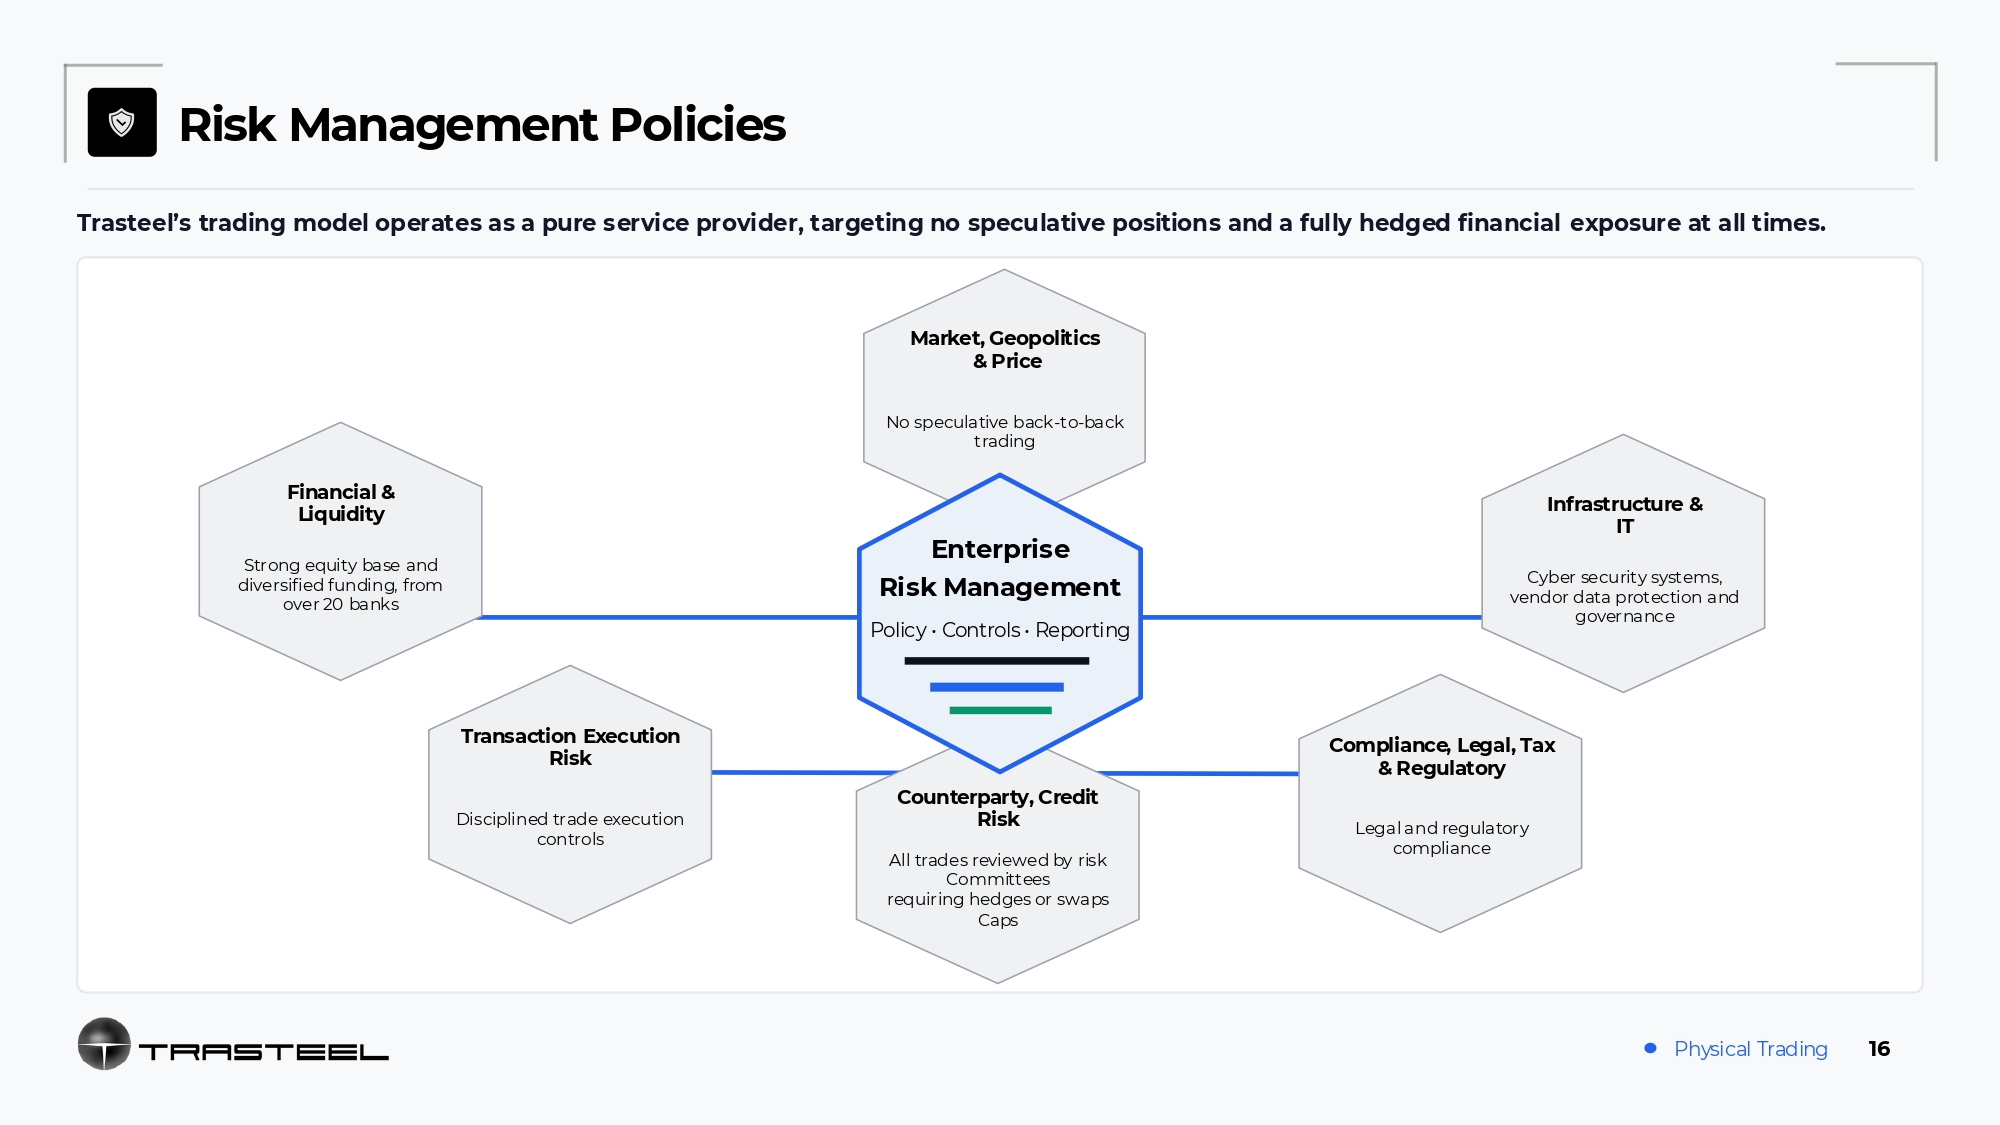
Risk Management Policies Trasteel’s trading model operates as a pure service provider, targeting no speculative positions and a fully hedged financial exposure at all times. Financial & Liquidity Market, Geopolitics & Price No speculative back - to - back trading Strong equity base and diversified funding, from over 20 banks Transaction Execution Risk Disciplined trade execution controls Enterprise Risk Management Policy • Controls • Reporting Counterparty, Credit Risk All trades reviewed by risk Committees requiring hedges or swaps Caps Infrastructure & IT Cyber security systems, vendor data protection and governance Compliance, Legal, Tax & Regulatory Legal and regulatory compliance Physical Trading 16
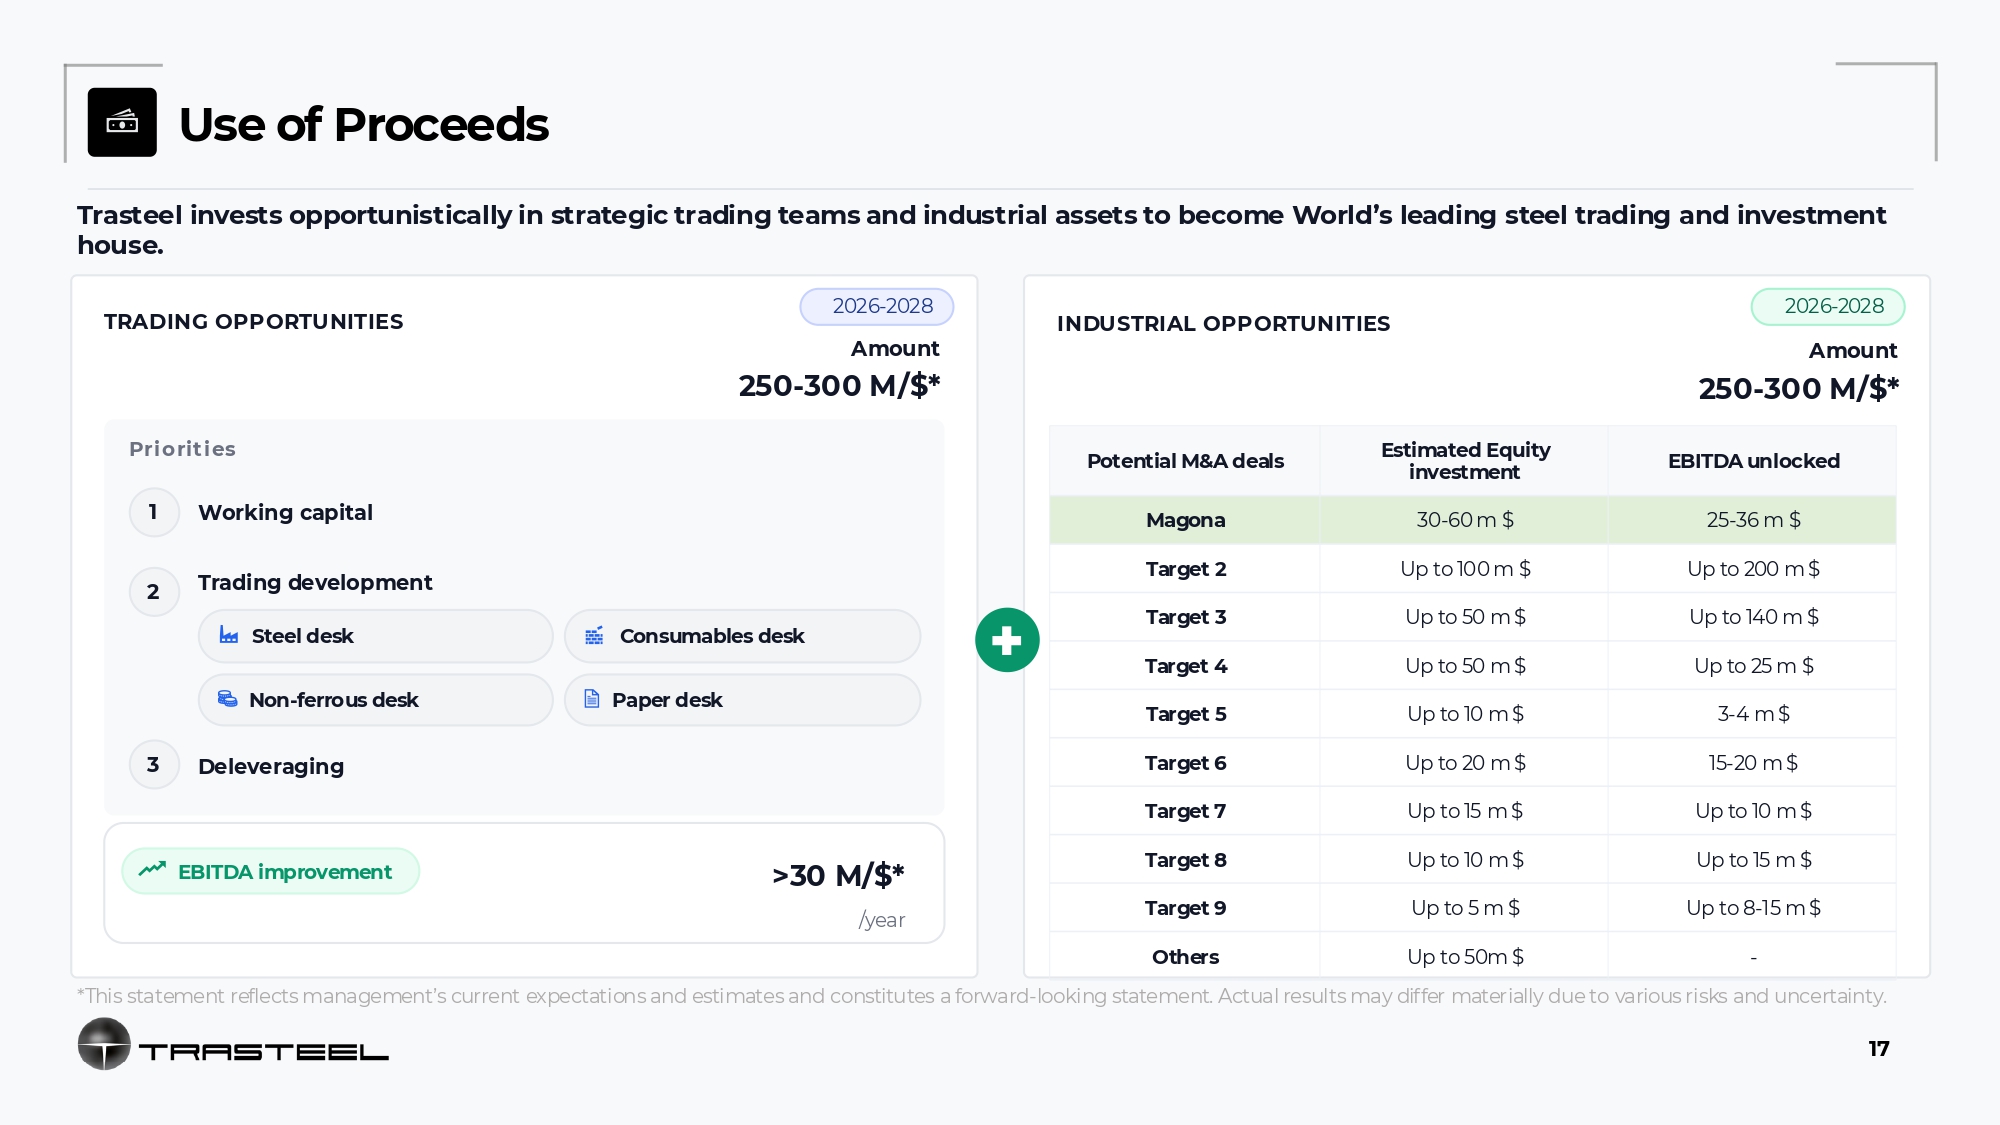
Use of Proceeds Trasteel invests opportunistically in strategic trading teams and industrial assets to become World’s leading steel trading and investment house. TRADING OPPORTUNITIES 2026 - 2028 Amount 250 - 300 M/$* Priorities 1 Working capital 2 Trading development Steel desk Consumables desk Non - ferrous desk Paper desk 3 Deleveraging EBITDA improvement >30 M/$* /year 2026 - 2028 INDUSTRIAL OPPORTUNITIES Amount 250 - 300 M/$* EBITDA unlocked Estimated Equity investment Potential M&A deals 25 - 36 m $ 30 - 60 m $ Magona Up to 200 m $ Up to 100 m $ Target 2 Up to 140 m $ Up to 50 m $ Target 3 Up to 25 m $ Up to 50 m $ Target 4 3 - 4 m $ Up to 10 m $ Target 5 15 - 20 m $ Up to 20 m $ Target 6 Up to 10 m $ Up to 15 m $ Target 7 Up to 15 m $ Up to 10 m $ Target 8 Up to 8 - 15 m $ Up to 5 m $ Target 9 - Up to 50m $ Others *This statement reflects management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainty. 17
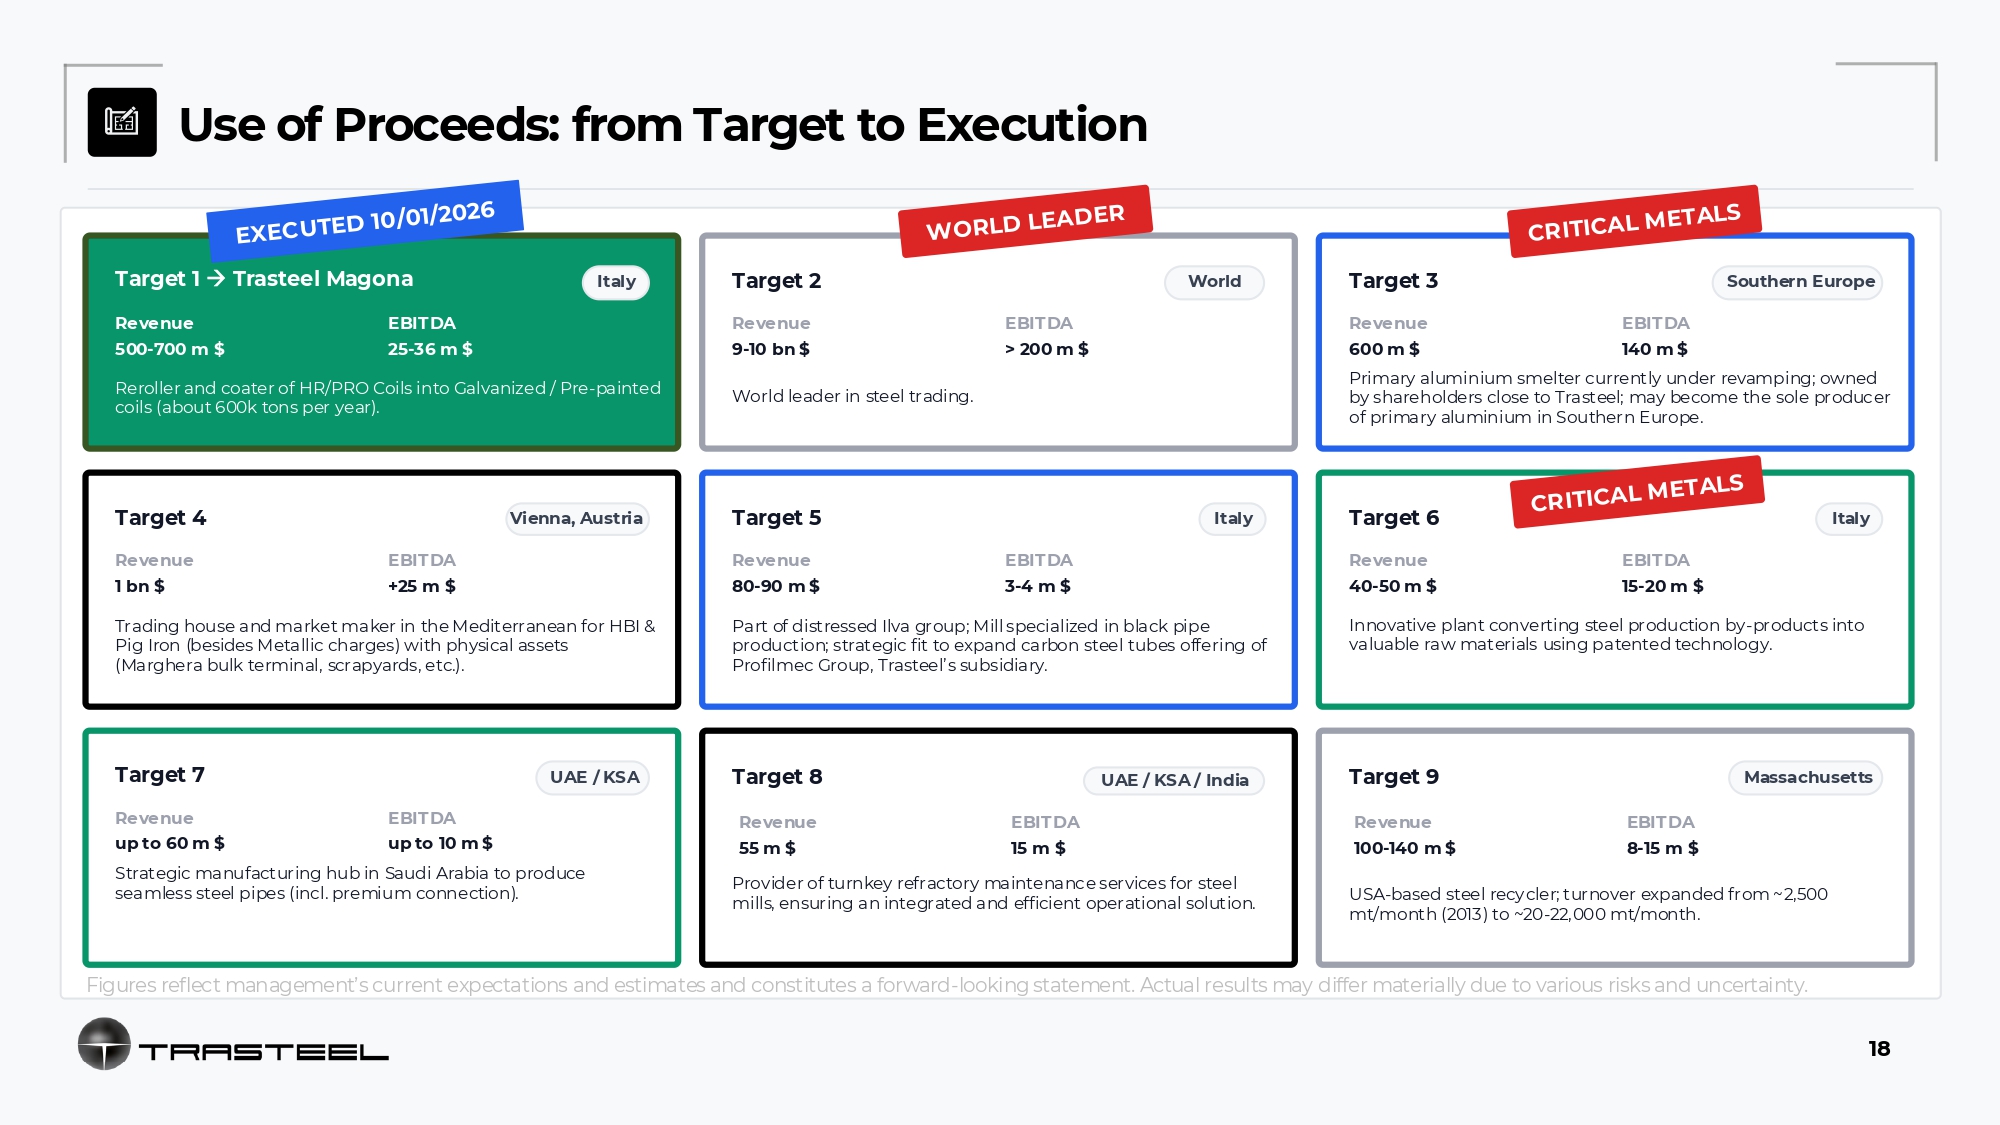
Use of Proceeds: from Target to Execution Target 1 Trasteel Magona Italy World Revenue 500 - 700 m $ EBITDA 25 - 36 m $ Target 2 Revenue 9 - 10 bn $ Southern Europe EBITDA > 200 m $ Target 3 Revenue 600 m $ EBITDA 140 m $ Reroller and coater of HR/PRO Coils into Galvanized / Pre - painted coils (about 600k tons per year). World leader in steel trading. Primary aluminium smelter currently under revamping; owned by shareholders close to Trasteel; may become the sole producer of primary aluminium in Southern Europe. Italy Target 6 Italy Target 5 Vienna, Austria Target 4 EBITDA Revenue EBITDA Revenue EBITDA Revenue 15 - 20 m $ 40 - 50 m $ 3 - 4 m $ 80 - 90 m $ +25 m $ 1 bn $ Trading house and market maker in the Mediterranean for HBI & Pig Iron (besides Metallic charges) with physical assets (Marghera bulk terminal, scrapyards, etc.). Part of distressed Ilva group; Mill specialized in black pipe production; strategic fit to expand carbon steel tubes offering of Profilmec Group, Trasteel’s subsidiary. Innovative plant converting steel production by - products into valuable raw materials using patented technology. Massachusetts Target 9 UAE / KSA / India Target 8 UAE / KSA Target 7 EBITDA Revenue EBITDA Revenue EBITDA Revenue 8 - 15 m $ 100 - 140 m $ 15 m $ 55 m $ up to 10 m $ up to 60 m $ Strategic manufacturing hub in Saudi Arabia to produce seamless steel pipes (incl. premium connection). Provider of turnkey refractory maintenance services for steel mills, ensuring an integrated and efficient operational solution. USA - based steel recycler; turnover expanded from ~2,500 mt/month (2013) to ~20 - 22,000 mt/month. Figures reflect management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainty. 18
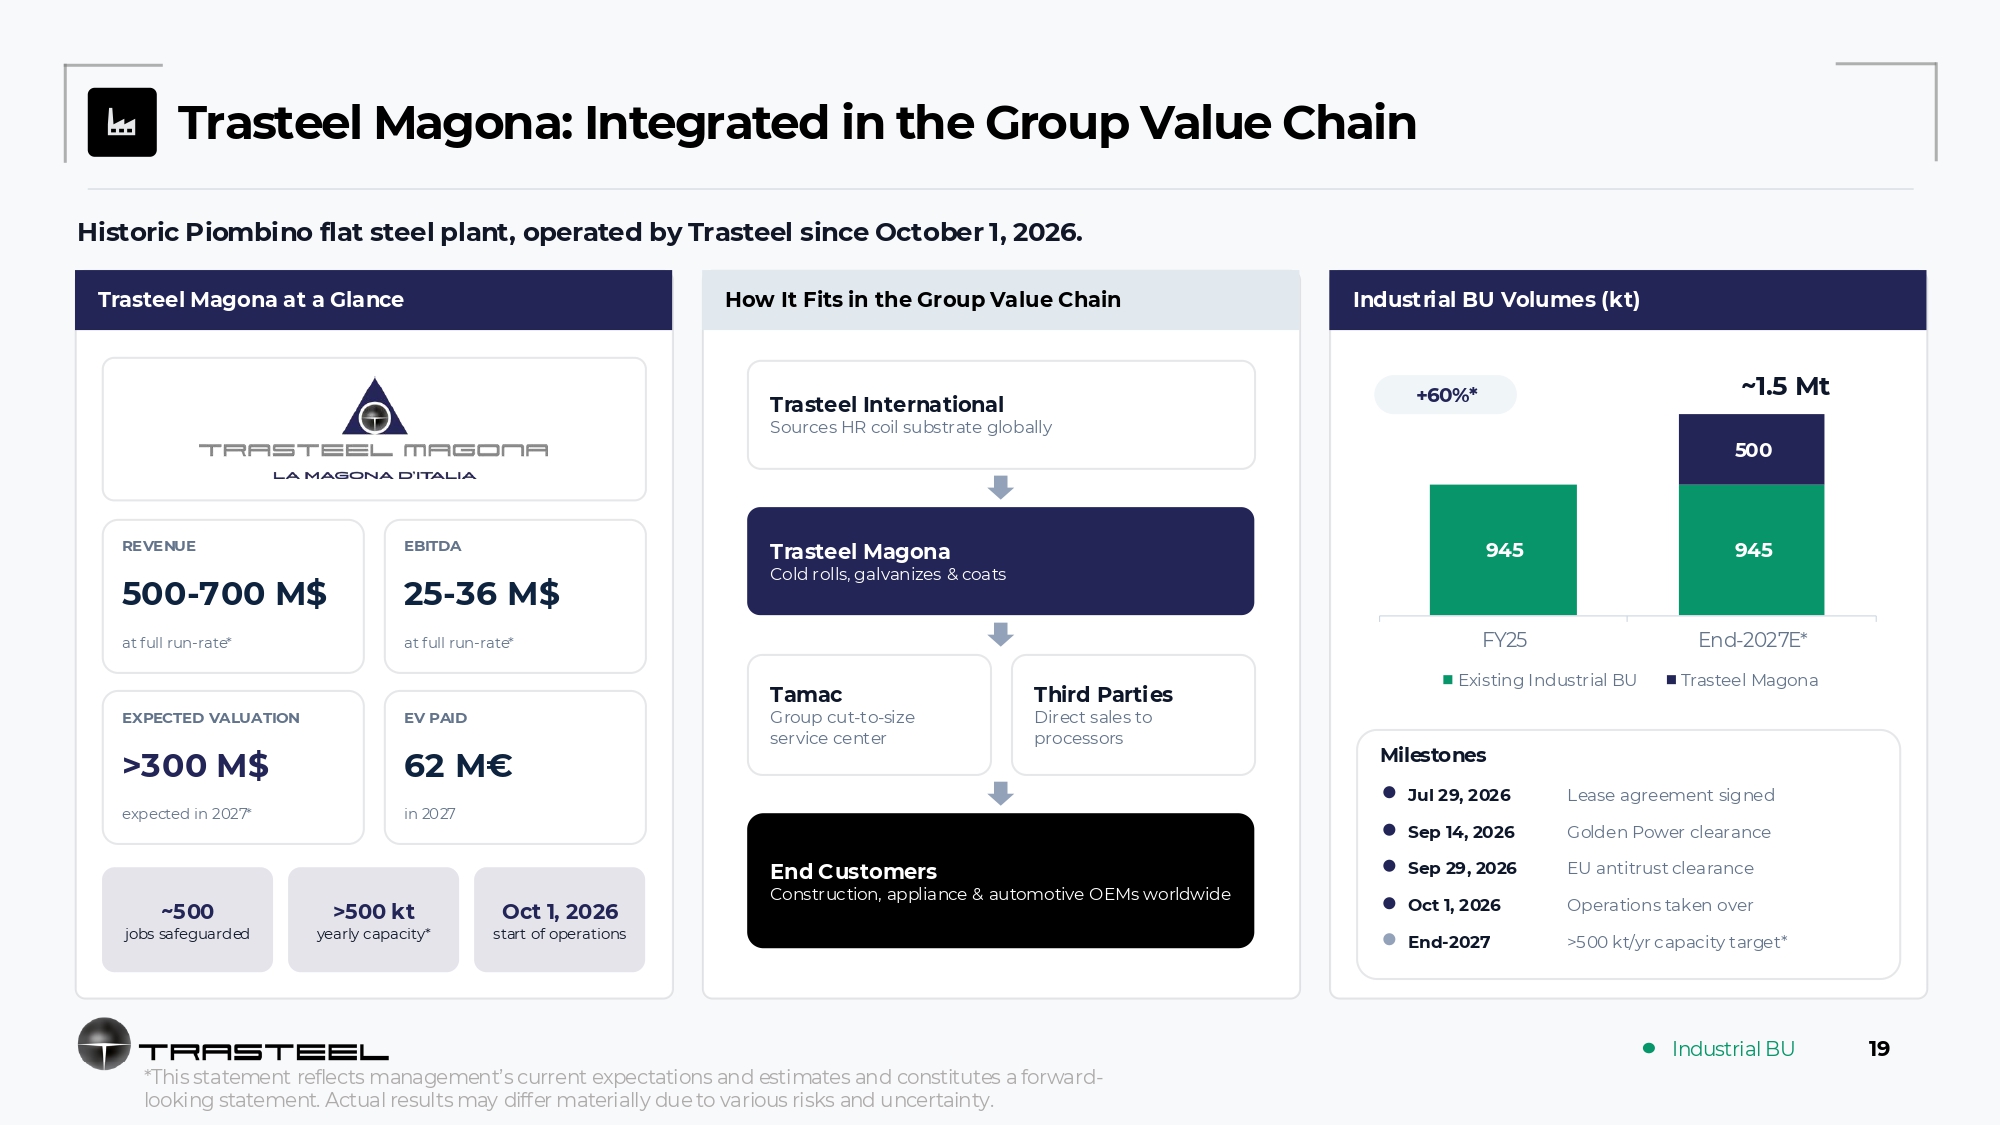
Trasteel Magona: Integrated in the Group Value Chain Historic Piombino flat steel plant, operated by Trasteel since October 1, 2026. Trasteel Magona at a Glance REVENUE EBITDA 500 - 700 M$ 25 - 36 M$ at full run - rate* at full run - rate* EXPECTED VALUATION EV PAID >300 M$ 62 M€ expected in 2027* in 2027 ~500 >500 kt Oct 1, 2026 jobs safeguarded yearly capacity* start of operations How It Fits in the Group Value Chain Trasteel International Sources HR coil substrate globally Trasteel Magona Cold rolls, galvanizes & coats Tamac Third Parties Group cut - to - size Direct sales to service center processors End Customers Construction, appliance & automotive OEMs worldwide Industrial BU Volumes (kt) +60%* ~1.5 Mt 945 945 500 FY25 Existing Industrial BU End - 2027E* Trasteel Magona Milestones Jul 29, 2026 Sep 14, 2026 Sep 29, 2026 Oct 1, 2026 End - 2027 Lease agreement signed Golden Power clearance EU antitrust clearance Operations taken over >500 kt/yr capacity target* Industrial BU 19 *This statement reflects management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainty.
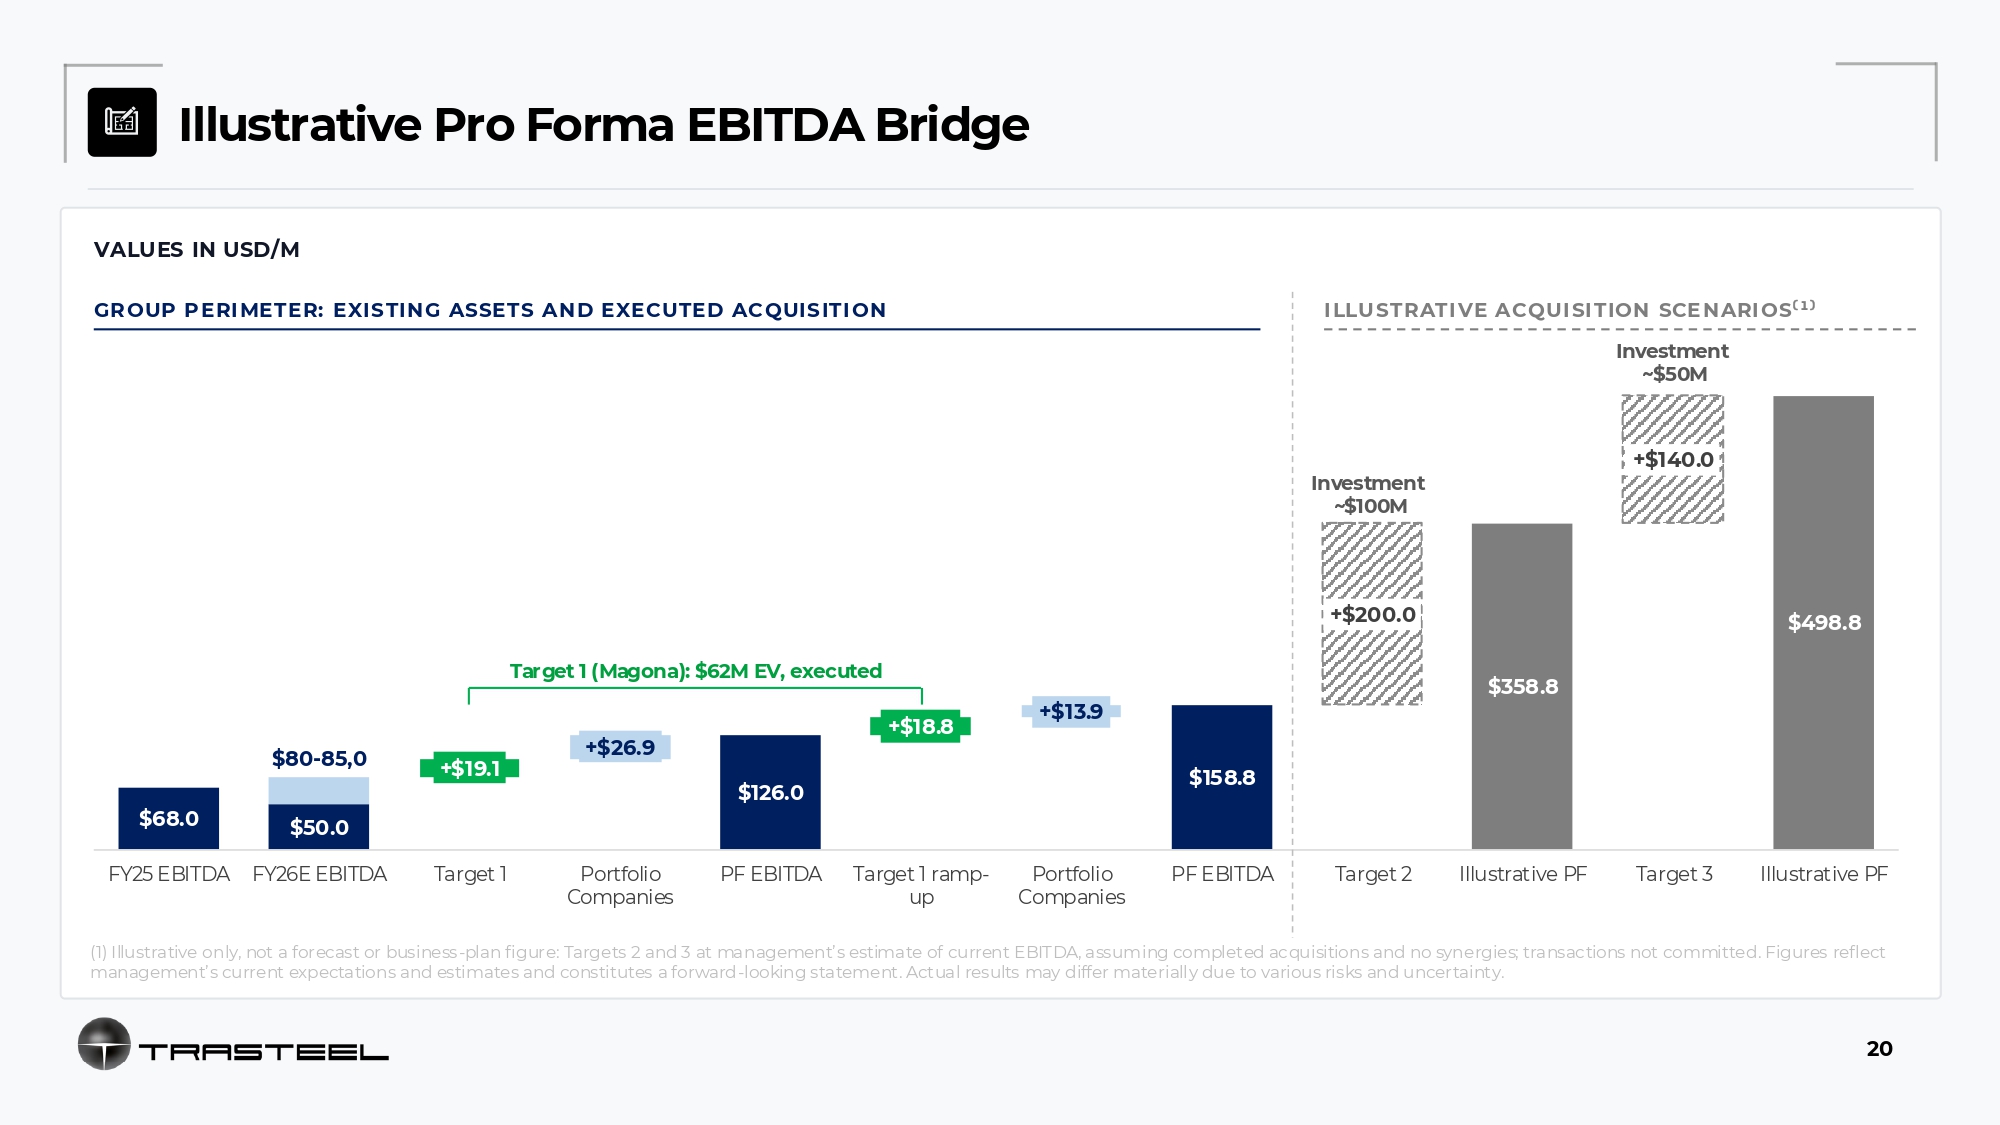
Illustrative Pro Forma EBITDA Bridge VALUES IN USD/M GROUP PERIMETER: EXISTING ASSETS AND EXECUTED ACQUISITION ILLUSTRATIVE ACQUISITION SCENARIOS ⁽ ¹ ⁾ +$140.0 +$200.0 +$13.9 +$18.8 $80 - 85,0 +$26.9 +$19.1 $68.0 $50.0 $126.0 $158.8 $358.8 $498.8 FY25 EBITDA FY26E EBITDA Target 1 Portfolio Companies PF EBITDA Target 1 ramp - up Portfolio Companies PF EBITDA Target 2 Illustrative PF Target 3 Illustrative PF Investment ~$50M Investment ~$100M Target 1 (Magona): $62M EV, executed (1) Illustrative only, not a forecast or business - plan figure: Targets 2 and 3 at management’s estimate of current EBITDA, assuming completed acquisitions and no synergies; transactions not committed. Figures reflect management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainty. 20
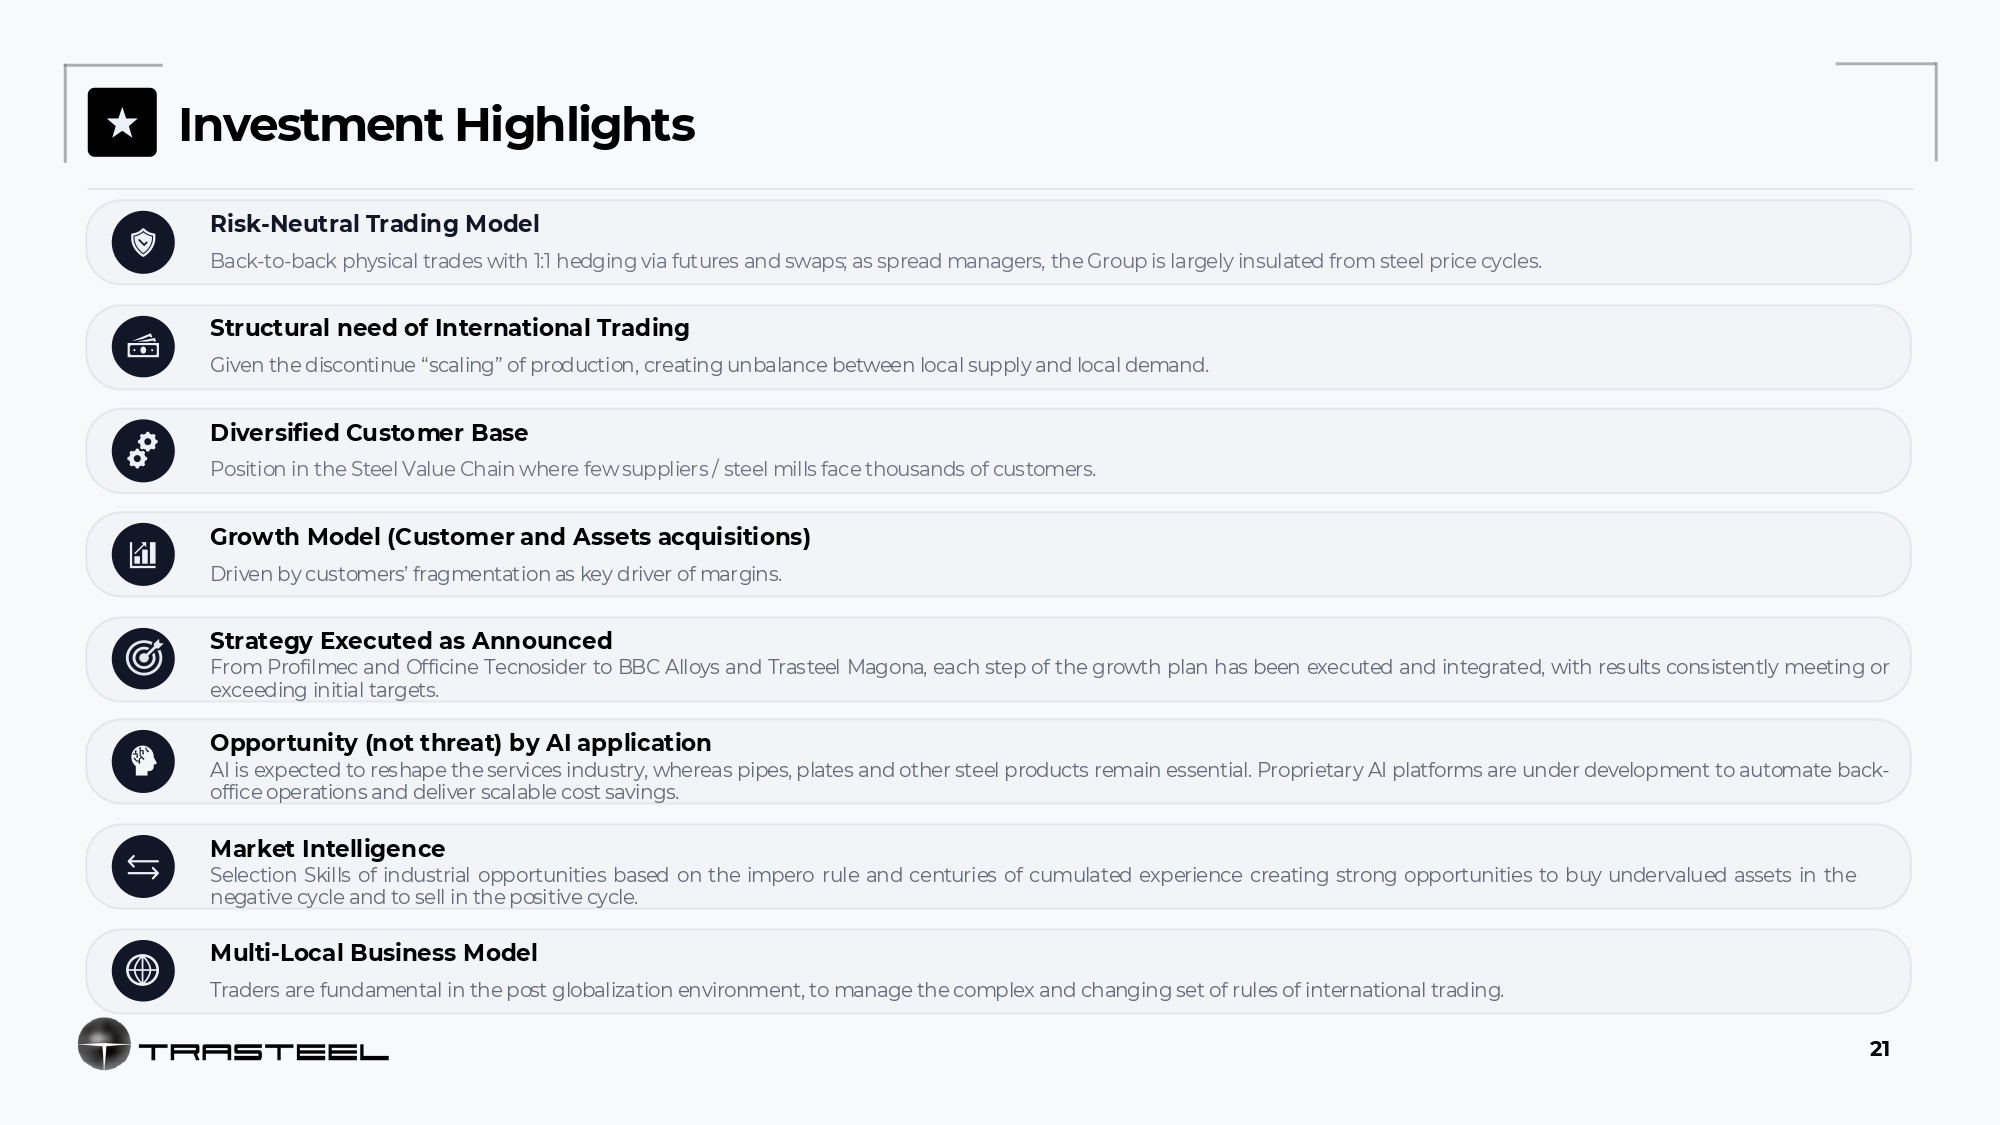
Investment Highlights Risk - Neutral Trading Model Back - to - back physical trades with 1:1 hedging via futures and swaps; as spread managers, the Group is largely insulated from steel price cycles. Structural need of International Trading Given the discontinue “scaling” of production, creating unbalance between local supply and local demand. Diversified Customer Base Position in the Steel Value Chain where few suppliers / steel mills face thousands of customers. Growth Model (Customer and Assets acquisitions) Driven by customers’ fragmentation as key driver of margins. Strategy Executed as Announced From Profilmec and Officine Tecnosider to BBC Alloys and Trasteel Magona, each step of the growth plan has been executed and integrated, with results consistently meeting or exceeding initial targets. Opportunity (not threat) by AI application AI is expected to reshape the services industry, whereas pipes, plates and other steel products remain essential. Proprietary AI platforms are under development to automate back - office operations and deliver scalable cost savings. Market Intelligence Selection Skills of industrial opportunities based on the impero rule and centuries of cumulated experience creating strong opportunities to buy undervalued assets in the negative cycle and to sell in the positive cycle. Multi - Local Business Model Traders are fundamental in the post globalization environment, to manage the complex and changing set of rules of international trading. 21
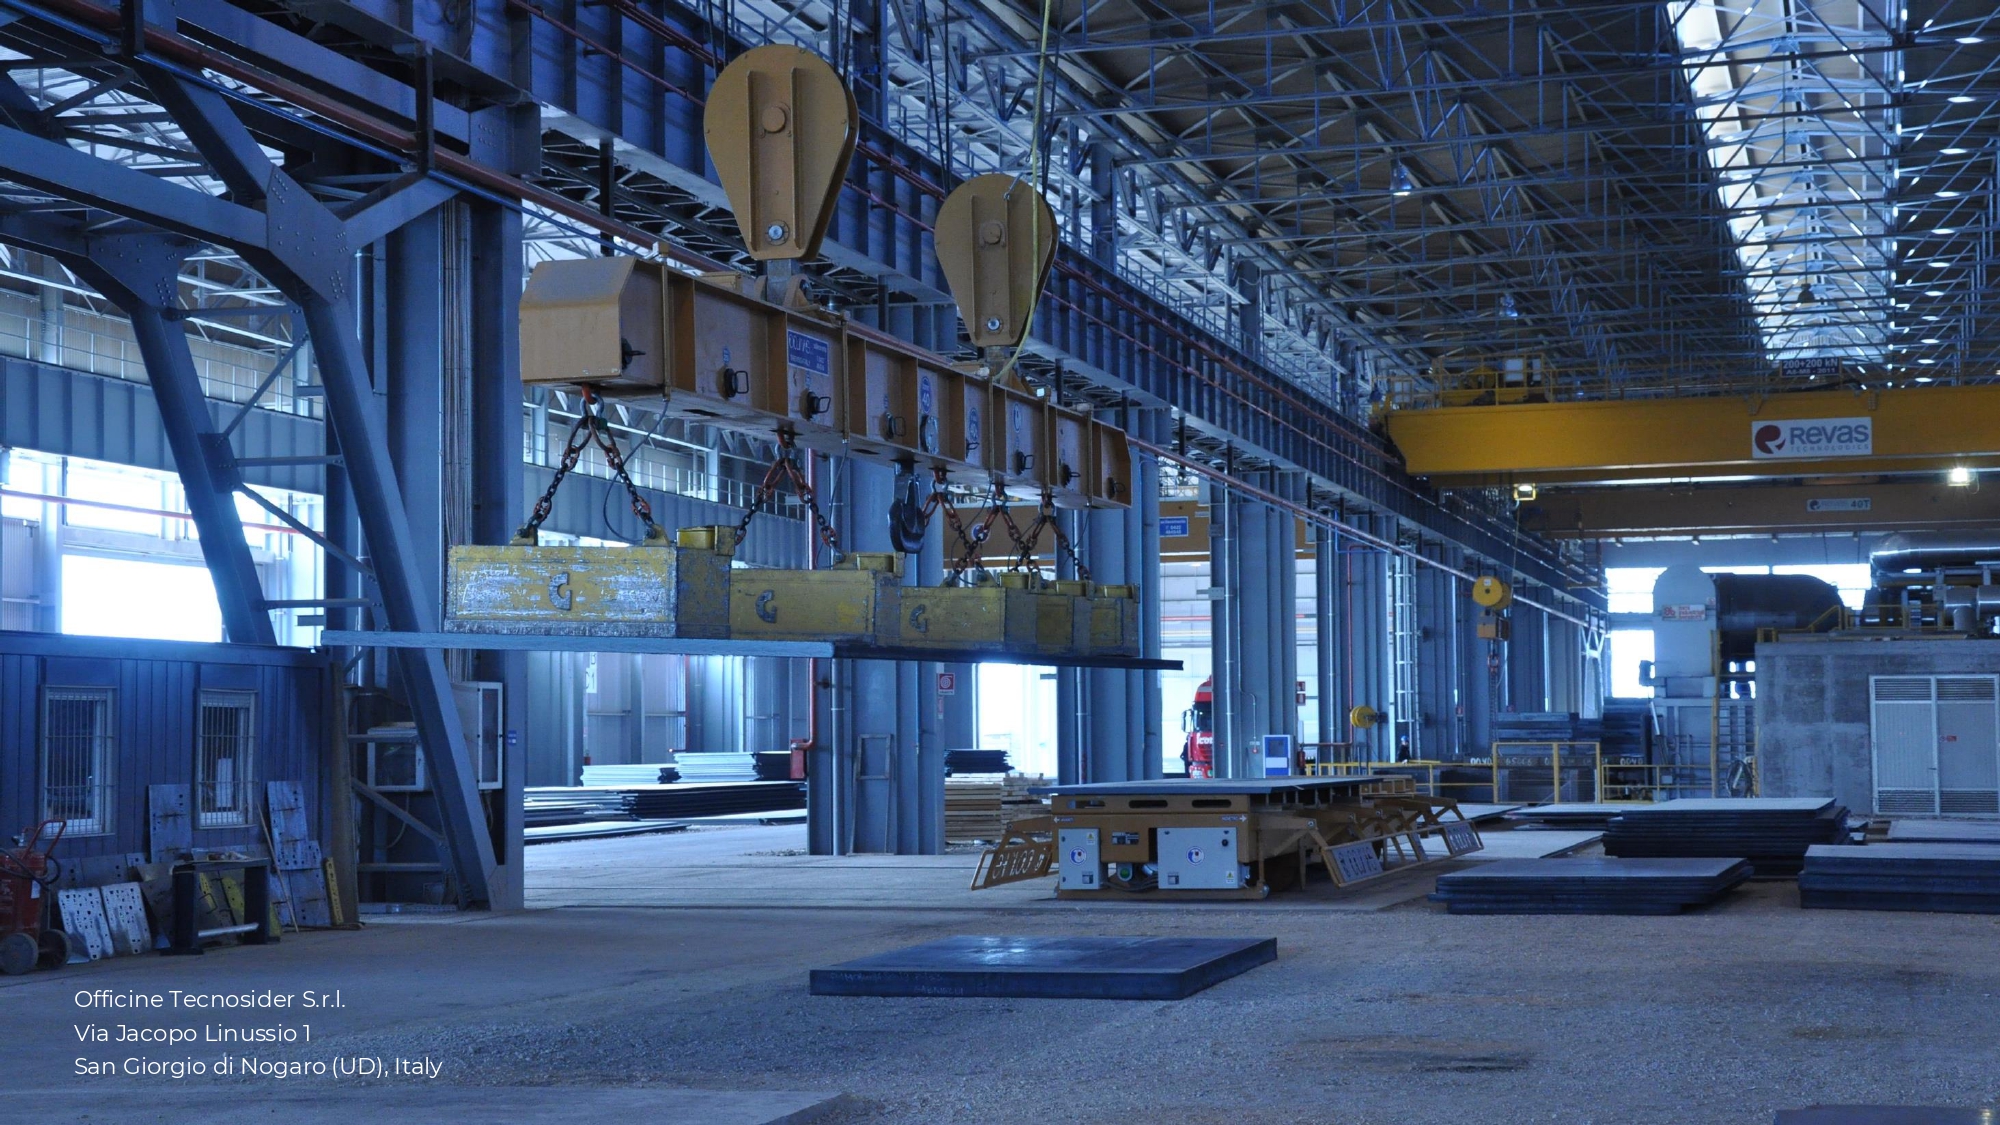
Officine Tecnosider S.r.l. Via Jacopo Linussio 1 San Giorgio di Nogaro (UD), Italy
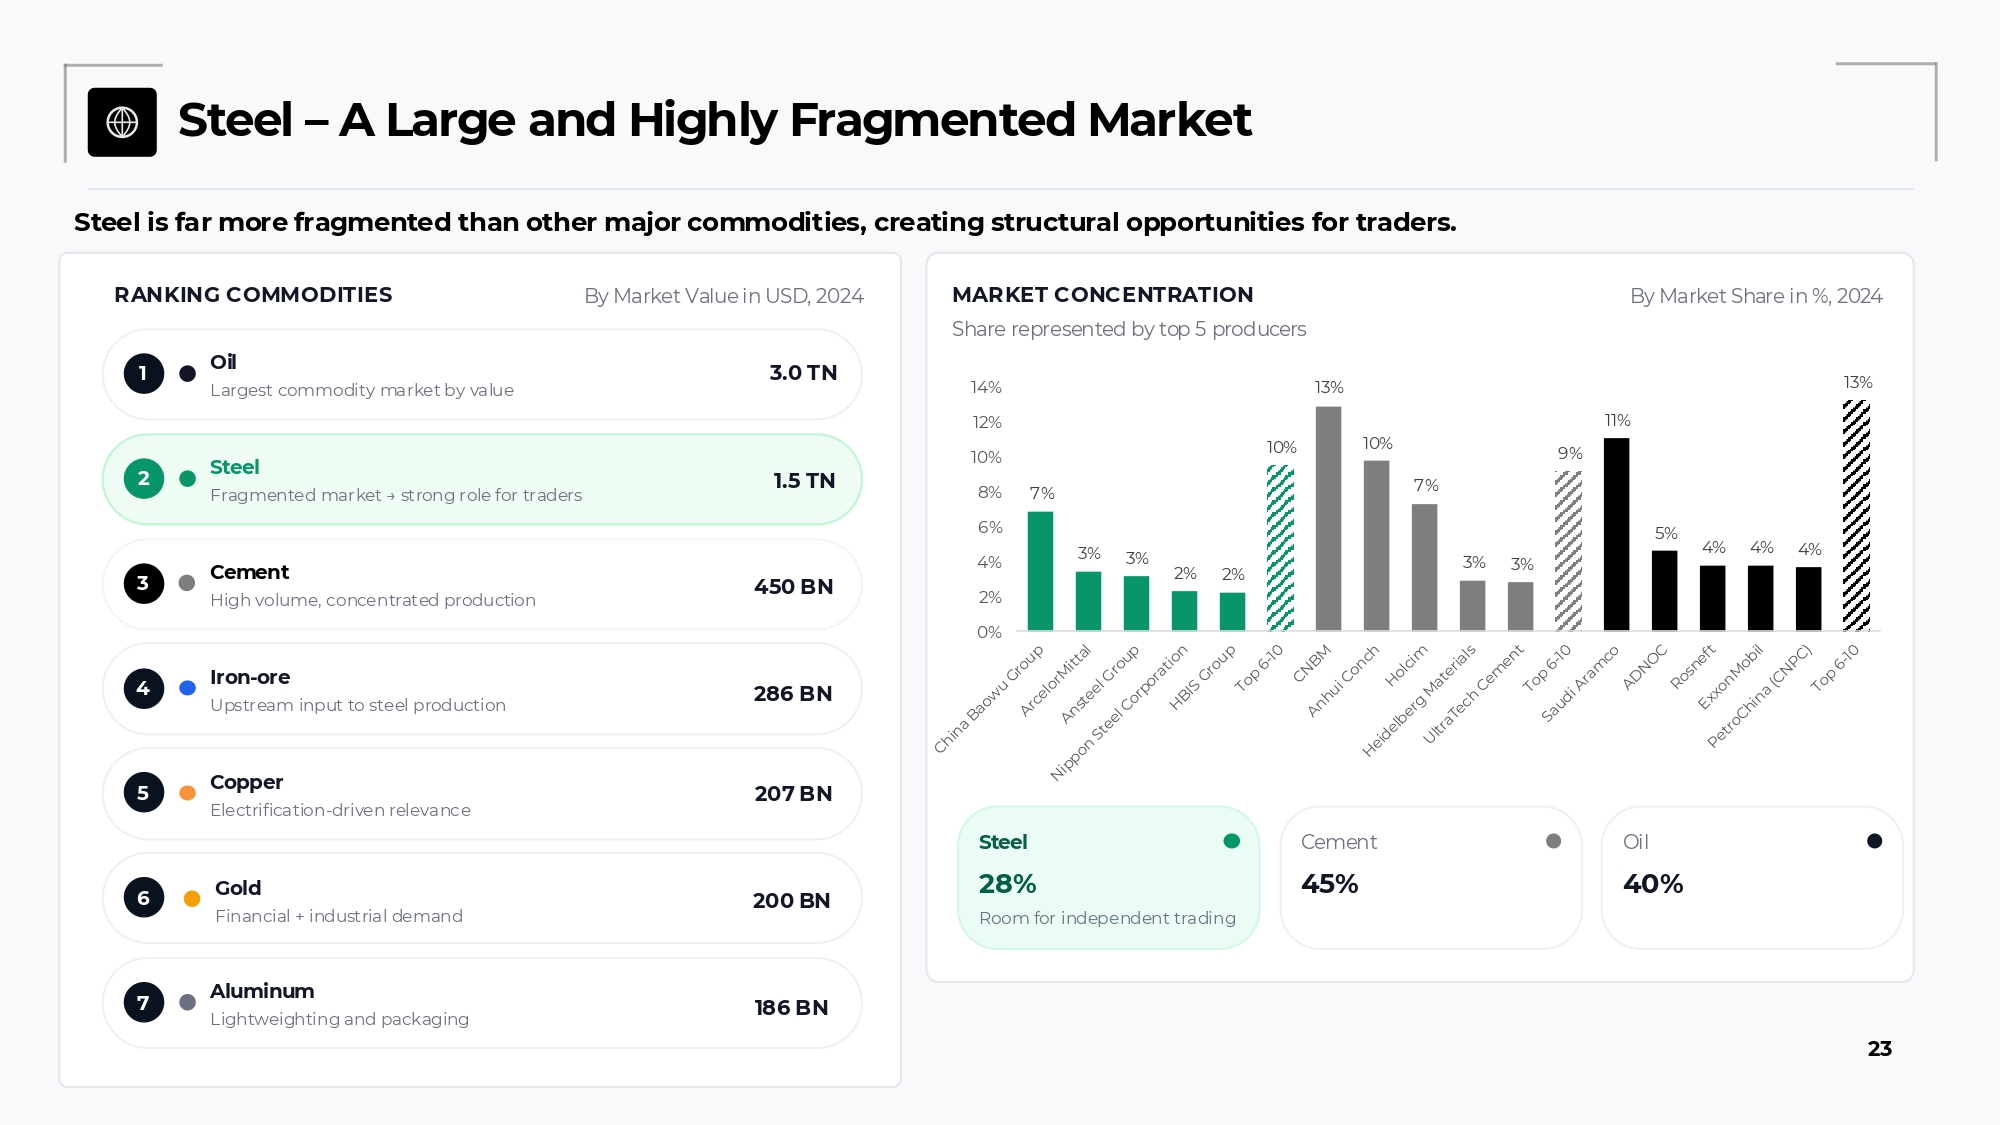
Steel – A Large and Highly Fragmented Market Steel is far more fragmented than other major commodities, creating structural opportunities for traders. RANKING COMMODITIES By Market Value in USD, 2024 1 Oil Largest commodity market by value 3.0 TN 2 Steel Fragmented market → strong role for traders 3 Cement High volume, concentrated production 4 Iron - ore Upstream input to steel production 5 6 7 MARKET CONCENTRATION Share represented by top 5 producers By Market Share in %, 2024 1.5 TN 450 BN 14% 12% 10% 8% 7% 6% 4% 2% 0% 13% 13% 11% 10% 10% 9% 7% 5% 3% 4% 4% 3% 4% 3% 2% 3% 2% 286 BN Copper Electrification - driven relevance 207 BN Steel 28% Room for independent trading Cement 45% Oil 40% Gold Financial + industrial demand 200 BN Aluminum Lightweighting and packaging 186 BN 23
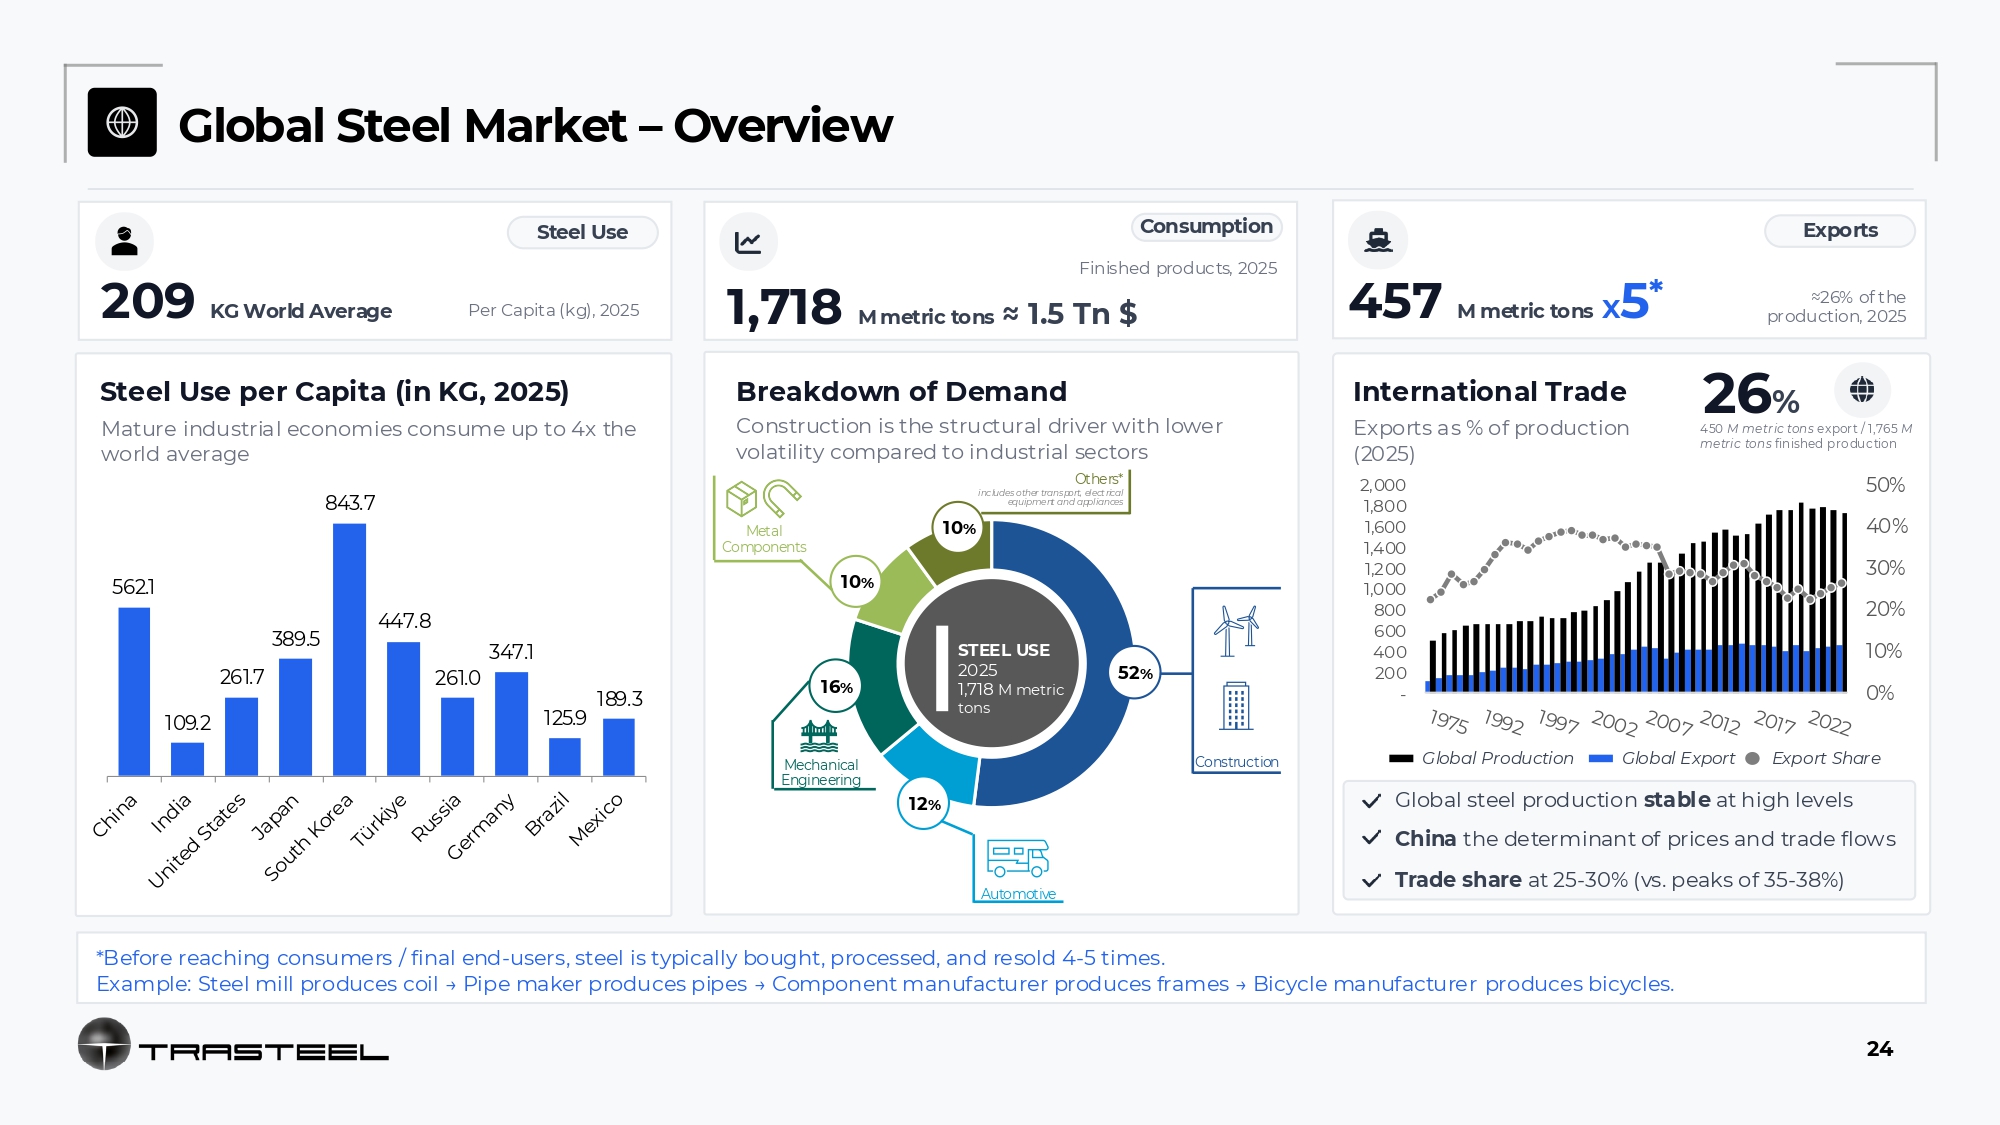
Global Steel Market – Overview Steel Use 209 KG World Average Per Capita (kg), 2025 Consumption Finished products, 2025 1,718 M metric tons ≈ 1.5 Tn $ Exports 457 M metric tons X 5 * ≈26% of the production, 2025 Steel Use per Capita (in KG, 2025) Mature industrial economies consume up to 4x the world average 843.7 26 % 450 M metric tons expor t / 1,765 M metric tons finished production 52 % Mechanical Engineering 16 % STEEL USE 2025 1,718 M metric tons Breakdown of Demand Construction is the structural driver with lower volatility compared to industrial sectors Others* includes other transport, electrical equipment and appliances Metal 10 % Components 10 % - 1,800 1,600 1,400 1,200 1,000 800 600 400 200 International Trade Exports as % of production (2025) 2,000 562.1 447.8 389.5 347.1 261.7 261.0 189.3 50% 40% 30% 20% 10% 0% 109.2 125.9 Construction 12 % Automotive Global Production Global Export Export Share Global steel production stable at high levels China the determinant of prices and trade flows Trade share at 25 - 30% (vs. peaks of 35 - 38%) *Before reaching consumers / final end - users, steel is typically bought, processed, and resold 4 - 5 times. Example: Steel mill produces coil → Pipe maker produces pipes → Component manufacturer produces frames → Bicycle manufacturer produces bicycles. 24
Officine Tecnosider S.r.l. Via Jacopo Linussio 1 San Giorgio di Nogaro (UD), Italy
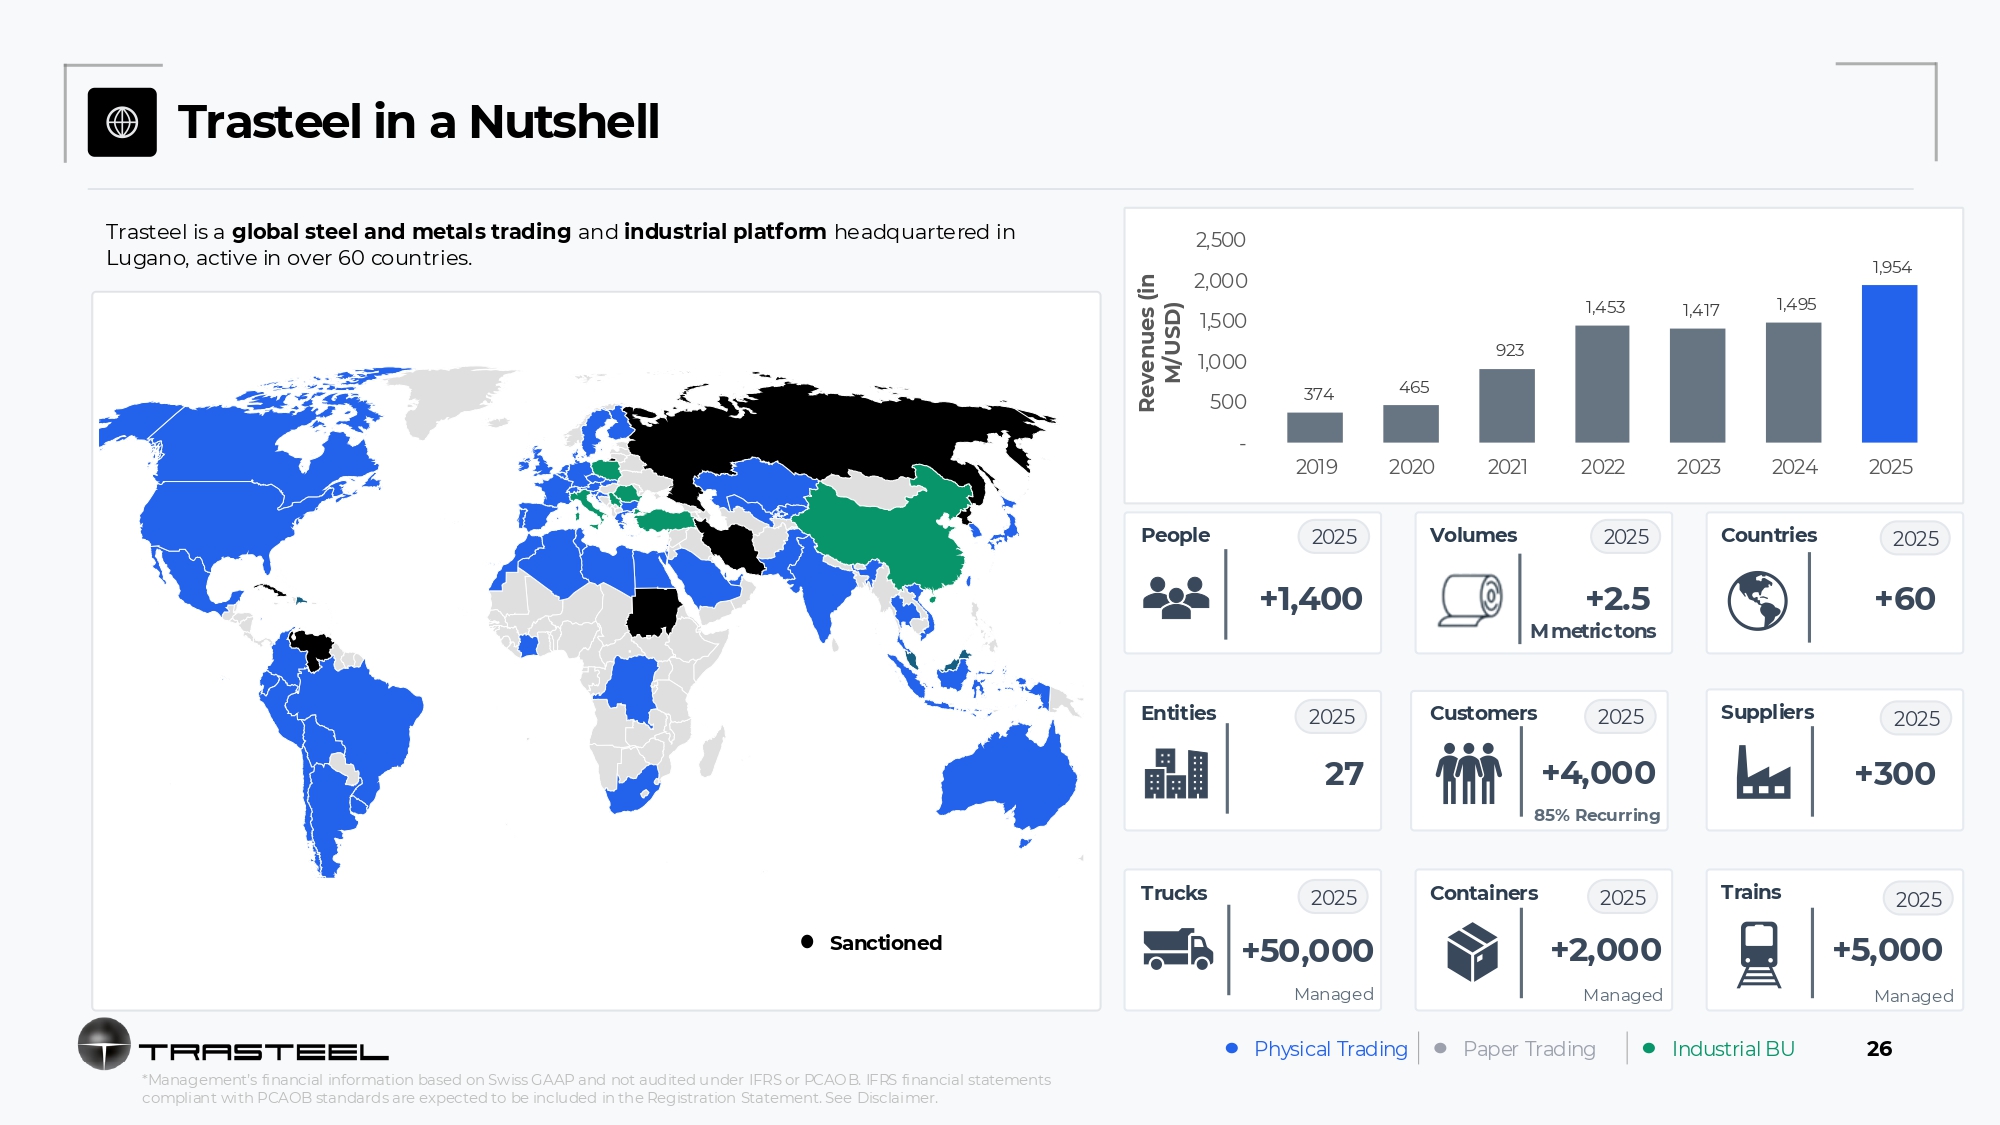
Trasteel in a Nutshell 26 Trasteel is a global steel and metals trading and industrial platform headquartered in Lugano, active in over 60 countries. Trading Activity Trading and Industrial Activity People Volumes Entities Customers Sanctioned Trucks Containers Countries Suppliers Trains 2025 2025 2025 +1,400 +2.5 M metric tons +60 2025 2025 2025 27 +4,000 85% Recurring +300 2025 +50,000 Managed 2025 +2,000 Managed 2025 +5,000 Managed Physical Trading 2,500 2,000 1,954 Revenues (in M/USD) 1,453 1,417 1,495 1,500 1,000 500 923 374 465 - 2019 2020 2021 2022 2023 2024 2025 Paper Trading Industrial BU *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer.
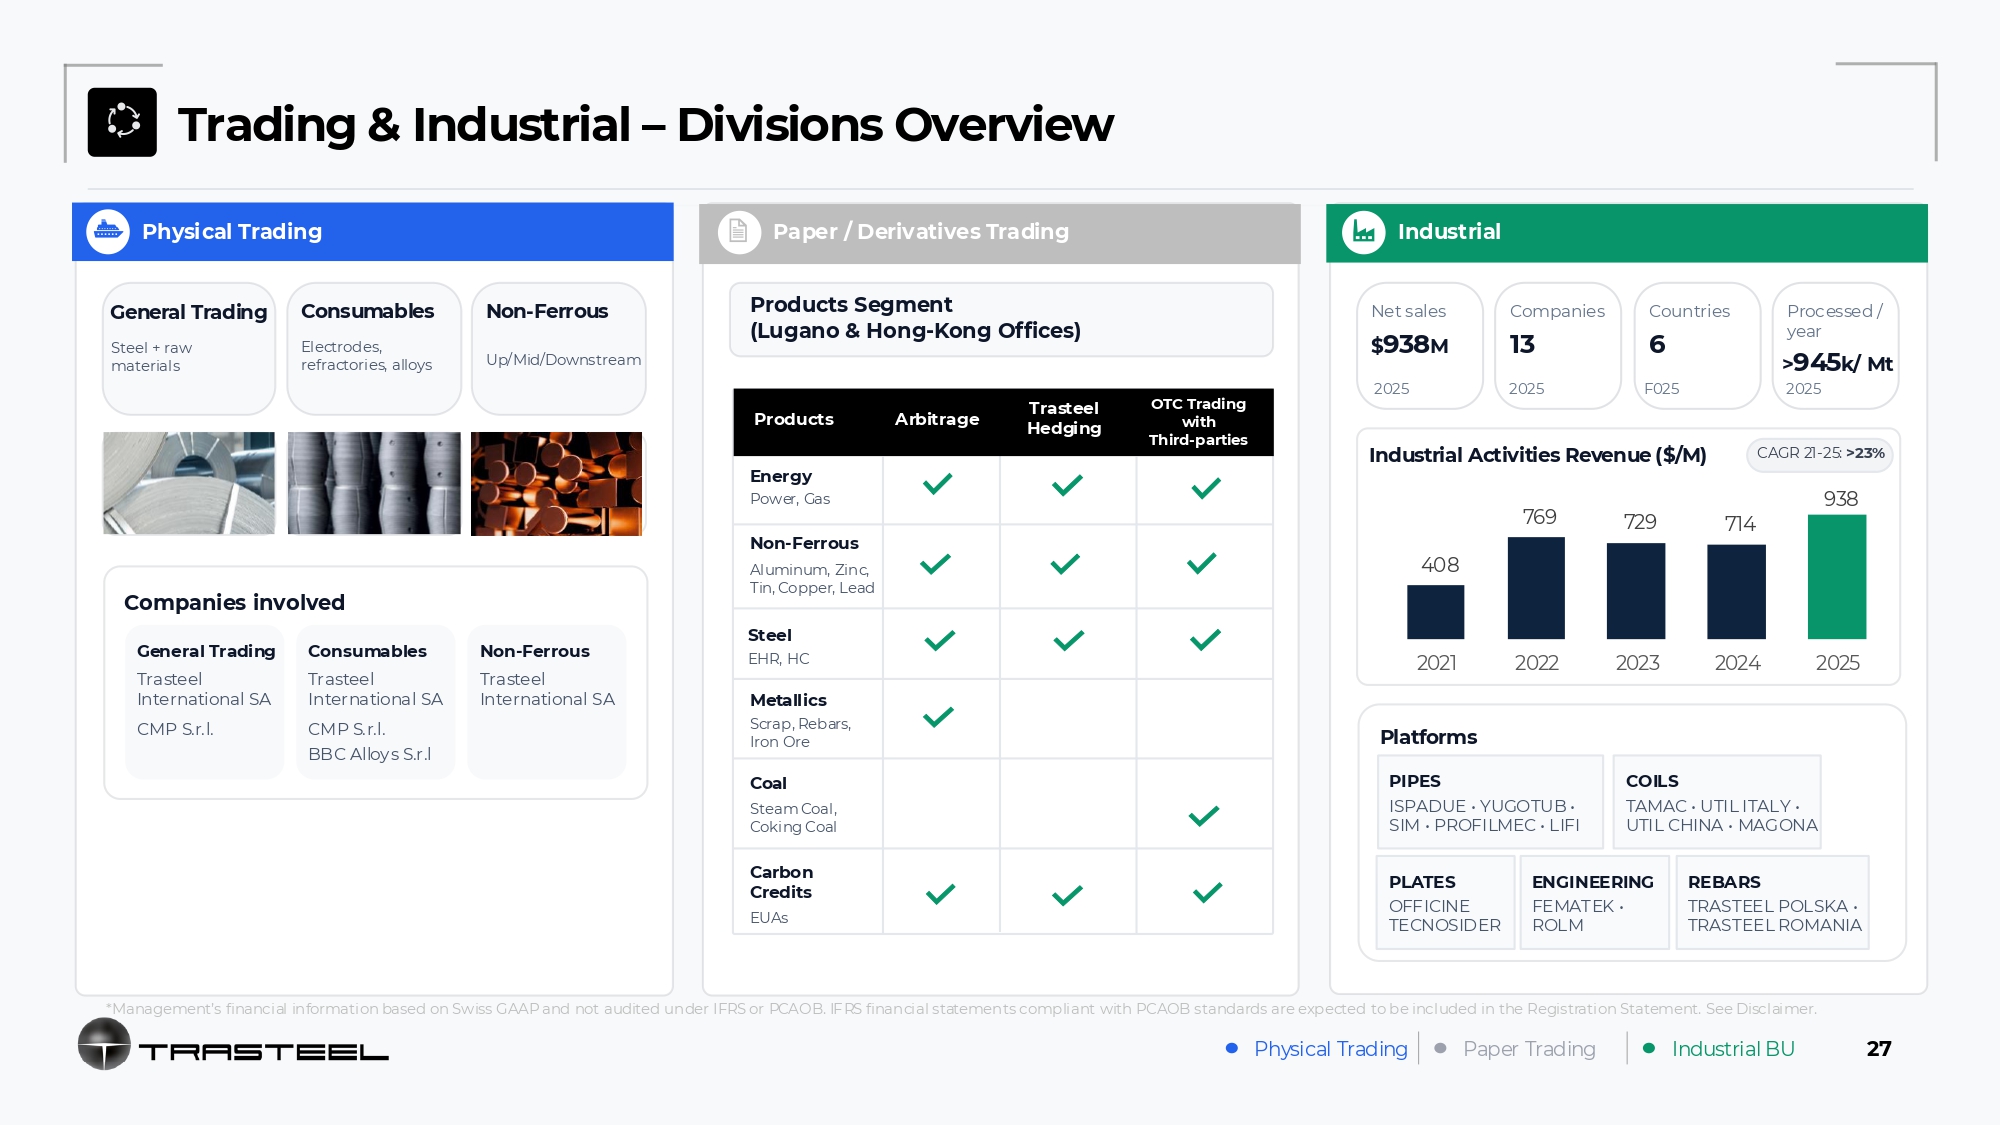
Trading & Industrial – Divisions Overview General Trading Steel + raw materials Consumables Electrodes, refractories, alloys Non - Ferrous Up/Mid/Downstream Companies involved General Trading Trasteel International SA CMP S.r.l. Physical Trading Paper / Derivatives Trading Products Segment (Lugano & Hong - Kong Offices) Consumables Trasteel International SA CMP S.r.l. BBC Alloys S.r.l Non - Ferrous Trasteel International SA OTC Trading with Third - parties Trasteel Hedging Arbitrage Products Energy Power, Gas Non - Ferrous Aluminum, Zinc, Tin, Copper, Lead Steel EHR, HC Metallics Scrap, Rebars, Iron Ore Coal Steam Coal, Coking Coal Carbon Credits EUAs Industrial Net sales $ 938 M 2025 Companies 13 2025 Countries 6 F025 Processed / year > 945 k/ Mt 2025 Industrial Activities Revenue ($/M) CAGR 21 - 25: >23% 938 769 729 714 408 2021 2022 2023 2024 2025 Platforms PIPES ISPADUE • YUGOTUB • SIM • PROFILMEC • LIFI COILS TAMAC • UTIL ITALY • UTIL CHINA • MAGONA PLATES OFFICINE TECNOSIDER ENGINEERING FEMATEK • ROLM REBARS TRASTEEL POLSKA • TRASTEEL ROMANIA *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. Physical Trading Paper Trading Industrial BU 27
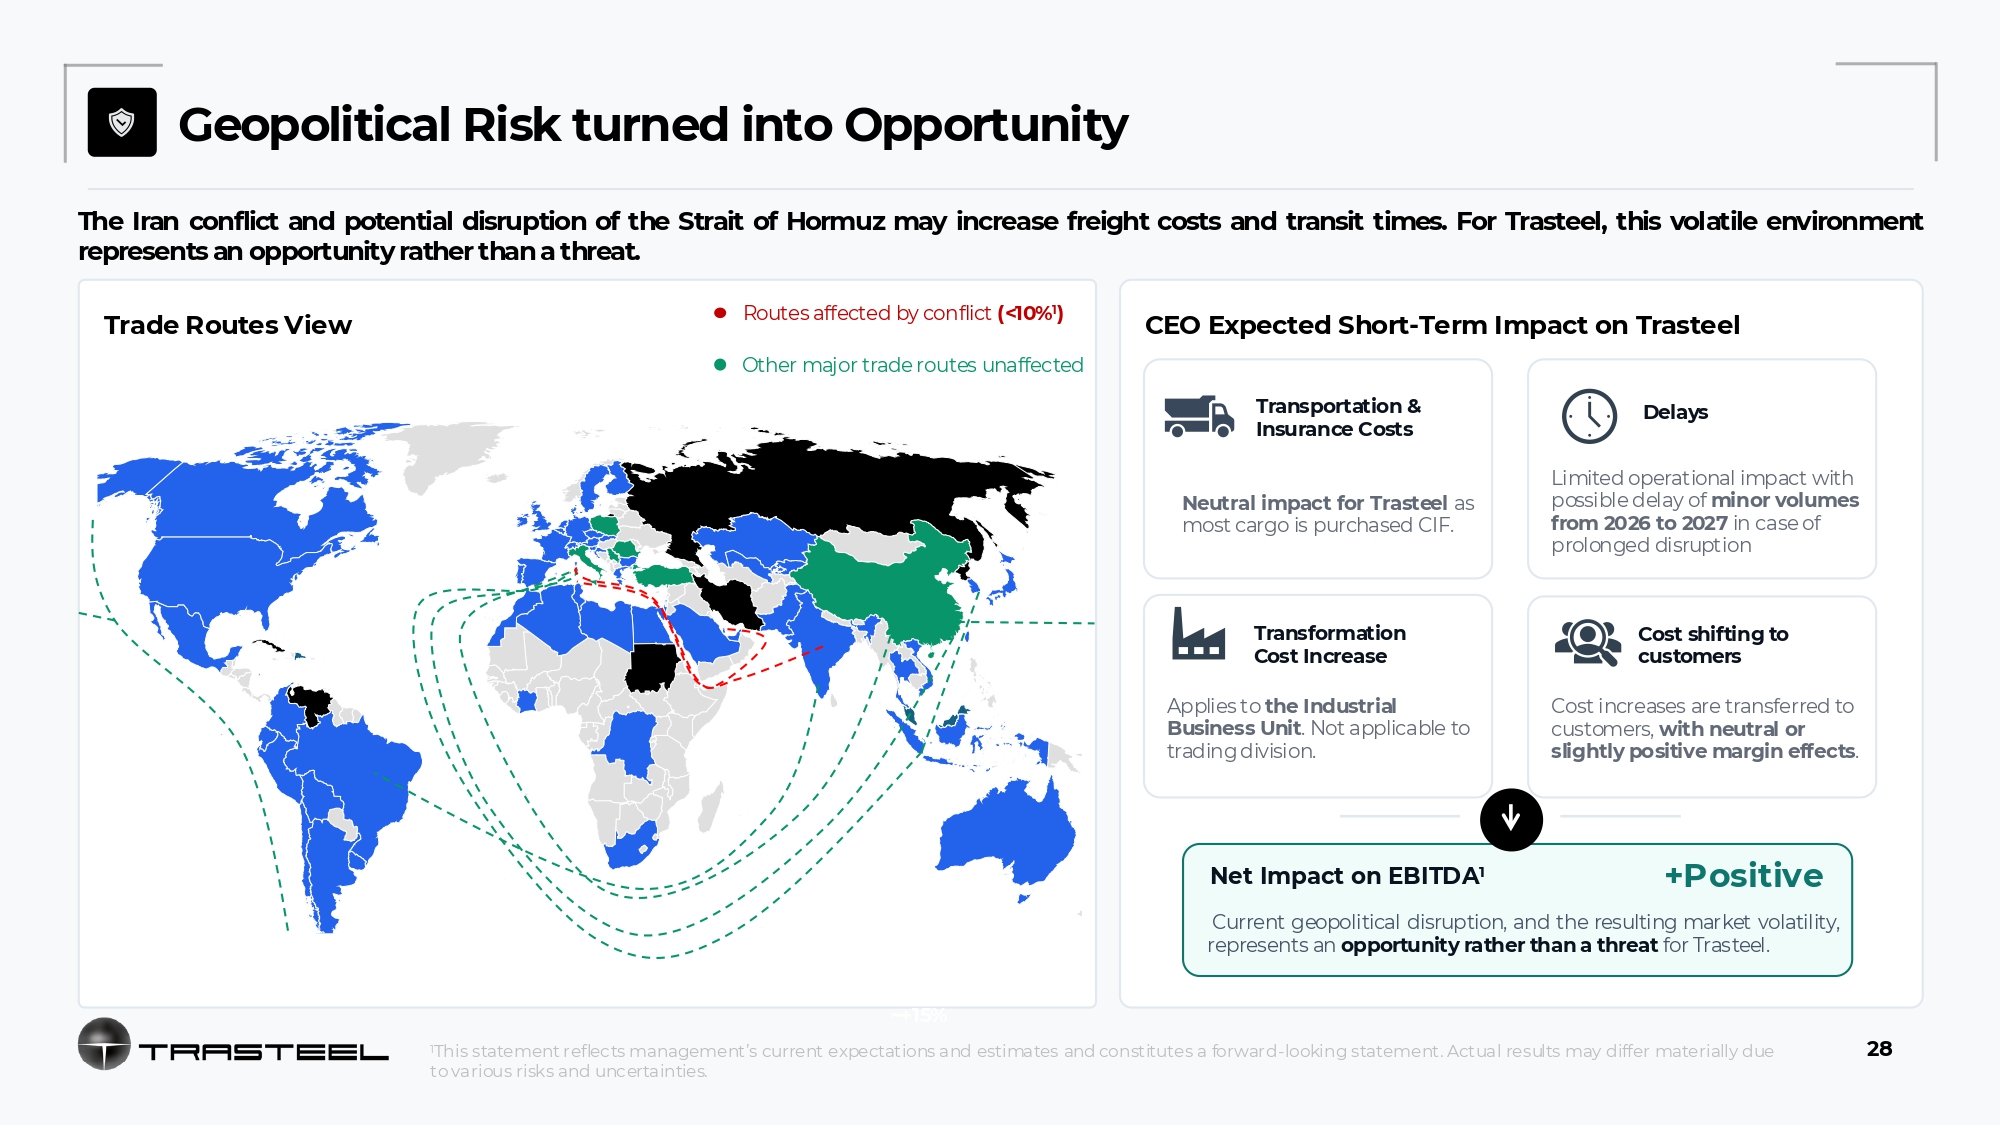
Geopolitical Risk turned into Opportunity The Iran conflict and potential disruption of the Strait of Hormuz may increase freight costs and transit times. For Trasteel, this volatile environment represents an opportunity rather than a threat. Routes affected by conflict (<10% 1 ) Other major trade routes unaffected Trade Routes View CEO Expected Short - Term Impact on Trasteel Transportation & Insurance Costs Neutral impact for Trasteel as most cargo is purchased CIF. Delays Limited operational impact with possible delay of minor volumes from 2026 to 2027 in case of prolonged disruption Transformation Cost Increase Cost shifting to customers Applies to the Industrial Business Unit . Not applicable to trading division. Cost increases are transferred to customers, with neutral or slightly positive margin effects . Net Impact on EBITDA 1 +Positive Current geopolitical disruption, and the resulting market volatility, represents an opportunity rather than a threat for Trasteel. ~+15% 1 This statement reflects management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainties. 28
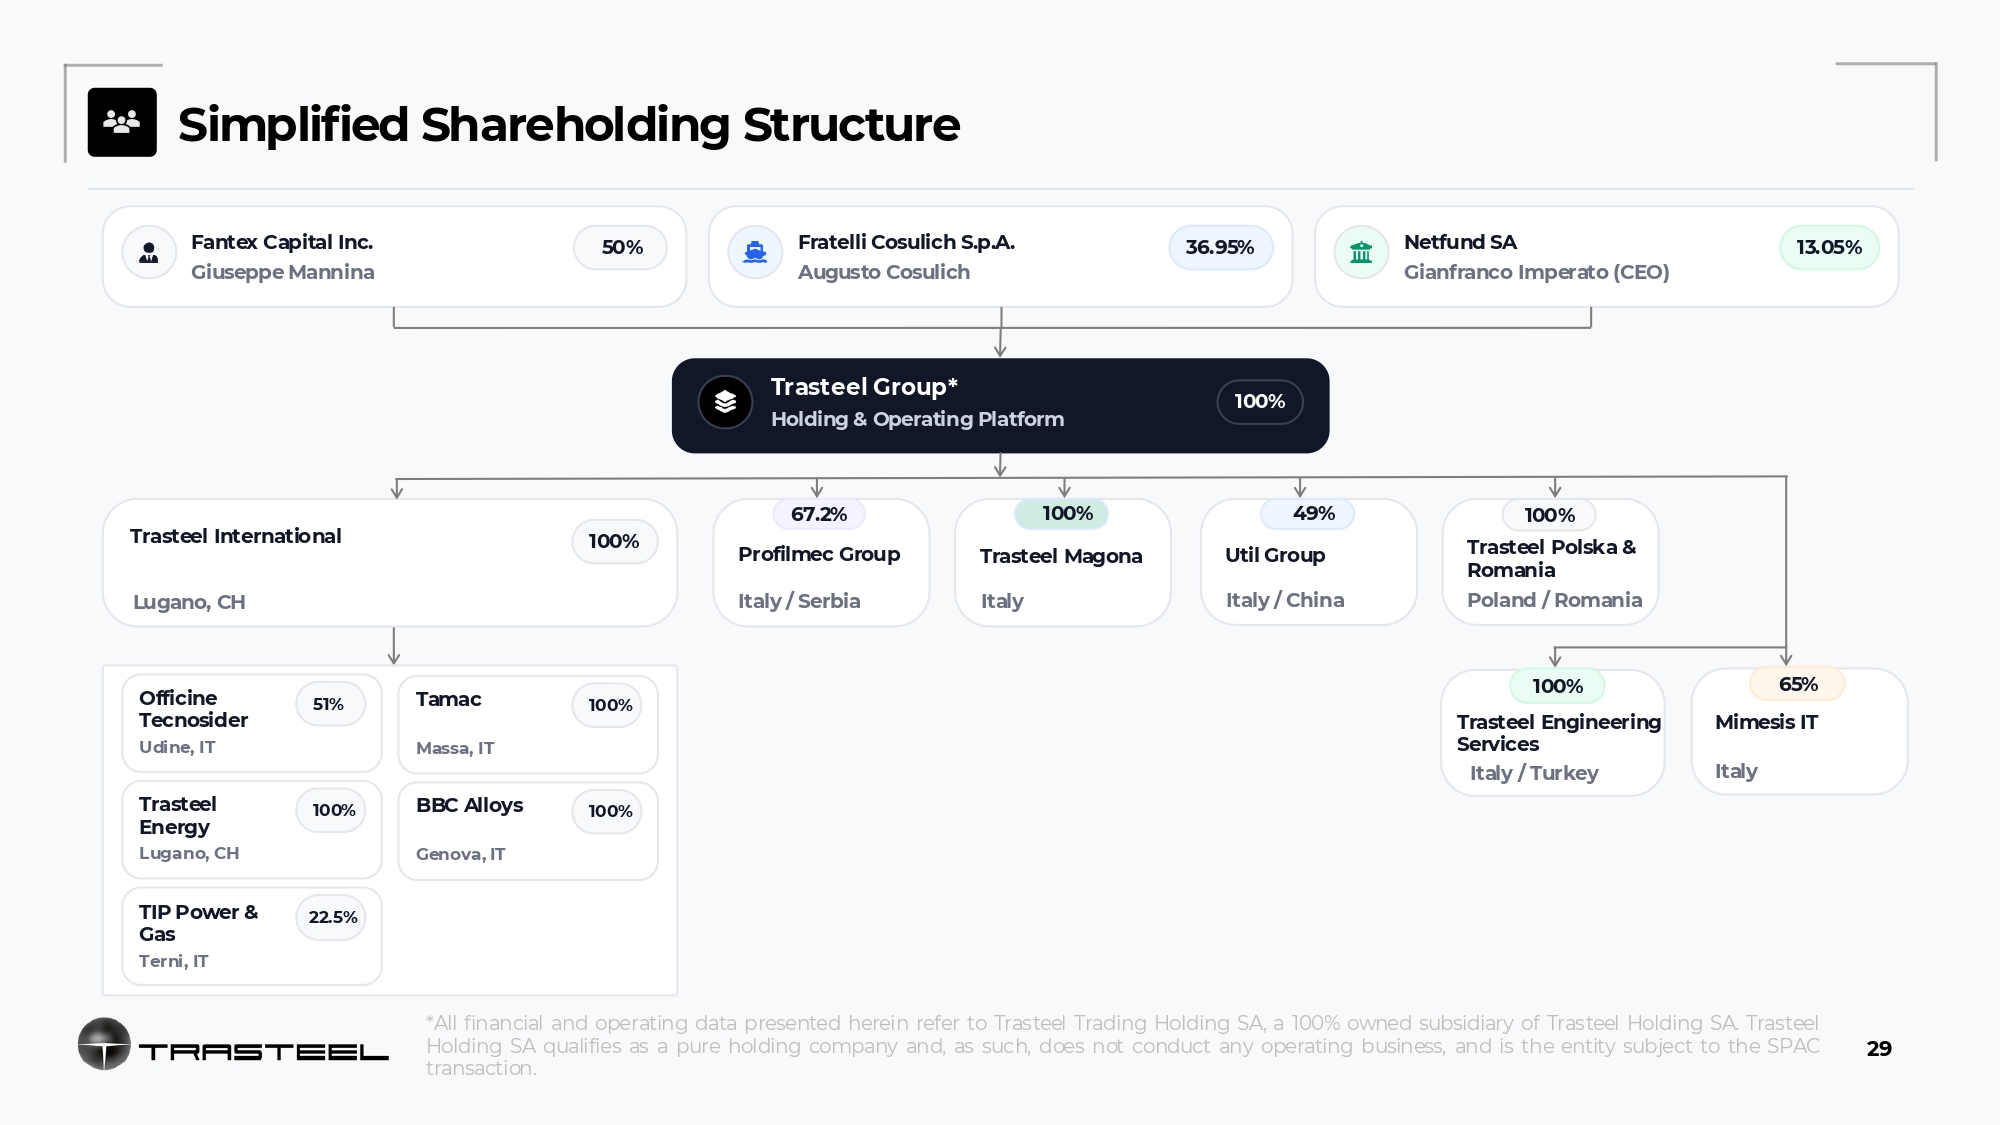
Simplified Shareholding Structure Fantex Capital Inc. Giuseppe Mannina 50% Fratelli Cosulich S.p.A. Augusto Cosulich 36.95% Netfund SA Gianfranco Imperato (CEO) 13.05% Trasteel Group* Holding & Operating Platform 100% Trasteel International 100% Lugano, CH 67.2% Profilmec Group Italy / Serbia 100% Trasteel Magona Italy Officine Tecnosider Udine, IT 51% Tamac 100% Massa, IT Trasteel Energy Lugano, CH 100% BBC Alloys 49% Util Group Italy / China 100% Trasteel Polska & Romania Poland / Romania 65% Mimesis IT Italy 100% Trasteel Engineering Services Italy / Turkey 100% Genova, IT TIP Power & Gas Terni, IT 22.5% *All financial and operating data presented herein refer to Trasteel Trading Holding SA, a 100 % owned subsidiary of Trasteel Holding SA . Trasteel Holding SA qualifies as a pure holding company and, as such, does not conduct any operating business, and is the entity subject to the SPAC transaction . 29
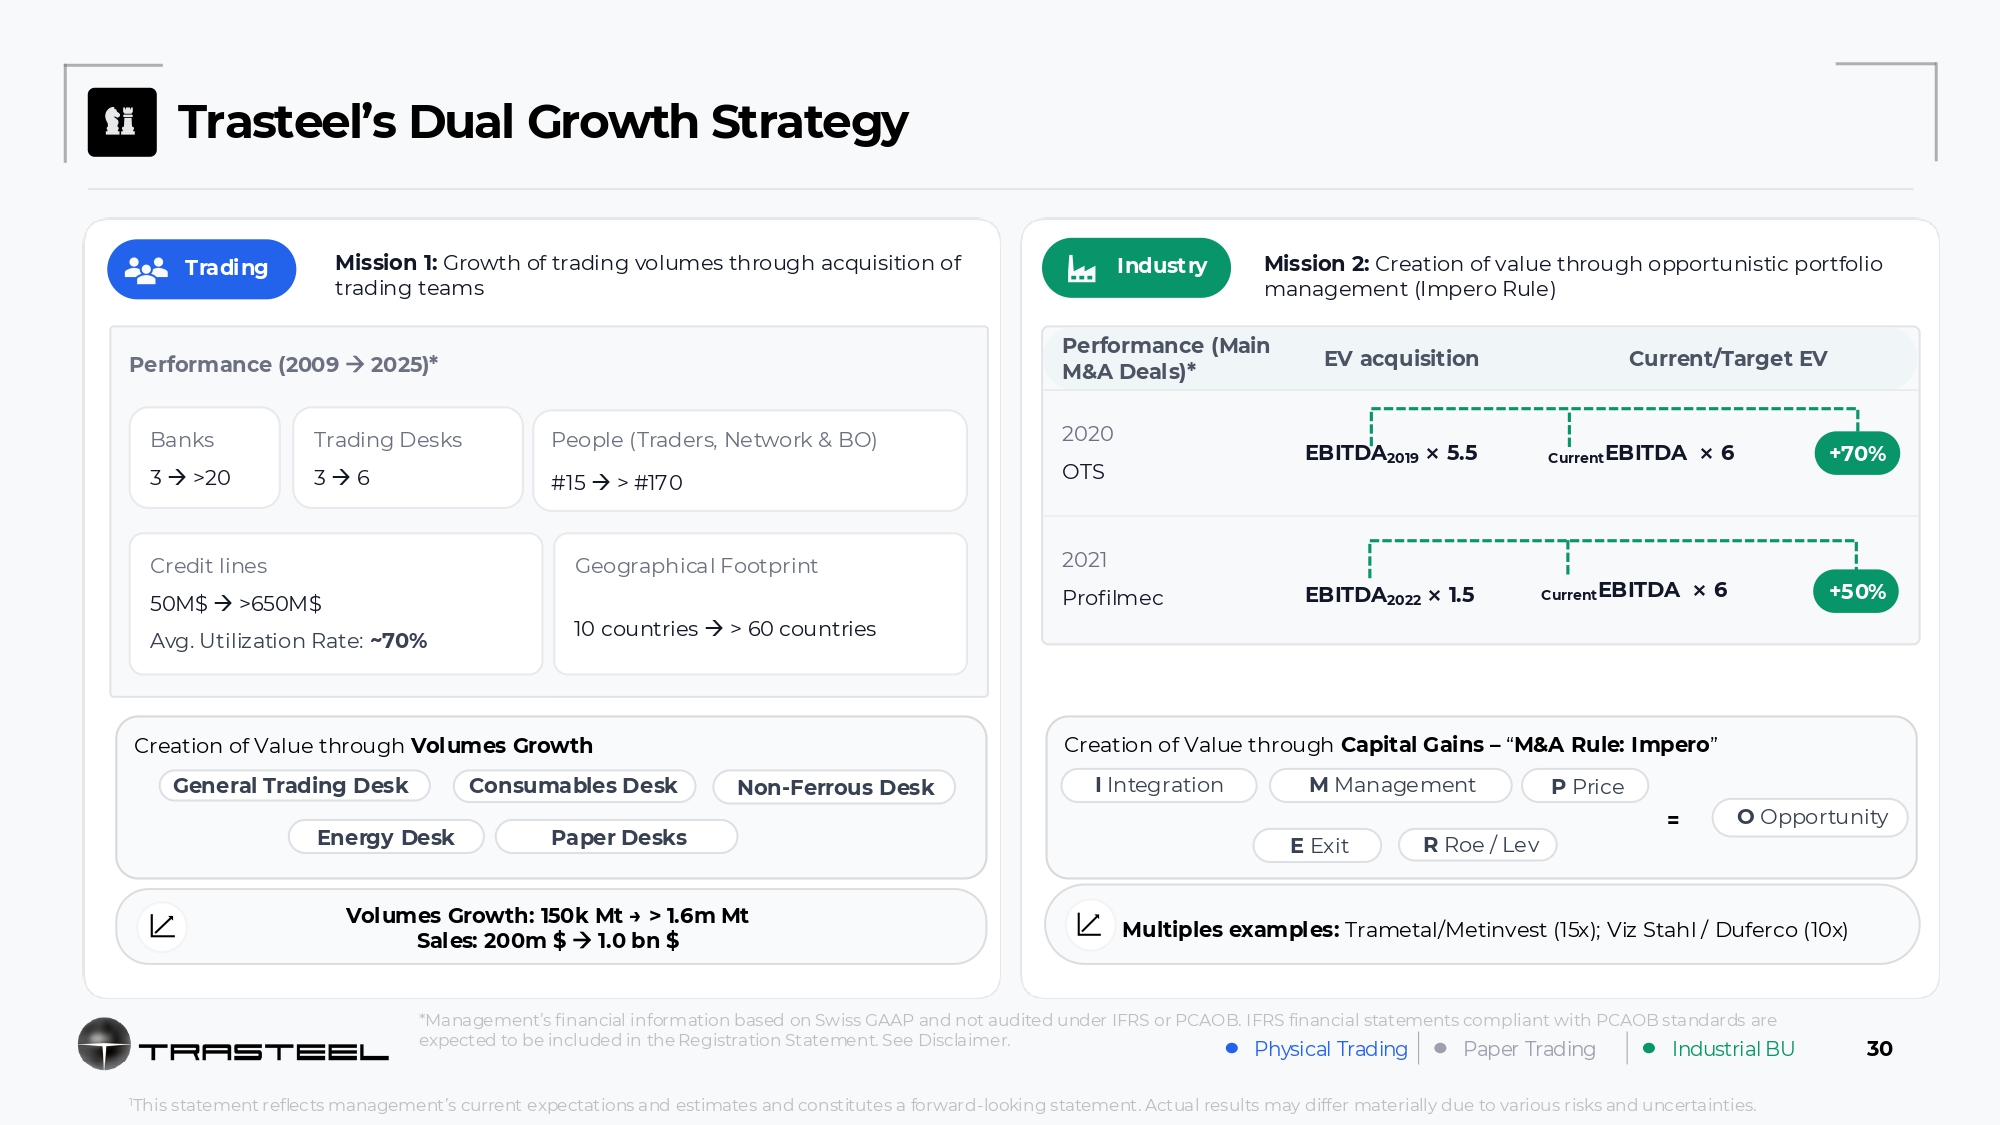
Trasteel’s Dual Growth Strategy Trading Mission 1: Growth of trading volumes through acquisition of trading teams Industry Mission 2: Creation of value through opportunistic portfolio management (Impero Rule) Performance (2009 2025)* Banks 3 >20 Trading Desks 3 6 People (Traders, Network & BO) #15 > #170 Credit lines 50M$ >650M$ Avg. Utilization Rate: ~70% Geographical Footprint Current/Target EV EV acquisition Performance (Main M&A Deals)* +70% Current EBITDA • 6 EBITDA 2019 • 5.5 2020 OTS +50% Current EBITDA • 6 EBITDA 2022 • 1.5 2021 Profilmec 10 countries > 60 countries Creation of Value through Volumes Growth General Trading Desk Consumables Desk Energy Desk Paper Desks Non - Ferrous Desk Volumes Growth: 150k Mt → > 1.6m Mt Sales: 200m $ 1.0 bn $ Multiples examples: Trametal/Metinvest (15x); Viz Stahl / Duferco (10x) Creation of Value through Capital Gains – “ M&A Rule: Impero ” I Integration M Management P Price = O Opportunity E Exit R Roe / Lev *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. Physical Trading Paper Trading Industrial BU 30 1 This statement reflects management’s current expectations and estimates and constitutes a forward - looking statement. Actual results may differ materially due to various risks and uncertainties.
Util Industries S.p.A. Via Papa Giovanni XXIII, 10 Villanova d’Asti (AT), Italy
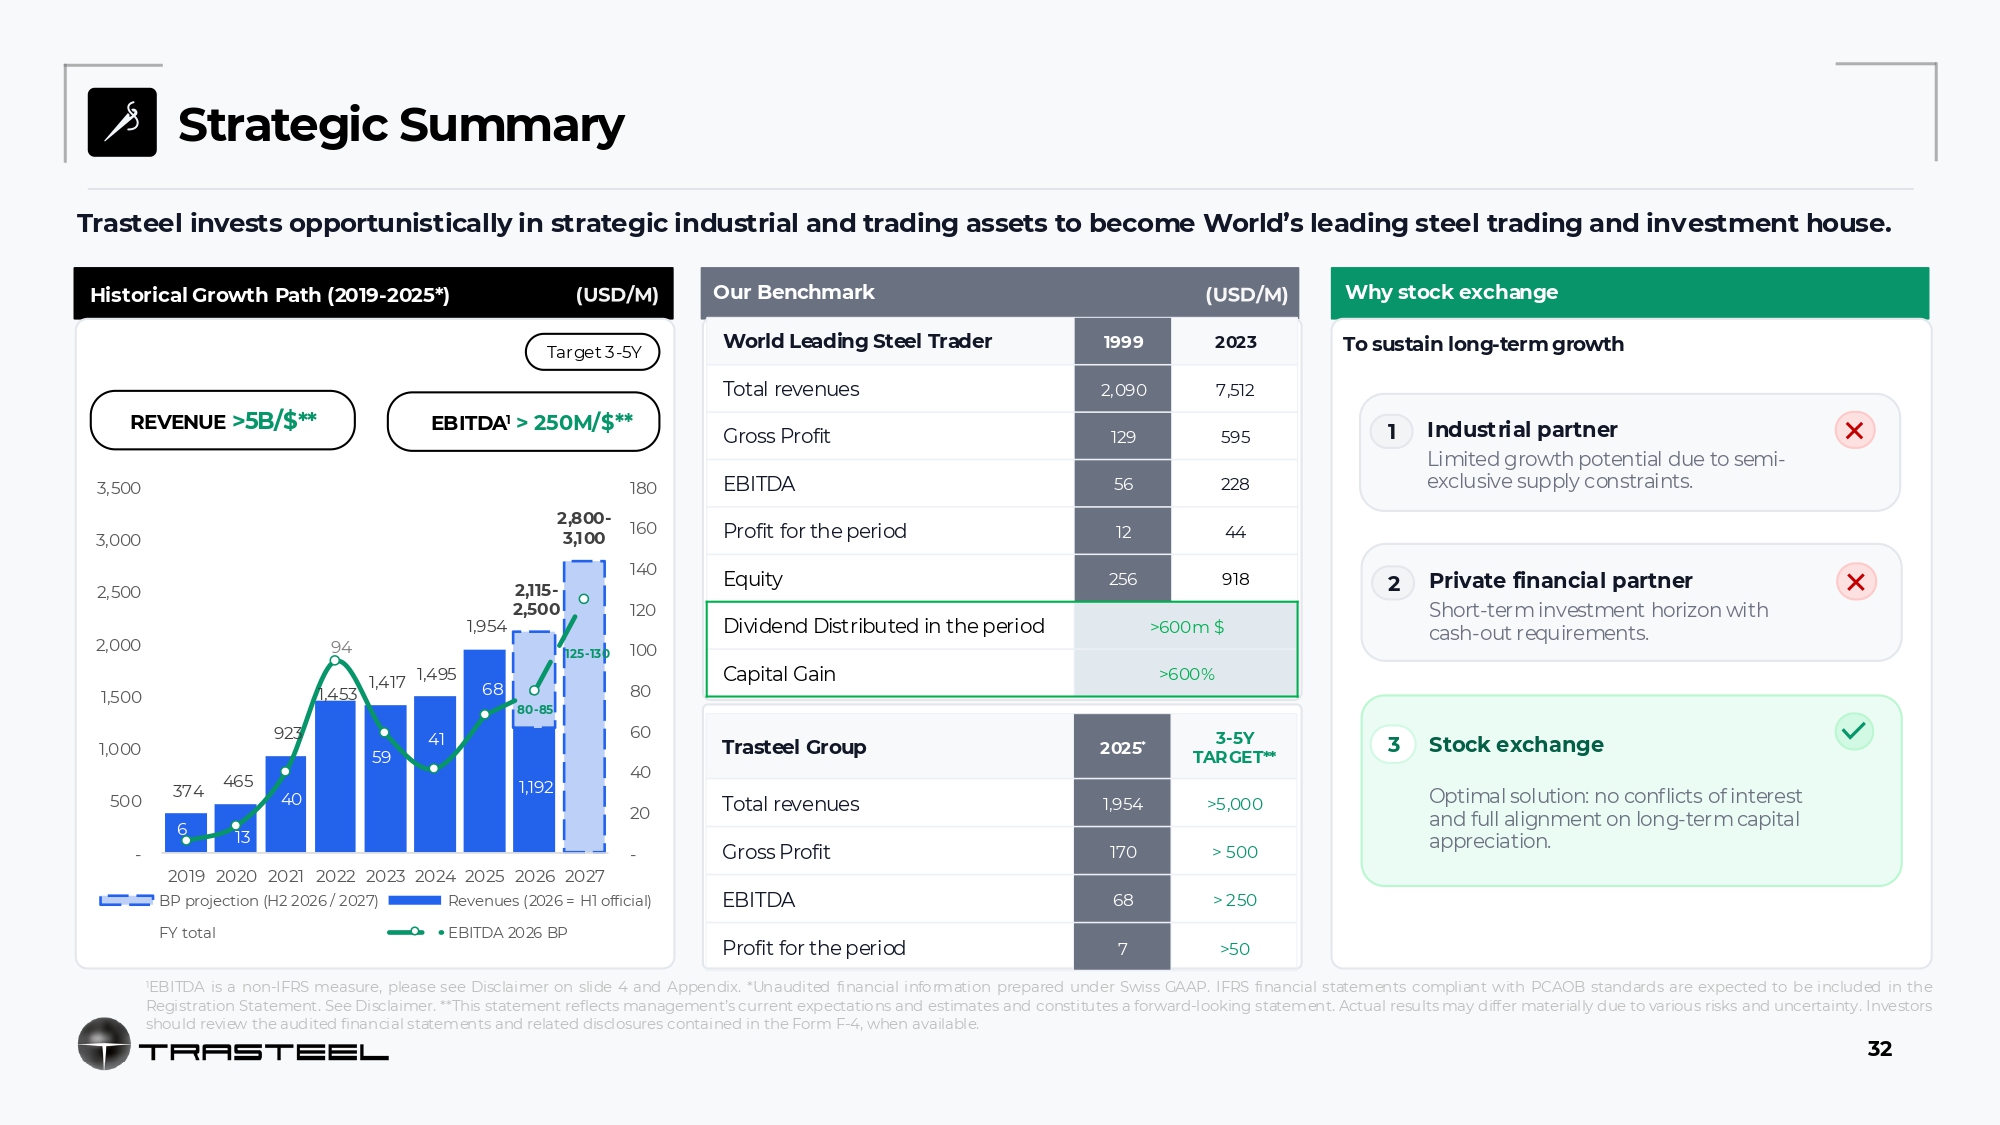
Strategic Summary Trasteel invests opportunistically in strategic industrial and trading assets to become World’s leading steel trading and investment house. Historical Growth Path (2019 - 2025*) Target 3 - 5Y EBITDA 1 > 250M/$** Why stock exchange Our Benchmark 2023 1999 World Leading Steel Trader 7,512 2,090 Total revenues 595 129 Gross Profit 228 56 EBITDA 44 12 Profit for the period 918 256 Equity >600m $ Dividend Distributed in the period >600% Capital Gain Trasteel Group 2025 * TA 3 - 5Y ** RGET Total revenues 1,954 >5,000 Gross Profit 170 > 500 EBITDA 68 > 250 Profit for the period 7 >50 To sustain long - term growth REVENUE >5B/$** 1 Industrial partner Limited growth potential due to semi - exclusive supply constraints. 3,500 180 2,800 - 3,100 160 3,000 140 2,500 2,115 - 2,500 2 Private financial partner Short - term investment horizon with cash - out requirements. 120 1,954 2,000 94 125 - 13 0 100 1,417 1,495 1,500 1,453 68 80 80 - 85 923 41 1,192 60 1,000 3 Stock exchange 59 374 465 40 500 40 20 6 13 Optimal solution : no conflicts of interest and full alignment on long - term capital appreciation . - - 2019 2020 2021 2022 2023 2024 2025 2026 2027 BP projection (H2 2026 / 2027) FY total Revenues (2026 = H1 official) EBITDA 2026 BP 1 EBITDA is a non - IFRS measure, please see Disclaimer on slide 4 and Appendix . *Unaudited financial information prepared under Swiss GAAP . IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement . See Disclaimer . **This statement reflects management’s current expectations and estimates and constitutes a forward - looking statement . Actual results may differ materially due to various risks and uncertainty . Investors should review the audited financial statements and related disclosures contained in the Form F - 4 , when available . 32
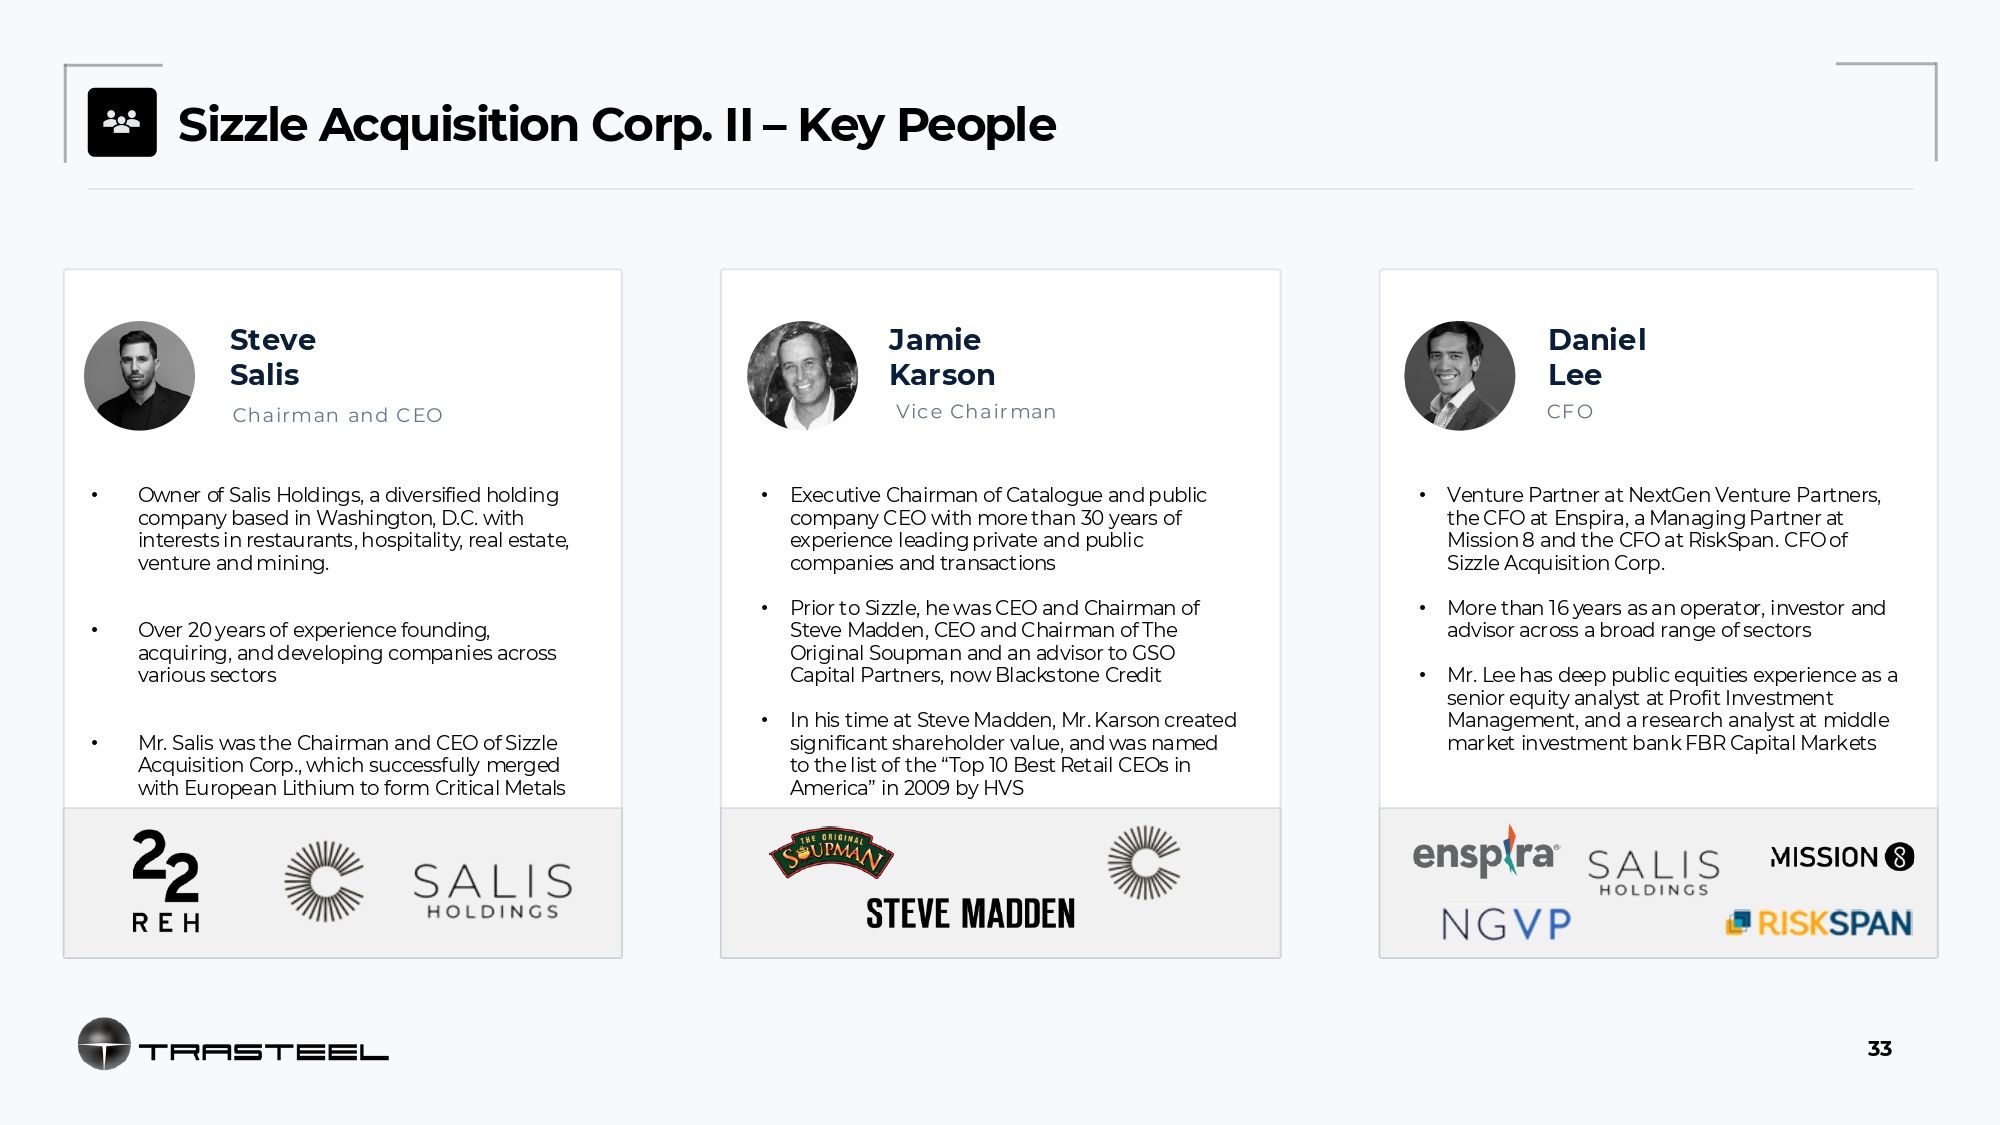
Sizzle Acquisition Corp. II – Key People Steve Salis • Owner of Salis Holdings, a diversified holding company based in Washington, D.C. with interests in restaurants, hospitality, real estate, venture and mining. • Over 20 years of experience founding, acquiring, and developing companies across various sectors • Mr . Salis was the Chairman and CEO of Sizzle Acquisition Corp . , which successfully merged with European Lithium to form Critical Metals Jamie Karson • Executive Chairman of Catalogue and public company CEO with more than 30 years of experience leading private and public companies and transactions • Prior to Sizzle, he was CEO and Chairman of Steve Madden, CEO and Chairman of The Original Soupman and an advisor to GSO Capital Partners, now Blackstone Credit • In his time at Steve Madden, Mr. Karson created significant shareholder value, and was named to the list of the “Top 10 Best Retail CEOs in America” in 2009 by HVS Daniel Lee • Venture Partner at NextGen Venture Partners, the CFO at Enspira, a Managing Partner at Mission 8 and the CFO at RiskSpan. CFO of Sizzle Acquisition Corp. • More than 16 years as an operator, investor and advisor across a broad range of sectors • Mr. Lee has deep public equities experience as a senior equity analyst at Profit Investment Management, and a research analyst at middle market investment bank FBR Capital Markets 33
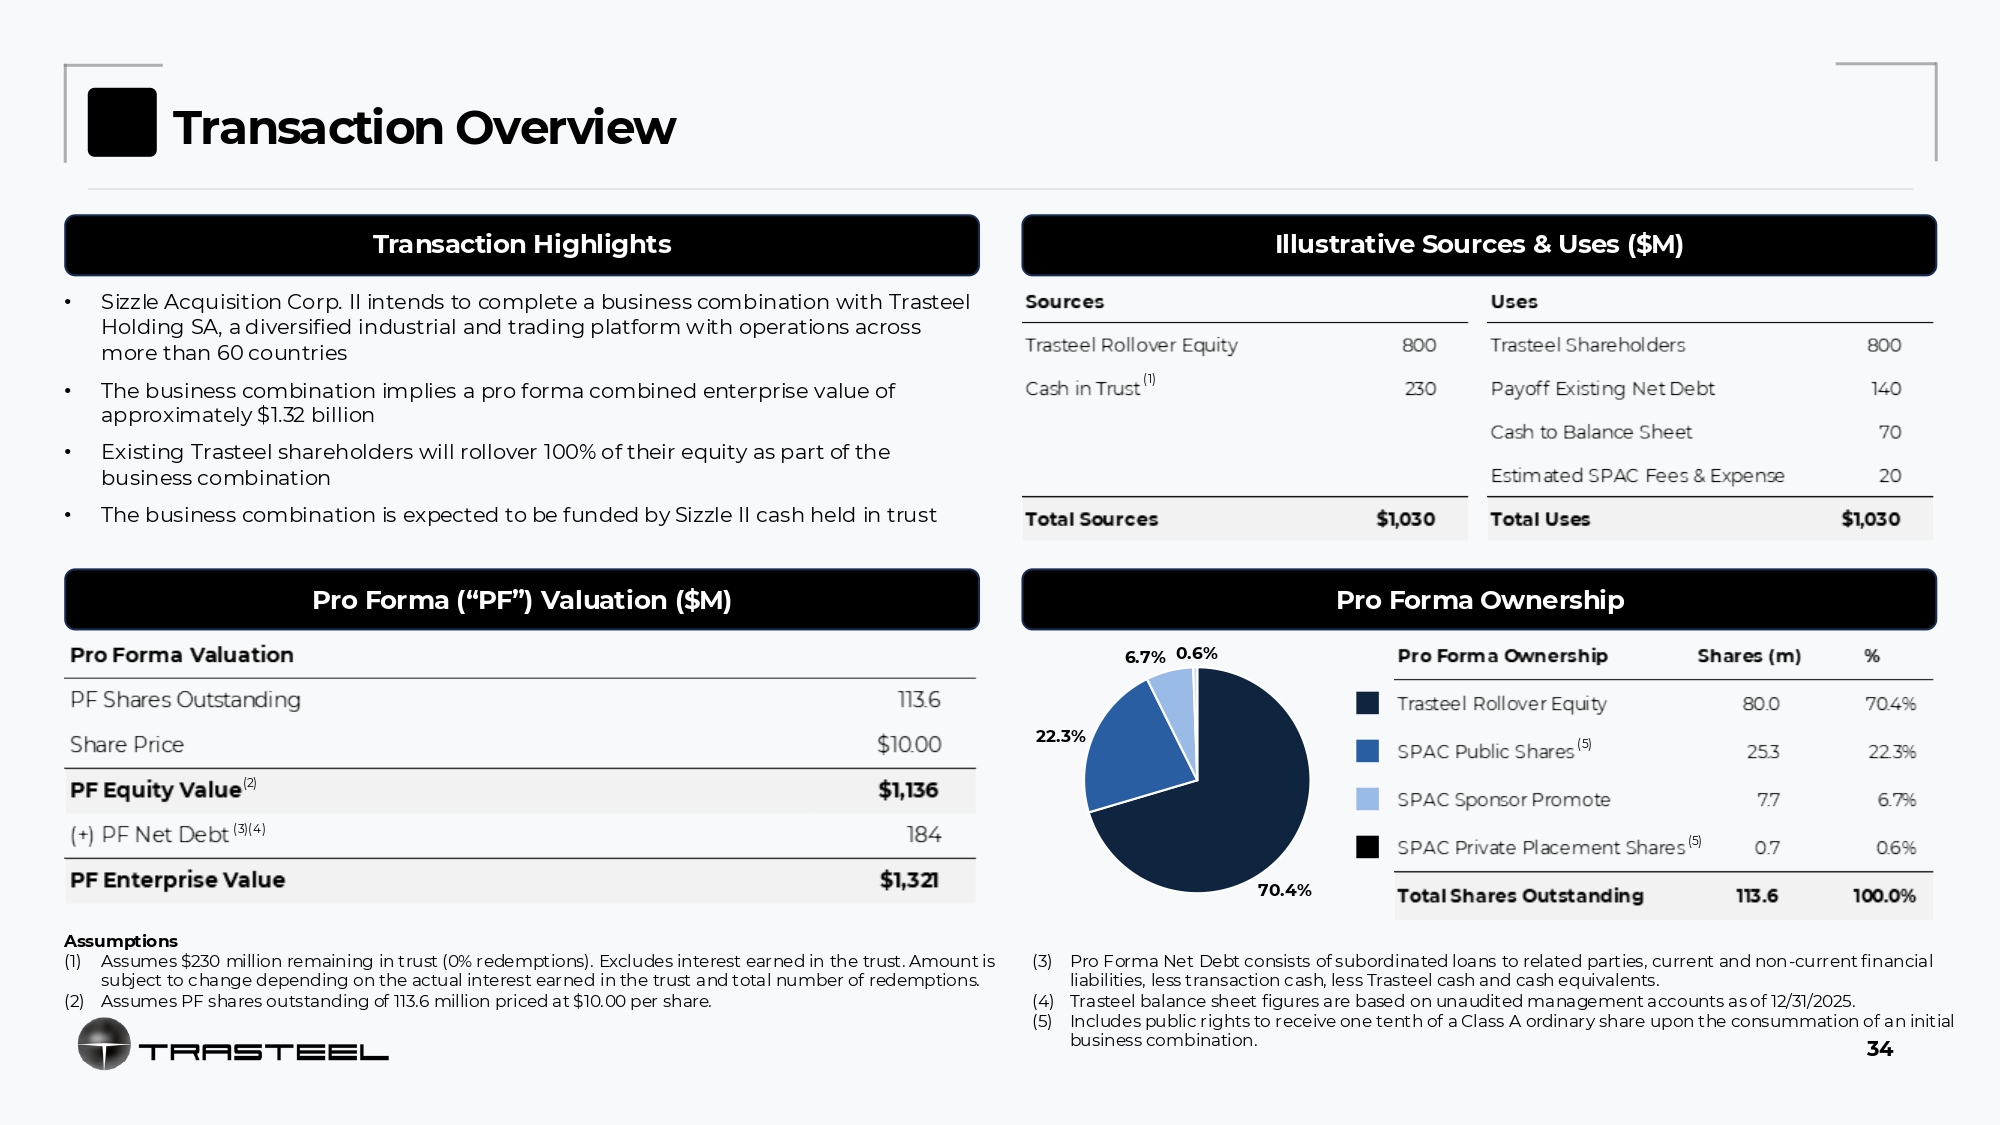
Transaction Overview Transaction Highlights Illustrative Sources & Uses ($M) • Sizzle Acquisition Corp. II intends to complete a business combination with Trasteel Holding SA, a diversified industrial and trading platform with operations across more than 60 countries • The business combination implies a pro forma combined enterprise value of approximately $1.32 billion • Existing Trasteel shareholders will rollover 100% of their equity as part of the business combination • The business combination is expected to be funded by Sizzle II cash held in trust (1) Pro Forma (“PF”) Valuation ($M) Pro Forma Ownership 6.7% 0.6% 22.3% (5) (2) (3)(4) (5) 70.4% Assumptions (1) Assumes $230 million remaining in trust (0% redemptions). Excludes interest earned in the trust. Amount is subject to change depending on the actual interest earned in the trust and total number of redemptions. (2) Assumes PF shares outstanding of 113.6 million priced at $10.00 per share. (3) Pro Forma Net Debt consists of subordinated loans to related parties, current and non - current financial liabilities, less transaction cash, less Trasteel cash and cash equivalents. (4) Trasteel balance sheet figures are based on unaudited management accounts as of 12/31/2025. (5) Includes public rights to receive one tenth of a Class A ordinary share upon the consummation of an initial business combination. 34
People Behind Steel Join us.
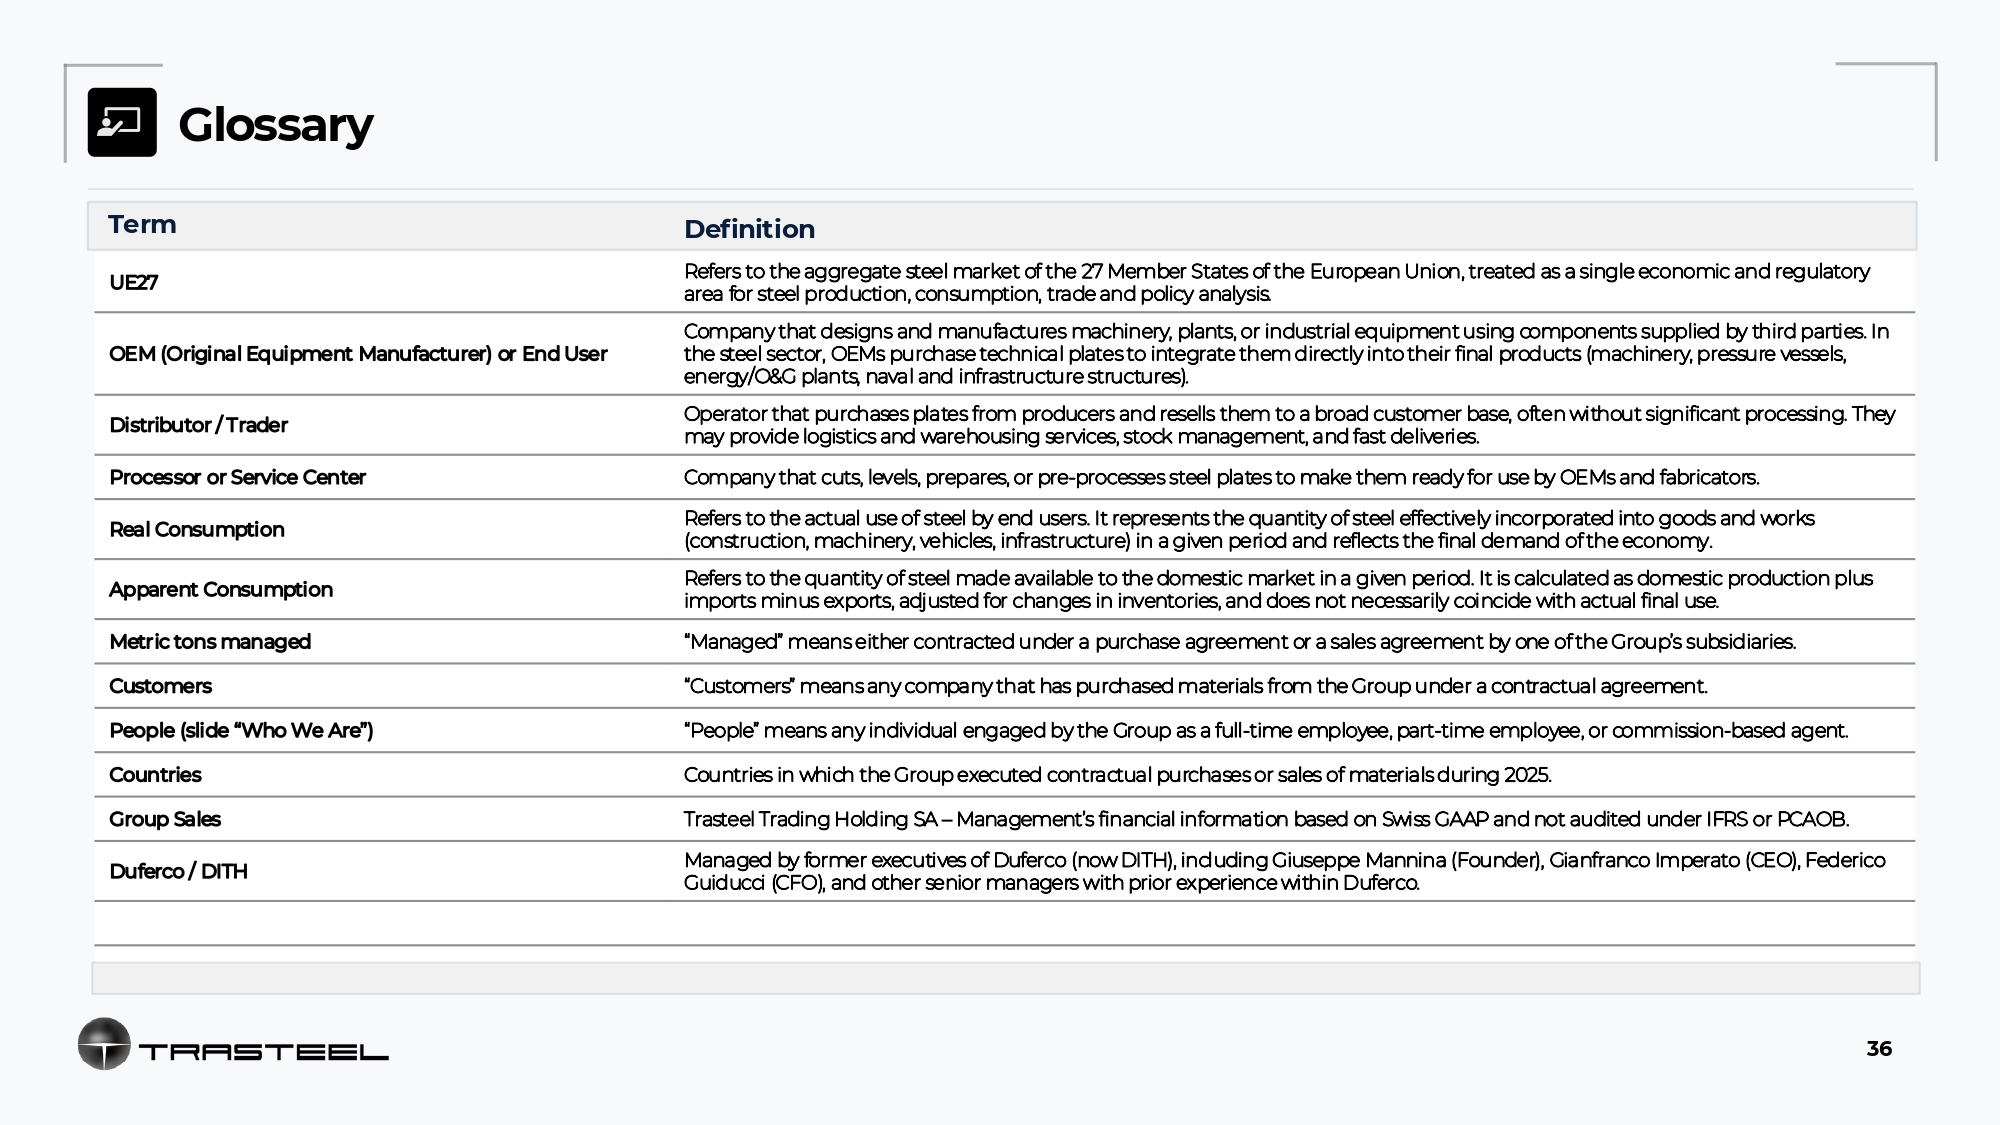
Glossary Term Definition 36
Risk Factors ( 1/3 ) All references to “we,” “us” or “our” refer to Trasteel Holding S . A . (“Company”) prior to the consummation of a potential transaction with a special purpose acquisition company (“SPAC”) . The risks described below are a non - exhaustive list of the key risks related to Company and the factors that could cause actual results to differ from the intentions and assumptions described in this Presentation . This list has been prepared solely for potential investors in this private placement transaction and not for any other purpose . You should carefully consider these risks and uncertainties, carry out your own due diligence, and consult with your own financial and legal advisors concerning the risks and suitability of an investment in this private placement transaction before making an investment decision . The list below is qualified in its entirety by disclosures contained in future documents filed or furnished with the Securities and Exchange Commission in respect of a potential transaction . The risks presented in such filings would include risks associated with the post - transaction operation of Company and the risks associated with the potential transaction, and these risks may differ significantly from, and will be more extensive than, those risks presented below . Company may be subject to the following factors, many of which are outside of Company’s control : Risks Related to Company’s Business and Industry We face risks related to the effect of economic uncertainty, and in the event of an economic downturn or slow recovery, our growth prospects, results of operations, cash flows and financial condition could be adversely impacted. Significant increases in, or sustained levels of, inflation may adversely affect our costs. Inflationary pressures have, and may continue to, impact the costs of steel products, raw materials, labor, energy, fuel, transportation and other inputs necessary for the trading and processing of steel products by our partners and customers, and our financial condition and customer demand may be adversely impacted. We operate in a highly competitive marketplace, and competition, including from large integrated steel producers and other independent trading houses, could negatively impact our business. We are impacted by global steel price cycles, and a sustained period of low steel prices or significant price volatility would materially adversely affect our sales, results of operations, cash flow, and financial condition. Unexpected or unfavorable changes in global steel supply and demand dynamics could have a materially adverse effect on our sales, results of operations, cash flow and financial condition. We increasingly depend on our industrial business unit, and our failure to successfully manage and integrate acquired industrial assets could have an adverse effect on our growth strategy and our sales, results of operations, cash flow, and financial condition. We may experience cyberattacks and data breaches and any failure to adequately maintain security and prevent unauthorized access to electronic and other confidential information could result in additional data breaches that could materially adversely affect our reputation, financial condition and operating results. Damage to the reputation of the Trasteel brand could adversely affect our sales. 37
Risk Factors ( 2/3 ) Our business and results of operations may be materially adversely affected by serious disruptions or catastrophic events, including public health issues, trade disputes, sanctions, weather, and geopolitical instability, including the ongoing conflict involving Israel and Hamas and joint U . S . /Israeli campaign in Iran and the potential disruption of key shipping routes, including the Strait of Hormuz, Suez Canal and Bab al - Mandab Strait . Military or other conflicts in the Middle East and Southwest Asia may lead to : Increased transportation and insurance costs – freight and insurance costs may increase significantly as a result of conflict - related disruptions to major trade routes; Delays in shipment and delivery – operational delays may occur for cargo transiting affected regions, which could impact the timing of revenues and customer commitments; Increased transformation costs – cost increases may apply to certain business units, which may or may not be fully transferable to customers; Increased volume and price volatility – publicly traded securities and commodity markets may experience heightened volatility as a result of geopolitical tensions; and Broader economic disruption – sustained conflict may result in expanded regional or global military operations, prolonged sanctions, and supply chain disruptions that could materially adversely affect our business, financial condition, and results of operations. The extent and duration of any such conflict and its impact on global trade routes may not be predicted and could be substantial. Risks Related to the Company Operating as a Public Company Prior to the potential de - SPAC transaction, there will have been no public market for Trasteel's shares, and there is no guarantee that an active and liquid market will develop. The market price of Trasteel’s ordinary shares could fluctuate significantly, which could result in substantial losses for purchasers of Trasteel’s ordinary shares. A significant portion of Trasteel's total outstanding shares following the closing of a potential transaction might not be immediately resold but could be sold into the market soon after such closing. This could cause the market price of Trasteel’s ordinary shares to drop significantly, even if Trasteel's business is doing well. If securities or industry analysts do not publish research or publish inaccurate or unfavorable research about Trasteel's business, the market price for Trasteel’s ordinary shares and trading volume could decline. Trasteel would incur increased costs as a result of operating as a public company, and its management would be required to devote substantial time to new compliance initiatives and corporate governance practices. Trasteel does not anticipate paying dividends and, as a result, your ability to achieve a return on capital of your investment may depend on appreciation in the price of Trasteel’s ordinary shares. Trasteel would have broad discretion over the use of cash balances it would receive as a result of the de - SPAC transaction and may not apply such balances in ways that increase the value of your investment. Members of Trasteel's management team have limited experience managing a public company, which may result in difficulty adequately operating and growing our business. 38
Risk Factors ( 3/3 ) Risks Related to a Potential Transaction Each of Trasteel and Sizzle Acquisition Corp. II would incur significant transaction costs in connection with the de - SPAC transaction. The consummation of the de - SPAC transaction would be subject to a number of conditions, and if those conditions are not satisfied or waived, the associated business combination agreement would be terminated and the potential transaction might not be completed. Sizzle Acquisition Corp. II could waive one or more of the conditions to the de - SPAC transaction, resulting in the consummation of the transaction notwithstanding divergence from assumptions on which the transaction is initially evaluated and approved. The ability to successfully effect the de - SPAC transaction and Trasteel's ability to successfully operate the business thereafter will be largely dependent upon the efforts of certain key personnel. The loss of such key personnel could negatively impact Trasteel's operations and financial results. There can be no assurance that Trasteel’s ordinary shares will be approved for listing on a stock exchange or that Trasteel will be able to comply with the continued listing standards of a stock exchange. Legal proceedings in connection with a potential transaction, the outcomes of which would be uncertain, could delay or prevent the completion of a potential transaction. The future grant and exercise of registration rights could adversely affect the market price of Trasteel’s ordinary shares following the consummation of the de - SPAC transaction. Significant redemptions by Sizzle Acquisition Corp. II's public shareholders could require Trasteel to raise future financing following the consummation of the de - SPAC transaction and reduce the public float of Trasteel’s ordinary shares. If Sizzle Acquisition Corp. II's due diligence investigation of Trasteel's business was inadequate and material risks are not uncovered, Trasteel’s shareholders following the consummation of the de - SPAC transaction could lose some or all of their investment. During the pre - closing period, Trasteel and Sizzle Acquisition Corp. II could be prohibited from entering into certain transactions that might otherwise be beneficial to Trasteel, Sizzle Acquisition Corp. II or their respective stakeholders. 39
Appendix
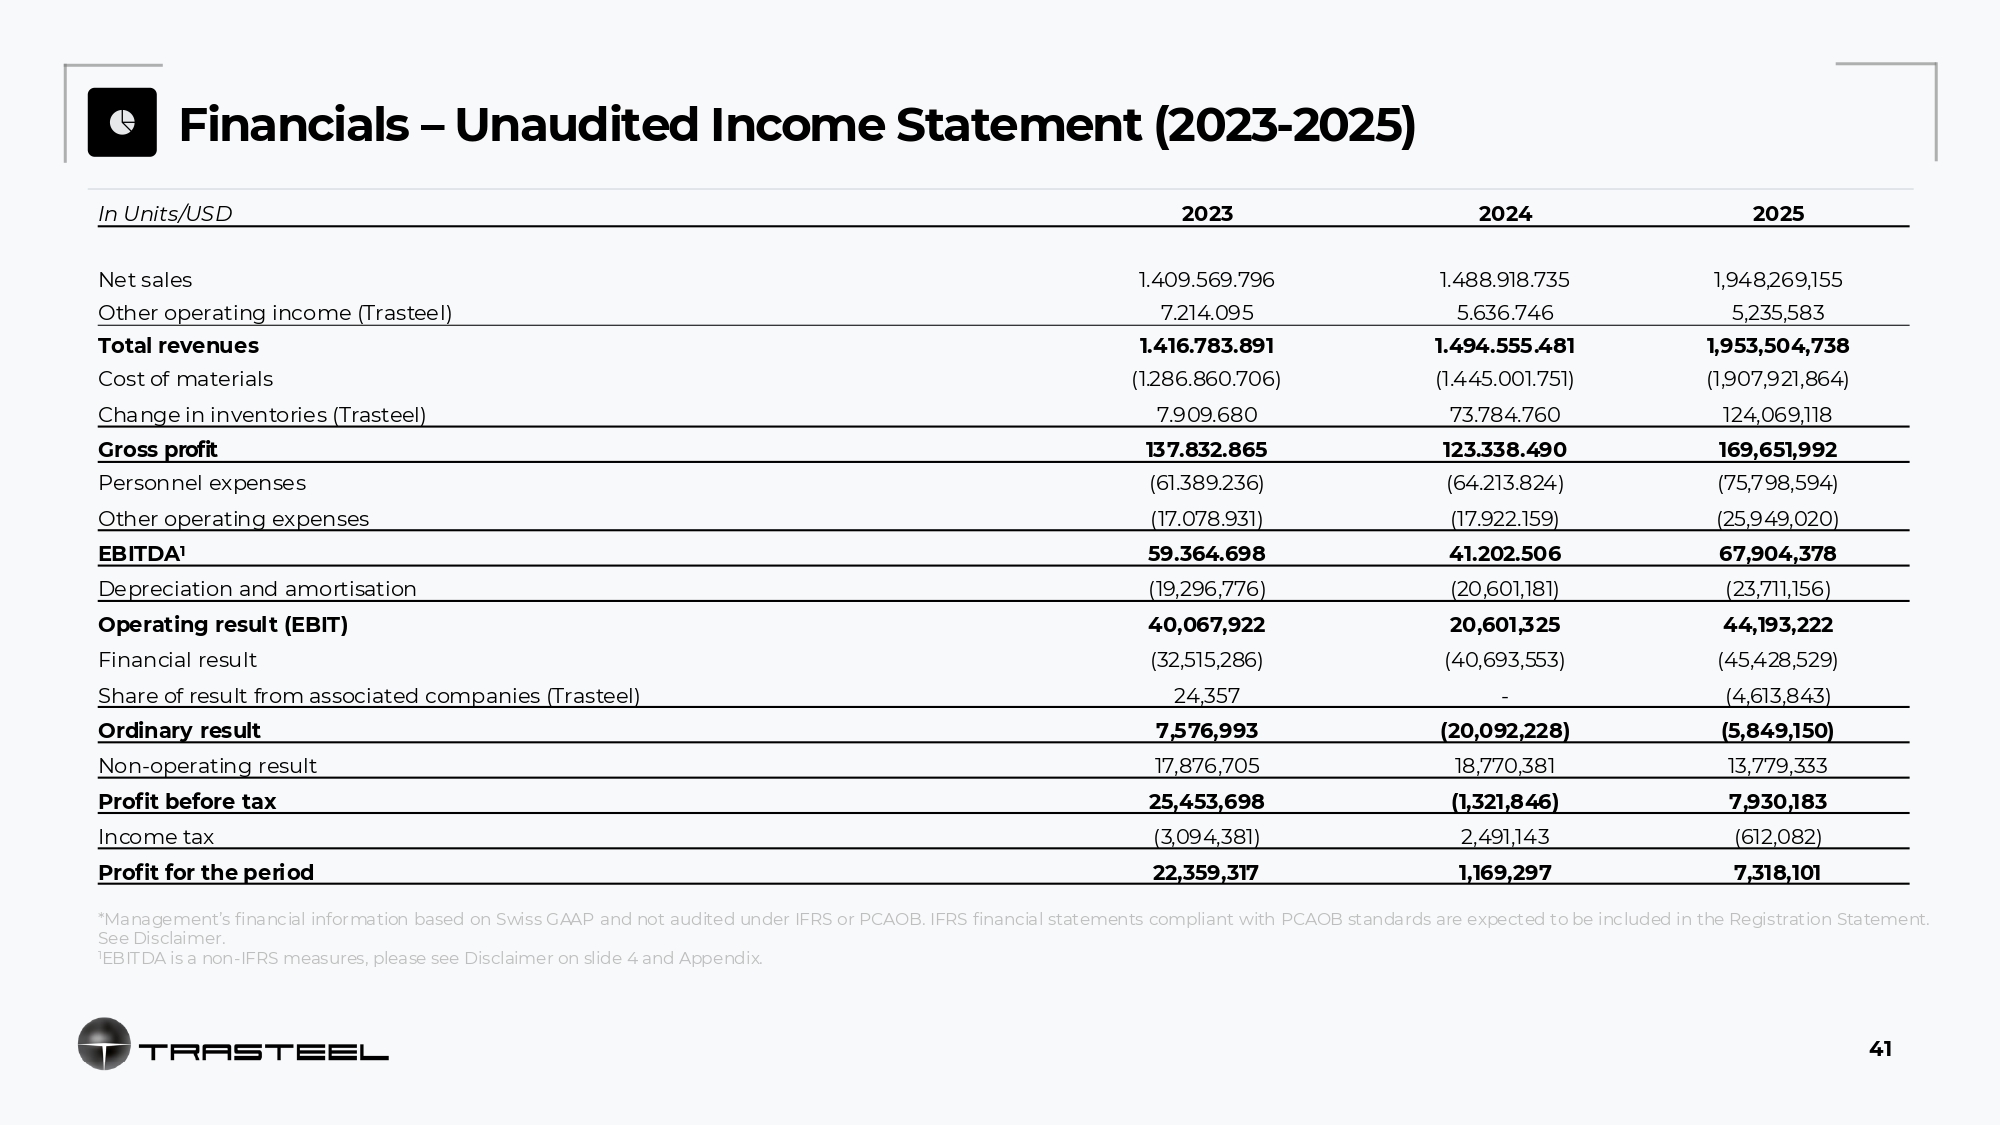
Financials – Unaudited Income Statement (2023 - 2025) 2025 2024 2023 In Units/USD 1,948,269,155 1.488.918.735 1.409.569.796 Net sales 5,235,583 5.636.746 7.214.095 Other operating income (Trasteel) 1,953,504,738 1.494.555.481 1.416.783.891 Total revenues (1,907,921,864) (1.445.001.751) (1.286.860.706) Cost of materials 124,069,118 73.784.760 7.909.680 Change in inventories (Trasteel) 169,651,992 123.338.490 137.832.865 Gross profit (75,798,594) (64.213.824) (61.389.236) Personnel expenses (25,949,020) (17.922.159) (17.078.931) Other operating expenses 67,904,378 41.202.506 59.364.698 EBITDA 1 (23,711,156) (20,601,181) (19,296,776) Depreciation and amortisation 44,193,222 20,601,325 40,067,922 Operating result (EBIT) (45,428,529) (40,693,553) (32,515,286) Financial result (4,613,843) - 24,357 Share of result from associated companies (Trasteel) (5,849,150) (20,092,228) 7,576,993 Ordinary result 13,779,333 18,770,381 17,876,705 Non - operating result 7,930,183 (1,321,846) 25,453,698 Profit before tax (612,082) 2,491,143 (3,094,381) Income tax 7,318,101 1,169,297 22,359,317 Profit for the period *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 1 EBITDA is a non - IFRS measures, please see Disclaimer on slide 4 and Appendix. 41
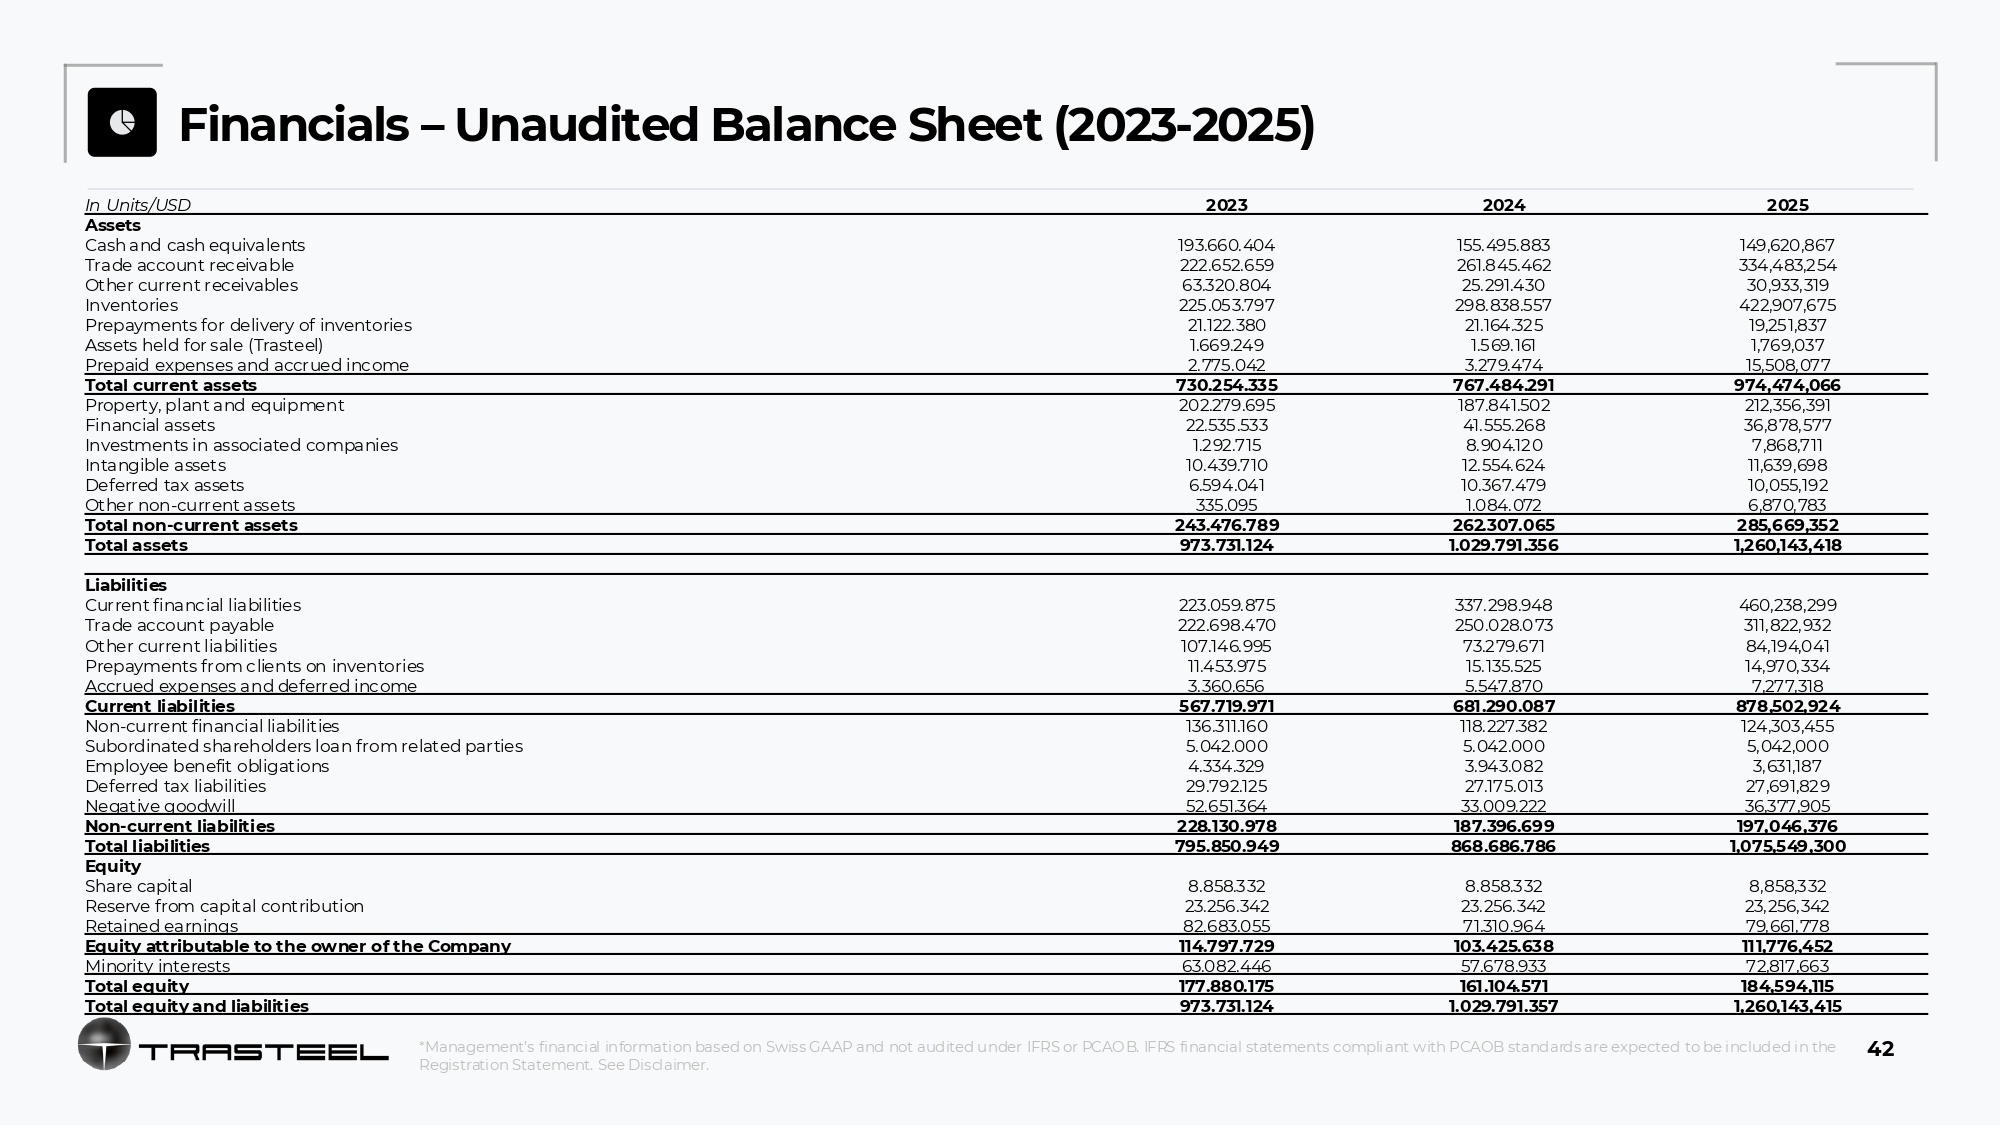
Financials – Unaudited Balance Sheet (2023 - 2025) 2025 2024 2023 In Units/USD Assets 149,620,867 155.495.883 193.660.404 Cash and cash equivalents 334,483,254 261.845.462 222.652.659 Trade account receivable 30,933,319 25.291.430 63.320.804 Other current receivables 422,907,675 298.838.557 225.053.797 Inventories 19,251,837 21.164.325 21.122.380 Prepayments for delivery of inventories 1,769,037 1.569.161 1.669.249 Assets held for sale (Trasteel) 15,508,077 3.279.474 2.775.042 Prepaid expenses and accrued income 974,474,066 767.484.291 730.254.335 Total current assets 212,356,391 187.841.502 202.279.695 Property, plant and equipment 36,878,577 41.555.268 22.535.533 Financial assets 7,868,711 8.904.120 1.292.715 Investments in associated companies 11,639,698 12.554.624 10.439.710 Intangible assets 10,055,192 10.367.479 6.594.041 Deferred tax assets 6,870,783 1.084.072 335.095 Other non - current assets 285,669,352 262.307.065 243.476.789 Total non - current assets 1,260,143,418 1.029.791.356 973.731.124 Total assets Liabilities 460,238,299 337.298.948 223.059.875 Current financial liabilities 311,822,932 250.028.073 222.698.470 Trade account payable 84,194,041 73.279.671 107.146.995 Other current liabilities 14,970,334 15.135.525 11.453.975 Prepayments from clients on inventories 7,277,318 5.547.870 3.360.656 Accrued expenses and deferred income 878,502,924 681.290.087 567.719.971 Current liabilities 124,303,455 118.227.382 136.311.160 Non - current financial liabilities 5,042,000 5.042.000 5.042.000 Subordinated shareholders loan from related parties 3,631,187 3.943.082 4.334.329 Employee benefit obligations 27,691,829 27.175.013 29.792.125 Deferred tax liabilities 36,377,905 33.009.222 52.651.364 Negative goodwill 197,046,376 187.396.699 228.130.978 Non - current liabilities 1,075,549,300 868.686.786 795.850.949 Total liabilities Equity 8,858,332 8.858.332 8.858.332 Share capital 23,256,342 23.256.342 23.256.342 Reserve from capital contribution 79,661,778 71.310.964 82.683.055 Retained earnings 111,776,452 103.425.638 114.797.729 Equity attributable to the owner of the Company 72,817,663 57.678.933 63.082.446 Minority interests 184,594,115 161.104.571 177.880.175 Total equity 1,260,143,415 1.029.791.357 973.731.124 Total equity and liabilities *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 42
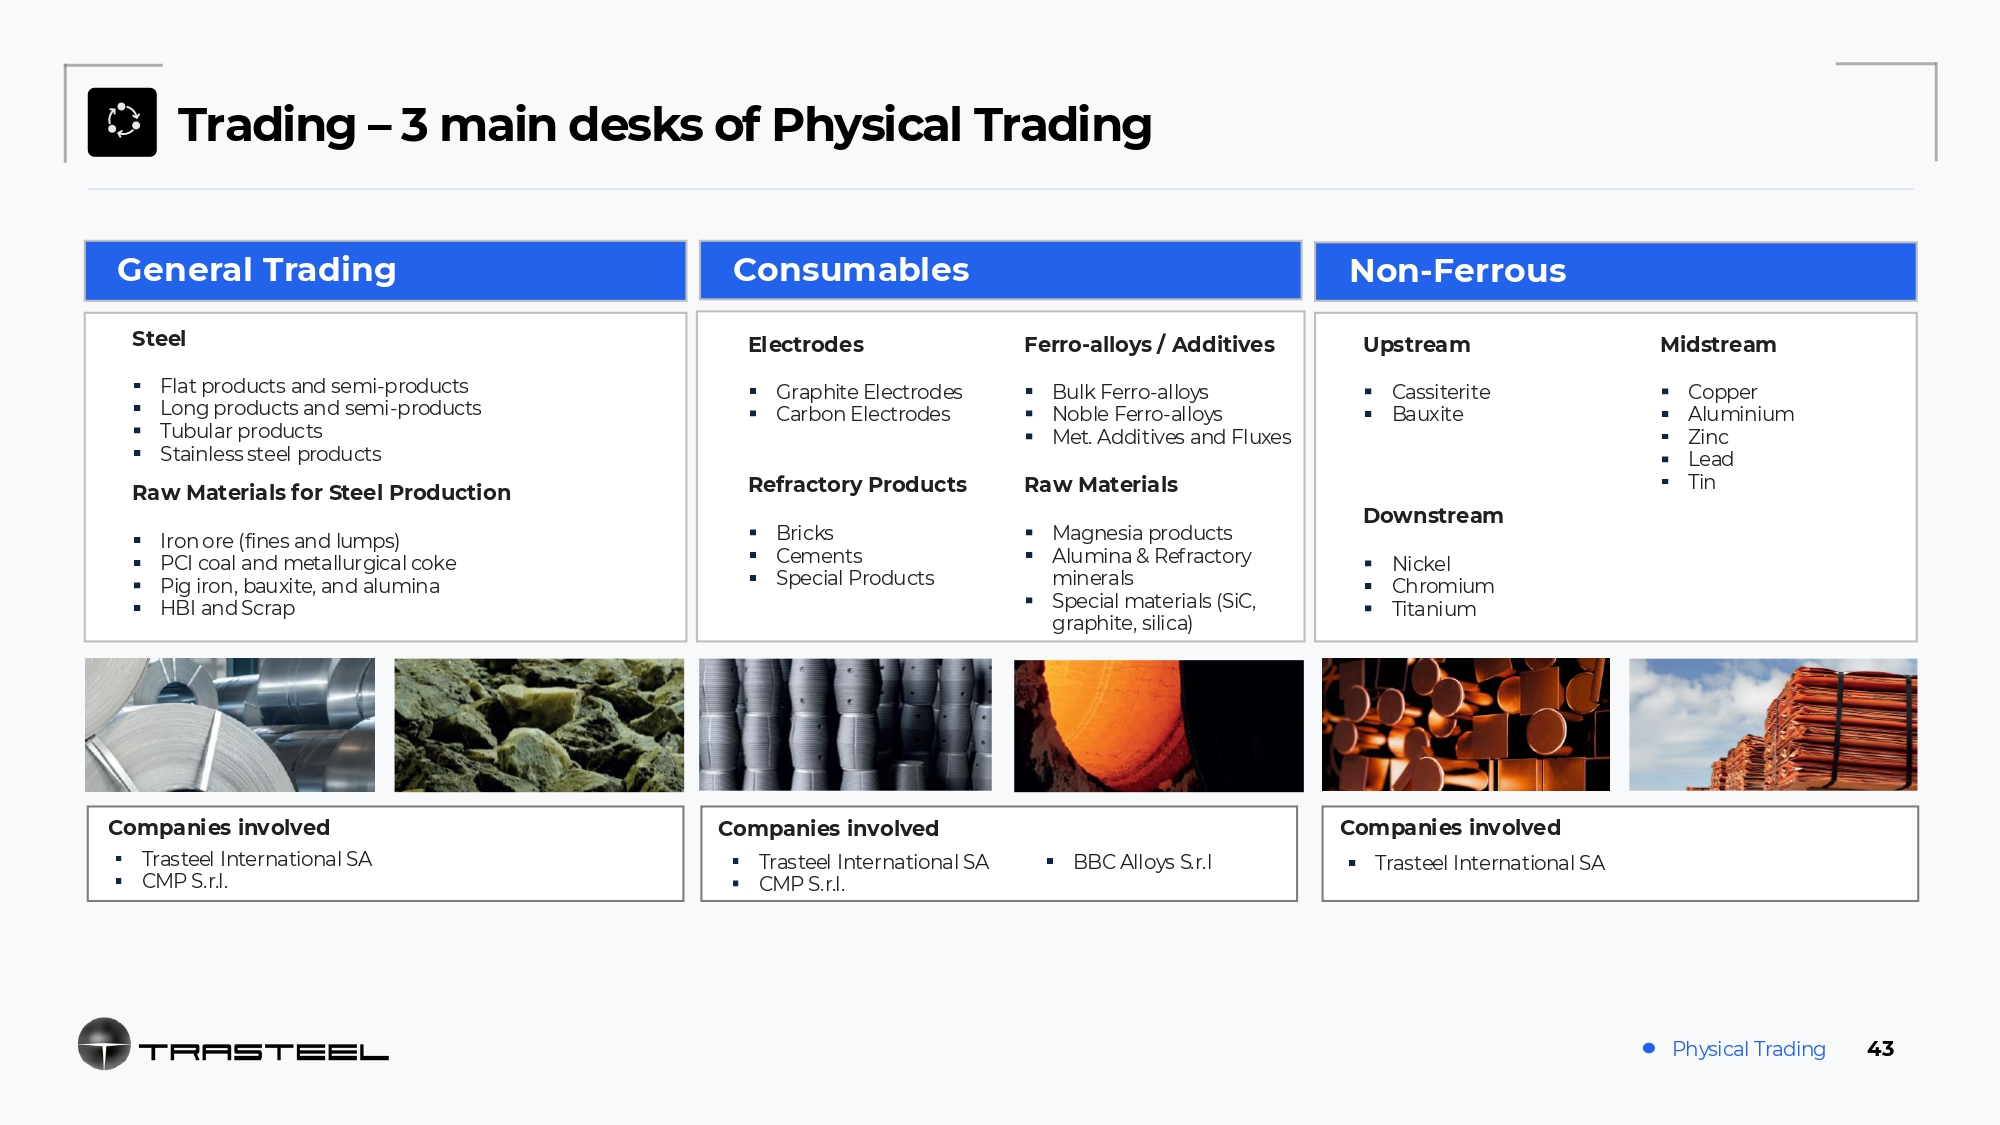
Trading – 3 main desks of Physical Trading General Trading Consumables Non - Ferrous Steel Flat products and semi - products Long products and semi - products Tubular products Stainless steel products Raw Materials for Steel Production Iron ore (fines and lumps) PCI coal and metallurgical coke Pig iron, bauxite, and alumina HBI and Scrap Ferro - alloys / Additives Bulk Ferro - alloys Noble Ferro - alloys Met. Additives and Fluxes Upstream Cassiterite Bauxite Raw Materials Electrodes Graphite Electrodes Carbon Electrodes Refractory Products Midstream Copper Aluminium Zinc Lead Tin Bricks Cements Special Products Magnesia products Alumina & Refractory minerals Special materials (SiC, graphite, silica) Downstream Nickel Chromium Titanium Companies involved Trasteel International SA CMP S.r.l. Companies involved Trasteel International SA CMP S.r.l. BBC Alloys S.r.l Companies involved Trasteel International SA Physical Trading 43
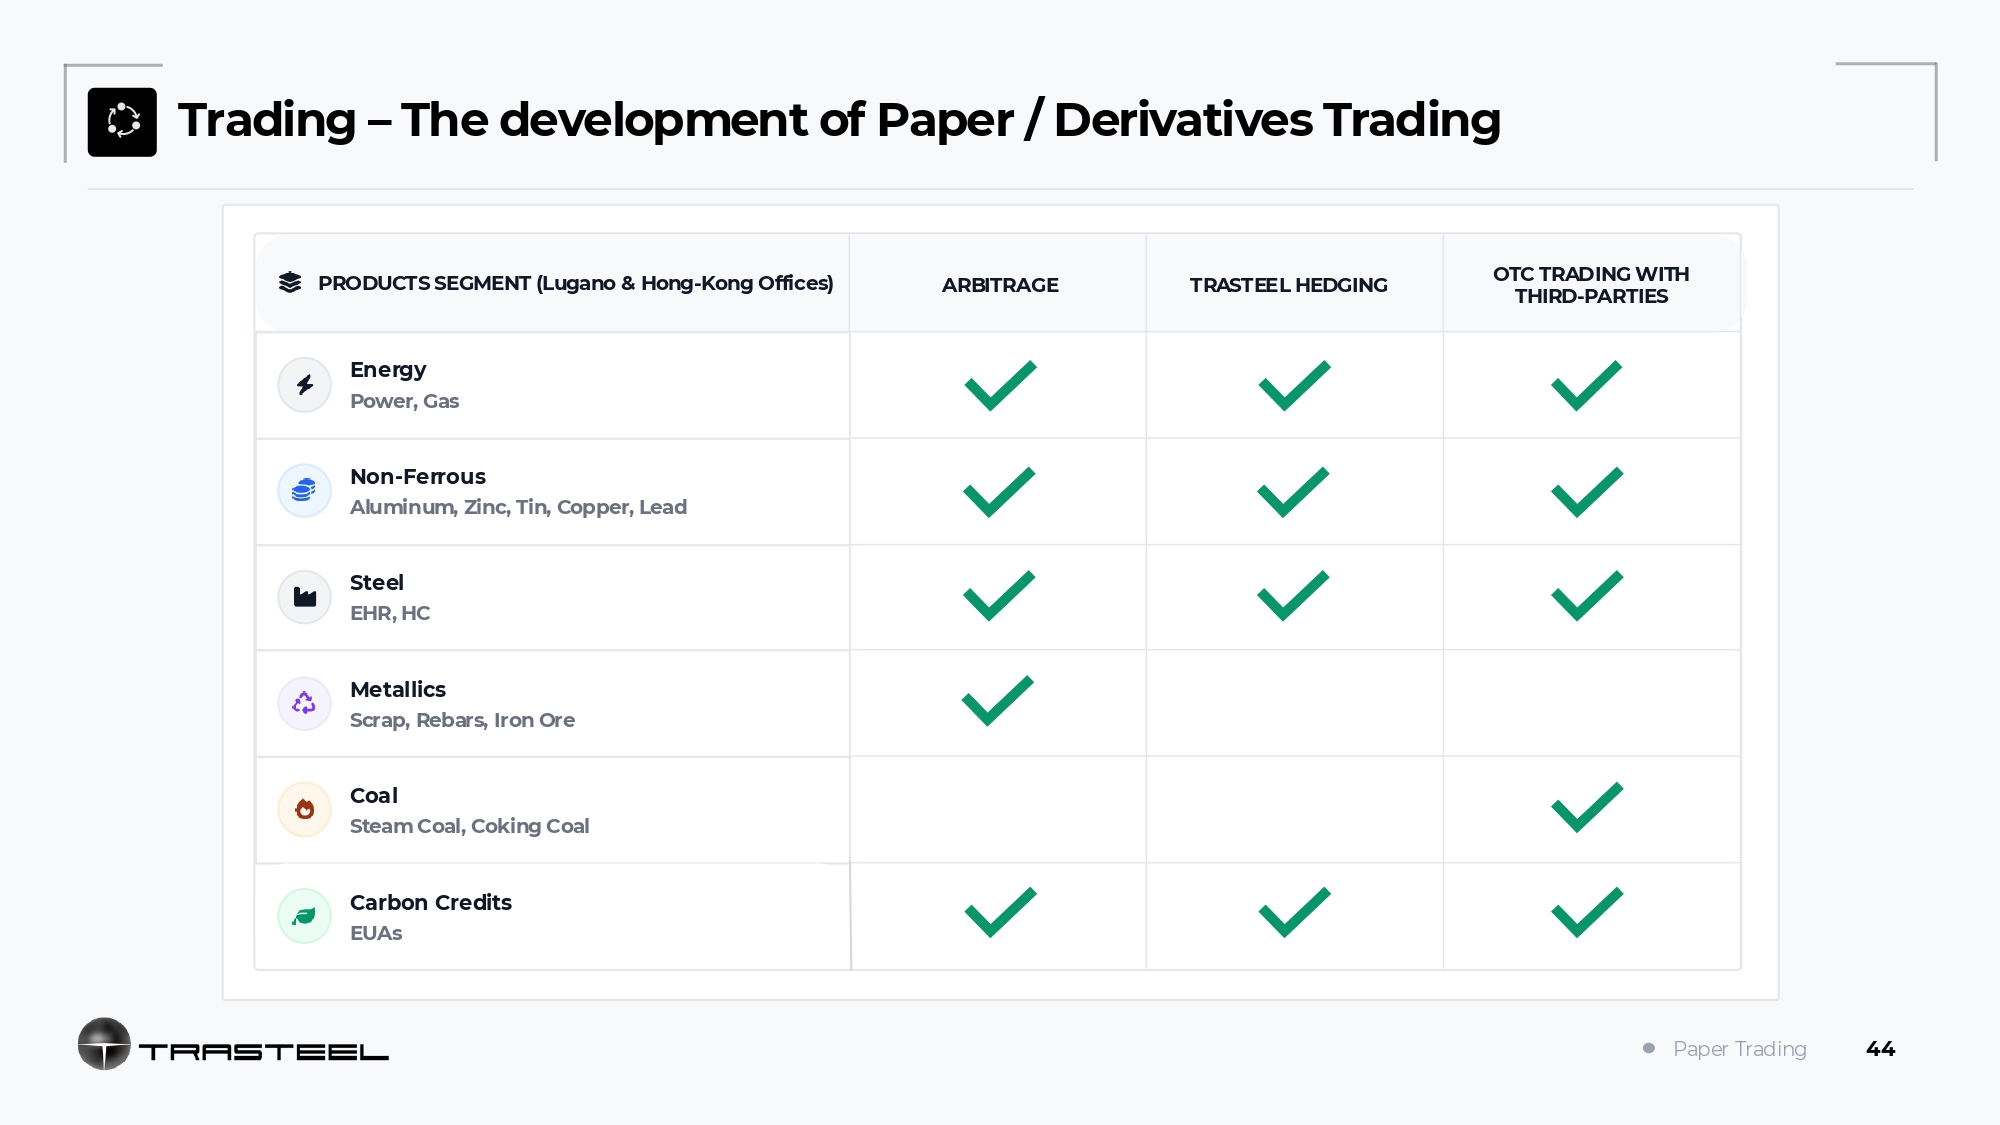
Trading – The development of Paper / Derivatives Trading OTC TRADING WITH THIRD - PARTIES TRASTEEL HEDGING ARBITRAGE PRODUCTS SEGMENT (Lugano & Hong - Kong Offices) Energy Power, Gas Non - Ferrous Aluminum, Zinc, Tin, Copper, Lead Steel EHR, HC Metallics Scrap, Rebars, Iron Ore Coal Steam Coal, Coking Coal Carbon Credits EUAs 44 Paper Trading
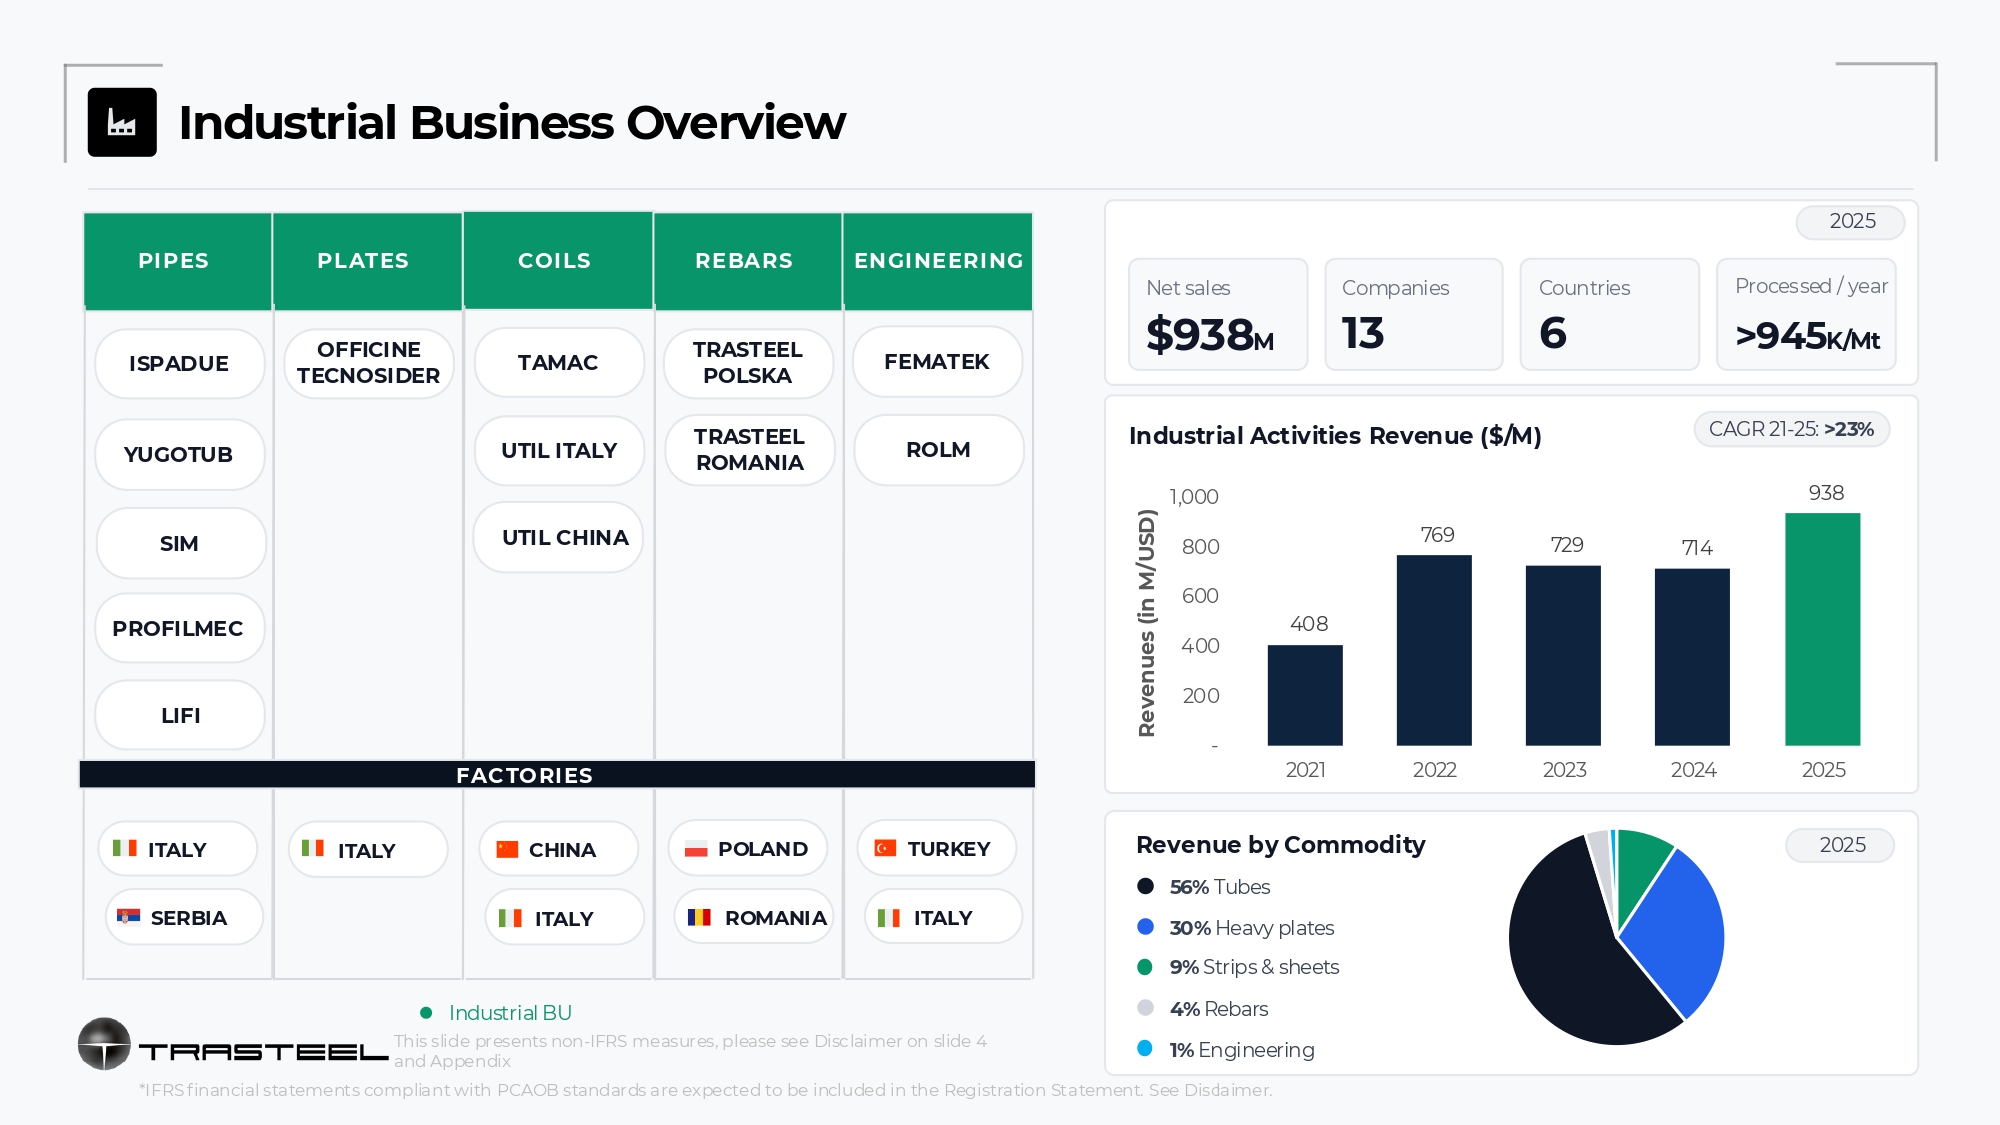
Industrial Business Overview 2025 Net sales $938 M Companies 13 Countries 6 Processed / year >945 K/Mt Industrial Activities Revenue ($/M) CAGR 21 - 25: >23% 45 Revenue by Commodity 56 % Tubes 30 % Heavy plates 9 % Strips & sheets 4 % Rebars 1 % Engineering 2025 ENGINEERING REBARS COILS PLATES PIPES FEMATEK ROLM TRASTEEL POLSKA TRASTEEL ROMANIA TAMAC UTIL ITALY UTIL CHINA OFFICINE TECNOSIDER ISPADUE YUGOTUB SIM PROFILMEC LIFI FAC TORIES TURKEY ITALY POLAND ROMANIA CHINA ITALY ITALY ITALY SERBIA 1,000 938 Revenues (in M/USD) 800 769 729 714 600 408 400 200 - 2021 2022 2023 2024 2025 Industrial BU This slide presents non - IFRS measures, please see Disclaimer on slide 4 and Appendix *IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer.
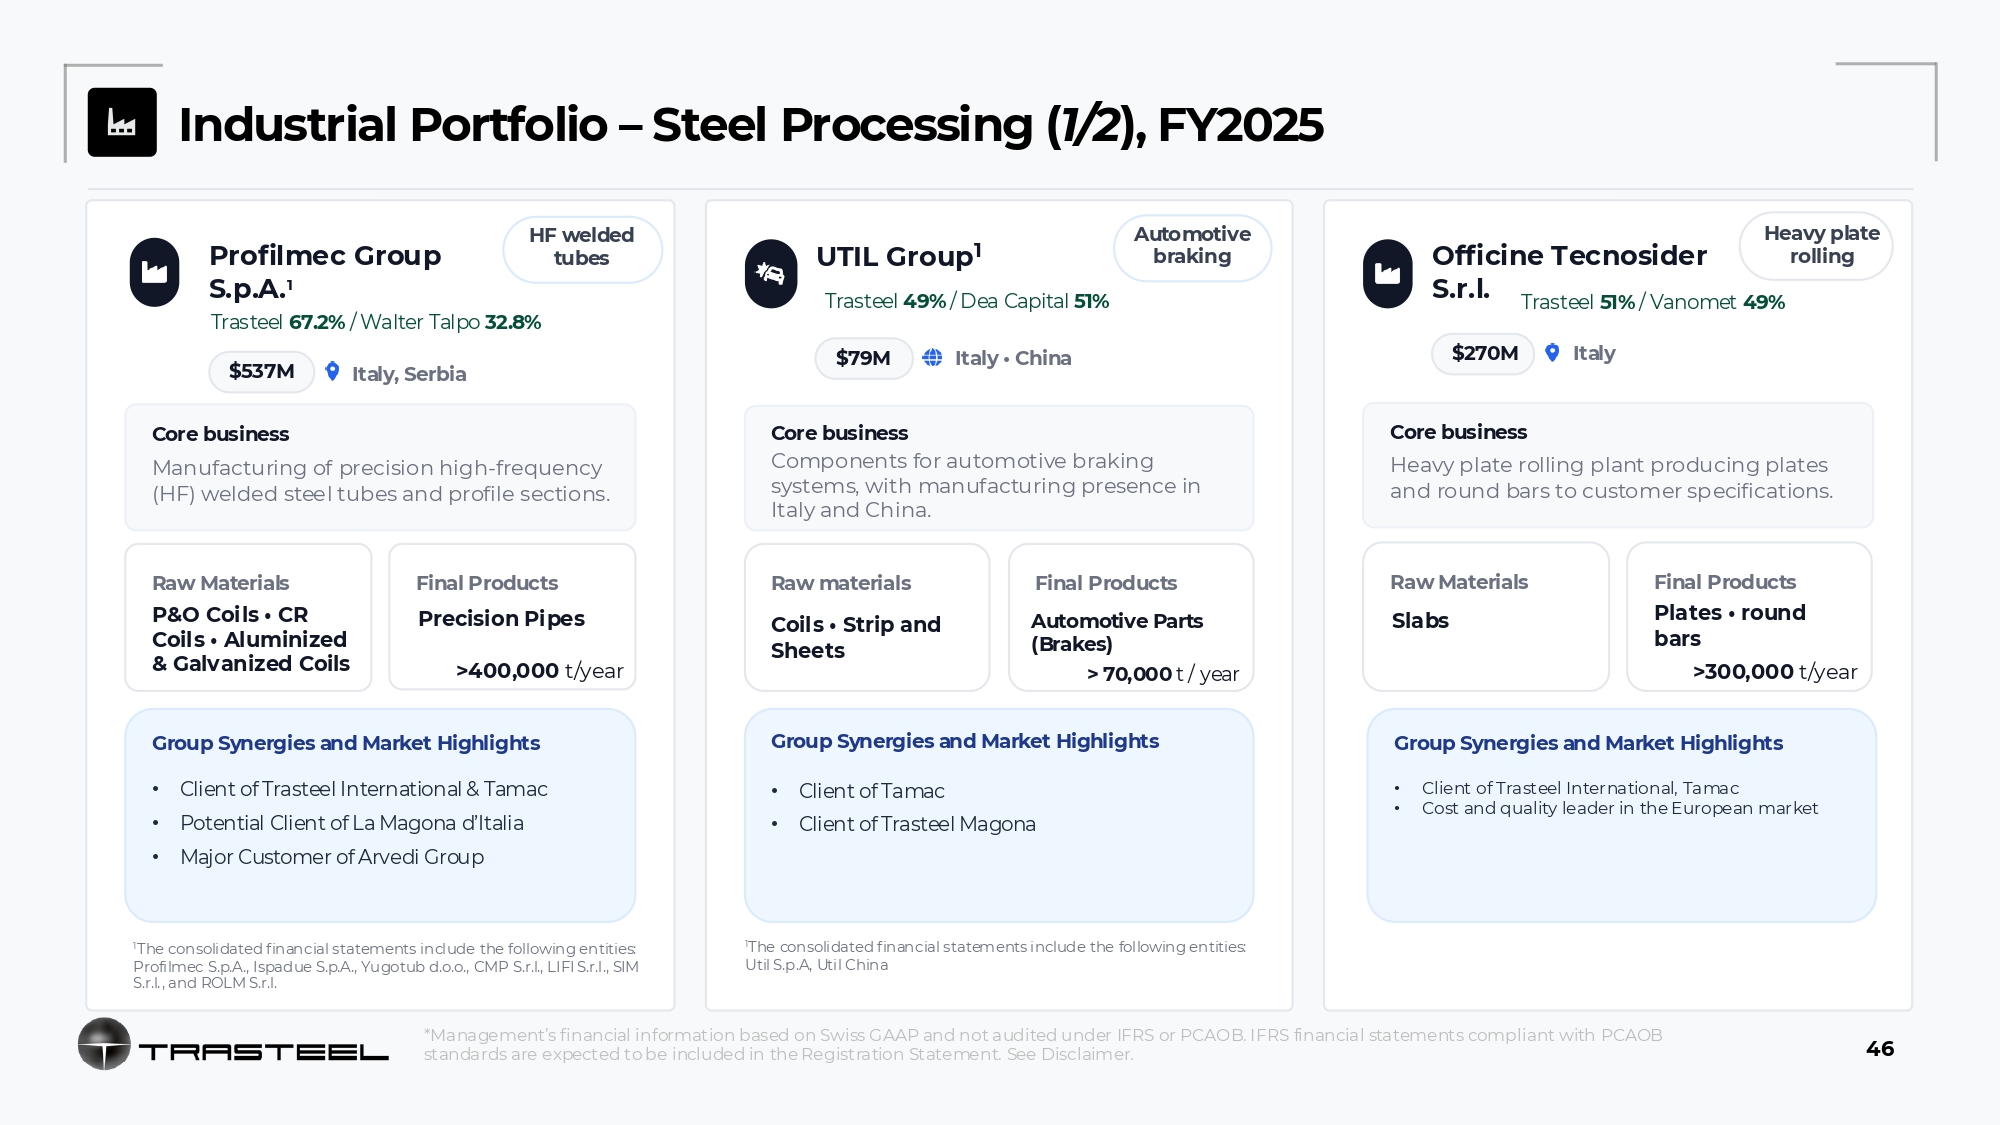
Industrial Portfolio – Steel Processing ( 1/2 ), FY2025 Profilmec Group S.p.A. 1 $537M HF welded tubes Italy, Serbia Core business Manufacturing of precision high - frequency (HF) welded steel tubes and profile sections. Raw Materials P&O Coils • CR Coils • Aluminized & Galvanized Coils >400,000 t/year Group Synergies and Market Highlights • Client of Trasteel International & Tamac • Potential Client of La Magona d’Italia • Major Customer of Arvedi Group UTIL Group 1 Automotive braking Group Synergies and Market Highlights • Client of Tamac • Client of Trasteel Magona Officine Tecnosider S.r.l. $270M Heavy plate rolling Trasteel 51% / Vanomet 49% Trasteel 67.2% / Walter Talpo 32.8% Trasteel 49% / Dea Capital 51% $79M Italy • China Italy Core business Components for automotive braking systems, with manufacturing presence in Italy and China. Core business Heavy plate rolling plant producing plates and round bars to customer specifications. Final Products Precision Pipes Raw materials Coils • Strip and Sheets Final Products Automotive Parts (Brakes) > 70,000 t / year Raw Materials Slabs Final Products Plates • round bars >300,000 t/year Group Synergies and Market Highlights • Client of Trasteel International, Tamac • Cost and quality leader in the European market 1 The consolidated financial statements include the following entities : Profilmec S . p . A . , Ispadue S . p . A . , Yugotub d . o . o . , CMP S . r . l . , LIFI S . r . l . , SIM S . r . l . , and ROLM S . r . l . 1 The consolidated financial statements include the following entities: Util S.p.A, Util China *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 46
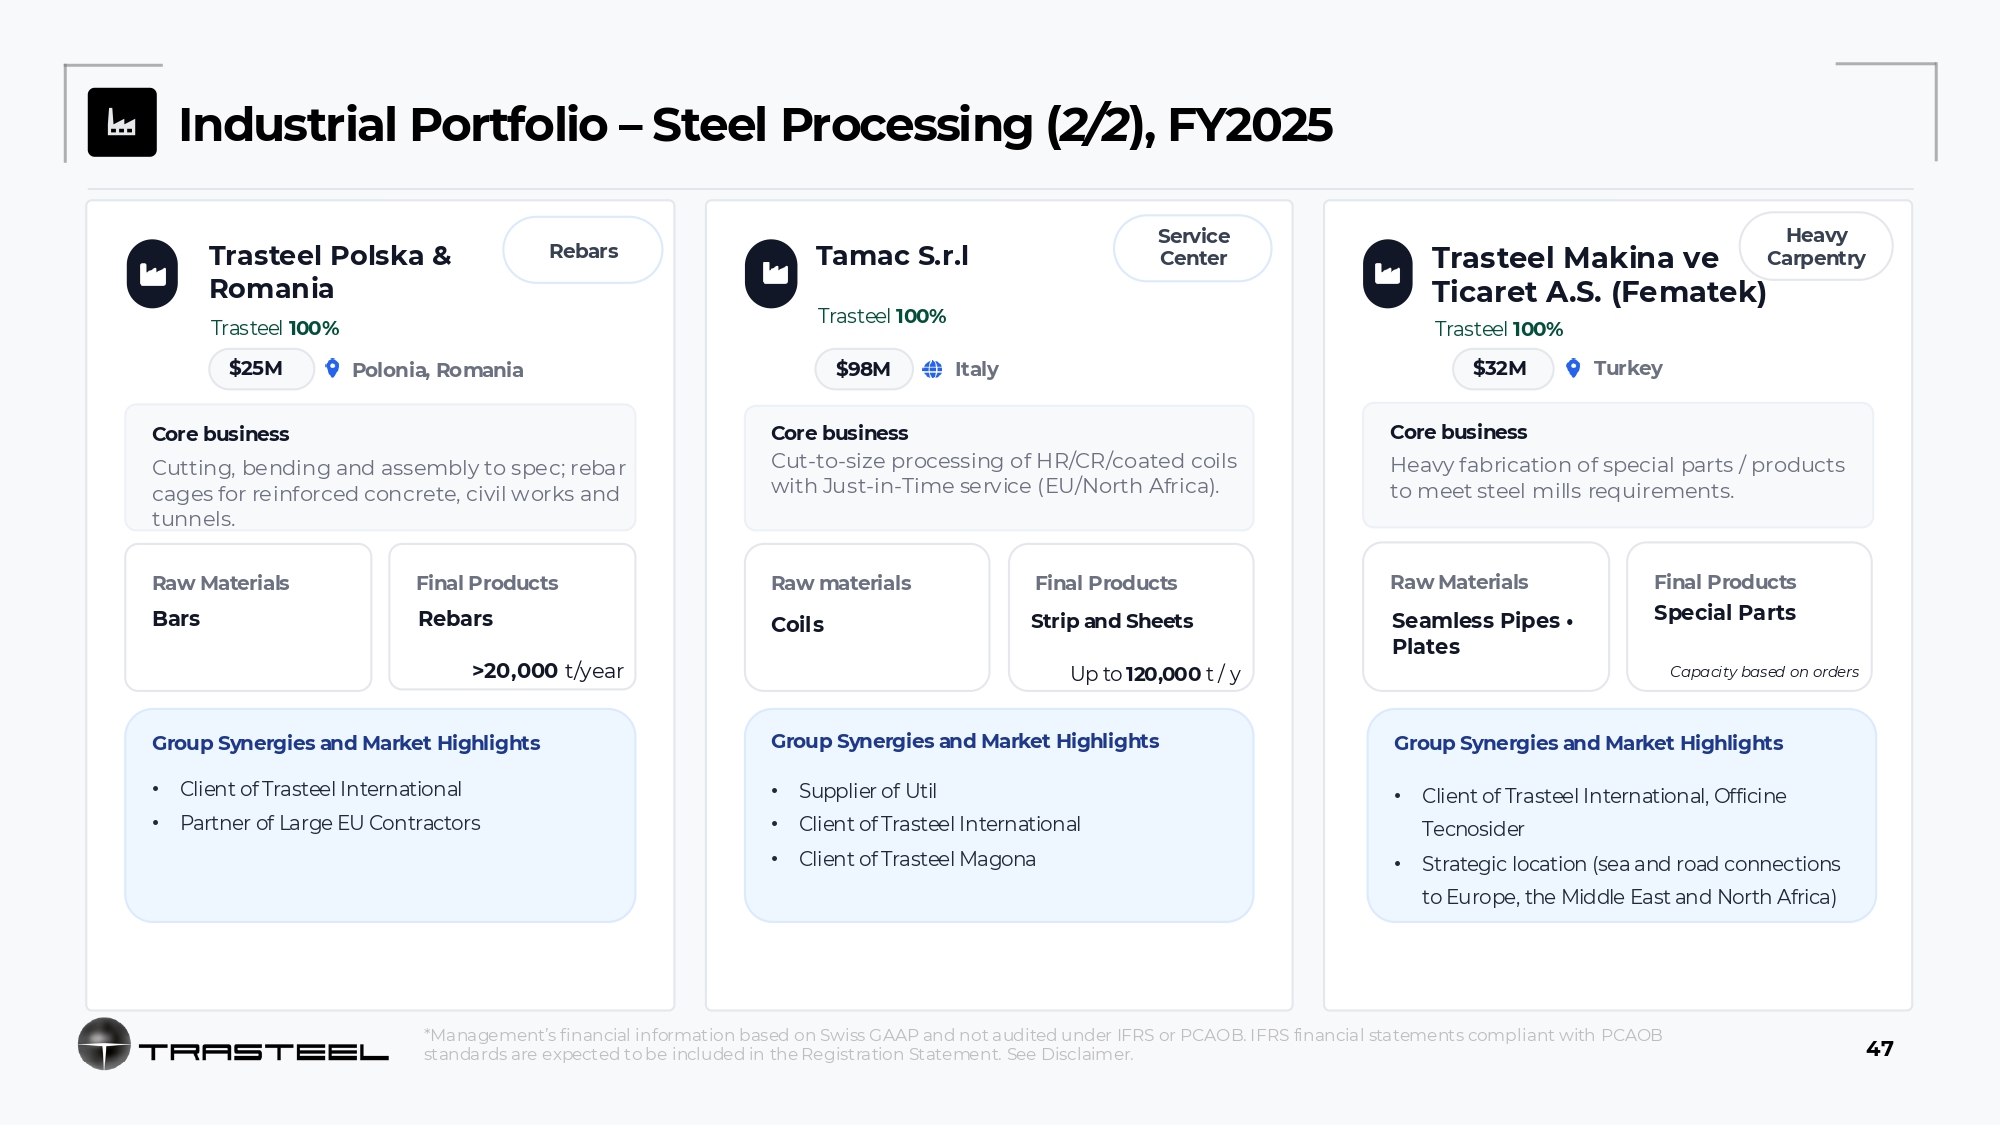
Industrial Portfolio – Steel Processing ( 2/2 ), FY2025 Trasteel Polska & Romania Trasteel 100% $25M Polonia, Romania Rebars Core business Cutting, bending and assembly to spec; rebar cages for reinforced concrete, civil works and tunnels. Raw Materials Bars >20,000 t/year Group Synergies and Market Highlights • Client of Trasteel International • Partner of Large EU Contractors Tamac S.r.l Service Center $98M Italy Up to 120,000 t / y Group Synergies and Market Highlights • Supplier of Util • Client of Trasteel International • Client of Trasteel Magona Trasteel Makina ve Heavy Carpentry Trasteel 100% Ticaret A.S. (Fematek) Trasteel 100% Core business Cut - to - size processing of HR/CR/coated coils with Just - in - Time service (EU/North Africa). $32M Turkey Core business Heavy fabrication of special parts / products to meet steel mills requirements. Final Products Rebars Raw materials Coils Final Products Strip and Sheets Raw Materials Seamless Pipes • Plates Final Products Special Parts Capacity based on orders Group Synergies and Market Highlights • Client of Trasteel International, Officine Tecnosider • Strategic location (sea and road connections to Europe, the Middle East and North Africa) *Management’s financial information based on Swiss GAAP and not audited under IFRS or PCAOB. IFRS financial statements compliant with PCAOB standards are expected to be included in the Registration Statement. See Disclaimer. 47
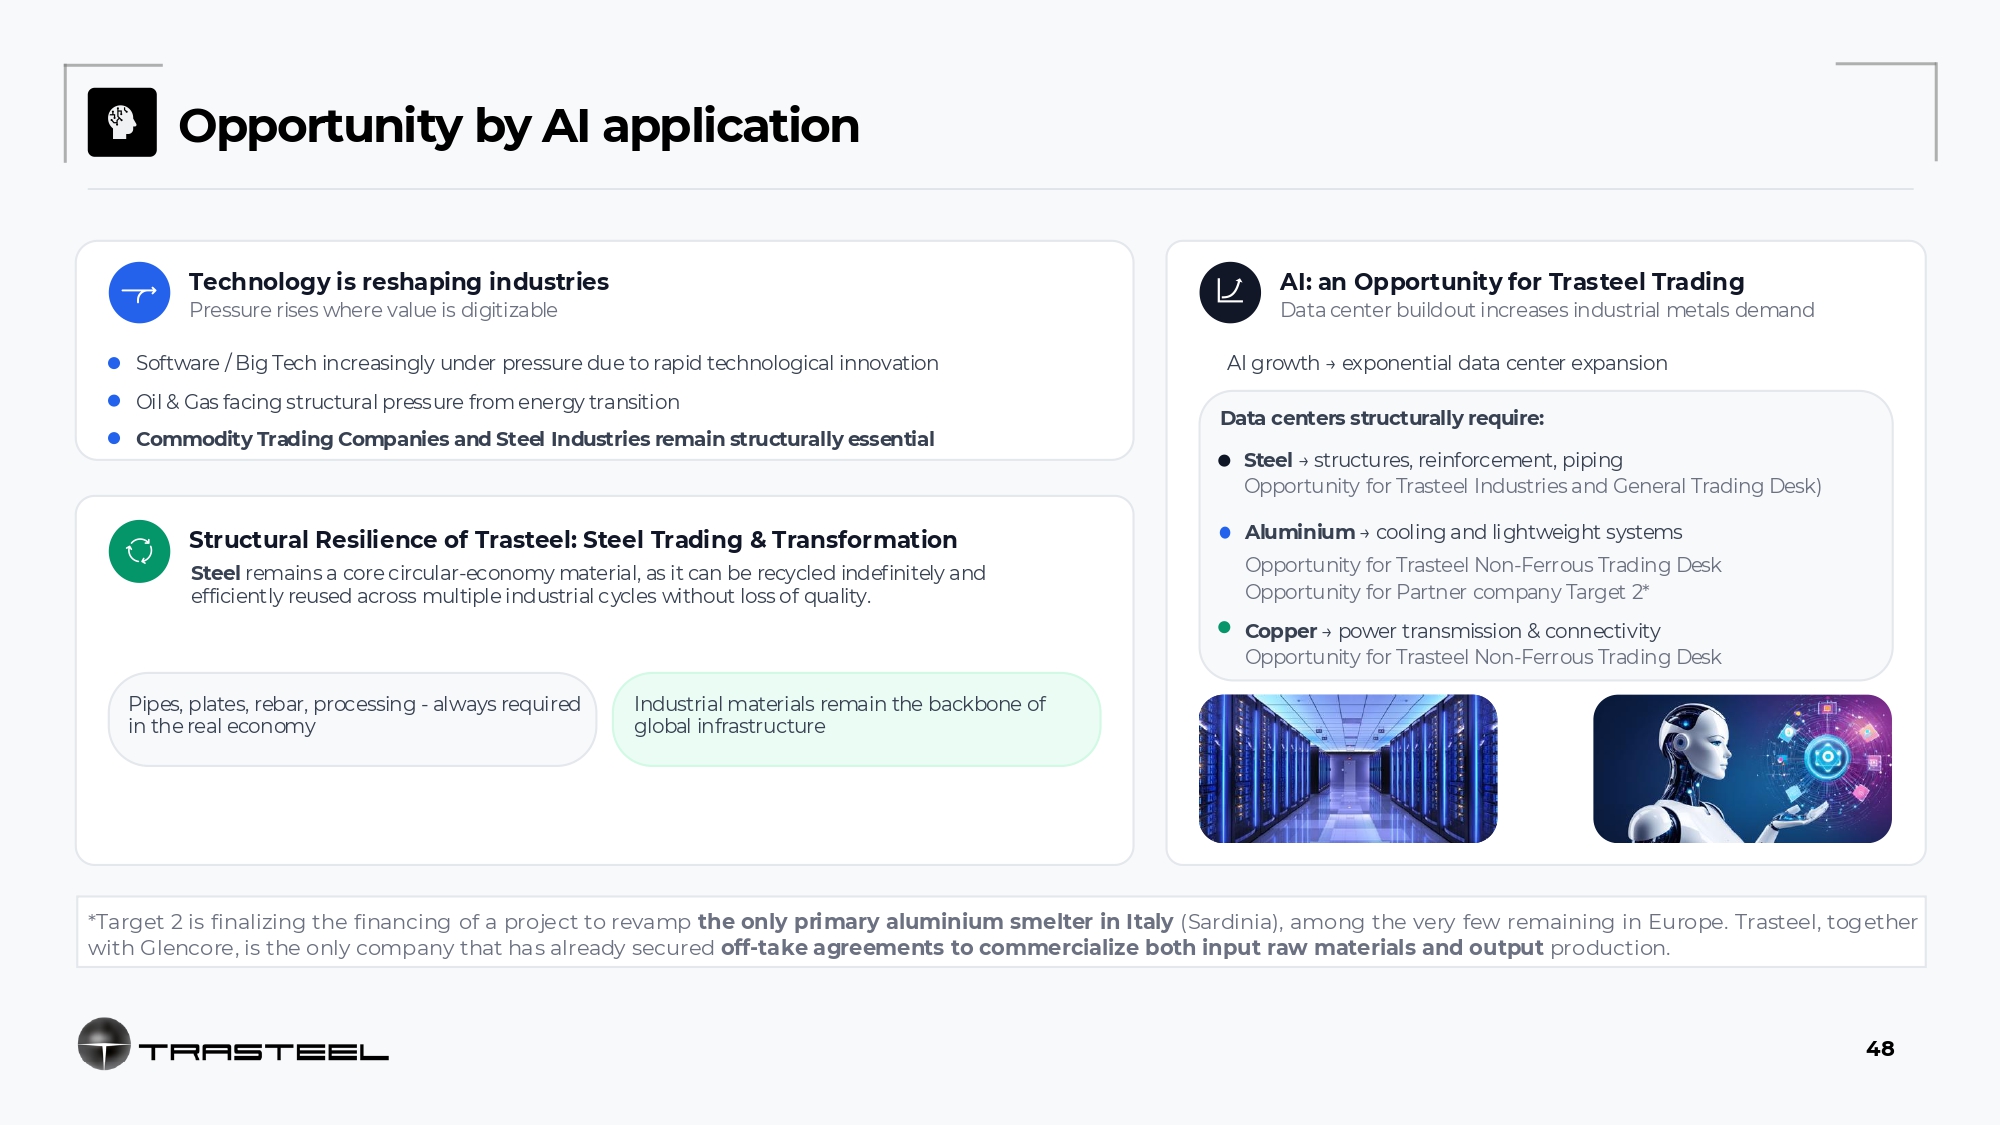
Opportunity by AI application Technology is reshaping industries Pressure rises where value is digitizable Structural Resilience of Trasteel: Steel Trading & Transformation Steel remains a core circular - economy material, as it can be recycled indefinitely and efficiently reused across multiple industrial cycles without loss of quality. Pipes, plates, rebar, processing - always required in the real economy Industrial materials remain the backbone of global infrastructure AI: an Opportunity for Trasteel Trading Data center buildout increases industrial metals demand Software / Big Tech increasingly under pressure due to rapid technological innovation Oil & Gas facing structural pressure from energy transition Commodity Trading Companies and Steel Industries remain structurally essential AI growth → exponential data center expansion Data centers structurally require: Steel → structures, reinforcement, piping Opportunity for Trasteel Industries and General Trading Desk) Aluminium → cooling and lightweight systems Opportunity for Trasteel Non - Ferrous Trading Desk Opportunity for Partner company Target 2* Copper → power transmission & connectivity Opportunity for Trasteel Non - Ferrous Trading Desk *Target 2 is finalizing the financing of a project to revamp the only primary aluminium smelter in Italy (Sardinia), among the very few remaining in Europe. Trasteel, together with Glencore, is the only company that has already secured off - take agreements to commercialize both input raw materials and output production. 48