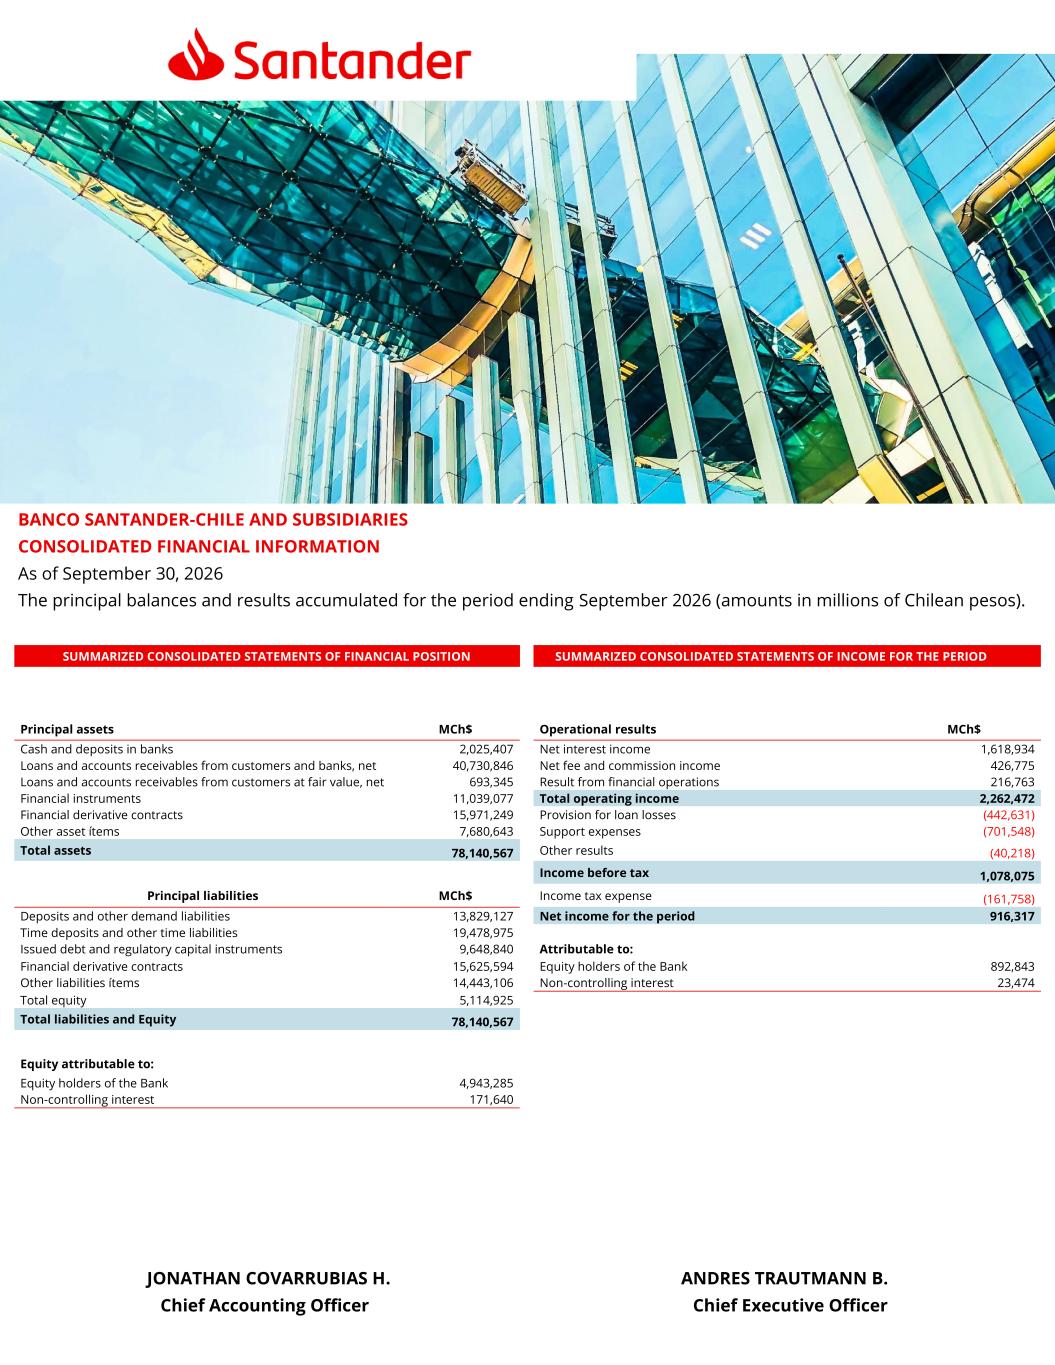
SUMMARIZED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION SUMMARIZED CONSOLIDATED STATEMENTS OF INCOME FOR THE PERIOD Principal assets MCh$ Operational results MCh$ Cash and deposits in banks 2,025,407 Net interest income 1,618,934 Loans and accounts receivables from customers and banks, net 40,730,846 Net fee and commission income 426,775 Loans and accounts receivables from customers at fair value, net 693,345 Result from financial operations 216,763 Financial instruments 11,039,077 Total operating income 2,262,472 Financial derivative contracts 15,971,249 Provision for loan losses (442,631) Other asset ítems 7,680,643 Support expenses (701,548) Total assets 78,140,567 Other results (40,218) Income before tax 1,078,075 Principal liabilities MCh$ Income tax expense (161,758) Deposits and other demand liabilities 13,829,127 Net income for the period 916,317 Time deposits and other time liabilities 19,478,975 Issued debt and regulatory capital instruments 9,648,840 Attributable to: Financial derivative contracts 15,625,594 Equity holders of the Bank 892,843 Other liabilities ítems 14,443,106 Non-controlling interest 23,474 Total equity 5,114,925 Total liabilities and Equity 78,140,567 Equity attributable to: Equity holders of the Bank 4,943,285 Non-controlling interest 171,640 BANCO SANTANDER-CHILE AND SUBSIDIARIES CONSOLIDATED FINANCIAL INFORMATION As of September 30, 2026 The principal balances and results accumulated for the period ending September 2026 (amounts in millions of Chilean pesos). JONATHAN COVARRUBIAS H. ANDRES TRAUTMANN B. Chief Accounting Officer Chief Executive Officer
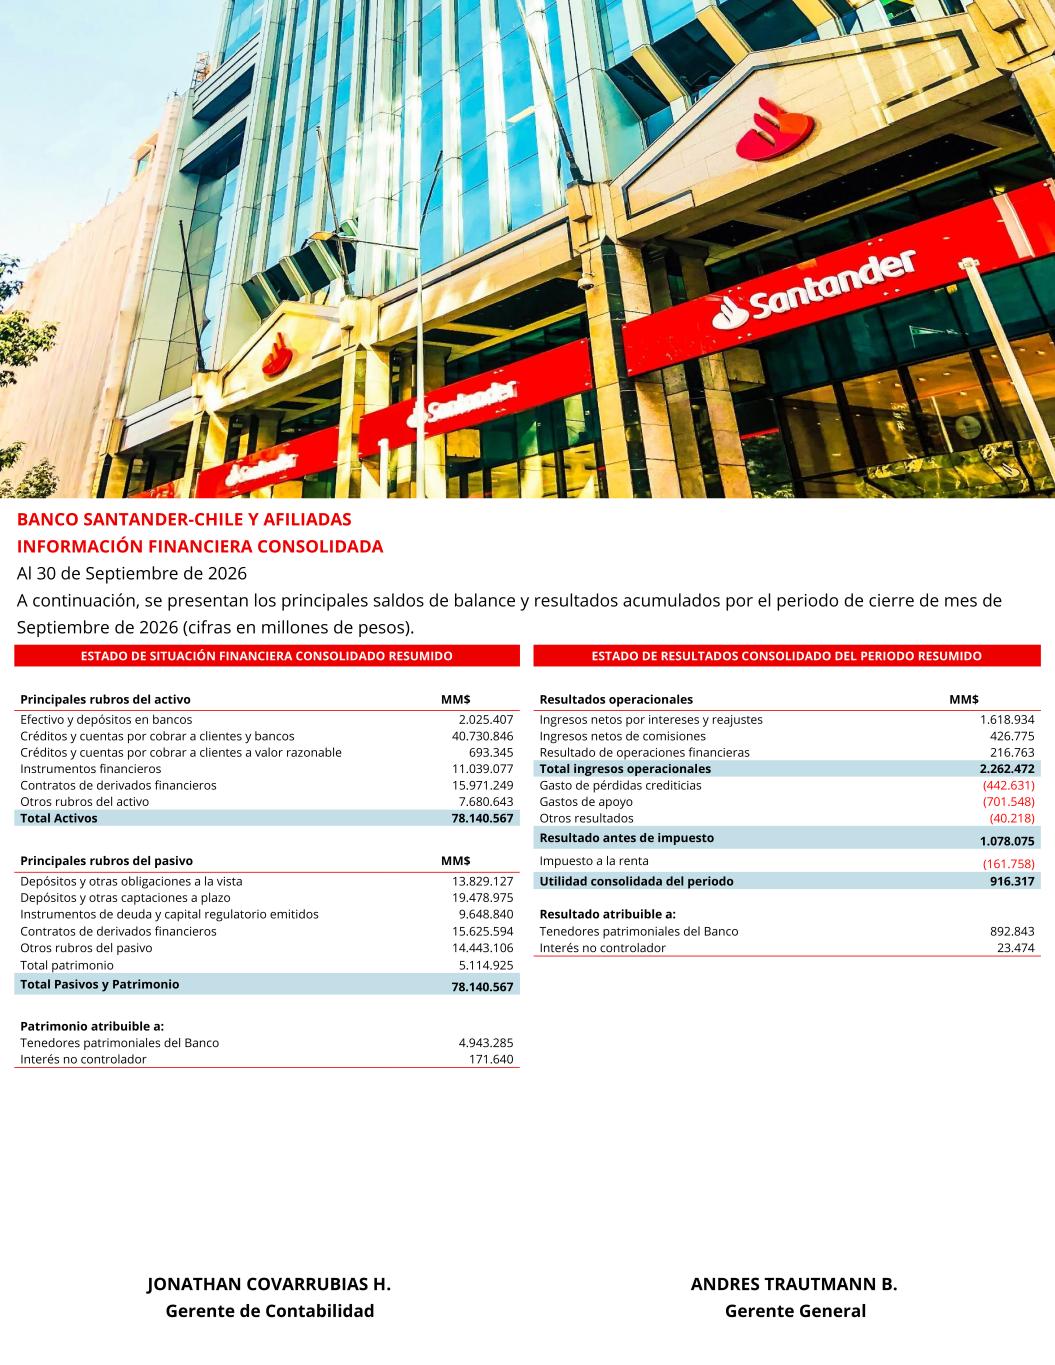
B ESTADO DE SITUACIÓN FINANCIERA CONSOLIDADO RESUMIDO ESTADO DE RESULTADOS CONSOLIDADO DEL PERIODO RESUMIDO Principales rubros del activo MM$ Resultados operacionales MM$ Efectivo y depósitos en bancos 2.025.407 Ingresos netos por intereses y reajustes 1.618.934 Créditos y cuentas por cobrar a clientes y bancos 40.730.846 Ingresos netos de comisiones 426.775 Créditos y cuentas por cobrar a clientes a valor razonable 693.345 Resultado de operaciones financieras 216.763 Instrumentos financieros 11.039.077 Total ingresos operacionales 2.262.472 Contratos de derivados financieros 15.971.249 Gasto de pérdidas crediticias (442.631) Otros rubros del activo 7.680.643 Gastos de apoyo (701.548) Total Activos 78.140.567 Otros resultados (40.218) Resultado antes de impuesto 1.078.075 Principales rubros del pasivo MM$ Impuesto a la renta (161.758) Depósitos y otras obligaciones a la vista 13.829.127 Utilidad consolidada del periodo 916.317 Depósitos y otras captaciones a plazo 19.478.975 Instrumentos de deuda y capital regulatorio emitidos 9.648.840 Resultado atribuible a: Contratos de derivados financieros 15.625.594 Tenedores patrimoniales del Banco 892.843 Otros rubros del pasivo 14.443.106 Interés no controlador 23.474 Total patrimonio 5.114.925 Total Pasivos y Patrimonio 78.140.567 Patrimonio atribuible a: Tenedores patrimoniales del Banco 4.943.285 Interés no controlador 171.640 BANCO SANTANDER-CHILE Y AFILIADAS INFORMACIÓN FINANCIERA CONSOLIDADA Al 30 de Septiembre de 2026 A continuación, se presentan los principales saldos de balance y resultados acumulados por el periodo de cierre de mes de Septiembre de 2026 (cifras en millones de pesos). JONATHAN COVARRUBIAS H. ANDRES TRAUTMANN B. Gerente de Contabilidad Gerente General
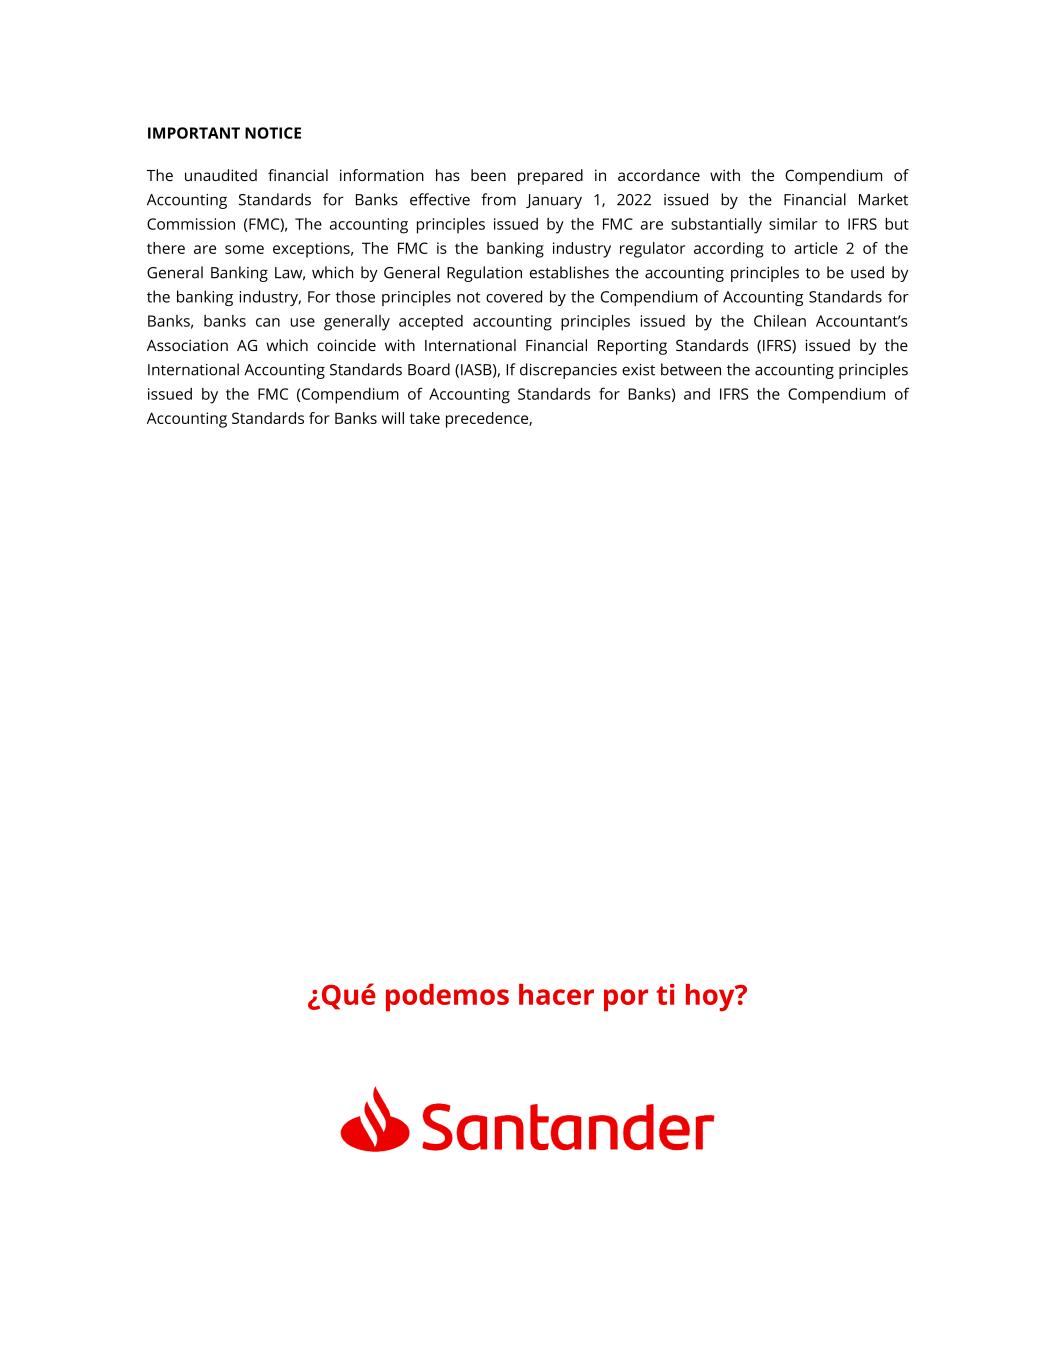
IMPORTANT NOTICE The unaudited financial information has been prepared in accordance with the Compendium of Accounting Standards for Banks effective from January 1, 2022 issued by the Financial Market Commission (FMC), The accounting principles issued by the FMC are substantially similar to IFRS but there are some exceptions, The FMC is the banking industry regulator according to article 2 of the General Banking Law, which by General Regulation establishes the accounting principles to be used by the banking industry, For those principles not covered by the Compendium of Accounting Standards for Banks, banks can use generally accepted accounting principles issued by the Chilean Accountant’s Association AG which coincide with International Financial Reporting Standards (IFRS) issued by the International Accounting Standards Board (IASB), If discrepancies exist between the accounting principles issued by the FMC (Compendium of Accounting Standards for Banks) and IFRS the Compendium of Accounting Standards for Banks will take precedence, ¿Qué podemos hacer por ti hoy?