Exhibit 99.73
Suite 2400, 1055 West Georgia Street.
Vancouver, B.C. V6E 3P3
March 31, 2026
GUNNISON COPPER CORP.
ANNUAL INFORMATION FORM
TABLE OF CONTENTS
| Page | ||
| PRELIMINARY NOTES | 1 | |
| Effective Date of Information | 1 | |
| Currency | 1 | |
| Metric Equivalents | 1 | |
| Special Note Regarding Forward-Looking Information | 1 | |
| Cautionary Note to U.S. Investors | 4 | |
| GLOSSARY | 5 | |
| ABBREVIATIONS | 8 | |
| CORPORATE STRUCTURE | 9 | |
| Name, Address and Incorporation | 9 | |
| Inter-corporate Relationships | 9 | |
| DESCRIPTION AND GENERAL DEVELOPMENT OF THE BUSINESS | 10 | |
| Three Year History | 10 | |
| Year Ended December 31, 2023 Developments | 10 | |
| Year Ended December 31, 2024 Developments | 14 | |
| Year Ended December 31, 2025 Developments | 16 | |
| Developments Subsequent to December 31, 2025 | 21 | |
| Outlook | 22 | |
| NARRATIVE DESCRIPTION OF THE BUSINESS | 23 | |
| Summary of the Business | 23 | |
| Competitive Conditions | 23 | |
| Employees | 23 | |
| Environmental Protection | 23 | |
| Social and Environmental Policies | 24 | |
| MINERAL PROPERTIES | 25 | |
| General | 25 | |
| Gunnison Project | 25 | |
| Johnson Camp Mine | 50 | |
| Property Description, Location and Access | 50 | |
| Other Assets | 70 | |
| RISK FACTORS | 70 | |
| DIVIDENDS | 86 | |
| DESCRIPTION OF CAPITAL STRUCTURE | 86 | |
| MARKET FOR SECURITIES | 86 | |
| Market | 86 | |
| Trading Price and Volume | 87 | |
| Prior Sales | 87 | |
| ESCROWED SECURITIES AND SECURITIES SUBJECT TO CONTRACTUAL RESTRICTION ON TRANSFER | 88 | |
| DIRECTORS AND OFFICERS | 88 | |
| Cease Trade Orders, Bankruptcies, Penalties or Sanctions | 90 | |
| Conflicts of Interest | 90 | |
| LEGAL PROCEEDINGS AND REGULATORY ACTIONS | 91 | |
| PROMOTERS | 91 | |
| INTEREST OF MANAGEMENT AND OTHERS IN MATERIAL TRANSACTIONS | 91 | |
| MATERIAL CONTRACTS | 91 | |
| 1 |
| INTEREST OF EXPERTS | 92 | |
| ADDITIONAL INFORMATION | 93 | |
| AUDIT COMMITTEE | 93 | |
| Audit Committee Charter | 93 | |
| Composition of the Audit Committee | 93 | |
| Relevant Education and Experience | 93 | |
| Reliance on Certain Exemptions | 94 | |
| Reliance on Exemption in Subsection 3.3(2) or Section 3.6 | 94 | |
| Reliance on Section 3.8 | 95 | |
| Audit Committee Oversight | 95 | |
| Pre-Approval Policies and Procedures | 95 | |
| External Auditor Service Fees | 95 | |
| SCHEDULE A | 96 | |
| 2 |
ANNUAL INFORMATION FORM
GUNNISON COPPER CORP.
PRELIMINARY NOTES
Effective Date of Information
The information contained in Gunnison Copper Corp.’s annual information form (“AIF” or “Annual Information Form”) is presented as of December 31, 2025 unless otherwise stated herein. Unless the context otherwise requires, all references to the “Company”, “we” or “us” shall mean Gunnison Copper Corp., together with its subsidiaries.
Currency
Unless specified otherwise, all references in the AIF to “dollars”, “$” or to “US$” are to United States of America dollars and all references to “Canadian dollars” or to “Cdn$” are to Canadian dollars.
Metric Equivalents
For ease of reference, the following factors for converting metric measurements into imperial equivalents are provided:
| To Convert From Metric | To Imperial | Multiply by |
| Hectares | Acres | 2.471 |
| Metres | Feet (ft.) | 3.281 |
| Kilometres (km.) | Miles | 0.621 |
| Tonnes | Tons (2000 pounds) | 1.102 |
Special Note Regarding Forward-Looking Information
This AIF and the documents incorporated by reference herein, contain “forward-looking information” and “forward looking statements” within the meaning of applicable Canadian and United States securities legislation (collectively herein referred to as “forward-looking statements”), including the “safe harbour” provisions of provincial securities legislation and the U.S. Private Securities Litigation Reform Act of 1995, Section 21E of the U.S. Securities Exchange Act of 1934, as amended (the “Exchange Act”), and Section 27A of the U.S. Securities Act of 1933, as amended (the “U.S. Securities Act”). Forward-looking statements may include, but are not limited to, information with respect to:
| ● | the future price of copper; | |
| ● | the development of and production from the Gunnison Project, JCM and the S&H Project (each as defined below); | |
| ● | our planned exploration and development activities; | |
| ● | the adequacy of our financial resources; | |
| ● | the estimation of mineral resources; | |
| ● | realization of mineral resource estimates; | |
| ● | construction plans at the Company’s mineral properties; | |
| ● | the potential of certain deposits to become economic satellite feeder deposits; | |
| ● | the timeline for commercial production at the Gunnison Project; | |
| ● | costs and timing of future development; |
| 1 |
| ● | results of future development programs; | |
| ● | production and processing estimates; | |
| ● | capital and operating cost estimates; | |
| ● | statements relating to the economic viability of the Gunnison Project or JCM, including mine life, total tons mined and processed, mining operations, Net Present Value, Internal Rate of Return and payback period; | |
| ● | statements related to the various transactions with Nuton (defined below); | |
| ● | approvals, consents and permits under applicable legislation; | |
| ● | our relationship with community stakeholders; | |
| ● | our executive compensation approach and practice; | |
| ● | litigation risks; currency fluctuations; and | |
| ● | environmental risks. |
Wherever possible, words such as “plans”, “expects”, “projects”, “assumes”, “budgeted”, “strategy”, “scheduled”, “estimates”, “forecasts”, “anticipates”, “believes”, “intends” “modeled” and similar expressions or statements that certain actions, events or results “may”, “could”, “would”, “might” or “will” be taken, occur or be achieved, or the negative forms of any of these terms and similar expressions, have been used to identify forward-looking statements. Statements concerning mineral resource estimates may also be deemed to constitute forward-looking statements to the extent that they involve estimates of the mineralization that will be encountered if the property is developed. Any statements that express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, objectives, assumptions or future events or performance are not statements of historical fact and may be forward-looking statements. Forward-looking statements are subject to a variety of known and unknown risks, uncertainties and other factors that could cause actual events or results to differ from those expressed or implied by the forward-looking statements, including, without limitation, the following risks and uncertainties referred to under the heading “Risk Factors” in this AIF.
| ● | operational risks inherent in the conduct of mining activities, including the risk of accidents, labour disputes, availability of reagents and power, increases in capital and operating costs and the risk of delays or increased costs that might be encountered during the development process; | |
| ● | risks inherent in the exploration and development of mineral deposits, including risks relating to changes in project parameters as plans continue to be redefined including the possibility that mining operations may not commence or be sustained at the Gunnison Project, JCM or the Company’s other properties; | |
| ● | assumptions regarding expected capital and operating costs and expenditures, production schedules, economic returns and other projections; | |
| ● | our production estimates, including accuracy thereof; | |
| ● | risks related to general economic conditions and in particular the potential impact of a global pandemic on the Company or its operations and the mining industry; | |
| ● | the fact that we have no mineral properties in commercial production and no history of production or revenue; | |
| ● | risks relating to variations in mineral resources, grade or recovery rates resulting from current exploration and development activities; | |
| ● | risks relating to variations in metallurgical assumptions including copper recovery and acid consumption; | |
| ● | risks related to fluctuations in the price of copper as the Company’s future revenues, if any, are expected to be derived from the sale of copper; | |
| ● | risks related to a reduction in the demand for copper in the Chinese market which could result in an extended period of lower prices and demand for copper; | |
| ● | financing, capitalization and liquidity risks, including the risk that the financing necessary to fund the development and construction activities at the Gunnison Project or JCM may not be available on satisfactory terms, or at all; |
| 2 |
| ● | the Company expects to incur losses for the foreseeable future; | |
| ● | risks associated with debt and the copper stream agreement; | |
| ● | risks related to the Nuton transactions, including Nuton’s right to terminate and cease providing further funding; | |
| ● | risks related to the Company obtaining and maintaining various permits required to conduct its current and anticipated future operations; | |
| ● | risks related to disputes concerning property titles and interest; | |
| ● | risks relating to the ability to access infrastructure; | |
| ● | risks related to the significant governmental regulation to which the Company is subject; | |
| ● | environmental risks; | |
| ● | climate change risks; | |
| ● | risks related to the adequacy of financial assurance arrangements with State and Federal Governments; | |
| ● | reliance on key personnel; | |
| ● | risks related to increased competition in the market for copper and related products and in the mining industry generally; | |
| ● | cybersecurity risks; | |
| ● | risks related to potential conflicts of interests among the Company’s directors and officers; | |
| ● | exchange rate fluctuations between the Canadian and United States dollar; | |
| ● | uncertainties inherent in the estimation of inferred mineral resources; | |
| ● | land reclamation requirements may be burdensome; | |
| ● | risks associated with the acquisition of any new properties or maintaining the current properties; | |
| ● | risks related to legal proceedings to which the Company may become subject; | |
| ● | potential liabilities associated with JCM (as defined herein); | |
| ● | our ability to comply with foreign corrupt practices regulations and anti-bribery laws; | |
| ● | changes to relevant legislation, accounting practices or increasing insurance costs; | |
| ● | significant growth could place a strain on our management systems; | |
| ● | share ownership by our significant shareholders and their ability to influence our governance; | |
| ● | risks relating to the Company’s Common Shares, including that future sales or issuances of our debt or equity securities may decrease the price of our securities; | |
| ● | the trading price of our Common Shares is subject to volatility due to market conditions; | |
| ● | the absence of dividends or intent to pay dividends in the near future; | |
| ● | certain actions under U.S. federal securities laws may be unenforceable; | |
| ● | our broad discretion relating to the use of any proceeds raised hereunder; | |
| ● | non-U.S. holders of Common Shares could be subject to U.S. federal income tax from the sale or other taxable disposition of Common Shares; | |
| ● | withholding to Non-U.S. investors will apply to our dividends on our Common Shares; | |
| ● | our being treated as a U.S. domestic corporation for U.S. federal income tax purposes; | |
| ● | the uncertainty of maintaining a liquid trading market for the Company’s Common Shares; | |
| ● | the absence of a market through which the Company’s securities, other than Common Shares, may be sold; and | |
| ● | risks related to the debt securities being unsecured. |
| 3 |
This list is not exhaustive of the factors that may affect any of our forward-looking statements. Although we have attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking statements, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such information will prove to be accurate, as actual results and future events could differ materially from those anticipated in such information. Forward-looking statements involve statements about the future and are inherently uncertain, and our actual achievements or other future events or conditions may differ materially from those reflected in the forward-looking statements due to a variety of risks, uncertainties and other factors, including, without limitation, those referred to in this AIF under the heading “Risk Factors” and elsewhere in this AIF and the documents incorporated by reference. Our forward-looking statements are based on the beliefs, expectations and opinions of management on the date the statements are made. In connection with the forward-looking statements contained in this AIF and the documents incorporated, or deemed to be incorporated, by reference, we have made certain assumptions about our business, including about our planned exploration, development and production activities; the accuracy of our mineral resource estimates; capital and operating cost estimates; production and processing estimates; the results, costs and timing of future exploration and drilling; timelines and similar statements relating to the economic viability of the Gunnison Project; timing and receipt of approvals, consents and permits under applicable legislation; and the adequacy of our financial resources. We have also assumed that no significant events will occur outside of our normal course of business. Although we believe that the assumptions inherent in the forward-looking statements are reasonable as of the date of this AIF, forward-looking statements are not guarantees of future performance and, accordingly, undue reliance should not be put on such statements due to the inherent uncertainty therein. For the reasons set forth above, prospective investors should not place undue reliance on forward-looking statements. Except as required by applicable securities laws, the Company does not undertake any obligation to publicly update or revise any forward-looking information.
Cautionary Note to U.S. Investors
Technical disclosure regarding our properties included in this AIF and in the documents incorporated herein by reference has not been prepared in accordance with the requirements of U.S. securities laws. Without limiting the foregoing, such technical disclosure uses terms that comply with reporting standards in Canada and certain estimates are made in accordance with National Instrument 43-101 — Standards of Disclosure for Mineral Projects (“NI 43-101”). NI 43-101 is a rule developed by the Canadian Securities Administrators that establishes standards for all public disclosure an issuer makes of scientific and technical information concerning mineral projects. Unless otherwise indicated, all mineral reserve and mineral resource estimates contained in the technical disclosure have been prepared in accordance with NI 43-101 and the Canadian Institute of Mining, Metallurgy and Petroleum Definition Standards on Mineral Resources and Reserves (“CIM Definition Standards”).
Canadian standards, including NI 43-101, differ significantly from the historical requirements of the Securities and Exchange Commission (the “SEC”), and mineral reserve and resource information contained or incorporated by reference in this AIF may not be comparable to similar information disclosed by U.S. companies.
Mining disclosure under U.S. securities law was previously required to comply with item 102 of Regulation S-K under the U.S. Securities Act and the Securities Exchange Act of 1934, as amended and SEC Industry Guide 7 (“SEC Industry Guide 7”). The SEC has adopted rules to replace SEC Industry Guide 7 with new mining disclosure rules under sub-part 1300 of Regulation S-K of the U.S. Securities Act (the “SEC Modernization Rules”) which became mandatory for U.S. reporting companies beginning with the first fiscal year commencing on or after January 1, 2021. Under the SEC Modernization Rules, the definitions of “proven mineral reserves” and “probable mineral reserves” have been amended to be substantially similar to the corresponding CIM Definition Standards and the SEC has added definitions to recognize “measured mineral resources”, “indicated mineral resources” and “inferred mineral resources” which are also substantially similar to the corresponding CIM Definition Standards; however, there are still differences in the definitions and standards under the SEC Modernization Rules and the CIM Definition Standards. As a foreign private issuer, the Company is permitted to continue to comply with NI 43-101 disclosure rules. Therefore, the Company’s mineral resources and reserves as determined in accordance with NI 43-101 may be significantly different than if they had been determined in accordance with the SEC Modernization Rules.
NOTICE PURSUANT TO TREASURY DEPARTMENT CIRCULAR 230: NOTHING CONTAINED IN THIS AIF CONCERNING ANY U.S. FEDERAL TAX ISSUE IS INTENDED OR WRITTEN TO BE USED, AND IT CANNOT BE USED, BY A HOLDER, FOR THE PURPOSE OF AVOIDING U.S. FEDERAL TAX PENALTIES UNDER THE CODE (AS DEFINED BELOW). THIS SUMMARY WAS WRITTEN TO SUPPORT MATTERS ADDRESSED BY THIS DOCUMENT. EACH HOLDER SHOULD SEEK U.S. FEDERAL TAX ADVICE, BASED ON SUCH HOLDER’S PARTICULAR CIRCUMSTANCES, FROM AN INDEPENDENT TAX ADVISOR.
| 4 |
GLOSSARY
In the AIF, unless otherwise defined or unless there is something in the subject matter or context inconsistent therewith, the following terms have the meanings set forth herein or therein:
“ADWR” means Arizona Department of Water Resources;
“AIF” or “Annual Information Form” means this annual information form and any appendices, schedules or attachments hereto;
“AzTech” means AzTech Minerals, Inc., an Arizona corporation, which was merged with and into Gunnison Arizona;
“BCBCA” means the Business Corporations Act (British Columbia), C-57, as amended;
“Business Day” means any day on which commercial banks are generally open for business other than a Saturday, Sunday or a day observed as a holiday (i) in Vancouver under the laws of British Columbia, (ii) in Toronto under the laws of Ontario, or (iii) under the federal laws of Canada;
“Code” means the U.S. Internal Revenue Code of 1986, as amended;
“Common Share” means the common (voting) shares in the capital of Gunnison;
“Company” means, collectively, Gunnison, Gunnison Arizona and Gunnison Holdings;
“Control Person” means any Person that holds or is one of a combination of Persons that holds a sufficient number of any of the securities of an issuer so as to affect materially the control of that issuer, or that holds more than 20% of the outstanding voting securities of an issuer except where there is evidence showing that the holder of those securities does not materially affect the control of the issuer;
“Definitive Agreement” means the agreement and plan of merger dated as of August 19, 2010 among Gunnison, Gunnison Arizona and AzTech, as amended from time to time;
“EPA” means the United States Environmental Protection Agency;
“Greenstone” means Greenstone Gunnison Holdings L.P., an affiliate of Greenstone Resources;
“Greenstone II” means Greenstone Resources II L.P., an affiliate of Greenstone Resources;
“Greenstone IR Agreement” means the Investor Rights Agreement dated August 13, 2014 between Greenstone and Gunnison, as amended by the Amending Agreement to the Greenstone IR Agreement dated January 19, 2018 between the Company, Greenstone and Greenstone No. 2; further amended by the Second Amending Agreement to the Greenstone IR Agreement, dated December 5, 2018 between the Company, Greenstone, Greenstone II, Greenstone No. 1 and Greenstone No. 2; and further amended by the Third Amending Agreement to the Greenstone IR Agreement, dated December 5, 2018 between the Company, Greenstone, Greenstone II, Greenstone No. 1, Greenstone No. 2 and Greenstone Resources;
“Greenstone No. 1” means Greenstone Co-Investment No. 1 (Gunnison) L.P. an affiliate of Greenstone Resources;
“Greenstone No. 2” means Greenstone Co-Investment No. 2 (Gunnison) L.P. an affiliate of Greenstone Resources;
| 5 |
“Greenstone Resources” means Greenstone Resources L.P.;
“Gunnison” or “GCC” means Gunnison Copper Corp. (formerly Excelsior Mining Corp.), a corporation incorporated under the laws of the Province of British Columbia;
“Gunnison Arizona” means Excelsior Mining Arizona, Inc. dba Gunnison Copper, a company incorporated under the laws of Arizona, and which is a wholly-owned subsidiary of Gunnison;
“Gunnison JCM” means Excelsior Mining JCM, Inc., a company incorporated under the laws of Arizona, and which was a wholly-owned subsidiary of Gunnison prior to its merger with Gunnison Arizona;
“Gunnison Holdings” means Excelsior Mining Holdings, Inc., a company incorporated under the laws of Arizona, and which is a wholly-owned subsidiary of Gunnison;
“Gunnison Project” means the Gunnison Copper Project consisting of unpatented mining claims, private land, exploration permits, mineral leases and direct ownership of mineral rights in an area that encompasses approximately 10 square miles, located in Cochise County, Arizona, approximately 62 miles east of Tucson, Arizona in the Johnson Camp mining district;
“Gunnison Technical Report” means the technical report entitled “Gunnison Project, NI 43-101 Technical Report, Preliminary Economic Assessment, Cochise County, Arizona” dated effective March 18, 2026 prepared by John Woodson, P.E., SME-RM, Jeffery Bickel, C.P.G., Dr. Abyl Sydykov, Ph.D., P.E., Dr. Terence P. McNulty, P.E., D.Sc., Rob Valceschini, P.E., R. Douglas Bartlett, C.P.G., Jacob Richey, P.E., Thomas M. Ryan, P.E. and Tyler Peck, P.E.
“IRS” means the United States Internal Revenue Service;
“JCM” or “Johnson Camp” means the Johnson Camp Copper mine located immediately adjacent to the Gunnison Project;
“JCM Purchase Agreement” means the asset purchase agreement dated October 7, 2015 between Christopher G. Linscott (as court appointed receiver for the assets of Nord) and Gunnison JCM pursuant to which Gunnison JCM acquires all of the assets of Nord as they relate to the JCM for total consideration of US$8.4 million;
“JCM Technical Report” means the technical report entitled “Johnson Camp Mine NI 43-101 Technical Report, Cochise County, Arizona”, dated effective March 18, 2026 prepared by prepared by John Woodson, PE, SME-RM, Jeffrey Bickel, CPG, Abyl Sydykov, PhD, PE, Scott Freestone, PE, Dr. Terence P. McNulty, PE, DSc, R. Douglas Bartlett, CPG, Jacob Richey, PE and Thomas M. Ryan, PE.
“Leverage Ratio Grace Period” has the meaning given to such term in “Risk Factors”;
“Nebari” means Nebari Natural Resources Credit Fund I, LP;
“Nebari Credit Agreement” means the second amended and restated credit agreement dated October 31, 2019, as amended, between Gunnison, Gunnison Arizona and Nebari pursuant to pursuant to which Nebari has provided the Nebari Credit Facility;
“Nebari Credit Facility” means the US$15 million credit facility provided by Nebari to Gunnison and Gunnison Arizona pursuant to the Nebari Credit Agreement;
| 6 |
“Non-U.S. Holder” means any beneficial owner of Common Shares that is neither a U.S. Holder nor a partnership (including an entity treated as a partnership for U.S. federal income tax purposes).
“Non-Voting Shares” means the non-voting shares of Gunnison;
“Nord” means Nord Resources Corporation;
“North Star Deposit” means the North Star Deposit of the Gunnison Project as identified on Figure 1-1 in this AIF;
“Nuton” means Nuton Technologies, LLC;
“Person” or “person” means a company or individual;
“Second ARCA” means the second amended and restated credit agreement dated April 23, 2025 between Gunnison, Gunnison Arizona, Gunnison Holdings and Nebari governing the Nebari Credit Facility;
“South Star Deposit” means the South Star Deposit of the Gunnison Project as identified on Figure 1-1 in this AIF;
“Stream Agreement” means the copper purchase and sale agreement (the “Stream Agreement”) dated October 30, 2018, as amended, between Triple Flag, Gunnison, Gunnison Arizona and Gunnison JCM pursuant to which Triple Flag has provided a deposit of US$65 million for the future purchase of refined copper from Gunnison Arizona;
“S&H or S&H Project” means the Strong and Harris copper-silver-zinc project located in Cochise County, Arizona as further described in the Gunnison Technical Report;
“Tax Act” means the Income Tax Act (Canada), as amended, including the regulations promulgated thereunder;
“Triple Flag” means Triple Flag International Ltd.;
“Trust” means the James L. Sullivan Trust dated November 24, 2004;
“TSX” or “Exchange” means the Toronto Stock Exchange;
“U.S.” or “United States” means the United States of America, any state thereof, and the District of Columbia;
“U.S. Holder” means a beneficial owner of Common Shares, that is, for U.S. federal income tax purposes: (i) a citizen or individual resident of the United States; (ii) a corporation (or other entity taxable as a corporation) organized under the laws of the United States, any state thereof or the District of Columbia; (iii) an estate whose income is subject to U.S. federal income taxation regardless of its source; or (iv) a trust that (1) is subject to the primary supervision of a court within the U.S. and the control of one or more U.S. persons for all substantial decisions or (2) has a valid election in effect under applicable Treasury Regulations to be treated as a U.S. person; and
Words importing the singular number, where the context requires, include the plural and vice versa and words importing any gender include all genders.
| 7 |
ABBREVIATIONS
In the AIF, unless otherwise defined or unless there is something in the subject matter or context inconsistent therewith, the following abbreviations have the meanings set forth herein or therein:
| Abbreviation | Term | |
| % | percent | |
| ADEQ | Arizona Department of Environmental Quality | |
| APP | Aquifer Protection Permit | |
| ASCu | Acid-soluble copper | |
| AzTech | AzTech Minerals, Inc. | |
| BADCT | Best-Available Demonstrated Control Technology | |
| cm | Centimeter | |
| CNCu | Cyanide-soluble Copper | |
| Cu | Copper | |
| CuS | Primary sulfide copper | |
| EIS | Economic Impact Study | |
| ft | foot (feet) | |
| GA | General Arrangement | |
| gpl | gram per liter | |
| gpm | gallons per minute | |
| G&A | General & Administrative | |
| Ha | hectares | |
| HDPE | High Density Polyethylene | |
| IRR | Internal Rate of Return | |
| ISR | In Situ Recovery | |
| km | kilometer | |
| kV | kilovolt | |
| lb | pound | |
| lixiviant | liquid medium used for metal extraction | |
| M | meter | |
| M3 | M3 Engineering & Technology Corp. | |
| Ma | million years ago | |
| MDA | Mine Development Associates | |
| Mlb | million pounds | |
| mm | millimeter | |
| NI 43-101 | Canadian National Instrument 43-101 | |
| NPV | Net Present Value | |
| PLS | Pregnant Leach Solution | |
| QA/QC | Quality Assurance/Quality Control | |
| RC | reverse circulation drilling | |
| SEC | U.S. Securities & Exchange Commission | |
| SG | specific gravity | |
| SX-EW | Solvent Extraction (SX) / Electrowinning (EW) | |
| TCu | Total copper | |
| UIC | Underground Injection Control | |
| WTP | Water treatment plant |
| 8 |
CORPORATE STRUCTURE
Name, Address and Incorporation
Gunnison was incorporated under the name “Excelsior Mining Corp.” pursuant to the provisions of the BCBCA on June 9, 2005 with an authorized capital of an unlimited number of Common Shares without par value.
On October 14, 2010, a special resolution of shareholders was passed to create a new class of shares, the Non-Voting Shares. Also on October 14, 2010, Gunnison effected consolidation of its Common Shares on the basis of three pre-consolidation Common Shares for one post-consolidation Common Share. Effective November 11, 2024, Gunnison changed its name from Excelsior Mining Corp. to Gunnison Copper Corp. Presently, the authorized share capital of Gunnison consists of an unlimited number of Common Shares, without nominal or par value, and an unlimited number of Non-Voting Shares, without nominal or par value. The Non-Voting Shares are convertible into Common Shares on the basis of one Non-Voting Common Share for one Common Share at the election of the holder of such Non-Voting Common Shares. All Common Share numbers reported in this AIF are reported on a post-consolidation basis with a corresponding adjustment to Common Share price if applicable.
The Common Shares are listed on the TSX under the trading symbol “GCU” and trade on OTCQB under the symbol “GCUMF” and on the Frankfurt Exchange under the symbol “3XS0”. Gunnison’s head office is located at Concord Place, 2999 N. 44th St, Suite 300, Phoenix, AZ, USA 85018 and its registered and records office is located at Suite 2400, 1055 West Georgia Street, Vancouver, British Columbia, V6E 3P3, Canada.
Inter-corporate Relationships
As set out in the corporate structure chart below, Gunnison has two wholly-owned subsidiaries, Gunnison Arizona and Excelsior Mining Holdings, Inc., both incorporated under the laws of Arizona.
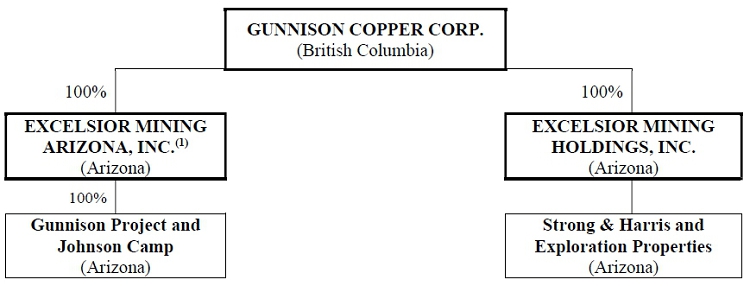
| 1. | Effective March 1, 2021, Gunnison JCM was merged with and into Gunnison Arizona. |
| 9 |
DESCRIPTION AND GENERAL DEVELOPMENT OF THE BUSINESS
Three Year History
The principal business of Gunnison is the acquisition, exploration and development of copper mineral properties in Arizona. Significant business, operations and management developments for Gunnison over the three most recently completed fiscal years have been as follows:
Year Ended December 31, 2023 Developments
Operations Update
On January 16, 2023, Gunnison announced that it had entered into a Collaboration Agreement with Nuton, a Rio Tinto venture, to evaluate the use of its Nuton™ copper heap leaching technologies at Gunnison’s Johnson Camp mine in Cochise County, Arizona.
On January 23, 2023, Gunnison announced that it had received approval from Arizona Department of Environmental Quality (ADEQ) for a new leach pad at the JCM facility. The Aquifer Protection Permit (APP) for Johnson Camp has been amended to include the construction and operation of a heap leach pad to produce copper from the legacy open pits at JCM.
On February 22, 2023, Gunnison announced the results of its Updated Preliminary Economic Assessment (“PEA”) on the Johnson Camp Mine Heap Leach, located in Cochise County, southeastern Arizona. The PEA considers the results of the drill program completed in 2022 and the implementation of sulfide leaching technology to improve recoveries. The Johnson Camp PEA was subsequently superseded and replaced by the JCM Technical Report.
On April 24, 2023, the Company announced that the EPA had issued an amendment to the Class III Underground Injection Control (“UIC”) Area Permit, that will allow for well stimulation to occur at the Gunnison Project. The permit amendment subsequently became fully effective on May 26, 2023. Well stimulation has the potential to fundamentally change the performance of the wellfield, and eliminate or reduce the need for the raffinate neutralization plant. The final regulatory approval step is the submission and approval by the EPA of well stimulation work plans. Gunnison received approval for a well stimulation work plan from the EPA in December 2023 and therefore has all regulatory approvals required to proceed with well stimulation trials. However, as disclosed below, at the present time Gunnison is focused on developing an open pit mining operation at the Gunnison Project.
Extension of Nebari Credit Facility
On January 30, 2023, Gunnison announced that it and its wholly-owned Gunnison Arizona had agreed with Nebari to extend the maturity date of the Nebari Credit Agreement.
The Company, Gunnison Arizona and Nebari have entered into a Second Amendment to the Nebari Credit Agreement (the “Second Amended ARCA”). The Second Amended ARCA provides for the extension of the maturity date of the existing US$15 million credit facility to March 31, 2025 (the “Extension”) and reduces the minimum cash balance requirement to US$2.5 million.
The Extension was subject to certain conditions including completion of a debenture offering by February 17, 2023 and conclusion of certain agreements with Triple Flag. All conditions to the extension were satisfied in February, 2023, including an amendment to the Stream Agreement to extend the Leverage Ratio Grace Period to March 31, 2025.
As consideration for the Second Amended ARCA the Company was required to issue common shares of the Company to nominees of Nebari in a number equal to US$450,000, converted to Canadian dollars at an exchange rate equal to the average market rate posted by the Bank of Canada for the 5 days preceding the issuance, divided by the lower of (i) the conversion price of the January 2023 Debenture Offering (defined below) and (ii) the volume weighted adjusted price of the Common Shares for the 5 trading days immediately preceding the issuance. In addition, commencing January 31, 2024 the Company was to begin amortizing US$5 million of the principal amount of the facility in monthly instalments of US$333,333.
| 10 |
On February 9, 2023, Gunnison announced that in connection with the Second Amended ARCA, it had issued 2,368,421 Common Shares to nominees of Nebari.
On February 22, 2023 the Company and Triple Flag entered into an amendment to the Stream Agreement to extend the leverage ratio grace period to March 31, 2025 to match the extended term of the Nebari credit facility.
Debenture Financing
On January 30, 2023, Gunnison announced that it had entered into agreements for a US$3 million private placement of unsecured convertible debentures (the “January 2023 Debenture Offering”).
Pursuant to the Debenture Offering, investors subscribed for a total of US$3 million principal amount of convertible debentures (the “January 2023 Debentures”). The terms of the January 2023 Debentures included:
| ● | a maturity date of three years from the date of closing (the “January 2023 Debenture Maturity Date”) and the principal amount, together with any accrued and unpaid interest, will be payable on the January 2023 Debenture Maturity Date, unless earlier converted in accordance with their terms; | |
| ● | the Debentures bear interest at the rate of 10% per annum, which interest will be payable on April 1, 2025 and on the January 2023 Debenture Maturity Date, unless earlier converted into Common Shares; | |
| ● | the principal amount of the January 2023 Debentures is convertible into Common Shares at the option of the holder at a conversion price of US$0.19 per Common Share; | |
| ● | the accrued and unpaid interest is convertible into Common Shares at a conversion price equal to the volume weighted average trading price on the Toronto Stock Exchange for the five trading days prior to the date of conversion; and | |
| ● | the January 2023 Debentures are unsecured. |
On February 9, 2023, Gunnison announced the closing of the January 2023 Debenture Offering.
Retirement of Director, Lord Robin Renwick
On March 31, 2023, Gunnison announced the retirement from the Board of Lord Robin Renwick who had served as a director of Gunnison since 2014.
Nuton Option Agreement
On July 31, 2023, Gunnison announced that it had entered into an option agreement (the “Nuton Option Agreement”) with Nuton to further evaluate the use of its Nuton™ copper heap leaching technologies (the “Nuton™ Technologies”) at Gunnison’s Johnson Camp mine in Cochise County, Arizona. Under the Nuton Option Agreement, Gunnison remains the operator and Nuton funds Gunnison’s costs associated with a two-stage work program at Johnson Camp. Nuton provided a US$3 million pre-payment to Gunnison for Stage 1 costs and a payment of US$2 million for an exclusive option to form a joint venture with Gunnison over the Johnson Camp Mine after the completion of Stage 2.
| 11 |
Under the terms of the Nuton Option Agreement, the Stage 1 work program involved Gunnison completing diamond drilling, permitting activities, detailed engineering, and project execution planning. Nuton completed mineralogy, predictive modelling, engineering and other test work. Based on the results of the Stage 1 work program, Nuton had the option to proceed to Stage 2 (which was subsequently exercised).
The Nuton Option Agreement required that if Nuton proceeds to Stage 2, it will make a US$5 million payment to Gunnison for the use of existing infrastructure at the Johnson Camp mine for the Stage 2 work program. Nuton will also be responsible for funding all of Gunnison’s costs associated with Stage 2. The full Stage 2 work program is anticipated to take up to five years but will proceed based on milestones related to engineering and mobilization, infrastructure and construction, mining, leaching, copper production and post-leach rinsing. Mining is expected to commence in year one. The completion of all milestones would result in full scale commercial production over several years at Johnson Camp utilizing NutonTM Technologies. Revenue from operations will first be used to pay back Stage 2 costs to Nuton and will then be credited to Gunnison’s account.
After the completion of Stage 2, Nuton will have the right to form a joint venture on Johnson Camp per mutually agreeable terms whereby Nuton will hold an initial 49% and Gunnison an initial 51%. The purpose of the joint venture is to continue the development of the Johnson Camp Mine using NutonTM Technologies. Should Nuton not exercise their joint venture rights, Nuton and Gunnison will discuss in good faith Gunnison’s continued use of the Nuton™ Technologies at the Johnson Camp Mine subject to certain licensing terms and conditions. The infrastructure arrangement at Johnson Camp under this Agreement are non-exclusive. During Stages 1 and 2, Gunnison may continue to use the Johnson Camp infrastructure for processing Gunnison solutions and other copper sources not related to the Stage 2 work program so long as capacity requirements for the Stage 2 work program are met.
JCM Drilling
On August 16, 2023, Gunnison announced that it had commenced drilling at JCM with, to further evaluate the use of its Nuton™ Technologies at JCM. The program consisted of drilling 6,000 feet of PQ core for the purposes of further metallurgical evaluation. The samples from this program were processed for mineralogy and tested using the Nuton™ process. The program was funded by Nuton pursuant to the Nuton Option Agreement.
Further Extension of Nebari Credit Facility
On November 30, 2023, Gunnison announced that it and its wholly-owned Gunnison Arizona had agreed with Nebari to extend the maturity date of its existing US$15 million credit facility to June 30, 2026 (see “Description and General Development of the Business – Three Year History – Year Ended December 31, 2023 – Extension of Nebari Credit Facility”).
The Company, Gunnison Arizona and Nebari entered into a Third Amendment to the Nebari Credit Agreement (the “Third Amended ARCA”). The Third Amended ARCA provides for the extension of the maturity date of the existing US$15 million credit facility to June 30, 2026 (the “Extension”). Nebari has also agreed to reduce the interest rate (the “Rate Reduction”) to 10.5% plus a rate supplement (the “Rate Supplement”) equal to the greater of (i) the forward-looking secured overnight financing rate (administered by CME Group Benchmark Administration Limited or a successor administrator) for a tenor of 3 months and (ii) 1.50%.
As consideration for the Third Amended ARCA as it relates to the Extension and Rate Reduction, the Company is required to issue Common Shares to nominees of Nebari in a number equal to US$1,050,224, converted to Canadian dollars at an exchange rate equal to the average market rate posted by the Bank of Canada for the 5 days preceding the issuance, divided by C$0.155 (US$0.11405). This amount includes a cash extension bonus plus an amount equal to the total additional amount of interest that would have been payable to the maturity date of the credit facility prior to the Rate Reduction.
| 12 |
In addition the early amortization of the credit facility has been extended such that the Company will begin amortizing the principal amount of the facility (and pro-rata repayment bonus (the “Repayment Bonus”) amount that already exists under the credit facility) in monthly instalments payable on the last day of each month of (i) commencing June 2024 to and including December 2024, seven equal monthly installments of US$206,000.00; (ii) commencing January 2025 to and including December 2025, twelve equal monthly installments of US$257,500.00; and (iii) commencing January 2026 to June 2026, six equal monthly installments of US $309,000.00.
On December 14, 2023, Gunnison announced that in connection with the Third Amended ARCA, it has issued 9,208,093 Common Shares to nominees of Nebari.
Financing
On November 30, 2023, Gunnison announced that in order to satisfy the condition to complete the Financing under the Third Amended ARCA, the Company has agreed to a transaction with Triple Flag USA Royalties Ltd (“Triple Flag Royalties”) and Greenstone on the following terms: (i) Greenstone shall sell 1.5% of its total 3% gross revenue royalty on the Johnson Camp Mine to Triple Flag Royalties for consideration of US$5.5 million in cash (the “Royalty Sale”); and (ii) Greenstone will concurrently complete a US$5.5 million financing with the Company that consists of US$3.1 million in Common Shares (the “2023 Share Offering”) and $2.4 million principal amount of convertible debentures (the “December 2023 Debenture Offering”). In order to facilitate these transactions, Greenstone first transferred the 1.5% gross revenue royalty on the Johnson Camp Mine to Gunnison for the proceeds of the 2023 Share Offering and December 2023 Debenture Offering, and then Gunnison re-sold the royalty to Triple Flag Royalties for US$5.5 million in cash.
Pursuant to the 2023 Share Offering, the Company issued Greenstone a total of 27,180,000 Common Shares at a price of US$0.11405 (C$0.155) per Common Share for aggregate gross proceeds of $3.1 million.
Pursuant to the December 2023 Debenture Offering, Greenstone will subscribe for a total of US$2.4 million principal amount of convertible debentures (the “December 2023 Debentures”). The terms of the December 2023 Debentures include:
| ● | a maturity date of September 30, 2026 (the “December 2023 Debenture Maturity Date”) and the principal amount, together with any accrued and unpaid interest, will be payable on the December 2023 Debenture Maturity Date, unless earlier converted in accordance with their terms; | |
| ● | the Debentures bear interest at the rate of 10.5% per annum plus the Rate Supplement, which interest will be payable on the December 2023 Debenture Maturity Date, unless earlier converted into Common Shares; | |
| ● | subject to the receipt of disinterested shareholder approval from the holders of the Common Shares at a duly and validly call meeting, the principal amount of the December 2023 Debentures is convertible into Common Shares at the option of the holder (or at the option of the Company on 30 days prior notice) at a conversion price of US$0.11405 per Common Share; | |
| ● | subject to receipt of shareholder approval (which was obtained), the accrued and unpaid interest is convertible into Common Shares at a conversion price equal to the volume weighted average trading price on the TSX for the five trading days prior to the date of conversion; and | |
| ● | the December 2023 Debentures are unsecured. |
| 13 |
The Company used the proceeds of the Share Offering and Debenture Offering for project development expenses and working capital.
On December 14, 2023, Gunnison announced the closing of the 2023 Share Offering and December 2023 Debenture Offering. Greenstone Resources and its affiliated entities, including Greenstone, previously held 116,028,937 Common Shares. Greenstone Resources also owns and controls 1,250,000 options to acquire Common Shares and a convertible debenture with principal amount of $1.5 million that is convertible into 7,894,736 Common Shares. As a result of the closing of the 2023 Share Offering and December 2023 Debenture Offering and conversion of the debentures held by Greenstone Resource and Greenstone (assuming conversion of all interest payments on the maturity date, using a conversion price of US$0.11405 and a SOFR rate of 5.3307%), Greenstone Resources and Greenstone would acquire ownership and control over an additional 57,383,369 Common Shares. As a result, together with the Common Shares currently owned and controlled by Greenstone Resources and its affiliated entities, including Greenstone, Greenstone Resources and its affiliated entities would hold a total of 173,412,306 Common Shares (assuming conversion of only the debentures held by Greenstone and assuming the conversion of all interest to maturity at US$0.11405).
On December 14, 2023 the Company and Triple Flag entered into a further amendment to the Stream Agreement to extend the leverage ratio grace period to September 30, 2026 to match the extended term of the Nebari credit facility. The holders of the January 2023 Debentures also agreed to extend the January 2023 Debenture Maturity Date to September 30, 2026.
Year Ended December 31, 2024 Developments
Nuton Option Agreement Update
On May 15, 2024, the Company announced that Nuton had elected to proceed to Stage 2 of the existing Nuton Option Agreement “Description and General Development of the Business – Three Year History – Year Ended December 31, 2023 – Nuton Option Agreement”). The purpose of the Nuton Option Agreement is for Nuton to evaluate the use of its Nuton™ copper heap leaching technologies at Gunnison’s Johnson Camp mine in Cochise County, Arizona. As Nuton elected to proceed to Stage 2, Nuton, Gunnison and Gunnison Arizona entered into the Nuton Technology Demonstration Agreement dated June 17, 2024 (the “Nuton Demonstration Agreement”). The Nuton Demonstration Agreement operates in conjunction with the Nuton Option Agreement and provides the framework for the Stage 2 work program at Johnson Camp. Under the Option Agreement and Nuton Demonstration Agreement, Gunnison remains the operator and Nuton funds Gunnison’s costs associated with a two-stage work program at Johnson Camp.
As Nuton has elected to proceed to Stage 2, it made a US$5 million payment to Gunnison for the use of existing infrastructure at the Johnson Camp mine for the Stage 2 work program. Nuton will also be responsible for funding all of Gunnison’s costs associated with Stage 2. The full Stage 2 work program is anticipated to take up to five years, and, if successful, will demonstrate key elements of the Nuton technologies at industrial scale. It will proceed based on milestones related to engineering and mobilization, infrastructure and construction, mining, leaching, copper production and post-leach rinsing. Mining is expected to commence in year one with first Nuton copper produced in 2025.
The completion of all milestones would result in full scale commercial production of Nuton copper over several years at Johnson Camp. Revenue from operations will first be used to pay back Stage 2 costs to Nuton and will then be credited to Gunnison’s account after fulfillment of Gunnison’s applicable royalty and stream obligations.
Appointment of Craig Hallworth as Chief Financial Officer
On August 1, 2024, the Company announced the appointment of Craig Hallworth as Chief Financial Officer and Senior Vice President of the Company, such appointment being effective September 3, 2024.
| 14 |
Litigation Update
On October 29, 2024, the Company announced that the proceedings brought by MM Fund (as plaintiff) in British Columbia and Ontario have been dismissed with prejudice. The Company and the plaintiff agreed to dismiss the proceedings on a no cost basis (see “Legal Proceedings and Regulatory Actions”).
Name Change
On November 11, 2024, the Company completed a corporate name change to “Gunnison Copper Corp.”
Johnson Camp Update
On August 8, 2024, the Company provided an update on construction at the Johnson Camp Mine, announcing that construction of the leach pad had commenced. Gunnison has completed the bulk of the planning & engineering and has mobilized crews to start construction. M3 Engineering based in Tucson has been awarded the EPCM contract. Earthworks related to the construction of the new leach pad has commenced, including crushing of the over-liner material. Rango Inc. from Mesa was awarded the leach pad construction and overliner crushing contract and is ramping up efforts to achieve the Gunnison milestones.
On October 21, 2024, the Company announced that it had received all permits required to commence operations at the Johnson Camp Mine.
On December 16, 2024, the Company provided construction update on the Johnson Camp Mine, announcing that the mining fleet has been mobilized, and mining activities such as pre-stripping have begun.
Gunnison Project Update
On November 14, 2024, the Company announced the results of a Preliminary Economic Assessment (“2024 Gunnison PEA”) on its 100%-owned Gunnison Project in the Cochise Mining District, Arizona. The Gunnison Project is presented as a conventional open pit and heap leach operation which will produce finished copper cathode for domestic U.S. consumption.
Gunnison has entered into an option agreement dated November 12, 2024 (the “Benson Option Agreement”) with certain local landowners providing the option (the “Benson Option”) for a period of six years to acquire a total of 3,906.57 acres of land (the “Option Land”). Portions of the Option Land will contain the proposed open pit and related infrastructure. The terms of the Benson Option Agreement require an initial payment of $1,000,000, and annual payments of $250,000 in years 2, 3, 4 and 5 of the Option. The final purchase price for exercise of the Option is based on the exercise date and is set forth in the table below:
| Final Payment Date | Total Price | |||
| During the period within 1 year from Effective Date | $ | 28,000,000 | ||
| During the period after 1 year but within 2 years from Effective Date | $ | 30,000,000 | ||
| During the period after 2 years but within 3 years from Effective Date | $ | 31,250,000 | ||
| During the period after 3 years but within 4 years from Effective Date | $ | 33,500,000 | ||
| During the period after 4 years but within 5 years from Effective Date | $ | 35,750,000 | ||
| During the period after 5 years but within 6 years from Effective Date | $ | 37,000,000 | ||
| 15 |
The Gunnison Project was previously designed as a copper in-situ recovery (“ISR”) mine using solvent extraction-electrowinning (“SX-EW”) to produce copper cathode. The ISR operation commenced ramp-up to production in 2020; however, as previously disclosed, it had operational issues related to low flow rates, so the Company began evaluating alternatives and opportunities to fix the ramp-up challenges. Well stimulation (small scale, shallow level, hydraulic fracking), has the potential to fundamentally change the performance of the wellfield and fix many of the low productivity issues. The Company has obtained a permit for well stimulation and the next step would be to conduct field trials. If well stimulation is successful, it could provide an operation with superior economics to the open pit operation and be in copper production much quicker than an open pit. However, due to the technical risks of ISR and substantially improved viability of the open pit operation, Gunnison intends to focus on an open pit operation as the alternative to ISR. If future financing is available for ISR activities, the Company may elect to conduct well stimulation field trials, but such field trials will not hinder the open pit studies. The Company intends to maintain the optionality of future ISR operations and well stimulation trials as this remains an asset to the Company. This includes maintaining full compliance with all regulatory and permit requirements, including maintaining hydraulic control, pumping, monitoring and regulatory reporting.
Please refer to “Mineral Properties” for a description of the results of the most recent preliminary economic assessment on the Gunnison Project, which are contained in the Gunnison Technical Report.
Year Ended December 31, 2025 Developments
48C Tax Credits
On January 16, 2025, the Company announced that the Company and Nuton have been selected to receive US$13.9 million in tax credits (the “48C tax credit”) under the Qualifying Advanced Energy Project Credit Program (the “48C program”) to expand production of Made in America copper, which is designated a Critical Material for Energy, from its Johnson Camp.
The 48C tax credit is part of the US$10 billion in funding under the Inflation Reduction Act of 2022 (“IRA”) to intensify clean energy manufacturing and recycling, industrial decarbonization, and critical materials projects in the US. In March 2024, the IRS allocated $4 billion in 48C credits. In April 2024, the Department of the Treasury and the Internal Revenue Service, in partnership with DOE, announced up to $6 billion in a second round of tax credit allocations and Gunnison and Nuton applied for these credits for the Johnson Camp project. Under the IRA, a qualifying advanced energy project credit can either be monetized through its sale for cash or by using it to offset income tax liability. Realization of the full amount of this tax credit is subject to satisfaction of the requirements set forth in Section 48C of the Internal Revenue Code including certification of the operational and employment plans set out in the application. The tax partnership has a period of two years within which to satisfy the certification requirements and claim the tax credits.
The actual allocation of the 48C tax credits as between the Company and Nuton is determined in a tax partnership agreement entered into between the parties which is discussed further below.
Comprehensive Financial Transaction
On March 3, 2025 the Company announced that it has agreed to a non-dilutive funding transaction (the “2025 Nuton Transaction”) with Nuton for $3 million in proceeds to Gunnison to be used toward its costs related to a Nuton testing program at the Gunnison Project, as well as the execution of a Tax Partnership Agreement between Gunnison and Nuton (the “Tax Partnership Agreement”) with an agreed-upon allocation of the potential future proceeds from Gunnison and Nuton’s award of 48C tax credits from the U.S. government.
| 16 |
Gunnison, Gunnison Arizona and Nuton have entered into a Collaboration Agreement dated February 28, 2025 (the “Gunnison Collaboration Agreement”) that provides for, among other things:
| ● | Nuton’s exclusivity over Stage 1 testing of novel heap leach processing technologies for sulfide mineralization at the Gunnison Open Pit, and | |
| ● | Agreed milestones to examine the potential for an extension to the Stage 2 Work Program at the Johnson Camp Mine. |
In exchange for the above:
| ● | Nuton provided $3 million to Gunnison to be used toward its expenses for the Nuton Stage 1 Viability study on the Gunnison Open Pit and other agreed purposes; and | |
| ● | Nuton and Gunnison will work within the parameters of the Tax Partnership Agreement to potentially allow for a portion of realized cash proceeds from the sale of 48C tax credits to be distributed to Gunnison to retire a significant portion, or all of, the Nebari debt, which will benefit the Stage 2 Work Program by reducing Gunnison’s debt service obligations. The receipt of the 48C tax credit is subject to Certification as outlined in IRS Notice 2023-44. There is no certainty that the receipt of the 48C tax credit will be satisfied. |
The parties have agreed to conduct a Stage 1 viability testing program of Nuton Technologies on sulfide mineralization at the Gunnison Open Pit (the “Stage 1 Gunnison Program”). The Stage 1 Gunnison Program will involve the collection and testing of samples from drill core from the Gunnison Project. The samples will be analyzed by Nuton for the purposes of determining the suitability of the Gunnison Project with Nuton Technologies.
Gunnison and Nuton have also agreed to work together to evaluate the possible extension of the Stage 2 Work Program at Johnson Camp. Nuton shall also receive a right of first offer over the use of any excess capacity from the SX/EW plant and related infrastructure and mining assets located at the Johnson Camp Mine.
Gunnison and Nuton (or its affiliates) have also agreed to negotiate in good faith an exclusive exploration agreement over all of Gunnison’s property for a 3-to-5-year term (or such term as agreed between the parties), on commercial terms that includes a specified work program, costs and timelines.
On April 24, 2025, the Company announced that the Company, Gunnison Arizona, Gunnison Holdings and Nebari entered into the Second ARCA. The Second ARCA encompasses certain amendments to the First Amended and Restated Credit Agreement dated December 22, 2021. The amendments provide for, amongst other matters, a suspension of principal amortization from February 1, 2025 until January 1, 2026, provide for potential partial conversion to equity of up to US$6.25 million of the principal amount at a price equal to US$0.2097 (converted from Cdn$0.30), and provide for a mechanism to repay a portion of the principal amount of the Second ARCA with proceeds to be received from sale of the previously announced 48C tax credits and through a potential refinancing process provide for an extension of the maturity date.
The Second ARCA was subject to certain conditions including conditional approval of the Toronto Stock Exchange, approval from Greenstone and Triple Flag, deferral of interest payments due under convertible debentures due to Greenstone and Triple Flag, certain agreements between Nebari and Triple Flag agreement and commencement of a work program by Gunnison to optimize certain opportunities identified in the preliminary economic assessment for the Gunnison Project. All of these conditions were satisfied.
| 17 |
Director Retirement
On March 20, 2025 Stephen Axcell retired as a director of the Company.
Listed Issuer Financing Exemption (LIFE) Private Placement of Units
On April 7, 2025, the Company announced it had closed a non-brokered private placement (the “April 2025 Offering”) consisting of 17,170,916 units (the “April 2025 Units”), with each Unit consisting of one common share and one-half of one common share purchase warrant (each full common share purchase warrant, a “April 2025 Warrant”) at a price of C$0.30 per Unit for aggregate gross proceeds of C$5.15 million. Each full April 2025 Warrant shall entitle the holder thereof to acquire one additional common share at a price of C$0.45 for a period of twenty-four (24) months from the closing date of the April 2025 Offering.
The April 2025 Offering was made to purchasers resident in all provinces of Canada, except Quebec, pursuant to the listed issuer financing exemption under Part 5A of NI 45-106 (the “Listed Issuer Financing Exemption”). Pursuant to the limitations of the Listed Issuer Financing Exemption, the April 2025 Units offered under the Listed Issuer Financing Exemption are not subject to resale restrictions pursuant to applicable Canadian securities laws.
Board Appointments
On May 15, 2025, the Company announced that Mr. Jason Howe and Mr. Joseph Galluci had been appointed to the Board of Directors.
Second Listed Issuer Financing Exemption (LIFE) Private Placement of Units
On July 18, 2025, the Company announced it had closed a non-brokered private placement (the “July 2025 Offering”) consisting of 28,874,100 units (the “July 2025 Units”), with each Unit consisting of one common share common and one common share purchase warrant (each common share purchase warrant, a “July 2025 Warrant”) at a price of C$0.30 per Unit for aggregate gross proceeds of C$8,662,230. Each July 2025 Warrant shall entitle the holder thereof to acquire one additional common share at a price of C$0.45 and any time on or before July 18, 2028.
The July 2025 Offering was made to purchasers resident in all provinces of Canada, except Quebec, pursuant to the Listed Issuer Financing Exemption. Pursuant to the limitations of the Listed Issuer Financing Exemption, the Units offered under the Listed Issuer Financing Exemption are not subject to resale restrictions pursuant to applicable Canadian securities laws.
Lunasonde
On December 19, 2025, the Company announced that it had entered into a Collaboration Framework Agreement (“CFA”) with Lunasonde. Under the CFA, Lunasonde will deploy its proprietary remote sensing technology to conduct an initial high-resolution subsurface survey over a defined portion of Gunnison’s mineral property portfolio within the Company’s Cochise Mining District in southern Arizona. The work program is expected to include test and calibration flights, followed by data processing and analysis to generate three-dimensional subsurface imaging of identified anomalies with the potential to host critical minerals.
COO Appointment
On October 9, 2025, the Company announced that the promotion of Robert Winton to Chief Operating Officer. Mr. Winton had served as Senior Vice President and Operations of the Company since August 2020.
| 18 |
Third Listed Issuer Financing Exemption (LIFE) Private Placement of Units and Concurrent 4-Month Hold Private Placement of Units
On October 30, 2025, the Company announced it had closed a non-brokered financing for aggregate gross proceeds of C$13,112,270.10 from the issuance of 29,138,378 units (the “October 2025 Units”). This total comprises: (i) a Listed Issuer Financing Exemption offering of 24,858,878 October 2025 Units for gross proceeds of C$11,186,495.10 (the “October 2025 LIFE Offering”); and (ii) a concurrent 4-Month Hold offering of 4,279,500 October 2025 Units for gross proceeds of C$1,925,775 (the “Hold Offering”, and together with the October 2025 LIFE Offering, the “October 2025 Offering”).
Each October 2025 Unit, issued at a price of C$0.45 per October 2025 Unit, consists of one Common Share and one-half of one common share purchase warrant (each whole warrant, a “October 2025 Warrant”). Each October 2025 Warrant entitles the holder to purchase one Common Share at a price of C$0.65 at any time on or before October 30, 2028.
Certain of the October 2025 Units were sold to purchasers resident in Canada pursuant to the Listed Issuer Financing Exemption. The securities issuable pursuant to the sale of these units to purchasers resident in Canada are immediately freely tradeable under applicable Canadian securities legislation.
The October 2025 Units issued in the Hold Offering were offered by way of private placement in Canada and in jurisdictions outside of Canada on a private placement or equivalent basis, in each case in accordance with all applicable laws. The securities issuable pursuant to the sale of these units were subject to a four-month hold period in Canada pursuant to applicable Canadian securities laws that expired March 1, 2026.
On October 31, 2025, the Company announced the closing a second and final tranche of the Hold Offering aggregate gross proceeds of C$150,000.30 from the issuance of 333,334 October 2025 Units to a single institutional investor. Each Warrant entitles the holder to purchase one Common Share at a price of C$0.65 at any time on or before October 31, 2028. The securities issuable pursuant to the sale of these units were subject to a four-month hold period in Canada pursuant to applicable Canadian securities laws that expired on March 1, 2026.
Passing of Director, Mr. Colin Kinley
On November 7, 2025, the Company announced the sudden passing of Mr. Colin Kinley, who had served as a director of Gunnison since 2010.
Repayment of Nebari Non-Convertible Secured Debt
On December 1, 2025, the Company announced that it has fully repaid the US$7.3 million non-convertible principal portion of the Second ARCA with Nebari. Following this repayment, the only remaining balance outstanding under the Second ARCA was the US$5.25 million convertible principal amount, which Nebari retains the right to convert to equity under the previously announced terms.
| 19 |
Gunnison Project Update
On June 17, 2025, the Company provided an update on the high-value-add (“HVA”) work programs at the Gunnison Project as follows:
| ● | Gravel By-Product Revenue - An experienced consulting firm has been engaged to investigate the viability of marketing gravel and limestone. | |
| ● | Limestone By-Product Revenue – The experienced consulting firm is also investigating the viability of marketing gravel and limestone by-products from the Gunnison open pit. | |
| ● | Mineralized Material Sorting - Drilling of all 3 holes totaling 3,899 feet targeting oxide mineralization in the Martin and Abrigo formations were competed in May. The core from these holes was sent for assaying and extensive mineralogical testing which was subsequently incorporated into the Gunnison Technical Report. | |
| ● | Permitting - Gunnison’s prior permitting and community track record is excellent. There is no federal permitting required. The Gunnison Copper Project is permitted today for in-situ recovery; however, amendments are needed. Trinity Consultants (Air Quality Permit) and Clear Creek (APP) have been engaged and have produced drafts for the permitting process. | |
| ● | Sulfide Investigation - Sulfide mineralization occurs in the bottom of the Gunnison Copper Project open pit design. Due to the previous ISR mining method the sulfide potential has been mostly untested. The plan is to collect appropriate samples and initiate metallurgical test work. The sulfides have the potential to add mine life, production rate and excite strategic interest such as the recent interest from Nuton who have an agreement with Gunnison to test the suitability of its proprietary sulfide leaching technology for the Project’s sulfide resources. |
On October 23, 2025, the Company announced the results from its ongoing HVA Work Program evaluating the commercial potential of limestone occurring within the planned Gunnison Open Pit mine plan. The evaluation indicates that a substantial portion of the limestone, material that is currently scheduled as waste in the mine plan, is suitable for a range of industrial end-use markets, including cement, agricultural lime, and premium paper filler/paint and coatings.
On February 25, 2026, the Company announced the results of an updated NI 43-101 Preliminary Economic Assessment (“PEA”). The PEA supersedes the 2024 PEA in all respects.
Please refer to “Mineral Properties – Gunnison Project” for a description of the results of the Gunnison PEA which are contained in the Gunnison Technical Report.
Johnson Camp Update
On March 21, 2025, the Company provided an update on construction at the Johnson Camp Mine, announcing that mining of mineralized material had commenced; material was being stockpiled in advance of the completion of the leach pads; Phase 1 leach pad construction was complete; and Phase-2 leach pad construction completion was expected in the near term.
On June 9, 2025, the Company provided a further construction update on the Johnson Camp Mine, announcing that construction activities are progressing as planned. The haul road to the run of mine oxide Phase-1 pad, PLS sump, culverts and overflow pond construction have started ahead of first acid irrigation. The pipelines from the leach pads to the SX/EW plant are nearing completion, and Phase-1 pad irrigation is anticipated by July 2025.
On July 22 2025, the Company provided an update on the Johnson Camp Mine construction, announcing that that mineral processing has commenced with first copper sales expected in September 2025. The overflow pond construction has been completed ahead of first acid irrigation. The pipelines from the leach pads to the SX/EW plant are complete, and Phase-1 pad leaching has started, with first copper cathode from Run-of-mine (ROM) oxide production using conventional leach technology scheduled for September. First copper using Nuton technology is expected before the end of the year.
| 20 |
On August 11, 2025, the Company provided a further update on the Johnson Camp Mine construction, announcing the final phase of the leach pad construction is on schedule. The on-pad crushing circuit, which will be used with the Nuton Technologies, has been installed and started commissioning activities. The agglomerator and processing equipment, which will also be used on the Nuton pad, has been placed and the Company is completing final mechanical and electrical construction of these components. The new LNG (liquid natural gas) system at the EW plant was fully commissioned and operating in line with electrowinning start-up.
On September 3, 2025, the Company announced that following the successful start-up of the solvent extraction and electrowinning circuit, copper cathode is now officially in production from run-of-mine ore. The Company achieved this critical milestone in late August, 2025 ahead of schedule.
On September 24, 2025, the Company announced that on September 15, 2025, the Company completed its inaugural copper sales, marking the start of revenue generation following successful commissioning.
On December 4, 2025, the Company announced that Rio Tinto has successfully produced the first copper from the Johnson Camp mine using its Nuton® Technology.
Developments Subsequent to December 31, 2025
Nebari Debt Fully Eliminated
On January 20, 2026, the Company announced that it had fully eliminated all outstanding principal owed to Nebari. The debt was finally eliminated when the Company received additional conversion notices from Nebari pursuant to the terms of the Second ARCA. Combined with Gunnison’s US$7.3 million repayment of Nebari’s non-convertible debt, and Nebari’s accumulated conversions of the remaining convertible principal, all principal amount outstanding under the Second ARCA have now been fully repaid or converted. Gunnison repaid the partial month of interest owing and obtained a release of the security documents associated with the debt.
Distribution of Greenstone Shares
On February 18, 2026 Greenstone Resources II LP (“Greenstone”) announced that it, together with its affiliates Greenstone Excelsior Holdings LP, Greenstone Co-Investment No 1 (Excelsior) LP and Greenstone Co-Investment No 2 (Excelsior) LP (together, the “Greenstone Group”), have completed an initial closing of the sale of 113,607,200 Common Shares owned by the Greenstone Group.
Johnson Camp Update
On January 15, 2026, the Company announced Rio Tinto’s strategic collaboration with Amazon Web Services (AWS) that will see AWS become Nuton® Technology’s first customer following the breakthrough first industrial-scale deployment of the innovative bioleaching technology at Johnson Camp Mine in December 2025. Under the agreement, AWS will use the first Nuton copper ever produced in components of its U.S. data centres, while also providing cloud-based data and analytics support to accelerate the optimisation of Nuton’s proprietary bioleaching technology at Johnson Camp Mine. Data centres use copper in a wide variety of applications, including electrical cables and busbars, windings in transformers and motors, printed circuit boards, and heat sinks on processors.
| 21 |
Outlook
Gunnison High Value Work Program
In 2026, Gunnison Copper will focus on advancing its flagship Gunnison Copper Project with the planned commencement of a pre-feasibility study (“PFS”) and progression of key permit amendments. As part of the PFS work program, Gunnison will continue to de-risk and optimize the Gunnison Project through ongoing metallurgical test work, infill drilling, geotechnical drilling, hydrology work, engineering, and other studies. In parallel, Gunnison will continue its exploration activities utilizing Lunasonde’s technology. The Company also expects to monetize its Section 48C tax credits in Q2 2026. At Johnson Camp Mine, the company will ramp up to commercial production, followed by full nameplate capacity targeted for Stage 2 by year-end.
Gunnison Copper Project - Pre-Feasibility Study & Permit Amendments
In Q4 2025, Gunnison continued planning work required on a PFS for the Gunnison Copper Project. The PFS objectives include converting the mineral resources in the mine plan to the Measured and Indicated level and into mineral reserves, in addition to advancements in the detail level of mine and plant engineering. The work program will include infill drilling, geotechnical drilling, metallurgical testing, hydrological work, engineering, and other studies. Results of the PFS are expected to be published by the end of 2027.
Concurrently with the PFS work program, Gunnison intends to file permit amendments with Arizona Department of Environmental Quality and the Arizona State Mine Inspector with respect to the existing Air, Aquifer Protection, and Mine Land Plan of Reclamation permits. Initial planning for the permit amendment process was completed during the 2025 HVA work program. These amendments will permit the open pit approach. In addition, a new state permit is required from the Arizona Department of Transportation to move a section of the Interstate 10 highway. Currently, the Gunnison Project is fully permitted for In-Situ leaching, which is the approach previously pursued. All required permits for the Gunnison open pit fall under the state permitting regime (i.e. no federal nexus). The permit amendments are expected to take approximately 18 to 24 months to receive. The Company is targeting to receive all permit amendments by the end of 2027.
Johnson Camp Mine Production
First production of copper cathode from the Run of Mine Oxide (“ROM”) circuit at the JCM was achieved in August 2025. In addition, the first copper cathode produced using Rio Tinto’s Nuton® Technology was successfully achieved in December 2025, marking a key milestone in the industrial-scale deployment of its proprietary bioleaching technology. The Nuton circuit is expected to continue ramping up through 2026 alongside the ROM circuit.
The Johnson Camp Mine SX/EW plant has an installed production capacity of 25 million lbs of finished copper cathode per year, with production intended for sale into the United States. Notably, the first Nuton copper produced at JCM has been supplied into the U.S. supply chain, with AWS announced as the first customer, utilizing this low-carbon copper in its data centre infrastructure. Ramp-up to nameplate capacity is expected over a six-month period as operations progress through commissioning and optimization, with expectation to reach the nameplate rate of production by year-end.
The construction and restart of the Johnson Camp Mine is fully funded by Nuton for the purpose of demonstrating their proprietary sulfide leaching technology. As a result, the mine plan for Stage 2 is currently designed to strip waste to access and prioritize the accelerated mining of primary sulfide material, which will be used to demonstrate the technology, which may result in higher mining costs versus a fully optimized mine plan that prioritized total profit. Similarly, processing costs are expected to be initially higher as the site goes through a rigorous optimization and refinement program related to introducing the new technology.
| 22 |
48C Tax Credits Monetization and Debt Reduction
The US$13.9M allocation of tax credits was granted to the Gunnison-Nuton Tax Partnership in January 2025 under the Qualifying Advanced Energy Project Credit Program of the Inflation Reduction Act. Under the United States Inflation Reduction Act, a qualifying advanced energy project credit can either be monetized through its sale for cash or by using it to offset income tax liabilities. These credits are expected to be monetized by mid 2026 through the sale of these credits in a free-market transaction following the completion of the certification process. Gunnison expects to receive up to US$8M in cash after Nuton’s allocation and reimbursement of costs, with the actual amount depending on the 48C tax credit certification process and how much can be realized from the sale of the certified credits.
The receipt of the 48C tax credit is subject to certification as outlined in IRS Notice 2023-44. There is no certainty that the conditions to the receipt of the 48C tax credit will be satisfied.
This section contains forward-looking information. Please refer to “Forward-Looking Information” for details on the risks and assumptions associated with such forward-looking information.
Significant Acquisitions
The Company has made no significant acquisitions for which disclosure is required under Part 8 of National Instrument 51-102.
NARRATIVE DESCRIPTION OF THE BUSINESS
Summary of the Business
The Company is focused on mining operations at its core assets, the Johnson Camp Mine and the Gunnison Project located in Cochise County, Arizona.
Competitive Conditions
The mineral exploration and mining business is a competitive business. The Company competes with numerous other companies and individuals in the search for and the acquisition of attractive mineral properties. The success of the Company will depend not only on its ability to operate and develop its properties but also on its ability to select and acquire suitable properties or prospects for development or mineral exploration.
The mineral resource industry is intensely competitive in all of its phases, and the Company competes with other mineral resource companies in connection with the acquisition of properties, the recruitment and retention of qualified personnel and contractors, the supply of equipment and, ultimately, customers for any copper that may be produced from the Gunnison Project if it reaches production. Many of the companies the Company competes with have greater financial resources, operational experience and technical facilities than the Company. Consequently, the Company’s future revenue, operations and financial condition could be materially adversely affected by competitive conditions. See also “Risk Factors”.
Employees
The Company had 106 employees as of December 31, 2025.
Environmental Protection
The Company understands the importance of environmental protection. The Company’s activities are subject to extensive federal, state and local laws and regulations governing environmental protection and employee health and safety. The Company is required to obtain government permits and comply with bonding requirements under environmental laws. All phases of the Company’s operations are subject to environmental regulation. These regulations mandate, among other things, the maintenance of air and water quality standards and land reclamation. They also set forth limitations on the generation, transportation, storage and disposal of solid and hazardous waste. Environmental legislation is evolving in a manner which will require stricter standards and enforcement, increased fines and penalties for non-compliance, and more stringent environmental assessments of proposed projects.
| 23 |
On October 23, 2024, and following an informational public meeting on September 26, 2024, and a review of a technical memorandum issued by ADWR’s Chief Hydrologist, the Director of the Department of Water Resources issued an Order initiating the proceedings to designate the Willcox Groundwater Basin as a subsequent active management area (“AMA”) pursuant to A.R.S. § 45-414. The Willcox Groundwater Basin includes the area where the Company’s Gunnison Project and JCM are located.
As a result of the AMA designation there are now restrictions on the Company’s ability to withdraw groundwater for use at its mineral projects and in order to withdraw groundwater the Company will have to comply with the terms of the Order. The Company anticipates that JCM would be eligible for grandfathered rights. Individuals and entities seeking to claim a grandfathered right must apply for a certificate of grandfathered right no later than fifteen months after the date of the designation of the AMA on January 8, 2025 (by April 8, 2026), in accordance with A.R.S. § 45-476. The grandfathered rights take into account groundwater use that occurred in the five-year period preceding the directors notice of proceedings to designate an AMA. A person who fails to apply for a certificate of grandfathered right within an active management area waives and relinquishes any right to withdraw or receive and use groundwater pursuant to a grandfathered right (A.R.S. § 45-477.01).
In addition, Arizona law provides for a process for the use of groundwater by mining operations within an AMA, even for operations without grandfathered rights. In particular, there are two types of withdrawal permits specifically tailored to mining operations: (1) the dewatering permit, (ARS § 54-513) and (2) the mineral extraction and metallurgical processing permit (ARS § 54-514). The statutes specify that ADWR “shall” issue the permits if the applicant meets the statutory requirements, which, depending on the type of permit, principally address the unavailability of reasonable-cost water from other sources and the use to be made of the water.
The environmental protection requirements affect the financial condition and operational performance and earnings of the Company as a result of the capital expenditures and operating costs needed to meet or exceed these requirements. These expenditures and costs may also have an impact on the competitive position of the Company to the extent that its competitors are subject to different requirements in other governmental jurisdictions. To date the effect of these requirements has been limited due to the small amount of production activity of the Company, but they are expected to have a larger effect in future years as the Company moves toward commercial production and eventual production expansion. There is no assurance that future changes in environmental regulation, if any, will not adversely affect the Company’s operations.
For further information related to environmental protection see “Mineral Properties – Gunnison Project – Mining Operations – Environmental and Permitting.”
Social and Environmental Policies
The Company places great emphasis on providing a safe and secure working environment for all of its employees and contractors, and it recognizes the importance of operating in a sustainable manner.
The Company’s Code of Business Conduct and Ethics (“Code of Conduct”) is the policy that sets out the standards which guide the conduct of the Company’s business and the behaviour of its employees, officers and our Board of Directors. The Code of Conduct, amongst other things, sets out standards in areas relating to:
| ● | Promotion and provision of a work environment in which individuals are treated with respect, provided with equal opportunity and is free of all forms of discrimination; |
| 24 |
| ● | Ethical business conduct and legal compliance, including without limitation prohibition against accepting or offering bribes; and | |
| ● | Commitment to health and safety in our business operations, and the identification, elimination or control of workplace hazards. |
The Company’s commitment to safety is defined in its Safety Handbook. The Company is committed to developing and maintaining programs that meet and where practical, exceed the requirements of the law. The Company’s ultimate goal is zero accidents and to earn the reputation of being a safety conscious operator.
MINERAL PROPERTIES
General
The Company’s only material mineral properties are the Gunnison Project and JCM.
Gunnison Project
The following represents the summary of the Gunnison Technical Report dated effective March 18, 2026 prepared by John Woodson, P.E., SME-RM, Jeffery Bickel, C.P.G., Dr. Abyl Sydykov, Ph.D., P.E., Dr. Terence P. McNulty, P.E., D.Sc., Rob Valceschini, P.E., R. Douglas Bartlett, C.P.G., Jacob Richey, P.E., Thomas M. Ryan, P.E. and Tyler Peck, P.E. Unless specifically noted otherwise, the following disclosure regarding the Gunnison Project has been prepared under the authority and supervision and with the consent of the authors, each a “qualified person” within the meaning of NI 43-101. The full Gunnison Technical Report is incorporated by reference into this AIF and is available under Gunnison’s corporate profile on SEDAR+ at www.sedarplus.ca. All references in this summary to Sections are to the Sections of the Technical Report. All dollar amounts or ‘$’ set out in this section are United States of America Dollars.
Summary
M3 Engineering & Technology Corporation (“M3”) was commissioned by Gunnison Copper Corp. (“GCC”) to update their October 2024 Preliminary Economic Assessment in accordance with the Canadian National Instrument 43-101 standards for reporting mineral properties, for the Gunnison Project (the “Gunnison Project”) in Cochise County, Arizona, USA. The updated Gunnison Project includes a new mine design for the Gunnison Deposit (Gunnison or Gunnison Deposit) as an open pit, using heap leaching to produce PLS that then reports to a Solvent Extraction and Electrowinning (SX-EW) plant. An addition to the mine plan is the Strong & Harris deposit (Strong & Harris or Strong & Harris Deposit) located three miles north of the Gunnison Deposit.
The biggest material change is to include pre-concentration of some of the mineralized materials via mechanical material sorters to reduce the amount of material delivered to the leach pad and to reduce the acid consumption of high-carbonate mineralized material. The plant capacity of the Gunnison Project remains as 175 million pounds per annum (mppa) of cathode copper. The SX-EW plant will be constructed in a single stage of development.
The project includes the construction of a sulfur-burning sulfuric acid plant, as in the previous study. The acid plant is 10% smaller than in the previous study but uses the same technology.
As part of the business plan, GCC has now included a cement plant and limestone plant to sell products from 177 million tons of high purity limestone that will be extracted from the Gunnison and Strong & Harris pits. The Gunnison Project is located about 62 miles east of Tucson, Arizona on the southeastern flank of the Little Dragoon Mountains in the Cochise Mining District. The property is within the copper porphyry belt of Arizona. The Gunnison Project hosts the Gunnison (formerly known as the I-10) Deposit and contains copper oxide and sulfide mineralization with associated molybdenum in potentially economic concentrations. Oxidized, mineralized bedrock lies 300 to 800 feet beneath of alluvial basin fill.
| 25 |
GCC contracted M3, RESPEC, Independent Mining Consultants, Call & Nicholas Inc, Geo-Logic Associates, Clear Creek Associates, and Burgex to prepare mine plans, mineral resource estimates, process plant designs, complete environmental studies, and cost estimates used for the Gunnison Technical Report. The costs are based on 1st quarter 2026 U.S. dollars.
Key Data
The key results of this PEA for the Gunnison Project are as follows:
| ● | Copper price: $4.60/lb. A premium of $0.0425/lb has been added for producing Grade A cathode copper. | |
| ● | The average annual production for years 1 to 15 is projected to be approximately 174 million pounds of copper. Total life of operation production is projected at approximately 3,187 million pounds of copper. | |
| ● | The Gunnison Project currently has 846.1 million short tons of measured and indicated oxide, transitional, and sulfide mineral resources at an average grade of 0.33% Total Copper (TCu) and inferred oxide, transitional, and sulfide mineral resources of 94 million short tons at an average grade of 0.21% TCu; using a cut-off grade of $0.05% total Copper for oxide and transition materials and 0.1% Total Copper for sulfide materials. The tonnage of material in the Gunnison conceptual mine plan used for this PEA is 641.6 million tons having an average grade of 0.37% TCu. | |
| ● | The anticipated heap leach recovery is estimated to be 90% of the AsCu and CNCu copper grade. 60% recovery for copper sulfide (CuS) material but only within the sulfide mineral domain using a sulfide recovery process (minimal CuS recovery in the Oxide or Transition mineral domains). | |
| ● | The average direct, life-of-mine operating cost is estimated to be $8.43 per ton of mineralized material mined, which is equivalent to $1.70/lb Cu. The average sustaining cash cost including royalties and sustaining capital costs is $10.20 per ton of mineralized material mined which is equivalent to $2.05/lb Cu. | |
| ● | The estimated initial capital cost is $1,555.6 million, including capitalized pre-production costs and acid plant. Expansion of the Leach Pad through Year 10 will add another $200.7 million in direct costs. Additions to Infrastructure and a plant to enhance sulfide leaching will add another $67.4 million. | |
| ● | Sustaining capital costs from mine equipment replacement is $51.8M over the LOM. Another $321.4 million is attributable to the addition of a cement/limestone plant that will add revenue and value to the operation in starting in Years 4 & 5. | |
| ● | The total cost for reclamation and closure is estimated to be $93.0 million and averages $0.034 per pound of copper recovered. A credit of $65.0 million is expected from salvage value of capital equipment from the mine. Another $26 million credit is included for the salvage value of the sulfuric acid plant and the cement/limestone plant. | |
| ● | The economic analysis for the Gunnison open pit after taxes indicates an Internal Rate of Return (IRR) of 22.5% and a payback period of 3.9 years. Based on a long-term average copper price of $4.60 per pound (plus $0.0425 Grade A cathode premium), the Net Present Value (NPV) after taxes is $1,959 million at an 8% discount rate. |
The PEA is preliminary in nature and includes inferred mineral resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves. There is no certainty that the conclusions reached in the PEA will be realized. Mineral resources that are not mineral reserves do not have demonstrated economic viability.
| 26 |
Property Description and Location
The Gunnison Project is located in Cochise County, Arizona, approximately 62 miles east of Tucson and 1.5 miles southeast of the historic Johnson Camp mining district. Figure is a general location map and property location near the US Interstate 10 (I-10) freeway. Total area is approximately 18,796 acres (7,606 Ha).
The Gunnison Project is held by GCC through its wholly owned subsidiary Excelsior Mining Arizona, Inc. (“GCAZ”). Acquisition of all mineral interest from the James L. Sullivan Trust was completed in January of 2015. These assets represent, among other things, the mineral rights to the Gunnison and Strong & Harris copper deposits.
Figure 1-1: Gunnison Project Location Map, Gunnison Project Area
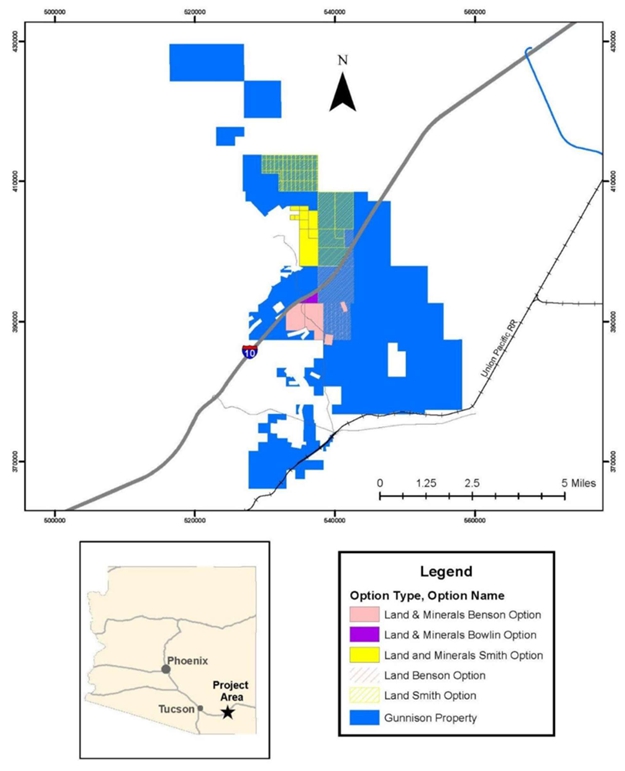
Accessibility, Climate, Local Resources, Infrastructure and Physiography
The Gunnison Project is located in a sparsely populated, flat to slightly undulating ranching and mining area about 65 road miles east of Tucson, Arizona. The Tucson metropolitan area is a major population center (approximately 1,000,000 persons) with a major airport and transportation hub and well-developed infrastructure and services that support the surrounding copper mining and processing industry. The towns of Benson and Willcox are nearby and combined with Tucson can supply sufficient skilled labor for the Gunnison Project.
| 27 |
Access to the Gunnison Project is via the I-10 freeway from Tucson and Benson to the west or Willcox to the east. The Gunnison Deposit can be accessed via good quality dirt roads heading approximately 1 mile east from the south side of “The Thing” travel center and roadside attraction on the Johnson Road exit from I-10. Strong & Harris is reached via the improved unpaved Johnson Road travelling approximately 3.5 miles north from I-10.
The elevation on the property ranges from approximately 4,600 to 4,900 feet above mean sea level in the eastern Basin and Range physiographic province of southeastern Arizona. The climate varies with elevation, but in general the summers are hot and dry, and winters are mild.
Vegetation on the property is typical of the upper Sonoran Desert and includes bunchgrasses, yucca, mesquite, and cacti.
History
There is no direct mining history of the Gunnison Deposit or Strong & Harris; however, the district has seen considerable copper, zinc, silver, and tungsten mining beginning in the 1880s and extending to the present day. Modern mining and leaching operations at the Johnson Camp Mine, began in the 1970s by Cyprus Minerals. Successor owners and operators include Arimetco, North Star, Summo Minerals, and Nord Resources Corporation. Nord mined fresh material until mid-2010 and maintained leaching operations until late 2015, when the property was purchased by GCC.
In 1970, a division of the Superior Oil Company (“Superior”) joint ventured into the northern half of the Gunnison Deposit with Cyprus and the private owners (J. Sullivan, pers. com.). During the early 1970s, Superior did most of the drilling and limited metallurgical testing on Gunnison and by early 1974 had defined several million tons of low-grade acid-soluble copper mineralization. According to Parsons (1974), oxide copper mineralization was discovered at what is now the Strong & Harris Deposit in drill cuttings “while a water well was being drilled, perhaps in the early 1960s.” A Mr. Strong and a Mr. Harris subsequently located mining claims on the present property. Modern-era exploration of the Strong & Harris project commenced in 1964. More than 100,000 feet of rotary and core drilling were done by various operators from the mid-1960s through 1992.
The Gunnison Project was previously designed as a copper in-situ recovery (“ISR”) mine using solvent extraction-electrowinning (“SX-EW”) to produce copper cathode. The ISR operation commenced ramp-up to production in 2020; however, it had operational issues related to low flow rates, so the Company began evaluating alternatives and opportunities to fix the ramp-up challenges. Well stimulation (small scale, shallow level, hydraulic fracking), has the potential to fundamentally change the performance of the wellfield and fix many of the low productivity issues. The Company has obtained a permit for well stimulation and the next step would be to conduct field trials. If well stimulation is successful, it could provide an operation with superior economics to the open pit operation and be in copper production much quicker than an open pit. However, due to the substantially improved viability of the open pit operation, GCC intends to focus on the open pit operation as the alternative to ISR. The Company intends to maintain the optionality of future ISR operations and well stimulation trials as this remains an asset to the Company. This includes maintaining full compliance with all regulatory and permit requirements, including maintaining hydraulic control, pumping, monitoring and regulatory reporting.
| 28 |
Geological Setting and Mineralization
The Gunnison Project, including the Gunnison and Strong & Harris copper deposits, is situated in the Mexican Highland section of the Basin and Range physiographic province. The province is characterized by fault-bounded mountains, typically with large igneous intrusions at their cores, separated by deep basins filled with Tertiary and Quaternary gravels.
The Gunnison Project (“Gunnison” or “Gunnison Deposit”) lies on the eastern edge of the Little Dragoon Mountains. The ages of the rocks range from 1.4-billion-year-old Pinal Group schists to recent Holocene sediments. The southern portion of the Little Dragoon Mountains consists predominately of the Tertiary Texas Canyon Quartz Monzonite whereas the Pinal Group schists and the Paleozoic sediments that host the regional copper mineralization dominate the northern half. The Strong & Harris deposit (“Strong & Harris” and “Strong & Harris Deposit”) is hosted in altered Paleozoic sedimentary rocks which are covered by an average of 425 feet of post-mineral and mostly unconsolidated valley fill near the northeast flank of the Little Dragoon Mountains and about three northwest of the Gunnison oxide copper deposit.
At Gunnison, Copper sulfide mineralization has formed preferentially in the proximal (higher metamorphic grade) skarn facies, particularly along stratigraphic units such as the Abrigo and Martin Formations near the contact with the quartz monzonite and within structurally complex zones. Primary mineralization occurs as stringers and veinlets of chalcopyrite and bornite. Primary (unoxidized) mineralization remains “open” (undetermined limits) at depth and to the north, south, and east. Oxidation of the mineralization occurs to a depth of approximately 1,600 feet, resulting in the formation of dominantly chrysocolla and tenorite with minor copper oxides and secondary chalcocite. The bulk of the copper oxide mineralization occurs as chrysocolla, which is formed as coatings on rock fractures and as vein fill. The remainder of the oxide mineralization occurs as replacement patches and disseminations.
Primary copper-zinc-silver mineralization at Strong & Harris is characterized by lenses of sulfide minerals emplaced more-or-less parallel to layering in favorable lithologic units, usually along bedding planes or in disseminated masses and blebs. Sub-units of the Earp Formation, particularly those immediately below its upper contact with the Colina Limestone, were the most favorable sites for deposition of the copper, zinc and silver minerals. However, mineralization is also present in the Colina Limestone above the Earp, as well as in the Horquilla Limestone. The Strong & Harris Deposit has been oxidized to varying degrees that generally decrease with depth. Three oxidation zones are currently recognized in the deposit: the oxide zone, the transition (or mixed) zone, and the sulfide zone.
Deposit Types
The Gunnison Deposit is a classic copper-bearing, skarn-type deposit. The Strong & Harris Deposit is a sub-type of or related to a classic copper skarn. Skarn deposits range in size from a few million to 500 million tons and are globally significant, particularly in the American Cordillera. The Gunnison Deposit is large, being at the upper end of the range of size for skarn deposits and is associated with a mineralized porphyry copper system that has been largely unexplored. Strong & Harris can be sub-categorized as distal skarn related to a porphyry copper system.
Exploration
Since Gunnison’s discovery, numerous companies have explored the area. During this time period, extensive drilling, and assaying, magnetic and IP geophysical surveys, metallurgical testing, hydrological studies, ISR tests, and preliminary mine designs and evaluations have occurred. The focus since the 1970s has been to utilize ISR or a combination of ISR and open pits as a potential mining strategy.
Stephen Twyerould first became involved with the Gunnison Project in mid-2005 and AzTech (later named Excelsior Mining Arizona, Inc.) became involved in mid-2006. Since that time, significant work has been completed such as cataloguing, reviewing, and compiling high-quality historical data spanning over thirty years of investigations by Superior Oil and Gas, Cyprus, Quintana, CF&I, Magma Copper Corporation, Phelps Dodge Corporation, and James Sullivan. GCC conducted detailed ground magnetics over the exploration targets in June 2011.
| 29 |
GCC initiated a re-logging program in December 2010 that was completed in the third quarter of 2011. In addition, a re-assaying program began in March 2011 during which all of the Magma holes were re-assayed. In May 2011, a re-assay program was initiated for the Quintana Minerals holes (DC, S, and T series) to include sequential copper analyses for cyanide-soluble (CNCu) and acid-soluble copper (ASCu). Previous results only included total copper (TCu) assays. From late in 2010 through early 2015, GCC has drilled 54 diamond drillholes, totaling 78,615 ft, for metallurgical samples and copper resource definition and expansion.
GCC has not conducted drilling at the Strong & Harris project. In 2019, GCC began a comprehensive technical review of the reports and project drill data. In 2020-2021, GCC completed a data compilation program to digitize and validate the Strong & Harris data. GCC commissioned Geotech Ltd to complete a helicopter-borne geophysical survey using the versatile time-domain electromagnetic (VTEM™) plus system between October 6th and October 21st, 2020 over the Gunnison Copper Project. Measurements were taken using the VTEM™ Plus system (vertical and in-line components of the EM response) and a horizontal magnetic gradiometer with two caesium sensors. The survey covered several copper deposits in the district, including Strong & Harris.
Drilling
The Gunnison Deposit drillhole database includes 217 drillholes totaling 245,509 feet. Among the total drillholes, 88 were historical drillholes that were completed by several companies. These holes extend to a depth of approximately 2,450 ft below the surface at the Gunnison Deposit and cover an area of approximately 310 acres, with additional drilling extending beyond this area. There is a slightly higher density of drilling along the central axis of the Gunnison Deposit.
The author of this section of the Gunnison Technical Report is aware of records for a total of 152 holes drilled within the Strong & Harris project, for a total of approximately 130,679 feet drilled. The author believes these holes were drilled in 1965 through 1992.
Sample Preparation, Analysis and Security
The laboratory sample preparation and analysis procedures used by the previous owners of the deposits are unknown; however, major commercial laboratories using best practices at the time completed the majority of analyses.
The data, information, samples, and core from the deposits have been under the control and security of AzTech Minerals since November 2006 and then GCC since October 2010. The original information and samples are stored at the Sullivan’s core storage facility in Casa Grande, with numerous copies held by GCC at its Phoenix, Arizona office. It is the opinion of RESPEC Company LLC (RESPEC) and the qualified person for this section of the report, the reviewer of the assay data for the Gunnison Technical Report, that the sample procedures, processes, and security are reasonable and adequate.
Data Verification
The verification of location and assay data in the drillhole database covers historic drilling and the verification of the data collected by GCC. No significant issues have been identified with respect to the data provided by GCC’s quality assurance/quality control (“QA/QC”) programs. QA/QC data are not available for the historical drilling programs at the Gunnison Deposit, but GCC analyses dominate the assays used directly in the estimation of the mineral resources. Additionally, most of the historical data were generated by well-known mining companies, and the GCC drill data are generally consistent with the results generated by the historical companies.
| 30 |
Assaying and QA/QC procedures were industry standard. The TCu, CNCu, and ASCu assays used to estimate grades in the Gunnison and Strong & Harris models are acceptable for estimating mineral resources, based on RESPEC’s and qualified person’s review of the available data for repeat, check, duplicate, standard and blank assays, and on paired comparisons of assay data from different drilling campaigns.
Mineral Processing and Metallurgical Testing
Column tests and other metallurgical testing conducted during the last decade or more, supplemented by recent developments, have supported the following predictions of heap leaching performance for copper-bearing material from the Gunnison resource that has been crushed to a nominal minus 6-inch product.
Copper extractions according to the mineralogical categories defined by assay procedure are as follows: acid-soluble copper (ASCu), 90%; cyanide-soluble copper (CNCu), 90%; and sulfide copper (CuS), 60% (CuS recovery is limited to the sulfide mineral domain). The predicted leaching response of primary sulfide minerals, essentially all chalcopyrite, assumes that accelerated oxidation and de-passivation of chalcopyrite will be at least moderately effective.
However, the copper will dissolve slowly over a period of several years due to kinetic limitations and imperfect solution access. For instance, chrysocolla, the dominant ASCu species, dissolves in two stages with declining rate as copper content in the layer silicate structure diminishes. Accordingly, the following approximate rates are predicted.
Table 1-1: Rates of Copper Extraction during Heap Leaching
|
Species |
Year 1 (%) | Year 2 (%) | Year 3 (%) |
| ASCu | 81 | 4.5 | 4.5 |
| CNCu | 81 | 4.5 | 4.5 |
| CuS | 48 | 9 | 3 |
Column tests and other metallurgical tests have indicated that acid consumptions for the dominant rock formations in the Gunnison resource will be as follows, expressed as pounds of 98% H2SO4 per ton of heap feed: Martin, 87.61; Strong & Harris carbonates, 87.51 Upper Abrigo, 48; Middle Abrigo, 48; Lower Abrigo, 24; and TQM/Bolsa/Pinal, 24.
In the Gunnison resource, much of the acid-consuming gangue is comprised of dolomite and/or calcite that contain little copper. This presents an opportunity for reducing acid costs by particle segregation, or “sorting”. Material sorting has been done manually for millennia and has been a common practice for decades in waste segregation, metal recycling, and upgrading of some types of mineralized material. However, major advances have been made during the last few years in sensor efficiency and sorting equipment capacity.
GCC contracted Steinert to conduct material sorting tests on cores selected from the main formations at the Gunnison Deposit. Table 1-2 shows the calculated results of the testing mainly on the Martin dolomite.
1 After material sorting. Pre-mineral sorting, the Martin Formation, and carbonates at Strong & Harris consume 135 lb/ton.
| 31 |
Table 1-2: Mineralized Material: Waste Percentages Calculated from Sorting Tests
| Mineralized Material: Waste Adjustments Based on Testing |
| % of internal Waste in Martin resource | 50% |
| % of Waste that can be removed by material sorting | 90% |
| Ratio of acid consumed by Waste / acid consumed by Mineralization | 6.01 |
| % or Mineralization lost to Waste | 1% |
| Calculated Martin Mineralization % | 54.5% |
| Calculated Martin Waste % | 45.5% |
Mineral Resource Estimate
The Gunnison Deposit Mineral Resources are classified in order of increasing geological and quantitative confidence into Inferred, Indicated, and Measured categories in accordance with the “CIM Definition Standards – For Mineral Resources and Mineral Reserves” and therefore Canadian National Instrument 43-101.
Table 1-3: Combined Oxide, Transitional, and Sulfide Resources
| Total Resources (Oxide + Transitional + Sulfide) | |||
|
Resource Class |
Short Tons (millions) | Total Cu (%) | Cu Pounds (millions) |
| Measured | 191.5 | 0.37 | 1,423 |
| Indicated | 654.5 | 0.31 | 3,768 |
| Measured + Indicated | 846.1 | 0.33 | 5,190 |
| Inferred | 94.0 | 0.21 | 397 |
Notes:
| 1. | Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability. | |
| 2. | Mineral Resources are reported within an optimized pit at a 0.05% total copper cut-off for oxide and transition material, and 0.1% cut-off for sulfide. | |
| 3. | Rounding may result in apparent discrepancies between tons, grade, and contained metal content. | |
| 4. | The Effective Date of the Mineral Resource estimate is January 23, 2026. |
The Strong & Harris project resources are summarized in Table 1-4.
Table 1-4 Strong & Harris Mineral Resources
(0.07% Cu cutoff)
|
Classification |
Short Tons (millions) |
% Cu |
% CuO x |
% Zn |
oz Ag/ ton |
Cu lbs (millions) |
CuOx lbs (millions) |
Zn lbs (millions) |
Ag oz (millions) |
| Inferred | 76.070 | 0.49 | 0.32 | 0.56 | 0.12 | 740.0 | 482.691 | 855.707 | 8.971 |
| 1. | The Effective Date of the mineral resources is January 23, 2026. | |
| 2. | The project mineral resources are shown in bold and are comprised of all model blocks at a 0.07% Cu cutoff that lie within optimized resource pits. | |
| 3. | Mineral resources that are not mineral reserves do not have demonstrated economic viability. | |
| 4. | The estimate of mineral resources may be materially affected by geology, environmental, permitting, legal, title, taxation, sociopolitical, marketing, or other relevant issues. | |
| 5. | Rounding as required by reporting guidelines may result in apparent discrepancies between tons, grade, and contained metal content. |
| 32 |
The estimate of mineral resources may be materially affected by geology, environmental, permitting, legal, title, taxation, sociopolitical, marketing, or other relevant issues. Potential risk factors include changes in metal prices, increases in operating costs, fluctuations in labor costs and availability, availability of investment capital, infrastructure failures, changes in government regulations, community engagement and socio-economic community relations, civil disobedience and protest, permitting and legal challenges, and general environmental concerns. However, the author of this section of the Gunnison Technical Report is not aware of any such factors that may materially affect the Gunnison or Strong & Harris mineral resources as of the date of the Gunnison Technical Report. The impact of taxation was taken into consideration when establishing cut-off grade.
The Mineral Resources presented herein are inclusive of the Economic Analysis presented below which therefore represents a subset of the Mineral Resources under slightly different economic inputs, most notably lower copper price.
Mineral Reserve Estimate
The Gunnison Project does not currently have any mineral reserves.
Mining Methods
Mining of the Gunnison and Strong & Harris Deposits is planned be accomplished using open pit hard rock mining methods assuming an automated haulage fleet. The mine plan was developed to produce 175 million pounds of recoverable copper per year with mining being completed by an owner-operated fleet. Mining of the deposit is expected to be accomplished with hydraulic front shovels and 320-ton trucks. Mining is planned on 50-ft bench heights in the Gunnison pit and 40-ft bench heights in the Strong & Harris pit.
An annual schedule was developed for the mine plan. Leach material will be dumped into near pit gyratory crushers to be conveyed either directly to the leach pad or through sorting prior to being conveyed to the leach pad. All leach material produced through Year 9 is planned to be treated in a conventional leach operation. Beginning in Year 10, a portion of the leach material is planned to be treated in a sulfide leach operation with the rest of the material treated in a conventional leach operation. The heap tonnage production varies by year as it is based on the requirement of 175 million pounds of recoverable copper being placed on the heap annually.
The mine plan presented in the Gunnison Technical Report is achieved by mining 9 phase expansions to achieve the ultimate pit limit in the Gunnison Deposit and a single phase at Strong & Harris. The phases are practical expansions of the Gunnison pit incorporating haul road designs, operating room for equipment and all practical mining requirements.
Pit slope angles are based on recommendations provided by Call and Nicholas Inc. (CNI). Overall pit slope angles were provided along with the recommendation that interramp slopes could be up to 3-degrees steeper. The shallow east dipping beds of the Paleozoic rock formations is the controlling factor for the 36-degree overall slopes in these rocks on the west pit wall.
The mine production schedule was developed using the phase designs, and the required leach pad feed rate to produce ~175 million pounds of recoverable copper per year. Sufficient waste is moved during the mine life to assure continued release of the required heap material. The cut-off grade of the mineralized material is generally $0.01 net of process. There are several years where cutoff grade was raised to maintain an annual feed of 175 million pounds of recoverable copper (years 7-10 and 14-19).
The waste storage areas (WRD) are east and west of the Gunnison pit and southeast of the Strong & Harris pit. The waste dumps are planned to be constructed in 50 ft lifts at an angle of 2.5:1.
| 33 |
Mining is planned to be executed using automated haulage with the remainder of the equipment being a conventional open pit mining fleet. The reference to specific equipment manufacturers is to illustrate equipment size and is not to be considered a recommendation by Independent Mining Consultants. Production drilling is expected to be accomplished with 141,000lb pull-down force class drills with mast lengths capable of single pass drilling 50 ft benches. Holes will be loaded with ANFO when dry and an emulsion slurry when wet. Hydraulic front shovels with 38 to 44-yard buckets are planned to load a majority of the material with a 30-yard front-end loader available to provide loading flexibility. The front-end loader is also assumed to re-handle 15% of material at the crusher as necessary. Haul trucks are planned to be 320-ton class trucks with 3,500 hp engines. Haul truck productivities are based on haulage time simulations for annual waste and leach material haul profiles. A fleet of auxiliary equipment to support the main operating equipment will be required. This will be comprised of 500 hp rubber-tired dozers, 600 hp track dozers, motor graders with 24-ft mold boards, 100-ton haul trucks fitted with 20,000-gallon water tanks and other support equipment.
Mine operations and maintenance labor increases to 266 persons at the end of Year 5 and stays between 250 and 300 persons until labor requirements decline in the last year of mining. There are expected to be 48 salaried staff for supervision, engineering, geology, and mineralized material control.
Pit Dewatering
Pit dewatering will be required during mining because both the Gunnison and the Strong & Harris pits are mostly below the water table in highly fractured bedrock. A groundwater flow model for the Gunnison ISR project was completed as part of the 2016 Aquifer Protection Permit (APP) application reviewed and approved by the Arizona Department of Environmental Quality (ADEQ) and the 2016 Underground Injection Control (UIC) Permit application reviewed and approved by the U.S. Environmental Protection Agency (EPA).
The 2016 groundwater flow model was expanded and updated to allow inclusion of the Strong & Harris open pit. Dewatering flow rates were predicted for both the Gunnison and Strong & Harris open pits by simulating the advancement of the open pits over the life of the mine. The drainage into a pit at the Gunnison Project site is likely to result in significant flows into the pit, up to about 4,500 gpm during the pit advancement. The predicted dewatering rates may be high due to simplifications incorporated in the model simulation. This rate of dewatering is recognized to be high relative to other open pit mines in Arizona. However, the mineralized body at Gunnison is quite fractured and broken relative to other mineralized bodies in Arizona therefore a high rate of dewatering is expected. The pumping rate to maintain a dry pit at the Strong & Harris mine is predicted to rise to between 75 and 100 gpm.
Recovery Methods
The open pit mining result in a copper-bearing pregnant leach solution (PLS) from which copper is extracted using the well-established SX-EW process. The Gunnison Project constructs an SX-EW plant in a single construction period prior to production to produce 175 mppa of cathode copper.
Open Pit-Heap Leach Recovery Methods
For the open pit-heap leach, mineralized oxide material from the open pit mine is placed on the leach pad as crushed material, described in Section 16. The oxide material will be irrigated with acidified raffinate pumped from the Gunnison Raffinate Pond. Copper-bearing PLS solutions are collected by an overliner collection system and discharged to the Leachate Collection Pond. PLS is pumped from the Leachate Collection Pond to the Gunnison SX Feed Tank.
The Gunnison open pit SX-EW Plant has the capacity to produce 175 mppa of cathode copper. This increase in capacity is accomplished by increasing the size of the SX mixer-settlers and adding additional electrowinning cells to the EW tankhouse. Commensurate increases to the capacities of the piping, tanks, and other equipment are required throughout the Gunnison open pit SX-EW Plant. The PLS from the leach pad provides the feed for the SX-EW process.
| 34 |
The location of the leach pad is southeast of the Gunnison pit in an area where the natural drainage is toward the southeast. The full leach pad will be approximately 909.6 acres in area and oriented to match existing topography so that it allows gravity drainage of solutions down to the southeastern toe of the pad for collection and transport by pumping system to the JCM PLS pond with one set of pumps and to the SX Feed Tank with another set. The Leach Pad will be constructed in four phases. The initial phase of the leach pad consists of approximately 244 acres of lined area and is constructed during the initial construction period for the mine and processing plant. Phase 2 adds an additional 212 acres of lined area of leach pad to be constructed in Year -1. Phase 3 adds an additional 210.8 acres of lined area at the beginning of Year 1. Phase 4 completes the lined area for a total lined footprint of 840.8 acres in Year 3 to provide the capacity for the Life of Mine.
One hundred (100%) percent of the material mined for exploitation will be crushed using mineral sizers to minus 6”. Sixty (60%) of this material will be diverted to a belt conveyor to be stacked mechanically on the leach pad without material sorting. The remaining forty (40%) of the material, which will have been identified as high-carbonate material, will be subjected to material sorting. A preliminary design for a Material Sorting plant consists of 32 sorters that handle three different size fractions. The sorted material will be combined with unsorted mineralization that will be conveyed and stacked on the leach pad. Material sorting was prepared to reject high carbonate mineralization to lower acid consumption on the leach pad. Capital ($220.3 million) and operating costs ($212.2 million LOM) were developed for this study to include material sorting.
GCC plans to employ sulfide leaching using an enhanced leaching technology similar to what is being demonstrated at GCC’s Johnson Camp Mine. Sulfide-rich materials become significant in starting in Year 10 of the mine plan. A location for sulfide leaching plant equipment has been reserved in the Gunnison site plan adjacent to the northeast corner of the leach pad. Sustaining capital of $56 million and operating costs of $0.37 material processed/ton and recoveries of 60% have been estimated for the sulfide leach material.
Sulfuric acid for the heap leach option is provided by a molten sulfur burning sulfuric acid plant constructed prior to operation to provide the acid necessary for leaching and SX-EW process. The acid plant is designed to produce 2,700 short tons per day (stpd) of 98% sulfuric acid which is sufficient to meet the process demand in most years. Molten sulfur is delivered to the plant by rail. In years when the demand exceeds acid plant capacity, sulfuric acid will be delivered by rail tank cars.
Gunnison Project Infrastructure
The northern extent of the Gunnison Pit requires relocation of Interstate 10 to be able to access the northern portion of the Gunnison Deposit. A portion of the freeway approximately 2.7 miles long will be rerouted to the north along with its interchange with Johnson Road. A new prefeasibility study was completed by Kimley Horn to relocate the Interstate. The preferred location of that interchange will be determined during roadway design in consultation with the Arizona Department of Transportation (ADOT), which has control of the Interstate and is the coordinating agency for the relocation design and construction. Access to the Gunnison SX-EW plant will be off Johnson Road south of the pit approximately 1 mile north of Dragoon.
The mine pit is located in the northern portion of the Gunnison Project area and is flanked by waste stockpiles to the east and west to store alluvial overburden and waste rock removed from the pit during the mining operation. Mineralized material removed from the pit is hauled to the leach pad located southeast of the pit. Crushed material is dumped on the leach pad, spread, ripped, and covered with a piping network to deliver acidified leach solution. The leach solution drains out of the southeast toe of the leach pad and collected as PLS in the Leachate Collection Ponds. The PLS is pumped to the SX Feed Tank for extraction in the Gunnison plant.
| 35 |
The Gunnison SX-EW plant will be constructed in the southeast corner of the site with a nominal copper production capacity of 175 mppa. The electrowinning building (tankhouse) will be a steel building with corrugated metal roofing and siding. It will contain 112 electrowinning cells on each end of the building (total of 224 cells) and a single automatic cathode stripping machine.
The Gunnison Tank Farm is located downhill from the SX area and the tankhouse to facilitate gravity drainage of solutions to the Tank Farm. The Tank Farm has a concrete containment that drains to a sump with an oil-water separator to return spilled liquid to the proper location for recycling. There is a Plant Runoff Pond located downstream of the Tank Farm to capture any surface flows in the event of an upset condition at the plant.
Ancillary facilities needed to support the Gunnison Project include buildings, ponds, tanks, and trenches. Ancillary buildings include an Administration Building, Warehouse, Plant Maintenance building, Change House, Security Building (gatehouse), and Sulfuric Acid Plant-Cogeneration complex. Other facilities will include ponds, and tanks. A new assay lab facility will be constructed to handle production samples, solution assays, and cathode sampling.
Power for the facility will be tapped from an existing 69 kilovolt (kV) power line or from a 115 kV line that could be tapped if the power requirements are too high for the 69 kV line. The existing power line will terminate at the new Gunnison Substation. The requirement to feed the SX-EW from a higher voltage transmission line will be evaluated as the project progresses.
For make-up water, mine dewatering water will be pumped to the 500,000 gallon process water/firewater tank. The lower 300,000 gallons in the storage tank will be reserved for fire suppression. Process water for plant use will be taken from the storage tank above this reserve level for fire suppression.
The sulfur-burning sulfuric acid plant will be constructed south of the Gunnison processing plant along with the accompanying rail spur and loading-unloading facilities. The plant design will be increased to produce 2,700 stpd of concentrated sulfuric acid. The waste heat from the acid making process produces steam to generate 38 MW of electrical power from a steam turbine generator. Of that amount, 11.4 MW of power will be required for operation of the acid plant, leaving 26.6 MW for delivery back to the power grid. The sulfuric acid plant includes molten sulfur day tanks, sulfur burner and waste-heat boiler, drying and adsorption tower area, cogeneration building, water treatment building, power distribution building and substation, cooling towers, office building, sulfuric acid storage area, and a rail yard for unloading molten sulfur and sulfuric acid.
Market Studies and Contracts
The use of consensus prices obtained by collating the prices used by peers or as provided by industry observers and analysts is recognized by the Canadian Institute of Mining and Metallurgy (CIM) for technical reports and has the advantage of providing prices that are acceptable to a wide body of industry professionals (peers). These prices are generally acceptable for most common commodities, major industrial minerals, and some minor minerals.
The PEA has selected $4.60 per pound copper through the end of mine life. A Grade A cathode credit of $0.0425 per lb has been added to the long-term copper price, bringing the expected copper price to $4.6425 per lb.
Market studies indicate that the long-term prices for the major reagents are as follows.
| Sulfuric Acid | $210/st purchased |
| Sulfuric Acid | $190/st for excess sulfuric acid produced that is sold on open market |
| Molten Sulfur | $160/st delivered to site. |
| 36 |
The price for sulfuric acid is predicted to be $210/st. Based on a delivered sulfur cost of $160/ton, the cost of acid produced in GCC’s sulfuric acid costs are estimated to be $47.46 for the 2,700 stpd acid plant for the Gunnison Project.
Environmental and Permitting
The open pit mining and heap leaching option has not been permitted. The open pit requires surface disturbance and relocation of an interstate highway.
Some additional environmental permits are required for an open pit mine at the Gunnison Project. Federal, state, and local government existing environmental permits are listed in Table 20-1. A permit from ADOT will be required for the planned relocation of Interstate 10. The permit may require additional environmental studies, including cultural, biological, and native plant surveys, depending on the I-10 routing.
An Aquifer Protection permit (APP) exists for the prior ISR mining activities. This permit will require major modifications to accommodate the open pit and discharging facilities that have the possibility of impacting an aquifer. Facilities that may be constructed at Gunnison that may require an amended APP include leach pads, waste rock stockpiles, non-stormwater ponds, process solution ponds (PLS and Raffinate), re-injection wells for a portion of the open pit dewatering, and the acid plant. Open pits are not regulated facilities if passive containment can be demonstrated.
Other existing permits requiring modification include the Arizona Mined Land Reclamation Plan, Air Quality permits, and the existing Underground Injection Control permit to accommodate the open pit.
Water management associated with the open pit mine will include dewatering of the pit and run-on and run-off controls. As discussed in Section 16.9, dewatering is expected to generate up to 4,500 gpm during pit development. This water can be used for a variety of uses including dust control, makeup water for mineralized material leaching, third party use agreements, or reinjected into other areas of the aquifer. The Gunnison Project is located in the Willcox Basin, which was formally designated as an Active Management Area (AMA) by the Arizona Department of Water Resources (ADWR) in January 2025. As such, water use and reinjection may be subject to additional requirements under ADWR’s AMA program. Surface water will be diverted around the pit, leach pad, process plant, and other non-APP facilities. Water will be managed using engineered features such as diversions or retention structures.
Reclamation and closure must be conducted on all APP-regulated facilities in accordance with the stipulations of the APP permit at the end of operations. Non-APP facilities, such as buildings and infrastructure, will be reclaimed in accordance with the approved Mined Land Reclamation Program overseen by the Arizona State Mine Inspector’s Office. Reclamation of the pit (which is not expected to be an APP-regulated facility) will consist of erosion control. At closure, the heap leach pad (an APP-regulated facility) and the waste rock stockpiles (which may be regulated under APP) will be managed to prevent, contain, or control discharges. In the case of the heap leach pad, it is anticipated that closure will include neutralizing or rinsing of all spent mineralized material, elimination of free liquids, stabilization of heap materials, and recontouring of the heap to eliminate ponding. The waste rock stockpile will be recontoured in a similar manner to eliminate ponding and minimize infiltration. Process solution and non-stormwater ponds will be closed in accordance with the approved APP closure plan. Other facilities such as the plant and buildings will be removed and the land surface will be contoured and graded.
| 37 |
Capital and Operating Costs
Capital Costs
Estimated CAPEX, or capital expenditures, include two components: (1) the initial CAPEX to undertake the detailed design, pre-strip, construct, and commission the mine, plant facilities, ancillary facilities, utilities, and complete on and offsite environmental mitigation and remediation; (2) the sustaining CAPEX for facilities expansions, mining equipment replacements, expected replacements of process equipment and ongoing environmental mitigation activities. The Table 1-5below summarizes the initial and sustaining CAPEX for the Gunnison Project.
Table1-5: Summary of Gunnison Project Capital Costs ($000s)
| Area | Detail | Initial CAPEX ($000s) |
Sustaining CAPEX ($000s) |
Total CAPEX ($000s) |
Direct Costs |
Mine Costs | 280,302 | 51,802 | 332,104 |
| Processing Plant | 738,540 | 211,583 | 950,123 | |
| Infrastructure | 92,020 | 378,019 | 470,039 | |
| Freight | 55,707 | 15,999 | 71,706 | |
| Indirect Costs | 193,757 | 32,900 | 226,658 | |
| Owner’s Costs, First Fills, & Light Vehicles | 23,657 | 0 | 23,657 | |
| Offsite Environmental Mitigation Costs | 0 | 0 | 0 | |
| Onsite Mitigation, Monitoring, and Closure Costs | 0 | 0 | 0 | |
| Total CAPEX without Contingency | 1,383,983 | 690,303 | 2,074,287 | |
| Contingency | 171,635 | 39,072 | 210,707 | |
| Total CAPEX with Contingency | 1,555,618 | 729,376 | 2,284,994 | |
The CAPEX estimate includes direct mining equipment and pre-stripping costs, process plant costs, and infrastructure such as the water systems, main substation, transmission lines, ancillary facilities, cement plant, sulfide plant, and highway relocation. The initial CAPEX also includes indirect costs for detailed design and engineering. Initial CAPEX also includes an estimate of contingency based on the accuracy and level of detail of the cost estimate. The purpose of the contingency provision is to make allowance for uncertain cost elements that may occur but are not included in the cost estimate. These cost elements include uncertainties concerning completeness, accuracy and characteristics or nature of material takeoffs, accuracy of labor and material rates, accuracy of labor productivity expectations, and accuracy of equipment pricing. The CAPEX estimates are considered to have an accuracy range of -25% to +30%.
The primary assumptions used to develop the CAPEX are provided below:
| ● | The estimate is based on 1st quarter 2026 costs. | |
| ● | All cost estimates were developed and are reported in United States of America (US) dollars. | |
| ● | Units of measure for this project are primarily in Imperial customary units. | |
| ● | At the time of this estimate, engineering was approximately 3% complete. | |
| ● | Contingency during the pre-production period is specific to each major component of the Gunnison Project as determined by the various consultants. | |
| ● | Qualified and experienced construction contractors will be available at the time of Gunnison Project execution. | |
| ● | No provision has been made for currency fluctuations. |
| 38 |
Mine Capital Costs
The mine capital includes two components: capital for equipment lease down payments/interest payments during pre-production and the cost of pre-stripping. Mine capital costs for mobile equipment were developed from the mine equipment list presented in Section 16 of the Gunnison Technical Report. Mine capital costs including equipment and pre-production development are presented in Table 1-6. Initial mine capital is $280.3 million, while sustaining mine capital costs are $51.8 million. An additional $185.6 million of waste stripping costs between the Years 1 and 15 included in Table 1-11 are applied to sustaining capital costs as deferred stripping.
Table 1-6: Summary of Mine Capital Costs ($000s)
Category |
Initial Capital | Sustaining Capital | Total Capital | ||
| Year -2 | Year -1 | Total | |||
| Preproduction Development | 106,742 | 130,829 | 237,571 | 237,571 | |
| Mining Equipment - Leased | 25,687 | 17,053 | 42,731 | 51,802 | 94,533 |
| TOTAL | 132,420 | 147,882 | 280,302 | 51,802 | 332,104 |
| 1. | Assumes equipment lease to purchase at 10% down | |
| 2. | Assumes interest only payments during pre-production |
Plant Capital Costs
Capital costs for the processing plant were estimated using budgetary equipment quotes, material take-offs (MTOs) for concrete, steel, and earthwork, estimates from vendors and consultants, and estimates based on experience with similar projects of this type. The direct capital cost estimate for the plant is shown in Table 1-7. Some of the costs and quantity estimates used by M3 were supplied by other consultants.
Table 1-7: Initial Process Direct Capital Cost
| Area Description | Initial ($000s) | Sustaining ($000s) | Total ($000s) |
| Plant General | 25,588 | 10,844 | 25,588 |
| Crushing, Stockpile, Material Sorting | 250,087 | 0 | 250,087 |
| Material Handling/Stacking | 215 | 0 | 215 |
| Leaching, Solution Ponds | 96,266 | 200,739 | 297,005 |
| Solvent Extraction (SX) | 60,024 | 0 | 60,024 |
| Tank Farm | 26,375 | 0 | 26,375 |
| Electrowinning (EW) | 83,160 | 0 | 83,160 |
| Reagents | 400 | 0 | 400 |
| Sulfuric Acid Plant | 196,423 | 0 | 196,423 |
| Plant Direct Capital Total | 738,540 | 211,583 | 950,123 |
The cost for the sulfuric acid plant was derived in 2021 by NORAM Engineering of Vancouver based on a conceptual design for the sulfuric acid plant at a capacity of 1,650 short tons per day (stpd). For the current 2026 Gunnison Open Pit PEA, the sulfuric acid plant cost was adjusted using the Power of 0.725 rule to a plant capacity of 2,700 stpd and then escalated to Q1 2026 dollars. The capital cost for the sulfuric acid plant is estimate at $196.4 million. Additional information regarding the sulfuric acid plant costs can be found in Section 21 of the Gunnison Technical Report.
A capital cost estimate for the integrated cement plant and limestone distribution infrastructure is included in the financial analysis for this project. Unlike the initial copper operation infrastructure, the cement plant is structured as expansion capital. Construction is scheduled for Years 4 and 5 of the mine life, allowing the facility to be funded entirely from cumulative project free cash flow following the payback of the initial copper project capital. The total direct expansion capital cost to construct the 1.2-million-ton-per-year capacity cement plant and associated limestone handling facilities is estimated at $321.42 million. Additionally, limestone pre-stripping capitalized costs of $4.1million are also included in the financial analysis. Additional information regarding the cement plant costs can be found in Section 21 of the Gunnison Technical Report.
| 39 |
Infrastructure includes site utilities, ancillary facilities, the cement plant, the sulfide plant, and highway relocation. Table 1-8 summarizes the direct costs for onsite infrastructure. Infrastructure costs that were not estimated by M3 have the source listed in parenthesis.
Table 1-8: Infrastructure Capital Cost Summary
| Onsite Infrastructure | Initial ($000s) | Sustaining ($000s) |
Total ($000s) |
| Fresh/Fire Water Systems | 6,288 | 0 | 6,288 |
| Main Substation, Transmission Power Line | 16,115 | 0 | 16,115 |
| Ancillary Facilities | 27,674 | 0 | 27,674 |
| Cement/Limestone Plant (Burgex) | 0 | 321,419 | 321,419 |
| Sulfide Plant (GCC) | 0 | 56,600 | 56,600 |
| Highway Relocation (Kimley Horn) | 41,943 | 0 | 41,943 |
| Total Infrastructure | 92,020 | 378,019 | 470,039 |
Indirect costs are those costs that cannot generally be assigned to a specific work area, as summarized in Table 1-9. This category includes “other indirect costs” that provide oversight and support the construction activities for the project.
Table1-9: Indirect Capital Cost Summary
| Indirect Cost Items | Initial ($000s) | Sustaining ($000s) | Total ($000s) |
| Contractor Labor/Non-Labor Indirect costs | 55,559 | 13,289 | 68,848 |
| EPCM | 107,423 | 14,452 | 121,875 |
| EPCM Temporary Facilities | 4,476 | 0 | 4,476 |
| EPCM Commissioning | 4,383 | 0 | 4,383 |
| Vendor Support | 6,575 | 1,548 | 8,122 |
| Vendor Pre-commissioning | 2,192 | 516 | 2,707 |
| Vendor Commissioning | 2,192 | 516 | 2,707 |
| Commissioning and Capital Spares | 10,958 | 2,579 | 13,537 |
| Total Indirect Costs | 193,757 | 32,900 | 226,658 |
Operating Cost (Opex)
The total life-of-mine (LoM) costs, operating costs per short ton ($/st) of processed material, and dollars per pound ($/lb) of cathode produced are summarized in Table 1-10. The project operating costs include mine operating, process plant operating, and general and administrative costs (G&A). Total production costs add royalty expense, reclamation & closure, salvage value, and property & severance taxes. Total costs in each category are divided by the total tonnage of processed material or the total pounds produced to arrive at the values shown in the table below.
| 40 |
Table 1-10: Operating and Production Costs
|
Area |
LoM ($000) |
$/st mineralized material processed |
$/lb Copper Recovered (US$) |
| Mine Operating Cost1 | 4,226,693 | 7.82 | 1.33 |
| SXEW Operating Cost | 512,427 | 0.95 | 0.16 |
| Heap Leach Operating Cost | 1,077,491 | 1.99 | 0.34 |
| G & A | 142,003 | 0.26 | 0.04 |
| Material Sorting | 212,173 | 0.39 | 0.07 |
| Sulfide Plant | 199,579 | 0.37 | 0.06 |
| Operating Costs | 6,370,366 | 11.78 | 2.00 |
| Royalties | 715,142 | 1.32 | 0.22 |
| Property & Severance Tax | 206,453 | 0.38 | 0.06 |
| Closure & Salvage Value | 1,598 | 0.00 | 0.00 |
| Other Production Costs | 923,192 | 1.71 | 0.29 |
| Total Operating Costs | 7,293,558 | 13.49 | 2.29 |
1. Mine Operating Costs includes total mining costs including lease payments less pre-stripping costs.
Mine Operating Costs
The LOM mine operating cost per lb over the LOM is 0.92/lb Cu plus the equipment leasing cost of $0.27/lb Cu, resulting in a full mine operating cost of $1.19/lb Cu.
Mine operating costs are summarized by material type: mineralized material, overburden waste, and hardrock waste (sedimentary) in Table 1-11. Pre-production mine operating costs of $237.6 million, deferred stripping costs of $185.7 million are included in Table 1-11 below but are applied as Capital costs. Limestone mining costs of $230.6 million are included in Table 1-11 but are allocated elsewhere in the cash flow model. The total mining cost per short ton of mineralized material not including equipment lease payments is $5.61, which equates to $1.12/lb Cu. After adding equipment leasing costs, then subtracting the pre-stripping, deferred stripping and limestone mining costs, the total mined operating cost is $1.19/lb Cu.
Table 1-11: Summary of Mine Operating Costs
|
Mined Type |
LoM ($M) |
$/st Mined Type |
$/st Mineralized Material Processed |
$/lb Copper Recovered (US$) |
| Mined Mineralized Material | 1,223.8 | 0.54 | 1.91 | 0.38 |
| Waste – Sedimentary | 1,151.8 | 0.50 | 1.80 | 0.36 |
| Waste – Alluvium | 1,223.8 | 0.54 | 1.91 | 0.38 |
| Total Mined Costs1 | 3,599.4 | 1.58 | 5.61 | 1.12 |
| Additional Cost of Lease Payments | 864.8 | 0.38 | 1.35 | 0.27 |
| Total Mined Costs including Lease Payments | 4,464.3 | 1.96 | 6.96 | 1.39 |
| Pre-Stripping Cost | (237.6) | (0.10) | (0.37) | (0.07) |
| Deferred Stripping Cost | (185.7) | (0.08) | (0.29) | (0.06) |
| Limestone Mining Cost | (230.6) | (0.10) | (0.36) | (0.07) |
| Total Mined Operating Costs | 3,810.4 | 1.67 | 5.94 | 1.19 |
| 41 |
Plant Operating Costs
The operating costs assume a heap leach with a planned average placement of 28.2 million short tons per year and an SX-EW facility producing copper cathodes. The process plant operating costs are summarized by the categories of labor, electric power, reagents & wear parts, maintenance parts, and supplies and services. Table 1-12 lists the operating costs for the Heap Leach and Table 1-13 lists the operating costs for the SX/EW.
Table 1-12: Heap Leach Opex Summary by Cost Element
|
Operating & Maintenance |
LoM Operating Cost ($000) |
$/st mineralized material processed | $/lb Copper Recovered (US$) |
% |
| Labor | 78,788 | 0.15 | 0.02 | 7.3% |
| Electrical Power | 217,879 | 0.40 | 0.07 | 20.2% |
| Reagents | 756,415 | 1.40 | 0.24 | 70.2% |
| Maintenance Parts | 23,186 | 0.04 | 0.01 | 2.2% |
| Supplies and Services | 1,222 | 0.00 | 0.00 | 0.1% |
| Total | 1,077,491 | 1.99 | 0.34 | 100.0% |
Table 1-13: SXEW Opex Summary by Cost Element
|
Operating & Maintenance |
LoM Operating Cost ($000) |
$/st mineralized material processed | $/lb Copper Recovered (US$) |
% |
| Labor | 135,145 | 0.25 | 0.042 | 26.4% |
| Electrical Power | 218,660 | 0.40 | 0.069 | 42.7% |
| Reagents | 91,431 | 0.17 | 0.029 | 17.8% |
| Maintenance Parts | 52,409 | 0.10 | 0.016 | 10.2% |
| Supplies and Services | 14,782 | 0.03 | 0.005 | 2.9% |
| Total | 512,427 | 0.95 | 0.16 | 100.0% |
General and Administrative Operating Costs
General and Administrative (G&A) costs include items such as site management, accounting, human resources, environmental and safety compliance, laboratory, community relations, communications, insurance, legal, training, and other costs not associated with either mining or processing. The LOM G&A cost is shown in Table 1-14 below and includes the $/st processed material and $/lb of copper.
Table 1-14: Summary General and Administrative Operating Cost
|
Item |
LoM Operating Cost ($000) | $/st mineralized material processed |
% |
| Labor | 66,114 | 0.12 | 44.7% |
| Accounting (excluding labor) | 1,408 | 0.00 | 1.0% |
| Safety & Environmental (excluding labor) | 1,221 | 0.00 | 0.8% |
| Human Resources (excluding labor) | 939 | 0.00 | 0.6% |
| Security (excluding labor) | 1,408 | 0.00 | 1.0% |
| Assay Lab (excluding labor) | 5,634 | 0.01 | 3.8% |
| Office Operating Supplies and Postage | 939 | 0.00 | 0.6% |
| Maintenance Supplies | 2,817 | 0.01 | 1.9% |
| Power | 1,408 | 0.00 | 1.0% |
| Communications | 1,878 | 0.00 | 1.3% |
| Small Vehicles | 2,817 | 0.01 | 1.9% |
| Claims Assessment | 469 | 0.00 | 0.3% |
| Legal & Audit | 6,573 | 0.01 | 4.4% |
| Consultants | 4,695 | 0.01 | 3.2% |
| Janitorial Services | 1,408 | 0.00 | 1.0% |
| Insurances | 37,558 | 0.07 | 25.4% |
| Subs, Dues, PR, and Donations | 1,127 | 0.00 | 0.8% |
| Travel, Lodging, and Meals | 3,756 | 0.01 | 2.5% |
| Recruiting/Relocation | 3,756 | 0.01 | 2.5% |
| Community Relations | 1,878 | 0.00 | 1.3% |
| Total | 147,802 | 0.27 | 100.0% |
| 42 |
Economic Analysis
The financial evaluation presents the determination of the Net Present Value (NPV), payback period (time in years to recapture the initial capital investment), and the Internal Rate of Return (IRR) for the Gunnison Project. Annual cash flow projections were estimated over the life of the operation based on the estimates of capital expenditures and production cost and sales revenue. The sales revenue is based on the production of a copper cathode for open pit mining.
New facilities include Crushing-Conveying system, the Heap Leach Pad, SX-EW plant, the facilities at the Mine Services Area, the ancillary buildings located at the SX-EW plant, and the sulfuric acid plant.
Infrastructure changes include realignment of Interstate 10 in the vicinity of the Gunnison open pit, rerouting/relocating the powerlines and substations for the new Gunnison SX-EW and installation of the rail spur into the Gunnison property and the railyard.
The sulfuric acid plant has been upsized from 1,650 stpd to 2,700 stpd to meet the new acid demand for the heap leach option.
Plant Production Statistics
The design basis for the process plant production is 175 mppa of copper cathode in a single large SX-EW facility. To achieve that production, up to the design capacity of approximately 32,000 gpm of PLS will be pumped from the PLS pond to the Gunnison plant.
Average annual production is projected to be approximately 174 million pounds of copper cathode over the 19-year life of mine. Total production for the life of the operation is projected at approximately 3,187 million pounds of copper.
Copper Sales
The copper cathodes are assumed to be shipped to buyers in the US market, with sales terms negotiated with each buyer. The financial model assumptions are based on experience with copper sales from similar operations in the US.
Working Capital
A 15-day delay of receipt of revenue from sales is assumed for accounts receivables. A delay of payment for accounts payable of 55 days is also incorporated into the financial model. An allowance for initial replacement parts inventory for the plant is also included. All the working capital is recaptured at the end of the mine life and the final value of these accounts is zero.
| 43 |
Revenue
Annual revenue is determined by applying estimated metal prices to the annual payable metal estimated for each operating year. Sales prices have been applied to all life of operation production without escalation or hedging. The revenue is the gross value of payable metals sold before treatment charges and transportation charges. The average copper price used in the evaluation is $4.64/lb for the life of the mine.
Royalty
There are three entities that are entitled to royalties: the State of Arizona, Greenstone and Altius. The State has a sliding scale royalty estimated at 5.5%, applied only to copper produced from State land.
The Greenstone royalty is paid at the rate of 3.0% of the value of copper produced, while the Altius royalty is paid at a flat rate of 1.50%.
The Bowlin royalty has an estimated LOM cost of $500,000, which equates to an incremental cost of $0.002/lb Cu. This royalty has not been included in the LOM discounted cash flow.
Royalties for the life of the operation are estimated at $715.1 million and average $0.22 per pound of copper recovered.
The Stream for the life of the operation are estimated at $310.9 million and average $0.10 per pound of copper recovered.
Property and Severance Taxes
Property and severance taxes are estimated to be $206.4 million and average $0.06 per pound of copper recovered. Property taxes were estimated to be approximately $3.5 million per year during copper production and $0.7M thereafter, totaling $97.9 million for the life of the operations. Severance taxes are calculated as 2.5% of net proceeds before taxes from mining. Severance taxes are estimated to be approximately $108.6 million for the life of the operation.
Reclamation and Closure
An allowance for reclamation and closure costs is estimated to be $92.6 million ($0.034/lb copper cathode). Reclamation and closure activities are assumed to occur for 3 years beginning the year after mining has ceased.
Income Taxes
Taxable income for income tax purposes is defined as metal revenues minus operating expenses, royalty, property and severance taxes, reclamation and closure expense, depreciation, and depletion. The combined federal and state corporate income tax rate in Arizona is 25.9 percent and is applied to ‘taxable income’ derived from the Gunnison Project.
Income taxes are estimated by applying state and federal tax rates to taxable income. The primary adjustments to taxable income are tax depreciation and the depletion deduction. Income taxes estimated in this manner total $1,788.1 million for the life of the Gunnison Project.
| 44 |
Net Present Value (NPV) and Internal Rate of Return (IRR)
The economic results after taxes for the Gunnison Project, as shown in Table, indicate an IRR of 22.5% and a payback period of 3.9 years. The NPV before taxes is $1.96 billion at an 8% discount rate using the mid-year convention. The analysis assumes 100% equity financing.
Table 1-15: Economic Results
| Item | Units | Base Case |
| Life of Mine | # years | 21 |
| Recovered Copper Cathode | millions lbs | 3,187 |
| Copper Price | $/lb | 4.6425 |
| Initial Capital | $ millions | 1,555 |
| Expansion Capital | $ millions | 682 |
| Sustaining Capital | $ millions | 587 |
| Payback Period | # years | 3.9 |
| Internal Rate of return (after-tax) | % | 22.5% |
| Copper Cash Cost (C1) | $/lb Copper recovered | 1.70 |
| All-In Copper Sustaining Cost (AISC) | $/lb Copper recovered | 2.05 |
| Net Present Value @ 8% (after-tax) | $ millions | 1,959 |
The PEA is preliminary in nature and includes inferred mineral resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves. There is no certainty that the conclusions reached in the PEA will be realized. Mineral resources that are not mineral reserves do not have demonstrated economic viability. The Gunnison Project’s after-tax economic results show greatest sensitivity to copper price fluctuations, followed by initial capital expenditures and operating cost changes. Table 1-16, Figure 1-2 and Figure 1-3 below illustrate these sensitivities.
Table 1-16: Sensitivity Analysis – Open Pit
| Copper Price Sensitivities | Units | $4.25/lb | $4.60/lb | $5.00/lb | $5.50/lb | $6.00/lb | $6.50/lb | $7.00/lb |
| NPV8 | M$ | 1,566 | 1,959 | 2,403 | 2,953 | 3,500 | 4,043 | 4,586 |
| IRR | % | 19.5% | 22.5% | 25.8% | 29.8% | 33.7% | 37.5% | 41.1% |
| Project Payback | years | 5.17 | 3.95 | 3.28 | 2.78 | 2.45 | 2.20 | 2.00 |
| LOM Cu Gross Revenue | M$ | 13,364,882 | 14,484,547 | 15,764,165 | 17,363,687 | 18,963,209 | 20,562,731 | 22,162,253 |
| LOM EBITDA | M$ | 13,520,441 | 14,588,504 | 15,808,666 | 17,333,310 | 18,857,478 | 20,381,280 | 21,904,794 |
| FCF - Unlevered (post- | ||||||||
| tax) | M$ | 9,031,003 | 9,867,503 | 10,818,120 | 12,005,261 | 13,192,045 | 14,378,553 | 15,564,846 |
| 45 |
Figure 1-2: Open Pit Capex – Opex NPV Sensitivity – After Tax
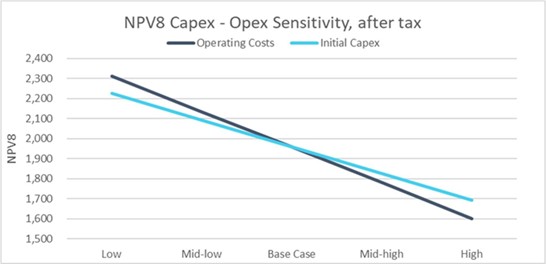
Figure 1-3: Open Pit Capex – Opex IRR Sensitivity – After Tax
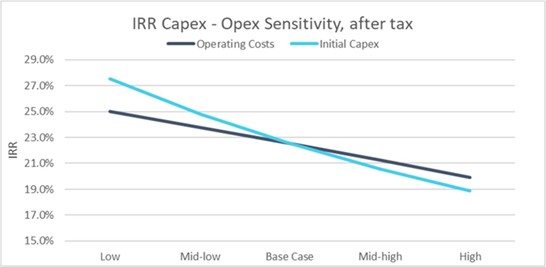
Adjacent Properties
The Gunnison Project lies within the porphyry copper metallogenic province of the southwestern United States. It is located in the Cochise Mining District, which is dominated by Cu-Zn skarns. With the acquisition of the Johnson Camp Mine, GCC now controls a majority of historical producing properties in the district. Tungsten and minor lead-silver-gold have been produced in adjacent properties in the district. In particular, tungsten has been historically produced in the area west of the Gunnison Project in the northern half of the Texas Canyon quartz monzonite stock before and during World War I. Lead-silver was also historically produced from Paleozoic limestones in the Gunnison Hills east of the Gunnison Project in the early 1900s (Cooper and Silver, 1964). Mineralization on adjacent properties is not necessarily indicative of the mineralization on the Gunnison Project. The author of this section of the Gunnison Technical Report has relied on reports by others (as referenced) for the information presented in this section and has been unable to verify the information.
| 46 |
Interpretation and Conclusions
A production schedule has been developed using input from independent consultants and existing Gunnison Project data. The production schedule anticipates recovery of 85% of the mineral resources in the mine plan resulting in production of 3,187 million pounds of cathode copper over a mine life of 21 years.
The economic analysis indicates an after-tax NPV of $1,960 million at a 8% discount rate with a projected IRR at 22.5%. Payback is anticipated in 3.9 years of production. The economics are based on a $4.60/lb copper price with a premium of $0.0425/lb added for producing Grade A cathode copper, a design copper production rate of 174 mppa for 21 years. Direct operating costs are estimated at $1.70/lb of copper, inclusive of Mining Operating costs. Initial CAPEX totals $1,555 million, which includes the mine, Gunnison SX-EW plant, leach pad and ponds, acid plant, rail spur, and owner’s costs. Sustaining capital costs of $587 million are projected for mine fleet replacement and additions to the leach pad.
The PEA is preliminary in nature and includes inferred mineral resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves. There is no certainty that the conclusions reached in the PEA will be realized. Mineral resources that are not mineral reserves do not have demonstrated economic viability.
Risks
Certain risks and opportunities are associated with the Gunnison Project, as is typical for mine development projects. These risks may include and are not limited to environmental permitting, title issues, taxation, public/political opposition, or legal impediments to operating this type of mining/processing operation at this location. The following project-specific risks have been identified along with the measures that GCC envisages to mitigate the risk.
| 1. | Slope Stability. Slope recommendations received from Call & Nicholas, Inc. (“CNI”) were based on recent strength testing as well as rock quality designation (RQD) data from core holes and experience at other Arizona mines in similar rock formations. Actual slope angles may have to be decreased, increasing the amount of waste handling required. | |
| Mitigation. Geotechnical drilling, along with further in-depth slope stability analysis, could result in achievable pit slope angles that are more shallow or steeper than the angles used in the analysis that will be presented in the report. | ||
| 2. | Blasting Costs. Drilling and blasting in the weakly cemented alluvium overburden is assumed to be significantly more productive than in the bedrock. Overestimation of blasting productivity in the overburden would result in increased costs. | |
| Mitigation. Additional investigation of the weakly cemented alluvium could remove uncertainties for this productivity differential. | ||
| 3. | Mine Design Uncertainty. The tonnage and grade expected to be placed on the leach pad could change as more drilling and engineering are completed. Metal prices, changes in metal recovery, or increases in operating costs could change the potential tonnage of heap leachable material. | |
| Mitigation. Additional investigation as the Gunnison Project moves toward implementation should reduce the uncertainty. | ||
| 4. | Copper Recovery. The heap leaching process for recovering copper from oxidized mineralization can be unpredictable. Metallurgical testing has established that coarse crushed mineralization is amenable to copper heap leaching and recovery. There is risk that additional testwork or actual performance could indicate the possibility of lower copper recoveries at the current crush size, acid application rate, or leach cycle estimates. | |
| Mitigation. Operational strategies will involve adjusting crush sizes, flowrates and acid strengths based on operational experience to maximize infiltration rates and increase PLS grades. |
| 47 |
| 5. | Leach Pad Flow Attenuation. Production of excess fines, compaction of lift surfaces on the leach pad, decrepitation of host rock mineralized material, and precipitation of minerals due to acid depletion could cause the formation of zones of low permeability. | |
| Mitigation. Placement and distribution of the leach material will be monitored to prevent compaction and enhance uniform distribution of leach solutions. Boreholes drilled through zones identified with low permeability can enhance vertical migration of solutions. Segregation or special treatment of materials that are identified as decrepitation (breaking down) and/or releasing fines may be necessary to mitigate this type of flow attenuation. | ||
| 6. | Acid Consumption/Cost. Acid consumption is estimated to range from 24 to 87 pounds of acid per ton of leach material based on the various rock types and carbonate content. The actual acid consumption could potentially be higher. | |
| Mitigation. Controlling excess sulfuric acid consumption may require careful management and segregation of the materials as they are placed on the leach pad. The height of each lift could be increased to reduce the time that the lower portion is subjected to leach solutions consuming acid. Placing geomembranes or low permeability layers between lifts could isolate depleted, acid-consuming materials at the bottom of the pad. Studies into mineralized material sorting to reject high carbonate-low copper mineralization will be conducted to determine the applicability and economics of this technique. Mineralized material sorting has the potential to reduce acid consumption in practice. Building an acid production facility greatly reduces the cost of acid, which helps mitigate higher acid consumptions. | ||
| 7. | Sulfide bacterial leaching is relatively new technology and may not produce expected results. | |
| Mitigation. Testwork from the Johnson Camp Mine Sulfide Leaching Demonstration may shed some light on the expected recoveries, acid consumption and costs. | ||
| 8. | Mineralized material Sorting Capacity and Scaling. There is inherent risk in implementing material sorting at the proposed treatment rate which is higher than established industry practice. | |
| Mitigation. Investigate during material sorting tests the copper losses at higher throughputs to test the efficiency of material sorting at the projected rates that Gunnison is planning. | ||
| 9. | Permitting Difficulties. Permitting mining projects in the western US and Arizona is unpredictable. Regulations and social attitudes can change. Although the Company has previously been able to obtain all operating permits in a reasonable time frame, there is no certainty this track record will continue. | |
| Mitigation. Permitting difficulties for changing the mining method for the deposit can be mitigated by developing support within the local community, identifying, and fixing potential areas of contention before they arise, getting support from community leaders in advance of applying for permits. Another measure is developing realistic permitting schedules that incorporate time to deal with challenges which also helps minimize deleterious consequences. | ||
| 10. | Equipment Financing. The initial mine CAPEX costs assume that equipment lease payments during pre-production will be interest-only payments. This is an unconventional equipment financing arrangement and may or may not be available at the time of project construction. | |
| Mitigation. Additional discussions with the financial arms of equipment manufacturers as the project progresses will provide a better understanding of what financing options are available. |
Opportunities
Several opportunities have been identified which could enhance the viability and economic attractiveness of the Gunnison open pit. Many of these opportunities may be realized by removal of risk and uncertainty that are present at the PEA level.
| 1. | Acid Consumption. Preliminary data suggest that sorting of this material has the potential to greatly reduce acid consumption and volume of material leached by removing 40 to 50 percent of the process stream as unmineralized, higher acid consuming, waste. This would result in significant savings on operating costs. | |
| 2. | Pit Slope Angles. The pit wall angles for the Gunnison open pit are considered reasonable based on the data available, however it is conceivable that pre-feasibility geotechnical data can steepen the pit walls in the gravel-alluvium, thus reducing pre-strip capital costs and life of mine waste mining costs. | |
| 3. | Copper Recoveries. The anticipated copper recovery is an estimate based on the best interpretation of existing test work. This copper recovery could be exceeded in practice. Improvements in the rate of recovery would mean lower flows from the leach pad for the same level of copper production, lowering operational costs., or the increased grade could result in higher copper production (revenue) for the same operating cost. Improvements in total copper recovered have the obvious benefit of increasing total revenue during the life of the mine. | |
| 4. | Increased Copper Price. The current financial analysis is based on an average, long-term copper price of $4.60 per pound based on current consensus pricing plus a $0.0425 per pound cathode premium. Current spot markets are currently 5% to 10% higher than long-term pricing estimates. Global demand increases for copper have the potential to drive copper prices higher, thereby increasing the economic (revenue) outlook for the Gunnison Project. | |
| 5. | Material Sorting Impacts to Recovery. Owing to the possibility of a constant leached residue assay irrespective of head assay, ASCu extractions from upgraded sorter material from the Martin formation and the Strong & Harris mineralization could be higher than predicted. | |
| 6. | Acid Consumption for Sorted Materials. Consumption of sulfuric acid could be much lower than predicted for unsorted heap feed. However, the predicted acid consumptions may also be lower than would have applied prior to sorting. | |
| 7. | Alluvium Mining. 61% of the waste mined in the pit is weakly cemented gravel (alluvium). The current design includes reduced drill and blast costs for this gravel including free digging of the top 50 feet however it is possible even more of this material will not need any drill and blast. This will be investigated in more detail during the planned PFS. | |
| 8. | Alternative Mining of Alluvium. The current removal of alluvium envisions the use of blast-haul operations. There are potential cost savings by developing other means of removal such as use of conveyors, dozers, or earth movers instead of blast-load-dump equipment. These will be investigated during the PFS”. |
| 48 |
| 9. | In-pit Leaching. In-pit leaching provides an opportunity to reduce operating costs and improve leach recovery over the life of mined mineralized material. The nature of the Gunnison Deposit and aquifer would allow control of leach solutions. | |
| 10. | Exploration Potential. Modern exploration activity has not occurred in the district. Exploration for the source of the porphyry copper sulfide mineralization at Gunnison has never been conclusively conducted and copper skarn deposits such as Gunnison are often associated with large nearby porphyry copper deposits. Significant areas of Earp Formation, Colina Limestone and Horquilla Limestone are under cover and have not been explored. These same formations host the mineralization in the Hermosa-Taylor deposits being developed by South 32 in southern Arizona. | |
| 11. | In-Pit Stockpiling. The mine plan has not considered the potential for in-pit waste stockpiles. Some areas of the open pit may be suitable for this, reducing hauling distances and costs. |
Recommendations
Based on the results of this PEA, it is recommended that GCC consider proceeding with a PFS of the open pit project which is expected to take approximately 18 months. A feasibility study will be proposed on successful completion of the PFS.
Additional drilling for resource verification and geotechnical coverage is recommended to support mine planning. Updating the acid plant design for the selected capacity is also recommended. Additional planning and costing work are required to establish the schedule and costs for the relocation of Interstate 10 and the addition of the rail spur to the Union Pacific Railroad.
Additional drilling will be required for metallurgical studies. Pilot metallurgical heap leach testing is recommended to investigate the recovery kinetics and flow characteristics for the heap leach design.
A mine plan, heap leach design, SX-EW design and highway move design are necessary to complete the PFS. GCC has proposed the list and budget for additional work that will support a pre-feasibility study shown in Table 1-17.
Table 1-17: Gunnison Project Pre-feasibility Budget
| Detail | Cost $ |
| Resource Upgrade | $9,343,000 |
| Metallurgy | $8,176,000 |
| Geotechnical | $210,000 |
| Pit design | $350,000 |
| Infrastructure design/PFS study | $1,710,000 |
| Total | $19,789,000 |
| 49 |
Johnson Camp Mine
The following represents the summary of the JCM Technical Report dated effective March 12, 2025 prepared by John Woodson, PE, SME-RM, Jeffrey Bickel, CPG, Abyl Sydykov, PhD, PE, Scott Freestone, PE, Dr. Terence P. McNulty, PE, DSc, R. Douglas Bartlett, CPG, Jacob Richey, PE and Thomas M. Ryan, PE. Unless specifically noted otherwise, the following disclosure regarding the Johnson Camp Mine has been prepared under the authority and supervision and with the consent of the authors, each a “qualified person” within the meaning of NI 43-101. The full JCM Technical Report is available under Gunnison’s corporate profile on SEDAR+ at www.sedarplus.ca. All references in this summary to Sections are to the Sections of the JCM Technical Report. All dollar amounts or ‘$’ set out in this section are United States of America Dollars.
Property Description, Location and Access
JCM is located in Cochise County, Arizona, approximately 65 miles east of Tucson in the historic Johnson Camp mining district. Figure 1-1 is a general location map and property location near the I-10 freeway.
Figure 1-1: Location of the JCM Property – January 2026
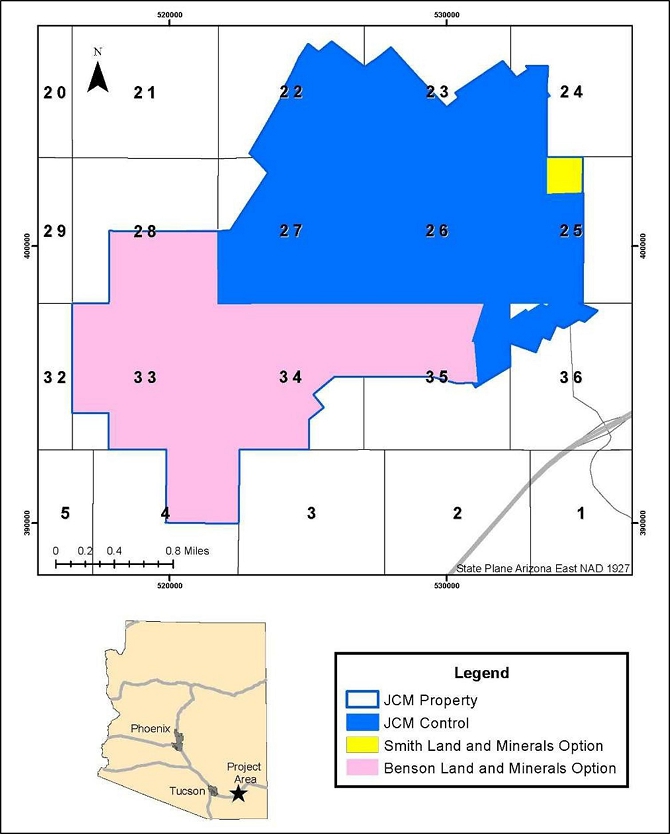
| 50 |
JCM is held by GCC through its wholly owned subsidiaries Excelsior Mining Arizona, Inc. and Excelsior Mining Holdings, Inc. Acquisition of the Nord Resources Corporation assets took place through a court-appointed receiver in December 2015.
Table 4-1: Summary of Land Packages that Constitute the Johnson Camp Property
| Claim Type | # of Claims | Approximate Area | Approximate Holding Costs | Surface Rights |
Federal Patented Lode Mining Claims |
53 | 759 acres 307 hectares |
Annual $1,450.64 | Controlled by GCAZ |
| Federal Unpatented | 83 | 1,293 acres | Annual $16,600.00 | Subject to US mining law |
| Fee Simple Lands | 4 | 617 acres 250 hectares |
Annual $1,060.40 | Controlled by GCAZ |
| Benson Option | 14 | 1786 acres 723 hectares |
Subject to Benson Option (see below) | Subject to Benson Option (see below) |
| Smith Option | 1 | 40 acres | Subject to Smith Option (see below) | Subject to Smith Option (see below) |
| Total | 155 | 4,495 acres 1,820 hectares |
Annual $19,111.04 |
Ownership of the unpatented mining claims is in the name of the holder (locator), subject to the paramount title of the United States of America, under the administration of the U.S. Bureau of Land Management (“BLM”). Under the Mining Law of 1872, which governs the location of unpatented mining claims on federal lands, the locator has the right to explore, develop, and mine minerals on unpatented mining claims without payments of production royalties to the U.S. government, subject to the surface management regulation of the BLM. As of the effective date, annual claim-maintenance fees are the only federal payments related to unpatented mining claims, and GCC represents these fees have been paid in full to August 31, 2025. The current annual holding costs for JCM is estimated at $19,111.04, including the county recording fees.
GCC has the right to use the surface of the Project in the form of patented mining claims and fee land parcels. The federal unpatented claims grant surface access but do not provide for surface ownership. Unpatented mining claims give the owner the right to develop and exploit valuable minerals contained within the claim, so long as the claim is properly located and validly maintained. There are sufficient surface rights held by GCC to conduct mining operations at the JCM Property.
There are 53 patented mining claims held in the name of GCAZ totaling 759 acres (307 ha). The claims include all surface and mineral rights. The claims are located on the ground and have no expiration dates.
There are 83 unpatented mining claims held by GCC in the name of GCAZ and GCH totaling 1,293 acres (524 ha). The unpatented claims are for minerals only, with no surface ownership. The BLM requires that all unpatented claims use a rental year from September 1 through August 31; claims for which fees are not paid by August 31st are automatically forfeited. The claims otherwise have no expiration dates and under current mining law can be held indefinitely if properly maintained. The claims are located on the ground and the location descriptions are filed with the BLM.
| 51 |
The JCM Property acquired by GCAZ includes Fee Simple Lands. There are four parcels of Fee Simple Lands all situated in Township 15S, Range 22E. Parcel 1 is situated on Section 26 and covers approximately 139 acres. Parcel 2 is situated on Section 26 and covers approximately 1 acre. Parcel 3 is situated on Sections 24 and 25 and covers approximately 53.44 acres. Parcel 4 is situated on Sections 23, 24, 25, and 26 and covers approximately 423.47 acres.
GCAZ has entered into an option agreement with certain landowners that provide GCAZ the right to acquire approximately 2,563.05 acres of Fee Simple Lands that are referred to as the “Smith Option”. The terms of the Smith Option agreement commenced in September 2022 and require an upfront fee of $40,000 and an annual fee of $30,000. GCAZ has a period of seven years to exercise the option at a price that starts at $3,500/acre in Year 1 and increases over the seven-year term at $500 per year to $6,500/acre in Year 7.
GCAZ has entered into an option agreement with certain landowners that provide GCAZ the right to acquire approximately 3898.14 acres of Fee Simple Lands that are referred to as the “Benson Option”. The terms of the Benson Option agreement commenced on November 12, 2024 and require an upfront fee of $1,000,000 and an annual fee of $250,000 in years two, three, four, five and six. GCAZ has a period of six years to exercise the option at a price that starts at $28,000,000 in Year 1 (with the $1 million credited against the purchase price) and increases over the six-year term at a rate of $2,000,000 per year (plus the $250,000 annual fee which is credited against the purchase price), to $37,000,000 in Year 6.
Triple Flag Royalty: Triple Flag USA Royalties Ltd. (“Triple Flag Royalties”) holds a 3.0% gross revenue royalty over the JCM Property. The gross revenue royalty is defined as royalty percentage times receipts, which is the sum of physical product receipts and deemed receipts. The Triple Flag Royalties royalty applies to the entirety of the JCM Property and production therefrom.
The JCM Property is also subject to a Metal Stream Agreement with Triple Flag International Ltd. (“Triple Flag”) that is applicable to all oxide minerals production from the parts of the Project located in the “Stream Area”. The Metal Stream Agreement is summarized in Table.
Table 4-2: Triple Flag Metal Stream Agreement for the JCM Property
| Stream Deliveries | Excelsior Mining Arizona Inc. (“Seller”) is required to deliver Grade A Copper Cathodes in an amount equal to the “Payable Copper”. The amount of Payable Copper is calculated based on a percentage of the amount of copper that is sold and delivered to Offtakers under the terms of Offtake Agreements (for percentages see heading – Payable Copper). | |
| Payment | The Buyer pays to the Seller a price for copper equal to 25% of the daily official LME Grade A Settlement quotation for copper quoted in U.S. Dollars, as published in the Metal Bulletin. | |
| Payable Copper | “Payable Copper” means a percentage of the Reference Copper equal to: |
Scenario |
Stage 1 (25 mppa) |
Stage 2 (75 mppa) |
Stage 3 (125 mppa) | |
| Upfront Deposit | 16.5% | 5.75% | 3.5% | |
Upfront Deposit + Expansion Option |
16.5% | 11.0% | 6.0% | |
At the current stage of the Project, the Buyer has made the initial Upfront Deposit ($65 million) and the Seller is ramping up to 25 mppa.
The “Expansion Option” provides Buyer the option to invest an additional $65 million in the event Seller approves an expansion to at least 50 mppa. |
| 52 |
RG Royalties, LLC holds a 2.5% net smelter returns (“NSR”) royalty interest in minerals produced and sold from the 15 patented claims. These 15 patented claims are also subject to the terms of a “Royalty Deed and Assignment of Royalty,” recorded with the Cochise County Recorder’s Office on June 19, 2009, at No. 2009-14847, and the “Grant of Production Payment” recorded with the Cochise County Recorder’s Office on June 10, 1999, at No. 1999-18419, as modified by a certain “Assignment of Production Payment” between Arimetco, Inc. and Styx Partners, L.P. (collectively, the “Production Payment Agreements”). The Production Payment Agreements provide for a non-participating payment of $0.02 per pound out of production during the calendar month in which copper produced from the 15 patented claims. The production payment is only payable when copper prices are in excess of $1.00 per pound and is capped at an aggregate of $1,000,000, of which $480,836 has been paid and/or accrued as of December 31, 2025.
On July 31, 2023, GCC announced that it had entered into the Nuton Option Agreement with Nuton to further evaluate the use of its Nuton™ copper heap leaching technologies (Nuton™ technologies) at Johnson Camp. Under the Nuton Option Agreement, GCC remains the operator and Nuton funds GCC’s costs associated with a two-stage work program at Johnson Camp.
The Nuton Option Agreement required that if Nuton proceeded to Stage 2, it would make a US$5 million payment to GCC for the use of existing infrastructure at the Johnson Camp mine for the Stage 2 work program. Nuton would also be responsible for funding all of GCC’s costs associated with Stage 2. On May 15, 2024, GCC announced that Nuton had elected to proceed to Stage 2 of the existing Nuton Option Agreement.
After the completion of Stage 2, Nuton has the right to exercise the option to joint venture and form a joint venture with GCU for Johnson Camp per mutually agreeable terms whereby Nuton would hold an initial 49% and GCC an initial 51%. The purpose of the Joint Venture is to continue the development of the Johnson Camp Mine using Nuton™ technologies. Should Nuton not exercise the option to form a joint venture, Nuton and GCC will discuss in good faith Gunnison’s continued use of the Nuton™ technologies at the Johnson Camp Mine subject to certain licensing terms and conditions to be agreed.
JCM operates under an Aquifer Protection Permit (APP), Air Quality Permit (AQP), a Resource Conservation and Recovery Act (RCRA) site specific ID number. All of these permits are issued and administered by the Arizona Department of Environmental Quality (ADEQ). The on-site septic system is grandfathered under the APP regulations and therefore does not require a permit. These permits have been amended as required to address the restart of open pit mining and construction of a new heap leach pad. JCM has a site wide Reclamation Plan approved by Arizona State Mine Inspector (ASMI).
Existing closure liabilities at the JCM are covered under the APP and the ASMI Reclamation Plan. These include closure of the existing ponds, the leach pad, and all other disturbed grounds. There are existing bonds in place to cover all closure obligations. The amended APP includes a compliance schedule item for updating closure costs and subsequent bonding of the leach pad closure in ten years from issuance of the amended APP.
| 53 |
There are no other known significant factors or risks that may affect access, title, or the right or ability to perform work on the property.
History
Exploration in the JCM area has taken place since the late 1800s and during that time, mining at JCM was considered archaic. Open pit mining commenced in 1975 by Cyprus and replaced the underground mining operations following the completion of an exploratory drilling program that defined the historical reserve of the Burro deposit. Cyprus and Arimetco collectively drilled 254 holes within both the Burro and Copper Chief pits. In 1999, Nord focused drilling exploration efforts on prospective targets outside of the pits such as the North and Keystone-Walnut areas. As a result of the four-phase exploration drilling program, 43 holes were drilled in the North area and 17 in the Keystone-Walnut area. Of the 60 drillholes, it was determined that no copper mineralization could be classified as reserves. Geological mapping was conducted by Nord in 2005 throughout the Burro and Copper Chief pit areas to identify and update existing geological maps. In 2008, Nord completed 25 drillholes that were placed at the extents of the Burro and Copper Chief pits to further delineate the resource. The drillholes confirmed mineralization to the north and south of the respective pits. An additional 6 drillholes were completed in 2010 by Nord that confirmed the geological and mineralogical continuity between the Burro and Copper Chief pits. The exploration programs carried out by Nord further defined the copper resources at the Burro and Copper Chief pits, along with indicating potential target areas for future development.
Copper-oxide mineralization has been mined at the Johnson Camp open-pit operation since 1975, most recently by Nord Resources Corporation from 2008 until 2010 Mining consisted of two open pits (Burro Pit and Copper Chief Pit), which are separated by roughly 2,000 feet along strike. The operation mined copper and processed the material via heap-leach and SX-EW. Previous operators include Cyprus Mines, Arimetco, and Nord Resources. This property is now controlled by GCC. Historically prior to GCC ownership, approximately 39 million tons of material and 187 million pounds of copper have been produced out of the Johnson Camp open pits.
A number of estimations of mineralized materials at the Johnson Camp Mine were carried out by historical operators. However, these historical estimates are relevant only for historical completeness and are not considered reliable. A qualified person has not done sufficient work to classify the historical estimate as current mineral resources or mineral reserves. All of these historical estimates are superseded by the mineral resource estimates presented in Section 14 of the technical report.
Geological Setting, Mineralization and Deposit Types
Regional, Local and Property Geology
The Johnson Camp Mine is located within the Mexican Highland region of the Basin and Range province, which is characterized by fault-bounded mountain ranges, with large intrusions forming the cores of the ranges. The Project lies on the eastern edge of the Little Dragoon Mountains within the Cochise mining district. The Little Dragoon Mountains are an isolated, fault bounded horst block comprised of rocks spanning from 1.4 billion years ago (Ga) Pinal Group schists to Holocene sediments. The southern portion of the Little Dragoon Mountains consists predominately of the Texas Canyon Quartz Monzonite of Tertiary age, whereas the Pinal Group schists and a sequence of Paleozoic sedimentary units dominate the northern half of the range. At Johnson Camp, the important Paleozoic host is the Cambrian Abrigo Formation. The Texas Canyon Quartz Monzonite is porphyritic intrusion that crops out to the southwest of the Burro Pit at the Johnson Camp Mine.
Several deformations have occurred in the area with the most recent being the latest Cretaceous-Paleocene Laramide Orogeny compression, followed by Miocene and younger Basin and Range extension that has modified the topography to its current appearance.
| 54 |
The stratigraphy of the Burro pit and Copper Chief pit includes, from lowest to highest, Pioneer shale, diabase sill, Bolsa quartzite, three members of the Abrigo formation, and the Martin dolomite. Most mineralization is hosted in the lower and middle members of the Abrigo formation.
Moderate to intense calc-silicate alteration including garnet, epidote, and diopside are common in various assemblages, most intense calc-silicate alteration in the Lower and Middle Abrigo formations. Pervasive quartz veining occurs in both the Abrigo Formation and underlying Bolsa Quartzite throughout the Johnson Camp Mine area. Quartz vein orientations are typically sub-parallel to the stratigraphic units.
Mineralization
Primary copper mineralization at the Johnson Camp Mine is dominantly found along bedding planes or in veins and replacements as chalcopyrite along with quartz and pyrite, closely associated with skarn and calc-silicate alteration in the rock. The host formations are generally within the Bolsa Quartzite, Diabase Units, Lower and Middle Abrigo Formations. Oxidized mineralization consists of chrysocolla, malachite, copper limonite, and manganiferous wad; decreases with depth; but penetrates faults and stratigraphic contacts. Supergene chalcocite and occasional native copper occur generally below the oxidized zone. Below the supergene zone, the mineralization transitions to primary sulfides with local zones of supergene mineralization.
Deposit Types
The Johnson Camp Mine copper deposit is a type of copper skarn. The copper skarn at Johnson Camp and collectively in the Cochise mining district is presumably related to the Texas Canyon Quartz Monzonite. Copper skarns generally form in calcareous shales, dolomites, and limestones peripheral or adjacent to the margins of diorite to granite intrusions that range from dikes and sills to large stocks or phases of batholithic intrusions, and frequently are associated with mineralized intrusions. Copper mineralization forms along structurally complex and fractured rocks and convert the calcareous shales and limestones to andradite-rich garnet assemblages near the intrusive body, and to pyroxene and wollastonite rich assemblages at areas more distal to the intrusive that are subject to retrograde alteration with mineral hydrated silicate assemblages that overprint earlier garnet and pyroxene.
Mineralization at Johnson Camp occurs approximately 500 ft northeast of known occurrences of the Texas Canyon Quartz Monzonite intrusion as proximal skarn related to a porphyry copper system. This assumption is supported by the high abundance of garnet-epidote alteration in the mineralized zones, and the characterization of the deposits in numerous historical publications.
Exploration
From 2016-2017, GCC catalogued and evaluated all data, drill core, pulp, and coarse reject material in the core shed inherited from Nord and subsequently commenced a re-logging and re-sampling program focused on soluble copper mineralization and assays.
In 2018, RESPEC began evaluating data provided by GCC for the purposes of building a new database to eventually create a new mineral resource estimate. These activities included:
| ● | Review of historical documentation prepared by GCC that discuss the overall project geology, details on historical soluble-copper analyses, and historical modeling of total copper and soluble copper. | |
| ● | Review of the Nord “10a” total copper and soluble copper resource modeling methodologies. | |
| ● | Detailed statistical analysis of historical data vs GCC results from 2016 and 2017 resampling of historical drill core and re-analyses of historical pulps. |
| 55 |
| ● | Implementation of the transformation of certain project data from original mine-grid coordinates (JCM Grid) into NAD1927 State Plane Arizona East FIPS coordinates using a 2-point rotation determined in 2016 by Darling Geomatics. | |
| ● | The re-creation of a version of the Nord “10a” block model in the new project coordinates. | |
| ● | Creation of project topography by contouring DEM, topography, and USGS 10 m NED data. | |
| ● | Creation of a RESPEC project drill-hole database. |
In 2022-2024, GCC completed several drilling programs at JCM in which 77 drill holes were completed totaling 29,377.5 feet.
| ● | In 2022, GCC completed a drilling program at JCM in which 44 drill holes were completed totaling 15,313 feet. | |
| ● | In 2023, GCC completed a drilling program at JCM in which 21 drill holes were completed totaling 11,872 feet. | |
| ● | In 2024, GCC completed a drilling program at JCM in which 12 drill holes were completed totaling 2,192.5 feet. |
Drilling
All of the drilling summarized in this section was conducted by historical operators from the 1960s through 2010. GCC completed a drilling program in 2022 to 2024 at the property focused on the Burro pit area.
The Johnson Camp Mine database contains 390 drill holes total 135,600 feet of drilling. Several drilling campaigns and operators span the contents of the database. Based on RESPEC’s current knowledge, historical operators of the campaigns include Cyprus Mining (171 drill holes), Arimetco (83 drill holes), Nord (31 drill holes), Sumitomo (12 drill holes), and 16 drill holes were completed by an operator unknown to RESPEC. GCC completed 77 drill holes in 2022 to 2024. Drilling is concentrated in and immediately around the historically producing open pits. Figure 10 1 below shows the collar locations for the drill holes in the database, and Table 10 1 is a breakdown of the drilling and operators in the Johnson Camp Mine area.
Table 10-1: Summary of Johnson Camp Drilling
| Operator | Year | Holes | Feet |
| Cyprus Mining | 1960 – 1986 | 171 | 59,818 |
| Arimetco | 1989 - 1997 | 83 | 24,637.5 |
| Summo USA Corp. | 1998 | 12 | 5,800 |
| Nord Resources Corp. | 2008-2010 | 31 | 14,368 |
| GCC | 2022 - 2024 | 77 | 29,377.5 |
| Unknown | 16 | 1,599 | |
| Totals | 390 | 135,600 | |
The drill contractor for the 2022 - 2024 GCC program was Godbe Drilling, using both LF70 and LF90 drill rigs. Godbe drilling set steel casing through the first five feet of bedrock, or through backfill in the pit and first five feet of bedrock. Downhole surveys were completed by Godbe drilling upon completion of drill hole using directional survey methods. Godbe drilling abandoned holes with mud and a grout cap. All GCC drillhole collars have been surveyed by Darling Geomatics using a Trimble GPS, which can be accurate to 0.05 ft horizontally and 0.2 ft vertically. GCC completed an infill and metallurgical core drilling program in the Burro pit area. 36 HQ core size (2.5-inch core diameter) infill holes and 8 PQ core size (3.3-inch core diameter) metallurgical holes were completed. Downhole surveys were conducted on all but 10 core holes of which two of the holes were redrilled with the original hole lacking a survey. In 2023, GCC completed metallurgical holes, 14 PQ core size and 1 PQ/HQ core size holes, and 6 condemnation holes, 2 PQ/HQ core size and 4 HQ core size holes. Downhole surveys were conducted on all, three of the drill holes were redrilled. In 2024, GCC completed 12 metallurgical holes, all of which were PQ core size. Downhole surveys were conducted on 4 of 12 drill holes, two of the drill holes were redrilled. Figure 10 1 above shows the collar locations for the drill holes in the database, with the blue holes illustrating the drillholes completed by GCC during the 2022 – 2024 drill programs.
| 56 |
GCC began production at the Johnson Camp Mine in 2025. Over 20,000 feet of blast hole drilling has been completed associated with advancement of production. Blast hole samples are assayed and logged; however, no formal QA/QC sampling has been established for the sampling of these holes and therefore they do not meet industry standards for sampling protocols. The author does not consider this drilling relevant for the mineral resources estimated in the report.
The author has determined that the drilling sampling procedures provided samples of drill intercepts that are representative of significant copper mineralization at JCM and of sufficient quality for use in the interpretations herein, and for the resource estimations discussed in Section 14 of the report. The author is unaware of any sampling or recovery factors that materially impact the mineral resources discussed in Section 14 of the report.
There is a general lack of down-hole deviation survey data for the historical holes in the Johnson Camp Mine area. While the paucity of such data is not unusual for drilling done prior to the 1990s, the lack of deviation data contributes a level of uncertainty as to the exact locations of drill samples at depth. However, these uncertainties are mitigated to a significant extent by the vertical orientation of nearly all drill holes, and the open-pit nature of any potential future mining operation that is based in part on data derived from the historical holes.
Sampling, Analysis and Data Verification
Sample Preparation, Analysis and Security
All of the historical drilling, sample preparation and analysis of the samples presented in the Gunnison Technical Report was under the control of the previous property owners. The laboratory sample preparation and analysis procedures used by the previous owners of the deposits are unknown; however, major commercial laboratories using best practices at the time completed the majority of analyses. Additionally, most of the historical data were generated by well-known mining companies. The certification status of some of the historical analytical laboratories is not known. Southwestern Assayers and Chemists is the predecessor to Skyline. The author believes the historical labs were independent commercial laboratories that were widely recognized and used by the mining industry at that time. The author has no information on the sample security methods and procedures used by historical operators. Little information is provided in the historical records pertaining to the results of historical QA/QC programs.
Following GCC’s purchase of the Johnson Camp Mine, a detailed inventory of historical drill core and sample pulp from the existing storage site near at the mine was undertaken. The core and pulp material at the Johnson Camp core shed was found to be well-organized. However, the physical state of the core shed itself was in poor condition. The facility had been exposed on one side by a broken bay door, and some core boxes and pulp containers were dilapidated or destroyed by rodents. GCC salvaged what material remained in-tact and transported it to their core facility in Casa Grande.
Drill core and pulp remaining from historical drilling was inspected and selected intervals were re-sampled by GCC in 2016 and 2017. The core was logged, photographed, and inspected by GCC staff. Samples were selected based on criteria developed by GCC for the purposes of data investigations. The GCC samples were prepared and analyzed at Skyline Laboratories (“Skyline”) in Tucson, Arizona. Skyline is an independent commercial laboratory that holds ISO 9001:2015 and ISO/IEC 17025:2017 accreditations.
| 57 |
From 2022 to 2024, GCC completed an infill and metallurgical core drilling program. The core was logged, photographed, and inspected by GCC staff and contractors. Samples were selected based on a suggested 10-foot length with flexibility to sample on geologic contacts and mineralization boundaries. All core samples were split using diamond blade saws and placed in bags. Internal QA/QC samples (standards, blanks, and ¼ core duplicates) were inserted approximately every tenth sample in the sequence. Metallurgical holes were sampled for assay by cutting an approximately 1/8 core slice down the core’s long axis for each interval. Slice locations were chosen by the logging geologist to ensure representative mineralization from the core was selected for each slice. The GCC samples were prepared and analyzed for ASCu and CNCu analyses at Skyline. ASCu, CNCu, TCu refer to sulfuric-acid-soluble copper, cyanide-soluble copper, and total copper, respectively.
For the 2022 to 2024 drilling program, drill core was temporarily stored at the GCC core facility at the Johnson Camp Mine for sample preparation; after sample preparation was complete, it was moved to the GCC core facility in Casa Grande, AZ. GCC’s samples were collected and stored in bags at the GCC core facility. The bags were placed into large mobile bins and made available for direct pickup by Skyline labs or were delivered to Skyline Labs by FCC staff. Upon pickup by Skyline or delivery to Skyline, Chain of Custody sheets were filled out and signed by GCC and Skyline.
GCC purchased commercial certified reference materials (“CRMs”) for use in the 2016-2017 resampling program and the 2022-2024 core drilling programs. The CRMs were inserted into the sample stream and analyzed with the core samples for total copper. The results were used to evaluate the analytical accuracy and precision of the analyses in GCC’s samples. The Skyline copper analyses of the GCC CRMs returned excellent results, with generally good precision and accuracy.
Documentation of the methods and procedures used for historical sample preparation, analyses, and sample security, as well as for quality assurance/quality control procedures and results, is incomplete and in many cases not available. Despite this, some of the historical assay certificates have been preserved and GCC was able to reasonably duplicate and/or verify the original results through resampling of historical core and new drilling. The author is therefore satisfied that the historical analytical data are adequate to support the current resources, interpretations, conclusions, and recommendations summarized in the technical report.
GCC’s sample preparation and analyses were performed at a well-known certified laboratory, and the sample security and QA/QC procedures are adequate to support the current resources, interpretations, conclusions, and recommendations summarized in the technical report.
Data Verification
Data verification, the process of confirming that data has been generated with proper procedures, has been accurately transcribed from the original source and is suitable to be used, has been performed by the author through reviews of original data and certificates, drill core, a site visit, and audits and analyses of GCC’s drill-hole database. As a part of the verification of historical assays, RESPEC also analyzed core-duplicate data generated by GCC in 2016 and 2017 and compared the results to historical assays.
Verification of mineralization was conducted during the author’s visits to GCC’s properties in March and May of 2021. During these site visit, drill core was examined pit faces with visible copper were observed at the property. The existence of the Johnson Camp Mine has been widely known in the industry for many years prior to GCC’s involvement and there is a documented production history of the mine from several companies (Cyprus, Arimetco, and Nord) that were well-known and reputable operators.
Explicit modeling of the copper mineralization was the most critical component to the estimation of the project mineral resources. This ‘hands-on’ approach provided meaningful verification of the historical data, whereby continuity and sensibility of meaningful geological variables, and the assays in the context of those variables, were carefully evaluated and considered.
| 58 |
There were no limitations on, or failure to conduct, the data verification for the Gunnison Technical Report other than those discussed in the technical report. The author has verified that the project data are adequate as used in the technical report, most significantly to support the estimation and classification of the mineral resources reported in the report.
Mineral Processing and Metallurgical Testing
Metallurgical testwork has been conducted in numerous campaigns by previous operators and owners including Superior Oil, Quintana Minerals, Phelps Dodge, Magma Copper, Arimetco, and Nord Resources. Testwork included many rounds of bottle roll and column testing. Early test programs indicated that total sulfuric acid consumption (before the electrowinning credit) will be approximately 9 lb H2SO4/lb of copper dissolved, that average PLS grade will be as high as 1.5 gpl Cu, and that about 65% of the total copper will dissolve, while as much as 95% of the ASCu could dissolve after sufficient contact time. This prior test work did not include augmented sulfide and transitional mineral leaching.
Nord Resources conducted eight column tests in 2011 on crushed and agglomerated material and 35 column tests in 2012 on crushed material minus 1” and minus 6”. Of these columns, 23 provided useful results to determine copper recovery and acid consumption. The results of some of the column tests produced ambiguous results regarding acid consumption (higher with a 6” crush than a 1” crush).
It is important to note that acid consumptions and copper extractions obtained from column tests do not faithfully predict acid consumptions or copper extractions that will be obtained in commercial heaps, as both will depend on leach cycle time, as well as various factors including care taken during heap construction and operation. Also, the original reports expressed copper recovery, which is misleading. It is more correct to use copper extraction. Copper recovery should apply to commercial cathode production and is always somewhat lower than the leaching extraction during column or heap leaching. For example, this difference can be attributed partially to the residual copper in the acidified raffinate (typically 5-10 percent of the copper in the PLS), which may not be completely recovered in subsequent leaching cycles.
Four column tests were conducted at Johnson Camp in 2022. These heap simulation tests were run on whole core intervals that were nominally minus 3 inches in diameter. The columns were 470 mm (18.5 inches) in diameter by 2.5 meters tall. All cores were Lower Abrigo lithology and had been logged as weak oxide and transition mineralization. Head assays ranged from 0.38 to 0.49% TCu with 0.02 to 0.27% CNCu and 0.08 to 0.14% ASCu. All four columns were acid-cured, but two were cured with a slow drip of acidic solution, while two were cured quickly and rested for 7 days before application of leaching solution. However, the curing solution was very strong with 200 grams of H2SO4 per liter, which not only dissolved a significant amount of gangue with free acid as low as pH 0.2, but also led to distorted net acid consumptions. Also, the relatively low ASCu head assays suggest either incorrect assays or extraction of most of the total copper. A comprehensive interpretation of the test results is not possible.
Information to date for a minus 1-inch (25 mm) to minus ½-inch (12.5 mm) crush indicates 80% average ASCu extraction for Bolsa Quartz lithology, and 80% for Lower Abrigo. ROM extractions will be approximately 10% lower. Net acid consumptions in pounds per ton of leach pad material will be approximately as follows for ROM: Upper Abrigo, 70; Middle Abrigo, 70; Lower Abrigo, 26; and Bolsa Quartzite, 22. For a minus 1-inch crushed and agglomerated heap feed, the net acid consumption will be about 35% higher for each lithology.
| 59 |
The 2024 pit shell design was based on more conservative copper extractions of 55% than the 72% extractions shown in Table below that represent column-to-ROM heap adjustments to the QP’s interpretation of available data.
Table 13-2:Pit Shell Assumed Copper Extractions for Oxide Material
|
Crush Size |
Lithology |
ASCu Extraction (%) |
CNCu Extraction (%) |
SCu Extraction (%) | Acid Consumption (lb/ton) |
|
ROM |
Bolsa Quartz | 72 | 45 | 15 | 22 |
| Upper/Middle Abrigo | 72 | 45 | 15 | 70 | |
| Lower Abrigo | 72 | 45 | 15 | 26 | |
| Minus 1-inch | Bolsa Quartz | 86 | 76 | 15 | 33 |
| Upper Abrigo | - | - | 15 | - | |
| Lower Abrigo | - | - | 15 | - |
Since 2022, Rio Tinto and its wholly-owned subsidiary, Nuton LLC, have been commercializing their process for enhanced bio-heap leaching of primary copper sulfides, especially, chalcopyrite, referred to as the Nuton™ technologies. At the core of the Nuton™ technologies is a portfolio of proprietary copper leaching technologies and capabilities – the culmination of almost 30 years of research and development. The Nuton™ technologies offer the potential to economically unlock known low-grade copper sulphide resources, copper sulphides with high-amounts of deleterious elements (such as arsenic), and copper-bearing waste and tailings, and also to achieve higher copper recoveries from primary copper sulphide material, allowing for significantly improved copper production. One of the associated advantages of NutonTM is the potential to deliver superior environmental performance, including more efficient water usage, lower carbon emissions, and the ability to reclaim mine sites by reprocessing mine waste. The current work is based on studies that were developed at Rio Tinto’s Bundoora Technical Development Centre in Australia and at Kennecott Utah Copper. It appears that the degree of augmentation may be increased by reliance on microbes that are unusually tolerant of very high temperatures.
Nuton has collected samples from JCM and is running column testwork on these samples using the Nuton™ technologies. Although the work is not yet complete, some generalizations can be made. With the aid of microorganisms and additives, primary sulfide zone samples in which chalcopyrite dominates the sulfide copper mineralization will result in copper leaching extractions up to 84% as indicated by column testing results. As with essentially all commercial heap leaching operations containing significant sulfide mineralization, there will be inter-lift aeration with low-pressure blowers.
It is the opinion of the author for this section that the following copper heap leaching results in Table 13 3 can be obtained at Johnson Camp, given reasonable care, and adherence to design operating conditions, and with tertiary crushing to a ½-inch (12.5 mm) P80. This prediction recognizes the need for conservatism, while assuming that significant near-term progress by NutonTM will be made on heap leaching of chalcopyrite and other refractory copper minerals. Anticipated sulfuric acid consumptions are 22 lb/ton for Bolsa quartzite and 26 lb/ton for Lower Abrigo under ROM conditions.
Table 13-3: Predicted ROM Heap Leaching Extractions
| ASCu | CNCu | SCu* | |
| ROM without augmentation | 72% | 45% | 15% |
| * SCu denotes chalcopyrite and other refractory sulfides | |||
Oxidation and leaching of pyrite and copper sulfides, especially chalcopyrite, will generate sulfuric acid, so these reactions will cause the net acid requirement for heap leaching to diminish during the first year of operation. Copper recoveries may be higher or lower than currently estimated. Acid consumption may be higher or lower than currently estimated.
| 60 |
Mineral Resource and Mineral Reserve Estimates
Mineral Resource Estimate
The mineral resource estimation for the Johnson Camp Mine was completed for disclosure in accordance with NI 43-101 with an effective date of December 31, 2025. The Johnson Camp Mine mineral resources are classified in order of increasing geological and quantitative confidence into Inferred, Indicated, and Measured categories in accordance with the “CIM Definition Standards - For Mineral Resources and Mineral Reserves” (2014).
The Johnson Camp Mine copper resources were modeled and estimated using information provided by GCC. The information is derived from historical core holes drilled by Cyprus Mining, Arimetco, Summo USA Corp., and Nord Resources Corp. The drill hole database also includes analyses performed by GCC on the historical core.
Mineral domains were modeled by RESPEC to respect the lithologic and structural interpretations of the deposit. Following statistical evaluation of the drillhole data, mineral domains were modeled on cross sections for total copper (“TCu”). Low-, mid-, and high-grade domains were modeled for total copper and were numbered 100, 200, and 300, respectively. Grade domains were interpreted based on copper grade domains that ideally correspond to the underlying geology. The grade domain ranges are shown in Table 14-4 below:
Table 14-4: Grade Domain Ranges
| Domain | Total Copper (%) | |
| 100 | ~0.025 to ~0.15 | |
| 200 | ~0.15 to 0.7 | |
| 300 | > ~0.7 |
Soluble copper ratios were estimated within the total copper domains and lithologic units and used to calculate a soluble copper grade.
The 100-foot-spaced cross-sectional mineral-domain polygons were used to code 20 x 20 x 20 (x, y, z)-foot blocks that comprise a digital model rotated to a bearing of 306°. The percentage volume of each mineral domain, as coded directly by the cross-sections, is stored within each block as a “partial percentage”, as is the partial percentage of the block that lies outside of the modeled metal domains (Domain 0). In other words, each block stores the partial percentage of each of the four domains for total copper. The oxidation model was used to domain the acid-soluble copper ratio and cyanide-soluble copper ratio estimates.
Total copper grades, as well as acid-soluble copper and cyanide-soluble copper ratios, were interpolated using inverse distance, ordinary kriging, and nearest-neighbor methods. The mineral resources reported herein were estimated by inverse distance interpolation as this method led to results that most appropriately respected the drill data and geology of the deposit.
Mineral resources were estimated for total copper (TCu), acid-soluble copper (ASCu), cyanide-soluble copper (CNCu), and sulfide copper (CuS). Once the final estimate was complete, a pit optimization was applied to the resource to evaluate if it has reasonable prospects for economic extraction. The pit shells created using these parameters were used to constrain the project mineral resources. The pit shells were limited on the west side of the Burro Pit to prevent from encroaching on the process plant and the leach pad. The in-pit mineralization was further constrained by the application of a cut-off of 0.12% TCu to all model blocks within the pit shells.
All reported in-pit mineralization is classified as Measured, Indicated, or Inferred shown in Table 14-15. Mineral resources that are not mineral reserves do not have demonstrated economic viability.
| 61 |
Table 14-15: Johnson Camp In-Pit Mineralization by Mineral Resources Classification
(0.12% TCu cut-off)
| Classification | Tons | % TCu | % ASCu | % CNCu | % CuS | lbs TCu | lbs ASCu | lbs CNCu | lbs CuS |
| Measured | 28,700,000 | 0.37 | 0.15 | 0.08 | 0.08 | 211,627,451 | 86,877,975 | 43,772,993 | 46,840,993 |
| Indicated | 67,915,000 | 0.34 | 0.15 | 0.06 | 0.06 | 456,179,565 | 209,866,810 | 75,574,932 | 74,818,932 |
| M&I | 96,615,000 | 0.35 | 0.15 | 0.06 | 0.06 | 667,807,000 | 296,745,000 | 119,348,000 | 121,660,000 |
| Inferred | 24,962,000 | 0.32 | 0.15 | 0.05 | 0.05 | 160,723,920 | 75,102,728 | 24,316,026 | 23,798,736 |
| 1. | The effective date of the mineral resources is December 31, 2025. | |
| 2. | The project mineral resources are shown in bold and are comprised of all model blocks at a 0.12% TCu cut-off that lie within optimized resource pits. | |
| 3. | Mineral resources that are not mineral reserves do not have demonstrated economic viability. | |
| 4. | The estimate of mineral resources may be materially affected by geology, environmental, permitting, legal, title, taxation, sociopolitical, marketing, or other relevant issues. | |
| 5. | Rounding as required by reporting guidelines may result in apparent discrepancies between tons, grade, and contained metal content. |
Future drilling, exploration, and resource definition at Johnson Camp Mine should focus on increasing the understanding of the distribution of cyanide soluble copper mineralization. Infill drilling in key areas to increase drill density, and drill-testing of the unconstrained limits of the deposit, particularly down-dip from known mineralization, should be prioritized.
The estimate of mineral resources may be materially affected by geology, environmental, permitting, legal, title, taxation, sociopolitical, marketing, or other relevant issues. Potential risk factors include changes in metal prices, increases in operating costs, fluctuations in labour costs and availability, availability of investment capital, infrastructure failures, changes in government regulations, community engagement and socio-economic community relations, civil disobedience and protest, permitting and legal challenges, and general environmental concerns. However, the author is not aware of any such factors that may materially affect the Johnson Camp Mine mineral resources as of the date of the technical report. The impact of taxation was taken into consideration when establishing cut-off grade.
Mineral Reserve Estimate
No mineral reserves are reported in the technical report. The author cautions that GCC has decided to commence construction and proceed production at the Project. GCC did not base this production decision on any feasibility study of Mineral Reserves demonstrating economic and technical viability of the mines. As a result, there may be increased uncertainty and risks of achieving any level of recovery of minerals from the mine at the project or the costs of such recovery. As the project does not have established Mineral Reserves, GCC faces higher risks that anticipated rates of production and production costs will not be achieved, each of which risks could have a material adverse impact on GCC’s ability to continue to generate anticipated revenues and cash flows to fund operations from the project and ultimately the profitability of the operation
Mining Operations
Mining of the Johnson Camp (JCM) deposit for the Nuton Demonstration is planned to be accomplished using conventional open pit hard rock mining methods. One and a half years remain of the 2.5-year mine plan that was developed to produce sulfide material for the Nuton Demonstration as quickly as possible. Mining of the deposit is expected to be accomplished with a combination of excavators and front end loaders with 70-100 ton haul trucks. Mining is planned on 20-ft bench heights. Mining will be performed by a contract miner.
The shift schedule for mining is 2-12 hour shifts 5 days per week plus 2 Saturdays a month through April 2026. This is expected to reduce to 1 shift per day starting in May of 2026. Measured and Indicated material with net of process greater than $0.01/ton is scheduled to be sent to the leach pad for processing.
| 62 |
Crushing and placement of the Nuton Demonstration material will be performed by a Contractor within the footprint of the leach pad. Placement of ROM leach material will be truck dumped in 15 to 30 ft lifts on the leach pad. The waste storage area is directly east of the pit. The waste dump is planned to be constructed in 40 ft lifts at a deposition angle of 2.5:1.
Phase 1 Mining
Drilling and blasting of Phase 1 is planned to be accomplished on 20 ft bench heights triple benched to 60ft benches at the ultimate pit limits. Loading and hauling will be performed on 20 ft benches by 9 cubic yard front end loaders or excavators loading 70 ton-haul trucks.
Phase 2 Mining
((4760 ft bench – 4600 ft bench)
In order to achieve the planned mining rates in 2026, Phase 2 may need to be mined on 30 ft bench heights double benched to 60ft benches at the ultimate pit limits down to the 4600 ft bench. Loading and hauling will be performed by 14 cubic yard front end loader or excavator loading 100-ton haul trucks and 70-ton trucks
(4600 ft bench – 4360 ft bench)
Below the 4600 ft bench, drilling and blasting of Phase 2 is planned to be accomplished on 20 ft bench heights triple benched to 60 ft benches at the ultimate pit limits. Loading and hauling will be performed on 20 ft benches by 14 cubic yard front end loaders and excavators loading 100-ton haul trucks down to the 4540 ft bench. Below the 4540 ft bench, loading and hauling will be performed on 20 ft benches by 9 cubic yard front end loaders or excavators loading 70 ton-haul trucks.
A fleet of auxiliary equipment to support the main operating equipment will be required. This will include 2-410 hp and 1-300 hp tracked dozers to maintain the waste dump, the placed ROM leached material, and cleanup in the mining phases. There will be 2-8,000 gallon water trucks and 2 motor graders with 14 ft/16 ft moldboards. There will also be a track drill and an excavator.
An estimate of equipment requirements is provided on Table 16-7. The equipment estimate is based on 2-12 hour shifts 5 days per week plus two Saturdays a month through April 2026 followed by a reduction to 1 shift per day starting in May of 2026.
Table 16-7: Expected Major Mining Equipment
| Equipment Type |
2026 Q1 |
2026 Q2 |
2026 Q3 |
2026 Q4 |
2027 Q1 |
2027 Q2 |
| Cat MD6200 Blast Hole Drill | 3 | 3 | 3 | 3 | 1 | 1 |
| 9 Cubic Yard Loader/Backhoe | 3 | 3 | 3 | 3 | 2 | 1 |
| 15 Cubic Yard Loader/Backhoe | 2 | 2 | 2 | 2 | 0 | 0 |
| 100 ton Haul Truck | 6 | 6 | 6 | 6 | 0 | 0 |
| 410 hp Track Dozer | 2 | 2 | 2 | 2 | 2 | 2 |
| 300 hp Track Dozer | 1 | 1 | 1 | 1 | 1 | 1 |
| Cat 14M/16M Motor Grader | 2 | 2 | 2 | 1 | 1 | 1 |
| 70 ton Water Truck 8kgal | 2 | 2 | 2 | 1 | 1 | 1 |
| 70 ton Haul Truck | 12 | 14 | 14 | 18 | 10 | 6 |
| Track Drill | 1 | 1 | 1 | 1 | 1 | 1 |
| Cat 336 Excavator | 1 | 1 | 1 | 1 | 1 | 1 |
| TOTAL | 23 | 22 | 18 | 16 | 15 | 10 |
| 63 |
For the planned three-year initial mining phase from the Burro Pit, the current dewatering rate of 50 gpm is representative of what can be expected during this phase of mining. As the pit is slightly deepened, this may increase to as much as 100 gpm.
Processing and Recovery Operations
The Johnson Camp Mine has a fully working SX-EW plant with a nameplate capacity of 25 million lbs of cathode copper per year when fully operating. For the Nuton Demonstration, a new heap leach pad, designated Pad 5, was completed construction. The leach pad hosts both ROM and crushed and agglomerated material separated by a dividing berm. Most of the new equipment will be located on top of Pad 5 with leach material transported to the pad by haul truck. The crushed and agglomerated material will be stacked with conveyors into an engineered heap. This material will be aerated and irrigated by a series of blowers and perforated piping. PLS flows from the crushed and ROM sections of the pad are measured and sampled independently before reporting to the existing PLS pond via a new pipeline. The PLS is being treated in the JCM SX-EW facility. JCM has three 2,500 ton sulfuric acid storage tanks that were installed in 2019.
Infrastructure, Permitting and Compliance Activities
Infrastructure
The Johnson Camp Mine is an existing and operating copper hydrometallurgical plant. The site includes two open pits, waste dumps, SX-EW plant facilities and mine infrastructure is in use now that mining operations in the Burro Pit have resumed. The new heap leach pad, Pad 5 was completed in 2025 for the placement of newly mined material (Figure 1-2).
| 64 |
Figure 1-2: Site Plan of the Johnson Camp Mine showing the location of new leach pad, Pad 5
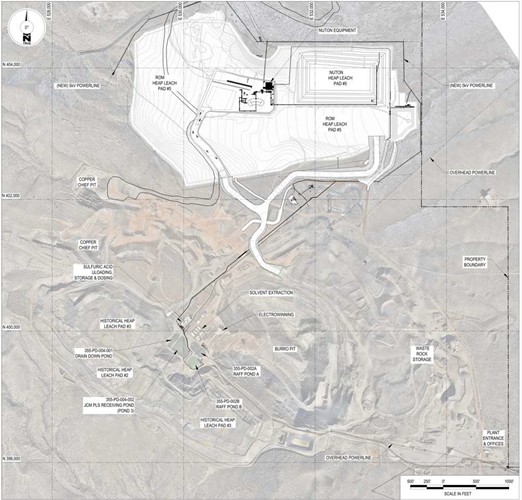
Water is supplied by two wells on site that produce 266 gpm of process make-up water. Additional water will be available from hydraulic control wells from the Gunnison wellfield and from pit dewatering.
An existing 69 kV power line runs to the JCM substation where power is stepped down to 5 kV for distribution around the JCM mine site. Power distribution to the equipment located on Pad 5 will be fed with power stepped up to 13.8 kV from the main JCM substation. The average power consumption for the JCM project is estimated to be 7.1 kW with a demand load of 10.7 kW.
Environmental and Permitting
The Johnson Camp Mine (JCM) is an active open pit mine. A processing (SX-EW) plant and associated ponds located at JCM are used to process pregnant leach solutions (PLS) from JCM. JCM has resumed mining of the open pit and will resume the heap leaching process using the mineralized material that will be placed on a new heap leach pad. Existing permits have been modified to address resumption of mining at JCM. Federal, state, and local government existing environmental permits are listed in Table 20-1.
| 65 |
Table 20-1: JCM Environmental Permits
| Agency | Permit | Description | Citation | When Required/ Permit No. |
Federal | ||||
| Agency | Permit | Description | Citation | When Required/ Permit No. |
| US Fish & Wildlife Service (USFW) | Incidental Take Permit | Mining activities that may affect species listed as endangered or threatened need to conduct studies to identify any targeted species and to apply for a permit to conduct their activities. Any identified threatened or endangered species identified in pre-mining surveys would need to be mitigated before mining could proceed. |
50 CFR Sections 7 and 10 |
None previously identified. New studies may be required prior to disturbing new ground. |
| State of Arizona | ||||
| Arizona Department of Environmental Quality (ADEQ) | ||||
| Air Quality Division | Air Quality Control Permit |
Ensures air pollutants from any source do not exceed the National Ambient Air Quality Standards |
ARS §49-402 | AQP-71633; covers the Gunnison Project and JCM |
| Groundwater Section | Aquifer Protection Permit | Covers surface impoundments, solid waste disposal facilities, mine tailings piles and ponds, heap leaching operations. This permit requires designs for the proper management of process facilities, ponds, tailings impoundments, and includes monitoring requirements to ensure compliance with the permit. |
AAC R18-9 Articles 1 – 4 |
P-100514; JCM has amended the APP to include a new leach pad. It may require an amendment at a later date for expansion. |
APP Closure Plan and Bonding for APP Facilities |
Closure strategy and estimated cost of closure, post closure monitoring, and surety bond. Bonding estimate must be approved by the agencies and the bond must be posted prior to commencement of construction. | AAC R18-9 Articles 1 – 4 |
Closure costs for the new leach pad have been provided with the APP amendment application. | |
| Waste Management Division | EPA ID Number |
Generators of hazardous waste must have an EPA ID prior to offering the waste for shipment. |
ARS §49-922 | Covers JCM |
| Pollution Prevention Plan | Plan identifying opportunities to reduce waste. | ARS §49- 961 thru 973 |
Report to be submitted annually | |
| Toxic Release Inventory | Submit Form R for quantity of copper in waste rock. | 40 CFR 372 | Report to be submitted annually | |
| Arizona Department of Water Resources | Willcox Active Management Area (AMA) | AMAs are subject to certain statutory and administrative regulations regarding withdrawal and use of groundwater. | ARS §45-402-599 | Requirements including application for Type 2 grandfathered rights, water conservation, withdrawal permits, and annual reporting may be required. |
| Arizona State Mine Inspector | Mined Land Reclamation Plan and Bond |
Exploration and mining activities on private land with greater than 5 acres disturbance. Does not include facilities covered in Aquifer Protection Permit. |
AAC R11- 2-101 thru 822 |
Approved April 2018; may require updating for future modifications. |
| Arizona Department of Agriculture | Notice of Intent to Clear Land |
Ensures enforcement of Arizona Native Plant Laws | ARS §3-904 | 60 days prior to new disturbance |
| Arizona Game and Fish Department | Ascertain whether or not the mining operation would endanger fish and game habitat, etc. | AAC Title 12 | No T&E Species identified. Additional plans may be required | |
| 66 |
Reclamation and closure costs for the JCM Project include reclamation of the leach pads, stockpiles, and waste dumps, closure of the JCM plant site and ponds, the JCM heaps and stockpiles and demolition of the ancillary buildings. Reclamation activities will be spread over three years sometime after the cessation of operations. The Closure Bond for these activities is $7,281,757.
Social
GCC has worked extensively to build sustainable partnerships and bring value to the community. GCC’s approach to community relations reinforces its core values and provides guidelines for making decisions on a variety of issues, ranging from charitable giving to resource development. To that end, GCC maintains a broad-based community relations and stakeholder outreach program. Various levels of activity and outreach occur as a function of the development of the project from prefeasibility and feasibility studies, through Project construction and operations, to closure and rehabilitation.
Capital and Operating Costs
The JCM Mineral Resource Estimate includes inferred resources. Inferred Mineral Resources are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves. In addition, NI 43-101 prohibits the disclosure of the results of an economic analysis that includes or is based on Inferred Mineral Resources. As a result, the author has determined that it is not permitted to provide forecasts of future capital or operating costs. As a result, the disclosure in this section is limited to a description of the capital and operating costs, and disclosure of historical amounts.
Capital Costs
The Johnson Camp Mine SX-EW plant was upgraded in 2019 and 2020 as part of the Stage 1 execution of the Gunnison ISR Copper Project. Upgrades included the replacement of the Raffinate pumps, the addition of three sulfuric acid tanks, and the addition of a third electrolyte filter in the Tank Farm. There were additional modifications and upgrades to some components of the JCM SX-EW plant as part of the JCM restart operation such as a new LNG storage tank and vaporizer, new organic tank, upgrades to Tankhouse 2 and SX second train, in addition to new anodes and cathodes.
The summary categories of expenditures are listed below:
| US$’000s | 2024 | Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 | Total |
| Leach Pad | 15,019 | 7,938 | 13,810 | 4,510 | 5,244 | 46,521 |
| Equipment & SX/EW | 6,551 | 5,117 | 6,878 | 11,086 | 4,001 | 33,633 |
| General Construction | 52 | 732 | 9,801 | 11,433 | 4,973 | 26,991 |
| EPCM | 2,227 | 2,155 | 1,645 | 3,361 | 1,520 | 10,908 |
| Commissioning & | 205 | 101 | 60 | 19 | 5 | 390 |
| Misc | ||||||
| Subtotal | 24,054 | 16,043 | 32,194 | 30,409 | 15,743 | 118,443 |
| Capitalized Carrying | 6,201 | 3,906 | 9,072 | 2,720 | 2,596 | 24,495 |
| Costs | ||||||
| Total | 30,255 | 19,949 | 41,266 | 33,129 | 18,339 | 142,938 |
The above table excludes mining costs of $47,794 incurred in 2025 that were accounted for as: $19,057 to ore stockpile inventory and $28,737 to capitalized deferred stripping costs.
| 67 |
Operating Costs
The plant operating cost includes labor, crushing/agglomerating, stacking, heap leach operation, and SX-EW costs. The plant operating costs exclude some of the direct costs specific to the Nuton Demonstration process and reagents, which are proprietary. Note that operating costs on a per-pound of copper basis are high due to the ramp up of copper production during the period.
| Unit Costs | Units | Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 | Total |
| Mining - Gross of Deferred Stripping | $/ton mined | 2.63 | 4.57 | 4.24 | 4.01 | 3.99 |
| Mining - Net of Deferred Stripping | $/ton mined | 0.27 | 1.89 | 1.57 | 1.95 | 1.58 |
| Leaching | $/ton stacked | - | - | 0.62 | 4.82 | 3.02 |
| SX/EW | $/lb Cu | - | 1.20 | 1.04 | 1.09 | |
| Cash Cost | $/lb Cu | - | - | 5.47 | 8.34 | 7.46 |
| All-In Sustaining Cash Cost | $/lb Cu | - | - | 26.78 | 17.75 | 20.52 |
Economic Analysis
There are no current estimates of Mineral Reserves on the project. While the project has a current Mineral Resource Estimate, the future production forecast is not based on that Mineral Resource Estimate. GCC made decisions to commence construction and enter production at the Project without having completed final feasibility studies. Accordingly, GCC did not base its construction and production decisions on any feasibility studies of Mineral Reserves demonstrating economic and technical viability of the Project, with positive cash flow. As a result, there is increased uncertainty and risks of achieving any level of recovery of minerals from the project or the costs of such recovery. As the project does not have established Mineral Reserves, GCC faces higher risks that the anticipated rates of production and production costs, such as those provided in the Gunnison Technical Report, will not be achieved. These risks could have a material adverse impact on GCC’s ability to continue to generate anticipated revenues and cash flows to fund operations from and ultimately achieve or maintain profitable operations at the project.
The Mineral Resource Estimate on the Project includes inferred resources. Inferred Mineral Resources are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves. In addition, NI 43-101 prohibits the disclosure of the results of an economic analysis that includes or is based on inferred Mineral Resources. As a result, the author has determined that it is not permitted to provide an economic analysis of the Project.
A Tax Partnership Agreement was formed between GCC and Nuton LLC through which all taxes filings related to the Johnson Camp Mine will be filed. The Tax Partnership is a flow through entity with tax attributes distributed to GCC and Nuton LLC on a pro-rata basis.
Income, property and severance taxes are applicable to the JCM operation. Taxable income for income tax purposes is defined as metal revenues minus operating expenses, royalty, property and severance taxes, reclamation and closure expense, depreciation, and depletion. The combined federal and state corporate income tax rate in Arizona is 24.9 percent, after accounting for the deductibility of state tax from federal taxable income, and is applied to ‘taxable income’ derived from the Johnson Camp Mine within the Tax Partnership Agreement. Severance taxes are calculated as 2.5% of 50% of the tax basis (EBITDA minus tax depreciation). Property tax is based on the cost approach.
Exploration, Development and Production
Production
Prior to the JCM Restart, the JCM open pits had not been operated since 2012 when Nord’s contract miner ceased operations and no new material was placed on the existing leach pads. Three adjacent heap leach pads, known as Pad 123 continued with residual leaching through 2017 and drain down from the heaps continues today. Pad 123 are now in the process of closure with occasional draindown after rainstorms. During the 12-month period ending December 31, 2024, a total of 308,341 lbs of copper cathode was produced. This production is solely from the existing material on the leach pad.
| 68 |
Physical production is summarized in Table 21-3. Recovery from the leach pad commenced in August 2025. JCM is still in the ramp up phase as production incrementally increases. The operating costs and quantities are indicative of project ramp up. The numbers in Table 21-3 represent combined ROM and Nuton production.
Tabe 21-3: Physical Production
| Mining | Units | 2025 |
| Material Mined | Short Tons | 2,186,160 |
| Grade - Cu | % | 0.336% |
| Grade - ASCu | % | 0.171% |
| Grade - CuCN | % | 0.071% |
| Grade - CuSU | % | 0.095% |
| Contained - Cu | Short Tons | 7,355 |
| Contained - ASCu | Short Tons | 3,744 |
| Contained - CuCN | Short Tons | 1,542 |
| Contained - CuSU | Short Tons | 2,073 |
| Waste Mined | Short Tons | 9,916,474 |
| Total Material Mined | Short Tons | 12,102,634 |
| Strip Ratio | Waste:Material | 4.54 |
| Processing | Units | Total |
| Material Stacked | Short Tons | 1,381,709 |
| Grade - Cu | % | 0.350% |
| Grade - ASCu | % | 0.199% |
| Grade - CuCN | % | 0.147% |
| Grade - CuSU | % | |
| Contained - Cu | Short Tons | 4,836 |
| Contained - ASCu | Short Tons | 2,748 |
| Contained - CuCN | Short Tons | 2,037 |
| Contained - CuSU | Short Tons | |
| Copper in PLS Solution | lbs | 1,304,651 |
| Acid Consumption | Short Tons | 11,393 |
| Cathode Produced | lbs | 1,410,137 |
| Sales | Units | Total |
| Cathode Sold | lbs | 1,127,400 |
| Realized Price | $/lb | 4.86 |
| Gross Revenue | US$’000s | 5,923 |
Recommendations
The authors have made the following recommendations for future exploration and development work
| 69 |
Geology and Mineral Resources
| ● | Continue to improve geology and estimation models acquired through continued mining development. | |
| ● | Continue to investigate and improve geochemical signature modeling, as a geological reconciliation of visual alteration logging, to test the oxidation zonation with the Burro pit. | |
| ● | Incorporate additional data density variability samples into sample workflow and update current density estimation procedures. | |
| ● | Update the geologic model using current software, modeling practices, and geologic understanding in alignment with the more recent block model update. While this is not expected to result in any material changes to the mineral resource estimate, it is good practice to maintain consistency between models at the site. |
Mining Method
| ● | Additional detail should be given to the construction and irrigation schedule of the stacked ROM leach material and also the Nuton Demonstration leach material on the leach pad. This will likely necessitate a refinement of the mine schedule. | |
| ● | Consideration should be given to the synergies between the Gunnison open pit and the Johnson Camp open pit for future planning work looking at mining beyond the Nuton Demonstration schedule. This could include: reduced streaming royalties on a % of price basis, shared acid production costs, shared SX-EW capacity. |
Mineral Processing
| ● | Continue with laboratory assessment of different reagent and additive parameters to further optimize the recovery and operating costs, as well as pre-empt potential anomalies. | |
| ● | Continue validation of bench testing methods for calibration to actual plant performance. | |
| ● | Design crushing-agglomerating system that is fit for service with respect to crush sizes and throughput. |
Other Assets
The Company does not have any material properties other than those described above.
RISK FACTORS
Investing in our securities is speculative and involves a high degree of risk due to the nature of our business and the present stage of its development. The following risk factors, as well as risks currently unknown to us, could materially adversely affect our future business, operations and financial condition and could cause them to differ materially from the estimates described in forward-looking statements relating to the Company, or its business, property or financial results, each of which could cause purchasers of our securities to lose part or all of their investment. The risks set out below are not the only risks we face; risks and uncertainties not currently known to us or that we currently deem to be immaterial may also materially and adversely affect our business, financial condition, results of operations and prospects. You should also refer to the other information set forth or incorporated by reference in this AIF.
| 70 |
Risks Related to the Business of the Company
Mining operations generally involve a high degree of risk.
Gunnison’s mining operations are subject to all of the hazards and risks normally encountered in the exploration for and development and production of metals, including, but not limited to: unusual and unexpected geologic formations, environmental hazards, seismic activity, structural collapse, fire, flooding, variations in grade, deposit size, density and other geological problems, hydrological conditions, metallurgical and other processing problems, mechanical equipment performance problems, industrial accidents, the unavailability of power, the unavailability of materials and equipment including reagents and fuel, acid supply, labour force disruptions, unanticipated transportation costs, unanticipated regulatory changes, unanticipated or significant changes in the costs of supplies including, but not limited to, petroleum and reagents, acid supply, and adverse weather conditions and other conditions involved in the drilling and removal of material, these and other hazards may cause damage to, or destruction of, all or part of the Gunnison Project or JCM and other facilities, injuries or death to employees, contractors or other persons at the Company’s mineral properties, severe damage to and destruction of the Company’s property, plant and equipment, and contamination of, or damage to, the environment, and may result in the suspension of the Company’s development and production activities. Safety measures implemented by the Company may not be successful in preventing or mitigating future accidents.
In addition, from time to time the Company may be subject to governmental investigations and claims and litigation filed on behalf of persons who are harmed while at its properties or otherwise in connection with the Company’s operations. To the extent that the Company is subject to personal injury or other claims or lawsuits in the future, it may not be possible to predict the ultimate outcome of these claims and lawsuits due to the nature of personal injury litigation. Similarly, if the Company is subject to governmental investigations or proceedings, the Company may incur significant penalties and fines, and enforcement actions against it could result in the closing of the Gunnison Project or JCM. If claims and lawsuits or governmental investigations or proceedings are finally resolved against the Company, the Company’s financial performance, financial position and results of operations could be materially adversely affected.
Gunnison maintains insurance to protect against certain risks. At a minimum, these comply with all regulatory requirements and contractual obligations of the Company. However, insurance will not cover all of the potential risks associated with the Company’s operations. Gunnison also may be unable to maintain insurance to cover certain risks at economically feasible premiums. Insurance coverage may not continue to be available or may not be adequate to cover all resulting losses or liability. Gunnison might also become subject to liability for pollution or other hazards against which it may not be insured, may be underinsured or that Gunnison may elect not to insure against because of premium costs or other reasons. Losses from these events may cause Gunnison to incur significant costs that could have a material adverse effect upon its financial position, results of operations or cash flows.
The successful start of mining operations at, and the development of, the Gunnison Project into a commercially viable mine cannot be assured.
The commercial viability of a mineral deposit is dependent upon a number of factors which are beyond the Company’s control, including the attributes of the deposit, commodity prices, government policies and regulation and environmental protection. Fluctuations in the market prices of minerals may render resources and deposits containing relatively lower grades of mineralization uneconomic. There is no certainty that Gunnison will be able to have available funds to finance mining operations, avoid potential increases in costs, recruit and train personnel, or that Gunnison will be able to update, renew and obtain all necessary permits to start the Gunnison Project or continue to operate JCM. Most of these activities require significant lead times, and Gunnison will be required to manage and advance these activities concurrently in order to begin production. A failure or delay in the completion of any one of these activities may delay production, possibly indefinitely, at the Gunnison Project and would have a material adverse effect on Gunnison’s business, prospects, financial position, results of operations and cash flows. There is no assurance that Gunnison will ever achieve commercial production or that Gunnison will ever be profitable if production is achieved.
| 71 |
Actual capital costs, operating costs and expenditures, production schedules and economic returns may differ significantly from those we have anticipated.
Our expected capital costs, operating costs and expenditures, All-In Costs, production schedules, economic returns and other projections for the Gunnison Project and JCM which are contained in the Gunnison Technical Report and JCM Technical Report, as applicable, are based on assumed or estimated future metals prices, cut-off grades, operating costs, capital costs and expenditures and other factors that each may prove to be inaccurate. Therefore, the Gunnison Technical Report or JCM Technical Report may prove to be unreliable if the assumptions or estimates do not reflect actual facts and events. For example, significant declines in market prices for copper or extended periods of inflation would have an adverse effect on the economic projections set forth in the Gunnison Technical Report or JCM Technical Report.
Any material reductions in estimates of mineralization or increases in capital costs and expenditures, or in our ability to maintain a projected budget or renew a particular mining permit, could also have a material adverse effect on projected production schedules and economic returns, as well as on our overall results of operations or financial condition. There is also a risk that rising costs for labour and material could have an adverse impact on forecasted construction costs and that shortages of labour and material could have a negative impact on any mine development schedule. An increase in any of these costs, or a lack of availability of commodities and goods, may have an adverse impact on our financial condition and results of operations.
The Company may be required to seek additional debt or equity capital in order to continue mining operations at the Gunnison Project and JCM and we may not be able to access capital on commercially reasonable terms or at all and, even if successful, we may not be able to raise enough capital to allow us to fully fund the costs required to continue mining operations at the Gunnison Project and JCM.
There is uncertainty relating to production estimates.
We have prepared estimates of future production and future production costs for the Gunnison Project and JCM. No assurance can be given that production estimates will be achieved. These production estimates are based on, among other things: the accuracy of resource estimates; the accuracy of our assumptions as to future events and circumstances; metallurgical, geological, geochemical and hydrological characteristics; and the accuracy of estimated rates and costs of mining and processing. Actual production may vary from estimates for a variety of reasons, including, among other things: actual material mined varying from estimates of grade, tonnage, dilution, metallurgical and other characteristics; short-term operating factors relating to the mineral resources, such as the need for sequential development of mineralized material bodies and the processing of new or different mineralized material grades; risk and hazards associated with mining; natural phenomena, such as inclement weather conditions, floods, earthquakes, cave-ins; and unexpected labour shortages or strikes. Failure to achieve production estimates could have an adverse impact on our future cash flows, earnings, results of operations and financial condition.
| 72 |
General economic conditions may adversely affect Gunnison’s growth, future profitability, ability to finance and operations.
Global financial conditions continue to be characterized as volatile. In recent years, global markets have been adversely impacted by various credit crises and significant fluctuations in metals prices and fuel and energy costs. Many industries, including the mining industry, have been impacted by these market conditions. Global financial conditions remain subject to sudden and rapid destabilizations in response to future events. A continued or worsened slowdown in the financial markets or other economic conditions, including but not limited to consumer spending, employment rates, business conditions, inflation, tariffs, fuel and energy costs, consumer debt levels, lack of available credit, the state of the financial markets, interest rates and tax rates, may adversely affect our growth and profitability. Future crises may be precipitated by any number of causes, including natural disasters, geopolitical instability, changes to energy prices or sovereign defaults. If increased levels of volatility continue or in the event of a rapid destabilization of global economic conditions, it may result in a material adverse effect on commodity prices, demand for metals, including, copper, availability of credit, investor confidence, and general financial market liquidity, all of which may adversely affect our business and the market price of our securities.
In addition, if there is an emergence of a global pandemic, it could have a material adverse effect on global economic conditions which may adversely impact our business and results of operations and the operations of our suppliers, contractors and service providers, and the demand for our production.
The development of our properties will be subject to all of the risks associated with establishing new mining operations.
Development of our mineral properties will require the operation of mines, processing plants and related infrastructure. In addition, the continuation of operations at JCM is contingent on the success of the Nuton Technologies increasing recovery rates of sulfide material and as a result making the JCM operation economically viable. As a result, we are and will continue to be subject to all of the risks associated with establishing new mining operations, restarting operations, and ramping-up or running operations, including:
| ● | the timing and cost, which can be considerable, of the construction and operation of mining and processing facilities; | |
| ● | the availability and cost of skilled labour, mining equipment and principal supplies needed for operations; | |
| ● | the need to maintain necessary environmental and other governmental approvals and permits; | |
| ● | the availability of funds to finance mining operations; | |
| ● | potential opposition from non-governmental organizations, environmental groups, local groups or other stakeholders which may delay or prevent mining operations; and | |
| ● | potential increases in construction and operating costs due to changes in the cost of labour, fuel, power, materials and supplies. |
It is common in new mining operations to experience unexpected costs, problems and delays during construction, development and mine start-up. Accordingly, we cannot provide assurance that our activities will result in profitable mining operations at our mineral properties.
Mineral resource calculations are only estimates.
Any figures presented for mineral resources in this AIF and the documents incorporated by reference are only estimates. There is a degree of uncertainty attributable to the calculation of mineral resources as they are determined based on assumed future prices, cut off grades and operating costs. Until mineral resources are actually mined and processed, the quantity of metal and grades must be considered as estimates only and no assurances can be given that some or all of the indicated levels of metals will be produced. In making determinations about whether to advance any part of the Gunnison Project to development, Gunnison must rely upon estimated calculations as to the mineral resources and grades of mineralization on the Gunnison Project. Presently none of the Company’s mineral projects have a mineral reserve estimate.
| 73 |
Estimating mineral reserves and mineral resources is a subjective process that relies on the judgment of the persons preparing the estimates. Estimates of mineral resources are, to a large extent, based on the interpretation of geological data obtained from drillholes and other sampling techniques. This information is used to calculate estimates of the configuration of the mineral resource, expected recovery rates, anticipated environmental conditions and other factors. As a result, mineral resource estimates for the Gunnison Project or JCM may require adjustments or downward revisions based upon further exploration or development work or upon actual production experience, thereby adversely impacting the economics of the Gunnison Project and JCM. In addition, the grade of mineralized material ultimately mined, if any, may differ from that indicated by drilling results. There can be no assurance that minerals recovered in small-scale tests will be duplicated in large-scale tests under on-site conditions or in production scale. Any material change in the quantity of mineralization or grade may render portions of the Company’s mineralization uneconomic and result in reduced reported mineralization. Any material reductions in estimates of mineralization, or of the Company’s ability to extract this mineralization, could have a material adverse effect on the Company’s results of operations or financial condition.
Changes in the market price of copper, which in the past has fluctuated widely, will affect the projected results of Gunnison’s operations, financial position and cash flows.
Gunnison’s revenues in the future, if any, are expected to be derived in large part from the sale of copper. The price of this commodity has fluctuated widely in recent years and is affected by factors beyond the control of Gunnison including, but not limited to international economic and political trends, changes in industrial demand, currency exchange fluctuations, economic inflation and expectations for the level of economic inflation in the consuming economies, interest rates, global and local economic health and trends, speculative activities, the availability and costs of substitutes and changes in the supply of this commodity due to new mine developments and mine closures. All of these factors, which are impossible to predict with certainty, will impact the viability of the Gunnison Project and JCM.
Reduction in the demand for copper in the Chinese markets may negatively impact Gunnison’s operations and financial condition.
China has been a significant driver of global demand for minerals and metals, including copper. A slowing in China’s economic growth could result in lower prices and demand for copper. Increasing tariffs on goods manufactured in China present a risk of slowing China’s economic growth. China is increasingly seeking strategic self-sufficiency in key commodities, including investments in existing businesses or new developments in other countries. These investments may adversely impact future copper demand and supply balances and prices.
| 74 |
Gunnison will require additional capital in the future, and no assurance can be given that such capital will be available at all or available on terms acceptable to Gunnison.
Gunnison currently has no significant cash flow from production. The construction and operation of the Gunnison Project, and continued operation of JCM, depends upon Gunnison’s ability to obtain financing through strategic partnerships, equity or debt financings, production-sharing arrangements or other dilutive or non-dilutive means. Nuton has agreed to fund the costs associated with the restart of mining operations at Johnson Camp; however, at any point Nuton can terminate the Nuton Option Agreement and Nuton Technology Demonstration Agreement and thereafter is no longer obligated to provide additional funding. There is no assurance that Nuton will continue to provide funding or that Gunnison will be successful in obtaining required financing on acceptable terms, or at all. If Gunnison is unable to obtain additional financing it may consider other options, such as (i) selling assets, (ii) selling equity, or (iii) selling interests in the Gunnison Project or JCM. If Gunnison raises additional funding by issuing additional equity securities or other securities that are convertible into equity securities, such financings may substantially dilute the interest of existing or future shareholders. Sales or issuances of a substantial number of securities, or the perception that such sales could occur, may adversely affect the prevailing market price of the Common Shares. With any additional sale or issuance of equity securities, investors will suffer dilution of their voting power and may experience dilution in earnings per share. If Gunnison raises additional funding by entering into stream agreements, royalty agreements or other similar agreements, the Company may be required to deliver a portion of future metals production or revenue derived from operations. Such contractual obligations may have a negative effect on our future financial condition and results of operations and investors may suffer dilution in earnings per share. There is no assurance we will be able to negotiate acceptable terms for the sale of any interests in the Gunnison Project. Failure to obtain additional financing could result in an indefinite postponement of further exploration and development of the Gunnison Project, and continued operations at JCM, and will have a material adverse effect on Gunnison’s business, prospects, financial position, results of operations and cash flows.
Gunnison has a limited history of mining operations and limited revenue from operations.
The Company commenced the ramp-up phase using ISR leading to commercial production at the Gunnison Project and achieved first copper production. However, due to issues related to ramp-up copper production, the Company has elected to advance an open pit mining operation at the Gunnison Project instead of an ISR operation. The open pit mining operation at the Gunnison Project will require several years of permitting, technical studies and financing prior to any operations occurring. As a result, there is no present copper production from the Gunnison Project. Nuton has funded the construction of the Johnson Camp mine and mining operations commenced in 2025. As such, Gunnison remains subject to many risks common to a start-up mining operation, including under-capitalization, cash shortages, limitations with respect to personnel, financial and other resources and lack of revenues. There can be no assurance that significant losses will not occur in the near future or that we will be profitable in the future. Gunnison’s operating expenses and capital expenditures may increase in the future as consultants, personnel and equipment costs associated with advancing development and commercial production of our properties increase. Gunnison expects to continue to incur losses unless and until such time, if ever, it enters into commercial production and generate sufficient revenues to fund its continuing operations. There can be no assurance that it will generate any revenues. If Gunnison is unable to generate significant revenues at the Gunnison Project or JCM, Gunnison will not be able to earn profits or continue operations.
Gunnison has a history of losses and expects to incur losses for the foreseeable future.
Gunnison has incurred losses since its inception and expects to incur losses for the foreseeable future. Gunnison expects to continue to incur losses unless and until such time as the Gunnison Project or JCM enters generates sufficient revenues from production to fund continuing operations. The operation of the Gunnison Project and JCM will require the commitment of substantial financial resources. The amount and timing of expenditures will depend on a number of factors, including the progress of mining operations, the results of consultant analysis and recommendations, the rate at which operating losses are incurred, the execution of any agreements with strategic partners, and Gunnison’s acquisition of additional properties. Some of these factors are beyond Gunnison’s control. There can be no assurance that Gunnison will ever achieve profitability.
| 75 |
Risks associated with 48C Tax Credits
Nuton and Gunnison have been selected to receive US$13.9 million in tax credits (48C) under the Qualifying Advanced Energy Project Credit Program to expand production of Made in America copper, which is designated a Critical Material for Energy, from its Johnson Camp Mine in Southern Arizona. However, the actual amount depending on the 48C tax credit certification process and how much can be realized from the sale of the certified credits. The receipt of the 48C tax credit is subject to Certification as outlined in IRS Notice 2023-44 Code including certification of the operational and employment plans set out in the application. There is no certainty that the conditions to the receipt of the 48C tax credit will be satisfied.
Risks associated with Copper Stream Agreement.
Pursuant to the Stream Agreement with Triple Flag, the Company is required to maintain a leverage ratio of 3.5:1.0. The leverage ratio is calculated as the ratio of indebtedness of the Company to net income (adjusted for certain items). The applicability of the leverage ratio has been suspended until September 30, 2026 (the “Leverage Ratio Grace Period”). Because the Gunnison project is not expected to be in production by the end of the Leverage Ratio Grace Period, management does not expect that the leverage ratio will be able to be met until sustained production is achieved. If the Company does not meet the leverage ratio prior to the end of the Leverage Ratio Grace Period, the Company will be in default of this covenant in the Stream Agreement. If the Company defaults, then Triple Flag will have certain options available to it. In a default scenario Triple Flag may demand from the Company all amounts and deliveries due from the Company to Triple Flag but not paid or made. In addition, Triple Flag may also elect to terminate the Stream Agreement. If Triple Flag terminates the Stream Agreement, it can seek to recover the greater of its target return amount and the value of the deliveries that would have occurred over the life of the Stream Agreement if it had not been terminated. If the Company is unable to repay all amounts owing to Triple Flag, the Company could lose its interest in the Gunnison Project.
Gunnison requires various permits in order to conduct its current and anticipated future operations, and any delays in obtaining or a failure to obtain such permits, or a failure to comply with the terms of any such permits that Gunnison has obtained or will obtain, could have a material adverse impact on Gunnison.
Gunnison’s current and anticipated future operations, including further exploration, evaluation, development and production activities on the Gunnison Project and JCM, require permits from various United States federal, state, and local government authorities. Obtaining or renewing governmental permits is a complex and time-consuming process. The duration and success of efforts to obtain and renew permits are contingent upon many variables not within Gunnison’s control.
Shortage of qualified and experienced personnel in the various levels of government could result in delays or inefficiencies. Backlog within the permitting agencies could affect the permitting timeline of the Gunnison Project and JCM. Other factors that could affect the permitting timeline include (i) the number of other large-scale projects currently in a more advanced stage of development which could slow down the review process for the Gunnison Project and JCM, and (ii) significant public response regarding the Gunnison Project or JCM that could lead to delays in the process or appeals of issued permits. There can be no assurance that all permits which Gunnison requires for its development activities and construction of expanded mining facilities and the conduct of mining operations will be obtainable or renewable on reasonable terms, or at all. Delays or a failure to obtain such permits, or the expiry, revocation or a failure to comply with the terms of any such permits that Gunnison has obtained, could have a material adverse impact on Gunnison.
| 76 |
Title and other rights to the Gunnison Project and the JCM cannot be guaranteed and may be subject to prior unregistered agreements, transfers or claims and other defects.
Gunnison cannot guarantee that title to the Gunnison Project or the JCM will not be challenged. Gunnison may not have, or may not be able to obtain, all necessary surface rights to develop, or all water rights needed to operate the Gunnison Project. In particular, certain portions of the Gunnison Project are subject to option agreements that require future payments to landowners to exercise the option and acquire title, including the Benson Option Agreement. If Gunnison does not make the required payments under these option agreements, including the Benson Option, it will not have the necessary surface or mineral rights to develop the open pit mining operation at the Gunnison Project as set out in the Gunnison Technical Report. In addition, title insurance generally is not available for mineral properties and Gunnison’s ability to ensure that it has obtained secure claim to individual mineral properties or mining concessions comprising the Gunnison Project and the JCM may be severely constrained; however, Gunnison Arizona does have title insurance for the portions of the JCM that are patented mining claims and fee title property. The Gunnison Project and the JCM may be subject to prior unregistered agreements, transfers or claims, and title may be affected by, among other things, undetected defects. Gunnison has not conducted surveys of all of the claims in which it holds direct or indirect interests. A successful challenge to the precise area and location of these claims could result in Gunnison being unable to operate on all or part of the Gunnison Project or the JCM as permitted or being unable to enforce its rights with respect to all or part of the Gunnison Project or the JCM. Surface owners may also be able to obtain damages or an injunction that prevents continued mining operations at the Gunnison Project. These circumstances could result in a material adverse impact on Gunnison and Gunnison not being compensated for its prior expenditures relating to the properties.
Gunnison needs to enter into contracts with external service and utility providers.
Mining, processing, development and exploration activities depend, to one degree or another, on adequate infrastructure. In order to develop a mine at the Gunnison Project, Gunnison will need to negotiate, conclude and maintain various agreements with external service and utility providers for power, water, transportation and shipping and these are important determinants that affect capital and operating costs.
There is no certainty that Gunnison will be able to conclude or maintain various agreements with external service and utility providers on economically feasible terms and this could have a material adverse effect on Gunnison’s results of operations, financial position and cash flows and render the development of a mine on the Gunnison Project unviable.
Gunnison is subject to significant governmental regulation.
Gunnison’s operations and exploration and development activities in the United States are subject to extensive federal, state and local laws and regulation governing various matters, including environmental protection, management and use of toxic substances and explosives, management of natural resources, exploration, development of mines, production and post-closure reclamation, exports, price controls, taxation, mining royalties, management of tailing and other waste generated by operations, labour standards and occupational health and safety, including mine safety, and historic and cultural preservation.
Failure to comply with applicable laws and regulations may result in civil or criminal fines or penalties or enforcement actions, including orders issued by regulatory or judicial authorities enjoining or curtailing operations or requiring corrective measures, installation of additional equipment or remedial actions, any of which could result in Gunnison incurring significant expenditures. Gunnison may also be required to compensate private parties suffering loss or damage by reason of a breach of such laws, regulations or permitting requirements. It is also possible that future laws and regulations, or a more stringent enforcement of current laws and regulations by governmental authorities, could cause Gunnison to incur additional expense, capital expenditures, restrictions on or suspensions of Gunnison’s operations and delays in the development of the Gunnison Project.
| 77 |
The Canadian Extractive Sector Transparency Measures Act (“ESTMA”), which became effective June 1, 2015, requires public disclosure of payments to governments by mining companies engaged in the commercial development of minerals who are either publicly listed in Canada or with business or assets in Canada. Mandatory annual reporting is required for extractive companies with respect to payments made to foreign and domestic governments at all levels, including entities established by two or more governments. ESTMA requires reporting on the payments of any taxes, royalties, fees, production entitlements, bonuses, dividends, infrastructure improvement payments, and any other prescribed payment over C$100,000. Failure to report, false reporting or structuring payments to avoid reporting may result in fines of up to C$250,000 (which may be concurrent). If we find ourselves subject to an enforcement action or in violation of ESTMA, this may result in significant penalties, fines and/or sanctions imposed on us resulting in a material adverse effect on our reputation.
Gunnison’s activities are subject to environmental laws and regulations that may increase Gunnison’s costs of doing business and restrict the Company’s operations.
All of Gunnison’s exploration, potential development and production activities in the United States are subject to regulation by governmental agencies under various environmental laws, including with respect to, air emissions, discharges into water, use of groundwater, management of waste, management of hazardous substances, protection of natural resources, antiquities and endangered species and reclamation of lands disturbed by mining operations. Environmental legislation, including with respect to climate change, in many countries is evolving and the trend has been towards stricter standards and enforcement, increased fines and penalties for non-compliance, more stringent environmental assessments of proposed projects and increasing responsibility for companies and their officers, directors and employees. Compliance with environmental laws and regulations may require significant capital outlays on behalf of Gunnison and may cause material changes or delays in Gunnison’s intended activities. There can be no assurance that future changes in environmental regulations will not adversely affect Gunnison’s business, and it is possible that future changes in these laws or regulations could have a significant adverse impact on some portion of Gunnison’s business, causing Gunnison to re-evaluate those activities at that time. Failure to comply with applicable environmental laws, regulations and permitting requirements may result in enforcement actions thereunder, including orders issued by regulatory or judicial authorities, causing operations to cease or to be curtailed, and may include corrective measures requiring capital expenditures, installation of additional equipment or remedial actions.
As disclosed under “Narrative Description of the Business - Environmental Protection” on October 23, 2024, the Director of the Department of Water Resources issued an Order initiating the proceedings to designate the Willcox Groundwater Basin as a subsequent AMA. The Willcox Groundwater Basin includes the area where the Company’s Gunnison Project and JCM are located. In order to utilize groundwater for the Company’s mineral projects it will have to obtain grandfathered rights or receive a withdrawal permit under Arizona law. In the event that such grandfathered rights are not available, or a withdrawal permit cannot be obtained, the Company will not have sufficient groundwater for its mineral project meaning it will not be able to commence or continue mining which would have a material adverse effect on our operations and profitability.
Environmental hazards may exist on the Gunnison Project or the JCM that are unknown to Gunnison at the present time and that have been caused by previous owners or operators or that may have occurred naturally. Gunnison may be liable for remediating such damage.
| 78 |
Climatic conditions can affect Gunnison future operations.
Arizona can be subject to periods of drought. Operations at the Gunnison Project and JCM will require water for normal operations. A lack of necessary water for a prolonged period of time could affect operations at the Gunnison Project and JCM, and materially adversely affect Gunnison’s results of operations. Arizona can also be subject to significant rainfall events which could result in flooding and materially adversely affect the Company’s results of operations.
Governments are moving to introduce climate change legislation and treaties at the international, national, state/provincial and local levels. The regulatory requirements are evolving and are not consistent across the jurisdictions in which we operate. However, regulation relating to emission levels (such as carbon taxes) and energy efficiency is becoming more stringent. If the current regulatory trend continues, we expect that this will result in increased costs at our operations. In addition, the physical risks of climate change may also have an adverse effect on our operations. These risks include the following:
| ● | Sea level rise: Changes in sea levels could affect ocean transportation and shipping facilities that are used to transport supplies, equipment to our operations and products from those operations to world markets. | |
| ● | Extreme weather events: Extreme weather events (such as increased frequency or intensity of hurricanes, increased snow pack, prolonged drought) have the potential to disrupt operations at our mine. Extended disruptions to supply lines could result in interruption to production. | |
| ● | Resource shortages: our facilities depend on regular supplies of consumables (stainless steel, copper cable, acid, etc.) and reagents to operate efficiently. In the event that the effects of climate change or extreme weather events cause prolonged disruption to the delivery of essential commodities, our production efficiency is likely to be reduced. |
The occurrence of such physical climate change events may result in substantial costs to respond to the event or recover from the event, and to prevent recurrent damage, through either the modification of, or addition to, existing infrastructure at our operations. The scientific community has predicted an increase, over time, in the frequency and severity of extraordinary or catastrophic natural phenomena as a result of climate change. We can provide no assurance that we will be able to predict, respond to, measure, monitor or manage the risks posed as a result. Physical climate change events, and the trend toward more stringent regulations aimed at reducing the effects of climate change, could impact our decision to pursue future opportunities, or maintain our existing operations, which could have an adverse effect on our business and our future operations.
We can provide no assurance that efforts to mitigate the risks of climate changes will be effective and that the physical risks of climate change will not have an adverse effect on our operations and profitability.
Failure to provide regulatory authorities with the required financial assurances could potentially result in the closure of one or more of our operations, which could result in a material adverse effect on our operating results and financial condition.
We are required by regulatory authorities of the State of Arizona and United States Federal Government to provide financial assurances sufficient to allow a third party to implement approved closure and reclamation plans if we are unable to do so. These laws are complex and govern the determination of the scope and cost of the closure and reclamation obligations and the amount and forms of financial assurance.
The amount and nature of the financial assurances are dependent upon a number of factors, including our financial condition and reclamation cost estimates. Changes to these amounts, as well as the nature of the collateral to be provided, could significantly increase our costs, making the maintenance and development of existing and new mines less economically feasible. Regulatory authorities may also require further financial assurances. To the extent that the value of the collateral provided to the regulatory authorities is or becomes insufficient to cover the amount of financial assurance we are required to post, we would be required to replace or supplement the existing security with more expensive forms of security, which might include cash deposits, which would reduce our cash available for operations and financing activities. We can provide no assurance that we will be able to maintain or add to our current level of financial assurance or that we will have sufficient capital resources to further supplement our existing security, which could result in a material adverse effect on our operating results and financial condition.
| 79 |
Gunnison may experience difficulty attracting and retaining qualified management and technical personnel to meet the needs of its anticipated growth.
Gunnison is dependent on the services of key executives including Gunnison’s Chief Executive Officer, Chief Financial Officer, Chief Operating Officer, and other highly skilled and experienced executives and personnel focused on managing Gunnison’s interests and the advancement of the Gunnison Project, and on identifying new opportunities for growth and funding. Due to Gunnison’s relatively small size, the loss of these persons or Gunnison’s inability to attract and retain additional highly skilled employees required for the development of Gunnison’s activities may have a material adverse effect on Gunnison’s business or future operations.
In addition, Gunnison anticipates that with the Gunnison Project development and operations at JCM, Gunnison will experience significant growth in its operations. Gunnison expects this growth to create new positions and responsibilities for management and technical personnel and to increase demands on its operating and financial systems. There can be no assurance that Gunnison will successfully meet these demands and effectively attract and retain additional qualified personnel to manage its anticipated growth. The failure to attract such qualified personnel to manage growth would have a material adverse effect on Gunnison’s business, financial position, results of operations and cash flows.
Increased competition could adversely affect Gunnison’s ability to attract necessary capital funding or acquire suitable producing properties or prospects for mineral exploration in the future.
The mining industry is intensely competitive. Significant competition exists for the acquisition of properties producing or capable of producing copper or other metals. Gunnison may be at a competitive disadvantage in acquiring additional mining properties because it must compete with other individuals and companies, many of which have greater financial resources, operational experience and technical capabilities than Gunnison. Gunnison also may encounter increasing competition from other mining companies in its efforts to hire experienced mining professionals. The Company’s competitors may be able to respond more quickly to new laws or regulations or emerging technologies, or devote greater resources to the expansion of their operations, than the Company can. In addition, current and potential competitors may make strategic acquisitions or establish cooperative relationships among themselves or with third parties. Increased competition could adversely affect Gunnison’s ability to attract necessary capital funding or to acquire suitable producing properties or prospects for mineral exploration in the future. If Gunnison is unsuccessful in acquiring additional mineral properties or services or qualified personnel it will not be able to grow at the rate it desires, or at all. The Company may not be able to compete successfully against current and future competitors, and any failure to do so could have a material adverse effect on the Company’s business, financial condition or results of operations.
Gunnison may experience cybersecurity threats.
Gunnison relies on secure and adequate operations of information technology systems in the conduct of its operations. Access to and security of the information technology systems are critical to Gunnison’s operations. To Gunnison’s knowledge, it has not experienced any material losses relating to disruptions to its information technology systems. Gunnison has implemented ongoing policies, controls and practices to manage and safeguard Gunnison and its stakeholders from internal and external cybersecurity threats and to comply with changing legal requirements and industry practice. Given that cyber risks cannot be fully mitigated and the evolving nature of these threats, Gunnison cannot assure that its information technology systems are fully protected from cybercrime or that the systems will not be inadvertently compromised, or without failures or defects. Disruptions to Gunnison’s information technology systems, including, without limitation, security breaches, power loss, theft, computer viruses, cyber-attacks, natural disasters, and non-compliance by third party service providers and inadequate levels of cybersecurity expertise and safeguards of third party information technology service providers, may adversely affect the operations of Gunnison as well as present significant costs and risks including, without limitation, loss or disclosure of confidential, proprietary, personal or sensitive information and third party data, material adverse effect on its financial performance, compliance with its contractual obligations, compliance with applicable laws, damaged reputation, remediation costs, potential litigation, regulatory enforcement proceedings and heightened regulatory scrutiny.
| 80 |
Conflicts of interest may arise among the Company’s directors and officers as a result of their involvement with, or shareholdings in, other mineral resource companies.
Certain of Gunnison’s directors and officers also serve as directors or officers for, or have significant shareholdings in, other companies involved in natural resource exploration and development or mining-related activities. To the extent that such other companies may participate in ventures in which Gunnison may participate in, or in ventures which Gunnison may seek to participate in, its directors and officers may have a conflict of interest in negotiating and concluding terms respecting the extent of such participation. In all cases where the Company’s directors and officers have an interest in other companies, such other companies may also compete with Gunnison for the acquisition of mineral property investments. Such associations may give rise to conflicts of interest for Gunnison’s directors and officers resulting in a material and adverse effect on the Company’s profitability, results of operation and financial condition. As a result of these potential conflicts of interest, Gunnison may miss the opportunity to participate in certain transactions, which may have a material adverse effect on its financial position. The directors of the Company are required by law to act honestly and in good faith with a view to the best interests of the Company and its shareholders and to disclose any interest which they may have in any project or opportunity of the Company, but each officer or director has the identical obligation to other companies for which such officer or director serves as an officer or director.
Gunnison is exposed to exchange rate fluctuations because it raises funds in Canadian dollars and its costs are incurred in United States dollars.
Exchange rate fluctuations may affect the costs that Gunnison incurs in its operations. Gunnison has historically raised funds in Canadian dollars and its costs are incurred principally in United States dollars. Any appreciation of the US dollar against the Canadian dollar will reduce the purchasing power of each Canadian dollar raised, which could increase the risk that the Company would not be able to finance its operations and projects. The Company has assessed this risk and has not presently adopted an active currency hedging program given the current currency exchange rates.
Uncertainty exists related to inferred mineral resources.
Inferred Resources are estimated on the basis of limited geological evidence and sampling and while, by definition, it can reasonably be expected that a majority of inferred mineral resources referred to in this prospectus could be upgraded to indicated resources with further exploration, there is no assurance of such further exploration will take place, or that further exploration will result in the Company’s inferred resources being converted into measured or indicated mineral resources as there may be limited ability to assess geological continuity. Due to the uncertainty that may attach to inferred mineral resources, there is no assurance that inferred mineral resources will be upgraded to resources with sufficient geological continuity to constitute proven and probable mineral reserves as a result of continued exploration.
| 81 |
Land reclamation requirements for the Company’s mineral properties may be burdensome.
Land reclamation requirements are generally imposed on mineral exploration companies (as well as companies with mining operations) in order to minimize long term effects of land disturbance. Reclamation may include requirements to:
| ● | treat ground and surface water to drinking water standards; | |
| ● | control dispersion of potentially deleterious effluents; and | |
| ● | reasonably re-establish pre-disturbance land forms and vegetation. |
In order to carry out reclamation obligations imposed on the Company in connection with exploration, development and production activities, Gunnison must allocate financial resources that might otherwise be spent on further exploration and development programs. In addition, regulatory changes could increase the Company’s obligations to perform reclamation and mine closing activities. If the Company is required to carry out unanticipated reclamation work, its financial position could be adversely affected.
Risks inherent in the acquisition of new properties.
Gunnison may actively pursue the acquisition of exploration, development and production assets consistent with its acquisition and growth strategy. From time to time, Gunnison may also acquire securities of or other interests in companies with respect to which it may enter into acquisitions or other transactions. Acquisition transactions involve inherent risks, including but not limited to:
| ● | accurately assessing the value, strengths, weaknesses, contingent and other liabilities and potential profitability of acquisition candidates; | |
| ● | ability to achieve identified and anticipated operating and financial synergies; | |
| ● | unanticipated costs; | |
| ● | diversion of management attention from existing business; | |
| ● | potential loss of key employees or key employees of any business acquired; | |
| ● | unanticipated changes in business, industry or general economic conditions that affect the assumptions underlying the acquisition; | |
| ● | decline in the value of acquired properties, companies or securities; | |
| ● | assimilating the operations of an acquired business or property in a timely and efficient manner; | |
| ● | maintaining the Company’s financial and strategic focus while integrating the acquired business or property; | |
| ● | implementing uniform standards, controls, procedures and policies at the acquired business, as appropriate; and | |
| ● | to the extent that the Company makes an acquisition outside of markets in which it has previously operated, conducting and managing operations in a new operating environment. |
Acquiring additional businesses or properties could place increased pressure on the Company’s cash flow (if any) if such acquisitions involve a cash consideration. The integration of the Company’s existing operations with any acquired business will require significant expenditures of time, attention and funds. Achievement of the benefits expected from consolidation would require the Company to incur significant costs in connection with, among other things, implementing financial and planning systems. The Company may not be able to integrate the operations of a recently acquired business or restructure the Company’s previously existing business operations without encountering difficulties and delays. In addition, this integration may require significant attention from the Company’s management team, which may detract attention from the Company’s day-to-day operations. Over the short-term, difficulties associated with integration could have a material adverse effect on the Company’s business, operating results, financial condition and the price of the Common Shares. In addition, the acquisition of mineral properties may subject the Company to unforeseen liabilities, including environmental liabilities, which could have a material adverse effect on the Company. There can be no assurance that any future acquisitions will be successfully integrated into the Company’s existing operations.
| 82 |
Any one or more of these factors or other risks could cause Gunnison not to realize the anticipated benefits of an acquisition of properties or companies, and could have a material adverse effect on its financial condition.
Gunnison may become subject to legal proceedings.
Due to the nature of its business, the Company may become subject to regulatory investigations, claims, lawsuits and other proceedings in the ordinary course of its business. The results of these legal proceedings cannot be predicted with certainty due to the uncertainty inherent in litigation, including the effects of discovery of new evidence or advancement of new legal theories, the difficulty of predicting decisions of judges and juries and the possibility that decisions may be reversed on appeal. There can be no assurances that these matters will not have a material adverse effect on the Company’s business.
Gunnison may be exposed to potential liabilities associated with the acquisition of JCM.
We conducted due diligence with respect to the JCM prior to our acquisition of such assets in December 2015; however, there is no certainty that our due diligence procedures revealed all of the risks and liabilities associated with the acquisition of JCM. There may be material environmental or other material liabilities that we are not aware of and, accordingly, the potential monetary cost of such liabilities is also unknown.
Failure to comply with the U.S. Foreign Corrupt Practices Act (“FCPA”), as well as the anti-bribery laws of the nations in which we conduct business (such as the Corruption of Foreign Public Officials Act of Canada (“CFPOA”)), could subject us to penalties and other adverse consequences.
Our business is subject to the FCPA which generally prohibits companies and company employees from engaging in bribery or other prohibited payments to foreign officials for the purpose of obtaining or retaining business. The FCPA also requires companies to maintain accurate books and records and internal controls, including at foreign-controlled subsidiaries. In addition, we are subject to other anti-bribery laws of the nations in which we conduct business that apply similar prohibitions as the FCPA (such as the CFPOA and the OECD Anti-Bribery Convention). Our employees or other agents may, without our knowledge and despite our efforts, engage in prohibited conduct under our policies and procedures and the FCPA or other anti-bribery laws that we may be subject to for which we may be held responsible. If our employees or other agents are found to have engaged in such practices, we could suffer severe penalties and other consequences that may have a material adverse effect on our business, financial condition and results of operations.
Legislative actions, potential new accounting pronouncements, and higher insurance costs are likely to impact our future financial position or results of operations.
Future changes in financial accounting standards may cause adverse, unexpected revenue fluctuations and affect our financial position or results of operations. New pronouncements and varying interpretations of pronouncements are expected to occur in the future. Compliance with changing regulations of corporate governance and public disclosure may result in additional expenses. All of these uncertainties are leading generally toward increasing insurance costs, which may adversely affect our business, results of operations and our ability to purchase any such insurance, at acceptable rates or at all, in the future.
| 83 |
A period of significant growth can place a strain on management systems.
If we experience a period of significant growth in the number of our personnel this could place a strain upon our management systems and resources. Our future will depend in part on the ability of our officers and other key employees to implement and improve our financial and management controls, reporting systems and procedures on a timely basis and to expand, train and manage our employee workforce. There can be no assurance that we will be able to effectively manage such growth. Our failure to do so could have a material adverse effect upon our business, prospects, results of operation and financial condition.
Negative Operating Cash Flow.
The Company had negative operating cash flow for its financial year ended December 31, 2025. To the extent that the Company has negative cash flow in future periods, the Company may need to deploy a portion of its cash reserves to fund such negative cash flow.
Risks Related to our Securities
Future sales or issuances of debt or equity securities could decrease the value of any existing Common Shares, dilute investors’ voting power, reduce our earnings per share and make future sales of our equity securities more difficult.
We may sell or issue additional debt or equity securities in offerings to finance our operations, exploration, development, acquisitions or other projects. Our significant shareholders, including Greenstone may also sell the Common Shares they hold in the future.
We cannot predict the size of future sales and issuances of debt or equity securities or the effect, if any, that future sales and issuances of debt or equity securities will have on the market price of the Common Shares.
Sales or issuances of a substantial number of equity securities, or the perception that such sales could occur, may adversely affect prevailing market prices for the Common Shares. With any additional sale or issuance of equity securities, investors will suffer dilution of their voting power and may experience dilution in the Company’s earnings per share. Sales of our Common Shares by shareholders might also make it more difficult for us to sell equity securities at a time and price that we deem appropriate.
Our Common Share price has experienced volatility and may be subject to fluctuation in the future based on market conditions.
The market prices for the securities of mining companies, including our own, have historically been highly volatile. The market has from time to time experienced significant price and volume fluctuations that are unrelated to the operating performance of any particular company. In addition, because of the nature of our business, certain factors such as our announcements and the public’s reaction, our operating performance and the performance of competitors and other similar companies, fluctuations in the market prices of our resources, government regulations, changes in earnings estimates or recommendations by research analysts who track our securities or securities of other companies in the resource sector, general market conditions, announcements relating to litigation, the arrival or departure of key personnel and the factors listed under the heading “Special Note Regarding Forward-Looking Information” can have an adverse impact on the market price of our Common Shares.
Any negative change in the public’s perception of our prospects could cause the price of our securities, including the price of our Common Shares, to decrease dramatically. Furthermore, any negative change in the public’s perception of the prospects of mining companies in general could depress the price of our securities, including the price of our Common Shares, regardless of our results. Following declines in the market price of a company’s securities, securities class-action litigation is often instituted. Litigation of this type, if instituted, could result in substantial costs and a diversion of our management’s attention and resources.
| 84 |
Future issuances of securities by us or sales by our existing shareholders may cause the price of our securities to fall.
The market price of our securities could decline as a result of issuances of securities by us or sales by our existing shareholders in the market, or the perception that these sales could occur. Sales of our Common Shares by shareholders might also make it more difficult for us to sell equity securities at a time and price that we deem appropriate. With an additional sale or issuance of equity securities, investors will suffer dilution of their voting power and may experience dilution in earnings per share.
Gunnison does not intend to pay dividends in the foreseeable future.
No dividends on the Company’s Common Shares have been declared or paid by Gunnison to date. Gunnison does not currently anticipate that dividends will be declared in the foreseeable future. Payment of future dividends, if any, will be at the discretion of Gunnison’s Board of Directors after taking into account many factors, including Gunnison’s operating results, financial condition and current and anticipated cash needs.
Non-U.S. Holders of Common Shares could be subject to U.S. federal income tax from the sale or other taxable disposition of Common Shares.
It is possible that the Company will be considered a U.S. real property holding corporation for U.S. federal income tax purposes if its assets are determined to consist primarily of “United States real property interests” as defined in the Internal Revenue Code of 1986, as amended, or the Code, and applicable Treasury regulations. Under the Foreign Investment in Real Property Tax Act, or FIRPTA, certain Non-U.S. Holders may or may in the future be subject to U.S. federal income tax on any gain from the disposition of shares of our Common Shares, in which case they would also be required to file U.S. tax returns with respect to such gain. In general, whether these FIRPTA provisions apply depends on the amount of our Common Shares that such Non-U.S. Holders hold. In addition, such Non-U.S. Holders may or may in the future be subject to withholding if, at the time they dispose of their shares, our common stock is not regularly traded on an established securities market within the meaning of the applicable Treasury regulations. So long as our Common Shares continue to be regularly traded on an established securities market, only a Non-U.S. Holder who has owned, actually or constructively, more than 5% of our Common Shares at any time during the shorter of (i) the five-year period ending on the date of disposition and (ii) the Non-U.S. Holder’s holding period for its shares may or may in the future be subject to U.S. federal income tax on the disposition of our Common Shares under FIRPTA.
Withholding to Non-U.S. investors will apply to our dividends on our Common Shares.
Because we are a U.S. corporation for U.S. federal income tax purposes, a 30% withholding tax (subject to reduction under an applicable tax treaty) will generally apply to dividend distributions we make to non-U.S. persons. Because we may not know the extent to which a distribution is a dividend for U.S. federal income tax purposes at the time it is made, for purposes of these withholding rules we may treat the entire distribution as a dividend.
The Company expects that it will be treated as a U.S. domestic corporation for U.S. federal income tax purposes.
The Company believes that it should be treated as a U.S. domestic corporation for U.S. federal income tax purposes under Section 7874 of the U.S. Internal Revenue Code and be subject to U.S. tax on its worldwide income. Treatment of the Company as a U.S. corporation for U.S. federal income tax purposes may have adverse tax consequences for non-U.S. shareholders. Holders of the Company’s Common Shares are urged to consult their own tax advisors regarding the acquisition, ownership and disposition of the Company’s Common Shares. This paragraph is only a brief summary of these tax rules.
| 85 |
There is no assurance of a sufficient liquid trading market for the Company’s Common Shares in the future.
Shareholders of the Company may be unable to sell significant quantities of Common Shares into the public trading markets without a significant reduction in the price of their Common Shares, or at all. There can be no assurance that there will be sufficient liquidity of the Company’s Common Shares on the trading market, and that the Company will continue to meet the listing requirements of the TSX or achieve listing on any other public listing exchange.
DIVIDENDS
Gunnison has not, since the date of its incorporation, declared or paid any dividends on its Common Shares and does not currently have a policy with respect to the payment of dividends. For the immediate future, Gunnison does not envisage any earnings arising from which dividends could be paid. The payment of dividends in the future will depend on Gunnison’s earnings, if any, Gunnison’s financial condition and such other factors as the directors of Gunnison consider appropriate.
DESCRIPTION OF CAPITAL STRUCTURE
The authorized share capital of Gunnison consists of an unlimited number of Common Shares and an unlimited number of Non-Voting Shares. As of the date of this AIF, 422,803,601 Common Shares and no Non-Voting Shares were issued and outstanding as fully paid and non-assessable shares.
The holders of the Common Shares are entitled to receive notice of and to attend and vote at all meetings of the shareholders of Gunnison and each Common Share confers the right to one vote in person or by proxy at all meetings of the shareholders of Gunnison. The holders of the Common Shares, subject to the prior rights, if any, of any other class of shares of Gunnison, are entitled to receive such dividends in any financial year as the Board of Directors of Gunnison may by resolution determine. In the event of the liquidation, dissolution or winding-up of Gunnison, whether voluntary or involuntary, the holders of the Common Shares are entitled to receive, subject to the prior rights, if any, of the holders of any other class of shares of Gunnison, the remaining property and assets of the Company.
The Non-Voting Shares are restricted securities within the meaning of National Instrument 51-102. Non-Voting Shares do not carry the right to vote at any meetings of the shareholders. Non-Voting shares may be converted at the option of the holder into Common Shares on the basis of one (1) Non-Voting Share for one (1) Common Share of Gunnison. As the Non-Voting Shares are convertible into Common Shares, pursuant to Multilateral Instrument 62-104, a take-over bid for the Common Shares must also be made to the holders of the Non-Voting Shares.
MARKET FOR SECURITIES
Market
Gunnison’s Common Shares are listed on the TSX under the trading symbol “GCU” and trade on the OTCQB under the symbol “GCUMF” and on the Frankfurt Exchange under the symbol “3XS”.
| 86 |
Trading Price and Volume
The following table sets out the monthly high and low trading prices and the monthly volume of trading of the Common Shares of Gunnison on the TSX for the most recently completed financial year:
| High (Cdn$) | Low (Cdn$) | Volume | |
| January 2025 | 0.21 | 0.18 | 1,155,875 |
| February 2025 | 0.195 | 0.17 | 1,456,536 |
| March 2025 | 0.44 | 0.175 | 7,778,352 |
| April 2025 | 0.33 | 0.21 | 4,165,797 |
| May 2025 | 0.31 | 0.2145 | 3,515,627 |
| June 2025 | 0.30 | 0.24 | 12,472,425 |
| July 2025 | 0.33 | 0.235 | 12,909,173 |
| August 2025 | 0.295 | 0.22 | 15,916,866 |
| September 2025 | 0.37 | 0.235 | 22,074,057 |
| October 2025 | 0.55 | 0.35 | 21,964,779 |
| November 2025 | 0.40 | 0.275 | 20,107,890 |
| December 2025 | 0.44 | 0.34 | 15,969,486 |
Prior Sales
The following summarizes the Common Shares and securities convertible into Common Shares issued by Gunnison during the most recently completed financial year.
|
Date |
Description |
Number of Securities |
Price per Share / Exercise Price ($)(1) |
| April 4, 2025 | Common Shares issued in financing | 17,004,249 | $0.30 |
| April 7, 2025 | Common Shares issued in financing | 17,004,249 | $0.30 |
| April 7, 2025 | Issue of Stock Options | 10,595,000 | $0.30(1) |
| May 14, 2025 | Issue of Stock Options | 3,000,000 | $0.30(1) |
| July 18, 2025 | Common Shares issued in financing | 28,874,100 | $0.30 |
| July 30, 2025 | Issue of Stock Options | 1,500,000 | $0.30(1) |
| July 31, 2025 | Issue of Stock Options | 500,000 | $0.30(1) |
| October 7, 2025 | Common Shares issued on Partial Debenture Conversion | 2,384,358 | $0.30 |
| October 15, 2025 | Common Shares issued on Partial Debenture Conversion |
2,384,358 | $0.30 |
| October 30, 2025 | Common Shares issued in financing | 24,858,878 | $0.45 |
| October 30, 2025 | Common Shares issued in financing | 4,279,500 | $0.45 |
| October 31, 2025 | Common Shares issued in financing | 333,334 | $0.45 |
| November 19, 2025 | Issue of Stock Options | 100,000 | $0.285(1) |
| December 11, 2025 | Issue of Stock Options | 500,000 | $0.39(1) |
| December 15, 2025 | Common Shares issued on Partial Debenture Conversion | 2,384,358 | $0.30 |
| December 19, 2025 | Common Shares issued on Partial Debenture Conversion | 2,384,358 | $0.30 |
| December 23, 2025 | Common Shares issued on Partial Debenture Conversion | 2,384,358 | $0.30 |
(1) Exercise Price
| 87 |
ESCROWED SECURITIES AND SECURITIES SUBJECT TO CONTRACTUAL RESTRICTION ON TRANSFER
As at December 31, 2025, Gunnison has no escrowed securities or securities subject to contractual restriction on transfer.
DIRECTORS AND OFFICERS
The names and provinces or states and countries of residence of the directors and officers of Gunnison as at December 31, 2025, positions held by them with Gunnison and their principal occupations for the past five years are as set forth below. The term of office of each of the present directors expires at the next annual general meeting of shareholders. After each such meeting, the Board of Directors appoints the Company’s officers and committees for the ensuing year.
Name, Province or State and Country of Ordinary Residence of Nominee(1) and Present Positions with Gunnison |
Principal Occupation during the last Five Years(1) |
Period from which person has been a Director or Officer | Number of Common Shares Held(2) |
| Stephen Twyerould Director, President, CEO Arizona, USA | President and Chief Executive Officer of Gunnison since October 14, 2010. | October 14, 2010 |
7,947,186 |
| Fred DuVal(3)(4)(5) Director, Chairman Arizona, USA | President of DuVal and Associates since 2001. | June 28, 2018 | Nil |
Jason Howe(3)(5) Director British Columbia, Canada |
Senior Vice President, Corporate Development of Capstone Copper Corp. from 2004 to 2022; President, CEO & Director of Zena Mining Corp. from 2008 to Present. | May 14, 2025 | 250,000 |
Joseph Gallucci(3)(4)(6) Director Quebec, Canada |
Managing Director, Head of Mining Investment Banking at Ventum Financial Corp. from January 2026 to present; Managing Director, Head of Investment Banking of Laurentian Bank Securities Inc. from January 2022 to December 2025; Managing Director, Head of Mining, Investment Banking of Laurentian Bank Securities Inc. from March 2019 to January 2022. | May 14, 2025 | Nil |
| 88 |
Name, Province or State and Country of Ordinary Residence of Nominee(1) and Present Positions with Gunnison |
Principal Occupation during the last Five Years(1) |
Period from which person has been a Director or Officer | Number of Common Shares Held(2) |
Roland Goodgame SVP Business Development Texas, USA |
Senior Vice President, Business Development of the Company since December, 2020; Senior Vice President from November, 2020 to December, 2020; Chief Operating Officer from April, 2017 to November, 2020; Executive Vice President of Gunnison from May, 2014 to April, 2017. | October 14, 2010 |
2,530,127 |
Craig Hallworth SVP & Chief Financial Officer Arizona, USA |
SVP & Chief Financial Officer of the Company since September 2024; Chief Financial, Arizona Business Unit at Hudbay Minerals, from 2019 to August 2024. | September 3, 2024 |
532,500 |
Robert Winton Chief Operating Officer Arizona, USA |
General Manager & Senior Vice President Operations of the Company since August, 2020; President & General Manager of Nystar Clarksville Inc. from January 2018 to August 2020; Vice President, MBU of Hudbay Minerals Inc. from September 1997 to June 2016. | August 24, 2020 |
622,750 |
Sheila Paine Corporate Secretary British Columbia, Canada |
Corporate Secretary of King & Bay West Management Corp. since December 2009. | May 17, 2010 | Nil |
| (1) | The information as to city and province of residence and principal occupation, not being within the knowledge of Gunnison, has been furnished by the respective directors individually. |
| (2) | Common Shares beneficially owned, directly and indirectly, or over which control or direction is exercised, at the date hereof, based upon the information furnished to Gunnison by individual directors and officers. Unless otherwise indicated, such Common Shares are held directly. These figures do not include Common Shares that may be acquired on the exercise of any stock options held by the respective directors or officers. |
| (3) | Current Member of the Audit Committee of Gunnison. |
| (4) | Current Member of the Compensation Committee of Gunnison. |
| (5) | Current Member of the Nominating and Corporate Governance Committee of Gunnison. |
As of the date of this AIF, the directors, officers and other members of Management of Gunnison, as a group beneficially owned, directly or indirectly, 11,882,063 Common Shares of Gunnison representing 2.81% of the total issued and outstanding Common Shares of Gunnison.
| 89 |
Cease Trade Orders, Bankruptcies, Penalties or Sanctions
Except as disclosed below, no director or executive officer of Gunnison is, or has been in the last 10 years, a director, chief executive officer or chief financial officer of any company (including Gunnison) of an issuer that, while that person was acting in that capacity,
| (a) | was the subject of a cease trade order or similar order or an order that denied the issuer access to any exemptions under Canadian securities legislation, for a period of more than 30 consecutive days; or | |
| (a) | was subject to an event that resulted, after that person ceased to be a director, chief executive officer or chief financial officer, in the company being the subject of a cease trade or similar order or an order that denied the issuer access to any exception under Canadian securities legislation, for a period of more than 30 consecutive days. |
Except as disclosed below, no director or executive officer or shareholder holding a sufficient number of securities of Gunnison to materially affect the control Gunnison:
| (a) | is, as at the date of this AIF, or has been within the 10 years before the date of this AIF, a director or executive officer of any company (including Gunnison) that while that person was acting in that capacity, or within a year of that person ceasing to act in the capacity, became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency or was subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold its assets; or | |
| (b) | has, within 10 years before the date of this AIF become bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency, or become subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold the assets of the director, executive officer or shareholder. |
No director or officer of Gunnison or a shareholder holding a sufficient number of Common Shares to affect materially the control of Gunnison has been subject to:
| (a) | any penalties or sanctions imposed by a court relating to securities legislation or by a securities regulatory authority or has entered into a settlement agreement with a securities regulatory authority; or | |
| (c) | any other penalties or sanctions imposed by a court or regulatory body that would likely be considered important to a reasonable investor in making an investment decision. |
On November 18, 2022, the British Columbia Securities Commission issued a cease trade order in respect of the securities of Great Panther Mining Limited (“Great Panther”) as a result of its inability to file its quarterly continuous disclosure documents in accordance with Canadian securities laws. On December 16, 2022, Great Panther made a voluntary assignment into bankruptcy under the Bankruptcy and Insolvency Act (Canada) and Alvarez & Marshall Canada Inc. was appointed licenses insolvency trustee of Great Panther’s estate. Joseph Gallucci was a director of Great Panther until December 16, 2022.
Conflicts of Interest
Certain directors and officers of Gunnison are also directors, officers or shareholders of other companies that are similarly engaged in the business of acquiring, developing and exploiting natural resource properties. Such associations to other public companies in the resource sector may give rise to conflicts of interest from time to time. As a result, opportunities provided to a director of Gunnison may not be made available to Gunnison, but rather may be offered to a company with competing interests. The directors and senior officers of Gunnison are required by law to act honestly and in good faith with a view to the best interests of Gunnison and to disclose any personal interest which they may have in any project or opportunity of Gunnison, and to abstain from voting on such matters.
| 90 |
The directors and officers of Gunnison are aware of the existence of laws governing the accountability of directors and officers for corporate opportunity and requiring disclosure by the directors of conflicts of interests and Gunnison will rely upon such laws in respect of any directors’ and officers’ conflicts of interest or in respect of any breaches of duty by any of its directors and officers.
LEGAL PROCEEDINGS AND REGULATORY ACTIONS
During the most recently completed financial year, (i) no penalties or sanctions were imposed against the Company by a court or regulatory body and (ii) no settlement agreements were entered into by the Company with a court or a securities regulatory authority. Except as disclosed below, the Company and its properties are not subject to any legal or other actions, current or pending, which may materially affect the Company’s operating results, financial position or property ownership.
PROMOTERS
No person has acted as a promoter of Gunnison during the last two most recently completed financial years or during the current financial year.
INTEREST OF MANAGEMENT AND OTHERS IN MATERIAL TRANSACTIONS
Other than as set forth below and other than transactions carried out in the ordinary course of business of the Company, none of the directors or executive officers of Gunnison, any shareholder directly or indirectly beneficially owning, or exercising control or direction over, more than 10% of the outstanding Common Shares, nor an associate or affiliate of any of the foregoing persons has had, during the three most recently completed financial years of the Company or during the current financial year, any material interest, direct or indirect, in any transactions that materially affected or would materially affect the Company.
As at December 31, 2025, Greenstone Resources, through its affiliates Greenstone, Greenstone II, Greenstone No. 1 and Greenstone No. 2, was the beneficial owner of 143,208,937 Common Shares representing approximately 33.88% of the issued and outstanding Common Shares. Mr. Haworth is a Managing Member of Greenstone Capital LLP and a Director of Greenstone Management Ltd., the General Partner to Greenstone Resources. The details of Greenstone’s strategic investments in Gunnison during the three most recently completed financial years are described under “Glossary” and “Description and General Development of the Business –Year Ended December 31, 2023 Developments”. Effective February 18, 2026, Greenstone, through its affiliates, disposed of a total of 113,607,200 if its previously held 143,208,737 and now holds a total of 29,601,737 Common Shares or 7.0% of the current issued and outstanding Common Shares (excluding any Common Shares issuable on the exercise of stock options or the conversion of convertible debentures).
TRANSFER AGENT AND REGISTRAR
Gunnison’s registrar and transfer agent is TSX Trust Company. with its office located at 733 Seymour Street, Suite 2310, Vancouver, British Columbia, V6B 0S6.
MATERIAL CONTRACTS
The Company has entered into the following material contracts:
| (a) | Definitive Agreement, as amended, as described in this AIF under “Glossary”. | |
| (b) | JCM Purchase Agreement as described in this AIF under “Glossary” | |
| (c) | Stream Agreement, as amended, as described in this AIF under “Glossary”. |
| 91 |
| (d) | Nuton Option Agreement, as amended, as described in the AIF under “Description and General Development of the Business – Three Year History – Year Ended December 31, 2023 Developments– Nuton Option Agreement”. | |
| (e) | Nuton Demonstration Agreement, as amended, as described in the AIF under “Description and General Development of the Business – Three Year History – Year Ended December 31, 2024 Developments– Nuton Option Agreement Update”. | |
| (f) | Gunnison Collaboration Agreement, as amended, as described in the AIF under “Description and General Development of the Business – Three Year History – Developments Subsequent to the Year Ended December 31, 2024 Developments – Comprehensive Financial Transaction”. | |
| (g) | Benson Option Agreement, as described in the AIF under “Description and General Development of the Business – Three Year History – Year Ended December 31, 2024 Developments – Gunnison Project Update”. |
INTEREST OF EXPERTS
The disclosure with respect to the Gunnison Project contained in this AIF is based on the Gunnison Technical Report jointly prepared by John Woodson, P.E., SME-RM, Jeffery Bickel, C.P.G., Dr. Abyl Sydykov, Ph.D., P.E., Dr. Terence P. McNulty, P.E., D.Sc., Rob Valceschini, P.E., R. Douglas Bartlett, C.P.G., Jacob Richey, P.E., Thomas M. Ryan, P.E. and Tyler Peck, P.E., each a qualified person as defined in NE 43-101. Each of Messrs. Woodson, Bickel, Sydykov, McNulty, Valceschini, Bartlett, Richey, Ryan and Peck has reviewed and approved the scientific and technical disclosure with respect to the Gunnison Project contained in this AIF under the heading “Mineral Properties”.
The disclosure with respect to JCM contained in the AIF is based on the JCM Technical Report jointly prepared by John Woodson, PE, SME-RM, Jeffrey Bickel, CPG, Abyl Sydykov, PhD, PE, Scott Freestone, PE, Dr. Terence P. McNulty, PE, DSc, R. Douglas Bartlett, CPG, Jacob Richey, PE and Thomas M. Ryan, PE, each a qualified person as defined in NI 43-101. Each of Messrs. Woodson, Bickel, Sydykov, Freestone, McNulty, Bartlett, Richey and Ryan has reviewed and approved the scientific and technical disclosure with respect to JCM contained in this AIF under the heading “Mineral Properties”.
The remainder of scientific and technical disclosure contained in this AIF has been reviewed and approved by Stephen Twyerould, Fellow of AUSIMM, President & CEO of the Company and a Qualified Person as defined by NI 43-101.
To the best knowledge of the Company, except for Mr. Twyerould, none of the qualified persons referenced above, or any director, officer, employee or partner thereof, as applicable, received or has received a direct or indirect interest in the property of the Company or of any associate or affiliate of the Company. As at the date hereof, the aforementioned persons (except for Mr. Twyerould), and the directors, officers, employees and partners, as applicable, of each of the aforementioned companies and partnerships beneficially own, directly or indirectly, in the aggregate, less than one percent of the securities of the Company. Except for Mr. Twyerould, none of the qualified persons referenced above is or is expected to be elected, appointed or employed as a director, officer or employee of the Company or any associate or affiliate of the Company. Mr. Twyerould is the President & CEO of the Company and information as to his ownership of securities of the Company is set forth under the heading “Directors and Officers” in this AIF.
The Company’s independent auditors are PricewaterhouseCoopers LLP, Chartered Professional Accountants, who have prepared an independent auditor’s report dated March 31, 2026 in respect of the Company’s consolidated financial statements as at December 31, 2025 and 2024 and for years then ended. PricewaterhouseCoopers LLP has advised that they are independent with respect to the Company within the meaning of the relevant rules and related interpretations prescribed by the relevant professional bodies in Canada, including the CPABC Code of Professional Conduct, and any applicable legislation or regulations.
| 92 |
ADDITIONAL INFORMATION
Additional information on the Company may be found on SEDAR+ at www.sedarplus.ca. Additional information, including directors’ and officers’ remuneration and indebtedness to Gunnison, principal holders of the securities of Gunnison and securities authorized for issuance under equity compensation plans, is contained in Gunnison’s management information circular for its most recent annual general meeting, which is filed on SEDAR+. Additional financial information is provided in Gunnison’s audited consolidated financial statements for the year ended December 31, 2025 and the related management’s discussion and analysis of financial conditions and results of operations, both of which are available on SEDAR+.
AUDIT COMMITTEE
Pursuant to the provisions of National Instrument 52-110 Audit Committees (“NI 52-110”), reporting issuers are required to provide disclosure with respect to its audit committee, including the text of the audit committee’s charter, composition of the committee, and the fees paid to the external auditor. Accordingly, the Company provides the following disclosure with respect to its Audit Committee.
Audit Committee Charter
Gunnison has adopted a Charter of the Audit Committee of the Board of Directors, which is attached as Schedule A to this AIF.
Composition of the Audit Committee
From January 1, 2025 to March 20, 2025, Gunnison’s Audit Committee was comprised of three directors: Stephen Axcell, Michael Haworth and Fred DuVal. As defined in NI 52-110, Mr. DuVal and Mr. Axcell were considered “independent” and are “financially literate”. Mr. Haworth is “financially literate”; however, as a nominee of Greenstone Resources he is not considered “independent”. Effective March 20, 2025, Mr. Axcell resigned as a director and Colin Kinley was appointed to the Audit Committee in place of Mr. Axcell. While Mr. Kinley is “financially literate”, he is the principal of Kinley Exploration, LLC. Kinley Exploration, LLC entered into a consulting agreement with Excelsior Arizona to provide consulting services to Excelsior Arizona with respect to the Company’s Gunnison Copper Project. Therefore, Mr. Kinley is not considered “independent” and he was appointed to temporarily fill the vacancy created by the resignation of Mr. Axcell. On June 26, 2025, following the Company’s annual general meeting, Messrs, Kinley and Haworth were re-appointed as members of the Audit Committee and Jason Howe was appointed as the third member of the Audit Committee. Mr. Howe is considered “independent” and is “financially literate”. On November 6, 2025, Mr. Kinley passed away and Joseph Gallucci was appointed to the Audit Committee in place of Mr. Kinley. Mr. Gallucci is considered “independent” and is “financially literate”.
Currently the Gunnison’s Audit Committee is comprised of three directors, Jason Howe, Fred DuVal and Joseph Gallucci. Messrs. Howe, DuVal and Gallucci are considered “independent”. All are “financially literate”.
Relevant Education and Experience
All of the present members of the Audit Committee (and former members in the case of Messrs. Axell, DuVal and Kinley) are senior level executive business persons with extensive experience in financial matters; each has a broad understanding of accounting principles used to prepare financial statements and varied experience as to general application of such accounting principles, as well as the internal controls and procedures necessary for financial reporting, garnered from working in their individual fields of endeavour. In addition, each of the members of the Audit Committee have knowledge of the role of an audit committee in the realm of reporting companies from their years of experience as directors or senior officers of public companies other than Gunnison.
| 93 |
Mr. DuVal is currently a consultant to many American businesses, and a member of Dentons Law, the largest law firm in the world. He is also a senior advisor to Macquarie Infrastructure on public-private partnerships. Mr. DuVal was the Democratic nominee for Governor of Arizona in 2014 and served as Chairman of the Arizona Board of Regents and on the Arizona Commerce Commission. Mr. DuVal was Chief of Protocol of the United States, Assistant to President Clinton in the White House and responsible for all Governors and state issues; he was also the Political Director for Vice President Al Gore. Mr. DuVal obtained a Bachelor of Arts, Luce Scholar for International Studies from Occidental College in 1976 and his J.D. from Arizona State University in 1980.
Mr. Howe is a seasoned mining executive with over 20 years of experience in corporate development, finance, and executive leadership. He has a proven track record in leading strategic acquisitions, fostering stakeholder relationships, and driving sustainable growth in the mining industry. Mr. Howe was a co-founder of Capstone Mining Corp. where he led their Business Development, Marketing and HR functions. In addition, Mr. Howe was co-founder of Silverstone Resources and served as CFO until its acquisition from Wheaton Precious Metals.
Mr. Gallucci is a capital markets executive and director with more than 20 years of experience including investment banking and equity research. His career has spanned across several firms including BMO Capital Markets, GMP Securities, Dundee Securities, he was a co-founder of Eight Capital where he led their Mining Investment Banking team and he was a Managing Director, Head of Investment Banking at Laurentian Bank Securities where he oversaw the entire investment banking franchise. His current role is Managing Director, Head of Mining Investment Banking at Ventum Financial Corp. where he oversees the mining practice. He has experience in corporate finance, and mergers & acquisitions including many notable transactions and was directly involved in raising over $1 billion for mining companies with a focus on base and precious metal companies.
Reliance on Certain Exemptions
At no time since the commencement of the Company’s most recently completed financial year, has the Company relied on any of the exemptions contained in the following sections of NI 52-110: section 2.4 (De Minimis Non-audit Services), section 3.2 (Initial Public Offerings), section 3.4 (Events Outside Control of Member), section 3.5 (Death, Disability or Resignation of Audit Committee Member) or an exemption from NI 52-110, in whole or in part, granted under Part 8 (Exemptions) of NI 52-110.
Reliance on Exemption in Subsection 3.3(2) or Section 3.6
As a result of Michael Haworth being a Managing Member of Greenstone Capital LLP and a Director of Greenstone Management Ltd., the General Partner to Greenstone Resources, the Company was relying on the exemption contained in subsection 3.3(2) (Controlled Companies) of NI 52-110. Neither Greenstone Capital LLP nor Greenstone Management Ltd. have securities trading on a marketplace. Mr. Haworth’s background as a Chartered Accountant allowed him to provide valuable oversight and analysis as a member of the Audit Committee. Mr. Haworth was also able to exercise the impartial judgement necessary for him to fulfill his responsibilities as an Audit Committee member, and his appointment is required by the best interests of the Company and its shareholders.
At no time since the commencement of the Company’s most recently completed financial year, has the Company relied on the exemptions contained section 3.6 (Temporary Exemption for Limited and Exceptional Circumstances) of NI 52-110.
| 94 |
Reliance on Section 3.8
At no time since the commencement of the Company’s most recently completed financial year, has the Company relied on section 3.8 (Acquisition of Financial Literacy) of NI 52-110.
Audit Committee Oversight
At no time since the commencement of the Company’s most recently completed financial year, has the Company’s Board of Directors failed to adopt a recommendation of the Audit Committee to nominate or compensate an external auditor.
Pre-Approval Policies and Procedures
Pursuant to the terms of the Company’s Audit Committee Charter, the Audit Committee is required to review and pre-approve any non-audit services provided by the Company’s external auditors. The Audit Committee has adopted a written Audit Committee Pre-Approval Policy with respect to audit and non-audit services to be performed by the Company’s external auditors. The Audit Committee will pre-approve all audit services provided by the external auditor through their recommendation of the external auditor as shareholders’ auditors at the Company’s annual meeting and through the Audit Committee’s review of the external auditor’s annual audit plan. The Audit Committee Chair may pre-approve a request for non-audit services where the aggregate fees are estimated to be less than or equal to $50,000 but the Chair must advise other Audit Committee members of such pre-approval no later than the next regularly scheduled Audit Committee meeting. For non-audit services where the aggregate fees are estimated to be greater than $50,000, the approval of the full Audit Committee is required. In no event can the external auditor undertake non-audit services prohibited by legislation or professional standards.
External Auditor Service Fees
In the following table, “audit fees” are fees billed by the Company’s external auditor for services provided in auditing the Company’s annual financial statements for the subject year and include audits of its subsidiaries and interim reviews of quarterly financial statements.
“Audit-related fees” are fees not included in audit fees that are billed by the auditor for assurance and related services that are reasonably related to the performance of the audit or review of the Company’s financial statements. During the Company’s fiscal years ended December 31, 2025 and December 31, 2024, there were no fees billed in this category.
“Tax fees” are fees billed by the auditor for professional services rendered for tax compliance, tax advice, corporate acquisitions, corporate reorganization and structuring. For the fiscal years ended December 31, 2025 and December 31, 2024 these fees related to Canadian and US tax compliance services, general tax consultations on matters related to Federal, Provincial, Payroll, Sales and US taxes.
“All other fees” are fees billed by the auditor for products and services not included in the foregoing categories.
The fees paid by Gunnison to its auditor during the Company’s fiscal years ended December 31, 2025 and December 31, 2024, by category, are as follows:
| Year Ended | Audit Fees | Audit Related Fees | Tax Fees | All Other Fees |
| December 31, 2025 | US$361,429 | Nil | Nil | US$25,300 |
| December 31, 2024 | US$223,959 | Nil | US$95,470 | US$15,413 |
| 95 |
SCHEDULE A
AUDIT COMMITTEE CHARTER
As of November 12, 2024
The following Audit Committee Charter was adopted by the Audit Committee of the Board of Directors and the Board of Directors of Gunnison Copper Corp. (the “Company”):
Mandate
The primary function of the audit committee (the “Committee”) is to assist the Company’s Board of Directors in fulfilling its financial oversight responsibilities by reviewing the financial reports and other financial information provided by the Company to regulatory authorities and shareholders, the Company’s systems of internal controls regarding finance and accounting and the Company’s auditing, accounting and financial reporting processes. Consistent with this function, the Committee will encourage continuous improvement of, and should foster adherence to, the Company’s policies, procedures and practices at all levels. The Committee’s primary duties and responsibilities are to:
| ● | serve as an independent and objective party to monitor the Company’s financial reporting and internal control system and review the Company’s financial statements; | |
| ● | review and appraise the performance of the Company’s external auditors; and | |
| ● | provide an open avenue of communication among the Company’s auditors, financial and senior management and the Board of Directors. |
Composition
The Committee shall be comprised of a minimum three directors as determined by the Board of Directors, all of whom shall be free from any relationship that, in the opinion of the Board of Directors, would interfere with the exercise of his or her independent judgment as a member of the Committee.
All members of the Committee shall have accounting or related financial management expertise. All members of the Committee who are not financially literate will work towards becoming financially literate to obtain a working familiarity with basic finance and accounting practices. For the purposes of this Audit Committee Charter, the definition of “financially literate” is the ability to read and understand a set of financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can presumably be expected to be raised by the Company’s financial statements.
The members of the Committee shall be elected by the Board of Directors at its first meeting following the annual shareholders’ meeting. Unless a Chair is elected by the full Board of Directors, the members of the Committee may designate a Chair by a majority vote of the full Committee membership. The position description and responsibilities of the Chair are set out in Schedule “A” attached hereto.
| 96 |
Meetings
The Committee shall meet a least quarterly, or more frequently as circumstances dictate. As part of its job to foster open communication, the Committee will meet at least annually with the Chief Financial Officer and the external auditors in separate sessions. The Committee may ask members of management of the Company or others to attend meetings or to provide information as necessary.
Quorum for the transaction of business at any meeting of the Committee shall be a majority of the number of members of the Committee or such greater number as the Committee shall by resolution determine.
Meetings of the Committee shall be held from time to time as the Committee or the Chair shall determine upon 48 hours’ notice to each of its members. The notice period may be waived by unanimous resolution of the Committee.
The Committee shall keep minutes of its meetings which shall be submitted to the Board. The Committee may, from time to time, appoint any person who need not be a member, to act as a secretary at any meeting.
Any matters to be determined by the Committee shall be decided by a majority of votes cast at a meeting of the Committee called for such purpose. Actions of the Committee may be taken by an instrument or instruments in writing signed by all of the members of the Committee, and such actions shall be effective as though they had been decided by a majority of votes cast at a meeting of the Committee called for such purpose. The Committee shall report its determinations to the Board at the next scheduled meeting of the Board, or earlier as the Committee deems necessary.
Responsibilities and Duties
To fulfill its responsibilities and duties, the Committee shall:
Documents/Reports Review
| ● | review and update this Audit Committee Charter as required; and | |
| ● | review the Company’s financial statements, MD&A and any annual and interim earnings press releases before the Company publicly discloses this information and any financial reports or other financial information (including quarterly financial statements), which are submitted to any governmental body, or to the public, including any certification, report, opinion, or review rendered by the external auditors. |
External Auditors
| ● | review annually, the performance of the external auditors who shall be ultimately accountable to the Company’s Board of Directors and the Committee as representatives of the shareholders of the Company; | |
| ● | obtain annually, a formal written statement of external auditors setting forth all relationships between the external auditors and the Company, consistent with the professional standards for the external auditors; | |
| ● | review and discuss with the external auditors any disclosed relationships or services that may impact the objectivity and independence of the external auditors; | |
| ● | take, or recommend that the Company’s full Board of Directors take appropriate action to oversee the independence of the external auditors, including the resolution of disagreements between management and the external auditor regarding financial reporting; |
| 97 |
| ● | recommend to the Company’s Board of Directors the selection and, where applicable, the replacement of the external auditors nominated annually for shareholder approval; | |
| ● | recommend to the Company’s Board of Directors the compensation to be paid to the external auditors; | |
| ● | at each meeting, consult with the external auditors, without the presence of management, about the quality of the Company’s accounting principles, internal controls and the completeness and accuracy of the Company’s financial statements; | |
| ● | review and approve the Company’s hiring policies regarding partners, employees and former partners and employees of the present and former external auditors of the Company; | |
| ● | review with management and the external auditors the audit plan for the year-end financial statements and intended template for such statements; and | |
| ● | review and pre-approve all audit and audit-related services, and any non-audit services, and the fees and other compensation related thereto provided by the Company’s external auditors in accordance with the Audit Committee Pre-Approval Policy. |
Financial Reporting Processes
| ● | in consultation with the external auditors, review with management the integrity of the Company’s financial reporting process, both internal and external; | |
| ● | consider the external auditors’ judgments about the quality and appropriateness of the Company’s accounting principles as applied in its financial reporting; | |
| ● | consider and approve, if appropriate, changes to the Company’s accounting principles and practices as suggested by the external auditors and management; | |
| ● | review significant estimates and judgments made by management in the preparation of the financial statements and the view of the external auditors as to appropriateness of such estimates and judgments; | |
| ● | following completion of the annual audit, review separately with management and the external auditors any significant difficulties encountered during the course of the audit, including any restrictions on the scope of work or access to required information; | |
| ● | review any significant disagreement among management and the external auditors in connection with the preparation of the financial statements; | |
| ● | review with the external auditors and management the extent to which changes and improvements in financial or accounting practices have been implemented; | |
| ● | review any complaints or concerns about any questionable accounting, internal accounting controls or auditing matters; | |
| ● | establish a procedure for the receipt, retention and treatment of complaints received by the Company regarding accounting, internal accounting controls or auditing matters; | |
| ● | establish a procedure for the confidential, anonymous submission by employees of the Company of concerns regarding questionable accounting or auditing matters; and | |
| ● | review with management the Chief Executive Officer and Chief Financial Officer certificates prepared in connection with the annual and interim continuous disclosure regulatory filings. |
| 98 |
Other Responsibilities
| ● | review and approve any related-party transactions; | |
| ● | the Committee shall perform any other activities consistent with this Audit Committee Charter and governing law, as the Committee or the Board deems necessary or appropriate. |
Authority
The Committee shall have the authority to:
| ● | engage independent counsel and other advisors including accounting or other consultants or experts as it determines necessary to carry out its duties; | |
| ● | set and pay the compensation for advisors employed by the Committee; | |
| ● | communicate directly with the external auditors; | |
| ● | access, on an unrestricted basis, the books and records of the Company; and | |
| ● | conduct any investigation appropriate to its responsibilities, and it may request the external auditors, as well as any officer of the Company, or outside counsel for the Company, to attend a meeting of the Committee or to meet with any members of, or advisors to, the Committee; | |
| ● | the Committee shall have the authority to engage the external auditors to perform a review of the interim financial statements. |
| 99 |
SCHEDULE “A”
Position Description for the Chair of the Audit Committee
| I. | Purpose |
The Chair of the Audit Committee of the Board shall be a director who is elected by the Board to act as the leader of the Committee in assisting the Board in fulfilling its financial reporting and control responsibilities to the shareholders of the Company.
| II. | Who may be Chair |
The Chair will be selected from amongst the directors of the Company who have a sufficient level of financial sophistication and experience in dealing with financial issues to ensure the leadership and effectiveness of the Committee.
| III. | Responsibilities |
The following are the primary responsibilities of the Chair:
| ● | chairing all meetings of the Committee in a manner that promotes meaningful discussion; | |
| ● | ensuring adherence to this Audit Committee Charter and that the adequacy of it is reviewed as required; | |
| ● | providing leadership to the Committee to enhance the Committee’s effectiveness, including: |
| ■ | providing the information to the Board relative to the Committee’s issues and initiatives and reviewing and submitting to the Board an appraisal of the Company’s independent auditors and internal auditing functions; | |
| ■ | ensuring that the Committee works as a cohesive team with open communication, as well as ensuring open lines of communication among the independent auditors, financial and senior management and the Board of Directors for financial and control matters; | |
| ■ | ensuring that the resources available to the Committee are adequate to support its work and to resolve issues in a timely manner; | |
| ■ | ensuring that the Committee serves as an objective party to monitor the Company’s financial reporting process and internal control systems, as well as to monitor the relationship between the Company and the independent auditors to ensure independence; | |
| ■ | ensuring that procedures are in place to assess the audit activities of the independent auditors; and | |
| ■ | ensuring that procedures are in place for dealing with complaints received by the Company regarding accounting, internal controls and auditing matters, and for employees to submit confidential anonymous concerns regarding questionable accounting or auditing matters. |
| ● | managing the Committee, including: |
| ■ | adopting procedures to ensure that the Committee can conduct its work effectively and efficiently, including committee structure and composition, scheduling, and management of meetings; | |
| ■ | preparing the agenda of the Committee meetings and ensuring pre-meeting material is distributed in a timely manner and is appropriate in terms of relevance, efficient format and detail; | |
| ■ | ensuring meetings are appropriate in terms of frequency, length and content; | |
| ■ | obtaining and reviewing with the Committee an annual report from the independent auditors, and arranging meetings with the auditors and financial management to review the scope of the proposed audit for the current year, its staffing and the audit procedures to be used; | |
| ■ | overseeing the Committee’s participation in the Company’s accounting and financial reporting process and the audits of its financial statements; | |
| ■ | ensuring that the auditors’ report directly to the Committee, as representatives of the Company’s shareholders; and | |
| ■ | annually reviewing with the Committee its own performance. |
| 100 |
SCHEDULE “B”
GUNNISON COPPER CORP.
AUDIT COMMITTEE PRE-APPROVAL POLICY
As of November 12, 2024
This Policy identifies the Audit Committee’s procedures and conditions for pre-approving audit, audit-related, tax and other non-audit services performed by a public accounting firm that acts as the independent auditor (the “Auditor”) responsible for auditing the consolidated financial statements of Gunnison Copper Corp. (the “Company”), and its subsidiaries and affiliates.
| 1. | Introduction |
The CPA Code of Professional Conduct (the “CPA Code”) sets out the rules for auditor independence. They include prohibitions or restrictions on services that may be provided by independent auditors to their audit clients. The independence rules identify non-audit services that are deemed inconsistent with an auditors’ independence (“Prohibited Services”). When determining whether a non-audit service is a Prohibited Service, specific reference will be made to the underlying independence rules.
In addition, under Canadian Securities Administrators (“CSA”) rules, a public company’s Audit Committee will be responsible for pre-approving all non-audit services to be provided to the company or its subsidiaries by the company’s independent auditors or the independent auditors of the company’s subsidiaries.
Under both the CPA Code and CSA rules, pre-approval of services by the Audit Committee may be accomplished either by specific approval of each engagement or by adopting pre-approval policies and procedures. The CSA rules require public companies to disclose in their Annual Information Form a description of the policies and procedures their Audit Committee has established to pre-approve non-audit services. The CSA rules also require public disclosure of fees paid to the independent auditors under the captions “Audit Fees”, Audit-Related Fees”, “Tax Fees”, and “All Other Fees”. The four categories of service, as defined in the CSA rules are:
Audit Services
Include services that are normally provided by the independent auditor in connection with statutory and regulatory filings or engagements.
Audit Related Services
Include services by an independent auditor that are reasonably related to the performance of the audit of the issuer’s financial statements and are not reported as Audit Services.
Tax Services
Include professional services rendered by an independent auditor for tax compliance, tax advice, and tax planning.
All Other Services
Include products and services provided by the independent auditor not included in the previous three categories.
| 101 |
| 2. | Permitted Services |
The Company and its subsidiaries will not engage the Auditor to carry out any Prohibited Service. The Audit Committee will consider the pre-approval of permitted services to be performed by the independent auditor in each of the following broad categories.
Audit Services
| ● | Audit of annual financial statements of the Company. | |
| ● | Review of quarterly interim financial statements. | |
| ● | Issuance of comfort letters to underwriters and consents to the securities administrators related to a debt or equity financing. |
Audit Related Services
| ● | Accounting consultations on specific issues. | |
| ● | Accounting and reporting consultations on proposed transactions. | |
| ● | Accounting work related to mergers and acquisitions. | |
| ● | Audit of employee benefits plan. | |
| ● | Due diligence assistance. | |
| ● | General advice on accounting standards. |
Tax Services
| ● | Compliance Income and Mining Taxes Services, including tax return preparation. | |
| ● | Payroll tax services. | |
| ● | Tax advice and consultations relating to proposed transactions. | |
| ● | Advice on GST and HST. | |
| ● | Other tax services not included in the audit and audit-related categories. |
Other Non-Audit Services
| ● | Valuation Services. | |
| ● | Information Technology Advisory and Risk Management Services. | |
| ● | Actuarial Services. | |
| ● | Forensic and Related Services. | |
| ● | Corporate Recovery Services. |
| 102 |
| ● | Transaction Services. | |
| ● | Corporate Finance Services. | |
| ● | Project Risk Management Services. | |
| ● | Operational Advisory and Risk Management Services. | |
| ● | Regulatory and Compliance Services. | |
| ● | Translation Services. |
| 3. | Approval of Permitted Services |
For permitted services the following pre-approval policies will apply:
| A. | Audit Services |
The Audit Committee will pre-approve all audit services provided by the Auditor through their recommendation of the Auditor as shareholders’ auditors at the Company’s annual meeting and through the Audit Committee’s review of the Auditor’s annual Audit Plan.
| B. | Pre-Approval of Audit Related, Tax Services and Other Non-Audit Services |
Annually, the Audit Committee will pre-approve the audit-related, tax and other non-audit services to be provided by the Auditor that are recurring or otherwise reasonably expected to be provided by the external auditor, including involvement with regulatory filings and offering documents. In addition, the Audit Committee will pre-approve the auditor entering into discussion with and providing preliminary advice to management in connection with accounting, internal controls and taxation matters where they are responding to management’s request and the fees for the services of this nature are to be less than $5,000 individually or $50,000 in aggregate during the year. Where the auditor presents an engagement letter in connection with any requested services, the pre-approval of the Audit Committee should be evidenced by the signature of the Audit Committee Chair or his designate. The Audit Committee shall be subsequently informed, at least quarterly, of the services for which the External Auditor has been actually engaged. Any additional requests for pre-approval shall be addressed on a case-by-case specific engagement basis as described in (C) below.
| C. | Approval of Additional Services |
With respect to services not covered in (A) or (B) above, the Company employee making the request will submit the request for service to the Chief Financial Officer of the Company. The request for service should include a description of the service, the estimated fee, a statement that the service is not a Prohibited Service and the reason the Auditor is being engaged. All fees related to tax services will be discussed and reviewed by the Audit Committee or its designee prior to beginning the proposed engagement.
| (i) | Services where the aggregate fees are estimated to be less than or equal to $50,000. |
Recommendations, in respect of each engagement, will be submitted by the Chief Financial Officer of the Company to the Chair of the Audit Committee for consideration and approval. The full Audit Committee will subsequently be informed of the service, at its next meeting. The engagement may commence upon approval of the Chair of the Audit Committee.
| (ii) | Services where the aggregate fees are estimated to be greater than $50,000. |
Recommendations, in respect of each engagement, will be submitted by the Chief Financial Officer of the Company to the full Audit Committee for consideration and approval, generally at its next meeting or at a special meeting called for the purpose of approving such services. The engagement may commence upon approval of the full Audit Committee.
| 103 |