Post-Qualification Offering Circular
Amendment No. 4
File No. 024-12541
As submitted to the Securities Exchange
Commission on October 9, 2026
PART II – INFORMATION REQUIRED IN OFFERING
CIRCULAR
PRELIMINARY OFFERING CIRCULAR
DATED October 9, 2026
An offering statement pursuant to Regulation A of the Securities Act
of 1933 relating to these securities has been filed with the Securities and
Exchange Commission. Information contained in this Preliminary Offering
Circular is subject to completion or amendment. These securities may not be
sold nor may offers to buy be accepted before the offering statement filed with
the Commission is qualified. This Preliminary Offering Circular does not
constitute an offer to sell or the solicitation of an offer to buy nor may
there be any sales of these securities in any state in which such offer,
solicitation or sale would be unlawful before registration or qualification
under the laws of any such state. We may elect to satisfy our obligation to
deliver a Final Offering Circular by sending you a notice within two business
days after the completion of our sale to you that contains the URL where the
Final Offering Circular or the offering statement in which such Final Offering
Circular was filed may be obtained.
This Post-Qualification Amendment amends the
Offering Statement on Form 1-A originally qualified by the U.S. Securities and
Exchange Commission on November 21, 2025 (File No. 024-12541). This
Post-Qualification Amendment No. 4 updates the Offering Circular to (i)
incorporate by reference the audited consolidated financial statements of
MacKenzie Realty Capital, Inc. as of and for the fiscal year ended June 30,
2026 contained in the Company's Annual Report on Form 10-K filed with the
Securities and Exchange Commission on September 28, 2026 (the “2026 Form 10-K”)
and (ii) reflect the temporary
suspension by our Board of Directors on September 11, 2026 of the Company's
share repurchase program with respect to the Company's Series A Preferred
Stock, Series B Preferred Stock, and Series C Preferred Stock (the “Repurchase
Program Suspension”), which the Company publicly announced in its Current Report on Form 8-K filed with the Commission on
September 30, 2026
and which was implemented to enable the Company to better react to strategic
alternatives that may from time to time be presented for evaluation by its
financial advisor, Maxim Group LLC.
MacKenzie Realty Capital, Inc.
Up to an aggregate of $71,681,755.55 of shares of Series A Preferred
Stock, shares of Series B Preferred Stock, and shares of Series C Preferred
Stock
$22.50 per Series A Share
$25.00 Per Series B or C Share
MacKenzie
Realty Capital, Inc. (the “Company”, “us”, “we”, “our” and other similar
terms), a Maryland corporation, was formed to generate both current income and
capital appreciation through real estate related investments, primarily in debt
and equity real estate related securities. As of December 31, 2020, however, we
have elected to withdraw our election to be regulated as a business development
company (“BDC”) under the Investment Company Act of 1940, as amended (the
“Investment Company Act”). Following
withdrawal of the election to be regulated as a BDC, our underlying investment
strategy remains very similar to the strategy we have historically
followed. We intend to increase our
control over our private investments, and to eventually consolidate those
investments for financial reporting purposes.
We conduct many of our operations through MacKenzie Realty Operating
Partnership, LP, a Delaware limited partnership (the “Operating Partnership”)
and through our multi-family subsidiary, MacKenzie Apartment Communities, Inc.
(“MAC”) and its operating partnership (“MAC OP”). The withdrawal also allows us to expand our
investment pool to include real, physical assets, as opposed to only investment
securities. We believe that this
expanded pool of potential investments will allow access to risk-adjusted
returns consistent with our investment objective, while allowing us to maintain
our REIT status.
We
commenced our most recent offering our Series A Preferred Stock, $0.0001 par
value per share (the “Series A Preferred Stock”), and Series B Preferred Stock,
$0.0001 par value per share (the “Series B Preferred Stock”), on January 29,
2025, upon qualification of the offering by the SEC. As of October 9, 2026, we
had sold an aggregate of $26,355,996.86 of shares of Series A Preferred Stock, Series
B Preferred Stock, and Series C Preferred Stock. We are offering to sell up to 637,171.16
shares of Series A Preferred Stock, 1,146,908.09 shares of Series B Preferred
Stock, and 1,146,908.09 shares of Series C Preferred Stock, $0.0001 par value
per share (the “Series C Preferred Stock”) of the Company. Of these amounts, 150,000
shares of each Series are reserved for the dividend reinvestment program. The minimum purchase requirement per investor
is $5,000 in preferred shares; however, we can waive the minimum purchase
requirement in our sole discretion. The primary difference between the three
series is that the Series A Preferred Stock is entitled to receive dividends at
the rate of 6% per annum on the Stated Value but can be purchased for 10% less
than the Stated Value ($22.50 per share), resulting in an effective rate per
annum of 6.67% based on the purchase price, whereas the Series B Preferred
Stock is entitled to receive dividends at the rate of 12% per annum, with 3%
expected to be paid quarterly on the applicable dividend payment date and 9% to
accrue for payment at the same time and in the same amounts per share with
distributions paid on the Company’s common stock, par value $0.0001 per share
(the “common stock”), beginning once holders of common stock have initially received
distributions equal to 10% per annum from and after December 31, 2022 on the $7.38
per share net asset value (“NAV”) of the common stock as of such date, and the
remainder of which will be paid no later than at redemption, liquidation or
conversion, and the Series C Preferred Stock, which will rank with respect to
dividend rights and the right to receive distributions upon liquidation,
winding-up or dissolution senior to the common stock and junior to the Series A
and Series B Preferred Stock (excluding the additional accrued 9% portion of
the Series B Preferred Stock dividend), is entitled to receive dividends at the
rate of 9% per annum. The sale of shares
pursuant to this offering is expected to continue until we raise the maximum
amount being offered, unless terminated by us at an earlier time in the
discretion of our Board of Directors.
We are
externally managed by MacKenzie Capital Management, LP, a California limited
partnership, or the “Manager”. We are advised, as to our real estate
investments, by an affiliate of the Adviser, MacKenzie Real Estate Advisers, LP
(the “Real Estate Adviser”), and as to our securities portfolio, by MCM
Advisers, LP (the “Investment Adviser”; together with the Real Estate Adviser,
the “Advisers” or “Adviser”). These
Advisers will make all investment decisions for us. Our Advisers intend
to employ a variety of acquisition strategies in building our portfolio of
investments, with a particular focus on obtaining properties in off-market
transactions, opportunistic and value-add situations, and similar transactions.
We have elected to be taxed, and currently, as of calendar year end
December 31, 2025, qualify, as a REIT for U.S. federal income tax purposes.
We do
not intend to list our preferred shares for trading on a stock exchange or
other trading market; however, our common stock is listed on the Nasdaq Capital
Market as of November 11, 2024 under the symbol “MKZR”.
Investing
in our preferred shares involves a high degree of risk. See “Risk Factors”
beginning on page 15 of this Offering
Circular for a discussion of the risks that should be considered in connection
with your investment in our shares.
These risks include, but are not limited to, the following:
● There
is no assurance that we will be able to successfully achieve our investment
objectives.
● Investors
will not have the opportunity to evaluate or approve any Investments prior to
our acquisition or financing thereof.
● Investors
will rely solely on the Adviser to manage us and our Investments. The
Adviser will have broad discretion to invest our capital and make decisions
regarding Investments.
● We
may not be able to invest the net proceeds of this offering on terms acceptable
to investors, or at all.
● Investors
will have limited control over changes in our policies and day-to-day
operations, which increases the uncertainty and risks you face as an investor.
In addition, our Board of Directors may approve changes to our policies,
including our policies with respect to distributions and redemption of shares
without prior notice or your approval.
● An
investor could lose all or a substantial portion of any investment made in us.
● There
is no public trading market for our preferred shares, and we are not obligated
to effectuate a liquidity event or a listing of our preferred shares on any
nationally recognized stock exchange by a certain date or at all. It will
thus be difficult for an investor to sell shares purchased from us.
● We
may fail to maintain our qualification as a REIT for federal income tax
purposes. We would then be subject to corporate level taxation and
regulation as an investment company and we would not be required to pay any
distributions to our stockholders.
● The
offering price of our shares was not established based upon any appraisals of
assets we own or may own. Thus, the initial offering price may not
accurately reflect the value of our assets at the time an investor’s investment
is made.
● Substantial
actual and potential conflicts of interest exist between our investors and our
interests or the interests of our Adviser, and our respective affiliates,
including conflicts arising out of (a) allocation of personnel to our
activities, (b) allocation of investment opportunities between us, and (c)
potential conflicts arising out of transactions between us, on the one hand,
and our Adviser and its affiliates, on the other hand, involving compensation
and incentive fees payable to our Adviser or dealings in real estate
transactions between us and the Adviser and its affiliates.
● There
are substantial risks associated with owning, financing, operating, leasing,
and managing real estate.
● The
amount of distributions we make is uncertain. We may fund distributions
from offering proceeds, borrowings, and the sale of assets, to the extent
distributions exceed our earnings or cash flows from our operations if we are
unable to make distributions from our cash flows from operations. There
is no limit on the amount of offering proceeds we may use to fund
distributions. Distributions paid from sources other than cash flow or
funds from operations may constitute a return of capital to our stockholders.
Rates of distributions may not be indicative of our actual operating
results. For example, on March 31, 2020, after assessing the
impacts of the COVID-19 pandemic, our Board of Directors unanimously approved
the suspension of regular quarterly dividends to our common stockholders. On
May 10, 2021, the Board of Directors reinstated the quarterly dividend at the
rate of $0.05 per share of common stock, which was increased to $0.06, $0.07,
$0.08, $0.09, $0.10, $0.11, $0.115, $0.12, and $0.125 per share of common stock
in the nine quarters thereafter, respectively.
For the quarters ended December 31, 2024, and March 31, 2025, the common
dividend was $0.05 cents per share of common stock. Thereafter, on May 12, 2025, the Board
decided to suspend paying a common dividend in light of current economic
uncertainties. While the Series A Preferred
Stock will accrue a 6% dividend on the Stated Value, payment of this dividend
is not guaranteed, only that it will be paid before any cash dividend may be
paid to the holders of shares of Series C Preferred Stock and common stock. While the Series B Preferred Stock will
accrue a 3% dividend, payment of this dividend is not guaranteed, only that it
will be paid before any cash dividend may be paid to the holders of shares of Series
C Preferred Stock and common stock, and the additional accrued 9% dividends on
the Series B Preferred Stock will start being paid at the same time and in the
same amount per share with distributions paid on the common stock once the holders
of common stock have initially received distributions equal to 10% per annum from
and after December 31, 2022 on the $7.38 per share net asset value per share
for the common stock as of such date, and the remaining amounts (if any) will be
paid no later than at redemption, liquidation or conversion. While the Series C Preferred Stock will
accrue a 9% dividend, payment of this dividend is not guaranteed, only that it
will be paid before any cash dividend may be paid to the holders of shares of common
stock, but after the priority dividend payments described above for the Series
A and Series B Preferred Stock have been satisfied (excluding the additional
accrued 9% portion of the Series B Preferred Stock dividend).
The
SEC does not pass upon the merits of or give its approval to any securities
offered or the terms of the offering, nor does it pass upon the accuracy or
completeness of any offering circular or other solicitation materials. These
securities are offered pursuant to an exemption from registration with the SEC;
however, the SEC has not made an independent determination that the securities
offered are exempt from registration.
The
use of projections or forecasts in this offering is prohibited. No one is
permitted to make any oral or written predictions about the cash benefits or
tax consequences you will receive from your investment in shares of our common
stock.
|
|
Per Share
|
Total Maximum
|
|
Offering Price (1)
|
$22.50/$25.00
|
$71,681,755.55 (2)
|
|
Underwriting
Discounts and Commissions (3)
|
$2.25/$2.50
|
$7,168,175.55
|
|
Proceeds to Us from this Offering
(Before Expenses) (4)
|
$20.25/$22.50
|
$64,513,580.00
|
1.
The
price per share has been arbitrarily determined by our Adviser to be $22.50 per
Series A Preferred share and $25.00 per Series B and C Preferred share.
2.
This
is a “best efforts” offering of an aggregate of $$61,556,755.55 of shares of
preferred stock in the primary offering ($10,961,351.11 for Series A, $25,297,702.22
for Series B, and $25,297,702.22for Series C) and $10,125,000.00 of shares of
preferred stock through the dividend reinvestment program ($[ ] for each Series A, B, and C). See
“Plan of Distribution” and “Series A, B and C Preferred Stock Dividend
Reinvestment Program.”
3.
We
will pay selected brokers (the “Selling Agents”) a sales load of 7.0% of the
offering price, which load is reduced based on the number of shares purchased
from a Selling Agent, and we will also pay our dealer manager, Arete Wealth
Management, LLC (“Arete”), a dealer manager fee of up to 1.9% of the offering
price (the “Dealer Adviser Fee”). If shares are purchased through investment
advisers, we will only pay the Dealer Adviser Fee to Arete, and no commissions
will be payable. For purposes of the table, we have assumed a sales charge of
7.0%. To the extent purchasers qualify for the volume discounts or purchase
through certain investment advisory accounts, the sales load amount shown in
the table would be less. Selling Agents will also receive a marketing support
fee of 1.1% of the offering price from us (the “Marketing Support Fee”) to
assist the Selling Agents in covering their costs for the marketing of the preferred
shares. For purchases through certain investment advisory accounts, Arete will
only receive the 1.9% Dealer Adviser Fee in lieu of commissions and no
Marketing Support Fee will be paid. The
total amount of all items of compensation from any source, payable to
underwriters, broker-dealers or affiliates thereof will not exceed an amount
that equals 10.0% of the gross proceeds of the offering. See “Arrangements with
Dealer Adviser and Selected Broker Dealers.”
4.
We
estimate that we will incur approximately $1,500,000 in costs in connection
with this offering (not including any costs or expenses incurred in connection
with the prior offerings of common stock and not including legal fees). All amounts over $825,000 (not including
legal fees), however, will be reimbursed by our Advisers, except to the extent
the full 10.0% in broker fees described above are not incurred. In such case,
the difference will be available to be paid or reimbursed by us to brokers for
marketing expenses or other non-cash compensation.
Generally,
no sale may be made to you in this offering if the aggregate purchase price you
pay is more than 10% of the greater of your annual income or net worth.
Different rules apply to accredited investors and non-natural persons. Before
making any representation that your investment does not exceed applicable
thresholds, we encourage you to review Rule 251(d)(2)(i)(C) of Regulation A.
For general information on investing, we encourage you to refer to www.investor.gov.
This Offering Circular uses the SEC
Registration Statement on Form S-11 disclosure format.
The mailing address of our principal
executive offices is:
MacKenzie Realty Capital, Inc.
89 Davis Road, Suite 100
Orinda, CA 94563
Attn: Investor Relations
Our
telephone number is 1.800.854.8357 and our website address is www.mackenzierealty.com.
You may direct inquiries to: investors@mackenziecapital.com.
This Offering Circular is dated October [
], 2026.
IMPORTANT
INFORMATION ABOUT THIS OFFERING CIRCULAR
Please
carefully read the information in this Offering Circular and any accompanying Offering
Circular supplements, which we refer to collectively as the Offering Circular.
You should rely only on the information contained in this Offering Circular. We
have not authorized anyone to provide you with different information. This Offering
Circular may only be used where it is legal to sell these securities. You
should not assume that the information contained in this Offering Circular is
accurate as of any date later than the date hereof or such other dates as are
stated herein or as of the respective dates of any documents or other
information incorporated herein by reference.
This Offering
Circular is part of an offering statement that we filed with the SEC, using a
continuous offering process. Periodically, as we make material investments, or
have other material developments, we will provide an Offering Circular Supplement
that may add, update or change information contained in this Offering Circular.
Any statement that we make in this Offering Circular will be modified or
superseded by any inconsistent statement made by us in a subsequent Offering Circular
Supplement. The offering statement we filed with the SEC includes exhibits that
provide more detailed descriptions of the matters discussed in this Offering Circular.
You should read this Offering Circular and the related exhibits filed with the
SEC and any Offering Circular Supplement, together with additional information
contained in our annual reports, quarterly reports and other reports and
information statements that we will file periodically with the SEC. See the
section entitled “Additional Information” below for more details.
The
offering statement and all supplements and reports that we have filed or will
file in the future can be read at the SEC website, www.sec.gov, or on our
website, www.mackenzierealty.com. The contents of our website (other than the
offering statement, this Offering Circular and the appendices and exhibits
thereto) are not incorporated by reference in or otherwise a part of this Offering
Circular.
Our
Adviser and those selling shares on our behalf in this offering will be
permitted to make a determination that the purchasers of shares in this
offering are “qualified purchasers” in reliance on the information and
representations provided by the shareholder regarding the shareholder’s
financial situation. Before making any representation that your investment does
not exceed applicable thresholds, we encourage you to review Rule
251(d)(2)(i)(C) of Regulation A. For general information on investing, we encourage
you to refer to www.investor.gov.
STATE LAW
EXEMPTION AND INVESTOR REQUIREMENTS
Our
preferred shares will be offered and sold only to purchasers who are “qualified
purchasers” (as defined in Regulation A). As a Tier 2 offering pursuant to
Regulation A, this offering will be exempt from state law “Blue Sky” review,
subject to meeting certain state filing requirements and complying with certain
anti-fraud provisions, to the extent that our preferred shares offered hereby
are offered and sold only to “qualified purchasers” or at a time when our
shares are listed on a national securities exchange.
The preferred
shares are offered only to “Qualified Purchasers”, which include: (i) “accredited
investors” under Rule 501(a) of Regulation D and (ii) all other investors so
long as their investment in our preferred shares does not represent more than
10% of the greater of their annual income or net worth (for natural persons),
or 10% of the greater of annual revenue or net assets at fiscal year-end (for
non-natural persons). We reserve the right to reject any investor’s
subscription in whole or in part for any reason, including if we determine in
our sole and absolute discretion that such investor is not a “qualified
purchaser” for purposes of Regulation A.
Generally,
no sale may be made to you in this offering if (a) excluding the value of your
home, furnishings and automobiles, you do not have either (i) a net worth of
more than $250,000 or (ii) a gross annual income of at least $70,000 and a net
worth of at least $70,000, and (b) the aggregate purchase price you pay is more
than 10% of the greater of your annual income or net worth. Different
rules apply for purposes of the Regulation A investor qualification requirement
to accredited investors and non-natural persons. Before making any
representation that your investment does not exceed applicable thresholds, we
encourage you to review Rule 251(d)(2)(i)(C) of Regulation A. For general
information on investing, we encourage you to refer to investor.gov.
For
more detailed information regarding investor requirements see “Investment
Limitations” on page 41 of this Offering Circular.
OFFERING
SUMMARY
This
offering summary highlights the information contained elsewhere in this
Offering Circular. Because it is a summary, it may not contain all the
information that you should consider before investing in our shares. To
fully understand this offering (the “Offering”), you should carefully read this
entire Offering Circular, including the more detailed information set forth
under the caption “Risk Factors.” Unless the context otherwise requires
or indicates, references in this Offering Circular to “us,” “we,” “our” or “our
company” refer to MacKenzie Realty Capital, Inc., a Maryland corporation.
MacKenzie Realty Capital, Inc.
MacKenzie
Realty Capital, Inc. was formed as of January 27, 2012, as a Maryland
corporation, and we are taxed as a REIT for federal income tax purposes.
Our objective is to acquire and develop a portfolio of mainly
institutional-quality apartment communities and office properties, primarily on
the West Coast of the United States. Our
common stock is listed on The Nasdaq Capital Market under the symbol “MKZR,”
and trading commenced on November 11, 2024.
On August 4, 2025, we effected a 1-for-10 reverse stock split of our
common stock (the “Reverse Stock Split”).
Effective January 1, 2026, we reorganized our real estate operations by
separating our multi-family residential portfolio from our commercial real
estate investments. We contributed our
multi-family residential properties and the Blue Ridge at Suisun Valley
development project to our newly formed, wholly owned subsidiary, MacKenzie
Apartment Communities, Inc. (“MAC”), which conducts its real estate operations
through MAC Operating Partnership, LP (“MAC OP”). Our commercial real estate investments
continue to be held through MacKenzie Realty Operating Partnership, LP (the
“Operating Partnership”).
We
were formed to generate both current income and capital appreciation through
real estate related investments, primarily in debt and equity real estate
related securities. As of December 31, 2020, however, we elected to withdraw
our election to be regulated as a business development company (“BDC”) under
the Investment Company Act of 1940, as amended (the “Investment Company
Act”). Following withdrawal of the
election to be regulated as a BDC, we have and intend to continue to invest in
private companies that directly or indirectly own real property, and increase
our control over our private investments, and to eventually consolidate those
investments for financial reporting purposes. We conduct many of our operations
through MacKenzie Realty Operating Partnership, LP, a Delaware limited
partnership (the “Operating Partnership”) and through our multi-family subsidiary,
MacKenzie Apartment Communities, Inc. (“MAC”) and its operating partnership
(“MAC OP”). The withdrawal of our BDC election has also allowed us to expand
our investment pool to include real, physical assets, as opposed to only
investment securities. We believe that this expanded pool of potential
investments allows access to risk-adjusted returns consistent with our
investment objective, while allowing us to maintain our REIT status.
We
utilize three key investment strategies — Value-Add, Opportunistic, and
Invest-to-Own — to drive growth in funds from operations and net asset value at
our properties, in order to maximize returns to our investors.
We
invest primarily through controlling positions (generally 90%) in joint
ventures with our network of some of the leading private regional apartment
owner/operators across the nation, which we believe enhances our ability to
access proprietary off-market transactions, and to deliver best-in-class
execution of multiple investment strategies across a substantial number of
markets. Upon execution of the initial business plan for the property, we will
often seek to increase our ownership to 100%, so that the property will be
wholly owned by us.
As
of the date of this Offering Circular, our portfolio consisted of (a) 9 commercial
real estate properties: Satellite Place Office Building located in Duluth, GA,
1300 Main Office Building, First & Main Office Building and Main Street
West Office Building located in Napa, CA, Woodland Corporate Center located in
Woodland, CA, 220 Campus Lane Office Building, Green Valley Medical Center and Green
Valley Executive Center located in Fairfield, CA, and One Harbor Center located
in Suisun, CA; (b) 5 residential apartment properties: Commodore Apartments and
The Park View Apartments located in Oakland, CA, Hollywood Apartments located
in Los Angeles, CA, Shoreline Apartments located in Concord, CA, and Aurora at
Green Valley located in Fairfield, CA; and (c) one multi-family residential
development project, Blue Ridge at Suisun Valley (“Blue Ridge”), located on
vacant land adjacent to our 220 Campus Lane Office Building in Fairfield, CA,
which is expected to consist of 84 multi-family residential units and the
entitlement process for which is ongoing.
In October 2025, we listed Woodland
Corporate Center
Two for sale, and in September 2026, we entered into a purchase and sale
agreement with a third party to sell the property, subject to customary closing
conditions.
Following the reorganization
effective January 1, 2026, our 5 multi-family residential properties and the Blue Ridge development project are held through MAC
OP, of which MAC is the sole general partner (and our wholly-owned subsidiary),
with MAC OP owning the properties directly or indirectly through various
operating subsidiaries (including Madison-PVT Partners LLC with respect to
Commodore Apartments, PVT-Madison Partners LLC with respect to The Park View Apartments,
PT Hillview GP, LLC with respect to Hollywood Apartments, MacKenzie-BAA IG
Shoreline LLC with respect to Shoreline Apartments, and MRC Aurora, LLC with
respect to Aurora at Green Valley). Our
commercial real estate properties continue to be held through the Operating
Partnership and its subsidiaries, including MacKenzie Satellite Place Corp. (which
holds Satellite Place Office Building); First & Main, LP; 1300 Main, LP;
Woodland Corporate Center Two, LP; Main Street West, LP; One Harbor Center, LP;
Green Valley Medical Center, LP; 220 Campus Lane, LLC; and GV Executive Center,
LLC. We also own 5 minority interests in
non-traded REITs, 2 general partnership interests in commercial properties, and
other real estate investments.
Our
primary intent is to purchase real estate interests, whether direct
investments, joint ventures, minority interests, or loans secured by real
estate. We refer to our investments in real property as “Investments”.
REIT Status
We
are currently treated as a REIT for federal income tax purposes. As long as we
maintain our qualification as a REIT, we generally will not be subject to
federal income or excise tax on income that we distribute to our shareholders.
Under
the Internal Revenue Code of 1986, as amended (the “Code”), a REIT is subject
to numerous organizational and operational requirements, including a
requirement that it annually distribute at least 90% of its REIT taxable income
(determined without regard to the deduction for dividends paid and excluding
net capital gain) to its shareholders.
If we
fail to maintain our qualification as a REIT in any year, our income will be
subject to federal income tax at regular corporate rates, regardless of our
distributions to shareholders, and we may be precluded from qualifying for
treatment as a REIT for the four-year period immediately following the taxable
year in which such failure occurs.
Even
if we qualify for treatment as a REIT, we may still be subject to state and
local taxes on our income and property and to federal income and excise taxes
on our undistributed income.
Investment Company
Act Considerations
We
intend to conduct our operations so that we will not be required to register as
an investment company under the Investment Company Act.
Management
Company is Externally Managed
We are
externally managed by MacKenzie Capital Management, LP, a California limited partnership
or the “Manager” and advised as to our real estate investments by its affiliate
MacKenzie Real Estate Advisers, LP (“Real Estate Adviser”) and as to any
securities by MCM Advisers, LP (“Investment Adviser”) (together, the “Advisers”
or “Adviser”). The Advisers will make all investment decisions for us.
The Advisers’ principals and their respective affiliates specialize in
acquiring, repositioning (where applicable) and managing commercial real estate
and related securities.
The Advisers
intend to apply this experience to identify suitable Investments and to present
an opportunity for outside investors to take advantage of the principals’
experience through a pooled investment vehicle.
The Advisers
will oversee our overall business and affairs and will have broad discretion to
make operating decisions on our behalf and to make Investments. Our
shareholders will not be involved in our day-to-day affairs.
Experienced Management Team
Our
management team has significant real estate experience, which includes
experience in acquisition, management, leasing, sales, development, and
financing of multiple properties. Overall, our management team has 100+
years combined experience in the real estate business as portfolio managers,
owners, lessors, and Realtors. Our management team has relevant
experience in managing private and public investment funds which invested in
real estate securities, but not directly in real estate. Our management team manages and advises one
other real estate fund with similar investment objectives and strategies to us:
MacKenzie REIT, Inc. (“MREIT”), which is a private REIT that owns an office
building, a grocery-anchored shopping mall, and an office and research and
development park, along with various other real estate assets. MREIT is an entity that resulted from the
merger of two older limited partnerships sponsored by unaffiliated sponsors
(including Concord Milestone Plus, LP which raised funds in 1987, which became
CMP Old Orchard, LP, and New Orleans Associates Limited Partnership which
raised funds in 1987). However, that entity is not currently public, is not
currently raising capital to make new investments, and generally focuses on
income-producing properties rather than growth opportunities. We will not compensate our management team;
they will receive renumeration through their employment by and ownership in our
Advisers.
Management Compensation
Our
Advisers and their affiliates will receive fees and expense reimbursements for
services relating to this Offering and the investment and management of our
assets. The items of compensation are summarized in the following table.
Neither of our Advisers nor their affiliates will receive any selling
commissions or dealer manager fees in connection with the offer and sale of our
preferred shares.
We
do not have an agreement to limit any losses suffered by our Advisers or the
Manager.
The projected compensation laid out below
relates to all stages of our company, including offering stage, organizational
stage, acquisition stage, and liquidation stage.
|
Base
Management Fee:
|
The base
management fee is equal to 1.25% per annum of our gross assets under
management (excluding depreciation and amortization).
The Base
Management Fee compensates our Adviser for managing all of our assets. The Real Estate Adviser and the Investment
Adviser will allocate this fee between themselves.
In
the fiscal year ending June 30, 2027, we expect to pay our Adviser
approximately $3,150,000 in Base Management Fees.
|
|
Acquisition Fees:
|
We
no longer pay our Adviser an acquisition fee.
|
|
Debt Financing Fee, Disposition Fee,
Property Management Fee
|
We
do not pay any such fees to our Adviser, but do anticipate paying debt
financing and property management fees to unaffiliated third parties. We
expect to pay property management fees based upon prevailing market rates,
but most such fees will be paid by the entities that own a property. PVT-Madison Partners, LLC and Madison-PVT
Partners, LLC pay their third-party property management firm a fee equal to
6% of gross collected revenue from such properties. Hillview Hollywood pays its third-party
property manager 4% of gross revenue, subject to a minimum $2,500 monthly
fee. MacKenzie Shoreline pays its
third-party property management firm 4% of gross collected revenue. We pay an
affiliate of our adviser, Wiseman Commercial, Inc., property management fees
equal to 5% of gross collected revenue for the
Wiseman Properties (as defined below).
We have not yet paid any debt financing fees, but our understanding of
the market rates for such services lead us to believe that such fees would
usually be in the range of 0.5% to 1% of the amount of the loan, depending
upon the size of the loan. If we sell a property, we would anticipate paying
market rate selling commissions to brokers, including Wiseman Commercial,
Inc., which we believe would usually be in the range of 3% to 6% of the sales
price.
|
|
Bonus Management Fee:
|
The
Real Estate Adviser will be entitled to receive a bonus management fee equal
to 5% of our adjusted funds from operations for each quarter.
The Bonus
Management Fee compensates our Adviser based upon the performance of the
assets in which we invest.
It
is impracticable to determine the amount of Bonus Management Fees that will
be paid in the next year, although we incurred a Bonus Management Fee of $26,876
in the Fiscal Year ended June 30, 2026.
|
|
Expense Reimbursements
|
In
addition to the compensation paid to the Adviser above, we shall reimburse
the Adviser and/or its Affiliates for all of the costs and expenses paid or
incurred by the Adviser that are in any way related to our operations or our
business or the services the Adviser provides to us pursuant to the Advisory
Agreement, including, but not limited to: organization and offering expenses;
expenses of managing and operating Assets owned by us, whether payable to an
Affiliate of us or a non-Affiliated Person; expenses connected with payments
of distributions in cash or otherwise made or caused to be made by us to the stockholders;
expenses of organizing, reorganizing, liquidating, or dissolving us and the
expenses of filing or amending the Articles of Incorporation or Articles
Supplementary establishing the terms of any preferred stock; transfer agent
expenses, and related software development costs, for the shares and of
maintaining communications with stockholders, including the cost of
preparation, printing, and mailing annual reports and other stockholder
reports, proxy statements and other reports required by governmental
entities; administrative service expenses (including salary, benefits, and
overhead costs of Affiliates and certain of the executive officers of us,
based upon the amount of time they spend on Company business other than
providing investment advice, as approved by Board); and audit, accounting,
and legal fees.
|
Conflicts of Interest
Our
officers and directors, and the owners and officers of our Adviser and its
affiliates are involved in, and will continue to be involved in, the ownership
and advising of over 100 other real estate entities and programs, the
vast majority of which are low-income housing projects. Only one other such entity has investment
objectives similar to us—MREIT, a private real estate investment trust advised
by the Adviser. Our Board, however, is
independent from MREIT, and only Mr. Patterson is a director of both us and
MREIT. Three of our four directors are
independent. MREIT owns an office
building, a grocery-anchored shopping mall, and an office and research and
development park, along with various other real estate assets. However, it is not currently public, is not
currently raising capital to make new investments, and generally focuses on
income-producing properties rather than growth opportunities. Our sponsor and advisers have committed to
providing us with the first chance at any investment opportunities so long as
we have new capital to invest.
These
pre-existing interests, and similar additional interests as may arise in the
future, may give rise to conflicts of interest with respect to our business,
our investments, and our investment opportunities. It is possible that investment opportunities
may arise that would be appropriate for both us and one of the other real
estate funds that is managed or advised by our Adviser. In such a case, it will be the responsibility
of the Board and the Adviser to resolve that potential conflict.
We
are subject to various conflicts of interest arising out of our relationship
with our advisers and affiliates, including conflicts related to the
arrangements pursuant to which our advisers and affiliates will be compensated
by us. The agreements and compensation arrangements between us and our advisers
and affiliates were not determined by arm’s-length negotiations. See
the “Management Compensation” section of this Offering Circular above. Some of
the conflicts of interest in our transactions with our advisers and affiliates,
and the limitations on our advisers adopted to address these conflicts, are
described below.
Our
advisers and affiliates try to balance our interests with their duties to other
programs sponsored by our sponsor and its affiliates. However, to the extent
that our advisers or their affiliates take actions that are more favorable to other entities than to us, these actions could have a
negative impact on our financial performance and, consequently, on
distributions to our stockholders and the value of our stock. In addition, our
directors, officers and certain of our stockholders may engage for their own
account in business activities of the types conducted or to be conducted by us
and our subsidiaries. For a description of some of the risks related to these
conflicts of interest, see the section of this Offering Circular captioned
“Risk Factors — Risks Related to Conflicts of Interest.”
Our independent directors have an obligation to serve on our
behalf in all situations in which a conflict of interest may arise, and all of
our directors have a fiduciary obligation to act on behalf of our stockholders.
Interests in Other Real Estate Programs
Affiliates of our advisers have sponsored
numerous private real estate programs, but none with similar investment
objectives to us other than MREIT because no other such programs raise capital
from investors to invest in commercial real estate properties (all other
programs that have raised capital from investors have invested in real estate
securities or low-income housing projects). MREIT employs a similar investment
strategy and has acquired or plans to acquire assets similar to ours and
non-traded REIT shares. The common investment strategy used by MREIT would
permit it to purchase certain properties that may also be suitable for our
portfolio.
MREIT’s primary investment strategy is to
invest in stabilized, income-producing properties but may also invest in
opportunistic growth opportunities and non-traded REITs, similar to properties
in which we invest. Other private funds advised by our advisers
may purchase non-traded REITs and other fractionalized real property
interests. Our advisers do not advise
any other real estate programs which target the purchase of properties,
however.
Affiliates of our officers and entities
owned or managed by such affiliates also may acquire or develop real estate for
their own accounts, and have done so in the past. Furthermore, affiliates of
our officers and entities owned or managed by such affiliates intend to form
additional real estate investment entities in the future, whether public or
private, which can be expected to have the same investment objectives and
policies as we do and which may be involved in the same geographic area, and
such persons may be engaged in sponsoring one or more of such entities at
approximately the same time as our shares of common or preferred stock are
being offered. Our Advisers and affiliates of our officers are not obligated to
present to us any particular investment opportunity that comes to their
attention, even if such opportunity is of a character that might be suitable
for investment by us. Our Advisers and affiliates likely will experience
conflicts of interest as they simultaneously perform services for us and other
affiliated real estate programs.
Any affiliated
entity, whether or not currently existing, could compete with us in the sale or
operation of our properties. We will seek to achieve any operating efficiency
or similar savings that may result from affiliated management of competitive
properties. However, to the extent that affiliates own or acquire a property
that is adjacent, or in close proximity, to a property we own, our property may
compete with the affiliate’s property for tenants or purchasers.
Every transaction that we enter into with
our Advisers or their affiliates is subject to an inherent conflict of
interest. Our board of directors may encounter conflicts of interest in
enforcing our rights against any affiliate in the event of a default by or
disagreement with an affiliate or in invoking powers, rights or options
pursuant to any agreement between us and our Advisers or any of their
affiliates.
Other Activities of Our Advisers and
affiliates
We rely on our advisers for the day-to-day operation of our business pursuant to
our advisory agreements. As a result of the interests of members of our Advisers’
management in other programs and the fact that they have also engaged and will
continue to engage in other business activities, our Advisers and affiliates will
have conflicts of interest in allocating their time between us and other
programs and other activities in which they are involved. However, our Advisers
believe that they and their affiliates have sufficient personnel to discharge
fully their responsibilities to all of such programs and other ventures in
which they are involved.
In addition, a majority of our executive
officers also serve as an officer of our Advisers or other affiliated entities.
As a result, these individuals owe fiduciary duties to these other entities,
which may conflict with the fiduciary duties that they owe to us and our
stockholders.
We may purchase properties or interests in
properties from affiliates of our Advisers. The prices we pay to affiliates of
our Advisers for these properties will not be the subject of arm’s-length negotiations, which could mean that
the acquisitions may be on terms less favorable to us than those negotiated
with unaffiliated parties. However, the price must be approved by a majority of
our directors, including a majority of our independent directors, who have no
financial interest in the transaction. If the price to us exceeds the cost paid
by our affiliate, our board of directors must determine that there is
substantial justification for the excess cost. Additionally, we may sell
properties or interests in properties to affiliates of our Advisers. The prices
we receive from affiliates of our Adviser for these properties will not be the
subject of arm’s-length negotiations,
which could mean that the dispositions may be on terms less favorable to us
than those negotiated with unaffiliated parties.
Competition
in Acquiring, Leasing and Operating Properties
Conflicts of interest will exist to the
extent that we may acquire properties in the same geographic areas where
properties owned by other programs, including those sponsored by our sponsor’s
affiliates are located. In such a case, a conflict could arise in the leasing
of properties in the event that we and another program, including another
program sponsored by our sponsor or its affiliates were to compete for the same
tenants, or a conflict could arise in connection with the resale of properties
in the event that we and another program, including another program sponsored
by our sponsor or its affiliates were to attempt to sell similar properties at
the same time. Conflicts of interest may also exist at such time as we or our
affiliates managing a property on our behalf seek to employ developers,
contractors or building managers, as well as under other circumstances.
Affiliated
Property Manager
When we acquired the “Wiseman Portfolio,” consisting of the
general partnership interests in 8 limited partnerships owning Class A or B
office buildings in Napa, Woodland, Fairfield, and Suisun City, CA, our Adviser
agreed to purchase the assets of the property management firm that managed the
properties, which is now known as Wiseman Commercial, Inc. (“Wiseman”). Wiseman continues to manage the leasing,
construction, and property for each of the Wiseman Portfolio properties under
the same terms as they were previously managed.
The Board has reviewed the terms of the management contracts and will
continue to review the terms of such agreements to attempt to ensure that we
are paying market rates for appropriate services.
Affiliated Transfer Agent
Our officers are also officers and
indirect owners of our transfer agent for Series A, B, and C Preferred Shares,
which is a registered transfer agent with the SEC. Computershare, Inc. is the
transfer agent for our common stock. The services our affiliated
preferred stock transfer agent provides are substantially similar to what a third-party
transfer agent would provide in the ordinary course of performing its functions
as a transfer agent, including, but not limited to: providing customer service
to our preferred stockholders, processing the distributions and any servicing
fees with respect to our preferred shares and issuing regular reports to our preferred
stockholders. Our transfer agent may retain and supervise third-party vendors
in its efforts to administer certain services. We believe that our affiliated
preferred stock transfer agent, through its knowledge and understanding of the
direct participation program industry which includes non-traded REITs, is particularly suited to provide us
with transfer agent and registrar services for our non-listed Series A, B and C
Preferred Stock. Our affiliated transfer agent also conducts transfer agent and
registrar services for MREIT, as well as other programs sponsored by our
sponsor. Our Board of Directors has
approved the terms of the transfer agent agreement, which provides for no
compensation to be paid to the affiliated transfer agent.
It is the duty of our board of directors
to evaluate the performance of our transfer agent. In addition, we will
reimburse our transfer agent for all reasonable expenses or other changes
incurred by it in connection with the provision of its services to us. Upon the
request of our transfer agent, we may also advance payment for substantial reasonable out-of-pocket expenditures to be incurred by it.
Receipt of Fees and Other Compensation by Our Advisers and
Affiliates
Our Advisers and affiliates receive
substantial fees from us. See “Management Compensation.” Some of these fees are
paid to our Advisers and affiliates regardless of the success or profitability
of the property. Specifically, our Advisers and affiliates receive:
● base management fees based on the gross
assets, and not based on performance of our properties; and
● bonus
management fee equal to 5% of adjusted funds from operations each quarter.
Although the base management fees are paid
regardless of success or profitability of a property, our independent directors
must approve all significant acquisitions or affiliated transactions as being
in the best interests of us and our stockholders. Further, if our independent
directors determine that the performance of our Advisers is unsatisfactory or
that the compensation to be paid to our Advisers is unreasonable, the
independent directors may take such actions as they deem to be in the best
interests of us and our stockholders under the circumstances, including
potentially terminating the advisory agreement and retaining a new Adviser.
The compensation
arrangements between us and our Advisers and affiliates could influence our Advisers’
advice to us, as well as the judgment of the affiliates of our Advisers who may
serve as our officers or directors. Among other matters, the compensation
arrangements could affect their judgment with respect to:
● the continuation, renewal or enforcement
of our agreements with our Advisers and affiliates, including the advisory
agreement;
● subsequent offerings of equity securities
by us, which may entitle our Advisers to additional asset management fees;
● property sales, which may entitle our
Advisers to possible success-based share of net sale proceeds;
● property acquisitions from other programs
sponsored by affiliates of our Advisers which may entitle such affiliates to
disposition fees and possible success-based sale fees in connection with its
services for the seller, as well as acquisition fees for our Advisers;
● property sales to other programs sponsored
by affiliates of our Advisers which may entitle such affiliates to acquisition
fees and expenses for its services to the buyer, as well as subordinated share
of net sale proceeds to our Advisers;
● whether
and when we seek to sell our assets and liquidate, which sale may entitle our
Advisers to a success-based distribution but could also adversely affect its
sales efforts for other programs depending upon the sales price.
Certain Conflict Resolution Procedures
Every transaction that we enter into with
our sponsor, our Advisers, or their affiliates will be subject to an inherent
conflict of interest. Our board of directors may encounter conflicts of
interest in enforcing our rights against any affiliate in the event of a
default by or disagreement with an affiliate or in invoking powers, rights, or
options pursuant to any agreement between us and our sponsor, our Advisers, or
any of their affiliates. In order to reduce or eliminate certain potential
conflicts of interest, we will address any conflicts of interest in two
distinct ways.
First, the nominating and corporate
governance committee of the Board will consider and act on any
conflicts-related matter required by our Articles of Amendment and Restatement
(“Charter”) or otherwise permitted by the Maryland General Corporation Law (“MGCL”)
where the exercise of independent judgment by any of our directors (who is not
an independent director) could reasonably be compromised, including approval of
any transaction involving our Advisers and their affiliates.
Second, our advisory agreements with our Advisers
contain a number of restrictions relating to (1) transactions we enter
into with our sponsor, our Advisers and their affiliates, (2) certain
future offerings, and (3) allocation of investment opportunities among
affiliated entities. These restrictions include, among others, the following:
● We will not purchase or lease properties
in which our sponsor, our Advisers, any of our directors or any of their
respective affiliates has an interest without a determination by a majority of
our directors, including a majority of the independent directors, not otherwise
interested in such transaction that such transaction is fair and reasonable to
us and at a price to us no greater than the cost of the property to the seller
or lessor, unless there is substantial justification for any amount that exceeds
such cost and such excess amount is determined to be reasonable. In no event
will we acquire any such property at an amount in excess of its appraised
value. We will not sell or lease properties to our sponsor, our Advisers, any
of our directors or any of their respective affiliates unless a majority of our
directors, including a majority of our independent directors, not otherwise
interested in the transaction determines that the transaction is fair and
reasonable to us.
● We will not make any loans to our sponsor,
our Advisers, any of our directors or any of their respective affiliates. In
addition, our sponsor, our Advisers, any of our directors and any of their
respective affiliates will not make loans to us or to joint ventures in which
we are a joint venture partner unless approved by a majority of our directors,
including a majority of the independent directors, not otherwise interested in
the transaction as fair, competitive and commercially reasonable, and no less
favorable to us than comparable loans between unaffiliated parties.
● Our Advisers and affiliates will be
entitled to reimbursement, at cost, for actual expenses incurred by them on
behalf of us or joint ventures in which we are a joint venture partner.
● Our
directors, including our independent directors, review the method used by our
Advisers for the allocation of the acquisition of properties by two or more
affiliated programs seeking to acquire similar types of properties (summarized
below) to ensure that it is applied fairly to us.
Our sponsor has adopted an investment
allocation policy with respect to real estate assets, which governs the
allocation of such investment opportunities among the programs sponsored by our
sponsor, and which provides as follows:
In the event that an investment
opportunity becomes available, our sponsor will first allocate such investment
opportunity to us. If we decline the
investment opportunity, our adviser will allocate such investment opportunity
to another program sponsored by our sponsor based on the following factors:
● the investment objectives of each program;
● the amount of funds available to each
program;
● the financial and investment
characteristics of each program, including investment size, potential leverage,
transaction structure and anticipated cash flows;
● the strategic location of the investment
in relationship to existing properties owned by each program;
● the effect of the investment on the
diversification of each program’s investments; and
● the
impact of the financial metrics of the investment on each program.
If, after consideration of the foregoing
factors, our sponsor determines that an investment opportunity is suitable for
two or more entities affiliated with our Advisers, then our sponsor will
allocate such investment opportunity among the entities in its sole and
absolute discretion, but generally will allocate such investment opportunity to
whichever entity has gone the longest since purchasing such an investment
opportunity.
If a subsequent development, such as a
delay in the closing of a property or a delay in the construction of a
property, causes any such investment, in the opinion of our Advisers, to be
more appropriate for a program other than the program that committed to make
the investment, our Advisers may determine that another program affiliated with
our Advisers or their affiliates will make the investment. Our directors,
including our independent directors, have a duty to ensure that the method used
by our Advisers for the allocation of the acquisition of properties by two or
more affiliated programs seeking to acquire similar types of properties is
applied fairly to us.
As a result of the foregoing, our Advisers
and affiliates could direct attractive investment opportunities to other
entities or even purchase them for their own account. Our advisory agreement
disclaims any interest in an investment opportunity known to our Advisers or
their affiliates that our advisers has not recommended to us.
We will not
accept goods or services from our sponsor, Advisers, or any affiliate thereof
or enter into any other transaction with our sponsor, advisers, or any
affiliate thereof unless a majority of our directors, including a majority of
our independent directors not otherwise interested in the transaction, approve
such transaction as fair and reasonable to us and on terms and conditions not
less favorable to us than those available from unaffiliated third parties.
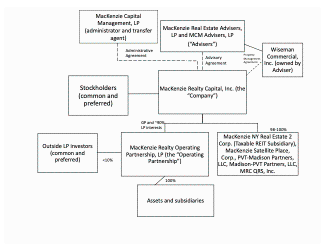
The following chart shows our ownership
structure and entities that are affiliated with our Advisers and sponsor.
|
*
|
The address of all of
these entities is 89 Davis Road, Suite 100, Orinda, CA 94563.
|
Investment Objectives
Our
primary investment objectives are:
● To acquire real estate assets at
substantial discounts to fair market value;
● To grow net cash from operations so that
an increasing amount of cash flow is available for distributions to investors
over the long term;
● To pay attractive and consistent cash
distributions;
● To preserve and protect shareholder value;
and
● To realize growth in the value of our
investment by timing their sale to maximize value.
There is no assurance that any of our
investment objectives will be met.
Investment Strategy
We
intend to use substantially all of the proceeds of this Offering to acquire,
manage, renovate or reposition, operate, selectively leverage, and lease
properties throughout the United States.
We
acquire primarily institutional-quality apartment and office properties where
we believe we can create long-term value for our stockholders, utilizing the
following investment strategies:
● Value-Add. We invest in
well-located institutional-quality properties with strong and stable cash flows
in demographically attractive knowledge economy growth markets where we believe
there exists significant potential for medium-term capital appreciation through
renovation or redevelopment, to reposition the asset and drive future rental
growth.
● Opportunistic. We invest in
properties available at opportunistic prices (i.e., at prices we believe are
below those available in an otherwise efficient market) that exhibit some
characteristics of distress, such as operational inefficiencies, significant
deferred capital maintenance, or broken capital structures providing an
opportunity for a substantial portion of total return attributable to
appreciation in value.
● Invest-to-Own. We selectively
invest in development of quality properties in target markets where we believe
we can capture significant premiums upon completion. We intend to use either
tender offers, a convertible loan, or convertible preferred equity structure to
provide income during the early stage and/or the ability to capture premiums at
completion by either acquiring controlling positions or exercising our
conversion rights to take ownership.
Please
see the Risk Factors Section beginning on page 16 of this Offering
Circular for the risks involved with this offering.
Distribution Policy
In
order to qualify as a REIT, we must distribute to our stockholders at least 90%
of our annual taxable income. We intend to make regular cash
distributions to our stockholders out of our cash available for distribution,
typically on a quarterly or annual basis for holders of our common and
preferred stock.
Our
Board of Directors will determine the amount of distributions to be distributed
to our stockholders on a quarterly basis. The board’s determination will be
based on a number of factors, including funds available from operations, our
capital expenditure requirements, and the annual distribution requirements
necessary to maintain our REIT qualification under the Code.
Our
distribution rate and payment frequency may vary from time to time. Generally,
our policy will be to pay distributions from cash flow from operations.
However, our distributions may be paid from sources other than cash flows from
operations, such as from the proceeds of this Offering, borrowings, advances
from our Adviser or from our Adviser’s deferral of its fees and expense
reimbursements, as necessary.
Limited Prospects for Future Liquidity
We currently do not plan to list
either the Series A Preferred Stock, the Series B Preferred Stock, or the
Series C Preferred Stock on any securities exchange. As discussed above, shares
of our common stock are listed on the Nasdaq Capital Market. In making a determination of whether any
future potential liquidity event is in our best interest, our Board may
consider a variety of criteria, including, but not limited to, portfolio
diversification, portfolio performance, our financial condition, potential
access to capital as a listed company, market conditions for the sale of our
assets or listing of our securities, internal management considerations and the
potential for stockholder liquidity.
Overview
of Significant Risk Factors
Investing in our preferred shares involves
a high degree of risk. You should carefully review the “Risk Factors”
section of this Offering Circular, beginning on page 16, which contains a detailed
discussion of the material risks that you should consider before you invest in
our preferred shares. Some of the more significant risks are those summarized
below:
● Investors will not have the opportunity to
evaluate or approve any Investments prior to our acquisition or financing
thereof.
● Investors will rely solely on the Adviser
to manage us and our Investments. The Adviser will have broad discretion
to invest our capital and make decisions regarding Investments.
● We may not be able to invest the net
proceeds of this Offering on terms acceptable to investors, or at all.
● We may change our targeted investment and
operational policies, including our policies with respect to distributions and
redemption of shares, without prior notice or your approval.
● An investor could lose all or a
substantial portion of the investment in us.
● There is no public trading market for our
preferred shares, and we are not obligated to effectuate a liquidity event or a
listing of our preferred shares on any nationally recognized stock exchange by
a certain date or at all. It will thus be difficult for an investor to
sell shares owned by the investor in us.
● We may fail to qualify or maintain our
qualification as a REIT for federal income tax purposes. We would then be
subject to corporate level taxation and regulation as an investment company and
we would not be required to pay any distributions to our stockholders.
● The offering price of our shares was not
established based upon any appraisals of assets we own or may own. Thus,
the initial offering price may not accurately reflect the value of our assets
at the time an investor’s investment is made.
● Substantial actual and potential conflicts
of interest exist between our investors and our interests or the interests of
our Adviser, and our respective affiliates, including conflicts arising out of
(a) allocation of personnel to our activities, (b) allocation of investment
opportunities between us, and (c) potential conflicts arising out of
transactions between us, on the one hand, and our Adviser and its affiliates,
on the other hand, involving compensation and incentive fees payable to our
Adviser or dealings in real estate transactions between us and the Adviser and
its affiliates.
● There are substantial risks associated
with owning, financing, operating, leasing and managing real estate.
● The amount of distributions we make is
uncertain. We may fund distributions from offering proceeds, borrowings,
and the sale of assets, to the extent distributions exceed our earnings or cash
flows from our operations if we are unable to make distributions from our cash
flows from operations. There is no limit on the amount of offering
proceeds we may use to fund distributions. Distributions paid from
sources other than cash flow or funds from operations may constitute a return
of capital to our stockholders. Rates of distributions may not be
indicative of our actual operating results.
● Accrued dividends with respect to the
Series B Preferred Stock might be treated as taxable dividends even though
holders do not receive any current cash.
● The purchasers of shares of Series A
Preferred Stock may have to report as current taxable income the difference
between the $22.50 per share issue price and the $25 per share redemption
premium as such redemption premium accretes.
● The Series C Preferred Stock ranks junior
to our Series A and Series B Preferred Stock (excluding the additional accrued 9% portion of the Series B Preferred
Stock dividend).
● The Series A, B and C Preferred Stock rank
junior to all of our indebtedness and other liabilities and are effectively
junior to all indebtedness and other liabilities of our subsidiaries.
We will pay substantial fees and reimburse
expenses to the Adviser. These fees and expenses will increase investors’
risk of loss and will reduce the amount available for Investments.
THE
OFFERING
|
Preferred stock offered by us..............................
|
|
637,171.16
shares of Series A Preferred Stock, 1,146,908.09 shares of Series B Preferred
Stock, and 1,146,908.09 shares of
Series C Preferred Stock, referred to herein as the “preferred shares.” Of these amounts, 150,000 shares of each
are reserved for the Dividend Reinvestment Program for each Series.
|
|
Preferred stock to be outstanding
after this Offering (assuming the maximum offering amount is sold).....................................
|
|
3,875,570
preferred shares, in a combination of Series A Preferred Stock, Series B
Preferred Stock, and Series C Preferred Stock.
|
|
Ranking...........................................................
|
|
The
preferred shares will rank, with respect to dividend rights and rights upon
liquidation, winding-up, or dissolution (i) senior to all classes of our
common stock, and to any other class or series of our capital stock issued in
the future unless the terms of that capital stock expressly provide that it
ranks senior to, or on parity with, the preferred shares, and (ii) junior to
any other class or series of our capital stock, the terms of which expressly
provide that it will rank senior to the preferred shares. The Series C Preferred Stock will rank junior,
with respect to dividend rights and rights upon liquidation, winding-up, or
dissolution, to the Series A Preferred Stock and B Preferred Stock (excluding
the additional accrued 9% portion of the Series B Preferred Stock dividend).
|
|
Stated Value.....................................................
|
|
Each
share of Series A Preferred Stock, Series B Preferred Stock, or Series C Preferred
Stock will have an initial “Stated Value” of $25.00, subject to appropriate
adjustment in relation to certain events as set forth in the Articles
Supplementary for each such Series.
|
|
Liquidation
Preference......................................
|
|
Upon any voluntary or involuntary
liquidation, dissolution or winding up of the Company, the holders of shares
of our preferred stock will be entitled to receive the following payments (in
each case, the “Liquidation Preference” applicable to such series):
Holders of Series A Preferred Stock will
be entitled to be paid, as the Liquidation Preference applicable to such
shares, an amount equal to the Stated Value of $25 per share, plus an amount
equal to any accrued and unpaid dividends thereon.
Holders of Series B Preferred Stock will
be entitled to be paid the Liquidation Preference applicable to the Series B
Preferred Stock, which is dependent on the Accrued Preference Value for each
share of such stock. The “Accrued
Preference Value” for each outstanding share of Series B Preferred Stock is
equal to (i) the Stated Value of $25.00 per share of Series B Preferred Stock
plus (ii) an amount equal to any accrued and unpaid dividends (whether
or not authorized or declared) thereon to and including the date of payment
of such amount, but without interest.
The Liquidation Preference for each
outstanding share of Series B Preferred Stock will be calculated as follows: (i)
from the Acquisition Date applicable to such share until the third
anniversary of such date, the dollar value of the Accrued Preference Value applicable
to such share as of the date such Liquidation Preference is calculated and
(ii) from and after the third anniversary of the Acquisition Date applicable
to such share, an amount equal to the greater of (A) the dollar value of the
Accrued Preference Value applicable to such share as of the date the
Liquidation Preference is calculated or (B) an amount equal to the dollar
value of the amount of common stock the holder of such share of Series B
Preferred Stock would be entitled to receive as of the date the Liquidation
Preference is calculated, pursuant to the provisions described below in this
summary under the heading “Series B Preferred Repurchase/Additional
Conversion Rights.”
Holders of Series C Preferred Stock will
be entitled to be paid, as the Liquidation Preference applicable to such
shares, an amount equal to the Stated Value of $25 per share, plus an amount
equal to any accrued and unpaid dividends thereon.
|
|
Dividend
rights.................................................
|
|
Holders of our preferred shares are
entitled to receive, when and as authorized by our Board of Directors and
declared by us out of legally available funds, cumulative cash dividends on
each preferred share at an annual rate of 6% for Series A Preferred Stock on
the Stated Value, at an annual rate of 3% for Series B Preferred Stock, and
at an annual rate of 9% for the Series C Preferred Stock. This is a preference, not a guarantee, but
is a term contained in the Company’s Charter; however, the Board could
suspend the dividend at any time, although it would continue to accrue. The dividend must be paid before the common
stock can be paid a dividend, and before the Adviser can receive any
incentive management fee. Further, the
Series B Preferred Stock will also accrue dividends at the rate of 9% per
annum on the Stated Value, which will begin to be paid at the same time and
in the same amounts per share with distributions paid to the holders of common
stock, once holders of common stock have initially received distributions from
and after December 31, 2022 equal to 10% per annum on the $7.38 per share NAV
of the common stock as of such date, and the remainder of which will be paid
no later than at redemption, liquidation or conversion. For additional
information, see “Description of Securities – Preferred Stock – Preferred
Dividend” herein.
|
|
Company
Special Redemption Right...................
|
|
If at any time the Company’s shares of common
stock are traded on a national securities exchange with at least three market
makers or a New York Stock Exchange Specialist, the Company will have the
right to redeem the preferred shares at any time at a redemption price equal
to (i) the Liquidation Preference for each share of Series A Preferred Stock,
(ii) the Accrued Preference Value for each share of Series B Preferred Stock,
and (iii) the Liquidation Preference for each share of Series C Preferred
Stock, in each case as of the Special Redemption Date selected by the
Company. For additional information, see “Description of Securities –
Preferred Stock – Special Redemption Rights” herein.
|
|
Company
Optional Early Redemption Right........
|
|
In addition to the Special Redemption Right
described above, we also may redeem preferred shares for cash, in whole or in
part from time to time, during an Early Redemption Period which began January
1, 2023 for the Series A Preferred Stock, on January 1, 2025 for the Series B
Preferred Stock, and will begin on January 1, 2027 for the Series C Preferred
Stock. The price per preferred share applicable to any such Optional Early
Redemption will be equal to (i) the Liquidation Preference for each share of
Series A Preferred Stock, (ii) the Accrued Preference Value for each share of
Series B Preferred Stock, and (iii) the Liquidation Preference for each share
of Series C Preferred Stock, in each
case as of the applicable Early Redemption Date selected by the Company. For
additional information, see “Description of Securities – Preferred Stock – Optional
Early Redemption” herein.
|
|
Holders’
Conversion Right.................................
|
|
Upon receipt of notice from us that we
intend to redeem the preferred shares pursuant to the Optional Early
Redemption Right, any holder thereof is entitled to elect instead to receive
shares of our common stock as follows with respect to the Series A Preferred Stock,
Series B Preferred Stock, and Series C Preferred Stock, and holders of the
Series B Preferred Stock also will have the conversion election in the event
we exercise the Company’s Special Redemption Right:
(i) Series
A Preferred Stock and Series C Preferred Stock Conversion Right: Each holder
of Series A Preferred Stock and Series C Preferred Stock shall be entitled to
elect to receive, in lieu of the aggregate Liquidation Preference for the
applicable number of preferred shares, the number of shares of common stock
equal to the value of such aggregate Liquidation Preference divided by $102.50.
(ii) Series B Preferred Stock Conversion
Right: Each holder of Series B Preferred Stock shall be entitled to elect to
receive, in lieu of the aggregate Accrued Preference Value for the applicable
number of preferred shares, the number of shares of common stock equal to
such aggregate Accrued Liquidation Preference divided by (i) the lower of $102.50
or the Board’s most recent estimated net asset value per share of common
stock, if the common stock is not then listed on a national securities
exchange or an over-the-counter market as reported by OTC Markets Group, Inc.
or another similar organization or (ii) if the common stock is then listed on
a national securities exchange or an over-the-counter market as described
above, the lower of $102.50 or the volume weighted average of the Last
Reported Sale Price per share of common stock as reported on such market for
the twenty (20) trading days prior to the Conversion Date (defined as the
date of the giving of notice of an exercise of conversion rights and
surrender of the underlying shares of Series B Preferred Stock to be
converted). For purposes of this calculation, the “Last Reported Sale Price”
for the common stock means, at any time that the common stock is listed on a
national securities exchange or an over-the-counter market as described
above, the closing sale price per share (or if no closing sale price is
reported, the average of the bid and ask prices or, if more than one in
either case, the average of the average bid and the average ask prices) on
that date as reported in composite transactions for the principal U.S.
national or regional securities exchange on which the common stock is traded.
For additional information, see “Description of Securities – Preferred Stock
– Conversion Right” herein.
|
|
Temporary
suspension of preferred stock share repurchase program……….
|
|
Our Board of Directors has temporarily
suspended our share repurchase program with respect to all three of our
Series A, Series B, and Series C Preferred Stock in order to enable the
Company to better react to strategic alternatives that may from time to time
be presented for evaluation by its financial advisor, Maxim Group LLC. The
Board expects to reassess the Repurchase Program Suspension in due course. See
“Description of Securities — Temporary Suspension of the Share Repurchase
Program with Respect to the Series A, Series B, and Series C Preferred Stock”
and “Risk Factors — Our board
of directors has temporarily suspended our preferred share repurchase program
with respect to the Series A, Series B, and Series C preferred shares.”
|
|
Series
A Preferred Repurchase Rights.................
|
|
The terms of the Series A Preferred
provide that upon the request of a holder of Series A Preferred Stock, we
may, at the sole discretion of the Company’s Board and subject to the
Repurchase Program Suspension described above, repurchase the Series A
Preferred shares held by such holder as set forth below. However, the subscription agreement for
purchases of Series A Preferred Stock pursuant to this Offering Circular at
$22.50 per share (the “Series A Purchase Price”) will provide that such
purchasers will not be eligible to request repurchase at such prices, but
rather, may only request repurchase at (i) 88% of the Series A Purchase Price
from the day the stockholder acquired such shares (the “Series A Acquisition
Date”) until one year thereafter, (ii) 91% of the Series A Purchase Price
from the first anniversary until the second anniversary of the Series A
Acquisition Date, (iii) 94% of the Series A Purchase Price from the second
anniversary until the third anniversary of the Series A Acquisition Date,
(iv) 97% of the Series A Purchase Price from the third anniversary until the
fourth anniversary of the Series A Acquisition Date, and (v) $25.00 per share
beginning on the fourth anniversary of the Series A Acquisition Date and thereafter
(collectively, the “Series A Repurchase Price Schedule”).
The Charter provides for the repurchase
of Series A Preferred Stock, at the sole discretion of the Company’s Board, for
(i) 88% of $25.00 (the “Series A Stated Value”) from the day the stockholder
acquired such shares (the “Series A Acquisition Date”) until one year
thereafter; (ii) 91% of the Series A Stated Value from the first anniversary
until the second anniversary of the Series A Acquisition Date; (iii) 94% of
the Series A Stated Value from the second anniversary until the third
anniversary of the Series A Acquisition Date; (iv) 97% of the Series A Stated
Value from the third anniversary until the fourth anniversary of the Series A
Acquisition Date; and (v) $25.00 per share beginning on the fourth
anniversary of the Series A Acquisition Date and thereafter. Additionally,
subject to Board discretion, in the case of the death or complete disability
of a stockholder, from and after the second anniversary of the Series A Acquisition
Date, we may repurchase the Series A Preferred shares held by such holder in
exchange for payment of $25.00 per share for such a repurchase. Subject to
the availability of an exemption from registration or an effective
registration statement, a holder of Series A Preferred Shares may request
that any such repurchase may be funded through the issuance of shares of
common stock. For additional information, see “Description of Securities –
Preferred Stock – Series A Preferred Share Repurchase Program; Repurchase Rights”
herein.
|
|
Series B
Preferred Repurchase/Additional
Conversion
Rights.............................................
|
|
Shares of Series B Preferred Stock will
not be considered for repurchase by the Company prior to the third
anniversary of the date each such share was issued to the initial holder
thereof (the “Series B Acquisition Date”). Thereafter, upon the request of a
holder of Series B Preferred Stock, we may, at the sole discretion of the
Company’s Board and subject to the Repurchase Program Suspension described above,
repurchase the Series B Preferred shares held by such holder for (i)
beginning on the third anniversary of the Acquisition Date and continuing for
a one-year period, 97% of the Accrued Preference Value and (ii) beginning on
the fourth anniversary of the Acquisition Date and thereafter, 100% of the Accrued
Preference Value. At the option of the holder of any shares of Series B
Preferred Stock as to which the Board approves such a repurchase request (or
at the option of the Board if the common stock is then listed on a national
securities exchange or an over-the-counter market as reported by OTC Markets
Group, Inc.), the applicable repurchase consideration may be paid – subject to
the availability of an exemption from registration or an effective
registration statement – by issuing a number of shares of common stock
determined by dividing such amount (A) by the lower of a price of $102.50 per
share of common stock or at the Board’s most recent estimated net asset value
per share of common stock, if the common stock is not then listed as
described above or (B) by the lower of $102.50 per share or a 20-day volume weighted average trading price, if
the common stock is then so listed. Additionally – and again subject to the
availability of an exemption from registration or an effective registration
statement – a holder of Series B Preferred shares shall also have the right
from and after the third anniversary of the applicable Acquisition Date, in
the event the Board declines such a requested cash redemption, to require the
Company to exchange such shares of Series B Preferred Stock for shares of
common stock in accordance with the timing and valuation criteria described
above. For additional information, see “Description of Securities – Preferred
Stock – Series B Preferred Share Repurchase Program; Additional Repurchase
and Conversion Rights” herein.
|
|
Series
C Preferred Repurchase Rights.................
|
|
Upon the request of a holder of Series C
Preferred Stock, we may, at the sole discretion of the Company’s Board and subject
to the Repurchase Program Suspension described above, repurchase the Series C
Preferred Stock held by such holder for (i) $22 per share from the day the
stockholder acquired such shares (the “Series C Acquisition Date”) until one
year thereafter; (ii) $22.75 per share from the first anniversary until the
second anniversary of the Series C Acquisition Date; (iii) $23.50 per share
from the second anniversary until the third anniversary of the Series C
Acquisition Date; (iv) $24.25 per share from the third anniversary until the
fourth anniversary of the Series C Acquisition Date; and (v) $25.00 per share
beginning on the fourth anniversary of the Series C Acquisition Date and
thereafter. Additionally, subject to Board discretion, in the case of the
death or complete disability of a stockholder, from and after the second
anniversary of the Series C Acquisition Date, we may repurchase the Series C
Preferred Stock held by such holder in exchange for payment of $25.00 per
share for such a repurchase. Subject to the availability of an exemption from
registration or an effective registration statement, a holder of Series C
Preferred Stock may request that any such repurchase may be funded through
the issuance of shares of common stock. For additional information, see
“Description of Securities – Preferred Stock – Series C Preferred Share
Repurchase Program; Repurchase Rights” herein.
|
|
Voting
rights....................................................
|
|
Our preferred shares will not be
entitled to vote except on limited matters affecting preferred shares.
|
|
Use
of Proceeds.................................................
|
|
If the maximum number of preferred
shares are sold, we estimate that the net proceeds of this Offering will be
approximately $64,513,580.00 after deducting organizational and offering
expenses and working capital reserves. See “Use of Proceeds”. Net
proceeds from this Offering will be used to acquire Investments, to pay for
expenses incurred by us from continued operations, and for any other proper
Company purpose.
|
|
|
|
|
Preferred Shares
As set forth in
the table above, we are offering a total of 637,171.16 shares of our Series A, 1,146,908.09
of our Series B, and 1,146,908.09 shares
of our Series C preferred stock at an initial price of $22.50 per share for the
Series A and $25.00 per share for the Series B and C. Holders of our Series A Preferred
Stock will share proportionately in any dividends authorized by our Board of
Directors and declared by us on the Series A Preferred Stock, holders of our
Series B Preferred Stock will share proportionately in any dividends authorized
by our Board of Directors and declared by us on the Series B Preferred Stock,
and holders of our Series C Preferred Stock will share proportionately in any
dividends authorized by our Board of Directors and declared by us on the Series
C Preferred Stock. Preferred shares will have limited voting rights. Preferred shares
offered through this Offering Circular do not have any pre-emptive purchasing
rights, nor are there cumulative voting rights.
Restrictions
on the Transfer of Preferred Shares
Generally,
our Investors will be able to freely transfer their shares to any other person
because the shares registered through this Offering Circular are “unrestricted.”
Holders
of our preferred shares will, however, be required to conform to the
requirements of our Subscription Agreement. The Subscription Agreement, among
other things, requires holders of our preferred shares to receive permission to
sell their shares. In fact, we can require a transferee, or the intended
purchaser of our preferred shares to provide an affidavit as to the quantity of
shares that are intended to be purchased.
The
purpose of this permission process is not to prevent the general transfer of
shares, but is rather intended to ensure that the intended purchaser of our preferred
shares will not hold more than an allowed 9.8% in value of the aggregate of our
outstanding shares of capital stock (defined to include all classes or series
of stock, including both common and preferred). This restriction is embodied in
our Charter. Our Charter also allows us to rule on any transfer of stock so
that we can again ensure that we do not endanger our standing as a REIT.
Ownership
Restrictions on Preferred Shares
Our
Charter contains a restriction on ownership of our shares that generally
prevents any one person from owning more than 9.8% (in value or in number of
shares, whichever is more restrictive) of the outstanding shares of our common stock
or more than 9.8% in value of the aggregate of our outstanding shares of
capital stock (defined to include all classes or series of stock, including
both common and preferred), unless otherwise excepted (prospectively or
retroactively) by our Board of Directors. Our Charter also contains other
restrictions designed to help us maintain our qualification as a REIT.
See “Description of Securities – Restrictions on Ownership and Transfer.”
Exempt
Offering
This
is a Tier 2 offering under Regulation A where the offered securities will not
be listed on a registered national securities exchange upon qualification. This
Offering is being conducted pursuant to an exemption from registration under
Regulation A of the Securities Act of 1933, as amended.
Tier
2 Reporting Requirement
Following
this Tier 2 Regulation A offering, we will be required to comply with certain
ongoing disclosure requirements under Rule 257 of Regulation A. Because we are already a reporting company
under Section 12 of the Exchange Act, we will continue to file:
(i)
an
annual report with the SEC on Form 10-K;
(ii)
quarterly
reports with the SEC on Form 10-Q; and
(iii)
current
reports with the SEC on Form 8-K.
The
necessity to file current reports will be triggered by certain corporate
events.
Contact
Information
The mailing
address of our principal executive offices is:
MacKenzie Realty Capital, Inc.
89 Davis Road, Suite 100, Orinda, CA 94563
Attn: Investor Relations
Our telephone number is 1.800.854.8357 and
our website address is www.mackenzierealty.com.
You
may direct inquiries to: Investors@mackenziecapital.com.
RISK
FACTORS
An investment in our common and
preferred stock involves substantial risks. You should specifically consider
the following material risks in addition to the other information contained in
this Offering Circular before purchasing shares. The occurrence of any of
the following risks might cause you to lose all or a significant part of your
investment.
The risks and
uncertainties discussed below are not the only ones we face, but do represent
those risks and uncertainties that we believe are most significant to our
business, operating results, prospects and financial condition. Some
statements in this Offering Circular, including statements in the following
risk factors, constitute forward-looking statements. As used herein, the term
“you” refers to our current stockholders or potential investors in our common
or preferred stock, as applicable. Please refer to the section entitled “Statements
Regarding Forward-Looking Information.”
Each prospective
investor should consider carefully, among other risks, the following material
risks, and should consult with his own legal, tax, and financial advisors with
respect thereto prior to investing in shares of our preferred shares.
RISK FACTORS SUMMARY
The
following is a summary of the most significant risks relating to our business
activities that we have identified. If any of these risks occur, our business,
financial condition, or results of operation, including our ability to generate
cash and make distributions, could be materially adversely affected. For a more
complete understanding of our material risk factors, this summary should be
read in conjunction with the detailed discussion of our risk factors, which
follows this summary.
Risks Related to Investing in Real
Estate
•
Real property investments are
subject to various risks, many of which are beyond our control, which could
cause declines in our operating revenues and/or the underlying value of one or
more of our properties.
•
The market for real estate
investments is highly competitive and investments in real estate-related assets
can be speculative.
•
Illiquidity of real estate investments could
significantly affect our ability to respond to adverse changes in the
performance of our properties and harm our financial condition.
•
We could be exposed to environmental
liabilities, which could impact the value of real properties that we may
acquire or underlying our investments.
•
We may not obtain independent
third-party appraisals or valuation reports on all of our investments.
•
We may be adversely affected by
unfavorable economic conditions, particularly in the specific geographic areas
where our investments are concentrated.
•
Inflation may adversely affect our
financial condition and results of operations.
•
Our success is materially dependent
on attracting qualified tenants and, when vacancies occur, we may not be able
to re-lease or renew leases at the properties held by us on terms favorable to
us, or at all.
•
The bankruptcy, insolvency, or
diminished creditworthiness of our tenants under their leases or delays by our
tenants in making rental payments could seriously harm our operating results
and financial condition.
•
Significant restrictions on transfer
and encumbrance of investments subject to mortgage or other debt financing are
expected, and we may experience delays in the sale of an investment.
•
We face possible risks associated
with climate change.
Risks Related to Our Financial Position
•
Future debt or capital stock
issuances by the Company could dilute the ownership interest of current
stockholders and could subject us to covenants restricting our future financial
and operating flexibility.
•
We do not have guaranteed cash flow,
and if we pay distributions from sources other than our cash flow from
operations, we will have fewer funds available for investments and our
stockholders’ overall return will be reduced.
•
We may in the future choose to pay
dividends in our own stock, in which case you may be required to pay income
taxes in excess of the cash dividends you receive.
Risks Related to Our Business Operations and
Strategy
•
We may change our targeted
investment and operational policies without stockholder consent.
•
Our Board of Directors can revoke
our REIT qualification without stockholder approval.
•
Our future growth will depend on our
ability to acquire real estate investments in several competitive real estate
markets, and lack of diversification in numbers or types of investments
increases our dependence on individual investments.
•
We may experience difficulty in
ultimately selling properties which no longer fit our investment criteria or
are impractical to lease and maintain, which could force us to sell a property
at a price that reduces the return to our investors.
•
Subject to broad investment
guidelines approved by our Board of Directors, we are dependent on the
investment analysis and management services provided by our Advisers and their
key personnel for our success.
•
Our investments will be carried at
estimated fair value as determined by our Advisers and there may be uncertainty
as to the value of these investments.
•
We, through our Advisers, are often
required to make a number of judgments in applying accounting policies, and
different estimates and assumptions in the application of these policies could
result in changes to our reporting of financial condition and results of
operations.
•
A cyber incident or deficiency in
our cybersecurity could disrupt our operations, compromise confidential
information, damage our business relationships and negatively impact our
financial results.
Risks
Related to Our Organization and Corporate Structure
•
Our Charter permits our Board of
Directors to issue stock with terms that may subordinate the rights of common
stockholders or preferred shareholders or discourage a third party from
acquiring us in a manner that might result in a premium price to our stockholders.
•
Our rights and the rights of our
shareholders to recover claims against our officers, directors, and our
Advisers are limited.
Risks Related to Conflicts of Interest
•
The Advisory Agreements with our
Advisers were not negotiated on an arm’s-length basis and may not be as
favorable to us as if they had been negotiated with an unaffiliated third
party.
•
We may have conflicts of interest
with our Adviser and other affiliates, which may result in investment decisions
that are not in the best interest of our stockholders.
•
The fees payable to our Real Estate
Adviser under the amended Advisory Management Agreement effective January 1,
2026, may cause our Real Estate Adviser’s economic interests to diverge from
the interests of our stockholders.
•
Our Advisers, their officers and
their respective affiliates will face conflicts of interest relating to the
purchase and leasing of real estate investments, and such conflicts may not be
resolved in our favor.
•
We have not adopted any specific
conflicts of interest policies, and, therefore, other than in respect of the
restrictions placed on our Advisers in the Advisory Agreements, we will be
reliant upon the good faith of our Advisers, officers, and directors in the
resolution of any conflict.
Risks Associated with Debt Financing
•
We expect to use mortgage and other
debt financing to acquire properties or interests in properties and otherwise
incur other indebtedness, which could subject us to the risk of losing
properties in foreclosure if our cash flow is insufficient to make loan
payments and reduce the cash available for distribution to stockholders.
•
High levels of debt or increases in
interest rates could increase the amount of our loan payments, which could
reduce the cash available for distribution to stockholders.
•
High mortgage rates may make it
difficult for us to finance or refinance properties, may require us to pay down
loans with investment capital, which could reduce the number of properties we
can acquire, our cash flow from operations, and the amount of cash
distributions we can make.
•
If we are required to make payments
under any “bad boy” carve-out guaranties that we may provide in connection with
certain mortgages and related loans, our business and financial results could
be materially adversely affected.
Risks Related to Our Taxation as a REIT
•
Failure to remain qualified as a
REIT would result in higher taxes and reduced cash available for distribution
to our stockholders.
•
Complying with minimum required
distributions and other REIT requirements may cause us to forego otherwise
attractive opportunities or liquidate otherwise attractive investments.
•
The stock ownership limit imposed by
the Code for REITs and in our Charter may inhibit market activity in our stock
and may restrict our business combination opportunities.
•
Dividends payable by REITs do not
qualify for the reduced tax rates available for some dividends, and a failure
to make required distributions would subject us to U.S. federal corporate
income tax.
•
The prohibited transactions tax may
subject us to tax on our gain from sales of property and limit our ability to
dispose of our properties.
•
We may be subject to adverse
legislative or regulatory tax changes that could reduce the market price of our
shares.
Risks Relating to Issuance of Warrants
•
There are unresolved
issues relating to the rights of the holder of our unfunded warrants, who has
taken the position that dividends are payable on those warrants notwithstanding
that we did not agree to pay such dividends, and any claims for participation
in future dividends could be material if and when we resume dividend payments
on our common stock.
Risks
Relating to Our Common Stock, Nasdaq Listing and Liquidity
•
We may be unable to satisfy the continued
listing standards of The Nasdaq Capital Market, and our common stock could be
delisted.
Risks Related to Our Preferred Shares and Your
Investment in This Offering
•
There is no trading market for our
preferred shares. Your ability to sell
your preferred shares, pursuant to our preferred share
repurchase program (which is currently suspended) or otherwise, will be limited
and you could lose your entire investment in this offering.
•
Shares of our preferred
stock have limited voting rights.
•
Shares of our preferred
stock have no participation in Company profits, while it is anticipated that
the shares of Series B Preferred Stock will participate in Company growth to a
significant extent.
•
Accrued dividends with
respect to the Series B Preferred Stock might be treated as taxable dividends
even though holders do not receive any current cash.
•
The Series C Preferred
Stock ranks junior to our Series A and Series B Preferred Stock (excluding the
additional accrued 9% portion of the Series B Preferred Stock dividend).
•
The Series A, B and C
Preferred Stock rank junior to all of our indebtedness and other liabilities
and are effectively junior to all indebtedness and other liabilities of our
subsidiaries.
•
Your interest in us will
be diluted if we issue additional shares, which could reduce the overall value
of your investment.
Risks Related to Investing in Real Estate
Real estate investments are subject to risks
particular to real property, including:
• Adverse changes in national and local economic and market
conditions, including the credit and securitization markets;
• Impacts from governmental laws and regulations, fiscal policies and
zoning ordinances, including the impact of environmental laws and regulations,
and related compliance costs, including costs to comply with future changes;
• Takings by condemnation or eminent domain;
• Real estate conditions, such as an oversupply of or a reduction in
demand for real estate space in the area, which could adversely affect market
rental rates;
• The perceptions of tenants and prospective tenants of the
convenience, attractiveness and safety of our properties;
• Competition from comparable properties;
• The occupancy rate of our properties;
• The ability to collect all rent from tenants on a timely basis;
• The effects of any bankruptcies or insolvencies of major tenants;
• The expense of re-leasing space;
• Changes in interest rates and in the availability, cost and terms
of mortgage funding;
• Economic or physical decline of the areas where our investments are
located;
• Deterioration in the physical condition of our investments and
resulting maintenance expenses;
• Acts of war or terrorism, including the consequences of terrorist
attacks;
• Acts of God, including earthquakes, floods and other natural
disasters, which may result in uninsured losses; and
• Cost of compliance with the Americans with Disabilities Act.
Any of these or similar events may reduce our
return from an affected property or investment and reduce or eliminate our
ability to make distributions to stockholders.
The market for real estate investments is highly
competitive.
Identifying attractive real estate investment
opportunities is difficult and involves a high degree of uncertainty.
Furthermore, the historical performance of a particular property or market is
not a guarantee or prediction of the property’s or market’s future performance.
There can be no assurance that we will be able to locate suitable acquisition
opportunities in our target markets, achieve our investment goal and
objectives, or fully deploy our cash.
Because of the recent growth in demand for real
estate investments, there may be increased competition among investors to
invest in the same asset classes as we do. This competition may lead to an
increase in investment prices or otherwise less favorable investment terms. If
this situation occurs with a particular investment, our return on that
investment is likely to be less than the return we could have achieved if we
had invested at a time of less investor competition for the investment. For
this and other reasons, the Real Estate Adviser is under no restrictions
concerning the timing of investments.
Real estate investments are not as liquid as
other types of assets, which may reduce economic returns to our stockholders.
Real estate investments are not as liquid as
some other types of investments. The market for the sale of real estate
properties can vary greatly and it may take a significant amount of time for us
to sell any particular property on favorable terms, if at all. As a result, our
ability to sell under-performing assets in our portfolio or respond to changes
in economic and other conditions may be relatively limited.
Investments in real estate-related assets can be
speculative.
Investments in real estate-related assets can
involve speculative risks and always involve substantial risks. No assurance
can be given that the Advisers will be able to execute the investment strategy
or that stockholders in the company will realize their investment objectives.
No assurance can be given that our stockholders will realize a substantial
return (if any) on their investment or that they will not lose their entire
investment in us. For this reason, each
prospective purchaser of our preferred shares should carefully read this
Offering Circular and all exhibits to this Offering Circular. All such
persons or entities should consult with their attorney or business advisor
prior to making an investment.
We will likely receive limited representations and warranties from sellers.
Investments will likely be acquired with limited
representations and warranties from the seller regarding the condition of the
investment, the status of leases, the presence of hazardous substances, the
status of governmental approvals and entitlements and other significant matters
affecting the use, ownership and enjoyment of the investment. As a result, if
defects in an investment or other matters adversely affecting an investment are
discovered, we may not be able to pursue a claim for damages against the seller
of the investment. The extent of damages that we may incur as a result of such
matters cannot be predicted, but potentially could result in a significant
adverse effect on the value of the affected investments.
We may be subject to the risk of liability and
casualty loss as the owner of an investment.
We will maintain insurance against certain
liabilities and other losses for an investment, but the insurance obtained will
not cover all amounts or types of loss. There is no assurance that any loss
that may occur will be insured or that, if insured, the insurance proceeds will
be sufficient to cover the loss.
There are certain categories of loss that may be
or may become uninsurable or not economically insurable, such as earthquakes,
floods and liabilities related to hazardous waste. Further, if losses arise
from hazardous substance contamination that cannot be recovered from a
responsible party, the financial viability of the affected investment may be
substantially impaired. It is possible that we will acquire an investment with
known or unknown environmental problems that may adversely affect our investments.
We could be exposed to environmental liabilities
with respect to investments to which we take title.
In the course of our business, and taking title
to properties, we could be subject to environmental liabilities with respect to
such properties. In such a circumstance, we may be held liable to a
governmental entity or to third parties for property damage, personal injury,
investigation and clean-up costs incurred by these parties in connection with
environmental contamination, or we may be required to investigate or clean up
hazardous or toxic substances or chemical releases at a property. The costs associated
with investigation or remediation activities could be substantial. If we become
subject to significant environmental liabilities, our business, financial
condition, liquidity and results of operations could be materially and
adversely affected.
Liability relating to environmental matters may
impact the value of the properties that we may acquire or underlying our
investments.
Under various U.S. federal, state and local
laws, an owner or operator of real property may become liable for the costs of
removal of certain hazardous substances released on its property. These laws
often impose liability without regard to whether the owner or operator knew of,
or was responsible for, the release of such hazardous substances. If we fail to
disclose environmental issues, we could also be liable to a buyer or lessee of
a property.
There
may be environmental problems associated with our properties which we were
unaware of at the time of acquisition. The presence of hazardous substances may
adversely affect our ability to sell real estate, including the affected
property, or to borrow additional funds using real estate as collateral. The
presence of hazardous substances, if any, on our properties may cause us to
incur substantial remediation costs and potential costs of indemnification in
the case of properties we sell or rent to others, thus harming our financial
condition. The discovery of material environmental liabilities attached to such
properties could have a material adverse effect on our results of operations
and financial condition and our ability to make distributions to our
stockholders.
Discovery of previously undetected
environmentally hazardous conditions, including mold or asbestos, may lead to
liability for adverse health effects and costs of remediating the problem could
adversely affect our operating results.
Under various U.S. federal, state and local
environmental laws, ordinances and regulations, a current or previous owner or
operator of real property may be liable for the cost of removal or remediation
of hazardous or toxic substances on, under or in such property. The costs of
removal or remediation could be substantial. Such laws often impose liability
whether or not the owner or operator knew of, or was responsible for, the
presence of such hazardous or toxic substances. Environmental laws also may impose
restrictions on the manner in which property may be used, and these
restrictions may require substantial expenditures. Environmental laws provide
for sanctions in the event of noncompliance and may be enforced by governmental
agencies or, in certain circumstances, by private parties. Certain
environmental laws and common law principles could be used to impose liability
for release of and exposure to hazardous substances, including
asbestos-containing materials into the air, and third parties may seek recovery
from owners or operators of real properties for personal injury or property
damage associated with exposure to released hazardous substances. The cost of
defending against claims of liability, of compliance with environmental
regulatory requirements, of remediating any contaminated property, or of paying
personal injury claims related to any contaminated property could materially
adversely affect our business, assets or results of operations and,
consequently, amounts available for distribution to our security holders.
Adverse economic conditions may negatively
affect our results of operations and, as a result, our ability to make
distributions to our stockholders or to realize appreciation in the value of
our investments.
Our operating results may be adversely affected
by market and economic challenges, which may negatively affect our returns and
profitability and, as a result, our ability to make distributions to our
stockholders or to realize appreciation in the value of our investments. These
market and economic challenges may include, but are not limited to, the
following:
- any future downturn in the U.S. economy and the related
reduction in spending, reduced home prices and high unemployment could
result in tenant defaults under leases, vacancies at our office,
industrial, retail or multifamily properties, and concessions or reduced
rental rates under new leases due to reduced demand;
- the rate of household formation or population growth in
our target markets or a continued or exacerbated economic slow-down
experienced by the local economies where our properties are located or by
the real estate industry generally may result in changes in the supply of
or demand for apartment units in our target markets; and
- the failure of the real estate market to attract the
same level of capital investment in the future that it attracts at the
time of our purchases or a reduction in the number of companies seeking to
acquire properties may result in the value of our investments not
appreciating or decreasing significantly below the amount we pay for these
investments.
The length and severity of any economic
slow-down or downturn cannot be predicted. Our operations and, as a result, our
ability to make distributions to our stockholders and/or our ability to realize
appreciation in the value of our properties could be materially and adversely
affected to the extent that an economic slow-down or downturn is prolonged or
becomes severe.
We may be adversely affected by unfavorable economic changes in
the specific geographic areas where our investments are concentrated.
We expect to diversify our investments and
expect that our real estate investments will be located throughout the United
States. However, our investments may nonetheless result in significant
concentration in one or more target markets. Our largest concentrations of
investments are in California and Georgia. Adverse conditions (including
business layoffs or downsizing, industry slowdowns, changing demographics and
other factors) in the areas where our investments are located and/or
concentrated, including any cities or towns within such target States, and
local real estate conditions (such as oversupply of, or reduced demand for,
office, industrial, retail or multifamily properties) may have an adverse
effect on the value of our investments. A material decline in the demand or the
ability of tenants to pay rent, or the general market for sales of multi-family
properties in such geographic areas may result in a material decline in our
cash available for distribution to our stockholders.
Inflation may
adversely affect our financial condition and results of operations.
Increased inflation
could have a more pronounced negative impact on any variable-rate debt we incur in the future and on our results
of operations. During times when inflation is greater than increases in rent,
the contracted rent increases called for under our leases may be unable to keep
pace with the rate of inflation. Additionally, substantial inflationary
pressures and increased costs may have an adverse impact on our tenants, which
may adversely affect the ability of our tenants to pay rent.
Our success is materially dependent on
attracting qualified tenants.
We will not collect revenue for a property while
it is vacant and we will be responsible for all utility costs and maintenance
services until we are able to lease it. Our success is dependent on the
financial stability of tenants in the aggregate. If we cannot rent our
properties or our tenants default on our leases or fail to comply with the
terms of our leases, our operations, financial performance, and the quality and
value of our properties could be negatively impacted.
We may not be able to re-lease or renew leases
at the investments held by us on terms favorable to us or at all.
We are subject to risks that upon expiration or
earlier termination of the leases for our properties that such properties may
not be re-leased or, if re-leased, the terms of the renewal or re-leasing
(including the costs of required renovations or concessions to tenants) may be
less favorable than current lease terms. Any of these situations may result in
extended periods where there is a significant decline in revenues or no
revenues generated by an investment. If we are unable to re-lease or renew leases
for all or substantially all of our investments, or if the rental rates upon
such renewal or re-leasing are significantly lower than expected, and if our
reserves for these purposes prove inadequate, or if we are required to make
significant renovations or concessions to tenants as part of the renewal or
re-leasing process, we will experience a reduction in net income and may be
required to reduce or eliminate distributions to our stockholders.
The bankruptcy, insolvency or diminished
creditworthiness of our tenants under their leases or delays by our tenants in
making rental payments could seriously harm our operating results and financial
condition.
We will lease our properties to tenants, and we
receive rents from our tenants during the terms of their respective leases. A
tenant’s ability to pay rent is often initially determined by the
creditworthiness of the tenant and the income of the tenant. However, if a
tenant’s credit deteriorates or a tenant’s income deteriorates, the tenant may
default on its obligations under its lease and the tenant may also become
bankrupt. The bankruptcy or insolvency of our tenants or other failure to pay
is likely to adversely affect the income produced by our real estate
investments. Any bankruptcy filings by or relating to one of our tenants could
bar us from collecting pre-bankruptcy debts from that tenant or its property,
unless we receive an order permitting us to do so from the bankruptcy court. A
tenant bankruptcy could delay our efforts to collect past due balances under
the relevant leases, and could ultimately preclude full collection of these
sums. If a tenant files for bankruptcy, we may not be able to evict the tenant
solely because of such bankruptcy or failure to pay. A court, however, may
authorize a tenant to reject and terminate its lease with us. In such a case,
our claim against the tenant for unpaid, future rent would be subject to a
statutory cap that might be substantially less than the remaining rent owed
under the lease. In addition, certain amounts paid to us within 90 days prior
to the tenant’s bankruptcy filing could be required to be returned to the
tenant’s bankruptcy estate. In any event, it is highly unlikely that a bankrupt
or insolvent tenant would pay in full amounts it owes us under its lease. In
other circumstances, where a tenant’s financial condition has become impaired,
we may agree to partially or wholly terminate the lease in advance of the
termination date in consideration for a lease termination fee that is likely
less than the agreed rental amount. If a lease is rejected by a tenant in
bankruptcy, we would have only a general unsecured claim for damages. Any
unsecured claim we hold against a bankrupt entity may be paid only to the
extent that funds are available and only in the same percentage as is paid to
all other holders of unsecured claims. We may recover substantially less than
the full value of any unsecured claims, which would harm our financial
condition.
We may not obtain audited results of prior
operations for certain properties in which we invest.
In
some cases, we will not obtain audited operating statements regarding the prior
operations of an investment. In such case, we will rely on unaudited financial
information provided by the sellers of the investments. Thus, it is possible
that information relied upon by us with respect to the acquisition of some of
the investments may not be accurate at the time that we acquire such
investment.
Significant restrictions on transfer and
encumbrance of investments subject to mortgage or other debt financing are
expected.
The terms of any mortgage or other debt
financing applicable to an investment are expected to prohibit the transfer or
further encumbrance of that investment or any interest in that investment
except with the lender’s prior consent, which consent each lender is expected
to be able to withhold. The relative illiquidity of the investments may prevent
or substantially impair our ability to dispose of an investment at times when
it may be otherwise advantageous for us to do so. If we were forced to immediately
liquidate some or all of our investments, the proceeds are likely to result in
a significant loss, if such a liquidation is possible at all.
We may not obtain independent third-party
appraisals or valuation reports on all of our investments.
We typically may not obtain independent
third-party appraisals or valuations, or other reports concerning an
investment, before we invest in such investment. If we do not obtain such
third-party appraisals or valuations, there can be no assurance that an
investment’s value will exceed its cost or that any sale or other disposition
of such investment will result in a profit. Third-party appraisals and other
reports may be prepared for lenders, in which case we typically will try to
obtain a copy of such appraisals and reports for review, as well as reliance
letters from the third-party preparers to allow us to rely on appraisals and
reports. To the extent we do not obtain such other reports or reliance letters
before making an investment, the risk of such investment may be increased.
We may experience
delays in the sale of an investment.
Should we need to
dispose of an investment, it may not be possible to sell any or all of our
investments at a favorable price, or at all, in the desired time frame. If we
are unable to sell our investments in the time frames or for the prices
anticipated, our ability to make distributions to you may be materially delayed
or reduced, you may not be able to get a return of capital as expected or you
may not have any liquidity with respect to your investment in our securities.
We face possible risks associated with climate change.
We may become subject to laws or regulations
related to climate change, which could cause our business, results of
operations and financial condition to be impacted adversely. Both the federal
government and many of the states and localities in which we operate have
enacted, and may continue to enact, certain climate change laws and regulations
or have begun regulating carbon footprints and greenhouse gas emissions.
Although these laws and regulations have not had any known material adverse
effects on our business to date, they could result in substantial costs,
including compliance costs, increased energy costs, retrofit costs and
construction costs, including monitoring and reporting costs, and capital
expenditures for environmental control facilities and other new equipment. We
cannot predict how future laws and regulations, or future interpretations of
current laws and regulations, related to climate change will affect our
business, results of operations and financial condition. Additionally, the potential
physical impacts of climate change on our operations are highly uncertain and
may include changes to global weather patterns, which could include local
changes in rainfall and storm patterns and intensities, water shortages,
changing sea levels and changing temperature averages or extremes. These
impacts may adversely affect our properties, our business, financial condition
and results of operations.
Additionally,
there has been increasing public focus by investors, environmental activists,
the media and governmental and nongovernmental organizations on a variety of
environmental, social and other sustainability matters. We may make commitments
relating to sustainability matters that affect us, including the design and
implementation of specific risk mitigation strategic initiatives relating to
sustainability. If we are not effective in addressing environmental, social and
other sustainability matters affecting our business, or setting and meeting
relevant sustainability goals, our reputation may suffer.
Risks Related to Our Financial Position
We are subject to risks associated with debt and
capital stock issuances, and such issuances may have consequences to holders of
shares of our securities.
Whenever we raise additional capital through the
issuance of equity securities, we could dilute the interests of holders of
shares of our current outstanding securities.
Further, we may incur indebtedness in the future
to finance our operations. Such indebtedness could result in important
consequences to holders of our common and preferred shares, including
subjecting us to covenants restricting our operating flexibility, increasing
our vulnerability to general adverse economic and industry conditions, limiting
our ability to obtain additional financing to fund future working capital,
capital expenditures and other general corporate requirements, requiring the
use of a portion of our cash flow from operations for the payment of principal
and interest on our indebtedness, thereby reducing our ability to use our cash
flow to fund working capital, acquisitions, capital expenditures, distributions
to our stockholders and general corporate requirements, and limiting our
flexibility in planning for, or reacting to, changes in our business and our
industry.
If we pay distributions from sources other than
our cash flow from operations, we will have fewer funds available for
investments and stockholders’ overall return will be reduced.
Although our distribution policy is to use our
cash flow from operations to make distributions, we are permitted to pay
distributions from any source, including offering proceeds, borrowings, or
sales of assets. We have not placed a cap on the use of proceeds to fund
distributions. Until the proceeds from our offering of
preferred stock pursuant to this Offering Circular are fully invested, we may
not generate sufficient cash flow from operations to fund the anticipated distributions
to our stockholders, including the incremental preferred stock distributions
attributable to shares sold pursuant to this offering. If we pay distributions
from sources other than our cash flow from operations, we will have fewer funds
available for investments, and your overall return may be reduced.
We do not have guaranteed cash flow.
There can be no assurance that cash flow or profits will be generated by
our investments. If the investments do not generate the anticipated amount of
cash flow, we may not be able to pay the anticipated distributions to our
stockholders without making such distributions from the net proceeds of any
offerings of capital stock or from reserves.
While we are subject to minimum distribution requirements to maintain
our status as a REIT, such distributions are not guaranteed and the
availability and timing of cash distributions is uncertain.
Our ability to pay dividends is dependent on our ability to purchase,
develop, or operate our assets profitably, and there are many factors that can
affect the availability and timing of cash distributions to stockholders.
Because we may receive rents and income from our properties and liquidations of
or distributions from our securities at various times during our fiscal year,
distributions paid may not reflect our income earned in that particular
distribution period. The amount of cash available for distribution will be
affected by many factors, including without limitation, the amount of income we
will earn from investments in target assets, the amount of our operating
expenses and many other variables. Actual cash available for distribution may
vary substantially from our expectations.
While we intend to fund the payment of quarterly distributions to
holders of our common and preferred shares entirely from distributable cash
flows, we may fund quarterly distributions to our stockholders from a
combination of available net cash flows, equity capital and proceeds from
borrowings. In the event we are unable to consistently fund future quarterly
distributions to stockholders entirely from distributable cash flows, the value
of our common and preferred shares may be negatively impacted.
We are generally required to distribute to our stockholders at least 90%
of our REIT taxable income, determined without regard to the dividends paid
deduction and excluding any net capital gain, each year to qualify as a REIT
under the Code, which we intend to satisfy through quarterly cash distributions
of all or substantially all of our REIT taxable income in such year, subject to
certain adjustments. Our Board of Directors will determine the amount and
timing of any distributions. In making such determinations, our directors will
consider all relevant factors, including the amount of cash available for
distribution, capital expenditures, general operational requirements and
applicable law. We intend over time to make regular quarterly distributions to
holders of our preferred shares. However, we bear all expenses incurred by our
operations, and the funds generated by operations, after deducting these
expenses, may not be sufficient to cover desired levels of distributions to
stockholders. In addition, our Board of Directors, in its discretion, may
retain any portion of such cash in excess of our REIT taxable income for
working capital. We cannot predict the amount of distributions we may make over
time.
We may in the future choose to pay dividends in our own stock, in which case you may be required to
pay income taxes in excess of the cash dividends you receive.
We may in the future distribute
taxable dividends that are payable in a combination of cash and shares of our
equity securities at the election of each stockholder. Taxable stockholders receiving
such dividends will be required to include the full amount of the dividend as
ordinary income to the extent of our current and accumulated earnings and
profits for United States federal income tax purposes. As a result, a U.S.
stockholder may be required to pay income taxes with respect to such dividends
in excess of the cash dividends received.
The IRS has issued guidance authorizing elective cash/stock dividends to
be made by public REITs where a cap of at least 20% is placed on the amount of
cash that may be paid as part of the dividend, provided that certain
requirements are met. It is unclear whether and to what extent we would be able
to or choose to pay taxable distributions in cash and stock. In addition, no
assurance can be given that the IRS will not impose additional requirements in
the future with respect to taxable cash/stock distributions, including on a
retroactive basis, or assert that the requirements for such taxable cash/stock
distributions have not been met.
Risks Related to Our Business Operations and
Strategy
We may change our targeted investment and
operational policies without stockholder consent.
We may change our investment and operational policies, including our
policies with respect to investments (including changes to our Advisers’
targeted assets and asset allocation), acquisitions, growth, operations,
indebtedness, capitalization and distributions, at any time without the consent
of our stockholders, which could result in our making investments that are
different from, and possibly riskier than, the types of investments described
in this filing. Any such changes may increase our exposure to interest rate
risk, default risk and real estate market fluctuations, all of which could
adversely affect our ability to make distributions. Furthermore, a change in
our asset allocation could result in our making investments in asset categories
different from those described in this Offering Circular.
The ability of our Board of Directors to revoke
our REIT qualification without stockholder approval may cause adverse
consequences to our stockholders.
Our Charter provides that our Board of Directors
may revoke or otherwise terminate our REIT election, without the approval of
our stockholders, if it determines that it is no longer in our best interest to
continue to qualify as a REIT. If we cease to qualify as a REIT, we would
become subject to U.S. federal income tax on our taxable income and would no
longer be required to distribute most of our taxable income to our
stockholders, which may have adverse consequences on our total return to our
stockholders.
Our future growth will depend upon our ability to
acquire real estate investments in several competitive real estate markets.
Our future growth will depend, in large part, upon our initial and
continued ability to acquire properties. We face significant competition with
respect to our acquisition and origination of assets from many other companies,
including other REITs, insurance companies, private investment funds, hedge
funds, specialty finance companies and other investors.
Some competitors may have a lower cost of funds and access to funding
sources that are not available to us. In addition, some of our competitors may
have higher risk tolerances or different risk assessments, which could allow
them to consider a wider variety of investments and establish more
relationships than us. Some of our competitors also may have greater financial
and operational resources, larger customer bases, and more established
relationships with their customers and suppliers than we do. The
competitive pressures we face, if not effectively managed, may have a material
adverse effect on our business, financial condition, liquidity and results of
operations.
Competition may limit the number of suitable investment opportunities
offered to us and may result in higher prices, lower yields and a narrower
spread of yields over our borrowing costs, making it more difficult for us to
identify and pursue opportunities consistent with our objectives and to acquire
new investments on attractive terms. This could delay our investment in
desirable assets. Any failure to identify or consummate investments on
satisfactory terms, or at all, may impede our growth, reduce our earnings per
share and negatively affect our cash available for distribution to our
stockholders.
Due diligence by our Advisers may not reveal all
of the liabilities associated with the investments being evaluated and may not
reveal other weaknesses in such investments, which could lead to investment
losses.
Because we intend to purchase real estate at
below-market-prices, there may not be enough time to investigate the condition
of any particular investment.
Before making an investment, our Advisers will
assess the strengths and weaknesses of a target investment property. The
Advisers will also consider other factors and characteristics that are material
to the performance of the investment. Such other factors may include the
pricing trends for similar properties in the area where the target investment
property is located. In making such assessments and otherwise conducting
customary due diligence, our Advisers rely on resources available to them and,
in some cases, an investigation by third parties. There can be no assurance
that our Advisers’ due diligence process will uncover all relevant facts or
that any investment will be successful.
We may experience difficulty in ultimately selling
any property or groups of properties which no longer fit our investment
criteria or are impractical to lease and maintain, which could force us to sell
a property at a price that reduces the return to our
investors.
The real estate market is affected by many factors that are out of our
control, including the availability of financing, interest rates and other
factors, as well as supply and demand for real estate investments. As a
result, we cannot predict whether we will be able to sell any property or
groups of properties which no longer fit our investment criteria or are
impractical to lease and maintain on favorable terms, or whether such sale
could be made at a favorable price or on terms acceptable to us. We also cannot
predict the length of time which will be needed to obtain a purchaser or to
complete the sale of any property.
In addition, the terms of our leases and the laws regulating REITs could
impact our ability to sell any property or groups of properties. To qualify as
a REIT for federal income tax purposes, we must continually satisfy various
tests, including tests regarding the nature of our assets which could restrict
our disposition strategy.
Lack of diversification in numbers or types of
investments increases our dependence on individual investments.
Our investment strategy depends in large part on
acquiring a diversified portfolio based on the number of properties or
investments we acquire relative to our total assets. Such diversification
reduces the risk that a default or other problem with any single property or
investment will have a material negative impact on our earnings.
Currently, our investments are concentrated in
nine commercial real estate properties and five multi-family residential
apartment properties, located primarily in the Oakland-San Francisco Bay area
in California. If, due to factors such as lack of adequate capital, or the
unavailability of suitable investment opportunities, we acquire relatively few
properties or acquire properties or investments that are significant (in terms
of capital invested) to our overall asset size, we may be unable to reduce the
degree of concentration of our portfolio, which could increase the risk of loss
to stockholders if a default or other problem arises.
Additionally, property sales may reduce the
aggregate amount of our property investment portfolio in value or number. As a
result, our portfolio could become more concentrated, thereby further reducing
the benefits of diversification by factors such as geography, property type,
tenancy, or other measures. While we intend to endeavor to grow and diversify
our portfolio through additional property acquisitions, we may never reach a
significant size to achieve true portfolio diversity.
Our success is materially dependent on the
financial stability of our tenants.
The success of our business is dependent on the financial stability of
the tenants occupying our properties. A default of a tenant on its lease
payments may cause us to lose some of the anticipated revenue from an
investment property.
Since our portfolio is relatively small, our exposure to each tenant may
be more significant than we expect. We believe that this exposure will diminish
(but not entirely) as we acquire more properties. In the event of a material
default, we may experience delays in enforcing our rights as landlords and we
may incur substantial costs in protecting our investment and possibly
re-letting the property, as the case may be. If a lease is terminated, we
cannot assure our investors that the property could be leased for the same
amount of rent previously received or that we could sell the property without
incurring a loss.
We are dependent on our Advisers and their key
personnel for our success.
We are, and will continue to be, advised by our Advisers and, pursuant
to the Advisory Agreement, our Advisers is not obligated to dedicate any
specific personnel exclusively to us, nor is its personnel obligated to
dedicate any specific portion of their time to the management of our business.
As a result, we cannot provide any assurances regarding the amount of
time our Advisers will dedicate to the management of our business. Moreover,
each of our officers and non-independent directors is also an employee of our
Advisers or one of its affiliates and has significant responsibilities for
other investment vehicles currently managed by affiliates, and may not always
be able to devote sufficient time to the management of our business.
Consequently, we may not receive the level of support and assistance that we
otherwise might receive if we were internally managed.
In addition, we offer no assurance that our Advisers will remain our
Advisers or that we will continue to have access to our Advisers’ principals
and professionals. The term of our Agreements with our Advisers only extends
until the end of each calendar year, with automatic one-year renewals, and may
be terminated earlier under certain circumstances. If the Agreement is
terminated or not renewed and no suitable replacement is found to manage us, we
may not be able to execute our business plan, which could have a material
adverse effect on our results of operations and our ability to make
distributions to our stockholders.
Our Board of Directors has approved very broad
investment guidelines for our Advisers and will not approve each investment and
financing decision made by our Advisers unless required by our investment
guidelines.
Our Advisers are authorized to follow very broad
investment guidelines established by our Board of Directors. Our Board of
Directors will periodically review our investment guidelines and our portfolio
of assets but will not, and will not be required to, review all of our proposed
investments, except in limited circumstances as set forth in our investment
policies.
Our Advisers have great latitude within the
broad parameters of our investment guidelines in determining the types and
amounts of assets in which to invest on our behalf, including making
investments that may result in returns that are substantially below
expectations or result in losses, which would materially and adversely affect
our business and results of operations, or may otherwise not be in the best
interests of our stockholders. Transactions entered into by our Advisers may be
costly, difficult or impossible to unwind by the time they are reviewed by our
Board of Directors.
Because stockholders will be unable to evaluate
the merits of these operational and investment guidelines, they will have to
rely entirely on the ability of our Advisers and Board of Directors to
formulate and follow these operational and investment guidelines.
Because we are dependent upon our Advisers and its
affiliates to conduct our operations, any adverse changes in the financial or
operational condition of our Advisers or its affiliates, or our relationship
with them, could hinder our operating performance and the return on your
investment.
We are dependent on our Advisers and their affiliates to manage our
operations and acquire and manage our portfolio of real estate assets. Under
the direction of our Board of Directors, and subject to our investment
guidelines, our Advisers makes all decisions with respect to the management of
our company. Our Advisers depend upon the fees and other compensation they
receive from us, and upon their ability to attract and retain skilled
personnel, in carrying out these functions. Any adverse changes in the financial
or operational condition of our Advisers and their affiliates, or in our
relationship with our Advisers, could hinder their ability to successfully
manage our operations and our portfolio of investments, which would adversely
affect us and our stockholders.
Our investments will be carried at estimated
fair value as determined by our Investment Adviser and there may be uncertainty
as to the value of these investments.
Substantially all of our investments are
illiquid, and the securities in which we invest are not publicly traded. To
determine our net asset value, our Investment Adviser estimates the fair value
of our assets in conjunction with our external valuation experts.
Because such valuations are inherently
uncertain, our value may fluctuate over short periods of time, and may be based
on numerous estimates and assumptions, our determinations of fair value of our
investments are inherently speculative and subject to errors. The value of our
shares could be adversely affected if our determinations regarding the fair
value of these investments are materially higher than the values that we
ultimately realize upon their disposal.
We, through our Advisers, are often required to
make a number of judgments in applying accounting policies, and different
estimates and assumptions in the application of these policies could result in
changes to our reporting of financial condition and results of operations.
Various
valuation estimates are used in the preparation of our consolidated financial
statements, including estimates related to asset and liability valuations (or
potential impairments) and various receivables. Often these estimates require
the use of market data values that may be difficult to assess, as well as
estimates of future performance or receivables collectability that may be
difficult to accurately predict. While we have identified those accounting
policies that are considered critical and have procedures in place to
facilitate the associated judgments, different assumptions in the application
of these policies could result in material changes to our consolidated
financial condition and results of operations.
The
occurrence of cyber incidents, or a deficiency in our cybersecurity, could
negatively impact our business by causing a disruption to our operations, a
compromise or corruption of our confidential information, and/or damage to our
business relationships, all of which could negatively impact our financial
results.
A
cyber incident is considered to be any adverse event that threatens the
confidentiality, integrity, or availability of our information resources. More
specifically, a cyber incident is an intentional attack or an unintentional
event that can include gaining unauthorized access to systems to disrupt
operations, corrupt data, or steal confidential information. As reliance on
technology by the Company, as well as the Advisers and tenants, has increased,
so have the risks posed to our systems, both internal and those we have
outsourced. Our three primary risks that could directly result from the
occurrence of a cyber incident include operational interruption, damage to our
relationship with our tenants, and private data exposure. We have implemented
processes, procedures and controls to help mitigate these risks, but these
measures, as well as our increased awareness of a risk of a cyber incident, do
not guarantee that our financial results will not be negatively impacted by
such an incident.
Risks Related to Our Organization and Corporate
Structure
Our Charter permits our Board of Directors to
issue stock with terms that may subordinate the rights of common stockholders
or preferred shareholders or discourage a third party from acquiring us in a
manner that might result in a premium price to our stockholders.
Our Charter permits our Board of Directors to
issue up to 80,000,000 shares of common stock and 20,000,000 preferred shares.
Our Board of Directors is permitted, subject to certain restrictions set forth
in our Charter, to authorize the issuance of shares of common stock and
preferred stock without stockholder approval. Further, our Board of Directors
may classify or reclassify any unissued shares of common or preferred stock
into other classes or series of stock and establish the preferences, conversion
or other rights, voting powers, restrictions, limitations as to dividends and
other distributions, qualifications, and terms or conditions of redemption of
the stock and may amend our Charter from time to time to increase or decrease
the aggregate number of shares or the number of shares of any class or series
that we have authority to issue without stockholder approval. Thus, our Board
of Directors could authorize us to issue shares of preferred stock ranking
senior to our common stock with respect to distribution rights upon our
liquidation, dissolution or winding up or with terms and conditions that could
have the effect of delaying, deferring or preventing a change in control of us,
including an extraordinary transaction such as a merger, tender offer or sale
of all or substantially all of our assets, that might provide a premium price
for holders of our common stock.
Our rights and the rights of our shareholders to
recover claims against our officers, directors and our Advisers are limited.
Maryland law provides that a director has no liability in that capacity
if he or she performs his or her duties in good faith, in a manner he or she
reasonably believes to be in the corporation’s best interests and with the care
that an ordinarily prudent person in a like position would use under similar
circumstances. Our Charter, in the case of our directors, officers, employees
and agents, and the advisory agreements, in the case of the Advisers, require
us to indemnify our directors, officers, employees and agents and the Advisers
and its affiliates for actions taken by them in good faith and without
negligence or misconduct.
Additionally, our Charter limits the liability of our directors and
officers for monetary damages to the fullest extent permitted under Maryland
law. Although our Charter does not allow us to exonerate and indemnify our
directors and officers to a greater extent than permitted under Maryland law,
we and our stockholders may have more limited rights against our directors,
officers, employees and agents, and our Advisers and its affiliates, than might
otherwise exist under common law, which could reduce our investor’s and our
recovery against them. In addition, we may be obligated to fund the defense
costs incurred by our directors, officers, employees and agents or the Advisers
in some cases which would reduce the cash available for distributions.
Risks Related to Conflicts of Interest
The Advisory Agreements with our Advisers were
not negotiated on an arm’s-length basis and may not be as favorable to us as if
they had been negotiated with an unaffiliated third party.
Our
executive officers, including one of our directors, are executives of our
Advisers. Our Advisory Agreements were negotiated between related parties and
their terms, including fees payable to our Advisers, may not be as favorable to
us as if it had been negotiated with an unaffiliated third party. In addition,
we may choose not to enforce, or to enforce less vigorously, our rights under
the Advisory Agreements because of our desire to maintain our ongoing
relationship with the Advisers and its affiliates.
We may have conflicts of interest with our
Advisers and other affiliates, which could result in investment decisions that
are not in the best interests of our stockholders.
There are numerous conflicts of interest between
our interests and the interests of our Advisers and its respective affiliates,
including conflicts arising out of allocation of personnel to our activities,
allocation of investment opportunities between us and investment vehicles
affiliated with our Advisers, purchase or sale of properties, including from or
to investment entities affiliated with our Advisers, and fee arrangements with
our Advisers that might induce our Advisers to make investment decisions that
are not in our best interests. Examples of these potential conflicts of
interest include, but are not limited to:
• Competition for the time and services of
personnel that work for us and our affiliates;
• Compensation payable by us to our
Advisers and their affiliates for their various services, which may not be on
market terms and is payable, in some cases, whether or not our stockholders
receive distributions;
• The possibility that our Advisers, their
officers and their respective affiliates will face conflicts of interest
relating to the purchase and leasing of properties and other investments, and
that such conflicts may not be resolved in our favor, thus potentially limiting
our investment opportunities, impairing our ability to make distributions and
adversely affecting the trading price of our stock;
• The possibility that if we acquire
properties from investment entities affiliated with our Advisers or their
affiliates, the price may be higher than we would pay if the transaction were
the result of arm’s-length negotiations with a third party;
• The possibility that our Advisers will
face conflicts of interest, since some of their officers are also our officers
and two serve as directors of ours, resulting in actions that may not be in the
long-term best interests of our stockholders;
• Our Advisers have considerable
discretion with respect to the terms and timing of our acquisition, disposition
and leasing transactions;
• The possibility that we may acquire or
merge with our Advisers, resulting in an internalization of our management
functions; and
• The possibility that the competing
demands for the time of our Advisers, their affiliates and our officers may
result in them spending insufficient time on our business, which may result in
our missing investment opportunities or having less efficient operations, which
could reduce our profitability and result in lower distributions to
stockholders.
Any
of these and other conflicts of interest between us and our Advisers could have
a material adverse effect on the returns on our investments, our ability to
make distributions to stockholders and the trading price of our stock.
The fees payable to our Real Estate Adviser
under the amended Advisory Management Agreement effective January 1, 2026 may
cause our Real Estate Adviser's economic interests to diverge from the
interests of our stockholders.
Effective January 1, 2026, we amended our
Advisory Management Agreement with the Real Estate Adviser. Under the amended
agreement, we pay the Real Estate Adviser (i) a base management fee equal to
1.25% per annum of our gross assets under management (excluding depreciation
and amortization), computed monthly based on our reported quarter-end gross
assets, and (ii) a bonus management fee equal to 5% of our adjusted funds from
operations, or AFFO, for each quarter. The amended agreement has a five-year term
that renews automatically each year unless we deliver a timely non-renewal
notice, and requires us to pay a substantial early termination fee if we
terminate the agreement other than for cause. Because our Real Estate Adviser
is an affiliate of ours and of our other Advisers and executive officers, and
because the Real Estate Adviser advises us on acquisitions, dispositions,
financings and other strategic transactions, the following features of these
fee arrangements create inherent conflicts of interest that may result in
decisions that are not aligned with our stockholders’ interests:
• Our base management fee is calculated
on our gross assets, not our stockholders’ equity or net asset value.
Because the base management fee is measured on the gross value of our assets,
the fee increases whenever we grow gross assets (for example, by acquiring
additional properties or by holding rather than divesting existing properties),
regardless of whether those actions increase per-share cash flow, per-share net
asset value or total returns to our stockholders. In particular, if we finance
acquisitions through additional mortgage debt, high-cost secured promissory
notes, affiliate borrowings, preferred stock issuances or other leverage, the
base management fee will increase even if the incremental leverage reduces our
stockholders’ equity, increases our financial risk profile, or dilutes
per-share cash flow. As a result, the fee structure could incentivize our Real
Estate Adviser to recommend that we (i) acquire additional properties even
where per-share stockholder value would decline, (ii) retain properties that
could otherwise be sold on more favorable terms, (iii) employ more leverage
than we would otherwise choose, or (iv) delay divestitures or portfolio
rebalancing that would reduce our gross assets under management.
• Our bonus management fee is tied to
AFFO, a non-GAAP measure calculated by our Real Estate Adviser using management
judgment about non-recurring items. AFFO is a non-GAAP financial measure
that we calculate through our Real Estate Adviser by making a number of
judgment-intensive adjustments to net income (loss), including adjustments for
real estate depreciation and amortization, straight-line rent, above- and
below-market lease amortization, acquisition-related costs, unrealized gains
and losses on investments, stock-based compensation, consulting, marketing and
listing-related costs, and other items that management and the Real Estate
Adviser determine, from time to time, to be “non-recurring” or not reflective
of ongoing operations. GAAP does not define AFFO or prescribe which items
should be treated as non-recurring, and reasonable minds may differ. Because
the Real Estate Adviser calculates the metric that directly determines its own
bonus management fee, there is an inherent incentive to characterize expenses
or losses as non-recurring (thereby increasing AFFO and the corresponding fee)
and to defer or de-emphasize adjustments that would reduce AFFO.
• The Advisory Management Agreement is
a related-party contract, has a long renewable term and imposes a substantial
early termination fee, which may make it difficult for us to renegotiate or
replace our Real Estate Adviser on terms favorable to our stockholders. The
amended Advisory Management Agreement was negotiated between us and our Real
Estate Adviser, which is an affiliate of our executive officers and other
Advisers. Although a majority of our Board of Directors is independent and
reviews and approves related-party arrangements, our Real Estate Adviser and
its affiliates have substantial influence over our management and operations.
The amended agreement has a five-year term that renews automatically each year,
and if we terminate the agreement for reasons other than “cause,” we must pay a
substantial early termination fee. As a result, even if our Board of Directors
were to conclude that the base management fee, the bonus management fee or
other terms of the amended Advisory Management Agreement are no longer in the
best interests of our stockholders, our practical ability to renegotiate,
restructure or replace the arrangement, including retaining an unaffiliated
manager, may be limited. Any inability to align our management fees with
stockholder interests, or to renegotiate or terminate the Advisory Management
Agreement on acceptable terms, could adversely affect our business, financial
condition, results of operations and the market price of our common stock.
Our Advisers, their officers and their
respective affiliates will face conflicts of interest relating to the purchase
and leasing of real estate investments, and such conflicts may not be resolved
in our favor.
Conflicts created by our Advisers’ relationships
with us and with other investment entities affiliated with our Advisers or
their affiliates, as described above, may severely curtail our investment
opportunities, impair our ability to make distributions and reduce the value of
stockholders’ investment in us. Our Advisers also advise other clients and such
clients may compete with us for investments. Our Advisers have policies in
place to deal with such potential conflicts, but such policies may result in other
clients buying assets that may be in our best interest to purchase.
Our Advisers and the personnel they provide are
not exclusively dedicated to management of our business.
If
the competing demands for the time of our Advisers, their key personnel, their
affiliates and our officers result in them spending insufficient time on our
business, we may miss investment opportunities or have less efficient
operations, which could reduce our profitability and result in lower
distributions to stockholders.
We have not adopted any specific conflicts of
interest policies, and, therefore, other than in respect of the restrictions
placed on our Advisers in the Advisory Agreements, we will be reliant upon the
good faith of our Advisers, officers and directors in the resolution of any
conflict.
We do not have a policy that expressly restricts
any of our directors, officers, stockholders or affiliates, including our
Advisers and their officers and employees, from having a pecuniary interest in
an investment in or from conducting, for their own account, business activities
of the type we conduct. This may mean that our ability to access the best
investments may be curtailed, which could result in greater than expected
operating expense, losses and reduced distributions to our shareholders.
Risks Associated with Debt Financing
We expect to use mortgage and other debt
financing to acquire properties or interests in properties and otherwise incur
other indebtedness, which increases our expenses and could subject us to the
risk of losing properties in foreclosure if our cash flow is insufficient to
make loan payments.
We are permitted to acquire real properties and
other real estate-related investments, including entity acquisitions, by either
assuming existing financing secured by the asset or borrowing new funds. In
addition, we may incur or increase our mortgage debt by obtaining loans secured
by some or all of our assets to obtain funds to acquire additional investments
or to pay distributions to our stockholders. We also may borrow funds if
necessary to satisfy the requirement that we distribute at least 90% of our annual
“REIT taxable income” (determined without regard to the dividends paid
deduction and excluding any net capital gain), or otherwise as is necessary or
advisable to assure that we maintain our qualification as a REIT for federal
income tax purposes.
There is no limit on the amount we may invest in
any single property or other asset or on the amount we can borrow to purchase
any individual property or other investment. If we mortgage a property and have
insufficient cash flow to service the debt, we risk an event of default which
may result in our lenders foreclosing on the properties securing the mortgage
and the loss of our interests in such properties if we are unable to repay or
refinance.
High levels of debt or increases in interest rates
could increase the amount of our loan payments, which could reduce the cash
available for distribution to stockholders.
Our policies do not limit us from incurring debt. For purposes of
calculating our leverage, we assume full consolidation of all of our real
estate investments, whether or not they would be consolidated under the
accounting principles generally accepted in the United States of America
(“GAAP”).
High debt levels will cause us to incur higher interest charges,
resulting in higher debt service payments, and may be accompanied by
restrictive covenants. Interest we pay reduces cash available for distribution
to stockholders. Additionally, with respect to our
variable-rate debt, increases in interest rates increase our interest costs,
which reduces our cash flow and our ability to make distributions to
you. In addition, if we need to repay existing debt during periods of
rising interest rates, we could be required to liquidate one or more of our
investments at times which may not permit realization of the maximum return on
such investments and could result in a loss. In addition, if we are unable to
service our debt, our lenders may foreclose on our interests in the real
property that secures such debt.
High mortgage rates may make it difficult for us
to finance or refinance properties, which could reduce the number of properties
we can acquire, our cash flow from operations and the amount of cash
distributions we can make.
To
qualify as a REIT, we generally will be required to distribute at least 90% of
our annual taxable income (determined without regard to the dividends paid
deduction and excluding any net capital gain) to our stockholders in each
taxable year, limiting our ability to retain internally generated cash.
Accordingly, our ability to acquire properties or to make capital improvements
to or remodel properties will depend on our ability to obtain debt or equity
financing from third parties or the sellers of properties. If mortgage debt is
unavailable at reasonable rates, we may not be able to finance the purchase of
properties. If we place mortgage debt on properties, we run the risk of being
unable to refinance the properties when the debt becomes due or of being unable
to refinance on favorable terms. If interest rates are higher when we refinance
the properties, our income could be reduced. The interest rate may increase on
some of our fixed-rate debt after the initial fixed rate period. If any of
these events occur, our cash flow would be reduced. This, in turn, would reduce
cash available for distribution to stockholders and may hinder our ability to
raise additional capital.
Our ability to obtain financing on reasonable terms
would be impacted by negative capital market conditions.
Recently, domestic and international financial markets have experienced
unusual volatility and uncertainty. Liquidity has tightened in overall
financial markets, including the investment grade debt and equity capital
markets. Consequently, there is greater uncertainty regarding our ability to
access the credit market in order to attract financing on reasonable terms.
Investment returns on our assets and our ability to make acquisitions could be
adversely affected by our inability to secure financing on reasonable terms, if
at all.
If we are required to make payments under any
“bad boy” carve-out guaranties that we may provide in connection with certain
mortgages and related loans, our business and financial results could be
materially adversely affected.
In obtaining certain nonrecourse loans, we may
provide standard carve-out guaranties. These guaranties are only applicable if
and when the borrower directly, or indirectly through agreement with an
affiliate, joint venture partner or other third party, voluntarily files a
bankruptcy or similar liquidation or reorganization action or takes other
actions that are fraudulent or improper (commonly referred to as “bad boy”
guaranties). Although we believe that “bad boy” carve-out guaranties are not
guaranties of payment in the event of foreclosure or other actions of the
foreclosing lender that are beyond the borrower’s control, some lenders in the
real estate industry have recently sought to make claims for payment under such
guaranties. In the event such claims were made against us under a “bad boy”
carve-out guaranty following foreclosure on mortgages or related loans, and
such claims were successful, our business and financial results could be
materially adversely affected.
Interest-only indebtedness may increase our risk
of default and ultimately may reduce our funds available for distribution to
our stockholders.
We may finance our property acquisitions using
interest-only mortgage indebtedness. During the interest-only period, the
amount of each scheduled payment will be less than that of a traditional
amortizing mortgage loan. The principal balance of the mortgage loan will not
be reduced (except in the case of prepayments) because there are no scheduled
monthly payments of principal during this period. After the interest-only
period, we will be required either to make scheduled payments of amortized
principal and interest or to make a lump-sum or “balloon” payment at maturity.
These required principal or balloon payments will increase the amount of our
scheduled payments and may increase our risk of default under the related
mortgage loan. If the mortgage loan has an adjustable interest rate, the amount
of our scheduled payments also may increase at a time of rising interest rates.
Increased payments and substantial principal or balloon maturity payments would
reduce the funds available for distribution to our stockholders.
We may use floating rate, interest-only or
short-term loans to acquire investments.
The Real Estate Adviser has the right, in its sole discretion, to
negotiate any debt financing, including obtaining (i) interest-only, (ii)
floating rate and/or (iii) short-term loans to acquire Investments. If the Real
Estate Adviser obtains floating rate loans, the interest rate would not be
fixed but would float with an established index (probably at higher interest
rates in the future). No principal would be repaid on interest-only loans.
Finally, we would be required to refinance short term loans at the end of a
relatively short period. The credit markets have recently been in flux and are
experiencing a malaise. No assurance can be given that the Real Estate Adviser
would be able to refinance with fixed-rate permanent loans in the future, on
favorable terms or at all, to refinance the short-term loans. In addition, no
assurance can be given that the terms of such future loans to refinance the
short-term loans would be favorable to us.
Risks Related to Our Taxation as a REIT
Our failure to qualify as a REIT would result in
higher taxes and reduced cash available for stockholders.
We intend to continue to operate in a manner so
as to qualify as a REIT for U.S. federal income tax purposes. Our initial and
continued qualification as a REIT depends on our satisfaction of certain asset,
income, organizational, distribution, and stockholder ownership requirements on
a continuing basis. Our ability to satisfy some of the asset tests depends upon
the fair market values of our assets, some of which are not able to be
precisely determined and for which we will not obtain independent appraisals.
If we were to fail to qualify as a REIT in any
taxable year, and certain statutory relief provisions were not available, we
would be subject to U.S. federal income tax, including any applicable
alternative minimum tax, on our taxable income at regular corporate rates, and
distributions to stockholders would not be deductible by us in computing our
taxable income. Any such corporate tax liability could be substantial and would
reduce the amount of cash available for distribution.
Unless entitled to relief under certain Code
provisions, we also would be disqualified from taxation as a REIT for the four
taxable years following the year during which we ceased to qualify as a REIT.
In addition, if we fail to qualify as a REIT, we will no longer be required to
make distributions. As a result of all these factors, our failure to qualify as
a REIT could impair our ability to expand our business and raise capital, and
it would adversely affect the value of our securities.
Failure to remain qualified as a REIT would cause us to be taxed
as a regular corporation, which would substantially reduce funds available for
distributions to our stockholders.
We have elected to be taxed as a REIT under the
federal income tax laws commencing with our taxable year ended December 31,
2014. We believe that we have and will continue to operate in a manner
qualifying us as a REIT for our taxable year ended December 31, 2026, and
intend to continue to so operate.
However, we cannot assure the stockholders that
we will remain qualified as a REIT. Moreover, our qualification and taxation as
a REIT depend upon our ability to meet on a continuing basis, through actual
annual operating results, certain qualification tests set forth in the federal
tax laws. Tax counsel will not review our compliance with those tests on a
continuing basis. Accordingly, no assurance can be given that our actual
results of operations for any particular taxable year will satisfy such requirements.
If
we fail to qualify as a REIT in any taxable year, we will face serious tax
consequences that will substantially reduce the funds available for
distributions to our stockholders because:
• we would be taxed as a regular domestic
corporation, which under current law, among other things, means being unable to
deduct distributions paid to stockholders in computing our taxable income and
being subject to U.S. federal income tax on our taxable income at corporate
income tax rates;
• we could be subject to the federal
alternative minimum tax and possibly increased state and local taxes;
• we would be required to pay taxes and,
therefore, our cash available for distribution to stockholders would be reduced
for each of the years during which we did not qualify as a REIT and for which
we had taxable income; and
• unless we are entitled to relief under
certain U.S. federal income tax laws, we could not re-elect REIT status until
the fifth calendar year after the year in which we failed to qualify as a REIT.
In addition, if we fail to qualify as a REIT, we
will no longer be required to make distributions. As a result of all these
factors, our failure to qualify as a REIT could impair our ability to expand
our business and raise capital, and it would adversely affect the value of our
securities.
REIT distribution requirements could adversely
affect our liquidity.
In order to maintain our REIT status and to meet the REIT distribution
requirements, we may need to borrow funds on a short-term basis or sell assets,
even if the then-prevailing market conditions are not favorable for these
borrowings or sales. To qualify as a REIT, we generally must distribute
to our stockholders at least 90% of our REIT taxable income each year,
determined without regard to the deduction for dividends paid and excluding any
net capital gain.
In addition, we will be subject to corporate income tax to the extent we
distribute less than 100% of our net taxable income including
any realized net capital gain. We intend to make distributions to our
stockholders to comply with the requirements of the Code for REITs and to
minimize or eliminate our corporate income tax obligation to the extent
consistent with our business objectives.
Our cash flows from operations may be insufficient to fund required
distributions as a result of differences in timing between the actual receipt
of income and the recognition of income for federal income tax purposes, or the
effect of non-deductible capital expenditures, the creation of reserves or
required debt service or amortization payments. The insufficiency of our cash
flows to cover our distribution requirements could have an adverse impact on
our ability to raise short- and long-term debt or sell equity securities in
order to fund distributions required to maintain our REIT status. We will be
subject to regular corporate income taxes on any undistributed REIT taxable
income each year. In addition, we will be subject to a 4% non-deductible excise
tax on the amount, if any, by which distributions paid by us in any calendar
year are less than the sum of 85% of our ordinary income, 95% of our capital
gain net income and 100% of our undistributed income from prior years.
Further, amounts distributed will not
be available to fund investment activities. We expect to fund our investments
by raising equity capital and through borrowings from financial institutions
and the debt capital markets. If we fail to obtain debt or equity capital in
the future, it could limit our ability to grow, which could have a material
adverse effect on the value of our preferred shares.
Complying with REIT requirements may cause us to
forego otherwise attractive opportunities or liquidate otherwise attractive
investments.
To maintain our qualification as a REIT for
federal income tax purposes, we must continually satisfy tests concerning,
among other things, the sources of our income, the nature and diversification
of our assets, the amounts we distribute to our stockholders and the ownership
of our capital stock. In order to meet these tests, we may be required to
forego investments we might otherwise make. Thus, compliance with the REIT
requirements may hinder our performance.
In particular, we must ensure that at the end of
each calendar quarter, at least 75% of the value of our assets consists of
cash, cash items, government securities and qualified real estate assets. The
remainder of our investment in securities (other than government securities,
qualified real estate assets and taxable REIT subsidiaries) generally cannot
include more than 10% of the outstanding voting securities of any one issuer or
more than 10% of the total value of the outstanding securities of any one issuer,
among other limitations.
In addition, in general, no more than 5% of the
value of our assets (other than government securities, qualified real estate
assets and taxable REIT subsidiaries) can consist of the securities of any one
issuer, and no more than 20% of the value of our assets can consist of the
securities of one or more taxable REIT subsidiaries. If we fail to comply with
these requirements at the end of any calendar quarter, we generally must
correct the failure within 30 days after the end of the calendar quarter or qualify
for certain statutory relief provisions to avoid losing our REIT qualification
and suffering adverse tax consequences. As a result, we may be required to
liquidate otherwise attractive investments. These actions could have the effect
of reducing our income and amounts available for distribution to our
stockholders.
The tax status of the Operating Partnership and
other partnerships could impact our qualification as a REIT.
If the IRS were to successfully challenge the
status of the Operating Partnership, MAC, MAC OP or any other partnership in
which we invest as a partnership or disregarded entity for U.S. federal income
tax purposes, such partnerships could be subject to an entity level tax and
could, depending on the circumstances, jeopardize our ability to qualify as a
REIT.
Even if we remain qualified as a REIT, we may
face other tax liabilities that reduce our cash flows.
Even if we remain qualified as a REIT, we may be
subject to certain federal, state and local taxes on our income and assets,
including taxes on any undistributed income, tax on income from some activities
conducted as a result of a foreclosure, and state or local income, property and
transfer taxes.
The stock ownership limit imposed by the Code
for REITs and in our Charter may inhibit market activity in our stock and may
restrict our business combination opportunities.
In order for us to maintain our qualification as
a REIT under the Code, not more than 50% in value of our outstanding stock may
be owned, directly or indirectly, by five or fewer individuals (as defined in
the Code to include certain entities) at any time during the last half of each
taxable year. Additionally, at least 100 persons must beneficially own our
capital stock during at least 335 days of each taxable year. Our Charter, with
certain exceptions, authorizes our directors to take such actions as are necessary
and desirable to preserve our qualification as a REIT.
Unless exempted by the Board of Directors, no
person may own more than 9.80% of the aggregate value of the outstanding shares
of our stock or more than 9.80% in value or in number of shares, whichever is
more restrictive, of the aggregate outstanding common or preferred shares of
the Company. The Board of Directors may not grant such an exemption to any
proposed transferee whose ownership in excess of 9.80% of the value of our
outstanding shares or more than 9.80% in value or in number of shares, whichever
is more restrictive, would result in the termination of our status as a REIT.
These ownership limits could delay or prevent a transaction or a change in our
control that might be in the best interest of our stockholders.
Dividends payable by REITs do not qualify for
the reduced tax rates available for some dividends.
The
maximum tax rate applicable to “qualified dividend income” payable to U.S.
stockholders that are taxed at individual rates is 20%. Dividends payable by
REITs, however, generally are not eligible for the reduced rates on qualified
dividend income. The more favorable rates applicable to regular corporate
qualified dividends could cause investors who are taxed at individual rates to
perceive investments in REITs to be relatively less attractive than investments
in the stocks of non-REIT corporations that pay dividends, which could
adversely affect the value of the shares of REITs, including our preferred
shares.
However, under current law, individual taxpayers
are entitled to claim a deduction in determining their taxable income of 20% of
ordinary REIT dividends (dividends other than capital gain dividends and
dividends attributable to certain qualified dividend income received by us),
which reduces the effective tax rate on such dividends. You are urged to
consult with your tax advisor regarding the effect of this rule on your
effective tax rate with respect to REIT dividends.
The prohibited transactions tax may subject us
to tax on our gain from sales of property and limit our ability to dispose of
our properties.
A REIT’s net income from prohibited transactions
is subject to a 100% tax. In general, prohibited transactions are sales or
other dispositions of property other than foreclosure property, held primarily
for sale to customers in the ordinary course of business.
Although we intend to acquire and hold all of
our assets as investments and not for sale to customers in the ordinary course
of business, the IRS may assert that we are subject to the prohibited
transaction tax equal to 100% of net gain upon a disposition of real property.
Although
a safe harbor to the characterization of the sale of real property by a REIT as
a prohibited transaction is available, not all of our prior property
dispositions qualified for the safe harbor and we cannot assure the
stockholders that we can comply with the safe harbor in the future or that we
have avoided, or will avoid, owning property that may be characterized as held
primarily for sale to customers in the ordinary course of business.
Failure to make required
distributions would subject us to U.S. federal corporate income tax.
We intend to continue to operate in a manner so
as to qualify as a REIT for U.S. federal income tax purposes. In order to
remain qualified as a REIT, we generally are required to distribute at least
90% of our REIT taxable income, determined without regard to the dividends paid
deduction and excluding any net capital gain, each year to our stockholders. To
the extent that we satisfy this distribution requirement, but distribute less
than 100% of our REIT taxable income, we will be subject to U.S. federal corporate
income tax on our undistributed taxable income. In addition, we will be subject
to a 4% nondeductible excise tax if the actual amount that we pay to our
stockholders in a calendar year is less than a minimum amount specified under
the Code.
Accrued dividends with respect
to the Series B Preferred Stock might be treated as taxable dividends even
though holders do not receive any current cash.
The terms of the Series B Preferred Stock
contemplate paying current dividends at a rate of 3% per annum, with additional
rights to dividends accruing at a rate of 9% per annum, which 9% will be paid
at the same time and in the same amounts per share as dividends on common stock
(after holders of the common stock have received a specified yield) or upon
redemption or liquidation. The tax
treatment of dividends accrued on the Series B Preferred Stock is a matter of
uncertainty and may depend, in part, on whether the Series B Preferred Stock is
treated as participating in corporate growth to any significant extent as
determined under the applicable Code Section 305 Treasury Regulations. The
Company believes that the Series B Preferred Stock will be treated as
participating in corporate growth to a significant extent given the stock’s
participation in dividends at the same time and in the same amounts per share with
distributions paid on the common stock once the common stock has received an
initial specified yield and the holders’ right to convert the Series B
Preferred Stock into common stock prior to liquidation at a price that reflects
future increases in the Company’s valuation. The Company's position, however,
is not free from doubt, and there can be no assurance that the IRS will not
take the position that the Series B Preferred Stock should not be treated as
participating in the Company’s growth to any significant extent and the accrued
dividends are currently taxable under the Treasury Regulations.
In the event the Series B Preferred Stock
is treated as not participating in corporate growth to any significant extent
within the meaning of the Code Section 305 Treasury Regulations, the IRS may
take the position that the unpaid accrued dividends constitute a “redemption
premium” taxable as deemed distribution under Section 305(b) and 305(c) of the
Code, if the redemption premium is in excess of a statutory de minimis amount. If
the accrued dividends are treated as a taxable redemption premium, such deemed
distributions generally would be required to be reported as taxable income under
timing principles similar to those governing the inclusion of accrued original
issue discount under Section 1272(a) of the Code. Under certain circumstances,
holders may have taxable income for U.S. federal income tax purposes, even
though they would not receive any cash or property in connection with the
increase in accrued dividends. Section 305(c) of the Code and the Treasury
Regulations promulgated thereunder also contemplate other circumstances in
which a taxable deemed distribution may be treated as having occurred.
Section 305(c) of the Code and the
applicable Treasury Regulations, however, do not directly address whether
accrued dividends will be treated as a redemption premium or otherwise might
give rise to a deemed distribution under the Code, and the preamble to the
Treasury Regulations explicitly provides that the IRS chose not to provide
rules providing for the taxation of accrued dividends pursuant to Section
305(c) of the Code. In light of the failure of the Treasury Regulations to
address the treatment of accrued dividends under Section 305(c) of the Code,
the Company believes that the accrual of dividends on the Series B Preferred
Stock will not be includable in the holder’s taxable income as disguised
redemption premium or otherwise until such dividends are authorized by our Board
of Directors, or any duly authorized committee thereof, and declared by the
Company and paid in cash. In addition, because under the terms of the Series B
Preferred Stock, the holder will likely realize upon the value of the accruing
dividends before redemption or liquidation through their conversion rights,
such accrued amounts should not be treated as a redemption premium for purposes
of Section 305(c) of the Code.
If the IRS were to take a contrary
position and treat an increase in the amount of accrued dividends as a current
distribution under Section 305(c) of the Code, then holders may have taxable
income to them for U.S. federal income tax purposes, even though holders would
not receive any cash in connection with the increase in accrued dividends.
Please consult your tax advisor and read
“Tax Treatment of the Company and its Security Holders” regarding the U.S.
federal income tax consequences of the accrual of dividends on the Series B
Preferred Stock.
The purchasers of shares of Series
A Preferred Stock may have to report as current taxable income the difference
between the $22.50 per share issue price and the $25 per share redemption
premium as such redemption premium accretes.
The Series A Preferred Stock will be
issued at a discount. Under Code section 305(c) and the regulations promulgated
thereunder, certain taxpayers are required to accrue as a current dividend the
accretion of a redemption premium. Given the applicable facts and circumstances,
we do not believe that you will need to report the accretion of the redemption
premium on a current basis, instead only upon the redemption of the Series A
Preferred Stock. If the IRS determines otherwise, a Series A Preferred Stock
shareholder may have to report dividend income on a current basis as the
redemption premium accretes, even though such holders would not receive any
cash in connection with the redemption premium's accretion.
We may be unable to generate sufficient revenue
from operations, operating cash flow or portfolio income to pay our operating
expenses, and our operating expenses could rise, diminishing our ability to pay
distributions to our stockholders.
As a REIT, we are generally required to
distribute at least 90% of our REIT taxable income, determined without regard
to the dividends paid deduction and excluding any net capital gain, each year
to our stockholders. To qualify for the tax benefits accorded to REITs, we
intend to continue to make distributions to our stockholders in amounts such
that we distribute all or substantially all our REIT taxable income each year,
subject to certain adjustments.
However, our ability to make distributions may
be adversely affected by the risk factors described herein. Our ability to make
and sustain cash distributions is based on many factors, including the return
on our investments, the size of our investment portfolio, operating expense
levels, and certain restrictions imposed by Maryland law.
Some
of the factors are beyond our control and a change in any such factor could
affect our ability to pay future distributions. No assurance can be given as to
our ability to pay distributions to our stockholders. In the event of a
downturn in our operating results and financial performance or unanticipated
declines in the value of our asset portfolio, we may be unable to declare or
pay annual distributions or make distributions to our stockholders. The timing
and amount of distributions are in the sole discretion of our Board of
Directors, which considers, among other factors, our earnings, financial
condition, debt service obligations and applicable debt covenants, REIT
qualification requirements and other tax considerations and capital expenditure
requirements as our Board of Directors may deem relevant from time to time.
We may be subject to adverse legislative or
regulatory tax changes that could reduce the market price of our shares.
At any time, the U.S. federal income tax laws governing REITs or the
administrative interpretations of those laws may be amended. We cannot predict
when or if any new U.S. federal income tax law, regulation or administrative
interpretation, or any amendment to any existing U.S. federal income tax law,
regulation or administrative interpretation, will be adopted, promulgated or
become effective and any such law, regulation, or interpretation may take
effect retroactively. We and our stockholders could be adversely affected by
any such change in the U.S. federal income tax laws, regulations or
administrative interpretations.
The Inflation Reduction Act of 2022 (the “IRA”) includes numerous tax
provisions that impact corporations, including the implementation of a
corporate alternative minimum tax as well as a 1% excise tax on certain stock
repurchases and economically similar transactions. However, REITs are excluded
from the definition of an “applicable corporation” and therefore are not
subject to the corporate alternative minimum tax. Additionally, stock
repurchases by REITs are specifically excepted from the 1% excise tax. The
impact of tax reform and any potential tax changes on our shares is uncertain.
Investors should consult their own tax advisors regarding changes in tax laws.
Risks Related to Our Preferred Shares and
Your Investment in This Offering
Because there is no market for our
preferred shares and the offering price of our shares was not established on an
independent basis, the actual value of preferred shares you purchase may be
substantially less than what you pay.
The Stated Value of our preferred shares
has been determined primarily by our capital needs. Because the offering price
is not based upon any independent valuation, the offering price may not be
indicative of the proceeds that you would receive upon liquidation. Further,
the offering price may be significantly more than the price at which the shares
would trade if they were to be listed on an exchange or actively traded by
broker-dealers.
You are limited in
your ability to sell your preferred shares pursuant to our preferred share
repurchase program. You may not be able to sell any of your shares back to us,
and if you do sell your shares, you may not receive the price you paid upon
subscription.
The Articles Supplementary establishing
the terms of the Series A, Series B, and Series C preferred stock contain a
repurchase program, which may provide you an opportunity to sell your shares
back to us. However, our share repurchase program contains certain restrictions
and limitations on the timing of any repurchases and the repurchase price. See “Description of Securities—Preferred
Stock—Series A Preferred Share Repurchase Program; Repurchase Rights,” “Description
of Securities—Preferred Stock—Series B Preferred Share Repurchase Program;
Repurchase Rights,” and “Description of Securities—Preferred Stock—Series
C Preferred Share Repurchase Program; Repurchase Rights.”
Therefore, you may
not be able to sell any of your preferred shares back to us pursuant to the
share repurchase program. Moreover, if you do sell your preferred shares
back to us, it is unlikely that you will receive the same price you paid for
the preferred shares being repurchased. In
addition, the share repurchase program described in this risk factor is
currently subject to the Repurchase Program Suspension, as described below. See
“Our board of directors has temporarily
suspended our preferred share repurchase program with respect to the Series A,
Series B, and Series C preferred shares.”
Our board of
directors has temporarily suspended our preferred share repurchase program with
respect to the Series A, Series B, and Series C preferred shares. During the Repurchase Program Suspension, you
will not be able to sell any of your preferred shares back to us pursuant to
our preferred share repurchase program, and there is no assurance of if or when
our preferred share repurchase program will be reinstated or, if it is
reinstated, that you will receive the price you paid upon subscription.
The Articles Supplementary establishing
the terms of the Series A, Series B, and Series C preferred stock contain a
repurchase program, which historically provided you an opportunity to sell your
preferred shares back to us. Our
preferred share repurchase program has always contained certain restrictions
and limitations on the timing of any repurchases and the repurchase price. In addition, on September 11, 2026, our board
of directors approved the temporary suspension of our preferred share
repurchase program with respect to the Series A, Series B, and Series C
preferred shares (the “Repurchase Program Suspension”) in order to enable us to
better react to strategic alternatives that may from time to time be presented
for evaluation by our financial advisor, Maxim Group LLC. The Repurchase
Program Suspension was publicly announced on our Current Report on Form 8-K
filed with the Securities and Exchange Commission on September 30, 2026. During the Repurchase Program Suspension, we
will not repurchase any Series A, Series B, or Series C preferred shares under
our preferred share repurchase program, and you will not be able to submit your
preferred shares to us for repurchase. Our board of directors expects to
reassess the Repurchase Program Suspension in due course, but we cannot predict
if or when the share repurchase program will be reinstated, and the Board may
elect to continue the Repurchase Program Suspension for an extended period,
terminate the share repurchase program entirely, or modify its terms. See “Description
of Securities—Preferred Stock—Series A Preferred Share Repurchase Program;
Repurchase Rights,” “Description of Securities—Preferred Stock—Series B
Preferred Share Repurchase Program; Repurchase Rights,” and “Description
of Securities—Preferred Stock—Series C Preferred Share Repurchase Program;
Repurchase Rights.”
Therefore, you will not be able to sell
any of your preferred shares back to us pursuant to our preferred share
repurchase program during the Repurchase Program Suspension, and there is no
assurance that our preferred share repurchase program will resume with respect
to the Series A, Series B, or Series C preferred shares. We have no obligation
to resume our preferred share repurchase program, and any decision to resume,
modify, or terminate our preferred share repurchase program is in our sole
discretion, subject to any required board approval. There is no established
public trading market for the Series A, Series B, or Series C preferred shares,
and our preferred share repurchase program has been one of the primary
mechanisms by which holders of such preferred shares could obtain liquidity. As
a result of the Repurchase Program Suspension, holders of Series A, Series B,
and Series C preferred shares should be prepared to hold their preferred shares
indefinitely and may be unable to sell or otherwise transfer them at a price
acceptable to them, or at all.
Our Board of Directors is reviewing
strategic alternatives, which may significantly affect our business and the
Series A, Series B, and Series C preferred shares.
The Company has engaged Maxim Group LLC
(“Maxim”) as our financial advisor to assist in evaluating potential strategic
alternatives. Our review of these alternatives is ongoing, and we have not
entered into any agreement with respect to any strategic transaction, nor can
we predict whether any such transaction will occur. The temporary suspension of
our preferred share repurchase program described above was adopted in part to
enable the Company to better react to any strategic alternatives that may be brought
to it by Maxim, and the duration of the Repurchase Program Suspension will
depend on, among other things, the progress and outcome of this review.
Therefore, you will not be able to sell any
of your preferred shares back to us pursuant to our preferred share repurchase
program during the Repurchase Program Suspension, and there is no assurance
that our preferred share repurchase program will be reinstated with respect to
the Series A, Series B, or Series C preferred shares. Although the Board
intends to reassess the Repurchase Program Suspension in due course, we have no
obligation to reinstate our preferred share repurchase program, and any
decision to reinstate, modify, or terminate our preferred share repurchase
program is in our sole discretion, subject to any required board approval. The
duration of the Repurchase Program Suspension will depend on, among other
things, the progress and outcome of our review of strategic alternatives with
Maxim Group LLC. There is no established public trading market for the Series
A, Series B, or Series C preferred shares, and our preferred share repurchase
program has been one of the primary mechanisms by which holders of such
preferred shares could obtain liquidity. As a result of the Repurchase Program
Suspension, holders of Series A, Series B, and Series C preferred shares should
be prepared to hold their preferred shares for an extended period, which could
be prolonged, and may be unable to sell or otherwise transfer them at a price
acceptable to them, or at all.
You could lose the
entire amount of your investment in our preferred stock.
An investment in preferred shares must be
considered speculative. No assurance can be given that the holders of preferred
shares will realize any return on their purchase of preferred shares or that
the holders of preferred shares will not lose their entire investment. For this
reason, prospective investors should carefully read this Offering Circular and
should consult with their own attorneys or business advisors.
The offering of our preferred
shares pursuant to this Offering Circular is made on a “best efforts” basis,
and does not involve any firm commitment underwriting, escrow or minimum
offering amount.
We are offering the preferred shares on a
“best-efforts” basis. The fact that this is not a firm commitment offering may
increase the time necessary to sell the Maximum Offering Amount. Further, there
is no minimum offering amount and no escrow provision for the Offering
Proceeds. Accordingly, the Offering Proceeds will be immediately available to
us upon acceptance of each investor’s subscription. If limited proceeds are
raised, we may not have sufficient funds to execute our business plan.
Our preferred
shares will have limited transferability and liquidity.
The absence of a public market for the
preferred shares could impair an investor’s ability to sell the preferred
shares owned by the investor at a fair price or at all. In addition, the
transfer of preferred shares will be subject to additional limitations. If an
investor is able to sell preferred shares, the investor may only be able to
sell them at a substantial discount to the price paid. Thus, prospective
investors should consider the purchase of preferred shares as an illiquid and a
long-term investment, and investors must be prepared to hold their preferred
shares until redeemed. Further, the sale of the shares may have adverse federal
income tax consequences.
You may be
restricted from acquiring or transferring certain amounts of our preferred
shares.
The stock ownership restrictions of the
Code for REITs and the 9.8% stock ownership limits in our Charter may inhibit
market activity in our capital stock and restrict our business combination
opportunities.
In order to qualify as a REIT, five or
fewer individuals, as defined in the Code to include specified private
foundations, employee benefit plans and trusts, and charitable trusts, may not
own, beneficially or constructively, more than 50% in value of our issued and
outstanding stock at any time during the last half of a taxable year.
Attribution rules in the Code determine if any individual or entity
beneficially or constructively owns our capital stock under this requirement.
Additionally, at least 100 persons must beneficially own our capital stock
during at least 335 days of a taxable year. To help ensure that we meet these
tests, among other purposes, our Charter restricts the acquisition and
ownership of shares of our capital stock.
Our Charter, with certain exceptions,
authorizes our board of directors to take such actions as are necessary and
desirable to preserve our qualification as a REIT. Unless exempted,
prospectively or retroactively, by our Board of Directors, our Charter
prohibits any person from beneficially or constructively owning more than 9.8% (in
value or in number of shares, whichever is more restrictive) of the outstanding
shares of our common stock or more than 9.8% in value of the aggregate of our
outstanding shares of capital stock (defined to include all classes or series
of stock, including both common and preferred). Our Board of Directors may not
grant an exemption from these restrictions to any proposed transferee whose
ownership in excess of such thresholds does not satisfy certain conditions
designed to ensure that we will not fail to qualify as a REIT. These restrictions
on transferability and ownership will not apply, however, if our Board of
Directors determines that it is no longer in our best interest to continue to
qualify as a REIT or that compliance is no longer required for REIT
qualification.
Shares of our
Series A, Series B, and Series C Preferred Stock have limited voting rights.
The preferred shares have no voting rights
except on matters relating to the preferences, conversion, and other rights of
the holders of preferred shares. Accordingly, holders of the preferred shares
will have no vote with respect to the election of directors to the Board, the
management of us or certain fundamental changes that may be proposed with
respect to us. Holders of preferred shares must rely entirely on the holders of
the common stock and the Board to make decisions regarding our management and
operation. The affirmative vote of holders of preferred shares entitled to cast
a majority of the votes entitled to be cast, voting as a class, is required to
approve (i) any amendment, alteration, or repeal of any of the provisions of
the respective Articles Supplementary that would materially and adversely
affect any preferences, conversion, and other rights, voting powers,
restrictions, limitations as to dividends and other distributions,
qualifications and terms and conditions of redemption of the Series A Preferred
Stock, Series B Preferred Stock, or Series C Preferred Stock or (ii) the
issuance of any class or series of preferred shares that ranks senior to the
Series A Preferred Stock, Series B Preferred
Stock, or Series C Preferred Stock with respect to the payment of dividends or
the distribution of assets upon our liquidation and dissolution.
Holders of Series A and C Preferred Stock will not have the opportunity to participate in Company growth to the same
extent as holders of Series B Preferred Stock.
The Series A and Series C Preferred Stock
entitles the holder of such shares to receive the preferred dividends prior to
any distributions paid to the holders of common stock, and the holder of such
preferred shares will not be entitled to receive any additional dividends based
upon our performance. The Series B Preferred Stock entitles the holder of such
shares to receive dividends at a rate of 3% per annum prior to any
distributions paid to the holders of common stock, with the remaining 9% per
annum dividend rate to accrue and be paid at the same time and in the same
amounts per share with distributions paid to the holders of common stock once
holders of common stock have initially received distributions equal to 10% per
annum from and after December 31, 2022 on the $7.38 per share net asset value
applicable to the common stock as of such date. In addition, the holders of the
Series B Preferred Stock can require the conversion of their Series B Preferred
Stock into shares of common stock, including on or after the third anniversary
of their acquisition of such shares, valued for such purposes at the lesser of
(1) $102.50 per share of common stock or (2) the Board’s most recent estimated
net asset value per share of common stock if the common stock is not traded on
a public exchange or at a specified market price if so traded. It is possible
that, over the life of the Company, the net asset value per share of common
stock will exceed $102.50. Therefore, it is possible that the Series B
Preferred Stock will participate in Company growth.
The Series C Preferred Stock ranks junior to our
Series A and Series B Preferred Stock.
In the event of our bankruptcy, liquidation, dissolution or winding-up
of our affairs, our assets will be available to pay obligations on the Series C
Preferred Stock only after all of our indebtedness and other liabilities have
been paid and the Liquidation Preference of the Series A and Series B Preferred
Stock has been satisfied. The rights of holders of the Series C Preferred Stock
to participate in the distribution of our assets rank junior to the prior
claims of our current and future creditors, the Series A and Series B Preferred
Stock and any future series or class of preferred stock we may issue that ranks
senior to the Series C Preferred Stock. The Series C Preferred Stock also will
rank junior, with respect to dividend rights and rights upon liquidation,
winding-up, or dissolution, to the Series A and B Preferred Stock (excluding
the additional accrued 9% portion of the Series B Preferred Stock dividend).
The Series A, B and C Preferred
Stock rank junior to all of our indebtedness and other liabilities and are
effectively junior to all indebtedness and other liabilities of our
subsidiaries.
In the event of our bankruptcy, liquidation, dissolution or winding-up
of our affairs, our assets will be available to pay obligations on the Series A,
B and C Preferred Stock only after all of our indebtedness and other
liabilities have been paid. The rights of holders of the Series A, B and C
Preferred Stock to participate in the distribution of our assets rank junior to
the prior claims of our current and future creditors and any future series or
class of preferred stock we may issue that ranks senior to the Series A, B and
C Preferred Stock.
In addition, the Series A, B and
C Preferred Stock effectively rank junior to all existing and future
indebtedness and other liabilities of (as well as any preferred equity
interests held by others in) our existing subsidiaries and any future
subsidiaries. Our existing subsidiaries are, and any future subsidiaries would
be, separate legal entities and have no legal obligation to pay any amounts to
us in respect of dividends due on the Series A, B and C Preferred Stock. If we
are forced to liquidate our assets to pay our creditors, we may not have
sufficient assets to pay amounts due on any or all of the Series A, B and C
Preferred Stock then outstanding. We and our subsidiaries have incurred and may
in the future incur substantial amounts of debt and other obligations that will
rank senior to the Series A, B and C Preferred Stock. We may incur additional
indebtedness and become more highly leveraged in the future, harming our
financial position and potentially limiting our cash available to pay
dividends. As a result, we may not have sufficient funds remaining to satisfy
our dividend obligations relating to our Series A, B and C Preferred Stock if
we incur additional indebtedness or issue additional preferred stock that ranks
senior to the Series A, B and C Preferred Stock.
Laws
intended to prohibit money laundering may
require us to disclose investor information to regulatory authorities.
The
Uniting and Strengthening America by Providing Appropriate Tools Required to
Intercept and Obstruct Terrorism Act of 2001, or the PATRIOT Act, requires that
financial institutions establish and maintain compliance programs to guard
against money laundering activities, and requires the Secretary of the U.S.
Department of Treasury to prescribe regulations in connection with anti-money
laundering policies of financial institutions.
The
Financial Crimes Enforcement Network, or FinCEN, an agency of the Department of
Treasury, has announced that it is likely that such regulations would subject
certain pooled investment vehicles to enact anti-money laundering policies.
It is
possible that there could be promulgated legislation or regulations that would
require us or our service providers to share information with governmental
authorities with respect to prospective investors in connection with the
establishment of anti-money laundering procedures. Such legislation
and/or regulations could require us to implement additional restrictions on the
transfer of our preferred shares to comply with such legislation and/or
regulations. We reserve the right to request such information as is necessary
to verify the identity of prospective shareholders and the source of the
payment of subscription monies, or as is necessary to comply with any customer
identification programs required by FinCEN and/or the SEC.
In the
event of delay or failure by a prospective shareholder to produce any
information required for verification purposes, an application for, or transfer
of, our preferred shares may be refused. We will not have the ability to reject
a transfer of our preferred shares where all necessary information is provided
and any other applicable transfer requirements, including those imposed under
the transfer provisions of our Charter, are satisfied.
Risk Related to Outbreaks of Infectious Diseases
Any future pandemic
or similar threat, and governmental responses thereto, could once again
materially and adversely impact or disrupt our financial condition, results of
operations, cash flows and performance, as well as adversely affect our and our
tenants’ financial condition and results of operations.
Our operating results
depend, in large part, on generating revenues from leases to residential or
commercial tenants, which in turn requires tenants to generate sufficient
income to pay their rents in a timely manner. Any local, regional, national or
international outbreak of a contagious disease or other public health emergency
- including any resurgence of COVID-19 or new strains of influenza,
coronaviruses or other pathogens - could adversely affect our operations and,
as a result, our ability to make distributions to our stockholders or to
realize appreciation in the value of our investments. Such events could result
in increases in unemployment, decrease the willingness of customers to
patronize our tenants’ retail facilities, discourage residents from renting in
our multi-family communities, cause shortages of employees to staff our
tenants’ operations, interrupt supplies from third parties upon which our
tenants rely, cause us or our tenants to temporarily close one or more of our
properties, result in governmental regulation adversely impacting our or our
tenants’ businesses and otherwise have a material adverse effect on our
business, financial condition and results of operations, especially where a
tenant may be unwilling or unable to pay rent in full on a timely basis. In
some cases, the companies in which we have invested may have to restructure tenants’
rent obligations, and they may not be able to do so on terms as favorable to us
as those currently in place. Numerous state, local, federal, and
industry-initiated efforts may also affect property owners’ ability to collect
rent or enforce remedies for the failure to pay rent. This may lead to
reduction or cancellation of distributions, which will in turn effect our
ability to pay our expenses and to pay distributions to our shareholders.
Risks
Relating to Potential Rescission Claims
Previous issuances of common shares under our dividend
reinvestment program may have violated certain federal and/or state securities
laws, and shareholders could file suit to seek rescission of such securities.
During
the period beginning June 2021 and ending December 2021, in an offering
pursuant to our registration statement on Form N-2, we made sales of securities
under our dividend reinvestment program pursuant to a deficient registration
statement (which registration statement became deficient by virtue of our
inadvertently failing to amend the registration statement to include the
then-current audit report of our auditors). Consequently, the offer and sale of
securities pursuant to the Form N-2 may have failed to comply fully with
Section 5 of the Securities Act which may trigger a right of rescission under
the Securities Act for investors that purchased shares of our common stock
during this period under our dividend reinvestment program.
Accordingly,
we may have liability to purchasers of such securities if they were to file
suit against us; the remedy could be to repurchase such securities at their
purchase price plus statutory interest, less the amount of any income received
with respect to such shares.
There may be claims relating to our possible non-compliance with
federal and/or state securities laws relating to the deficient Form N-2
referenced above, and we may continue to be contingently liable for rescission
or damages of an indeterminate amount.
It
is possible that regulators could pursue enforcement actions or impose
penalties and fines against us with respect to any violations of securities
laws relating to the issuance of dividend reinvestment program shares under the
deficient Form N-2 referenced above.
If we have to repurchase shares as discussed above, it may affect
our cash balances.
If
we have to repurchase shares of our common stock issued under the deficient
registration statement referenced above, such rescission payments will be
funded from our existing cash balances. Any rescission payments would reduce
funds available to us for our operations. If all persons issued shares without
registration were to successfully file suit and force rescission, we could need
to pay a total of approximately $865,000 and our results of operations, cash
balances or financial condition will be negatively affected.
Risks
Relating to Issuance of Warrants
There are unresolved issues related to rights of the warrant
holder.
In
February 2025, we issued pre-funded and unfunded warrants to a single
institutional investor pursuant to warrant agreements that granted the investor
the right to share in dividends. This dividend right is undisputed with respect
to pre-funded warrants to purchase up to 1,292,265 shares of common stock
(although after August 2025, this issue became moot when the investor exercised
all its prefunded warrants). However, the Company did not agree to pay
dividends on unfunded warrants to purchase 4,239,448 shares of common stock.
Nonetheless, the investor has taken the position that dividends are payable on
its unfunded warrants. The Company attempted to resolve this misunderstanding
with the investor, but no resolution has been reached.
The holder of unfunded warrants could assert claims for dividends
on the unfunded warrants.
The unfunded warrants became exercisable at the
end of August 2025, six months after issuance of the warrants. From and after
that time, the holder of the unfunded warrants could bring claims for
participation rights in any dividends declared by the Company on its common
stock. While the Company has suspended the payment of dividends on its common
stock while experiencing negative cash flow, such potential claims by the
holder of the unfunded warrants could be material if and when the Company
re-starts dividend payments.
Risks
Relating to Our Common Stock, Nasdaq Listing and Liquidity
We may be unable to satisfy the continued listing standards of The
Nasdaq Capital Market, and our common stock could be delisted.
Our common stock is listed on The Nasdaq Capital
Market. To maintain that listing, we must satisfy Nasdaq’s continued listing
standards, which include a minimum bid price of $1.00 per share, a minimum
stockholders’ equity requirement, a minimum market value of publicly held
shares, a minimum public float and other quantitative and qualitative
requirements. There can be no assurance that our common stock will continue to
satisfy the minimum bid price rule or Nasdaq’s other continued listing
standards. If we fail to satisfy any of these requirements, Nasdaq may commence
delisting procedures. Any future delisting could, among other things, reduce
the liquidity and market price of our common stock, cause us to lose our
eligibility to use Form S-3 to register the offer and sale of our securities on
a shelf basis, make it more difficult and expensive for us to raise capital,
and result in “events of default” or other adverse consequences under our
existing financings.
DETERMINATION
OF OFFERING PRICE AND MARKET PRICE
Initial
Offering Price
The
initial offering price and Stated Value per share for our Series A Preferred
Stock, Series B Preferred Stock, and Series C Preferred Stock were arbitrarily
determined by our Adviser.
Determination
of Market Price
We
are not stating a market price for the shares of Series A Preferred Stock, the
Series B Preferred Stock, or the Series C Preferred Stock offered under this
Offering Circular because there is no market for any series of our preferred
shares.
Valuation
of Our Real Properties
It
is our intent to use independent valuation experts with experience conducting
appraisals or valuations in each of our target markets. We will select our
appraisers based on their familiarity with real estate and their ability to
track and adjust valuations based on real-world events that may materially
impact the value of our assets. Our Adviser will be responsible for ensuring
that the independent valuation expert discharges its responsibilities in
accordance with our valuation guidelines as herein described, and will
periodically receive and review such information about the valuation of our assets
and liabilities as it deems necessary to exercise its oversight responsibility.
All such independent 3rd party appraisals shall be conducted in conformance
with the Uniform Standards of Professional Practice.
According
to our guidelines, we will ask our real estate appraisers to develop “open
market value” for our properties. Open market value is also known as “fair
value.” In order to establish a fair value, we will ask our appraisers to
consider three factors:
● Sales
Comparison
● Income
Production
● Cost
to Rebuild
Net
Asset Value
Previous
to our common stock being traded on the OTCQX and listed on the Nasdaq Capital
Market, we prepared an estimate of net asset value (“NAV”) of our common stock,
which we will no longer do.
No
Warrants Offered
We
are not offering any warrants to any investor as an inducement to invest in us.
We
are not offering any warrants, nor are there any warrants held by any officer,
director, promotor or other affiliated person or entity.
For
the purpose of this Offering Circular, a warrant is defined as an obligation by
us to accept money for purchase of shares at a predetermined price.
PLAN OF DISTRIBUTION
We are offering
up to $71,681,755.55
in our preferred shares pursuant to this Offering
Circular, up to $61,556,755.55
in the primary offering on a “best efforts” basis, and $10,125,000.00
through our dividend reinvestment program. Of these totals, we are offering $10,961,351.11
of Series A, $25,297,702.22of Series B, and $25,297,702.22 of Series C which
are on “best efforts” basis, and $3,375,000 through our dividend reinvestment
program for each Series, or 150,000 shares each.
We have entered a
Marketing Services Agreement with Arete to act as our dealer manager for this
offering. Arete may be an underwriter within the meaning of the Securities Act
in connection with its activities in this offering. Arete has no commitment to purchase
any preferred shares and will manage the offering process with other broker‑dealers
and sell directly to persons purchasing through advisory accounts. Arete will receive a Dealer Manager Fee of up to 1.9% of the gross
offering proceeds as compensation for acting as the dealer manager, a portion
of which fee may be waived or re-allowed to Selling Agents by Arete when wholesaling fees are not incurred. Arete will retain a portion of this amount and will
pay the balance to its wholesalers (who are also employed by the Manager). When
Arete sells to persons buying preferred shares
in an investment advisory account, Arete will
receive the 1.9% Dealer Manager Fee in lieu of all commissions.
Except as provided below, Selling Agents will receive
selling commissions of 7.0% of the gross proceeds of preferred shares sold in
the offering, and we may pay them a 1.1% Marketing Support Fee. We will not pay
referral or similar fees to any accountants, attorneys or other persons in
connection with the distribution of the preferred shares. The total
compensation paid to broker‑dealers will not exceed 10.0% of the gross proceeds
of preferred shares sold in the offering, and if the offering terminates prior
to reaching the maximum offering proceeds, broker‑dealers will immediately
refund any amount of compensation in excess of 10.0%.
We will not pay selling commissions or Dealer Manager Fees
on shares issued under our DRIP.
We have agreed to indemnify the participating broker‑dealers,
including Arete, against certain liabilities
arising under the Securities Act and liabilities arising from breaches of our
representations and warranties contained in the Marketing
Services Agreement. The broker‑dealers participating in the offering of
preferred shares are not obligated to obtain any subscriptions on our behalf,
and we cannot assure you that any preferred shares will be sold. Any person
acting as a broker‑dealer will not be indemnified by us for any losses,
liabilities or expenses arising from or out of an alleged violation of federal
or state securities laws by such party unless one or more of the following
conditions are met: (i) there has been a successful adjudication on the merits
of each count involving alleged securities law violations as to the particular
indemnitee; (ii) such claims have been dismissed with prejudice on the merits
by a court of competent jurisdiction as to the particular indemnitee; and (iii)
a court of competent jurisdiction approves a settlement of the claims against a
particular indemnitee and finds that indemnification of the settlement and the
related costs should be made, and the court considering the request for
indemnification has been advised of the position of the SEC and of the
published position of any state securities regulatory authority in which our
shares were offered or sold as to indemnification for violations of securities
laws.
Our executive officers and directors and their immediate
family members, as well as officers and employees of our Adviser and its
affiliates and their immediate family members and other individuals designated
by management, and, if approved by our Board of Directors, may purchase
preferred shares in this offering and may be charged a reduced rate for certain
fees and expenses in respect of such purchases. We expect that a limited number
of preferred shares will be sold to individuals so designated by management,
net of all selling commissions and Dealer Manager Fees, shortly after the
commencement of the offering. However, except for certain share ownership
restrictions contained in our Charter, there is no limit on the number of
preferred shares that may be sold to such persons. In addition, the selling
commission and the Dealer Manager Fee may be reduced or waived in connection
with certain categories of sales, such as sales for which a volume discount
applies, sales to certain institutional investors, sales through investment
advisers or banks acting as trustees or fiduciaries and sales to our
affiliates. The amount of net proceeds to us will not be affected by reducing
or eliminating the selling commissions or the Dealer Manager Fee payable in
connection with sales to such institutional investors and affiliates. Our
Adviser and its affiliates will be expected to hold their preferred shares
purchased as stockholders for investment and not with a view towards
distribution.
We are offering volume discounts to investors who purchase
more than $250,000 worth of our preferred shares through the same selected
broker‑dealer in our offering. The net proceeds to us from a sale eligible for
a volume discount will be the same, but the selling commissions payable to the
selected broker‑dealer will be reduced. The following table shows the
discounted price per Share and the reduced selling commissions payable for
volume sales of our preferred shares.
|
Dollar Amount of preferred shares Purchased
|
|
|
Purchase Price per
Incremental Unit
in Volume
Discount Range(1)
|
|
|
|
|
|
|
Reduced Commission Rate
|
|
|
$
|
1 – $ 250,000
|
|
|
$
|
25.00
|
|
|
|
7.0%
|
|
|
$
|
250,001 – 500,000
|
|
|
|
24.75
|
|
|
|
6.0%
|
|
|
$
|
500,001 – 750,000
|
|
|
|
24.50
|
|
|
|
5.0%
|
|
|
$
|
750,001 – 1,000,000
|
|
|
|
24.25
|
|
|
|
4.0%
|
|
|
$
|
1,000,001 –1,500,000
|
|
|
|
24.00
|
|
|
|
3.0%
|
|
|
$ 1,500,001 and up
|
|
|
|
23.75
|
|
|
|
2.0%
|
|
|
(1)
|
Assumes
a $25.00 per Share offering price. Discounts will be adjusted appropriately
for changes in the offering price, as, for example, for the Series A being
sold at $22.50.
|
We will apply the reduced selling price per Share and
selling commissions to the incremental preferred shares within the indicated
range only. Thus, for example, assuming a price per Share of $25, a purchase of
$500,000 would result in a weighted average purchase price of approximately
$24.87 per Share as shown below:
● $250,000 at $25.00 per Share (total: 10,000 preferred
shares) and a 7.0% commission;
● $250,000 at $24.75 per Share (total: 10,101 preferred
shares) and a 6.0% commission
To qualify for a volume discount as a result of multiple
purchases of our preferred shares you must use the same selected broker‑dealer
and you must mark the “Additional Investment” space on the subscription
agreement. We are not responsible for failing to combine purchases if you fail
to mark the “Additional Investment” space. Once you qualify for a volume
discount, you will be eligible to receive the benefit of such discount for
subsequent purchases of preferred shares through the same selected broker‑dealer.
To the extent purchased through the same selected broker‑dealer,
the following persons may combine their purchases as a “single purchaser” for
the purpose of qualifying for a volume discount:
● an individual, his spouse, their children under the age of
21 and all pension or trust funds established by each such individual;
● a corporation, partnership, association, joint‑stock
company, trust fund or any organized group of persons, whether incorporated or
not;
● an employees’ trust, pension, profit‑sharing or other
employee benefit plan qualified under Section 401(a) of the Internal Revenue
Code; and
● all commingled trust funds maintained by a given bank.
In the event a person wishes to have his order combined with
others as a “single purchaser,” that person must request such treatment in
writing at the time of subscription setting forth the basis for the discount
and identifying the orders to be combined. Any request will be subject to our
verification that the orders to be combined are made by a single purchaser. If
the subscription agreements for the combined orders of a single purchaser are
submitted at the same time, then the commissions payable and discounted share
price will be allocated pro rata among the combined orders on the basis of the
respective amounts being combined. Otherwise, the volume discount provisions
will apply only to the order that qualifies the single purchaser for the volume
discount and the subsequent orders of that single purchaser.
Only preferred shares purchased in our offering pursuant to
this Offering Circular are eligible for volume discounts. Preferred shares
issued through our DRIP will not count toward the threshold limits listed above
that qualify you for the different discount levels. In
the ordinary course of business, Arete and/or its affiliates may in the future
engage in financial advisory, investment banking and other transactions with us
for which customary compensation will be paid.
Offering
Amount and Distribution
We
are offering a maximum of $[ ] of our
shares at an anticipated offering price of $22.50 per share for the Series A or
$25.00 per share for the Series B and C. The minimum purchase requirement is
$5,000 in shares; however, we can waive the minimum purchase requirement in our
sole discretion.
We
will hold bi-monthly closings of the offering, providing an effective date of
the first of the month for subscriptions accepted on or prior to the 15th
of the month, and an effective date of the 1st of the following
month for subscriptions accepted between the 16th and the last day
of each month. Upon acceptance of
subscriptions, we will immediately use the proceeds for the purposes described
in this Offering Circular.
How to Subscribe
To
subscribe for preferred shares, an investor must complete and sign the
Subscription Agreement attached hereto as Appendix A, selecting whether you are
purchasing Series A, Series B, or Series C Preferred Stock. The investor must
deliver to our transfer agent, MacKenzie Capital Management, LP, the fully
executed Subscription Agreement and a check for the full subscription price
made payable to “MacKenzie Realty Capital, Inc.” The mailing address follows:
MacKenzie Realty Capital, Inc.
89 Davis Road, Suite 100
Orinda, CA 94563
If
you elect to participate in both the dividend reinvestment program, dividends
earned from shares purchased will automatically be reinvested pursuant to such
program. For a discussion of our dividend reinvestment program, see “Series A, B
and C Preferred Stock Dividend Reinvestment Program,” and Appendix B.
Acceptance
of Subscriptions
We
have the right, to be exercised in our sole discretion, to accept or reject any
subscription in whole or in part for a period of 30 days after receipt of the
subscription. Any subscription not accepted within 30 days of receipt will be
deemed rejected.
Investment
Limitations
Generally,
if you do not fall within the definition of a “Qualified Purchaser”, no sale
may be made to you in this offering.
An
investment in our preferred shares involves significant risks and is only
suitable for persons who have adequate financial means, desire a relatively
long-term investment, and will not need liquidity from their investment. This
investment is not suitable for persons who seek liquidity or guaranteed income,
or who seek a short-term investment.
Generally,
if you are not an “accredited investor” as defined in Rule 501(a) of Regulation
D (17 CFR Sec. 230.501(a)) no sale may be made to you in this offering if the
aggregate purchase price you pay is more than 10% of the greater of your annual
income or net worth. Different rules apply to accredited investors and
non-natural persons. Before making any representation that your investment does
not exceed applicable thresholds, we encourage you to review Rule
251(d)(2)(i)(C) of Regulation A. For general information on investing, we
encourage you to refer to sec.gov.
As
a Tier 2 Regulation A offering, investors must comply with the 10% limitation
to investment in the Offering. The only investor in this Offering exempt from
this limitation is an Accredited Investor, as defined under Rule 501 of
Regulation D. If you meet one of the following tests you should qualify as an
Accredited Investor:
(i) You are a
natural person who has had individual income in excess of $200,000 in each of
the two most recent years, or joint income with your spouse in excess of
$300,000 in each of these years, and have a reasonable expectation of reaching
the same income level in the current year;
(ii) You are a natural
person and your individual net worth, or joint net worth with your spouse,
exceeds $1,000,000 at the time you purchase shares (please see below on how to
calculate your net worth);
(iii) You are an executive
officer or general partner of the issuer or a manager or executive officer of
the general partner of the issuer;
(iv) You are an organization
described in Section 501(c)(3) of the Internal Revenue Code of 1986, as
amended, or the Code, a corporation, a Massachusetts or similar business trust
or a partnership, not formed for the specific purpose of acquiring the shares,
with total assets in excess of $5,000,000;
(v)
You are a bank or a savings and loan association or other
institution as defined in the Securities Act, a broker or dealer registered
pursuant to Section 15 of the Securities Exchange Act of 1934, as amended, or
the Exchange Act, an insurance company as defined by the Securities Act, an
investment company registered under the Investment Company Act of 1940, as
amended, or the Investment Company Act, or a business development company as
defined in that act, any Small Business Investment Company licensed by the
Small Business Investment Act of 1958 or a private business development company
as defined in the Investment Advisers Act of 1940;
(vi) You are an entity
(including an Individual Retirement Account trust) in which each equity owner
is an accredited investor;
(vii) You are a trust with total
assets in excess of $5,000,000, your purchase of shares is directed by a person
who either alone or with his purchaser representative(s) (as defined in
Regulation D promulgated under the Securities Act) has such knowledge and
experience in financial and business matters that he is capable of evaluating
the merits and risks of the prospective investment, and you were not formed for
the specific purpose of investing in the shares; or
(viii) You are a plan
established and maintained by a state, its political subdivisions, or any
agency or instrumentality of a state or its political subdivisions, for the
benefit of its employees, if such plan has assets in excess of $5,000,000.
Under
Rule 251 of Regulation A, non-accredited, non-natural investors are subject to
the investment limitation and may only invest funds which do not exceed 10% of
the greater of the purchaser’s revenue or net assets (as of the purchaser’s
most recent fiscal year end). A non-accredited, natural person may only invest
funds which do not exceed 10% of the greater of the purchaser’s annual income
or net worth (please see below on how to calculate your net worth).
NOTE:
For the purposes of calculating your net worth, or Net Worth, it is defined as
the difference between total assets and total liabilities. This calculation
must exclude the value of your primary residence and may exclude any
indebtedness secured by your primary residence (up to an amount equal to the
value of your primary residence). In the case of fiduciary accounts, net worth
and/or income suitability requirements may be satisfied by the beneficiary of
the account or by the fiduciary, if the fiduciary directly or indirectly
provides funds for the purchase of the shares.
Reports
Reporting
Requirements under Tier 2 of Regulation A.
We
will continue to comply with our ongoing reporting obligation faced by issuers
under the Exchange Act.
Delivery
of Reports
We
shall be deemed to have made a report available to each stockholder as required
if we have either (i) filed such report with the SEC via its EDGAR system and
such report is publicly available on such system, or (ii) made such report
available on any website maintained by us and available for viewing by the
stockholders.
Tax
Information
On
or before March 31st of the year immediately following our tax year, which is
currently January 1 through December 31, we will send to each stockholder such
tax information as shall be reasonably required for federal and state income
tax reporting purposes.
Stock
Certificates
We
do not anticipate issuing stock certificates representing shares purchased in
this Offering to the stockholders. However, we are permitted to issue stock
certificates and may do so at the request of our transfer agent. The number of
shares held by each stockholder, and each stockholder’s percentage of the
aggregate outstanding shares, will be maintained by our transfer agent.
USE
OF PROCEEDS
Our preferred
shares will be offered at $22.50 per share for Series A and $25.00 per share
for Series B and C. We expect to use substantially all of the net
proceeds from this Offering, including the dividend reinvestment program (after
paying or reimbursing organization and offering expenses) to invest in and
manage a diverse portfolio of Investments.
We
expect that any expenses or fees payable to our Adviser for its services in
connection with managing our daily affairs, including but not limited to, the
selection and acquisition or origination of our investments, will be paid from
cash flow from operations.
If
such fees and expenses are not paid from cash flow (or waived) they will reduce
the cash available for investment and distribution and will directly impact our
NAV. See “Management Compensation” for more details regarding the fees
that will be paid to our Adviser and its affiliates.
We may
not be able to promptly invest the net proceeds of this Offering in Investments. In the interim, we may invest
in short-term, highly liquid or other authorized investments, subject to the
requirements for qualification as a REIT. Such short-term investments will not
earn as high of a return as we expect to earn on our real estate-related
investments.
SERIES
A, B AND C PREFERRED STOCK DIVIDEND REINVESTMENT PROGRAM
The
Dividend Reinvestment Program (“DRIP”) provides holders of record of our preferred
shares an opportunity to automatically reinvest all of their cash distributions
received on the preferred shares in additional preferred shares at a discounted
price. The following discussion
summarizes the principal terms of the DRIP.
Appendix B to this Offering Circular contains the full text of our DRIP.
The
Plan will be administered by the Administrator, or any successor bank or trust
company that we may from time to time designate. Certain of the administrative
support to the Administrator may be performed by its designated affiliates.
Our
Series A, Series B, and Series C Preferred Stock purchased directly from us
under the Plan will be priced at $22.50 per share, a 10% discount with respect
to the Series B and C offering price. Any shares sold pursuant to the DRIP are
considered part of the shares offered under this Offering Circular. At the conclusion of this Offering, we hope
to continue the DRIP through another exempt offering of preferred shares, but
continued participation in the DRIP may be subject to available exemptions in
your state; therefore, we reserve the right to restrict participation in the
DRIP to residents of only some states. The DRIP highlights include:
● Any
holder of preferred shares may elect to participate in the DRIP.
● Preferred
shares are issued at a 10% discount to the Stated Value of $25 per Share, or at
$22.50 per share.
● Shares
purchased will be maintained in your name in book-entry form at no charge to
you.
● Detailed
recordkeeping and reporting will be provided at no charge to you.
● You
may opt-out of the DRIP at any time.
● Holders
of Series A Preferred Stock in the DRIP will be issued Series A Preferred Stock.
● Holders
of Series B Preferred Stock in the DRIP will be issued Series B Preferred Stock,
each purchased at the discounted price above, but with a new Stated Value of
$25 per Share.
● Holders
of Series C Preferred Stock in the DRIP will be issued Series C Preferred Stock,
each purchased at the discounted price above, but with a new Stated Value of
$25 per Share.
GENERAL
INFORMATION ABOUT US
Organization
MacKenzie Realty
Capital, Inc. (the “Parent Company” together with its subsidiaries as discussed
below, collectively, the “Company,” “we,” “us,” or “our”) was incorporated
under the general corporation laws of the State of Maryland on January 27,
2012. We have elected to be treated as a real estate investment trust (“REIT”)
as defined under Subchapter M of the Internal Revenue Code of 1986, as amended
(the “Code”). We are authorized to issue 100,000,000 shares, of which (i)
80,000,000 are designated as common stock, with a $0.0001 par value per share;
and (ii) 20,000,000 are designated as preferred stock, with a $0.0001 par value
per share. We commenced our operations on February 28, 2013, and our fiscal
year-end is June 30.
We are registered under
Section 12(b) of the Securities Exchange Act of 1934 (the “Exchange Act”), and
we will continue to file periodic reports on Form 10-K, Form 10-Q, and Form
8-K, as well as file proxy statements and other reports required under the Exchange
Act.
We filed our initial
registration statement with the Securities and Exchange Commission (“SEC”) in 2012 and have since completed multiple public offerings of our common stock. On November 6, 2024, The Nasdaq
Stock Market (“Nasdaq”) approved the listing of our common stock, and trading
commenced on the Nasdaq Capital
Market on November 11, 2024.
We are externally managed by
MacKenzie Capital Management, LP (“MacKenzie”) under a turnkey administration
agreement dated and effective as of January 1, 2021 (the “Administration
Agreement”). MCM Advisers, LP (the “Investment Adviser”), an affiliate of MacKenzie,
advises us in our assessment, acquisition, and divestiture of securities under
the advisory agreement amended and restated effective January 1, 2021 (the
“Amended and Restated Investment Advisory Agreement”). Another affiliate of MacKenzie,
MacKenzie Real Estate Advisers, LP (the “Real Estate Adviser”; together, the
“Investment Adviser” and the “Real Estate Adviser” may be referred to as
“Adviser” or “Advisers” as appropriate) advises us in our assessment,
acquisition, and divestiture of real estate assets under the Advisory Management Agreement, dated
January 27, 2021 and as amended on December 29, 2025, effective January 1, 2026
(as amended, the “Advisory Management Agreement”). Under the Advisory
Management Agreement, as amended, we pay the Real Estate Adviser (i) a base
management fee equal to 1.25% per annum of our gross assets under management
(excluding depreciation and amortization), paid monthly, and (ii) a bonus
management fee equal to 5% of our adjusted funds from operations for each
quarter. The Advisory Management Agreement has a five-year term that renews
automatically on each January 1 unless we deliver a timely non-renewal notice,
and requires us to pay a substantial early termination fee if we terminate the
agreement other than for cause. See Note 8 to the consolidated financial
statements included in this report for additional information about the terms
of these arrangements and the fees paid to our Advisers. We pursue a strategy focused on investing primarily in real
estate assets, and to a lesser extent (intended to be less than 20% of our
portfolio) in illiquid or non-traded debt and equity securities issued by U.S.
companies generally owning commercial real estate. These
companies are likely to be non-traded REITs, small-capitalization publicly
traded REITs, public and private real estate limited partnerships, and limited
liability companies.
Prior to January 1,
2026, the Company conducted substantially all of its real estate operations
through MacKenzie Realty Operating Partnership, LP (the “Operating
Partnership”), which was formed in May 2020. Effective January 1, 2026, the
Company reorganized its real estate operations by separating its multi-family
residential portfolio from its commercial real estate investments. The Company
contributed its multi-family residential properties (Commodore, The Park View,
Hollywood and Shoreline Apartments and Aurora at Green Valley) and Blue Ridge
at Suisun Valley (“Blue Ridge”) development project to MacKenzie Apartment
Communities, Inc. (“MAC”), a newly formed entity, in exchange for 1,906,580
shares of MAC, representing all of the outstanding shares of MAC at the time of
the contribution, on a 1:1 basis with the Parent Company’s outstanding shares
at the time of the contribution. Blue Ridge is a planned multi-family
residential development project located on vacant land adjacent to the
Company’s 220 Campus Lane Office Building in Fairfield, California. The project
is expected to consist of 84 multi-family residential units, and the
entitlement process is ongoing. The Parent Company is the sole shareholder of
MAC as of June 30, 2026. On January 8, 2026, the Board of Directors of MAC
approved an estimated net asset value of the common stock of MAC equal to
$18.10 per share for MAC’s common stock. The estimated net asset value solely
applies to MAC common stock and does not reflect the net asset value of the Parent
Company’s common stock. The contributed properties and development project are
held by MAC Operating Partnership, LP (“MAC OP”), of which MAC is the sole
general partner and owner of all limited partnership units (except for 1 unit
held by the Operating Partnership to ensure there are 2 partners in MAC OP).
MAC OP directly or indirectly owns and operates five residential properties and
one development project. Following the reorganization, the Company’s commercial
real estate investments continued to be held through the Operating Partnership.
As of June 30, 2026, we own all limited
partnership units of the Operating Partnership except for 81,909.89 Class A
Limited Partnership units, 1,063,239.94 Series A preferred units and
43,212.86 Series B preferred units. Upon a limited partner’s
request for redemption or upon liquidation of the Operating Partnership, the 81,909.89 Class A
Limited Partnership units are convertible into shares
of the Company’s common stock on the basis
of 1 share of common stock for every 10 units or, at the Company’s election,
for cash based upon the 10-day average trading price of the Company’s common
stock, also on the basis of 1 share of common stock for every 10 units (as a
result of the Company’s 1-for-10 common stock reverse stock split (the
“Reverse Stock Split”) on August 4, 2025; previously the units were convertible
on the basis of 1 share of common stock for every 1 unit). Upon a request of a
holder of Series A or Series B preferred units, the Company may elect to
repurchase such units with the Company’s common stock based upon the volume
weighted average price per share of common stock for the twenty (20) trading
days prior to the repurchase date, or at the Company’s election or upon liquidation,
the 1,063,239.94 Series A preferred units are entitled to a liquidation preference
of $26,580,999 (based on the stated value of
$25 per share for the Series A preferred units) and the 43,212.86
Series B preferred units are entitled to a liquidation preference of $1,080,322
(based on the stated value of $25 per share for the Series B preferred units).
The Parent Company has contributed net capital
of $72,457,055 to the Operating Partnership since inception; thus, the Class A,
Series A and Series B preferred units represent approximately 28.23% of all capital
contributions.
The
consolidated financial statements include
the accounts of the Parent Company, the Operating Partnership, MAC, MAC OP, MacKenzie NY
Real Estate 2 Corp. (“MacKenzie NY 2”), a taxable REIT subsidiary, and their majority-owned
and controlled subsidiaries, including joint
ventures and property-owning entities acquired or formed to own, operate,
develop, or manage multi-family, office, and mixed-use real estate properties.
The consolidated entities include Madison-PVT Partners LLC (“Madison”),
PVT-Madison Partners LLC (“PVT”), Hollywood Hillview Owner, LLC (“Hollywood
Hillview”), MacKenzie-BAA IG Shoreline LLC (“MacKenzie Shoreline”), MacKenzie
Satellite Place Corp. (“MacKenzie Satellite”), MRC Aurora, LLC (“MRC Aurora”), 220 Campus Lane, LLC (“220 Campus Lane”), Campus Lane Residential, LLC (“Campus Lane Residential”), GV Executive Center, LLC
(“GVEC”), Innovate Napa, LLC
(“Innovate Napa”), MRC QRS, Inc. (“MRC QRS”), and various limited partnerships
(each a “Wiseman Partnership”) acquired in connection with the Wiseman
transaction, including First & Main, LP (“First & Main”), 1300 Main, LP
(“1300 Main”), Woodland Corporate Center Two, LP (“Woodland Corporate Center
Two”), Main Street West, LP (“Main Street West”), One Harbor Center, LP (“One
Harbor Center”), and Green Valley Medical Center, LP (“Green Valley Medical
Center”). Each Wiseman Partnership owns a Class A or B office property in Napa,
Fairfield, Suisun, or Woodland, California (the “Wiseman Properties”).
Intercompany balances and transactions are eliminated in consolidation.
We are conducting a
Regulation A offering of our preferred stock pursuant to an offering circular
qualified by the SEC on November 21, 2025, (as amended, the “Offering
Circular”) which permits the offer and sale of up to $72.90 million of Series
A, Series B, and Series C preferred stock, at an offering price of $22.50 per
Series A share and $25.00 per Series B or Series C share. Prior Regulation A
offerings have been terminated or superseded.
In November 2024, we filed a
new shelf registration statement on Form S-3 (the “Form S-3 Registration
Statement”) to sell our common and preferred stock, warrants, rights and units
up to an aggregate of $75 million. The Form S-3 Registration Statement was
declared effective by the SEC on January 15, 2025. Also on January 15, 2025, we
entered into an Equity Distribution Agreement (the “ATM Sales Agreement”) with
Maxim Group LLC (the “Sales Agent” or “Maxim”) pursuant to which we may issue
and sell shares of our common stock, covered by the prospectus supplement filed
with the SEC on January 15, 2025 and accompanying base prospectus dated January
15, 2025 (together, the “ATM Prospectus”), subject to maintaining
compliance with General Instruction I.B.6 of Form S-3 Registration Statement which requires that in no event will we sell securities in a
public primary offering with a value exceeding more than one-third of our
public float in any 12-month period so long as our public float remains below
$75 million.
On January 7, 2026, in connection
with the at the market offering
program (the “ATM Offering”) through which the
Company may sell up to $20,000,000 of shares of the Company’s common stock at $0.0001 par value
per share, the Company entered into an amendment to the ATM Sales Agreement
with Maxim.
In accordance with the
terms of the amendment, the ATM Sales Agreement will now terminate upon the
earlier of (i) the issuance and sale of all of the common stock subject
to the ATM Sales Agreement, (ii) termination of the ATM Sales Agreement by the
Company or the Sales Agent with 15 days written notice, or (iii) July 15, 2027.
On August 26, 2024, the
Company entered into a letter agreement with Maxim to provide general financial
advisory and investment banking services to the Company in connection with,
among other things, strategic planning, potential uplisting to a U.S. exchange
(Nasdaq, New York Stock Exchange), and potential rights offering, equity
issuance or other mechanisms to enhance corporate and shareholder value. In
connection with the agreement, the Company issued to Maxim’s affiliate in a
private placement 13,300 shares of common
stock, representing approximately 1% of the Company’s outstanding stock. The
common stock does not have any conversion
rights.
On August 4, 2025, the
Company effected a 1-for-10 Reverse Stock Split of its common stock. In
connection with the Reverse Stock Split, the Company amended its charter to
temporarily increase the par value of the common stock from $0.0001 per share
to $0.001 per share and, on the same date, further amended its charter to
restore the par value to $0.0001 per share. The Reverse Stock Split did not
change the number of authorized shares of common stock. Prior to the Reverse
Stock Split, the Company had 16,760,978 shares of common stock outstanding.
Immediately following the Reverse Stock Split (and after giving effect to the
payment of cash in lieu of fractional shares), the Company had 1,675,776 shares of common stock outstanding. No
fractional shares were issued as a result of the Reverse Stock Split.
Stockholders entitled to receive a fractional share instead received a cash
payment equal to the fraction of a share multiplied by the closing price of the
Company’s common stock on The Nasdaq Capital Market on August 1, 2025, as
adjusted for the Reverse Stock Split, without interest. All common share and
per-share information in the accompanying consolidated financial statements and
notes have been retroactively adjusted to reflect the Reverse Stock Split.
As of June 30, 2026, we
have raised approximately $125.76 million from our common stock public offerings (including $4.83 million from our Registered Offering and the concurrent private
placement, and $1.83 million from the ATM offering), $19.90 million from our Series A preferred stock offering, $3.72
million from our Series B preferred
stock offering and $1.37 million from our Series C preferred stock offering pursuant to the Offering Circular. As of June 30, 2026, we
have issued shares of common stock, Series A preferred stock, Series B preferred stock, and Series C preferred stock with gross proceeds of $15.56 million, $0.63
million, $0.04 million, and a
minimal worth of shares, respectively, under our
dividend reinvestment plans (each a “DRIP” and together the “DRIPs”). Of the
total shares issued by us as of June 30, 2026, we have repurchased approximately $14.28 million in shares of common stock, $2.41 million in shares of Series A
preferred stock and $0.15 million in shares of Series B preferred stock, respectively, under our share repurchase program. As of June 30, 2026, we
have 2,512,270 shares of common stock, 733,447.24 shares of Series A preferred stock, 124,627.52 shares of Series B
preferred stock, and 54,707.09
shares of Series C preferred stock outstanding.
Investment
Objective
Our
investment objective is to generate current income and capital appreciation
through the acquisition of real estate assets and debt and equity real
estate-related investments. Our independent directors review our investment
policies periodically, at least annually, to confirm that our policies are in
the best interests of our stockholders. Each such determination and the basis
thereof are contained in the minutes of our Board of Directors meetings.
We
seek to accomplish our objective by rigorously analyzing the value of and risks
associated with potential acquisitions, and, for up to 20% of our total assets,
by acquiring real estate securities at significant discounts to their net asset
value.
Our
Corporate Information
Our
offices are currently located at 89 Davis Road, Suite 100, Orinda, CA 94563 and
our telephone number is (925) 631-9100 or (800) 854-8357. We relocated to our
current address from 1640 School Street, Moraga, CA 94556 in June 2018.
Investment
Strategy
Following
withdrawal of our election to be regulated as a BDC in 2020, we have continued
to invest in private companies that directly or indirectly own real property,
increased our control over our private investments, and consolidated those
investments for financial reporting purposes when appropriate, and we intend to
continue to do the same. We conduct many of our operations through the
Operating Partnership. The withdrawal of our BDC election has also allowed
us to expand our investment pool to include real, physical assets, as opposed
to only investment securities. We believe that this expanded pool of potential
investments allows access to risk-adjusted returns consistent with our
investment objective, while allowing us to maintain our REIT status.
We
engage in various investment strategies to achieve our overall investment
objectives. The strategy we select depends upon, among other things, market
opportunities, the skills and experience of the Advisers’ investment team and
our overall portfolio composition. We generally seek to acquire assets that
produce ongoing distributable income for investors, yet with a primary focus on
purchasing such assets at a discount from what the Advisers estimate to be the
actual or potential value of the real estate.
When
evaluating opportunities to buy properties, we look for opportunistic and
value-add situations similar to our approach to targeting real estate
securities, including unique situations and value-added opportunities. We
evaluate the broader market, the property’s position in the market, the needs
our capital can address, and the track record of the sponsor or operator
bringing the opportunity to us. We do not generally engage brokers to search
for or acquire properties, and the majority of our properties were acquired in
“off market” transactions.
We
acquire mid-market properties that may be too small to attract most
institutions, and where we believe we can create long-term value for our
stockholders utilizing the following investment strategies.
• Value-Add. We invest in
well-located properties with strong and stable cash flows in demographically
attractive economic growth markets where we believe there exists significant
potential for medium-term capital appreciation through renovation or
redevelopment, to reposition the asset and drive future rental growth.
• Opportunistic. We invest
in properties available at opportunistic prices (i.e., at prices we believe are
below those available in an otherwise efficient market) that exhibit some
characteristics of distress, such as operational inefficiencies, significant
deferred capital maintenance, or broken capital structures providing an
opportunity for a substantial return from appreciation in value.
• Invest-to-Own. We may
invest in the development of properties in target markets where we believe we
can capture significant development premiums upon completion. We generally use
a mezzanine loan or convertible preferred equity structure which provides
income during the development stage and/or the ability to capture development
premiums at completion by exercising our conversion rights to take ownership.
We
intend to continue our historical activities related to tender offers for
shares of non-traded REITs to boost our short-term cash flow and to support our
distributions, subject to the constraint that such securities will not exceed
20% of our portfolio. We believe this niche strategy will allow us to pay
distributions that are supported by cash flow rather than paying back
investors’ capital, although there can be no assurance that some portion of any
distribution is not a return of capital. This strategy can boost cash-flow in
two ways: (1) most such non-traded REITs pay regular cash distributions; and
(2) when such non-traded REIT shares are liquidated or sold, we may realize a
profit from having purchased the shares at a discount to the underlying net
asset value.
Types
of Investments
We
target real estate-related investments which may include equity interests in
LLCs, tenancies-in-common, mortgages, loans, bonds, other real estate-related
investment entities, or direct ownership of real property. We intend to
purchase primarily majority interests in properties or companies that own
properties so that we can consolidate them into our financial statements. We
may purchase non-controlling interests, but we intend that such investments
will constitute less than 20% of our portfolio. We do not invest in general
partnerships or other entities that do not afford limited liability to their
security owners. However, limited liability entities in which we invest may
hold interests in general partnerships, joint ventures, or other non-limited
liability entities.
Investment
Selection
Our
Adviser's investment team is responsible for all aspects of our investment
process. The current members of the investment team are Glen Fuller, Chip
Patterson, Robert Dixon, Angche Sherpa, and Christine Simpson. The investment
strategy involves a team approach, whereby potential transactions are screened
by various members of the investment team.
Our
process for acquiring targeted real estate typically involves three steps: (i)
identifying assets of the type we may be interested in acquiring; (ii)
evaluating the assets to estimate their value or potential value to us, and
(iii) either acquiring such assets directly or through our network of real
estate partners. Different circumstances may require different procedures, or
different combinations of procedures, and we adjust our acquisition strategy to
fit the circumstances. Nonetheless, the typical stages of our investment
selection process are as follows:
Deal
Generation/Origination
We
source investments through long-standing relationships with real estate
operators, developers, industry contacts, brokers, commercial and investment
bankers, entrepreneurs, services providers such as lawyers and accountants, as
well as current and former clients, portfolio companies and investors. Our
Adviser's investment team supplements these lead generators by also utilizing
broader marketing efforts, such as advertisements in real estate periodicals,
newspapers and other publications, attendance at prospective borrower industry
conventions and the like.
Screening
In
screening potential investments, the Adviser's investment team utilizes a
value-oriented investment philosophy and commits resources to managing downside
exposure.
Due
Diligence
In
conducting due diligence, the Adviser uses publicly available information as
well as information from its relationships with former and current management
teams, investors, consultants, competitors, and investment bankers. Our
Adviser's due diligence typically includes:
● review
of operating history, appraisals, market reports, vacancies, deferred
maintenance;
● review
of historical and prospective financial information and regulatory disclosures;
● research
relating to the property’s management, industry, markets, products and services,
and competitors;
● verification
of collateral; and
● appraisals
or opinions of value by third party advisers.
Upon
the completion of due diligence and a decision to proceed with an investment,
the investment professionals leading the investment present the investment
opportunity to the Adviser's investment team, which then determines whether to
pursue the potential investment. Additional due diligence with respect to any
investment may be conducted on our behalf by attorneys and independent
accountants prior to the closing of the investment, as well as other outside
third-party advisers, as appropriate. Any fees and expenses incurred by the
Adviser to oversee due diligence investigations undertaken by third parties are
subject to reimbursement by us, if not otherwise reimbursed by the prospective
borrower, which reimbursements are in addition to any management or incentive
fees payable by us under the advisory agreement (the “Investment Advisory
Agreement”).
Monitoring
Our
Adviser monitors our investments on an ongoing basis. Our Adviser has several
methods of evaluating and monitoring the performance and value of the assets in
which we invest, which include the following:
● Assessment
of success in adhering to business plans and compliance with covenants;
● Periodic
and regular contact with property management to discuss financial position,
requirements, and accomplishments;
● Comparisons
to other properties in the geographic area or sector, if any;
● Attendance
at and participation in our board meetings; and
● Review
of monthly and quarterly consolidated financial statements and financial
projections for properties.
Staffing
We
do not currently have any employees. Our day-to-day investment operations are
managed by the Adviser. Our Adviser may hire additional investment
professionals, based upon its needs. We also entered into an administration
agreement with MacKenzie (the “Administration Agreement”), under which
we reimburse MacKenzie for our allocable portion of overhead and other expenses
incurred by it in performing its obligations, including rent, the fees and
expenses associated with performing compliance functions, and the compensation
of our chief financial officer, our chief compliance officer (or
"CCO"), and any administrative support staff. We have also retained MacKenzie as our
transfer agent, for which we have been reimbursing them for certain software
development costs.
Board
Approval of the Investment Advisory Agreement
Our
advisory and administrative services agreements were initially approved by our
Board of Directors in January 2021, and have been reviewed and approved
annually since 2021. Such approvals were made on the basis of an evaluation
satisfactory to our Board of Directors including a consideration of, among
other factors, (i) the nature, quality, and extent of the advisory and other
services to be provided under the agreements, (ii) the investment performance
of the personnel who manage REITs with objectives similar to ours, to the
extent available, (iii) comparative data with respect to advisory fees or
similar expenses paid by other REITs with similar investment objectives, to the
extent available, and (iv) information about the services to be performed and
the personnel performing such services under each of the agreements.
On
December 29, 2025, our Board of Directors, including a majority of our
independent directors, unanimously approved an amendment to the Advisory
Management Agreement with the Real Estate Adviser, effective January 1, 2026,
that replaced the prior asset management, incentive management, acquisition,
financing and disposition fee structure with a base management fee equal to
1.25% per annum of our gross assets under management (excluding depreciation
and amortization), paid monthly, and a bonus management fee equal to 5% of our
adjusted funds from operations for each quarter. In approving the amendment,
our Board of Directors considered, among other factors, the anticipated effect
of the amended fee structure on our total advisory expenses as compared to the
prior structure, the nature and scope of the services to be provided by the
Real Estate Adviser, comparative data with respect to advisory fees paid by
other externally managed REITs, and the alignment of the amended fee structure
with the current scale and strategy of our real estate portfolio.
Our
internet address is www.mackenzierealty.com. We are a
reporting company and file reports, proxy statements, and other information
with the SEC. The SEC maintains an internet site that contains reports, proxy
and information statements, and other information regarding issuers that file
electronically with the SEC at http://www.sec.gov. We make
available free of charge on or through our website our annual report on Form
10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and
amendments to those reports filed or furnished pursuant to Section 13(a) or
15(d) of the Exchange Act as soon as reasonably practicable after we
electronically file such material with, or furnish it to, the SEC.
COMPANY POLICY REGARDING CERTAIN ACTIVITIES
Issuing
Securities Senior to Preferred Shares
Our
current policy is to not issue securities superior to our Series A and Series B
Preferred Stock, or to issue securities senior to Series C Preferred Stock
other than Series A or B Preferred Stock.
This Policy cannot be changed by the officers and directors without a
vote of the holders of the preferred shares.
Borrowing
Money
We
intend to purchase real estate assets. We may choose:
● to
borrow money to help with the purchase of property;
● to
borrow money to help with the rehabilitation of already purchased property;
● to
borrow money against (leverage) already owned properties to help with the
purchase and rehabilitation of other properties; and
● to
borrow money to facilitate our daily operation.
Making
Loans to Others
Our
current policy does not allow us to make loans to individuals. This policy may
be changed by the Board of Directors without a vote by the shareholders.
We have
no history of making loans to other individuals.
Investing
for Purpose of Controlling Other Entities
We
may invest to take over control of others, obtain control of others, or merge
with other entities. This policy may be changed by the officers or the Board of
Directors without a vote by the shareholders.
We
have some history of investing in the securities of other issuers for the
purpose of exercising control, as we did with Addison Corporate Center.
Underwriting
the Securities of Other Issuers
Our
current policy does not allow us to underwrite the securities of other issuers.
This policy may be changed by the officers or the Board of Directors without a
vote by the shareholders.
We
have no history of underwriting the securities of other issuers.
Acting as an
Investment Company
Our
current policy does not allow us to primarily engage in the purchase and sale
(or turnover) of our investments. We intend to elect to be treated as a REIT.
As such, we will be required to invest most all of our capital in real estate.
However,
we envision that there may be instances where we will need to invest in assets
other than real estate, such as:
● if
a large number of investors invest through this Offering close in time to each
other, it will take time for us to identify appropriate real estate
investments;
● We
may continue to invest up to 20% of our total assets in real estate securities;
or
● if
we have capital not in use, we may invest the capital for a short or long
period of time in something other than real estate.
If
some or all of these happen, we will invest the capital not invested in real
estate in other assets or securities, but securities will not comprise more
than 20% of our portfolio.
This
policy may be changed by the officers or the Board of Directors without a vote
by the shareholders.
We previously
engaged in the purchase and sale of investment securities as a BDC.
Using
Company Stock to Acquire Investments
We
may use our stock or OP units to acquire property.
We
have a history of using our OP Units to acquire property, such as we did with
the Addison Corporate Center and the Wiseman transaction.
Redemption
of Preferred Shares
Please
see below in “Description of Securities—Preferred Stock—Optional Early
Redemption” for all of the details on our policy on redemption of preferred
shares.
We may
decide to reacquire our preferred shares when appropriate.
Annual
Reports to Stockholders
Our
current policy is to issue reports to shareholders four times a year:
● An
annual report substantially on the SEC’s Form 10-K, which will include our
financials audited by our auditor;
● A
quarterly report after quarters 1, 2, and 3, in the form of the SEC’s Form
10-Q, which will include financials for the subject quarter, but the financials
will not be audited by our auditor.
Our
current policy is to make a report available to each stockholder by filing such
report with the SEC via its Electronic Data Gathering, Analysis and Retrieval,
or EDGAR, system.
INVESTMENT STRATEGIES AND POLICIES
Investment
Objectives
Our
investment objectives include:
Purchase Real
Estate Assets at attractive prices
By
purchasing real estate at attractive prices, we intend to maximize the number
of properties, i.e., investments, that can be acquired using the Proceeds of
this Offering.
Develop Rental
Income Stream
We
intend to acquire real estate assets and up to 20% real property-backed securities
for our REIT. As we acquire Investments, these Investments will serve as the
base of rental income. Rental income is our intended means of generating
operating profits, supplemented by our limited investments in real estate
securities, which we hope to distribute to our Shareholders.
Preserve Capital
and Grow Capital
By
acquiring Investments at attractive prices, we believe that the overall value
of our assets will be significantly improved as operations improve and/or
renovations are made. Such acquisitions also mean that we may be able to
preserve capital during downward trends in the real estate market.
Market
Opportunity
Based
on our Adviser’s prior experience, we believe that recent market events make
this an opportune time to invest in properties for the purpose of long-term
investment.
Primary
Investments in Real Estate
We
intend to acquire real estate throughout the United States.
Our Adviser,
through its affiliates, has established a strong deal sourcing and transaction
execution presence in these regions of the United States.
We
will not make any investments outside of the United States.
Types
of Real Estate to be Acquired
We
intend to use substantially all of the proceeds of this Offering to acquire,
manage, renovate or reposition, operate, selectively leverage, lease and,
following appropriate holding periods, opportunistically sell multifamily and
commercial real estate properties.
Proposed
Plan of Operations
Acquiring Property
We
intend to acquire a portfolio of multifamily and commercial real estate properties
utilizing an equity acquisition strategy.
We may
acquire properties that are distressed in order to maximize the amount of real
estate that can be acquired using the proceeds of this Offering.
We believe
we can acquire distressed properties in at least two ways:
Our
investment strategies since our inception have included making loans to or
investments in previously syndicated projects that had encountered difficulties
with occupancy, financing, tenant improvements or other cash needs. Certain of our portfolio companies have
encountered additional cash shortfalls, and, in some cases, we have provided
additional capital to the extent that we owned the majority of the project
(such as, previously, in the case of Addison Corporate Center and the Britannia
investment). We may encounter future
opportunities to provide needed cash, and, in such cases, we would seek to
consolidate the portfolio company into our financial statements.
In
addition to properties acquired in multiple stages, as described above, we may
acquire distressed properties by direct purchases. When we purchase properties directly, we will
generally rely on a local sponsor, manager, or general partner with relevant
market knowledge and proven track record of turning around distressed
properties.
In
many cases, properties will require significant renovation. Proceeds from this
Offering will also be used to fund such renovation efforts.
Financing
Investment Acquisitions
We
anticipate that, with respect to Investments either acquired with debt
financing or refinanced, the debt financing amount generally would be up to
approximately 70% of the acquisition price of a particular Investment.
Particular
Investments may be more highly leveraged. Further, the Adviser expects that any
debt financing for an Investment will be secured by that Investment or the
interests in an entity that owns that Investment.
The
aggregate indebtedness of our investment portfolio is expected to be
approximately 50-60% of the all-in cost of all portfolio investments (direct
and indirect).
We
will have the ability to exercise discretion as to the types of financing
structures we utilize. For example, we may obtain new mortgage loans to finance
property acquisitions, acquire properties subject to debt or otherwise incur
secured or unsecured indebtedness at the property level at any time. The use of
leverage will enable us to acquire more properties than if leverage is not
used. However, leverage will also increase the risks associated with an
investment in our preferred shares. See “Risk Factors.”
Leveraging
Investments
Leverage,
as used in this Offering Circular, means the borrowing of money based on the
equity available in certain Investments. The use of leverage will enable
us to acquire more properties than if leverage is not used. However, leverage
will also increase the risks associated with an Investment in our preferred
shares. See “Risk Factors.”
The Adviser
may also elect to enter into one or more credit facilities with financial
institutions. Any such credit facility may be unsecured or secured, including
by a pledge of or security interest granted in our assets.
The
Board has authorized the Adviser to leverage any investment to a maximum of 80%
of the appraised value, said appraised value established at the time of
submitting a loan application.
Manner
of Liquidating Investments
Investments
may be disposed of by sale on an all-cash basis or upon other terms as
determined by the Adviser in its sole discretion. We may accept purchase money
obligations and other forms of consideration (including other real properties)
in exchange for one or more investments. In connection with acquisitions or
dispositions of investments, we may enter into certain guarantee or
indemnification obligations relating to environmental claims, breaches of
representations and warranties, claims against certain financial defaults and
other matters, and may be required to maintain reserves against such obligations.
In addition, we may dispose of less than 100% of our ownership interest in any
investment in the sole discretion of the Adviser.
We
will consider all viable exit strategies for our investments, including single
asset and/or portfolio sales to institutions, investment companies, real estate
investment trusts, individuals, and 1031 exchange buyers.
Growth
Policy
Our
policy is to acquire properties primarily for the accumulation of capital
gains.
Diversity
in Investments
Our
aim is that no more than 10% of all capital will be invested in any specific
property. We will seek to procure as many investments that we can in order to
meet this policy consideration, but our Board may decide to exceed this
guideline from time to time.
No
Guarantee as to Success
We
cannot assure you that we will attain these objectives or that the value of our
assets will not decrease. Furthermore, within our investment objectives and
policies, our Adviser will have substantial discretion with respect to the
selection of specific investments and the purchase and sale of our assets.
Our Board of Directors will review our investment guidelines at least
annually to determine whether our investment guidelines, property selection
criteria, leverage policy and other investment policies continue to fulfill our
investment objectives and continue to be in the best interests of our
shareholders.
Our
investment policies will provide the Adviser with substantial discretion with
respect to the selection, purchase and sale of specific Investments, subject to
the limitations in the Advisory Agreement. We may revise the investment
policies, which are described below, without the approval of our stockholders.
We will review the investment policies at least annually to determine whether
the policies are in the best interests of our stockholders.
Prospective
Investors are reminded that an investment in us is speculative and that we may
or may not succeed and that any investment a Potential Investor makes may be
lost.
Investment
in Real Estate Mortgages
We
may invest in real estate mortgages and bridge financing.
Investment
in Other Securities
We
intend to conduct operations so that we will not be required to register as an
investment company under the Investment Company Act.
We
expect that our investments in real estate will represent the substantial
majority of our total asset mix, which would not subject us to the Investment
Company Act. In order to maintain an exemption from regulation under the
Investment Company Act, we intend to engage primarily in the business of buying
real estate, and these investments are expected to be made within a year after
the Offering ends.
If we
are unable to invest a significant portion of the proceeds of the Offering in
properties within one year of the termination of such Offering, we may avoid
being required to register as an investment company by temporarily investing
any unused proceeds in government securities with low returns, which would
reduce the cash available for distribution to stockholders and possibly lower
your returns.
In the
event we cannot invest all of the proceeds of this Offering in real estate as
we are required to do, we would invest money in low-yield, U.S. Government
Securities, or maintain the liquidity of such proceeds until they may be
invested in real estate.
To
qualify for an exemption under the Investment Company Act, we are required to
hold at least 60% of our assets in real property. The Investment Company
Act defines an investment company as any issuer that is or holds itself out as
being engaged primarily in the business of investing, reinvesting or trading in
securities. Section 3(a)(1)(C) of the Investment Company Act defines an
investment company as any issuer that is engaged or proposes to engage in the
business of investing, reinvesting, owning, holding or trading in securities
and owns or proposes to acquire investment securities having a value exceeding
40% of the value of the issuer’s total assets (exclusive of U.S. government
securities and cash items) on an unconsolidated basis, which we refer to as the
40% test. Excluded from the term “investment securities,” among other things,
are U.S. Government securities. We
intend, however, to limit our securities portfolio to 20% of our total assets.
It is
possible that the staff of the SEC could disagree with any of our
determinations. If the staff of the SEC were to disagree with our
analysis under the Investment Company Act, we would need to adjust our
investment strategy. Any such adjustment in our strategy could have a
material adverse effect on us.
Although
we will monitor our holdings and income in an effort to comply with the
exclusions contained in the Investment Company Act, there can be no assurance
that we will be able to remain in compliance or to maintain our exclusion from
registration. Any of the foregoing could require us to adjust our strategy,
which could limit our ability to make certain investments or require us to sell
assets in a manner, at a price or at a time that we otherwise would not have
chosen. Compliance with exclusion from the Investment Company Act may
also require that we not sell certain property or assets to maintain such
exclusion from registration. This could negatively affect the value of
our preferred shares, the sustainability of our business model and our ability
to make distributions.
Registration
under the Investment Company Act would require us to comply with a variety of
substantive requirements that impose, among other things:
● limitations
on capital structure;
● restrictions
on specified investments;
● restrictions
on leverage or senior securities;
● restrictions
on unsecured borrowings;
● prohibitions
on transactions with affiliates; and
● compliance
with reporting, record keeping, voting, proxy disclosure and other rules and
regulations that would significantly increase our operating expenses.
If we
were required to register as an investment company but failed to do so, we
could be prohibited from engaging in our business, and criminal and civil
actions could be brought against us. Registration with the SEC as an
investment company would be costly, would subject us to a host of complex
regulations and would divert attention from the conduct of our business, which
could materially and adversely affect us. In addition, if we purchase or
sell any real estate assets to avoid becoming an investment company under the
Investment Company Act, our net asset value, the amount of funds available for
investment and our ability to pay distributions to our shareholders could be
materially adversely affected.
TAX TREATMENT OF THE COMPANY AND ITS SECURITY HOLDERS
WE URGE YOU TO
CONSULT YOUR TAX ADVISOR REGARDING THE SPECIFIC TAX CONSEQUENCES TO YOU OF THE
PURCHASE, OWNERSHIP AND SALE OF OUR PREFERRED STOCK AND OF OUR ELECTION TO BE
TAXED AS A REIT. SPECIFICALLY, YOU ARE URGED TO CONSULT YOUR OWN TAX ADVISOR
REGARDING THE FEDERAL, STATE, LOCAL, FOREIGN, AND OTHER TAX CONSEQUENCES OF
SUCH PURCHASE, OWNERSHIP, SALE AND ELECTION, AND REGARDING POTENTIAL CHANGES IN
APPLICABLE TAX LAWS.
The
following is a summary of the current material U.S. federal income tax
considerations relating to our company, our election to be taxed as a REIT and
the purchase, ownership or disposition of our securities offered pursuant to this
Offering Circular. For purposes of this discussion, references to “we,” “our”
and “us” mean only MacKenzie Realty Capital, Inc., and not its subsidiaries,
except as otherwise indicated. This summary is for general information only and
is not intended as individual tax advice. The information in this summary is
based on:
● the
Code;
● current,
temporary and proposed Treasury regulations promulgated under the Code;
● the
legislative history of the Code;
● current
administrative interpretations and practices of the IRS; and
● court
decisions;
in each case, as of the date of this Offering
Circular. In addition, the administrative interpretations and practices of the
IRS include its practices and policies as expressed in private letter rulings
that are not binding on the IRS except with respect to the particular taxpayers
who requested and received those rulings. The sections of the Code and the
corresponding Treasury Regulations that relate to qualification and taxation as
a REIT are highly technical and complex. The following discussion sets forth
certain material aspects of the sections of the Code that govern the federal
income tax treatment of a REIT and holders of its securities. This summary is
qualified in its entirety by the applicable Code provisions, Treasury
Regulations promulgated under the Code, and administrative and judicial
interpretations thereof. Future legislation, Treasury Regulations,
administrative interpretations and practices and/or court decisions may
adversely affect the tax considerations contained in this discussion. Any such
change could apply retroactively to transactions preceding the date of the
change. We have not requested and do not intend to request a ruling from the
IRS that we qualify as a REIT, and the statements in this Offering Circular are
not binding on the IRS or any court. Thus, we can provide no assurance that the
tax considerations contained in this discussion will not be challenged by the
IRS or will be sustained by a court if challenged by the IRS. This summary does not discuss any state,
local or non-U.S. tax consequences associated with the purchase, ownership, or
disposition of our securities or our election to be taxed as a REIT. You are
urged to consult your tax advisors regarding the tax consequences to you of:
● the
acquisition, ownership and sale or other disposition of our securities,
including the United States federal, state, local, foreign and other tax
consequences;
● our
election to be taxed as a REIT for United States federal income tax purposes;
and
● potential
changes in the applicable tax laws.
Tax
matters are very complicated and the tax consequences to a U.S. person or a
Non-U.S. person of an investment in our securities will depend on the facts of
his, her, or its particular situation. We encourage investors to consult their
own tax advisers regarding the specific consequences of such an investment,
including tax reporting requirements, the applicability of federal, state,
local and foreign tax laws and the effect of any possible changes in the tax
laws.
Federal
Income Taxation of MRC
We have elected to be
taxed as a REIT under Sections 856 through 860 of the Code and applicable
Treasury Regulations, which set forth the requirements for qualifying as a
REIT, commencing with our taxable year beginning January 1, 2014. We believe that we have been organized and
operated in a manner so as to qualify for taxation as a REIT under the Code and
we intend to continue to operate in such a manner. No assurance, however, can be given that we
in fact have qualified or will remain qualified as a REIT. See “—Failure to
Qualify”.
Our qualification and
taxation as a REIT depend upon our ability to meet the various qualification
tests imposed under the Code, which are discussed below, including through
actual annual operating results, asset composition, distribution levels and
diversity of stock ownership, the results of which have not been and will not
be reviewed by Husch Blackwell LLP.
Accordingly, no assurance can be given that our actual results of
operations for any particular taxable year will satisfy those
requirements. Further, the anticipated
federal income tax treatment described in this discussion may be changed, perhaps
retroactively, by legislative, administrative or judicial action at any
time. The information in this section,
is based on the Code, current, temporary and proposed Treasury Regulations, the
Code legislative history, current IRS administrative interpretations and
practices, and court decisions. The
reference to IRS interpretations and practices includes IRS practices and
policies as endorsed in private letter rulings, which are not binding on the
IRS except with respect to the taxpayer that receives the ruling. In each case,
these sources are relied upon as they exist on the date of this Offering
Circular. No assurance can be given that
future legislation, regulations, administrative interpretations and court
decisions will not significantly change current law, or adversely affect
existing interpretations of existing law, on which the opinion and the
information in this section are based.
Any change of this kind could apply retroactively to transactions
preceding the date of the change. Even if there is no change in applicable law,
no assurance can be provided that the statements made in the following
discussion, will not be challenged by the IRS or will be sustained by a court
if so challenged.
The remainder of this
section discusses U.S. federal income tax consequences to us and to our
stockholders as a result of our election to be taxed as a REIT. For as long as
we qualify for taxation as a REIT, we generally will not be subject to federal
corporate income taxes on net income that we currently distribute to
stockholders. This treatment substantially eliminates the “double taxation” (at
the corporate and security holder levels) that generally results from
investment in a “C” corporation. A “C” corporation is a corporation that
generally is required to pay tax at the corporate level, and C corporations are
currently taxed at a flat 21.0% rate for federal income tax purposes. Double
taxation means taxation once at the corporate level when income is earned and
once again at the stockholder level when the income is distributed.
Notwithstanding a REIT election, however, we will be subject to federal income
tax in the following circumstances:
● First,
we will be taxed at regular corporate rates on any undistributed REIT taxable
income, including undistributed net capital gains, provided, however, that
properly designated undistributed capital gains will effectively avoid taxation
at the stockholder level.
● Second,
if we have (i) net income from the sale or other disposition of “foreclosure
property” (which is, in general, property acquired by foreclosure or otherwise
on default of a loan secured by the property) that is held primarily for sale
to customers in the ordinary course of business or (ii) other nonqualifying
income from foreclosure property, we will be subject to tax at the highest
corporate rate on such income.
● Third,
if we have net income from prohibited transactions (which are, in general,
certain sales or other dispositions of property (other than foreclosure
property) held primarily for sale to customers in the ordinary course of
business), such income will be subject to a 100.0% tax on prohibited
transactions.
● Fourth,
if we should fail to satisfy the 75.0% gross income test or the 95.0% gross
income test (as discussed below), and have nonetheless maintained our
qualification as a REIT because certain other requirements have been met, we
will be subject to a tax in an amount equal to the greater of either (i) the
amount by which 75.0% of our gross income exceeds the amount qualifying under
the 75.0% test for the taxable year or (ii) the amount by which 95.0% of our
gross income exceeds the amount of our income qualifying under the 95.0% test
for the taxable year, multiplied in either case by a fraction intended to
reflect our profitability.
● Fifth,
if we should fail to satisfy any of the asset tests (as discussed below) for a
particular quarter and do not qualify for certain de minimis exceptions but
have nonetheless maintained our qualification as a REIT because certain other
requirements are met, we will be subject to a tax equal to the greater of (i)
$50,000 or (ii) the amount determined by multiplying the highest corporate tax
rate by the net income generated by the nonqualifying assets that caused us to
fail such test.
● Sixth,
if we fail to satisfy REIT requirements (other than the income or asset tests)
and the violation is due to reasonable cause and not due to willful neglect, we
will maintain our REIT status but we must pay a penalty of $50,000 for each
such failure.
● Seventh,
if we should fail to distribute during each calendar year at least the sum of
(i) 85.0% of our REIT ordinary income for such year; (ii) 95.0% of our REIT
capital gain net income for such year (for this purpose such term includes
capital gains which we elect to retain but which we report as distributed to
our stockholders; see “Annual Distribution Requirements” below); and (iii) any undistributed taxable income from
prior years, we would be subject to a 4.0% excise tax on the excess of such
required distribution over the amounts actually distributed.
● Eighth, we would be
subject to a 100.0% penalty tax with respect to amounts received (or on certain
expenses deducted by a taxable REIT subsidiary) if arrangements among us, our
tenants and a taxable REIT subsidiary were not comparable to similar
arrangements among unrelated parties.
● Ninth, if we sell
property subject to the built-in gains tax, we will be subject to a corporate
level tax on such built-in gains if such assets are sold during the five-year
period following the acquisition of such property. Built-in gain assets are assets whose fair
market value exceeds the REIT’s adjusted tax basis at the time the asset was
acquired from a C corporation and our initial tax basis in the asset is less
than the fair market value of that asset. The results described in this
paragraph with respect to the recognition of gain assume that the C corporation
will refrain from making an election to receive different treatment under
applicable Treasury Regulations on its tax return for the year in which we
acquire the asset from the C corporation. Treasury Regulations exclude from the
application of this built-in gains tax any gain from the sale of property we
acquire in an exchange under Section 1031 (a like-kind exchange) or 1033 (an
involuntary conversion) of the Code.
● Tenth, our subsidiaries
that are C corporations, including our “taxable REIT subsidiaries,” generally
will be required to pay federal corporate income tax on their earnings.
● Eleventh, we may elect
to retain and pay income tax on our net capital gain. In that case, a
stockholder would include its proportionate share of our undistributed net
capital gain (to the extent we make a timely designation of such gain to the
stockholder) in its income, would be deemed to have paid the tax that we paid
on such gain, and would be allowed a credit for its proportionate share of the
tax deemed to have been paid, and an adjustment would be made to increase the
basis of the stockholder in our capital stock.
Requirements
for Qualification as a REIT
The Code defines a REIT
as a corporation, trust or association:
(i)
that is managed by one
or more trustees or directors;
(ii)
that issues transferable
shares or transferable certificates of beneficial interest to evidence its
beneficial ownership;
(iii)
that would be taxable as
a domestic corporation but for Code Sections 856 through 860;
(iv)
that is not a financial
institution or an insurance company within the meaning of the Code;
(v)
that is beneficially
owned by 100 or more persons;
(vi)
not more than 50.0% in
value of the outstanding capital stock of which is owned, directly or
indirectly, by five or fewer individuals (as defined in the Code to include
certain entities) during the last half of each taxable year after applying
certain attribution rules;
(vii)
that makes an election
to be treated as a REIT for the current taxable year or has made an election
for a previous taxable year which has not been terminated or revoked; and
(viii)
which meets certain
other tests, described below, regarding the nature of its income and assets.
The Code provides that
conditions (i) through (iv), inclusive, must be met during the entire taxable
year and that condition (v) must be met during at least 335 days of a taxable
year of 12 months, or during a proportionate part of a taxable year of less
than 12 months. Condition (vi) must be met during the last half of each taxable
year. For purposes of determining stock
ownership under condition (vi), a supplemental unemployment compensation
benefits plan, a private foundation or a portion of a trust permanently set
aside or used exclusively for charitable purposes generally is considered an
individual. However, a trust that is a
qualified trust under Code Section 401(a) generally is not considered an
individual, and beneficiaries of a qualified trust are treated as holding
shares of a REIT in proportion to their actuarial interests in the trust for
purposes of condition (vi). MRC should
satisfy conditions (v) and (vi) based upon existing ownership. If we fail to
satisfy these stock ownership requirements, we will fail to qualify as a
REIT. We believe that we have been
organized, have operated and have issued sufficient shares of stock with
sufficient diversity of ownership to allow us to satisfy conditions (i) through
(viii), inclusive, during the relevant time periods. In addition, our Charter
provides for restrictions regarding ownership and transfer of our shares which
are intended to assist us in continuing to satisfy the share ownership
requirements described in conditions (v) and (vi) above. These restrictions, however, do not ensure
that we have previously satisfied, and may not ensure that we will, in all
cases, be able to continue to satisfy, the share ownership requirements
described in conditions (v) and (vi) above. If we fail to satisfy these share
ownership requirements, except as provided in the next sentence, our status as
a REIT will terminate. If, however, we
comply with the rules contained in applicable Treasury Regulations that require
us to ascertain the actual ownership of our shares and we do not know, or would
not have known through the exercise of reasonable diligence, that we failed to
meet the requirement described in condition (vi) above, we will be treated as
having met this requirement. See
“—Failure to Qualify”. In addition, we
may not maintain our status as a REIT unless our taxable year is the calendar
year and we comply with the recordkeeping requirements of the Code and the
Treasury Regulations promulgated thereunder.
We have and will continue to have a calendar taxable year.
Ownership
of Interests in Partnerships, Limited Liability Companies and Qualified REIT
Subsidiaries
In the case of a REIT
that is a partner in a partnership or a member in a limited liability company
treated as a partnership for federal income tax purposes, Treasury Regulations
provide that the REIT will be deemed to own its proportionate share of the assets
of the partnership or limited liability company, as the case may be, based on
its interest in partnership capital, subject to special rules relating to the
10.0% asset test described below. Also, the REIT will be deemed to be entitled
to its proportionate share of the income of that entity. The assets and gross
income of the partnership or limited liability company retain the same
character in the hands of the REIT, including satisfying the gross income tests
and the asset tests. Thus, our pro rata share of the assets and items of income
of any partnership or limited liability company treated as a partnership or
disregarded entity for federal income tax purposes, including such
partnership’s or limited liability company’s share of these items of any
partnership or limited liability company treated as a partnership or
disregarded entity for federal income tax purposes in which it owns an
interest, would be treated as our assets and items of income for purposes of
applying the requirements described in this discussion, including the gross
income and asset tests described below. A
brief summary of the rules governing the federal income taxation of
partnerships and limited liability companies is set forth below in “—Tax
Aspects of Our Operating Through Partnerships and Limited Liability Companies.”
We have sufficient
control of our subsidiary partnerships and limited liability companies and
intend to operate them in a manner consistent with the requirements for our
qualification as a REIT. If we become a limited partner or non-managing member
in any partnership or limited liability company and such entity takes or
expects to take actions that could jeopardize our status as a REIT or require
us to pay tax, we may be forced to dispose of our interest in such entity. In addition, it is possible that a partnership
or limited liability company could take an action which could cause us to fail
a gross income or asset test, and that we would not become aware of such action
in time to dispose of our interest in the partnership or limited liability
company or take other corrective action on a timely basis. In that case, we
could fail to qualify as a REIT unless we were entitled to relief, as described
below.
We may from time to time
own and operate certain properties through subsidiaries that we intend to be
treated as “qualified REIT subsidiaries” under the Code. If a REIT owns a corporate subsidiary that is
a “qualified REIT subsidiary,” the separate existence of that subsidiary
generally will be disregarded for federal income tax purposes. Generally, a qualified REIT subsidiary is a
corporation, other than a taxable REIT subsidiary, all of the capital stock of
which is owned by the REIT. All assets,
liabilities and items of income, deduction and credit of the qualified REIT
subsidiary will be treated as assets, liabilities and items of income,
deduction and credit of the REIT itself for all purposes under the Code,
including all REIT qualification tests.
A qualified REIT subsidiary of ours will not be subject to federal
corporate income taxation, although it may be subject to state and local
taxation in some states.
The
Bipartisan Budget Act of 2015 adopted a centralized partnership audit regime
generally applicable to U.S. federal income tax audits of partnerships
(potentially including partnerships in which we are a partner) and the
collection of any tax resulting from such audits or other tax proceedings.
Under the new rules, which are generally effective for taxable years beginning
after December 31, 2017, among other changes and subject to certain exceptions,
any audit adjustment to items of income, gain, loss, deduction, or credit of a
partnership (and any partner’s distributive share thereof) is generally
determined, and taxes, interest, or penalties attributable thereto are assessed
and collected, at the partnership level in the year the audit is finalized, although
in certain cases, the partnership can require the partners, instead of the
partnership, to pay any resulting tax. Therefore, partnerships in which we
directly or indirectly invest could be required to pay additional taxes,
interest, and penalties as a result of an audit adjustment, and we, as a direct
or indirect partner of these partnerships, could be required to bear the
economic burden of those taxes, interest, and penalties even though we, as a
REIT, may not otherwise have been required to pay additional corporate-level
taxes as a result of the related audit adjustment. The potential application of
the centralized partnership audit regime to a partnership or limited liability
company in which we invest is governed by the Code and applicable Treasury
Regulations, as well as the provisions of each partnership or limited liability
company agreement and elections made by the partnership representative on
behalf of the partnership.
Ownerships of Interests in Taxable REIT Subsidiaries
A “taxable REIT
subsidiary” is an entity taxable as a corporation in which we own stock and
that elects with us to be treated as a taxable REIT subsidiary under Section
856(l) of the Code. In addition, if one of our taxable REIT subsidiaries owns,
directly or indirectly, securities representing more than 35.0% of the vote or
value of a subsidiary corporation, that subsidiary will also be treated as a
taxable REIT subsidiary of ours. A taxable REIT subsidiary is subject to
federal income tax, and state and local income tax where applicable, as a
regular “C” corporation.
Generally, a taxable
REIT subsidiary can perform impermissible tenant services without causing us to
receive impermissible tenant services income under the REIT income tests.
Subject to the tests described below, a taxable REIT subsidiary may own assets that
are not considered real estate assets. Therefore, we may utilize taxable REIT
subsidiaries to hold certain non-REIT qualifying investments. However, several
provisions regarding the arrangements between a REIT and its taxable REIT
subsidiaries ensure that a taxable REIT subsidiary will be subject to an
appropriate level of federal income taxation. For example, a taxable REIT
subsidiary is limited in its ability to deduct interest payments made to us. In
addition, we will be obligated to pay a 100.0% penalty tax with respect to some
payments that we receive or on certain expenses deducted by the taxable REIT
subsidiary if the economic arrangements among us, our tenants and the taxable
REIT subsidiary are not comparable to similar arrangements among unrelated
parties.
Income
Tests
In order for us to
maintain qualification as a REIT, certain separate percentage tests relating to
the source of our gross income must be satisfied annually. First, at least
75.0% of our gross income (excluding gross income from prohibited transactions)
for each taxable year generally must be derived directly or indirectly from
investments relating to real property or mortgages on real property (including
“rents from real property,” gain, and, in certain circumstances, interest) or
from certain types of temporary investments.
Second, at least 95.0% of our gross income (excluding gross income from
prohibited transactions, certain hedging transactions, and certain foreign
currency gains) for each taxable year must be derived from such real property
investments described above, dividends, interest and gain from the sale or
disposition of stock or securities or from any combination of the foregoing.
Rents received by us
will qualify as “rents from real property” in satisfying the above gross income
tests only if several conditions are met.
First, the amount of rent generally must not be based in whole or in part
on the income or profits of any person.
However, amounts received or accrued generally will not be excluded from
“rents from real property” solely by reason of being based on a fixed
percentage or percentages of receipts or sales.
Second, rents received
from a tenant will not qualify as “rents from real property” if we, or a direct
or indirect owner of 10.0% or more of our stock, actually or constructively
owns 10.0% or more of such tenant (a “Related Party Tenant”). We may, however, lease our properties to a
taxable REIT subsidiary and rents received from that subsidiary generally will
not be disqualified from being “rents from real property” by reason of our
ownership interest in the subsidiary if at least 90.0% of the property in
question is leased to unrelated tenants and the rent paid by the taxable REIT
subsidiary is substantially comparable to the rent paid by the unrelated
tenants for comparable space, as determined pursuant to the rules in Code Section
856(d)(8).
Third, if rent
attributable to personal property that is leased in connection with a lease of
real property is greater than 15.0% of the total rent received under the lease,
then the portion of rent attributable to such personal property will not
qualify as “rents from real property.”
This 15.0% test is based on relative fair market value of the real and
personal property. If the rent
attributable to personal property does not exceed 15.0% of the total rent
received under the lease, then the portion of the rent attributable to such
personal property will qualify as “rents from real property” and the personal
property will be treated as a real estate asset for purposes of the 75.0%
assets test (as discussed below). In
addition, in the case of any obligation secured by a mortgage on both real and
personal property, if the fair market value of such personal property does not
exceed 15.0% of the total fair market value of all such property, interest on
such obligation is qualifying interest for purposes of the 75.0% gross income
test and the obligation will be treated as a real estate asset for purposes of
the 75.0% assets test.
Generally for rents to
qualify as “rents from real property” for the purposes of the gross income
tests, we are only allowed to provide services that are both “usually or
customarily rendered” in connection with the rental of real property and not
otherwise considered “rendered to the occupant.” Income received from any other
service will be treated as “impermissible tenant service income” unless the
service is provided through an independent contractor that bears the expenses
of providing the services and from whom we derive no revenue or through a
taxable REIT subsidiary, subject to specified limitations. The amount of impermissible tenant service
income we receive is deemed to be the greater of the amount actually received
by us or 150.0% of our direct cost of providing the service. If the
impermissible tenant service income exceeds 1.0% of our total income from a
property, then all of the income from that property will fail to qualify as
rents from real property. If the total amount of impermissible tenant service
income from a property does not exceed 1.0% of our total income from that
property, the income will not cause the rent paid by tenants of that property
to fail to qualify as rents from real property, but the impermissible tenant
service income itself will not qualify as rents from real property.
To the extent our
taxable REIT subsidiaries pay dividends, we generally will derive our allocable
share of such dividend. Such dividend income will qualify under the 95.0%, but
not the 75.0%, gross income test. We will monitor the amount of the dividend and
other income from our taxable REIT subsidiaries and will take actions intended
to keep this income, and any other nonqualifying income, within the limitations
of the gross income tests. Although we expect these actions will be sufficient
to prevent a violation of the gross income tests, we cannot guarantee that such
actions will in all cases prevent such a violation.
If we fail to satisfy
one or both of the 75.0% or 95.0% gross income tests for any taxable year, we
may nevertheless qualify as a REIT for such year if we are entitled to relief
under certain provisions of the Code. The relief provisions generally will be
available if our failure to meet such tests was due to reasonable cause and not
due to willful neglect, and, following the REIT’s identification of the failure
to meet either of the gross income tests, a description of each item of the
REIT’s gross income shall be included in a schedule for the relevant taxable
year that is filed in accordance with the applicable Treasury Regulations. It
is not possible, however, to state whether in all circumstances we would be
entitled to the benefit of these relief provisions. As discussed above, even if
these relief provisions were to apply, a tax would be imposed with respect to
the excess net income.
Hedging Transactions
From time to time, we or
our subsidiaries may enter into hedging transactions with respect to one or
more of our or our subsidiaries’ assets or liabilities. Our or our
subsidiaries’ hedging activities may include entering into interest rate swaps,
caps, and floors, options to purchase such items, and futures and forward
contracts. Income and gain from “hedging transactions” will be excluded from
gross income for purposes of both the 75.0% and 95.0% gross income tests. A
“hedging transaction” means (1) any transaction entered into in the normal
course of our or our subsidiaries’ trade or business primarily to manage the
risk of interest rate, price changes, or currency fluctuations with respect to
borrowings made or to be made, or ordinary obligations incurred or to be
incurred, to acquire or carry real estate assets, (2) any transaction entered
into primarily to manage the risk of currency fluctuations with respect to any
item of income or gain that would be qualifying income under the 75.0% or 95.0%
gross income test (or any property which generates such income or gain) or (3)
any hedging transaction entered into in connection with the extinguishment of
specified indebtedness or disposal of property with respect to a position
entered into under (1) or (2) above, if the position would be ordinary
property. We are required to clearly identify any such hedging transaction
before the close of the day on which it was acquired, originated, or entered
into and to satisfy other identification requirements. We intend to structure
any hedging transactions in a manner that does not jeopardize our qualification
as a REIT; however, no assurance can be given that our hedging activities will
give rise to income that qualifies for purposes of either or both of the gross
income tests.
Prohibited Transaction
Income
Any gain that we realize
on the sale of property held as inventory or otherwise held primarily for sale
to customers in the ordinary course of business, including our share of any
such gain realized either directly or through any subsidiary partnerships and
limited liability companies, will be treated as income from a prohibited
transaction that is subject to a 100.0% penalty tax, unless certain safe harbor
exceptions apply. This prohibited
transaction income may also adversely affect our ability to satisfy the gross
income tests for qualification as a REIT.
Under existing law, whether property is held as inventory or primarily
for sale to customers in the ordinary course of a trade or business is a
question of fact that depends on all the facts and circumstances surrounding
the particular transaction. We do not
intend, and do not intend to permit any of our subsidiary partnerships or
limited liability companies, to enter into any sales that are prohibited
transactions. However, the IRS may
successfully contend that some or all of the sales made by our subsidiary
partnerships or limited liability companies are prohibited transactions. We
would be required to pay the 100.0% penalty tax on our allocable share of the
gains resulting from any such sales.
Penalty Tax
Any redetermined rents,
redetermined deductions or excess interest we generate will be subject to a
100.0% penalty tax. In general, redetermined rents are rents from real property
that are overstated as a result of any services furnished to any of our tenants
by a taxable REIT subsidiary of ours, and redetermined deductions and excess
interest represent any amounts that are deducted by a taxable REIT subsidiary
of ours for amounts paid to us that are in excess of the amounts that would
have been deducted based on arm’s length negotiations. Rents we receive will
not constitute redetermined rents if they qualify for certain safe harbor
provisions contained in the Code.
Currently, our taxable
REIT subsidiaries do not provide any services to our tenants or conduct other
material activities. However, a taxable REIT subsidiary of ours may in the
future provide services to certain of our tenants and pay rent to us. We intend
to set any fees paid to our taxable REIT subsidiaries for such services, and
any rent payable to us by our taxable REIT subsidiaries, at arm’s length rates,
although the amounts paid may not satisfy the safe-harbor provisions described
above. These determinations are inherently factual, and the IRS has broad
discretion to assert that amounts paid between related parties should be
reallocated to clearly reflect their respective incomes. If the IRS
successfully made such an assertion, we would be required to pay a 100.0%
penalty tax on the excess of an arm’s length fee for tenant services over the
amount actually paid, or on the excess rents paid to us.
Asset
Tests
At the close of each
quarter of our taxable year, we must satisfy six tests relating to the nature
of our assets.
- At least 75.0% of the value of
our total assets must be represented by “real estate assets,” cash, cash
items and government securities. Our real estate assets include, for this
purpose, our allocable share of real estate assets held by the
partnerships in which we own an interest, and the non‑corporate
subsidiaries of these partnerships, as well as stock or debt instruments
held for less than one year purchased with the proceeds of an offering of
shares or long term debt. Real estate assets are defined to include debt
instruments issued by publicly offered REITs that are not secured by a
real estate asset (a “nonqualified publicly offered REIT debt
instrument”). Although treated as a real estate asset, the gain on the
sale of a nonqualified publicly offered REIT debt instrument does not qualify
for purposes of the 75.0% gross income test and not more than 25.0% of the
value of our total assets may be represented by nonqualified publicly
offered REIT debt instruments.
- Not more than 25.0% of the
value of our total assets may be represented by securities, other than
those in the 75.0% asset class.
- Except for certain investments
in REITs, qualified REIT subsidiaries, and taxable REIT subsidiaries, the
value of any one issuer’s securities owned by us may not exceed 5.0% of
the value of our total assets.
- Except for certain investments
in REITs, qualified REIT subsidiaries and taxable REIT subsidiaries, we
may not own more than 10.0% of the total voting power of any one issuer’s
outstanding securities.
- Except for certain investments
in REITs, qualified REIT subsidiaries and taxable REIT subsidiaries, we
may not own more than 10.0% of the total value of the outstanding
securities of any one issuer, other than securities that qualify for the
debt safe harbors discussed below.
As described further below, solely for purposes the 10.0% value
test, the determination of our interest in the assets of an entity treated
as a partnership for federal income tax purposes in which we own an
interest will be based on our proportionate interest in any securities
issued by the partnership, excluding for this purpose certain securities
described in the Code.
- Not more than 20.0% of our
total assets may be represented by the securities of one or more taxable
REIT subsidiaries.
For purposes of these
asset tests, any shares of qualified REIT subsidiaries are not taken into
account, and any assets owned by the qualified REIT subsidiary are treated as
owned directly by the REIT.
Securities, for purposes
of the assets tests, may include debt we hold.
However, the following types of arrangements generally will not be
considered securities held by us for purposes of the 10.0% value test: (1) Straight
debt securities of an issuer which meet the requirements of Code Section
856(m)(2), discussed below; (2) Any loan to an individual or an estate; (3) Any
Code Section 467 rental agreement, other than with certain related persons; (4)
Any obligation to pay rents from real property as defined in Code Section
856(d)(1); (5) Any security issued by a state or any political subdivision
thereof, the District of Columbia, a foreign government or any political
subdivision thereof, or the Commonwealth of Puerto Rico, but only if the
determination of any payment received or accrued under such security does not
depend in whole or in part on the profits of any entity not described in the
category or payments on any obligation issued by such an entity; (6) Any
security issued by a REIT; or (7) Any other arrangement as determined by the IRS. Under Code Section 856(m)(2), debt generally
will constitute “straight debt” if the debt is a written unconditional promise
to pay on demand or on a specified date a sum certain in money (1) which is not
convertible, directly or indirectly, into stock and (2) the interest rate (and
the interest payment dates) of which is not contingent on the profits, the
borrower’s discretion or similar factors. However, a security may satisfy the
definition of “straight debt” even though the time of payment of interest or
principal thereunder is subject to a contingency, if: (i) such contingency does
not have the effect of changing the effective yield to maturity more than the
greater of 0.25% or 5.0% of the annual yield to maturity, or (ii) neither the
aggregate issue price nor the aggregate face amount of the issuer’s debt
instruments held by the REIT exceeds $1 million and not more than 12 months of
unaccrued interest can be required to be prepaid thereunder. Second, a security
can satisfy the definition of “straight debt” even though the time or amount of
any payment thereunder is subject to a contingency upon a default or the
exercise of a prepayment right by the issuer of the debt, provided that such
contingency is consistent with customary commercial practice.
Certain “look-through”
rules apply in determining a REIT partner’s share of partnership securities for
purposes of the 10.0% value test. Under
such rules, a REIT’s interest as a partner in a partnership is not considered a
security, and the REIT is deemed to own its proportionate share of each of the
assets of the partnership. The REIT’s interest in the partnership assets is the
REIT’s proportionate interest in any securities issued by the partnership,
other than securities qualifying for the above safe harbors. Therefore, a REIT that is a partner in a
partnership must look through both its equity interest and interest in non-safe
harbor debt securities issued by the partnership. Any non-safe harbor debt instrument issued by
a partnership will not be considered a security to the extent of the REIT’s
interest as a partner in the partnership.
Also, any non-safe harbor debt instrument issued by a partnership will
not be considered a security if at least 75% of the partnership’s gross income
(excluding gross income from prohibited transactions) is derived from the
sources described in Code Section 856(c)(3), which sets forth the general REIT
income test.
Certain corporate or
partnership securities that otherwise would qualify under the straight debt
safe harbor will not so qualify if the REIT holding such securities, and any of
its controlled taxable REIT subsidiaries, holds other securities of the issuer
which are not securities qualifying for any safe harbors if such non-qualifying
securities have an aggregate value greater than 1.0% of the issuer’s
outstanding securities.
The asset tests must be
satisfied at the close of each calendar quarter of our taxable year in which we
(directly or through any partnership or limited liability company) acquire
securities in the applicable issuer, and also at the close of each calendar
quarter in which we increase our ownership of securities of such issuer
(including as a result of an increase in our interest in any partnership or
limited liability company). Also, after
initially meeting the asset tests at the close of any quarter, we will not lose
our status as a REIT for failure to satisfy the asset tests at the end of a
later quarter solely by reason of changes in asset values. If we fail to
satisfy an asset test because we acquire securities or other property during a
quarter (including as a result of an increase in our interest in any
partnership or limited liability company), we may cure this failure by
disposing of sufficient nonqualifying assets within 30 days after the close of
that quarter. We believe that we have maintained, and we intend to maintain,
adequate records of the value of our assets to ensure compliance with the asset
tests. If we fail to cure any noncompliance with the asset tests within the
30-day cure period, we would cease to qualify as a REIT unless we are eligible
for certain relief provisions discussed below.
Certain relief
provisions may be available to us if we discover a failure to satisfy the asset
tests described above after the 30-day cure period. Under these provisions, we will be deemed to
have met the 5.0% and 10.0% asset tests, and will not lose our REIT status, if
the value of our nonqualifying assets (i) does not exceed the lesser of (a)
1.0% of the total value of our assets at the end of the applicable quarter or
(b) $10,000,000, and (ii) we dispose of the nonqualifying assets or otherwise
satisfy such tests within (a) six months after the last day of the quarter in
which the failure to satisfy the asset tests is discovered or (b) the period of
time prescribed by Treasury Regulations to be issued. In addition, if a REIT
fails to meet any of the asset test requirements for a particular quarter after
the 30-day cure period, and the failure exceeds the above-described de minimis
standard, then the REIT still will be considered to have satisfied these tests
if the REIT satisfies several requirements. First, the REIT’s failure to
satisfy the particular asset test must be due to reasonable cause and not due
to willful neglect. Second, the REIT must file a schedule of the assets
resulting in such failure with the IRS in accordance with the Treasury Regulations
and must dispose of the assets within six months after the last day of the
quarter in which the REIT identified the failure (or such other time period
prescribed by the IRS) or otherwise meet the requirements of those rules by the
end of such time period. Finally, the REIT must pay a tax equal to the greater
of $50,000 or the amount determined by multiplying the highest corporate tax
rate by the net income generated by the assets described in the schedule for
the period beginning on the first date that the failure occurs and ending on
the date when the REIT disposes of such assets or the end of the first quarter
when the REIT no longer fails to satisfy the particular asset test.
Although we believe we
have satisfied the asset tests described above and plan to take steps to ensure
that we satisfy such tests for any quarter with respect to which retesting is
to occur, there can be no assurance that we will always be successful, or will
not require a reduction in our overall interest in an issuer (including in a
taxable REIT subsidiary). If we fail to cure any noncompliance with the asset
tests in a timely manner, and the relief provisions described above are not
available, we would cease to qualify as a REIT.
Annual
Distribution Requirements
To maintain our
qualification as a REIT, we are required to distribute dividends, other than
capital gain dividends, to our stockholders in an amount at least equal to the
sum of:
● 90.0% of our REIT
taxable income; and
● 90.0% of the net income
(after tax), if any, from foreclosure property, minus
● the sum of certain items
of noncash income.
For these purposes, our
“REIT taxable income” is computed without regard to the dividends paid
deduction and our net capital gain. In addition, our REIT taxable income will
be reduced by any taxes we are required to pay on any gain we recognize from
the disposition of any asset we acquired from a corporation which was or had
been a C corporation in a transaction in which our tax basis in the asset was
less than the fair market value of the asset, in each case determined at the
time we acquired the asset, within the five-year period following our
acquisition of such asset. See “Tax Liabilities and Attributes Inherited from
Other Entities.” Noncash income means income attributable to leveled stepped
rents, original issue discount on purchase money debt, cancellation of
indebtedness, or a like-kind exchange that is later determined to be taxable.
Certain limitations exist with respect to the recognition of net operating
losses, which limitations could affect the timing and amount of recognition of
net operating losses generated by us (or our taxable REIT subsidiaries). In
addition, certain limitations potentially apply to our deductibility of
interest expenses, which generally limit the deduction for net business
interest to 30.0% of the borrower’s adjusted taxable income (excluding
non-business income and net business interest income, among other items). If we
(or our taxable REIT subsidiaries) qualify as a real estate trade or business
under the Code and applicable Treasury Regulations, we can potentially elect not
to be subject to the net business interest limitation in exchange for
depreciation of certain property using longer depreciation schedules that would
otherwise be available.
We generally must pay,
or be treated as paying, the distribution in the taxable year to which they
relate. At our election, a distribution will be treated as paid in a taxable
year if the dividends are declared before we timely file our tax return for the
year and paid within 12 months of the end of the tax year but before the first
regular dividend payment made after such declaration. These distributions are
treated as received by our stockholders in the year in which received. This is
so even though these distributions relate to the prior year for purposes of the
90.0% distribution requirement. The aggregate amount of dividends designated by
the REIT as a capital gain dividend or qualified dividend income cannot exceed
the dividends paid or deemed paid by the REIT under Section 858 of the Code
with respect to such year.
If we declare a dividend
in October, November, or December of any year with a record date in one of
these months and pay the dividend on or before January 31 of the following
year, we will be treated as having paid the dividend on December 31 of the year
in which the dividend was declared.
These distributions will be treated as received by our stockholders on
December 31 of the declaration year.
To the extent that we do
not distribute all of our net capital gain or distribute at least 90.0%, but
less than 100.0%, of our “REIT taxable income,” as adjusted, we will be subject
to tax on the nondistributed amount at regular capital gains and ordinary
corporate tax rates. Furthermore, if we
should fail to distribute during each calendar year at least the sum of (i)
85.0% of our REIT ordinary income for such year; (ii) 95.0% of our REIT capital
gain income for such year; and (iii) any undistributed taxable income from
prior periods, we will be subject to a 4.0% excise tax on the excess of such
required distribution over the amounts actually distributed.
We may elect to retain
and pay tax on net long-term capital gains and require our stockholders to
include their proportionate share of such undistributed net capital gains in
their income. If we make such election, stockholders
would receive a tax credit attributable to their share of the capital gains tax
paid by us, and would receive an increase in the basis of their shares in us in
an amount equal to the security holder’s share of the undistributed net
long-term capital gain reduced by the amount of the credit. Further, any undistributed net long-term
capital gains that are included in the income of our stockholders pursuant to
this rule will be treated as distributed for purposes of the 4.0% excise tax.
We intend to continue to
make timely distributions sufficient to satisfy the annual distribution
requirements. It is possible, however, that we, from time to time, may not have
sufficient cash or liquid assets to meet the distribution requirements due to
timing differences between the actual receipt of income and actual payment of
deductible expenses and the inclusion of such income and deduction of such
expenses in arriving at our taxable income, or if the amount of nondeductible
expenses such as principal amortization or capital expenditures exceeds the
amount of noncash deductions. In the event that such timing differences occur,
in order to meet the distribution requirements, we may arrange for short-term,
or possibly long-term, borrowing to permit the payment of required
dividends. If the amount of
nondeductible expenses exceeds noncash deductions, we may refinance our
indebtedness to reduce principal payments and may borrow funds for capital
expenditures.
Under certain
circumstances, we may be able to rectify a failure to meet the distribution
requirement for a year by paying “deficiency dividends” to stockholders in a
later year that may be included in our deduction for dividends paid for the
earlier year. Thus, we may avoid being
taxed on amounts distributed as deficiency dividends; however, we will be
required to pay interest to the IRS based upon the amount of any deduction
taken for deficiency dividends. While
the payment of a deficiency dividend will apply to a prior year for purposes of
our REIT distribution requirements, it will be treated as an additional
distribution to our stockholders in the year such dividend is paid.
Failure
to Qualify
If we fail to qualify
for taxation as a REIT in any taxable year and no relief provisions apply, we
will be subject to tax (including any applicable alternative minimum tax for
years beginning prior to January 1, 2018) on our taxable income at regular corporate
rates. Distributions to stockholders in any year in which we fail to qualify
will not be deductible by us, nor will such distributions be required to be
made. In such event, the distributions would be subject to tax to the
stockholders as described under “Federal Income Tax Considerations for Holders
of Our Capital Stock.” Unless entitled
to relief under specific statutory provisions, we will also be disqualified
from taxation as a REIT for the four taxable years following the year during
which qualification was lost. It is not
possible to state whether in all circumstances we would be entitled to such
statutory relief.
Further, if we fail to
satisfy one or more REIT qualification requirements, other than the income or
asset tests (for which limited relief provisions are described above under
“—Income Tests” and “—Asset Tests”), we could avoid losing our qualification as
a REIT provided such violations are due to reasonable cause and not due to
willful neglect, and provided further that we pay a penalty of $50,000 for each
such failure.
Tax
Aspects of Our Operating Through Partnerships and the Limited Liability
Companies
General. Some of our
investments are held indirectly through partnerships and limited liability
companies that we believe are and will continue to be treated as partnerships
or disregarded entities for federal income tax purposes. In general, entities
that are treated as partnerships or disregarded entities for federal income tax
purposes are “pass-through” entities which are not required to pay federal
income tax. Rather, partners or members
of such entities are allocated their shares of the items of income, gain, loss,
deduction and credit of the partnership or limited liability company and are
potentially required to pay tax on this income, without regard to whether they
receive a distribution from the partnership or limited liability company. We will include in our income our share of
these partnership and limited liability company items for purposes of the
various gross income tests, the computation of our REIT taxable income, and the
REIT distribution requirements.
Moreover, for purposes of the asset tests, we will include our pro rata
share of assets held by these partnerships and limited liability companies,
based on our interests in each such entity.
Entity Classification. Our interests in the partnerships and limited liability
companies involve special tax considerations, including the possibility that
the IRS might challenge the status of these entities as disregarded entities or
partnerships. For example, an entity
that would otherwise be treated as a partnership for federal income tax
purposes may nonetheless be taxable as a corporation if it is a “publicly
traded partnership” and certain other requirements are met. A partnership or limited liability company
would be treated as a publicly traded partnership if its interests are traded
on an established securities market or are readily tradable on a secondary
market or a substantial equivalent thereof, within the meaning of applicable
Treasury Regulations. Interests in a
partnership are not treated as readily tradable on a secondary market, or the
substantial equivalent thereof, if all interests in the partnership were issued
in one or more transactions that were not required to be registered under the
Securities Act, and the partnership does not have more than 100 partners at any
time during the taxable year of the partnership, taking into account certain
ownership attribution and anti-avoidance rules (the “100 Partner Safe
Harbor”). If any of our partnerships and
limited liability companies do not qualify for the 100 Partner Safe Harbor, the
interests in such partnerships and limited liability companies would
nonetheless be viewed as not readily tradable on a secondary market or the
substantial equivalent thereof if the sum of the percentage interests in
capital or profits transferred during any taxable year does not exceed 2.0% of
the total interests in any such partnership’s or limited liability company’s
capital or profits, subject to certain exceptions. We believe our partnerships and limited
liability companies will be classified as partnerships or disregarded entities
for federal income tax purposes, and we do not anticipate that any of them will
be treated as a publicly traded partnership that is taxable as a corporation. If any of our partnerships or limited
liability companies were to be treated as a publicly traded partnership, it
would be taxable as a corporation unless it qualified for the statutory “90.0%
qualifying income exception.” Under that
exception, a publicly traded partnership is not subject to corporate-level tax
if 90.0% or more of its gross income consists of dividends, interest, “rents
from real property” (as that term is defined for purposes of the rules
applicable to REITs, with certain modifications), gain from the sale or other
disposition of real property, and certain other types of qualifying
income. However, if any such entity did
not qualify for this exception or was otherwise taxable as a corporation, it
would be required to pay an entity-level tax on its income. In this situation, the character of our
assets and items of gross income would change and could prevent us from
satisfying the REIT asset tests and possibly the REIT income tests. This, in turn, could prevent us from qualifying
as a REIT. See “—Failure to Qualify” for
a discussion of the effect of our failure to meet these tests. In addition, a change in the tax status of
any of our partnerships or limited liability companies might be treated as a
taxable event. If so, we might incur a
tax liability without any related cash payment.
Allocations of Income, Gain, Loss and Deduction. A partnership agreement will generally
determine the allocation of income and loss among partners. These allocations, however, will be
disregarded for tax purposes if they do not comply with the provisions of Section
704(b) of the Code and the Treasury Regulations thereunder. Generally, Section 704(b) of the Code and the
Treasury Regulations thereunder require that partnership allocations respect
the economic arrangement of the partners.
If an allocation of partnership income or loss does not comply with the requirements of Section 704(b) of the Code and
the Treasury Regulations thereunder, the item
subject to the allocation will be reallocated in accordance with the partners’
interests in the partnership. This
reallocation will be determined by taking into account all of the facts and
circumstances relating to the economic arrangement of the partners with respect
to such item.
Tax Allocations With Respect to the Properties. Under Section 704(c) of the Code, income,
gain, loss and deduction attributable to appreciated or depreciated property
that is contributed to a partnership in exchange for an interest in the
partnership, must be allocated in a manner so that the contributing partner is
charged with the unrealized gain or benefits from the unrealized loss
associated with the property at the time of the contribution. The amount of the
unrealized gain or unrealized loss generally is equal to the difference between
the fair market value or book value and the adjusted tax basis of the
contributed property at the time of contribution (this difference is referred
to as a book-tax difference), as adjusted from time to time. These allocations are solely for federal
income tax purposes and do not affect the book capital accounts or other
economic or legal arrangements among the partners. Treasury Regulations issued under Section
704(c) of the Code provide partnerships with a choice of several methods of
accounting for book-tax differences.
Depending on the method we choose in connection with any particular
contribution of a property by us to a partnership or limited liability company,
the carryover basis of each of the contributed interests in the properties in
the hands of such partnership or limited liability company (1) could cause us
to be allocated lower amounts of depreciation deductions for tax purposes than
would be allocated to us if any of the contributed properties were to have a tax
basis equal to its respective fair market value at the time of the contribution
and (2) could cause us to be allocated taxable gain in the event of a sale of
such contributed interests or properties in excess of the economic or book
income allocated to us as a result of such sale, with a corresponding benefit
to the other partners in our partnerships.
An allocation described in clause (2) above might cause us or the other
partners to recognize taxable income in excess of cash proceeds in the event of
a sale or other disposition of property, which might adversely affect our
ability to comply with the REIT distribution requirements. See “—Requirements
for Qualification as a REIT” and “—Annual Distribution Requirements.”
Any property acquired by
a partnership or limited liability company in which we hold an interest in a
taxable transaction will initially have a tax basis equal to its fair market
value, and Section 704(c) of the Code generally will not apply.
Tax
Liabilities and Attributes Inherited from Other Entities
From time to time,
we may acquire “C” corporations in transactions in which the basis of the
corporations’ assets in our hands is determined by reference to the basis of
the assets in the hands of the acquired corporations, or carry-over basis
transactions. In the case of assets we
acquire from a “C” corporation in a carry-over basis transaction, if we dispose
of any such asset in a taxable transaction (including by deed in lieu of
foreclosure) during the five year period beginning on the date of the carry-over
basis transaction, then we will be required to pay tax at the highest regular
corporate tax rate on the gain recognized to the extent of the excess of (1)
the fair market value of the asset over (2) our adjusted tax basis in the
asset, in each case determined as of the date of the carry-over basis
transaction. The foregoing result with
respect to the recognition of gain assumes that the “C” corporation will
refrain from making an election to receive different treatment under applicable
Treasury Regulations on its tax return for the year in which we acquire the
asset from the “C” corporation. Any
taxes we pay as a result of such gain would reduce the amount available for
distribution to our stockholders.
Our tax basis in the
assets we acquire in a carry-over basis transaction may be lower than the
assets’ fair market values at the time of such acquisition. This lower tax basis could cause us to have
lower depreciation deductions and more gain on a subsequent sale of the assets,
and to have a correspondingly larger required distribution of income or gain to
our stockholders, than would be the case if we had directly purchased the
assets in a taxable transaction. In
addition, in such a carry-over basis transaction, we will succeed to any tax
liabilities and earnings and profits of the acquired “C” corporation.
To qualify as a REIT, we
must distribute any such earnings and profits by the close of the taxable year
in which such transaction occurs. Any adjustments to the acquired corporation’s
income for taxable years ending on or before the date of the transaction,
including as a result of an examination of the corporation’s tax returns by the
IRS, could affect the calculation of the corporation’s earnings and
profits. If the IRS were to determine
that we acquired earnings and profits from a corporation that we failed to
distribute prior to the end of the taxable year in which the carry-over basis
transaction occurred, we could avoid disqualification as a REIT by using
“deficiency dividend” procedures. Under
these procedures, we generally would be required to distribute any such
earnings and profits to our stockholders as a dividend within 90 days of the
determination and pay a statutory interest charge at a specified rate to the
IRS.
Federal
Income Tax Considerations for Holders of Capital Stock
The following is a
summary of the material federal income tax consequences to you of purchasing,
owning and disposing of our capital stock.
This discussion does not purport to be complete or to deal with all
aspects of federal income taxation that may be relevant to security holders in
light of their particular circumstances or who are subject to special rules,
such as: banks, thrift institutions and certain other financial institutions;
“S” corporations; real estate investment trusts; regulated investment
companies; insurance companies; brokers and dealers in securities or
currencies; certain securities traders; tax-exempt investors (except to the
limited extent discussed in “—Taxation of Tax-Exempt Stockholders” below);
partnerships, pass through-entities and persons holding our capital stock
through a partnership or other pass-through entity; holders subject to the
alternative minimum tax; holders who receive capital stock through the exercise
of employee stock options or otherwise as compensation; individual retirement
accounts; certain tax-deferred accounts; persons holding our capital stock as
part of a hedge, straddle, conversion, integrated or other risk reduction or
constructive sale transaction; U.S. expatriates; U.S. persons (as defined
below) whose functional currency is not the U.S. dollar; and foreign investors
(except to the limited extent discussed in “—Taxation of Non-U.S. Stockholders”
below). Tax matters are very
complicated, and the tax consequences of an investment in and holding of our securities
will depend on the particular facts of each investor’s situation. Investors are
advised to consult their own tax advisors with respect to the application to
their own circumstances of the general federal income taxation rules described
below and with respect to other federal, state, local or foreign tax
consequences to them before making an investment in our securities. Unless otherwise noted, this discussion
assumes that investors are U.S. persons and hold our securities as capital
assets.
A “U.S. person”
generally is a beneficial owner of our securities that is, for U.S. federal
income tax purposes, any one of the following:
● a citizen or resident of
the United States;
● a corporation,
partnership or other entity created in or organized under the laws of the
United States or any political subdivision thereof;
● an estate, the income of
which is subject to U.S. federal income taxation regardless of its source; or
● a trust that (i) is
subject to the supervision of a court within the United States and the control
of a United States person or (ii) has a valid election in effect under
applicable Treasury Regulations to be treated as a U.S. person.
A “Non‑U.S. holder” is a
beneficial owner of our securities that is not a U.S. person.
If
a partnership (including an entity or arrangement treated as a partnership for
U.S. federal income tax purposes) holds our securities, the tax treatment of a
partner in the partnership will generally depend upon the status of the partner
and the activities of the partnership. A prospective security holder that is a
partnership holding our securities or a partner of such a partnership should
consult his, her or its own tax adviser with respect to the purchase, ownership
and disposition of our securities.
Taxation of Taxable U.S. Common or Preferred Stockholders. As long as we qualify as a REIT, distributions
made to our taxable U.S. common or preferred stockholders, as applicable, out
of current or accumulated earnings and profits (and not designated as capital
gain dividends or retained capital gains) will be taken into account by them as
ordinary income, and corporate stockholders will not be eligible for the
dividends received deduction as to such amounts.
If we receive qualified
dividend income and designate such portion of our distributions as qualified
dividend income in a written notice mailed not later than 60 days after the
close of its taxable year, an individual U.S. stockholder may qualify (provided
holding period and certain other requirements are met) to treat such portion of
the distribution as qualified dividend income, eligible to be taxed at the
reduced maximum rate of generally 20.0%.
Qualified dividend income is, in general, dividend income from taxable
domestic corporations and qualified foreign corporations. A qualified foreign corporation generally
excludes any foreign corporation which for the taxable year of the corporation
in which the dividend was paid, or the preceding taxable year, is a passive
foreign investment company. The total
amount that can be designated by us as qualified dividend income generally
cannot exceed the sum of (1) our qualified dividend income for the tax year,
(2) the amount of our REIT taxable income and income taxed under the Code Section
337(d) Treasury Regulations, minus the tax on these items, for the prior year
and (3) the amount of any earnings and profits that were distributed by us for
the tax year and accumulated in a tax year during which we were not subject to
the REIT rules. However,
pursuant to Section 857(g) the aggregate amount of dividends designated by
us as qualified dividend income or capital gain dividends (as discussed below)
with respect to any taxable year may not exceed tax dividends paid by us with
respect to such year. For these purposes, dividends paid after the close of the
taxable year pursuant to Section 858 shall be treated as paid with respect
to such year.
Distributions in excess
of current and accumulated earnings and profits will not be taxable to a
stockholder to the extent that they do not exceed the adjusted basis of such
stockholder’s stock, but rather will reduce the adjusted basis of such shares
as a return of capital. To the extent
that such distributions exceed the adjusted basis of a stockholder’s stock,
they will be included in income as long‑term capital gain (or short‑term
capital gain if the shares have been held for one year or less), assuming the
shares are a capital asset in the hands of the stockholder. In addition, any
dividend declared by us in October, November or December of any year payable to
a stockholder of record on a specific date in any such month shall be treated
as both paid by us and received by the stockholder on December 31 of such year,
provided that the dividend is actually paid by us during January of the
following calendar year. For purposes of
determining what portion of a distribution is attributable to current or
accumulated earnings and profits, earnings and profits will first be allocated
to distributions made to holders of any shares of our preferred stock
outstanding at the applicable time, to the extent that the dividends payable on
such preferred stock is payable prior to the dividends on the common stock.
Stockholders may not include in their individual income tax returns any net
operating losses or capital losses of ours.
For tax years beginning
after December 31, 2017, and prior to January 1, 2026, noncorporate
stockholders are generally eligible to deduct up to 20.0% of the amount of
ordinary REIT dividends that are not designated as capital gain dividends or
qualified dividend income, subject to certain limitations.
In general, any gain or
loss realized upon a taxable disposition of shares by a stockholder who is not
a dealer in securities will be treated as a long‑term capital gain or loss if
the shares have been held for more than one year, otherwise as short‑term
capital gain or loss. However, any loss
upon a sale or exchange of stock by a stockholder who has held such shares for
six months or less (after applying certain holding period rules) generally will
be treated as long‑term capital loss to the extent of distributions from us
required to be treated by such stockholder as long‑term capital gain.
Distributions that we
properly designate as capital gain dividends will be taxable to stockholders as
gains (to the extent that they do not exceed our actual net capital gain for
the taxable year and to the extent they do not exceed the limitation under Section
857(g) of the Code, discussed above) from the sale or disposition of a capital
asset held for greater than one year. If we designate any portion of a dividend
as a capital gain dividend, a U.S. stockholder will receive an IRS Form 1099‑DIV
indicating the amount that will be taxable to the stockholder as capital
gain. However, stockholders that are
corporations may be required to treat up to 20.0% of certain capital gain
dividends as ordinary income. A portion
of capital gain dividends received by noncorporate taxpayers may be subject to
tax at a 25.0% rate to the extent attributable to certain gains realized on the
sale of real property. In addition,
noncorporate taxpayers are generally taxed at a maximum rate of 20.0% on net
long‑term capital gain (generally, the excess of net long‑term capital gain
over net short‑term capital loss) attributable to gains realized on the sale of
property held for greater than one year.
Distributions we make
and gain arising from the sale or exchange by a stockholder of shares of our
stock will not be treated as passive activity income, and, as a result,
stockholders generally will not be able to apply any “passive losses” against
such income or gain. Distributions we
make (to the extent they do not constitute a return of capital) generally will
be treated as investment income for purposes of computing the investment
interest limitation. Gain arising from the sale or other disposition of our
stock (or distributions treated as such) will not be treated as investment
income under certain circumstances.
Upon any taxable sale or
other disposition of our common stock or preferred stock, a U.S. stockholder
will recognize gain or loss for federal income tax purposes on the disposition
of our stock in an amount equal to the difference between:
● the amount of cash and
the fair market value of any property received on such disposition; and
● the U.S. stockholder’s
adjusted basis in such stock for tax purposes.
Gain or loss will be
capital gain or loss if the common or preferred stock has been held by the U.S.
stockholder as a capital asset. The applicable tax rate will depend on the
stockholder’s holding period in the asset (generally, if an asset has been held
for more than one year it will produce long‑term capital gain) and the
stockholder’s tax bracket. A U.S.
stockholder who is an individual or an estate or trust and who has long‑term
capital gain will be subject to a maximum capital gain rate of 20.0%. However, to the extent that the capital gain
realized by a non‑corporate stockholder on the sale of REIT stock corresponds
to the REIT’s “unrecaptured Section 1250 gain,” such gain may be subject to tax
at a rate of 25.0%. Stockholders are
advised to consult with their own tax advisors with respect to their capital
gain tax liability.
Taxation of U.S.
Preferred Stockholders on a Conversion of Preferred Stock into Common Stock. Except as provided below, a U.S. stockholder
generally will not recognize gain or loss upon the conversion of preferred
stock into shares of common stock and cash in lieu of fractional shares, except
that a U.S. stockholder’s receipt of cash in lieu of a fractional share of common
stock generally will result in capital gain or loss (measured by the difference
between the cash received in lieu of the fractional share of common stock and
the U.S. stockholder’s tax basis in the fractional share of common stock).
A U.S. stockholder’s tax
basis in shares of common stock received upon conversion of the preferred stock
(and any fractional shares of our common stock treated as received then
exchanged for cash) will equal the basis of the converted shares of preferred
stock, and the holding period of such shares of common stock will include the
holding period of the converted shares of the preferred stock.
Any of our common stock
received in a conversion that is attributable to accrued and unpaid dividends
on the preferred stock likely will be treated as a distribution taxable as a
dividend to the extent of the Company’s earning and profits.
Taxation of U.S.
Preferred Stockholders on a Redemption of Preferred Stock. A redemption of shares of preferred stock will
generally be a taxable event. If the redemption is treated as a sale or
exchange, instead of a dividend, a U.S. holder generally will recognize capital
gain or loss (which will be long-term capital gain or loss, if the U.S.
holder’s holding period for the preferred stock exceeds one year) equal to the
difference between the amount realized by the U.S. holder and the U.S. holder’s
adjusted tax basis in the preferred stock redeemed. A payment made in redemption
of the preferred stock may be treated as a dividend, rather than as payment in
exchange for the preferred stock, unless the redemption:
● is “not essentially
equivalent to a dividend” with respect to a U.S. holder under Section 302(b)(1)
of the Code;
● is a “substantially
disproportionate” redemption with respect to a U.S. holder under Section
302(b)(2) of the Code;
● results in a “complete
redemption” of a U.S. holder’s stock interest in the Company under Section
302(b)(3) of the Code; or
● is a redemption of stock
held by a non-corporate shareholder, which results in a partial liquidation of
the Company under Section 302(b)(4) of the Code.
In determining whether
any of these tests has been met, a U.S. holder must take into account not only
shares of the preferred and common stock that the U.S. holder actually owns,
but also shares of stock that the U.S. holder constructively owns within the
meaning of Section 318 of the Code.
A redemption payment
will be treated as “not essentially equivalent to a dividend” if it results in
a “meaningful reduction” in a U.S. holder’s aggregate stock interest in the
Company, which will depend on the U.S. holder’s particular facts and circumstances
at such time.
Satisfaction of the
“complete redemption” and “substantially disproportionate” exceptions is
dependent upon compliance with the objective tests set forth in Section
302(b)(3) and Section 302(b)(2) of the Code, respectively. A redemption will
result in a “complete redemption” if either all of the shares of our stock
actually and constructively owned by a U.S. holder are exchanged in the
redemption or all of the shares of our stock actually owned by the U.S. holder
are exchanged in the redemption and the U.S. holder is eligible to waive, and
the U.S. holder effectively waives, the attribution of shares of our stock
constructively owned by the U.S. holder in accordance with the procedures
described in Section 302(c)(2) of Code.
A redemption does not
qualify for the “substantially disproportionate” exception if the stock
redeemed is only non-voting stock, and for this purpose, stock which does not
have voting rights until the occurrence of an event is not voting stock until
the occurrence of the specified event. Accordingly, any redemption of the
preferred stock generally will not qualify for this exception because the
voting rights of the preferred stock is limited.
For purposes of the “redemption from
non-corporate shareholders in a partial liquidation” test, a distribution will
be treated as in partial liquidation of a corporation if the distribution is
not essentially equivalent to a dividend (determined at the corporate level
rather than the shareholder level) and the distribution is pursuant to a plan
and occurs within the taxable year in which the plan was adopted or within the
succeeding taxable year. For these purposes, a distribution is generally not
essentially equivalent to a dividend if the distribution results in a corporate
contraction. The determination of what constitutes a corporate contraction is
factual in nature and has been interpreted under case law to include the
termination of a business or line of business. Each U.S. holder of the
preferred stock should consult its own tax advisors to determine whether a
payment made in redemption of the preferred stock will be treated as a dividend
or a payment in exchange for the preferred stock. If the redemption payment is
treated as a dividend, the rules discussed above in “Taxation of Taxable U.S.
Common or Preferred Stockholders” apply.
If any amount received
by a U.S. holder in redemption of preferred stock is treated as a distribution of
a dividend, Treasury Regulation Section 1.302-2(c) provides that proper
adjustment of the basis of the remaining stock will be made with respect to the
stock redeemed. The IRS proposed
regulations in 2009 which provided detailed rules with respect to the shifting
of basis in such situations. The IRS
withdrew those proposed regulations in 2019, without finalizing any regulations
addressing the issues raised by the proposed regulations. Thus, the law is not clear as to how such
basis would be shifted among shares owned by the shareholder whose shares were
redeemed, and potentially related parties if the redeeming shareholder redeemed
all of his or her shares.
If the redemption
payment is treated as a dividend, the rules discussed above in “Taxation of
Taxable U.S. Common or Preferred Stockholders” will apply to such payment. If
preferred stock is redeemed and treated as a sale or exchange under Section 302
of the Code, any accrued and unpaid dividends that have been declared before
the call for redemption which are included in the total redemption payment are
treated as dividends and taxed as discussed in “Taxation of Taxable U.S. Common
or Preferred Stockholders.” To the extent that such accrued dividends are not
yet declared, the amounts attributable to such dividends arguably are treated
as part of the redemption proceeds taxable under Section 302 of the Code,
although such treatment depends on the particular facts involved.
Taxation of Tax‑Exempt Stockholders. Provided that a tax‑exempt stockholder has not
held our common or preferred stock as “debt financed property” within the
meaning of the Code, the dividend income from us will not be unrelated business
taxable income, referred to as UBTI, to a tax‑exempt stockholder. Similarly,
income from the sale of common or preferred stock will not constitute UBTI
unless the tax‑exempt stockholder has held its stock as debt financed property
within the meaning of the Code or has used the stock in a trade or business.
However, for a tax‑exempt stockholder that is a social club, voluntary employee
benefit association or supplemental unemployment benefit trust exempt from
federal income taxation under Code Sections 501(c)(7), (c)(9) or (c)(17),
respectively, or a single parent title‑holding corporation exempt under Code
Section 501(c)(2) the income of which is payable to any of the aforementioned
tax‑exempt organizations, income from an investment in our securities will
constitute UBTI unless, with respect to certain of these organizations, the
organization properly sets aside or reserves such amounts for purposes
specified in the Code. These tax-exempt stockholders should consult their own
tax advisors concerning these “set aside” and reserve requirements and other
requirements under the Code.
A “qualified trust”
(defined to be any trust described in Code Section 401(a) and exempt from tax
under Code Section 501(a)) that holds more than 10.0% of the value of the
shares of a REIT may be required, under certain circumstances, to treat a
portion of distributions from the REIT as UBTI.
This requirement will apply for a taxable year only if (i) the REIT
satisfies the requirement that not more than 50.0% of the value of its shares
be held by five or fewer individuals (the “five or fewer requirement”) only by
relying on a special “look‑through” rule under which shares held by qualified
trust stockholders are treated as held by the beneficiaries of such trusts in
proportion to their actuarial interests therein; and (ii) the REIT is
“predominantly held” by qualified trusts.
A REIT is “predominantly held” by qualified trusts if either (i) a
single qualified trust holds more than 25.0% of the value of the REIT shares,
or (ii) one or more qualified trusts, each owning more than 10.0% of the value
of the REIT shares, hold in the aggregate more than 50.0% of the value of the
REIT shares. If the foregoing requirements are met, the percentage of any REIT
dividend treated as UBTI to a qualified trust that owns more than 10.0% of the
value of the REIT shares is equal to the ratio of (i) the UBTI earned by the
REIT (computed as if the REIT were a qualified trust and therefore subject to
tax on its UBTI) to (ii) the total gross income (less certain associated
expenses) of the REIT for the year in which the dividends are paid. A de minimis exception applies where the
ratio set forth in the preceding sentence is less than 5.0% for any year.
The provisions requiring
qualified trusts to treat a portion of REIT distributions as UBTI will not
apply if the REIT is able to satisfy the five or fewer requirement without
relying on the “look‑through” rule.
Taxation of Non‑U.S. Stockholders. The rules governing U.S. federal income
taxation of nonresident alien individuals, foreign corporations, foreign
partnerships and other foreign stockholders (collectively, “Non‑U.S.
stockholders”) are complex, and no attempt will be made herein to provide more
than a limited summary of such rules. The discussion does not consider any
specific facts or circumstances that may apply to a particular Non‑U.S.
stockholder. Prospective Non‑U.S.
stockholders should consult with their own tax advisors to determine the impact
of U.S. federal, state and local income tax laws with regard to an investment
in our stock, including any reporting requirements.
Distributions that are
not attributable to gain from sales or exchanges by us of U.S. real property
interests and not designated by us as capital gain dividends or retained
capital gains will be treated as dividends of ordinary income to the extent
that they are made out of our current or accumulated earnings and profits. Such distributions ordinarily will be subject
to a withholding tax equal to 30.0% of the gross amount of the distribution. If
a Non‑U.S. stockholder qualifies for benefits under an applicable income tax
treaty, the 30.0% U.S. federal income tax withholding rate on dividend
distributions to such stockholder may be reduced significantly. However, if income from the investment in our
stock is treated as effectively connected with the Non‑U.S. stockholder’s
conduct of a U.S. trade or business, the Non‑U.S. stockholder generally will be
subject to a tax at graduated rates in the same manner as U.S. stockholders are
taxed with respect to such dividends (and may also be subject to a branch
profits tax of up to 30.0% if the stockholder is a foreign corporation). We expect to withhold U.S. income tax at the
rate of 30.0% on the gross amount of any dividends paid to a Non‑U.S.
stockholder that are not designated as capital gain dividends, unless either:
● a lower treaty rate
applies and the Non‑U.S. stockholder files with us an IRS Form W‑8BEN evidencing eligibility for that reduced rate
or
● the Non‑U.S. stockholder
files an IRS Form W‑8ECI with us claiming that the distribution is income
treated as effectively connected to a U.S. trade or business.
A non‑U.S. stockholder
will not incur tax on a distribution in excess of our current and accumulated
earnings and profits if the excess portion of the distribution does not exceed
the adjusted basis of its stock. Instead, the excess portion of the
distribution will reduce the adjusted basis of that stock. A non‑U.S. stockholder will be subject to tax
on a distribution that exceeds both our current and accumulated earnings and
profits and the adjusted basis of its stock, if the non‑U.S. stockholder
otherwise would be subject to tax on gain from the sale or disposition of its
stock, as described below. Because we generally cannot determine at the time we
make a distribution whether or not the distribution will exceed our current and
accumulated earnings and profits, we normally will withhold tax on the entire
amount of any distribution at the same rate as we would withhold on a
dividend. However, a non‑U.S.
stockholder may obtain a refund of amounts that we withhold if we later
determine that a distribution in fact exceeded our current and accumulated
earnings and profits.
Additional withholding
regulations may require us to withhold 15.0% of any distribution that exceeds
our current and accumulated earnings and profits. Consequently, although we intend to withhold
at a rate of 30.0% on the entire amount of any distribution, to the extent that
we do not do so, we will generally withhold at a rate of 15.0% on any portion
of a distribution not subject to withholding at a rate of 30.0%.
Except as discussed
below with respect to 10.0% or less holders of regularly traded classes of
stock, for any year in which we qualify as a REIT, a non‑U.S. stockholder
generally will incur tax on distributions by us that are attributable to gain
from our sale or exchange of USRPIs under special provisions of the U.S.
federal income tax laws known as the Foreign Investment in Real Property Act,
or “FIRPTA.” The term USRPIs includes interests in real property and shares in
corporations at least 50.0% of whose assets consist of interests in U.S. real
property, as determined under the Code and applicable Treasury Regulations.
Under those rules, a non‑U.S. stockholder is taxed on distributions by us
attributable to gain from sales of USRPIs as if the gain were effectively
connected with a United States trade or business of the non‑U.S. stockholder. A
non‑U.S. stockholder thus would be taxed on such a distribution at the normal
capital gain rates applicable to U.S. stockholders, subject to applicable
alternative minimum tax and a special alternative minimum tax in the case of a
nonresident alien individual. A non‑U.S. corporate stockholder not entitled to
treaty relief or exemption also may be subject to the 30.0% branch profits tax
on such a distribution. We must withhold 21.0% of any distribution that we
could designate as a capital gain dividend. A non‑U.S. stockholder may receive
a credit against its tax liability for the amount we withhold. However, FIRPTA
and the 21.0% withholding tax generally will not apply to any capital gain
dividend with respect to any class of our stock which is regularly traded on an
established securities market located in the United States if the recipient
non‑U.S. stockholder did not own more than 10.0% of such class of stock at any
time during the one-year period ending on the date of distribution. Instead,
any capital gain dividend will be treated as an ordinary distribution subject
to the rules discussed above, which generally impose a 30.0% withholding tax
(unless reduced by a treaty). Also, the branch profits tax will not apply to
such a distribution.
A non‑U.S. stockholder
generally will not incur tax under FIRPTA with respect to gain on a sale of our
common or preferred stock as long as at all times during the testing period
non‑U.S. persons hold, directly or indirectly, less than 50.0% in value of our
stock, as determined under the Code and applicable Treasury Regulations. We
cannot assure you that that test will be met, but, if such test is satisfied,
the sale of our stock will not be subject to tax under FIRPTA, regardless of
the percentage owned by such holder and whether our stock is regularly traded
on an established securities market. Even if we meet this test, pursuant to
“wash sale” rules under FIRPTA, a non‑U.S. stockholder may incur tax under
FIRPTA to the extent such stockholder disposes of stock within a certain period
prior to a capital gain distribution and directly or indirectly (including
through certain affiliates) reacquires stock within certain prescribed periods.
However, a non‑U.S. stockholder generally will not incur tax under FIRPTA on a
disposition of the shares of our common or preferred stock if such non‑U.S.
stockholder owned, actually or constructively, at all times during a specified
testing period, 10.0% or less of the total fair market value of a class of our
stock that is “regularly traded” on an established securities market or, in
certain cases as provided under the applicable Treasury Regulations, if the
non-U.S. stockholder owns a specified interest in shares of a class of our
stock that is not publicly traded on an established securities market. If our
common stock is listed, then for as long as it is regularly traded on an
established securities market, a non‑U.S. stockholder should not incur tax
under FIRPTA with respect to gain on a sale of our common stock if it owns,
actually or constructively, 10.0% or less of our common stock. If the gain on
the sale of our stock were taxed under FIRPTA, a non‑U.S. stockholder would be
taxed on that gain in the same manner as U.S. stockholders subject to
applicable alternative minimum tax and a special alternative minimum tax in the
case of nonresident alien individuals. Furthermore, a non‑U.S. stockholder
generally will incur tax on gain not subject to FIRPTA if:
● the gain is effectively
connected with the non‑U.S. stockholder’s United States trade or business, in
which case the non‑U.S. stockholder generally will be subject to the same
treatment as U.S. stockholders with respect to such gain; or
● the non‑U.S. stockholder
is a nonresident alien individual who was present in the United States for 183
days or more during the taxable year and has a “tax home” in the United States,
in which case the non‑U.S. stockholder generally will incur a 30.0% tax on his
or her capital gains derived from sources within the United States.
REIT stock held by
certain qualified collective investment entities will not be treated as a USRPI
subject to FIRPTA. In addition, certain
foreign retirement and pension funds are exempt from FIRPTA.
State and Local Taxes
We and our stockholders
may be subject to state or local taxation in various state or local
jurisdictions, including those in which we or they transact business or reside
(although U.S. stockholders who are individuals generally should not be
required to file state income tax returns outside of their state of residence
with respect to our operations and distributions). The state and local tax treatment of us and
our stockholders may not conform to the federal income tax consequences
discussed above. Consequently,
prospective stockholders should consult their own tax advisors regarding the
effect of state and local tax laws on an investment in our common or preferred stock.
Information
Reporting and Backup Withholding
Applicable Treasury
Regulations provide presumptions regarding the status of holders when payments
to the holders cannot be reliably associated with appropriate documentation
provided to the payor. Because the application
of these Treasury Regulations varies depending on the stockholder’s particular
circumstances, you are advised to consult your tax advisor regarding the
information reporting requirements applicable to you.
U.S. Holders.
A U.S. holder may be subject to information reporting and backup withholding
when such holder receives payments on our stock or proceeds from the sale or
other taxable disposition of our stock. Certain U.S. holders are exempt from
backup withholding, including generally corporations and certain tax-exempt
organizations. A U.S. holder will be subject to backup withholding if such
holder is not otherwise exempt and such holder:
● fails to furnish the holder’s taxpayer
identification number, which for an individual is ordinarily his or her social
security number;
● furnishes an incorrect taxpayer identification
number;
● is notified by the IRS that the holder
previously failed to properly report payments of interest or dividends; or
● fails to certify under penalties of perjury that
the holder has furnished a correct taxpayer identification number and that the
IRS has not notified the holder that the holder is subject to backup
withholding.
Backup withholding is
not an additional tax. Any amounts withheld under the backup withholding rules
may be allowed as a refund or a credit against a U.S. holder’s U.S. federal
income tax liability, provided the required information is timely furnished to
the IRS. U.S. holders should consult their tax advisors regarding their
qualification for an exemption from backup withholding and the procedures for
obtaining such an exemption.
Non-U.S. Holders. Payments of dividends on our stock generally will not be subject
to backup withholding, provided the applicable withholding agent does not have
actual knowledge or reason to know the holder is a U.S. person and the holder
either certifies its non-U.S. status, such as by furnishing a valid IRS Form
W-8BEN or W-8BEN-E (or other applicable successor form) or W-8ECI, or otherwise
establishes an exemption. Similarly, payments of dividends to non-U.S. holders
generally will not be subject to information reporting if required
documentation is provided proving that the holder is a foreign beneficial owner
or otherwise exempt. In addition, proceeds of the sale or other taxable
disposition of our stock within the United States or conducted through certain
U.S.-related brokers generally will not be subject to backup withholding or
information reporting, if the applicable withholding agent receives the
certification described above and does not have actual knowledge or reason to
know that such holder is a U.S. person, or the holder otherwise establishes an
exemption. Proceeds of a disposition of our stock conducted through a non-U.S.
office of a non-U.S. broker generally will not be subject to backup withholding
or information reporting.
Copies of information
returns that are filed with the IRS may also be made available under the
provisions of an applicable treaty or agreement to the tax authorities of the
country in which the non-U.S. holder resides or is established.
Backup withholding is
not an additional tax. Any amounts
withheld under the backup withholding rules may be allowed as a refund or a
credit against a non-U.S. holder’s U.S. federal income tax liability, provided
the required information is timely furnished to the IRS.
Tax
Consequences of Participation in Dividend Reinvestment Plan
If you elect to
participate in our dividend reinvestment program and are subject to federal
income taxation, you will incur a tax liability for dividends allocated to you
even though you have elected not to receive the dividends in cash but rather to
have the dividends withheld and reinvested pursuant to our dividend
reinvestment program. Specifically, you will be treated as if you have received
the dividend from us in cash and then applied such dividend to the purchase of
additional shares. In addition, to the extent you purchase shares through our
dividend reinvestment program at a discount to their fair market value, you
will be treated for tax purposes as receiving an additional dividend equal to
the amount of the discount, if any. You will be taxed on the amount of the
dividend as a dividend to the extent such distribution is from current or
accumulated earnings and profits, unless we have designated all or a portion of
the distribution as a capital gain distribution. You may be subject to backup
withholding if you fail to comply with certain tax requirements. See
“Information Reporting and Backup Withholding.”
Additional Considerations
Medicare Tax. A 3.8% tax will generally be imposed on the
net investment income of certain individuals with a modified adjusted gross
income of over $200,000 ($250,000 in the case of joint filers) and on the
undistributed net investment income of certain estates and trusts. For these purposes, “net investment income” will
generally include interest (including interest on our debt securities),
dividends (including dividends paid with respect to our stock), annuities,
royalties, rent, net gain attributable
to the disposition of property not held in a trade or business (including net
gain from the sale, exchange or other
taxable disposition of shares of our stock) and certain other income, but will
be reduced by any deductions properly allocable to such income or net gain.
Foreign Accounts. Withholding taxes may be imposed under Sections 1471 to 1474 of
the Code (such Sections commonly referred to as the Foreign Account Tax
Compliance Act, or “FATCA”) on certain types of payments made to “foreign
financial institutions” (as specially defined in the Code) and certain other
non-U.S. entities (including payments to U.S. holders who hold shares of our
capital stock through such a foreign financial institution or non-U.S. entity).
Specifically, a 30.0%
withholding tax may be imposed on dividends on our capital stock paid to a
foreign financial institution or to a non-financial foreign entity, unless (1)
the foreign financial institution undertakes certain diligence and reporting, (2)
the non-financial foreign entity either certifies it does not have any
“substantial United States owners” (as defined in the Code) or furnishes
identifying information regarding each substantial United States owner, or (3)
the foreign financial institution or non-financial foreign entity otherwise
qualifies for an exemption from these rules. If the payee is a foreign
financial institution and is subject to the diligence and reporting
requirements in (1) above, it must enter into an agreement with the U.S.
Department of the Treasury requiring, among other things, that it undertake to
identify accounts held by certain “specified United States persons” or “United
States-owned foreign entities” (each as defined in the Code), annually report
certain information about such accounts, and withhold 30.0% on certain payments
to non-compliant foreign financial institutions and certain other account
holders. Foreign financial institutions located in jurisdictions that have an
intergovernmental agreement with the United States governing FATCA may be
subject to different rules.
Under the applicable
Treasury Regulations and IRS guidance, withholding under FATCA generally
applies to payments of dividends but does not currently apply to payments of
gross proceeds from a sale or other disposition of capital stock, although it
may apply to such gross proceeds in the future. Because we may not know the
extent to which a distribution is a dividend for U.S. federal income tax
purposes at the time it is made, for purposes of the FATCA withholding we may
treat the entire distribution as a dividend. Prospective investors should
consult their tax advisors regarding these withholding provisions.
DESCRIPTION
OF SECURITIES
The following description is based on relevant portions of
the MGCL and on our Charter and Third Amended and Restated Bylaws (“Bylaws”).
This summary is not necessarily complete, and we refer you to the MGCL and our
Charter and Bylaws for a more detailed description of the provisions summarized
below.
Capital Stock
Our authorized stock consists of 100,000,000 shares of
stock, par value $0.0001 per share, 80,000,000 which are initially designated
as common stock, and 20,000,000 of which are initially designated as preferred
stock. As noted above, the Company
offered and sold in a registered direct offering (the “Registered Offering”),
pre-funded warrants to purchase up to 129,226.50 shares of common stock; and,
in a concurrent private placement and together with the Registered Offering,
unregistered warrants to purchase up to an aggregate of 423,944.85 shares of
common stock. The exercise price for each warrant was $17.10 per share, and the
purchase price for each pre-funded warrant was $17.099 per share. The common
stock warrants consist of Series A common stock warrants and Series B common
stock warrants. The Series A common stock warrants to purchase up to 141,314.95
shares of common stock are exercisable following the six-month anniversary of
the closing date of the offering and expire 18 months from the investment date.
The Series B common stock warrants to purchase up to 282,629.90 shares of
common stock are exercisable following the six-month anniversary of the closing
date of the and expire five years from the date of issuance. There are no other
outstanding options or warrants to purchase our stock. No stock has been
authorized for issuance under any equity compensation plans. We use a fiscal
year‑end of June 30. Under Maryland law, our stockholders generally are not
personally liable for our debts or obligations. As of October 9, 2026, we have the following
authorized and outstanding number of shares of common and preferred stock:
|
(1)
Title of Class
|
|
(2)
Amount
Authorized
|
|
(3)
Amount Held
by Us or for
Our Account
|
|
(4)
Amount
Outstanding
Exclusive of
Amounts
Shown Under Column (3)
|
|
Common
stock
|
|
|
80,000,000
|
|
|
|
-
|
|
|
|
2,774,688
|
|
|
Preferred
Stock: Series A, B, and C
|
|
|
20,000,000
|
|
|
|
|
|
|
|
944,583.37
|
|
Under our Charter, our Board of Directors is
authorized to classify and reclassify any unissued shares of stock into other
classes or series of stock without obtaining stockholder approval, provided
that the aggregate number of shares of all classes does not exceed the total
number of authorized shares. As permitted by the MGCL, our Charter provides
that the Board of Directors, without any action by our stockholders, may amend
the Charter from time to time to increase or decrease the aggregate number of
shares of stock or the number of shares of stock of any class or series that we
have authority to issue under our Charter. Additionally, our Charter authorizes
our Board of Directors, without any action by our stockholders, to classify or
reclassify any unissued shares to set or change the preferences, conversion or
other rights, restrictions, limitations as to dividends or other distributions,
qualifications or terms and conditions of redemption for each class or series.
Under our Charter, stockholders are not required to contribute additional
capital.
Preferred Stock
In General.
The securities being offered hereby are investments in a corporation that has
elected to be taxed as a real estate investment trust, or REIT, which owns and
invests in the Investments and conducts some of its operations through the
Operating Partnership. Shares of Series A Preferred Stock are being offered by
us at $22.50 per preferred share and Shares of Series B and Series C Preferred
Stock are being offered by us at $25.00 per preferred share (the “Purchase
Price”). The minimum subscription amount is $5,000, except that we, in our sole
discretion, may permit certain investors to purchase fewer preferred shares.
Preferred Dividend. The holders of the Series A preferred shares will be entitled to
receive preferred cumulative cash dividends on each preferred share at an
annual rate of 6% on the Stated Value and holders of the Series B preferred
shares will be entitled to receive preferred cumulative
cash dividends on each preferred share at an annual rate of 12% on the Stated
Value, with 3% per annum intended to be paid on a quarterly basis on the
applicable dividend payment date and with the additional 9% per annum intended
to begin to be paid at the same time and in the same amounts per share with
distributions paid per share to the holders of common stock, once holders of common
stock have initially received aggregate distributions equal to 10% per annum from
and after December 31, 2022 on the $7.38 per share NAV applicable to the common
stock as of such date, and the remainder of which will be paid no later than at
redemption, liquidation or conversion, and the holders of the Series C preferred
shares will be entitled to receive preferred cumulative cash dividends on each
preferred share at an annual rate of 9% on the Stated Value (for each Series, the
“Preferred Dividend”). While our Charter sets forth the preferred shares’
preference as to such dividends, there can be no assurance if or when they will
be paid. The Board has the ability to suspend the payment of the Preferred
Dividend at any time. As of the date
hereof, the Preferred Dividend has always been paid on time on all outstanding
preferred shares.
Ranking.
The preferred shares will rank, with respect to dividend rights and rights upon
liquidation, winding-up, or dissolution (i) senior to all classes of our common
stock, and to any other class or series of our capital stock issued in the
future unless the terms of that capital stock expressly provide that it ranks
senior to, or on parity with, the preferred shares, and (ii) junior to any
other class or series of our capital stock, the terms of which expressly
provide that it will rank senior to the preferred shares. The Series C Preferred Stock will rank
junior, with respect to dividend rights and rights upon liquidation,
winding-up, or dissolution, to the Series A and B Preferred Stock (excluding
the additional accrued 9% portion of the Series B Preferred Stock dividend).
Term of Investment. The preferred shares shall continue to accrue a Preferred Dividend
until they have been redeemed or repurchased (see below).
Liquidation Preference. Upon any voluntary or involuntary liquidation,
dissolution or winding up of the Company, the holders of shares of our
preferred stock will be entitled to receive the following payments (in each
case, the “Liquidation Preference” applicable to such series):
Series A and C Preferred Stock Liquidation Preference — Holders of Series A and Series C Preferred Stock
will be entitled to be paid, as the Liquidation Preference applicable to such
shares, an amount equal to the Stated Value of $25 per share, plus an amount
equal to any accrued and unpaid dividends thereon.
Series B Preferred Stock Liquidation Preference — Holders of Series B Preferred Stock will be
entitled to be paid the Liquidation Preference applicable to the Series B
Preferred Stock, which is dependent on the Accrued Preference Value for each
share of such stock. The “Accrued
Preference Value” for each outstanding share of Series B Preferred Stock is
equal to the sum of (i) the Stated Value of $25.00 per share of Series B
Preferred Stock plus (ii) an amount equal to any accrued and unpaid dividends
(whether or not authorized or declared) thereon to and including the date of
payment of such amount, but without interest.
The Liquidation Preference for each outstanding share
of Series B Preferred Stock will be calculated as follows: (i) from the
Acquisition Date applicable to such share until the third anniversary of such
date, the dollar value of the Accrued Preference Value applicable to such share
as of the date such Liquidation Preference is calculated and (ii) from and
after the third anniversary of the Acquisition Date applicable to such share,
an amount equal to the greater of (A) the dollar value of the Accrued Preference
Value applicable to such share as of the date the Liquidation Preference is
calculated or (B) an amount equal to the dollar value of the amount of common
stock the holder of such share of Series B Preferred Stock would be entitled to
receive as of the date the Liquidation Preference is calculated, pursuant to
the provisions described below in this summary under the heading “Series B
Preferred Repurchase/Additional Conversion Rights.”
Optional Early Redemption Right. Subject to the special redemption rights described
below, we may, at our option, redeem shares of Series A Preferred Stock, Series
B Preferred Stock, or Series C Preferred Stock, in whole or in part from time
to time, for cash during the Early Redemption Period (which began on January 1,
2023 for the Series A Preferred Stock, on January 1, 2025 for the Series B
Preferred Stock, and which begins on January 1, 2027 for the Series C Preferred
Stock) at a price per share equal to the applicable Liquidation Preference as
of the date on which the preferred shares are redeemed (the “Early Redemption
Date”). The price per preferred share applicable to any such Optional Early
Redemption will be equal to (i) the Liquidation Preference for each share of
Series A and Series C Preferred Stock and (ii) the Accrued Preference Value for
each share of Series B Preferred Stock, in each case as of the applicable Early
Redemption Date selected by the Company.
The Early Redemption Date will be selected by us and will
be not less than 15 or more than 60 days after the date on which we send notice
of the early redemption. Such notice will include: (i) the Early Redemption
Date; (ii) the redemption price payable on the Early Redemption Date,
including, without limitation, a statement as to whether or not accrued and
unpaid dividends will be payable as part of the redemption price or payable on
the next dividend payment date to the record holder at the close of business on
the relevant dividend record date as described above; and (iii) that dividends
on the shares to be redeemed will cease to accrue on such redemption date. If
less than all of the preferred shares held by any holder are to be redeemed,
the notice mailed to such holder will also specify the number of preferred
shares held by such holder to be redeemed.
Any redemption of some but not all of either the Series
A Preferred Stock, the Series B Preferred Stock, or the Series C Preferred
Stock will be done on a pro rata basis unless the Board elects to provide the
holders of the Series A Preferred Stock, the Series B Preferred Stock, or the
Series C Preferred Stock (as applicable) a “first come, first served”
redemption option.
If notice of redemption of any preferred shares has
been given and if the funds necessary for such redemption have been set apart
by us for the benefit of the holders of any preferred shares so called for
redemption, then, from and after the redemption date, dividends will cease to
accrue on such preferred shares, such preferred shares will be redeemed in
accordance with the notice and will no longer be deemed outstanding and all
rights of the holders of such preferred shares will terminate, except the right
to receive the redemption price payable upon such redemption without interest
thereon. No further action on the part of the holders of such preferred shares
will be required.
Special Redemption Rights. In connection with a Special Redemption Event, we
have the right to redeem the preferred shares at any time on a date selected by
us in our sole discretion (the “Special Redemption Date”) at a redemption price
that is equal to the Stated Value plus an amount equal to all accrued and
unpaid dividends thereon to, and including, the Special Redemption Date (in the
case of the Series A or Series C Preferred Stock) or at a redemption price that
is equal to Accrued Preference Value as of the redemption date (in the case of
the Series B Preferred Stock), even if the Special Redemption Event should occur
prior to January 1, 2025 (in the case of the Series B Preferred Stock). In the
case of our exercise of this right in connection with a Special Redemption
Event, a holder of Series A or C Preferred Stock would not have the Conversion
Rights described above that would be applicable to an Optional Early Redemption
of such shares.
A “Special Redemption Event” means the date on which
the shares of common stock are traded on a national securities exchange with at
least three market makers or a New York Stock Exchange specialist.
Conversion Right. Upon receipt of notice from us that we intend to redeem the preferred
shares pursuant to the Optional Early Redemption Right described above, any
holder thereof is entitled to elect instead to receive shares of our common
stock as follows with respect to either the Series A Preferred Stock, Series B
Preferred Stock, or Series C Preferred Stock, and holders of the Series B
Preferred Stock also will have the conversion election described below in the
event we exercise the Company’s Special Redemption Right:
(i) Series A Preferred Conversion Right: Each holder of Series A and C Preferred Stock shall
be entitled to elect to receive, in lieu of the aggregate Liquidation
Preference for the applicable number of preferred shares, the number of shares
of common stock equal to the value of such aggregate Liquidation Preference
divided by $102.50 subject to availability of an exemption from registration
under the Securities Act of 1933, as amended, or an effective registration
statement.
(ii) Series B and C Preferred Conversion Right: Each holder of Series B Preferred Stock shall be
entitled to elect to receive, in lieu of the aggregate Accrued Preference Value
or Liquidation Preference, respectively, for the applicable number of preferred
shares, the number of shares of common stock equal to such aggregate Accrued
Liquidation Preference or Liquidation Preference divided by (i) the lower of $102.50
or the Board’s most recent estimated net asset value per share of common stock,
if the common stock is not then listed on a national securities exchange or an
over-the-counter market as reported by OTC Markets Group, Inc. or another
similar organization or (ii) if the common stock is then listed on a national
securities exchange or an over-the-counter market as described above, the lower
of $102.50 or the volume weighted average of the Last Reported Sale Price per
share of common stock as reported on such market for the twenty (20) trading
days prior to the Conversion Date (defined as the date of the giving of notice
of an exercise of conversion rights and surrender of the underlying shares of
Series B Preferred Stock to be converted). For purposes of this calculation,
the “Last Reported Sale Price” for the common stock means, at any time that the
common stock is listed on a national securities exchange or an over-the-counter
market as described above, the closing sale price per share (or if no closing
sale price is reported, the average of the bid and ask prices or, if more than
one in either case, the average of the average bid and the average ask prices)
on that date as reported in composite transactions for the principal U.S.
national or regional securities exchange on which the common stock is traded.
Temporary Suspension of the Share Repurchase Program
with Respect to the Series A, Series B, and Series C Preferred Stock. On September 11, 2026, our Board of Directors
approved the temporary suspension of the Company's share repurchase program
with respect to all three of our Series A Preferred Stock, Series B Preferred
Stock, and Series C Preferred Stock (the “Repurchase Program Suspension”), which
the Company publicly announced on its Current Report on Form 8-K filed with the
Securities and Exchange Commission on September 30, 2026. The Board implemented
the Repurchase Program Suspension in order to enable the Company to better
react to strategic alternatives that may from time to time be presented for
evaluation by its financial advisor, Maxim Group LLC. During the Repurchase Program Suspension, we
will not repurchase any shares of Series A, Series B, or Series C Preferred
Stock under the share repurchase program, and holders will not be able to
submit shares of Series A, Series B, or Series C Preferred Stock for
repurchase. The Board expects to reassess the Repurchase Program Suspension in
due course. We may terminate, modify, or
reinstate the share repurchase program at any time in our sole discretion,
subject to any required Board approval; any such action will be publicly
announced on Form 8-K. Investors should not purchase Series A, Series B, or
Series C Preferred Stock in reliance on the availability of the share
repurchase program as a source of liquidity. See “Risk Factors — Our board
of directors has temporarily suspended our preferred share repurchase program
with respect to the Series A, Series B, and Series C preferred shares.”
Series A Preferred Share Repurchase Program; Repurchase
Rights. Upon the request of a
stockholder, we may, at the sole discretion of the Board and subject to the
Repurchase Program Suspension described above, repurchase the Series A preferred
shares held by such stockholder as follows:
(i) Beginning on the day a stockholder acquires their preferred
shares (the “Series A Acquisition Date”) and continuing for a one-year period,
the purchase price for the repurchased preferred shares will be equal to 88% of
the Series A Stated Value for the preferred
shares;
(ii) Beginning on the first anniversary of the Series A Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased preferred shares will be equal to 91% of the Series A Stated Value
for the preferred shares;
(iii) Beginning on the second anniversary of the Series A Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased preferred shares will be equal to 94% of the Series A Stated Value
for the preferred shares;
(iv) Beginning on the third anniversary of the Series A Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased preferred shares will be equal to 97% of the Series A Stated Value
for the preferred shares; and
(v) Beginning on the fourth anniversary of the Series A Acquisition
Date and thereafter, the purchase price for the repurchased preferred shares
will be equal to 100% of the Series A Stated Value for the preferred shares.
Notwithstanding the above and subject to the sole
discretion of the Board, in the case of the death or complete disability of a
stockholder (but not for general redemption requests), for the period beginning
on the second anniversary of the Series A Acquisition Date and thereafter, the
purchase price for the repurchased preferred shares will be equal to 100% of
the Liquidation Preference for the preferred shares.
Further, a stockholder may request that any repurchase
be funded with shares of common stock pursuant to the terms of the Conversion
Right. That is, if pursuant to the above, the shareholder requests redemption,
such redemption may be paid, at the shareholder’s request, in shares of common
stock at an issuance price of $102.50 per share, subject to availability of an
exemption from registration or an effective registration statement.
If the stockholder requests repurchase at a time when our
common stock is listed on a national securities exchange or an over-the-counter
market, then we may elect to pay such repurchase amount in shares of common
stock based on the volume weighted average price per share of common stock for
the twenty (20) trading days prior to date of the repurchase.
Notwithstanding the above, the subscription agreement
for purchases of Series A Preferred Stock pursuant to this Offering Circular at
$22.50 per share (the “Series A Purchase Price”) will provide that such
purchasers will not be eligible to request repurchase at such prices, but rather,
may only request repurchase at (i) 88% of the Series A Purchase Price from the
day the stockholder acquired such shares (the “Series A Acquisition Date”)
until one year thereafter, (ii) 91% of the Series A Purchase Price from the
first anniversary until the second anniversary of the Series A Acquisition
Date, (iii) 94% of the Series A Purchase Price from the second anniversary
until the third anniversary of the Series A Acquisition Date, (iv) 97% of the
Series A Purchase Price from the third anniversary until the fourth anniversary
of the Series A Acquisition Date, and (v) $25.00 per share beginning on the
fourth anniversary of the Series A Acquisition Date and thereafter
(collectively, the “Series A Repurchase Price Schedule”).
Series B Preferred Share Repurchase Program; Additional
Repurchase and Conversion Rights. Shares
of Series B Preferred Stock will not be considered for repurchase by the
Company prior to the third anniversary of the day a stockholder acquired their Series
B Preferred Stock (the “Series B Acquisition Date”). Thereafter, upon the
request of a stockholder, we may, at the sole discretion of the Board and subject
to the Repurchase Program Suspension described above, repurchase the Series B Preferred
Stock held by such stockholder for cash as follows:
(i) Beginning on the third anniversary of the Series B Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased Series B Preferred Stock will be equal to 97% of the Accrued Preference
Value for such Series B Preferred Stock; and
(ii) Beginning on the fourth anniversary of the Series B Acquisition
Date and thereafter, the purchase price for the repurchased Series B Preferred
Stock will be equal to 100% of the Accrued Preference Value for such Series B Preferred
Stock.
At the option of the holder of any shares of Series B
Preferred Stock as to which the Board approves such a repurchase request (or at
the option of the Board if the common stock is then listed on a national
securities exchange or an over-the-counter market as reported by OTC Markets
Group, Inc.), the applicable repurchase consideration may be paid – subject to
the availability of an exemption from registration or an effective registration
statement – by issuing a number of shares of common stock determined by
dividing such amount (A) by the lower of a price of $102.50 per share of common
stock or at the Board’s most recent estimated net asset value per share of
common stock, if the common stock is not then listed as described above or (B)
by the lower of $102.50 per share or a 20-day volume weighted average trading
price, if the common stock is then so listed.
Additionally – and again subject to the availability
of an exemption from registration or an effective registration statement – a
holder of Series B Preferred Stock will have the right from and after the third
anniversary of the applicable Series B Acquisition Date, in the event the Board
declines such a requested cash redemption, to require the Company to exchange
such shares of Series B Preferred Stock for shares of common stock in
accordance with the timing and valuation criteria described above.
We anticipate processing requests for repurchase by us
of shares of Series A Preferred Stock, Series B Preferred Stock, or Series C
Preferred Stock under the Share Repurchase Program on a quarterly basis.
Series C Preferred Share Repurchase Program;
Repurchase Rights. Upon the request
of a stockholder, we may, at the sole discretion of the Board and subject to
the Repurchase Program Suspension described above, repurchase the Series C preferred
shares held by such stockholder as follows:
(vi) Beginning on the day a stockholder acquires their
preferred shares (the “Series C Acquisition Date”) and continuing for a
one-year period, the purchase price for the repurchased preferred shares will
be equal to 88% of the Purchase Price for the preferred shares (or $22 per
Preferred Share);
(vii) Beginning on the first anniversary of the Series C Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased preferred shares will be equal to 91% of the Purchase Price for the
preferred shares (or $22.75 per Preferred Share);
(viii)
Beginning on the
second anniversary of the Series C Acquisition Date and continuing for a
one-year period, the purchase price for the repurchased preferred shares will
be equal to 94% of the Purchase Price for the preferred shares (or $23.50 per
Preferred Share);
(ix) Beginning on the third anniversary of the Series C Acquisition
Date and continuing for a one-year period, the purchase price for the
repurchased preferred shares will be equal to 97% of the Purchase Price for the
preferred shares (or $24.25 per Preferred Share); and
(x) Beginning on the fourth anniversary of the Series C Acquisition
Date and thereafter, the purchase price for the repurchased preferred shares
will be equal to 100% of the Purchase Price for the preferred shares (or $25.00
per Preferred Share).
Notwithstanding the above and subject to the sole
discretion of the Board, in the case of the death or complete disability of a
stockholder (but not for general redemption requests), for the period beginning
on the second anniversary of the Series C Acquisition Date and thereafter, the
purchase price for the repurchased preferred shares will be equal to 100% of
the Purchase Price for the preferred shares (or $25.00 per Preferred
Share).
Further, a stockholder may request that any repurchase
be funded with shares of common stock pursuant to the terms of the Conversion
Right. That is, if pursuant to the above, the shareholder requests redemption,
such redemption may be paid, at the shareholder’s request, in shares of common
stock at an issuance price of $102.50 per share, subject to availability of an
exemption from registration or an effective registration statement.
If the stockholder requests repurchase at a time when
our common stock is listed on a national securities exchange or an
over-the-counter market, then we may elect to pay such repurchase amount in
shares of common stock based on the volume weighted average price per share of
common stock for the twenty (20) trading days prior to date of the repurchase,
less a 5% discount to account for trading costs.
Voting Rights.
The affirmative vote of holders entitled to cast a majority of the votes
entitled to be cast by holders of outstanding shares of Series A Preferred
Stock, Series B Preferred Stock, or Series C Preferred Stock, voting separately
as a class, shall be necessary to: (i) authorize or create, or increase the
authorized or issued amount of, any class or series of shares expressly
designated ranking senior to the Series A Preferred Stock, Series B Preferred
Stock, and Series C Preferred Stock with respect to payment of dividends or the
distribution of assets upon voluntary or involuntary liquidation, dissolution
or winding up of our affairs, or reclassify any authorized shares of Series A
Preferred Stock, Series B Preferred Stock, or Series C Preferred Stock into any
such shares, or create, authorize or issue any obligations or security
exchangeable or convertible into or evidencing the right to purchase any such
shares or (ii) approve any amendment, alteration or repeal of any of the
provisions of the Charter (including Articles Supplementary establishing the
terms of such series), whether by merger, consolidation or otherwise, that
would materially adversely affect any preferences, conversion and other rights,
voting powers, restrictions, limitations as to dividends and other
distributions, qualifications and terms and conditions of redemption of the
Series A Preferred Stock, Series B Preferred Stock, or Series C Preferred Stock,
as the case may be; provided, however, that the amendment, alteration or
repeal of any provision of the Charter (including Articles Supplementary establishing
the terms of such series) in connection with any merger, consolidation or other
event shall not be deemed to materially and adversely affect the preferences,
conversion and other rights, voting powers, restrictions, limitations as to
dividends and other distributions, qualifications and terms and conditions of
redemption of the Series A Preferred Stock, Series B Preferred Stock, or Series
C Preferred Stock, and the holders shall have no right to vote thereon, if,
following such merger, consolidation or other event, the Series A Preferred
Stock, Series B Preferred Stock, or Series C Preferred Stock remains
outstanding with the terms thereof materially unchanged or the holders receive
equity securities of the successor or survivor of such merger, consolidation or
other event with preferences, conversion and other rights, voting powers,
restrictions, limitations as to dividends and other distributions,
qualifications and terms and conditions of redemption that are substantially
identical to those of the Series A Preferred, Series B Preferred Stock, or
Series C Preferred Stock, taking into account that, upon the occurrence of such
merger, consolidation or other event, we may not be the surviving entity and
the surviving entity may not be a corporation.
Assignment by us. We will have the right to assign the obligations of the preferred
shares to a separate corporation provided that such corporation becomes the
successor in interest to us.
Non-Certificated Interests. Unless otherwise provided by the Board, we will not
issue shares in certificated form. Information regarding restrictions on the
transferability of our shares that, under Maryland law, would otherwise have
been required to appear on our share certificates will instead be furnished to
stockholders upon request and without charge. These requests should be
delivered or mailed to 89 Davis Road, Suite 100, Orinda, CA 94563.
We or our transfer agent will maintain a stock ledger
that contains the name and address of each stockholder and the number of shares
of each class that the stockholder holds. With respect to uncertificated stock,
we will continue to treat the stockholder registered on our stock ledger as the
owner of the shares until the new owner delivers a properly executed form to us
or our transfer agent, which form we or our transfer agent will provide to any
registered holder upon request.
Right
to Dividends
Holders
of our preferred shares are entitled to receive distributions authorized by our
Board and declared by us out of legally available funds.
Some
or all of our distributions may be paid from sources other than cash flow from
operations, such as from the proceeds of this Offering, cash advances to us by
our Adviser, the sale of our assets, cash resulting from a waiver of asset
management fees and borrowings (including borrowings secured by our assets) in
anticipation of future operating cash flow until such time as we have
sufficient cash flow from operations to fully fund the payment of distributions
therefrom.
Our
policy is to pay distributions from cash flow from operations. Because we may
receive income from interest or rents at various times during our fiscal year
and because we may need cash flow from operations during a particular period to
fund capital expenditures and other expenses, we expect that from time to time
we will declare distributions in anticipation of cash flow that we expect to
receive during a later period and we will pay these distributions in advance of
our actual receipt of these funds.
We may
fund such advanced distributions from third party borrowings, offering
proceeds, sale proceeds, advances from our Adviser or sponsors or from our Adviser’s
deferral of its base management fee. To the extent that we make payments or
reimburse certain expenses to our Adviser pursuant to our Advisory Agreement,
our cash flow and therefore our ability to make distributions from cash flow,
as well as cash flow available for investment, will be negatively impacted.
See “Management Compensation.”
We are
required to make distributions sufficient to satisfy the requirements for
qualification as a REIT for tax purposes. Generally, distributed income will
not be taxable to us under the Code if we distribute at least 90% of our REIT
taxable income.
Distributions
are authorized at the discretion of our Board, in accordance with our earnings,
cash flow, anticipated cash flow and general financial condition. The Board’s
discretion will be directed, in substantial part, by its intention to cause us
to continue to qualify as a REIT.
Many
of the factors that can affect the availability and timing of cash
distributions to stockholders are beyond our control, and a change in any one
factor could adversely affect our ability to pay future distributions. There
can be no assurance that future cash flow will support distributions at the
rate that such distributions are paid in any particular distribution period.
Under
Maryland law, we may issue our securities as stock dividends in lieu of making
cash distributions to stockholders. We may issue securities as stock dividends
in the future.
Preemptive
and Sinking Fund Rights
Our
preferred shares will not be subject to any sinking fund or any preemptive
rights to purchase or subscribe for any additional shares of our stock or any
other security that we may issue.
Common Stock.
In General. Our Charter authorizes us to issue up to 100,000,000 shares of
capital stock, of which 80,000,000 are classified as common stock, $0.0001 par
value per share. All shares of our common stock have equal dividend,
distribution, liquidation and other rights, and have no preference, cumulative,
preemptive, conversion or exchange rights. All of the outstanding shares of our
common stock are duly authorized, validly issued, fully paid and nonassessable.
Market. Our common stock currently trades on the Nasdaq Capital Market
under the trading symbol “MKZR.”
Liquidation
Rights. Subject to the restrictions on ownership and transfer of stock set
forth in our Charter and except as may otherwise be specified in our Charter, all
shares of our common stock have equal rights as to liquidation, dissolution or
winding up. The holders of common stock are entitled to share ratably in the
aggregate assets of the Company available for distribution after we pay all
debts and other liabilities. The rights of holders of common stock upon
liquidation, dissolution or winding up are subject to the terms of any series
of preferred stock.
Conversion, Preemptive, and Redemption Rights;
Sinking Fund Provisions.
All shares of our common stock do not have any preference, cumulative,
preemptive, conversion or exchange rights.
Voting Rights. Subject to the restrictions on ownership and transfer of stock
set forth in our Charter and except as may otherwise be specified in our
Charter, all holders of our common stock are entitled to one vote per share on
all matters upon which stockholders are entitled to vote, including elections
of directors. Except as provided with respect to any other class or series of
stock, the holders of our common stock possess exclusive voting power. Our
Charter generally provides for approval of charter amendments and other
extraordinary transactions by the stockholders entitled to cast at least a
majority of the votes entitled to be cast on the matter. Under the MGCL,
amendments to our Charter and other extraordinary transactions must first be
declared advisable by our Board. Therefore, except with respect to the election
or removal of our directors, prior to a stockholder vote, our Board must first
adopt a resolution that the proposed action is advisable and directing the
matter to be submitted to the stockholders. Our Charter and Bylaws also provide
that the Board of Directors has the exclusive power and authority to adopt,
implement and from time alter, amend or repeal the Bylaws of the Company.
Under our Bylaws, directors are elected by a
plurality of the votes cast at a meeting of stockholders, assuming the presence
of a quorum. There is no cumulative voting in the election of directors.
Our Charter provides that the number of
directors may be increased or decreased by the Board from time to time pursuant
to our Bylaws, but shall never be less than the minimum number required by the
MGCL nor more than fifteen. Any vacancy may be filled in the manner provided in
the Bylaws. Under the Bylaws, any vacancy on the Board for any cause other than
an increase in the number of directors may be filled by a majority of the
remaining directors, even if such a majority is less than a quorum. Any vacancy
in the number of directors created by an increase in the number of directors
may be filled by a majority of the entire Board. Any individual so elected as
director shall serve until the next annual meeting of stockholders and until
such director’s successor is duly elected and qualifies. Except as may
otherwise be provided in the terms of any preferred shares issued by the
Company, directors are elected annually.
Restrictions
on Transfer; Change of Control. All holders of common stock are subject to
the ownership limitations and transfer restrictions set forth in our Charter,
designed to protect the Company’s status as a REIT. See “Certain Provisions of
MGCL and Our Charter and Bylaws – Restrictions on Ownership and Transfer” below
for additional details. The ownership limitations generally prohibit ownership
of more than 9.8% of the aggregate of the outstanding shares of common stock by
any single stockholder, either beneficially or constructively, and ownership of
more than 9.8% in value of the aggregate of our outstanding shares of capital
stock (defined to include all classes or series of stock, including both common
and preferred). The ownership limitations could delay, defer or prevent a
change in control of us that might involve a premium price for holders of our
common stock, or might otherwise be in the best interest of our stockholders.
Limitation on Liability of Directors and Officers; Indemnification
and Advance of Expenses
Maryland
law permits a Maryland corporation to include in its charter a provision
limiting the liability of its directors and officers to the corporation and its
stockholders for money damages except for liability resulting from (i) actual
receipt of an improper benefit or profit in money, property or services or (ii)
active and deliberate dishonesty established by a final judgment as being
material to the cause of action. Our Charter contains such a provision which
eliminates directors’ and officers’ liability to the maximum extent permitted
by Maryland law.
Our
Charter obligates us, to the maximum extent permitted by Maryland law, to
indemnify and pay or reimburse reasonable expenses in advance of final
disposition of a proceeding to, (a) any individual who is a present or former
director or officer of ours and who is made or threatened to be made a party
to, or witness in, the proceeding by reason of his or her service in that
capacity or (b) any individual who, while a director or officer of ours and at
our request, serves or has served as a director, officer, member, manager,
partner or trustee of another corporation, real estate investment trust, limited
liability company, partnership, joint venture, trust, employee benefit plan or any
other enterprise and who is made or threatened to be made a party to, or
witness in, the proceeding by reason of his or her service in that capacity.
The Charter also permits us, with the approval of the Board of Directors, to
indemnify and advance expenses to any person who served a predecessor of us in
any of the capacities described above and any of our employees or agents or any
employees or agents of our predecessor.
Maryland
law requires a corporation (unless its charter provides otherwise, which our
Charter does not) to indemnify a director or officer who has been successful in
the defense of any proceeding to which he or she is made, or threatened to be
made, a party by reason of his or her service in that capacity. Maryland law
permits a corporation to indemnify its present and former directors and
officers, among others, against judgments, penalties, fines, settlements and
reasonable expenses actually incurred by them in connection with any proceeding
to which they may be made, or threatened to be made, a party by reason of their
service in those or other capacities unless it is established that (i) the act
or omission of the director or officer was material to the matter giving rise
to the proceeding and (a) was committed in bad faith or (b) was the result of
active and deliberate dishonesty, (ii) the director or officer actually
received an improper personal benefit in money, property or services or (iii)
in the case of any criminal proceeding, the director or officer had reasonable
cause to believe that the act or omission was unlawful. However, under Maryland
law, a Maryland corporation may not indemnify for an adverse judgment in a suit
by or in the right of the corporation or for a judgment of liability on the
basis that a personal benefit was improperly received unless, in either, case a
court orders indemnification, and then only for expenses. In addition, Maryland
law permits a corporation to advance or reimburse reasonable expenses to a
director or officer in advance of final disposition of a proceeding upon the
corporation’s receipt of (y) a written affirmation by the director or officer
of his or her good faith belief that he or she has met the standard of conduct
necessary for indemnification by the corporation and (z) a written undertaking
by him or her or on his or her behalf to repay the amount paid or reimbursed by
the corporation if it is ultimately determined that the standard of conduct was
not met.
Certain Provisions of the MGCL and Our Charter
and Bylaws
The
MGCL and our Charter and Bylaws contain provisions that could make it more
difficult for a potential acquirer to acquire us by means of a tender offer,
proxy contest or otherwise. These provisions are expected to discourage certain
coercive takeover practices and inadequate takeover bids and to encourage
persons seeking to acquire control of us to negotiate first with our Board of
Directors. We believe that the benefits of these provisions outweigh the
potential disadvantages of discouraging any such acquisition proposals because,
among other things, the negotiation of such proposals may improve their terms.
Restrictions on Ownership and Transfer
In
order for us to qualify as a REIT under the Internal Revenue Code of 1986, as
amended (the “Code”), not more than 50% in value of our outstanding shares may
be owned, directly or indirectly, by five or fewer individuals (defined in the
Code to include certain entities) during the last half of a taxable year and
shares must be beneficially owned by 100 or more persons at least 335 days of a
taxable year of twelve months (or during a proportionate part of a shorter
taxable year). In addition, certain percentages of our gross income must be
from particular activities.
In
order to assist our Board of Directors in preserving our status as a REIT by
complying with the ownership concentration limits described above, among other
purposes, our Charter generally prohibits any person (subject to certain
exceptions described below) from beneficially or constructively owning more
than:
● 9.8% of our common stock
by value or by number of shares, whichever is more restrictive (the “Common
Stock Ownership Limit”); or
● 9.8% in value of the
aggregate of our outstanding shares of capital stock (defined to include all
classes or series of stock, including both common and preferred) (the “Aggregate
Stock Ownership Limit”).
Our
Charter also prohibits any person from:
● beneficially or constructively owning shares of
our capital stock that would result in our being “closely held” under Section
856(h) of the Code or otherwise failing to qualify as a REIT; and
● making any transfer of shares of our capital
stock that, if effective, would result in our being beneficially owned by fewer
than 100 persons (as determined under Section 856(a)(5) of the Code).
Any
person who acquires or attempts or intends to acquire beneficial or
constructive ownership of shares of our capital stock that will or may violate
any of the foregoing restrictions on transferability and ownership is required
to give notice immediately to us (or, in the case of a proposed or attempted
transaction, to provide us with at least 15 days prior written notice) and, in
either case, to provide us with such other information as we may request in
order to determine the effect of such transfers or ownership on our status as a
REIT.
Our
Board of Directors may, upon receipt of certain representations and agreements
and in its sole discretion, prospectively or retroactively, waive the Aggregate
Stock Ownership Limit and the Common Stock Ownership Limit and may establish or
increase a different limit on ownership, or excepted holder limit, for a
particular stockholder if the stockholder’s ownership in excess of the
ownership limit would not result in our being “closely held” under Section
856(h) of the Code (without regard to whether the ownership interest is held
during the last half of a taxable year) or otherwise failing to qualify as a REIT.
As
a condition of granting a waiver of the ownership limit or creating an excepted
holder limit, our Board of Directors may, but is not required to, require an
opinion of counsel or ruling of the IRS satisfactory to our Board as it may
deem necessary or advisable to determine or ensure our status as a REIT and may
impose such other conditions or restrictions as it deems appropriate.
In
connection with granting a waiver of the ownership limits or creating or
modifying an excepted holder limit, or at any other time, our Board may
increase or decrease the ownership limit unless, after giving effect to any
increased or decreased ownership limit, five or fewer persons could
beneficially own, in the aggregate, more than 49.9% in value of the shares of
our stock then outstanding or we would otherwise fail to qualify as a REIT. A
decreased ownership limit will not be effective to any person whose percentage
of ownership of our stock is in excess of the decreased ownership limit until
the person’s ownership of our stock equals or falls below the decreased
ownership limit, but any further acquisition of our stock will be subject to
the decreased ownership limit.
In
the event of any attempted transfer of our shares of capital stock which, if
effective, would result in any person beneficially or constructively owning
shares in excess, or in violation, of the transfer or ownership limitations
described above (including any applicable excepted holder limit) or result in
us being “closely held” under Section 856(h) of the Code (without regard to
whether the ownership interest is held during the last half of a taxable year)
or otherwise failing to qualify as a REIT under the Code, then that number of
shares of capital stock, the beneficial or constructive ownership of which
otherwise would cause such person (referred to in our Charter as a “Prohibited
Owner”) to violate the transfer or ownership limitations (rounded up to the nearest
whole share), will be automatically transferred to a charitable trust for the
exclusive benefit of a charitable beneficiary, and the Prohibited Owner will
not acquire any rights in such shares. This automatic transfer will be
considered effective as of the close of business on the business day before the
violative transfer, subject to the following:
● if a transfer to a
charitable trust, as described above, would be ineffective for any reason to
prevent a violation of the restrictions described above, the transfer that
would have resulted in such violation will be void ab initio, and the
proposed transferee shall acquire no rights in such shares; and
● any transfer that
results in the violation of the restriction relating to our shares of capital
stock being beneficially owned by fewer than 100 persons will be void ab
initio, and the intended transferee shall acquire no rights in such shares.
Shares
held in the charitable trust will continue to constitute issued and outstanding
shares of our capital stock. The Prohibited Owner will not benefit economically
from ownership of any shares held in the charitable trust, will have no rights
to dividends or other distributions and will not possess any rights to vote or
other rights attributable to the shares of capital stock held in the charitable
trust. The trustee of the charitable trust will be appointed by us and must be
unaffiliated with us or any Prohibited Owner and will have all voting rights
and rights to dividends or other distributions with respect to shares of
capital stock held in the charitable trust, and these rights will be exercised
for the exclusive benefit of the trust’s charitable beneficiary. Any dividend
or other distribution paid before our discovery that shares of capital stock
have been transferred to the trustee are required by our Charter to be paid by
the recipient of such dividend or distribution to the trustee upon demand, and
any dividend or other distribution authorized but unpaid will be paid when due
to the trustee. Any dividend or distribution so paid to the trustee is required
to be held in trust for the trust’s charitable beneficiary. Subject to Maryland
law, effective as of the date that such shares of stock have been transferred
to the trustee, the trustee, in its sole discretion, will have the authority,
subject to us not having already taken irreversible corporate action on the
basis of any such vote, to:
● rescind as void any vote
cast by a Prohibited Owner prior to our discovery that such shares have been
transferred to the trust; and
● recast such vote;
provided, however, that if we have already taken irreversible corporate action,
then the trustee shall not have the authority to rescind and recast such vote.
Within
20 days of receiving notice from us that shares of capital stock have been
transferred to the charitable trust, and unless we buy the shares first as
described below, the trustee will sell the shares held in the charitable trust
to a person, designated by the trustee, whose ownership of the shares will not
violate the ownership limitations in our Charter. Upon the sale, the interest
of the charitable beneficiary in the shares sold will terminate and the trustee
will distribute the net proceeds of the sale to the Prohibited Owner and to the
charitable beneficiary. The Prohibited Owner will receive the lesser of:
● the price paid by the Prohibited Owner for the
shares or, if the Prohibited Owner did not give value for the shares in
connection with the event causing the shares to be held in the charitable trust
(for example, in the case of a gift or devise), the market price of the shares
on the day of the event causing the shares to be held in the charitable trust;
and
● the price per share received by the trustee from
the sale or other disposition of the shares held in the charitable trust (less
any commission and other expenses of a sale).
The
trustee may reduce the amount payable to the Prohibited Owner by the amount of
dividends and distributions paid to the Prohibited Owner and owed by the
Prohibited Owner to the trustee. Any net sale proceeds in excess of the amount
payable to the Prohibited Owner will be paid immediately to the charitable
beneficiary. If, before our discovery that shares of stock have been
transferred to the charitable trust, such shares are sold by a Prohibited
Owner, then:
● such shares will be deemed to have been sold on
behalf of the charitable trust; and
● to the extent that the Prohibited Owner received
an amount for such shares that exceeds the amount that the Prohibited Owner was
entitled to receive as described above, the excess must be paid to the trustee
upon demand.
In
addition, shares of stock held in the charitable trust will be deemed to have
been offered for sale to us, or our designee, at a price per share equal to the
lesser of:
● the price per share in the transaction that
resulted in such transfer to the charitable trust (or, in the case of a gift or
devise, the market price at the time of the gift or devise); and
● the market price on the date we, or our
designee, accept such offer.
We
may reduce the amount payable to the Prohibited Owner by the amount of
dividends and distributions paid to the Prohibited Owner and owed by the
Prohibited Owner to the trustee. We may pay the amount of such reduction to the
trustee for the benefit of the charitable beneficiary. We will have the right
to accept such deemed offer until the trustee has sold the shares of capital
stock held in the charitable trust. Upon such a sale to us, the interest of the
charitable beneficiary in the shares sold will terminate and the trustee will
distribute the net proceeds of the sale to the Prohibited Owner and any
dividends or other distributions held by the trustee will be paid to the
charitable beneficiary.
All
certificated shares of our capital stock will bear a legend referring to the
restrictions described above.
Every
owner of 5% or more (or such lower percentage as required by the Code or the
regulations promulgated thereunder) of all classes or series of our capital
stock, within 30 days after the end of each taxable year, is required to give
us written notice, stating such person’s name and address, the number of shares
of each class and series of our capital stock beneficially owned by such owner
and a description of the manner in which the shares are held. Each such owner
must also provide us with such additional information as we may request in
order to determine the effect, if any, of such beneficial ownership on our
status as a REIT and to ensure compliance with the restrictions on ownership
and transfer of our shares. In addition, each stockholder will upon demand be
required to provide us with such information as we may request, in order to
determine our status as a REIT and to comply with the requirements of any
taxing authority or governmental authority or to determine such compliance.
These
ownership limitations could delay, defer or prevent a transaction or a change
in control of us that might involve a premium price for holders of our common
stock, or might otherwise be in the best interest of our stockholders. The
foregoing restrictions on transferability and ownership will not apply if our
Board of Directors determines that it is no longer on our best interest to
attempt to qualify, or continue to qualify, as a REIT, or that compliance with
such restrictions is no longer necessary in order for us to qualify as a REIT.
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION
AND RESULTS OF OPERATIONS
Statements by MacKenzie Realty Capital, Inc., together with its
subsidiaries as discussed in Note 1 of the financial statements included in
this Offering Circular (collectively, the “Company,” “we,” or “us”) contained
herein, other than historical facts, may constitute “forward-looking
statements.” These statements may relate to, among other things, future
events or our future performance or financial condition. In some cases,
stockholders can identify forward-looking statements by terminology such as
“may,” “might,” “believe,” “will,” “provided,” “anticipate,” “future,” “could,”
“growth,” “plan,“ “intend,” “expect,” “should,” “would,” “if,” “seek,” “possible,”
“potential,” “likely” or the negative of such terms or comparable terminology.
These forward-looking statements involve known and unknown risks, uncertainties
and other factors that may cause our actual results, levels of activity,
performance or achievements to be materially different from any anticipated
results, levels of activity, performance or achievements expressed or implied
by such forward-looking statements. An economic downturn could impair our
ability to continue to operate, which could lead to the loss of some or all of
our investments, a contraction of available credit and/or an inability to
access the equity markets could impair our lending and investment activities,
and interest rate volatility could adversely affect our results, particularly
if we elect to use leverage as a part of our investment strategy.
Further,
we may experience fluctuations in our operating results due to a number of
factors, including the effect of the return on our equity investments, the
interest rates payable on our debt investments, the default rates on such
investments, the level of our expenses, variations in and the timing of the
recognition of realized and unrealized gains or losses, the degree to which we
encounter competition in our markets and general economic conditions. As a
result of these factors, results for any period should not be relied upon as
being indicative of performance in future periods.
For
a discussion of additional factors that could cause our actual results to
differ from forward-looking statements contained herein, please refer to the
discussions presented under the heading “Risk Factors” above beginning on page 15 of this Offering Circular and in Item 1A of our
Annual Report on Form 10-K for the year ended June 30, 2026, as filed with the
SEC.
Overview
Historically,
we were an externally managed non-diversified closed-end management investment
company that elected to be treated as a BDC under the Investment Company Act of
1940 (the “1940 Act”), but we withdrew our election to be treated as a BDC on
December 31, 2020. Our objective remains to generate both current income and
capital appreciation through real estate-related investments. We have elected
to be treated as a REIT under the Code and as a REIT, we are not subject to
federal income taxes on amounts that we distribute to the stockholders,
provided that, on an annual basis, we generally distribute at least 90% of our
REIT taxable income (determined without regard to the dividends paid deduction
and excluding any net capital gain) to the stockholders and meet certain other
conditions. To the extent that we satisfy the annual distribution requirement
but distribute less than 100% of our REIT taxable income, we will be subject to
U.S. federal corporate income tax on our undistributed REIT taxable income. In
addition, we will be subject to a 4% nondeductible excise tax if the actual
amount that we pay to our stockholders in a calendar year is less than a
minimum amount specified under U.S. federal tax laws. Our wholly owned
subsidiary, MacKenzie NY Real Estate 2 Corp. (“MacKenzie NY 2”), is subject to
corporate federal and state income tax on its taxable income at regular
statutory rates.
We
are managed by the Advisers, and MacKenzie provides the non-investment
management services and administrative services necessary for us to operate.
Investment Plan
We generally seek to invest in real estate assets. We intend to
invest at least 80% of our total assets in equity or debt in real estate
assets. We can invest up to 20% of our total assets in investment securities of
real estate companies. A real estate company is one that (i) derives at least
50% of its revenue from the ownership, construction, financing, management or
sale of commercial, industrial or residential real estate and land; or (ii) has
at least 50% of its assets invested in such real estate. We will not invest in
general partnerships, joint ventures, or other entities that do not afford
limited liability to their security holders. However, limited liability
entities in which we invest may hold interests in general partnerships, joint
ventures, or other non-limited liability entities. When purchasing securities,
we generally favor purchasing securities issued by entities that have (i)
completed the initial offering of their securities, (ii) operated for a period
of at least two years, and typically more than five years, from the completion
of their initial offering, and (iii) fully invested their capital in real
properties or other real estate related investments.
Our investment objective is to generate current income and capital
appreciation through the acquisition of real estate assets and debt and equity
real estate-related investments. Our independent directors review our
investment policies periodically, at least annually, to confirm that our
policies are in the best interests of our stockholders. Each such determination
and the basis thereof are contained in the minutes of our Board of Directors
meetings.
We seek to accomplish our objective by rigorously analyzing the
value of and risks associated with potential acquisitions, and, for up to 20%
of our total assets, by acquiring real estate securities at significant
discounts to their net asset value.
We intend to expand our investment strategy to include acquisition
of distressed real properties. Like our other investments, we would expect to
hold distressed properties and infuse funds as necessary to extract unrealized
value.
We will engage in various investment strategies to achieve our
overall investment objectives. The strategy we select depends upon, among other
things, market opportunities, the skills and experience of the Advisers’
investment team and our overall portfolio composition. We generally seek to
acquire assets that produce ongoing distributable income for investors, yet
with a primary focus on purchasing such assets at a discount from what the
Advisers estimate to be the actual or potential value of the real estate.
We intend to continue our historical activities related to
launching tender offers to purchase shares of non-traded REITs in order to
boost our short-term cash flow and to support our distributions, subject to the
constraint that such securities will not exceed 20% of our portfolio. We
believe this niche strategy will allow us to pay distributions that are
supported by cash flow rather than paying back investors’ capital, although
there can be no assurance that some portion of any distribution is not a return
of capital.
Rental, Reimbursement
and Other Property Income
We generate rental
revenue by leasing office space and apartment units to a building’s tenants.
These tenant leases fall under the scope of Accounting Standards Codification
(“ASC”) Topic 842, and are classified as operating leases. Revenues from such
leases are recognized on a straight-line basis over the terms of the lease
agreements.
Investment Income
We generate revenues in
the form of operating income, capital gains and dividends on dividend-paying
equity securities or other equity interests that we acquire, in addition to
interest on any debt investments that we hold. Further, we may generate revenue
in the form of commitment, origination, structuring or diligence fees,
monitoring fees, fees for providing managerial assistance and possibly
consulting fees and performance-based fees. Any such fees are generated in
connection with our investments and recognized as earned.
Expenses
Our primary operating
expenses include the payment of: (i) advisory fees to our Advisers; (ii) our
allocable portion of overhead and other expenses incurred by MacKenzie in
performing its obligations under the Administration Agreement; and (iii) other real
estate properties operating expenses, including interest expenses on debt
obtained to finance our property acquisitions, as detailed below. Our
investment advisory fees compensate our Investment Adviser and Real Estate
Adviser for their work in identifying, evaluating, negotiating, closing,
monitoring and servicing our investments. Our expenses must be billed to and
paid by us, except that MacKenzie may be reimbursed for actual cost of goods
and services used by us and certain necessary administrative expenses. We will
bear all other expenses of our operations and transactions, including:
● the cost of operating and maintaining real
estate properties;
● the cost of calculating our net asset value,
including the cost of any third-party valuation services;
● the cost of effecting sales and repurchases of
our shares and other securities;
● interest payable on debt, if any, to finance our
investments;
● fees payable to third parties relating to, or
associated with, making investments, including fees and expenses associated
with performing due diligence reviews of prospective investments and
third-party advisory fees;
● transfer agent and safekeeping fees;
● fees and expenses associated with marketing
efforts;
● federal and state registration fees, and any
stock exchange listing fees in the future;
● federal, state, and local taxes;
● independent directors' fees and expenses;
● brokerage commissions;
● fidelity bond, directors and officers errors and
omissions liability insurance, and other insurance premiums;
● direct costs and expenses of administration,
including printing, mailing, and staff;
● fees and expenses associated with independent
audits and outside legal costs;
● costs associated with our reporting and
compliance obligations under the Exchange Act, and applicable federal and state
securities laws; and
● all other expenses incurred by either MacKenzie
or us in connection with administering our business, including payments under
the Administration Agreement that will be based upon our allocable portion of
overhead and other expenses incurred by MacKenzie in performing its obligations
under the Administration Agreement, including rent, the fees and expenses
associated with performing compliance functions, and our allocable portion of
the costs of compensation and related expenses of our Chief Compliance Officer,
our Chief Financial Officer, Director of Accounting and Financial Reporting,
General Counsel, and any administrative support staff.
Portfolio Investment Composition
As
of June 30, 2026, we owned interests in various real estate limited
partnerships and REITs. In addition, we held investments in entities that own
real estate where we have sufficient control for the investments to be
considered non-securities for purposes of the Investment Company Act of 1940,
but not enough control to require consolidation of their financial statements
with ours. These investments are reported as “Equity method investments, at
fair value.” The following table summarizes the composition of our investments
at fair value as of June 30, 2026 and 2025:
| |
Fair Value |
| Investments, at fair value |
| | June 30, 2026 | |
| | June 30, 2025 | |
| Highlands REIT, Inc. |
| $ | 9,916 | |
| $ | 37,403 | |
| Moody National REIT II,
Inc. |
| | - | |
| | 2,963 | |
| National Healthcare
Properties, Inc. |
| | 203,510 | |
| | 740,894 | |
| SmartStop Self Storage
REIT, Inc. - Class A |
| | - | |
| | 29,154 | |
| Starwood Real Estate Income
Trust, Inc. - Class I |
| | 72,736 | |
| | - | |
| Starwood Real Estate Income
Trust, Inc. - Class S |
| | 2,247,873 | |
| | 939,114 | |
| Strategic Storage Trust VI,
Inc. Class P |
| | 16,111 | |
| | - | |
| Total |
| $ | 2,550,146 | |
| $ | 1,749,528 | |
| |
| | | |
| | | |
| |
Fair Value |
| Equity method investments,
at fair value |
| | June 30, 2026 | |
| | June 30, 2025 | |
| Lakemont Partners, LLC |
| $ | 740,260 | |
| $ | 711,740 | |
| Martin Plaza Associates, LP |
| | 405,080 | |
| | 531,544 | |
| Westside Professional
Center I, LP |
| | 1,201,807 | |
| | 882,167 | |
| Total |
| $ | 2,347,147 | |
| $ | 2,125,451 | |
In
addition to our investment securities, we currently own and manage nine
commercial real estate properties: Satellite Place Office Building located in
Duluth, GA, 1300 Main Office Building, First & Main Office Building and
Main Street West Office Building located in Napa, CA, Woodland Corporate Center
located in Woodland, CA, 220 Campus Lane Office Building, Green Valley Medical
Center and Green Valley Executive Center located in Fairfield, CA and One
Harbor Center located in Suisun, CA and five residential apartments: Aurora at
Green Valley located in Fairfield, CA, Commodore Apartments and The Park View
Apartments, located in Oakland, CA, Hollywood Apartments located in Los
Angeles, CA, and the Shoreline Apartments located in Concord, CA.
Aurora
at Green Valley is owned through our subsidiary MRC Aurora. 1300 Main Office
Building, First & Main Office Building, Main Street West Office Building,
Woodland Corporate Center, Hollywood Apartments, Shoreline Apartments and Green
Valley Medical Center are owned through our subsidiary, the Operating
Partnership; Commodore Apartments is owned through our subsidiary, Madison; The
Park View Apartments is owned through our subsidiary, PVT and Satellite Place
Office Building are owned through our subsidiary, MacKenzie Satellite. In
October 2025, we listed Woodland Corporate Center Two for sale, and in
September 2026, we entered into a purchase and sale agreement with a third
party to sell the property. The sale is subject to customary closing conditions.
We own our properties through our subsidiaries, which are listed
in the table below.
| Property: |
Property Owners |
| Commodore Apartments |
Madison-PVT Partners LLC |
| The Park View Apartments |
PVT-Madison Partners LLC |
| Hollywood Apartments |
PT Hillview GP, LLC |
| Shoreline Apartments |
MacKenzie-BAA IG Shoreline LLC |
| Aurora at Green Valley |
MRC Aurora, LLC |
| Satellite Place Office
Building |
MacKenzie Satellite Place Corp. |
| First & Main Office
Building |
First & Main, LP |
| 1300 Main Office Building |
1300 Main, LP |
| Woodland Corporate Center |
Woodland Corporate Center Two, LP |
| Main Street West Office
Building |
Main Street West, LP |
| 220 Campus Lane Office
Building |
220 Campus Lane, LLC |
| Green Valley Executive
Center |
GV Executive Center, LLC |
| One Harbor Center |
One Harbor Center, LP |
| Green Valley Medical Center |
Green Valley Medical Center, LP |
We use occupancy rate as a key performance indicator to evaluate
the performance of our real estate properties. Average occupancy rates on our
commercial and residential properties are 65% and 90%, respectively, as of the
measurement date. We believe occupancy rate provides investors with a useful
measure of the revenue-generating capacity of our portfolio. Management uses
occupancy rate to monitor leasing progress, identify re-leasing risk, and
compare portfolio performance across periods.
In connection with the formation of MAC, MAC OP was established as
the operating partnership through which substantially all of MAC’s business is
conducted. The contributed properties and development project are held through
subsidiaries of MAC OP, which directly or indirectly owns and operates a
portfolio of five residential properties and one development project. MAC owns
all of the limited partnership units of MAC OP except for one unit owned by the
Operating Partnership and is the sole general partner of MAC OP.
Commercial Properties:
The following commercial
properties are owned through subsidiaries of the Operating Partnership:
1300 Main Office Building
1300 Main Office
Building contains 20,145 square feet, of which approximately 13,900 square feet
is office space and the remainder is designated as retail space. As of June 30,
2026, the property is 70% occupied by 6 tenants. The following table shows the
largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Wilson Daniels
|
Wine Wholesaler
|
| | 6,712 | |
| $ | 382,544 | |
06/15/2031
|
1, 5 years
|
|
Bao Ling Li
|
Restaurant
|
| | 3,212 | |
| $ | 179,340 | |
11/30/2030
|
No
|
|
Catered With
Class
|
Restaurant
|
| | 2,409 | |
| $ | 106,962 | |
03/02/2031
|
1, 3 years
|
|
Edward Jones
|
Financial Services
|
| | 1,059 | |
| $ | 72,116 | |
04/30/2029
|
1, 5 years
|
The following
information pertains to lease expirations at 1300 Main Office Building:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2028
|
| | 1 | |
| | 225 | |
| $ | 6,156 | |
| | 1 | % |
|
2029
|
| | 1 | |
| | 1,059 | |
| $ | 72,116 | |
| | 9 | % |
|
2030
|
| | 1 | |
| | 3,212 | |
| $ | 179,340 | |
| | 23 | % |
|
Thereafter
|
| | 3 | |
| | 9,704 | |
| $ | 526,102 | |
| | 67 | % |
First & Main Office Building
First & Main Office
Building contains 27,398 square feet, of which approximately 19,000 square feet
is office space and the remainder is designated as retail space. As of June 30,
2026, the property is 87% occupied by 8 tenants. The following table shows the
largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
GVM Law
|
Legal Services
|
| | 9,470 | |
| $ | 526,303 | |
09/20/2036
|
2, 5 years
|
|
Brotlemarkle
|
Accounting Services
|
| | 4,366 | |
| $ | 256,769 | |
07/31/2030
|
2, 5 years
|
|
Napa
Palisades
|
Restaurant
|
| | 3,462 | |
| $ | 204,166 | |
08/31/2040
|
No
|
|
Phoenix Ultra
Lounge
|
Restaurant
|
| | 2,220 | |
| $ | 130,320 | |
09/30/2037
|
No
|
The following
information pertains to lease expirations at First & Main Office Building:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2027
|
| | 1 | |
| | 1,135 | |
| $ | 77,070 | |
| | 6 | % |
|
2029
|
| | 1 | |
| | 1,307 | |
| $ | 74,292 | |
| | 5 | % |
|
Thereafter
|
| | 6 | |
| | 21,505 | |
| $ | 1,229,611 | |
| | 89 | % |
Main Street West Office
Building
Main Street West Office
Building contains 38,135 square feet, of which approximately 32,600 square feet
is office space and the remainder is designated as retail space. As of June 30,
2026, the property is 97% occupied by 9 tenants. AUL Corporation elected to
terminate its lease as of February 3, 2025. The following table shows the
largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Napa
County
|
District
Attorney Offices
|
| | 13,806 | |
| $ | 1,137,882 | |
12/31/2027
|
No
|
|
State of California
|
Health Care
|
| | 4,697 | |
| $ | 263,184 | |
10/31/2028
|
No
|
|
Strategies To
Empower People
|
Health Care
|
| | 4,875 | |
| $ | 231,831 | |
01/28/2028
|
No
|
|
Descor
Inc.
|
Construction
|
| | 4,066 | |
| $ | 216,000 | |
12/29/2030
|
No
|
The following
information pertains to lease expirations at Main Street West Office Building:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2026
|
| | 2 | |
| | 2,940 | |
| $ | 122,000 | |
| | 5 | % |
|
2027
|
| | 2 | |
| | 15,941 | |
| $ | 1,266,854 | |
| | 54 | % |
|
2028
|
| | 2 | |
| | 9,572 | |
| $ | 495,014 | |
| | 21 | % |
|
Thereafter
|
| | 3 | |
| | 8,725 | |
| $ | 482,268 | |
| | 20 | % |
Satellite Place Office
Building
Satellite Place Office
Building contains 134,785 square feet, all of which is office space. As of June
30, 2026, the property is approximately 33% occupied by 5 tenants. The
following table shows the largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Codoxo
|
Healthcare Software
|
| | 13,956 | |
| $ | 304,598 | |
06/30/2030
|
No
|
|
Polytron
|
Title Services
|
| | 10,737 | |
| $ | 223,791 | |
04/30/2031
|
2, 5 years
|
|
Ampirical
|
Engineering Consulting
|
| | 9,790 | |
| $ | 213,814 | |
09/30/2030
|
2, 5 years
|
|
OS
National LLC
|
Title Services
|
| | 6,188 | |
| $ | 125,479 | |
11/30/2028
|
1, 3 years
|
The following
information pertains to lease expirations at Satellite Place Office Building:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2028
|
| | 1 | |
| | 6,188 | |
| $ | 125,479 | |
| | 13 | % |
|
2029
|
| | 1 | |
| | 4,383 | |
| $ | 100,842 | |
| | 10 | % |
|
2030
|
| | 2 | |
| | 23,746 | |
| $ | 518,411 | |
| | 54 | % |
|
Thereafter
|
| | 1 | |
| | 10,737 | |
| $ | 223,791 | |
| | 23 | % |
Woodland Corporate Center
Woodland Corporate
Center contains 37,034 square feet, of which 7,797 square feet are laboratories
and the rest is office space. All of the laboratory space is occupied by Agtech
Innovation. Beginning October 2025, the property has been marketed for sale.
Accordingly, Woodland Corporate Center is classified as an asset held for sale
as of June 30, 2026. During the year ended June 30, 2026, we recorded an
impairment loss on assets held for sale of $1,687,783 on Woodland Corporate
Center which was our only asset held for sale. The impairment was primarily
attributable to the estimated fair value of the property being below its
carrying value. In determining the estimated fair value as of June 30, 2026, we
considered a third-party appraisal of the property and the purchase price being
negotiated with a prospective third-party buyer. Based on our assessment of the
anticipated sale, we used the negotiated purchase price in our June 30, 2026
impairment analysis. In September 2026, the Company entered into a purchase and
sale agreement with a third party to sell Woodland Corporate Center, subject to
customary closing conditions.
As of June 30, 2026, the property is 100%
occupied by 14 tenants. The following table shows the largest tenants and
square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Agtech Innovation
|
Research and Development
|
| | 12,940 | |
| $ | 342,951 | |
04/09/2031
08/31/2032
12/21/2032
|
No
|
|
Children’s Home
Society
|
Non-Profit
Education
|
| | 4,042 | |
| $ | 155,461 | |
10/31/2028
|
No
|
|
Burger Rehab
|
Physical Therapy
|
| | 4,013 | |
| $ | 127,437 | |
09/22/2028
|
No
|
|
SunFoods, LLC
|
Foods
|
| | 3,388 | |
| $ | 126,315 | |
05/31/2031
|
No
|
The following information pertains to lease
expirations at Woodland Corporate Center:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2026
|
| | 1 | |
| | 1,433 | |
| $ | 46,068 | |
| | 4 | % |
|
2027
|
| | 2 | |
| | 2,160 | |
| $ | 87,426 | |
| | 7 | % |
|
2028
|
| | 5 | |
| | 10,826 | |
| $ | 383,818 | |
| | 31 | % |
|
Thereafter
|
| | 6 | |
| | 22,615 | |
| $ | 707,364 | |
| | 58 | % |
Green Valley Executive Center
Green Valley Executive
Center contains 46,101 square feet, of which approximately 41,600 square feet
is office space and the remainder is designated as retail space. As of June 30,
2026, the property is 94% occupied by 15 tenants. The following table shows the
largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
| |
Renewal options
| |
|
Community
Housing
Opportunities
|
Real Estate
|
| | 8,510 | |
| $ | 352,596 | |
08/31/2026
08/31/2029
|
| | 11 | year |
|
Larsen & Toubro
Limited, Inc.
|
Multinational
Conglomerate
|
| | 5,130 | |
| $ | 285,324 | |
02/13/2028
|
| |
No
| |
|
Arkshire Financial,
LLC
|
Insurance
|
| | 5,408 | |
| $ | 240,336 | |
02/28/2029
|
| |
No
| |
|
Sticky Rice
|
Restaurant
|
| | 4,388 | |
| $ | 193,017 | |
08/17/2034
|
| |
No
| |
The following
information pertains to lease expirations at Green Valley Executive Center:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2026
|
| | 2 | |
| | 5,687 | |
| $ | 241,776 | |
| | 12 | % |
|
2027
|
| | 2 | |
| | 2,131 | |
| $ | 109,668 | |
| | 5 | % |
|
2028
|
| | 2 | |
| | 6,975 | |
| $ | 375,168 | |
| | 19 | % |
|
Thereafter
|
| | 10 | |
| | 28,608 | |
| $ | 1,266,222 | |
| | 64 | % |
One Harbor Center
One Harbor Center
contains 49,573 square feet, all of which is office space. As of June 30, 2026,
the property is 76% occupied by 11 tenants. The following table shows the
largest tenants and square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Shimmick
Construction
Company, Inc.
|
Construction
|
| | 10,221 | |
| $ | 351,984 | |
05/15/2027
|
No
|
|
Equiventure
|
Health Care
|
| | 6,446 | |
| $ | 238,008 | |
11/16/2033
|
4, 5 years
|
|
Wiseman
Company
Mgt.
|
Real Estate
|
| | 4,883 | |
| $ | 178,332 | |
06/01/2028
|
No
|
|
Connections
for Life
|
Healthcare
|
| | 3,443 | |
| $ | 109,235 | |
03/29/2036
|
No
|
The following
information pertains to lease expirations at One Harbor Center:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2026
|
| | 2 | |
| | 4,765 | |
| $ | 173,292 | |
| | 13 | % |
|
2027
|
| | 1 | |
| | 10,221 | |
| $ | 351,984 | |
| | 25 | % |
|
2028
|
| | 3 | |
| | 9,441 | |
| $ | 363,840 | |
| | 26 | % |
|
Thereafter
|
| | 5 | |
| | 13,450 | |
| $ | 498,385 | |
| | 36 | % |
Green Valley Medical
Center
Green Valley Medical
Center contains 31,590 square feet, of which approximately 20,100 square feet
is office space, approximately 8,300 square feet is health care space, and the
remainder is designated as retail space. As of June 30, 2026, the property is
87% occupied by 12 tenants. The following table shows the largest tenants and
square footage occupied:
|
Largest Tenants
|
Business
|
| |
Square Ft. Occupied
| |
| |
Annual Base Rent
| |
Lease Expiration
|
Renewal options
|
|
Cal OES
|
State Emergency Services
|
| | 7,605 | |
| $ | 301,721 | |
08/31/2031
|
No
|
|
California Forever
|
Real Estate
|
| | 3,341 | |
| $ | 217,216 | |
09/17/2029
|
No
|
|
Jethro Nicolas et al
|
Health Care
|
| | 3,409 | |
| $ | 147,288 | |
04/14/2035
|
No
|
|
Green Valley Oral
Surgery
|
Health Care
|
| | 2,179 | |
| $ | 104,874 | |
05/07/2029
|
2, 10 years
|
The following
information pertains to lease expirations at Green Valley Medical Center:
|
Year
|
| |
Number of Leases Expiring
| |
| |
Total Area
| |
| |
Annual Base Rent
| |
| |
Percentage of Gross Rent
| |
|
2026
|
| | 1 | |
| | 1,332 | |
| $ | 69,490 | |
| | 6 | % |
|
2027
|
| | 2 | |
| | 2,624 | |
| $ | 103,620 | |
| | 8 | % |
|
2028
|
| | 1 | |
| | 2,179 | |
| $ | 104,874 | |
| | 9 | % |
|
Thereafter
|
| | 8 | |
| | 21,420 | |
| $ | 938,211 | |
| | 77 | % |
220 Campus Lane Office
Building
220 Campus Lane Office Building was purchased in
September 2023. The property was vacant at the time of acquisition. Following
the acquisition, we renovated the building and commenced leasing activities. As
of June 30, 2026, the building was approximately 26% leased, with four tenants
occupying an aggregate of 11,246 square feet. The annualized base rent from
these tenants totals approximately $363,648.
Residential Properties:
Effective January 1, 2026, the Company
contributed all of its multi-family residential properties, consisting of
Commodore Apartments, The Park View Apartments, Hollywood Apartments, Shoreline
Apartments and Aurora at Green Valley, as well as the Blue Ridge development
project, to MAC. The contributed properties and development project are held
through subsidiaries of MAC OP, through which substantially all of MAC’s
business is conducted. MAC owns all of the limited partnership units and is the
sole general partner of MAC OP.
Commodore Apartments
Commodore Apartments is a mid-rise apartment
building built in 1912 and has 48 units. As of June 30, 2026, Commodore
Apartments is approximately 89.6% occupied.
The Park View Apartments
The Park View Apartments is also a mid-rise
apartment building built in 1929 and has 39 units. As of June 30, 2026, The Park View Apartments is approximately 89.7% occupied.
Hollywood Apartments
Hollywood Apartments, located in Los Angeles,
CA, is a mid-rise apartment building built in 1917 and has 54 units. The
property contains approximately 38,000 square feet of net rentable apartment
area and 8,610 square feet of retail space. All of the retail space is
currently occupied by restaurants and nightclubs. As of June 30, 2026, the apartment units are 88.9%
occupied.
Shoreline Apartments
Shoreline Apartments is a mid-rise apartment
building built in 1968 and renovated in 2015 which has 84 units. As of June 30,
2026, Shoreline Apartments building is approximately 89.3% occupied.
Aurora at Green Valley
Aurora at Green Valley is a newly constructed
multi-family residential community consisting of 72 units across three
buildings, along with a clubhouse. The project was financed through $10 million
of preferred equity capital (including $7.23 million from outside investors)
and a $17.15 million construction loan from Valley Strong Credit Union. The
clubhouse opened in mid-June 2025 for pre-leasing activity. Construction of the
residential buildings was completed in phases. The first residential building was
completed in July 2025, with leasing commencing in August 2025. The remaining
two buildings were completed in August and September 2025, with leasing
commencing shortly thereafter. As of June 30, 2026, the property was
approximately 93.1% occupied. As of the date of this report, the property is 100% leased.
The following table
provides information regarding each of the residential properties as of June
30, 2026:
|
Property Name
|
Sector
|
Location
|
| |
Square
Feet
| |
| |
Units
| |
| |
Percentage Leased
| |
| |
Annual
Base Rent
| |
| |
Monthly Base Rent/Occupied Unit
| |
|
The Park
View
Apartments
|
Multi-Family
Residential
|
Oakland, CA
|
| | 31,020 | |
| | 39 | |
| | 89.7 | % |
| $ | 1,023,703 | |
| $ | 2,433 | |
|
Commodore
Apartments
|
Multi-Family
Residential
|
Oakland, CA
|
| | 26,635 | |
| | 48 | |
| | 89.6 | % |
| $ | 832,239 | |
| $ | 1,613 | |
|
Hollywood
Apartments
|
Multi-Family
Residential
|
Los Angeles,
CA
|
| | 37,971 | |
| | 54 | |
| | 88.9 | % |
| $ | 1,227,641 | |
| $ | 2,131 | |
|
Hollywood
Apartments
(Retail Space)
|
Retail
|
Los Angeles,
CA
|
| | 8,610 | |
| | 1 | |
| | 100 | % |
| $ | 353,657 | |
| $ | 29,471 | |
|
Shoreline
Apartments
|
Multi-Family
Residential
|
Concord, CA
|
| | 68,350 | |
| | 84 | |
| | 89.3 | % |
| $ | 1,901,495 | |
| $ | 2,113 | |
|
Aurora at Green
Valley
|
Multi-Family
Residential
|
Fairfield, CA
|
| | 54,936 | |
| | 72 | |
| | 93.1 | % |
| $ | 2,014,572 | |
| $ | 2,506 | |
Campus Lane Land Development (known as Blue Ridge)
In addition to our commercial
and residential real estate properties, we own a vacant parcel adjacent to the
220 Campus Lane Office Building in Fairfield, California (the “Campus Lane
Land”). This parcel of land was acquired with the objective of developing a
multi-family residential community and is owned by the MAC OP through its
subsidiary, Campus
Lane Residential, LLC (“Campus Lane Residential”).
This
project, known as Blue Ridge, is expected to consist of 84 luxury multi-family
units in Solano County, one of the fastest-growing counties in California. The entitlement process for the vacant land is
on-going. Our goal is to commence construction in fall 2027; however, this is
subject to the city’s approval of our development application submitted in
April 2024 and to securing the necessary financial resources. The Company is currently evaluating potential development
and financing structures for the project, including discussions with a
third-party developer pursuant to which the Company may contribute the land and
the third party may arrange construction financing and development capital for
the project.
We currently do not have plans for any other major
renovation or development of any properties except for Blue Ridge, as discussed
above. Each property is being held for income generation and potential value
appreciation through increased occupancy and/or rental rates. We maintain
property and liability insurance policies on all properties, which we believe
are adequate and in line with industry standards.
Material Changes in Financial Condition
Real estate assets
During the year ended June 30, 2026, total real estate
assets, net decreased by $11.84 million. The decrease was attributable to the
reclassification of $11.71 million of net real estate assets related to
Woodland Corporate Center Two to assets held for sale as of June 30, 2026, and
to $9.27 million of additional depreciation and amortization. These decreases
were partially offset by $9.14 million of real estate additions, including
$6.39 million related to the capitalization of additional construction costs at
Aurora at Green Valley.
Mortgage notes payable, net
During
the year ended June 30, 2026, the Company borrowed an additional $10.55 million
on the MRC Aurora construction loan from Valley Strong Credit Union, primarily
to fund building expenditures associated with the completion of Aurora at Green
Valley. During the year ended June 30, 2026, the Company also entered into a $12.24 million
loan agreement with Meriwest Credit Union on April 6, 2026 to refinance its
$10.37 million prior loan with Exchange Bank, which is secured by the First & Main Office
Building.
Current Market and Economic Conditions
The markets in which our
properties operate are highly competitive, and each property faces unique
competitive challenges based upon local economic, political, and legal factors.
Our West Coast multi-family residential properties are generally restricted
from raising rents significantly by local rent control laws. Rent control can
result in average rents that are significantly below market, and this provides
some buffer against declining rents in a recession. However, in order to
encourage development, rent control usually does not apply to newer properties.
Since older properties may be unable to raise rents as needed, they may be
unable to make improvements that could allow them to compete with newer
properties.
Our consolidated office
properties, 1300 Main Office Building, First & Main Office Building, Main
Street West Office Building, One Harbor Center, Satellite Place Office
Building, Woodland Corporate Center, 220 Campus Lane Office Building and Green
Valley Executive Center are all Class A suburban office properties and are
located in Napa, Woodland, Suisun City and Fairfield, California and Duluth,
Georgia. Available office space is plentiful in each market in which our office
properties are located, which magnifies the competitive challenges that we face
in these markets.
The broader economy has
been experiencing increased levels of inflation, higher interest rates and
tightening monetary and fiscal policies. While the Federal Reserve began
reducing the federal funds rate in the fourth quarter of 2024 and continued
reducing the rate during 2025, interest rates remain elevated compared to
recent historical levels, which continues to impact real estate valuations and
financing costs. We currently have fixed and variable interest rates for our
loans. The rise in overall interest rates caused an increase in our
variable-rate borrowing costs resulting in an increase in interest expense. The
cumulative effect of the prior rate increases may adversely impact real estate
asset values. In addition, a prolonged period of high and persistent inflation
has increased our operating costs and could result in further increases. The
current market and economic conditions could have a material impact on our
business, cash flow and results of operations. It could also impact our ability
to find suitable acquisitions, sell properties, and raise equity and debt
capital.
Results of Operations
Commercial Properties
The commercial
properties owned by us during the Fiscal Years Ended June 30, 2026 (“Fiscal 2026”) and June 30, 2025
(“Fiscal 2025”) are as follows:
| Fiscal
2026 |
|
Fiscal 2025 |
| |
|
|
| Satellite
Place Office Building |
|
Satellite Place Office
Building |
| First
& Main Office Building |
|
First & Main Office
Building |
| 1300
Main Office Building |
|
1300 Main Office Building |
| Main
Street West Office Building |
|
Main Street West Office
Building |
| Woodland
Corporate Center |
|
Woodland Corporate Center |
| 220
Campus Lane Office Building |
|
220 Campus Lane Office
Building |
| Green
Valley Executive Center |
|
Green Valley Executive Center |
| One
Harbor Center |
|
One Harbor Center |
| Green
Valley Medical Center |
|
Green Valley Medical Center |
Rental, reimbursements and other property income:
During
the year ended June 30, 2026, we generated $13.07 million in rental and reimbursements revenues from
our nine commercial properties, compared to $16.17 million during the year
ended June 30, 2025. The $3.10 million decrease was primarily
attributable to a $3.59 million decrease in
rental and other property income at
our Satellite Place Office Building, primarily due to approximately $3.0 million of lease termination
income recognized in the 2025 period related to the early termination of a
tenant’s lease in December 2024. The decrease at Satellite Place was partially
offset by a $0.23 million increase in rental income at our Main Street West Office Building,
as most of the space vacated following an early lease
termination in February 2025 was re-leased to Napa County effective January 1, 2026.
Expenses:
Property operating and
maintenance expenses:
Operating
and maintenance expenses mainly consist of real estate taxes, utilities, repair
and maintenance, cleaning, landscape, security, property management fees,
insurance, and various other administrative expenses incurred in the operation
of our commercial real estate assets. During the year ended June 30, 2026, we
incurred operating and maintenance expenses of $4.90 million in the operation of our nine commercial
properties, compared to $4.65 million during the year ended June 30, 2025. The increase in the
operating expenses was mainly due to higher utilities costs and real estate
taxes.
Depreciation and
amortization:
During
the year ended June 30, 2026, we recorded depreciation and amortization of $6.09 million
attributable to the depreciation and amortization of real estate and intangible
assets of our nine commercial properties, compared to $9.24 million during the year ended June 30, 2025. The decrease in
total depreciation and amortization of $3.15 million was mainly due to the impairment of assets
related to our Main Street West Office
Building and the write-off of tenant improvements, leasehold improvements,
lease commissions, and in-place lease related to our Satellite Place Office
Building due to an early lease termination of its anchor tenant in December
2024. The decrease was also due to the classification of the Woodland
Corporate Center Two building as held for sale in October 2025, upon which
depreciation and amortization ceased.
Interest expense:
During the year
ended June 30, 2026, we recorded $4.84 million
of interest expense related to mortgage notes payable associated with the
Company’s nine commercial properties, compared to $5.02 million during the year
ended June 30, 2025.
The decrease of $0.19
million was primarily due to lower interest expense resulting from the Main
Street West loan refinancing in May 2025. The decrease was partially offset by
higher interest expense resulting from the First & Main loan paying higher
interest rates between the old loan’s maturity and the new refinancing in April
2026.
Other operating expenses:
Other operating expenses
include professional fees, printing and mailing, and other general and
administrative expenses. During the year ended June 30, 2026, we recorded $0.60
million of other operating expenses associated with the Company’s nine commercial
properties, compared to $0.89 million during the year ended June 30, 2025. The
decrease in other operating expenses was mainly due to lower legal and
professional fees at our Main Street West Office Building. During the year
ended June 30, 2025, Main Street West incurred additional legal and
professional fees while the property was under a court-appointed receiver.
Residential Properties
The residential properties owned by us during Fiscal 2026 and 2025 are as follows:
| Fiscal
2026 |
|
Fiscal 2025 |
| |
|
|
| Commodore
Apartments |
|
Commodore Apartments |
| The
Park View Apartments |
|
The Park View Apartments |
| Hollywood
Apartments |
|
Hollywood Apartments |
| Shoreline
Apartments |
|
Shoreline Apartments |
| Aurora
at Green Valley |
|
|
Rental, reimbursements
and other property income:
During
the year ended June 30, 2026, we generated $6.94 million in rental and reimbursements revenues from
our five residential properties, compared to $5.89 million from our four
residential properties during the year ended June 30, 2025. The increase in
rental revenues was mainly due to the completion of the Aurora at Green Valley in
July 2025 and the commencement of leasing in August 2025.
Expenses:
Property operating and
maintenance expenses:
Operating
and maintenance expenses mainly consist of real estate taxes, utilities, repair
and maintenance, cleaning, landscape, security, property management fees,
insurance, and various other administrative expenses incurred in the operation
of our residential real estate assets. During the year ended June 30, 2026, we
incurred operating and maintenance expenses of $3.18 million in the operation of our five residential
properties, compared to $2.73 million in the
operation of our four residential properties during the year
ended June 30, 2025.
The increase in the operating expenses was mainly due to the completion of
Aurora at Green Valley in July 2025 and the commencement of
leasing in August 2025. Aurora at Green Valley
consists of three residential buildings and a clubhouse, resulting in
additional operating costs during the 2026 period.
Depreciation and
amortization:
During
the year ended June 30, 2026, we recorded depreciation and amortization of $3.05 million
attributable to the depreciation and amortization of real estate and intangible
assets of our five residential properties, compared to $2.19 million on our four residential properties
during the year
ended June 30, 2025.
The increase in total depreciation and amortization of $0.86 million was mainly due to the completion
of Aurora at Green Valley in July 2025 and the commencement of
leasing in August 2025, which resulted in
additional depreciation and amortization during the 2026 period.
Interest expense:
During the year
ended June 30, 2026, we recorded $3.36 million
related to mortgage notes payable associated with the Company’s five
residential properties and debt on the Campus Lane Land, compared to $3.12
million related to the Company’s four residential properties and debt on the
Campus Lane Land during the year ended June 30, 2025. During the year ended
June 30, 2026, $0.19 million of interest incurred on the Aurora construction
loan and the Blue Ridge loan was capitalized. During the year ended June 30,
2025, $0.14 million of interest incurred on the Aurora construction loan and
the Blue Ridge loan was capitalized.
The $0.25 million
increase was primarily due to $1.26 million of interest expense and loan fee
amortization related to the Aurora at Green Valley construction loan following
the completion of construction in July 2025. Prior to the completion of Aurora
at Green Valley, interest expense on the construction loan was capitalized. The
increase was partially offset by lower interest expense resulting from the
refinancing of Hollywood Apartments in March 2025.
Other operating expenses:
Other operating expenses
include professional fees, printing and mailing, and other general and
administrative expenses. During the year ended June 30, 2026, we recorded $0.61
million of other operating expenses associated with the Company’s five residential
properties, compared to $0.71 million during the year ended June 30, 2025. The
decrease in other operating expenses was mainly due to the decrease in tenant
settlement and bad debt expenses at our Hollywood Apartments. The
decrease was partially offset by the other operating expenses associated with
the completion of Aurora at Green Valley in July 2025.
Corporate and Other
The corporate and other
operations during Fiscal 2026 and 2025 are as follows:
Investment income:
Investment
income is made up of dividends, distributions from operations, distributions
from sales/capital transactions, interest, and other investment income. Total
investment income during the years ended June 30, 2026, and 2025, were $0.25 million and $0.07 million, respectively.
The increase was mainly due to higher dividend and distribution income from our
non-traded REIT investments.
Unallocated corporate expenses:
Unallocated corporate
expenses include corporate overhead expenses that are not directly attributable
to one of our business segments and include asset management and incentive
management fees, administrative costs and transfer agent reimbursements, and other
corporate operating expenses.
Our
asset management and incentive management fees are based on the advisory
agreements that were effective January 1, 2021, and subsequently amended
effective January 1, 2026.
Asset management fee:
Base management fees under the amended Advisory Management Agreement effective
January 1, 2026, and asset management fees under
the Advisory Management Agreement prior to such amendment, for the years ended June 30, 2026 and 2025 were $3.39
million and $3.45 million, respectively. The decrease was primarily due to the
lower base management fee rate under the amended Advisory Management Agreement,
effective January 1, 2026. The amended agreement provides for a base management
fee of 1.25% per annum of gross assets under management, excluding depreciation
and amortization, compared to the prior agreement, which provided for a fee
based on invested capital at 3.00% of the first $20 million, 2.00% of the next
$80 million, and 1.50% of amounts over $100 million.
Incentive or bonus
management fee:
Under the Advisory
Management Agreement effective January 1, 2021, we were previously subject to
an incentive management fee equal to 15% of all distributions once shareholders
had received cumulative distributions equal to 6% from the effective date of the
agreement. Effective January 1, 2026, the amended Advisory Management Agreement
replaced the incentive management fee, as well as the acquisition, financing
and disposition fees, with a bonus management fee equal to 5% of adjusted funds
from operations each quarter. During the year ended June 30, 2026, we incurred
bonus management fees of $0.03 million for the quarter ended March 31, 2026
under the amended Advisory Management Agreement. We did not incur any incentive
or bonus management fees during the year ended June 30, 2025. The slight
increase was primarily due to the bonus management fee earned based on adjusted
funds from operations under the amended Advisory Management Agreement.
Administrative cost and
transfer agent reimbursements:
Costs reimbursed to MacKenzie for the
year ended June 30, 2026 were $0.88
million as compared to $0.67 million for the year ended June 30,
2025. The increase was due
to an increase in the allocable portion of overhead and other expenses incurred
by MacKenzie in comparison to June 30, 2025, as a result of the increase in the number of
real estate assets owned by us since June 30, 2025.
During the year ended June 30, 2026,
no transfer agent cost reimbursements were paid to MacKenzie. During the year
ended June 30, 2025, there were $0.01 million
transfer agent cost reimbursements paid to MacKenzie.
Interest expense:
During the year
ended June 30, 2026, we recorded $1.72 million
of interest expense related to the Company’s line of credit agreement and note
purchase agreement, compared to $0.38 million during the year ended June 30, 2025.
The increase was
attributable to additional borrowings by the Parent Company under the line of
credit with PRES and promissory notes issued to Streeterville Capital, LLC.
Other operating expenses:
Other operating expenses
include professional fees, directors’ fees, printing and mailing expense, and
other general and administrative expenses. Other operating expenses for the
years ended June 30, 2026 and 2025, were $1.29
million and $2.95 million, respectively. The decrease in other operating
expenses was mainly due to the decrease in legal, professional and consulting
fees since June
30, 2025.
Net realized gain on
sale of investments:
During
the year
ended June 30, 2026, we recorded a net realized gain of $0.02
million
as compared to $0.13
million
net realized gain during the year ended June 30, 2025. Total net realized gain
for the year ended June 30, 2026, was realized from the sale of four publicly
traded REIT securities and five non-traded REIT securities. Total net realized
gain for the year ended June 30, 2025, was realized from the sale of three
non-traded REIT securities and one limited partnership interest.
Net unrealized gain
(loss) on investments:
During
the year ended June 30, 2026, we recorded a net unrealized gain of $1.21 million,
which was net of $1.33 million of unrealized
loss reclassification adjustment. The reclassification adjustments are the
accumulated unrealized gains or losses as of the end of the prior period that
are realized during the current period. Accordingly, the net unrealized losses
excluding the reclassification adjustment for the year ended June 30, 2026,
were $0.12 million, which resulted from fair value
depreciation of $0.54
million from non-traded REIT securities and fair value appreciations of $0.39 million
from general partnership interests and $0.03 million
from limited partnership interests.
During
the year ended June 30, 2025, we recorded a net unrealized loss of $0.72
million, which was net of $0.17 million of unrealized gain
reclassification adjustment. The reclassification adjustments are the
accumulated unrealized gains or losses as of the end of the prior period that
are realized during the current period. Accordingly, the net unrealized losses
excluding the reclassification adjustment for the year ended June 30, 2025,
were $0.55 million,
which resulted from fair value depreciations of $0.69
million from general partnership interests, $0.08 million from limited partnership interests and fair
value appreciations of $0.22 million from non-traded REIT securities.
Income tax provision
(benefit):
The Parent Company has elected to be treated as a REIT for tax
purposes under the Code and, as a REIT, is not subject to federal income taxes
on amounts that it distributes to the stockholders, provided that, on an annual
basis, it generally distributes at least 90% of its REIT taxable income
(determined without regard to the dividends paid deduction and excluding any
net capital gain) to the stockholders and meets certain other conditions. To
the extent it satisfies the annual distribution requirement but distributes
less than 100% of its REIT taxable income, it will be subject to U.S. federal
corporate income tax on its undistributed taxable income. In addition, it will
be subject to a 4% nondeductible excise tax if the actual amount that it pays
to its stockholders in a calendar year is less than a minimum amount specified
under U.S. federal tax laws.
The Parent Company satisfied the annual dividend
payment and other REIT requirements for the tax year ended December 31, 2025.
Therefore, it did not incur any tax expense or excise tax on its income from
operations during the quarterly periods within the tax year 2025. Although the
Board of Directors suspended the Company’s regular quarterly common stock
dividend effective May 19, 2025, based on the Company’s current estimates, any
REIT taxable income for the tax year 2026, if any, is expected to be fully covered
by the dividends-paid deduction, including dividends paid on its preferred
stock. Accordingly, the Parent Company did not record any provision for federal
income taxes during the fiscal periods within the tax year 2026.
MacKenzie NY 2 is
subject to corporate federal and state income tax on its taxable income at
regular statutory rates. As of June 30, 2026, it did not have any taxable
income for tax years 2025
and 2026. Therefore, we did not record any tax provisions during any fiscal
periods within the tax years 2025 and 2026.
MacKenzie Satellite, MRC QRS and MAC are qualified REIT subsidiaries of the
Parent Company. Therefore, they do not file a separate tax return.
The Operating Partnership is a
limited partnership. 220 Campus Lane, GVEC and Innovate
Napa are
limited liability companies. First & Main, 1300 Main, Woodland Corporate
Center Two, Main Street West, One Harbor Center, LP and Green Valley Medical
Center, LP are limited partnerships. Accordingly, all income tax liabilities of
these entities ultimately flow through to the Company, with the exception of
minority membership interests. Therefore, no income tax provisions are recorded
for these entities.
MAC OP is a limited
partnership. Hollywood Hillview, MacKenzie Shoreline, Madison, PVT, Campus Lane Residential and MRC Aurora are
limited liability companies. Accordingly, all income tax liabilities of these
entities ultimately flow through to the Company, with the exception of minority
membership interests. Therefore, no income tax provisions are recorded for
these entities.
Non-GAAP Financial Measures
The Company believes
that Funds from Operations (“FFO”), as defined by the National Association of
Real Estate Investment Trusts (“NAREIT”), and Adjusted Funds from Operations
(“AFFO”) are meaningful supplemental non-GAAP measures of operating performance.
Management believes these measures provide investors with additional
information that is useful in evaluating the operating performance of the
Company’s real estate portfolio, facilitate comparisons of operating
performance between reporting periods and with other REITs, and assist in
evaluating the Company’s ability to generate cash from its core operating
activities.
Historical cost accounting under GAAP requires
real estate assets, other than land, to be depreciated over their estimated
useful lives. Because real estate values have historically fluctuated based on
market conditions and other factors, management believes that presentations of
operating results that include historical cost depreciation may be less
informative in evaluating the operating performance of a REIT.
Consistent with the current definition established by NAREIT,
FFO is defined as net income (loss), computed in accordance with GAAP,
excluding gains or losses from sales of depreciable real estate and impairment
write-downs of depreciable real estate, plus depreciation and amortization
related to real estate assets.
The Company defines AFFO
as FFO adjusted to exclude items that management believes are not
representative of the Company’s ongoing operating performance. These
adjustments include the effects of straight-line rental revenue, amortization
of above-market and below-market lease intangibles, amortization of deferred
financing costs, debt mark-to-market adjustments, unrealized gain (loss) on
investments at fair value, and other non-cash or non-recurring items, such as
consulting and marketing fees and stock issued as part of our listing efforts,
when applicable. The consulting and marketing fees and stock issuances
presented as adjustments in the AFFO reconciliation below were incurred in
connection with the completed listing of our common stock on the Nasdaq Global
Market. Because that listing is a one-time event that has occurred, we do not
expect these listing-related consulting and marketing fees or share issuances
to recur in future periods.
Management uses FFO and
AFFO, together with GAAP financial measures, to evaluate period-over-period
operating performance, assess the operating performance of the Company’s real
estate portfolio, evaluate trends in the Company’s business, and make operating
and capital allocation decisions. In addition, under the Advisory Management
Agreement, as amended effective January 1, 2026, AFFO is used in determining
the quarterly bonus management fee payable to the Company’s Real Estate
Adviser. Management prepares the quarterly FFO and AFFO calculations and the
related bonus management fee calculation, which are reviewed and approved by
the Company’s Board of Directors.
FFO and AFFO are
supplemental measures of operating performance and should not be considered
alternatives to net income (loss), cash flows from operating activities, or any
other measure of financial performance or liquidity determined in accordance
with GAAP. These measures do not represent cash generated from operating
activities and do not reflect changes in working capital, capital expenditures,
principal payments on debt, leasing costs, tenant improvements, or other cash
requirements necessary to operate the Company’s business.
AFFO is not a measure
defined by GAAP or NAREIT, and there is no standardized method of calculating
AFFO. Accordingly, the Company’s computation of AFFO may not be comparable to
similarly titled measures reported by other REITs. In addition, FFO may not be
comparable to FFO reported by other REITs that do not define FFO in accordance
with the current NAREIT definition or that interpret the current NAREIT
definition differently than the Company.
The calculation of AFFO
requires management to use judgment in the application of accounting policies,
including making estimates and assumptions regarding, among other things: (i)
the fair value of investments and the resulting unrealized gain (loss) on
investments at fair value recognized for the period; (ii) straight-line rent
adjustments; (iii) the identification, valuation, and estimated useful lives of
above-market and below-market lease intangibles and the related amortization;
(iv) the amortization of loan fees and debt mark-to-market, and the fair value
estimates that underlie such amounts; and (v) the identification and
classification of items that management considers non-cash or non-recurring,
including consulting and marketing fees and stock issued as part of the
Company’s listing efforts. Management’s determination of whether a particular
item is “non-recurring” is itself a judgment, and items previously classified
as non-recurring may recur in future periods. Actual results could differ from
these estimates, and changes in the underlying judgments or assumptions could
result in a materially different calculation of AFFO. Because AFFO is used to
determine the quarterly bonus management fee payable to our Real Estate Adviser
under the Advisory Management Agreement, changes in management’s judgments or
assumptions in calculating AFFO may also affect the amount of that fee.
The following table
reconciles net income (loss), the most directly comparable GAAP financial
measure, to FFO and AFFO for the years ended June 30, 2026 and 2025:
| |
|
|
|
|
|
|
Year Ended June 30, |
| |
|
|
|
|
|
|
| | 2026 | |
| | 2025 | |
| Net
income (loss) |
| $ | (14,127,610 | ) |
| $ | (23,970,277 | ) |
| |
|
|
|
|
|
|
| | | |
| | | |
| FFO
Adjustments: |
| | | |
| | | |
| Real
estate depreciation and amortization |
| | 9,141,627 | |
| | 11,432,557 | |
| Impairment
of assets held for sale |
| | 1,687,783 | |
| | - | |
| Impairment
of depreciable real estate |
| | - | |
| | 9,500,167 | |
| FFO |
|
| | (3,298,200 | ) |
| | (3,037,553 | ) |
| |
|
|
|
|
|
|
| | | |
| | | |
| AFFO
Adjustments: |
| | | |
| | | |
| Unrealized
(gain) loss on investments at fair value |
| | (1,212,101 | ) |
| | 715,504 | |
| Straight-line
rent adjustment |
| | (205,958 | ) |
| | (154,952 | ) |
| Amortization
of above-market and below-market lease intangibles |
| | (161,645 | ) |
| | (544,103 | ) |
| Amortization
of loan fees and debt mark-to-market |
| | 1,367,580 | |
| | 1,377,272 | |
| Other
adjustments (non-recurring and non-cash transactions): |
| | | |
| | | |
| |
Stock issued for
advisory services (1) |
| | - | |
| | 465,500 | |
| |
Stock issued for
marketing amortization (2) |
| | 37,363 | |
| | 162,637 | |
| |
One-time consulting
fees (3) |
| | - | |
| | 225,000 | |
| |
One-time marketing
fees (4) |
| | - | |
| | 225,000 | |
| AFFO |
| $ | (3,472,961 | ) |
| $ | (565,695 | ) |
(1) This represents the issuance of 13,300 shares of common stock to
Maxim’s affiliate in a private placement, representing approximately 1% of the
Company’s outstanding stock. On August 26, 2024, the Company entered into a
letter agreement with Maxim to provide general financial advisory and
investment banking services to the Company in connection with, among other
things, strategic planning, uplisting to a U.S. exchange (Nasdaq, New York
Stock Exchange), and potential rights offering, equity issuance or other
mechanisms to enhance corporate and shareholder value.
(2) This represents the amortization of prepaid marketing expenses in
relation to the common stock issued to Outside The Box Capital Inc. (“OTB
Capital”) in a private placement. On January 30, 2025, the Company entered into
a letter agreement with OTB Capital to provide marketing and distribution
services to communicate information about the Company.
(3) This represents consulting fees to IR Agency in connection with
the completed listing of our common stock on the Nasdaq Global Market.
(4) This represents consulting fees to Interactive Offers, LLC in
connection with the completed listing of our common stock on the Nasdaq Global
Market.
FFO losses increased
from $3.04 million for the year ended June 30, 2025 to $3.30 million for the
year ended June 30, 2026, primarily driven by lower rental, reimbursements and
other property income, due to the early lease termination by a tenant at the Satellite
Place Office Building; higher interest expense, mainly due to additional
borrowings from PRES and promissory notes issued to Streeterville Capital, LLC;
and higher property operating and maintenance expenses due to the completion of
Aurora at Green Valley. These factors were partially offset by lower general
and administrative expenses, lower professional fees and improved results from
investments at fair value.
AFFO loss increased from
$0.57 million for the year ended June 30, 2025 to $3.47 million for the year
ended June 30, 2026, primarily due to the factors affecting FFO, a $1.93
million unfavorable change in the adjustment for unrealized gains and losses on
investments at fair value, and a $1.04 million decrease in other AFFO
adjustments, primarily due to lower stock issued for advisory and marketing
services and lower listing-related consulting and marketing fees. These factors
were partially offset by changes in other AFFO adjustments.
Liquidity and Capital
Resources
Capital Resources:
We offered to sell up to
5 million shares of common stock in our first public offering and up to 15
million shares of common stock in each of our second and third public
offerings. We have raised total gross proceeds of $119.10 million from the
issuance of common stock under the public offerings, consisting
of $42.46 million from our
first public offering, which concluded in October 2016, $67.99 million from the
second public offering, which concluded in October 2019, and $8.65 million from
our third public offering, which concluded in October 2020. In addition, we
have raised $15.56 million from the issuance of shares of common stock under the
common stock DRIP as of June 30, 2026. Out of the total proceeds from DRIPs, we
have utilized a total of $14.28 million to repurchase shares of common stock under the share
repurchase program. We have raised $19.90 million through the sale of our Series A preferred stock, $3.72
million through the sale of our Series B preferred stock and $1.37 million through
the sale of our Series C preferred stock pursuant to
a Regulation A offering as of June 30, 2026. In addition, we have raised $0.67 million from the
issuance of shares of Series A, Series B and Series C preferred stock under the
preferred stock DRIP. In January 2025, the Offering Circular was qualified by
the SEC for the sale of 1,286,638.62 shares of Series A and 1,267,216.17 shares
of Series B preferred stock. The Offering Circular was amended in October 2025
to offer up to 645,545.52 shares of Series A Preferred Stock, 1,161,981.94
shares of Series B Preferred Stock, and 1,159,219.11 shares of Series C Preferred Stock. Of these
amounts, 150,000 shares of each series are reserved for the preferred stock DRIP. On January 15, 2025,
our shelf registration statement on Form S-3 for the sale of up to $75 million
in common stock, preferred stock, warrants, and units was declared effective by
the SEC, and we entered into an equity distribution agreement with Maxim to
issue and sell our common stock for an aggregate gross sales price of up
to $20 million pursuant to the at-the-market offering
described in the ATM Prospectus, subject to maintaining compliance with General
Instruction I.B.6 of Form S-3. As of June 30, 2026, under the ATM Offering, we had sold 111,716.60 shares of common stock for gross proceeds of approximately $1.80 million. In addition,
on February 28, 2025, the Company offered and sold 153,403.40 shares of the
Company’s common stock, pre-funded warrants to purchase up to 129,226.50 shares
of common stock, and warrants to
purchase up to an aggregate of 423,944.85 shares of common stock. The gross
proceeds to the Company from this transaction were approximately $4.83 million, before deducting
the placement agent’s fees and other offering expenses payable by the Company.
In July and August 2025, 129,226.50 shares of common
stock were issued upon exercise of all of the
pre-funded warrants. All share amounts are presented after giving effect to the
Reverse Stock Split.
We plan to fund future investments with the net
proceeds raised from our preferred equity offering and any future offerings of
securities and cash flows from operations, as well as interest earned from the
temporary investment of cash in U.S. government securities and other
high-quality debt investments that mature in one year or less. However, we have not raised as much from
our preferred equity offering in the past fiscal year as we did in previous
years, at least in part due to rising interest rates making the preferred
return less attractive. Thus, there is no guarantee that we can raise
sufficient funds to meet our goals in terms of growth, strategic or necessary
loan rebalancing, and additional investments. We
also may fund a portion of our investments through borrowings from banks and
issuances of senior securities. We also may borrow money within the underlying
companies in which we have majority ownership.
We
intend to utilize leverage to enhance the total returns of our portfolio.
Historically, we were only able to access leverage at attractive costs through
a credit facility, but the termination of our BDC status effective December 31,
2020 provided us with greater flexibility in choosing among different
alternatives for raising capital through debt, equity participation features
(such as warrants and convertible notes) and/or additional classes of stock
(such as preferred) in order to facilitate capital formation.
Our
aggregate borrowings (if any), secured and unsecured, are expected to be
reasonable in relation to our net assets and will be reviewed by the Board of
Directors at least quarterly.
We
used the funds raised from our public offerings to invest in portfolio
companies and to pay operating expenses.
We finished the year ended June 30, 2026, with
cash and cash equivalents, and restricted cash of approximately $3.81
million. Our principal demands for cash
are to fund operating and administrative expenses, debt service obligations,
and dividends on our common and Series A, B and C preferred stock. In addition,
we may also use cash to purchase additional properties. We expect to fund our
material cash requirements over the next year through a combination of cash on
hand, net cash provided by our property operations, new capital raised from our
Series A, B and C preferred stock, and new borrowings at the underlying
companies.
Cash Flows:
Fiscal 2026:
For the year ended June
30, 2026, we experienced a net decrease in cash of $0.31
million. During this year, we used net cash of $3.31 million in our
operating activities and $9.14 million in our investing activities and
generated net cash of $12.14 million in our financing activities.
The net cash outflow of
$3.31 million from operating activities resulted from
$22.67 million used in operating expenses, offset by
cash inflows of $19.11 million of rental revenues and $0.25
million of investment income.
The net cash outflow of $9.14 million from
investing activities resulted primarily from $9.15 million of investments in
real estate assets through our subsidiaries, including $6.39 million of
construction costs related to Aurora at Green Valley and approximately $2.76
million of tenant improvements and other capitalized costs related to our other
properties. The Company also used $3.70 million for purchases of equity
investments, partially offset by $3.71 million of proceeds from the sale of
investments.
The net cash inflow of $12.14
million from financing activities resulted from $22.80 million of additional
mortgage borrowings, $3.63 million of additional notes payable, $1.37
million of issuance of Series C preferred stock, $1.15
million from issuance of Series A preferred stock, $0.41
million proceeds from borrowings under the affiliated party line of credit, $0.33
million from issuance of Series B preferred stock and $0.32
million from issuance of common stock, offset by cash outflows of $11.66 million payments on
existing mortgage notes payables, $2.05 million payment on
existing notes, $1.53 million capital distributions to
non-controlling interests holders, $0.94 million payment of
dividends to Series A preferred stockholders, $0.92 million payment of
financing fees, $0.38 million payment of selling commissions and
fees, $0.27 million repayment of finance lease liabilities,
$0.06 million payment of dividends to Series B
preferred stockholders, $0.05 million payment of dividends to Series C
preferred stockholders and $0.01 million change in capital pending acceptance.
Fiscal 2025:
For the year
ended June 30, 2025, we experienced a net decrease in cash of $8.96
million. During this year, we used net cash of $1.69 million in our operating activities, used net
cash of $19.12 million in our investing activities and generated net
cash of $11.85 million in our financing activities.
The net cash outflow of
$1.69 million from operating activities resulted from $22.29
million used in operating expenses, offset by cash inflows of $20.52 million of rental revenues and
$0.08 million of investment income.
The net cash outflow of $19.12 million from investing activities resulted from $18.90 million of real estate acquisitions
through our subsidiaries, and $1.18 million purchases of equity investments,
offset by cash inflow of $0.96 million from sale
of investments.
The net cash inflow of
$11.85 million from financing activities resulted from $48.47 million of
additional mortgage borrowings, $9.59 million proceeds from borrowings under
the affiliated party line of credit, $5.57 million of capital contributions by
non-controlling interests holders, $3.79 million of issuance of common stock,
$1.94 million of issuance of pre-funded warrants, $1.65 million of issuance of
Series B preferred stock, $1.12 million of additional notes payable, $0.38
million of issuance of Series A common stock warrants, $0.23 million of
issuance of Series A preferred stock and $0.22 million of issuance of Series B
common stock warrants, offset by cash outflow of $48.89 million payments on
existing mortgage notes payables, $4.80 million payment of dividends to common
stockholders, $2.32 million payment of financing fees, $1.88 million payment of
selling commissions and fees, $1.49 million capital distributions to
non-controlling interests holders, $0.95 million payment of dividends to Series
A preferred stockholders, $0.28 million change in capital pending acceptance, $0.23
million repayment of finance lease liabilities, $0.22 million payment on
existing notes, $0.04 million payment of dividends to Series B preferred
stockholders and $0.01 million redemption of Series A preferred stock.
Material Cash
Obligations
We have entered into two
contracts under which we have material future commitments: (i) the Advisory
Management Agreement and the Amended and Restated Investment Advisory
Agreement, under which the Advisers serve as our advisers, and (ii) the Administration Agreement,
under which MacKenzie furnishes us with certain non-investment management
services and administrative services necessary to conduct our day-to-day
operations. Each of these agreements is terminable by either party upon proper
notice. Payments under the Advisory Management Agreement, as amended effective
January 1, 2026, will be (i) a base management fee equal to 1.25% per annum of
gross assets under management (excluding depreciation and amortization), paid
monthly, and (ii) a bonus management fee equal to 5% of adjusted funds from
operations each quarter. The bonus management fee replaces any incentive fee,
acquisition fee, financing fee, or disposition fee that was payable under the
prior agreement. Payments under the Administration Agreement will occur on an
ongoing basis as expenses are incurred on our behalf by MacKenzie. However, if
MacKenzie withdraws as our administrator, it will be liable for any expenses we
incur as a result of such withdrawal. For additional information concerning the
terms of these agreements and related fees paid, see Note 8 in the consolidated
financial statements included in this report.
Our material cash requirements over
the next year and thereafter also include:
• Scheduled principal and interest
payments on our mortgage notes payable, line of credit and notes payable. As of
June 30, 2026, our mortgage notes payable had an aggregate outstanding
principal balance of approximately $134.21 million, with scheduled maturities
in fiscal years 2027 through 2033. Our line of credit with PRES (as extended,
maturing December 31, 2027) had an aggregate outstanding principal balance of
$10 million while notes payable, net had an aggregate outstanding principal
balance of approximately $3.86 million, including $2.94 million outstanding
under the Streeterville Capital, LLC secured promissory notes maturing on various
dates through July 2027 and September 2027, in each case as described in Note
10 to the consolidated financial statements. See Note 10 for a discussion of
the material terms, guarantees and required principal payments of our
indebtedness.
• Dividends declared on our Series
A, Series B and Series C preferred stock, which are payable pro-rata at the
rate of $0.125, $0.0625 (in cash) and $0.1875 per share per month for the
Series A, Series B and Series C preferred stock, respectively, subject to the
discretion of our Board of Directors. See Note 14 for a discussion of preferred
stock dividends declared during fiscal 2026. The Company suspended the regular
quarterly dividend on its common stock effective May 19, 2025, and the common
stock dividend remains suspended.
• Operating expenses incurred in the
ordinary course of business, including property operating and maintenance
expenses, real estate taxes, insurance, professional fees, director fees and
other general and administrative expenses.
We expect to fund these material
cash requirements through a combination of cash on hand, net cash provided by
our property operations, borrowings under the line of credit with PRES, secured
promissory notes and other borrowings at the Company and its subsidiaries,
mortgage refinancings, sales or contributions of properties, and net proceeds
from the Regulation A preferred stock offering under the Offering Circular and
from the sale of common stock under the ATM Offering.
Borrowings
On January 22, 2025, we
entered into a revolving line of credit agreement with PRES, an affiliate of
the Adviser, of
up to $10,000,000. Interest will accrue on any unpaid principal balance on the
note at a fixed annual interest rate of 10%. In addition, an origination fee of 2% will be charged on each
advance and the sum will be added to the principal balance. The original
maturity date of the loan was June 1, 2026. On September 24, 2025, the maturity date was extended to December
31, 2027. The loan requires monthly interest beginning on March 1, 2025, with
the remaining principal balance due at maturity. As of June 30, 2026, the
Company has borrowed $10 million in entirety, which includes $196,078 of loan origination fees, under the line of credit.
We use the proceeds from
this credit facility on a short-term basis to bridge the gap between our asset
acquisition expenditures and debt refinancings. We are subject to various
customary covenants and restrictions on our operations, such as covenants that
may (i) require us to maintain certain financial ratios, including asset
coverage, debt to equity and interest coverage, and a minimum net worth, and/or
(ii) restrict our ability to incur liens or additional debt, merge, sell
assets, make certain investments and/or distributions or engage in transactions
with affiliates. We also borrow money within the underlying companies in which
we have majority ownership.
As of June 30, 2026, the
Company was not in compliance with the required debt service coverage ratio
under the MacKenzie Satellite Mortgage Notes Payable. As a result of the
covenant violation, the remaining unpaid principal balance of approximately
$5.8 million is presented in the fiscal year ending June 30, 2027 maturity
category in the table below. See Note 10, Debt, for additional information.
The table below presents
the total loans outstanding at the underlying companies as of June 30, 2026,
and the fiscal years those loans mature:
Fiscal Year Ending June 30, :
|
|
Principal
|
|
|
2027
|
|
$
|
21,165,512
|
|
|
|
|
|
|
|
|
2028
|
|
|
39,192,469
|
|
|
|
|
|
|
|
|
2029
|
|
|
4,726,550
|
|
|
|
|
|
|
|
|
2030
|
|
|
27,435,197
|
|
|
|
|
|
|
|
|
2031
|
|
|
26,508,005
|
|
|
|
|
|
|
|
|
Thereafter
|
|
|
29,441,453
|
|
|
|
|
|
|
|
|
Total
|
|
$
|
148,469,186
|
|
Critical Accounting Policies and Estimates
Below is a discussion of the accounting policies and
estimates that management considers critical in that they involve significant
management judgments and assumptions, require estimates about matters that are
inherently uncertain and because they are important for understanding and
evaluating our reported financial results. These judgments affect the reported
amounts of assets and liabilities and our disclosure of contingent assets and
liabilities at the dates of the consolidated financial statements and the
reported amounts of revenue and expenses during the reporting periods. With
different estimates or assumptions, materially different amounts could be
reported in our consolidated financial statements. Additionally, other
companies may utilize different estimates that may impact the comparability of
our results of operations to those of companies in similar businesses. In
addition to the discussion below, our critical accounting policies are
discussed in Note 2 of our consolidated financial statements, which are part of
this annual report beginning on page F-1.
Real Estate Purchase
Price Allocations
In accordance with the guidance for business combinations, upon
the acquisition of real estate properties, we evaluate whether the transaction
is a business combination or an asset acquisition. If the transaction does not
meet the definition of a business combination, we record the assets acquired,
the liabilities assumed, and any non-controlling interest as of the acquisition
date, measured at their relative fair values. Acquisition-related costs are
capitalized in the period incurred and are added to the components of the real
estate assets acquired. We assess the acquisition-date fair values of all
tangible assets, identifiable intangible assets, and assumed liabilities using
methods similar to those used by independent appraisers (e.g., discounted cash
flow analysis) and that utilize appropriate discount and/or capitalization
rates and available market information. Estimates of future cash flows are
based on several factors including historical operating results, known and
anticipated trends, and market and economic conditions. The fair value of
tangible assets of an acquired property considers the value of the property as
if it was vacant. Intangible assets include the value of in-place leases, which
represents the estimated fair value of the net cash flows of leases in place at
the time of acquisition, as compared to the net cash flows that would have
occurred had the property been vacant at the time of acquisition and subject to
lease-up. We amortize the value of in-place leases to expense over the remaining
non-cancelable term of the respective leases, which is on average five years.
Estimates of the fair values of the tangible assets, identifiable intangibles
and assumed liabilities require us to make significant assumptions to estimate
market lease rates, property operating expenses, carrying costs during lease-up
periods, discount rates, market absorption periods, prevailing interest rates,
and the number of years the property will be held for investment. The use of
inappropriate assumptions could result in an incorrect valuation of acquired
tangible assets, identifiable intangible assets, and assumed liabilities, which
could impact the amount of our net income (loss). Differences in the amount
attributed to the fair value estimate of the various assets acquired can be
significant based upon the assumptions made in calculating these estimates.
Fair Value Measurements
GAAP establishes a hierarchical disclosure
framework which prioritizes and ranks the level of market price observables
used in measuring investments at fair value. Market price is impacted by a
number of factors, including the type of investment and the characteristics
specific to the investment. Investments with readily available actively quoted
prices or for which fair value can be measured from actively quoted prices
generally will have a higher degree of market price observables and a lesser
degree of judgment used in measuring fair value.
Investments measured and reported at fair value
are classified and disclosed in one of the following categories:
Level
I – Quoted
prices are available in active markets for identical investments as of the
reporting date. The type of investments included in Level I are publicly traded
equity securities. We do not adjust the quoted price for these investments even
in situations where we hold a large position and a sale could reasonably impact
the quoted price.
Level II – Price inputs are quoted
prices for similar financial instruments in active markets; quoted prices for
identical or similar financial instruments in markets that are not active; and
model-derived valuations in which all significant inputs or significant value-drivers
are observable in active markets. Investments which are generally included in
this category are publicly traded equity securities with restrictions.
Level III – Pricing inputs are
unobservable and include situations where there is little, if any, market
activity for the investment. Fair values for these investments are estimated by
management using valuation methodologies that consider a range of factors,
including but not limited to the price at which the investment was acquired,
the nature of the investment, local market conditions, trading values on public
exchanges for comparable securities, current and projected operating
performance, financial condition, and financing transactions subsequent to the
acquisition of the investment. The inputs into the determination of fair value
require significant judgment by management. Due to the inherent uncertainty of
these estimates, these values may differ materially from the values that would
have been used had an active market for these investments existed.
In certain cases, the inputs used to measure fair value may fall
into different levels of the fair value hierarchy. In such cases, an
investment’s level within the fair value hierarchy is based on the lowest level
of input that is significant to the fair value measurement. Management’s
assessment of the significance of a particular input to the fair value
measurement, in its entirety, requires judgment and considers factors specific
to the investment.
Valuation of
Investments
Our consolidated financial statements include investments that are
measured at their estimated fair values in accordance with GAAP. Our valuation
procedures are summarized below:
Securities for which market quotations are readily available on an
exchange will be valued at such price as of the closing price on the day
closest to the valuation date. Where a security is traded but in limited
volume, we may instead utilize the weighted average closing price of the
security over the prior 10 trading days. We may value securities that do not
trade on a national exchange by using published secondary market trading
information. When doing so, we first confirm that GAAP recognizes the trading
price as the fair value of the security.
Securities for which reliable market data is not
readily available or for which the pricing source does not provide a valuation
or methodology or provides a valuation or methodology that, in the judgment of
the Investment Adviser or Board of Directors, does not represent fair value,
are valued as follows: (i) each portfolio company or investment is initially
valued by the investment professionals responsible for the portfolio
investment; (ii) preliminary valuation conclusions are documented and discussed
with our senior management; and (iii) the Board of Directors will discuss
valuations and determine the fair value of each investment in our portfolio in
good faith based on the input of the Investment Adviser and, where appropriate
and necessary, the respective third‑party valuation firms.
The recommendation of fair value will generally be based on the
following factors, as relevant:
• the nature and realizable value of any
collateral;
• the portfolio company’s ability to make
payments;
• the portfolio company’s earnings and
discounted cash flow;
• the markets in which the issuer does
business; and
• comparisons to publicly traded
securities.
Securities for which market data is not readily available or for
which a pricing source is not sufficient may include the following:
• private placements and restricted
securities that do not have an active trading market;
• securities whose trading has been
suspended or for which market quotes are no longer available;
• debt securities that have recently gone
into default and for which there is no current market;
• securities whose prices are stale;
• securities affected by significant
events; and
• securities that the Investment Adviser
believes were priced incorrectly.
Valuation of Real
Property
Valuation of real
property used to evaluate impairment of real property held for use, held for
sale, or to determine the fair value of certain real properties held by equity
method investments accounted for using the fair value method, involve
subjective judgments and estimates. To determine the valuation of the real
estate properties, management utilizes the income approach, either the
discounted cash flow or direct capitalization valuation model. Determining fair
value requires management to make estimates of future cash flows, which are
based on a number of inputs and assumptions, including property
operations, terminal capitalization rates, and discount rates. We estimate
future leasing activities and associated costs, generally over a ten-year
period, to determine the fair value of the property. Once the fair value
is determined, we determine whether any impairment is required and document our
conclusion. As part of their review of our quarterly and annual reports, the
Board of Directors reviews the valuations and impairment determinations. In
addition, we may obtain a third-party appraisal on directly owned properties.
The inputs used in the valuation of real property are
unobservable and accordingly, the notes to our consolidated financial
statements describe the uncertainty with respect to the possible effect of such
valuations, and any changes in such valuations, on our consolidated financial
statements.
Below is a discussion of additional accounting
policies and estimates. While management determined these to be not critical,
they are still considered to be significant and relevant for understanding and
evaluating our reported financial results.
Use of Estimates
The preparation of consolidated financial statements requires
management to make estimates and assumptions that affect reported asset values,
liabilities, revenues, expenses and unrealized gains (losses) on investments
during the reporting period. Material estimates are susceptible to change, and
actual results could differ from those estimates.
Revenue Recognition
Rental revenue, net of
concessions, which is derived primarily from lease contracts and includes rents
that each tenant pays in accordance with the terms of each lease agreement, is
recognized on a straight-line basis over the term of the lease, when collectability
is determined to be probable.
Minimum rent, including
rental abatements, lease incentives, and contractual fixed increases
attributable to operating leases are recognized on a straight-line basis over
the term of the related leases when collectability is probable. Amounts
expected to be received in later years are recorded as deferred rent
receivable. If the lease provides for tenant improvements, we determine whether
the tenant improvements, for accounting purposes, are owned by the tenant or
us. When we are the owner of the tenant improvements, the tenant is not
considered to have taken physical possession or have control of the physical
use of the leased asset until the tenant improvements are substantially
completed. When the tenant is the owner of the tenant improvements, any tenant
improvement allowance (including amounts that can be taken in the form of cash
or a credit against the tenant’s rent) that is funded is treated as a lease
incentive and amortized as a reduction of rental revenue over the lease term.
Tenant improvement
ownership is determined based on various factors including, but not limited to:
• whether
the lease stipulates how a tenant improvement allowance may be spent;
• whether
the lessee or lessor supervises the construction and bears the risk of cost
overruns;
• whether
the amount of a tenant improvement allowance is in excess of market rates;
• whether
the tenant or landlord retains legal title to the improvements at the end of
the lease term;
• whether
the tenant improvements are unique to the tenant or general purpose in nature;
and
• whether
the tenant improvements are expected to have any residual value at the end of
the lease.
In accordance with ASC
Topic 842, we determine whether collectability of lease payments in an
operating lease is probable. If we determine the lease payments are not
probable of collection, we fully reserve for rent and reimbursement
receivables, including deferred rent receivable, and recognize rental income on
a cash basis.
Distributions received
from investments are evaluated by management and recorded as dividend income or
a return of capital (reduction of investment) on the ex-dividend date.
Operational dividends or distributions received from portfolio investments are
recorded as investment income. Distributions resulting from the sale or
refinance of an investee’s underlying assets are compared to the estimated
value of the remaining assets and are recorded as a return of capital or as
investment income as appropriate.
Realized gains or losses on investments are
recognized in the period of disposal, distribution, or exchange and are
measured by the difference between the proceeds from the sale or distribution
and the cost of the investment. Investments are disposed of on a first-in,
first-out basis. Net change in unrealized gain (loss) reflects the net change
in portfolio investment values during the reporting period, including the
reversal of previously recorded unrealized gains or losses.
Variable Interest Entities
We evaluate the need to
consolidate other entities in when we have invested in their securities in
accordance with ASC Topic 810, Consolidation. In determining whether we
have a controlling interest in a variable interest entity that requires us to
consolidate the accounts of that entity, management considers factors such as
ownership interest, authority to make decisions and contractual and substantive
participating rights of the partners/members, as well as whether the entity is
a variable interest entity for which we are the primary beneficiary.
Real Estate Assets,
Capital Additions, Depreciation and Amortization
We capitalize costs,
including certain indirect costs, incurred for capital additions, including
redevelopment, development, and construction projects. We also allocate certain
department costs, including payroll, at the corporate levels as “indirect costs”
of capital additions, if such costs clearly relate to capital additions. We
also capitalize interest, property taxes, and insurance during periods in which
redevelopment, development, and construction projects are in progress. Cost
capitalization begins once the development or construction activity commences
and ceases when the asset is ready for its intended use. Repair and maintenance
and tenant turnover costs are expensed as incurred. Repair and maintenance and
tenant turnover costs include all costs that do not extend the useful life of
the real estate asset. Depreciation and amortization expense are computed on
the straight-line method over the asset’s estimated useful life. We consider
the period of future benefit of an asset to determine its appropriate useful
life and anticipate the estimated useful lives of assets by class to be
generally as follows:
| Buildings |
16 - 45 years |
| |
|
| Building
improvements |
1 - 15 years |
| |
|
Land
improvements
|
5 - 15 years |
| |
|
| Furniture,
fixtures and equipment |
3 - 11 years |
| |
|
| In-place
leases |
1 - 10 years |
Impairment of Real Estate Assets
We continually monitor events
and changes in circumstances that could indicate that the carrying value of our
real estate and related intangible assets may not be recoverable. When
indicators of potential impairment emerge, we assess whether we will recover
the carrying value of the asset through its undiscounted future cash flows and
its eventual disposition. Based on this assessment, if we do not believe that
we will recover the carrying value of the real estate and related intangible
assets, we will record an impairment loss to the extent that the carrying value
exceeds the estimated fair value of the real estate and related intangible
assets.
2026, we recorded an impairment loss on assets held for sale of $1,687,783, which is discussed in Note 5. During the year ended June 30, 2025, due to an
early lease termination by the anchor tenant at our Main Street West Office
Building, we recognized an accumulated impairment loss of $9,500,167. We utilized a
third-party appraisal to estimate the fair value of the property and determine
the impairment amount. We consider these inputs as Level III measurements
within the fair value hierarchy.
Assets and Liabilities Held for Sale
We classify long-lived assets to be sold as held for sale in the
period in which all of the following criteria are met:
- Management,
having the authority to approve the action, commits to a plan to sell the
asset (disposal group);
- The asset
(disposal group) is available for immediate sale in its present condition
subject only to terms that are usual and customary for sales of such
assets (disposal groups);
- An
active program to locate a buyer and other actions required to complete
the plan to sell the asset (disposal group) have been initiated;
- The sale of the asset (disposal group) is probable, and
transfer of the asset (disposal group) is expected to qualify for
recognition as a completed sale within one year, except if events or
circumstances beyond our control extend the period of time required to
sell the asset or disposal group beyond one year;
- The asset (disposal group) is being actively marketed for
sale at a price that is reasonable in relation to its current fair value.
The price at which a long-lived asset (disposal group) is being marketed
is indicative of whether the entity currently has the intent and ability
to sell the asset (disposal group). A market price that is reasonable in
relation to fair value indicates that the asset (disposal group) is
available for immediate sale, whereas a market price in excess of fair
value indicates that the asset (disposal group) is not available for
immediate sale; and
- Actions required to complete the plan indicate that it is
unlikely that significant changes to the plan will be made or that the
plan will be withdrawn.
On the day that these criteria are met, we suspend
depreciation on the investment properties held for sale, including depreciation
for tenant improvements and additions, as well as on the amortization of
acquired in-place leases. Assets and liabilities of the disposal group are
presented separately on the consolidated balance sheets and measured at the
lower of carrying value or fair value less costs to sell. Prior year balances
have been reclassified as assets and liabilities held for sale for comparative purposes
on the consolidated balance sheet as of June 30, 2025. Woodland Corporate
Center Two was listed for sale as discussed in Note 5.
Dividends to
Stockholders
We pay quarterly distributions to stockholders
to the extent that we have income from operations available. Our quarterly
distributions, if any, will be determined by our Board of Directors after a
review and distributed pro-rata to holders of our shares; we declare
distributions on a monthly basis, but pay each quarter. Any distributions to
our stockholders will be declared out of assets legally available for
distribution. In no event are we permitted to borrow money to make
distributions if the amount of such distributions would exceed our annual
accrued and received revenues, less operating costs. Distributions in kind are
not permitted, except as provided in our Charter.
We have elected to be treated as a REIT under
the Code. As a REIT, we are not subject to federal income taxes on amounts that
we distribute to the stockholders, provided that, on an annual basis, we
generally distribute at least 90% of our REIT taxable income (determined without regard to the dividends paid deduction
and excluding any net capital gain) to the stockholders and meet certain
other conditions. To the extent that we satisfy the annual distribution
requirement but distribute less than 100% of our REIT taxable income, we will
be subject to U.S. federal corporate income tax on our undistributed REIT
taxable income. In addition, we will be subject to a 4% nondeductible excise
tax if the actual amount that we pay to our stockholders in a calendar year is
less than a minimum amount specified under U.S. federal tax laws.
We
have DRIPs that provide for reinvestment of our dividends and other
distributions on behalf of stockholders for any individual stockholder who
elects to participate in the DRIPs, provided that the applicable DRIP is
permitted by the state in which the stockholders reside. We can offer no
assurance that we will achieve results that will permit the payment of any cash
distributions. On
March 4, 2024, the Board of Directors suspended the common stock share
repurchase program and common stock DRIP in connection with trading of its
common stock on the OTCQX Best Market. When our common stock became eligible
for trading on OTC Markets in April 2024, the share repurchase program
automatically terminated, and the Board of Directors will decide whether, and
when, to reinstate the common stock DRIP.
During the year ended June 30, 2026, the Board
approved the following quarterly dividends:
| |
Dividends |
| |
Common Stock |
Series A Preferred
Stock |
Series B Preferred
Stock |
|
Series C Preferred
Stock |
| During
the Quarter Ended |
| | Per Share | |
| | Amount | |
| | Per Share | |
| | Amount | |
| | Per Share | |
| | Amount | |
|
| | Per Share | |
| | Amount | |
| September
30, 2025 |
| $ | - | |
| $ | - | |
| $ | 0.375 | |
| $ | 285,758 | |
| $ | 0.750 | |
| $ | 88,878 | |
|
| $ | 0.563 | |
| $ | 6,465 | |
| December
31, 2025 |
| | - | |
| | - | |
| | 0.375 | |
| | 280,892 | |
| | 0.750 | |
| | 90,198 | |
|
| | 0.563 | |
| | 18,915 | |
| March
31, 2026 |
| | - | |
| | - | |
| | 0.375 | |
| | 276,780 | |
| | 0.750 | |
| | 92,230 | |
|
| | 0.563 | |
| | 27,189 | |
| June
30, 2026 |
| | - | |
| | - | |
| | 0.375 | |
| | 274,125 | |
| | 0.750 | |
| | 93,469 | |
|
| | 0.563 | |
| | 30,022 | |
| |
| $ | - | |
| $ | - | |
| $ | 1.500 | |
| $ | 1,117,555 | |
| $ | 3.000 | |
| $ | 364,775 | |
* |
| $ | 2.250 | |
| $ | 82,591 | |
* Of the total dividends declared for Series B during
the year ended June 30, 2026, $273,582 was an increase in liquidation
preference and $91,193 was the cash dividend.
On May 19, 2025, following a review of the Company’s
financials, the current economic climate, the potential impact of new tariffs
on demand for office and retail space, and the increased likelihood of a
near-term recession, the Company announced that the Board of Directors approved
the suspension of the regular quarterly dividend on the Company’s common stock
effective immediately. This decision was made to preserve liquidity and will
remain in effect until further notice.
NO LEGAL PROCEEDINGS
We are not currently subject to any
material pending legal proceedings, nor, to our knowledge, is any material
legal proceeding threatened against us.
SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND
MANAGEMENT
As of the October 9, 2026, to our knowledge,
there were no persons that owned 25% or more of the outstanding voting
securities and no person would be deemed to control us. Our directors are
divided into two groups - non-independent directors and independent directors.
Independent directors are defined by The Nasdaq Stock Market (“Nasdaq”) Director Independence Criteria.
The following table shows the amount of our
common and preferred stock beneficially owned as of September 28, 2026, based
on a total of 2,774,688 shares of our common stock, 754,282 shares of Series A
Preferred Stock, 125,876 shares of Series B Preferred Stock and 60,559 shares
of Series C Preferred Stock outstanding on September 28, 2026, by (1) each of
our directors and nominees for director, (2) our executive officers and (3) all
directors and executive officers as a group.
The following table also shows the amount of our common stock beneficially owned by
Armistice Capital, LLC which differs significantly from the amount that was
reported on the Schedule 13G/A filed with the SEC on November 14, 2025, in
which Armistice Capital, LLC reported beneficial ownership of only 92,924
shares of our common stock (4.99% of our outstanding common stock as of the
9/30/2025 event date). Armistice Capital, LLC owns warrants entitling it to
acquire up to 282,629.90 additional shares of our common stock within 60 days
hereof, subject to the applicable 9.8% ownership limit in the warrants and our
Charter. Thus, pursuant to the requirements of SEC Rule 13d-3, Armistice
Capital is deemed to own 9.8%, or 271,919 shares, of our common stock. We have previously notified Armistice Capital
of the Company’s position, but they declined to correct their apparent error
and have not continued to file Schedule 13Gs as a greater than 5% shareholder
is required to do.
To our knowledge, apart from the executive
officer ownership discussed below, no other person or group owns more than 5%
of our common or preferred stock. The number of shares beneficially owned by
each entity, person, director or executive officer is determined under the
rules of the Securities and Exchange Commission (the “SEC”) and the information is not necessarily indicative of
beneficial ownership for any other purpose. Under such rules, beneficial
ownership includes any shares as to which the individual has the sole or shared
voting power or investment power and also any shares that the individual has
the right to acquire within 60 days of September 28, 2026, through the exercise
of any instrument. Unless otherwise indicated, each person has the sole
investment and voting power, or shares such powers with his spouse, with
respect to the shares set forth in the table. Unless known otherwise by us, the
beneficial ownership information is based on each beneficial owner’s most
recent Form 3, Form 4, Form 5, Schedule 13D or Schedule 13G, as applicable,
filed with the SEC.
With respect to the Executive Officers listed
below, they are limited partners of MPF Successors, LP, as well as officers of
its general partner, which owns 5,569 shares of our common stock in the
Company. Each of the Executive Officers also is a limited partner, and an
officer of the general partner, of our Adviser, which owns 86,855 shares of our
common stock. Accordingly, each such officer may be deemed to share voting
power and investment power over shares owned by the Adviser and by MPF
Successors, LP. Additionally, Mr. Dixon owns 54,241 shares directly, Mr. Sherpa
owns 160 shares directly and Ms. Simpson owns 250 shares directly. The Berniece
Patterson Legacy Trust (“BPLT”) owns 100,000 shares of our common stock,
and pursuant to the terms of the trust instrument governing BPLT, each of
Messrs. Dixon, Fuller and Patterson may be deemed to have or share voting and
investment power over the shares held by BPLT. Each of Messrs. Dixon, Fuller
and Patterson disclaims beneficial ownership of the BPLT shares except to the
extent of his pecuniary interest. Because the same 100,000 BPLT shares are
attributable to each of Messrs. Dixon, Fuller and Patterson (and are counted in
each of their rows below), those shares are counted only once for purposes of
the aggregate holdings of all directors and executive officers as a group. Ms.
Bluth, Mr. Sherpa and Ms. Simpson are not BPLT beneficiaries and are not
attributed the BPLT shares. The address of each beneficial owner is 89 Davis
Road, Suite 100, Orinda, CA 94563.
Name and Address of Beneficial Owner
|
|
Number of Common Shares Beneficially Owned (a)(b)
|
|
Percent of Class
|
Number of Series A Preferred Shares Owned (a)
|
Percent of Class
|
|
Number of Series B Preferred Shares Owned (a)
|
|
Percent of Class
|
Number of Series C Preferred Shares Owned (a)
|
|
Percent of Class
|
|
5% Owners:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Armistice Capital, LLC
|
|
271,919 (c)
|
|
9.8%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Independent Directors:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Tim Dozois
|
|
508
|
|
*
|
5,449.62
|
*
|
|
4,444.44
|
|
3.5%
|
-
|
|
-
|
|
Tom Frame
|
|
597
|
|
*
|
501.74
|
*
|
|
-
|
|
-
|
-
|
|
-
|
|
Kjerstin Hatch
|
|
-
|
|
-
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Non-Independent Director:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Charles “Chip” Patterson
|
|
192,424
|
|
6.9%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Executive Officers:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Angche Sherpa
|
|
92,584
|
|
3.3%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Glen Fuller
|
|
192,424
|
|
6.9%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Jeri Bluth
|
|
92,424
|
|
3.3%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Christine Simpson
|
|
92,674
|
|
3.3%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Chip Patterson
|
|
192,424
|
|
6.9%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Robert Dixon
|
|
246,665
|
|
8.9%
|
-
|
-
|
|
-
|
|
-
|
-
|
|
-
|
|
Directors and Officers as a group (9 persons)
|
|
249,291
|
|
9.0%
|
6,323.86
|
*
|
|
4,444.44
|
|
3.5%
|
-
|
|
-
|
* Represents
less than 1% of the number of shares outstanding.
Security
Ownership by Our Adviser
Currently,
affiliates of our Adviser own shares of our common stock, but none of the
preferred shares. No person has been promised any stock or warrants to
purchase shares, save by participation in this Offering.
DIRECTORS AND EXECUTIVE OFFICERS
Our Board of Directors oversees our
management. The Board of Directors currently consists of three members, two of
whom are Independent Directors. Each director is elected annually by our stockholders. Our Board of Directors elects our officers, who serve at
the discretion of the Board of Directors. The responsibilities of each director
will include, among other things, the oversight of our investment activity, the
valuation of our assets, and oversight of our financing arrangements. The Board
of Directors has also established an audit committee and a nominating and
corporate governance committee and may establish additional committees in the
future.
Our Adviser has been providing
advice to clients about real estate‑related assets and other investments since
1982. Much of that advice has focused on the types of real estate‑related
investments MRC intends to make, through the Adviser’s management of the Legacy
Funds and many other similarly organized investment vehicles. Accordingly, our
officers and directors who are affiliated with our Adviser and/or Manager have
the requisite experience with the types of assets we seek to acquire.
Board
of Directors and Executive Officers
Directors
| Name |
| | Age | |
Position |
|
Director |
| Since |
| Interested Director |
| | | |
|
|
|
| Chip
Patterson |
| | 55 | |
Chairman of the Board of
Directors, Secretary, and General Counsel |
|
2019 |
| Independent Directors |
| | | |
|
|
|
| Tim
Dozois |
| | 64 | |
Director |
|
2012 |
| Tom Frame |
| | 84 | |
Director |
|
2012 |
| Kjerstin
Hatch |
| | 53 | |
Director |
|
2024 |
The address for each of our
directors is 89 Davis Road, Suite 100, Orinda, CA 94563.
Executive
Officers Who Are Not Directors
| | | | | |
| Name |
| | Age | |
Position |
| Robert
Dixon |
| | 55 | |
Chief Executive Officer and
President |
| Angche Sherpa |
| | 45 | |
Chief Financial Officer and Treasurer |
| Glen
Fuller |
| | 52 | |
Chief Operating Officer |
| Christine Simpson |
| | 61 | |
Chief Portfolio Manager |
| Jeri
Bluth |
| | 51 | |
Chief Compliance Officer |
The address for each of our
executive officers is 89 Davis Road, Suite 100, Orinda, CA 94563.
Biographical Information
Directors
Our directors have been divided into
two groups — interested directors and Independent Directors. An Independent
Director is defined in the Nasdaq Board Independence Standards, but generally
is someone who is not associated, and has not been associated within the last three
years, directly or indirectly, with us or our affiliates.
Interested Director
Charles
“Chip” Patterson. Mr.
Patterson, an MRC Executive Officer since May of 2012, is
managing director, general counsel, and senior vice president of the Investment
Adviser, the Adviser, and the Manager, and a director of their general partner,
and a beneficial owner of all three companies, all since 2005. Mr. Patterson is Mr. Fuller’s step-brother
and Mr. Dixon’s brother-in-law.
Mr. Patterson graduated magna cum
laude from the University of Michigan Law School with a J.D. degree and with
high distinction and Phi Beta Kappa from the University of California at
Berkeley with a B.A. degree in Political Science. Prior to joining the Manager
in July 2003, he was a securities and corporate finance attorney with the
national law firm of Davis Wright Tremaine LLP. Prior to law school, Chip
Patterson taught physics, chemistry, and math at the high school level for
three years. He also has prior experience in sales, retail, and banking, and is
a licensed California Real Estate Broker. He has extensive history with the
Adviser’s affiliated private funds, familiarity with our investment platform,
and extensive knowledge of the real estate industry, legal and regulatory
framework governing investment companies, business development companies,
investment advisers, and investment valuation process.
Independent Directors
Tim Dozois. Mr. Dozois, an MRC director since May of 2012, was Vice
President, Secretary and Corporate Counsel for Pendrell Corporation, a Nasdaq
listed company specializing in intellectual property solutions, from June of
2010 until early 2018. From January 1996 until March of 2010, Mr. Dozois was an
equity partner of Davis Wright Tremaine LLP, a Seattle-based national law firm,
where he specialized in private securities work and structured financings, with
a particular emphasis on the acquisition, financing and management of real
property assets. He has nearly 30 years of experience supporting leading
corporations in securities law compliance, mergers, acquisitions, and real
estate acquisition, financing, and management.
Mr. Dozois received his B.S. in
Financial Management from Oregon State University and his J.D. from the
University of Oregon School of Law, where he was Order of the Coif.
Tom Frame. Mr. Frame, an MRC director since May of 2012, was a co‑founder
of TransCentury Property Management and solely founded Paradigm Investment
Corporation. TransCentury began in May of 1973 and has syndicated and managed
over 10,000 residential units. During the last 35 years, Mr. Frame has been a
principal in the acquisition, financing, restoration, and sale of over
$500,000,000 in residential and commercial real estate. Paradigm was founded in
June 1986 to sponsor and manage private, closed end “mutual funds.” Paradigm
managed a portfolio of over $7,000,000 in limited partnership securities. The
last of the funds successfully liquidated in December of 2000.
Mr. Frame received a B.A. degree in
Mathematics from the University of Kansas in June 1964, a J.D. degree from the
San Francisco Law School in June 1975, and an M.B.A. with honors from
Pepperdine University in April 1986. Mr. Frame is currently managing his own
investments which include residential units, commercial property, and a
portfolio of securities.
Kjerstin
Hatch. Ms. Hatch, an MRC director since
September 23,2024, is the Founder and a Managing Principal of Lapis Advisers,
LLP and has focused her career in special situation securities. She founded Lapis Advisers in 2009 to invest
in the municipal marketplace with an emphasis on underperforming bonds and
securities. She has served as a
portfolio manager and acquisitions specialist in alternative investments for
over thirty years, managing over a thousand investments in municipal bonds,
illiquid real estate and over 150 distressed and bankrupt companies totaling
well in excess of $2 billion. Ms. Hatch
has a depth of experience in valuing and analyzing investments with a specific
emphasis on real estate assets, healthcare assets, senior living, educational
and housing assets. She has decades of
experience in underwriting financial statements and annual audits for both
public and private borrowers.
Ms. Hatch earned a Bachelor of Arts
degree in the Political Economy of Industrialized Societies from the University
of California, Berkeley.
Executive Officers Who Are Not
Directors
Robert E.
Dixon. Mr. Dixon is managing director and chief investment officer of
MacKenzie and the Adviser, where he has been employed since 2005. He is a
director of their general partner and a beneficial owner of all three
companies. Mr. Dixon is Mr. Fuller’s and Mr. Patterson’s brother-in-law.
Robert Dixon served as an officer
and director of Sutter Holding Company, Inc. from March 2002 until 2005. Mr.
Dixon founded Sutter Capital Management, LLC, an investment management firm, in
1998 and sold it in 2005 to MCM Advisers, Inc. Mr. Dixon has been president of
Sutter Capital Management since its founding. Mr. Dixon received his M.B.A.
degree from Cornell University in 1998 and has held the Chartered Financial
Analyst® designation since 1996. From October 1994 to June 1996 he worked for
MacKenzie Patterson, Inc. as a securities research analyst. He worked for
Lehman Brothers, Inc. in equity sales and trading during 1993 and 1994. Mr.
Dixon received his B.A. degree in Economics from the University of California
at Los Angeles in 1992.
Angche Sherpa. Mr. Sherpa was appointed to Chief Financial Officer in
July 2021 after the retirement of Mr. Koslosky. He has been employed by our
administrator, MacKenzie Capital Management, LP (“MacKenzie”), since 2012.
Prior to his appointment, he was Director of Accounting and Financial Reporting
of MacKenzie.
Mr. Sherpa graduated from San
Francisco State University in 2006 with a Bachelor of Science degree in
Business Administration (Accounting) with high honors. He obtained his
Certified Public Accountant license from California Board of Accountancy in
January 2011. Prior to joining MacKenzie, he worked as staff auditor from 2007
through 2008 and senior auditor from 2009 through 2012 at a national public
accounting firm Moss Adams LLP. During his career at Moss Adams, he led various
audit teams involved in auditing financial services companies including private
equity, asset management, and real estate investment companies.
Glen W. Fuller. Mr. Fuller is managing director and chief operating
officer of MacKenzie and the Adviser, where he has been employed since 2000. He
is a director of their general partner and a beneficial owner of all three
companies. Mr. Fuller is Mr. Dixon’s brother-in-law and Mr. Patterson’s
step-brother.
Prior to becoming senior vice
president of the Manager, he was with the Manager for two years as a portfolio
manager and research analyst. Prior to joining the Manager, Mr. Fuller spent
two years running the over the counter trading desk for North Coast Securities
Corp. (previously Morgan Fuller Capital Group) with responsibility for both the
proprietary and retail trading desks. Mr. Fuller was also the registered
options principal and registered municipal bond principal for North Coast
Securities Corp., a registered broker‑dealer. Mr. Fuller previously held his
FINRA Series 7, general securities registration. Mr. Fuller has a B.A. degree
in Management. Mr. Fuller has also spent time working on the floor of the New
York Stock Exchange as a trading clerk and on the floor of the Pacific Stock
Exchange in San Francisco as an assistant specialist for LIT America.
Jeri R. Bluth. Ms. Bluth is the chief compliance officer for MacKenzie
and the Adviser, where she has been employed since 1996. She owns a beneficial
interest in each MacKenzie, the Adviser, and their general partner. Mrs. Bluth
oversees compliance for all the funds advised by the Adviser, and she oversees
MRC’s compliance with our Code of Ethics, Bylaws, Charter, and applicable rules
and regulations.
Mrs. Bluth began her career with
MacKenzie Patterson Fuller, Inc. in July of 1996 in the Investor Services
Department. During Mrs. Bluth’s career with the Manager, she graduated from St.
Mary’s College of California in June 2001, with a B.A. degree in Business
Management.
Christine E. Simpson. Ms. Simpson is the chief portfolio manager for MacKenzie
and the Adviser, where she has been employed since 1990. She owns a beneficial
interest in each MacKenzie, the Adviser, and their general partner. She is responsible for the day‑to‑day
operations of the Manager’s research department.
During Mrs. Simpson’s career with
the Manager, she graduated: with a B.A. degree in Business Management from St.
Mary’s College of California in October 2004 (with honors), with an M.S. degree
in Financial Analysis and Investment Management in September 2006, and an
M.B.A. in June 2008. As a result of these and other professional experiences,
Mrs. Simpson possesses particular knowledge and experience in real estate that
strengthen the investment committee’s collective qualifications, skills and
experience.
Board
Leadership Structure
Our Board of Directors monitors and
performs an oversight role with respect to our business and affairs, including
with respect to investment practices and performance, compliance with
regulatory requirements and the services, expenses and performance of our
service providers. Among other things, our Board of Directors approves the
appointment of our Adviser and officers, reviews and monitors the services and
activities performed by our Adviser and executive officers and approves the
engagement, and reviews the performance of, our independent registered public
accounting firm. Our Board also quarterly ratifies our Adviser’s selection of assets
for our portfolio.
Under our Bylaws, our Board of
Directors may designate a chairman to preside over the meetings of the Board of
Directors and meetings of the stockholders and to perform such other duties as
may be assigned to him by the board. We do not have a fixed policy as to
whether the chairman of the board should be an Independent Director and believe
that we should maintain the flexibility to select the chairman and reorganize
the leadership structure, from time to time, based on the criteria that is in
our best interests and our stockholders best interests at such times.
Presently, Chip Patterson serves as
the chairman of our Board of Directors. Chip Patterson is not an Independent
Director because he is on the investment committee of our Adviser and is the
manager and managing member of our Adviser and Administrator,
respectively. We believe Mr. Patterson
is qualified to serve on our Board of Directors because of his history with
affiliated private funds, familiarity with our investment platform and his
extensive knowledge of the real estate industry, legal and regulatory framework
governing investment companies, business development companies, investment
advisers, and investment valuation process. We believe that we are best served
through this existing leadership structure, as Mr. Patterson’s relationship
with our Adviser provides an effective bridge and encourages an open dialogue
between management and the Board of Directors, ensuring that both groups act
with a common purpose.
Our Board of Directors does not
currently have a designated lead Independent Director. We are aware of the
potential conflicts that may arise when a non‑Independent Director is chairman
of the board, but believe these potential conflicts are offset by our strong
corporate governance policies. Our corporate governance policies include
regular meetings of the Independent Directors in executive session without the
presence of interested directors and management, the establishment of audit and
nominating and corporate governance committees comprised solely of Independent
Directors and the appointment of a Chief Compliance Officer, with whom the Independent
Directors meet regularly without the presence of interested directors and other
members of management, for administering our compliance policies and
procedures.
None of the Directors currently
serves as a director for any other public company. Further, no Director holds
any ownership interest in MRC. The Independent Directors will be paid an annual
retainer of $48,000 and the chair of the audit committee will be paid an
additional retainer of $1,000 and each Director will be paid a meeting
attendance fee of $1,000 for attending in‑person meetings and $500 for
telephonic meetings, not expected to be held more than quarterly, of the Board
and the audit committee.
We recognize that different board
leadership structures are appropriate for companies in different situations. We
believe that the Board’s structure is appropriate for our operations and having
a class of securities which is registered under the 1934 Act, in that its
members possess an appropriate depth and breadth of experience relating to our
planned investment program. We intend to re‑examine our corporate governance
policies on an ongoing basis to ensure that they continue to meet our needs.
Board’s Role In Risk Oversight
Our Board of Directors performs its
risk oversight function primarily through (i) its three standing committees,
which report to the entire Board of Directors and are comprised solely of
Independent Directors, and (ii) active monitoring of our chief compliance
officer and our compliance policies and procedures.
As described below in more detail
under “Committees of the Board of Directors,” the audit committee, the
compensation committee, and the nominating committee assist the Board of
Directors in fulfilling its risk oversight responsibilities. The audit
committee’s risk oversight responsibilities include overseeing our accounting
and financial reporting processes, our systems of internal controls regarding
finance and accounting, our valuation process, and audits of our consolidated
financial statements. The nominating committee’s risk oversight
responsibilities include selecting, researching and nominating directors for
election by our stockholders, developing and recommending to the board a set of
corporate governance principles and overseeing the evaluation of the board and
our management. The compensation
committee assists the Board with oversight of the performance of, and the fees
paid to, the Company’s external advisers, and oversight of the compensation of
our Independent Directors. We do not
compensate our non-independent directors or any of our other executive officers
and, because we are externally managed, we have no employees at the corporate
level.
Our Board of Directors also performs
its risk oversight responsibilities with the assistance of the CCO. The Board
of Directors will annually review a written report from the CCO discussing the
adequacy and effectiveness of our compliance policies and procedures and those
of our service providers. The CCO’s annual report will address, at a minimum,
(i) the operation of our compliance policies and procedures and those of our
service providers since the last report; (ii) any material changes to such
policies and procedures since the last report; (iii) any recommendations for
material changes to such policies and procedures as a result of the CCO’s
annual review; and (iv) any compliance matter that has occurred since the date
of the last report about which the Board of Directors would reasonably need to
know to oversee our compliance activities and risks. In addition, the CCO will
meet separately in executive session with the Independent Directors at least
once each year.
We recognize that different board
roles in risk oversight are appropriate for companies in different situations.
We intend to re‑examine the manners in which the board administers its
oversight function on an ongoing basis to ensure that they continue to meet our
needs.
Committees
of the Board of Directors
An audit committee, a compensation
committee, and a nominating committee have been established by our Board of
Directors. All directors are expected to attend at least 75.0% of the aggregate
number of meetings of the Board of Directors and of the respective committees
on which they serve. We require each director to make a diligent effort to
attend all board and committee meetings as well as each annual meeting of our
stockholders.
Audit Committee
The
audit committee operates under a charter approved by our Board of Directors,
which contains the responsibilities of the audit committee. The audit
committee’s responsibilities include establishing guidelines and making
recommendations to our Board of Directors regarding the valuation of our loans
and investments, selecting our independent registered public accounting firm,
reviewing with such independent registered public accounting firm the planning,
scope and results of their audit of our consolidated financial statements, pre‑approving
the fees for services performed, reviewing with the independent registered
public accounting firm the adequacy of internal control systems, reviewing our
annual consolidated financial statements and periodic filings and receiving our
audit reports and consolidated financial statements. The audit committee is
currently composed of Messrs. Dozois and Frame, and Ms. Hatch, all of whom are
Independent Directors as defined by the Nasdaq Board Independence Standards.
Mr. Dozois serves as chairman of the audit committee. We have determined that
Mr. Dozois is an audit committee financial expert, as defined in SEC
rules. The audit committee met 4 times
during the fiscal year ended June 30, 2026.
Nominating
Committee
The nominating committee operates
under a charter approved by our Board of Directors. The members of the
nominating committee are Messrs. Dozois and Frame, and Ms. Hatch, all of whom
are Independent Directors. Mr. Frame serves as chairman of the nominating
committee. The nominating committee is responsible for selecting, researching
and nominating directors for election by our stockholders, selecting nominees
to fill vacancies on the Board of Directors or a committee thereof, developing
and recommending to the Board of Directors a set of corporate governance
principles and overseeing the evaluation of the Board of Directors and our
management. The nominating committee currently does not consider nominees recommended
by our stockholders.
The nominating committee seeks
candidates who possess the background, skills and expertise to make a
significant contribution to the Board of Directors, our operations, and our
stockholders. In considering possible candidates for election as a director, the
nominating committee takes into account, in addition to such other factors as
it deems relevant, the desirability of selecting directors who:
● are of high character and integrity;
● are accomplished in their respective fields, with superior
credentials and recognition;
● have relevant expertise and experience upon which to be able
to offer advice and guidance to management;
● have sufficient time available to devote to our affairs;
● are able to work with the other members of the Board of
Directors and contribute to our success;
● can represent the long‑term interests of our stockholders as
a whole; and
● are selected such that the Board of Directors represents a
range of backgrounds and experience.
The nominating committee has not
adopted a formal policy with regard to the consideration of diversity in
identifying director nominees. In determining whether to recommend a director
nominee, the nominating committee considers and discusses diversity, among
other factors, with a view toward the needs of the Board of Directors as a
whole. The nominating committee generally conceptualizes diversity expansively
to include, without limitation, concepts such as race, gender, national origin,
differences of viewpoint, professional experience, education, skill and other
qualities that contribute to the Board of Directors, when identifying and
recommending director nominees. The nominating committee believes that the
inclusion of diversity as one of many factors considered in selecting director
nominees is consistent with the nominating committee’s goal of creating a Board
of Directors that best serves our needs and the interests of our stockholders.
The nominating committee met one time
in the fiscal year ended June 30, 2026.
Compensation
Committee
Effective September 23, 2024, in
connection with our application to list the Company’s common stock on Nasdaq,
the Board of Directors established a separate Compensation Committee composed
of Messrs. Dozois and Frame and Ms. Hatch, all of whom are Independent
Directors. At the present time, the
Compensation Committee’s responsibilities will include only assisting the Board
with oversight of the performance of, and the fees paid to, the Company’s
external advisers, and oversight of the compensation of our Independent
Directors. We do not compensate our
non-independent directors or any of our other executive officers and, because
we are externally managed, we have no employees at the corporate level.
Compensation of Directors
Our Independent Directors receive an
annual retainer of $48,000. They also receive $1,000 plus reimbursement of
reasonable out‑of‑pocket expenses incurred in connection with attending each
board meeting in person and $500 for each telephonic meeting, and also receive
$500 plus reimbursement of reasonable out‑of‑pocket expenses incurred in
connection with attending each committee meeting. In addition, the chairman of
the audit committee receives an annual fee of $1,000 and each chairman of any
other committee receives an annual fee of $1,000 for their additional services,
if any, in these capacities. No compensation is expected to be paid to
directors who are not Independent Directors.
Compensation of Executive Officers
None of our officers receives direct
compensation from us. However, all of the executive officers, through their
indirect financial interest in our Adviser, will be entitled to a portion of
any advisory fees paid by us to our Adviser under the Advisory Agreement. The
Advisory Agreement will be reapproved on an annual basis by our Board of
Directors, including a majority of our Independent Directors.
EXECUTIVE COMPENSATION
Summary Compensation Of Executive
Officers
None of our named Executive Officers
was paid any cash compensation or granted any equity by us in either of the
last two fiscal years. As such, we have not included a Summary Compensation
Table. Further, we do not plan to award
any named Executive Officer any compensation for their services; they will only
be compensated through their ownership of our Advisers, and our Advisers will
compensate their executive officers out of the fees we pay our Advisers. Working
through our Advisers, our named Executive Officers, together with employees of
our Advisers, will perform asset management, acquisition of real estate assets,
property management, and financial management. Fees for these services
will be paid to our Advisers, and our Executive Officers will realize growth as
owners / members of our Advisers.
No Executive Has Any Outstanding Equity Awards
No named Executive Officer has any
unexercised options, stock that has not vested, or any equity incentive plan
awards.
We Have No Executive Officer
Retirement Plan
We have no plan that provides for
the payment of retirement benefits, or benefits that will be paid primarily
following retirement, including but not limited to tax-qualified defined
benefit plans, supplemental executive retirement plans, tax-qualified defined contribution
plans and nonqualified defined contribution plans.
No Plan Of Payment On Termination,
Resignation, Or Change In Control
We have no contract, agreement, plan
or arrangement that provide for the payment of a named Executive Officer at,
following, or in connection with resignation, retirement or other termination
of a named executive officer. We also have no contract, agreement, plan or
arrangement that provide for the payment of a named Executive Officer upon a
change in control or a change in the named executive officer’s responsibilities
following a change in control.
CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS
Advisory &
Administration Agreements
We entered into an
Advisory Management Agreement (i) with MCM Advisers, LP, which is owned by MPF
Founders LP, MPF Principals LP, and MPF Successors LP; and (ii) with MacKenzie
Real Estate Advisers, LP (“MREA”), which is owned by the same
individuals as own the owners of MCM Advisers, LP. Effective January 1, 2026,
the Company and MREA entered into a First Amendment to Advisory Management
Agreement (the “First Amendment”), disclosed on the Company’s Current
Report on Form 8-K filed December 30, 2025. Under the First Amendment, (i) the
Asset Management Fee was replaced with a monthly Base Management Fee equal to
1.25% of AUM; (ii) the Acquisition Fees and Subordinated Incentive Fee were
replaced with a quarterly Bonus Management Fee equal to 5% of the Company’s
AFFO from the prior quarter; and (iii) the term of the Advisory Management
Agreement was reset to five years from the Amendment Date, with the Company
retaining the discretion (revisited on each anniversary) to extend the
expiration date by an additional year. If the Company does not extend the term
by November 30 of any year, the Adviser may either (a) terminate the agreement
and receive an early termination fee equal to 24 times the Base Management Fee
paid for the month prior to termination or (b) continue the agreement for the
remaining term with the Base Management Fee increased to 2% of AUM. If the
Company elects to terminate the agreement, it must pay a termination fee equal
to three times the fees paid under the fee provisions during the 12 months
prior to termination; if the agreement is terminated by the Company for Cause
(as defined in the First Amendment), no termination fee is payable. Our
executive officers are employees of the Advisers, and our non-Independent
Director has extensive relationships with the Advisers. The Advisers’ address
is 89 Davis Road, Suite 100, Orinda, CA 94563. The Advisers’ affiliates manage
several private equity funds, and the Advisers and their affiliates may also
manage other funds in the future that may have investment mandates that are
similar, in whole and in part, with ours.
The Advisers and
affiliates may determine that an investment is appropriate for us and for one
or more of those other funds. In such event, depending on the availability of
such investment and other appropriate factors, the Advisers or its affiliates
may determine that we should invest side-by-side with one or more other funds.
Any such investments will be made only to the extent permitted by applicable
law and consistent with our Advisers’ allocation procedures, available upon
request.
MacKenzie Capital
Management, a California limited partnership, serves as our manager and
administrator. The principal executive offices of our Manager are located at 89
Davis Road, Suite 100, Orinda, CA. Our non-independent director has extensive
relationships with the Advisers. Pursuant to an Administration Agreement, our
Manager furnishes us with office facilities, equipment and clerical,
bookkeeping and recordkeeping services at such facilities. Under the
Administration Agreement, our Manager also performs, or oversees the
performance of, our required administrative services, which include, among
other things, being responsible for the financial records which we are required
to maintain and preparing reports to our stockholders. In addition, our Manager
assists us in determining and publishing our net asset value, oversees the
preparation and filing of our tax returns and the printing and dissemination of
reports to our stockholders, and generally oversees the payment of our expenses
and the performance of administrative and professional services rendered to us
by others. Payments under the Administration Agreement are equal to an amount
based upon our allocable portion of our Manager’s overhead in performing its
obligations under the Administration Agreement, including rent, the fees and
expenses associated with performing compliance functions and our allocable
portion of the compensation of our chief financial officer and our allocable
portion of the compensation of any administrative support staff. All such
allocations will be approved by the Independent Directors. Under the
Administration Agreement, our Manager also provides on our behalf managerial
assistance to those portfolio companies that request such assistance.
Our
Manager also provides administrative services to the Advisers. As a result, the
Advisers also reimburse our Manager for its allocable portion of our Manager’s
overhead, including rent, the fees and expenses associated with performing
compliance functions for the Advisers, and its allocable portion of the
compensation of any administrative support staff. To the extent the Advisers or
any affiliates manage other investment vehicles in the future, no portion of
any administrative services provided by our Manager to such other investment
vehicles will be charged to us.
License Agreement
We
have entered into the Administrative Agreement with our Manager under which it
has granted to us a non-exclusive, royalty-free license to use the name
“MacKenzie.” Under this agreement, we have a right to use the MacKenzie name
for so long as we engage the Adviser to serve as our investment adviser. Other
than with respect to this limited license, we will have no legal right to the
“MacKenzie” name.
Line of Credit
On January 22, 2025, we
entered into a line of credit agreement (“Line of Credit”) with
Patterson Real Estate Services, LP (“PRES”), an affiliate of the
Company’s Adviser. In accordance with the Line of Credit, we may borrow from
time to time up to $10,000,000 in maximum principal balance under the Line of
Credit, which balance shall bear interest at the annual rate of 10%. Each draw
on the Line of Credit shall incur a 2% origination fee payable to PRES, which
amount shall be added to the outstanding balance along with the applicable
advance. The Line of Credit had a stated maturity date of June 1, 2026, which
was extended through December 31, 2027.
On September 28, 2026, the maximum principal balance of the Line of
Credit was increased to $18,000,000.
The Board, including all
Independent Directors, approved of the Line of Credit after considering the
alternatives available in the market, the affiliation of PRES to our Adviser,
and our ability to make use of the Line of Credit in the best interests of stockholders.
Related Party
Transaction Approval
In
order to ensure that we did not engage in any affiliated transactions that are
unfair to the Company, we implemented certain written policies and procedures
whereby our executive officers screen each of our transactions for any possible
affiliations between the issuer in which we invest, us, companies controlled by
us and our executive officers and directors. We do not enter into any agreements
unless and until we are satisfied that doing so does not violate our Charter or
raise conflict of interest concerns or, if such concerns existed, we took
appropriate actions to seek board review for such transaction. Our Board of
Directors reviews these on an annual basis. In addition, our Board of Directors
approves all our advisory and administrative agreements.
We
have also adopted a Code of Ethics which applies to, among others, our senior
officers, including our Chief Executive Officer and Chief Financial Officer, as
well as all of our officers, directors and employees. Our Code of Ethics
requires that all employees and directors avoid any conflict, or the appearance
of a conflict, between an individual’s personal interests and our interests.
Pursuant to our Code of Ethics, each employee and director must disclose any
conflicts of interest, or actions or relationships that might give rise to a
conflict, to our Chief Compliance Officer. Our Audit Committee is charged with
approving any waivers under our Code of Ethics.
SELECTION, MANAGEMENT AND CUSTODY OF INVESTMENTS
Our
External Adviser
Our
Adviser will be responsible for:
● the selection, purchase and sale of our portfolio
investments;
● our financing activities;
● leasing of our Investment to tenants;
● sales of our assets in order to provide liquidity;
● maintenance and risk mitigation (including insurances
acquisition)
● providing us with real estate advisory services.
Our Adviser
will be responsible for our day-to-day operations and will perform (or will
cause to be performed) such services and activities relating to our assets and
operations as may be appropriate.
Accordingly,
we believe that our success will depend significantly upon the experience,
skill, resources, relationships and contacts of the senior officers and key
personnel of our Adviser and its affiliates. We believe that our future success
depends, in large part, upon our Adviser’s ability to hire and retain highly
skilled managerial, operational and marketing personnel.
See
Advisory Agreement and Exhibits 6.7 and 6.8.
Investment
Discretion
Our Adviser
is authorized to follow very broad investment guidelines established by our
Board of Directors. Our Board of Directors will periodically review our
investment guidelines and our portfolio of assets but will not, and will not be
required to, review all of our proposed investments, except in limited
circumstances as set forth in our investment policies.
In
addition, in conducting periodic reviews, our Board of Directors may rely
primarily on information provided to them by our Adviser.
Our Adviser
has great latitude within the broad parameters of our investment guidelines in
determining the types and amounts of assets in which to invest on our behalf,
including making investments that may result in returns that are substantially
below expectations or result in losses, which would materially and adversely
affect our business and results of operations, or may otherwise not be in the
best interests of our stockholders.
Even
though our Adviser will be providing real estate advisory services, our Adviser
is not a licensed asset manager.
SAFEKEEPING, TRANSFER AND DIVIDEND PAYING AGENT AND REGISTRAR
Our cash is held in safekeeping by
Summit Financial located at 2969 Broadway, Oakland CA 94611. Charles Schwab
& Co, Inc., 1945 Northwestern Drive, El Paso, Texas 79912-1108 serves as
custodian for most of our traded securities.
US Bank National Association, located at 1555 N. Rivercenter Drive,
Suite 300, Milwaukee, Wisconsin 53212, will serve as custodian with respect to
our non‑traded assets. MacKenzie Capital Management, LP will act as our
transfer agent, dividend paying agent, and registrar with respect to our
Preferred Shares, and Computershare, Inc. will so act with respect to our
common stock. The principal business address of our transfer agent for
preferred shares is 89 Davis Road, Suite 100, Orinda, CA 94563.
INVESTMENTS THROUGH CUSTODIAL ACCOUNTS
If you would like to purchase shares
through a custodial account (e.g., for an IRA or investment adviser custodial
account), we will pay the set-up fees for such account if you invest a minimum
of $50,000. After we pay the set-up fee, you will be responsible for the annual
maintenance fees charged by the custodian.
INDEPENDENT AUDITORS
The consolidated financial statements and
financial statement schedule of MacKenzie Realty Capital, Inc.(the “Company”)
incorporated in this Offering Statement by reference from the Annual Report on
Form 10-K of the Company for the year ended June 30, 2026, have been audited by
Baker Tilly US, LLP, independent auditors, as stated in their report, which is incorporated
herein by reference.
AVAILABLE INFORMATION
We have filed with the SEC a
registration statement on Form 1-A, together with all amendments and related
exhibits, under the Securities Act, with respect to our preferred shares
offered hereby.
We file with or submit to the SEC
annual, quarterly and current periodic reports, proxy statements and other
information meeting the informational requirements of the Exchange Act. We are
also required to provide stockholders with quarterly reports containing the
information contained in any quarterly report filed by us with the SEC. The SEC maintains an Internet site that
contains reports, proxy and information statements and other information filed
electronically by us with the SEC which is available on the SEC’s website at http://www.sec.gov. This information
will also be available free of charge by contacting us at MacKenzie Realty
Capital, Inc., 89 Davis Road, Suite 100, Orinda, CA 94563, by telephone at
(925) 631‑9100 or (800) 854‑8357, or on our website at http://www.mackenzierealty.com.
POLICIES WITH RESPECT TO CERTAIN TRANSACTIONS
Policy
Regarding Conflicts in Pecuniary Interest
We
do not have a policy that expressly restricts any of our directors, officers,
stockholders or affiliates, including our Adviser and its officers and
employees, from having a pecuniary interest in an investment in or from
conducting, for their own account, business activities of the type we conduct.
As
stated extensively in this Offering Circular, some members of our Board and
Executive Officers are the same individuals that serve as board members of our Adviser
and of several other investment structured and managed by them.
Competition
with Adviser and Affiliates
Our
Code of Ethics requires that all employees and directors avoid any conflict, or
the appearance of a conflict, between an individual’s personal interests and
our interests. Pursuant to our Code of Ethics, each employee and director must
disclose any conflicts of interest, or actions or relationships that might give
rise to a conflict, to our Chief Compliance Officer. Our Audit Committee is
charged with approving any waivers under our Code of Ethics.
LIMITATIONS OF LIABILITY
Liability
of our Directors and Officers is Limited
Maryland
law permits a Maryland corporation to include in its charter a provision
limiting the liability of its directors and officers to the corporation and its
stockholders for money damages except for liability resulting from (i) actual
receipt of an improper benefit or profit in money, property or services or (ii)
active and deliberate dishonesty established by a final judgment as being
material to the cause of action. Our Charter contains such a provision which
eliminates directors’ and officers’ liability to the maximum extent permitted
by Maryland law.
Our
Charter obligates us, to the maximum extent permitted by Maryland law, to
indemnify and pay or reimburse reasonable expenses in advance of final
disposition of a proceeding to, (a) any individual who is a present or former
director or officer of ours and who is made or threatened to be made a party
to, or witness in, the proceeding by reason of his or her service in that
capacity or (b) any individual who, while a director or officer of ours and at
our request, serves or has served as a director, officer, member, manager,
partner or trustee of another corporation, real estate investment trust, limited
liability company, partnership, joint venture, trust, employee benefit plan or any
other enterprise and who is made or threatened to be made a party to, or
witness in, the proceeding by reason of his or her service in that capacity.
The Charter also permits us, with the approval of the Board of Directors, to
indemnify and advance expenses to any person who served a predecessor of us in
any of the capacities described above and any of our employees or agents or any
employees or agents of our predecessor.
Maryland
law requires a corporation (unless its charter provides otherwise, which our
Charter does not) to indemnify a director or officer who has been successful in
the defense of any proceeding to which he or she is made, or threatened to be
made, a party by reason of his or her service in that capacity. Maryland law
permits a corporation to indemnify its present and former directors and
officers, among others, against judgments, penalties, fines, settlements and
reasonable expenses actually incurred by them in connection with any proceeding
to which they may be made, or threatened to be made, a party by reason of their
service in those or other capacities unless it is established that (i) the act
or omission of the director or officer was material to the matter giving rise
to the proceeding and (a) was committed in bad faith or (b) was the result of
active and deliberate dishonesty, (ii) the director or officer actually
received an improper personal benefit in money, property or services or (iii)
in the case of any criminal proceeding, the director or officer had reasonable
cause to believe that the act or omission was unlawful. However, under Maryland
law, a Maryland corporation may not indemnify for an adverse judgment in a suit
by or in the right of the corporation or for a judgment of liability on the
basis that a personal benefit was improperly received unless, in either, case a
court orders indemnification, and then only for expenses. In addition, Maryland
law permits a corporation to advance or reimburse reasonable expenses to a
director or officer in advance of final disposition of a proceeding upon the
corporation’s receipt of (y) a written affirmation by the director or officer
of his or her good faith belief that he or she has met the standard of conduct
necessary for indemnification by the corporation and (z) a written undertaking
by him or her or on his or her behalf to repay the amount paid or reimbursed by
the corporation if it is ultimately determined that the standard of conduct was
not met.
Liability
of our Adviser is Limited
Upon
approval of our Board of Directors, we are authorized to indemnify and advance
expenses to our Adviser. This obligation arises under our Advisory Agreement.
See Exhibit 6.8.
SEC
Position on Indemnification for Securities Act Liabilities
Insofar
as indemnification for liabilities arising under the Securities Act of 1933 may
be permitted to directors, officers or persons controlling the Company pursuant
to the foregoing provisions, the Company has been informed that in the opinion
of the Securities and Exchange Commission such indemnification is against
public policy as expressed in the Act and is therefore unenforceable.
Incorporation of Certain Financial Statement
Information by Reference
The following financial statement
information is incorporated by reference into this Offering Circular from our
Annual Report on Form 10-K for the fiscal year ended June 30, 2026, filed with
the Securities and Exchange Commission on September 28, 2026 (the “2026 Form10-K”):
- our audited consolidated balance sheets as of June 30, 2026 and June 30, 2025;
- our audited consolidated statements of operations, comprehensive income (loss), stockholders' equity, and cash flows for the fiscal years ended June 30, 2026 and June 30, 2025; and
- the related notes to the audited consolidated financial statements and the report of Baker Tilly US, LLP, our independent registered public accounting firm, thereon.
The 2026 Form 10-K, including the
financial statement information incorporated by reference into this Offering
Circular, is readily available and accessible free of charge on our website at
www.mackenzierealty.com/sec-filings, and on the SEC's EDGAR website at www.sec.gov.
We will provide, without charge, to each
holder of the securities offered hereby (including any beneficial owner) upon
written or oral request a copy of the financial statement information that has
been incorporated by reference in this Offering Circular. Requests for copies
should be directed to: Investor Relations, MacKenzie Realty Capital, Inc., 89
Davis Road, Suite 100, Orinda, CA 94563; telephone: (925) 631-9100 / (800)
854-8357; email: investors@mackenziecapital.com. The financial statement
information incorporated by reference may also be accessed at www.mackenzierealty.com/sec-filings.
MACKENZIE REALTY CAPITAL, INC.
UP TO $71,681,755.55 IN SHARES OF SERIES A, SERIES B,
AND SERIES C PREFERRED STOCK
OFFERING CIRCULAR
You should rely only on the information contained in this Offering
Circular. No dealer, salesperson or other individual has been authorized to
give any information or to make any representations that are not contained in
this Offering Circular. If any such information or statements are given or
made, you should not rely upon such information or representation. This Offering
Circular does not constitute an offer to sell any securities other than those
to which this Offering Circular relates, or an offer to sell, or a solicitation
of an offer to buy, to any person in any jurisdiction where such an offer or
solicitation would be unlawful. This Offering Circular speaks as of the date
set forth above. You should not assume that the delivery of this Offering Circular
or that any sale made pursuant to this Offering Circular implies that the
information contained in this Offering Circular will remain fully accurate and
correct as of any time subsequent to the date of this Offering Circular.
October [ ], 2026
PART III
INDEX OF EXHIBITS
Exhibit No.
|
Description of Document
|
| |
|
|
|
Contribution Agreement by and between MacKenzie Realty Operating Partnership, LP and the Addison Group, dated June 8, 2020 (incorporated by reference to the Registrant’s Form 8-K
(File No. 814-00961), filed on June 9, 2020)
|
| |
|
|
|
Membership Interest Purchase Agreement with The Wiseman Company, LLC, dated April 12, 2022 (incorporated by reference to the Registrant’s Form 8-K (File No. 000-55006), filed on
April 18, 2022)
|
| |
|
|
|
Contribution Agreement by and between MacKenzie Realty Capital, Inc., MacKenzie Realty Operating Partnership, LP and MacKenzie Apartment Communities, Inc., dated January 1, 2026 (incorporated by
reference to Registrant’s Form 10-Q, filed on May 15, 2026)
|
| |
|
|
|
Series A Preferred Articles Supplementary (incorporated by reference to Registrant’s Form 1-A (File No. 000-55006), filed on April 12, 2021)
|
| |
|
|
|
Series B Preferred Articles Supplementary (incorporated by reference to Registrant’s Form 1-A POS (File No. 024-11503), filed on November 13, 2023)
|
| |
|
|
|
Articles of Amendment and Restatement of MacKenzie Realty Capital, Inc., effective as of January 10, 2025 (incorporated by reference to the Registrant’s Form 8-K/A, filed on January 10,
2025)
|
| |
|
|
|
Articles Supplementary for the Series C Preferred Stock (incorporated by reference to the Registrant’s Offering Statement on Form 1-A, filed June 6, 2025)
|
| |
|
|
|
Third Amended and Restated Bylaws of MacKenzie Realty Capital, Inc., effective as of January 8, 2025 (incorporated by reference to the Registrant’s Form 8-K/A, filed on January 10, 2025)
|
| |
|
|
|
First Amendment of Charter Dated August 1, 2025 (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed on August 1, 2025)
|
| |
|
|
|
Second Amendment of Charter Dated August 1, 2025 (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed on August 1, 2025)
|
| |
|
4.1
|
Description of Securities (incorporated by reference to the Registrant’s Form 10-K (File No. 001-42402), filed on September 28, 2026) |
| |
|
|
|
Partnership Unit Designation of the Series A Preferred Limited Partnership Units of MacKenzie Realty Operating Partnership, LP (incorporated by reference to Registrant’s Form 10-K (File No.
000-55006), filed on September 28, 2022)
|
| |
|
10.1
|
Agreement of general financial advisory and investment banking services with Maxim Group LLC (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed on
August 27, 2024) |
| |
|
|
10.2 |
Agreement of Limited Partnership of MacKenzie Realty Operating Partnership, LP, Dated May 20, 2020 (incorporated by reference to the Registrant’s Form 8-K (File No. 814-00961 filed
on June 9, 2020) |
| |
|
|
10.3 |
Operating Agreement of PVT-Madison Partners LLC (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed onMarch 11, 2021) |
| |
|
|
10.4 |
Operating Agreement of Madison-PVT Partners LLC (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed onMarch 11, 2021) |
| |
|
|
10.5 |
Form of Investment Adviser Introducing Agreement (pre-December 2016) (incorporated by reference to the Registration Statement on Form N-2 (File No. 333-212804) filed on August 1,
2016) |
| |
|
|
10.6 |
Amended Administration Agreement with MacKenzie Capital Management, LP (incorporated by reference to Registrant’s Form 10-K (File No. 000-55006), filed on September 28, 2021) |
| |
|
|
10.7 |
Form of Investor Services Agreement with MacKenzie Capital Management, LP dated November 1, 2018 (incorporated by reference to Post-Effective Amendment No. 6 to the Registration
Statement on Form N-2 (File No. 333-212804), filed on May 10, 2019) |
| |
|
|
|
First Amendment to Advisory Management Agreement with MacKenzie Real Estate Advisers, LP (incorporated by reference to Exhibit 10.22 of the Registrant’s Form 8-K, filed on December 30, 2025)
|
| |
|
|
10.9 |
Amended And Restated Investment Advisory Agreement (incorporated by reference to Registrant’s Form 8-K (File No. 000-55006), filed on January 27, 2021) |
| |
|
|
10.10 |
Operating Agreement by and between MacKenzie Realty Operating Partnership, LP and the Hollywood Hillview Owner LLC, dated October 4, 2021 (incorporated by reference to the
Registrant’s Form 8-K (File No. 000-55006 filed on October 5, 2021) |
| |
|
|
10.11 |
Dividend Reinvestment Plan (incorporated by reference to Registrant’s Form S-3 (File No. 000-55006), filed on December 22, 2021) |
| |
|
|
10.12 |
Operating Agreement by and between MacKenzie Realty Operating Partnership, LP and the MacKenzie-BAA IG Shoreline LLC, dated January 25, 2022 (incorporated by reference to the
Registrant’s Form 8-K (File No. 000-55006 filed on May 20, 2022) |
| |
|
|
10.14 (i) |
Equity Distribution Agreement dated January 15, 2025 by and between MacKenzie Realty Capital, Inc. and Maxim Group LLC (incorporated by reference to the Registrant’s
Form 8-K, filed on January 15, 2025) |
| |
|
|
10.14 (ii) |
Amendment to the Equity Distribution Agreement, dated January 7, 2026, by and between MacKenzie Realty Capital, Inc. and Maxim Group LLC (incorporated by reference to the Registrant’s
Form 8-K, filed on January 14, 2026) |
| |
|
|
10.15 |
Agreement of Limited Partnership of MAC Operating Partnership, LP, dated March 4, 2026 (incorporated by reference to the Registrant’s Quarterly Report on Form 10Q,
filed on May 15, 2026) |
| |
|
|
10.16 |
Securities Purchase Agreement, dated November 18, 2024, between the company and purchaser (incorporated by reference to the Registrant’s Form 8-K, filed on March 3,
2025) |
| |
|
|
10.17 |
Forbearance, Settlement, and Release Agreement dated March 25, 2025, related to Main Street West Property Indebtedness (incorporated by reference to the Registrant’s
Form 8-K, filed on March 31, 2025) |
| |
|
|
10.18 (i) |
Note Purchase Agreement dated June 11, 2025 by and between the Company and Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed
on June 11, 2025) |
|
10.18 (ii) |
Secured Promissory Note #1 dated June 11, 2025 issued by the Company in favor of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on June 11,
2025)
|
| |
|
|
10.18 (iii) |
Security Agreement dated June 11, 2025 by MRC QRS, Inc. in favor of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on June
11, 2025) |
| |
|
|
10.18 (iv) |
Guaranty dated June 11, 2025 by MRC QRS, Inc. for the benefit of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on June 11, 2025)
|
| |
|
|
10.18 (v) |
Stock Pledge Agreement dated June 11, 2025 by and between the Company and Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on
June 11, 2025) |
| |
|
10.19
|
Secured Promissory Note #2 dated August 1, 2025 issued by the Company in favor of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on January 21, 2026) |
| |
|
|
10.20 |
Secured Promissory Note #3 dated January 15, 2026 issued by the Company in favor of Streeterville Capital, LLC (incorporated by reference to Exhibit 10.2 of the Registrant’s Form 8-K, filed on January 21, 2026)
|
| |
|
10.21(i)
|
Note Purchase Agreement dated March 6, 2026 by and between the Company and Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K,
filed on March 6, 2026)
|
| |
|
| 10.21(ii) |
Secured Promissory Note dated March 6, 2026 issued by the Company in favor of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K,
filed on March 6, 2026)
|
| |
|
| 10.21(iii) |
Security Agreement dated March 6, 2026 by MRC QRS, Inc. in favor of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on
March 6, 2026)
|
| |
|
| 10.21(iv) |
Guaranty dated March 6, 2026 by MRC QRS, Inc. for the benefit of Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed on March
6, 2026)
|
| |
|
| 10.21(v) |
Stock Pledge Agreement dated March 6, 2026 by and between the Company and Streeterville Capital, LLC (incorporated by reference to the Registrant’s Form 8-K, filed
on March 6, 2026)
|
| |
|
| 11.1 |
Consent of Baker Tilly US, LLP* |
| |
|
| 11.2 |
Consent of Venable LLP (included in Exhbit 12.1) |
| |
|
| 12.1 |
Opinion of Venable LLP as to the legality of the securities being qualified (incorporated by reference to the Company's Offering Statement on Form 1-A, filed June 6, 2025) |
| |
|
|
16.1 |
Letter dated June 9, 2025 from Moss Adams to the Securities and Exchange Commission confirming the disclosures contained in Item 4.01 of the report on Form 8-K (incorporated
by reference to the Registrant’s Form 8-K, filed on June 10, 2025) |
| |
|
|
19 |
Insider Trading Policy of MacKenzie Realty Capital, Inc. contained in Item 10 of the report on Form 10-K (incorporated by reference to the Registrant’s Form 10-K,
filed on September 29, 2025) |
| |
|
|
21.1 |
List of Subsidiaries of the Registrant (incorporated by reference to the Registrant’s Form 10-K (File No. 001-42402), filed on September 28, 2026) |
| |
|
|
97.1 |
MacKenzie Realty Capital, Inc. Executive Compensation Clawback Policy, effective as of October 2, 2023. (incorporated by reference
to the Registrant’s Form 10-K, filed on September 29, 2025) |
** Management contract or compensatory plan or arrangement filed pursuant to Item 601(b) (10) (iii) of Regulation S-K.
All other exhibits for which provision is made in the applicable regulations of the Securities and Exchange Commission are not required under the related instruction or are inapplicable and
therefore have been omitted.
SIGNATURES
Pursuant to the requirements of Regulation A, the issuer certifies that it has reasonable grounds to believe that it meets all
of the requirements for filing on Form 1-A and has duly caused this offering statement to be signed on its behalf by the undersigned, thereunto duly authorized, in the City of Orinda, State of California, on October 9,
2026.
Mackenzie Realty Capital, Inc.
By: /s/ Robert Dixon
Name: Robert Dixon
Title: Chief Executive Officer
This offering statement has been signed below by the following persons in the capacities and on the dates indicated.
|
Signature
|
Title
|
Date
|
|
|
|
|
|
/s/ Robert Dixon
|
Chief Executive Officer
|
October 9, 2026
|
|
Robert Dixon
|
(Principal Executive Officer)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Angche Sherpa
|
Chief Financial Officer
|
October 9, 2026
|
|
Angche Sherpa
|
(Principal Financial and Accounting Officer)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Chip Patterson
|
Director
|
October 9, 2026
|
|
Chip Patterson
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Tim Dozois
|
Director
|
October 9, 2026
|
|
Tim Dozois
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Tom Frame
|
Director
|
October 9, 2026
|
|
Tom Frame
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Kjerstin Hatch
|
Director
|
October 9, 2026
|
|
Kjerstin Hatch
|
|
|