Exhibit 99.2 NASDAQ: DTI BUILDING FOR THE FUTURE DTI TO ACQUIRE SALTIRE ENERGY DRILLINGTOOLS.COM
FORWARD LOOKING STATEMENTS This presentation contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”) and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), including statements within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements include, among other things, statements regarding the proposed acquisition of Saltire Energy Limited (Saltire) by Drilling Tools International Corporation (DTI); the anticipated timing, completion and benefits of the transaction; expected synergies, financial impact, business plans, market opportunities and future operating performance of the combined company; and other statements that are not historical facts. The words “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intend,” “may,” “might,” “plan,” “possible,” “potential,” “predict,” “project,” “should,” “will,” “would,” and similar expressions identify forward-looking statements, but the absence of these words does not mean that a statement is not forward looking. These statements are based on DTI’s and Saltire’s current expectations, assumptions and beliefs and are subject to risks, uncertainties and changes in circumstances that could cause actual results to differ materially from those expressed or implied. These risks include, among others: the possibility that the transaction may not be completed on the anticipated terms or timing, or at all; failure to satisfy closing conditions, including DTI stockholder approval and the financing conditions, or obtain required regulatory approvals including Nasdaq listing approval; disruption to the businesses of DTI or Saltire during the pendency of the transaction; the risk that anticipated benefits, cost savings or synergies may not be realized as expected or within the anticipated timeframe; integration challenges; customer, employee, supplier or other stakeholder reactions; transaction-related costs; risks related to the cross-border nature of the transaction; foreign exchange rate fluctuations between the U.S. dollar and British pound sterling; differences in legal, regulatory, tax and accounting frameworks between the United States and the United Kingdom; competitive, economic, market and industry conditions; and other risks described in DTI’s filings with the Securities and Exchange Commission. Forward-looking statements speak only as of the date of this presentation. Neither DTI nor Saltire undertakes any obligation to update or revise these statements, except as required by applicable law. This presentation is for informational purposes only and does not constitute an offer to sell or the solicitation of an offer to buy any securities, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. In connection with the proposed transaction, DTI intends to file with the SEC a registration statement, proxy statement or other documents. Investors and security holders of DTI are urged to read the proxy statement/prospectus and any other relevant documents filed with the SEC when they become available, because they will contain important information about DTI, Saltire and the proposed transaction. This presentation includes Adjusted EBITDA, Adjusted EBITDA Margin, and Adjusted Free Cash Flow, each a non-GAAP financial measure. Adjusted EBITDA is net income (loss) before interest, taxes, depreciation, and amortization, adjusted for impairment, stock-based compensation, restructuring, transaction costs, and other non-recurring items. Adjusted Free Cash Flow is Adjusted EBITDA less Gross Capital Expenditures. Reconciliations are in DTI’s press release and SEC filings. DTI is unable to reconcile forward-looking non-GAAP measures without unreasonable effort, because certain items are uncertain or out of DTI’s control. 2
TRANSACTION OVERVIEW BY THE CEO Acquiring Saltire Energy Building for the Future This transaction brings together two highly complementary businesses to create a larger, more balanced and resilient global platform. The addition of Saltire is expected to meaningfully improve our scale, expand our Eastern Hemisphere presence, and strengthen our margin profile and free cash flow generation capabilities on day one. This deal also broadens our customer relationships, and we gain a proven team with deep industry knowledge and expertise. The combined company pairs the stability and cash generation of our North American business with direct exposure to markets we believe will be an increasingly important source of growth in the future. Just as importantly, Saltire’s founders, the Loggie family, are retaining a significant ownership position in the combined company. This reflects a shared conviction that these businesses are stronger together and that the most meaningful value creation is still ahead of us. We are building for the future, and this partnership will further solidify our foundation.” Wayne Prejean Chairman of the Board and Chief Executive Officer 3
Transaction Highlights 1 Natural Strategic Fit 2 Transformational Scale and Diversification 3 Immediate Financial Enhancement Building for the Future 4 Compelling Standalone Economics 5 Clear Deleveraging Path 6 Long-term Seller Alignment 4
Building for the Future Delivering Value to Customers & Stockholders Customers Stockholders • Meets growing demand with a • Provides enhanced exposure to global one-stop-shop platform global rig activity and energy security tailwinds • Proven, high-performing teams with deep knowledge and expertise in • Superior execution through the most technically challenging disciplined management and best drilling environments operating practices • Enhances our capability to innovate • Expected to be accretive to and deploy leading technology (e.g., Adjusted EBITDA margin & ClearPath & Drill-N-Ream) Adjusted FCF per share without cost synergies in Year 1 • Improved performance for (1) customers through increased • Cash and stock transaction with financial strength an attractive 5.5x EV/EBITDA multiple paid 1) Based on a purchase price of approximately $80 million of cash, 17.4 million shares of DTI common stock 5 valued at a 20-day VWAP as of 10/1/26, and Saltire’s run rate EBITDA of $22.5 million
Structured for Success • Cash consideration – approximately $80 million • Share consideration – 17.4 million shares Deal Structure • Accretive cash and stock transaction • Chairman & CEO: Wayne Prejean Leadership & Governance • Mike Loggie, Saltire’s founder, and all members of Saltire’s management team to remain with DTI • Subject to customary regulatory approvals and closing conditions and satisfaction of the financing conditions Next Steps • Approval from DTI stockholders • Expected to close in the first quarter of 2027 6
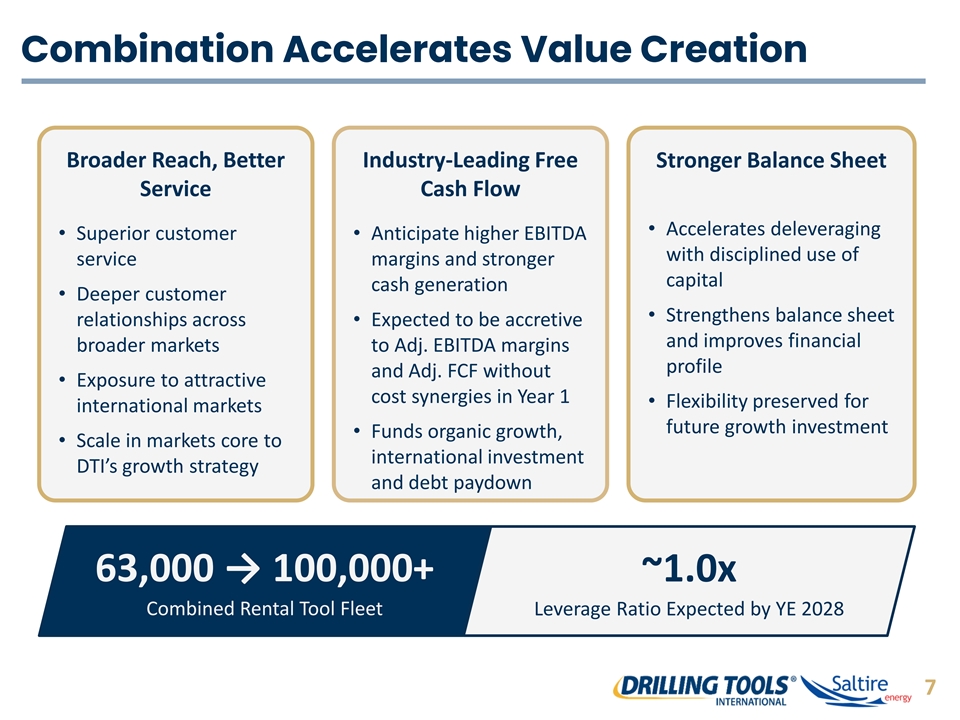
Combination Accelerates Value Creation Broader Reach, Better Industry-Leading Free Stronger Balance Sheet Service Cash Flow • Accelerates deleveraging • Superior customer • Anticipate higher EBITDA with disciplined use of service margins and stronger capital cash generation • Deeper customer • Strengthens balance sheet relationships across • Expected to be accretive and improves financial broader markets to Adj. EBITDA margins profile and Adj. FCF without • Exposure to attractive cost synergies in Year 1 • Flexibility preserved for international markets future growth investment • Funds organic growth, • Scale in markets core to international investment DTI’s growth strategy and debt paydown 63,000 → 100,000+ ~1.0x Combined Rental Tool Fleet Leverage Ratio Expected by YE 2028 7
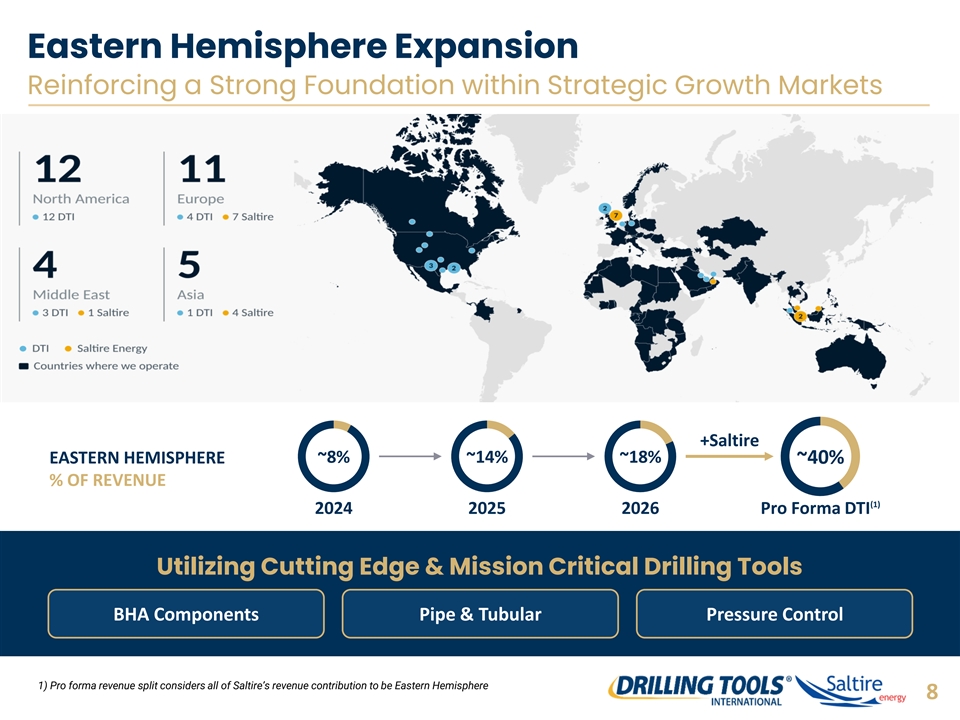
Eastern Hemisphere Expansion Reinforcing a Strong Foundation within Strategic Growth Markets +Saltire ~8% ~14% ~18% EASTERN HEMISPHERE ~40% % OF REVENUE (1) 2024 2025 2026 Pro Forma DTI Utilizing Cutting Edge & Mission Critical Drilling Tools BHA Components Pipe & Tubular Pressure Control 1) Pro forma revenue split considers all of Saltire’s revenue contribution to be Eastern Hemisphere 8
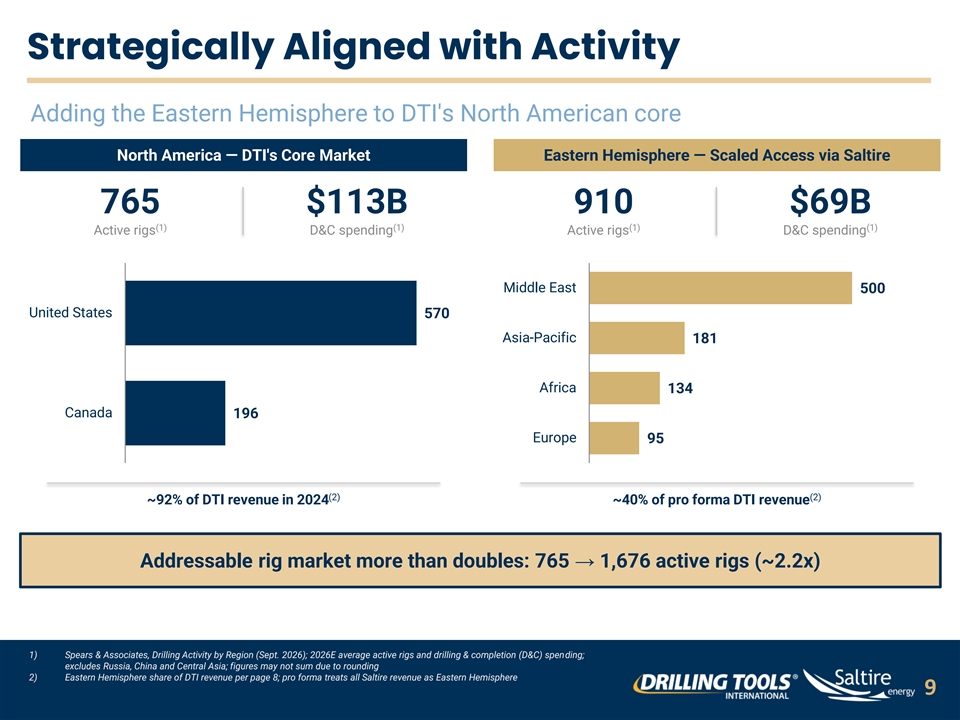
Strategically Aligned with Activity Adding the Eastern Hemisphere to DTI's North American core North America — DTI's Core Market Eastern Hemisphere — Scaled Access via Saltire 765 $113B 910 $69B (1) (1) (1) (1) Active rigs D&C spending Active rigs D&C spending Middle East 500 United States 570 Asia-Pacific 181 Africa 134 Canada 196 Europe 95 (2) (2) ~92% of DTI revenue in 2024 ~40% of pro forma DTI revenue Addressable rig market more than doubles: 765 → 1,676 active rigs (~2.2x) 1) Spears & Associates, Drilling Activity by Region (Sept. 2026); 2026E average active rigs and drilling & completion (D&C) spending; excludes Russia, China and Central Asia; figures may not sum due to rounding 2) Eastern Hemisphere share of DTI revenue per page 8; pro forma treats all Saltire revenue as Eastern Hemisphere 9
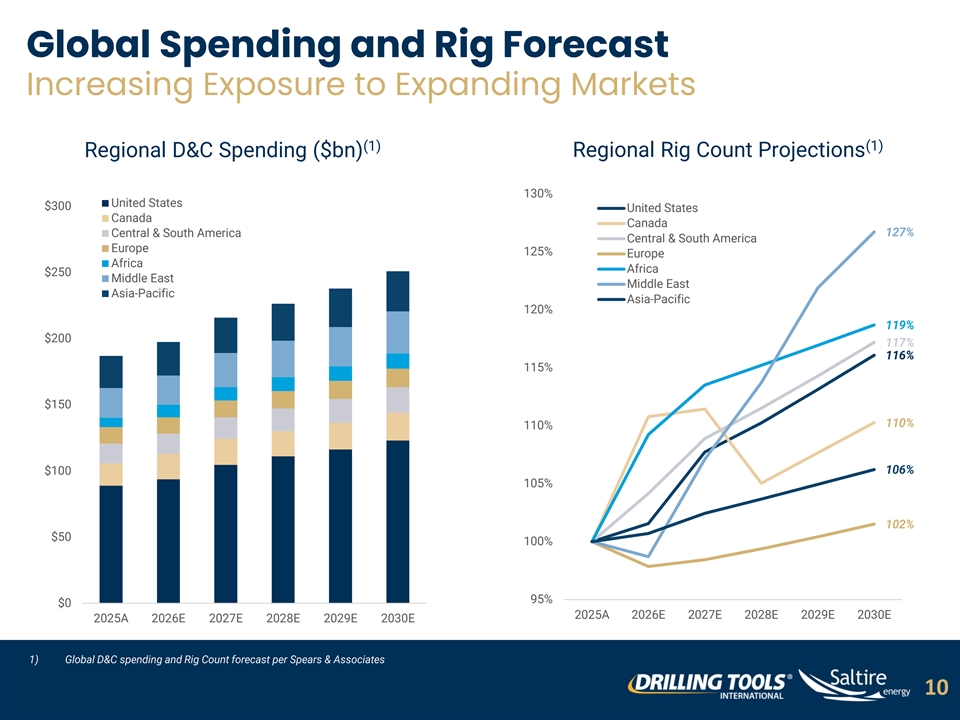
Global Spending and Rig Forecast Increasing Exposure to Expanding Markets (1) (1) Regional D&C Spending ($bn) Regional Rig Count Projections 130% United States $300 United States Canada Canada 127% Central & South America Central & South America Europe 125% Europe Africa Africa $250 Middle East Middle East Asia-Pacific Asia-Pacific 120% 119% $200 117% 116% 115% $150 110% 110% $100 106% 105% 102% $50 100% 95% $0 2025A 2026E 2027E 2028E 2029E 2030E 2025A 2026E 2027E 2028E 2029E 2030E 1) Global D&C spending and Rig Count forecast per Spears & Associates 10
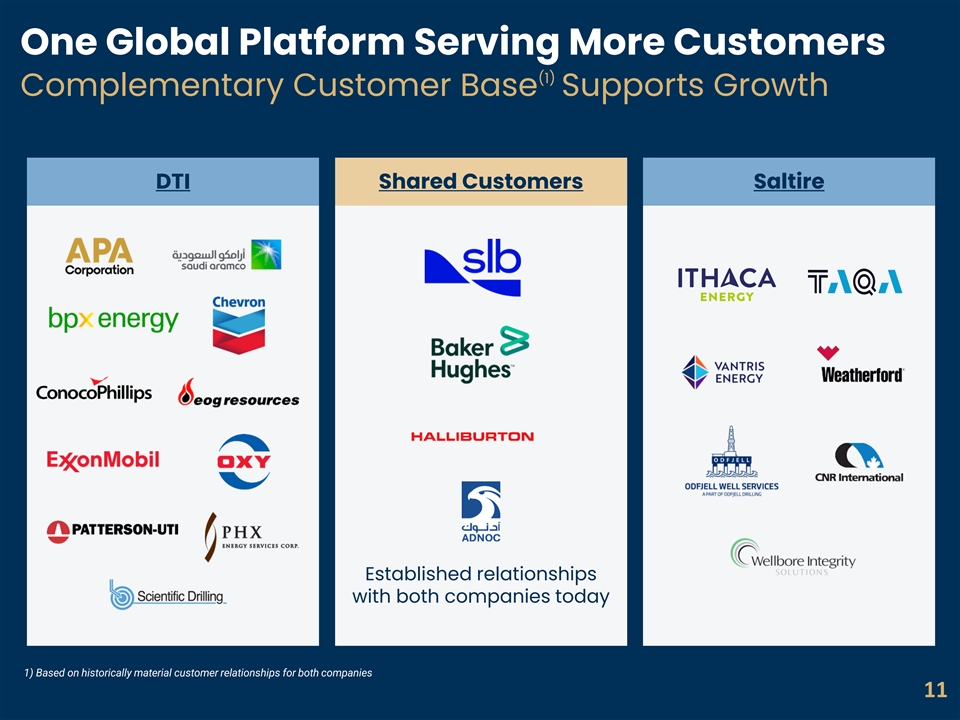
One Global Platform Serving More Customers (1) Complementary Customer Base Supports Growth DTI Shared Customers Saltire Established relationships with both companies today 1) Based on historically material customer relationships for both companies 11
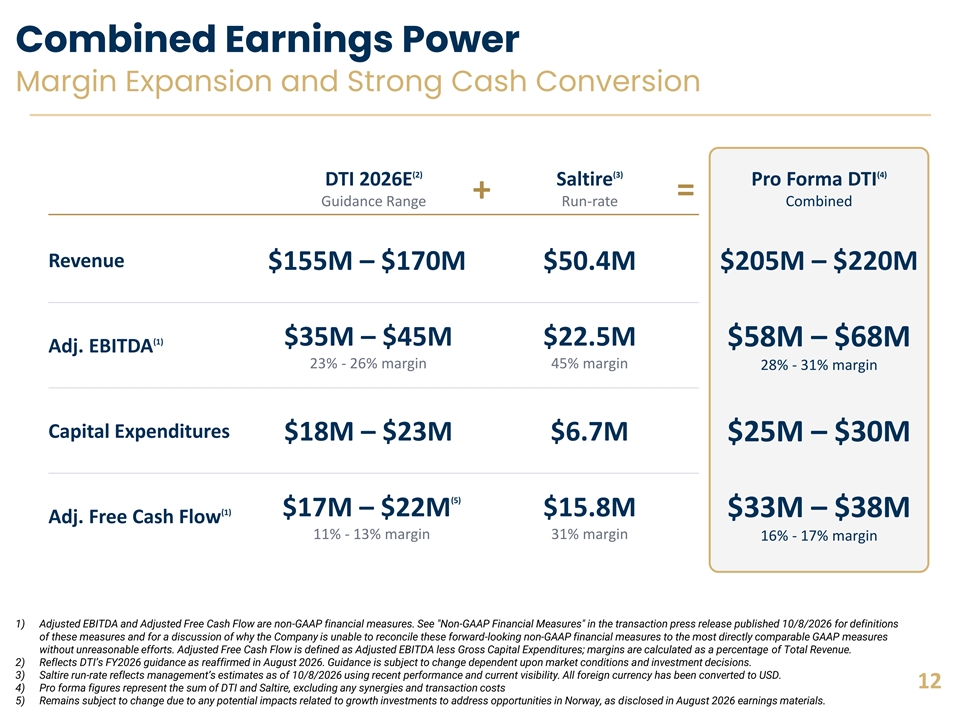
Combined Earnings Power Margin Expansion and Strong Cash Conversion (2) (3) (4) DTI 2026E Saltire Pro Forma DTI + = Guidance Range Run-rate Combined Revenue $155M – $170M $50.4M $205M – $220M (1) $35M – $45M $22.5M $58M – $68M Adj. EBITDA 23% - 26% margin 45% margin 28% - 31% margin Capital Expenditures $18M – $23M $6.7M $25M – $30M (5) (1) $17M – $22M $15.8M $33M – $38M Adj. Free Cash Flow 11% - 13% margin 31% margin 16% - 17% margin 1) Adjusted EBITDA and Adjusted Free Cash Flow are non-GAAP financial measures. See Non-GAAP Financial Measures in the transaction press release published 10/8/2026 for definitions of these measures and for a discussion of why the Company is unable to reconcile these forward-looking non-GAAP financial measures to the most directly comparable GAAP measures without unreasonable efforts. Adjusted Free Cash Flow is defined as Adjusted EBITDA less Gross Capital Expenditures; margins are calculated as a percentage of Total Revenue. 2) Reflects DTI’s FY2026 guidance as reaffirmed in August 2026. Guidance is subject to change dependent upon market conditions and investment decisions. 3) Saltire run-rate reflects management’s estimates as of 10/8/2026 using recent performance and current visibility. All foreign currency has been converted to USD. 12 4) Pro forma figures represent the sum of DTI and Saltire, excluding any synergies and transaction costs 5) Remains subject to change due to any potential impacts related to growth investments to address opportunities in Norway, as disclosed in August 2026 earnings materials.
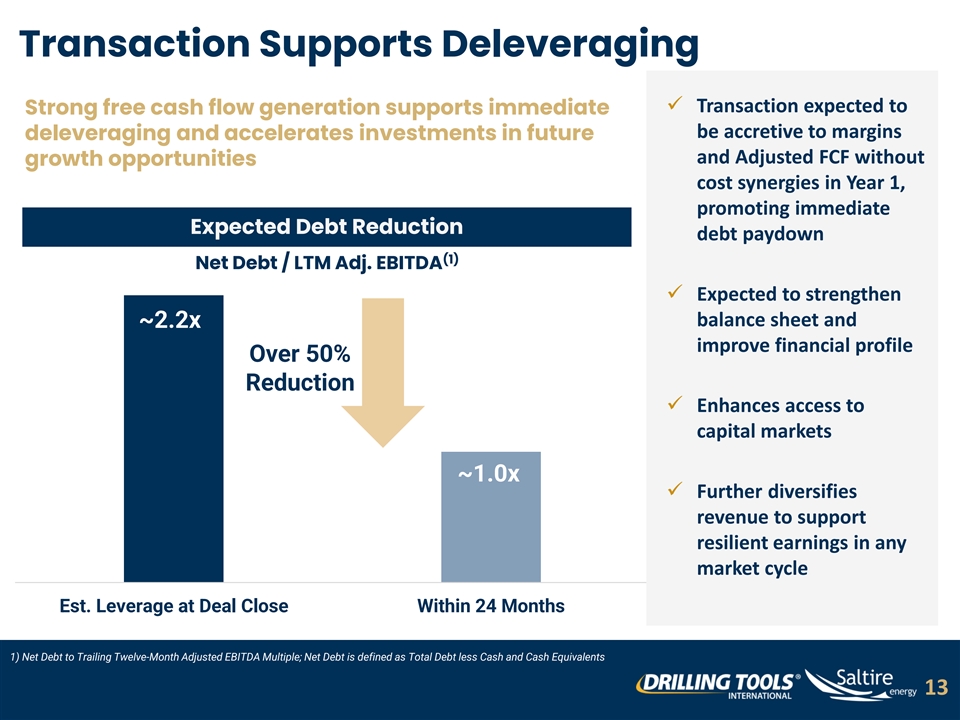
Transaction Supports Deleveraging ✓ Transaction expected to Strong free cash flow generation supports immediate be accretive to margins deleveraging and accelerates investments in future and Adjusted FCF without growth opportunities cost synergies in Year 1, promoting immediate Expected Debt Reduction debt paydown (1) Net Debt / LTM Adj. EBITDA ✓ Expected to strengthen balance sheet and ~2.2x improve financial profile Over 50% Reduction ✓ Enhances access to capital markets ~1.0x ✓ Further diversifies revenue to support resilient earnings in any market cycle Est. Leverage at Deal Close Within 24 Months 1) Net Debt to Trailing Twelve-Month Adjusted EBITDA Multiple; Net Debt is defined as Total Debt less Cash and Cash Equivalents 13
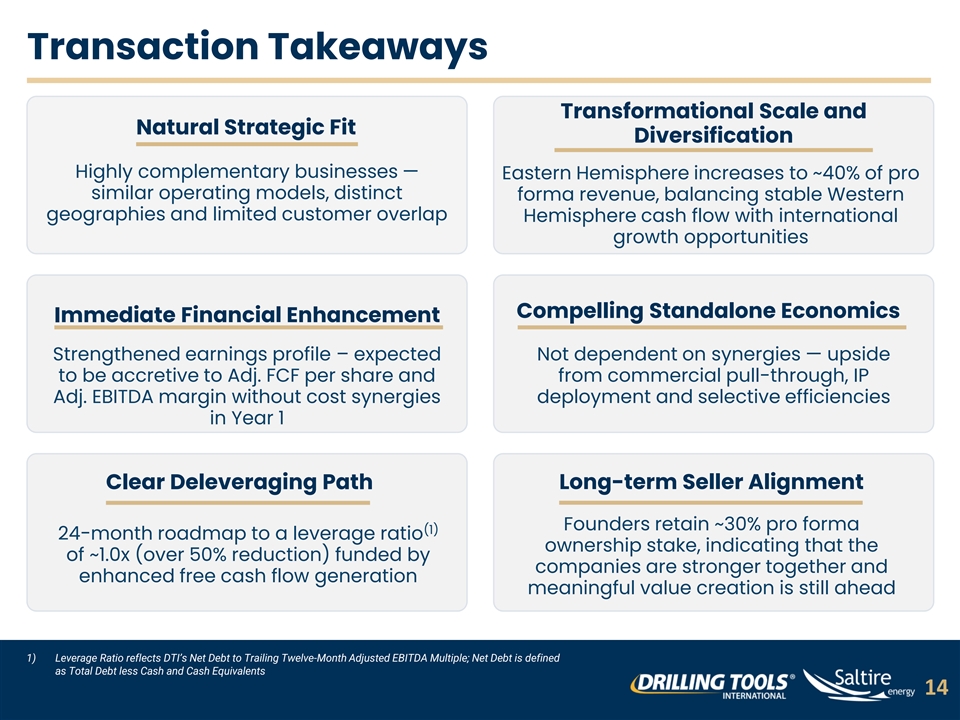
Transaction Takeaways Transformational Scale and Natural Strategic Fit Diversification Highly complementary businesses — Eastern Hemisphere increases to ~40% of pro similar operating models, distinct forma revenue, balancing stable Western geographies and limited customer overlap Hemisphere cash flow with international growth opportunities Compelling Standalone Economics Immediate Financial Enhancement Strengthened earnings profile – expected Not dependent on synergies — upside to be accretive to Adj. FCF per share and from commercial pull-through, IP Adj. EBITDA margin without cost synergies deployment and selective efficiencies in Year 1 Clear Deleveraging Path Long-term Seller Alignment Founders retain ~30% pro forma (1) 24-month roadmap to a leverage ratio ownership stake, indicating that the of ~1.0x (over 50% reduction) funded by companies are stronger together and enhanced free cash flow generation meaningful value creation is still ahead 1) Leverage Ratio reflects DTI’s Net Debt to Trailing Twelve-Month Adjusted EBITDA Multiple; Net Debt is defined as Total Debt less Cash and Cash Equivalents 14