These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Exhibit 99.2 Investor Presentation October 5, 2026 NASDAQ: DSGR S T R I C T L Y P R I V A T E A N D C O N F I D E N T I A L
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Disclaimers Title bar/Bullets 68 87 128 By accepting this presentation, the recipient agrees (in addition to any obligations it may have under any confidentiality agreement) that neither it nor its agents, representatives, directors, officers, affiliates or employees will copy, reproduce or distribute to others this presentation, in whole or in part, at any time without the prior written consent of the Company and that it will keep permanently confidential all information contained herein not already in the public domain. This presentation has been prepared by or on behalf of Distribution Solutions Group, Inc. (together with its subsidiaries, the ACCENTS “Company” or “DSG”) to assist interested parties in making their own evaluation of the Company and does not purport to be all-inclusive or to contain all of the information regarding the Company. In giving this presentation, none of the Company or any of its subsidiaries, or any of any such person’s directors, officers, employees, agents, affiliates or advisers, undertakes any obligation to amend, correct or update this presentation or to provide the recipient with access to any additional information that may arise in connection with it. Certain information contained herein is derived from official or 2 85 third-party sources. Third party industry publications, studies and surveys generally state that the data contained therein have been obtained from sources believed to be reliable, but that there is no guarantee of the accuracy or completeness of such data. While the Company believes that each of 25 141 1 these publications, studies and surveys has been prepared by a reputable source, the Company has not independently verified the data contained therein. In addition, certain of the data contained in this presentation come from the Company’s own internal research and estimates based on the 70 250 knowledge and experience of the Company’s management in the market in which the Company operates. While the Company believes that such internal research and estimates and such other data are reasonable and reliable, they, and, where applicable, their underlying methodology and 68 173 assumptions, have not been verified by any independent source for accuracy or completeness and are subject to change without notice. 87 185 2 NO OFFER OR SOLICITATION 128 211 In the United States, this presentation is intended solely for, and is being furnished only to, persons that the issuer and the initial purchasers reasonably believe to be qualified institutional buyers (“QIBs”) as defined in Rule 144A under the U.S. Securities Act of 1933, as amended (the “Securities Act”). Outside the United States, this presentation is intended solely for, and is being furnished only to, persons who are not U.S. persons (as defined in Regulation S under the Securities Act) and who are located outside the United States in offshore transactions in reliance on Regulation S. Any 142 210 person that is not a QIB (in the United States) or that does not satisfy the foregoing (outside the United States) should not review these materials. By accepting this Presentation in the United States, you will be deemed to represent that you are either a QIB or a non-U.S. person. 169 221 3 This presentation is for informational purposes only and does not constitute an offer to sell or the solicitation of an offer to buy any securities, nor shall there be any sale, issuance or transfer of any securities, in any jurisdiction in contravention of applicable law. Any offer of notes will be made only 216 239 by means of the confidential offering memorandum. This presentation is qualified in its entirety by reference to the confidential offering memorandum relating to the offering. Investors should read the confidential offering memorandum in its entirety prior to making any investment decision. 255 255 FINANCIAL INFORMATION 196 231 4 This presentation contains financial information derived from the Company’s internal records or audited or unaudited financial statements for the relevant period. Such financial information is not a comprehensive statement of the Company’s financial results for the period and should not be viewed 38 168 as a substitute for full financial statements. The financial information is not necessarily indicative of any future period, and actual results may differ materially. The financial information should be read together with any relevant risk factors and forward-looking statements, and has been prepared by, and is the responsibility of, the Company’s management. 239 249 NON-GAAP FINANCIAL MEASURES, SEC REGULATION G GAAP RECONCILIATIONS 129 205 5 Some of the financial information and data contained in this presentation, such as Adjusted EBITDA, Pro Forma Adjusted EBITDA, Free Cash Flow, Net Working Capital, Adjusted Revenue, Adjusted EBITDA Margin, Free Cash Flow Conversion, Return on Net Working Capital (“RONWC”) and 35 167 Total Net Leverage Ratio have not been prepared in accordance with U.S. generally accepted accounting principles (“GAAP”). The Company believes that these non-GAAP financial measures provide useful information to management and investors regarding certain financial and business trends 213 238 relating to DSG’s financial condition and results of operations. DSG does not consider non-GAAP measures to be an alternative to financial measures determined in accordance with GAAP. The principal limitation of these non-GAAP financial measures is they may exclude significant expense and 213 238 income items that are required by GAAP to be recognized in our consolidated financial statements. In addition, they reflect the exercise of management’s judgment about which expense and income items are excluded or included (including on a pro forma basis) in determining these non-GAAP 6 214 239 financial measures. The presentation of these non-GAAP financial measures is not meant to be considered in isolation or as a substitute for results or guidance prepared and presented in accordance with GAAP. A reconciliation of the non-GAAP financial measures to the nearest comparable GAAP financial measures is contained in the appendix. 30 146 CAUTIONARY NOTE REGARDING FORWARD-LOOKING STATEMENTS 124 213 Hyperlink This presentation contains certain “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, Section 21E of the Securities Exchange Act of 1934, as amended, and the “safe-harbor” provisions under the Private Securities Litigation Reform Act of 153 234 1995, that involve risks and uncertainties. The terms “aim,” “anticipate,” “believe,” “contemplates,” “continues,” “could,” “ensure,” “estimate,” “expect,” “forecasts,” “if,” “intend,” “likely,” “may,” “might,” “objective,” “outlook,” “plan,” “positioned,” “potential,” “predict,” “probable,” “project,” “shall,” “should,” 0 98 “strategy,” “will,” “would,” and variations of them and other words and terms of similar meaning and expression (and the negatives of such words and terms) are intended to identify forward-looking statements. Followed 80 205 Forward-looking statements can also be identified by the fact that they do not relate strictly to historical or current facts. Such forward-looking statements are based on current expectations and involve inherent risks, uncertainties and assumptions, including factors that could delay, divert or change Hyperlink 117 255 any of them, and could cause actual outcomes to differ materially from current expectations. DSG can give no assurance that any goal or plan set forth in forward-looking statements can be achieved and DSG cautions readers not to place undue reliance on such statements. DSG undertakes no obligation to release publicly any revisions to forward-looking statements as a result of new information, future events or otherwise. Each forward-looking statement speaks only as of the date on which such statement is made, and DSG undertakes no obligation to update any such statement to TABLE reflect events or circumstances arising after such date. Actual results may differ materially from those projected as a result of certain risks and uncertainties. Factors that could cause or contribute to such differences or that might otherwise impact DSG’s business, financial condition and results of operations include the risks that potential acquisitions may not be consummated on the terms currently contemplated, or at all, and that DSG may encounter difficulties integrating the business of DSG with the business of other companies that DSG has combined with or may otherwise combine 50 with and that certain assumptions with respect to such business or transactions, including whether the acquisition would be accretive to DSG and any cost savings and synergies, could prove to be inaccurate. Certain risks associated with DSG’s business are also discussed from time to time in the Lines 56 reports DSG files with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K, Quarterly Reports on Form 10-Q and Current Reports on Form 8-K or other reports the Company may file from time to time with the Securities and Exchange Commission, 62 which should be reviewed carefully. ADDITIONAL INFORMATION ABOUT THE MERGER AND WHERE TO FIND IT 68 In connection with the proposed merger of Eclipse Acquisitions Merger Sub, Inc., a Delaware corporation, with and into the Company (the “Merger”), with the Company continuing as the surviving corporation, becoming a wholly owned subsidiary of Eclipse Intermediate Acquisitions, LLC, a Highlights 87 Delaware limited liability company, and an indirect wholly owned subsidiary of Eclipse Parent Acquisitions, LLC, a Delaware limited liability company and affiliate of Luther King Capital Management Corporation (“LKCM”), the Company intends to file with the U.S. Securities and Exchange 128 Commission (the “SEC”) a definitive proxy statement on Schedule 14A (the “Proxy Statement”). Additionally, on September 1, 2026, in connection with the Merger, the Company, LKCM and certain of their respective affiliates jointly filed with the SEC a transaction statement on Schedule 13E-3 (the “Schedule 13E-3”). The Proxy Statement and a proxy card will be sent or otherwise made available to stockholders of the Company entitled to vote at the special meeting relating to the Merger. This communication is not a substitute for the Proxy Statement, the Schedule 13E-3 or any other document that the Company may file with the SEC in connection with the proposed Merger. BEFORE MAKING ANY VOTING DECISION, INVESTORS AND SECURITY HOLDERS OF THE COMPANY ARE URGED TO READ THE PROXY STATEMENT, THE SCHEDULE 13E-3 AND OTHER RELEVANT DOCUMENTS (INCLUDING ANY AMENDMENTS OR SUPPLEMENTS THERETO) FILED WITH THE SEC CAREFULLY AND IN THEIR ENTIRETY WHEN THEY BECOME AVAILABLE BECAUSE THEY WILL CONTAIN IMPORTANT INFORMATION ABOUT THE COMPANY AND THE MERGER. Investors and security holders will be able to obtain copies of the Proxy Statement, the Schedule 13E-3 and other documents filed with the SEC by the Company free of charge from the SEC’s website at www.sec.gov or from the Company’s website. PARTICIPANTS IN THE SOLICITATION The Company and certain of its directors, executive officers and other members of management and employees may be deemed to be participants in the solicitation of proxies from the Company’s stockholders in connection with the Merger. Information regarding the Company’s directors and executive officers is available in the Company’s proxy statement for its most recent annual meeting (the “Annual Proxy Statement”) of stockholders and in other documents filed by the Company with the SEC. Additional information regarding the interests of those persons and other persons who may be deemed participants in the Merger is included in the Schedule 13E-3 and will also be included in the Proxy Statement and other materials to be filed with SEC in connection with the Merger. To the extent holdings of the Company’s securities by its directors or executive officers have changed since the amounts set forth in the Annual Proxy Statement, such changes have been or will be reflected on Initial Statements of Beneficial Ownership of Securities on Form 3 or Statements of Change in Ownership on Form 4 filed with the SEC. 1
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Today’s Agenda and Presenters Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 1 70 250 68 173 87 185 2 128 211 1 Transaction Overview 142 210 169 221 3 216 239 255 255 2 LKCM Headwater Investments Overview 196 231 4 38 168 239 249 129 205 5 35 167 3 Distribution Solutions Group Overview 213 238 213 238 6 214 239 4 Investment Highlights 30 146 124 213 Hyperlink 153 234 0 98 Followed 5 Historical Financial Overview 80 205 Hyperlink 117 255 J. BRYAN KING RON KNUTSON TYLER ESPOSITO TABLE 50 6 Appendix Lines 56 62 Chairman and Chief Executive Officer, DSG Executive Vice President and Vice President Managing Partner, LKCM Headwater Chief Financial Officer Leveraged Finance 68 Highlights 87 128 2
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Transaction Overview
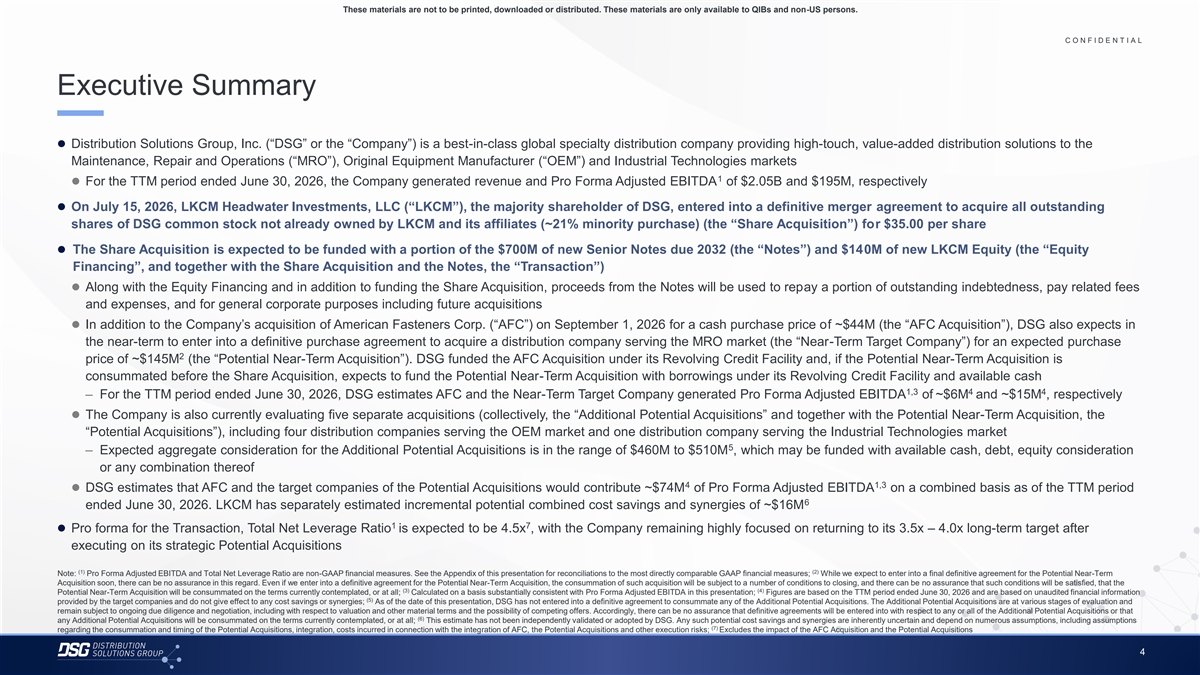
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Executive Summary Title bar/Bullets 68 87 128 ACCENTS ⚫ Distribution Solutions Group, Inc. (“DSG” or the “Company”) is a best-in-class global specialty distribution company providing high-touch, value-added distribution solutions to the 2 85 25 141 Maintenance, Repair and Operations (“MRO”), Original Equipment Manufacturer (“OEM”) and Industrial Technologies markets 1 70 250 1 ⚫ For the TTM period ended June 30, 2026, the Company generated revenue and Pro Forma Adjusted EBITDA of $2.05B and $195M, respectively 68 173 87 185 2 ⚫ On July 15, 2026, LKCM Headwater Investments, LLC (“LKCM”), the majority shareholder of DSG, entered into a definitive merger agreement to acquire all outstanding 128 211 shares of DSG common stock not already owned by LKCM and its affiliates (~21% minority purchase) (the “Share Acquisition”) for $35.00 per share 142 210 169 221 3 216 239 ⚫ The Share Acquisition is expected to be funded with a portion of the $700M of new Senior Notes due 2032 (the “Notes”) and $140M of new LKCM Equity (the “Equity 255 255 Financing”, and together with the Share Acquisition and the Notes, the “Transaction”) 196 231 4 38 168 ⚫ Along with the Equity Financing and in addition to funding the Share Acquisition, proceeds from the Notes will be used to repay a portion of outstanding indebtedness, pay related fees 239 249 and expenses, and for general corporate purposes including future acquisitions 129 205 5 35 167 ⚫ In addition to the Company’s acquisition of American Fasteners Corp. (“AFC”) on September 1, 2026 for a cash purchase price of ~$44M (the “AFC Acquisition”), DSG also expects in 213 238 the near-term to enter into a definitive purchase agreement to acquire a distribution company serving the MRO market (the “Near-Term Target Company”) for an expected purchase 213 238 6 214 239 2 price of ~$145M (the “Potential Near-Term Acquisition”). DSG funded the AFC Acquisition under its Revolving Credit Facility and, if the Potential Near-Term Acquisition is 30 146 consummated before the Share Acquisition, expects to fund the Potential Near-Term Acquisition with borrowings under its Revolving Credit Facility and available cash 124 213 Hyperlink 1,3 4 4 153 234 – For the TTM period ended June 30, 2026, DSG estimates AFC and the Near-Term Target Company generated Pro Forma Adjusted EBITDA of ~$6M and ~$15M , respectively 0 98 Followed⚫ The Company is also currently evaluating five separate acquisitions (collectively, the “Additional Potential Acquisitions” and together with the Potential Near-Term Acquisition, the 80 205 Hyperlink 117 255 “Potential Acquisitions”), including four distribution companies serving the OEM market and one distribution company serving the Industrial Technologies market 5 TABLE – Expected aggregate consideration for the Additional Potential Acquisitions is in the range of $460M to $510M , which may be funded with available cash, debt, equity consideration 50 or any combination thereof Lines 56 62 4 1,3 ⚫ DSG estimates that AFC and the target companies of the Potential Acquisitions would contribute ~$74M of Pro Forma Adjusted EBITDA on a combined basis as of the TTM period 6 68 ended June 30, 2026. LKCM has separately estimated incremental potential combined cost savings and synergies of ~$16M Highlights 87 128 1 7 ⚫ Pro forma for the Transaction, Total Net Leverage Ratio is expected to be 4.5x , with the Company remaining highly focused on returning to its 3.5x – 4.0x long-term target after executing on its strategic Potential Acquisitions (1) (2) Note: Pro Forma Adjusted EBITDA and Total Net Leverage Ratio are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures; While we expect to enter into a final definitive agreement for the Potential Near-Term Acquisition soon, there can be no assurance in this regard. Even if we enter into a definitive agreement for the Potential Near-Term Acquisition, the consummation of such acquisition will be subject to a number of conditions to closing, and there can be no assurance that such conditions will be satisfied, that the (3) (4) Potential Near-Term Acquisition will be consummated on the terms currently contemplated, or at all; Calculated on a basis substantially consistent with Pro Forma Adjusted EBITDA in this presentation; Figures are based on the TTM period ended June 30, 2026 and are based on unaudited financial information (5) provided by the target companies and do not give effect to any cost savings or synergies; As of the date of this presentation, DSG has not entered into a definitive agreement to consummate any of the Additional Potential Acquisitions. The Additional Potential Acquisitions are at various stages of evaluation and remain subject to ongoing due diligence and negotiation, including with respect to valuation and other material terms and the possibility of competing offers. Accordingly, there can be no assurance that definitive agreements will be entered into with respect to any or all of the Additional Potential Acquisitions or that (6) any Additional Potential Acquisitions will be consummated on the terms currently contemplated, or at all; This estimate has not been independently validated or adopted by DSG. Any such potential cost savings and synergies are inherently uncertain and depend on numerous assumptions, including assumptions (7) regarding the consummation and timing of the Potential Acquisitions, integration, costs incurred in connection with the integration of AFC, the Potential Acquisitions and other execution risks; Excludes the impact of the AFC Acquisition and the Potential Acquisitions 4
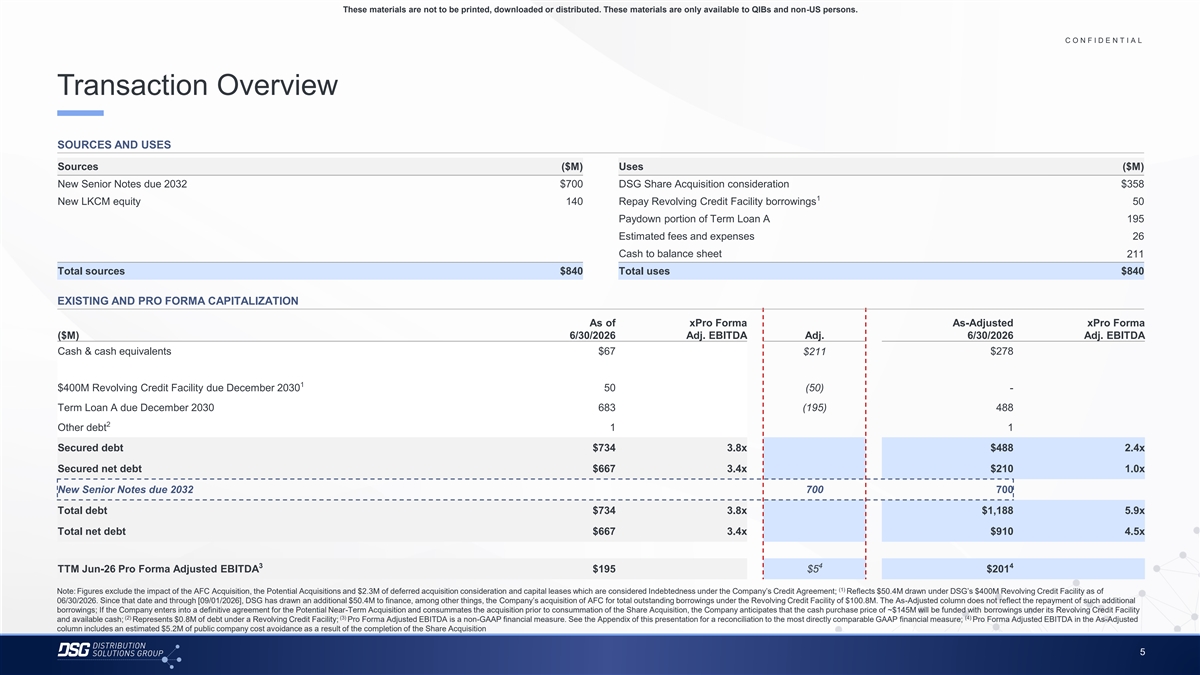
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Transaction Overview Title bar/Bullets 68 87 128 ACCENTS SOURCES AND USES 2 85 25 141 1 Sources ($M) Uses ($M) 70 250 New Senior Notes due 2032 $700 DSG Share Acquisition consideration $358 68 173 1 87 185 2 New LKCM equity 140 Repay Revolving Credit Facility borrowings 50 128 211 Paydown portion of Term Loan A 195 142 210 169 221 Estimated fees and expenses 26 3 216 239 Cash to balance sheet 211 255 255 Total sources $840 Total uses $840 196 231 4 38 168 239 249 EXISTING AND PRO FORMA CAPITALIZATION 129 205 5 35 167 As of xP ro Forma As-Adjusted xPro Forma ($M) 6/30/2026 Adj. EBITDA Adj. 6/30/2026 Adj. EBITDA 213 238 213 238 6 Cash & cash equivalents $67 $211 $278 214 239 30 146 124 213 Hyperlink 1 $400M Revolving Credit Facility due December 2030 50 (50) - 153 234 Term Loan A due December 2030 683 (195) 488 0 98 Followed 80 205 2 Hyperlink Other debt 1 1 117 255 Secured debt $734 3.8x $488 2.4x TABLE 50 Secured net debt $667 3.4x $210 1.0x Lines 56 62 New Senior Notes due 2032 700 700 68 Total debt $734 3.8x $1,188 5.9x Highlights 87 128 Total net debt $667 3.4x $910 4.5x 3 4 4 TTM Jun-26 Pro Forma Adjusted EBITDA $195 $5 $201 (1) Note: Figures exclude the impact of the AFC Acquisition, the Potential Acquisitions and $2.3M of deferred acquisition consideration and capital leases which are considered Indebtedness under the Company’s Credit Agreement; Reflects $50.4M drawn under DSG’s $400M Revolving Credit Facility as of 06/30/2026. Since that date and through [09/01/2026], DSG has drawn an additional $50.4M to finance, among other things, the Company’s acquisition of AFC for total outstanding borrowings under the Revolving Credit Facility of $100.8M. The As-Adjusted column does not reflect the repayment of such additional borrowings; If the Company enters into a definitive agreement for the Potential Near-Term Acquisition and consummates the acquisition prior to consummation of the Share Acquisition, the Company anticipates that the cash purchase price of ~$145M will be funded with borrowings under its Revolving Credit Facility (2) (3) (4) and available cash; Represents $0.8M of debt under a Revolving Credit Facility; Pro Forma Adjusted EBITDA is a non-GAAP financial measure. See the Appendix of this presentation for a reconciliation to the most directly comparable GAAP financial measure; Pro Forma Adjusted EBITDA in the As-Adjusted column includes an estimated $5.2M of public company cost avoidance as a result of the completion of the Share Acquisition 5
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. LKCM Headwater Investments Overview
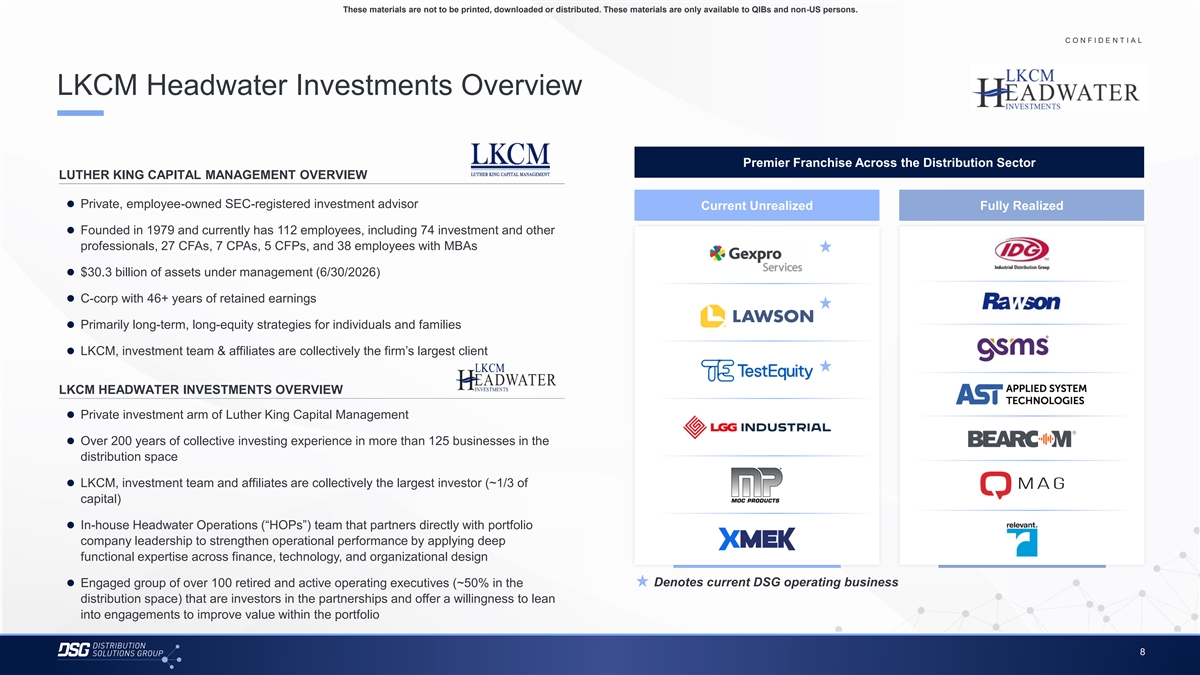
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 LKCM Headwater Investments Overview Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 Premier Franchise Across the Distribution Sector 1 70 250 LUTHER KING CAPITAL MANAGEMENT OVERVIEW 68 173 87 185 2 ⚫ Private, employee-owned SEC-registered investment advisor Current Unrealized Fully Realized 128 211 142 210 ⚫ Founded in 1979 and currently has 112 employees, including 74 investment and other 169 221 3 216 239 professionals, 27 CFAs, 7 CPAs, 5 CFPs, and 38 employees with MBAs 255 255 196 231⚫ $30.3 billion of assets under management (6/30/2026) 4 38 168 239 249⚫ C-corp with 46+ years of retained earnings 129 205 5 35 167 ⚫ Primarily long-term, long-equity strategies for individuals and families 213 238 213 238 6 ⚫ LKCM, investment team & affiliates are collectively the firm’s largest client 214 239 30 146 124 213 Hyperlink LKCM HEADWATER INVESTMENTS OVERVIEW 153 234 0 98 Followed⚫ Private investment arm of Luther King Capital Management 80 205 Hyperlink 117 255 ⚫ Over 200 years of collective investing experience in more than 125 businesses in the TABLE distribution space 50 Lines 56 62⚫ LKCM, investment team and affiliates are collectively the largest investor (~1/3 of capital) 68 Highlights 87 128 ⚫ In-house Headwater Operations (“HOPs”) team that partners directly with portfolio company leadership to strengthen operational performance by applying deep functional expertise across finance, technology, and organizational design Denotes current DSG operating business ⚫ Engaged group of over 100 retired and active operating executives (~50% in the distribution space) that are investors in the partnerships and offer a willingness to lean into engagements to improve value within the portfolio 8
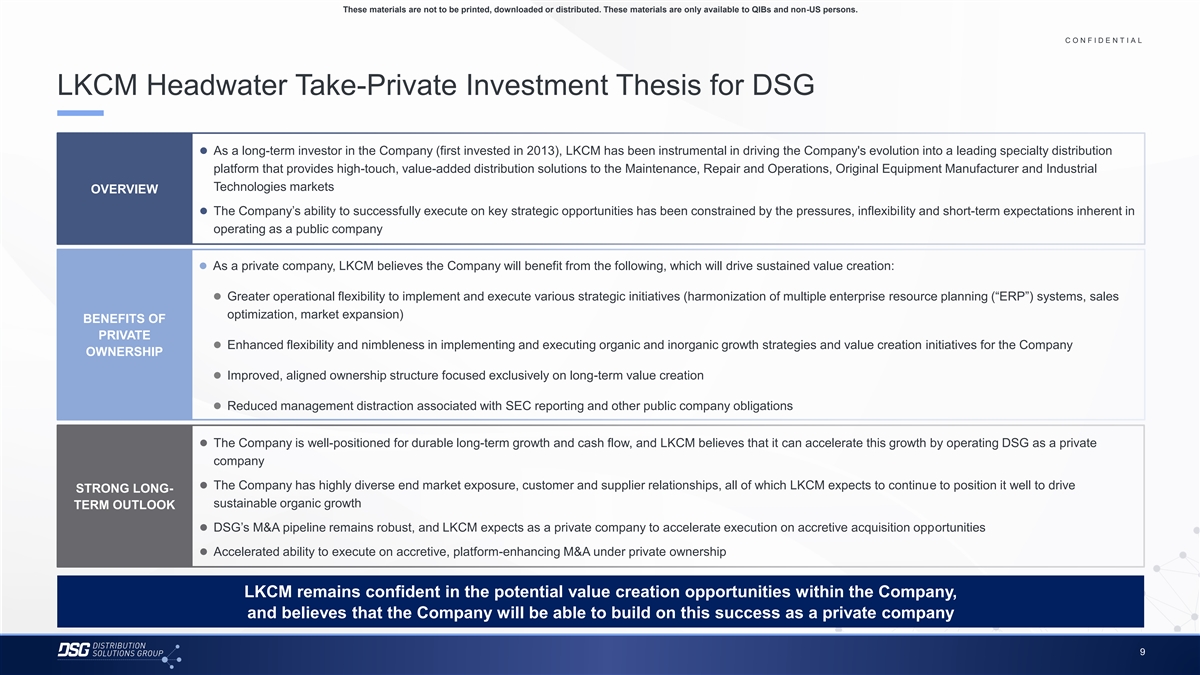
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 LKCM Headwater Take-Private Investment Thesis for DSG Title bar/Bullets 68 87 128 ACCENTS ⚫ As a long-term investor in the Company (first invested in 2013), LKCM has been instrumental in driving the Company's evolution into a leading specialty distribution 2 85 25 141 1 platform that provides high-touch, value-added distribution solutions to the Maintenance, Repair and Operations, Original Equipment Manufacturer and Industrial 70 250 Technologies markets 68 173 OVERVIEW 87 185 2 128 211 ⚫ The Company’s ability to successfully execute on key strategic opportunities has been constrained by the pressures, inflexibility and short-term expectations inherent in 142 210 operating as a public company 169 221 3 216 239 255 255 ⚫ As a private company, LKCM believes the Company will benefit from the following, which will drive sustained value creation: 196 231 4 38 168 ⚫ Greater operational flexibility to implement and execute various strategic initiatives (harmonization of multiple enterprise resource planning (“ERP”) systems, sales 239 249 129 205 5 optimization, market expansion) 35 167 BENEFITS OF PRIVATE 213 238 ⚫ Enhanced flexibility and nimbleness in implementing and executing organic and inorganic growth strategies and value creation initiatives for the Company 213 238 6 OWNERSHIP 214 239 30 146 ⚫ Improved, aligned ownership structure focused exclusively on long-term value creation 124 213 Hyperlink 153 234 ⚫ Reduced management distraction associated with SEC reporting and other public company obligations 0 98 Followed 80 205 Hyperlink 117 255 ⚫ The Company is well-positioned for durable long-term growth and cash flow, and LKCM believes that it can accelerate this growth by operating DSG as a private TABLE company 50 Lines 56 62 ⚫ The Company has highly diverse end market exposure, customer and supplier relationships, all of which LKCM expects to continue to position it well to drive STRONG LONG- sustainable organic growth 68 TERM OUTLOOK Highlights 87 128 ⚫ DSG’s M&A pipeline remains robust, and LKCM expects as a private company to accelerate execution on accretive acquisition opportunities ⚫ Accelerated ability to execute on accretive, platform-enhancing M&A under private ownership LKCM remains confident in the potential value creation opportunities within the Company, and believes that the Company will be able to build on this success as a private company 9
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Distribution Solutions Group Overview
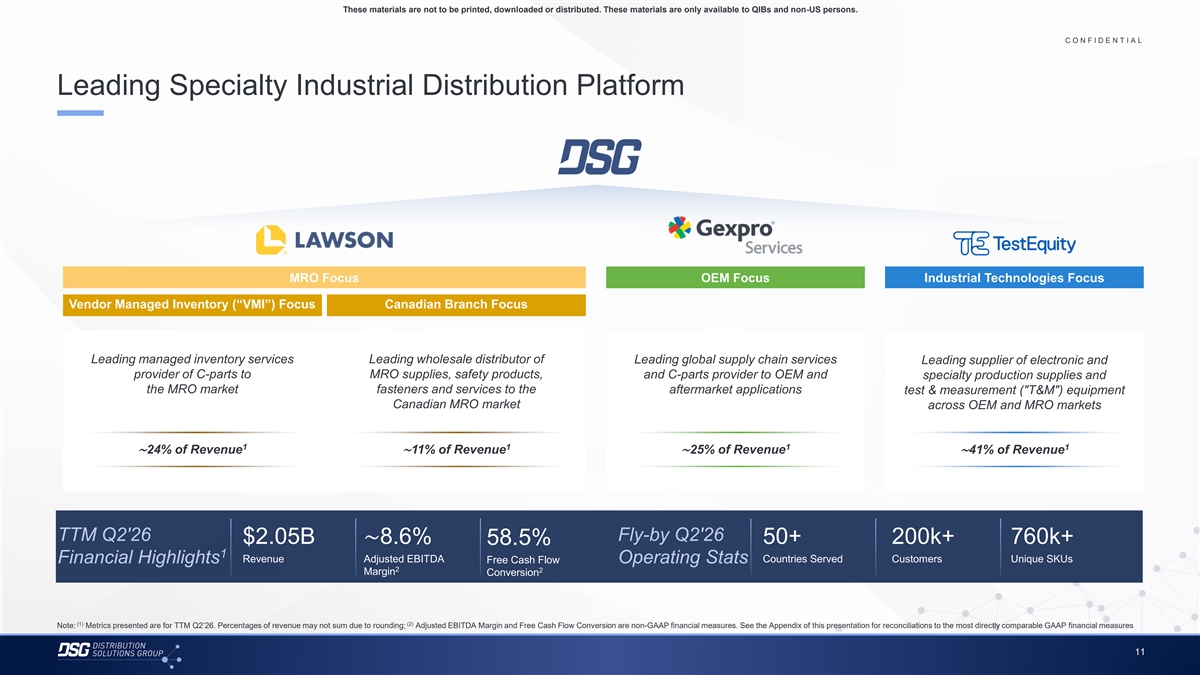
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Leading Specialty Industrial Distribution Platform Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 1 70 250 68 173 87 185 2 128 211 142 210 169 221 3 216 239 255 255 196 231 4 MRO Focus OEM Focus Industrial Technologies Focus 38 168 239 249 Vendor Managed Inventory (“VMI”) Focus Canadian Branch Focus 129 205 5 35 167 213 238 213 238 6 214 239 Leading managed inventory services Leading wholesale distributor of Leading global supply chain services Leading supplier of electronic and 30 146 provider of C-parts to MRO supplies, safety products, and C-parts provider to OEM and specialty production supplies and 124 213 Hyperlink the MRO market fasteners and services to the aftermarket applications test & measurement ( T&M ) equipment 153 234 Canadian MRO market across OEM and MRO markets 0 98 Followed 80 205 Hyperlink 117 255 1 1 1 1 TABLE ∼24% of Revenue∼11% of Revenue∼25% of Revenue∼41% of Revenue 50 Lines 56 62 68 Highlights 87 128 TTM Q2'26 Fly-by Q2'26 $2.05B∼8.6% 50+ 200k+ 760k+ 58.5% 1 Revenue Adjusted EBITDA Countries Served Customers Unique SKUs Financial Highlights Free Cash Flow Operating Stats 2 2 Margin Conversion (1) (2) Note: Metrics presented are for TTM Q2’26. Percentages of revenue may not sum due to rounding; Adjusted EBITDA Margin and Free Cash Flow Conversion are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures 11
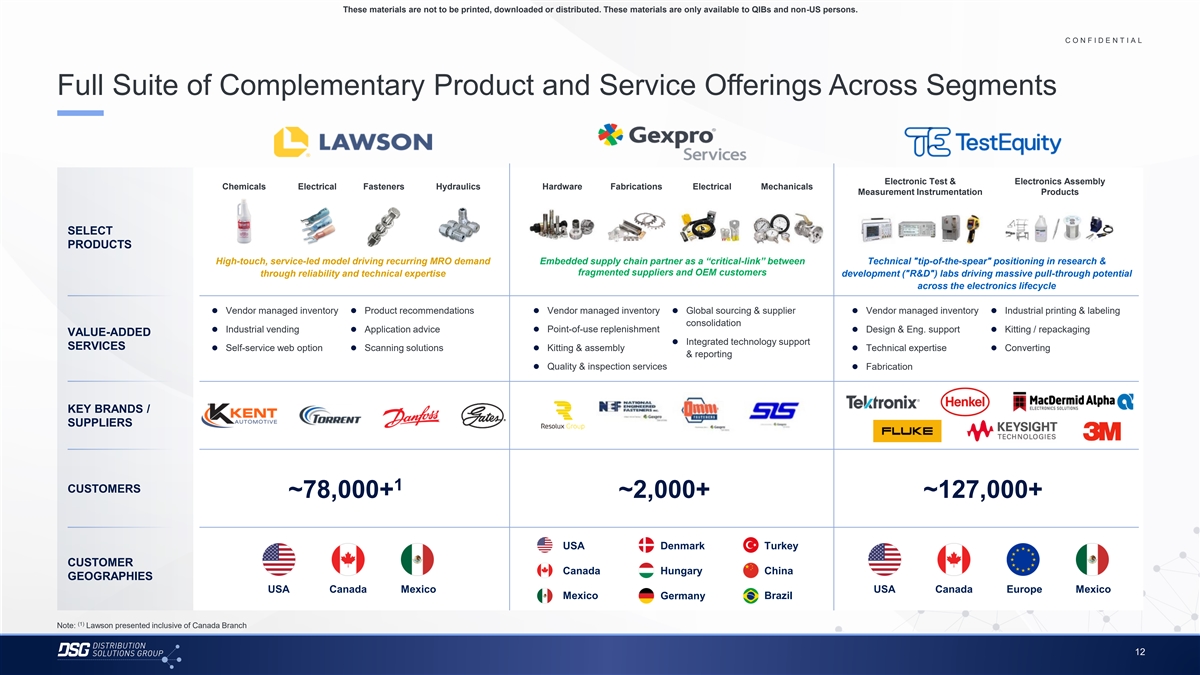
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Full Suite of Complementary Product and Service Offerings Across Segments Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 1 70 250 Electronic Test & Electronics Assembly Chemicals Electrical Fasteners Hydraulics Hardware Fabrications Electrical Mechanicals 68 173 Measurement Instrumentation Products 87 185 2 128 211 142 210 SELECT 169 221 3 PRODUCTS 216 239 High-touch, service-led model driving recurring MRO demand Embedded supply chain partner as a “critical-link” between Technical tip-of-the-spear positioning in research & 255 255 196 231 fragmented suppliers and OEM customers through reliability and technical expertise development ( R&D ) labs driving massive pull-through potential 4 38 168 across the electronics lifecycle 239 249 129 205⚫ Vendor managed inventory⚫ Product recommendations⚫ Vendor managed inventory⚫ Global sourcing & supplier ⚫ Vendor managed inventory⚫ Industrial printing & labeling 5 35 167 consolidation ⚫ Industrial vending⚫ Application advice⚫ Point-of-use replenishment⚫ Design & Eng. support⚫ Kitting / repackaging VALUE-ADDED 213 238 ⚫ Integrated technology support 213 238 SERVICES ⚫ Self-service web option⚫ Scanning solutions⚫ Kitting & assembly⚫ Technical expertise⚫ Converting 6 & reporting 214 239 ⚫ Quality & inspection services⚫ Fabrication 30 146 124 213 Hyperlink l 153 234 KEY BRANDS / 0 98 Followed 80 205 SUPPLIERS Hyperlink 117 255 TABLE 50 Lines 56 62 1 CUSTOMERS ~78,000+ ~2,000+ ~127,000+ 68 Highlights 87 128 USA Denmark Turkey CUSTOMER Canada Hungary China GEOGRAPHIES USA Canada Mexico USA Canada Europe Mexico Mexico Germany Brazil (1) Note: Lawson presented inclusive of Canada Branch 12
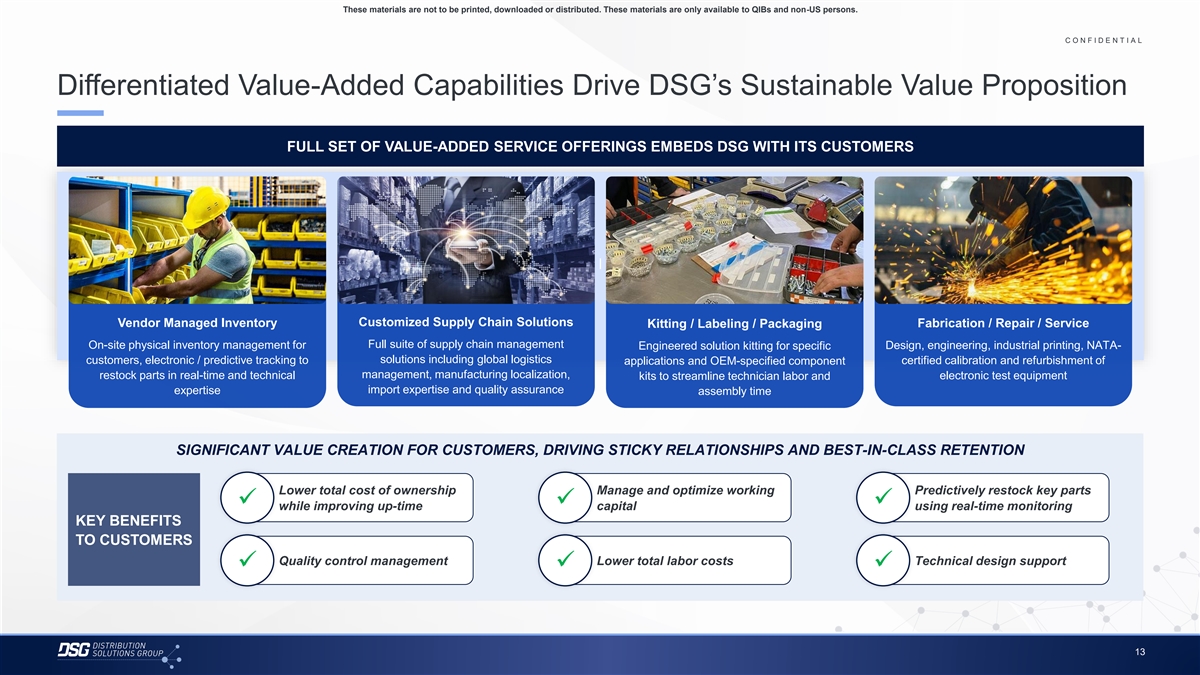
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Differentiated Value-Added Capabilities Drive DSG’s Sustainable Value Proposition Title bar/Bullets 68 87 128 ACCENTS FULL SET OF VALUE-ADDED SERVICE OFFERINGS EMBEDS DSG WITH ITS CUSTOMERS 2 85 25 141 1 70 250 68 173 87 185 2 128 211 142 210 169 221 3 216 239 255 255 l 196 231 4 38 168 239 249 129 205 5 35 167 Customized Supply Chain Solutions Vendor Managed Inventory Fabrication / Repair / Service Kitting / Labeling / Packaging 213 238 Full suite of supply chain management On-site physical inventory management for Design, engineering, industrial printing, NATA- 213 238 Engineered solution kitting for specific 6 214 239 customers, electronic / predictive tracking to solutions including global logistics applications and OEM-specified component certified calibration and refurbishment of 30 146 management, manufacturing localization, restock parts in real-time and technical electronic test equipment kits to streamline technician labor and 124 213 Hyperlink expertise import expertise and quality assurance assembly time 153 234 0 98 Followed 80 205 Hyperlink 117 255 TABLE SIGNIFICANT VALUE CREATION FOR CUSTOMERS, DRIVING STICKY RELATIONSHIPS AND BEST-IN-CLASS RETENTION 50 Lines 56 62 Lower total cost of ownership Manage and optimize working Predictively restock key parts ✓✓✓ 68 while improving up-time capital using real-time monitoring Highlights 87 KEY BENEFITS 128 TO CUSTOMERS Quality control management Lower total labor costs Technical design support ✓✓✓ 13
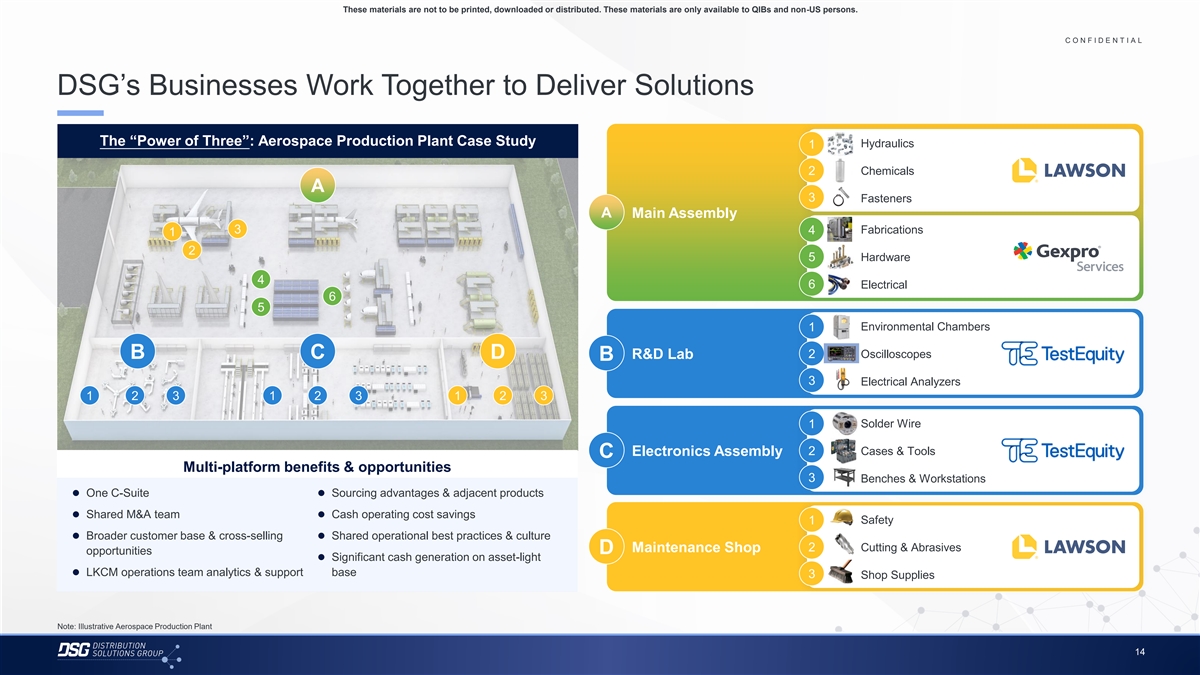
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 DSG’s Businesses Work Together to Deliver Solutions Title bar/Bullets 68 87 128 ACCENTS The “Power of Three”: Aerospace Production Plant Case Study Hydraulics 1 2 85 25 141 1 70 250 2 Chemicals A 68 173 3 Fasteners 87 185 2 128 211 A Main Assembly 142 210 3 Fabrications 4 1 169 221 3 216 239 2 5 Hardware 255 255 196 231 4 4 38 168 6 Electrical 6 239 249 5 129 205 5 35 167 Environmental Chambers 1 213 238 213 238 6 2 Oscilloscopes 214 239 B C D R&D Lab B 30 146 3 Electrical Analyzers 124 213 Hyperlink 153 234 1 2 3 1 2 3 1 2 3 0 98 Followed 80 205 Solder Wire 1 Hyperlink 117 255 TABLE 2 Cases & Tools Electronics Assembly C 50 Multi-platform benefits & opportunities Lines 56 3 Benches & Workstations 62 ⚫ One C-Suite⚫ Sourcing advantages & adjacent products 68 Highlights 87⚫ Shared M&A team⚫ Cash operating cost savings Safety 1 128 ⚫ Broader customer base & cross-selling ⚫ Shared operational best practices & culture 2 Cutting & Abrasives Maintenance Shop D opportunities ⚫ Significant cash generation on asset-light ⚫ LKCM operations team analytics & support base 3 Shop Supplies Note: Illustrative Aerospace Production Plant 14
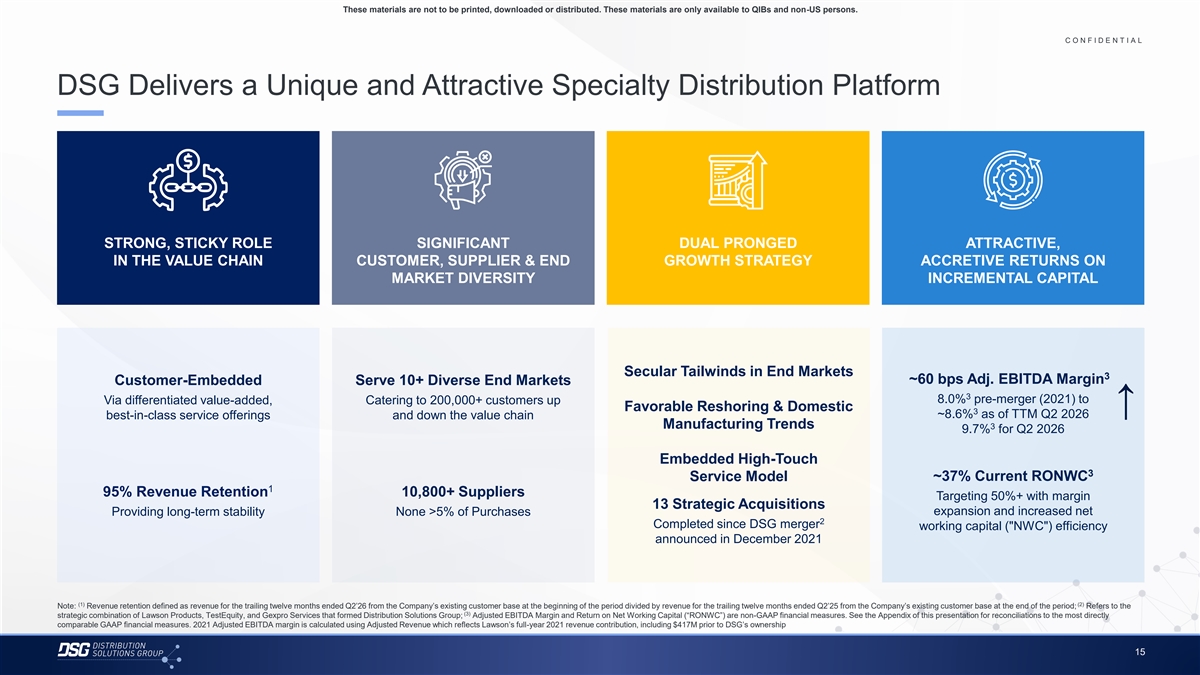
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 DSG Delivers a Unique and Attractive Specialty Distribution Platform Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 1 70 250 68 173 87 185 2 128 211 142 210 169 221 3 STRONG, STICKY ROLE SIGNIFICANT DUAL PRONGED ATTRACTIVE, 216 239 IN THE VALUE CHAIN CUSTOMER, SUPPLIER & END GROWTH STRATEGY ACCRETIVE RETURNS ON 255 255 196 231 4 MARKET DIVERSITY INCREMENTAL CAPITAL 38 168 239 249 129 205 5 35 167 213 238 213 238 6 214 239 Secular Tailwinds in End Markets 30 146 3 ~60 bps Adj. EBITDA Margin Customer-Embedded Serve 10+ Diverse End Markets 124 213 Hyperlink 153 234 3 8.0% pre-merger (2021) to Via differentiated value-added, Catering to 200,000+ customers up Favorable Reshoring & Domestic ↑ 0 98 3 ~8.6% as of TTM Q2 2026 Followed best-in-class service offerings and down the value chain 80 205 Hyperlink Manufacturing Trends 3 117 255 9.7% for Q2 2026 TABLE Embedded High-Touch 50 3 Lines 56 Service Model ~37% Current RONWC 62 1 95% Revenue Retention 10,800+ Suppliers Targeting 50%+ with margin 68 13 Strategic Acquisitions Providing long-term stability None >5% of Purchases expansion and increased net Highlights 87 2 128 Completed since DSG merger working capital ( NWC ) efficiency announced in December 2021 (1) (2) Note: Revenue retention defined as revenue for the trailing twelve months ended Q2’26 from the Company’s existing customer base at the beginning of the period divided by revenue for the trailing twelve months ended Q2’25 from the Company’s existing customer base at the end of the period; Refers to the (3) strategic combination of Lawson Products, TestEquity, and Gexpro Services that formed Distribution Solutions Group; Adjusted EBITDA Margin and Return on Net Working Capital (“RONWC”) are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures. 2021 Adjusted EBITDA margin is calculated using Adjusted Revenue which reflects Lawson’s full-year 2021 revenue contribution, including $417M prior to DSG’s ownership 15
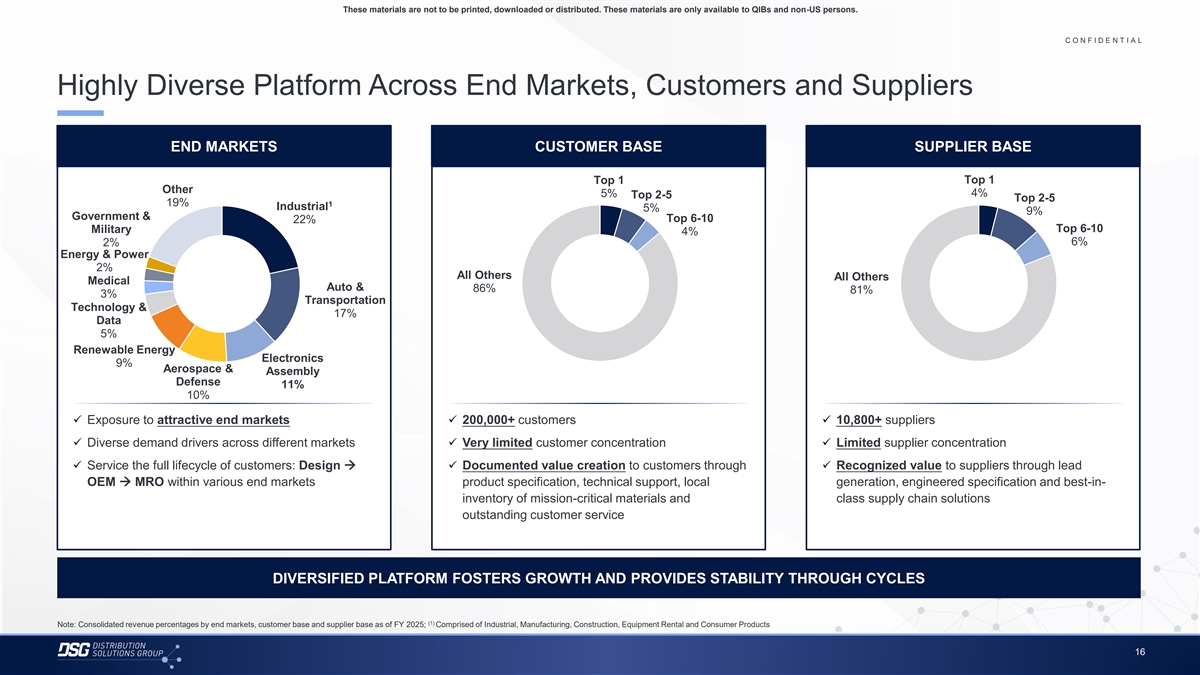
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Highly Diverse Platform Across End Markets, Customers and Suppliers Title bar/Bullets 68 87 128 ACCENTS END MARKETS CUSTOMER BASE SUPPLIER BASE 2 85 25 141 1 70 250 Top 1 Top 1 68 173 Other 5% 4% Top 2-5 Top 2-5 87 185 2 19% 1 Industrial 5% 128 211 9% Government & Top 6-10 22% 142 210 Top 6-10 Military 4% 169 221 3 6% 2% 216 239 Energy & Power 255 255 2% 196 231 4 All Others All Others Medical 38 168 Auto & 86% 81% 3% 239 249 Transportation Technology & 129 205 5 17% 35 167 Data 5% 213 238 213 238 6 Renewable Energy 214 239 Electronics 9% Aerospace & Assembly 30 146 Defense 124 213 Hyperlink 11% 153 234 10% 0 98 Followed 80 205✓ Exposure to attractive end markets✓ 200,000+ customers✓ 10,800+ suppliers Hyperlink 117 255 ✓ Diverse demand drivers across different markets✓ Very limited customer concentration✓ Limited supplier concentration TABLE 50 ✓ Service the full lifecycle of customers: Design →✓ Documented value creation to customers through ✓ Recognized value to suppliers through lead Lines 56 OEM → MRO within various end markets product specification, technical support, local generation, engineered specification and best-in- 62 inventory of mission-critical materials and class supply chain solutions 68 Highlights 87 outstanding customer service 128 DIVERSIFIED PLATFORM FOSTERS GROWTH AND PROVIDES STABILITY THROUGH CYCLES (1) Note: Consolidated revenue percentages by end markets, customer base and supplier base as of FY 2025; Comprised of Industrial, Manufacturing, Construction, Equipment Rental and Consumer Products 16
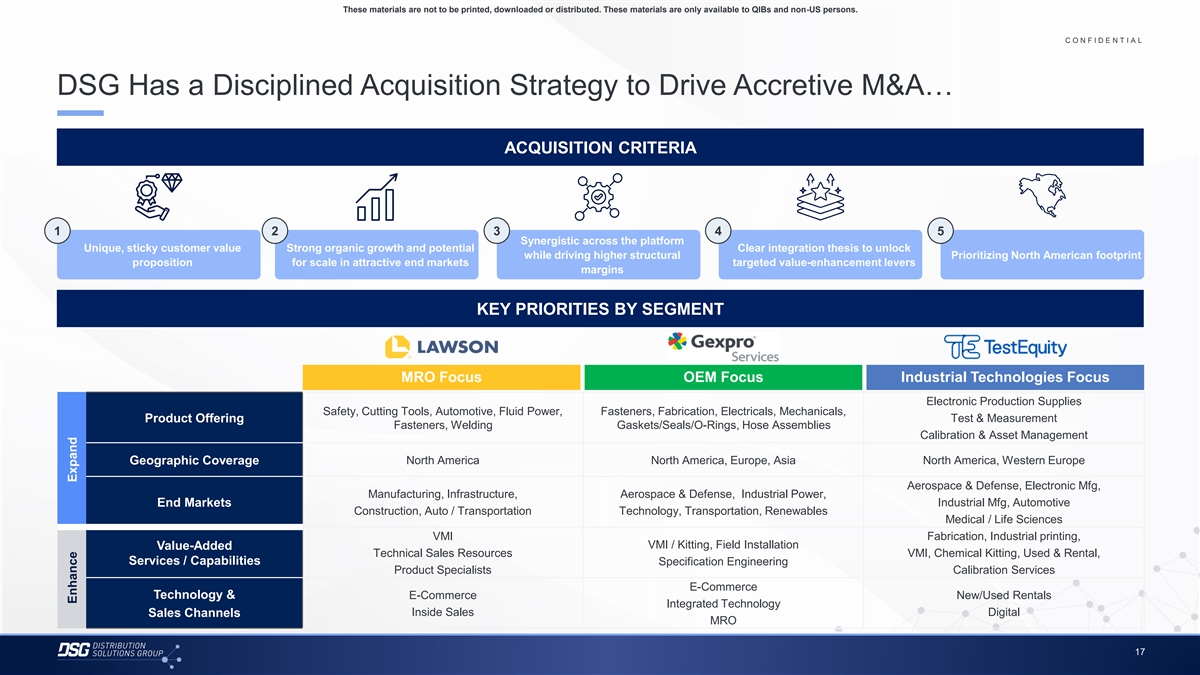
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 DSG Has a Disciplined Acquisition Strategy to Drive Accretive M&A… Title bar/Bullets 68 87 128 ACCENTS ACQUISITION CRITERIA 2 85 25 141 1 70 250 68 173 87 185 2 128 211 142 210 1 2 3 4 5 169 221 3 Synergistic across the platform 216 239 Unique, sticky customer value Strong organic growth and potential Clear integration thesis to unlock while driving higher structural Prioritizing North American footprint 255 255 proposition for scale in attractive end markets targeted value-enhancement levers margins 196 231 4 38 168 239 249 129 205 KEY PRIORITIES BY SEGMENT 5 35 167 213 238 213 238 6 214 239 30 146 MRO Focus OEM Focus Industrial Technologies Focus 124 213 Hyperlink 153 234 Electronic Production Supplies 0 98 Safety, Cutting Tools, Automotive, Fluid Power, Fasteners, Fabrication, Electricals, Mechanicals, Followed Test & Measurement Product Offering 80 205 Hyperlink Fasteners, Welding Gaskets/Seals/O-Rings, Hose Assemblies 117 255 Calibration & Asset Management TABLE Geographic Coverage North America North America, Europe, Asia North America, Western Europe 50 Lines 56 62 Aerospace & Defense, Electronic Mfg, Manufacturing, Infrastructure, Aerospace & Defense, Industrial Power, Industrial Mfg, Automotive End Markets 68 Construction, Auto / Transportation Technology, Transportation, Renewables Highlights 87 Medical / Life Sciences 128 VMI Fabrication, Industrial printing, VMI / Kitting, Field Installation Value-Added Technical Sales Resources VMI, Chemical Kitting, Used & Rental, Services / Capabilities Specification Engineering Product Specialists Calibration Services E-Commerce Technology & E-Commerce New/Used Rentals Integrated Technology Inside Sales Digital Sales Channels MRO 17 Enhance Expand
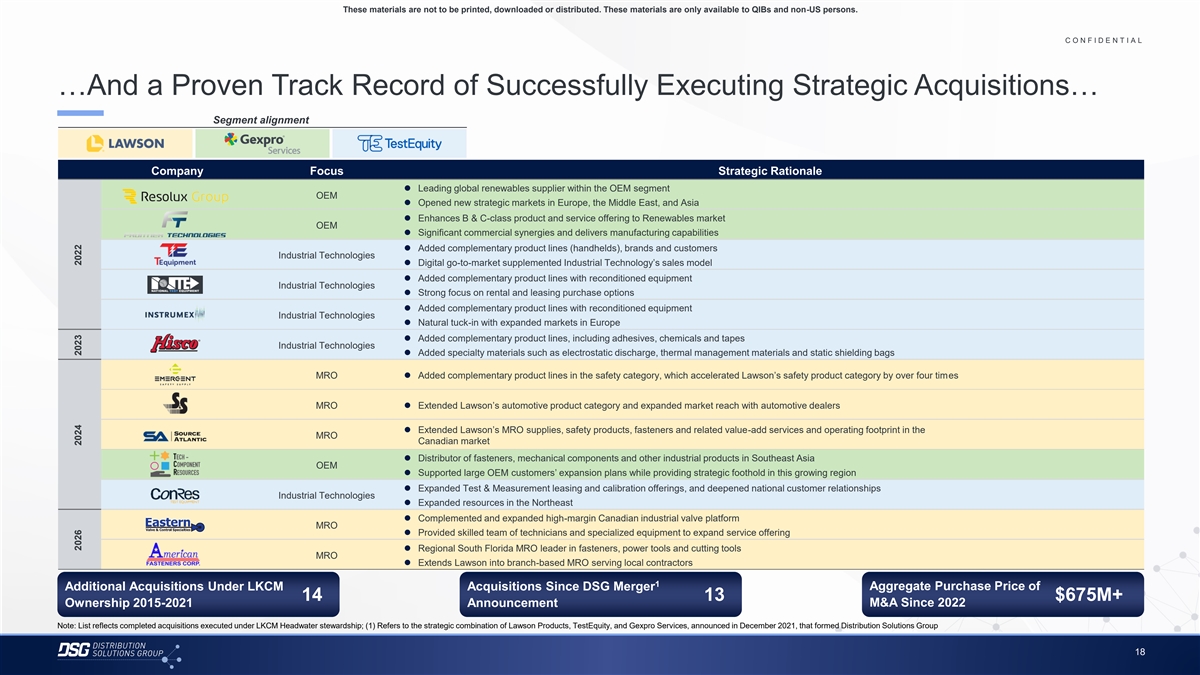
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE …And a Proven Track Record of Successfully Executing Strategic Acquisitions… Text 50 56 62 …And a Proven Track Record of Successfully Executing Strategic Acquisitions… Title bar/Bullets 68 87 128 Segment alignment ACCENTS 2 85 25 141 1 70 250 Company Focus Strategic Rationale ⚫ Leading global renewables supplier within the OEM segment 68 173 OEM 87 185 2 ⚫ Opened new strategic markets in Europe, the Middle East, and Asia 128 211 ⚫ Enhances B & C-class product and service offering to Renewables market OEM 142 210 ⚫ Significant commercial synergies and delivers manufacturing capabilities 169 221 3 216 239 ⚫ Added complementary product lines (handhelds), brands and customers Industrial Technologies ⚫ Digital go-to-market supplemented Industrial Technology’s sales model 255 255 196 231 4 ⚫ Added complementary product lines with reconditioned equipment 38 168 Industrial Technologies ⚫ Strong focus on rental and leasing purchase options 239 249 ⚫ Added complementary product lines with reconditioned equipment 129 205 5 Industrial Technologies 35 167 ⚫ Natural tuck-in with expanded markets in Europe 213 238 ⚫ Added complementary product lines, including adhesives, chemicals and tapes Industrial Technologies 213 238 6 ⚫ Added specialty materials such as electrostatic discharge, thermal management materials and static shielding bags 214 239 30 146 MRO⚫ Added complementary product lines in the safety category, which accelerated Lawson’s safety product category by over four times 124 213 Hyperlink 153 234 MRO⚫ Extended Lawson’s automotive product category and expanded market reach with automotive dealers 0 98 Followed 80 205 Hyperlink 117 255⚫ Extended Lawson’s MRO supplies, safety products, fasteners and related value-add services and operating footprint in the MRO Canadian market TABLE ⚫ Distributor of fasteners, mechanical components and other industrial products in Southeast Asia 50 OEM ⚫ Supported large OEM customers’ expansion plans while providing strategic foothold in this growing region Lines 56 62 ⚫ Expanded Test & Measurement leasing and calibration offerings, and deepened national customer relationships Industrial Technologies ⚫ Expanded resources in the Northeast 68 Highlights 87 ⚫ Complemented and expanded high-margin Canadian industrial valve platform 128 MRO ⚫ Provided skilled team of technicians and specialized equipment to expand service offering ⚫ Regional South Florida MRO leader in fasteners, power tools and cutting tools MRO ⚫ Extends Lawson into branch-based MRO serving local contractors 1 Additional Acquisitions Under LKCM Acquisitions Since DSG Merger Aggregate Purchase Price of 14 13 $675M+ M&A Since 2022 Ownership 2015-2021 Announcement Note: List reflects completed acquisitions executed under LKCM Headwater stewardship; (1) Refers to the strategic combination of Lawson Products, TestEquity, and Gexpro Services, announced in December 2021, that formed Distribution Solutions Group 18 2026 2024 2023 2022
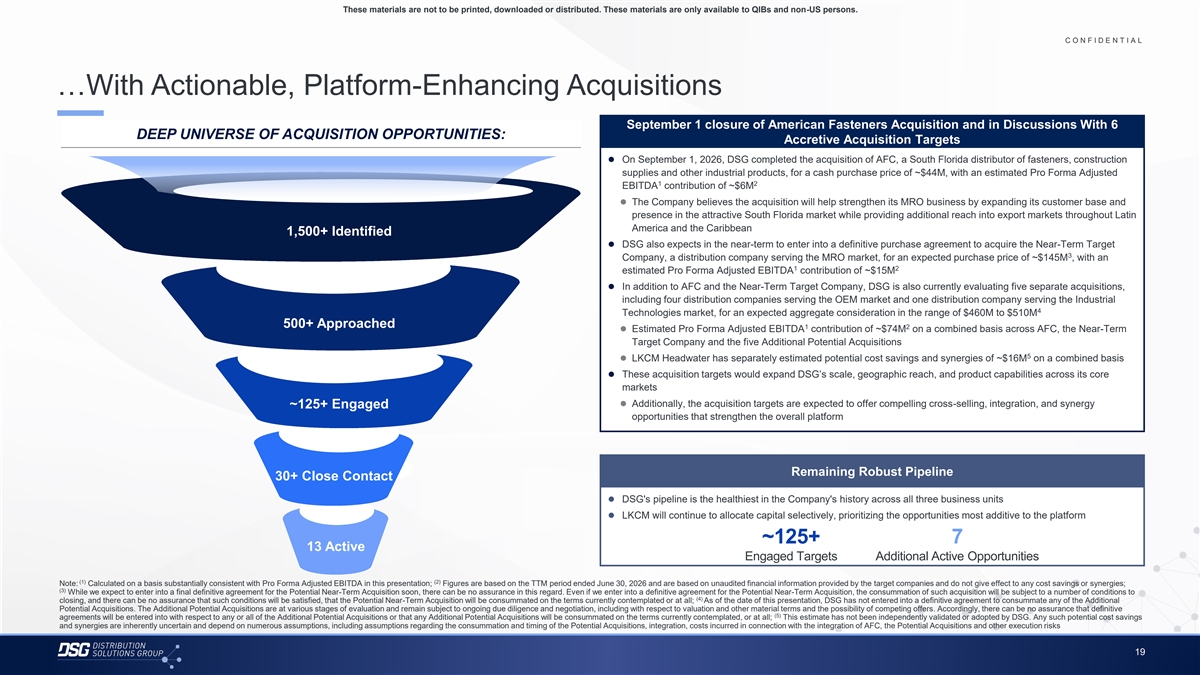
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 …With Actionable, Platform-Enhancing Acquisitions Title bar/Bullets 68 87 128 September 1 closure of American Fasteners Acquisition and in Discussions With 6 ACCENTS DEEP UNIVERSE OF ACQUISITION OPPORTUNITIES: Accretive Acquisition Targets 2 85 ⚫ On September 1, 2026, DSG completed the acquisition of AFC, a South Florida distributor of fasteners, construction 25 141 1 70 250 supplies and other industrial products, for a cash purchase price of ~$44M, with an estimated Pro Forma Adjusted 1 2 EBITDA contribution of ~$6M 68 173 87 185 2 ⚫ The Company believes the acquisition will help strengthen its MRO business by expanding its customer base and 128 211 presence in the attractive South Florida market while providing additional reach into export markets throughout Latin 142 210 America and the Caribbean 1,500+ Identified 169 221 3 ⚫ DSG also expects in the near-term to enter into a definitive purchase agreement to acquire the Near-Term Target 216 239 3 Company, a distribution company serving the MRO market, for an expected purchase price of ~$145M , with an 255 255 1 2 estimated Pro Forma Adjusted EBITDA contribution of ~$15M 196 231 4 38 168 ⚫ In addition to AFC and the Near-Term Target Company, DSG is also currently evaluating five separate acquisitions, 239 249 including four distribution companies serving the OEM market and one distribution company serving the Industrial 129 205 4 5 Technologies market, for an expected aggregate consideration in the range of $460M to $510M 35 167 500+ Approached 1 2 ⚫ Estimated Pro Forma Adjusted EBITDA contribution of ~$74M on a combined basis across AFC, the Near-Term 213 238 Target Company and the five Additional Potential Acquisitions 213 238 6 5 214 239 ⚫ LKCM Headwater has separately estimated potential cost savings and synergies of ~$16M on a combined basis 30 146 ⚫ These acquisition targets would expand DSG’s scale, geographic reach, and product capabilities across its core 124 213 Hyperlink markets 153 234 ⚫ Additionally, the acquisition targets are expected to offer compelling cross-selling, integration, and synergy ~125+ Engaged 0 98 Followed opportunities that strengthen the overall platform 80 205 Hyperlink 117 255 TABLE 50 Remaining Robust Pipeline Lines 56 30+ Close Contact 62 ⚫ DSG's pipeline is the healthiest in the Company's history across all three business units 68 Highlights 87⚫ LKCM will continue to allocate capital selectively, prioritizing the opportunities most additive to the platform 128 ~125+ 7 13 Active Engaged Targets Additional Active Opportunities (1) (2) Note: Calculated on a basis substantially consistent with Pro Forma Adjusted EBITDA in this presentation; Figures are based on the TTM period ended June 30, 2026 and are based on unaudited financial information provided by the target companies and do not give effect to any cost savings or synergies; (3) While we expect to enter into a final definitive agreement for the Potential Near-Term Acquisition soon, there can be no assurance in this regard. Even if we enter into a definitive agreement for the Potential Near-Term Acquisition, the consummation of such acquisition will be subject to a number of conditions to (4) closing, and there can be no assurance that such conditions will be satisfied, that the Potential Near-Term Acquisition will be consummated on the terms currently contemplated or at all; As of the date of this presentation, DSG has not entered into a definitive agreement to consummate any of the Additional Potential Acquisitions. The Additional Potential Acquisitions are at various stages of evaluation and remain subject to ongoing due diligence and negotiation, including with respect to valuation and other material terms and the possibility of competing offers. Accordingly, there can be no assurance that definitive (5) agreements will be entered into with respect to any or all of the Additional Potential Acquisitions or that any Additional Potential Acquisitions will be consummated on the terms currently contemplated, or at all; This estimate has not been independently validated or adopted by DSG. Any such potential cost savings and synergies are inherently uncertain and depend on numerous assumptions, including assumptions regarding the consummation and timing of the Potential Acquisitions, integration, costs incurred in connection with the integration of AFC, the Potential Acquisitions and other execution risks 19
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Investment Highlights
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Attractive Take-Private Opportunity with a Compelling Credit Story Title bar/Bullets 68 87 128 ACCENTS Best-in-Class Management Team with Proven Track Record and Clear Vision for Value Creation 1 2 85 25 141 1 70 250 68 173 87 185 2 128 211 142 210 Diversified Exposure to Attractive End Markets Supported by Secular Tailwinds 169 221 2 3 216 239 255 255 196 231 4 38 168 239 249 129 205 5 Differentiated Multi-Platform Strategy with Sustainable Competitive Moat, Creating a True “One- 35 167 3 213 238 Stop-Shop” Platform for Customers while Driving Up-Time 213 238 6 214 239 30 146 124 213 Hyperlink 153 234 0 98 Followed 4 Mission-Critical Partner to Customers and Suppliers Across All Aspects of the Value Chain 80 205 Hyperlink 117 255 TABLE 50 Lines 56 62 Broad End Market Exposure Across OEM and MRO Applications, Embedded within Customer Workflows, 68 5 Highlights 87 Underpins Durable, Recurring Demand 128 Attractive Financial Profile and Disciplined Approach to Capital Allocation, with a Strong Balance Sheet and Free 6 Cash Flow Generation 21
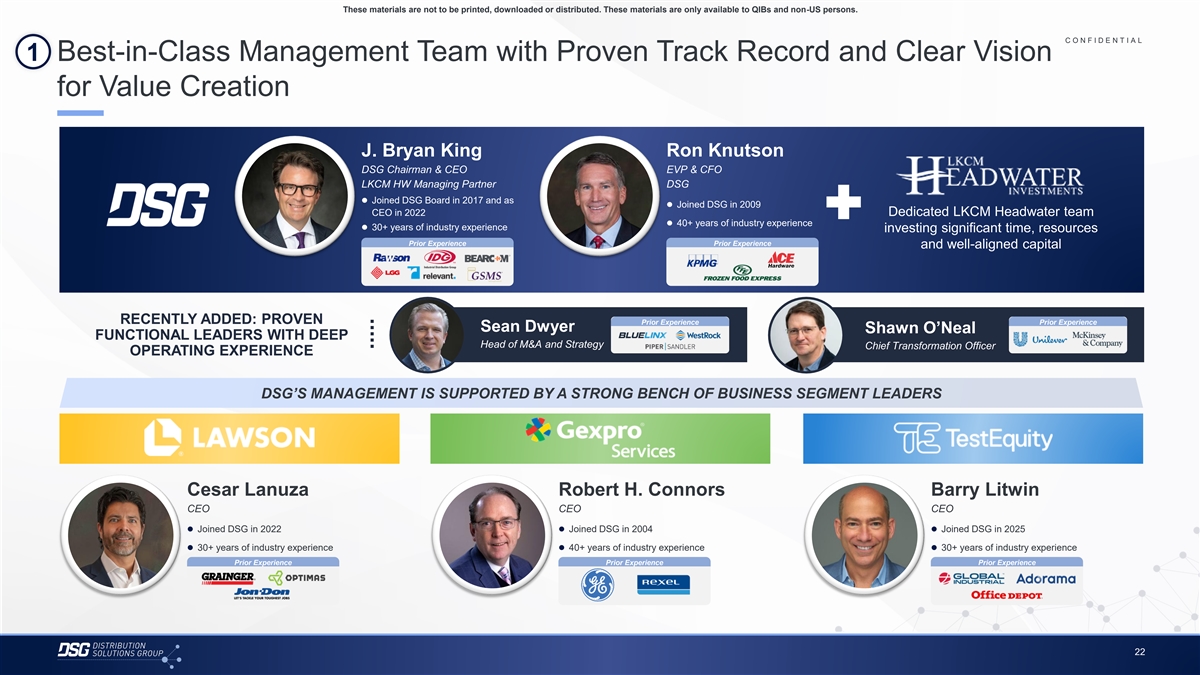
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE 1 Best-in-Class Management Team with Proven Track Record and Clear Vision Text 50 56 62 for Value Creation Title bar/Bullets 68 87 128 ACCENTS 2 85 J. Bryan King Ron Knutson 25 141 1 DSG Chairman & CEO EVP & CFO 70 250 LKCM HW Managing Partner DSG 68 173 87 185⚫ Joined DSG Board in 2017 and as 2 ⚫ Joined DSG in 2009 128 211 CEO in 2022 Dedicated LKCM Headwater team ⚫ 40+ years of industry experience 142 210⚫ 30+ years of industry experience investing significant time, resources 169 221 3 Prior Experience Prior Experience 216 239 and well-aligned capital 255 255 196 231 4 38 168 239 249 129 205 5 35 167 RECENTLY ADDED: PROVEN Prior Experience Prior Experience Sean Dwyer Shawn O’Neal FUNCTIONAL LEADERS WITH DEEP 213 238 Head of M&A and Strategy Chief Transformation Officer 213 238 6 OPERATING EXPERIENCE 214 239 30 146 124 213 Hyperlink 153 234 DSG’S MANAGEMENT IS SUPPORTED BY A STRONG BENCH OF BUSINESS SEGMENT LEADERS 0 98 Followed 80 205 Hyperlink 117 255 TABLE 50 Lines 56 62 Cesar Lanuza Robert H. Connors Barry Litwin 68 CEO CEO CEO Highlights 87 128 ⚫ Joined DSG in 2022⚫ Joined DSG in 2004⚫ Joined DSG in 2025 ⚫ 30+ years of industry experience⚫ 40+ years of industry experience⚫ 30+ years of industry experience Prior Experience Prior Experience Prior Experience 22
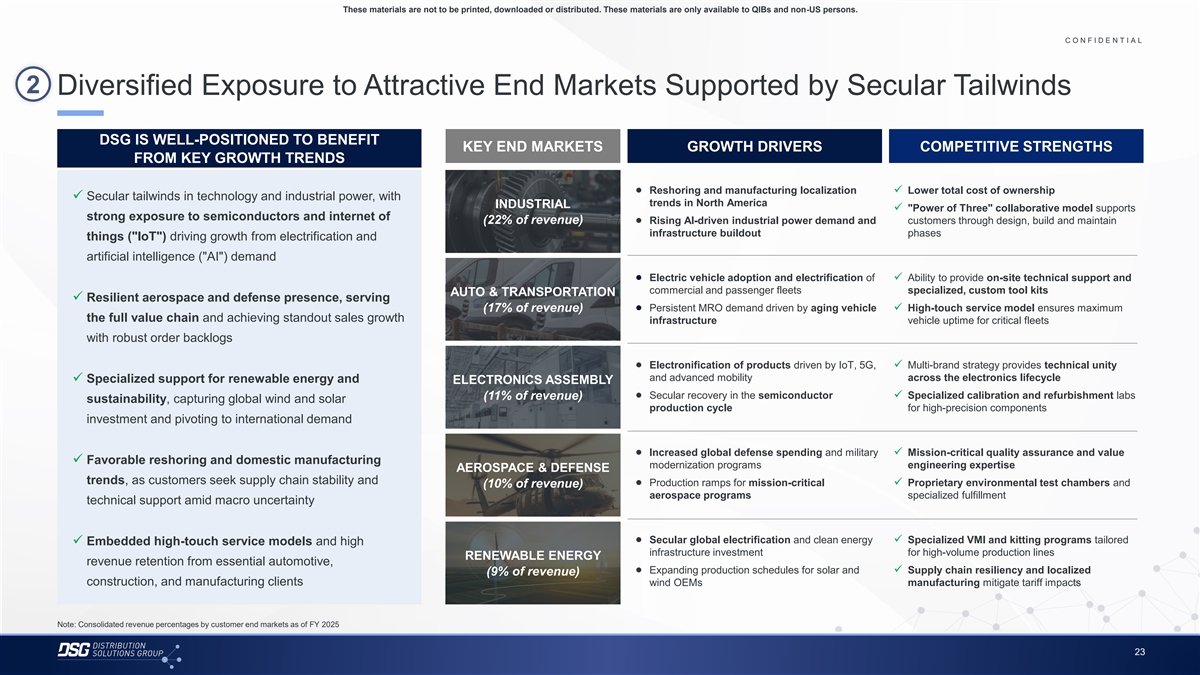
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 2 Diversified Exposure to Attractive End Markets Supported by Secular Tailwinds Title bar/Bullets 68 87 128 ACCENTS DSG IS WELL-POSITIONED TO BENEFIT KEY END MARKETS GROWTH DRIVERS COMPETITIVE STRENGTHS 2 85 FROM KEY GROWTH TRENDS 25 141 1 70 250 68 173 ● Reshoring and manufacturing localization ✓ Lower total cost of ownership ✓ Secular tailwinds in technology and industrial power, with 87 185 2 trends in North America INDUSTRIAL ✓ Power of Three collaborative model supports 128 211 strong exposure to semiconductors and internet of (22% of revenue) ● Rising AI-driven industrial power demand and customers through design, build and maintain 142 210 infrastructure buildout phases 169 221 things ( IoT ) driving growth from electrification and 3 216 239 artificial intelligence ( AI ) demand 255 255 196 231 4 ● Electric vehicle adoption and electrification of ✓ Ability to provide on-site technical support and 38 168 commercial and passenger fleets specialized, custom tool kits AUTO & TRANSPORTATION ✓ Resilient aerospace and defense presence, serving 239 249 (17% of revenue) ● Persistent MRO demand driven by aging vehicle ✓ High-touch service model ensures maximum 129 205 5 the full value chain and achieving standout sales growth 35 167 infrastructure vehicle uptime for critical fleets 213 238 with robust order backlogs 213 238 6 214 239 ● Electronification of products driven by IoT, 5G, ✓ Multi-brand strategy provides technical unity 30 146 and advanced mobility across the electronics lifecycle ✓ Specialized support for renewable energy and ELECTRONICS ASSEMBLY 124 213 Hyperlink 153 234 ● Secular recovery in the semiconductor ✓ Specialized calibration and refurbishment labs (11% of revenue) sustainability, capturing global wind and solar production cycle for high-precision components 0 98 Followed investment and pivoting to international demand 80 205 Hyperlink 117 255 TABLE ● Increased global defense spending and military ✓ Mission-critical quality assurance and value ✓ Favorable reshoring and domestic manufacturing 50 modernization programs engineering expertise AEROSPACE & DEFENSE Lines 56 trends, as customers seek supply chain stability and ● Production ramps for mission-critical ✓ Proprietary environmental test chambers and 62 (10% of revenue) aerospace programs specialized fulfillment technical support amid macro uncertainty 68 Highlights 87 128 ● Secular global electrification and clean energy ✓ Specialized VMI and kitting programs tailored ✓ Embedded high-touch service models and high infrastructure investment for high-volume production lines RENEWABLE ENERGY revenue retention from essential automotive, ● Expanding production schedules for solar and ✓ Supply chain resiliency and localized (9% of revenue) construction, and manufacturing clients wind OEMs manufacturing mitigate tariff impacts Note: Consolidated revenue percentages by customer end markets as of FY 2025 23
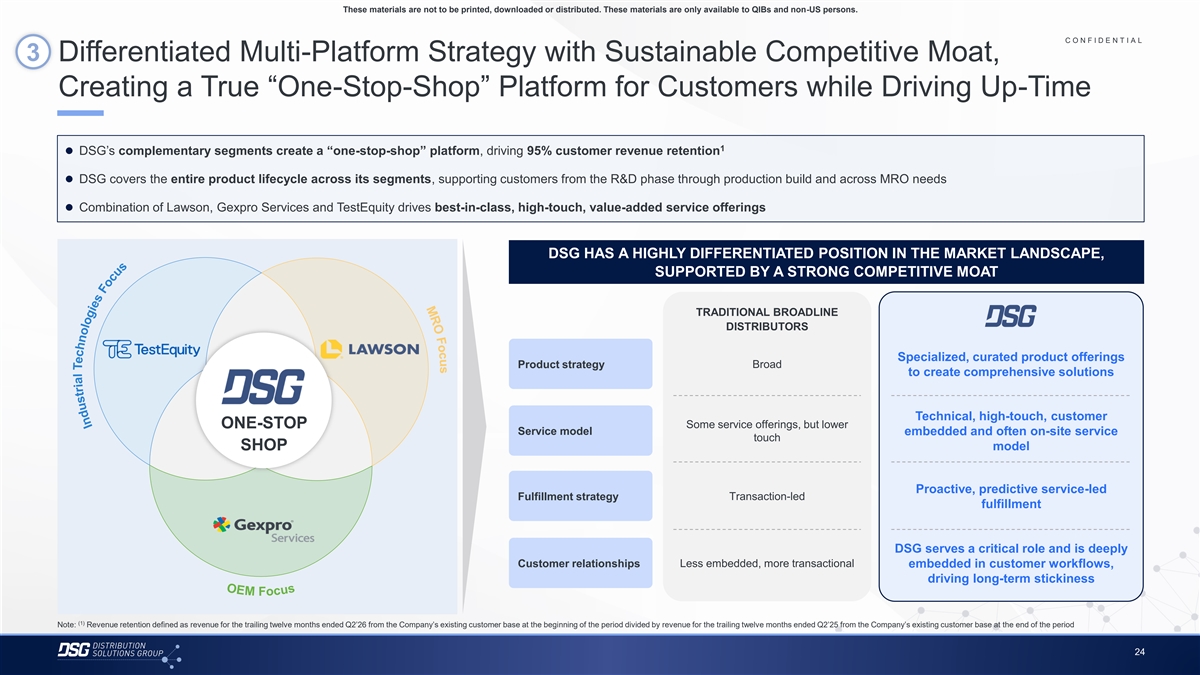
s u c o F O R M O E M These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE 3 Differentiated Multi-Platform Strategy with Sustainable Competitive Moat, Text 50 56 62 Creating a True “One-Stop-Shop” Platform for Customers while Driving Up-Time Title bar/Bullets 68 87 128 ACCENTS 1 ⚫ DSG’s complementary segments create a “one-stop-shop” platform, driving 95% customer revenue retention 2 85 25 141 1 70 250 ⚫ DSG covers the entire product lifecycle across its segments, supporting customers from the R&D phase through production build and across MRO needs 68 173 87 185 2 ⚫ Combination of Lawson, Gexpro Services and TestEquity drives best-in-class, high-touch, value-added service offerings 128 211 142 210 169 221 3 216 239 DSG HAS A HIGHLY DIFFERENTIATED POSITION IN THE MARKET LANDSCAPE, 255 255 196 231 SUPPORTED BY A STRONG COMPETITIVE MOAT 4 38 168 239 249 129 205 5 TRADITIONAL BROADLINE 35 167 DISTRIBUTORS 213 238 213 238 6 214 239 Specialized, curated product offerings Broad Product strategy to create comprehensive solutions 30 146 124 213 Hyperlink 153 234 0 98 Followed Technical, high-touch, customer 80 205 ONE-STOP Some service offerings, but lower Hyperlink 117 255 Service model embedded and often on-site service touch SHOP model TABLE 50 Lines 56 62 Proactive, predictive service-led Fulfillment strategy Transaction-led 68 fulfillment Highlights 87 128 DSG serves a critical role and is deeply Customer relationships Less embedded, more transactional embedded in customer workflows, driving long-term stickiness (1) Note: Revenue retention defined as revenue for the trailing twelve months ended Q2’26 from the Company’s existing customer base at the beginning of the period divided by revenue for the trailing twelve months ended Q2’25 from the Company’s existing customer base at the end of the period 24 F o c u s s u c o F s e i g o l o n h c e T l a i r t s u d n I
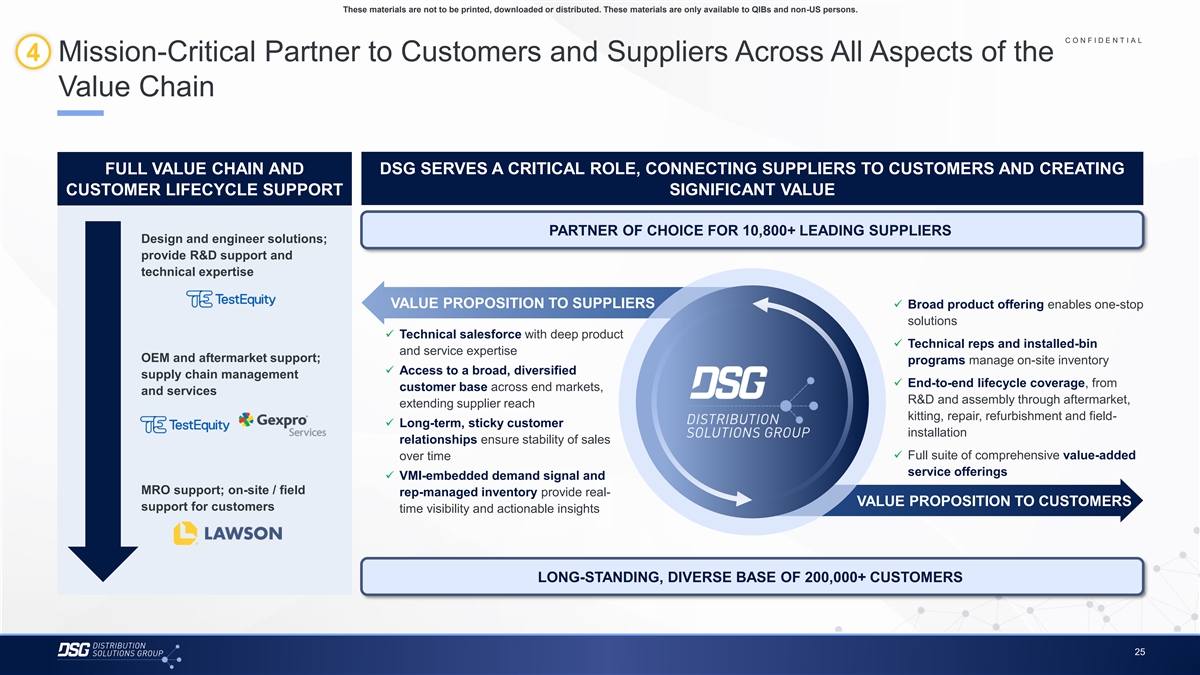
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE 4 Mission-Critical Partner to Customers and Suppliers Across All Aspects of the Text 50 56 62 Value Chain Title bar/Bullets 68 87 128 ACCENTS 2 85 25 141 1 FULL VALUE CHAIN AND DSG SERVES A CRITICAL ROLE, CONNECTING SUPPLIERS TO CUSTOMERS AND CREATING 70 250 68 173 CUSTOMER LIFECYCLE SUPPORT SIGNIFICANT VALUE 87 185 2 128 211 142 210 PARTNER OF CHOICE FOR 10,800+ LEADING SUPPLIERS 169 221 3 Design and engineer solutions; 216 239 provide R&D support and 255 255 196 231 technical expertise 4 38 168 239 249 VALUE PROPOSITION TO SUPPLIERS✓ Broad product offering enables one-stop 129 205 5 35 167 solutions ✓ Technical salesforce with deep product 213 238 ✓ Technical reps and installed-bin 213 238 6 and service expertise 214 239 OEM and aftermarket support; programs manage on-site inventory ✓ Access to a broad, diversified 30 146 supply chain management 124 213 Hyperlink✓ End-to-end lifecycle coverage, from customer base across end markets, and services 153 234 R&D and assembly through aftermarket, extending supplier reach 0 98 Followed kitting, repair, refurbishment and field- 80 205 ✓ Long-term, sticky customer Hyperlink 117 255 installation relationships ensure stability of sales TABLE ✓ Full suite of comprehensive value-added over time 50 service offerings Lines 56 ✓ VMI-embedded demand signal and 62 MRO support; on-site / field rep-managed inventory provide real- VALUE PROPOSITION TO CUSTOMERS 68 support for customers time visibility and actionable insights Highlights 87 128 LONG-STANDING, DIVERSE BASE OF 200,000+ CUSTOMERS 25
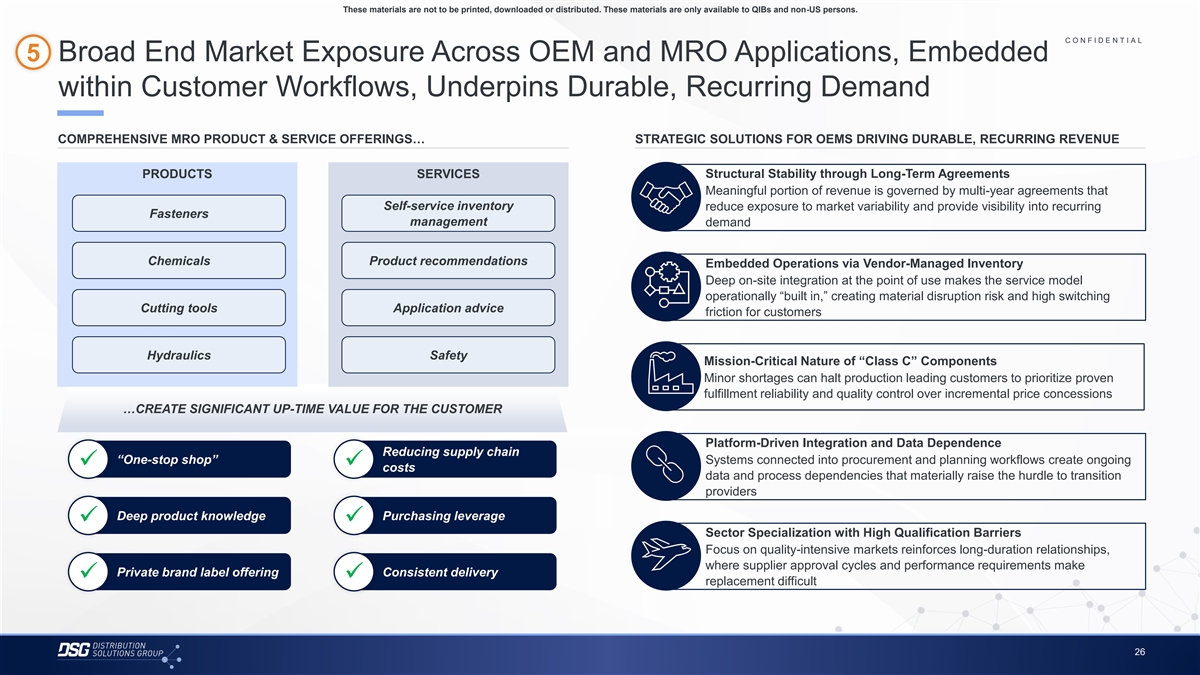
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE 5 Broad End Market Exposure Across OEM and MRO Applications, Embedded Text 50 56 62 within Customer Workflows, Underpins Durable, Recurring Demand Title bar/Bullets 68 87 128 ACCENTS COMPREHENSIVE MRO PRODUCT & SERVICE OFFERINGS… STRATEGIC SOLUTIONS FOR OEMS DRIVING DURABLE, RECURRING REVENUE 2 85 25 141 1 70 250 PRODUCTS SERVICES Structural Stability through Long-Term Agreements 68 173 Meaningful portion of revenue is governed by multi-year agreements that 87 185 2 Self-service inventory reduce exposure to market variability and provide visibility into recurring 128 211 Fasteners management demand 142 210 169 221 3 216 239 Chemicals Product recommendations 255 255 Embedded Operations via Vendor-Managed Inventory 196 231 4 Deep on-site integration at the point of use makes the service model 38 168 operationally “built in,” creating material disruption risk and high switching 239 249 Cutting tools Application advice 129 205 5 friction for customers 35 167 213 238 213 238 6 214 239 Hydraulics Safety Mission-Critical Nature of “Class C” Components 30 146 Minor shortages can halt production leading customers to prioritize proven 124 213 Hyperlink 153 234 fulfillment reliability and quality control over incremental price concessions 0 98 …CREATE SIGNIFICANT UP-TIME VALUE FOR THE CUSTOMER Followed 80 205 Hyperlink 117 255 Platform-Driven Integration and Data Dependence TABLE Reducing supply chain “One-stop shop” Systems connected into procurement and planning workflows create ongoing 50 ✓✓ costs Lines 56 data and process dependencies that materially raise the hurdle to transition 62 providers 68 Highlights 87 Deep product knowledge Purchasing leverage ✓✓ 128 Sector Specialization with High Qualification Barriers Focus on quality-intensive markets reinforces long-duration relationships, where supplier approval cycles and performance requirements make Private brand label offering Consistent delivery ✓✓ replacement difficult 26
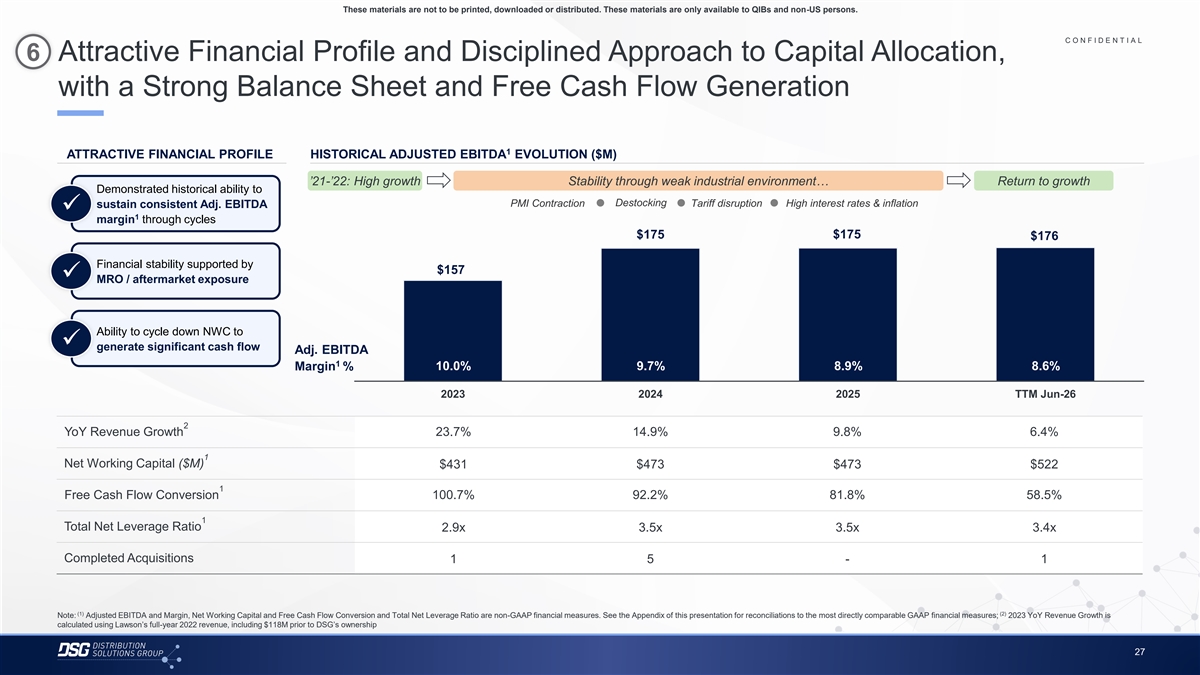
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE 6 Attractive Financial Profile and Disciplined Approach to Capital Allocation, Text 50 56 62 with a Strong Balance Sheet and Free Cash Flow Generation Title bar/Bullets 68 87 128 ACCENTS 1 2 85 ATTRACTIVE FINANCIAL PROFILE HISTORICAL ADJUSTED EBITDA EVOLUTION ($M) 25 141 1 70 250 ’21-’22: High growth Stability through weak industrial environment… Return to growth 68 173 Demonstrated historical ability to 87 185 2 Destocking PMI Contraction Tariff disruption High interest rates & inflation sustain consistent Adj. EBITDA 128 211✓ 1 margin through cycles 142 210 $175 $175 169 221 $176 3 216 239 255 255 Financial stability supported by $157 196 231 4 ✓ MRO / aftermarket exposure 38 168 239 249 129 205 5 35 167 Ability to cycle down NWC to 213 238 ✓ 213 238 generate significant cash flow 6 Adj. EBITDA 214 239 1 10.0% 9.7% 8.9% 8.6% Margin % 30 146 124 213 Hyperlink 153 234 2023 2024 2025 TTM Jun-26 0 98 Followed 80 205 2 Hyperlink 117 255 YoY Revenue Growth 23.7% 14.9% 9.8% 6.4% TABLE 1 50 Net Working Capital ($M) $431 $473 $473 $522 Lines 56 62 1 Free Cash Flow Conversion 100.7% 92.2% 81.8% 58.5% 68 Highlights 87 1 128 Total Net Leverage Ratio 2.9x 3.5x 3.5x 3.4x Completed Acquisitions 1 5 - 1 (1) (2) Note: Adjusted EBITDA and Margin, Net Working Capital and Free Cash Flow Conversion and Total Net Leverage Ratio are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures; 2023 YoY Revenue Growth is calculated using Lawson’s full-year 2022 revenue, including $118M prior to DSG’s ownership 27
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Historical Financial Overview
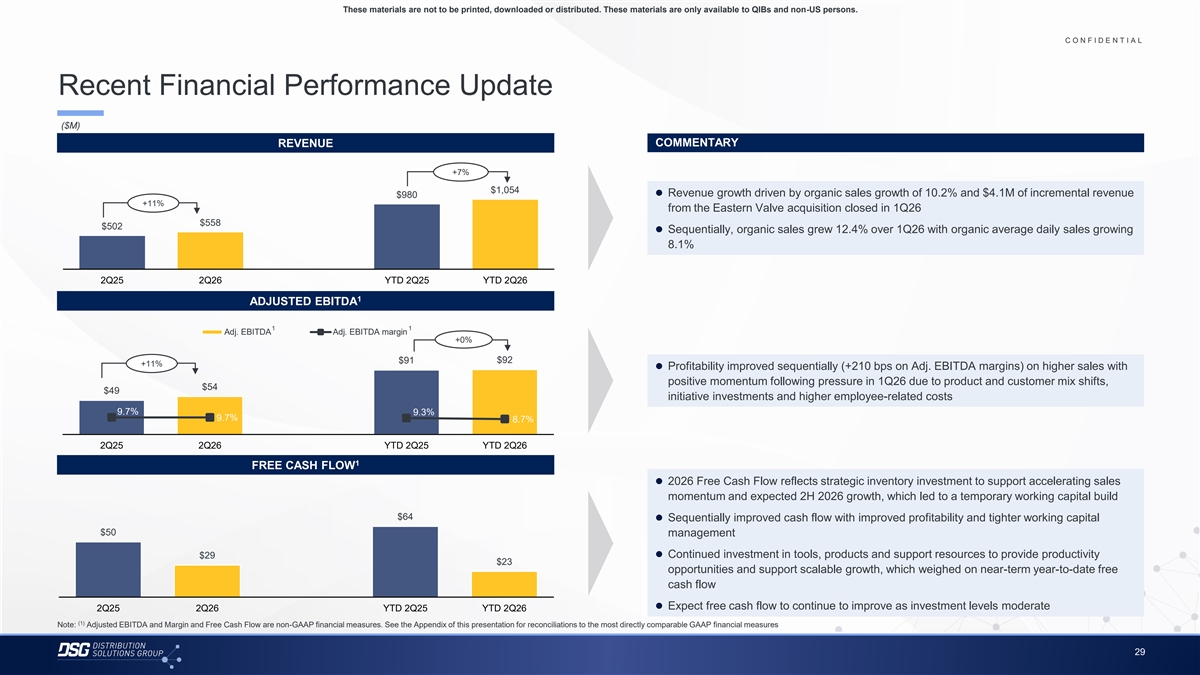
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Recent Financial Performance Update Title bar/Bullets 68 87 128 ($M) ACCENTS REVENUE COMMENTARY 2 85 25 141 1 70 250 +7% 68 173 $1,054 ⚫ Revenue growth driven by organic sales growth of 10.2% and $4.1M of incremental revenue $980 87 185 2 +11% from the Eastern Valve acquisition closed in 1Q26 128 211 $558 $502 142 210 ⚫ Sequentially, organic sales grew 12.4% over 1Q26 with organic average daily sales growing 169 221 3 8.1% 216 239 255 255 196 231 4 2Q25 2Q26 YTD 2Q25 YTD 2Q26 38 168 1 239 249 ADJUSTED EBITDA 129 205 5 35 167 1 1 Adj. EBITDA Adj. EBITDA margin 213 238 +0% 213 238 6 214 239 $91 $92 +11% ⚫ Profitability improved sequentially (+210 bps on Adj. EBITDA margins) on higher sales with 30 146 positive momentum following pressure in 1Q26 due to product and customer mix shifts, 124 213 Hyperlink $54 $49 153 234 initiative investments and higher employee-related costs 0 98 9.7% 9.3% Followed 9.7% 8.7% 80 205 Hyperlink 117 255 2Q25 2Q26 YTD 2Q25 YTD 2Q26 TABLE 1 50 FREE CASH FLOW Lines 56 ⚫ 2026 Free Cash Flow reflects strategic inventory investment to support accelerating sales 62 momentum and expected 2H 2026 growth, which led to a temporary working capital build 68 Highlights 87 $64 ⚫ Sequentially improved cash flow with improved profitability and tighter working capital 128 $50 management $29⚫ Continued investment in tools, products and support resources to provide productivity $23 opportunities and support scalable growth, which weighed on near-term year-to-date free cash flow ⚫ Expect free cash flow to continue to improve as investment levels moderate 2Q25 2Q26 YTD 2Q25 YTD 2Q26 (1) Note: Adjusted EBITDA and Margin and Free Cash Flow are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures 29
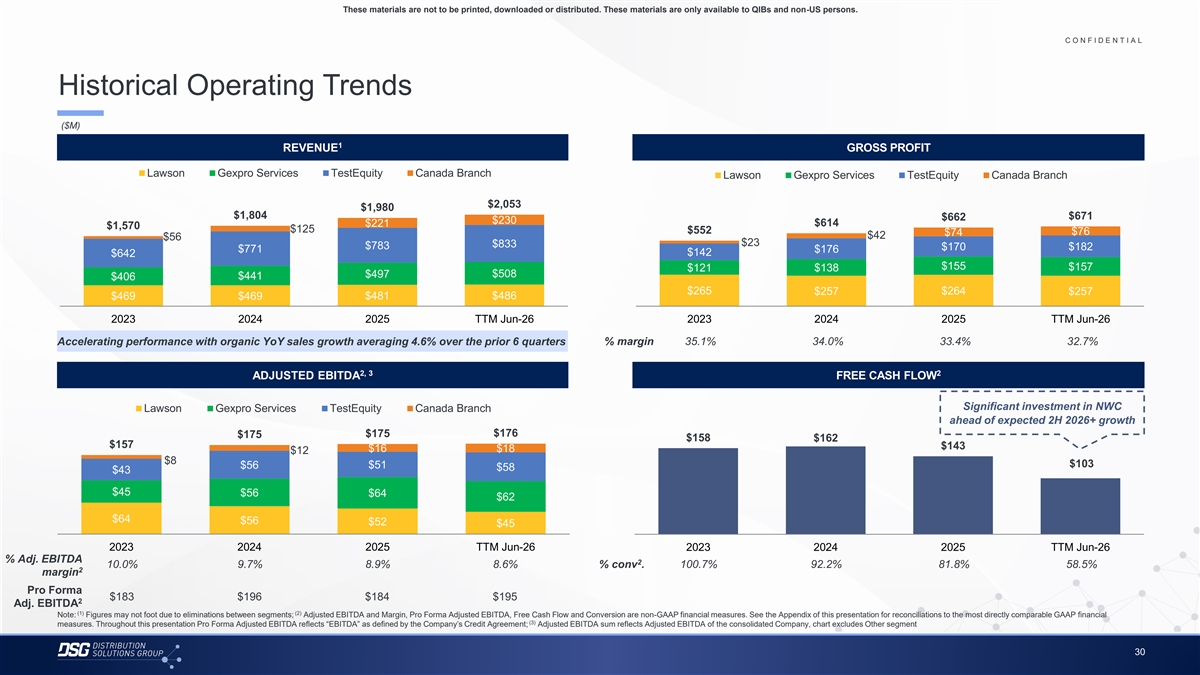
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Historical Operating Trends Title bar/Bullets 68 87 128 ($M) ACCENTS 1 REVENUE GROSS PROFIT 2 85 25 141 1 70 250 Lawson Gexpro Services TestEquity Canada Branch Lawson Gexpro Services TestEquity Canada Branch 68 173 87 185 2 $2,053 $1,980 128 211 $1,804 $671 $662 $230 $614 $221 $1,570 142 210 $125 $552 $76 $74 $42 169 221 $56 3 $23 $833 216 239 $783 $170 $182 $771 $176 $142 $642 255 255 $155 $157 $121 $138 196 231 $508 4 $497 $441 $406 38 168 $265 $257 $264 $257 $469 $469 $481 $486 239 249 129 205 5 35 167 2023 2024 2025 TTM Jun-26 2023 2024 2025 TTM Jun-26 213 238 % margin 35.1% 34.0% 33.4% 32.7% Accelerating performance with organic YoY sales growth averaging 4.6% over the prior 6 quarters 213 238 6 214 239 2, 3 2 30 146 ADJUSTED EBITDA FREE CASH FLOW 124 213 Hyperlink 153 234 Significant investment in NWC Lawson Gexpro Services TestEquity Canada Branch 0 98 Followed 80 205 ahead of expected 2H 2026+ growth Hyperlink 117 255 $176 $175 $175 $158 $162 $157 $143 TABLE $16 $18 $12 $8 50 $103 $56 $51 $58 $43 Lines 56 62 $45 $56 $64 $62 68 Highlights 87 $64 $56 $52 $45 128 2023 2024 2025 TTM Jun-26 2023 2024 2025 TTM Jun-26 % Adj. EBITDA 2 10.0% 9.7% 8.9% 8.6% % conv . 100.7% 92.2% 81.8% 58.5% 2 margin Pro Forma $183 $196 $184 $195 2 Adj. EBITDA (1) (2) Note: Figures may not foot due to eliminations between segments; Adjusted EBITDA and Margin, Pro Forma Adjusted EBITDA, Free Cash Flow and Conversion are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial (3) measures. Throughout this presentation Pro Forma Adjusted EBITDA reflects “EBITDA” as defined by the Company’s Credit Agreement; Adjusted EBITDA sum reflects Adjusted EBITDA of the consolidated Company, chart excludes Other segment 30
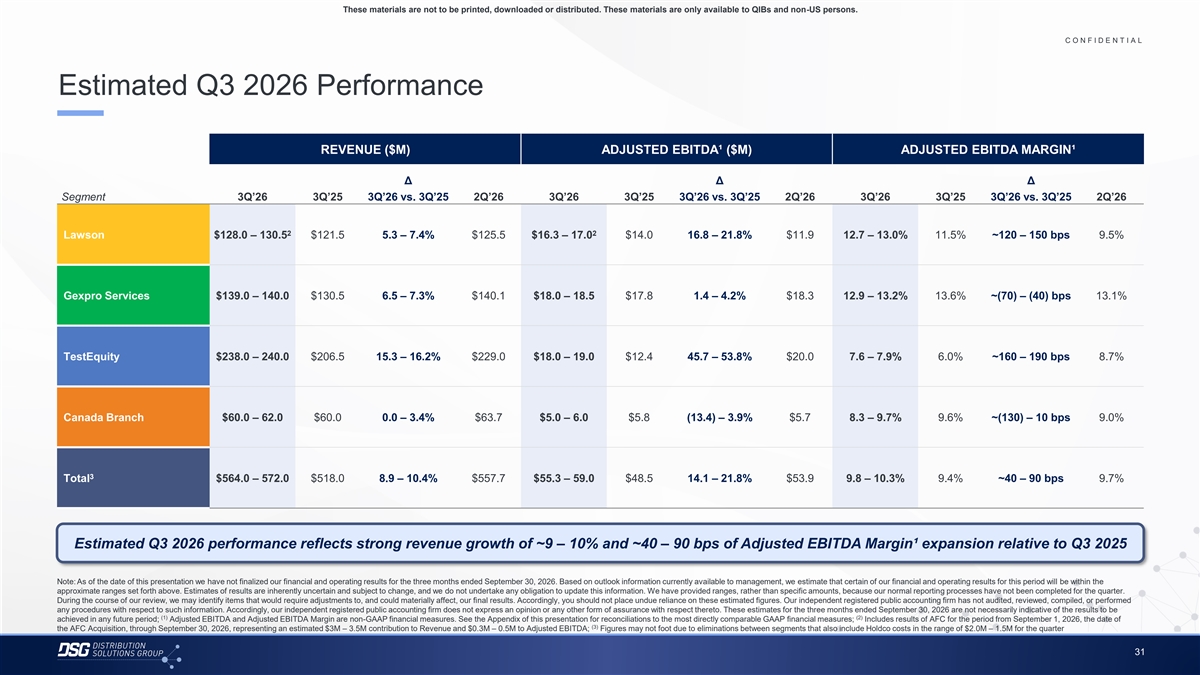
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Estimated Q3 2026 Performance Title bar/Bullets 68 87 128 ACCENTS REVENUE ($M) ADJUSTED EBITDA¹ ($M) ADJUSTED EBITDA MARGIN¹ 2 85 25 141 1 70 250 Δ Δ Δ 68 173 Segment 3Q’26 3Q’25 3Q’26 vs. 3Q’25 2Q’26 3Q’26 3Q’25 3Q’26 vs. 3Q’25 2Q’26 3Q’26 3Q’25 3Q’26 vs. 3Q’25 2Q’26 87 185 2 128 211 142 210 2 2 Lawson $128.0 – 130.5 $121.5 5.3 – 7.4% $125.5 $16.3 – 17.0 $14.0 16.8 – 21.8% $11.9 12.7 – 13.0% 11.5% ~120 – 150 bps 9.5% 169 221 3 216 239 255 255 196 231 4 38 168 Gexpro Services $139.0 – 140.0 $130.5 6.5 – 7.3% $140.1 $18.0 – 18.5 $17.8 1.4 – 4.2% $18.3 12.9 – 13.2% 13.6% ~(70) – (40) bps 13.1% 239 249 129 205 5 35 167 213 238 213 238 6 214 239 TestEquity $238.0 – 240.0 $206.5 15.3 – 16.2% $229.0 $18.0 – 19.0 $12.4 45.7 – 53.8% $20.0 7.6 – 7.9% 6.0% ~160 – 190 bps 8.7% 30 146 124 213 Hyperlink 153 234 0 98 Followed Canada Branch $60.0 – 62.0 $60.0 0.0 – 3.4% $63.7 $5.0 – 6.0 $5.8 (13.4) – 3.9% $5.7 8.3 – 9.7% 9.6% ~(130) – 10 bps 9.0% 80 205 Hyperlink 117 255 TABLE 50 Lines 56 3 Total $564.0 – 572.0 $518.0 8.9 – 10.4% $557.7 $55.3 – 59.0 $48.5 14.1 – 21.8% $53.9 9.8 – 10.3% 9.4% ~40 – 90 bps 9.7% 62 68 Highlights 87 128 Estimated Q3 2026 performance reflects strong revenue growth of ~9 – 10% and ~40 – 90 bps of Adjusted EBITDA Margin¹ expansion relative to Q3 2025 Note: As of the date of this presentation we have not finalized our financial and operating results for the three months ended September 30, 2026. Based on outlook information currently available to management, we estimate that certain of our financial and operating results for this period will be within the approximate ranges set forth above. Estimates of results are inherently uncertain and subject to change, and we do not undertake any obligation to update this information. We have provided ranges, rather than specific amounts, because our normal reporting processes have not been completed for the quarter. During the course of our review, we may identify items that would require adjustments to, and could materially affect, our final results. Accordingly, you should not place undue reliance on these estimated figures. Our independent registered public accounting firm has not audited, reviewed, compiled, or performed any procedures with respect to such information. Accordingly, our independent registered public accounting firm does not express an opinion or any other form of assurance with respect thereto. These estimates for the three months ended September 30, 2026 are not necessarily indicative of the results to be (1) (2) achieved in any future period; Adjusted EBITDA and Adjusted EBITDA Margin are non-GAAP financial measures. See the Appendix of this presentation for reconciliations to the most directly comparable GAAP financial measures; Includes results of AFC for the period from September 1, 2026, the date of (3) the AFC Acquisition, through September 30, 2026, representing an estimated $3M – 3.5M contribution to Revenue and $0.3M – 0.5M to Adjusted EBITDA; Figures may not foot due to eliminations between segments that also include Holdco costs in the range of $2.0M – 1.5M for the quarter 31
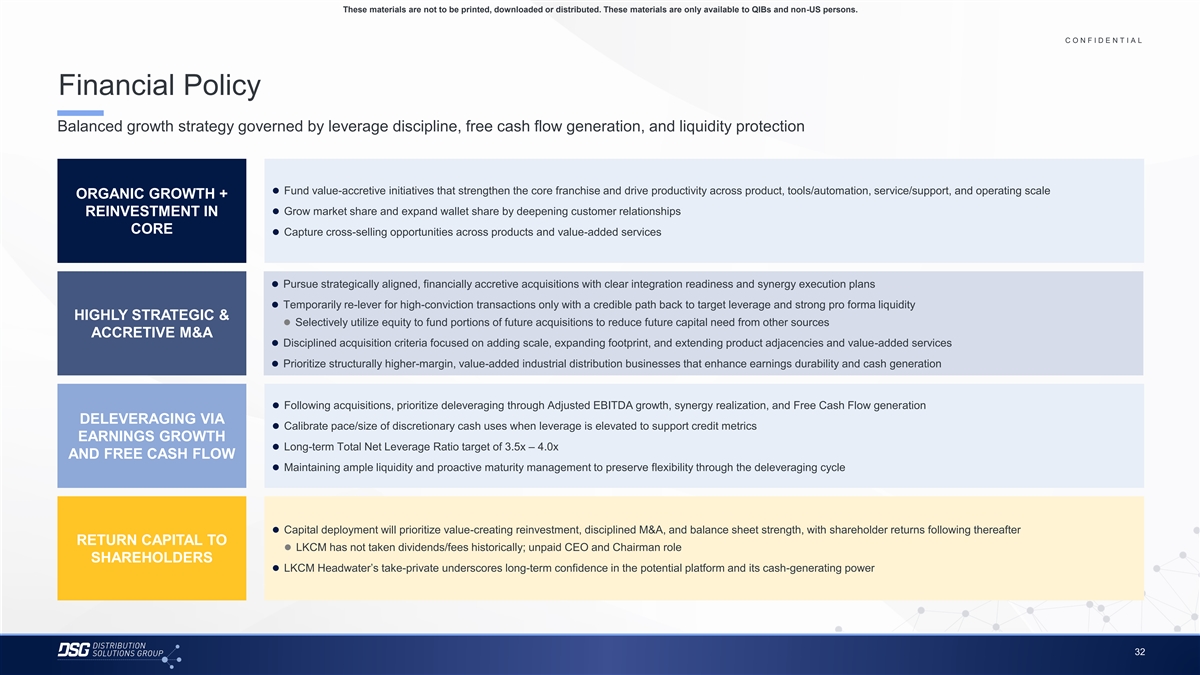
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Financial Policy Title bar/Bullets 68 87 128 Balanced growth strategy governed by leverage discipline, free cash flow generation, and liquidity protection ACCENTS 2 85 25 141 1 70 250 68 173 ⚫ Fund value-accretive initiatives that strengthen the core franchise and drive productivity across product, tools/automation, service/support, and operating scale ORGANIC GROWTH + 87 185 2 128 211 ⚫ Grow market share and expand wallet share by deepening customer relationships REINVESTMENT IN 142 210 CORE ⚫ Capture cross-selling opportunities across products and value-added services 169 221 3 216 239 255 255 196 231 4 38 168 ⚫ Pursue strategically aligned, financially accretive acquisitions with clear integration readiness and synergy execution plans 239 249 ⚫ Temporarily re-lever for high-conviction transactions only with a credible path back to target leverage and strong pro forma liquidity 129 205 5 HIGHLY STRATEGIC & 35 167 ⚫ Selectively utilize equity to fund portions of future acquisitions to reduce future capital need from other sources ACCRETIVE M&A 213 238 ⚫ Disciplined acquisition criteria focused on adding scale, expanding footprint, and extending product adjacencies and value-added services 213 238 6 214 239 ⚫ Prioritize structurally higher-margin, value-added industrial distribution businesses that enhance earnings durability and cash generation 30 146 124 213 Hyperlink 153 234 ⚫ Following acquisitions, prioritize deleveraging through Adjusted EBITDA growth, synergy realization, and Free Cash Flow generation 0 98 Followed 80 205 DELEVERAGING VIA Hyperlink ⚫ Calibrate pace/size of discretionary cash uses when leverage is elevated to support credit metrics 117 255 EARNINGS GROWTH ⚫ Long-term Total Net Leverage Ratio target of 3.5x – 4.0x TABLE AND FREE CASH FLOW 50 ⚫ Maintaining ample liquidity and proactive maturity management to preserve flexibility through the deleveraging cycle Lines 56 62 68 Highlights 87 128 ⚫ Capital deployment will prioritize value-creating reinvestment, disciplined M&A, and balance sheet strength, with shareholder returns following thereafter RETURN CAPITAL TO ⚫ LKCM has not taken dividends/fees historically; unpaid CEO and Chairman role SHAREHOLDERS ⚫ LKCM Headwater’s take-private underscores long-term confidence in the potential platform and its cash-generating power 32
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. Appendix
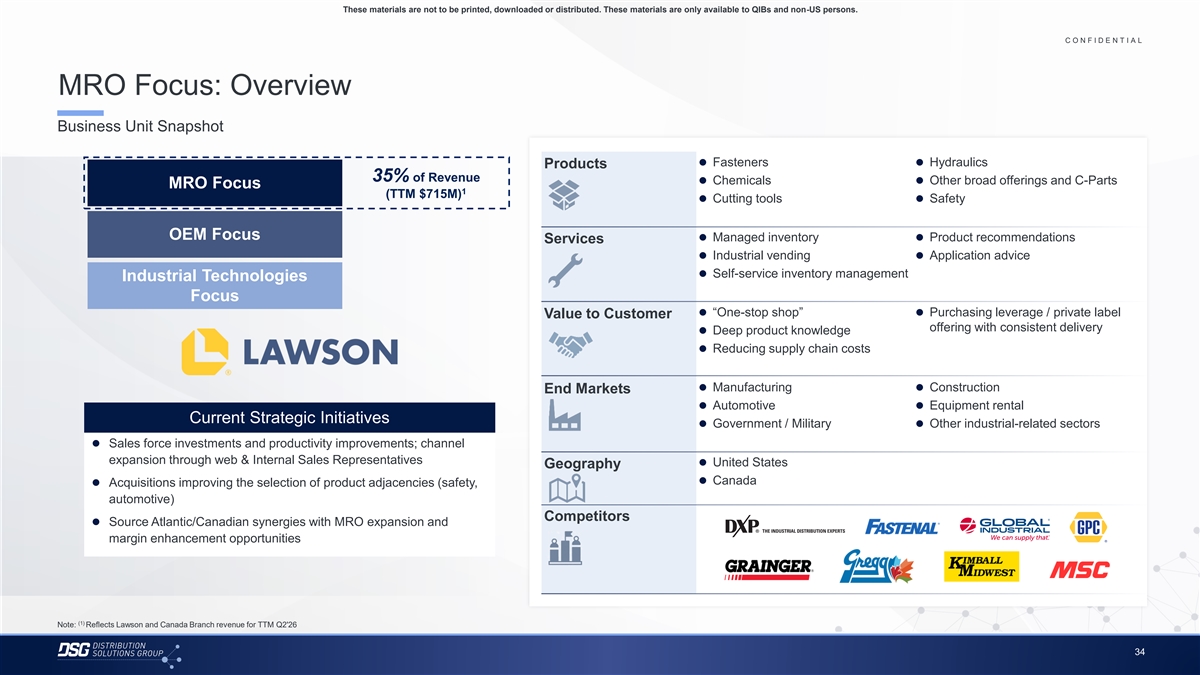
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 MRO Focus: Overview Title bar/Bullets 68 87 128 Business Unit Snapshot ACCENTS 2 85 25 141 ⚫ Fasteners⚫ Hydraulics 1 Products 70 250 35% of Revenue ⚫ Chemicals⚫ Other broad offerings and C-Parts MRO Focus 68 173 1 (TTM $715M) 87 185⚫ Cutting tools⚫ Safety 2 128 211 142 210 169 221 OEM Focus 3⚫ Managed inventory⚫ Product recommendations Services 216 239 ⚫ Industrial vending ⚫ Application advice 255 255 196 231 4⚫ Self-service inventory management Industrial Technologies 38 168 Focus 239 249 129 205 5 ⚫ “One-stop shop”⚫ Purchasing leverage / private label Value to Customer 35 167 offering with consistent delivery ⚫ Deep product knowledge 213 238 213 238 6 ⚫ Reducing supply chain costs 214 239 30 146 124 213 Hyperlink ⚫ Manufacturing⚫ Construction End Markets 153 234 ⚫ Automotive⚫ Equipment rental 0 98 Followed Current Strategic Initiatives 80 205 ⚫ Government / Military⚫ Other industrial-related sectors Hyperlink 117 255 ⚫ Sales force investments and productivity improvements; channel TABLE expansion through web & Internal Sales Representatives ⚫ United States 50 Geography Lines 56 ⚫ Canada ⚫ Acquisitions improving the selection of product adjacencies (safety, 62 automotive) 68 Highlights 87 Competitors ⚫ Source Atlantic/Canadian synergies with MRO expansion and 128 margin enhancement opportunities (1) Note: Reflects Lawson and Canada Branch revenue for TTM Q2'26 34
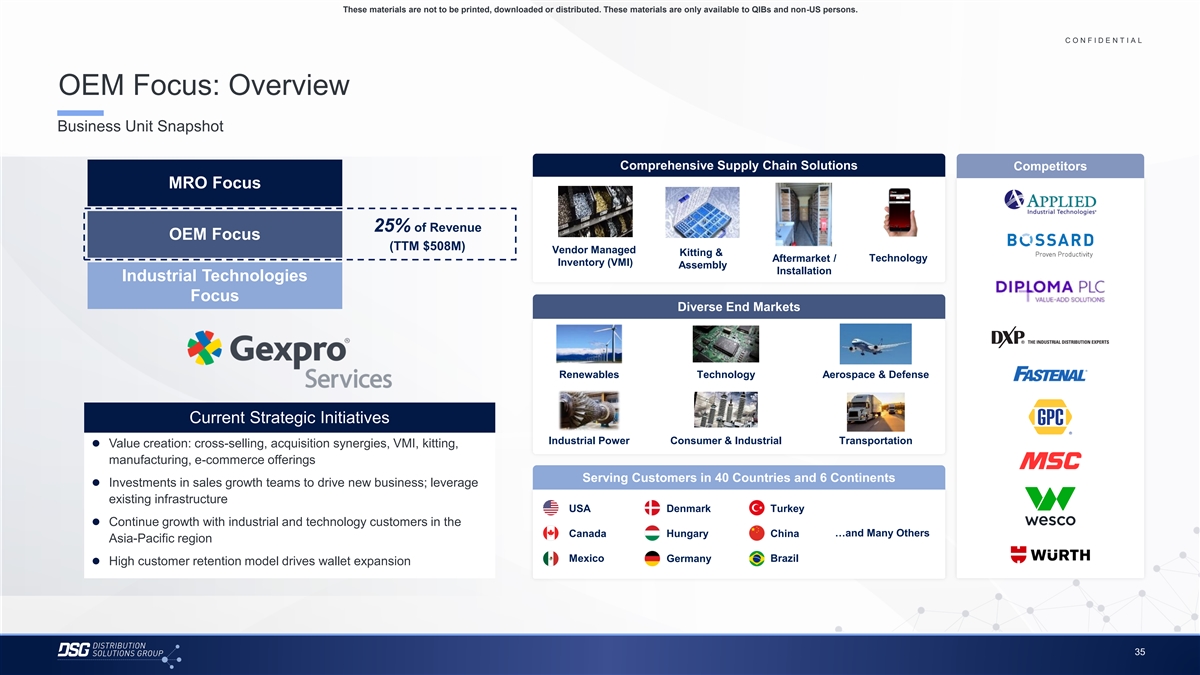
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 OEM Focus: Overview Title bar/Bullets 68 87 128 Business Unit Snapshot ACCENTS 2 85 25 141 1 Comprehensive Supply Chain Solutions Competitors 70 250 MRO Focus 68 173 87 185 2 128 211 142 210 25% of Revenue 169 221 OEM Focus 3 216 239 (TTM $508M) Vendor Managed Kitting & Aftermarket / Technology Inventory (VMI) 255 255 Assembly Installation 196 231 4 Industrial Technologies 38 168 Focus 239 249 Diverse End Markets 129 205 5 35 167 213 238 213 238 6 214 239 30 146 Renewables Technology Aerospace & Defense 124 213 Hyperlink 153 234 0 98 Followed Current Strategic Initiatives 80 205 Hyperlink 117 255 Industrial Power Consumer & Industrial Transportation ⚫ Value creation: cross-selling, acquisition synergies, VMI, kitting, TABLE manufacturing, e-commerce offerings 50 Lines 56 Serving Customers in 40 Countries and 6 Continents ⚫ Investments in sales growth teams to drive new business; leverage 62 existing infrastructure 68 USA Denmark Turkey Highlights 87 ⚫ Continue growth with industrial and technology customers in the 128 …and Many Others Canada Hungary China Asia-Pacific region Mexico Brazil Germany ⚫ High customer retention model drives wallet expansion 35
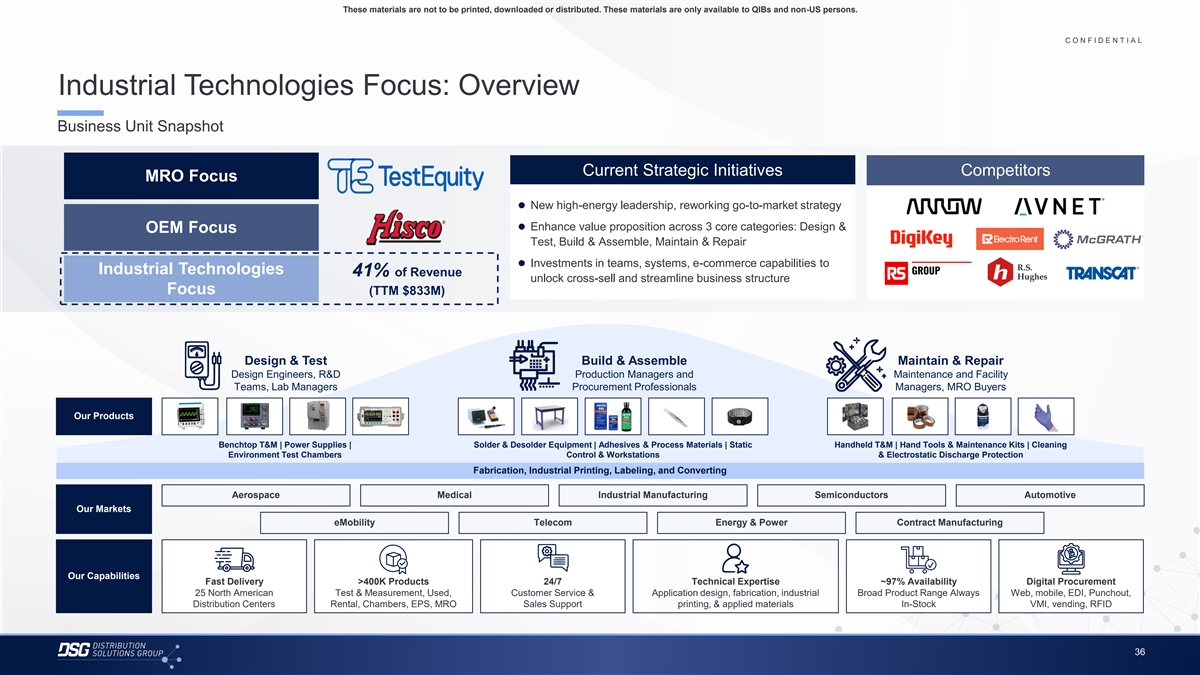
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Industrial Technologies Focus: Overview Title bar/Bullets 68 87 128 Business Unit Snapshot ACCENTS 2 85 25 141 1 70 250 Current Strategic Initiatives Competitors MRO Focus 68 173 87 185 2 ⚫ New high-energy leadership, reworking go-to-market strategy 128 211 142 210⚫ Enhance value proposition across 3 core categories: Design & OEM Focus 169 221 3 Test, Build & Assemble, Maintain & Repair 216 239 255 255⚫ Investments in teams, systems, e-commerce capabilities to Industrial Technologies 196 231 41% of Revenue 4 unlock cross-sell and streamline business structure 38 168 Focus (TTM $833M) 239 249 129 205 5 35 167 213 238 213 238 6 214 239 Design & Test Build & Assemble Maintain & Repair 30 146 Design Engineers, R&D Production Managers and Maintenance and Facility 124 213 Hyperlink Teams, Lab Managers Procurement Professionals Managers, MRO Buyers 153 234 0 98 Followed Our Products 80 205 Hyperlink 117 255 Benchtop T&M | Power Supplies | Solder & Desolder Equipment | Adhesives & Process Materials | Static Handheld T&M | Hand Tools & Maintenance Kits | Cleaning TABLE Environment Test Chambers Control & Workstations & Electrostatic Discharge Protection 50 Fabrication, Industrial Printing, Labeling, and Converting Lines 56 62 Aerospace Medical Industrial Manufacturing Semiconductors Automotive 68 Our Markets Highlights 87 eMobility Telecom Energy & Power Contract Manufacturing 128 Our Capabilities Fast Delivery >400K Products 24/7 Technical Expertise ~97% Availability Digital Procurement 25 North American Test & Measurement, Used, Customer Service & Application design, fabrication, industrial Broad Product Range Always Web, mobile, EDI, Punchout, Distribution Centers Rental, Chambers, EPS, MRO Sales Support printing, & applied materials In-Stock VMI, vending, RFID 36
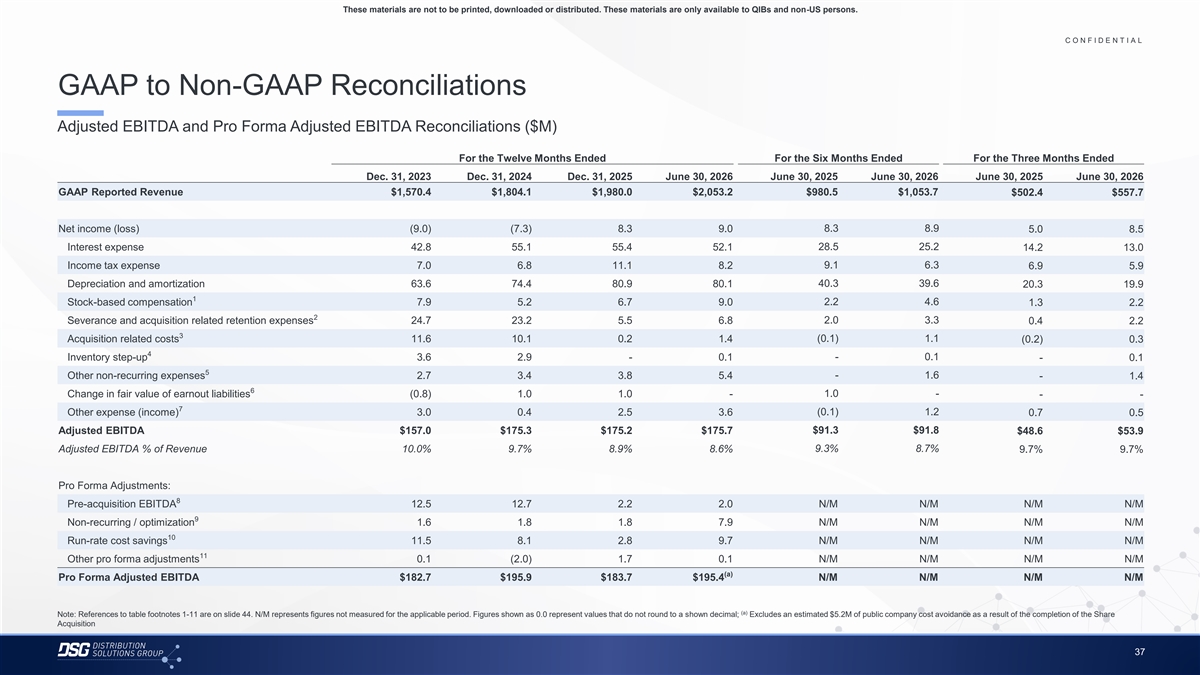
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations Title bar/Bullets 68 87 128 Adjusted EBITDA and Pro Forma Adjusted EBITDA Reconciliations ($M) ACCENTS 2 85 For the Twelve Months Ended For the Six Months Ended For the Three Months Ended 25 141 1 70 250 Dec. 31, 2023 Dec. 31, 2024 Dec. 31, 2025 June 30, 2026 June 30, 2025 June 30, 2026 June 30, 2025 June 30, 2026 68 173 GAAP Reported Revenue $1,570.4 $1,804.1 $1,980.0 $2,053.2 $980.5 $1,053.7 $502.4 $557.7 87 185 2 128 211 142 210 Net income (loss) (9.0) (7.3) 8.3 9.0 8.3 8.9 5.0 8.5 169 221 3 216 239 28.5 25.2 Interest expense 42.8 55.1 55.4 52.1 14.2 13.0 255 255 Income tax expense 7.0 6.8 11.1 8.2 9.1 6.3 6.9 5.9 196 231 4 38 168 40.3 39.6 Depreciation and amortization 63.6 74.4 80.9 80.1 20.3 19.9 1 239 249 Stock-based compensation 7.9 5.2 6.7 9.0 2.2 4.6 1.3 2.2 129 205 5 2 35 167 Severance and acquisition related retention expenses 24.7 23.2 5.5 6.8 2.0 3.3 0.4 2.2 3 213 238 (0.1) 1.1 Acquisition related costs 11.6 10.1 0.2 1.4 (0.2) 0.3 213 238 6 4 214 239 Inventory step-up 3.6 2.9 - 0.1 - 0.1 - 0.1 5 30 146 Other non-recurring expenses 2.7 3.4 3.8 5.4 - 1.6 - 1.4 124 213 Hyperlink 6 153 234 1.0 - Change in fair value of earnout liabilities (0.8) 1.0 1.0 - - - 7 0 98 Other expense (income) 3.0 0.4 2.5 3.6 (0.1) 1.2 0.7 0.5 Followed 80 205 Hyperlink 117 255 $91.3 $91.8 Adjusted EBITDA $157.0 $175.3 $175.2 $175.7 $48.6 $53.9 TABLE Adjusted EBITDA % of Revenue 10.0% 9.7% 8.9% 8.6% 9.3% 8.7% 9.7% 9.7% 50 Lines 56 62 Pro Forma Adjustments: 8 Pre-acquisition EBITDA 12.5 12.7 2.2 2.0 N/M N/M N/M N/M 68 Highlights 87 9 Non-recurring / optimization 1.6 1.8 1.8 7.9 N/M N/M N/M N/M 128 10 Run-rate cost savings 11.5 8.1 2.8 9.7 N/M N/M N/M N/M 11 Other pro forma adjustments 0.1 (2.0) 1.7 0.1 N/M N/M N/M N/M (a) Pro Forma Adjusted EBITDA $182.7 $195.9 $183.7 $195.4 N/M N/M N/M N/M (a) Note: References to table footnotes 1-11 are on slide 44. N/M represents figures not measured for the applicable period. Figures shown as 0.0 represent values that do not round to a shown decimal; Excludes an estimated $5.2M of public company cost avoidance as a result of the completion of the Share Acquisition 37
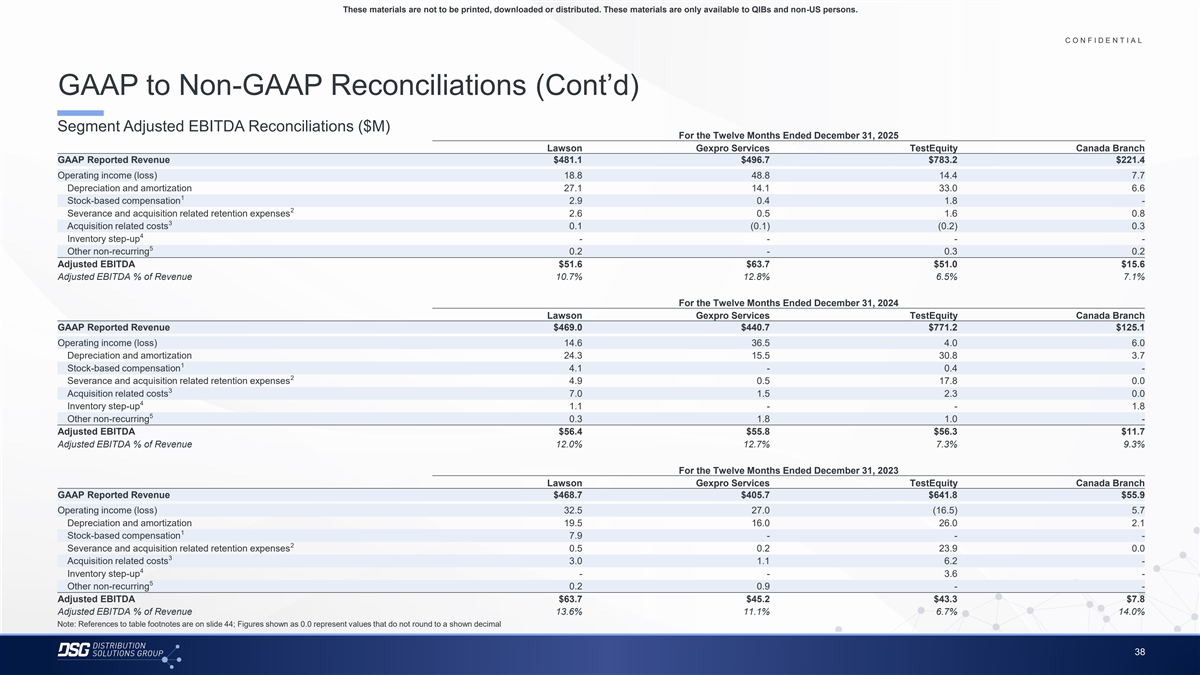
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont’d) Title bar/Bullets 68 87 128 Segment Adjusted EBITDA Reconciliations ($M) For the Twelve Months Ended December 31, 2025 ACCENTS Lawson Gexpro Services TestEquity Canada Branch 2 85 GAAP Reported Revenue $481.1 $496.7 $783.2 $221.4 25 141 1 70 250 Operating income (loss) 18.8 48.8 14.4 7.7 Depreciation and amortization 27.1 14.1 33.0 6.6 68 173 1 87 185 2 Stock-based compensation 2.9 0.4 1.8 - 128 211 2 Severance and acquisition related retention expenses 2.6 0.5 1.6 0.8 3 Acquisition related costs 0.1 (0.1) (0.2) 0.3 142 210 4 169 221 3 Inventory step-up - - - - 216 239 5 Other non-recurring 0.2 - 0.3 0.2 255 255 Adjusted EBITDA $51.6 $63.7 $51.0 $15.6 196 231 4 Adjusted EBITDA % of Revenue 10.7% 12.8% 6.5% 7.1% 38 168 239 249 For the Twelve Months Ended December 31, 2024 129 205 5 Lawson Gexpro Services TestEquity Canada Branch 35 167 GAAP Reported Revenue $469.0 $440.7 $771.2 $125.1 213 238 Operating income (loss) 14.6 36.5 4.0 6.0 213 238 6 Depreciation and amortization 24.3 15.5 30.8 3.7 214 239 1 Stock-based compensation 4.1 - 0.4 - 30 146 2 Severance and acquisition related retention expenses 4.9 0.5 17.8 0.0 124 213 Hyperlink 3 153 234 Acquisition related costs 7.0 1.5 2.3 0.0 4 Inventory step-up 1.1 - - 1.8 0 98 5 Followed Other non-recurring 0.3 1.8 1.0 - 80 205 Hyperlink 117 255 Adjusted EBITDA $56.4 $55.8 $56.3 $11.7 Adjusted EBITDA % of Revenue 12.0% 12.7% 7.3% 9.3% TABLE 50 For the Twelve Months Ended December 31, 2023 Lines 56 Lawson Gexpro Services TestEquity Canada Branch 62 GAAP Reported Revenue $468.7 $405.7 $641.8 $55.9 68 Operating income (loss) 32.5 27.0 (16.5) 5.7 Highlights 87 Depreciation and amortization 19.5 16.0 26.0 2.1 128 1 Stock-based compensation 7.9 - - - 2 Severance and acquisition related retention expenses 0.5 0.2 23.9 0.0 3 Acquisition related costs 3.0 1.1 6.2 - 4 Inventory step-up - - 3.6 - 5 Other non-recurring 0.2 0.9 - - Adjusted EBITDA $63.7 $45.2 $43.3 $7.8 Adjusted EBITDA % of Revenue 13.6% 11.1% 6.7% 14.0% Note: References to table footnotes are on slide 44; Figures shown as 0.0 represent values that do not round to a shown decimal 38
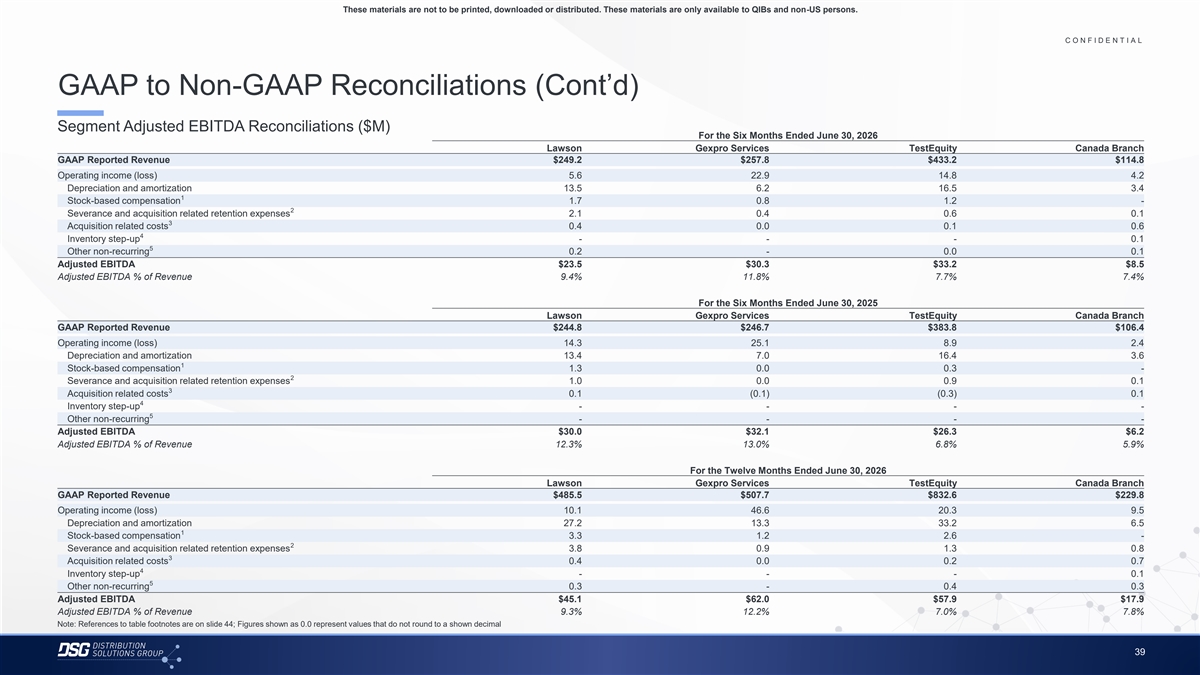
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont’d) Title bar/Bullets 68 87 128 Segment Adjusted EBITDA Reconciliations ($M) For the Six Months Ended June 30, 2026 ACCENTS Lawson Gexpro Services TestEquity Canada Branch 2 85 GAAP Reported Revenue $249.2 $257.8 $433.2 $114.8 25 141 1 70 250 Operating income (loss) 5.6 22.9 14.8 4.2 Depreciation and amortization 13.5 6.2 16.5 3.4 68 173 1 87 185 2 Stock-based compensation 1.7 0.8 1.2 - 128 211 2 Severance and acquisition related retention expenses 2.1 0.4 0.6 0.1 3 Acquisition related costs 0.4 0.0 0.1 0.6 142 210 4 169 221 3 Inventory step-up - - - 0.1 216 239 5 Other non-recurring 0.2 - 0.0 0.1 255 255 Adjusted EBITDA $23.5 $30.3 $33.2 $8.5 196 231 4 Adjusted EBITDA % of Revenue 9.4% 11.8% 7.7% 7.4% 38 168 239 249 For the Six Months Ended June 30, 2025 129 205 5 Lawson Gexpro Services TestEquity Canada Branch 35 167 GAAP Reported Revenue $244.8 $246.7 $383.8 $106.4 213 238 Operating income (loss) 14.3 25.1 8.9 2.4 213 238 6 Depreciation and amortization 13.4 7.0 16.4 3.6 214 239 1 Stock-based compensation 1.3 0.0 0.3 - 30 146 2 Severance and acquisition related retention expenses 1.0 0.0 0.9 0.1 124 213 Hyperlink 3 153 234 Acquisition related costs 0.1 (0.1) (0.3) 0.1 4 Inventory step-up - - - - 0 98 5 Followed Other non-recurring - - - - 80 205 Hyperlink 117 255 Adjusted EBITDA $30.0 $32.1 $26.3 $6.2 Adjusted EBITDA % of Revenue 12.3% 13.0% 6.8% 5.9% TABLE 50 For the Twelve Months Ended June 30, 2026 Lines 56 Lawson Gexpro Services TestEquity Canada Branch 62 GAAP Reported Revenue $485.5 $507.7 $832.6 $229.8 68 Operating income (loss) 10.1 46.6 20.3 9.5 Highlights 87 Depreciation and amortization 27.2 13.3 33.2 6.5 128 1 Stock-based compensation 3.3 1.2 2.6 - 2 Severance and acquisition related retention expenses 3.8 0.9 1.3 0.8 3 Acquisition related costs 0.4 0.0 0.2 0.7 4 Inventory step-up - - - 0.1 5 Other non-recurring 0.3 - 0.4 0.3 Adjusted EBITDA $45.1 $62.0 $57.9 $17.9 Adjusted EBITDA % of Revenue 9.3% 12.2% 7.0% 7.8% Note: References to table footnotes are on slide 44; Figures shown as 0.0 represent values that do not round to a shown decimal 39
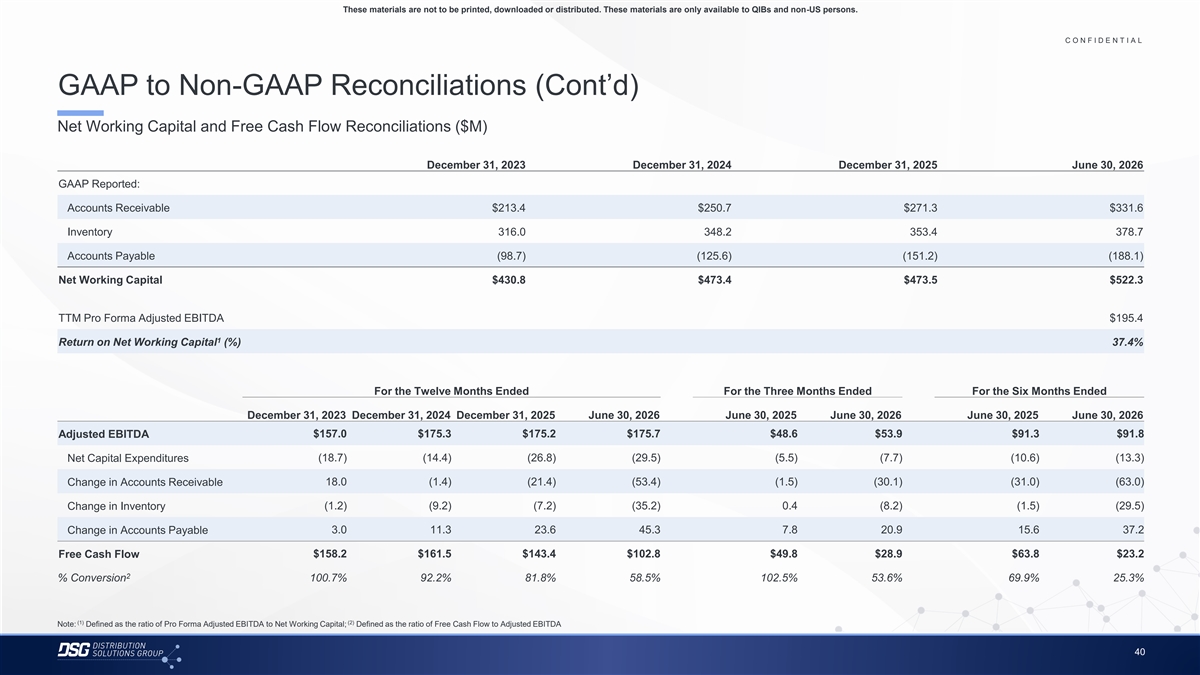
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont’d) Title bar/Bullets 68 87 128 Net Working Capital and Free Cash Flow Reconciliations ($M) ACCENTS 2 85 25 141 1 December 31, 2023 December 31, 2024 December 31, 2025 June 30, 2026 70 250 GAAP Reported: 68 173 87 185 2 Accounts Receivable $213.4 $250.7 $271.3 $331.6 128 211 142 210 Inventory 316.0 348.2 353.4 378.7 169 221 3 216 239 Accounts Payable (98.7) (125.6) (151.2) (188.1) 255 255 196 231 4 Net Working Capital $430.8 $473.4 $473.5 $522.3 38 168 239 249 129 205 5 TTM Pro Forma Adjusted EBITDA $195.4 35 167 213 238 1 Return on Net Working Capital (%) 37.4% 213 238 6 214 239 30 146 124 213 Hyperlink For the Twelve Months Ended For the Three Months Ended For the Six Months Ended 153 234 0 98 Followed December 31, 2023 December 31, 2024 December 31, 2025 June 30, 2026 June 30, 2025 June 30, 2026 June 30, 2025 June 30, 2026 80 205 Hyperlink 117 255 Adjusted EBITDA $157.0 $175.3 $175.2 $175.7 $48.6 $53.9 $91.3 $91.8 TABLE Net Capital Expenditures (18.7) (14.4) (26.8) (29.5) (5.5) (7.7) (10.6) (13.3) 50 Lines 56 18.0 (1.4) (21.4) (53.4) (1.5) (30.1) (31.0) (63.0) Change in Accounts Receivable 62 68 (1.2) (9.2) (7.2) (35.2) 0.4 (8.2) (1.5) (29.5) Change in Inventory Highlights 87 128 3.0 11.3 23.6 45.3 7.8 20.9 15.6 37.2 Change in Accounts Payable $158.2 $161.5 $143.4 $102.8 $49.8 $28.9 $63.8 $23.2 Free Cash Flow 2 % Conversion 100.7% 92.2% 81.8% 58.5% 102.5% 53.6% 69.9% 25.3% (1) (2) Note: Defined as the ratio of Pro Forma Adjusted EBITDA to Net Working Capital; Defined as the ratio of Free Cash Flow to Adjusted EBITDA 40
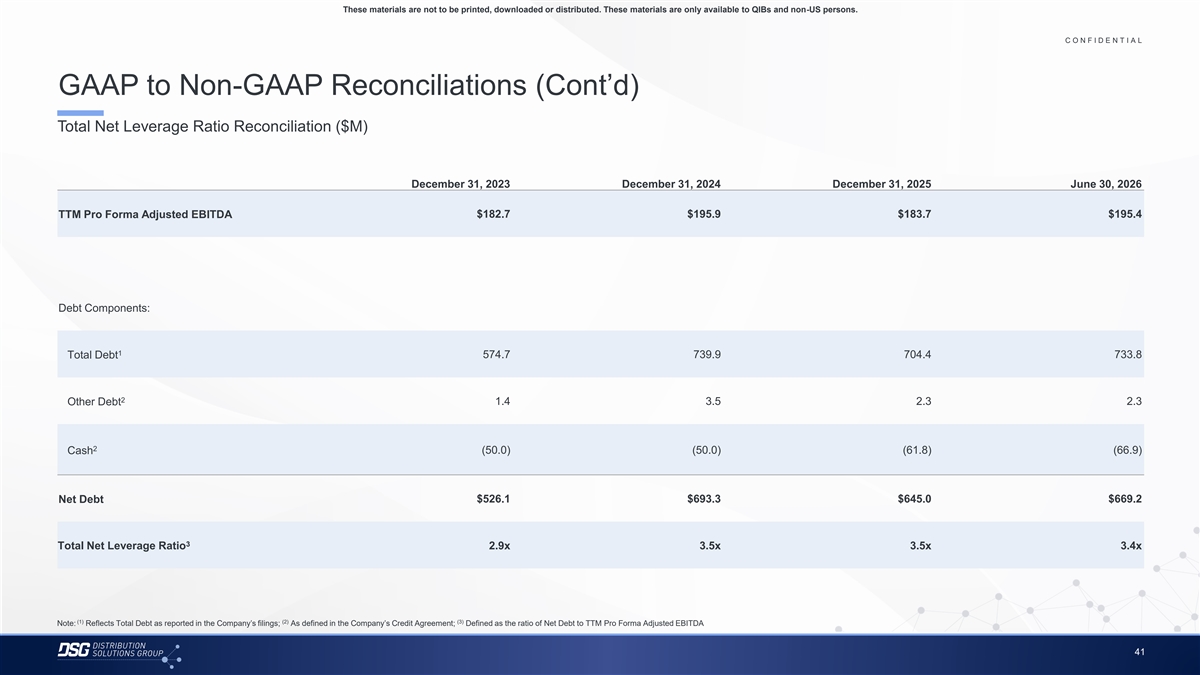
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont’d) Title bar/Bullets 68 87 128 Total Net Leverage Ratio Reconciliation ($M) ACCENTS 2 85 25 141 1 70 250 December 31, 2023 December 31, 2024 December 31, 2025 June 30, 2026 68 173 87 185 2 128 211 TTM Pro Forma Adjusted EBITDA $182.7 $195.9 $183.7 $195.4 142 210 169 221 3 216 239 255 255 196 231 4 38 168 239 249 Debt Components: 129 205 5 35 167 213 238 213 238 6 1 Total Debt 574.7 739.9 704.4 733.8 214 239 30 146 124 213 Hyperlink 153 234 2 Other Debt 1.4 3.5 2.3 2.3 0 98 Followed 80 205 Hyperlink 117 255 2 TABLE Cash (50.0) (50.0) (61.8) (66.9) 50 Lines 56 62 Net Debt $526.1 $693.3 $645.0 $669.2 68 Highlights 87 128 3 Total Net Leverage Ratio 2.9x 3.5x 3.5x 3.4x (1) (2) (3) Note: Reflects Total Debt as reported in the Company’s filings; As defined in the Company’s Credit Agreement; Defined as the ratio of Net Debt to TTM Pro Forma Adjusted EBITDA 41
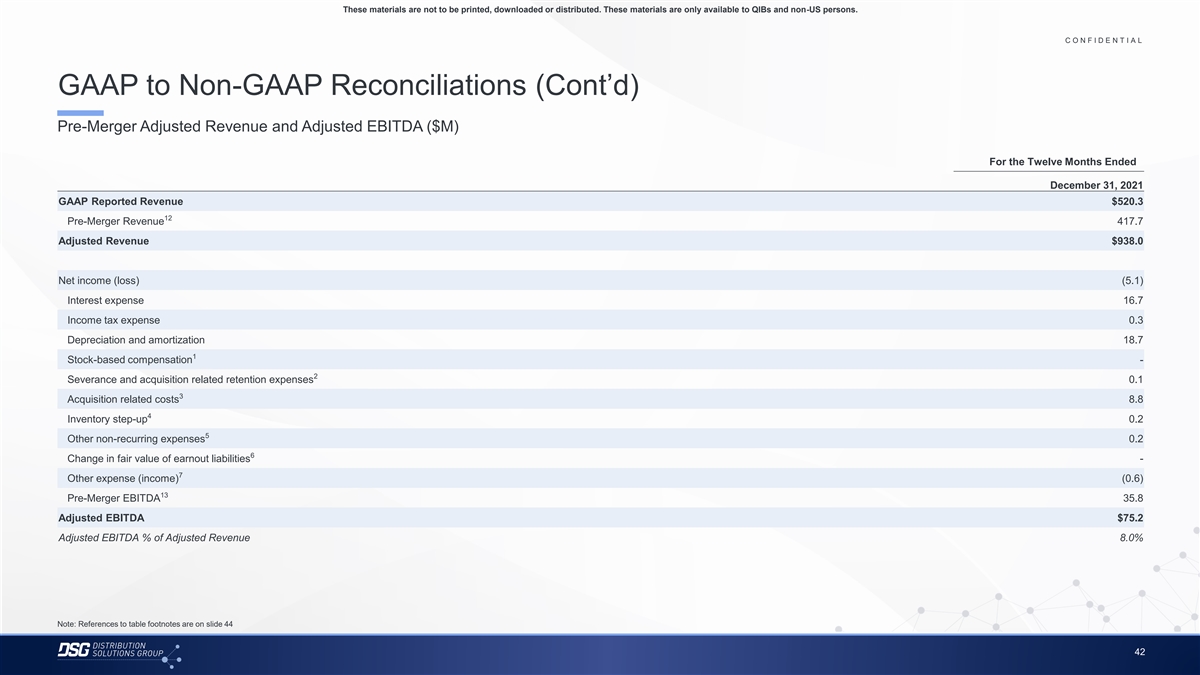
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont’d) Title bar/Bullets 68 87 128 Pre-Merger Adjusted Revenue and Adjusted EBITDA ($M) ACCENTS 2 85 25 141 For the Twelve Months Ended 1 70 250 December 31, 2021 68 173 87 185 2 GAAP Reported Revenue $520.3 128 211 12 Pre-Merger Revenue 417.7 142 210 169 221 3 Adjusted Revenue $938.0 216 239 255 255 196 231 4 Net income (loss) (5.1) 38 168 239 249 Interest expense 16.7 129 205 5 35 167 Income tax expense 0.3 213 238 Depreciation and amortization 18.7 213 238 6 214 239 1 Stock-based compensation - 30 146 2 Severance and acquisition related retention expenses 0.1 124 213 Hyperlink 153 234 3 Acquisition related costs 8.8 0 98 Followed 4 Inventory step-up 0.2 80 205 Hyperlink 117 255 5 Other non-recurring expenses 0.2 TABLE 6 Change in fair value of earnout liabilities - 50 Lines 56 7 Other expense (income) (0.6) 62 13 Pre-Merger EBITDA 35.8 68 Highlights 87 Adjusted EBITDA $75.2 128 Adjusted EBITDA % of Adjusted Revenue 8.0% Note: References to table footnotes are on slide 44 42
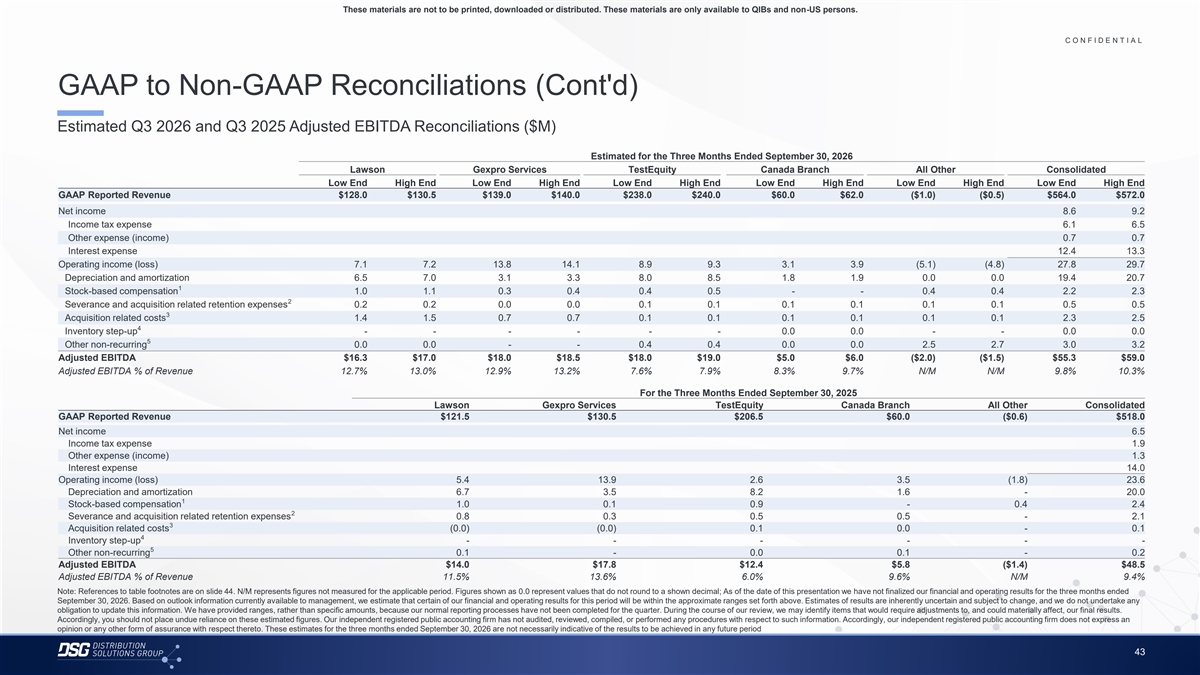
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 GAAP to Non-GAAP Reconciliations (Cont'd) Title bar/Bullets 68 87 128 Estimated Q3 2026 and Q3 2025 Adjusted EBITDA Reconciliations ($M) ACCENTS 2 85 Estimated for the Three Months Ended September 30, 2026 25 141 1 Lawson Gexpro Services TestEquity Canada Branch All Other Consolidated 70 250 Low End High End Low End High End Low End High End Low End High End Low End High End Low End High End 68 173 GAAP Reported Revenue $128.0 $130.5 $139.0 $140.0 $238.0 $240.0 $60.0 $62.0 ($1.0) ($0.5) $564.0 $572.0 87 185 2 128 211 Net income 8.6 9.2 Income tax expense 6.1 6.5 142 210 169 221 Other expense (income) 0.7 0.7 3 216 239 Interest expense 12.4 13.3 255 255 Operating income (loss) 7.1 7.2 13.8 14.1 8.9 9.3 3.1 3.9 (5.1) (4.8) 27.8 29.7 196 231 4 Depreciation and amortization 6.5 7.0 3.1 3.3 8.0 8.5 1.8 1.9 0.0 0.0 19.4 20.7 38 168 1 Stock-based compensation 1.0 1.1 0.3 0.4 0.4 0.5 - - 0.4 0.4 2.2 2.3 239 249 2 Severance and acquisition related retention expenses 0.2 0.2 0.0 0.0 0.1 0.1 0.1 0.1 0.1 0.1 0.5 0.5 129 205 5 3 Acquisition related costs 1.4 1.5 0.7 0.7 0.1 0.1 0.1 0.1 0.1 0.1 2.3 2.5 35 167 4 Inventory step-up - - - - - - 0.0 0.0 - - 0.0 0.0 213 238 5 Other non-recurring 0.0 0.0 - - 0.4 0.4 0.0 0.0 2.5 2.7 3.0 3.2 213 238 6 214 239 Adjusted EBITDA $16.3 $17.0 $18.0 $18.5 $18.0 $19.0 $5.0 $6.0 ($2.0) ($1.5) $55.3 $59.0 Adjusted EBITDA % of Revenue 12.7% 13.0% 12.9% 13.2% 7.6% 7.9% 8.3% 9.7% N/M N/M 9.8% 10.3% 30 146 124 213 Hyperlink For the Three Months Ended September 30, 2025 153 234 Lawson Gexpro Services TestEquity Canada Branch All Other Consolidated 0 98 Followed GAAP Reported Revenue $121.5 $130.5 $206.5 $60.0 ($0.6) $518.0 80 205 Hyperlink 117 255 Net income 6.5 Income tax expense 1.9 TABLE Other expense (income) 1.3 50 Interest expense 14.0 Lines 56 Operating income (loss) 5.4 13.9 2.6 3.5 (1.8) 23.6 62 Depreciation and amortization 6.7 3.5 8.2 1.6 - 20.0 1 Stock-based compensation 1.0 0.1 0.9 - 0.4 2.4 68 2 Highlights 87 Severance and acquisition related retention expenses 0.8 0.3 0.5 0.5 - 2.1 3 128 Acquisition related costs (0.0) (0.0) 0.1 0.0 - 0.1 4 Inventory step-up - - - - - - 5 Other non-recurring 0.1 - 0.0 0.1 - 0.2 Adjusted EBITDA $14.0 $17.8 $12.4 $5.8 ($1.4) $48.5 Adjusted EBITDA % of Revenue 11.5% 13.6% 6.0% 9.6% N/M 9.4% Note: References to table footnotes are on slide 44. N/M represents figures not measured for the applicable period. Figures shown as 0.0 represent values that do not round to a shown decimal; As of the date of this presentation we have not finalized our financial and operating results for the three months ended September 30, 2026. Based on outlook information currently available to management, we estimate that certain of our financial and operating results for this period will be within the approximate ranges set forth above. Estimates of results are inherently uncertain and subject to change, and we do not undertake any obligation to update this information. We have provided ranges, rather than specific amounts, because our normal reporting processes have not been completed for the quarter. During the course of our review, we may identify items that would require adjustments to, and could materially affect, our final results. Accordingly, you should not place undue reliance on these estimated figures. Our independent registered public accounting firm has not audited, reviewed, compiled, or performed any procedures with respect to such information. Accordingly, our independent registered public accounting firm does not express an opinion or any other form of assurance with respect thereto. These estimates for the three months ended September 30, 2026 are not necessarily indicative of the results to be achieved in any future period 43
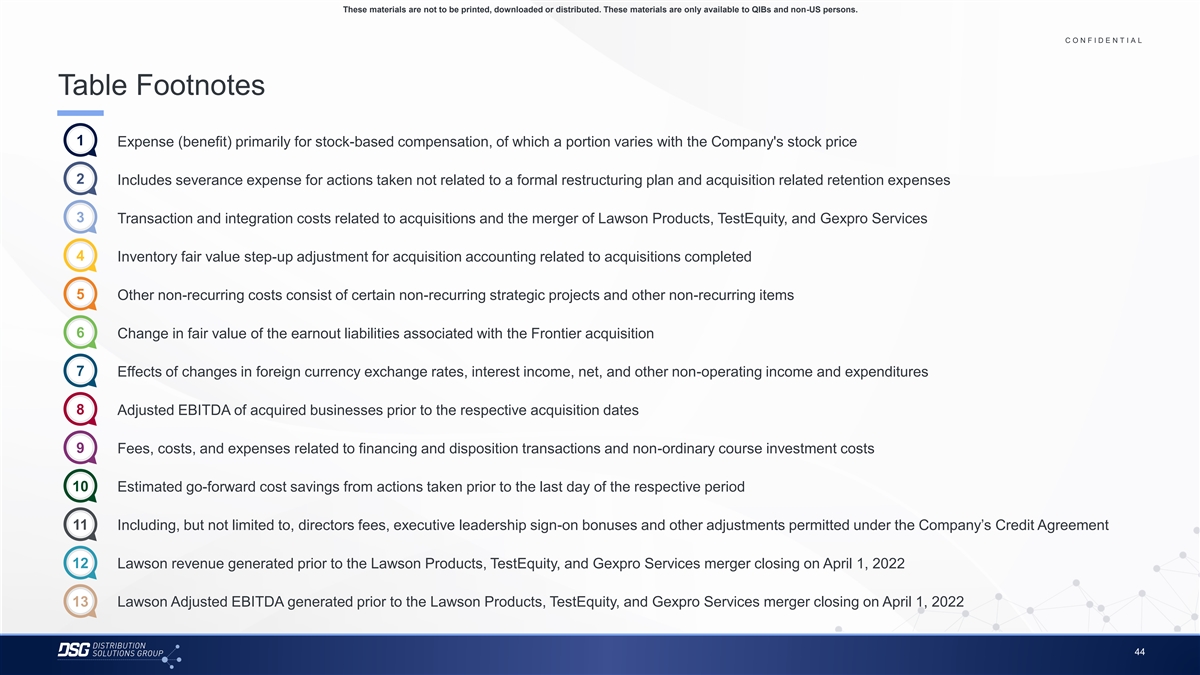
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. C O N F I D E N T I A L COLOR PALETTE Text 50 56 62 Table Footnotes Title bar/Bullets 68 87 128 ACCENTS 1 1. Expense (benefit) primarily for stock-based compensation, of which a portion varies with the Company's stock price 2 85 25 141 1 70 250 2 2. Includes severance expense for actions taken not related to a formal restructuring plan and acquisition related retention expenses 68 173 87 185 2 128 211 3 3. Transaction and integration costs related to acquisitions and the merger of Lawson Products, TestEquity, and Gexpro Services 142 210 169 221 3 216 239 4 4. Inventory fair value step-up adjustment for acquisition accounting related to acquisitions completed 255 255 196 231 4 38 168 5 5. Other non-recurring costs consist of certain non-recurring strategic projects and other non-recurring items 239 249 129 205 5 35 167 6 6. Change in fair value of the earnout liabilities associated with the Frontier acquisition 213 238 213 238 6 214 239 7 30 146 7. Effects of changes in foreign currency exchange rates, interest income, net, and other non-operating income and expenditures 124 213 Hyperlink 153 234 0 98 8. 8 Adjusted EBITDA of acquired businesses prior to the respective acquisition dates Followed 80 205 Hyperlink 117 255 TABLE 9. 9 Fees, costs, and expenses related to financing and disposition transactions and non-ordinary course investment costs 50 Lines 56 62 10 10. Estimated go-forward cost savings from actions taken prior to the last day of the respective period 68 Highlights 87 128 11 11. Including, but not limited to, directors fees, executive leadership sign-on bonuses and other adjustments permitted under the Company’s Credit Agreement 12 12. Lawson revenue generated prior to the Lawson Products, TestEquity, and Gexpro Services merger closing on April 1, 2022 13 13. Lawson Adjusted EBITDA generated prior to the Lawson Products, TestEquity, and Gexpro Services merger closing on April 1, 2022 44
These materials are not to be printed, downloaded or distributed. These materials are only available to QIBs and non-US persons. 45 38