Exhibit 99.2


LOGO

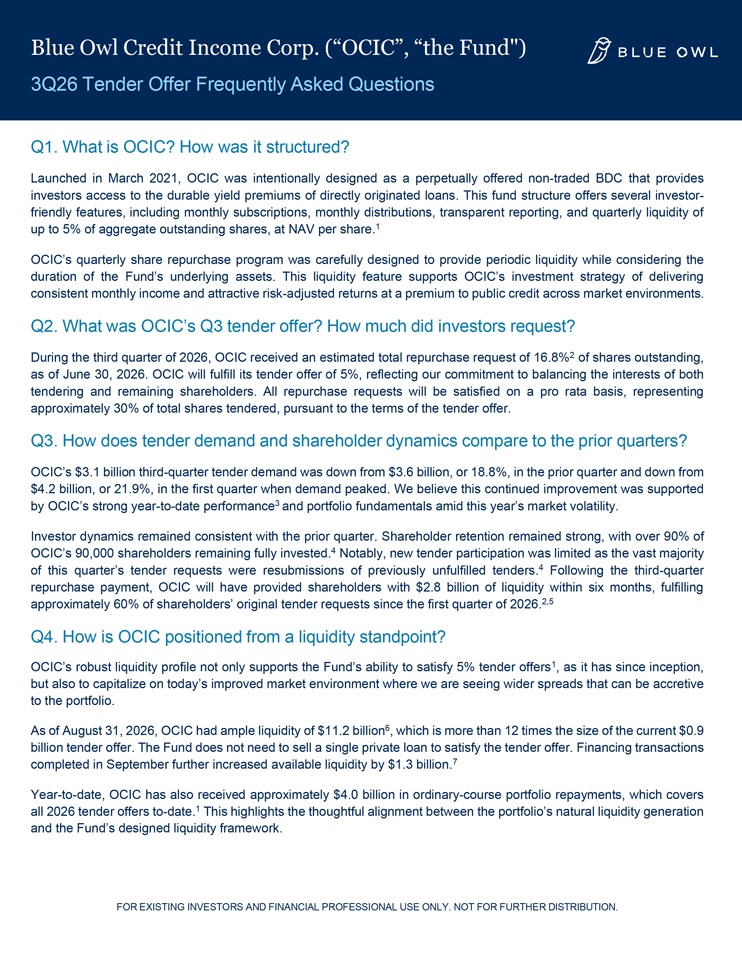
Q1. What is OCIC? How was it structured?Launched in March 2021, OCIC was intentionally designed as a perpetually offered non-traded BDC that provides investors access to the durable yield premiums of directly originated loans. This fund structure offers several investor-friendly features, including monthly subscriptions, monthly distributions, transparent reporting, and quarterly liquidity of up to 5% of aggregate outstanding shares, at NAV per share.1OCIC’s quarterly share repurchase program was carefully designed to provide periodic liquidity while considering the duration of the Fund’s underlying assets. This liquidity feature supports OCIC’s investment strategy of delivering consistent monthly income and attractive risk-adjusted returns at a premium to public credit across market environments.Q2. What was OCIC’s Q3 tender offer? How much did investors request?During the third quarter of 2026, OCIC received an estimated total repurchase request of 16.8%2 of shares outstanding, as of June 30, 2026. OCIC will fulfill its tender offer of 5%, reflecting our commitment to balancing the interests of both tendering and remaining shareholders. All repurchase requests will be satisfied on a pro rata basis, representing approximately 30% of total shares tendered, pursuant to the terms of the tender offer.Q3. How does tender demand and shareholder dynamics compare to the prior quarters?OCIC’s $3.1 billion third-quarter tender demand was down from $3.6 billion, or 18.8%, in the prior quarter and down from$4.2 billion, or 21.9%, in the first quarter when demand peaked. We believe this continued improvement was supported by OCIC’s strong year-to-date performance3 and portfolio fundamentals amid this year’s market volatility.Investor dynamics remained consistent with the prior quarter. Shareholder retention remained strong, with over 90% of OCIC’s 90,000 shareholders remaining fully invested.4 Notably, new tender participation was limited as the vast majority of this quarter’s tender requests were resubmissions of previously unfulfilled tenders.4 Following the third-quarter repurchase payment, OCIC will have provided shareholders with $2.8 billion of liquidity within six months, fulfilling approximately 60% of shareholders’ original tender requests since the first quarter of 2026.2,5Q4. How is OCIC positioned from a liquidity standpoint?OCIC’s robust liquidity profile not only supports the Fund’s ability to satisfy 5% tender offers1, as it has since inception, but also to capitalize on today’s improved market environment where we are seeing wider spreads that can be accretive to the portfolio.As of August 31, 2026, OCIC had ample liquidity of $11.2 billion6, which is more than 12 times the size of the current $0.9 billion tender offer. The Fund does not need to sell a single private loan to satisfy the tender offer. Financing transactions completed in September further increased available liquidity by $1.3 billion.7Year-to-date, OCIC has also received approximately $4.0 billion in ordinary-course portfolio repayments, which covers all 2026 tender offers to-date.1 This highlights the thoughtful alignment between the portfolio’s natural liquidity generation and the Fund’s designed liquidity framework.FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.


LOGO

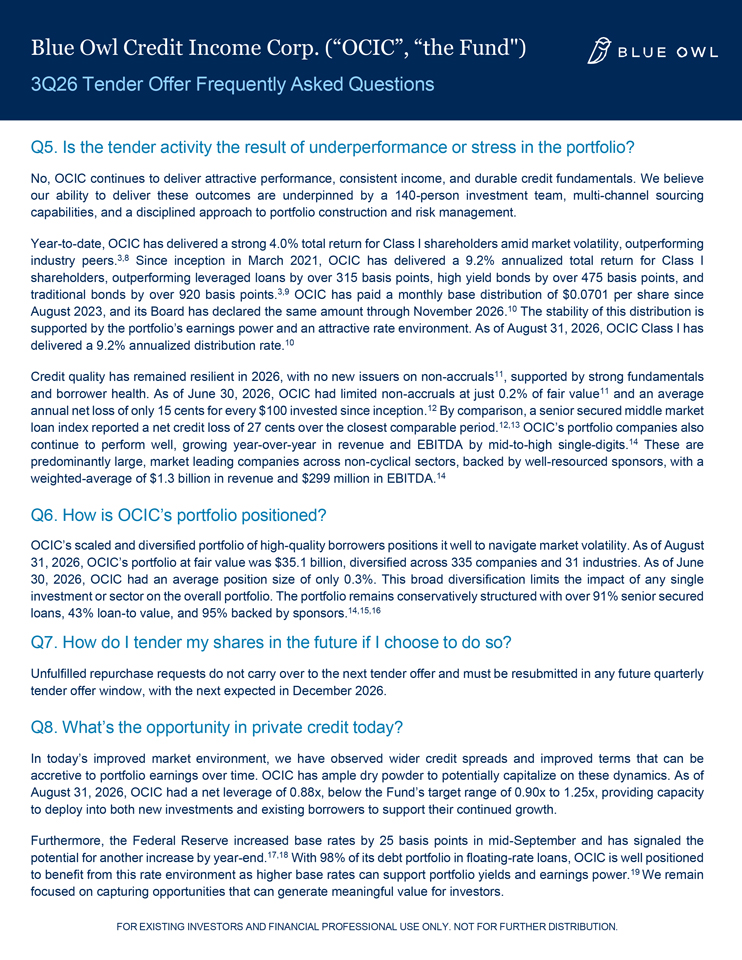
Q5. Is the tender activity the result of underperformance or stress in the portfolio?No, OCIC continues to deliver attractive performance, consistent income, and durable credit fundamentals. We believe our ability to deliver these outcomes are underpinned by a 140-person investment team, multi-channel sourcing capabilities, and a disciplined approach to portfolio construction and risk management.Year-to-date, OCIC has delivered a strong 4.0% total return for Class I shareholders amid market volatility, outperforming industry peers.3,8 Since inception in March 2021, OCIC has delivered a 9.2% annualized total return for Class I shareholders, outperforming leveraged loans by over 315 basis points, high yield bonds by over 475 basis points, and traditional bonds by over 920 basis points.3,9 OCIC has paid a monthly base distribution of $0.0701 per share since August 2023, and its Board has declared the same amount through November 2026.10 The stability of this distribution is supported by the portfolio’s earnings power and an attractive rate environment. As of August 31, 2026, OCIC Class I has delivered a 9.2% annualized distribution rate.10Credit quality has remained resilient in 2026, with no new issuers on non-accruals11, supported by strong fundamentals and borrower health. As of June 30, 2026, OCIC had limited non-accruals at just 0.2% of fair value11 and an average annual net loss of only 15 cents for every $100 invested since inception.12 By comparison, a senior secured middle market loan index reported a net credit loss of 27 cents over the closest comparable period.12,13 OCIC’s portfolio companies also continue to perform well, growing year-over-year in revenue and EBITDA by mid-to-high single-digits.14 These are predominantly large, market leading companies across non-cyclical sectors, backed by well-resourced sponsors, with a weighted-average of $1.3 billion in revenue and $299 million in EBITDA.14Q6. How is OCIC’s portfolio positioned?OCIC’s scaled and diversified portfolio of high-quality borrowers positions it well to navigate market volatility. As of August 31, 2026, OCIC’s portfolio at fair value was $35.1 billion, diversified across 335 companies and 31 industries. As of June 30, 2026, OCIC had an average position size of only 0.3%. This broad diversification limits the impact of any single investment or sector on the overall portfolio. The portfolio remains conservatively structured with over 91% senior secured loans, 43% loan-to value, and 95% backed by sponsors.14,15,16Q7. How do I tender my shares in the future if I choose to do so?Unfulfilled repurchase requests do not carry over to the next tender offer and must be resubmitted in any future quarterly tender offer window, with the next expected in December 2026.Q8. What’s the opportunity in private credit today?In today’s improved market environment, we have observed wider credit spreads and improved terms that can be accretive to portfolio earnings over time. OCIC has ample dry powder to potentially capitalize on these dynamics. As of August 31, 2026, OCIC had a net leverage of 0.88x, below the Fund’s target range of 0.90x to 1.25x, providing capacity to deploy into both new investments and existing borrowers to support their continued growth.Furthermore, the Federal Reserve increased base rates by 25 basis points in mid-September and has signaled the potential for another increase by year-end.17,18 With 98% of its debt portfolio in floating-rate loans, OCIC is well positioned to benefit from this rate environment as higher base rates can support portfolio yields and earnings power.19 We remain focused on capturing opportunities that can generate meaningful value for investors.FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.


LOGO

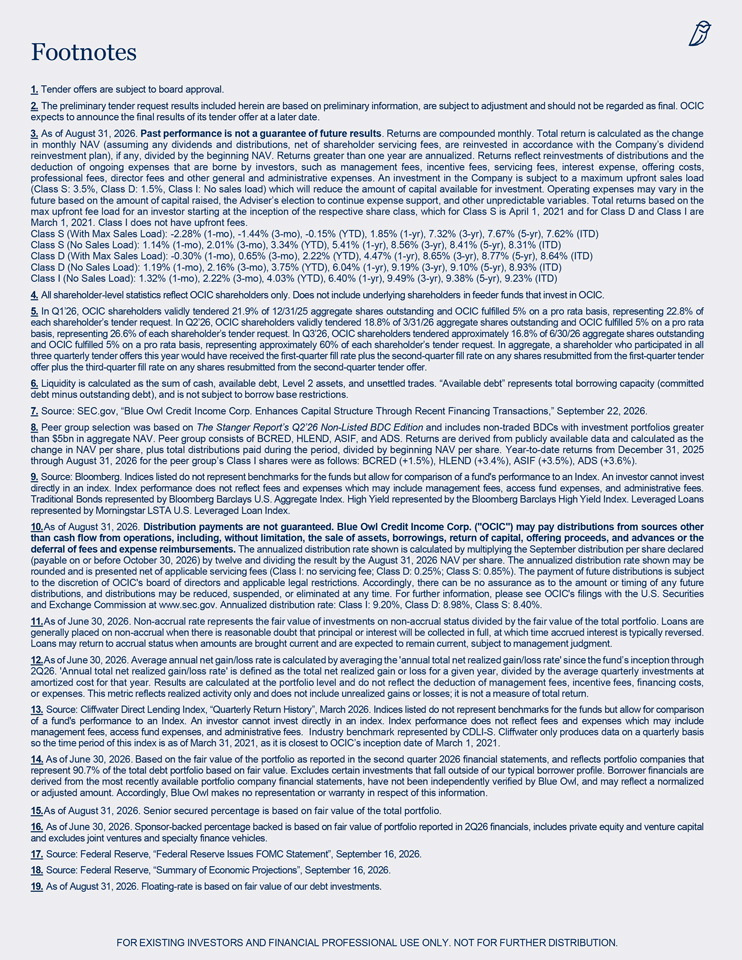
FootnotesTender offers are subject to board approval.The preliminary tender request results included herein are based on preliminary information, are subject to adjustment and should not be regarded as final. OCIC expects to announce the final results of its tender offer at a later date.As of August 31, 2026. Past performance is not a guarantee of future results. Returns are compounded monthly. Total return is calculated as the change in monthly NAV (assuming any dividends and distributions, net of shareholder servicing fees, are reinvested in accordance with the Company’s dividend reinvestment plan), if any, divided by the beginning NAV. Returns greater than one year are annualized. Returns reflect reinvestments of distributions and the deduction of ongoing expenses that are borne by investors, such as management fees, incentive fees, servicing fees, interest expense, offering costs, professional fees, director fees and other general and administrative expenses. An investment in the Company is subject to a maximum upfront sales load (Class S: 3.5%, Class D: 1.5%, Class I: No sales load) which will reduce the amount of capital available for investment. Operating expenses may vary in the future based on the amount of capital raised, the Adviser’s election to continue expense support, and other unpredictable variables. Total returns based on the max upfront fee load for an investor starting at the inception of the respective share class, which for Class S is April 1, 2021 and for Class D and Class I are March 1, 2021. Class I does not have upfront fees.Class S (With Max Sales Load): -2.28% (1-mo), -1.44% (3-mo), -0.15% (YTD), 1.85% (1-yr), 7.32% (3-yr), 7.67% (5-yr), 7.62% (ITD)Class S (No Sales Load): 1.14% (1-mo), 2.01% (3-mo), 3.34% (YTD), 5.41% (1-yr), 8.56% (3-yr), 8.41% (5-yr), 8.31% (ITD)Class D (With Max Sales Load): -0.30% (1-mo), 0.65% (3-mo), 2.22% (YTD), 4.47% (1-yr), 8.65% (3-yr), 8.77% (5-yr), 8.64% (ITD)Class D (No Sales Load): 1.19% (1-mo), 2.16% (3-mo), 3.75% (YTD), 6.04% (1-yr), 9.19% (3-yr), 9.10% (5-yr), 8.93% (ITD)Class I (No Sales Load): 1.32% (1-mo), 2.22% (3-mo), 4.03% (YTD), 6.40% (1-yr), 9.49% (3-yr), 9.38% (5-yr), 9.23% (ITD)All shareholder-level statistics reflect OCIC shareholders only. Does not include underlying shareholders in feeder funds that invest in OCIC.In Q1’26, OCIC shareholders validly tendered 21.9% of 12/31/25 aggregate shares outstanding and OCIC fulfilled 5% on a pro rata basis, representing 22.8% of each shareholder’s tender request. In Q2’26, OCIC shareholders validly tendered 18.8% of 3/31/26 aggregate shares outstanding and OCIC fulfilled 5% on a pro rata basis, representing 26.6% of each shareholder’s tender request. In Q3’26, OCIC shareholders tendered approximately 16.8% of 6/30/26 aggregate shares outstanding and OCIC fulfilled 5% on a pro rata basis, representing approximately 60% of each shareholder’s tender request. In aggregate, a shareholder who participated in all three quarterly tender offers this year would have received the first-quarter fill rate plus the second-quarter fill rate on any shares resubmitted from the first-quarter tender offer plus the third-quarter fill rate on any shares resubmitted from the second-quarter tender offer.Liquidity is calculated as the sum of cash, available debt, Level 2 assets, and unsettled trades. “Available debt” represents total borrowing capacity (committed debt minus outstanding debt), and is not subject to borrow base restrictions.Source: SEC.gov, “Blue Owl Credit Income Corp. Enhances Capital Structure Through Recent Financing Transactions,” September 22, 2026.Peer group selection was based on The Stanger Report’s Q2’26 Non-Listed BDC Edition and includes non-traded BDCs with investment portfolios greater than $5bn in aggregate NAV. Peer group consists of BCRED, HLEND, ASIF, and ADS. Returns are derived from publicly available data and calculated as the change in NAV per share, plus total distributions paid during the period, divided by beginning NAV per share. Year-to-date returns from December 31, 2025 through August 31, 2026 for the peer group’s Class I shares were as follows: BCRED (+1.5%), HLEND (+3.4%), ASIF (+3.5%), ADS (+3.6%).Source: Bloomberg. Indices listed do not represent benchmarks for the funds but allow for comparison of a fund’s performance to an Index. An investor cannot invest directly in an index. Index performance does not reflect fees and expenses which may include management fees, access fund expenses, and administrative fees. Traditional Bonds represented by Bloomberg Barclays U.S. Aggregate Index. High Yield represented by the Bloomberg Barclays High Yield Index. Leveraged Loans represented by Morningstar LSTA U.S. Leveraged Loan Index.As of August 31, 2026. Distribution payments are not guaranteed. Blue Owl Credit Income Corp. (“OCIC”) may pay distributions from sources other than cash flow from operations, including, without limitation, the sale of assets, borrowings, return of capital, offering proceeds, and advances or the deferral of fees and expense reimbursements. The annualized distribution rate shown is calculated by multiplying the September distribution per share declared (payable on or before October 30, 2026) by twelve and dividing the result by the August 31, 2026 NAV per share. The annualized distribution rate shown may be rounded and is presented net of applicable servicing fees (Class I: no servicing fee; Class D: 0.25%; Class S: 0.85%). The payment of future distributions is subject to the discretion of OCIC’s board of directors and applicable legal restrictions. Accordingly, there can be no assurance as to the amount or timing of any future distributions, and distributions may be reduced, suspended, or eliminated at any time. For further information, please see OCIC’s filings with the U.S. Securities and Exchange Commission at www.sec.gov. Annualized distribution rate: Class I: 9.20%, Class D: 8.98%, Class S: 8.40%.As of June 30, 2026. Non-accrual rate represents the fair value of investments on non-accrual status divided by the fair value of the total portfolio. Loans are generally placed on non-accrual when there is reasonable doubt that principal or interest will be collected in full, at which time accrued interest is typically reversed. Loans may return to accrual status when amounts are brought current and are expected to remain current, subject to management judgment.As of June 30, 2026. Average annual net gain/loss rate is calculated by averaging the ‘annual total net realized gain/loss rate’ since the fund’s inception through 2Q26. ‘Annual total net realized gain/loss rate’ is defined as the total net realized gain or loss for a given year, divided by the average quarterly investments at amortized cost for that year. Results are calculated at the portfolio level and do not reflect the deduction of management fees, incentive fees, financing costs, or expenses. This metric reflects realized activity only and does not include unrealized gains or losses; it is not a measure of total return.Source: Cliffwater Direct Lending Index, “Quarterly Return History”, March 2026. Indices listed do not represent benchmarks for the funds but allow for comparison of a fund’s performance to an Index. An investor cannot invest directly in an index. Index performance does not reflect fees and expenses which may include management fees, access fund expenses, and administrative fees. Industry benchmark represented by CDLI-S. Cliffwater only produces data on a quarterly basis so the time period of this index is as of March 31, 2021, as it is closest to OCIC’s inception date of March 1, 2021.As of June 30, 2026. Based on the fair value of the portfolio as reported in the second quarter 2026 financial statements, and reflects portfolio companies that represent 90.7% of the total debt portfolio based on fair value. Excludes certain investments that fall outside of our typical borrower profile. Borrower financials are derived from the most recently available portfolio company financial statements, have not been independently verified by Blue Owl, and may reflect a normalized or adjusted amount. Accordingly, Blue Owl makes no representation or warranty in respect of this information.As of August 31, 2026. Senior secured percentage is based on fair value of the total portfolio.As of June 30, 2026. Sponsor-backed percentage backed is based on fair value of portfolio reported in 2Q26 financials, includes private equity and venture capital and excludes joint ventures and specialty finance vehicles.Source: Federal Reserve, “Federal Reserve Issues FOMC Statement”, September 16, 2026.Source: Federal Reserve, “Summary of Economic Projections”, September 16, 2026.As of August 31, 2026. Floating-rate is based on fair value of our debt investments.FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.
LOGO

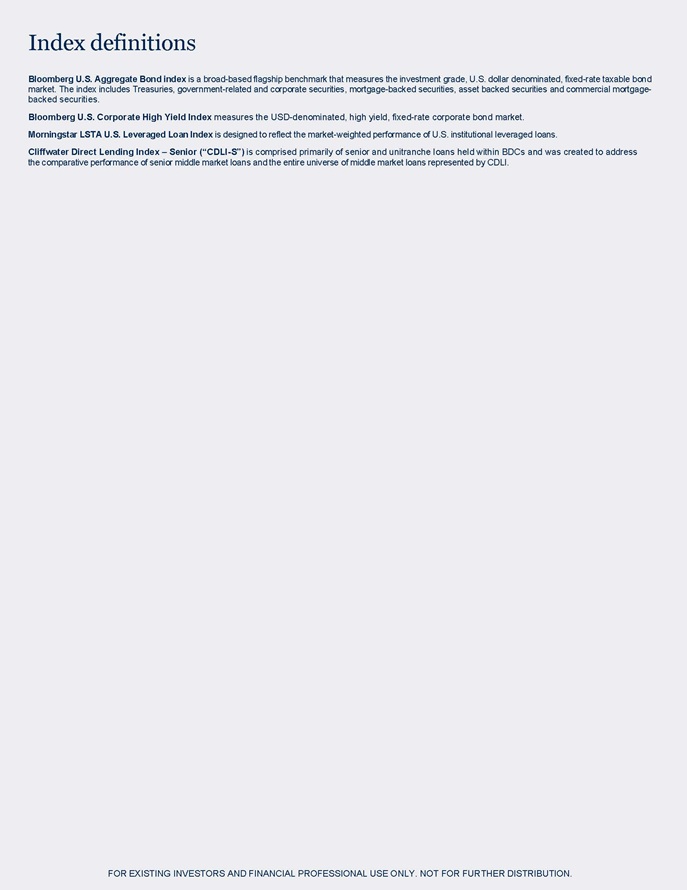
Index definitions Bloomberg U.S. Aggregate Bond index is a broad-based flagship benchmark that measures the investment grade, U.S. dollar denominated, fixed-rate taxable bond market. The index includes Treasuries, government-related and corporate securities, mortgage-backed securities, asset backed securities and commercial mortgage-backed securities. Bloomberg U.S. Corporate High Yield Index measures the USD-denominated, high yield, fixed-rate corporate bond market. Morningstar LSTA U.S. Leveraged Loan Index is designed to reflect the market-weighted performance of U.S. institutional leveraged loans. Cliffwater Direct Lending Index – Senior (“CDLI-S”) is comprised primarily of senior and unitranche loans held within BDCs and was created to address the comparative performance of senior middle market loans and the entire universe of middle market loans represented by CDLI. FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.

LOGO

Summary of risk factors An investment in Blue Owl Credit Income Corp. (“OCIC”) is speculative and involves a high degree of risk, including the risk of a substantial loss of investment, as well as substantial fees and costs, all of which can impact an investor’s return. The following are some of the risks involved in an investment in OCIC’s common shares; however, an investor should carefully consider the fees and expenses and information found in the “Risk Factors” section of the OCIC prospectus before deciding to invest: You should not expect to be able to sell your shares regardless of how OCIC performs. If you are able to sell your shares, you likely will receive less than your purchase price. OCIC does not intend to list its shares on any securities exchange and does not expect a secondary market in its shares to develop. OCIC has implemented a share repurchase program pursuant to which it intends to conduct quarterly repurchases of a limited number of outstanding shares of its common stock. OCIC’s board of directors has complete discretion to determine whether OCIC will engage in any share repurchase, and if so, the terms of such repurchase. OCIC’s share repurchase program will include numerous restrictions that limit your ability to sell your shares. As a result, share repurchases may not be available each month. While OCIC intends to continue to conduct quarterly tender offers as described above, it is not required to do so and may suspend or terminate the share repurchase program at any time. You should consider that you may not have access to the money you invest for an indefinite period of time. The incentive fees payable by OCIC to Blue Owl Credit Advisors LLC (the “Adviser”) may create an incentive for the Adviser to pursue investments that are riskier or more speculative than would be the case in the absence of such compensation arrangement. An investment in shares of OCIC’s common stock is not suitable for you if you need access to the money you invest. Because you will be unable to sell your shares, you will be unable to reduce your exposure in any market downturn. Distributions on OCIC’s common stock may exceed OCIC’s taxable earnings and profits. Therefore, portions of the distributions that OCIC pays may represent a return of capital to you for U.S. federal tax purposes. A return of capital is a return of a portion of your original investment in shares of OCIC’s common stock. As a result, a return of capital will (i) lower your adjusted tax basis in your shares and thereby increase the amount of capital gain (or decrease the amount of capital loss) realized upon a subsequent sale or redemption of such shares, and (ii) reduce the amount of funds OCIC has for investment in portfolio companies. OCIC has not established any limit on the extent to which it may use offering proceeds to fund distributions. Distributions are not guaranteed. Distributions also may be funded in significant part, directly or indirectly, from (i) the waiver of certain investment advisory fees, that will not be subject to repayment to the Adviser and/or (ii) the deferral of certain investment advisory fees that may be subject to repayment to the Adviser and/or (iii) the reimbursement of certain operating expenses, that will be subject to repayment to the Adviser and its affiliates. Significant portions of distributions may not be based on investment performance. In the event distributions are funded from waivers and/or deferrals of fees and reimbursements by OCIC’s affiliates, such funding may not continue in the future. If OCIC’s affiliates do not agree to reimburse certain of its operating expenses or waive certain of their advisory fees, then significant portions of OCIC’s distributions may come from sources other than cash flows from operations. The repayment of any amounts owed to OCIC’s affiliates will reduce future distributions to which you would otherwise be entitled. As required by the Investment Company Act of 1940, as amended (the “1940 Act”), a significant portion of OCIC’s investment portfolio is and will be recorded at fair value as determined in good faith by the Adviser, under the supervision of OCIC’s board of directors, pursuant to Rule 2a-5 under the 1940 Act. As a result, there is and will be uncertainty as to the value of OCIC’s portfolio investments. If a subscription request, including the full subscription amount, is not received in good order at least five business days prior to the first day of the month, the investor may not be eligible to purchase securities during that month’s offering. Accordingly, if the subscription is not withdrawn, such investor will not know the net asset value per share until the following month’s net asset value is determined, which will be a significant period of time from the initial subscription. The payment of fees and expenses will reduce the funds available for investment, the net income generated, the funds available for distribution and the book value of the common shares. In addition, the fees and expenses paid will require investors to achieve a higher total net return in order to recover their initial investment. Please see OCIC’s prospectus for details regarding its fees and expenses. OCIC invests in securities that are rated below investment grade by rating agencies or that would be rated below investment grade if they were rated. Below investment grade securities, which are often referred to as “junk,” have predominantly speculative characteristics with respect to the issuer’s capacity to pay interest and repay principal. They may also be illiquid and difficult to value. The Adviser and its affiliates face a number of conflicts with respect to OCIC. Currently, the Adviser and Its affiliates manage other investment entities, including Blue Owl Capital Corporation and Owl Blue Owl Capital Corporation II, and are not prohibited from raising money for and managing future investment entities that make the same types of investments as those OCIC targets. As a result, the time and resources that the Adviser devotes to OCIC may be diverted. In addition, OCIC may compete with any such investment entity also managed by the Adviser for the same investors and investment opportunities. Furthermore, the Adviser may face conflicts of interest with respect to services it may perform for companies in which OCIC invests as it may receive fees in connection with such services that may not be shared with OCIC. The information provided above is not directed at any particular investor or category of investors and is provided solely as general information about Blue Owl Capital Inc.’s products and services to regulated financial intermediaries and to otherwise provide general Investment education. No information contained herein should be regarded as a suggestion to engage in or refrain from any investment-related course of action as Blue Owl Securities LLC, its affiliates, and OCIC are not undertaking to provide Impartial investment advice, act as an impartial adviser, or give advice in a fiduciary capacity with respect to the materials presented herein. FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.

LOGO

Important information Unless otherwise noted the report date referenced herein is as of October 2, 2026. Past performance is not a guarantee of future results. The material presented is proprietary information regarding Blue Owl Capital Inc. (“Blue Owl”), its affiliates and investment program, funds sponsored by Blue Owl, including the Blue Owl Credit, Real Assets, and the GP Strategic Capital Funds (collectively the “Blue Owl Funds”) as well as investment held by the Blue Owl Funds. An investment in the Fund or other investment vehicle entails a high degree of risk. Investors should consider all of the risk factors set forth in the “Certain Risk Factors and Actual and Potential Conflicts of Interest” of the PPM or Prospectus, each of which could have an adverse effect on the Fund or other investment vehicle and on the value of Interests. An investment in the Fund or other investment vehicle is suitable only for sophisticated investors and requires the financial ability and willingness to accept the high risks and lack of liquidity associated with an investment in the Fund or other investment vehicle. Investors in the Fund or other investment vehicle must be prepared to bear such risks for an indefinite period of time. There will be restrictions on transferring interests in the Fund or other investment vehicle, and the investment performance of the Fund or other investment vehicle may be volatile. Investors must be prepared to hold their interests in the Fund or other investment vehicle until its dissolution and should have the financial ability and willingness to accept the risk characteristics of the Fund’s or other investment vehicle’s investments. There can be no assurances or guarantees that the Fund’s or other investment vehicles investment objectives will be realized that the Fund’s or other investment vehicle investment strategy will prove successful or that investors will not lose all or a portion of their investment in the Fund. Furthermore, investors should not construe the performance of any predecessor funds or other investment vehicle as providing any assurances or predictive value regarding future performance of the Fund. The views expressed and, except as otherwise indicated, the information provided are as of the report date and are subject to change, update, revision, verification, and amendment, materially or otherwise, without notice, as market or other conditions change. Since these conditions can change frequently, there can be no assurance that the trends described herein will continue or that any forecasts are accurate. In addition, certain of the statements contained in this material may be statements of future expectations and other forward-looking statements that are based on the current views and assumptions and involve known and unknown risks and uncertainties (including those discussed below) that could cause actual results, performance, or events to differ materially from those expressed or implied in such statements. These statements may be forward-looking by reason of context or identified by words such as “may, will, should, expects, plans, intends, anticipates, believes, estimates, predicts, potential or continue” and other similar expressions. Neither Blue Owl, its affiliates, nor any of Blue Owl’s or its affiliates’ respective advisers, members, directors, officers, partners, agents, representatives or employees or any other person (collectively the “Blue Owl Entities”) is under any obligation to update or keep current the information contained in this document. This material contains information from third party sources which Blue Owl has not verified. No representation or warranty, express or implied, is given by or on behalf of the Blue Owl Entities as to the accuracy, fairness, correctness or completeness of the information or opinions contained in this material and no liability whatsoever (in negligence or otherwise) is accepted by the Blue Owl Entities for any loss howsoever arising, directly or indirectly, from any use of this material or its contents, or otherwise arising in connection therewith. All investments are subject to risk, including the loss of the principal amount invested. These risks may include limited operating history, uncertain distributions, inconsistent valuation of the portfolio, changing interest rates, leveraging of assets, reliance on the investment advisor, potential conflicts of interest, payment of substantial fees to the investment advisor and the dealer manager, potential illiquidity, and liquidation at more or less than the original amount invested. Diversification will not guarantee profitability or protection against loss. Performance may be volatile, and the NAV may fluctuate. Performance Information: Where performance returns have been included in this material, OCIC has included herein important information relating to the calculation of these returns as well as other pertinent performance related definitions. OCIC intends to sell our shares at a net offering price that we believe reflects the net asset value per share as determined in accordance with the Fund’s share pricing policy. This material is for informational purposes only and is not an offer or a solicitation to sell or subscribe for any fund or other investment vehicle and does not constitute investment, legal, regulatory, business, tax, financial, accounting, or other advice or a recommendation regarding any securities of Blue Owl, of any fund or investment vehicle managed by Blue Owl, or of any other issuer of securities. Only a definitive offering document (i.e.: Prospectus or Private Placement Memorandum or other offering material) can make such an offer. Within the United States and Canada, securities are offered through Blue Owl Securities LLC, member of FINRA/SIPC, as Dealer Manager. Copyright© Blue Owl Capital Inc. 2026. All rights reserved. This material is proprietary and may not be reproduced, transferred, or distributed in any form without prior written permission from Blue Owl. It is delivered on an “as is” basis without warranty or liability by accepting the information, you agree to abide by all applicable copyright and other laws, as well as any additional copyright notices or restrictions contained in the information. FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.

LOGO

55242.3 OCIC-FAQ-3Q26 FOR EXISTING INVESTORS AND FINANCIAL PROFESSIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.