Exhibit 99.1
Building America's domestic rare earth supply chain INVESTOR PRESENTATION October 2026 TM business combination with Hall Chadwick Acquisition Corp. (NASDAQ: HCAC)
2 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” LEGAL Disclaimer Purpose. This investor presentation (the "Presentation") is provided for informational purposes only and has been prepared to assist i nte rested parties in making their own evaluation with respect to a potential business combination (the "Transaction") between Hall Chadwick Acquisition Corp ("HCAC ") and REEcycle Holdings, Inc. ("REEcycle" or the "Company") and a related private placement. No offer or solicitation. This Presentation does not constitute an offer to sell, or a solicitation of an offer to buy, any securities, nor a solicitat ion of any vote or approval, in any jurisdiction in which such offer, solicitation or sale would be unlawful. No offering of securities shall be made except by m ean s of a prospectus meeting the requirements of Section 10 of the Securities Act of 1933, as amended, or an exemption therefrom. Any placement of REEcycle securities will be made only to accredited investors pursuant to an exemption from registration. Forward - looking statements. This Presentation contains forward - looking statements, including statements regarding the Transaction, the Company’s plant commi ssioning and commercial timelines, production capacity, recovery rates, feedstock supply, partnerships with data - centre operators and other c ounterparties, market size and pricing, government support and future financial performance. Words such as “expect”, “target”, “anticipate”, “believe”, “plan”, “will” and simil ar expressions identify forward - looking statements. These statements are based on current expectations and assumptions that are inherently uncertain and subject to risks that could ca use actual results to differ materially, including those described in the risk factors in the appendix and in the registration statement on Form S - 4 relating to the Transaction. Neither REEcycle nor HCAC undertakes any obligation to update forward - looking statements except as required by law. Risk factors. Factors that may cause actual results to differ materially include, without limitation: the Company’s early stage and limited op erating history; the ability to commission and operate the Duncan, Oklahoma demonstration facility and to scale the process to commercial volumes; the availability and cos t of end - of - life magnet feedstock and the performance of the Drive Disassembly Machine; the absence of definitive offtake agreements; rare earth price volatility; reli anc e on patents licensed from the University of Houston, including the licence’s commercial production milestone; changes in government policy and support; environmental, health and saf ety and permitting requirements; the ability to complete the Transaction on the expected timetable, the level of redemptions by HCAC public shareholders and the ability to s ati sfy the minimum cash condition.
3 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” LEGAL Disclaimer (continued) Projections and estimates. Any projections, estimates, targets or forecasts in this Presentation (including capacity, capex, recovery rates, timelines a nd market data) are illustrative, are based on numerous assumptions and have not been independently verified or examined by any independent accountant. They sh oul d not be relied upon as a guarantee of future performance. Certain financial information regarding REEcycle is preliminary and remains subject to completion of audit and S EC review. Industry and market data. Information concerning the rare earth industry, market size, pricing, competitors and public - company comparisons has been obtain ed from third - party sources, company filings and internal estimates. Neither REEcycle nor HCAC has independently verified such information and no re presentation is made as to its accuracy or completeness. Third - party company data is shown for context only and not as a basis for valuation. Additional information and where to find it. In connection with the Transaction, HCAC has filed a registration statement on Form S - 4 to the U.S. Securities and Exchange Commission (the “SEC”) on October 1, 2026, which includes a preliminary proxy statement/prospectus. When available, the defin iti ve proxy statement/prospectus will be mailed to HCAC shareholders. Investors and security holders are urged to read the registration statement, the proxy statement/prospectu s a nd all other relevant documents filed with the SEC because they will contain important information about the Transaction. The registration statement and the other documents fil ed with the SEC may be obtained free of charge at www.sec.gov. Recipients should consult the registration statement in evaluating this Presentation. Participants in the solicitation. HCAC, REEcycle and their respective directors and executive officers may be deemed participants in the solicitation of proxie s f rom HCAC shareholders in connection with the Transaction. Information about HCAC’s directors and officers is set out in its SEC filing s; additional information regarding the interests of participants will be included in the proxy statement/prospectus. Trademarks and defined terms. "REEcycle" and the REEcycle logo are trademarks of Rare Resource Recycling, Inc. All other trademarks are the property of the ir respective owners. "MREO" means mixed rare earth oxide; "DDM" means the Drive Disassembly Machine; "DPA" means the Defense Production Ac t; "tpa" means tonnes per annum. All dollar amounts are US$ unless otherwise stated. Distribution restriction. Certain operating information in this Presentation is drawn from REEcycle’s reporting under its DPA Title III agreement. Coun ter parties referenced in that reporting are described generically in this Presentation and may be disclosed under a non - disclosure agreement.
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 4 1 Introduction 1 – 6 Cover, disclaimer, Executive Chairman address and board and management 2 The Transaction 7 – 11 HCAC transaction, use of proceeds, PIPE structure and pro forma capital structure 3 The Investment Case 12 – 15 Investment highlights, four U.S. supply challenges and U.S. government backing 4 Market & Industry Overview 16 – 21 National - security priority, structural deficit, magnet demand and AI data centres 5 Technology & Supply 22 – 28 Recycling pathway, patented process, pricing, modular design and North American landscape 6 Commercialization & Team 29 – 32 Strategic roadmap, feedstock and offtake and demonstration plant 7 Financials & Peer Comparison 33 – 35 Management estimates and select public comparable companies CONTENTS Table of Contents
5 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” LEADERSHIP Executive Chairman Address Chairman and substantial shareholder MICK MCMULLEN Lead Investor and Chair 33 years of experience Michael “Mick” McMullen has served as a director and Executive Chair of REEcycle since October 2025 and as a non - executive board chair since August 2022. Mr. McMullen has also served as a director and Executive Chair of Metals Acquisition Corp. II (NYSE:MTAL) since December 2025. Mr. McMullen served as Chief Executive Officer and a director of MAC Copper Limited (formerly Metals Acquisition Corp.), from July 2021 to October 2025, when it was acquired by a wholly owned subsidiary of Harmony Gold Mining Company Limited. Previously, Mr. McMullen served as the CEO and President at Detour Gold Corporation, a gold producer in Canada, from May 2019 to January 2020. From December 2013 to May 2017, Mr. McMullen held various roles at Stillwater Mining Company, including CEO, and as Technical Advisor from May 2013 to December 2018. Mr. McMullen’s prior experience involved the identification, acquisition, development, and operation of a variety of mining assets across North and South America, Europe, Australia and Africa. In addition, he has provided technical and financial advisory services to many of the larger PE funds, activist funds, and banks providing mining finance. Mr. McMullen is a qualified Geologist and received his B.Sc. from Newcastle University in 1992.
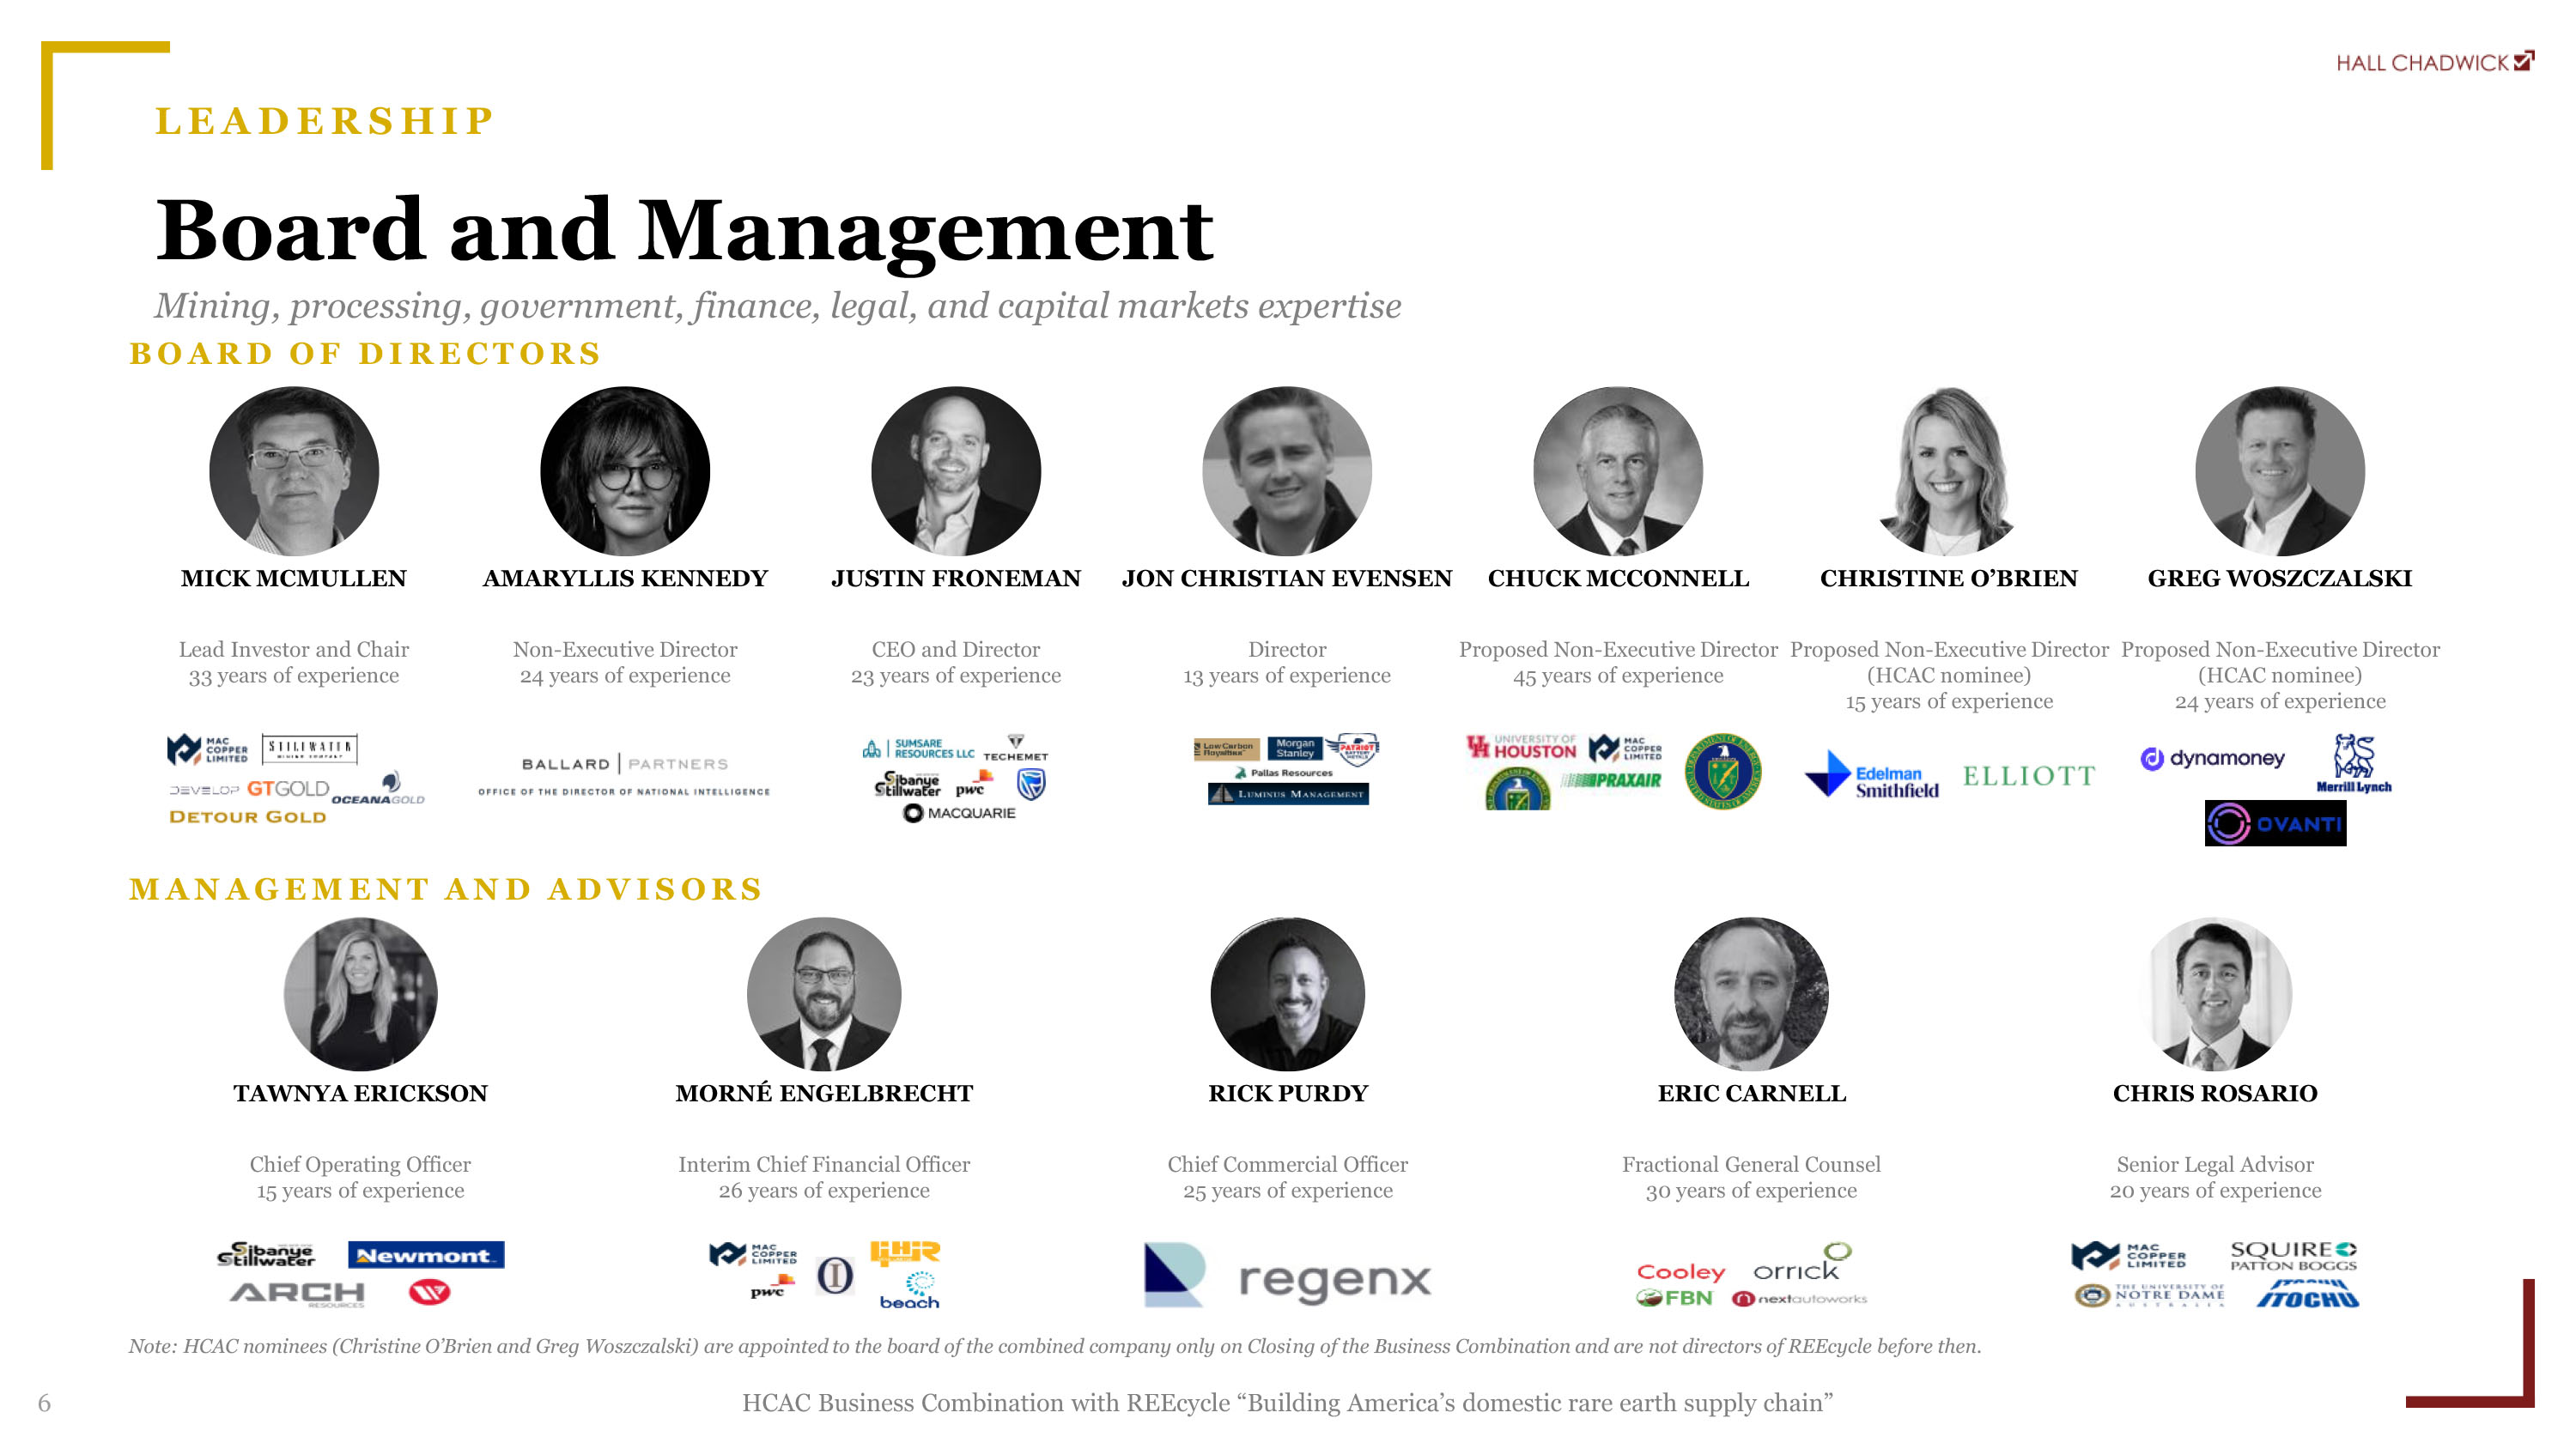
6 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” LEADERSHIP Board and Management Mining, processing, government, finance, legal, and capital markets expertise BOARD OF DIRECTORS MICK MCMULLEN Lead Investor and Chair 33 years of experience AMARYLLIS KENNEDY Non - Executive Director 24 years of experience JUSTIN FRONEMAN CEO and Director 23 years of experience JON CHRISTIAN EVENSEN Director 13 years of experience CHUCK MCCONNELL Proposed Non - Executive Director 45 years of experience CHRISTINE O’BRIEN Proposed Non - Executive Director (HCAC nominee) 15 years of experience GREG WOSZCZALSKI Proposed Non - Executive Director (HCAC nominee) 24 years of experience MANAGEMENT AND ADVISORS TAWNYA ERICKSON Chief Operating Officer 15 years of experience MORNÉ ENGELBRECHT Interim Chief Financial Officer 26 years of experience RICK PURDY Chief Commercial Officer 25 years of experience ERIC CARNELL Fractional General Counsel 30 years of experience CHRIS ROSARIO Senior Legal Advisor 20 years of experience Note: HCAC nominees (Christine O’Brien and Greg Woszczalski) are appointed to the board of the combined company only on Closi ng of the Business Combination and are not directors of REEcycle before then.
SECTION 1 The Transaction TM (NASDAQ: HCAC)
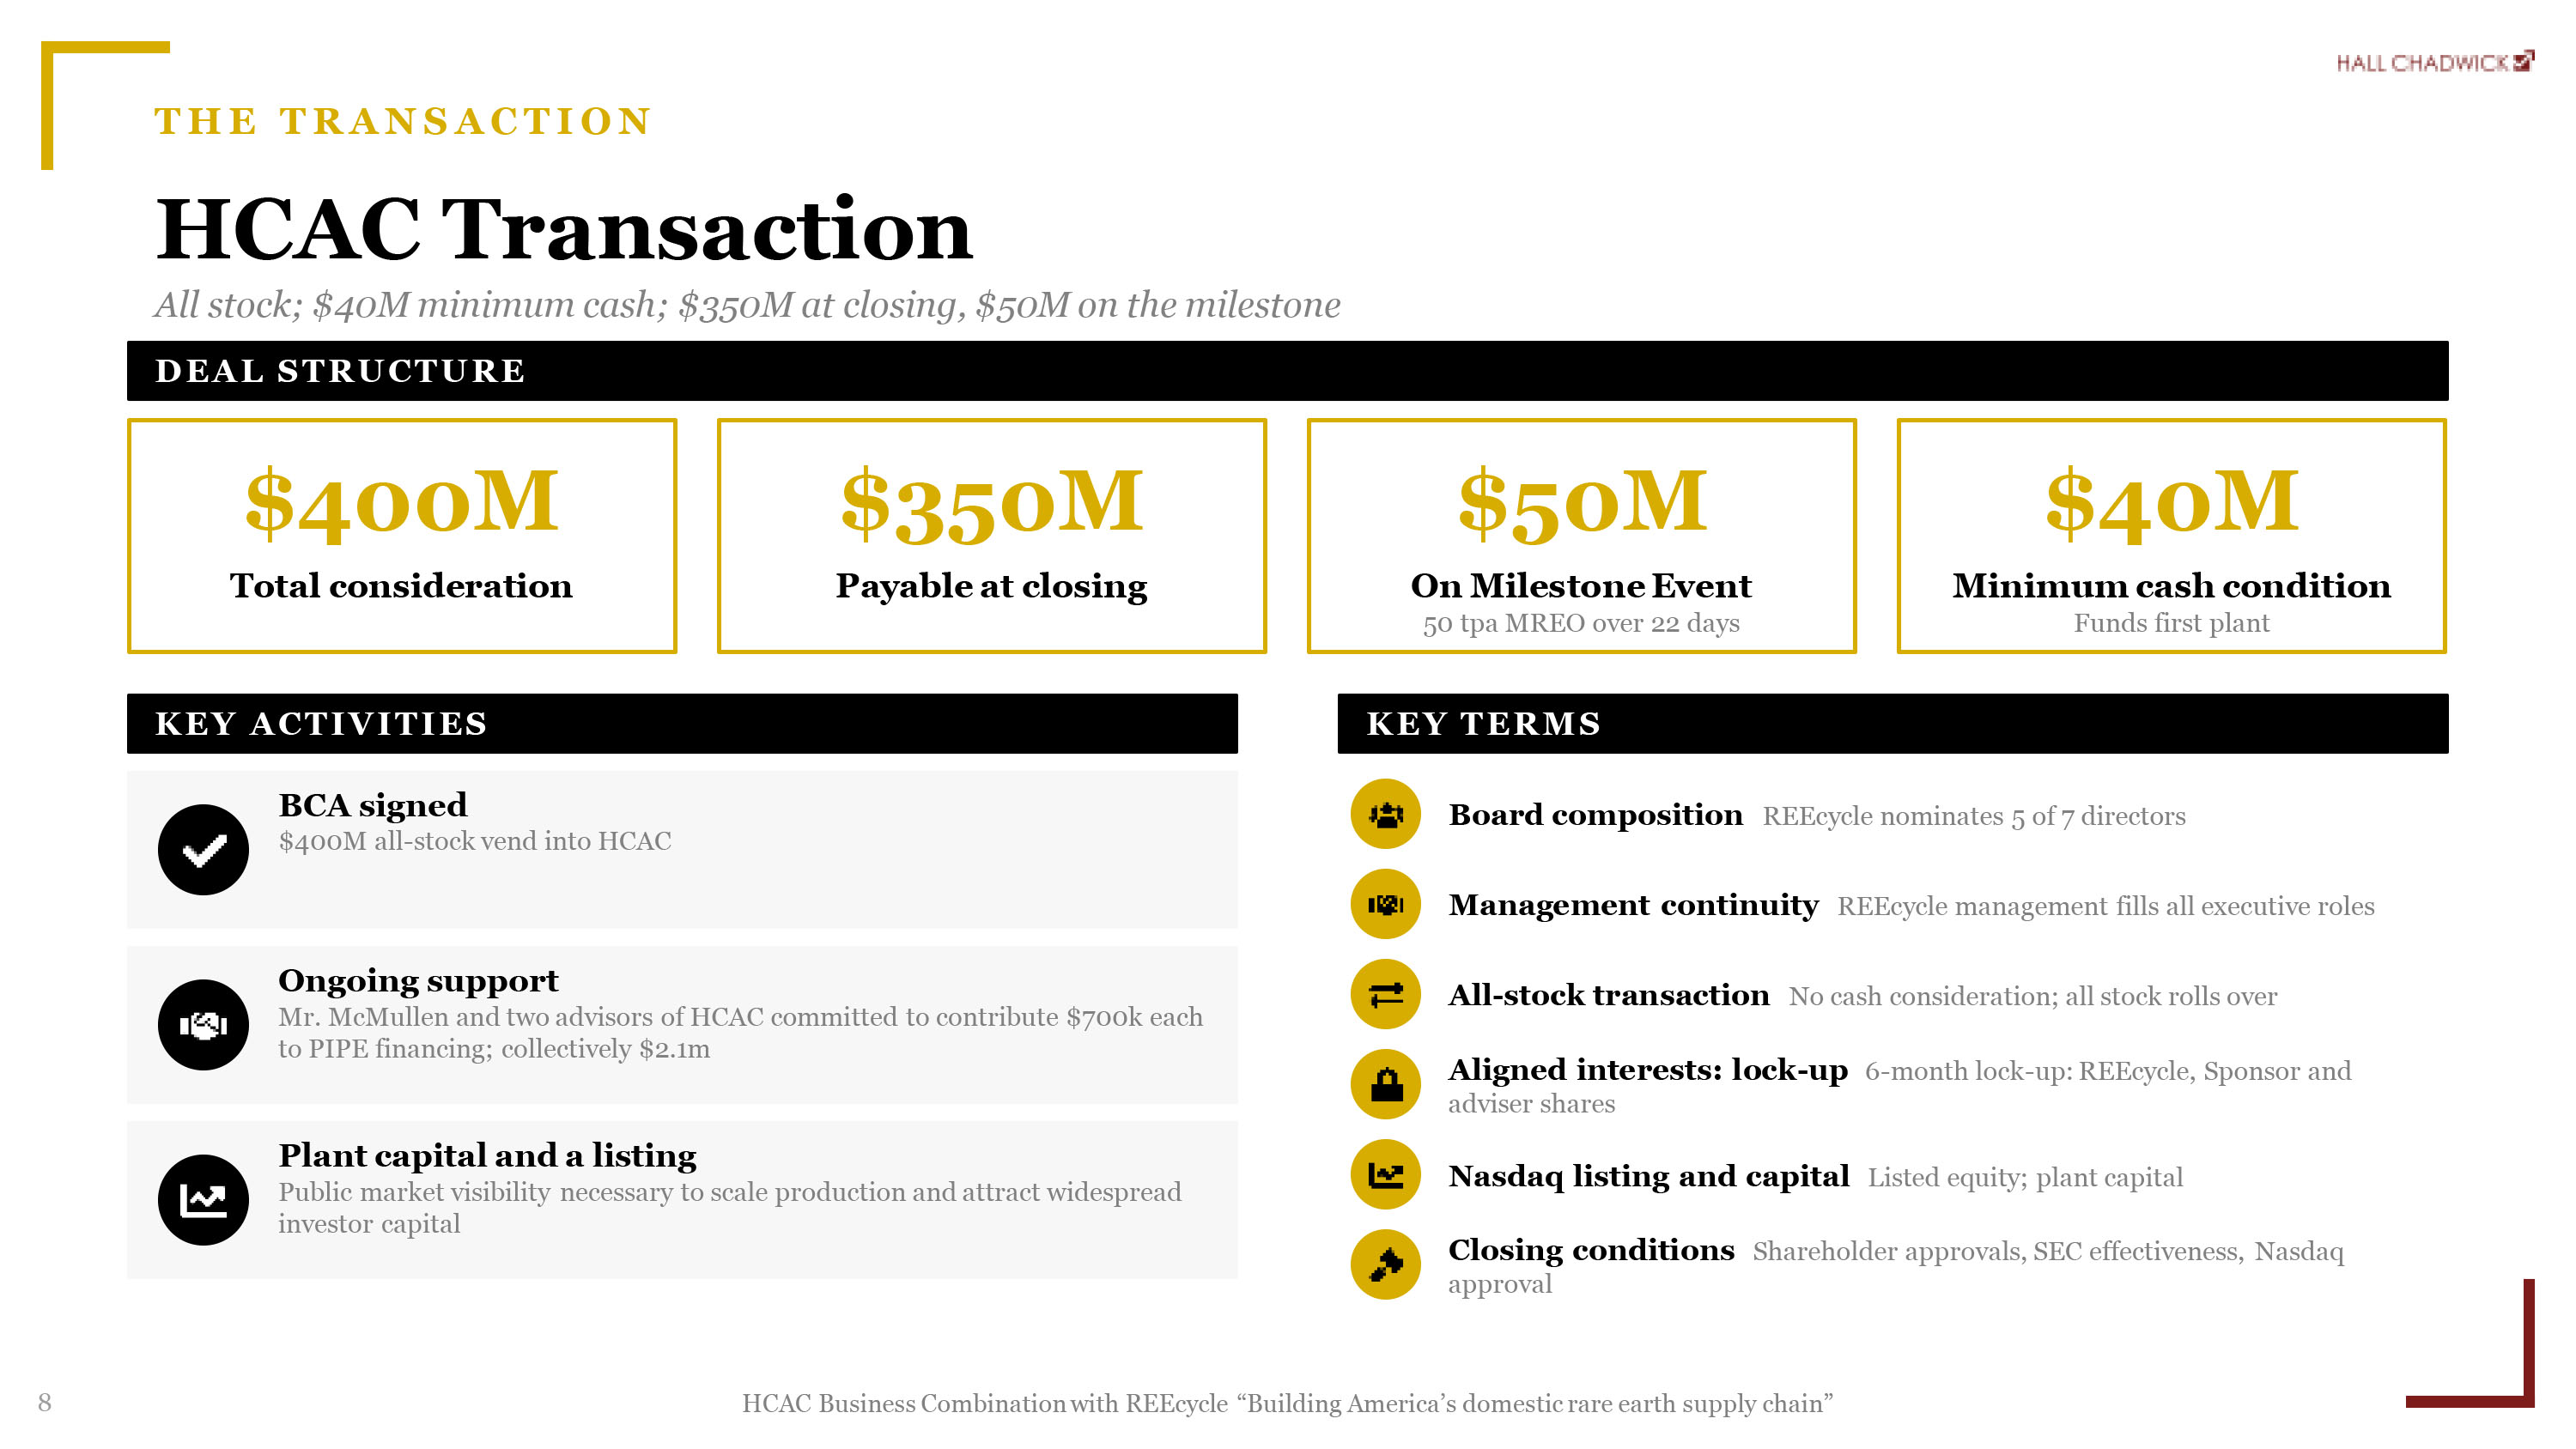
8 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” THE TRANSACTION HCAC Transaction All stock; $40M minimum cash; $350M at closing, $50M on the milestone DEAL STRUCTURE $400M Total consideration $350M Payable at closing $50M On Milestone Event 50 tpa MREO over 22 days $40M Minimum cash condition Funds first plant KEY ACTIVITIES KEY TERMS BCA signed $400M all - stock vend into HCAC Ongoing support Mr. McMullen and two advisors of HCAC committed to contribute $700k each to PIPE financing; collectively $2.1m Plant capital and a listing Public market visibility necessary to scale production and attract widespread investor capital Board composition REEcycle nominates 5 of 7 directors Management continuity REEcycle management fills all executive roles All - stock transaction No cash consideration; all stock rolls over Aligned interests: lock - up 6 - month lock - up: REEcycle, Sponsor and adviser shares Nasdaq listing and capital Listed equity; plant capital Closing conditions Shareholder approvals, SEC effectiveness, Nasdaq approval
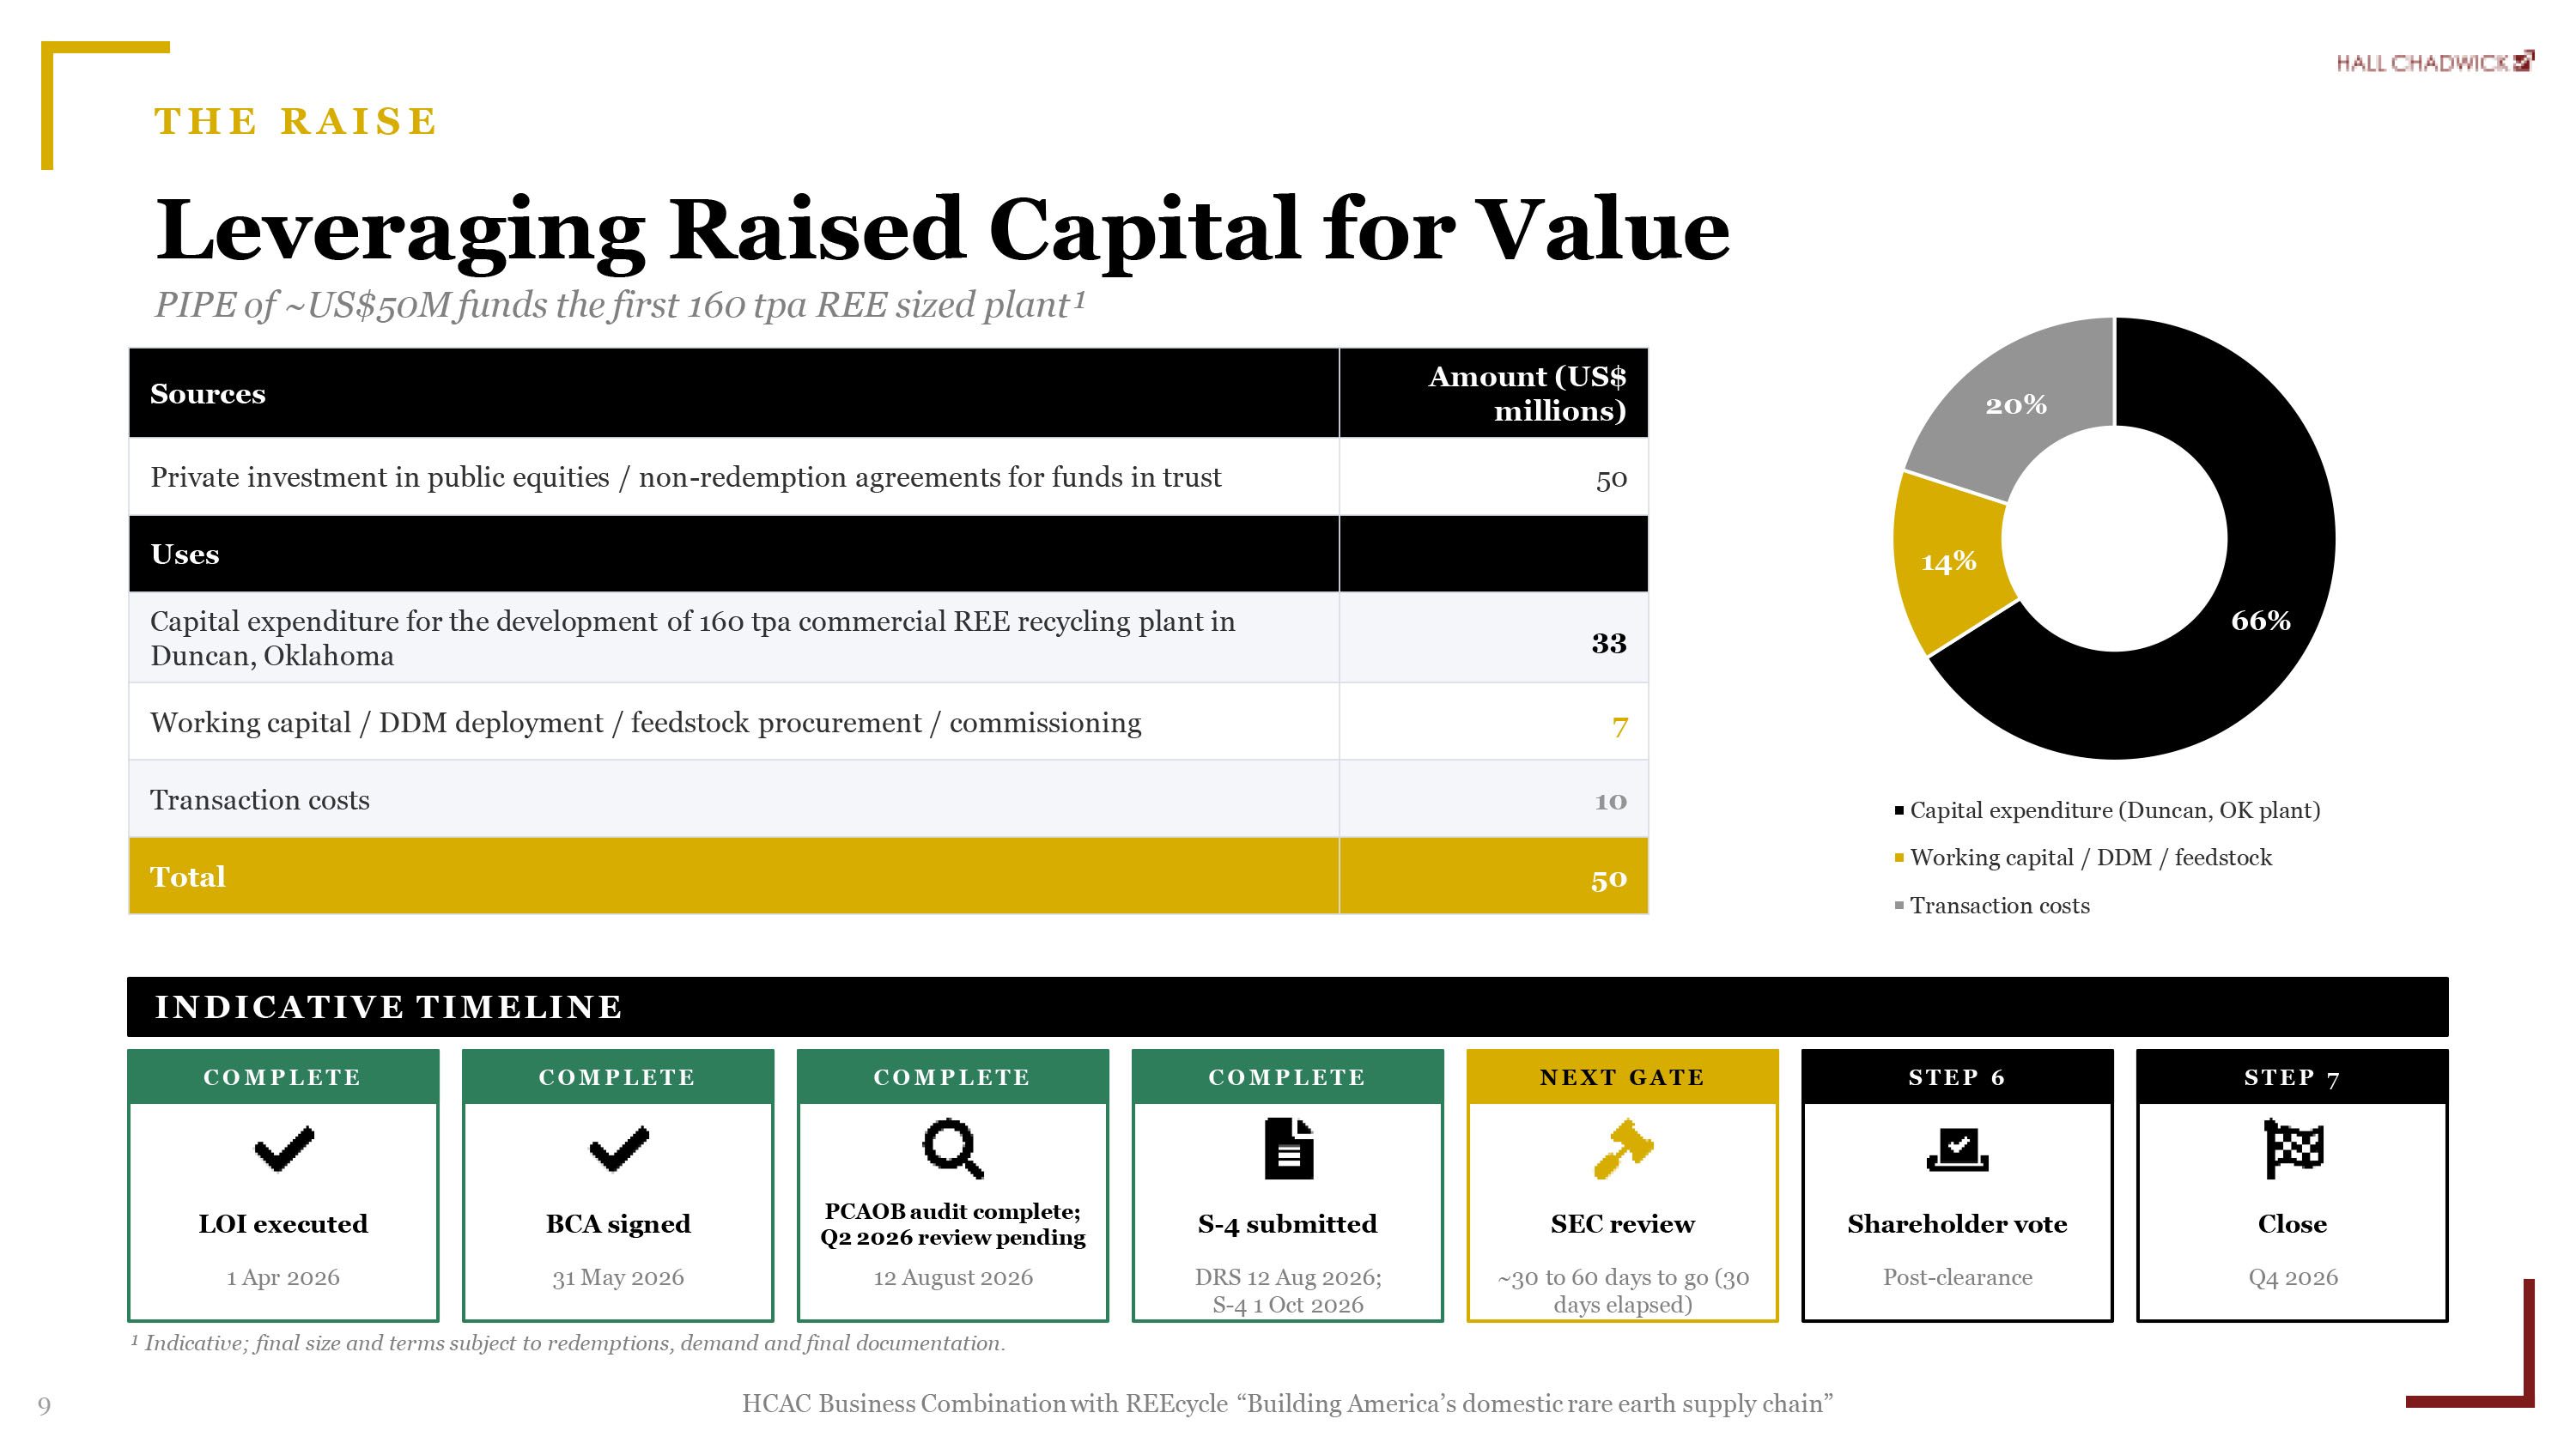
9 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” THE RAISE Leveraging Raised Capital for Value PIPE of ~US$50M funds the first 160 tpa REE sized plant¹ Amount (US$ millions) Sources 50 Private investment in public equities / non - redemption agreements for funds in trust Uses 33 Capital expenditure for the development of 160 tpa commercial REE recycling plant in Duncan, Oklahoma 7 Working capital / DDM deployment / feedstock procurement / commissioning 10 Transaction costs 50 Total 66% 14% 20% Capital expenditure (Duncan, OK plant) Working capital / DDM / feedstock Transaction costs INDICATIVE TIMELINE COMPLETE LOI executed 1 Apr 2026 COMPLETE BCA signed 31 May 2026 COMPLETE PCAOB audit complete; Q2 2026 review pending 12 August 2026 COMPLETE S - 4 submitted DRS 12 Aug 2026; S - 4 1 Oct 2026 NEXT GATE SEC review ~30 to 60 days to go (30 days elapsed) STEP 6 Shareholder vote Post - clearance STEP 7 Close Q4 2026 ¹ Indicative; final size and terms subject to redemptions, demand and final documentation.
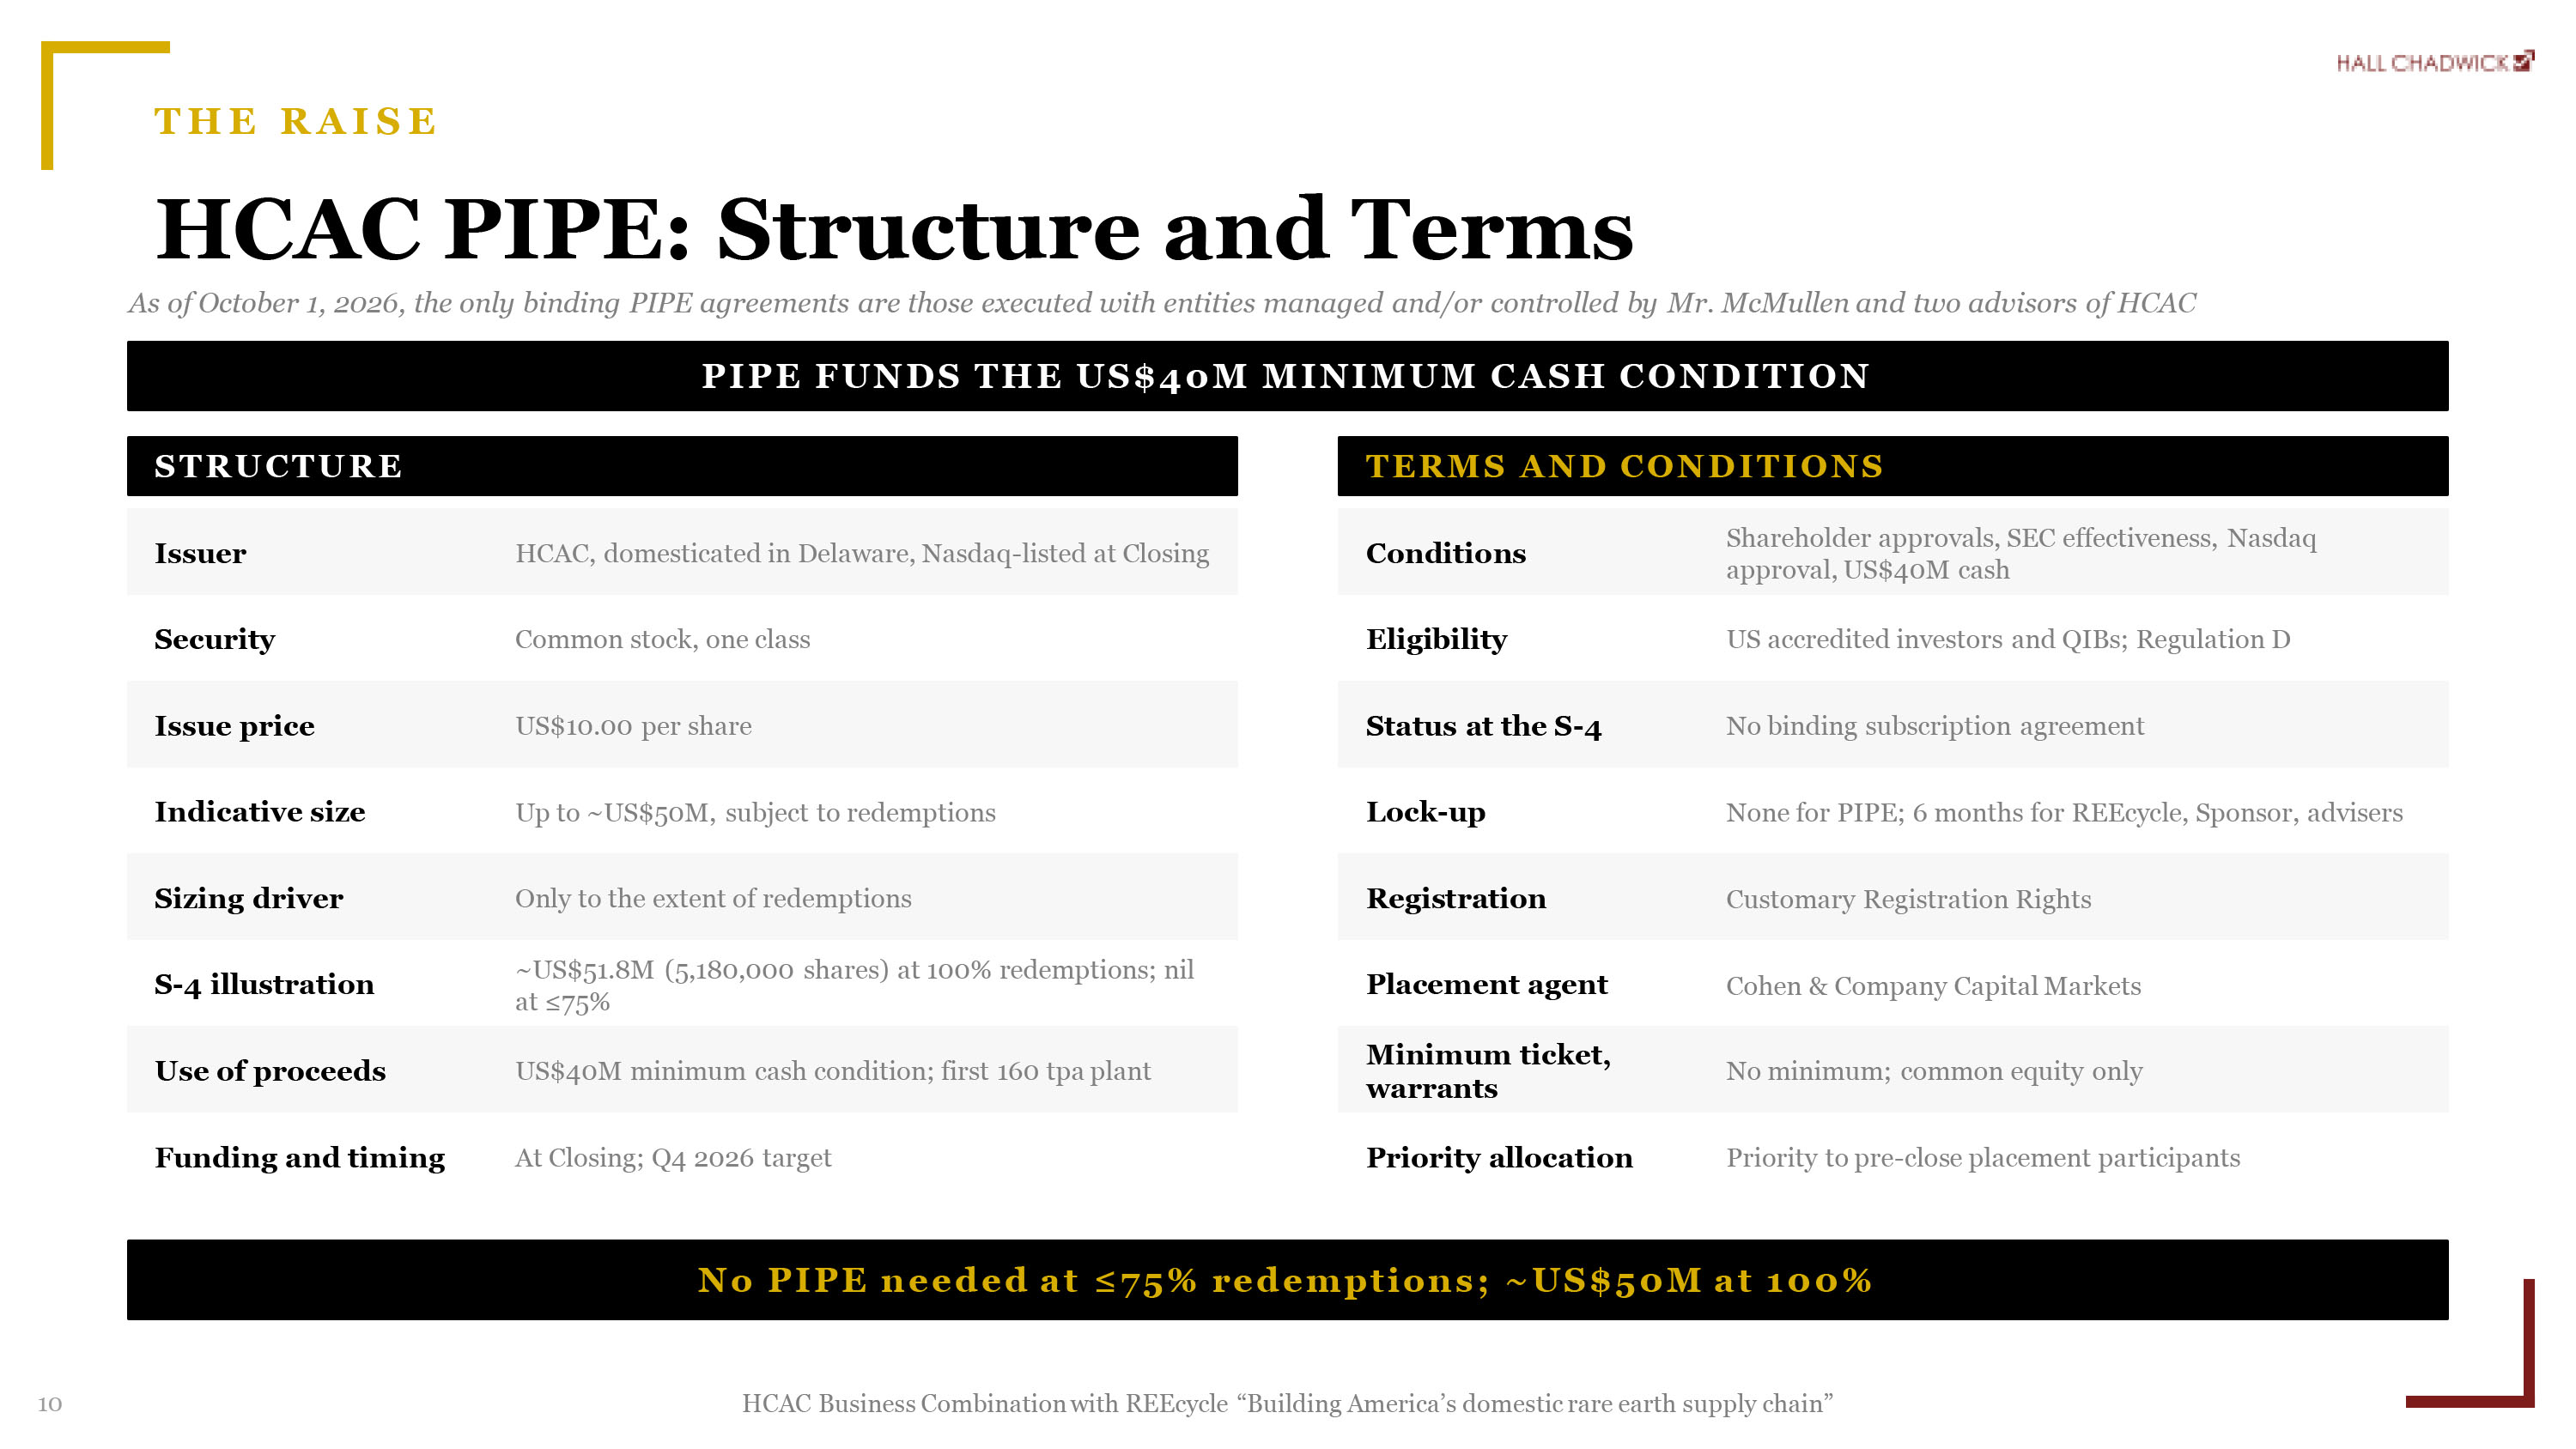
10 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” THE RAISE HCAC PIPE: Structure and Terms As of October 1, 2026, the only binding PIPE agreements are those executed with entities managed and/or controlled by Mr. McMullen and two advisors of HCAC PIPE FUNDS THE US$40M MINIMUM CASH CONDITION STRUCTURE TERMS AND CONDITIONS Issuer HCAC, domesticated in Delaware, Nasdaq - listed at Closing Security Common stock, one class Issue price US$10.00 per share Indicative size Up to ~US$50M, subject to redemptions Sizing driver Only to the extent of redemptions S - 4 illustration ~US$51.8M (5,180,000 shares) at 100% redemptions; nil at ≤75% Use of proceeds US$40M minimum cash condition; first 160 tpa plant Funding and timing At Closing; Q4 2026 target Conditions Shareholder approvals, SEC effectiveness, Nasdaq approval, US$40M cash Eligibility US accredited investors and QIBs; Regulation D Status at the S - 4 No binding subscription agreement Lock - up None for PIPE; 6 months for REEcycle, Sponsor, advisers Registration Customary Registration Rights Placement agent Cohen & Company Capital Markets Minimum ticket, warrants No minimum; common equity only Priority allocation Priority to pre - close placement participants No PIPE needed at ≤75% redemptions; ~US$50M at 100%
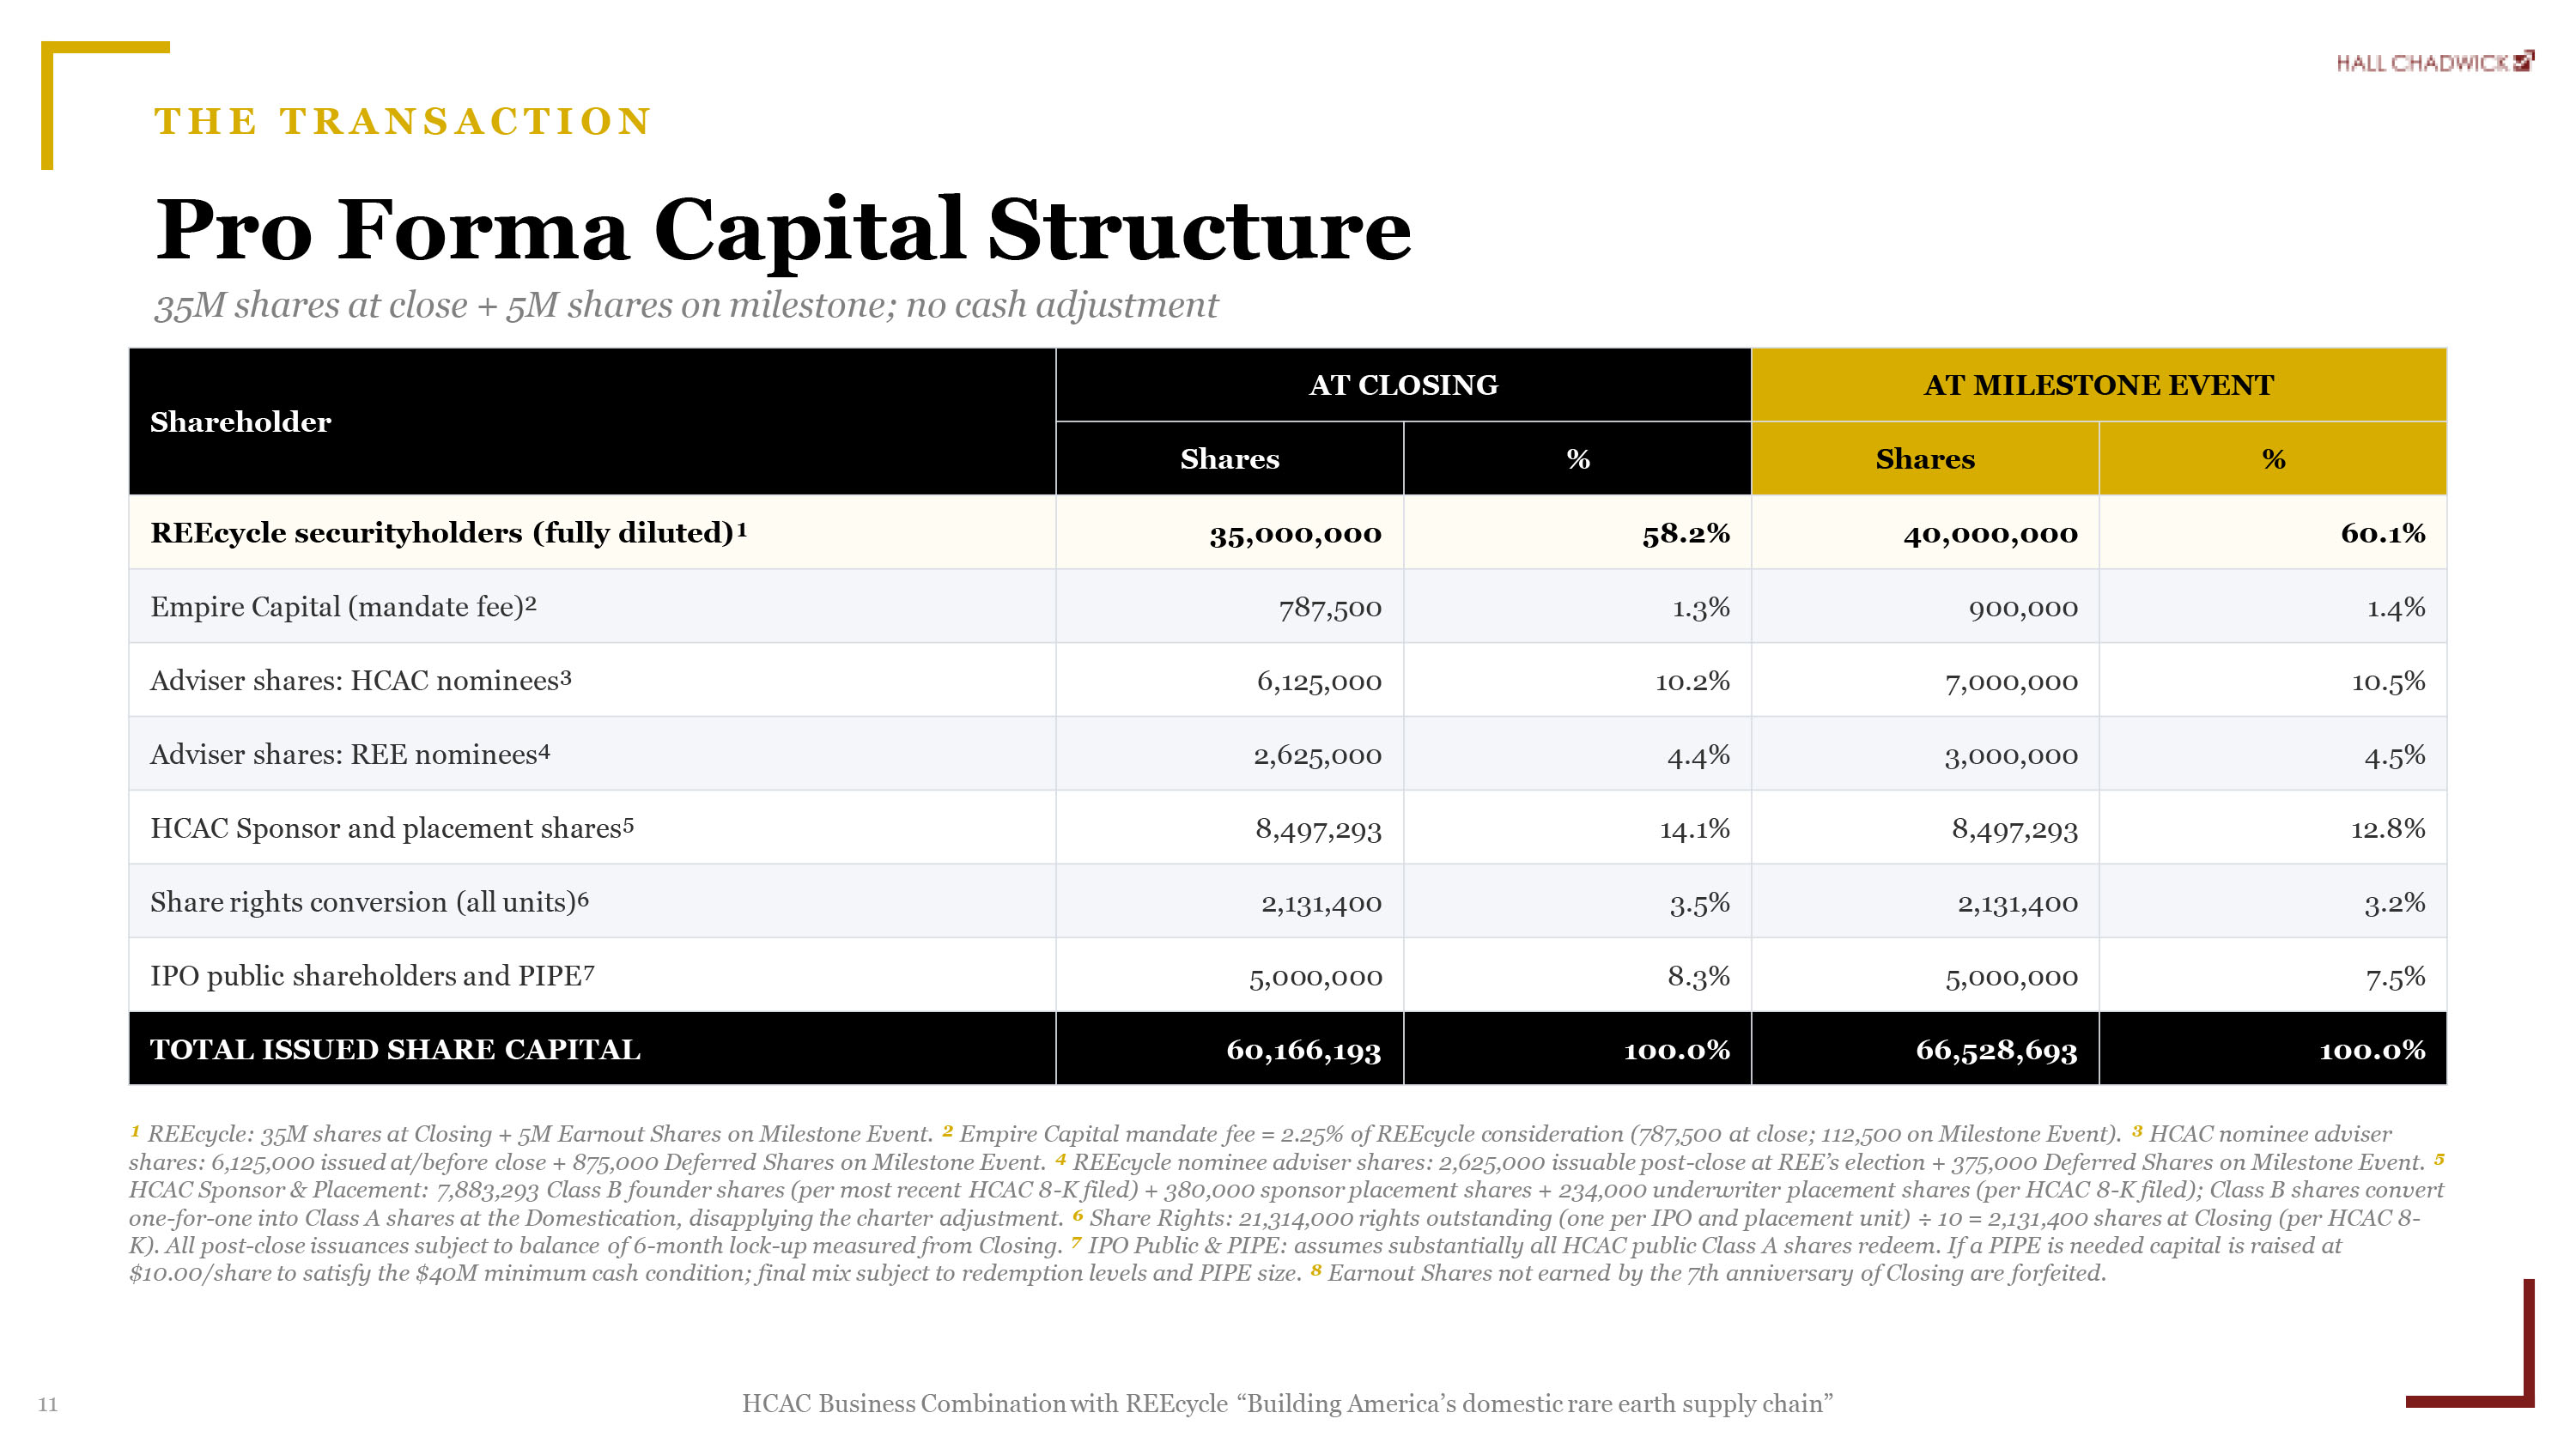
11 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” THE TRANSACTION Pro Forma Capital Structure 35M shares at close + 5M shares on m ilestone; no cash adjustment AT MILESTONE EVENT AT CLOSING Shareholder % Shares % Shares 60.1% 40,000,000 58.2% 35,000,000 REEcycle securityholders (fully diluted)¹ 1.4% 900,000 1.3% 787,500 Empire Capital (mandate fee)² 10.5% 7,000,000 10.2% 6,125,000 Adviser shares: HCAC nominees³ 4.5% 3,000,000 4.4% 2,625,000 Adviser shares: REE nominees⁴ 12.8% 8,497,293 14.1% 8,497,293 HCAC Sponsor and placement shares⁵ 3.2% 2,131,400 3.5% 2,131,400 Share rights conversion (all units)⁶ 7.5% 5,000,000 8.3% 5,000,000 IPO public shareholders and PIPE⁷ 100.0% 66,528,693 100.0% 60,166,193 TOTAL ISSUED SHARE CAPITAL ¹ REEcycle: 35M shares at Closing + 5M Earnout Shares on Milestone Event. ² Empire Capital mandate fee = 2.25% of REEcycle consideration (787,500 at close; 112,500 on Milestone Event). ³ HCAC nominee adviser shares: 6,125,000 issued at/before close + 875,000 Deferred Shares on Milestone Event. ⁴ REEcycle nominee adviser shares: 2,625,000 issuable post - close at REE’s election + 375,000 Deferred Shares on Milestone Event. ⁵ HCAC Sponsor & Placement: 7,883,293 Class B founder shares (per most recent HCAC 8 - K filed) + 380,000 sponsor placement shares + 234,000 underwriter placement shares (per HCAC 8 - K filed); Class B shares convert one - for - one into Class A shares at the Domestication, disapplying the charter adjustment. ⁶ Share Rights: 21,314,000 rights outstanding (one per IPO and placement unit) ÷ 10 = 2,131,400 shares at Closing (per HCAC 8 - K). All post - close issuances subject to balance of 6 - month lock - up measured from Closing. ⁷ IPO Public & PIPE: assumes substantially all HCAC public Class A shares redeem. If a PIPE is needed capital is raised at $10.00/share to satisfy the $40M minimum cash condition; final mix subject to redemption levels and PIPE size. ⁸ Earnout Shares not earned by the 7th anniversary of Closing are forfeited.
SECTION 2 The Investment Case TM (NASDAQ: HCAC)
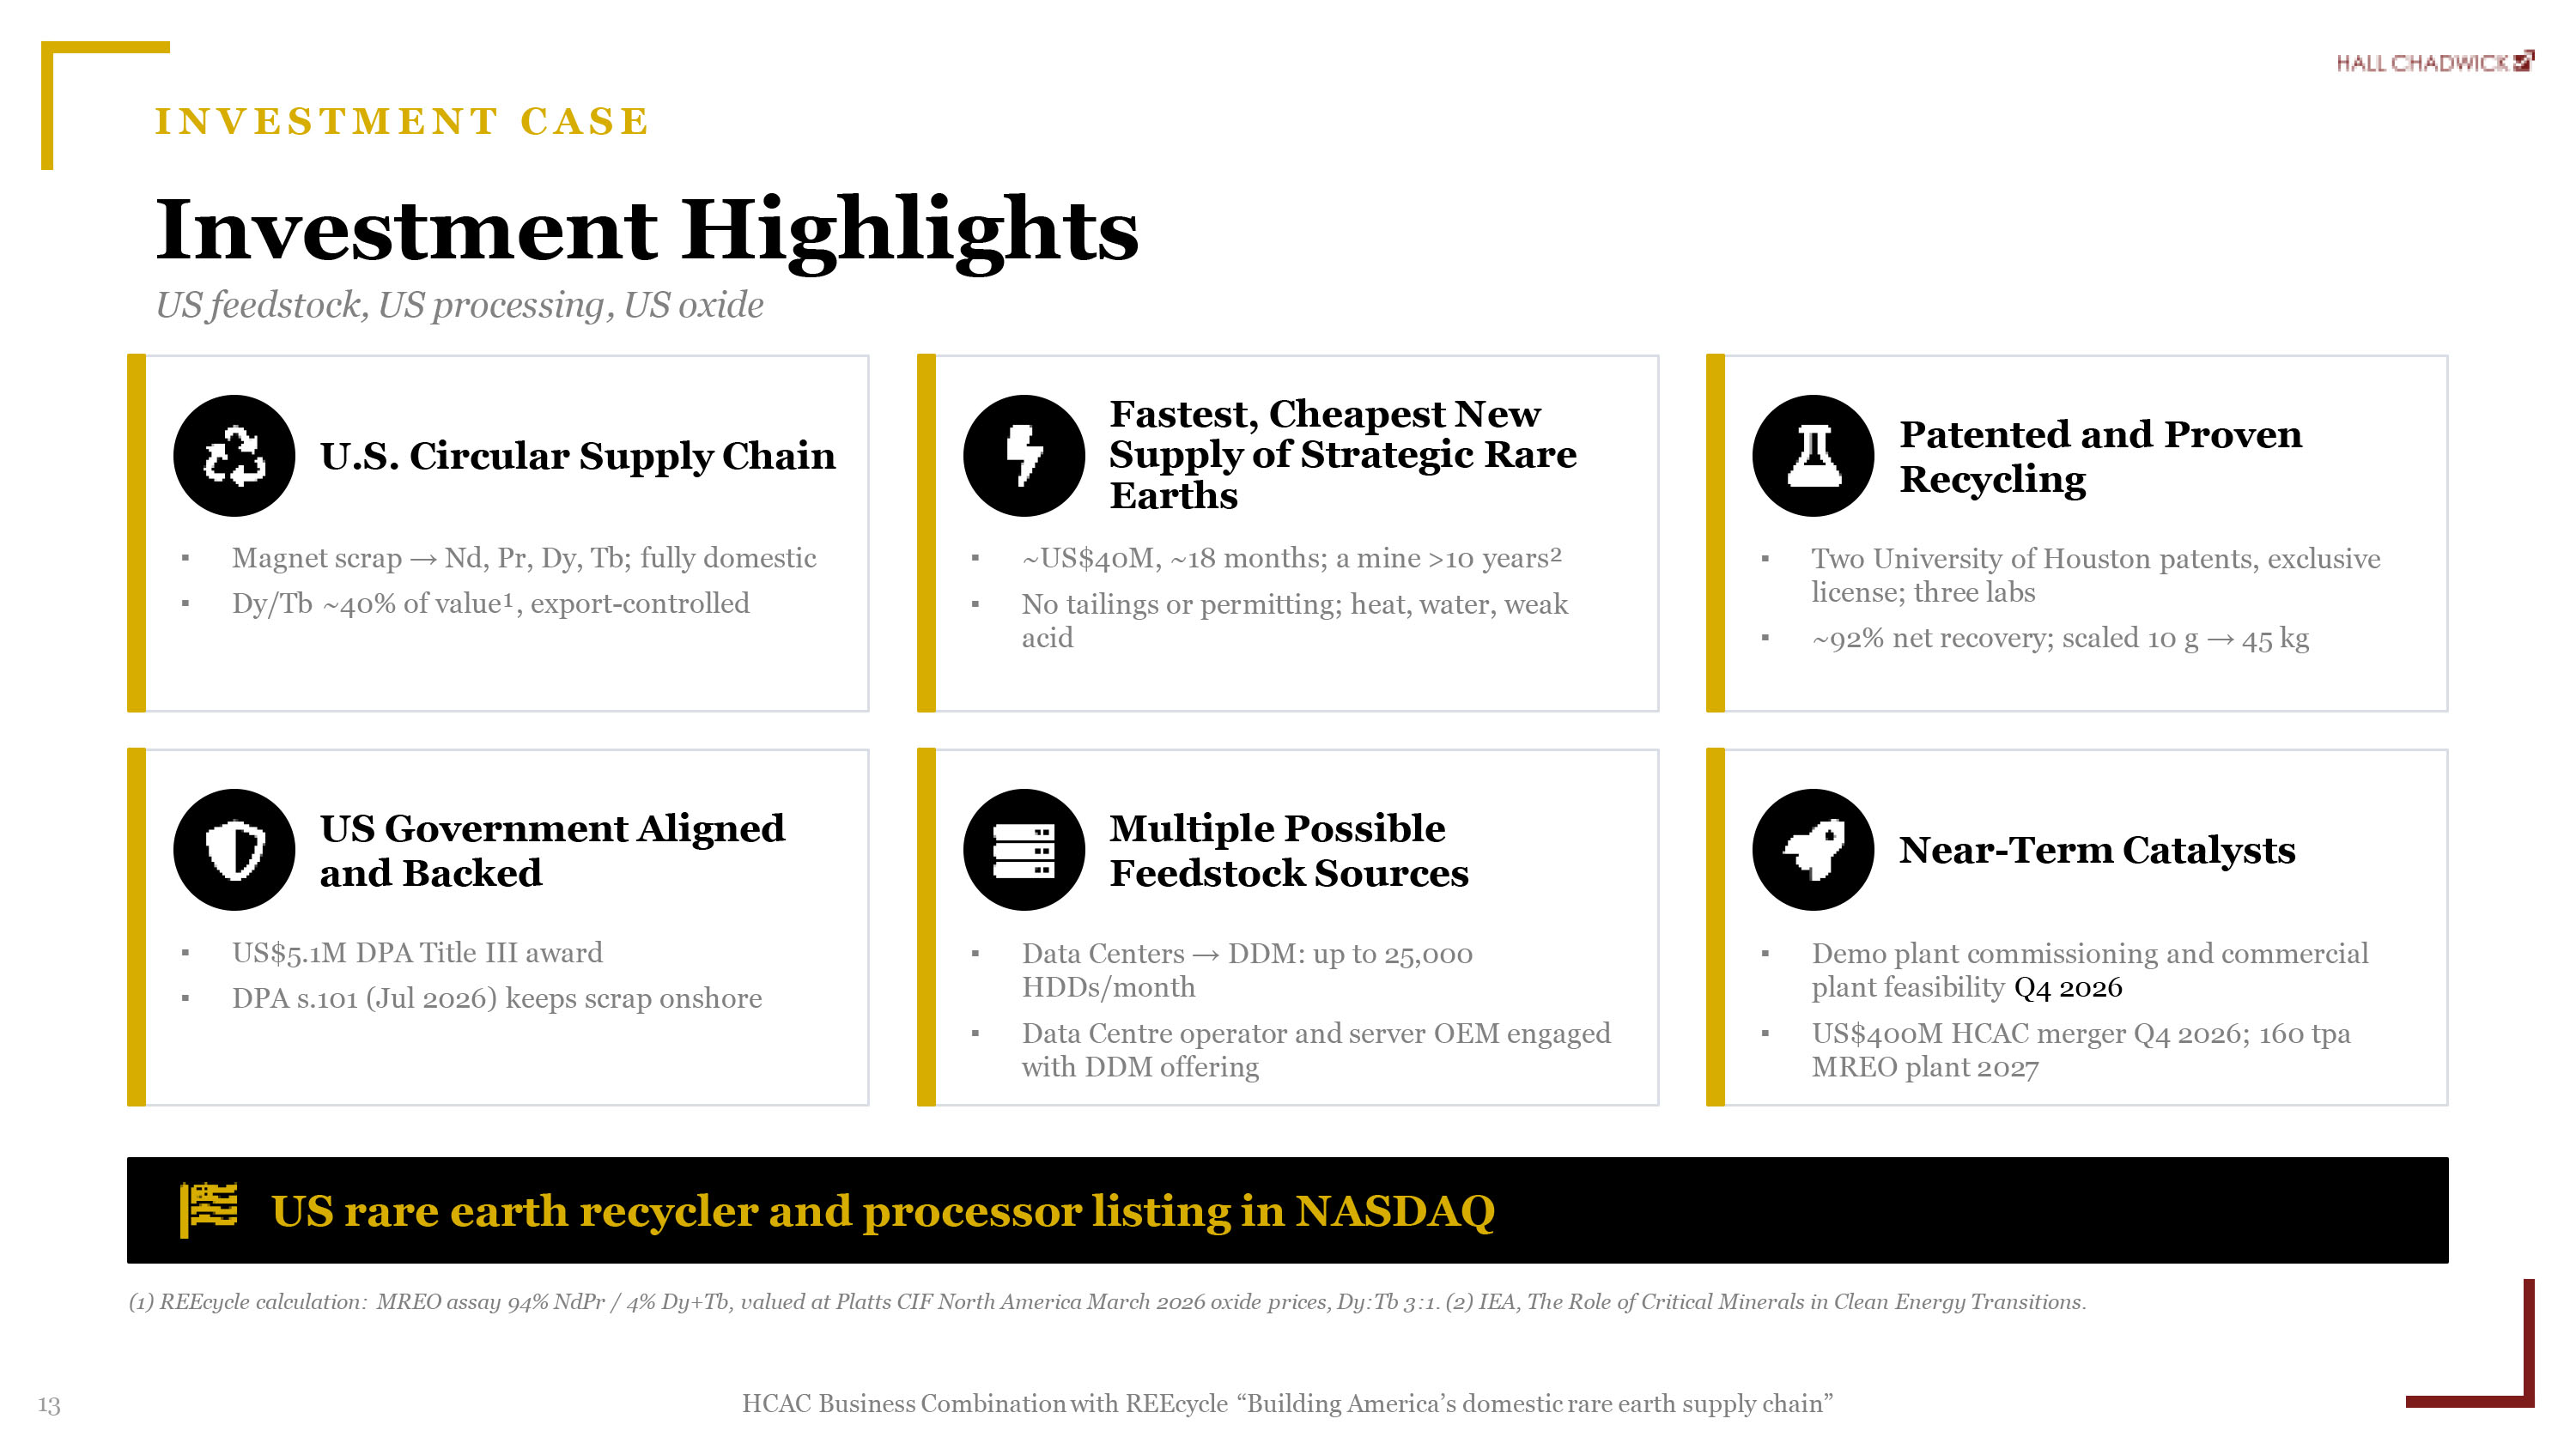
13 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” INVESTMENT CASE Investment Highlights US feedstock, US processing, US oxide U.S. Circular Supply Chain ▪ Magnet scrap → Nd, Pr, Dy, Tb; fully domestic ▪ Dy/Tb ~40% of value¹, export - controlled Fastest, Cheapest New Supply of Strategic Rare Earths ▪ ~US$40M, ~18 months; a mine >10 years² ▪ No tailings or permitting; heat, water, weak acid Patented and Proven Recycling ▪ Two University of Houston patents, exclusive license; three labs ▪ ~92% net recovery; scaled 10 g → 45 kg US Government Aligned and Backed ▪ US$5.1M DPA Title III award ▪ DPA s.101 (Jul 2026) keeps scrap onshore Multiple Possible Feedstock Sources ▪ Data Centers → DDM: up to 25,000 HDDs/month ▪ Data Centre operator and server OEM engaged with DDM offering Near - Term Catalysts ▪ Demo plant commissioning and commercial plant feasibility Q4 2026 ▪ US$400M HCAC merger Q4 2026; 160 tpa MREO plant 2027 US rare earth recycler and processor listing in NASDAQ (1) REEcycle calculation: MREO assay 94% NdPr / 4% Dy+Tb, valued at Platts CIF North America March 2026 oxide prices, Dy:Tb 3 :1. (2) IEA, The Role of Critical Minerals in Clean Energy Transitions.
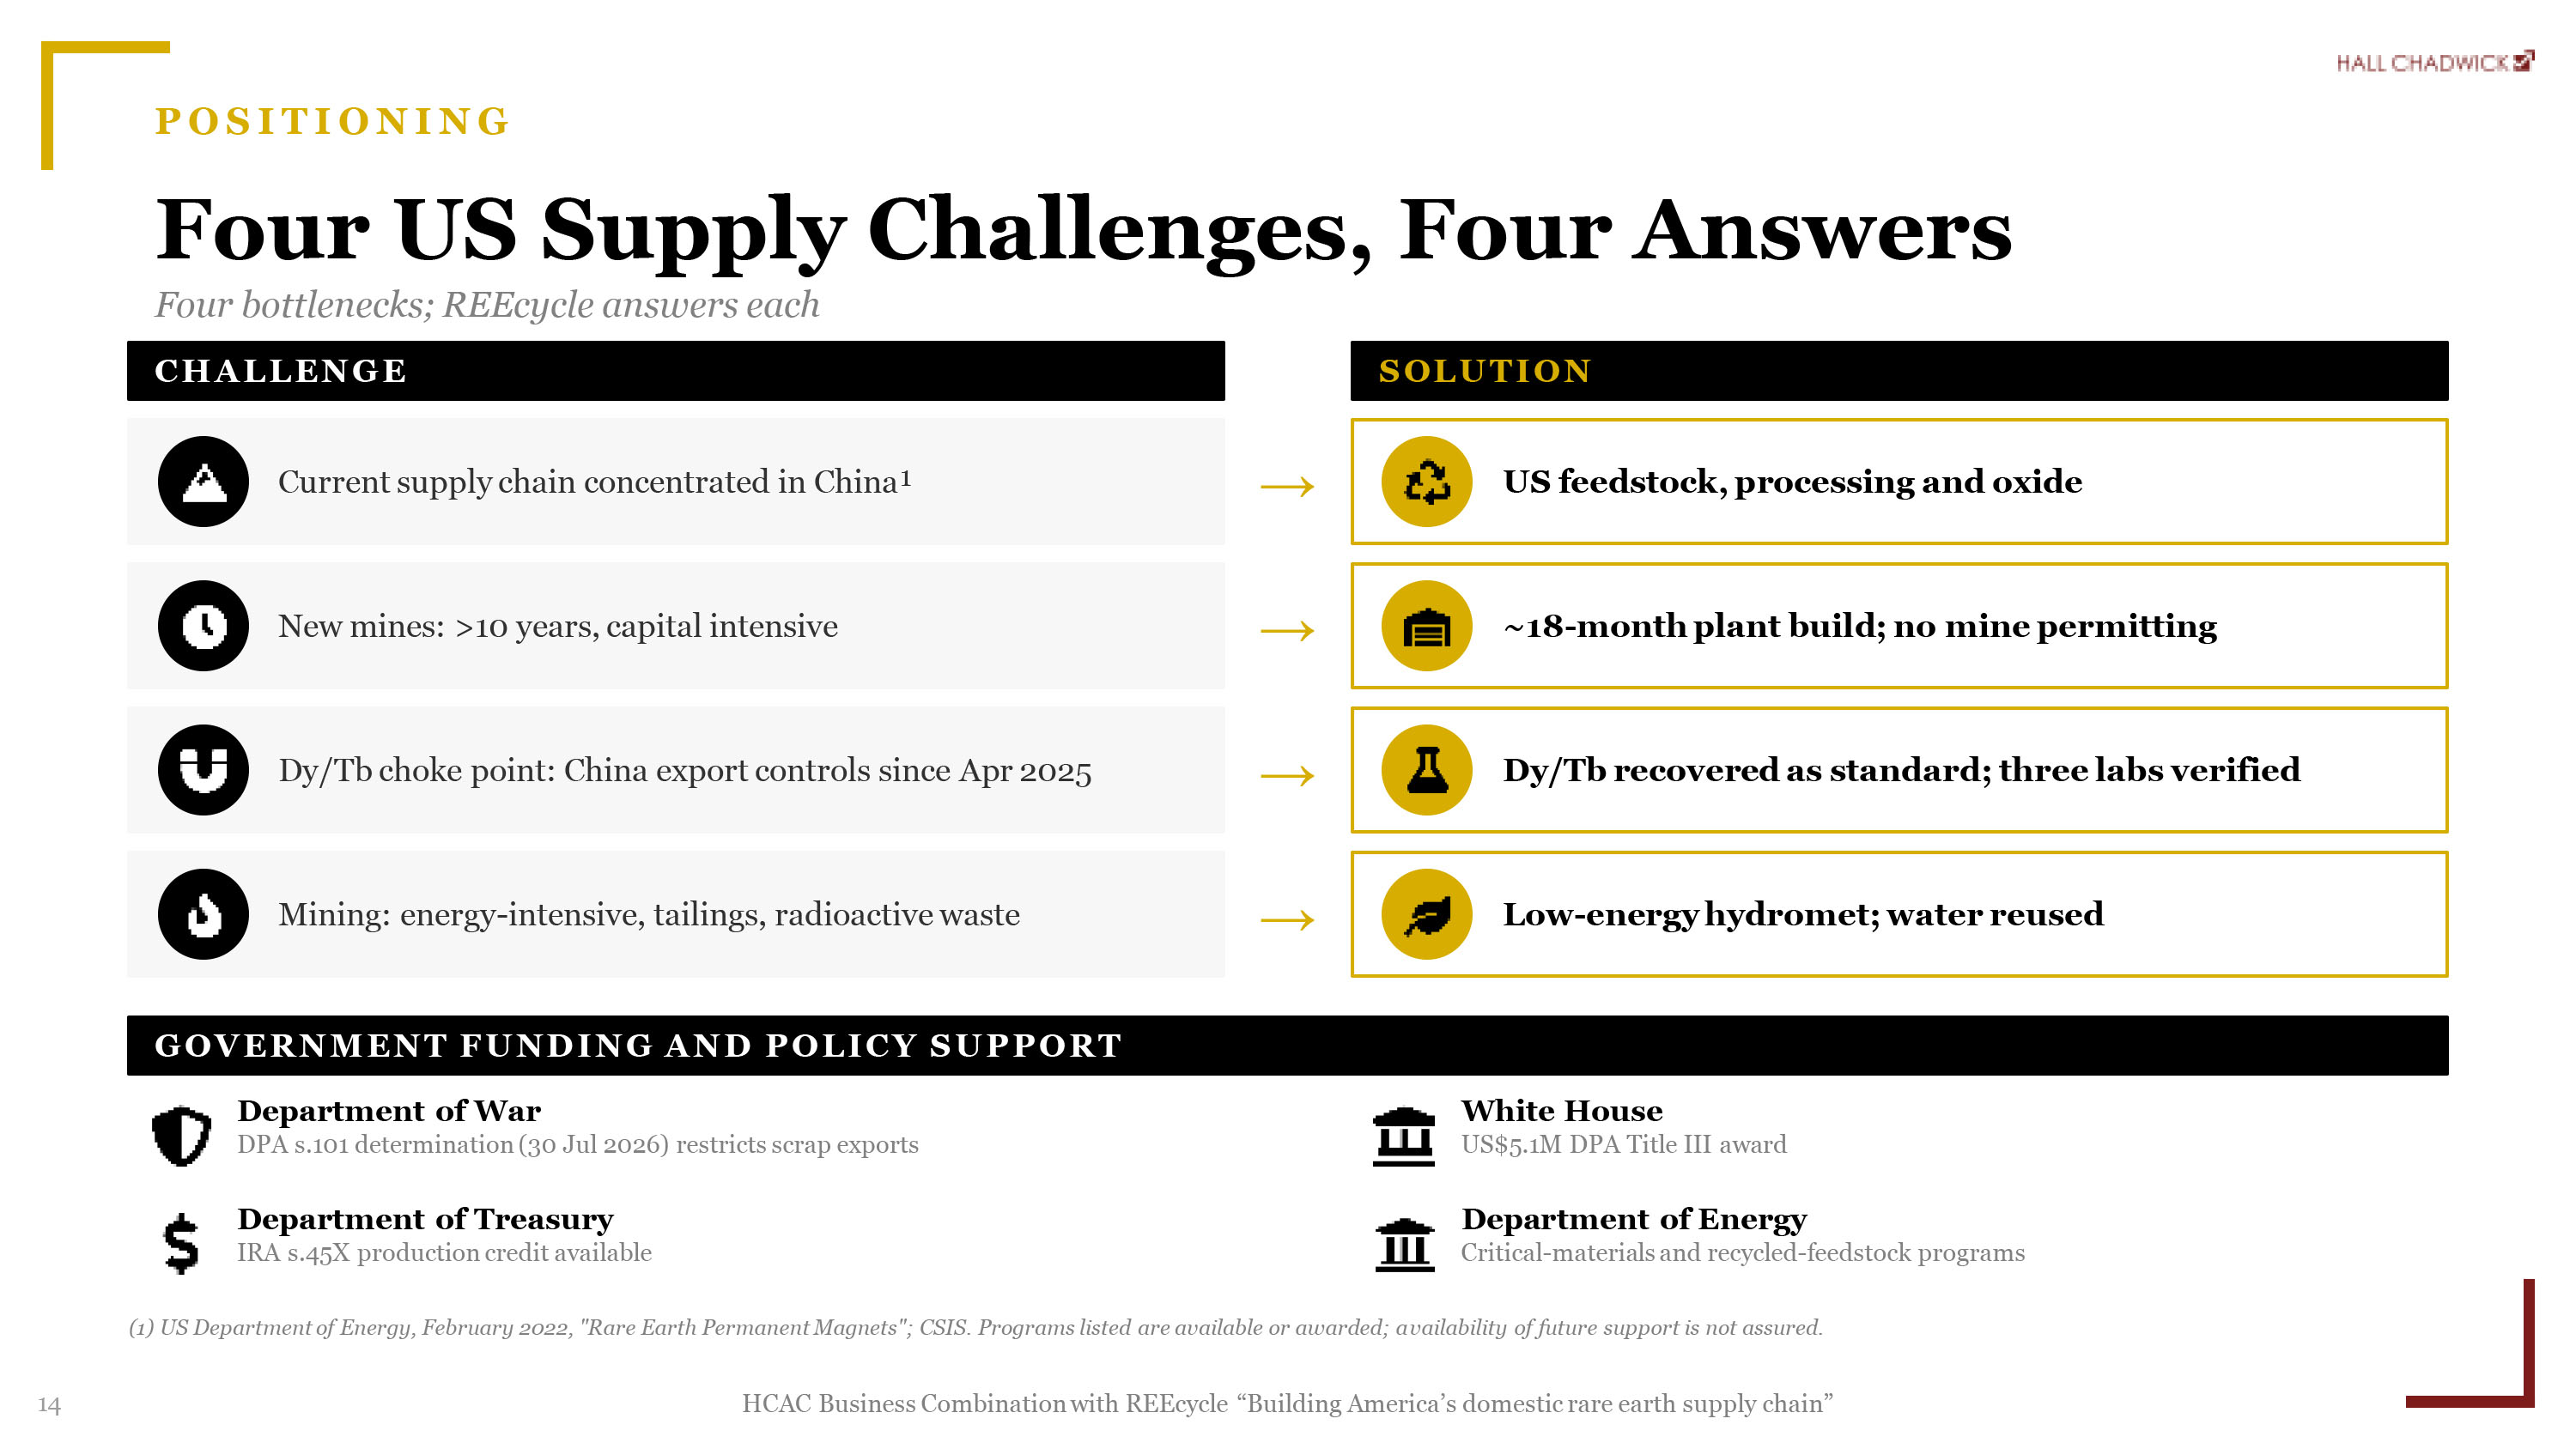
14 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” POSITIONING Four US Supply Challenges, Four Answers Four bottlenecks; REEcycle answers each CHALLENGE SOLUTION Current supply chain concentrated in China¹ → US feedstock, processing and oxide New mines: >10 years, capital intensive → ~18 - month plant build; no mine permitting Dy/Tb choke point: China export controls since Apr 2025 → Dy/Tb recovered as standard; three labs verified Mining: energy - intensive, tailings, radioactive waste → Low - energy hydromet; water reused GOVERNMENT FUNDING AND POLICY SUPPORT Department of War DPA s.101 determination (30 Jul 2026) restricts scrap exports White House US$5.1M DPA Title III award Department of Treasury IRA s.45X production credit available Department of Energy Critical - materials and recycled - feedstock programs (1) US Department of Energy, February 2022, "Rare Earth Permanent Magnets"; CSIS. Programs listed are available or awarded; a vai lability of future support is not assured.
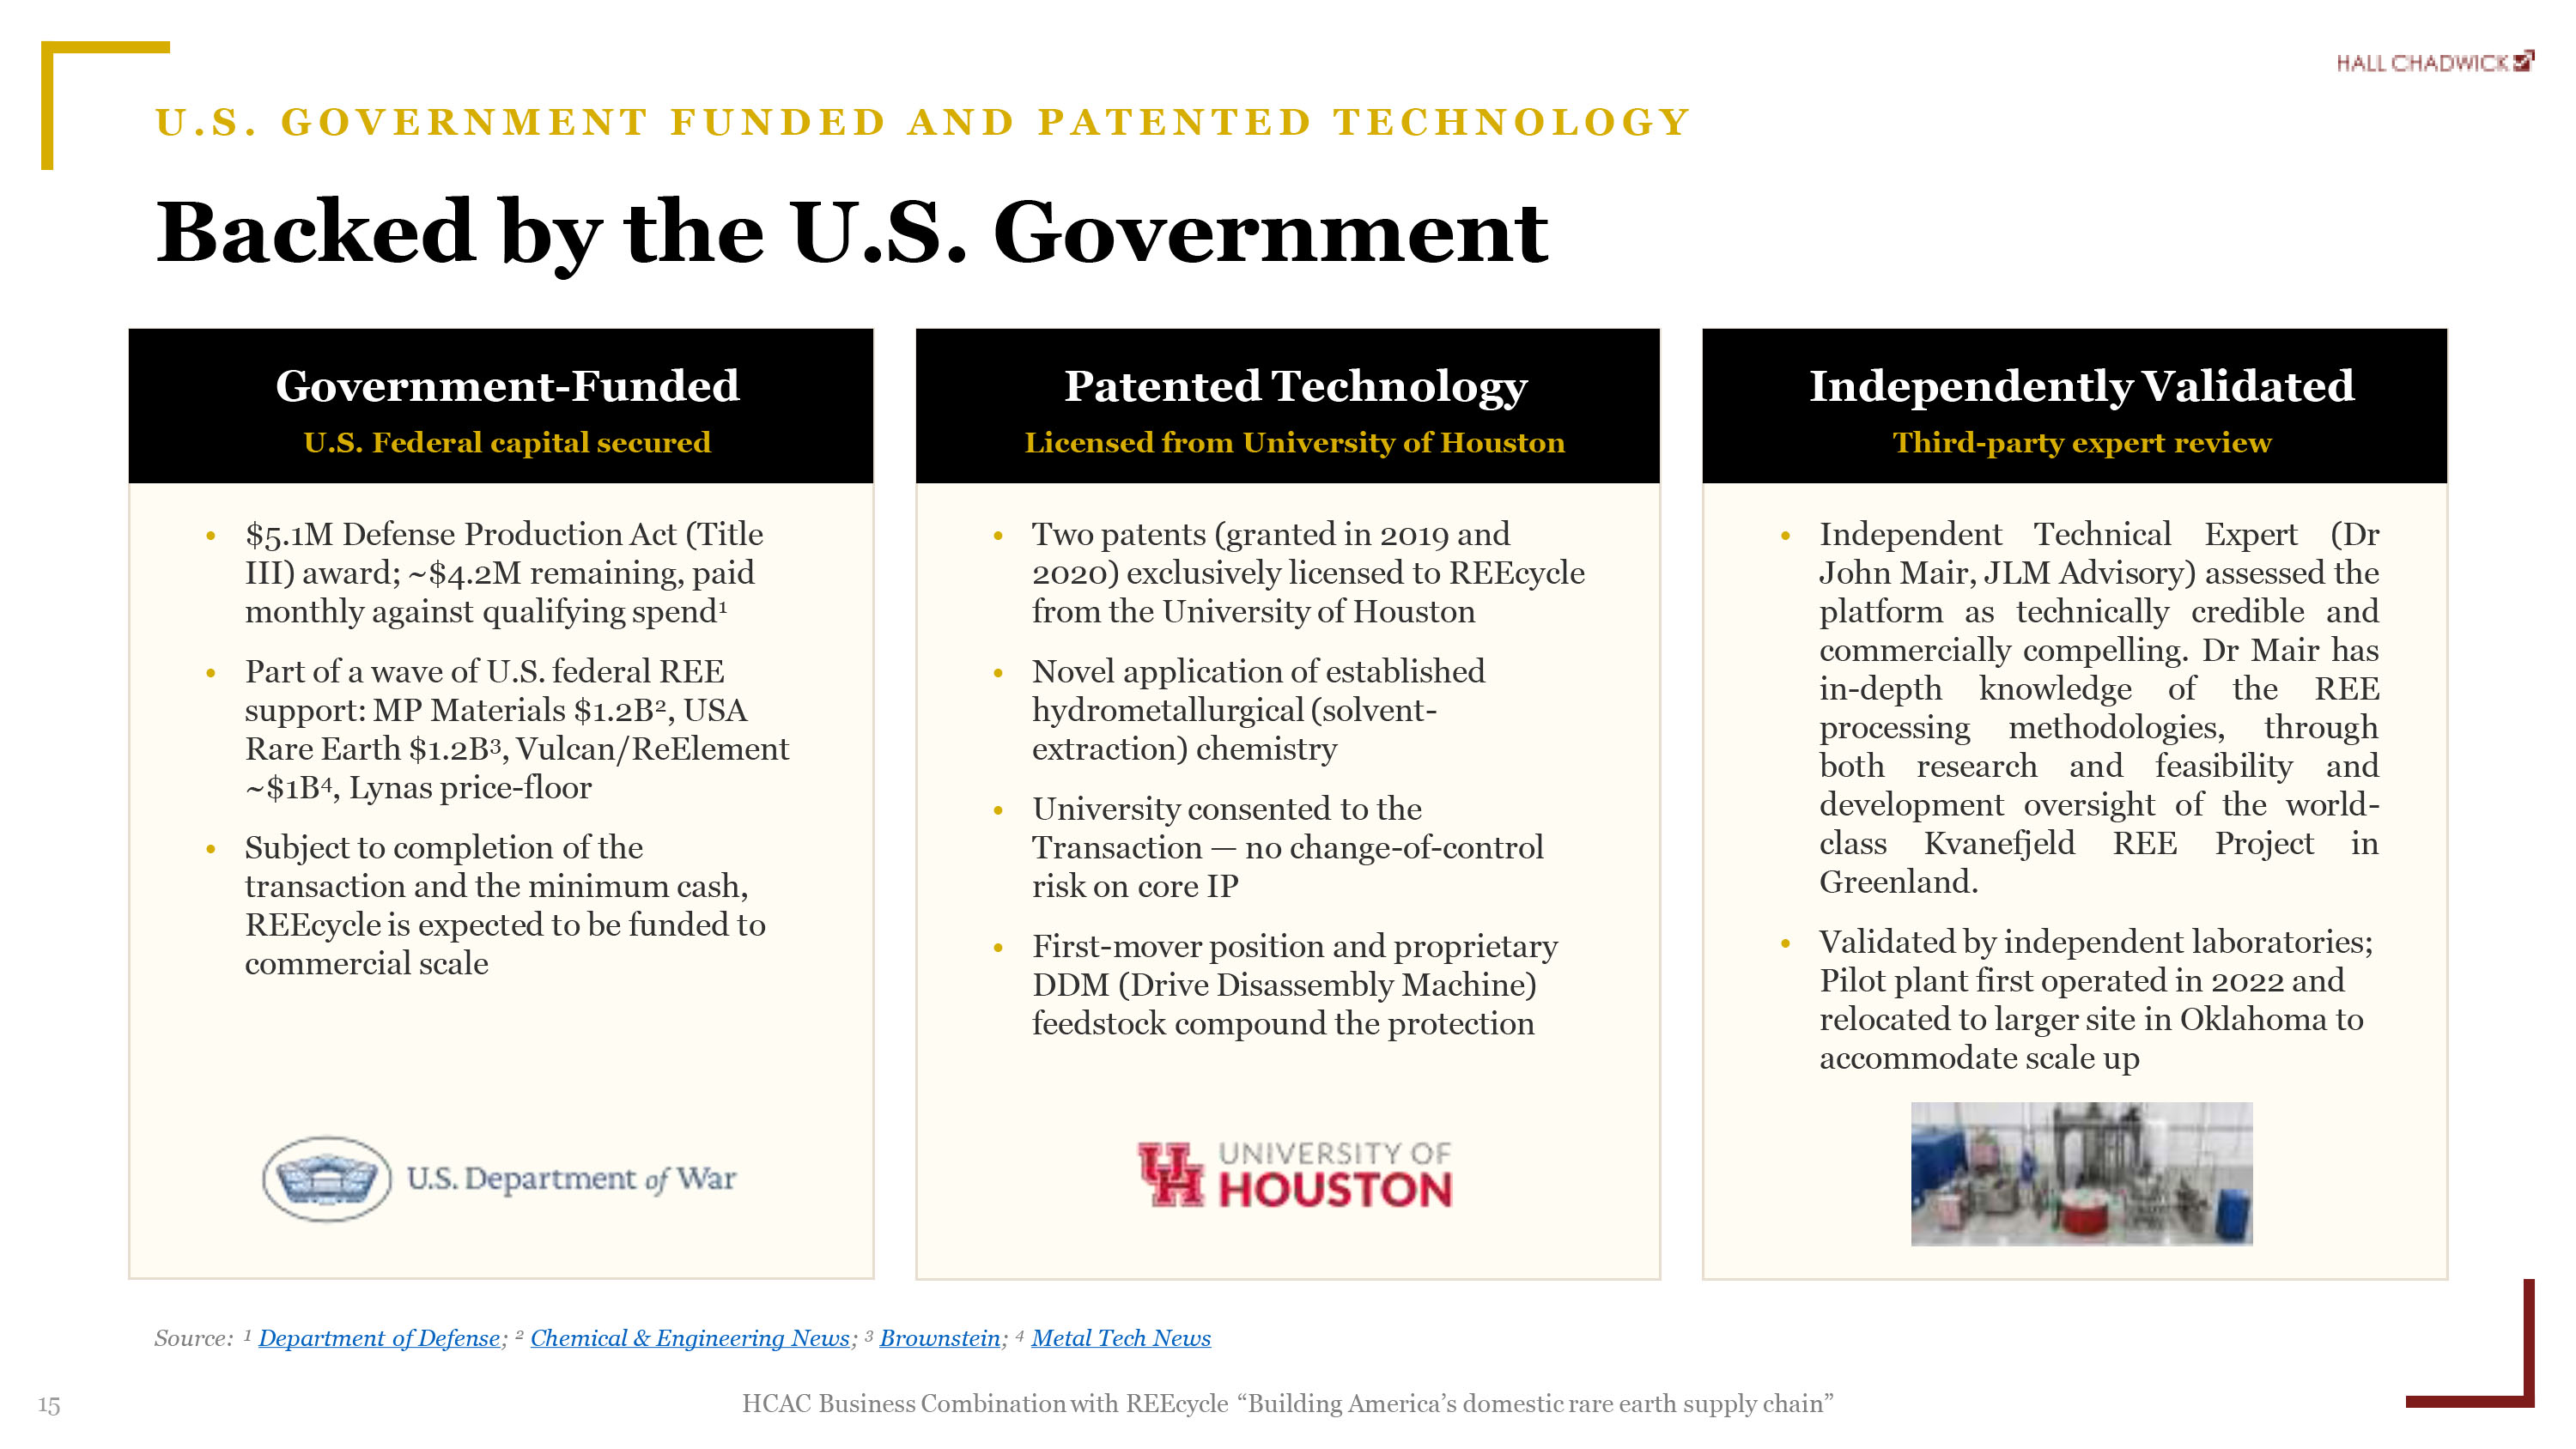
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 15 U.S. GOVERNMENT FUNDED AND PATENTED TECHNOLOGY Source: ¹ Department of Defense; 2 Chemical & Engineering News; 3 Brownstein; 4 Metal Tech News Government - Funded U.S. Federal capital secured Patented Technology Licensed from University of Houston Independently Validated Third - party expert review • $5.1M Defense Production Act (Title III) award; ~$4.2M remaining, paid monthly against qualifying spend 1 • Part of a wave of U.S. federal REE support: MP Materials $1.2B 2, USA Rare Earth $1.2B 3, Vulcan/ReElement ~$1B 4, Lynas price - floor • Subject to completion of the transaction and the minimum cash, REEcycle is expected to be funded to commercial scale • Two patents (granted in 2019 and 2020) exclusively licensed to REEcycle from the University of Houston • Novel application of established hydrometallurgical (solvent - extraction) chemistry • University consented to the Transaction — no change - of - control risk on core IP • First - mover position and proprietary DDM (Drive Disassembly Machine) feedstock compound the protection • Independent Technical Expert (Dr John Mair, JLM Advisory) assessed the platform as technically credible and commercially compelling. Dr Mair has in - depth knowledge of the REE processing methodologies, through both research and feasibility and development oversight of the world - class Kvanefjeld REE Project in Greenland. • Validated by independent laboratories; Pilot plant first operated in 2022 and relocated to larger site in Oklahoma to accommodate scale up Backed by the U.S. Government
SECTION 3 Market & Industry Overview TM (NASDAQ: HCAC)
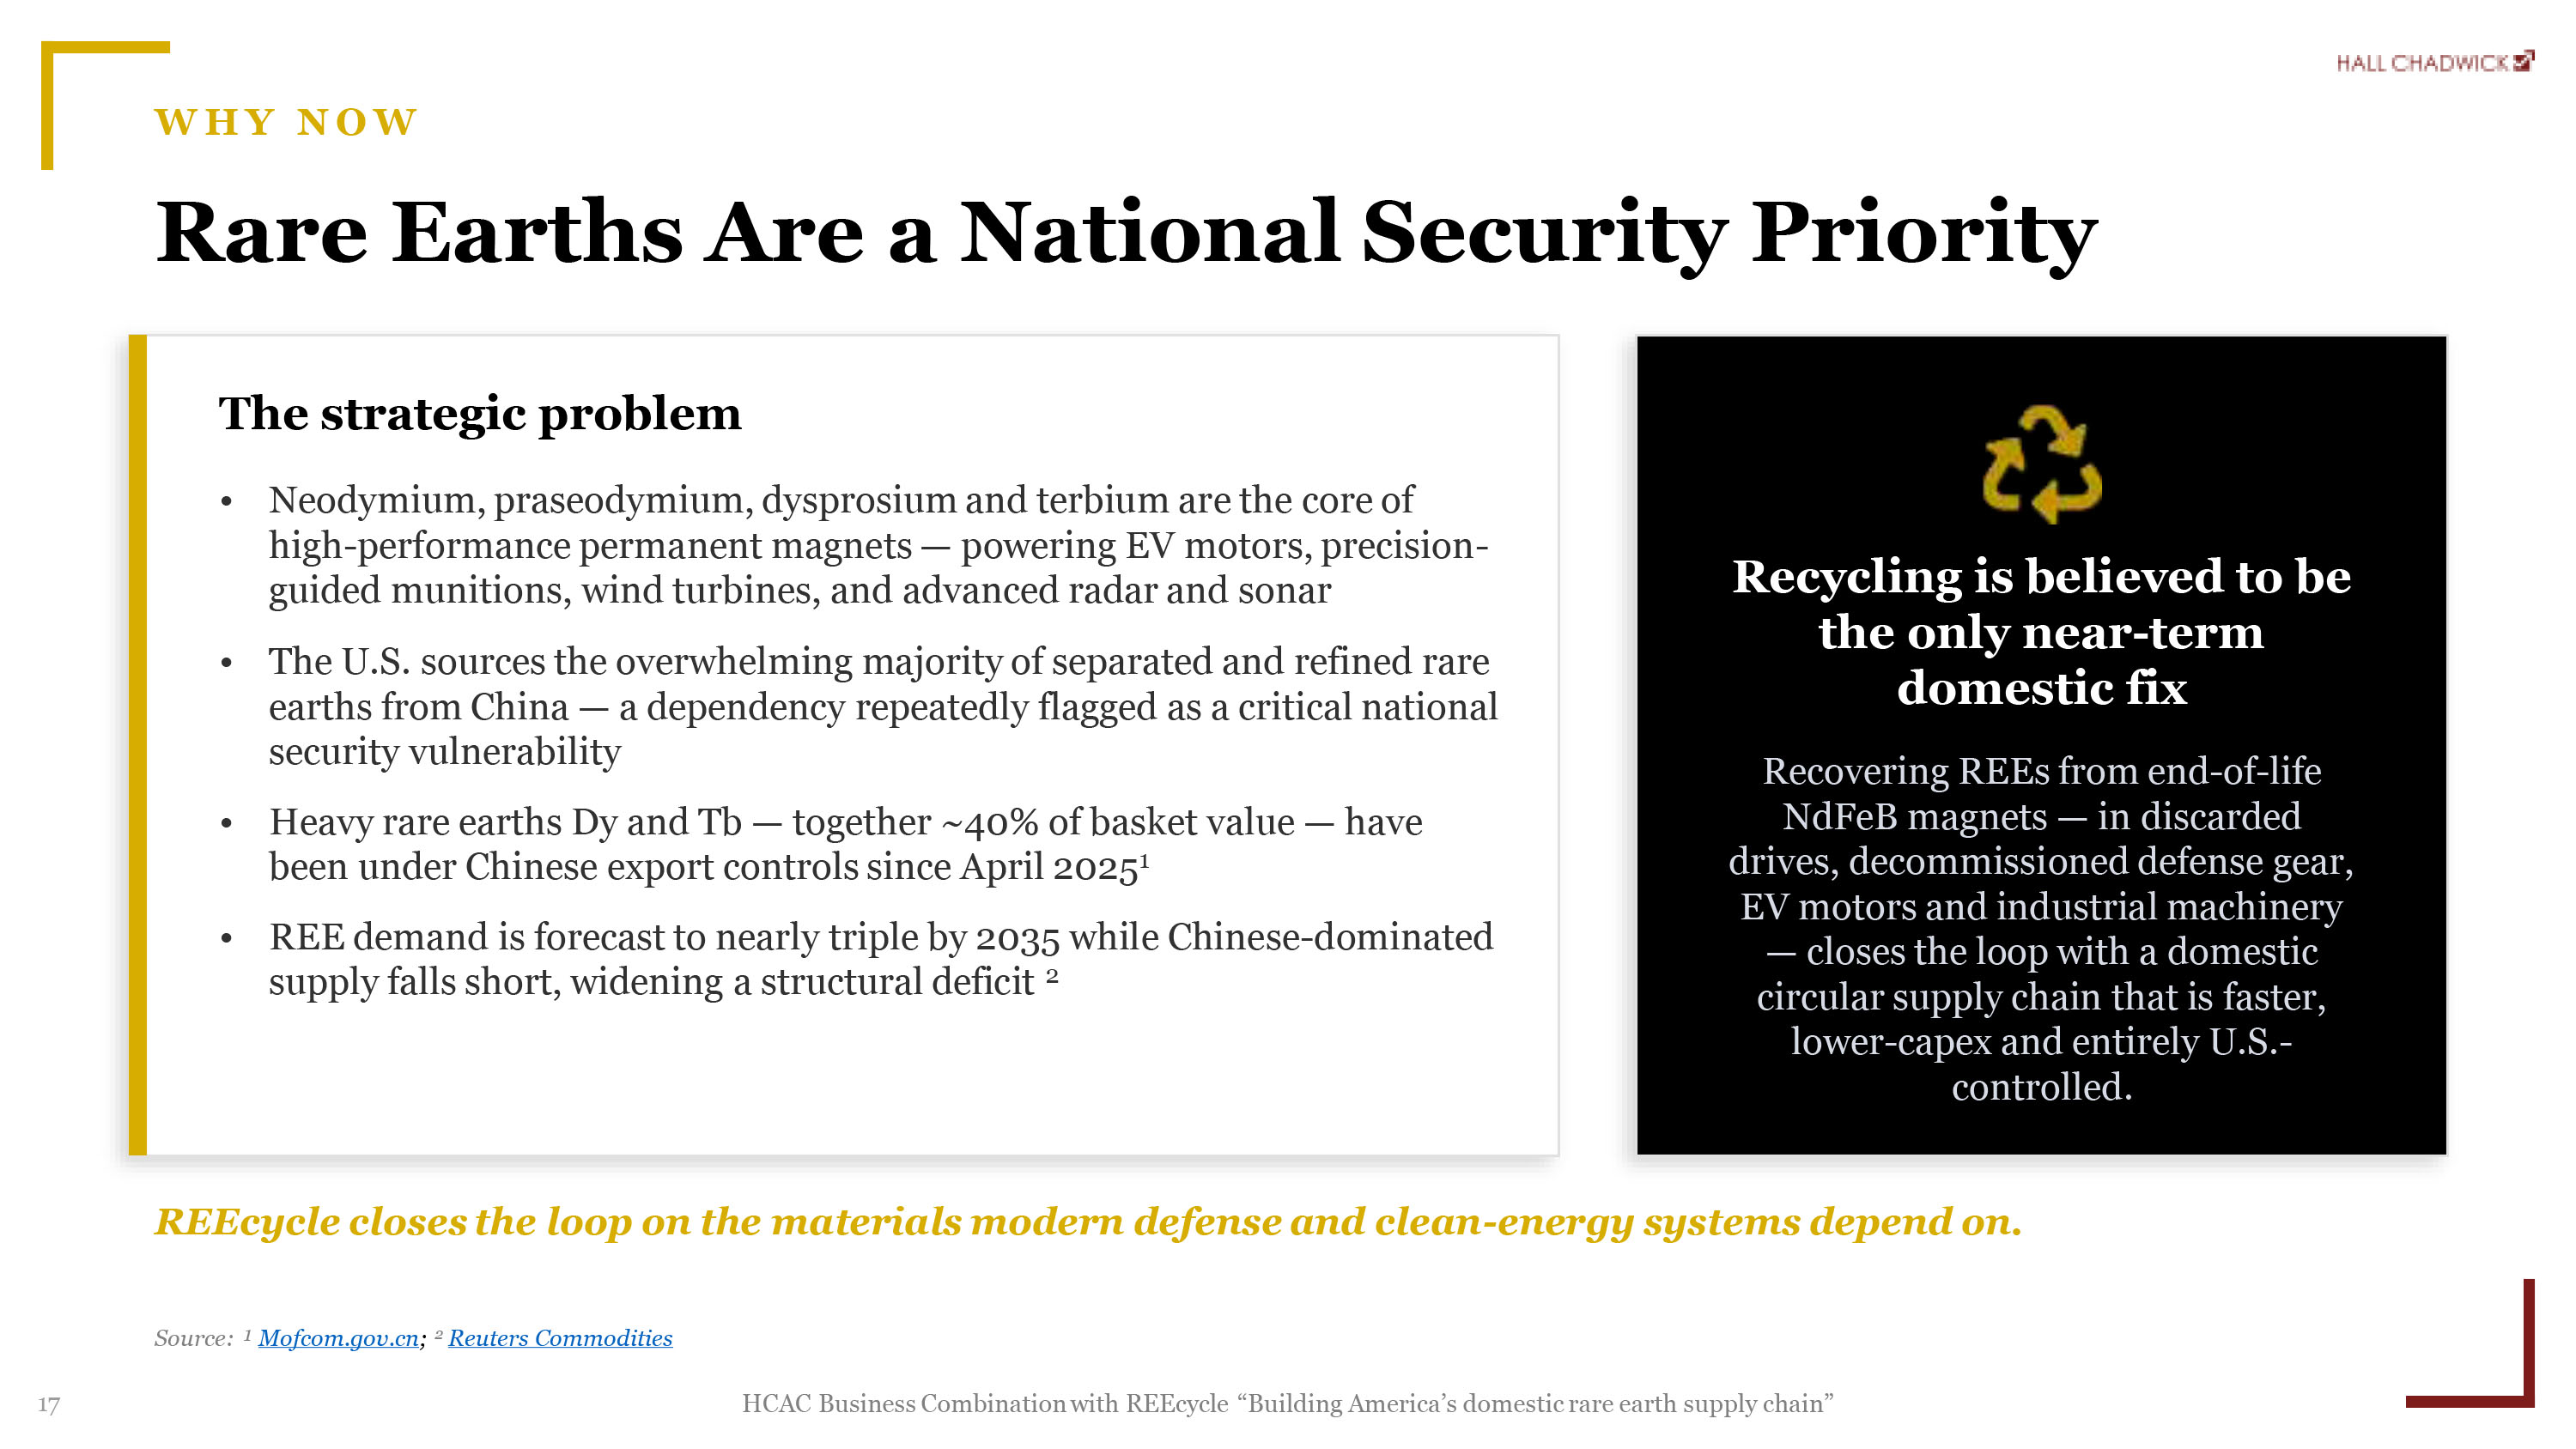
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 17 WHY NOW Rare Earths Are a National Security Priority The strategic problem • Neodymium, praseodymium, dysprosium and terbium are the core of high - performance permanent magnets — powering EV motors, precision - guided munitions, wind turbines, and advanced radar and sonar • The U.S. sources the overwhelming majority of separated and refined rare earths from China — a dependency repeatedly flagged as a critical national security vulnerability • Heavy rare earths Dy and Tb — together ~40% of basket value — have been under Chinese export controls since April 2025 1 • REE demand is forecast to nearly triple by 2035 while Chinese - dominated supply falls short, widening a structural deficit 2 Recycling is believed to be the only near - term domestic fix Recovering REEs from end - of - life NdFeB magnets — in discarded drives, decommissioned defense gear, EV motors and industrial machinery — closes the loop with a domestic circular supply chain that is faster, lower - capex and entirely U.S. - controlled. REEcycle closes the loop on the materials modern defense and clean - energy systems depend on. Source: ¹ Mofcom.gov.cn; 2 Reuters Commodities
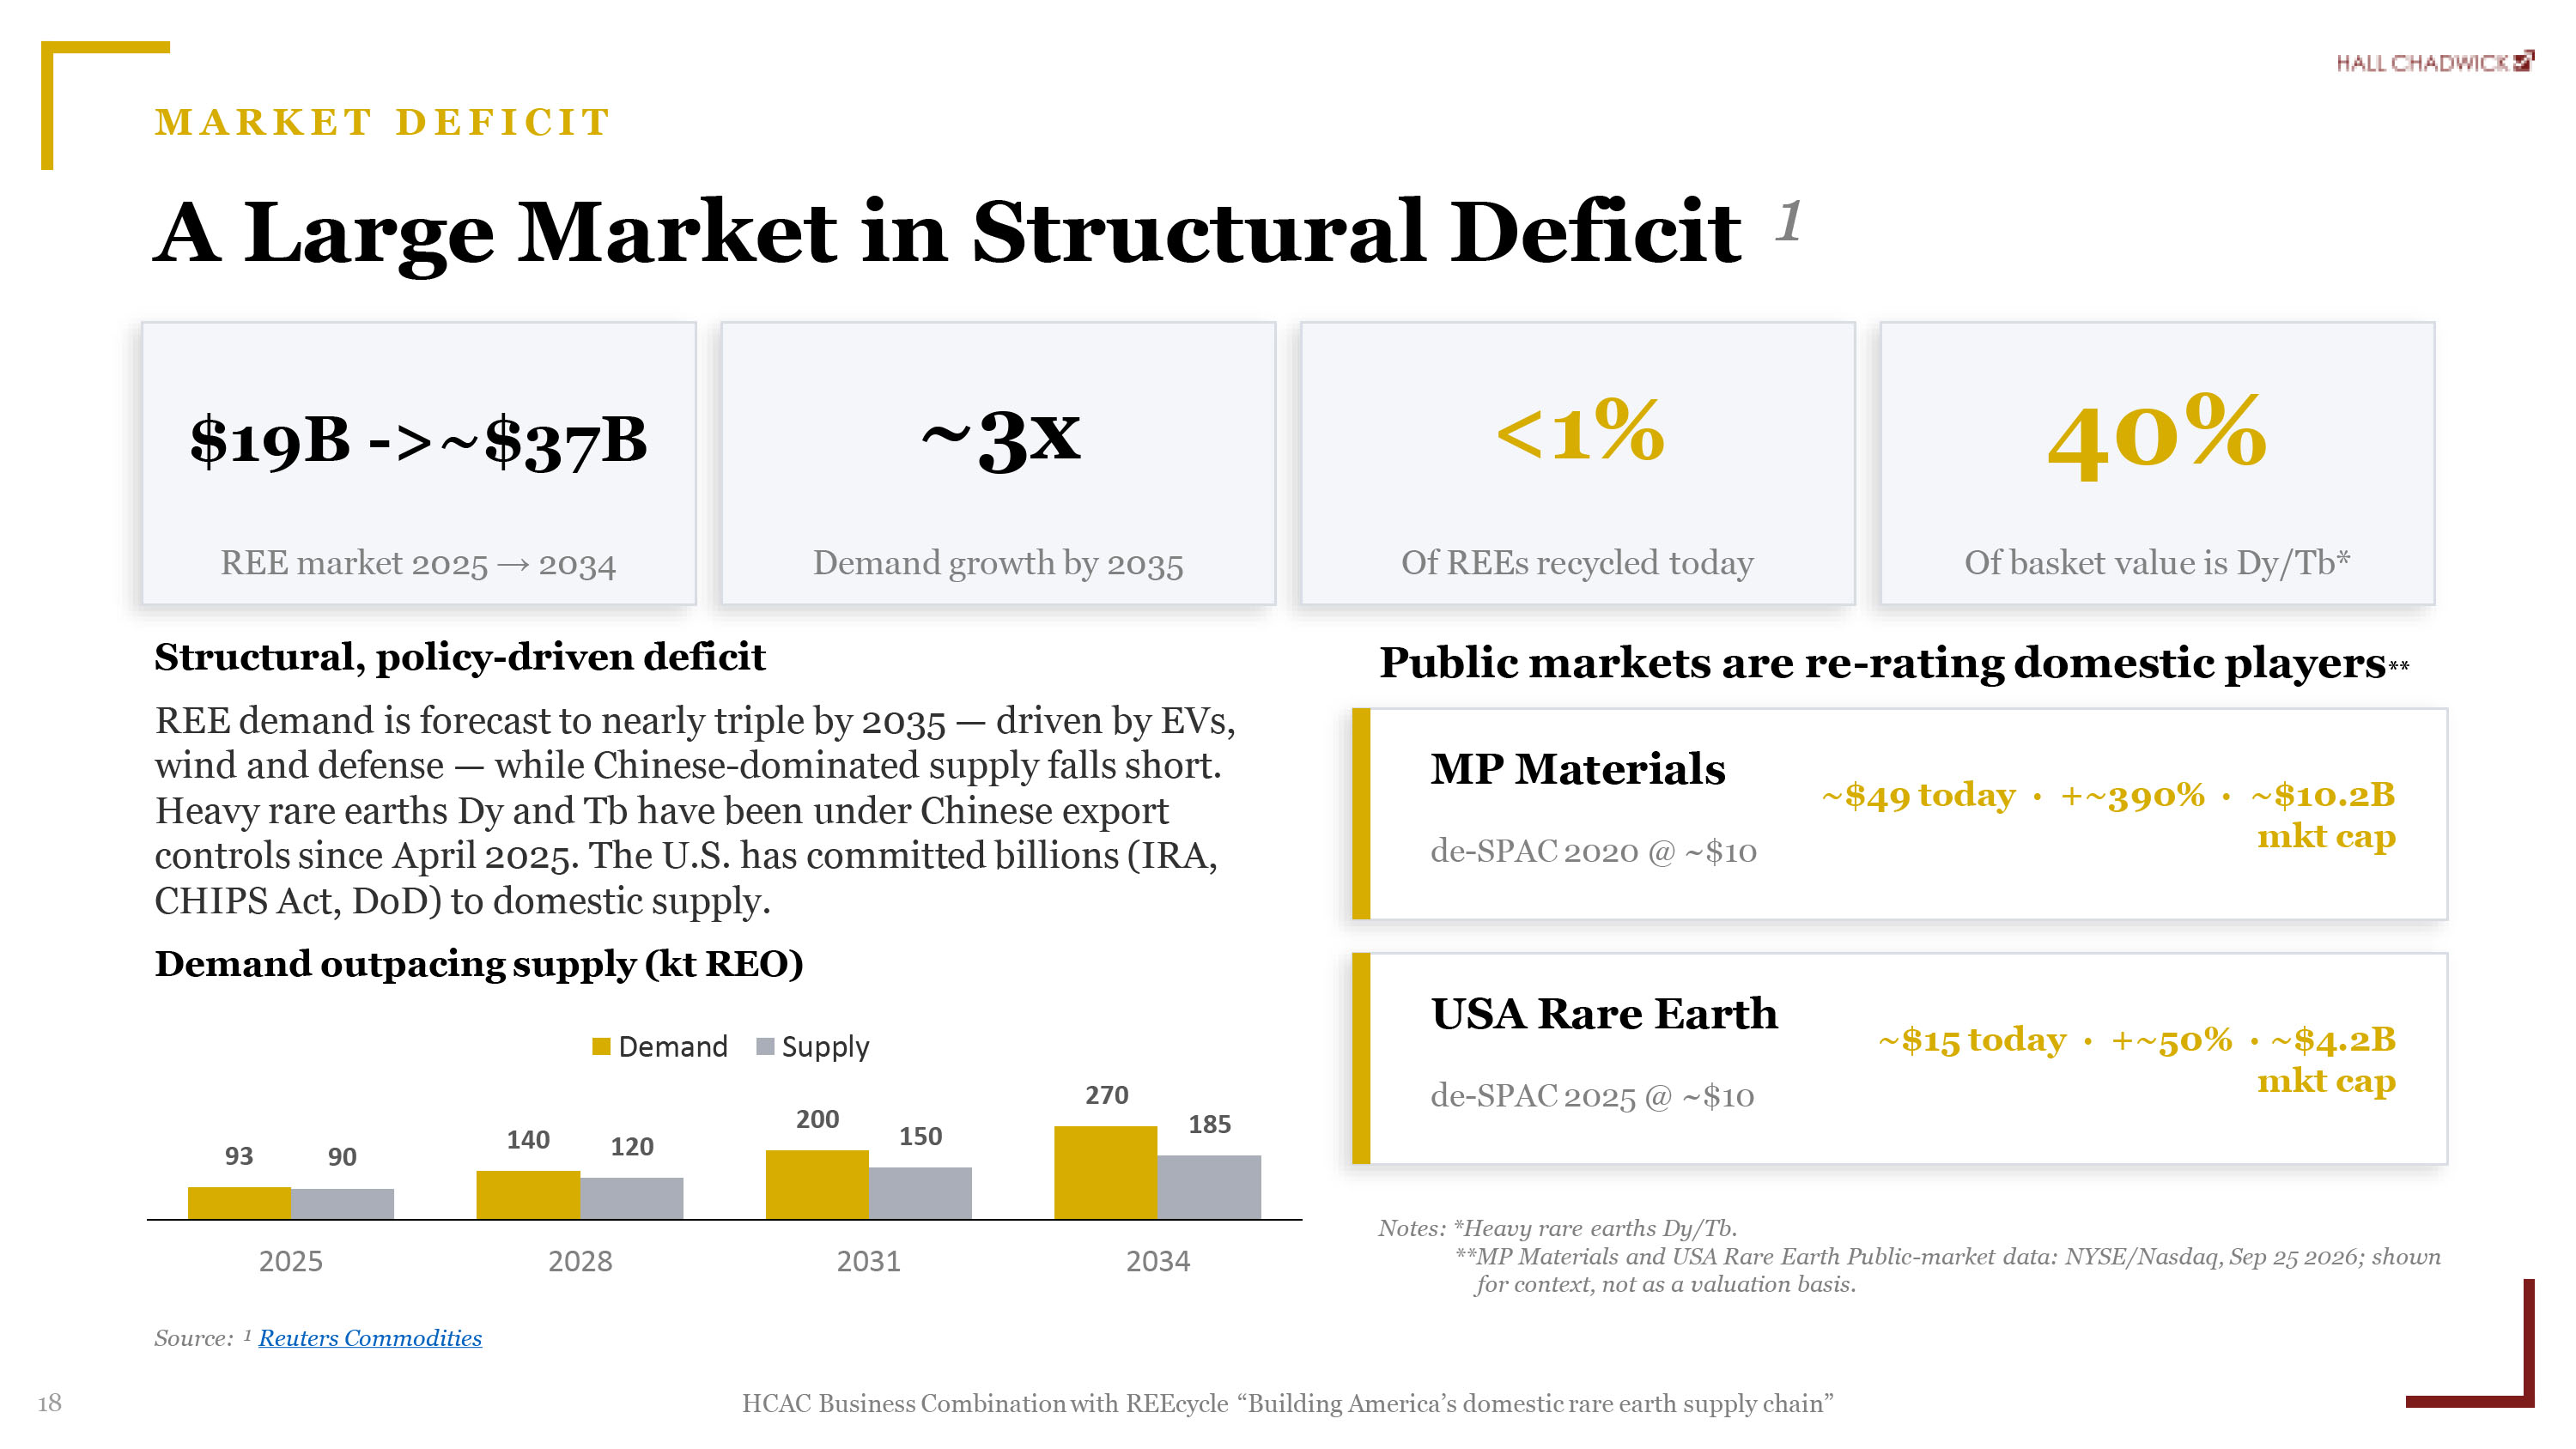
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 18 MARKET DEFICIT A Large Market in Structural Deficit ¹ $19B - >~$37B REE market 2025 → 2034 ~3x Demand growth by 2035 <1% Of REEs recycled today 40% Of basket value is Dy/Tb* Structural, policy - driven deficit REE demand is forecast to nearly triple by 2035 — driven by EVs, wind and defense — while Chinese - dominated supply falls short. Heavy rare earths Dy and Tb have been under Chinese export controls since April 2025. The U.S. has committed billions (IRA, CHIPS Act, DoD) to domestic supply. Public markets are re - rating domestic players ** MP Materials de - SPAC 2020 @ ~$10 ~$49 today · +~390% · ~$10.2B mkt cap USA Rare Earth de - SPAC 2025 @ ~$10 ~$15 today · +~50% · ~$4.2B mkt cap Notes: *Heavy rare earths Dy/Tb. **MP Materials and USA Rare Earth Public - market data: NYSE/Nasdaq, Sep 25 2026; shown for context, not as a valuation basis. 93 140 200 270 90 120 150 185 2025 2028 2031 2034 Demand Supply Demand outpacing supply (kt REO) Source: ¹ Reuters Commodities
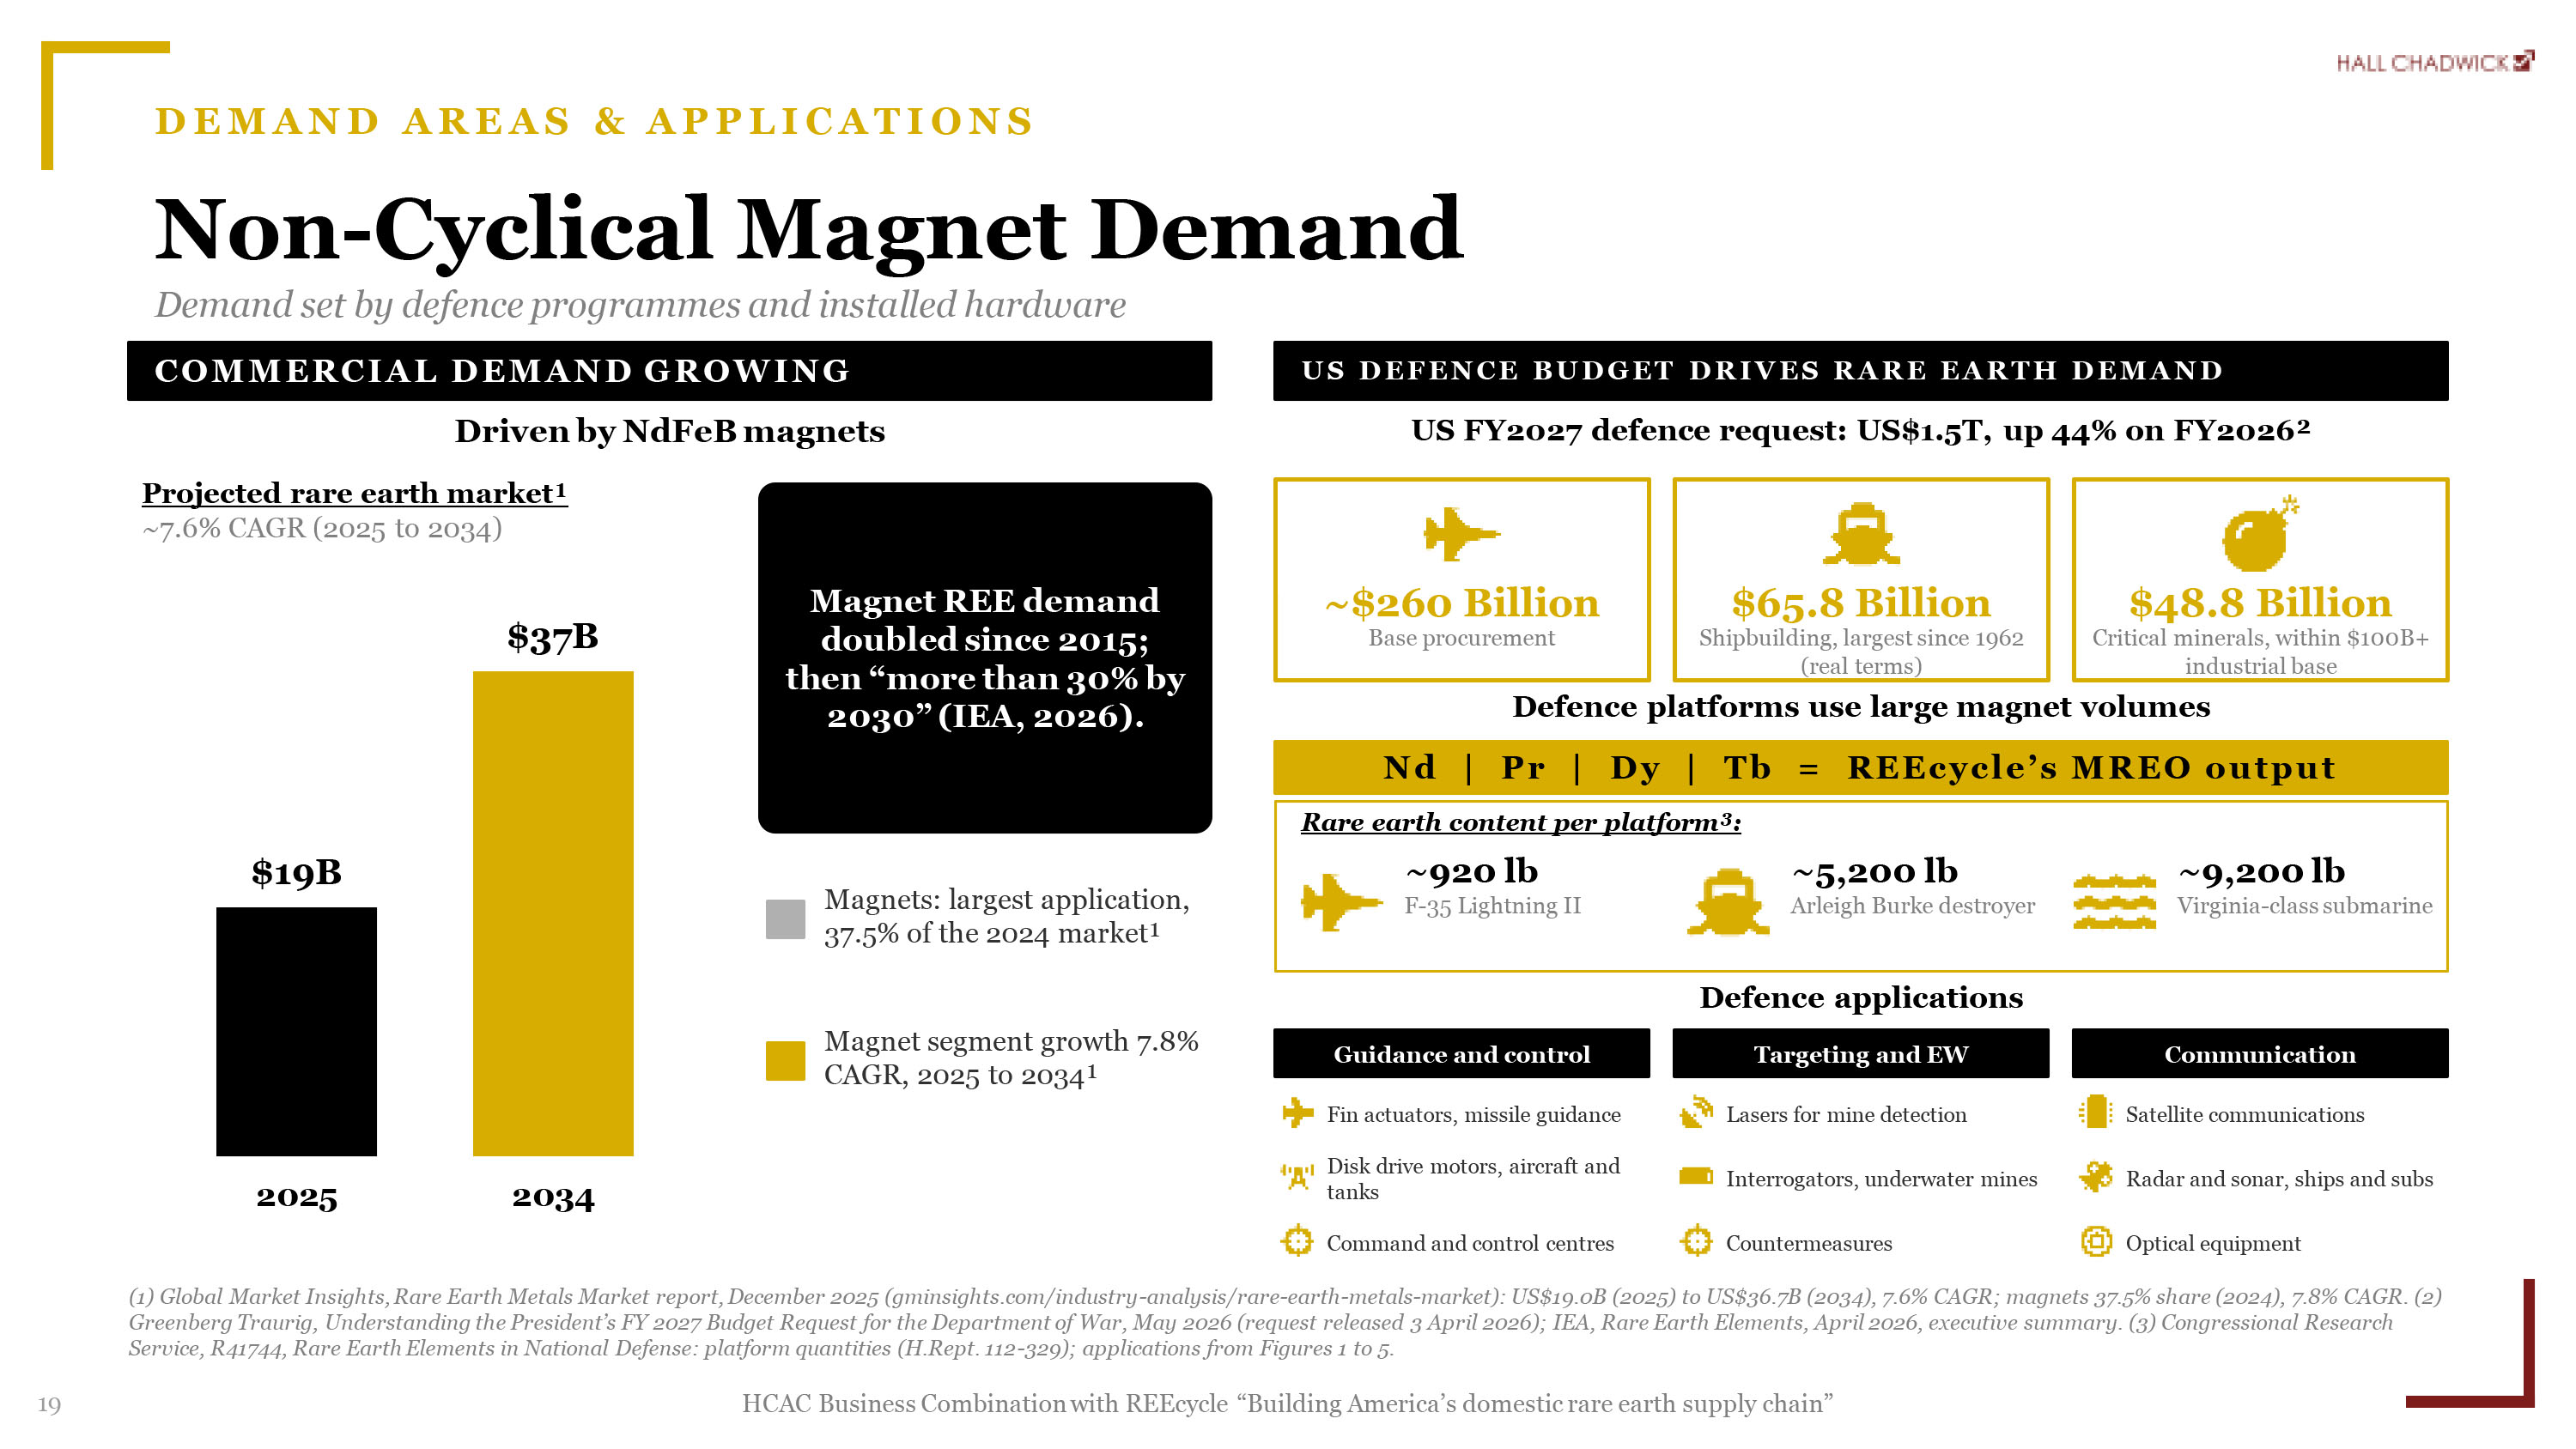
19 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” DEMAND AREAS & APPLICATIONS Non - Cyclical Magnet Demand Demand set by defence programmes and installed hardware COMMERCIAL DEMAND GROWING Driven by NdFeB magnets Projected rare earth market¹ ~7.6% CAGR (2025 to 2034) $19B $37B 2025 2034 Magnet REE demand doubled since 2015; then “more than 30% by 2030” (IEA, 2026). Magnets: largest application, 37.5% of the 2024 market¹ Magnet segment growth 7.8% CAGR, 2025 to 2034¹ US DEFENCE BUDGET DRIVES RARE EARTH DEMAND US FY2027 defence request: US$1.5T, up 44% on FY2026² ~$260 Billion Base procurement $65.8 Billion Shipbuilding, largest since 1962 (real terms) $48.8 Billion Critical minerals, within $100B+ industrial base Defence platforms use large magnet volumes Nd | Pr | Dy | Tb = REEcycle’s MREO output Rare earth content per platform³: ~920 lb F - 35 Lightning II ~5,200 lb Arleigh Burke destroyer ~9,200 lb Virginia - class submarine Defence applications Guidance and control Fin actuators, missile guidance Disk drive motors, aircraft and tanks Command and control centres Targeting and EW Lasers for mine detection Interrogators, underwater mines Countermeasures Communication Satellite communications Radar and sonar, ships and subs Optical equipment (1) Global Market Insights, Rare Earth Metals Market report, December 2025 (gminsights.com/industry - analysis/rare - earth - metals - m arket): US$19.0B (2025) to US$36.7B (2034), 7.6% CAGR; magnets 37.5% share (2024), 7.8% CAGR. (2) Greenberg Traurig, Understanding the President’s FY 2027 Budget Request for the Department of War, May 2026 (request released 3 April 2026); IEA, Rare Earth Elements, April 2026, executive summary. (3) Congressional Research Service, R41744, Rare Earth Elements in National Defense: platform quantities (H.Rept. 112 - 329); applications from Figures 1 to 5.
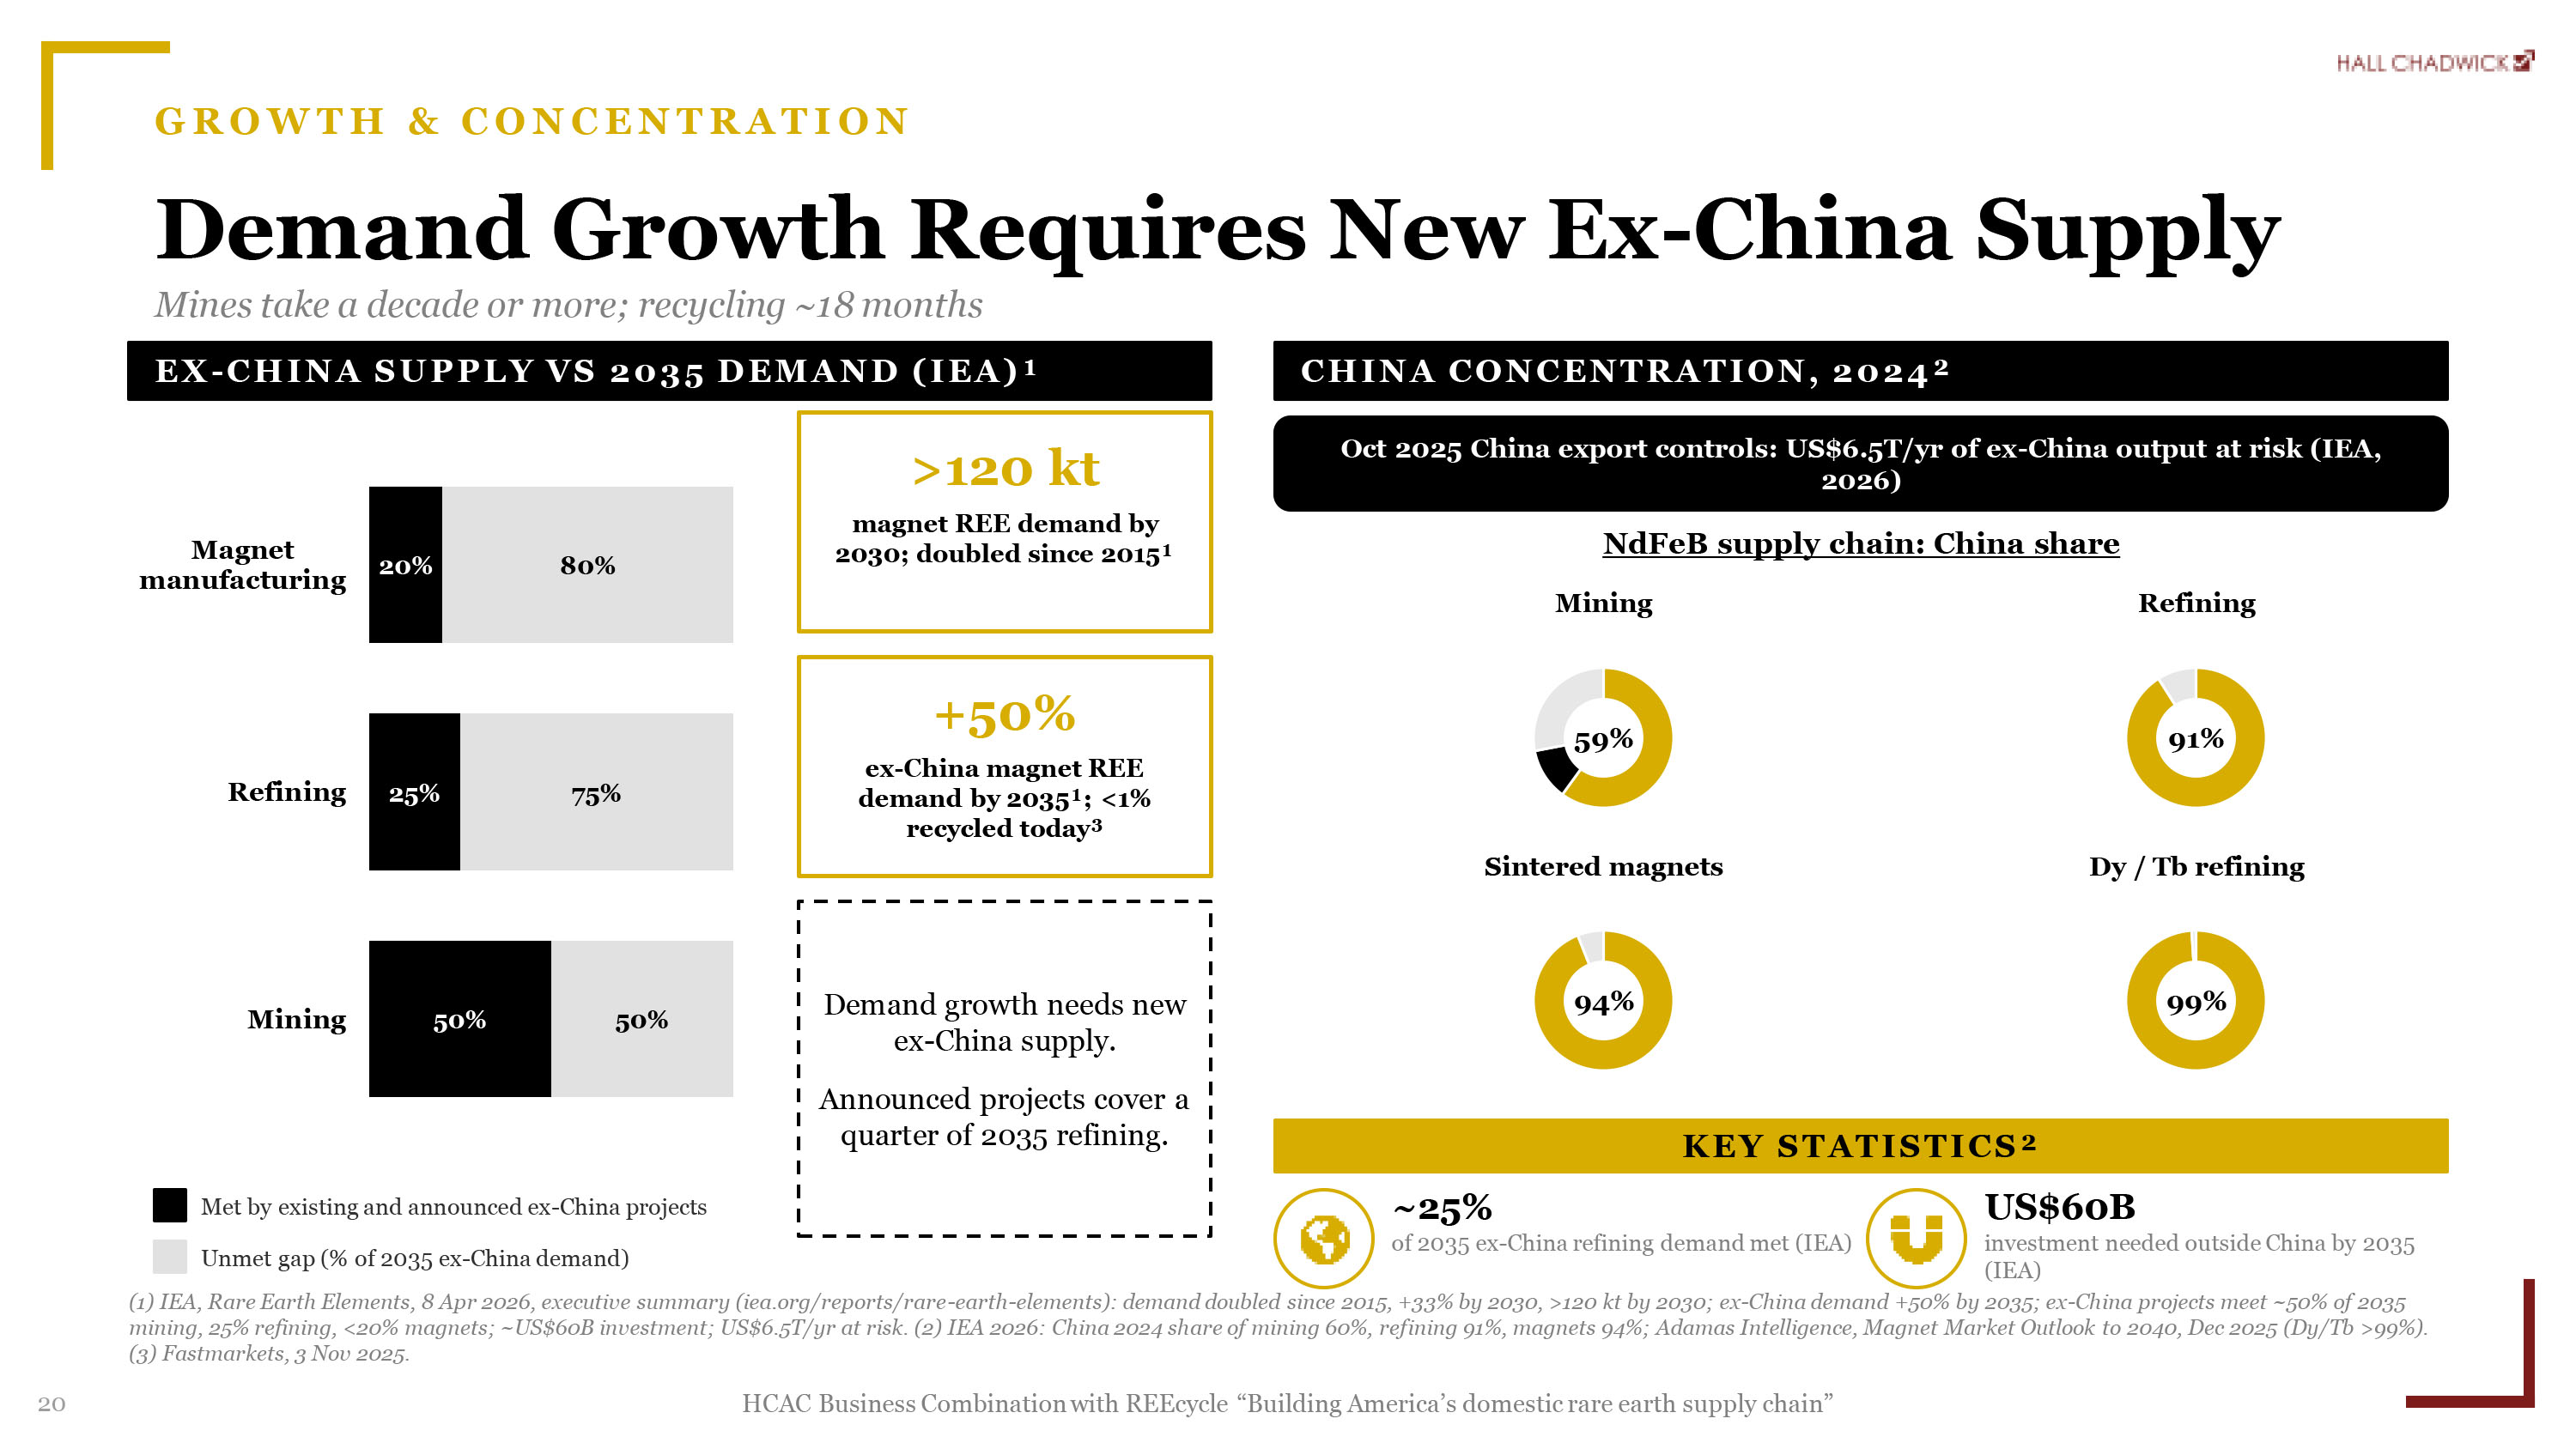
20 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” GROWTH & CONCENTRATION Demand Growth Requires New Ex - China Supply Mines take a decade or more; recycling ~18 months EX - CHINA SUPPLY VS 2035 DEMAND (IEA)¹ 50% 25% 20% 50% 75% 80% Mining Refining Magnet manufacturing Met by existing and announced ex - China projects Unmet gap (% of 2035 ex - China demand) >120 kt magnet REE demand by 2030; doubled since 2015¹ +50% ex - China magnet REE demand by 2035¹; <1% recycled today³ Demand growth needs new ex - China supply. Announced projects cover a quarter of 2035 refining. CHINA CONCENTRATION, 2024² Oct 2025 China export controls: US$6.5T/yr of ex - China output at risk (IEA, 2026) NdFeB supply chain: China share Mining 59% Refining 91% Sintered magnets 94% Dy / Tb refining 99% KEY STATISTICS² ~25% of 2035 ex - China refining demand met (IEA) US$60B investment needed outside China by 2035 (IEA) (1) IEA, Rare Earth Elements, 8 Apr 2026, executive summary (iea.org/reports/rare - earth - elements): demand doubled since 2015, +3 3% by 2030, >120 kt by 2030; ex - China demand +50% by 2035; ex - China projects meet ~50% of 2035 mining, 25% refining, <20% magnets; ~US$60B investment; US$6.5T/yr at risk. (2) IEA 2026: China 2024 share of mining 60%, ref ini ng 91%, magnets 94%; Adamas Intelligence, Magnet Market Outlook to 2040, Dec 2025 (Dy/Tb >99%). (3) Fastmarkets, 3 Nov 2025.
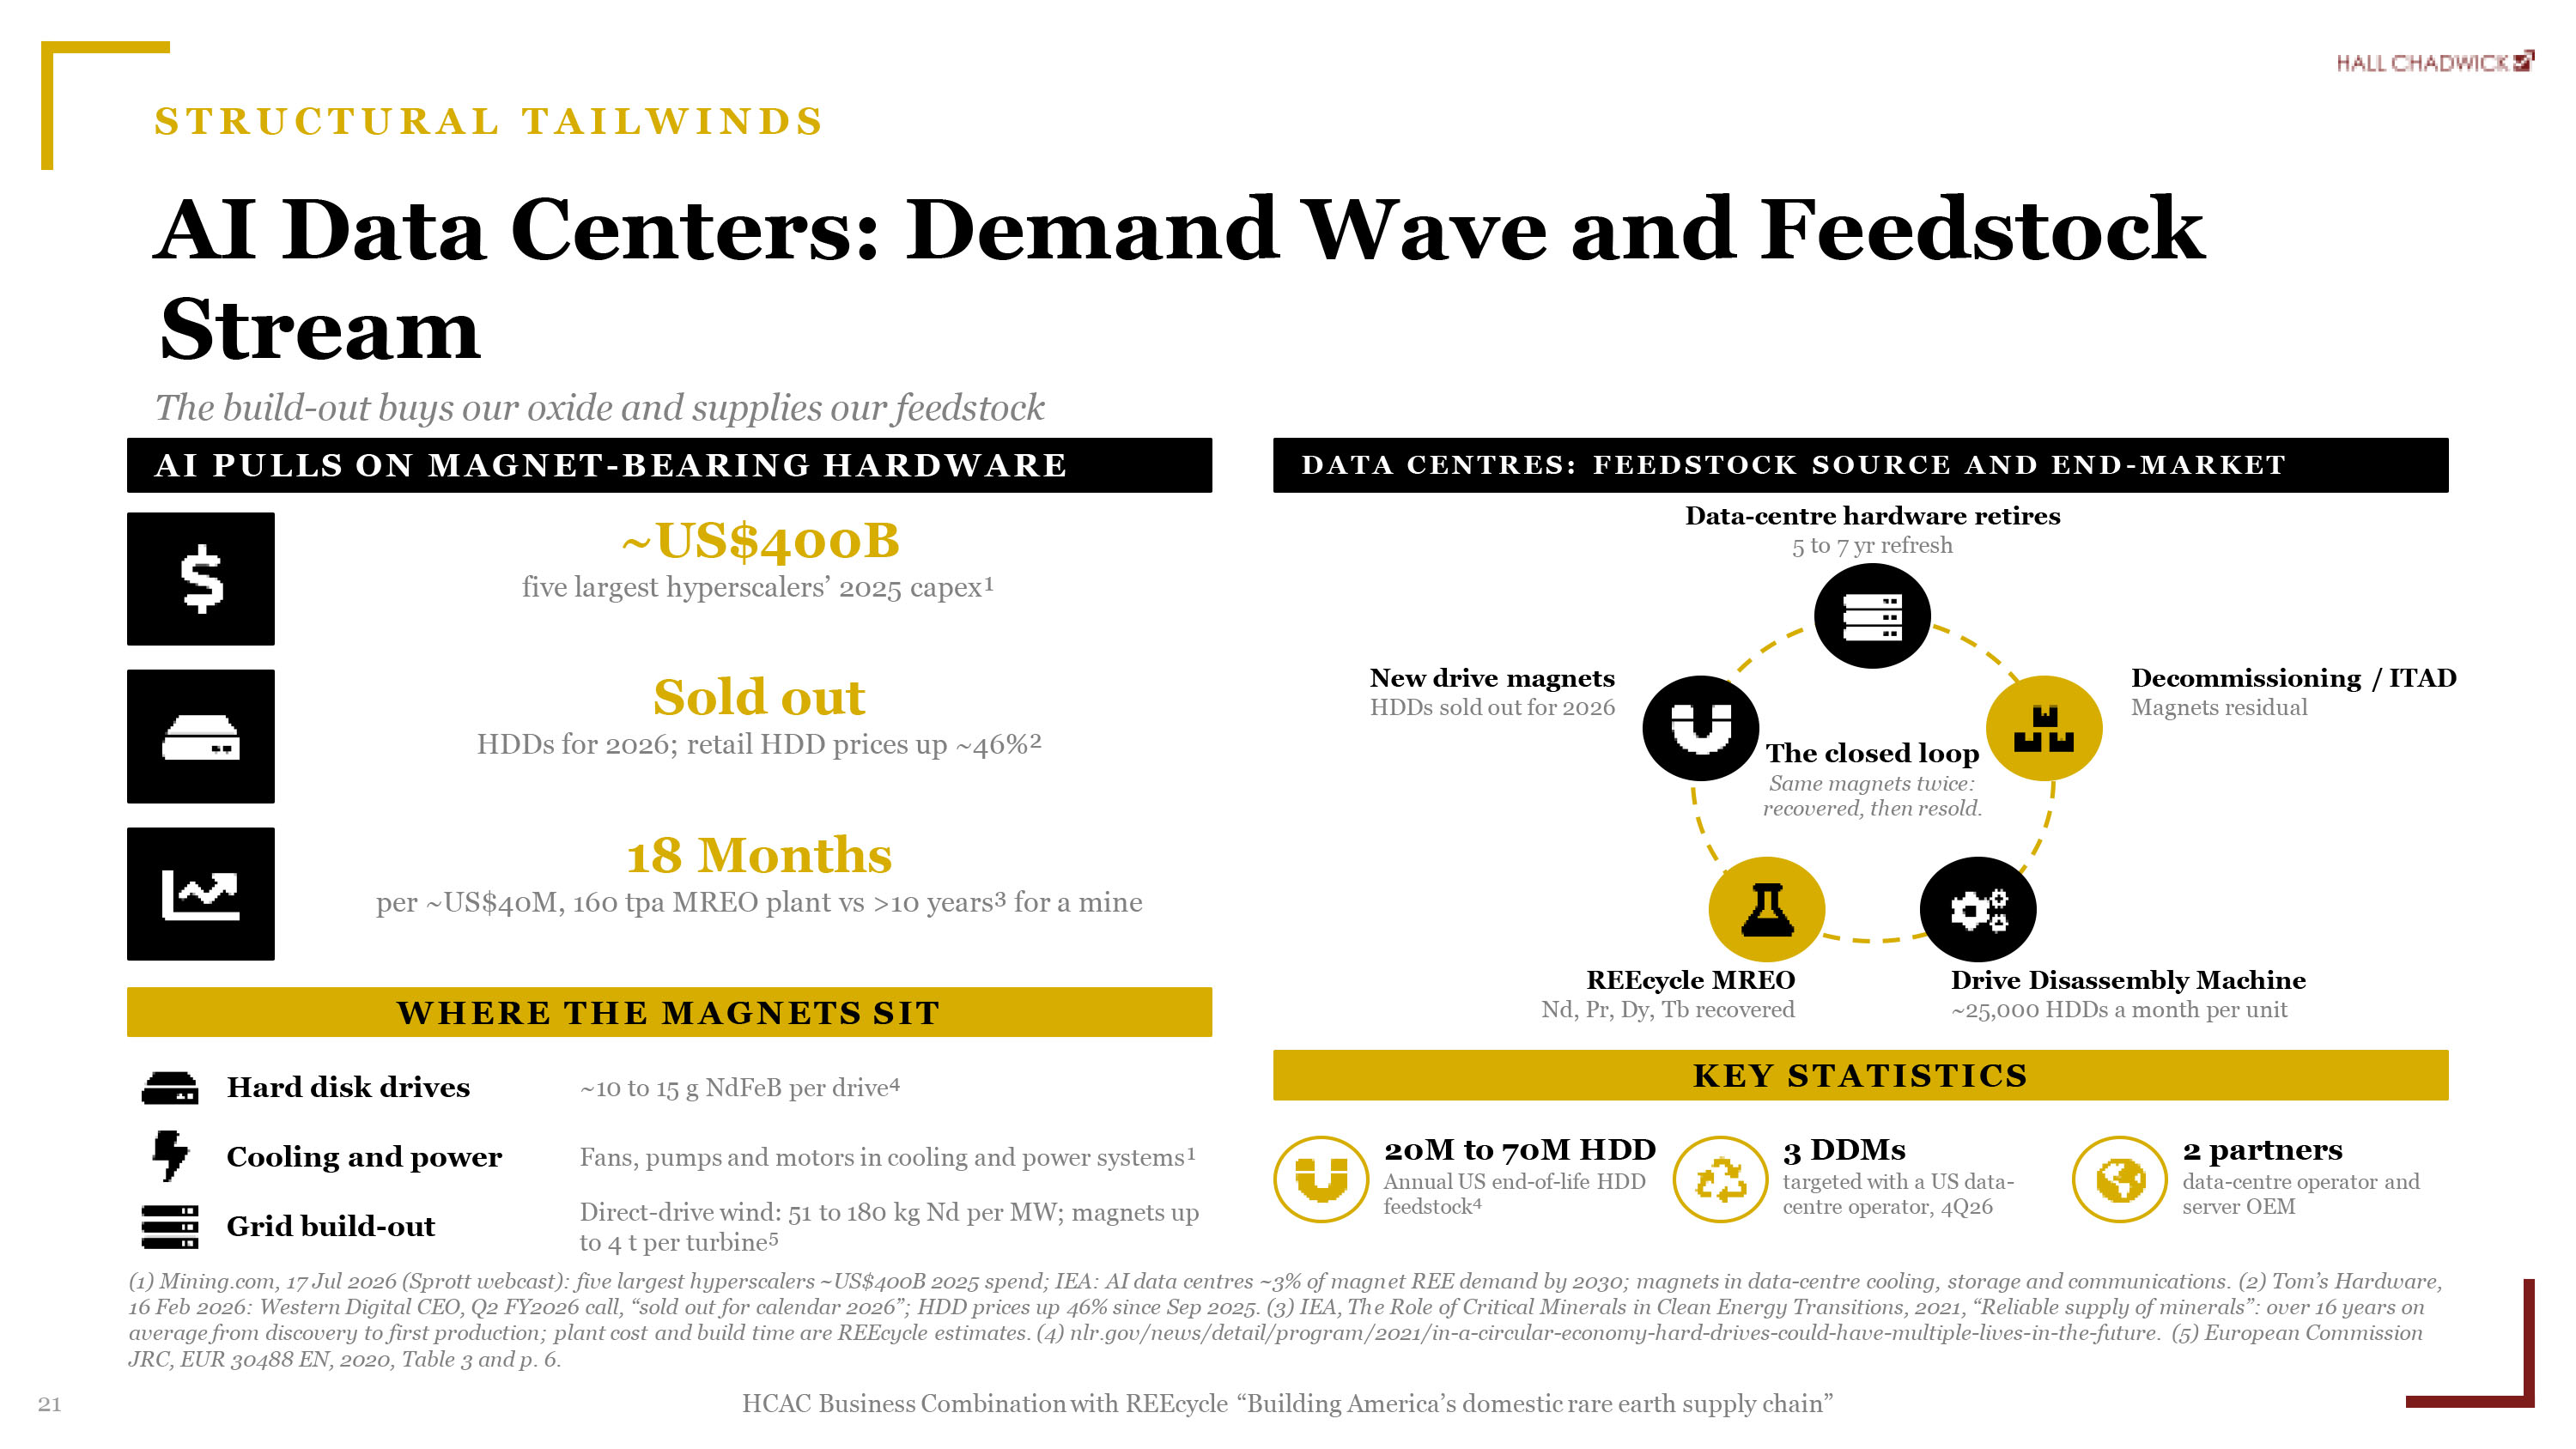
21 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” STRUCTURAL TAILWINDS Stream The build - out buys our oxide and supplies our feedstock AI PULLS ON MAGNET - BEARING HARDWARE ~US$400B five largest hyperscalers’ 2025 capex¹ Sold out HDDs for 2026; retail HDD prices up ~46%² 18 Months per ~US$40M, 160 tpa MREO plant vs >10 years³ for a mine WHERE THE MAGNETS SIT Hard disk drives ~10 to 15 g NdFeB per drive⁴ Cooling and power Fans, pumps and motors in cooling and power systems¹ Grid build - out Direct - drive wind: 51 to 180 kg Nd per MW; magnets up to 4 t per turbine⁵ DATA CENTRES: FEEDSTOCK SOURCE AND END - MARKET Data - centre hardware retires 5 to 7 yr refresh The closed loop Same magnets twice: recovered, then resold. Decommissioning / ITAD Magnets residual Drive Disassembly Machine ~25,000 HDDs a month per unit REEcycle MREO Nd, Pr, Dy, Tb recovered New drive magnets HDDs sold out for 2026 KEY STATISTICS 20M to 70M HDD Annual US end - of - life HDD feedstock⁴ 3 DDMs targeted with a US data - centre operator, 4Q26 2 partners data - centre operator and server OEM (1) Mining.com, 17 Jul 2026 (Sprott webcast): five largest hyperscalers ~US$400B 2025 spend; IEA: AI data centres ~3% of magn et REE demand by 2030; magnets in data - centre cooling, storage and communications. (2) Tom’s Hardware, 16 Feb 2026: Western Digital CEO, Q2 FY2026 call, “sold out for calendar 2026”; HDD prices up 46% since Sep 2025. (3) IEA, Th e R ole of Critical Minerals in Clean Energy Transitions, 2021, “Reliable supply of minerals”: over 16 years on average from discovery to first production; plant cost and build time are REEcycle estimates. (4) nlr.gov/news/detail/program /20 21/in - a - circular - economy - hard - drives - could - have - multiple - lives - in - the - future. (5) European Commission JRC, EUR 30488 EN, 2020, Table 3 and p. 6. AI Data Centers : Demand Wave and Feedstock
SECTION 4 Technology & Supply TM (NASDAQ: HCAC)
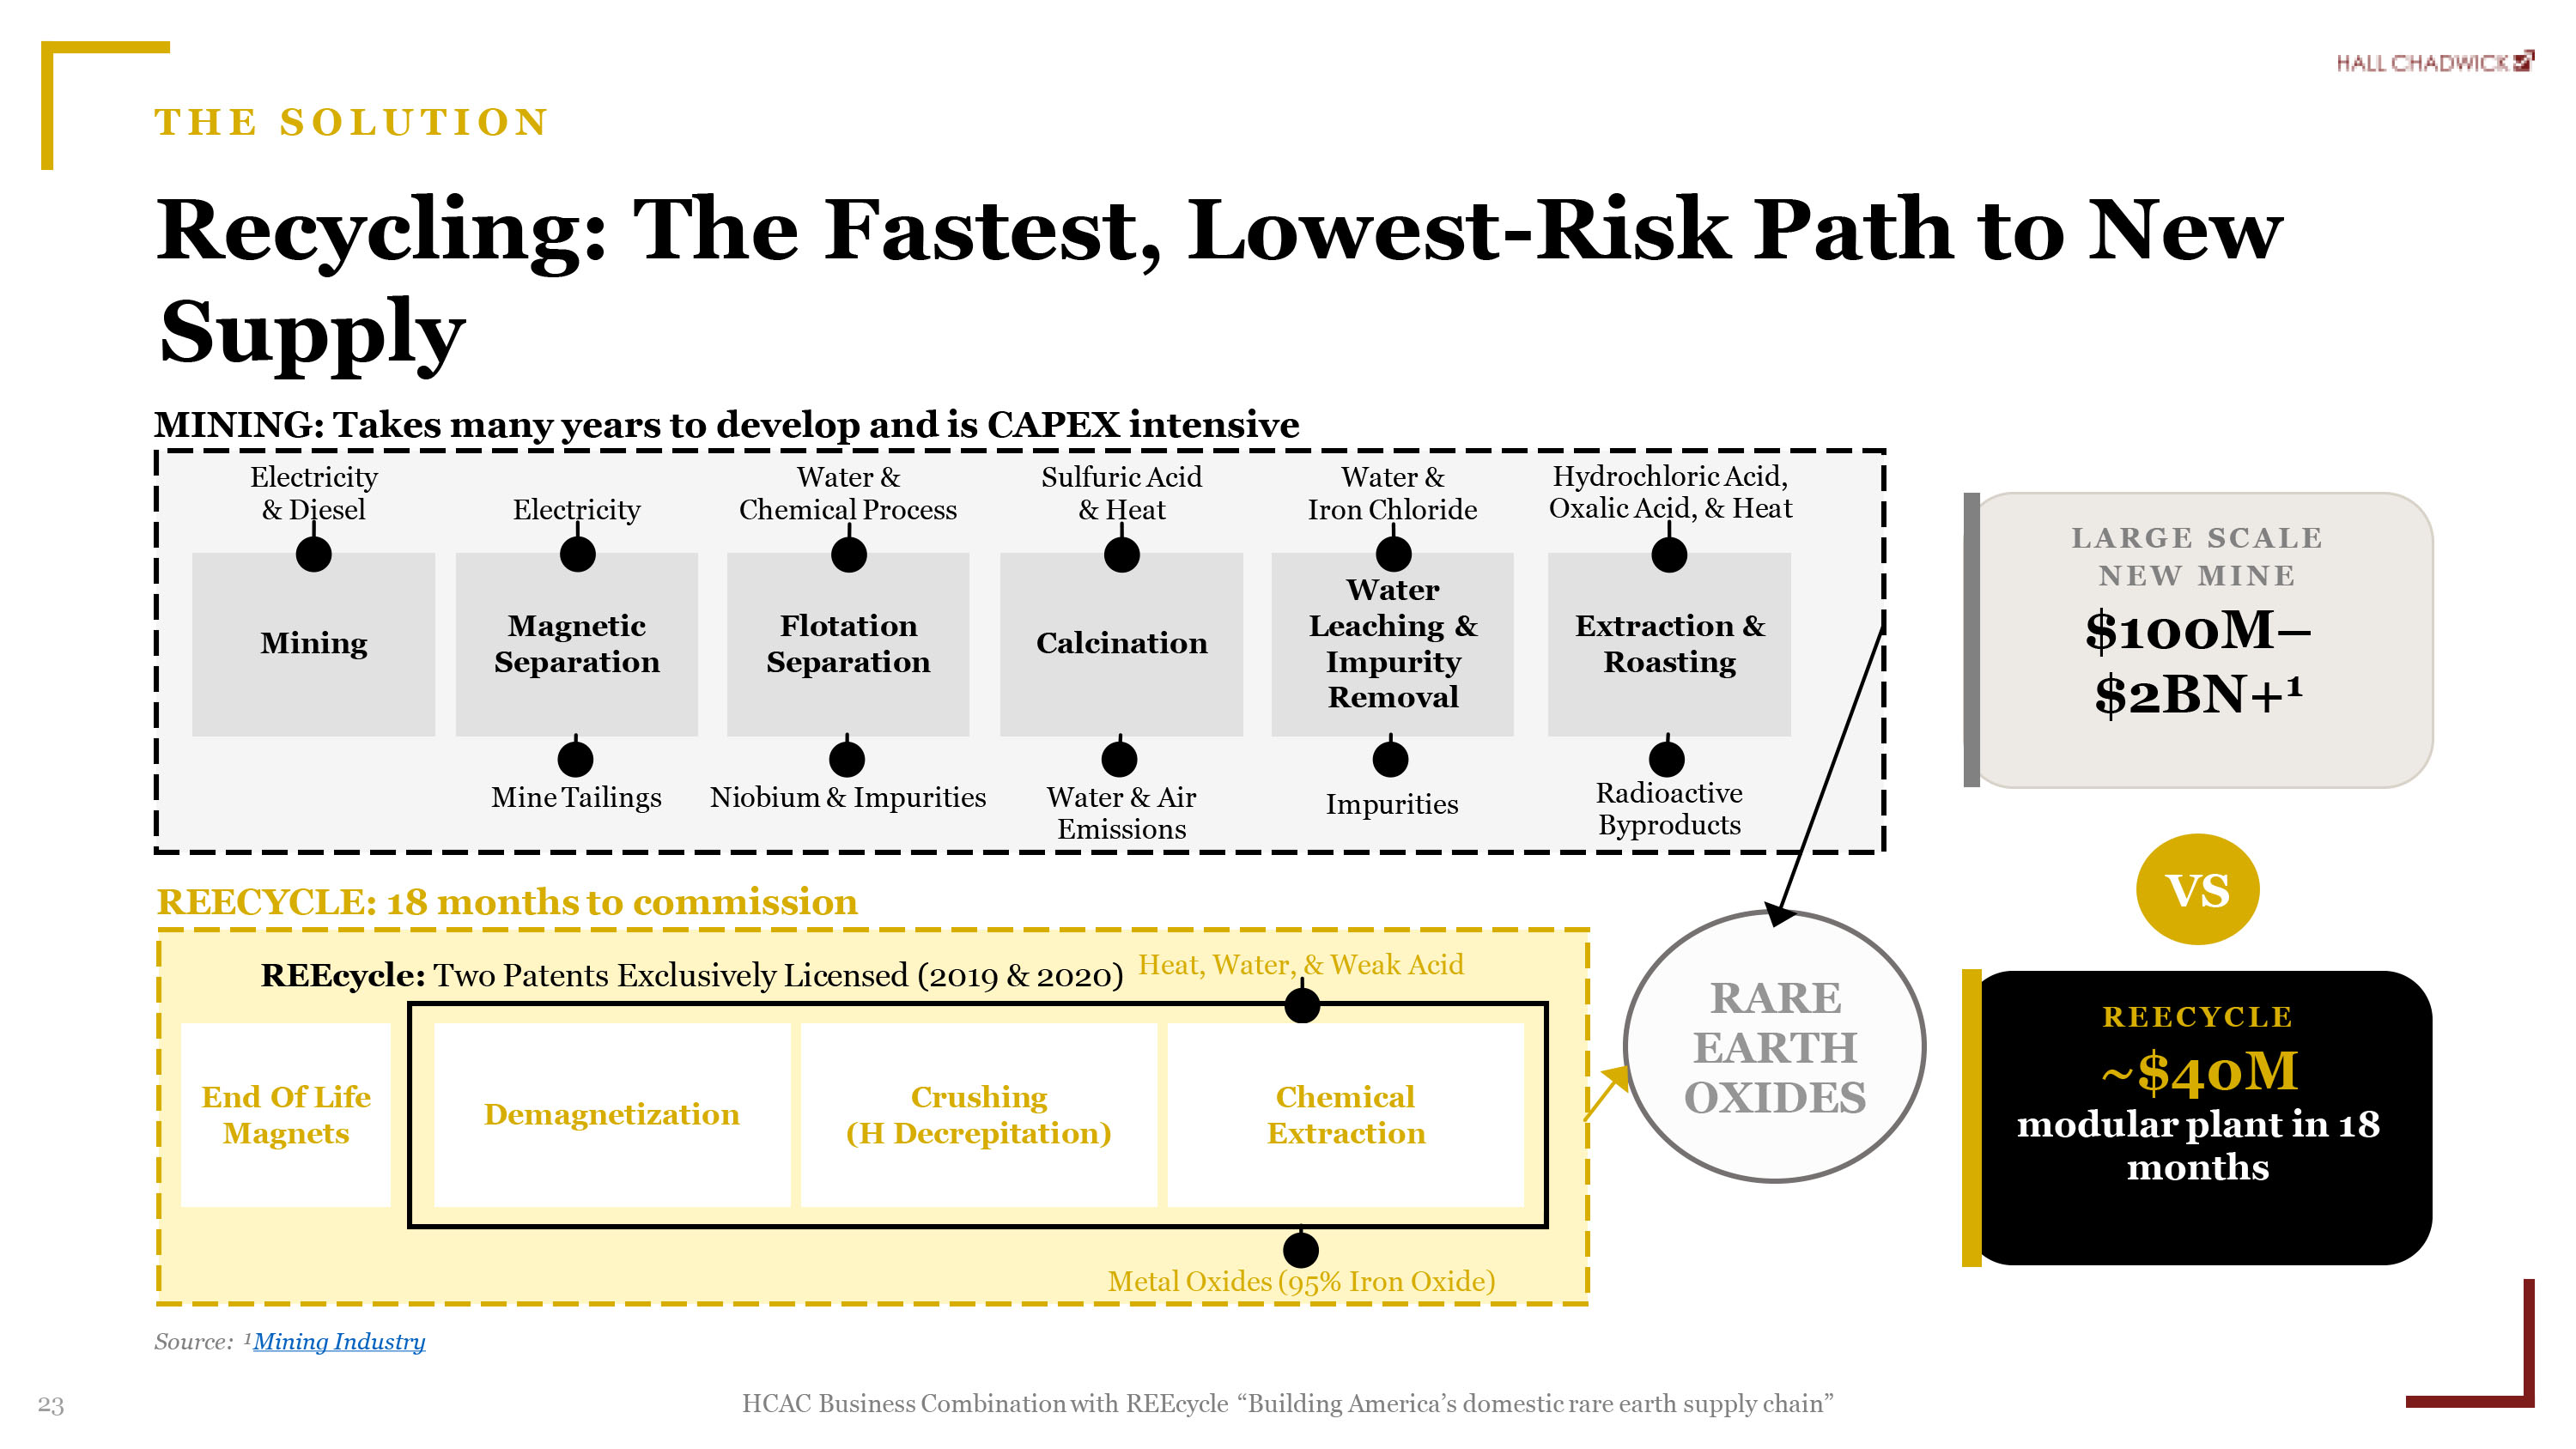
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 23 THE SOLUTION Supply Electricity & Diesel Mining Magnetic Separation Flotation Separation Calcination Water Leaching & Impurity Removal Extraction & Roasting Electricity Water & Chemical Process Sulfuric Acid & Heat Water & Iron Chloride Hydrochloric Acid, Oxalic Acid, & Heat Mine Tailings Niobium & Impurities Water & Air Emissions Impurities Radioactive Byproducts Heat, Water, & Weak Acid Metal Oxides (95% Iron Oxide) End Of Life Magnets Demagnetization Crushing (H Decrepitation) Chemical Extraction REEcycle : Two Patents Exclusively Licensed (2019 & 2020) RARE EARTH OXIDES MINING: Takes many years to develop and is CAPEX intensive REECYCLE: 18 months to commission LARGE SCALE NEW MINE $100M – $2BN+ 1 REECYCLE ~$40M modular plant in 18 months VS Source: ¹ Mining Industry Recycling: The Fastest, Lowest - Risk Path to New
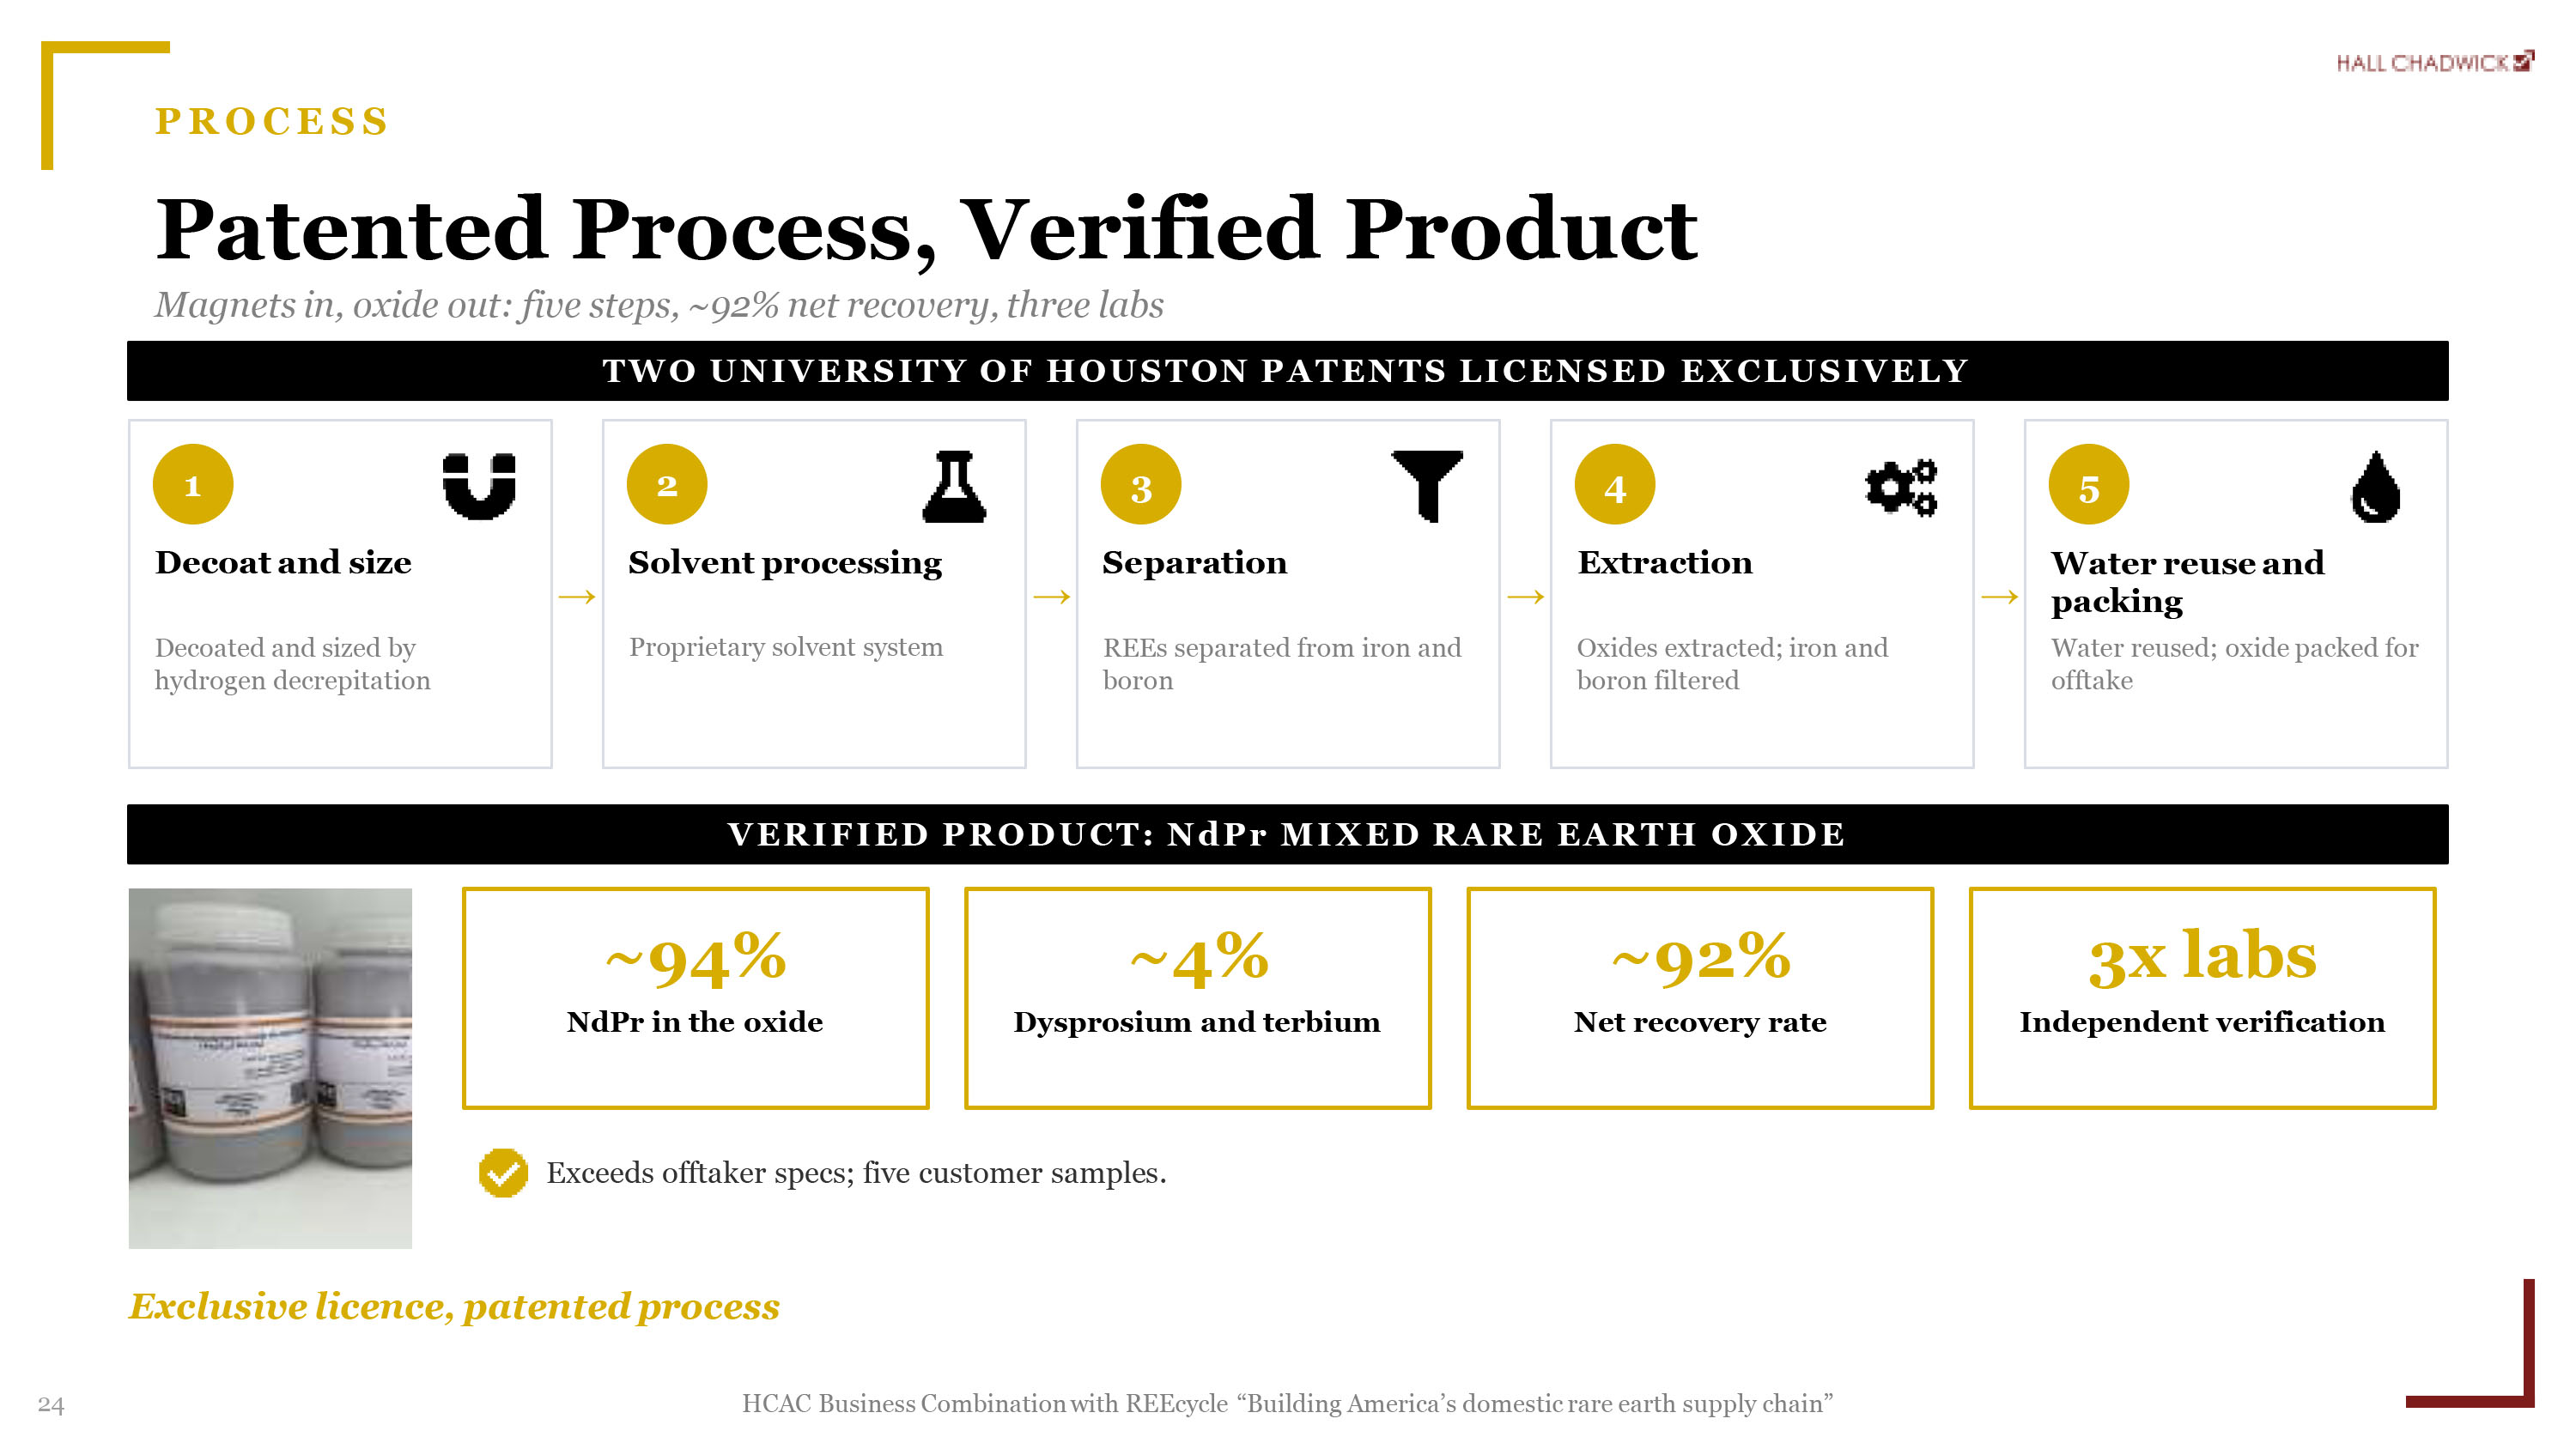
24 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” PROCESS Patented Process, Verified Product Magnets in, oxide out: five steps, ~92% net recovery, three labs TWO UNIVERSITY OF HOUSTON PATENTS LICENSED EXCLUSIVELY 1 Decoat and size Decoated and sized by hydrogen decrepitation → 2 Solvent processing Proprietary solvent system → 3 Separation REEs separated from iron and boron → 4 Extraction Oxides extracted; iron and boron filtered → 5 Water reuse and packing Water reused; oxide packed for offtake VERIFIED PRODUCT: NdPr MIXED RARE EARTH OXIDE ~94% NdPr in the oxide ~4% Dysprosium and terbium ~92% Net recovery rate 3x labs Independent verification Exceeds offtaker specs; five customer samples. Exclusive licence, patented process
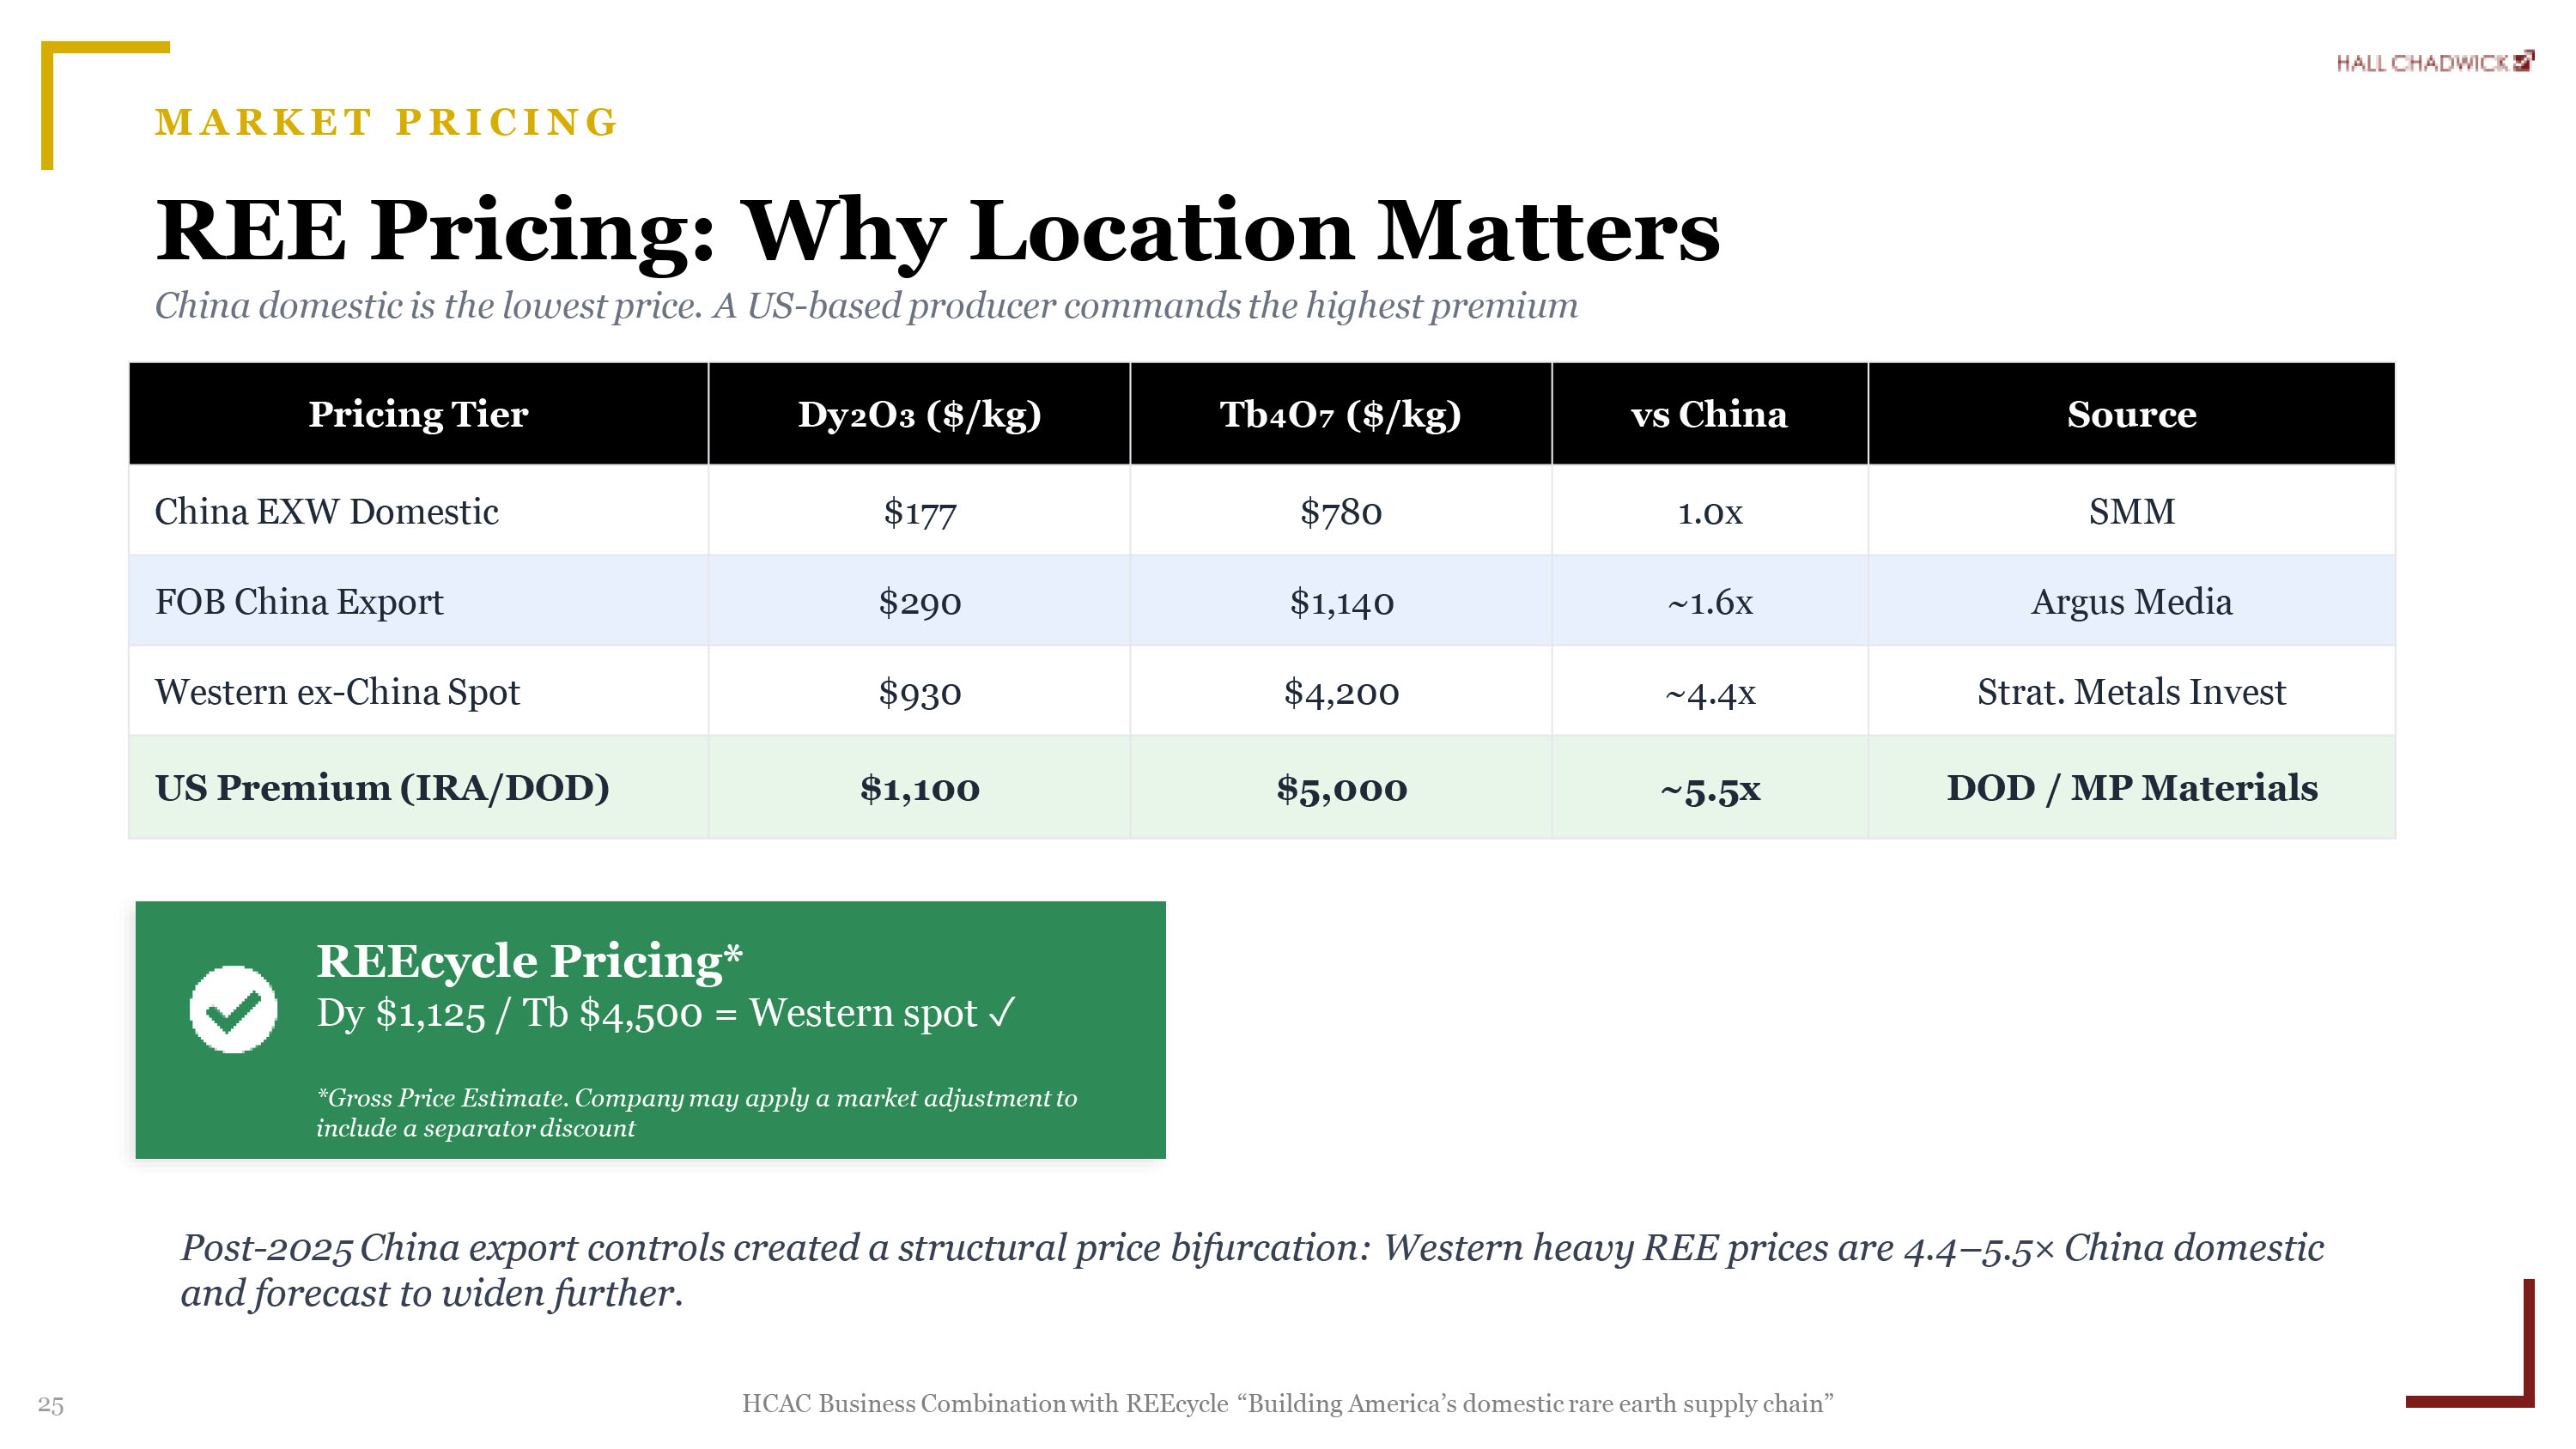
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 25 Source vs China Tb₄O₇ ($/kg) Dy₂O₃ ($/kg) Pricing Tier SMM 1.0x $780 $177 China EXW Domestic Argus Media ~1.6x $1,140 $290 FOB China Export Strat. Metals Invest ~4.4x $4,200 $930 Western ex - China Spot DOD / MP Materials ~5.5x $5,000 $1,100 US Premium (IRA/DOD) REEcycle Pricing* Dy $1,125 / Tb $4,500 = Western spot ✓ *Gross Price Estimate. Company may apply a market adjustment to include a separator discount Previous HCAC Model Pricing Dy $290 / Tb $1,140 = Stale FOB China ✗ Post - 2025 China export controls created a structural price bifurcation: Western heavy REE prices are 4.4 – 5.5 × China domestic and forecast to widen further. MARKET PRICING China domestic is the lowest price. A US - based producer commands the highest premium REE Pricing: Why Location Matters
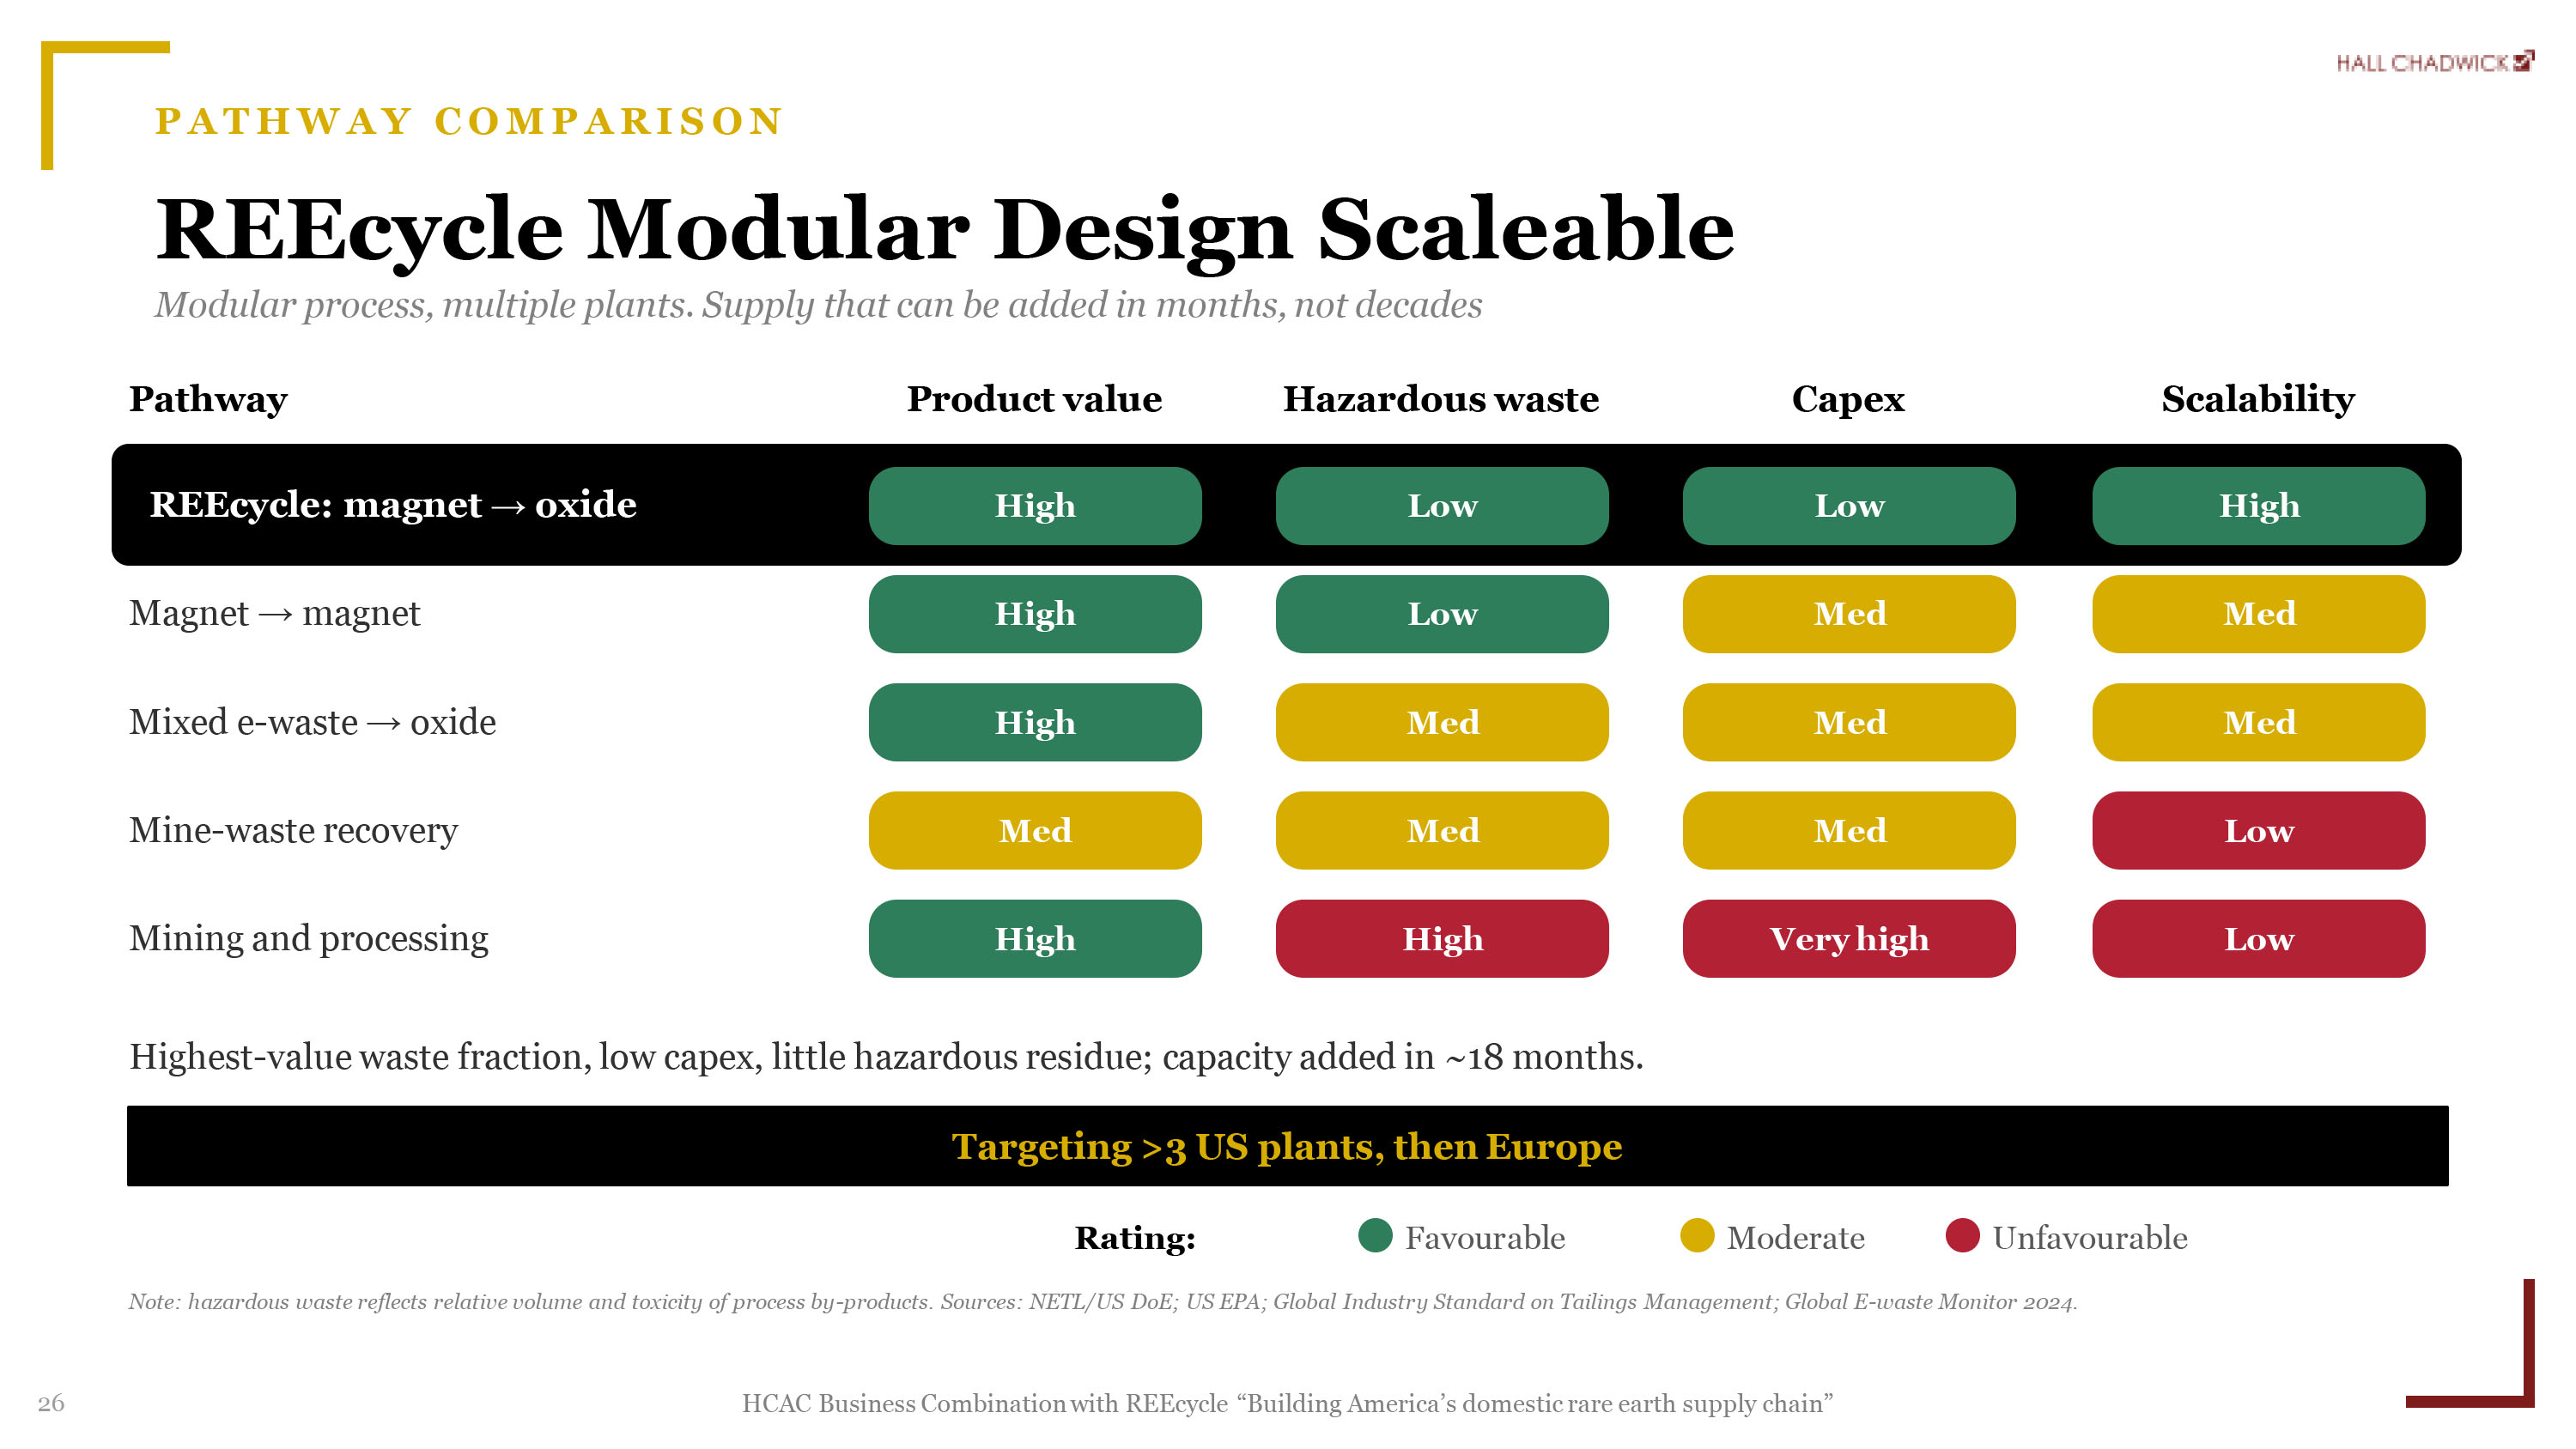
26 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” PATHWAY COMPARISON REEcycle Modular Design Scaleable Modular process, multiple plants. Supply that can be added in months, not decades Pathway Product value Hazardous waste Capex Scalability REEcycle: magnet → oxide High Low Low High Magnet → magnet High Low Med Med Mixed e - waste → oxide High Med Med Med Mine - waste recovery Med Med Med Low Mining and processing High High Very high Low Highest - value waste fraction, low capex, little hazardous residue; capacity added in ~18 months. Targeting >3 US plants, then Europe Rating: Favourable Moderate Unfavourable Note: hazardous waste reflects relative volume and toxicity of process by - products. Sources: NETL/US DoE; US EPA; Global Industr y Standard on Tailings Management; Global E - waste Monitor 2024.
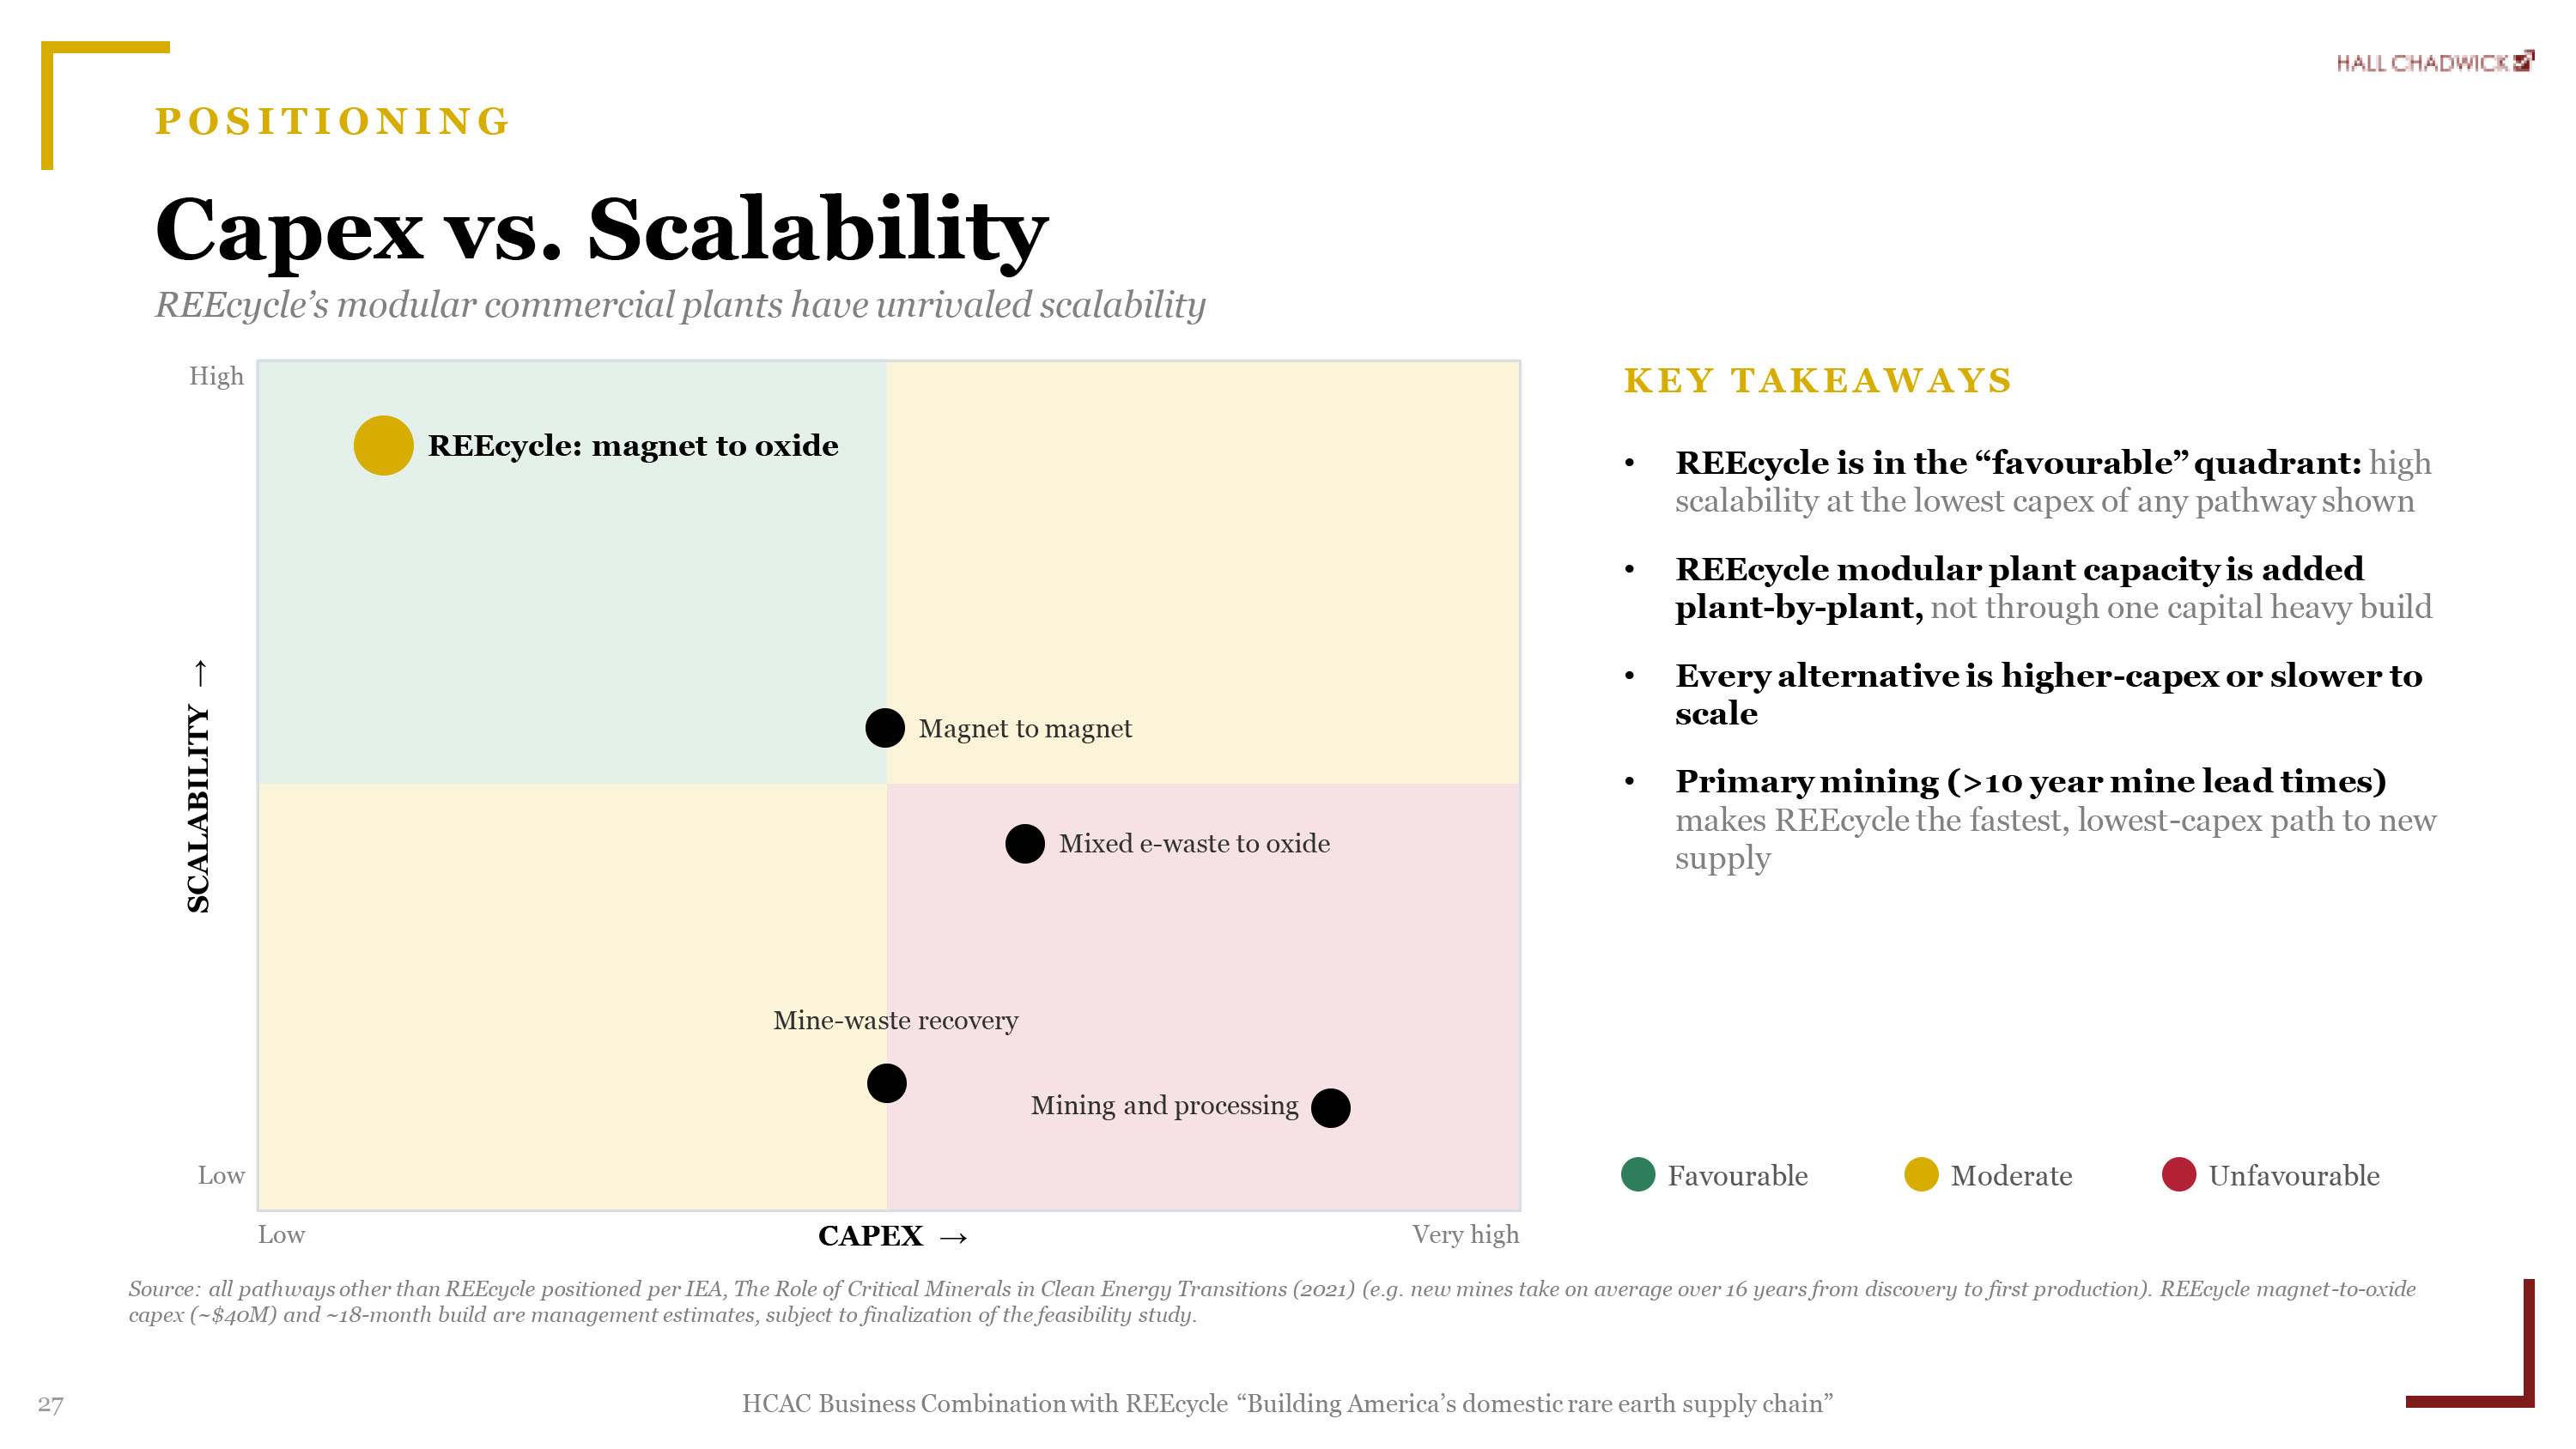
27 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” POSITIONING Capex vs. Scalability REEcycle’s modular commercial plants have unrivaled scalability High Low SCALABILITY → Low Very high CAPEX → REEcycle: magnet to oxide Magnet to magnet Mixed e - waste to oxide Mine - waste recovery Mining and processing KEY TAKEAWAYS • REEcycle is in the “favourable” quadrant: high scalability at the lowest capex of any pathway shown • REEcycle modular plant capacity is added plant - by - plant, not through one capital heavy build • Every alternative is higher - capex or slower to scale • Primary mining ( >10 year mine lead times) makes REEcycle the fastest, lowest - capex path to new supply Favourable Moderate Unfavourable Source: all pathways other than REEcycle positioned per IEA, The Role of Critical Minerals in Clean Energy Transitions (2021) (e .g. new mines take on average over 16 years from discovery to first production). REEcycle magnet - to - oxide capex (~$40M) and ~18 - month build are management estimates, subject to finalization of the feasibility study.
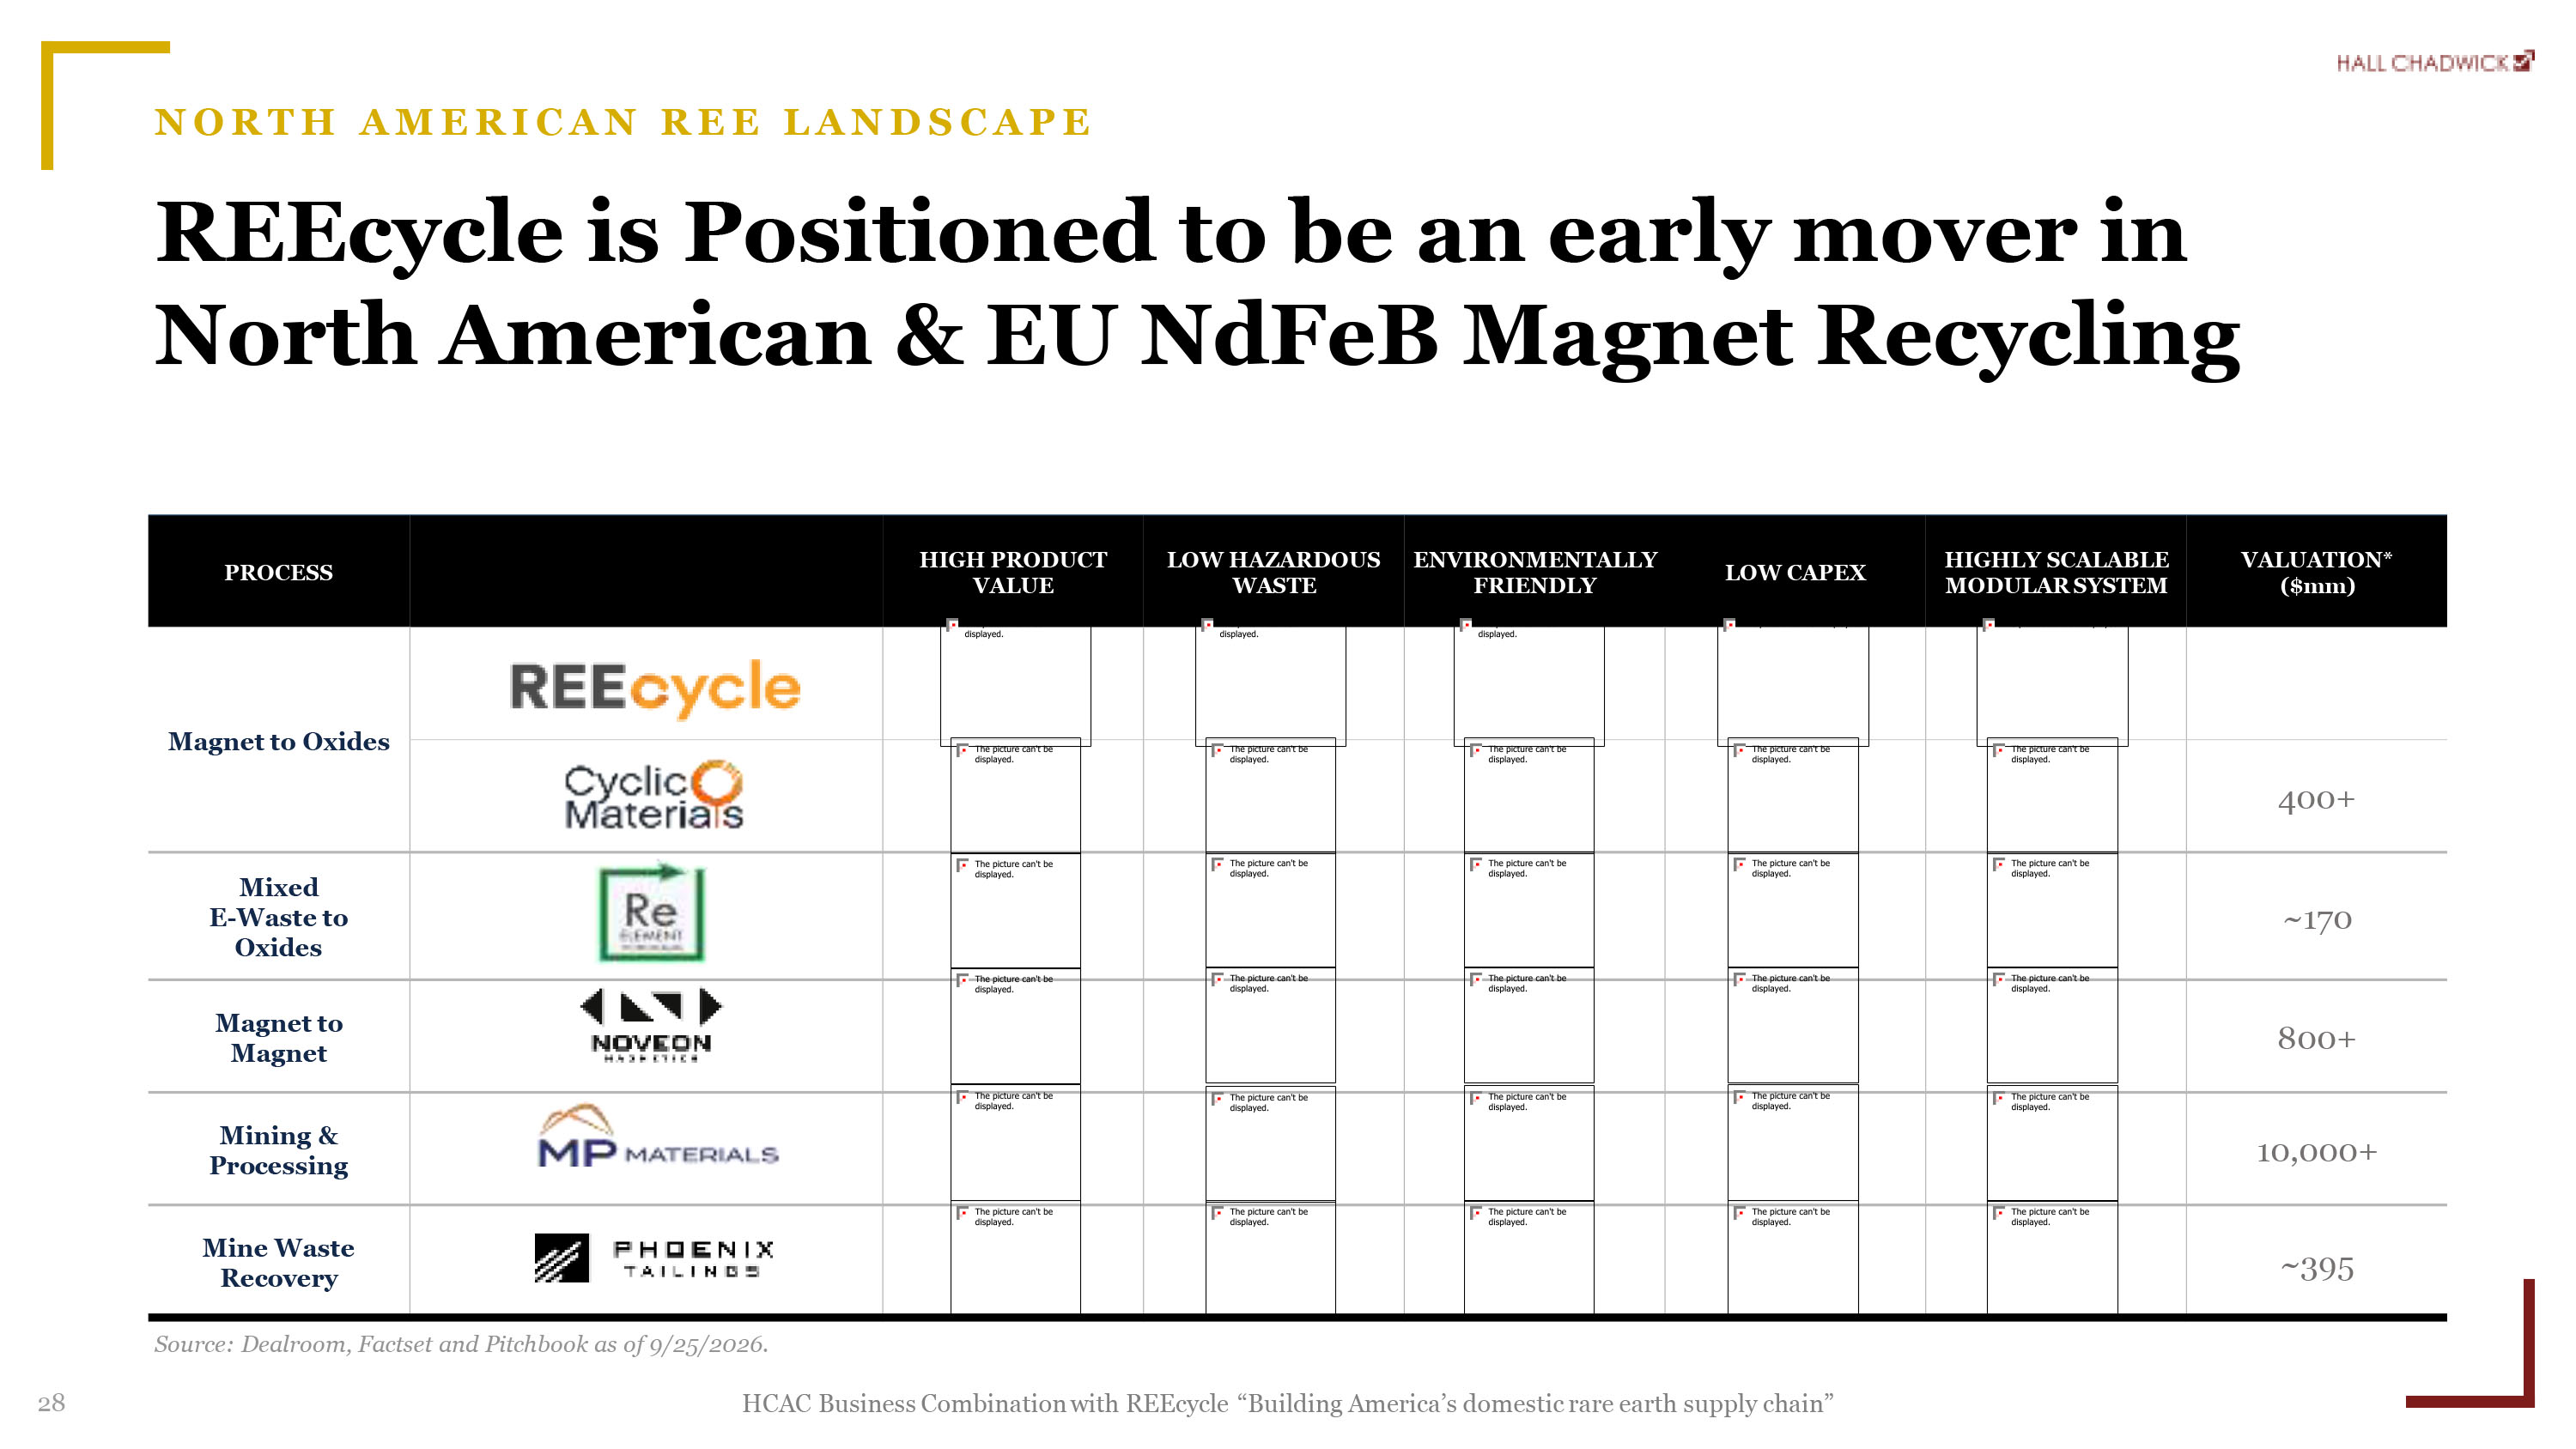
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 28 VALUATION* ($mm) HIGHLY SCALABLE MODULAR SYSTEM LOW CAPEX ENVIRONMENTALLY FRIENDLY LOW HAZARDOUS WASTE HIGH PRODUCT VALUE PROCESS Magnet to Oxides 400+ ~170 Mixed E - Waste to Oxides 800+ Magnet to Magnet 10,000+ Mining & Processing ~395 Mine Waste Recovery Source: Dealroom, Factset and Pitchbook as of 9/25/2026. NORTH AMERICAN REE LANDSCAPE REEcycle is Positioned to be an early mover in North American & EU NdFeB Magnet Recycling
SECTION 5 Commercialization & Team TM (NASDAQ: HCAC)
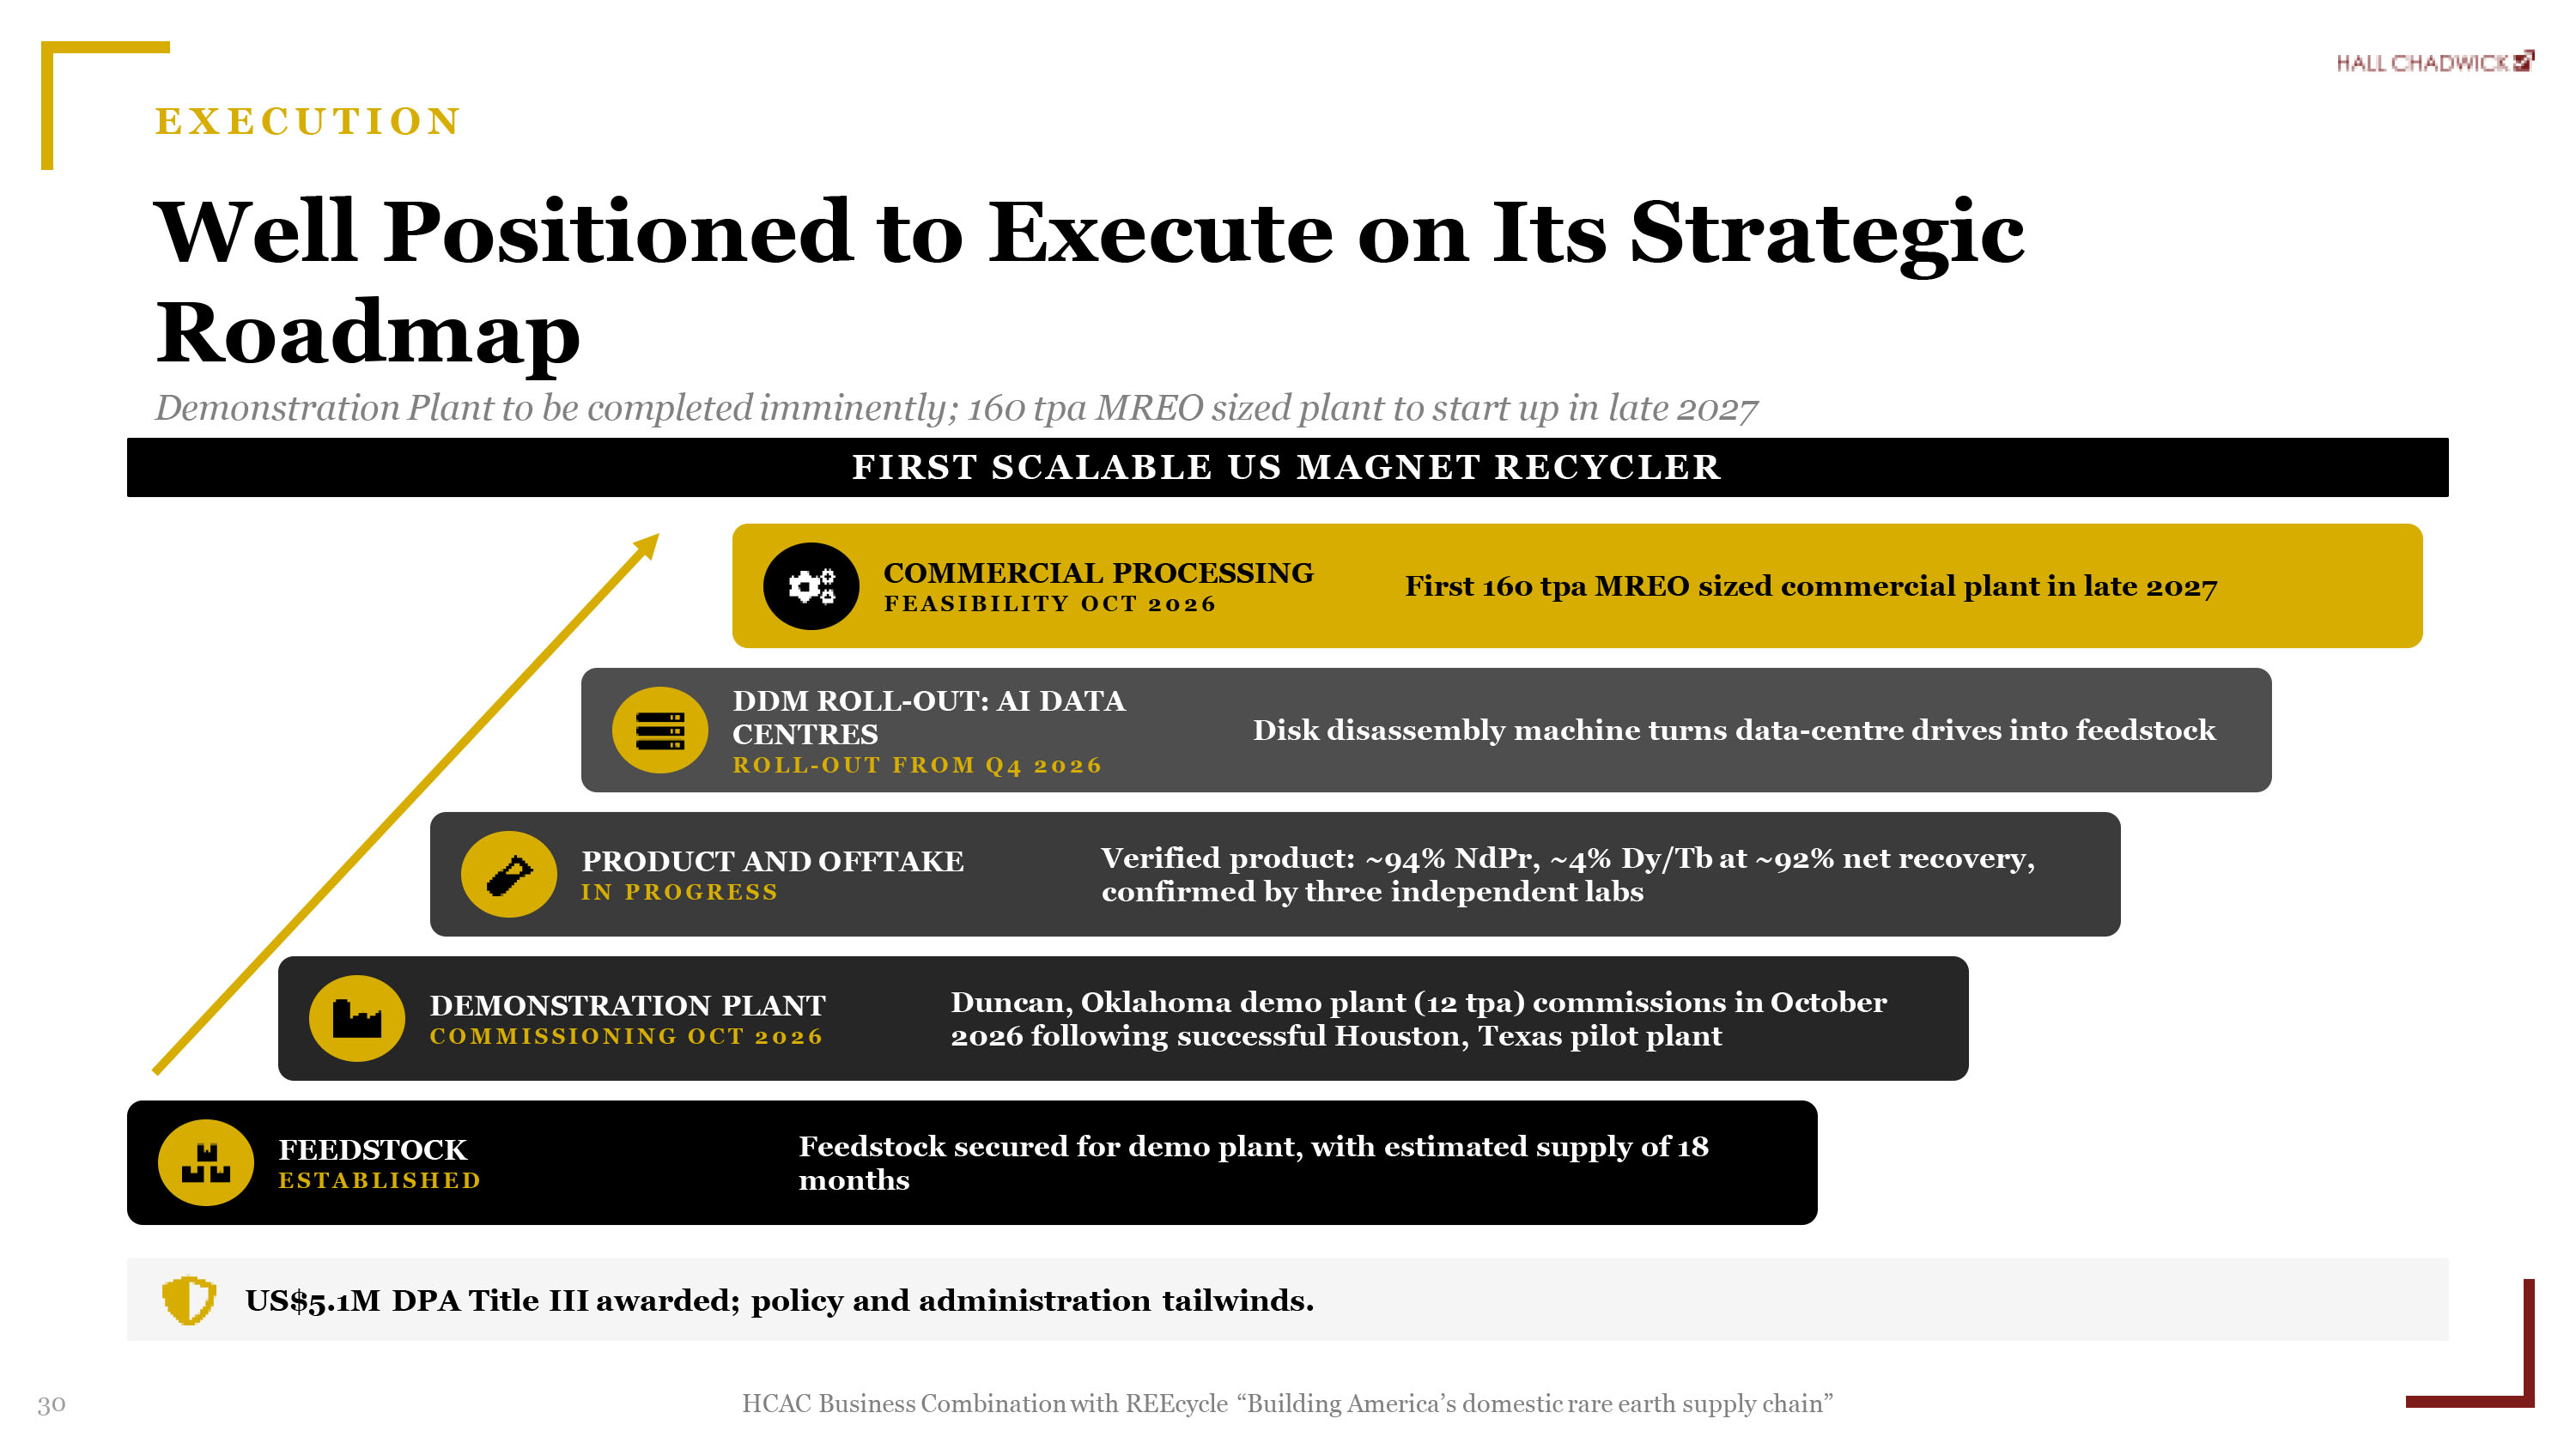
30 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” EXECUTION Well Positioned to Execute on Its Strategic Roadmap Demonstration Plant to be completed imminently; 160 tpa MREO sized plant to start up in late 2027 FIRST SCALABLE US MAGNET RECYCLER COMMERCIAL PROCESSING FEASIBILITY OCT 2026 First 160 tpa MREO sized commercial plant in late 2027 DDM ROLL - OUT: AI DATA CENTRES ROLL - OUT FROM Q4 2026 Disk disassembly machine turns data - centre drives into feedstock PRODUCT AND OFFTAKE IN PROGRESS Verified product: ~94% NdPr, ~4% Dy/Tb at ~92% net recovery, confirmed by three independent labs DEMONSTRATION PLANT COMMISSIONING OCT 2026 Duncan, Oklahoma demo plant (12 tpa) commissions in October 2026 following successful Houston, Texas pilot plant FEEDSTOCK ESTABLISHED Feedstock secured for demo plant, with estimated supply of 18 months US$5.1M DPA Title III awarded; policy and administration tailwinds.
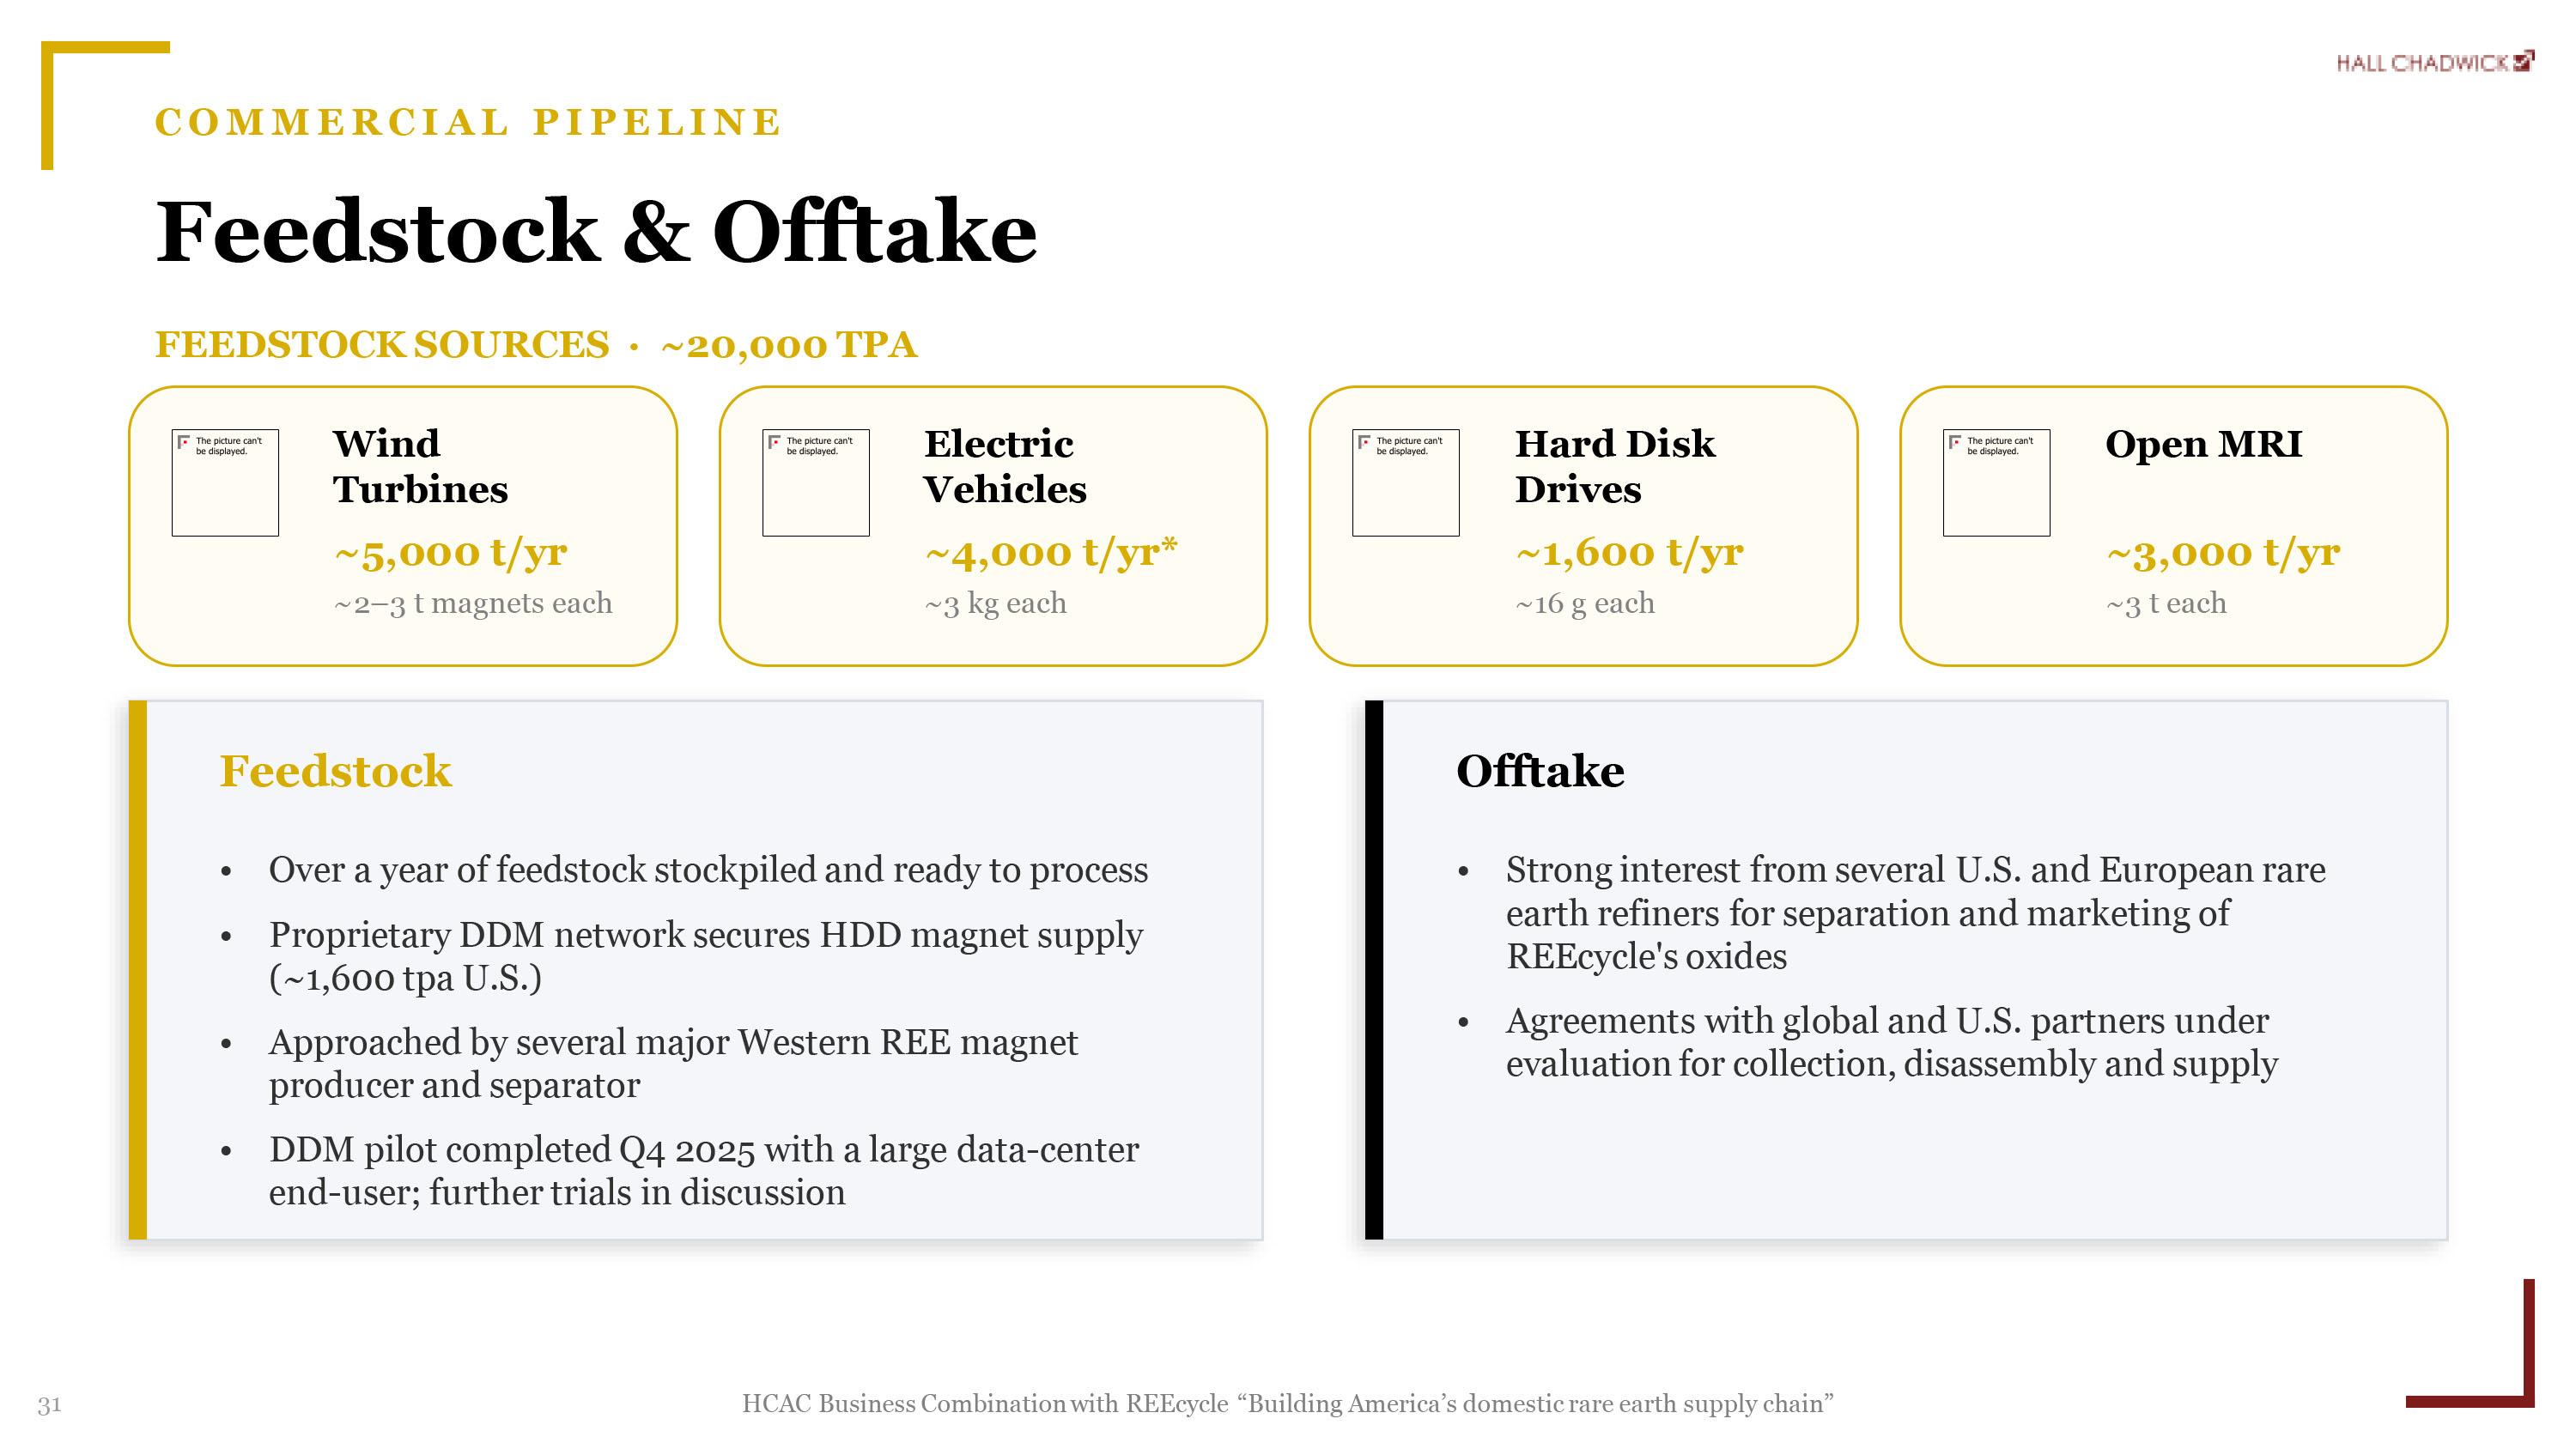
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 31 COMMERCIAL PIPELINE Feedstock & Offtake Feedstock • Over a year of feedstock stockpiled and ready to process • Proprietary DDM network secures HDD magnet supply (~1,600 tpa U.S.) • Approached by several major Western REE magnet producer and separator • DDM pilot completed Q4 2025 with a large data - center end - user; further trials in discussion Offtake • Strong interest from several U.S. and European rare earth refiners for separation and marketing of REEcycle's oxides • Agreements with global and U.S. partners under evaluation for collection, disassembly and supply FEEDSTOCK SOURCES · ~20,000 TPA Wind Turbines ~5,000 t/yr ~2 – 3 t magnets each Electric Vehicles ~4,000 t/yr* ~3 kg each Hard Disk Drives ~1,600 t/yr ~16 g each Open MRI ~3,000 t/yr ~3 t each
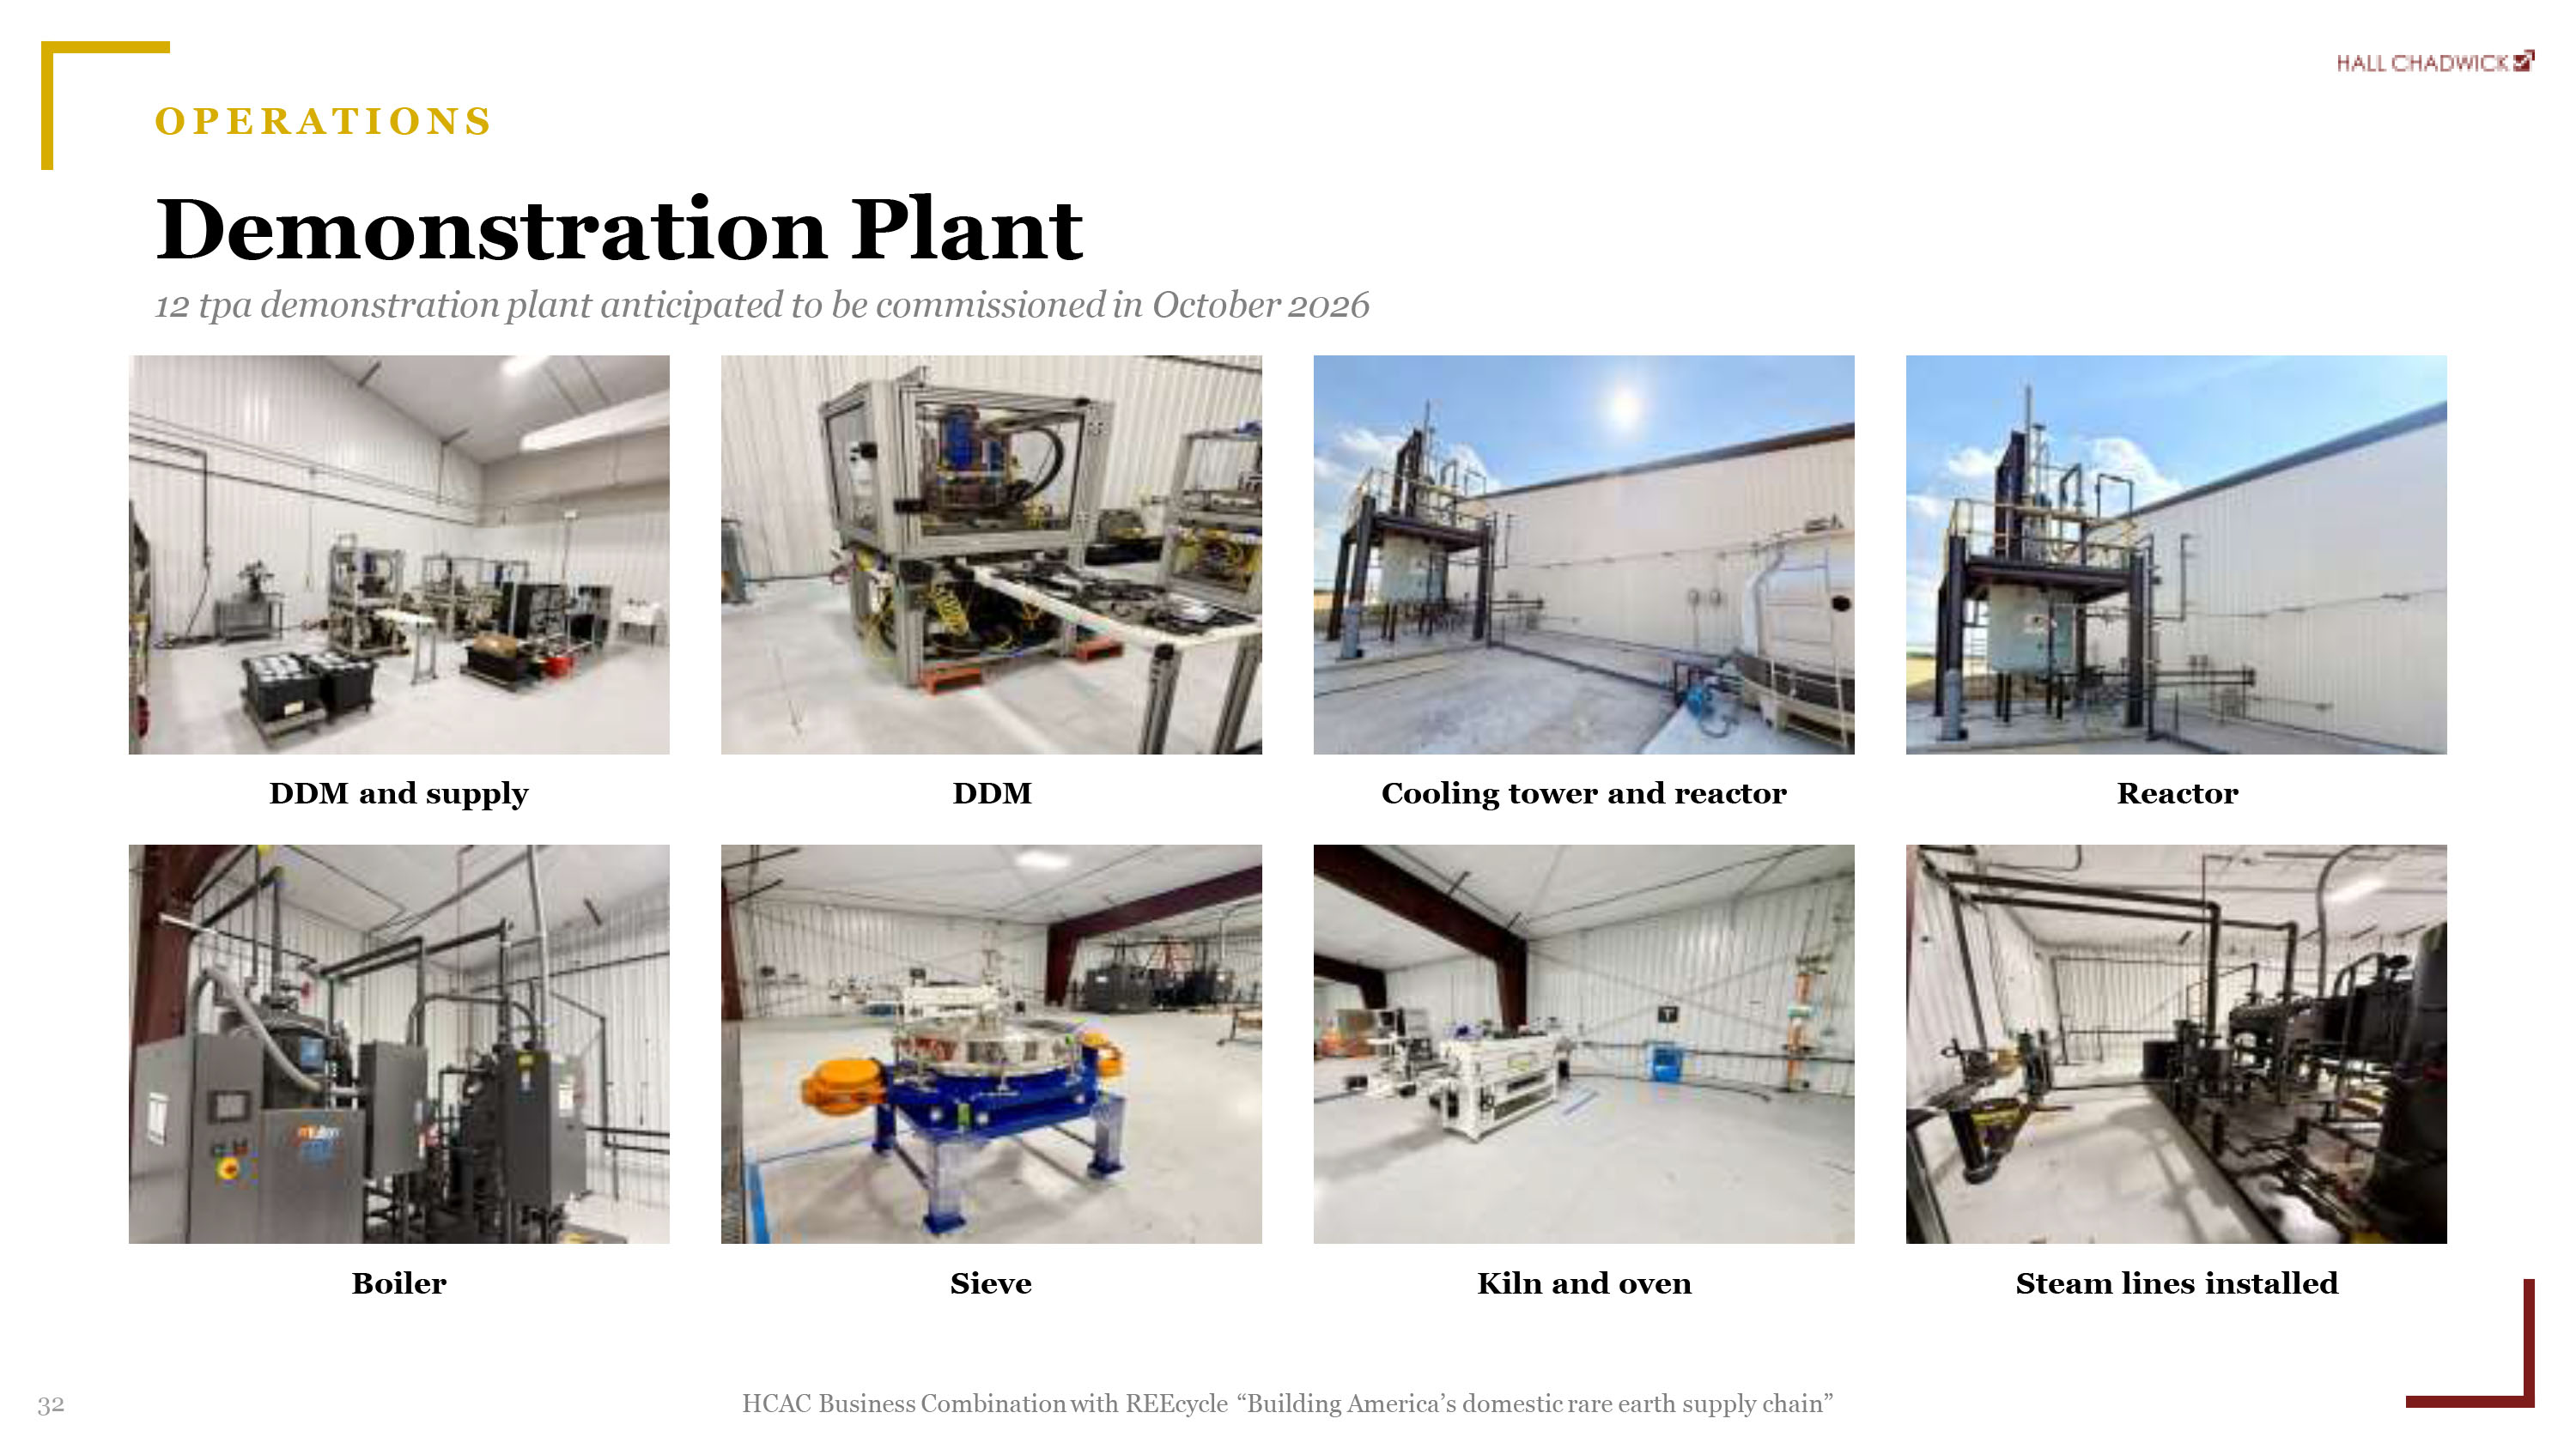
32 HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” OPERATIONS Demonstration Plant 12 tpa demonstration plant anticipated to be commissioned in October 2026 DDM and supply DDM Cooling tower and reactor Reactor Boiler Sieve Kiln and oven Steam lines installed
SECTION 6 Financials & Peer Comparison TM (NASDAQ: HCAC)
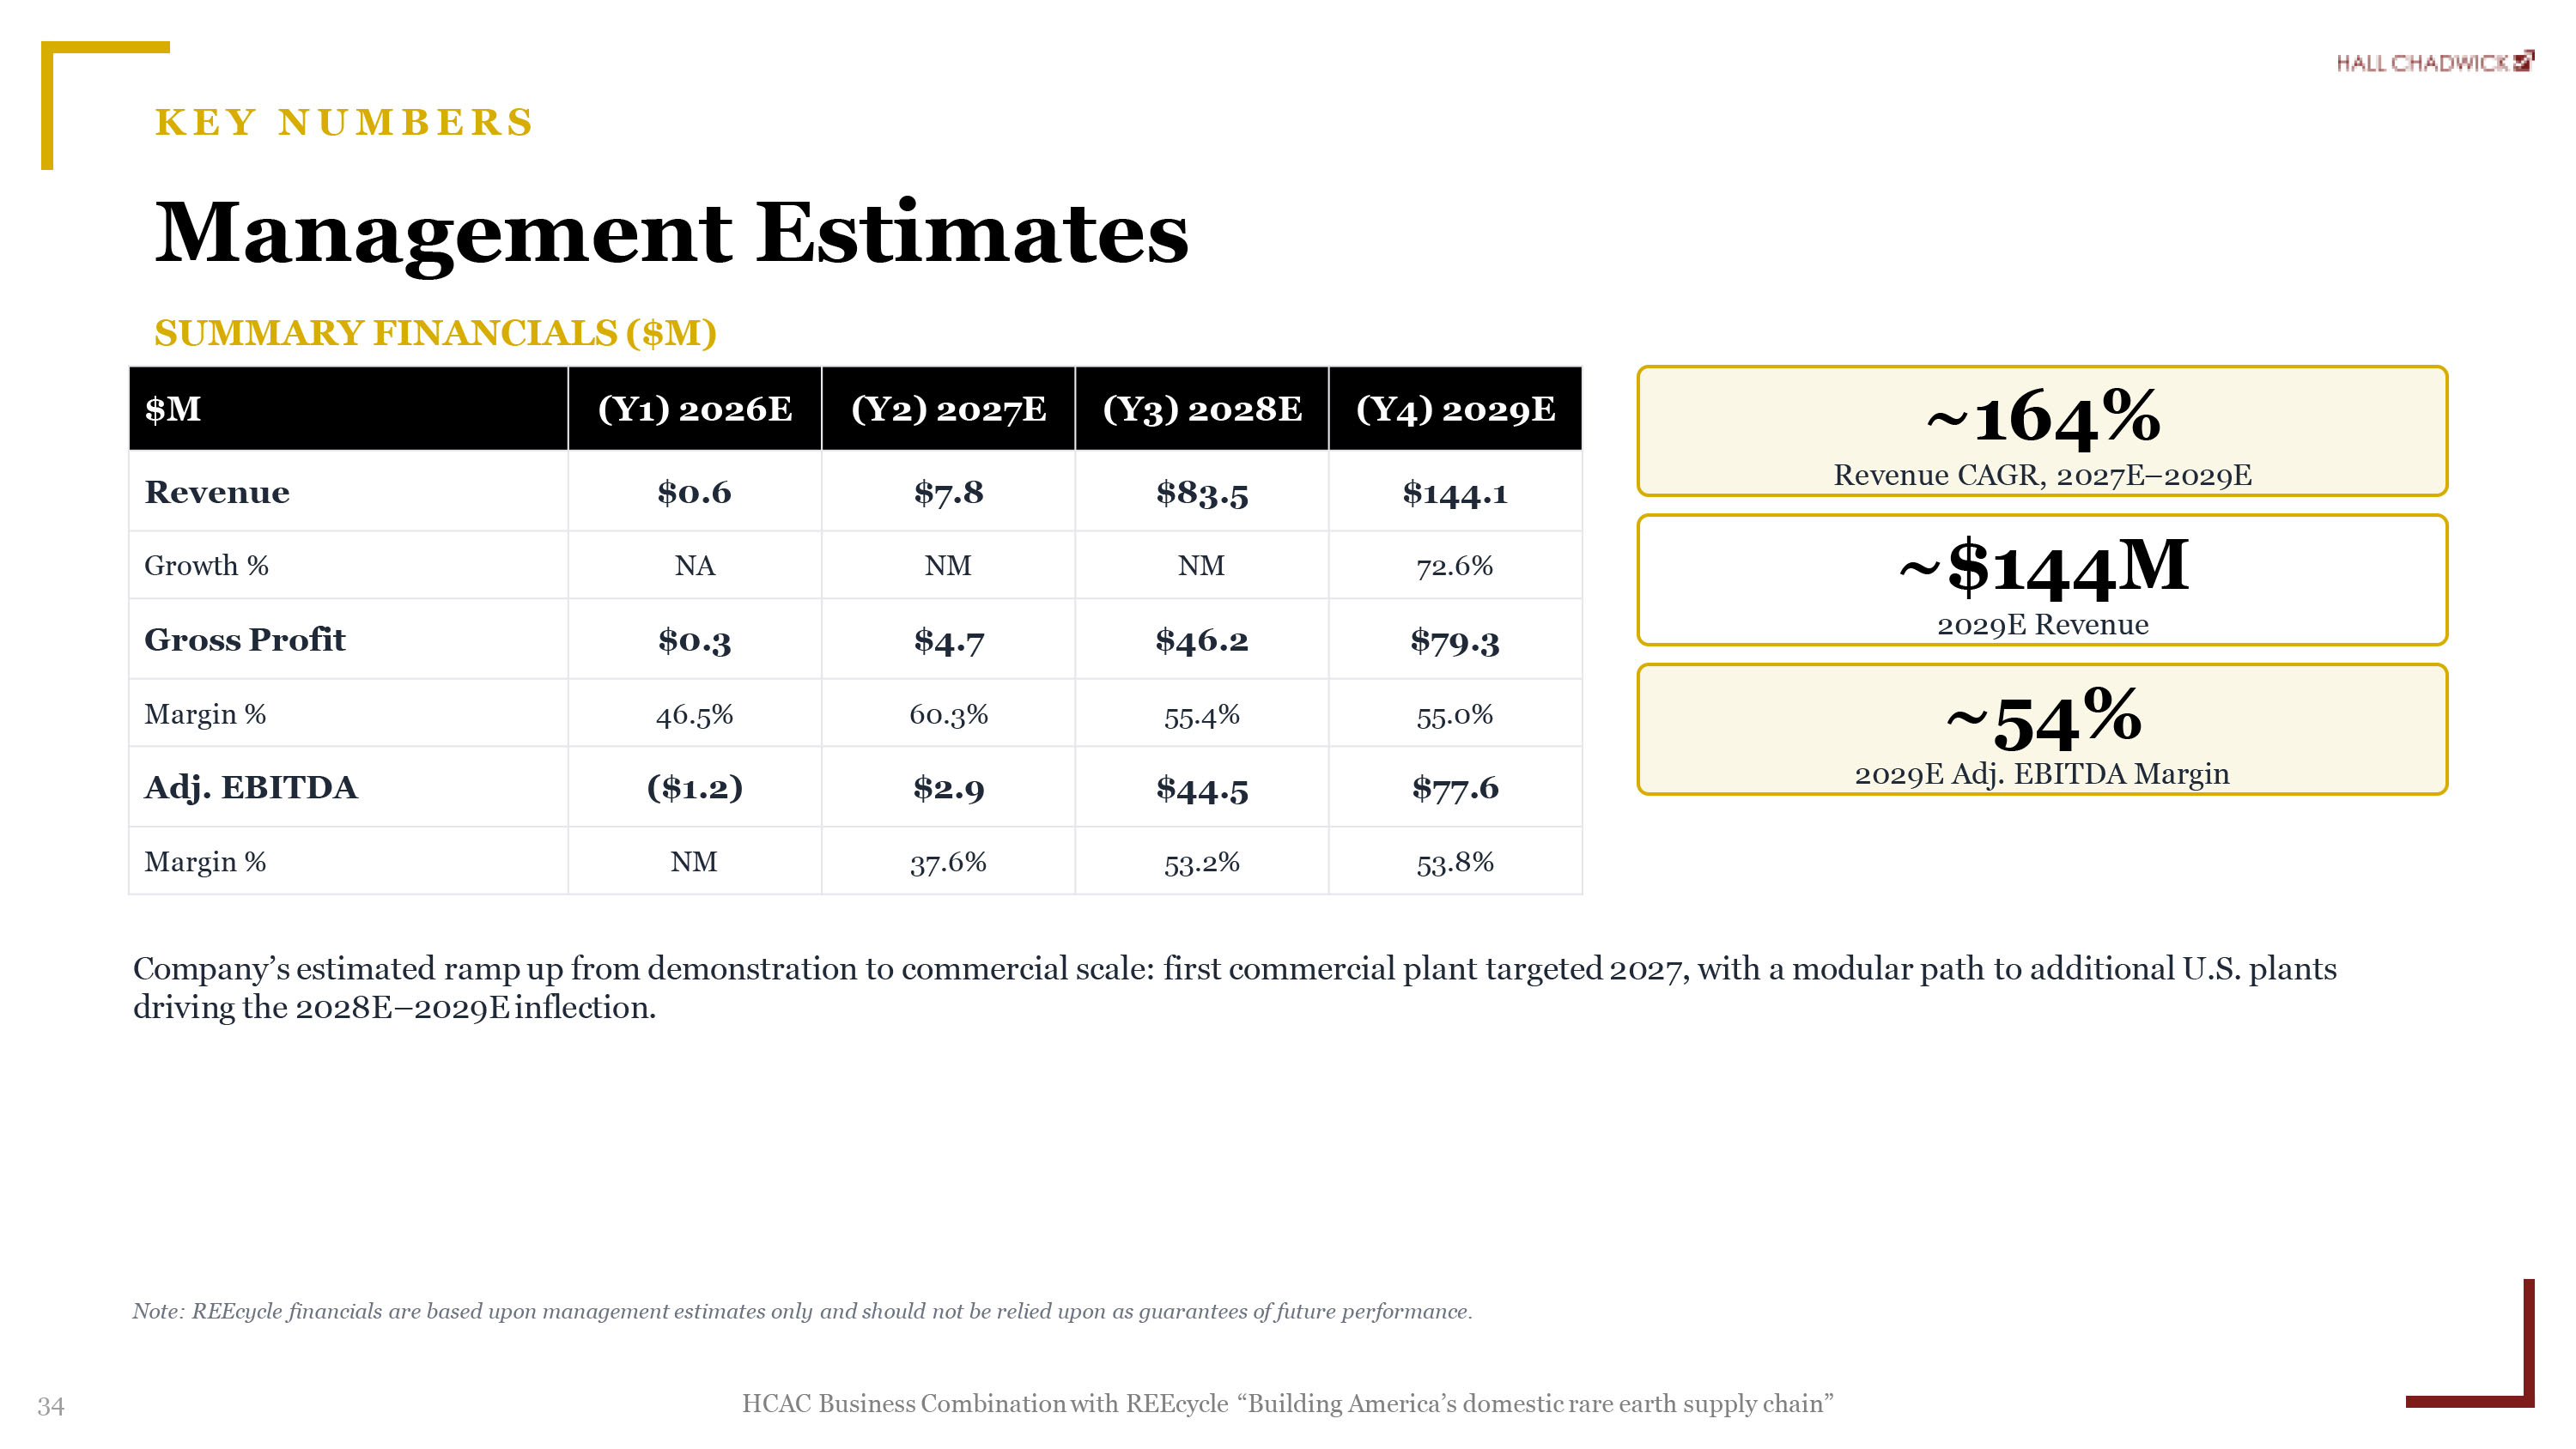
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 34 SUMMARY FINANCIALS ($M) (Y4) 2029E (Y3) 2028E (Y2) 2027E (Y1) 2026E $M $144.1 $83.5 $7.8 $0.6 Revenue 72.6% NM NM NA Growth % $79.3 $46.2 $4.7 $0.3 Gross Profit 55.0% 55.4% 60.3% 46.5% Margin % $77.6 $44.5 $2.9 ($1.2) Adj. EBITDA 53.8% 53.2% 37.6% NM Margin % ~164% Revenue CAGR, 2027E – 2029E ~$144M 2029E Revenue ~54% 2029E Adj. EBITDA Margin Company’s estimated ramp up from demonstration to commercial scale: first commercial plant targeted 2027, with a modular path to additional U.S. plants driving the 2028E – 2029E inflection. Note: REEcycle financials are based upon management estimates only and should not be relied upon as guarantees of future performance. KEY NUMBERS Management Estimates
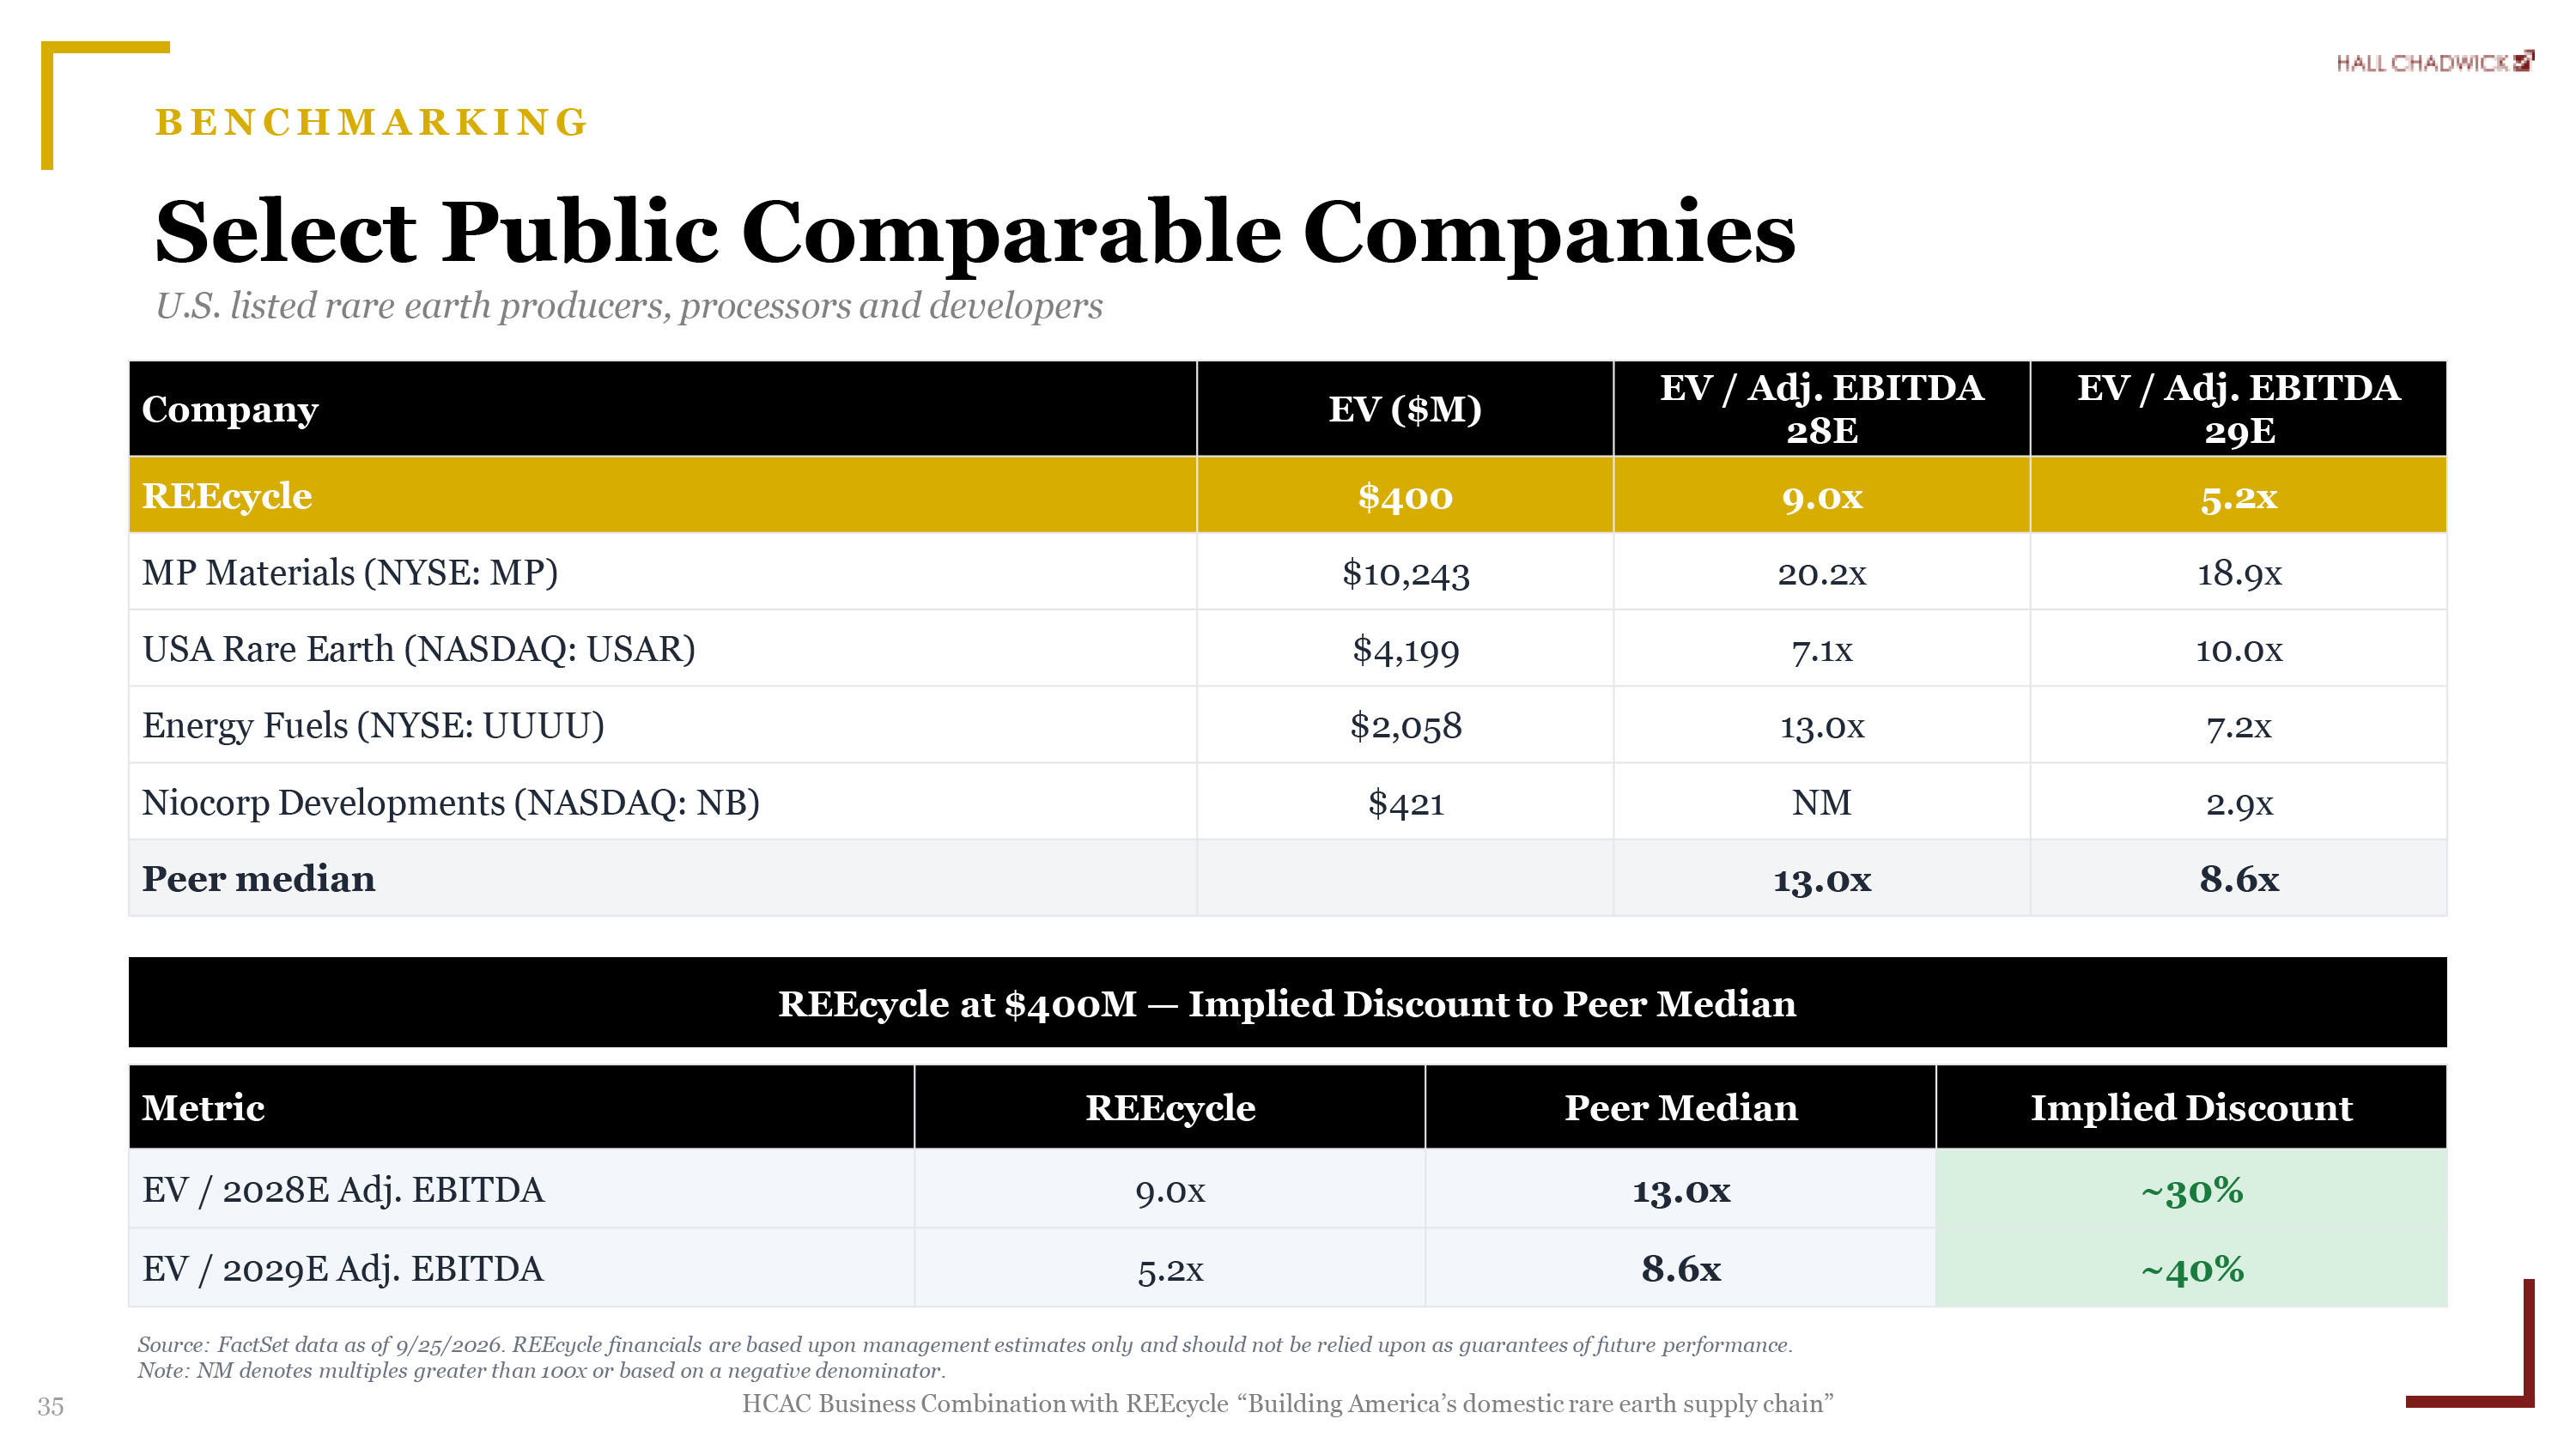
HCAC Business Combination with REEcycle “Building America’s domestic rare earth supply chain” 35 EV / Adj. EBITDA 29E EV / Adj. EBITDA 28E EV ($M) Company 5.2x 9.0x $400 REEcycle 18.9x 20.2x $10,243 MP Materials (NYSE: MP) 10.0x 7.1x $4,199 USA Rare Earth (NASDAQ: USAR) 7.2x 13.0x $2,058 Energy Fuels (NYSE: UUUU) 2.9x NM $421 Niocorp Developments (NASDAQ: NB) 8.6x 13.0x Peer median REEcycle at $400M — Implied Discount to Peer Median Implied Discount Peer Median REEcycle Metric ~30% 13.0x 9.0x EV / 2028E Adj. EBITDA ~40% 8.6x 5.2x EV / 2029E Adj. EBITDA BENCHMARKING Select Public Comparable Companies Source: FactSet data as of 9/25/2026. REEcycle financials are based upon management estimates only and should not be relied upon as guarantees of future performance. Note: NM denotes multiples greater than 100x or based on a negative denominator. U.S. listed rare earth producers, processors and developers
Thank You TM (NASDAQ: HCAC)