Exhibit 99.2
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Private Placement of Subordinated Notes CONFIDENTIAL September 10, 2026 First Keystone Corporation Holding Company for: FOR INSTITUTIONAL USE ONLY |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Notice to Recipients 2 This confidential presentation (this “Presentation”) has been prepared solely for general informational purposes by First Keystone Corporation (the “Company,” the “holding company,” “we,” or “our”), a Pennsylvania corporation and the registered bank holding company for First Keystone Community Bank (the “Bank”), a Pennsylvania state-chartered, non-member bank, supervised and regulated by the Federal Deposit Insurance Corporation (the “FDIC”) and the Pennsylvania Department at Banking and Securities, and is being furnished solely for use by prospective investors considering participating in the proposed private offering (the “Offering”) of the Company’s unsecured subordinated notes (the “Securities”). No representation or warranty as to the accuracy, completeness, or fairness of such information is being made by the Company or any other person, and neither the Company, any of its affiliates nor any other person shall have any liability for any information contained herein, or for any omissions from this Presentation or any other written or oral information or communications transmitted or made available to the recipient by the Company or its affiliates or any other person in the course of the recipient’s evaluation of the Company or the Offering. The Company reserves the right to withdraw or amend the Offering for any reason and to reject any prospective investment in the Securities, in whole or in part. The Securities are not a bank deposit or bank account, and are not, and will not be, insured or guaranteed by the FDIC or any other federal or state government agency. Neither the Securities, the Offering, nor the investment in the Securities has been approved or disapproved by the Securities and Exchange Commission (the “SEC”), the FDIC, the Board of Governors of the Federal Reserve System, the Office of the Comptroller of the Currency, or any other federal or state regulatory authority, nor has any authority passed upon or endorsed the merits of the Offering or the accuracy or adequacy of this Presentation. Any representation to the contrary is a criminal offense. The Securities referenced in this Presentation have not and will not be registered under the Securities Act of 1933, as amended (the “Securities Act”), or any state securities laws, and may not be offered or resold absent registration or pursuant to an applicable exemption from registration under applicable law. The Company is subject to the reporting requirements of Section 15 of the Securities Exchange Act of 1934, as amended. The Securities are being offered only to entities that (i) qualify as an institutional “accredited investor,” as defined in Rule 501(a)(1)-(3) or (7) of Regulation D promulgated under the Securities Act, or a “qualified institutional buyer” as defined in Rule 144A under the Securities Act and (ii) agree to make the representations set forth in the note purchase agreement (the “NPA”) with respect to the Securities. This Presentation does not constitute an offer to sell, or a solicitation of an offer to buy, any securities of the Company by any person in any jurisdiction in which it is unlawful for such person to make such an offering or solicitation. This document is not a prospectus or offering document for any securities. The Company has authorized Performance Trust Capital Partners, LLC, an SEC-registered broker-dealer, to act as its sole lead placement agent in the Offering. The distribution of this presentation and any offering and sale of the securities in certain jurisdictions may be restricted by law. The Company requires a person into whose possession this document comes to inform themselves about and to observe any such restrictions. This document does not constitute an offer of, or any invitation to purchase, any securities in any jurisdiction, territory or state in which such offer or invitation would be unlawful. In making an investment decision, prospective investors must rely on their own examination of the Company and the Securities, including the merits and risks involved. The Company is not providing any legal, business, investment, tax or other advice regarding an investment in the Securities. Prospective investors should consult with their own legal, tax, investment and accounting advisers with respect to the consequences of an investment in the Securities and whether such investor is legally permitted to purchase the Securities. Except as otherwise indicated, this Presentation speaks as of the date hereof. The delivery of this Presentation shall not, under any circumstances, create any implication that there has been no change in the affairs of the Company after the date hereof, and the Company assumes no obligation to update such information, except to the extent required by applicable law. You will be given the opportunity to ask questions of and receive answers from Company representatives concerning the Company’s business and financial condition and the terms and of the Offering, and the Company may provide you with additional relevant information that you may reasonably request to the extent the Company possesses such information or can obtain it without unreasonable effort or expense. Except for information provided in response to such requests, the Company has not authorized any other person to give you information that is not found in this Presentation. If such unauthorized information is obtained or provided, the Company cannot and does not assume responsibility for its accuracy, credibility, or validity. This Presentation may contain statistics and other data that in some cases has been obtained or compiled from information made available by third-party service providers or other industry sources, and which may have relied upon artificial intelligence tools to generate such statistics and data. The Company makes no representation or warranty, express or implied, with respect to the accuracy, reasonableness or completeness of such information or other information made available in connection with any further investigation of the Company. The Company believes that such information is accurate and that the sources from which it has been obtained are reliable. The Company cannot guarantee the accuracy of such information, however, and has not independently verified such information. The Company is not making any implied or express representation or warranty as to the accuracy or completeness of such information or of the information summarized herein or made available in connection with any further investigation of the Company. The Company expressly disclaims any and all liability which may be based on such information, errors therein or omissions therefrom to the fullest extent permitted by applicable law. This Presentation contains certain annualized, pro forma, projected and estimated information, including projected pro forma information that reflects the Company’s current expectations and assumptions related to this Offering and the use of proceeds. This information does not purport to present the results that the Company will ultimately realize and is subject to this notice and the disclaimer on page 3. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. In addition to financial measures presented in accordance with U.S. generally accepted accounting principles (“GAAP”), this Presentation contains certain non-GAAP financial measures, including, without limitation, the ratio of Tangible Common Equity to Tangible Assets (TCE/TA), Core Net Revenue, Debt Service Coverage Ratio, Core Deposits, Adjusted Return on Average Tangible Common Equity (ROATCE), Adjusted Return on Average Assets (ROAA), and Adjusted Noninterest Expense / Average Assets. The presentation of non-GAAP financial information is not intended to be considered in isolation, as a substitute for, or superior to any measure prepared in accordance with GAAP. Other companies may use similarly titled non-GAAP financial measures that are calculated differently from the way the Company calculates such measures or may use different non-GAAP financial measures to evaluate their financial condition or results of operations, either of which could reduce the usefulness of the non-GAAP financial measures contained in this Presentation as tools for comparison. You should understand how such other companies calculate their financial measures similar to, or with names similar to, the non-GAAP financial measures the Company has discussed herein when comparing such non-GAAP financial measures. Financial information included in this Presentation may be based on unaudited financial information regarding the Company and/or the Bank. This Presentation contains non-public information. You understand that the U.S. securities laws as well as the securities laws of other jurisdictions prohibit any person in possession of “material non-public information” about a company from purchasing or selling, directly or indirectly, securities of such company (including entering into short selling, derivative or hedging transactions involving such securities), or from communicating such information to any other person, under circumstances in which it is reasonably foreseeable that such person is likely to purchase or sell such securities. |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Offering Disclaimer This Presentation is confidential and may not be reproduced or redistributed, passed on or divulged, directly or indirectly, to any other person. The Company reserves the right to request the return of this Presentation at any time. The receipt of this Presentation does not create, nor is it intended to create, a binding and enforceable contract or commitment between the Company and any other party, and this Presentation may not be relied upon by any party as the basis for a contract or commitment to purchase the Securities. Any purchase and sale of the Securities will be governed solely by the Note Purchase Agreement (“NPA”), and the information contained herein will be superseded in its entirety by such NPA. In the event that any portion of this Presentation is inconsistent with or contrary to any of the terms of the NPA, the NPA shall control. Each potential investor should review the NPA, make such investigation as it deems necessary to arrive at an independent evaluation of an investment in the Securities mentioned in this Presentation. The Securities will not be registered for public sale and will be subject to significant restrictions and limitations on resale or transfer. Only potential investors who can bear the risk of an unregistered illiquid investment should consider investing in the Securities. Investments in the Securities are considered speculative, involve risks and investors could experience an entire loss of principal. You should carefully consider, without limitation, the following risk factors related to an investment in the Securities: (1) the Securities will be unsecured and subordinated to any existing and future senior indebtedness and will be structurally subordinated to the indebtedness and other liabilities of the Company’s subsidiaries, which means that creditors of the Company’s subsidiaries generally will be paid from those subsidiaries’ assets before holders of the Securities would have any claims to those assets (2) the Securities will not be insured or guaranteed by the FDIC, any other governmental agency or any of the Company’s subsidiaries; (3) the NPA does not generally limit the Company’s ability to incur additional indebtedness, grant or incur a lien on its assets, sell or otherwise dispose of assets, pay dividends or repurchase its capital stock; (4) payments on the Securities may depend on receipt of dividends and distributions from the Bank; (5) the Company may not be able to generate sufficient cash to service all of its debt, including the Securities; (6) regulatory guidelines may restrict the Company’s ability to pay the principal of, and accrued and unpaid interest on, the Securities, regardless of whether the Company is the subject of an insolvency proceeding; and (7) holders of the Securities will have limited rights, including limited rights of acceleration, if there is an event of default. This summary is not exhaustive. Additional information regarding risks may be provided in additional offering materials, if and when available. This Presentation contains forward-looking statements that are subject to risks and uncertainties. Any statements in this Presentation about expectations, beliefs, plans, objectives, assumptions or future events or performance are not historical facts and are forward-looking statements. These statements are often, but not always, made through the use of words or phrases such as “may,” “should,” “could,” “would,” “will,” “predict,” “potential,” “believe,” “likely,” “expect,” “anticipate,” “seek,” “estimate,” “intend,” “plan,” “project” and similar expressions. Annualized, pro forma, projected and estimated numbers are used for illustrative purposes only, are not forecasts and may not reflect actual results. Forward-looking statements are not a guarantee of future performance or results, are based on information available at the time the statements are made and involve known and unknown assumptions, risks, uncertainties and other factors that could cause the Company’s actual results to differ materially from the information contained in or implied by the forward-looking statements and can change as a result of many possible events or factors, not all of which are known to us or in the Company’s control. The following factors could cause the Company’s actual results to differ materially from those contained or implied by the forward-looking statements made in this Presentation: changes in assumptions underlying the establishment of allowances for credit losses, and other estimates; short-term and long-term effects of inflation and rising costs to the Company and its customers; the risks of changes in interest rates on levels, composition and costs of deposits, loan demand, and the values and liquidity of loan collateral, securities, and interest sensitive assets and liabilities; the effects of future economic, business and market conditions; future actions or inactions of the United States government, including the effects of short-term and long-term federal budget and tax negotiations and a failure to increase the government debt limit or a prolonged shutdown of the federal government; legislative and regulatory changes, including changes in banking, securities, and tax laws and regulations and their application by our regulators; the Company’s ability to maintain adequate liquidity by retaining deposit customers and secondary funding sources, especially if the Company’s or banking industry’s reputation becomes damaged; computer systems and infrastructure may be vulnerable to attacks by hackers or breached due to employee error, malfeasance, or other disruptions despite security measures implemented by the Company; risks inherent in making loans, such as repayment risks and fluctuating collateral values; governmental monetary and fiscal policies; changes in accounting policies, rules and practices; competition with other banks and financial institutions, and companies outside of the banking industry, including companies that have substantially greater access to capital and other resources; demand, development and acceptance of new products and services; problems with technology utilized by the Company; changing trends in customer profiles and behavior; success of acquisitions and operating initiatives, changes in business strategy or development of plans, and management of growth; reliance on senior management, including the ability to attract and retain key personnel; inadequate design or circumvention of disclosure controls and procedures or internal controls; acts of war or terrorism or geopolitical instability. The foregoing factors could cause actual results or outcomes to differ materially from those expressed in any forward-looking statements made by the Company, and you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made and the Company does not undertake any obligation to update any forward-looking statement or statements to reflect events or circumstances after the date on which such statement is made or to reflect the occurrence of unanticipated events. New factors emerge from time to time, and it is not possible for the Company to predict which will arise. In addition, the Company cannot assess the impact of each factor on the Company’s business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. 3 |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Table of Contents I Executive Summary 5 II Management Team Overview 12 III Capital Highlights 14 IV Assets Highlights 18 V Liabilities Highlights 24 VI Income Statement Highlights 26 VII Appendix 31 4 |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 I. Executive Summary 5 |
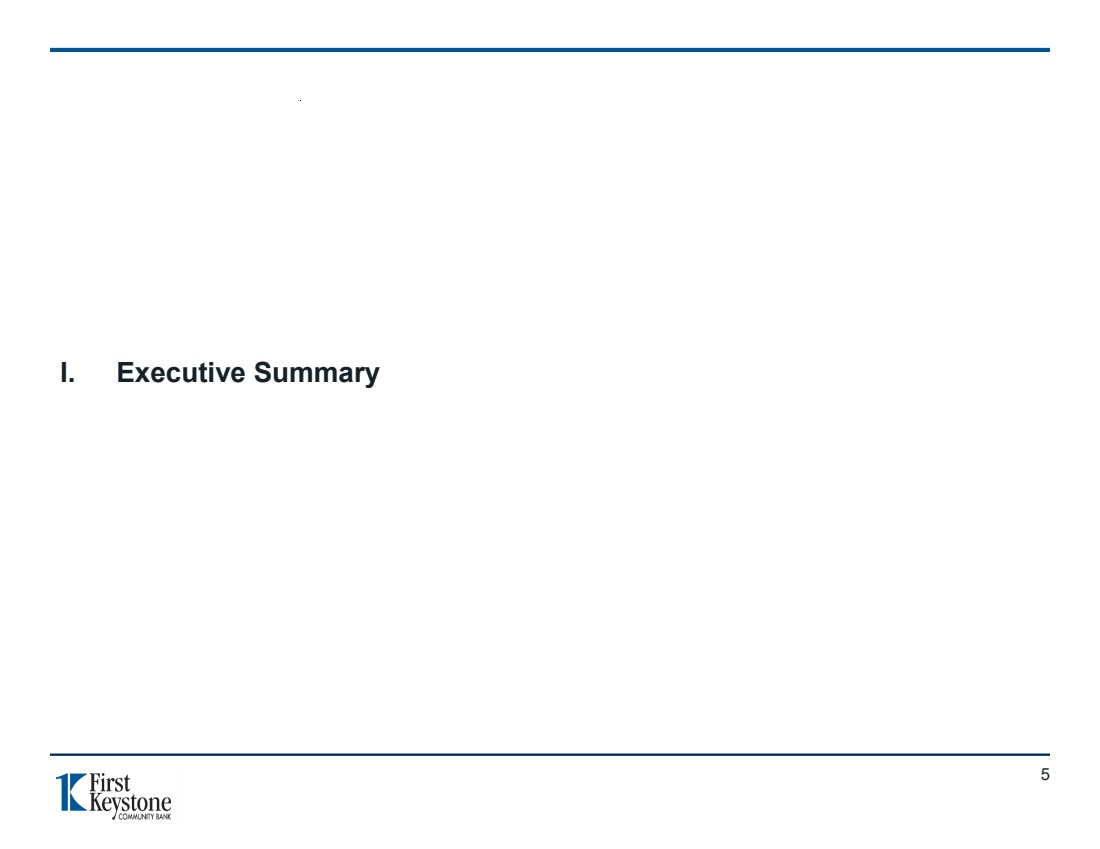
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Terms of the Offered Securities Issuer: First Keystone Corporation (“Company” or “FKYS”), the bank holding company of First Keystone Community Bank (“Bank”) Security: Unsecured Fixed-to-Floating Rate Subordinated Notes Principal Amount: $30.0 million Term: 10-year term Coupon: Fixed [X]% for 5 years; floating thereafter at three-month term SOFR plus [X]% Optional Redemption: Optional redemption 5 years after issuance date; optional redemption prior thereto upon the occurrence of certain events Regulatory Capital: Structured to comply with requirements for Tier 2 capital treatment at the Company Use of Proceeds: Redemption of existing subordinated debt and general corporate purposes Expected Closing: September 2026 Offering Type: Private Placement Sole Lead Placement Agent: Performance Trust Capital Partners, LLC 6 |
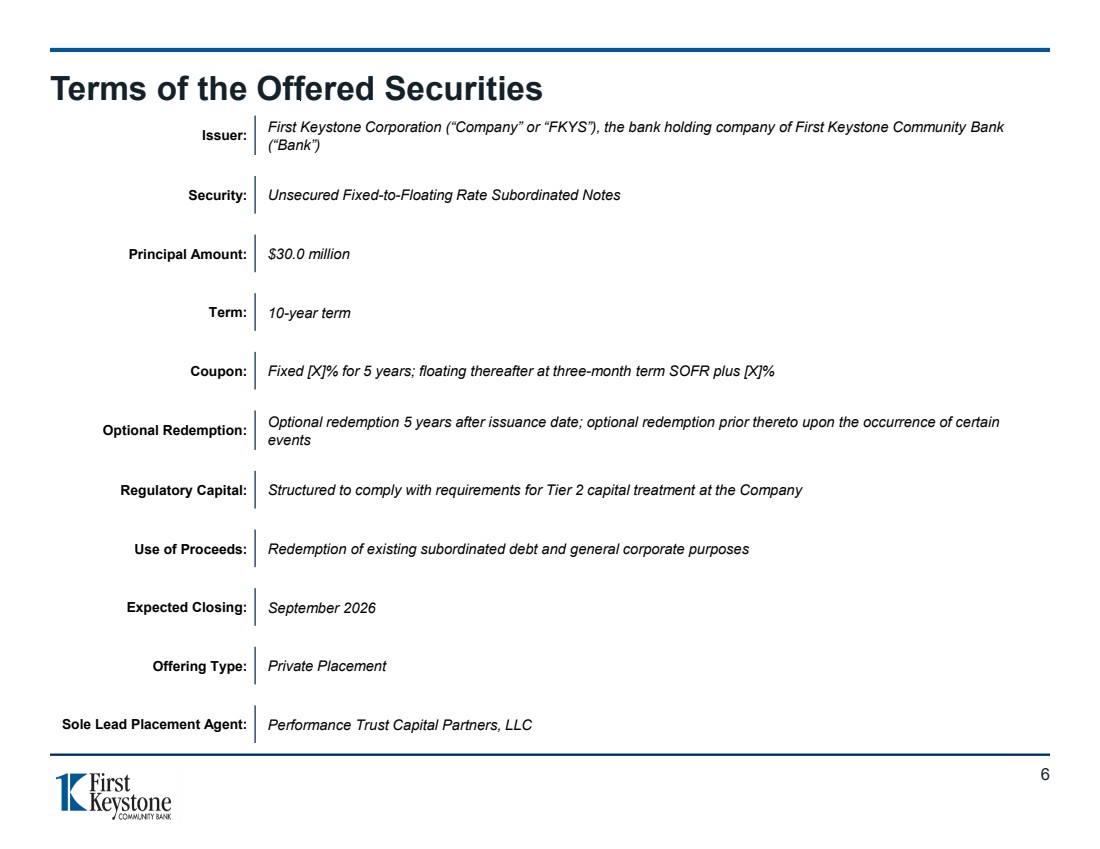
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Investment Highlights Source: S&P Capital IQ Pro, Company documents Note: Consolidated (GAAP) financial data, unless otherwise noted (1) Bank-level financial data, Core deposits are a non-GAAP financial measure; please see page 39 for a reconciliation (2) Debt Service Coverage Ratio is a non-GAAP financial measure; please see page 17 for further detail and a reconciliation 7 160+ Year Legacy of Community-Focused Leadership ▪ Founded in 1864, First Keystone Community Bank has served its communities for over 160 years and was the first financial institution in Berwick, PA ▪ Ownership embedded in the local communities it serves with shareholders including the Berwick Volunteer Fireman’s Relief Association, Berwick Historical Society, and the Berwick Public Library Scarcity-Valued Core Deposit Franchise Anchored in Attractive Markets ▪ The Bank’s primary market sits at the epicenter of Pennsylvania's data center boom, with Amazon’s $20 billion investment plans into Berwick, PA – driving an influx of commercial activity, employment, and economic expansion directly within the Bank’s deposit footprint ▪ 87.7%(1) core deposits driving Q2’26 cost of interest-bearing deposits of 2.75%(1) Consistent Earnings Power Intact with Long-Term Profitability Track Record ▪ 10-year median ROAA of 0.94% from 2016Y to 2025Y; Q2’26 ROAA of 0.97% ▪ Non-cash goodwill impairment ($19.1mm, Q1’24) and a single-quarter provision build ($3.9mm, Q4’25) represent non-recurring events with no impact on tangible book value trajectory or ongoing earnings capacity Conservative Asset Quality Profile ▪ Median NPAs / Assets of 0.33% across the last 14 quarters (Q1’23 – Q2’26) ▪ Net Charge-Offs / Avg Loans below 0.10% for 19 out of the last 22 quarters Healthy Debt Issuance Metrics(2) ▪ More than adequate debt service coverage with pro forma interest coverage of 9.5x (if issued at 6.75%) ▪ Pro forma debt / equity of 22.2% and pro forma double leverage ratio of 117.7% |
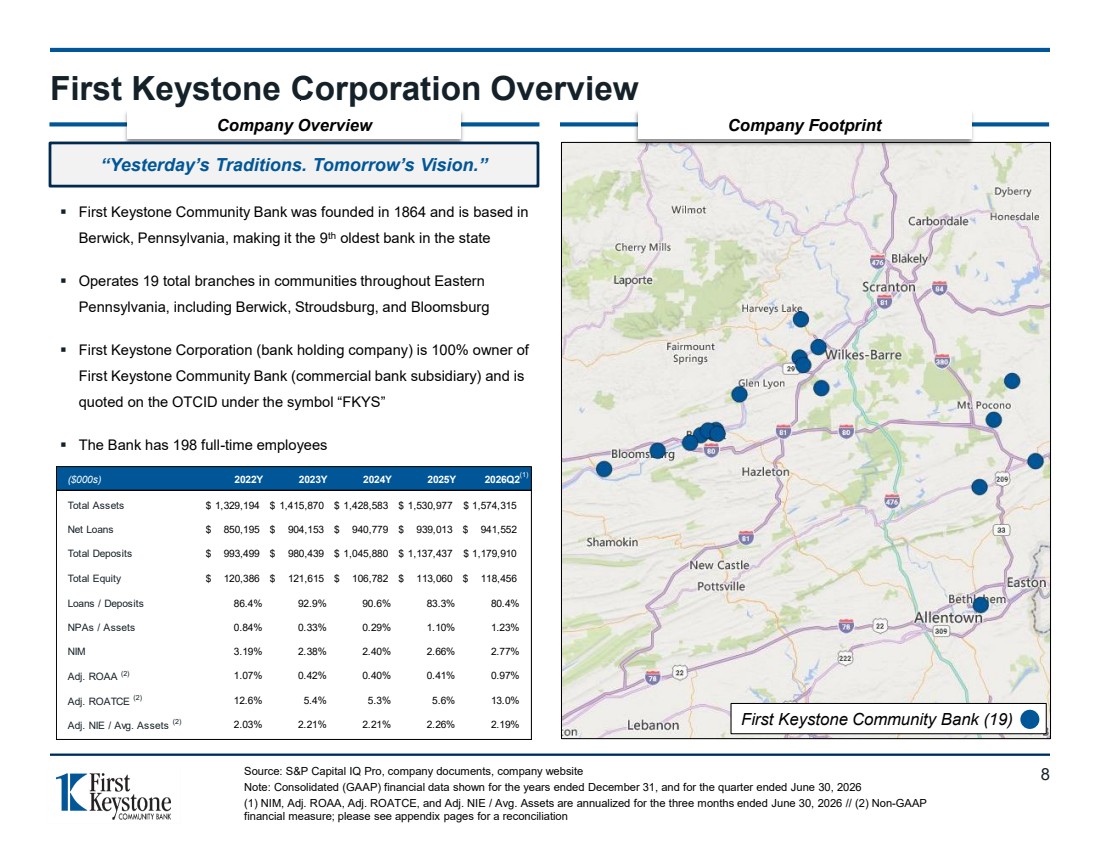
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 First Keystone Community Bank (19) First Keystone Corporation Overview Source: S&P Capital IQ Pro, company documents, company website Note: Consolidated (GAAP) financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) NIM, Adj. ROAA, Adj. ROATCE, and Adj. NIE / Avg. Assets are annualized for the three months ended June 30, 2026 // (2) Non-GAAP financial measure; please see appendix pages for a reconciliation ($000s) 2022Y 2023Y 2024Y 2025Y 2026Q2 Total Assets $ 1,329,194 $ 1,415,870 $ 1,428,583 $ 1,530,977 $ 1,574,315 Net Loans $ 850,195 $ 904,153 $ 940,779 $ 939,013 $ 941,552 Total Deposits $ 993,499 $ 980,439 $ 1,045,880 $ 1,137,437 $ 1,179,910 Total Equity $ 120,386 $ 121,615 $ 106,782 $ 113,060 $ 118,456 Loans / Deposits 86.4% 92.9% 90.6% 83.3% 80.4% NPAs / Assets 0.84% 0.33% 0.29% 1.10% 1.23% NIM 3.19% 2.38% 2.40% 2.66% 2.77% Adj. ROAA (2) 1.07% 0.42% 0.40% 0.41% 0.97% Adj. ROATCE (2) 12.6% 5.4% 5.3% 5.6% 13.0% Adj. NIE / Avg. Assets (2) 2.03% 2.21% 2.21% 2.26% 2.19% 8 Company Overview Company Footprint ▪ First Keystone Community Bank was founded in 1864 and is based in Berwick, Pennsylvania, making it the 9th oldest bank in the state ▪ Operates 19 total branches in communities throughout Eastern Pennsylvania, including Berwick, Stroudsburg, and Bloomsburg ▪ First Keystone Corporation (bank holding company) is 100% owner of First Keystone Community Bank (commercial bank subsidiary) and is quoted on the OTCID under the symbol “FKYS” ▪ The Bank has 198 full-time employees “Yesterday’s Traditions. Tomorrow’s Vision.” (1) |
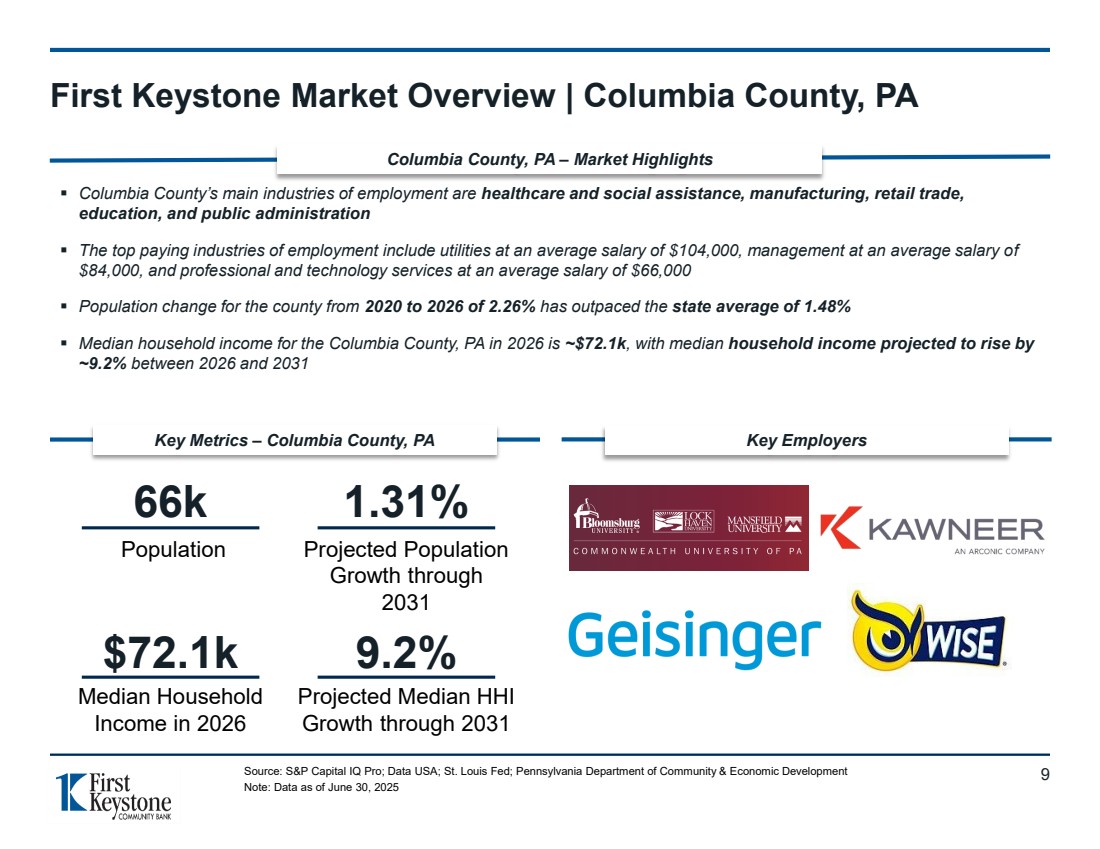
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 ▪ Columbia County’s main industries of employment are healthcare and social assistance, manufacturing, retail trade, education, and public administration ▪ The top paying industries of employment include utilities at an average salary of $104,000, management at an average salary of $84,000, and professional and technology services at an average salary of $66,000 ▪ Population change for the county from 2020 to 2026 of 2.26% has outpaced the state average of 1.48% ▪ Median household income for the Columbia County, PA in 2026 is ~$72.1k, with median household income projected to rise by ~9.2% between 2026 and 2031 Source: S&P Capital IQ Pro; Data USA; St. Louis Fed; Pennsylvania Department of Community & Economic Development Note: Data as of June 30, 2025 9 66k Population $72.1k Median Household Income in 2026 1.31% Projected Population Growth through 2031 9.2% Projected Median HHI Growth through 2031 Columbia County, PA – Market Highlights Key Metrics – Columbia County, PA Key Employers First Keystone Market Overview | Columbia County, PA |
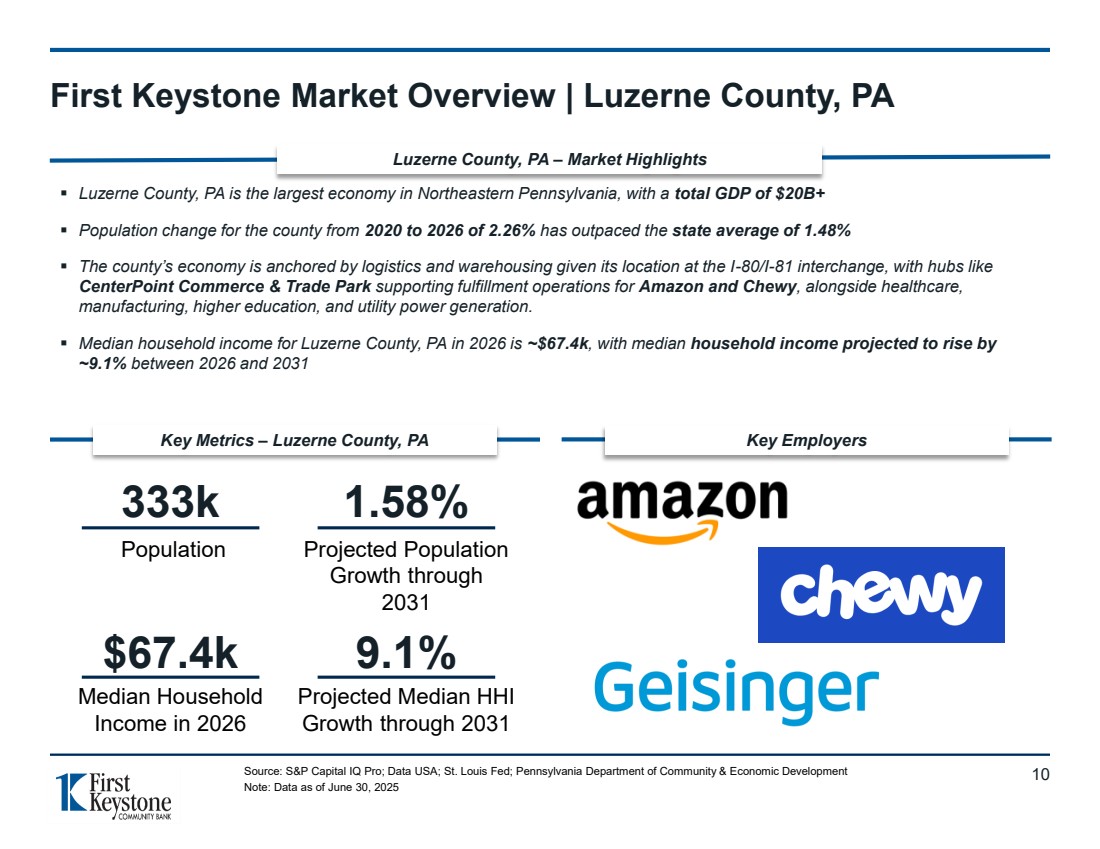
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 ▪ Luzerne County, PA is the largest economy in Northeastern Pennsylvania, with a total GDP of $20B+ ▪ Population change for the county from 2020 to 2026 of 2.26% has outpaced the state average of 1.48% ▪ The county’s economy is anchored by logistics and warehousing given its location at the I-80/I-81 interchange, with hubs like CenterPoint Commerce & Trade Park supporting fulfillment operations for Amazon and Chewy, alongside healthcare, manufacturing, higher education, and utility power generation. ▪ Median household income for Luzerne County, PA in 2026 is ~$67.4k, with median household income projected to rise by ~9.1% between 2026 and 2031 Source: S&P Capital IQ Pro; Data USA; St. Louis Fed; Pennsylvania Department of Community & Economic Development Note: Data as of June 30, 2025 10 333k Population $67.4k Median Household Income in 2026 1.58% Projected Population Growth through 2031 9.1% Projected Median HHI Growth through 2031 Luzerne County, PA – Market Highlights Key Metrics – Luzerne County, PA Key Employers First Keystone Market Overview | Luzerne County, PA |
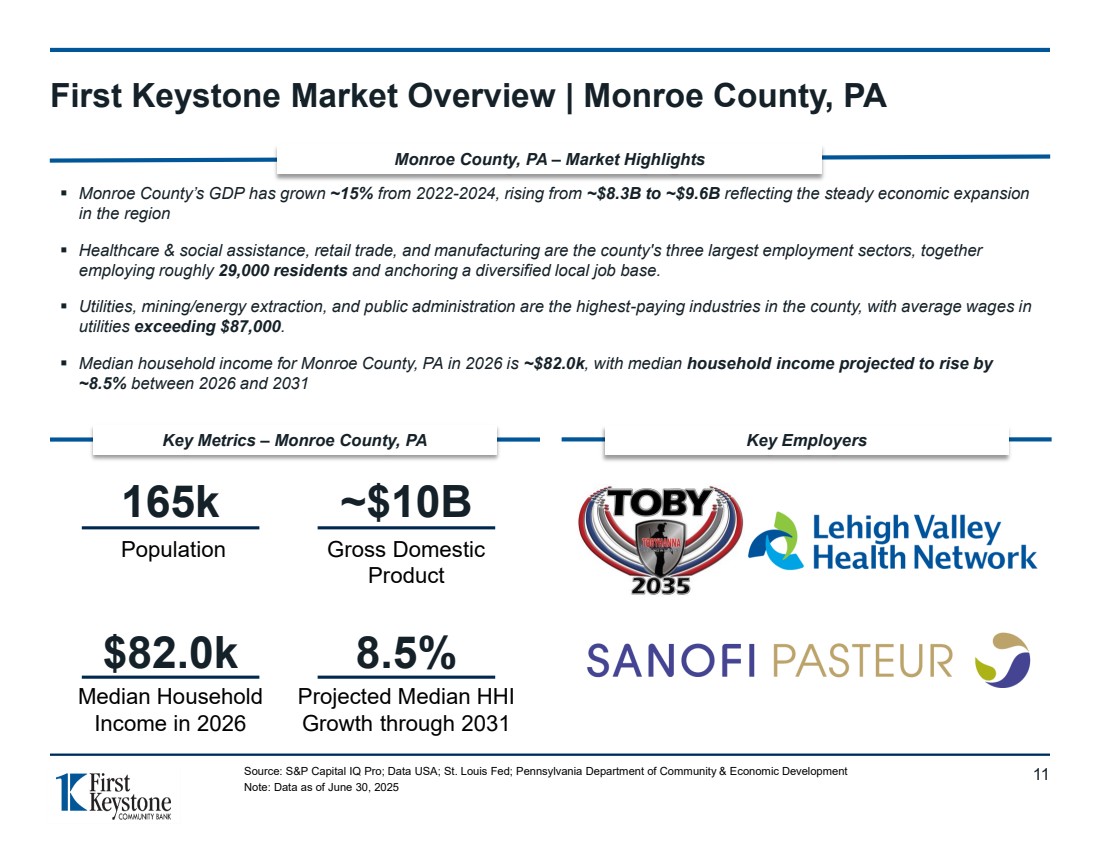
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 ▪ Monroe County’s GDP has grown ~15% from 2022-2024, rising from ~$8.3B to ~$9.6B reflecting the steady economic expansion in the region ▪ Healthcare & social assistance, retail trade, and manufacturing are the county's three largest employment sectors, together employing roughly 29,000 residents and anchoring a diversified local job base. ▪ Utilities, mining/energy extraction, and public administration are the highest-paying industries in the county, with average wages in utilities exceeding $87,000. ▪ Median household income for Monroe County, PA in 2026 is ~$82.0k, with median household income projected to rise by ~8.5% between 2026 and 2031 Source: S&P Capital IQ Pro; Data USA; St. Louis Fed; Pennsylvania Department of Community & Economic Development Note: Data as of June 30, 2025 11 165k Population $82.0k Median Household Income in 2026 ~$10B Gross Domestic Product 8.5% Projected Median HHI Growth through 2031 Monroe County, PA – Market Highlights Key Metrics – Monroe County, PA Key Employers First Keystone Market Overview | Monroe County, PA |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 II. Management Team Overview 12 |
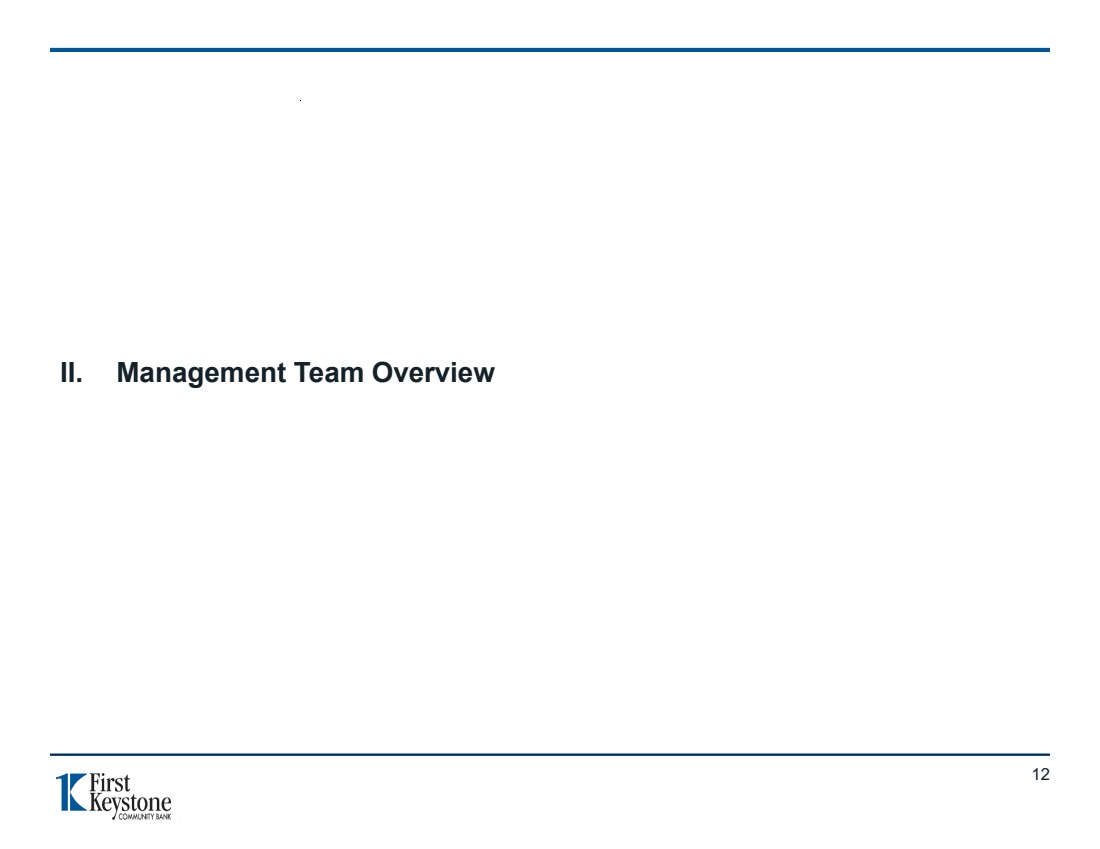
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Experienced Management Team Source: Company documents 13 Jack serves as the President and Chief Executive Officer and sits on the Board of Directors of the Corporation and the Bank. He previously served as Chief Operating Officer of the Corporation and the Bank. Jack served as Chief Banking Officer for Penns Woods Bancorp, Inc., Williamsport, Pennsylvania, and Luzerne Bank, Luzerne, Pennsylvania since January 2021. He also served as Regional President for Luzerne Bank. He is active in the community currently serving as Chairman of the Lands at Hillside Farms, Board Member of Leadership Northeast, and Treasurer of Pennsylvania State Police Camp Cadet Troop P. Jack is a graduate of King’s College and the Pennsylvania Bankers Association. Jack W. Jones – President and Chief Executive Officer Years in Banking: 29 Michelle serves as the Chief Operating Officer of the Corporation and the Bank. Prior to joining First Keystone, she was the Chief Data Officer for Penns Woods Bancorp, Inc. (holding company for Jersey Shore State Bank and Luzerne Bank). She published several articles in various financial services magazines, presented at various banking conferences, and taught various banking courses for the American Bankers Association and the American Institute of Banking. Michelle is a graduate of Bloomsburg University of Pennsylvania, the School of Bank Marketing and Management, the Central Atlantic Advanced School of Banking, and the Central Atlantic Commercial Lending School. Michelle M. Karas – SVP, Chief Operating Officer Years in Banking: 31 Stacy serves as the Chief Financial Officer of the Corporation and the Bank. She has worked for First Keystone since the start of her career holding various roles including Controller, Accounting Manager, and Accounting Reporting Analyst. She has demonstrated a strong commitment to First Keystone and has developed expertise in financial reporting, regulatory compliance, budgeting, tax planning, and asset / liability management. She is a graduate of Pennsylvania College of Technology where she majored in Accounting. Stacy Gordner – SVP, Chief Financial Officer Years in Banking: 13 |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 III. Capital Highlights 14 |
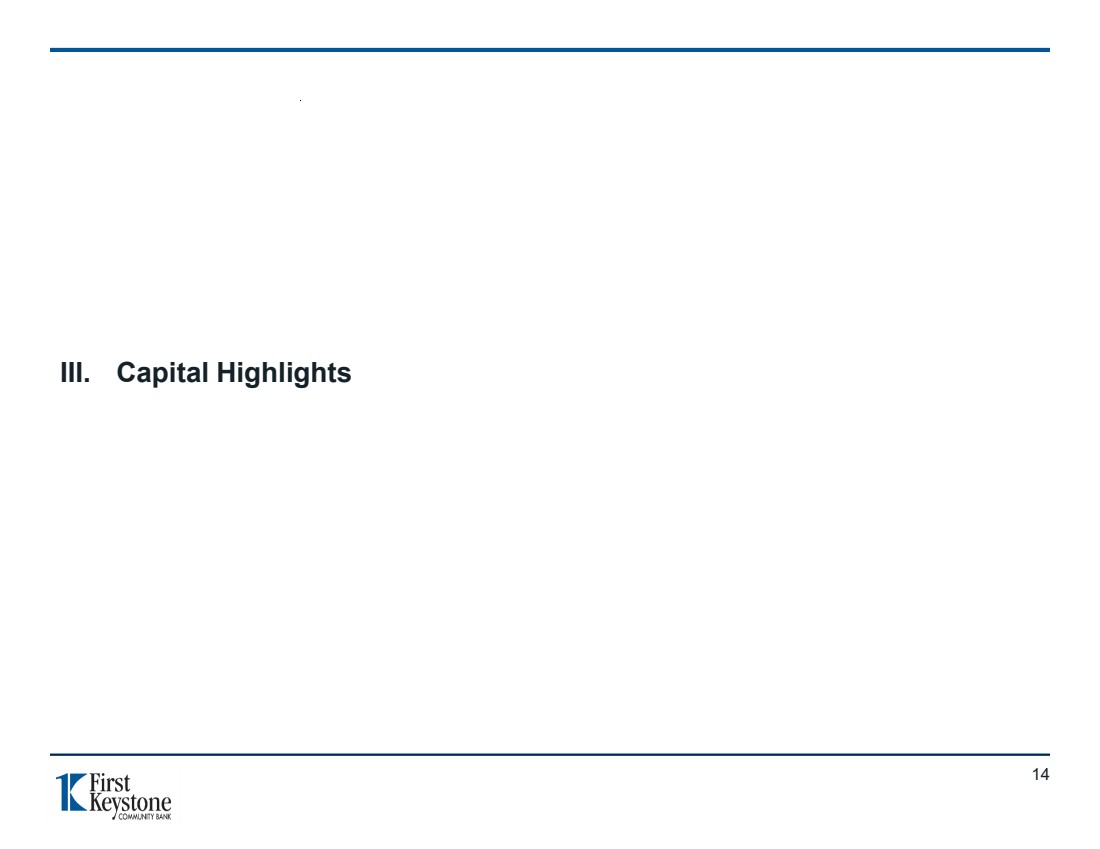
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 0. % 0. % 0.2 % 9.6 2% 9.6 9% 6. % .6 % .6 9% 6. 2% 6.2 % 0.0 0% .0 0% .0 0% 2.0 0% 6.0 0% 2 0.0 0% 0.0 0% .0 0% .0 0% 2.0 0% 6.0 0% 2 0.0 0% 2022 202 202 202 2026Q2 Bank-level Capital Ratios Source: S&P Capital IQ Pro Note: Bank-level financial data shown for the years ended December 31, and the quarter ended June 30, 2026 (1) As defined in 12 CFR 225.2(r) 15 First Keystone Community Bank has maintained regulatory capital in excess of regulatory well-capitalized thresholds (1) . Well-Capitalized Lev. Ratio (5.0%) Well-Capitalized Total RBC Ratio (10.0%) Total RBC Ratio Leverage Ratio |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 $134,852 $30,000 $8,864 CET1 Capital Existing Sub Debt New Sub Debt AACL $135,452 $25,000 $8,864 06/30/26 – Pro Forma ($000s) 06/30/26 – Actual ($000s) Capital Structure | Regulatory Capital Ratios Source: S&P Capital IQ Pro, Company documents Note: Assumes net proceeds are reinvested at 20% risk-weighting 16 Modeling Assumptions: Subordinated Debt Raise Consolidated Capital Structure ▪ Assumes $30.0mm in gross offering proceeds from the Offering ▪ Assumes $0.6mm of offering expenses ▪ Assumes proceeds are used to redeem existing subordinated debt of $25.0mm ▪ Assumes $2.4mm of the net offering proceeds are down streamed to the Bank ▪ Assumes $2.0mm of the net offering proceeds are retained at the Company Consolidated Capital Ratios Bank-level Capital Ratios ($000s) First Keystone Corporation Actual Sub Debt Pro Forma Consolidated Pro Forma Regulatory Capital 06/30/26 Adj. 06/30/26 Common Equity Before Adjustments $ 118,456 $ (600) $ 117,856 Less: DTAs from NOL and Tax Credit – – – Less: Goodwill Net of DTLs – – – Less: Other Intangible Assets Net of DTLs – – – Less: AOCI - Unrealized Gains (16,575) – (16,575) Less: AOCI - Cash Flow Hedges (421) – (421) Common Equity Tier 1 Capital $ 135,452 $ (600) $ 134,852 Additional Tier 1 Capital Instruments – – – Less: Additional Tier 1 Capital Deductions – – – Additional Tier 1 Capital – – – Total Tier 1 Capital $ 135,452 $ (600) $ 134,852 Tier 2 Capital Instruments 25,000 5,000 30,000 AACL Includable in Tier 2 Capital 8,864 – 8,864 Total Tier 2 Capital 33,864 5,000 38,864 Total Capital $ 169,316 $ 4,400 $ 173,716 Average Total Consolidated Assets 1,549,617 5,000 1,554,617 Less: Deductions from CET1 and Additional T1 – – – Less: Other Deductions from Leverage Ratio – – – Total Assets for Leverage Ratio 1,549,617 5,000 1,554,617 Total Risk-Weighted Assets 978,814 1,000 979,814 Leverage Ratio 8.74% 8.67% Common Equity Tier 1 Ratio 13.84% 13.76% Tier 1 Risk-Based Ratio 13.84% 13.76% Total Risk-Based Capital Ratio 17.30% 17.73% ($000s) First Keystone Community Bank Actual Sub Debt Pro Forma Bank Level Pro Forma Regulatory Capital 06/30/26 Adj. 06/30/26 Common Equity Before Adjustments $ 136,268 2,400 $ 138,668 Less: DTAs from NOL and Tax Credit – – – Less: Goodwill Net of DTLs – – – Less: Other Intangible Assets Net of DTLs - – – Less: AOCI - Unrealized Gains (16,575) – (16,575) Less: AOCI - Cash Flow Hedges (421) – (421) Common Equity Tier 1 Capital $ 153,264 $ 2,400 $ 155,664 Additional Tier 1 Capital Instruments – – – Less: Additional Tier 1 Capital Deductions – – – Additional Tier 1 Capital – – – Total Tier 1 Capital $ 153,264 $ 2,400 $ 155,664 Tier 2 Capital Instruments – – – AACL Includable in Tier 2 Capital 8,864 – 8,864 Total Tier 2 Capital 8,864 – 8,864 Total Capital $ 162,128 $ 2,400 $ 164,528 Average Total Assets 1,581,670 2,400 1,584,070 Less: Deductions from CET1 and Additional T1 – – – Less: Other Deductions from Leverage Ratio – – – Total Assets for Leverage Ratio 1,581,670 2,400 1,584,070 Total Risk-Weighted Assets 999,060 480 999,540 Leverage Ratio 9.69% 9.83% Common Equity Tier 1 Ratio 15.34% 15.57% Tier 1 Risk-Based Ratio 15.34% 15.57% Total Risk-Based Capital Ratio 16.23% 16.46% |
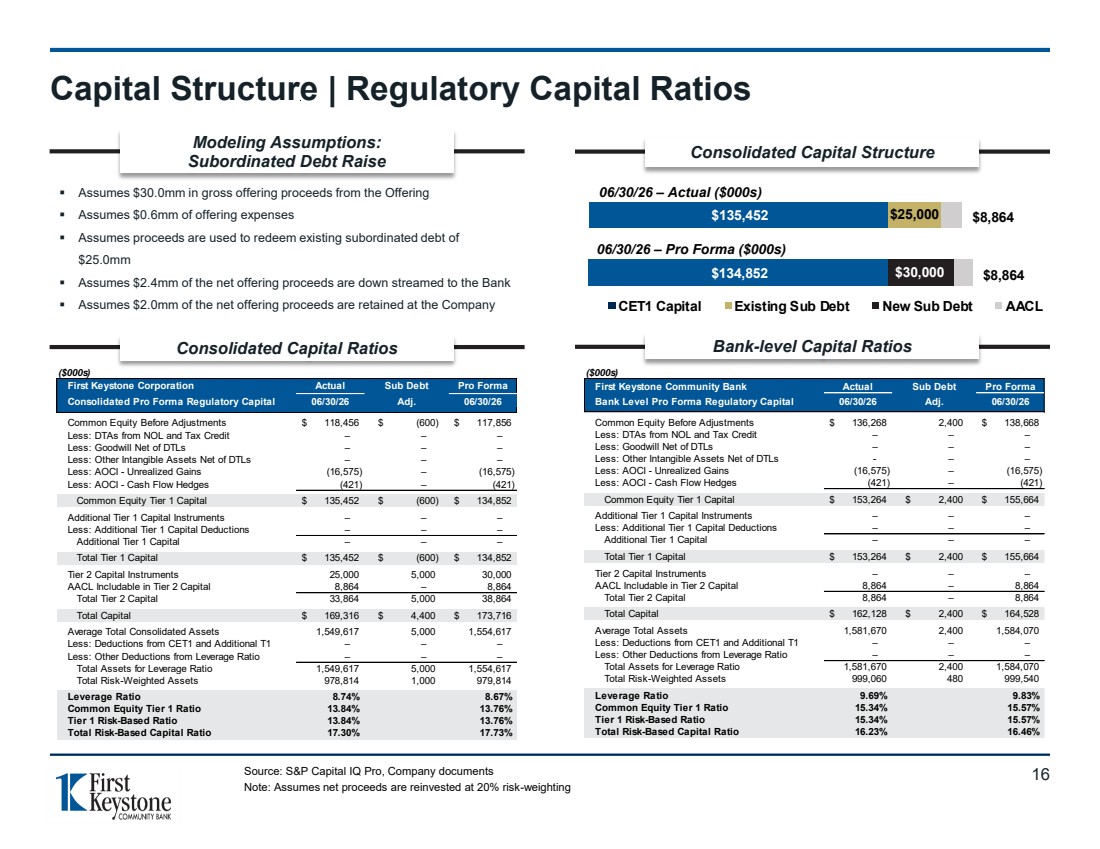
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Strong Debt Service Coverage & Low Leverage Source: S&P Capital IQ Pro, Company documents Note: Debt Service Coverage Ratio is a non-GAAP financial measure and assumes no leveraging of the capital 17 ($000s) Actual Pro Forma Interest Coverage 2026Q2 Ann. 2026Q2 Ann. Consolidated Pre-Tax Earnings Consolidated Pre-Tax Income 17,288 17,288 Plus: Interest Expense on Existing Debt 1,996 1,996 Pre-Tax Earnings Before BHC Debt Interest Expense 19,284 19,284 BHC Debt Interest Expense New Sub Debt Interest Expense at 6.50% – 1,950 New Sub Debt Interest Expense at 6.75% – 2,025 New Sub Debt Interest Expense at 7.00% – 2,100 Plus: Interest Expense on Existing Debt 1,980 – Total Interest Expense - New Sub Debt at 6.50% 1,980 1,950 Total Interest Expense - New Sub Debt at 6.75% 1,980 2,025 Total Interest Expense - New Sub Debt at 7.00% 1,980 2,100 Pro Forma Interest Coverage - A / B 9.7x 9.9x Pro Forma Interest Coverage - A / C 9.7x 9.5x Pro Forma Interest Coverage - A / D 9.7x 9.2x Pro Forma Debt / Equity and Double Leverage Consolidated Equity 118,456 117,856 Existing Sub Debt 25,000 – New Sub Debt – 30,000 Debt / Equity (excluding AOCI) 18.4% 22.2% Bank Equity 136,268 138,668 Double Leverage Ratio 115.0% 117.7% A B C D |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 IV. Assets Highlights 18 |
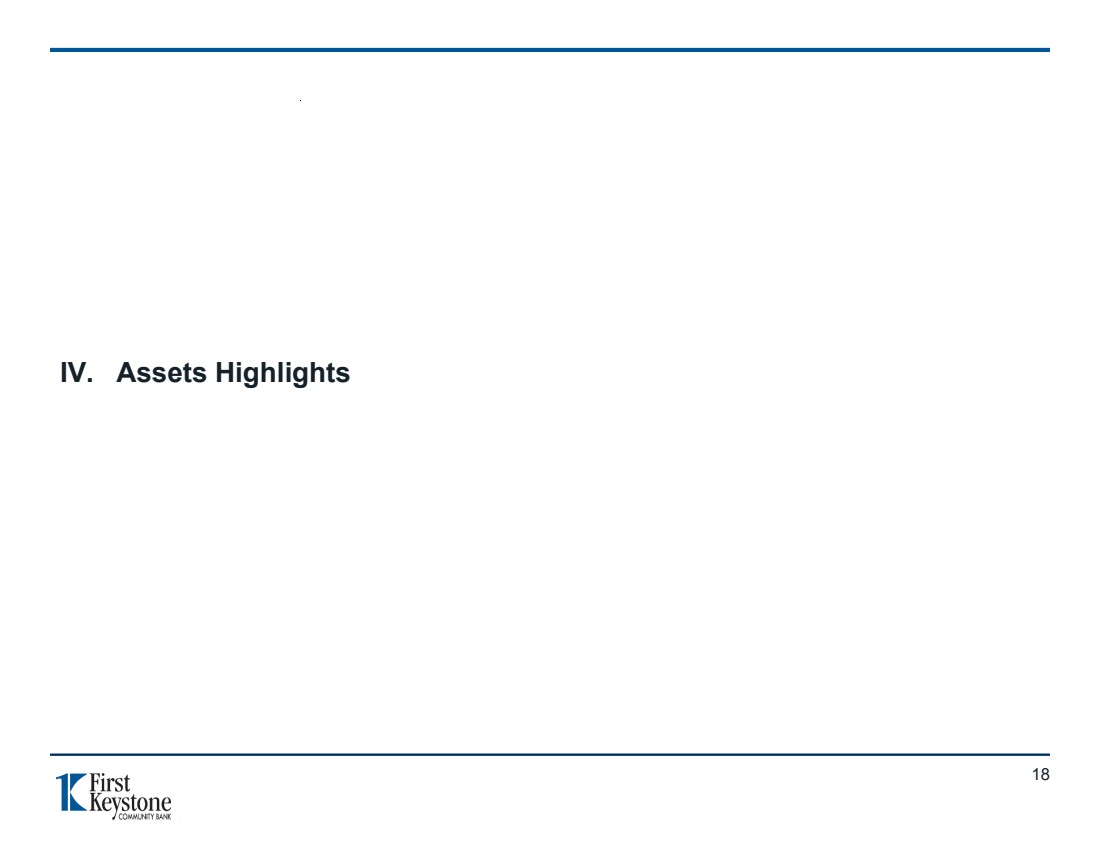
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 $ 20 $ 22 $ 07 $ $ $ 0 $60 $90 $ 20 $ 0 2022 202 202 202 2026Q2 $99 $9 0 $ ,0 6 $ , 7 $ , 0 $2 0 $ 00 $7 0 $ ,000 $ ,2 0 2022 202 202 202 2026Q2 $850 $904 $941 $939 $942 – $250 $500 $750 $1,000 $1,250 2022Y 2023Y 2024Y 2025Y 2026Q2 $ , 29 $ , 6 $ , 29 $ , $ , 7 $ 0 $700 $ ,0 0 $ , 00 $ ,7 0 2022 202 202 202 2026Q2 Tactical Balance Sheet Growth Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data for the years ended December 31, and for the quarter ended June 30, 2026 19 First Keystone Corporation demonstrates core, steady growth on both sides of the balance sheet. Total Deposits ($mm) Total Assets ($mm) Total Net Loans ($mm) Total Equity ($mm) |
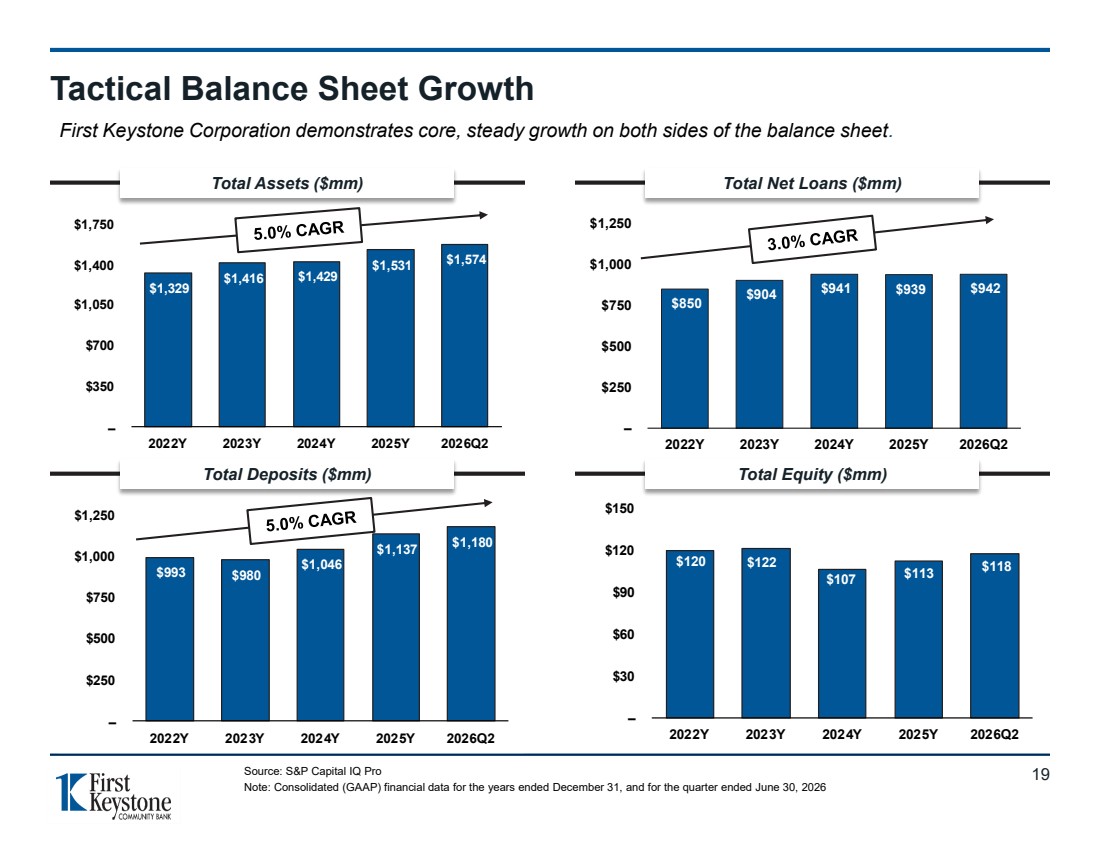
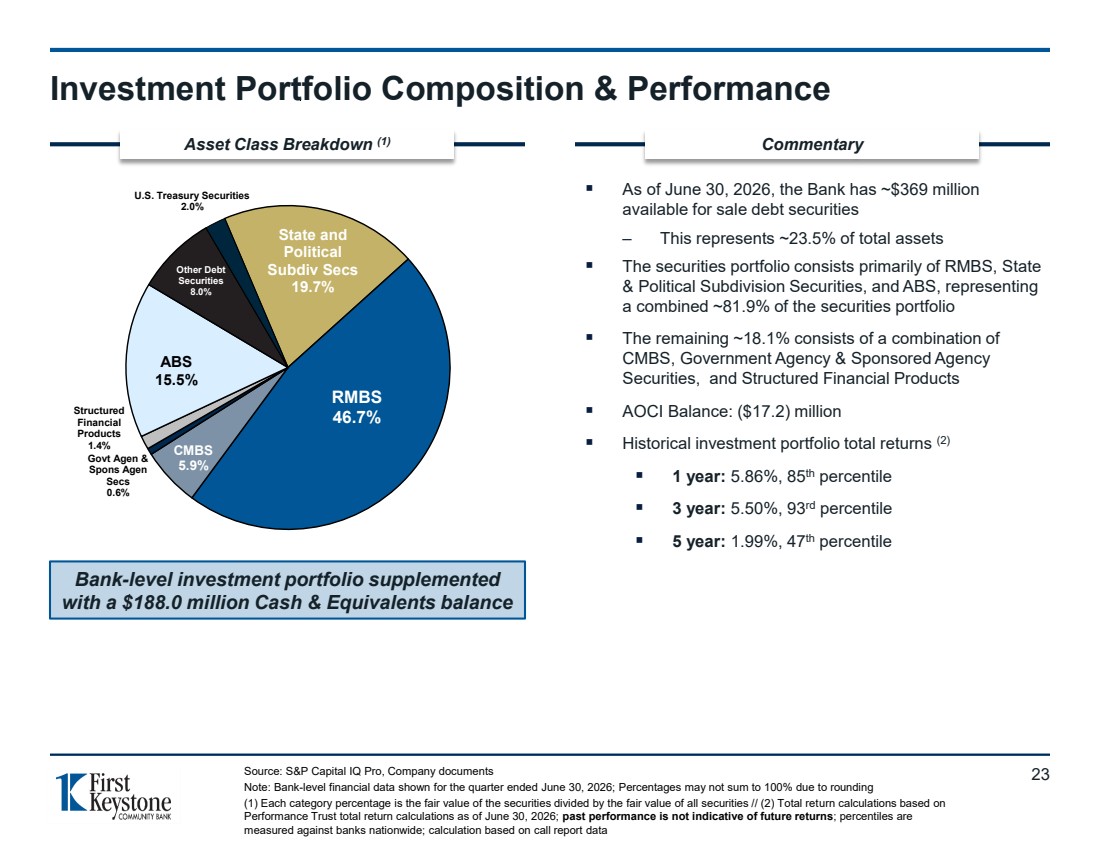
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 $850 $904 $941 $939 $942 $- $250 $500 $750 $1,000 $1,250 2022Y 2023Y 2024Y 2025Y 2026Q2 Loan Portfolio Diversification & Growth Source: S&P Capital IQ Pro Note: Bank-level financial data shown for the quarter ended June 30, 2026 (1) Consolidated (GAAP) financial data for the years ended December 31, and for the quarter ended June 30, 2026 // (2) 06/30/26 post raise assumes $2.4mm of the net new subordinated debt offering gross proceeds are down streamed to the Bank // (3) Includes Non-Owner Occupied CRE, CRE (Not Secured by RE), Construction & Land Development, and Multifamily Loans 20 Total Net Loans (1) ($mm) 1-4 Family 34.7% Non Owner Occupied CRE, 11.8% Multifamily Loans 10.1% Construction & Land Dev 3.2% Owner Occupied CRE 29.0% Commercial & Industrial 7.2% Farm Loans, 0.4% Consumer & Other, 0.5% Ag Prod Loans, 0.1% Other Loans, 3.1% Loan Composition Regulatory Loan Composition 06/30/26 Balance % of Bank TRBC Post Raise % of TRBC (2) 1-4 Family Residential $329,790 203% 200% Non-Owner Occupied CRE 112,056 69% 68% Owner Occupied CRE 275,296 170% 167% Commercial & Industrial 68,371 42% 42% Construction & Land Development 29,914 18% 18% Multifamily 95,883 59% 58% Consumer 4,671 3% 3% Farm Loans 3,786 2% 2% Ag Prod 1,244 1% 1% Other Loans 29,275 18% 18% Total Loans $950,331 Total CRE (Ex owner occupied) $237,898 147% 145% ($000s) (3) Diversified portfolio with no loan category greater than 35% of the portfolio |
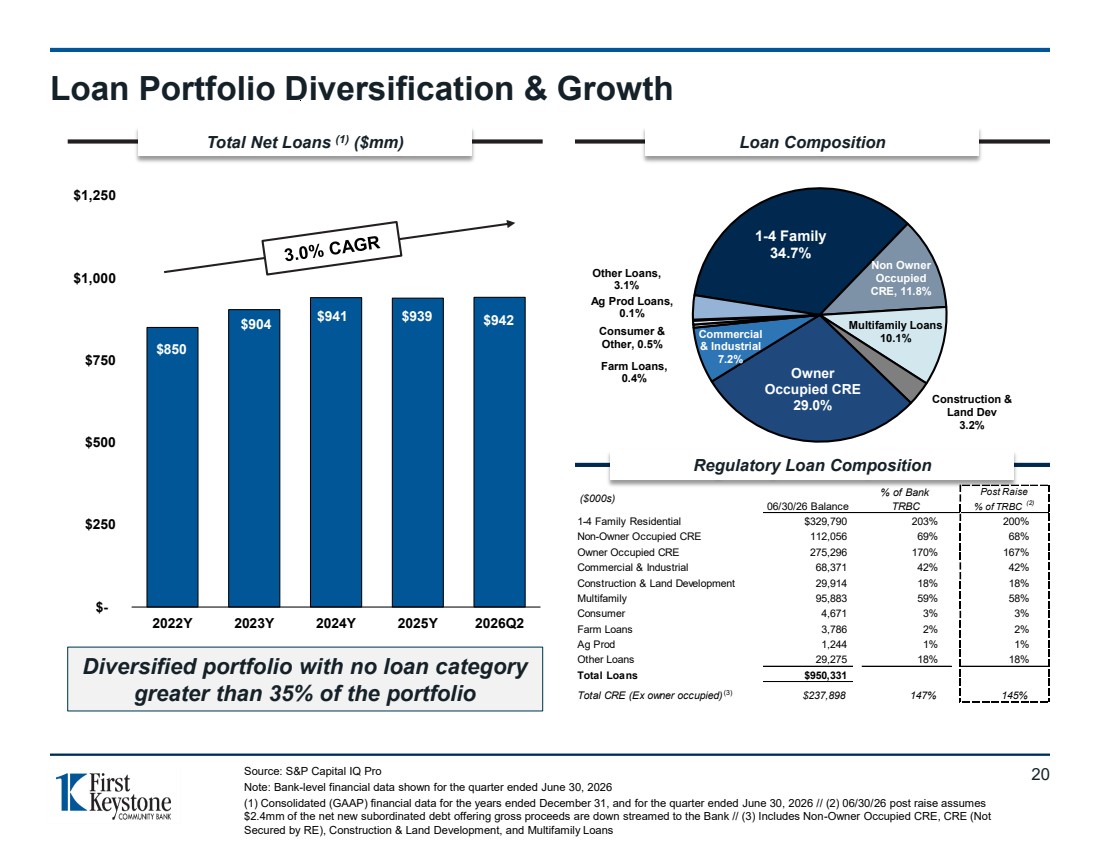
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Historical Bank Loan Composition & Yields Source: S&P Capital IQ Pro Note: Bank-level financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 First Keystone Community Bank Loan Composition Since 2022 2022Y 2023Y 2024Y 2025Y 2026Q2 Loan Composition Balance % of Total Balance % of Total Balance % of Total Balance % of Total Balance % of Total Construction $34,604 4.0% $31,643 3.5% $32,180 3.4% $30,497 3.2% $29,914 3.1% 1-4 Family 293,701 34.2% 312,612 34.3% 321,689 33.9% 326,894 34.5% 329,790 34.7% Multifamily 99,172 11.6% 100,146 11.0% 103,196 10.9% 98,810 10.4% 95,883 10.1% Comm RE (Non Farm/Res) 333,374 38.8% 363,341 39.9% 390,575 41.2% 395,015 41.6% 387,352 40.8% C&I 56,369 6.6% 66,909 7.3% 67,105 7.1% 67,276 7.1% 68,371 7.2% Farm RE 4,029 0.5% 3,751 0.4% 4,161 0.4% 3,792 0.4% 3,786 0.4% Agricultural 860 0.1% 671 0.1% 939 0.1% 986 0.1% 1,244 0.1% Consumer 5,415 0.6% 5,824 0.6% 6,459 0.7% 5,012 0.5% 4,671 0.5% Other 30,945 3.6% 26,181 2.9% 22,147 2.3% 20,143 2.1% 29,320 3.1% Total Gross Loans $858,469 100.0% $911,078 100.0% $948,451 100.0% $948,425 100.0% $950,331 100.0% Yield on 1-4 Family Loans 4.91% 5.39% 5.88% 6.25% 6.36% Yield on All Other RE Loans 4.00% 4.46% 5.14% 5.67% 5.89% Yield on C&I Loans 4.42% 5.96% 6.68% 6.25% 6.17% Yield on Loans 4.39% 4.89% 5.56% 5.99% 6.13% ($000s) 21 First Keystone Community Bank’s loan yields continue to increase as growth accelerates, and lower-rate lending rolls off the balance sheet. |
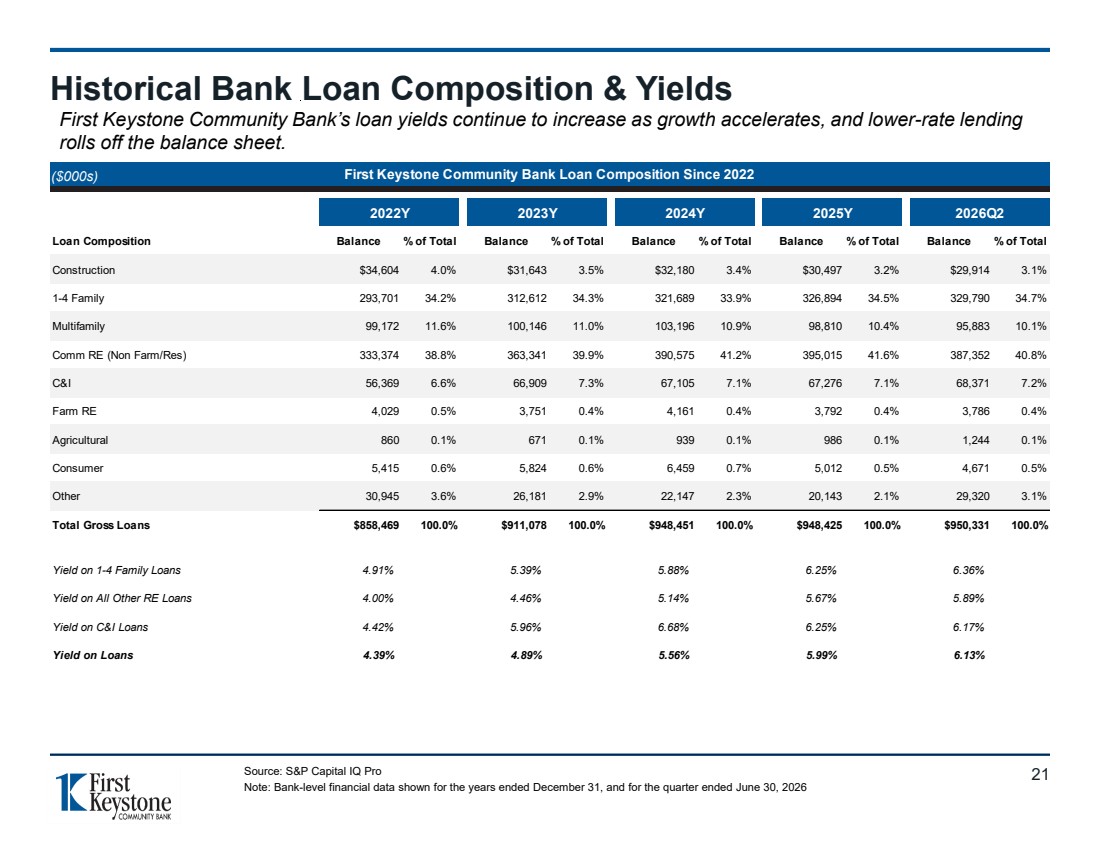
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Asset Quality & Reserve Coverage Ratios Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 22 0.02% 0.00% 0. 0% 0. % 0.02% 0.20% 0.00% 0.20% 0. 0% 0.60% 2022 202 202 202 2026Q2 NCOs / Avg. Loans (%) Loan Loss Reserves remain stable with net recoveries in the most recent quarter LLR / Total Loans (%) 0. % 0. % 0.29% . 0% .2 % 0.00% 0. 0% .00% . 0% 2.00% 2. 0% 2022 202 202 202 2026Q2 Recent NPA Commentary NPAs / Assets (%) 0.96% 0.76% 0. % 0.99% 0.92% 0.00% 0. 0% .00% . 0% 2.00% 2022 202 202 202 2026Q2 ▪ Two credits placed on non-accrual in Q4 2025 drive the increase ▪ Hotel operator — $9.4mm: paying as agreed; non-accrual reflects a collateral shortfall, not payment default ▪ Collateral appraised at $8.7mm net of costs to sell, covering ~93% of the balance; $707k specific allocation ▪ Real estate developer — $2.4mm: property acquired for luxury residential conversion; $2.0mm charged off in Q4 2025 against a $4.4mm principal balance ▪ No collateral deficiency remains post-charge-off; loan in foreclosure |
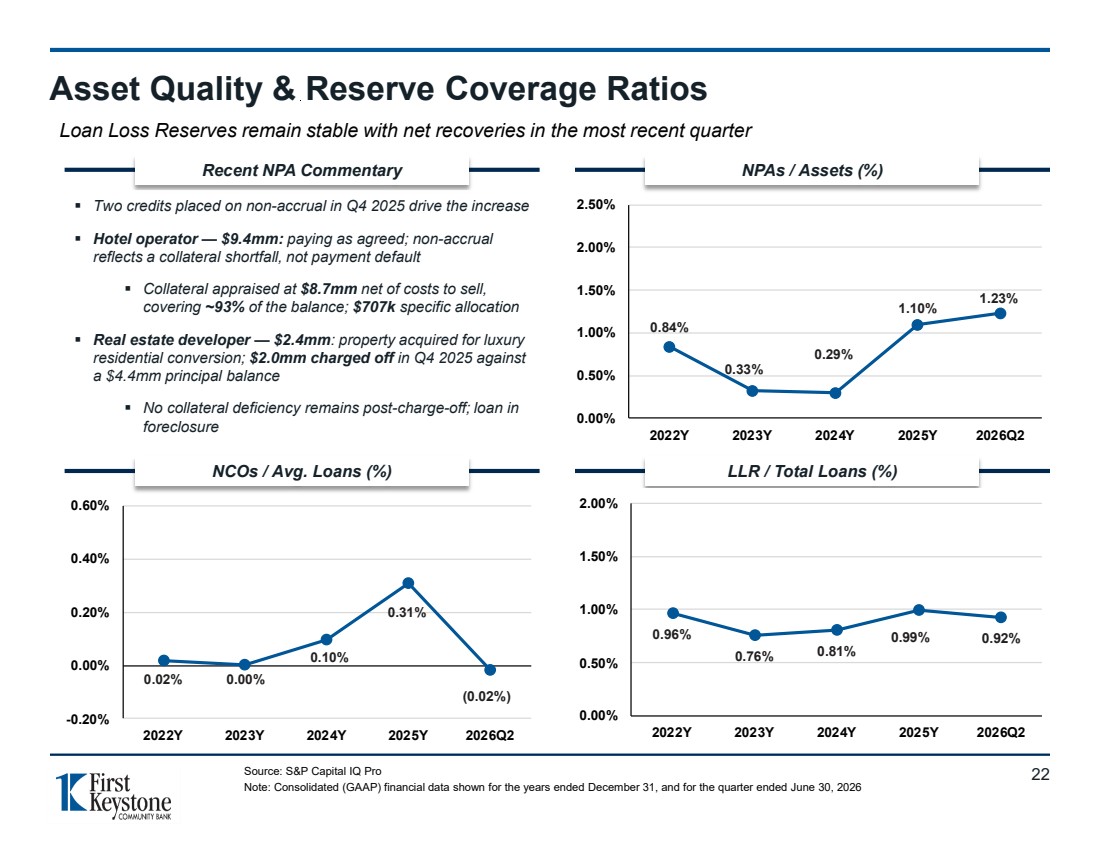
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Investment Portfolio Composition & Performance ▪ As of June 30, 2026, the Bank has ~$369 million available for sale debt securities – This represents ~23.5% of total assets ▪ The securities portfolio consists primarily of RMBS, State & Political Subdivision Securities, and ABS, representing a combined ~81.9% of the securities portfolio ▪ The remaining ~18.1% consists of a combination of CMBS, Government Agency & Sponsored Agency Securities, and Structured Financial Products ▪ AOCI Balance: ($17.2) million ▪ Historical investment portfolio total returns (2) ▪ 1 year: 5.86%, 85th percentile ▪ 3 year: 5.50%, 93rd percentile ▪ 5 year: 1.99%, 47th percentile Source: S&P Capital IQ Pro, Company documents Note: Bank-level financial data shown for the quarter ended June 30, 2026; Percentages may not sum to 100% due to rounding (1) Each category percentage is the fair value of the securities divided by the fair value of all securities // (2) Total return calculations based on Performance Trust total return calculations as of June 30, 2026; past performance is not indicative of future returns; percentiles are measured against banks nationwide; calculation based on call report data State and Political Subdiv Secs 19.7% RMBS 46.7% CMBS 5.9% Govt Agen & Spons Agen Secs 0.6% Structured Financial Products 1.4% ABS 15.5% Other Debt Securities 8.0% U.S. Treasury Securities 2.0% 23 Asset Class Breakdown (1) Commentary Bank-level investment portfolio supplemented with a $188.0 million Cash & Equivalents balance |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 V. Liabilities Highlights 24 |
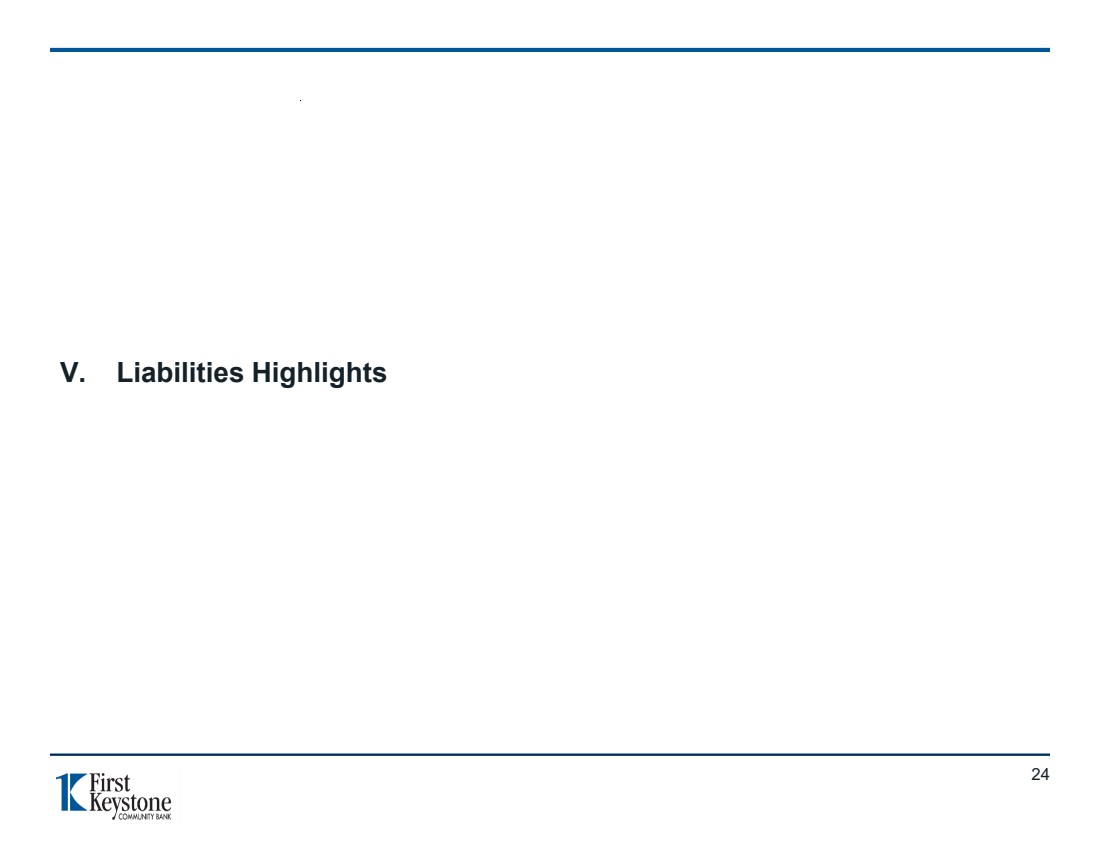
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Deposit Composition Source: S&P Capital IQ Pro, Company documents Note: Bank-level financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) Core deposits defined as total deposits minus total brokered deposits minus time deposits >$250k; Core deposits are a Non-GAAP financial measure; please see page 39 for a reconciliation $976 $894 $913 $970 $1,040 – $300 $600 $900 $1,200 2022Y 2023Y 2024Y 2025Y 2026Q2 $1.2B #VALUE! Total Deposits Total Deposits Deposits ($000) NIB $ 231,799 19.6% IB Demand, Savings, & MMDA 459,319 38.7% Retail Time (<100k) 270,342 22.8% Jumbo Time (>100k) 224,110 18.9% Total $ 1,185,570 100.0% MRQ Cost of Deposits: 2.23% #VALUE! NIB 19.6% IB Demand, Savings, & MMDA 38.7% Retail Time (<100k) 22.8% Jumbo Time (>100k) 18.9% 25 Bank Deposit Composition Core Deposit (1) Trends ($ in millions) Top 10 Deposit Relationships Deposit Balance Total Deposits Relationship ($000s) (%) Relationship 1 $35,343 3.0% Relationship 2 21,097 1.8% Relationship 3 18,015 1.5% Relationship 4 12,621 1.1% Relationship 5 11,911 1.0% Relationship 6 11,611 1.0% Relationship 7 11,010 0.9% Relationship 8 10,972 0.9% Relationship 9 10,755 0.9% Relationship 10 8,785 0.7% Total $152,120 12.8% |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 VI. Income Statement Highlights 26 |
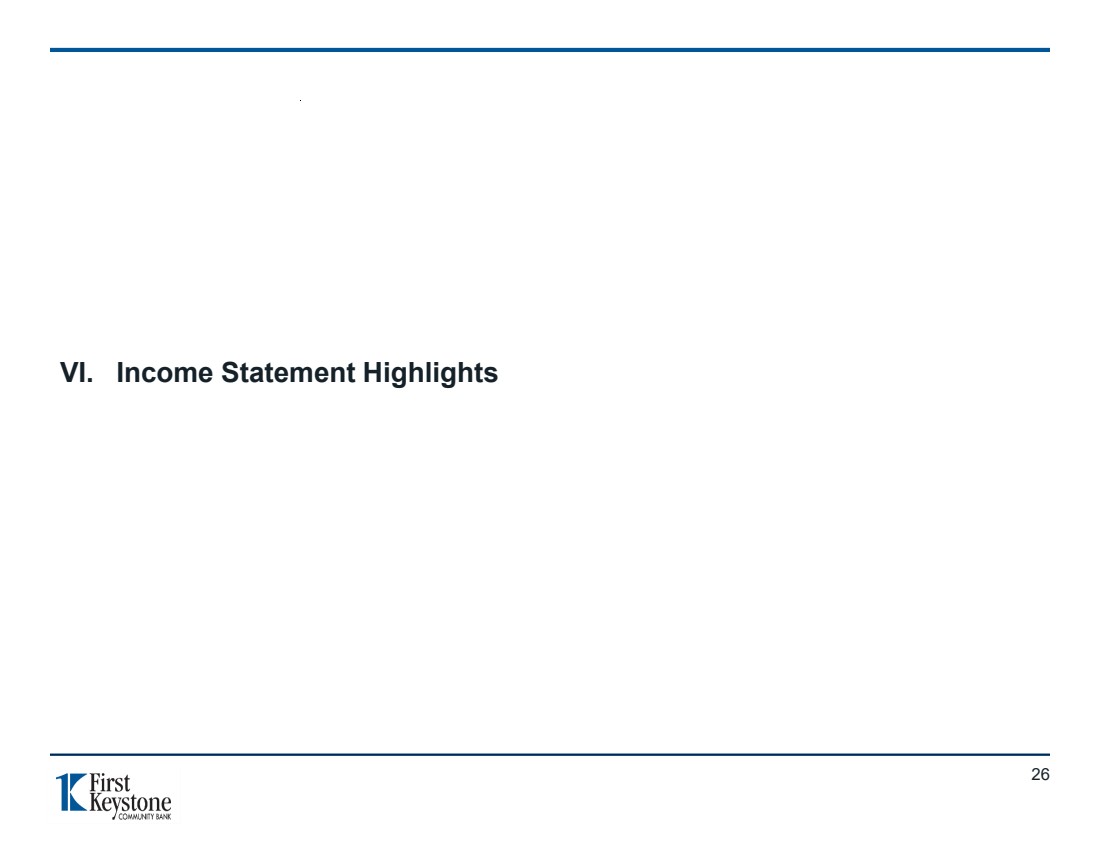
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 $43,677 $35,390 $38,871 $44,495 $48,348 $26,777 $29,294 $31,515 $33,613 $33,968 $6,177 $6,274 $6,592 $6,844 $7,084 $- $5,000 $10,000 $15,000 $20,000 $25,000 $30,000 $35,000 $40,000 $45,000 $50,000 2022Y 2023Y 2024Y 2025Y 2026Q2 Net Interest Income Noninterest Expense Noninterest Income Core Net Revenue(1) Detail Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) Core Net Revenue is a non-GAAP financial measure; please see page 36 for a reconciliation // (2) 2024Y Noninterest Expense excludes impact of $19.1mm goodwill impairment charge // (3) 2026Q2 annualized for the three months ended June 30, 2026 27 First Keystone Corporation has maintained a strong P&L amidst recent headwinds for the banking industry. ($000s) (3) (2) $37,500 $29,116 $32,279 $37,651 $41,264 |
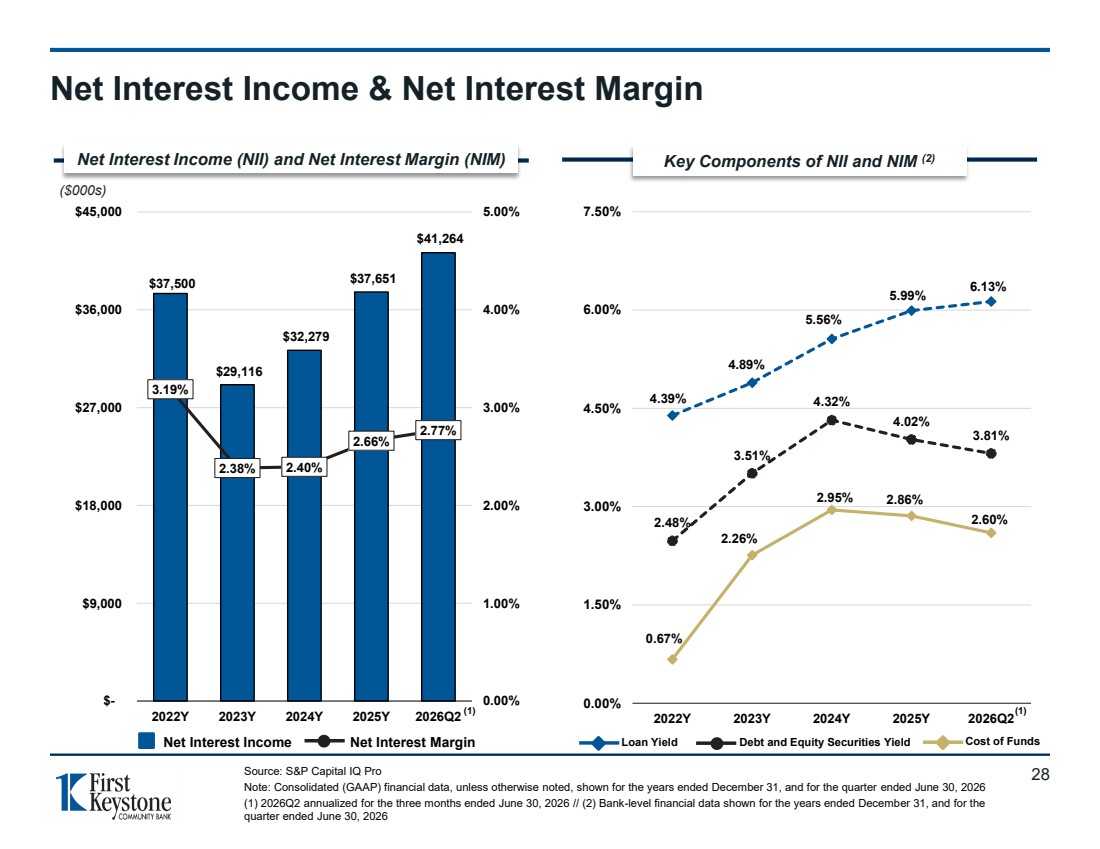
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Net Interest Income & Net Interest Margin Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data, unless otherwise noted, shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) 2026Q2 annualized for the three months ended June 30, 2026 // (2) Bank-level financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 28 $37,500 $29,116 $32,279 $37,651 $41,264 3.19% 2.38% 2.40% 2.66% 2.77% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% $- $9,000 $18,000 $27,000 $36,000 $45,000 2022Y 2023Y 2024Y 2025Y 2026Q2 Net Interest Income (NII) and Net Interest Margin (NIM) Key Components of NII and NIM (2) ($000s) Net Interest Income Net Interest Margin Loan Yield Debt and Equity Securities Yield Cost of Funds 4.39% 4.89% 5.56% 5.99% 6.13% 2.48% 3.51% 4.32% 4.02% 3.81% 0.67% 2.26% 2.95% 2.86% 2.60% 0.00% 1.50% 3.00% 4.50% 6.00% 7.50% 2022Y 2023Y 2024Y 2025Y 2026Q2 (1) (1) |
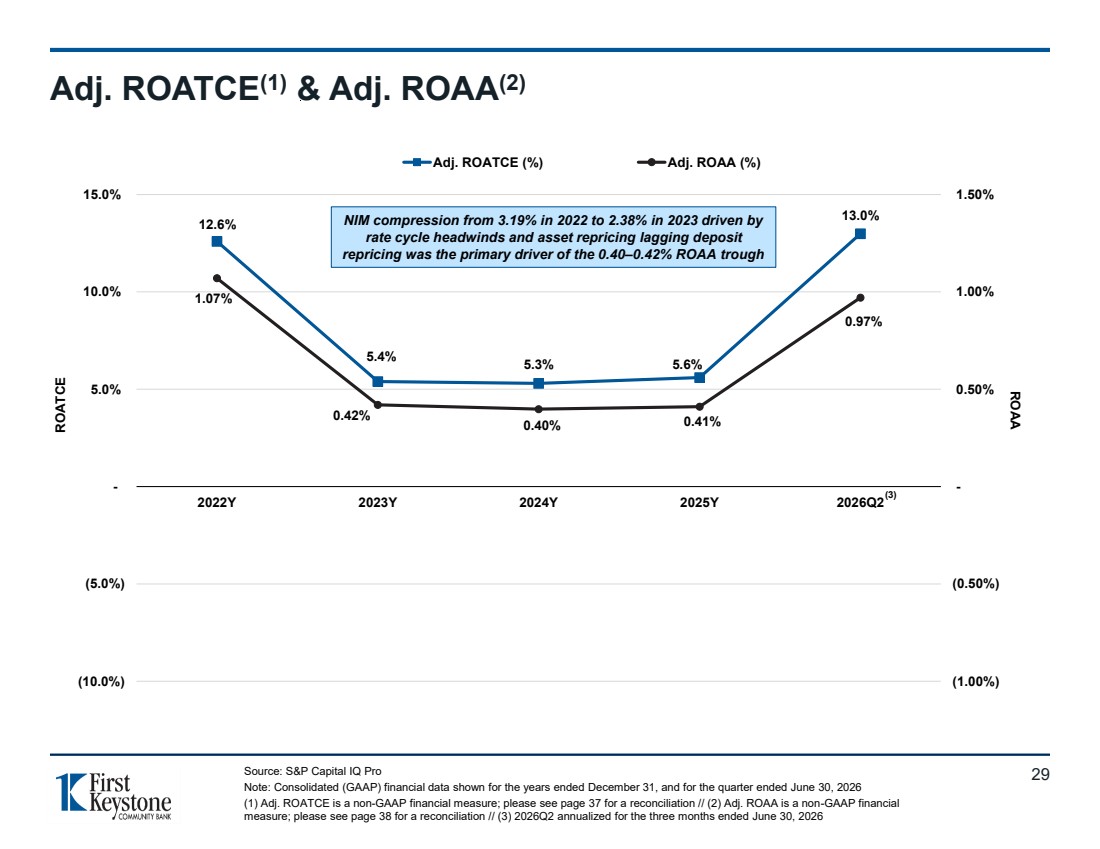
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Adj. ROATCE(1) & Adj. ROAA(2) Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) Adj. ROATCE is a non-GAAP financial measure; please see page 37 for a reconciliation // (2) Adj. ROAA is a non-GAAP financial measure; please see page 38 for a reconciliation // (3) 2026Q2 annualized for the three months ended June 30, 2026 29 12.6% 5.4% 5.3% 5.6% 13.0% 1.07% 0.42% 0.40% 0.41% 0.97% (1.00%) (0.50%) - 0.50% 1.00% 1.50% (10.0%) (5.0%) - 5.0% 10.0% 15.0% 2022Y 2023Y 2024Y 2025Y 2026Q2 ROAA ROATCE Adj. ROATCE (%) Adj. ROAA (%) (3) NIM compression from 3.19% in 2022 to 2.38% in 2023 driven by rate cycle headwinds and asset repricing lagging deposit repricing was the primary driver of the 0.40–0.42% ROAA trough |
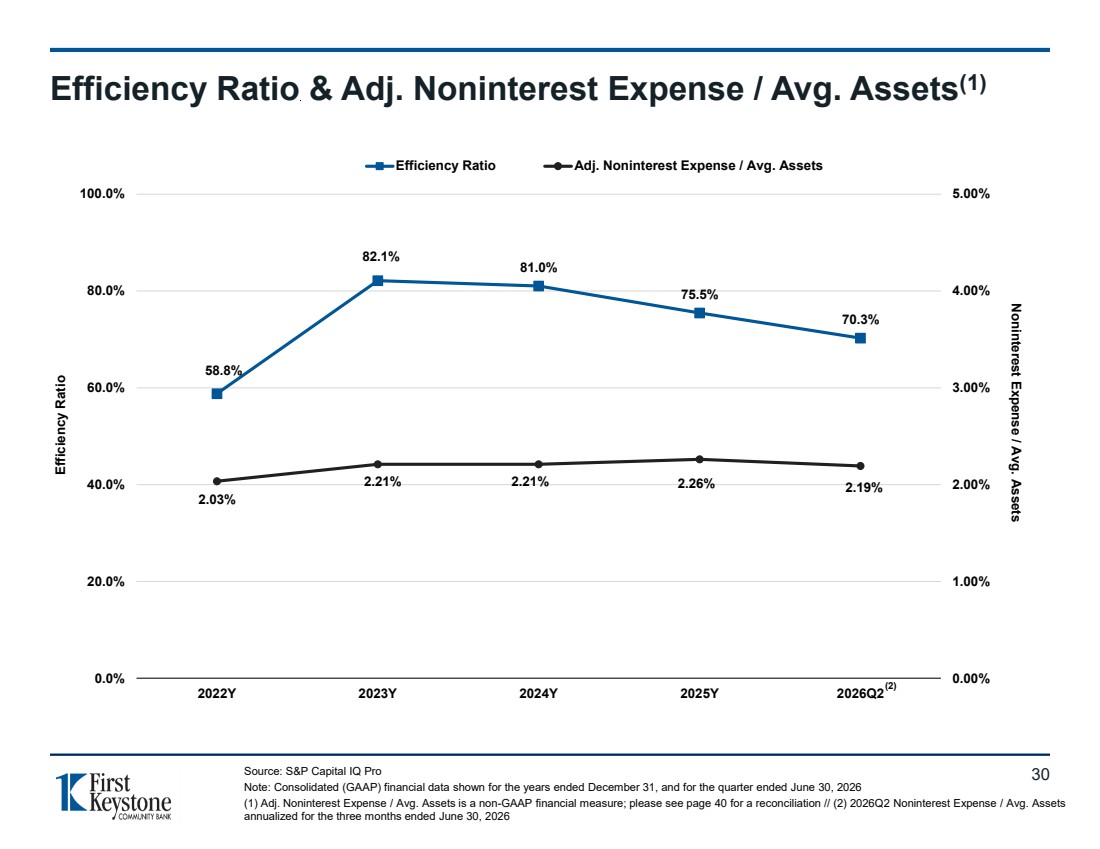
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Efficiency Ratio & Adj. Noninterest Expense / Avg. Assets(1) Source: S&P Capital IQ Pro Note: Consolidated (GAAP) financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 (1) Adj. Noninterest Expense / Avg. Assets is a non-GAAP financial measure; please see page 40 for a reconciliation // (2) 2026Q2 Noninterest Expense / Avg. Assets annualized for the three months ended June 30, 2026 30 58.8% 82.1% 81.0% 75.5% 70.3% 2.03% 2.21% 2.21% 2.26% 2.19% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 0.0% 20.0% 40.0% 60.0% 80.0% 100.0% 2022Y 2023Y 2024Y 2025Y 2026Q2 Noninterest Expense / Avg. Assets Efficiency Ratio Efficiency Ratio Adj. Noninterest Expense / Avg. Assets (2) |
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 VII. Appendix 31 |
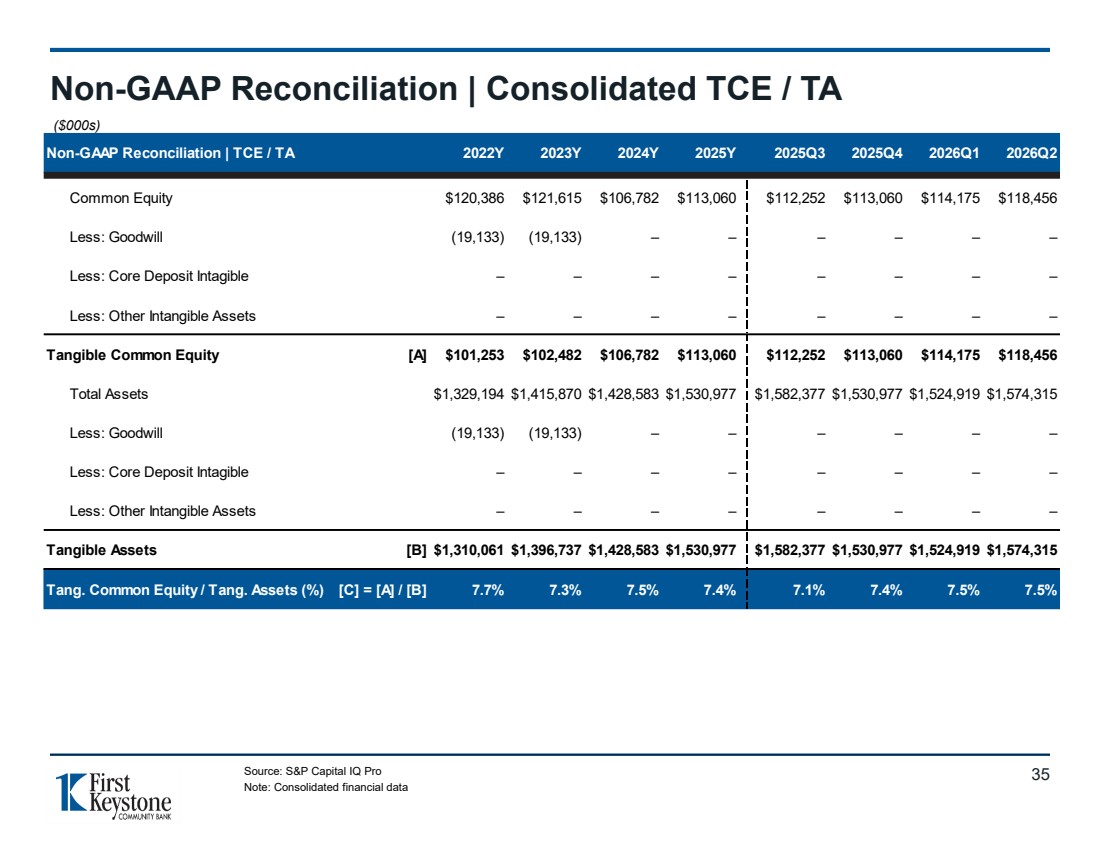
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Financial Highlights Source: S&P Capital IQ Pro Note: Consolidated financial data shown; operating revenue defined as net interest income plus noninterest income (1) Non-GAAP financial measure; please see appendix pages for a reconciliation // (2) Bank-level financial data 12/31/2022 As of and for the Years Ended: As of and for the Quarters Ended: 6/30/2026 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2025 12/31/2025 3/31/2026 6/30/2026 CAGR Balance Sheet Total Assets ($000s) 1,329,194 1,415,870 1,428,583 1,530,977 1,582,377 1,530,977 1,524,919 1,574,315 5.0% Net Loans ($000s) 850,195 904,153 940,779 939,013 949,733 939,013 923,577 941,552 3.0% Total Deposits ($000s) 993,499 980,439 1,045,880 1,137,437 1,192,494 1,137,437 1,131,289 1,179,910 5.0% Total Equity ($000s) 120,386 121,615 106,782 113,060 112,252 113,060 114,175 118,456 (0.5%) Loans / Deposits (%) 86.4 92.9 90.6 83.3 80.3 83.3 82.4 80.4 (Cash + Securities) / Assets (%) 29.6 29.8 29.3 34.4 35.7 34.4 35.1 36.1 TCE / TA (%) 7.7 7.3 7.5 7.4 7.1 7.4 7.5 7.5 Tier 1 Leverage Ratio (%) 10.4 10.4 10.2 9.6 9.8 9.6 9.7 9.7 Profitability Adj. Net Income ($000s) 14,024 5,560 5,672 6,152 2,808 (623) 1,959 3,777 Adj. ROAA (%) 1.07 0.42 0.40 0.41 0.74 (0.16) 0.51 0.97 Adj. ROATCE (%) 12.6 5.4 5.3 5.6 10.2 (2.2) 6.9 13.0 Net Interest Margin (%) 3.19 2.38 2.40 2.66 2.64 2.63 2.49 2.77 Efficiency Ratio (%) 58.8 82.1 81.0 75.5 70.8 77.4 84.7 70.3 Noninterest Inc / Revenue (%) 14.1 17.7 17.0 15.4 15.9 15.2 15.2 14.7 Adj. Noninterest Exp / AA (%) 2.03 2.21 2.21 2.26 2.12 2.32 2.39 2.19 Asset Quality (%) NPLs/ Loans (%) 1.31 0.51 0.44 1.77 0.43 1.77 1.81 2.04 NPAs/ Assets (%) 0.84 0.33 0.29 1.10 0.26 1.10 1.11 1.23 Reserves/ NPAs (%) 73.8 150.0 182.1 56.1 192.1 56.1 53.5 45.3 NCOs/ Avg Loans (%) 0.02 0.00 0.10 0.31 0.01 1.06 (0.01) (0.02) 32 Strong balance sheet growth paired with efficient earnings and high-quality assets. (1) (2) (1) (1) (1) |
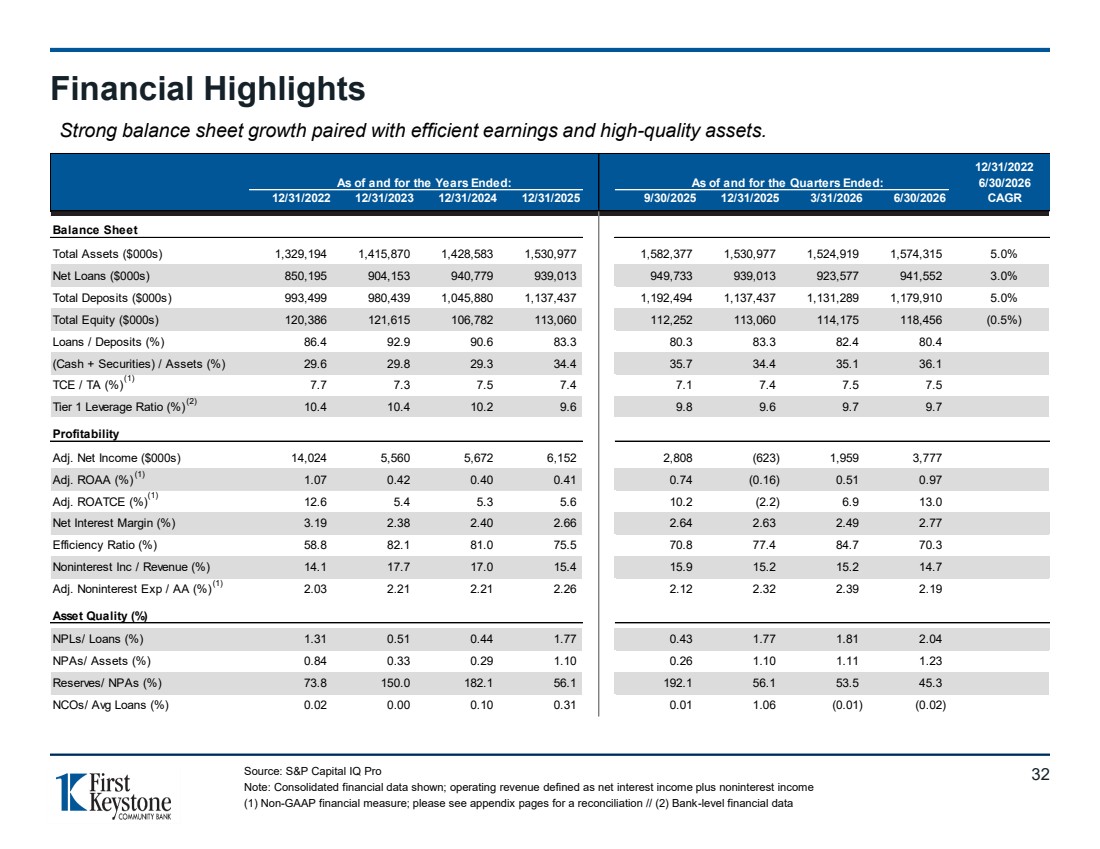
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Historical Consolidated Balance Sheet Source: Audited financial statements provided by the Company Note: Consolidated financial data shown; Unaudited financial data shown for the quarter ended June 30, 2026 33 For the Year Ended December 31, For Qtr Ended June 30, ($000s) 2022 2023 2024 2025 2026 ASSETS Cash and due from banks $9,441 $9,462 $9,933 $8,755 $9,004 Interest-bearing deposits in other banks 1,297 7,551 7,321 112,494 178,957 Total cash and cash equivalents 10,738 17,013 17,254 121,249 187,961 Debt securities available-for-sale, at fair value 373,444 392,968 390,288 394,226 369,084 Marketable equity securities, at fair value 1,699 1,482 1,587 1,810 2,358 Restricted investment in bank stocks, at cost 7,136 10,885 8,984 8,944 8,979 Loans held for investment 858,398 910,864 947,714 947,285 948,848 Loans held for sale 71 214 737 1,140 1,483 Allowance for credit losses (8,274) (6,925) (7,672) (9,412) (8,779) Net loans 850,195 904,153 940,779 939,013 941,552 Premises and equipment, net 19,024 19,611 20,272 19,377 19,028 Operating lease right-of-use assets 1,541 1,472 1,400 1,326 1,304 Accrued interest receivable 4,391 5,201 4,993 4,997 4,664 Cash surrender value of bank owned life insurance 25,389 26,010 26,679 26,362 26,706 Investments in low-income housing partnerships 3,763 5,961 5,152 4,333 3,924 Goodwill 19,133 19,133 – – – Deferred income taxes 9,129 8,695 7,725 6,463 5,750 Other assets 3,612 3,286 3,470 2,877 3,005 Total Assets $1,329,194 $1,415,870 $1,428,583 $1,530,977 $1,574,315 LIABILITIES AND SHAREHOLDERS' EQUITY Non-interest bearing $231,754 $198,569 $203,583 $206,823 $230,888 Interest bearing 761,745 781,870 842,297 930,614 949,022 Total deposits 993,499 980,439 1,045,880 1,137,437 1,179,910 Short-term borrowings 153,418 153,468 134,426 136,845 135,604 Long-term borrowings 25,000 122,000 106,000 106,000 106,000 Subordinated debentures 25,000 25,000 25,000 25,000 25,000 Operating lease liabilities 2,029 1,976 1,920 1,862 1,847 Accrued interest payable 563 2,823 2,152 2,735 2,517 Other liabilities 9,299 8,549 6,423 8,038 4,981 Total Liabilities $1,208,808 $1,294,255 $1,321,801 $1,417,917 $1,455,859 Preferred stock – – – – – Common stock 12,502 12,705 12,901 13,007 13,108 Surplus 42,439 44,004 45,072 45,888 46,717 Retained earnings 100,712 100,260 80,148 79,327 81,544 Accumulated other comprehensive loss (29,558) (29,645) (25,630) (19,453) (17,204) Treasury stock (5,709) (5,709) (5,709) (5,709) (5,709) Total Shareholders' Equity $120,386 $121,615 $106,782 $113,060 $118,456 Total Liabilities & Shareholders' Equity $1,329,194 $1,415,870 $1,428,583 $1,530,977 $1,574,315 |
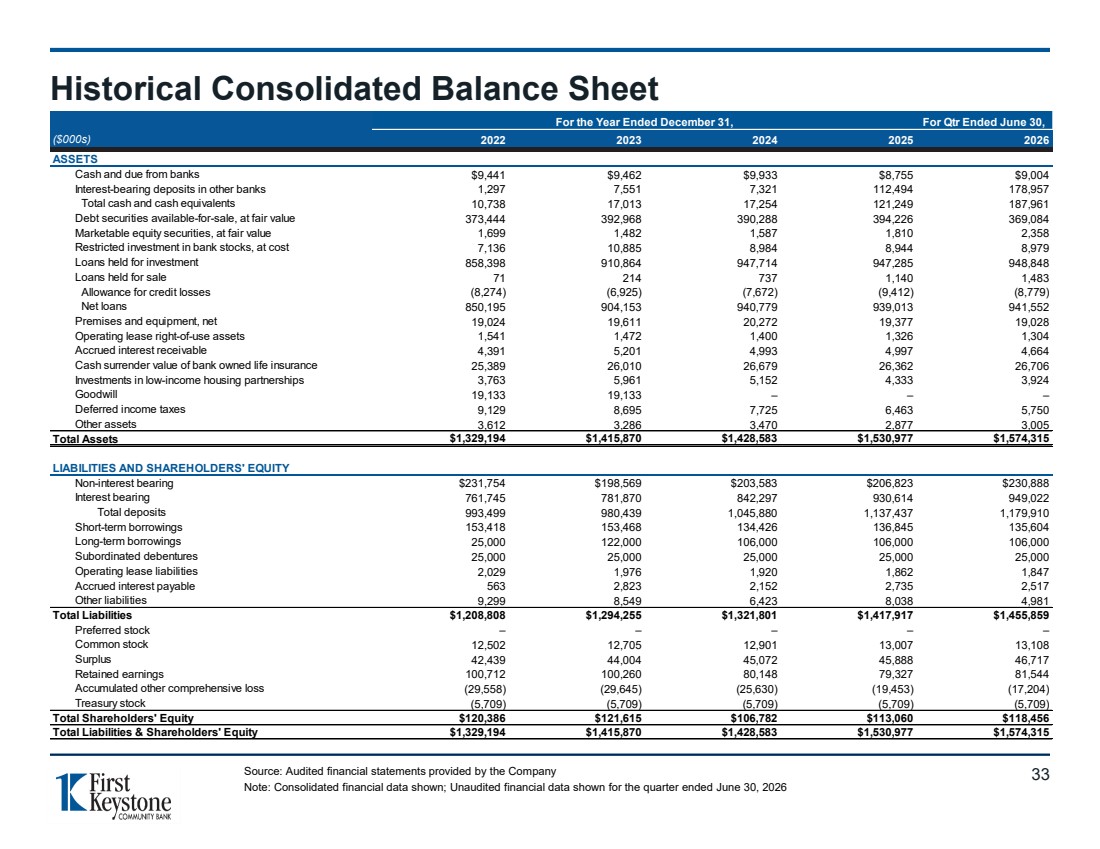
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Historical Consolidated Income Statement 34 For the Year Ended December 31, For the Six Months Ended June 30, ($000s) 2022 2023 2024 2025 2026 INTEREST INCOME & EXPENSE Interest and fees on loans $35,372 $42,747 $51,187 $57,289 $28,484 Interest and dividend income on securities Taxable 7,394 12,311 17,743 15,832 7,224 Tax-exempt 3,312 1,166 1,074 935 416 Dividends 55 56 57 67 39 Dividend income on restricted investment in bank stocks 264 669 928 816 407 Interest on interest-bearing deposits in other banks 16 39 433 2,260 2,648 Total Interest Income $46,413 $56,988 $71,422 $77,199 $39,218 Interest on deposits 5,259 17,108 25,276 27,501 13,379 Interest on short-term borrowings 1,935 8,774 7,720 5,989 2,937 Interest on long-term borrowings 628 896 5,053 4,964 2,461 Interest on subordinated debt 1,091 1,094 1,094 1,094 994 Total Interest Expense $8,913 $27,872 $39,143 $39,548 $19,771 Net Interest Income $37,500 $29,116 $32,279 $37,651 $19,447 Provision for credit losses (264) (217) 1,640 4,701 (689) Net Interest Income after Provision for Credit Losses $37,764 $29,333 $30,639 $32,950 $20,136 NONINTEREST ITEMS Trust department 975 931 1,051 1,068 581 Service charges and fees 2,193 2,205 2,247 2,366 1,099 Increase in cash surrender value of life insurance 597 621 669 666 344 ATM fees and debit card income 2,146 2,195 2,228 2,261 1,143 Net gains on sales of mortgage loans (7) 65 80 143 59 Net securities gains (846) (118) 105 224 548 Gains from life insurance proceeds – – – 255 – Other 273 257 317 340 184 Total Noninterest Income $5,331 $6,156 $6,697 $7,323 $3,958 Salaries and employee benefits 14,554 16,055 17,228 17,879 9,195 Occupancy, net 1,936 2,119 2,191 2,315 1,211 Furniture and equipment expense 594 637 676 836 425 Computer expense 1,493 1,571 1,478 1,704 1,061 Professional services 1,270 1,440 1,617 1,611 904 Pennsylvania shares tax 1,238 861 1,070 1,119 543 FDIC insurance, net 490 703 1,097 1,251 643 ATM and debit card fees 899 1,146 1,003 1,208 609 Data processing fees 915 1,304 1,022 1,475 813 Advertising 389 528 560 449 182 Goodwill impairment – – 19,133 – – Other 2,999 2,881 3,509 4,061 2,025 Total Noninterest Expense $26,777 $29,245 $50,584 $33,908 $17,611 Income before income tax $16,318 $6,244 ($13,248) $6,365 $6,483 Income tax expense 2,294 684 (45) 213 747 Net Income (Loss) $14,024 $5,560 ($13,203) $6,152 $5,736 Source: Audited financial statements provided by the Company Note: Consolidated financial data shown; Unaudited financial data shown for the six months ended June 30, 2026; Goodwill Impairment in 2024Y was the result of goodwill impairment testing performed due to the decrease of the Company’s stock price during 2024Q1 |
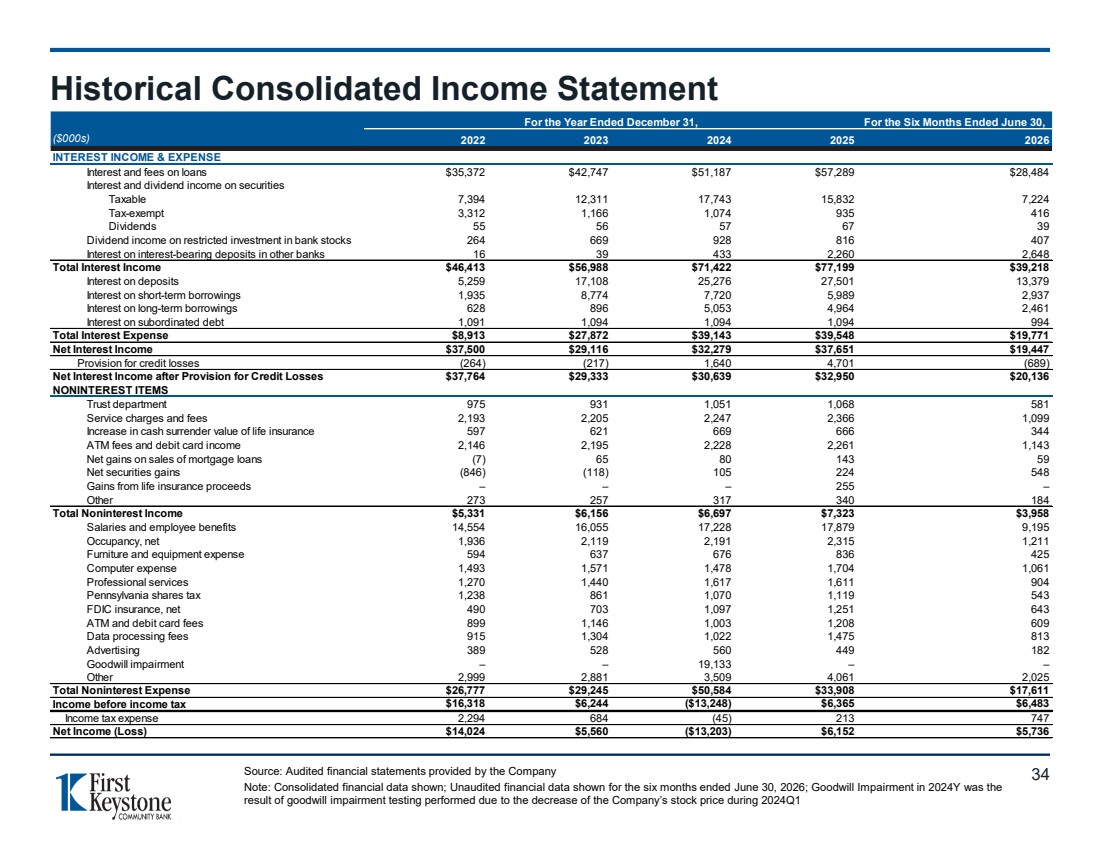
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Consolidated TCE / TA Source: S&P Capital IQ Pro Note: Consolidated financial data 35 ($000s) Non-GAAP Reconciliation | TCE / TA 2022Y 2023Y 2024Y 2025Y 2025Q3 2025Q4 2026Q1 2026Q2 Common Equity $120,386 $121,615 $106,782 $113,060 $112,252 $113,060 $114,175 $118,456 Less: Goodwill (19,133) (19,133) – – – – – – Less: Core Deposit Intagible – – – – – – – – Less: Other Intangible Assets – – – – – – – – Tangible Common Equity [A] $101,253 $102,482 $106,782 $113,060 $112,252 $113,060 $114,175 $118,456 Total Assets $1,329,194 $1,415,870 $1,428,583 $1,530,977 $1,582,377 $1,530,977 $1,524,919 $1,574,315 Less: Goodwill (19,133) (19,133) – – – – – – Less: Core Deposit Intagible – – – – – – – – Less: Other Intangible Assets – – – – – – – – Tangible Assets [B] $1,310,061 $1,396,737 $1,428,583 $1,530,977 $1,582,377 $1,530,977 $1,524,919 $1,574,315 Tang. Common Equity / Tang. Assets (%) [C] = [A] / [B] 7.7% 7.3% 7.5% 7.4% 7.1% 7.4% 7.5% 7.5% |
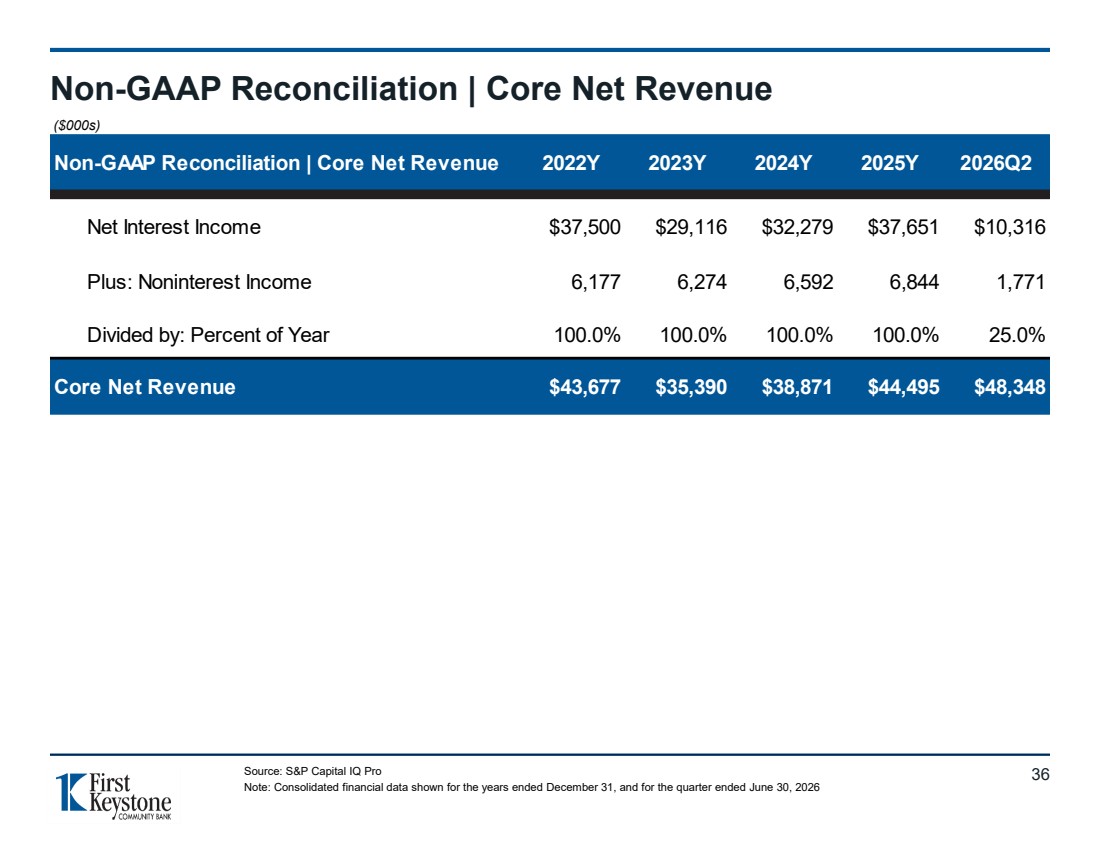
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Core Net Revenue Source: S&P Capital IQ Pro Note: Consolidated financial data shown for the years ended December 31, and for the quarter ended June 30, 2026 36 Non-GAAP Reconciliation | Core Net Revenue 2022Y 2023Y 2024Y 2025Y 2026Q2 Net Interest Income $37,500 $29,116 $32,279 $37,651 $10,316 Plus: Noninterest Income 6,177 6,274 6,592 6,844 1,771 Divided by: Percent of Year 100.0% 100.0% 100.0% 100.0% 25.0% Core Net Revenue $43,677 $35,390 $38,871 $44,495 $48,348 ($000s) |
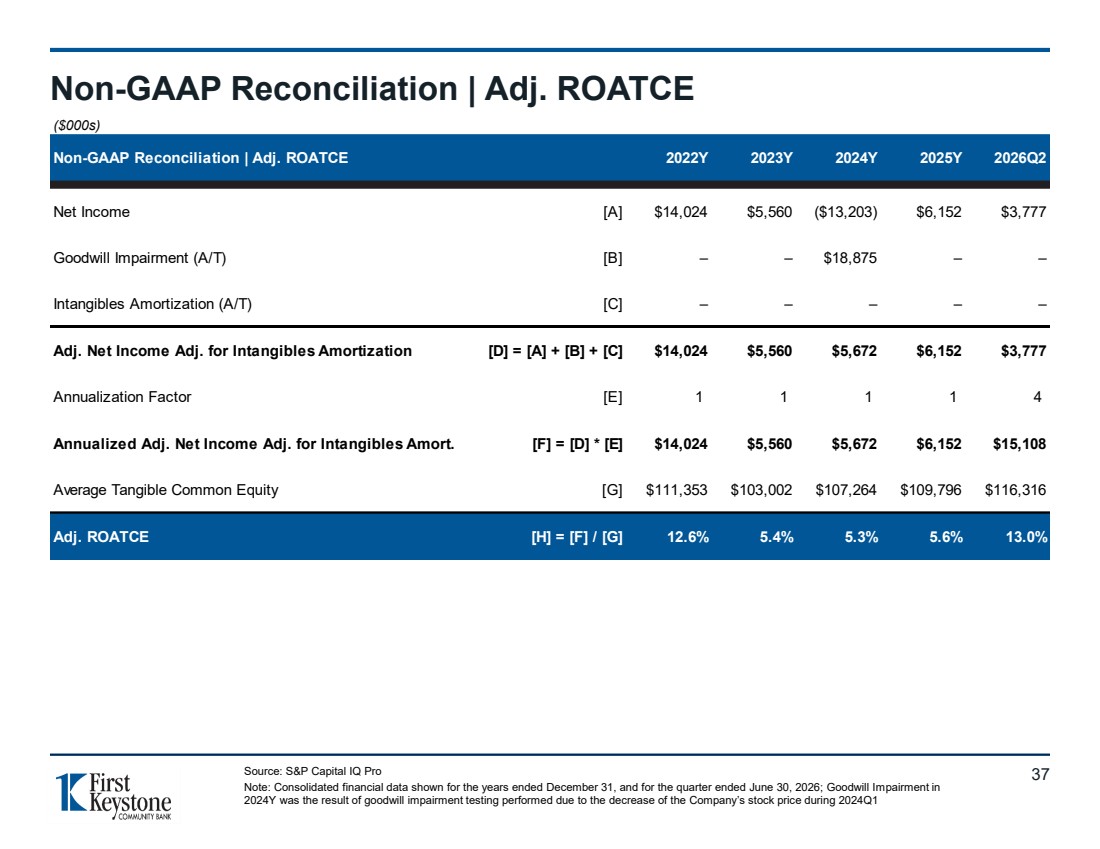
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Adj. ROATCE 2022Y 2023Y 2024Y 2025Y 2026Q2 Net Income [A] $14,024 $5,560 ($13,203) $6,152 $3,777 Goodwill Impairment (A/T) [B] – – $18,875 – – Intangibles Amortization (A/T) [C] – – – – – Adj. Net Income Adj. for Intangibles Amortization [D] = [A] + [B] + [C] $14,024 $5,560 $5,672 $6,152 $3,777 Annualization Factor [E] 1 1 1 1 4 Annualized Adj. Net Income Adj. for Intangibles Amort. [F] = [D] * [E] $14,024 $5,560 $5,672 $6,152 $15,108 Average Tangible Common Equity [G] $111,353 $103,002 $107,264 $109,796 $116,316 Adj. ROATCE [H] = [F] / [G] 12.6% 5.4% 5.3% 5.6% 13.0% Non-GAAP Reconciliation | Adj. ROATCE 37 ($000s) Source: S&P Capital IQ Pro Note: Consolidated financial data shown for the years ended December 31, and for the quarter ended June 30, 2026; Goodwill Impairment in 2024Y was the result of goodwill impairment testing performed due to the decrease of the Company’s stock price during 2024Q1 |
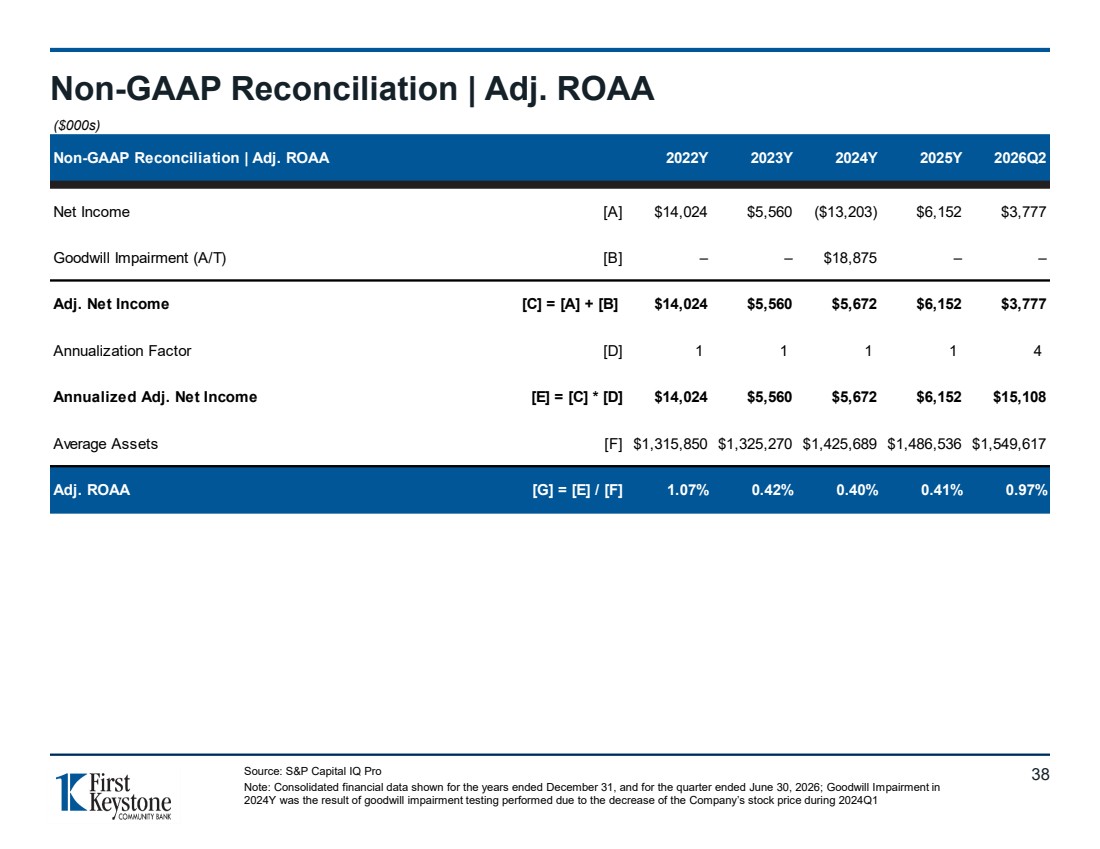
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Adj. ROAA 2022Y 2023Y 2024Y 2025Y 2026Q2 Net Income [A] $14,024 $5,560 ($13,203) $6,152 $3,777 Goodwill Impairment (A/T) [B] – – $18,875 – – Adj. Net Income [C] = [A] + [B] $14,024 $5,560 $5,672 $6,152 $3,777 Annualization Factor [D] 1 1 1 1 4 Annualized Adj. Net Income [E] = [C] * [D] $14,024 $5,560 $5,672 $6,152 $15,108 Average Assets [F] $1,315,850 $1,325,270 $1,425,689 $1,486,536 $1,549,617 Adj. ROAA [G] = [E] / [F] 1.07% 0.42% 0.40% 0.41% 0.97% Non-GAAP Reconciliation | Adj. ROAA 38 ($000s) Source: S&P Capital IQ Pro Note: Consolidated financial data shown for the years ended December 31, and for the quarter ended June 30, 2026; Goodwill Impairment in 2024Y was the result of goodwill impairment testing performed due to the decrease of the Company’s stock price during 2024Q1 |
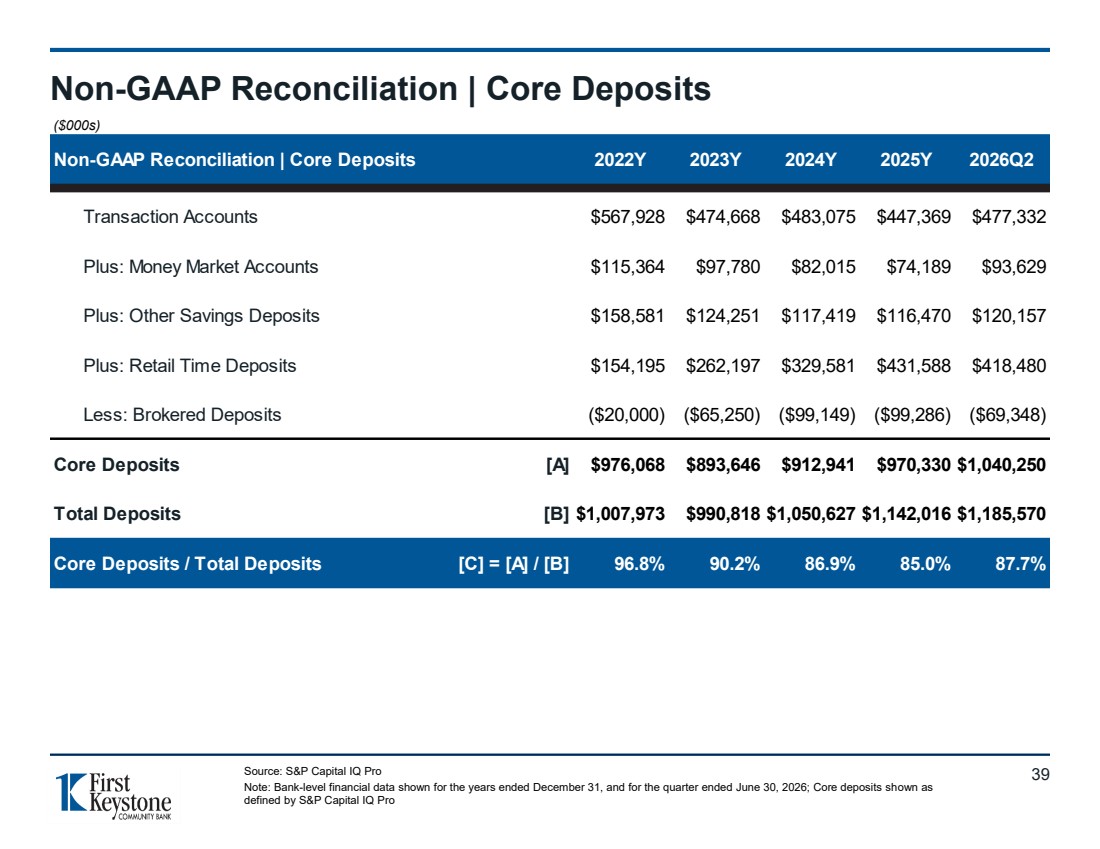
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Core Deposits Source: S&P Capital IQ Pro Note: Bank-level financial data shown for the years ended December 31, and for the quarter ended June 30, 2026; Core deposits shown as defined by S&P Capital IQ Pro 39 Non-GAAP Reconciliation | Core Deposits 2022Y 2023Y 2024Y 2025Y 2026Q2 Transaction Accounts $567,928 $474,668 $483,075 $447,369 $477,332 Plus: Money Market Accounts $115,364 $97,780 $82,015 $74,189 $93,629 Plus: Other Savings Deposits $158,581 $124,251 $117,419 $116,470 $120,157 Plus: Retail Time Deposits $154,195 $262,197 $329,581 $431,588 $418,480 Less: Brokered Deposits ($20,000) ($65,250) ($99,149) ($99,286) ($69,348) Core Deposits [A] $976,068 $893,646 $912,941 $970,330 $1,040,250 Total Deposits [B] $1,007,973 $990,818 $1,050,627 $1,142,016 $1,185,570 Core Deposits / Total Deposits [C] = [A] / [B] 96.8% 90.2% 86.9% 85.0% 87.7% ($000s) |
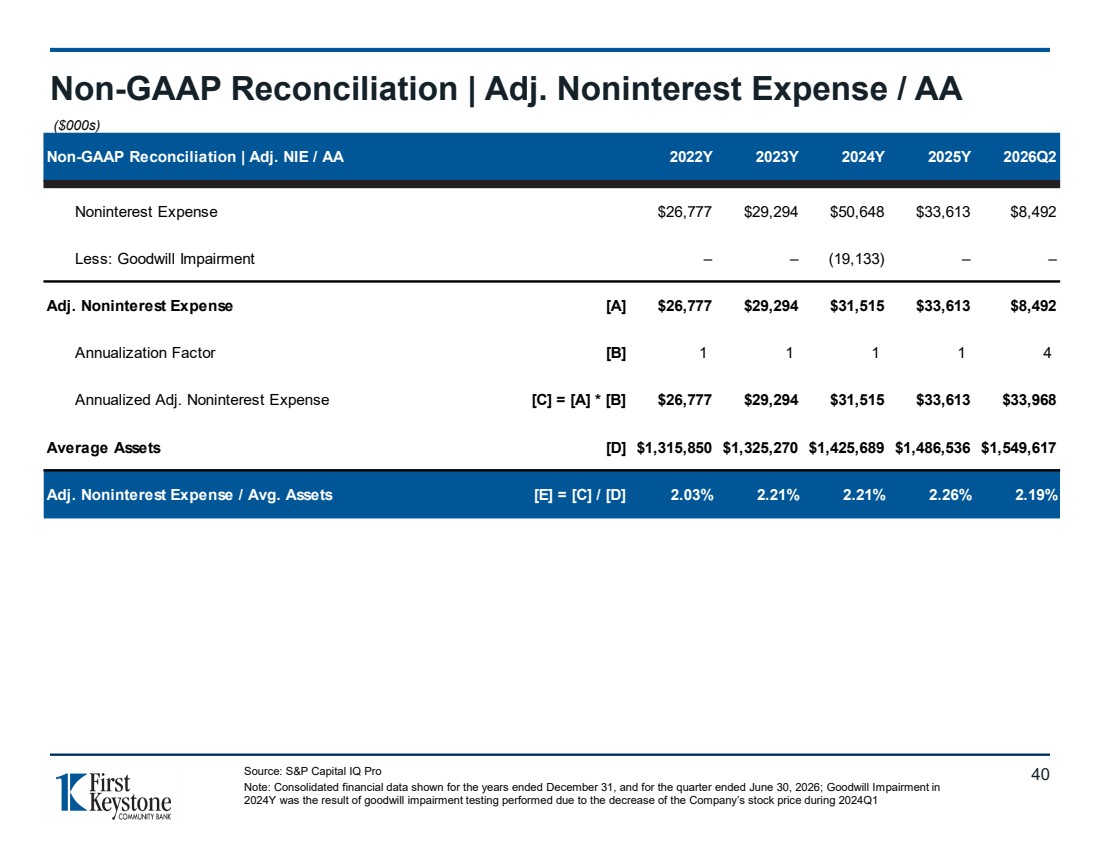
| 35-31-32 1-86-151 Secondary Primary Font Color 0-0-0 195-178-103 Non-GAAP Reconciliation | Adj. Noninterest Expense / AA Source: S&P Capital IQ Pro Note: Consolidated financial data shown for the years ended December 31, and for the quarter ended June 30, 2026; Goodwill Impairment in 2024Y was the result of goodwill impairment testing performed due to the decrease of the Company’s stock price during 2024Q1 40 ($000s) Non-GAAP Reconciliation | Adj. NIE / AA 2022Y 2023Y 2024Y 2025Y 2026Q2 Noninterest Expense $26,777 $29,294 $50,648 $33,613 $8,492 Less: Goodwill Impairment – – (19,133) – – Adj. Noninterest Expense [A] $26,777 $29,294 $31,515 $33,613 $8,492 Annualization Factor [B] 1 1 1 1 4 Annualized Adj. Noninterest Expense [C] = [A] * [B] $26,777 $29,294 $31,515 $33,613 $33,968 Average Assets [D] $1,315,850 $1,325,270 $1,425,689 $1,486,536 $1,549,617 Adj. Noninterest Expense / Avg. Assets [E] = [C] / [D] 2.03% 2.21% 2.21% 2.26% 2.19% |