Exhibit 99.6
Rebuttal Findings_Redacted
Seller:
Deal ID:
Total Loan Count: 22
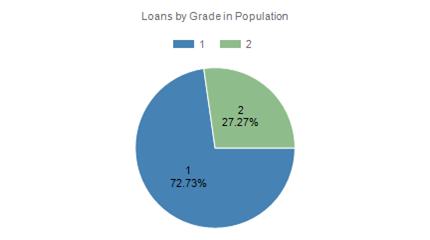
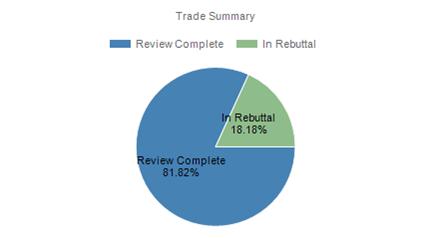
| Loans by Grade in Population | Trade Summary | ||||||
| Loan Grade | Count | Percentage | Loan Status | Count | Percentage | ||
| 1 | 16 | 72.73% | Review Complete | 18 | 81.82% | ||
| 2 | 6 | 27.27% | In Rebuttal | 4 | 18.18% | ||
| |
| |
| Finding Status | Final Finding Grade | ||||||||||
| Initial Findings Grade | Count | Rebuttal Received | Responses Given | Open | Resolved | UpHeld | Void | 3 | 4 | 2 | 1 |
| 3 | 26 | 26 | 26 | 0 | 24 | 0 | 0 | 0 | 0 | 2 | 24 |
| 2 | 5 | 0 | 0 | 4 | 0 | 0 | 0 | 0 | 0 | 5 | 0 |
| 1 | 42 | 0 | 0 | 42 | 0 | 0 | 0 | 0 | 0 | 0 | 42 |
| Initial Finding Grade | Final Finding Grade | ||||||
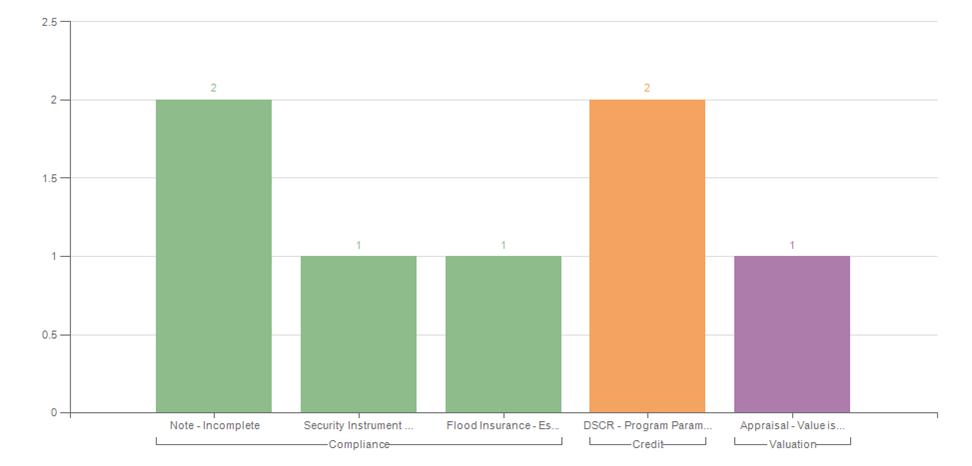
| Exceptions | Count | 3 | 4 | 2 | 3 | 4 | 2 |
| Compliance | 8 | 4 | 0 | 4 | 0 | 0 | 4 |
| HUD1 - Missing (All) | 4 | 4 | 0 | 0 | 0 | 0 | 0 |
| Note - Incomplete | 2 | 0 | 0 | 2 | 0 | 0 | 2 |
| Security Instrument - Inaccurate | 1 | 0 | 0 | 1 | 0 | 0 | 1 |
| Flood Insurance - Escrow Notice | 1 | 0 | 0 | 1 | 0 | 0 | 1 |
| Credit | 19 | 19 | 0 | 0 | 0 | 0 | 2 |
| DSCR - Program Parameters - Other | 6 | 6 | 0 | 0 | 0 | 0 | 2 |
| Hazard Insurance - Missing/Insufficient | 2 | 2 | 0 | 0 | 0 | 0 | 0 |
| Condo - Documentation | 2 | 2 | 0 | 0 | 0 | 0 | 0 |
| Final Application - Missing | 2 | 2 | 0 | 0 | 0 | 0 | 0 |
| DSCR - Missing HUD | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Flood Certificate - Missing | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Program Parameters - Cash-Out, Delayed Financing | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| DSCR - Missing Entity Documentation | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Assets - Minimum Reserves | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Credit - Other | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Credit Missing - One or More Reports Missing | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| Valuation | 4 | 3 | 0 | 1 | 0 | 0 | 1 |
| Appraisal - Value is not supported within 10% of original appraisal amount | 3 | 3 | 0 | 0 | 0 | 0 | 0 |
| Appraisal - Value is supported within 10% of original appraisal amount | 1 | 0 | 0 | 1 | 0 | 0 | 1 |
 |
| Loan Number | Loan ID | Last Name | Note Date | Original Loan Amount | QM Status | ATR Status | Compliance Exceptions | Credit Exceptions | Property Valuation Exceptions | Compensating Factors | DD Start Date | DD Delivery Date | Initial Rating | Final Rating | Initial Credit Rating | Final Credit Rating | Initial Compliance Rating | Final Compliance Rating | Initial Property Valuation Rating | Final Property Valuation Rating | Initial Overall Grade(Moody's) | Final Overall Grade(Moody's) | Initial Credit Grade (Moody's) | Final Credit Grade (Moody's) | Initial Property Valuation Grade (Moody's) | Final Property Valuation Grade (Moody's) | Initial Compliance Grade (Moody's) | Final Compliance Grade (Moody's) | Initial Overall Grade (S&P) | Final Overall Grade (S&P) | Initial Credit Grade (S&P) | Final Credit Grade (S&P) | Initial Property Valuation Grade (S&P) | Final Property Valuation Grade (S&P) | Initial Compliance Grade (S&P) | Final Compliance Grade (S&P) | Initial Overall Grade (Fitch) | Final Overall Grade (Fitch) | Initial Credit Grade (Fitch) | Final Credit Grade (Fitch) | Initial Property Valuation Grade (Fitch) | Final Property Valuation Grade (Fitch) | Initial Compliance Grade (Fitch) | Final Compliance Grade (Fitch) | Initial Overall Loan Grade (DBRS Morningstar) | Final Overall Loan Grade (DBRS Morningstar) | Initial Credit Grade (DBRS Morningstar) | Final Credit Grade (DBRS Morningstar) | Initial Property Valuation Grade (DBRS Morningstar) | Final Property Valuation Grade (DBRS Morningstar) | Initial Compliance Grade(DBRS Morningstar) | Final Compliance Grade(DBRS Morningstar) | Initial Overall Loan Grade (KBRA) | Final Overall Loan Grade (KBRA) | Initial Credit Grade (KBRA) | Final Credit Grade (KBRA) | Initial Property Valuation Grade (KBRA) | Final Property Valuation Grade (KBRA) | Initial Compliance Grade(KBRA) | Final Compliance Grade(KBRA) |
| XXXX | 1181 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Open) Security Instrument - Inaccurate- The security instrument was not completed accurately. The loan is a XXXX year fixed close-end product. The Open-end form was utilized for the Security Instrument when a Close-end form should have been used; however, the Security Instrument covers the correct debt and terms. |
(Clear) Credit - Other- The subject note, mortgage and title commitment reflect incorrect zip codes for some of the subject property addresses. These documents reflect the addresses to be: XXXX. However, a USPS zip code search confirms the addresses to be: XXXX.The USPS confirmed that the addresses match that of the appraisals and flood certificates in the loan file. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains CDAs, dated XX/XX/XXXX and XX/XX/XXXX which supports the appraised values. |
XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | ||
| XXXX | 1184 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Open) Flood Insurance - Escrow Notice- The loan was subject to XXXX and the Notice to Borrower in Special Flood Hazard Area Disclosure was not received XXXX days prior to closing. National Flood Insurance Act (NFIA) & Implementing Regulations XXXX USC 4012a(d) // 12 CFR 208.25(e)(2) |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 2 | 2 | 1 | 1 | 2 | 2 | 1 | 1 | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | ||
| XXXX | 1186 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is not supported within 10% of original appraisal amount- The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. The required CDA was not provided. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
XXXX | XXXX | 3 | 1 | 1 | 1 | 1 | 1 | 3 | 1 | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | ||
| XXXX | 1188 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) DSCR - Program Parameters - Other- The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the XXXX date. The Certificate of Good Standing provided was dated XX/XX/XXXX, which was XXXX days prior to the XXXX date and was expired. An updated Certificate of Good Standing was required and not provided. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | ||
| XXXX | 1189 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) DSCR - Program Parameters - Other- The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the XXXX date. The Certificate of Good Standing provided was dated XX/XX/XXXX, which was XXXX days prior to the XXXX date and was expired. An updated Certificate of Good Standing was required and not provided. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | ||
| XXXX | 1187 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) DSCR - Program Parameters - Other- The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the Note date with the exception of Entities formed in the last XXXX months prior to the XXXX date. The subject Entity was formed XXXX months prior to the subject transaction and an updated Certificate of Good Standing was not provided as require. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is not supported within 10% of original appraisal amount- The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. The required CDA was not provided. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 3 | 1 | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | ||
| XXXX | 1169 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Open) Note - Incomplete- The following section of the Note is incomplete: The Loan Agreement was not executed by the Lender. |
(Clear) Final Application - Missing- The Final application is missing as required by guides. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX, which supports value. |
XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | ||
| XXXX | 1185 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Open) Note - Incomplete- The following section of the Note is incomplete: The Loan Agreement was not executed by the Lender. |
(Clear) Final Application - Missing- The Final application is missing as required by guides. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) (Clear) Credit Missing - One or More Reports Missing- Not all required credit reports are within the file. The loan file was missing the co-borrower's credit report. Response 1 (XX/XX/XXXX XX:XXPM) Explanation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX, which supports value. |
XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | ||
| XXXX | 1176 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1182 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) HUD1 - Missing (All)- There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 3 | 1 | 1 | 1 | 3 | 1 | 1 | 1 | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | ||
| XXXX | 1180 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1175 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Waived) DSCR - Program Parameters - Other- The subject's loan amount was $XXXX. Per the investor guidelines, the minimum loan amount allowed was $XXXX. Subject's loan amount is less than the minimum allowed. Response 1 (XX/XX/XXXX XX:XXAM) Page XXXX of the guide allows a minimum loan amount of $XXXX. (XXXX) Response 2 (XX/XX/XXXX XX:XXAM) Waiver granted by Investor. (Waive) (Waived) DSCR - Program Parameters - Other- The subjects Note date was XX/XX/XXXX. The subject property was purchased XX/XX/XXXX (XXXX months prior to the subject transaction). The appraised value was $XXXX. Per the investor guidelines, for properties owned less than XXXX months prior to the subject's Note date, the loan amount cannot exceed the lower of XXXX% of total cost (purchase price + verified cost of improvements or XXXX allowable XXXX of As-Is-Value. The subject was purchased for $XXXX + documented rehab cost of $XXXX = $XXXX X XXXX% = XXXX loan amount allowable of $XXXX. Subjects loan amount of $XXXX exceeds maximum allowed loan amount of $XXXX. Response 1 (XX/XX/XXXX XX:XXPM) Waiver granted by Investor. (Waive) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX. XXXX DSCR. XXXX months of reserves. | XXXX | XXXX | 3 | 2 | 3 | 2 | 1 | 1 | 1 | 1 | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | |
| XXXX | 1183 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is not supported within 10% of original appraisal amount- The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. Secondary appraisal product was not provided. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
XXXX | XXXX | 3 | 1 | 1 | 1 | 1 | 1 | 3 | 1 | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | ||
| XXXX | 1168 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) HUD1 - Missing (All)- There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: TILA Accuracy, MDIA, XXXX, XXXX, XXXX, XXXX, XXXX, RESPA XXXX review, and final HUD-XXXX accuracy. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
(Clear) DSCR - Missing Entity Documentation- The file is missing the entity Resolution as required per the guidelines. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) (Clear) Condo - Documentation- The loan file did not contain a condo questionnaire as required to determine the warrantability as required by the guidelines. Reviewer unable to determine if the project involved in any litigation, what percentage is or is not delinquent by XXXX days or more, percentage owned by any single person/entity, and amount of reserves. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) (Clear) Condo - Documentation- The condo commercial common policy declarations expiration date of XX/XX/XXXX expired as of the note date XX/XX/XXXX. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) (Clear) Hazard Insurance - Missing/Insufficient- Guidelines require insurer rating to meet insurance rating requirements and is missing from the file. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. File contains CDA dated XX/XX/XXXX which supports the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | ||
| XXXX | 1179 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) HUD1 - Missing (All)- There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: XXXX, XXXX, and Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
(Clear) Assets - Minimum Reserves- the subject transaction required XXXX months of PITIA reserves in the amount of $XXXX. Verified funds from XXXX XXXX accounts supported funds in the amount of $XXXX leaving a shortage of reserves in the amount of $XXXX. The subject is a cash out refinance and per the investor guidelines cash out proceeds can be used for reserves. The Closing Disclosure was missing from the loan file and could reflect sufficient cash to cover the remaining reserves. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | ||
| XXXX | 1172 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX, which supports value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1177 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1171 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1178 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) Hazard Insurance - Missing/Insufficient- The loan was missing current hazard insurance policy on the subject property with sufficient coverage/replacement cost, with acceptable deductible limits, and XXXX months rent loss insurance as required per the guidelines. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
(Open) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX which does not support the appraised value within 10%; however, the guidelines allow for the lower value to be used. Per the rating agencies, this is graded as an EV2. |
XXXX | XXXX | 3 | 2 | 3 | 1 | 1 | 1 | 2 | 2 | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | ||
| XXXX | 1170 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) No Credit Findings- The loan meets all applicable credit guidelines. |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX, which supports value. |
XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | ||
| XXXX | 1174 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) No Compliance Findings- The loan is in compliance with all applicable laws and regulations. |
(Clear) DSCR - Program Parameters - Other- XXXX requirement has not been met. The subject transaction is a rate and term refinance and property was acquired by the borrower on XX/XX/XXXX. Per the appraisal, the subject property was listed for sale from XX/XX/XXXX - XX/XX/XXXX for $XXXX. Guidelines require a letter of explanation from the borrower. In addition, a confirmation by the underwriter that the listing has been removed from MLS is required. Response 1 (XX/XX/XXXX XX:XXAM) Documentation received. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | ||
| XXXX | 1173 | XXXX | XXXX | XXXX | GQM Exempt - Business Purpose | (Clear) HUD1 - Missing (All)- There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: TILA Accuracy, MDIA, XXXX, XXXX, XXXX, XXXX, XXXX, RESPA XXXX review, and final HUD-XXXX accuracy. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
(Clear) DSCR - Missing HUD- Missing HUD as required. The final HUD for the subject transaction is missing from the loan file. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) (Clear) Program Parameters - Cash-Out, Delayed Financing- Guidelines indicate that if the property has been owned more than three (XXXX) months but less than twelve (XXXX) months from acquisition date to Note date the loan amount cannot exceed the lower of XXXX% of total cost (purchase price + verified cost improvements) or XXXX allowable % of As-Is Value. XXXX is a cash-out transaction and the property was purchased within the prior XXXX months; however, a copy of the HUD from the purchase transaction is not present in the loan file. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) (Clear) Flood Certificate - Missing- The flood certificate is missing. The loan file does not contain a flood certificate as required. Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
(Clear) Appraisal - Value is supported within 10% of original appraisal amount- The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. |
XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A |
| Loan Number | Loan ID | Finding # | Last Name | Note Date | DD Start Date | DD Delivery Date | Audit Category | Audit Issue | Finding ID | Exception Finding | Remediation Status | Exception Rebuttal | Exception Response | Status Comment | Compensating Factors | SOL Expiration Date | Initial Findings Grade | Final Findings Grade | Initial Loan Grade | Final Loan Grade |
| XXXX | 1168 | 1 of 6 | XXXX | XXXX | XXXX | XXXX | Compliance | HUD1 - Missing (All) | XXXX | There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: TILA Accuracy, MDIA, XXXX, XXXX, QM XXXX, XXXX, XXXX, RESPA XXXX review, and final HUD-XXXX accuracy. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) please see attached summary from closing |
Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1168 | 2 of 6 | XXXX | XXXX | XXXX | XXXX | Credit | Condo - Documentation | XXXX | The condo commercial common policy declarations expiration date of XX/XX/XXXX expired as of the note date XX/XX/XXXX. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) The condo commercial common policy declarations is from XX/XX/XXXX and expires as of XX/XX/XXXX |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1168 | 3 of 6 | XXXX | XXXX | XXXX | XXXX | Credit | Condo - Documentation | XXXX | The loan file did not contain a condo questionnaire as required to determine the warrantability as required by the guidelines. Reviewer unable to determine if the project involved in any litigation, what percentage is or is not delinquent by XXXX days or more, percentage owned by any single person/entity, and amount of reserves. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Condo questionnaire attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1168 | 4 of 6 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Missing Entity Documentation | XXXX | The file is missing the entity Resolution as required per the guidelines. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXAM) Resolution attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1168 | 5 of 6 | XXXX | XXXX | XXXX | XXXX | Credit | Hazard Insurance - Missing/Insufficient | XXXX | Guidelines require insurer rating to meet insurance rating requirements and is missing from the file. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Please see attached rating |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1168 | 6 of 6 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. File contains CDA dated XX/XX/XXXX which supports the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1169 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | Note - Incomplete | XXXX | The following section of the Note is incomplete: The Loan Agreement was not executed by the Lender. | Cleared | 2 | 2 | 3 | 2 | |||||
| XXXX | 1169 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | Final Application - Missing | XXXX | The Final application is missing as required by guides. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Signed loan application attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 2 | |||
| XXXX | 1169 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX, which supports value. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1170 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1170 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1170 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX, which supports value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1171 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1171 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1171 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1172 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1172 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1172 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX, which supports value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1173 | 1 of 5 | XXXX | XXXX | XXXX | XXXX | Compliance | HUD1 - Missing (All) | XXXX | There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: TILA Accuracy, MDIA, XXXX, XXXX, QM XXXX, XXXX, XXXX, RESPA XXXX review, and final HUD-XXXX accuracy. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Funding statement from closing attached |
Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1173 | 2 of 5 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Missing HUD | XXXX | Missing HUD as required. The final HUD for the subject transaction is missing from the loan file. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Funding statement from closing attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1173 | 3 of 5 | XXXX | XXXX | XXXX | XXXX | Credit | Flood Certificate - Missing | XXXX | The flood certificate is missing. The loan file does not contain a flood certificate as required. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Flood cert attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1173 | 4 of 5 | XXXX | XXXX | XXXX | XXXX | Credit | Program Parameters - Cash-Out, Delayed Financing | XXXX | Guidelines indicate that if the property has been owned more than three (XXXX) months but less than twelve (XXXX) months from acquisition date to Note date the loan amount cannot exceed the lower of XXXX% of total cost (purchase price + verified cost improvements) or XXXX allowable % of As-Is Value. XXXX is a cash-out transaction and the property was purchased within the prior XXXX months; however, a copy of the HUD from the purchase transaction is not present in the loan file. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) HUD from Purchase attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1173 | 5 of 5 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1174 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1174 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | Guideline requirement has not been met. The subject transaction is a rate and term refinance and property was acquired by the borrower on XX/XX/XXXX. Per the appraisal, the subject property was listed for sale from XX/XX/XXXX - XX/XX/XXXX for $XXXX. Guidelines require a letter of explanation from the borrower. In addition, a confirmation by the underwriter that the listing has been removed from MLS is required. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXAM) Please see attached borrower Letter of Explanation regarding the prior listing history for the subject property. The property has been removed from the MLS and confirmed no longer actively listed for sale. |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1174 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1175 | 1 of 4 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1175 | 2 of 4 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | The subject's loan amount was $XXXX. Per the investor guidelines, the minimum loan amount allowed was $XXXX. Subject's loan amount is less than the minimum allowed. | Waived | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Per the investor and ECF guidelines the minimum loan amount is $XXXXk Rebuttal 2 (XX/XX/XXXX XX:XXPM) Please see Adamas&#XXXX; rate sheet for eligibility. The Adamas rate sheet supersedes the ECF guidelines where any differences or discrepancies exist. |
Response 1 (XX/XX/XXXX XX:XXAM) Page XXXX of the guide allows a minimum loan amount of $XXXX. (XXXX) Response 2 (XX/XX/XXXX XX:XXAM) Waiver granted by Investor. (Waive) |
XXXX. XXXX DSCR. XXXX months of reserves. | 3 | 2 | 3 | 2 | ||
| XXXX | 1175 | 3 of 4 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | The subjects Note date was XX/XX/XXXX. The subject property was purchased XX/XX/XXXX (XXXX months prior to the subject transaction). The appraised value was $XXXX. Per the investor guidelines, for properties owned less than XXXX months prior to the subject's Note date, the loan amount cannot exceed the lower of XXXX% of total cost (purchase price + verified cost of improvements or XXXX allowable XXXX of As-Is-Value. The subject was purchased for $XXXX + documented rehab cost of $XXXX = $XXXX X XXXX% = XXXX loan amount allowable of $XXXX. Subjects loan amount of $XXXX exceeds maximum allowed loan amount of $XXXX. | Waived | Rebuttal 1 (XX/XX/XXXX XX:XXAM) Waiver granted by the Investor for the $XXXX loan amount |
Response 1 (XX/XX/XXXX XX:XXPM) Waiver granted by Investor. (Waive) |
3 | 2 | 3 | 2 | |||
| XXXX | 1175 | 4 of 4 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1176 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1176 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1176 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1177 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1177 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1177 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA, dated XX/XX/XXXX which supports the appraised value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1178 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1178 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | Hazard Insurance - Missing/Insufficient | XXXX | The loan was missing current hazard insurance policy on the subject property with sufficient coverage/replacement cost, with acceptable deductible limits, and XXXX months rent loss insurance as required per the guidelines. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Insurance policy attached marked special coverage |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 2 | |||
| XXXX | 1178 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX which does not support the appraised value within 10%; however, the guidelines allow for the lower value to be used. Per the rating agencies, this is graded as an EV2. | Cleared | 2 | 2 | 3 | 2 | |||||
| XXXX | 1179 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | HUD1 - Missing (All) | XXXX | There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. As a result the following reviews could not be performed: XXXX, XXXX, and Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Funding Statement attached |
Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1179 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | Assets - Minimum Reserves | XXXX | the subject transaction required XXXX months of PITIA reserves in the amount of $XXXX. Verified funds from XXXX XXXX accounts supported funds in the amount of $XXXX leaving a shortage of reserves in the amount of $XXXX. The subject is a cash out refinance and per the investor guidelines cash out proceeds can be used for reserves. The Closing Disclosure was missing from the loan file and could reflect sufficient cash to cover the remaining reserves. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Funding Statement attached. Thank you |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1179 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1180 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1180 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1180 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 1 | 1 | |||||
| XXXX | 1181 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | Security Instrument - Inaccurate | XXXX | The security instrument was not completed accurately. The loan is a XXXX year fixed close-end product. The Open-end form was utilized for the Security Instrument when a Close-end form should have been used; however, the Security Instrument covers the correct debt and terms. | Acknowledged | 2 | 2 | 3 | 2 | |||||
| XXXX | 1181 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | Credit - Other | XXXX | The subject note, mortgage and title commitment reflect incorrect zip codes for some of the subject property addresses. These documents reflect the addresses to be: XXXX. However, a USPS zip code search confirms the addresses to be: XXXX. The USPS confirmed that the addresses match that of the appraisals and flood certificates in the loan file. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Please see the attached remedy |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 2 | |||
| XXXX | 1181 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains CDAs, dated XX/XX/XXXX and XX/XX/XXXX which supports the appraised values. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1182 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | HUD1 - Missing (All) | XXXX | There is no evidence of a HUD-XXXX Settlement Statement provided in the loan file. Real Estate Settlement Procedures Act (Regulation X) 12 CFR 1024.8(a) | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Funding Statement attached |
Response 1 (XX/XX/XXXX XX:XXPM) The documentation provided is sufficient to clear the finding. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1182 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1182 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1183 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1183 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1183 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is not supported within 10% of original appraisal amount | XXXX | The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. Secondary appraisal product was not provided. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Please see the attached value conclusions |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1184 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | Flood Insurance - Escrow Notice | XXXX | The loan was subject to XXXX and the Notice to Borrower in Special Flood Hazard Area Disclosure was not received XXXX days prior to closing. National Flood Insurance Act (NFIA) & Implementing Regulations XXXX USC 4012a(d) // 12 CFR 208.25(e)(2) | Cleared | 2 | 2 | 2 | 2 | |||||
| XXXX | 1184 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 2 | 2 | |||||
| XXXX | 1184 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 2 | 2 | |||||
| XXXX | 1185 | 1 of 4 | XXXX | XXXX | XXXX | XXXX | Compliance | Note - Incomplete | XXXX | The following section of the Note is incomplete: The Loan Agreement was not executed by the Lender. | Cleared | 2 | 2 | 3 | 2 | |||||
| XXXX | 1185 | 2 of 4 | XXXX | XXXX | XXXX | XXXX | Credit | Credit Missing - One or More Reports Missing | XXXX | Not all required credit reports are within the file. The loan file was missing the co-borrower's credit report. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) Credit is not required for XXXX as they are a Non-Guarantor Percent Ownership: XXXX % |
Response 1 (XX/XX/XXXX XX:XXPM) Explanation received is sufficient. (Resolved) |
3 | 1 | 3 | 2 | |||
| XXXX | 1185 | 3 of 4 | XXXX | XXXX | XXXX | XXXX | Credit | Final Application - Missing | XXXX | The Final application is missing as required by guides. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) XXXX app attached |
Response 1 (XX/XX/XXXX XX:XXPM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 2 | |||
| XXXX | 1185 | 4 of 4 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. The loan file contains a CDA dated XX/XX/XXXX, which supports value. | Cleared | 1 | 1 | 3 | 2 | |||||
| XXXX | 1186 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1186 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | No Credit Findings | XXXX | The loan meets all applicable credit guidelines. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1186 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is not supported within 10% of original appraisal amount | XXXX | The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. The required CDA was not provided. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) CDA Attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1187 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1187 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the Note date with the exception of Entities formed in the last XXXX months prior to the XXXX date. The subject Entity was formed XXXX months prior to the subject transaction and an updated Certificate of Good Standing was not provided as require. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) XXXX attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1187 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is not supported within 10% of original appraisal amount | XXXX | The Loan file did not contain an AVM, CDA, Field Review, 2nd appraisal or CU score at XXXX or under to support the origination appraised value. The required CDA was not provided. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXPM) CDA attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1188 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1188 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the XXXX date. The Certificate of Good Standing provided was dated XX/XX/XXXX, which was XXXX days prior to the XXXX date and was expired. An updated Certificate of Good Standing was required and not provided. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXAM) Updated COGS from XX/XX/XXXX attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1188 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1189 | 1 of 3 | XXXX | XXXX | XXXX | XXXX | Compliance | No Compliance Findings | XXXX | The loan is in compliance with all applicable laws and regulations. | Cleared | 1 | 1 | 3 | 1 | |||||
| XXXX | 1189 | 2 of 3 | XXXX | XXXX | XXXX | XXXX | Credit | DSCR - Program Parameters - Other | XXXX | The subject closed in the name of XXXX which was formed XX/XX/XXXX. The Note date was XX/XX/XXXX. The investor guidelines required a Certificate of Good Standing within XXXX days from the XXXX date. The Certificate of Good Standing provided was dated XX/XX/XXXX, which was XXXX days prior to the XXXX date and was expired. An updated Certificate of Good Standing was required and not provided. | Resolved | Rebuttal 1 (XX/XX/XXXX XX:XXAM) Updated COGS from XX/XX/XXXX attached |
Response 1 (XX/XX/XXXX XX:XXAM) Documentation received is sufficient. (Resolved) |
3 | 1 | 3 | 1 | |||
| XXXX | 1189 | 3 of 3 | XXXX | XXXX | XXXX | XXXX | Valuation | Appraisal - Value is supported within 10% of original appraisal amount | XXXX | The appraised value was supported within 10% and all applicable appraisal guidelines were satisfied. A CDA dated XX/XX/XXXX was provided and supported the appraised value. | Cleared | 1 | 1 | 3 | 1 |
| Loan Number | Loan ID | Original Loan Amount | DD Start Date | DD Delivery Date | Initial Rating | Final Rating | Initial Credit Rating | Final Credit Rating | Initial Compliance Rating | Final Compliance Rating | Initial Property Valuation Rating | Final Property Valuation Rating | Initial Overall Grade(Moody's) | Final Overall Grade(Moody's) | Initial Credit Grade (Moody's) | Final Credit Grade (Moody's) | Initial Property Valuation Grade (Moody's) | Final Property Valuation Grade (Moody's) | Initial Compliance Grade (Moody's) | Final Compliance Grade (Moody's) | Initial Overall Grade (S&P) | Final Overall Grade (S&P) | Initial Credit Grade (S&P) | Final Credit Grade (S&P) | Initial Property Valuation Grade (S&P) | Final Property Valuation Grade (S&P) | Initial Compliance Grade (S&P) | Final Compliance Grade (S&P) | Initial Overall Grade (Fitch) | Final Overall Grade (Fitch) | Initial Credit Grade (Fitch) | Final Credit Grade (Fitch) | Initial Property Valuation Grade (Fitch) | Final Property Valuation Grade (Fitch) | Initial Compliance Grade (Fitch) | Final Compliance Grade (Fitch) | Initial Overall Loan Grade (DBRS Morningstar) | Final Overall Loan Grade (DBRS Morningstar) | Initial Credit Grade (DBRS Morningstar) | Final Credit Grade (DBRS Morningstar) | Initial Property Valuation Grade (DBRS Morningstar) | Final Property Valuation Grade (DBRS Morningstar) | Initial Compliance Grade(DBRS Morningstar) | Final Compliance Grade(DBRS Morningstar) | Initial Overall Loan Grade (KBRA) | Final Overall Loan Grade (KBRA) | Initial Credit Grade (KBRA) | Final Credit Grade (KBRA) | Initial Property Valuation Grade (KBRA) | Final Property Valuation Grade (KBRA) | Initial Compliance Grade(KBRA) | Final Compliance Grade(KBRA) |
| XXXX | 1181 | XXXX | XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B |
| XXXX | 1184 | XXXX | XXXX | XXXX | 2 | 2 | 1 | 1 | 2 | 2 | 1 | 1 | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B | B | B | A | A | A | A | B | B |
| XXXX | 1186 | XXXX | XXXX | XXXX | 3 | 1 | 1 | 1 | 1 | 1 | 3 | 1 | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A |
| XXXX | 1188 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A |
| XXXX | 1189 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A |
| XXXX | 1187 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 3 | 1 | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A |
| XXXX | 1169 | XXXX | XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B |
| XXXX | 1185 | XXXX | XXXX | XXXX | 3 | 2 | 3 | 1 | 2 | 2 | 1 | 1 | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B | C | B | C | A | A | A | B | B |
| XXXX | 1176 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1182 | XXXX | XXXX | XXXX | 3 | 1 | 1 | 1 | 3 | 1 | 1 | 1 | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A |
| XXXX | 1180 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1175 | XXXX | XXXX | XXXX | 3 | 2 | 3 | 2 | 1 | 1 | 1 | 1 | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A | C | B | C | B | A | A | A | A |
| XXXX | 1183 | XXXX | XXXX | XXXX | 3 | 1 | 1 | 1 | 1 | 1 | 3 | 1 | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A | C | A | A | A |
| XXXX | 1168 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A |
| XXXX | 1179 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A |
| XXXX | 1172 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1177 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1171 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1178 | XXXX | XXXX | XXXX | 3 | 2 | 3 | 1 | 1 | 1 | 2 | 2 | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A | C | B | C | A | B | B | A | A |
| XXXX | 1170 | XXXX | XXXX | XXXX | 1 | 1 | 1 | 1 | 1 | 1 | 1 | 1 | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A | A |
| XXXX | 1174 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 1 | 1 | 1 | 1 | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A | C | A | C | A | A | A | A | A |
| XXXX | 1173 | XXXX | XXXX | XXXX | 3 | 1 | 3 | 1 | 3 | 1 | 1 | 1 | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A | C | A | C | A | A | A | C | A |
Valuation Securitization Report
| LOAN INFORMATION | ORIGINATION VALUES | AVM VALUES | DESK REVIEW VALUES | BPO VALUES | FIELD REVIEW VALUES | 2055 VALUES | OTHER VALUES | UPDATED MULTIPROPERTY VALUES | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Seller Loan ID | Customer Loan ID | Subject Address | Subject City | Subject State | Subject Zip | Note Date | Original Loan Amount | Sales Price | PIW Indicator | Appraised Value | Value for LTV | Appraisal Form Type | Appraisal Date | Appraisal Company Name | AVM Confidence Score | AVM FSD Score | Market Condition | Second Appraisal Value | Variance Amount | Variance Percent | Second Appraisal Date | Second Appraisal Type | Appraised Value | Variance Amount | Variance Percent | Company | Confidence Score | AVM FSD Score | Appraisal Date | Appraised Value | Variance Amount | Variance Percent | Company | Risk Score | Appraisal Date | Appraised Value | Variance Amount | Variance Percent | Company | Appraisal Date | Appraised Value | Variance Amount | Variance Percent | Company | Appraisal Date | Appraised Value | Variance Amount | Variance Percent | Company | Appraisal Date | Appraised Value | Variance Amount | Variance Percent | Company | Appraisal Date | Aggregate Appraised Value | Aggregate Variance Amount | Aggregate Variance Percent | Is Eligible for Rep and Warrant Relief per Loan Collateral Advisor? | Collateral Underwriter Risk Score |
| XXXX | 1172 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1173 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1178 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -16.071% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1168 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1073 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1183 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Increasing | XXXX | XXXX | -8.873% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-01 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-02 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-03 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -8.824% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-04 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -9.091% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-05 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-06 | XXXX | XXXX | XX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -8.088% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1185 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1169 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1179 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1176 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1182 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1170 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -5.882% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1177 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1174 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1171 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1188 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Decreasing | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1187 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -5.530% | XXXX | XXXX | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||
| XXXX | 1189 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Increasing | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1186 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 7.288% | XXXX | XXXX | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||
| XXXX | 1184 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | -5.263% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1175 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Stable | XXXX | XXXX | 0.000% | XXXX | XXXX | |||||||||||||||||||||||||||||||||||||||||
| XXXX | 1180 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | 1004 | XXXX | XXXX | Increasing | XXXX | XXXX | 23.445% | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | 0.000% | XXXX | XXXX | ||||||||||||||||||||||||||||||||||
| XXXX | 1181 | XXXX | XXXX | XX | XXXX | XXXX | XXXX | No | XXXX | XXXX | Stable | |||||||||||||||||||||||||||||||||||||||||||||||||
| Report Pulled: | 9/29/2026 | |
| Loan Count: | 22 / 27 | |
| Fields Reviewed | Discrepancy Count | Percentage |
| Debt Service Coverage Ratio | 4 | 18.18% |
| LTV | 1 | 4.55% |
| Report Pulled: | 9/29/2026 | |||||
| Loan Count: | 22 / 27 | |||||
| Audit ID | Loan Number | Loan ID | Borrower Last Name | Field | Tape Data | Review Data |
| XXXX | XXXX | 1173 | XXXX | Debt Service Coverage Ratio | XXXX | XXXX |
| XXXX | XXXX | 1175 | XXXX | Debt Service Coverage Ratio | XXXX | XXXX |
| XXXX | XXXX | 1177 | XXXX | Debt Service Coverage Ratio | XXXX | XXXX |
| XXXX | XXXX | 1178 | XXXX | LTV | XXXX | XXXX |
| XXXX | XXXX | 1185 | XXXX | Debt Service Coverage Ratio | XXXX | XXXX |
| Loan Number | Loan ID | Program | Document Type | Asset Depletion Flag | Length of Income Verification in months | Investment DSCR (Rent/PITIA) | Rent DSCR | PITIA DSCR | Number of Borrowers | Number of Natural Borrowers | Borrower/Guarantor Resident Indicator National | Co Borrower/Guarantor Resident Indicator | Borrower 3/Guarantor Resident Indicator | Borrower 4/Guarantor Resident Indicator | Borrower Guarantor/Employment Indicator | Co Borrower/Guarantor Employment Indicator | Borrower 3 Employment Indicator | Borrower 4 Employment Indicator | TILA Status | Lease in-Place for Investment Property | Short Term Rental Flag | Most Recent Bankruptcy Type | Most Recent Bankruptcy Discharge Date | Number of Bankruptcy Events | Months Bankruptcy 7 11 (Application Date) | Months Bankruptcy 13 (Application Date) | Most Recent Deed in Lieu Date | Number of Deed in Lieu Events | Months Deed in Lieu (Application Date) | Most Recent Short Sale Date | Number of Short Sale Events | Months Short Sale (or Pre FC) (Application Date) | Most Recent Foreclosure Date | Number of Foreclosure Events | Months Foreclosure (Application Date) | Original Qualifying FICO | Borrower Original FICO: Equifax | Borrower Original FICO: Experian | Borrower Original FICO: Transunion | Borrower Original FICO | Co-Borrower Original FICO: Equifax | Co-Borrower Original FICO: Experian | Co-Borrower Original FICO: Trans Union | Co Borrower Original FICO | Borrower 3 Original FICO: Equifax | Borrower 3 Original FICO: Experian | Borrower 3 Original FICO: Trans Union | Borrower 3 Original FICO | Borrower 4 Original FICO: Equifax | Borrower 4 Original FICO: Experian | Borrower 4 Original FICO: TransUnion | Borrower 4 Original FICO |
| XXXX | 1168 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1169 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 3 | 2 | U.S. Citizen | U.S. Citizen | 0 | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||
| XXXX | 1170 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 3 | 2 | U.S. Citizen | U.S. Citizen | 0 | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||
| XXXX | 1171 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1172 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1173 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1174 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1175 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1176 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1177 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1178 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1179 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1180 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1181 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 3 | 2 | U.S. Citizen | U.S. Citizen | 0 | 0 | GQM Exempt - Business Purpose | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||
| XXXX | 1182 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1183 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1184 | 30 YR | DSCR | 0 | 12 to 23 months income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 1 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1185 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 3 | 2 | U.S. Citizen | U.S. Citizen | 0 | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||
| XXXX | 1186 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1187 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1188 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | ||||||||||||||||||||||||||||||||
| XXXX | 1189 | 30 YR | DSCR | 0 | 11 months or less income verification | XXXX | XXXX | XXXX | 2 | 1 | U.S. Citizen | 0 | GQM Exempt - Business Purpose | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX |
| Loan Number | Loan ID | QM Status | ATR | Exempt Reason | TRID Flag | Bank Statement Flag | Business/Personal Bank Statement | Foreign National Flag | Bank Statement Months | Number of Units | Lease In Place Indicator | Short Term Rental indicator | Title Vesting Type | Entity Name | Guarantee | Recourse | AUS/GSE Eligible Flag | Non-QM DocType Flag | Non-QM DTI Flag | Non-QM Points and Fees Flag | Non-QM Appendix Q Flag | Non-QM IO Flag | Non-QM Investment Property Exemption Flag | Non-QM Business Purpose / Foreign National | Non-QM Loan Term Exceeds 30 yrs | Primary Borrower Retired Flag | Co-Borrower Retired Flag | State of Formation | Length of Self-Employment | Co-Borrower Length of Self-Employment | Qualifying Rent | Rent from Lease | Rent from Market Survey | Business Expense-to-Income Ratio | Source of Business Expense-to-Income Ratio | Third Party Preparer | Debt Service Coverage Ratio (DSCR) | Rent Source | DSCR PITIA | Residual Income | Borr 1 - Income Qual Months Personal Bank Statements | Borr 1 - Income Qual Months Business Bank Statements | Borr 1 - Income Qual Years W2 | Borr 1 - Income Qual Years Tax Returns | Borr 1 - Income Qual WVOE Months | Borr 1 - Income Qual PNL Letter | Borr 1 - Income Qual CPA Letter | Borr 1 - Income Qual Number Paystubs | Borr 2 - Income Qual Months Personal Bank Statements | Borr 2 -Income Qual Months Business Bank Statements | Borr 2 - Income Qual Years W2 | Borr 2 - Income Qual Years Tax Returns | Borr 2 - Income Qual WVOE Months | Borr 2 - Income Qual PNL Letter | Borr 2 - Income Qual CPA Letter | Borr 2 - Income Qual Number Paystubs | Borrower Last Name | Borrower First Name | Co Borrower Last Name | Co Borrower First Name | Subject Street Address | Subject City | Subject State | Subject Zip | MERs Min # | Qualifying Value |
| XXXX | 1168 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | NY | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1169 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1170 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | DE | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1171 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | DE | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1172 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1173 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | NY | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1174 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1175 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | OH | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1176 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | OH | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1177 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | MO | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1178 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | MD | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1179 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | NY | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1180 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | MD | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1181 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 6 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | PA | 0 | 0 | XXXX | XXXX | XXXX | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | |||||||||||||||
| XXXX | 1181-01 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-02 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-03 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-04 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-05 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1181-06 | 1 | 0 | 0 | XXXX | XXXX | Market Survey | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | ||||||||||||||||||||||||||||||||||||||||||||||||||
| XXXX | 1182 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | NY | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Lease | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1183 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1184 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 1 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | MA | 0 | 0 | XXXX | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | |||||||
| XXXX | 1185 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1186 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1187 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1188 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX | ||||||||
| XXXX | 1189 | GQM Exempt - Business Purpose | N/A | 0 | 0 | 0 | 1 | 0 | 0 | LLC | XXXX | Yes | Full Recourse | 0 | 1 | 0 | 0 | 0 | 1 | 0 | 0 | 0 | 0 | TX | 0 | 0 | XXXX | XXXX | XXXX | Market Survey | XXXX | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | XX | XXXX | XXXX | XXXX |
| Loan Number | Loan ID | The Original Principal and Interest Payment Amount | Hazard Insurance Monthly Payment Amount | Property Tax Monthly Expense Payment | Flood Insurance Monthly Payment Amount | HOA Dues Monthly Payment Amount | Qualifying PITIA | EIN (Employer Identification Number) |
| XXXX | 1168 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | |
| XXXX | 1169 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1170 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1171 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1172 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1173 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1174 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1175 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1176 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1177 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1178 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1179 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1180 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1181 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1182 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1183 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1184 | XXXX | XXXX | XXXX | XXXX | XXXX | XXXX | |
| XXXX | 1185 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1186 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1187 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1188 | XXXX | XXXX | XXXX | XXXX | XXXX | ||
| XXXX | 1189 | XXXX | XXXX | XXXX | XXXX | XXXX |
| Loan Number | Loan ID | Leasehold | Mortgage Assumable Flag |
| XXXX | 1172 | 0 | 0 |
| XXXX | 1170 | 0 | 0 |
| XXXX | 1177 | 0 | 0 |
| XXXX | 1174 | 0 | 0 |
| XXXX | 1171 | 0 | 0 |
| XXXX | 1173 | 0 | 0 |
| XXXX | 1178 | 0 | 0 |
| XXXX | 1168 | 0 | 0 |
| XXXX | 1183 | 0 | 0 |
| XXXX | 1175 | 0 | 0 |
| XXXX | 1179 | 0 | 0 |
| XXXX | 1181 | 0 | 0 |
| XXXX | 1181-01 | 0 | |
| XXXX | 1181-02 | 0 | |
| XXXX | 1181-03 | 0 | |
| XXXX | 1181-04 | 0 | |
| XXXX | 1181-05 | 0 | |
| XXXX | 1181-06 | 0 | |
| XXXX | 1185 | 0 | 0 |
| XXXX | 1169 | 0 | 0 |
| XXXX | 1176 | 0 | 0 |
| XXXX | 1182 | 0 | 0 |
| XXXX | 1180 | 0 | 0 |
| XXXX | 1187 | 0 | 0 |
| XXXX | 1188 | 0 | 0 |
| XXXX | 1189 | 0 | 0 |
| XXXX | 1186 | 0 | 0 |
| XXXX | 1184 | 0 | 0 |