Exhibit 99.1
12770 Coit Road, Suite 907 ●
Dallas, Texas 75251
(972) 385-0354 ● info@haasandcobb.com
HAASANDCOBB.COM
May 26, 2026
Mr. Jesse J. Allen
EON Resources, Inc.
3730 Kirby Drive, Suite 1200
Houston, Texas 77098
Mr. Allen:
As requested, Haas and Cobb Petroleum Consultants (hereinafter referred to as “Haas & Cobb”) has prepared an estimate of certain hydrocarbon Reserves owned by “EON Resources, Inc.” (hereinafter referred to as “EON”) The properties located in the Grayburg-Jackson Field, Eddy County, New Mexico. The properties have historically produced from Seven Rivers, Queen, Grayburg, and San Andres (SR-Q-G-SA) reservoirs in descending depth order. The scope of this report is limited to Reserves attributable to the historical SR-Q-G-SA completions (“Legacy”) and the implementation and expansion of the Seven Rivers waterflood (“SVRV”). This report may not include a full inventory of EON’s total Proved and Probable Reserves. It is our understanding that as of the effective date of this report, EON had established a carried partnership with a third-party operator to further develop the San Andres formation and was in the final stages of acquiring additional assets in offsetting fields; neither has been evaluated for inclusion as Reserves herein. This report was completed on February 13, 2026.
Production data was generally available through December 31, 2025. As of January 1, 2026, EON’s net Reserves, future net income (“FNI”), and net present worth discounted at 10 percent per annum (“NPV”) have been estimated to be as follows:
TABLE 1
EON RESOURCES, INC. – NET RESERVES AND VALUE
AS OF DECEMBER 31, 2025
| Net Reserves | Future Net Cashflow | |||||||||||||||
| Reserve Category | Oil & Condensate (bbl) | Residue Gas (Mcf) | FNI ($) | NPV Disc. 10% ($) | ||||||||||||
| Legacy SR-Q-G-SA-PDP | 287,635 | 159,575 | 5,354,856 | 3,715,511 | ||||||||||||
| SVRV Waterflood PDP | 1,566,755 | 472,292 | 34,045,423 | 21,540,314 | ||||||||||||
| Total Proved Producing | 1,854,390 | 631,867 | 39,400,280 | 25,255,825 | ||||||||||||
| SVRV Waterflood (RTP) PDNP | 661,177 | -62,512 | 19,902,625 | 9,346,826 | ||||||||||||
| Total Proved | 2,515,567 | 569,356 | 59,302,905 | 34,602,651 | ||||||||||||
| SVRV Waterflood Probable DNP | 4,807,752 | 721,164 | 109,847,760 | 26,552,181 | ||||||||||||
| SVRV Waterflood Probable UD | 4,178,377 | 626,752 | 114,284,377 | 18,877,476 | ||||||||||||
| Total Probable | 8,986,129 | 1,347,916 | 224,132,137 | 45,429,657 | ||||||||||||
| * | Totals in Table 1 may not exactly match values in the attached cash flow summaries and tabular summaries due to computer rounding. |

FNI is after deducting estimated operating and future development costs, severance, and ad valorem taxes, but before Federal income taxes. Total net Proved and Probable Reserves are defined as those natural gas and hydrocarbon liquid Reserves to EON’s interests after deducting all royalties, overriding royalties, and reversionary interests owned by outside parties that become effective upon payout of specified monetary balances. All Reserves estimates have been prepared using standard engineering practices generally accepted by the petroleum industry and conform to guidelines developed and adopted by the SEC. All hydrocarbon liquid Reserves are expressed in United States barrels (“bbl”) of 42 gallons. Natural gas Reserves are expressed in thousand standard cubic feet (“Mcf”) at the contractual pressure and temperature bases and include shrinkage adjustment related to field and plant losses.
Haas & Cobb has completed this report in accordance with the definitions of set forth in Rule 4-10(a) of Regulation S-X of the U.S. Securities and Exchange Commission (“SEC”). This evaluation conforms to the FASB Accounting Standards Codification Topic 932, Extractive Industries - Oil and Gas, except that future income taxes are excluded and, as requested, abandonment costs have not been included in our estimates of future net income. This report was prepared for EON’s inclusion as an exhibit in their filing with the SEC. It is Haas & Cobb’s opinion that the assumptions, data, methods, and procedures used in the preparation of this report are suitable for use in SEC filings.
DISCUSSION
EON’s leasehold covers approximately 13,700 acres in the Grayburg-Jackson Field. Historical production has been from Seven Rivers, Queen, Grayburg, and San Andres (SR-Q-G-SA) reservoirs ranging in depth from 1,500 to 4,000 feet. The production forecast for the historical SR-Q-G-SA completions is the basis for the Legacy reserves estimate. Forecasts for Legacy properties were prepared using decline curve analysis.
Ongoing focus on the Seven Rivers waterflood implementation by EON is reflected as SVRV Waterflood. Although the Seven Rivers interval is behind-pipe in many future Seven Rivers producers or injectors, a material number of planned producers and injectors will require new drill wellbores. The Proved Developed Non-Producing Reserves are associated with returning 19 injectors to service the SVRV waterflood. An additional 170 development patterns have been categorized according to the producer status with 127 patterns being Probable Developed Non-Producing (Prob-DNP) and 43 patterns being Probable Undeveloped (Prob-UD). Forecasts for the SVRV were prepared using decline curve analysis, volumetrics, and simulation. Reserves for the 170 development patterns, included in the Proved classification in prior years’ reports, have been designated as Probable as EON re-evaluates budget and other business considerations in the current fiscal cycle.
COMMODITY PRICES
Pursuant to SEC guidelines, the cash flow projections in this report utilize the unweighted 12-month arithmetic average of the first-day-of month benchmark prices for January 2025 through December 2025. The benchmark price for natural gas is the NYMEX Natural Gas Henry Hub settlement price for each respective month and the benchmark price for hydrocarbon liquids is the price received for West Texas Intermediate (“WTI”) crude oil at the Cushing, OK sales point.
The benchmark price for WTI crude oil sold at Cushing, OK during this time period is $65.34 per bbl. For crude oil, the benchmark price is held constant throughout the life of the wells and is adjusted for crude quality, marketing fees, BS&W, purchaser bonuses, and basis differentials, resulting in a weighted average received price of $64.54 per bbl.
The benchmark price for natural gas delivered at Henry Hub during this time period is $3.39 per MMBTU. The Henry Hub price was held constant throughout the life of the wells and is adjusted for BTU content, marketing costs, and basis differentials, resulting in a weighted average received price of $2.82 per Mcf.
| EON Resources, Inc. | April 20, 2026 | Page | 2 |
| | ||
Summary level revenue accounting data for the period of January 1, 2025 through September 30, 2025 were generally used in this evaluation.
OPERATING COSTS
The lease operating expenses used in this evaluation for producing wells represent the average of recent historical monthly operating expenses allocated using a fixed and variable expense model. For non-producing and undeveloped wells, operating expenses were estimated based on knowledge of analogous wells producing under similar conditions. The lease operating expenses in this report represent field level expenses and do not include COPAS expenses properties.
Operating expense data for the period of January 1, 2025 through September 30, 2025 were generally used in this evaluation and were not escalated.
CAPITAL COSTS
Where available, capital costs were generally estimated using recent historical information reported for analogous expenditures. Capital costs provided by EON have been reviewed by Haas & Cobb for reasonableness and were not escalated in this evaluation.
Asset Retirement Obligations (“ARO”) have not been included in this evaluation. As such, they should be captured in the company level financial disclosure.
DISCLAIMERS
The Proved and Probable Reserves presented in this report are estimates only and should not be construed as being exact quantities. They may or may not be actually recovered; and, if recovered, the revenues therefrom and the actual costs related thereto could be more or less than the estimated amounts. Because of governmental policies and uncertainties of supply and demand, the product prices and the costs incurred in recovering these Reserves may vary from the price and cost assumptions in this report. Because these estimates are based on existing governmental regulations, changes could affect the ability to recover these Reserves. In any case, quantities of Reserves may increase or decrease as a result of future operations.
This report may not include a full inventory of EON’s total Proved and Probable Reserves. It is our understanding that as of the effective date of this report, EON had established a carried partnership with a third-party operator to further develop the San Andres formation and was in the final stages of acquiring additional assets in offsetting fields; neither has been evaluated for inclusion as Reserves herein.
Reserves estimates for individual properties included in this report are only valid when considered within the context of the overall report and should not be considered independently. The future net income and net present value estimates contained in this report do not represent an estimate of fair market value.
All information pertaining to the operating expenses, prices, and the interests of EON in the properties appraised has been accepted as represented. It was not considered necessary to make a field examination of the appraised properties. Data used in performing this appraisal were obtained from EON, public sources, and our own files. Supporting work papers pertinent to the appraisal are retained in our files and are available to you or designated parties at your convenience. It should be understood that the financial information supplied by EON for 2025 has not yet been audited and has been accepted as represented.
It was beyond the scope of this Haas & Cobb report to evaluate the potential environmental liability costs from the operation and abandonment of these properties. In addition, no evaluation was made to determine the degree of operator compliance with current environmental rules, regulations, and reporting requirements. Therefore, no estimate of the potential economic liability, if any, from environmental concerns is included in the forecasts presented herein.
| EON Resources, Inc. | April 20, 2026 | Page | 3 |
| | ||
Nothing contained in this report is intended to create or confer, or shall be construed as having created or conferred, any rights in any third party, and all claims, rights, remedies, and obligations of Haas & Cobb or EON, as the case may be, in connection with this report shall accrue or apply solely to Haas & Cobb or EON. For all purposes of this paragraph, the term “third party” means any party other than EON or Haas & Cobb, including without limitation EON’s owners, prospective investors, lenders or prospective lenders, partners or prospective partners, and vendors or other service providers. Without the express written consent of Haas & Cobb, only EON is entitled to rely on this report and any information, conclusions, and/or opinions contained herein.
Haas & Cobb is independent with respect to EON as provided in the Standards Pertaining to the Estimating and Auditing of Oil and Gas Reserves Information promulgated by the SPE.
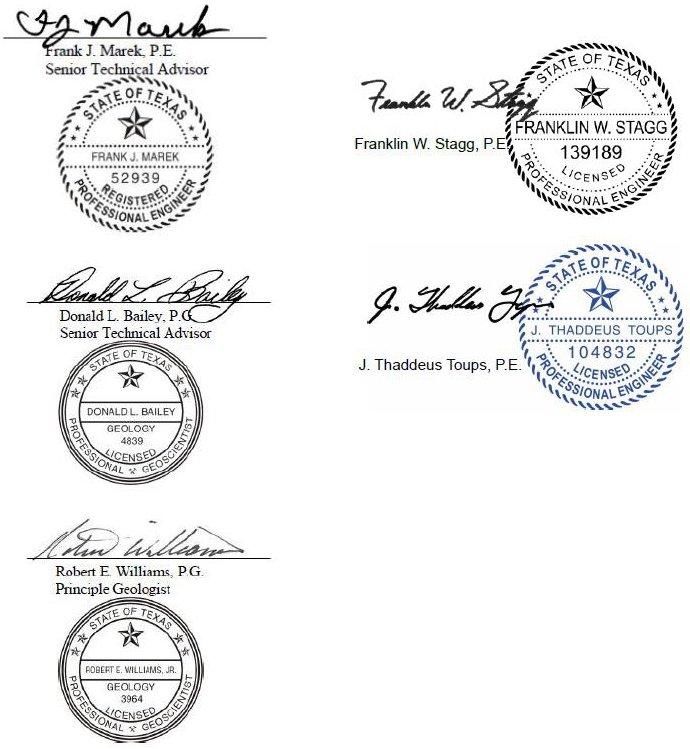
The technical persons primarily responsible for conducting this Report meets the requirements regarding qualifications, independence, objectivity, and confidentiality, as defined by the SPE Standards. J. Thaddeus Toups, a Licensed Professional Engineer in the State of Texas, has been practicing consulting petroleum engineering at Haas & Cobb since 2004 and has over 20 years of industry experience. Franklin W. Stagg, a Licensed Professional Engineer in the State of Texas, has been practicing consulting petroleum engineering at Haas & Cobb since 2016 and has over 10 years of industry experience. This report was prepared with guidance and input from other professionals in the firm with over 40 years of experience.
GENERAL INFORMATION
Attached are summary tables of economic analysis of predicted future performance. Other tables identify the properties appraised with summary Reserves and the economic factors applicable to each. A list of tables is included.
We appreciate this opportunity to have been of service and hope that this report will fulfill your requirements.
[Remainder of page intentionally left blank. Signature page follows.]
| EON Resources, Inc. | April 20, 2026 | Page | 4 |
| | ||
| Respectfully submitted, | |||
| Haas and Cobb Petroleum Consultants, LLC | |||
| F-26129 | |||
| EON Resources, Inc. | April 20, 2026 | Page | 5 |
| | ||