Preliminary Draft | Subject to Review and indicates information that has been omitted on the basis of a confidential treatment Revision by Citi’s Fairness Opinion Committee request pursuant to Rule 24b-2 of the Securities Exchange Act of 1934, as amended. This information has been Citi | Investment Banking filed separately with the Securities and Exchange Commission. Exhibit 16(c)(xxvi) Project Stellar Special Committee Discussion Materials May 5, 2026 Strictly Private and Confidential
Preliminary Draft | Subject to Review and Revision by Citi’s Fairness Opinion Committee Confidential Material Disclaimer The following pages contain material provided to the Special Committee of the Board of Directors (the “Special Committee”) of Utz Brands, Inc. (the “Company”) by Citigroup Global Markets Inc. (“Citi”) in connection with a possible transaction involving the Company. The accompanying material was compiled or prepared on a confidential basis solely for the use of the Special Committee of the Company and not with a view toward public disclosure under any securities laws or otherwise. The information contained in the accompanying material was obtained from the Company and public sources. Any estimates and projections contained herein have been prepared or adopted by management of the Company, obtained from public sources, or are based upon such estimates and projections, and involve numerous and significant subjective determinations, and there is no assurance that such estimates and projections will be realized. Citi does not take responsibility for such estimates and projections, or the basis on which they were prepared. No representation or warranty, express or implied, is made as to the accuracy or completeness of such information and nothing contained herein is, or shall be relied upon as, a representation, whether as to the past, the present or the future. In preparing the accompanying material, Citi assumed and relied, without independent verification, upon the accuracy and completeness of all financial and other information and data publicly available or provided to or otherwise reviewed by or discussed with Citi and upon the assurances of the managements of the Company, that they are not aware of any relevant information that has been omitted or that remains undisclosed to Citi. The accompanying material was not prepared for use by readers not as familiar with the Company as the Special Committee of the Company and, accordingly, neither the Company nor Citi nor their respective legal or financial advisors or accountants take any responsibility for the accompanying material if used by persons other than the Special Committee of the Company. The accompanying material is necessarily based upon information available to Citi, and financial, stock market and other conditions and circumstances existing and disclosed to Citi, as of the date of the accompanying material. Citi does not have any obligation to update or otherwise revise the accompanying material. Nothing contained herein shall be construed as legal, tax or accounting advice. 2
1. Ithaca Diligence Requests
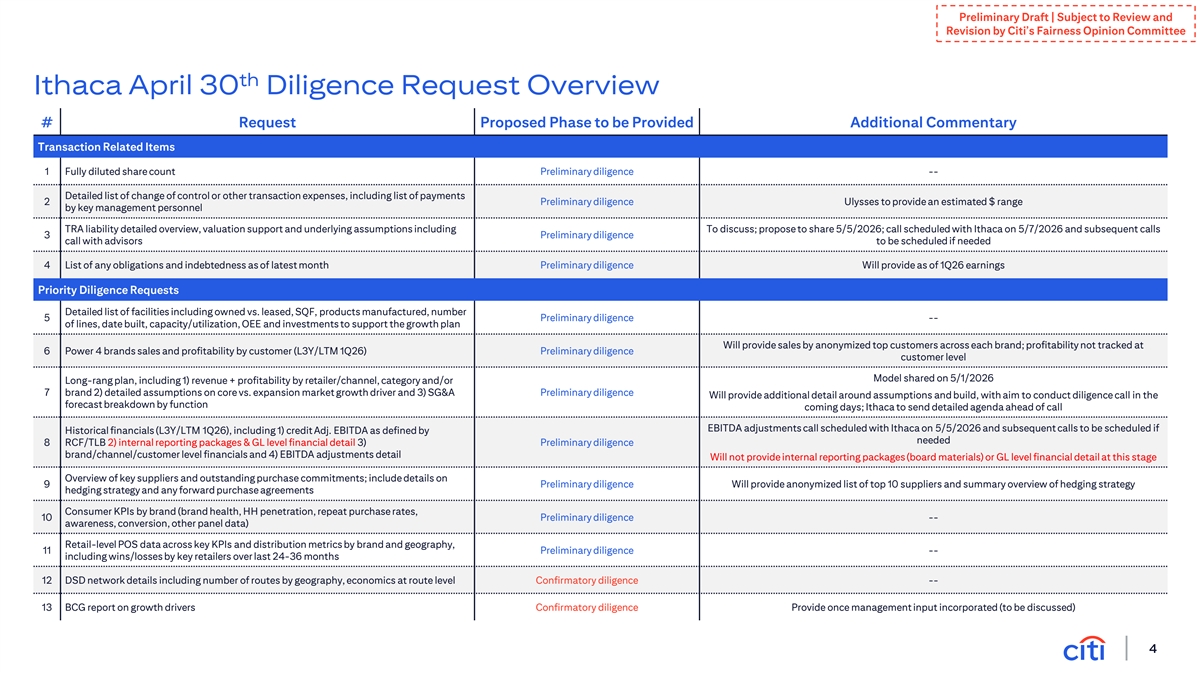
Preliminary Draft | Subject to Review and Revision by Citi’s Fairness Opinion Committee th Ithaca April 30 Diligence Request Overview # Request Proposed Phase to be Provided Additional Commentary Transaction Related Items 1 Fully diluted share count Preliminary diligence -- Detailed list of change of control or other transaction expenses, including list of payments 2 Preliminary diligence Ulysses to provide an estimated $ range by key management personnel TRA liability detailed overview, valuation support and underlying assumptions including To discuss; propose to share 5/5/2026; call scheduled with Ithaca on 5/7/2026 and subsequent calls 3 Preliminary diligence call with advisors to be scheduled if needed 4 List of any obligations and indebtedness as of latest month Preliminary diligence Will provide as of 1Q26 earnings Priority Diligence Requests Detailed list of facilities including owned vs. leased, SQF, products manufactured, number 5 Preliminary diligence -- of lines, date built, capacity/utilization, OEE and investments to support the growth plan Will provide sales by anonymized top customers across each brand; profitability not tracked at 6 Power 4 brands sales and profitability by customer (L3Y/LTM 1Q26) Preliminary diligence customer level Model shared on 5/1/2026 Long-rang plan, including 1) revenue + profitability by retailer/channel, category and/or 7 brand 2) detailed assumptions on core vs. expansion market growth driver and 3) SG&A Preliminary diligence Will provide additional detail around assumptions and build, with aim to conduct diligence call in the forecast breakdown by function coming days; Ithaca to send detailed agenda ahead of call EBITDA adjustments call scheduled with Ithaca on 5/5/2026 and subsequent calls to be scheduled if Historical financials (L3Y/LTM 1Q26), including 1) credit Adj. EBITDA as defined by needed 8 RCF/TLB 2) internal reporting packages & GL level financial detail 3) Preliminary diligence brand/channel/customer level financials and 4) EBITDA adjustments detail Will not provide internal reporting packages (board materials) or GL level financial detail at this stage Overview of key suppliers and outstanding purchase commitments; include details on 9 Preliminary diligence Will provide anonymized list of top 10 suppliers and summary overview of hedging strategy hedging strategy and any forward purchase agreements Consumer KPIs by brand (brand health, HH penetration, repeat purchase rates, 10 Preliminary diligence -- awareness, conversion, other panel data) Retail-level POS data across key KPIs and distribution metrics by brand and geography, 11 Preliminary diligence -- including wins/losses by key retailers over last 24-36 months 12 DSD network details including number of routes by geography, economics at route level Confirmatory diligence -- 13 BCG report on growth drivers Confirmatory diligence Provide once management input incorporated (to be discussed) 4
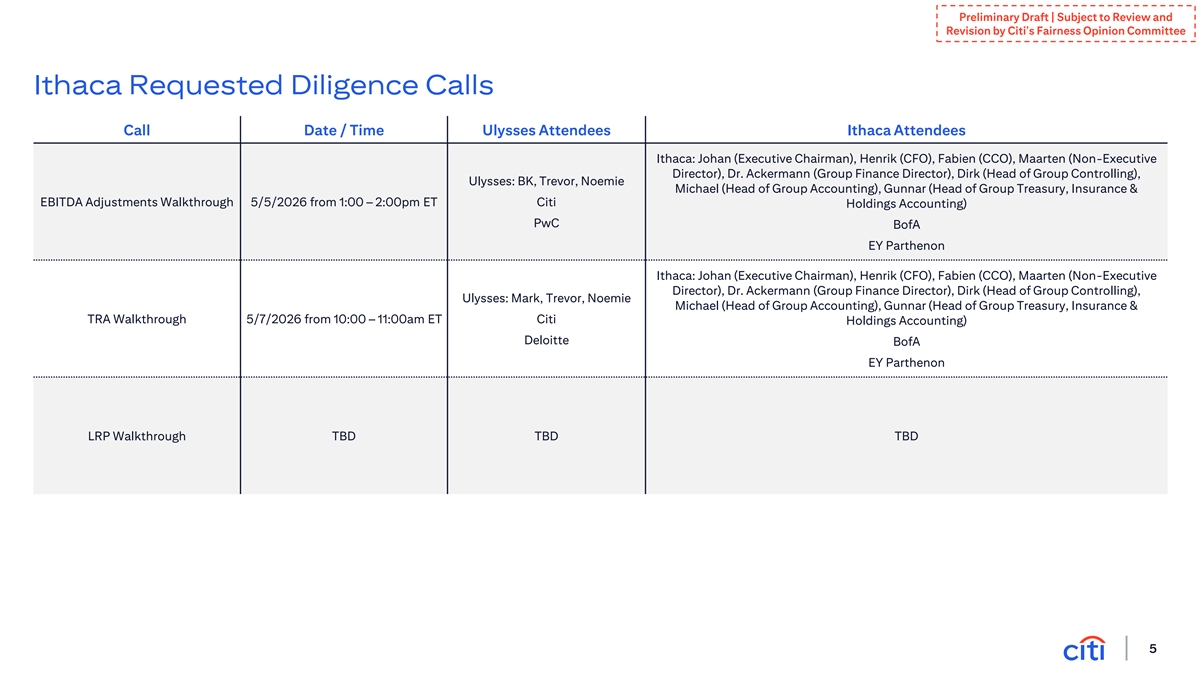
Preliminary Draft | Subject to Review and Revision by Citi’s Fairness Opinion Committee Ithaca Requested Diligence Calls Call Date / Time Ulysses Attendees Ithaca Attendees Ithaca: Johan (Executive Chairman), Henrik (CFO), Fabien (CCO), Maarten (Non-Executive Director), Dr. Ackermann (Group Finance Director), Dirk (Head of Group Controlling), Ulysses: BK, Trevor, Noemie Michael (Head of Group Accounting), Gunnar (Head of Group Treasury, Insurance & EBITDA Adjustments Walkthrough 5/5/2026 from 1:00 – 2:00pm ET Citi Holdings Accounting) PwC BofA EY Parthenon Ithaca: Johan (Executive Chairman), Henrik (CFO), Fabien (CCO), Maarten (Non-Executive Director), Dr. Ackermann (Group Finance Director), Dirk (Head of Group Controlling), Ulysses: Mark, Trevor, Noemie Michael (Head of Group Accounting), Gunnar (Head of Group Treasury, Insurance & TRA Walkthrough 5/7/2026 from 10:00 – 11:00am ET Citi Holdings Accounting) Deloitte BofA EY Parthenon LRP Walkthrough TBD TBD TBD 5
2. Additional Alternative Counterparty Analysis
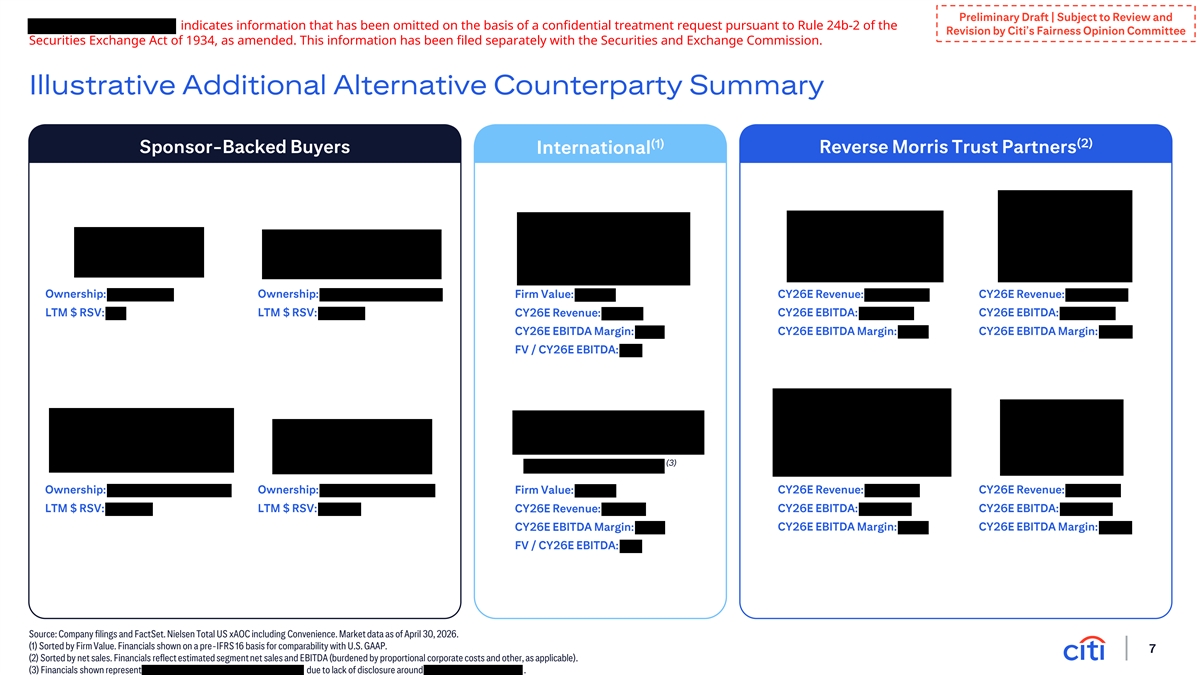
Preliminary Draft | Subject to Review and indicates information that has been omitted on the basis of a confidential treatment request pursuant to Rule 24b-2 of the Revision by Citi’s Fairness Opinion Committee Securities Exchange Act of 1934, as amended. This information has been filed separately with the Securities and Exchange Commission. Illustrative Additional Alternative Counterparty Summary (2) (1) Sponsor-Backed Buyers International Reverse Morris Trust Partners Ownership: Ownership: CY26E Revenue: CY26E Revenue: Firm Value: LTM $ RSV: LTM $ RSV: CY26E Revenue: CY26E EBITDA: CY26E EBITDA: CY26E EBITDA Margin: CY26E EBITDA Margin: CY26E EBITDA Margin: FV / CY26E EBITDA: (3) Ownership: Ownership: Firm Value: CY26E Revenue: CY26E Revenue: LTM $ RSV: LTM $ RSV: CY26E Revenue: CY26E EBITDA: CY26E EBITDA: CY26E EBITDA Margin: CY26E EBITDA Margin: CY26E EBITDA Margin: FV / CY26E EBITDA: Source: Company filings and FactSet. Nielsen Total US xAOC including Convenience. Market data as of April 30, 2026. (1) Sorted by Firm Value. Financials shown on a pre-IFRS 16 basis for comparability with U.S. GAAP. 7 (2) Sorted by net sales. Financials reflect estimated segment net sales and EBITDA (burdened by proportional corporate costs and other, as applicable). (3) Financials shown represent due to lack of disclosure around .
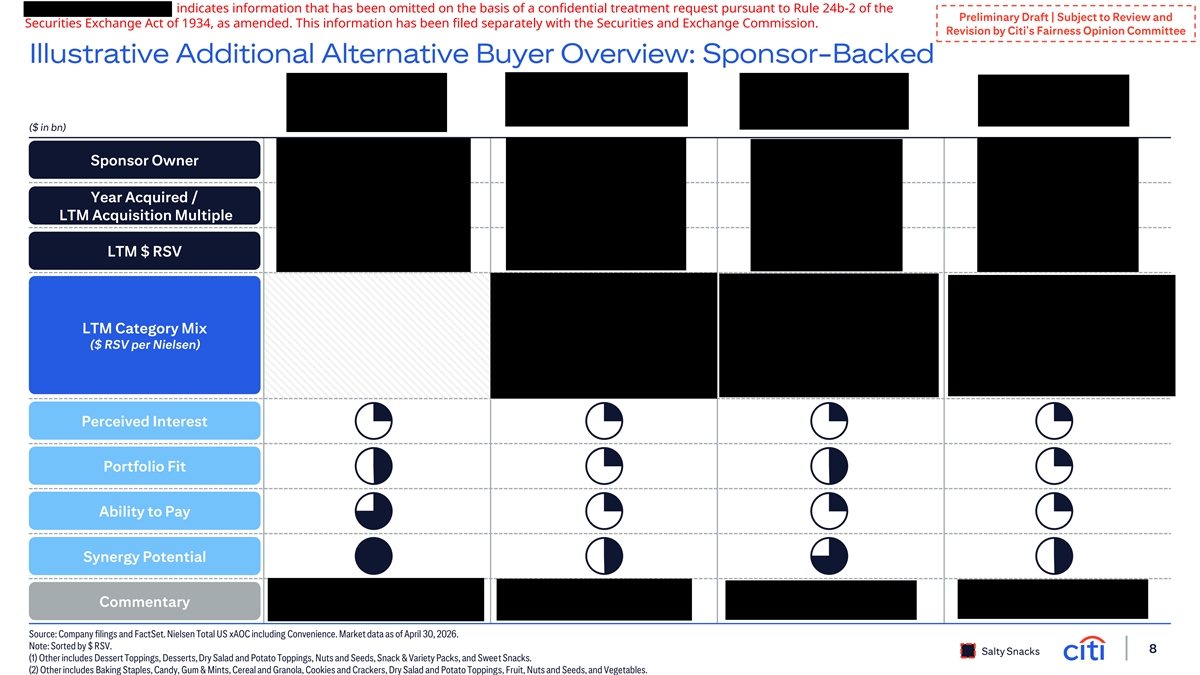
indicates information that has been omitted on the basis of a confidential treatment request pursuant to Rule 24b-2 of the Preliminary Draft | Subject to Review and Securities Exchange Act of 1934, as amended. This information has been filed separately with the Securities and Exchange Commission. Revision by Citi’s Fairness Opinion Committee Illustrative Additional Alternative Buyer Overview: Sponsor-Backed ($ in bn) Sponsor Owner Year Acquired / LTM Acquisition Multiple LTM $ RSV LTM Category Mix ($ RSV per Nielsen) Perceived Interest Portfolio Fit Ability to Pay Synergy Potential Commentary Source: Company filings and FactSet. Nielsen Total US xAOC including Convenience. Market data as of April 30, 2026. Note: Sorted by $ RSV. 8 Salty Snacks (1) Other includes Dessert Toppings, Desserts, Dry Salad and Potato Toppings, Nuts and Seeds, Snack & Variety Packs, and Sweet Snacks. (2) Other includes Baking Staples, Candy, Gum & Mints, Cereal and Granola, Cookies and Crackers, Dry Salad and Potato Toppings, Fruit, Nuts and Seeds, and Vegetables.
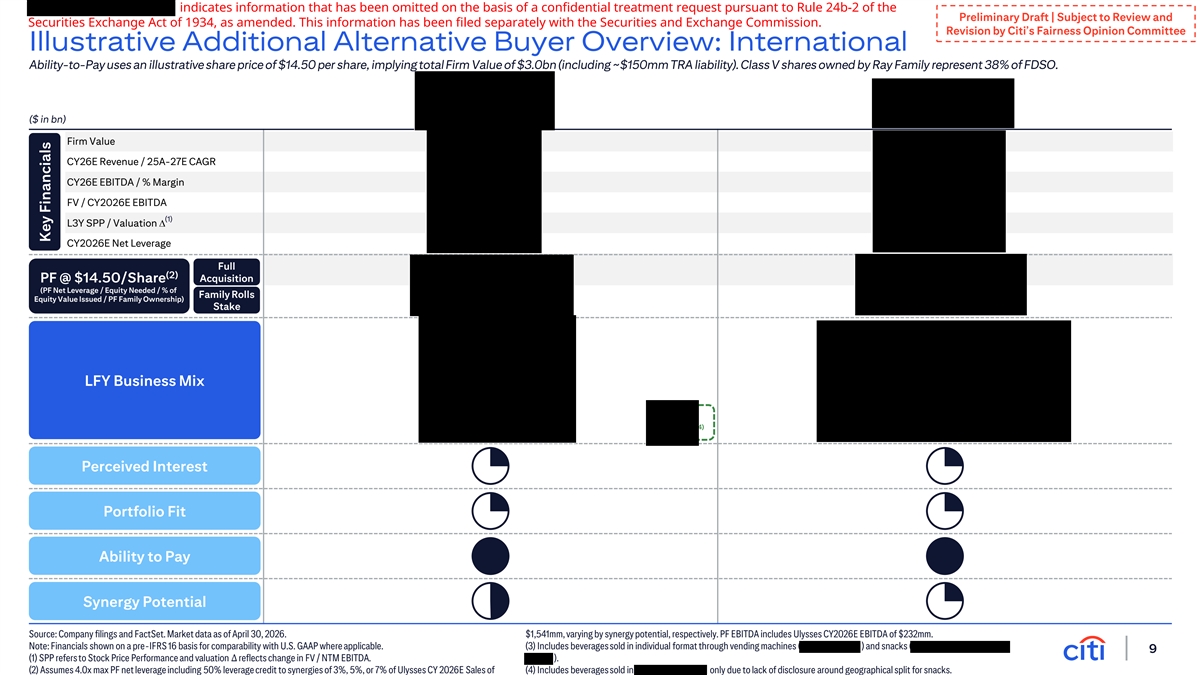
indicates information that has been omitted on the basis of a confidential treatment request pursuant to Rule 24b-2 of the Preliminary Draft | Subject to Review and Securities Exchange Act of 1934, as amended. This information has been filed separately with the Securities and Exchange Commission. Revision by Citi’s Fairness Opinion Committee Illustrative Additional Alternative Buyer Overview: International Ability-to-Pay uses an illustrative share price of $14.50 per share, implying total Firm Value of $3.0bn (including ~$150mm TRA liability). Class V shares owned by Ray Family represent 38% of FDSO. ($ in bn) Firm Value CY26E Revenue / 25A-27E CAGR CY26E EBITDA / % Margin FV / CY2026E EBITDA (1) L3Y SPP / Valuation D CY2026E Net Leverage Full (2) PF @ $14.50/Share Acquisition (PF Net Leverage / Equity Needed / % of Family Rolls Equity Value Issued / PF Family Ownership) Stake LFY Business Mix 4) Perceived Interest Portfolio Fit Ability to Pay Synergy Potential Source: Company filings and FactSet. Market data as of April 30, 2026. $1,541mm, varying by synergy potential, respectively. PF EBITDA includes Ulysses CY2026E EBITDA of $232mm. Note: Financials shown on a pre-IFRS 16 basis for comparability with U.S. GAAP where applicable. (3) Includes beverages sold in individual format through vending machines ( ) and snacks ( 9 (1) SPP refers to Stock Price Performance and valuation ∆ reflects change in FV / NTM EBITDA. ). (2) Assumes 4.0x max PF net leverage including 50% leverage credit to synergies of 3%, 5%, or 7% of Ulysses CY 2026E Sales of (4) Includes beverages sold in only due to lack of disclosure around geographical split for snacks. Ke Key Fina y Financ ncia ials ls
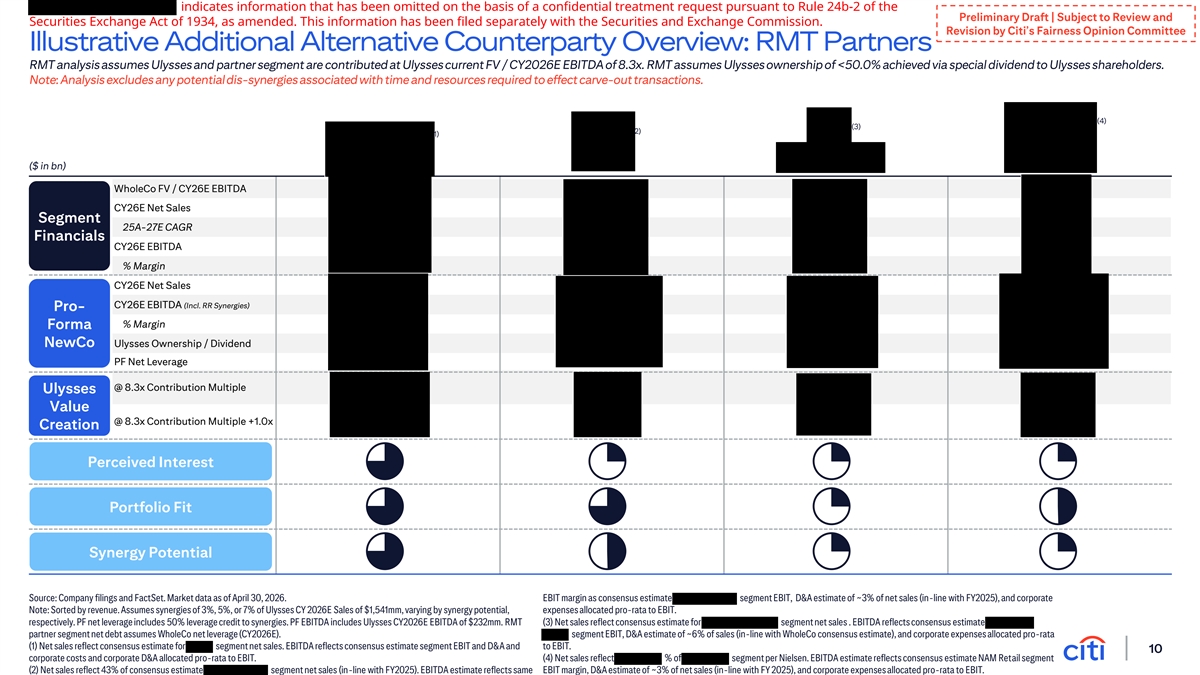
indicates information that has been omitted on the basis of a confidential treatment request pursuant to Rule 24b-2 of the Preliminary Draft | Subject to Review and Securities Exchange Act of 1934, as amended. This information has been filed separately with the Securities and Exchange Commission. Revision by Citi’s Fairness Opinion Committee Illustrative Additional Alternative Counterparty Overview: RMT Partners RMT analysis assumes Ulysses and partner segment are contributed at Ulysses current FV / CY2026E EBITDA of 8.3x. RMT assumes Ulysses ownership of <50.0% achieved via special dividend to Ulysses shareholders. Note: Analysis excludes any potential dis-synergies associated with time and resources required to effect carve-out transactions. (4) (3) 2) 1) ($ in bn) WholeCo FV / CY26E EBITDA CY26E Net Sales Segment 25A-27E CAGR Financials CY26E EBITDA % Margin CY26E Net Sales CY26E EBITDA (Incl. RR Synergies) Pro- % Margin Forma NewCo Ulysses Ownership / Dividend PF Net Leverage @ 8.3x Contribution Multiple Ulysses Value @ 8.3x Contribution Multiple +1.0x Creation Perceived Interest Portfolio Fit Synergy Potential Source: Company filings and FactSet. Market data as of April 30, 2026. EBIT margin as consensus estimate segment EBIT, D&A estimate of ~3% of net sales (in-line with FY2025), and corporate Note: Sorted by revenue. Assumes synergies of 3%, 5%, or 7% of Ulysses CY 2026E Sales of $1,541mm, varying by synergy potential, expenses allocated pro-rata to EBIT. respectively. PF net leverage includes 50% leverage credit to synergies. PF EBITDA includes Ulysses CY2026E EBITDA of $232mm. RMT (3) Net sales reflect consensus estimate for segment net sales . EBITDA reflects consensus estimate partner segment net debt assumes WholeCo net leverage (CY2026E). segment EBIT, D&A estimate of ~6% of sales (in-line with WholeCo consensus estimate), and corporate expenses allocated pro-rata (1) Net sales reflect consensus estimate for segment net sales. EBITDA reflects consensus estimate segment EBIT and D&A and to EBIT. 10 corporate costs and corporate D&A allocated pro-rata to EBIT. (4) Net sales reflect % of segment per Nielsen. EBITDA estimate reflects consensus estimate NAM Retail segment (2) Net sales reflect 43% of consensus estimate segment net sales (in-line with FY2025). EBITDA estimate reflects same EBIT margin, D&A estimate of ~3% of net sales (in-line with FY 2025), and corporate expenses allocated pro-rata to EBIT.