Exhibit 99(c)(4)
Project X Discussion Materials for the Special Committee July 31, 2026
Exhibit 99(c)(4)
Project X Discussion Materials for the Special Committee July 31, 2026
Contents 1 Situation update 4 1 Situation update 4 2 Preliminary financial analysis 12 2 Preliminary financial analysis 12 Appendix 21 Appendix 21 A Selected Company Analysis 22 A Selected Company Analysis 22 B Precedent Transactions Analysis 28 B Precedent Transactions Analysis 28 C WACC and Cost of Equity 33 C WACC and Cost of Equity 33 D Management Forecast 38 D Management Forecast 38 E DDM Analysis 49 E DDM Analysis 49 F Additional supplemental materials 52 F Additional supplemental materials 52 Strictly Confidential |
Disclaimer This presentation was prepared by Rothschild & Co US Inc. (“Rothschild & Co” or “R&Co”) on a confidential basis for the benefit and internal use of the Unaffiliated Committee (the “Special Committee” or “SC”) of the Board of Directors of ReNew Energy Global plc (“ReNew” or the “Company”) in the context of the Special Committee’s consideration of the matters described herein. In creating this presentation, Rothschild & Co has relied upon information that is publicly available or which was provided to Rothschild & Co by or on behalf of the Company’s management, including, without limitation, management operating and financial forecasts or projections. Such information involves numerous significant assumptions and subjective determinations that may or may not be correct. Rothschild & Co has not assumed any responsibility for independent verification of any of such information contained herein, including, but not limited to, any forecasts or projections set forth herein, and Rothschild & Co has relied on such information being complete and accurate in all material respects. Accordingly, no representation or warranty, express or implied, can be made or is made by Rothschild & Co as to the accuracy or completeness of any such information or the achievability of any such forecasts or projections. Except where otherwise indicated, this presentation speaks as of the date hereof and is necessarily based upon the information available to Rothschild & Co and financial, stock market and other conditions and circumstances existing and disclosed to Rothschild & Co as of the date hereof, all of which are subject to change. Rothschild & Co does not have any obligation to update, bring-down, review or reaffirm this presentation. Under no circumstances should the delivery of this presentation imply that any information or analyses included in this presentation would be the same if made as of any other date. Nothing contained in this presentation is, or shall be relied upon as, a promise or representation as to the past, present or future. Nothing contained herein shall be deemed to be a recommendation from Rothschild & Co to any party, including without limitation, any security holder of the Company, to enter into any transaction or to take any course of action. By accepting these materials, the Special Committee acknowledges that Rothschild & Co is not in the business of providing (and the Special Committee is not relying on Rothschild & Co for) legal, tax or accounting advice, and the Special Committee should receive (and rely on) separate and qualified legal, tax and accounting advice. These materials do not constitute an offer or solicitation to sell or purchase any securities. Rothschild & Co is not acting in any capacity as a fiduciary or agent of the Special Committee, the Board of Directors of the Company, the Company or the Company’s security holders. In the ordinary course of their asset management, merchant banking and other business activities, affiliates of Rothschild & Co may at any time hold long or short positions, and may trade or otherwise effect transactions, for their own accounts or the accounts of their clients in equity, debt or other securities (or related derivative securities) or financial instruments of the Company or any of its affiliates or any other company that may be involved in any transaction. This presentation is confidential and was not prepared with a view to public disclosure or filing thereof under state or federal securities laws or otherwise. This presentation may not be copied by, or disclosed or made available to, any person without the prior written consent of Rothschild & Co. This presentation was not prepared for use by readers not as familiar with the business and affairs of the Company as the Special Committee, and accordingly, Rothschild & Co does not take any responsibility for the accuracy or completeness of any material if used by persons other than the Special Committee. Rothschild & Co shall not have any liability, whether direct or indirect, in contract or tort or otherwise, to any person in connection with this presentation. Strictly Confidential | 3
1 Situation update
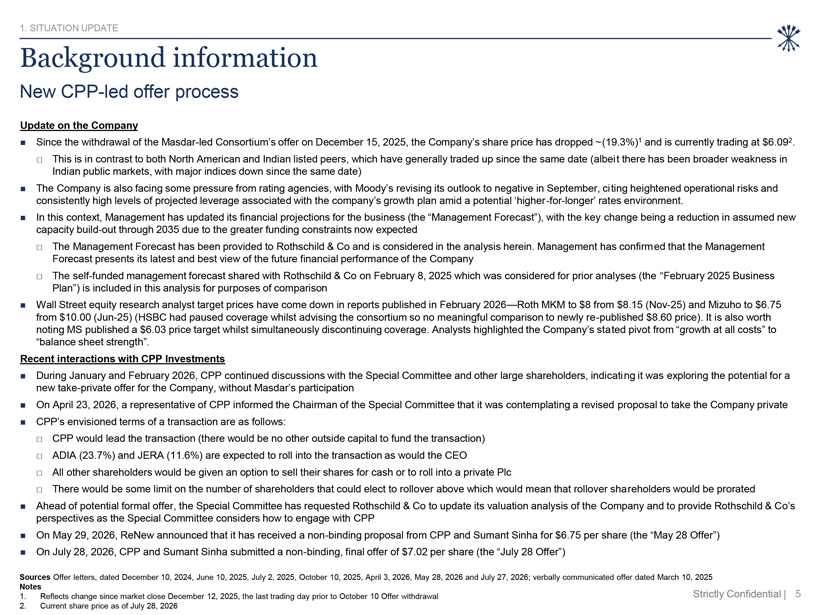
1. SITUATION UPDATE Background information New CPP-led offer process Update on the Company Since the withdrawal of the Masdar-led Consortium’s offer on December 15, 2025, the Company’s share price has dropped ~(19.3%) 1 and is currently trading at $6.09 2. This is in contrast to both North American and Indian listed peers, which have generally traded up since the same date (albeit there has been broader weakness in Indian public markets, with major indices down since the same date) The Company is also facing some pressure from rating agencies, with Moody’s revising its outlook to negative in September, citing heightened operational risks and consistently high levels of projected leverage associated with the company’s growth plan amid a potential ‘higher-for-longer’ rates environment. In this context, Management has updated its financial projections for the business (the “Management Forecast”), with the key change being a reduction in assumed new capacity build-out through 2035 due to the greater funding constraints now expected The Management Forecast has been provided to Rothschild & Co and is considered in the analysis herein. Management has confirmed that the Management Forecast presents its latest and best view of the future financial performance of the Company The self-funded management forecast shared with Rothschild & Co on February 8, 2025 which was considered for prior analyses (the “February 2025 Business Plan”) is included in this analysis for purposes of comparison Wall Street equity research analyst target prices have come down in reports published in February 2026—Roth MKM to $8 from $8.15 (Nov-25) and Mizuho to $6.75 from $10.00 (Jun-25) (HSBC had paused coverage whilst advising the consortium so no meaningful comparison to newly re-published $8.60 price). It is also worth noting MS published a $6.03 price target whilst simultaneously discontinuing coverage. Analysts highlighted the Company’s stated pivot from “growth at all costs” to “balance sheet strength”. Recent interactions with CPP Investments During January and February 2026, CPP continued discussions with the Special Committee and other large shareholders, indicating it was exploring the potential for a new take-private offer for the Company, without Masdar’s participation On April 23, 2026, a representative of CPP informed the Chairman of the Special Committee that it was contemplating a revised proposal to take the Company private CPP’s envisioned terms of a transaction are as follows: CPP would lead the transaction (there would be no other outside capital to fund the transaction) ADIA (23.7%) and JERA (11.6%) are expected to roll into the transaction as would the CEO All other shareholders would be given an option to sell their shares for cash or to roll into a private Plc There would be some limit on the number of shareholders that could elect to rollover above which would mean that rollover shareholders would be prorated Ahead of potential formal offer, the Special Committee has requested Rothschild & Co to update its valuation analysis of the Company and to provide Rothschild & Co’s perspectives as the Special Committee considers how to engage with CPP On May 29, 2026, ReNew announced that it has received a non-binding proposal from CPP and Sumant Sinha for $6.75 per share (the “May 28 Offer”) On July 28, 2026, CPP and Sumant Sinha submitted a non-binding, final offer of $7.02 per share (the “July 28 Offer”) Sources Offer letters, dated December 10, 2024, June 10, 2025, July 2, 2025, October 10, 2025, April 3, 2026, May 28, 2026 and July 27, 2026; verbally communicated offer dated March 10, 2025 Notes 1. Reflects change since market close December 12, 2025, the last trading day prior to October 10 Offer withdrawal Strictly Confidential | 5 2. Current share price as of July 28, 2026
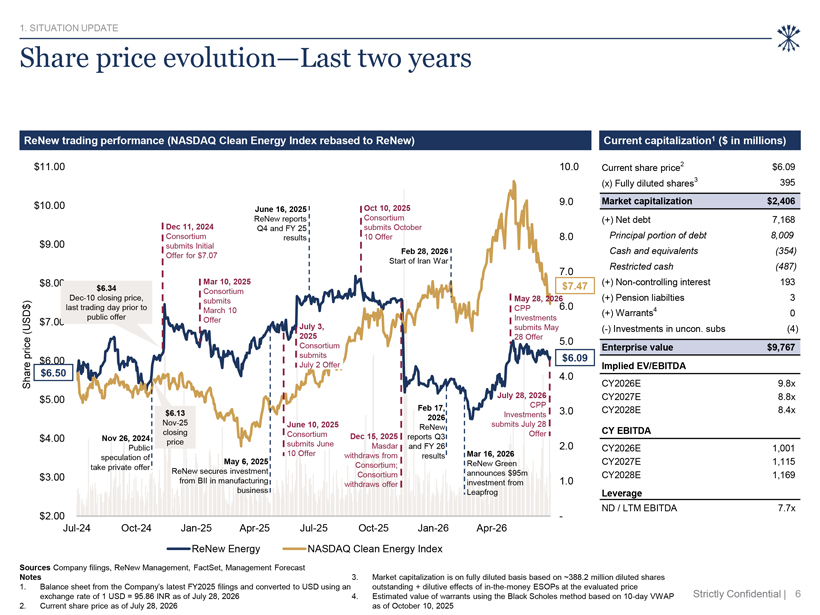
1. SITUATION UPDATE Share price evolution—Last two years ReNew trading performance (NASDAQ Clean Energy Index rebased to ReNew) Current capitalization1 ($ in millions) $11.00 10.0 Current share price2 $6.09 (x) Fully diluted shares3 395 $10.00 Oct 10, 2025 9.0 Market capitalization $2,406 June 16, 2025 ReNew reports Consortium (+) Net debt 7,168 Dec 11, 2024 Q4 and FY 25 submits October $9.00 Consortium results 10 Offer 8.0 Principal portion of debt 8,009 submits Initial Feb 28, 2026 Cash and equivalents (354) Offer for $7.07 Start of Iran War Restricted cash (487) 7.0 $8.00 $6.34 Mar 10, 2025 $7.47 (+) Non-controlling interest 193 Dec-10 closing price, Consortium ) submits May 28, 2026 6.0 (+) Pension liabilties 3 last trading day prior to March 10 CPP 4 (+) Warrants 0 public offer Offer Investments $7.00 (USD$ July 3, submits May (-) Investments in uncon. subs (4) 2025 28 Offer ce 5.0 Consortium Enterprise value $9,767 pri submits $6.09 $6.00 $6.50 July 2 Offer Implied EV/EBITDA 4.0 Share CY2026E 9.8x $5.00 July 28, 2026 CY2027E 8.8x Feb 17, CPP $6.13 3.0 CY2028E 8.4x 2026 Investments Nov-25 June 10, 2025 submits July 28 ReNew CY EBITDA closing Consortium Offer $4.00 Nov 26, 2024 Dec 15, 2025 reports Q3 price submits June Public 10 Offer Masdar and FY 26 2.0 CY2026E 1,001 withdraws from results Mar 16, 2026 speculation of May 6, 2025 ReNew Green CY2027E 1,115 take private offer Consortium; ReNew secures investment announces $95m $3.00 Consortium CY2028E 1,169 from BII in manufacturing investment from 1.0 withdraws offer business Leapfrog Leverage ND / LTM EBITDA 7.7x $2.00 -Jul-24 Oct-24 Jan-25 Apr-25 Jul-25 Oct-25 Jan-26 Apr-26 ReNew Energy NASDAQ Clean Energy Index Sources Company filings, ReNew Management, FactSet, Management Forecast Notes 3. Market capitalization is on fully diluted basis based on ~388.2 million diluted shares 1. Balance sheet from the Company’s latest FY2025 filings and converted to USD using an outstanding + dilutive effects of in-the-money ESOPs at the evaluated price exchange rate of 1 USD = 95.86 INR as of July 28, 2026 4. Estimated value of warrants using the Black Scholes method based on 10-day VWAP Strictly Confidential | 6 2. Current share price as of July 28, 2026 as of October 10, 2025
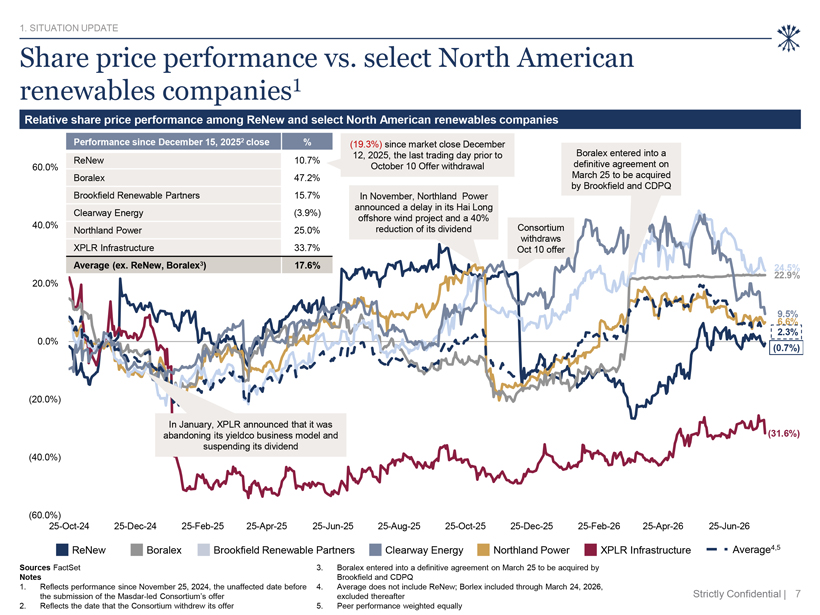
1. SITUATION UPDATE Share price performance vs. select North American renewables companies1 Relative share price performance among ReNew and select North American renewables companies Performance since December 15, 20252 close % (19.3%) since market close December 12, 2025, the last trading day prior to Boralex entered into a ReNew 10.7% definitive agreement on 60.0% October 10 Offer withdrawal Boralex 47.2% March 25 to be acquired by Brookfield and CDPQ Brookfield Renewable Partners 15.7% In November, Northland Power announced a delay in its Hai Long Clearway Energy (3.9%) offshore wind project and a 40% 40.0% reduction of its dividend Consortium Northland Power 25.0% withdraws XPLR Infrastructure 33.7% Oct 10 offer Average (ex. ReNew, Boralex3) 17.6% 24.5% 20.0% 22.9% 9.5% 6.6% 2.3% 0.0% (0.7%) (20.0%) In January, XPLR announced that it was abandoning its yieldco business model and (31.6%) suspending its dividend (40.0%) (60.0%) 25-Oct-24 25-Dec-24 25-Feb-25 25-Apr-25 25-Jun-25 25-Aug-25 25-Oct-25 25-Dec-25 25-Feb-26 25-Apr-26 25-Jun-26 ReNew Boralex Brookfield Renewable Partners Clearway Energy Northland Power XPLR Infrastructure Average4,5 Sources FactSet 3. Boralex entered into a definitive agreement on March 25 to be acquired by Notes Brookfield and CDPQ 1. Reflects performance since November 25, 2024, the unaffected date before 4. Average does not include ReNew; Borlex included through March 24, 2026, the submission of the Masdar-led Consortium’s offer excluded thereafter Strictly Confidential | 7 2. Reflects the date that the Consortium withdrew its offer 5. Peer performance weighted equally
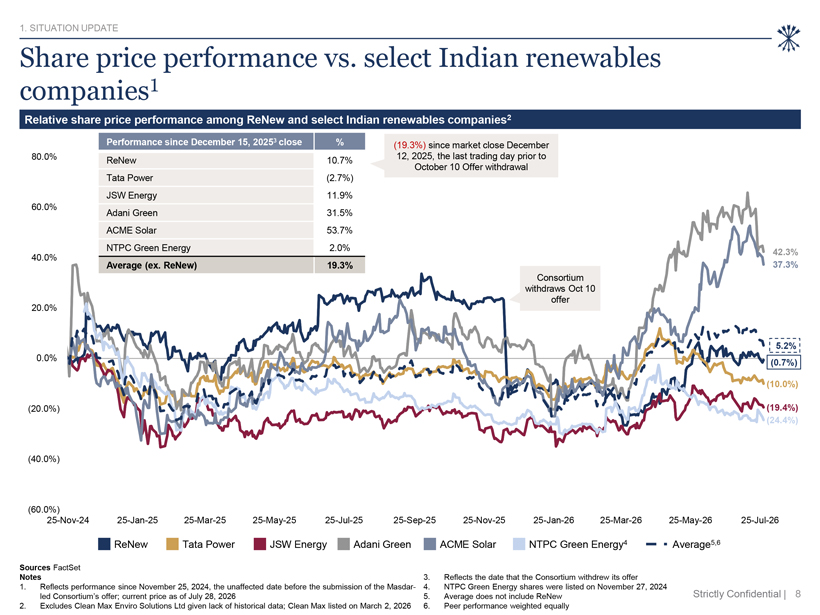
1. SITUATION UPDATE Share price performance vs. select Indian renewables companies1 Relative share price performance among ReNew and select Indian renewables companies2 Performance since December 15, 20253 close % (19.3%) since market close December 80.0% 12, 2025, the last trading day prior to ReNew 10.7% October 10 Offer withdrawal Tata Power (2.7%) JSW Energy 11.9% 60.0% Adani Green 31.5% ACME Solar 53.7% NTPC Green Energy 2.0% 42.3% 40.0% Average (ex. ReNew) 19.3% 37.3% Consortium withdraws Oct 10 20.0% offer 5.2% 0.0% (0.7%) (10.0%) (20.0%) (19.4%) (24.4%) (40.0%) (60.0%) 25-Nov-24 25-Jan-25 25-Mar-25 25-May-25 25-Jul-25 25-Sep-25 25-Nov-25 25-Jan-26 25-Mar-26 25-May-26 25-Jul-26 ReNew Tata Power JSW Energy Adani Green ACME Solar NTPC Green Energy4 Average5,6 Sources FactSet Notes 3. Reflects the date that the Consortium withdrew its offer 1. Reflects performance since November 25, 2024, the unaffected date before the submission of the Masdar- 4. NTPC Green Energy shares were listed on November 27, 2024 led Consortium’s offer; current price as of July 28, 2026 5. Average does not include ReNew Strictly Confidential | 8 2. Excludes Clean Max Enviro Solutions Ltd given lack of historical data; Clean Max listed on March 2, 2026 6. Peer performance weighted equally
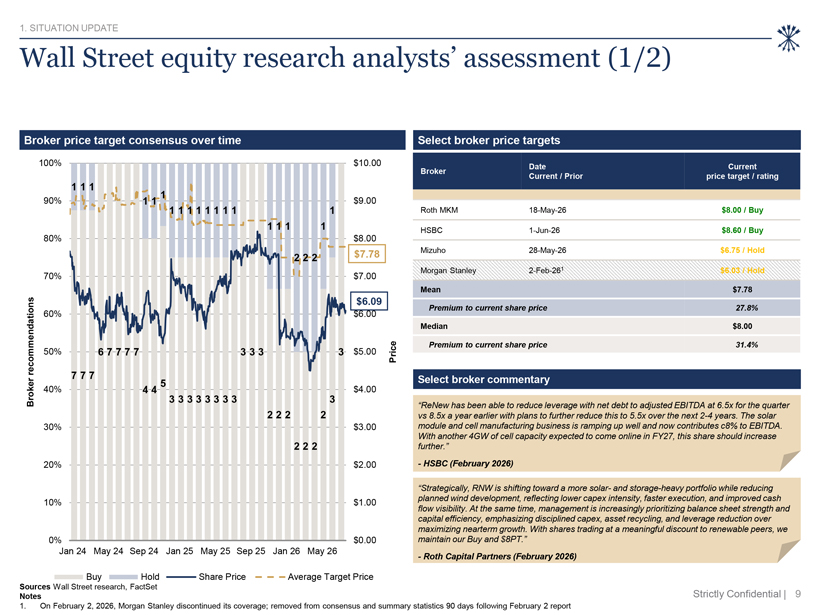
1. SITUATION UPDATE Wall Street equity research analysts’ assessment (1/2) Broker price target consensus over time Select broker price targets 100% $10.00 Date Current Broker Current / Prior price target / rating 1 1 1 1 90% 1 1 $9.00 1 1 1 1 1 1 1 1 1 Roth MKM 18-May-26 $8.00 / Buy 1 1 1 1 HSBC 1-Jun-26 $8.60 / Buy 80% $8.00 $7.78 Mizuho 28-May-26 $6.75 / Hold 2 2 2 70% $7.00 Morgan Stanley 2-Feb-261 $6.03 / Hold Mean $7.78 $6.09 ions Premium to current share price 27.8% 60% $6.00 ndat Median $8.00 e m Premium to current share price 31.4% om 50% 6 7 7 7 7 3 3 3 3 $5.00 Price rec 7 7 7 e r 5 Select broker commentary 40% 4 4 $4.00 Brok 3 3 3 3 3 3 3 3 3 “ReNew has been able to reduce leverage with net debt to adjusted EBITDA at 6.5x for the quarter 2 2 2 2 vs 8.5x a year earlier with plans to further reduce this to 5.5x over the next 2-4 years. The solar 30% $3.00 module and cell manufacturing business is ramping up well and now contributes c8% to EBITDA. With another 4GW of cell capacity expected to come online in FY27, this share should increase 2 2 2 further.” 20% $2.00 - HSBC (February 2026) “Strategically, RNW is shifting toward a more solar- and storage-heavy portfolio while reducing planned wind development, reflecting lower capex intensity, faster execution, and improved cash 10% $1.00 flow visibility. At the same time, management is increasingly prioritizing balance sheet strength and capital efficiency, emphasizing disciplined capex, asset recycling, and leverage reduction over maximizing nearterm growth. With shares trading at a meaningful discount to renewable peers, we 0% $0.00 maintain our Buy and $8PT.” Jan 24 May 24 Sep 24 Jan 25 May 25 Sep 25 Jan 26 May 26 - Roth Capital Partners (February 2026) Buy Hold Share Price Average Target Price Sources Wall Street research, FactSet Notes Strictly Confidential | 9 1. On February 2, 2026, Morgan Stanley discontinued its coverage; removed from consensus and summary statistics 90 days following February 2 report
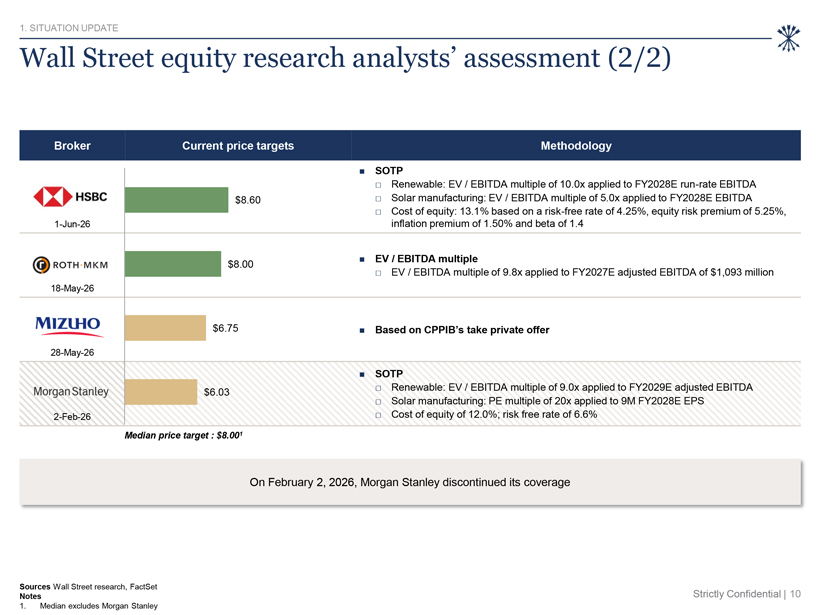
1. SITUATION UPDATE Wall Street equity research analysts’ assessment (2/2) Broker Current price targets Methodology SOTP Renewable: EV / EBITDA multiple of 10.0x applied to FY2028E run-rate EBITDA $8.60 Solar manufacturing: EV / EBITDA multiple of 5.0x applied to FY2028E EBITDA Cost of equity: 13.1% based on a risk-free rate of 4.25%, equity risk premium of 5.25%, 1-Jun-26 inflation premium of 1.50% and beta of 1.4 EV / EBITDA multiple $8.00 EV / EBITDA multiple of 9.8x applied to FY2027E adjusted EBITDA of $1,093 million 18-May-26 $6.75 Based on CPPIB’s take private offer 28-May-26 SOTP Renewable: EV / EBITDA multiple of 9.0x applied to FY2029E adjusted EBITDA $6.03 Solar manufacturing: PE multiple of 20x applied to 9M FY2028E EPS 2-Feb-26 Cost of equity of 12.0%; risk free rate of 6.6% Median price target : $8.001 On February 2, 2026, Morgan Stanley discontinued its coverage Sources Wall Street research, FactSet Notes Strictly Confidential | 10 1. Median excludes Morgan Stanley
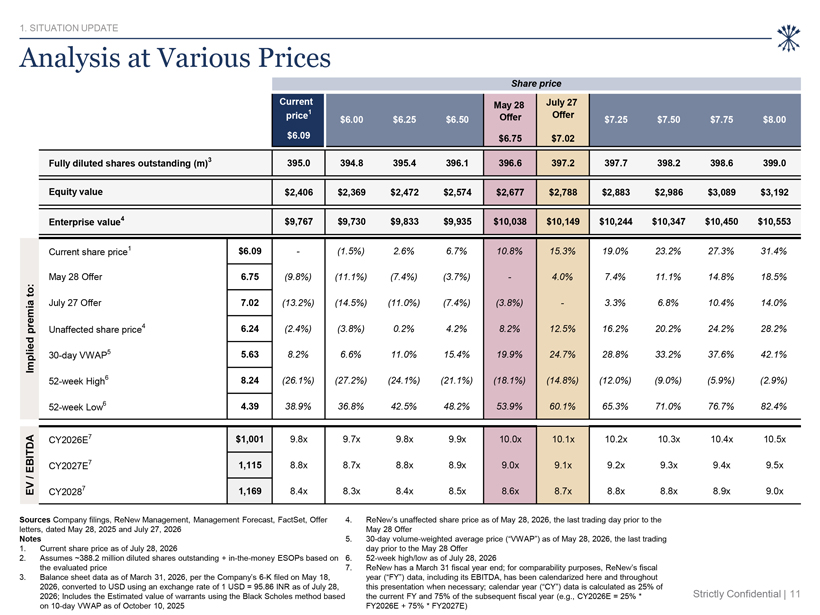
1. SITUATION UPDATE Analysis at Various Prices Share price Current May 28 July 27 price1 Offer $6.00 $6.25 $6.50 Offer $7.25 $7.50 $7.75 $8.00 $6.09 $6.75 $7.02 Fully diluted shares outstanding (m)3 395.0 394.8 395.4 396.1 396.6 397.2 397.7 398.2 398.6 399.0 Equity value $2,406 $2,369 $2,472 $2,574 $2,677 $2,788 $2,883 $2,986 $3,089 $3,192 Enterprise value4 $9,767 $9,730 $9,833 $9,935 $10,038 $10,149 $10,244 $10,347 $10,450 $10,553 Current share price1 $6.09 - (1.5%) 2.6% 6.7% 10.8% 15.3% 19.0% 23.2% 27.3% 31.4% May 28 Offer 6.75 (9.8%) (11.1%) (7.4%) (3.7%)—4.0% 7.4% 11.1% 14.8% 18.5% to : ia July 27 Offer 7.02 (13.2%) (14.5%) (11.0%) (7.4%) (3.8%)—3.3% 6.8% 10.4% 14.0% m pre Unaffected share price4 6.24 (2.4%) (3.8%) 0.2% 4.2% 8.2% 12.5% 16.2% 20.2% 24.2% 28.2% Implied 30-day VWAP5 5.63 8.2% 6.6% 11.0% 15.4% 19.9% 24.7% 28.8% 33.2% 37.6% 42.1% 52-week High6 8.24 (26.1%) (27.2%) (24.1%) (21.1%) (18.1%) (14.8%) (12.0%) (9.0%) (5.9%) (2.9%) 52-week Low6 4.39 38.9% 36.8% 42.5% 48.2% 53.9% 60.1% 65.3% 71.0% 76.7% 82.4% DA CY2026E7 $1,001 9.8x 9.7x 9.8x 9.9x 10.0x 10.1x 10.2x 10.3x 10.4x 10.5x EBIT CY2027E7 1,115 8.8x 8.7x 8.8x 8.9x 9.0x 9.1x 9.2x 9.3x 9.4x 9.5x / EV CY20287 1,169 8.4x 8.3x 8.4x 8.5x 8.6x 8.7x 8.8x 8.8x 8.9x 9.0x Sources Company filings, ReNew Management, Management Forecast, FactSet, Offer 4. ReNew’s unaffected share price as of May 28, 2026, the last trading day prior to the letters, dated May 28, 2025 and July 27, 2026 May 28 Offer Notes 5. 30-day volume-weighted average price (“VWAP”) as of May 28, 2026, the last trading 1. Current share price as of July 28, 2026 day prior to the May 28 Offer 2. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on 6. 52-week high/low as of July 28, 2026 the evaluated price 7. ReNew has a March 31 fiscal year end; for comparability purposes, ReNew’s fiscal 3. Balance sheet data as of March 31, 2026, per the Company’s 6-K filed on May 18, year (“FY”) data, including its EBITDA, has been calendarized here and throughout 2026, converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, this presentation when necessary; calendar year (“CY”) data is calculated as 25% of 2026; Includes the Estimated value of warrants using the Black Scholes method based the current FY and 75% of the subsequent fiscal year (e.g., CY2026E = 25% * Strictly Confidential | 11 on 10-day VWAP as of October 10, 2025 FY2026E + 75% * FY2027E)
2 Preliminary financial analysis
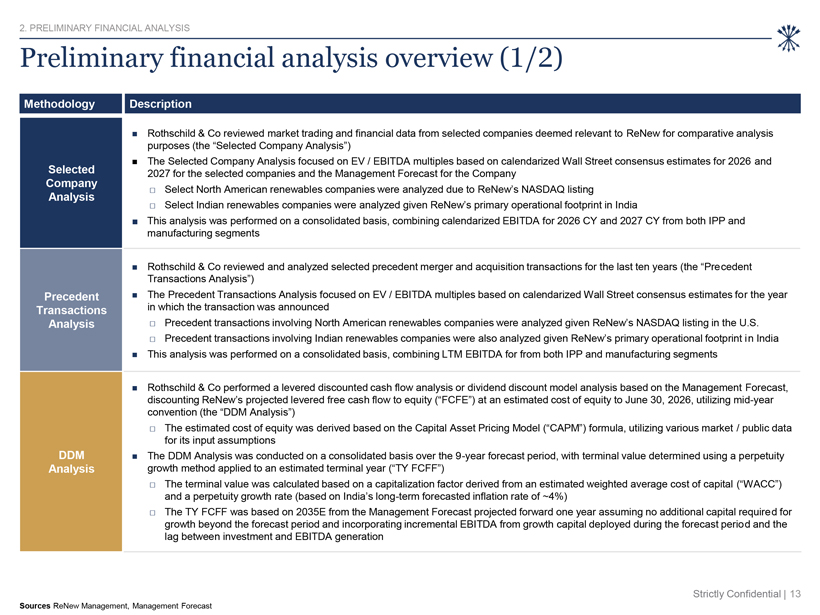
2. PRELIMINARY FINANCIAL ANALYSIS Preliminary financial analysis overview (1/2) Methodology Description Rothschild & Co reviewed market trading and financial data from selected companies deemed relevant to ReNew for comparative analysis purposes (the “Selected Company Analysis”) The Selected Company Analysis focused on EV / EBITDA multiples based on calendarized Wall Street consensus estimates for 2026 and Selected 2027 for the selected companies and the Management Forecast for the Company Company Select North American renewables companies were analyzed due to ReNew’s NASDAQ listing Analysis Select Indian renewables companies were analyzed given ReNew’s primary operational footprint in India ¦ This analysis was performed on a consolidated basis, combining calendarized EBITDA for 2026 CY and 2027 CY from both IPP and manufacturing segments Rothschild & Co reviewed and analyzed selected precedent merger and acquisition transactions for the last ten years (the “Precedent Transactions Analysis”) Precedent The Precedent Transactions Analysis focused on EV / EBITDA multiples based on calendarized Wall Street consensus estimates for the year Transactions in which the transaction was announced Analysis Precedent transactions involving North American renewables companies were analyzed given ReNew’s NASDAQ listing in the U.S. Precedent transactions involving Indian renewables companies were also analyzed given ReNew’s primary operational footprint in India This analysis was performed on a consolidated basis, combining LTM EBITDA for from both IPP and manufacturing segments Rothschild & Co performed a levered discounted cash flow analysis or dividend discount model analysis based on the Management Forecast, discounting ReNew’s projected levered free cash flow to equity (“FCFE”) at an estimated cost of equity to June 30, 2026, utilizing mid-year convention (the “DDM Analysis”) The estimated cost of equity was derived based on the Capital Asset Pricing Model (“CAPM”) formula, utilizing various market / public data for its input assumptions DDM The DDM Analysis was conducted on a consolidated basis over the 9-year forecast period, with terminal value determined using a perpetuity Analysis growth method applied to an estimated terminal year (“TY FCFF”) The terminal value was calculated based on a capitalization factor derived from an estimated weighted average cost of capital (“WACC”) and a perpetuity growth rate (based on India’s long-term forecasted inflation rate of ~4%) The TY FCFF was based on 2035E from the Management Forecast projected forward one year assuming no additional capital required for growth beyond the forecast period and incorporating incremental EBITDA from growth capital deployed during the forecast period and the lag between investment and EBITDA generation Strictly Confidential | 13 Sources ReNew Management, Management Forecast
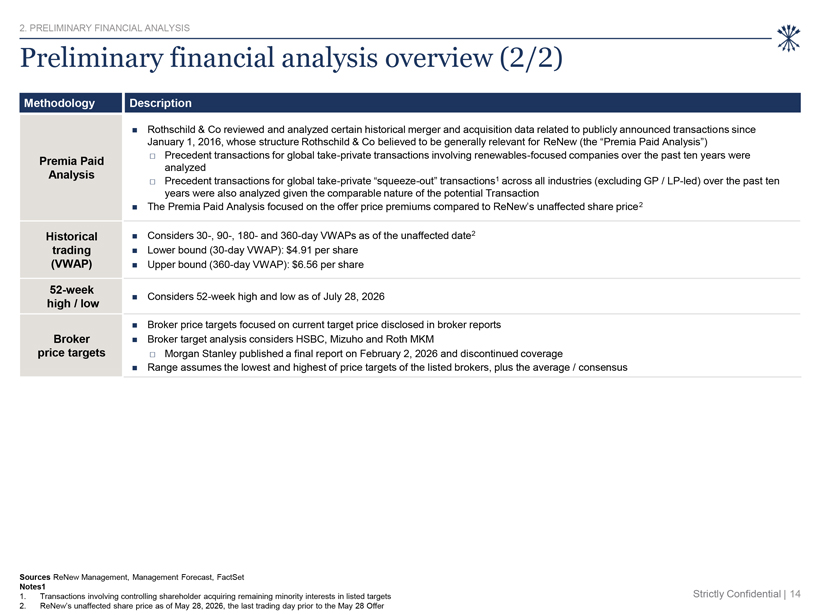
2. PRELIMINARY FINANCIAL ANALYSIS Preliminary financial analysis overview (2/2) Methodology Description Rothschild & Co reviewed and analyzed certain historical merger and acquisition data related to publicly announced transactions since January 1, 2016, whose structure Rothschild & Co believed to be generally relevant for ReNew (the “Premia Paid Analysis”) Precedent transactions for global take-private transactions involving renewables-focused companies over the past ten years were Premia Paid analyzed Analysis 1 Precedent transactions for global take-private “squeeze-out” transactions across all industries (excluding GP / LP-led) over the past ten years were also analyzed given the comparable nature of the potential Transaction The Premia Paid Analysis focused on the offer price premiums compared to ReNew’s unaffected share price2 Historical Considers 30-, 90-, 180- and 360-day VWAPs as of the unaffected date2 trading Lower bound (30-day VWAP): $4.91 per share (VWAP) Upper bound (360-day VWAP): $6.56 per share 52-week Considers 52-week high and low as of July 28, 2026 high / low Broker price targets focused on current target price disclosed in broker reports Broker Broker target analysis considers HSBC, Mizuho and Roth MKM price targets Morgan Stanley published a final report on February 2, 2026 and discontinued coverage Range assumes the lowest and highest of price targets of the listed brokers, plus the average / consensus Sources ReNew Management, Management Forecast, FactSet Notes1 1. Transactions involving controlling shareholder acquiring remaining minority interests in listed targets Strictly Confidential | 14 2. ReNew’s unaffected share price as of May 28, 2026, the last trading day prior to the May 28 Offer
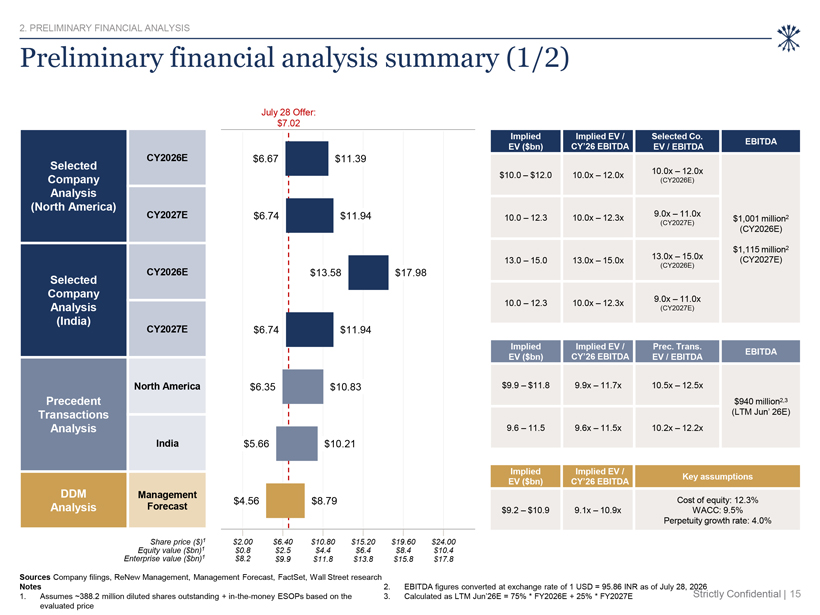
2. PRELIMINARY FINANCIAL ANALYSIS Preliminary financial analysis summary (1/2) July 28 Offer: $7.02 Implied Implied EV / Selected Co. EBITDA EV ($bn) CY’26 EBITDA EV / EBITDA CY2026E $6.67 $11.39 Selected 10.0x – 12.0x $10.0 – $12.0 10.0x – 12.0x Company (CY2026E) Analysis (North America) CY2027E 9.0x – 11.0x $6.74 $11.94 10.0 – 12.3 10.0x – 12.3x (CY2027E) $1,001 million2 (CY2026E) $1,115 million2 13.0x – 15.0x (CY2027E) 13.0 – 15.0 13.0x – 15.0x (CY2026E) CY2026E $13.58 $17.98 Selected Company 9.0x – 11.0x 10.0 – 12.3 10.0x – 12.3x Analysis (CY2027E) (India) CY2027E $6.74 $11.94 Implied Implied EV / Prec. Trans. EBITDA EV ($bn) CY’26 EBITDA EV / EBITDA North America $6.35 $10.83 $9.9 – $11.8 9.9x – 11.7x 10.5x – 12.5x Precedent $940 million2,3 Transactions (LTM Jun’ 26E) Analysis 9.6 – 11.5 9.6x – 11.5x 10.2x – 12.2x India $5.66 $10.21 Implied Implied EV / Key assumptions EV ($bn) CY’26 EBITDA DDM Management $4.56 $8.79 Cost of equity: 12.3% Analysis Forecast $9.2 – $10.9 9.1x – 10.9x WACC: 9.5% Perpetuity growth rate: 4.0% Share price ($)1 $2.00 $6.40 $10.80 $15.20 $19.60 $24.00 Equity value ($bn)1 $0.8 $2.5 $4.4 $6.4 $8.4 $10.4 Enterprise value ($bn)1 $8.2 $9.9 $11.8 $13.8 $15.8 $17.8 Sources Company filings, ReNew Management, Management Forecast, FactSet, Wall Street research Notes 2. EBITDA figures converted at exchange rate of 1 USD = 95.86 INR as of July 28, 2026 1. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the 3. Calculated as LTM Jun’26E = 75% * FY2026E + 25% * FY2027E Strictly Confidential | 15 evaluated price
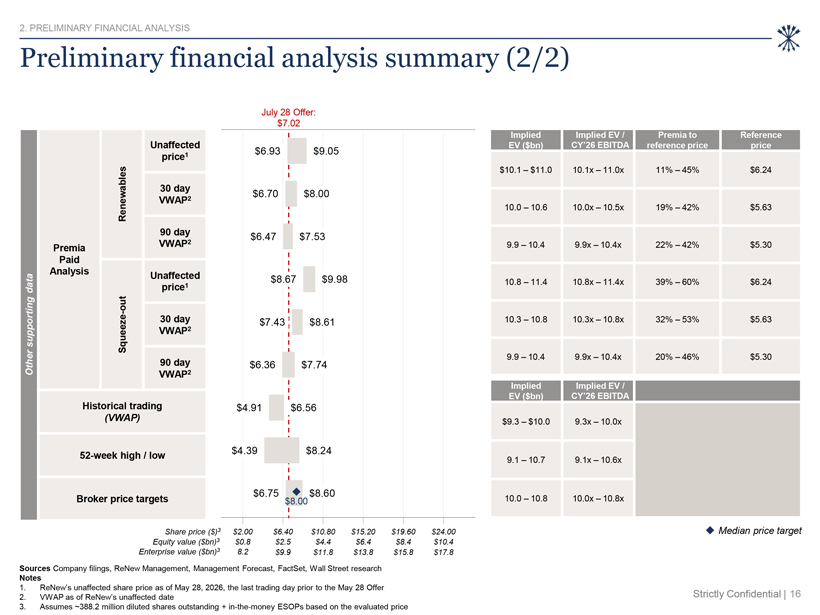
2. PRELIMINARY FINANCIAL ANALYSIS Preliminary financial analysis summary (2/2) July 28 Offer: $7.02 Implied Implied EV / Premia to Reference Unaffected EV ($bn) CY’26 EBITDA reference price price 1 $6.93 $9.05 price $10.1 – $11.0 10.1x – 11.0x 11% – 45% $6.24 30 day $6.70 $8.00 VWAP2 Renewables 10 .0 – 10.6 10 .0x – 10.5x 19% – 42% $5.63 90 day $6.47 $7.53 VWAP2 9 9 .– 10.4 9 9x . – 10.4x 22% – 42% $5.30 Premia Paid Analysis Unaffected $8.67 $9.98 1 10.8 – 11.4 10.8x – 11.4x 39% – 60% $6.24 data price—out 30 day $7.43 $8.61 10 3 .– 10.8 10 3x . – 10.8x 32% – 53% $5.63 supporting VWAP2 Squeeze 9 9 .– 10.4 9 9x . – 10.4x 20% – 46% $5.30 90 day $6.36 $7.74 Other VWAP2 Implied Implied EV / EV ($bn) CY’26 EBITDA Historical trading $4.91 $6.56 (VWAP) $9.3 – $10.0 9.3x – 10.0x $4.39 $8.24 52-week high / low 9.1 – 10.7 9.1x – 10.6x $6.75 $8.60 Broker price targets $8.00 10.0 – 10.8 10.0x – 10.8x Share price ($)3 $2.00 $6.40 $10.80 $15.20 $19.60 $24.00 Median price target Equity value ($bn)3 $0.8 $2.5 $4.4 $6.4 $8.4 $10.4 Enterprise value ($bn)3 8.2 $9.9 $11.8 $13.8 $15.8 $17.8 Sources Company filings, ReNew Management, Management Forecast, FactSet, Wall Street research Notes 1. ReNew’s unaffected share price as of May 28, 2026, the last trading day prior to the May 28 Offer 2. VWAP as of ReNew’s unaffected date Strictly Confidential | 16 3. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the evaluated price
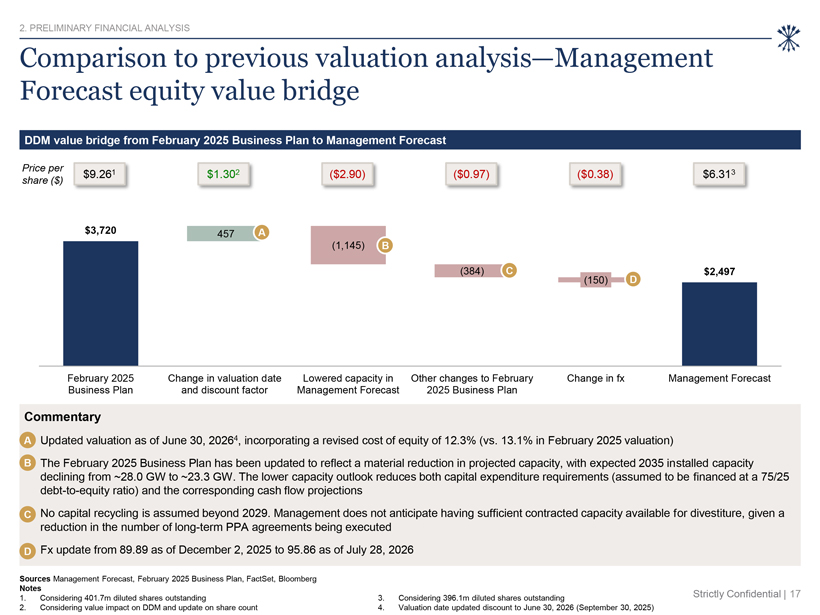
2. PRELIMINARY FINANCIAL ANALYSIS Comparison to previous valuation analysis—Management Forecast equity value bridge DDM value bridge from February 2025 Business Plan to Management Forecast Price per 1 2 3 $9.26 $1.30 ($2.90) ($0.97) ($0.38) $6.31 share ($) $3,720 457 A (1,145) B (384) C (150) D $2,497 February 2025 Change in valuation date Lowered capacity in Other changes to February Change in fx Management Forecast Business Plan and discount factor Management Forecast 2025 Business Plan Commentary A Updated valuation as of June 30, 20264, incorporating a revised cost of equity of 12.3% (vs. 13.1% in February 2025 valuation) B The February 2025 Business Plan has been updated to reflect a material reduction in projected capacity, with expected 2035 installed capacity declining from ~28.0 GW to ~23.3 GW. The lower capacity outlook reduces both capital expenditure requirements (assumed to be financed at a 75/25 debt-to-equity ratio) and the corresponding cash flow projections C No capital recycling is assumed beyond 2029. Management does not anticipate having sufficient contracted capacity available for divestiture, given a reduction in the number of long-term PPA agreements being executed D Fx update from 89.89 as of December 2, 2025 to 95 .86 as of July 28, 2026 Sources Management Forecast, February 2025 Business Plan, FactSet, Bloomberg Notes 1. Considering 401.7m diluted shares outstanding 3. Considering 396.1 m diluted shares outstanding Strictly Confidential | 17 2. Considering value impact on DDM and update on share count 4. Valuation date updated discount to June 30, 2026 (September 30, 2025)
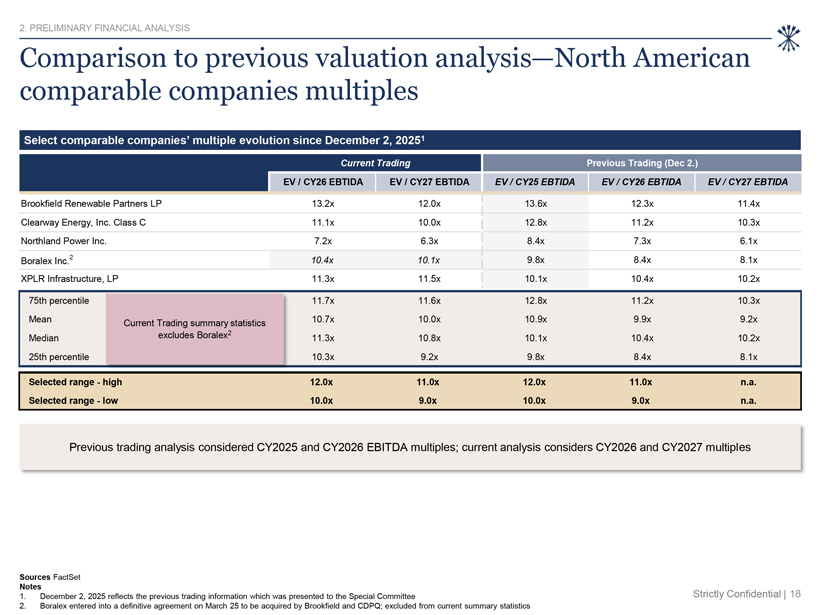
2. PRELIMINARY FINANCIAL ANALYSIS Comparison to previous valuation analysis—North American comparable companies multiples Select comparable companies’ multiple evolution since December 2, 20251 Current Trading Previous Trading (Dec 2.) EV / CY26 EBTIDA EV / CY27 EBTIDA EV / CY25 EBTIDA EV / CY26 EBTIDA EV / CY27 EBTIDA Brookfield Renewable Partners LP 13.2x 12.0x 13.6x 12.3x 11.4x Clearway Energy, Inc. Class C 11.1x 10.0x 12.8x 11.2x 10.3x Northland Power Inc. 7.2x 6.3x 8.4x 7.3x 6.1x Boralex Inc.2 10.4x 10.1x 9.8x 8.4x 8.1x XPLR Infrastructure, LP 11.3x 11.5x 10.1x 10.4x 10.2x 75th percentile 11.7x 11.6x 12.8x 11.2x 10.3x Mean Current Trading summary statistics 10.7x 10.0x 10.9x 9.9x 9.2x excludes Boralex2 Median 11.3x 10.8x 10.1x 10.4x 10.2x 25th percentile 10.3x 9.2x 9.8x 8.4x 8.1x Selected range—high 12.0x 11.0x 12.0x 11.0x n.a. Selected range—low 10.0x 9.0x 10.0x 9.0x n.a. Previous trading analysis considered CY2025 and CY2026 EBITDA multiples; current analysis considers CY2026 and CY2027 multiples Sources FactSet Notes 1. December 2, 2025 reflects the previous trading information which was presented to the Special Committee Strictly Confidential | 18 2. Boralex entered into a definitive agreement on March 25 to be acquired by Brookfield and CDPQ; excluded from current summary statistics
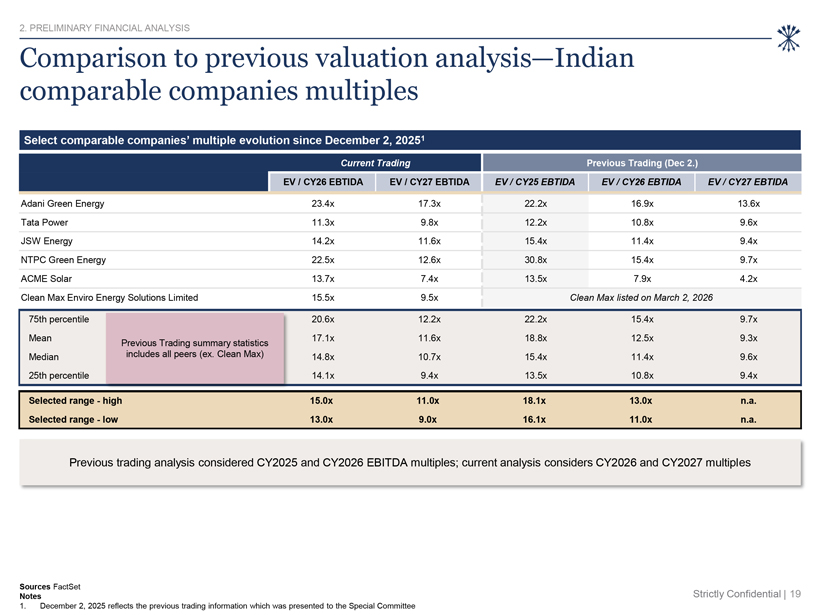
2. PRELIMINARY FINANCIAL ANALYSIS Comparison to previous valuation analysis—Indian comparable companies multiples Select comparable companies’ multiple evolution since December 2, 20251 Current Trading Previous Trading (Dec 2.) EV / CY26 EBTIDA EV / CY27 EBTIDA EV / CY25 EBTIDA EV / CY26 EBTIDA EV / CY27 EBTIDA Adani Green Energy 23.4x 17.3x 22.2x 16.9x 13.6x Tata Power 11.3x 9.8x 12.2x 10.8x 9.6x JSW Energy 14.2x 11.6x 15.4x 11.4x 9.4x NTPC Green Energy 22.5x 12.6x 30.8x 15.4x 9.7x ACME Solar 13.7x 7.4x 13.5x 7.9x 4.2x Clean Max Enviro Energy Solutions Limited 15.5x 9.5x Clean Max listed on March 2, 2026 75th percentile 20.6x 12.2x 22.2x 15.4x 9.7x Mean 17.1x 11.6x 18.8x 12.5x 9.3x Previous Trading summary statistics Median includes all peers (ex. Clean Max) 14.8x 10.7x 15.4x 11.4x 9.6x 25th percentile 14.1x 9.4x 13.5x 10.8x 9.4x Selected range—high 15.0x 11.0x 18.1x 13.0x n.a. Selected range—low 13.0x 9.0x 16.1x 11.0x n.a. Previous trading analysis considered CY2025 and CY2026 EBITDA multiples; current analysis considers CY2026 and CY2027 multiples Sources FactSet Notes Strictly Confidential | 19 1. December 2, 2025 reflects the previous trading information which was presented to the Special Committee
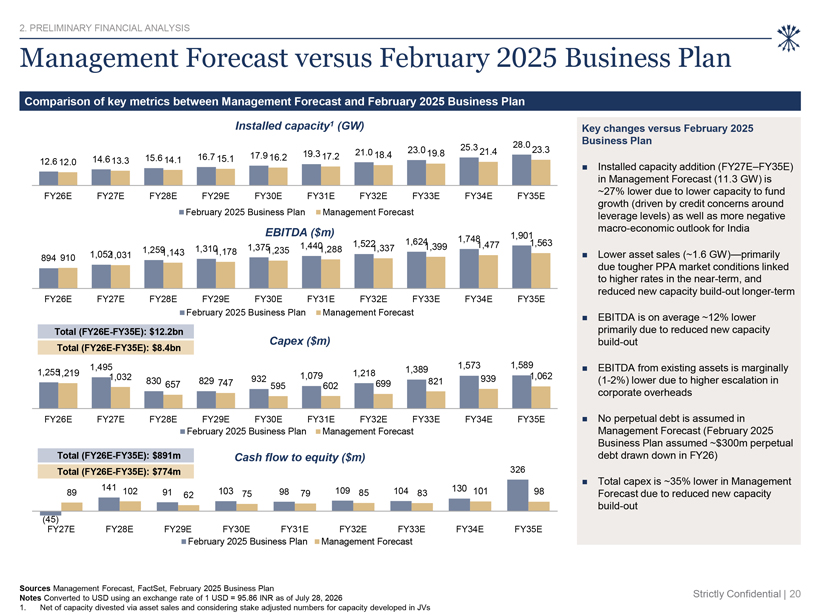
2. PRELIMINARY FINANCIAL ANALYSIS Management Forecast versus February 2025 Business Plan Comparison of key metrics between Management Forecast and February 2025 Business Plan Installed capacity1 (GW) Key changes versus February 2025 28.0 Business Plan 23.0 25.3 23.3 17.9 19.3 21.0 18.4 19.8 21.4 14.6 15.6 14.1 16.7 15.1 16.2 17.2 12.6 12.0 13.3 Installed capacity addition (FY27E–FY35E) in Management Forecast (11.3 GW) is ~27% lower due to lower capacity to fund FY26E FY27E FY28E FY29E FY30E FY31E FY32E FY33E FY34E FY35E February 2025 Business Plan Management Forecast growth (driven by credit concerns around leverage levels) as well as more negative EBITDA ($m) macro-economic outlook for India 1,748 1,901 1,522 1,624 1,477 1,563 1,310 1,375 1,440 1,288 1,337 1,399 1,259 1,143 1,178 1,235 894 910 1,052 1,031 Lower asset sales (~1.6 GW)—primarily due tougher PPA market conditions linked to higher rates in the near-term, and FY26E FY27E FY28E FY29E FY30E FY31E FY32E FY33E FY34E FY35E reduced new capacity build-out longer-term February 2025 Business Plan Management Forecast EBITDA is on average ~12% lower Total (FY26E-FY35E): $12.2bn primarily due to reduced new capacity Capex ($m) build-out Total (FY26E-FY35E): $8.4bn 1,495 1,573 1,589 EBITDA from existing assets is marginally 1,255 1,219 1,218 1,389 1,032 932 1,079 939 1,062 (1-2%) lower due to higher escalation in 830 657 829 747 699 821 595 602 corporate overheads FY26E FY27E FY28E FY29E FY30E FY31E FY32E FY33E FY34E FY35E No perpetual debt is assumed in February 2025 Business Plan Management Forecast Management Forecast (February 2025 Business Plan assumed ~$300m perpetual Total (FY26E-FY35E): $891m Cash flow to equity ($m) debt drawn down in FY26) Total (FY26E-FY35E): $774m 326 Total capex is ~35% lower in Management 141 102 103 109 104 130 101 89 91 62 75 98 79 85 83 98 Forecast due to reduced new capacity build-out (45) FY27E FY28E FY29E FY30E FY31E FY32E FY33E FY34E FY35E February 2025 Business Plan Management Forecast Sources Management Forecast, FactSet, February 2025 Business Plan Notes Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 Strictly Confidential | 20 1. Net of capacity divested via asset sales and considering stake adjusted numbers for capacity developed in JVs
Appendix
A Selected Company Analysis
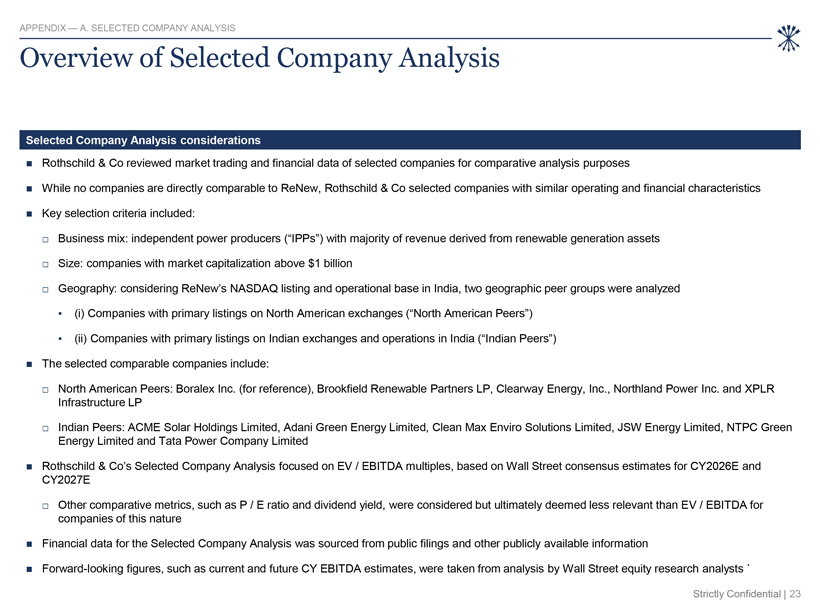
APPENDIX — A. SELECTED COMPANY ANALYSIS Overview of Selected Company Analysis Selected Company Analysis considerations Rothschild & Co reviewed market trading and financial data of selected companies for comparative analysis purposes While no companies are directly comparable to ReNew, Rothschild & Co selected companies with similar operating and financial characteristics Key selection criteria included: Business mix: independent power producers (“IPPs”) with majority of revenue derived from renewable generation assets Size: companies with market capitalization above $1 billion Geography: considering ReNew’s NASDAQ listing and operational base in India, two geographic peer groups were analyzed (i) Companies with primary listings on North American exchanges (“North American Peers”) (ii) Companies with primary listings on Indian exchanges and operations in India (“Indian Peers”) The selected comparable companies include: North American Peers: Boralex Inc. (for reference), Brookfield Renewable Partners LP, Clearway Energy, Inc., Northland Power Inc. and XPLR Infrastructure LP Indian Peers: ACME Solar Holdings Limited, Adani Green Energy Limited, Clean Max Enviro Solutions Limited, JSW Energy Limited, NTPC Green Energy Limited and Tata Power Company Limited Rothschild & Co’s Selected Company Analysis focused on EV / EBITDA multiples, based on Wall Street consensus estimates for CY2026E and CY2027E Other comparative metrics, such as P / E ratio and dividend yield, were considered but ultimately deemed less relevant than EV / EBITDA for companies of this nature Financial data for the Selected Company Analysis was sourced from public filings and other publicly available information Forward-looking figures, such as current and future CY EBITDA estimates, were taken from analysis by Wall Street equity research analysts ` Strictly Confidential | 23
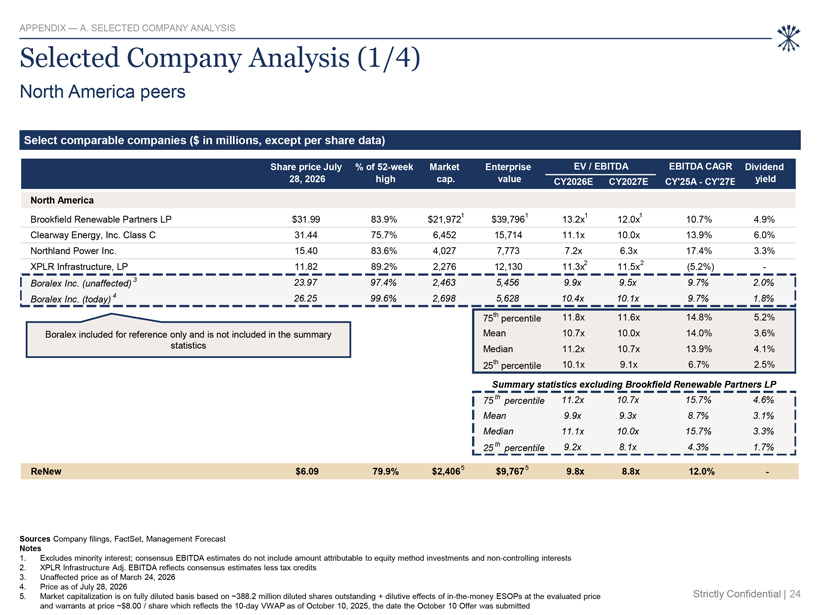
APPENDIX — A. SELECTED COMPANY ANALYSIS Selected Company Analysis (1/4) North America peers Select comparable companies ($ in millions, except per share data) Share price July % of 52-week Market Enterprise EV / EBITDA EBITDA CAGR Dividend 28, 2026 high cap. value CY2026E CY2027E CY’25A—CY’27E yield North America Brookfield Renewable Partners LP $31.99 83.9% $21,9721 $39,7961 13.2x1 12.0x1 10.7% 4.9% Clearway Energy, Inc. Class C 31.44 75.7% 6,452 15,714 11.1x 10.0x 13.9% 6.0% Northland Power Inc. 15.40 83.6% 4,027 7,773 7.2x 6.3x 17.4% 3.3% XPLR Infrastructure, LP 11.82 89.2% 2,276 12,130 11.3x2 11.5x2 (5.2%) - Boralex Inc. (unaffected) 3 23.97 97.4% 2,463 5,456 9.9x 9.5x 9.7% 2.0% Boralex Inc. (today) 4 26.25 99.6% 2,698 5,628 10.4x 10.1x 9.7% 1.8% 75th percentile 11.8x 11.6x 14.8% 5.2% Boralex included for reference only and is not included in the summary Mean 10.7x 10.0x 14.0% 3.6% statistics Median 11.2x 10.7x 13.9% 4.1% 25th percentile 10.1x 9.1x 6.7% 2.5% Summary statistics excluding Brookfield Renewable Partners LP 75 th percentile 11.2x 10.7x 15.7% 4.6% Mean 9.9x 9.3x 8.7% 3.1% Median 11.1x 10.0x 15.7% 3.3% 25 th percentile 9.2x 8.1x 4.3% 1.7% ReNew $6.09 79.9% $2,4065 $9,7675 9.8x 8.8x 12.0% - Sources Company filings, FactSet, Management Forecast Notes 1. Excludes minority interest; consensus EBITDA estimates do not include amount attributable to equity method investments and non-controlling interests 2. XPLR Infrastructure Adj. EBITDA reflects consensus estimates less tax credits 3. Unaffected price as of March 24, 2026 4. Price as of July 28, 2026 5. Market capitalization is on fully diluted basis based on ~388.2 million diluted shares outstanding + dilutive effects of in-the-money ESOPs at the evaluated price Strictly Confidential | 24 and warrants at price ~$8.00 / share which reflects the 10-day VWAP as of October 10, 2025, the date the October 10 Offer was submitted
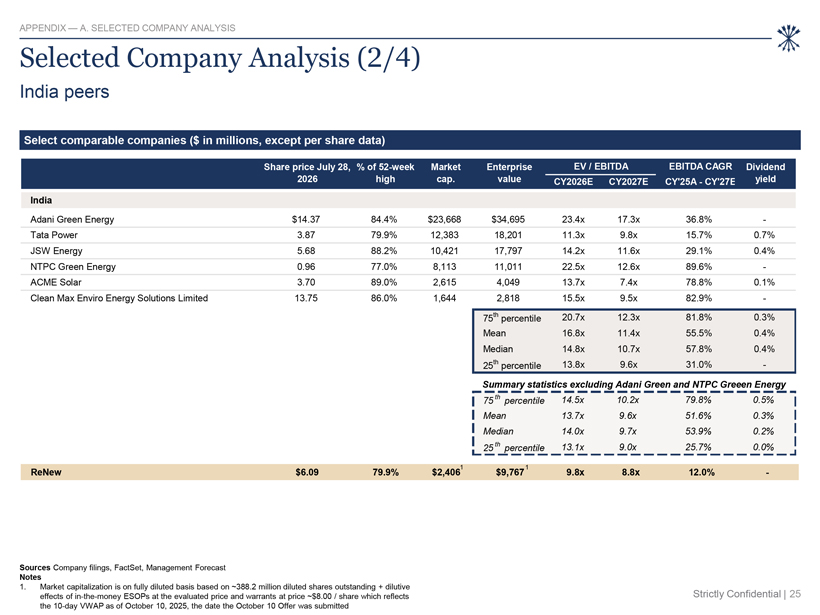
APPENDIX — A. SELECTED COMPANY ANALYSIS Selected Company Analysis (2/4) India peers Select comparable companies ($ in millions, except per share data) Share price July 28, % of 52-week Market Enterprise EV / EBITDA EBITDA CAGR Dividend 2026 high cap. value CY2026E CY2027E CY’25A—CY’27E yield India Adani Green Energy $14.37 84.4% $23,668 $34,695 23.4x 17.3x 36.8% -Tata Power 3.87 79.9% 12,383 18,201 11.3x 9.8x 15.7% 0.7% JSW Energy 5.68 88.2% 10,421 17,797 14.2x 11.6x 29.1% 0.4% NTPC Green Energy 0.96 77.0% 8,113 11,011 22.5x 12.6x 89.6% -ACME Solar 3.70 89.0% 2,615 4,049 13.7x 7.4x 78.8% 0.1% Clean Max Enviro Energy Solutions Limited 13.75 86.0% 1,644 2,818 15.5x 9.5x 82.9% - 75th percentile 20.7x 12.3x 81.8% 0.3% Mean 16.8x 11.4x 55.5% 0.4% Median 14.8x 10.7x 57.8% 0.4% 25th percentile 13.8x 9.6x 31.0% - Summary statistics excluding Adani Green and NTPC Greeen Energy 75 th percentile 14.5x 10.2x 79.8% 0.5% Mean 13.7x 9.6x 51.6% 0.3% Median 14.0x 9.7x 53.9% 0.2% 25 th percentile 13.1x 9.0x 25.7% 0.0% 1 1 ReNew $6.09 79.9% $2,406 $9,767 9.8x 8.8x 12.0% - Sources Company filings, FactSet, Management Forecast Notes 1. Market capitalization is on fully diluted basis based on ~388.2 million diluted shares outstanding + dilutive effects of in-the-money ESOPs at the evaluated price and warrants at price ~$8.00 / share which reflects Strictly Confidential | 25 the 10-day VWAP as of October 10, 2025, the date the October 10 Offer was submitted
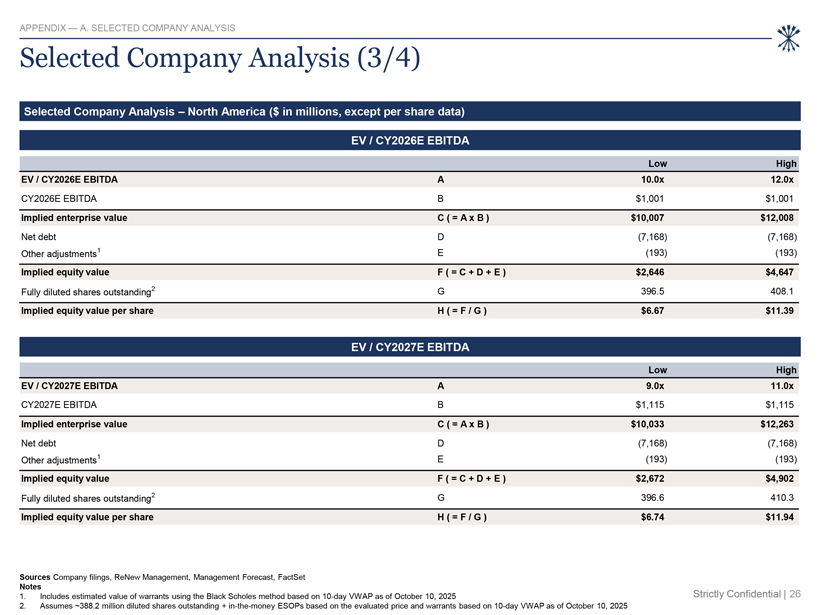
APPENDIX — A. SELECTED COMPANY ANALYSIS Selected Company Analysis (3/4) Selected Company Analysis – North America ($ in millions, except per share data) EV / CY2026E EBITDA Low High EV / CY2026E EBITDA A 10.0x 12.0x CY2026E EBITDA B $1,001 $1,001 Implied enterprise value C ( = A x B ) $10,007 $12,008 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $2,646 $4,647 Fully diluted shares outstanding2 G 396.5 408.1 Implied equity value per share H ( = F / G ) $6.67 $11.39 EV / CY2027E EBITDA Low High EV / CY2027E EBITDA A 9.0x 11.0x CY2027E EBITDA B $1,115 $1,115 Implied enterprise value C ( = A x B ) $10,033 $12,263 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $2,672 $4,902 Fully diluted shares outstanding2 G 396.6 410.3 Implied equity value per share H ( = F / G ) $6.74 $11.94 Sources Company filings, ReNew Management, Management Forecast, FactSet Notes 1. Includes estimated value of warrants using the Black Scholes method based on 10-day VWAP as of October 10, 2025 Strictly Confidential | 26 2. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the evaluated price and warrants based on 10-day VWAP as of October 10, 2025
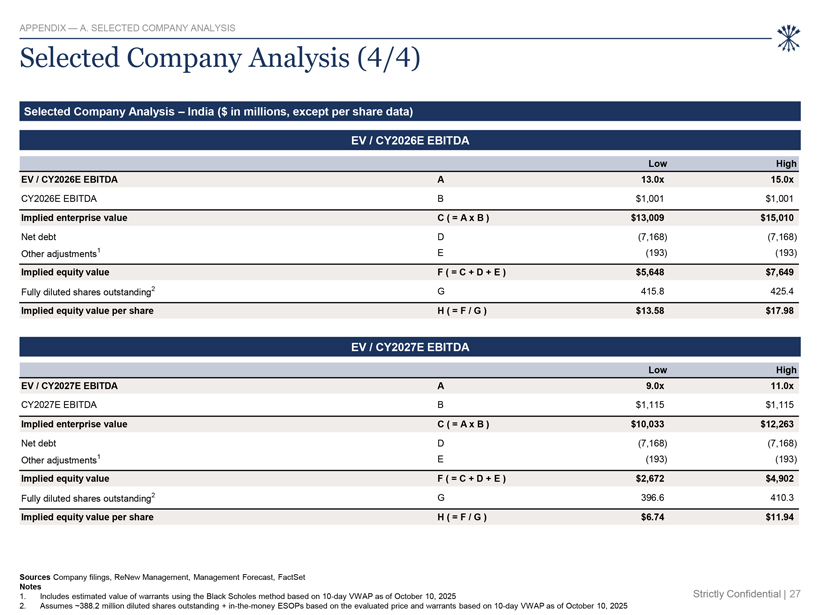
APPENDIX — A. SELECTED COMPANY ANALYSIS Selected Company Analysis (4/4) Selected Company Analysis – India ($ in millions, except per share data) EV / CY2026E EBITDA Low High EV / CY2026E EBITDA A 13.0x 15.0x CY2026E EBITDA B $1,001 $1,001 Implied enterprise value C ( = A x B ) $13,009 $15,010 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $5,648 $7,649 Fully diluted shares outstanding2 G 415.8 425.4 Implied equity value per share H ( = F / G ) $13.58 $17.98 EV / CY2027E EBITDA Low High EV / CY2027E EBITDA A 9.0x 11.0x CY2027E EBITDA B $1,115 $1,115 Implied enterprise value C ( = A x B ) $10,033 $12,263 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $2,672 $4,902 Fully diluted shares outstanding2 G 396.6 410.3 Implied equity value per share H ( = F / G ) $6.74 $11.94 Sources Company filings, ReNew Management, Management Forecast, FactSet Notes 1. Includes estimated value of warrants using the Black Scholes method based on 10-day VWAP as of October 10, 2025 Strictly Confidential | 27 2. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the evaluated price and warrants based on 10-day VWAP as of October 10, 2025
B Precedent Transactions Analysis
APPENDIX — B. PRECEDENT TRANSACTIONS ANALYSIS Overview of Precedent Transactions Analysis Precedent Transactions Analysis considerations Rothschild & Co reviewed and analyzed certain financial information and historical merger and acquisition data related to selected public and private transactions that involved target companies operating in the renewable power generation and non-regulated power sectors Rothschild & Co’s Precedent Transactions Analysis focused on the implied EV / EBITDA multiples of the select precedent transactions, based on the terminal enterprise value of the target business implied by the transaction consideration and the estimated EBITDA of the target in the full calendar year in which the transaction was announced In line with the approach taken in the Selected Company Analysis, Rothschild & Co considered two categories of transactions, namely those involving renewables companies listed and / or operating in North America, and those involving renewables companies listed and / or operating in India Financial data for the Precedent Transactions Analysis was sourced from public filings and other publicly available information Forward-looking figures, such as CY EBITDA estimates, were taken from analysis by Wall Street equity research analysts at the time of transaction announcement Several factors limit the comparability of select precedent transactions, including differences in size, geography, business model and contract profile Each transaction involved unique circumstances, inherently differing from ReNew’s specific context Consequently, multiples-based analysis should not be solely relied upon quantitatively when considering the proposed Transaction Strictly Confidential | 29
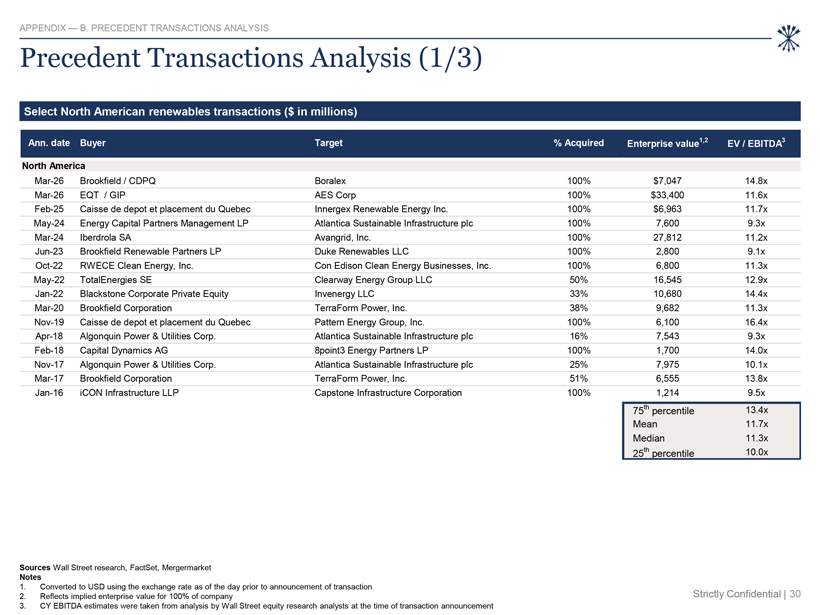
APPENDIX — B. PRECEDENT TRANSACTIONS ANALYSIS Precedent Transactions Analysis (1/3) Select North American renewables transactions ($ in millions) Ann. date Buyer Target % Acquired Enterprise value1,2 EV / EBITDA3 North America Mar-26 Brookfield / CDPQ Boralex 100% $7,047 14.8x Mar-26 EQT / GIP AES Corp 100% $33,400 11.6x Feb-25 Caisse de depot et placement du Quebec Innergex Renewable Energy Inc. 100% $6,963 11.7x May-24 Energy Capital Partners Management LP Atlantica Sustainable Infrastructure plc 100% 7,600 9.3x Mar-24 Iberdrola SA Avangrid, Inc. 100% 27,812 11.2x Jun-23 Brookfield Renewable Partners LP Duke Renewables LLC 100% 2,800 9.1x Oct-22 RWECE Clean Energy, Inc. Con Edison Clean Energy Businesses, Inc. 100% 6,800 11.3x May-22 TotalEnergies SE Clearway Energy Group LLC 50% 16,545 12.9x Jan-22 Blackstone Corporate Private Equity Invenergy LLC 33% 10,680 14.4x Mar-20 Brookfield Corporation TerraForm Power, Inc. 38% 9,682 11.3x Nov-19 Caisse de depot et placement du Quebec Pattern Energy Group, Inc. 100% 6,100 16.4x Apr-18 Algonquin Power & Utilities Corp. Atlantica Sustainable Infrastructure plc 16% 7,543 9.3x Feb-18 Capital Dynamics AG 8point3 Energy Partners LP 100% 1,700 14.0x Nov-17 Algonquin Power & Utilities Corp. Atlantica Sustainable Infrastructure plc 25% 7,975 10.1x Mar-17 Brookfield Corporation TerraForm Power, Inc. 51% 6,555 13.8x Jan-16 iCON Infrastructure LLP Capstone Infrastructure Corporation 100% 1,214 9.5x 75th percentile 13.4x Mean 11.7x Median 11.3x 25th percentile 10.0x Sources Wall Street research, FactSet, Mergermarket Notes 1. Converted to USD using the exchange rate as of the day prior to announcement of transaction 2. Reflects implied enterprise value for 100% of company Strictly Confidential | 30 3. CY EBITDA estimates were taken from analysis by Wall Street equity research analysts at the time of transaction announcement
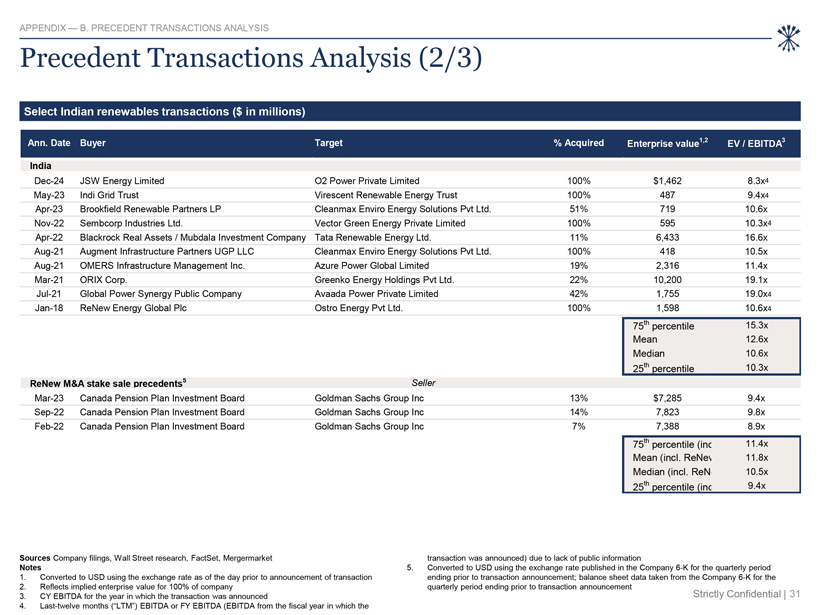
APPENDIX — B. PRECEDENT TRANSACTIONS ANALYSIS Precedent Transactions Analysis (2/3) Select Indian renewables transactions ($ in millions) Ann. Date Buyer Target % Acquired Enterprise value1,2 EV / EBITDA3 India Dec-24 JSW Energy Limited O2 Power Private Limited 100% $1,462 8.3x4 May-23 Indi Grid Trust Virescent Renewable Energy Trust 100% 487 9.4x4 Apr-23 Brookfield Renewable Partners LP Cleanmax Enviro Energy Solutions Pvt Ltd. 51% 719 10.6x Nov-22 Sembcorp Industries Ltd. Vector Green Energy Private Limited 100% 595 10.3x4 Apr-22 Blackrock Real Assets / Mubdala Investment Company Tata Renewable Energy Ltd. 11% 6,433 16.6x Aug-21 Augment Infrastructure Partners UGP LLC Cleanmax Enviro Energy Solutions Pvt Ltd. 100% 418 10.5x Aug-21 OMERS Infrastructure Management Inc. Azure Power Global Limited 19% 2,316 11.4x Mar-21 ORIX Corp. Greenko Energy Holdings Pvt Ltd. 22% 10,200 19.1x Jul-21 Global Power Synergy Public Company Avaada Power Private Limited 42% 1,755 19.0x4 Jan-18 ReNew Energy Global Plc Ostro Energy Pvt Ltd. 100% 1,598 10.6x4 75th percentile 15.3x Mean 12.6x Median 10.6x 25th percentile 10.3x ReNew M&A stake sale precedents5 Seller Mar-23 Canada Pension Plan Investment Board Goldman Sachs Group Inc 13% $7,285 9.4x Sep-22 Canada Pension Plan Investment Board Goldman Sachs Group Inc 14% 7,823 9.8x Feb-22 Canada Pension Plan Investment Board Goldman Sachs Group Inc 7% 7,388 8.9x 75th percentile (inc 11.4x Mean (incl. ReNe 11.8x Median (incl. ReN 10.5x 25th percentile (inc 9.4x Sources Company filings, Wall Street research, FactSet, Mergermarket transaction was announced) due to lack of public information Notes 5. Converted to USD using the exchange rate published in the Company 6-K for the quarterly period 1. Converted to USD using the exchange rate as of the day prior to announcement of transaction ending prior to transaction announcement; balance sheet data taken from the Company 6-K for the 2. Reflects implied enterprise value for 100% of company quarterly period ending prior to transaction announcement 3. CY EBITDA for the year in which the transaction was announced Strictly Confidential | 31 4. Last-twelve months (“LTM”) EBITDA or FY EBITDA (EBITDA from the fiscal year in which the
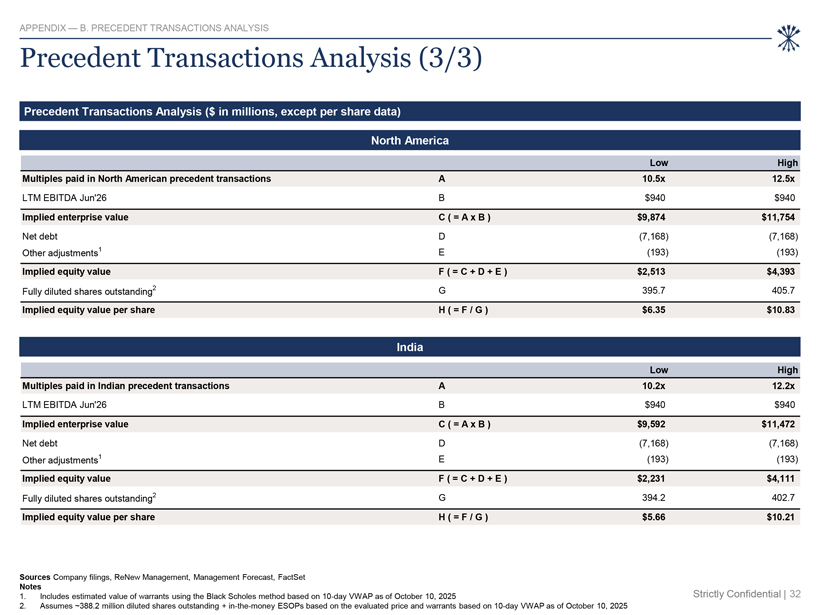
APPENDIX — B. PRECEDENT TRANSACTIONS ANALYSIS Precedent Transactions Analysis (3/3) Precedent Transactions Analysis ($ in millions, except per share data) North America Low High Multiples paid in North American precedent transactions A 10.5x 12.5x LTM EBITDA Jun’26 B $940 $940 Implied enterprise value C ( = A x B ) $9,874 $11,754 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $2,513 $4,393 Fully diluted shares outstanding2 G 395.7 405.7 Implied equity value per share H ( = F / G ) $6.35 $10.83 India Low High Multiples paid in Indian precedent transactions A 10.2x 12.2x LTM EBITDA Jun’26 B $940 $940 Implied enterprise value C ( = A x B ) $9,592 $11,472 Net debt D (7,168) (7,168) Other adjustments1 E (193) (193) Implied equity value F ( = C + D + E ) $2,231 $4,111 Fully diluted shares outstanding2 G 394.2 402.7 Implied equity value per share H ( = F / G ) $5.66 $10.21 Sources Company filings, ReNew Management, Management Forecast, FactSet Notes 1. Includes estimated value of warrants using the Black Scholes method based on 10-day VWAP as of October 10, 2025 Strictly Confidential | 32 2. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the evaluated price and warrants based on 10-day VWAP as of October 10, 2025
C WACC and Cost of Equity
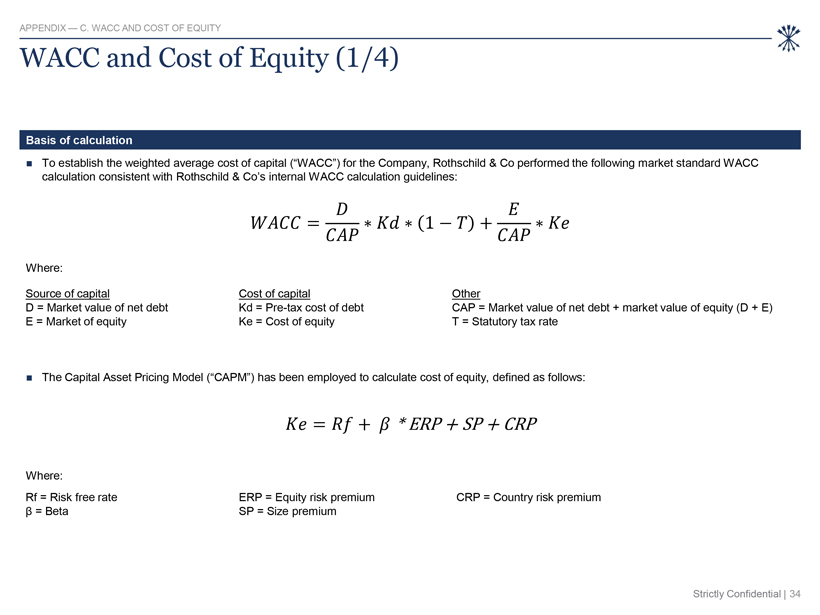
APPENDIX — C. WACC AND COST OF EQUITY WACC and Cost of Equity (1/4) Basis of calculation To establish the weighted average cost of capital (“WACC”) for the Company, Rothschild & Co performed the following market standard WACC calculation consistent with Rothschild & Co’s internal WACC calculation guidelines: Where: Source of capital Cost of capital Other D = Market value of net debt Kd = Pre-tax cost of debt CAP = Market value of net debt + market value of equity (D + E) E = Market of equity Ke = Cost of equity T = Statutory tax rate The Capital Asset Pricing Model (“CAPM”) has been employed to calculate cost of equity, defined as follows: * ERP + SP + CRP Where: Rf = Risk free rate ERP = Equity risk premium CRP = Country risk premium â = Beta SP = Size premium Strictly Confidential | 34
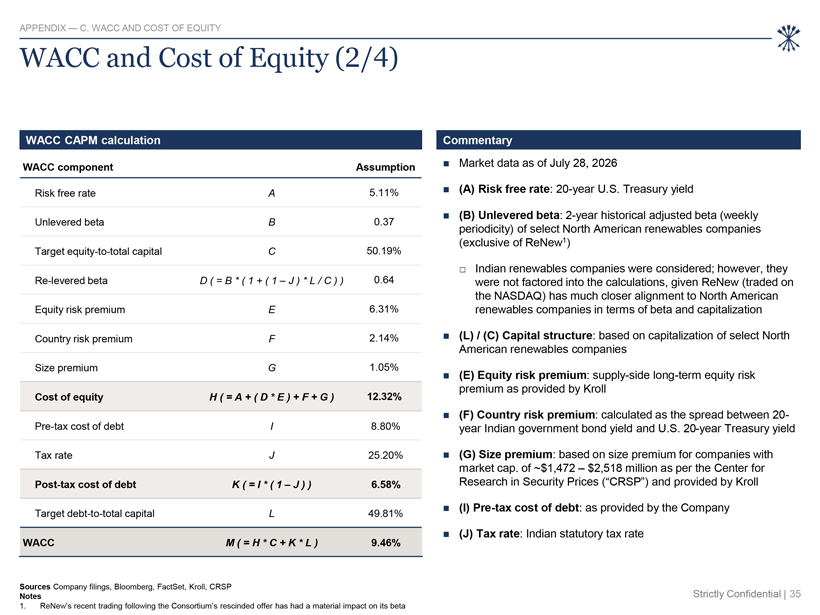
APPENDIX — C. WACC AND COST OF EQUITY WACC and Cost of Equity (2/4) WACC CAPM calculation Commentary WACC component Assumption Market data as of July 28, 2026 Risk free rate A 5.11% (A) Risk free rate: 20-year U.S. Treasury yield (B) Unlevered beta: 2-year historical adjusted beta (weekly Unlevered beta B 0.37 periodicity) of select North American renewables companies (exclusive of ReNew1) Target equity-to-total capital C 50.19% Indian renewables companies were considered; however, they Re-levered beta D ( = B * ( 1 + ( 1 – J ) * L / C ) ) 0.64 were not factored into the calculations, given ReNew (traded on the NASDAQ) has much closer alignment to North American Equity risk premium E 6.31% renewables companies in terms of beta and capitalization Country risk premium F 2.14% (L) / (C) Capital structure: based on capitalization of select North American renewables companies Size premium G 1.05% (E) Equity risk premium: supply-side long-term equity risk premium as provided by Kroll Cost of equity H ( = A + ( D * E ) + F + G ) 12.32% (F) Country risk premium: calculated as the spread between 20-Pre-tax cost of debt I 8.80% year Indian government bond yield and U.S. 20-year Treasury yield Tax rate J 25.20% (G) Size premium: based on size premium for companies with market cap. of ~$1,472 – $2,518 million as per the Center for Post-tax cost of debt K ( = I * ( 1 – J ) ) 6.58% Research in Security Prices (“CRSP”) and provided by Kroll (I) Pre-tax cost of debt: as provided by the Company Target debt-to-total capital L 49.81% WACC M ( = H * C + K * L ) 9.46% (J) Tax rate: Indian statutory tax rate Sources Company filings, Bloomberg, FactSet, Kroll, CRSP Notes Strictly Confidential | 35 1. ReNew’s recent trading following the Consortium’s rescinded offer has had a material impact on its beta
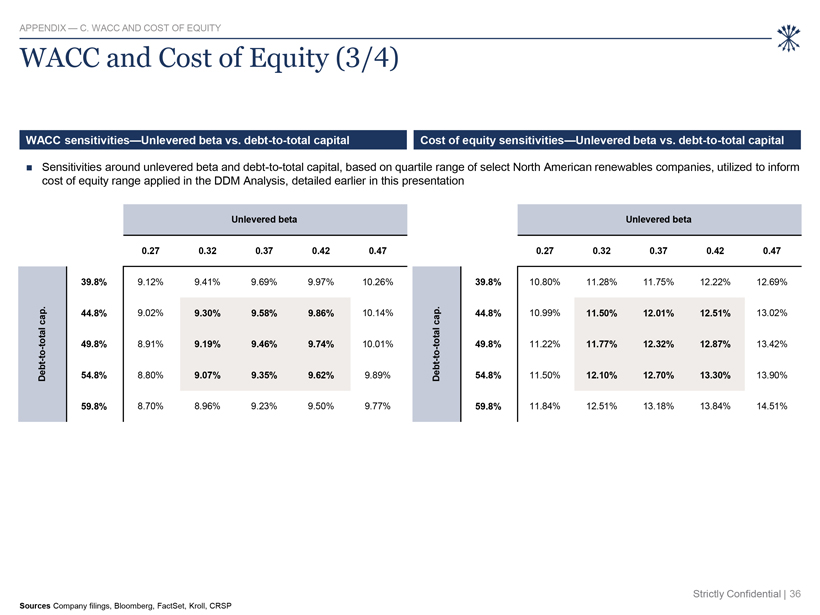
APPENDIX — C. WACC AND COST OF EQUITY WACC and Cost of Equity (3/4) WACC sensitivities—Unlevered beta vs. debt-to-total capital Cost of equity sensitivities—Unlevered beta vs. debt-to-total capital Sensitivities around unlevered beta and debt-to-total capital, based on quartile range of select North American renewables companies, utilized to inform cost of equity range applied in the DDM Analysis, detailed earlier in this presentation Unlevered beta Unlevered beta 0.27 0.32 0.37 0.42 0.47 0.27 0.32 0.37 0.42 0.47 39.8% 9.12% 9.41% 9.69% 9.97% 10.26% 39.8% 10.80% 11.28% 11.75% 12.22% 12.69% . . ap 44.8% 9.02% 9.30% 9.58% 9.86% 10.14% ap 44.8% 10.99% 11.50% 12.01% 12.51% 13.02% c c—total 49.8% 8.91% 9.19% 9.46% 9.74% 10.01% - total 49.8% 11.22% 11.77% 12.32% 12.87% 13.42% - to—to Debt 54.8% 8.80% 9.07% 9.35% 9.62% 9.89% Debt 54.8% 11.50% 12.10% 12.70% 13.30% 13.90% 59.8% 8.70% 8.96% 9.23% 9.50% 9.77% 59.8% 11.84% 12.51% 13.18% 13.84% 14.51% Strictly Confidential | 36 Sources Company filings, Bloomberg, FactSet, Kroll, CRSP
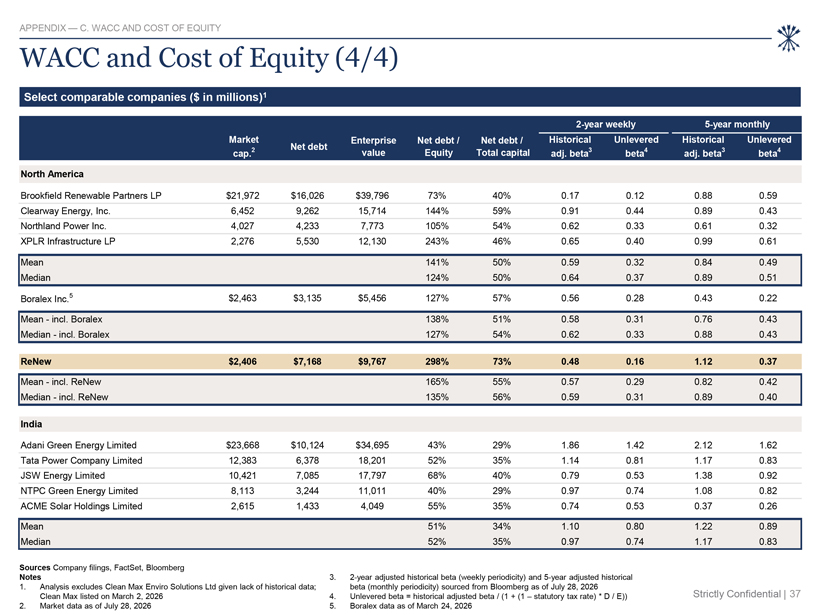
APPENDIX — C. WACC AND COST OF EQUITY WACC and Cost of Equity (4/4) Select comparable companies ($ in millions)1 2-year weekly 5-year monthly Market Enterprise Net debt / Net debt / Historical Unlevered Historical Unlevered 2 Net debt 3 4 3 4 cap. value Equity Total capital adj. beta beta adj. beta beta North America Brookfield Renewable Partners LP $21,972 $16,026 $39,796 73% 40% 0.17 0.12 0.88 0.59 Clearway Energy, Inc. 6,452 9,262 15,714 144% 59% 0.91 0.44 0.89 0.43 Northland Power Inc. 4,027 4,233 7,773 105% 54% 0.62 0.33 0.61 0.32 XPLR Infrastructure LP 2,276 5,530 12,130 243% 46% 0.65 0.40 0.99 0.61 Mean 141% 50% 0.59 0.32 0.84 0.49 Median 124% 50% 0.64 0.37 0.89 0.51 Boralex Inc.5 $2,463 $3,135 $5,456 127% 57% 0.56 0.28 0.43 0.22 Mean—incl. Boralex 138% 51% 0.58 0.31 0.76 0.43 Median—incl. Boralex 127% 54% 0.62 0.33 0.88 0.43 ReNew $2,406 $7,168 $9,767 298% 73% 0.48 0.16 1.12 0.37 Mean—incl. ReNew 165% 55% 0.57 0.29 0.82 0.42 Median—incl. ReNew 135% 56% 0.59 0.31 0.89 0.40 India Adani Green Energy Limited $23,668 $10,124 $34,695 43% 29% 1.86 1.42 2.12 1.62 Tata Power Company Limited 12,383 6,378 18,201 52% 35% 1.14 0.81 1.17 0.83 JSW Energy Limited 10,421 7,085 17,797 68% 40% 0.79 0.53 1.38 0.92 NTPC Green Energy Limited 8,113 3,244 11,011 40% 29% 0.97 0.74 1.08 0.82 ACME Solar Holdings Limited 2,615 1,433 4,049 55% 35% 0.74 0.53 0.37 0.26 Mean 51% 34% 1.10 0.80 1.22 0.89 Median 52% 35% 0.97 0.74 1.17 0.83 Sources Company filings, FactSet, Bloomberg Notes 3. 2-year adjusted historical beta (weekly periodicity) and 5-year adjusted historical 1. Analysis excludes Clean Max Enviro Solutions Ltd given lack of historical data; beta (monthly periodicity) sourced from Bloomberg as of July 28, 2026 Clean Max listed on March 2, 2026 4. Unlevered beta = historical adjusted beta / (1 + (1 – statutory tax rate) * D / E)) Strictly Confidential | 37 2. Market data as of July 28, 2026 5. Boralex data as of March 24, 2026
D Management Forecast
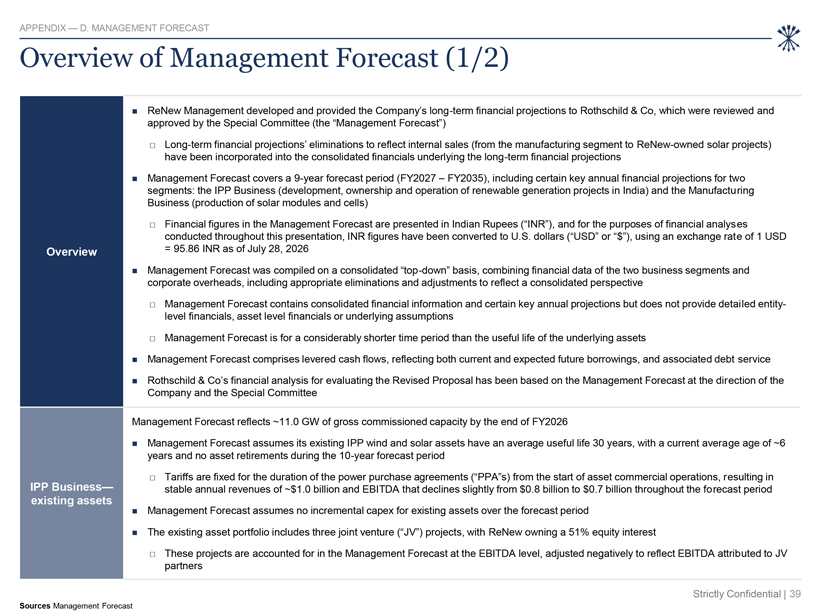
APPENDIX — D. MANAGEMENT FORECAST Overview of Management Forecast (1/2) ReNew Management developed and provided the Company’s long-term financial projections to Rothschild & Co, which were reviewed and approved by the Special Committee (the “Management Forecast”) Long-term financial projections’ eliminations to reflect internal sales (from the manufacturing segment to ReNew-owned solar projects) have been incorporated into the consolidated financials underlying the long-term financial projections Management Forecast covers a 9-year forecast period (FY2027 – FY2035), including certain key annual financial projections for two segments: the IPP Business (development, ownership and operation of renewable generation projects in India) and the Manufacturing Business (production of solar modules and cells) Financial figures in the Management Forecast are presented in Indian Rupees (“INR”), and for the purposes of financial analyses conducted throughout this presentation, INR figures have been converted to U.S. dollars (“USD” or “$”), using an exchange rate of 1 USD Overview = 95.86 INR as of July 28, 2026 Management Forecast was compiled on a consolidated “top-down” basis, combining financial data of the two business segments and corporate overheads, including appropriate eliminations and adjustments to reflect a consolidated perspective Management Forecast contains consolidated financial information and certain key annual projections but does not provide detailed entity-level financials, asset level financials or underlying assumptions Management Forecast is for a considerably shorter time period than the useful life of the underlying assets Management Forecast comprises levered cash flows, reflecting both current and expected future borrowings, and associated debt service Rothschild & Co’s financial analysis for evaluating the Revised Proposal has been based on the Management Forecast at the direction of the Company and the Special Committee Management Forecast reflects ~11.0 GW of gross commissioned capacity by the end of FY2026 Management Forecast assumes its existing IPP wind and solar assets have an average useful life 30 years, with a current average age of ~6 years and no asset retirements during the 10-year forecast period Tariffs are fixed for the duration of the power purchase agreements (“PPA”s) from the start of asset commercial operations, resulting in IPP Business— stable annual revenues of ~$1.0 billion and EBITDA that declines slightly from $0.8 billion to $0.7 billion throughout the forecast period existing assets Management Forecast assumes no incremental capex for existing assets over the forecast period The existing asset portfolio includes three joint venture (“JV”) projects, with ReNew owning a 51% equity interest These projects are accounted for in the Management Forecast at the EBITDA level, adjusted negatively to reflect EBITDA attributed to JV partners Strictly Confidential | 39 Sources Management Forecast
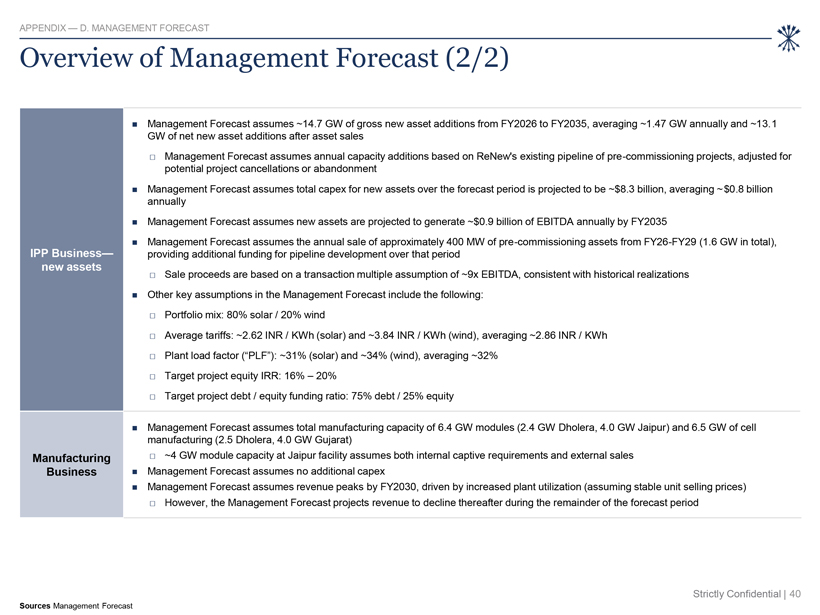
APPENDIX — D. MANAGEMENT FORECAST Overview of Management Forecast (2/2) Management Forecast assumes ~14.7 GW of gross new asset additions from FY2026 to FY2035, averaging ~1.47 GW annually and ~13.1 GW of net new asset additions after asset sales Management Forecast assumes annual capacity additions based on ReNew’s existing pipeline of pre-commissioning projects, adjusted for potential project cancellations or abandonment Management Forecast assumes total capex for new assets over the forecast period is projected to be ~$8.3 billion, averaging ~$0.8 billion annually Management Forecast assumes new assets are projected to generate ~$0.9 billion of EBITDA annually by FY2035 Management Forecast assumes the annual sale of approximately 400 MW of pre-commissioning assets from FY26-FY29 (1.6 GW in total), IPP Business— providing additional funding for pipeline development over that period new assets Sale proceeds are based on a transaction multiple assumption of ~9x EBITDA, consistent with historical realizations Other key assumptions in the Management Forecast include the following: Portfolio mix: 80% solar / 20% wind Average tariffs: ~2.62 INR / KWh (solar) and ~3.84 INR / KWh (wind), averaging ~2.86 INR / KWh Plant load factor (“PLF”): ~31% (solar) and ~34% (wind), averaging ~32% Target project equity IRR: 16% – 20% Target project debt / equity funding ratio: 75% debt / 25% equity Management Forecast assumes total manufacturing capacity of 6.4 GW modules (2.4 GW Dholera, 4.0 GW Jaipur) and 6.5 GW of cell manufacturing (2.5 Dholera, 4.0 GW Gujarat) Manufacturing ~4 GW module capacity at Jaipur facility assumes both internal captive requirements and external sales Business Management Forecast assumes no additional capex Management Forecast assumes revenue peaks by FY2030, driven by increased plant utilization (assuming stable unit selling prices) However, the Management Forecast projects revenue to decline thereafter during the remainder of the forecast period Strictly Confidential | 40 Sources Management Forecast
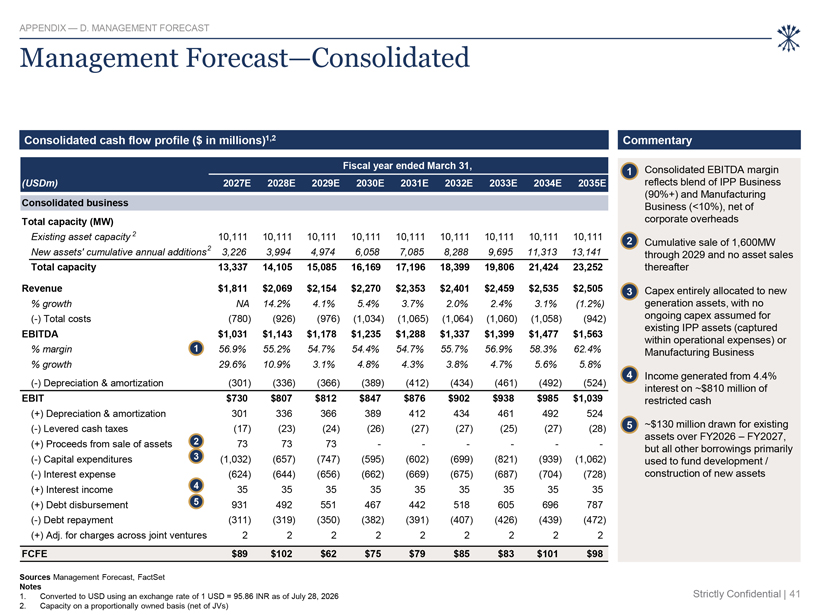
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—Consolidated Consolidated cash flow profile ($ in millions)1,2 Commentary Fiscal year ended March 31, Consolidated EBITDA margin 1 (USDm) 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E reflects blend of IPP Business Consolidated business (90%+) and Manufacturing Business (<10%), net of Total capacity (MW) corporate overheads Existing asset capacity 2 10,111 10,111 10,111 10,111 10,111 10,111 10,111 10,111 10,111 2 2 Cumulative sale of 1,600MW New assets’ cumulative annual additions 3,226 3,994 4,974 6,058 7,085 8,288 9,695 11,313 13,141 through 2029 and no asset sales Total capacity 13,337 14,105 15,085 16,169 17,196 18,399 19,806 21,424 23,252 thereafter Revenue $1,811 $2,069 $2,154 $2,270 $2,353 $2,401 $2,459 $2,535 $2,505 3 Capex entirely allocated to new % growth NA 14.2% 4.1% 5.4% 3.7% 2.0% 2.4% 3.1% (1.2%) generation assets, with no (-) Total costs (780) (926) (976) (1,034) (1,065) (1,064) (1,060) (1,058) (942) ongoing capex assumed for existing IPP assets (captured EBITDA $1,031 $1,143 $1,178 $1,235 $1,288 $1,337 $1,399 $1,477 $1,563 % margin 1 56.9% 55.2% 54.7% 54.4% 54.7% 55.7% 56.9% 58.3% 62.4% within operational expenses) or Manufacturing Business % growth 29.6% 10.9% 3.1% 4.8% 4.3% 3.8% 4.7% 5.6% 5.8% (-) Depreciation & amortization (301) (336) (366) (389) (412) (434) (461) (492) (524) 4 Income generated from 4.4% interest on ~$810 million of EBIT $730 $807 $812 $847 $876 $902 $938 $985 $1,039 restricted cash (+) Depreciation & amortization 301 336 366 389 412 434 461 492 524 5 ~$130 million drawn for existing (-) Levered cash taxes (17) (23) (24) (26) (27) (27) (25) (27) (28) assets over FY2026 – FY2027, (+) Proceeds from sale of assets 2 73 73 73 — ——-but all other borrowings primarily (-) Capital expenditures 3 (1,032) (657) (747) (595) (602) (699) (821) (939) (1,062) used to fund development / (-) Interest expense (624) (644) (656) (662) (669) (675) (687) (704) (728) construction of new assets (+) Interest income 4 35 35 35 35 35 35 35 35 35 (+) Debt disbursement 5 931 492 551 467 442 518 605 696 787 (-) Debt repayment (311) (319) (350) (382) (391) (407) (426) (439) (472) (+) Adj. for charges across joint ventures 2 2 2 2 2 2 2 2 2 FCFE $89 $102 $62 $75 $79 $85 $83 $101 $98 Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 Strictly Confidential | 41 2. Capacity on a proportionally owned basis (net of JVs)
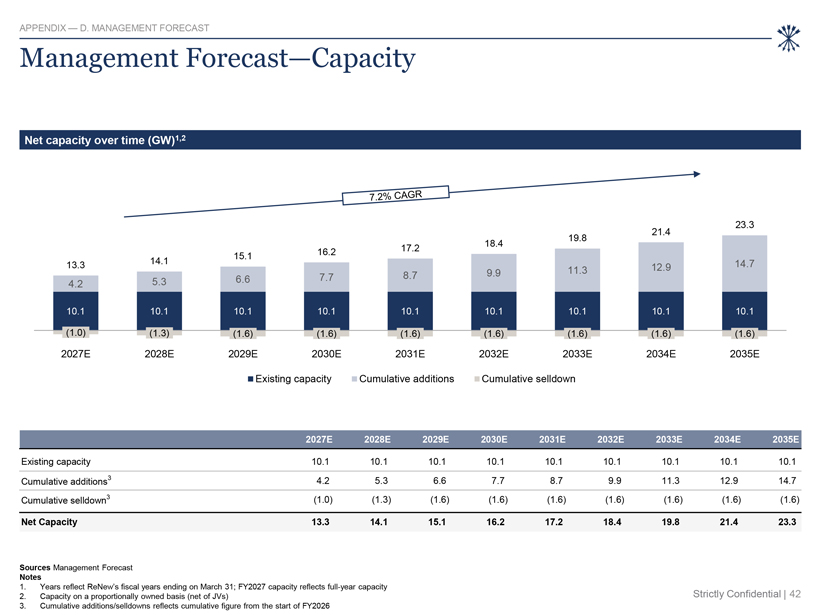
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—Capacity Net capacity over time (GW)1,2 23.3 21.4 19.8 18.4 15.1 16.2 17.2 13.3 14.1 14.7 11.3 12.9 7.7 8.7 9.9 4.2 5.3 6.6 10.1 10.1 10.1 10.1 10.1 10.1 10.1 10.1 10.1 (1.0) (1.3) (1.6) (1.6) (1.6) (1.6) (1.6) (1.6) (1.6) 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E Existing capacity Cumulative additions Cumulative selldown 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E Existing capacity 10.1 10.1 10.1 10.1 10.1 10.1 10.1 10.1 10.1 Cumulative additions3 4.2 5.3 6.6 7.7 8.7 9.9 11.3 12.9 14.7 Cumulative selldown3 (1.0) (1.3) (1.6) (1.6) (1.6) (1.6) (1.6) (1.6) (1.6) Net Capacity 13.3 14.1 15.1 16.2 17.2 18.4 19.8 21.4 23.3 Sources Management Forecast Notes 1. Years reflect ReNew’s fiscal years ending on March 31; FY2027 capacity reflects full-year capacity 2. Capacity on a proportionally owned basis (net of JVs) Strictly Confidential | 42 3. Cumulative additions/selldowns reflects cumulative figure from the start of FY2026
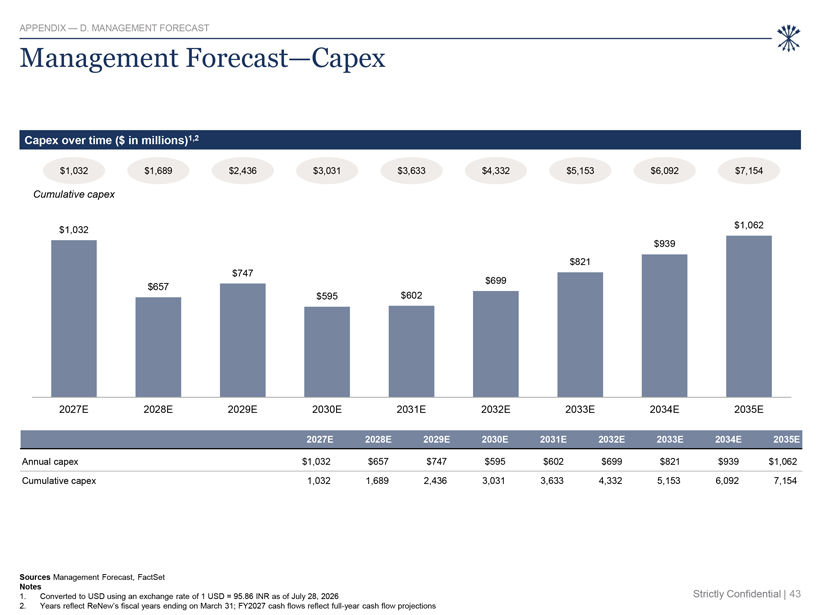
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—Capex Capex over time ($ in millions)1,2 $1,032 $1,689 $2,436 $3,031 $3,633 $4,332 $5,153 $6,092 $7,154 Cumulative capex $1,062 $1,032 $939 $821 $747 $699 $657 $602 $595 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E Annual capex $1,032 $657 $747 $595 $602 $699 $821 $939 $1,062 Cumulative capex 1,032 1,689 2,436 3,031 3,633 4,332 5,153 6,092 7,154 Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 Strictly Confidential | 43 2. Years reflect ReNew’s fiscal years ending on March 31; FY2027 cash flows reflect full-year cash flow projections
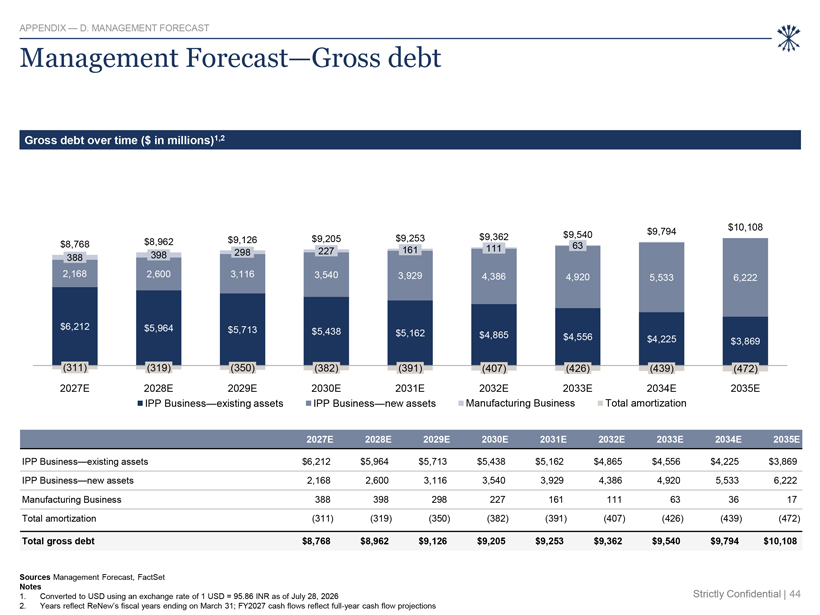
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—Gross debt Gross debt over time ($ in millions)1,2 $9,794 $10,108 $9,253 $9,362 $9,540 $8,962 $9,126 $9,205 $8,768 111 63 298 227 161 388 398 2,168 2,600 3,116 3,540 3,929 4,386 4,920 5,533 6,222 $6,212 $5,964 $5,713 $5,438 $5,162 $4,865 $4,556 $4,225 $3,869 (311) (319) (350) (382) (391) (407) (426) (439) (472) 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets IPP Business—new assets Manufacturing Business Total amortization 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets $6,212 $5,964 $5,713 $5,438 $5,162 $4,865 $4,556 $4,225 $3,869 IPP Business—new assets 2,168 2,600 3,116 3,540 3,929 4,386 4,920 5,533 6,222 Manufacturing Business 388 398 298 227 161 111 63 36 17 Total amortization (311) (319) (350) (382) (391) (407) (426) (439) (472) Total gross debt $8,768 $8,962 $9,126 $9,205 $9,253 $9,362 $9,540 $9,794 $10,108 Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 Strictly Confidential | 44 2. Years reflect ReNew’s fiscal years ending on March 31; FY2027 cash flows reflect full-year cash flow projections
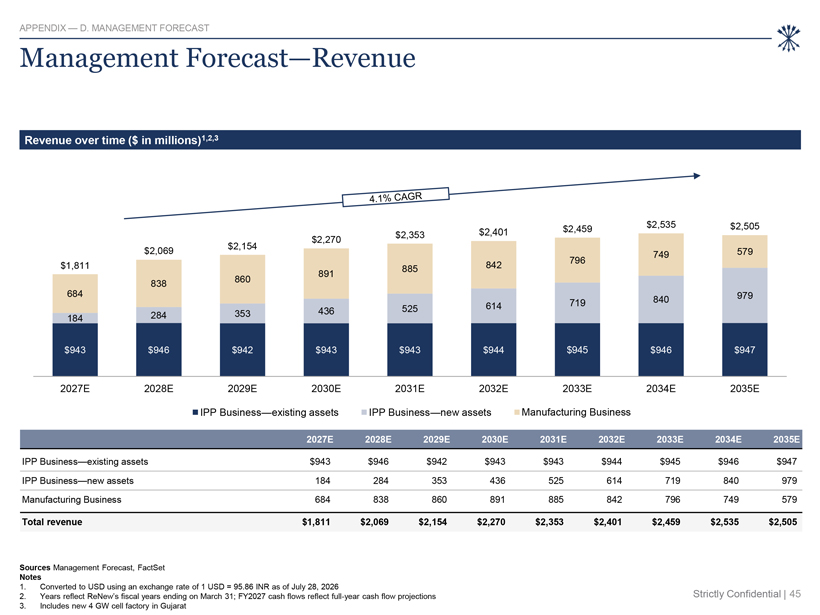
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—Revenue Revenue over time ($ in millions)1,2,3 $2,535 $2,505 $2,401 $2,459 $2,353 $2,270 $2,154 $2,069 749 579 796 $1,811 891 885 842 838 860 684 979 719 840 525 614 284 353 436 184 $943 $946 $942 $943 $943 $944 $945 $946 $947 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets IPP Business—new assets Manufacturing Business 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets $943 $946 $942 $943 $943 $944 $945 $946 $947 IPP Business—new assets 184 284 353 436 525 614 719 840 979 Manufacturing Business 684 838 860 891 885 842 796 749 579 Total revenue $1,811 $2,069 $2,154 $2,270 $2,353 $2,401 $2,459 $2,535 $2,505 Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 2. Years reflect ReNew’s fiscal years ending on March 31; FY2027 cash flows reflect full-year cash flow projections Strictly Confidential | 45 3. Includes new 4 GW cell factory in Gujarat
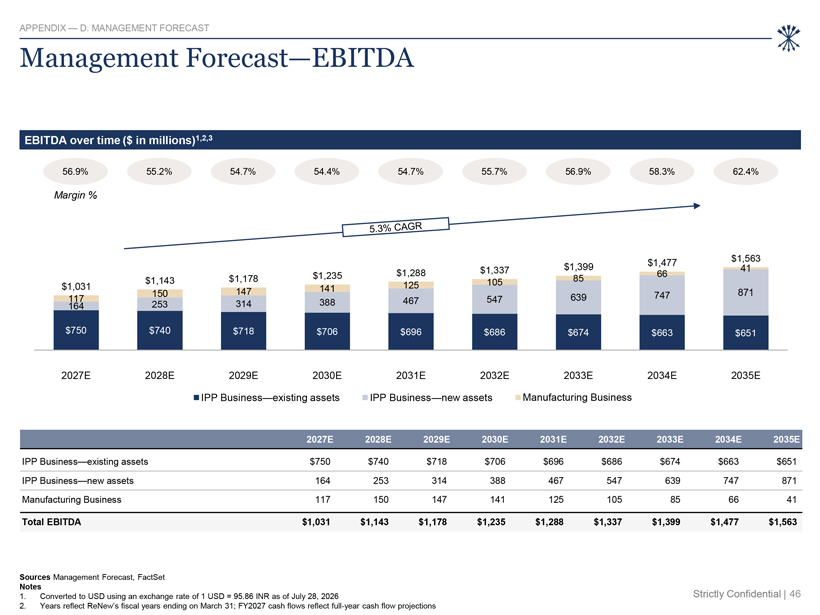
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—EBITDA EBITDA over time ($ in millions)1,2,3 56.9% 55.2% 54.7% 54.4% 54.7% 55.7% 56.9% 58.3% 62.4% Margin % $1,563 $1,399 $1,477 $1,337 41 $1,235 $1,288 66 $1,143 $1,178 105 85 $1,031 141 125 150 147 747 871 117 467 547 639 164 253 314 388 $750 $740 $718 $706 $696 $686 $674 $663 $651 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets IPP Business—new assets Manufacturing Business 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E IPP Business—existing assets $750 $740 $718 $706 $696 $686 $674 $663 $651 IPP Business—new assets 164 253 314 388 467 547 639 747 871 Manufacturing Business 117 150 147 141 125 105 85 66 41 Total EBITDA $1,031 $1,143 $1,178 $1,235 $1,288 $1,337 $1,399 $1,477 $1,563 Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 Strictly Confidential | 46 2. Years reflect ReNew’s fiscal years ending on March 31; FY2027 cash flows reflect full-year cash flow projections
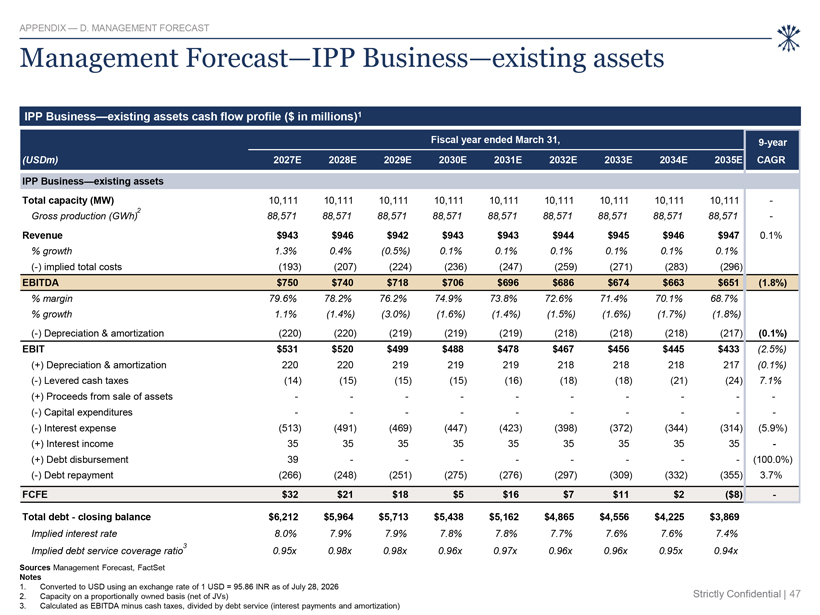
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—IPP Business—existing assets IPP Business—existing assets cash flow profile ($ in millions)1 Fiscal year ended March 31, 9-year (USDm) 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E CAGR IPP Business—existing assets Total capacity (MW) 10,111 10,111 10,111 10,111 10,111 10,111 10,111 10,111 10,111 - 2 Gross production (GWh) 88,571 88,571 88,571 88,571 88,571 88,571 88,571 88,571 88,571 - Revenue $943 $946 $942 $943 $943 $944 $945 $946 $947 0.1% % growth 1.3% 0.4% (0.5%) 0.1% 0.1% 0.1% 0.1% 0.1% 0.1% (-) implied total costs (193) (207) (224) (236) (247) (259) (271) (283) (296) EBITDA $750 $740 $718 $706 $696 $686 $674 $663 $651 (1.8%) % margin 79.6% 78.2% 76.2% 74.9% 73.8% 72.6% 71.4% 70.1% 68.7% % growth 1.1% (1.4%) (3.0%) (1.6%) (1.4%) (1.5%) (1.6%) (1.7%) (1.8%) (-) Depreciation & amortization (220) (220) (219) (219) (219) (218) (218) (218) (217) (0.1%) EBIT $531 $520 $499 $488 $478 $467 $456 $445 $433 (2.5%) (+) Depreciation & amortization 220 220 219 219 219 218 218 218 217 (0.1%) (-) Levered cash taxes (14) (15) (15) (15) (16) (18) (18) (21) (24) 7.1% (+) Proceeds from sale of assets — — — — - -(-) Capital expenditures — — — — —(-) Interest expense (513) (491) (469) (447) (423) (398) (372) (344) (314) (5.9%) (+) Interest income 35 35 35 35 35 35 35 35 35 -(+) Debt disbursement 39 — — — — (100.0%) (-) Debt repayment (266) (248) (251) (275) (276) (297) (309) (332) (355) 3.7% FCFE $32 $21 $18 $5 $16 $7 $11 $2 ($8) - Total debt—closing balance $6,212 $5,964 $5,713 $5,438 $5,162 $4,865 $4,556 $4,225 $3,869 Implied interest rate 8.0% 7.9% 7.9% 7.8% 7.8% 7.7% 7.6% 7.6% 7.4% 3 Implied debt service coverage ratio 0.95x 0.98x 0.98x 0.96x 0.97x 0.96x 0.96x 0.95x 0.94x Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 2. Capacity on a proportionally owned basis (net of JVs) Strictly Confidential | 47 3. Calculated as EBITDA minus cash taxes, divided by debt service (interest payments and amortization)
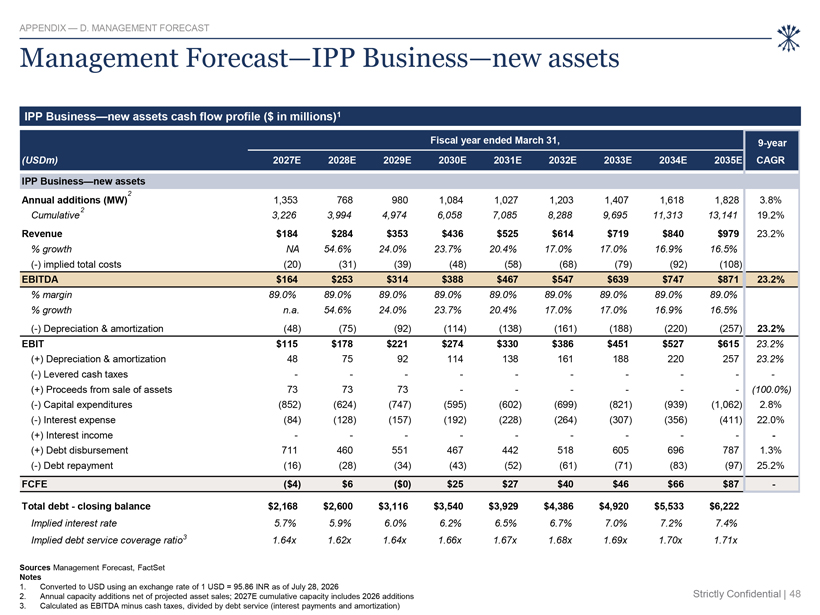
APPENDIX — D. MANAGEMENT FORECAST Management Forecast—IPP Business—new assets IPP Business—new assets cash flow profile ($ in millions)1 Fiscal year ended March 31, 9-year (USDm) 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E CAGR IPP Business—new assets 2 Annual additions (MW) 1,353 768 980 1,084 1,027 1,203 1,407 1,618 1,828 3.8% 2 Cumulative 3,226 3,994 4,974 6,058 7,085 8,288 9,695 11,313 13,141 19.2% Revenue $184 $284 $353 $436 $525 $614 $719 $840 $979 23.2% % growth NA 54.6% 24.0% 23.7% 20.4% 17.0% 17.0% 16.9% 16.5% (-) implied total costs (20) (31) (39) (48) (58) (68) (79) (92) (108) EBITDA $164 $253 $314 $388 $467 $547 $639 $747 $871 23.2% % margin 89.0% 89.0% 89.0% 89.0% 89.0% 89.0% 89.0% 89.0% 89.0% % growth n.a. 54.6% 24.0% 23.7% 20.4% 17.0% 17.0% 16.9% 16.5% (-) Depreciation & amortization (48) (75) (92) (114) (138) (161) (188) (220) (257) 23.2% EBIT $115 $178 $221 $274 $330 $386 $451 $527 $615 23.2% (+) Depreciation & amortization 48 75 92 114 138 161 188 220 257 23.2% (-) Levered cash taxes — — — — - -(+) Proceeds from sale of assets 73 73 73 — — — (100.0%) (-) Capital expenditures (852) (624) (747) (595) (602) (699) (821) (939) (1,062) 2.8% (-) Interest expense (84) (128) (157) (192) (228) (264) (307) (356) (411) 22.0% (+) Interest income — — — — - -(+) Debt disbursement 711 460 551 467 442 518 605 696 787 1.3% (-) Debt repayment (16) (28) (34) (43) (52) (61) (71) (83) (97) 25.2% FCFE ($4) $6 ($0) $25 $27 $40 $46 $66 $87 - Total debt—closing balance $2,168 $2,600 $3,116 $3,540 $3,929 $4,386 $4,920 $5,533 $6,222 Implied interest rate 5.7% 5.9% 6.0% 6.2% 6.5% 6.7% 7.0% 7.2% 7.4% Implied debt service coverage ratio3 1.64x 1.62x 1.64x 1.66x 1.67x 1.68x 1.69x 1.70x 1.71x Sources Management Forecast, FactSet Notes 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 2. Annual capacity additions net of projected asset sales; 2027E cumulative capacity includes 2026 additions Strictly Confidential | 48 3. Calculated as EBITDA minus cash taxes, divided by debt service (interest payments and amortization)
E DDM Analysis
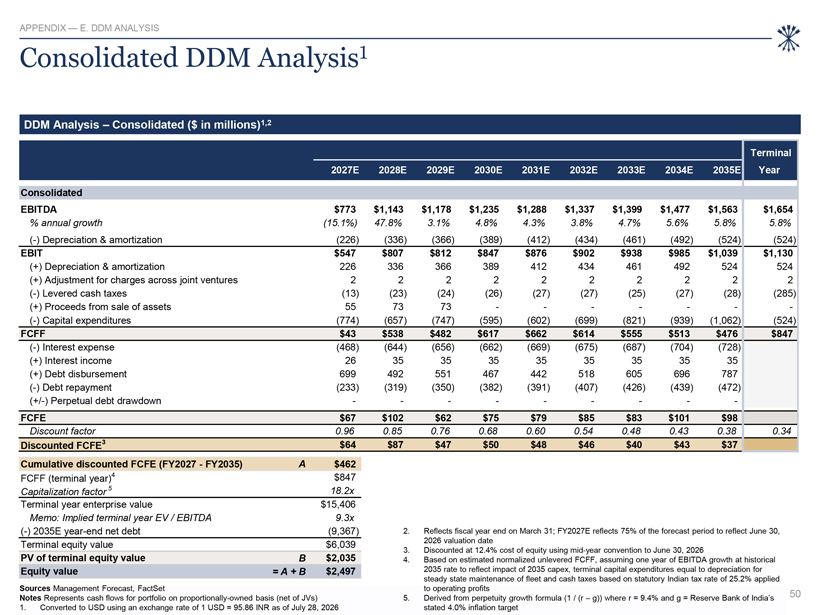
APPENDIX — E. DDM ANALYSIS Consolidated DDM Analysis1 DDM Analysis – Consolidated ($ in millions)1,2 Terminal 2027E 2028E 2029E 2030E 2031E 2032E 2033E 2034E 2035E Year Consolidated EBITDA $773 $1,143 $1,178 $1,235 $1,288 $1,337 $1,399 $1,477 $1,563 $1,654 % annual growth (15.1%) 47.8% 3.1% 4.8% 4.3% 3.8% 4.7% 5.6% 5.8% 5.8% (-) Depreciation & amortization (226) (336) (366) (389) (412) (434) (461) (492) (524) (524) EBIT $547 $807 $812 $847 $876 $902 $938 $985 $1,039 $1,130 (+) Depreciation & amortization 226 336 366 389 412 434 461 492 524 524 (+) Adjustment for charges across joint ventures 2 2 2 2 2 2 2 2 2 2 (-) Levered cash taxes (13) (23) (24) (26) (27) (27) (25) (27) (28) (285) (+) Proceeds from sale of assets 55 73 73 — — — -(-) Capital expenditures (774) (657) (747) (595) (602) (699) (821) (939) (1,062) (524) FCFF $43 $538 $482 $617 $662 $614 $555 $513 $476 $847 (-) Interest expense (468) (644) (656) (662) (669) (675) (687) (704) (728) (+) Interest income 26 35 35 35 35 35 35 35 35 (+) Debt disbursement 699 492 551 467 442 518 605 696 787 (-) Debt repayment (233) (319) (350) (382) (391) (407) (426) (439) (472) (+/-) Perpetual debt drawdown — — — — - FCFE $67 $102 $62 $75 $79 $85 $83 $101 $98 Discount factor 0.96 0.85 0.76 0.68 0.60 0.54 0.48 0.43 0.38 0.34 Discounted FCFE3 $64 $87 $47 $50 $48 $46 $40 $43 $37 Cumulative discounted FCFE (FY2027—FY2035) A $462 FCFF (terminal year)4 $847 Capitalization factor 5 18.2x Terminal year enterprise value $15,406 Memo: Implied terminal year EV / EBITDA 9.3x (-) 2035E year-end net debt (9,367) 2. Reflects fiscal year end on March 31; FY2027E reflects 75% of the forecast period to reflect June 30, Terminal equity value $6,039 2026 valuation date PV of terminal equity value B $2,035 3. Discounted at 12.4% cost of equity using mid-year convention to June 30, 2026 4. Based on estimated normalized unlevered FCFF, assuming one year of EBITDA growth at historical Equity value = A + B $2,497 2035 rate to reflect impact of 2035 capex, terminal capital expenditures equal to depreciation for steady state maintenance of fleet and cash taxes based on statutory Indian tax rate of 25.2% applied Sources Management Forecast, FactSet to operating profits Notes Represents cash flows for portfolio on proportionally-owned basis (net of JVs) 5. Derived from perpetuity growth formula (1 / (r – g)) where r = 9.4% and g = Reserve Bank of India’s 50 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 stated 4.0% inflation target
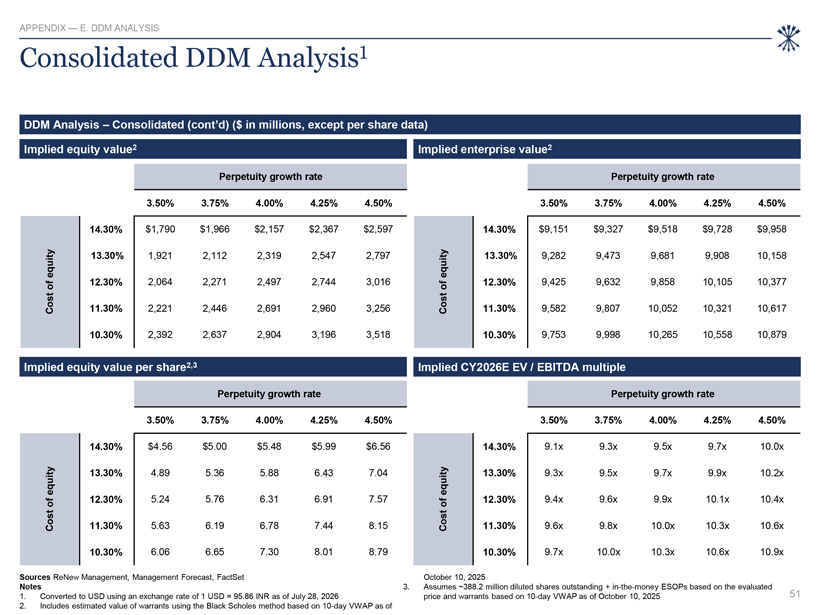
APPENDIX — E. DDM ANALYSIS Consolidated DDM Analysis1 DDM Analysis – Consolidated (cont’d) ($ in millions, except per share data) Implied equity value2 Implied enterprise value2 Perpetuity growth rate Perpetuity growth rate 3.50% 3.75% 4.00% 4.25% 4.50% 3.50% 3.75% 4.00% 4.25% 4.50% 14.30% $1,790 $1,966 $2,157 $2,367 $2,597 14.30% $9,151 $9,327 $9,518 $9,728 $9,958 uity 13.30% 1,921 2,112 2,319 2,547 2,797 uity 13.30% 9,282 9,473 9,681 9,908 10,158 q e e q of 12.30% 2,064 2,271 2,497 2,744 3,016 of 12.30% 9,425 9,632 9,858 10,105 10,377 t t s o o s C 11.30% 2,221 2,446 2,691 2,960 3,256 C 11.30% 9,582 9,807 10,052 10,321 10,617 10.30% 2,392 2,637 2,904 3,196 3,518 10.30% 9,753 9,998 10,265 10,558 10,879 Implied equity value per share2,3 Implied CY2026E EV / EBITDA multiple Perpetuity growth rate Perpetuity growth rate 3.50% 3.75% 4.00% 4.25% 4.50% 3.50% 3.75% 4.00% 4.25% 4.50% 14.30% $4.56 $5.00 $5.48 $5.99 $6.56 14.30% 9.1x 9.3x 9.5x 9.7x 10.0x y t 13.30% 4.89 5.36 5.88 6.43 7.04 y t 13.30% 9.3x 9.5x 9.7x 9.9x 10.2x ui eq eq ui f 12.30% 5.24 5.76 6.31 6.91 7.57f 12.30% 9.4x 9.6x 9.9x 10.1x 10.4x o o Cost 11.30% 5.63 6.19 6.78 7.44 8.15 Cost 11.30% 9.6x 9.8x 10.0x 10.3x 10.6x 10.30% 6.06 6.65 7.30 8.01 8.79 10.30% 9.7x 10.0x 10.3x 10.6x 10.9x Sources ReNew Management, Management Forecast, FactSet October 10, 2025 Notes 3. Assumes ~388.2 million diluted shares outstanding + in-the-money ESOPs based on the evaluated 1. Converted to USD using an exchange rate of 1 USD = 95.86 INR as of July 28, 2026 price and warrants based on 10-day VWAP as of October 10, 2025 51 2. Includes estimated value of warrants using the Black Scholes method based on 10-day VWAP as of
F Additional supplemental materials
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Overview of Premia Paid Analysis Premia Paid Analysis considerations Rothschild & Co reviewed and analyzed certain financial information and historical merger and acquisition data related to selected public transactions Rothschild & Co reviewed premiums paid in completed transactions announced since January 1, 2016, involving the acquisition of controlling interests and subsequent delisting of public targets Two categories of transactions, in particular, were considered: (i) Precedent transactions involving renewables-focused companies with transaction values exceeding $300 million (ii) Precedent transactions involving controlling shareholders acquiring remaining minority interests in listed targets, specifically all-cash transactions exceeding $100 million in transaction value For each transaction, Rothschild & Co assessed final offer premium per share vs. the unaffected share price1 and various VWAPs Select reference ranges for implied ReNew share price, as shown in Section 4 are based on the premia to the Company’s unaffected share price1 Financial data for the Premia Paid Analysis was sourced from public filings and other publicly available information Several factors limit the comparability of selected precedent transactions, including differences in size, geography, business model and contract profile Each transaction involved unique circumstances, inherently differing from ReNew’s specific context Consequently, premia-based analysis should not be solely relied upon quantitatively when considering the proposed Transaction Sources Wall Street research, FactSet Notes Strictly Confidential | 53 1. ReNew’s unaffected share price as of May 28, 2026, the last trading day prior to the May 28 Offer
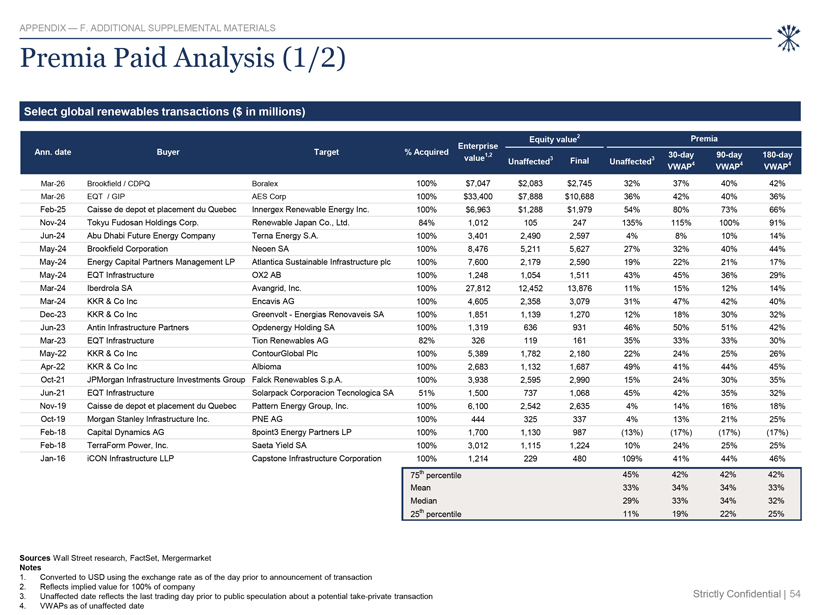
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Premia Paid Analysis (1/2) Select global renewables transactions ($ in millions) Equity value2 Premia Enterprise Ann. date Buyer Target % Acquired 1,2 30-day 90-day 180-day value Unaffected3 Final Unaffected3 VWAP4 VWAP4 VWAP4 Mar-26 Brookfield / CDPQ Boralex 100% $7,047 $2,083 $2,745 32% 37% 40% 42% Mar-26 EQT / GIP AES Corp 100% $33,400 $7,888 $10,688 36% 42% 40% 36% Feb-25 Caisse de depot et placement du Quebec Innergex Renewable Energy Inc. 100% $6,963 $1,288 $1,979 54% 80% 73% 66% Nov-24 Tokyu Fudosan Holdings Corp. Renewable Japan Co., Ltd. 84% 1,012 105 247 135% 115% 100% 91% Jun-24 Abu Dhabi Future Energy Company Terna Energy S.A. 100% 3,401 2,490 2,597 4% 8% 10% 14% May-24 Brookfield Corporation Neoen SA 100% 8,476 5,211 5,627 27% 32% 40% 44% May-24 Energy Capital Partners Management LP Atlantica Sustainable Infrastructure plc 100% 7,600 2,179 2,590 19% 22% 21% 17% May-24 EQT Infrastructure OX2 AB 100% 1,248 1,054 1,511 43% 45% 36% 29% Mar-24 Iberdrola SA Avangrid, Inc. 100% 27,812 12,452 13,876 11% 15% 12% 14% Mar-24 KKR & Co Inc Encavis AG 100% 4,605 2,358 3,079 31% 47% 42% 40% Dec-23 KKR & Co Inc Greenvolt—Energias Renovaveis SA 100% 1,851 1,139 1,270 12% 18% 30% 32% Jun-23 Antin Infrastructure Partners Opdenergy Holding SA 100% 1,319 636 931 46% 50% 51% 42% Mar-23 EQT Infrastructure Tion Renewables AG 82% 326 119 161 35% 33% 33% 30% May-22 KKR & Co Inc ContourGlobal Plc 100% 5,389 1,782 2,180 22% 24% 25% 26% Apr-22 KKR & Co Inc Albioma 100% 2,683 1,132 1,687 49% 41% 44% 45% Oct-21 JPMorgan Infrastructure Investments Group Falck Renewables S.p.A. 100% 3,938 2,595 2,990 15% 24% 30% 35% Jun-21 EQT Infrastructure Solarpack Corporacion Tecnologica SA 51% 1,500 737 1,068 45% 42% 35% 32% Nov-19 Caisse de depot et placement du Quebec Pattern Energy Group, Inc. 100% 6,100 2,542 2,635 4% 14% 16% 18% Oct-19 Morgan Stanley Infrastructure Inc. PNE AG 100% 444 325 337 4% 13% 21% 25% Feb-18 Capital Dynamics AG 8point3 Energy Partners LP 100% 1,700 1,130 987 (13%) (17%) (17%) (17%) Feb-18 TerraForm Power, Inc. Saeta Yield SA 100% 3,012 1,115 1,224 10% 24% 25% 25% Jan-16 iCON Infrastructure LLP Capstone Infrastructure Corporation 100% 1,214 229 480 109% 41% 44% 46% 75th percentile 45% 42% 42% 42% Mean 33% 34% 34% 33% Median 29% 33% 34% 32% 25th percentile 11% 19% 22% 25% Sources Wall Street research, FactSet, Mergermarket Notes 1. Converted to USD using the exchange rate as of the day prior to announcement of transaction 2. Reflects implied value for 100% of company 3. Unaffected date reflects the last trading day prior to public speculation about a potential take-private transaction Strictly Confidential | 54 4. VWAPs as of unaffected date
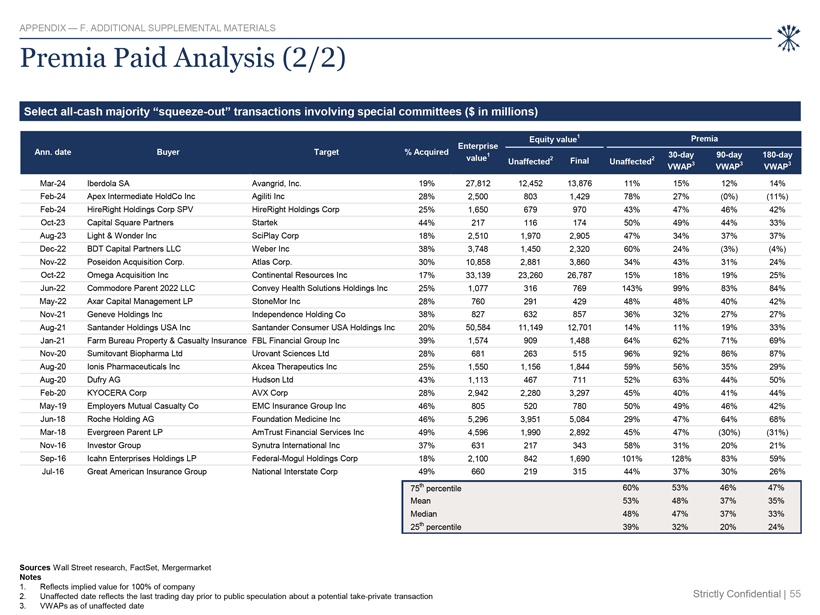
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Premia Paid Analysis (2/2) Select all-cash majority “squeeze-out” transactions involving special committees ($ in millions) Equity value1 Premia Enterprise Ann. date Buyer Target % Acquired 1 30-day 90-day 180-day value Unaffected2 Final Unaffected2 VWAP3 VWAP3 VWAP3 Mar-24 Iberdola SA Avangrid, Inc. 19% 27,812 12,452 13,876 11% 15% 12% 14% Feb-24 Apex Intermediate HoldCo Inc Agiliti Inc 28% 2,500 803 1,429 78% 27% (0%) (11%) Feb-24 HireRight Holdings Corp SPV HireRight Holdings Corp 25% 1,650 679 970 43% 47% 46% 42% Oct-23 Capital Square Partners Startek 44% 217 116 174 50% 49% 44% 33% Aug-23 Light & Wonder Inc SciPlay Corp 18% 2,510 1,970 2,905 47% 34% 37% 37% Dec-22 BDT Capital Partners LLC Weber Inc 38% 3,748 1,450 2,320 60% 24% (3%) (4%) Nov-22 Poseidon Acquisition Corp. Atlas Corp. 30% 10,858 2,881 3,860 34% 43% 31% 24% Oct-22 Omega Acquisition Inc Continental Resources Inc 17% 33,139 23,260 26,787 15% 18% 19% 25% Jun-22 Commodore Parent 2022 LLC Convey Health Solutions Holdings Inc 25% 1,077 316 769 143% 99% 83% 84% May-22 Axar Capital Management LP StoneMor Inc 28% 760 291 429 48% 48% 40% 42% Nov-21 Geneve Holdings Inc Independence Holding Co 38% 827 632 857 36% 32% 27% 27% Aug-21 Santander Holdings USA Inc Santander Consumer USA Holdings Inc 20% 50,584 11,149 12,701 14% 11% 19% 33% Jan-21 Farm Bureau Property & Casualty Insurance FBL Financial Group Inc 39% 1,574 909 1,488 64% 62% 71% 69% Nov-20 Sumitovant Biopharma Ltd Urovant Sciences Ltd 28% 681 263 515 96% 92% 86% 87% Aug-20 Ionis Pharmaceuticals Inc Akcea Therapeutics Inc 25% 1,550 1,156 1,844 59% 56% 35% 29% Aug-20 Dufry AG Hudson Ltd 43% 1,113 467 711 52% 63% 44% 50% Feb-20 KYOCERA Corp AVX Corp 28% 2,942 2,280 3,297 45% 40% 41% 44% May-19 Employers Mutual Casualty Co EMC Insurance Group Inc 46% 805 520 780 50% 49% 46% 42% Jun-18 Roche Holding AG Foundation Medicine Inc 46% 5,296 3,951 5,084 29% 47% 64% 68% Mar-18 Evergreen Parent LP AmTrust Financial Services Inc 49% 4,596 1,990 2,892 45% 47% (30%) (31%) Nov-16 Investor Group Synutra International Inc 37% 631 217 343 58% 31% 20% 21% Sep-16 Icahn Enterprises Holdings LP Federal-Mogul Holdings Corp 18% 2,100 842 1,690 101% 128% 83% 59% Jul-16 Great American Insurance Group National Interstate Corp 49% 660 219 315 44% 37% 30% 26% 75th percentile 60% 53% 46% 47% Mean 53% 48% 37% 35% Median 48% 47% 37% 33% 25th percentile 39% 32% 20% 24% Sources Wall Street research, FactSet, Mergermarket Notes 1. Reflects implied value for 100% of company 2. Unaffected date reflects the last trading day prior to public speculation about a potential take-private transaction Strictly Confidential | 55 3. VWAPs as of unaffected date
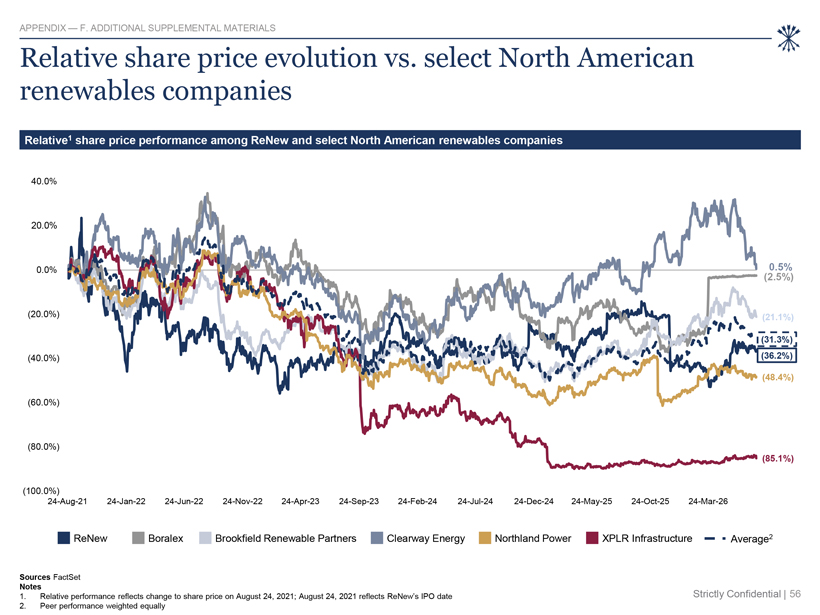
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Relative share price evolution vs. select North American renewables companies Relative1 share price performance among ReNew and select North American renewables companies 40.0% 20.0% 0.0% 0.5% (2.5%) (20.0%) (21.1%) (31.3%) (40.0%) (36.2%) (48.4%) (60.0%) (80.0%) (85.1%) (100.0%) 24-Aug-21 24-Jan-22 24-Jun-22 24-Nov-22 24-Apr-23 24-Sep-23 24-Feb-24 24-Jul-24 24-Dec-24 24-May-25 24-Oct-25 24-Mar-26 ReNew Boralex Brookfield Renewable Partners Clearway Energy Northland Power XPLR Infrastructure Average2 Sources FactSet Notes 1. Relative performance reflects change to share price on August 24, 2021; August 24, 2021 reflects ReNew’s IPO date Strictly Confidential | 56 2. Peer performance weighted equally
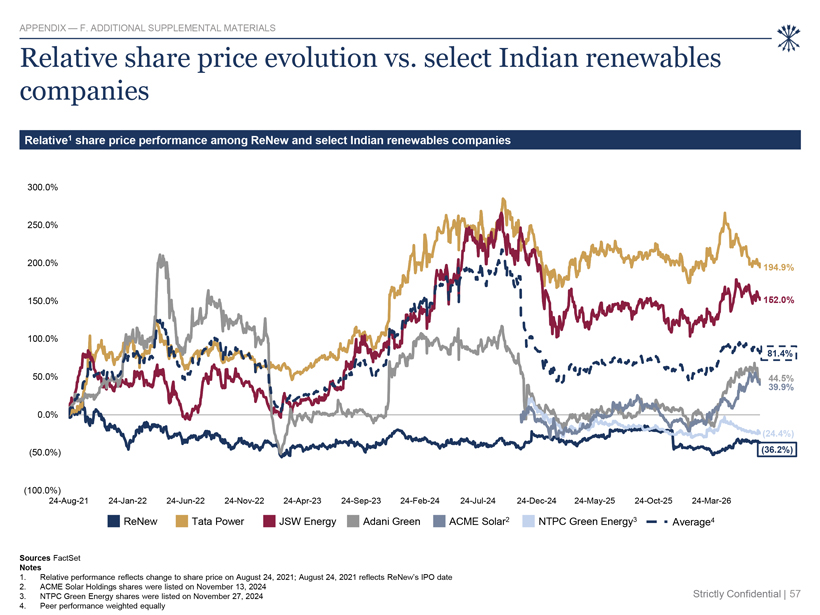
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Relative share price evolution vs. select Indian renewables companies Relative1 share price performance among ReNew and select Indian renewables companies 300.0% 250.0% 200.0% 194.9% 150.0% 152.0% 100.0% 81.4% 50.0% 44.5% 39.9% 0.0% (24.4%) (50.0%) (36.2%) (100.0%) 24-Aug-21 24-Jan-22 24-Jun-22 24-Nov-22 24-Apr-23 24-Sep-23 24-Feb-24 24-Jul-24 24-Dec-24 24-May-25 24-Oct-25 24-Mar-26 ReNew Tata Power JSW Energy Adani Green ACME Solar2 NTPC Green Energy3 Average4 Sources FactSet Notes 1. Relative performance reflects change to share price on August 24, 2021; August 24, 2021 reflects ReNew’s IPO date 2. ACME Solar Holdings shares were listed on November 13, 2024 3. NTPC Green Energy shares were listed on November 27, 2024 Strictly Confidential | 57 4. Peer performance weighted equally
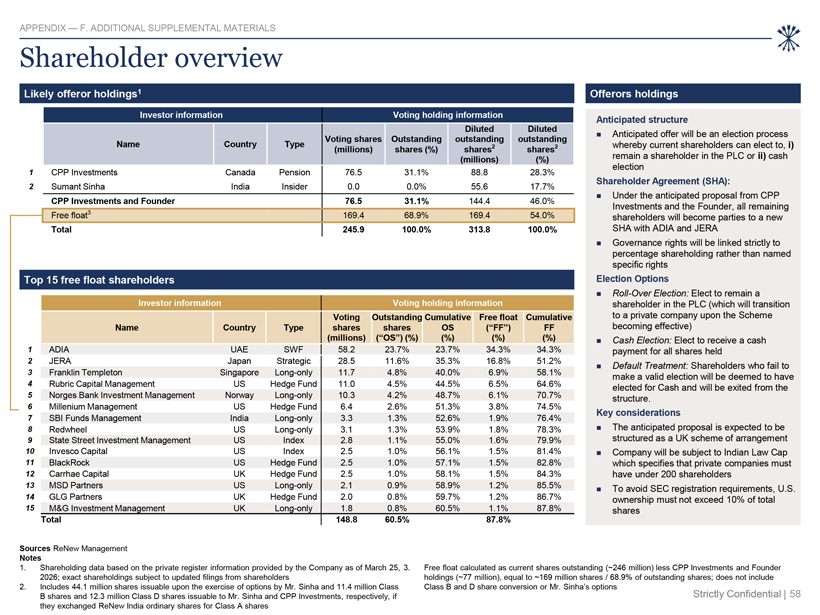
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS Shareholder overview Likely offeror holdings1 Offerors holdings Investor information Voting holding information Anticipated structure Diluted Diluted Anticipated offer will be an election process Voting shares Outstanding outstanding outstanding Name Country Type 2 2 whereby current shareholders can elect to, i) (millions) shares (%) shares shares (millions) (%) remain a shareholder in the PLC or ii) cash election 1 CPP Investments Canada Pension 76.5 31.1% 88.8 28.3% Shareholder Agreement (SHA): 2 Sumant Sinha India Insider 0.0 0.0% 55.6 17.7% Under the anticipated proposal from CPP CPP Investments and Founder 76.5 31.1% 144.4 46.0% 3 Investments and the Founder, all remaining Free float 169.4 68.9% 169.4 54.0% shareholders will become parties to a new Total 245.9 100.0% 313.8 100.0% SHA with ADIA and JERA Governance rights will be linked strictly to percentage shareholding rather than named specific rights Top 15 free float shareholders Election Options Roll-Over Election: Elect to remain a Investor information Voting holding information shareholder in the PLC (which will transition Voting Outstanding Cumulative Free float Cumulative to a private company upon the Scheme Name Country Type shares shares OS (“FF”) FF becoming effective) (millions) (“OS”) (%) (%) (%) (%) Cash Election: Elect to receive a cash 1 ADIA UAE SWF 58.2 23.7% 23.7% 34.3% 34.3% payment for all shares held 2 JERA Japan Strategic 28.5 11.6% 35.3% 16.8% 51.2% Default Treatment: Shareholders who fail to 3 Franklin Templeton Singapore Long-only 11.7 4.8% 40.0% 6.9% 58.1% 4 Rubric Capital Management US Hedge Fund 11.0 4.5% 44.5% 6.5% 64.6% make a valid election will be deemed to have 5 Norges Bank Investment Management Norway Long-only 10.3 4.2% 48.7% 6.1% 70.7% elected for Cash and will be exited from the structure. 6 Millenium Management US Hedge Fund 6.4 2.6% 51.3% 3.8% 74.5% Key considerations 7 SBI Funds Management India Long-only 3.3 1.3% 52.6% 1.9% 76.4% 8 Redwheel US Long-only 3.1 1.3% 53.9% 1.8% 78.3% The anticipated proposal is expected to be 9 State Street Investment Management US Index 2.8 1.1% 55.0% 1.6% 79.9% structured as a UK scheme of arrangement 10 Invesco Capital US Index 2.5 1.0% 56.1% 1.5% 81.4% Company will be subject to Indian Law Cap 11 BlackRock US Hedge Fund 2.5 1.0% 57.1% 1.5% 82.8% which specifies that private companies must 12 Carrhae Capital UK Hedge Fund 2.5 1.0% 58.1% 1.5% 84.3% have under 200 shareholders 13 MSD Partners US Long-only 2.1 0.9% 58.9% 1.2% 85.5% To avoid registration requirements, U.S. SEC 14 GLG Partners UK Hedge Fund 2.0 0.8% 59.7% 1.2% 86.7% ownership must not exceed 10% of total 15 M&G Investment Management UK Long-only 1.8 0.8% 60.5% 1.1% 87.8% shares Total 148.8 60.5% 87.8% Sources ReNew Management Notes 1. Shareholding data based on the private register information provided by the Company as of March 25, 3. Free float calculated as current shares outstanding (~246 million) less CPP Investments and Founder 2026; exact shareholdings subject to updated filings from shareholders holdings (~77 million), equal to ~169 million shares / 68.9% of outstanding shares; does not include 2. Includes 44.1 million shares issuable upon the exercise of options by Mr. Sinha and 11.4 million Class Class B and D share conversion or Mr. Sinha’s options B shares and 12.3 million Class D shares issuable to Mr. Sinha and CPP Investments, respectively, if Strictly Confidential | 58 they exchanged ReNew India ordinary shares for Class A shares
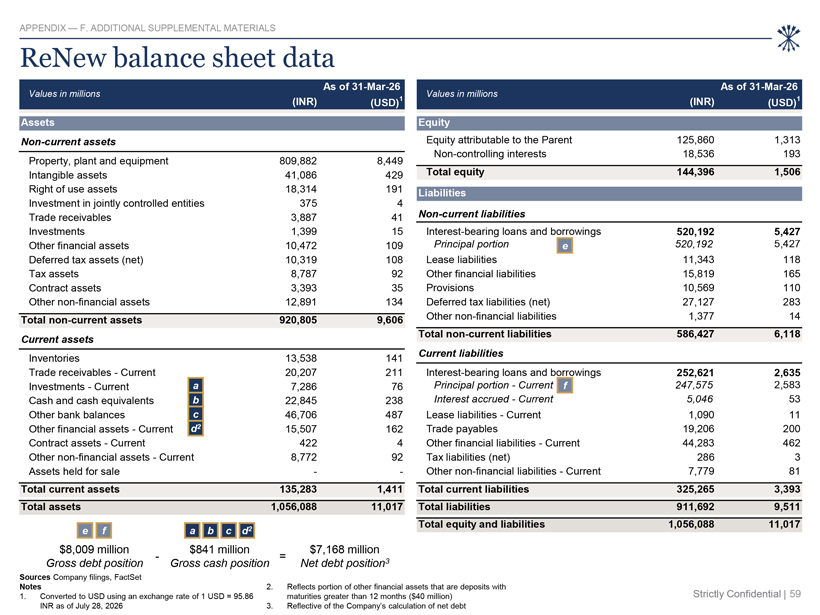
APPENDIX — F. ADDITIONAL SUPPLEMENTAL MATERIALS ReNew balance sheet data As of 31-Mar-26 As of 31-Mar-26 Values in millions Values in millions (INR) (USD)1 (INR) (USD)1 Assets Equity Non-current assets Equity attributable to the Parent 125,860 1,313 Non-controlling interests 18,536 193 Property, plant and equipment 809,882 8,449 Intangible assets 41,086 429 Total equity 144,396 1,506 Right of use assets 18,314 191 Liabilities Investment in jointly controlled entities 375 4 Trade receivables 3,887 41 Non-current liabilities Investments 1,399 15 Interest-bearing loans and borrowings 520,192 5,427 Other financial assets 10,472 109 Principal portion e 520,192 5,427 Deferred tax assets (net) 10,319 108 Lease liabilities 11,343 118 Tax assets 8,787 92 Other financial liabilities 15,819 165 Contract assets 3,393 35 Provisions 10,569 110 Other non-financial assets 12,891 134 Deferred tax liabilities (net) 27,127 283 Total non-current assets 920,805 9,606 Other non-financial liabilities 1,377 14 Total non-current liabilities 586,427 6,118 Current assets Current liabilities Inventories 13,538 141 Trade receivables—Current 20,207 211 Interest-bearing loans and borrowings 252,621 2,635 Investments—Current a 7,286 76 Principal portion—Current f 247,575 2,583 Cash and cash equivalents b 22,845 238 Interest accrued—Current 5,046 53 Other bank balances c 46,706 487 Lease liabilities—Current 1,090 11 Other financial assets—Current d2 15,507 162 Trade payables 19,206 200 Contract assets—Current 422 4 Other financial liabilities—Current 44,283 462 Other non-financial assets—Current 8,772 92 Tax liabilities (net) 286 3 Assets held for sale — Other non-financial liabilities—Current 7,779 81 Total current assets 135,283 1,411 Total current liabilities 325,265 3,393 Total assets 1,056,088 11,017 Total liabilities 911,692 9,511 Total equity and liabilities 1,056,088 11,017 e f a b c d2 $8,009 million $841 million $7,168 million - = Gross debt position Gross cash position Net debt position3 Sources Company filings, FactSet Notes 2. Reflects portion of other financial assets that are deposits with 1. Converted to USD using an exchange rate of 1 USD = 95.86 maturities greater than 12 months ($40 million) Strictly Confidential | 59 INR as of July 28, 2026 3. Reflective of the Company’s calculation of net debt