Exhibit 99.1
LETTER OF TRANSMITTAL
SUMISHO AIR LEASE CORPORATION
Offer to Exchange
$800,000,000 4.400% Senior Notes due 2028
that have been registered under the Securities Act of 1933
for any and all outstanding 4.400% Senior Notes due 2028
(CUSIP Nos. 873923 AA4 / U81972 AA6)
and
$1,200,000,000 4.500% Senior Notes due 2029
that have been registered under the Securities Act of 1933
for any and all outstanding 4.500% Senior Notes due 2029
(CUSIP Nos. 873923 AC0 / U81972 AB4)
and
$1,500,000,000 4.850% Senior Notes due 2031
that have been registered under the Securities Act of 1933
for any and all outstanding 4.850% Senior Notes due 2031
(CUSIP Nos. 873923 AE6 / U81972 AC2)
and
$500,000,000 5.500% Senior Notes due 2036
that have been registered under the Securities Act of 1933
for any and all outstanding 5.500% Senior Notes due 2036
(CUSIP Nos. 873923 AG1 / U81972 AD0)
Pursuant to the Prospectus dated , 2026
THE EXCHANGE OFFER WILL EXPIRE AT 5:00 P.M., NEW YORK CITY TIME, ON , 2026, UNLESS EXTENDED (SUCH TIME AND DATE, AS THE SAME MAY BE EXTENDED FROM TIME TO TIME, THE “EXPIRATION TIME”). TENDERS MAY BE WITHDRAWN AT ANY TIME PRIOR TO THE EXPIRATION TIME.
The exchange agent is:
Computershare Trust Company, N.A.
By hand delivery, mail or overnight courier at:
Computershare Trust Company, N.A.
1505 Energy Park Drive
St. Paul, MN 55108
Attn: Biddel Tekeste
By email:
biddel.tekeste@computershare.com
Confirm by telephone:
612-448-7420
TO TENDER OUTSTANDING NOTES, THIS LETTER OF TRANSMITTAL (OR AN AGENT’S MESSAGE) MUST BE DELIVERED TO THE EXCHANGE AGENT AS SET FORTH ABOVE, WITH ALL REQUIRED DOCUMENTATION, AT OR PRIOR TO THE EXPIRATION TIME. DELIVERY OF THIS LETTER OF TRANSMITTAL TO AN ADDRESS OTHER THAN AS SET FORTH ABOVE, OR TRANSMISSION TO AN EMAIL ADDRESS OTHER THAN THE ONE LISTED ABOVE, WILL NOT CONSTITUTE VALID DELIVERY TO THE EXCHANGE AGENT.
2
The instructions set forth in this Letter of Transmittal should be read carefully before this Letter of Transmittal is completed.
By execution of this Letter of Transmittal, the undersigned acknowledges receipt of the prospectus, dated , 2026 (the “Prospectus”), of Sumisho Air Lease Corporation, a Delaware corporation (the “Company”), and this Letter of Transmittal, which together constitute the offer of the Company (the “Exchange Offer”) to exchange up to $800,000,000 aggregate principal amount of new 4.400% Senior Notes due 2028 (the “2028 Exchange Notes”), up to $1,200,000,000 aggregate principal amount of new 4.500% Senior Notes due 2029 (the “2029 Exchange Notes”), up to $1,500,000,000 aggregate principal amount of new 4.850% Senior Notes due 2031 (the “2031 Exchange Notes”), and up to $500,000,000 aggregate principal amount of new 5.500% Senior Notes due 2036 (the “2036 Exchange Notes” and, together with the 2028 Exchange Notes, 2029 Exchange Notes and 2031 Exchange Notes, the “Exchange Notes”) that have been registered under the Securities Act of 1933, as amended (the “Securities Act”), for a like principal amount of the applicable series of outstanding 4.400% Senior Notes due 2028 (the “Outstanding 2028 Notes”), 4.500% Senior Notes due 2029 (the “Outstanding 2029 Notes”), 4.850% Senior Notes due 2031 (the “Outstanding 2031 Notes”), and 5.500% Senior Notes due 2036 (the “Outstanding 2036 Notes” and, together with the Outstanding 2028 Notes, Outstanding 2029 Notes and Outstanding 2031 Notes, the “Outstanding Notes”), subject to the terms and conditions set forth therein. Recipients of the Prospectus should carefully read the Prospectus, including the requirements described in the Prospectus with respect to eligibility to participate in the Exchange Offer.
On April 8, 2026, Air Lease Corporation, a Delaware corporation, completed the merger (the “Merger”) of Takeoff Merger Sub Inc., a Delaware corporation and the original issuer of the Outstanding Notes, with and into Air Lease Corporation, with Air Lease Corporation surviving the Merger as an indirect subsidiary of Sumisho Air Lease Corporation Designated Activity Company, an Irish private limited company. Upon consummation of the Merger, Air Lease Corporation changed its name to Sumisho Air Lease Corporation and, in accordance with the Indenture governing the Outstanding Notes and related agreements, the Outstanding Notes became the Company’s obligations.
The Company is making the Exchange Offer pursuant to the registration rights agreement that it entered into on March 24, 2026 with the initial purchasers of the Outstanding Notes. Upon consummation of the Exchange Offer, the Company will accept any and all Outstanding Notes that are properly tendered in the Exchange Offer and not withdrawn prior to the Expiration Time. If you do not exchange your Outstanding Notes for Exchange Notes in the Exchange Offer, your Outstanding Notes will remain outstanding and continue to accrue interest but will not retain any rights under the registration rights agreement, except as otherwise specified therein.
Capitalized terms used but not defined herein have the meaning given to them in the Prospectus.
PLEASE READ THIS ENTIRE LETTER OF TRANSMITTAL CAREFULLY BEFORE CHECKING ANY BOXES.
This Letter of Transmittal is to be used to tender Outstanding Notes:
| | if certificates representing tendered Outstanding Notes are to be physically delivered herewith; or |
| | if a tender is made by book-entry transfer to the Exchange Agent’s account at The Depository Trust Company (“DTC”) through DTC’s Automated Tender Offer Program (“ATOP”) pursuant to the procedures set forth in “The Exchange Offer - How to Tender Outstanding Notes for Exchange” in the Prospectus, unless an Agent’s Message (as defined below) is transmitted in lieu thereof. |
The term “Agent’s Message” means a message, electronically transmitted by DTC to the Exchange Agent, forming part of a book-entry transfer, which states that DTC has received an express acknowledgement from the tendering holder of the Outstanding Notes that such holder has received and agrees to be bound by, and makes each of the representations and warranties contained in, this Letter of Transmittal, and, further, that such holder agrees that the Company may enforce this Letter of Transmittal against such holder.
3
Only registered holders are entitled to tender their Outstanding Notes for exchange in the Exchange Offer. In order for any holder of Outstanding Notes to tender in the Exchange Offer all or any portion of such holder’s Outstanding Notes, the Exchange Agent must receive, at or prior to the Expiration Time, this Letter of Transmittal or an Agent’s Message, the certificates for all physically tendered Outstanding Notes or a confirmation of the book-entry transfer of the Outstanding Notes being tendered into the Exchange Agent’s account at DTC, and all documents required by this Letter of Transmittal, or a notice of guaranteed delivery.
Any participant in DTC’s system whose name appears on a security position listing as the registered owner of Outstanding Notes and who wishes to make book-entry delivery of Outstanding Notes to the Exchange Agent’s account at DTC can execute the tender through ATOP, for which the Exchange Offer will be eligible, by following the applicable procedures thereof. Upon such tender of Outstanding Notes:
| | DTC will verify the acceptance of the tender and execute a book-entry delivery of the tendered Outstanding Notes to the Exchange Agent’s account at DTC; |
| | DTC will send to the Exchange Agent for its acceptance an Agent’s Message forming part of such book-entry transfer; and |
| | transmission of the Agent’s Message by DTC will satisfy the terms of the Exchange Offer as to execution and delivery of a Letter of Transmittal by the participant identified in the Agent’s Message. |
Delivery of documents to DTC does not constitute delivery to the Exchange Agent.
In order to properly complete this Letter of Transmittal, a holder of Outstanding Notes must:
| | complete the box entitled “Description of Outstanding Notes Tendered”; |
| | if appropriate, check and complete the boxes relating to book-entry transfer, guaranteed delivery, broker dealers, special issuance instructions, and special delivery instructions; |
| | complete the box entitled “Sign Here to Tender Your Outstanding Notes in the Exchange Offer”; and |
| | complete the IRS Form W-9 accompanying this Letter of Transmittal or the applicable IRS Form W-8, which may be obtained from the Exchange Agent. |
If a holder of Outstanding Notes desires to tender Outstanding Notes for exchange and, at or prior to the Expiration Time, (1) such holder’s Outstanding Notes are not immediately available, (2) such holder cannot deliver to the Exchange Agent his, her, or its Outstanding Notes, this Letter of Transmittal, and all other documents required hereby, or (3) such holder cannot complete the procedures for book-entry transfer, then such holder must tender the Outstanding Notes pursuant to the guaranteed delivery procedures set forth in the section of the Prospectus entitled “The Exchange Offer—Guaranteed Delivery Procedures.” See Instruction 2 of this Letter of Transmittal.
The Exchange Offer may be extended, terminated, or amended as provided in the Prospectus. During any such extension of the Exchange Offer, all Outstanding Notes previously tendered and not withdrawn pursuant to the Exchange Offer will remain subject to the Exchange Offer. The Exchange Offer is scheduled to expire at 5:00 p.m., New York City time, on , 2026, unless extended by the Company.
Persons who are beneficial owners of Outstanding Notes but are not registered holders and who desire to tender Outstanding Notes should contact the registered holder of such Outstanding Notes and instruct such registered holder to tender on such beneficial owner’s behalf.
4
SIGNATURES MUST BE PROVIDED BELOW.
PLEASE READ THE ACCOMPANYING INSTRUCTIONS CAREFULLY.
The undersigned hereby tenders for exchange the Outstanding Notes described in the box below entitled “Description of Outstanding Notes Tendered” pursuant to the terms and conditions described in the Prospectus and this Letter of Transmittal.
| DESCRIPTION OF OUTSTANDING 2028 NOTES TENDERED |
||||||||
| (1) Name and Address of Registered Holder (Please fill in, if blank) |
(2) Outstanding Notes’ Certificate Numbers(A) |
(3) Principal Amount Tendered for Exchange(B) |
||||||
| $ | ||||||||
| $ | ||||||||
| (A) | Need not be completed if Outstanding Notes are being delivered by book-entry transfer. |
| (B) | The minimum permitted tender is $2,000 in principal amount of Outstanding Notes and integral multiples of $1,000 in excess thereof. If this column is left blank, it will be assumed that the holder is tendering all of such holder’s Outstanding Notes. |
| DESCRIPTION OF OUTSTANDING 2029 NOTES TENDERED |
||||||||
| (1) Name and Address of Registered Holder (Please fill in, if blank) |
(2) Outstanding Notes’ Certificate Numbers(A) |
(3) Principal Amount Tendered for Exchange(B) |
||||||
| $ | ||||||||
| $ | ||||||||
| (A) | Need not be completed if Outstanding Notes are being delivered by book-entry transfer. |
| (B) | The minimum permitted tender is $2,000 in principal amount of Outstanding Notes and integral multiples of $1,000 in excess thereof. If this column is left blank, it will be assumed that the holder is tendering all of such holder’s Outstanding Notes. |
| DESCRIPTION OF OUTSTANDING 2031 NOTES TENDERED |
||||||||
| (1) Name and Address of Registered Holder (Please fill in, if blank) |
(2) Outstanding Notes’ Certificate Numbers(A) |
(3) Principal Amount Tendered for Exchange(B) |
||||||
| $ | ||||||||
| $ | ||||||||
| (A) | Need not be completed if Outstanding Notes are being delivered by book-entry transfer. |
| (B) | The minimum permitted tender is $2,000 in principal amount of Outstanding Notes and integral multiples of $1,000 in excess thereof. If this column is left blank, it will be assumed that the holder is tendering all of such holder’s Outstanding Notes. |
| DESCRIPTION OF OUTSTANDING 2036 NOTES TENDERED |
||||||||
| (1) Name and Address of Registered Holder (Please fill in, if blank) |
(2) Outstanding Notes’ Certificate Numbers(A) |
(3) Principal Amount Tendered for Exchange(B) |
||||||
| $ | ||||||||
| $ | ||||||||
| (A) | Need not be completed if Outstanding Notes are being delivered by book-entry transfer. |
| (B) | The minimum permitted tender is $2,000 in principal amount of Outstanding Notes and integral multiples of $1,000 in excess thereof. If this column is left blank, it will be assumed that the holder is tendering all of such holder’s Outstanding Notes. |
| ☐ | CHECK HERE IF TENDERED OUTSTANDING NOTES ARE ENCLOSED HEREWITH. |
| ☐ | CHECK HERE IF TENDERED OUTSTANDING NOTES ARE BEING DELIVERED BY BOOK-ENTRY TRANSFER MADE TO THE ACCOUNT MAINTAINED BY THE EXCHANGE AGENT WITH DTC AND COMPLETE THE FOLLOWING: |
| Name of Tendering Institution: | ||
| DTC Account Number: | Transaction Code Number: | |
5
By crediting Outstanding Notes to the Exchange Agent’s account at DTC in accordance with ATOP and by complying with applicable ATOP procedures with respect to the Exchange Offer, including transmitting an Agent’s Message to the Exchange Agent in which the holder of the Outstanding Notes acknowledges and agrees to be bound by the terms of this Letter of Transmittal, the participant in ATOP confirms on behalf of itself and the beneficial owners of such Outstanding Notes all provisions of this Letter of Transmittal applicable to it and such beneficial owners as if it had completed the information required herein and executed and delivered this Letter of Transmittal to the Exchange Agent.
| ☐ | CHECK HERE IF TENDERED OUTSTANDING NOTES ARE BEING DELIVERED PURSUANT TO A NOTICE OF GUARANTEED DELIVERY PREVIOUSLY SENT TO THE EXCHANGE AGENT AND COMPLETE THE FOLLOWING (FOR USE ONLY BY ELIGIBLE INSTITUTIONS (AS DEFINED BELOW)): |
| Name of Registered Holder: |
| Window Ticket Number (if any): |
| Date of Execution of Notice of Guaranteed Delivery: |
| Name of Institution that Guaranteed Delivery: |
| ☐ | CHECK HERE AND COMPLETE THE FOLLOWING IF YOU ARE A BROKER-DEALER AND WISH TO RECEIVE 10 ADDITIONAL COPIES OF THE PROSPECTUS AND 10 COPIES OF ANY AMENDMENTS OR SUPPLEMENTS THERETO: |
| Name: |
| Address: |
6
Ladies and Gentlemen:
Upon the terms and subject to the conditions of the Exchange Offer, the undersigned hereby tenders to the Company for exchange the Outstanding Notes indicated above. Subject to, and effective upon, acceptance for exchange of the Outstanding Notes tendered herewith, the undersigned hereby sells, assigns, and transfers to the Company all right, title, and interest in and to all such Outstanding Notes tendered for exchange hereby. The undersigned hereby irrevocably constitutes and appoints the Exchange Agent as the true and lawful agent and attorney-in-fact of the undersigned (with full knowledge that the Exchange Agent also acts as agent of the Company) with respect to such Outstanding Notes, with full power of substitution and resubstitution (such power of attorney being deemed to be an irrevocable power coupled with an interest) to:
| | deliver certificates representing such Outstanding Notes, or transfer ownership of such Outstanding Notes on the account books maintained by DTC, together, in each such case, with all accompanying evidences of transfer and authenticity to the Company; |
| | present and deliver such Outstanding Notes for transfer on the books of the Company; and |
| | receive all benefits or otherwise exercise all rights and incidents of beneficial ownership of such Outstanding Notes, all in accordance with the terms of the Exchange Offer. |
The undersigned represents and warrants that he, she, or it has full power and authority to tender, exchange, assign, and transfer the Outstanding Notes and to acquire the Exchange Notes issuable upon the exchange of such tendered Outstanding Notes, and that, when the Outstanding Notes are accepted for exchange, the Company will acquire good and unencumbered title to the tendered Outstanding Notes, free and clear of all liens, restrictions, charges, and encumbrances and not subject to any adverse claim. The undersigned also warrants that he, she, or it will, upon request, execute and deliver any additional documents deemed by the Exchange Agent or the Company to be necessary or desirable to complete the exchange, assignment, and transfer of tendered Outstanding Notes or transfer ownership of such Outstanding Notes on the account books maintained by DTC.
The undersigned further agrees that acceptance of any and all validly tendered Outstanding Notes by the Company and the issuance of Exchange Notes in exchange therefor shall constitute performance in full by the Company of certain of its obligations under the registration rights agreement that was filed as an exhibit to the registration statement of which the Prospectus is a part.
The undersigned also acknowledges that the Exchange Offer is being made by the Company in reliance on interpretations by the staff of the Securities and Exchange Commission (the “SEC”), as set forth in no-action letters issued to third parties. The Company believes that Exchange Notes may be offered for resale, resold, and otherwise transferred by holders thereof (other than any such holder that is an “affiliate” of the Company within the meaning of Rule 405 under the Securities Act or that tenders Outstanding Notes for the purpose of participating in a distribution of the Exchange Notes), without compliance with the registration and prospectus delivery provisions of the Securities Act, provided that such Exchange Notes are acquired in the ordinary course of such holder’s business, and such holders have no arrangement or understanding with any person to participate in the distribution of the Exchange Notes. However, the Company does not intend to request that the SEC consider, and the SEC has not considered, the Exchange Offer in the context of a no-action letter and therefore the Company cannot guarantee that the staff of the SEC would make a similar determination with respect to the Exchange Offer. The undersigned acknowledges that if the interpretation of the Company of the above mentioned no-action letters is incorrect, such holder may be held liable for any offers, resales or transfers by the undersigned of the Exchange Notes that are in violation of the Securities Act. The undersigned further acknowledges that neither the Company nor the Exchange Agent will indemnify any holder for any such liability under the Securities Act.
7
The undersigned represents and warrants that:
| | such holder is not an “affiliate” of the Company within the meaning of Rule 405 under the Securities Act, or, if it is an “affiliate” of the Company, it will comply with the registration and prospectus delivery requirements of the Securities Act to the extent applicable; |
| | the Exchange Notes acquired in the Exchange Offer will be obtained in the ordinary course of such holder’s business; |
| | neither such holder nor, to the actual knowledge of such holder, any other person receiving Exchange Notes from such holder, has any arrangement or understanding with any person to participate in the distribution of such Exchange Notes; |
| | if the holder is not a broker-dealer, such holder is not engaged in, and does not intend to engage in, a distribution of the Exchange Notes; and |
| | if such holder is a broker-dealer that will receive Exchange Notes for its own account in exchange for Outstanding Notes, the Outstanding Notes being tendered for exchange were acquired by it as a result of market-making activities or other trading activities, and it will deliver a prospectus meeting the requirements of the Securities Act in connection with any resale of the Exchange Notes received in respect of such Outstanding Notes pursuant to the Exchange Offer; however, by so acknowledging and by delivering a prospectus in connection with the resale of the Exchange Notes, the undersigned will not be deemed to admit that it is an “underwriter” within the meaning of the Securities Act, and such holder will comply with the applicable provisions of the Securities Act with respect to resale of any Exchange Notes. |
Any holder of Outstanding Notes who is an affiliate of the Company who tenders Outstanding Notes in the Exchange Offer for the purpose of participating in a distribution of the Exchange Notes:
| | may not rely on the position of the staff of the SEC enunciated in its series of interpretive no-action letters with respect to exchange offers; and |
| | must comply with the registration and prospectus delivery requirements of the Securities Act in connection with any secondary resale transaction and be identified as an underwriter in the prospectus. |
All authority conferred or agreed to be conferred pursuant to this Letter of Transmittal and every obligation of the undersigned hereunder shall be binding upon the successors, assigns, heirs, executors, administrators, trustees in bankruptcy, and personal and legal representatives of the undersigned and shall not be affected by, and shall survive, the death or incapacity of the undersigned.
Outstanding Notes properly tendered may be withdrawn at any time at or prior to the Expiration Time in accordance with the terms of the Prospectus and this Letter of Transmittal.
The Exchange Offer is subject to certain conditions, some of which may be waived or modified by the Company, in whole or in part, at any time and from time to time, as described in the Prospectus under the caption “The Exchange Offer—Conditions to the Exchange Offer.” The undersigned recognizes that as a result of such conditions the Company may not be required to accept for exchange, or to issue Exchange Notes in exchange for, any of the Outstanding Notes validly tendered hereby. All tendering holders, by execution of this Letter of Transmittal, waive any right to receive any notice of the acceptance or rejection of their Outstanding Notes for exchange.
The Company is not aware of any jurisdiction in which the making of the Exchange Offer or the tender of Outstanding Notes in connection therewith would not be in compliance with the laws of such jurisdiction. If the making of the Exchange Offer would not be in compliance with the laws of any jurisdiction, the Exchange Offer will not be made to the registered holders residing in such jurisdiction.
Unless otherwise indicated under “Special Issuance Instructions” below, please return any certificates representing Outstanding Notes not tendered or not accepted for exchange and certificates representing Exchange Notes issued in exchange for Outstanding Notes in the name of the holder appearing under “Description of Outstanding Notes Tendered.” Similarly, unless otherwise indicated under “Special Delivery Instructions,” please mail any certificates representing Outstanding Notes not tendered or not accepted for exchange (and accompanying documents, as appropriate) and any certificates representing Exchange Notes issued in exchange for Outstanding Notes to the address of the holder appearing under “Description of Outstanding Notes Tendered.” In the event that both the “Special
8
Issuance Instructions” and the “Special Delivery Instructions” are completed, please issue the certificates representing the Exchange Notes issued in exchange for the Outstanding Notes accepted for exchange in the name of, and return any Outstanding Notes not tendered or not accepted for exchange to, the person so indicated. Unless otherwise indicated under “Special Issuance Instructions,” in the case of a book-entry delivery of Outstanding Notes, please credit the account of the undersigned maintained at DTC appearing under the table “Description of Outstanding Notes Tendered” with any Outstanding Notes not accepted for exchange or any Exchange Notes issued in exchange for Outstanding Notes. The undersigned recognizes that the Company has no obligation pursuant to the special issuance instructions to transfer any Outstanding Notes from the name of the holder thereof if the Company does not accept for exchange any of the Outstanding Notes so tendered or if such transfer would not be in compliance with any transfer restrictions applicable to such Outstanding Notes.
SPECIAL ISSUANCE INSTRUCTIONS
(SEE INSTRUCTIONS 1, 6, 7 AND 8)
To be completed ONLY if (i) certificates for Exchange Notes issued for Outstanding Notes, or certificates for Outstanding Notes not exchanged for Exchange Notes, or certificates for Outstanding Notes not tendered for exchange are to be issued in the name of someone other than the undersigned, or (ii) Outstanding Notes tendered by book-entry transfer that are not exchanged are to be returned by credit to an account maintained at DTC other than the account indicated above.
Issued to:
| Name: | ||
| (Please Print) | ||
| Address: | ||
|
|
||
|
|
||
| (Including Zip Code) | ||
(Taxpayer Identification Number or Social Security Number) |
||
| Credit Outstanding Notes not exchanged and delivered by book-entry transfer to the DTC account set forth below: | ||
(DTC Account Number) |
||
9
SPECIAL DELIVERY INSTRUCTIONS
(SEE INSTRUCTIONS 1, 6, 7 AND 8)
To be completed ONLY if the certificates for Exchange Notes issued for Outstanding Notes, certificates for Outstanding Notes not exchanged for Exchange Notes, or certificates for Outstanding Notes not tendered for exchange are to be sent to someone other than the undersigned or to the undersigned at an address other than that shown above.
Mail to:
| Name: | ||
| (Please Print) | ||
| Address: | ||
|
|
||
|
|
||
| (Including Zip Code) | ||
(Taxpayer Identification Number or Social Security Number) |
||
SIGN HERE TO TENDER YOUR OUTSTANDING NOTES IN THE EXCHANGE OFFER
Signature of holder of Outstanding Notes
Dated: , 2026
Must be signed by the registered holder of Outstanding Notes exactly as the name appears on certificate(s) representing the Outstanding Notes or on a security position listing or by a person authorized to become a registered holder by certificates and documents transmitted herewith. If signature is by an attorney-in-fact, executor, administrator, trustee, guardian, officer of a corporation or other person acting in a fiduciary or representative capacity, please provide the following information and see Instruction 6.
| Capacity (Full Title): | - | |
| Name: | - | |
| (Please type or print) | ||
| Address: | - | |
| (Include Zip Code) | ||
| Area Code and Telephone Number: | - | |
GUARANTEE OF SIGNATURE
(IF REQUIRED - SEE INSTRUCTIONS 1 AND 6)
| Authorized Signature: | - | |
| Name: | - | |
| (Please type or print) | ||
| Title: | - | |
| Name of Firm: | - | |
| Address: | - | |
| (Include Zip Code) | ||
| Area Code and Telephone Number: | - | |
Dated: , 2026
10
IMPORTANT: COMPLETE AND SIGN THE FORM W-9
ACCOMPANYING THIS LETTER OF TRANSMITTAL
INSTRUCTIONS
Forming Part of the Terms and Conditions of the Exchange Offer
1. Guarantee of Signature. Any signature on this Letter of Transmittal need not be guaranteed if the Outstanding Notes tendered hereby are tendered:
| | by the registered holder of Outstanding Notes thereof, unless such holder has completed either the box entitled “Special Issuance Instructions” or the box entitled “Special Delivery Instructions” above; or |
| | for the account of an Eligible Institution. The term “Eligible Institution” means an institution that is a member in good standing of a Medallion Signature Guarantee Program recognized by the Exchange Agent, for example, the Securities Transfer Agents Medallion Program, the Stock Exchanges Medallion Program, or the New York Stock Exchange Medallion Signature Program. An Eligible Institution includes firms that are members of a registered national securities exchange, members of the Financial Industry Regulatory Authority, Inc., commercial banks or trust companies having an office in the United States, or certain other eligible guarantors. |
In all other cases, any signature on this Letter of Transmittal must be guaranteed by an Eligible Institution.
2. Delivery of this Letter of Transmittal and Certificates for Outstanding Notes or Book-Entry Confirmations; Guaranteed Delivery Procedures. In order for a holder of Outstanding Notes to tender all or any portion of such holder’s Outstanding Notes, the Exchange Agent must receive either a properly completed and duly executed Letter of Transmittal or, if tendering by book-entry transfer, an Agent’s Message with respect to such holder, the certificates for all physically tendered Outstanding Notes, or a confirmation of the book-entry transfer of the Outstanding Notes being tendered into the Exchange Agent’s account at DTC, and any other required documents, at or prior to the Expiration Time, or the tendering holder must comply with the guaranteed delivery procedures set forth below. Delivery of the documents to DTC does not constitute delivery to the Exchange Agent.
The method of delivery to the Exchange Agent of this Letter of Transmittal, Outstanding Notes, and all other required documents is at the election and risk of the holder thereof. If such delivery is by mail, it is suggested that holders use properly insured registered mail, return receipt requested, and that the mailing be sufficiently in advance of the Expiration Time to permit delivery to the Exchange Agent at or prior to such date. Except as otherwise provided below, the delivery will be deemed made when actually received or confirmed by the Exchange Agent. This Letter of Transmittal and Outstanding Notes tendered for exchange should be sent only to the Exchange Agent, not to the Company or DTC.
If holders desire to tender Outstanding Notes for exchange pursuant to the Exchange Offer and, if at or prior to the Expiration Time:
| | certificates representing such Outstanding Notes are not lost but are not immediately available; |
| | time will not permit this Letter of Transmittal, certificates representing Outstanding Notes, or other required documents to reach the Exchange Agent; or |
| | the procedures for book-entry transfer cannot be completed; |
11
such holder may effect a tender of Outstanding Notes for exchange in accordance with the guaranteed delivery procedures set forth in the Prospectus under the caption “The Exchange Offer - Guaranteed Delivery Procedures.” Pursuant to the guaranteed delivery procedures:
| | at or prior to the Expiration Time, the Exchange Agent must have received from an Eligible Institution, at the address of the Exchange Agent set forth above, a properly completed and duly executed Notice of Guaranteed Delivery (by email, mail, or hand delivery) substantially in the form provided by the Company setting forth the name and address of the registered holder of such Outstanding Notes, the certificate numbers, and the principal amount of Outstanding Notes being tendered for exchange and stating that the tender is being made thereby and guaranteeing that, within three New York Stock Exchange trading days after the date of execution of the Notice of Guaranteed Delivery, a properly completed and duly executed Letter of Transmittal, together with certificates representing the Outstanding Notes (or confirmation of book-entry transfer of such Outstanding Notes into the Exchange Agent’s account with DTC and an Agent’s Message) and any other documents required by this Letter of Transmittal and the instructions hereto, will be deposited by such Eligible Institution with the Exchange Agent; and |
| | this Letter of Transmittal, properly completed, together with duly executed certificates for all physically delivered Outstanding Notes in proper form for transfer (or confirmation of book-entry transfer of such Outstanding Notes into the Exchange Agent’s account with DTC and an Agent’s Message) and all other required documents, must be received by the Exchange Agent within three New York Stock Exchange trading days after the date of execution of the Notice of Guaranteed Delivery. |
All tendering holders, by execution of this Letter of Transmittal, waive any right to receive any notice of the acceptance or rejection of their Outstanding Notes for exchange.
3. Inadequate Space. If the space provided in the box entitled “Description of Outstanding Notes Tendered” above is not adequate, the certificate numbers and principal amounts of Outstanding Notes tendered should be listed on a separate signed schedule affixed hereto.
4. Withdrawal of Tenders. A tender of Outstanding Notes may be withdrawn at any time prior to the Expiration Time by delivery of a written notice of withdrawal to the Exchange Agent at the address set forth on the cover of this Letter of Transmittal. To be effective, a notice of withdrawal must:
| | be received by the Exchange Agent at or prior to the Expiration Time; |
| | specify the name of the person having tendered the Outstanding Notes to be withdrawn; |
| | identify the Outstanding Notes to be withdrawn (including the certificate number or numbers, if applicable, and principal amount of such Outstanding Notes); |
| | specify the principal amount of Outstanding Notes to be withdrawn; |
| | where certificates for Outstanding Notes were transmitted, specify the name in which such Outstanding Notes are registered, if different from that of the withdrawing holder, and the serial numbers of the particular certificates to be withdrawn; |
| | if Outstanding Notes have been tendered pursuant to the procedures for book-entry transfer, specify the name and number of the account at the book-entry transfer facility to be credited with the withdrawn Outstanding Notes and otherwise comply with the procedures of DTC; |
| | include a statement that such holder is withdrawing his, her, or its election to have such Outstanding Notes exchanged; |
| | signed by the holder in the same manner as the original signature on the Letter of Transmittal by which such Outstanding Notes were tendered, with such signature guaranteed by an Eligible Institution (unless such withdrawing holder is an Eligible Institution), or be accompanied by documents of transfer (including a signature guarantee by an Eligible Institution) sufficient to permit the trustee under the Indenture to register the transfer of such Outstanding Notes into the name of the person withdrawing the tender; and |
| | specify the name in which any such Outstanding Notes are to be registered, if different from that of the person tendering the Outstanding Notes. |
12
The Exchange Agent will return the properly withdrawn Outstanding Notes promptly following receipt of the notice of withdrawal. All questions as to the validity of notices of withdrawal, including time of receipt, will be determined by the Company in its sole discretion and such determination will be final and binding on all parties.
Any Outstanding Notes so withdrawn will be deemed not to have been validly tendered for exchange for purposes of the Exchange Offer. Any Outstanding Notes that have been tendered for exchange but that are not exchanged for any reason will be returned to the holder thereof without cost to such holder (or, in the case of Outstanding Notes tendered by book-entry transfer into the Exchange Agent’s account at DTC pursuant to the book-entry transfer procedures described above, such Outstanding Notes will be credited to an account with DTC specified by the holder) promptly after withdrawal, rejection of tender, or termination of the Exchange Offer. Properly withdrawn Outstanding Notes may be retendered by following one of the procedures described under the caption “The Exchange Offer—How to Tender Outstanding Notes for Exchange” in the Prospectus at any time at or prior to the Expiration Time.
5. Partial Tenders. Tenders of Outstanding Notes will be accepted only in minimum denominations of $2,000 and integral multiples of $1,000 in excess thereof. If a tender for exchange is to be made with respect to less than the entire principal amount of any Outstanding Notes, fill in the principal amount of Outstanding Notes that are tendered for exchange in column (3) of the box entitled “Description of Outstanding Notes Tendered,” as more fully described in the footnotes thereto. A blank in column (3) of the box will indicate that the holder is tendering all of such holder’s Outstanding Notes. In the case of a partial tender for exchange, a new certificate, in fully registered form, for the remainder of the principal amount of the Outstanding Notes will be sent to the holders of Outstanding Notes unless otherwise indicated in the boxes entitled “Special Issuance Instructions” or “Special Delivery Instructions” above, as soon as practicable after the expiration or termination of the Exchange Offer.
6. Signatures on this Letter of Transmittal; Bond Powers and Endorsements.
| | If this Letter of Transmittal is signed by the registered holder of the Outstanding Notes tendered for exchange hereby, the signature must correspond exactly with the name as written on the face of the certificate(s) or on a security position listing without alteration, enlargement or any change whatsoever. |
| | If any of the Outstanding Notes tendered hereby are owned of record by two or more joint owners, all such owners must sign this Letter of Transmittal. If any tendered Outstanding Notes are registered in different names on several certificates, it will be necessary to complete, sign, and submit as many separate copies of this Letter of Transmittal and any necessary or required documents as there are names in which certificates are held. |
| | If this Letter of Transmittal or any certificates or bond powers are signed by trustees, executors, administrators, guardians, attorneys-in-fact, officers of corporations, or others acting in a fiduciary or representative capacity, such persons should so indicate when signing, and proper evidence satisfactory to the Company of its authority to so act must be submitted, unless waived by the Company. |
| | If this Letter of Transmittal is signed by the registered holder of the Outstanding Notes listed and transmitted hereby, no endorsements of certificates or separate bond powers are required, unless certificates for Outstanding Notes not tendered or not accepted for exchange are to be issued or returned in the name of a person other than the holder thereof. In such event, signatures on this Letter of Transmittal or such certificates must be guaranteed by an Eligible Institution (unless signed by an Eligible Institution). |
13
| | If this Letter of Transmittal is signed by a person other than the registered holder of the Outstanding Notes, the certificates representing such Outstanding Notes must be properly endorsed for transfer by the registered holder or be accompanied by a properly completed bond power from the registered holder, in either case signed by such registered holder exactly as the name of the registered holder of the Outstanding Notes appears on the certificates. Signatures on the endorsement or bond power must be guaranteed by an Eligible Institution (unless signed by an Eligible Institution). |
| | If the Outstanding Notes or the Exchange Notes issued in exchange for the Outstanding Notes are to be issued in the name of a person other than the registered holder, this Letter of Transmittal must be accompanied by bond powers or other documents of transfer sufficient to permit the trustee under the Indenture to register the transfer of such Outstanding Notes into the name of such person. |
7. Transfer Taxes. Except as set forth in this Instruction 7, the Company will pay or cause to be paid any transfer taxes applicable to the exchange of Outstanding Notes pursuant to the Exchange Offer. If, however, a transfer tax is imposed for any reason other than the exchange of Exchange Notes for Outstanding Notes pursuant to the Exchange Offer, then the amount of any transfer taxes (whether imposed on the registered holder or any other persons) will be payable by the tendering holder. If satisfactory evidence of the payment of such taxes or exemptions therefrom is not submitted with this Letter of Transmittal, the amount of such transfer taxes will be billed directly to such tendering holder.
8. Special Issuance and Delivery Instructions. If the Exchange Notes are to be issued or if any Outstanding Notes not tendered or not accepted for exchange are to be issued or sent to a person other than the person signing this Letter of Transmittal or to an address other than that shown above, the appropriate boxes on this Letter of Transmittal should be completed. Holders of Outstanding Notes tendering Outstanding Notes by book-entry transfer may request that Outstanding Notes not accepted for exchange be credited to such other account maintained at DTC as such holder may designate. In such event, all signatures on this Letter of Transmittal must be guaranteed by an Eligible Institution.
9. Irregularities. All questions as to the forms of all documents and the validity of (including time of receipt) and acceptance of the tenders and withdrawals of Outstanding Notes will be determined by the Company, in its sole discretion, which determination shall be final and binding. Alternative, conditional, or contingent tenders will not be considered valid. The Company reserves the absolute right to reject any or all tenders of Outstanding Notes that are not in proper form or the acceptance of which would, in the Company’s opinion, be unlawful. The Company also reserves the right to waive any defects or irregularities as to the tender of any particular Outstanding Notes. The Company’s interpretation of the terms and conditions of the Exchange Offer (including the instructions in this Letter of Transmittal) will be final and binding. Any defect or irregularity in connection with tenders of Outstanding Notes must be cured within such time as the Company determines, unless waived by the Company. Tenders of Outstanding Notes shall not be deemed to have been made until all defects or irregularities have been waived by the Company or cured. Neither the Company nor the Exchange Agent, nor any other person will be under any duty to give notice of any defects or irregularities in tenders of Outstanding Notes, or will incur any liability to registered holders or beneficial owners of Outstanding Notes for failure to give such notice.
10. Waiver of Conditions. To the extent permitted by applicable law, the Company reserves the right to waive any and all conditions to the Exchange Offer as described under “The Exchange Offer—Conditions to the Exchange Offer” in the Prospectus, and accept for exchange any Outstanding Notes tendered. To the extent that the Company waives any condition to the Exchange Offer, it will waive such condition as to all Outstanding Notes.
11. Tax Identification Number and Backup Withholding. Federal income tax law generally requires that a holder of Outstanding Notes whose tendered Outstanding Notes are accepted for exchange or such holder’s assignee (in either case, the “Payee”), provide the Exchange Agent (the “Payor”) with such Payee’s correct Taxpayer Identification Number (“TIN”), which, in the case of a Payee who is an individual, is usually such Payee’s social security number. If the Payor is not provided with the correct TIN or an adequate basis for an exemption, such Payee may be subject to a $50 penalty imposed by the Internal Revenue Service and backup withholding at the applicable withholding rate (which is currently 24%) on all reportable payments (such as interest), that are made to the Payee with respect to the Exchange Notes. If withholding results in an overpayment of taxes, a refund may be obtained, provided that the required information is timely furnished to the Internal Revenue Service.
14
TO PREVENT BACKUP WITHHOLDING, EACH PAYEE THAT IS A “UNITED STATES PERSON” FOR U.S. FEDERAL INCOME TAX PURPOSES MUST PROVIDE THE EXCHANGE AGENT SUCH PAYEE’S CORRECT TIN BY COMPLETING THE IRS FORM W-9 ACCOMPANYING THIS LETTER OF TRANSMITTAL, CERTIFYING THAT THE TIN PROVIDED IS CORRECT (OR THAT SUCH PAYEE IS AWAITING A TIN) AND THAT:
| | the Payee is exempt from backup withholding; |
| | the Payee has not been notified by the Internal Revenue Service that such Payee is subject to backup withholding as a result of a failure to report all interest or dividends; or |
| | the Internal Revenue Service has notified the Payee that such Payee is no longer subject to backup withholding. |
If the Payee does not have a TIN, such Payee should consult the instructions accompanying the enclosed IRS Form W-9 (the “W-9 Instructions”) for instructions on applying for a TIN. A Payee who has not been issued a TIN and has applied for a TIN or intends to apply for a TIN in the near future should complete the IRS Form W-9 as indicated in the W-9 Instructions. If such a Payee does not provide his, her, or its TIN to the Exchange Agent within 60 days, backup withholding on all reportable payments will begin and continue until such Payee furnishes such Payee’s TIN to the Exchange Agent.
If the Outstanding Notes are held in more than one name or are not in the name of the actual owner, consult the W-9 Instructions for information on which TIN to report.
Exempt Payees are not subject to these backup withholding and reporting requirements. To prevent possible erroneous backup withholding, an exempt Payee must enter its correct TIN in Part 1 of the IRS Form W-9, check the “Exempt payee” box in such form, and sign and date the form. See the W-9 Instructions for additional instructions. In order for a Payee that is not a “United States person” for U.S. federal income tax purposes to qualify as exempt from these backup withholding and information reporting requirements, such person must complete and submit an appropriate IRS Form W-8, signed under penalty of perjury attesting to such exempt status. Such form may be obtained from the Exchange Agent.
Holders should refer to the Prospectus for a summary of material U.S. federal income tax consequences of the acquisition, ownership, and disposition of the Exchange Notes. Holders are urged to consult their own tax advisors with respect to the particular U.S. federal income tax consequences to them of the acquisition, ownership, and disposition of the Exchange Notes and the tax consequences under federal, state, local, and non-U.S. tax laws and the possible effects of changes in tax laws.
12. Mutilated, Lost, Stolen, or Destroyed Outstanding Notes. Any holder of Outstanding Notes whose Outstanding Notes have been mutilated, lost, stolen, or destroyed should contact the Exchange Agent at the address or telephone number set forth on the cover of this Letter of Transmittal for further instructions.
13. Requests for Assistance or Additional Copies. Requests for assistance with respect to the procedures for tendering or withdrawing tenders of Outstanding Notes or for additional copies of the Prospectus, this Letter of Transmittal, the Notice of Guaranteed Delivery, or the W-9 Instructions may be directed to the Exchange Agent at its address set forth on the cover of this Letter of Transmittal.
14. Incorporation of this Letter of Transmittal. This Letter of Transmittal shall be deemed to be incorporated in, and acknowledged and accepted by, a tender through DTC’s ATOP procedures by any participant on behalf of itself and the beneficial owners of any Outstanding Notes so tendered by such participant.
IMPORTANT - This Letter of Transmittal, together with certificates for tendered Outstanding Notes, with any required signature guarantees or an Agent’s Message in lieu thereof, together with all other required documents or a Notice of Guaranteed Delivery must be received by the Exchange Agent at or prior to the Expiration Time.
15
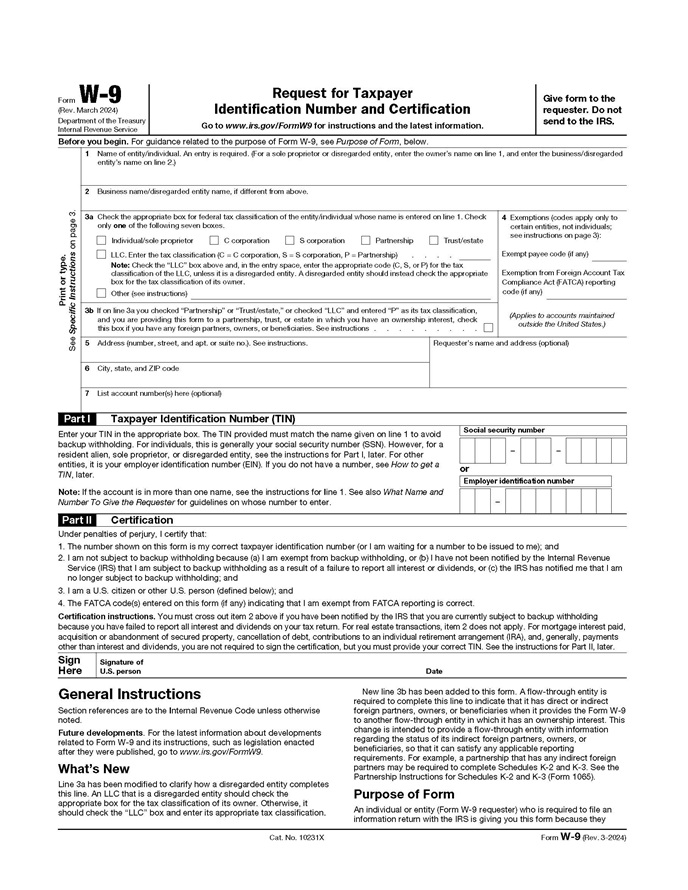
Request for Taxpayer Form W-9 Give form to the (Rev. March 2024) Identification Number and Certification requester. Do not Department of the Treasury Go to www.irs.gov/FormW9 for instructions and the latest information. send to the IRS. Internal Revenue Service Before you begin. For guidance related to the purpose of Form W-9, see Purpose ofFonn, below. 1 Name of entity/individual. An entry is required. (For a sole proprietor or disregarded entity, enter the owner’s name on line 1, and enter the business/disregarded entity’s name on line 2.) 2 Business name/disregarded entity name, if different from above. c,; <I) 3a Check the appropriate box for federal tax classification of the entity/individual whose name is entered on line 1. Check 4 Exemptions (codes apply only to 0) only one of the following seven boxes. certain entities, not individuals; “” Q. Individual/sole proprietor C corporation S corporation Partnership D Trust/estate see instructions on page 3): C ... 0 LLC. Enter the tax classification (C = C corporation, S = S corporation, P = Partnership) Exempt payee code (if any) <I) C: --- for the tax ---... ~-52 ti Note: Check the “LLC” box above and, in the entry space, enter the appropriate code (C, S, or P) classification of the LLC, unless it is a disregarded entity. A disregarded entity should instead check the appropriate Exemption from Foreign Account Tax 5 2 box for the tax classification of its owner. Compliance Act (FATCA) reporting .§~ Other (see instructions) code (if any) a. <., ~ 3b If on line 3a you checked “Partnership” or “Trust/estate,” or checked “LLC” and entered “P” as its tax classification, (Applies to accounts maintained &l and you are providing this form to a partnership, trust, or estate in which you have an ownership interest, check outside the United States.) ~ this box if you have any foreign partners, owners, or beneficiaries. See instructions <I) <I) 5 Address (number, street, and apt. or suite no.). See instructions. Requester’s name and address (optional) (f) 6 City, state, and ZIP code 7 List account number(s) here (optional) Taxpayer Identification Number (TIN) mn: I Sociaf security number I Enter your TIN in the appropriate box. The TIN provided must match the name given on line 1 to avoid backup withholding. For individuals, this is generally your social security number (SSN). However, for a resident alien, sole proprietor, or disregarded entity, see the instructions for Part I, later. For other [Il]-ITJ-1 I I I I entities, it is your employer identification number (EIN). If you do not have a number, see How to get a TIN, later. or I Employer identification number Note: If the account is in more than one name, see the instructions for line 1. See also What Name and Number To Give the Requester for guidelines on whose number to enter. Certification Under penalties of perjury, I certify that: 1. The number shown on this form is my correct taxpayer identification number (or I am w aiting for a number to be issued to me); and 2. I am not subject to backup withholding because (a) I am exempt from backup withholding, or (b) I have not been notified by the Internal Revenue Service (IRS) that I am subject to backup withholding as a result of a failure to report all interest or dividends, or (c) the IRS has notified me that I am no longer subject to backup withholding; and 3. I am a U.S citizen or other U.S. person (defined below); and 4. The FATCA code(s) entered on this form Of any) indicating that I am exempt from FATCA reporting is correct. Certification instructions. You must cross out item 2 above if you have been notified by the IRS that you are currently subject to backup withholding because you have failed to report all interest and dividends on your tax return. For real estate transactions, item 2 does not apply. For mortgage interest paid, acquisition or abandonment of secured property, cancellation of debt, contributions to an individual retirement arrangement (IRA), and, generally, payments other than interest and dividends, you are not required to sign the certification, but you must provide your correct TIN. See the instructions for Part II, later. Sign I Signature of Here . U.S. person Date General Instructions New line 3b has been added to this form. A flow-through entity is required to complete this line to indicate that it has direct or indirect Section references are to the Internal Revenue Code unless otherwise foreign partners, owners, or beneficiaries when it provides the Form W-9 noted. to another flow-through entity in which it has an ownership interest. This change is intended to provide a flow-through entity with information Future developments. For the latest information about developments regarding the status of its indirect foreign partners, owners, or related to Form W-9 and its instructions, such as legislation enacted beneficiaries, so that it can satisfy any applicable reporting after they were published, go to www.irs.gov/FormW9. requirements. For example, a partnership that has any indirect foreign What’s New partners may be required to complete Schedules K-2 and K-3. See the Partnership Instructions for Schedules K-2 and K-3 (Form 1065). Line 3a has been modified to clarify how a disregarded entity completes this line. An LLC that is a disregarded entity should check the Purpose of Form appropriate box for the tax classification of its owner. Otherwise, it An individual or entity (Form W-9 requester) who is required to file an should check the “LLC” box and enter its appropriate tax classification. information return with the IRS is giving you this form because they Cat. No. 10231X Form W-9 (Rev. 3-2024)
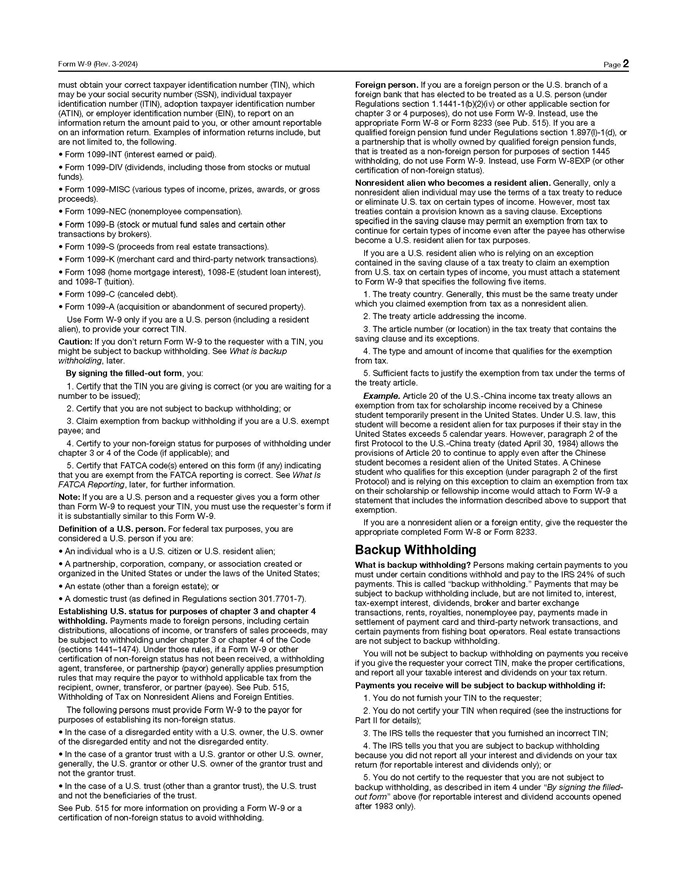
Form W-9 (Rev. 3-2024) Page 2 must obtain your correct taxpayer identification number (TIN), which Foreign person. If you are a foreign person or the U.S. branch of a may be your social security number (SSN), individual taxpayer foreign bank that has elected to be treated as a U.S. person (under identification number (ITIN), adoption taxpayer identification number Regulations section 1.1441-1 (b)(2)(iv) or other applicable section for (ATIN), or employer identification number (EIN), to report on an chapter 3 or 4 purposes), do not use Form W-9. Instead, use the information return the amount paid to you, or other amount reportable appropriate Form W-8 or Form 8233 (see Pub. 515). If you are a on an information return. Examples of information returns include, but qualified foreign pension fund under Regulations section 1.897(1)-1 (d), or are not limited to, the following. a partnership that is wholly owned by qualified foreign pension funds, that is treated as a non-foreign person for purposes of section 1445 Form 1099-INT (interest earned or paid). withholding, do not use Form W-9. Instead, use Form W-8EXP (or other Form 1099-DIV (dividends, including those from stocks or mutual certification of non-foreign status). funds). Nonresident alien who becomes a resident alien. Generally, only a Form 1099-MISC (various types of income, prizes, awards, or gross proceeds). nonresident alien individual may use the terms of a tax treaty to reduce or eliminate U.S. tax on certain types of income. However, most tax Form 1099-NEC (nonemployee compensation). treaties contain a provision known as a saving clause. Exceptions specified in the saving clause may permit an exemption from tax to Form 1099-B (stock or mutual fund sales and certain other continue for certain types of income even after the payee has otherwise transactions by brokers). become a U.S. resident alien for tax purposes. Form 1099-S (proceeds from real estate transactions). If you are a U.S. resident alien who is relying on an exception Form 1099-K (merchant card and third-party network transactions). contained in the saving clause of a tax treaty to claim an exemption Form 1098 (home mortgage interest), 1098-E (student loan interest), from U.S. tax on certain types of income, you must attach a statement and 1098-T (tuition). to Form W-9 that specifies the following five items. Form 1099-C (canceled debt). 1. The treaty country. Generally, this must be the same treaty under which you claimed exemption from tax as a nonresident alien. Form 1099-A (acquisition or abandonment of secured property). 2. The treaty article addressing the income. Use Form W-9 only if you are a U.S. person (including a resident alien), to provide your correct TIN. 3. The article number (or location) in the tax treaty that contains the Caution: If you don’t return Form W-9 to the requester with a TIN, you saving clause and its exceptions. might be subject to backup withholding. See What is backup 4. The type and amount of income that qualifies for the exemption withholding, later. from tax. By signing the filled-out form, you: 5. Sufficient facts to justify the exemption from tax under the terms of the treaty article. 1. Certify that the TIN you are giving is correct (or you are waiting for a number to be issued); Example. Article 20 of the U.S.-China income tax treaty allows an exemption from tax for scholarship income received by a Chinese 2. Certify that you are not subject to backup withholding; or student temporarily present in the United States. Under U.S. law, this 3. Claim exemption from backup withholding if you are a U.S. exempt payee;and student will become a resident alien for tax purposes if their stay in the United States exceeds 5 calendar years. However, paragraph 2 of the 4. Certify to your non-foreign status for purposes of withholding under first Protocol to the U.S.-China treaty (dated April 30, 1984) allows the chapter 3 or 4 of the Code (if applicable); and provisions of Article 20 to continue to apply even after the Chinese student becomes a resident alien of the United States. A Chinese 5. Certify that FATCA code(s) entered on this form (if any) indicating student who qualifies for this exception (under paragraph 2 of the first that you are exempt from the FATCA reporting is correct. See What Is Protocol) and is relying on this exception to claim an exemption from tax FATCA Reporting, later, for further information. on their scholarship or fellowship income would attach to Form W-9 a Note: If you are a U.S. person and a requester gives you a form other than Form W-9 to request your TIN, you must use the requester’s form if statement that includes the information described above to support that it is substantially similar to this Form W-9. exemption. Definition of a U.S. person. For federal tax purposes, you are If you are a nonresident alien or a foreign entity, give the requester the appropriate completed Form W-8 or Form 8233. considered a U.S. person if you are: An individual who is a U.S. citizen or U.S. resident alien; Backup Withholding A partnership, corporation, company, or association created or What is backup withholding? Persons making certain payments to you organized in the United States or under the laws of the United States; must under certain conditions withhold and pay to the IRS 24% of such An estate (other than a foreign estate); or payments. This is called “backup withholding.” Payments that may be subject to backup withholding include, but are not limited to, interest, A domestic trust (as defined in Regulations section 301. 7701-7). tax-exempt interest, dividends, broker and barter exchange Establishing U.S. status for purposes of chapter 3 and chapter 4 transactions, rents, royalties, nonemployee pay, payments made in withholding. Payments made to foreign persons, including certain settlement of payment card and third-party network transactions, and distributions, allocations of income, or transfers of sales proceeds, may certain payments from fishing boat operators. Real estate transactions be subject to withholding under chapter 3 or chapter 4 of the Code are not subject to backup withholding. (sections 1441-1474). Under those rules, if a Form W-9 or other You will not be subject to backup withholding on payments you receive certification of non-foreign status has not been received, a withholding if you give the requester your correct TIN, make the proper certifications, agent, transferee, or partnership (payor) generally applies presumption and report all your taxable interest and dividends on your tax return. rules that may require the payor to withhold applicable tax from the recipient, owner, transferor, or partner (payee). See Pub. 515, Payments you receive will be subject to backup withholding if: Withholding of Tax on Nonresident Aliens and Foreign Entities. 1. You do not furnish your TIN to the requester; The following persons must provide Form W-9 to the payor for 2. You do not certify your TIN when required (see the instructions for purposes of establishing its non-foreign status. Part II for details); In the case of a disregarded entity with a U.S. owner, the U.S. owner 3. The IRS tells the requester that you furnished an incorrect TIN; of the disregarded entity and not the disregarded entity. 4. The IRS tells you that you are subject to backup withholding In the case of a granter trust with a U.S. granter or other U.S. owner, because you did not report all your interest and dividends on your tax generally, the U.S. granter or other U.S. owner of the granter trust and return (for reportable interest and dividends only); or not the granter trust. 5. You do not certify to the requester that you are not subject to In the case of a U.S. trust (other than a granter trust), the U.S. trust backup withholding, as described in item 4 under “By signing the filled-and not the beneficiaries of the trust. out fonn” above (for reportable interest and dividend accounts opened See Pub. 515 for more information on providing a Form W-9 or a after 1983 only). certification of non-foreign status to avoid withholding.
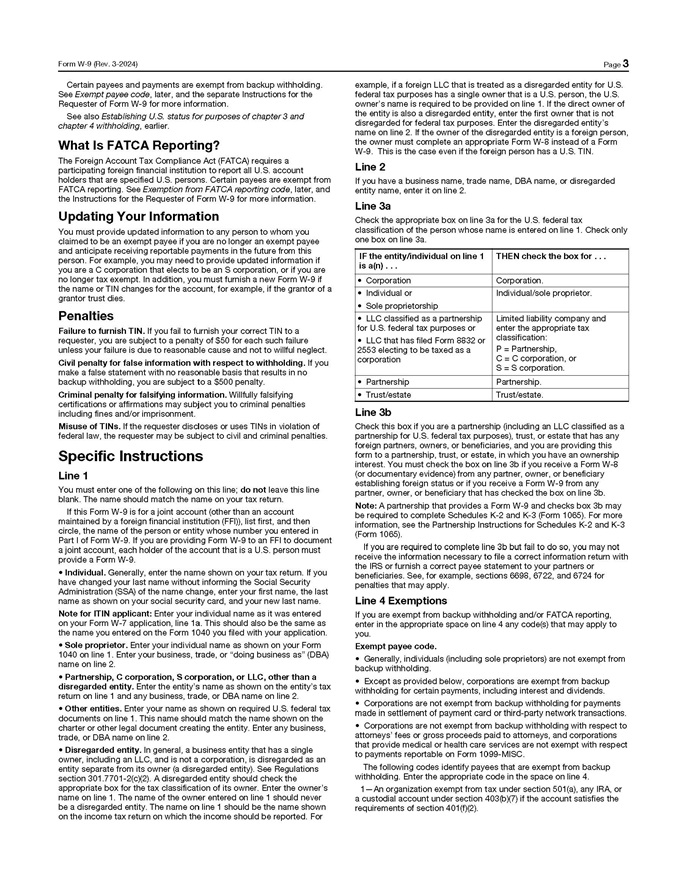
Form W-9 (Rev. 3-2024) Page3 Certain payees and payments are exempt from backup withholding. example, if a foreign LLC that is treated as a disregarded entity for U.S. See Exempt payee code, later, and the separate Instructions for the federal tax purposes has a single owner that is a U.S. person, the U.S. Requester of Form W-9 for more information. owner’s name is required to be provided on line 1. If the direct owner of the entity is also a disregarded entity, enter the first owner that is not See also Establishing U.S. status for purposes of chapter 3 and disregarded for federal tax purposes. Enter the disregarded entity’s chapter 4 withholding, earlier. name on line 2. If the owner of the disregarded entity is a foreign person, What Is FATCA Reporting? the owner must complete an appropriate Form W-8 instead of a Form W-9. This is the case even if the foreign person has a U.S. TIN. The Foreign Account Tax Compliance Act (FATCA) requires a participating foreign financial institution to report all U.S. account Line 2 holders that are specified U.S. persons. Certain payees are exempt from If you have a business name, trade name, DBA name, or disregarded FATCA reporting. See Exemption from FATCA reporting code, later, and entity name, enter it on line 2. the Instructions for the Requester of Form W-9 for more information. Line 3a Updating Your Information Check the appropriate box on line 3a for the U.S. federal tax You must provide updated information to any person to whom you classification of the person whose name is entered on line 1. Check only claimed to be an exempt payee if you are no longer an exempt payee one box on line 3a. and anticipate receiving reportable payments in the future from this IF the entity/individual on line 1 THEN check the box for person. For example, you may need to provide updated information if is a(n) you are a C corporation that elects to be an S corporation, or if you are no longer tax exempt. In addition, you must furnish a new Form W-9 if . Corporation Corporation. the name or TIN changes for the account, for example, if the granter of a . Individual or Individual/sole proprietor. granter trust dies. . . Sole proprietorship Penalties LLC classified as a partnership Limited liability company and for U.S. federal tax purposes or enter the appropriate tax Failure to furnish TIN. If you fail to furnish your correct TIN to a classification: requester, you are subject to a penalty of $50 for each such failure LLC that has filed Form 8832 or unless your failure is due to reasonable cause and not to willful neglect. 2553 electing to be taxed as a P = Partnership, corporation C = C corporation, or Civil penalty for false information with respect to withholding. If you S = S corporation. make a false statement with no reasonable basis that results in no . backup withholding, you are subject to a $500 penalty. . Partnership Partnership. Criminal penalty for falsifying information. Willfully falsifying Trust/estate Trust/estate. certifications or affirmations may subject you to criminal penalties including fines and/or imprisonment. Line 3b Misuse of TINs. If the requester discloses or uses TINs in violation of Check this box if you are a partnership (including an LLC classified as a federal law, the requester may be subject to civil and criminal penalties. partnership for U.S. federal tax purposes), trust, or estate that has any foreign partners, owners, or beneficiaries, and you are providing this Specific Instructions form to a partnership, trust, or estate, in which you have an ownership interest. You must check the box on line 3b if you receive a Form W-8 Line 1 (or documentary evidence) from any partner, owner, or beneficiary establishing foreign status or if you receive a Form W-9 from any You must enter one of the following on this line; do not leave this line blank. The name should match the name on your tax return. partner, owner, or beneficiary that has checked the box on line 3b. If this Form W-9 is for a joint account (other than an account Note: A partnership that provides a Form W-9 and checks box 3b may maintained by a foreign financial institution (FFI)), list first, and then be required to complete Schedules K-2 and K-3 (Form 1065). For more circle, the name of the person or entity whose number you entered in information, see the Partnership Instructions for Schedules K-2 and K-3 Part I of Form W-9. If you are providing Form W-9 to an FFI to document (Form 1065). If you are required to complete line 3b but fail to do so, you may not a joint account, each holder of the account that is a U.S. person must receive the information necessary to file a correct information return with provide a Form W-9. Individual. Generally, enter the name shown on your tax return. If you the IRS or furnish a correct payee statement to your partners or have changed your last name without informing the Social Security beneficiaries. See, for example, sections 6698, 6722, and 6724 for Administration (SSA) of the name change, enter your first name, the last penalties that may apply. name as shown on your social security card, and your new last name. Line 4 Exemptions Note for ITIN applicant: Enter your individual name as it was entered If you are exempt from backup withholding and/or FATCA reporting, on your Form W-7 application, line 1a. This should also be the same as enter in the appropriate space on line 4 any code(s) that may apply to the name you entered on the Form 1040 you filed with your application. you. Sole proprietor. Enter your individual name as shown on your Form Exempt payee code. 1040 on line 1. Enter your business, trade, or “doing business as” (DBA) Generally, individuals (including sole proprietors) are not exempt from name on line 2. backup withholding. Partnership, C corporation, S corporation, or LLC, other than a Except as provided below, corporations are exempt from backup disregarded entity. Enter the entity’s name as shown on the entity’s tax withholding for certain payments, including interest and dividends. return on line 1 and any business, trade, or DBA name on line 2. Corporations are not exempt from backup withholding for payments Other entities. Enter your name as shown on required U.S. federal tax documents on line 1. This name should match the name shown on the made in settlement of payment card or third-party network transactions. charter or other legal document creating the entity. Enter any business, Corporations are not exempt from backup withholding with respect to trade, or DBA name on line 2. attorneys’ fees or gross proceeds paid to attorneys, and corporations that provide medical or health care services are not exempt with respect Disregarded entity. In general, a business entity that has a single owner, including an LLC, and is not a corporation, is disregarded as an to payments reportable on Form 1099-MISC. entity separate from its owner (a disregarded entity). See Regulations The following codes identify payees that are exempt from backup section 301.7701-2(c)(2). A disregarded entity should check the withholding. Enter the appropriate code in the space on line 4. appropriate box for the tax classification of its owner. Enter the owner’s 1-An organization exempt from tax under section 501 (a), any IRA, or name on line 1. The name of the owner entered on line 1 should never a custodial account under section 403(b)(7) if the account satisfies the be a disregarded entity. The name on line 1 should be the name shown requirements of section 401 (f)(2). on the income tax return on which the income should be reported. For
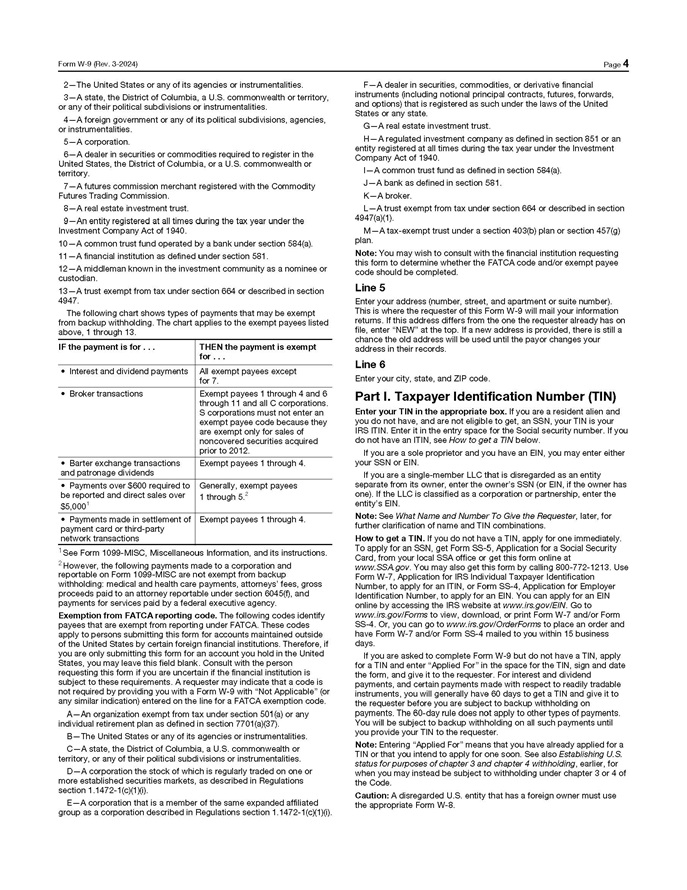
Form W-9 (Rev. 3-2024) Page 4 2-The United States or any of its agencies or instrumentalities. F-A dealer in securities, commodities, or derivative financial 3-A state, the District of Columbia, a U.S. commonwealth or territory, instruments Qncluding notional principal contracts, futures, forwards, and options) that is registered as such under the laws of the United or any of their political subdivisions or instrumentalities. States or any state. 4-A foreign government or any of its political subdivisions, agencies, G-A real estate investment trust. or instrumentalities. H-A regulated investment company as defined in section 851 or an 5-A corporation. 6-A dealer in securities or commodities required to register in the entity registered at all times during the tax year under the Investment United States, the District of Columbia, or a U.S. commonwealth or Company Act of 1940. I-A common trust fund as defined in section 584(a). territory. J-A bank as defined in section 581. 7-A futures commission merchant registered with the Commodity Futures Trading Commission. K-A broker. 8-A real estate investment trust. L-A trust exempt from tax under section 664 or described in section 4947(a)(1). 9-An entity registered at all times during the tax year under the Investment Company Act of 1940. M-A tax-exempt trust under a section 403(b) plan or section 457(g) plan. 10-A common trust fund operated by a bank under section 584(a). 11-A financial institution as defined under section 581. Note: You may wish to consult with the financial institution requesting 12-A middleman known in the investment community as a nominee or this form to determine whether the FATCA code and/or exempt payee custodian. code should be completed. 13-A trust exempt from tax under section 664 or described in section Line 5 4947. Enter your address (number, street, and apartment or suite number). The following chart shows types of payments that may be exempt This is where the requester of this Form W-9 will mail your information from backup withholding. The chart applies to the exempt payees listed returns. If this address differs from the one the requester already has on above, 1 through 13. file, enter “NEW” at the top. If a new address is provided, there is still a chance the old address will be used until the payor changes your IF the payment is for ... THEN the payment is exempt address in their records. for Interest and dividend payments All exempt payees except Line 6 for 7. Enter your city, state, and ZIP code. Broker transactions Exempt payees 1 through 4 and 6 Part I. Taxpayer Identification Number (TIN) through 11 and all C corporations. S corporations must not enter an Enter your TIN in the appropriate box. If you are a resident alien and exempt payee code because they you do not have, and are not eligible to get, an SSN, your TIN is your are exempt only for sales of IRS ITIN. Enter it in the entry space for the Social security number. If you noncovered securities acquired do not have an ITIN, see How to get a TIN below. prior to 2012. If you are a sole proprietor and you have an EIN, you may enter either Barter exchange transactions Exempt payees 1 through 4. your SSN or EIN. and patronage dividends If you are a single-member LLC that is disregarded as an entity Payments over $600 required to Generally, exempt payees separate from its owner, enter the owner’s SSN (or EIN, if the owner has be reported and direct sales over 2 one). If the LLC is classified as a corporation or partnership, enter the 1 through 5. entity’s El N. $5,000’ Note: See What Name and Number To Give the Requester, later, for Payments made in settlement of Exempt payees 1 through 4. further clarification of name and TIN combinations. payment card or third-party network transactions How to get a TIN. If you do not have a TIN, apply for one immediately. 1 To apply for an SSN, get Form SS-5, Application for a Social Security See Form 1099-MISC, Miscellaneous Information, and its instructions. 2 Card, from your local SSA office or get this form online at However, the following payments made to a corporation and www.SSAgov. You may also get this form by calling 800-772-1213. Use reportable on Form 1099-MISC are not exempt from backup Form W-7, Application for IRS Individual Taxpayer Identification withholding: medical and health care payments, attorneys’ fees, gross Number, to apply for an ITIN, or Form SS-4, Application for Employer proceeds paid to an attorney reportable under section 6045(1), and Identification Number, to apply for an EIN. You can apply for an EIN payments for services paid by a federal executive agency. online by accessing the IRS website at www.irs.gov/EIN. Go to Exemption from FATCA reporting code. The following codes identify www.irs.gov/Forms to view, download, or print Form W-7 and/or Form payees that are exempt from reporting under FATCA. These codes SS-4. Or, you can go to www.irs.gov/OrderForms to place an order and apply to persons submitting this form for accounts maintained outside have Form W-7 and/or Form SS-4 mailed to you within 15 business of the United States by certain foreign financial institutions. Therefore, if days. you are only submitting this form for an account you hold in the United If you are asked to complete Form W-9 but do not have a TIN, apply States, you may leave this field blank. Consult with the person for a TIN and enter “Applied For” in the space for the TIN, sign and date requesting this form if you are uncertain if the financial institution is the form, and give it to the requester. For interest and dividend subject to these requirements. A requester may indicate that a code is payments, and certain payments made with respect to readily tradable not required by providing you with a Form W-9 with “Not Applicable” (or instruments, you will generally have 60 days to get a TIN and give it to any similar indication) entered on the line for a FATCA exemption code. the requester before you are subject to backup withholding on A-An organization exempt from tax under section 501 (a) or any payments. The 60-day rule does not apply to other types of payments. individual retirement plan as defined in section 7701(a)(37). You will be subject to backup withholding on all such payments until you provide your TIN to the requester. B- The United States or any of its agencies or instrumentalities. Note: Entering “Applied For” means that you have already applied for a C-A state, the District of Columbia, a U.S. commonwealth or TIN or that you intend to apply for one soon. See also Establishing U.S. territory, or any of their political subdivisions or instrumentalities. status for purposes of chapter 3 and chapter 4 withholding, earlier, for D-A corporation the stock of which is regularly traded on one or when you may instead be subject to withholding under chapter 3 or 4 of more established securities markets, as described in Regulations the Code. section 1.1472-1(c)(1)(i). Caution: A disregarded U.S. entity that has a foreign owner must use E-A corporation that is a member of the same expanded affiliated the appropriate Form W-8. group as a corporation described in Regulations section 1.1472-1 (c)(1)(i).
Form W-9 (Rev. 3-2024) Page 5 Part II. Certification For this type of account: Give name and EIN of: To establish to the withholding agent that you are a U.S. person, or 8. Disregarded entity not owned by an The owner resident alien, sign Form W-9. You may be requested to sign by the individual withholding agent even if item 1, 4, or 5 below indicates otherwise. 9. A valid trust, estate, or pension trust Legal entity4 For a joint account, only the person whose TIN is shown in Part I 10. Corporation or LLC electing corporate The corporation should sign (when required). In the case of a disregarded entity, the status on Form 8832 or Form 2553 person identified on line 1 must sign. Exempt payees, see Exempt payee 11 Association, club, religious, charitable, The organization code, earlier. educational, or other tax-exempt organization Signature requirements. Complete the certification as indicated in items 1 through 5 below. 12. Partnership or multi-member LLC The partnership 1. Interest, dividend, and barter exchange accounts opened 13. A broker or registered nominee The broker or nominee before 1984 and broker accounts considered active during 1983. 14. Account with the Department of The public entity You must give your correct TIN, but you do not have to sign the Agriculture in the name of a public certification. entity (such as a state or local 2. Interest, dividend, broker, and barter exchange accounts government, school district, or prison) that receives agricultural program opened after 1983 and broker accounts considered inactive during payments 1983. You must sign the certification or backup withholding will apply. If 15. Grantor trust filing Form 1041 or The trust you are subject to backup withholding and you are merely providing your correct TIN to the requester, you must cross out item 2 in the under the Optional Filing Method 2, requiring Form 1099 (see Regulations certification before signing the form. section 1.671-4(b)(2)(i)(B)) 3. Real estate transactions. You must sign the certification. You may 1 List first and circle the name of the person whose number you furnish. cross out item 2 of the certification. If only one person on a joint account has an SSN, that person’s number 4. Other payments. You must give your correct TIN, but you do not must be furnished. have to sign the certification unless you have been notified that you have previously given an incorrect TIN. “Other payments” include 2 Circle the minor’s name and furnish the minor’s SSN. payments made in the course of the requester’s trade or business for 3 You must show your individual name on line 1, and enter your business rents, royalties, goods (other than bills for merchandise), medical and or DBA name, if any, on line 2. You may use either your SSN or EIN (if health care services Qncluding payments to corporations), payments to you have one), but the IRS encourages you to use your SSN. a nonemployee for services, payments made in settlement of payment 4 card and third-party network transactions, payments to certain fishing List first and circle the name of the trust, estate, or pension trust. (Do boat crew members and fishermen, and gross proceeds paid to not furnish the TIN of the personal representative or trustee unless the attorneys (including payments to corporations). legal entity itself is not designated in the account title.) * Note: The granter must also provide a Form W-9 to the trustee of the 5. Mortgage interest paid by you, acquisition or abandonment of secured property, cancellation of debt, qualified tuition program trust. ** For more information on optional filing methods for granter trusts, see payments (under section 529), ABLE accounts (under section 529A), the Instructions for Form 1041. IRA, Coverdell ESA, Archer MSA or HSA contributions or distributions, and pension distributions. You must give your correct Note: If no name is circled when more than one name is listed, the TIN, but you do not have to sign the certification. number will be considered to be that of the first name listed. What Name and Number To Give the Requester Secure Your Tax Records From Identity Theft For this type of account: Give name and SSN of: Identity theft occurs when someone uses your personal information, 1. Individual The individual such as your name, SSN, or other identifying information, without your 2. Two or more individuals ijoint account) The actual owner of the account or, permission to commit fraud or other crimes. An identity thief may use your SSN to get a job or may file a tax return using your SSN to receive other than an account maintained by if combined funds, the first individual a refund. an FFI on the account 1 To reduce your risk: 3. Two or more U.S. persons Each holder of the account ijoint account maintained by an FFI) Protect your SSN, 4. Custodial account of a minor The minor2 Ensure your employer is protecting your SSN, and (Uniform Gift to Minors Act) Be careful when choosing a tax return preparer. 5. a. The usual revocable savings trust The grant or-trustee 1 (grantor is also trustee) If your tax records are affected by identity theft and you receive a b. So-called trust account that is not The actual owner 1 notice from the IRS, respond right away to the name and phone number printed on the IRS notice or letter. a legal or valid trust under state law 3 If your tax records are not currently affected by identity theft but you 6. Sole proprietorship or disregarded The owner think you are at risk due to a lost or stolen purse or wallet, questionable entity owned by an individual The grantor credit card activity, or a questionable credit report, contact the IRS 7. Grantor trust filing under Optional Identity Theft Hotline at 800-908-4490 or submit Form 14039. Filing Method 1 (see Regulations section 1.671-4(b)(2)(i)(A)) .. For more information, see Pub. 5027, Identity Theft Information for Taxpayers.
Form W-9 (Rev. 3-2024) Page 6 Victims of identity theft who are experiencing economic harm or a Privacy Act Notice systemic problem, or are seeking help in resolving tax problems that have not been resolved through normal channels, may be eligible for Section 6109 of the Internal Revenue Code requires you to provide your Taxpayer Advocate Service (TAS) assistance. You can reach TAS by correct TIN to persons Qncluding federal agencies) who are required to calling the TAS toll-free case intake line at 877-777-4 778 or TTY/TDD file information returns with the IRS to report interest, dividends, or 800-829-4059. certain other income paid to you; mortgage interest you paid; the acquisition or abandonment of secured property; the cancellation of Protect yourself from suspicious emails or phishing schemes. debt; or contributions you made to an IRA, Archer MSA, or HSA. The Phishing is the creation and use of email and websites designed to person collecting this form uses the information on the form to file mimic legitimate business emails and websites. The most common act information returns with the IRS, reporting the above information. is sending an email to a user falsely claiming to be an established Routine uses of this information include giving it to the Department of legitimate enterprise in an attempt to scam the user into surrendering Justice for civil and criminal litigation and to cities, states, the District of private information that will be used for identity theft. Columbia, and U.S. commonwealths and territories for use in The IRS does not initiate contacts with taxpayers via emails. Also, the administering their laws. The information may also be disclosed to other IRS does not request personal detailed information through email or ask countries under a treaty, to federal and state agencies to enforce civil taxpayers for the PIN numbers, passwords, or similar secret access and criminal laws, or to federal law enforcement and intelligence information for their credit card, bank, or other financial accounts. agencies to combat terrorism. You must provide your TIN whether or not If you receive an unsolicited email claiming to be from the IRS, you are required to file a tax return. Under section 3406, payers must forward this message to phishing@irs.gov. You may also report misuse generally withhold a percentage of taxable interest, dividends, and of the IRS name, logo, or other IRS property to the Treasury Inspector certain other payments to a payee who does not give a TIN to the payor. General for Tax Administration (TIGTA) at 800-366-4484. You can Certain penalties may also apply for providing false or fraudulent forward suspicious emails to the Federal Trade Commission at information. spam@uce.gov or report them at www.ftc.gov/complaint. You can contact the FTC at www.ftc.gov/idtheft or 877-IDTHEFT (877-438-4338). If you have been the victim of identity theft, see www.ldentityTheft.gov and Pub. 5027. Go to www.irs.gov/ldentityTheft to learn more about identity theft and how to reduce your risk.