EXHIBIT 99.19
CordovaCann Corp.
Unaudited Condensed Interim Consolidated Financial Statements
For the Three and Six Months Ended December 31, 2021 and 2020
(Expressed in Canadian Dollars)
INDEX
|
| Page |
| |
| Notice to Reader Issued by Management |
| 2 |
|
| Unaudited Condensed Interim Consolidated Statements of Financial Position |
| 3 |
|
| Unaudited Condensed Interim Consolidated Statements of Operations and Comprehensive Loss |
| 4 |
|
| Unaudited Condensed Interim Consolidated Statements of Changes in Equity |
| 5 |
|
| Unaudited Condensed Interim Consolidated Statements of Cash Flow |
| 6 |
|
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| 7-39 |
|
CordovaCann Corp.
Notice to Reader Issued by Management
Under National Instrument 51-102, Part 4, Subsection 4.3(3)(a), if an auditor has not performed a review of the condensed interim consolidated financial statements, they must be accompanied by a notice to this effect.
The accompanying unaudited condensed interim consolidated financial statements have been prepared and are the responsibility of the Company’s management. The Company’s independent auditor has not performed a review of the unaudited condensed interim consolidated financial statements.
February 28, 2022
| 2 |
| CordovaCann Corp. |
| Unaudited Condensed Interim Consolidated Statements of Financial Position |
| (Expressed in Canadian Dollars) |
| As at |
| December 31, 2021 $ |
|
| June 30, 2021 $ |
| ||
|
|
|
|
|
|
|
| ||
| ASSETS |
|
|
|
|
|
| ||
| Current |
|
|
|
|
|
| ||
| Cash and cash equivalents |
|
| 950,631 |
|
|
| 1,058,494 |
|
| Restricted cash (Note 25) |
|
| 1,016,966 |
|
|
| - |
|
| Accounts receivable |
|
| 60,765 |
|
|
| 7,924 |
|
| Prepaid expenses and deposits |
|
| 370,865 |
|
|
| 332,771 |
|
| Inventory (Note 5) |
|
| 514,151 |
|
|
| 504,521 |
|
| Biological assets (Note 6) |
|
| 24,019 |
|
|
| 26,611 |
|
| Other deposit - current portion (Note 23) |
|
| 211,727 |
|
|
| 199,463 |
|
| Total current assets |
|
| 3,149,124 |
|
|
| 2,129,784 |
|
| Other deposit (Note 23) |
|
| - |
|
|
| 101,351 |
|
| Right-of-use assets (Note 7) |
|
| 5,003,780 |
|
|
| 3,169,655 |
|
| Property and equipment, net (Note 8) |
|
| 3,738,803 |
|
|
| 6,059,622 |
|
| Intangible assets (Note 9) |
|
| 5,243,967 |
|
|
| 5,243,967 |
|
| Licenses (Note 13) |
|
| 459,372 |
|
|
| 569,662 |
|
| Total assets |
|
| 17,595,046 |
|
|
| 17,274,041 |
|
| LIABILITIES |
|
|
|
|
|
|
|
|
| Current |
|
|
|
|
|
|
|
|
| Accounts payable and accrued liabilities |
|
| 3,309,534 |
|
|
| 3,326,171 |
|
| Harmonized sales tax payable |
|
| 48,054 |
|
|
| 98,916 |
|
| Mortgage payable (Note 15) |
|
| 828,844 |
|
|
| 1,566,067 |
|
| Consideration payable (Note 10) |
|
| - |
|
|
| 39,292 |
|
| Income taxes payable |
|
| 286,180 |
|
|
| 315,362 |
|
| Contract liability (Note 17) |
|
| 49,656 |
|
|
| 48,832 |
|
| Lease liability (Note 14) |
|
| 576,024 |
|
|
| 438,856 |
|
| Promissory notes payable (Note 16) |
|
| 1,024,740 |
|
|
| 1,017,772 |
|
| Total current liabilities |
|
| 6,123,032 |
|
|
| 6,851,268 |
|
| Deferred tax liability |
|
| 36,540 |
|
|
| 36,540 |
|
| Contract liability (Note 17) |
|
| 157,539 |
|
|
| 178,071 |
|
| Lease liability (Note 14) |
|
| 4,794,978 |
|
|
| 2,889,789 |
|
| Total liabilities |
|
| 11,112,089 |
|
|
| 9,955,668 |
|
| SHAREHOLDERS' EQUITY |
|
|
|
|
|
|
|
|
| Share capital (Note 20) |
|
| 28,158,509 |
|
|
| 26,145,146 |
|
| Shares to be issued (Note 20) |
|
| - |
|
|
| 923,590 |
|
| Share subscriptions received in advance (Note 18) |
|
| - |
|
|
| 647,296 |
|
| Contributed surplus |
|
| 7,820,775 |
|
|
| 7,844,814 |
|
| Equity portion of convertible debentures |
|
| 336,127 |
|
|
| 306,877 |
|
| Accumulated deficit |
|
| (30,804,723 | ) |
|
| (29,453,390 | ) |
| Accumulated other comprehensive income |
|
| 115,267 |
|
|
| 77,875 |
|
| Total shareholders' equity attributable to Cordova shareholders |
|
| 5,625,955 |
|
|
| 6,492,208 |
|
| Non-controlling interest |
|
| 857,002 |
|
|
| 826,165 |
|
| Total equity |
|
| 6,482,957 |
|
|
| 7,318,373 |
|
| Total liabilities and shareholders' equity |
|
| 17,595,046 |
|
|
| 17,274,041 |
|
Nature of operations and going concern (Note 1) Commitments (Note 23)
Related party transactions (Note 24)
Subsequent events (Note 29)
Approved on behalf of the Board:
| “Dale Rasmussen”, Director |
| “Thomas M. Turner, Jr.”, Director |
| (signed) |
| (signed) |
|
|
|
|
The accompanying notes are an integral part of these condensed interim consolidated financial statements.
| 3 |
| CordovaCann Corp. |
| Unaudited Condensed Interim Consolidated Statements of Operations and Comprehensive Loss |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
|
|
| Three Months Ended December 31, 2021 |
|
| Three Months Ended December 31, 2020 |
|
| Six Months Ended December 31, 2021 |
|
| Six Months Ended December 31, 2020 |
| ||||
|
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||
| Revenue |
|
| 3,486,983 |
|
|
| 2,441,857 |
|
|
| 7,261,696 |
|
|
| 4,278,669 |
|
| Cost of sales |
|
| (2,555,237 | ) |
|
| (1,595,132 | ) |
|
| (5,244,460 | ) |
|
| (2,777,271 | ) |
| Gross profit |
|
| 931,746 |
|
|
| 846,725 |
|
|
| 2,017,236 |
|
|
| 1,501,398 |
|
| Expenses |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Consulting fees |
|
| 168,447 |
|
|
| 169,418 |
|
|
| 389,912 |
|
|
| 323,434 |
|
| Share based compensation (Note 21, 22 ) |
|
| - |
|
|
| 60,528 |
|
|
| 1,920 |
|
|
| 178,126 |
|
| Professional fees |
|
| 22,087 |
|
|
| 116,012 |
|
|
| 49,642 |
|
|
| 188,608 |
|
| Shareholders information services |
|
| 52,896 |
|
|
| 42,871 |
|
|
| 108,739 |
|
|
| 79,242 |
|
| Salaries and wages |
|
| 512,519 |
|
|
| 238,361 |
|
|
| 993,542 |
|
|
| 427,741 |
|
| Office and general |
|
| 222,910 |
|
|
| 198,515 |
|
|
| 507,745 |
|
|
| 344,539 |
|
| Depreciation (Note 8) |
|
| 58,534 |
|
|
| 25,463 |
|
|
| 146,073 |
|
|
| 38,102 |
|
| Amortization of right-of-use assets (Note 7) |
|
| 199,800 |
|
|
| 101,159 |
|
|
| 382,952 |
|
|
| 188,904 |
|
| Amortization of licenses (Note 13) |
|
| 55,145 |
|
|
| 27,145 |
|
|
| 110,290 |
|
|
| 54,291 |
|
| Leases and utilities |
|
| 120,528 |
|
|
| 109,641 |
|
|
| 341,436 |
|
|
| 181,327 |
|
|
|
|
| 1,412,866 |
|
|
| 1,089,113 |
|
|
| 3,032,251 |
|
|
| 2,004,314 |
|
| Loss before other income |
|
| (481,120 | ) |
|
| (242,388 | ) |
|
| (1,015,015 | ) |
|
| (502,916 | ) |
| Interest expenses (Note 15, 16, 19) |
|
| 32,138 |
|
|
| 178,874 |
|
|
| 74,024 |
|
|
| 363,493 |
|
| Interest on lease liability (Note 14) |
|
| 140,528 |
|
|
| 50,563 |
|
|
| 260,446 |
|
|
| 95,601 |
|
| Accretion expense (Note 16, 19) |
|
| 9,270 |
|
|
| 20,843 |
|
|
| 35,782 |
|
|
| 91,758 |
|
| Foreign exchange (gain) loss |
|
| 12,839 |
|
|
| 19,335 |
|
|
| (74,538 | ) |
|
| 77,893 |
|
| Other income |
|
| (42,613 | ) |
|
| (35,084 | ) |
|
| (75,150 | ) |
|
| (35,084 | ) |
| Loss before income taxes |
|
| (633,282 | ) |
|
| (476,919 | ) |
|
| (1,235,579 | ) |
|
| (1,096,577 | ) |
| Income taxes expense |
|
| 4,420 |
|
|
| - |
|
|
| 50,180 |
|
|
| - |
|
| Deferred tax recovery |
|
| - |
|
|
| (1,403 | ) |
|
| - |
|
|
| (3,335 | ) |
| Net loss |
|
| (637,702 | ) |
|
| (475,516 | ) |
|
| (1,285,759 | ) |
|
| (1,093,242 | ) |
| Loss per share - basic and diluted |
|
| (0.01 | ) |
|
| (0.01 | ) |
|
| (0.01 | ) |
|
| (0.01 | ) |
| Weighted average number of outstanding common shares - basic and diluted |
|
| 97,545,253 |
|
|
| 83,973,353 |
|
|
| 96,184,761 |
|
|
| 73,303,913 |
|
| Net loss |
|
| (637,702 | ) |
|
| (475,516 | ) |
|
| (1,285,759 | ) |
|
| (1,093,242 | ) |
| Foreign exchange translation adjustment |
|
| 81,613 |
|
|
| (37,896 | ) |
|
| 37,392 |
|
|
| (14,279 | ) |
| Total comprehensive loss |
|
| (556,089 | ) |
|
| (513,412 | ) |
|
| (1,248,367 | ) |
|
| (1,107,521 | ) |
| Net loss attributable to: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| CordovaCann Corp. |
|
| (682,662 | ) |
|
| (616,906 | ) |
|
| (1,351,333 | ) |
|
| (1,383,621 | ) |
| Non-controlling interest |
|
| 44,960 |
|
|
| 141,390 |
|
|
| 65,574 |
|
|
| 290,379 |
|
The accompanying notes are an integral part of these condensed interim consolidated financial statements.
| 4 |
| CordovaCann Corp. |
| Unaudited Condensed Interim Consolidated Statements of Changes in Equity |
| (Expressed in Canadian Dollars) |
|
|
|
|
|
| Number of Common Shares |
|
| Share Capital |
|
| Contributed Surplus |
|
| Equity Portion of Convertible Debentures |
|
| Contingently Issuable Shares |
|
| Shares to be Issued |
|
| Share Subscriptions Received in Advance |
|
| Accumulated Deficit |
|
| Accumulated Other Comprehensive Income |
|
| Non-controlling interests |
|
| Shareholders' Equity |
| ||||||||||||
|
|
| Note |
|
| # |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||||||||||
| Balance, June 30, 2020 |
|
|
|
|
| 65,948,832 |
|
|
| 19,697,180 |
|
|
| 6,709,782 |
|
|
| 862,913 |
|
|
| 2,040,000 |
|
|
| 510,000 |
|
|
| - |
|
|
| (24,159,690 | ) |
|
| (41,599 | ) |
|
| 658,103 |
|
|
| 6,276,689 |
| |
| Shares issued as part of contingent consideration |
|
| 20 |
|
|
| 6,000,000 |
|
|
| 1,020,000 |
|
|
| - |
|
|
| - |
|
|
| (510,000 | ) |
|
| (510,000 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 0 |
|
| Common shares issued for private placement |
|
| 20 |
|
|
| 3,024,521 |
|
|
| 967,846 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 967,846 |
|
| Issuance of warrants |
|
| 22 |
|
|
| - |
|
|
| - |
|
|
| 178,126 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 178,126 |
|
| Interest on convertible debentures |
|
| 19 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 87,300 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 87,300 |
|
| Change in ownership interests in 2734158 Ontario Inc. |
|
| 10 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (139,891 | ) |
|
| - |
|
|
| (165,376 | ) |
|
| (305,267 | ) |
| Shares issued as part of contingent consideration |
|
| 20 |
|
|
| 9,000,000 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (1,530,000 | ) |
|
| 1,530,000 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| — |
|
| Acquisition of Manitoba Ltd. |
|
|
|
|
|
| - |
|
|
| - |
|
|
| 700,657 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 817,298 |
|
|
| 1,517,955 |
|
| Dividend paid to NCI |
|
| 10 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (98,975 | ) |
|
| (98,975 | ) |
| Warrant portion of promissory note payable |
|
| 16 |
|
|
| - |
|
|
| - |
|
|
| 15,823 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 15,823 |
|
| Foreign currency translation adjustment |
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (14,279 | ) |
|
| - |
|
|
| (14,279 | ) |
| Net loss for the period |
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (1,383,621 | ) |
|
| - |
|
|
| 290,379 |
|
|
| (1,093,242 | ) |
| Balance, December 31, 2020 |
|
|
|
|
|
| 83,973,353 |
|
|
| 21,685,026 |
|
|
| 7,604,388 |
|
|
| 950,213 |
|
|
| - |
|
|
| 1,530,000 |
|
|
| - |
|
|
| (25,683,202 | ) |
|
| (55,878 | ) |
|
| 1,501,429 |
|
|
| 7,531,976 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Balance, June 30, 2021 |
|
|
|
|
|
| 93,151,074 |
|
|
| 26,145,146 |
|
|
| 7,844,814 |
|
|
| 306,877 |
|
|
| - |
|
|
| 923,590 |
|
|
| 647,296 |
|
|
| (29,453,390 | ) |
|
| 77,875 |
|
|
| 826,165 |
|
|
| 7,318,373 |
|
| Common shares issued for private placement |
|
| 20 |
|
|
| 3,379,379 |
|
|
| 1,013,814 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (647,296 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| 366,518 |
|
| Exercise of options |
|
| 21 |
|
|
| 200,000 |
|
|
| 75,959 |
|
|
| (25,959 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 50,000 |
|
| Issuance of warrants |
|
| 22 |
|
|
| - |
|
|
| - |
|
|
| 1,920 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 1,920 |
|
| Interest on convertible debentures |
|
| 19 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 29,250 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 29,250 |
|
| Dividend paid to NCI |
|
| 10 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (34,737 | ) |
|
| (34,737 | ) |
| Shares issued as part of conversion of debentures |
|
| 20 |
|
|
| 5,354,400 |
|
|
| 923,590 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (923,590 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
| Foreign currency translation adjustment |
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 37,392 |
|
|
| - |
|
|
| 37,392 |
|
| Net loss for the period |
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (1,351,333 | ) |
|
| - |
|
|
| 65,574 |
|
|
| (1,285,759 | ) |
| Balance, December 31, 2021 |
|
|
|
|
|
| 102,084,853 |
|
|
| 28,158,509 |
|
|
| 7,820,775 |
|
|
| 336,127 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| (30,804,723 | ) |
|
| 115,267 |
|
|
| 857,002 |
|
|
| 6,482,957 |
|
The accompanying notes are an integral part of these condensed interim consolidated financial statements.
| 5 |
| CordovaCann Corp. |
| Unaudited Condensed Interim Consolidated Statements of Cash Flows |
| For the Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
|
|
| 2021 |
|
| 2020 |
| ||
|
|
| $ |
|
| $ |
| ||
| Operating activities |
|
|
|
|
|
| ||
| Net loss for the period |
|
| (1,248,367 | ) |
|
| (1,107,521 | ) |
| Adjusted for non-cash items: |
|
|
|
|
|
|
|
|
| Income taxes payable |
|
| 50,180 |
|
|
| - |
|
| Share based compensation |
|
| 1,920 |
|
|
| 178,126 |
|
| Amortization of right-of-use assets |
|
| 382,952 |
|
|
| 188,904 |
|
| Amortization of licenses |
|
| 110,290 |
|
|
| 54,291 |
|
| Depreciation |
|
| 146,073 |
|
|
| 38,102 |
|
| Interest expense |
|
| 74,024 |
|
|
| 363,493 |
|
| Interest on lease liability |
|
| 260,446 |
|
|
| 95,601 |
|
| Deferred tax recovery |
|
| - |
|
|
| (3,335 | ) |
| Accretion expense |
|
| 35,782 |
|
|
| 91,758 |
|
| Shares issued on settlement of fees |
|
| - |
|
|
| 85,100 |
|
| Changes in non-cash working capital items: |
|
|
|
|
|
|
|
|
| Prepaid expenses and deposits |
|
| (38,094 | ) |
|
| (29,715 | ) |
| Accounts receivable |
|
| (52,841 | ) |
|
| - |
|
| Inventory |
|
| (69,281 | ) |
|
| (276,113 | ) |
| Income taxes payable |
|
| (29,182 | ) |
|
| — |
|
| Harmonized sales tax receivable |
|
| (50,862 | ) |
|
| 84,011 |
|
| Accounts payable and accrued liabilities |
|
| (16,637 | ) |
|
| (49,929 | ) |
| Cash provided by (used in) operating activities |
|
| (443,597 | ) |
|
| (287,227 | ) |
| Investing activities |
|
|
|
|
|
|
|
|
| Additions to property and equipment |
|
| (362,083 | ) |
|
| (393,393 | ) |
| Proceeds from disposal of property and equipment |
|
| 2,726,680 |
|
|
| - |
|
| Payment towards subsidiary NCI shares |
|
| (39,292 | ) |
|
| (72,539 | ) |
| Cash provided by (used in) investing activities |
|
| 2,325,305 |
|
|
| (465,932 | ) |
| Financing activities |
|
|
|
|
|
|
|
|
| Repayment of promissory notes |
|
| (632,707 | ) |
|
| (130,355 | ) |
| Proceeds from issuance of promissory notes |
|
| 757,290 |
|
|
| - |
|
| Repayment of mortgage payable |
|
| (755,789 | ) |
|
| - |
|
| Payment of lease liabilities |
|
| (434,783 | ) |
|
| (196,325 | ) |
| Proceeds from other deposit |
|
| 103,336 |
|
|
| - |
|
| Proceeds from share subscriptions received in advance |
|
| - |
|
|
| 684,835 |
|
| Proceeds from the exercise of warrants |
|
| 50,000 |
|
|
| - |
|
| Payment of dividends to non-controlling interest shareholders |
|
| (34,737 | ) |
|
| (98,975 | ) |
| Proceeds from issuance of common shares |
|
| - |
|
|
| 552,501 |
|
| Cash provided by (used in) financing activities |
|
| (947,390 | ) |
|
| 811,681 |
|
| Effect of exchange rate changes on cash |
|
| (25,215 | ) |
|
| 40,099 |
|
| Net increase in cash and cash equivalents |
|
| 909,103 |
|
|
| 98,621 |
|
| Cash and cash equivalents, beginning of period |
|
| 1,058,494 |
|
|
| 647,739 |
|
| Cash and cash equivalents, end of period |
|
| 1,967,597 |
|
|
| 746,360 |
|
| Cash and cash equivalents consist of: |
|
|
|
|
|
|
|
|
| Cash |
|
| 950,631 |
|
|
| 746,360 |
|
| Restricted cash |
|
| 1,016,966 |
|
|
| - |
|
The accompanying notes are an integral part of these condensed interim consolidated financial statements.
| 6 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
1. NATURE OF OPERATIONS AND GOING CONCERN
CordovaCann Corp. (the “Company” or “CordovaCann” or “Cordova”) is a Canadian-domiciled company focused on building a leading, diversified cannabis products business across multiple jurisdictions including Canada and the United States. CordovaCann primarily provides services and investment capital to the processing, production and retail vertical markets of the cannabis industry. The Company’s principal address is 217 Queen Street West, Suite 401, Toronto, Ontario, M5V 0R2.
The Company’s common shares currently trade on the Canadian Securities Exchange under the symbol “CDVA” and in the United States on the OTCQB under the symbol “LVRLF”.
These consolidated financial statements of the Company have been prepared in accordance with International Financial Reporting Standards (“IFRS”) as promulgated by the International Accounting Standards Board (“IASB”) on a going concern basis which presumes the realization of assets and discharge of liabilities in the normal course of business for the foreseeable future. There is substantial doubt about the Company's ability to continue as a going concern as the Company incurred a comprehensive loss of $1,248,367 (December 31, 2020 – $1,107,521) during the six months ended December 31, 2021 and has a total accumulated deficit of $30,804,723 (June 30, 2021 – $29,453,390) as at December 31, 2021. The Company’s ability to continue as a going concern is dependent upon its ability to access sufficient capital until it has profitable operations and it raises a material concern. To this point, all operational activities and overhead costs have been funded through equity issuances, debt issuances and related party advances.
The Company believes that continued funding from equity and debt issuances will provide sufficient cash flow for it to continue as a going concern in its present form until its operations become profitable and cash flow positive, however, there can be no assurances that the Company will achieve this. Accordingly, these consolidated financial statements do not include any adjustments related to the recoverability and classification of recorded asset amounts or the amount and classification of liabilities or any other adjustments that might be necessary should the Company be unable to continue as a going concern.
2. BASIS OF PREPARATION
(a) Statement of Compliance
These condensed interim consolidated financial statements of the Company and its subsidiaries were prepared using accounting policies consistent with IFRS as issued by the IASB and interpretations of the IFRS Interpretations Committee (“IFRIC”).
These condensed interim consolidated financial statements were authorized for issue by the Company’s Board of Directors on February 28, 2022.
| 7 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
2. BASIS OF PREPARATION (continued)
(b) Basis of Presentation
These condensed interim consolidated financial statements have been prepared on a historical cost basis, except biological assets which were measured at fair value. Historical cost is based on the fair value of the consideration given in exchange for assets. In addition, these condensed interim consolidated financial statements have been prepared using the accrual basis of accounting, except for cash flow information.
(c) Functional and Presentation Currency
These condensed interim consolidated financial statements are presented in Canadian dollars, which is the Company’s presentation currency.
Translation of foreign-currency transactions
Transactions in foreign currencies are translated to the respective functional currencies of each subsidiary at exchange rates at the dates of the transactions. Monetary assets and liabilities denominated in foreign currencies at the reporting date are translated to the functional currency at the exchange rate at that date. The foreign currency gain or loss resulting from the settlement of such transactions and from the translation at the reporting date of monetary assets and liabilities denominated in foreign currencies are recognized in profit or loss.
Translation of financial statements of subsidiaries
In translating the financial statements of the Company's foreign subsidiaries from their functional currencies into the Company's presentation currency of Canadian dollars, statement of financial position accounts are translated using the closing exchange rate in effect at the statement of financial position date and income and expense accounts are translated using an average exchange rate prevailing during the reporting period. Adjustments resulting from the translation, if any, are included in accumulated other comprehensive income (loss) in shareholders' equity (deficiency).
(d) Use of Estimates and Judgements
The preparation of these condensed interim consolidated financial statements in accordance with IFRS requires management to make judgements, estimates and assumptions that affect the application of accounting policies and reported amounts of assets and liabilities at the date of the consolidated financial statements and reported amounts of expenses during the reporting period. Actual outcomes could differ from these estimates. These condensed interim consolidated financial statements include estimates, which, by their nature, are uncertain. The impacts of such estimates are pervasive throughout these consolidated financial statements, and may require accounting adjustments based on future occurrences. The estimates and underlying assumptions are reviewed on a regular basis. Revisions to accounting estimates are recognized in the period in which the estimate is revised and in any future periods affected. The key assumptions concerning the future, and other key sources of estimation uncertainty as of the date of the statement of financial position that have a significant risk of causing material adjustment to the carrying amounts of assets and liabilities within the next fiscal year arise in connection with the valuation of financial instruments, valuation of acquired assets, fair value of share purchase warrants, share-based payments and deferred tax assets.
| 8 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
2. BASIS OF PREPARATION (continued)
(e) Basis of Consolidation
These condensed interim consolidated financial statements include those of the Company and its subsidiaries, which are the entities controlled by the Company. Control over an investee is achieved when the Company has power over the investee, has exposure or rights to variable returns from its involvement with the investee and has the ability to use its power over the investee to affect the amount of its returns. The financial statements of subsidiaries are included in the condensed interim consolidated financial statements from the date that control commences until the date that control ceases.
The following table lists the Company’s subsidiaries and their functional currencies:
| Name of Subsidaries | Place of Incorporation | Proportion of Ownership | Currency |
| CordovaCann Holdings Canada, Inc. | Ontario, Canada | 100% | Canadian Dollars |
| Cordova Investments Canada, Inc. | Ontario, Canada | 100% | Canadian Dollars |
| 2734158 Ontario Inc. | Ontario, Canada | 60.45% | Canadian Dollars |
| 10062771 Manitoba Ltd. | Manitoba, Canada | 51.00% | Canadian Dollars |
| CordovaCann Holdings, Inc. | Delaware, USA | 100% | Canadian Dollars |
| Cordova CO Holdings, LLC | Colorado, USA | 100% | United States Dollars |
| Cordova OR Holdings, LLC | Oregon, USA | 100% | United States Dollars |
| CDVA Enterprises, LLC | California, USA | 100% | United States Dollars |
| Cordova CA Holdings, LLC | California, USA | 100% | United States Dollars |
| Cordova OR Operations, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt Farms, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt OR Retail, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt Holdings, Inc. | Oregon, USA | 100% | United States Dollars |
| Future Processing, LLC | Oregon, USA | 100% | United States Dollars |
| Extraction Technologies, LLC | Washington, USA | 100% | United States Dollars |
| Cordova WA Holdings, LLC | Washington, USA | 100% | United States Dollars |
3. SIGNIFICANT ACCOUNTING POLICIES
The significant accounting policies used in the preparation of these condensed interim consolidated financial statements are synonymous with the significant accounting polices of the Company’s annual audited financial statements for the year ended June 30, 2021.
New standards not yet adopted and interpretations issued but not yet effective
The following IFRS standards have been recently issued by the IASB. Pronouncements that are irrelevant or not expected to have a significant impact have been excluded.
| 9 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
3. SIGNIFICANT ACCOUNTING POLICIES (continued)
IFRS 10 - Consolidated Financial Statements ("IFRS 10")
IFRS 10 and IAS 28 – Investments in Associates and Joint Ventures (“IAS 28”) were amended in September 2014 to address a conflict between the requirements of IAS 28 and IFRS 10 and clarify that in a transaction involving an associate or joint venture, the extent of gain or loss recognition depends on whether the assets sold or contributed constitute a business. The effective date of these amendments is yet to be determined, however early adoption is permitted.
Amendments to IFRS 3: Definition of a Business
In October 2018, the IASB issued “Definition of a Business (Amendments to IFRS 3)”. The amendments clarify the definition of a business, with the objective of assisting entities to determine whether a transaction should be accounted for as a business combination or as an asset acquisition. The amendment provides an assessment framework to determine when a series of integrated activities is not a business. The amendments are effective for business combinations occurring on or after the beginning of the first annual reporting period beginning on or after January 1, 2020. The Company has evaluated the potential impact of these amendments and concluded that there is no impact to the Company’s condensed interim consolidated financial statements.
Amendments to IAS 1: Classification of Liabilities as Current or Non-current
The amendment clarifies the requirements relating to determining if a liability should be presented as current or non-current in the statement of financial position. Under the new requirement, the assessment of whether a liability is presented as current or non-current is based on the contractual arrangements in place as at the reporting date and does not impact the amount or timing of recognition. The amendment applies retrospectively for annual reporting periods beginning on or after January 1, 2022. The Company is currently evaluating the potential impact of these amendments on the Company’s condensed interim consolidated financial statements.
Amendments to IAS 37: Onerous Contracts and the cost of Fulfilling a Contract
The amendment specifies that ‘cost of fulfilling’ a contract comprises the ‘costs that relate directly to the contract’. Costs that relate directly to a contract can either be incremental costs of fulfilling that contract or an allocation of other costs that relate directly to fulfilling contracts. The amendment is effective for annual periods beginning on or after January 1, 2022 with early application permitted. The Company is currently evaluating the potential impact of these amendments on the Company’s condensed interim consolidated financial statements.
| 10 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
4. SIGNIFICANT ACCOUNTING JUDGEMENTS AND ESTIMATES
Information about critical judgments in applying accounting policies and estimates that have the most significant effect on the amounts recognized in these condensed interim consolidated financial statements is included in the following:
Determination of control
The control principle in IFRS 10 sets out the three elements of control: power over the investee; exposure, or rights, to variable returns from involvement with the investee; and the ability to use power over the investee to affect the amount of those returns. Judgement is required in assessing these three elements and reaching a conclusion on obtaining of control of a business.
Income taxes
The measurement of income taxes payable and deferred income tax assets and liabilities requires management to make judgments in the interpretation and application of the relevant tax laws. The actual amount of income taxes only becomes final upon filing and acceptance of the tax return by the relevant tax authorities, which occurs subsequent to the issuance of these condensed interim consolidated financial statements.
Impairment of long-lived assets
Assets, including property and equipment, are reviewed for impairment whenever events or changes in circumstances indicate that their carrying amounts exceed their recoverable amounts. If an impairment assessment is required, the assessment of fair value often requires estimates and assumptions such as discount rates, exchange rates, commodity prices, rehabilitation and restoration costs, future capital requirements and future operating performance. Changes in such estimates could impact recoverable values of these assets. Estimates are reviewed regularly by management.
Useful lives of depreciable assets
The Company estimates the useful lives for an item of depreciable assets to its significant parts and depreciates separately each such part. Management reviews the useful lives of depreciable assets and their significant parts at each reporting date based on the expected utility of the assets to the Company. Actual results, however, may vary due to a variety of factors including technical obsolescence.
Valuation of biological assets and inventory
Management is required to make a number of estimates in calculating the fair value of biological assets and harvested hemp inventory. These estimates include a number of assumptions including estimations of the stage of growth of the hemp, pre-harvest and post-harvest costs, sales price and expected yields. Inventories of harvested finished goods and packaging materials are valued at the lower of cost or net realizable value. Management determines net realizable value, which is the estimated selling price less the estimated costs to completion, and the estimated selling costs. The Company estimates the net realizable value of inventories by using the most reliable evidence available at each reporting date. The future realization of these inventories may be different from estimated realization. A change to these assumptions could impact the Company's inventory valuation and gross profit from sales of inventories.
| 11 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
4. SIGNIFICANT ACCOUNTING JUDGEMENTS AND ESTIMATES (continued)
Share-based payment transactions
The Company measures the cost of equity-settled transactions with goods and services received by reference to the fair value of the equity instruments at the date at which they are granted. Estimating fair value for share-based payment transactions requires determining the most appropriate valuation model, which is dependent on the terms and conditions of the grant. This estimate also requires determining the most appropriate inputs to the valuation model including the expected life of the stock option, volatility and dividend yield and making assumptions about them. The assumptions and models used for estimating fair value for share-based payment transactions are disclosed in Note 21 and Note 22.
Provisions and contingencies
The amount recognized as provision, including legal, contractual, constructive and other exposures or obligations, is the best estimate of the consideration required to settle the related liability, including any related interest charges, taking into account the risks and uncertainties surrounding the obligation. In addition, contingencies will only be resolved when one or more future events occur or fail to occur. Therefore, the assessment of contingencies inherently involves the exercise of significant judgment and estimates of the outcome of future events. The Company assesses its liabilities and contingencies based upon the best information available, relevant tax laws and other appropriate requirements.
Determination of purchase price allocations and contingent consideration
Judgements are made in determining the fair value of assets and liabilities, including the valuation of separately identifiable intangibles acquired as part of an acquisition. Further, estimates are made in determining the value of contingent consideration payments that should be recorded as part of the consideration on the date of acquisition and changes in contingent consideration payable in subsequent reporting periods, if any. Contingent consideration payments are generally based on acquired businesses achieving certain performance targets. The estimates are based on management’s best assessment of the related inputs used in the valuation models, such as future cash flows and discount rates. Future performance results that differ from management’s estimates could result in changes to liabilities recorded, which are recorded as they arise through profit or loss.
Valuation of convertible debentures
The convertible debentures were separated into their equity and/or liability components at the date of issuance, in accordance with the substance of the contractual agreements. The conversion options require an estimation of the fair value of a similar liability that doesn’t have an associated equity component by using a suitable discount rate at initial recognition and each extension date. The carrying amount of the conversion options is then determined by deducting the fair value of the financial liability from the fair value of the convertible debenture as a whole. A convertible debenture for which the Company is able to avoid a contractual obligation to pay cash is classified as an equity instrument.
| 12 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
4. SIGNIFICANT ACCOUNTING JUDGEMENTS AND ESTIMATES (continued)
Leases
Management applies judgment in reviewing each of its contractual arrangements to determine whether the arrangement contains a lease. Leases that are recognized are subject to further management judgment and estimation in various areas specific to the arrangement, including lease term and discount rate. In determining the lease term to be recognized, Management considers all facts and circumstances that create an economic incentive to exercise an extension operation, or not to exercise a termination option. Where the rate implicit in a lease is not readily determinable, the discount rate of lease obligations are estimated using a discount rate estimating the Company's specific incremental borrowing rate. The incremental borrowing rate represents the rate that the Company would incur to obtain the funds necessary to purchase an asset of a similar value, with similar payment terms and security, in a similar economic environment.
5. INVENTORY
The Company’s inventory includes purchased products and harvested cannabis plants. The Company’s cost of inventory during the three and six months ended December 31, 2021 amounted to $2,555,237 and $5,244,460, respectively (December 31, 2020 - $1,595,132 and $2,771,271, respectively). Included in inventory, is the transfer of biological assets upon harvest amounted to $126,116 (Note 6). The Company’s inventory as at December 31, 2021 amounted to $514,151 (June 30, 2021 - $504,521).
6. BIOLOGICAL ASSETS
The biological assets of the Company consist of cannabis plants. The Company’s cannabis operations are located in Clackamas County, Oregon. The composition of the biological assets for the three and six months ended December 31, 2021 is as follows:
|
|
|
| $ |
|
| Balance, June 30, 2020 |
|
| - |
|
| Product costs capitalized |
|
| 120,082 |
|
| Fair value adjustment on biological assets |
|
| 166,458 |
|
| Exchange realignment |
|
| (921 | ) |
| Transferred to inventory upon harvest |
|
| (259,008 | ) |
| Balance, June 30, 2021 |
|
| 26,611 |
|
| Product costs capitalized |
|
| 59,651 |
|
| Fair value adjustment on biological assets |
|
| 64,719 |
|
| Foreign exchange adjustment |
|
| (846 | ) |
| Transferred to inventory upon harvest |
|
| (126,116 | ) |
| Balance, December 31, 2021 |
|
| 24,019 |
|
Assumptions:
Biological assets are valued in accordance with IAS 41 – Agriculture (“IAS 41”) and are presented at their fair values less costs to sell at the point of harvest. The estimates and assumptions used are subject to volatility in uncontrollable market conditions, may significantly impact the fair value of biological assets.
| 13 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
6. BIOLOGICAL ASSETS (continued)
Biological assets represent a level 3 asset in the fair value hierarchy. For in process biological assets, the fair value at the point of harvest is adjusted based on the stage of growth.
When determining the fair value of biological assets, the Company makes estimates and uses assumptions as follows:
|
| · | Expected costs required to grow the cannabis up to the point of harvest; |
|
| · | Estimated selling price per lb; |
|
| · | Expected yield from cannabis plants; and |
|
| · | Estimated stage of growth - As at December 31, 2021, on average, the biological assets were estimated as 83% complete as to the next expected harvest date. |
The following table quantifies each significant unobservable input and provides the impact of a 5% increase or decrease that each input would have on the fair value of biological assets:
|
|
| Range of inputs |
| Sensitivity |
| Impact on fair value as at December 31, 2021 ($) |
| |
| Estimated selling price per lb |
| $1,000 - $1,400 |
| Increase 5% |
|
| 1,571 |
|
|
|
|
|
| Decrease 5% |
|
| (1,241 | ) |
| Estimated yield per cannabis plant |
| 70 - 84 grams |
| Increase 5% |
|
| 1,571 |
|
|
|
|
|
| Decrease 5% |
|
| (1,241 | ) |
The estimations made by the Company, are subject to change, and differences from the anticipated yield will be reflected in the gain or loss on biological assets in future periods.
7. RIGHT-OF-USE ASSETS
The Company recognized the right-of-use asset for it leased properties as follows:
|
|
| $ |
| |
| Balance, June 30, 2020 |
|
| 2,539,670 |
|
| Additions during the year |
|
| 963,489 |
|
| Acquisition of a subsidiary |
|
| 101,333 |
|
| Depreciation for the year |
|
| (434,837 | ) |
| Balance, June 30, 2021 |
|
| 3,169,655 |
|
| Additions during the period |
|
| 2,227,188 |
|
| Depreciation for the period |
|
| (382,952 | ) |
| Foreign exchange translation |
|
| (10,111 | ) |
| Balance, December 31, 2021 |
|
| 5,003,780 |
|
Leased properties are amortized over the terms of their respective leases.
Included in additions during the six months ended December 31, 2021 is the addition of the lease on the Oregon Property in connection with a sale-leaseback, as further described in Note 8.
| 14 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
8. PROPERTY AND EQUIPMENT, NET
Property and equipment, net consists of the following:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Machinery |
|
|
|
|
|
|
|
|
|
| ||||||||
|
|
|
|
|
|
|
|
| Construction |
|
| Leasehold |
|
| and |
|
| Computer |
|
| Furnitures |
|
|
|
| ||||||||
|
|
| Land |
|
| Building |
|
| in progress |
|
| improvements |
|
| equipment |
|
| equipment |
|
| and fixtures |
|
| Total |
| ||||||||
|
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||||||
| Cost |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| As at June 30, 2020 |
|
| 545,120 |
|
|
| 1,417,312 |
|
|
| 1,833,653 |
|
|
| 1,113,867 |
|
|
| - |
|
|
| 44,645 |
|
|
| 30,984 |
|
|
| 4,985,581 |
|
| Additions |
|
| - |
|
|
| - |
|
|
| - |
|
|
| 356,337 |
|
|
| 5,657 |
|
|
| 84,394 |
|
|
| 294,607 |
|
|
| 740,995 |
|
| Disposals |
|
| - |
|
|
| - |
|
|
| - |
|
|
| (11,384 | ) |
|
| - |
|
|
| (13,444 | ) |
|
| (22,229 | ) |
|
| (47,057 | ) |
| Acquisition of subsidiaries |
|
| 417,183 |
|
|
| 1,036,378 |
|
|
| - |
|
|
| 3,889 |
|
|
| 323,823 |
|
|
| - |
|
|
| 12,251 |
|
|
| 1,793,524 |
|
| Translation adjustment |
|
| (60,124 | ) |
|
| (143,324 | ) |
|
| - |
|
|
| (155,296 | ) |
|
| (11,023 | ) |
|
| - |
|
|
| - |
|
|
| (369,767 | ) |
| Transfer |
|
| - |
|
|
| - |
|
|
| (1,833,653 | ) |
|
| 1,833,653 |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
| Impairment charge |
|
| (95,429 | ) |
|
| (248,115 | ) |
|
| - |
|
|
| (320,999 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| (664,543 | ) |
| As at June 30, 2021 |
|
| 806,750 |
|
|
| 2,062,252 |
|
|
| - |
|
|
| 2,820,066 |
|
|
| 318,457 |
|
|
| 115,595 |
|
|
| 315,613 |
|
|
| 6,438,734 |
|
| Additions |
|
| - |
|
|
| 24,311 |
|
|
| - |
|
|
| 205,509 |
|
|
| - |
|
| 36,384 |
|
|
| 95,879 |
|
|
| 362,083 |
| |
| Disposals |
|
| (403,524 | ) |
|
| (1,019,086 | ) |
|
| - |
|
|
| (1,162,803 | ) |
|
| - |
|
|
| - |
|
|
| - |
|
|
| (2,585,413 | ) |
| Translation adjustment |
|
|
|
|
|
| 135,943 |
|
|
| - |
|
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 135,943 |
|
| Impairment charge |
|
|
|
|
|
|
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
| |
| As at December 31, 2021 |
|
| 403,226 |
|
|
| 1,203,420 |
|
|
| - |
|
|
| 1,862,772 |
|
|
| 318,457 |
|
|
| 151,979 |
|
|
| 411,492 |
|
|
| 4,351,347 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Accumulated depreciation |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| As at June 30, 2020 |
|
| - |
|
|
| - |
|
|
| - |
|
|
| (2,027 | ) |
|
| - |
|
|
| (2,708 | ) |
|
| (1,033 | ) |
|
| (5,768 | ) |
| Depreciation |
|
| - |
|
|
| (46,365 | ) |
| - |
|
|
| (256,534 | ) |
|
| (22,379 | ) |
|
| (29,711 | ) |
|
| (28,487 | ) |
|
| (383,476 | ) | |
| Disposals |
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| 1,097 |
|
|
| 1,097 |
|
| Translation adjustment |
|
| - |
|
|
| 1,551 |
|
|
| - |
|
|
| 6,735 |
|
|
| 749 |
|
|
| - |
|
|
| - |
|
|
| 9,035 |
|
| As at June 30, 2021 |
|
| - |
|
|
| (44,814 | ) |
|
| - |
|
|
| (251,826 | ) |
|
| (21,630 | ) |
|
| (32,419 | ) |
|
| (28,423 | ) |
|
| (379,112 | ) |
| Depreciation |
|
| - |
|
|
| (14,983 | ) |
|
| - |
|
|
| (69,389 | ) |
|
| (7,638 | ) |
|
| (24,117 | ) |
|
| (29,946 | ) |
|
| (146,073 | ) |
| Disposals |
|
| - |
|
|
| 30,076 |
|
|
| - |
|
|
| (22,570 | ) |
|
| (34,047 | ) |
|
| (10,764 | ) |
|
| (50,054 | ) |
|
| (87,359 | ) |
| Translation adjustment |
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
|
| - |
|
| As at December 31, 2021 |
|
| - |
|
|
| (29,721 | ) |
|
| - |
|
|
| (343,785 | ) |
|
| (63,315 | ) |
|
| (67,300 | ) |
|
| (108,423 | ) |
|
| (612,544 | ) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net book value ($) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| At June 30, 2020 |
|
| 545,120 |
|
|
| 1,417,312 |
|
|
| 1,833,653 |
|
|
| 1,111,840 |
|
|
| - |
|
|
| 41,937 |
|
|
| 29,951 |
|
|
| 4,979,813 |
|
| At June 30, 2021 |
|
| 806,750 |
|
|
| 2,017,437 |
|
|
| - |
|
|
| 2,568,240 |
|
|
| 296,827 |
|
|
| 83,176 |
|
|
| 287,190 |
|
|
| 6,059,622 |
|
| At December 31, 2021 |
|
| 403,226 |
|
|
| 1,173,699 |
|
|
| - |
|
|
| 1,518,987 |
|
|
| 255,142 |
|
|
| 84,679 |
|
|
| 303,069 |
|
|
| 3,738,803 |
|
During the three and six months ended December 31, 2021, the Company incurred a depreciation expense in the amount of $58,534 and $146,073, respectively (December 31, 2020 - $25,463 and $38,102, respectively).
Oregon - Land, building and construction in progress
On April 4, 2018, the Company entered into an agreement to acquire a 27.5% interest of Cordova OR Operations, LLC (“OR Operations”) for the acquisition of land and buildings. Under the terms of this agreement, the Company acquired a 27.5% membership interest in OR Operations for $534,311 (US $400,000). On June 19, 2019, the Company purchased the remaining 72.5% interest in OR Operations for $1,361,048 (US$1,040,000) (Note 11). Construction in progress in mounted to $1,760,861 during the year ended June 30, 2019.
On August 4, 2021, OR Operations sold all of its land, building, and construction-in-progress (the “Oregon Property”) for $2,726,680 (US $2,200,000) and entered into an agreement to lease the Oregon Property from the buyer (the “Lease”). The Lease will allow the Company to operate on the Oregon Property for ten years, and provides options for two subsequent ten-year renewal periods. Proceeds from the sale were used to retire debts related to the Oregon Property and to finance the planned expansion in Oregon.
| 15 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
8. PROPERTY AND EQUIPMENT, NET (continued)
The Lease was signed on July 20, 2021 and commenced on August 1, 2021. Certain amounts have been placed in escrow by the buyer to allow the completion of the buildout, as disclosed in Note 25. There is no rent payable during the first three months of the Lease and subsequent payments amount to $27,267 (US $22,000) per month for the reminder of the first year, with annual payment escalators thereafter.
The selling price of $2,726,680 for the Oregon Property was lower than its carrying value, which indicated the impairment of these assets and resulted of impairment loss in the amount of $664,543 during the year ended June 30, 2021.
Leasehold improvements
Leasehold improvements include those acquired as part of the asset acquisition of Star Buds International Inc., as disclosed in Note 9 in the amount of $1,060,224.
9. ASSET ACQUISITION OF STAR BUDS INTERNATIONAL INC.
On April 8, 2020 (the “Closing date”), the Company completed the purchase of certain tangible assets and intellectual property (the “Assets”) of an arm’s length Canadian cannabis corporation (the “Transaction”), Star Buds International Inc. (the “Vendor” or “Star Buds”).
To acquire the Assets from the Vendor, the Company:
|
| (i) | issued 12,500,000 common shares of the Company on the Closing date of the Transaction, in exchange for the Assets held and related to five retail cannabis stores and four medical cannabis clinics; |
|
| (ii) | agreed to issue 3,000,000 common shares of the Company for each additional lease assignment in Alberta to the Company, up to a maximum of 6,000,000 common shares of the Company; |
|
| (iii) | agreed to issue 3,000,000 common shares of the Company for the opening of each retail store, up to a maximum of 15,000,000 common shares of the Company. Each store must be opened by April 8, 2021 for the Vendor to receive this additional consideration; |
|
| (iv) | issued a three-year promissory note for $527,967 with interest at 6% per annum payable upon maturity (the “Closing Promissory Note”). The fair value of the promissory notes was determined to be $381,093 (Note 19 (e)); |
|
| (v) | agreed to issue two additional three-year promissory notes in amounts $222,500 and $196,832 upon obtaining assignment of two specific leases to the Company. Such additional notes to have same terms as the Closing Promissory Note. The fair values of the promissory notes were determined to be $160,603 and $142,075 (Note 19 (e)). |
The consideration payables as per note (ii) and (iii) above are considered a contingent consideration. Management assessed the probability of the issuance of shares noted in (ii) and (iii) above to be highly probable. The total fair value of the 21,000,000 contingently issuable shares is estimated to be $3,570,000. The Company has referred to IFRS 3 by analogy and accordingly, the contingent consideration has been recorded as part of the cost of the purchase. The contingent consideration of shares has been classified as equity, as the number of shares to be issued has been fixed based on the Company’s share price a day prior to the closing date.
| 16 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
9. ASSET ACQUISITION OF STAR BUDS INTERNATIONAL INC. (continued)
On May 8, 2020, the Company obtained two additional lease assignments in Alberta and issued 6,000,000 common shares of the Company to the Vendor. Accordingly, the value of the 6,000,000 common shares amounting to $1,020,000 was transferred from contingently issuable shares to share capital.
On July 27, 2020, the Company issued 6,000,000 common shares in relation to the opening of two additional retail stores under the Star Buds brand name. The Company had opened the retail store in Barrie as at June 30, 2020 and accordingly, the value of 6,000,000 common shares amounting to $1,020,000 was transferred from shares to be issued ($510,000) and contingently issuable shares ($510,000) to share capital.
On January 6, 2021, the Company issued the final 9,000,000 common shares in relation to the opening of three additional retail stores under the Star Buds brand name.
| Consideration paid |
|
|
| |
| 33,500,000 common shares at $0.17 per share |
|
| 5,695,000 |
|
| Initial promissory note (iv) |
|
| 381,093 |
|
| Additional promissory notes (v) |
|
| 302,678 |
|
|
|
|
| 6,378,771 |
|
| Liabilities assumed |
|
| 55,000 |
|
|
|
|
| 6,433,771 |
|
| Amount allocated to: |
|
|
|
|
| Leasehold improvements |
|
| 1,060,224 |
|
| Rental deposits |
|
| 129,580 |
|
| Star Buds trade name |
|
| 5,243,967 |
|
|
|
|
| 6,433,771 |
|
No amortization or impairment was recorded in relation to the intangible asset – Starbuds trade name during the three and six months ended December 31, 2021 (December 31, 2020 - $nil).
10. ACQUISITION OF 2734158 ONTARIO INC.
On May 15, 2020, the Company entered into a subscription agreement to acquire 50.1% ownership interest in 2734158 Ontario Inc. (”273 Ontario”) by subscribing to 501,000 common shares of 273 Ontario for a total consideration of $723,000 (the “Acquisition”). Pursuant to the subscription agreement, the subscription price (the “Subscription Price”) was paid as follows:
|
| · | payment of $200,000 on May 15, 2020 for the issuance of 138,589 common shares; |
|
| · | payment of $200,000 on June 15, 2020 for the issuance of 138,589 common shares; |
|
| · | payment of $200,000 on July 15, 2020 for the issuance of 138,589 common shares; and |
|
| · | payment of $123,000 on August 15, 2020 for the issuance of 85,233 common shares. |
The following table summarises the recognized amounts of assets acquired and liabilities assumed at the date of acquisition.
| 17 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
10. ACQUISITION OF 2734158 ONTARIO INC. (continued)
| Cash |
|
| 48,850 |
|
| Other assets |
|
| 59,040 |
|
| Computer equipment |
|
| 16,337 |
|
| Furniture and fixture |
|
| 27,222 |
|
| Leasehold improvement |
|
| 46,081 |
|
|
|
|
|
|
|
| Liabilities assumed |
|
| (20,328 | ) |
| Total identifiable net assets acquired |
|
| 177,202 |
|
On August 15, 2020, the total Subscription Price of $723,000 was fully paid to 2734158 Ontario Inc.
The non-controlling interest is calculated as follow.
| Consideration |
|
| 723,000 |
|
| Ownership acquired |
|
| 50.1 | % |
| Fair value of assets acquired |
|
| 1,443,114 |
|
| Consideration |
|
| (723,000 | ) |
| Non-controlling interest |
|
| 720,114 |
|
Licenses allocated from the acquisition has been recognized as follows.
| Consideration transferred |
|
| 723,000 |
|
| Consideration received by 273 Ontario |
|
| (723,000 | ) |
| Non-controlling interest |
|
| 720,114 |
|
| Fair value of identifiable net assets |
|
| (177,202 | ) |
| Fair value of licences |
|
| 542,912 |
|
On September 17, 2020, the Company acquired an additional 10.35% of the common shares of 273 Ontario not previously owned by Cordova (the “Additional Shares”). The total purchase price for the Additional Shares amounted to $305,267, of which $72,539 was paid on closing, and the remaining amounts will be paid as follows:
|
| · | payment of $157,167 paid on the earlier of retail license approval of Cordova by the Alcohol and Gaming Commission of Ontario or January 15, 2021 (the “License Payment”); |
|
| · | payment of $36,269 on the date three months after the License Payment; and |
|
| · | payment of $39,292 on the date nine months after the License Payment |
As Cordova previously controlled 273 Ontario with 50.1% ownership interest, this transaction resulted in a change to Cordova’s ownership stake and was accounted for as an equity transaction.
The $139,095 difference between the carrying value $166,172 for the non-controlling interests and the 305,267 consideration paid was recognized directly in deficit.
| 18 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
10. ACQUISITION OF 2734158 ONTARIO INC. (continued)
During the year ended June 30, 2021, the Company paid $72,539 on closing and the License Payment for total payments in the amount of $265,975. During the three and six months ended December 31, 2021, the Company paid the remaining $39,292 outstanding. The total amount outstanding for the payment of the Additional Shares as at December 31, 2021 was $nil (June 30, 2021 - $39,292).
During the year ended June 30, 2021, 273 Ontario paid dividends in the amount of $450,000. Of the $450,000 dividends paid, $177,975 were paid to the non-controlling interest shareholders of 273 Ontario.
During the six months ended December 31, 2021, 273 Ontario paid dividends in the amount of $87,831. Of the $87,831 paid, $34,737 was paid to the non-controlling interest shareholders of 273 Ontario.
11. ACQUISITION OF 10062771 MANITOBA LTD.
On December 1, 2020, the Company acquired 51% of the issued and outstanding shares of 10062771 Manitoba Ltd. (“Manitoba Ltd”), a Manitoba-based cannabis retail venture (the “Transaction”). Manitoba Ltd is considered to be a related party by virtue of a common officer and director. Per the terms of the Transaction, the Company acquired 51% of the issued and outstanding shares of Manitoba Ltd on a fully-diluted basis (the “Purchased Shares”). The consideration for the Purchases Shares was one hundred fifty thousand dollars ($150,000) payable in cash on closing of the Transaction (the “Consideration”). In addition, Cordova has agreed to loan up to one hundred fifty thousand dollars ($150,000) to Manitoba Ltd to enable the opening of the second store in Manitoba Ltd. On June 21, 2021, the Company entered into a promissory note agreement with Manitoba Ltd for the loan of $150,000 with the initial tranche of $100,000 having been provided.
The following table summarises the recognized amounts of assets acquired and liabilities assumed at the date of acquisition.
| Cash |
|
| 29,795 |
|
| Prepaid expenses |
|
| 4,595 |
|
| Inventory |
|
| 72,265 |
|
| Furnitures and fixtures |
|
| 12,251 |
|
| Leasehold improvements |
|
| 3,889 |
|
| Right-of-use asset |
|
| 101,333 |
|
| Lease liability |
|
| (101,333 | ) |
| Liabilities assumed |
|
| (101,317 | ) |
| Total identifiable net assets acquired |
|
| 21,478 |
|
On December 1, 2020, the total Subscription Price of $150,000 was fully paid to Manitoba Ltd.
The fair value of non-controlling interest at the acquisition date was calculated as follows:
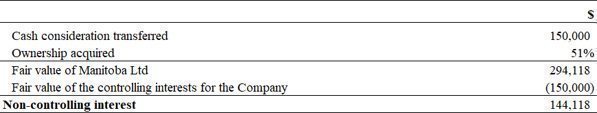
| 19 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
11. ACQUISITION OF 10062771 MANITOBA LTD. (continued)
The Company recognized the intangible assets – licenses at the acquisition date and calculated their fair value as follows:
| Cash consideration |
|
| 150,000 |
|
| Consideration received by Manitoba Ltd. |
|
| (150,000 | ) |
| Non-controlling interest |
|
| 144,118 |
|
| Deferred tax liability |
|
| 45,359 |
|
| Fair value of identifiable assets |
|
| (21,478 | ) |
| Fair value of licenses |
|
| 167,999 |
|
12. ACQUISITION OF EXTRACTION TECHNOLOGIES, LLC
On February 26, 2021, the Company, through its wholly-owned subsidiary, Cordova WA Holdings, LLC, completed the acquisition of Extraction Technologies, LLC (“Extraction Tech”), an arm’s length Washington-based company (the “Washington Acquisition”). The Washington Acquisition includes the purchase of a 10,900 sq. ft. manufacturing building, processing equipment, and contracts with tolling and white label customers. The Consideration for the Washington Acquisition is three million (3,000,000) common shares of the Company issued on closing and five hundred thousand (500,000) common shares for every US $125,000 in EBITDA generated by Extraction Tech during the 12-month period beginning on the 3-month anniversary post-closing and ending on the 15-month anniversary of the closing date (the “Earnout Payment”). The maximum Earnout Payment that can be earned by Extraction Tech is four million (4,000,000) common shares.
The Earnout Payment is considered a contingent consideration. As at February 26, 2021 and December 31, 2021, management has assessed that the Earnout Payment is considered highly improbable and accordingly has not recognized the Earnout Payment.
In accordance with the Company’s accounting policies and IFRS 3, the measurement period for the Transaction shall not exceed one year from acquisition date. Accordingly, the accounting for the Transaction date has only been provisionally determined as at February 26, 2021 and December 31, 2021. The following table summarizes the fair value of consideration paid on acquisition date and the allocation of the Consideration to the assets and liabilities acquired. The Company has yet to determine and value any intangible assets that may have been acquired as part of the Transaction and the probably of the Earnout Payment being made. Once this has been determined, the value of the provisional goodwill may change. These changes may be material.
| 20 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
12. ACQUISITION OF EXTRACTION TECHNOLOGIES, LLC (continued)
|
|
| $ |
| |
| Consideration paid |
|
|
| |
| 3,000,000 Common shares |
|
| 953,250 |
|
| Earnout share consideration |
|
| - |
|
| Total consideration: |
|
| 953,250 |
|
|
|
|
|
|
|
| Purchase Price Allocation |
|
|
|
|
| Accounts receivable |
|
| 2,258 |
|
| Inventory |
|
| 5,178 |
|
| Bank overdraft |
|
| (2,266 | ) |
| Capital assets |
|
| 1,777,385 |
|
| Mortgage payable |
|
| (829,305 | ) |
|
|
|
| 953,250 |
|
13. LICENSE
|
|
| $ |
| |
| Cost |
|
|
| |
| As at June 30, 2020 |
|
| 542,912 |
|
| Acquistion of a subsidiary (Note 11) |
|
| 167,999 |
|
| As at June 30, 2021 |
|
| 710,911 |
|
| Additions (disposals) |
|
| - |
|
| As at December 31, 2021 |
|
| 710,911 |
|
| Accumulated amortization |
|
|
|
|
| As at June 30, 2020 |
|
| - |
|
| Amortization |
|
| (141,249 | ) |
| As at June 30, 2021 |
|
| (141,249 | ) |
| Amortization |
|
| (110,290 | ) |
| As at December 31, 2021 |
|
| (251,539 | ) |
| Net book value ($) |
|
|
|
|
| As at June 30, 2020 |
|
| 542,912 |
|
| As at June 30, 2021 |
|
| 569,662 |
|
| As at December 31, 2021 |
|
| 459,372 |
|
During the three and six months ended December 31, 2021, amortization expense in relation to this license amounted to $55,145 and $110,290, respectively (December 31, 2020 – $27,145 and $54,291, respectively).
| 21 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
14. LEASE LIABILITY
The following table represents the lease obligations for the Company as at December 31, 2021:
|
|
| $ |
| |
| Balance, June 30, 2020 |
|
| 2,582,484 |
|
| Additions |
|
| 922,394 |
|
| Acquisition of a subsidiary |
|
| 101,333 |
|
| Interest expense |
|
| 223,799 |
|
| Lease payments |
|
| (501,365 | ) |
| Balance, June 30, 2021 |
|
| 3,328,645 |
|
| Additions |
|
| 2,227,188 |
|
| Interest expense |
|
| 260,446 |
|
| Lease payments |
|
| (434,783 | ) |
| Foreign exchange translation |
|
| (10,494 | ) |
| Balance, December 31, 2021 |
|
| 5,371,002 |
|
| Allocated as: |
|
|
|
|
|
| ||
|
|
| December 31, |
|
| June 30, |
| ||
|
|
| 2021 |
|
| 2021 |
| ||
|
|
| $ |
|
| $ |
| ||
| Current |
|
| 576,024 |
|
|
| 438,856 |
|
| Long-term |
|
| 4,794,978 |
|
|
| 2,889,789 |
|
| Total |
|
| 5,371,002 |
|
|
| 3,328,645 |
|
The following table presents the contractual undiscounted cash flows for lease obligations as at December 31, 2021:
|
|
| $ |
| |
| Less than one year |
|
| 1,106,080 |
|
| One to five years |
|
| 4,211,389 |
|
| More than five years |
|
| 2,536,512 |
|
| Total undiscounted lease obligation |
|
| 7,853,981 |
|
The Company has a lease with a term less than 12 months and recorded $21,196 and $42,392, respectively (December 31, 2020 - $12,330 and $24,660, respectively) of rent expense attributed to short-term leases during the three and six months ended December 31, 2021.
| 22 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
15. MORTGAGE PAYABLE
Oregon Mortgage
On June 16, 2019, the Company obtained financing through a mortgage (the “Mortgage”) in the amount of $696,117 (US $531,915) against a property that has title to 6 acres of real estate in Clackamas County, Oregon (the “Property”). The Mortgage was due in six months from the date of the agreement at an initial draw of $654,350 (US $500,000), implying interest at a rate of 12.77% per annum. The Mortgage after the date of default bears interest at 12% per annum, payable monthly, until the repayment of the outstanding amount. The Mortgage was secured by a first charge on the Property.
On June 12, 2020, the Company entered into a new mortgage (the “New Mortgage’), in the amount of $815,760 (US $600,000), and paid off the existing Mortgage and accrued interest of $724,894 (USD$531,914). The New Mortgage bears interest at 12%, is secured by a first charge on the Property and matures on December 15, 2020. The transaction cost of $52,045 was deducted from the initial carrying value of the mortgage payable and was recognized into profit and loss over the term of the mortgage payable.
On August 4, 2021, the Oregon Mortgage was fully paid off upon the closing of selling Oregon Property (Note 8).
Oregon Mortgage as at December 31, 2021 amounted $nil (June 30, 2021 – $755,789). Total interest expense in relation to the Oregon Mortgage for the three and six months ended December 31, 2021 amounted to $nil and $7,517, respectively (December 31, 2020 – $67,216 and $117,011, respectively).
Washington Mortgage
On February 26, 2021, the Company completed the Washington Acquisition (Note 12) and assumed a mortgage payable in the amount of $829,305 (US $653,768) (the “Washington Mortgage”). The Washington Mortgage was entered into on September 28, 2020 by the vendors of the Washington Acquisition with an initial amount of $874,921 (US $654,000) and matures on October 1, 2022. The Washington Mortgage bears interest at 12.5%, payable monthly, and secured by a first charge on the property acquired as part of the Washington Acquisition.
As at December 31, 2021, the amount outstanding under the Washington Mortgage amounted to $828,844 (June 30, 2021 - $810,278).
16. PROMISSORY NOTES PAYABLE
Promissory Note A – February 1, 2019
On February 1, 2019, the Company issued an unsecured promissory note (the “Promissory Note A”) in the principal amount of $196,425 (US $150,000). The Promissory Note A matured on May 1, 2019 and bears interest at a rate of 10% per annum, accrued monthly and due at maturity. As at the date of these consolidated financial statements, the Promissory Note A is in default and remains outstanding. In connection with the Promissory Note A, the Company also issued warrants for the purchase of 150,000 common shares of the Company exercisable until January 31, 2020 at a price of $1.00 per share.
| 23 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
16. PROMISSORY NOTES PAYABLE (continued)
The Promissory Note A was determined to be a compound instrument, comprising a liability and warrants. The initial carrying amount of the financial liability was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no warrants. Using the residual method, the carrying amount of the warrants issued is the difference between the principal amount and the initial fair value of the financial liability. The fair value of the liability was determined to be $192,142 (US $146,729). The residual value of $4,283 (US $3,271) was allocated to warrants. The carrying value of the Promissory Note A, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note A, such that the carrying amount of the financial liability will equal the principal balance at maturity.
As at December 31, 2021, $46,391 was outstanding under Promissory Note A (June 30, 2021 – $44,732). Interest expense of $315 and $630, respectively, (December 31, 2020 - $1,629 and $4,959, respectively) was recorded for the three and six months ended December 31, 2021.
Promissory Note B – June 12, 2019
On June 12, 2019, the Company issued a secured promissory note (the “Promissory Note B”) in the principal amount of $261,740 (US $200,000). The Promissory Note B matured on June 30, 2020 and bears interest at a rate of 15% per annum, accrued monthly and due at maturity. The Promissory Note B was secured by a convertible preferred shares investment which was subsequently called. As at December 31, 2021 and June 30, 2021, the value of the Promissory Note B amounted to $nil.
Promissory Note C – June 19, 2019
On June 19, 2019, the Company issued secured promissory notes (the “Promissory Note C”) in the aggregate principal amount of $654,350 (US $500,000). The Promissory Note C matured on December 18, 2019 and bears interest at a rate of 15% per annum, accrued monthly and due at maturity. The Promissory Note C is secured by a general security interest over all the assets of Cordova OR Holdings, LLC, a wholly owned subsidiary of the Company and parent to OR Operations. In connection with the Promissory Note C, the Company issued warrants for the purchase of 200,000 common shares of the Company exercisable until June 18, 2021 at a price of $1.00 per share.
The Promissory Note C was determined to be a compound instrument, comprising of a liability and warrants. The initial carrying amount of the financial liability was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no warrants. Using the residual method, the carrying amount of the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $652,675 (US $489,152). The residual value of $14,367 (US $10,848) was allocated to warrants. The carrying value of the Promissory Note C, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
| 24 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
16. PROMISSORY NOTES PAYABLE (continued)
On December 16, 2019, the Company extended the maturity date of the Promissory Note C to March 19, 2020 (the “Extension”) in exchange for a one-time fee in the amount $13,142 (US $10,000), due at maturity and the issuance of additional warrants for the purchase of 200,000 common shares of the Company exercisable until June 18, 2021 at a price of $0.30 per share.
On the date of the Extension, the fair value of the liability was determined to be $696,151 (US $530,643). The residual value of $8,995 (US $6,857) was allocated to warrants. The carrying value of Promissory Note C, as a result of the Extension, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
On March 16, 2020, the Company extended the maturity date of the Promissory Note C to June 19, 2020 in exchange for a fee in the amount $13,142 (US $10,000), due at maturity. On June 15, 2020, the Company extended the maturity date of the Promissory Note C to December 19, 2020 in exchange for a fee in the amount $40,472 (US $29,750), due at maturity.
On December 15, 2020, the Company extended the maturity date of the Promissory Note C to December 15, 2021 (the “Second Extension”) in exchange for a one-time fee in the amount $54,113 (US $42,200), the issuance of “Warrants – #A” for the purchase of 200,000 common shares of the Company exercisable until December 31, 2022 at a price of $0.32 per share, and the issuance of “Warrants - #B” for the purchase of 200,000 common shares of the Company exercisable until December 31, 2022 at a price of $0.50 per share.
On the date of the Second Extension, the fair value of the liability was determined to be $655,272 (US $515,070). The residual value of $15,823 (US $12,437) was allocated to warrants. The carrying value of Promissory Note C, as a result of the Extension, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
The Company repaid Promissory Note C during the six months ended December 31, 2021.
As at December 31, 2021, the value of the Promissory Note C amounted to $nil (June 30, 2021 - $477,672). Interest expense of $nil and $15,687, respectively (December 31, 2020 - $39,990 and $83,372, respectively) was recorded for the three and six months ended December 31, 2021.
Promissory Note D – October 28, 2019
On October 28, 2019, the Company issued a promissory note (the “Promissory Note D”) in the principal amount of $391,680 (US $300,000). The Promissory Note D matured on June 30, 2020 and bears interest at a rate of 5% per annum, accrued monthly and due at maturity. Subsequent to the issuance, the Promissory Note D was extended until October 31, 2020 for a one-time fee of US $40,000. Interest on the Promissory Note D subsequent to the maturity date bears interest at 15% per annum.
| 25 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
16. PROMISSORY NOTES PAYABLE (continued)
On May 25, 2020, the Company issued 453,720 common shares of the Company at a price of $0.25 per share for $113,317 (US $78,150) of Promissory Note D. On August 17, 2020, the Company issued 125,507 common shares of the Company at a price of $0.32 per share for $40,162 (US $29,750) of Promissory Note. On February 19, 2021, the Company issued 1,085,062 common shares of the Company at a price of $0.32 per share for $347,220 (US $257,200) of Promissory Note D. During the year ended June 30, 2021 the $391,680 (US $300,000) of Promissory Note D with accrued interest payable were fully settled by common shares.
Interest expense of $nil (December 31, 2020 – $16,949 and $33,497, respectively) were recorded for the three and six months ended December 31, 2021.
Promissory Note E – April 8, 2020
On April 28, 2020, the Company issued a promissory note (the “Promissory Note E-1”) in the principal amount of $527,967 (Note 12 (iv)). The Promissory Note E-1 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $381,093 for the Promissory Note E-1 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
On May 8, 2020, the Company repaid $90,803 of the principal in cash and issued 181,250 of its common shares to settle $72,500 of the principal outstanding. On June 30, 2020 the Company repaid $20,000 of the principal.
On August 13, 2020 and August 17, 2020, the Company repaid a total of $15,000 of the principal in cash and issued 585,936 of its common shares to settle $187,500 of the principal. On March 5, 2021 and April 1, 2021, the Company repaid a total of $14,000 of the principal in cash.
During the six months ended December 31, 2021, the Company paid and settled $145,456 worth of principal and interest in respect to Promissory Note E-1.
As at December 31, 2021, the value of the Promissory Note E-1 amounted to $nil (June 30, 2021 - $124,008). Interest and accretion expense of $nil and $990, and $nil and $19,028, respectively, (December 31, 2020 - $2,150 and $5,998, and $3,248 and $58,462, respectively) were recorded for the three and six months ended December 31, 2021.
On June 8, 2020, the Company issued a promissory note (the “Promissory Note E-2”) in the principal amount of $225,000 (Note 12(v)). The Promissory Note E-2 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $160,603 for the Promissory Note E-2 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
During the three and six months ended December 31, 2021, the Company paid and settled $59,543 worth of principal in respect to Promissory Note E-2.
| 26 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
16. PROMISSORY NOTES PAYABLE (continued)
As at December 31, 2021, the value of the Promissory Note E-2 amounted to $148,629 (June 30, 2021 - $194,821). Interest and accretion expense of $2,500 and $5,520, and $4,748 and $7,830, respectively (December 31, 2020 - $3,365 and $6,730, and $4,586 and $9,049, respectively) was recorded for the three and six months ended December 31, 2021.
On June 8, 2020, the Company issued a promissory note (the “Promissory Note E-3”) in the principal amount of $196,832 (Note 12(v)). The Promissory Note E-3 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $142,075 for the Promissory Note E-3 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
As at December 31, 2021, the value of the Promissory Note E-3 amounted to $185,191 (June 30, 2021 - $172,347). Interest and accretion expense of $2,945 and $5,889, and $4,523 and $8,924, respectively (December 31, 2020 - $2,977 and $5,954, and $4,057 and $8,005, respectively) were recorded for the three and six months ended December 31, 2021.
Demand Notes – Six Months Ended December 31, 2021
During the six months ended December 31, 2021, the Company issued short-term promissory notes (the “Demand Notes”) to certain arm's-length parties. These Demand Notes are unsecured, mature 12 months from the date of issuance, bear interest at a rate of 20% per annum, calculated in arrears compounded annually and payable on maturity. The Company may elect to repay the Demand Notes earlier than maturity for an early repayment penalty of 15% of the principal inclusive of all interest accrued until the date of payment.
The aggregate amount of Demand Notes issued during the six months ended December 31, 2021 amounted to $757,290 (US $600,000).
On December 31, 2021, the Company repaid $126,780 (US $100,000) of the principal amount and $3,682 (US $2,904) of accrued interest. Further, due to the Company’s election for early repayment, fees in the amount of $15,335 (US $12,096) were charged and paid, which has been included in office and general expenses in the Company’s condensed interim consolidated statement of operations and comprehensive loss.
As at December 31, 2021, the principal amount of the Demand Notes amounted to $633,900 (US $500,000) and accrued interest on the Demand Notes amounted to $10,629 (US $8,384). Interest expense for the three and six months ended December 31, 2021 amounted to $14,226 (December 31, 2020 - $nil).
| 27 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
17. CONTRACT LIABILITY
The Company’s contract liability is deferred revenue which relates to revenue expected to be recognized in the future related to performance obligations that are unsatisfied (or partially unsatisfied) which amounted to $207,195 (June 30, 2021 - $nil). Details of the Company’s contract liability is noted as follows:
|
|
| December 31, 2021 |
|
| June 30, 2021 |
| ||
| Opening balance |
| $ | 226,903 |
|
| $ | - |
|
| Additions |
|
| - |
|
|
| 244,133 |
|
| Changes in exchange rates |
|
| 5,049 |
|
|
| - |
|
| Revenue recognized from contract liability |
|
| (24,757 | ) |
|
| (17,230 | ) |
| Ending balance |
| $ | 207,195 |
|
| $ | 226,903 |
|
| Current portion |
| $ | 49,656 |
|
| $ | 48,832 |
|
| Long-term portion |
|
| 157,539 |
|
|
| 178,071 |
|
18. SHARE SUBSCRIPTIONS RECEIVED IN ADVANCE
During the year ended June 30, 2021, the Company received a total of $647,296 in deposits related to a non-brokered private placement financing. On August 19, 2021, the Company closed the non-brokered private placement financing, pursuant to which the Company issued 3,379,379 units at a price of $0.30 per unit for gross proceeds of $1,013,814; of which $661,530 was received in cash and $352,284 was issued in settlement of outstanding fees and debt (Note 20).
19. CONVERTIBLE DEBENTURES
a) Convertible Debentures Series A-1 – March 13, 2019
On March 13, 2019, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-1”) of the Company for gross proceeds of $600,000; of which $350,000 was received in cash and $250,000 was issued in settlement of outstanding fees with a fair value amounting to $237,300. The balance of $12,700 has been recorded as a loss on settlement of fees.
Each Debenture Unit of Series A-1 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-1”) and 500 common share purchase warrants (the “Warrants of Series A-1”) of the Company. The Debentures of Series A-1 mature on March 12, 2021 and bear interest at a rate of 10% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-1 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $1.00 per share.
| 28 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
19. CONVERTIBLE DEBENTURES (continued)
The Company also has the option to force conversion of the Debentures of Series A-1 and any accrued interest at the same conversion price if the Company’s common shares trade above $2.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Each full Warrant of Series A-1 entitles the holder to purchase one common share of the Company until March 12, 2021 at an exercise price of $1.20 per share. 300,000 Warrants of Series A-1 were issued related to the Debenture Units of Series A-1.
The Debenture Units of Series A-1 are determined to be a compound instrument, comprising a liability, a conversion feature and warrants. Both conversion feature and warrants met the fixed for fixed criteria and were therefore presented as equity instruments in accordance with IAS 32. The fair value of the debt component was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no conversion rights. Using the residual method, the carrying amount of the conversion feature and the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $508,439. The residual value of $91,561 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $62,498 and $29,063, respectively. The carrying value of the Debentures of Series A-1, net of the equity components, have been accreted using the effective interest rate method over the term of the debentures, such that the carrying amount of the financial liability will equal the principal balance at maturity.
The equity component from the initial recognition resulted taxable temporary difference. The Company recognized the deferred tax liabilities of $24,264, which was charged directly to the carrying amount of the two equity components. Subsequent changes in the deferred tax liability are recognized in profit and loss as deferred tax recovery.
On January 16, 2020, the Company issued 271,164 common shares at $1.00 per share as a result of a partial conversion of the outstanding Debentures of Series A-1 with a face value of principal $250,000 and accrued interest of $21,164. The debt in the amount of $271,164 and the equity in the amount of $21,979, were transferred to share capital upon conversion.
During the year ended June 30, 2021, the principal amount of $25,000 and accrued interest of $5,000 for a total of $30,000 was repaid on maturity. The remaining Debenture Units of Series A-1 were converted into the Convertible Debentures Series A-4 offering. The principal amount of $325,000, the accrued interest of $65,000, for total transfer of $390,000 were transferred to Convertible Debentures Series A-3.
| 29 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
19. CONVERTIBLE DEBENTURES (continued)
b) Convertible Debentures Series A-2 – August 14, 2019
On August 14, 2019, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-2”) of the Company for gross proceeds of $713,000.
Each Debenture Unit of Series A-2 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-2”) and 500 common share purchase warrants (the “Warrants of Series A-2”) of the Company. The Debentures of Series A-2 mature on August 13, 2021 and bear interest at a rate of 10% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-2 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $1.00 per share. The Company also has the option to force conversion of the Debentures of Series A-2 and any accrued interest at the same conversion price if the Company’s common shares trade above $2.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Each full Warrant of Series A-2 entitles the holder to purchase one common share of the Company until August 13, 2021 at an exercise price of $1.20 per share. As a result, 356,500 Warrants of Series A-2 were issued related to the Debenture Units of Series A-2.
The Debenture Units of Series A-2 were determined to be a compound instrument, comprising a liability, a conversion feature and warrants. The fair value of debt component was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no conversion rights. Using the residual method, the carrying amount of the conversion feature and the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $604,195. The residual value of $108,805 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $74,989 and $33,816, respectively. The deferred tax liability of $28,833 was charged directly to the carrying amount of these two equity components. The carrying value of the Debentures of Series A-2, net of the equity components, have been accreted using the effective interest rate method over the term of the debentures, such that the carrying amount of the financial liability will equal the principal balance at maturity.
On April 22, 2020, the Debenture Units of Series A-2 were converted into the Convertible Debentures Series A-3 offering. The principal amount of $713,000, the accrued interest of 49,614 and loss of $1,614, for total transfer of $761,000 were transferred to Convertible Debentures Series A-3. The total amount of interest and accretion amounted to $49,614 and $33,454, respectively. The Company recorded deferred tax recovery of $28,833 for the year ended June 30, 2020.
| 30 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
19. CONVERTIBLE DEBENTURES (continued)
c) Convertible Debentures Series A-3 – April 22, 2020
On April 22, 2020, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-3”) of the Company for gross proceeds of $1,164,000.
Each Debenture Unit of Series A-3 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-3”) and 2,000 common share purchase warrants (the “Warrants of Series A-3”) of the Company. The Debentures of Series A-3 mature on April 21, 2021 and bear interest at a rate of 15% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-3 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $0.25 per share. The Company also has the option to force conversion of the Debentures of Series A-3 and any accrued interest at the same conversion price if the Company’s common shares trade above $0.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Furthermore, the Debentures of Series A-3 and accrued interest shall automatically convert into common shares of the Company at maturity. Each full Warrant of Series A-3 entitles the holder to purchase one common share of the Company until April 21, 2022 at an exercise price of $0.30 per share. As a result, 2,328,000 Warrants of Series A-3 were issued related to the Debenture Units of Series A-3.
Prior to closing of the Offering, the Company exercised its rights of early repayment in respect of certain of the Convertible Debentures of Series A-2 of the Company issued on August 14, 2019 and, in connection with its election for early repayment, holders of the Convertible Debentures of Series A-2 directed the Company to retain the funds representing such repayment and to apply such funds towards satisfaction of the purchase price for the respective Debenture of Series A-3. The Company issued an aggregate of 761 Debenture Units to the subscribers of the Debentures of Series A-2.
The Debenture Units of Series A-3 were determined to be an equity instrument, comprising a conversion feature and warrants as a result of the Company being able to avoid a contractual obligation to pay cash related to the principal and interest at maturity. The subscription amount of $1,164,000 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $748,990 and $415,010, respectively. The interest expense related to the Debenture Units of Series A-3 are added to the equity portion of convertible debt as accrued.
On April 24, 2021, the Company elected to automatically convert the Debentures of Series A-3 (Note 20).
During the three and six months ended December 31, 2021, interest of $nil was recorded in the equity portion of the convertible debt (June 30, 2021 - $142,490).
d) Convertible Debentures Series A-4 – March 12, 2021
On March 12, 2021, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-4”) of the Company for gross proceeds of $390,000.
| 31 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
19. CONVERTIBLE DEBENTURES (continued)
Each Debenture Unit of Series A-4 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-4”) and 1,000 common share purchase warrants (the “Warrants of Series A-4”) of the Company. The Debentures of Series A-4 mature on March 12, 2022 and bear interest at a rate of 15% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-3 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $0.50 per share. The Company also has the option to force conversion of the Debentures of Series A-4 and any accrued interest at the same conversion price if the Company’s common shares trade above $0.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Furthermore, the Debentures of Series A-4 and accrued interest shall automatically convert into common shares of the Company at maturity. Each full Warrant of Series A-4 entitles the holder to purchase one common share of the Company until March 12, 2023 at an exercise price of $0.75 per share.
Prior to closing of the Offering, the Company exercised its rights of early repayment in respect of certain of the Convertible Debentures of Series A-1 of the Company issued on March 13, 2019 and, in connection with its election for early repayment, holders of the Convertible Debentures of Series A-1 directed the Company to retain the funds representing such repayment and to apply such funds towards satisfaction of the purchase price for the respective Debenture of Series A-4. The Company issued an aggregate of 390 Debenture Units to the subscribers of the Debentures of Series A-1.
The Debenture Units of Series A-4 were determined to be an equity instrument, comprising a conversion feature and warrants as a result of the Company being able to avoid a contractual obligation to pay cash related to the principal and interest at maturity. The subscription amount of $390,000 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $208,452 and $181,548, respectively. The interest expense related to the Debenture Units of Series A-4 are added to the equity portion of convertible debt as accrued.
During the three and six months ended December 31, 2021, interest of $14,625 and $29,250, respectively, was recorded in the equity portion of the convertible debt (June 30, 2021 - $16,512).
20. SHARE CAPITAL
The authorized share capital of the Company consists of an unlimited number of common shares.
During the six months ended December 31, 2021, the Company had the following common share transactions:
|
| · | On December 17, 2021 and in connection with the automatic conversion of shares relating to Convertible Debentures Series A-3, 5,354,400 common shares were issued. $923,590 was transferred from shares to be issued to share capital; |
|
|
|
|
|
| · | On August 19, 2021, the Company closed a non-brokered private placement financing, pursuant to which the Company issued 3,379,379 units at a price of $0.30 per unit for gross proceeds of $1,013,814; of which $661,530 was received in cash and $352,284 was issued in settlement of outstanding fees and debt, which included $97,500 which was outstanding to a director of the Company. These units were comprised of a common share and a share purchase warrant exercisable at $0.45 per share for a period of 24 months from the date of issuance; and |
| 32 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
20. SHARE CAPITAL (continued)
|
| · | On August 1, 2021 and in connection with the exercise of stock-options by consultants, 200,000 common shares were issued at a price of $0.25 per share. |
During the year ended June 30, 2021, the Company had the following common share transactions:
|
| · | On February 26, 2021, the Company issued 3,000,000 common shares of the Company for the acquisition of Extraction Technologies, LLC (Note 15); |
|
| · | On February 19, 2021, the Company issued 6,177,721 common shares of the Company at a price of $0.32 per share for gross proceeds of $1,976,870; of which $1,380,400 was received in cash and $596,570 was issued in settlement of outstanding fees and debt; |
|
| · | On January 6, 2021, the Company issued 9,000,000 common shares of the Company at a price of $0.17 per share in relation to the asset acquisition of Star Buds for the opening of three cannabis retail stores under the Starbuds trade name; |
|
| · | On August 17, 2020, the Company issued 3,024,521 common shares of the Company at a price of $0.32 per share for gross proceeds of $967,846; of which $552,501 was received in cash and $415,345 was issued in settlement of outstanding fees and debt; and |
|
| · | On July 27, 2020, the Company issued 6,000,000 common shares of the Company at a price of $0.17 per share in relation to the asset acquisition of Starbuds for the opening of two cannabis retail stores under the Starbuds trade name. |
|
| · | On January 16, 2020, the Company issued 271,164 common shares of the Company at a price of $1.00 per share as a result of a partial conversion of the Debentures of Series A-1, as disclosed in Note 22. |
Shares to be issued
During the year ended June 30, 2021 and in connection with the automatic conversion of shares relating to Convertible Debentures Series A-3, 5,354,400 common shares were classified as shares to be issued. On December 17, 2021, these common shares were issued.
As at December 31, 2021, the value of shares to be issued amounted to $nil (June 30, 2021 – $923,590).
Contingently issuable shares
As at December 31, 2021 and June 30, 2021, there were 4,000,000 contingently issuable shares of the Company in relation to the Washington Acquisition (Note 12).
21. OPTIONS
On November 22, 2018, the Company’s shareholders approved and the Company adopted a rolling stock option plan (the “Option Plan”), under which the Board of Directors may from time to time, in its discretion, grant to directors, officers, employees and consultants of the Company. Pursuant to the Option Plan, the Company may issue options for such period and exercise price as may be determined by the Board of Directors, and in any case not exceeding ten (10) years from the date of grant with the total options issued under the Option Plan not exceeding ten percent (10%) of the common shares of the Company, outstanding at the time of the granting of such options. The minimum exercise price of an option granted under the Option plan must not be less than the market value of the common shares on the date such option is granted.
| 33 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
21. OPTIONS (continued)
Outstanding options as at December 31, 2021 are as follows:
|
|
| Options Outstanding |
|
| Weighted Average Exercise Price |
|
| Weighted Average Life Remaining (yrs) |
| |||
| Executive Officers |
|
| 300,000 |
|
| $ | 0.25 |
|
|
| 1.15 |
|
| Directors |
|
| 3,550,000 |
|
| $ | 0.28 |
|
|
| 1.28 |
|
| Consultants |
|
| 1,250,000 |
|
| $ | 0.41 |
|
|
| 1.33 |
|
|
|
|
| 5,100,000 |
|
|
|
|
|
|
|
|
|
| Grant Date |
| Expiry Date |
| Options Outstanding |
|
| Options Exercisable |
|
| Exercise Price |
|
| Fair Value |
| ||||
| Feb. 25, 2020(iii) |
| Feb. 24, 2023 |
|
| 600,000 |
|
|
| 600,000 |
|
| $ | 0.25 |
|
| $ | 103,838 |
|
| Apr. 7, 2020(iv) |
| Apr. 6, 2023 |
|
| 3,000,000 |
|
|
| 3,000,000 |
|
| $ | 0.25 |
|
| $ | 369,426 |
|
| May 16, 2020(v) |
| May 5, 2023 |
|
| 1,500,000 |
|
|
| 1,500,000 |
|
| $ | 0.45 |
|
| $ | 396,036 |
|
The fair value of these issued stock options were determined using the Black-Scholes Option Pricing Model with the following range of assumptions:
| Stock price | $0.19-0.405 |
| Risk-free interest rate | 0.33-1.37 % |
| Expected life | 3 years |
| Estimated volatility in the market price of the common shares | 112-124 % |
| Dividend yield | nil |
During the six months ended December 31, 2021 and in connection with stock options previously issued to consultants, stock options were exercised for the purchase of 200,000 common shares of the Company at an exercise price of $0.25 per share for gross proceeds of $50,000. As a result of this exercise, contributed surplus in the amount of $25,959 was transferred to share capital.
There were no stock options issued during the six months ended December 31, 2021 and year ended June 30, 2021.
During the year ended June 30, 2021, 1,750,000 stock options expired unexercised.
During the three and six months ended December 31, 2021, the Company expensed $nil (December 31, 2020 - $nil) of the fair value of the stock options.
| 34 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
22. WARRANTS
|
|
| Warrants Outstanding |
|
| Weighted Average Exercise Price |
|
| Weighted Average Life Remaining (years) |
| |||
| June 30, 2020 |
|
| 10,249,500 |
|
|
| 0.53 |
|
|
| 2.00 |
|
| Issued |
|
| 6,790,000 |
|
|
| 0.35 |
|
|
| 1.97 |
|
| Expired |
|
| (1,450,000 | ) |
|
| 1.29 |
|
|
| 0.00 |
|
| June 30, 2021 |
|
| 15,589,500 |
|
| $ | 0.38 |
|
|
| 1.30 |
|
| Issued |
|
| 3,379,379 |
|
|
| 0.45 |
|
|
| 2.00 |
|
| Expired |
|
| (356,500 | ) |
|
| 1.20 |
|
|
| - |
|
| December 31, 2021 |
|
| 18,612,379 |
|
| $ | 0.38 |
|
|
| 0.97 |
|
During the six months ended December 31, 2021:
|
| · | The Company issued 3,379,379 common share purchase warrants in connection with a non-brokered private placement; |
|
| · | 356,500 common share purchase warrants expired, unexercised; and |
|
| · | No common share purchase warrants were forfeited or cancelled. |
During the year ended June 30, 2021:
|
| · | the Company issued 6,790,000 common share purchase warrants in to employees and directors, for the amendment of promissory notes payable, and a convertible debenture financing; |
|
| · | 1,450,000 common share purchase warrants expired, unexercised; and |
|
| · | No common share purchase warrants were forfeited or cancelled. |
The fair value of these issued warrants of was determined using the Black-Scholes Option Pricing Model with the following range of assumptions:
| Stock price | $0.19-0.35 |
| Risk-free interest rate | 0.26-0.32 % |
| Expected life | 1-3 years |
| Estimated volatility in the market price of the common shares | 87-89 % |
| Dividend yield | nil |
During the three and six months ended December 31, 2021, the Company expensed $nil and $1,920, respectively (December 31, 2020 – $60,528 and $178,126), in the fair value of warrants as a result of the issuances which have been recorded as share based compensation.
| 35 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
23. COMMITMENTS
(a) Employment Agreements
The Company is party to certain employments agreements with key executives of the Company that contain clauses requiring additional payments of up to two times the annual entitlements under these agreements upon occurrence of certain events, such as a change of control. As a triggering event has not taken place, the contingent payments have not been reflected in these condensed interim consolidated financial statements.
(b) Deposit in Joint Forces
On November 7, 2019, the Company advanced CDN $408,840 (US $300,000) to a non-arm’s length party in exchange for Promissory Note D (the “Joint Forces Deposit”).
On October 12, 2020, the Company entered into a settlement agreement (the “Settlement”), settling the outstanding Joint Forces Deposit for a payment term over 2 years for a total of US $338,000. The proceeds of the Settlement will be received by the beneficiaries of Promissory Note D. As a result, a gain on Settlement was recorded in the amount of $51,023 (US $38,000) during the year ended June 30, 2020.
Accordingly, the Joint Forces Deposit was determined to be a financial instrument and recorded at amortized cost. The initial carrying amount of the financial asset was determined by discounting the stream of future payments of interest and principal at a market interest rate of 8% which is estimated to be the lending rate available to the Company for similar instruments. The balance of the Joint Forces Deposit amounted to $211,727 as at December 31, 2021 (June 30, 2021 – $300,814). Interest income in relation to the Joint Forces Deposit amounted to $4,937 and $10,993, respectively, during the three and six months ended December 31, 2021 (December 31, 2020 – $7,801 and $15,829, respectively).
(c) COVID-19
On March 11, 2020, the World Health Organization declared the outbreak of the novel strain of coronavirus (“COVID-19”) a pandemic, which has resulted in governments worldwide enacting emergency measures to combat the spread of the virus. These measures have caused material disruption to businesses globally resulting in an economic slowdown. The COVID-19 pandemic has impacted revenue in the Canadian consumer market, as governments have imposed retail access restrictions to curbside pickup at points during the pandemic, and have changed their purchasing patterns to reflect the slow-down in the market. The sale of consumer cannabis has been recognized as an essential service across Canada. All of the Company’s facilities in Canada and the United States continue to be operational and the Company continues to work closely with local, national and international government authorities to ensure that the Company is following the required protocols and guidelines related to COVID-19 within each region.
The duration and impact of the COVID-19 outbreak is unknown at this time, as is the efficacy of the government and central bank interventions. It is not possible to reliably estimate the length and severity of these developments and the impact on the financial results and condition of the Company and its operating subsidiaries in future periods as well as the Company’s ability to find new business opportunities, raise capital or restructure the Company’s finances. The effects of any such changes could be material, which could result in, among other things, impairment of long-lived assets. The Company is closely monitoring the impact of COVID-19 on all aspects of its business.
| 36 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
24. RELATED PARTY TRANSACTIONS
Related party transactions as at and for the three and six months ended December 31, 2021 and 2020, not disclosed elsewhere in these condensed interim consolidated financial statements are as follows:
a) During the three and six months ended December 31, 2021, the Company expensed $165,000 and $330,000, respectively (December 31, 2020 – $97,050 and $194,100, respectively), in fees payable to officers and directors of the Company and in fees payable to a corporation related by virtue of a common officer and director. As at December 31, 2021, the Company had fees payable to officers and directors of the Company of $1,742,234 (June 30, 2021 – $1,494,228).
25. RESTRICTED CASH
Restricted cash relates to an amount held in an escrow account by the buyer of the Oregon Property (the “Escrow Account”). The amount held in the Escrow Account is non-interest bearing and restricted for the completion of the buildout of the Oregon Property (Note 8). During the three and six months ended December 31, 2021, there was no amount withdrawn from the Escrow Account. The balance as at December 31, 2021 amounted to $1,016,966 (June 30, 2021 – $nil).
26. FINANCIAL INSTRUMENTS AND RISK FACTORS
The fair value hierarchy that reflects the significance of inputs used in making fair value measurements is as follows:
Level 1: quoted prices in active markets for identical assets or liabilities;
Level 2: inputs other than quoted prices included in Level 1 that are observable for the asset or liability, either directly (i.e. as prices) or indirectly (i.e. from derived prices); and
Level 3: inputs for the asset or liability that are not based upon observable market data.
Assets are classified in their entirety based on the lowest level of input that is significant to the fair value measurement.
The fair values of the Company’s financial instruments consisting of cash and cash equivalents, restricted cash, accounts receivable, promissory notes payable, mortgage payable and accounts payable and accrued liabilities approximate their carrying value due to the relatively short term maturities of these instruments.
Risk Management Policies
The Company, through its financial assets and liabilities, is exposed to various risks. The Company has established policies and procedures to manage these risks, with the objective of minimizing any adverse effect that changes in these variables could have on these condensed interim consolidated financial statements. The following analysis provides a measurement of risks as at December 31, 2021:
| 37 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
26. FINANCIAL INSTRUMENTS AND RISK FACTORS (continued)
Credit Risk
The Company's maximum exposure to credit risk, which will cause a financial loss to the Group due to failure to discharge an obligation by the counterparties, totals the carrying amount of these assets as stated in the consolidated statements of financial position. The Company's principal financial assets are cash, restricted investments and accounts receivable, which represent the Company's exposure to credit risk in relation to financial assets. The credit risk on cash and restricted investments is mitigated by transacting with banks with high credit ratings assigned by international credit-rating agencies. An allowance for expected credit losses is established based upon factors surrounding the credit risk of specific accounts, historical trends and other information when necessary.
Liquidity Risk
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they fall due within one year. The Company’s approach to managing liquidity risk is to ensure, as far as possible, that it will have sufficient liquidity to meet its liabilities when due, under both normal and stressed conditions, without incurring unacceptable losses or risking damage to the Company’s reputation.
As at December 31, 2021, there is substantial doubt about the Company’s ability to continue as a going concern primarily due to its history of losses and negative working capital. Liquidity risk continues to be a key concern in the development of future operations.
Market Risk
(i) Interest Rate Risk
Interest rate risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate because of changes in market interest rates. The interest rates on all of the Company’s existing debt are fixed, and therefore it is not currently subject to any significant interest rate risk.
(ii) Foreign Currency Risk
The Company is exposed to foreign currency risk from fluctuations in foreign exchange rates and the degree of volatility in these rates due to the timing of their accounts payable balances. The risk is mitigated by timely payment of creditors and monitoring of foreign exchange fluctuations by management. As at December 31, 2021, the Company did not use derivative instruments to hedge its exposure to foreign currency risk.
(iii) Price Risk
The Company’s operations do not involve the direct input or output of any commodities and therefore it is not subject to any significant commodity price risk. In addition, the Company does not have any equity investments in other listed public companies, and therefore it is not subject to any significant stock market price risk.
| 38 |
| CordovaCann Corp. |
| Notes to the Unaudited Condensed Interim Consolidated Financial Statements |
| For the Three and Six Months Ended December 31, 2021 and 2020 |
| (Expressed in Canadian Dollars) |
27. CAPITAL MANAGEMENT
The Company’s definition of capital includes all components of shareholders’ equity excluding non-controlling interest. As at December 31, 2021, the Company’s capital amounted to $5,625,955 (June 30, 2021 – $6,492,208). The Company’s objectives when managing capital are as follows:
(i) to safeguard the Company’s ability to continue as a going concern; and
(ii) to raise sufficient capital to meet its business objectives.
The Company manages its capital structure and makes adjustments to it, based on the general economic conditions, the Company’s short-term and long-term capital requirements. To secure the additional capital necessary to pursue these plans, the Company may attempt to raise additional funds through the issuance of equity or debt.
28. COMPARATIVE AMOUNTS
Certain comparative figures have been reclassified to conform to the condensed interim consolidated financial statement presentation adopted for the current period. Such reclassifications did not have an impact on previously reported net and comprehensive loss.
29. SUBSEQUENT EVENTS
Subsequent to December 31, 2021 and in connection with share purchase warrants previously issued as part of a private placement, share purchase warrants were exercised for the purchase of 700,000 common shares of the Company at an exercise price of $0.30 per share for gross proceeds of $210,000.
| 39 |
CordovaCann Corp.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS AND SIX MONTHS ENDED DECEMBER 31, 2021
Prepared as at February 28, 2022
Management Discussion and Analysis
The following discussion and analysis by management of the financial results and condition of CordovaCann Corp. for the three and six months ended December 31, 2021 should be read in conjunction with the condensed interim consolidated financial statements for the three and six months ended December 31, 2021 and the annual audited consolidated financial statements for the year ended June 30, 2021. The financial statements and the financial information herein have been prepared in accordance with International Financial Reporting Standards (“IFRS”), as issued by the International Accounting Standards Board (“IASB”).
All dollars referred to herein are expressed in Canadian dollars except where indicated otherwise. This management discussion and analysis is prepared by management as at February 28, 2022.
In this report, the words “us”, “we” “our”, the “Company” and “CordovaCann” have the same meaning unless otherwise stated and refer to CordovaCann Corp. and its subsidiaries.
Overview
Business Overview
CordovaCann Corp. (formerly LiveReel Media Corporation) (the “Company” or “CordovaCann” or “Cordova”) is a Canadian-domiciled company focused on building a leading, diversified cannabis products business across multiple jurisdictions including Canada and the United States. CordovaCann primarily provides services and investment capital to the processing, production and retail vertical markets of the cannabis industry. On January 3, 2018, the Company changed its name from LiveReel Media Corporation to CordovaCann Corp. The Company’s principal address is 217 Queen Street West, Suite 401, Toronto, Ontario, M5V 0R2.
The Company’s common shares (the “Common Shares”) currently trade on the Canadian Securities Exchange under the symbol “CDVA” and in the United States on the OTCQB under the symbol “LVRLF”.
On September 4, 2018, the Company incorporated Cordova Investments Canada, Inc., a wholly-owned Ontario-based subsidiary (“Cordova Investments Canada”) to act as the Company’s parent holding company in Canada.
On November 6, 2018, the Company incorporated Cordova CA Holdings, LLC, a California limited liability company (“Cordova CA”), as a wholly-owned subsidiary of CordovaCann USA to act as the Company’s primary holding subsidiary in the State of California.
On November 6, 2018, the Company incorporated CDVA Enterprises, LLC, a California limited liability company (“CDVA Enterprises”), as a wholly-owned subsidiary of CordovaCann USA, to act as the Company’s primary operating subsidiary in the State of California.
On October 28, 2019, Eric Lowy resigned as a Director of the Company.
On April 8, 2020, Ashish Kapoor resigned as a Director of the Company. Furthermore, Benjamin Higham and Jakob Ripshtein were appointed as Directors of the Company.
On May 19, 2020, the Company acquired 50.1% ownership in 2734158 Ontario Inc.
On May 16, 2020, Nathan Nienhuis resigned as a Director and chief operating officer of the Company. Dale Rasmussen was appointed as a Director of the Company.
On August 17, 2020, Henry Kloepper resigned as a Director of the Company.
| 2 |
On September 21, 2020, the Company acquired an additional 10.35% equity stake in 2734158 Ontario Inc. bringing its total ownership of the corporation to 60.45%.
On November 20, 2020, Cannabilt Farms, LLC, a wholly-owned subsidiary the Company, was granted a Marijuana Production License in Oregon.
On December 2, 2020, the Company acquired 51% ownership in 10062771 Manitoba Ltd.
On December 8, 2020, the Company incorporated Cordova WA Holdings, LLC, a Washington limited liability Company (“Cordova WA”), as a wholly-owned subsidiary of CordovaCann USA to act as the Company’s primary operating subsidiary in the State of Washington.
Key Transaction Summaries
Summary of Star Buds Asset Acquisition.
On April 8, 2020, the Company, through its wholly-owned subsidiary, Cordova Investments, Canada Inc., completed the purchase of certain real assets and intellectual property (the “Assets”) of an arm’s length Canadian cannabis corporation (the “Star Buds Transaction”). The Assets acquired will enable the Company to open five recreational cannabis stores in Western Canada under an established brand name, with the exclusive right to open more stores in Canada. In conjunction with the Star Buds Transaction, seasoned industry veterans, Mr. Jakob Ripshtein and Mr. Ben Higham joined the Company’s board of directors.
Starbuds International Inc., the vendor of the Assets (the “Vendor” or “Star Buds”) is a British Columbia based cannabis venture that owns a network of recreational cannabis retail stores in Western Canada awaiting final provincial regulatory approvals. The Company purchased the Assets related to five such recreational stores and expects to have them opened in 2021. These stores will leverage the Star Buds brand name and proven business model that has created one of the most profitable cannabis retail companies in the United States over the last seven years. These stores also expect to be able to utilize the intellectual property of well-established Star Buds product lines of flower, concentrates, and edibles. The Company plans on leveraging the Star Buds business model and the platform to open additional stores throughout Canada.
As consideration to the Vendor for the Star Buds Transaction, the Company:
| (i) | issued twelve million five hundred thousand (12,500,000) common shares of the Company at close, in exchange for the Assets held related to five retail cannabis stores and four medical cannabis clinics; |
| (ii) | issued three million (3,000,000) common shares of the Company for each additional lease assignment in Alberta to the Company, for a total of six million (6,000,000) common shares of the Company; |
| (iii) | issued fifteen million (15,000,000) common shares of the Company for the first five (5) Star Buds stores opened before April 8, 2021; |
| (iv) | issued a three-year promissory note for five hundred twenty-seven thousand and three hundred dollars (CDN $527,967.49) accruing interest at six percent per annum payable upon maturity (the “Closing Promissory Note”); and |
| (v) | issued two additional three-year promissory notes in amounts of two hundred twenty-two thousand and five hundred dollars (CDN $222,500) and one hundred ninety-six thousand and eight hundred (CDN $196,832) for obtaining assignment of two specific leases to Company. Such additional notes to have same terms as the Closing Promissory Note. |
| 3 |
Summary of Investment in 2734158 Ontario Inc.
On May 19, 2020, the Company completed the purchase of its initial stake of 2734158 Ontario Inc. (“273”), an arm’s length Ontario-based cannabis retail venture (the “Ontario Transaction”). Cordova invested seven hundred twenty-three thousand dollars ($723,000) in 273 in exchange for 50.1% of 273. Cordova invested two hundred thousand dollars ($200,000) for 21.7% of 273 at the close of the Transaction, and invested (i) two hundred thousand dollars ($200,000) on June 14, 2020, (ii) two hundred thousand dollars ($200,000) on July 14, 2020, and (iii) one hundred twenty-three thousand dollars ($123,000) on August 13, 2020, which collectively gave the Company ownership of 50.1% of 273 after all payments were made. The Transaction is subject to approval from the Alcohol and Gaming Commission of Ontario and compliance with all applicable laws, rules and regulations. Cordova holds 4 of 6 board seats of 273 and has a right of first refusal on any future sale of primary or secondary shares in 273. The retail stores are operated by 273 under the Star Buds brand name, and Cordova is leveraging its assets of Starbuds International Inc. to provide 273 with retail store designs and layouts, standard operating procedures, staff training, financing resources and systems support. On September 17, 2020, the Company acquired an additional 10.35% of the common shares of 273 not previously owned by Cordova (the “Additional Shares”) bringing its accumulated ownership of 273 to 60.45%. The total purchase price for the Additional Shares amounted to $305,267, of which $265,975 was paid during the year end June 30, 2021 and the remainder $39,292 was paid during the three months ending September 30, 2021. As at the date of this Report, there is no outstanding amount for the Additional Shares.
Summary of Manitoba Transaction
On December 2, 2020, the Company, through its wholly owned subsidiary Cordova Investments Canada, Inc., completed the purchase of a 51% stake in 10062771 Manitoba Ltd. (“Manitoba Ltd.”) a Manitoba-based cannabis retail venture (the “Manitoba Transaction”). The purchase price for the shares was one hundred fifty thousand dollars ($150,000) payable to Manitoba Ltd. and six million (6,000,000) warrants of the Company to be granted to the current shareholders of Manitoba Ltd., with each warrant entitling the holder thereof to purchase one common share in the capital of the Company at an exercise price of $0.32 until November 30, 2022. In addition, the Company has agreed to loan up to one hundred fifty thousand dollars ($150,000) to Manitoba Ltd. to enable the opening of the second store in Manitoba. The stores will be operated by Manitoba Ltd. under the Star Buds brand name, and the Company will provide the financing resources and systems support as needed. The Company also has a right of first refusal regarding any future primary issuance or secondary sale of shares of Manitoba Ltd., and has a call option to purchase all of the outstanding equity interests of Manitoba Ltd. at any time following the two-year anniversary of the closing date at a valuation equivalent to four times the trailing twelve months normalized EBITDA of Manitoba Ltd.
Summary of Oregon Transaction
On April 4, 2018, Cordova OR entered into an agreement to acquire Cordova OR Operations, LLC (“OR Operations) for the acquisition of land and building for a total purchase price of US $1,440,000. Under the terms of the agreement, Cordova OR acquired a 27.5% membership interest in OR Operations for $534,311 (US $400,000) on April 4, 2018, and acquired the remaining 72.5% interest on June 19, 2019 for $1,361,048 (US $1,040,000). The assets of OR Operations consists of land, building and construction in progress with the construction in progress funded by Cordova OR. The total assets acquired through the transaction amounted to $3,645,389. The Company intends to continue its buildout the Oregon property to complete the construction and establish cultivation and processing facilities on the premises. On November 20, 2020, Cannabilt Farms, LLC, a wholly-owned subsidiary the Company, was granted a Marijuana Production License in Oregon. On August 4, 2021, the Company sold all of its land, building and equipment (the “Oregon Property”) for US $2,200,000 and entered into an agreement to lease the Oregon Property from the buyer (the “Sale Leaseback”). The Sale Leaseback will allow the Company to operate the Oregon Property for ten years, and provides options for two subsequent ten-year renewal periods. Proceeds from the sale were used to retire debts related to the Oregon Property and finance the planned Oregon expansion. A total of US $600,000 of the purchase price has been placed in escrow by the buyer to allow the Company to complete its buildout of the facility. The Sale Leaseback was signed on July 20, 2021 and commenced on August 1, 2021.
| 4 |
Summary of Washington Transaction
On February 26, 2021, Cordova WA entered into an agreement to acquire 100% of Extraction Technologies, LLC (“Extraction Tech”), a Washington-based company that provides cannabis extraction services to multiple cannabis licensed processors and will enable Cordova to provide manufactured cannabis products on both a white label and branded basis throughout the state of Washington. Extraction Tech owns a manufacturing building, processing equipment and contracts with tolling and white label customers. The consideration for the Transaction was three million (3,000,000) common shares of the Company on the closing date and an earnout payment of five hundred thousand (500,000) common shares of the Company for every $125,000 US dollars in EBITDA generated by Extraction Tech during the 12-month period beginning on the 3-month anniversary of the closing date and ending of the 15-month anniversary of the closing date. The maximum earnout payment that can be earned by Extraction Tech is four million (4,000,000) common shares, which will be earned if the business generates $1,000,000 US dollars or greater in EBITDA over that 12-month period.
Selected Financings
On October 19, 2017 and pursuant to a debt conversion agreement, the Company issued 7,681,110 Common Shares and fully settled $384,055 owing under a shareholder loan at a price of $0.05 per Common Share.
On December 14, 2017 and in connection with a private placement, the Company issued 5,532,500 Common Shares at a price of $0.10 per Common Share for total gross proceeds of $553,250; of which $533,250 was received in cash and $20,000 was received in services provided by a consultant.
On March 12, 2018 and in connection with a private placement, the Company issued 890,074 Common Shares at a price of $1.08 per Common Share for total gross proceeds of $959,251; all of which was received in cash.
On June 12, 2018 and June 15, 2018 in connection with a private placement, the Company issued 2,390,800 and 20,000 Common Shares, respectively, at a price of $1.95 per Common Share for total gross proceeds of $4,703,025; of which $4,400,163 was received in cash and $302,862 was received in services provided by consultants.
On March 13, 2019 and in connection with a private placement, the Company issued 600 unsecured subordinated convertible debenture units, each unit consisting of a principal amount of $1,000 and 500 warrants, for total gross proceeds of $600,000; of which $350,000 was received in cash and $250,000 was issued in settlement of outstanding fees.
On May 4, 2019, and in connection with warrants previously issued to a consultant, warrants were exercised for the purchase of 750,000 Common Shares of the Company at an exercise price of $0.15 per share for total gross proceeds of $112,500.
On August 14, 2019 and in connection with a private placement, the Company issued 713 unsecured subordinated convertible debenture units, each unit consisting of a principal amount of $1,000 and 500 warrants, for total gross proceeds of $713,000.
On April 24, 2020 and in connection with a private placement, the Company issued 1,164 unsecured subordinated convertible debenture units, each unit consisting of a principal amount of $1,000 and 2,000 warrants, for total gross proceeds of $1,164,000. 761 of the 1,164 issued unsecured subordinated convertible debenture units related to a prior private placement on August 14, 2019 where holders of such convertible debentures elected for early repayment allowing settlement of their convertible debentures plus accrued interest for an aggregate settlement amount of $761,000.
On May 25, 2020, the Company issued 6,210,190 common shares of the Company at a price of $0.25 per share for gross proceeds of $1,552,548; of which $1,411,680 was received in cash and $140,868 was issued in settlement of outstanding fees and debt.
| 5 |
On August 17, 2020, the Company issued 3,024,521 common shares of the Company for gross proceeds of $967,846; of which $552,501 was received in cash and $415,345 was issued in settlement of outstanding fees and debt.
On February 19, 2021, the Company issued 6,117,718 common shares of the Company for gross proceeds of $1,976,870; of which $1,380,400 was received in cash and $596,570 was issued in settlement of outstanding fees and debt.
On August 19, 2021, the Company closed a non-brokered private placement financing, pursuant to which the Company issued 3,379,379 units at a price of $0.30 per unit for gross proceeds of $1,013,814; of which $661,530 was received in cash and $352,284 was issued in settlement of outstanding fees and debt.
The following table summarizes financial information for the 2nd quarter of fiscal 2022 and the preceding seven quarters:
|
|
| Dec 31, |
|
| Sep 30, |
|
| Jun 30, |
|
| Mar 31, |
|
| Dec 31, |
|
| Sep 30, |
|
| Jun 30, |
|
| Mar 31, |
| ||||||||
| Quarter Ended |
| 2021 |
|
| 2021 |
|
| 2021 |
|
| 2021 |
|
| 2020 |
|
| 2020 |
|
| 2020 |
|
| 2020 |
| ||||||||
|
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||||||
| Revenue |
|
| 3,486,983 |
|
|
| 3,774,713 |
|
|
| 3,255,490 |
|
|
| 2,784,686 |
|
|
| 2,441,857 |
|
|
| 1,836,812 |
|
|
| 166,773 |
|
|
| - |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loss from continuing operations |
|
| (637,702 | ) |
|
| (648,057 | ) |
|
| (2,948,269 | ) |
|
| (443,400 | ) |
|
| (475,516 | ) |
|
| (617,726 | ) |
|
| (2,661,796 | ) |
|
| (22,910 | ) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net loss per share – basic and diluted |
|
| 0.007 |
|
|
| 0.007 |
|
|
| 0.032 |
|
|
| 0.005 |
|
|
| 0.006 |
|
|
| 0.009 |
|
|
| 0.050 |
|
|
| 0.021 |
|
Number of Common Shares
There were 102,084,853 Common Shares issued and outstanding as at December 31, 2021 and 102,784,853 Common Shares issued and outstanding as at February 28, 2022 being the date of this report. There were 5,100,000 options issued at outstanding as at December 31, 2021 and February 28, 2022. There were 18,612,879 and 17,912,879 warrants, respectively, issued and outstanding as at both December 31, 2021 and February 28, 2022.
Business Environment
Compliance with Applicable State Law
Each licensee of the Intellectual Property complies with applicable U.S. state licensing requirements as follows: (1) each licensee is licensed pursuant to applicable U.S. state law to cultivate, possess and/or distribute cannabis in such state; (2) renewal dates for such licenses are docketed by legal counsel and/or other advisors; (3) random internal audits of the licensee’s business activities are conducted by the applicable state regulator and by the respective investee to ensure compliance with applicable state law; (4) each employee is provided with an employee handbook that outlines internal standard operating procedures in connection with the cultivation, possession and distribution of cannabis to ensure that all cannabis inventory and proceeds from the sale of such cannabis are properly accounted for and tracked, using scanners to confirm each customer’s legal age and the validity of each customer’s drivers’ license; (5) each room that cannabis inventory and/or proceeds from the sale of such inventory enter is monitored by video surveillance; (6) software is used to track cannabis inventory from seed-to-sale; and (7) each licensee is contractually obligated to comply with applicable state law in connection with the cultivation, possession and/or distribution of cannabis. CordovaCann’s U.S. legal counsel reviews, from time to time, the licenses and documents referenced above in order to confirm such information and identify any deficiencies.
| 6 |
Colorado’s Cannabis Regulatory Environment
For the purposes of Staff Notice 51-352 (Revised) – Companies with U.S. Marijuana-Related Activities) (“Staff Notice 51-352”), the assets and interests held by CordovaCann in Colorado are classified as “ancillary” involvement in the U.S. cannabis industry.
Colorado authorized the cultivation, possession and distribution of cannabis by certain licensed Colorado cannabis businesses. The Colorado Marijuana Enforcement Division regulates Colorado’s cannabis regulatory program. CordovaCann is advised by U.S. legal counsel and/or other advisors in connection with Colorado’s cannabis regulatory program. CordovaCann only engages in transactions with Colorado cannabis businesses that hold licenses that are in good standing to cultivate, possess and/or distribute cannabis in Colorado in compliance with Colorado’s cannabis regulatory program. To the extent required by Colorado’s cannabis regulatory program, CordovaCann has fully disclosed and/or registered each financial interest CordovaCann holds in such Colorado cannabis business.
Oregon’s Cannabis Regulatory Environment
For the purposes of Staff Notice 51-352, the assets and interests held by CordovaCann in Oregon are classified as “ancillary” involvement in the U.S. cannabis industry.
Oregon authorized the cultivation, possession and distribution of cannabis by certain licensed Oregon cannabis businesses. The Oregon Liquor Control Commission regulates Oregon’s cannabis regulatory program. CordovaCann is advised by U.S. legal counsel and/or other advisors in connection with Oregon’s cannabis regulatory program. CordovaCann only engages in transactions with Oregon cannabis businesses that hold licenses that are in good standing to cultivate, possess and/or distribute cannabis in Oregon in compliance with Oregon’s cannabis regulatory program. To the extent required by Oregon’s cannabis regulatory program, CordovaCann has fully disclosed and/or registered each financial interest CordovaCann holds in such Oregon cannabis business.
California’s Cannabis Regulatory Environment
For the purposes of Staff Notice 51-352, the assets and interests contemplated to be held by CordovaCann in California are classified as “ancillary” involvement in the U.S. cannabis industry.
California authorized the cultivation, possession and distribution of cannabis by certain licensed California cannabis businesses. The California Bureau of Cannabis Control regulates California’s cannabis regulatory program. CordovaCann is advised by U.S. legal counsel and/or other advisors in connection with California’s cannabis regulatory program. CordovaCann only engages in transactions with California cannabis businesses that hold licenses that are in good standing to cultivate, possess and/or distribute cannabis in California in compliance with California’s cannabis regulatory program. To the extent required by California’s cannabis regulatory program, CordovaCann has fully disclosed and/or registered each financial interest CordovaCann holds in such California cannabis business.
Washington’s Cannabis Regulatory Environment
For the purposes of Staff Notice 51-352, the assets and interests contemplated to be held by CordovaCann in Washington are classified as “ancillary” involvement in the U.S. cannabis industry.
Washington authorized the cultivation, possession and distribution of cannabis by certain licensed Washington cannabis businesses. The Washington State Liquor and Cannabis Board regulates Washington’s cannabis regulatory program. CordovaCann is advised by U.S. legal counsel and/or other advisors in connection with Washington’s cannabis regulatory program. CordovaCann only engages in transactions with Washington cannabis businesses that hold licenses that are in good standing to cultivate, possess and/or distribute cannabis in Washington in compliance with Washington’s cannabis regulatory program. To the extent required by Washington’s cannabis regulatory program, CordovaCann has fully disclosed and/or registered each financial interest CordovaCann holds in such Washington cannabis business.
| 7 |
COVID-19
On March 11, 2020, the World Health Organization declared the outbreak of the novel strain of coronavirus (“COVID-19”) a pandemic, which has resulted in governments worldwide enacting emergency measures to combat the spread of the virus. These measures have caused material disruption to businesses globally resulting in an economic slowdown. The COVID-19 pandemic has impacted revenue in the Canadian consumer market, as governments have imposed retail access restrictions to curbside pickup at points during the pandemic, and have changed their purchasing patterns to reflect the slow-down in the market. The sale of consumer cannabis has been recognized as an essential service across Canada. All of the Company’s facilities in Canada and the United States continue to be operational and the Company continues to work closely with local, national and international government authorities to ensure that the Company is following the required protocols and guidelines related to COVID-19 within each region.
The duration and impact of the COVID-19 outbreak is unknown at this time, as is the efficacy of the government and central bank interventions. It is not possible to reliably estimate the length and severity of these developments and the impact on the financial results and condition of the Company and its operating subsidiaries in future periods as well as the Company’s ability to find new business opportunities, raise capital or restructure the Company’s finances. The effects of any such changes could be material, which could result in, among other things, impairment of long-lived assets. The Company is closely monitoring the impact of COVID-19 on all aspects of its business.
Risk Factors
The following are certain risk factors relating to the business carried on by the Company that prospective holders of Common Shares should carefully consider.
Risks specifically related to the United States regulatory system.
The Company’s investments operate in a new industry which is highly regulated, highly competitive and evolving rapidly. As such, new risks may emerge, and management may not be able to predict all such risks or be able to predict how such risks may result in actual results differing from the results contained in any forward-looking statements.
The Company’s investments incur ongoing costs and obligations related to regulatory compliance. Failure to comply with regulations may result in additional costs for corrective measures, penalties or in restrictions of operations. In addition, changes in regulations, more vigorous enforcement thereof or other unanticipated events could require extensive changes to operations, increased compliance costs or give rise to material liabilities, which could have a material adverse effect on the business, results of operations and financial condition of the Company’s investments and, therefore, on the Company’s prospective returns. Further, the Company may be subject to a variety of claims and lawsuits. Adverse outcomes in some or all of these claims may result in significant monetary damages or injunctive relief that could adversely affect our ability to conduct our business. Litigation and other claims are subject to inherent uncertainties and management’s view of these matters may change in the future. A material adverse impact on our financial statements could also occur for the period in which the effect of an unfavorable final outcome becomes probable and reasonably capable of being estimated. The industry is subject to extensive controls and regulations which may significantly affect the financial condition of market participants. The marketability of any product may be affected by numerous factors that are beyond the control of the Company’s investments and which cannot be predicted, such as changes to government regulations, including those relating to taxes and other government levies which may be imposed. Changes in government levies, including taxes, could reduce the Company’s investments’ earnings and could make future capital investments or the Company’s investments’ operations uneconomic. The industry is also subject to numerous legal challenges, which may significantly affect the financial condition of market participants and which cannot be reliably predicted.
| 8 |
CordovaCann is expected to continue to derive a portion of its revenues from the cannabis industry in certain states of the United States, which is illegal under United States federal law. While the Company’s business activities are compliant with applicable state and local laws, such activities remain illegal under United States federal law. CordovaCann is involved in the cannabis industry in the United States where local and state laws permit such activities or provide limited defenses to criminal prosecutions. The enforcement of relevant laws is a significant risk.
Over half of the U.S. states have enacted comprehensive legislation to regulate the sale and use of medical cannabis. Notwithstanding the permissive regulatory environment of medical cannabis at the state level, cannabis continues to be categorized as a Schedule 1 controlled substance under the United States Controlled Substances Act of 1970. As such, cannabis-related practices or activities, including without limitation, the cultivation, manufacture, importation, possession, use or distribution of cannabis, are illegal under United States federal law. Strict compliance with state laws with respect to cannabis will neither absolve the Company of liability under United States federal law, nor will it provide a defense to any federal proceeding which may be brought against the Company. Any such proceedings brought against the Company may adversely affect the Company’s operations and financial performance.
Because of the conflicting views between state legislatures and the federal government of the United States regarding cannabis, investments in cannabis businesses in the United States are subject to inconsistent legislation, regulation, and enforcement. Unless and until the United States Congress amends the United States Controlled Substances Act with respect to cannabis or the Drug Enforcement Agency reschedules or de-schedules cannabis (and as to the timing or scope of any such potential amendments there can be no assurance), there is a risk that federal authorities may enforce current federal law, which would adversely affect the current and future investments of the Company in the United States. As a result of the tension between state and federal law, there are a number of risks associated with the Company’s existing and future investments in the United States.
For the reasons set forth above, the Company’s existing interests in the United States cannabis market may become the subject of heightened scrutiny by regulators, stock exchanges, clearing agencies and other authorities in Canada. It has been reported by certain publications in Canada that the Canadian Depository for Securities Limited may implement policies that would see its subsidiary, CDS Clearing and Depository Services Inc. (“CDS”), refuse to settle trades for cannabis companies that have investments in the United States. CDS is Canada’s central securities depository, clearing and settlement hub settling trades in the Canadian equity, fixed income and money markets. The TMX Group, the owner and operator of CDS, subsequently issued a statement on August 17, 2017 reaffirming that there is no CDS ban on the clearing of securities of companies with cannabis-related activities in the United States, despite media reports to the contrary and that the TMX Group was working with regulators to arrive at a solution that will clarify this matter, which would be communicated at a later time.
On February 8, 2018, following discussions with the Canadian Securities Administrators (“CSA”) and recognized Canadian securities exchanges, the TMX Group announced the signing of a Memorandum of Understanding (“TMX MOU”) with Aequitas NEO Exchange Inc., the Canadian Securities Exchange (“CSE”), the Toronto Stock Exchange, and the TSX Venture Exchange. The TMX MOU outlines the parties’ understanding of Canada’s regulatory framework applicable to the rules, procedures, and regulatory oversight of the exchanges and CDS as it relates to companies with cannabis-related activities in the United States. The TMX MOU confirms, with respect to the clearing of listed securities, that CDS relies on the exchanges to review the conduct of listed companies. As a result, there is no CDS ban on the clearing of securities of companies with cannabis-related activities in the United States. However, there can be no guarantee that this approach to regulation will continue in the future. If such a ban were to be implemented, it would have a material adverse effect on the ability of holders of Common Shares to make and settle trades. In particular, the Common Shares would become highly illiquid as until an alternative was implemented, investors would have no ability to affect a trade of the Common Shares through the facilities of a stock exchange. The Company has obtained eligibility with the Depository Trust Company (“DTC”) for its Common Share quotation on the OTCQB and such DTC eligibility provides another possible avenue to clear Common Shares in the event of a CDS ban.
| 9 |
The activities of CordovaCann’s investments are, and will continue to be, subject to evolving regulation by governmental authorities. The Company’s investments are directly or indirectly engaged in the medical and recreational cannabis industry in the United States and Canada, where local state laws permit such activities. The legality of the production, extraction, distribution and use of cannabis differs among each North American jurisdictions.
CordovaCann’s investments have been focused in three states that have legalized the medical and/or recreational use of cannabis, being Oregon, Colorado and California. Over half of the U.S. states have enacted legislation to legalize and regulate the sale and use of medical cannabis. However, the U.S. federal government has not enacted similar legislation. As such, the cultivation, manufacture, distribution, sale and use of cannabis remains illegal under U.S. federal law.
Further, on January 4, 2018, U.S. Attorney General, Jeff Sessions, formally rescinded the standing DOJ federal policy guidance governing enforcement of marijuana laws, as set forth in a series of memos and guidance from 2009-2014, principally the Cole Memorandum. The Cole Memorandum generally directed U.S. Attorneys not to enforce the federal marijuana laws against actors who are compliant with state laws, provided enumerated enforcement priorities were not implicated. The rescission of this memo and other Obama-era prosecutorial guidance did not create a change in federal law as the Cole Memorandums were never legally binding; however, the revocation removed the DOJ’s guidance to U.S. Attorneys that state-regulated cannabis industries substantively in compliance with the Cole Memorandum’s guidelines should not be a prosecutorial priority. The federal government of the United States has always reserved the right to enforce federal law regarding the sale and disbursement of medical or recreational marijuana, even if state law sanctioned such sale and disbursement. Although the rescission of the above memorandums does not necessarily indicate that marijuana industry prosecutions are now affirmatively a priority for the DOJ, there can be no assurance that the federal government will not enforce such laws in the future.
Additionally, there can be no assurance that state laws legalizing and regulating the sale and use of cannabis will not be repealed or overturned, or that local governmental authorities will not limit the applicability of state laws within their respective jurisdictions. It is also important to note that local and city ordinances may strictly limit and/or restrict the distribution of cannabis in a manner that could make it extremely difficult or impossible to transact business in the cannabis industry. If the federal government begins to enforce federal laws relating to cannabis in states where the sale and use of cannabis is currently legal, or if existing state laws are repealed or curtailed, the Company’s investments in such businesses would be materially and adversely affected notwithstanding the fact that the Company is not directly engaged in the sale or distribution of cannabis. Federal actions against any individual or entity engaged in the marijuana industry or a substantial repeal of marijuana related legislation could adversely affect the Company, its business and its investments.
In light of the political and regulatory uncertainty surrounding the treatment of U.S. cannabis-related activities, including the rescission of the Cole Memorandum discussed above, on February 8, 2018, the CSA published Staff Notice 51-352 setting out the CSA’s disclosure expectations for specific risks facing companies with cannabis-related activities in the United States. Staff Notice 51-352 confirms that a disclosure-based approach remains appropriate for companies with U.S. cannabis-related activities. Staff Notice 51-352 includes additional disclosure expectations that apply to all companies with U.S. cannabis-related activities, including those with direct and indirect involvement in the cultivation and distribution of cannabis, as well as companies that provide goods and services to third parties involved in the U.S. cannabis industry. The Company views Staff Notice 51-352 favourably, as it provides increased transparency and greater certainty regarding the views of the exchanges and the regulators regarding the Company’s existing operations and strategic business plan as well as the Company’s ability to pursue further investments and opportunities in the United States.
The Company’s investments in the United States are subject to applicable anti-money laundering laws and regulations.
The Company is subject to a variety of laws and regulations domestically and in the United States that involve money laundering, financial recordkeeping and proceeds of crime, including the U.S. Currency and Foreign Transactions Reporting Act of 1970 (commonly known as the Bank Secrecy Act), as amended by Title III of the Uniting and Strengthening America by Providing Appropriate Tools Required to Intercept and Obstruct Terrorism Act of 2001 (USA PATRIOT Act), the Proceeds of Crime (Money Laundering) and Terrorist Financing Act (Canada), as amended and the rules and regulations thereunder, and any related or similar rules, regulations or guidelines, issued, administered or enforced by governmental authorities in the United States and Canada. Further, under U.S. federal law, banks or other financial institutions that provide a cannabis business with a checking account, debit or credit card, small business loan, or any other service could be found guilty of money laundering, aiding and abetting, or conspiracy.
| 10 |
Despite these laws, FinCEN issued a memorandum on February 14, 2014 outlining the pathways for financial institutions to bank marijuana businesses in compliance with federal enforcement priorities. The FinCEN Memorandum states that in some circumstances, it is permissible for banks to provide services to cannabis-related businesses without risking prosecution for violation of federal money laundering laws. It refers to supplementary guidance that Deputy Attorney General Cole issued to federal prosecutors relating to the prosecution of money laundering offenses predicated on cannabis-related violations of the United States Controlled Substances Act on the same day (the “2014 Cole Memo”). The 2014 Cole Memo has been rescinded as of January 4, 2018, along with the Cole Memorandum, removing guidance that enforcement of applicable financial crimes was not a DOJ priority.
Attorney General Sessions’ revocation of the Cole Memorandum and the 2014 Cole Memo has not affected the status of the FinCEN Memorandum, nor has the Department of the Treasury given any indication that it intends to rescind the FinCEN Memorandum itself. Though it was originally intended for the 2014 Cole Memo and the FinCEN Memorandum to work in tandem, the FinCEN Memorandum appears to remain in effect as a standalone document which explicitly lists the eight enforcement priorities originally cited in the rescinded Cole Memorandum. Although the FinCEN Memorandum remains intact, indicating that the Department of the Treasury and FinCEN intend to continue abiding by its guidance, it is unclear whether the current administration will continue to follow the guidelines of the FinCEN Memorandum.
The Company’s investments, and any proceeds thereof, are considered proceeds of crime due to the fact that cannabis remains illegal federally in the United States. This restricts the ability of the Company to declare or pay dividends, effect other distributions or subsequently repatriate such funds back to Canada. Furthermore, while the Company has no current intention to declare or pay dividends on its Common Shares in the foreseeable future, the Company may decide or be required to suspend declaring or paying dividends without advance notice and for an indefinite period of time.
The Company’s investments in the United States may be subject to heightened scrutiny by Canadian authorities.
For the reasons set forth above, the Company’s existing investments in the United States, and any future investments, may become the subject of heightened scrutiny by regulators, stock exchanges and other authorities in Canada. As a result, the Company may be subject to significant direct and indirect interaction with public officials. There can be no assurance that this heightened scrutiny will not in turn lead to the imposition of certain restrictions on the Company’s ability to invest in the United States or any other jurisdiction, in addition to those described herein.
Although the TMX MOU has confirmed that there is currently no CDS ban on the clearing of securities of companies with cannabis-related activities in the United States, there can be no guarantee that this approach to regulation will continue in the future. If such a ban were to be implemented, it would have a material adverse effect on the ability of holders of Common Shares to make and settle trades. In particular, the Common Shares would become highly illiquid as until an alternative was implemented, investors would have no ability to affect a trade of the Common Shares through the facilities of a stock exchange.
Change in laws, regulations and guidelines.
Each investment’s current and proposed operations are subject to a variety of laws, regulations and guidelines, including, but not limited to, those relating to the manufacture, management, transportation, storage and disposal of cannabis, as well as laws and regulations relating to health and safety (including those for consumable products), the conduct of operations and the protection of the environment. These laws and regulations are broad in scope and subject to evolving interpretations. If any changes to such laws, regulations and guidelines occur, which are matters beyond the control of the Company, the Company may incur significant costs in complying with such changes or it may be unable to comply therewith, which in turn may result in a material adverse effect on the Company’s business, financial condition and results of operation. In addition, violations of these laws, or allegations of such violations, could disrupt certain aspects of the Company’s business plan and result in a material adverse effect on certain aspects of its planned operations.
| 11 |
Changes in regulations, more vigorous enforcement thereof, the imposition of restrictions on the Company’s ability to operate in the U.S. as a result of the federally illegal nature of cannabis in the U.S. or other unanticipated events could require extensive changes to the Company’s operations, increased compliance costs or give rise to material liabilities, which could have a material adverse effect on the business, results of operations and financial condition of the Company.
United States tax residence of the Company.
The Company, which is and will continue to be a Canadian corporation generally would be classified as a non-United States corporation (and, therefore, as a non-United States tax resident) under general rules of United States federal income taxation. Section 7874 of the United States Tax Code, however, contains rules that can cause a non-United States corporation to be taxed as a United States corporation for United States federal income tax purposes. The rules described in this paragraph are relatively new, their application is complex and there is little guidance regarding their application. Under section 7874 of the United States Tax Code, a corporation created or organized outside the United States (i.e., a non-United States corporation) will nevertheless be treated as a United States corporation for United States federal income tax purposes (such treatment is referred to as an “Inversion”) if each of the following three conditions are met (i) the non-United States corporation acquires, directly or indirectly, or is treated as acquiring under applicable United States Treasury Regulations, substantially all of the assets held, directly or indirectly, by a United States corporation, (ii) after the acquisition, the former stockholders of the acquired United States corporation hold at least 80% (by vote or value) of the shares of the non-United States corporation by reason of holding shares of the United States acquired corporation, and (iii) after the acquisition, the non-United States corporation’s expanded affiliated group does not have substantial business activities in the non-United States corporation’s country of organization or incorporation when compared to the expanded affiliated group’s total business activities (clauses (i) – (iii), collectively, the “Inversion Conditions”). For this purpose, “expanded affiliated group” means a group of corporations where (i) the non-United States corporation owns stock representing more than 50% of the vote and value of at least one member of the expanded affiliated group, and (ii) stock representing more than 50% of the vote and value of each member is owned by other members of the group. The definition of an “expanded affiliated group” includes partnerships where one or more members of the expanded affiliated group own more than 50% (by vote and value) of the interests of the partnership.
If the Company is treated as a United States corporation for United States federal income tax purposes under section 7874 of the United States Tax Code (which is considered likely, although no definitive determination of this matter has been reached, and no tax ruling has been sought or obtained in this regard), the Company would be considered a United States tax resident and subject to United States federal income tax on its worldwide income. However, for Canadian tax purposes, the Company is expected, regardless of any application of section 7874 of the United States Tax Code, to be treated as a Canadian resident Company (as defined in the Tax Act) for Canadian income tax purposes. As a result, if the Company is considered a United States corporation under section 7874, the Company would be subject to taxation both in Canada and the United States which could have a material adverse effect on its financial condition and results of operations. In addition, any distributions paid by the Company to a holder of Common Shares may be subject to United States withholding tax as well as any applicable Canadian withholding tax. A Non-United States Holder may also be subject to United States tax, including withholding tax, on disposition of its Common Shares.
| 12 |
Passive Foreign Investment Company.
There is a risk that the Company may, in the future, be construed as a passive foreign investment Company (“PFIC”). If the Company is a PFIC, its shareholders in the U.S. are likely subject to adverse U.S. tax consequences. Under U.S. federal income tax laws, if a Company is a PFIC for any year, it could have adverse U.S. federal income tax consequences to a U.S. shareholder with respect to its investment in Common Shares. The Company may earn royalty and franchise revenue which may be treated as passive income unless the royalty and franchise revenue is derived in the active conduct of a trade or business. Assessing whether royalty or franchise revenue received by the Company and its subsidiaries is derived in the active conduct of a trade or business involves substantial factual and legal ambiguity. Based on current business plans and financial expectations, the Company expects that it will not be a PFIC for its current tax year. PFIC classification is fundamentally factual in nature, generally cannot be determined until the close of the tax year in question, and is determined annually. Furthermore, because PFIC determinations are made annually, it is possible that the Company will meet the requirements to be treated as a PFIC in one or more years, but not meet such requirements in other years. U.S. shareholders should consult their own tax advisors regarding the potential adverse tax consequences to owning PFIC stock, and whether they are able to and should make any elections or take other actions to mitigate such potential adverse tax consequences.
If the Company is deemed to be an investment Company under the United States Investment Company Act of 1940, as amended (the “Investment Company Act”), it may be required to institute burdensome compliance requirements and its activities may be restricted.
The Company intends to conduct its operations so that it is not required to register as an investment Company under the Investment Company Act. Section 3(a)(1)(C) of the Investment Company Act defines an investment Company as any Company that is engaged or proposes to engage in the business of investing, reinvesting, owning, holding or trading in securities and owns or proposes to acquire investment securities having a value exceeding 40.0% of the value of the Company’s total assets (exclusive of government securities and cash items) on an unconsolidated basis. However, any Company primarily engaged, directly or through a wholly-owned subsidiary or subsidiaries, in a business or businesses other than that of investing, reinvesting, owning, holding, or trading in securities is exempt from the requirements of the Investment Company Act under Section 3(b)(1).
If the Company is deemed to be an investment Company under the Investment Company Act, its activities may be restricted, including restrictions on the nature of the Company’s investments and restrictions on the issuance of securities. In addition, the Company may have imposed upon it burdensome requirements, including:
|
| · | registration as an investment Company; |
|
| · | adoption of a specific form of corporate structure; and |
|
| · | reporting, record keeping, voting, proxy and disclosure requirements and other rules and regulations. |
In summary, if the Company were to be characterized as an investment Company, the inability of the Company to satisfy such regulatory requirements, whether on a timely basis or at all, could, under certain circumstances, have a material adverse effect on the Company and its ability to continue pursuing its business plan could be limited.
The Company's Common Shares are considered to be penny stock, which may adversely affect the liquidity of its Common Shares.
The capital stock of the Company would be classified as “penny stock” as defined in Reg. § 240.3a51-1 promulgated under the Securities Exchange Act of 1934 (the “1934 Act”). In response to perceived abuse in the penny stock market generally, the 1934 Act was amended in 1990 to add new requirements in connection with penny stocks. In connection with effecting any transaction in a penny stock, a broker or dealer must give the customer a written risk disclosure document that (a) describes the nature and level of risk in the market for penny stocks in both public offerings and secondary trading, (b) describes the broker’s or dealer’s duties to the customer and the rights and remedies available to such customer with respect to violations of such duties, (c) describes the dealer market, including “bid” and “ask” prices for penny stock and the significance of the spread between the bid and ask prices, (d) contains a toll-free telephone number for inquiries on disciplinary histories of brokers and dealers, and (e) define significant terms used in the disclosure document or the conduct of trading in penny stocks. In addition, the broker-dealer must provide to a penny stock customer a written monthly account statement that discloses the identity and number of shares of each penny stock held in the customer’s account, and the estimated market value of such shares. The extensive disclosure and other broker-dealer compliance related to penny stocks may result in reducing the level of trading activity in the secondary market for such stocks, thus limiting the ability of the holder to sell such stock.
| 13 |
Additional financing.
The continued development of the Company will require additional financing. There is no guarantee that the Company will be able to achieve its business objectives. The Company intends to fund its future business activities by way of additional offerings of equity and/or debt financing as well as through anticipated positive cash flow from operations in the future. The failure to raise or procure such additional funds or the failure to achieve positive cash flow could result in the delay or indefinite postponement of current business objectives. There can be no assurance that additional capital or other types of financing will be available if needed or that, if available, will be on terms acceptable to the Company. If additional funds are raised by offering equity securities, existing shareholders could suffer significant dilution. Any debt financing secured in the future could involve the granting of security against assets of the Company and also contain restrictive covenants relating to capital raising activities and other financial and operational matters, which may make it more difficult for the Company to obtain additional capital and to pursue business opportunities, including potential acquisitions. The Company will require additional financing to fund its operations until positive cash flow is achieved.
The Company’s access to both public and private capital and its ability to access financing to support continuing operations and investments may be further restricted due to uncertainty and the changing nature of the marijuana regulatory environment in jurisdictions in which the Company operates.
Investments may be pre-revenue.
The Company has made and may make future investments in entities that have no significant sources of operating cash flow and no revenue from operations. As such, the Company’s investments are subject to risks and uncertainties including the risk that the Company’s investments will not be able to:
|
| · | implement or execute their current business plan, or create a business plan that is sound; |
|
| · | maintain their anticipated management team; and/or |
|
| · | raise sufficient funds in the capital markets or otherwise to effectuate their business plan. |
If the Company’s investments cannot execute any one of the foregoing, their businesses may fail, which could have a materially adverse impact on the business, financial condition and operating results of the Company.
Lack of control over operations of investments.
The Company relies on its investments to execute on their business plans and to produce medical and/or recreational cannabis products, and holds contractual rights and minority equity interests relating to the operation of the Company’s investments. The operators of the Company’s investments have significant influence over the results of operations of the Company’s investments. Further, the interests of the Company and the operators of the Company’s investments may not always be aligned. As a result, the cash flows of the Company are dependent upon the activities of third parties which creates the risk that at any time those third parties may: (i) have business interests or targets that are inconsistent with those of the Company; (ii) take action contrary to the Company’s policies or objectives; (iii) be unable or unwilling to fulfill their obligations under their agreements with the Company; or (iv) experience financial, operational or other difficulties, including insolvency, which could limit or suspend a third party’s ability to perform its obligations. In addition, payments may flow through the Company’s investments, and there is a risk of delay and additional expense in receiving such revenues. Failure to receive payments in a timely fashion, or at all, under the agreements to which the Company is entitled may have a material adverse effect on the Company. In addition, the Company must rely, in part, on the accuracy and timeliness of the information it receives from the Company’s investments, and use such information in its analyses, forecasts and assessments relating to its own business. If the information provided by investment entities to the Company contains material inaccuracies or omissions, the Company’s ability to accurately forecast or achieve its stated objectives, or satisfy its reporting obligations, may be materially impaired.
| 14 |
Private companies and illiquid securities.
The Company may invest in securities of private companies. In some cases, the Company may be restricted by contract or generally by applicable securities laws from selling such securities for a period of time. Such securities may not have a ready market and the inability to sell such securities or to sell such securities on a timely basis or at acceptable prices may impair the Company’s ability to exit such investments when the Company considers it appropriate.
Unfavourable publicity or consumer perception.
The regulated cannabis industry in the United States and Canada is at an early stage of its development. The Company believes the medical and recreational cannabis industry is highly dependent on consumer perception regarding the safety and efficacy of recreational and medical cannabis. Consumer perceptions regarding legality, morality, consumption, safety, efficacy and quality of cannabis are mixed and evolving. Consumer perception can be significantly influenced by scientific research or findings, regulatory investigations, litigation, media attention and other publicity regarding the consumption of cannabis products. There can be no assurance that future scientific research, findings, regulatory proceedings, litigation, media attention or other research findings or publicity will be favourable to the cannabis market or any particular product, or consistent with earlier publicity. Future research reports, findings, regulatory proceedings, litigation, media attention or other publicity that are perceived as less favourable than, or that question, earlier research reports, findings or publicity could have a material adverse effect on the demand for cannabis and on the business, results of operations, financial condition and cash flows of the Company. Further, adverse publicity reports or other media attention regarding cannabis in general, or associating the consumption of cannabis with illness or other negative effects or events, could have such a material adverse effect on the business of the Company. Such adverse publicity reports or other media attention could arise even if the adverse effects associated with such products resulted from consumers’ failure to consumer such products legally, appropriately or as directed.
Public opinion and support for medical and recreational cannabis use has traditionally been inconsistent and varies from jurisdiction to jurisdiction. Legalization of medical and recreational cannabis remains a controversial issue subject to differing opinions surrounding the level of legalization (for example, legalization of medical marijuana as opposed to legalization in general).
Limited operating history.
Since March 1997, when it was created by amalgamation, the Company has had no significant revenues or earnings from operations. The Company has operated at a loss to date and may continue to sustain operating losses for the foreseeable future. There is no assurance that the Company will ever be profitable. Therefore, it is difficult for investors to evaluate the Company’s operations and prospects which may increase the risks associated with an investment in the Company.
Although the Company expects to generate some revenues from its investments, many of the investments will only start generating revenues in future periods and, accordingly, the Company is therefore expected to remain subject to many of the risks common to early-stage enterprises for the foreseeable future, including challenges related to laws, regulations, licensing, integrating and retaining qualified employees; making effective use of limited resources; achieving market acceptance of existing and future solutions; competing against companies with greater financial and technical resources; acquiring and retaining customers; and developing new solutions. There is no assurance that the Company will be successful in achieving a return on shareholders’ investment and the likelihood of success must be considered in light of the early stage of operations.
| 15 |
Competition.
The Company competes with other companies for financing and investment opportunities in the cannabis industry. Some of these companies may possess greater financial resources than the Company. Such competition may result in the Company being unable to enter into desirable strategic agreements or similar transactions, to recruit or retain qualified employees or to acquire the capital necessary to fund its investments. Existing or future competition in the cannabis industry, including, without limitation, the entry of large multinational entities into the industry, could materially adversely affect the Company’s prospects for entering into additional agreements in the future. In addition, the Company currently competes with other cannabis streaming and royalty companies, some of which may possess greater financial resources than the Company.
There is potential that the Company will face intense competition from other companies, some of which can be expected to have longer operating histories and more financial resources and experience than the Company. Increased competition by larger and better financed competitors, including competitors to the Company’s investments, could materially and adversely affect the business, financial condition and results of operations of the Company. It is possible that larger competitors could establish price setting and cost controls which would effectively “price out” certain of the Company’s investments operating within and in support of the medical and recreational cannabis industry.
Because of the early stage of the industry in which the Company will operate, the Company expects to face additional competition from new entrants. To become and remain competitive, the Company will require research and development, marketing, sales and support. The Company may not have sufficient resources to maintain research and development, marketing, sales and support efforts on a competitive basis, which could materially and adversely affect the business, financial condition and results of operations of the Company.
Banking.
Since the production and possession of cannabis is currently illegal under U.S. federal law, it is possible that banks may refuse to open bank accounts for the deposit of funds from businesses involved with the cannabis industry. The inability to open bank accounts with certain institutions could materially and adversely affect the business of the Company.
Currency fluctuations.
Certain revenues and expenses of the Company are expected to be denominated in U.S. dollars, and therefore may be exposed to significant currency exchange fluctuations. Recent events in the global financial markets have been coupled with increased volatility in the currency markets. Fluctuations in the exchange rate between the U.S. dollar and the Canadian dollar may have a material adverse effect on the Company’s business, financial condition and operating results. CordovaCann may, in the future, establish a program to hedge a portion of its foreign currency exposure with the objective of minimizing the impact of adverse foreign currency exchange movements; however, there can be no assurance that such a program will effectively mitigate currency risks.
Risks associated with strategic transactions.
As part of the Company’s overall business strategy, the Company intends to pursue select strategic acquisitions, leasing and lending transactions and licensing agreements which would provide additional product offerings, vertical integrations, additional industry expertise, and a stronger industry presence in both existing and new jurisdictions. The success of any such strategic transactions will depend, in part, on the ability of the Company to realize the anticipated benefits and synergies from integrating the Company’s investments into the businesses of the Company. Future strategic actions may expose it to potential risks, including risks associated with: (a) the integration of new operations, services and personnel; (b) unforeseen or hidden liabilities; (c) the diversion of resources from the Company’s existing business and technology; (d) potential inability to generate sufficient revenue to offset new costs; (e) the expenses of acquisitions; and (f) the potential loss of or harm to relationships with both employees and existing users resulting from its integration of new businesses. In addition, any proposed acquisitions may be subject to regulatory approval.
| 16 |
While the Company intends to conduct reasonable due diligence in connection with such strategic transactions, there are risks inherent in any transaction. Specifically, there could be unknown or undisclosed risks or liabilities of such companies for which the Company is not sufficiently indemnified. Any such unknown or undisclosed risks or liabilities could materially and adversely affect the Company’s financial performance and results of operations. The Company could encounter additional transaction and integration related costs or other factors such as the failure to realize all of the benefits from the strategic actions. All of these factors could cause dilution to the Company’s earnings per share or decrease or delay the anticipated accretive effect of the transaction and cause a decrease in the market price of the Company’s Common Shares.
Bankruptcy or insolvency of investments.
There is no guarantee that the Company will be able to effectively enforce any interests it may have in the Company’s investments. A bankruptcy or other similar event related to an investment of CordovaCann that precludes a party from performing its obligations under an agreement may have a material adverse effect on the Company. Furthermore, as an equity investor, should an investment have insufficient assets to pay its liabilities, it is possible that other liabilities will be satisfied prior to the liabilities owed to the Company. In addition, bankruptcy or other similar proceedings are often a complex and lengthy process, the outcome of which may be uncertain and could result in a material adverse effect on the Company.
Research and market development.
Although the Company, itself and through its investments, is committed to researching and developing new markets and products and improving existing products, there can be no assurances that such research and market development activities will prove profitable or that the resulting markets and/or products, if any, will be commercially viable or successfully produced and marketed.
The Company must rely largely on its own market research to forecast sales as detailed forecasts are not generally obtainable from other sources at this early stage of the medical and recreational cannabis industry in North America.
The Company is operating its business in a relatively new medical and recreational cannabis industry and market. Accordingly, there are no assurances that this industry and market will continue to exist or grow as currently estimated or anticipated, or function and evolve in a manner consistent with management’s expectations and assumptions. Any event or circumstance that affects the recreational or medical cannabis industry or market could have a material adverse effect on the Company’s business, financial condition and results of operations. Due to the early stage of the regulated cannabis industry, forecasts regarding the size of the industry and the sales of products by the Company’s investments are inherently difficult to prepare with a high degree of accuracy and reliability. A failure in the demand for products to materialize as a result of competition, technological change or other factors could have a material adverse effect on the business, results of operations and financial condition of the Company’s investments, and consequently, the Company.
Reliance on management.
The success of the Company is dependent upon the ability, expertise, judgment, discretion and good faith of its senior management. Qualified individuals are in high demand, and the Company may incur significant costs to attract and retain them. In addition, the Company’s lean management structure may be strained as the Company pursues growth opportunities in the future. The loss of the services of such individuals or an inability to attract other suitably qualified persons when needed, could have a material adverse effect on the Company’s ability to execute on its business plan and strategy, and the Company may be unable to find adequate replacements on a timely basis, or at all.
CordovaCann’s future success depends substantially on the continued services of its executive officers, consultants and advisors. If one or more of its executive officers or key personnel were unable or unwilling to continue in their present positions, the Company might not be able to replace them easily or at all. In addition, if any of its executive officers or key employees joins a competitor or forms a competing Company, the Company may lose know-how, key professionals and staff members. These executive officers and key employees could compete with and take customers away which could materially and adversely affect the Company’s prospects, financial performance and results of operations.
| 17 |
Operation permits and authorizations.
The Company’s investments may not be able to obtain or maintain the necessary licenses, permits, authorizations or accreditations, or may only be able to do so at great cost, to operate their respective businesses. In addition, the Company’s investments may not be able to comply fully with the wide variety of laws and regulations applicable to the cannabis industry. Failure to comply with or to obtain the necessary licenses, permits, authorizations or accreditations could result in restrictions on an investment’s ability to operate in the cannabis industry, which could have a material adverse effect on the Company’s business.
Litigation.
CordovaCann may become party to litigation from time to time in the ordinary course of business which could adversely affect its business. Should any litigation in which the Company becomes involved be determined against the Company, such a decision could adversely affect the Company’s ability to continue operating and the market price for the Common Shares and could use significant resources. Even if the Company is involved in litigation and wins, litigation can redirect significant resources. Litigation may also create a negative perception of the Company.
Liability, enforcement complaints, etc.
CordovaCann’s participation in the cannabis industry may lead to litigation, formal or informal complaints, enforcement actions, and inquiries by various federal, state, or local governmental authorities into or against the Company or its investments. Litigation, complaints, and enforcement actions involving either of the Company or its investments could consume considerable amounts of financial and other corporate resources, which could have an adverse effect on the Company’s future cash flows, earnings, results of operations and financial condition.
Product liability.
Certain of the Company’s investments manufacture, process and/or distribute products designed to be ingested by humans, and therefore face an inherent risk of exposure to product liability claims, regulatory action and litigation if products are alleged to have caused significant loss or injury. In addition, previously unknown adverse reactions resulting from human consumption of cannabis alone or in combination with other medications or substances could occur. A product liability claim or regulatory action against an investment entity of CordovaCann could result in increased costs, could adversely affect the Company’s reputation, and could have a material adverse effect on the results of operations and financial condition of the Company.
Reliance on key inputs.
The cultivation, extraction and processing of cannabis and derivative products is dependent on a number of key inputs and their related costs including raw materials, electricity, water and other local utilities. Any significant interruption or negative change in the availability or economics of the supply chain for key inputs could materially impact the business, financial condition and operating results of the Company’s investments. Some of these inputs may only be available from a single supplier or a limited group of suppliers. If a sole source supplier was to go out of business, the relevant investment entity might be unable to find a replacement for such source in a timely manner or at all. Any inability to secure required supplies and services or to do so on appropriate terms could have a materially adverse impact on the business, financial condition and operating results of an investment, and consequently, the Company.
| 18 |
Price volatility of publicly traded securities.
In recent years, the securities markets in the United States and Canada have experienced a high level of price and volume volatility, and the market prices of securities of many companies have experienced wide fluctuations in price which have not necessarily been related to the operating performance, underlying asset values or prospects of such companies. There can be no assurance that continuing fluctuations in price will not occur. It may be anticipated that any quoted market for the Common Shares of CordovaCann will be subject to market trends generally, notwithstanding any potential success of CordovaCann in creating revenues, cash flows or earnings. The value of the Common Shares would be affected by such volatility. An active public market for the Company’s Common Shares might not develop or be sustained. If an active public market for the Company’s Common Shares does not develop, the liquidity of a shareholder’s investment may be limited and the share price may decline.
Management of growth.
CordovaCann may experience a period of significant growth in the number of personnel that may place a strain upon its management systems and resources. Its future will depend in part on the ability of its officers and other key personnel to implement and improve financial and management controls, reporting systems and procedures on a timely basis and to expand, train, motivate and manage the workforce. CordovaCann’s current and planned personnel, systems, procedures and controls may be inadequate to support its future operations.
Dividends.
CordovaCann has not paid dividends in the past and the Company does not anticipate paying any dividends in the foreseeable future. Dividends paid by the Company would be subject to tax and, potentially, withholdings.
Any decision to declare and pay dividends in the future will be made at the discretion of the Company’s Board of Directors and will depend on, among other things, financial results, cash requirements, contractual restrictions and other factors that the Company’s Board of Directors may deem relevant. As a result, investors may not receive any return on an investment in the Common Shares unless they sell their Common Shares for a price greater than that which such investors paid for them.
Risk factors related to dilution.
The Company may issue additional securities in the future, which may dilute a shareholder’s holdings in the Company. The Company’s articles permit the issuance of an unlimited number of Common Shares. The directors of the Company have discretion to determine the price and the terms of further issuances. Moreover, additional Common Shares will be issued by the Company on the exercise of options under the Company’s Option Plan and upon the exercise of outstanding warrants.
Intellectual property and proprietary protection.
The success of the Company will depend, in part, on the ability of the Company and the Company’s investments to maintain, enhance and protect its intellectual property, including various existing and potential proprietary techniques and processes. The Company and the Company’s investments may be vulnerable to competitors who develop competing technology, whether independently or as a result of acquiring access to the proprietary products and trade secrets of the Company or the Company’s investments. In addition, effective future patent, copyright and trade secret protection may be unavailable or limited in certain foreign countries and may be unenforceable under the laws of certain jurisdictions.
The Company relies on a combination of laws and contractual provisions to establish and protect its rights in it intellectual property. There can be no assurance that the steps taken to protect proprietary rights will be adequate to deter misappropriation of intellectual property or technology. The Company may face claims alleging infringement of intellectual property rights held by others. Such claims, whether or not meritorious, may result in the expenditure of significant financial and managerial resources, legal fees, result in injunctions, temporary restraining orders and/or require the payment of damages. An adverse determination in legal proceedings, a costly litigation process or a costly settlement could have a material adverse effect on the Company’s business, prospects, revenues, operating results and financial condition.
| 19 |
Insurance coverage.
CordovaCann currently does not have insurance coverage. The Company is likely to require insurance coverage in the future. There can be no assurance that adequate insurance coverage will be available to the Company in the future, or that if available, that such insurance will be obtainable by the Company at a commercially justifiable premium. There also can be no assurance that any insurance coverage obtained by the Company will be sufficient to cover claims to which the Company may become subject. If insurance coverage is unavailable to cover any such claims, the Company’s financial resources, results of operations and prospects could be adversely affected. If the Company were to incur substantial liability and such damages were in excess of policy limits, there could be a material adverse effect on the Company’s business, financial condition and results of operations.
Operational risks.
CordovaCann and its investments may be affected by a number of operational risks and may not be adequately insured for certain risks, including: labour disputes; catastrophic accidents; fires; blockades or other acts of social activism; changes in the regulatory environment; impact of non-compliance with laws and regulations; natural phenomena, such as inclement weather conditions, floods, earthquakes and ground movements. There is no assurance that the foregoing risks and hazards will not result in damage to, or destruction of, the Company’s investments’ properties, grow facilities and extraction facilities, personal injury or death, environmental damage, adverse impacts on the Company’s investments’ operations, costs, monetary losses, potential legal liability and adverse governmental action, any of which could have an adverse impact on the Company’s future cash flows, earnings and financial condition on the Company. Also, the Company’s investments may be subject to or affected by liability or sustain loss for certain risks and hazards against which they may elect not to insure because of the cost. This lack of insurance coverage could have an adverse impact on the Company’s future cash flows, earnings, results of operations and financial condition.
Costs of maintaining a public listing.
As a public company, there are costs associated with legal, accounting and other expenses related to regulatory compliance. Securities legislation and the rules and policies of securities exchanges require listed companies to, among other things, adopt corporate governance and related practices, and to continuously prepare and disclose material information, all of which add to a company’s legal and financial compliance costs. CordovaCann may also elect to devote greater resources than it otherwise would have on communication and other activities typically considered important by publicly traded companies.
Holding Company.
CordovaCann is a holding Company and essentially all of its assets are the capital stock of its material subsidiaries. As a result, investors in CordovaCann are subject to the risks attributable to its subsidiaries. Consequently, CordovaCann’s cash flows and ability to complete current or desirable future enhancement opportunities are dependent on the earnings of its subsidiaries and investments and the distribution of those earnings to CordovaCann. The ability of these entities to pay dividends and other distributions will depend on their operating results and will be subject to applicable laws and regulations which require that solvency and capital standards be maintained by such companies and contractual restrictions contained in the instruments governing any debt arrangements. In the event of a bankruptcy, liquidation or reorganization of any of CordovaCann’s material subsidiaries, holders of indebtedness and trade creditors may be entitled to payment of their claims from the assets of those subsidiaries before CordovaCann.
| 20 |
Difficulty implementing business strategy.
The growth and expansion of the Company is heavily dependent upon the successful implementation of its business strategy. There can be no assurance that the Company will be successful in the implementation of its business strategy.
Conflicts of interest.
Certain of the Company’s directors and officers are, and may continue to be, involved in other business ventures through their direct and indirect participation in, among other things, corporations, partnerships and joint ventures, that may become potential competitors of the technologies, products and services the Company intends to provide. Situations may arise in connection with potential acquisitions or opportunities where the other interests of these directors and officers conflict with or diverge from the Company’s interests. In accordance with applicable corporate law, directors who have a material interest in or who are parties to a material contract or a proposed material contract with the Company are required, subject to certain exceptions, to disclose that interest and generally abstain from voting on any resolution to approve the transaction. In addition, the directors and officers are required to act honestly and in good faith with a view to the Company’s best interests. However, in conflict of interest situations, the Company’s directors and officers may owe the same duty to another Company and will need to balance their competing interests with their duties to the Company. Circumstances (including with respect to future corporate opportunities) may arise that may be resolved in a manner that is unfavourable to the Company.
Previous operations.
The Company recently changed its focus from the identification and evaluation of assets for purchase in the media, technology and consumer industries, to a provider of services and investment capital to companies in the cannabis sector. The Company also changed its name on January 3, 2018 from “LiveReel Media Corporation” to “CordovaCann Corp.”. While the Company has now divested all of its assets relating to its previous business, there is no guarantee that liabilities relating to the previous business will not negatively impact the Company’s current or future operations or financial performance. Management is not aware of any liabilities relating to its previous business operations.
Resale of Common Shares.
Although the Common Shares are listed on the CSE and the OTCQB, there can be no assurance that an active and liquid market for the Common Shares will develop or be maintained and an investor may find it difficult to resell any securities of the Company. In addition, there can be no assurance that the publicly-traded stock price of the Company will be high enough to create a positive return for investors. Further, there can be no assurance that the Common Shares will be sufficiently liquid so as to permit investors to sell their position in the Company without adversely affecting the stock price. In such event, the probability of resale of the Common Shares would be diminished.
Forward Looking Statements
Certain statements contained in this report are forward-looking statements. All statements, other than statements of historical facts, included herein or incorporated by reference herein, including without limitation, statements regarding the Company’s business strategy, plans and objectives of management for future operations and those statements preceded by, followed by or that otherwise include the words “believe”, “expects”, “anticipates”, “intends”, “estimates” or similar expressions or variations on such expressions are forward-looking statements. We can give no assurances that such forward-looking statements will prove to be correct.
| 21 |
Each forward-looking statement reflects the Company’s current view of future events and is subject to risks, uncertainties and other factors that could cause actual results to differ materially from any results expressed or implied by the Company’s forward-looking statements.
Risks and uncertainties include, but are not limited to:
|
| · | lack of substantial operating history; |
|
| · | the impact of competition; and |
|
| · | the enforceability of legal rights. |
Important factors that could cause the actual results to differ from materially from the Company’s expectations are disclosed in more detail set forth under the heading “Risk Factors” above. The Company’s forward-looking statements are expressly qualified in their entirety by this cautionary statement.
Business Plan and Strategy
CordovaCann is committed to assembling a premier cannabis business with a vision to becoming a global industry leader. The Company is focused on working with leading cannabis production, processing and retail operators in key jurisdictions that will enable CordovaCann to serve national and international markets that have legal, regulated medical, and/or recreational cannabis industries. The Company intends to leverage its production, processing and retail operations to establish a global multi-jurisdictional platform that provides consistent formulations of best-of-breed brands delivering predictable consumer experiences.
CordovaCann has entered into strategic relationships and investments with cannabis operators in Canada and the United States. The Company will provide a variety of resources and services to these respective operators including, but not limited to: capital commitments, strategic positioning, brand development, best operating practices, access to intellectual property, administrative assistance, and general business consulting. Over the next twelve months, CordovaCann is focused on growing its retail operations in both Canada and the United States, as well as expanding the throughput of its Oregon and Washington operations. Moving forward, the Company will also seek partnerships with cannabis operators in key legal markets not currently served by CordovaCann, as well as seek to expand operations in those markets where the Company already has a presence. CordovaCann plans to develop various end products for distribution in each of its current markets as well as to service other brands and intellectual property owners with its growing processing and manufacturing platforms with a view to allowing these clients and prospective clients to gain access to our distribution channels to generate additional revenue for the Company. The platform that the Company is building will seek to ensure that the end products are consistent across all jurisdictions by maintaining strict and professional standard operating procedures covering everything from formulation, packaging, branding, marketing and sales to deliver a superior end user experience.
CordovaCann’s long-term focus is to continue expanding its reach into additional legal markets, and the Company expects to organically build and forge strategic relationships with cannabis producers, processors and retailers globally. The Company will likely develop and acquire additional operations and products to further penetrate its current markets and move into new markets, and will leverage these additions to broaden its channels for distribution. Additionally, CordovaCann may invest in additional parts of the cannabis value chain in markets where such assets are legal and provide a competitive advantage and significant operating leverage for the Company.
| 22 |
Results of Operations
|
|
| Three Months Ended |
|
| Three Months Ended |
|
| Six Months Ended |
|
| Six Months Ended |
| ||||
|
|
|
| December31,2021 |
|
|
| December 31,2020 |
|
|
| December 31,2021 |
|
|
| December 31,2020 |
|
|
|
|
| $ |
|
|
| $ |
|
|
| $ |
|
|
| $ |
|
| Revenue |
|
| 3,486,983 |
|
|
| 2,441,857 |
|
|
| 7,261,696 |
|
|
| 4,278,669 |
|
| Cost of sales |
|
| 2,555,237 |
|
|
| 1,595,132 |
|
|
| 5,244,460 |
|
|
| 2,777,271 |
|
| Expenses |
|
| 1,412,866 |
|
|
| 1,089,113 |
|
|
| 3,032,251 |
|
|
| 2,004,314 |
|
| Other expense |
|
| 152,162 |
|
|
| 234,531 |
|
|
| 220,564 |
|
|
| 593,661 |
|
| Net loss for the period |
|
| (637,702 | ) |
|
| (475,516 | ) |
|
| (1,285,759 | ) |
|
| (1,093,242 | ) |
| Net loss per share |
|
| (0.01 | ) |
|
| (0.01 | ) |
|
| (0.01 | ) |
|
| (0.01 | ) |
Revenue
For the three and six months ended December 31, 2021, the Company's revenue amounted to $3,486,983 and $7,261,696, respectively, as compared to $2,441,857 and $4,278,669, respectively for the three and six months ended December 31, 2020. The significant increase in revenue relates to the expansion in retail operations of the Company during the past twelve months in the provinces of Ontario, Manitoba and Alberta. Further, investments in Washington and Oregon operations have also contributed to the revenue during the six months ended December 31, 2021.
Cost of Sales and Gross Margin
For the three and six months ended December 31, 2021, the Company incurred $2,555,237 and $5,244,460, respectively, as compared to $1,595,132 and $2,777,271, for the three and six months ended December 31, 2020 of cost of sales and gross margin of $931,746 and $2,017,236, respectively (December 31, 2020 - $846,725 and $1,501,398, respectively), primarily related to its retail operations. The increase in cost of sales directly relates to the increased revenue from the retail operations and the Company’s operations in Oregon and Washington.
Expenses
The Company incurred the following operating expenses over the three and six months ended December 31, 2021, and 2020:
|
|
| Three Months Ended December 31, 2021 |
|
| Three Months Ended December 31, 2020 |
|
| Six Months Ended December 31, 2021 |
|
| Six Months Ended December 31, 2020 |
| ||||
|
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||
| Consulting fees |
|
| 168,447 |
|
|
| 169,418 |
|
|
| 389,912 |
|
|
| 323,434 |
|
| Share based compensation |
|
| - |
|
|
| 60,528 |
|
|
| 1,920 |
|
|
| 178,126 |
|
| Professional fees |
|
| 22,087 |
|
|
| 116,012 |
|
|
| 49,642 |
|
|
| 188,608 |
|
| Shareholders information services |
|
| 52,896 |
|
|
| 42,871 |
|
|
| 108,739 |
|
|
| 79,242 |
|
| Salaries and wages |
|
| 512,519 |
|
|
| 238,361 |
|
|
| 993,542 |
|
|
| 427,741 |
|
| Office and general |
|
| 222,910 |
|
|
| 198,515 |
|
|
| 507,745 |
|
|
| 344,539 |
|
| Depreciation |
|
| 58,534 |
|
|
| 25,463 |
|
|
| 146,073 |
|
|
| 38,102 |
|
| Amortization of right-of-use assets |
|
| 199,800 |
|
|
| 101,159 |
|
|
| 382,952 |
|
|
| 188,904 |
|
| Amortization of licenses |
|
| 55,145 |
|
|
| 27,145 |
|
|
| 110,290 |
|
|
| 54,291 |
|
| Leases and utilities |
|
| 120,528 |
|
|
| 109,641 |
|
|
| 341,436 |
|
|
| 181,327 |
|
|
|
|
| 1,412,866 |
|
|
| 1,089,113 |
|
|
| 3,032,251 |
|
|
| 2,004,314 |
|
| 23 |
The overall analysis of the key expenses above is as follows:
Consulting Fees
Consulting fees for the three and six months ended December 31, 2021 amounted to $168,447 and $389,912, respectively, as compared to $169,418 and $323,434, respectively for the three and six months ended December 31, 2020. Consulting fees related to fees accrued for the officers of the Company and other consultants that support the Company and have remained consistent over the comparable periods.
Share Based Compensation
Share based compensation for the three and six months ended December 31, 2021 amounted to $nil and $1,920, respectively, as compared to $60,528 and $178,126, respectively for the three and six months ended December 31, 2020. The share-based compensation expense for the three and six months ended December 31, 2021 and 2020 was in relation to the graded vesting of warrants that were issued previously.
Professional Fees
Professional fees for the three and six months ended December 31, 2021 amounted to $22,087 and $49,642, respectively, as compared to $116,012 and $188,608, respectively for the three and six months ended December 31, 2020. Professional fees for the three and six months ended December 31, 2021 and 2020 were comprised of legal and audit fees and the higher amounts in 2020 reflect the increased acquisition activity during that period. The additional legal fees incurred during the six months ended December 31, 2020 related to costs associated with financings and transaction costs associated with the acquisition of the additional non-controlling interest in 2734158 Ontario Inc., as mentioned above.
Shareholder Information Services
Shareholders information services for the three and six months ended December 31, 2021 amounted to $52,896 and $108,739, respectively, as compared to $42,871 and $79,242, respectively for the three and six months ended December 31, 2020. Shareholder information services for the three and six months ended December 31, 2021, and 2020 were comprised of director fees, transfer agent fees, other filing fees and investor relation services.
Salaries and wages
Salaries and wages for the three and six months ended December 31, 2021 amounted to $512,519 and $993,542, respectively, as compared to $238,361 and $427,741, respectively for the three and six months ended December 31, 2020. The salaries and wages expenses are related to the employees hired for the Company’s retail cannabis operations and the increase in the expense is due to additional retail locations operating for the six months ended December 31, 2021 in contrast to the comparative period.
Office and General
Office and general for the three and six months ended December 31, 2021 amounted to $222,910 and $507,745, respectively, as compared to $198,515 and $344,539, respectively for the three and six months ended December 31, 2020. Office and general costs were primarily comprised of administrative, travel and other expenses incurred by the Company and its employees and consultants. The increase in office and general costs during the six months ended December 31, 2021 was primarily a result of increased activity related to the retail cannabis stores and associated administrative expenses for those locations.
Depreciation
Depreciation for the three and six months ended December 31, 2021 amounted to $58,534 and $146,073, respectively, as compared to $25,463 and $38,102, respectively for the three and six months ended December 31, 2020. Depreciation relates to the depreciation of tangible assets purchased for the Company’s retail cannabis stores. The increase in depreciation is as a result of an increase in the cost base of the Company’s tangible assets.
| 24 |
Amortization of right-of-use assets
Amortization of right-of-use assets for the three and six months ended December 31, 2021 amounted to $199,800 and $382,952, respectively, as compared to $101,159 and $188,904, respectively for the three and six months ended December 31, 2020. Amortization relates to the Company’s retail leases entered into as part of the Star Buds acquisition, the Ontario leases, the Manitoba leases, and the Oregon lease as a result of the sales-lease back transaction during the three and six months ended December 31, 2021. The increase in amortization during the comparative period is a result of the additional retail leases entered into subsequent to December 31, 2020.
Amortization of licenses
Amortization of licenses for the three and six months ended December 31, 2021 amounted to $55,145 and $110,290, respectively, as compared to $27,145 and $54,291, respectively for the three and six months ended December 31, 2020. Amortization of licenses relates to the retail cannabis license acquired as part of the acquisition of 2734158 Ontario Inc. during the year ended June 30, 2020 and the retail cannabis license acquired as part of the acquisition of 10062771 Manitoba Ltd. during the year ended June 30, 2021.
Leases and utilities
Leases and utilities for the three and six months ended December 31, 2021 amounted to $120,528 and $341,436, respectively, as compared to $109,641 and $181,327, respectively for the three and six months ended December 31, 2020. Lease and utilities expenses relate to the leases entered into through the Company’s retail platforms as well as the sale-leaseback transaction for its Oregon Property.
Other Income
The overall analysis of other income is as follows:
|
|
| Three Months Ended December 31, 2021 |
|
| Three Months Ended December 31, 2020 |
|
| Six Months Ended December 31, 2021 |
|
| Six Months Ended December 31, 2020 |
| ||||
|
|
| $ |
|
| $ |
|
| $ |
|
| $ |
| ||||
| Interest expenses |
|
| 32,138 |
|
|
| 178,874 |
|
|
| 74,024 |
|
|
| 363,493 |
|
| Interest on lease liability |
|
| 140,528 |
|
|
| 50,563 |
|
|
| 260,446 |
|
|
| 95,601 |
|
| Accretion expense |
|
| 9,270 |
|
|
| 20,843 |
|
|
| 35,782 |
|
|
| 91,758 |
|
| Foreign exchange (gain) loss |
|
| 12,839 |
|
|
| 19,335 |
|
|
| (74,538 | ) |
|
| 77,893 |
|
| Other income |
|
| (42,613 | ) |
|
| (35,084 | ) |
|
| (75,150 | ) |
|
| (35,084 | ) |
|
|
|
| 152,162 |
|
|
| 234,531 |
|
|
| 220,564 |
|
|
| 593,661 |
|
Interest expense
Interest expenses for the three and six months ended December 31, 2021 amounted to $32,138 and $74,024, respectively, as compared to $178,874 and $363,493, respectively for the three and six months ended December 31, 2020. The interest expense during the three and six months ended December 31, 2021 and 2020 was primarily in relation to convertible debentures, promissory notes and mortgages issued. The reduction in interest during three and six months ended December 31, 2021 is primary due to the repayment of the mortgage related to the Oregon Property and general reduction of promissory notes and convertible debentures through repayments and settlements over the past twelve months.
Interest on lease liability
Interest on lease liability for the three and six months ended December 31, 2021 amounted to $140,528 and $260,446, respectively, as compared to $50,563 and $95,601, respectively for the three and six months ended December 31, 2020. Interest on lease liability relates to the Company’s retail leases entered into as part of the Star Buds acquisition, the Ontario leases, the Manitoba leases, and the Oregon lease as a result of the sales-lease back transaction during the six months ended December 31, 2021. The increase in interest on lease liability during the comparative period is a result of the additional retail leases entered into subsequent to December 31, 2020.
| 25 |
Accretion expense
Accretion expense for the three and six months ended December 31, 2021 amounted to $9,270 and $35,782, respectively, as compared to $20,843 and $91,758, respectively for the three and six months ended December 31, 2020. Accretion expense primarily relates to a discount on convertible debentures and promissory notes issued in relation to the Star Buds transaction as noted above. The decrease in accretion expense is due to the maturity of certain convertible debentures and promissory notes.
Foreign exchange (gain) loss
Foreign exchange (gain) loss for the three and six months ended December 31, 2021 amounted to $12,839 and ($74,538), respectively, as compared to $19,335 and $77,893, respectively for the three and six months ended December 31, 2020. The foreign exchange gains and losses during the three and six months ended December 31, 2021, and 2020 were a result of the exchange rate fluctuations related to transactions based in United States Dollars.
Other income
Other income for the three and six months ended December 31, 2021 amounted to $42,613 and $75,150, respectively, as compared to $35,084 and $35,084, respectively for the three and six months ended December 31, 2020. Other income is related to rental of the Company’s Washington property as well sale of data related to its retail operations.
Liquidity and Capital Resources
Working Capital
As at December 31, 2021, the Company had total assets of $17,595,046 (June 30, 2021 - $17,274,041) consisting of the following:
|
|
| December 31, 2021 $ |
|
| June 30, 2021 $ |
| ||
| ASSETS |
|
|
|
|
|
| ||
| Current |
|
|
|
|
|
| ||
| Cash and cash equivalents |
|
| 950,631 |
|
|
| 1,058,494 |
|
| Restricted cash |
|
| 1,016,966 |
|
|
| - |
|
| Accounts receivable |
|
| 60,765 |
|
|
| 7,924 |
|
| Prepaid expenses and deposits |
|
| 370,865 |
|
|
| 332,771 |
|
| Inventory |
|
| 514,151 |
|
|
| 504,521 |
|
| Biological assets |
|
| 24,019 |
|
|
| 26,611 |
|
| Other deposit - current portion |
|
| 211,727 |
|
|
| 199,463 |
|
| Total current assets |
|
| 3,149,124 |
|
|
| 2,129,784 |
|
| Other deposit |
|
| - |
|
|
| 101,351 |
|
| Right-of-use assets |
|
| 5,003,780 |
|
|
| 3,169,655 |
|
| Property and equipment, net |
|
| 3,738,803 |
|
|
| 6,059,622 |
|
| Intangible assets |
|
| 5,243,967 |
|
|
| 5,243,967 |
|
| Licenses |
|
| 459,372 |
|
|
| 569,662 |
|
| Total assets |
|
| 17,595,046 |
|
|
| 17,274,041 |
|
The increase in assets from June 30, 2021 to December 31, 2021 was primarily the result of the increase in restricted cash, inventory and right-of-use assets during the six months ended December 31, 2021. The restricted cash relates to funds escrowed for completion of construction of the Oregon facilities as well as the security deposits related to the sale-leaseback transaction. The increase in right-of-use assets is due to additional retail locations operating during the six months ended December 31, 2021 as well as the asset related to the Oregon lease.
| 26 |
As at December 31, 2021, the Company had total liabilities of $11,112,089 (June 30, 2021 - $9,955,668) consisting of the following:
|
|
| December 31, 2021 $ |
|
| June 30, 2021 $ |
| ||
| LIABILITIES |
|
|
|
|
|
| ||
| Current |
|
|
|
|
|
| ||
| Accounts payable and accrued liabilities |
|
| 3,309,534 |
|
|
| 3,326,171 |
|
| Harmonized sales tax payable |
|
| 48,054 |
|
|
| 98,916 |
|
| Mortgage payable |
|
| 828,844 |
|
|
| 1,566,067 |
|
| Consideration payable |
|
| - |
|
|
| 39,292 |
|
| Income taxes payable |
|
| 286,180 |
|
|
| 315,362 |
|
| Contract liability |
|
| 49,656 |
|
|
| 48,832 |
|
| Lease liability |
|
| 576,024 |
|
|
| 438,856 |
|
| Promissory notes payable |
|
| 1,024,740 |
|
|
| 1,017,772 |
|
| Total current liabilities |
|
| 6,123,032 |
|
|
| 6,851,268 |
|
| Deferred tax liability |
|
| 36,540 |
|
|
| 36,540 |
|
| Contract liability |
|
| 157,539 |
|
|
| 178,071 |
|
| Lease liability |
|
| 4,794,978 |
|
|
| 2,889,789 |
|
| Total liabilities |
|
| 11,112,089 |
|
|
| 9,955,668 |
|
The increase in liabilities from June 30, 2021 to December 31, 2021 was primarily related to the increase in the lease liability as a result of the sale-leaseback transaction of the Oregon Property partially offset by the repayments of mortgage payable and promissory notes payable. During the six months ended December 31, 2021, the Company used proceeds from its sale-leaseback to repay for the associated liabilities on the Oregon Property.
As at December 31, 2021, the Company had a working capital deficiency of $2,973,908 as compared to a working capital deficiency of $4,721,484 as at June 30, 2021. The Company’s ability to continue as a going concern is dependent upon its ability to access sufficient capital until it has profitable operations and raises a material concern. To this point, all cashflow shortfall from operational activities and overhead costs have been funded through equity issuances, debt issuances and related party advances.
Cash Used In Operating Activities
The Company was provided cash in operating activities in the amount of $443,597 (December 31, 2020 – $287,227 cash used in operating activities) for the six months ended December 31, 2021 due to the reasons discussed above.
Cash Provided by (used in) Investing Activities
The Company received proceeds from investing activities in the amount of $2,325,305 (December 31, 2020 – used cash in the amount of $465,932) for the six months ended December 31, 2021. The investing activities during the six months ended December 31, 2021 were primarily related the sale-leaseback transaction on the Oregon Property and additions to property and equipment for the Company’s retail stores.
Cash Provided By (used in) From Financing Activities
The Company used cash in financing activities in the amount $947,390 (December 31, 2020 – received proceeds of $811,681) during the six months ended December 31, 2021. The financing activities during the six months ended December 31, 2021 related to the repayment of the Oregon Mortgage, other debt and lease liabilities. The financing activities proceeds during the six months ended December 31, 2020 were in relation to the proceeds received from a common share offering that closed on August 17, 2020, and share subscriptions received for a common share offering that closed on February 19, 2021.
| 27 |
Share Capital
The authorized share capital of the Company consists of an unlimited number of common shares.
During the six months ended December 31, 2021, the Company had the following common share transactions:
|
| · | On December 17, 2021 and in connection with the automatic conversion of shares relating to Convertible Debentures Series A-3, 5,354,400 common shares were issued. $923,590 was transferred from shares to be issued to share capital; |
|
| · | On August 19, 2021, the Company closed a non-brokered private placement financing, pursuant to which the Company issued 3,379,379 units at a price of $0.30 per unit for gross proceeds of $1,013,814; of which $661,530 was received in cash and $352,284 was issued in settlement of outstanding fees and debt, which included $97,500 which was outstanding to a director of the Company. These units were comprised of a common share and a share purchase warrant exercisable at $0.45 per share for a period of 24 months from the date of issuance; and |
|
| · | On August 1, 2021 and in connection with the exercise of stock-options by consultants, 200,000 common shares were issued at a price of $0.25 per share. |
During the year ended June 30, 2021, the Company had the following common share transactions:
|
| · | On February 26, 2021, the Company issued 3,000,000 common shares of the Company for the acquisition of Extraction Technologies, LLC (Note 15); |
|
| · | On February 19, 2021, the Company issued 6,177,721 common shares of the Company at a price of $0.32 per share for gross proceeds of $1,976,870; of which $1,380,400 was received in cash and $596,570 was issued in settlement of outstanding fees and debt; |
|
| · | On January 6, 2021, the Company issued 9,000,000 common shares of the Company at a price of $0.17 per share in relation to the asset acquisition of Star Buds for the opening of three cannabis retail stores under the Starbuds trade name; |
|
| · | On August 17, 2020, the Company issued 3,024,521 common shares of the Company at a price of $0.32 per share for gross proceeds of $967,846; of which $552,501 was received in cash and $415,345 was issued in settlement of outstanding fees and debt; and |
|
| · | On July 27, 2020, the Company issued 6,000,000 common shares of the Company at a price of $0.17 per share in relation to the asset acquisition of Starbuds for the opening of two cannabis retail stores under the Starbuds trade name. |
|
| · | On January 16, 2020, the Company issued 271,164 common shares of the Company at a price of $1.00 per share as a result of a partial conversion of the Debentures of Series A-1, as disclosed in Note 22. |
Shares to be issued
During the year ended June 30, 2021 and in connection with the automatic conversion of shares relating to Convertible Debentures Series A-3, 5,354,400 common shares were classified as shares to be issued. As at December 31, 2021, the value of shares to be issued amounted to $nil (June 30, 2021 – $923,590).
Contingently issuable shares
As at December 31, 2021 and June 30, 2021, there were 4,000,000 contingently issuable shares of the Company in relation to the Washington Acquisition
| 28 |
Warrants
|
|
| Warrants Outstanding |
|
| Weighted Average Exercise Price |
|
| Weighted Average Life Remaining (years) |
| |||
| June 30, 2020 |
|
| 10,249,500 |
|
|
| 0.53 |
|
|
| 2.00 |
|
| Issued |
|
| 6,790,000 |
|
|
| 0.35 |
|
|
| 1.97 |
|
| Expired |
|
| (1,450,000 | ) |
|
| 1.29 |
|
|
| 0.00 |
|
| June 30, 2021 |
|
| 15,589,500 |
|
| $ | 0.38 |
|
|
| 1.30 |
|
| Issued |
|
| 3,379,379 |
|
|
| 0.45 |
|
|
| 2.00 |
|
| Expired |
|
| (356,500 | ) |
|
| 1.20 |
|
|
| - |
|
| December 31, 2021 |
|
| 18,612,379 |
|
| $ | 0.38 |
|
|
| 0.97 |
|
During the six months ended December 31, 2021:
|
| · | The Company issued 3,379,379 common share purchase warrants in connection with a non-brokered private placement; |
|
| · | 356,500 common share purchase warrants expired, unexercised; and |
|
| · | No common share warrants were forfeited or cancelled. |
During the year ended June 30, 2021:
|
| · | the Company issued 6,790,000 common share purchase warrants in to employees and directors, for the amendment of promissory notes payable, and a convertible debenture financing; |
|
| · | 1,450,000 common share purchase warrants expired, unexercised; and |
|
| · | No common share warrants were forfeited or cancelled. |
The fair value of these issued warrants of was determined using the Black-Scholes Option Pricing Model with the following range of assumptions: tock price of $0.19-$0.35, risk-free rate of 0.26-0.32%, expected life of 1-3 years, estimated volatility in the market price of common shares of 87-89% and a dividend yield of nil.
During the three and six months ended December 31, 2021, the Company expensed $nil and $1,920, respectively (December 31, 2020 – $60,528 and $178,126), in the fair value of warrants as a result of the issuances which have been recorded as share based compensation.
Stock Options
|
|
| |||||||||||||||||
| Grant Date |
| Expiry Date |
| Options Outstanding |
|
| Options Exercisable |
|
| Exercise Price |
|
| Fair Value |
| ||||
| Feb. 25, 2020(iii) |
| Feb. 24, 2023 |
|
| 600,000 |
|
|
| 600,000 |
|
| $ | 0.25 |
|
| $ | 103,838 |
|
| Apr. 7, 2020(iv) |
| Apr. 6, 2023 |
|
| 3,000,000 |
|
|
| 3,000,000 |
|
| $ | 0.25 |
|
| $ | 369,426 |
|
| May 16, 2020(v) |
| May 5, 2023 |
|
| 1,500,000 |
|
|
| 1,500,000 |
|
| $ | 0.45 |
|
| $ | 396,036 |
|
| 29 |
The fair value of these issued stock options were determined using the Black-Scholes Option Pricing Model with the following range of assumptions:
| Stock price | $0.19-0.405 |
| Risk-free interest rate | 0.33-1.37 % |
| Expected life | 3 years |
| Estimated volatility in the market price of the common shares | 112-124 % |
| Dividend yield | nil |
During the six months ended December 31, 2021 and in connection with stock options previously issued to consultants, stock options were exercised for the purchase of 200,000 common shares of the Company at an exercise price of $0.25 per share for gross proceeds of $50,000. As a result of this exercise, contributed surplus in the amount of $25,959 was transferred to share capital.
There were no stock options issued during the six months ended December 31, 2021 and year ended June 30, 2021.
During the year ended June 30, 2021, 1,750,000 stock options expired unexercised.
During the three and six months ended December 31, 2021, the Company expensed $nil (December 31, 2020 - $nil) of the fair value of the stock options.
MORTGAGE PAYABLE
Oregon Mortgage
On June 16, 2019, the Company obtained financing through a mortgage (the “Mortgage”) in the amount of $696,117 (US $531,915) against a property that has title to 6 acres of real estate in Clackamas County, Oregon (the “Property”). The Mortgage was due in six months from the date of the agreement at an initial draw of $654,350 (US $500,000), implying interest at a rate of 12.77% per annum. The Mortgage after the date of default bears interest at 12% per annum, payable monthly, until the repayment of the outstanding amount. The Mortgage was secured by a first charge on the Property.
On June 12, 2020, the Company entered into a new mortgage (the “New Mortgage’), in the amount of $815,760 (US $600,000), and paid off the existing Mortgage and accrued interest of $724,894 (USD$531,914). The New Mortgage bears interest at 12%, is secured by a first charge on the Property and matures on December 15, 2020. The transaction cost of $52,045 was deducted from the initial carrying value of the mortgage payable and was recognized into profit and loss over the term of the mortgage payable.
On August 4, 2021, the Oregon Mortgage was fully paid off upon the closing of selling Oregon Property.
Oregon Mortgage as at December 31, 2021 amounted $nil (June 30, 2021 – $755,789). Total interest expense in relation to the Oregon Mortgage for the three and six months ended December 31, 2021 amounted to $nil and $7,517, respectively (December 31, 2020 – $67,216 and $117,011, respectively).
Washington Mortgage
On February 26, 2021, the Company completed the Washington Acquisition (Note 15) and assumed a mortgage payable in the amount of $829,305 (US $653,768) (the “Washington Mortgage”). The Washington Mortgage was entered into on September 28, 2020 by the vendors of the Washington Acquisition with an initial amount of $874,921 (US $654,000) and matures on October 1, 2022. The Washington Mortgage bears interest at 12.5%, payable monthly, and secured by a first charge on the property acquired as part of the Washington Acquisition.
As at December 31, 2021, the amount outstanding under the Washington Mortgage amounted to $828,844 (June 30, 2021 - $810,278).
| 30 |
PROMISSORY NOTES PAYABLE
Promissory Note A – February 1, 2019
On February 1, 2019, the Company issued an unsecured promissory note (the “Promissory Note A”) in the principal amount of $196,425 (US $150,000). The Promissory Note A matured on May 1, 2019 and bears interest at a rate of 10% per annum, accrued monthly and due at maturity. As at the date of these consolidated financial statements, the Promissory Note A is in default and remains outstanding. In connection with the Promissory Note A, the Company also issued warrants for the purchase of 150,000 common shares of the Company exercisable until January 31, 2020 at a price of $1.00 per share.
The Promissory Note A was determined to be a compound instrument, comprising a liability and warrants. The initial carrying amount of the financial liability was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no warrants. Using the residual method, the carrying amount of the warrants issued is the difference between the principal amount and the initial fair value of the financial liability. The fair value of the liability was determined to be $192,142 (US $146,729). The residual value of $4,283 (US $3,271) was allocated to warrants. The carrying value of the Promissory Note A, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note A, such that the carrying amount of the financial liability will equal the principal balance at maturity.
As at December 31, 2021, $46,391 was outstanding under Promissory Note A (June 30, 2021 – $44,732). Interest expense of $315 and $630, respectively, (December 31, 2020 - $1,629 and $4,959, respectively) was recorded for the three and six months ended December 31, 2021.
Promissory Note B – June 12, 2019
On June 12, 2019, the Company issued a secured promissory note (the “Promissory Note B”) in the principal amount of $261,740 (US $200,000). The Promissory Note B matured on June 30, 2020 and bears interest at a rate of 15% per annum, accrued monthly and due at maturity. The Promissory Note B was secured by a convertible preferred shares investment which was subsequently called. As at December 31, 2021 and June 30, 2021, the value of the Promissory Note B amounted to $nil.
Promissory Note C – June 19, 2019
On June 19, 2019, the Company issued secured promissory notes (the “Promissory Note C”) in the aggregate principal amount of $654,350 (US $500,000). The Promissory Note C matured on December 18, 2019 and bears interest at a rate of 15% per annum, accrued monthly and due at maturity. The Promissory Note C is secured by a general security interest over all the assets of Cordova OR Holdings, LLC, a wholly owned subsidiary of the Company and parent to OR Operations. In connection with the Promissory Note C, the Company issued warrants for the purchase of 200,000 common shares of the Company exercisable until June 18, 2021 at a price of $1.00 per share.
The Promissory Note C was determined to be a compound instrument, comprising of a liability and warrants. The initial carrying amount of the financial liability was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no warrants. Using the residual method, the carrying amount of the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $652,675 (US $489,152). The residual value of $14,367 (US $10,848) was allocated to warrants. The carrying value of the Promissory Note C, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
| 31 |
On December 16, 2019, the Company extended the maturity date of the Promissory Note C to March 19, 2020 (the “Extension”) in exchange for a one-time fee in the amount $13,142 (US $10,000), due at maturity and the issuance of additional warrants for the purchase of 200,000 common shares of the Company exercisable until June 18, 2021 at a price of $0.30 per share.
On the date of the Extension, the fair value of the liability was determined to be $696,151 (US $530,643). The residual value of $8,995 (US $6,857) was allocated to warrants. The carrying value of Promissory Note C, as a result of the Extension, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
On March 16, 2020, the Company extended the maturity date of the Promissory Note C to June 19, 2020 in exchange for a fee in the amount $13,142 (US $10,000), due at maturity. On June 15, 2020, the Company extended the maturity date of the Promissory Note C to December 19, 2020 in exchange for a fee in the amount $40,472 (US $29,750), due at maturity.
On December 15, 2020, the Company extended the maturity date of the Promissory Note C to December 15, 2021 (the “Second Extension”) in exchange for a one-time fee in the amount $54,113 (US $42,200), the issuance of “Warrants – #A” for the purchase of 200,000 common shares of the Company exercisable until December 31, 2022 at a price of $0.32 per share and the issuance of “Warrants - #B” for the purchase of 200,000 common shares of the Company exercisable until December 31, 2022 at a price of $0.50 per share.
On the date of the Second Extension, the fair value of the liability was determined to be $655,272 (US $515,070). The residual value of $15,823 (US $12,437) was allocated to warrants. The carrying value of Promissory Note C, as a result of the Extension, net of the warrant component, has been accreted using the effective interest rate method over the term of the Promissory Note C, such that the carrying amount of the financial liability will equal the principal balance at maturity.
The Company repaid Promissory Note C during the six months ended December 31, 2021.
As at December 31, 2021, the value of the Promissory Note C amounted to $nil (June 30, 2021 - $477,672). Interest expense of $nil and $15,687, respectively (December 31, 2020 - $39,990 and $83,372, respectively) was recorded for the three and six months ended December 31, 2021.
Promissory Note D – October 28, 2019
On October 28, 2019, the Company issued a promissory note (the “Promissory Note D”) in the principal amount of $391,680 (US $300,000). The Promissory Note D matured on June 30, 2020 and bears interest at a rate of 5% per annum, accrued monthly and due at maturity. Subsequent to the issuance, the Promissory Note D was extended until October 31, 2020 for a one-time fee of US $40,000. Interest on the Promissory Note D subsequent to the maturity date bears interest at 15% per annum.
On May 25, 2020, the Company issued 453,720 common shares of the Company at a price of $0.25 per share for $113,317 (US $78,150) of Promissory Note D. On August 17, 2020, the Company issued 125,507 common shares of the Company at a price of $0.32 per share for $40,162 (US $29,750) of Promissory Note. On February 19, 2021, the Company issued 1,085,062 common shares of the Company at a price of $0.32 per share for $347,220 (US $257,200) of Promissory Note D.
Interest expense of $nil (December 31, 2020 – $16,949 and $33,497, respectively) were recorded for the three and six months ended December 31, 2021.
| 32 |
Promissory Note E – April 8, 2020
On April 28, 2020, the Company issued a promissory note (the “Promissory Note E-1”) in the principal amount of $527,967 (Note 12 (iv)). The Promissory Note E-1 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $381,093 for the Promissory Note E-1 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
On May 8, 2020, the Company repaid $90,803 of the principal in cash and issued 181,250 of its common shares to settle $72,500 of the principal outstanding. On June 30, 2020 the Company repaid $20,000 of the principal.
On August 13, 2020 and August 17, 2020, the Company repaid a total of $15,000 of the principal in cash and issued 585,936 of its common shares to settle $187,500 of the principal. On March 5, 2021 and April 1, 2021, the Company repaid a total of $14,000 of the principal in cash.
During the six months ended December 31, 2021, the Company paid and settled $145,456 worth of principal and interest in respect to Promissory Note E-1.
As at December 31, 2021, the value of the Promissory Note E-1 amounted to $nil (June 30, 2021 - $124,008). Interest and accretion expense of $nil and $990, and $nil and $19,028, respectively, (December 31, 2020 - $2,150 and $5,998, and $3,248 and $58,462, respectively) were recorded for the three and six months ended December 31, 2021.
On June 8, 2020, the Company issued a promissory note (the “Promissory Note E-2”) in the principal amount of $225,000 (Note 12(v)). The Promissory Note E-2 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $160,603 for the Promissory Note E-2 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
During the three and six months ended December 31, 2021, the Company paid and settled $59,543 worth of principal in respect to Promissory Note E-2.
On June 8, 2020, the Company issued a promissory note (the “Promissory Note E-3”) in the principal amount of $196,832 (Note 12(v)). The Promissory Note E-3 matures on April 8, 2023 and bears interest at a rate of 6% per annum, calculated in arrears, compounded annually and payable at maturity. The fair value of $142,075 for the Promissory Note E-3 was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt.
As at December 31, 2021, the value of the Promissory Note E-3 amounted to $185,191 (June 30, 2021 - $172,347). Interest and accretion expense of $2,945 and $5,889, and $4,523 and $8,924, respectively (December 31, 2020 - $2,977 and $5,954, and $4,057 and $8,005, respectively) were recorded for the three and six months ended December 31, 2021.
Demand Notes – Six Months Ended December 31, 2021
During the six months ended December 31, 2021, the Company issued short-term promissory notes (the “Demand Notes”) to certain arm's-length parties. These Demand Notes are unsecured, mature 12 months from the date of issuance, bear interest at a rate of 20% per annum, calculated in arrears compounded annually and payable on maturity. The Company may elect to repay the Demand Notes earlier than maturity for an early repayment penalty of 15% of the principal inclusive of all interest accrued until the date of payment.
| 33 |
The aggregate amount of Demand Notes issued during the six months ended December 31, 2021 amounted to $757,290 (US $600,000).
On December 31, 2021, the Company repaid $126,780 (US $100,000) of the principal amount and $3,682 (US $2,904) of accrued interest. Further, due to the Company’s election for early repayment, fees in the amount of $15,335 (US $12,096) were charged and paid, which has been included in office and general expenses in the Company’s condensed interim consolidated statement of operations and comprehensive loss.
As at December 31, 2021, the principal amount of the Demand Notes amounted to $633,900 (US $500,000) and accrued interest on the Demand Notes amounted to $10,629 (US $8,384). Interest expense for the three and six months ended December 31, 2021 amounted to $14,226 (December 31, 2020 - $nil).
CONVERTIBLE DEBENTURES
a) Convertible Debentures Series A-1 – March 13, 2019
On March 13, 2019, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-1”) of the Company for gross proceeds of $600,000; of which $350,000 was received in cash and $250,000 was issued in settlement of outstanding fees with a fair value amounting to $237,300. The balance of $12,700 has been recorded as a loss on settlement of fees.
Each Debenture Unit of Series A-1 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-1”) and 500 common share purchase warrants (the “Warrants of Series A-1”) of the Company. The Debentures of Series A-1 mature on March 12, 2021 and bear interest at a rate of 10% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-1 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $1.00 per share. The Company also has the option to force conversion of the Debentures of Series A-1 and any accrued interest at the same conversion price if the Company’s common shares trade above $2.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Each full Warrant of Series A-1 entitles the holder to purchase one common share of the Company until March 12, 2021 at an exercise price of $1.20 per share. 300,000 Warrants of Series A-1 were issued related to the Debenture Units of Series A-1.
The Debenture Units of Series A-1 are determined to be a compound instrument, comprising a liability, a conversion feature and warrants. Both conversion feature and warrants met the fixed for fixed criteria and were therefore presented as equity instruments in accordance with IAS 32. The fair value of the debt component was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no conversion rights. Using the residual method, the carrying amount of the conversion feature and the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $508,439. The residual value of $91,561 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $62,498 and $29,063, respectively. The carrying value of the Debentures of Series A-1, net of the equity components, have been accreted using the effective interest rate method over the term of the debentures, such that the carrying amount of the financial liability will equal the principal balance at maturity.
The equity component from the initial recognition resulted taxable temporary difference. The Company recognized the deferred tax liabilities of 24,264, which was charged directly to the carrying amount of the two equity components. Subsequent changes in the deferred tax liability are recognized in profit and loss as deferred tax recovery.
| 34 |
On January 16, 2020, the Company issued 271,164 common shares at $1.00 per share as a result of a partial conversion of the outstanding Debentures of Series A-1 with a face value of principal $250,000 and accrued interest of $21,164. The debt in the amount of $271,164 and the equity in the amount of $21,979, were transferred to share capital upon conversion.
During the year ended June 30, 2021, the principal amount of $25,000 and accrued interest of $5,000 for a total of $30,000 was repaid on maturity. The remaining Debenture Units of Series A-1 were converted into the Convertible Debentures Series A-4 offering. The principal amount of $325,000, the accrued interest of $65,000, for total transfer of $390,000 were transferred to Convertible Debentures Series A-3.
a) Convertible Debentures Series A-2 – August 14, 2019
On August 14, 2019, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-2”) of the Company for gross proceeds of $713,000.
Each Debenture Unit of Series A-2 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-2”) and 500 common share purchase warrants (the “Warrants of Series A-2”) of the Company. The Debentures of Series A-2 mature on August 13, 2021 and bear interest at a rate of 10% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-2 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $1.00 per share. The Company also has the option to force conversion of the Debentures of Series A-2 and any accrued interest at the same conversion price if the Company’s common shares trade above $2.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Each full Warrant of Series A-2 entitles the holder to purchase one common share of the Company until August 13, 2021 at an exercise price of $1.20 per share. As a result, 356,500 Warrants of Series A-2 were issued related to the Debenture Units of Series A-2.
The Debenture Units of Series A-2 were determined to be a compound instrument, comprising a liability, a conversion feature and warrants. The fair value of debt component was determined by discounting the stream of future payments of interest and principal at a market interest rate of 19% which is estimated to be the borrowing rate available to the Company for similar instruments of debt having no conversion rights. Using the residual method, the carrying amount of the conversion feature and the warrants issued is the difference between the principal amount and the initial fair value of the financial liability.
The fair value of the liability was determined to be $604,195. The residual value of $108,805 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $74,989 and $33,816, respectively. The deferred tax liability of $28,833 was charged directly to the carrying amount of these two equity components. The carrying value of the Debentures of Series A-2, net of the equity components, have been accreted using the effective interest rate method over the term of the debentures, such that the carrying amount of the financial liability will equal the principal balance at maturity.
On April 22, 2020, the Debenture Units of Series A-2 were converted into the Convertible Debentures Series A-3 offering. The principal amount of $713,000, the accrued interest of 49,614 and loss of $1,614, for total transfer of $761,000 were transferred to Convertible Debentures Series A-3. The total amount of interest and accretion amounted to $49,614 and $33,454, respectively. The Company recorded deferred tax recovery of $28,833 for the year ended June 30, 2020.
b) Convertible Debentures Series A-3 – April 22, 2020
On April 22, 2020, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-3”) of the Company for gross proceeds of $1,164,000.
| 35 |
Each Debenture Unit of Series A-3 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-3”) and 2,000 common share purchase warrants (the “Warrants of Series A-3”) of the Company. The Debentures of Series A-3 mature on April 21, 2021 and bear interest at a rate of 15% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-3 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $0.25 per share. The Company also has the option to force conversion of the Debentures of Series A-3 and any accrued interest at the same conversion price if the Company’s common shares trade above $0.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Furthermore, the Debentures of Series A-3 and accrued interest shall automatically convert into common shares of the Company at maturity. Each full Warrant of Series A-3 entitles the holder to purchase one common share of the Company until April 21, 2022 at an exercise price of $0.30 per share. As a result, 2,328,000 Warrants of Series A-3 were issued related to the Debenture Units of Series A-3.
Prior to closing of the Offering, the Company exercised its rights of early repayment in respect of certain of the Convertible Debentures of Series A-2 of the Company issued on August 14, 2019 and, in connection with its election for early repayment, holders of the Convertible Debentures of Series A-2 directed the Company to retain the funds representing such repayment and to apply such funds towards satisfaction of the purchase price for the respective Debenture of Series A-3. The Company issued an aggregate of 761 Debenture Units to the subscribers of the Debentures of Series A-2.
The Debenture Units of Series A-3 were determined to be an equity instrument, comprising a conversion feature and warrants as a result of the Company being able to avoid a contractual obligation to pay cash related to the principal and interest at maturity. The subscription amount of $1,164,000 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $748,990 and $415,010, respectively. The interest expense related to the Debenture Units of Series A-3 are added to the equity portion of convertible debt as accrued.
On April 24, 2021, the Company elected to automatically convert the Debentures of Series A-3. Accordingly, these have been classified as shares to be issued.
During the three and six months ended December 31, 2021, interest of $nil was recorded in the equity portion of the convertible debt (June 30, 2021 - $142,490).
d) Convertible Debentures Series A-4 – March 12, 2021
On March 12, 2021, the Company closed a non-brokered private placement of unsecured subordinated convertible debenture units (the “Debenture Units of Series A-4”) of the Company for gross proceeds of $390,000.
Each Debenture Unit of Series A-4 consists of $1,000 principal amount of unsecured subordinated convertible debentures (the “Debentures of Series A-4”) and 1,000 common share purchase warrants (the “Warrants of Series A-4”) of the Company. The Debentures of Series A-4 mature on March 12, 2022 and bear interest at a rate of 15% per annum, accrued monthly and payable at maturity. The outstanding principal amount of the Debentures of Series A-3 and any accrued interest is convertible into common shares of the Company at the option of the holder at any time prior to the maturity date at a conversion price of $0.50 per share. The Company also has the option to force conversion of the Debentures of Series A-4 and any accrued interest at the same conversion price if the Company’s common shares trade above $0.50 per share for ten consecutive trading days on the Canadian Securities Exchange. Furthermore, the Debentures of Series A-4 and accrued interest shall automatically convert into common shares of the Company at maturity. Each full Warrant of Series A-4 entitles the holder to purchase one common share of the Company until March 12, 2023 at an exercise price of $0.75 per share.
Prior to closing of the Offering, the Company exercised its rights of early repayment in respect of certain of the Convertible Debentures of Series A-1 of the Company issued on March 13, 2019 and, in connection with its election for early repayment, holders of the Convertible Debentures of Series A-1 directed the Company to retain the funds representing such repayment and to apply such funds towards satisfaction of the purchase price for the respective Debenture of Series A-4. The Company issued an aggregate of 390 Debenture Units to the subscribers of the Debentures of Series A-1.
| 36 |
The Debenture Units of Series A-4 were determined to be an equity instrument, comprising a conversion feature and warrants as a result of the Company being able to avoid a contractual obligation to pay cash related to the principal and interest at maturity. The subscription amount of $390,000 was allocated to the equity portion of convertible debt and warrants based on their pro-rata fair values of $208,452 and $181,548, respectively. The interest expense related to the Debenture Units of Series A-4 are added to the equity portion of convertible debt as accrued.
During the three and six months ended December 31, 2021, interest of $14,625 and $29,250, respectively, was recorded in the equity portion of the convertible debt (June 30, 2021 - $16,512).
Key Contractual Obligations
There are no other key contractual obligations as at December 31, 2021 other than leases entered into through its retail operations disclosed in details in the accompanying financial statements.
On July 20, 2021, the Company entered into a lease agreement with the buyer of Oregon Property. The lease commenced on August 1, 2021 with the initial term of ten years and two subsequent ten-year renewal periods. There is no rent payable during the first three months of the Lease and subsequent payments amount to subsequent payments amount to $27,267 (US $22,000) per month for the reminder of the first year, with annual payment escalators thereafter.
Off Balance Sheet Arrangements
As at December 31, 2021, the Company did not have any off-Balance Sheet arrangements, including any relationships with unconsolidated entities or financial partnerships to enhance perceived liquidity.
Transactions with Related Parties
Related party transactions as at and for the three and six months ended December 31, 2021 and 2020, not disclosed elsewhere in these condensed interim consolidated financial statements are as follows:
|
| a) | During the three and six months ended December 31, 2021, the Company expensed $165,000 and $330,000, respectively (December 31, 2020 – $97,050 and $194,100, respectively), in fees payable to officers and directors of the Company and in fees payable to a corporation related by virtue of a common officer and director. As at December 31, 2021, the Company had fees payable to officers and directors of the Company of $1,742,234 (June 30, 2021 – $1,494,228). |
Financial and Derivative Instruments
The Company, through its financial assets and liabilities, is exposed to various risks. The Company has established policies and procedures to manage these risks, with the objective of minimizing any adverse effect that changes in these variables could have on these condensed interim consolidated financial statements. The following analysis provides a measurement of risks as at December 31, 2021:
Credit risk is the risk of financial loss to the Company if a customer or counterparty to a financial instrument fails to meet its contractual obligations. The Company is not exposed to any significant credit risk.
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they fall due within one year. The Company’s approach to managing liquidity risk is to ensure, as far as possible, that it will have sufficient liquidity to meet its liabilities when due, under both normal and stressed conditions, without incurring unacceptable losses or risking damage to the Company’s reputation. As at December 31, 2021, there is substantial doubt about the Company’s ability to continue as a going concern primarily due to its history of losses. Liquidity risk continues to be a key concern in the development of future operations.
| 37 |
Interest rate risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate because of changes in market interest rates. The interest rates on all of the Company’s existing debt are fixed, and therefore it is not currently subject to any significant cash flow interest rate risk.
The Company is exposed to foreign currency risk from fluctuations in foreign exchange rates and the degree of volatility in these rates due to the timing of their accounts payable balances. The risk is mitigated by timely payment of creditors and monitoring of foreign exchange fluctuations by management. As at December 31, 2021, the Company did not use derivative instruments to hedge its exposure to foreign currency risk.
The Company’s operations do not involve the direct input or output of any commodities and therefore it is not subject to any significant commodity price risk. In addition, the Company does not have any equity investment in other listed public companies, and therefore it is not subject to any significant stock market price risk.
Critical Accounting Policies
These consolidated financial statements of the Company and its subsidiaries were prepared using accounting policies consistent with International Financial Reporting Standards (“IFRS”) as issued by the International Accounting Standards Board (“IASB”) and interpretations of the IFRS Interpretations Committee (“IFRIC”).
The significant accounting policies used in the preparation of these condensed interim consolidated financial statements are described below.
Basis of Presentation
These consolidated financial statements have been prepared on a historical cost basis, except where otherwise disclosed. Historical cost is based on the fair value of the consideration given in exchange for assets. In addition, these consolidated financial statements have been prepared using the accrual basis of accounting, except for cash flow information.
Functional and Presentation Currency
These consolidated financial statements are presented in Canadian dollars, which is the Company’s presentation currency.
Translation of foreign-currency transactions
Transactions in foreign currencies are translated to the respective functional currencies of each subsidiary at exchange rates at the dates of the transactions. Monetary assets and liabilities denominated in foreign currencies at the reporting date are translated to the functional currency at the exchange rate at that date. The foreign currency gain or loss resulting from the settlement of such transactions and from the translation at the reporting date of monetary assets and liabilities denominated in foreign currencies are recognized in profit or loss.
Translation of financial statements of subsidiaries
In translating the financial statements of the Company's foreign subsidiaries from their functional currencies into the Company's presentation currency of Canadian dollars, statement of financial position accounts are translated using the closing exchange rate in effect at the statement of financial position date and income and expense accounts are translated using an average exchange rate prevailing during the reporting period. Adjustments resulting from the translation, if any, are included in accumulated other comprehensive income (loss) in shareholders' equity (deficiency).
| 38 |
Use of Estimates and Judgements
The preparation of these consolidated financial statements in accordance with IFRS requires management to make judgements, estimates and assumptions that affect the application of accounting policies and reported amounts of assets and liabilities at the date of the consolidated financial statements and reported amounts of expenses during the reporting period. Actual outcomes could differ from these estimates. These consolidated financial statements include estimates, which, by their nature, are uncertain. The impacts of such estimates are pervasive throughout these consolidated financial statements, and may require accounting adjustments based on future occurrences. The estimates and underlying assumptions are reviewed on a regular basis. Revisions to accounting estimates are recognized in the period in which the estimate is revised and in any future periods affected. The key assumptions concerning the future, and other key sources of estimation uncertainty as of the date of the statement of financial position that have a significant risk of causing material adjustment to the carrying amounts of assets and liabilities within the next fiscal year arise in connection with the valuation of financial instruments, valuation of acquired assets, fair value of share purchase warrants, share-based payments and deferred tax assets.
Basis of Consolidation
These consolidated financial statements include those of the Company and of the entities controlled by the Company (the “subsidiaries”). Control over an investee is achieved when the Company has power over the investee, has exposure or rights to variable returns from its involvement with the investee and has the ability to use its power over the investee to affect the amount of its returns. The financial statements of subsidiaries are included in the consolidated financial statements from the date that control commences until the date that control ceases.
The following table lists the Company’s subsidiaries and their functional currencies.
| Name of Subsidaries | Place of Incorporation | Proportion of Ownership | Currency |
| CordovaCann Holdings Canada, Inc. | Ontario, Canada | 100% | Canadian Dollars |
| Cordova Investments Canada, Inc. | Ontario, Canada | 100% | Canadian Dollars |
| 2734158 Ontario Inc. | Ontario, Canada | 60.45% | Canadian Dollars |
| 10062771 Manitoba Ltd. | Manitoba, Canada | 51.00% | Canadian Dollars |
| CordovaCann Holdings, Inc. | Delaware, USA | 100% | Canadian Dollars |
| Cordova CO Holdings, LLC | Colorado, USA | 100% | United States Dollars |
| Cordova OR Holdings, LLC | Oregon, USA | 100% | United States Dollars |
| CDVA Enterprises, LLC | California, USA | 100% | United States Dollars |
| Cordova CA Holdings, LLC | California, USA | 100% | United States Dollars |
| Cordova OR Operations, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt Farms, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt OR Retail, LLC | Oregon, USA | 100% | United States Dollars |
| Cannabilt Holdings, Inc. | Oregon, USA | 100% | United States Dollars |
| Future Processing, LLC | Oregon, USA | 100% | United States Dollars |
| Extraction Technologies, LLC | Washington, USA | 100% | United States Dollars |
| Cordova WA Holdings, LLC | Washington, USA | 100% | United States Dollars |
| 39 |
Share-based payments
Share-based payments to employees are measured at the fair value of the instruments issued and recognized over the expected service periods. Share-based payments to non-employees are measured at the fair value of goods or services received or the fair value of the equity instruments issued, if it is determined the fair value of the goods or services cannot be reliably measured, and are recorded at the date the goods or services are received. The corresponding amount is recorded to the stock options reserve. The fair value of options is determined using the Black-Scholes Option Pricing Model which incorporates all market vesting conditions. The number of shares and options expected to vest is reviewed and adjusted at the end of each reporting period such that the amount recognized for services received as consideration for the equity instruments granted shall be based on the number of equity instruments that will eventually vest.
Compound financial instruments
Compound financial instruments issued by the Company are comprised of convertible debentures that can be converted into common shares and promissory notes payable attached with warrants. The Compound financial instruments are segregated into their debt and equity components or derivative liability components at the date of issue, in accordance with the substance of the contractual agreements. The conversion feature of the convertible promissory notes is presumed to be classified as a derivative financial liability unless it meets all the criteria to recognize as equity instrument. One of criteria is that the conversion option exchanges a fixed amount of shares for a fixed amount of cash ("fixed for fixed").
If the conversion feature meets the fixed for fixed criteria, the conversion option will be classified as equity components. Equity instruments are instruments that evidence a residual interest in the assets of an entity after deducting all of its liabilities. Therefore, when the initial carrying amount of the compound financial instruments is allocated to its equity and liability components, the equity component is assigned the residual amount after deducting from the fair value of the instrument as a whole the amount separately determined for the liability component. The sum of the carrying amounts assigned to the liability and equity components on initial recognition is always equal to the fair value that would be ascribed to the instrument as a whole. No gain or loss arises from initially recognizing the components of the instrument separately.
If the conversion feature does not meet the fixed for fixed criteria, the conversion option will be recorded as derivative financial liability, which must be separately accounted for at fair value on initial recognition. The carrying amount of the debt component, on initial recognition, is recalculated as the difference between the proceeds of the convertible promissory notes as a whole and the fair value of the derivative financial liabilities. Subsequent to initial recognition, the derivative financial liability is re-measured at fair value at the end of each reporting period with changes in fair value recognized in the statement of operation for each reporting period, while the debt component is accreted to the face value of the debt using the effective interest method.
Transaction costs are allocated to the debt and equity components in proportion to the allocation of the proceeds on initial recognition. Transaction costs allocated to equity components will be accounted for as a deduction from equity, net of any related income tax benefit; cost allocated to the derivative financial liability component are expensed; and cost allocated to the debt component are offset against the carrying amount of the liability and included in the determination of the effective interest rate.
The liability component of a compound financial instrument is recognized initially at the fair value of a similar liability that does not have an equity conversion option. The equity component is recognized initially as the difference between the fair value of the computed financial instrument as a whole and the fair value of the liability component. Any directly attributable transaction costs are allocated to the liability and equity components in proportion to their initial carrying amounts. Subsequent to initial recognition, the liability component of a compound financial instrument is measured at amortized cost using the effective interest method. The equity component of a compound financial instrument is not re-measured subsequent to initial recognition except on conversion or upon expiration, when the carrying value of the equity portion is transferred to common shares or contributed surplus.
| 40 |
Financial instruments
The Company recognizes a financial asset or a financial liability when it becomes a party to the contractual provisions of the instrument. Under IFRS 9, such financial assets or financial liabilities are initially recognized at fair value and the subsequent measurement depends on their classification.
Financial assets
IFRS 9 uses a single approach to determine whether a financial asset is classified and measured at amortized cost or at fair value. The classification and measurement of financial assets is based on the Company’s business models for managing its financial assets and whether the contractual cash flows represent solely payments of principal and interest (“SPPI”). Financial assets are initially measured at fair value and are subsequently measured at either (i) amortized cost; (ii) fair value through other comprehensive income (“FVTOCI”); or (iii) at fair value through profit or loss (“FVTPL”).
Amortized cost - Financial assets classified and measured at amortized cost are those assets that are held within a business model whose objective is to hold financial assets in order to collect contractual cash flows, and the contractual terms of the financial asset give rise to cash flows that are SPPI. Financial assets classified at amortized cost are measured using the effective interest method.
Fair value through other comprehensive income - Financial assets classified and measured at FVTOCI are those assets that are held within a business model whose objective is achieved by both collecting contractual cash flows and selling financial assets, and the contractual terms of the financial asset give rise to cash flows that are SPPI. This classification includes certain equity instruments where IFRS 9 allows an entity to make an irrevocable election to classify the equity instruments, on an instrument-by-instrument basis, that would otherwise be measured at FVTPL to present subsequent changes in FVTOCI.
FVTPL - Financial assets classified and measured at FVTPL are those assets that do not meet the criteria to be classified at amortized cost or at FVTOCI. This category includes debt instruments whose cash flow characteristics are not SPPI or are not held within a business model whose objective is either to collect contractual cash flows, or to both collect contractual cash flows and sell the financial asset.
Financial liabilities
Under IFRS 9, financial liabilities are primarily classified at amortized cost with limited exceptions. Financial liabilities are derecognized when the obligation specified in the contract is discharged, cancelled or expires. The Company's accounting policy for each category is as follows:
FVTPL - This category comprises derivatives, liabilities acquired or incurred principally for the purpose of selling or repurchasing it in the near term, and certain financial liabilities that were designated at FVTPL from inception.
Amortized cost - Financial liabilities are recognized initially at fair value net of directly attributable transaction costs. They are subsequently recognized at amortized cost using effective interest method with interest expense recognized on an effective yield basis.
Financial assets and liabilities are offset and the net amount is presented in the statement of financial position when the Company has a legal right to offset the amounts and it intends to either settle on a net basis or realize the asset and settle the liability simultaneously.
| 41 |
The following table summarizes the classification of the Company’s financial instruments:
| IFRS 9 | |
| Classification | |
| Financial assets | |
| Cash and cash equivalents | Amortized cost |
| Promissory note receivable | Amortized cost |
| Other deposit | Amortized cost |
| Other investment | FVTPL |
| Financial liabilities | |
| Accounts payable and accrued liabilities | Amortized cost |
| Convertible debentures | Amortized cost |
| Mortgage payable | Amortized cost |
| Debenture unit deposits | Amortized cost |
| Promissory notes payable | Amortized cost |
The adoption of IFRS 9 did not have an impact on the Company’s classification and measurement of financial assets and liabilities. On adoption of IFRS 9 on July 1, 2018, there was no change in the carrying value of the financial instruments on transition from IAS 39. IFRS 9 uses an expected credit loss impairment model as opposed to an incurred credit loss model under IAS 39. The impairment model is applicable to financial assets measured at amortized cost where any expected future credit losses are provided for, irrespective of whether a loss event has occurred as at the reporting date. For accounts receivable excluding taxes receivable, the Company utilized a provision matrix, as permitted under the simplified approach, and has measured the expected credit losses based on lifetime expected credit losses taking into consideration historical credit loss experience and financial factors specific to the debtors and other factors. The carrying amount of trade receivables is reduced for any expected credit losses through the use of an allowance account. Changes in the carrying amount of the allowance account are recognized in the statement of comprehensive income. At the point when the Company is satisfied that no recovery of the amount owing is possible, the amount is considered not recoverable and the financial asset is written off. The adoption of the new expected credit loss impairment model had a negligible impact on the carrying amounts of financial assets at amortized cost.
Impairment of long-lived assets
Long-lived assets, including property, plant and equipment and intangible assets are reviewed for impairment at each statement of financial position date or whenever events or changes in circumstances indicate that the carrying amount of an asset exceeds its recoverable amount. For the purpose of impairment testing, assets that cannot be tested individually are grouped together into the smallest group of assets that generates cash inflows from continuing use that are largely independent of the cash inflows of other assets or groups of assets (the cash-generating unit, or "CGU").
The recoverable amount of an asset or a CGU is the higher of its fair value, less costs to sell, and its value in use. If the carrying amount of an asset exceeds its recoverable amount, an impairment charge is recognized immediately in profit or loss equal to the amount by which the carrying amount exceeds the recoverable amount. Where an impairment loss subsequently reverses, the carrying amount of the asset is increased to the lesser of the revised estimate of recoverable amount, and the carrying amount that would have been recorded had no impairment loss been recognized previously.
Inventories
Inventories for finished cannabis goods are initially valued at cost, and subsequently at the lower of cost and net realizable value. Cost is determined using the average costing method. Net realizable value is determined as the estimated selling price in the ordinary course of business less the estimated costs of completion and the estimated costs necessary to make the sale. The Company reviews inventory for obsolete, redundant and slow-moving goods and any such inventories identified are written down to net realizable value.
| 42 |
Revenue
Revenue from the sale of cannabis goods is recognized when the significant risks and rewards of ownership have been transferred, generally at the date of transfer of ownership title. Revenue from the sale of goods is measured at the fair value of the consideration received.
Evaluation of Disclosure Control and Procedures
The term "disclosure controls and procedures" is defined in Rules 13a-15(e) and 15d-15(e) of the Securities Exchange Act of 1934, or the Exchange Act. This term refers to the controls and procedures of a company that are designed to ensure that information required to be disclosed by a company in the reports that it files or submits under the Exchange Act is recorded, processed, summarized and reported within the time periods specified by the Securities and Exchange Commission. Our management, including our Chief Executive Officer and Chief Financial Officer, together with the members of our Audit Committee have evaluated the effectiveness of our disclosure controls and procedures as of the end of the period covered by this report. Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer have concluded that our disclosure controls and procedures were ineffective as of the end of the period covered by this report.
There were no changes to our internal control over financial reporting since December 31, 2021 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Outlook
Current Outlook
Management continues to take an active approach to examining business opportunities in the cannabis industry that could enhance shareholder returns. The focus in the near term is to continue to grow its retail operations in Canada where the Company has established a strong presence in the Province of Ontario, Manitoba and Alberta. The Company will continue to grow in these provinces while expecting to open its first store in Kelowna, British Columbia in the near future. With presence in four key provinces, the Company is expecting to grow its retail operations both through development of new stores as well as looking for acquisition opportunities in strategic markets.
Alongside the retail operations in Canada, the Company is also focussing on growth its presence over the west coast of the USA. Along with its growing operations in Oregon and Washington, the Company is actively pursuing new opportunities in additional states to add to its portfolio consistent with its goal of having vertically integrated operations in key global cannabis markets.
Public Securities Filings
Additional information regarding the Company is filed with the Canadian Securities Administrators at www.sedar.com and with the United States Securities and Exchange Commission and can be viewed at www.edgar.gov.
| 43 |