Exhibit 99.1
2026 1
Disclaimer (1 of 2) 2
Disclaimer (2 of 2) 3
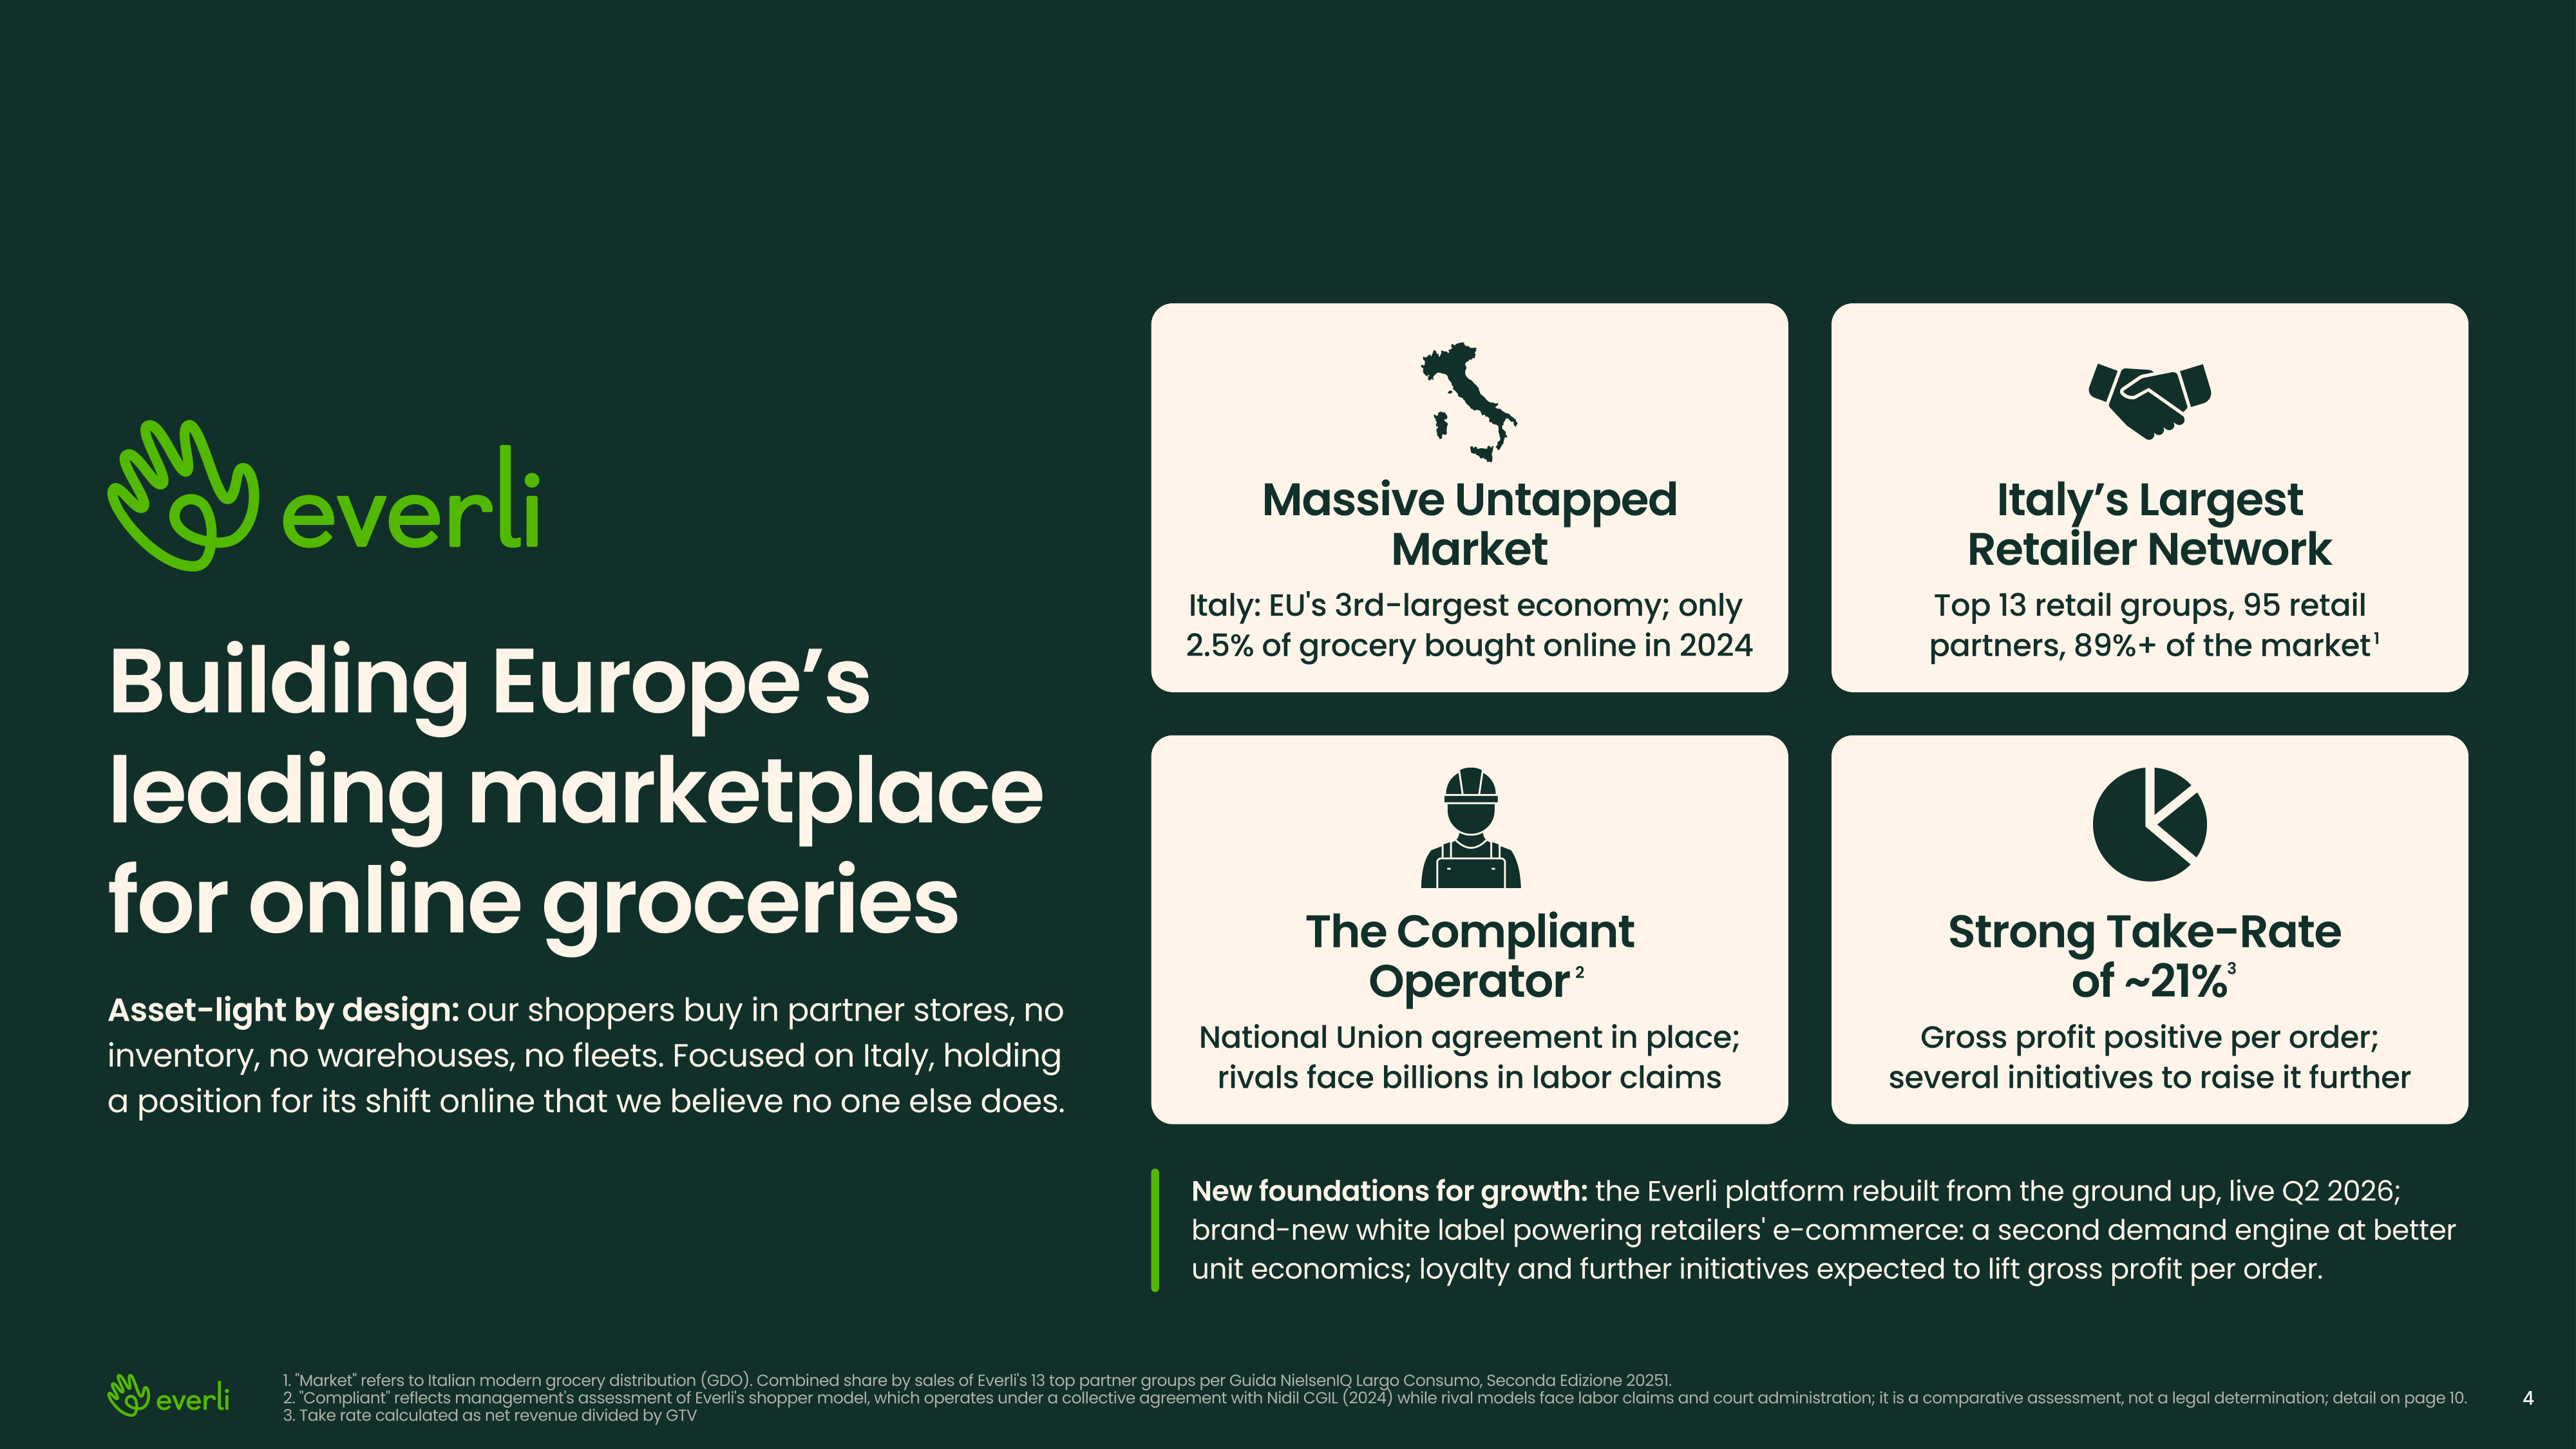
Building Europes leading marketplace for online groceries Asset-light by design: our shoppers buy in partner stores, no inventory, no warehouses, no fleets. Focused on Italy, holding a position for its shift online that we believe no one else does. Massive Untapped Market Italy: EU's 3rd-largest economy; only ( 2.5% of grocery bought online in 2024 Italys Largest Retailer Network Top 13 retail groups,€95 retail partners, 89%+ of the market 1 The Compliant Operator 2 Strong Take-Rate ( of ~21% 3 National Union agreement in place; rivals face billions in labor claims Gross profit positive per order; several initiatives to raise it further New foundations for growth:€the Everli platform rebuilt from the ground up, live Q2 2026; brand-new white label powering retailers' e-commerce: a second demand engine at better unit economics; loyalty and further initiatives expected to lift gross profit per order.1. "Market" refers to Italian modern grocery distribution (GDO). Combined share by sales of Everli's 13 top partner groups per Guida NielsenIQ Largo Consumo, Seconda Edizione 20251. 2. "Compliant" reflects management's assessment of Everli's shopper model, which operates under a collective agreement with Nidil CGIL (2024) while rival models face labor claims and court administration; it is a comparative assessment, not a legal determination; detail on page 10. 3. Take rate calculated as net revenue divided by GTV 4
1 Company Overview 5
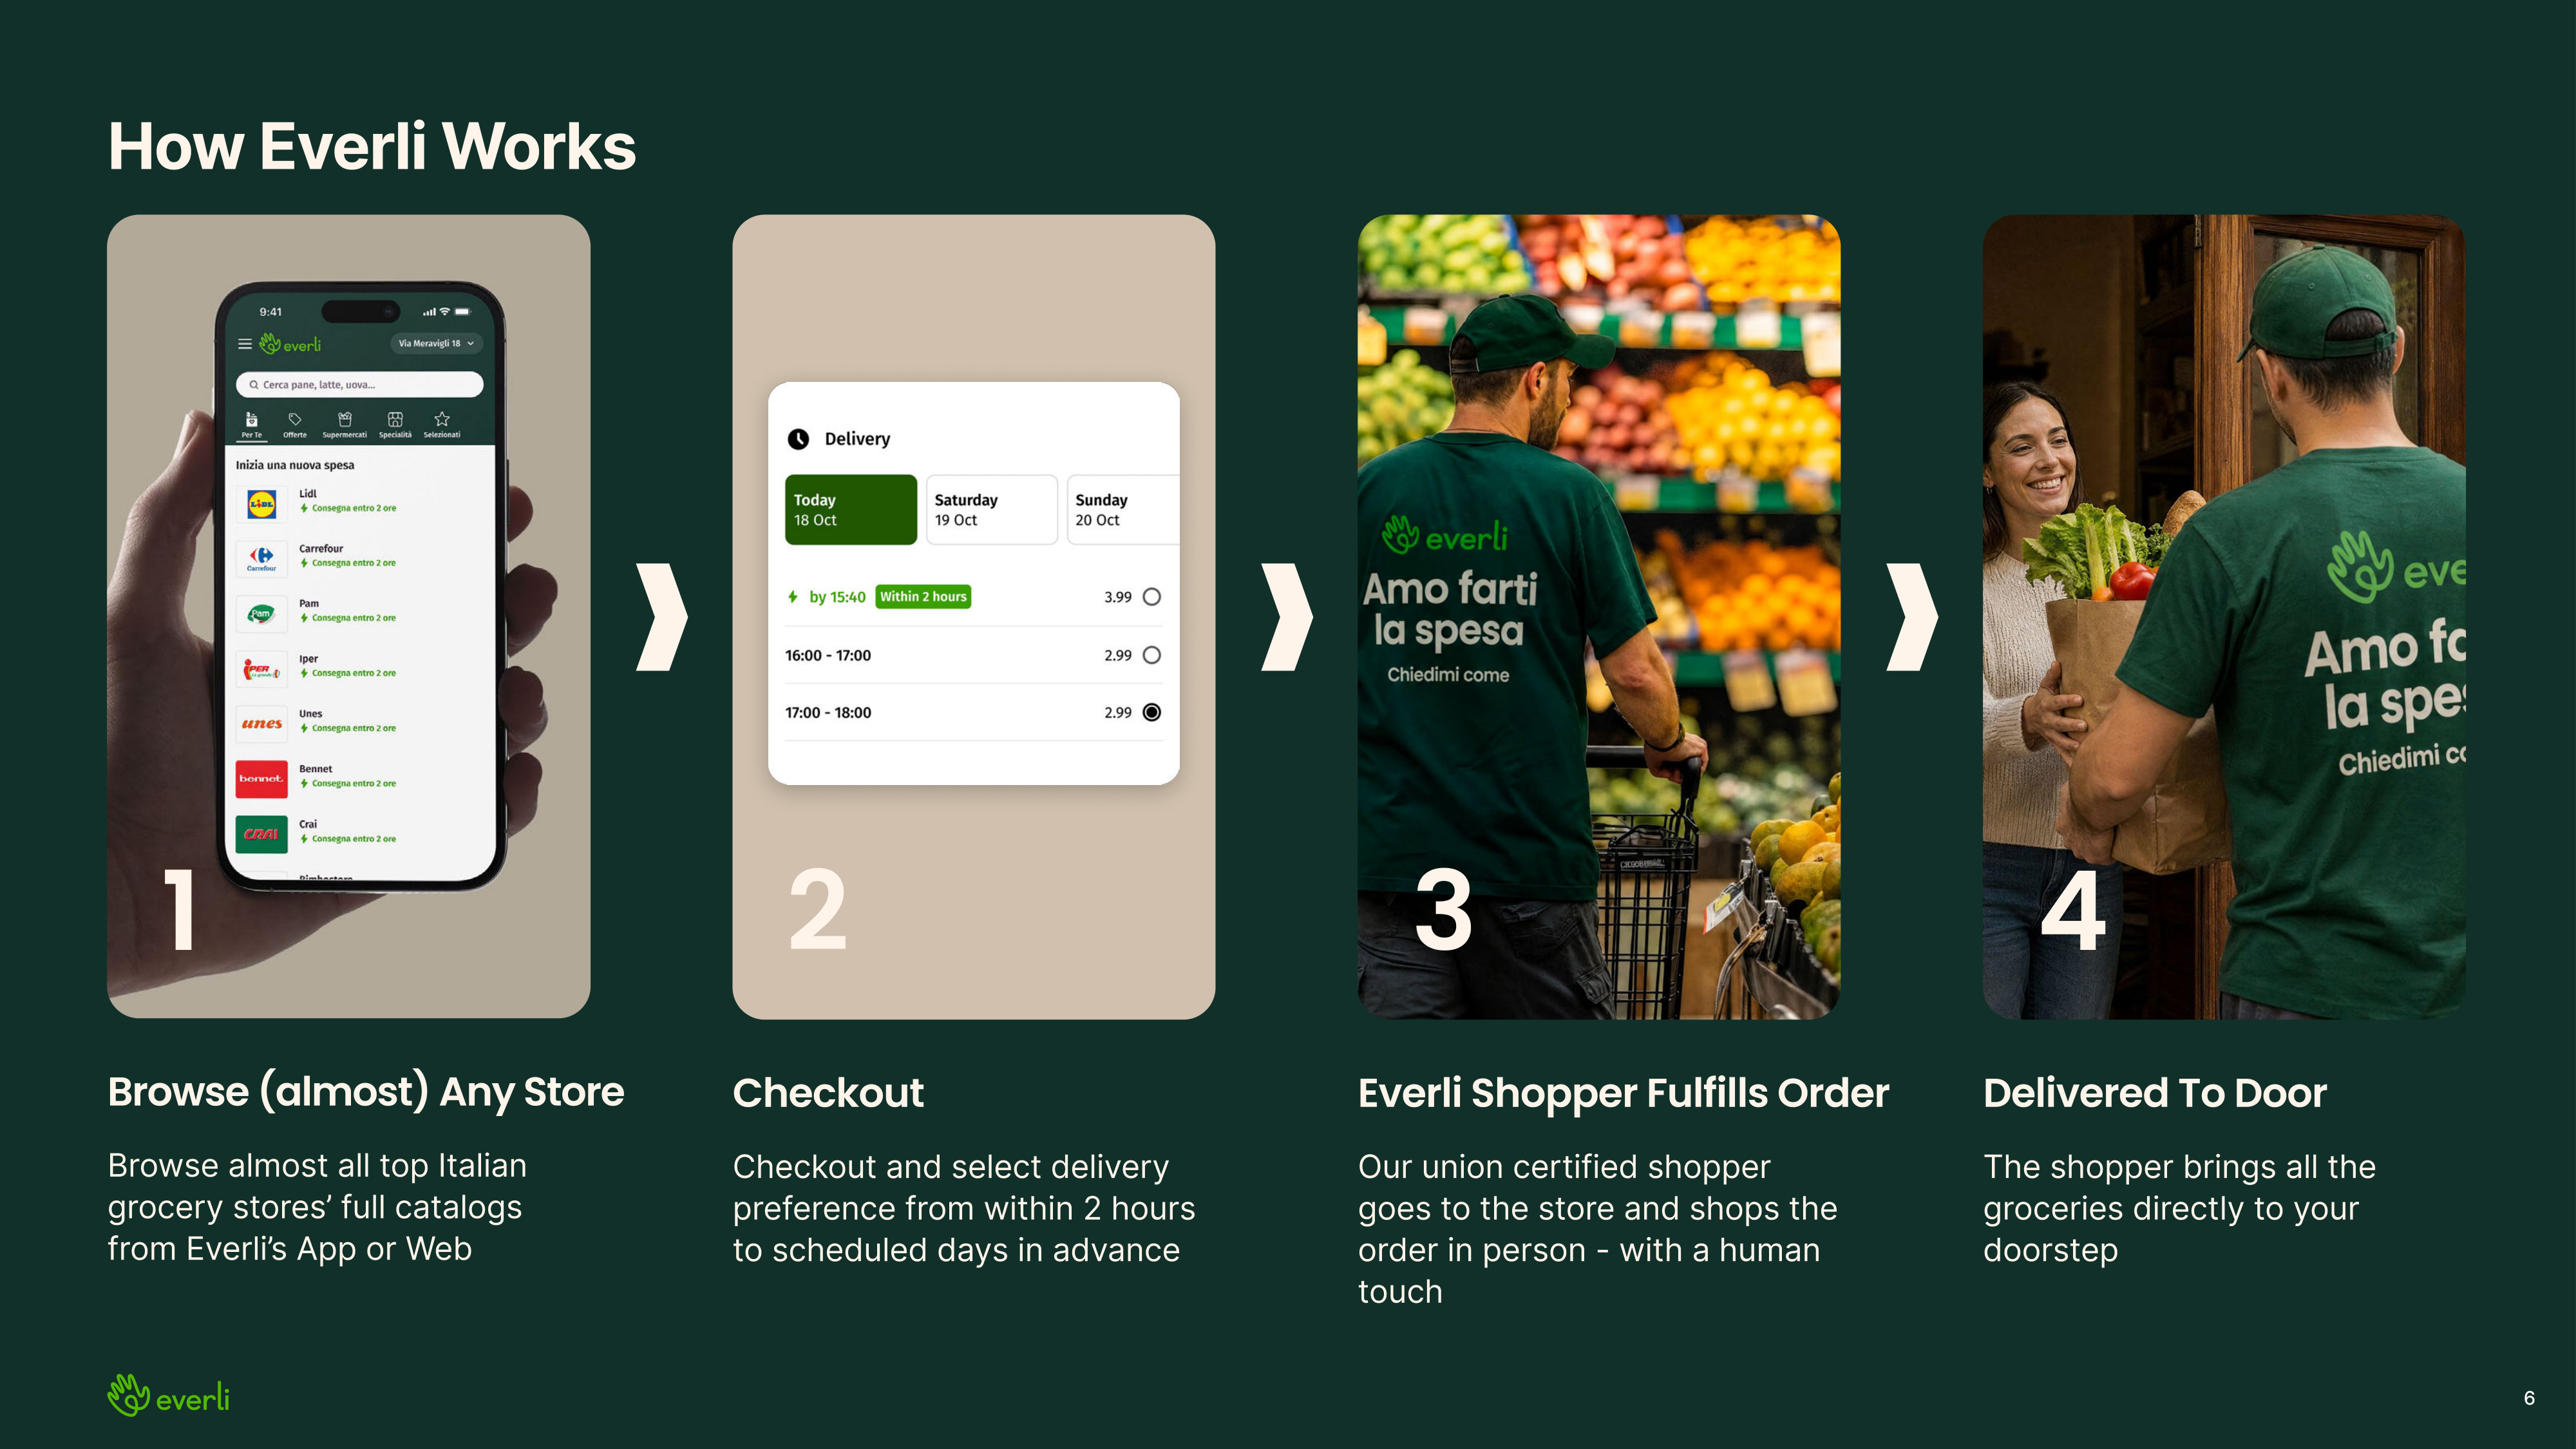
How Everli Works 2 1 3 Browse (almost) Any Store Browse almost all top Italian grocery stores full catalogs from Everlis App or Web Checkout Checkout and select delivery preference from within 2 hours to scheduled days in advance Everli Shopper Fulfills Order Our union certified shopper goes to the store and shops the order in person - with a human touch 4 Delivered To Door The shopper brings all the groceries directly to your doorstep 6
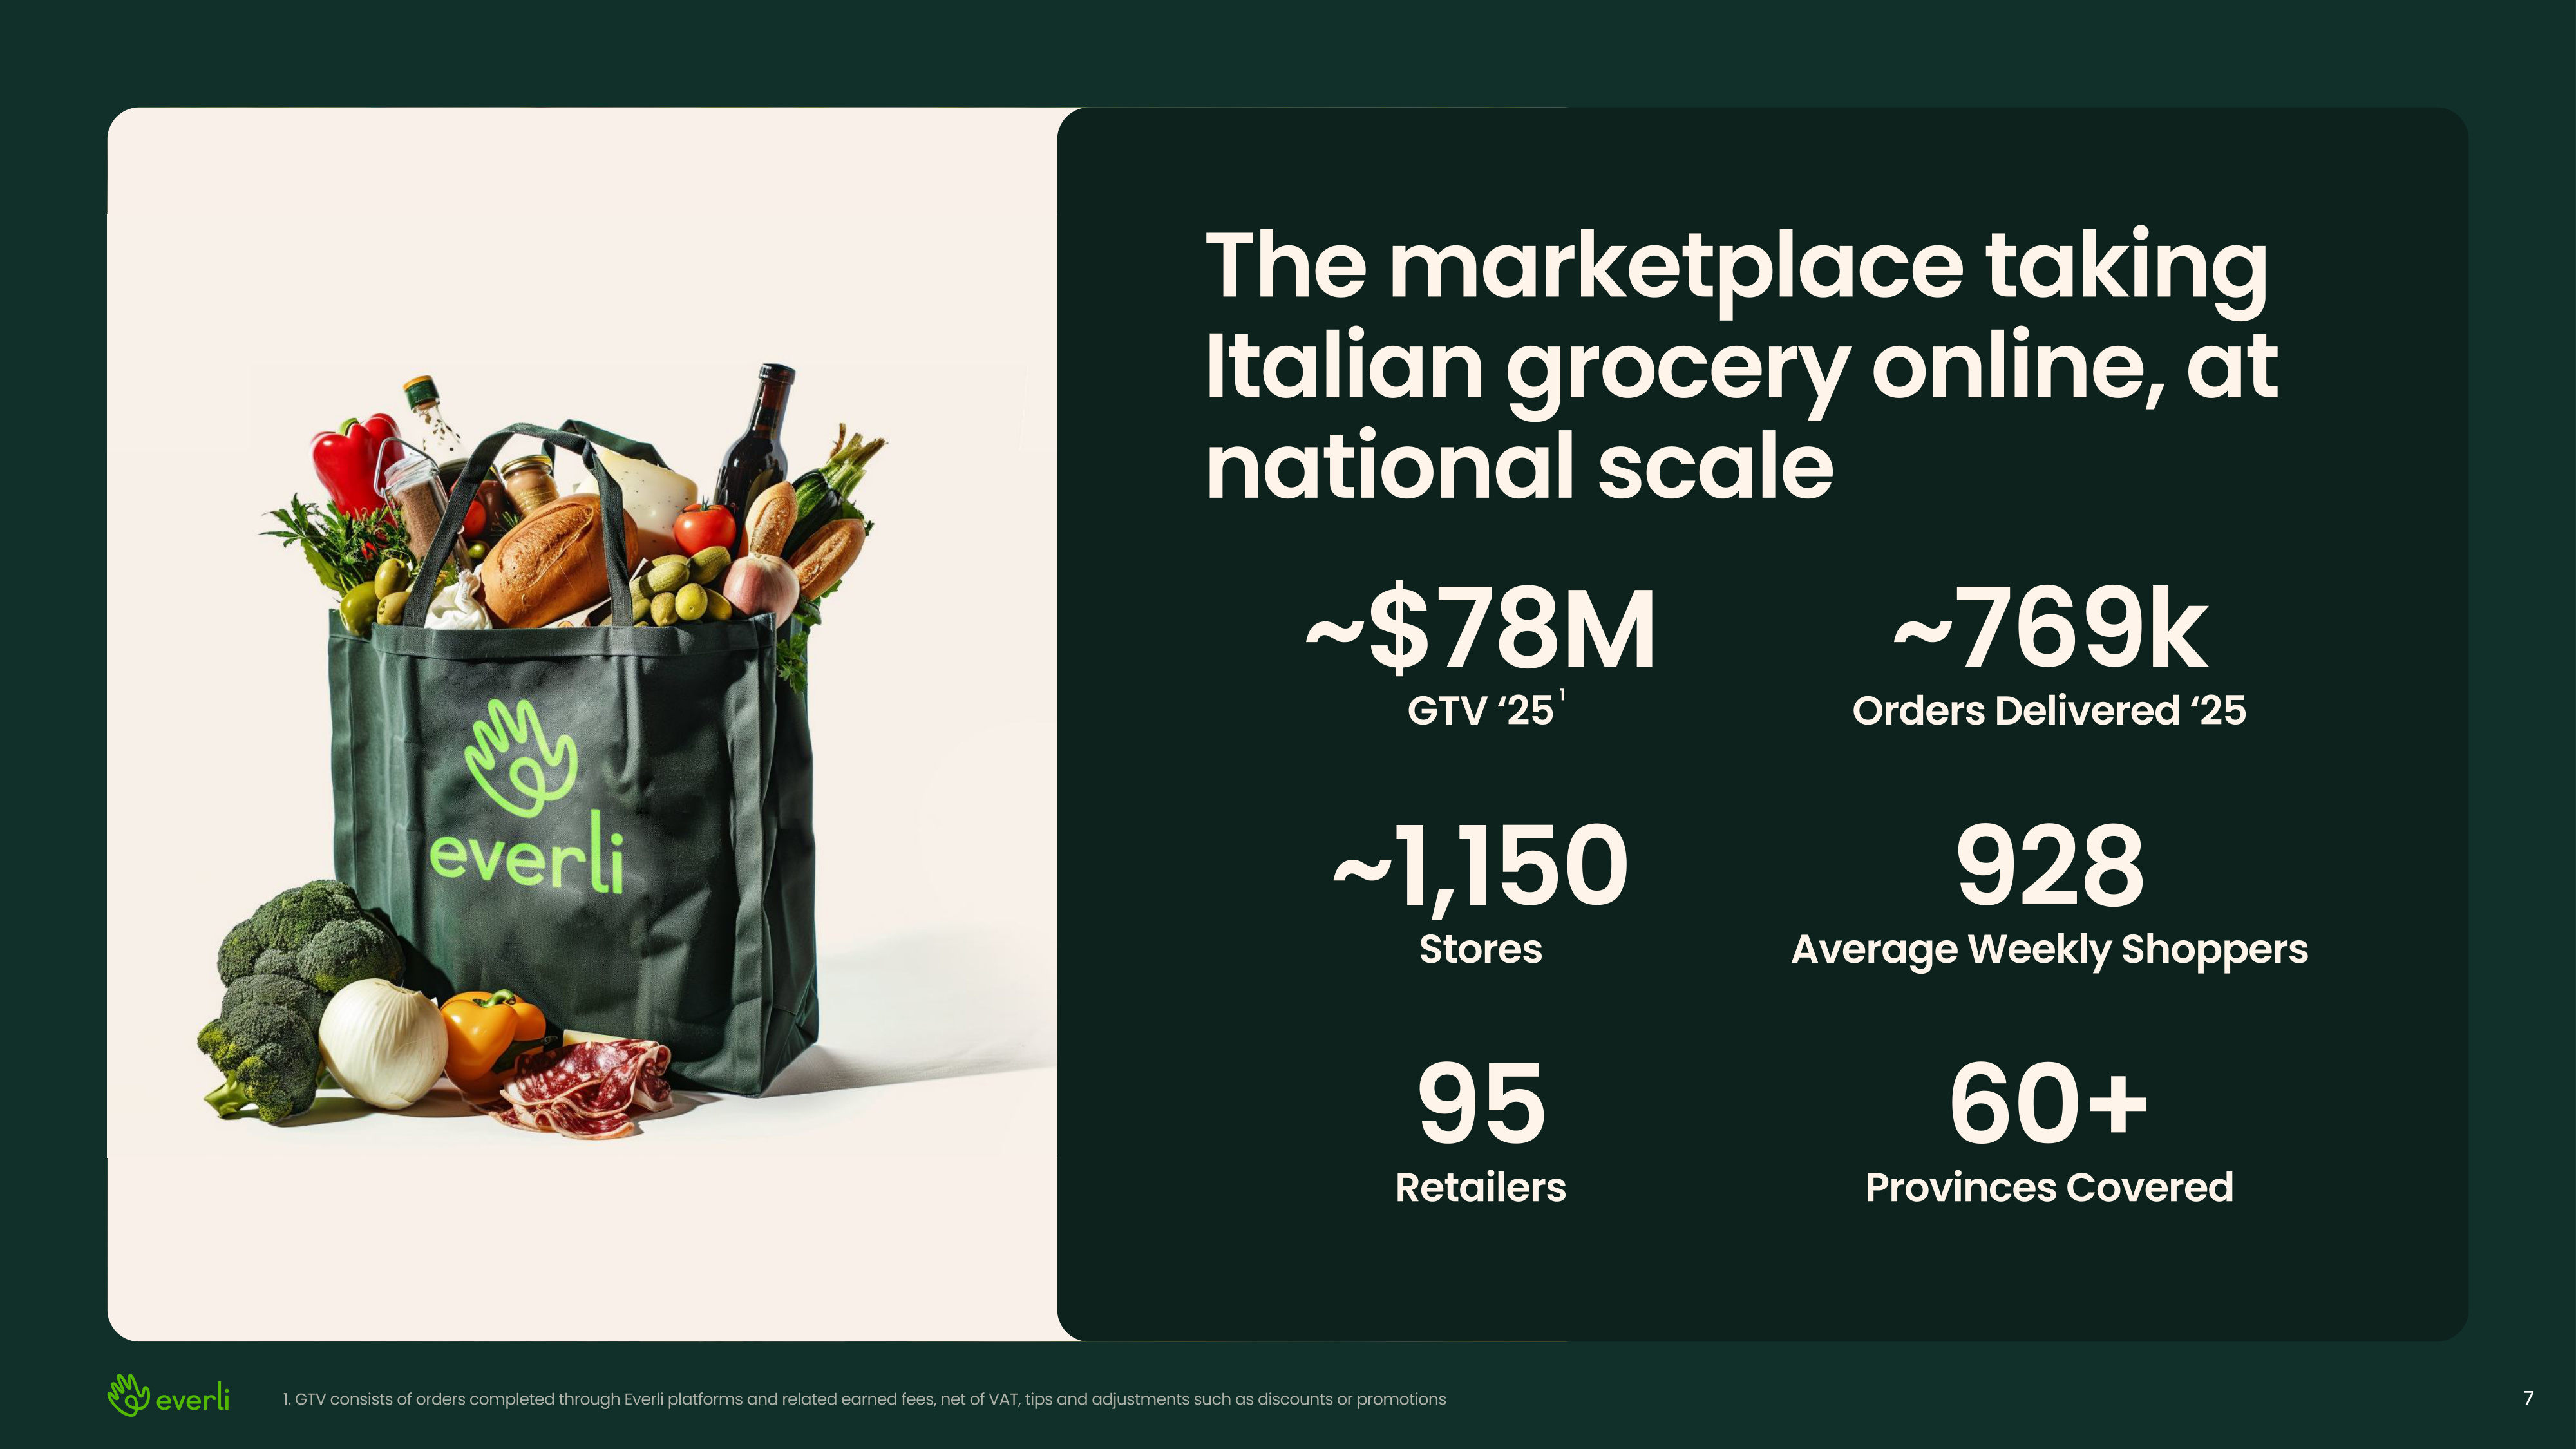
~$78M GTV 25 ~1,150 Stores 95 Retailers The marketplace taking Italian grocery online, at national scale 1 ~769k Orders Delivered 25 928 Average Weekly Shoppers 60+ Provinces Covered1. GTV consists of orders completed through Everli platforms and related earned fees, net of VAT, tips and adjustments such as discounts or promotions 7
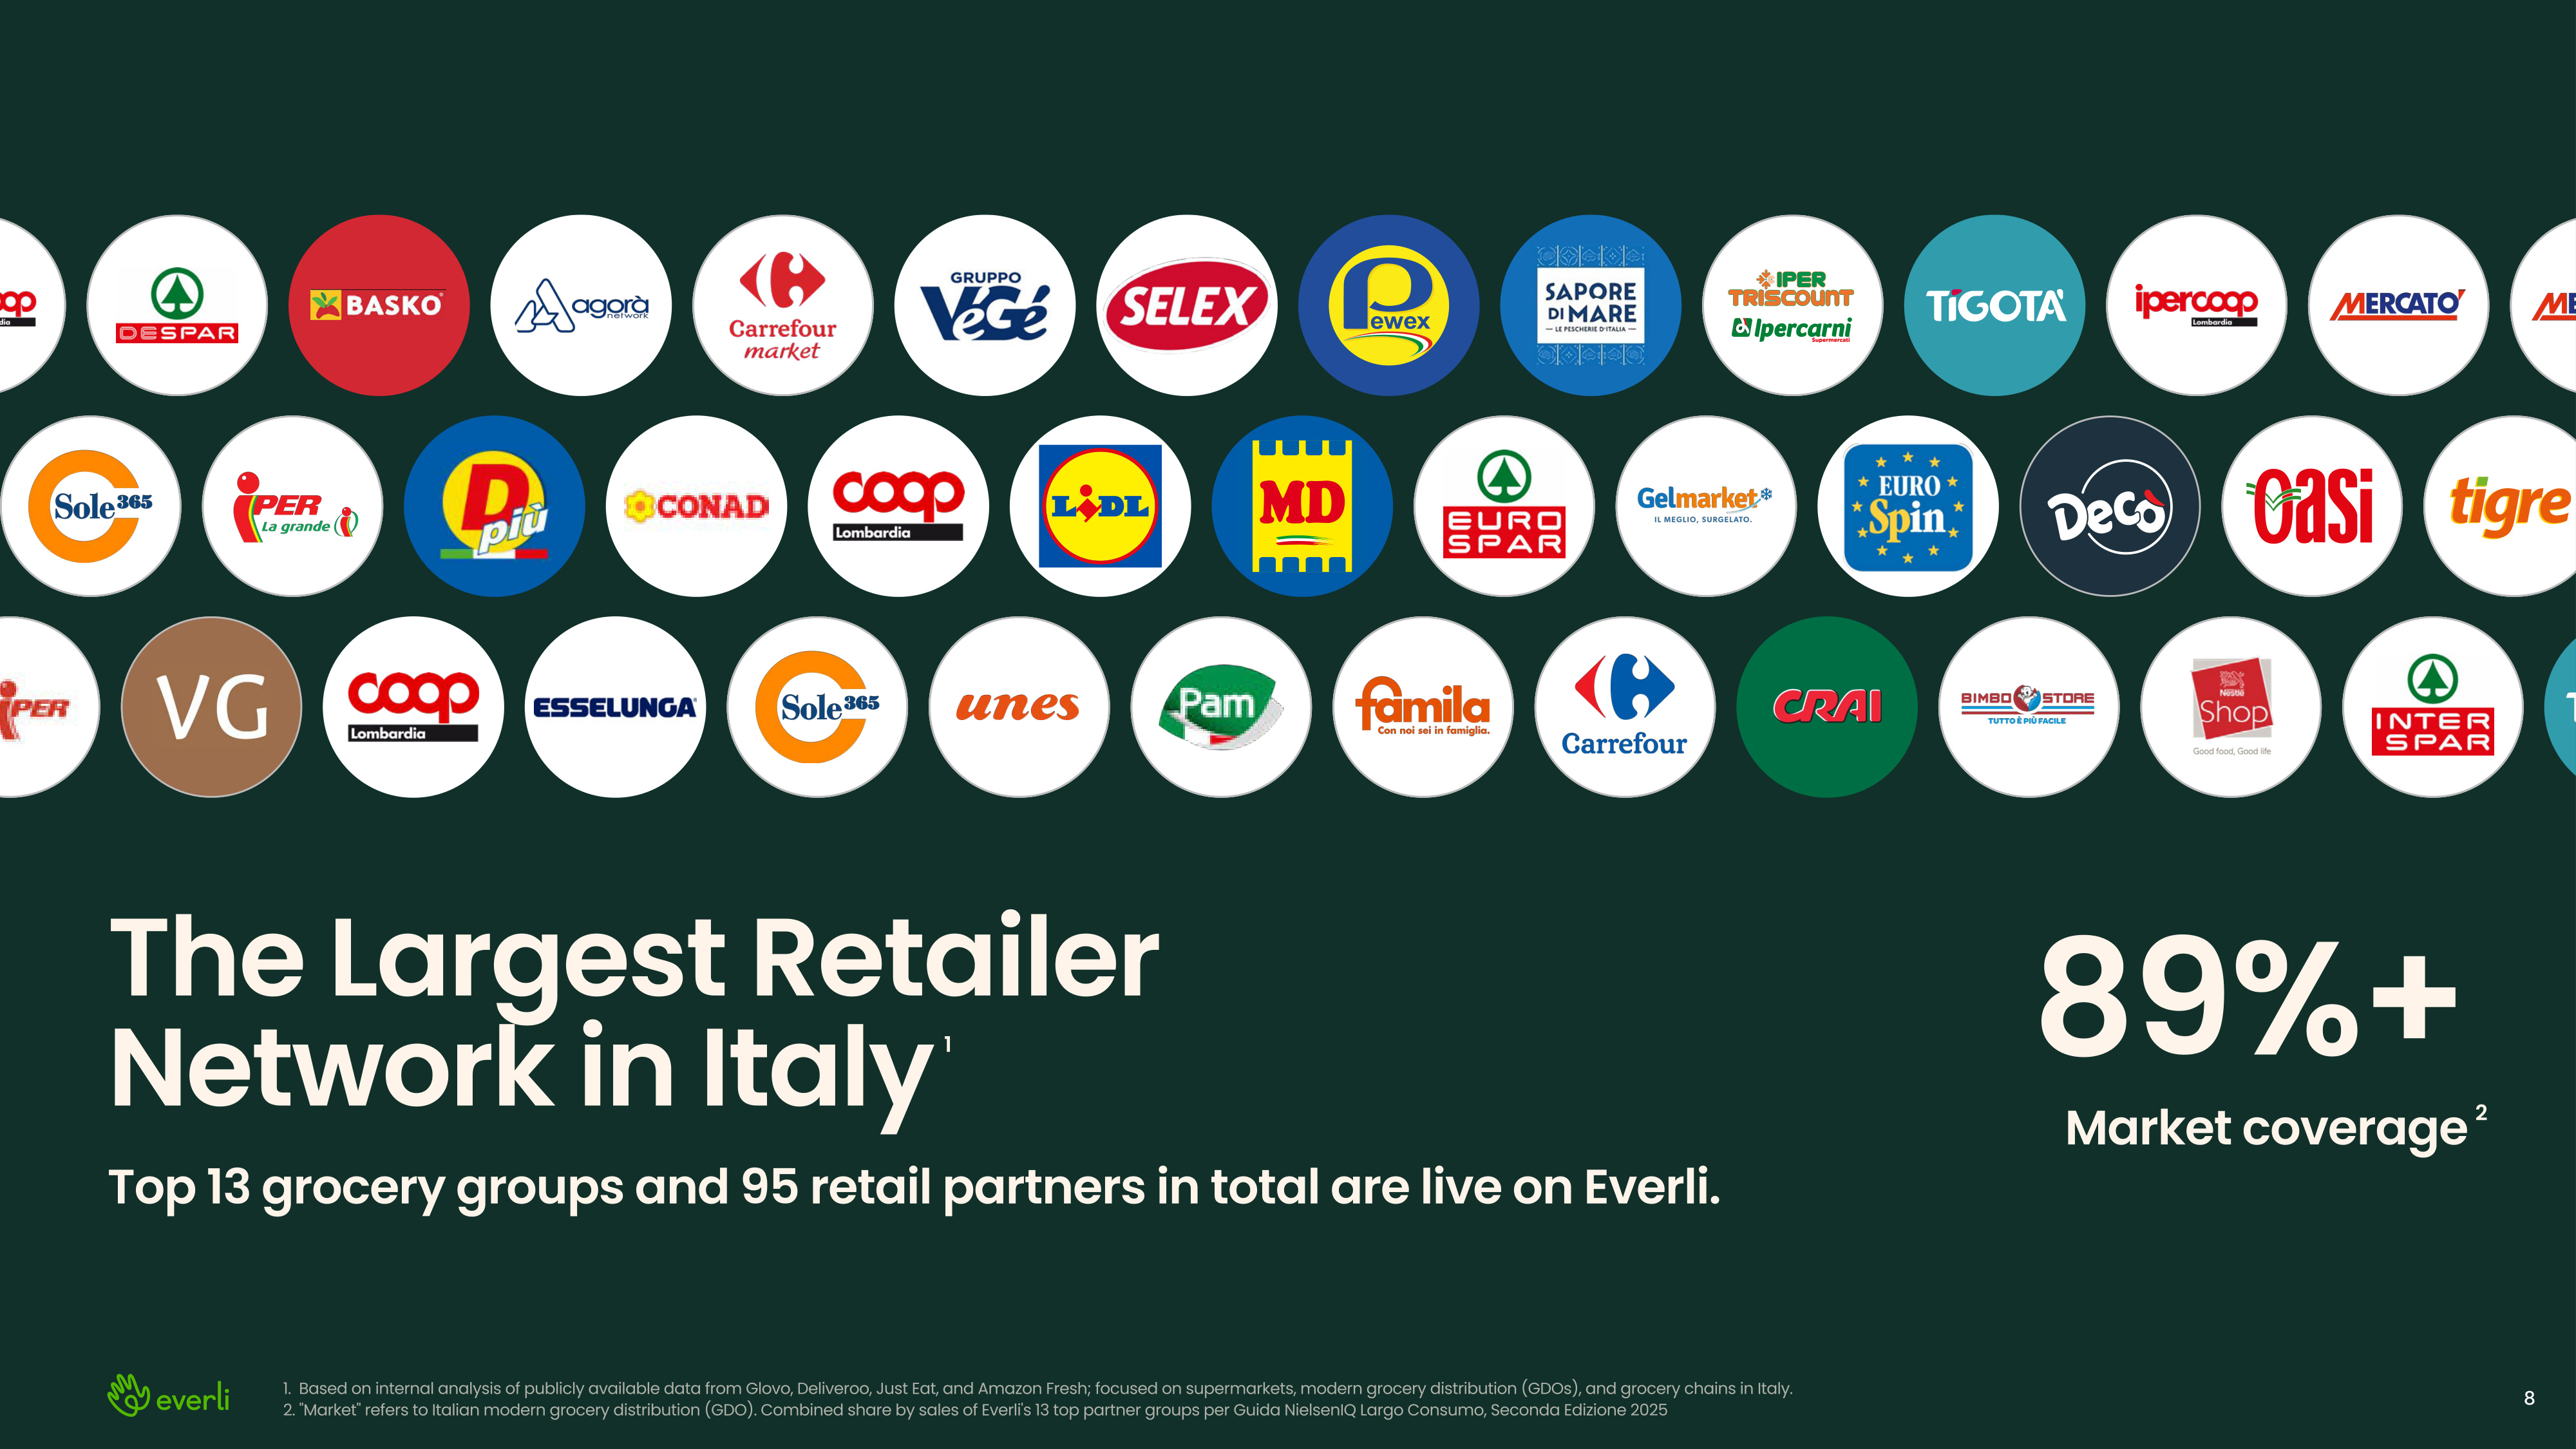
The Largest Retailer ( Network in Italy 1 89%+ Market coverage 2 Top 13 grocery groups and 95 retail partners in total are live on Everli.1. Based on internal analysis of publicly available data from Glovo, Deliveroo, Just Eat, and Amazon Fresh; focused on supermarkets, modern grocery distribution (GDOs), and grocery chains in Italy.2. "Market" refers to Italian modern grocery distribution (GDO). Combined share by sales of Everli's 13 top partner groups per Guida NielsenIQ Largo Consumo, Seconda Edizione 2025 8
Overview | Why Retailers Love Us Retailers Get Online Sales Without Lifting a Finger Everli takes retailers online and runs every order end to end: no staff, no infrastructure, no operational changes. Everli drives e-commerce volume using retailers existing footprint Everli shoppers fulfill orders end-to-end from picking to paying in store, like a regular customer, to delivery No staff, tech, or logistics required by the retailer No CapEx, no fixed costs: a commission on completed sales One integration, once: every store becomes a digital storefront the day it goes live 9
Overview | The Regulatory Moat Compliance isn't our cost. It's our license to scale. Everli holds the only union agreement in Italian gig delivery. Our labor model is an asset we deploy, fair pay included. Rival models face billions of euros in claims; the two largest have been under judicial administration since 2026. 1 2 1. As of August 31, 2026; based on internal management research and Nidil CGIL. (2024, May 29). Shopper, primo accordo tra sindacati e Assogrocery. https://www.nidil.cgil.it/shopper-primo-accordo-tra-sindacati-e-assogrocery/ 2. Italian public records, ongoing. Milan prosecutors (2021) sought ~¬733M in sanctions plus INPS claims above ¬1B against four delivery platforms; Tribunale di Milano 3237/2023 ordered back contributions. Judicial administration: Foodinho/Glovo (Feb 9, 2026), Deliveroo Italy (March 2026). 10
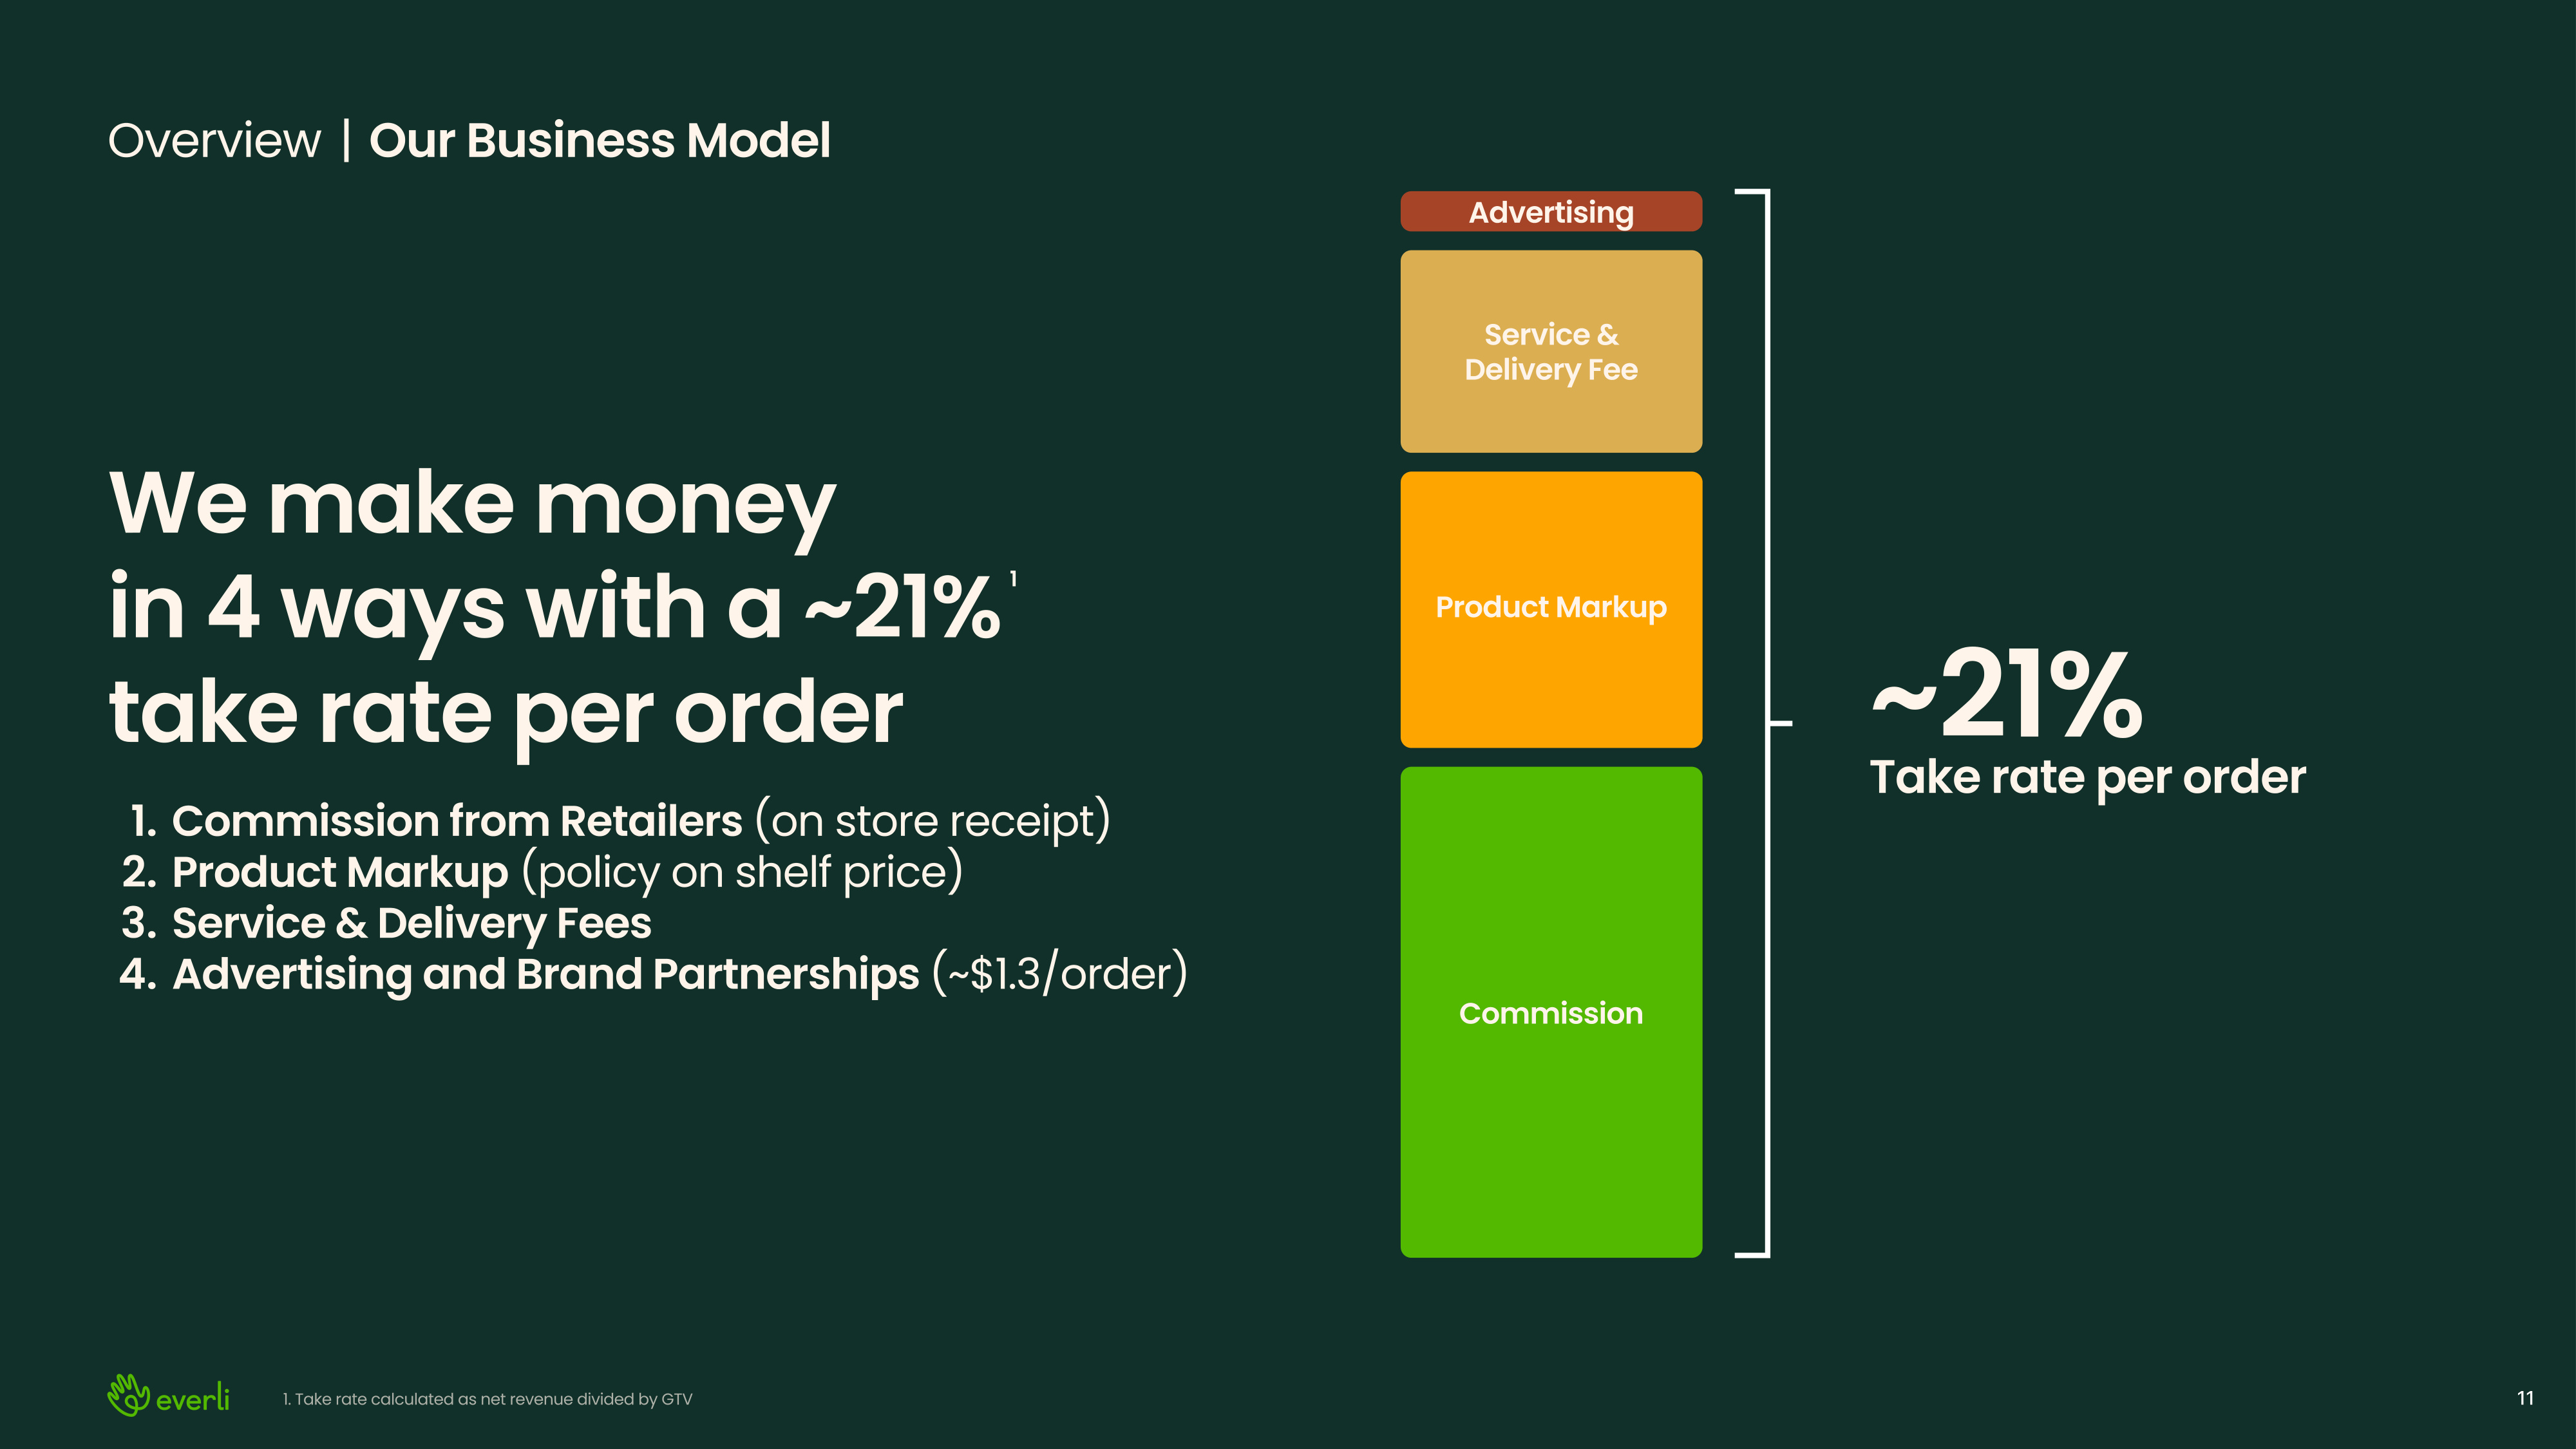
Overview | Our Business Model We make money ( in 4 ways with a ~21% ( take rate per order 1 Commission from Retailers (on store receipt) Product Markup (policy on shelf price) Service & Delivery Fees Advertising and Brand Partnerships (~$1.3/order) 1. Take rate calculated as net revenue divided by GTV Advertising Service & Delivery Fee Product Markup Commission ~21% ( Take rate per order 11
2 Market Opportunity 12
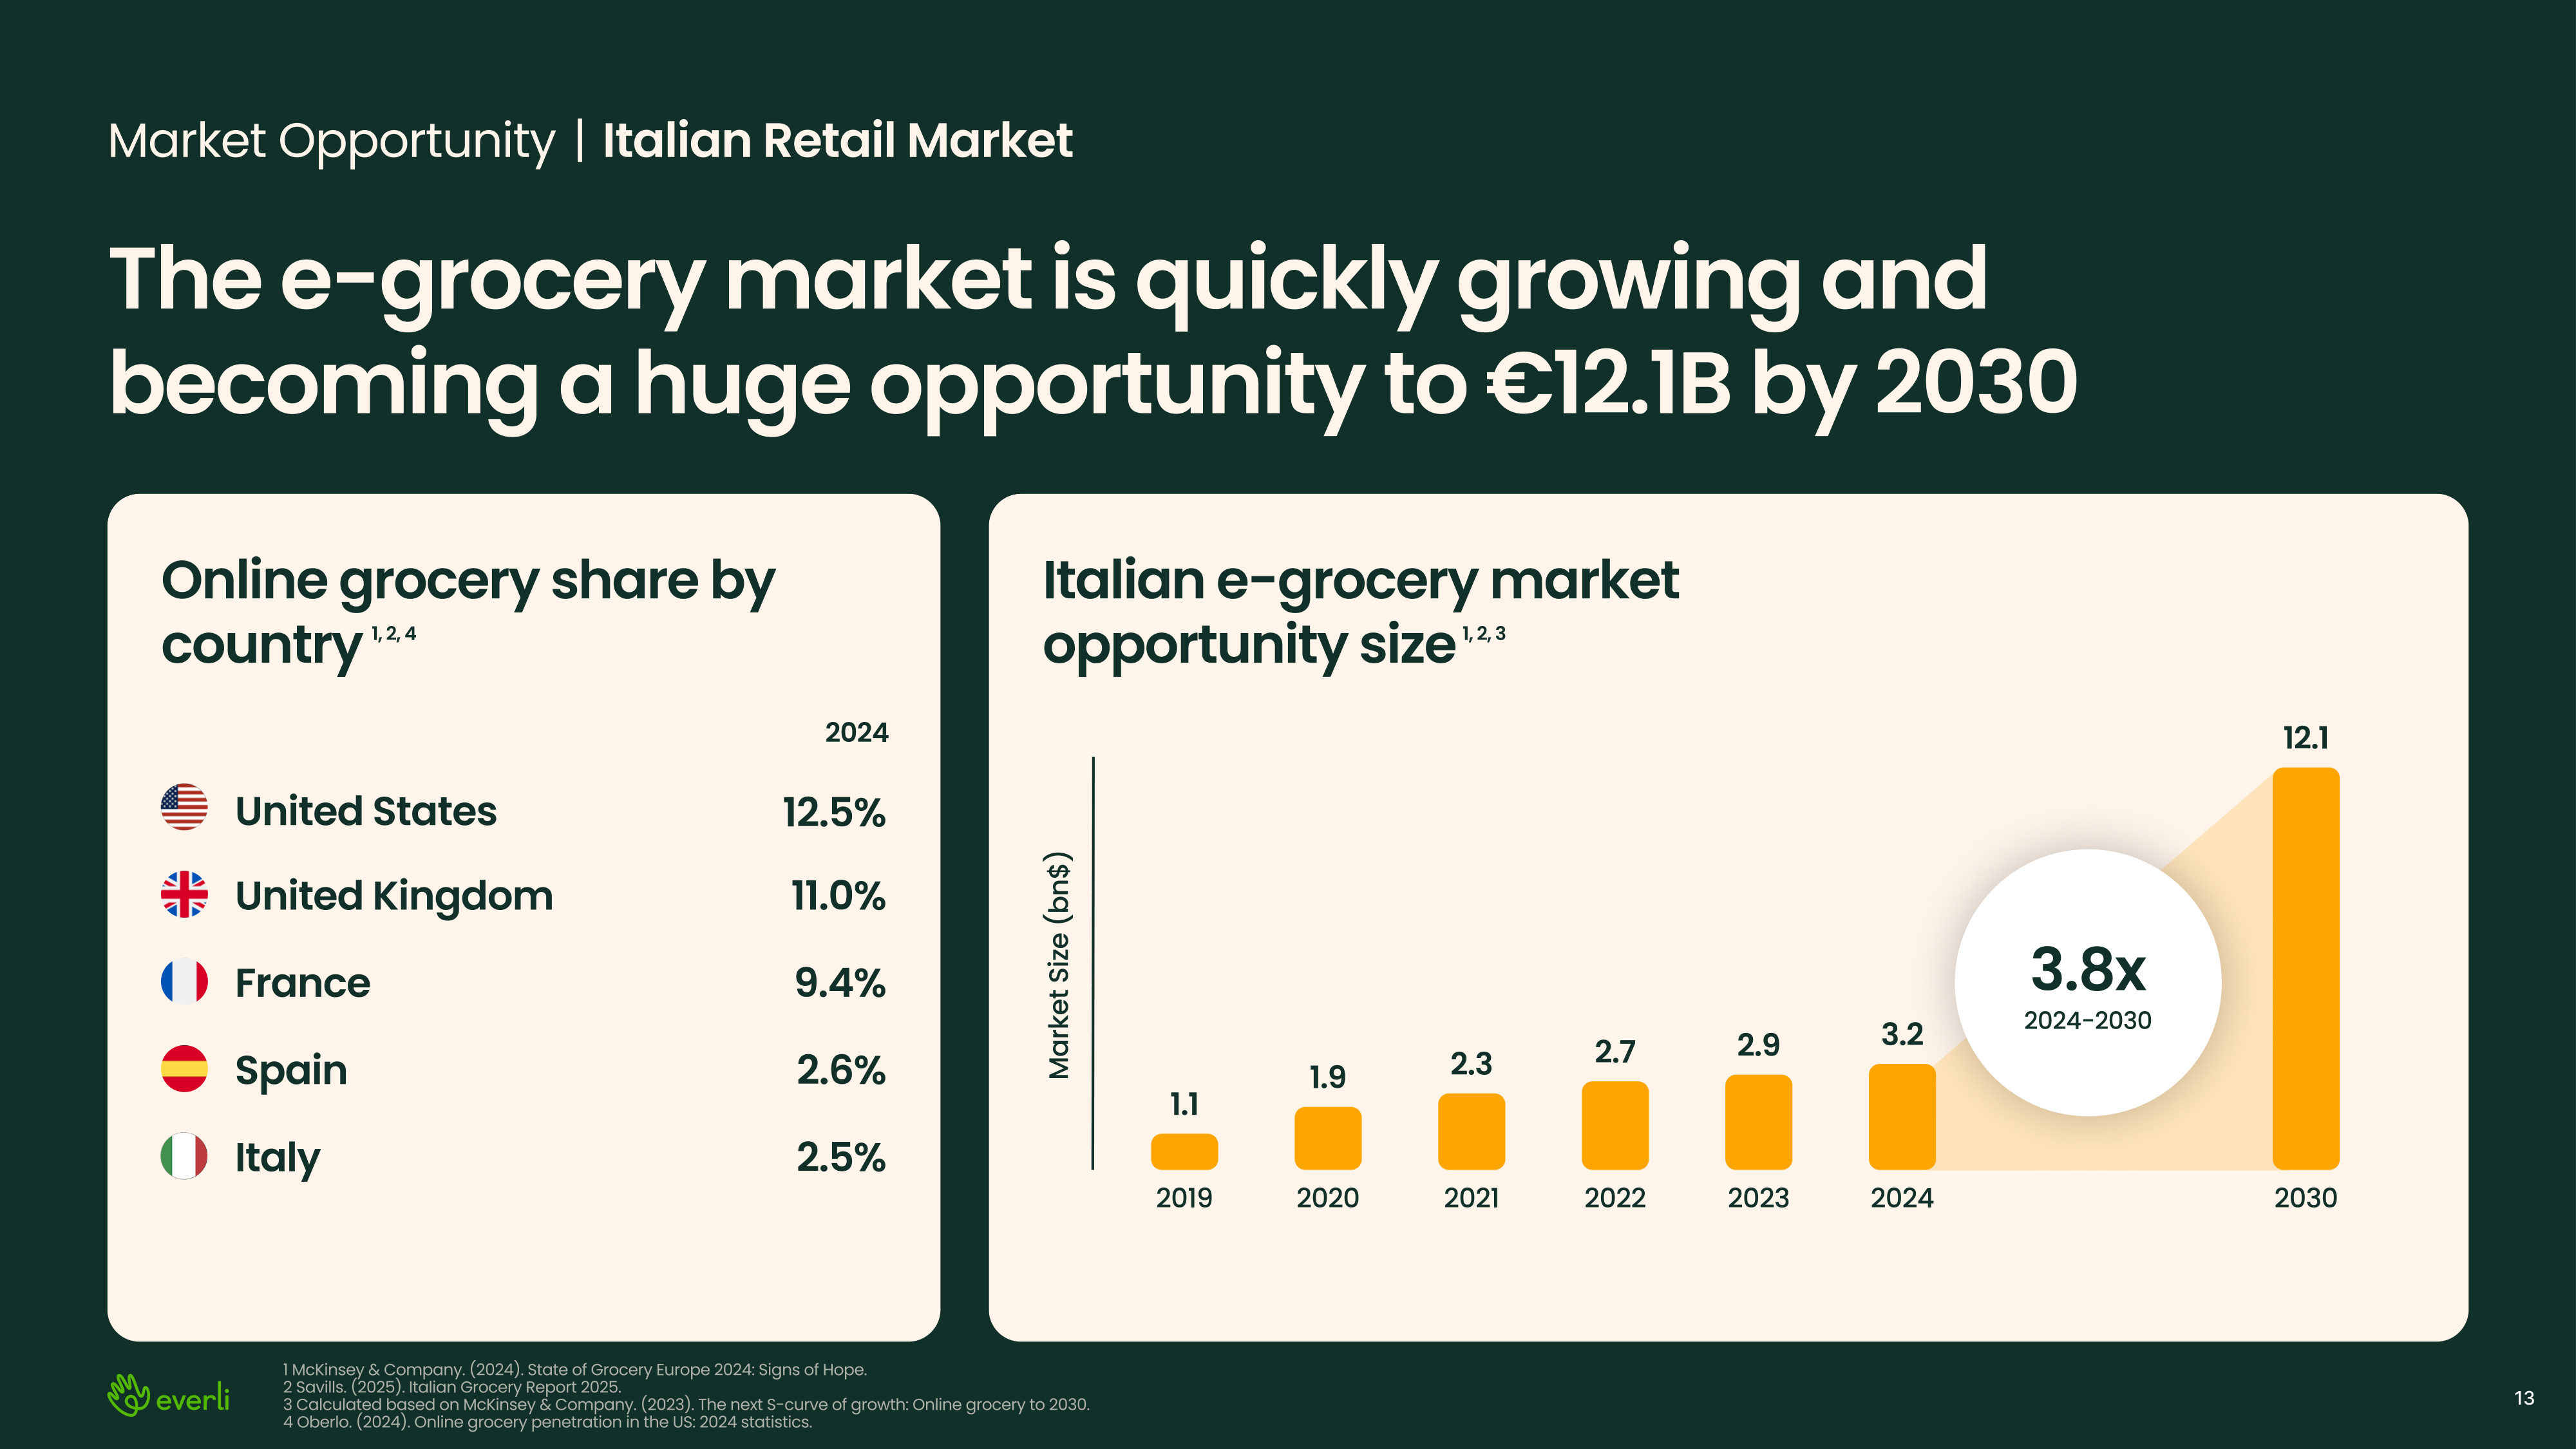
Market Opportunity | Italian Retail Market The e-grocery market is quickly growing and becoming a huge opportunity to ¬12.1B by 2030 Online grocery share by country 1, 2, 4 Italian e-grocery market opportunity size 1, 2, 3 Market Size (bn$) 1.1 2019 2020 2021 2022 2023 2024 2024 12.5% 11.0% 9.4% 2.6% 2.5% United States United Kingdom France Spain Italy 3.2 3.8x 2024-2030 2.9 2.7 2.3 1.9 1 McKinsey & Company. (2024). State of Groc ery Europe 2024: Signs of Hope. 2 Savills. (2025). Italian Grocery Report 2025. 3 Calculated based on McKinsey & Company. (2023). The next S-curve of growth: Online grocery to 2030. 4 Oberlo. (2024). Online grocery penetration in the US: 2024 statistics. 12.1 2030 13
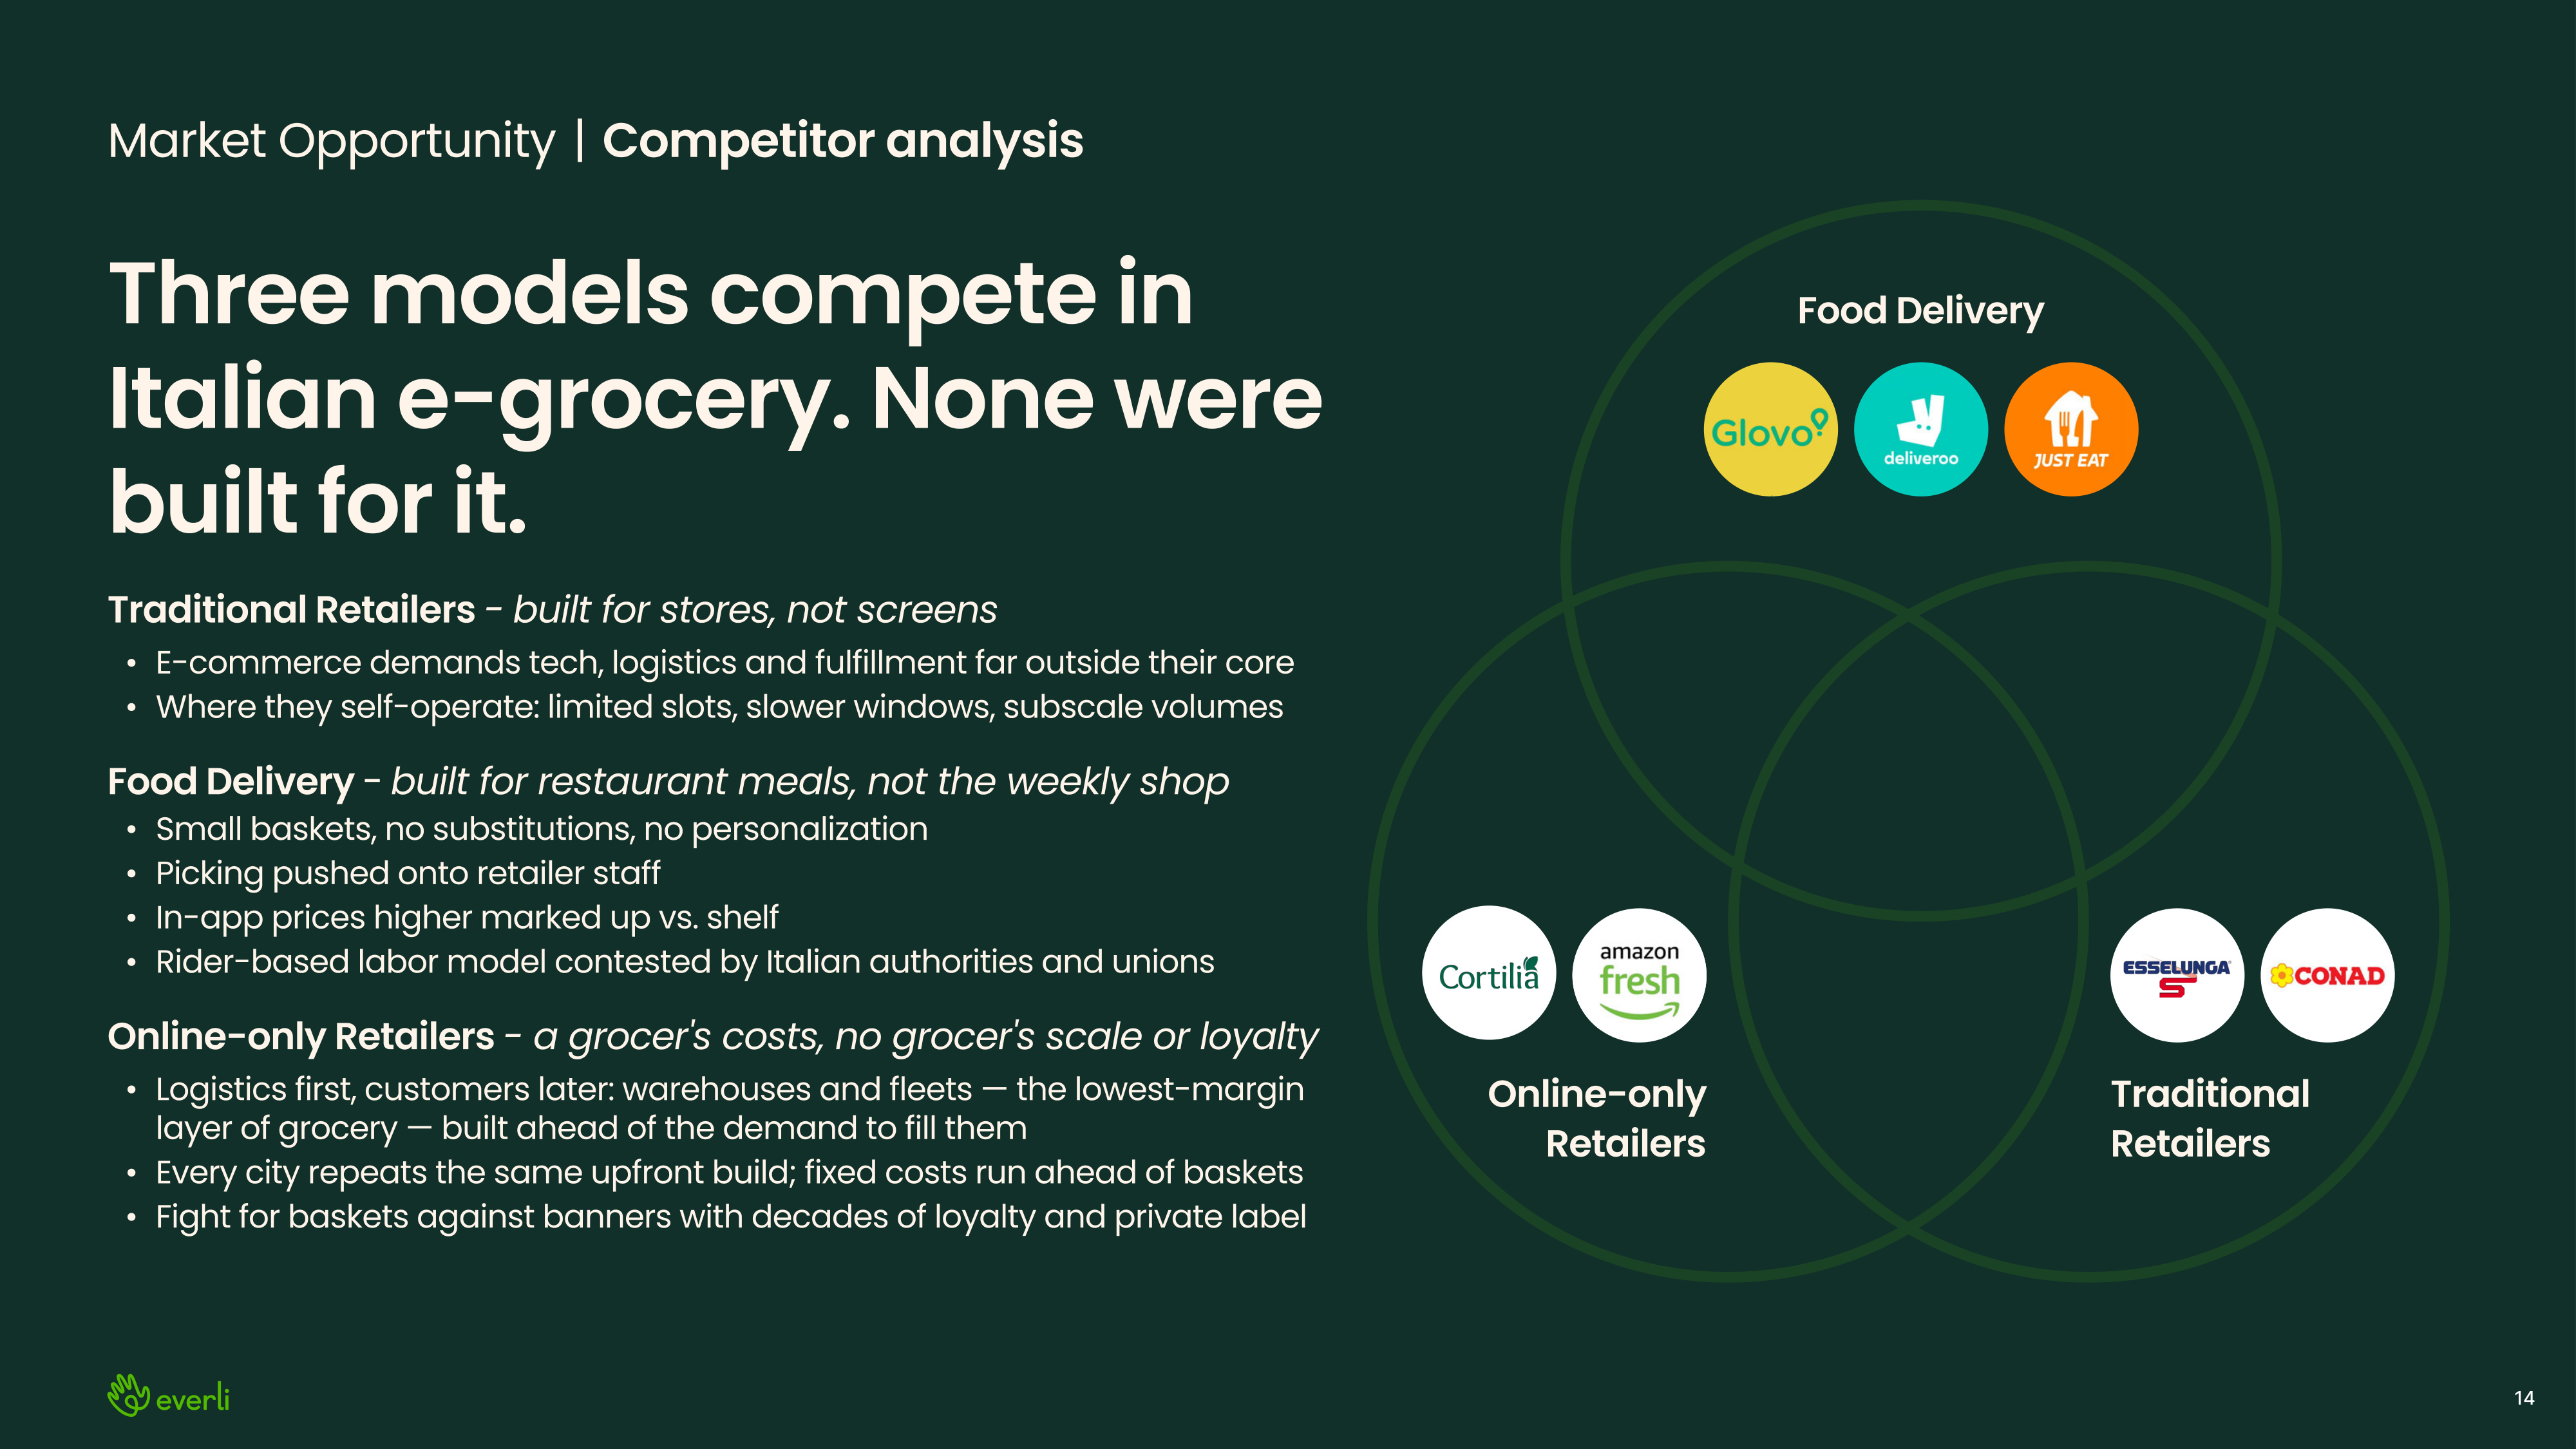
Market Opportunity | Competitor analysis Three models compete in Italian e-grocery. None were built for it. Traditional Retailers - built for stores, not screens E-commerce demands tech, logistics and fulfillment far outside their core Where they self-operate: limited slots, slower windows, subscale volumes Food Delivery - built for restaurant meals, not the weekly shop Small baskets, no substitutions, no personalization Picking pushed onto retailer staff In-app prices higher marked up vs. shelf Rider-based labor model contested by Italian authorities and unions Online-only Retailers - a grocer's costs, no grocer's scale or loyalty Logistics first, customers later: warehouses and fleets — the lowest-margin layer of grocery — built ahead of the demand to fill them Every city repeats the same upfront build; fixed costs run ahead of baskets Fight for baskets against banners with decades of loyalty and private label Online-only Retailers Food Delivery Traditional Retailers 14
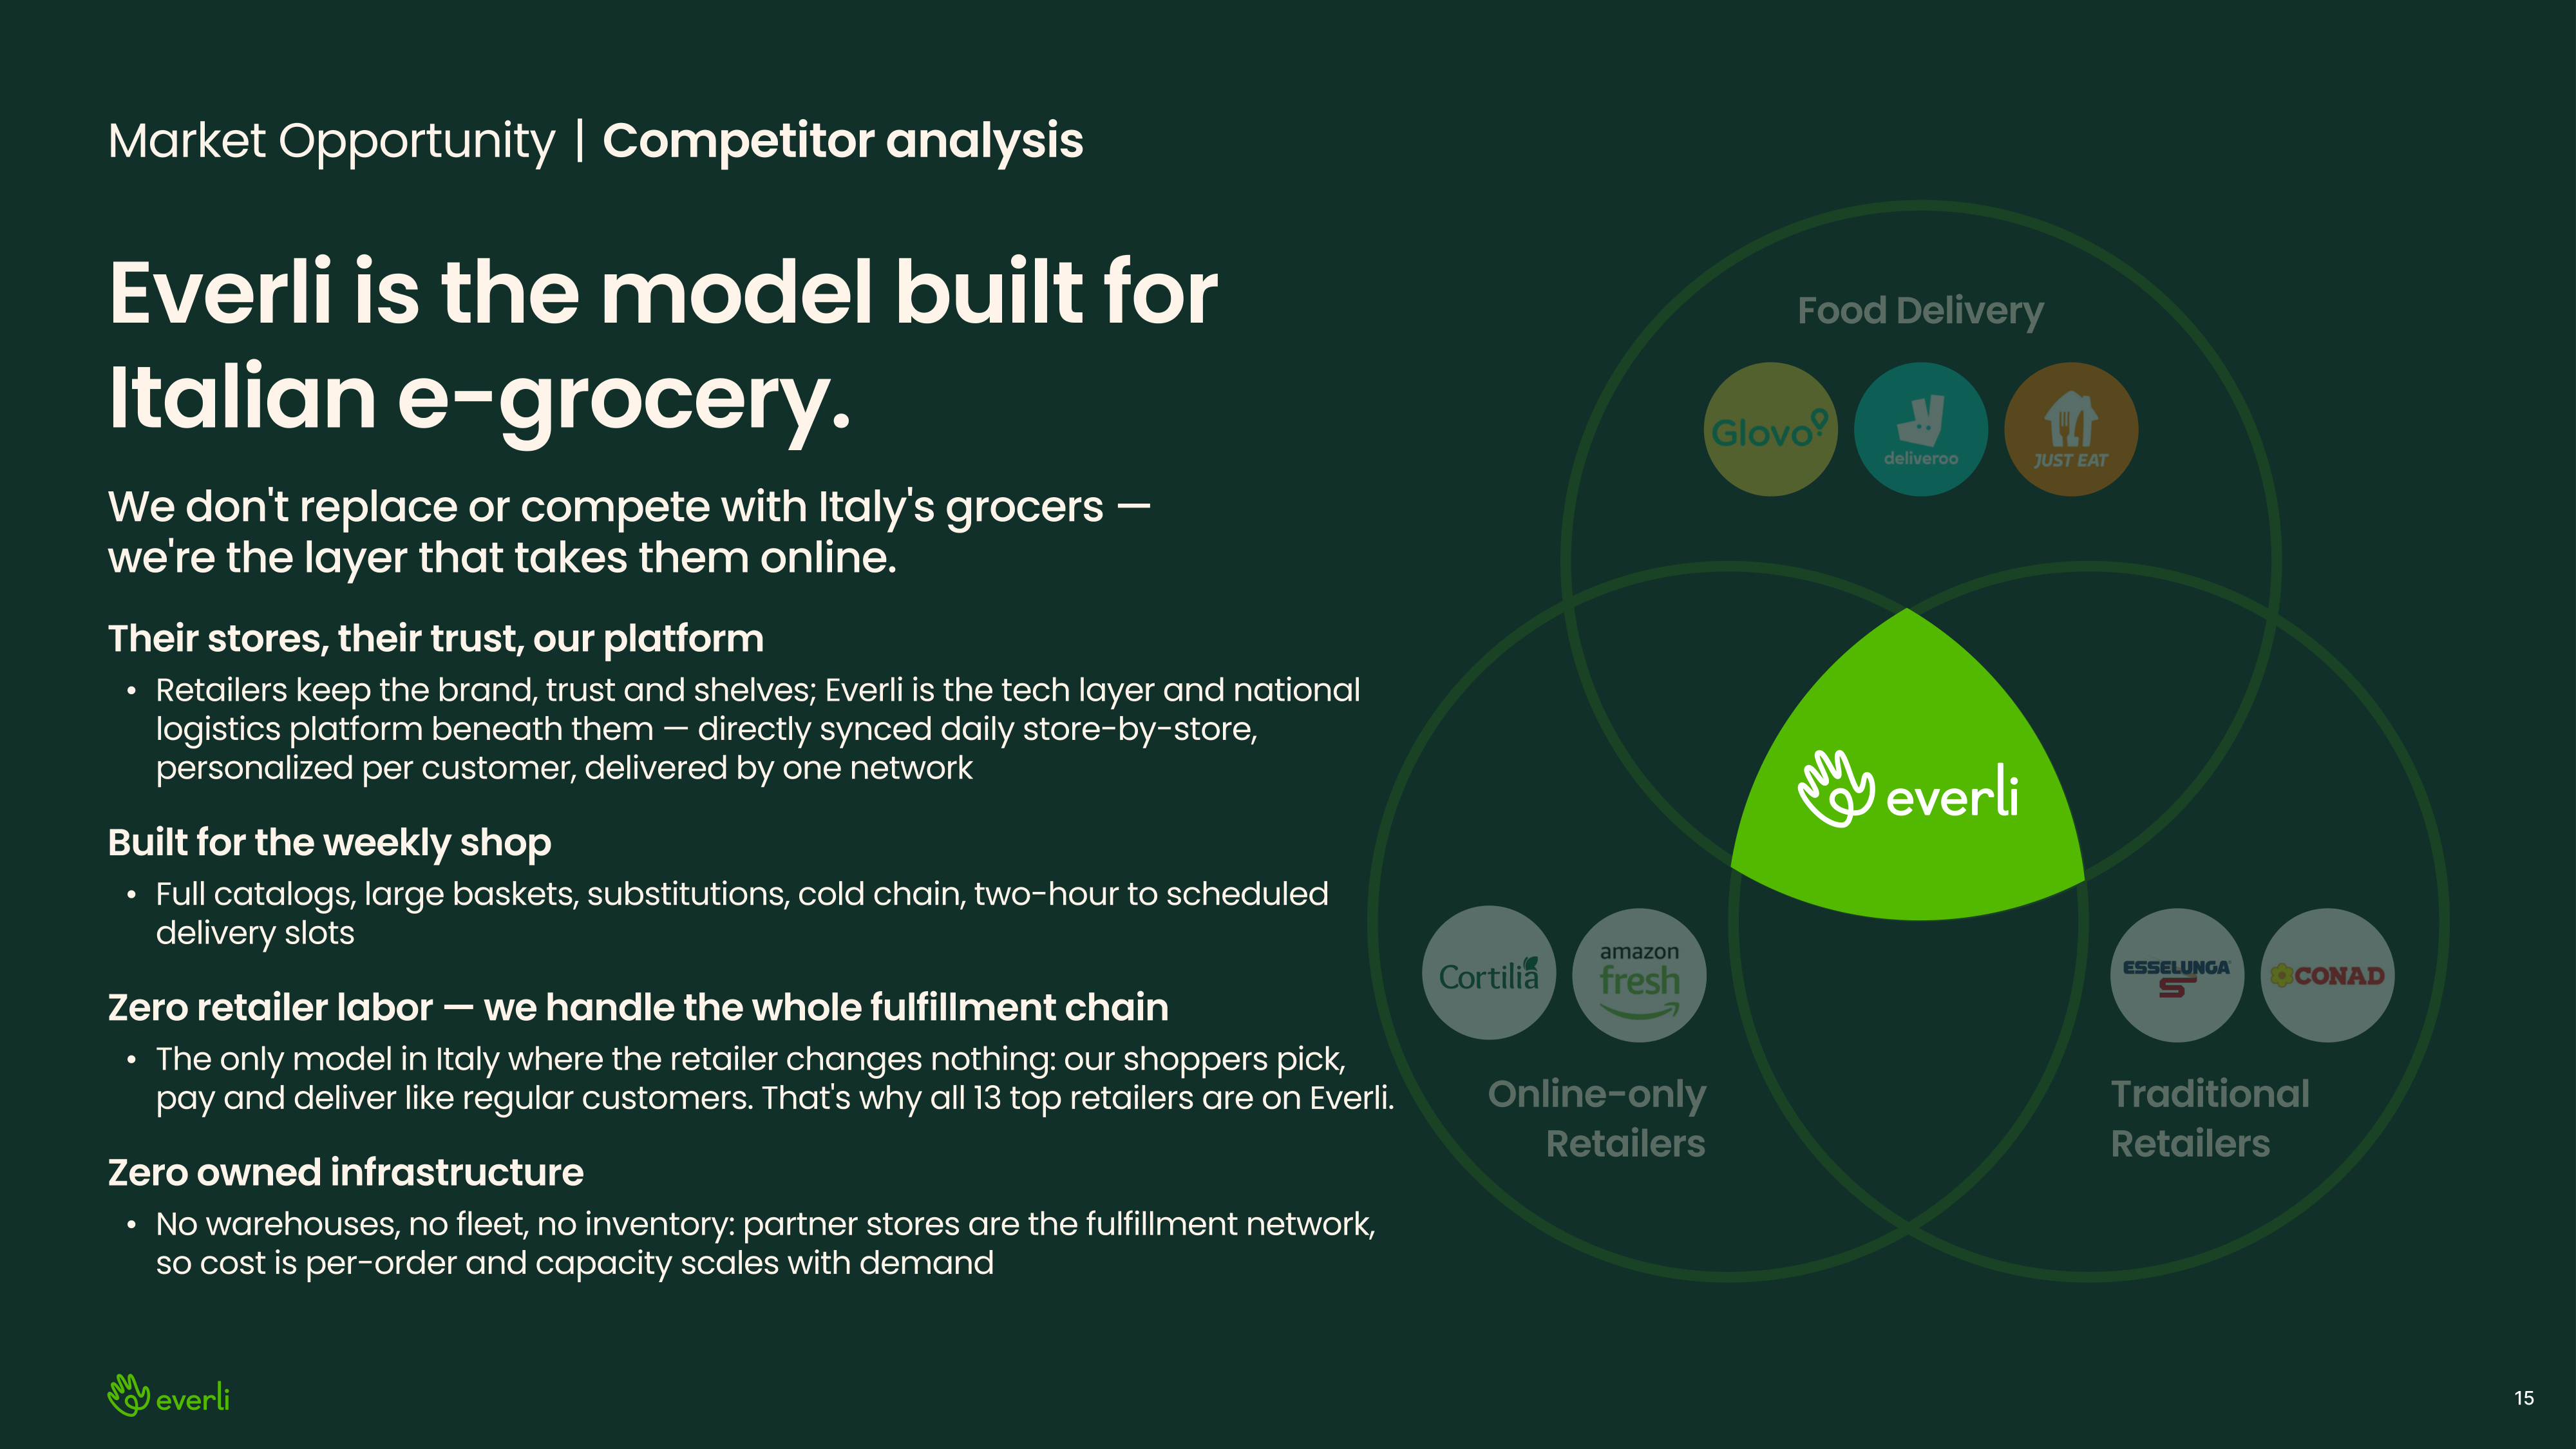
Market Opportunity | Competitor analysis Everli is the model built for Italian e-grocery. We don't replace or compete with Italy's grocers ( we're the layer that takes them online. Their stores, their trust, our platform Retailers keep the brand, trust and shelves; Everli is the tech layer and national logistics platform beneath them directly synced daily store-by-store, personalized per customer, delivered by one network Built for the weekly shop Full catalogs, large baskets, substitutions, cold chain, two-hour to scheduled delivery slots Food Delivery Zero retailer labor we handle the whole fulfillment chain The only model in Italy where the retailer changes nothing: our shoppers pick, ( pay and deliver like regular customers. That's why all 13 top retailers are on Everli. Zero owned infrastructure No warehouses, no fleet, no inventory: partner stores are the fulfillment network, ( so cost is per-order and capacity scales with demand Online-only Retailers Traditional Retailers 15
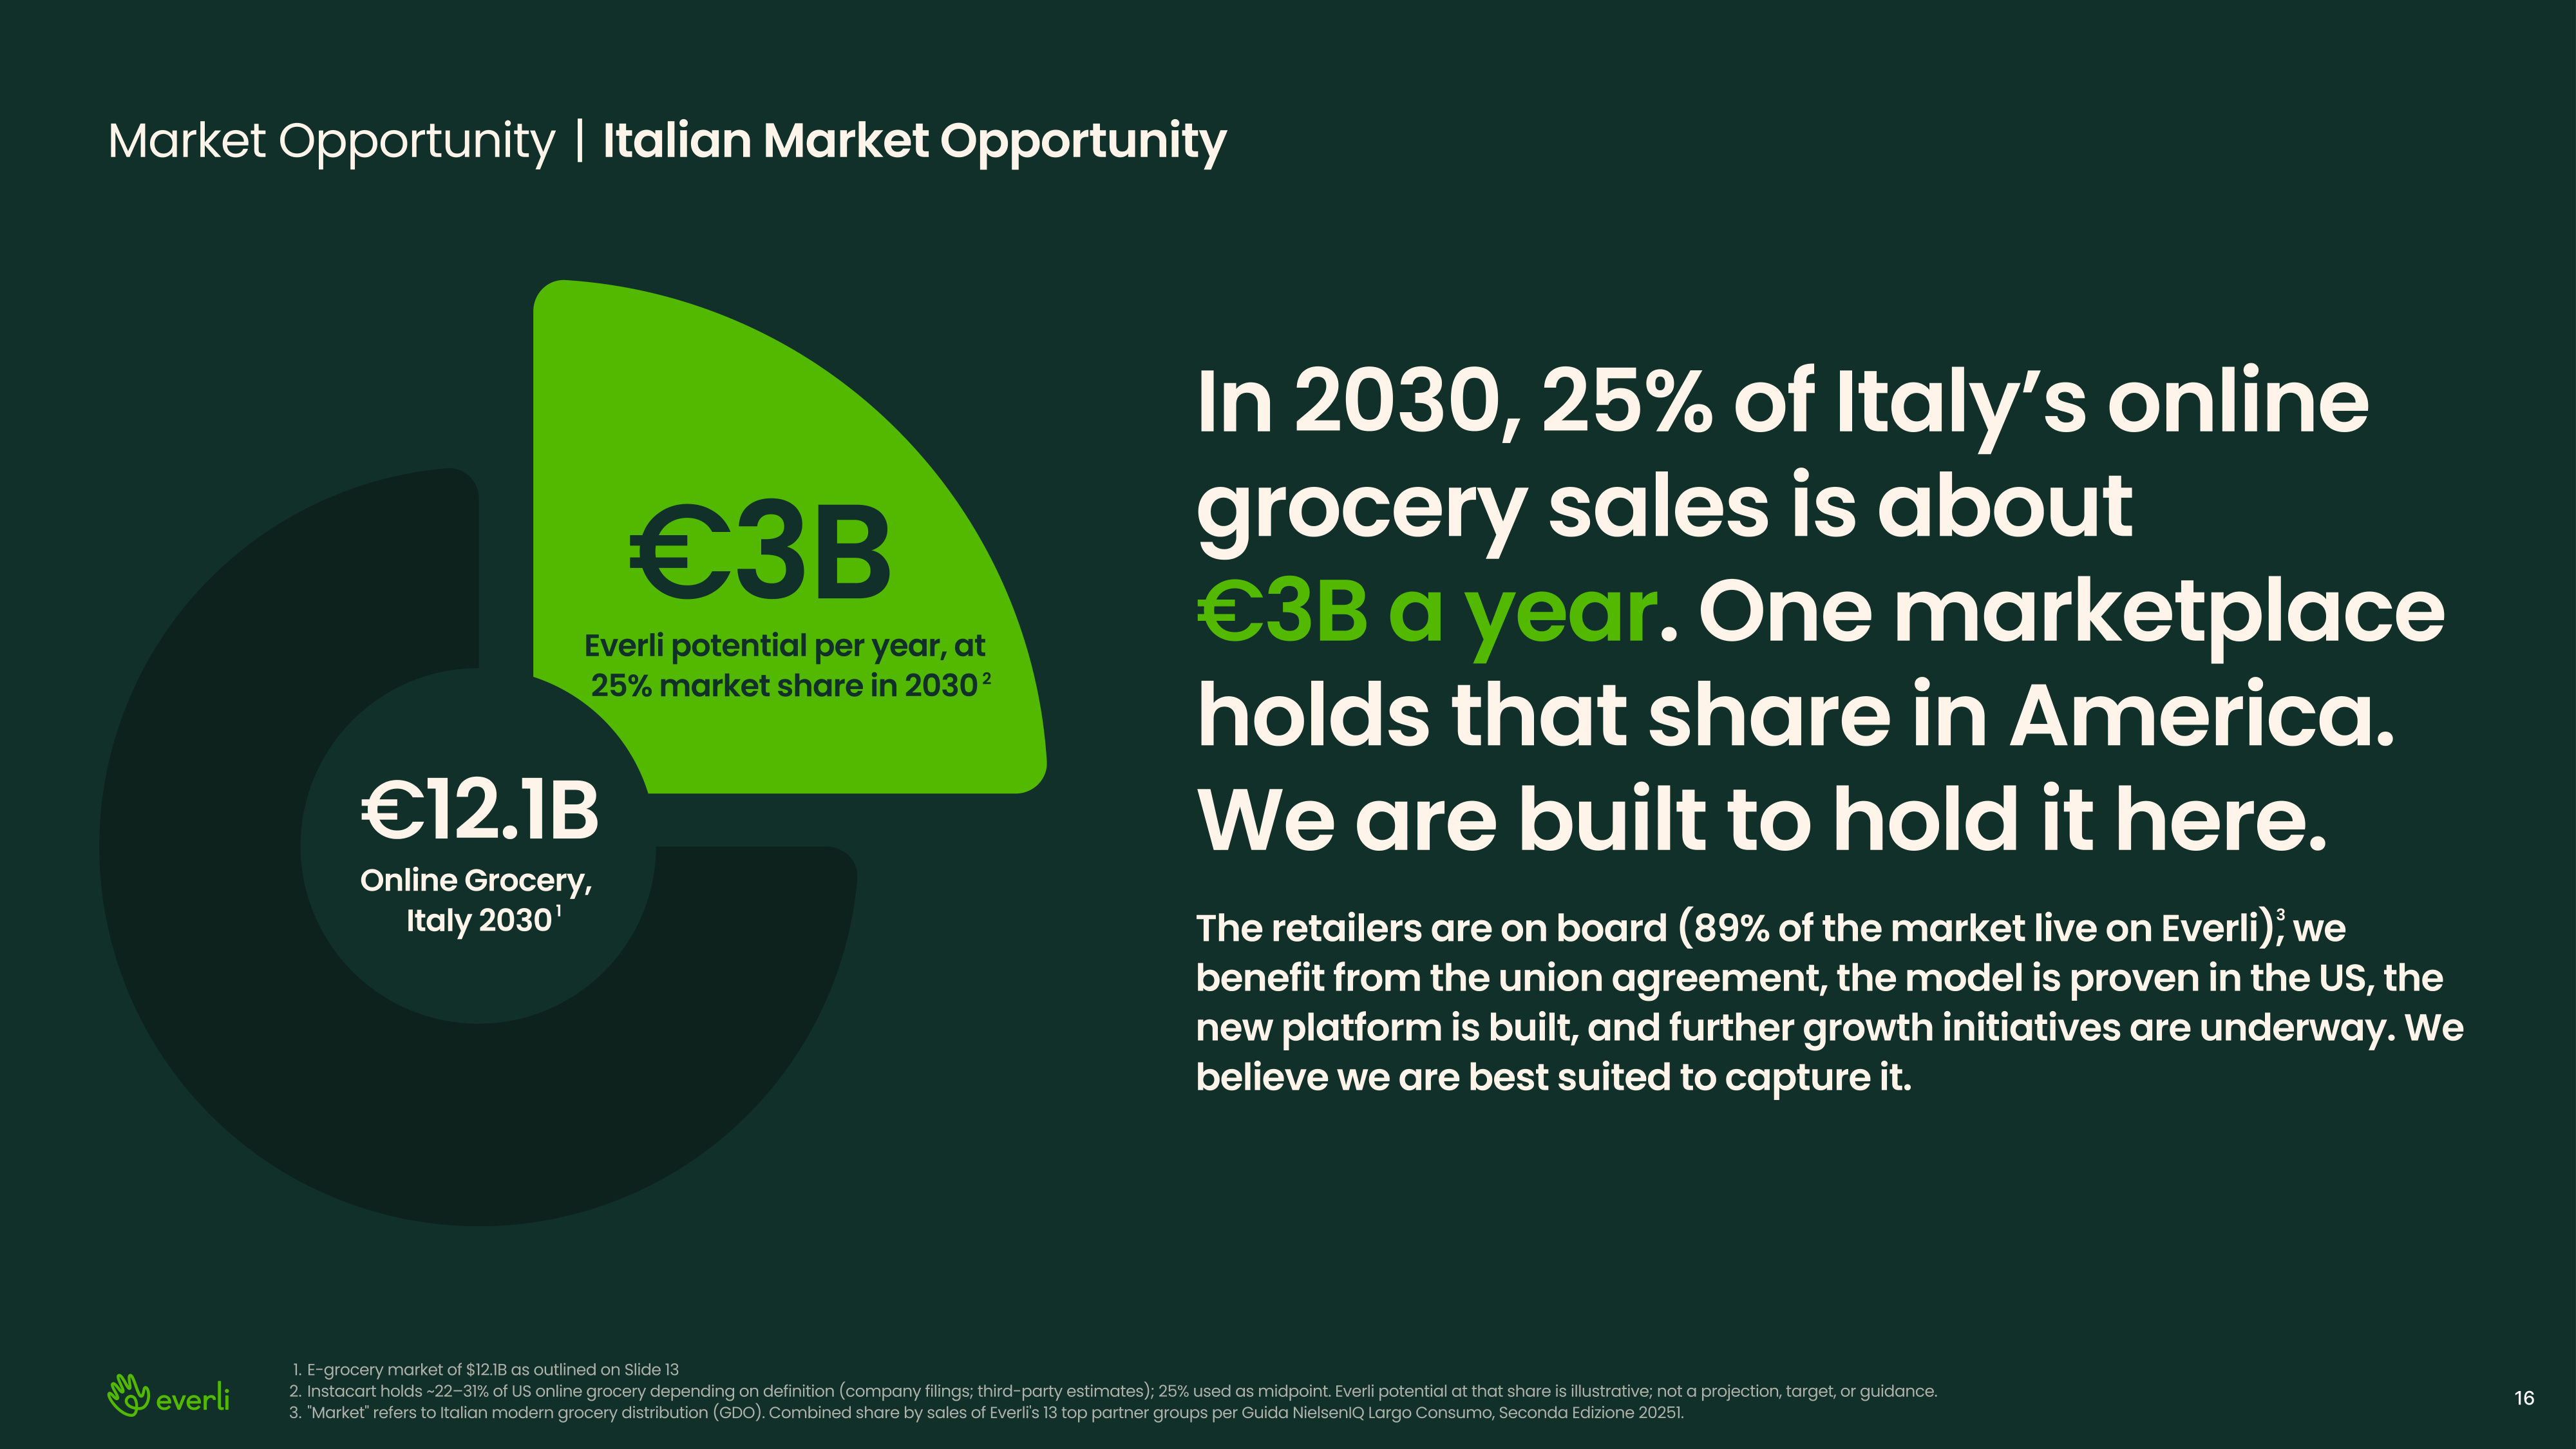
Market Opportunity | Italian Market Opportunity In 2030, 25% of Italyˇs online grocery sales is about ( ¬3B a year. One marketplace holds that share in America. We are built to hold it here. Everli potential per year, at 25% market share in 2030 ¬3B 2 ¬12.1B Online Grocery, ( Italy 2030 1 The retailers are on board (89% of the market live on Everli), we benefit from the union agreement, the model is proven in the US, the new platform is built, and further growth initiatives are underway. We believe we are best suited to capture it. 3 roery arket o a outine on ie ntaart o o onine roery epenin on einition opany iin tirparty etiate ue a ipoint eri potentia at tat are i iutratie not a proetion taret or uiane 16
3 Growth ( Strategy 17
Growth Strategy | Overview Growth Pillars 1 Logistics Accelerate fulfillment growth & strengthen network efficiency to capture scale advantages 2 Technology Build scalable, best-in-class product to be clear market leader in Europe 3 White-label Offer 360° e-commerce, tech & logistics to retailers, unlocking new demand from B2B channel 4 Expansion Lead digitalization of Italy's $150B market with the position already built. Then Europe, once Italy is won. 5 Reach Profitability With scaled reach & fixed cost base, efficiencies unlock and EBITDA begins to turn positive€ 18
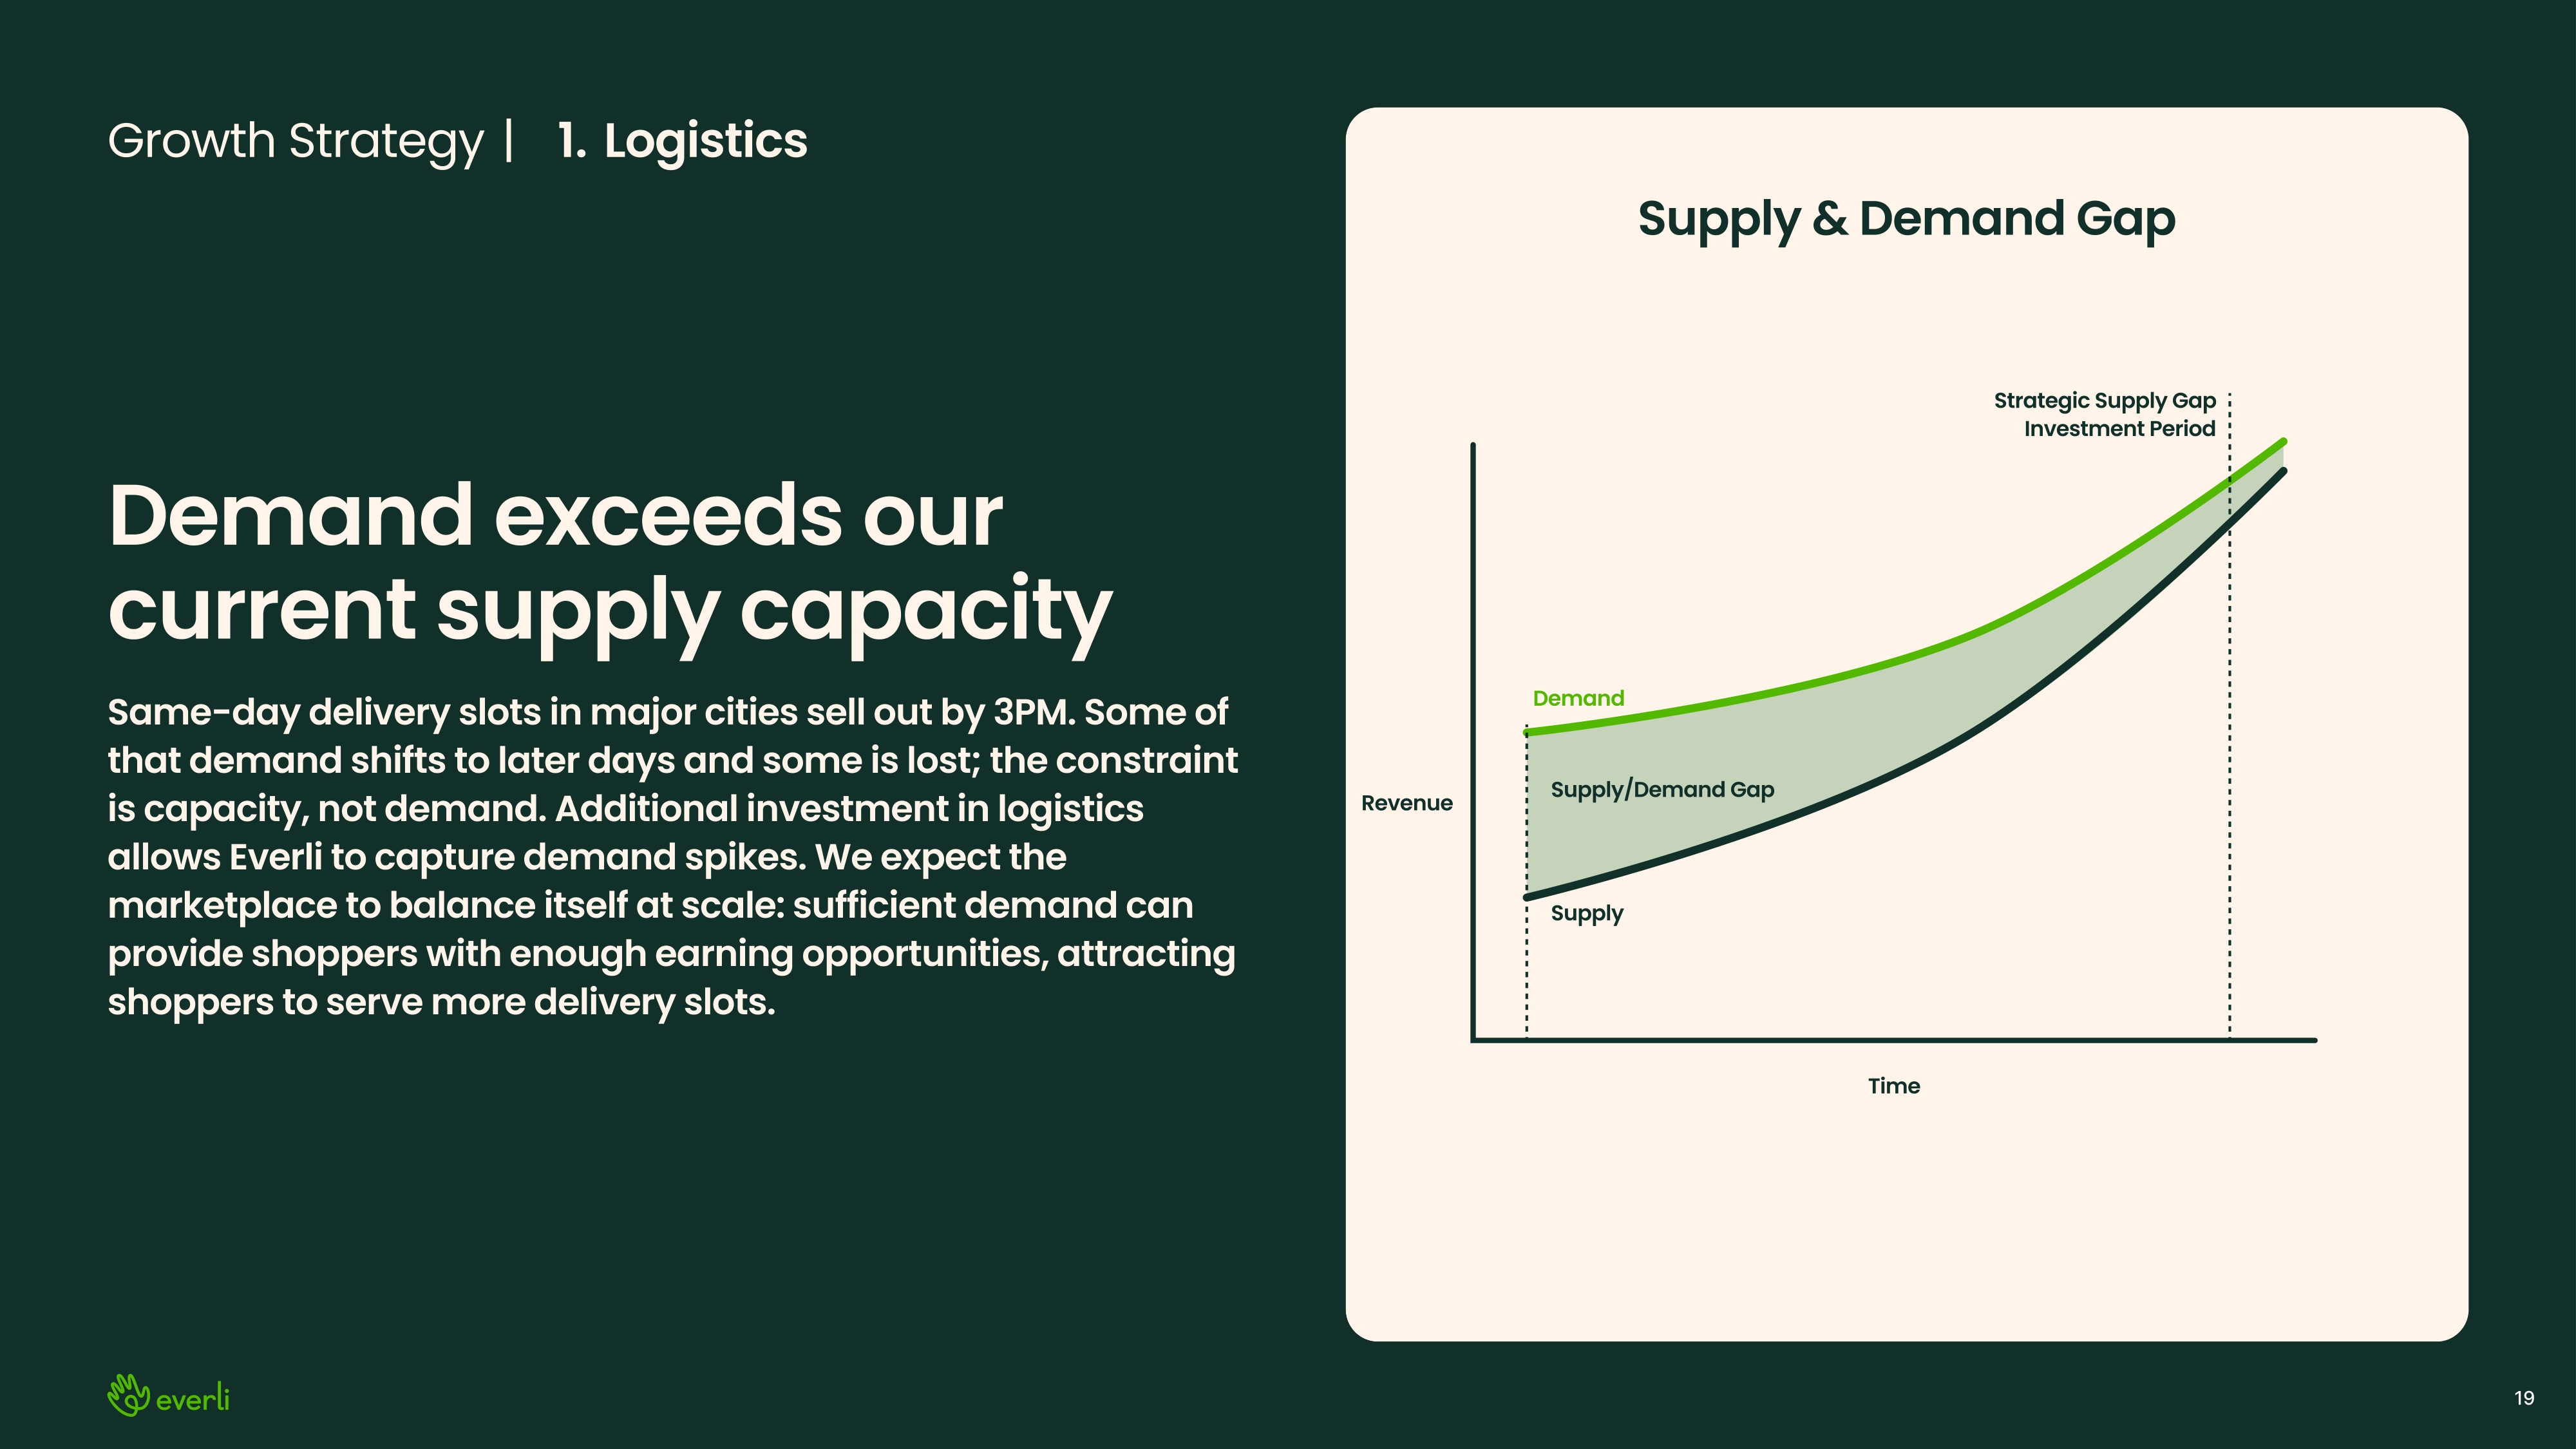
Growth Strategy | Logistics Demand exceeds our current supply capacity Same-day delivery slots in major cities sell out by 3PM. Some of that demand shifts to later days and some is lost; the constraint is capacity, not demand. Additional investment in logistics allows Everli to capture demand spikes. We expect the marketplace to balance itself at scale: sufficient demand can provide shoppers with enough earning opportunities, attracting shoppers to serve more delivery slots. Revenue Supply & Demand Gap Strategic Supply Gap Investment Period Demand Supply/Demand Gap Supply Time 19
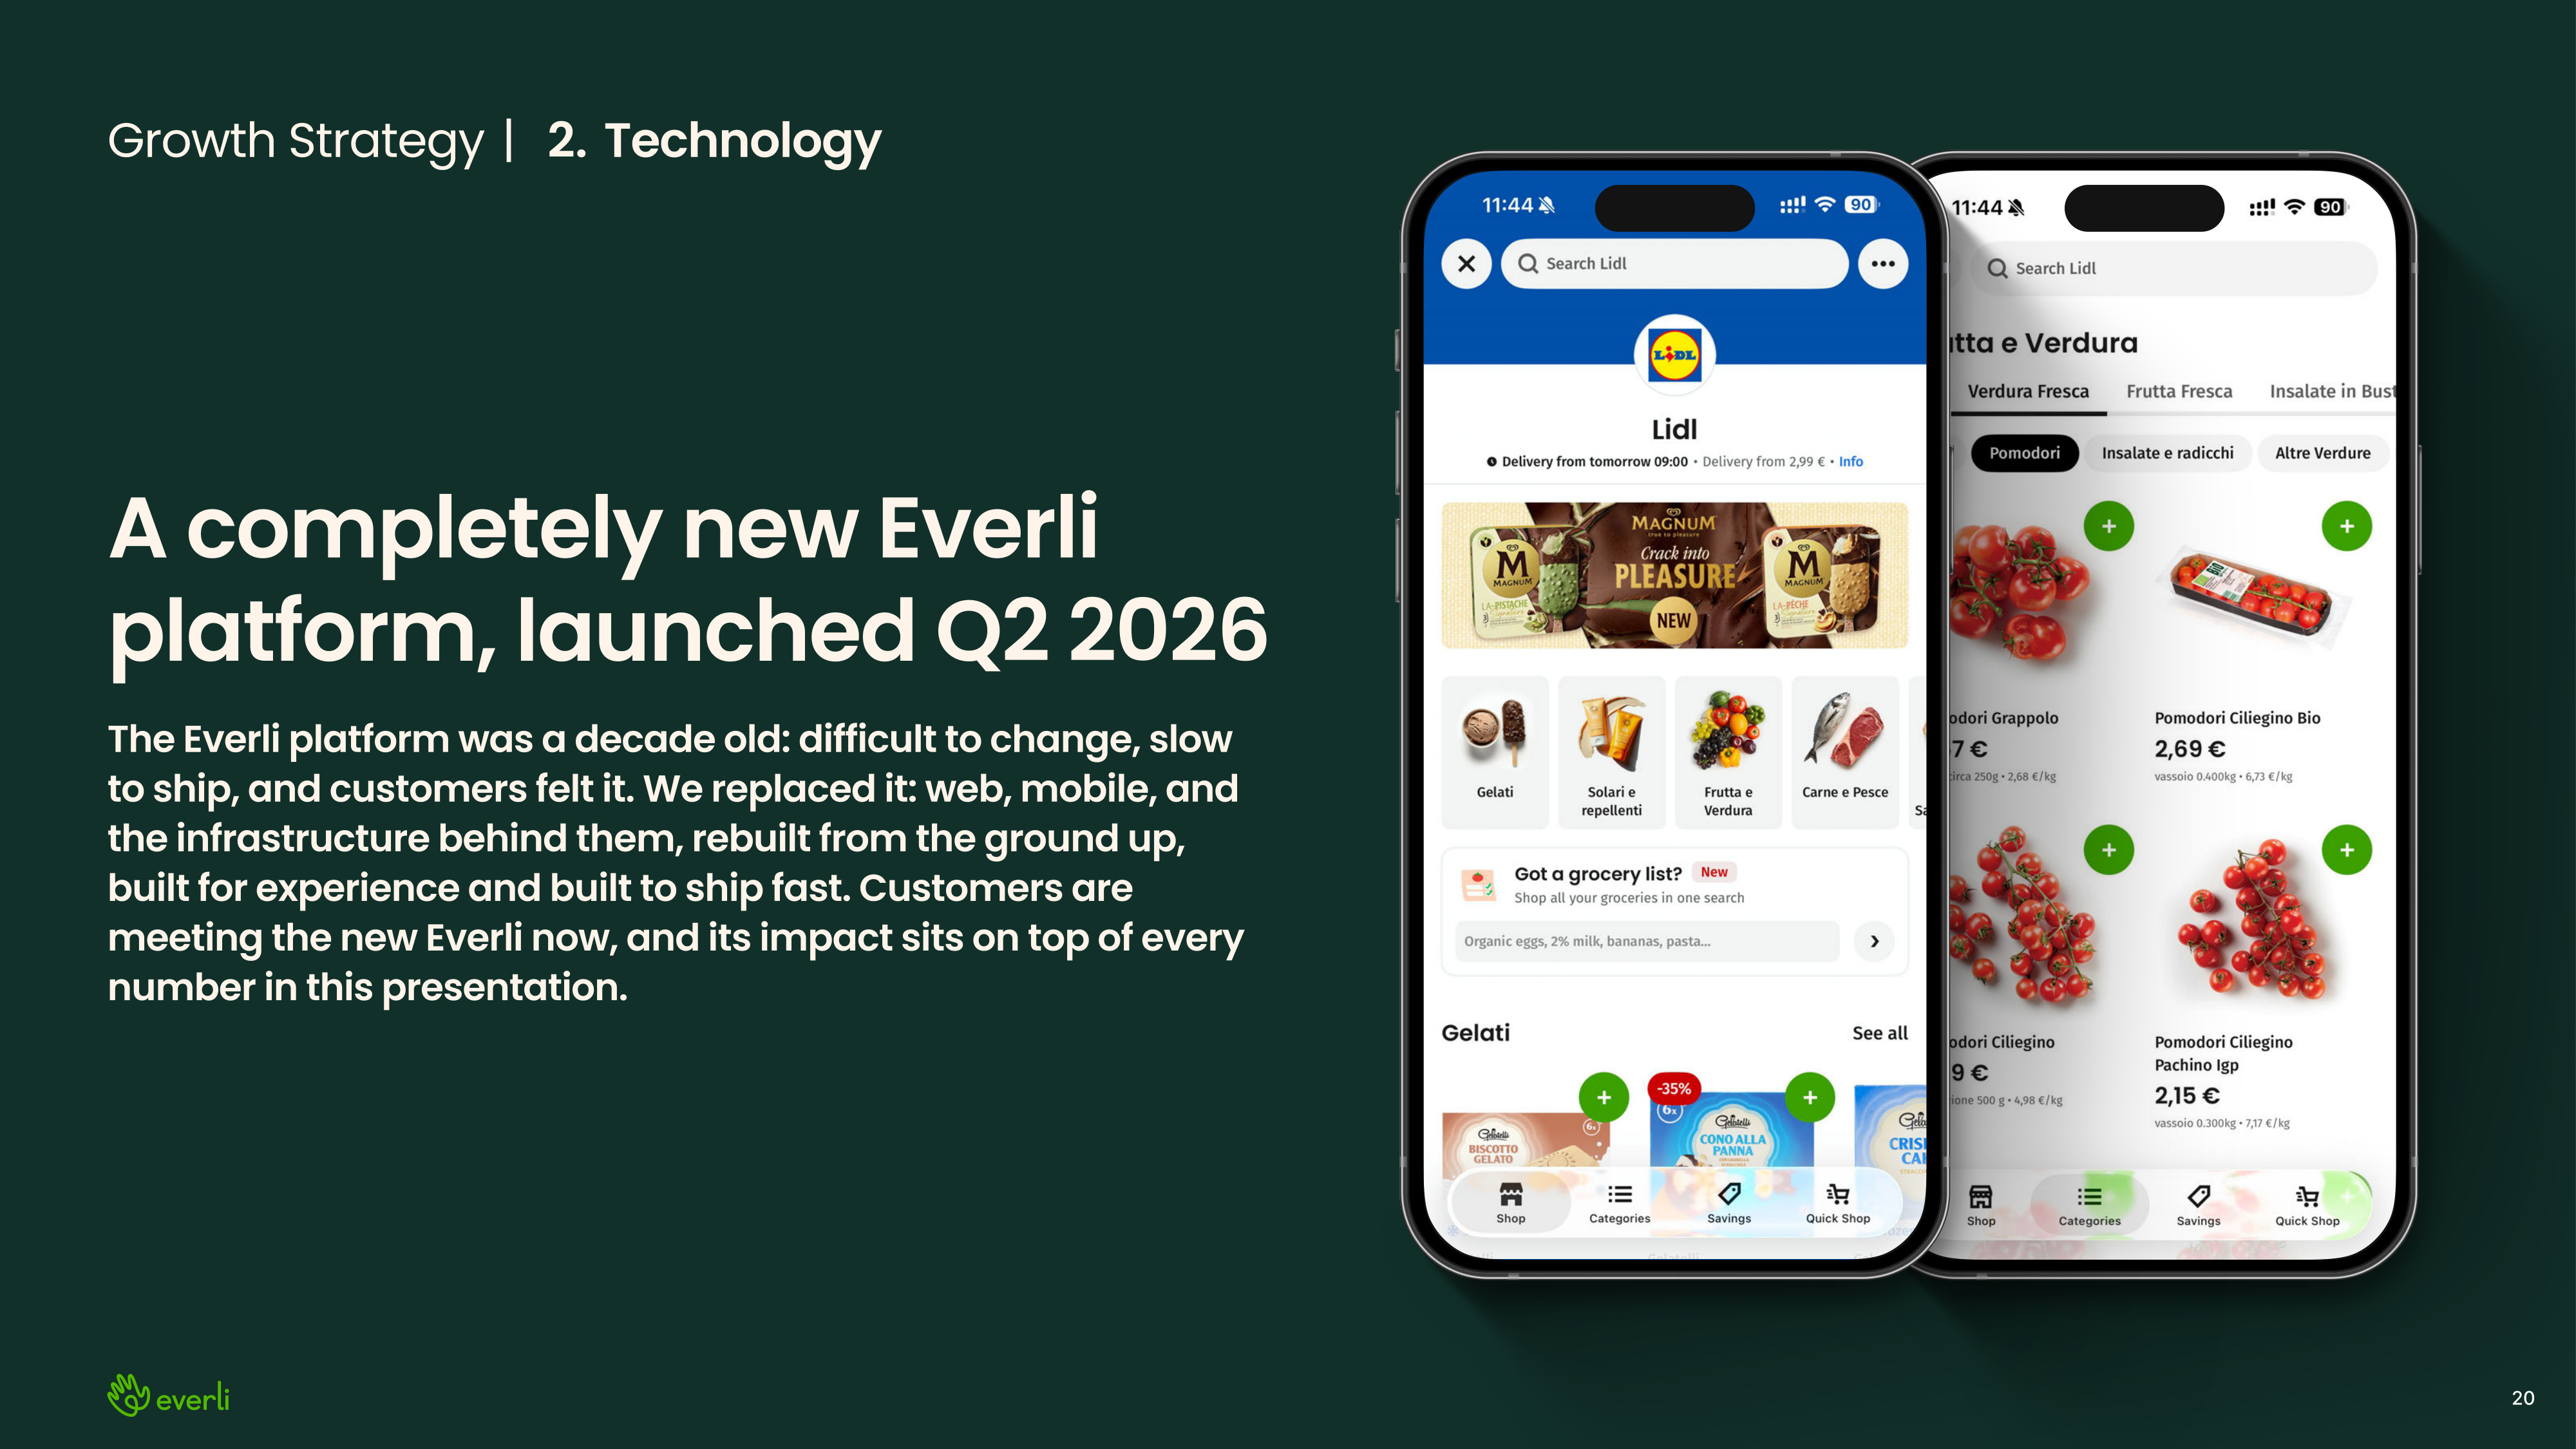
Growth Strategy | Technology A completely new Everli platform, launched Q2 2026 The Everli platform was a decade old: difficult to change, slow to ship, and customers felt it. We replaced it: web, mobile, and the infrastructure behind them, rebuilt from the ground up, built for experience and built to ship fast. Customers are meeting the new Everli now, and its impact sits on top of every number in this presentation. Search Store 1st Category 1st Category 20 1st Category 1st Category 1st Category 1st LIDL
Growth Strategy | Technology We invest in automation, AI and intelligence across the platform, designed to scale volume faster than costs Grocery marketplaces win on cost discipline, and engineering it in is Everli's next focus: automation and intelligence applied to how orders are routed, to the entire customer experience at every step, and to how the company operates and decides. The first systems are already in production on the new platform; the same intelligence will extend through logistics, operations, and the customer experience. The gains compound with scale; that gap between volume and cost is one of the places the long-term margin may come from. 21
Every retailer wants online growth. ( No retailer's margin can pay for it. The best grocers spent a hundred years getting good at one hard thing. The internet handed them three more: a storefront, a delivery network, an app that has to feel world-class and stay that way. All of it funded from a market that is 2.5% online. None of it was the job they signed up for. So we took it off their hands. 22
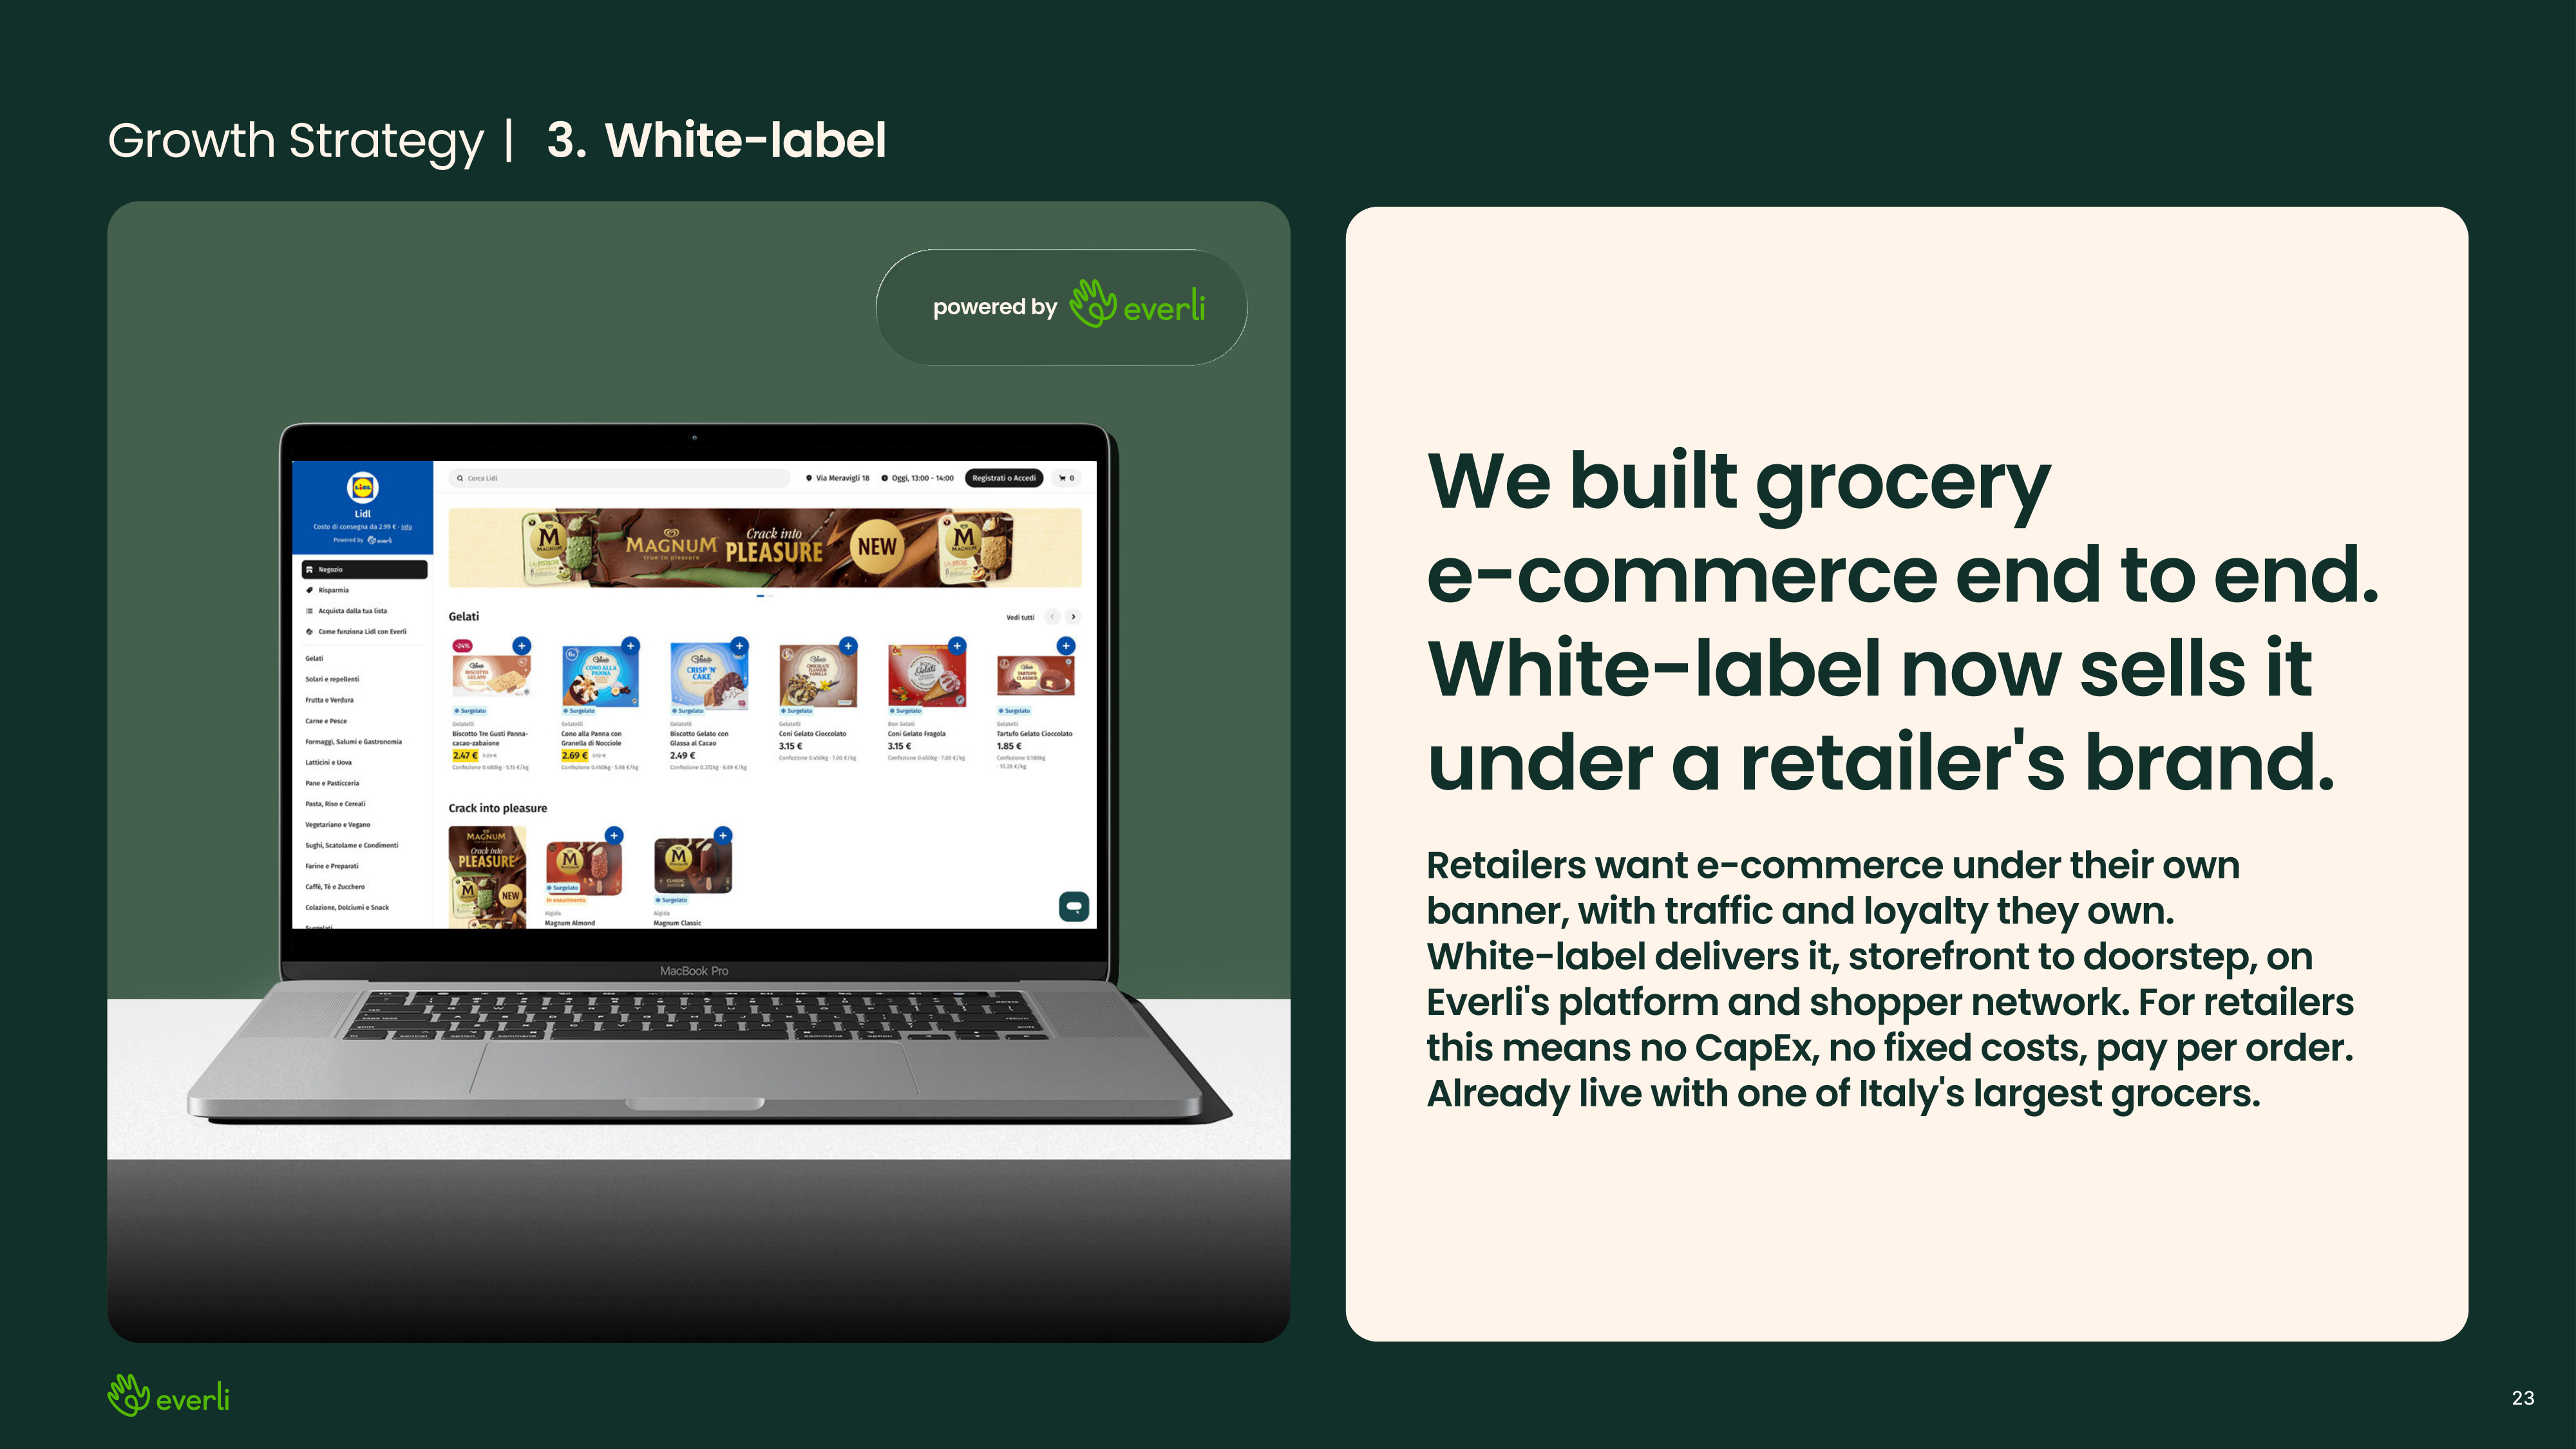
Growth Strategy | White-label powered by We built grocery ( e-commerce end to end. White-label now sells it under a retailer's brand. Retailers want e-commerce under their own banner, with traffic and loyalty they own. ( White-label delivers it, storefront to doorstep, on Everli's platform and shopper network. For retailers this means no CapEx, no fixed costs, pay per order. Already live with one of Italy's largest grocers. 23
4 Financial Overview 24
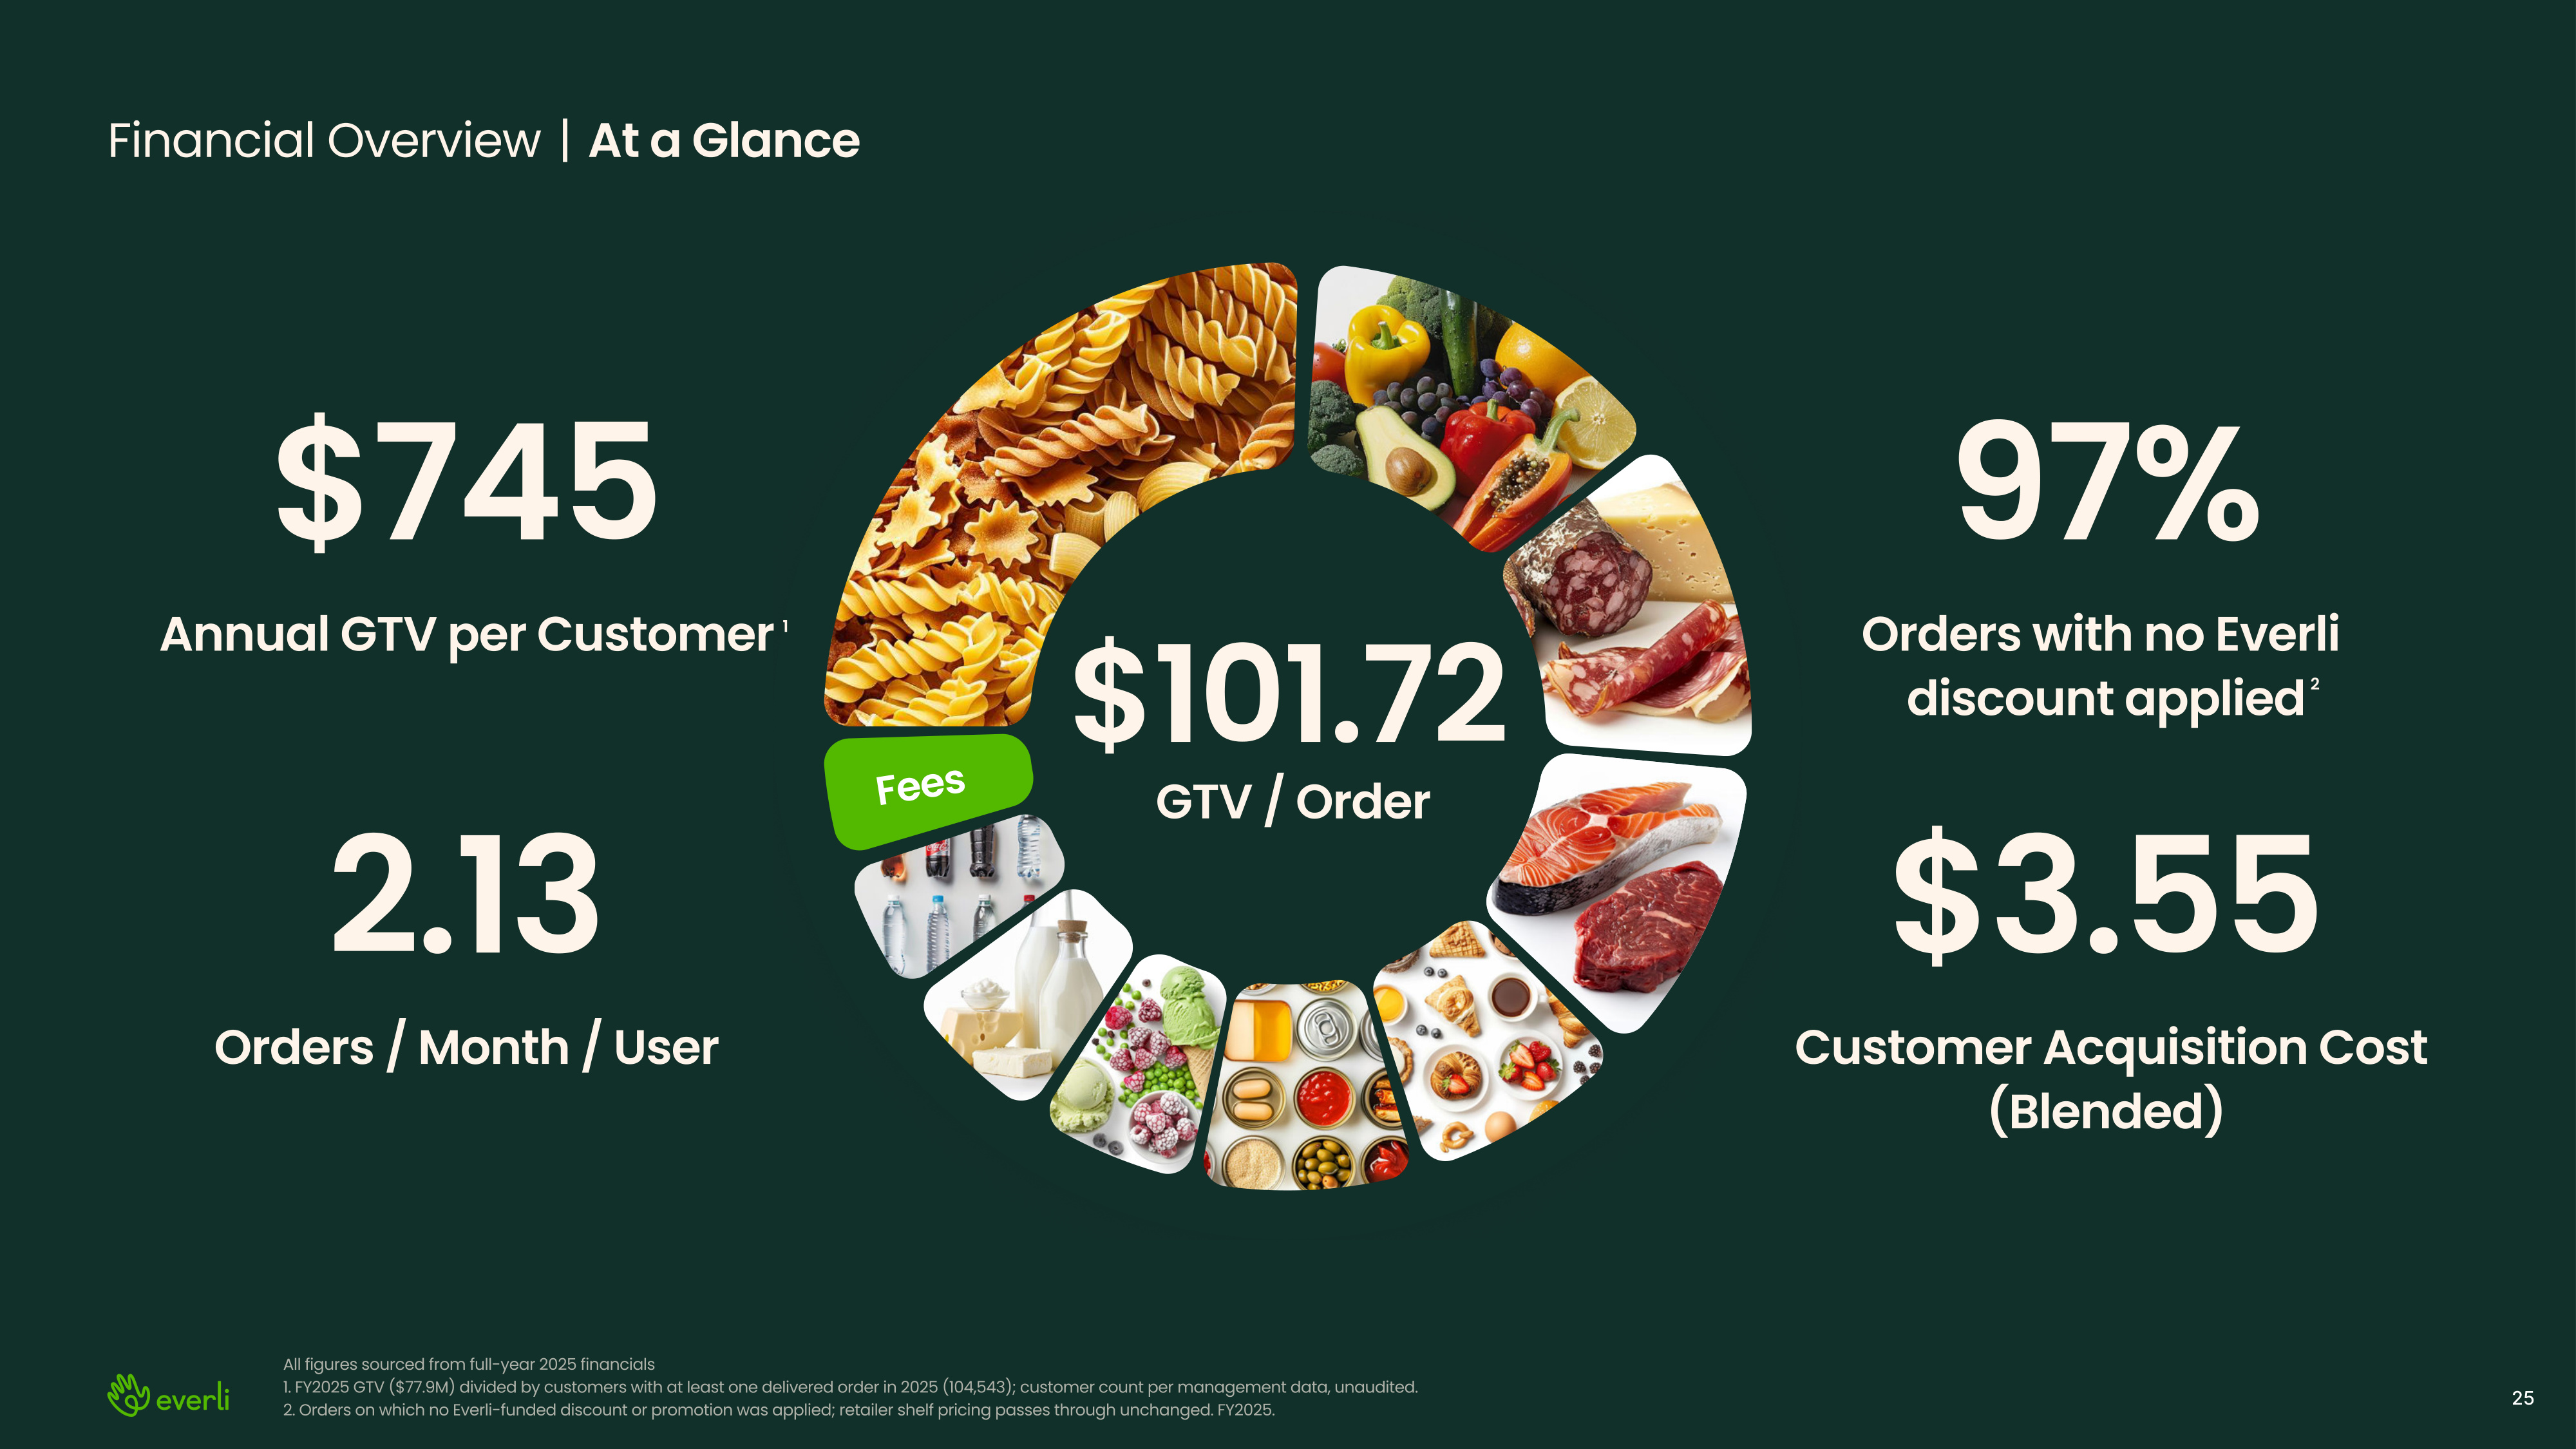
Financial Overview | At a Glance $745 97% Annual GTV per Customer 1 Orders with no Everli discount applied 2 $101.72 GTV / Order 2.13 Orders / Month / User Fees $3.55 Customer Acquisition Cost( (Blended) All figures sourced from full-year 2025 financials 1. FY2025 GTV ($77.9M) divided by customers with at least one delivered order in 2025 (104,543); customer count per management data, unaudited. 2. Orders on which no Everli-funded discount or promotion was applied; retailer shelf pricing passes through unchanged. FY2025. 25
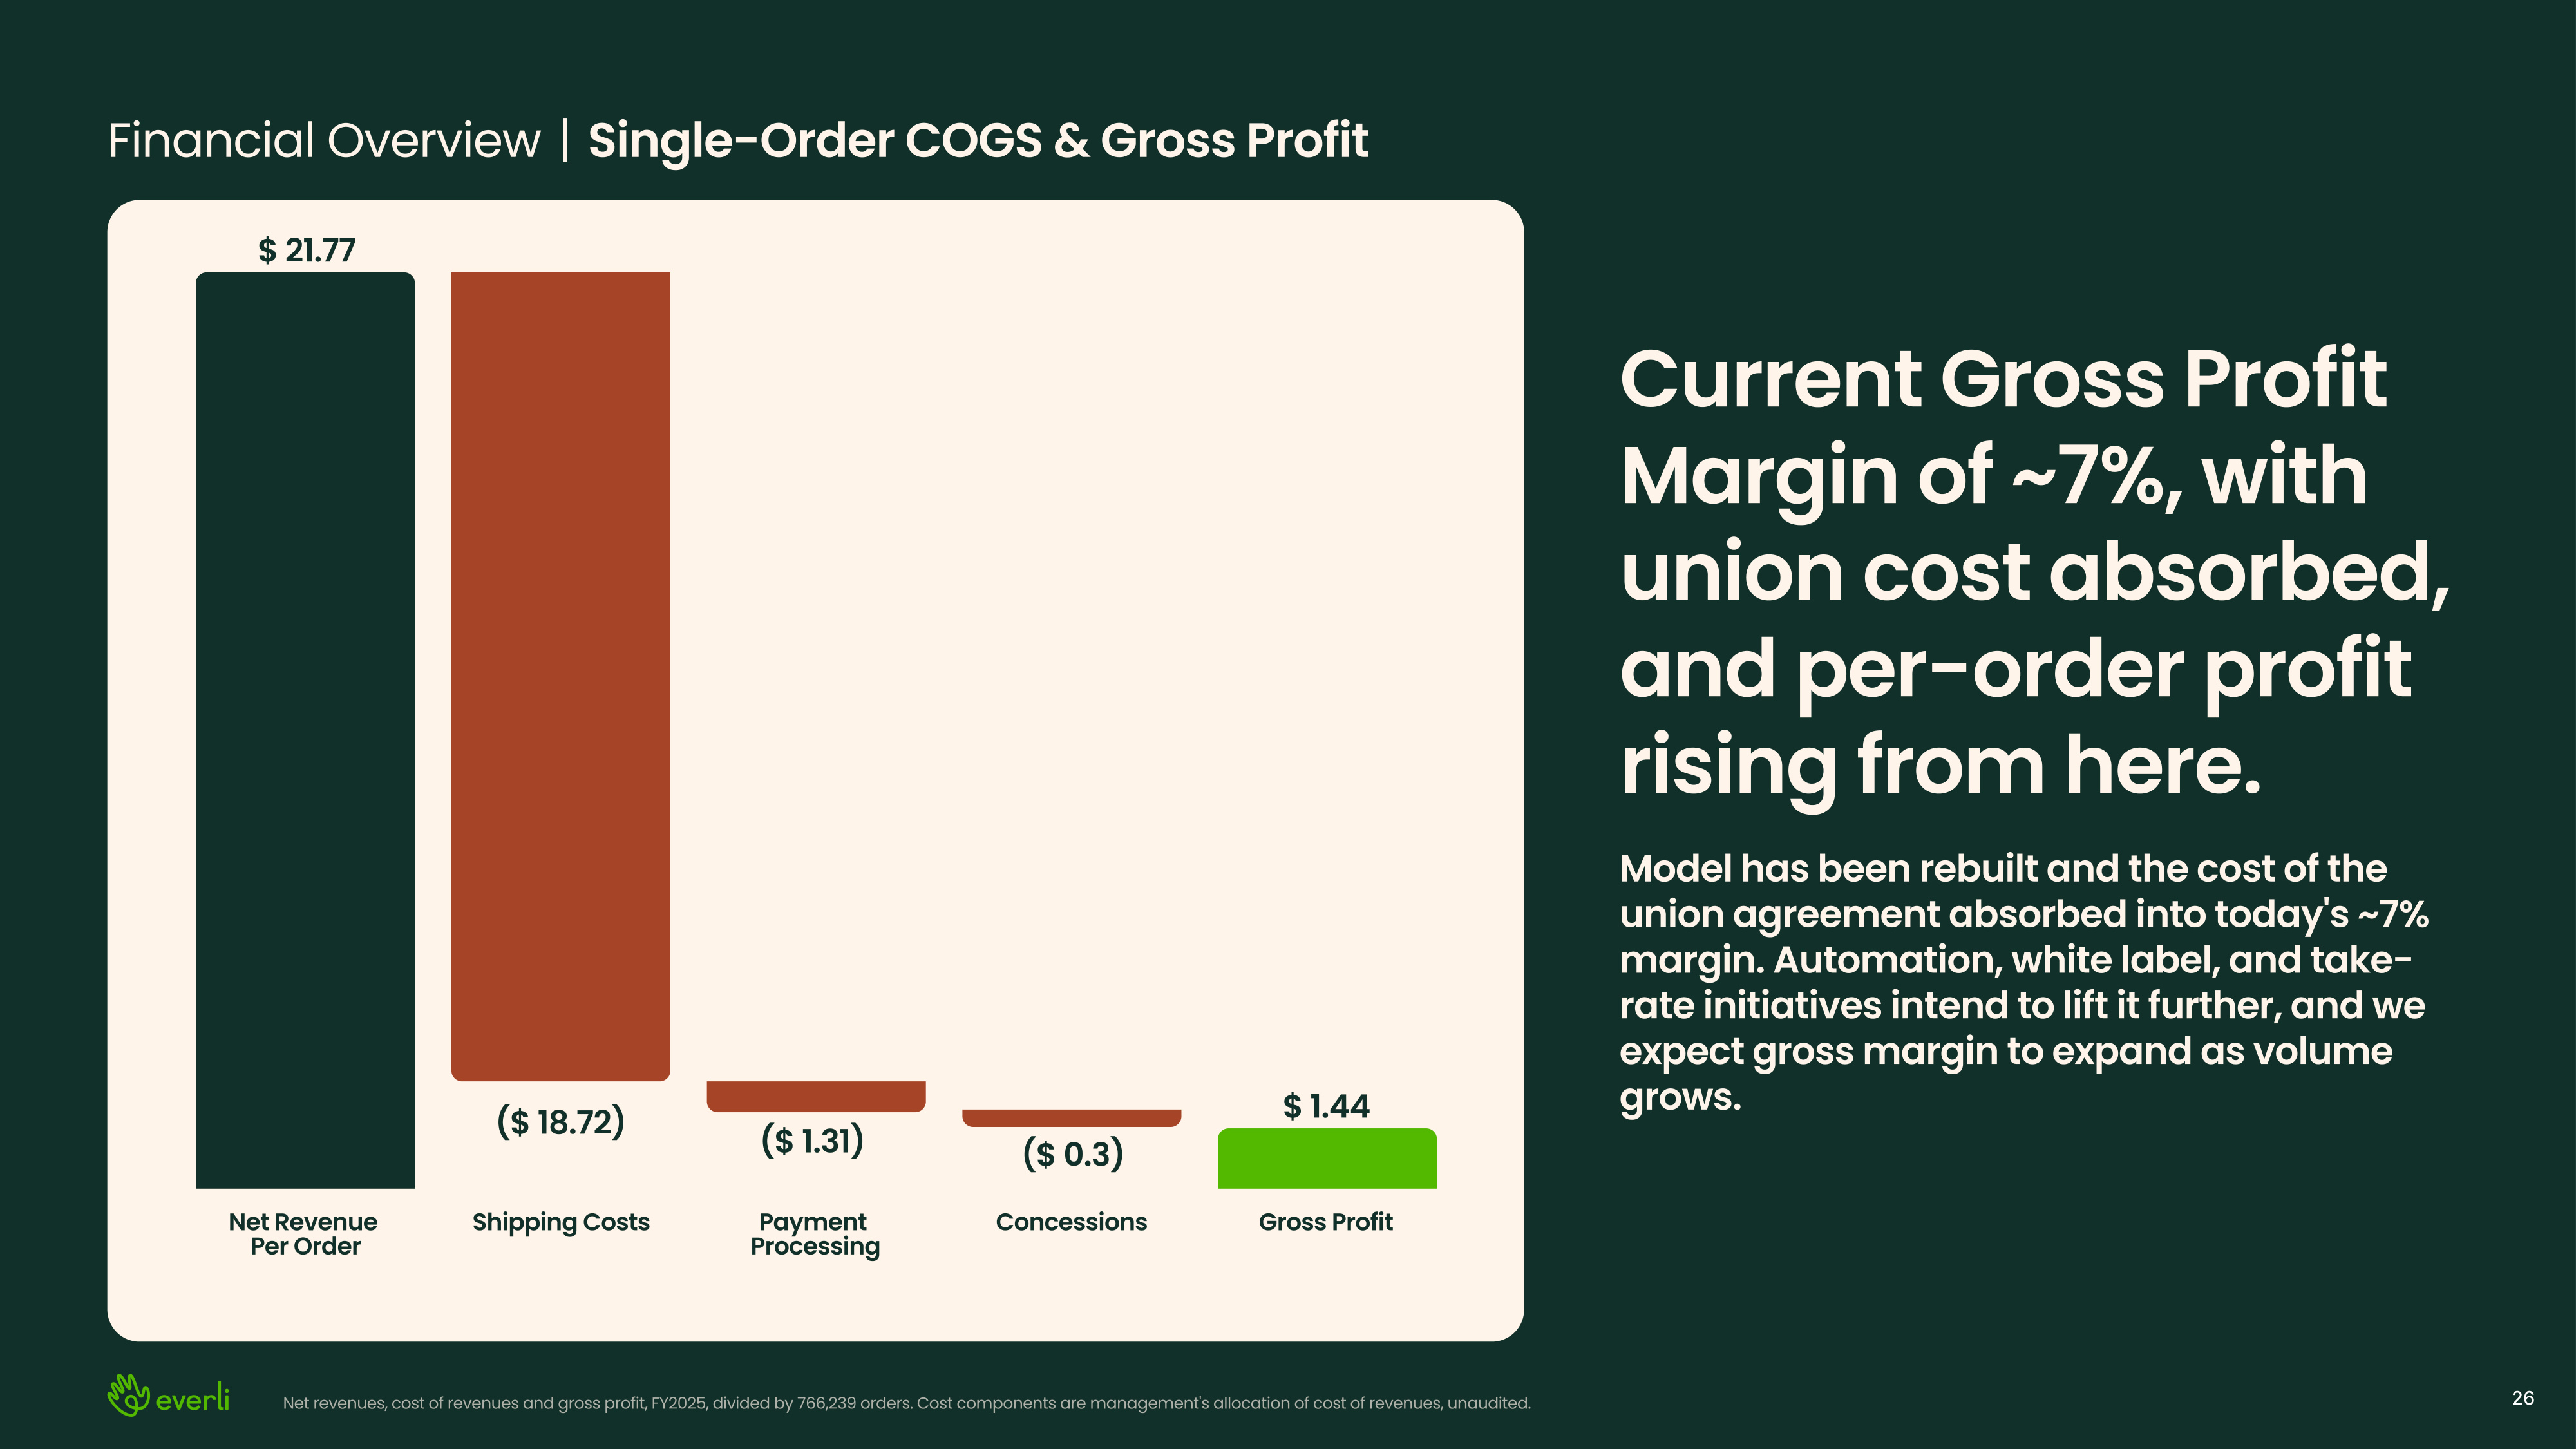
Financial Overview | Single-Order COGS & Gross Profit€ $ 21.77 ($ 18.72) ($ 1.31) Payment ( Processing Current Gross Profit Margin of ~7%, with union cost absorbed, and per-order profit rising from here. Model has been rebuilt and the cost of the union agreement absorbed into today's ~7% margin. Automation, white label, and take- rate initiatives intend to lift it further, and we expect gross margin to expand as volume grows. $ 1.44 ($ 0.3) Concessions Net Revenue ( Per Order Shipping Costs Gross Profit Net revenues, cost of revenues and gross profit, FY2025, divided by 766,239 orders. Cost components are management's allocation of cost of revenues, unaudited. 26
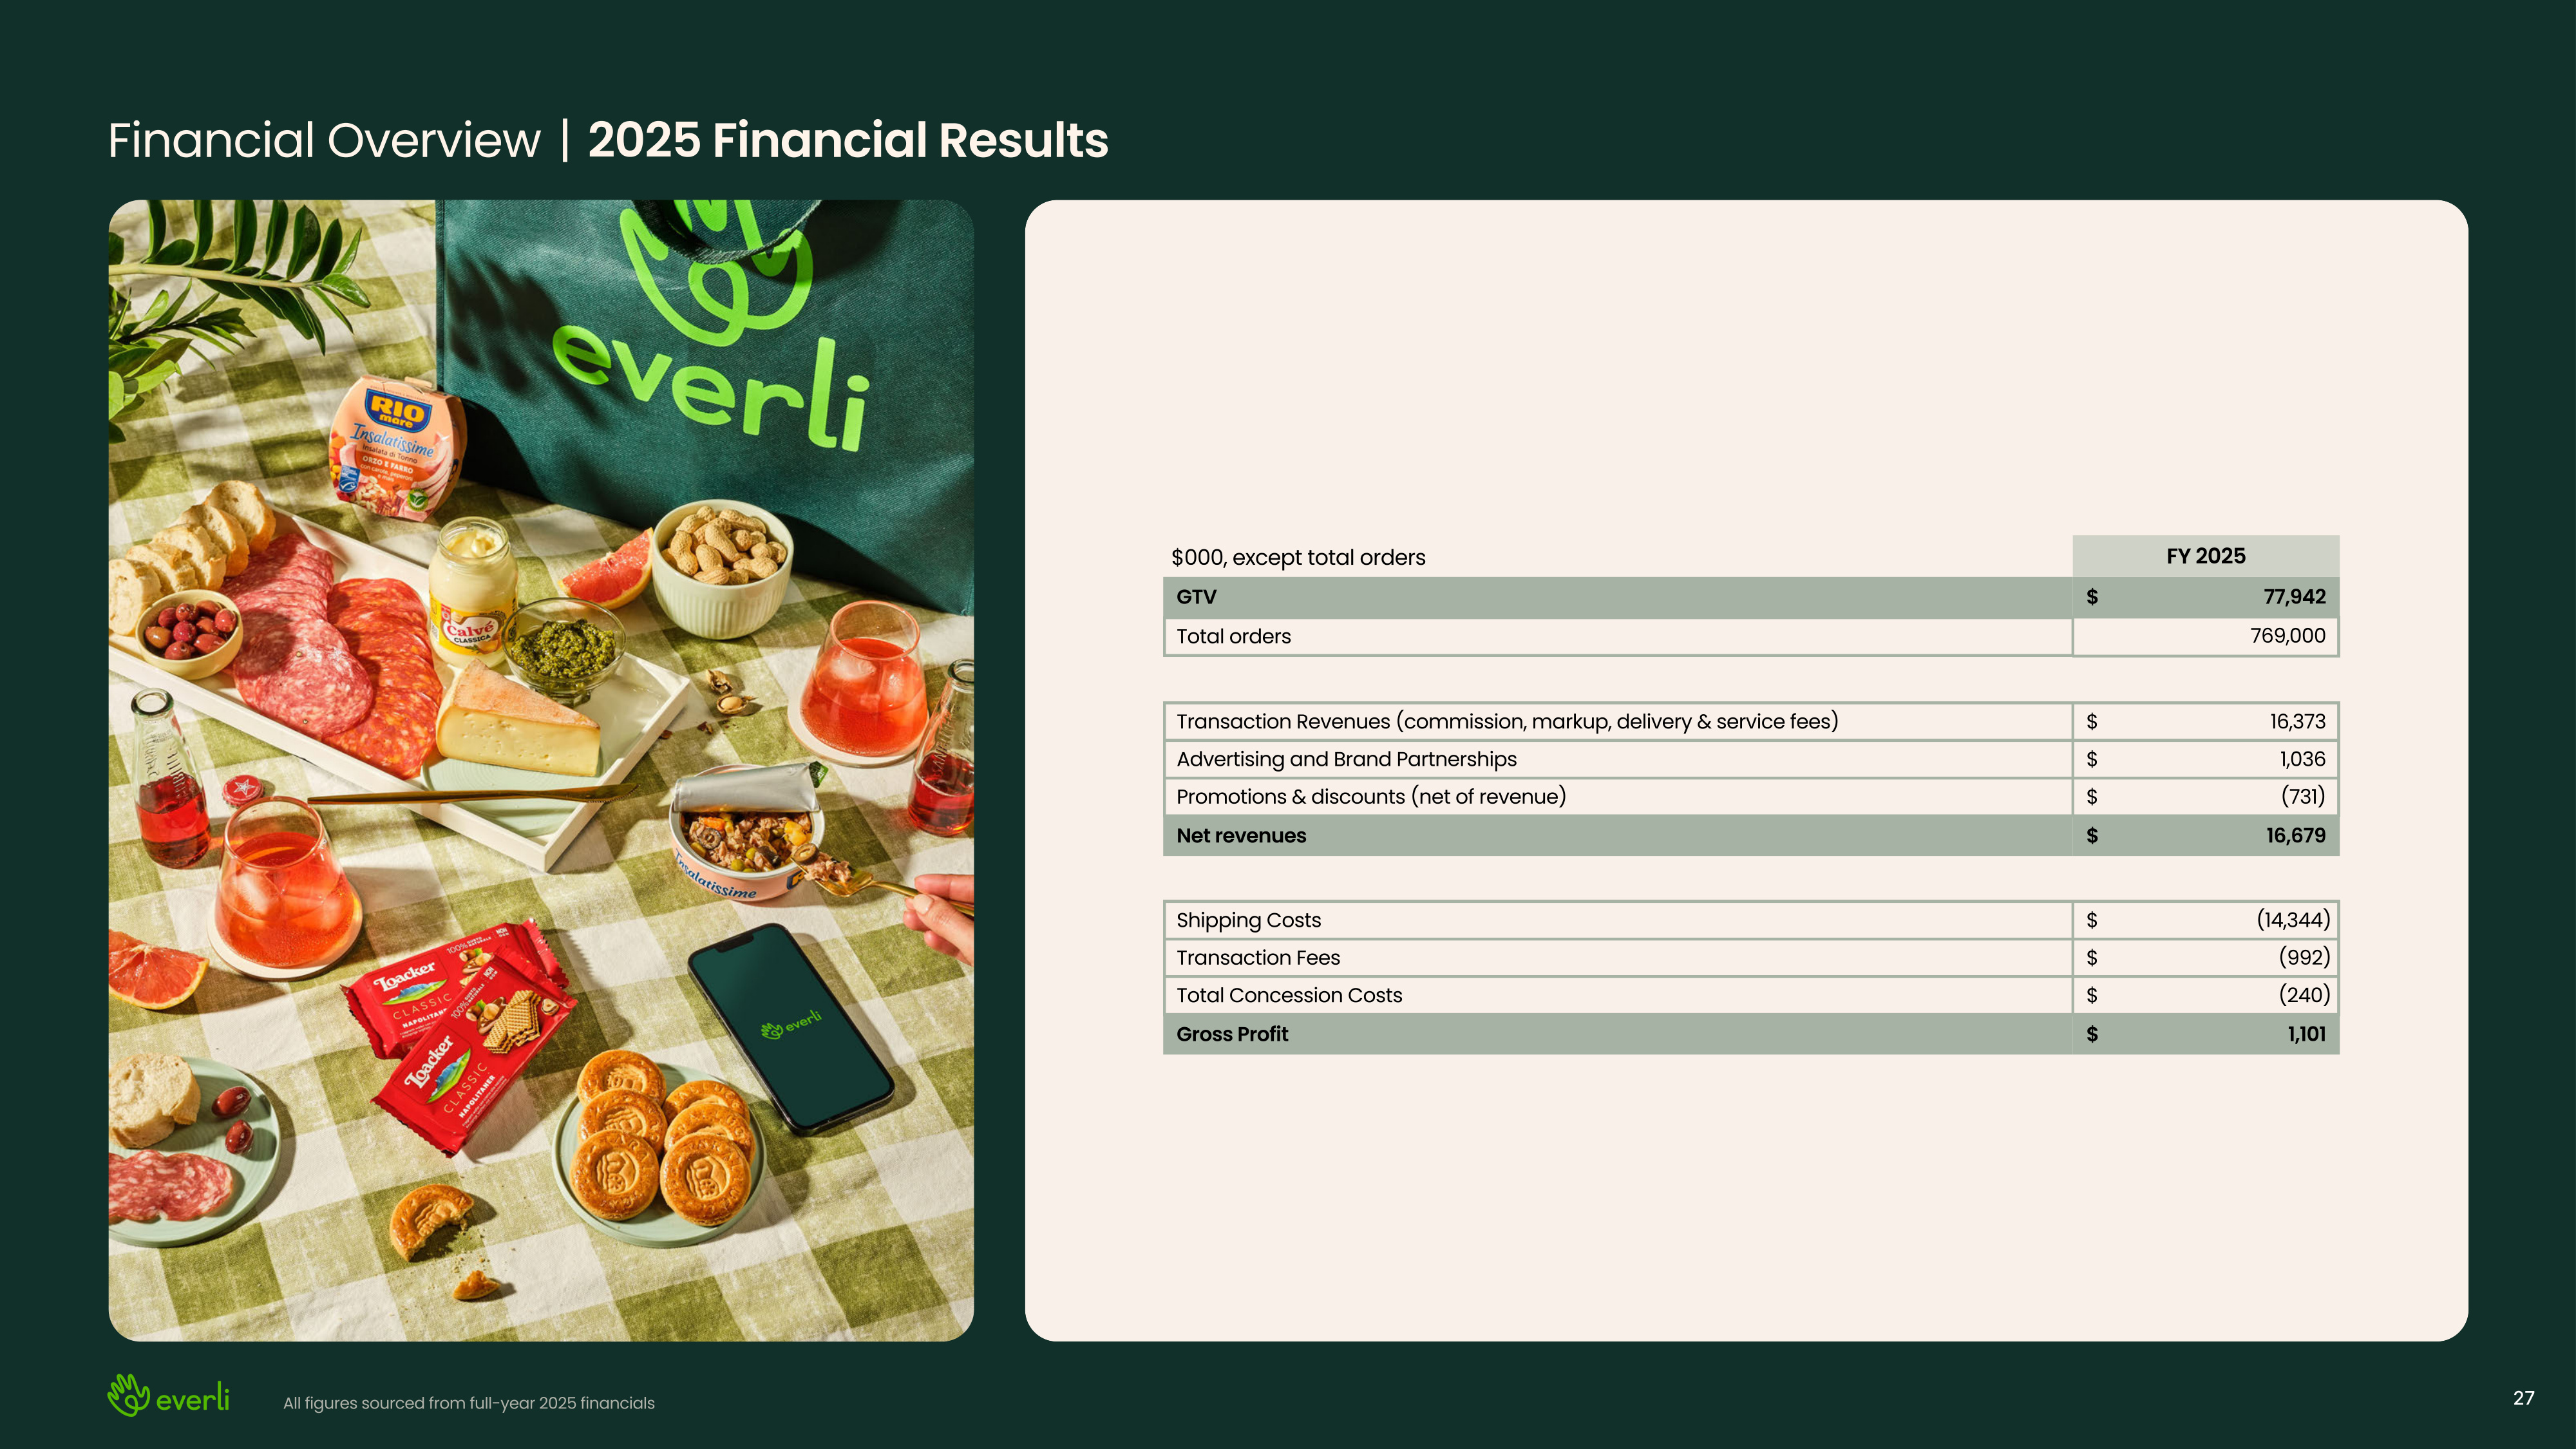
Financial Overview | 2025 Financial Results All figures sourced from full-year 2025 financials $000, except total orders GTV Total orders Transaction Revenues (commission, markup, delivery & service fees) Advertising and Brand Partnerships Promotions & discounts (net of revenue) Net revenues Shipping Costs Transaction Fees Total Concession Costs Gross Profit $ $ $ $ $ $ $ $ $ FY 2025 77,942 769,000 16,373 1,036 (731) 16,679 (14,344) (992) (240) 1,101 27
Whitelabel 5 Transaction Overview 28
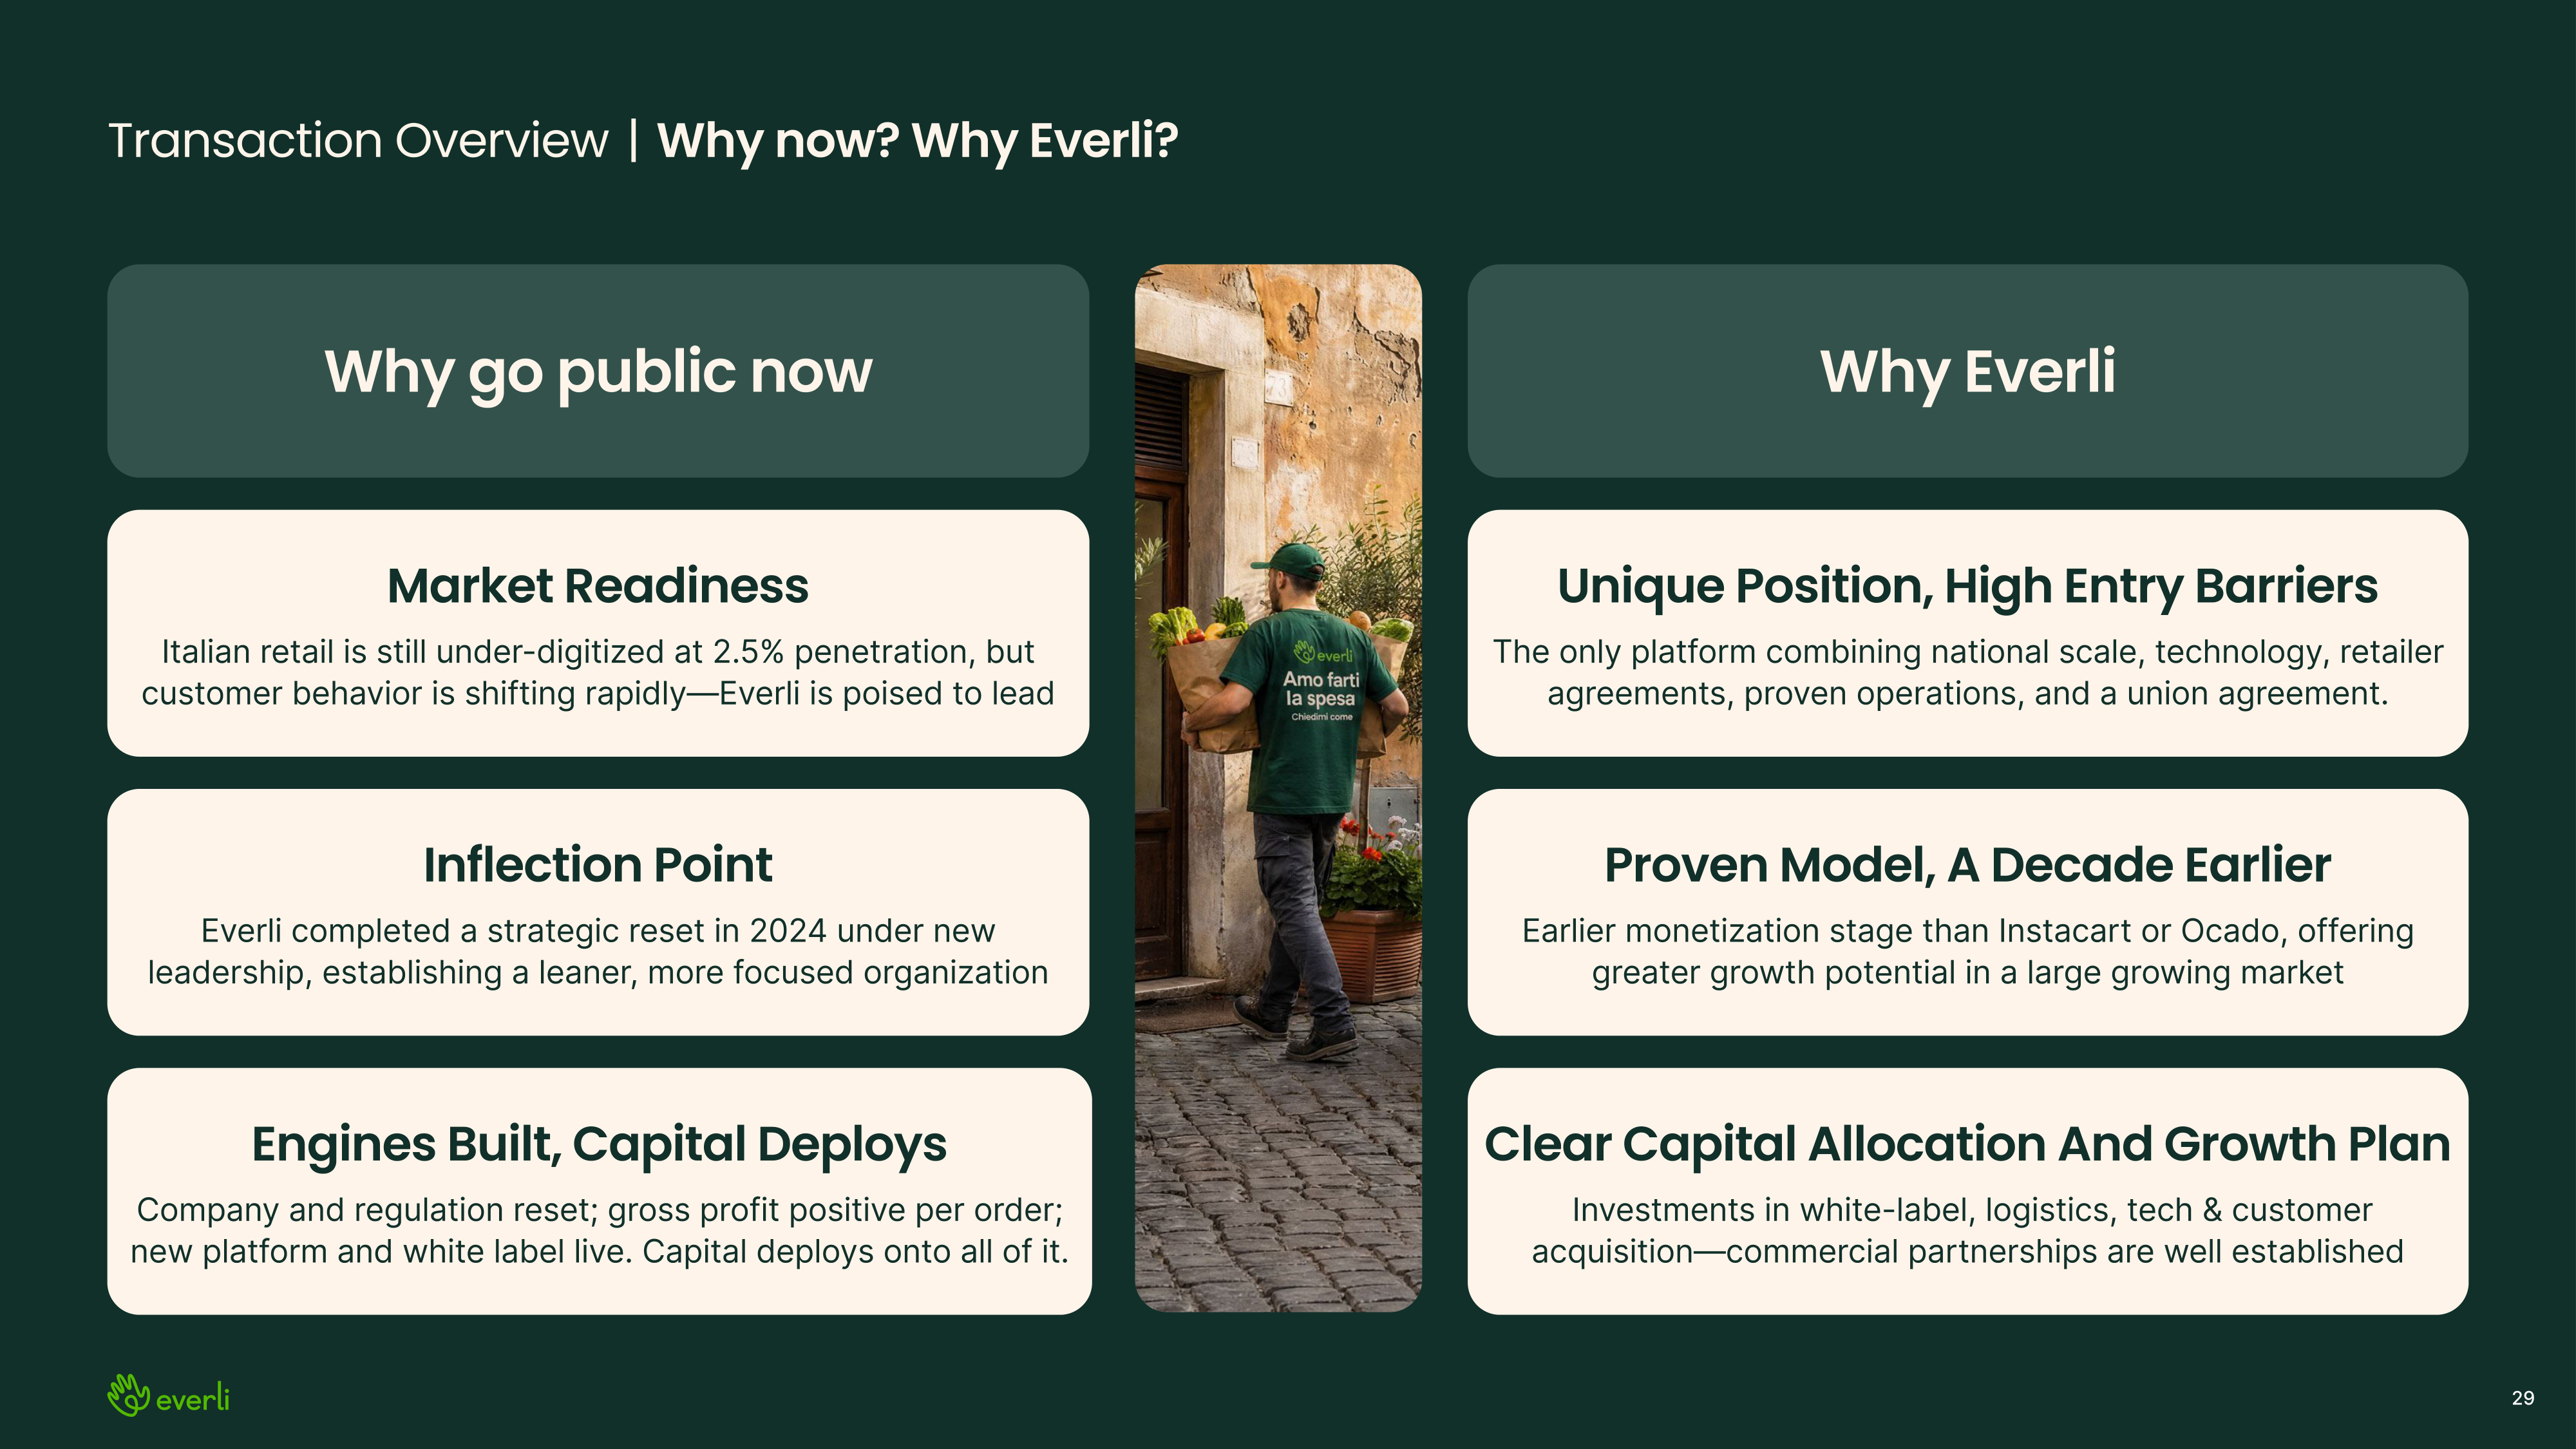
Transaction Overview | Why now? Why Everli? Why go public now Market Readiness Italian retail is still under-digitized at 2.5% penetration, but customer behavior is shifting rapidlyEverli is poised to lead Inflection Point Everli completed a strategic reset in 2024 under new leadership, establishing a leaner, more focused organization Engines Built, Capital Deploys Company and regulation reset; gross profit positive per order; new platform and white label live. Capital deploys onto all of it. Why Everli Unique Position, High Entry Barriers The only platform combining national scale, technology, retailer agreements, proven operations, and a union agreement. Proven Model, A Decade Earlier Earlier monetization stage than Instacart or Ocado, offering greater growth potential in a large growing market Clear Capital Allocation And Growth Plan €Investments in white-label, logistics, tech & customer acquisitioncommercial partnerships are well established 29
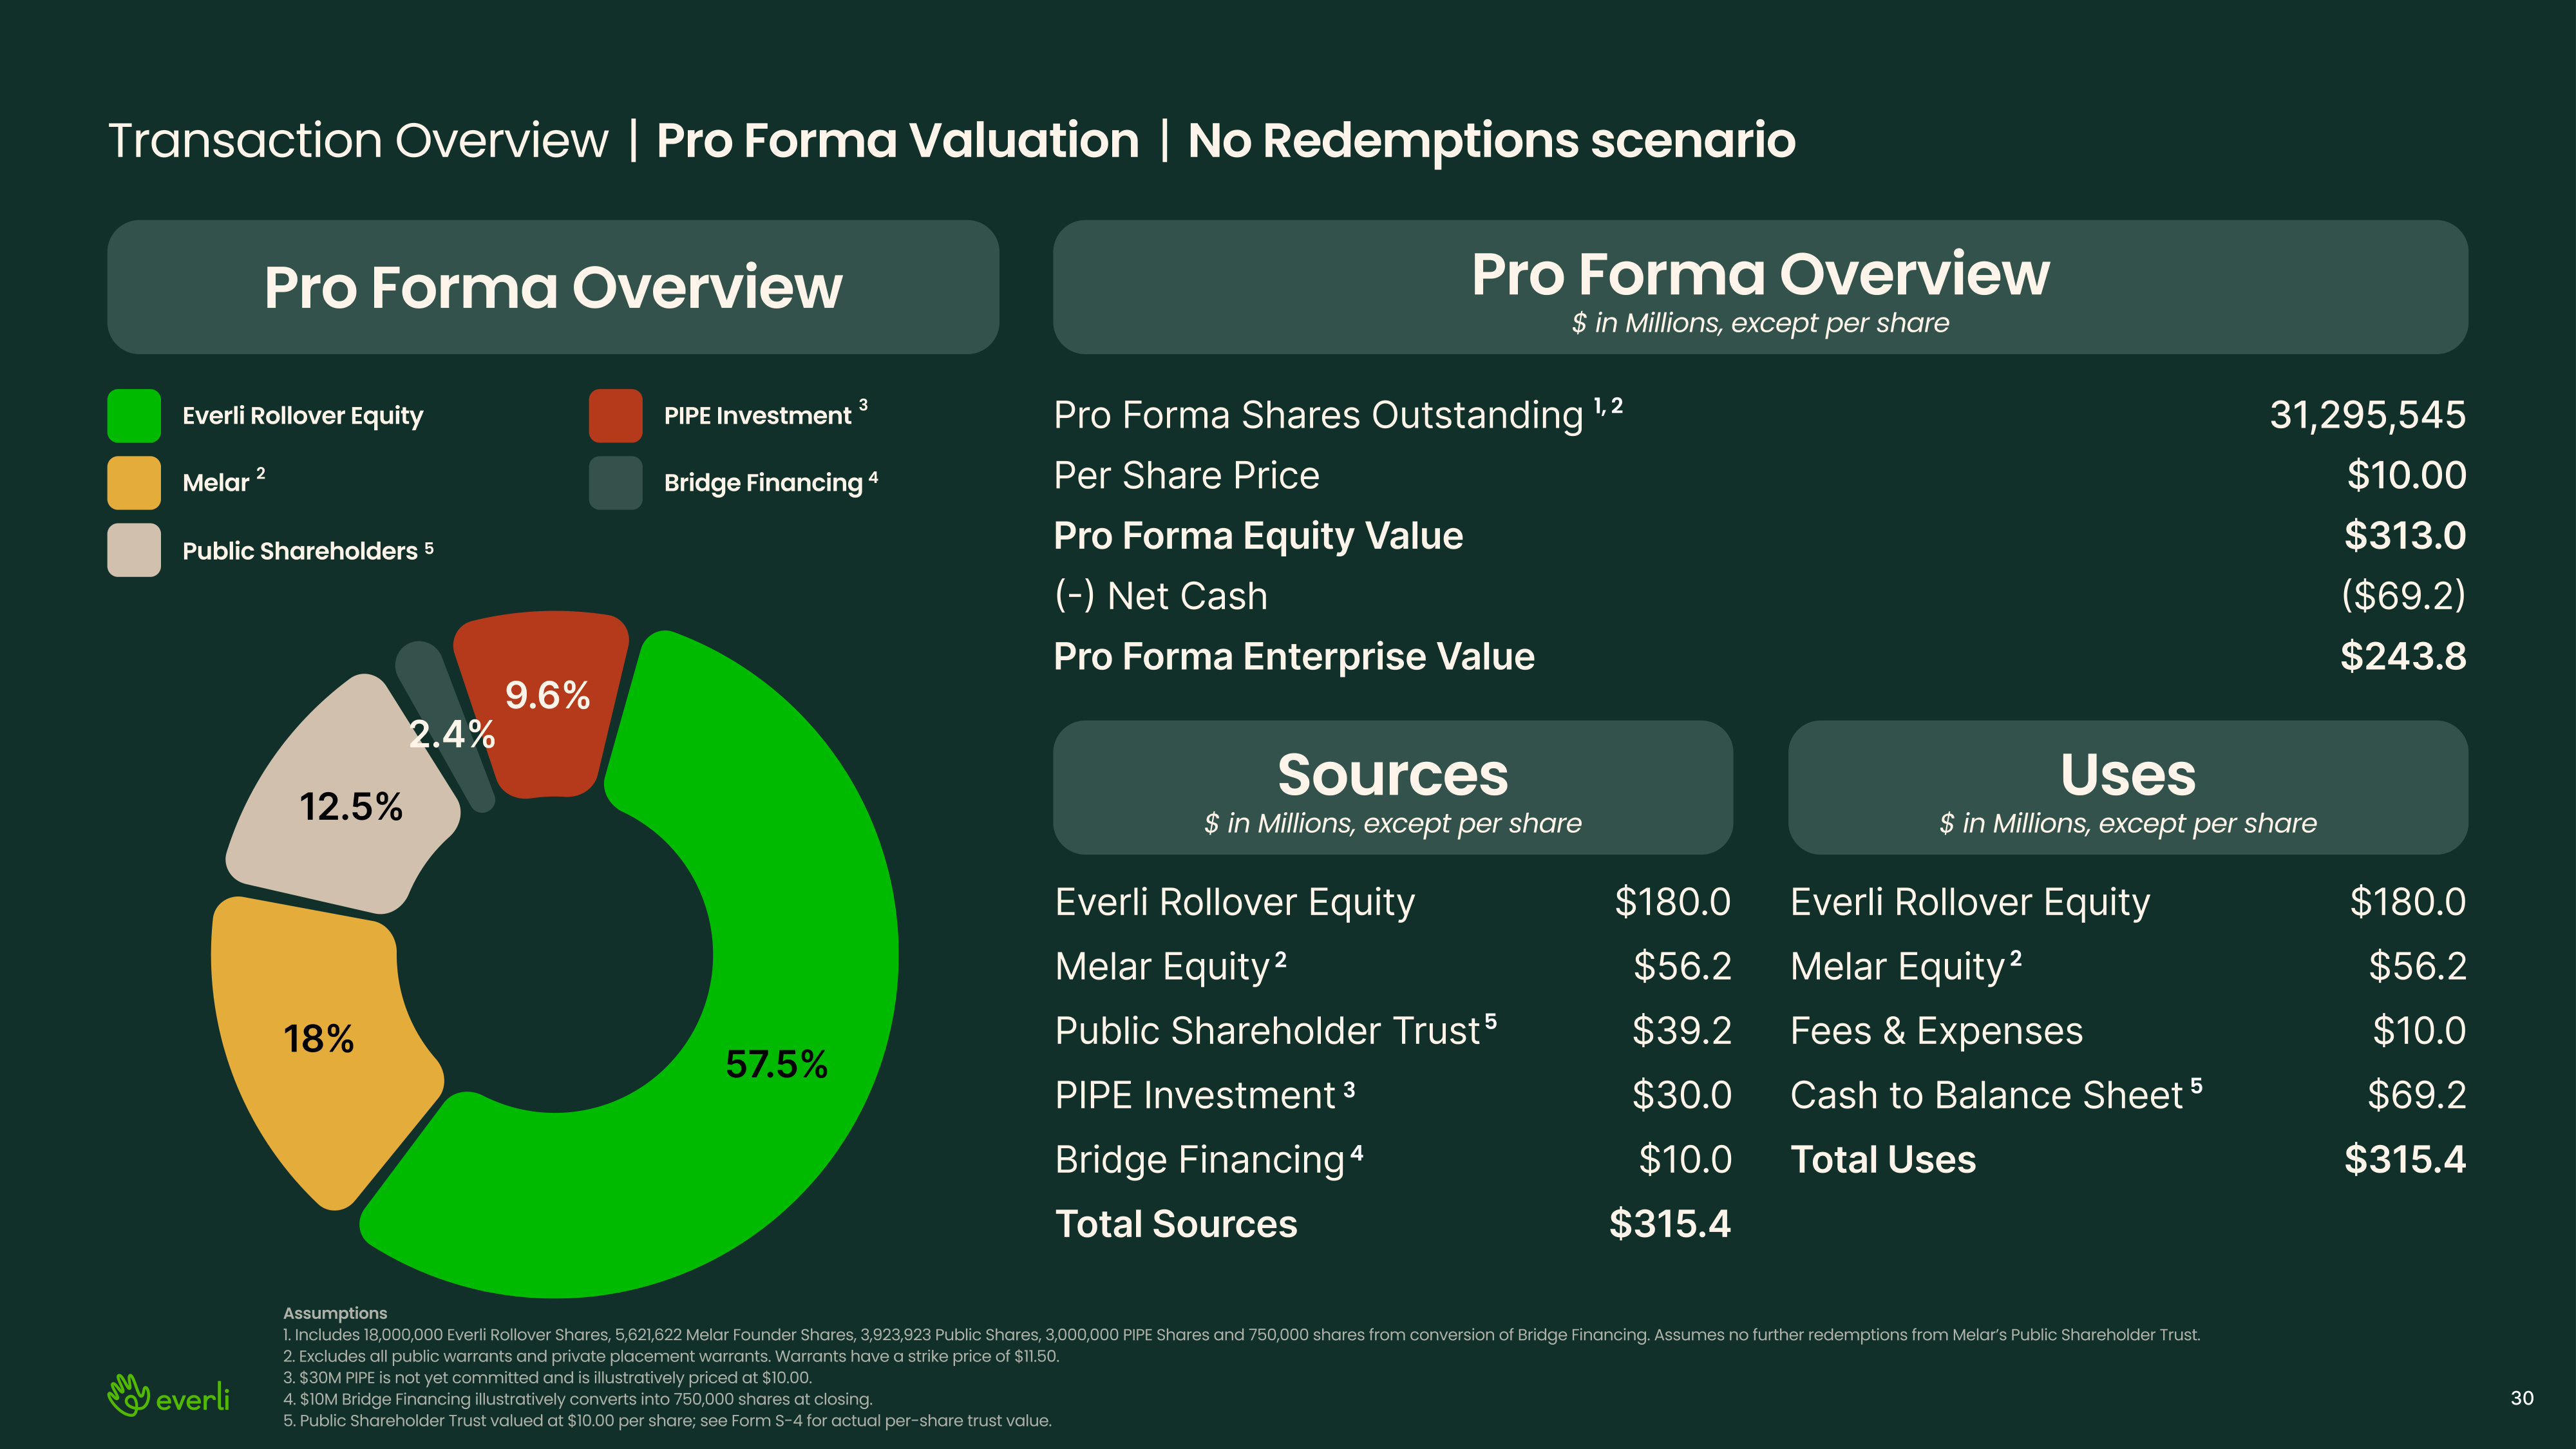
Transaction Overview | Pro Forma Valuation | No Redemptions scenario Pro Forma Overview 3 PIPE Investment Pro Forma Overview $ in Millions, except per share Pro Forma Shares Outstanding 1, 2 Per Share Price Pro Forma Equity Value (-) Net Cash Pro Forma Enterprise Value 31,295,545 $10.00 $313.0 ($69.2) $243.8 Everli Rollover Equity Melar 2 Bridge Financing 4 Public Shareholders 5 12.5% 2.4% 9.6% Sources $ in Millions, except per share Uses $ in Millions, except per share Everli Rollover Equity $180.0 Everli Rollover Equity Melar Equity $56.2 Melar Equity 2 2 Public Shareholder Trust $39.2 Fees & Expenses 5 PIPE Investment $30.0 Cash to Balance Sheet 5 3 Bridge Financing $10.0 Total Uses 4 Total Sources $315.4 Assumptions 1. Includes 18,000,000 Everli Rollover Shares, 5,621,622 Melar Founder Shares, 3,923,923 Public Shares, 3,000,000 PIPE Shares and 750,000 shares from conversion of Bridge Financing. Assumes no further redemptions€from Melarˇs Public Shareholder Trust.(2. Excludes all public warrants and private placement warrants. Warrants have a strike price of $11.50. 3. $30M PIPE is not yet committed and is illustratively priced at $10.00. 4. $10M Bridge Financing€illustratively€converts into 750,000 shares at closing. 5. Public Shareholder Trust valued at $10.00 per share; see Form S-4 for actual per-share trust value. $180.0 $56.2 $10.0 $69.2 $315.4 18% 57.5% 30
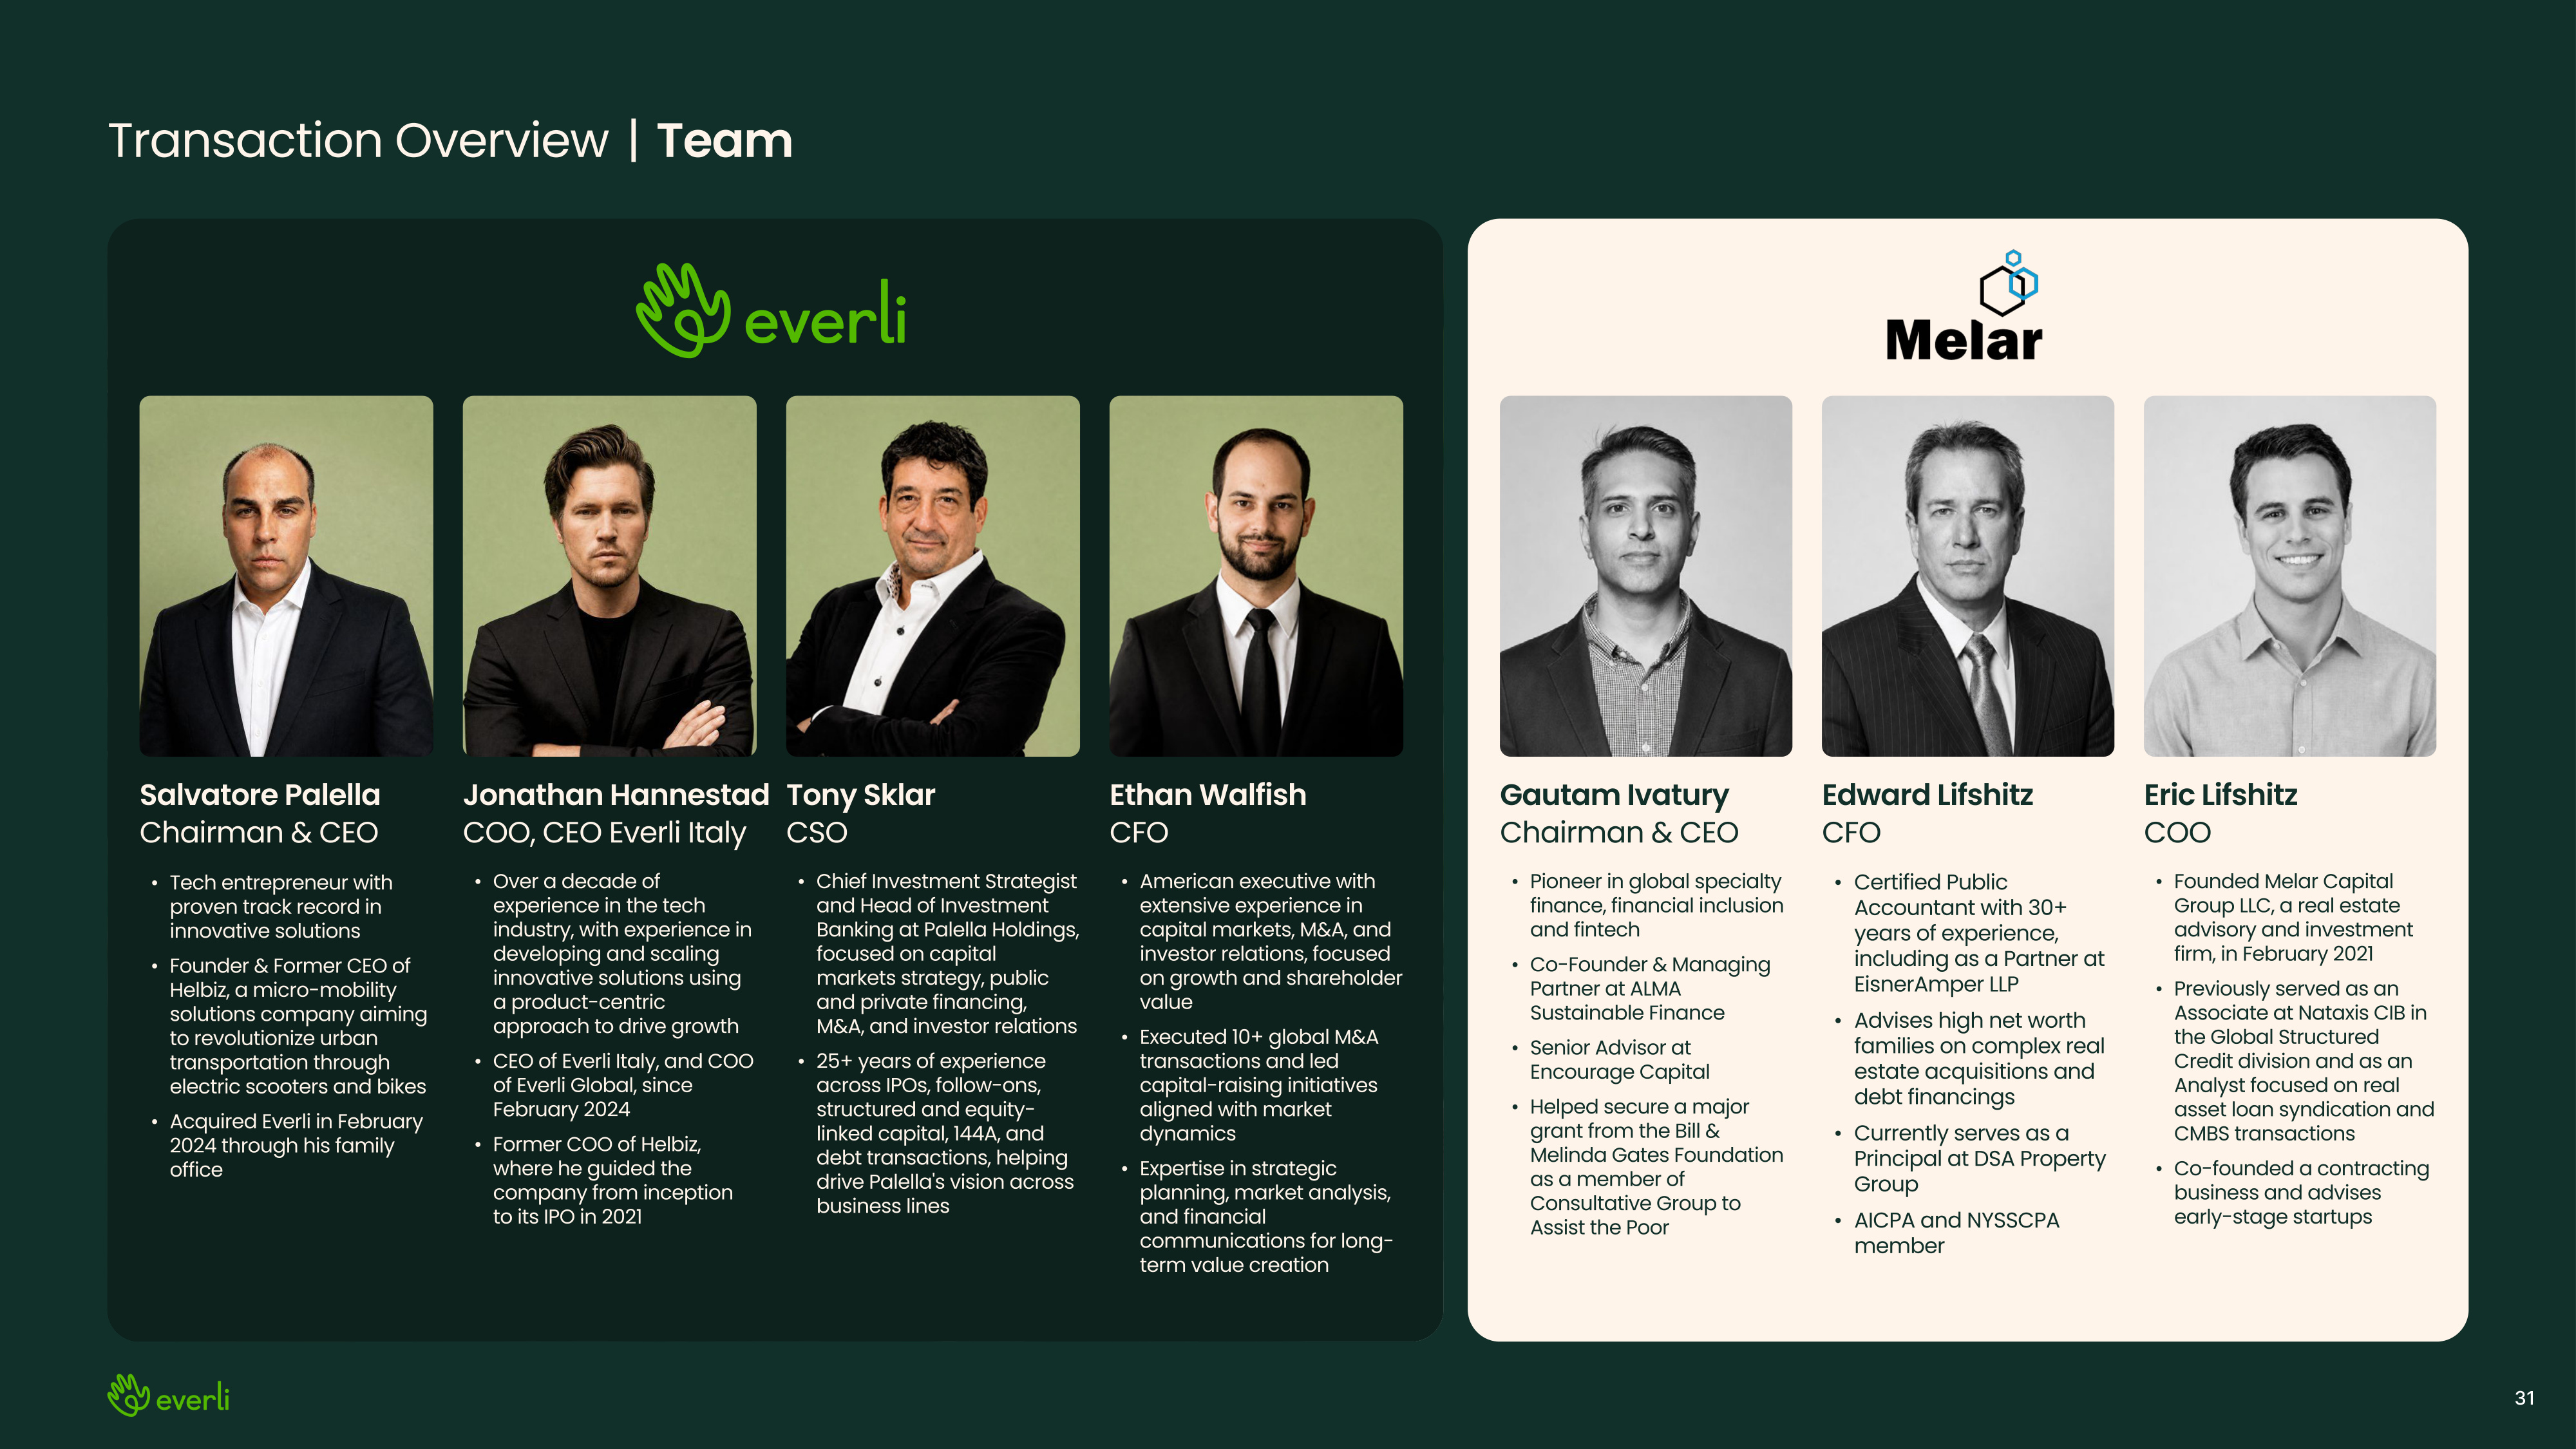
Transaction Overview | Team Salvatore Palella Chairman & CEO Tech entrepreneur with proven track record in innovative solutions Founder & Former CEO of Helbiz, a micro-mobility solutions company aiming to revolutionize urban transportation through electric scooters and bikes Acquired Everli in February 2024 through his family office Over a decade of experience in the tech industry, with experience in developing and scaling innovative solutions using a product-centric approach to drive growth CEO of Everli Italy, and COO of Everli Global, since February 2024 Former COO of Helbiz, where he guided the company from inception to its IPO in 2021 Chief Investment Strategist and Head of Investment Banking at Palella Holdings, focused on capital markets strategy, public and private financing, M&A, and investor relations 25+ years of experience across IPOs, follow-ons, structured and equity- linked capital, 144A, and debt transactions, helping drive Palella's vision across business lines American executive with extensive experience in capital markets, M&A, and investor relations, focused on growth and shareholder value Executed 10+ global M&A transactions and led capital-raising initiatives aligned with market dynamics Expertise in strategic planning, market analysis, and financial communications for long- term value creation Jonathan Hannestad Tony Sklar Ethan Walfish COO, CEO Everli Italy CSO CFO Gautam Ivatury Edward Lifshitz€ Eric Lifshitz€ Chairman & CEO€ CFO COO Pioneer in global specialty finance, financial inclusion and fintech Co-Founder & Managing Partner at ALMA Sustainable Finance Senior Advisor at Encourage Capital Helped secure a major grant from the Bill & Melinda Gates Foundation as a member of Consultative Group to Assist the Poor Certified Public Accountant with 30+ years of experience, including as a Partner at EisnerAmper LLP Advises high net worth families on complex real estate acquisitions and debt financings Currently serves as a Principal at DSA Property Group AICPA and NYSSCPA member Founded Melar Capital Group LLC, a real estate advisory and investment firm, in February 2021 Previously served as an Associate at Nataxis CIB in the Global Structured Credit division and as an Analyst focused on real asset loan syndication and CMBS transactions Co-founded a contracting business and advises early-stage startups 31
thank you 32
Appendix 33
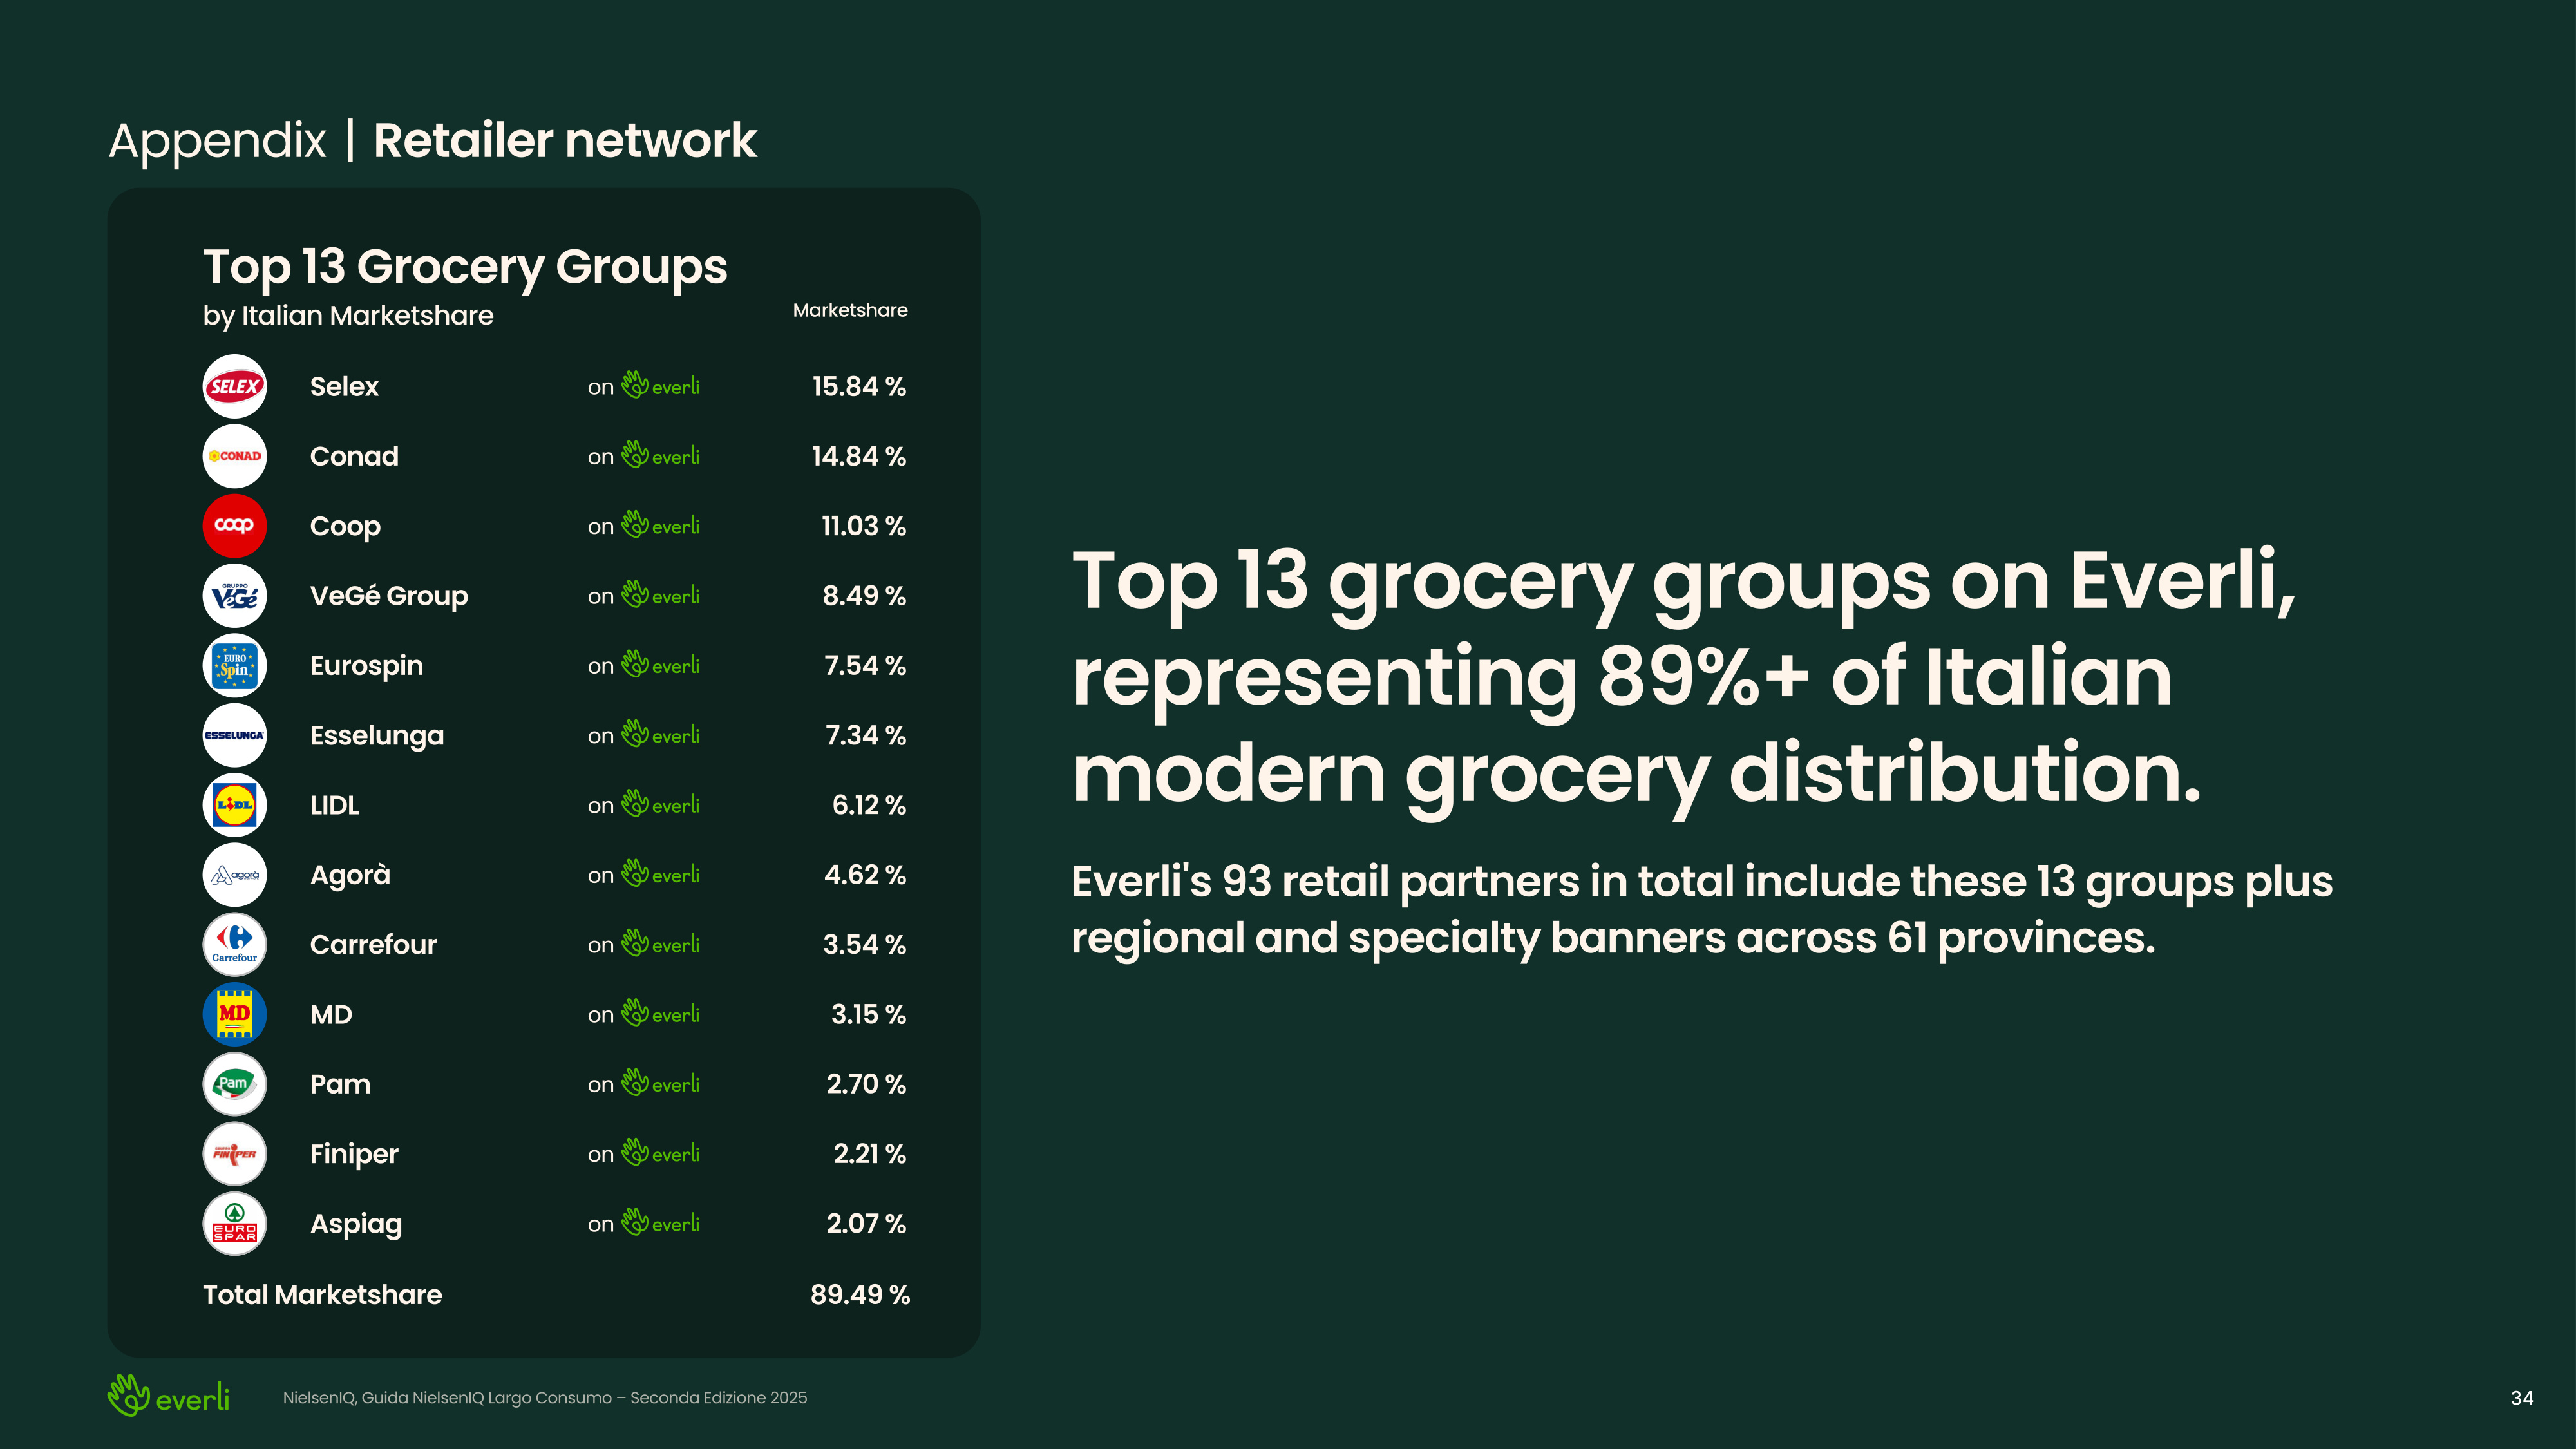
Overview Appendix | | Retail Partners Retailer network Top 13 Grocery Groups by Italian Marketshare Marketshare 15.84 % 14.84 % 11.03 % 8.49 % 7.54 % 7.34 % 6.12 % 4.62 % 3.54 % 3.15 % 2.70 % 2.21 % 2.07 % 89.49 % Selex on Conad on Coop on VeGé Group on Eurospin on Esselunga on LIDL on Agorà on Carrefour on MD on Pam on Finiper on Aspiag on Total Marketshare Top 13 grocery groups on Everli, representing 89%+ of Italian modern grocery distribution. Everli's 93 retail partners in total include these 13 groups plus regional and specialty banners across 61 provinces. NielsenIQ, Guida NielsenIQ Largo Consumo Seconda Edizione 2025 34
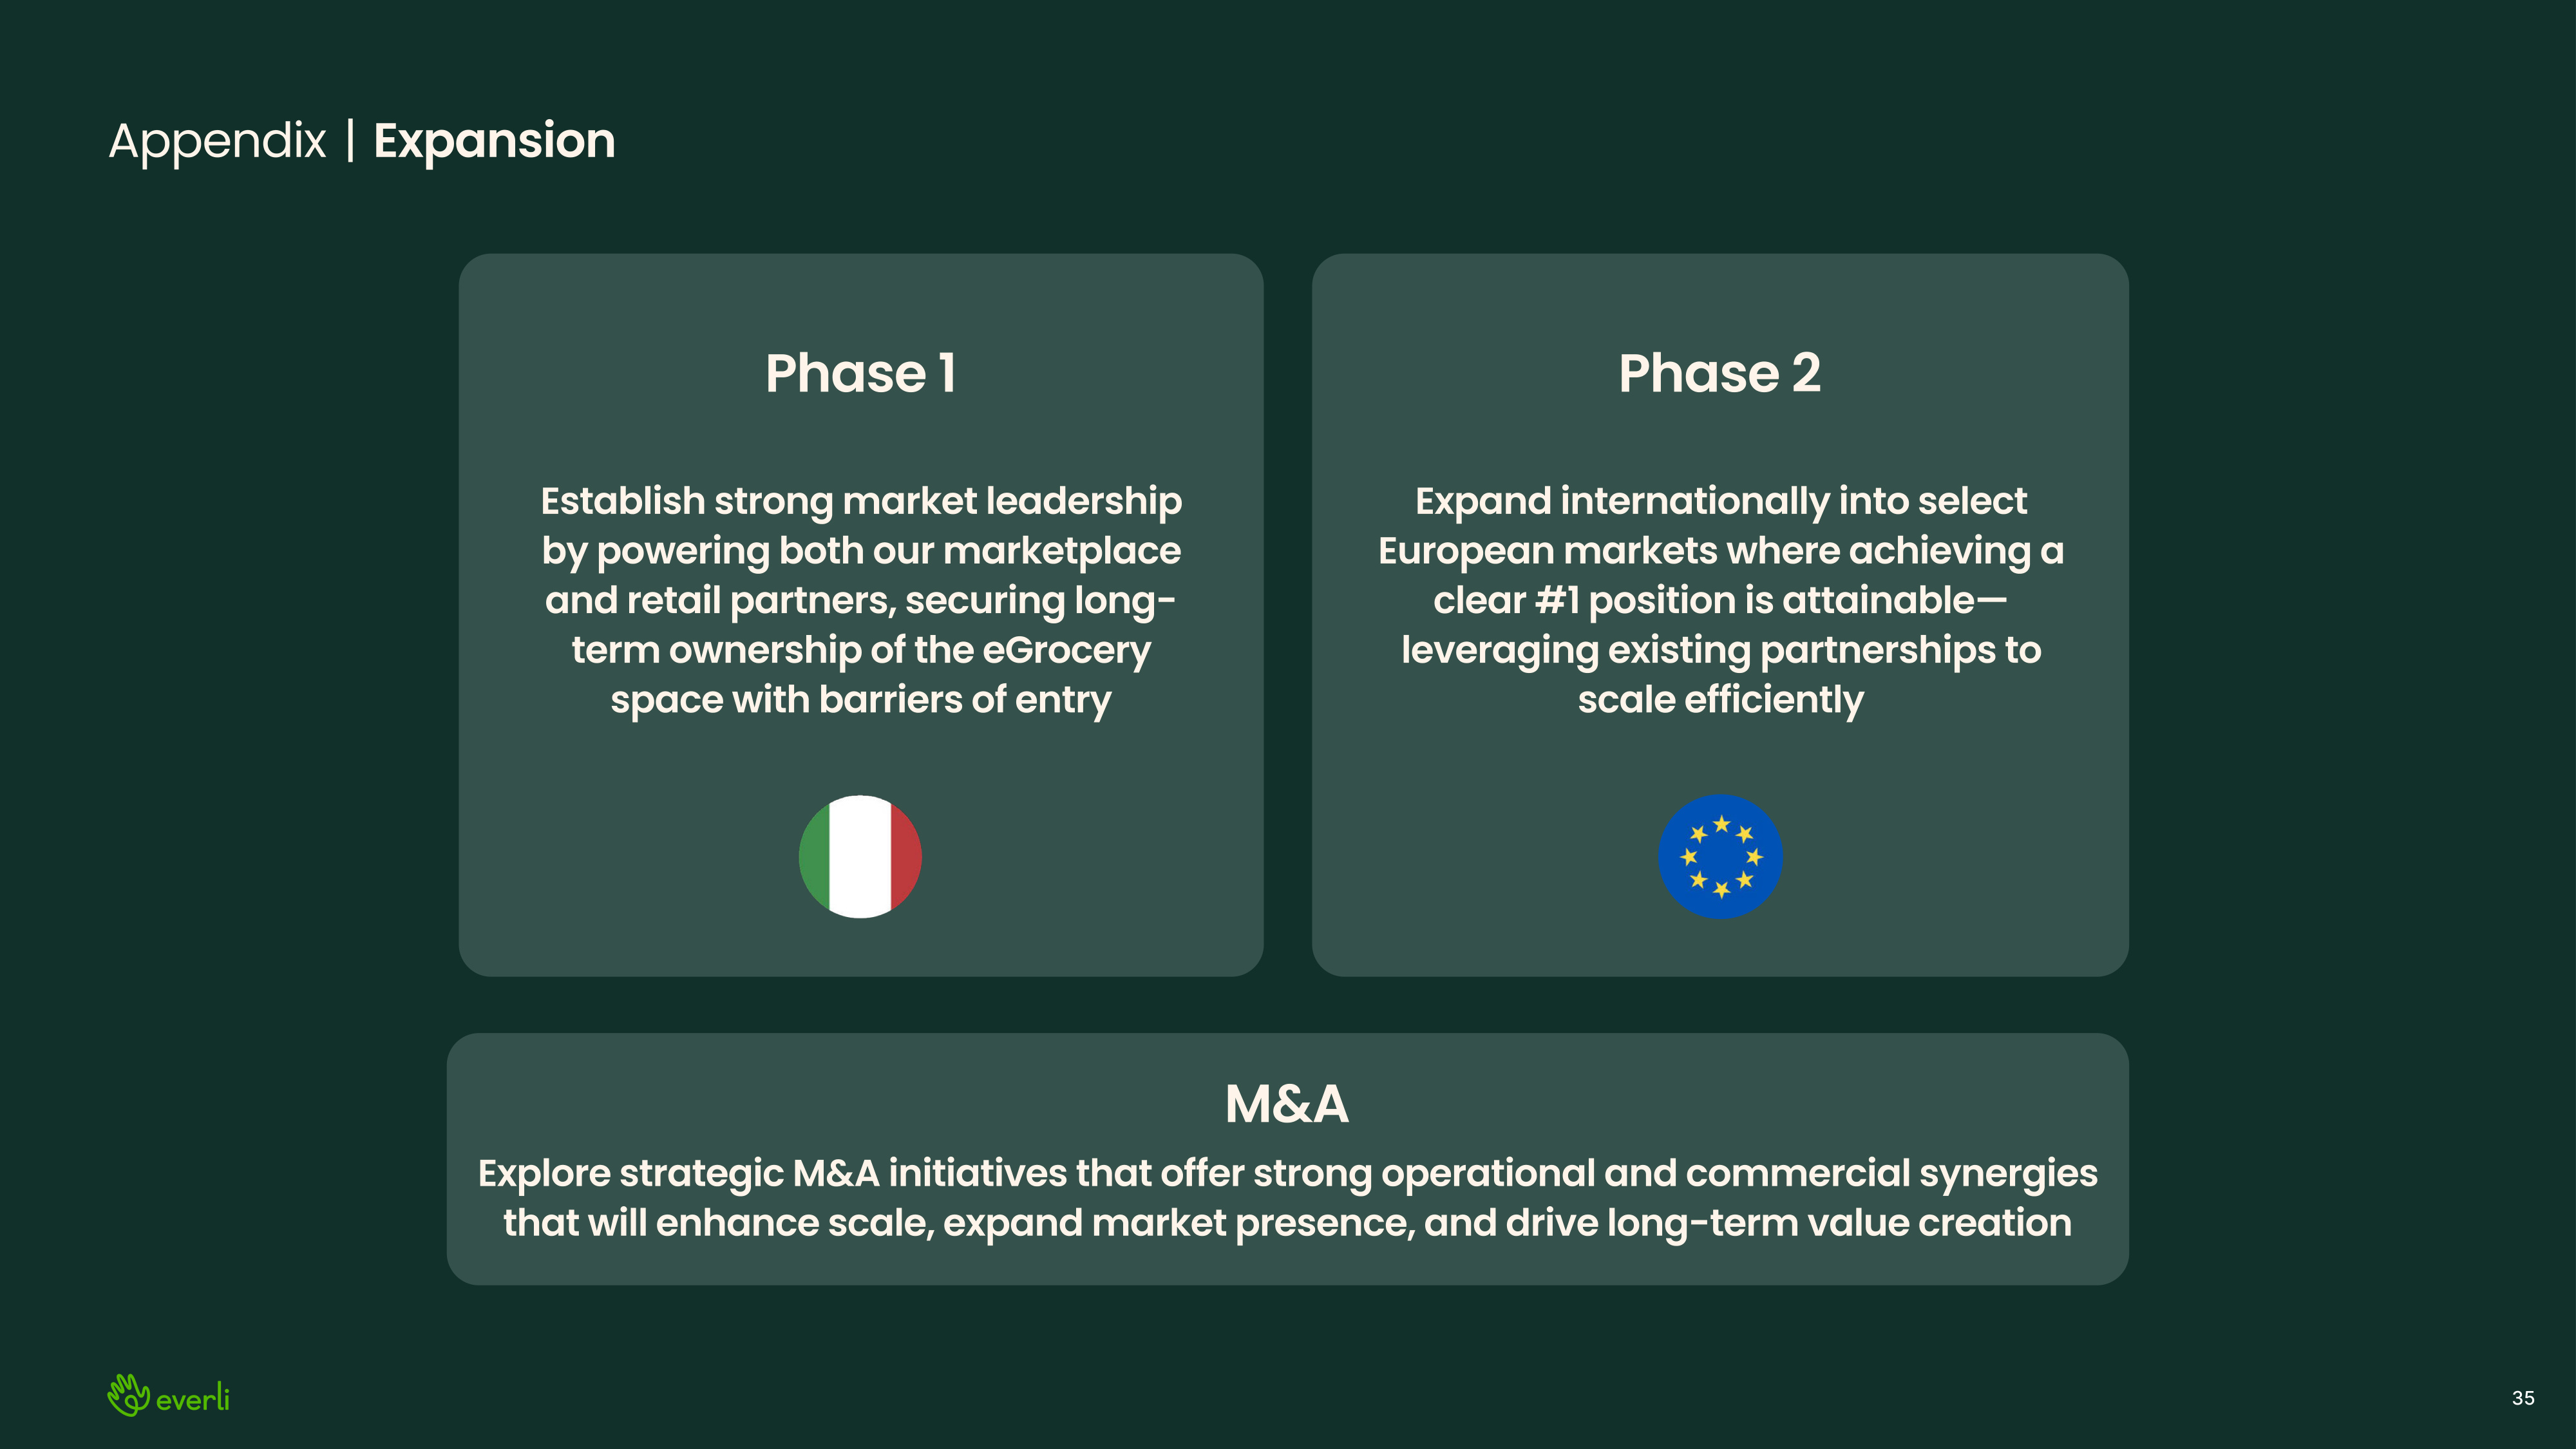
Appendix | Expansion Phase 11 Phase 2 Establish strong market leadership by powering both our marketplace and retail partners, securing long- term ownership of the eGrocery space with barriers of entry Expand internationally into select European markets where achieving a clear #1 position is attainable leveraging existing partnerships to scale efficiently M&A Explore strategic M&A initiatives that offer strong operational and commercial synergies that will enhance scale, expand market presence, and drive long-term value creation 35