Table of Contents

Exhibit 99.1


LOGO

Dear Flex Ltd. Shareholder,

We are pleased to announce a significant strategic initiative for Flex Ltd. (“Flex”). As part of our ongoing commitment to creating value and sharpening our focus on core business priorities, Flex intends to separate its current offerings across power, cooling, and cloud into an independent, publicly traded company, Axiom Solutions International, Inc. (“Axiom”).

The completion of this spin-off is subject to the approval of Flex’s Board of Directors, our shareholders, and the High Court of the Republic of Singapore (“High Court Approval”). Upon receiving these approvals and completing the transaction, Flex will continue to advance its leadership as a diversified technology, manufacturing, and supply chain partner, while Axiom will emerge as a leading provider of critical infrastructure technologies built around power delivery, advanced cooling, and rack-scale integration for high-density computing and industrial applications.

The spin-off will be effected through a distribution of between approximately 88.0% to 94.0% of all issued and outstanding shares of Axiom common stock, by way of a distribution in specie to Flex shareholders of record on a pro rata basis as of the record date of the Distribution (the “Distribution Record Date”). For every      ordinary shares in the capital of Flex (“Flex ordinary shares”) held as of the Distribution Record Date, each Flex shareholder will receive      shares of Axiom common stock. Axiom shares will be issued in book-entry form only; no physical share certificates will be distributed. The Distribution will be effected by way of a court-approved capital reduction (the “Capital Reduction”) under the Companies Act 1967 of Singapore (the “Singapore Companies Act”).

Following the separation, Flex’s ordinary shares will continue to trade on Nasdaq under the symbol “FLEX” and, subject to requisite approvals, Axiom common stock is expected to be listed on the Nasdaq Stock Market LLC (“Nasdaq”) under the symbol “AXM.” You do not need to take any action or pay any consideration to receive your Axiom shares, nor will you need to surrender or exchange your Flex shares.

We expect the Distribution of Axiom common stock to be tax-free to Flex shareholders for U.S. federal income tax purposes, except for any cash received in lieu of fractional shares. We recommend that you consult your tax advisor regarding the specific tax consequences of the Distribution, including any state, local, or non-U.S. tax implications.

We encourage you to review the enclosed information statement, which provides important information about the spin-off, Axiom’s business, financial condition, and operations, as well as the Distribution process.

Flex’s Board of Directors believes this separation will maximize value for all Flex shareholders by creating two focused companies—Flex, which can concentrate more fully on the high-complexity markets where its capabilities and scale create the greatest advantage, and Axiom, dedicated to supporting the growing demand for power-dense infrastructure across data center, utility, industrial, and edge applications. We thank you for your continued commitment to Flex and look forward to your support of both Flex and Axiom in the future.

Sincerely,

The Board of Directors of Flex Ltd.

Table of Contents

LOGO

Dear Future Axiom Shareholder,

I am pleased to introduce Axiom Solutions International, Inc. (“Axiom”), a new independent company formed from Flex Ltd.’s power, cooling, and cloud businesses. Axiom, a leader in critical digital and electrical infrastructure, develops and manufactures end-to-end infrastructure technologies built around power delivery, advanced cooling, and rack-scale integration for high-density computing and industrial applications.

Demand for digital infrastructure is increasing power density, compressing deployment timelines, and raising system complexity. These trends are driving the need for coordinated power, cooling, and integration delivered as factory-built, scalable infrastructure. Axiom is designed to address these requirements through capabilities spanning utility and facility power infrastructure, embedded power systems, advanced liquid cooling, and rack-scale integration.

As an independent company, Axiom brings deep expertise across power, thermal management, and infrastructure integration with an integrated portfolio that enables faster time-to-capacity, improved reliability, and improved performance at scale. In this new chapter, Axiom will focus on expanding these capabilities, deepening customer relationships, and scaling our global engineering and manufacturing footprint. We believe this focus positions Axiom to support the growing demand for power-dense infrastructure across data center, utility, industrial, and edge applications.

Thank you for your interest and support.

Sincerely,

Revathi Advaithi

Chief Executive Officer

Axiom Solutions International, Inc.


Table of Contents

Information contained herein is subject to completion or amendment. A Registration Statement on Form 10 relating to these securities has been filed with the U.S. Securities and Exchange Commission under the U.S. Securities Exchange Act of 1934, as amended.


PRELIMINARY INFORMATION STATEMENT AND SUBJECT TO COMPLETION, DATED SEPTEMBER 15, 2026

INFORMATION STATEMENT

Axiom Solutions International, Inc.

Common Stock

$0.0001 Par Value per Share


This information statement is being furnished in connection with the distribution (the “Distribution”) by Flex Ltd. (“Flex”) to its shareholders of Axiom Solutions International, Inc. (“Axiom,” “Spinco” or the “Company”), a wholly owned subsidiary of Flex. Prior to such Distribution, Flex, Spinco and their applicable affiliates will consummate a series of transactions to separate Flex and Spinco, resulting in Flex continuing to own the Flex business (as defined herein) and Spinco owning the Cloud & Power Infrastructure business (as defined herein), as more fully described in this information statement. Flex will effect the Distribution by distributing between approximately 88.0% to 94.0% of the outstanding shares of Spinco common stock owned by Flex, by way of a distribution in specie to Flex shareholders of record on a pro rata basis as of the record date of the Distribution (the “Distribution Record Date”). The Distribution is subject to certain conditions, as set forth in this information statement.

On the Distribution Date (as defined herein), each holder of Flex ordinary shares will receive for each Flex ordinary share held as of    Central time on    , 2026, the Distribution Record Date,     share[s] of Spinco common stock (the “Distribution Ratio”). Each such holder will receive cash in lieu of any fractional shares resulting from the application of the Distribution Ratio. We expect our common stock will be distributed by Flex to you on or about    , 2027 (the “Distribution Date”). As discussed under the section of this information statement entitled “The Separation and Distribution—Trading Between the Record Date and the Distribution Date,” if you sell your Flex ordinary shares in the “regular-way” market after the Distribution Record Date and up to and including the Distribution Date, you also will be selling your right to receive shares of Spinco common stock in the Distribution.

The Capital Reduction (as defined herein) and Distribution by Flex requires the affirmative vote of the holders of at least three-fourths of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting. Subject to satisfaction of the conditions to the Distribution (including the Flex Shareholder Approvals (as defined herein)), shareholders of Flex entitled to receive shares in the Distribution will not be required to take any action to receive Spinco common stock in the Distribution but are urged to read this entire information statement carefully. You do not need to pay any consideration or exchange or surrender your existing Flex ordinary shares or take any other action to receive your shares of Spinco common stock.

The Distribution is intended to be tax-free to Flex shareholders (except with respect to any cash received in lieu of fractional shares) for U.S. federal income tax purposes. You should consult your tax advisor as to the particular consequences of the Distribution to you, including the applicability and effect of any U.S. federal, state, and local, and any non-U.S., tax laws.

There is no current trading market for our common stock, although we expect that a limited market, commonly known as a “when-issued” trading market, will develop shortly before the Distribution Date, and we expect “regular-way” trading of our common stock to begin on the first trading day following the completion of the Distribution. We intend to apply to list our common stock on the Nasdaq Stock Market LLC (“Nasdaq”) under the symbol “AXM.” Approval of our listing application by Nasdaq is a condition to the Distribution. See “Risk Factors—Risks Related to Our Common Stock—Our common stock may not be listed on Nasdaq, which could negatively impact the price of our common stock and your ability to sell our common stock.”

This information statement is being furnished solely to provide information to Flex shareholders who are entitled to receive shares of our common stock in the Distribution. The information statement is not, and is not to be construed as, an inducement or encouragement to buy, hold or sell any of our securities or securities of Flex. We


Table of Contents

believe that the information in this information statement is accurate as of the date set forth on the cover. Changes to the information contained in this information statement may occur after that date, and none of us, Flex, the Spinco Board of Directors (as defined herein) or the Flex Board of Directors (as defined herein) undertake any obligation to update such information, except in the normal course of our and Flex’s public disclosure obligations and practices and as required by applicable federal securities laws.

At the time our registration statement, of which this information statement is a part, is declared effective by the United States Securities and Exchange Commission (the “SEC”), Spinco will become subject to the information and reporting requirements of the Securities Exchange Act of 1934, as amended, and the rules and regulations promulgated thereunder (the “Exchange Act”), and, in accordance with the Exchange Act, we will file periodic reports (including Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q and Current Reports on Form 8-K), proxy statements, and other information with the SEC. The SEC maintains a website, www.sec.gov, that contains periodic reports, proxy statements and information statements and other information regarding issuers, like us, that file electronically with the SEC. We encourage you to review our periodic reports, proxy statements and information statements and any other information we file with the SEC when they are made available, as they will contain important information about Spinco, in particular for periods after the date of this information statement.

In reviewing the information statement, you should carefully consider the matters described under the caption “Risk Factors” beginning on page 34.

Neither the SEC nor any state securities commission has approved or disapproved of these securities or determined if this information statement is truthful or complete. Any representation to the contrary is a criminal offense.

This information statement does not constitute an offer to sell or the solicitation of an offer to buy any securities.

This information statement is first being made available to Flex shareholders on or about     , 2026, and a Notice of Internet Availability of Information Statement Materials containing instructions describing how to access this information statement was first mailed to Flex shareholders on or about     , 2026. This information statement will be mailed to Flex shareholders who previously elected to receive a paper copy of Flex’s materials.


The date of this information statement is     , 2026.


Table of Contents

TABLE OF CONTENTS


SUMMARY OF HISTORICAL AND UNAUDITED PRO FORMA COMBINED FINANCIAL DATA

     19  

QUESTIONS AND ANSWERS ABOUT THE SEPARATION AND DISTRIBUTION

     23  

RISK FACTORS

     34  

CAUTIONARY STATEMENT CONCERNING FORWARD-LOOKING STATEMENTS

     69  

THE SEPARATION AND DISTRIBUTION

     70  

UNITED STATES FEDERAL INCOME TAX CONSEQUENCES OF THE DISTRIBUTION

     82  

DIVIDEND POLICY

     86  

CAPITALIZATION

     87  

UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION

     88  

NOTES TO UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION

     93  

BUSINESS

     104  

MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS

     114  

MANAGEMENT

     138  

COMPENSATION DISCUSSION AND ANALYSIS

     147  

DIRECTOR COMPENSATION

     193  

CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS

     194  

SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT

     203  

DESCRIPTION OF MATERIAL INDEBTEDNESS

     205  

DESCRIPTION OF CAPITAL STOCK

     206  

WHERE YOU CAN FIND MORE INFORMATION

     236  

INDEX TO COMBINED FINANCIAL STATEMENTS

     F-1  


i


Table of Contents

PRESENTATION OF INFORMATION

Unless otherwise indicated or the context otherwise requires, references in this information statement to:


“we,” “us,” “our,” “Axiom,” “Spinco,” and the “Company” refer to Axiom Solutions International, Inc., a Texas corporation and its subsidiaries.


“Bonus Issuance” refers to issuance of Bonus Shares in the proportion to be determined by the Flex Board of Directors in their sole discretion of such number of Bonus Share(s) for every existing Flex ordinary share(s) held by each Flex shareholder of record as of the Record Date, on a pari passu basis, fractions of a Bonus Share to be disregarded.


“Bonus Shares” refers to the new ordinary shares in the capital of Flex to be allotted and issued pursuant to the Bonus Issuance, and each, a “Bonus Share.”


“Capital Reduction” refers to the court-approved capital reduction to be carried out by Flex pursuant to Section 78G of the Singapore Companies Act in order to effect the Distribution.


“Cloud & Power Infrastructure business” refers to Flex’s cloud and power infrastructure business.


“Distribution” refers to the distribution of between approximately 88.0% to 94.0% of all of the then issued and outstanding shares of Spinco common stock to be carried out by Flex by way of a distribution in specie to Flex shareholders on a pro rata basis based on the number of Flex ordinary shares held by each such Flex shareholder of record as of the Distribution Record Date.


“Distribution Date” refers to the date of the Distribution, which is expected to be on or about     , 2027.


“Effective Time” refers to 12:01 a.m., New York City Time, on the Distribution Date.


“Flex” or “RemainCo” refers to Flex Ltd., a Singapore-incorporated public company limited by shares (company registration no. 199002645H), or, as the case may be, Flex Ltd. and its subsidiaries.


“Flex Board of Directors” refers to the board of directors of Flex.


“Flex business” refers to the business, activities, and operations of Flex other than the Cloud & Power Infrastructure business, in each case as conducted prior to the Distribution Date by Flex or Spinco (or any of their respective predecessors).


“Flex ordinary shares” refers to the ordinary shares in the capital of Flex.


“Flex shareholders” refers to holders of record of Flex ordinary shares in their capacity as such.


“Flex Shareholder Approvals” refers to the affirmative vote by the holders of (i) a simple majority of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting of Flex in favor of the Bonus Issuance and (ii) at least three-fourths of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting of Flex in favor of the Capital Reduction and Distribution.


“Internal Reorganization” refers to the allocation, transfer, or conveyance by Flex of the entities, assets, and liabilities in advance of the Distribution so that Spinco and its subsidiaries are allocated, transferred, or conveyed the entities, assets, and liabilities of the Cloud & Power Infrastructure business, while the remaining entities, assets, and liabilities will remain with Flex.


“High Court Approval” refers to the approval of the High Court of the Republic of Singapore of the Capital Reduction.


“Person” refers to any natural person, firm, individual, corporation, business trust, joint venture, association, bank, land trust, trust company, company, limited liability company, partnership or other organization or entity, whether incorporated or unincorporated, or any governmental entity.


ii


Table of Contents
   

“Record Date” or “Distribution Record Date” refers to the date to be set by the Flex Board of Directors or an officer authorized to make such determination by the Board to determine the Flex shareholders eligible to receive the Bonus Shares or, as the case may be, the distribution of Spinco common stock.


“RemainCo Group” refers to (i) RemainCo, (ii) each Person (other than any member of the Spinco Group) that is a direct or indirect subsidiary of RemainCo immediately prior to the Distribution (but after giving effect to the Internal Reorganization) and (iii) each Person that becomes a subsidiary of RemainCo following the Distribution; provided that the RemainCo Group shall not include the Persons on Schedule 1.1(179) of the Separation Agreement (as defined below).


“RemainCo Protected Customer” refers to any customer of the RemainCo Restricted Business as conducted immediately prior to the Effective Time.


“RemainCo Restricted Business” refers to contract manufacturing services generally, but shall exclude (i) integration of modular power equipment and associated enclosures and (ii) contract manufacturing services in the Cloud & Compute business. For the avoidance of doubt the RemainCo Restricted Business includes contract manufacturing services for the Power, Cooling, and Networking product businesses, in any jurisdiction worldwide.


“Restricted Period” refers to the three-year period following the Distribution.


“Singapore Companies Act” refers to the Companies Act 1967 of Singapore, as amended or modified.


“Spinco Board of Directors” refers to the board of directors of the Company.


“Spinco Cash Distribution” shall mean the cash distribution in an amount equal to the outstanding Indebtedness incurred by Flex in connection with its acquisition of EPC Power Corp. to be made, or caused to be made by Spinco to RemainCo.


“Spinco common stock” refers to the shares of common stock, par value $0.0001 per share, of Spinco.


“Spinco Financing Arrangements” refers to the bridge loan, term loan or other indebtedness for borrowed money to be incurred by Spinco immediately prior to or substantially concurrently with the effective time of the Distribution on terms and conditions reasonably acceptable to Flex.


“Spinco Group” refers to (a) Spinco, (b) each Person (other than any member of the RemainCo Group) that is a direct or indirect subsidiary of Spinco immediately prior to the Distribution (but after giving effect to the Internal Reorganization) and (c) each Person that becomes a subsidiary of Spinco following the Distribution, including those Persons listed on Schedule 1.1(179) under the caption “Subsidiaries” of the Separation Agreement.


“Spinco Protected Customers” refers to any customer of the Spinco Restricted Business as conducted immediately prior to the Effective Time.


“Spinco Restricted Business” refers to (i) the Power business, excluding contract manufacturing services; (ii) the Cooling business, excluding contract manufacturing services; and (iii) the Cloud & Compute business, including contract manufacturing services generally and, for the avoidance of doubt, including contract manufacturing services related to CPU and AI-accelerated servers, compute trays, fabrication of associated racks and enclosures, and integration into those racks, but shall exclude contract manufacturing services for Networking products, in any jurisdiction worldwide.


“Spin-Off” refers to the separation of the Cloud & Power Infrastructure business from Flex’s other businesses following the Internal Reorganization, the Distribution and the creation, as a result of the separation and distribution, of an independent, publicly traded company, Axiom Solutions International, Inc., holding the entities, assets and liabilities associated with the Cloud & Power Infrastructure business.


Spinco’s historical assets, liabilities, products, businesses, or activities generally refer to the historical assets, liabilities, products, businesses, or activities of the Cloud & Power Infrastructure business as conducted by Flex prior to the completion of the Spin-Off.


iii


Table of Contents

Unless the context otherwise requires, the information included in this information statement about Spinco assumes the completion of all of the transactions referred to in this information statement in connection with the Spin-Off. This information statement describes the business to be transferred to Spinco by Flex in the separation as if the transferred business was our business for all historical periods described. References in this information statement to our historical assets, liabilities, products, businesses, or activities of our business are generally intended to refer to the historical assets, liabilities, products, businesses, or activities of the transferred business as the business was conducted as part of Flex and its subsidiaries prior to the completion of all the transactions referred to in this information statement in connection with the Spin-Off.

This information statement is being furnished solely to provide information to Flex shareholders who will receive shares of Spinco common stock in the Distribution. It is not and is not to be construed as an inducement or encouragement to buy or sell any of Spinco’s securities or any securities of Flex. This information statement describes Spinco’s business, Spinco’s relationship with Flex, and how the Spin-Off affects Flex and its shareholders and provides other information to assist you in evaluating the benefits and risks of holding or disposing of Spinco common stock that you will receive in the Distribution. You should be aware of certain risks relating to the Spin-Off, Spinco’s business and ownership of Spinco common stock, which are described under the section of this information statement entitled “Risk Factors.”

FINANCIAL STATEMENT INFORMATION

This information statement includes certain historical combined financial and other data for Spinco (referred to as the Cloud & Power Infrastructure business of Flex Ltd. or the Business in the historical combined financial statements and related notes thereto). In connection with the Spin-Off, Spinco will become the holder of the assets and liabilities of all of Flex’s Cloud & Power Infrastructure business (as defined herein). Spinco is the registrant under the registration statement of which this information statement forms a part and will be the financial reporting entity following the completion of the Spin-Off. Flex is presently, and will continue to be, a financial reporting entity following the Spin-Off. This information statement also includes summary unaudited pro forma condensed combined balance sheet data as of June 26, 2026, and summary unaudited pro forma condensed combined statement of operations data for the three months ended June 26, 2026 and the fiscal year ended March 31, 2026, which present our combined financial position and results of operations after giving effect to the separation and distribution, and the other transactions described under “Unaudited Pro Forma Condensed Combined Financial Information.” The unaudited pro forma condensed combined financial information is presented for illustrative purposes only and is not necessarily indicative of the operating results or financial position that would have occurred if the relevant transactions had been consummated on the date indicated, nor is it indicative of future operating results. You should read the sections of this information statement entitled “Unaudited Pro Forma Condensed Combined Financial Information” and “Notes to Unaudited Pro Forma Condensed Combined Financial Information,” which are qualified in their entirety by reference to our combined financial statements and related notes thereto, the consolidated financial statements of Flex and related notes thereto and the financial and other information, including in the sections of this information statement entitled “Risk Factors,” “Capitalization” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations.”

NON-GAAP FINANCIAL INFORMATION

This information statement also contains certain financial measures, including adjusted operating income, adjusted net income (loss) and free cash flow, that are not required by, or prepared in accordance with, accounting principles generally accepted in the United States (“GAAP”). We refer to these measures as “non-GAAP” financial measures. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations—Non-GAAP Financial Measures” for our definitions of these non-GAAP measures, information about how and why we use these non-GAAP measures, and a reconciliation of each of these non-GAAP measures to its most directly comparable financial measure calculated in accordance with GAAP.


iv


Table of Contents

MARKET, INDUSTRY AND OTHER DATA

Unless otherwise indicated, information contained in this information statement concerning our industry and the markets in which we operate, including our general expectations and market position, market opportunity, and market share, is based on information from third-party sources, our own analysis of data received from these third-party sources, our own internal data, market research that we commission, and management estimates. Our management estimates are derived from publicly available information, our knowledge of our industry and assumptions based on such information and knowledge, which we believe to be reasonable. Assumptions and estimates of our and our industry’s future performance are necessarily subject to a high degree of uncertainty and risk due to a variety of factors, including those described under the section of this information statement entitled “Risk Factors.” These and other factors could cause future performance to differ materially from our assumptions and estimates. For additional information, see the sections of this information statement entitled “Risk Factors” and “Cautionary Statement Concerning Forward-Looking Statements.”

TRADEMARKS AND TRADE NAMES

This information statement may contain trade names, trademarks, or service marks belonging to other companies. Such trade names, trademarks, or service marks are the property of their respective owners, and we do not intend any use or display of other parties’ trademarks, trade names, or service marks to imply a relationship with, or endorsement or sponsorship of us by, these other parties.


v


Table of Contents

INFORMATION STATEMENT SUMMARY

This summary highlights some of the information in this information statement relating to Spinco, our separation from Flex and the Distribution of our common stock by Flex to its shareholders. For a more complete understanding of our business and the separation and distribution, you should read carefully the more detailed information set forth under the sections of this information statement entitled “Risk Factors,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” “Business” and “The Separation and Distribution” and the other information included in this information statement.

Axiom Solutions International, Inc.

Spinco is a global, high-growth critical digital and electrical infrastructure company, providing end-to-end power and thermal management technologies and integrated infrastructure systems serving artificial intelligence (“AI”) data centers and mission-critical applications. Through its critical power and electrical infrastructure portfolio, Spinco delivers electrification solutions that enable the efficient generation, distribution, and management of power. On May 5, 2026, Flex announced its plan to separate its businesses into two distinct, publicly traded companies through a distribution of Spinco shares to Flex shareholders. The Spin-Off will create two companies with distinct growth strategies that are poised to drive significant customer and shareholder value. Spinco will operate the Cloud & Power Infrastructure business, and Flex will continue to operate its business other than the Cloud & Power Infrastructure business.

Business Overview

General


LOGO

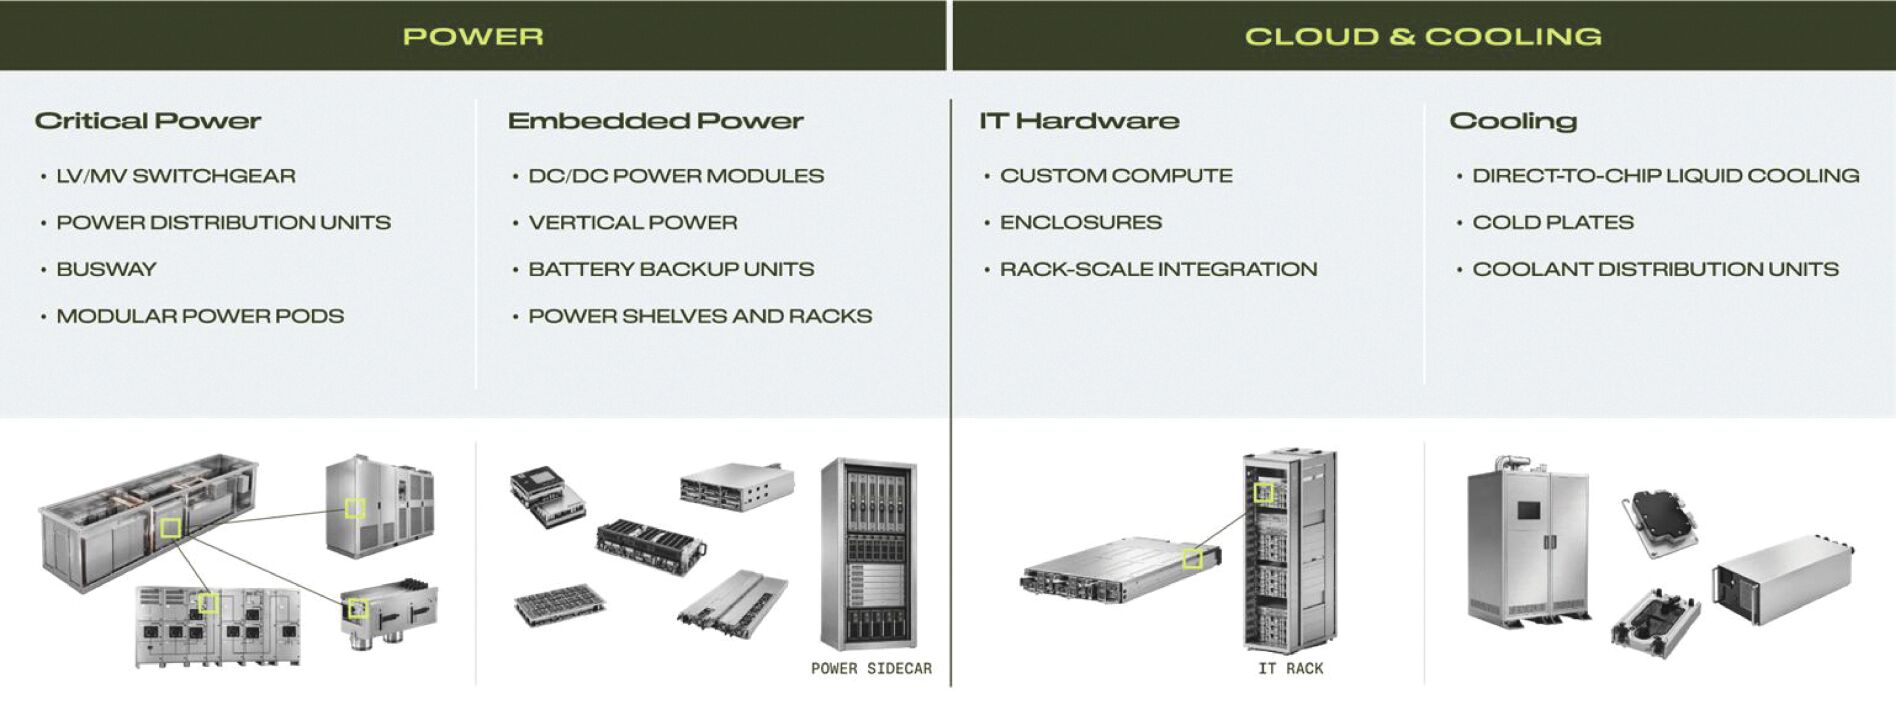
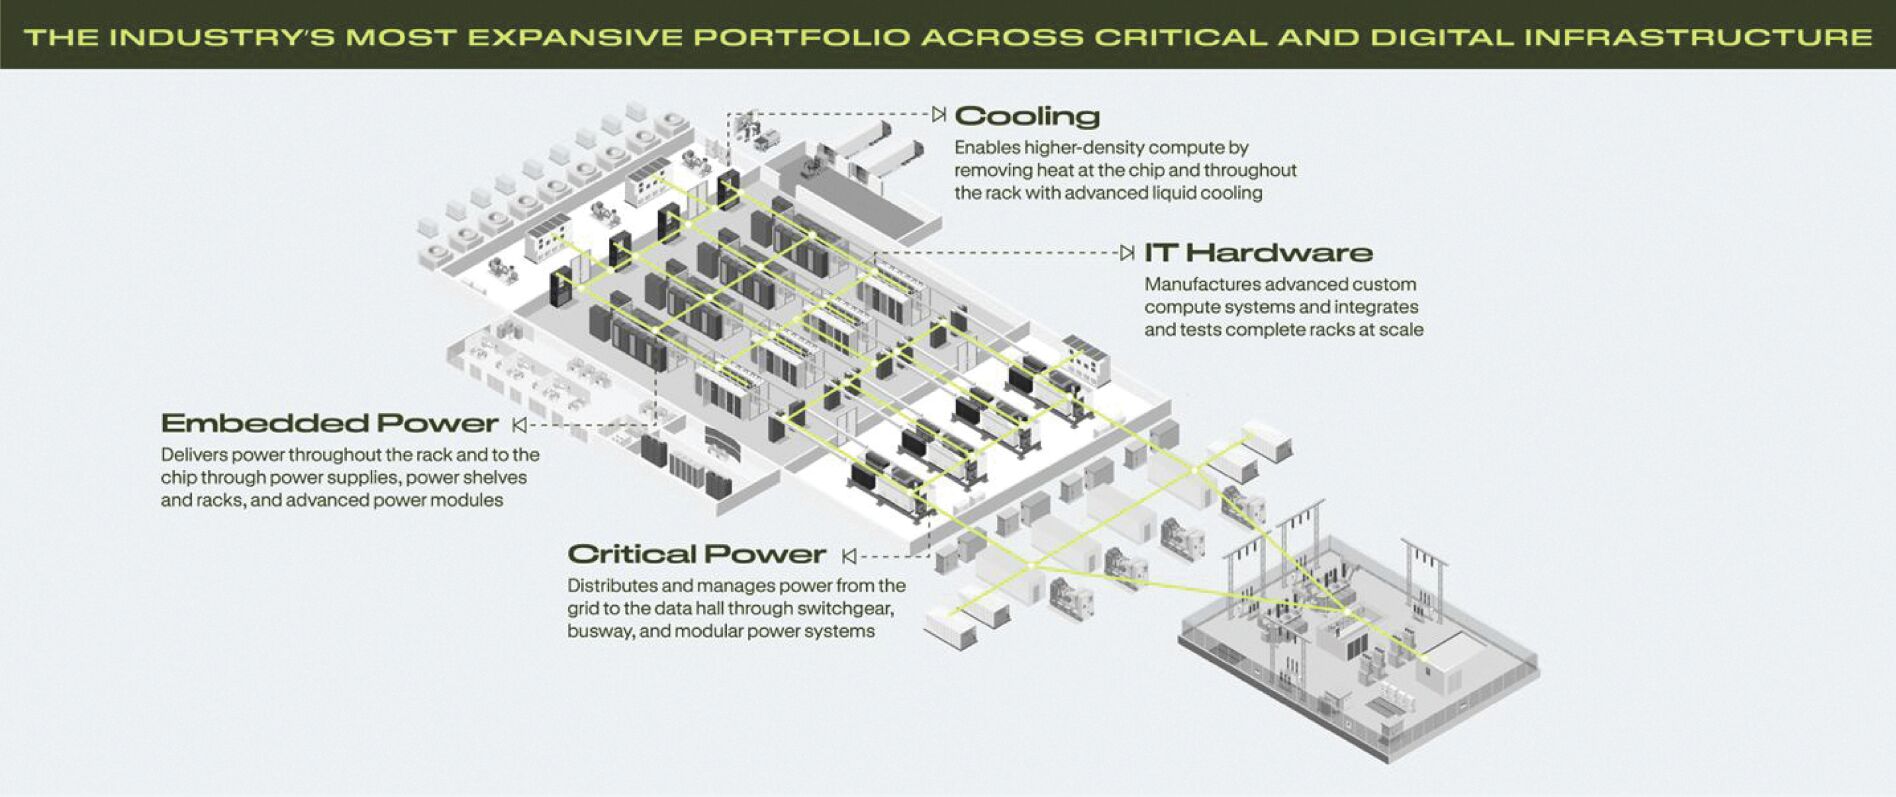
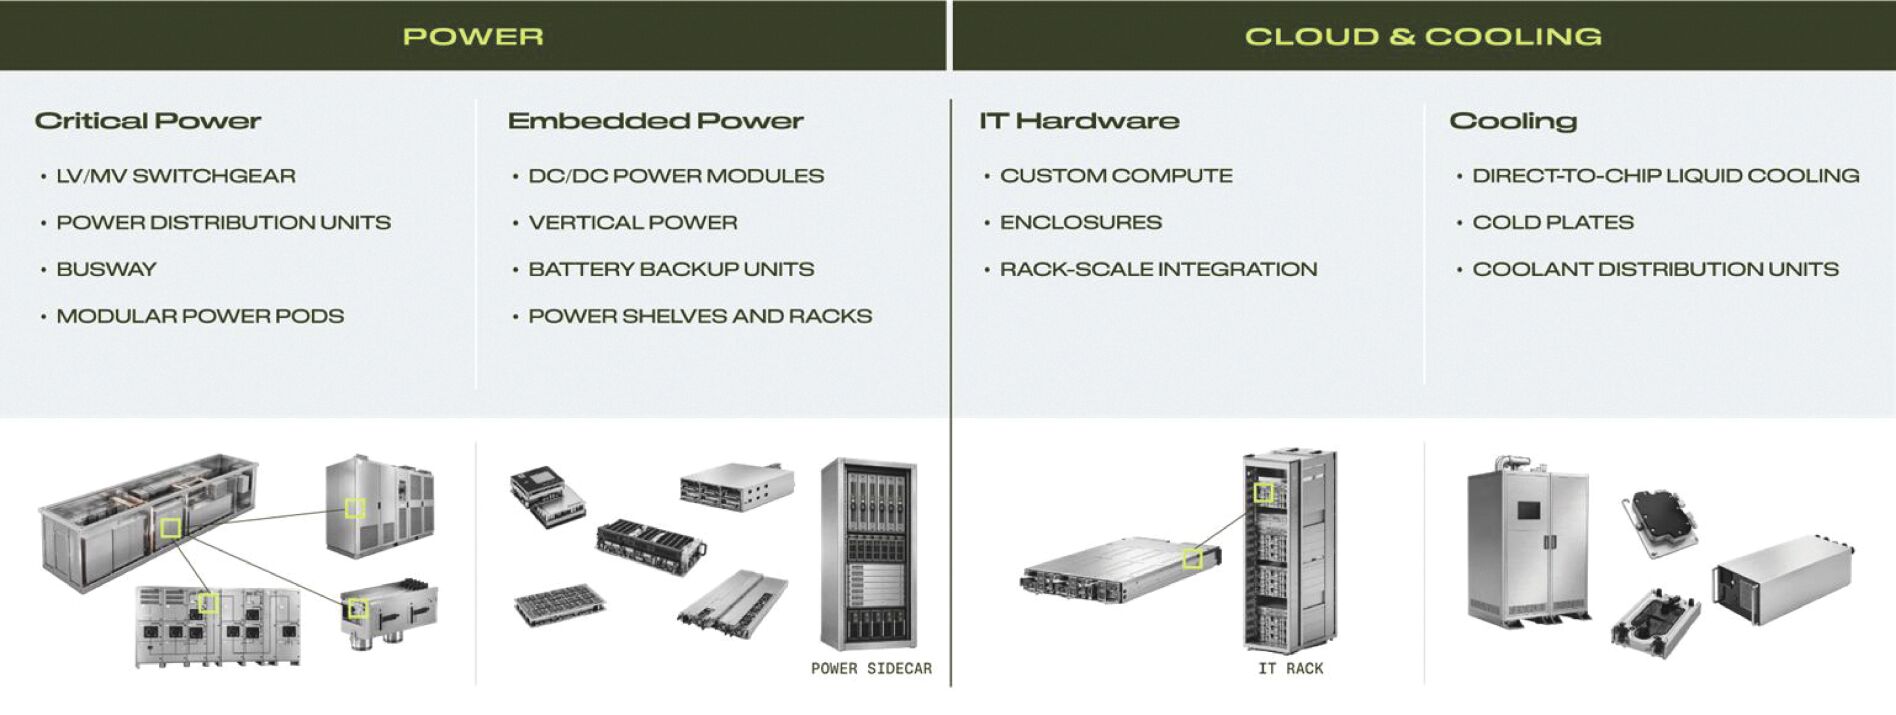
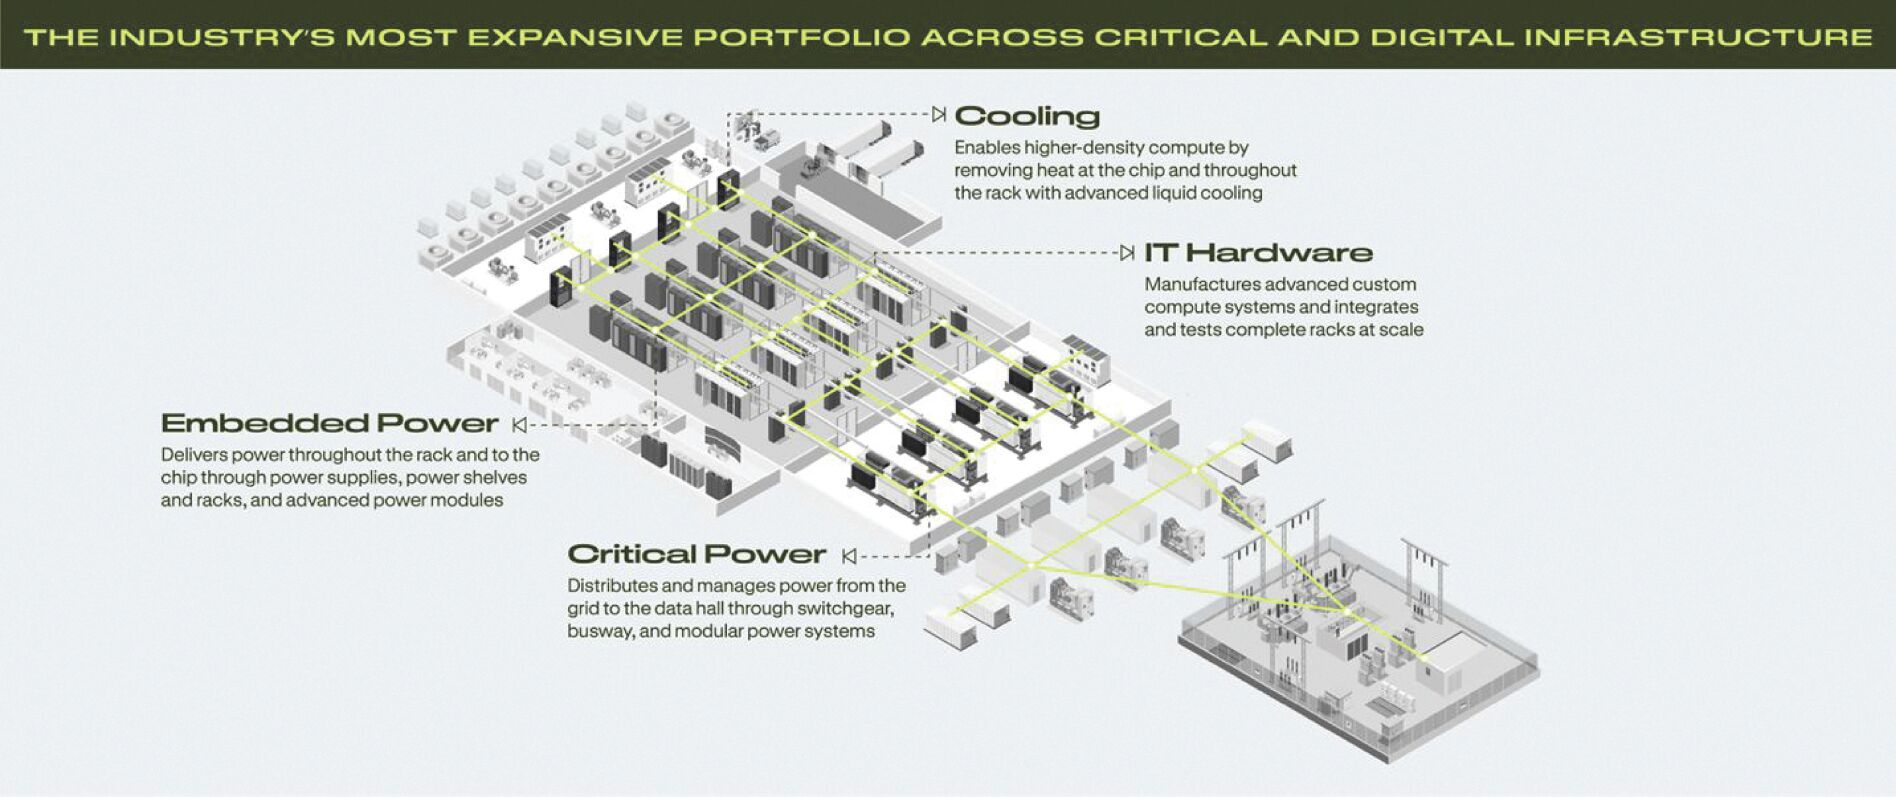
As a global leader in critical digital infrastructure, Spinco delivers end-to-end power and thermal management technologies for AI data centers and mission-critical applications. With deep expertise across critical power infrastructure, embedded and distributed power systems, power electronics, electrified architectures, advanced cooling, and compute integration, Spinco delivers system-level coordinated architectures that address power density, thermal performance and infrastructure scalability to replace fragmented, multi-vendor approaches. These integrated platforms support the scalable and reliable deployment of power-dense infrastructure across artificial intelligence and high-performance computing, cloud and service providers, industrial automation, edge computing, utilities, and modern data centers.


1


Table of Contents

Spinco operates a proprietary, globally integrated platform, supported by advanced engineering, manufacturing, and service capabilities across the full power value chain. By integrating power, cooling, and compute at the system level, Spinco enables faster time-to-capacity, improved infrastructure reliability, and scalable performance as power densities and thermal complexity continue to increase. The company is well positioned to benefit from long-duration secular trends including accelerating electrification, rising power intensity, and increasing infrastructure complexity while supporting customers’ energy-efficiency, power-optimization, and decarbonization objectives. These dynamics are driving a sustained, multi-year buildout of digital infrastructure, particularly as artificial intelligence adoption accelerates.

Spinco maintains a global footprint serving customers in approximately 14 countries, with 19 manufacturing sites, eight design, engineering, product introduction, and service centers, and a workforce of approximately 31,000 employees, including contractors, as of June 26, 2026.

Spinco will be headquartered in Austin, Texas.

Industry Overview


LOGO

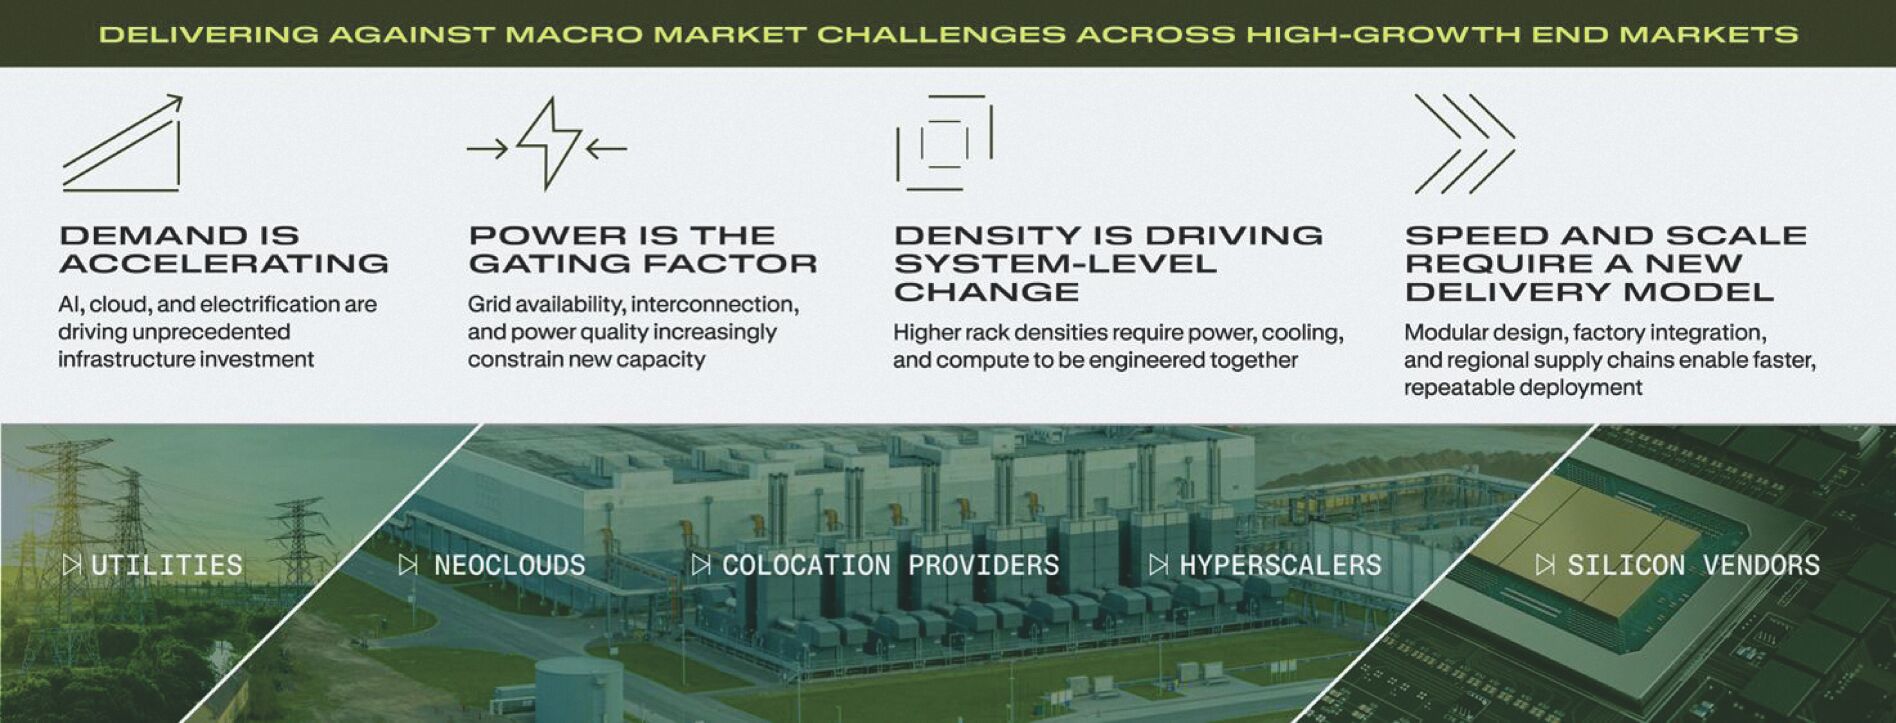
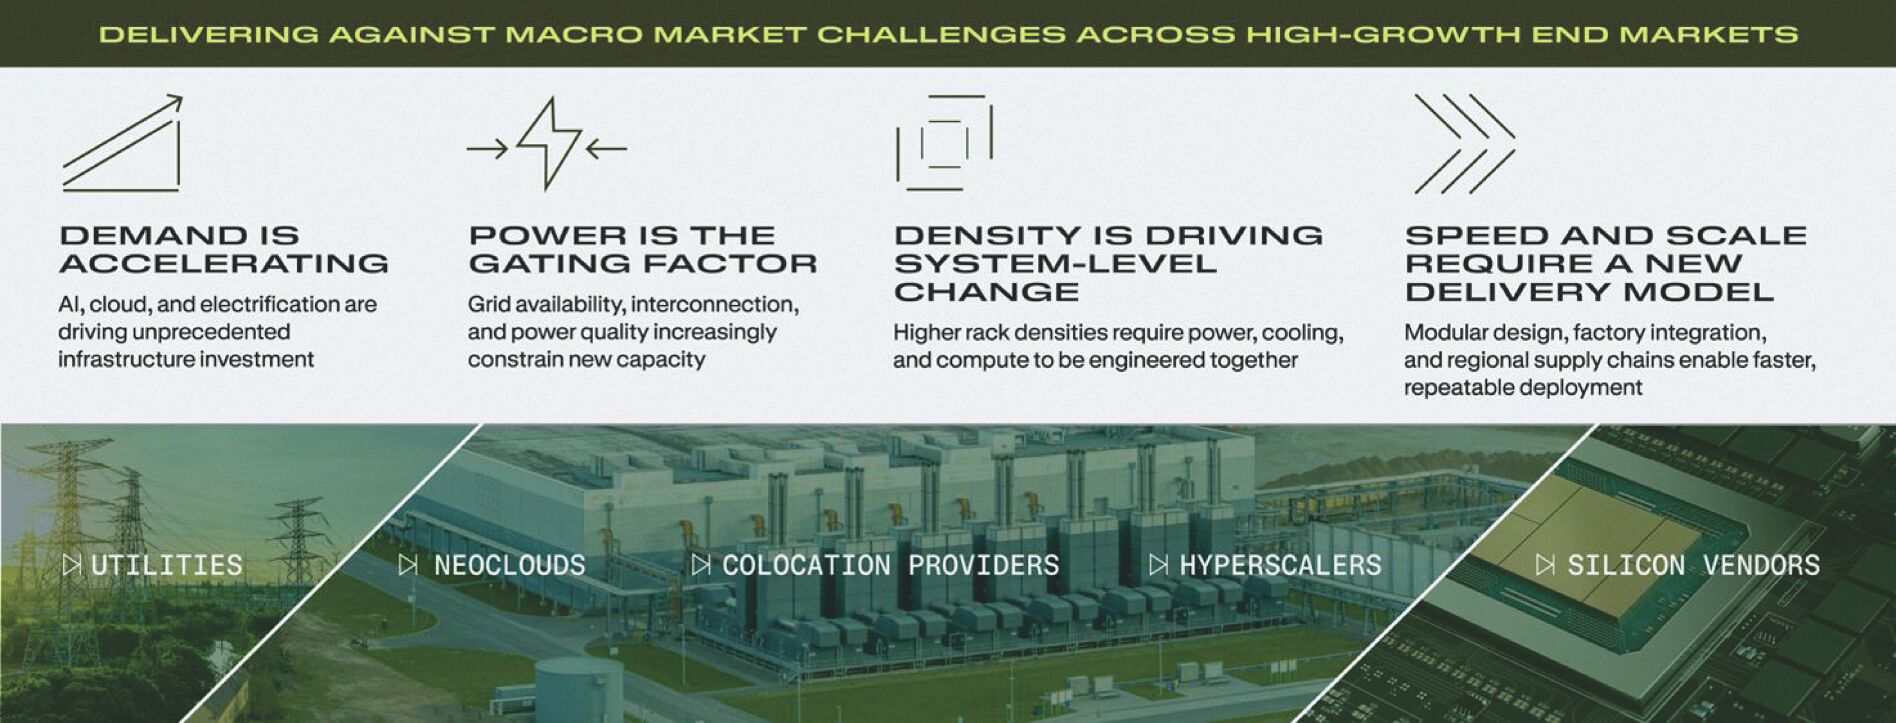
The global digital infrastructure industry is experiencing significant growth driven by increasing demand for compute capacity and the associated requirements for power delivery, cooling, and rapid infrastructure deployment. As cloud computing, high-performance computing, and artificial intelligence workloads expand, data center operators, hyperscalers, and colocation providers are investing in infrastructure capable of supporting significantly higher power density and thermal loads. This is a generational transformation that requires a unified system with holistic integration support from grid to chip.

This growth is also increasing demand for utility-scale power infrastructure. New data center deployments require substantial grid capacity, substation buildouts, and expanded facility-level power distribution to support megawatt- scale deployments. As a result, power availability, interconnection timelines, and utility infrastructure have become critical factors in determining deployment speed and location. These dynamics are driving closer coordination between utility power, facility infrastructure, and rack-level architectures.

Data centers can be broadly categorized into the following primary types, each characterized by distinct requirements for power infrastructure, cooling, and compute integration:


Cloud/Hyperscale: Large-scale facilities used to support cloud applications and AI workloads. This portion of the industry is growing rapidly as operators invest in high-density infrastructure and large-scale power capacity. Examples include Microsoft, Amazon Web Services, and Google Cloud.


2


Table of Contents
   

Colocation/Multi-tenant: Facilities that provide shared infrastructure for customers to deploy compute equipment. Colocation operators are expanding capacity to support higher power densities and liquid-cooled deployments. Examples include Digital Realty, Equinix, and QTS.


Neocloud: Providers delivering AI-optimized infrastructure as a service, typically focused on high-density deployments for training and inference workloads. Examples include CoreWeave, Nebius, and Lambda Labs.


Enterprise: On-premises data centers operated by large enterprises. Growth in this segment has generally been more modest but continues to require upgrades to support higher-density infrastructure.

The addressable market for digital infrastructure includes facility and rack-level power systems, embedded power electronics, advanced cooling technologies, and integrated infrastructure platforms. According to publicly available research published by Goldman Sachs Research in September 2026, industry forecasts suggest that global power demand from data centers is forecast to increase by as much as 170% by 2030 compared to 2025. With hyperscale customers targeting 1+ megawatt racks and transitioning to higher-voltage power architectures, these trends are increasing the importance of coordinated power delivery, cooling, and rack-level integration.

The need for speed and scale with end-to-end integration is accelerating across all customer segments. As infrastructure requirements increase, customers are prioritizing rapid deployment, consistent architecture, and the ability to scale across multiple locations. Time to capacity, execution certainty, and deployment efficiency have become critical considerations. Constraints on the availability of skilled field labor are further increasing the value of shifting assembly, integration, and testing into controlled factory environments. Prefabricated, factory-integrated, and modular infrastructure solutions are gaining adoption as customers seek to reduce on-site complexity and bring capacity online more quickly.

Higher power density is also driving changes in rack architecture and system integration. GPU-dense deployments require significantly more power per rack, advanced cooling approaches, and tighter coordination between power delivery and compute integration. These requirements increase system complexity and favor vendors capable of delivering coordinated infrastructure solutions.

The industry is also shaped by regionalization, supply chain resilience, and energy efficiency priorities. Data center operators are seeking localized manufacturing, modular deployment strategies, and more efficient power and cooling architectures to reduce lead times and manage operational risk. These factors influence vendor selection and long-term infrastructure planning.

These trends are accelerating demand for power-dense, modular infrastructure that can be deployed rapidly and scaled efficiently. As deployments grow in size and complexity, coordinated power delivery, cooling, and rack-level integration are becoming critical to bringing capacity online.


3


Table of Contents

Our Segments and Geographic Revenues


LOGO

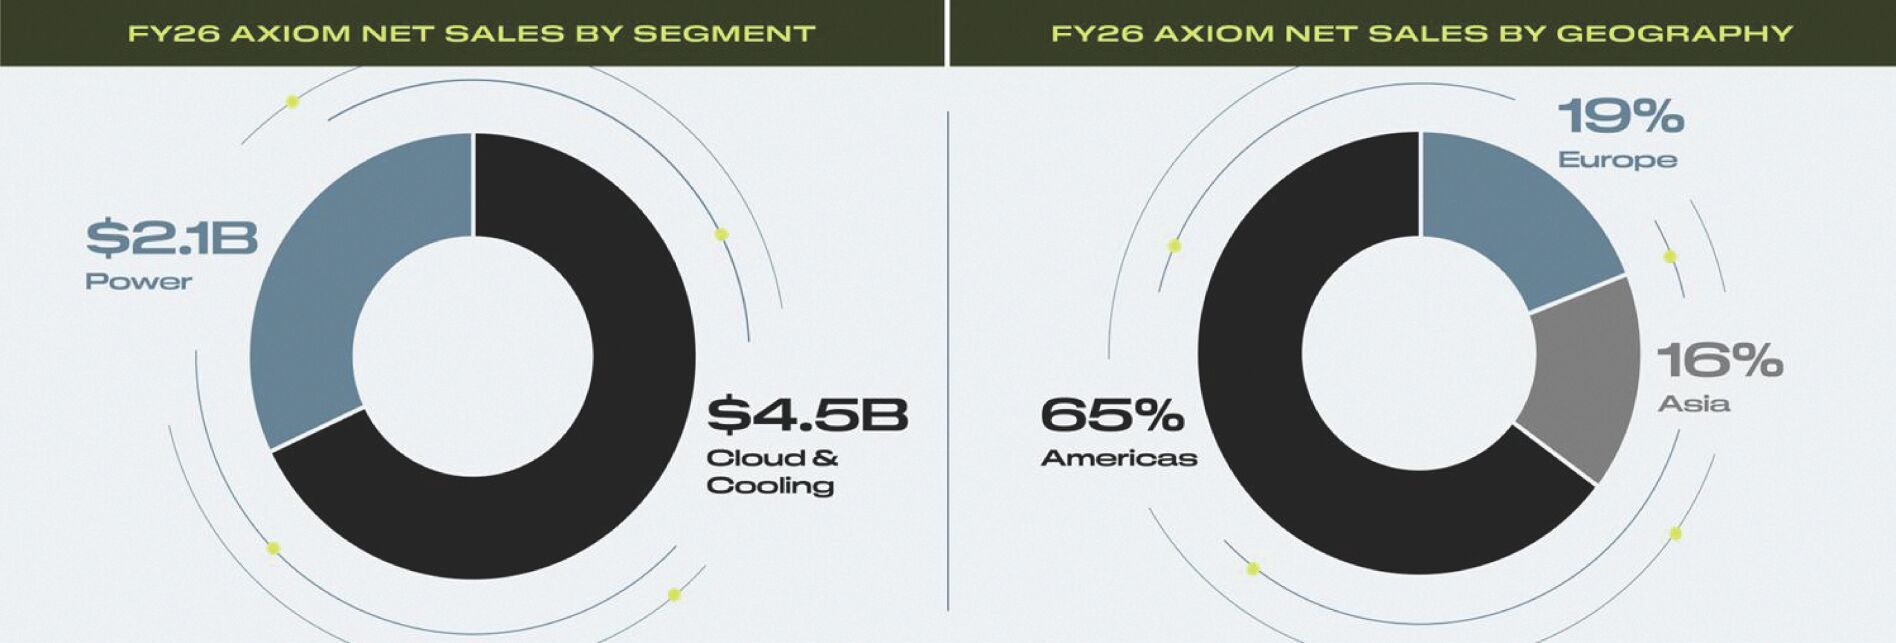
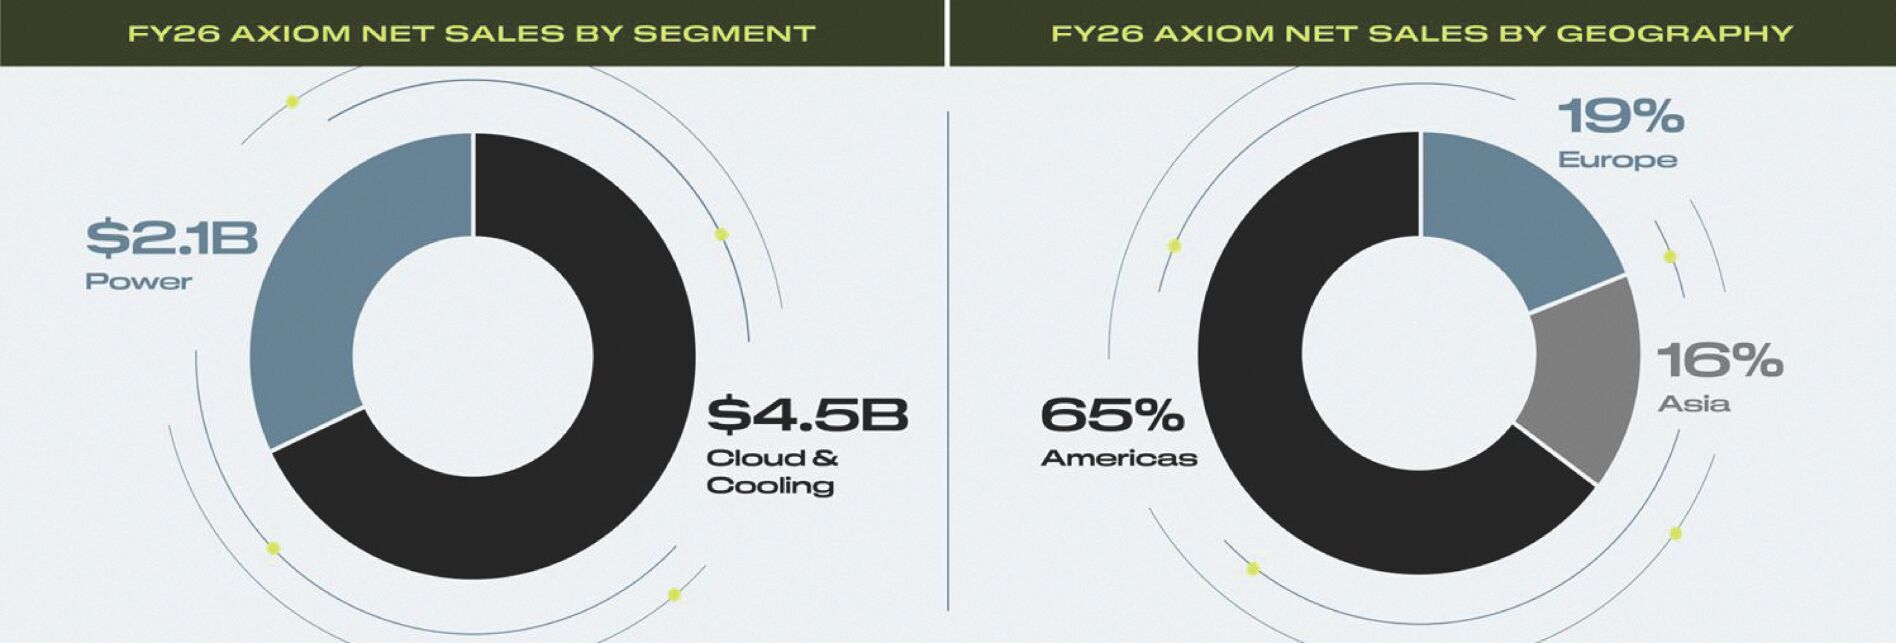
We have aligned our businesses across two operating segments: Power and Cloud & Cooling. Net sales for fiscal year 2026 increased by 38%, or $1.8 billion, to $6.6 billion from the prior year. Net sales for our Cloud & Cooling segment increased $1 billion, or 29%, to $4.5 billion from the prior year, primarily driven by the Company’s largest two customers scaling up storage infrastructure within data centers, in conjunction with increasing AI demand. Net sales for our Power segment increased $0.8 billion, or 62%, to $2.1 billion from the prior year, primarily driven by customers scaling up power capabilities and building data center infrastructure, in conjunction with increasing AI demand.

We have established an extensive network of manufacturing facilities in the world’s major markets (Asia, the Americas, and Europe) to serve both multinational and regional customers. For the fiscal year ended March 31, 2026, 65% of our net revenue was derived from customers in the Americas, 19% from customers in Europe, and 16% from customers in Asia. Our geographic revenue mix may fluctuate from period to period based on customer demand, product mix, and the timing of program ramps with key customers.

Our Competitive Strengths


LOGO


4


Table of Contents

We believe the following competitive strengths set Spinco’s business apart:

Power-Anchored Grid-to-Chip Integrated Architecture: We provide critical digital and electrical infrastructure solutions built around power delivery and management, spanning utility and facility power infrastructure, embedded rack and chip-level power systems, advanced liquid cooling, and rack-scale compute integration. This integrated architecture allows us to coordinate power, cooling, and compute at the system level rather than delivering discrete components. By designing these layers as a coordinated architecture, we help customers reduce integration complexity, improve performance, and support reliable operation in high-density deployments.

Speed and Time-to-Capacity: We integrate, assemble, and test power, cooling, and compute infrastructure in controlled factory environments to enable rapid deployment and scalable expansion. By integrating power, cooling, and compute in factory environments, we deliver pre-engineered and pre-tested modules that can reduce on-site integration requirements. This approach enables customers to bring capacity online more quickly, improve deployment consistency, and scale infrastructure across multiple locations.

Differentiated Product IP and System Integration Capabilities: We develop and manufacture proprietary technologies including facility and rack-level power systems, embedded power electronics, liquid cooling technologies, prefabricated power infrastructure, and rack-scale integration. This product and manufacturing depth enables greater control over system performance, design optimization, supply continuity, and execution, supporting delivery of coordinated infrastructure platforms that span multiple layers of deployment, from facility power to rack-level integration.

Engineering and Innovation Capabilities: Our multidisciplinary engineering capabilities span power delivery, cooling, and rack-scale integration. Our innovative portfolio includes technologies such as a UL-certified capacitive energy storage system (CESS) for fast backup power and microjet liquid cooling technology obtained through the acquisition of JetCool (as defined herein), designed to support high-power chip cooling. We also offer modular rack-level cooling distribution units and prefabricated power skids. We continue to invest in research and development to support increasing compute density and evolving power and cooling requirements.

Global Footprint and Regional Reach: Spinco operates a global manufacturing footprint supporting production and assembly in proximity to customer deployments. Our global presence includes engineering, manufacturing, operations, sales, and service locations across 14 countries. This geographic footprint enables localized sourcing, diversified supply chains, and operational flexibility. This footprint supports regional sourcing, capacity flexibility, consistent execution, and on-site support with timely-delivery across complex, multi-site programs.

Deep Customer Relationships and Program Execution: We maintain strong relationships with leading hyperscalers, colocation providers, silicon companies, utilities, and technology OEMs. Our customer engagement model emphasizes early collaboration and, in certain cases, co-development. Our engineering and manufacturing teams work closely with customers to translate their complex technology roadmaps into scalable deployments and multi-year programs, supporting evolving infrastructure requirements.

Our Strategy

Our strategy is to drive profitable, above-market growth by expanding our power-anchored infrastructure platform, accelerating customers’ time to capacity and scaling our global engineering, manufacturing and execution capabilities. We intend to strengthen our innovative portfolio across power, cooling, and rack-scale integration, deepen strategic customer relationships, improve operational execution and deploy capital toward technologies and capabilities that enhance our competitive position.


5


Table of Contents

Expand and Differentiate Our Integrated Platform: We continue to invest in technologies spanning utility and facility power infrastructure, embedded rack and chip-level power systems, advanced liquid cooling, and rack-scale compute integration. Our architecture is designed to integrate these capabilities into coordinated infrastructure platforms that support higher power density and rapid deployment. By expanding our portfolio across these areas, we aim to deliver more complete solutions, reduce integration complexity, improve system performance and increase our content in customer deployments.

Enable Faster Deployment and Accelerate Time to Capacity: Customers are increasingly prioritizing speed, consistency, and scalability in infrastructure deployment. We intend to expand our factory-integrated, pre-engineered modules that combine power delivery, cooling, and rack-scale integration. This approach reduces on-site complexity, shortens deployment timelines, and enables customers to scale capacity consistently across multiple locations. We continue to enhance our modular designs, testing capabilities, and manufacturing processes to support rapid deployment and repeatable execution.

Deepen Strategic Customer Relationships: We partner with hyperscalers, colocation providers, silicon vendors, OEMs, and utilities early in their technology and infrastructure roadmaps to develop infrastructure platforms aligned with evolving requirements. Our engagement model emphasizes early collaboration, co-development, and long-term program execution. By expanding our participation across utility power, facility infrastructure, embedded power, cooling, and rack-scale integration, we aim to deepen customer relationships and increase content per deployment.

Advance Next-Generation Power Density and Cooling Technologies: We are focused on advancing technologies that support increasing power density and thermal requirements. Our strategy includes continued development of high-capacity power delivery architectures, advanced liquid cooling technologies, and rack-level integration capabilities. We also invest in monitoring, control, and system coordination capabilities to support reliable operation in high-density deployments. These efforts are intended to expand our role in next-generation infrastructure architectures.

Scale Global Operations and Regional Manufacturing: We leverage our global engineering and manufacturing footprint to support regional deployment and customer growth with consistent execution. Our investments are focused on expanding capacity, enhancing automation, and improving manufacturing efficiency across our sites. We continue to invest in regionalized production, advanced manufacturing processes, and integrated testing capabilities to support deployment speed, supply chain resilience, and cost competitiveness.

Pursue Strategic Acquisitions: We intend to build on our strong M&A track record and selectively pursue acquisitions that expand our power, cooling, and integration capabilities while expanding our product and service offerings and strengthening our global scale. Recent acquisitions include JetCool Technologies Inc., which expanded our direct-to-chip liquid cooling capabilities, and Electrical Power Products and Crown Technical Systems (“Crown”), both of which strengthened our critical power and utility infrastructure offerings. On September 3, 2026, Flex announced that it entered into a definitive agreement to acquire EPC Power, a leading provider of intelligent power conversion solutions for data center and grid applications, for $4.4 billion. The addition of EPC Power Corp. (“EPC Power”)’s differentiated power conversion capabilities to Spinco’s existing power, cooling and compute portfolio broadens Spinco’s product offerings across data center and electrical infrastructure, positioning it for the transition to next-generation 800V data center power architectures as AI workloads drive higher power densities. We intend to continue evaluating opportunities that enhance our technology portfolio, expand solution scope, and support growth in integrated infrastructure platforms.


6


Table of Contents

Competitive Landscape

We operate in highly competitive global markets spanning power infrastructure, cooling technologies, and integrated rack-scale systems. We compete with providers of facility and rack-level power infrastructure, integrated infrastructure platforms, and manufacturing and system integration services.

These competitors include global providers of critical power and cooling infrastructure such as Vertiv Holdings Co., Eaton Corporation plc, Schneider Electric SE, and nVent Electric plc; suppliers of embedded and rack-level power solutions such as Delta Electronics, Inc., Lite-On Technology Corporation, and Super Micro Computer, Inc.; and electronics manufacturing services providers and original design manufacturers that support hyperscale customers, including Celestica Inc., Jabil Inc., and Foxconn.

Competition varies by program and solution scope. In power infrastructure and cooling deployments, we compete with providers of facility-level and rack-level power and thermal solutions. In integrated rack-scale systems and coordinated deployments, we compete with electric manufacturing service (“EMS”) providers, original design manufacturers (“ODMs”), and vertically integrated suppliers. Customers frequently use competitive bidding and multi-sourcing strategies, and some hyperscale customers have expanded internal manufacturing capabilities, which can affect outsourcing opportunities.

We compete on a broad range of factors, including product performance and reliability; engineering and system design capabilities; ability to integrate power, cooling, and compute; manufacturing quality and yield; time to capacity; total landed cost; global footprint and proximity to customers; new product introduction and ramp capabilities; supply chain management; and after-market and lifecycle services. The relative importance of these factors varies by customer and by program.

The competitive landscape is dynamic and influenced by increasing power density, liquid cooling adoption, and compressed deployment timelines. These trends are driving demand for coordinated infrastructure solutions and are reshaping competition across traditional power infrastructure providers, cooling suppliers, and system integration vendors.

Recent Development

EPC Power Acquisition

On September 3, 2026, Flex, ACS Acquisitions, Inc., a Delaware corporation and wholly owned subsidiary of Flex (the “Purchaser”), EPC Power, and Charge Parent, LLC, a Delaware limited liability company (the “Seller”), entered into a Stock Purchase Agreement (the “Purchase Agreement”), pursuant to which the Purchaser will acquire all of the equity interests (the “Equity Interests”) of EPC Power from the Seller (such transaction, the “EPC Power Acquisition”). EPC Power is expected to become part of the Cloud and Power Infrastructure business, which Flex plans to separate into Spinco in the Spin-Off. Flex is a party to the Purchase Agreement solely for purposes of guaranteeing the due and punctual performance of the Purchaser’s obligations thereunder.

The Purchaser has agreed to acquire the Equity Interests for aggregate cash consideration of $4.4 billion, payable at the closing of the EPC Power Acquisition, subject to customary adjustments as set forth in the Purchase Agreement. The Purchase Agreement contains a “locked box” mechanism in which the enterprise value of EPC Power has been fixed as of June 30, 2026 (the “Locked Box Date”). EPC Power and the Seller have agreed to customary protections against leakage of value from EPC Power between the Locked Box Date and the date of the closing, subject to customary exceptions for permitted leakage.

The Purchase Agreement contains customary representations, warranties and covenants by the parties. The EPC Power Acquisition is expected to close in the fourth quarter of 2026, subject to the satisfaction or waiver of


7


Table of Contents

certain customary closing conditions, including, among other things, the expiration or termination of the applicable waiting period (and any extension thereof) under the Hart-Scott-Rodino Antitrust Improvements Act of 1976, as amended.

The Purchase Agreement also includes customary termination provisions, including, among others, the ability of Purchaser or the Seller to terminate the Purchase Agreement if the EPC Power Acquisition has not been consummated on or before December 31, 2026, subject to two automatic three-month extensions under certain circumstances.

The foregoing description of the Purchase Agreement does not purport to be complete and is qualified in its entirety by reference to the full text of the Purchase Agreement, a copy of which is filed as an exhibit to the Registration Statement on Form 10, of which this information statement forms a part.

In connection with the Purchase Agreement, on September 3, 2026, Flex entered into a Senior Unsecured 364-Day Bridge Facility Commitment Letter (the “Debt Commitment Letter”) with Citigroup Global Markets Inc., Bank of America, N.A. and BofA Securities, Inc.

The Debt Commitment Letter provides for a senior unsecured 364-day bridge loan credit facility in an aggregate principal amount of up to $4.4 billion (the “Bridge Facility”), which is intended to be available to Flex to finance, together with other sources of funds, the EPC Power Acquisition and related expenses in the event that Flex has not obtained other permanent financing prior to the closing of the EPC Power Acquisition. The Bridge Facility is subject to customary conditions precedent to funding, including the consummation of the EPC Power Acquisition materially in accordance with the terms of the Purchase Agreement, the absence of a Material Adverse Effect (as defined in the Purchase Agreement) and other customary funding conditions for facilities of this type.

Flex intends to replace the Bridge Facility with a combination of debt and equity financing.

Summary of Risk Factors

An investment in Spinco common stock is subject to a number of risks, including market, financial, regulatory and operational risks related to our business and operations, the Spin-Off and our common stock. Set forth below are some, but not all, of these risks.

Risks Related to Our Business and Operations


Our revenue is concentrated among a limited number of customers, which subjects us to significant revenue variability, margin pressure, and counterparty risk.


Customer commitments are limited and demand is cyclical, which may create inventory exposure, capacity utilization challenges, and significant period-to-period variability in our results.


Our concentration of accounts receivable and deposits with a small number of customers increases counterparty and collection risk.


Our customer contracts may permit termination for convenience or on short notice.


We may incur significant losses if customer-specific capital equipment becomes impaired or obsolete.


Our relationships with key customers may require us to improve our products, services, and capabilities, which may involve significant technological and design challenges.


Constrained supply and dependence on single- or limited-source components may elongate lead times, increase costs, and create misalignment with customer obligations.


8


Table of Contents
   

Customer-directed suppliers and components may increase our supply chain risk.


Our dependence on customer and third-party power and water availability, cost, and permitting may delay projects or impair economics.


Third-party facility control, retrofit requirements, and capacity utilization variability may introduce delays, performance risks, and contractual exposure.


Physical climate and geopolitical risks could disrupt our facilities, supply chains, and customer programs.


Rapid technology shifts require continuous capability upgrades and may render existing solutions less competitive or obsolete.


Working capital intensity and access to financing may constrain growth and increase earnings volatility.


Capital markets and interest rate volatility may constrain our customers’ and partners’ ability to fund sites and power, indirectly affecting program ramps and growth visibility.


Our business depends on continued capital investment in digital infrastructure, and any reduction in such spending could materially harm our results.

Risks Related to the Spin-Off


We may not achieve some or all of the expected benefits of the Spin-Off, and the Spin-Off may adversely impact our business.


We may not be able to prevent or detect all errors or fraud, and as a newly standalone public company, we will need to establish our own internal control environment.


We are being spun off from our parent company, Flex, and our historical and pro forma financial information is not necessarily representative of the results that we would have achieved as a separate, publicly traded company and, therefore, may not be a reliable indicator of our future results.


Flex may fail to perform under various transaction agreements that will be executed as part of the Spin-Off, or we may fail to have necessary systems and services in place when Flex is no longer obligated to provide services under the various agreements.


In connection with the Spin-Off, Flex will indemnify us for certain liabilities. However, there can be no assurance that the indemnity will be sufficient to protect us against the full amount of such liabilities, or that Flex’s ability to satisfy its indemnification obligations will not be impaired in the future.


In connection with our separation, we will assume and indemnify Flex for certain liabilities. If we are required to make payments pursuant to these indemnities to Flex, we would need to meet those obligations and our financial results could be adversely impacted.


If the Distribution, together with certain related transactions, does not qualify for the Intended Tax Treatment, you and Flex could be subject to significant U.S. federal income tax liability and, in certain circumstances, we could be required to indemnify Flex for material taxes pursuant to indemnification obligations under the anticipated Tax Matters Agreement.


To preserve the tax-free treatment to Flex and its shareholders of the Distribution and certain related transactions, under the Tax Matters Agreement that we anticipate entering into with Flex, we will be restricted from taking certain actions after the Distribution that could adversely impact the Intended Tax Treatment of the Distribution and such related transactions.


9


Table of Contents
   

Ms. Advaithi will serve as our Chief Executive Officer and as one of our directors as well as the chair of the Flex Board of Directors, and certain of our directors and executive officers may continue to own shares of Flex, which overlap may give rise to conflicts of interest.


The transfer of certain employees from Flex to us contemplated by the Separation will not be complete at the time of the Distribution.

Risks Related to Our Common Stock


We cannot be certain that an active trading market for our common stock will develop or be sustained after the Spin-Off and, following the Spin-Off, our stock price may fluctuate significantly.


Any sales of substantial amounts of shares of our common stock in the public market, or the perception that such sales might occur, in connection with the Distribution or otherwise, may cause the market price of our common stock to decline.


Your percentage of ownership in us may be diluted in the future.


The completion of the Spin-Off is subject to the Flex Shareholder Approvals and the High Court Approval, which may not be satisfied, and the Spin-Off may not occur.


10


Table of Contents

Summary of the Separation and Distribution

The following provides a summary of the terms of the separation and distribution. For a more detailed description of the matters described below, see the section of this information statement entitled “The Separation and Distribution.”

Distributing Company

Flex Ltd. is a Singapore-incorporated registered public company limited by shares (company registration no. 199002645H). Following the Spin-Off, Flex will own between approximately 6.0% to 12.0% of our common stock for a period of up to 24 months following the Distribution.

Distributed Company

Axiom Solutions International, Inc., a Texas corporation and, prior to the Spin-Off, a wholly owned subsidiary of Flex. Flex formed Spinco as a corporation in Delaware on April 7, 2026, for the purpose of effectuating the planned Spin-Off, and subsequently converted it into a Texas corporation pursuant to a plan of conversion. Spinco has engaged in no business activities to date and it has no material assets or liabilities of any kind, other than those incident to its formation and those incurred in connection with the Spin-Off. Pursuant to a reorganization, prior to the Spin-Off, we will receive the legal entities containing the Cloud and Power Infrastructure business of Flex and its subsidiaries. After completion of the separation and distribution, we will be an independent, publicly traded company.

Distribution Ratio

Each holder of Flex ordinary shares will receive for each ordinary share of Flex held at     Central time on    , 2026, the Distribution Record Date,     share[s] of Spinco common stock. Cash will be distributed in lieu of fractional shares, as described in the section of this information statement entitled “The Separation and Distribution—General Treatment of Fractional Shares of Common Stock.” Please note that if you sell your Flex ordinary shares on or before the Distribution Date, then the buyer of those shares may, in certain circumstances, be entitled to receive the shares of our common stock distributed on the Distribution Date.

Distributed Securities

Flex will distribute between approximately 88.0% to 94.0% of Spinco common stock owned by Flex, which will be between approximately 88.0% to 94.0% of Spinco’s common stock outstanding immediately prior to the Distribution. Based on the approximately     Flex ordinary shares outstanding on    , and applying the Distribution Ratio for each Flex ordinary share, Flex will distribute an aggregate of approximately     shares of Spinco common stock to Flex shareholders who hold Flex ordinary shares as of the Distribution Record Date. The number of shares that Flex will distribute to its shareholders will be reduced to the extent that cash payments are to be made in lieu of the issuance of fractional shares of Spinco common stock, as described below. Following the Distribution, Flex intends to dispose of all of the Spinco common stock that it retains after the Distribution through one or more subsequent exchanges of Spinco common stock for Flex debt held by Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, in each case during the 24-month period following the Distribution.

Record Date

The Distribution Record Date is expected to be     Central time on    , 2026 (the “record date”).


11


Table of Contents

Distribution Date

The Distribution Date is expected to be on or about    , 2027.

Distribution

On the Distribution Date, Flex, with the assistance of Computershare Trust Company, N.A., the distribution agent, will electronically distribute shares of Spinco common stock to your bank or brokerage firm on your behalf or through the systems of The Depository Trust Company (“DTC”) (if you hold your Flex shares through a bank or brokerage firm that uses DTC) or to you in book-entry form (if you hold your Flex shares in book-entry form). You will not be required to make any payment or surrender or exchange your Flex ordinary shares or take any other action to receive your shares of Spinco common stock on the Distribution Date. Your bank or brokerage firm will credit your account for the shares of Spinco common stock or the distribution agent or the transfer agent will mail you a book-entry account statement that reflects your shares of Spinco common stock. Please note that if you sell your Flex ordinary shares on or before the Distribution Date, then the buyer of those shares may, in certain circumstances, be entitled to receive the shares of our common stock distributed on the Distribution Date. For more information, see the section of this information statement entitled “The Separation and Distribution—Trading Between the Record Date and the Distribution Date.”

Distribution Agent

The distribution agent, transfer agent and registrar for Spinco common stock will be Computershare Trust Company, N.A.

Reasons for the Spin-Off

Flex has significantly strengthened its businesses and optimized its portfolio over the last several years and, as a continuation of that transformation, the Flex Board of Directors concluded that the separation of its Cloud & Power Infrastructure business as an independent, publicly traded company will accelerate the pace of its transformation and unlock future value potential. The Spin-Off will create two strong, stand-alone businesses, each of which will have leading positions in the markets they serve and will be better positioned to deliver long-term growth and sustainable value creation for all shareholders:


Flex will focus on its advanced manufacturing services business comprised of its Integrated Technology Solutions and the Regulated Manufacturing Solutions business; and


Spinco will hold the Cloud & Power Infrastructure business.

The Flex Board of Directors believes that separating the Cloud & Power Infrastructure business from the remainder of Flex and distributing Spinco shares to Flex shareholders is in the best interests of Flex for a number of reasons, including:


Simplified Investment Profile and Enhanced Ability to Allocate Capital on a Focused Basis. The business which will constitute Spinco differs significantly in several respects from the remaining businesses of Flex, including the nature of the business, growth profile, business cycles, and secular growth drivers. The Spin-Off will simplify how investors evaluate each business, streamline the investment profiles of both businesses, permit investors to better evaluate the individual merits, performance and future prospects of each company’s business, and provide investors the ability to invest in each company separately based on those distinct characteristics, all of which may enhance each company’s marketability. The Spin-Off will also enable investors to allocate capital on a more focused basis, with Spinco providing exposure more consistent with growth end-markets in the data center, AI infrastructure, and grid modernization sectors compared to Flex as a combined company today. The Spin-Off may also attract new investors that either chose not to invest in, or assess the merits of, pre-Spin-Off Flex given its complexity and its exposure to disparate markets and trends.


12


Table of Contents
   

Increased Management Focus on Core Business and Distinct Opportunities. The Spin-Off will result in dedicated, independent management for each of the businesses and enable the respective management teams to adopt strategies and pursue objectives specific to their respective businesses and better focus on strengthening their respective core businesses and operations. Enhancing the management focus with respect to each business is also expected to increase operating flexibility, and allow each company to pursue opportunities for growth distinct to their respective businesses. In addition, the Spin-Off will give each respective management team the opportunity to focus on the goals and expectations of such company’s respective investors. The separation of the experienced management teams and other key personnel operating the businesses will result in the ability for each company to better satisfy the needs of its respective shareholders.


Improved Operational and Strategic Flexibility. The Spin-Off will permit each business to pursue its own business interests, operating priorities and strategies more effectively without having to consider the impact on the business of the other company or on the balance and composition of pre-Spin-Off Flex’s overall portfolio and will enhance operational flexibility for both businesses.


Tailored Capital Allocation Strategies Align with Distinct Business Strategies and Industry Specific Dynamics. The Spin-Off will permit each company to implement a capital structure and flexible capital deployment policy that is optimized for its strategy and business needs, and that is aligned with each company’s target investor base. Flex believes that the Spin-Off will provide flexibility to better manage capital structure based on each company’s forecasted cash generation, planned investments, credit rating requirements, acquisition activity, and capital returns, among other factors, and accordingly will allow each company to invest capital (or return capital to its investors) at the time and in the manner most appropriate for its distinct strategic priorities and business needs. Each company will also have direct access to the debt and equity capital markets to fund its growth strategies, and the ability to concentrate its financial resources solely on its own operations.


Facilitate Potential Mergers and Acquisitions and Resulting Synergies. As a result of the Spin-Off, each company is expected to be better situated to pursue future acquisitions, joint ventures, and other strategic opportunities as well as internal expansion that is more closely aligned with such company’s strategic goals and expected growth opportunities.


Separate Acquisition Currency. The Spin-Off will provide each of Flex and Spinco with its own distinct equity currency that relates solely to its business to use in pursuing strategic opportunities. For example, each of Flex and Spinco will be able to pursue strategic acquisitions in which potential sellers would prefer equity or to raise cash by issuing equity to public or private investors. This benefit is particularly compelling for Spinco, where acquisition target valuations in the data center and AI infrastructure sectors remain elevated.


Improved Talent Attraction, Retention, and Alignment of Management Incentives. The Spin-Off will enable each company to design and implement equity compensation programs that are directly tied to the performance and value of its respective business. The ability to offer equity incentives linked directly to the performance of each individual company is expected to improve each company’s ability to recruit, retain, and provide incentive compensation to employees through equity compensation plans that offer more direct correlation between employees’ compensation and the performance of the business for which such employees are responsible. This direct linkage between equity compensation and business performance is expected to enhance management focus and accountability.

The Flex Board of Directors also considered potentially negative factors in evaluating the Spin-Off, including:


The potential for increased aggregated ongoing administrative costs for the two companies operating on a stand-alone basis post-Spin-Off, such as expenses associated with reporting and compliance as public companies and separate working capital requirements, overhead, insurance, financing, and other operating costs, as well the potentially higher cost of capital as separate companies.


13


Table of Contents
   

The inability to take advantage of pre-Spin-Off Flex’s size, purchasing power, borrowing leverage, and available capital for investments. After the Spin-Off, as standalone companies, Spinco and/or Flex may be unable to obtain goods and services at prices or on terms as favorable as those currently obtained by pre-Spin-Off Flex, and the degree to which Flex will be leveraged could adversely affect its business, financial condition, results of operations, and cash flows.


One-time costs we expect to incur related to the Spin-Off and in connection with the transition to becoming a stand-alone public company including, among others, professional services costs, tax expense, recruiting, and other costs associated with hiring for two stand-alone corporate structures, and costs to separate IT systems and create two separate stand-alone IT structures.


The potential for execution risks related to the Spin-Off, including disruption to the business as a result of the Spin-Off and the possibility that Spinco and/or Flex do not achieve the expected benefits of the Spin-Off for a variety of reasons.


The Spin-Off may divert management’s time and attention, which could have a material adverse effect on the business, results of operations, financial condition, and cash flows of Spinco.


Following the Spin-Off, Spinco and/or Flex may be more susceptible to market fluctuations and other events particular to one or more of their products than they currently are as pre-Spin-Off Flex.


Spinco’s revenues are expected to be more concentrated among a limited number of customers, which may increase Spinco’s exposure to changes in the purchasing decisions, financial condition, or business strategies of these customers, and may affect Spinco’s ability to negotiate favorable terms or affect its credit ratings.


The potential that reduced business diversification, with each post-Spin-Off company operating with a smaller product portfolio than pre-Spin-Off Flex, could increase the volatility of earnings and cash flow.


Certain costs and liabilities that were otherwise less significant to pre-Spin-Off Flex could be more significant to Flex and/or Spinco after the Spin-Off as smaller, stand-alone companies.


Flex’s ordinary shares and Spinco’s common stock could experience selling pressure after the Spin-Off as certain pre-Spin-Off shareholders may not be interested in holding an investment in one or both of the two post-Spin-Off companies.


Flex and/or Spinco may be restricted in their ability to pursue certain opportunities that may have otherwise been available in order to preserve the tax-free nature of the Distribution and related transactions for U.S. federal income tax purposes.


There may be, or there may be the appearance of, conflicts of interest or differences in strategy in Spinco’s relationship with Flex. Actual, potential, or perceived conflicts could give rise to investor dissatisfaction, settlements with shareholders, litigation or regulatory inquiries, or enforcement actions.

The Flex Board of Directors concluded that the potential benefits of the Spin-Off outweighed these factors and risks. The Flex Board of Directors also considered these potential benefits and potentially negative factors in light of the risk that the Spin-Off is abandoned or otherwise not completed, resulting in Flex not separating into two independent, publicly traded companies.

In view of the wide variety of factors considered in connection with the evaluation of the Spin-Off and the complexity of these matters, the Flex Board of Directors did not find it useful to, and did not attempt to, quantify, rank or otherwise assign relative weights to the factors considered.

The anticipated benefits of the Spin-Off are based on a number of assumptions, and there can be no assurance that such benefits will materialize to the extent anticipated, or at all. In the event the Spin-Off does not result in such benefits, the costs associated with the Spin-Off could have an adverse effect on each company individually


14


Table of Contents

and in the aggregate. For more information, see the section of this information statement entitled “The Separation and Distribution—General—Reasons for the Spin-Off” and “Risk Factors.”

Aspects of the Spin-Off may increase the risks associated with ownership of shares of Spinco common stock. In connection with the Spin-Off, Spinco expects to incur indebtedness pursuant to the Spinco Financing Arrangements and to complete the Spinco Cash Distribution to Flex prior to or substantially concurrently with the consummation of the Spin-Off. The terms of such indebtedness are subject to change and will be finalized prior to the closing of the Spin-Off.

Reasons for Flex’s Retention of Between Approximately 6.0% to 12.0% of Spinco Common Stock

Flex’s plan to transfer less than all of the Spinco common stock to its shareholders in the Distribution is motivated by its desire to establish, in an efficient and non-taxable, cost-effective manner, an appropriate capital structure for each of Flex and Spinco, including by reducing, directly or indirectly, Flex’s indebtedness during the 24-month period following the Distribution. Flex’s retention of shares of our common stock is expected to increase its financial flexibility and support the establishment of optimal capital structures for each of Flex and Spinco by allowing Flex to reduce leverage in a tax-efficient manner. Flex intends to dispose of all of the retained shares of Spinco common stock after the Distribution through one or more subsequent exchanges of Spinco common stock for Flex debt held by Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, in each case during the 24-month period following the Distribution.

Conditions to the Distribution

The Distribution is subject to the satisfaction or waiver of the following conditions, among others:


The SEC will have declared effective the registration statement of which this information statement forms a part, with no stop order relating to the registration statement in effect, and no proceedings for such purpose will be pending before, or threatened by, the SEC.


The distribution of this information statement (or a notice of internet availability thereof) to holders of Flex ordinary shares whose names appear on the Branch Register of Members maintained in the United States of America.


The holders of a simple majority of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Bonus Issuance.


The holders of at least three-fourths of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Capital Reduction and Distribution.


The High Court Approval is obtained.


Flex shall have issued the Bonus Shares and immediately cancelled the Bonus Shares issued in the Bonus Issuance.


Nasdaq will have approved the listing of Spinco common stock, subject to official notice of issuance.


Flex having lodged with the Accounting and Corporate Regulatory Authority of Singapore (the “ACRA”) a copy of the Court order approving the Capital Reduction and the Distribution and a notice containing the reduction information within 90 days beginning with the date the order was made, or within such longer period as the ACRA may, on the application of Flex, allow, and the ACRA having recorded such information lodged in the appropriate register.


15


Table of Contents
   

Flex will have received a tax opinion from its tax counsel, Skadden, Arps, Slate, Meagher and Flom LLP (“Skadden”), substantially to the effect that, among other things, for U.S. federal income tax purposes, (i) the Distribution, together with certain related transactions, will qualify as a reorganization within the meaning of sections 368(a)(1)(D), 361 and 355 of the Internal Revenue Code of 1986, as amended (the “Code,” and such qualification, the “Intended Tax Treatment”), and (ii) holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code (the “Tax Opinion”).


Flex will have received an opinion from a nationally recognized independent appraisal firm in form and substance satisfactory to Flex, confirming that after giving effect to the Distribution, Flex and Spinco will each be solvent and adequately capitalized.


All actions and filings necessary or appropriate under applicable securities laws or “blue sky” laws and the rules and regulations thereunder will have been taken.


No preliminary or permanent injunction or other order, decree, or ruling issued by a governmental authority, and no statute, rule, regulation, or executive order promulgated or enacted by any governmental authority will be in effect preventing the consummation of, or materially limiting the benefits of, the transactions contemplated by the separation and distribution agreement.


Those reorganization transactions with respect to the Flex business and Cloud & Power Infrastructure business to be completed prior to the Distribution will have been effectuated in all material respects.


The Flex Board of Directors will have declared the Distribution and approved all related transactions (and such declaration or approval will not have been withdrawn).


No event or development will have occurred or failed to occur that, in the judgment of the Flex Board of Directors, in its sole discretion, prevents the consummation of, or makes it inadvisable to effect the separation, the Distribution, or the other related transactions.


Any required governmental approvals or consents under any material contracts necessary to consummate the Distribution and the transactions contemplated by the separation and distribution agreement and the ancillary agreements will have been obtained and be in full force and effect.


Prior to or substantially concurrently with the consummation of the Distribution, the financing for the Spinco Financing Arrangements will be available on terms acceptable to Flex and Spinco will have completed the Spinco Financing Arrangements and received the proceeds in respect thereof and Spinco will have completed the Spinco Cash Distribution.


Each of the ancillary agreements will have been executed and delivered by each party thereto.

Flex and Spinco cannot assure you that any or all of these conditions will be met, and the Flex Board of Directors may also waive conditions to the Distribution in its sole discretion. If the Spin-Off is completed and the Flex Board of Directors waives any such condition, such waiver could have a material adverse effect on Flex’s and Spinco’s respective business, financial condition, or results of operations, including, without limitation, as a result of litigation relating to any preliminary or permanent injunctions that sought to prevent the consummation of the Spin-Off, or the failure of Flex and Spinco to obtain any required regulatory approvals. As of the date hereof, the Flex Board of Directors does not intend to waive any of the conditions described herein.

The fulfillment of the above conditions will not create any obligation on behalf of Flex to effect the Spin-Off, and Flex may at any time decline to go forward with the Spin-Off. Until the Spin-Off has occurred, Flex has the right not to complete the Spin-Off, even if all the conditions have been satisfied, if, at any time prior to the Distribution, the Flex Board of Directors determines, in its sole discretion, that the Spin-Off is not in the best


16


Table of Contents

interests of Flex, that a sale or other alternative is in the best interests of Flex, or that market conditions or other circumstances are such that it is not advisable at that time to separate the Cloud & Power Infrastructure business from Flex.

Stock Exchange Listing

We intend to apply to list our common stock on Nasdaq under the symbol “AXM.”

Relationship between Flex and Spinco Following the Spin-Off

Following the completion of the Spin-Off, Flex and Spinco will be independent companies. Flex will own between approximately 6.0% to 12.0% of our common stock following the Distribution and we expect that the relationship between Flex and Spinco will be governed by the ancillary agreements. These agreements will collectively provide for the allocation between Spinco and Flex of Flex and Spinco’s assets, employees, liabilities, and obligations (including employee benefits, intellectual property, and tax-related assets and liabilities) attributable to periods prior to, at and after the Spinco’s Spin-Off from Flex. The Separation Agreement will include reciprocal non-competition and customer non-solicitation restrictions applicable worldwide during the Restricted Period. Generally, Spinco and its subsidiaries would be restricted from engaging in the RemainCo Restricted Business or soliciting any RemainCo Protected Customer, while RemainCo and its subsidiaries would be restricted from engaging in the Spinco Restricted Business or soliciting any Spinco Protected Customer, subject to specified exceptions. For additional information regarding these agreements, see the sections of this information statement entitled “Risk Factors—Risks Related to the Spin-Off” and “Certain Relationships and Related Transactions.”

Principal Executive Office

As part of the Spin-Off, Spinco was incorporated as a corporation in Delaware on April 7, 2026 and was subsequently converted to a Texas corporation pursuant to a plan of conversion. Our principal executive offices are currently located at 10025 Alterra Parkway, Suite No. 1900, Austin, Texas 78758, and our telephone number is currently    . We maintain a website at axiomsolutions.com. The information contained on our website or that can be accessed through our website neither constitutes part of this information statement nor is incorporated by reference herein, and investors should not rely on any such information in deciding whether to invest in our common stock.

Reasons for Furnishing This Information Statement; Changes in the Terms of the Spin-Off

This information statement is being furnished solely to provide information to Flex shareholders who are entitled to receive shares of our common stock in the Distribution. The information statement is not, and is not to be construed as, an inducement or encouragement to buy, hold, or sell any of our securities or securities of Flex. We believe that the information in this information statement is accurate as of the date set forth on the cover.

Changes may occur after that date and none of us, Flex, the Spinco Board of Directors or the Flex Board of Directors undertake any obligation to update such information, except as required by applicable federal securities laws.

Flex does not intend to notify its shareholders of any modifications to the terms of the Spin-Off, including the waiver of any conditions to the Distribution, that, in the judgment of the Flex Board of Directors, are not material. However, the Flex Board of Directors would likely consider material matters such as significant changes to the Distribution Ratio, or significant changes to the assets to be contributed or the liabilities to be assumed in the separation, as well as any waiver of the conditions that the Flex Board of Directors receives the Tax Opinion, obtains the Flex Shareholder Approvals, or obtains the High Court Approval with respect to the Spin-Off. To the extent that the Flex Board of Directors determines that any modification by Flex materially


17


Table of Contents

changes the material terms of the Spin-Off, including through the waiver of a condition to the Distribution, Flex will notify Flex shareholders in a manner reasonably calculated to inform them about the modification as may be required by law, by, for example, publishing a press release, filing a current report on Form 8-K, or making available a supplement to this information statement. As of the date hereof, the Flex Board of Directors does not intend to waive any of the conditions described herein.


18


Table of Contents

SUMMARY OF HISTORICAL AND UNAUDITED PRO FORMA COMBINED FINANCIAL DATA

The following tables set forth certain selected historical combined financial data as of June 26, 2026, March 31, 2026 and March 31, 2025, the three-months ended June 26, 2026 and June 27, 2025, and for the fiscal years ended March 31, 2026, 2025 and 2024, and have been derived from our unaudited pro forma combined financial information, unaudited condensed combined financial statements and historical audited combined financial statements and notes thereto included elsewhere in this information statement. The following tables also present certain unaudited pro forma combined financial information. The unaudited pro forma adjustments to the combined statements of operations assume that the Spin-Off and related transactions occurred as of April 1, 2025, which was the first day of the 2026 fiscal year. The unaudited pro forma combined balance sheet gives effect to the Spin-Off and related transactions as if they had occurred on June 26, 2026, our latest balance sheet date. The combined financial statements include the assets, liabilities, revenues and expenses that management has determined are specifically or primarily identifiable to Spinco as well as direct and indirect costs that are attributable to our operations.

The certain select combined financial data below is only a summary and should be read in conjunction with the sections of this information statement titled “Unaudited Pro Forma Combined Financial Information,” “Capitalization” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” as well as our combined financial statements and the notes thereto included elsewhere in this information statement.

The certain select combined financial data is based upon available information and assumptions that we believe are reasonable and supportable and may not necessarily reflect what our financial condition, results of operations or cash flows would have been had we been a standalone company during the periods presented, including changes that will occur in our operations and capital structure as a result of the Spin-Off, such as changes in financing, operations, cost structure and personnel needs of our business.

A final determination regarding our capital structure has not yet been made, and the ancillary agreements have not been finalized. As such, the unaudited pro forma combined financial information may be revised in future amendments to reflect the impact on our capital structure and the final form of those agreements, to the extent any such revisions would be deemed material.


19


Table of Contents

Summary Select Combined Financial Data


    Pro Forma     Historical  
    Three-Month
Period Ended
    Year Ended     Three-Month
Periods Ended
    Years ended  
(In millions, except per share
amounts)
  June 26, 2026     March 31, 2026     June 26, 2026     June 27, 2025     March 31, 2026     March 31, 2025     March 31, 2024  

Net sales

  $ 2,403     $ 7,031     $ 2,202     $ 1,626     $ 6,614     $ 4,799     $ 3,244  

Cost of sales

    2,122       6,301       1,937       1,434       5,831       4,176       2,843  


Gross profit

    281       730       265       192       783       623       401  

Selling, general and administrative expenses

    107       384       82       57       253       184       123  

Intangible amortization

    28       90       18       13       50       36       32  


Operating income

    146       256       165       122       480       403       246  

Interest expense

    58       232       1       2       5       6       4  

Other charges (income), net

    (1     (12           2       (7     8       (1


Income from operations before income taxes

    89       36       164       118       482       389       243  

Provision for (benefit from) income taxes

    (2     (436     11       14       69       69       61  


Net income

  $ 91     $ 472     $ 153     $ 104     $ 413     $ 320     $ 182  


Summary Historical Combined Balance Sheets


     Pro Forma      Historical  
     As of      As of  
(In millions)    June 26, 2026      June 26, 2026      March 31, 2026      March 31, 2025  

Cash and cash equivalents

   $ 1,100      $ 20      $ 7      $ 24  

Total assets

   $ 14,637      $ 8,269      $ 6,032      $ 3,343  

Short-term debt

   $ 4,374      $      $      $  

Long-term debt

   $ 34      $      $      $  

Total liabilities

   $ 9,693      $ 4,743      $ 4,069      $ 1,824  


Total equity

   $ 4,944      $ 3,526      $ 1,963      $ 1,519  


Total liabilities and equity

   $ 14,637      $ 8,269      $ 6,032      $ 3,343  


In addition to our operating results, as calculated in accordance with accounting principles generally accepted in the United States (“GAAP”), we use, and plan to continue using non-GAAP financial measures when monitoring and evaluating operating performance and liquidity. The non-GAAP financial measures presented in this information statement are supplemental measures of our performance and our liquidity that we believe help investors understand our financial condition and operating results and assess our future prospects. For more information about our non-GAAP financial measures see “Management’s Discussion and Analysis of Financial Condition and Results of Operations—Non-GAAP Financial Measures.”


20


Table of Contents

Adjusted Operating Income


    Pro Forma     Historical  
    Three-Month
Period Ended
    Year Ended     Three-Month
Periods Ended
    Years ended  
(In millions)   June 26, 2026     March 31, 2026     June 26, 2026     June 27, 2025     March 31, 2026     March 31, 2025     March 31, 2024  

GAAP operating income

    146     $ 256     $ 165     $ 122     $ 480     $ 403     $ 246  

Intangible amortization

    43       141       20       13       50       36       32  

Stock-based compensation

    15       40       13       9       33       23       14  

Restructuring

          10             1       10       5       3  

Legal and other

    12       56       12       3       16       5        


Non-GAAP operating income


216


$503


$210


$148

    $ 589     $ 472     $ 295  


Adjusted Net Income


    Pro Forma     Historical  
    Three-Month
Period Ended
    Year Ended     Three-Month
Periods Ended
    Years ended  
(In millions)   June 26, 2026     March 31, 2026     June 26, 2026     June 27, 2025     March 31, 2026     March 31, 2025     March 31, 2024  

GAAP net income

  $ 91     $ 472     $ 153     $ 104     $ 413     $ 320     $ 182  

Intangible amortization

    43       141       20       13       50       36       32  

Stock-based compensation

    15       40       13       9       33       23       14  

Restructuring

          10             1       10       5       3  

Legal and other

    12       56       12       3       16       5        

Adjustments for taxes (1)

    (18     (484     (9     (8     (24     (16     (11


Non-GAAP net income


$143

    $ 235      

$189


$122

    $ 498     $ 373     $ 220  


(1)

Adjustment for taxes relates to the tax effects of the various adjustments that we incorporate into non-GAAP measures in order to provide a more meaningful measure on non-GAAP net income and certain adjustments related to non-recurring settlements of tax contingencies or other non-recurring tax charges, when applicable. During the Pro Forma year ended March 31, 2026, the Company recorded $484 million of tax benefit, of which $422 million of the benefit relates to an anticipated deferred tax asset, net of valuation allowance, related to stepped-up tax basis amortization that will be generated by an intercompany transaction involving Spinco intangible property that will occur prior to the separation of the Spinco business.


21


Table of Contents

Free Cash Flow


    Historical  
    Three-Month
Periods Ended
    Years Ended  
(In millions)   June 26, 2026     June 27, 2025     March 31, 2026     March 31, 2025     March 31, 2024  

Net cash provided by (used in) operating activities

  $ (69   $ 200     $ 411     $ 175     $ 242  

Purchases of property and equipment

    (160     (42     (238     (104     (78

Proceeds from the disposition of property and equipment

                1       6       7  


Free cash flow


$(229)


$158


$174

    $ 77     $ 171  


22


Table of Contents

QUESTIONS AND ANSWERS ABOUT THE SEPARATION AND DISTRIBUTION


What is Spinco and why is Flex separating
Spinco’s business and distributing Spinco’s stock?

Spinco currently is a wholly owned subsidiary of Flex that was formed to hold assets and liabilities related to the Cloud & Power Infrastructure business. The separation of Spinco from Flex and the Distribution of Spinco common stock are intended to provide you with equity investments in two separate companies, each of which will be able to focus on their respective businesses. Flex and Spinco believe that the Spin-Off will result in enhanced long-term performance of each business for the reasons discussed in the section of this information statement entitled “The Separation and Distribution—General—Reasons for the Spin-Off.”


Why am I receiving this document?

Flex is making this document available to you because you are a holder of Flex ordinary shares. If you are a holder of Flex ordinary shares as of      Central time on     , 2026, the Distribution Record Date, you will be entitled to receive a number of shares of Spinco common stock equal to the Distribution Ratio (defined below) for each Flex ordinary share that you hold at such time. This document will help you understand how the separation and Distribution will affect your investment in Flex and your investment in Spinco after the Spin-Off.


How will the Spin-Off of Spinco from Flex work?

To effect the Spin-Off, Flex will undertake a series of internal reorganization transactions pursuant to which, among other transactions, Spinco will hold the Cloud & Power Infrastructure business and Flex will distribute between approximately 88.0% to 94.0% of the outstanding shares of common stock of Spinco by way of a distribution in specie to Flex shareholders on a pro rata basis based on the number of Flex ordinary shares held by each such Flex shareholder as of the Distribution Record Date. The Distribution will be effected by way of the Capital Reduction under the Singapore Companies Act. To effect the Capital Reduction, Flex will first need to capitalize its reserves through the Bonus Issuance. Following the completion of the Spin-Off, Spinco, holding the Cloud & Power Infrastructure business, will be an independent, publicly traded company.


What business will Spinco engage in after the
Spin-Off?

Spinco will engage in the Cloud & Power Infrastructure business after the Spin-Off. For additional details regarding Spinco’s business, see the section of this information statement entitled “Business.”


Why is the Spin-Off of Spinco structured as
a distribution?

Flex believes that a distribution, together with certain related transactions, of Spinco shares to Flex shareholders, which Flex intends to be tax-free for U.S. federal income tax purposes (except with respect to any cash received in lieu of fractional shares), is an efficient way to separate the Cloud & Power Infrastructure business in a manner that is expected to create long-term benefits and value for Flex, Spinco and their respective


23


Table of Contents
 

shareholders. Flex intends to retain between approximately 6.0% to 12.0% of our common stock for a period of up to 24 months following the Spin-Off (the “Retained Shares”).


What will be distributed in the Distribution?

Flex will effect the Distribution by distributing between approximately 88.0% to 94.0% of all issued and outstanding shares of Spinco common stock pro rata to the holders of Flex ordinary shares as of      Central time on     , 2026, the Distribution Record Date. Your proportionate interest in Flex will not change as a result of the Distribution. For a more detailed description, see the section of this information statement entitled “The Separation and Distribution.”


What is the record date for the Distribution?

The Distribution Record Date is Central time on     , 2026.


When will the Distribution occur?

Assuming receipt of the Flex Shareholder Approvals and the High Court Approval and the timely satisfaction of other necessary conditions to the Distribution, as described in this information statement, it is expected that between approximately 88.0% to 94.0% of the shares of Spinco common stock held by Flex will be distributed by Flex on or about     , 2027, to Flex shareholders as of      Central time on     , 2026, the Distribution Record Date. However, no assurance can be provided as to the timing of the Distribution or that all conditions to the Distribution will be met.


Is a shareholder vote required to approve the
Spin-Off?

The Bonus Issuance by Flex requires the affirmative vote of the holders of a simple majority of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting, and the Capital Reduction and Distribution by Flex requires the affirmative vote of the holders of at least three-fourths of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting (the “Flex Shareholder Approvals”).


What do shareholders need to do to participate in
the Distribution?

The Bonus Issuance by Flex requires the affirmative vote of the holders of a simple majority of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting, and the Capital Reduction and Distribution by Flex requires the affirmative vote of the holders of at least three-fourths of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting. Subject to satisfaction of the conditions to the Distribution (including the Flex Shareholder Approvals), shareholders of Flex entitled to receive shares in the Distribution will not be required to take any action to receive Spinco common stock in the Distribution, but you are urged to read this entire information statement carefully. You do not need to pay any consideration or exchange or surrender your existing Flex ordinary shares or take any other action to receive your shares of Spinco common stock.


24


Table of Contents

What will govern my rights as a Spinco shareholder?

Your rights as a Spinco shareholder will be governed by Texas law, as well as the amended and restated certificate of formation and amended and restated bylaws of Spinco. For additional details regarding Spinco common stock and Spinco shareholder rights, see the section of this information statement entitled “Description of Capital Stock.”


Will I receive physical certificates representing
shares of Spinco common stock following the
Spin-Off?

No. Following the Spin-Off, Spinco will not issue physical certificates representing shares of Spinco common stock, even if requested. If you own Flex ordinary shares as of the Distribution Record Date, Flex, with the assistance of the distribution agent, will electronically distribute shares of Spinco common stock to you or to your brokerage firm on your behalf by way of direct registration form. “Direct registration form” refers to a method of recording share ownership when no physical share certificates are issued to shareholders, as is the case in this Distribution. The distribution agent or the transfer agent will mail you a book-entry account statement that reflects your shares of Spinco common stock, or your bank or brokerage firm will credit your account for the shares.


Following the Spin-Off, shareholders whose shares are held in book-entry form may request that their shares of Spinco common stock held in book-entry form be transferred to a brokerage or other account at any time.


How many shares of Spinco common stock will
I receive in the Distribution?

Subject to obtaining the Flex Shareholder Approvals and the High Court Approval, Flex will distribute to you a number of shares of Spinco common stock equal to the Distribution Ratio for each Flex ordinary share held by you as of the Distribution Record Date. Based on approximately      issued and outstanding Flex ordinary shares as of     , 2026, an aggregate of approximately      shares of Spinco common stock will be distributed. For additional information on the Distribution, see the section of this information statement entitled “The Separation and Distribution.”


Will Spinco issue fractional shares of its common
stock in the Distribution?

No. Spinco will not issue fractional shares of its common stock in the Distribution. Fractional shares that Flex shareholders would otherwise have been entitled to receive will be aggregated and sold in the public market by the distribution agent. The aggregate net cash proceeds of these sales will be distributed pro rata (based on the fractional share such holder would otherwise be entitled to receive) to those Flex shareholders who would otherwise have been entitled to receive fractional shares. Recipients of cash in lieu of fractional shares will not be entitled to any interest on the amounts of payment made in lieu of fractional shares. The receipt of cash in lieu of fractional shares will generally be taxable to the recipient shareholders for U.S. federal income tax purposes as described in the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.”


25


Table of Contents

What are the conditions to the Distribution?

The Distribution is subject to the satisfaction or waiver of the following conditions, among others:


The SEC will have declared effective the registration statement of which this information statement forms a part, with no stop order relating to the registration statement in effect, and no proceedings for such purpose will be pending before, or threatened by, the SEC.


The distribution of this information statement (or a notice of internet availability thereof) to holders of Flex ordinary shares whose names appear on the Branch Register of Members maintained in the United States of America.


The holders of a simple majority of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Bonus Issuance.


The holders of at least three-fourths of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Capital Reduction and Distribution.


The High Court Approval is obtained.


Flex shall have issued the Bonus Shares and immediately cancelled the Bonus Shares issued in the Bonus Issuance.


Nasdaq will have approved the listing of Spinco common stock, subject to official notice of issuance.


Flex having lodged with the ACRA a copy of the Court order approving the Capital Reduction and the Distribution and a notice containing the reduction information within 90 days beginning with the date the order was made, or within such longer period as the ACRA may, on the application of Flex, allow, and the ACRA having recorded such information lodged in the appropriate register.


Flex will have received the Tax Opinion. See the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.”


Flex will have received an opinion from a nationally recognized independent appraisal firm in form and substance satisfactory to Flex, confirming that after giving effect to the Distribution, Flex and Spinco will each be solvent and adequately capitalized.


All actions and filings necessary or appropriate under applicable securities laws or “blue sky” laws and the rules and regulations thereunder will have been taken.


No preliminary or permanent injunction or other order, decree, or ruling issued by a governmental authority, and no statute, rule, regulation, or executive order promulgated or enacted by any governmental authority will be in effect preventing the consummation of, or materially limiting the benefits of, the


26


Table of Contents
 

transactions contemplated by the separation and distribution agreement.


Those reorganization transactions with respect to the Flex business and Cloud & Power Infrastructure business to be completed prior to the Distribution will have been effectuated in all material respects.


The Flex Board of Directors will have declared the Distribution and approved all related transactions (and such declaration or approval will not have been withdrawn).


No event or development will have occurred or failed to occur that, in the judgment of the Flex Board of Directors, in its sole discretion, prevents the consummation of, or makes it inadvisable to effect the separation, the Distribution, or the other related transactions.


Any required governmental approvals or consents under any material contracts necessary to consummate the Distribution and the transactions contemplated by the separation and distribution agreement and the ancillary agreements will have been obtained and be in full force and effect.


Prior to or substantially concurrently with the consummation of the Distribution, the financing for the Spinco Financing Arrangements will be available on terms acceptable to Flex and Spinco will have completed the Spinco Financing Arrangements and received the proceeds in respect thereof and Spinco shall have completed the Spinco Cash Distribution.


Each of the ancillary agreements will have been executed and delivered by each party thereto.


Flex and Spinco cannot assure you that any or all of these conditions will be met, and the Flex Board of Directors may also waive conditions to the Distribution in its sole discretion. Flex may decline at any time to go forward with the Distribution, whether or not the conditions are satisfied, and the Spin-Off would then not occur. For a more detailed description, see the section of this information statement entitled “The Separation and Distribution—General—Conditions to the Distribution.”


What is the expected date of completion of
the Spin-Off?

The completion and timing of the Spin-Off are dependent upon a number of conditions. Assuming receipt of the Flex Shareholder Approvals and the High Court Approval and the timely satisfaction of other necessary conditions to the Distribution, as described in this information statement, it is expected that the shares of Spinco common stock will be distributed by Flex on or about     , 2027 to the holders of record of Flex ordinary shares as of the Distribution Record Date. However, no assurance can be provided as to the timing of the Spin-Off or that all conditions to the Spin-Off will be met.


27


Table of Contents

Can Flex decide to cancel the Spin-Off even if all
the conditions have been met?

Yes. The Spin-Off will not be effective until the Distribution is complete. The Distribution is subject to the satisfaction or waiver by Flex of certain conditions. See “The Separation and Distribution—General—Conditions to the Distribution.” The fulfillment of such conditions will not create any obligation on behalf of Flex to effect the Spin-Off, and Flex may at any time decline to go forward with the Spin-Off. Until the Spin-Off has occurred, Flex has the right not to complete the Distribution, even if all the conditions have been satisfied, if, at any time prior to the Distribution, the Flex Board of Directors determines, in its sole discretion, that the Spin-Off is not in the best interests of Flex, that a sale or other alternative is in the best interests of Flex, or that market conditions or other circumstances are such that it is not advisable at that time to separate the Cloud & Power Infrastructure business from Flex.


What if I want to sell my Flex ordinary shares or
my Spinco common stock?

You should consult with your financial advisors, such as your stockbroker, bank, or tax advisor.


What is “regular-way” and “ex-distribution”
trading?

Beginning on or shortly before the Distribution Record Date and continuing up to and through the Distribution Date, it is expected that there will be two markets in Flex ordinary shares: a “regular-way” market and an “ex-distribution” market. Flex ordinary shares that trade in the “regular-way” market will trade with an entitlement to shares of Spinco common stock distributed pursuant to the Distribution. Flex ordinary shares that trade in the “ex-distribution” market will trade without an entitlement to shares of Spinco common stock distributed pursuant to the Distribution. Each shareholder trading in Flex shares would make any decision as to whether to trade one or more of such shareholder’s shares in Flex in the “regular-way” market or the “ex-distribution” market.


If you decide to sell any of your Flex ordinary shares after the Distribution Record Date and before the Distribution Date, you should make sure your stockbroker, bank, or other nominee understands whether you want to sell your Flex ordinary shares with or without your entitlement to Spinco common stock pursuant to the Distribution.


Where will I be able to trade shares of Spinco
common stock?

Spinco intends to apply to list its common stock on Nasdaq under the symbol “AXM.” Spinco expects that trading in shares of its common stock will begin on a “when-issued” basis shortly before the Distribution Date and will continue up to and through the Distribution Date and that “regular-way” trading in Spinco common stock will begin on the first trading day following the Distribution Date. “When-issued” trading refers to a sale or purchase made conditionally because the security has been authorized but not yet issued. If trading


28


Table of Contents
 

begins on a “when-issued” basis, you may purchase or sell Spinco common stock up to and through the Distribution Date, but your transaction will not settle until after the Distribution Date. Spinco cannot predict the trading prices for its common stock before, on or after the Distribution Date.


What will happen to the listing of Flex ordinary
shares?

Prior to the completion of the Spin-Off, Flex will continue to trade on Nasdaq under the symbol “FLEX.” Any changes to Flex’s name or ticker symbol will be announced separately by Flex.


Will the number of shares of Flex ordinary shares
that I own change as a result of the Distribution?

No. The number of Flex ordinary shares that you own will not change as a result of the Distribution.


What are the U.S. federal income tax consequences
of the separation and distribution?

It is a condition to the completion of the Distribution that Flex receives the Tax Opinion, substantially to the effect that, among other things, for U.S. federal income tax purposes, (i) the Distribution, together with certain related transactions, will qualify for the Intended Tax Treatment, and (ii) holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code. Nevertheless, this condition may be waived by Flex in its sole discretion.


Accordingly, and so long as the Distribution, together with certain related transactions, qualifies for the Intended Tax Treatment, no gain or loss should be recognized by a U.S. Holder (as defined in the section entitled “United States Federal Income Tax Consequences of the Distribution”) for U.S. federal income tax purposes, and no amount should be included in a U.S. Holder’s income, for U.S. federal income tax purposes, upon the receipt of shares of Spinco common stock pursuant to the Distribution. A U.S. Holder will, however, recognize gain or loss for U.S. federal income tax purposes with respect to cash (if any) received in lieu of a fractional share of Spinco common stock.


For more information regarding the potential U.S. federal income tax consequences of the Distribution, see the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.” You should consult your tax advisor as to the particular consequences of the Distribution to you, including the applicability and effect of any U.S. federal, state, and local, and any non-U.S., tax laws.


How will I determine my tax basis in the Spinco
shares I receive in the Distribution?

Assuming that the Distribution is tax-free to Flex shareholders (except with respect to any cash received in lieu of fractional shares) for


29


Table of Contents
 

U.S. federal income tax purposes, your aggregate tax basis in your Flex ordinary shares held by you immediately prior to the Distribution will be allocated between your Flex ordinary shares and the shares of Spinco common stock that you receive in the Distribution (including any fractional share interest in Spinco common stock for which cash is received) in proportion to the relative fair market values of each immediately following the Distribution. Flex will provide its shareholders with information to enable them to compute their tax basis in both Flex and Spinco shares. This information will be posted on Flex’s website following the Distribution Date.


You should consult your tax advisor about the particular consequences of the Distribution to you, including a situation where you have purchased Flex shares at different times or for different amounts and the application of state, local and non-U.S. tax laws. For a more detailed description, see the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.


What will Spinco’s relationship be with Flex
following the Spin-Off?

Following the completion of the Spin-Off, Flex and Spinco will be independent companies. Flex intends to retain between approximately 6.0% to 12.0% of our common stock for a period of up to 24 months following the Distribution, and we expect that the relationship between Flex and Spinco will be governed by the ancillary agreements. These agreements will collectively provide for the allocation between Spinco and Flex of Flex’s and Spinco’s assets, employees, liabilities, and obligations (including employee benefits, intellectual property, and tax-related assets and liabilities) attributable to periods prior to, at and after Spinco’s Spin-Off from Flex. The Separation Agreement will also include reciprocal non-competition and customer non-solicitation restrictions applicable worldwide during the Restricted Period (three years following the Distribution). Generally, Spinco and its subsidiaries would be restricted from engaging in the RemainCo Restricted Business or soliciting any RemainCo Protected Customer, while RemainCo and its subsidiaries would be restricted from engaging in the Spinco Restricted Business or soliciting any Spinco Protected Customer, subject to specified exceptions. For additional information regarding these agreements, see the sections of this information statement entitled “Risk Factors—Risks Related to the Spin-Off” and “Certain Relationships and Related Transactions.”


How will Flex vote any shares of Spinco common
stock it retains?

Flex is expected to agree to vote any shares of Spinco common stock that it retains in proportion to the votes cast by Spinco’s other shareholders and is expected to grant Spinco a proxy with respect to such retained shares. For additional information on these voting arrangements, see “Certain Relationships and Related Transactions.”


30


Table of Contents

What does Flex intend to do with any shares of
Spinco common stock it retains?

Flex intends to dispose of all of the Spinco common stock that it retains after the Distribution through one or more subsequent exchanges of Spinco common stock for Flex debt held by one or more Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, within the 24-month period following the Distribution.


Will I have appraisal rights in connection with
the Distribution?

No. Holders of Flex ordinary shares are not entitled to appraisal rights in connection with the Distribution.


Are there risks associated with owning Spinco
common stock?

Yes. Ownership of Spinco common stock is subject to both general and specific risks relating to Spinco’s business, the industry in which it operates, its ongoing contractual relationships with Flex and its status as a separate, publicly traded company. Ownership of Spinco common stock is also subject to risks relating to the Spin-Off, including that following the Spin-Off, Spinco’s business will be less diversified than Flex’s business prior to the Spin-Off. These risks are described in the section of this information statement entitled “Risk Factors.” You are encouraged to read that section carefully.


Who will manage Spinco after the Spin-Off?

Following the Spin-Off, Spinco will be led by Revathi Advaithi, who will be Spinco’s Chief Executive Officer. Ms. Advaithi will also serve in a transitional role as the non-executive chair of the Flex Board of Directors following the Spin-Off for a period of up to 24 months following the Distribution. Ms. Advaithi may have actual or apparent conflicts of interest with respect to matters involving or affecting each of Flex or Spinco. See “Risk Factors—Ms. Advaithi will serve as our Chief Executive Officer and as one of our directors as well as the chair of the Flex Board of Directors, and certain of our directors and executive officers will continue to own shares or equity awards of Flex, which overlap may give rise to conflicts of interest” and “Certain Relationships and Related Transactions.”


For more information regarding Spinco’s expected named executive officers and other members of its management team, see the section of this information statement entitled “Management.”


What will Spinco’s dividend policy be after
the Spin-Off?

We do not currently intend to pay any cash dividends in the foreseeable future. We currently intend to retain all available funds and future earnings, if any, for the operation of our business and to strengthen our financial position and flexibility. The payment of cash dividends in the future will be dependent upon our revenue and


31


Table of Contents
 

earnings, capital requirements, and general financial condition and results of operations, as well as applicable law, regulatory constraints, industry practice, and other business considerations determined by our board of directors to be relevant. The payment of any cash dividends will be within the discretion of the Spinco Board of Directors. In addition, the terms governing our current or future debt may also limit or prohibit dividend payments. Accordingly, we cannot guarantee that we will ever pay dividends in the future or that we would continue to pay any dividends that we may commence in the future. For more information regarding Spinco’s dividend policy, see the section of this information statement entitled “Dividend Policy.”


What will happen to Flex equity awards in
connection with the Spin-Off?

Any equity awards relating to Flex ordinary shares that are outstanding at the time of Distribution will be adjusted to reflect the impact of the separation. Generally, (1) each unvested Flex equity award held by an employee or non-employee director who will continue at Flex after the completion of the Spin-Off (or held by an employee whose transfer to Spinco will occur sometime after the Spin-Off) will be adjusted and become a post-Separation Flex award relating to Flex ordinary shares and (2) each unvested Flex equity award held by an employee transitioning to Spinco will be converted to a Spinco award relating to shares of Spinco common stock.


We expect that Flex equity awards outstanding at the time of the Distribution will be adjusted with the intent to maintain the economic value of those awards before and after the Spin-Off, using a ratio that takes into account the average closing trading price of Flex ordinary shares over the ten trading days prior to the separation and the average of either the post-separation average closing trading price of Flex ordinary shares or the post-separation per share closing trading price of Spinco common stock, as applicable, over ten trading days following the Separation. Additional details regarding the treatment of Flex equity awards in connection with the separation are set forth below under “Treatment of Equity Incentive Arrangements.”


Will the Distribution of Spinco common stock affect
the market price of Flex ordinary shares?

As a result of the Distribution, we expect the trading price of Flex ordinary shares to be different from the trading price of Flex ordinary shares immediately prior to the Distribution because the trading price will no longer reflect the combined value of the businesses. Furthermore, until the market has fully analyzed the value of Flex without the business comprising Spinco, the price of Flex ordinary shares may fluctuate. There can be no assurance that, following the Spin-Off, the combined value of Flex ordinary shares and Spinco common stock will equal or exceed what the value of Flex ordinary shares would have been as of the same time and date in the absence of the Distribution.


32


Table of Contents

Will Spinco incur any debt prior to or at the time of
the Distribution?

In connection with the Spin-Off, we expect to incur indebtedness of up to $4.4 billion pursuant to the Spinco Financing Arrangements and to complete the Spinco Cash Distribution to Flex. The terms of such indebtedness are subject to change and will be finalized prior to the closing of the Spin-Off. We will provide additional information regarding the specific terms of any such indebtedness in a subsequent amendment to this information statement. See “The Separation and Distribution—Incurrence/Treatment of Debt” for more information.


Who will be the distribution agent, transfer agent,
and registrar for Spinco common stock?

The distribution agent, transfer agent, and registrar for Spinco common stock will be Computershare Trust Company, N.A. For questions relating to the transfer or mechanics of the stock distribution, you should contact Computershare Trust Company, N.A. toll free number at     .


Where can I find more information about Flex
and Spinco?

If you have any questions relating to Flex, you should contact:


Flex Investor Relations


Michelle Simmons


Phone: (669) 242-6332


Email: michelle.simmons@flex.com

Website: http://investors.flex.com


After the Distribution, Spinco shareholders who have any questions relating to Spinco should contact Spinco through any means set forth below, or at the phone numbers or email addresses posted on our website:


Phone:     

Email:     


Website: axiomsolutions.com


33


Table of Contents

RISK FACTORS

The risks and uncertainties described below could materially and adversely impact our business, financial condition, and results of operations, could cause actual results to differ materially from our expectations and projections, and could cause the market value of our stock to decline. You should consider these risk factors when evaluating us and our common stock and when reading the rest of this information statement, including the sections entitled “Business” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our financial statements and related notes included elsewhere in this document. These risk factors may not include all of the important factors that could affect our business or our industry or that could cause our future financial results to differ materially from historic or expected results or cause the market price of our common stock to fluctuate or decline. Additional risks and uncertainties not currently known to us or that we currently believe are immaterial also may impair our business, results of operations, liquidity, and financial condition.

Risks Related to Our Business and Operations

Customer and Revenue Risks

Our revenue is concentrated among a limited number of customers, which subjects us to significant revenue variability, margin pressure, and counterparty risk.

A relatively small number of customers have historically accounted for, and are expected to continue to account for, a majority of our revenue. The loss of one or more of our largest customers, or a significant reduction in sales to any of these customers, could materially and adversely affect our business, financial condition, and results of operations. For the fiscal year ended March 31, 2026, our top two customers represented 34% and 30% of our revenue, respectively. Collectively, our top two customers accounted for 64% and our top 10 customers accounted for 87% of our revenue.

Our customer base is concentrated in part due to the structure of the digital infrastructure industry, in which a limited number of hyperscale cloud providers, colocation companies, and large enterprises represent a substantial portion of market demand. This industry structure may make it difficult or impractical for us to materially diversify our customer base, and we expect that customer concentration will continue for the foreseeable future.

Our dependence on a concentrated customer base subjects us to significant risks. These customers typically have substantial purchasing power and negotiating leverage, which they may use to obtain favorable pricing, extended payment terms, or other concessions that could reduce our margins or adversely affect our cash flows. As our customers grow larger through consolidation or organic growth, their bargaining power may increase further. In addition, decisions by one or more significant customers to shift their purchases to our competitors, to vertically integrate and manufacture products internally, to develop their own infrastructure that may compete with us, or to reduce the volume of products or services they purchase from us could have a material adverse effect on our business. Our customers may have pre-existing or concurrent relationships with, or may themselves be, current or potential competitors, which may affect such customers’ decisions to purchase our products and services or the terms on which they are willing to do so. Certain hyperscale customers have developed, or may develop, internal capabilities that compete with our offerings, and these customers may choose to reduce their reliance on third-party providers like us over time.

Certain of our customer contracts contain change of control, assignment, or consent provisions that may be triggered by the separation or the Distribution. If we are unable to obtain required consents from customers, or if customers exercise termination or other contractual rights in connection with the separation, our business, financial condition, and results of operations could be materially and adversely affected. Our contracts with our top two customers require consents in connection with the separation. We have engaged with these customers regarding the separation and, based on discussions to date, expect to obtain the required consents prior to the completion of the Distribution. However, we cannot provide any assurance that such consents will be obtained,


34


Table of Contents

or that they will be obtained on terms acceptable to us. In addition, even if consents are not technically required, customers may use the separation as an opportunity to renegotiate pricing, reduce order volumes, or otherwise modify their relationships with us. See “Risks Related to the Spin-Off” for additional information regarding third-party consent requirements.

We may not be able to replace lost revenue from a key customer with revenue from new customers or increased sales to existing customers on a timely basis or at all. This could materially and adversely affect our business, financial condition, and results of operations.

Customer commitments are limited and demand is cyclical, which may create inventory exposure, capacity utilization challenges, and significant period-to-period variability in our results.

Our customers generally do not commit to long-term production schedules or provide binding forecasts of their product needs, and our contracts with customers typically do not require them to purchase any minimum quantities. Customer purchase orders are often subject to cancellation, modification, or rescheduling, in some cases with limited or no penalties. Many agreements provide for non-cancellable/non-returnable (NCNR) terms or other inventory liability coverage, and some agreements include contractual price reductions or other pricing mechanisms over the term, which can adversely affect revenue and margins. Our customers may terminate their relationships with us or significantly reduce or delay orders at any time, including as a result of changes in their own business conditions, product demand, technology strategy, or for convenience. Our inability to accurately forecast customer demand or manage order volatility can result in excess or obsolete inventory, non-cancellable outstanding firm purchase orders which are no longer required requiring cancellation at a cost, manufacturing inefficiencies, and increased costs.

In addition, our contracts with customers are often for finite terms and are subject to renewal or renegotiation upon expiration. We cannot assure you that our customers will renew their contracts with us or, if they do, that the terms of any renewal will be as favorable as our current contract terms. Customers may use contract renewal cycles as an opportunity to demand price concessions, impose additional requirements, or reduce order volumes. Our failure to renew contracts with key customers, or to renew them on terms that are favorable to us, could materially and adversely affect our business, financial condition, and results of operations.

Because our customers operate in highly competitive, rapidly evolving end markets, their demand can be cyclical, project-driven, and influenced by capital spending cycles, regulatory developments, and technology transitions. These dynamics can cause significant period-to-period variability in orders, forecasts, and backlog conversion. We generally do not obtain firm, long-term purchase commitments from our customers, and we often experience reduced lead times in customer orders that may be shorter than the lead time we require to procure necessary components and materials.

When demand is reduced, delayed, or cancelled, we may face excess and obsolete inventory, underutilized assets, margin pressure, adverse working capital effects, and increased cash needs. Forecast error, combined with rapid technology transitions, can lead to excess and obsolete inventory, expedite fees, higher logistics costs, suboptimal factory loading, and variability in revenue and gross margin from period to period. Many factors outside of our control impact our customers and their ordering behavior, including recession in end markets, changing technology and industry standards, commercial acceptance for products, product obsolescence, and loss of business. This could materially and adversely affect our business, financial condition, and results of operations.

Our concentration of accounts receivable and deposits with a small number of customers increases counterparty and collection risk.

A significant portion of our accounts receivable is concentrated among a small number of customers. This concentration of credit risk increases our exposure to nonpayment, late payment, or financial distress affecting any one of these customers. If one or more of our key customers experiences financial difficulties, delays


35


Table of Contents

payments, disputes amounts owed, or becomes subject to bankruptcy or insolvency proceedings, we could experience material losses or be required to write off a substantial portion of our accounts receivable. In addition, the failure of a key customer to pay amounts owed to us when due could adversely affect our liquidity and our ability to meet our own financial obligations. We periodically review the creditworthiness of our customers; however, such reviews may not be effective in identifying potential credit risks or in preventing nonpayment. Extended payment terms or credit support structures may not fully mitigate this risk. If customers experience financial difficulty or insolvency, we may be unable to collect amounts owed on a timely basis, if at all.

Our customer contracts may permit termination for convenience or on short notice.

Certain of our customer contracts contain provisions that permit the customer to terminate the agreement for convenience upon prior written notice, which notice periods may be relatively short. If a key customer were to exercise its termination rights, we may not be entitled to receive payment for work in process, stranded inventory, or other costs incurred in anticipation of future orders. We may not have adequate contractual protections, such as termination fees or wind-down payments, to offset the financial impact of an early termination by a significant customer. The termination or non-renewal of a contract with any of our largest customers, or a significant reduction in orders under such a contract, could materially and adversely affect our business, financial condition, and results of operations.

We may incur significant losses if customer-specific capital equipment becomes impaired or obsolete.

We make investments in capital equipment that is designed for or dedicated to specific customers, products, or programs. These investments are often based on forecasts of customer demand and anticipated long-term relationships. In certain cases, such equipment has limited alternative use and may not be readily redeployable to other customers or applications without significant modification or additional cost. If a customer reduces, delays, or terminates its orders, exits a product line, experiences financial distress, or otherwise ceases to do business with us, we may be unable to recover the carrying value of the related equipment. In such circumstances, we may be required to recognize impairment charges or write-offs for these assets, which could be material to our financial condition and results of operations.

In addition, the timing and magnitude of customer demand may differ from our expectations, leading to underutilization of such equipment and reduced returns on our investments. While we may seek contractual protections, including customer commitments or reimbursement provisions, such protections may be insufficient or may not be enforceable in all cases. Any significant impairment, write-off, or accelerated depreciation of customer-specific capital equipment could adversely affect our results of operating, cash flows, and financial position.

Our relationships with key customers may require us to improve our products, services, and capabilities, which may involve significant technological and design challenges.

Our customers may place considerable pressure on us to meet tight development schedules, capacity availability timelines, and evolving technical specifications. Accordingly, we may be required to devote a substantial amount of our resources, including engineering, research and development, and capital expenditures, to satisfying the demands of our largest customers, which could divert resources from other strategic initiatives or delay our completion of other important development projects. Failure to meet customer-imposed development requirements or timelines could impair our relationships with these customers, negatively impact forecasted sales, and could materially and adversely affect our business, financial condition, and results of operations.


36


Table of Contents

Supply Chain, Technology, and Operational Risks

Constrained supply and dependence on single- or limited-source components may elongate lead times, increase costs, and create misalignment with customer obligations.

A delay or interruption in supply from a supplier, especially for critical components such as custom or customer-specified semiconductors, power modules, and high-speed interconnect components, which in some cases are sourced from a single or limited number of suppliers, could significantly impact our operations and our customers if we are unable to deliver finished products in a timely manner. Quality or reliability issues at any of our suppliers, or financial difficulties that affect their production and ability to supply us with components, could halt or delay production of a customer’s product or result in claims against us for failure to meet required customer specifications. Replacing a single- or limited-source supplier could delay production because replacement suppliers, if available, may be subject to capacity constraints or other output limitations. If we cannot secure timely and cost-effective supply aligned with customer schedules, we may incur expedite premiums, carry higher inventory, miss delivery windows, or face penalties and reputational harm.

Our production has in the past been, and may in the future be, adversely affected by delays and increased costs resulting from issues our suppliers face, including geopolitical conflicts and increased energy prices. Our inability to make scheduled shipments may cause us to experience a reduction in sales, increase in inventory levels and costs, and could adversely affect relationships with existing and prospective customers.

Customer-directed suppliers and components may increase our supply chain risk.

Certain of our customers direct or require us to purchase components, materials, or subsystems from specified suppliers. In some cases, these customer-directed suppliers may be sole sources for the required components or may be geographically concentrated. We may have limited ability to qualify alternative suppliers or pass through cost increases for customer-specified components. If a customer-directed supplier experiences supply disruptions, quality issues, financial distress, or other problems, we could be unable to meet our customer’s requirements and could be exposed to warranty claims, contract penalties, or liability, even if the underlying issue was attributable to the customer-directed supplier. Our customers may not agree to share responsibility for these supply chain risks, and we may bear a disproportionate share of the exposure.

Our dependence on customer and third-party power and water availability and permitting may delay projects or impair economics.

Our ability to deliver and expand certain solutions and services depends on our customers and third-party data center operators securing sufficient and reliable electrical power and water at acceptable costs and within required timelines. Limitations on power generation, transmission, and distribution capacity, utility interconnection lead times, curtailments, outages, and volatility in energy markets may delay energization, restrict available capacity, increase operating costs, and materially affect project economics and contractual performance. Public utility planned outages, broader grid reliability events, and inflationary or geopolitical pressures on energy prices may further increase volatility for our customers and partners, affecting our schedules and costs. Similarly, water scarcity, drought conditions, competing demands for water resources, and regulatory restrictions on water use may constrain data center cooling capacity, limit site selection, increase operating costs, or delay project timelines.

In several markets, regulators and local authorities have imposed or considered data center development moratoria, stricter energy efficiency standards, caps on usage, or other conditions to approvals. These measures may delay or prevent site development or expansion and increase compliance costs. If customers or third-party operators are unable to secure timely and cost-effective power, or if approval processes are delayed or restricted, we could experience project delays, missed milestones, service-level exposure under our contracts, reduced margins, and lost or deferred revenue.


37


Table of Contents

Third-party facility control, retrofit requirements, and capacity utilization variability may introduce delays, performance risks, and contractual exposure.

As rack power densities increase and liquid or hybrid cooling becomes more prevalent, many existing data center facilities require retrofits to power distribution, structural supports, fluid handling, and interconnect infrastructure. In cases where customers or third-party operators manage these retrofits, we have limited control over their timing, execution, and quality. In certain circumstances, our contractual performance obligations may still be evaluated against end-to-end service-level agreements (“SLAs”). If required retrofits or interconnect upgrades are delayed, deficient, or incompatible with our integrated solutions, we may experience schedule slippage, rework, increased warranty or service obligations, or other adverse commercial consequences, even though these constraints are outside our direct control. These risks may become more pronounced as customers accelerate adoption of high-density racks and liquid cooling systems requiring complex facility modifications. Misalignment between contracted program volumes and actual customer usage, whether from program push-outs, changes in deployment plans, or infrastructure delays, can also result in underutilized capacity, excess capacity costs, and inventory exposures. If infrastructure readiness issues prevent timely integration or energization, we could face SLA penalties, margin compression, increased working capital needs, and significant period-to-period variability in our results.

Physical climate and geopolitical risks could disrupt our facilities, supply chains, and customer programs.

Our facilities and those of our customers and suppliers are exposed to acute and chronic physical risks, including extreme weather, drought, wildfire, flooding, and seismic events, which may increase in frequency and severity due to climate change. Such events can cause outages, delay production or deployments, impair logistics, increase insurance and energy costs, and reduce available water or power at customer or third-party sites.

Geopolitical tensions-including those affecting the China-Taiwan corridor and other critical regions for semiconductor manufacturing and component sourcing, as well as the conflicts in Ukraine and the Middle East, including the recent conflict involving Iran, can exacerbate supply disruptions, extend lead times, and increase costs. Our global operations are subject to inherent risks including changes in local tax rates and incentives, labor unrest, political instability, armed conflict, social unrest, terrorism, and natural disasters. Any of these events could disrupt operations at one or more of our sites or those of our customers, suppliers, and logistics partners, with the impact potentially magnified in areas where we or they have multiple facilities in close proximity.

Rapid technology shifts require continuous capability upgrades and may render existing solutions less competitive or obsolete.

Our industry is characterized by frequent platform transitions, increasing rack power densities, adoption of liquid and hybrid cooling, evolving power delivery architecture and interconnect standards, and changing security and manageability requirements. To remain competitive, we must continually invest in engineering, validation, supply chain enablement, specialized integration capabilities, capital equipment, and technical support. If we fail to anticipate or timely align with evolving specifications, standards, or density requirements, or if competitors adopt innovations more quickly, our win rates, pricing, and margins may suffer, and we may incur inventory write-downs and rework charges.

Many of our competitors are well-capitalized and may develop superior products, adapt more quickly to technological changes, industry changes, or customer requirements. The emergence of new technologies, industry standards, or customer requirements may render our power delivery systems, cooling solutions, integration capabilities, inventory, or processes less competitive or obsolete. Our acquisition and implementation of new technologies and equipment, and the expansion of our offerings, may require significant expense or capital investment, which could reduce our operating margins or adversely affect our business, financial condition and results of operations. If we fail to keep pace with technological change or evolving market needs, or to develop and introduce competitive products or solutions on a timely manner, we may lose customers and experience decreased or delayed market acceptance and sales of our products and solutions.


38


Table of Contents

Financial and Working Capital Risks

Working capital intensity and access to financing may constrain growth and increase earnings volatility.

Delivering our products, solutions and services can require significant upfront commitments for customer-specific materials, tooling, integration capacity, specialized test equipment, and inventory. Our ability to fund growth depends on internally generated cash and access to debt and other financing on acceptable terms. Market disruptions, interest rate volatility, bank sector instability, or adverse credit conditions could increase borrowing costs, limit available capital, or delay funding, constraining project delivery and capacity expansion.

High fixed and semi-fixed costs in our manufacturing operations, and elevated inventory levels for customer programs, can magnify the impact of utilization variability and project delays, adversely impacting our earnings and cash flows. Our operations are working capital intensive, and inventories, accounts receivable, and accounts payable are significant components of our net asset base. Numerous factors impact our working capital and cash flow, including fluctuations in revenues, fluctuations in collections of receivables and timing of payables, timing and size of capital expenditures, and our ability to manage materials purchasing and payment policies and to optimize our terms and conditions with suppliers. If we fail to manage our working capital effectively, our business, financial condition, results of operations, and liquidity could be materially and adversely affected.

We may not be able to obtain financing arrangements on acceptable terms or in amounts sufficient to meet our needs in the future, which could harm our ability to grow our business. Failure to obtain required capital when needed could reduce our ability to pursue program pipelines and meet customer commitments.

Capital markets and interest rate volatility may constrain our customers’ and partners’ ability to fund sites and power, indirectly affecting program ramps and growth visibility.

The development and expansion of data center capacity and utility and power infrastructure, including site acquisition, power procurement, and infrastructure buildouts, are capital intensive and often depend on access to debt and equity markets. Higher interest rates, tighter credit conditions, or reduced investor appetite for digital infrastructure or utility capital investment may lead customers to delay or scale back projects, renegotiate commercial terms, or reprioritize spend, which can reduce our order flow and slow ramps. Broader concerns regarding global economic conditions, financial market volatility, geopolitical developments, energy costs, inflation, and the availability or cost of credit have contributed to increased uncertainty. All of the foregoing factors are outside of our control and may adversely affect our results of operations.

Operational and Strategic Risks

We may encounter difficulties with acquisitions, including the EPC Power Acquisition, and divestitures, which could harm our business.

As part of our growth strategy, we intend to selectively pursue acquisitions, joint ventures, and strategic alliances. On September 3, 2026, Flex announced that it entered into a definitive agreement to purchase EPC Power, a leading provider of intelligent power conversion solutions for data center and grid applications, for $4.4 billion. EPC Power is expected to become part of the Cloud and Power Infrastructure business, which Flex plans to separate into Spinco in the Spin-Off. Whether we realize the anticipated benefits from such activities depends, in part, upon the successful integration of the acquired businesses, the performance and development of the underlying products, capabilities, or technologies, our correct assessment of assumed liabilities, and the management of the operations. The integration of acquired businesses may not be successful and could result in disruption to other parts of our business. In addition, acquisitions involve numerous risks and challenges, including: diversion of management’s attention from the normal operation of our business; potential loss of key employees and customers of the acquired companies; difficulties managing and integrating operations in geographically dispersed locations; the potential for deficiencies in internal controls at acquired companies; increases in our expenses and working capital requirements, which reduce our return on invested capital; lack of experience operating in the geographic market or industry sector of the acquired business; the need to implement


39


Table of Contents

financial and other systems and add management resources; failure to realize anticipated benefits, such as cost savings and revenue enhancements; and exposure to unanticipated liabilities of acquired companies. The EPC Power Acquisition and any future acquisitions may require additional equity financing, which could be dilutive to our existing shareholders, or additional debt financing, which could increase our leverage and potentially affect our credit ratings. In addition, divestitures involve significant risks, including difficulty finding financially sufficient buyers or selling on acceptable terms in a timely manner. Divestitures could adversely affect our profitability and, under certain circumstances, require us to record impairment charges or a loss as a result of the transaction. These and other factors could harm our ability to achieve anticipated levels of profitability or realize other anticipated benefits of an acquisition or divestiture, and could adversely affect our business and results of operations.

We may not achieve some or all of the expected benefits of our restructuring activities, and our restructuring activities could adversely affect our ability to execute our business strategy.

Following the Spin-Off, we expect to evaluate our operations as a standalone company and may undertake restructuring actions to optimize our cost structure, establish independent functions, or align our operations with our strategic priorities. We will also incur costs associated with creating capabilities previously provided by Flex. Restructuring activities may be costly and disruptive, require significant management attention, and may not achieve the anticipated benefits on the expected timeline or at all. Any failure to achieve expected benefits could have a material adverse effect on our competitive position and results of operations.

We may encounter difficulties expanding or consolidating our operations or introducing new competencies or offerings, which could adversely affect our results of operations.

As we expand our business, open new sites, enter new markets, products, and technologies, invest in research, design and development, transfer business within our network, consolidate certain operations, or introduce new business models or programs, we may encounter difficulties that result in higher than expected costs associated with such activities. Potential difficulties include our ability to manage growth effectively; to maintain existing business relationships during periods of transition; to anticipate disruptions in our operations that may impact our ability to deliver to customers on time, produce quality products, and ensure overall customer satisfaction; and to respond rapidly to changes in customer demand or volumes.

We may also encounter difficulties in ramping and executing new programs. Ramping new programs can range from several months to over a year before production starts, and often requires significant up-front investments and increased working capital. These programs may generate lower margins or losses during and following the ramp period, or may not achieve the expected financial performance, due to production ramp inefficiencies, lower than expected volume, or delays in ramping to volume. Our customers may significantly change these programs, or even cancel them altogether, due to decreases in their end-market demand or in the actual or anticipated success of their products in the marketplace.

We depend on our ability to attract, retain, and develop highly skilled personnel, and our failure to do so could seriously harm our business.

To successfully operate as an independent public company and implement our business plans, we must identify, attract, develop, motivate, train, and retain key employees, including qualified executives, management, engineering, sales, marketing, IT support, and service personnel. The market for such individuals is highly competitive. We may not be successful in attracting, integrating, or retaining qualified personnel to meet our current growth plans or future needs. Attracting and retaining key employees in a competitive marketplace requires us to provide a competitive compensation package. If our total compensation package is not viewed as competitive, our ability to attract, motivate, and retain key employees could be weakened, and failure to successfully hire or retain key employees and executives could adversely impact us.

Changes in our executive management team may also cause disruptions in, and harm to, our business. Failure to have an effective succession plan in place for our key executive officers could significantly delay or prevent us from achieving our business or development objectives and could materially harm our business.


40


Table of Contents

Cybersecurity and Data Risks

Cybersecurity, data privacy, and operational-technology risks could disrupt our operations, damage our reputation, and expose us to liability.

We rely on our information systems, some of which are managed by third parties, to process, transmit, and store electronic information (including sensitive data such as confidential business information and personally identifiable information relating to employees, customers, vendors, and other business partners), and to manage or support critical business processes and activities, including manufacturing, design and engineering services, financial reporting, inventory management, procurement, invoicing, and electronic communications. Our ability to effectively manage our business depends on the security, reliability, and adequacy of these information systems. We may be adversely affected if these information systems break down, fail, or are no longer supported.

Like many other corporations in our industry, we and third parties upon which we rely have faced, and may continue to face, attempts to gain unauthorized access to our systems, networks, and cloud resources, or those of our customers, vendors, and third-party service providers. Threat actors continue to evolve in sophistication and use techniques that change frequently, may be difficult to detect, and may remain dormant for extended periods. Artificial intelligence (“AI”) techniques may also be utilized to increase the number and technical sophistication of such attempted breaches. Due to increasing geopolitical tensions and conflicts, we and the third parties upon which we rely may be vulnerable to a heightened risk of cyberattacks that could materially disrupt our systems, operations, supply chain, and ability to serve our customers, any of which could reduce revenues and harm our operational performance.

Our ability to monitor third parties’ information security practices is limited, supply chain attacks have increased in frequency and severity, and we cannot guarantee that third parties, including cloud or hosted solutions providers, have not been compromised or that their systems are free from exploitable defects. A material incident could result in unauthorized access to, or loss of, confidential information and trade secrets, unfavorable publicity, loss of competitive advantage, governmental inquiry and oversight, difficulty in marketing and selling our products and services, significant costs related to rebuilding internal systems, higher insurance premiums, allegations by our customers that we have not performed our contractual obligations, litigation by affected parties, and financial penalties, fines, or obligations for damages related to the theft or misuse of our information or other assets.

We may be required to invest significant additional resources to comply with evolving cybersecurity regulations, including those addressing artificial intelligence, and to modify and enhance our information systems, security and controls, and to investigate and remediate any security vulnerabilities.

We are subject to laws and regulations in the U.S. and other countries relating to privacy and the collection, use, transfer, storage, and security of personal data, including the European Union General Data Protection Regulation, as well as controls or rules imposed by customer or other contracts relating to the same. Data protection laws continue to develop and may have conflicting requirements across jurisdictions; compliance can be costly, and any failure to comply with these laws or other data protection standards could subject us to legal and reputational risks, government inquiries, and significant penalties and fines. Our liability insurance may not be sufficient in type or amount to cover us against claims related to security breaches, cybersecurity attacks, and other related incidents.

Reputational and Stakeholder Risks

Exposure to financially troubled customers or suppliers could adversely affect our business, financial condition, and results of operations.

Our customers may experience financial distress, consolidation, and cyclical demand. If a customer experiences financial difficulty or insolvency, we may be unable to collect amounts owed to us on a timely basis, if at all, and demand for our products and services may decline. These events could require us to increase our allowance for credit losses, write down inventory, reduce revenue, and increase our working capital requirements due to higher inventory levels and longer collection periods.


41


Table of Contents

If a supplier experiences financial difficulty, we may face supply interruptions, reduced allocations, less favorable terms, or the need to qualify alternative sources, which could increase costs, delay production, and affect our ability to meet delivery schedules. Any of these developments could adversely affect our business, financial condition, results of operations, and cash flows.

Our business could be impacted as a result of actions by activist shareholders or others.

We may be subject, from time to time, to legal and business challenges in the operation of our company due to actions instituted by activist shareholders or others. Responding to such actions could be costly and time-consuming, may not align with our business strategies, and could divert the attention of our Board of Directors and senior management from the pursuit of our business strategies. Perceived uncertainties as to our future direction as a result of shareholder activism may lead to the perception of a change in the direction of the business or other instability and may make it more difficult to attract and retain qualified personnel and business partners and may affect our relationships with customers, vendors, and other third parties.

Negative publicity, regardless of accuracy, could harm our reputation and adversely affect our business, financial condition, and results of operations.

Media coverage concerning our industry, company, brand, personnel, or operations can spread rapidly through digital platforms and social media, making it difficult to remediate. Our ability to maintain and enhance our brand depends on adapting to this evolving media environment. Negative commentary may reduce customer trust and demand for our products and services, which could negatively impact our performance.

Risks Related to Our Industry

Our business depends on continued capital investment in digital infrastructure, and any reduction in such spending could materially harm our results of operations.

We primarily serve customers in the digital infrastructure market, including hyperscale/cloud, colocation, and enterprise data center operators. A majority of our revenue is derived from products and services that support high-density computing infrastructure for cloud, AI, and machine learning (“ML”) workloads, as well as other high-performance and data-intensive applications. As a result, our business, financial condition, and results of operations are significantly dependent on the level and timing of capital expenditures by our customers, particularly hyperscalers.

The digital infrastructure industry is subject to rapid technological change, intense competition, and evolving customer priorities. Capital expenditure cycles among hyperscalers and other data center operators can be volatile and may be influenced by factors outside our control, including macroeconomic conditions, changes in credit availability, shifts in customer investment priorities, technological developments or alternative deployment architectures (such as orbital or undersea data centers) that reduce demand for our products or render certain solutions less competitive, and regulatory developments or public policy changes affecting AI development or deployment. Because we are focused on the data center market and lack significant diversification across other industries, a sustained decline in AI-related or other accelerated compute and data-center capital spending could adversely affect our business, financial condition, results of operations, and prospects.

Overall market trends of increased demand for compute capacity, power infrastructure, and advanced cooling driven by AI and cloud applications have supported recent growth, but there can be no assurance that such trends will continue. Advances in model architectures, training and inference techniques, algorithmic efficiency, and semiconductor design may materially reduce the compute, power, and cooling resources required per unit of AI workload, which could reduce the volume of infrastructure Spinco’s customers require even if AI adoption continues to grow. Consolidation among our customers, reduction in spending on digital infrastructure, or shifts in market size toward larger customers may result in lower sales volumes and, pricing pressure. Any sustained reduction in customer spending could adversely affect our business, financial condition, and results of operations.


42


Table of Contents

In addition, the substantial data center capacity currently under construction may come online faster than demand develops, which could result in excess capacity, declining utilization, falling prices for compute and colocation services, deferred or cancelled projects, and financial distress among Spinco’s customers. Because Spinco’s revenue is concentrated in the data center market, any such developments could result in a rapid and pronounced decline in demand, order cancellations, inventory and capital equipment impairments, and adverse effects on Spinco’s business, financial condition, and results of operations.

Our industry is highly competitive, and competitive pressures could reduce our market share, revenues, and profitability.

We operate in a highly competitive industry. Some of our competitors have greater scale and offer a broader range of services, and may have greater name recognition, geographic market presence, manufacturing, and research and development capabilities. They may be better able to take advantage of acquisition opportunities, may be willing or able to make sales or provide services at lower margins than we do, or may adapt more quickly than we do to new technologies, evolving industry trends, and changing customer requirements.

We also face indirect competition from current and prospective customers who decide to manufacture products internally, or insource previously outsourced business. Competition may cause pricing pressures, reduced profits, or a loss of market share, any of which could materially and adversely affect our business, financial condition, results of operations, and cash flows.

Increases in prices for energy and other commodities may adversely affect our results of operations.

We rely on various energy sources in our production and transportation activities. Increases in prices for energy and other commodities have resulted in, and may result in further, increased raw material and component costs and transportation costs. Any increase in our costs that we are unable to recover in our pricing to our customers would negatively impact our margins and results of operations. To the extent we cannot compensate for cost increases through productivity improvements or price increases to our customers, our margins may decline, materially affecting our business, financial condition, results of operations, and cash flows. Geopolitical instability and volatility in energy markets may further exacerbate these risks.

Evolving regulations relating to energy, utilities, and data center development could adversely affect our business.

Government authorities in the U.S. and other jurisdictions have enacted, proposed, or are considering laws and regulations relating to data center development and permitting, energy and water consumption, grid reliability, and environmental and community impacts, which may result in new requirements, delays, or restrictions on the development, expansion, or operation of data centers or related infrastructure. Regulatory developments, such as moratoria or pauses on data center development, enhanced permitting or review processes, requirements to fund or share in the cost of grid or other utility upgrades, or operational restrictions relating to energy use, water consumption, noise mitigation, or other community-impact measures, could increase our customers’ costs, delay or reduce their planned investments, limit the scale or location of data center deployments, or otherwise constrain their ability to deploy or expand AI/ML infrastructure, which could adversely impact demand for our products and solutions. In addition, political and popular opposition to the construction, expansion or operation of data centers, which has increased and become more organized in some areas, could lead to additional measures restricting or limiting data center development, expansion and operation and heighten these risks.

Risks Related to the International Nature of our Business

We conduct operations globally and are subject to the risks inherent in international operations, which could adversely affect our business, financial condition, and results of operations.

We maintain operations, supply chain relationships, and customer relationships across numerous countries. Our global operations subject us to a variety of risks that could materially harm our business, including: longer payment cycles; ineffective legal protection of our intellectual property rights in certain countries; labor unrest,


43


Table of Contents

including labor strikes, difficulties in staffing, and geographic labor shortages; environmental protection laws and regulations, including those related to climate change; expropriation of private enterprises; natural disasters and exposure to infectious disease, epidemics, and pandemics on our business operations in geographic locations impacted by outbreaks; political or social unrest; cultural differences and differences in local business customs; and a potential reversal of current favorable policies encouraging foreign investment or foreign trade by our host countries.

The geographic distances between our global operations create logistical and communications challenges that could adversely affect our business.

The geographic distances between the Americas, Asia, and Europe create a number of logistical and communications challenges for us. These challenges include managing operations across multiple time zones, directing the manufacture and delivery of products across long distances, coordinating procurement of components and raw materials and their delivery to multiple locations, and coordinating the activities and decisions of our management team, which may be based in a number of different countries. Facilities in several different locations may be involved at different stages of the production process of a single product, leading to additional logistical difficulties.

Global economic conditions, including inflationary pressures, currency volatility, trade conflicts, geopolitical uncertainty, and instability in financial markets, may adversely affect our business, financial condition, results of operations, and access to capital.

Our operations and the execution of our business plans and strategies are subject to the effects of global economic trends, geopolitical risks, and demand or supply shocks from events that could include political crises and conflict, war, terrorist attacks, natural disasters, or actual or threatened public health emergencies. Our business is also affected by local and regional economic environments, supply chain constraints, and policies in the U.S. and other markets that we serve, including interest rates, monetary policy, inflation, commodity prices, currency volatility, currency controls or other limitations on the ability to expatriate cash, sovereign debt levels, and actual or anticipated defaults on sovereign debt. Changes in local economic conditions or outlooks, such as lower rates of investment or economic growth in China, Europe, or other key markets, may affect the demand for or profitability of our products and services.

We operate in emerging markets where economic, political, and legal risks are heightened. Political changes and trends such as protectionism, economic nationalism, and restrictions on multinational companies can interfere with our global operating model, supply chain, production costs, customer relationships, customer demand, and competitive position. Such measures can be imposed suddenly and unpredictably. Changes in policies by the U.S. or other governments could negatively affect our results of operations due to changes in duties, tariffs, or taxes, or limitations on currency or fund transfers, as well as government-imposed restrictions on producing certain products in, or shipping them to, specific countries.

We are subject to complex and evolving trade policies, tariffs, and export controls, and failure to comply or adapt to changes could restrict our business or result in penalties.

Due to the global nature of our business, we are subject to a complex system of import- and export-related laws and regulations in the United States and other countries, including economic sanctions administered by the U.S. Department of the Treasury’s Office of Foreign Assets Control and similar laws in other jurisdictions. Our products, services, and technology are regulated by these trade control and customs regimes, and in some cases require licenses or other authorizations. Our ability to obtain and maintain such licenses and authorizations on a timely basis, or at all, is subject to risks and uncertainties, including changing laws, regulations, foreign policies, and geopolitical factors.

Non-compliance with these laws and regulations by us, our customers, or our suppliers can result in a wide range of penalties, including denial of import or export privileges, fines, criminal penalties, administrative sanctions, seizure of inventory, import detention, and loss of business. Delays or denials of licenses can prevent or defer sales, and if we are not successful in obtaining or maintaining necessary licenses or authorizations in a timely


44


Table of Contents

manner, previously recognized revenue and profit may need to be reversed. Moreover, we could be subject to reputational harm if any of our customers, former customers, or vendors were subject to U.S. sanctions or did business with sanctioned countries.

Any expansion of export, sanctions, or import restrictions, including the imposition of new tariffs or trade restrictions, tariff increases, anti-dumping or countervailing duties, trade embargoes, or retaliatory measures by affected countries, could adversely affect our competitive position, financial condition, results of operations, or liquidity.

Tariffs, trade restrictions, changes in trade policy, including heightened trade volatility, and uncertainty regarding trade agreements may adversely affect our business.

Political developments such as protectionism and economic nationalism have resulted in, and may continue to result in, tariffs, trade restrictions, and other barriers that may interfere with our operations, supply chain, and competitive position. Throughout 2025 and into 2026, the U.S. administration imposed varying levels of tariffs on goods imported from China and other countries. Further escalation of trade tensions could materially increase our product input costs, contract customer demand, or otherwise adversely affect our business. We generally seek to pass tariff costs through to our customers, which can affect reported net sales, operating income margins, and the timing of operating cash flows. To the extent we are unable to recover tariff costs, our results of operations could be adversely affected. The United States-Mexico-Canada Agreement is subject to a joint review process in 2026, and there can be no assurance that the agreement will not be amended, suspended, or terminated. In addition, on February 20, 2026, the U.S. Supreme Court struck down certain tariffs imposed under the International Emergency Economic Powers Act (“IEEPA”), following which the U.S. administration announced a new 10% global tariff under Section 122 of the Trade Act of 1974. These developments have created uncertainty regarding the future rate, scope, and enforceability of tariffs, the availability of refunds for invalidated tariffs, and the potential for alternative legislative or executive actions. Any material changes to trade agreements or ongoing uncertainty regarding U.S. trade policies could adversely affect our business, financial condition, and results of operations.

We have operations in China that are subject to evolving laws, regulations, policies, and geopolitical risks that could adversely affect our business.

We have operations located in China that could be adversely affected by evolving laws, regulations, and policies, including with regard to import and export tariffs and restrictions, and information security and privacy, as well as changes in the political and geopolitical environment involving China. U.S.-China bilateral trade relations remain uncertain. U.S. trade actions, including imposing tariffs on certain goods imported from China or deemed to be of Chinese origin, as well as the potential for new tariffs, trade embargoes, or sanctions by the U.S. and countermeasures imposed by China in response, could adversely affect our business, including in the form of increased cost of goods sold, decreased margins, increased pricing for customers, and reduced sales. U.S. technology export controls with respect to China, which are intended in part to restrict China’s ability to obtain advanced computing chips, develop and maintain supercomputers, and manufacture advanced semiconductors, have adversely impacted certain of our customers and end markets and may continue to do so.

Additionally, increased tensions between mainland China and Taiwan could disrupt the operations of companies in Taiwan that are critical to the global supply of semiconductors and other electronic components on which many of our customers depend. Any such disruption could have significant adverse effects on our supply chain and ability to serve our customers.

Geopolitical uncertainty, including as a result of armed conflicts, may adversely affect our business, financial condition, and results of operations.

We may have facilities in regions subject to geopolitical tensions. If these facilities were to be damaged, destroyed, or otherwise unable to operate, whether due to war, acts of hostility, or terrorist acts, such an event


45


Table of Contents

could jeopardize our ability to develop, manufacture, and deliver certain products and adversely affect our operations and results of operations. Our operations have been, and could continue to be, disrupted by the absence of employees called to active duty to perform military service.

The Russia-Ukraine conflict, the Israel-Hamas war, the recent military actions in Iran by the U.S. and Israel and other conflicts in the Middle East, and other hostilities or armed conflicts, or the interruption or curtailment of trade or transport between the countries where our facilities are located and their respective trading partners, have in the past and could in the future adversely affect our operations and results of operations. Political, economic, and military instability in these or other regions could lead to an increase in cyberattacks and disruptions and instability in global markets (including increases in inflation rates, increases in energy prices, and adverse effects on currency exchange rates and financial markets), supply chains, and industries that could negatively impact our business, financial condition, and results of operations.

Increased international political volatility, including changes to previously accepted trade or other government policies or legislation in the U.S. and Europe, instability in parts of Europe and the Middle East, as well as strained international relations, anti-immigrant activities, social unrest, fears of terrorism, enhanced national security measures, and armed conflicts, may materially hinder our ability to conduct business, or may reduce demand for our products or services.

Operations in foreign countries present risks associated with inflation, infrastructure, and labor conditions that could adversely affect our business.

Inflation may impact our profits and cash flows. In many jurisdictions in which we operate, governmental authorities exercise significant influence over many aspects of the economy, and their actions could have a significant effect on our business. We could be harmed by inadequate infrastructure, including lack of adequate power supply, transportation, raw materials, or components in certain locations. In addition, we may encounter labor disruptions, including labor strikes or claims, and rising labor costs (including minimum wage increases that are government-mandated from time to time), in particular within the lower-cost regions in which we operate due to, among other things, demographic changes and economic development in those regions. Any increase in labor costs that we are unable to recover in our pricing to our customers could adversely impact our margins and results of operations.

Financial Risks

We may not be able to access the capital and credit markets on terms that are favorable to us, or at all, including in connection with the EPC Power Acquisition.

Our business relies on the availability of financing. In connection with the EPC Power Acquisition, Flex intends to replace the Bridge Facility with a combination of debt and equity financing at Spinco. The capital and credit markets have in the past experienced and may continue to experience extreme volatility or disruptions that may lead to uncertainty and liquidity issues for both borrowers and investors. Certain customers and suppliers, as well as our business, may need access to credit and trade finance lines and other financing instruments for certain transactions. Additionally, we may need to access the capital markets to supplement our existing funds and cash generated from operations to satisfy our needs for working capital or capital expenditure requirements.

A variety of factors beyond our control could impact the availability or cost of capital, such as domestic or international economic conditions, including as a result of: tariffs or the imposition of new tariffs, trade wars, barriers, or restrictions or threats of such actions; increases in key benchmark interest rates and/or credit spreads; the adoption of new or amended banking or capital market laws or regulations; and the repricing of market risks and volatility in capital and financial markets.

In the event of adverse capital and credit market conditions, we may be unable to obtain capital market or other financing on favorable terms, or at all, and changes in credit ratings issued by nationally recognized credit-rating agencies could adversely affect our ability to obtain capital market or other financing and the cost of such financing. Such factors may impact our ability, or the ability of our customers or suppliers, to obtain debt financing, guarantees, or hedging from financial institutions, which could limit our growth and materially and adversely affect our business, financial condition, results of operations, and cash flows.


46


Table of Contents

We are subject to the risk of increasing income and other taxes, tax audits, and changes in tax laws, any of which may adversely affect our financial performance.

We conduct business operations in a number of countries and are subject to income and other taxes in the United States and numerous foreign jurisdictions. Our future effective tax rates could be affected by changes in the mix of earnings in countries with differing statutory tax rates; changes in tax laws, regulations and judicial rulings (or changes in the interpretation thereof); changes in generally accepted accounting principles; changes in the valuation of deferred tax assets and liabilities; changes in the amount of earnings permanently reinvested offshore; and changes related to tax holidays or incentives. From time to time we may benefit from tax incentives or similar programs, and changes to or the expiration of such programs could affect our income tax expense.

The international tax environment continues to change as a result of both coordinated efforts by governments and unilateral measures designed to address perceived international tax avoidance. The Organization for Economic Co-operation and Development (the “OECD”) and participating countries continue to work toward implementation of a global minimum tax rate of 15% as part of its Base Erosion and Profit Shifting project, and many countries in which we operate have enacted or are enacting laws based on these proposals. These rules could increase tax complexity and uncertainty, adversely impact our effective tax rate and cash tax liability, and reduce the benefits achieved from tax incentives. However, in January 2026, the OECD released a “side-by-side” package introducing new safe harbors and providing an exemption for U.S.-based multinational companies from parts of the global minimum tax framework. We continue to evaluate the impact of proposed and enacted legislative changes to our effective tax rate and cash flows as new guidance becomes available in each country.

We and our subsidiaries are regularly subject to tax return audits and examinations by various taxing jurisdictions. We develop our tax filing positions based upon the anticipated nature and structure of our business and the tax laws, administrative practices, and judicial decisions currently in effect, all of which are subject to change or differing interpretations, possibly with retroactive effect. Should additional taxes be assessed as a result of a current or future examination, or should tax laws change in a manner adverse to us, there could be a material adverse effect on our tax provision, financial condition, results of operations, and cash flows.

Fluctuations in foreign currency exchange rates could increase our operating costs and adversely affect our results of operations.

We have operations located in various parts of the world, and a portion of our purchase and sale transactions are denominated in currencies other than the U.S. dollar. A significant portion of our operational costs, including payroll, site costs, locally sourced supplies and inventory, and income taxes, are denominated in various non-U.S. dollar currencies. Currency exchange rates fluctuate daily as a result of changes in political and economic conditions, and a significant increase in the value of certain local currencies relative to the U.S. dollar could adversely affect our financial results and cash flows by increasing both our costs and the costs of our local supply base.

We may use financial instruments such as forward exchange contracts, swap contracts, and options to hedge our foreign currency exposure. However, our hedging strategy may not fully mitigate the longer-term impacts of changes to foreign exchange rates, and if our hedging activities are not successful or if counterparties default on their obligations, we may experience significant unexpected expenses or fluctuations in our results of operations.

Changes in accounting standards and subjective assumptions, estimates, and judgments by management related to complex accounting matters, could significantly affect our financial results or financial condition.

Generally accepted accounting principles and related accounting pronouncements, implementation guidelines, and interpretations regarding a wide range of matters relevant to our business, such as revenue recognition, asset impairment and fair value determinations, inventories, business combinations and intangible asset valuations, leases, and litigation, are highly complex and involve many subjective assumptions, estimates, and judgments. Changes in these rules or their interpretation or changes in underlying assumptions, estimates, or judgments could have a material adverse effect on our business, results of operations, and financial position.


47


Table of Contents

Legal and Regulatory Risks

Litigation, investigations, or enforcement actions could result in significant liabilities, operational restrictions, and reputational harm.

We are, from time to time, subject to claims, lawsuits, investigations, and regulatory or administrative proceedings across the jurisdictions where we operate. These matters may involve commercial disputes; regulatory compliance; intellectual property; product liability; employment and labor; privacy and data protection; securities and governance; and tax. Adverse outcomes, whether by judgment, settlement, consent decree, or otherwise, could require monetary payments, penalties, injunctive relief, operational changes, monitorships, remedial measures, or enhanced compliance controls.

Even if we prevail, we may incur substantial costs, increased insurance premiums, and management distraction that disrupts operations and harms our reputation with customers, suppliers, employees, and regulators. Outcomes are unpredictable, and accruals and insurance coverage may be insufficient or unavailable. Securities class actions or derivative litigation may also follow volatility in our securities or disclosures. Any of these could materially affect our business, financial condition, results of operations, and cash flows.

Our compliance program may not prevent violations of anti-corruption and related laws, which could result in severe penalties, business restrictions, and reputational harm.

We conduct business in numerous jurisdictions with stringent anti-corruption, anti-bribery, and related compliance requirements, including the U.S. Foreign Corrupt Practices Act, the UK Bribery Act, and similar laws elsewhere. We maintain policies, procedures, training, and internal controls designed to promote compliance and prohibit offering, promising, authorizing, or providing anything of value to government officials or other counterparties to obtain or retain business. However, we cannot assure that our employees, agents, consultants, or other third parties acting on our behalf will comply with these requirements at all times. Our risk may be heightened in jurisdictions where corruption is perceived to be more prevalent.

Actual or alleged violations could result in investigations, significant civil and criminal fines and penalties, disgorgement, monitorships, and reputational damage. Any of these events could adversely affect our business, financial condition, results of operations, and could require substantial management time and resources to address.

Inadequate protection of our intellectual property and exposure to third-party intellectual property claims could adversely affect our business and results of operations.

We develop and own, and in some cases license, intellectual property used in our engineering, design, and manufacturing services and in our products. Although we use a range of measures to protect our intellectual property, including contractual and security controls and seeking patent and trademark protection where appropriate, these measures may not prevent infringement, misappropriation or other unauthorized disclosure or use of our intellectual property or innovations. Moreover, protecting against the unauthorized use of proprietary technology is difficult and expensive and we may need to litigate with third parties to enforce or defend patents issued to us and our other intellectual property rights or to determine the enforceability and validity of our proprietary rights or those of others. If we cannot adequately protect or enforce our intellectual property rights, we could lose the competitive advantages of our proprietary technology.

Our activities may expose us, our suppliers, and our customers to claims that our services, products, processes, designs, or components infringe, misappropriate, or otherwise violate third-party intellectual property rights, or that we have breached license or other contractual provisions. We also sometimes enter into patent, software, or other licenses that condition our use of third-party technology and restrict the scope of permitted activities. While licensing is not a significant component of our business, disputes may still arise over coverage or compliance,


48


Table of Contents

our licensors may fail to maintain, enforce, or protect the licensed intellectual property, and we may decide not to take certain licenses, any of which could increase the likelihood of third-party assertions and require us to modify or limit certain activities, products, or services.

Because we provide design and engineering services in addition to manufacturing, customers often seek to allocate intellectual property risk to us to a greater extent than in traditional manufacturing engagements, including requiring broad intellectual property indemnities. Assertions against our customers may trigger indemnification obligations, require us to participate in defense, or result in disputes over responsibility between us and our customers. Moreover, we could become subject to large indemnity payments or damages claims from contractual breach, which could harm our business results, cash flows, financial condition, or prospects.

If infringement, misappropriation, or other similar claims are brought against us or our customers, whether or not they have merit, we could be required to expend significant resources on defense, and we or our customers could be required to develop non-infringing alternatives, obtain licenses, or cease, delay, or modify the affected services, products, or features. Suitable alternatives may be unavailable or costly, licenses may not be available on commercially reasonable terms or at all, and any litigation or dispute resolution could be lengthy, disruptive, and expensive and may not be resolved in our or our customers’ favor.

We also face heightened risks to our intellectual property in certain foreign jurisdictions, including risks of theft, reverse engineering, or misuse; limitations in the availability, scope, or enforceability of intellectual property rights; and challenges in obtaining effective remedies. In some countries in which we operate, intellectual property laws and enforcement mechanisms may be weaker than in the United States, and legal or administrative requirements may require us to compromise protections or yield certain rights to technology, data, or other intellectual property to conduct business in such countries or access certain markets. Any inability to obtain, maintain, or enforce our intellectual property rights in jurisdictions where we operate could result in the loss of competitive advantage, reduced revenue, and other adverse consequences that could affect our business, financial condition, and results of operations.

In addition, our corporate name, trade names, and related brand identity may be subject to challenge. Competitors or other third parties may use trade names, trademarks, or service marks similar to ours, which could impede our ability to build brand identity and lead to third party claims. If we are required to rebrand or change our trade names as a result of third-party claims or other circumstances, we could incur substantial costs related to marketing, packaging, legal compliance, and customer communications, and we may experience operational disruptions and a period of reduced brand recognition that adversely affects demand for our products and services. The collective impact of these risks could be material to our business, financial condition, and results of operations.

Defects or failures in our products or solutions could lead to liability and warranty claims, contractual penalties, and reputational harm.

If our products, manufacturing processes, or design and engineering services contain defects or deficiencies, demand for our offerings may decline, our reputation may be harmed, and we may be exposed to product liability and warranty claims and other customer claims. We also may be required to undertake service-based remediation, such as onsite field service actions, retrofits, or component replacements, and may incur SLA or other contractual penalties, any of which can be costly, disruptive, and exceed remediation costs. Even when customers, suppliers, or third parties are responsible, indemnification may be unavailable, delayed, or inadequate, and insurance may be inadequate, unavailable, or uneconomic.

Because we frequently build to customer specifications, including for hyperscaler and cloud customers, and integrate third-party components, defects may arise or be alleged due to customer design choices, supplier quality issues, component failures, or quality and process variances, including materials, testing, or other supply-chain issues. These issues can halt integration or delay shipments and deployments, require additional service actions


49


Table of Contents

or other corrective measures, increase costs, trigger claims for failure to meet specifications, and damage customer relationships.

As we expand higher-value design, engineering, and solutions offerings, our early-stage execution risks and warranty exposure may increase, and pricing may not fully cover associated warranty and service-remediation costs. Quality or execution issues during ramps can amplify costs and contribute to variability in our results. Integration of control software and firmware in our infrastructure solutions also introduces reliability, interoperability, and cybersecurity risks, including vulnerabilities in third-party or customer-specified software components.

Failure to comply with employment and related laws and regulations could adversely affect our business and financial performance.

We are subject to U.S. and foreign employment, labor, benefits, immigration, and related laws governing, among other things, wage-and-hour, worker classification, workplace safety, anti-discrimination and retaliation, leave and accommodations, collective bargaining and works councils, termination benefits, work authorization, and handling of employee data. These requirements vary by jurisdiction and change frequently, and regulatory actions or changes in labor legislation could facilitate union organizing or impose additional employer obligations. Portions of our workforce are, or may become, represented by labor unions, including as a result of acquisitions or organizing campaigns, and we have experienced organizing activity at certain facilities. Work stoppages, strikes, or other labor disruptions could adversely affect our operations and customer relationships. Government agencies and private plaintiffs, including through class or collective actions, regularly pursue audits, investigations, and enforcement. Adverse outcomes may include monetary penalties, back pay, damages, tax assessments, injunctive or equitable relief requiring changes to our practices, restrictions on staffing models, and immigration-related sanctions. Compliance efforts, disputes, and remediation can be costly and disruptive, and insurance coverage may be limited. Any of the foregoing could materially and adversely affect our business, financial condition, results of operations, and reputation.

We are subject to extensive environmental, health and safety, and producer responsibility laws; violations or alleged violations may result in fines, production suspensions, costly remediation, product recalls, and limitations on facility expansion.

Our operations are regulated by federal, state, local, and international environmental, health and safety, and product stewardship requirements governing worker health and safety; the generation, use, storage, transportation, discharge, and disposal of materials, including hazardous substances; product content and recyclability; and end-of-life producer responsibility. Applicable regimes include the EU Waste Electrical and Electronic Equipment Directive, China’s regulation on electronic information products, and the EU carbon border adjustment mechanism, among others.

We may also face liability to customers regarding materials used in procured components. Non-compliance, or allegations thereof, could lead customers to refuse purchases and could trigger fines, penalties, production suspension, product sales prohibitions, product recalls, and costly changes to operations, procurement, and inventory management. We are responsible for cleanup at certain current and former facilities and at certain third-party sites, and some environmental laws impose strict liability without fault for investigation and remediation of releases. More stringent standards, or new findings of contamination, could increase our liabilities and costs. Additional environmental matters may arise at sites where no issue is currently known or at sites we may acquire.

Evolving sustainability expectations and related disclosure regimes may increase costs, create legal exposure, and adversely impact our operations, talent attraction, and access to capital.

Governments, investors, customers, employees, and other stakeholders continue to focus on sustainability matters, including climate change and greenhouse gas emissions, environmental stewardship, responsible


50


Table of Contents

sourcing, human capital, and related matters. These expectations have led to multiple and evolving reporting regimes, including the EU Corporate Sustainability Reporting Directive (“CSRD”) and California’s climate statutes, and many customers and investors impose sustainability requirements through policies or procurement terms or investment standards. Meeting these expectations and reporting obligations involves operational, financial, legal, regulatory, and reputational risks, may require additional resources and controls, and may be affected by evolving and inconsistent standards for identifying, measuring, and reporting sustainability metrics. At the same time, “anti-ESG/DEI” legislation and policies in certain jurisdictions may impose additional, and potentially conflicting, compliance obligations and litigation risks. Failure or perceived failure to meet goals that we may announce, adhere to public statements, or comply with reporting requirements on announced timelines could adversely affect our reputation, customer relationships, talent recruitment and retention, and investment attractiveness, and could result in enforcement actions or private litigation.

Climate change regulation could disrupt our operations and supply chain and increase our costs.

Several jurisdictions have enacted or are considering climate-related disclosure and due diligence laws, such as the EU CSRD, EU Taxonomy, the EU Corporate Sustainability Due Diligence Directive, and California’s climate statutes, that may directly or indirectly affect our operations and those of our suppliers. Compliance and adaptation may require increased energy, production, transportation, and raw material costs, higher capital expenditures, and higher insurance costs, and inconsistent requirements across jurisdictions may further increase compliance burden. The impact of future climate regulation and policy remains uncertain, and increased public scrutiny regarding climate matters can also affect our reputation. Any of these developments could have a material adverse effect on our business, financial condition, and results of operations.

Risks Related to the Spin-Off

We may not achieve some or all of the expected benefits of the Spin-Off, and the Spin-Off may adversely impact our business.

We may not realize any strategic, financial, operational, or other benefits from the Spin-Off. We cannot predict with certainty if or when anticipated benefits will occur or the extent to which they will be achieved. Following the completion of the Spin-Off, our operational and financial profile will change and we will face new risks. Following the completion of the Spin-Off, we will be a smaller and less-diversified company compared to Flex prior to the Spin-Off, and may be more vulnerable to changing market conditions. As part of Flex, we have been able to enjoy certain benefits from Flex’s operating diversity, size, and purchasing power, as well as opportunities to pursue integrated initiatives with Flex’s other businesses. As an independent, publicly traded company, we will not have the same benefits. While we believe that the Spin-Off will position each company to better unlock its full standalone long-term potential, we cannot assure you that following the Spin-Off we will be successful. Further, there can be no assurance that the combined value of the shares of the two resulting companies will be equal to or greater than what the value of Flex ordinary shares would have been had the Spin-Off not occurred. After the Spin-Off, Flex or we may offer products or engage in businesses that compete with the other company’s products or businesses, subject to the reciprocal restrictions described below.

The non-competition and customer non-solicitation restrictions in the Separation Agreement may limit our ability to compete and pursue certain business opportunities.

The Separation Agreement will impose reciprocal non-competition and customer non-solicitation restrictions applicable worldwide on Spinco and Flex and their respective subsidiaries during the Restricted Period, which will be the three years following the Distribution. Spinco generally would be restricted from engaging in the RemainCo Restricted Business, meaning contract manufacturing services generally but excluding (i) integration of modular power equipment and associated enclosures and (ii) contract manufacturing services in the Cloud & Compute business. For the avoidance of double, the RemainCo Restricted Business includes contract manufacturing services for the Power, Cooling, and Networking product businesses, in any jurisdiction


51


Table of Contents

worldwide. Spinco also generally would be restricted from soliciting any RemainCo Protected Customer. Flex generally would be restricted from engaging in the Spinco Restricted Business, meaning (i) the Power business, excluding contract manufacturing services; (ii) the Cooling business, excluding contract manufacturing services; and (iii) the Cloud & Compute business, including contract manufacturing services generally and for the avoidance of doubt, including contract manufacturing services related to CPU and AI-accelerated servers, compute trays, fabrication of associated racks and enclosures, and integration into those racks, but excluding contract manufacturing services for Networking products, and from soliciting any Spinco Protected Customer. Among other exceptions, (a) Spinco would be permitted to continue contract manufacturing in the Power, Cooling and Networking product businesses only for customers for which Spinco or any member of the Spinco Group has such business as of immediately prior to the Effective Time, including associated future programs with such customers and (b) RemainCo would be permitted to continue the Compute business for certain customers. These restrictions may limit Spinco’s ability to compete in certain markets, pursue certain customers, or complete acquisitions or other strategic transactions during the Restricted Period, which could materially and adversely affect our business, financial condition and results of operations. See “Certain Relationships and Related Transactions—Agreements with Flex—The Separation Agreement—Non-Competition and Customer Non-Solicitation.”

We may incur material costs and expenses as a result of the Spin-Off.

We may incur costs and expenses greater than those we currently expect to incur as a result of the Spin-Off. These increased costs and expenses may arise from various factors, including financial reporting and costs associated with complying with federal securities laws (including compliance with Sarbanes-Oxley Act of 2002, as amended (the “Sarbanes-Oxley Act”)). We will also incur ongoing costs and dis-synergies in connection with, or as a result of, the separation and related restructuring transactions, including costs of operating as independent, publicly traded companies that the two businesses will no longer be able to share. We cannot assure you that these costs will not be material to our business.

We may not be able to prevent or detect all errors or fraud, and as a newly standalone public company, we will need to establish our own internal control environment.

As a newly standalone public company following the Spin-Off, we will need to establish and maintain our own financial, accounting, and reporting systems and internal control over financial reporting. Certain functions for our business have historically been performed or supported by Flex, and following the separation, we must implement these functions independently. We may face challenges in designing and implementing controls that were previously provided by Flex or that must be modified to reflect our standalone operations, and there can be no assurance that we will successfully establish and maintain adequate internal controls.

Due to the inherent limitations of internal control systems, misstatements due to error or fraud may occur and may not be detected in a timely manner or at all. Over time, certain aspects of a control system may become inadequate because of changes in conditions, or the degree of compliance with policies or procedures may deteriorate. In connection with our ongoing assessment of the effectiveness of our internal control over financial reporting, we may discover “material weaknesses” in our internal controls that could result in material misstatements not being prevented or detected on a timely basis.

The existence of any material weakness may require significant management time and remediation expense, may result in errors requiring corrective adjustments or restatements, may cause us to fail to meet reporting obligations, and may cause shareholders to lose confidence in our reported financial information, any of which could materially and adversely affect the market price of our securities and our ability to maintain compliance with securities laws and stock exchange listing requirements.


52


Table of Contents

If we fail to maintain proper and effective internal controls, our ability to produce accurate and timely financial statements could be impaired, our stock price and our ability to access the capital markets could be adversely impacted, and investors’ views of us could be harmed.

The Sarbanes-Oxley Act requires, among other things, that we maintain effective internal control over financial reporting and disclosure controls and procedures. In particular, we must perform system and process evaluation and testing of our internal control over financial reporting to allow management and our independent registered public accounting firm to report on the effectiveness of our internal control over financial reporting, as required by Section 404 of the Sarbanes-Oxley Act, with auditor attestation of the effectiveness of our internal controls, beginning as early as our second required annual report on Form 10-K based on current SEC rules. To comply with these requirements, we may need to upgrade our systems, implement additional financial and management controls, reporting systems and procedures and hire additional accounting and finance staff. We expect to incur additional annual expenses for the purpose of addressing these and other public-company reporting requirements. If we are unable to upgrade our financial and management controls, reporting systems, IT systems and procedures in a timely and effective fashion, our ability to comply with financial reporting requirements and other rules that apply to reporting companies under the Exchange Act, could be impaired. If we are not able to comply with the requirements of Section 404 in a timely manner or if we or our independent registered public accounting firm identifies deficiencies in our internal control over financial reporting that are deemed to be material weaknesses, the market price of shares of common stock could decline and we could be subject to sanctions or investigations by the SEC or other regulatory authorities, which would require additional financial and management resources.

Our ability to comply with Section 404 requires us to be able to prepare timely and accurate financial statements. Any delay in the implementation of, or disruption in the transition to, new or enhanced systems, procedures or controls may cause our operations to suffer, and we may be unable to conclude that our internal control over financial reporting is effective and to obtain an unqualified report on internal controls from our auditors as required under Section 404 of the Sarbanes-Oxley Act. Moreover, we cannot be certain that these measures would ensure that we implement and maintain adequate controls over our financial processes and reporting in the future. Even if we were to conclude, and our auditors were to concur, that our internal control over financial reporting provided reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with GAAP, because of its inherent limitations, internal control over financial reporting might not prevent or detect fraud or misstatements. This, in turn, could have an adverse impact on trading prices for our shares of common stock and could adversely affect our ability to access the capital markets. See “—Risks Related to the Spin-Off—As we build our IT infrastructure and transition our data to our own systems, we could incur substantial additional costs and experience temporary business interruptions, including cybersecurity incidents.”

We are being spun-off from our parent company, Flex, and our historical and pro forma financial information is not necessarily representative of the results that we would have achieved as a separate, publicly traded company and, therefore may not be a reliable indicator of our future results.

We are being spun-off from our parent company, Flex, and have no operating history as an independent, publicly traded company. The historical information about us in this information statement refers to our business as part of pre-Spin-Off Flex. Our historical and pro forma financial information included in this information statement is derived from the combined financial statements and accounting records of Flex. Accordingly, the historical and pro forma financial information included in this information statement does not necessarily reflect the financial condition, results of operations, or cash flows that we would have achieved as a separate, publicly traded company during the periods presented or those that we will achieve in the future primarily as a result of the factors described below:


we may need to make significant investments to replicate or outsource certain systems, infrastructure, and functional expertise after the Spin-Off. These initiatives to develop our independent ability to operate will be costly to implement. We may not be able to operate our business as efficiently or at comparable costs, and our profitability may decline;


53


Table of Contents
   

how we finance our working capital or other cash requirements may differ from how we financed those requirements as part of pre-Spin-Off Flex. After the Spin-Off, our access to and cost of debt financing will be different from the historical access to and cost of debt financing under pre-Spin-Off Flex. Differences in access to and cost of debt financing are likely to result in differences in interest rates charged to us on financings, the amounts of indebtedness, types of financing structures and debt markets that may be available to us, which may have an adverse effect on our business, financial condition, results of operations, and cash flows; and


in preparing our financial statements, pre-Spin-Off Flex made allocations of costs and corporate expenses deemed to be attributable to our business. However, these costs and expenses reflect the costs and expenses attributable to our business operated as part of a larger organization and do not necessarily reflect costs and expenses that would be incurred by us had we been operating independently. As a result, our historical financial information may not be a reliable indicator of future results.

For additional information about the past financial performance of our business and the basis of presentation of the historical combined financial statements and the unaudited pro forma combined financial statements of our business, see the sections of this information statement entitled “Unaudited Pro Forma Condensed Combined Financial Information,” “Notes to Unaudited Pro Forma Condensed Combined Financial Information,” “Summary of Historical and Unaudited Pro Forma Combined Financial Data” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” as well as the combined financial statements and accompanying notes, included elsewhere in this information statement.

Flex may fail to perform under various transaction agreements that will be executed as part of the Spin-Off, or we may fail to have necessary systems and services in place when Flex is no longer obligated to provide services under the various agreements.

We and Flex will enter into certain agreements, such as the Separation Agreement, a Transition Services Agreement, a Tax Matters Agreement, an Employee Matters Agreement, an Intellectual Property Matters Agreement, a Stockholder’s and Registration Rights Agreement, Cross-Supply Agreements, and a Site Services Agreement, as discussed in greater detail in the section of this information statement entitled “Certain Relationships and Related Transactions—Agreements with Flex,” which may provide for the performance by each company for the benefit of the other for a period of time after the Spin-Off. If Flex is unable to satisfy its obligations under these agreements, including its indemnification obligations in favor of us, we could incur operational difficulties or losses.

If we do not have in place our own systems and services, and do not have agreements with other providers of these services when the transitional or other agreements terminate, or if we do not implement the new systems or replace Flex’s services successfully, we may not be able to operate our business effectively, which could disrupt our business and have a material adverse effect on our business, financial condition, and results of operations. These systems and services may also be more expensive to install, implement, and operate, or less efficient than the systems and services Flex is expected to provide during the transition period.

In connection with the Spin-Off, Flex will indemnify us for certain liabilities. However, there can be no assurance that the indemnity will be sufficient to protect us against the full amount of such liabilities, or that Flex’s ability to satisfy its indemnification obligations will not be impaired in the future.

Flex will agree to indemnify us for certain liabilities as discussed further in the section of this information statement entitled “Certain Relationships and Related Transactions.” However, third parties could also seek to hold us responsible for liabilities that Flex has agreed to retain, and there can be no assurance that the indemnity from Flex will be sufficient to protect us against the full amount of such liabilities, or that Flex will be able to fully satisfy its indemnification obligations. In addition, Flex’s insurers may attempt to deny coverage to us for liabilities associated with certain occurrences of indemnified liabilities prior to the Spin-Off.


54


Table of Contents

In connection with our separation, we will assume and indemnify Flex for certain liabilities. If we are required to make payments pursuant to these indemnities to Flex, we would need to meet those obligations and our financial results could be adversely impacted.

We will agree to assume and indemnify Flex for, certain liabilities as discussed further in the section of this information statement entitled “Certain Relationships and Related Transactions.” Payments pursuant to these indemnities may be significant and could adversely impact our business, financial condition, results of operations, and cash flows, particularly indemnities relating to our actions that could impact the tax-free nature of the Distribution.

If the Distribution, together with certain related transactions, does not qualify for the Intended Tax Treatment, you and Flex could be subject to significant U.S. federal income tax liability and, in certain circumstances, we could be required to indemnify Flex for material taxes pursuant to indemnification obligations under the anticipated Tax Matters Agreement.

It is a condition to the completion of the Distribution that Flex receives the Tax Opinion, substantially to the effect that, among other things, the Distribution, together with certain related transactions, will qualify for the Intended Tax Treatment and that holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code. However, this condition may be waived by Flex in its sole discretion. The Tax Opinion will rely on certain facts, assumptions, representations, and undertakings from Flex and us, including those regarding the past and future conduct of the companies’ respective businesses and other matters. Nevertheless, an opinion of counsel, such as the Tax Opinion, neither binds the IRS nor precludes the IRS or the courts from adopting a contrary position. Moreover, Flex does not intend to request a ruling from the IRS on issues related to the U.S. federal income tax consequences of the Distribution and certain related transactions. Therefore, notwithstanding the Tax Opinion, the IRS could determine that the Distribution or any such related transaction is taxable if it determines that any of these facts, assumptions, representations, or undertakings are not correct or have been violated, or that the Distribution should be taxable for other reasons, including if the IRS were to disagree with the conclusions in the Tax Opinion. For more information regarding the Tax Opinion, see the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.”

If the Distribution or any of the above referenced related transactions is determined to be taxable for U.S. federal income tax purposes, a shareholder of Flex that has received shares of our stock in the Distribution and Flex could each incur significant U.S. federal income tax liabilities. In addition, Flex and we could incur significant U.S. federal income tax obligations, whether under applicable law or under the Tax Matters Agreement that we intend to enter into with Flex. For a discussion of the tax consequences of the Distribution, together with certain related transactions, please refer to the section entitled “United States Federal Income Tax Consequences of the Distribution.”

To preserve the tax-free treatment to Flex and its shareholders of the Distribution and certain related transactions, under the Tax Matters Agreement that we anticipate entering into with Flex, we will be restricted from taking certain actions after the Distribution that could adversely impact the Intended Tax Treatment of the Distribution and such related transactions.

To preserve the tax-free treatment to Flex and its shareholders of the Distribution and certain related transactions, under the Tax Matters Agreement that we anticipate entering into with Flex, we may be restricted from taking certain actions after the Distribution that could adversely impact the Intended Tax Treatment of the Distribution, together with certain related transactions. Failure to adhere to any such restrictions, including in certain circumstances that may be outside of our control, could result in tax being imposed on Flex for which we could bear responsibility and for which we could be obligated to indemnify Flex. In addition, even if we are not responsible for tax liabilities of Flex under the anticipated Tax Matters Agreement, we nonetheless could potentially be liable under applicable tax law for certain of such liabilities if such taxes were not paid.


55


Table of Contents

The terms of the anticipated Tax Matters Agreement may, furthermore, restrict us from taking certain actions, particularly for the two years following the Spin-Off, including (among other things) the ability to freely issue stock, to merge or agree to merge with a third party, to be acquired or agree to be acquired by certain parties and to raise additional equity capital. Any such restrictions could impair our ability to implement strategic initiatives. Also, any indemnity obligation to Flex might discourage, delay or prevent a change of control that we or our shareholders may otherwise consider favorable. These restrictions may limit our ability to enter into certain strategic transactions or other transactions that we may believe to be in the best interests of our shareholders or that might increase the value of our business. In addition, under the anticipated Tax Matters Agreement, we may be required to indemnify Flex against certain tax liabilities as a result of the acquisition of our stock or assets, even if we did not participate in or otherwise facilitate the acquisition. For a discussion of the Tax Matters Agreement, see the section of this information statement entitled “Certain Relationships and Related Transactions—Agreements with Flex—Tax Matters Agreement.”

There is uncertainty regarding the potential application of Section 367(b) of the Code to the Distribution, which could result in material U.S. federal income tax liability to U.S. Holders.

The U.S. federal income tax treatment of the Distribution to U.S. Holders (as defined in the section entitled “United States Federal Income Tax Consequences of the Distribution”) depends in part on the interpretation and application of Section 367(b) of the Code and certain Treasury Regulations promulgated thereunder, including Treasury Regulations Section 1.367(b)-3(c). Flex understands that it is not possible for its tax counsel, Skadden, to reach a more definitive conclusion regarding whether holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) are required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code, as the U.S. federal income tax treatment of the Distribution to such holders depends in part on the interpretation and application of Section 367(b) of the Code and Treasury Regulations promulgated thereunder, including Treasury Regulations Section 1.367(b)-3(c). These rules are complex, and there is significant uncertainty as to whether such Treasury Regulations should be interpreted as applying to the Distribution because Flex is a non-U.S. corporation that is not a controlled foreign corporation for U.S. federal income tax purposes, and the Distribution is structured as a pro rata distribution of Spinco common stock to holders of Flex ordinary shares. Thus, the applicability of these Treasury Regulations is unclear.

Accordingly, certain conclusions in the Tax Opinion will relate to matters for which there is no legal authority directly on point, and such conclusions will therefore necessarily be based upon analysis and interpretation of certain authorities. Based upon such analysis and authorities, the Tax Opinion will provide that holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code.

Flex does not intend to request a ruling from the IRS on issues related to the U.S. federal income tax consequences of the Distribution and certain related transactions. Moreover, the Tax Opinion will not be binding upon the IRS or any court. As such, there is a risk that the IRS could assert, contrary to the conclusions reached in the Tax Opinion, that Treasury Regulations Section 1.367(b)-3(c) does apply to the Distribution.

If the IRS were to successfully assert that such Treasury Regulations apply to the Distribution, the receipt of Spinco common stock pursuant to the Distribution would be taxable to a U.S. Holder whose Flex ordinary shares have a fair market value of $50,000 or more on the Distribution Date, and such U.S. Holder would be required to recognize gain (but not loss) upon the Distribution, but there is no clear guidance regarding how such gain should be computed. Such amounts may be significant, potentially resulting in material U.S. federal income tax liabilities. However, if the fair market value of a U.S. Holder’s Flex ordinary shares is less than $50,000 on the Distribution Date, these rules would not apply, and the Distribution would not be taxable to such holder pursuant to such rules. U.S. Holders are urged to consult their tax advisor as to the applicability of these Treasury Regulations and how to determine the amount of any gain that would be required to be recognized. See the section entitled “United States Federal Income Tax Consequences of the Distribution” for more information.


56


Table of Contents

The Spin-Off and related internal restructuring transactions may expose us to potential liabilities arising out of state and federal fraudulent conveyance laws and legal dividend requirements.

Although the Flex Board of Directors expects to receive a solvency opinion, the Spin-Off could be challenged under various state and federal fraudulent conveyance laws. Fraudulent conveyances or transfers are generally defined to include (a) transfers made or obligations incurred with the actual intent to hinder, delay or defraud current or future creditors or (b) transfers made or obligations incurred for less than reasonably equivalent value when the debtor was insolvent, or that rendered the debtor insolvent, inadequately capitalized or unable to pay its debts as they become due. A creditor or an entity acting on behalf of a creditor (including, without limitation, a trustee or debtor-in-possession in a bankruptcy by us or Flex or any of our or its respective subsidiaries) may bring a lawsuit alleging that the Spin-Off or any of the related transactions constituted a fraudulent conveyance. If a court accepts these allegations, it could impose a number of remedies, including, without limitation, voiding the Distribution and returning our assets or shares and subjecting Flex and/or us to liability.

We may have received better terms from unaffiliated third parties than the terms we will receive in our agreements with Flex.

The agreements we will enter into with Flex in connection with the Spin-Off, including the ancillary agreements, were prepared while we were still a wholly owned subsidiary of Flex. Accordingly, during the period in which the terms of those agreements were prepared, we did not have a board of directors or management team that was independent of Flex. While the parties believe the terms reflect arm’s-length terms, there can be no assurance that we would not have received better terms from unaffiliated third parties than the terms we will receive in our agreements with Flex. For more information, see the section of this information statement entitled “Certain Relationships and Related Transactions—Agreements with Flex.”

Some contracts and other assets which will need to be transferred or assigned from Flex or its affiliates to us in connection with the Spin-Off may require the consent of a third party. If such consent is not given, we may not be entitled to the benefit of such contracts and other assets in the future, which could adversely impact our financial condition and future results of operations.

In connection with the Spin-Off, a number of contracts and licenses with third-parties and other assets are to be transferred or assigned from (x) Flex or its affiliates to us or our anticipated subsidiaries or (y) us or our affiliates to Flex or its subsidiaries. However, the transfer or assignment of certain of these contracts, licenses, or assets may require the consent of a third party to such a transfer or assignment. Similarly, in some circumstances, we and another business unit of Flex are joint beneficiaries of contracts, and we or Flex will need to (x) enter into a new agreement with the third-party to replicate the existing contract, (y) be assigned and delegated the portion of the existing contract related to the applicable business or (z) use commercially reasonable efforts to provide for an alternative arrangement to obtain the same or reasonably similar benefits and burdens of the applicable portion of the existing contract. It is possible that some parties may use the requirement of a consent or the fact that the Spin-Off is occurring to seek more favorable contractual terms from us, to terminate the contract or license or to otherwise request additional accommodations, commitments, or other agreements from us. If we are unable to obtain such consents on commercially reasonable and satisfactory terms or if the contracts are terminated, we may be unable to obtain the benefits, assets, and contractual commitments which are intended to be allocated to us as part of the Spin-Off. The failure to timely complete the assignment of existing contracts, licenses, or assets, or the negotiation of new arrangements, or a termination of any of those arrangements, could have a material adverse impact on our financial condition and future results of operations. To the extent we require a specific arrangement and agree to less favorable terms in connection with obtaining any consent to retain that arrangement, the basis for that arrangement may be less favorable than currently held by us and could adversely impact our financial conditions and future results of operations. In addition, where we do not intend to obtain consent from third-party counterparties based on our belief that no consent is required, the third-party counterparties may challenge a transfer of assets on the basis that the terms of the applicable commercial arrangements require the third-party counterparties’ consent. We may incur substantial litigation and other costs in connection with any such claims and, if we do not prevail, our ability to use these assets could be materially and adversely impacted.


57


Table of Contents

In connection with the Spin-Off, we expect to incur debt obligations that could materially and adversely affect our business, results of operations, cash flows, and financial condition.

In connection with the completion of the Spin-Off, we expect to incur indebtedness of up to $4.4 billion pursuant to the Spinco Financing Arrangements and to complete the Spinco Cash Distribution to Flex. The terms of such indebtedness are subject to change and will be finalized prior to the closing of the Spin-Off.

Our ability to make payments on and to refinance our indebtedness, including the debt incurred in connection with the Spin-Off, as well as any future debt that we may incur, will depend on our ability to generate cash in the future from operations, financings or asset sales. Our ability to generate cash is subject to general economic, financial, competitive, legislative, regulatory and other factors that are beyond our control, as well as the risk factors set forth herein.

If our cash flow from operations is less than we anticipate, or if our cash requirements are more than we expect, we may require additional access to capital and may need to incur additional debt or raise additional funds.

If our cash flow from operations is less than we anticipate, or if our cash requirements are more than we expect, we may require additional access to capital and may need to incur additional debt or raise additional funds. However, debt or equity financing may not be available to us on terms acceptable or favorable to us, if at all, and will depend on a number of factors, many of which are beyond our control, such as the state of the credit and financial markets and other economic, financial, and geopolitical factors. If we incur additional debt or raise capital through the issuance of preferred stock, the terms of the debt or preferred stock issued may give the holders thereof rights, preferences, and privileges senior to those of holders of our common stock, particularly in the event of liquidation. The terms of such debt may also impose additional and more stringent restrictions on our operations than we are currently subject to. If we raise funds through the issuance of additional equity, your percentage ownership in us would be diluted. If we are unable to raise additional capital when needed, it could affect our financial condition, which could adversely impact your investment in us.

Following the Spin-Off, the value of your ordinary shares of Flex and common stock of Spinco may collectively trade at an aggregate price less than what Flex ordinary shares might have traded at had the Spin-Off not occurred.

The ordinary shares of Flex and common stock of Spinco that you may hold following the Spin-Off may collectively trade (taking into account the Distribution Ratio) at a value less than the price at which Flex ordinary shares might have traded had the Spin-Off not occurred or as it was trading prior to the Spin-Off. Reasons for this potential difference include the future performance of either Flex or Spinco as separate, independent companies, and the future shareholder base and market for Flex ordinary shares and Spinco’s common stock and the prices at which such shares individually trade.

Until the Distribution occurs, Flex has the sole discretion to change the terms of the Spin-Off in ways which may be unfavorable to us.

Completion of the Distribution will be contingent upon the satisfaction or waiver of customary conditions, including, among other things, the effectiveness of appropriate filings with the SEC. For a more detailed description of these conditions, see the section of this information statement entitled “The Separation and Distribution—General—Conditions to the Distribution.” Until the Distribution occurs, Flex will have the sole and absolute discretion to determine and change the terms of the Spin-Off, including the allocation of assets and liabilities, the establishment of the Distribution Record Date and distribution date, the conditions to the Distribution, and all other terms. These changes could be unfavorable to us. In addition, until the Spin-Off has occurred, Flex has the right not to complete the Spin-Off, even if all the conditions have been satisfied, if, at any time prior to the Distribution, the Flex Board of Directors determines, in its sole discretion, that the Spin-Off is not in the best interests of Flex, that a sale or other alternative is in the best interests of Flex, or that market conditions or other circumstances are such that it is not advisable at that time to separate our business from Flex. We cannot provide any assurances that the Distribution will be completed.


58


Table of Contents

Certain entities or assets that are part of our separation from Flex may not be transferred to us at or prior to the Distribution or at all.

Certain entities and assets that are part of our separation from Flex may not be transferred at or prior to the Distribution because the entities or assets, as applicable, are subject to governmental or third-party approvals that we may not receive prior to the Distribution. It is currently anticipated that all material transfers will occur without material delays beyond the Distribution, but we cannot offer any assurance that such transfers will ultimately occur or not be delayed for an extended period of time. To the extent such transfers do not occur at or prior to the Distribution, under the separation and distribution agreement, the benefits and burdens of owning such assets and/or entities will, to the extent reasonably possible and permitted by applicable law, be provided to the applicable party.

In the event such transfers do not occur or are significantly delayed because we do not receive the required approvals, we may not realize all of the anticipated benefits of our separation from Flex and we may be dependent on Flex for transition services for a longer period of time than would otherwise be the case.

The separation could give rise to disputes or other unfavorable effects, which could materially and adversely affect our business, financial condition, and results of operations.

The separation may lead to increased operating and other expenses, of both a nonrecurring and a recurring nature, and to changes to certain operations, which expenses or changes could arise pursuant to arrangements made between Flex and us or could trigger contractual rights of, and obligations to, third parties. Disputes with third parties could also arise out of these transactions, and we could experience unfavorable reactions to the separation from employees, lenders, ratings agencies, regulators, or other interested parties. These increased expenses, changes to operations, disputes with third parties, or other effects could materially and adversely affect our business, financial condition, and results of operations. In addition, following the separation, disputes with Flex could arise in connection with one or more of the ancillary agreements or certain other agreements.

Ms. Advaithi will serve as our Chief Executive Officer and as one of our directors as well as the non-executive chair of the Flex Board of Directors, and certain of our directors and executive officers will continue to own shares or equity awards of Flex, which overlap may give rise to conflicts of interest.

Following the Distribution, Ms. Advaithi will serve as our Chief Executive Officer and as one of our directors. Ms. Advaithi is also expected to fill a transitional role as the non-executive chair of the Flex Board of Directors. Ms. Advaithi may have actual or apparent conflicts of interest with respect to matters involving or affecting each of Flex or Spinco. For example, there will be the potential for a conflict of interest when we on the one hand, and Flex and its respective subsidiaries and successors on the other hand, are party to commercial transactions concerning the same or adjacent investments. In addition, after the Distribution, even though our board of directors will consist of a majority of directors who are independent, and any of our expected executive officers who are currently employees of Flex will cease to be employees of Flex, certain of our directors and executive officers will continue to have financial interests in Flex ordinary shares. However, no director or executive officer of Spinco is expected to beneficially own 1% or more of Flex ordinary shares following the Distribution. These financial interests could create actual, apparent, or potential conflicts of interest if we and Flex pursue the same corporate opportunities or when these individuals are faced with decisions that could have different implications for our company and Flex. See “Certain Relationships and Related Transactions—Procedures for Approval of Related Person Transactions” for a discussion of certain procedures we will institute to help ameliorate such potential conflicts that may arise.

The separation may result in disruptions to relationships with customers, suppliers, and other business partners.

While we intend to manage our operations to minimize any disruptions to our customers, suppliers, and business partners, uncertainty related to the separation may nevertheless lead to disruption in those relationships. These disruptions, if not managed by us, could have an adverse effect on our business, financial condition, results of operations, and prospects.


59


Table of Contents

After the separation, we may be unable to make, on a timely or cost-effective basis, the changes necessary to operate as an independent company, and we may experience a loss of institutional knowledge as a result of employee transitions.

At the completion of the separation, we may not have the infrastructure, systems, or personnel necessary to operate effectively as an independent company, including with respect to the functionality and reliability of our information technology systems, without relying on Flex to provide certain transitional services. We may need additional personnel or third-party service providers to successfully operate our business. Upon the completion of the separation, we will enter into a transition services agreement with Flex pursuant to which we will provide certain services to Flex, and Flex will provide certain services to us, to allow us to continue to operate in substantially the same manner following the separation and to benefit from the continuation of certain services for a certain amount of time post-separation and certain cost efficiencies in sharing certain resources and personnel. We cannot assure you that we will be able to successfully implement the infrastructure or retain or hire the personnel necessary to operate as a separate company or that we will not incur costs in excess of anticipated costs to establish such infrastructure and retain or hire such personnel.

In addition, in connection with the Spin-Off, certain employees who have historically supported our business may remain with Flex, retire, or otherwise depart. These employees may possess significant institutional knowledge regarding our operations, customer relationships, supply chain, technology systems, and business processes that have been accumulated over many years. The loss of such institutional knowledge could result in operational inefficiencies, delays in decision-making, disruptions to customer and supplier relationships, and increased costs as we train new personnel or hire replacements. The departure of key personnel with specialized expertise could also impair our ability to maintain continuity in our operations and strategic initiatives. Even where employees transfer to us from Flex, changes in organizational structure, reporting relationships, or corporate culture following the Spin-Off could result in the departure of valuable employees who might otherwise have remained. We may not be able to fully replicate or retain the institutional knowledge held by departing employees, which could have a material adverse effect on our business, financial condition, and results of operations.

The physical separation and reorganization of manufacturing operations in connection with the Spin-Off may disrupt our business and result in increased costs.

In connection with the Spin-Off, we will be required to physically separate and reorganize certain manufacturing operations. This process may involve the relocation of manufacturing equipment and production lines, the division or reconfiguration of shared manufacturing facilities, the establishment of new manufacturing capabilities, and the reconfiguration of supply chain and logistics networks. These activities are complex and may result in significant costs, production downtime, unabsorbed labor and overhead, or delays in fulfilling customer orders. During the transition period, we may experience disruptions to manufacturing continuity, including interruptions in production schedules, reduced manufacturing capacity, quality control issues, or inefficiencies as we establish standalone operations. The transfer of manufacturing know-how, processes, and institutional knowledge from Flex may not occur smoothly or completely, which could adversely affect our ability to maintain product quality and operational efficiency. In addition, the allocation of manufacturing capacity, equipment, and facilities between Spinco and Flex may not be optimal for our business needs, and we may need to incur significant capital expenditures to build or acquire additional manufacturing capacity.

The transfer of certain employees from Flex to us contemplated by the separation will not be complete at the time of the Distribution.

In connection with the separation, Flex has agreed to transfer to us, through asset transfers, dividends, contributions and similar transactions, the entities, assets, liabilities and obligations that we will hold following the separation of our business from Flex’s other businesses. As set forth more fully in “The Separation and Distribution” and “Certain Relationships and Related Transactions,” we expect to enter into the Separation Agreement and a number of other agreements with Flex prior to the Distribution.


60


Table of Contents

Certain of these transactions will not be complete at the time of the Distribution. In particular, at the completion of the Distribution, we expect that a substantial portion of the employees that support our business in certain jurisdictions will remain employed by legal entities that are owned by Flex and not by us. While we have entered into the Employee Matters Agreement and the Transition Services Agreement with Flex that, together, provide for the eventual transfer of such employees to us following the completion of the Distribution (as well as certain other terms, including the allocation of employee-related liabilities and how such employees’ efforts must be directed), future developments such as unanticipated delays in setting up business operations or fulfilling applicable legal or regulatory requirements necessary to employ such employees in the countries in which we operate are difficult to predict, and could prevent or further delay the transfer of certain employees to legal entities owned by us, which could deprive us of key personnel and adversely impact our business and results of operations.

Risks Related to Our Common Stock

We cannot be certain that an active trading market for our common stock will develop or be sustained after the Spin-Off and, following the Spin-Off, our stock price may fluctuate significantly.

A public market for our common stock does not currently exist. We expect that shortly before the Distribution Date, trading of shares of our common stock will begin on a “when-issued” basis on     and will continue through the Distribution Date. However, we cannot guarantee that an active trading market will develop or be sustained for our common stock after the Spin-Off. If an active trading market does not develop, our shareholders may have difficulty selling their shares of our common stock at an attractive price, or at all. Nor can we predict the prices at which shares of our common stock may trade after the Spin-Off.

Similarly, we cannot predict the effect of the Spin-Off on the trading prices of our common stock. Subject to the completion of the Spin-Off, we expect our common stock to be listed and traded on Nasdaq under the symbol “AXM.” The combined trading prices of Flex ordinary shares and our common stock after the separation, as adjusted for any changes in the combined capitalization of these companies, may not be equal to or greater than the trading price of Flex ordinary shares prior to the Spin-Off. Until the market has fully evaluated the business of Flex without our business, or fully evaluated us, the price at which Flex ordinary shares or our common stock trades may fluctuate significantly.

Our common stock may not be listed on Nasdaq, which could negatively impact the price of our common stock and your ability to sell our common stock.

Approval of our listing application by Nasdaq is a condition to the Distribution, and we intend to apply to have our common stock listed on Nasdaq under the symbol “AXM.” However, there can be no assurance that we will be able to meet Nasdaq’s initial listing requirements. If we fail to satisfy the initial listing requirements or Nasdaq exercises its discretion to deny our listing application, the Distribution may not occur, or, if the condition is waived and the Distribution occurs, our common stock would not be listed on a national securities exchange. In such case, our stock could be quoted on an over-the-counter market. These quotation services are generally considered to be a less efficient and less visible market than a national securities exchange. Trading on an over-the-counter market could reduce the liquidity and market price of our common stock and may make it more difficult for investors to buy or sell shares of our common stock.

The market price of our common stock may fluctuate significantly due to a number of factors, some of which may be beyond our control, including:


our business profile, market capitalization, or capital allocation policies may not fit the investment objectives of Flex’s current shareholders, causing a shift in our investor base and our common stock may not be included in some indices in which Flex ordinary shares are included, causing certain holders to sell their shares of our common stock;


our quarterly or annual earnings, or those of other companies in our industry;


the failure of securities analysts to cover our common stock after the Spin-Off;


61


Table of Contents
   

actual or anticipated fluctuations in our results of operations;


changes in earnings estimates by securities analysts or our ability to meet those estimates;


our ability to meet our forward looking guidance;


the operating and stock price performance of other comparable companies;


overall market fluctuations and domestic and worldwide economic conditions; and


other factors described in this “Risk Factors” section and elsewhere in this information statement.

Stock markets in general have experienced volatility that has often been unrelated to the operating performance of a particular company. Broad market and industry factors may materially harm the market price of our common stock, regardless of our operating performance. In the past, following periods of volatility in the market price of a company’s securities, shareholder derivative lawsuits, and/or securities class action litigation has often been instituted against such company. Such litigation, if instituted against us, could result in substantial costs and a diversion of management’s attention and resources.

In addition, investors may have difficulty accurately valuing our common stock. Investors often value companies based on the stock prices and results of operations of other comparable companies. Investors may find it difficult to find comparable companies and to accurately value our common stock, which may cause the trading price of our common stock to fluctuate.

Any sales of substantial amounts of shares of our common stock in the public market, or the perception that such sales might occur, in connection with the Distribution or otherwise, may cause the market price of our common stock to decline.

Upon completion of the Distribution, we expect that we will have an aggregate of approximately     shares of our common stock issued and outstanding based upon approximately     Flex ordinary shares issued and outstanding as of      , 2026. The shares of our common stock will be freely tradeable without restriction or further registration under the Securities Act of 1933, as amended (the “Securities Act”), unless the shares are owned by one of our “affiliates,” as that term is defined in Rule 405 under the Securities Act.

We are unable to predict whether large amounts of our common stock will be sold in the open market following the Spin-Off. We are also unable to predict whether a sufficient number of buyers would be in the market at that time. Flex investors who have an investment strategy of tracking an index fund may sell the shares of Spinco common stock that they receive in the Distribution if Spinco is not listed on the same index. As a result, the price of Spinco common stock may decline or experience volatility as Spinco’s shareholder base changes. Whether related to the foregoing or otherwise, sales of substantial amounts of shares of our common stock in the public market following the Spin-Off, or the perception that such sales might occur, may cause the market price of our common stock to decline.

In addition, Flex is retaining between approximately 6.0% to 12.0% of our common stock. Flex intends to dispose of such shares of Spinco common stock that it owns after the Distribution through one or more subsequent exchanges of Spinco common stock for Flex debt held by Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, in each case during the 24-month period following the Distribution. Any disposition by Flex, or any significant shareholder, of Spinco common stock, or the perception that such dispositions could occur, could adversely affect prevailing market prices for Spinco common stock.

We do not intend to pay cash dividends for the foreseeable future.

The timing, declaration, amount, and payment of future dividends to shareholders falls within the discretion of our board of directors and will depend on many factors, including our financial condition, earnings, capital requirements of our business, and covenants associated with debt obligations, as well as legal requirements,


62


Table of Contents

regulatory constraints, industry practice, and other factors that our board of directors deems relevant. We do not intend to, and there can be no assurance that we will, pay any dividend in the future.

Your percentage of ownership in us may be diluted in the future.

Your percentage ownership in us may be diluted because of equity issuances of our common stock for acquisitions, capital market transactions or otherwise, including, without limitation, equity awards that we may grant to our directors, officers, and employees. Such issuances may have a dilutive effect on our earnings per share, which could adversely affect the market price of our common stock.

In addition, our amended and restated certificate of formation will authorize us to issue, without the approval of our shareholders, one or more classes or series of preferred stock having such designation, powers, preferences, and relative, participating, optional, and other special rights, including preferences over our common stock respecting dividends and distributions, as our board of directors generally may determine. The terms of one or more classes or series of preferred stock could dilute the voting power or reduce the value of our common stock. For example, we could grant the holders of preferred stock the right to elect some number of our directors in all events or on the happening of specified events or to veto specified transactions. Similarly, the repurchase or redemption rights or liquidation preferences we could assign to holders of preferred stock could affect the residual value of our common stock. See the section entitled “Description of Capital Stock.”

The Warrant issued to Amazon may result in additional dilution of our common stock in connection with the Distribution.

On August 15, 2025, Flex issued a warrant (the “Warrant”) to Amazon.com NV Investment Holdings LLC (the “Warrantholder”), a wholly-owned subsidiary of Amazon.com, Inc. (“Amazon”), to purchase up to an aggregate of 3,859,851 ordinary shares of Flex (the “Warrant Shares”) at an exercise price of $51.29 per share, which expires on August 15, 2030. The Warrant Shares are subject to vesting based on qualifying payments (as defined in the Warrant) for the purchase of all products and services by or on behalf of Amazon and its affiliates over the term of the Warrant. The Warrant also provides that, upon certain distributions (which would include the Distribution), the exercise price will be adjusted, concurrent with the Distribution Record Date, by reducing the exercise price by the per share fair market value (as defined in the Warrant) of the Distribution. The Warrant further provides that the exercise price may not be reduced below $0.01 per share and that if the exercise price becomes $0.01, then the Warrantholder will be entitled to participate in the Distribution as if the Warrantholder had previously exercised and would be the holder of all Warrant Shares, whether vested or not, subject to the Warrant before the Distribution Record Date. Flex, Spinco and the Warrantholder are negotiating and expect to execute an amendment to the Warrant which will provide that, instead of Spinco shares, the Warrantholder would receive a fully vested warrant to purchase up to a specified number of Spinco shares at an exercise price of $0.01 per share (the “Spinco Warrant”). As a result, we expect that the exercise price of the Flex Warrant will be reduced to $0.01 per share and that, upon the consummation of the Distribution, the Warrantholder will receive the Spinco Warrant.

Provisions of Texas law, our amended and restated certificate of formation and our amended and restated bylaws, may prevent or delay an acquisition of our company, which could decrease the market price of Spinco common stock.

Texas law contains, and our amended and restated certificate of formation and amended and restated bylaws will contain, provisions that are intended to deter coercive takeover practices and inadequate takeover bids by making such practices or bids unacceptably expensive to the bidder and to encourage prospective acquirers to negotiate with our board of directors rather than to attempt a hostile takeover. These provisions include, among others:


provisions regarding the election of directors, classes of directors, the term of office of directors, and the filling of director vacancies;


limit on the ability of shareholders to call a special meeting to those shareholders or groups of shareholders owning at least [20]% of our shares entitled to vote at such meeting;


63


Table of Contents
   

removal of directors only for cause, by the affirmative vote of the holders of a majority of the voting power of all of the then-issued and outstanding shares of stock entitled to vote generally at an election of directors, voting together as a single class;


our board of directors has the authority to determine designations and the powers, preferences, and relative, participating, optional, or other special rights, and qualifications, limitations, or restrictions thereof, including, without limitation, the dividend rate, conversion rights, redemption price, and liquidation preference, of any series of shares of preferred stock, and to fix the number of shares constituting any such series, and to increase or decrease the number of shares of any such series (but not below the number of shares thereof then outstanding);


advance notice requirements applicable to shareholders for director nominations and other business to be brought before meetings of shareholders;


requirements that, for so long as we are a “nationally listed corporation” within the meaning of Section 21.373 of the Texas Business Organizations Code (the “TBOC”), a shareholder or group of shareholders seeking to submit a proposal for approval at a meeting of shareholders must satisfy specific share ownership, holding period, and solicitation requirements;


a requirement that specified internal corporate claims, including derivative actions, claims alleging breaches of fiduciary duty, claims arising under the TBOC or our organizational documents, claims governed by the internal affairs doctrine, and “internal entity claims” (as defined in the TBOC) be brought exclusively in the Texas Business Court in the Third Business Court Division of the State of Texas, subject to the alternative forums specified in our amended and restated certificate of formation;


a waiver of the right to trial by jury for any “internal entity claim” as defined in Section 2.115 of the TBOC;


a requirement that a shareholder or group of shareholders seeking to institute or maintain certain derivative proceedings against our directors or officers must beneficially own at least 3% of our outstanding shares, which threshold will automatically increase to the maximum permitted threshold if the TBOC is amended to permit a higher threshold;


our bylaws may be amended or repealed and new bylaws may be adopted, by our board of directors, unless our amended and restated certificate of formation or Texas law reserves that power exclusively to our shareholders in whole or in part or our shareholders, in amending, repealing or adopting a particular bylaw expressly provide that our board of directors may not amend or repeal a particular bylaw. Unless our amended and restated certificate of formation or a bylaw adopted by our shareholders provides otherwise, our shareholders may also amend or repeal our bylaws or adopt new bylaws by the affirmative vote of the holders of a majority of the voting power of all of the then-issued and outstanding shares of stock entitled to vote thereon.

Public shareholders who might desire to participate in these types of transactions may not have an opportunity to do so, even if the transaction is considered favorable to shareholders. These anti-takeover provisions could substantially impede the ability of public shareholders to benefit from a change in control or a change in our management and board of directors and, as a result, may adversely affect the market price of Spinco common stock and your ability to realize any potential change of control premium.

In addition, following the Distribution, we expect to qualify as an “issuing public corporation” (as defined in the TBOC) subject to Title 2, Chapter 21, Subchapter M of the TBOC, which we refer to as the “Texas Business Combination Law.” Subject to certain exceptions, the Texas Business Combination Law prohibits an issuing public corporation from engaging in specified business combinations with an affiliated shareholder, or an


64


Table of Contents

affiliate or associate of an affiliated shareholder, for a period of three years after the date the shareholder became an affiliated shareholder, unless:


before the affiliated shareholder became an affiliated shareholder, our board of directors approved the business combination or the acquisition of shares that resulted in the shareholder becoming an affiliated shareholder; or


the business combination is approved by the affirmative vote of the holders of at least two-thirds (2/3) of our outstanding voting shares not beneficially owned by the affiliated shareholder or an affiliate or associate of the affiliated shareholder, at the meeting of shareholders called for that purpose, not less than six months after the affiliated shareholder became an affiliated shareholder. This approval may not be obtained by written consent.

For purposes of Texas Business Combination Law, an “affiliated shareholder” (as defined in the TBOC) generally includes a person who beneficially owns, or owned during the preceding three-year period, 20% or more of the corporation’s outstanding shares. A “business combination” (as defined in the TBOC) includes specified mergers, share exchanges, conversions, asset dispositions, issuance or transfers of shares, liquidation or dissolution proposals, recapitalizations, and other transactions involving an affiliated shareholder or its affiliates or associates.

The Texas Business Combination Law also includes limited exceptions, including for certain inadvertent acquisitions of affiliated shareholder status, certain transfers by will or intestacy, and certain business combinations with a wholly owned Texas subsidiary. An issuing public corporation may also elect not to be governed by the Texas Business Combination Law in its original certificate of formation or bylaws or by a later amendment approved by at least two-thirds of the outstanding voting shares not held by affiliated shareholders, subject to an 18-month delayed effectiveness period and limitations for existing affiliated shareholders.

Neither the amended and restated certificate of formation nor the amended and restated bylaws contains any provisions expressly providing that we will not be subject to the Texas Business Combinations Law. As a result, the Texas Business Combination Law may have the effect of inhibiting a non-negotiated merger or other business combination involving us, even if such a merger or combination would be beneficial to our shareholders.

We believe these provisions will protect our shareholders from coercive or otherwise unfair takeover tactics by requiring potential acquirers to negotiate with our board of directors and by providing our board of directors with more time to assess any acquisition proposal. These provisions are not intended to make us immune from takeovers. However, these provisions will apply even if an acquisition proposal may be considered beneficial by some shareholders and could delay or prevent an acquisition that our board of directors determines is not in the best interests of us and our shareholders. These provisions may also prevent or discourage attempts to remove and replace incumbent directors.

Our amended and restated certificate of formation will contain an exclusive forum provision, and a waiver of the right to trial by jury for any “internal entity claim,” that could limit a shareholder’s ability to bring a claim in a judicial forum that the shareholder believes is favorable for such disputes and may discourage lawsuits against us and any of our directors, officers, or other employees.

Our amended and restated certificate of formation will provide that, unless we consent in writing to the selection of an alternative forum, the Texas Business Court in the Third Business Court Division of the State of Texas (the “Austin Business Court”) (or, if the Austin Business Court lacks jurisdiction or otherwise may not, or may decline to, hear the applicable cause of action, the Texas Business Court in the First Business Court Division of the State of Texas (the “Dallas Business Court”) or, if the Dallas Business Court lacks jurisdiction or otherwise may not hear, or may decline to hear the applicable cause of action the United States District Court for the Western District of Texas, Austin Division (the “Federal Court”) or if the Federal Court lacks jurisdiction or


65


Table of Contents

otherwise may not, or may decline to, hear the applicable cause of action, the state district court of Travis County, Texas) is the sole and exclusive forum for (i) any derivative action or proceeding brought on our behalf, (ii) any action asserting a claim of breach of a fiduciary duty owed by any directors, officers, or shareholders to us or our shareholders, (iii) any action asserting a claim against us or our current or former directors, officers, employees, or shareholders arising pursuant to any provision of the TBOC or our amended and restated certificate of formation or amended and restated bylaws, (iv) any action asserting a claim against us or any of our directors, officers, or shareholders governed by the internal affairs doctrine, (v) any action asserting an “internal entity claim,” as that term is defined in Section 2.115 of the TBOC, or (vi) any other action or proceeding in which the Business Court of the State of Texas has jurisdiction (the “Texas Exclusive Forum Provision”).

Our amended and restated certificate of formation includes a jury trial waiver consisting of the following language: TO THE FULLEST EXTENT PERMITTED BY THE TBOC, UNLESS THE CORPORATION CONSENTS IN WRITING TO A JURY TRIAL, THE CORPORATION AND EACH SHAREHOLDER, DIRECTOR, OFFICER AND EMPLOYEE OF THE CORPORATION HEREBY IRREVOCABLY AND UNCONDITIONALLY WAIVE ANY RIGHT THAT THE CORPORATION OR SUCH PERSON MAY HAVE TO A TRIAL BY JURY IN ANY LEGAL ACTION, PROCEEDING, CAUSE OF ACTION, COUNTERCLAIM, CROSS-CLAIM OR THIRD-PARTY CLAIM ARISING OUT OF OR RELATING TO ANY “INTERNAL ENTITY CLAIM” AS THAT TERM IS DEFINED IN SECTION 2.115 OF THE TBOC, AND EACH SHAREHOLDER AGREES THAT SUCH SHAREHOLDER’S HOLDING OR ACQUISITION OF SHARES OF STOCK OF THE CORPORATION OR, TO THE EXTENT PERMITTED BY LAW, OPTIONS OR RIGHTS TO ACQUIRE SHARES OF STOCK OF THE CORPORATION FOLLOWING THE ADOPTION OF THIS AMENDED AND RESTATED CERTIFICATE OF FORMATION CONSTITUTES SUCH SHAREHOLDER’S INTENTIONAL AND KNOWING WAIVER OF ANY RIGHT TO TRIAL BY JURY WITH RESPECT TO SUCH CLAIMS.

Our amended and restated certificate of formation will further provide that the Federal Court (or, if the Federal Court lacks jurisdiction or otherwise may not, or may decline to, hear the applicable cause of action, any other federal district court of the United States) will, to the fullest extent permitted by law, be the exclusive forum for resolving any complaint asserting a cause of action arising under the Securities Act (the “Federal Forum Provision”).

The Texas Exclusive Forum Provision is intended to apply to claims arising under Texas state law and would not apply to direct claims brought pursuant to the Securities Act or the Exchange Act or any other claim for which the federal courts have exclusive jurisdiction. In addition, the Federal Forum Provision is intended to apply to claims arising under the Securities Act and would not apply to claims brought pursuant to the Exchange Act.

Section 27 of the Exchange Act creates exclusive federal jurisdiction over all suits brought to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder. However, Section 22 of the Securities Act creates concurrent jurisdiction for federal and state courts over all suits brought to enforce a duty or liability created by the Securities Act or the rules and regulations thereunder. Accordingly, there is uncertainty as to whether a court would enforce the Federal Forum Provision as written in connection with claims arising under the Securities Act. Any person purchasing or otherwise acquiring any interest in any of our securities will be deemed to have notice of, and to have consented to, these provisions.

The exclusive forum provisions we will include in our amended and restated certificate of formation will not relieve us of our duties to comply with the federal securities laws and the rules and regulations thereunder and, accordingly, actions by our shareholders to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder must be brought in federal courts. Our shareholders will not be deemed to have waived our compliance with these laws, rules, and regulations.

The exclusive forum provisions we will include in our amended and restated certificate of formation may limit a shareholder’s ability to bring a claim in a judicial forum of its choosing for disputes with the Company or its


66


Table of Contents

directors, officers, or other employees, which may discourage lawsuits against us and our directors, officers, and other employees. In addition, shareholders who bring a claim in the applicable Texas court pursuant to the Texas Exclusive Forum Provision could face additional litigation costs in pursuing any such claim, particularly if they do not reside in or near Texas. The court in the designated forum under our exclusive forum provisions may also reach different judgments or results than would other courts, including courts where a shareholder would otherwise choose to bring the action, and such judgments or results may be more favorable to us than to our shareholders. Further, the enforceability of similar exclusive forum provisions in other companies’ organizational documents has been challenged in legal proceedings, and it is possible that a court could find any of our exclusive forum provisions to be inapplicable to, or unenforceable in respect of, one or more of the specified types of actions or proceedings. If a court were to find all or any part of our exclusive forum provisions to be inapplicable or unenforceable in an action, we might incur additional costs associated with resolving such action in other jurisdictions, which could adversely affect our business, operating results, and financial condition.

The price of Flex ordinary shares historically has been volatile, and the price of our common stock may be volatile as well. This volatility may affect the price at which you could sell your common stock, and the sale of substantial amounts of our common stock could adversely affect the price of our common stock.

The market price of Flex ordinary shares has been volatile, and the price of our common stock may also be volatile. This volatility may affect the price at which you could sell your common stock. Our stock price may be subject to significant price and volume fluctuations in response to market and other factors, including:


actual or anticipated fluctuations in our results of operations, including those resulting from the seasonality and cyclicality of our business;


perceptions about our business strategy, relationships with key customers, suppliers, and partners, and our ability to execute on strategic initiatives;


announcements of technological innovations or new products and services by us or our competitors, which may impact demand for our existing products or increase the risk of inventory obsolescence;


strategic actions by us or our competitors, such as acquisitions, divestitures, or restructurings;


responses to the announcement of the separation;


periods of severe pricing pressures due to oversupply or price erosion resulting from competitive pressures or industry consolidation;


developments related to intellectual property, including patents or proprietary rights, and any litigation;


proposed or adopted regulatory changes or developments or anticipated or pending investigations, proceedings, or litigation that involve or affect us or our competitors;


conditions and trends in the data center infrastructure solutions, cloud computing, and broader technology industries;


contraction in our operating results or growth rates that are lower than our previous high growth rate periods;


failure to meet analysts’ revenue or earnings estimates, changes in financial estimates, or publication of research reports and recommendations by financial analysts relating specifically to us or our industry in general;


announcements relating to debt or equity financings, dividends and share repurchases; and


macroeconomic conditions that affect the market generally, including developments related to market conditions for our industry.

In addition, the sale of substantial amounts of shares of our common stock, or the perception that these sales may occur, could adversely affect the market price of our common stock. Further, the stock market is subject to


67


Table of Contents

fluctuations in the stock prices and trading volumes that affect the market prices of the stock of public companies, including us. These broad market fluctuations have adversely affected and may continue to adversely affect the market price of shares of our common stock. For example, expectations concerning general economic conditions may cause the stock market to experience extreme price and volume fluctuations from time to time that particularly affect the stock prices of many high technology companies. These fluctuations may be unrelated to the operating performance of the companies.

Securities class action lawsuits are often brought against companies after periods of volatility in the market price of their securities, and any such lawsuits filed against us could result in substantial costs and a diversion of resources and management’s attention.

The completion of the Spin-Off is subject to the Flex Shareholder Approvals and the High Court Approval, which may not be satisfied, and the Spin-Off may not occur.

Flex plans to complete the Spin-Off and effect the Distribution by way of the Capital Reduction. To effect the Capital Reduction, Flex will first need to capitalize its reserves through the Bonus Issuance. The Capital Reduction and the Distribution will be effected in compliance with Flex’s Constitution and Singapore law, which requires the High Court Approval following and in addition to the receipt of the Flex Shareholder Approvals. The Capital Reduction and the Distribution cannot be effected absent the Flex Shareholder Approvals and the High Court Approval. As a result, Spinco and Flex may not be able to complete the Spin-Off on the terms described in this information statement or on other acceptable terms or at all.

If securities or industry analysts do not publish research or reports about our business, or if they downgrade their recommendations regarding our common stock, our stock price and trading volume could decline.

The trading market for our common stock will be influenced by the research and reports that industry or securities analysts publish about us or our business. If any of the analysts who may cover us downgrade our common stock or publish inaccurate or unfavorable research about our business, our common stock price may decline. If analysts cease coverage of us or fail to regularly publish reports on us, we could lose visibility in the financial markets, which in turn could cause our common stock price or trading volume to decline and our common stock to be less liquid.


68


Table of Contents

CAUTIONARY STATEMENT CONCERNING FORWARD-LOOKING STATEMENTS

This information statement and other materials that Flex and Spinco have filed or will file with the SEC contain, or will contain, forward-looking statements within the meaning of the federal securities laws. These forward-looking statements include, but are not limited to, statements regarding Spinco’s product and technology position, the anticipated benefits, timing and effects of the Spin-Off and all statements regarding Spinco’s expected future position, results of operations, cash flows, dividends, financing plans, business strategy, budgets, capital expenditures, competitive positions, growth opportunities, plans and objectives of management. Forward-looking statements also include statements containing forward-looking words, such as “will,” “may,” “designed to,” “believe,” “should,” “anticipate,” “plan,” “expect,” “intend,” “estimate,” “could,” “would,” “project,” “continue,” “potential,” “forecast,” “approximate,” “upside,” “target,” and similar expressions or the use of future tense. Statements concerning business outlook or future economic performance, anticipated profitability, revenues, expenses, dividends or other financial items, and products or services line growth of Spinco, together with other statements that are not historical facts, are forward-looking statements based on current expectations, estimates, assumptions and information available at the time they are made. Statements concerning current conditions may also be forward-looking if they imply trends or a continuation of such conditions.

Forward-looking statements are inherently uncertain, and shareholders and other potential investors must recognize that actual results may differ materially from Spinco’s expectations as a result of a variety of factors, including, without limitation, those discussed below. These forward-looking statements are based upon management’s current expectations and are subject to known and unknown risks, uncertainties and other factors, many of which Spinco is unable to predict or control, that may cause actual results, performance, or plans to differ materially from those expressed or implied by such forward-looking statements. These factors include, without limitation: volatility in global economic conditions; business conditions and growth in the digital infrastructure industry; pricing trends and fluctuations in average selling prices; the availability and cost of commodity materials and specialized components; actions by competitors; unexpected advances in competing technologies; and other risks and uncertainties described in the sections entitled “Summary of the Separation and Distribution,” “Risk Factors,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” “Business,” and “The Separation and Distribution.” You should not place undue reliance on these forward-looking statements, which speak only as of the date they are made. Spinco undertakes no obligation to update any forward-looking statements to reflect new information or events.

Risks and uncertainties related to the Spin-Off include, but are not limited to: the future operating results of the stand-alone business; value creation associated with the separation and stand-alone business; the anticipated qualification of the Spin-Off as a tax-free transaction for U.S. federal income tax purposes; the expected relationship of the two businesses post-separation; whether the Spin-Off will be completed on the expected terms and on the anticipated timeline or at all, including the possibility that the conditions to the Spin-Off may not be satisfied, including that a governmental entity may prohibit, delay, or refuse to grant a necessary approval; the expected benefits and costs of the Spin-Off, including that the expected benefits will not be realized within the expected time frame, in full or at all; potential adverse reactions or changes to Spinco’s business relationships with their respective customers, suppliers, or other partners resulting from the announcement and completion of the Spin-Off; competitive responses to the announcement or completion of the Spin-Off; potential adverse effects on Spinco’s stock prices resulting from the announcement or completion of the Spin-Off; unexpected costs, liabilities, charges, or expenses resulting from the Spin-Off; litigation relating to the Spin-Off; the inability to retain key personnel of Spinco as a result of the Spin-Off; disruption of management time from ongoing business operations due to the Spin-Off; impacts of geopolitical conflicts; and any changes in general economic and/or industry-specific conditions. In addition to the factors set forth above, the Spin-Off is subject to other economic, competitive, legal, governmental, technological, regulatory, and other factors that may affect the Spin-Off and Spinco’s plans, results, or stock price and which are set forth under the sections entitled “Summary of the Separation and Distribution,” “Risk Factors,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” “Business,” and “The Separation and Distribution.” Many of these factors are beyond Spinco’s control. Spinco cautions investors that forward-looking statements are not guarantees of future performance. Spinco does not intend, or undertake any obligation, to publish revised forward-looking statements to reflect events or circumstances after the date of this information statement or to reflect the occurrence of unanticipated events.


69


Table of Contents

THE SEPARATION AND DISTRIBUTION

General

On May 5, 2026, Flex announced its intention to separate into two standalone, publicly traded companies. Flex has determined to implement this separation through the Spin-Off of Flex’s Cloud & Power Infrastructure business to its shareholders. Flex intends to effect the Spin-Off pursuant to an internal reorganization followed by a distribution of between approximately 88.0% to 94.0% of the shares of our common stock, by way of a distribution in specie to Flex shareholders of record on a pro rata basis as of the Distribution Record Date, subject to certain conditions. The Distribution is expected to take place on or about    , 2027. On the Distribution Date, each holder of Flex ordinary shares will receive for each Flex ordinary share held as of     Central time on    , 2026, the Distribution Record Date,     share[s] of Spinco common stock (the “Distribution Ratio”). The Distribution will be effected by way of Capital Reduction under the Singapore Companies Act. Following the Distribution, Spinco will be a separate, publicly traded company. You will not be required to make any payment, surrender or exchange your Flex ordinary shares or take any other action to receive your shares of Spinco common stock to which you are entitled on the Distribution Date. The number of shares you own of Flex will not change as a result of the Spin-Off. On the Distribution Date, Flex will hold between approximately 6.0% to 12.0% of Spinco common stock. Following the Distribution, Flex intends to dispose of all of the Spinco common stock that it retains through one or more subsequent exchanges of Spinco common stock for Flex debt held by Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, in each case during the 24-month period following the Distribution.

The Distribution of our common stock as described in this information statement is subject to the satisfaction or waiver of certain conditions. Until the Spin-Off has occurred, Flex has the right not to complete the Spin-Off, even if all the conditions have been satisfied, if, at any time prior to the Distribution, the Flex Board of Directors determines, in its sole discretion, that the Spin-Off is not in the best interests of Flex, that a sale or other alternative is in the best interests of Flex, or that market conditions or other circumstances are such that it is not advisable at that time to separate the Cloud & Power Infrastructure business from Flex. We cannot provide any assurances that the Distribution will be completed. For a more detailed description of these conditions, see the section of this information statement entitled “The Separation and Distribution—General—Conditions to the Distribution.”

Reasons for the Spin-Off

In early 2025, the Flex Board of Directors authorized a comprehensive review of Flex’s business portfolio and capital allocation options. Throughout 2025 and into early 2026, the Flex Board of Directors met regularly to review and evaluate Flex’s businesses and available strategic opportunities with the assistance of financial and legal advisors. During this process, the Flex Board of Directors considered detailed analyses from Flex’s management and financial advisors regarding Flex’s portfolio composition, valuation considerations, capital structure alternatives, and potential strategic transactions. After an extensive evaluation process, the Flex Board of Directors concluded that Flex has significantly strengthened its businesses and optimized its portfolio over the last several years and that, as a continuation of that transformation, the separation of its Cloud & Power Infrastructure business as an independent, publicly-traded company at this time will accelerate the pace of its transformation and unlock future value potential. The Flex Board of Directors believes that the Spin-Off provides a tax-efficient opportunity for investors to more accurately assess the value of each company based on its individual merits, performance and future prospects, which the Flex Board of Directors believes may reduce the cost of capital and enhance the competitive positioning of both Flex and Spinco as standalone companies. In addition, the Flex Board of Directors believes that the separation will allow the management teams of each company to focus on their respective businesses and strategies, without competing internally for capital, research and development investment, or other corporate resources.


70


Table of Contents

The Spin-Off will create two strong, stand-alone businesses, each of which will have leading positions in the markets they serve and will be better positioned to deliver long-term growth and sustainable value creation for all shareholders:


Flex will focus on its advanced manufacturing services business comprised of its Integrated Technology Solutions and the Regulated Manufacturing Solutions businesses; and


Spinco will hold the Cloud & Power Infrastructure business.

In connection with its evaluation of available strategic opportunities, the Flex Board of Directors, with the assistance of its financial and legal advisors, considered a range of strategic alternatives, including maintaining the status quo; a complete spin-off of the Cloud & Power Infrastructure business with Flex not retaining any shares of Spinco common stock; a partial separation through an initial public offering of Spinco followed by a spin-off at a later date; and a spin-off of the Cloud & Power Infrastructure business with Flex retaining between approximately 6.0% to 12.0% of the shares of Spinco common stock followed by a tax-efficient monetization of the retained stake. In determining that a spin-off with a retained stake would be more favorable to Flex and its shareholders than other potential alternatives, the Flex Board of Directors considered a number of factors, including the potential reaction of investors, the timing and certainty of execution, the ability of each company to use its own equity currency to pursue its strategic objectives, and the strategic flexibility of Flex and Spinco after the Spin-Off. In determining to retain between approximately 6.0% to 12.0% of the shares of Spinco common stock, the Flex Board of Directors considered that a spin-off retaining such shares would enable Flex to reduce additional leverage at a later date in a tax-efficient manner using proceeds from the monetization of the retained equity stake. See “—Reasons for Flex’s Retention of Between Approximately 6.0% to 12.0% of Spinco Common Stock.”

After considering these and a variety of other factors in evaluating the Spin-Off, the Flex Board of Directors concluded that the other alternatives considered did not present the same advantages to Flex shareholders as the Spin-Off, and that the separation of the Cloud & Power Infrastructure business into an independent, publicly traded company, with Flex initially retaining between approximately 6.0% to 12.0% of the shares of Spinco common stock is the most attractive alternative for enhancing value for Flex and its shareholders.

The Flex Board of Directors believes that the separation of the Cloud & Power Infrastructure business is particularly compelling given accelerating demand for power-dense infrastructure and the increasing complexity of coordinated power delivery, cooling, and rack-scale integration requirements. Creating an independent company focused on integrated infrastructure platforms positions Spinco to meet the accelerating infrastructure and power demands with focus and agility.

The Flex Board of Directors believes that separating the Cloud & Power Infrastructure business from the remainder of Flex and distributing Spinco shares to Flex shareholders is in the best interests of Flex for a number of reasons, including:


Simplified Investment Profile and Enhanced Ability to Allocate Capital on a Focused Basis. The business which will constitute Spinco differs significantly in several respects from the remaining businesses of Flex, including the nature of the business, growth profile, business cycles, and secular growth drivers. The Spin-Off will simplify how investors evaluate each business, streamline the investment profiles of both businesses, permit investors to better evaluate the individual merits, performance and future prospects of each company’s business, and provide investors the ability to invest in each company separately based on those distinct characteristics, all of which may enhance each company’s marketability. The Spin-Off will also enable investors to allocate capital on a more focused basis, with Spinco providing exposure to growth in power-dense infrastructure supporting data centers, AI workloads, and grid modernization sectors compared to Flex as a combined company today. The Spin-Off may also attract new investors that either chose not to invest in, or assess the merits of, pre-Spin-Off Flex given its complexity and its exposure to disparate markets and trends.


Increased Management Focus on Core Business and Distinct Opportunities. The Spin-Off will result in dedicated, independent management for each of the businesses and enable the respective


71


Table of Contents
 

management teams to adopt strategies and pursue objectives specific to their respective businesses and better focus on strengthening their respective core businesses and operations. Enhancing the management focus with respect to each business is also expected to increase operating flexibility, and allow each company to pursue opportunities for growth distinct to their respective businesses. In addition, the Spin-Off will give each respective management team the opportunity to focus on the goals and expectations of such company’s respective investors. The separation of the experienced management teams and other key personnel operating the businesses will result in the ability for each company to better satisfy the needs of its respective shareholders.


Improved Operational and Strategic Flexibility. The Spin-Off will permit each business to pursue its own business interests, operating priorities and strategies more effectively without having to consider the impact on the business of the other company or on the balance and composition of pre-Spin-Off Flex’s overall portfolio and will enhance operational flexibility for both businesses.


Tailored Capital Allocation Strategies Align with Distinct Business Strategies and Industry Specific Dynamics. The Spin-Off will permit each company to implement a capital structure and flexible capital deployment policy that is optimized for its strategy and business needs, and that is aligned with each company’s target investor base. Flex believes that the Spin-Off will provide flexibility to better manage capital structure based on each company’s forecasted cash generation, planned investments, credit rating requirements, acquisition activity, and capital returns, among other factors, and accordingly will allow each company to invest capital (or return capital to its investors) at the time and in the manner most appropriate for its distinct strategic priorities and business needs. Each company will also have direct access to the debt and equity capital markets to fund its growth strategies, and the ability to concentrate its financial resources solely on its own operations.


Facilitate Potential Mergers and Acquisitions and Resulting Synergies. As a result of the Spin-Off, each company is expected to be better situated to pursue future acquisitions, joint ventures, and other strategic opportunities as well as internal expansion that is more closely aligned with such company’s strategic goals and expected growth opportunities.


Separate Acquisition Currency. The Spin-Off will provide each of Flex and Spinco with its own distinct equity currency that relates solely to its business to use in pursuing strategic opportunities. For example, each of Flex and Spinco will be able to pursue strategic acquisitions in which potential sellers would prefer equity or to raise cash by issuing equity to public or private investors. This benefit is particularly compelling for Spinco, where acquisition target valuations in the data center and AI infrastructure sectors remain elevated.


Improved Talent Attraction, Retention, and Alignment of Management Incentives. The Spin-Off will enable each company to design and implement equity compensation programs that are directly tied to the performance and value of its respective business. The ability to offer equity incentives linked directly to the performance of each individual company is expected to improve each company’s ability to recruit, retain, and provide incentive compensation to employees through equity compensation plans that offer more direct correlation between employees’ compensation and the performance of the business for which such employees are responsible. This direct linkage between equity compensation and business performance is expected to enhance management focus and accountability.

The Flex Board of Directors also considered potentially negative factors in evaluating the Spin-Off, including:


The potential for increased aggregate ongoing administrative costs for the two companies operating on a stand-alone basis post-Spin-Off, such as expenses associated with reporting and compliance as public companies and separate working capital requirements, overhead, insurance, financing, and other operating costs, as well the potentially higher cost of capital as separate companies.


The inability to take advantage of pre-spin-off Flex’s size, purchasing power, borrowing leverage, and available capital for investments. After the Spin-Off, as standalone companies, Spinco and/or Flex may


72


Table of Contents
 

be unable to obtain goods and services at prices or on terms as favorable as those currently obtained by pre-Spin-Off Flex, and the degree to which Flex will be leveraged could adversely affect its business, financial condition, results of operations, and cash flows.


One-time costs we expect to incur related to the Spin-Off and in connection with the transition to becoming a stand-alone public company including, among others, professional services costs, tax expense, recruiting, and other costs associated with hiring for two stand-alone corporate structures, and costs to separate IT systems and create two separate stand-alone IT structures.


The potential for execution risks related to the Spin-Off, including disruption to the business as a result of the Spin-Off and the possibility that Spinco and/or Flex do not achieve the expected benefits of the Spin-Off for a variety of reasons.


The Spin-Off may divert management’s time and attention, which could have a material adverse effect on the business, results of operations, financial condition, and cash flows of Spinco.


Following the Spin-Off, Spinco and/or Flex may be more susceptible to market fluctuations and other events particular to one or more of their products than they currently are as pre-Spin-Off Flex.


Spinco’s revenues are expected to be more concentrated among a limited number of customers, which may increase Spinco’s exposure to changes in the purchasing decisions, financial condition, or business strategies of these customers, and may affect Spinco’s ability to negotiate favorable terms or affect its credit ratings.


The potential that reduced business diversification, with each post-Spin-Off company operating with a smaller product portfolio than pre-Spin-Off Flex, could increase the volatility of earnings and cash flow.


Certain costs and liabilities that were otherwise less significant to pre-Spin-Off Flex could be more significant to Flex and/or Spinco after the Spin-Off as smaller, stand-alone companies.


Flex’s ordinary shares and Spinco’s common stock could experience selling pressure after the Spin-Off as certain pre-Spin-Off shareholders may not be interested in holding an investment in one of the two post-Spin-Off companies.


Flex and/or Spinco may be restricted in their ability to pursue certain opportunities that may have otherwise been available in order to preserve the tax-free nature of the Distribution and related transactions for U.S. federal income tax purposes.


There may be, or there may be the appearance of, conflicts of interest or differences in strategy in Spinco’s relationship with Flex. Actual, potential, or perceived conflicts could give rise to investor dissatisfaction, settlements with shareholders, litigation or regulatory inquiries, or enforcement actions.

The Flex Board of Directors concluded that the potential benefits of the Spin-Off outweighed these factors and risks. The Flex Board of Directors also considered these potential benefits and potentially negative factors in light of the risk that the Spin-Off is abandoned or otherwise not completed, resulting in Flex not separating into two independent, publicly traded companies.

In view of the wide variety of factors considered in connection with the evaluation of the Spin-Off and the complexity of these matters, the Flex Board of Directors did not find it useful to, and did not attempt to, quantify, rank or otherwise assign relative weights to the factors considered.

The anticipated benefits of the Spin-Off are based on a number of assumptions, and there can be no assurance that such benefits will materialize to the extent anticipated, or at all. In the event the Spin-Off does not result in such benefits, the costs associated with the Spin-Off could have an adverse effect on each company individually and in the aggregate. For more information, see the section of this information statement entitled “Risk Factors.”

Aspects of the Spin-Off may increase the risks associated with ownership of shares of Spinco common stock. In connection with the Spin-Off, Spinco expects to incur indebtedness pursuant to the Spinco Financing Arrangements and to complete the Spinco Cash Distribution to Flex prior to or substantially concurrently with


73


Table of Contents

the consummation of the Spin-Off. The terms of such indebtedness are subject to change and will be finalized prior to the closing of the Spin-Off.

Reasons for Flex’s Retention of Between Approximately 6.0% to 12.0% of Spinco Common Stock

In considering the appropriate structure for the Spin-Off, the Flex Board of Directors determined that, immediately after the Distribution, Flex will retain between approximately 6.0% to 12.0% of the outstanding shares of our common stock. Flex’s plan to transfer less than all of the Spinco common stock to its shareholders in the Distribution is motivated by its desire to establish, in an efficient and non-taxable, cost-effective manner, an appropriate capital structure for each of Flex and Spinco, including by reducing, directly or indirectly, Flex’s indebtedness during the 24-month period following the Distribution. Flex’s retention of shares of our common stock is expected to increase its financial flexibility and support the establishment of optimal capital structures for each of Flex and Spinco by allowing Flex to reduce leverage in a tax-efficient manner. Flex intends to dispose of all of the Retained Shares after the Distribution through one or more subsequent exchanges of Spinco common stock for Flex debt held by Flex creditors and/or through distributions of Spinco common stock to Flex shareholders as dividends or as non-cash consideration in exchange for issued and outstanding Flex ordinary shares pursuant to an off-market purchase on equal access scheme as prescribed by the Singapore Companies Act, in each case during the 24-month period following the Distribution.

Formation of a Holding Company Prior to the Distribution and Internal Reorganization

As part of the Spin-Off, Flex formed Spinco as a corporation in Delaware on April 7, 2026, for the purpose of transferring to Spinco certain assets and liabilities, including certain entities holding assets and liabilities, associated with the Cloud & Power Infrastructure business in anticipation of the planned Spin-Off, and subsequently converted it into a Texas corporation pursuant to a plan of conversion. Spinco has engaged in no business activities to date, and it has no material assets or liabilities of any kind, other than those incident to its formation and those incurred in connection with the Spin-Off. Prior to the Distribution, Flex and its subsidiaries expect to complete the Internal Reorganization pursuant to which (i) Flex and its subsidiaries will transfer the assets and liabilities associated with the Cloud & Power Infrastructure business to Spinco or certain entities which will become its subsidiaries and transfer the equity interests of certain entities holding such assets and liabilities to Spinco and (ii) Spinco and its subsidiaries will transfer the assets and liabilities associated with the Flex business that are held by Spinco’s subsidiaries, if any, to Flex or its subsidiaries, in each case, as set forth in the Separation Agreement (as defined herein). The Internal Reorganization involves the formation of new subsidiaries in U.S. or non-U.S. jurisdictions to own and operate the Cloud & Power Infrastructure business in such jurisdictions, as applicable. Flex and its subsidiaries will also transfer all or a portion of certain other corporate and shared assets and liabilities to Spinco (or certain entities which will become its subsidiaries) and Spinco and its subsidiaries will also transfer all or a portion of certain other corporate and shared assets and liabilities to Flex or its subsidiaries, in each case, pursuant to the terms of the Separation Agreement. Following the Spin-Off, Flex will continue to hold the Flex business.

The Bonus Issuance, Capital Reduction and Distribution

Flex plans to complete the Spin-Off and effect the Distribution by way of the Capital Reduction. The Capital Reduction and the Distribution will be effected in compliance with Flex’s Constitution and Singapore law. To effect the Capital Reduction, Flex will first need to capitalize its reserves through the Bonus Issuance.

The Bonus Issuance requires the affirmative vote of a simple majority of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting of Flex. The Capital Reduction requires the affirmative vote of at least three-quarters of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting of Flex. The Bonus Issuance, Capital Reduction and the Distribution cannot be effected absent the Flex Shareholder Approvals and the High Court Approval.

Flex currently expects to complete the Bonus Issuance, the Capital Reduction and the Distribution as promptly as reasonably practicable after receipt of the High Court Approval and the satisfaction (or, to the extent permitted


74


Table of Contents

by applicable law, waiver by the parties entitled to the benefit thereof) of the conditions to the Distribution, other than those conditions that by definition cannot be completed prior to the Distribution.

Reasons for Furnishing this Information Statement; Changes in the Terms of the Spin-Off

This information statement is being furnished solely to provide information to Flex shareholders who are entitled to receive shares of our common stock in the Distribution. The information statement is not, and is not to be construed as, an inducement or encouragement to buy, hold, or sell any of our securities or securities of Flex. We believe that the information in this information statement is accurate as of the date set forth on the cover.

Changes may occur after that date and none of us, Flex, the Spinco Board of Directors or the Flex Board of Directors undertake any obligation to update such information, except as required by applicable federal securities laws.

Flex does not intend to notify its shareholders of any modifications to the terms of the Spin-Off, including the waiver of any conditions to the Distribution, that, in the judgment of the Flex Board of Directors, are not material. However, the Flex Board of Directors would likely consider material matters such as significant changes to the Distribution Ratio, or significant changes to the assets to be contributed or the liabilities to be assumed in the separation, as well as any waiver of the conditions that the Flex Board of Directors receives the Tax Opinion, obtains the Flex Shareholder Approvals, or obtains the High Court Approval with respect to the Spin-Off. To the extent that the Flex Board of Directors determines that any modification by Flex materially changes the material terms of the Spin-Off, including through the waiver of a condition to the Distribution, Flex will notify Flex shareholders in a manner reasonably calculated to inform them about the modification as may be required by law, by, for example, publishing a press release, filing a current report on Form 8-K, or making available a supplement to this information statement. As of the date hereof, the Flex Board of Directors does not intend to waive any of the conditions described herein.

Conditions to the Distribution

The Distribution is subject to the satisfaction or waiver of the following conditions, among others:


The SEC will have declared effective the registration statement of which this information statement forms a part, with no stop order relating to the registration statement in effect, and no proceedings for such purpose will be pending before, or threatened by, the SEC.


The distribution of this information statement (or a notice of internet availability thereof) to holders of Flex ordinary shares whose names appear on the Branch Register of Members maintained in the United States of America.


The holders of a simple majority of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Bonus Issuance.


The holders of at least three-fourths of the Flex ordinary shares present and voting at the extraordinary general meeting must affirmatively vote in favor of the Capital Reduction and Distribution.


The High Court Approval is obtained.


Flex shall have issued the Bonus Shares and immediately cancelled the Bonus Shares issued in the Bonus Issuance.


Nasdaq will have approved the listing of Spinco common stock, subject to official notice of issuance.


Flex having lodged with the ACRA a copy of the Court order approving the Capital Reduction and the Distribution and a notice containing the reduction information within 90 days beginning with the date the order was made, or within such longer period as the ACRA may, on the application of Flex, allow, and the ACRA having recorded such information lodged in the appropriate register.


Flex will have received the Tax Opinion. See the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.”


75


Table of Contents
   

Flex will have received an opinion from a nationally recognized independent appraisal firm in form and substance satisfactory to Flex, confirming that after giving effect to the Distribution, Flex and Spinco will each be solvent and adequately capitalized.


All actions and filings necessary or appropriate under applicable securities laws or “blue sky” laws and the rules and regulations thereunder will have been taken.


No preliminary or permanent injunction or other order, decree, or ruling issued by a governmental authority, and no statute, rule, regulation, or executive order promulgated or enacted by any governmental authority will be in effect preventing the consummation of, or materially limiting the benefits of, the transactions contemplated by the separation and distribution agreement.


Those reorganization transactions with respect to the Flex business and Cloud & Power Infrastructure business to be completed prior to the Distribution will have been effectuated in all material respects.


The Flex Board of Directors will have declared the Distribution and approved all related transactions (and such declaration or approval will not have been withdrawn).


No event or development will have occurred or failed to occur that, in the judgment of the Flex Board of Directors, in its sole discretion, prevents the consummation of, or makes it inadvisable to effect the separation, the Distribution, or the other related transactions.


Any required governmental approvals or consents under any material contracts necessary to consummate the Distribution and the transactions contemplated by the separation and distribution agreement and the ancillary agreements will have been obtained and be in full force and effect.


Prior to or substantially concurrently with the consummation of the Distribution, the financing for the Spinco Financing Arrangements will be available on terms acceptable to Flex and Spinco will have completed the Spinco Financing Arrangements and received the proceeds in respect thereof and Spinco will have completed the Spinco Cash Distribution.


Each of the ancillary agreements will have been executed and delivered by each party thereto.

Flex and Spinco cannot assure you that any or all of these conditions will be met, and the Flex Board of Directors may also waive conditions to the Distribution in its sole discretion. If the Spin-Off is completed and the Flex Board of Directors waives any such condition, such waiver could have a material adverse effect on Flex’s and Spinco’s respective business, financial condition, or results of operations, including, without limitation, as a result of litigation relating to any preliminary or permanent injunctions that sought to prevent the consummation of the Spin-Off, or the failure of Flex and Spinco to obtain any required regulatory approvals. As of the date hereof, the Flex Board of Directors does not intend to waive any of the conditions described herein.

The fulfillment of the above conditions will not create any obligation on behalf of Flex to effect the Spin-Off, and Flex may at any time decline to go forward with the Spin-Off. Until the Spin-Off has occurred, Flex has the right not to complete the Spin-Off, even if all the conditions have been satisfied, if, at any time prior to the Distribution, the Flex Board of Directors determines, in its sole discretion, that the Spin-Off is not in the best interests of Flex, that a sale or other alternative is in the best interests of Flex, or that market conditions or other circumstances are such that it is not advisable at that time to separate the Cloud & Power Infrastructure business from Flex.

The Number of Shares You Will Receive

For each Flex ordinary share that you own as of     Central time on    , 2026, the Distribution Record Date, you will receive a number of shares of Spinco common stock equal to the Distribution Ratio on or about    , 2027, the Distribution Date. The actual number of shares of Spinco common stock to be distributed will be determined based on the total number of issued and outstanding Flex ordinary shares on the Distribution Record Date.


76


Table of Contents

Transferability of Shares You Receive

Shares of Spinco common stock distributed to holders in connection with the Distribution will be transferable without registration under the Securities Act, except for shares received by persons who may be deemed to be Spinco affiliates. Persons who may be deemed to be Spinco affiliates after the Distribution generally include individuals or entities that control, are controlled by or are under common control with Spinco, which may include certain of Spinco’s executive officers, directors or principal shareholders. Securities held by Spinco affiliates will be subject to resale restrictions under the Securities Act. Spinco affiliates will be permitted to sell shares of Spinco common stock only pursuant to an effective registration statement or an exemption from the registration requirements of the Securities Act, such as the exemption afforded by Rule 144 under the Securities Act.

When and How You Will Receive the Distributed Shares

Flex expects to distribute the shares of Spinco common stock on or about    , 2027, the Distribution Date. Computershare Trust Company, N.A. will serve as the transfer agent and registrar for our common stock and as distribution agent in connection with the Distribution.

If you own Flex ordinary shares as of     Central time on    , 2026, the Distribution Record Date, the shares of Spinco common stock that you will be entitled to receive in the Distribution will be issued electronically, as of the Distribution Date, to you in direct registration form or to your broker, bank, or other nominee on your behalf. If you are a registered holder, the distribution agent will then mail you a direct registration account statement that reflects your shares of Spinco common stock. Direct registration form refers to a method of recording share ownership when no physical share certificates are issued to shareholders, as is the case in this Distribution. If you sell your Flex ordinary shares in the “regular-way” market up to and including the Distribution Date, you will be selling your right to receive shares of Spinco common stock in the Distribution.

If you hold your Flex ordinary shares through a brokerage firm or bank, the brokerage firm or bank would be said to hold the Flex ordinary shares in “street name” and ownership would be recorded on the brokerage firm or bank’s books and your brokerage firm or bank will credit your account for the shares of Spinco common stock that you are entitled to receive in the Distribution. If you have any questions concerning the mechanics of having shares held in “street name,” we encourage you to contact your bank or brokerage firm.

Flex shareholders will not be required to make any payment or surrender or exchange their Flex ordinary shares or take any other action to receive their shares of our common stock.

Treatment of Equity Incentive Arrangements

We expect that Flex equity awards outstanding at the time of the Distribution will be adjusted with the intent to maintain the economic value of those awards before and after the Spin-Off, using a ratio that takes into account the average closing trading price of Flex ordinary shares over the ten trading days prior to the separation and the average of either the post-separation average closing trading price of Flex ordinary or the post-separation per share closing trading price of Spinco common stock, as applicable, over ten trading days following the separation. Flex equity awards held by Spinco employees and non-employee directors generally will be converted into Spinco equity awards, and Flex equity awards held by Flex employees and non-employee directors, as well as by Spinco employees transferring to Spinco some time after the separation (each such employee a “Delayed Transfer Spinco Employee”), will be adjusted and remain outstanding as awards denominated in shares of Flex ordinary shares (with Spinco using commercially reasonable efforts to replace any Flex equity awards forfeited by such Delayed Transfer Spinco Employee at the time such employee transfers to Spinco). For performance-based awards, the performance metrics for in-progress performance periods will be adjusted to reflect the Spin-Off. However, a one-time supplemental performance-based awards granted to the expected CEO of Spinco will convert to a Spinco award with no alterations to the performance measures.


77


Table of Contents

Additionally, the in-progress performance for a one-time supplemental performance-based award granted to the expected Chief Operating Officer of Spinco will be measured at the time of the Spin-Off, after which such award will remain subject to the same time-based vesting schedule. The treatment of each type of Flex equity award, is further discussed in “Compensation Discussion and Analysis—Treatment of Outstanding Equity Awards at the Time of the Spin-Off.”


Type of Award


Treatment

Flex RSUs


Outstanding Flex RSUs held by Spinco employees and non-employee directors will be converted into Spinco restricted stock units with substantially equivalent economic value. Outstanding Flex RSUs held by Flex employees and non-employee directors will be adjusted and remain outstanding as Flex RSUs. In each case, the adjusted awards will be subject to the same terms including the original vesting schedule.


EPS PSUs


The EPS PSUs will be adjusted or converted to Spinco PSUs in a manner similar to outstanding Flex RSUs generally, as described above. For performance periods that are at least 75% complete as of the Distribution Date will be determined based on actual results achieved through the Distribution Date. For all other performance periods, the EPS growth target goals will be adjusted to reflect the separation and allocated proportionately between Flex and Spinco. In each case, the final payout will be based on the average performance achieved across the three one-year performance measurement periods, and the original vesting schedule will remain unchanged.


rTSR PSUs


The rTSR PSUs held by Flex employees will be adjusted or converted to Spinco PSUs in a manner similar to outstanding Flex RSUs generally, as described above. With respect to the performance goals, the value of Spinco stock distributed to Flex shareholders on the Distribution Date will be treated as a special dividend and assumed as a reinvestment in Flex’s rTSR calculation for any performance period that remains in progress on the Distribution Date. Flex’s rTSR performance will be adjusted to reflect the Spin-Off, and the original vesting schedule will remain unchanged.


For the rTSR PSUs held by Spinco employees, performance for completed performance cycles will be banked as of the Distribution Date. For performance periods that remain in progress, performance will be based on actual performance as of the Distribution Date.


Non-CEO OP PSUs


The Supplemental PSUs granted to Hooi Tan in 2024 will be converted to Spinco RSUs in a manner similar to outstanding Flex RSUs generally, as described above. The outstanding performance period, which is expected to be at least 75% complete as of the Distribution Date, will be


78


Table of Contents

Type of Award


Treatment


determined based on actual results achieved through the Distribution Date. The original vesting schedule will remain unchanged.


CEO Supplemental Equity Award


The CEO’s supplemental PSU award that vests based on achievement of OP targets of the Cloud & Power Infrastructure business that is outstanding at the Distribution Date will be converted into Spinco PSUS in a manner similar to outstanding Flex RSUs generally, as described above, with no changes to the original award terms, performance metrics and targets, or the performance period.

General Treatment of Fractional Shares of Common Stock

Flex will not distribute any fractional common stock shares to its shareholders. Instead, the transfer agent will aggregate fractional shares into whole shares, sell the whole shares in the open market at prevailing market prices, and distribute the aggregate cash proceeds (net of discounts and commissions) of the sales pro rata (based on the fractional shares such holder would otherwise be entitled to receive) to each holder who otherwise would have been entitled to receive a fractional share of common stock in the Distribution. The transfer agent, in its sole discretion, without any influence by Flex or us, will determine when, how, through which broker-dealer and at what price to sell the whole shares. Any broker-dealer used by the transfer agent will not be an affiliate of either Flex or us. Neither we nor Flex will be able to guarantee any minimum sale price in connection with the sale of these shares. Recipients of cash in lieu of fractional shares of common stock will not be entitled to any interest on the amounts of payment made in lieu of fractional shares.

The aggregate net cash proceeds of these sales will be taxable for U.S. federal income tax purposes. For an explanation of the material United States federal income tax consequences of the Distribution, see the section of this information statement entitled “United States Federal Income Tax Consequences of the Distribution.” If you are the registered holder of Flex ordinary shares, you will receive a check from the Distribution agent in an amount equal to your pro rata share of the aggregate net cash proceeds of the sale. The amount of this payment will depend on the prices at which the transfer agent sells the aggregated fractional shares of our common stock in the open market shortly after the Distribution date and will be reduced by any amount required to be withheld for tax purposes and any brokerage fees and other expenses incurred in connection with these sales of fractional shares. If you hold your Flex ordinary shares through a bank or brokerage firm, your bank or brokerage firm will receive, on your behalf, your pro rata share of the aggregate net cash proceeds of the sales and will electronically credit your account for your share of such proceeds.

Results of the Spin-Off

Immediately following the Spin-Off, Spinco will be a separate, publicly traded company, and we expect to have approximately     shares of our common stock outstanding as a result of the Distribution. The actual number of shares to be distributed will be determined after    , 2026, the Distribution Record Date. The Distribution will not affect the number of issued and outstanding Flex ordinary shares.

Market for Spinco Common Stock

There is currently no public market for our common stock. A condition to the Distribution is the listing of our common stock shares on Nasdaq. We intend to apply to list our common stock on Nasdaq under the symbol “AXM.” We have not and will not set the initial price of shares of our common stock. The initial price will be established by the public markets.


79


Table of Contents

We cannot predict the price at which shares of our common stock will trade after the Distribution. In fact, the combined trading prices, after the Spin-Off, of shares of our common stock that each Flex shareholder will receive in the Distribution and the ordinary shares of Flex held at the Distribution Record Date may not equal the “regular-way” trading price of a Flex ordinary share immediately prior to completion of the Spin-Off. The price at which shares of our common stock trade may fluctuate significantly, particularly until an orderly public market develops. Trading prices for our common stock will be determined in the public markets and may be influenced by many factors.

Trading Between the Record Date and the Distribution Date

Beginning on or shortly before the Distribution Record Date and continuing up to and including the Distribution date, Flex expects that there will be two markets in Flex ordinary shares: a “regular-way” market and an “ex-Distribution” market. Flex ordinary shares that trade on the “regular-way” market will trade with an entitlement to shares of Spinco common stock distributed pursuant to the Distribution. Flex ordinary shares that trade on the “ex-Distribution” market will trade without an entitlement to shares of Spinco common stock distributed pursuant to the Distribution. Each shareholder trading in Flex shares would make any decision as to whether to trade one or more of such shareholder’s shares in Flex in the “regular-way” market or the “ex-Distribution” market. If you sell Flex ordinary shares in the “regular-way” market up to and including through the Distribution Date, you will be selling your right to receive shares of Spinco common stock in the Distribution. If you own Flex ordinary shares as of     Central time on    , 2026, the Distribution Record Date, and sell those shares on the “ex-Distribution” market up to and including through the Distribution Date, you will receive the shares of Spinco common stock that you are entitled to receive pursuant to your ownership as of the Distribution Record Date.

Furthermore, beginning shortly before the Distribution Date and continuing up to and including the Distribution Date, we expect that there will be a “when-issued” market in our common stock. “When-issued” trading refers to a sale or purchase made conditionally because the security has been authorized but not yet issued. The “when-issued” trading market will be a market for our common stock that will be distributed to holders of Flex ordinary shares on or about    , 2027, the Distribution Date. If you own Flex ordinary shares as of     Central time on    , 2026, the Distribution Record Date, you will be entitled to a number of shares of Spinco common stock equal to the Distribution Ratio for each Flex ordinary share you hold. You may trade this entitlement to our shares, without the Flex shares you own, on the “when-issued” market. On the first trading day following the Distribution Date, “when-issued” trading with respect to our common stock will end, and “regular-way” trading will begin.

Transaction and Separation Costs

We expect to incur certain costs in connection with our establishment as a standalone public company. These one-time and non-recurring separation costs primarily relate to employee-related costs such as recruitment expenses, costs to establish certain standalone functions and information technology systems, professional services fees, and other separation-related costs during our transition to being a stand-alone public company. Except as otherwise set forth in the Separation Agreement, any such costs incurred prior to the completion of the Spin-Off will be borne by Flex, and any such costs incurred from and after the completion of the Spin-Off will be borne by the applicable party incurring such costs.

Incurrence/Treatment of Debt

Spinco intends to incur certain indebtedness pursuant to the Spinco Financing Arrangements in connection with the Spin-Off. If Spinco enters into arrangements for such indebtedness prior to the effectiveness of the Registration Statement on Form 10, of which this information statement forms a part, a description of such arrangements will be included in an amendment to this information statement.


80


Table of Contents

Regulatory Approval

Our registration statement on Form 10, of which this information statement forms a part, must become effective prior to the Distribution, and shares of Spinco common stock to be distributed must have been approved for listing on Nasdaq, subject to official notice of Distribution.

Further, under Singapore law, following and in addition to the Flex Shareholder Approvals, the Capital Reduction and the Distribution will be submitted to and must be approved by the High Court of the Republic of Singapore. Flex currently expects to complete the Capital Reduction and the Distribution as promptly as reasonably practicable after receipt of the High-Court Approval and the satisfaction (or, to the extent permitted by applicable law, waiver by the parties entitled to the benefit thereof) of the conditions to the Distribution, other than those conditions that by definition cannot be completed prior to the Distribution. For additional detail, see the section titled “The Bonus Issuance, Capital Reduction and Distribution” beginning on page 74.

Shareholder Vote

The Bonus Issuance by Flex requires the affirmative vote by the holders of a simple majority of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting.

The Capital Reduction and Distribution by Flex requires the affirmative vote by the holders of at least three-fourths of the Flex ordinary shares present and voting (in person or by proxy) at the extraordinary general meeting.

No Appraisal Rights

Flex shareholders do not have appraisal rights under the Singapore Companies Act or contractual appraisal rights under Flex’s Constitution in connection with the Distribution. As holders of shares of Spinco common stock following the Distribution, Flex shareholders will not have appraisal rights under applicable law or contractual appraisal rights under the amended and restated certificate of formation of Spinco.


81


Table of Contents

UNITED STATES FEDERAL INCOME TAX CONSEQUENCES OF THE DISTRIBUTION

The following discussion is a summary of the generally applicable U.S. federal income tax consequences that may be relevant to Flex and to the holders of Flex ordinary shares in connection with the Distribution. This discussion is based on the Code, the Treasury Regulations promulgated thereunder, judicial interpretations thereof, and administrative rulings and published positions of the IRS, all as in effect as of the date hereof and all of which are subject to change or differing interpretations, possibly with retroactive effect. Any such change could affect the accuracy of the statements and conclusions set forth herein. This summary assumes that the Distribution will be consummated in accordance with the separation and distribution agreement and as described in this information statement.

Except as specifically described below, this summary is limited to holders of Flex ordinary shares that are U.S. Holders, as defined immediately below. For purposes of this summary, a “U.S. Holder” is a beneficial owner of Flex ordinary shares that is, for U.S. federal income tax purposes:


an individual who is a citizen or a resident of the United States;


a corporation, or other entity taxable as a corporation for U.S. federal income tax purposes, created or organized under the laws of the United States or any state thereof or the District of Columbia;


an estate, the income of which is includible in gross income for U.S. federal income tax purposes regardless of its source; or


a trust, (a) the administration of which is subject to the primary supervision of a U.S. court and which has one or more U.S. persons who have the authority to control all substantial decisions of the trust or (b) that has a valid election in effect under applicable Treasury Regulations to be treated as a U.S. person.

This discussion is limited to U.S. Holders of Flex ordinary shares that hold their Flex ordinary shares as “capital assets” within the meaning of Section 1221 of the Code (generally, property held for investment). Further, this discussion is for general information only and does not purport to address all aspects of U.S. federal income taxation that may be relevant to a particular holder in light of their particular circumstances, nor does it address the consequences to holders subject to special treatment under the United States federal income tax laws, such as:


dealers or traders in securities or currencies;


traders that elect to use a mark-to-market method of accounting;


tax-exempt entities;


banks, financial institutions, or insurance companies;


pension plans, cooperatives, real estate investment trusts, regulated investment companies, or grantor trusts;


persons who acquired Flex ordinary shares pursuant to the exercise of any employee stock options or otherwise as compensation;


persons who actually or constructively own 10% or more, by voting power or value, of Flex ordinary shares;


persons owning Flex ordinary shares as part of a straddle, hedge, conversion, constructive sale, or other integrated transaction for U.S. federal income tax purposes;


certain former citizens or long-term residents of the U.S.;


persons whose functional currency is not the U.S. dollar;


persons who are subject to special accounting rules under Section 451(b) of the Code;


82


Table of Contents
   

partnerships or other entities or arrangements subject to tax as partnerships for U.S. federal income tax purposes or persons holding Flex ordinary shares through such entities; or


persons who hold Flex ordinary shares through an individual retirement account, tax-qualified retirement plan, or other tax-deferred account.

If a partnership (or any other entity or arrangement subject to tax as a partnership for U.S. federal income tax purposes) is a beneficial owner of Flex ordinary shares, the tax treatment of a partner in such partnership will generally depend on the status of the partner and the activities of the partnership. A partnership for U.S. federal income tax purposes that beneficially owns shares of Flex and its partners are urged to consult their tax advisor as to the tax consequences of the Distribution.

In addition, this discussion does not address any U.S. state or local or non-U.S. tax considerations or any U.S. federal estate, gift, or minimum tax considerations, or the Medicare tax on certain net investment income.

HOLDERS OF FLEX ORDINARY SHARES SHOULD CONSULT THEIR TAX ADVISORS REGARDING THE PARTICULAR TAX CONSIDERATIONS RELEVANT TO THEM REGARDING THE DISTRIBUTION, INCLUDING THE APPLICABILITY AND EFFECT OF U.S. FEDERAL, STATE, LOCAL, AND NON-U.S. TAX LAWS.

Tax Opinion

It is a condition to the completion of the Distribution that Flex receives the Tax Opinion from its tax counsel, Skadden, substantially to the effect that, among other things, for U.S. federal income tax purposes, (i) the Distribution, together with certain related transactions, will qualify as a reorganization within the meaning of sections 368(a)(1)(D), 361 and 355 of the Code, and (ii) holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code. This condition may be waived by Flex in its sole discretion.

In rendering the Tax Opinion to be given as of the closing of the Distribution, Skadden will rely on (i) customary representations and covenants made by Flex and Spinco, including those contained in certificates of officers of Flex and Spinco and (ii) specified assumptions, including an assumption regarding the completion of the Distribution and certain related transactions in the manner contemplated by the transaction agreements. In addition, Skadden’s ability to provide the Tax Opinion will depend on the absence of changes in existing facts or law between the date of this information statement and the closing date of the Distribution. If any of the representations, covenants, or assumptions on which Skadden will rely are inaccurate, Skadden may not be able to provide the Tax Opinion, or the tax consequences of the Distribution could differ from those described below.

Furthermore, Flex understands that it is not possible for its tax counsel, Skadden, to reach a more definitive conclusion regarding whether holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) are required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code, as the U.S. federal income tax treatment of the Distribution to such holders depends in part on the interpretation and application of Section 367(b) of the Code and Treasury Regulations promulgated thereunder, including Treasury Regulations Section 1.367(b)-3(c). These rules are complex, and there is significant uncertainty as to whether such Treasury Regulations would apply to the Distribution because Flex is a non-U.S. corporation that is not a controlled foreign corporation for U.S. federal income tax purposes, and the Distribution is structured as a pro rata distribution of Spinco common stock to holders of Flex ordinary shares. Thus, the applicability of these Treasury Regulations is unclear.

Accordingly, certain conclusions in the Tax Opinion will relate to matters for which there is no legal authority directly on point, and such conclusions will therefore necessarily be based upon analysis and interpretation of


83


Table of Contents

certain authorities. Based upon such analysis and authorities, the Tax Opinion will provide that holders of Flex ordinary shares that are United States persons (as defined in Section 7701(a)(30) of the Code) should not be required to recognize gain pursuant to the Distribution by reason of the application of certain Treasury Regulations promulgated under Section 367(b) of the Code.

However, an opinion of counsel, such as the Tax Opinion, will not be binding upon the IRS or any court, and Flex does not intend to request a ruling from the IRS on issues related to the U.S. federal income tax consequences of the Distribution and certain related transactions. In light of the uncertainties noted above, we cannot assure you that the IRS will agree with the conclusions expected to be set forth in the Tax Opinion, and it is possible that the IRS or another tax authority could adopt a position contrary to one or all of those conclusions and that a court could sustain that contrary position. Moreover, if any of the facts, representations, assumptions, or undertakings described or made in connection with the Tax Opinion are not correct, are incomplete or have been violated, Flex’s ability to rely on the Tax Opinion, including with respect to the Intended Tax Treatment, could be jeopardized. As of the date of this information statement, we are not aware of any facts or circumstances, however, that would cause these facts, representations, or assumptions to be untrue or incomplete or that would cause any of these undertakings to fail to be complied with, in any material respect.

Treatment of the Distribution

Assuming the Distribution, together with certain related transactions, qualifies as a reorganization within the meaning of sections 368(a)(1)(D), 361 and 355 of the Code, for U.S. federal income tax purposes:


no gain or loss should be recognized by, or be includible in the income of, a U.S. Holder solely as a result of the receipt of our common stock in the Distribution, except with respect to any cash received in lieu of fractional shares;


the aggregate tax basis of the Flex ordinary shares and shares of Spinco common stock (including any fractional shares deemed received, as discussed below) in the hands of each U.S. Holder immediately after the Distribution will be the same as the aggregate tax basis of the Flex ordinary shares held by such holder immediately prior to the Distribution, allocated between the Flex ordinary shares and shares of Spinco common stock in proportion to their relative fair market value immediately following the Spin-Off; and


the holding period with respect to shares of Spinco common stock received by a U.S. Holder (including any fractional shares deemed received, as discussed below) will include the holding period of the Flex ordinary shares with respect to which such Spinco common stock was received.

A U.S. Holder that has acquired different blocks of Flex ordinary shares at different times or at different prices should consult its tax advisors regarding the allocation of its aggregate adjusted basis among, and its holding period of, our shares distributed with respect to blocks of Flex ordinary shares.

If, notwithstanding the conclusions that we expect to be included in the Tax Opinion, it is ultimately determined that the Distribution does not qualify as tax-free under Sections 368(a)(1)(D), 361 and 355 of the Code for U.S. federal income tax purposes, then Flex may recognize gain. In addition, each U.S. Holder that receives shares of Spinco common stock in the Distribution would be treated as receiving a distribution in an amount equal to the fair market value of Spinco common stock that was distributed to such holder, which would generally be taxed as a dividend.

Even if the Distribution otherwise qualifies for tax-free treatment under Sections 368(a)(1)(D), 361 and 355 of the Code, the Distribution may result in corporate level taxable gain under Section 355(e) of the Code if either Flex or Spinco undergoes a 50% or greater ownership change as part of a plan or series of related transactions that includes the Distribution, potentially including transactions occurring after the Distribution. If an acquisition or issuance of stock triggers the application of Section 355(e) of the Code, Flex would recognize such taxable gain, but the Distribution would be tax-free to each Flex shareholder (except with respect to any tax on any cash received in lieu of fractional shares).


84


Table of Contents

Furthermore, if the IRS were to successfully assert that Treasury Regulations Section 1.367(b)-3(c) applies to the Distribution, the receipt of Spinco common stock pursuant to the Distribution would be taxable to a U.S. Holder whose Flex ordinary shares have a fair market value of $50,000 or more on the Distribution Date, and such U.S. Holder would be required to recognize gain (but not loss) upon the Distribution, but there is no clear guidance regarding how such gain should be computed. Such amounts may be significant, potentially resulting in material U.S. federal income tax liabilities. However, if the fair market value of a U.S. Holder’s Flex ordinary shares is less than $50,000 on the Distribution Date, these rules would not apply, and the Distribution would not be taxable to such holder pursuant to such rules. U.S. Holders are urged to consult their tax advisor as to the applicability of these Treasury Regulations and how to determine the amount of any gain that would be required to be recognized.

A U.S. Holder that receives cash instead of fractional shares of Spinco common stock should be treated as though such U.S. Holder first received a distribution of a fractional share of Spinco common stock and then sold it for the amount of cash received. Such U.S. Holder should recognize capital gain or loss, measured by the difference between the cash received for such fractional share and the U.S. Holder’s tax basis in the fractional share, as determined above. Such capital gain or loss should generally be a long-term capital gain or loss if the U.S. Holder’s holding period for such U.S. Holder’s Flex ordinary shares exceeds one year on the Distribution Date.

U.S. Treasury Regulations require certain holders of Flex ordinary shares who receive Spinco common stock in the Distribution to attach a detailed statement setting forth certain information relating to the Distribution to their respective U.S. federal income tax returns for the year in which the Distribution occurs. Within a reasonable period after the Distribution, Flex will provide holders who receive our common stock in the Distribution with access to an IRS Form 8937 setting forth information relating to the Distribution. In addition, all holders are required to retain permanent records relating to the amount, basis, and fair market value of Spinco common stock received in the Distribution and to make those records available to the IRS upon request of the IRS.


85


Table of Contents

DIVIDEND POLICY

We do not currently intend to pay any cash dividends in the foreseeable future. We currently intend to retain all available funds and future earnings, if any, for the operation of our business and to strengthen our financial position and flexibility. The payment of cash dividends in the future will be dependent upon our revenue and earnings, capital requirements and general financial condition, and results of operations, as well as applicable law, regulatory constraints, industry practice, and other business considerations determined by our board of directors to be relevant. The payment of any cash dividends will be within the discretion of the Spinco Board of Directors. In addition, the terms governing our current or future debt may also limit or prohibit dividend payments. Accordingly, we cannot guarantee that we will ever pay dividends in the future or that we would continue to pay any dividends that we may commence in the future.

In addition, under the TBOC, Spinco may not make a distribution (as such term is defined under TBOC Section 21.002) that (a) violates our certificate of formation, (b) would render Spinco insolvent (as such term is defined under TBOC Section 1.002) or (c) exceeds our surplus (which is defined as the amount by which our net assets exceed our stated capital, as such terms are defined under TBOC Section 21.002). A dividend payable in our own shares is subject to further limitations under the TBOC, including, but not limited to, that we may not pay a share dividend in authorized but unissued shares of any class if our surplus is less than the amount required to be transferred to our stated capital at the time such share dividend is made. The Spinco Board of Directors may base determinations of whether Spinco is or would be insolvent and the amount or value of our net assets, stated capital, or surplus on our financial statements prepared in accordance with generally accepted accounting principles, a fair valuation or information from any other method that is reasonable under the circumstances, or as otherwise permitted by the TBOC.


86


Table of Contents

CAPITALIZATION

The following table sets forth our cash and cash equivalents and capitalization as of June 26, 2026, on a historical basis and on a pro forma basis to give effect to the Spin-Off and related transactions as if they had occurred on June 26, 2026. You should review the following table in conjunction with the sections of this information statement entitled “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” “Unaudited Pro Forma Condensed Combined Financial Information,” our unaudited condensed combined financial statements and the accompanying notes thereto included elsewhere in this information statement.


     As of June 26, 2026  
($ in millions)    Historical      Pro Forma  

Cash


Cash and cash equivalents

   $ 20      $ 1,100  


Indebtedness


Short-term debt

            4,374  

Long-term debt

            34  


Total debt

            4,408  


Equity


Common stock, par value $0.0001


Additional paid-in capital

            4,933  

Net parent investment

     3,515         

Accumulated other comprehensive income

     11        11  


Total equity

     3,526        4,944  

Total capitalization

   $ 3,526      $ 9,352  


We have not yet finalized our post-Distribution capitalization. Adjusted financial data reflecting our post-Distribution capitalization will be included in an amendment to the registration statement of which this information statement forms a part.


87


Table of Contents

UNAUDITED PRO FORMA COMBINED FINANCIAL INFORMATION

The following unaudited pro forma combined financial statements consist of an unaudited pro forma combined balance sheet as of June 26, 2026 and unaudited pro forma combined statement of operations for the three months ended June 26, 2026 and the year ended March 31, 2026. This unaudited pro forma financial information has been derived from the historical audited combined financial statements for the year ended March 31, 2026 and our unaudited condensed combined financial statements as of and for the three months ended June 26, 2026 included elsewhere in this information statement. All significant pro forma adjustments and their underlying assumptions are described more fully in the notes to unaudited pro forma combined financial statements, which you should read in conjunction with such unaudited pro forma combined financial statements.

The unaudited pro forma combined statement of operations gives effect to the Pro Forma Transactions (as defined below) as if they had occurred on April 1, 2025, the first day of Spinco’s fiscal year 2026. The unaudited pro forma combined balance sheet gives effect to the pro forma transactions as if they had occurred on June 26, 2026, Flex’s latest balance sheet date.

The unaudited pro forma combined financial statements include certain transaction accounting adjustments that reflect the accounting for transactions in accordance with GAAP and autonomous entity adjustments that reflect certain incremental expenses or other charges necessary, if any, to present fairly our unaudited pro forma combined statement of operations and unaudited pro forma combined balance sheet as of and for the periods indicated as if Spinco was a separate standalone entity. The following unaudited pro forma combined financial statements illustrates the effects of the following transactions (collectively, the “Pro Forma Transactions”):


the transfer and/or contractual allocation to Spinco pursuant to the Separation Agreement, Tax Matters Agreement and Employee Matters Agreement of certain residual corporate and other shared assets and liabilities that were not included in the historical combined financial statements;


the purchase price accounting adjustments and related financing for the contemplated acquisition of EPC Power Corp. (“EPC Power”), which we refer to as EPC Power PPA and Related Financing


the impact of the Transition Services Agreement and other transaction-related agreements between Spinco and Flex and the provisions contained therein (see “Certain Relationships and Related Transactions”);


the effect of our anticipated post-Distribution capital structure, including the issuance of approximately 786 million shares of Spinco common stock;


transaction and incremental income and costs expected to be incurred as an autonomous entity and specifically related to the Spin-Off; and


other adjustments described in the notes to the unaudited pro forma combined financial statements.

EPC Power Acquisition

On September 3, 2026, Flex entered into a definitive agreement to acquire EPC Power (the “EPC Power Acquisition”) for aggregate consideration of approximately $4.4 billion, subject to customary adjustments. The EPC Power Acquisition will be funded with a combination of debt and equity, including potential equity-linked securities. EPC Power adds power conversion capabilities, including differentiated grid-forming technology, for data center and utility applications. Based on the expected timing of closing of the EPC Power Acquisition during 2026, the EPC Power business will be transferred by Flex to Spinco in conjunction with the Spin-Off. The Company concluded that the criteria in Article 11 of Regulation S-X, including that the EPC Power Acquisition is probable, were met; thus, these pro forma financial statements reflect the impact of the EPC Power Acquisition method of accounting in accordance with the Accounting Standards Codification 805, Business Combinations (“ASC 805”).


88


Table of Contents

The unaudited pro forma condensed combined balance sheet gives effect to the EPC Power Acquisition as if it had occurred on June 26, 2026. The unaudited pro forma condensed combined statements of operations give effect to the EPC Power Acquisition for the three months ended June 26, 2026 and the year ended March 31, 2026 as if the acquisition had occurred on April 1, 2025. The historical financial information of EPC Power has been derived from the annual financial statements for the year ended December 31, 2025 and the unaudited interim financial statements for the six months ended June 30, 2026, included elsewhere in this information statement.

The pro forma adjustments reflect management’s preliminary estimates and assumptions based on information currently available and are subject to change as additional information becomes available and analyses are finalized, including the completion of the purchase accounting assessment and valuation procedures. Accordingly, actual adjustments may differ materially from those presented herein.

The Spin-Off

The unaudited pro forma combined financial statements have been prepared to include transaction accounting (including the impact of changes to Flex’s legal entity structure in anticipation of the Spin-Off) and autonomous entity adjustments to reflect the financial condition and results of operations as if Spinco were a standalone entity. Transaction adjustments have been presented to show the impact and associated cost as a direct result of the legal separation from Flex, including the establishment of Spinco’s expected capital structure and funding at the time of Spin-Off, and the Tax Matters Agreement. Autonomous entity adjustments have been presented to show the impact of items such as the Transition Services Agreement, lease arrangements with third parties and Flex and certain incremental costs expected to be incurred as an autonomous entity. Actual future costs incurred may differ from these estimates.

The unaudited pro forma combined financial statements were prepared in accordance with Article 11 of Regulation S-X, as amended. The unaudited pro forma combined financial statements are subject to the assumptions and adjustments described in the accompanying notes. The Pro Forma Transactions are based on available information and assumptions we believe are reasonable; however, such adjustments are subject to change. A final determination regarding our capital structure has not yet been made, and the Separation agreement, Tax Matters Agreement, Transition Services Agreement, Employee Matters Agreement,

and other transaction-related agreements have not been finalized. As such, the unaudited pro forma combined financial statements may be revised in future amendments to reflect the impact on our capital structure and the final form of those agreements, to the extent any such revisions would be deemed material.

The unaudited pro forma combined financial statements have been presented for informational purposes only. The unaudited pro forma information is not necessarily indicative of our results of operations or financial condition had the Spin-Off and the related transactions been completed on the dates assumed and should not be relied upon as a representation of our future performance or financial position as a separate public company. The historical combined financial statements have been derived from Flex’s historical accounting records and include certain corporate overhead and other shared costs which have been allocated to Spinco. The allocations have been determined on a reasonable basis; however, the amounts are not necessarily representative of the amounts that would have been reflected in the financial statements had the Company been an entity that operated independently of Flex during the periods or at the dates presented. See Note 1, “Organization of the Company” and Note 12, “Related Party Transactions” to the combined financial statements included elsewhere in this information statement for further information on the allocation of corporate and other shared costs. The following unaudited pro forma combined financial statements should be read in conjunction with our historical audited combined financial statements and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” included elsewhere in this information statement.


89


Table of Contents

UNAUDITED PRO FORMA COMBINED BALANCE SHEET


          Transaction Accounting Adjustments                      
As of June 26, 2026 (in millions)1   Spinco
Historical
    EPC Power
Historical
Adjusted
(Note 1)
    EPC Power
PPA and
related
financing
(Note 2)
        Other
Transaction
Accounting
Adjustments

(Note 3)
        Autonomous
Entity
Adjustments

(Note 4)
        Pro Forma  

ASSETS


Current assets:


Cash and cash equivalents

  $ 20     $ 141     $       $ 939     3(a)    $       $ 1,100  

Accounts receivable, net of allowance for credit losses

    1,810       127                               1,937  

Contract assets

    488                                     488  

Inventories

    1,813       171       4     2(d)                      1,988  

Customer-controlled inventory

    1,161                                     1,161  

Other current assets

    272       96                               368  


Total current assets

    5,564       535       4         939                 7,042  

Property and emquipment, net

    766       19               73     3(d)              858  

Operating lease right-of-use assets, net

    205       15               11     3(d)      24     4(e)      255  

Goodwill

    971       110       3,450     2(b)                      4,531  

Intangible assets, net

    716       41       939     2(c)                      1,696  

Other non-current assets

    47       5       (211   2(f)      420     3(g), 3(h)      (6   4(d)      255  


Total assets

  $ 8,269     $ 725     $ 4,182       $ 1,443       $ 18       $ 14,637  


LIABILITIES AND EQUITY


Current liabilities:


Accounts payable

  $ 3,688     $ 98     $       $       $       $ 3,786  

Accrued payroll and benefits

    104                     6     3(c)      1     4(g)      111  

Deferred revenue and customer working capital advances

    361       285                               646  

Other current liabilities

    323       62       4,410     2(a), 2(e)      1     3(d)      3     4(e)      4,799  


Total current liabilities

    4,476       445       4,410         7         4         9,342  

Operating lease liabilities, non-current

    182       15               1     3(d)      21     4(e)      219  

Long-term debt

          34                               34  

Other non-current liabilities

    85       13                               98  


Total liabilities

  $ 4,743     $ 507     $ 4,410       $ 8       $ 25       $ 9,693  

Equity


Common stock, par value $0.0001

  $     $     $       $     3(b)    $       $  

Additional paid-in capital

            4,940     3(b). 3(e)      (7   4(d)      4,933  

Net Parent Investment

    3,515       218       (228       (3,505   3(b)               

Accumulated other comprehensive income (loss)

    11                                     11  


Total equity

    3,526       218       (228       1,435         (7       4,944  


Total liabilities and equity

  $ 8,269     $ 725     $ 4,182       $ 1,443       $ 18       $ 14,637  


1 - For purposes of the unaudited pro forma condensed combined balance sheet, EPC Power Corp.’s historical balance sheet as of June 30, 2026 has been combined with Spinco’s historical balance sheet as of June 26, 2026. The difference between the respective reporting dates is not expected to have a material impact on the pro forma financial information presented.


90


Table of Contents

UNAUDITED PRO FORMA COMBINED STATEMENT OF OPERATIONS


          Transaction Accounting Adjustments                      
For the three months ended June 26, 2026 (in millions, except share and per
share data) 1
  Spinco
Historical
    EPC Power
Historical
Adjusted
(Note 1)
    EPC Power
PPA and
related
financing
(Note 2)
        Other
Transaction
Accounting
Adjustments

(Note 3)
        Autonomous
Entity
Adjustments

(Note 4)
        Pro Forma  

Net sales

  $ 2,202     $ 174     $       $       $ 27     4(b)    $ 2,403  

Cost of sales

    1,937       139       13     2(c)      5     3(c), 3(d)      28     4(a), 4(b), 4(f)      2,122  


Gross profit (loss)

    265       35       (13       (5       (1       281  

Selling, general and administrative expenses

    82       18           2(d)          3(c)      7     4(a), 4(c), 4(e), 4(f), 4(g)      107  

Intangible amortization

    18       2       8     2(c)                      28  


Operating income (loss)

    165       15       (21       (5       (8       146  

Interest expense

    1       1       56     2(a)                      58  

Other charges (income), net

          (1                         4(a)      (1


Income (loss) from operations before income taxes

    164       15       (77       (5       (8       89  

Provision for (benefit from) income taxes

    11             (23   2(g)      11     3(f)      (1   4(d)      (2


Net income (loss)

  $ 153     $ 15     $ (54     $ (16     $ (7     $ 91  


Pro forma earnings per share:


Basic

                    0.12  

Diluted

                    0.12  

Weighted average shares outstanding:


Basic

                    786  

Diluted

                    786  

1 - For purposes of the unaudited pro forma condensed combined statement of operations for the three months ended June 26, 2026, EPC Power’s historical results for the three months ended June 30, 2026 have been combined with Spinco’s historical results for the three months ended June 26, 2026. The difference between the respective reporting dates is not expected to have a material impact on the pro forma financial information presented.


91


Table of Contents

UNAUDITED PRO FORMA COMBINED STATEMENT OF OPERATIONS


          Transaction Accounting Adjustments                
Year Ended March 31, 2026 (in millions, except share and per share data)1   Spinco
Historical
    EPC Power
Historical
Adjusted
(Note 1)
    EPC Power
PPA and

related
financing
(Note 2)
        Other
Transaction
Accounting
Adjustments

(Note 3)
        Autonomous
Entity
Adjustments

(Note 4)
        Pro Forma  

Net sales

  $ 6,614     $ 196     $       $       $ 221     4(b)    $ 7,031  

Cost of sales

    5,831       163       55     2(c), 2(d)      34     3(c), 3(d)      218     4(a), 4(b), 4(f)      6,301  


Gross profit (loss)

    783       33       (55       (34       3         730  

Selling, general and administrative expenses

    253       46       36     2(e)      3     3(c)      46     4(a), 4(c), 4(e), 4(f), 4(g)      384  

Intangible amortization

    50       9       31     2(c)                      90  


Operating income (loss)

    480       (22     (122       (37       (43       256  

Interest expense

    5       1       226     2(a)                      232  

Other charges (income), net

    (7     (1                     (4   4(a)      (12


Income (loss) from operations before income taxes

    482      
(22

    (348       (37       (39       36  

Provision for (benefit from) income taxes

    69      

 
    (97   2(g)      (402   3(f)      (6   4(d)      (436


Net income (loss)

  $ 413     $
(22

  $ (251     $ 365       $ (33     $ 472  


Pro forma earnings per share:


Basic

                    0.60  

Diluted

                    0.60  

Weighted average shares outstanding:


Basic

                    786  

Diluted

                    786  

1 - For purposes of the unaudited pro forma condensed combined statements of operations, EPC Power Corp.’s historical results for the year ended December 31, 2025 have been combined with Spinco’s historical results for the year ended March 31, 2026. The difference between the respective reporting dates is consistent with the age-of-financial-statement provisions of Regulation S-X and is not expected to have a material impact on the pro forma financial information presented.


92


Table of Contents

NOTES TO UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION

Note 1. EPC Power Historical Adjusted

Management has performed a preliminary review of EPC Power historical accounting policies and financial statement presentation to assess conformity with those of Spinco. Based on this review, management did not identify any material differences in accounting policies requiring adjustment in the accompanying unaudited pro forma condensed combined financial information. The accompanying unaudited pro forma condensed combined financial information includes certain reclassification adjustments to EPC Power’s historical financial statement presentation to conform to Spinco’s presentation. These reclassifications had no impact on EPC Power’s reported results. Management’s review of EPC Power’s accounting policies and financial statement presentation is preliminary and subject to change as additional information becomes available and a more comprehensive evaluation is completed following the acquisition. Accordingly, additional reclassification or conformity adjustments may be identified in future periods.

1a) Reclassification Adjustments for EPC (Balance Sheet as of June 30, 2026) (in millions):


UNAUDITED RECLASS COMBINED BALANCE SHEET        

Spinco


EPC

   EPC Power
Historical
     Adjustments     Notes     EPC Power
Historical
Adjusted
 

ASSETS


Cash and cash equivalents

   Cash and cash equivalents    $ 139      $ 2       (a)     $ 141  
   Restricted cash      2        (2     (a)        

Accounts receivable, net of allowance for credit losses

   Accounts receivable      127                127  

Inventories

   Inventories, net      171            171  

Other current assets

               96       (b)       96  
   Prepaid expenses and other      42        (42     (b)        
   Inflation reduction act energy tax credit      54        (54     (b)        


Total current assets

        535                535  


Property and equipment, net

   Property and equipment, net      19                19  

Operating lease right-of-use assets, net

   Right-of-use asset, operating      15                15  

Goodwill

   Goodwill, net      110                110  

Intangible assets, net

   Intangible assets, net      41                41  

Other non-current assets

           5       (c)       5  
   Other assets      5        (5     (c)        


Total assets

      $ 725      $       $ 725  


93


Table of Contents
UNAUDITED RECLASS COMBINED BALANCE SHEET        

Spinco


EPC

   EPC Power
Historical
    Adjustments     Notes     EPC Power
Historical
Adjusted
 

LIABILITIES AND EQUITY


Accounts payable

   Accounts payable    $ 98     $       $ 98  

Deferred revenue and customer working capital advances

          285       (d)       285  
   Customer deposits      282       (282     (d)        
   Current portion of unearned warranty revenue      3       (3     (d)        

Other current liabilities

          62       (e)       62  
   Current portion of operating lease liability      2       (2     (e)        
   Accrued expenses      60       (60     (e)        
   Short-term debt                  (e)        

Total current liabilities

        445               445  


Long-Term Liabilities


Operating lease liabilities, non-current

   Operating lease liability, net      15               15  

Long-term debt, net

   Long-term debt      34               34  

Other non-current liabilities

              13       (f     13  
   Unearned warranty revenue, net      13       (13     (f      


Total liabilities

      $ 507     $       $ 507  


Equity


Common stock, par value $0.0001


Additional paid-in capital


Net Parent Investment

              218       (g     218  
   Additional paid-in capital                  (g      
   Redeemable preferred units          (g  
   Series A units      206       (206     (g      
   Preferred units      59       (59     (g      
   Accumulated deficit      (47     47       (g      
   Accumulated other comprehensive income                  (g      

Accumulated other comprehensive income (loss)

                    (g      

Total equity

        218               218  


Total liabilities and equity

      $ 725     $       $ 725  


94


Table of Contents
a)

Reclassification of Restricted Cash to Cash and Cash Equivalents

b)

Reclassification of Prepaid expenses and other and Inflation reduction act energy tax credit to Other current assets.

c)

Reclassification of Other Assets to Other non-current assets.

d)

Reclassification of Customer deposits and Current portion of unearned warranty revenue to Deferred revenue and customer working capital advances.

e)

Reclassification of Current portion of operating lease liability and Accrued expenses and Short-term debt to Other current liabilities.

f)

Reclassification of Unearned warranty revenue to Other non-current liabilities.

g)

Reclassification of historical equity to Net Parent Investment.


95


Table of Contents

1b) Reclassification Adjustments for EPC (Statement of Operations for 3 months ended - June 30, 2026) (in millions):


UNAUDITED RECLASS COMBINED STATEMENT OF OPERATIONS  

Spinco


EPC

   EPC Power
Historical
    Adjustments     Notes     EPC Power
Historical
Adjusted
 

Net sales

   Net Sales    $  174     $       $ 174  

Cost of sales

   Cost of goods sold      139               139  


Gross profit

        35               35  

Selling, general and administrative expenses

            18       (a)         18  
   Research and development      5       (5     (a)        
   Selling, general and administrative expenses      13       (13     (a)        

Intangible amortization

   Amortization expense      2               2  


Operating income

        15               15  

Interest expense

   Interest expense      1               1  

Other charges (income), net

          (1     (b)       (1
   Other income      (1     1       (b)        
   Other taxes                  (b)        


Income from operations before income taxes

        15               15  

Provision for income taxes

   Income Tax Expense                 


Net income

      $ 15     $       $ 15  


a)

Reclass of Research and development and Selling, general and administrative expenses to Selling, general and administrative expenses.

b)

Reclass of Other income and Other taxes to Other charges (income), net.


96


Table of Contents

1c) Reclassification Adjustments for EPC (Statement of Operations for Year Ended December 31, 2025 ) (in millions):


UNAUDITED RECLASS COMBINED STATEMENT OF OPERATIONS  

Spinco


EPC Historical

   EPC Power
Historical
    Adjustments     Notes     EPC Power
Historical
Adjusted
 

Net sales

   Net Sales    $ 180     $ 15       (a)     $ 196  
   Net Sales - related parties      15       (15     (a)        

Cost of sales

   Cost of goods sold       163         —          163  


Gross profit

        33               33  

Selling, general and administrative expenses

          46       (b)       46  
   Research and development      15       (15     (b)        
   Selling, general and administrative expenses      31       (31     (b)        

Intangible amortization

   Amortization expense      9               9  


Operating income (loss)

        (22             (22

Interest expense

   Interest expense      (1             1  

Other charges (income), net

          (1     (c)       (1
   Other income      (1     1       (c)        
   Other taxes                  (c)        


Income (loss) from operations before income taxes

        (22             (22

Provision for income taxes

   Income Tax Expense                     


Net income (loss)

      $ (22   $       $ (22


a)

Reclass of Net Sales and Net Sales - related parties to Net sales.

b)

Reclass of Research and development and Selling, general and administrative expenses to Selling, general and administrative expenses.

c)

Reclass of Other income and Other taxes to Other charges (income), net.

Note 2 - EPC Power PPA and Related Financing

2(a) Reflects adjustments to record the financing associated with the EPC Transaction. Based on management’s current expectations, the transaction is assumed to be funded through a 364-day bridge loan credit facility in an aggregate principle amount of $4.4 billion (the “Bridge Facility”). Spinco will incur indebtedness of up to approximately $4.4 billion, or enter into other financing arrangements, the proceeds of which will be used to pay off outstanding indebtedness under the Bridge Facility. The unaudited pro forma balance sheet reflects the estimated debt obligation and related financing costs associated with the Bridge Facility. The unaudited pro forma condensed combined statements of operations for the three months ended June 26, 2026 and the year ended March 31, 2026 have been adjusted to reflect the estimated interest expense associated for the $4.4 billion Bridge Facility, which management currently expects will represent indebtedness assumed by Spinco in connection with the contemplated Spin-Off. Management intends to replace the Bridge Facility with a combination of debt and equity. The expected interest rate associated with the Bridge Facility is approximately SOFR + 1.438%. Interest expense presented for the three months ended June 26, 2026 assumes the Bridge Facility is extended at similar terms. This rate may materially differ from actual rates based on finalization of borrowing terms.

A hypothetical increase or decrease of 1/8th of a percent (0.125%) in the assumed interest rate would increase or decrease annual interest expense by approximately $6 million, with a corresponding impact on pre-tax income. Preliminary debt issuance costs are estimated to be $26 million to raise funds associated with the Bridge Facility. These accordingly have been reflected as a reduction to the debt liability and increase to interest expense.


97


Table of Contents

The ultimate financing structure, including the allocation of indebtedness among Flex, Spinco and other affiliated entities following the contemplated Spinoff, has not yet been finalized and may differ materially from the assumptions reflected in the accompanying unaudited pro forma condensed combined financial information. Accordingly, actual financing arrangements, related interest expense and capital structure may differ materially from those presented herein.

2(b) Reflects the estimated goodwill expected to arise from the contemplated acquisition of EPC Power based on the preliminary allocation of the anticipated purchase consideration to the estimated fair values of the identifiable assets to be acquired and liabilities to be assumed less any historical goodwill recorded by EPC Power. The estimated fair values of the acquired assets, assumed liabilities, identifiable intangible assets, and related deferred tax effects are subject to change pending the completion of detailed valuation analyses and other studies necessary to finalize the allocation of purchase consideration under ASC 805. Accordingly, the final purchase price allocation may differ materially from the estimates reflected in these unaudited pro forma condensed combined financial statements, including the amount ultimately recognized as goodwill.

The table below summarizes management’s preliminary estimate of the allocation of the expected purchase consideration as if the EPC Power Acquisition had occurred on June 26, 2026 for purposes of the unaudited pro forma condensed combined financial information.


(in millions)

   EPC  

Assets


Cash and Cash equivalents

   $ 141  

Accounts receivable, net of allowance for credit losses

     127  

Inventories

     175  

Other current assets

     96  

Property and equipment, net

     19  

Operating lease right-of-use assets, net

     15  

Intangible assets, net

     980  

Other non-current assets

     (206


Total Assets

   $ 1,347  


Liabilities


Accounts payable

   $ 98  

Deferred revenue and customer working capital advances

     285  

Other current liabilities

     62  

Operating lease liabilities, non-current

     15  

Other non-current liabilities

     47  

Total Liabilities

     507  


Net Assets Acquired (a)

     840  


Estimated purchase consideration (b)

     4,400  


Estimated goodwill (b) - (a)

   $ 3,560  


98


Table of Contents

2(c) Reflects an adjustment to record the identifiable intangible assets contemplated in the EPC Transaction at their estimated fair values and to eliminate EPC’s historical intangible asset carrying amounts which amounted to $41 million as of June 30, 2026. The preliminary purchase price allocation replaces the historical carrying values of EPC’s intangible assets with estimated acquisition-date fair values assigned to the identifiable intangible assets acquired. Based on the Company’s preliminary valuation analysis, the estimated fair values, useful lives and related annual amortization of the identifiable intangible assets are as follows:


(in millions)

   Estimated
Fair Value
     Estimated
Useful Lives
     Annual
Amortization
 

Amortization on fair value of Intangible assets:


Developed technology

   $ 470        9 years      $ 52  

Customer contracts and related relationships

     440        14 years        31  

Brand assets

     70        9 years        8  


Total EPC intangible assets

     980           91  

Less: Historical EPC Power amortization

           9  


Net pro forma amortization adjustment

   $  980         $  82  


2(d) Reflects an adjustment to record EPC Power’s acquired inventory at its estimated fair value as of the acquisition date. The adjustment increases the unaudited pro forma condensed combined balance sheet to reflect the preliminary fair value of EPC Power’s finished goods and work-in-process inventory of approximately $4 million. The estimated fair value is preliminary and subject to change upon completion of the purchase price allocation and related valuation analyses. The unaudited pro forma condensed combined statement of operations for the year ended March 31, 2026 has been adjusted to increase cost of sales by the corresponding inventory step-up amount, as the acquired inventory is expected to be sold within one year of the acquisition date. No adjustment has been reflected in the three months ended June 26, 2026, as the effects of the inventory fair value adjustment are assumed to have been fully recognized during the annual period presented.

2(e) Represents the accrual of one-time additional transaction costs incurred by Spinco subsequent to June 26, 2026. The associated transaction costs are reflected as expense in the Company’s pro forma results for the fiscal year ended March 31, 2026. These costs will not affect the Company’s statement of operations beyond 12 months after the EPC Power Acquisition date.

2(f) Represents a decrease to deferred tax assets of $211 million primarily related to fair value adjustments associated with acquired intangible assets. Deferred taxes have been calculated using the federal and a blended state tax rate of 24.5%. The estimated deferred tax adjustments are preliminary and subject to material change. Such changes may result from, among other things, the deductibility of transaction-related costs, and other assumptions that will be finalized upon consummation of the Transaction.

2(g) Represents changes to the historical tax provision for EPC and the tax effect of the transaction accounting adjustments. EPC’s historic income tax provision was zero due to a full valuation allowance. Once combined with Spinco, there will be a tax provision or benefit recorded related to EPC’s operations as the combined company will not have a valuation allowance. Therefore, adjustment includes recording an income tax provision based upon the unaudited pro forma combined statements of operations as if EPC were included within the Spinco U.S. filing group. Additionally, this adjustment reflects tax effects of fair value adjustments arising from purchase accounting for the EPC Power Acquisitions and other transaction accounting adjustments, tax effected using the federal and a blended state tax rate of 24.5% for the three months ended June 26, 2026 and the year ended March 31, 2026. The federal and blended state tax rate used for the unaudited pro forma condensed combined financial statements will likely vary from the actual effective tax rates in periods as of and subsequent to the completion of the EPC Power Acquisition depending on post-Transaction activities, including legal entity restructuring and integration with Spinco, deductibility of transaction-related costs, geographical mix of earnings, realizability of deferred tax assets, among other things.


99


Table of Contents

Note 3. Other Transaction Accounting Adjustments

3(a) Reflects an adjustment to cash and additional paid-in capital to give effect to the estimated cash capitalization of approximately $1.1 billion that Spinco is expected to hold immediately following the Spin-Off. The adjustment represents the difference between the historical cash balances reflected in the historical financial statements and the estimated cash balance to be transferred to Spinco at separation pursuant to the contemplated Separation Agreement.

3(b) Reflects the reclassification of Flex’s net investment in the Company, which was recorded in Net Parent Investment, to additional paid-in capital and common stock to reflect the assumed issuance of 786 million shares of our common stock at a par value of $0.0001 per share pursuant to the separation and distribution agreement immediately prior to the Spin-Off. We have assumed the number of outstanding shares of our common stock based on the number Flex ordinary shares outstanding on June 26, 2026, and an assumed Distribution Ratio of 2.0 shares of our common stock for each share of Flex common stock. While the final Distribution Ratio has not yet been determined, the Company currently contemplates a Distribution Ratio ranging from 1.0 to 3.0 shares of our common stock for each share of Flex common stock. For purposes of these calculations, the assumed Distribution Ratio reflects the midpoint of such contemplated range. The actual number of shares issued will not be known until the Distribution Record Date. We expect between approximately 6.0% to 12.0% of our common stock will continue to be owned by Flex.

3(c) Reflects adjustment for certain employee related liabilities and compensation expense for employees that have historically been shared with other Flex businesses and will be transferred to Spinco from Flex and Flex affiliates in connection with the Spin-Off. Given the anticipated growth of Spinco, employees that partially supported Spinco historically are now intended to transfer and this adjustment reflects the incremental cost above historical allocations. The table below provides further details on the addition of this compensation expense to the unaudited pro forma combined statements of operations for the three months ended June 26, 2026 and for the year ended March 31, 2026:


(in millions)    Three Months
Ended June 26,
2026
     For the Year
Ended March 31,
2026
 

Cost of sales

   $   1      $   17  

Selling, general and administrative

     —         3  

3(d) Reflects assets, liabilities and certain operations that will be transferred to us from Flex (generally, the shared assets and liabilities to be transferred primarily relate to facilities and certain operational support assets) or removal of assets and liabilities expected to be retained by Flex in the unaudited pro forma combined balance sheet as of June 26, 2026. The estimated impact of assets and liabilities transferred to us is $108 million and $5 million, respectively, and assets and liabilities retained by Flex is $24 million and $3 million, respectively. Given the anticipated growth of Spinco, certain assets that were not historically used by the business are expected to convey at with Spinco. $4 million for the three months ended June 26, 2026 and $17 million for the year ended March 31, 2026 of incremental depreciation expense is included in cost of sales and reflects the amount in excess of the historical allocated depreciation which was attributed to the Company based on historical usage of the assets.

3(e) The additional paid-in capital adjustments are summarized below:


(in millions)    As of June 26,
2026
 

Cash receipt from Flex 3(a)

   $  939  

Spinco common stock issuance 3(b)


Additional conveying employees 3(c)

     (6

Additional conveying assets and liabilities 3(d)

     82  

Deferred taxes 3(g)

     420  

Net parent investment 3(b)

     3,505  


Total adjustment

   $  4,940  


100


Table of Contents

3(f) Reflects the tax effects of the transaction accounting adjustments using the applicable statutory tax rates and expected changes to our effective tax rate caused by changes to our legal entity structure that are expected to occur in anticipation of the Spin-Off. The transaction accounting adjustments resulted in $11 million tax expense and $402 million tax benefit for the three months ended June 26, 2026 and the year ended March 31, 2026, respectively. This adjustment also includes a tax charge of $11 million and $29 million related to the expected change to our legal entity structure for the three months ended June 26, 2026 and the year ended March 31, 2026, respectively. Additionally, for the year ended March 31, 2026, the adjustment includes a tax benefit of $422 million related to a one-time, non-cash benefit related to a step-up in tax basis that will be generated by an intercompany transaction involving Spinco intangible property that will occur prior to the separation of the Spinco business. The tax provision impact of this transaction is based on estimated amounts that may change upon the completion of the valuation of assets and liabilities. Due to the complexity of the calculations, which includes estimates of fair value and future taxable income by jurisdiction, the tax provision impact could increase or decrease materially.

3(g) Reflects the deferred tax effects of the pro forma adjustments at the applicable statutory income tax rates. Additionally, reflects $422 million related to an anticipated deferred tax asset, net of valuation allowance, related to stepped-up tax basis amortization that will be generated by an intercompany transaction involving Spinco intangible property that will occur prior to the separation of the Spinco business. The tax provision impact of this transaction is based on estimated amounts that may change upon the completion of the valuation of assets and liabilities. Due to the complexity of the calculations, which includes estimates of fair value and future taxable income by jurisdiction, the tax provision impact could increase or decrease materially.

3(h) Reflects the estimated accounting impact associated with certain customer warrants that contain anti-dilution provisions triggered upon consummation of the Spin-Off. Under the terms of the existing warrant agreement, the Warrantholder will receive a fully vested warrant to purchase a specified number of Spinco common shares at an exercise price of $0.01 per share (the “Spinco Warrant”).

The Company is evaluating the accounting implications of the Spinco Warrant, including the allocation of the resulting accounting effects between Spinco and Flex. For purposes of the unaudited pro forma financial statements, a deferred cost asset is expected to be recorded, equal to the portion of the original grant date fair value of warrants issued to the Warrantholder which will be subject to accelerated vesting in connection with the Spin-Off. The deferred cost asset is expected to be amortized as a reduction of revenue as future sales are made to the Warrantholder. The ultimate accounting treatment, valuation, and attribution between Spinco and Flex remain subject to final analysis. Accordingly, no adjustment has been reflected.

Note 4. Autonomous Entity Adjustments

Autonomous entity adjustments are necessary to reflect Spinco as an autonomous entity after separation from Flex. The terms of the agreements underlying these autonomous entity adjustments will be materially complete prior to effectiveness of the registration statement and executed in conjunction with the Spin-Off.

4(a) Reflects the effects of the Transition Services Agreement the Company intends to enter into with Flex prior to the Spin-Off in connection with the Distribution whereby Flex will continue to provide the Company functional support (primarily information technology infrastructure and applications, finance shared services, and shared facility usage at facilities retained by Flex) and the Company will continue to provide Flex functional support (primarily shared facility usage at facilities conveying with Spinco). These arrangements are intended to facilitate operational continuity following the Spin-Off while the Company establishes standalone systems, processes, and capabilities and reflect incremental costs to Spinco as they begin to operate as a standalone entity. The adjustment was calculated using assumed variable costs at arm’s length pricing over expected contract duration.

The Transaction Services Agreement impact to net income was a $7 million decrease for the three months ended June 26, 2026 and $38 million decrease for the year ended March 31, 2026, respectively.


101


Table of Contents

4(b) Reflects the impact of cross supply agreements expected to be executed prior to the Spin-Off in connection with the separation, pursuant to which Flex and Spinco will continue to supply finished goods to one another at contractually defined transfer prices. Under these arrangements, finished goods will be manufactured at certain historically commingled sites and sold to the counterparty entity at a markup, with the purchasing entity subsequently selling the finished goods to third-party customers. The cross supply pricing assumptions are based on management’s current estimates and are consistent with the expected terms of the definitive agreements. The adjustment is calculated by applying expected contract rates to historical activity which may not be indicative of actual volumes in future periods.

The cross supply agreement impact to net income was a $2 million decrease for the three months ended June 26, 2026 and $1 million increase for the year ended March 31, 2026, respectively.

4(c) Reflects recurring additional charges from contracts with vendors that are expected to be incurred by the Company as an autonomous entity following the Spin-Off. These charges relate to incremental insurance for Spinco directors and officers as well as insurance at Spinco’s manufacturing, research and development, and administrative facilities.

These adjustments are comprised of estimated incremental recurring expenses of $1 million for the three months ended June 26, 2026 and $6 million for the year ended March 31, 2026. The adjustment was calculated based on the expected annual costs under new contracts, net of historical cost allocations expected to be replaced.

4(d) Represents the tax impact of the autonomous entity pro forma adjustments for the three months ended June 26, 2026 and the year ended March 31, 2026, respectively. The tax impact reflects the expected tax effects of the incremental costs and expenses required for Spinco to operate as a standalone entity following the Spin-Off. The adjustment was calculated by applying Spinco’s assumed U.S. statutory tax rate to the other autonomous entity pro forma adjustments.

4(e) Reflects the net impact of lease arrangements with third parties and sublease arrangements with Flex for facilities that will be entered into prior to the Spin-Off. Spinco intends to enter into incremental third-party leases for administrative space and Flex intends to sublease manufacturing space from real estate conveying with Spinco. For leases Spinco enters into with third-parties, this adjustment records the operating lease right-of-use asset and related operating lease liabilities based on the estimated present value of the lease payments over the lease term. These arrangements are expected to provide the facilities necessary to support Spinco’s manufacturing, administrative, research and development, and other operational activities as a standalone company following the separation. The adjustment was calculated based on expected payments under lease and sublease arrangements.

Incremental operating lease expense is estimated to be $1 million and $2 million for the three months ended June 26, 2026 and for the year ended March 31, 2026, respectively. Incremental leasing income is estimated to be $5 million and $20 million for the three months ended June 26, 2026 and for the year ended March 31, 2026, respectively.

4(f) Reflects the reclassification of certain facility-related costs from cost of sales to selling, general and administrative expenses associated with real estate that will be conveyed to Spinco and partially subleased to Flex following the Spin-Off. Under the anticipated sublease arrangement, reimbursements received from Flex represent costs associated with managing and administering corporate real estate assets rather than costs directly attributable to Spinco’s manufacturing activities. Accordingly, these amounts have been reclassified from cost of sales to selling, general and administrative expenses in the accompanying pro forma financial information.

$3 million and $16 million were reclassed from cost of sales to selling, general and administrative expenses for the three months ended June 26, 2026 and for the year ended March 31, 2026 respectively.

4(g) Reflects the impact of new compensation agreements for new and existing executives of Spinco and includes an increase in salary, bonus, and stock-based compensation. These adjustments reflect incremental


102


Table of Contents

compensation costs expected to be incurred as Spinco establishes a standalone management structure and public company governance organization following the separation from Flex.

Incremental operating expense related to the salary and bonus is estimated to be $3 million and $14 million for the three months ended June 26, 2026 and for the year ended March 31, 2026, respectively. Additionally, Spinco expects to grant incremental stock-based compensation awards to certain members of Spinco management in connection with the Spin-Off. As of the date of this filing, such awards have not yet been authorized and the amount and form of such awards has not been determined.

These estimates were derived using expected compensation arrangement for executives including salary, bonus, and benefits for executive personnel following the Spin-Off.

Note 5. Earnings Per Share

The following table sets forth the computation of pro forma basic and diluted earnings per share for the year ended March 31, 2026, and for the three months ended June 26, 2026.


(in millions, except for per share data)

  For the Year
Ended March 31,
2026
    For the
Three-Month
Period Ended
June 26, 2026
 

Numerator:


Pro forma net income attributable to Spinco

    472       91  

Denominator:


Shares of Flex Common Stock outstanding (1)

    369       369  

Warrants (2)

    [●]       [●]  

Additional Flex share gross up (3)

    24       24  


Flex shares eligible for distribution (1) + (2) + (3)

    393       393  

Distribution ratio (4)

    2       2  

Pro Forma weighted average shares (basic)

    786       786  

Pro Forma weighted average shares (diluted) (5)

    786       786  

Pro forma net income per share attributable to Flex Common Stock:


Basic

    0.60       0.12  

Diluted

    0.60       0.12  


(1)

Representative of Flex’s ordinary shares outstanding of 369.4 million at June 26, 2026.

(2)

Reflects up to [●] million shares of common stock that the Warrantholder is eligible to receive in connection with the significant distribution as a result of the triggering provision of the Warrant caused by the Spin-off. Further, because the Warrant prohibits the exercise price from being reduced below $0.01 per share, the exercise price is expected to be reduced to that minimum amount. As a result, the Warrantholder is expected to be entitled to participate in the Distribution as if it had exercised the Warrant and held a specified number of shares immediately prior to the record date. Accordingly, the resulting shares increase Spinco’s total outstanding shares included in basic and diluted earnings per share calculations.

(3)

Represents the Flex ordinary share gross-up necessary to retain a 6% stake in Spinco subsequent to the Spin-Off date of 23.6 million shares. These shares will be an addition to the total Flex shares eligible for conversion and distribution to Spinco.

(4)

The shares issued upon such exercise are assumed to participate in the Distribution and receive Spinco common stock based on the assumed Distribution Ratio of 2 shares of Spinco common stock for each share of Flex common stock.

(5)

Pro forma basic and diluted earnings per share and pro forma weighted-average basic and diluted shares outstanding reflect the number of shares of Spinco common stock which are expected to be outstanding upon completion of the Spin-Off (see note 3(b) above). The actual dilutive effect following the completion of the Spin-Off will depend on various factors, including the impact of Flex and Spinco equity-based compensation arrangements. We cannot estimate the dilutive effects at this time.


103


Table of Contents

BUSINESS

Our Company

Spinco is a global, high-growth critical digital and electrical infrastructure company, providing end-to-end power and thermal management technologies and integrated infrastructure systems serving AI data centers and mission-critical applications. Through its critical power and electrical infrastructure portfolio, Spinco delivers electrification solutions that enable the efficient generation, distribution, and management of power.


LOGO

As a global leader in critical digital infrastructure, Spinco delivers end-to-end power and thermal management technologies for AI data centers and mission-critical applications. With deep expertise across critical power infrastructure, embedded and distributed power systems, power electronics, electrified architectures, advanced cooling, and compute integration, Spinco delivers system-level coordinated architectures that address power density, thermal performance and infrastructure scalability to replace fragmented, multi-vendor approaches.

These integrated platforms support the scalable and reliable deployment of power-dense infrastructure across artificial intelligence and high-performance computing, cloud and service providers, industrial automation, edge computing, utilities, and modern data centers.

Spinco operates a proprietary, globally integrated platform, supported by advanced engineering, manufacturing, and service capabilities across the full power value chain. By integrating power, cooling, and compute at the system level, Spinco enables faster time-to-capacity, improved infrastructure reliability, and scalable performance as power densities and thermal complexity continue to increase. The company is well positioned to benefit from long-duration secular trends including accelerating electrification, rising power intensity, and increasing infrastructure complexity while supporting customers’ energy-efficiency, power-optimization, and decarbonization objectives. These dynamics are driving a sustained, multi-year buildout of digital infrastructure, particularly as artificial intelligence adoption accelerates.

Spinco maintains a global footprint serving customers in approximately 14 countries, with 19 manufacturing sites, eight design, engineering, product introduction, and service centers, and a workforce of approximately 31,000 employees, including contractors, as of June 26, 2026.

Spinco will be headquartered in Austin, Texas.


104


Table of Contents

Industry Overview


LOGO

The global digital infrastructure industry is experiencing significant growth driven by increasing demand for compute capacity and the associated requirements for power delivery, cooling, and rapid infrastructure deployment. As cloud computing, high-performance computing, and artificial intelligence workloads expand, data center operators, hyperscalers, and colocation providers are investing in infrastructure capable of supporting significantly higher power density and thermal loads. This is a generational transformation that requires a unified system with holistic integration support from grid to chip.

This growth is also increasing demand for utility-scale power infrastructure. New data center deployments require substantial grid capacity, substation buildouts, and expanded facility-level power distribution to support megawatt-scale deployments. As a result, power availability, interconnection timelines, and utility infrastructure have become critical factors in determining deployment speed and location. These dynamics are driving closer coordination between utility power, facility infrastructure, and rack-level architectures.

Data centers can be broadly categorized into the following primary types, each characterized by distinct requirements for power infrastructure, cooling, and compute integration:


Cloud/Hyperscale: Large-scale facilities used to support cloud applications and AI workloads. This portion of the industry is growing rapidly as operators invest in high-density infrastructure and large-scale power capacity. Examples include Microsoft, Amazon Web Services, and Google Cloud.


Colocation/Multi-tenant: Facilities that provide shared infrastructure for customers to deploy compute equipment. Colocation operators are expanding capacity to support higher power densities and liquid-cooled deployments. Examples include Digital Realty, Equinix, and QTS.


Neocloud: Providers delivering AI-optimized infrastructure as a service, typically focused on high-density deployments for training and inference workloads. Examples include CoreWeave, Nebius, and Lambda Labs.


Enterprise: On-premises data centers operated by large enterprises. Growth in this segment has generally been more modest but continues to require upgrades to support higher-density infrastructure.

The addressable market for digital infrastructure includes facility and rack-level power systems, embedded power electronics, advanced cooling technologies, and integrated infrastructure platforms. According to publicly available research published by Goldman Sachs Research in September 2026, industry forecasts suggest that global power demand from data centers is forecast to increase by as much as 170% by 2030 compared to 2025. With hyperscale customers targeting 1+ megawatt racks and transitioning to higher-voltage power architectures, these trends are increasing the importance of coordinated power delivery, cooling, and rack-level integration.


105


Table of Contents

The need for speed and scale with end-to-end integration is accelerating across all customer segments. As infrastructure requirements increase, customers are prioritizing rapid deployment, consistent architecture, and the ability to scale across multiple locations. Time to capacity, execution certainty, and deployment efficiency have become critical considerations. Constraints on the availability of skilled field labor are further increasing the value of shifting assembly, integration, and testing into controlled factory environments. Prefabricated, factory-integrated, and modular infrastructure solutions are gaining adoption as customers seek to reduce on-site complexity and bring capacity online more quickly.

Higher power density is also driving changes in rack architecture and system integration. GPU-dense deployments require significantly more power per rack, advanced cooling approaches, and tighter coordination between power delivery and compute integration. These requirements increase system complexity and favor vendors capable of delivering coordinated infrastructure solutions.

The industry is also shaped by regionalization, supply chain resilience, and energy efficiency priorities. Data center operators are seeking localized manufacturing, modular deployment strategies, and more efficient power and cooling architectures to reduce lead times and manage operational risk. These factors influence vendor selection and long-term infrastructure planning.

These trends are accelerating demand for power-dense, modular infrastructure that can be deployed rapidly and scaled efficiently. As deployments grow in size and complexity, coordinated power delivery, cooling, and rack-level integration are becoming critical to bringing capacity online.

Our Segments and Geographic Revenues


LOGO

We have aligned our businesses across two operating segments: Power and Cloud & Cooling. Net sales for fiscal year 2026 increased by 38%, or $1.8 billion, to $6.6 billion from the prior year. Net sales for our Cloud & Cooling segment increased $1 billion, or 29%, to $4.5 billion from the prior year, primarily driven by the Company’s largest two customers scaling up storage infrastructure within data centers, in conjunction with increasing AI demand. Net sales for our Power segment increased $0.8 billion, or 62%, to $2.1 billion from the prior year, primarily driven by customers scaling up power capabilities and building data center infrastructure, in conjunction with increasing AI demand.

We have established an extensive network of manufacturing facilities in the world’s major markets (Asia, the Americas, and Europe) to serve both multinational and regional customers. For the fiscal year ended March 31, 2026, 65% of our net revenue was derived from customers in the Americas, 19% from customers in Europe, and 16% from customers in Asia. Our geographic revenue mix may fluctuate from period to period based on customer demand, product mix, and the timing of program ramps with key customers.


106


Table of Contents

Our Competitive Strengths


LOGO

We believe the following competitive strengths set Spinco’s business apart:

Power-Anchored Grid-to-Chip Integrated Architecture: We provide critical digital and electrical infrastructure solutions built around power delivery and management, spanning utility and facility power infrastructure, embedded rack and chip-level power systems, advanced liquid cooling, and rack-scale compute integration. This integrated architecture allows us to coordinate power, cooling, and compute at the system level rather than delivering discrete components. By designing these layers as a coordinated architecture, we help customers reduce integration complexity, improve performance, and support reliable operation in high-density deployments.

Speed and Time-to-Capacity: We integrate, assemble, and test power, cooling, and compute infrastructure in controlled factory environments to enable rapid deployment and scalable expansion. By integrating power, cooling, and compute in factory environments, we deliver pre-engineered and pre-tested modules that can reduce on-site integration requirements. This approach enables customers to bring capacity online more quickly, improve deployment consistency, and scale infrastructure across multiple locations.

Differentiated Product IP and System Integration Capabilities: We develop and manufacture proprietary technologies including facility and rack-level power systems, embedded power electronics, liquid cooling technologies, prefabricated power infrastructure, and rack-scale integration. This product and manufacturing depth enables greater control over system performance, design optimization, supply continuity, and execution, supporting delivery of coordinated infrastructure platforms that span multiple layers of deployment, from facility power to rack-level integration.

Engineering and Innovation Capabilities: Our multidisciplinary engineering capabilities span power delivery, cooling, and rack-scale integration. Our innovative portfolio includes technologies such as a UL-certified capacitive energy storage system (CESS) for fast backup power and microjet liquid cooling technology obtained through the acquisition of JetCool, designed to support high-power chip cooling. We also offer modular rack-level cooling distribution units and prefabricated power skids. We continue to invest in research and development to support increasing compute density and evolving power and cooling requirements.

Global Footprint and Regional Reach: Spinco operates a global manufacturing footprint supporting production and assembly in proximity to customer deployments. Our global presence includes engineering, manufacturing, operations, sales, and service locations across 14 countries. This geographic footprint enables localized sourcing, diversified supply chains, and operational flexibility. This footprint supports regional sourcing, capacity flexibility, consistent execution, and on-site support with timely-delivery across complex, multi-site programs.


107


Table of Contents

Deep Customer Relationships and Program Execution: We maintain strong relationships with leading hyperscalers, colocation providers, silicon companies, utilities, and technology OEMs. Our customer engagement model emphasizes early collaboration and, in certain cases, co-development. Our engineering and manufacturing teams work closely with customers to translate their complex technology roadmaps into scalable deployments and multi-year programs, supporting evolving infrastructure requirements.

Our Strategy

Our strategy is to drive profitable, above-market growth by expanding our power-anchored infrastructure platform, accelerating customers’ time to capacity and scaling our global engineering, manufacturing and execution capabilities. We intend to strengthen our innovative portfolio across power, cooling, and rack-scale integration, deepen strategic customer relationships, improve operational execution and deploy capital toward technologies and capabilities that enhance our competitive position.

Expand and Differentiate Our Integrated Platform: We continue to invest in technologies spanning utility and facility power infrastructure, embedded rack and chip-level power systems, advanced liquid cooling, and rack-scale compute integration. Our architecture is designed to integrate these capabilities into coordinated infrastructure platforms that support higher power density and rapid deployment. By expanding our portfolio across these areas, we aim to deliver more complete solutions, reduce integration complexity, improve system performance and increase our content in customer deployments.

Enable Faster Deployment and Accelerate Time to Capacity: Customers are increasingly prioritizing speed, consistency, and scalability in infrastructure deployment. We intend to expand our factory-integrated, pre-engineered modules that combine power delivery, cooling, and rack-scale integration. This approach reduces on-site complexity, shortens deployment timelines, and enables customers to scale capacity consistently across multiple locations. We continue to enhance our modular designs, testing capabilities, and manufacturing processes to support rapid deployment and repeatable execution.

Deepen Strategic Customer Relationships: We partner with hyperscalers, colocation providers, silicon vendors, OEMs, and utilities early in their technology and infrastructure roadmaps to develop infrastructure platforms aligned with evolving requirements. Our engagement model emphasizes early collaboration, co-development, and long-term program execution. By expanding our participation across utility power, facility infrastructure, embedded power, cooling, and rack-scale integration, we aim to deepen customer relationships and increase content per deployment.

Advance Next-Generation Power Density and Cooling Technologies: We are focused on advancing technologies that support increasing power density and thermal requirements. Our strategy includes continued development of high-capacity power delivery architectures, advanced liquid cooling technologies, and rack-level integration capabilities. We also invest in monitoring, control, and system coordination capabilities to support reliable operation in high-density deployments. These efforts are intended to expand our role in next-generation infrastructure architectures.

Scale Global Operations and Regional Manufacturing: We leverage our global engineering and manufacturing footprint to support regional deployment and customer growth with consistent execution. Our investments are focused on expanding capacity, enhancing automation, and improving manufacturing efficiency across our sites. We continue to invest in regionalized production, advanced manufacturing processes, and integrated testing capabilities to support deployment speed, supply chain resilience, and cost competitiveness.

Pursue Strategic Acquisitions: We intend to build on our strong M&A track record and selectively pursue acquisitions that expand our power, cooling, and integration capabilities while expanding our product and service offerings and strengthening our global scale. Recent acquisitions include JetCool Technologies Inc., which expanded our direct-to-chip liquid cooling capabilities, and Electrical Power Products and Crown Technical Systems, both of which strengthened our critical power and utility infrastructure offerings. On September 3, 2026,


108


Table of Contents

Flex announced that it entered into a definitive agreement to acquire EPC Power, a leading provider of intelligent power conversion solutions for data center and grid applications, for $4.4 billion. The addition of EPC Power’s differentiated power conversion capabilities to Spinco’s existing power, cooling and compute portfolio broadens Spinco’s product offerings across data center and electrical infrastructure, positioning it for the transition to next-generation 800V data center power architectures as AI workloads drive higher power densities. We intend to continue evaluating opportunities that enhance our technology portfolio, expand solution scope, and support growth in integrated infrastructure platforms.

Our Portfolio and Reported Segments

Spinco provides integrated infrastructure platforms built around power delivery, cooling, and rack-scale integration for high-density computing and industrial environments. Our solutions span utility and facility power infrastructure, embedded rack and chip-level power systems, advanced liquid cooling, and rack-scale compute integration. These capabilities are designed to work together as coordinated systems that support power-dense deployments and rapid infrastructure expansion.

We will report our operations in two segments: Power and Cloud & Cooling. For each segment, we provide engineered products, services, and solutions through direct sales to hyperscalers, colocation providers, OEMs, and other infrastructure customers.

Our Power segment is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment also supports grid modernization and related power infrastructure applications.

Our Cloud & Cooling segment includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments. These offerings are frequently deployed in combination with our power infrastructure to deliver coordinated system-level solutions.

The following table summarizes our key capabilities and their role in supporting data center infrastructure.


Segment


Key Capabilities


Role in Data Center

Power


Power distribution units, backup power, power shelves, energy storage systems, power modules, voltage regulator modules, and vertical power delivery technologies


Facility-level power intake and distribution and high-efficiency rack and board-level power delivery; resilient infrastructure for megawatt-class deployments and optimized for dense AI compute environments

Cloud & Cooling


Integrated racks and servers, networking integration, advanced compute hardware, and liquid cooling systems (cold plates, coolant distribution units (CDUs)), and hybrid cooling


Turnkey compute and cooling solutions; enables rapid deployment and reliable operation of high-density workloads

See Note 11 to our combined financial statements for segment and geographic information.

Customer Concentration and Relationship Management

We sell to a concentrated set of large cloud, colocation, and silicon technology customers. Our largest customer accounted for 34%, 39% and 26% of net sales during fiscal years 2026, 2025 and 2024, respectively. Another significant customer accounted for 30%, 27% and 34% of net sales during fiscal years 2026, 2025 and 2024, respectively. Our top 10 customers accounted for 87%, 88% and 87% of net sales during fiscal years 2026, 2025 and 2024, respectively. Our array of customers that we serve are focused on the development of data centers and electrical utilities that support data centers and we are concentrated on the largest participants in those markets.


109


Table of Contents

We generally operate under master supply agreements that establish the framework for our relationships but typically do not include minimum purchase commitments or fixed pricing. We bid and are awarded business on a program-by-program basis, and customers typically issue purchase orders and rolling forecasts that may be cancellable or reschedulable under applicable terms. Many agreements provide for non-cancellable/non-returnable (“NCNR”) terms or other inventory liability coverage, and in certain cases we obtain customer deposits. See “Risk Factors—Customer and Revenue Risks” and Note 2 to our combined financial statements for significant customer information, as well as “Management’s Discussion and Analysis of Financial Condition and Results of Operations—Liquidity and Capital Resources.”

Supply Chain Management

We rely on a global network of suppliers for key components. To mitigate risks from items sourced from limited suppliers, component allocation, supply constraints, and price volatility, we use various strategies including qualifying alternative components where practicable, holding safety stock, and, in some cases, securing customer deposits or other inventory liability coverage. Certain components, including high-power semiconductors, may be subject to allocation, which could impact delivery schedules and margins. See “Risk Factors-Supply Chain, Technology, and Operational Risks.”

Working Capital Practices

We generally procure materials against customer purchase orders and forecasts and calibrate inventory to supplier lead times and program ramps. Where appropriate, we obtain customer deposits or NCNR commitments or other inventory liability coverage. Customer orders may be cancellable or reschedulable under applicable contract terms, which can affect inventory levels and cash flows. Payment terms with customers and suppliers vary by program and region. See “Management’s Discussion and Analysis of Financial Condition and Results of Operation—Liquidity and Capital Resources” for additional information.

Seasonality

Our business is not materially impacted by seasonality.

Intellectual Property

Our intellectual property—including patents, trademarks, copyrights, and unregistered proprietary technology (such as trade secrets, business processes, confidential information and know-how)—supports our product development, manufacturing, and services offerings. Our strategy includes filing patent applications, globally for proprietary new products, applications and manufacturing technology where appropriate, unless we determine to protect such products, applications or technology (or portions of them) through trade secrets or confidentiality restrictions rather than patents, taking into consideration the nature of the products, applications and technologies at issue, as well as the nature of the protections afforded by patents and trade secrets in applicable jurisdictions.

Customers of our design and manufacturing services typically grant us a license to their technology for use in providing design and manufacturing services for their products. These licenses are generally non-exclusive, are typically provided without charge, and terminate upon a material breach of the agreement or conclusion of the related program. We also have certain strategic collaborations and cross-license arrangements with certain third parties. These agreements may grant each party access to the other’s relevant intellectual property to enable commercialization of the developed solution, and may include customary provisions related to ownership or licensing of developed intellectual property, usage restrictions, and indemnification or defense obligations.

Although certain proprietary intellectual property rights are important to our company’s success, we do not believe that we are materially dependent on any particular patent, trademark, license or group of related patents, trademarks, or licenses. We seek to identify and protect our intellectual property, including our trade secrets and


110


Table of Contents

other confidential and proprietary information, through internal and external controls, including policies, procedures, and contractual protections including confidentiality agreements with our employees and third parties and through a combination of patents, trademarks, and other legal and contractual rights.

Although we take steps to protect our trade secrets, confidential information and other intellectual property, we cannot assure that misappropriation will not occur. Moreover, although we believe that our intellectual property assets and licenses are sufficient for the operation of our business as we currently conduct it, from time to time third parties may assert patent or other intellectual property infringement claims against us or our commercial partners and, in some cases, we may have liability exposure related to such assertions even if directed against our commercial partners. Intellectual property disputes can be costly and time-consuming and, if resolved adversely, could require us to obtain licenses on unfavorable terms, pay damages, or modify or cease offerings. For additional information, see “Risk Factors—Inadequate protection of our intellectual property and exposure to third-party intellectual property claims could adversely affect our business and results of operations.”

Human Capital

Our business depends on a skilled and engaged global workforce. As of June 26, 2026, we employed approximately 31,000 employees including approximately 2,000 of our contractor workforce. As of June 26, 2026, approximately 15,000 were located in the Americas; 10,000 were located in Asia; and 6,000 were located in Europe.

We focus on attracting, developing, and retaining talent and providing opportunities for career growth. We offer a broad range of training, mentoring, and career advancement opportunities, and support employees in developing individualized development plans, identifying goals, and pursuing them. We also conduct regular talent and performance reviews to support development and succession planning. Our employees receive market-informed compensation and benefits, including base pay, bonuses, and employee benefits, which are benchmarked to relevant labor markets.

We maintain programs intended to support employee well-being, including physical, mental, financial, and social health. We seek to provide a safe and healthy workplace and comply with applicable occupational health and safety requirements. We maintain environmental, health, and safety management processes, conduct regular training and audits, track safety performance metrics, and implement corrective actions as appropriate.

Competitive Landscape

We operate in highly competitive global markets spanning power infrastructure, cooling technologies, and integrated rack-scale systems. We compete with providers of facility and rack-level power infrastructure, integrated infrastructure platforms, and manufacturing and system integration services.

These competitors include global providers of critical power and cooling infrastructure such as Vertiv Holdings Co., Eaton Corporation plc, Schneider Electric SE and nVent Electric plc; suppliers of embedded and rack-level power solutions such as Delta Electronics, Inc., Lite-On Technology Corporation, and Super Micro Computer, Inc.; and electronics manufacturing services providers and original design manufacturers that support hyperscale customers, including Celestica Inc., Jabil Inc., and Foxconn.

Competition varies by program and solution scope. In power infrastructure and cooling deployments, we compete with providers of facility-level and rack-level power and thermal solutions. In integrated rack-scale systems and coordinated deployments, we compete with EMS providers, ODMs, and vertically integrated suppliers. Customers frequently use competitive bidding and multi-sourcing strategies, and some hyperscale customers have expanded internal manufacturing capabilities, which can affect outsourcing opportunities.


111


Table of Contents

We compete on a broad range of factors, including product performance and reliability; engineering and system design capabilities; ability to integrate power, cooling, and compute; manufacturing quality and yield; time to capacity; total landed cost; global footprint and proximity to customers; new product introduction and ramp capabilities; supply chain management; and after-market and lifecycle services. The relative importance of these factors varies by customer and by program.

The competitive landscape is dynamic and influenced by increasing power density, liquid cooling adoption, and compressed deployment timelines. These trends are driving demand for coordinated infrastructure solutions and are reshaping competition across traditional power infrastructure providers, cooling suppliers, and system integration vendors.

Properties

Spinco’s portfolio of owned and leased properties, including manufacturing facilities, design, engineering and product introduction centers, research and development centers, and administrative offices, provides the physical infrastructure necessary to support our global operations. Our principal facilities are strategically located to optimize production, logistics, and customer access. Our corporate headquarters will be located in Austin, Texas in a facility that we lease.

Our global footprint includes facilities that support our business. Recent facility investments include:


North America: A new facility in Dallas, Texas, dedicated to data center integration and power systems production. This site boosts capacity for grid-to-chip power infrastructure, including power pods, distribution units, and switchgear, and serves as a hub for modular production and faster deployment across the U.S.


Europe: Expanded critical power capacity with new sites in Poland and Ireland. These facilities support regional demand and enhance our ability to deliver localized solutions for European data center customers.


Asia and Rest of World: We maintain design and engineering centers in Singapore and Taiwan that support product development and serve customers in regional markets.

These facilities support our strategy to regionalize production and serve customers in key markets. As of the date of this information statement, the square footage of our manufacturing facilities by region is as follows:


     Approximate
Square Footage
(In millions)
 

Americas

     5.2  

Europe

       1.7  

Asia

     4.0  


Total

     10.9  


We believe our facilities are well-maintained and suitable for our current operational needs, with capacity for expected near-term growth.

Regulatory Considerations

We design, manufacture, integrate, and deploy power and infrastructure solutions. As a global provider, our operations are influenced by a broad range of evolving laws and regulations, including trade and export controls (including sanctions), anti-corruption, employment, and data privacy and cybersecurity. We maintain compliance programs and quality management systems intended to address these requirements; however, new, modified or more stringent rules, changes in enforcement, or customer-specific standards can increase costs, require process or supply-chain changes, delay programs, or otherwise adversely affect our operations.


112


Table of Contents

In addition, regulatory developments affecting our customers and their facility providers-such as data center siting and permitting, energy-efficiency and usage, waste heat reuse and emissions rules, telecommunications and connectivity requirements, and AI-related frameworks-may impact site readiness, delivery timelines, and demand for our solutions. We monitor legal changes across jurisdictions and work with customers, suppliers, and logistics partners to support compliance, but cannot predict the scope, timing, or impact of future requirements, and any failure to comply could have a material adverse effect on our business, results of operations, financial condition, and competitive position. See the section entitled “Risk Factors—Legal and Regulatory Risks” for a more detailed description of the regulatory risks we face.

Environmental and Other Legal Proceedings

We are subject to a variety of extensive and changing federal, state, local and international environmental, health and safety, product safety and stewardship, and producer responsibility laws and regulations, including those concerning, among other things, the health and safety of our employees, the generation, use, storage, transportation, discharge and disposal of certain materials (including chemicals and hazardous materials) used in or derived from our operations, the investigation and remediation of contaminated sites, and climate change and other sustainability-related matters. We have implemented processes and procedures aimed to ensure that our operations comply with all applicable laws and regulations. Environmental legislation also occurs at the product level. We work with our customers in connection with compliance with applicable product-level environmental legislation in the jurisdictions where products are manufactured and/or offered for use and sale by our customers.


113


Table of Contents

MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS

This section should be read in conjunction with the audited combined financial statements and related notes, included in this information statement, as well as the information contained in the sections of this information statement titled “Unaudited Pro Forma Combined Financial Information.” This section contains forward-looking statements. See the sections of this information statement titled “Cautionary Statement Concerning Forward-Looking Statements” and “Risk Factors” for a discussion of the uncertainties, risks and assumptions associated with these forward-looking statements that could cause future results to differ materially from those reflected in this section. The financial information discussed below and included in this information statement may not necessarily reflect what our financial condition, results of operations or cash flows would have been had we been a standalone company during the periods presented or what our financial condition, results of operations and cash flows may be in the future.

OVERVIEW

Spinco is a global provider of end-to-end power and thermal management products and integrated infrastructure systems serving AI data centers and mission-critical applications. Through its critical power and electrical infrastructure portfolio, Spinco delivers electrification solutions that enable the efficient generation, distribution, and management of power. Deep expertise across critical power infrastructure, embedded and distributed power systems, power electronics, electrified architectures, advanced cooling, and compute integration allows Spinco to deliver coordinated, system-level solutions designed to replace fragmented, multi-vendor approaches. As of June 26, 2026, Spinco reports its financial performance based on two operating and reportable segments as follows:

(i) Power is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment supports grid modernization and related power infrastructure applications.

(ii) Cloud & Cooling includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments.

Spinco operates a proprietary, globally integrated platform, supported by advanced engineering, manufacturing, and service capabilities across the full power value chain.

By integrating power, cooling, and compute at the system level, Spinco enables faster time-to-capacity, improved infrastructure reliability, and scalable performance as power densities and thermal complexity continue to increase. The Company is well positioned to benefit from accelerating electrification and power-intensity trends while supporting customers’ energy-efficiency, power-optimization, and decarbonization objectives.

We are continuously evaluating our capital structure in response to the current environment and expect that our current financial condition, including our liquidity sources are adequate to fund future commitments and growth. See additional discussion in the “Liquidity and Capital Resources” section below.

Spin-Off from Flex

Flex plans to separate into two standalone, publicly traded companies. Flex has determined to implement this separation through the Spin-Off of Flex’s Cloud & Power Infrastructure business to its shareholders. Flex intends to effect the Spin-Off pursuant to an internal reorganization followed by a pro rata distribution of between approximately 88.0% to 94.0% of the shares of our common stock held by Flex to holders of Flex ordinary shares. Completion of the Spin-Off is subject to certain conditions which are described more fully under “The Separation and Distribution.”


114


Table of Contents

Relationship with Flex

The combined financial statements included in this information statement are derived from Flex’s historical accounting records and presented on a standalone basis as if Spinco’s operations had been conducted independently from Flex. The combined financial statements are prepared in accordance with GAAP and Flex’s historical accounting policies by aggregating financial information from the components of Spinco’s and Flex’s accounting records directly attributable to Spinco.

The combined financial statements include all revenues and costs directly attributable to the Spinco business and an allocation of expenses related to certain Flex corporate functions. When direct usage was identifiable, costs were allocated based on usage; otherwise, costs were primarily allocated on a basis of revenue, headcount, square footage, utilization, or value added margin. Spinco and Flex consider these allocations to be a reasonable reflection of the utilization of services or the benefits received. However, the allocations may not be indicative of the actual expense that would have been incurred had Spinco operated as an independent, standalone entity, nor are they indicative of future expenses of Spinco.

In connection with the Spin-Off, we intend to enter into the Separation Agreement, the Stockholder’s and Registration Rights Agreement and certain other agreements with Flex, including the Transition Services Agreement, the Tax Matters Agreement, the Employee Matters Agreement, the Intellectual Property Matters Agreement, real estate-related agreements, other confidentiality-related and commercial agreements, and other agreements, as described in “Certain Relationships and Related Transactions.” We generally expect to be able to utilize Flex’s services for a transitional period following the Spin-Off before we replace these services over time with services supplied either internally or by third parties. The expenses for the services may vary from the historical costs directly billed and allocated to us for the same services.

We expect to incur certain costs in connection with our establishment as a standalone public company. These one-time and non-recurring separation costs primarily relate to employee-related costs such as recruitment expenses, costs to establish certain standalone functions and information technology systems, professional services fees, and other separation-related costs during our transition to being a stand-alone public company. Except as otherwise set forth in the Separation Agreement, any such costs incurred prior to the completion of the Spin-Off will be borne by Flex, and any such costs incurred from and after the completion of the Spin-Off will be borne by the applicable party incurring such costs.

Update on Component Shortages and Logistical Constraints on our Business

Component shortages experienced in the recent past have largely subsided; however, logistical constraints persist which have increased freight costs. We continue to monitor potential supply chain disruptions, as a result of emerging and evolving geopolitical tensions and tariff implementations. Refer to “Risk FactorsConstrained supply and dependence on single- or limited-source components may elongate lead times, increase costs, and create misalignment with customer obligations” and “—Global economic conditions, including inflationary pressures, currency volatility, trade conflicts, geopolitical uncertainty, and instability in financial markets, may adversely affect our business, financial condition, results of operations, and access to capital.”

Tariffs

The U.S. tariffs imposed or proposed in recent periods, which continue to evolve as a result of changes in trade policy and related legal developments, and other countries’ potential retaliatory tariffs and import/export restrictions, may materially increase our product input costs and negatively affect global economic conditions contracting customer demand. As a manufacturer, we seek to recover the cost of tariffs by passing tariff costs to our customers which would increase net sales, decrease operating income margins, and negatively affect operating cash flow timing. During the quarter ended June 26, 2026 and the fiscal year ended March 31, 2026, tariff costs paid and recoveries from our customers had a negligible impact on our profitability. If, in the future, we are no longer able to fully pass through these tariffs, our results from operations and cash flows would be


115


Table of Contents

negatively impacted. On February 20, 2026, the U.S. Supreme Court ruled that tariffs imposed under the International Emergency Economic Powers Act (“IEEPA”) were not authorized by Congress, invalidating a significant portion of tariffs announced in April 2025. On April 20, 2026, the U.S. government opened a system to facilitate refunds for IEEPA tariffs paid. We are collecting refunds on tariffs paid and do not expect that any refunds received would have a material effect on our financial position or performance. We will continue to monitor changes in global trade policy and employ measures to mitigate the impact of tariffs and leverage competitive opportunities. However, despite these efforts, the Company may not be able to fully mitigate the impact of changes in trade policy. See “Risk FactorsTariffs, trade restrictions, changes in trade policy, including heightened trade volatility, and uncertainty regarding trade agreements may adversely affect our business.”

Memory Pricing Environment

During the first quarter of fiscal year 2027, market prices for memory components, including DRAM and NAND products, remained elevated as industry supply continued to be constrained by strong demand from AI and data center applications. The Company generally expects to pass through increases in memory costs to its customers, where contractual mechanisms permit recovery of component cost increases, however, sustained increases in memory pricing could continue to favorably impact net sales, while unfavorably impacting our gross profit percentage and increasing inventory balances and working capital requirements.

Business Overview

We are a global provider of end-to-end power and thermal management products and integrated infrastructure systems, with revenues of $2.2 billion for the three-month period ended June 26, 2026 and $6.6 billion in the fiscal year ended March 31, 2026. We have an extensive network of manufacturing facilities in the world’s major markets (Asia, the Americas, and Europe) to serve the data center deployment needs of both multinational and regional customers. We design, build, ship, and service products for our customers through a network of 39 locations in 14 countries across four continents. The following tables set forth the relative percentages and dollar amounts of net sales by region and by country, and net property and equipment, by country, based on the location of our manufacturing sites (amounts may not sum due to rounding):


     Three-Month Periods Ended  
     June 26,
2026
    June 27,
2025
 
     (In millions)  

Net sales by region:


Americas

   $ 1,539        70   $ 1,175        72

Europe

     338        15     271        17

Asia

     325        15     180        11


   $ 2,202        $ 1,626     


Net sales by country:


Mexico

   $ 777        35   $ 528        32

U.S.

     760        35     646        40

Malaysia

     258        12     117        7

Poland

     110        5     47        3

UK

     95        4     76        5

Israel

     92        4     109        7

Other

     110        5     103        6


   $ 2,202        $ 1,626     


116


Table of Contents
     As of June 26,
2026
    As of March 31,
2026
 
     (In millions)  

Property and equipment, net:


Mexico

   $ 442        58   $ 334        59

Malaysia

     118        15     97        17

U.S.

     92        12     26        5

China

     49        7     48        8

Poland

     26        3     25        4

Other

     39        5     38        7


   $ 766        $ 568     


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Net sales by region:


Americas

   $ 4,320        65   $ 3,335        69   $ 2,055        63

Europe

     1,245        19     941        20     710        22

Asia

     1,049        16     523        11     479        15


   $ 6,614        $ 4,799        $ 3,244     


Net sales by country:


U.S.

   $ 2,457        37   $ 1,537        32   $ 1,331        41

Mexico

     1,856        28     1,790        37     720        22

Malaysia

     701        11     298        6     177        5

UK

     392        6     353        7     288        9

Israel

     381        6     347        7     289        9

China

     339        5     219        5     290        9

Other

     488        7     255        6     149        5


   $ 6,614        $ 4,799        $ 3,244     


     As of March 31,  
     2026     2025  
     (In millions)  

Property and equipment, net:


Mexico

   $ 334        59   $ 112        46

Malaysia

     97        17     67        27

China

     48        8     19        8

U.S.

     26        5     6        2

Poland

     25        4     15        6

Other

     38        7     27        11


   $ 568        $ 246     


We believe that the combination of our extensive open innovation platform solutions, design and engineering services, significant scale and global presence, and manufacturing campuses, including many in low-cost geographic areas provide us with a competitive advantage and strong differentiation in the market for designing, manufacturing and servicing data center products for leading multinational and regional customers. Specifically, we help customers reduce handoffs between power, cooling, and IT teams and improve reliability for high-density workloads.


117


Table of Contents

Our operating results are affected by a number of factors, including the following:


global economic conditions, including inflationary pressures, currency volatility, trade conflicts, and geopolitical uncertainty and instability in financial markets;


the mix of products and services we are providing to customers and the evolution of the data center landscape;


our ability to achieve commercially viable products and services demanded by our customers;


our concentration among a limited number of customers;


the effects on our business due to the quickly evolving infrastructure for data centers, with certain products encountering shortened lifecycles;


evolving regulations relating to energy, utilities, and data center development;


the effects that current credit and market conditions could have on the liquidity and financial condition of our customers and suppliers, including any impact on their ability to meet their contractual obligations;


the impacts on our business due to component shortages, disruptions in transportation or other supply chain related constraints;


integration of acquired businesses and facilities;


increased labor costs due to adverse labor conditions in the markets we operate;


fluctuations in foreign currency exchange rates;


changes in tax legislation;


changes in trade regulations and treaties; and


exposure to infectious disease, epidemics and pandemics on our business operations in geographic locations impacted by an outbreak and on the business operations of our customers and suppliers.

We also are subject to other risks as outlined in “Risk Factors.”

Net sales for the three-month period ended June 26, 2026 increased by $0.6 billion, or 35%, to $2.2 billion from the three-month period ended June 27, 2025. Net sales for our Cloud & Cooling segment rose $0.2 billion, or 14%, from $1.2 billion in the three-month period ended June 27, 2025 to $1.4 billion in the three-month period ended June 26, 2026 due to increased market demand. Net sales in the Power segment increased by $0.4 billion, or 107%, largely driven by market demand combined with contributions from the recent Electrical Power Products, Inc. (“EPP”) acquisition. Our three-month period ended June 26, 2026 gross profit totaled $0.3 billion, representing an increase of $0.1 billion, or 38%, from the three-month period ended June 27, 2025. Our three-month period ended June 26, 2026 net income totaled $0.2 billion, representing an increase of $0.1 billion, or 47%, compared to the three-month period ended June 27, 2025, due to the factors explained above net of a $0.5 billion increase in cost of goods sold from growth in the business.

Net sales for fiscal year 2026 increased by 38%, or $1.8 billion, to $6.6 billion from the prior year. Net sales for our Cloud & Cooling segment increased $1 billion, or 29%, to $4.5 billion from the prior year, primarily driven by the Company’s largest two customers scaling up storage infrastructure within data centers associated with increasing AI demand. Net sales for our Power segment increased $0.8 billion, or 62%, to $2.1 billion from the prior year, primarily driven by customers scaling up power capabilities and building data center infrastructure. Our fiscal year 2026 gross profit totaled $0.8 billion, representing an increase of $0.2 billion, or 26%, from the prior year. Our fiscal year 2026 net income totaled $0.4 billion, representing an increase of $0.1 billion, or 29%, compared to fiscal year 2025, due to the factors explained above net of a $0.1 billion increase in selling, general and administrative expenses from growth in the business.


118


Table of Contents

CRITICAL ACCOUNTING ESTIMATES

The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities, the disclosure of contingent assets and liabilities at the date of the financial statements, and the reported amounts of revenues and expenses during the reporting period. Due to global economic conditions, including the impact of ongoing trade conflicts and tariffs, and geopolitical conflicts, there has been and we expect there will continue to be uncertainty and disruption in the global economy and financial markets. We have made estimates and assumptions taking into consideration certain possible impacts due to the foregoing factors. These estimates may change, as new events occur, and additional information is obtained. Actual results may differ from previously estimated amounts, and such differences may be material to the combined financial statements. Estimates and assumptions are reviewed periodically, and the effects of revisions are reflected in the period they occur.

We believe the following critical accounting estimates affect our more significant judgments and estimates used in the preparation of our combined financial statements. For further discussion of our significant accounting policies, refer to note 2, “Summary of Accounting Policies,” in the notes to the combined financial statements for further details.

Revenue Recognition

In determining the appropriate amount of revenue to recognize, the Company applies the following steps: (i) identifies the contracts with the customers; (ii) identifies performance obligations in the contracts; (iii) determines the transaction price; (iv) allocates the transaction price to the performance obligations per the contracts; and (v) recognizes revenue when (or as) the Company satisfies a performance obligation. Further, the Company assesses whether control of the products or services promised under the contract is transferred to the customer at a point in time (“PIT”) or over time (“OT”). The Company is first required to evaluate whether its contracts meet the criteria for OT recognition. For certain contracts the Company has determined that for a portion of its contracts the Company is manufacturing products for which there is no alternative use (due to the unique nature of the customer-specific product and intellectual property restrictions) and the Company has an enforceable right to payment including a reasonable profit for work-in-progress inventory with respect to these contracts. For certain other contracts, the Company’s performance creates and enhances an asset that the customer controls as the Company performs under the contract. As a result, revenue is recognized under these contracts OT based on the cost-to-cost method as it best depicts the transfer of control to the customer measured based on the ratio of costs incurred to date as compared to the total estimated costs at completion of the performance obligation. For all other contracts that do not meet these criteria, the Company recognizes revenue when it has transferred control of the related manufactured products which generally occurs upon delivery and passage of title to the customer. Service contract revenue is recognized on an over time basis using the output method. Certain customer contracts include buy-sell arrangements under which the Company purchases raw materials from customers and incorporates those materials into finished goods that are subsequently sold back to the same customers (buy-sell arrangements). The Company accounts for buy-sell arrangements by reducing the transaction price associated with the related sale. As a result, net sales were reduced by approximately $2.4 billion and $0.8 billion during the three-month periods ended June 26, 2026 and June 27, 2025, respectively, and by $4.3 billion, $1.6 billion and $0.8 billion during fiscal years 2026, 2025 and 2024, respectively, for buy-sell arrangements. Refer to note 4, “Revenue,” in the notes to the combined financial statements for further details.

Customer Contracts and Related Obligations

Certain of our customer agreements include potential price adjustments which may result in variable consideration. These price adjustments include, but are not limited to, sharing of cost savings, committed price reductions, purchase price variances earned over the period that are contractually required to be paid to the customers, rebates, refunds tied to performance metrics such as on-time delivery, and other periodic pricing


119


Table of Contents

resets that may be refundable to customers. The Company estimates the variable consideration related to these price adjustments as part of the total transaction price and recognizes revenue in accordance with the pattern applicable to the performance obligation, subject to a constraint. The Company constrains the amount of revenues recognized for these contractual provisions based on our best estimate of the amount which will not result in a significant reversal of revenue in a future period. The Company determines the amounts to be recognized based on the amount of potential refunds required by the contract, historical experience and other surrounding facts and circumstances. Often these obligations are settled with the customer in a period after shipment through various methods which include reduction of prices for future purchases, issuance of a payment to the customer, or issuance of a credit note applied against the customer’s accounts receivable balance. In many instances, the agreement is silent on the settlement mechanism. Any difference between the amount accrued for potential refunds and the actual amount agreed to with the customer is recorded as an increase or decrease in revenue. Refer to note 4, “Revenue,” in the notes to the combined financial statements for further details.

Inventory Valuation

Our inventories are stated at the lower of cost (on a first-in, first-out basis) or net realizable value. Our industry is characterized by rapid technological change, short-term customer commitments and rapid changes in demand. We purchase our inventory based on forecasted demand and anticipated component shortages, and we estimate write downs for excess and obsolete inventory based on our regular reviews of inventory quantities on hand, and the latest forecasts of product demand and production requirements from our customers. If actual market conditions or our customers’ product demands are less favorable than those projected, additional write downs may be required. In addition, unanticipated changes in the liquidity or financial position of our customers and/or changes in economic conditions may require additional write downs for inventories due to our customers’ inability to fulfill their contractual obligations with regard to inventory procured to fulfill customer demand.

Carrying Value of Long-Lived Assets

We review property and equipment and acquired amortizable intangible assets for impairment at least annually and whenever events or changes in circumstances indicate that the carrying amount of the asset group may not be recoverable. An impairment loss is recognized when the carrying amount of the asset group exceeds its fair value. Recoverability of property and equipment and acquired amortizable intangible assets are measured by comparing their carrying amount to the projected cash flows the assets are expected to generate. If such asset groups are determined to be impaired, the impairment loss recognized, if any, is the amount by which the carrying amount of the property and equipment and acquired amortizable intangible assets exceeds fair value. Our judgments regarding projected cash flows for an extended period of time and the fair value of assets may be impacted by changes in market conditions, the general business environment and other factors including geopolitical conflicts, which remain highly uncertain and unpredictable. If our actual results relating to cash flows and fair value of assets are not consistent with our estimates and assumptions, it could result in material impairment charges in the future.

Business Combinations

In business combinations, the fair value of the net assets acquired and the results of the acquired businesses are included in the Company’s combined financial statements from the acquisition dates forward. The Company is required to make estimates and assumptions that affect the reported amounts of assets and liabilities and results of operations during the reporting period. Estimates are used in accounting for, among other things, the fair value of acquired net operating assets, property and equipment, intangible assets and related deferred tax balances, useful lives of plant and equipment and amortizable lives for acquired intangible assets. Any excess of the purchase consideration over the fair value of the identified assets and liabilities acquired is recognized as goodwill and if the fair value of assets acquired and liabilities assumed exceeds the purchase consideration a gain on bargain purchase is recognized.


120


Table of Contents

The Company estimates the preliminary fair value of acquired assets and liabilities as of the date of acquisition based on information available at that time. Contingent consideration is recorded at fair value as of the date of the acquisition with subsequent adjustments recorded in earnings. The valuation of acquired assets and liabilities is subject to further management review and may change between the preliminary allocation and end of the one-year purchase price allocation period. Refer to note 10, “Business Acquisitions,” in the notes to the combined financial statements for further details on our acquisitions.

Goodwill

Goodwill is tested for impairment on an annual basis and whenever events or changes in circumstances indicate that the carrying amount of goodwill may not be recoverable. Recoverability of goodwill is measured at the reporting unit level by comparing the reporting unit’s carrying amount, including goodwill, to the fair value of the reporting unit, which is measured based upon, among other factors, market multiples for comparable companies as well as a discounted cash flow analysis. These approaches use significant unobservable inputs, or Level 3 inputs, as defined by the fair value hierarchy and require us to make various judgmental assumptions about sales, operating margins, growth rates and discount rates which consider our budgets, business plans and economic projections, and are believed to reflect market participant views. Some of the inherent estimates and assumptions used in determining fair value of the reporting units are outside the control of management, including interest rates, cost of capital, tax rates, market EBITDA comparables and credit ratings. While we believe we have made reasonable estimates and assumptions to calculate the fair value of the reporting units, it is possible a material change could occur. If our actual results are not consistent with our estimates and assumptions used to calculate fair value, it could result in material impairments of our goodwill. Refer to note 2, “Summary of Accounting Policies,” in the notes to the combined financial statements for further details on our goodwill.

Income Taxes

Our deferred income tax assets represent temporary differences between the carrying amount and the tax basis of existing assets and liabilities, which will result in deductible amounts in future years, including net operating loss carry forwards. Based on estimates, the carrying value of our net deferred tax assets assumes that it is more likely than not that we will be able to generate sufficient future taxable income in certain tax jurisdictions to realize these deferred income tax assets. Our judgments regarding future profitability may change due to future market conditions, changes in U.S. or international tax laws and other factors. If these estimates and related assumptions change in the future, we may be required to increase or decrease our valuation allowance against deferred tax assets previously recognized, resulting in additional or lesser income tax expense.

We are regularly subject to tax return audits and examinations by various taxing jurisdictions around the world, and there can be no assurance that the final determination of any tax examinations will not be materially different than that which is reflected in our income tax provisions and accruals. Should additional taxes be assessed as a result of a current or future examination, there could be a material adverse effect on our tax position, operating results, financial position and cash flows. Refer to note 9, “Income Taxes,” in the notes to the combined financial statements for further discussion of our tax position.

RESULTS OF OPERATIONS

Three-Month Periods Ended June 26, 2026 and June 27, 2025

The following table sets forth, for the periods indicated, certain statements of operations data expressed as a percentage of net sales (amounts may not sum due to rounding). The financial information and the discussion below should be read in conjunction with the combined financial statements and notes thereto.


121


Table of Contents

The data below, and discussion that follows, represents our results from operations, and relative percentages.


     Three-Month Periods Ended  
     June 26,
2026
    June 27,
2025
 

Net sales

     100.0     100.0

Cost of sales

     88.0     88.2


Gross profit

     12.0     11.8

Selling, general and administrative expenses

     3.7     3.5

Intangible amortization

     0.8     0.8


Operating income

     7.5     7.5

Interest expense

     —      0.1

Other charges (income), net

     —      0.1


Income before income taxes

     7.5     7.3

Provision for income taxes

     0.6     0.9


Net income

     6.9     6.4


Net sales

The following table sets forth our net sales by segment, and their relative percentages:


     Three-Month Periods Ended  
     June 26,
2026
    June 27,
2025
 
     (In millions)  

Net sales:


Cloud & Cooling

   $ 1,436        65   $ 1,256        77

Power

     766        35     370        23


   $ 2,202        $ 1,626     


Net sales for the three-month period ended June 26, 2026 increased by $0.6 billion, or 35%, to $2.2 billion from the three-month period ended June 27, 2025. Net sales for our Cloud & Cooling segment rose $0.2 billion, or 14%, from $1.2 billion in the three-month period ended June 27, 2025 to $1.4 billion in the three-month period ended June 26, 2026 due to increased market demand. Net sales in the Power segment increased by $0.4 billion, or 107%, largely driven by market demand combined with contributions from the EPP acquisition.

Net sales for the three-month period ended June 26, 2026, compared to the three-month period ended June 27, 2025, increased from $1.2 billion to $1.5 billion in the Americas, remained consistent at $0.3 billion in Europe and increased from $0.2 billion to $0.3 billion in Asia.

Our largest customer accounted for 42% and 38% of net sales during the three-month periods ended June 26, 2026 and June 27, 2025, respectively. Another significant customer accounted for 22% and 34% of net sales during the three-month periods ended June 26, 2026 and June 27, 2025, respectively. Our array of customers that we serve are focused on the development of data centers and electrical utilities that support data centers and we are concentrated on the largest participants in those spaces.

Cost of sales

Cost of sales is affected by a number of factors, including new product initiatives, product mix, labor cost fluctuations by region, component costs and availability and capacity utilization.


122


Table of Contents

Cost of sales during the three-month period ended June 26, 2026 totaled $1.9 billion, representing an increase of $0.5 billion, or 35%, from $1.4 billion during the three-month period ended June 27, 2025, in line with the revenue growth. Cost of sales remained at 88% of net sales for the three-month periods ended June 26, 2026 and June 27, 2025 as costs grew proportionately with revenue.

Cost of sales in Cloud & Cooling increased $0.2 billion, or 15%, from the three-month period ended June 27, 2025 and cost of sales in Power for the three-month period ended June 26, 2026 increased $0.3 billion, or 106%, from the three-month period ended June 27, 2025.

Gross profit

Gross profit is affected by a fluctuation in cost of sales elements as outlined above and further by a number of factors, including product lifecycles, unit volumes, product mix, pricing, competition, new product introductions, and the expansion or consolidation of manufacturing facilities, as well as specific restructuring activities initiated from time to time. In the case of new product initiatives, profitability normally lags revenue growth due to product start-up costs, lower manufacturing volumes with new product launches, operational inefficiencies, and under-absorbed overhead. Gross margin for new products often improves over time as manufacturing volumes increase and as our utilization rates and overhead absorption improves. As a result of these various factors, our gross margin varies from period to period.

Gross profit during the three-month period ended June 26, 2026 increased $0.1 billion to $0.3 billion, from $0.2 billion during the three-month period ended June 27, 2025. Gross profit remained at 12% of net sales for the three-month periods ended June 26, 2026 and June 27, 2025 due to the factors outlined above.

Segment income

An operating segment’s performance is evaluated based on its segment income. Segment income is defined as net sales less cost of sales, and selling, general and administrative expenses, and does not include amortization of intangibles, stock-based compensation, certain restructuring charges, legal and other, interest expense, and other charges (income).

The following table sets forth segment income and margins. Segment margins in the table below may not recalculate exactly due to rounding.


     Three-Month Periods Ended  
     June 26,
2026
    June 27,
2025
 
     (In millions)  

Segment income:


Cloud & Cooling

   $ 112        7.8   $ 107        8.5

Power

     102        13.3     44        11.9

Cloud & Cooling segment margin decreased 70 basis points to 7.8%, for the three-month period ended June 26, 2026, from 8.5% for the three-month period ended June 27, 2025. The margin decrease during the period was driven by increased labor and overheads as the business scales.

Power segment margin increased 140 basis points to 13.3%, for the three-month period ended June 26, 2026, from 11.9% for the three-month period ended June 27, 2025. The margin increase in the Power segment was primarily driven by significant growth in the Power segment including the acquisition of EPP.

Selling, general and administrative expenses

Selling, general and administrative expenses (“SG&A”) totaled $82 million, during the three-month period ended June 26, 2026, compared to $57 million during the three-month period ended June 27, 2025, increasing by


123


Table of Contents

$25 million primarily due to a $5 million increase in employee costs (including stock-based compensation), a $14 million increase in various corporate allocations, in line with growth of the business and a $9 million increase in transaction costs.

Intangible amortization

Amortization of intangible assets was $20 million (including $2 million recorded within cost of sales) in the three-month period ended June 26, 2026 compared to $13 million in the three-month period ended June 27, 2025, increasing due to the EPP acquisition.

Interest expense

Interest expense was $1 million during the three-month period ended June 26, 2026, compared to $2 million during the three-month period ended June 27, 2025, decreasing $1 million from reduced accounts receivable factoring during the period.

Other Charges (Income), net

Other charges were $0 million in the three-month period ended June 26, 2026, compared to charges of $2 million in the three-month period ended June 27, 2025, due to favorable foreign exchange movements.

Income taxes


     Three-Month Periods
Ended
 
     June 26,
2026
    June 27,
2025
 
     (In millions)  

Income before income taxes

   $ 164     $ 118  

Provision for income taxes

     11       14  


Effective tax rate

     7 %      12 % 


For the three-month period ended June 26, 2026, the effective tax rate was lower as compared to the three-month period ended June 27, 2025, primarily due to changes in jurisdictional earnings mix.

Net income

Net income was $153 million during the three-month period ended June 26, 2026, compared to $104 million during the three-month period ended June 27, 2025, driven by the factors outlined above.

Fiscal Years Ended March 31, 2026, 2025 and 2024

The following table sets forth, for the periods indicated, certain statements of operations data expressed as a percentage of net sales (amounts may not sum due to rounding). The financial information and the discussion below should be read in conjunction with the combined financial statements and notes thereto.


124


Table of Contents

The data below, and discussion that follows, represents our results from operations, and relative percentages.


     Fiscal Year Ended March 31,  
     2026     2025     2024  

Net sales

     100.0     100.0     100.0

Cost of sales

     88.2     87.0     87.6


Gross profit

     11.8     13.0     12.4

Selling, general and administrative expenses

     3.8     3.8     3.8

Intangible amortization

     0.8     0.8     1.0


Operating income

     7.2     8.4     7.6

Interest expense

     0.1     0.1     0.1

Other charges (income), net

     (0.1 )%      0.2     — 


Income before income taxes

     7.2     8.1     7.5

Provision for income taxes

     1.0     1.4     1.9


Net income

     6.2     6.7     5.6


Net sales

The following table sets forth our net sales by segment, and their relative percentages:


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Net sales:


Cloud & Cooling

   $ 4,529        68   $ 3,508        73   $ 2,222        68

Power

     2,085        32     1,291        27     1,022        32


   $ 6,614        $ 4,799        $ 3,244     


Net sales for fiscal year 2026 increased by $1.8 billion, or 38%, to $6.6 billion from the prior year. Net sales for our Cloud & Cooling segment rose $1 billion, or 29%, from $3.5 billion in fiscal year 2025 to $4.5 billion in fiscal year 2026 due to steady growth in revenue from our two largest customers amid increased market demand for cloud server storage and distributed control systems. Net sales in the Power segment increased by $0.8 billion, or 62%, largely driven by $0.5 billion growth in Embedded Power from increased demand in the data center market and $0.2 billion related to acquisitions in the United States and Poland.

Net sales for fiscal year 2025 increased by $1.6 billion, or 48%, to $4.8 billion from the prior year. Net sales for our Cloud & Cooling segment rose $1.3 billion, or 58%, from $2.2 billion in fiscal year 2024 to $3.5 billion in fiscal year 2025 due to strong data center demand for integrated server racks and enclosures, largely related to increasing AI demand. Net sales in the Power segment increased by $0.3 billion, or 26%, with strong growth in both Critical and Embedded Power due to increasing data center demand for facility and server rack power requirements.

Net sales for the fiscal year ended March 31, 2026 increased from $3.3 billion to $4.3 billion in the Americas, increased from $0.9 billion to $1.2 billion in Europe and increased from $0.5 billion to $1 billion in Asia.

Our largest customer accounted for 34%, 39% and 26% of net sales during fiscal years 2026, 2025 and 2024, respectively. Another significant customer accounted for 30%, 27% and 34% of net sales during fiscal years 2026, 2025 and 2024, respectively. Our array of customers that we serve are focused on the development of data centers and electrical utilities that support data centers and we are concentrated on the largest participants in those space.


125


Table of Contents

Cost of sales

Cost of sales is affected by a number of factors, including new product initiatives, product mix, labor cost fluctuations by region, component costs and availability and capacity utilization.

Cost of sales during fiscal year 2026 totaled $5.8 billion, representing an increase of $1.6 billion, or 40%, from $4.2 billion during fiscal year 2025. In fiscal year 2026, the 40% increase in cost of sales exceeded the 38% increase in net sales as costs to ramp new contracts impacted margins. Cost of sales during fiscal year 2025 totaled $4.2 billion, representing an increase of $1.4 billion, or 47%, from $2.8 billion during fiscal year 2024. In fiscal year 2025, the 47% increase in cost of sales was in line with the 48% increase in net sales. Cost of sales remained between 87% and 88% of net sales for fiscal years 2026, 2025 and 2024 as costs grew proportionately with revenue. Cost of sales in Cloud & Cooling increased $1 billion, or 31%, from fiscal year 2025 and cost of sales in Power for fiscal year 2026 increased $0.7 billion, or 66%, from fiscal year 2025.

Gross profit

Gross profit is affected by a fluctuation in cost of sales elements as outlined above and further by a number of factors, including product lifecycles, unit volumes, product mix, pricing, competition, new product introductions, and the expansion or consolidation of manufacturing facilities, as well as specific restructuring activities initiated from time to time. In the case of new product initiatives, profitability normally lags revenue growth due to product start-up costs, lower manufacturing volumes with new product launches, operational inefficiencies, and under-absorbed overhead. Gross margin for new products often improves over time as manufacturing volumes increase and as our utilization rates and overhead absorption improves. As a result of these various factors, our gross margin varies from period to period.

Gross profit during fiscal year 2026 increased $0.2 billion to $0.8 billion, from $0.6 billion during fiscal year 2025. Gross profit during fiscal year 2025 increased $0.2 billion to $0.6 billion, from $0.4 billion during fiscal year 2024. Gross profit remained between 12% and 13% of net sales for fiscal years 2026, 2025 and 2024 due to the factors outlined above.

Segment income

An operating segment’s performance is evaluated based on its segment income. Segment income is defined as net sales less cost of sales, and selling, general and administrative expenses, and does not include amortization of intangibles, stock-based compensation, certain restructuring charges, legal and other, interest expense, and other charges (income).

The following table sets forth segment income and margins. Segment margins in the table below may not recalculate exactly due to rounding.


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Segment income:


Cloud & Cooling

   $ 343        7.6   $ 311        8.9   $ 186        8.4

Power

     258        12.4     174        13.5     117        11.4

Cloud & Cooling segment margin decreased 130 basis points to 7.6%, for fiscal year 2026, from 8.9% for fiscal year 2025. The margin decrease during the period was driven by costs to ramp the business. Cloud & Cooling segment margin increased by 50 basis points for fiscal year 2025. The margin increase was driven by strong sales growth giving improved fixed cost coverage and favorable mix.


126


Table of Contents

Power segment margin decreased 110 basis points to 12.4%, for fiscal year 2026, from 13.5% for fiscal year 2025. The margin decrease in the Power segment was primarily driven by increased costs as the business scales. Power segment margin increased by 210 basis points for fiscal year 2025. The margin increase was driven by strong sales growth across both critical and embedded power giving improved fixed cost coverage and productivity improvements.

Selling, general and administrative expenses

Selling, general and administrative expenses (“SG&A”) totaled $253 million, during fiscal year 2026, compared to $184 million during fiscal year 2025, increasing by $69 million primarily due to a $28 million increase in employee costs (including stock-based compensation), a $32 million increase in various corporate allocations, in line with growth of the business and an $11 million increase in transaction costs.

SG&A totaled $184 million, during fiscal year 2025, compared to $123 million during fiscal year 2024, increasing by $61 million primarily due to an increase of $14 million in employee costs (including stock-based compensation), an increase of $39 million in various corporate allocations, in line with growth of the business and a $5 million increase in transaction costs.

Intangible amortization

Amortization of intangible assets was $50 million in fiscal year 2026 compared to $36 million in fiscal year 2025, reflecting a full-year of amortization of the intangible assets from the Crown Technical Systems (“Crown”) and JetCool Technologies Inc (“JetCool”) acquisitions.

Amortization of intangible assets was $36 million in fiscal year 2025 compared to $32 million in fiscal year 2024, reflecting increases in intangible assets from the Crown and JetCool acquisitions.

Interest expense

Interest expense was $5 million during fiscal year 2026, compared to $6 million during fiscal year 2025, decreasing $1 million from reduced accounts receivable factoring during the year.

Interest expense was $6 million during fiscal year 2025, compared to $4 million during fiscal year 2024, increasing $2 million from an increase in accounts receivable factoring in line with growth of the business.

Other Charges (Income), net

Other income totaled $7 million in fiscal year 2026, compared to charges of $8 million in fiscal year 2025, due to favorable foreign exchange movements.

Other charges totaled $8 million in fiscal year 2025, compared to income of $1 million in fiscal year 2024, primarily due to unfavorable foreign exchange movements.

Income taxes


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Income before income taxes

   $ 482     $ 389     $ 243  

Provision for income taxes

     69       69       61  


Effective tax rate

     14     18     25


127


Table of Contents

For the year ended March 31, 2026, the effective tax rate was lower as compared to the years ended March 31, 2025 and March 31, 2024, primarily due to changes in jurisdictional earnings mix.

Net income

Net income was $413 million during fiscal year 2026, compared to $320 million during fiscal year 2025, driven by the factors outlined above.

Net income was $320 million during fiscal year 2025, compared to $182 million during fiscal year 2024, driven by the factors outlined above.

NON-GAAP FINANCIAL MEASURES

To supplement Spinco’s selected financial data presented consistent with GAAP, the Company discloses certain non-GAAP financial measures that exclude certain charges and gains, including non-GAAP operating income and non-GAAP net income. These supplemental measures exclude certain legal and other charges, restructuring charges, stock-based compensation expense, intangible amortization, other discrete events as applicable and the related tax effects. These non-GAAP measures are not in accordance with or an alternative for GAAP and may be different from non-GAAP measures used by other companies. We believe that these non-GAAP measures have limitations in that they do not reflect all of the amounts associated with Spinco’s results of operations as determined in accordance with GAAP and that these measures should only be used to evaluate Spinco’s results of operations in conjunction with the corresponding GAAP measures. The presentation of this additional information is not meant to be considered in isolation or as a substitute for the most directly comparable GAAP measures. We compensate for the limitations of non-GAAP financial measures by relying upon GAAP results to gain a complete picture of the Company’s performance.

In calculating non-GAAP financial measures, we exclude certain items to facilitate a review of the comparability of the Company’s operating performance on a period-to-period basis because such items are not, in our view, related to the Company’s ongoing operational performance. We use non-GAAP measures to evaluate the operating performance of our business, for comparison with forecasts and strategic plans, for calculating return on investment, and for benchmarking performance externally against competitors. In addition, management’s incentive compensation is determined using certain non-GAAP measures. Since we find these measures to be useful, we believe that investors benefit from seeing results “through the eyes” of management in addition to seeing GAAP results. We believe that these non-GAAP measures, when read in conjunction with the Company’s GAAP financials, provide useful information to investors by offering:


the ability to make more meaningful period-to-period comparisons of the Company’s ongoing operating results;


the ability to better identify trends in the Company’s underlying business and perform related trend analysis;


a better understanding of how management plans and measures the Company’s underlying business; and


an easier way to compare the Company’s operating results against analyst financial models and operating results of competitors that supplement their GAAP results with non-GAAP financial measures.

Below are definitions and reconciliations of certain non-GAAP financial measures to the most directly comparable financial measures calculated and presented in accordance with GAAP.

Adjusted Operating Income

Adjusted operating income is defined as income from operations adjusted for amortization of intangibles; stock-based compensation expense; restructuring charges; and legal and other charges.


128


Table of Contents

Adjusted Net Income

Adjusted net income is defined as net income adjusted for amortization of intangibles; stock-based compensation; restructuring charges; legal and other charges and adjustments for taxes.

Free Cash Flow

Free cash flow is cash flow from operations net of capital expenditures and proceeds from the disposition of property and equipment.

Description of Adjustments

Intangible amortization consists of non-cash charges that can be impacted by, among other things, the timing and magnitude of acquisitions. The Company considers its operating results without these charges when evaluating its ongoing performance and forecasting its earnings trends, and therefore excludes such charges when presenting non-GAAP financial measures. The Company believes that the assessment of its operations excluding these costs is relevant to its assessment of internal operations and comparisons to the performance of its competitors.

Stock-based compensation consists of non-cash charges for the estimated fair value of unvested restricted share units granted to employees and assumed in business acquisitions. The Company believes that the exclusion of these charges provides for more accurate comparisons of its operating results to peer companies due to the varying available valuation methodologies, subjective assumptions and the variety of award types. In addition, the Company believes it is useful to investors to understand the specific impact stock-based compensation expense has on its operating results.

Restructuring includes severance charges at existing sites and corporate SG&A functions and other charges related to the closures and consolidations of certain operating sites and targeted activities to restructure the business. These costs may vary by size based on the Company’s initiatives, are not directly related to ongoing core business results, and do not reflect expected future operating expenses. These costs are excluded by the Company’s management in assessing current operating performance and forecasting its earnings trends and are therefore excluded by the Company from its non-GAAP measures.

Legal and other consist primarily of costs not directly related to core business results and may include matters relating to commercial disputes, government regulatory and compliance, intellectual property, antitrust, tax, product liability claims and other issues on a global basis as well as acquisition related costs. These costs are excluded by the Company’s management in assessing current operating performance and forecasting its earnings trends and are therefore excluded by the Company from its non-GAAP measures.

Adjustments for taxes relates to the tax effects of the various adjustments that we incorporate into non-GAAP measures in order to provide a more meaningful measure on non-GAAP net income and certain adjustments related to non-recurring settlements of tax contingencies or other non-recurring tax charges, when applicable.


129


Table of Contents
     Three-Month Periods Ended  
     June 26, 2026     June 27, 2025  
     (In millions, except percentages)  

GAAP operating income and margin %

   $ 165        7.5   $ 122        7.5

Intangible amortization

     20          13     

Stock-based compensation

     13          9     

Restructuring

     —           1     

Legal and other

     12          3     


Non-GAAP operating income and margin %

   $ 210        9.5   $ 148        9.1


GAAP provision for income taxes

   $ 11        $ 14     

Intangible amortization benefit

     3          5     

Other tax related adjustments

     6          3     


Non-GAAP provision for income taxes

   $ 20        $ 22     


GAAP net income

   $ 153        $ 104     

Intangible amortization

     20          13     

Stock-based compensation

     13          9     

Restructuring

     —           1     

Legal and other

     12          3     

Adjustments for taxes

     (9        (8   


Non-GAAP net income

   $ 189        $ 122     


Free Cash Flow:


Net cash provided by (used in) operating activities

   $ (69      $ 200     

Purchases of property and equipment

     (160        (42   

Proceeds from the disposition of property and equipment

     —           —      


Free Cash Flow

   $ (229      $ 158     


130


Table of Contents
     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions, except percentages)  

GAAP operating income and margin %

   $ 480        7.2   $ 403        8.4   $ 246        7.6

Intangible amortization

     50          36          32     

Stock-based compensation

     33          23          14     

Restructuring

     10          5          3     

Legal and other

     16          5          —      


Non-GAAP operating income and margin %

   $ 589        8.9   $ 472        9.8   $ 295        9.1


GAAP provision for income taxes

   $ 69        $ 69        $ 61     

Intangible amortization benefit

     11          8          7     

Other tax related adjustments

     13          8          4     


Non-GAAP provision for income taxes

   $ 93        $ 85        $ 72     


GAAP net income

   $ 413        $ 320        $ 182     

Intangible amortization

     50          36          32     

Stock-based compensation

     33          23          14     

Restructuring

     10          5          3     

Legal and other

     16          5          —      

Adjustments for taxes

     (24        (16        (11   


Non-GAAP net income

   $ 498        $ 373        $ 220     


Free Cash Flow:


Net cash provided by operating activities

   $ 411        $ 175        $ 242     

Purchases of property and equipment

     (238        (104        (78   

Proceeds from the disposition of property and equipment

     1          6          7     


Free Cash Flow

   $ 174        $ 77        $ 171     


LIQUIDITY AND CAPITAL RESOURCES

Sources of Historical Liquidity

As part of Flex, Spinco has been dependent upon Flex for certain working capital and financing requirements. Flex uses a centralized approach to cash management and financing of its operations. Accordingly, a substantial portion of the cash earned by the Spinco business is regularly cleared to Flex at Flex’s discretion, and Flex funds Spinco’s operating and investing activities as needed. This arrangement is not reflective of the manner in which the Spinco business would have financed its operations had it been a standalone business separate from Flex during the periods presented. Transfers of cash between Flex and the Spinco business are included within the Net Transfers to Parent on the combined statements of cash flows and the combined statements of equity included elsewhere in this information statement.

In conjunction with the planned Spin-Off, we will thoroughly evaluate our liquidity needs, capital structure and sources of capital on a standalone basis.

Future Sources of Liquidity

In connection with the Spin-Off, we expect to incur indebtedness in an amount of up to $4.4 billion pursuant to the Spinco Financing Arrangements and to complete the Spinco Cash Distribution to Flex prior to or substantially concurrently with the consummation of the Spin-Off. The terms of such indebtedness are subject to change and will be finalized prior to the closing of the Spin-Off.


131


Table of Contents

Following the Spin-Off, our capital structure and sources of liquidity will change from our historical capital structure because we will no longer be part of Flex’s centralized treasury management and centralized funding program. Our ability to fund our operating needs will depend on our ability to generate positive cash flows from operations, and on our ability to obtain debt financing on acceptable terms or to issue additional equity or equity-linked securities not anticipated in this information statement. Management believes that our cash balances and funds provided by operating activities will be sufficient to meet our working capital requirements, capital expenditures, and other liquidity needs for at least the next twelve months. Cash flows used by operating activities were primarily driven by changes in net working capital. We expect working capital requirements to continue to fluctuate with the growth of the business. We believe we can also access various capital markets to further supplement our liquidity position if necessary.

We expect to utilize our cash flows to continue to invest in our business, growth strategies, people and the communities we operate in.

Three-Month Period Ended June 26, 2026

Cash used in operating activities was $69 million during the three-month period ended June 26, 2026. The total cash used in operating activities resulted primarily from $153 million of net income for the period plus $63 million of non-cash charges such as depreciation, amortization, non-cash lease expense, restructuring, deferred income taxes and stock-based compensation. Non-cash charges increased with growth in the business compared to previous periods. These cash inflows of $216 million were offset by a use of cash from a net increase in our operating assets and liabilities of $285 million, primarily driven by increases in accounts receivable, contract assets, inventory, and customer-controlled inventory, partially offset by an increase in accounts payable and other operating liabilities, as the growing business required increased working capital.

We believe net working capital is a key metric that measures our liquidity. Net working capital is calculated as current assets less current liabilities. Net working capital increased by $444 million to $1,088 million as of June 26, 2026 from $644 million as of March 31, 2026. The increase was primarily driven by a $474 million increase in accounts receivable, a $231 million increase in contract assets, a $215 million increase in inventories, and a $161 million increase in customer-controlled inventory, partially offset by a $409 million increase in accounts payable. The increase in net working capital reflects growth of the business in the three-month period ended June 26, 2026 which contributed to cash used in operating activities of $69 million during the period.

Cash used in investing activities totaled $1,294 million during the three-month period ended June 26, 2026. This was primarily driven by $1,134 million cash paid for the acquisition of Electrical Power Products, Inc., net of cash acquired, as well as $160 million of net capital expenditures for property and equipment, (net of proceeds on asset sales) to continue expanding capabilities and capacity in support of our businesses. Refer to note 7, “Business Acquisitions,” in the notes to the combined financial statements for further discussion of our business acquisitions.

Cash provided by financing activities was $1,378 million during the three-month period ended June 26, 2026, which was driven by net transfers from Flex, primarily to fund the acquisition of Electrical Power Products, Inc.

Fiscal Year 2026

Cash provided by operating activities was $411 million during fiscal year 2026. The total cash provided by operating activities resulted primarily from $413 million of net income for the period plus $169 million of non-cash charges such as depreciation, amortization, non-cash lease expense, restructuring, deferred income taxes and stock-based compensation. Non-cash charges generally increased with growth in the business compared to fiscal year 2025. These cash inflows of $582 million were partially offset by a net increase in our operating assets and liabilities of $171 million, primarily driven by increases in accounts receivable, contract assets, inventory, and customer-controlled inventory, partially offset by an increase in accounts payable and other operating liabilities, as the growing business required increased working capital.


132


Table of Contents

We believe net working capital is a key metric that measures our liquidity. Net working capital is calculated as current assets less current liabilities. Net working capital increased by $147 million to $644 million as of March 31, 2026 from $497 million as of March 31, 2025. The increase was primarily driven by a $432 million increase in inventories, a $701 million increase in accounts receivable and a $793 million increase in customer-controlled inventory, partially offset by a $1,982 million increase in accounts payable. The increase in net working capital reflects growth of the business in fiscal year 2026 which contributed to cash provided by operating activities of $411 million during the period.

Cash used in investing activities totaled $277 million during fiscal year 2026. This was primarily driven by $237 million of net capital expenditures for property and equipment, (net of proceeds on asset sales) to continue expanding capabilities and capacity in support of our businesses, as well as $40 million cash paid for the acquisition of Bielsko Biala, net of cash acquired. Refer to note 10, “Business Acquisitions,” in the notes to the combined financial statements for further discussion of our business acquisitions.

Cash used in financing activities was $151 million during fiscal year 2026, which was driven by net transfers to Flex.

Fiscal Year 2025

Cash provided by operating activities was $175 million during fiscal year 2025. The total cash provided by operating activities resulted primarily from $320 million of net income for the period plus $92 million of non-cash charges such as depreciation, amortization, non-cash lease expense, restructuring, deferred income taxes and stock-based compensation. Non-cash charges generally increased with growth in the business compared to the prior year, except for deferred income taxes, which reflected a tax benefit in fiscal year 2025 compared to an expense in the previous year. These cash inflows of $412 million were partially offset by a net increase in our operating assets and liabilities of $237 million, primarily driven by increases in accounts receivable and inventory, partially offset by an increase in accounts payable and other operating liabilities, as the growing business required increased working capital.

We believe net working capital is a key metric that measures our liquidity. Net working capital is calculated as current assets less current liabilities. Net working capital increased by $223 million to $497 million as of March 31, 2025 from $274 million as of March 31, 2024. The increase was primarily driven by a $365 million increase in inventories, a $301 million increase in accounts receivable and a $130 million increase in customer-controlled inventory, partially offset by a $595 million increase in accounts payable. The increase in net working capital reflects higher production during fiscal year 2025 which contributed to cash provided by operating activities of $175 million during the period.

Cash used in investing activities totaled $445 million during fiscal year 2025. This was primarily driven by $347 million of cash paid for the acquisitions of Crown and JetCool, net of cash acquired, and $98 million of net capital expenditures for property and equipment, (net of proceeds on asset sales) to continue expanding capabilities and capacity in support of our businesses. Refer to note 10, “Business Acquisitions,” in the notes to the combined financial statements for further discussion of our business acquisitions.

Cash provided by financing activities was $281 million during fiscal year 2025, which was driven by net transfers from Flex, primarily to fund the acquisitions of Crown and JetCool.

Fiscal Year 2024

Cash provided by operating activities was $242 million during fiscal year 2024. The total cash provided by operating activities resulted primarily from $182 million of net income for the period plus $97 million of non-cash charges such as depreciation, amortization, non-cash lease expense, restructuring, deferred income taxes and stock-based compensation. These additions were partially offset by a net increase in our operating assets and liabilities as growth in the business required increased working capital.


133


Table of Contents

Cash used in investing activities totaled $71 million during fiscal year 2024. This was due to $71 million of capital expenditures for property and equipment to continue expanding capabilities and capacity in support of our Cloud & Cooling and Power segments.

Cash used in financing activities was $167 million during fiscal year 2024 due to net transfers to Flex.

Warrant

On August 15, 2025, Flex issued a the Warrant to the Warrantholder, a wholly-owned subsidiary of Amazon, to purchase the Warrant Shares, at an exercise price of $51.29 per share, which expires on August 15, 2030. The Warrant Shares are subject to vesting based on qualifying payments (as defined in the Warrant) for the purchase of all products and services by or on behalf of Amazon and its affiliates over the term of the Warrant. The Warrant also provides that, upon certain distributions (which would include the Distribution), the exercise price will be adjusted, concurrent with the Distribution Record Date, by reducing the exercise price by the per share fair market value (as defined in the Warrant) of the Distribution. The Warrant further provides that the exercise price may not be reduced below $0.01 per share and that if the exercise price becomes $0.01, then the Warrantholder will be entitled to participate in the Distribution as if the Warrantholder had previously exercised and would be the holder of all Warrant Shares, whether vested or not, subject to the Warrant before the Distribution Record Date. Flex, Spinco and the Warrantholder are negotiating and expect to execute an amendment to the Warrant which will provide that, instead of Spinco shares, the Warrantholder would receive the Spinco Warrant. As a result, we expect that the exercise price of the Flex Warrant will be reduced to $0.01 per share and that, upon the consummation of the Distribution, the Warrantholder will receive the Spinco Warrant.

Material Cash Requirements from Contractual Obligations and Commitments

The Company has several commitments under operating leases for warehouses, buildings, and equipment, as well as non-cancellable purchase orders for capital expenditures. The Company also has a number of finance leases with an immaterial impact on its combined financial statements. Leases have remaining lease terms ranging from one year to 20 years. The following table summarizes future lease payments under non-cancellable leases and non-cancellable purchase orders for capital expenditures as of March 31, 2026:


     Total      1 Year or Less      2–3 Years      4–5 Years      Greater Than
5 Years
 
     (In millions)  

Contractual Obligations:


Operating leases, net of subleases

   $ 226      $ 33      $ 65      $ 52      $ 76  

Capital expenditures

     148        121        27                

We also have outstanding firm purchase orders with certain suppliers for the purchase of inventory, which are not included in the table above. The majority of the purchase obligations are generally short-term in nature. We generally do not enter into non-cancellable purchase orders for materials until we receive a corresponding production forecast from our customers. Our purchase obligations can fluctuate significantly from period to period and can materially impact our future operating asset and liability balances, and our future working capital requirements. We intend to use our existing cash balances, together with anticipated cash flows from operations to fund our existing and future contractual obligations.

Capital Expenditures

Our capital expenditures primarily consist of continuing investments in property and equipment to support new production and expand the capacity to grow our business. For the years ended March 31, 2026, 2025 and 2024, our capital expenditures were $238 million, $104 million and $78 million, respectively. This was partially offset by the proceeds from the disposition of property and equipment of $1 million, $6 million and $7 million for the years ended March 31, 2026, 2025 and 2024, respectively.


134


Table of Contents

Parent Company Credit Support

Flex provides Spinco with parent credit support in certain jurisdictions. To support Spinco in selling products and services globally, Flex entered into and may enter into contracts on behalf of Spinco or issue parent company guarantees or letters of credit. Flex also provides similar credit support for some non-customer related activities of Spinco. There are no known instances historically where payments or performance from Flex were required under parent company guarantees relating to Spinco’s customer contracts. As such, no amounts related to parent company guarantees have been recorded by Spinco in the condensed combined financial statements as of or for the three-month periods ended June 26, 2026 and June 27, 2025 or in the combined financial statements as of or for the years ended March 31, 2026, 2025 and 2024. See “Certain Relationships and Related Transactions.”

RECENT ACCOUNTING PRONOUNCEMENTS

Refer to note 2, “Summary of Accounting Policies,” in the notes to the combined financial statements for recent accounting pronouncements.


135


Table of Contents

QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK

INTEREST RATE RISK

As of June 26, 2026, we had cash and cash equivalents of $20 million. Our cash and cash equivalents are held for working capital purposes. We do not enter into investments for trading or speculative purposes.

Our exposures to market risk for changes in interest rates relate primarily to the Bridge Facility (described above) which bears a floating interest rate, and a rising interest rate environment may increase the amount of interest paid. Each 100 basis point increase in the initial rate would increase annual interest expense by approximately $44 million, assuming the loan remains outstanding.


136


Table of Contents

FOREIGN CURRENCY EXCHANGE RISK

We transact business in various foreign countries and are, therefore, subject to risk of foreign currency exchange rate fluctuations. Although Flex uses financial instruments to hedge certain foreign currency risks, we are not fully protected against foreign currency fluctuations and our reported results of operations could be affected by changes in foreign currency exchange rates. To manage our exposures and mitigate the impact of currency fluctuations on the operations of our foreign subsidiaries, we hedge our main transactional exposures through the use of foreign exchange forward and option contracts. Accordingly, the combined statement of operations include the impact of Flex’s derivative financial instruments that are deemed to be associated with our operations and has been allocated to us utilizing a reasonable allocation method. The recorded fair values of the associated assets and liabilities were not material to the Company’s combined financial position. Following the Spin-Off, we intend to implement a standalone foreign currency risk management program.


137


Table of Contents

MANAGEMENT

Directors and Executive Officers Following the Spin-Off

Executive Officers

Following the Spin-Off, we will be an independent, publicly traded company. The following table sets forth information regarding individuals who are expected to serve as Spinco’s executive officers, including their positions after the Spin-Off, and is followed by biographies of each such executive officer. While some of Spinco’s executive officers are currently employees of Flex, after the Spin-Off, none of these individuals will be employees of Flex. The information set forth below is as of     , 2026.


Name

   Age   

Position

Revathi Advaithi

   58   

Chief Executive Officer

Kevin Krumm

   52   

Chief Financial Officer

Rob Campbell

   63   

Chief Commercial Officer

Kwanghooi (Hooi) Tan

   49   

Chief Operating Officer

Scott Offer

   61   

Chief Legal Officer

Biographies

Revathi Advaithi. Ms. Advaithi is expected to serve as our Chief Executive Officer. Ms. Advaithi currently serves as the Chief Executive Officer of Flex, a role she has held since February 2019, and will continue to serve as the Chief Executive Officer of Flex until the completion of the Spin-Off. After the completion of the Spin-Off, Ms. Advaithi will serve as the Chairperson of the Flex Board of the Directors. Prior to joining Flex, Ms. Advaithi was President and Chief Operating Officer, Electrical Sector, of Eaton Corporation plc (NYSE: ETN), a power management company, from September 2015 until February 2019. Prior to that, she served as President of Electrical Sector, Americas of Eaton from April 2012 through August 2015. Ms. Advaithi joined Eaton in 1995 and led the Electrical Sector in the Americas and Asia-Pacific, with a three-year assignment in Shanghai. Between 2002 and 2008, Ms. Advaithi worked at Honeywell in leadership roles spanning manufacturing, procurement, supply chain, and sourcing. She returned to Eaton in 2008 as Vice President and General Manager of the Electrical Components Division. In 2023, she was appointed by the U.S. President to the Advisory Committee for Trade Policy and Negotiations and the Advisory Committee on Supply Chain Competitiveness. Ms. Advaithi serves on the Board of Directors of Uber Technologies, Inc (NYSE: UBER). She holds a BE in mechanical engineering from the Birla Institute of Technology and Science in Pilani, India, and an MBA in international business from the Thunderbird School of Global Management.

Kevin Krumm. Mr. Krumm is expected to serve as our Chief Financial Officer. Mr. Krumm has served as Chief Financial Officer of Flex since January 6, 2025. In this role, he oversees the finance function, spanning corporate accounting, financial planning and analysis, internal audit, investor relations, tax, and treasury. He is focused on shareholder value creation and driving the Company’s long-term financial framework. Prior to joining the Company, Mr. Krumm served as Executive Vice President and Chief Financial Officer of APi Group Corporation (NYSE: APG), a global life safety services provider specializing in fire safety and security, a position he held since September 2021. Prior to that, since December 2019, Mr. Krumm served as Corporate Treasurer and Senior Vice President of Global Finance Shared Services for Ecolab Inc. (NYSE: ECL), a global manufacturer of water, hygiene and infection prevention solutions. During his 15-year tenure at Ecolab, he also held roles leading the Industrial segment finance team, regional finance teams in Europe, the Middle East and Africa, Asia and Latin America, and leading international integration efforts for a major acquisition. He began his career in public accounting working for consulting firms PwC, Arthur Andersen and Deloitte, with a heavy emphasis on M&A and corporate finance. Mr. Krumm holds a BA in accounting from the University of Northern Iowa and an MBA from the University of Chicago Booth School of Business.


138


Table of Contents

Rob Campbell. Mr. Campbell is expected to serve as our Chief Commercial Officer. Mr. Campbell joined Flex in 2015 and currently serves as President of Communications, Enterprise and Cloud, where he leads the company’s growth in hyperscale, cloud and communications infrastructure markets.

Kwanghooi (Hooi) Tan. Mr. Tan is expected to serve as our Chief Operating Officer. Mr. Tan has served as Chief Operating Officer of Flex since October 2024, where he leads global manufacturing, procurement, supply chain, operational excellence, and quality systems. Prior to his current role, he served as Flex’s President, Global Operations and Components from April 2022 until September 2024. Over the course of his 23 years at Flex, Mr. Tan has held many leadership roles, including Senior Vice President, Global Operations from May 2016 until March 2022, overseeing more than 100 facilities across 30 countries. He also led operations for the Company’s Asia region, where he drove impactful productivity and efficiency programs and delivered significant P&L improvements. Prior to joining Flex, Mr. Tan worked at Solectron, an electronics manufacturing company for OEMs, where he held a variety of leadership roles in operations, program management, business development and government affairs. He holds a BS in electrical engineering from Purdue University.

Scott Offer. Mr. Offer is expected to serve as our Chief Legal Officer. Mr. Offer has served as Executive Vice President, General Counsel of Flex since September 2016 and leads its global legal function, including government relations, corporate governance, brand protection and security, intellectual property, contracts, litigation, and ethics and compliance. In 2025, he was named one of the Top 20 General Counsel of the Last Two Decades by the Financial Times Innovative Lawyers program for pioneering legal department innovation and transformation. Prior to joining Flex, Mr. Offer served as Senior Vice President and General Counsel at Lenovo. Before that, he served as Senior Vice President and General Counsel for Motorola Mobility, a Google company, and prior to that, Senior Vice President and General Counsel, Motorola Mobility, Inc. Before joining Motorola in 2010, he worked for the law firm Boodle Hatfield. Mr. Offer holds a law degree from the London School of Economics and Political Science and is qualified as a lawyer in the United Kingdom and the United States.

Directors

The following table sets forth information with respect to those persons who are expected to serve on the Spinco Board of Directors following the completion of the Spin-Off, and is followed by biographies of each such individual. The Flex Board of Directors will continue to evaluate the composition of the future board in order to reflect an appropriate mix of skills, experience and attributes, and additional individuals may be added to the Spinco Board of Directors in the future. The information set forth below is as of     , 2026.


Name

   Age   

Title

William D. Watkins

   73   

Chair of the Spinco Board of Directors

Revathi Advaithi

   58   

Chief Executive Officer and Director

Mark Eubanks

   54   

Director

Michael E. Hurlston

   59   

Director

David Johnson

   59   

Director

Charles K. Stevens, III

   66   

Director

Maryrose Sylvester

   60   

Director

Biographies

William D. Watkins. Mr. Watkins is expected to serve as the Chair of our Board of Directors. Mr. Watkins has served as a member of the Flex Board of Directors since 2009, and currently serves as Independent Chair of the Board of Directors and Chair of the Nominating and Governance Committee, and will continue to serve in these roles until the completion of the Spin-Off. Prior to joining Flex, Mr. Watkins was Chief Executive Officer of Imergy Power Systems, Inc., a leading innovator in cost-effective energy storage solutions, from 2013 to 2016, and was appointed Chairperson of the Board in January 2015, a position he held until August 2016. Prior to that, Mr. Watkins served as Chairperson of the Board of Bridgelux, Inc., a leading light emitting diode developer,


139


Table of Contents

from February 2013 to December 2013 and as its Chief Executive Officer from January 2010 to February 2013. He previously served as Chief Executive Officer of Seagate Technology (Nasdaq: STX), a provider of electronic data storage solutions and systems, from 2004 through January 2009, and as Seagate’s President and Chief Operating Officer from 2000 until 2004. During that time, he was responsible for Seagate’s hard disc drive operations, including recording heads, media and other components, and related R&D and product development organizations. Mr. Watkins joined Seagate in 1996 in connection with the company’s merger with Conner Peripherals. Mr. Watkins currently serves on the board of directors of Nextpower Inc. (NASDAQ: NXT). Mr. Watkins previously served on the boards of directors of Avaya Holdings Corp. from 2017 to 2023 and Maxim Integrated Products, Inc. from 2008 to 2021. Mr. Watkins’ extensive operational and management experience leading technology manufacturing businesses on a global scale, deep understanding of the electronics and semiconductor industries, and technology and cybersecurity experience as an executive serving businesses in encryption, enterprise, desktop, mobile computing, and electronics industries, qualify him to serve as a director of Spinco.

Revathi Advaithi. Ms. Advaithi is expected to serve as a member of our Board of Directors. Ms. Advaithi’s current service as Flex’s Chief Executive Officer, with a broad and deep understanding of Flex, the industries in which it participates, and the strategic actions necessary to deliver long-term profitable growth, together with her leadership experience in engineering, operations, logistics, and international supply chain management, qualify her to serve as a director of Spinco. See “Executive Officers” above for Ms. Advaithi’s biography.

Mark Eubanks. Mr. Eubanks is expected to serve as a member of our Board of Directors. Mr. Eubanks has served as President, Chief Executive Officer, and director of The Brink’s Company (NYSE: BCO), a leading global provider of cash and valuables management, digital retail solutions, and ATM managed services, since May 2022. Prior to that, he served as The Brink’s Company’s Executive Vice President and Chief Operating Officer from September 2021 to May 2022. Before joining The Brink’s Company, Mr. Eubanks served as President, Europe, Middle East and Africa for Otis Worldwide Corporation (NYSE: OTIS) from April 2019 to September 2020. Prior to that, he served as Group President, Electrical Products, for Eaton Corporation plc (NYSE: ETN), a global power management company, from 2015 to 2019. Mr. Eubanks currently serves as an Advisory Board Member for the University of Florida College of Electrical and Computer Engineering. He holds an MBA from Emory University and a BS in electrical engineering from the University of Florida. Mr. Eubanks’ experience as a public company chief executive officer leading global operations, combined with his deep background in the electrical products and power management industries and international operational expertise across multiple geographic regions, qualify him to serve as a director of Spinco.

Michael E. Hurlston. Mr. Hurlston is expected to serve as a member of the Spinco Board of Directors. With over 30 years of business and technology leadership experience, Mr. Hurlston currently serves as President and Chief Executive Officer of Lumentum Holdings Inc. (Nasdaq: LITE), a market-leading designer and manufacturer of innovative optical and photonic products for cloud/AI, networking, and industrial applications. Prior to joining Lumentum in February 2025, he served as President and Chief Executive Officer and as a director of Synaptics Incorporated (Nasdaq: SYNA), a global leader in IoT semiconductor solutions and human interface solutions combining IoT and AI, from 2019 to 2025. Before joining Synaptics, Mr. Hurlston was Chief Executive Officer and a member of the board of directors of Finisar Corporation, a leader in optical communications, from 2018 to 2019. He also served as Executive Vice President, Worldwide Sales and in a variety of management roles over the course of his nearly 20-year career with Broadcom Limited (Nasdaq: AVGO), a leading developer and supplier of a broad range of semiconductor solutions. Mr. Hurlston currently serves on the board of directors of Lumentum Holdings Inc. (Nasdaq: LITE) and Astera Labs, Inc. (Nasdaq: ALAB). He previously served on the boards of directors of Synaptics Incorporated (Nasdaq: SYNA) from 2019 to 2025 and Ubiquiti Inc. (NYSE: UI) from 2016 to 2021. He also serves on the Board of Executive Trustees of the UC Davis Foundation. He received his BS in electrical engineering and his MBA from the University of California, Davis. Mr. Hurlston’s experience as a public company chief executive officer, deep expertise in the semiconductor industry, significant technology and global experience, and proven track record of growing large technology businesses to achieve consistent profitable growth and market penetration, qualify him to serve as a director of Spinco.


140


Table of Contents

David Johnson. Mr. Johnson is expected to serve as a member of our Board of Directors. Mr. Johnson has served as Executive Vice President and Chief Financial Officer of Corteva, Inc. (NYSE: CTVA), a global developer and supplier of agricultural products and digital farming solutions (“Corteva”), since September 2024, and has more than 30 years of experience in strategic and financial planning, risk assessment, mergers and acquisitions, global tax strategies, international operations, and internal controls. Mr. Johnson is expected to become the Chief Financial Officer of Vylor Inc., the future publicly-traded, advanced seed and genetics company that will result from Corteva’s planned separation scheduled for October 1, 2026. Prior to his current role, he served as Atkore Inc.’s (NYSE: ATKR) Chief Financial Officer and Chief Accounting Officer from August 2018 through August 2024. Before joining Atkore Inc., Mr. Johnson served in various finance leadership roles at Eaton Corporation plc (NYSE: ETN) from 1995 through 2018. Most recently at Eaton, Mr. Johnson was Vice President-Finance & Operations for the electrical sector business, where he was responsible for sector financial planning, analysis, and reporting, compliance, credit and collections, government accounting, global purchasing, manufacturing strategies, and logistics and distribution. Prior to that, Mr. Johnson was Vice President-Finance and Planning for the Americas region (Eaton Electrical) where he was responsible for reporting, planning, acquisitions, and implementing common financial policies and reporting across numerous recently acquired businesses. During his tenure at Eaton, Mr. Johnson held other roles of progressive responsibility, including plant controller, division controller, Director of Finance & Business Development, Vice President of Finance & Business Development, and Vice President of Finance & Planning—Europe, Middle East, and Asia. Mr. Johnson earned an MBA from Duquesne University and a BS in finance from Indiana University of Pennsylvania. Mr. Johnson’s significant leadership experience as a public company chief financial officer, deep expertise in financial and accounting operations, mergers and acquisitions, and international finance, and his extensive background in the electrical sector and global manufacturing industries, qualify him to serve as a director of Spinco.

Charles K. Stevens, III. Mr. Stevens is expected to serve as a member of the Spinco Board of Directors. Mr. Stevens retired as Executive Vice President and Chief Financial Officer of General Motors Company (NYSE: GM) in March 2019, after a 40-year career at the global automotive company that designs, manufactures, markets, and distributes vehicles and vehicle parts, and sells financial services. From 1994 to 2005, he held several leadership positions in General Motors’ Asia Pacific region, including China, Singapore, Indonesia and Thailand. He returned to North America in 2006 and assumed the role of CFO for General Motors Canada, CFO for GM Mexico in 2008 and CFO for GM North America in 2010. In 2014, Mr. Stevens was named Executive Vice President and CFO of General Motors Corporation, where he was responsible for leading the company’s financial and accounting operations worldwide. Mr. Stevens currently serves on the boards of directors of Genuine Parts Company (NYSE: GPC) and Masco Corporation (NYSE: MAS). He previously served on the boards of directors of Eastman Chemical Company (NYSE: EMN) from 2020 to 2024 and Tenneco Inc. from 2020 to 2022. He received his BIA from General Motors Institute (now Kettering University) and MBA from the University of Michigan-Flint. Mr. Stevens’ significant leadership experience in financial and accounting operations at a large, global publicly held manufacturing company, valuable understanding of international financial matters, risk evaluation and management, and mergers and acquisitions, and his extensive current and past public company board experience, qualify him to serve as a director of Spinco.

Maryrose Sylvester. Ms. Sylvester is expected to serve as a member of the Spinco Board of Directors. Ms. Sylvester most recently served as U.S. Managing Director and U.S. Head of Electrification for ABB Ltd (NYSE: ABB), a global technology company operating in the areas of electrification, robotics, power, and automation, from June 2019 to August 2020. Prior to joining ABB Ltd, she spent more than 30 years at GE (NYSE: GE), where she held a number of leadership roles including President and CEO of GE Current, a digital power service business delivering integrated energy systems, from 2015 to 2019, President and CEO of GE Lighting, a leading global lighting provider, from 2011 to 2015, and President and CEO of GE Intelligent Platforms, an industrial automation provider, from 2006 to 2011. Her global supply chain experience during her tenure at GE includes roles as Director of Sourcing for GE Lighting in Budapest, Hungary, and Global Sourcing Director for GE Lighting. Ms. Sylvester currently serves on the boards of directors of Harley-Davidson, Inc. (NYSE: HOG), Vontier Corporation (NYSE: VNT), and Waste Management, Inc. (NYSE: WM). She holds a


141


Table of Contents

BSBA in procurement and production management from Bowling Green State University and an MBA from Cleveland State University. Ms. Sylvester’s extensive experience in leading and transforming global industrial businesses, her significant knowledge and expertise in product development and delivering technology-enabled and energy-efficient, sustainable solutions, and her experience serving on large public company boards, qualify her to serve as a director of Spinco.

Our Board Following the Spin-Off and Corporate Governance Guidelines

Upon completion of the Spin-Off, we expect that the Spinco Board of Directors will be comprised of      directors. After completion of the Spin-Off, the Spinco Board of Directors is expected to consist of such number of directors as shall be determined from time to time solely by resolution of the Spinco Board of Directors. The directors will be divided into three classes, as nearly equal in number as is reasonably possible, with staggered three-year terms. At each annual meeting of shareholders, the successors to directors whose terms then expire will be elected to serve from the time of election and qualification until the third annual meeting following election. Our directors will be divided among the three classes as follows:

[●]

We have not yet set the date of the first annual meeting of shareholders to be held following the Spin-Off. We expect that any additional directorships resulting from an increase in the number of directors will be distributed among the three classes so that, as nearly as possible, each class will consist of one-third of the directors. The division of our board of directors into three classes with staggered three-year terms may delay or prevent a change of our management or a change of control.

The Spinco Board of Directors is expected to adopt corporate governance guidelines (the “Corporate Governance Guidelines”) that will provide a framework for the effective governance of Spinco. The Corporate Governance Guidelines will address significant corporate governance issues, including, among other things: the appointment, role, and responsibilities of Spinco’s Lead Independent Director, if any; director nominee qualifications; director independence; limitations on director service on other boards; director orientation and continuing education; annual performance evaluations of the Spinco Board of Directors and committees; and succession planning and management development. A copy of the Corporate Governance Guidelines will be available at our website at axiomsolutions.com.

Director Independence

The Spinco Board of Directors will annually review the relationship that each director has with Spinco. Following such annual review, only those directors who the Spinco Board of Directors affirmatively determines do not have a relationship which, in the opinion of the Spinco Board of Directors, would interfere with the exercise of independent judgment in carrying out the responsibilities of a director, under the listing standards of Nasdaq, will be considered independent directors. At the time of the Spin-Off, the Corporate Governance Guidelines are expected to adopt the definition of independence described in the director independence requirements for Nasdaq-listed companies. In doing so, the Spinco Board of Directors will take into account certain factors listed in the Corporate Governance Guidelines and such other factors as it may deem relevant. A majority of the Spinco Board of Directors will be comprised of independent directors upon completion of the Spin-Off. We expect that all directors, except Ms. Advaithi who will be the Chief Executive Officer of Spinco, will meet the independence requirements set forth in the listing standards of Nasdaq at the time of the Spin-Off. There are no family relationships among any of our directors or executive officers.

Board Committees

Effective upon the completion of the Spin-Off, the Spinco Board of Directors is expected to have three standing committees: an Audit Committee, a Compensation and People Committee, and a Nominating and Governance


142


Table of Contents

Committee. The principal functions of each committee are briefly described below. We intend to comply with the listing requirements and other rules and regulations of Nasdaq, as amended or modified from time to time, with respect to each of these committees and each of these committees will be composed exclusively of independent directors. Additionally, the Spinco Board of Directors may, from time to time, establish other committees to facilitate the Spinco Board of Directors’ oversight of management of the business and affairs of Spinco.

Audit Committee

The purpose of the Audit Committee of the Spinco Board of Directors (“Audit Committee”) will be to assist the Spinco Board of Directors in discharging its oversight responsibility by: (i) reviewing the integrity of the accounting and financial reporting processes of Spinco and its subsidiaries and the audit of Spinco’s financial statements; (ii) overseeing Spinco’s compliance with legal and regulatory requirements; (iii) reviewing the independent accountants’ qualifications and independence; (iv) overseeing the performance of Spinco’s internal audit function and Spinco’s independent accountants; and (v) preparing the report required by the rules of the SEC to be included in Spinco’s annual proxy statement. Among other things, the Audit Committee will also:


be directly responsible for appointing, compensating, and overseeing independent accountants, with input from management;


pre-approve all audit and non-audit services provided by our independent accountants;


review annual and quarterly financial statements;


review adequacy of accounting and financial personnel resources;


oversee and appoint our chief audit executive and review the internal audit plan and internal controls;


review and discuss with management risk assessment and enterprise risk management policies, including risks related to financial reporting, accounting, internal controls, fraud, capital structure, legal and regulatory compliance, and cybersecurity;


review and discuss with management the implementation of legal and regulatory requirements regarding public disclosure of topics covered by the corporate responsibility and sustainability programs; and


oversee the ethics and compliance program.

Compensation and People Committee

The purpose of the Compensation and People Committee of the Spinco Board of Directors (“Compensation and People Committee”) will be to (i) carry out responsibilities of the Spinco Board of Directors relating to the compensation of Spinco’s executives, (ii) produce the Compensation Committee Report for inclusion in Spinco’s proxy statement, in accordance with applicable rules and regulations, and (iii) periodically review Spinco’s people policies, programs, and initiatives. Among other things, the Compensation and People Committee will also:


evaluate and approve executive officer compensation;


review Spinco’s people programs and initiatives;


review and approve corporate goals and objectives for Spinco Chief Executive Officer’s compensation and evaluate Spinco Chief Executive Officer’s performance in light of those goals and objectives;


oversee incentive and equity-based compensation plans;


review and make changes to benefit plans, or recommend changes to the Spinco Board of Directors if required;


143


Table of Contents
   

review and approve the compensation recovery (clawback) policy, or amendment to the policy, that is applicable to executive officers, and oversee and administer such policy;


review and approve stock ownership guidelines applicable to executive officers; and


oversee the Chief Executive Officer succession planning process and senior leadership development program.

Nominating and Governance Committee

The purpose of the Nominating and Governance Committee of the Spinco Board of Directors (“Nominating and Governance Committee”) will be to (i) develop and recommend to the Spinco Board of Directors a set of corporate governance principles applicable to Spinco, (ii) identify individuals qualified to become members of the Spinco Board of Directors and, consistent with criteria approved by the Spinco Board of Directors, make recommendations to the Spinco Board of Directors regarding director candidates for membership on the Spinco Board of Directors, (iii) assist the Spinco Board of Directors in overseeing Spinco’s corporate responsibility and sustainability policies and programs and (iv) oversee the evaluation of the Spinco Board of Directors. Among other things, the Nominating and Governance Committee will also:


evaluate and recommend the size and composition of board and committees and functions of committees;


develop and recommend board membership criteria;


identify, evaluate, and recommend director candidates;


review corporate governance issues and practices;


manage the annual board and committee evaluation process;


review and make recommendations on non-employee director compensation; and


review and oversee responses regarding shareholder proposals relating to corporate governance, corporate responsibility, or sustainability matters.

Leadership Structure

The Spinco Board of Directors will not have a policy with respect to whether the roles of Chair of the Spinco Board of Directors (“Chair of the Board”) and Chief Executive Officer should be separate and, if they are to be separate, whether the Chair of the Board should be selected from Spinco’s non-employee directors or should be an employee. We believe the leadership structure of the Spinco Board of Directors at any point in time should be based upon an assessment of the needs of the Spinco Board of Directors and the Company at the time after giving consideration to, among other things, Spinco’s business plans, strategic opportunities, and succession planning priorities. The Spinco Board of Directors will also consider the views of shareholders, including as it relates to director independence, as well as corporate governance and industry trends. Spinco’s Corporate Governance Guidelines will provide that the Spinco Board of Directors will appoint a Lead Independent Director if the Chair of the Board is not an independent director under Nasdaq listing standards or if the Spinco Board of Directors otherwise deems it appropriate. Spinco’s Lead Independent Director, if appointed, will play an important role in maintaining effective independent oversight of the Company.

Role of the Spinco Board of Directors in Risk Oversight

The Spinco Board of Directors will be responsible for overseeing the risk management process and exercise this risk oversight through both the Spinco Board of Directors and its committees. The Audit Committee will oversee


144


Table of Contents

the enterprise risk management, internal audit and internal controls processes and policies, and our Chief Audit Executive. It will also oversee financial reporting, accounting, internal controls, fraud, and capital structure; cybersecurity; legal and regulatory compliance, including our ethics and compliance program; legal and regulatory requirements regarding public disclosure of topics that will be covered by our corporate responsibility and sustainability programs; tax and transfer pricing matters; and general business risks. The Compensation and People Committee will oversee compensation programs, policies, and practices; equity and other incentive plans; recruiting, engagement, and retention; people programs, policies, and practices; and Chief Executive Officer succession planning and senior leadership development. The Nominating and Governance Committee will oversee board and committee composition, including board leadership structure; director succession planning; corporate governance policies and practices; and corporate responsibility and sustainability policies and programs, including related to human rights and environmental and climate change.

While Spinco’s management will be responsible for the day-to-day management of the various risks facing Spinco, the Spinco Board of Directors, both as a full board and through its committees, will be responsible for monitoring management’s actions and decisions. As a part of its oversight responsibilities, the Spinco Board of Directors and the Audit Committee will regularly monitor management’s processes for identifying and addressing areas of material risk to Spinco. In doing so, the Spinco Board of Directors and the Audit Committee will receive regular assistance and input from the other committees of the Spinco Board of Directors, as well as regular reports from members of senior management.

Selection of Nominees for Directors

The Nominating and Governance Committee will be responsible for recommending nominees for membership to the Spinco Board of Directors. The Nominating and Governance Committee may receive suggestions for candidates from individual Board members, including Spinco’s Chief Executive Officer, as well as from shareholders of Spinco. The Corporate Governance Guidelines will include qualification guidelines for director nominees. All candidates will be evaluated by the Nominating and Governance Committee using these qualification guidelines and any other factors the Nominating and Governance Committee deems relevant.

Shareholders wishing to recommend individuals for consideration as directors must contact the Nominating and Governance Committee by delivering a written notice to Spinco’s Corporate Secretary at our principal executive offices and including the following in the notice: the name and address of the shareholder as they appear on our books or other proof of share ownership; the class and number of shares of our common stock beneficially owned by the shareholder as of the date the shareholder gives written notice; a description of all arrangements or understandings between the shareholder and the director candidate and any other person(s) pursuant to which the recommendation or nomination is to be made by the shareholder; the name, age, business address and residence address of the director candidate and a description of the director candidate’s business experience for at least the previous five years; the principal occupation or employment of the director candidate; the class and number of shares of our common stock beneficially owned by the director candidate; the consent of the director candidate to serve as a member of the Spinco Board of Directors if appointed or elected; and any other information required to be disclosed with respect to a director nominee in solicitations for proxies for the election of directors pursuant to applicable rules of the SEC. The committee may require additional information as it deems reasonably required to determine the eligibility of the director candidate to serve as a member of the Spinco Board of Directors. Shareholders recommending candidates for consideration by our board in connection with the next annual meeting of shareholders should submit their written recommendation no later than      of the year of that meeting. The committee will evaluate director candidates recommended by shareholders for election to the Spinco Board of Directors in the same manner and using the same criteria as it uses for any other director candidate. If the committee determines that a shareholder-recommended candidate is suitable for membership on the Spinco Board of Directors, it will include the candidate in the pool of candidates to be considered for nomination upon the occurrence of the next vacancy on the Spinco Board of Directors or in connection with the next annual meeting of shareholders. Shareholders wishing to nominate directors for inclusion in Spinco’s proxy


145


Table of Contents

statement pursuant to the proxy access provisions in Spinco’s bylaws, or to otherwise nominate directors for election at Spinco’s annual meeting of shareholders, must follow the procedures described in Spinco’s bylaws.

Code of Business Ethics

Prior to the completion of our Spin-Off from Flex, we will adopt a Code of Business Ethics that applies to our directors, officers, and employees, including our Chief Executive Officer and Chief Financial Officer. The Code of Business Ethics will be designed to deter wrongdoing and to promote, among other things:


honest and ethical conduct, including the ethical handling of conflicts of interest;


full, fair, accurate, timely, and understandable disclosure in Company reports;


compliance with applicable laws and governmental rules and regulations;


prompt internal reporting of violations of the Code of Business Ethics; and


the protection of the Company’s legitimate business interests.

Spinco will make a copy of the Code of Business Ethics available on its website at axiomsolutions.com. To the extent required by rules adopted by the SEC and Nasdaq, we intend to promptly disclose future amendments to certain provisions of the Code of Business Ethics, or waivers of such provisions granted to executive officers and directors, on our website under the Corporate Governance section at axiomsolutions.com.

Compensation and People Committee Interlocks and Insider Participation

During Spinco’s fiscal year ended     , Spinco was not yet incorporated for the full fiscal year, was not an independent company and did not have a Compensation and People Committee or any other committee serving a similar function. Decisions as to the compensation of those who will serve as Spinco executive officers were made by Flex, as described in the section of this information statement entitled “Compensation Discussion and Analysis.”


146


Table of Contents

COMPENSATION DISCUSSION AND ANALYSIS

Introduction

During Spinco’s fiscal year ended March 31, 2026, Spinco was not yet incorporated, was not an independent company and did not have a compensation committee or any other committee serving a similar function.

For purposes of this Compensation Discussion and Analysis (“CD&A”) and the disclosure that follows, Ms. Advaithi, who currently serves as the Chief Executive Officer of Flex and is expected to serve as our Chief Executive Officer; Mr. Krumm, who currently serves as the Chief Financial Officer of Flex and is expected to serve our Chief Financial Officer; Mr. Tan, who currently serves as the Chief Operating Officer of Flex and is expected to serve as our Chief Operating Officer; and Mr. Offer, who currently serves as Executive Vice President and General Counsel of Flex and is expected to serve as Executive Vice President and General Counsel of Spinco are the only individuals who served as executive officers of Flex during fiscal year 2026 and are expected to serve in an executive officer role at Spinco. We refer to these individuals as our “named executive officers” or “NEOs” for purposes of the CD&A and the disclosure that follows. The CD&A discusses Flex’s historical compensation programs as applied to Ms. Advaithi and Messrs. Krumm, Tan and Offer, and outlines certain aspects of Spinco’s anticipated post-Distribution compensation structure for those individuals.

At the time of the Spin-Off, Spinco will have in place executive compensation programs, policies, and practices for its executive officers that are generally similar to those of Flex. Spinco is currently a part of Flex, and its Compensation and People Committee will be formed in connection with the Spin-Off. We expect the executive compensation programs, policies and practices for our executive officers will align incentives more closely with Spinco’s performance, strategic initiatives, industry peers and the long-term interests of our shareholders, which is expected to help us attract, retain and motivate highly qualified personnel. Accordingly, after the Spin-Off, we will review the compensation for all of our executive officers and determine the appropriate compensation, benefits and perquisites for them, and accordingly the compensation, benefits and perquisites provided to them after the Spin-Off will not necessarily be the same as those discussed below.

Executive Summary

Flex Practice

Flex’s pay programs align executive compensation with Flex’s performance and shareholder value creation. Flex uses a mix of performance metrics that reward different aspects of company achievement across short-term and long-term objectives.

Going Forward

After the Spin-Off, we will review the compensation for all of our executive officers and determine the appropriate compensation, benefits and perquisites for them, and accordingly the compensation, benefits and perquisites provided to them after the Spin-Off will not necessarily be the same as those discussed below.


147


Table of Contents

Summary of Flex’s Compensation Program Changes for Fiscal Year 2026

For fiscal year 2026, Flex made the following refinements to the design of its compensation program, as described below.


Program Element


Fiscal Year 2026 Design Changes


Rationale for Change

Long-Term Incentive Equity Award Mix


Increased the weighting of PSUs to 67% (from 50%), and decreased RSUs to 33% (from 50%)


To place a greater emphasis on driving performance and delivering Flex shareholder value

Long-Term Incentive EPS PSU Payout Scale


Increased the maximum payout potential to 250% of target (from 200%); capped at 200% of target when relative TSR is in the bottom quartile of the peer group


To incentivize exceptional EPS performance over a three-year period, while ensuring payouts are supported by adequate Flex shareholder returns

Annual Incentive Bonus Metrics


Removed the sustainability modifier from the bonus plan


NEOs and functional leaders incorporate sustainability goals into their individual objectives for the year. This realignment supports coordinated execution across the pillars of our sustainability program and promotes shared, team-based accountability.

Fiscal Year 2026 Executive Compensation Summary

Flex Practice

Flex’s executive compensation program is structured to be competitive and allow Flex to attract and retain a high-caliber leadership team. Further, it is intended to provide direct alignment between pay and performance. The illustrations below show the key elements of Flex’s direct compensation for its NEOs in fiscal year 2026 and how those elements were allocated. A majority of target pay is performance-based, with 92% at-risk for our CEO and 83% at-risk for Flex’s other NEOs (on average), as detailed below.


LOGO


(1) 

PSUs are shown at face value (the target number of shares awarded multiplied by the closing stock price on the grant date).


148


Table of Contents
(2) 

Excludes Supplemental Equity Award granted to Ms. Advaithi in fiscal year 2026, further described on page 164.

(3) 

Represents an average for Flex’s four other NEOs for fiscal year 2026, which included Messrs. Krumm, Tan and Offer and Michael P. Hartung, President and Chief Commercial Officer of Flex.


LOGO

Going Forward

We anticipate that our executive compensation program upon the Spin-Off will generally include the same elements as Flex’s executive compensation programs. Following the Spin-Off, our Compensation and People Committee will review the primary elements of our executive compensation program, and mix thereof, to ensure they meet our business needs and strategic objectives. This will include a review of base salary as well as short-term and long-term incentive programs and other elements of compensation.

Further, the Flex Compensation and People Committee, with recommendations from Semler Brossy, adopted a peer group for Spinco to help inform its decision-making with respect to the Spinco’s executive compensation program and ensure that such program supports Spinco’s recruitment and retention needs and is fair and efficient. Consistent with the determination of the Flex peer group, the Flex Compensation and People Committee selected companies for inclusion in Spinco’s peer group based on (1) comparability of revenues and market capitalization (2) the extent to which they compete with Spinco for executive talent because they operate in a similar industry, and (3) other qualitative factors such as business fit and complexity. This compensation peer group is comprised of the following companies:


Amphenol


Equinix


NetApp


TE Connectivity

Celestica


Fabrinet


nVent Electric


TTM Technologies

Ciena Corporation


Keysight Tech


Seagate Tech.


Vertiv

Eaton


Marvell


Super Micro Comp


Western Digital


149


Table of Contents

Compensation Philosophy

Flex Practice

Flex’s compensation philosophy centers on meaningful pay-for-performance alignment. Flex’s compensation programs link executive pay to Flex’s short-term and long-term objectives and the creation of shareholder value. Flex designs its compensation programs to attract, retain, and motivate top executive talent by offering competitive pay opportunities tied to rigorous performance goals, while balancing the need to avoid excessive risk-taking and maintaining cost discipline. Flex actively manages its pay-for-performance philosophy as described below.


Program Feature


Overview

Competitive pay   

Flex regularly benchmarks pay against a set of industry peers.


Flex’s base salaries and target cash compensation are competitively positioned for our NEOs to manage fixed costs and emphasize paying for performance.

Substantial emphasis on at-risk compensation   

Programs are designed to link pay delivery to the achievement of pre-determined performance goals that directly correlate with enhanced shareholder value.


92% of Ms. Advaithi’s fiscal year 2026 target total direct compensation was at-risk (excluding the one-time supplemental performance-based equity award granted in fiscal 2026) and, on average, 83% of target total direct compensation for its other NEOs was at-risk.


At-risk compensation is based on the achievement of core financial metrics and/or is subject to market risk based on stock price and/or relative TSR performance. Incentive outcomes are based on a formulaic calculation of results against pre-determined financial or TSR-based performance targets.


Formulaic funding results under the annual incentive plan are modified based on individual performance (+/-10 percentage points).


The Flex Board of Directors, or the Flex Compensation and People Committee if so delegated by the Flex Board of Directors, maintains the authority to adjust annual incentive bonus payouts if such payouts do not align with Flex’s overall performance.

Focus on long-term performance   

While measurement of short-term results maintains day-to-day focus, Flex believes that shareholder value is built over the long term.


For Ms. Advaithi’s fiscal year 2026 target total direct compensation, 78% was in the form of long-term incentives, two-thirds of which were linked to the achievement of relative TSR performance or adjusted EPS growth goals (excluding the one-time supplemental performance-based equity award granted in fiscal 2026). On average, 64% of target total direct compensation for our other NEOs was in the form of long-term incentives, tied to achievement of the same objectives as Ms. Advaithi. For additional information on Ms. Advaithi’s one-time supplemental performance-based equity award, see the section titled “Other Long-Term Incentive Compensation Award Granted during FY26” on page 164.


Flex emphasizes the NEOs’ alignment with our shareholders’ long-term interests by enforcing rigorous share ownership guidelines.

Flex’s compensation program is highly responsive to changes in its operating and stock price performance, as illustrated below with respect to our CEO’s total direct compensation.


150


Table of Contents

LOGO


Illustrative Assumptions


Bonus & RSU Payouts


Stock Price

Low Performance Scenario

  50% of Target   $21.79 (Grant Price -50%)

High Performance Scenario

  150% of Target   $65.36 (Grant Price +50%)

Going Forward

We anticipate that our executive compensation objectives and approach will initially be similar to Flex’s. Following the Spin-Off, our Compensation and People Committee will review these objectives and approach to ensure they meet our business needs and strategic objectives.


151


Table of Contents

Compensation-Setting Process and Decisions

Flex Practice

Alignment with Compensation and Corporate Governance Best Practices

The Flex Compensation and People Committee regularly reviews Flex’s compensation programs, peer company data, and best practices in executive compensation. Flex has adopted corporate governance and compensation practices and policies that the Flex Compensation and People Committee, along with the Flex Board of Directors, believes help to advance its compensation goals and philosophy.


What Flex Does


What Flex Does Not Do

The Flex Compensation and People Committee is composed entirely of independent members with a robust review process.


Flex uses a pay-for-performance executive compensation model that focuses primarily on corporate performance, with the majority of executive compensation at-risk and long-term.


Flex maintains a recoupment policy so Flex can clawback compensation paid to an executive officer in the event of a material restatement of financial results.


The Flex Compensation and People Committee retains an independent compensation advisor.


Flex conducts regular shareholder outreach and considers shareholder advisory votes and views in determining executive compensation strategies.


Flex maintains robust share ownership guidelines for NEOs and directors.


Flex does not enter into NEO employment agreements.


Flex does not pay severance in the event of an executive’s voluntary resignation or retirement.


Flex does not allow hedging or short sales of Company equity, and Flex does not permit using our shares as collateral for margin accounts or pledging of Company equity as collateral for loans.


Flex does not provide excise tax gross-ups with respect to compensation provided in connection with a change of control event.


Flex does not have automatic single-trigger accelerated vesting of equity awards upon a change of control.


Flex does not provide excessive or non-customary executive perquisites.


Flex does not pay dividends or dividend equivalents on our unvested equity awards.


Flex does not permit option/SAR repricing (including cash buyouts) under our equity incentive plan without shareholder approval.

Flex Compensation and People Committee

The Flex Compensation and People Committee oversees compensation of its CEO, all other NEOs, and other executive officers, recommending appropriate pay levels to the Flex Board of Directors. The Committee also administers Flex’s equity compensation plans, evaluates the effectiveness of its executive compensation programs, monitors say-on-pay results, and reviews talent assessment and succession planning.

The Flex Compensation and People Committee regularly assesses Flex’s compensation programs to ensure they support Flex’s business and human capital strategies. It also monitors market trends and changes in competitive pay practices. Based on these reviews, the Committee may approve program changes or recommend such changes to the Flex Board of Directors.

Flex Independent Consultants and Advisors

The Flex Compensation and People Committee has the authority to retain and terminate any independent, third-party compensation consultants and to obtain advice and assistance from internal and external legal,


152


Table of Contents

accounting, and other advisors. During fiscal year 2026, the Flex Compensation and People Committee retained FW Cook as its independent compensation consultant.

FW Cook furnished the Flex Compensation and People Committee reports on the following topics: Flex peer group composition, compensation data and analysis relating to the compensation of Flex’s executive officers, short- and long-term compensation program design, compensation program risk assessment, annual share utilization and shareholder dilution levels resulting from equity plans, executive share ownership and retention values, perquisites reviews, and regulatory updates.

The Flex Compensation and People Committee confirmed that there are no personal or business relationships between any FW Cook employee and any member of the Flex Compensation and People Committee or any of its executive officers beyond the Flex relationship. Based on this information and other factors, including the factors set forth under Rule 10C-1 under the Exchange Act, the Flex Compensation and People Committee assessed the independence of FW Cook and concluded that no conflict of interest exists that would prevent FW Cook from independently advising the Flex Compensation and People Committee. Outside of engaging on executive and director compensation and related matters, FW Cook does not provide any other services to Flex.

Role of Executive Officers in Flex’s Compensation Decisions

The Flex Compensation and People Committee meets with Flex’s CEO and other executives to obtain recommendations with respect to the structure of Flex’s compensation programs. The CEO and certain other executives also assess the performance of other individual executives and make recommendations regarding their compensation. Decisions related to the compensation of the CEO (including recommendations to the Flex Board of Directors regarding the same) are made independently by the Flex Compensation and People Committee, without input from management. In addition, Flex’s CEO and other executives develop recommendations for performance measures and target performance goals under Flex’s incentive plans based on Flex management’s business forecast—both at Flex and segment levels. These recommendations are approved by the Flex Compensation and People Committee as well as by the Flex Board of Directors when appropriate.

Going Forward

The Spinco Compensation and People Committee will determine its appropriate role and the appropriate role of Spinco management, and independent members of the Spinco Board of Directors in designing and approving executive officer compensation. Initially, the roles of each party are expected to be similar to Flex’s process.

After the Spin-Off, the Spinco Compensation and People Committee will retain an independent compensation consultant to advise on executive and director compensation matters.

Flex Executive Compensation Peer Group

Relying upon data provided by Flex’s independent compensation consultant, the Flex Compensation and People Committee undertakes a review, on an annual basis, of the compensation peers that Flex uses to provide insight into market-competitive executive pay programs, levels and practices. The criteria used to develop the peer group were largely unchanged from fiscal year 2025, continuing with revenue and market cap as the financial measures, as well as similar industry focus and publicly listed companies with headquarters in the U.S. as the other selection criteria. Applying these criteria, carried over from fiscal year 2025, did not result in any peer group changes – Flex continued with the same 14 peer companies as in fiscal year 2025.


153


Table of Contents

LOGO


(1)

Initial industry selection criteria focused on companies assigned to the following GICS codes: Hardware and Equipment (4520) and Capital Goods (2010). Additional selection criteria were:


Emphasis on technology and electronics or other specialty manufacturers (rather than pure distributors); and


Business-to-business technology, machinery, or electronic peripheral providers.

Flex’s peer group for fiscal year 2026 compensation decisions consisted of the following companies:


Arrow Electronics, Inc.


Jabil Inc.


TD SYNNEX Corporation

Avnet, Inc.


PACCAR Inc.


Textron Inc.

Corning Incorporated


Parker Hannifin Corporation


Western Digital Corporation

Cummins Inc.


Sanmina Corporation


Xerox Holdings Corporation

Hewlett Packard Enterprise Company


Seagate Technology Holdings plc


The peer group revenue and market cap summary statistics, as of the time of the analysis, are shown below.


LOGOLOGO

In addition to Flex’s peer group companies, the Flex Compensation and People Committee reviews standardized surveys of large technology and manufacturing firms to evaluate the competitiveness of Flex’s compensation programs in the context of broader market practices.


154


Table of Contents

Going Forward

We anticipate that our executive compensation process upon the Spin-Off will generally follow the same process as Flex’s executive compensation process. Following the Spin-Off, our Compensation and People Committee will review all aspects of its process and may make adjustments that it believes are appropriate in establishing our executive compensation process.

Further, the Flex Compensation and People Committee, with recommendations from Semler Brossy, adopted a peer group for Spinco to help inform its decision-making with respect to the Spinco’s executive compensation program and ensure that such program supports the Company’s recruitment and retention needs and is fair and efficient. Consistent with the determination of the Flex peer group, the Flex Compensation and People Committee selected companies for inclusion in Spinco’s peer group based on (1) comparability of revenues and market capitalization (2) the extent to which they compete with the Company for executive talent because they operate in a similar industry, and (3) other qualitative factors such as business fit and complexity. This compensation peer group is comprised of the following companies:


Amphenol

  Equinix   NetApp   TE Connectivity

Celestica

  Fabrinet   nVent Electric   TTM Technologies

Ciena Corporation

  Keysight Tech   Seagate Tech.   Vertiv

Eaton

  Marvell   Super Micro Comp   Western Digital

Following the Spin-Off, our Compensation and People Committee will review the peer group on a periodic basis and determine whether any changes are appropriate based on its view of the competitive environment in which we operate.

Fiscal Year 2026 Executive Compensation

Base Salary

Flex Practice

The Flex Compensation and People Committee typically reviews base salaries every year and makes recommendations to the Flex Board of Directors about adjusting or maintaining salary levels to reflect competitive market data, individual performance, internal equity and promotions or changes in responsibilities.

The following table sets forth the base salaries of our NEOs serving on the last day of fiscal year 2026. None of our NEOs’ base salaries were increased in fiscal year 2026 from fiscal year 2025.


Name and Title

   Annualized
Base Salary
for Fiscal Year
2025
($)
     Annualized
Base Salary
for Fiscal Year
2026
($)
     Percentage
Change
 

Revathi Advaithi
Chief Executive Officer

     1,325,000        1,325,000        0.0

Kevin Krumm
Chief Financial Officer

     832,000        832,000        0.0

Hooi Tan
Chief Operating Officer

     735,000        735,000        0.0

Scott Offer
Executive Vice President, General Counsel

     663,000        663,000        0.0

Going Forward

Following the Spin-Off, we anticipate that our Compensation and People Committee will establish base salary levels for our named executive officers taking into account a review of benchmarking data for similar roles, individual performance, and competitive positioning.


155


Table of Contents

Incentive Bonus Plan

Flex Practice

In designing the incentive bonus plan, Flex’s CEO and management team develop and recommend performance metrics, weightings and targets, which are reviewed and are subject to final approval by the Flex Compensation and People Committee. Fiscal year 2026 corporate level performance metrics and weightings, which were unchanged from fiscal year 2025, except for the removal of the sustainability modifier, were as follows:


Metrics

   Fiscal Year 2026 Weightings  

Adjusted OP

     40

Adjusted FCF

     35

Revenue

     25

Individual Performance


Used as an additive modifier

(+/– 10


%) 

The adjusted operating profit (“OP”) from continuing operations, adjusted free cash flow (“FCF”), and revenue metrics and weightings remained the same from fiscal year 2025 to fiscal year 2026 and focus on profitability, conversion of profit into free cash flow through working capital and inventory management, and top line growth.

Adjusted OP acts as both a metric within the plan, and the overall funding metric of Flex’s global bonus program, as illustrated below on page 158. Adjusted OP achievement generates an enterprise-wide funding pool based on the same adjusted OP targets as used for the Corporate NEO bonus plan, which acts to ensure affordability and alignment to shareholder returns. Flex uses a range around OP, where aggregate bonus payouts must be within +/-20% of Corporate adjusted OP achievement. This maintains the connection between enterprise-wide bonus plan results and payouts as well as pay for performance alignment.

Flex continued with an individual performance modifier to the incentive bonus plan for fiscal year 2026, which can adjust the final bonus payout +/- 10 percentage points. Final bonus payouts are subject to the bonus plan cap of 200% of target.

The following table summarizes the key features of Flex’s fiscal year 2026 incentive bonus plan.


Feature


Component


Objectives

Performance targets   

Based on key short-term corporate and segment financial metrics


Aligns executive incentives with performance


Rewards achievement of short-term objectives

Performance measures   

Revenue and adjusted OP at Flex and segment level, and adjusted FCF at the Flex level


Weightings for these metrics are fixed and measured at the corporate and segment levels for the applicable executives


Adjusted OP measured at the Flex level is also used as the funding metric for aggregate bonus payouts across Flex


Emphasizes pay-for-performance by linking individual compensation to performance on metrics that are key drivers of shareholder value


Promotes accountability by tying payouts to achievement of minimum performance thresholds


Ties aggregate payouts to Flex’s overall profitability, helping to ensure affordability

Bonus modifier   

Individual performance


Enables the Committee to differentiate pay based on individual NEO’s performance


156


Table of Contents

Feature


Component


Objectives

Bonus payments   

Based on achievement of financial performance objectives and individual performance


Target bonus opportunities set at percentage of base salary, based on executive’s level of responsibility


Additive individual performance modifier can adjust bonus payouts by up to +/-10 percentage points


Annual incentive bonuses range from 0% of target to a maximum of 200% of target


No payout awarded for any measure where threshold performance is not achieved


If threshold performance is not achieved for all metrics, bonus payout is capped at 100%


The Flex Board of Directors, or the Compensation and People Committee if so delegated by the Flex Board of Directors, has the authority to adjust bonus payouts if appropriate in the context of Flex’s overall performance


Reflects Flex’s emphasis on pay-for- performance by linking individual compensation to financial performance


Encourages accountability for all financial performance goals by conditioning bonus payments on the achievement of at least the minimum thresholds on all measures and capping funding at 100% if performance is not above threshold on all financial goals

Non-GAAP Adjustments

Flex used adjusted non-GAAP performance measures (adjusted OP and adjusted FCF) for its incentive bonus plan in fiscal year 2026, and adjusted EPS in its fiscal 2026 adjusted EPS growth PSU grants. Using adjusted measures eliminates the distorting effect of certain unusual income or expense items. The adjusted performance measures are consistent with those used in Flex’s quarterly earnings releases. The adjustments are intended to align award payout opportunities with the underlying growth of Flex’s business and avoid misalignment in outcomes based on unusual items.

In calculating non-GAAP financial measures, Flex excluded certain items to make it easier to compare Flex’s operating performance on a period-to-period basis because such items are not, in the Flex Compensation and People Committee’s view, related to Flex’s ongoing operational performance. The non-GAAP measures are used to more accurately evaluate Flex’s operating performance, to calculate return on investment, and to benchmark performance against competitors. For fiscal year 2026, non-GAAP adjustments consisted of excluding intangible amortization, customer-related asset impairments (recoveries); restructuring charges; after-tax stock-based compensation expense; one-time legal impacts; investment impairments; equity in earnings; and other tax impacts. All adjustments are subject to approval by the Flex Compensation and People Committee to ensure that payout levels are consistent with performance. See Annex A to this information statement for a reconciliation of GAAP to non-GAAP financial measures. For purposes of calculating performance under Flex’s incentive bonus plan in fiscal year 2026, Flex has excluded the impact from extraordinary items or events that would have had an unanticipated impact, corporate transactions (including acquisitions or dispositions), and other unusual or nonrecurring items.


157


Table of Contents

Target Incentive Awards

Fiscal year 2026 bonus targets for the NEOs as a percent of base salary are shown below. They were not increased from fiscal year 2025.


Name and Title

   Fiscal year 2026
Target Bonus
(% of Salary)
    Fiscal year
2026 Target ($)
 

Revathi Advaithi
Chief Executive Officer

     165     2,186,250  

Kevin Krumm
Chief Financial Officer

     115     956,800  

Hooi Tan
Chief Operating Officer

     110     808,500  

Scott Offer
Executive Vice President, General Counsel

     100     663,000  

Incentive Payouts for NEOs

The table below sets forth the payout opportunities that were available to Ms. Advaithi and Messrs. Krumm, Tan and Offer based on different levels of corporate performance. These targets are considered rigorous and were validated within the context of analyst expectations.

Performance targets are determined based on financial plans approved by the Flex Board of Directors—both at company and segment levels. Maximum payout levels were tied to “stretch” levels of performance.


LOGO


Actual Payout Based on Performance

(1)

Threshold payout on Revenue was 93% of target, on Adjusted OP metric was 85% of target, and for Adjusted FCF metric was 60% of target.

(2)

Bonus Achievement excludes OP funding and individual performance factors.

OP Funding Factor

The fiscal year 2026 adjusted OP funding factor was 101%. Formulaic funding of all Flex bonus plans was lower in aggregate than what funding would have been if based on corporate OP. Per the mechanics of the executive bonus plans, funding of the bonus plans was adjusted based on positive OP performance.

Individual Performance Modifier

An additive individual performance bonus modifier was included in the bonus plan for NEOs in fiscal year 2026. The modifier can adjust bonus payouts by up to +/-10 percentage points. Based on the year-end assessment of


158


Table of Contents

individual performance, bonuses were positively adjusted as denoted below for Ms. Advaithi and Messrs. Krumm and Tan.


NEO


Fiscal Year 2026 Individual Performance Highlights

   Individual Performance
Modifier Adjustment
Revathi Advaithi   

Delivered strong operational performance during fiscal year 2026, as highlighted above


Positioned Flex to capitalize on the generational transformation in electrical infrastructure and accelerating AI data center demand


Executed strategic initiatives that drove significant shareholder creation


Expanded key portfolio segments while advancing plans to spin off the Cloud and Power Infrastructure (CPI) segment

   +10%
Kevin Krumm   

Significant efforts and contributions that yielded very strong fiscal year 2026 financial results, and led the implementation of a new segment reporting structure to enhance investor transparency


Successfully transitioned into the CFO role while strengthening and scaling the finance organization to support evolving business needs


Played a key role in advancing the planned Spin-Off of Flex’s CPI segment

   +10%

Hooi Tan


Significant efforts and contributions that yielded very strong fiscal year 2026 financial results, including operational efficiency improvements while maintaining business continuity amid geopolitical challenges


Played a key role in advancing the planned Spin-Off of Flex’s CPI segment

   +10%

For fiscal year 2026, Flex’s performance resulted in payouts as shown below:


LOGO

Final Incentive Awards for the NEOs

The fiscal year 2026 bonus payout levels for the NEOs were as follows:


Name

   Fiscal Year 2026 Annual
Incentive Bonus Target
(Potential Bonus as a
percentage of Base Salary)
    Fiscal Year 2026
Annual Incentive
Actual Bonus
($)
     Fiscal Year 2026 Actual
Annual Incentive Bonus
as a Percentage of Full
Year Target Bonus
 

Revathi Advaithi

     165     3,950,117        180.68

Kevin Krumm

     115     1,728,746        180.68

Hooi Tan

     110     1,460,798        180.68

Scott Offer

     100     1,131,608        170.68


159


Table of Contents

Going Forward

Following the Spin-Off, we anticipate that our Compensation and People Committee will develop an incentive bonus plan focused on near-term operational and financial goals that support our business objectives, while also allowing for meaningful pay differentiation tied to performance of individuals and groups. We have not yet identified the specific performance measures that will apply under the Spinco plan following the Spin-Off. Our new incentive bonus plan will be prorated for our partial fiscal year starting on April 1, 2027. The first full year of our incentive bonus plan will be from January 1, 2028 through December 31, 2028.

Long-Term Share-Based Incentive Compensation

Flex Practice

In June 2025, the Flex Board of Directors, upon the recommendation of the Flex Compensation and People Committee, granted share-based long-term incentives to Flex’s senior executives as an incentive to maximize Flex’s long-term performance and drive shareholder value creation. These awards are designed to align the interests of NEOs with those of Flex’s shareholders and to give each NEO a significant incentive to manage Flex from the perspective of an owner with a direct stake in the business. Long-term equity awards are also intended to promote retention, since unvested shares are forfeited if an executive voluntarily leaves Flex.

One-third of the long-term incentive value was delivered in the form of service-based RSUs. rTSR PSUs represent 20% of Flex’s executive officers’ share-based long-term incentive awards (based on face value of the awards) in fiscal year 2026 and the remaining 47% was delivered in the form of adjusted EPS growth PSUs. The actual grant value mix disclosed in the tables of this information statement may deviate from this 33/20/47 RSU/rTSR PSU/EPS PSU mix due to the Monte Carlo accounting valuation required by SEC rules to be used for the tabular disclosure of rTSR PSUs. The Flex Compensation and People Committee believes this targeted one-third/two-thirds allocation between RSUs and PSUs links long-term compensation to Flex’s long-term performance and shareholder outcomes and promotes retention.

In addition to the awards granted in June 2025 under Flex’s fiscal year 2026 long-term incentive compensation program, the Flex Board of Directors, upon the recommendation of the Flex Compensation and People Committee, granted a one-time performance-based long-term incentive equity award to our CEO for the achievement of rigorous performance goals related to Flex’s CPI business. See below section titled “Other Long-Term Incentive Compensation Award Granted During FY26” on page 164.

Restricted Share Unit Awards (RSUs)

One-third of each NEO’s fiscal year 2026 share-based long-term incentive award is in the form of RSUs. These service-based RSUs vest in three equal installments on the first three anniversaries of the grant date, subject to continued employment. Payouts are made in shares and the value of an RSU award increases or decreases based on share price performance from the grant date, further aligning the interests of the executive with long-term shareholder value creation. Before an RSU vests, the holder has no ownership rights in the shares and is not entitled to dividends or dividend equivalents.

rTSR PSUs

Twenty percent of each NEO’s fiscal year 2026 share-based long-term incentive award is in the form of rTSR PSUs. The rTSR PSU awards granted in fiscal year 2026 will be earned (or not), at up to a maximum of 200% of target, based upon Flex’s percentile rank of TSR over a three-year period compared to the rTSR peer group companies (described below). Performance is measured over three discrete measurement periods—of 12-, 24-, and 36-months—within each three-year cycle, as illustrated below. The rTSR PSU final payout will be based on the average payouts of these three performance periods and does not occur until after the conclusion of the full 36-month performance period.


160


Table of Contents

LOGO

The use of discrete measurement periods is intended to minimize the potential impact of short-term share price volatility at the end of the performance period. In addition, having vesting occur following conclusion of the final three-year performance period aligns value delivery with longer-term absolute TSR performance. The Flex Compensation and People Committee believes that this approach encourages NEOs to focus on generating long-term shareholder returns and results in payouts that more accurately reflect the shareholder experience over the full three-year cycle.

The number of shares earned is dependent on the percentile rank achieved, within each of the 12-, 24- and 36-month periods, as shown below.


LOGO

Note: Straight-line interpolation is used to determine shares earned when results are between targets.

The TSR peer group is reviewed and updated annually based on the filtering criteria below.


1.

Reflect likely competitors for investor funds


2.

Focus on the same or similar industries to Flex and subject to similar macroeconomic forces


3.

Approximate the margin range for electronic manufacturing industry


161


Table of Contents

These considerations resulted in the following selection methodology:

Fourteen companies in the compensation peer group at the time of selection, together with companies that met all of the following criteria:


1.

Industry membership in Technology Hardware & Equipment (GICS code 4520) and Capital Goods (2010)


2.

Trailing four quarter revenue is between 0.2x-to-5.0x Flex’s


3.

12-month average market cap is between 0.2x-to-6.0x Flex’s


4.

Three-year average operating margin is 10% or less

Based on the selection methodology listed above, Flex’s fiscal year 2026 TSR peer group is comprised of the following:


Acer Inc.


GE Vernova, Inc.


Rush Enterprises

AECOM


Giga-Byte Technology


Sandisk Corporation

APi Group


GMS


Sanmina Corporation*

Arrow Electronics, Inc.*


Hewlett Packard Enterprise*


Seagate Technology Holdings plc*

ASUSTek Computer Inc.


HP Inc.


Spirit AeroSystems

AtkinsRéalis


Huntington Ingalls Industries


StandardAero

AUO Corporation


Icahn Enterprises L.P.


Stanley Black & Decker, Inc.

Avnet, Inc.*


Ingram Micro Holding Corporation


Super Micro Computer, Inc.

Beacon Roofing Supply, Inc.


Innolux Corporation


Synnex Technology International Corp.

Bombardier Inc.


Insight Enterprises Inc.


TD SYNNEX Corporation*

CDW Corporation


Intevac Corporation


Textron Inc.*

Celestica Inc.


Jabil Inc.*


UFP Industries, Inc.

Coherent Corp


MasTec Inc.


Walsin Lihwa Corp.

Comfort Systems USA


Micro-Star International


WESCO International, Inc.

Compal Electronics, Inc.


Oshkosh Corporation


Western Digital Corporation*

Corning Incorporated*


PACCAR Inc.*


Wistron Corporation

Cummins Inc.*


Parker-Hannifin Corporation*


Wiwynn Corp.

EMCOR Group, Inc.


Pegatron Corporation


WPG Holdings

Far Eastern New Century


Primoris Services


WSP Global Inc.

Ferguson Enterprises


Quanta Computer Incorporated


WT Microelectronics Co. Ltd.

Finning International Inc.


Quanta Services


Xerox Holdings Corporation*

Fluor Corporation


Resideo Technologies


Zhen Ding Technology

The TSR peer group contains companies headquartered and listed in the U.S., Canada and Taiwan as a reflection of the global nature of the industry in which Flex operates.

Adjusted EPS Growth PSUs

Flex has incorporated adjusted EPS growth PSUs into Flex’s LTI program since fiscal year 2022 to support continued focus on achieving Flex’s long-term financial strategy. For FY26, these PSUs represent 47% of Flex’s participating NEOs’ share-based long-term incentive awards (based on the target value of the awards as described below) and will be earned (or not), at up to a maximum of 250% of target, based upon Flex’s achievement of adjusted EPS growth targets. Further, to the extent that Flex’s rTSR is in the bottom quartile of the peer group, as described above, EPS Growth PSU funding is capped at 200% of target.

In setting the adjusted EPS growth targets, the Flex Compensation and People Committee considered the following inputs:


Flex’s historical EPS growth performance;


162


Table of Contents
   

Peer company (both compensation and US-based TSR peers) historical non-GAAP EPS growth performance;


Flex’s long-term financial strategy; and


Flex’s investor guidance for fiscal year 2026.

Performance is measured over a three-year period in three discrete annual measurements, as illustrated below. Performance for each year is averaged at the end of the three-year period to determine the final percentage of shares that vest (as a percent of target).


LOGO

Adjusted EPS growth rates will be calculated using non-GAAP adjustments summarized on page 157 of this information statement. Adjusted EPS used for purposes of adjusted EPS growth PSU performance calculations will exclude the impact of extraordinary items or events that have an unanticipated impact, corporate transactions (including acquisitions or dispositions), and other unusual or nonrecurring items. For purposes of adjusted EPS, the impact of unplanned share repurchases attributable to corporate transactions (including acquisitions or dispositions) will also be excluded. The rationale for excluding the impact of significant items or events that have an unanticipated impact is to focus participants on factors within their control and preserve the incentive orientation of the plan in the face of significant, unforeseen business disruptions or other events. The objective of excluding the impact of M&A is to measure performance on the same basis and business composition as in place at the start of the performance period. See also Annex A to this information statement for a reconciliation of GAAP to non-GAAP financial measures.

Grants During Fiscal Year 2026

The Flex Compensation and People Committee and the Flex Board of Directors considered the following factors when determining the value of the fiscal year 2026 NEO equity awards:


Peer group compensation data for similarly situated executives;


Future potential to contribute to the Flex’s growth and potential to grow in current role and expand scope of responsibility and contribution over time; and


Individual performance and internal equity.


163


Table of Contents

Awards Granted under Flex’s FY26 Long-Term Incentive Compensation Program

The table below summarizes the approved fiscal year 2026 PSU and service-based RSU awards granted in June 2025 to our NEOs under Flex’s long-term incentive compensation program.


NEO

   Target rTSR-Based
PSUs (Shares)
     Target Adjusted
EPS Growth-
Based
PSUs (Shares)
     Service-Based
RSUs (Shares)
     Target Total
Equity Award
Value ($)
 
Revathi Advaithi      57,378        134,840        94,675        12,500,000  
Kevin Krumm      13,311        31,282        21,964        2,900,000  
Hooi Tan      13,311        31,282        21,964        2,900,000  
Scott Offer      12,164        28,586        20,071        2,650,000  

The target award values shown above vary from the values shown in the Summary Compensation Table and Grants of Plan-Based Awards Table because the accounting cost of Flex’s rTSR PSUs is based on a Monte Carlo valuation. The target award value is determined and then allocated among various award types. The number of shares is calculated by dividing the target value by the share price on the grant date, rounded down to the nearest whole share. The actual value ultimately earned is determined based on Flex’s multi-year TSR performance relative to the TSR peer group, its adjusted EPS growth performance, as well as its stock price performance.

Other Long-Term Incentive Compensation Award Granted During FY26

On June 19, 2025, the Flex Board of Directors, upon the recommendation of the Flex Compensation and People Committee, approved the grant of a one-time supplemental equity award (the “Supplemental Equity Award”) to our CEO Revathi Advaithi. The grant is 100% performance-based with a target value of $25 million and can only be earned for the achievement of highly rigorous goals for the Flex’s data center business (which constitutes the business of Spinco) over a multi-year period, with funding subject to a payout cap tied to Flex’s rTSR for further accountability to Flex’s shareholders.

Rationale and Considerations for Granting the Supplemental Equity Award

The Flex Compensation and People Committee and the Flex Board of Directors determined that granting this one-time Supplemental Equity Award is in the best interests of the Flex and that the amount and terms of the award have been carefully tailored to fit Flex’s strategic objective of growing its data center business, as well as Flex’s consistent long-term goal of incremental shareholder value creation. The Supplemental Equity Award was approved with the advice and input of the Flex Compensation and People Committee’s independent compensation consultant, which included a review of relevant benchmarking data.

Award Size and Structure

The Supplemental Equity Award for Ms. Advaithi has a grant date fair value at target of $25 million and consists entirely of at-risk PSUs, designed to lock in the CEO to drive execution of Flex’s Cloud and Power Infrastructure business growth strategy and unlock shareholder value. The Supplemental Equity Award vests based on rigorous fiscal year 28 Cloud and Power Infrastructure business OP targets and includes a meaningful rTSR cap, as further described below.

The Supplemental Equity Award cliff-vests after performance is certified following the end of the performance period, subject to Ms. Advaithi’s continued service through such date. The number of PSUs earned, if any, will be primarily based on the performance of the Cloud and Power Infrastructure business measured at the end of fiscal year 2028, as noted above, with payouts ranging from 0% to 250% of the target PSUs granted. The underlying performance goals are rigorous and, if achieved, are expected to drive significant shareholder value creation.


164


Table of Contents

Further, to strengthen alignment to Flex’s shareholders’ experience, the Supplemental Equity Award is subject to an overall payout cap based on Flex’s rTSR over a three-year period beginning on June 19, 2025, and ending on June 19, 2028. The maximum number of PSUs underlying the Supplemental Equity Award is capped at:


250% of target if rTSR is at or above the median,


200% of target if rTSR is below the median, and


100% of target if rTSR is below the 25th percentile.

Shareholder Value Creation Since Grant Date

Since the grant date of the Supplemental Equity Award on June 19, 2025, Flex has meaningfully outperformed relevant benchmarks with respect to share price performance. Flex’s +221% TSR through June 1, 2026 has delivered superior returns to Flex’s shareholders, compared to the S&P 500 (+29%) and Flex’s compensation peer group (+92%) over the same period.


LOGO

As discussed above, the Supplemental Equity Award was granted with Flex’s consistent long-term goal of incremental shareholder value creation, which has already borne fruit. Flex’s superior TSR performance since the grant date of the Supplemental Equity Award through June 1, 2026 has resulted in $37.0 billion in incremental value creation for its shareholders. In addition, since Flex’s announcement on May 5, 2026 of the planned Spin-Off, Flex shareholders have experienced $18.8 billion in incremental value creation.


165


Table of Contents

LOGO

The Flex Board of Directors believes that Flex’s superior performance since the date of grant, as well as the overwhelmingly positive market reaction to the announcement of the Spin-Off, are clear indications that the Supplemental Equity Award is working as intended – focusing on the strategic objective of growing the data center business, as well as creating incremental value for Flex’s shareholders.

At the Distribution Date, the Supplemental Equity Award will be converted into an award relating to Spinco stock with no changes to the original award terms, performance metrics and targets or the performance period described above or the termination provisions described below.

Supplemental Equity Award Termination Provisions

To further enhance its retentive effect, the Supplemental Equity Award is subject to continued service requirements that are more restrictive than those applicable to Flex’s standard equity awards. Unlike other outstanding equity awards held by Ms. Advaithi, if Ms. Advaithi retires, such retirement will not entitle her to accelerated or continued vesting of the Supplemental Equity Award. Moreover, unlike other outstanding equity awards held by Ms. Advaithi, if Ms. Advaithi’s employment with Flex is terminated due to her Disability (as such term is defined in the plan), such termination will not entitle her to accelerated or continued vesting of the Supplemental Equity Award.

The agreement evidencing the Supplemental Equity Award provides that if Ms. Advaithi’s employment with Flex is terminated (i) by Flex without “cause” or (ii) due to a voluntary termination for “good reason” (as each such term is defined in the award agreement), in either case absent a change of control of Flex, Ms. Advaithi is entitled to ratable vesting of the Supplemental Equity Award determined by multiplying (x) the number of shares vesting based on actual performance measured at the conclusion of the three-year performance period by (y) a fraction, the numerator of which is the number of days Ms. Advaithi provided services to Flex from the date of grant until her termination of employment, and the denominator of which is the total number of days from the date of grant through the completion of the three-year performance period. The treatment of the Supplemental Equity Award in the event of Ms. Advaithi’s death will be the same as for other awards of PSUs granted to Flex’s executive officers, as previously disclosed.

Additionally, if Ms. Advaithi’s employment is terminated (i) by Flex without “cause” or (ii) due to a voluntary termination for “good reason,” in either case during the period beginning on the consummation of a change of control of Flex and ending 24 months following such change of control, Ms. Advaithi is entitled to 100% accelerated vesting of the Supplemental Equity Award based upon (x) actual performance if the three-year performance period is complete as of the date of such termination, or (y) target performance if the three-year performance period is incomplete as of such termination.


166


Table of Contents

Payouts of Prior PSUs

The performance period for the rTSR PSUs granted in fiscal year 2023 ended in fiscal year 2026. The fiscal year 2023 rTSR PSU grants measured Flex’s TSR relative to a custom peer group from June 1, 2022 (the grant date), through June 2, 2025 (the performance period end), using a trailing 20-day average trading price for both the beginning and the end of the performance period. Performance is measured over a three-year performance period with three discrete measurement periods—of 12-, 24-, and 36- months—using an average of the three measurement periods to determine the final performance. The percentile ranking for the three measurement periods was an average of 88.83%, which was above the 75th percentile, resulting in a 200% of target (maximum) payout for this award.

The performance period for the adjusted EPS growth-based PSUs granted in fiscal year 2024 ended in fiscal year 2026. Vesting was based on the Flex’s adjusted EPS growth, measured over a three-year period (April 1, 2023, through March 31, 2026) in three discrete annual fiscal year measurements during the three-year performance period, and averaged with respect to all three adjusted EPS measurement periods. Flex’s fiscal year 2024 to 2026 adjusted EPS growth maximum goal was 12%. The actual adjusted EPS growth average was 18.9% over the three-year performance period, resulting in a maximum 200% of target payout for this award.

Going Forward

Following the Spin-Off, we intend for our long-term incentive award program to initially be similar to Flex’s program. Our Compensation and People Committee will review our program with the goal of ensuring it is effective in attracting, retaining and motivating skilled executives and aligning the interests of management and shareholders.

Timing of Equity Award Grants

Flex Practice

The Flex Compensation and People Committee approves all equity awards granted to its executive officers on or before the grant date. Annual equity awards are typically granted to executive officers in June following the completion and release of financial results for the preceding fiscal year. The Flex Compensation and People Committee may also grant equity awards at other times during the year due to special circumstances, including to new executive officers upon hire or promotion or a change in an executive officer’s role or scope of responsibilities.

As a matter of good corporate governance, Flex does not grant equity awards in anticipation of the release of material nonpublic information and, in any event, Flex does not time the release of material nonpublic information in coordination with grants of equity awards in a manner that intentionally benefits its executive officers.

Going Forward

We anticipate that our equity award grant practices initially will be comparable to those of Flex. Following the Spin-Off, our Compensation and People Committee and management will review such practices to ensure they meet our business and strategic needs and the objectives of our executive compensation program.

Benefits

Non-qualified Deferred Compensation Awards

Flex Practice

Each NEO participates in the Flex Ltd. 2010 Deferred Compensation Plan, as amended and restated on June 6, 2025 (the “Flex NQDC Plan” or “Flex’s NQDC Plan”), which promotes retention by providing a long-term


167


Table of Contents

savings opportunity on a tax-efficient basis. In addition to being eligible to defer voluntary contributions, Flex makes annual awards to its executive officers under the Flex NQDC Plan, the key terms of which are summarized below.


Flex NQDC Plan Design Element


Description

Annual Targeted Amount


Target amount is 30% of each participant’s base salary (for ongoing contributions).


Maximum amount is 37.5% of each participant’s base salary, if the performance-based portion is funded at maximum.


Subject to approval of the Flex Compensation and People Committee


Subject to offsets for non-U.S. executives’ pension and other benefits

Targeted Contributions


50% of the targeted contributions (15% of salary at target) is based on the corporate funding level of the annual corporate bonus plan.


50% of the targeted contributions (15% of salary) is fixed and not tied to performance.

Vesting Schedule


Flex’s contributions, together with earnings on those contributions, will vest in full after four years, provided the participant remains employed by Flex.

Investment of Balances


Deferred balances in a participant’s account are deemed to be invested in hypothetical investments designated by the participant.


Investment options generally mirror those available under Flex’s tax-qualified 401(k) plan.


The appreciation, if any, in the account balances is due solely to the performance of these underlying investments.

Distribution Options


Vested balances are generally distributed in a lump-sum payment on the applicable vesting date.


Modifications to the Distribution Date are subject to compliance with Section 409A of the Internal Revenue Code.

The deferred account balances are unfunded and unsecured obligations of Flex, receive no preferential standing, and are subject to the same risks as any of Flex’s other general obligations.

Flex may make an additional discretionary matching contribution in connection with voluntary deferrals to reflect limitations on Flex’s matching contributions under Flex’s 401(k) plan.

Flex Deferred Compensation Awards for Fiscal Year 2026

During fiscal year 2026, Ms. Advaithi and Messrs. Krumm, Tan and Offer each received deferred compensation awards with a value that was 34.7% of their respective fiscal year 2025 base salaries; with Mr. Krumm’s value pro-rated to his hire date in January 2025. The award values are reflected as Flex contributions to the NEOs’ deferral accounts, with half of the contributions being based on the performance of Flex’s fiscal year 2025 corporate annual incentive plan.

Voluntary Contributions

Under the Flex NQDC Plan, participants may defer up to 70% of their base salary and bonus, net of certain statutory and benefit deductions. Participants are 100% vested in their own deferrals at all times.


168


Table of Contents

Additional Information

For additional information about the NEOs’ contributions to their respective deferral accounts, Company contributions to the NEOs’ deferral accounts, earnings on the NEOs’ deferral accounts, withdrawals from the NEOs’ deferral accounts, and deferral account balances as of the end of fiscal year 2026, see the section titled “Executive Compensation—Nonqualified Deferred Compensation in Fiscal Year 2026.

Going Forward

We anticipate that we will adopt a similar non-qualified deferred compensation plan as the one maintained by Flex upon the Spin-Off. Following the Spin-Off, our Compensation and People Committee will review the non-qualified deferred compensation plan adopted by Spinco to ensure that it meets our business needs and strategic objectives.

Executive Perquisites

Flex Practice

Perquisites represent a small part of the overall compensation program for the NEOs. In fiscal year 2026, Flex paid premiums on long-term disability insurance for all of the NEOs.

Under Flex’s Corporate Aircraft Use Policy, Flex permits Ms. Advaithi to fly on a company-provided aircraft for personal travel subject to availability, subject to an annual cap, above which reimbursement to Flex is required. Flex provides this benefit to Ms. Advaithi for additional security, as well as for efficiency, so she can use her travel time more productively for Flex. Ms. Advaithi is taxed on the value of this personal usage according to applicable tax rules. There is no tax gross-up paid on the income attributable to this value. During fiscal year 2026, the aggregate incremental cost to Flex for Ms. Advaithi’s personal aircraft use was $118,940, which is detailed in the Summary Compensation Table.

During fiscal year 2026, the Flex Compensation and People Committee approved executive financial planning and tax preparation services valued at up to $18,000 per year per participant. The Flex Compensation and People Committee believes that providing these services enables our executives to concentrate on their responsibilities without the distraction of managing their personal finances and assists in attracting and retaining top talent. Participating executives are responsible for the taxes related to the imputed income associated with this benefit; Flex does not provide any tax gross-up.

Executive Security

The Flex Board of Directors believes that Flex’s executives should not be exposed to personal security risks arising from their roles at Flex and that providing appropriate security measures is in the best interests of Flex. At the Flex Board of Directors’ direction, during fiscal year 2026 Flex engaged an independent, third-party security firm to conduct a comprehensive security assessment of risks applicable to its CEO and certain other senior executives. The assessment provided recommendations focused on personal and residential protection measures.

During fiscal year 2026, Flex incurred limited personal security costs for Ms. Advaithi in connection with one trip that included a personal component. The incremental cost associated with this personal security support is included in the “All Other Compensation” column of the Summary Compensation Table. No other named executive officer incurred reportable personal security costs during fiscal year 2026.

Relocation Assignments

In accordance with Flex’s executive relocation policy, Flex agreed to reimburse documented and reasonable expenses that Mr. Krumm incurred in connection with his relocation to the Austin, Texas area where Flex has


169


Table of Contents

corporate offices. In fiscal year 2026, these expenses were $131,212. Additional relocation expenses will be paid in fiscal year 2027 given that elements of his relocation were not completed by the end of fiscal year 2026. These benefits are quantified under the “All Other Compensation” column in the Summary Compensation Table.

401(k) Plan

Under the Flex 401(k) plan, all of Flex’s U.S. employees, including our NEOs, are eligible to receive matching contributions. Flex also offers annual discretionary matching contributions based on company performance and other economic factors as determined at the end of the fiscal year. For fiscal year 2026, Flex elected not to make discretionary contributions on behalf of any of our NEOs.

Other Benefits

Our NEOs are eligible to participate in all of the Flex’s employee benefit plans, such as medical, dental, vision, group life, disability, and accidental death and dismemberment insurance, in each case on the same basis as other U.S. employees, subject to applicable law.

Going Forward

Following the Spin-Off, we anticipate that our benefits and perquisites upon the Spin-Off will generally include the same benefits and perquisites as provided by Flex. Following the Spin-Off, the Spinco Compensation and People Committee will review the benefits and perquisites provided by us to ensure they support our efforts to attract and retain talented executives.

Termination and Change of Control Arrangements

The Flex Board of Directors and the Flex Compensation and People Committee believe severance and change of control arrangements are important components of the overall executive compensation program. Severance arrangements help attract and retain executives with the experience needed to drive success. Change of control provisions help to secure the continued employment and dedication of the NEOs, to reduce any concern that they might have regarding their own continued employment prior to or following a change of control of Flex and to promote continuity of management during a corporate transaction. Accordingly, Flex maintains certain arrangements, described below, pursuant to which the NEOs are entitled to certain severance and change of control protections. The benefits under these arrangements are described and quantified under the section titled “Executive Compensation—Potential Payments Upon Termination or Change of Control.” Flex does not have employment agreements with any of our current NEOs.

The following chart describes the benefits that would be provided to the NEOs under the Flex Ltd. Executive Severance Plan, as amended and restated on March 5, 2025 (the “Flex Executive Severance Plan”) and the Flex Ltd. 2017 Equity Incentive Plan (as amended and restated in 2023, and as subsequently amended, the “Flex 2017 Equity Incentive Plan”) in the event of a qualifying termination generally (that is, a qualifying termination outside a change of control), and the benefits that would be provided in the event of a qualifying termination within 24 months after a change of control. Benefits under the Flex Executive Severance Plan are contingent upon the participant entering into and complying with the terms of a transition agreement (“Transition Agreement”) and/or a release of claims, including any customary non-competition, non-solicitation, non-disclosure, non-disparagement, and cooperation provisions:


Flex Executive Severance
Plan Termination Benefit


General Severance Provisions
 (Qualifying Termination Outside a Change of Control) 


Change of Control Severance Provisions
(Qualifying Termination within 24 Months
after a Change of Control)

Salary and Bonus


For the CEO, two years’ continued payment of base salary and two years of her target annual bonus amount


For the CEO, lump sum payment of 2.99 times the sum


170


Table of Contents

Flex Executive Severance
Plan Termination Benefit


General Severance Provisions
 (Qualifying Termination Outside a Change of Control) 


Change of Control Severance Provisions
(Qualifying Termination within 24 Months
after a Change of Control)


For the other NEOs, base salary continuation during the transition period provided in the Transition Agreement, and a pro-rated annual bonus for the fiscal year in which the transition period begins, based on actual performance through the end of the fiscal year


of base salary and target annual bonus amount


For the other NEOs, lump sum payment of two times the sum of base salary and target annual bonus amount

Equity and Deferred Compensation (NQDC) Vesting


For the CEO, two years’ continued vesting of outstanding equity awards and deferred compensation awards


For the other NEOs:


Outstanding equity awards (including, but not limited to, time-based RSUs and PSUs), and deferred compensation awards continue vesting during the transition period, and


Following the transition period, accelerated vesting of RSUs (but not PSUs) and deferred compensation awards that would have vested during the one-year period following the transition period, subject to the participant signing an additional release of claims and compliance with post-termination covenants under the Transition Agreement


For the CEO and other NEOs, accelerated vesting of any unvested service-based equity awards in accordance with the Flex 2017 Equity Incentive Plan and accelerated vesting of any unvested deferred compensation. PSU vesting will accelerate with funding based upon actual performance for completed periods during the measurement period and target performance for unfinished periods during the measurement period

Benefits Continuation


For the CEO, benefits coverage continuation for two years


For the other NEOs, benefits coverage continuation for duration of transition period provided in the Transition Agreement


For the CEO, benefits coverage continuation for three years


For the other NEOs, benefits coverage continuation for two years

The following are death, disability and retirement benefits applicable for all NEOs with respect to Flex RSU, PSU and NQDC awards.


Termination Scenario


Description of RSU, PSU and NQDC Treatment

Death or Disability


RSU and NQDC vesting will accelerate upon the occurrence of these events


PSU vesting will accelerate with funding based upon actual performance for completed periods during the measurement period and target performance for unfinished periods during the measurement period, and pro-rated for length of time employed during the performance period

Retirement


Retirement is defined as:


Sum of age and service credits is equal to at least 65


Minimum length of service is 5 years


171


Table of Contents

Termination Scenario


Description of RSU, PSU and NQDC Treatment


Minimum age is 55


Unvested RSUs and NQDC would continue to vest, with PSUs vesting based on actual performance at the end of the performance cycle


Unvested PSUs would be pro-rated for length of time employed during the performance period


The retirement provision is not applicable to the Supplemental Equity Award granted to Ms. Advaithi on June 19, 2025

Going Forward

We expect that we will adopt an executive severance plan substantially similar to the Flex Ltd. Executive Severance Plan. Following the Spin-Off, our Compensation and People Committee will review the non-executive severance plan adopted by us to ensure that it meets our business needs and strategic objectives.

Executive Share Ownership Guidelines

Flex Practice

Flex maintains robust share ownership guidelines in order to closely align the interests of senior management with those of Flex’s shareholders. The ownership guidelines for Flex’s executive officers are summarized below.


Ownership Guideline Design Element


Description

Targeted Ownership Value


CEO – 6x salary


CFO – 3.5x salary


Other NEOs – 2.5x salary

Forms of Ownership Counted Toward Guideline


All Ordinary Shares held outright by our executives


Unvested service-based RSUs

Compliance Period


Five years for newly hired or newly promoted executives


If an executive’s stock ownership requirement is increased, a three-year compliance transition period will be provided to acquire the incremental shares

Unearned performance-based equity awards and shares underlying unexercised stock options (whether vested or unvested, whether time- or performance-based and whether in-the-money or not) do not count as stock owned for purposes of the guidelines.

The Flex Compensation and People Committee and our Nominating and Governance Committee both monitor the share ownership of management.

Going Forward

We expect that we will adopt substantially similar stock ownership guidelines in connection with the Spin-Off.


172


Table of Contents

Executive Incentive Compensation Recoupment Policy

Flex Practice

Flex maintains an amended and restated Executive Incentive Compensation Recoupment Policy (the “Recoupment Policy”), as required by the Dodd-Frank Wall Street Reform & Consumer Protection Act and corresponding listing standards adopted by Nasdaq regarding compensation recovery.

Flex’s Recoupment Policy applies in the event Flex is required to prepare an accounting restatement due to material noncompliance with any financial reporting requirement under the federal securities laws, including any required accounting restatement to correct an error in previously issued financial statements that is material to the previously issued financial statements, or that would result in a material misstatement if the error were corrected in the current period or left uncorrected in the current period (a “Financial Restatement”). Pursuant to Flex’s Recoupment Policy, Flex will promptly recover any erroneously awarded incentive-based compensation, on a no-fault basis, received by any current or former executive officer of Flex, including Flex’s NEOs, during the three completed fiscal years immediately preceding the date on which Flex is required to prepare a Financial Restatement.

In addition to erroneously awarded incentive-based compensation, under Flex’s Recoupment Policy, the Flex Compensation and People Committee, as administrator of the Recoupment Policy, may, to the extent it deems appropriate, cancel outstanding equity awards, including time- or performance-based awards, where the Flex Board of Directors or the Flex Compensation and People Committee took into account the financial performance of Flex in granting such awards and the financial results were subsequently reduced due to a Financial Restatement. The Recoupment Policy also provides that incentive compensation may be recovered from certain other direct reports of Flex’s CEO under certain specified circumstances if deemed appropriate by the Flex Compensation and People Committee.

Going Forward

Our Compensation and People Committee is expected to adopt a substantially similar recoupment policy in connection with the Spin-Off.

Executive Compensation

The following table sets forth the fiscal year 2026 compensation for:


Revathi Advaithi, our Chief Executive Officer;


Kevin Krumm, our Chief Financial Officer;


Hooi Tan, our Chief Operating Officer, and


Scott Offer, our Vice President, General Counsel.

The executive officers included in the Summary Compensation Table are referred to in this information statement as our NEOs. A detailed description of the plans and programs under which our NEOs received the following compensation can be found in the section titled “Compensation Discussion and Analysis” of this information statement. Additional information about these plans and programs is included in the additional tables and discussions that follow the Summary Compensation Table.


173


Table of Contents

Summary Compensation Table


Name and
Principal Position

  Year     Salary
($)(3)
    Bonus
($)(4)
    Share
Awards
($)(5)
    Non-Equity
Incentive Plan
Compensation
($)(6)
    Change
in Pension
Value and
Nonqualified
Deferred
Compensation
Earnings
($)(7)
    All Other
Compensation
($)(8)(9)
    Total
($)(10)
 

Revathi Advaithi
Chief Executive Officer

    2026       1,325,000       —        38,446,348       3,950,117       68,487       601,186       44,391,138  

Kevin Krumm
Chief Financial Officer(1)

    2026       832,000       —        3,099,287       1,728,746       —        219,906       5,879,939  

Hooi Tan
Chief Operating Officer(2)

    2026       735,000       —        3,099,287       1,460,798       83,489       102,788       5,481,362  

Scott Offer
Executive Vice President, General Counsel

    2026       663,000       —        2,832,188       1,131,608       122,450       248,370       4,997,616  


(1)

Mr. Krumm was appointed as Flex’s Chief Financial Officer effective January 6, 2025.

(2)

A portion of Mr. Tan’s compensation in fiscal year 2025 was paid in Singapore dollars. Such amounts have been converted to U.S. dollars using a conversion rate of 1.34, which is the average of the monthly translation rates for fiscal year 2025.

(3)

The reported salary amounts in any year may differ from the annual base salary amount reported due to the timing of payroll periods and/or the effective date of the change in base salary.

(4)

The amount shown for Mr. Krumm is a sign-on bonus paid upon commencement of employment with Flex, which he is required to repay if, within 24 months of the employment commencement date, he either voluntarily terminates his employment with Flex (other than for “good reason”) or Flex terminates his employment for “cause” (as such terms are defined in the Flex Executive Severance Plan).

(5)

Share awards consist of service-based RSUs, adjusted EPS growth PSUs, rTSR PSUs, and Supplemental Equity Award PSUs (for Ms. Advaithi only). The amounts in this column do not reflect compensation actually received by the NEOs, nor do they reflect the actual value that will be realized by the NEOs. Instead, the amounts reflect the grant date fair value for grants made by Flex in fiscal year 2026, calculated in accordance with FASB ASC Topic 718. The adjusted EPS growth and rTSR PSUs included in this column are at the target number of shares as follows for fiscal year 2026: 192,218 PSUs or $9,234,461 for Ms. Advaithi; 44,593 PSUs or $2,142,316 for Mr. Krumm; 44,593 PSUs or $2,142,316 for Mr. Tan; and 40,750 PSUs or $1,957,694 for Mr. Offer. The Supplemental Equity Award PSUs included in this column are at the target number of shares as follows for fiscal year 2026: 543,124 PSUs or $25,086,898 for Ms. Advaithi. The maximum number of shares for the adjusted EPS growth PSUs are as follows for fiscal year 2026: 337,100 PSUs or $14,687,447 for Ms. Advaithi; 78,205 PSUs or $3,407,392 for Mr. Krumm; 78,205 PSUs or $3,407,392 for Mr. Tan; and 71,465 PSUs or $3,113,730 for Mr. Offer. The maximum number of shares for the Supplemental Equity Award PSUs for fiscal year 2026: 1,357,810 PSUs or $62,717,244 for Ms. Advaithi. For additional information regarding the assumptions made in calculating the amounts reflected in this column, see Note 5 to Flex’s audited consolidated financial statements, “Share-Based Compensation,” included in Flex’s Annual Report on Form 10-K for the fiscal year ended March 31, 2026.

(6)

The amounts in this column represent incentive cash bonuses earned in fiscal year 2026. For additional information, see the section titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Incentive Bonus Plan” of this information statement.


174


Table of Contents
(7)

The amounts in this column represent the above-market earnings on the vested portions of the nonqualified deferred compensation accounts of the NEOs. None of our NEOs participated in any defined benefit or actuarial pension plans in any period presented. For additional information, see the table below entitled “Nonqualified Deferred Compensation in Fiscal Year 2026.

(8)

The following table provides a breakdown of compensation included in the “All Other Compensation” column for fiscal year 2026.


Name

   Pension/
Savings Plan
Company
Match
Expenses/
Social  Security
($)(a)
     Medical/
Enhanced
Long-Term
Disability
($)(b)
     Tax
Preparation
Expenses
($)(c)
     Personal
Aircraft
Usage
($)(d)
     Other
($)(e)
     Total
($)
 
Revathi Advaithi      473,688        7,217        —         118,940        1,341        601,186  
Kevin Krumm      82,436        6,258        —         —         131,212        219,906  
Hooi Tan      97,162        —         5,626        —         —         102,788  
Scott Offer      243,917        4,453        —         —         —         248,370  


  (a)

The amounts in this column represent Flex’s regular employer matching contributions to the 401(k) saving plan accounts and employer contributions to the deferral accounts (i.e., deferred compensation awards) under the deferred compensation plan.


401(k) contributions for Ms. Advaithi and Messrs. Krumm and Offer were $13,800, $15,187 and $13,800, respectively. The amount of $13,673 for Mr. Tan represents the contribution to the Singapore Provident fund.


Deferred compensation plan awards for Ms. Advaithi and Messrs. Krumm, Tan and Offer were $459,888, $67,249 and $255,107 and $230,117, respectively.

  (b)

The amounts in this column represent Flex’s contributions to the executive long-term disability program, which provides additional benefits beyond the basic employee long-term disability program.

  (c)

The amount in this column represents Mr. Tan’s expenses related to tax preparation assistance regarding his relocation.

  (d)

Represents the aggregate incremental cost to Flex for the personal use of corporate aircraft by Ms. Advaithi, who may be accompanied by her spouse and other family members and guests. This is calculated using an hourly rate for each flight hour based on the variable operating costs to Flex, including fuel, maintenance, crew travel expenses, catering, landing fees, and other miscellaneous variable costs. Since corporate aircraft are primarily used for business travel, Flex does not include costs that Flex would have incurred regardless of whether there was any personal aircraft usage, such as depreciation, hanger rental, and insurance costs.

  (e)

The amounts in this column represent Ms. Advaithi’s limited personal security cost in connection with one trip that included a personal component, and Mr. Krumm’s relocation expenses incurred in fiscal year 2026.

(9)

Total amounts may not add up due to rounding.


175


Table of Contents

Grants of Plan-Based Awards in Fiscal Year 2026

The following table presents information about non-equity incentive plan awards and RSU and PSU awards that Flex granted in our 2026 fiscal year to the NEOs. Flex did not grant any stock options to our NEOs during the 2026 fiscal year.


          Estimated Future Payouts Under
Non-Equity Incentive Plan Awards(1)
    Estimated Future Payouts Under
Equity Incentive Plan  Awards(2)
    All Other Share
Awards: Number
of Shares of
Stock or Units
(#)(3)
    Grant Date
Fair Value
of Share
Awards
($)(4)
 

Name

  Grant
Date
    Threshold
($)
    Target
($)
    Maximum
($)
    Threshold
(#)
    Target
(#)
    Maximum
(#)
 

Revathi Advaithi

    6/12/2025 (5)            67,420       134,840       337,100         5,874,979  
    6/12/2025 (6)            14,344       57,378       114,756         3,359,482  
    6/12/2025                   94,675       4,124,990  
    6/19/2025 (7)            271,562       543,124       1,357,810         25,086,898  
      808,913       2,186,250       4,372,500            

Kevin Krumm

    6/12/2025 (5)            15,641       31,282       78,205         1,362,957  
    6/12/2025 (6)            3,327       13,311       26,622         779,359  
    6/12/2025                   21,964       956,971  
      354,016       956,800       1,913,600            

Hooi Tan

    6/12/2025 (5)            15,641       31,282       78,205         1,362,957  
    6/12/2025 (6)            3,327       13,311       26,622         779,359  
    6/12/2025                   21,964       956,971  
      299,145       808,500       1,617,000            

Scott Offer

    6/12/2025 (5)            14,293       28,586       71,465         1,245,492  
    6/12/2025 (6)            3,041       12,164       24,328         712,202  
    6/12/2025                   20,071       874,493  
      245,310       663,000       1,326,000            


(1)

These amounts show the range of possible payouts under our cash incentive programs for fiscal year 2026. The amounts correspond to the range of possible payouts under the incentive bonus plan. The maximum payment represents 200% of the target payment. The threshold payment represents 37.2% of target payout levels for all NEOs. For the annual incentive bonus plan, the amounts actually earned for fiscal year 2026 are reported as Non-Equity Incentive Plan Compensation in the Summary Compensation Table. For additional information, see the section titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Incentive Bonus Plan of this information statement.

(2)

Shows the range of estimated future vesting of the adjusted EPS growth and rTSR PSUs granted to all of the NEOs in fiscal year 2026 under the Flex 2017 Equity Incentive Plan, as well as the range of estimated future vesting of the Supplemental Equity Award PSUs granted to Ms. Advaithi in fiscal year 2026 under the Flex 2017 Equity Incentive Plan. The adjusted EPS growth PSUs granted on June 12, 2025 cliff-vest after three years, with the vesting based upon a yearly EPS measurement period and averaged over the performance period. The maximum payout for each NEO represents 250% of the target payout levels. If Flex’s TSR performance over the three-year EPS performance period is below the 25th percentile rank relative to rTSR peer companies, then the maximum shares will be capped at 200% of the target shares. The threshold payout for the adjusted EPS growth PSUs for each NEO represents 50% of the target payout.

The rTSR PSUs cliff-vest after three years, with vesting based on the percentile rank of Flex’s TSR relative to the return of Flex’s TSR peer group. The maximum payout for each NEO represents 200% of the target payout. The threshold payout for the rTSR PSUs for each NEO represents 25% of target payout.

The Supplemental Equity Award PSUs granted to Ms. Advaithi cliff-vest after three years based on rigorous goals tied to the CPI business as further described in the section above titled “Other Long-Term Incentive Compensation Award Granted During FY26” of this information statement. The maximum payout represents 250% of the target payout levels. The threshold payout for Ms. Advaithi’s Supplemental Equity


176


Table of Contents

Award PSUs represents 50% of the target payout. The maximum shares may be subject to the TSR cap based on the achievement levels set forth below:


250% of target if rTSR is at or above the median,


200% of target if rTSR is below the median, and


100% of target if rTSR is below the 25th percentile.

For additional information regarding the equity awards granted to the NEOs in fiscal year 2026, see the section titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Long-Term Share-Based Incentive Compensation” of this information statement.


(3)

Shows the number of service-based RSUs granted in fiscal year 2026 under the Flex 2017 Equity Incentive Plan. For each NEO, the RSUs vest in three annual installments at a rate of one-third per year. For additional information, see the section titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Long-Term Share-Based Incentive Compensation of this information statement.

(4)

This column shows the grant date fair value of service-based RSUs, adjusted EPS growth PSUs, rTSR PSUs and Supplemental Equity Award PSUs, at the target level, under FASB ASC Topic 718 granted to the NEOs in fiscal year 2026. The grant date fair value is the amount that Flex will expense in its financial statements over the awards’ vesting schedule. For service-based RSUs, adjusted EPS growth PSUs and Supplemental Equity Award PSUs, the grant date fair value is the closing price of Flex’s ordinary shares on the grant date. For rTSR PSUs where vesting is contingent on meeting a market condition, the grant date fair value was calculated using a Monte Carlo simulation. Additional information on the valuation assumptions is included in Note 5 of Flex’s audited consolidated financial statements, “Share-Based Compensation,” included in Flex’s Annual Report on Form 10-K for the fiscal year ended March 31, 2026.

(5)

This row shows the adjusted EPS growth PSUs.

(6)

This row shows the rTSR PSUs.

(7)

This row shows Ms. Advaithi’s Supplemental Equity Award PSUs.

Outstanding Equity Awards at 2026 Fiscal Year-End

The following table presents information about outstanding share awards held by our NEOs as of March 31, 2026. The table shows information about: (i) service-based RSUs and (ii) PSUs.


177


Table of Contents

The market value of the share awards is based on the closing price of Flex’s ordinary shares as of March 31, 2026, which was $65.46. For PSUs, the number of unearned shares and the market values shown assume all performance criteria are met at threshold, target or maximum depending on performance through March 31, 2026. For additional information on our equity incentive programs, see the section titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive CompensationLong-Term Share-Based Incentive Compensation” of this information statement.


     Share Awards  

Name

   Number of Shares
or Units of Stock
That Have Not
Vested
(#)
    Market Value of
Shares or Units of
Stock That Have Not
Vested
($)
     Equity Incentive Plan
Awards: Number of
Unearned Shares,
Units or Other Rights
That Have Not Vested
(#)(1)
    Equity Incentive Plan
Awards: Market or Payout
Value of Unearned Shares,
Units or Other Rights That
Have Not Vested
($)(2)
 

Revathi Advaithi

     85,021 (3)      5,565,475        255,062 (8)      16,696,359  
     109,478 (3)      7,166,430        164,216 (9)      10,749,579  
     94,675 (3)      6,197,426        114,756 (10)      7,511,928  
     255,062 (4)      16,696,359        164,216 (11)      10,749,579  
          337,100 (12)      22,066,566  
          1,357,810 (13)      88,882,243  

Kevin Krumm

     95,497 (5)      6,251,234        26,622 (10)      1,742,676  
     21,964 (5)      1,437,763        78,205 (12)      5,119,299  

Hooi Tan

     23,981 (6)      1,060,125        48,582 (8)      3,180,178  
     72,578 (6)      1,569,796        35,970 (9)      2,354,596  
     21,964 (6)      4,750,956        26,622 (10)      1,742,676  
     48,582 (4)      1,437,763        35,970 (11)      2,354,596  
          145,156 (14)      9,501,912  
          78,205 (12)      5,119,299  

Scott Offer

     14,574 (7)      954,014        43,724 (8)      2,862,173  
     18,768 (7)      1,228,553        28,150 (9)      1,842,699  
     20,071 (7)      1,313,848        24,328 (10)      1,592,511  
     43,724 (4)      2,862,173        28,150 (11)      1,842,699  
          71,465 (12)      4,678,099  


(1)

This column includes rTSR PSUs and adjusted EPS growth PSUs granted in fiscal years 2024, 2025 and 2026 under the Flex 2017 Equity Incentive Plan, as well as Supplemental Equity Award PSUs granted to Ms. Advaithi in fiscal year 2026 under the Flex 2017 Equity Incentive Plan. Vesting of the rTSR PSUs granted in fiscal years 2024, 2025 and 2026 is based on Flex’s TSR relative to the return of Flex’s TSR peer group over the three-year performance period. Vesting of the adjusted EPS growth PSUs granted in fiscal years 2024, 2025 and 2026 to all NEOs is based upon Flex’s adjusted EPS growth over the yearly measurement period and averaged over the 3-year performance period. Vesting of the adjusted EPS growth PSUs granted in fiscal year 2025 to Mr. Tan is based upon Flex’s three-year compounded annual growth rate, or CAGR. Vesting of the Supplemental Equity Award PSUs granted in fiscal year 2026 to Ms. Advaithi is based upon Flex’s CPI business measured at the end of fiscal year 2028, subject to an overall payout cap based upon Flex’s rTSR return over a three-year period beginning on June 19, 2025 and ending on June 19, 2028.

(2)

The projected payouts of the rTSR PSUs for the 2023-2026, 2024-2027 and 2025-2028 cycles are shown at maximum. The projected payout of the adjusted EPS growth PSUs for the 2024-2027 and 2025-2026 cycles are shown at maximum. The adjusted EPS growth PSUs granted in fiscal year 2025 to Mr. Tan and the Supplemental Equity Award PSU granted to Ms. Advaithi are shown at maximum.

(3)

85,021 shares vest on June 14, 2026; 109,478 shares vest at a rate of 54,739 shares per year for two years, with the first vesting date on June 12, 2026; and 94,675 shares vest at a rate of 31,558 shares per year for three years, with the first vesting date on June 12, 2026.


178


Table of Contents
(4)

Actual results for adjusted EPS growth PSUs paid out on May 8, 2026.

(5)

95,497 shares vest at a rate of 47,748 shares per year for two years, with the first vesting date on January 6, 2027; and 21,964 shares vest at a rate of 7,321 shares per year for three years, with the first vesting date on June 12, 2026.

(6)

16,195 shares vest on June 14, 2026; 23,981 shares vest at a rate of 11,990 shares per year for two years, with the first vesting date on June 12, 2026; 72,578 shares vest on September 25, 2027; and 21,964 shares vest at a rate of 7,321 shares per year for three years, with the first vesting date on June 12, 2026.

(7)

14,574 shares vest on June 14, 2026; 18,768 shares vest at a rate of 9,384 shares per year for two years, with the first vesting date on June 12, 2026; and 20,071 shares vest at a rate of 6,690 shares per year for three years, with the first vesting date on June 12, 2026.

(8)

Unvested rTSR PSUs to vest date on June 14, 2026, assuming a maximum payout of 200%.

(9)

Unvested rTSR PSUs to vest date on June 12, 2027, assuming a maximum payout of 200%.

(10)

Unvested rTSR PSUs to vest date on June 12, 2028, assuming a maximum payout of 200%.

(11)

Unvested remaining adjusted EPS growth PSUs to vest in May 2027 assuming a maximum payout of 200%.

(12)

Unvested remaining adjusted EPS growth PSUs to vest in May 2028, assuming a maximum payout of 250%.

(13)

Unvested remaining Supplemental Equity Award PSUs to vest in June 2028 assuming a maximum payout of 250%.

(14)

Unvested remaining adjusted EPS growth CAGR PSUs to vest in May 2028 and May 2029 assuming a maximum payout of 200%.

Shares Vested in Fiscal Year 2026

The following table presents information for each of the NEOs regarding the number of shares acquired upon the vesting of share awards in the form of RSUs and PSUs during fiscal year 2026 and the value realized, in each case before payment of any applicable withholding tax and broker commissions. There were no option exercises by the NEOs in 2026 and the NEOs do not hold any unexercised options.


     Share Awards  

Name

   Number of Shares
Acquired on Vesting
(#)
     Value Realized
on Vesting
($)(1)
 

Revathi Advaithi

     1,035,876        42,920,452  

Kevin Krumm

     47,748        2,962,525  

Hooi Tan

     189,487        7,857,966  

Scott Offer

     185,261        7,673,289  


(1)

The amounts in this column reflect the aggregate dollar amount realized upon the vesting of RSUs and PSUs determined by multiplying the number of Ordinary Shares underlying such awards by the market value of the underlying shares on the vesting date.

Nonqualified Deferred Compensation in Fiscal Year 2026

Each of the NEOs participates in Flex’s NQDC Plan. Flex’s deferred compensation program is intended to promote retention by providing a long-term savings opportunity on a tax-efficient basis. Under Flex’s NQDC Plan, participating officers may defer up to 70% of their base salary and bonus, net of certain statutory and benefit deductions. Flex may make a discretionary matching contribution for these deferrals to reflect limitations on our matching contribution under the 401(k) plan. Under this plan, Flex may also make annual contributions, in amounts up to 37.5% of each participant’s base salary (subject to offsets for non-U.S. executives’ pension and other benefits), which will cliff-vest after four years. For these annual contributions, 50% of the funding is paid as a percent of base salary and the remaining 50% is performance-based, up to a maximum of 150%. Amounts credited to the deferral accounts are deemed to be invested in hypothetical investments selected by a participant or an investment manager on behalf of each participant. Participants in Flex’s NQDC Plan may receive their


179


Table of Contents

vested deferred compensation balances upon termination of employment at such time as is specified in their deferral agreements, which may include a lump sum payment or installment payments made over a period of years. Participants also may elect in-service distributions through a lump sum payment or in installments over a period of up to ten years.

Under our deferred compensation plan, Flex entered into trust agreements providing for the establishment of irrevocable trusts into which Flex are required to deposit cash or other assets as specified in the applicable deferral agreement, equal to the aggregate amount required to be credited to the participant’s deferral account, less any applicable taxes to be withheld. The deferred account balances of the participants in our deferred compensation plan are unfunded and unsecured obligations of Flex, receive no preferential standing, and are subject to the same risks as any of our other general obligations.

For a discussion of the contributions granted to each of the NEOs and their vesting terms, including vesting upon the executive’s termination or a change of control of Flex, see the sections titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Deferred Compensation Awards of this information statement and Executive Compensation—Potential Payments Upon Termination or Change of Control” below.

The following table presents information for fiscal year 2026 about: (i) contributions to the NEOs’ deferred compensation plan accounts by the executive; (ii) contributions to the NEOs’ deferred compensation plan accounts by Flex; (iii) aggregate earnings (or losses) on the deferred compensation plan accounts; (iv) aggregate withdrawals and distributions from the deferred compensation plan accounts; and (v) the deferred compensation plan account balances as of the end of the fiscal year. For fiscal year 2026, Ms. Advaithi and Messrs. Krumm, Offer and Tan each received deferred cash awards with a value that averaged approximately 34.7% of their respective fiscal year 2025 base salaries.

Nonqualified Deferred Compensation Table


Name

   Executive
Contributions in
Last Fiscal Year
($)(1)
     Registrant
Contributions in
Last Fiscal Year
($)(2)
     Aggregate
Earnings (Losses)
in Last Fiscal Year
($)(3)
    Aggregate
Withdrawals/
Distributions
($)
    Aggregate
Balance at  Fiscal
Year-End
($)(4)
 

Revathi Advaithi

     —         459,888        68,487       (493,794     1,832,451  

Kevin Krumm

     —         67,249        (5,153     —        480,802  

Hooi Tan

     —         255,107        83,489       (92,134     908,433  

Scott Offer

     142,141        230,117        122,450       —        1,301,939  


(1)

Reflects portions of the salary and/or bonus payments deferred by our NEOs during the fiscal year.

(2)

These amounts represent employer contributions under Flex’s NQDC Plan. These awards cliff-vest after four years. These amounts, including any earnings or losses thereon, will be reported under the “All Other Compensation” column of the Summary Compensation Table. For additional information on these contributions and their vesting terms, including vesting upon the executive’s termination or change of control of Flex, see the sections titled “Compensation Discussion and Analysis—Fiscal Year 2026 Executive Compensation—Deferred Compensation Awards and Executive Compensation—Potential Payments Upon Termination or Change of Control” of this information statement.

(3)

Reflects earnings (or losses) for each NEO on both the vested and unvested portions of the executive’s deferred compensation account(s). The above-market portion of the earnings on the vested portion of the executive’s deferred compensation account(s) is included under the “Change in Pension Value and Nonqualified Deferred Compensation Earnings” column in the Summary Compensation Table.

(4)

The amount in this column with respect to Mr. Offer includes the sum of the amounts that he deferred in prior years and previously reported as compensation in the Summary Compensation Table in respect of the applicable year. No other NEOs have voluntarily contributed to Flex’s NQDC Plan. The aggregate balance at fiscal year-end 2025 was in the amounts of $1,797,871 for Ms. Advaithi, $418,706 for Mr. Krumm, $661,971 for Mr. Tan, and $949,377 for Mr. Offer.


180


Table of Contents

Potential Payments Upon Termination or Change of Control

As described in the section titled “Compensation Discussion and Analysis” of this information statement, our NEOs do not have employment agreements with us. Our NEOs are eligible for certain termination and change of control benefits under the Flex Executive Severance Plan, Flex’s NQDC Plan and the Flex 2017 Equity Incentive Plan.

Acceleration of Vesting of Deferred Compensation

If the employment of any participant in Flex’s NQDC Plan is involuntarily terminated by Flex without cause or is terminated by the executive with good reason within two years following a change of control (as defined in Flex’s NQDC Plan), the entire unvested portion of the deferred compensation account of the NEO will vest. The entire unvested portion of a participant’s deferred compensation account also will vest if the NEO’s employment terminates as a result of death or disability. If a participant in Flex’s NQDC Plan ceases to provide services to Flex due to a qualifying retirement (generally meaning a voluntary termination of service after the participant has attained the age of 55, completed at least 5 years of service as an employee of Flex, and the sum of age and service is equal to at least 65), the unvested portion of the NEO’s deferred compensation account will continue to vest, subject to the NEO signing a release of claims, complying with post-termination restrictive covenants, and (if required by Flex in its discretion), providing up to 6 months advance written notice of retirement. As described below under the heading “Executive Severance Plan,” if the employment of a participant in Flex’s NQDC Plan is terminated by Flex without cause or by the NEO for good reason, but not within two years following a change of control, the NEO generally would be entitled to continued vesting of the NEO’s deferred compensation account for a specified period following termination.

Acceleration of Vesting of Equity Awards

The number of unvested equity awards held by each NEO as of March 31, 2026, is listed above in the Outstanding Equity Awards at 2026 Fiscal Year-End table. All unvested outstanding equity awards held by the NEOs at the end of fiscal year 2026 were granted under the Flex 2017 Equity Incentive Plan.

Subject to any waiver by the Flex Compensation and People Committee, all unvested RSU awards, PSU awards and unvested stock options held by a plan participant will be forfeited if the participant ceases to provide services to Flex, except for certain termination reasons such as retirement, death, disability, or involuntary termination without cause or for “good reason” (as defined in Flex’s Executive Severance Plan) within 24 months after a change of control.

Treatment of Certain Awards Upon Retirement

Certain award agreements for RSUs, rTSR PSUs, and adjusted EPS growth PSUs granted under the Flex 2017 Equity Incentive Plan provide that if a plan participant ceases to provide services to Flex due to a qualifying retirement (meaning a voluntary termination of service after the participant has attained the age of fifty-five (55) years; completed at least five (5) years of service as an employee of Flex; and the sum of age and service is equal to at least 65), then the award will not terminate. RSUs would continue to vest, and a pro rata number for the length of time employed during the performance period shall be issued to the participant at the end of the performance cycle for rTSR PSUs and adjusted EPS growth PSUs. However, the Supplemental Equity Award PSUs granted to Ms. Advaithi during fiscal year 2026 and the PSUs and RSUs granted as supplemental equity awards to Mr. Tan during fiscal year 2025, respectively, do not provide for accelerated or continued vesting upon retirement. Among our NEOs, Ms. Advaithi and Mr. Offer meet the retirement criteria.

Treatment of Certain Awards Upon Death or Disability

Certain award agreements for RSUs, rTSR PSUs, and adjusted EPS growth PSUs granted under the Flex 2017 Equity Incentive Plan provide that if a plan participant ceases to provide services to Flex due to death or


181


Table of Contents

disability, then the awards will accelerate after the qualifying termination. RSUs will immediately vest. rTSR PSUs and adjusted EPS growth PSUs will be prorated and immediately vest as follows: completed cycles will vest based on actual performance and unfinished cycles will vest at target. The Supplemental Equity Award PSUs granted to Ms. Advaithi during fiscal year 2026 provide for prorated vesting in the event of her death, but do not provide for accelerated vesting in the event of her disability.

Double-Trigger Vesting Upon a Change of Control

The Flex 2017 Equity Incentive Plan is a “double trigger” equity plan, meaning that unvested equity awards vest immediately only if (i) there is a change of control of Flex and (ii)(x) such awards are not converted, assumed or replaced by the successor or survivor corporation or (y) such awards are converted, assumed or replaced by the successor or survivor corporation, and the participant incurs an involuntarily termination of service as described below.

Under the terms of the Flex 2017 Equity Incentive Plan, unless otherwise provided in the applicable award agreement or other agreement between Flex and the participant, in the event of a change of control of Flex (as defined in the Flex 2017 Equity Incentive Plan) in which the participant’s awards are not converted, assumed, or replaced by a successor or survivor corporation, or a parent or subsidiary thereof, then all forfeiture restrictions on such awards will lapse immediately prior to the change of control and, following the consummation of such a change of control, all such awards will terminate and cease to be outstanding.

Under the terms of the Flex 2017 Equity Incentive Plan, as amended effective March 5, 2025, with respect to both then-outstanding and future awards, where awards under the Flex 2017 Equity Incentive Plan are assumed or continued after a change of control, those awards will be treated as follows in the event of a participant’s “Involuntary Termination of Service” within 24 months after the change of control:


Outstanding equity awards with vesting based solely upon continued employment (or other service), such as RSUs, will vest in full immediately upon the participant’s Involuntary Termination of Service (and any stock options or stock appreciation rights will become fully exercisable and remain exercisable for 90 days after the Involuntary Termination of Service, but not beyond the latest date that the stock option or stock appreciation right could have expired in accordance with its original terms under any circumstances); and


Outstanding equity awards with vesting based in whole or in part upon the achievement of performance goals, such as rTSR PSUs and EPS growth PSUs, will vest in full (i) at the “target” level of performance, to the extent that the applicable performance period (or any portion of the performance period that is designated as a separate measurement period) has not been completed as of the participant’s Involuntary Termination of Service, or (ii) based upon the actual level of achievement of the applicable performance goals during the applicable performance period (or any portion of the performance period that is designated as a separate measurement period), to the extent that such period has been completed as of the participant’s Involuntary Termination of Service.

For purposes of “double-trigger” vesting of equity awards in connection with a change of control, an “Involuntary Termination of Service” means (a) the termination of the participant’s service by Flex (or any successor or survivor corporation, or a parent or subsidiary thereof) without “cause” (as defined in the Flex 2017 Equity Incentive Plan) and not as a result of the participant’s death or disability, or (b) where the participant, such as each of the NEOs, is a party to an arrangement, such as the Flex Executive Severance Plan, that defines “good reason” with respect to the participant, the participant’s termination of service for “good reason” as so defined.

Flex Executive Severance Plan

Flex’s Executive Severance Plan covers all of the NEOs and certain other senior level employees of Flex. Under the Flex Executive Severance Plan, in the event of a qualifying termination of employment by the company


182


Table of Contents

without “cause” (and not as a result of death or disability) or by a participant for “good reason” (each such term as defined in the Flex Executive Severance Plan), the participant will receive the following benefits, subject to the participant entering into and complying with the terms of a Transition Agreement and/or a release of claims, including any customary non-competition, non-solicitation, non-disclosure, non-disparagement, and cooperation provisions:

General Severance Provisions (Qualifying Termination Outside a Change of Control):


For the CEO, two years’ continued payment of base salary and two years of her target annual bonus amount, or for the other NEOs, base salary continuation during the transition period provided in the Transition Agreement and a pro-rated annual bonus for the fiscal year in which the transition period begins, based on actual performance through the end of the fiscal year;


For the CEO, two years’ continued vesting of outstanding equity awards and deferred compensation awards, or for the other NEOs, continued vesting of outstanding equity awards during the transition period and accelerated vesting following the transition period of RSUs and deferred compensation awards that would have vested during the one-year period following the transition period; and


Benefits coverage continuation for two years (for the CEO) or during the transition period (for the other NEOs).

Change of Control Severance Provisions (Qualifying Termination Within 24 Months After a Change of Control):


The sum of the participant’s base salary and target annual bonus multiplied by 2.99 (for the CEO) or by two (for the other NEOs), payable in a single lump sum;


Accelerated vesting of the participant’s outstanding equity awards in accordance with the terms and conditions of the Flex 2017 Equity Incentive Plan and any unvested deferred compensation awards; and


Continued employee benefits coverage for three years (for the CEO) or for two years (for the other NEOs).

There are no tax gross-ups in the Flex Executive Severance Plan.

Potential Payments Upon Termination or Change of Control as of March 31, 2026

The following table and accompanying notes show the estimated payments and benefits that would have been provided to each NEO as a result of (i) the accelerated vesting of deferred compensation in the case of a change of control with a termination of employment, (ii) the accelerated vesting of restricted and performance share unit awards in the event of a change of control if such awards are not assumed by the successor company in connection with the change of control, (iii) involuntary termination without cause or voluntary termination for good reason under Flex’s Executive Severance Plan, (iv) retirement, or (v) death or disability.


183


Table of Contents

Calculations for this table assume that the triggering event took place on March 31, 2026, the last business day of fiscal year 2026, and are based on the price per share of Flex’s ordinary shares on such date, which was $65.46. The following table does not include potential payouts under our NEOs’ nonqualified deferred compensation plans relating to vested benefits.


Name

   Change in Control
with Termination
($)(1)
     Change in
Control and No
Assumption of
Award
($)(2)
     Involuntary Termination
without Cause or
Voluntary Termination for
Good Reason
($)(3)
     Retirement
($)(4)
     Death or
Disability
($)(5)
 

Revathi Advaithi

        —            —         —   

Base Salary Continuation

     3,961,750        —         2,650,000        —         —   

Benefits Continuation

     82,177        —         54,785        —         —   

Bonus Payments

     6,536,888        —         4,372,500        3,950,117        3,950,117  

Vesting of Deferred Compensation

     1,832,451        —         966,830        1,832,451        1,832,451  

Vesting of Service-based RSUs

     18,929,330        18,929,330        16,863,478        18,929,330        18,929,330  

Vesting of Performance-based RSUs

     97,812,056        97,812,056        46,734,360        44,076,007        54,048,969  


Total(6)

     129,154,652        116,741,386        71,641,953        68,797,905        78,760,867  


Kevin Krumm


Base Salary Payment Continuation

     1,664,000        —         832,000        —         —   

Benefits Continuation

     51,739        —         25,870        —         —   

Bonus Payments

     1,913,600        —         1,728,746        —         1,728,746  

Vesting of Deferred Compensation

     479,359        —         —         —         479,359  

Vesting of Service-based RSUs

     7,688,997        7,688,997        7,209,699        —         7,688,997  

Vesting of Performance-based RSUs

     3,601,631        3,601,631        —         —         1,011,357  


Total(6)

     15.399.326        11,290,628        9,796,315        —         10,908,459  


184


Table of Contents

Name

   Change in Control
with Termination
($)(1)
     Change in
Control and No
Assumption of
Award
($)(2)
     Involuntary Termination
without Cause or
Voluntary Termination for
Good Reason
($)(3)
     Retirement
($)(4)
     Death or
Disability
($)(5)
 

Hooi Tan

     —         —         —         —         —   

Base Salary Payment Continuation

     1,470,000        —         735,000        —         —   

Benefits Continuation

     50,091        —         25,046        —         —   

Bonus Payments

     1,617,000        —         1,460,798        1,460,798        1,460,798  

Vesting of Deferred Compensation

     1,011,244        —         531,069        1,011,244        1,011,244  

Vesting of Service-based RSUs

     9,060,711        9,060,711        8,581,413        4,309,755        9,060,711  

Vesting of Performance-based RSUs

     16,363,953        16,363,953        5,247,317        7,819,568        12,570,524  


Total(6)      29,572,999        25,424,664        16,580,643        14,601,365        24,103,277  


Scott Offer


Base Salary Payment Continuation

     1,326,000        —         663,000        —         —   

Benefits Continuation

     35,767        —         17,884        —         —   

Bonus Payments

     1,326,000        —         1,131,608        1,131,608        1,131,608  

Vesting of Deferred Compensation

     985,202        —         529,855        985,202        985,202  

Vesting of Service-based RSUs

     3,496,415        3,496,415        3,058,422        3,496,415        3,496,415  

Vesting of Performance-based RSUs

     11,302,607        11,302,607        5,247,317        7,732,419        7,732,419  


Total(6)

     18,471,991        14,799,022        10,648,086        13,345,644        13,345,644  


(1)

The amounts shown represent the estimated value of compensation paid in the event of a participant’s qualifying termination within 24 months after a change of control. In regard to equity, RSUs will immediately vest in full and PSUs will immediately vest as follows: completed cycles will vest based on actual performance and unfinished cycles will vest at target. All amounts shown in this column represent the intrinsic value of the awards based on the closing price of Flex’s ordinary shares on March 31, 2026, the assumed date of the double-trigger event.

(2)

The amounts shown represent the estimated value of the accelerated vesting of RSUs and PSUs following a change of control under the terms of the Flex 2017 Equity Incentive Plan, which assumes that such RSUs and PSUs are not assumed or replaced by the successor corporation or its parent. RSUs will immediately vest in full and PSUs will immediately vest as follows: completed cycles will vest based on actual performance and unfinished cycles will vest at target. All amounts shown in this column represent the intrinsic value of the awards based on the closing price of Flex’s ordinary shares on March 31, 2026, the assumed date of the change of control event.

(3)

The amounts shown represent the estimated value of payments under the Flex Executive Severance Plan contingent upon the participant entering into and adhering to a Transition Agreement and/or a release of claims. The table above illustrates a 12-month transition period (24 months for the CEO) for demonstration purposes; the actual transition period may vary. For PSUs, the reported amounts assume that completed cycles will vest based on the actual performance of those cycles, while uncompleted cycles will vest at target during the transition period.

(4)

For termination of service due to retirement, except as otherwise described below: (i) RSUs will continue to vest until fully vested; (ii) the PSUs will not terminate; and (iii) a pro rata number of vested shares shall be issued to the executive upon the vesting of the PSU award pursuant to achieving the performance criteria at


185


Table of Contents
 

the end of the original performance period. However, the Supplemental Equity Award PSUs granted to Ms. Advaithi during fiscal year 2026 and the PSUs and RSUs granted as supplemental equity awards to Mr. Tan during fiscal year 2025, respectively, do not provide for accelerated or continued vesting upon retirement. The amounts reported assume completed cycles will vest based on actual performance of completed cycles and unfinished cycles will vest at target. As of the fiscal year ended March 31, 2026, among our NEOs, Ms. Advaithi and Mr. Offer were retirement eligible.

(5)

For termination of service due to death or disability, (i) unvested RSUs will immediately vest in full, and (ii) PSUs generally will be pro-rated and immediately vest as follows: completed cycles will vest based on actual performance and unfinished cycles will vest at target. Bonus is prorated for termination of service due to death only. However, the Supplemental Equity Award PSUs granted to Ms. Advaithi during fiscal year 2026 do not provide for accelerated vesting in the event of her disability.

(6)

Total amounts may not add up due to rounding.

Treatment of Incentive Bonus Awards

Pursuant to our Employee Matters Agreement, the annual incentive bonus awards for each of our NEOs for the year in which the Spin-Off occurs will be evaluated through the date of the Spin-Off by the Flex Compensation and People Committee, with the resulting award amount banked. Following the Spin-Off, performance metrics will be adjusted to exclude us. The Employee Matters Agreement further provides that any incentive bonus amount attributable to the period following the Spin-Off through the remainder of the performance period, if applicable, will be determined by our Compensation and People Committee with respect to our employees and by the Flex Compensation and People Committee with respect to Flex employees, and the final incentive bonus payout is anticipated to be based on achievement of the performance goals for the full 12-month performance period (Flex’s fiscal year) and will remain subject to continued employment with us or Flex, as applicable, through the applicable payment date.

Following the Spin-Off, we expect that the our Compensation and People Committee will develop our own incentive bonus plan with performance measures to be based on near-term operational and financial goals that support our business objectives. Our new incentive bonus plan will be prorated for our partial fiscal year starting on April 1, 2027. The first full year of our incentive bonus plan will be from January 1, 2028 through December 31, 2028.

Treatment of Outstanding Equity Awards at the Time of the Spin-Off

We expect outstanding Flex equity awards to be adjusted in connection with the Spin-Off in accordance with the following principles:


Award adjustments will be designed to preserve the aggregate economic value of each recipient’s outstanding equity awards before and after the Spin-Off, using a ratio that takes into account the average closing trading price of Flex common stock over the 10 trading days prior to the separation and the average of either the post-separation average closing trading price of Flex common stock or the post-separation per share closing trading price of Spinco common stock, as applicable, over 10 trading days following the separation.


Except as described below with respect to the PSUs, the terms of the equity awards, including applicable vesting schedules, will generally remain unchanged.


Outstanding equity awards held by employees and non-employee directors of Spinco at the time of the Spin-Off will be converted into equity awards denominated in shares of Spinco common stock.


Outstanding equity awards held by Flex employees and non-employee directors at the time of Spin-Off will remain outstanding as awards denominated in shares of Flex common stock.


186


Table of Contents

The following table summarizes the expected treatment of each type of Flex equity award. As a result of the adjustments to such awards in connection with the Spin-Off, the precise number of shares underlying the adjusted equity awards will not be known until the Distribution Date or shortly thereafter.


Type of Award


Treatment

Flex RSUs


Outstanding Flex RSUs held by Spinco employees and non-employee directors will be converted into Spinco restricted stock units with substantially equivalent economic value. Outstanding Flex RSUs held by Flex employees and non-employee directors will be adjusted and remain outstanding as Flex RSUs. In each case, the adjusted awards will be subject to the same terms including the original vesting schedule.

EPS PSUs


The EPS PSUs will be adjusted or converted to Spinco PSUs in a manner similar to outstanding Flex RSUs generally, as described above. For performance periods that are at least 75% complete as of the Distribution Date will be determined based on actual results achieved through the Distribution Date. For all other performance periods, the EPS growth target goals will be adjusted to reflect the separation and allocated proportionately between Flex and Spinco. In each case, the final payout will be based on the average performance achieved across the three one-year performance measurement periods, and the original vesting schedule will remain unchanged.

Non-CEO OP PSUs


The Supplemental PSUs granted to Hooi Tan in 2024 will be converted to Spinco RSUs in a manner similar to outstanding Flex RSUs generally, as described above. The outstanding performance period, which is expected to be at least 75% complete as of the Distribution Date will be determined based on actual results achieved through the Distribution Date. The original vesting schedule will remain unchanged.

rTSR PSUs


The rTSR PSUs held by Flex employees will be adjusted or converted to Spinco PSUs in a manner similar to outstanding Flex RSUs generally, as described above. With respect to the performance goals, the value of Spinco stock distributed to Flex shareholders on the Distribution Date will be treated as a special dividend and assumed as a reinvestment in Flex’s rTSR calculation for any performance period that remains in progress on the Distribution Date. Flex’s rTSR performance will be adjusted to reflect the Spin-Off, and the original vesting schedule will remain unchanged.


For the rTSR PSUs held by Spinco employees, performance for completed performance cycles will be banked as of the Distribution Date. For performance periods that remain in progress, performance will be based on actual performance as of the Distribution Date.

CEO Supplemental Equity Award


The CEO’s supplemental PSU award that vests based on achievement of OP targets of the Cloud & Power Infrastructure business that is outstanding at the Distribution Date will be converted into Spinco performance-based restricted PSUS in a manner similar to outstanding Flex RSUs generally, as described above, with no changes to the original award terms, performance metrics and targets, or the performance period.

Spinco Plans to be Adopted in Connection with the Spin-Off

Spinco 2027 EIP

In connection with the Spin-Off, Spinco expects to adopt the Axiom Solutions International, Inc. 2027 Equity Incentive Plan (the “2027 EIP”). The 2027 EIP will become effective as of the Distribution Date, subject to the occurrence of the Distribution, and will authorize Spinco to grant incentive awards, including stock options (both “incentive stock options” and “nonqualified stock options”), share appreciation rights, restricted shares, RSUs, other share-based awards and cash awards, to its and its subsidiaries’ eligible employees, non-employee directors, independent contractors and consultants following the Distribution. The following summary of the material terms of the 2027 EIP is qualified in its entirety by reference to the full text of the 2027 EIP, the form of which is incorporated by reference herein and is filed as Exhibit [10.7] to the Form 10 of which this information statement forms a part.


187


Table of Contents

Term of the 2027 EIP

Unless terminated earlier, the 2027 EIP will continue until ten (10) years from the effective date.

Eligibility

All of our employees and directors and those of our subsidiaries and affiliates, including officers, members of our Board of Directors (including both employee and non-employee directors), and consultants of Spinco and our subsidiaries and affiliates, will be eligible to be selected as award recipients under the 2027 EIP. Awards under the 2027 EIP will generally be exercisable or payable only while the participant is an employee, director or consultant, as applicable. However, certain awards may be paid or exercised following certain terminations of service, a change of control event, or the retirement, death or disability of the participant.

Administration

The 2027 EIP will be administered by the Spinco Compensation and People Committee, which will have complete discretion, subject to the provisions of the 2027 EIP, to select each eligible individual to whom awards will be granted and to determine the type and amount of awards to be granted, the timing of such awards, and the other terms and conditions of awards granted under the 2027 EIP. Under the terms of the 2027 EIP, the Spinco Compensation and People Committee will be able to delegate its authority under the 2027 EIP to a committee of the Spinco Board of Directors or to one or more officers of Spinco, except for awards granted to Section 16 officers or directors of the Company. The Spinco Compensation and People Committee will also have the power to interpret the 2027 EIP and award agreements thereunder, to establish rules and regulations relating to the 2027 EIP, and to make all other determinations necessary or advisable for administering the 2027 EIP.

Shares Available for Awards

The total number of shares of Spinco common stock available for grant and issuance after the effective date of the 2027 EIP will be 10% of our shares of common stock outstanding as of the date of the Spin-Off. Each share of common stock that is subject to any award will count against the aggregate 2027 EIP limit as one share. To the extent that an award terminates, is forfeited, is cancelled, expires, lapses for any reason, or is settled in cash, any shares under such award in respect of such termination, forfeiture, cancellation, expiration, lapse or settlement in cash, will again be available for the grant of an award pursuant to the 2027 EIP. Shares that are withheld (if and to the extent permitted by applicable law) to satisfy the grant or exercise price or tax withholding obligations pursuant to any award will also be added back to the aggregate number of shares available for grant under the 2027 EIP.

Valuation

The fair market value of our shares of common stock on any relevant date under the 2027 EIP will be the closing sales price per share on that date as quoted on Nasdaq.

Limitation on Non-Employee Director Compensation

The aggregate value of cash compensation and grant date fair market value of shares that may be paid or granted during any calendar year of the Company to any non-employee director shall not exceed $1,000,000.

Repricing Prohibited Without Shareholder Approval

Under the 2027 EIP, the Spinco Compensation and People Committee may not, without the approval of our shareholders, (a) lower the exercise price of an option or grant price of a share appreciation right after it is granted, (b) cancel an option or share appreciation right when the exercise price or grant price exceeds the fair


188


Table of Contents

market value of a share of common stock in exchange for cash or another award (other than in connection with a change of control or substitute awards), or (c) take any other action with respect to an option or share appreciation right that would be treated as a repricing under the rules and regulations of Nasdaq.

Performance Measures

In granting awards that are contingent upon the achievement of certain performance goals, the Spinco Compensation and People Committee will base a performance goal on one or more of the following performance criteria or such other specific performance criteria determined appropriate by the Spinco Compensation and People Committee, which may be applied to the performance of Spinco or any of its affiliates, or any business unit of Spinco or any of its affiliates:


net revenue and/or net revenue growth;


earnings before income taxes and amortization and/or earnings before income taxes and amortization growth;


operating income and/or operating income growth;


net income and/or net income growth;


cash flow, operating income, or net income margins;


earnings per share and/or earnings per share growth;


total shareholder return and/or total shareholder return growth;


stock price;


return on equity;


operating or free cash flow;


economic value added;


return on invested capital;


environmental, social and governance objectives; and


individual objectives.

The 2027 EIP will provide that the Spinco Compensation and People Committee, in its discretion, may provide for the appropriate adjustments or modifications of the performance goals for a performance period to reflect any objectively determinable component of a performance goal, including foreign exchange gains and losses, asset write downs, acquisitions and divestitures, change in fiscal year, unbudgeted capital expenditures, special charges such as restructuring or impairment charges, debt refinancing costs, unusual or noncash items, infrequently occurring, nonrecurring or one-time events affecting Spinco or its financial statements, or changes in law or accounting principles, or any other events or occurrences for which the Spinco Compensation and People Committee determines an adjustment or modification should be made.

Dividends and Dividend Equivalents

Under the 2027 EIP, no dividends or dividend equivalents may be paid to a plan participant with respect to an award prior to the vesting of such award. Subject to the preceding sentence, a full-value award (generally an award other than a stock option or share appreciation right) may provide for dividends or dividend equivalents to accrue on behalf of a participant as of each dividend payment date during the period between the date the award is granted and the date the award is exercised, vested, expired, credited or paid, and to be converted to vested cash or shares at the same time and in all events subject to the same restrictions and risk of forfeiture that apply to the shares to which such dividends or dividend equivalents relate.


189


Table of Contents

Adjustments

The Spinco Compensation and People Committee will be required to make certain adjustments to the 2027 EIP and to the outstanding awards under the 2027 EIP in the event of any stock split, stock dividend, recapitalization, combination of shares, exchange of shares, Spin-Off, extraordinary cash dividend or other change affecting the outstanding common stock as a class without Spinco’s receipt of consideration. In the event of such a change, appropriate adjustments will be made to:


the maximum number and/or class of securities issuable under the 2027 EIP;


the maximum number and/or class of securities for which any participant may be granted awards under the terms of the 2027 EIP or that may be granted generally under the terms of the 2027 EIP; and


the number and/or class of securities and price per share of common stock in effect under each outstanding award.

Any such adjustments to the outstanding awards will be effected in a manner as to preclude the enlargement or dilution of rights and benefits under such awards. However, in no event will fractions of a share be issued and the Spinco Compensation and People Committee shall determine, in its discretion, whether cash shall be given in lieu of fractional shares or whether such fractional shares shall be eliminated by rounding down as appropriate.

Change of Control

In the event of a change of control (as defined in the 2027 EIP), the Spinco Compensation and People Committee may arrange for the surviving corporation to assume or substitute outstanding awards under the 2027 EIP. Alternatively, in the event of a change of control, the Spinco Compensation and People Committee may provide for the cancellation and exchange of outstanding awards equal to the excess (if any) of the consideration paid to the Company’s shareholders in the change of control over the aggregate exercise price of such awards.

Where awards are assumed or continued after a change of control, our Compensation and People Committee may provide that one or more awards will automatically accelerate upon an involuntary termination of service (as defined in the 2027 EIP) within a designated period following the effective date of such change of control. If the Spinco Compensation and People Committee so determines, any such award will, immediately upon an involuntary termination of service following a change of control, become fully exercisable and all forfeiture restrictions on such award will lapse.

Unless otherwise provided in the applicable award agreement or other plan or agreement between Spinco and the participant, in the event of a change of control in which the participant’s awards are not converted, assumed, or replaced by a successor or survivor corporation, or a parent or subsidiary thereof, then such awards will automatically vest and become fully exercisable and all forfeiture restrictions on such awards will lapse immediately prior to the change of control and, following the consummation of such a change of control, all such awards will terminate and cease to be outstanding.

Deferral

The Spinco Compensation and People Committee may, in an award agreement or otherwise, provide or permit for the deferred delivery of shares or cash upon settlement, vesting or other events with respect to awards.

Compliance with Section 409A of the Internal Revenue Code of 1986, as Amended

To the extent applicable, it is intended that the 2027 EIP and any grants made under the 2027 EIP will comply with or be exempt from the provisions of Section 409A of the Code, so that the income inclusion provisions of Section 409A(a)(1) of the Code do not apply to the participants. The 2027 EIP and any grants made under the 2027 EIP will be administered and interpreted in a manner consistent with this intent.


190


Table of Contents

Prohibition on Transfers of Awards

In general, awards granted under the 2027 EIP may not be transferred in any manner other than by will or by the laws of descent and distribution. Awards may, if so provided in the applicable award agreement, be transferred to family members or charitable institutions through a gift, pursuant to conditions and procedures established by our Compensation and People Committee. Options and share appreciation rights may not be transferred to a third-party financial institution for value.

Withholding Taxes

Spinco or any of its affiliates, as appropriate, may deduct or withhold, or require a participant to remit to Spinco, an amount sufficient to satisfy U.S. federal, state and local taxes and any taxes imposed by jurisdictions outside of the United States (including income tax, social insurance contributions, payment on account and any other taxes that may be due) required by law to be withheld with respect to any taxable event concerning a participant arising as a result of the 2027 EIP. In addition, Spinco or any of its affiliates may take any action as may be necessary in its opinion to satisfy withholding obligations for the payment of taxes by any means authorized by the Spinco Compensation and People Committee. No shares of common stock will be delivered under the 2027 EIP to any participant or other person until the participant or such other person has made arrangements acceptable to the Spinco Compensation and People Committee for the satisfaction of applicable tax obligations arising as a result of awards made under the 2027 EIP.

Spinco Executive Severance Plan (“Spinco Executive Severance Plan”)

In connection with the Spin-Off, Spinco expects to adopt the Spinco Executive Severance Plan. The Spinco Executive Severance Plan will become effective as of the Distribution Date, subject to the occurrence of the Distribution, and will provide certain severance benefits both before or after a change of control of Spinco to ensure that executives remain focused on our business during a period of uncertainty. Each of our NEOs will be participants in the Spinco Executive Severance Plan.

The Spinco Executive Severance Plan will provide benefits in the event of a qualifying termination by Spinco without “cause” (and not as a result of death or disability) or by a participant for “good reason” (each such term as defined in the Spinco Executive Severance Plan) generally and in the event of a qualifying termination within 24 months after a change of control of Spinco, as set forth in the table below. Eligibility to receive benefits under the Spinco Executive Severance Plan will be subject to the participant entering into and complying with a transition and release agreement in a form provided by Spinco, which will include customary non-competition, non-solicitation, non-disclosure, non-disparagement and cooperation provisions (“Transition Agreement”).


Spinco ESP Termination Benefit


General Severance Provisions

(Qualifying Termination Outside a

Change of Control)


Change of Control Severance Provisions
(Qualifying Termination within 24 Months
after a Change of Control)

Salary and Bonus


For the CEO, two years’ continued payment of base salary and two years of her target annual bonus amount


For the other NEOs, base salary continuation during the transition period provided in the Transition Agreement, and a pro-rated annual bonus for the fiscal year in which the transition period begins, based on actual performance through the end of the fiscal year


For the CEO, lump sum payment of 2.99 times the sum of base salary and target annual bonus amount


For the other NEOs, lump sum payment of two times the sum of base salary and target annual bonus amount


191


Table of Contents

Spinco ESP Termination Benefit


General Severance Provisions

(Qualifying Termination Outside a

Change of Control)


Change of Control Severance Provisions
(Qualifying Termination within 24 Months
after a Change of Control)

Equity and Deferred Compensation Vesting


For the CEO, two years’ continued vesting of outstanding equity awards and deferred compensation awards


For the other NEOs:


Outstanding equity awards (including, but not limited to, time-based RSUs and PSUs), and deferred compensation awards continue vesting during the transition period, and


Following the transition period, accelerated vesting of RSUs (but not PSUs) and deferred compensation awards that would have vested during the one-year period following the transition period, subject to the participant signing an additional release of claims and compliance with post-termination covenants under the Transition Agreement


For the CEO and other NEOs, accelerated vesting of any unvested service-based equity awards in accordance with the 2027 EIP and accelerated vesting of any unvested deferred compensation. PSU vesting will accelerate with funding based upon actual performance for completed periods during the measurement period and target performance for unfinished periods during the measurement period

Benefits Continuation


For the CEO, benefits coverage continuation for two years


For the other NEOs, benefits coverage continuation for duration of transition period provided in the Transition Agreement


For the CEO, benefits coverage continuation for three years


For the other NEOs, benefits coverage continuation for two years

Spinco Deferred Compensation Plan (“Spinco NQDC Plan”)

In connection with the Spin-Off, Spinco expects to adopt the Spinco NQDC Plan. Under the Spinco NQDC Plan, participating officers may defer up to 70% of their base salary and bonus, net of certain statutory and benefit deductions. Spinco may make a discretionary matching contribution for these deferrals to reflect limitations on Spinco’s matching contribution under our 401(k) plan, which will be substantially similar to the Spinco 401(k) plan. Under the Spinco NQDC Plan, we may also make annual contributions in amounts up to 37.5% of each participant’s base salary (subject to offsets for non-U.S. executives’ pension and other benefits), which will cliff-vest after four years. For these annual contributions, 50% of the funding is paid as a percent of base salary and the remaining 50% is performance-based, up to a maximum of 150%. Amounts credited to the deferral accounts are deemed to be invested in hypothetical investments selected by a participant or an investment manager on behalf of each participant. Participants in the Spinco NQDC Plan will be able to receive their vested deferred compensation balances upon termination of employment at such time as is specified in their deferral agreements, which may include a lump sum payment or installment payments made over a period of years. Participants also may elect in-service distributions through a lump sum payment or in installments over a period of up to 10 years.


192


Table of Contents

DIRECTOR COMPENSATION

Following the Spin-Off, we expect to adopt a non-employee director compensation program similar in structure to the current compensation program for non-employee directors of Flex, as described below. The terms of our non-employee director compensation program have not yet been determined.

We anticipate that our non-employee director compensation program will consist of two components:


Annual cash compensation, in amounts that vary based on committee and chair service; and


Annual discretionary restricted share unit awards.

It is anticipated that non-employee directors will be permitted to elect to receive their annual cash compensation, or any portion thereof, in the form of fully vested, unrestricted shares of Spinco. This share election option emphasizes equity compensation, which ties director pay to stock price performance.

In addition to their annual compensation, we anticipate that non-employee directors will be reimbursed for reasonable out-of-pocket expenses incurred in connection with attending board and committee meetings in person and for fees to attend continuing education courses, up to $10,000 per director per fiscal year.

Our Nominating and Governance Committee will periodically review and make recommendations to our Board of Directors regarding the form and amount of compensation for non-employee directors.


193


Table of Contents

CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS

Procedures for Approval of Related Person Transactions

The Spinco Board of Directors will establish a Related Person Transaction Policy prior to completion of the Spin-Off. The purpose of this policy is to describe the procedures used to identify, review, approve and disclose, if necessary, any transaction, arrangement or relationship (including any financial transaction, such as any indebtedness or guarantee of indebtedness) or any series of similar transactions, arrangements or relationships in which: (i) Spinco or any of its subsidiaries was, is to be a participant; (ii) the aggregate amount involved exceeds or is expected to exceed $120,000; and (iii) a related person had or will have a direct or indirect material interest. For purposes of the policy, a related person is: (i) a director or a nominee for director of Spinco; (ii) any executive officer of Spinco; (iii) any beneficial owner of more than 5% of our common stock (or any other class of voting securities); or (iv) any immediate family member of any of the foregoing persons.

Under the policy, once a related person transaction has been identified, the Audit Committee will review the transaction for approval or ratification. In determining whether to approve or ratify a related person transaction, the committee is to consider all relevant facts and circumstances of the related person transaction available to the committee. The committee may approve only those related person transactions that are in the best interests of Spinco and its shareholders, as the committee determines in good faith. No member of the committee will participate in any consideration of a related party transaction with respect to which that member or any member of his or her immediate family is a related person.

Agreements with Flex

Following the completion of the Spin-Off, Flex and Spinco will be independent companies. Flex will own between approximately 6.0% to 12.0% of our common stock following the Distribution and we expect that the relationship between Flex and Spinco will be governed by the ancillary agreements. These agreements will collectively provide for the allocation between Spinco and Flex of Flex and Spinco’s assets, employees, liabilities, and obligations (including employee benefits, intellectual property, and tax-related assets and liabilities) attributable to periods prior to, at and after the Spin-Off.

The material agreements described below are filed as exhibits to the registration statement on Form 10 of which this information statement is a part, and the summaries below set forth the current terms of the agreements that Spinco believes are material. These summaries are qualified in their entirety by reference to the full text of the applicable agreements, which are incorporated by reference into this information statement.

The Separation Agreement

The separation and distribution agreement (the “Separation Agreement”) will set forth Spinco’s agreement with Flex regarding the principal transactions necessary to separate Spinco from Flex. It will also set forth other agreements that govern certain aspects of Spinco’s relationship with Flex after the completion of the Distribution. The parties intend to enter into the Separation Agreement immediately before the Distribution of Spinco common stock to Flex shareholders. This summary of the Separation Agreement is qualified in its entirety by reference to the full text of the Separation Agreement.

Transfer of Assets and Assumption of Liabilities. The Separation Agreement will identify assets to be transferred to or retained by, liabilities to be assumed or retained by, and contracts to be assigned to each of Spinco and Flex as part of the reorganization of Flex, and will describe when and how these transfers, assumptions and assignments will occur, although many of the transfers, assumptions, and assignments will have already occurred prior to the parties’ entering into the Separation Agreement. In particular, the Separation Agreement will provide that, among other things, subject in each case to the terms and conditions contained therein, the following assets will be


194


Table of Contents

contractually allocated to us: (i) generally, assets primarily related to our business, (ii) the equity interests of subsidiaries intended to be our subsidiaries after the Spin-Off, together with any joint venture or other minority equity interests intended to be owned by us after the Spin-Off, (iii) certain real property set forth on schedule, (iv) contracts and intellectual property primarily related to our business or set forth on a schedule, (v) certain IT assets and IT contracts primarily related to our business or set forth on a schedule, (vi) cash and cash equivalents, notes, interest receivables, other financial assets and derivative instruments owned by members of our group, (vii) accounts and notes receivable to the extent related to our business, (viii) credits, prepaid expenses, rebates, deferred charges, advance payments, security deposits and other prepaid items to the extent related to our business other than for certain accounts receivables that are below threshold amounts and primarily related to Flex, (ix) permits, consents and registrations exclusively related to our business, and (x) accruals, counterclaims, insurance claims, rights to coverage under insurance policies, warranties, contractual indemnities and other similar rights, in each case to the extent related to a liability allocated to us. Generally, all other assets of Flex will be contractually retained by Flex, subject to the terms and conditions of the Separation Agreement, including any exceptions specified therein.

Similarly, subject in each case to the terms and conditions contained in the Separation Agreement, including any exceptions specified therein, liabilities related to our business will generally be contractually allocated to us, including liabilities (i) constituting environmental liabilities to the extent related to our business or real property allocated to us, (ii) relating to our discontinued or divested operations and businesses, (iii) for indebtedness incurred by any member of our group, (iv) for checks issued but not drawn and accounts payable to the extent related to our business, (v) relating to indemnification obligations to our current or former directors and officers or to our ownership of joint ventures and minority investments, including related credit agreements, guarantees, indemnities or credit support instruments given for the benefit of any such joint venture or minority investment, and (vi) relating to litigation and other actions primarily related to our business, in addition to jointly-related actions set forth or meeting financial thresholds. Liabilities not otherwise specifically allocated will generally be contractually allocated to the party to whose business such liabilities primarily relate.

The allocation of liabilities with respect to taxes, except for payroll taxes and reporting and other tax matters expressly covered by the employee matters agreement, are solely covered by the tax matters agreement (see the sections below entitled “Tax Matters Agreement” and “Employee Matters Agreement”).

Except as may expressly be set forth in the Separation Agreement or any ancillary agreement, all assets will be transferred on an “as is,” “where is” basis and the respective transferees will bear the economic and legal risks that any conveyance will prove to be insufficient to vest in the transferee good title, free and clear of any security interest, that any necessary consents or governmental approvals are not obtained, and that any requirements of laws or judgments are not complied with.

Further Assurances. To the extent that any transfers of assets or contractual allocations of liabilities contemplated by the Separation Agreement have not been consummated on or prior to the Distribution Date, the parties agree to cooperate with each other to effect such transfers or assumptions while holding such assets or liabilities for the benefit of the appropriate party so that all the benefits and burdens relating to such asset or liability inure to the party contractually allocated such asset or liability. Each party agrees to use commercially reasonable efforts to take or to cause to be taken all actions, and to do, or to cause to be done, all things reasonably necessary under applicable law or contractual obligations to consummate and make effective the transactions contemplated by the Separation Agreement.

Intergroup Accounts. The Separation Agreement provides that, subject to certain specified exceptions in the Separation Agreement, schedules or any ancillary agreement, certain accounts that were formerly intercompany accounts within Flex will be settled prior to the Distribution.

Release of Claims and Indemnification. Except as otherwise provided in the Separation Agreement, each party will fully release and forever discharge the other parties and their respective subsidiaries and affiliates from all liabilities existing or arising from any acts or events occurring or failing to occur or alleged to have occurred or


195


Table of Contents

to have failed to occur or any conditions existing or alleged to have existed on or before the Spin-Off. The releases will not extend to obligations or liabilities under any agreements between the parties that remain in effect following the Spin-Off pursuant to the Separation Agreement or any ancillary agreement. These releases are subject to certain exceptions set forth in the Separation Agreement.

Spinco Cash Distribution. The Separation Agreement provides that, prior to or substantially concurrently with the consummation of the Distribution, Spinco shall pay the Spinco Cash Distribution to Flex as consideration for the Contribution. It is a condition to the consummation of the Distribution that the Spinco Cash Distribution shall have been completed or will be completed substantially concurrently with the Distribution.

Shared Contracts. Contracts that relate to both our business and the Flex business will generally be partially assigned, amended, bifurcated or replicated so that each party or its group receives the rights and benefits, and assumes the related liabilities, inuring to its respective business, and each party has agreed to use commercially reasonable efforts to obtain any consents required to effect such allocation.

Information in this information statement with respect to the assets and liabilities of the parties following the separation is presented based on the allocation of such assets and liabilities pursuant to the Separation Agreement, unless the context otherwise requires. Certain of the liabilities and obligations to be assumed by one party or for which one party will have an indemnification obligation under the Separation Agreement and the other agreements relating to the separation may be, and following the separation may continue to be, the legal or contractual liabilities or obligations of another party. Each such party that continues to be subject to such legal or contractual liability or obligation will rely on the applicable party that assumed the liability or obligation or the applicable party that undertook an indemnification obligation with respect to the liability or obligation, as applicable, under the Separation Agreement, to satisfy the performance and payment obligations or indemnification obligations with respect to such legal or contractual liability or obligation.

The Distribution. The Separation Agreement will also govern the rights and obligations of the parties regarding the proposed Distribution. The Separation Agreement provides that prior to the Distribution, Spinco shall issue to Flex, as a stock dividend, such number of shares of Spinco common stock such that the number of shares of Spinco common stock then outstanding shall be equal to the number of shares of Spinco common stock necessary to effect the Distribution. Flex will cause its agent to distribute to Flex shareholders as of the applicable record date for the Distribution between approximately 88.0% to 94.0% of the outstanding shares of Spinco’s common stock. Flex will have the sole and absolute discretion to determine (and change) the terms of, and whether to proceed with, the Distribution and, to the extent it determines to so proceed, to determine the Distribution Date.

Conditions. The Separation Agreement will provide that the Distribution is subject to several conditions that must be satisfied or waived by Flex in its sole discretion. For further information regarding the conditions relating to Spinco’s separation from Flex, see the section entitled “The Separation and Distribution—Conditions to the Distribution.”

Insurance. Following the Spin-Off, we will generally be responsible for obtaining and maintaining, at our own cost, our own insurance coverage for liabilities for which we are assuming responsibility, although we will continue to have coverage under certain insurance policies issued to Flex or other entities for certain matters that arise out of or relate to acts, omissions or occurrences that occurred prior to the Spin-Off, subject to the terms, conditions and exclusions of such policies.

Non-Competition and Customer Non-Solicitation. The Separation Agreement will include reciprocal non-competition and customer non-solicitation restrictions applicable worldwide during the Restricted Period, which will run for three years following the Distribution. Spinco and its subsidiaries generally will be restricted from engaging in the RemainCo Restricted Business in any country in which the RemainCo Restricted Business operated immediately prior to the Effective Time, meaning contract manufacturing services generally but


196


Table of Contents

excluding (i) integration of modular power equipment and associated enclosures and (ii) contract manufacturing services in the Cloud & Compute business. For the avoidance of doubt, the RemainCo Restricted Business includes contract manufacturing services for the Power, Cooling, and Networking product businesses, in any jurisdiction worldwide. Spinco also generally will be restricted from directly or indirectly soliciting, inducing or encouraging any RemainCo Protected Customer to cease doing business with any member of the RemainCo Group with respect to the RemainCo Restricted Business to divert or redirect any business of such RemainCo Protected Customer away from any member of the RemainCo Group with respect to the RemainCo Restricted Business.

RemainCo and its subsidiaries generally will be restricted from engaging in the Spinco Restricted Business in any country in which the Spinco Restricted Business operated immediately prior to the Effective Time, meaning (i) the Power products business, excluding contract manufacturing services; (ii) the Cooling business, excluding contract manufacturing services; and (iii) the Cloud & Compute business, including contract manufacturing services generally and, for the avoidance of doubt, including contract manufacturing services related to CPU and AI-accelerated servers, compute trays, fabrication of associated racks and enclosures, and integration into those racks, but excluding contract manufacturing services for Networking products, and from directly or indirectly soliciting, inducing or encouraging any Spinco Protected Customer to cease doing business with any member of the Spinco Group with respect to the Spinco Restricted Business or to divert or redirect any business of such Spinco Protected Customer away from any member of the Spinco Group with respect to the Spinco Restricted Business.

The restrictions would be subject to specified exceptions, including exceptions permitting (a) Spinco and its subsidiaries to continue contract manufacturing in the Power, Cooling and Networking product businesses only for customers for which Spinco or any member of the Spinco Group has such business as of immediately prior to the Effective Time, including associated future programs with such customers and (b) RemainCo and its subsidiaries to continue the Compute business for certain customers. Additional exceptions would apply to certain passive investments, acquisitions, dispositions and changes of control, and Flex’s retained interest in Spinco and its monetization or disposition. Certain acquisitions of competing businesses would be permitted, subject in some circumstances, to separation and divestiture requirements. The terms of these restrictions and related procedures remain subject to finalization.

Dispute Resolution. Except as otherwise set forth in the Separation Agreement, disputes between Spinco and Flex arising out of the Separation Agreement or the transactions contemplated thereby that are not resolved between the separation management offices to be established by each of Spinco and Flex following the Spin-Off, will first be subject to a negotiation period between the parties’ appointed representatives, not to exceed 30 days unless otherwise agreed. If the dispute is not resolved during this period, it will be submitted, at the request of either party, to final and binding arbitration administered by JAMS before a three-member arbitral tribunal, with the arbitration governed by the Federal Arbitration Act. The Separation Agreement will also include a waiver of the right to a jury trial and confidentiality provisions applicable to the arbitration proceedings.

Term, Termination and Amendment. Prior to the Distribution, the Flex Board of Directors will have the unilateral right to terminate the Separation Agreement, and to amend, modify or abandon the Distribution, in each case without the consent of Spinco or Flex’s shareholders. After the Distribution, the Separation Agreement may only be terminated or amended by a written agreement signed by both parties. Notwithstanding the foregoing, certain provisions benefiting third-party beneficiaries, including the indemnification provisions of the Separation Agreement, access to insurance for insured persons and the director and officer indemnification obligations described above, may not be terminated or amended after the Distribution in a manner adverse to those beneficiaries without their consent.

Other Matters Governed by the Separation Agreement. Other matters governed by the Separation Agreement include, among others, access to the exchange of information, confidentiality of proprietary information, retention of records, cooperation in connection with financial reporting and audits, the treatment of transfers not


197


Table of Contents

completed prior to the Distribution and the related third-party consent process, allocation of expenses incurred in connection with the Spin-Off.

Delayed Transfer. If any asset transfers or liability assumptions contemplated by the Separation Agreement are not completed by the effective time of the Distribution, the parties must use commercially reasonable efforts to complete them as soon as practicable.

Transition Services Agreement

Flex and Spinco will enter into a transition services agreement (the “Transition Services Agreement”) which will govern the provision of certain transitional services from Flex to Spinco and from Spinco to Flex, to help facilitate Flex’s and Spinco’s respective transitions to standalone businesses in connection with the Spin-Off. The services to be provided by and to either Flex or Spinco will principally be set forth in one or more schedules attached to the Transition Services Agreement, and will include services currently being provided by Flex or Spinco to the other that Flex and Spinco will need to continue receiving following the Spin-Off to operate our respective businesses, including information technology and other infrastructure-related services, among others. The services will be provided for a specified period of time depending on the type and scope of services to be provided, up to two years from the effective date of the Transition Services Agreement.

This summary of the Transition Services Agreement is qualified in its entirety by reference to the full text of the form of Transition Services Agreement, which is attached hereto as Exhibit 10.1 to the Registration Statement on Form 10, of which this information statement forms a part.

Tax Matters Agreement

In connection with the Spin-Off, Flex and Spinco will enter into a tax matters agreement (the “Tax Matters Agreement”) that will govern the parties’ respective rights, responsibilities and obligations with respect to tax liabilities and benefits, tax attributes, the preparation and filing of tax returns, the control of audits and other tax proceedings, and other matters regarding taxes.

The Tax Matters Agreement will provide special rules that allocate tax liabilities in the event the Distribution or certain related transactions fail to qualify as transactions that are tax-free for U.S. federal income tax purposes (other than any cash that Flex shareholders receive in lieu of fractional shares). Under the Tax Matters Agreement, Spinco will generally agree to indemnify Flex and its affiliates against any and all tax-related liabilities incurred by them relating to the Distribution and certain related transactions, to the extent caused by any representation by Spinco being incorrect or an acquisition of Spinco’s stock or assets or by any other action undertaken or failure to act by Spinco. This indemnification will apply even if Flex has permitted Spinco to take an action that would otherwise have been prohibited under the tax-related covenants described below.

Pursuant to the Tax Matters Agreement, Spinco will agree to certain covenants that contain restrictions intended to preserve the tax-free status of the Distribution and certain related transactions. Spinco may take certain actions prohibited by these covenants only if Spinco obtains and provides to Flex an opinion from a U.S. tax counsel or accountant of recognized national standing or a favorable private letter ruling from a taxing authority, in each case satisfactory to Flex, to the effect that such action would not affect the tax-free status of these transactions, or if Spinco obtains prior written consent of Flex, in its sole and absolute discretion, waiving such requirement. Spinco will be barred from taking any action, or failing to take any action, including any action or failure to take any action that would be inconsistent with the Tax Opinion, where such action or failure to take any action adversely affects the tax-free status of these transactions. In addition, during the period ending two years after the Distribution Date, these covenants will include specific restrictions on Spinco’s (i) discontinuing the active conduct of Spinco’s trade or business; (ii) liquidating, merging or consolidating with any other person; (iii) amending Spinco’s charter (or other organizational documents) or taking any other action, whether through a shareholder vote or otherwise, affecting the voting rights of Spinco’s common stock; (iv) sales of assets outside


198


Table of Contents

the ordinary course of business; and (v) entering into any other corporate transaction (including issuances of Spinco stock or securities convertible into Spinco stock, but excluding certain compensatory arrangements), which would cause Spinco to undergo a 40% or greater change in its stock ownership or otherwise be expected to result in the failure to preserve the tax-free treatment of these transactions.

This summary of the Tax Matters Agreement is qualified in its entirety by reference to the full text of the form of Tax Matters Agreement, which is attached hereto as Exhibit 10.2 to the Registration Statement on Form 10, of which this information statement forms a part.

Employee Matters Agreement

Flex and Spinco will enter into an employee matters agreement (the “Employee Matters Agreement”) in connection with the Spin-Off to allocate liabilities and responsibilities relating to employment matters, employee compensation and benefit plans and programs and other related matters. The Employee Matters Agreement also sets forth the general principles relating to employee matters both with respect to domestic and international employees, including with respect to collective bargaining agreements, workers’ compensation, payroll matters, regulatory filings, paid time off, commencing or continuing participation in employee benefit plans, and the sharing of employee information. Except as specifically provided in the Employee Matters Agreement, we will generally be responsible for all employment and employee compensation and benefits-related liabilities relating to our employees and other service providers. In particular, we will assume certain assets and liabilities with respect to our employees under Flex’s nonqualified deferred compensation plans. Generally, except as may be provided in the Transition Services Agreement, each of our employees will cease active participation in Flex compensation and benefit plans as of the Spin-Off. The Employee Matters Agreement also provides that we will establish certain compensation and benefit plans for the benefit of our employees following the Spin-Off, including a 401(k) savings plan for U.S. employees, which will accept direct rollovers of account balances from the Flex 401(k) savings plan for any of our employees who elect to do so. Following the Spin-Off, we will assume and be responsible for any Flex annual bonus payments and any other cash-based incentive awards to our employees with respect to the year in which the Spin-Off occurs. Treatment of cash-based incentive awards under the Employee Matters Agreement is further discussed in “Compensation Discussion and Analysis—Treatment of Incentive Bonus Awards.” Flex long-term incentive compensation awards held by Spinco employees will be treated as described in “Compensation Discussion and Analysis—Treatment of Outstanding Equity Awards at the Time of the Spin-Off.”

This summary of the Employee Matters Agreement is qualified in its entirety by reference to the full text of the form of Employee Matters Agreement, which is attached hereto as Exhibit 10.3 to the Registration Statement on Form 10, of which this information statement forms a part.

Intellectual Property Matters Agreement

Flex and Spinco will enter into an intellectual property matters agreement (the “Intellectual Property Matters Agreement”) in connection with the Spin-Off, which agreement will set forth the terms and conditions pursuant to which Flex and Spinco may use certain patents, know-how (including trade secrets), copyrights, and software contractually allocated to the other party under the Separation Agreement in the conduct of our respective businesses and natural evolutions thereof. Except for certain software that may be subject to separate or different license terms, each respective license will be non-exclusive, royalty-free, worldwide, irrevocable and non-terminable. Such licenses will be sublicensable to affiliates and to third parties in the operation of the applicable licensee’s business, but not for the independent use of any third party.

The Intellectual Property Matters Agreement will not be terminable by either party and may only be modified with the prior written consent of both Flex and Spinco. In addition, the agreement will be assignable in whole or in relevant part to affiliates or to a successor to all or a portion of the business or assets to which the agreement relates (subject to certain limitations applicable upon specified change-of-control or assignment events), but will not otherwise be assignable without consent of the other party.


199


Table of Contents

This summary of the Intellectual Property Matters Agreement is qualified in its entirety by reference to the full text of the form of Intellectual Property Matters Agreement, which is attached hereto as Exhibit 10.4 to the Registration Statement on Form 10, of which this information statement forms a part.

Stockholder’s and Registration Rights Agreement

Flex and Spinco will enter into a stockholder’s and registration rights agreement (the “Stockholder’s and Registration Rights Agreement”), pursuant to which Spinco will agree that, upon the request of Flex, Spinco will use its reasonable best efforts to effect the registration under applicable federal and state securities laws of any shares of Spinco common stock retained by Flex. In addition, Flex will agree to vote any shares of Spinco common stock that it retains immediately after the separation in proportion to the votes cast by Spinco’s other shareholders. In connection with such agreement, Flex will grant Spinco a proxy to vote its shares of Spinco common stock in such proportion. This proxy, however, will be automatically revoked as to any particular share upon any sale or transfer of such share from Flex to a person other than Flex, and neither the Stockholder’s and Registration Rights Agreement nor proxy will limit or prohibit any such sale or transfer.

This summary of the Stockholder’s and Registration Rights Agreement is qualified in its entirety by reference to the full text of the form of Stockholder’s and Registration Rights Agreement, which is attached hereto as Exhibit 10.5 to the Registration Statement on Form 10, of which this information statement forms a part.

Cross-Supply Agreements

Flex and Spinco will enter into a series of product manufacturing and supply agreements (collectively, the “Cross-Supply Agreements”) in connection with the Spin-Off, pursuant to which each party will continue to manufacture and supply certain products to, or purchase certain manufacturing services from, the other party following the Distribution. These arrangements are intended to preserve continuity of supply to the parties’ respective customers at sites that have historically been operated on a commingled basis, under which finished goods will be manufactured at such sites and sold to the counterparty at a markup, with the purchasing party subsequently selling those finished goods to third-party customers. The Cross-Supply Agreements reflect a number of different commercial models, including buy-sell arrangements, turnkey arrangements, subcontracting arrangements, consignment arrangements and long-term mechanical supply arrangements, which differ principally in the allocation between the parties of responsibility for procuring raw materials and ownership of materials and equipment. The specific products, sites, customers, pricing, volumes and other commercial terms applicable to each arrangement are set forth in individual contract supplements, and relevant terms of the underlying customer agreements, including quality, service level and delivery requirements, are generally mirrored or passed through to the supplying party.

Pricing under the Cross-Supply Agreements is generally based on the supplying party’s costs plus an agreed markup, or, in the case of the long-term mechanical supply arrangements, on the parties’ existing intercompany pricing, in each case subject to periodic true-ups for inflation, currency exchange rate movements and, in certain cases, tariffs. Payment terms are intended to be substantially cash- or working-capital neutral for the supplying party. Each Cross-Supply Agreement will continue until the last contract supplement thereunder expires or is terminated. The term of each contract supplement is specified in that contract supplement, and each contract supplement for an ongoing arrangement with no specified end date has an initial term of three years, renewable for successive two-year terms by mutual written consent. No extension or renewal is permitted if it would be inconsistent with, or would be reasonably likely to prevent, the tax-free status of the Distribution and certain related transactions. The purchasing party is generally permitted to terminate a contract supplement for convenience upon advance written notice, and each party has customary termination rights for material breach, nonpayment, insolvency, extended force majeure and violations of applicable anti-corruption and sanctions laws. The agreements also contain customary limited product warranties, reciprocal indemnities and limitations of liability, including a cap on the supplying party’s aggregate liability with customary exceptions, as well as provisions governing the disposition of inventory and equipment upon expiration or termination.


200


Table of Contents

Other Agreements

Spinco and/or certain of its subsidiaries also will enter into certain other agreements with Flex and/or certain of its subsidiaries in connection with the Spin-Off, including those described below.

Real Estate-Related Agreements

Spinco and/or certain of its subsidiaries intend to enter into certain leases and other real estate-related agreements with Flex and/or certain of its subsidiaries, the terms and conditions and costs of which will be specified in each such agreement.

In connection with the separation and distribution, Flex and Spinco expect to take certain steps to allocate leased and owned real property used in the Spinco business. Depending on the applicable site, such steps may include assigning certain third-party leases from Flex entities to Spinco entities, conveying certain owned sites from Flex entities to Spinco entities and, for sites that, following the Distribution, will remain shared or otherwise entangled, leases, subleases, lease-split arrangements or other occupancy arrangements between the Flex and Spinco entities to address such parties’ continued use of the applicable portions of such sites.

In particular, a Spinco subsidiary and a Flex subsidiary expect to enter into a long-term lease arrangement pursuant to which the Flex subsidiary will continue to occupy certain buildings and related areas at the Guadalajara, Mexico campus following the Distribution (the “Guadalajara Lease”). The Guadalajara Lease is expected to address the leased premises, the term, rent and other charges as well as access to and use of common areas and shared infrastructure and the parties’ respective maintenance and repair obligations.

Spinco and/or certain of its subsidiaries also intend to enter into certain site services agreements with Flex and/or certain of its subsidiaries governing the provision of certain facility, utility and other site-based services at shared or otherwise operationally interdependent sites, including the Guadalajara, Mexico campus. The applicable services, terms and costs will be specified in each such agreement.

For certain lease assignments, or changes in the ownership or control of the applicable tenants, the consent of (or notice to) the applicable landlords may be required. Additionally, where applicable, security deposits, bank guarantees, parent guarantees or other forms of security or credit support may need to be transferred, replaced or otherwise addressed. The foregoing arrangements, including the specific terms thereof, remain subject to the completion of the separation and distribution planning and the negotiation, finalization and execution of the definitive documentation in respect thereof.

Other Confidentiality-Related and Commercial Agreements

Spinco and/or certain of its subsidiaries intend to enter into certain confidentiality and other commercial agreements with Flex and/or certain of its subsidiaries, the terms and conditions and costs of which will be specified in each such agreement, which are intended to be on an arm’s-length basis and reflect market terms. Such commercial agreements are expected to include a services agreement pursuant to which Flex will continue to provide certain services to the customers of Spinco and its affiliates, including value-added fulfillment, logistics, freight management and product manufacturing at certain sites located in Netherlands, Brazil, Czechia and Hong Kong. As compensation for these services, Flex will be entitled to retain from net sales received from Spinco’s customers amounts calculated in accordance with the applicable service exhibit, generally based on either a cost-plus methodology or specified fixed and variable fees, with certain variable fees subject to an annual true-up.

Engagement with Fragment Data Technologies

Certain subsidiaries of Flex entered into agreements with Fragment Data Technologies, Inc. (“Fragment”), effective August 21, 2026, pursuant to which Fragment provides to Flex an agentic AI end-to-end payment


201


Table of Contents

processing technology platform to help support automation of Flex’s procure-to-pay systems (the “Fragment Engagement”). The co-founder and Chief Executive Officer of Fragment is Pranav Mulgund, son of Revathi Advaithi, Flex’s Chief Executive Officer. The Fragment Engagement is subject to a spending cap, which requires that the aggregate fees thereunder shall not exceed $2.5 million during the 12-month period following approval by the Flex Board of Directors and its Nominating, Governance and Public Responsibility Committee. The Fragment Engagement contains certain right-to-use provisions, permitting Spinco to use the platform during this 12-month period. Upon expiration of such initial period, the Fragment Engagement is subject to re-evaluation and re-approval by mutual written agreement. Any such renewal will require review and approval in accordance with Flex’s Statement of Policy with Respect to Related-Person Transactions.

Certain Relationships and Potential Conflicts of Interest

Following the Distribution, there will be an overlap between an officer of Spinco and the Flex Board of Directors. Revathi Advaithi (the “Overlap Person”), the current Chief Executive Officer of Flex, is expected to step down as Chief Executive Officer of Flex and will become the Chief Executive Officer of Spinco in connection with the Distribution. Following the Distribution she will also serve on the Spinco Board of Directors and will serve as Chair of the Flex Board of Directors for a transitional period not to exceed 24 months.

The Overlap Person may have actual or apparent conflicts of interest with respect to matters involving or affecting each company. For example, conflicts may arise if there are issues or disputes under the commercial arrangements that will exist between Flex and us. Also, there could be a conflict of interest between us, on the one hand, and Flex, on the other hand, with respect to Flex’s disposal of the Retained Shares through one or more exchanges of Spinco common stock for Flex debt and/or Flex ordinary shares. In addition, after the Distribution, certain of our directors and officers may continue to own shares of Flex.

In the event of any potential conflict of interest, we expect the Overlap Person to (i) inform the Spinco Board of Directors of any actual or potential conflict, (ii) recuse herself, if necessary, from any discussions or decisions involving such matters and (iii) act in accordance with our Code of Business Conduct and Ethics.

See “—Procedures for Approval of Related Person Transactions” for a discussion of certain procedures we will institute to help ameliorate such potential conflicts that may arise.


202


Table of Contents

SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT

The following information sets forth the anticipated Spinco beneficial ownership, which is being included to supplement investor understanding.

As of the date hereof, all of our outstanding shares of common stock are owned by Flex. Immediately after the Distribution, Flex will own between approximately 6.0% to 12.0% of our common stock for a period of up to 24 months following the Distribution.

The following table provides information with respect to the expected beneficial ownership of our common stock immediately after the Distribution, giving effect to the Distribution Ratio of two shares of our common stock for every one Flex ordinary share by (i) each person whom we believe (based on the assumptions described below) will be a beneficial owner of more than five percent of our outstanding shares of common stock, (ii) each of our expected directors, and named executive officers and (iii) all expected directors and executive officers as a group. While the final Distribution Ratio has not yet been determined, the Company currently contemplates a Distribution Ratio ranging from 1.0 to 3.0 shares of our common stock for each share of Flex common stock. For purposes of these calculations, the assumed Distribution Ratio reflects the midpoint of such contemplated range.

Following the separation and distribution, Spinco expects to have an aggregate of approximately [●] million shares of our common stock outstanding based upon approximately [●] million Flex ordinary shares issued and outstanding on [●], 2026, excluding treasury shares, assuming no further Flex ordinary shares are issued pursuant to the exercise of Flex equity awards and applying the Distribution Ratio to each Flex ordinary share. Beneficial ownership is determined in accordance with the rules of the SEC.

To the extent our directors and executive officers own Flex ordinary shares at the time of the Spin-Off, they will participate in the Distribution on the same terms as other holders of Flex ordinary shares.


203


Table of Contents

Unless otherwise indicated, the business address of each director, director nominee, and named executive officer shown in the table below is 10025 Alterra Parkway, Suite No. 1900, Austin, Texas 78758. None of Spinco’s directors or named executive officers are expected to own one percent or more of Spinco common stock.


Name and Address of Beneficial Owner    Shares of
Spinco
Common

Stock to be
Beneficially
Owned

Upon the
Distribution
     % of
Class
 

Greater than 5% Shareholders:


Flex Ltd.

     [●      [●]

BlackRock, Inc.(a)

     [57,063,240      [●]

Vanguard Capital Management(b)

     [55,445,564      [●]

PRIMECAP Management Company(c)

     [46,717,750      [●]

Janus Henderson Group plc(d)

     [44,662,890      [●]

FMR LLC(e)

     [39,061,272      [●]

Vanguard Portfolio Management(f)

     [38,765,540      [●]

Directors:


Mark Eubanks

     —         *  

Michael E. Hurlston

     59,358        *  

David Johnson

     —         *  

Charles K. Stevens, III

     45,426        *  

Maryrose Sylvester

     26,214        *  

William D. Watkins

     197,816        *  

Named Executive Officers:


Revathi Advaithi

     2,493,266        *  

Kevin Krumm

     60,570        *  

Scott Offer(h)

     231,828        *  

All Directors and Executive Officers as a group (11persons) ((h))

     3,114,478        *  
 
*

Less than one percent (1%)


(a)

Based on a Schedule 13G/A filed with the SEC on July 28, 2026. BlackRock Inc. would have sole voting power over 53,039,424 shares and sole dispositive power over 57,063,240 shares. BlackRock Inc.’s address is 50 Hudson Yards, New York, NY 10001.


(b)

Based on a Schedule 13G filed with the SEC on July 31, 2026. Vanguard Capital Management would have sole voting power over 7,425,616 shares and sole dispositive power over 55,445,564 shares. Vanguard Capital Management’s address is 100 Vanguard Blvd., Malvern, PA 19355.


(c)

Based on a Schedule 13G/A filed with the SEC on August 6, 2026. PRIMECAP Management Company would have sole voting power over 46,233,510 shares and sole dispositive power over 46,717,750 shares. PRIMECAP Management Company’s address is 177 E. Colorado Blvd., 11th Floor, Pasadena, CA 91105.


(d)

Based on a Schedule 13G/A filed with the SEC on February 17, 2026. Janus Henderson Group plc would have shared voting power over 44,662,890 shares and shared dispositive power over 44,662,890 shares. Janus Henderson Group plc’s address is 201 Bishopsgate, EC2M 3AE, United Kingdom.


(e)

Based on a Schedule 13G filed with the SEC on August 6, 2026. FMR LLC would have sole voting power over 38,579,242 shares and sole dispositive power over 39,061,272 shares. FMR LLC’s address is 245 Summer Street, Boston, Massachusetts 02210.


(f)

Based on a Schedule 13G filed with the SEC on April 29, 2026. Vanguard Portfolio Management would have sole voting power over 98,470 shares and sole dispositive power over 38,765,540 shares. Vanguard Portfolio Management’s address is 100 Vanguard Blvd., Malvern, PA 19355.


(g)

Includes [109,442] shares that would be held indirectly by a family trust, in which Mr. Offer is a trustee.


(h)

This represents the aggregate for all executive officers and directors as a group.


204


Table of Contents

DESCRIPTION OF MATERIAL INDEBTEDNESS

In connection with the Spin-Off, Spinco is expected to enter into certain senior credit facilities, which we expect will consist of an aggregate principal amount of up to $5,650 million that will be available through (i) a 364-day bridge loan credit facility in an aggregate principal amount of $4,400 million (the “Bridge Facility”) and (ii) a five-year senior secured revolving credit facility with committed availability of up to $1,250 million, which we expect will be undrawn as of the date we complete the Spin-Off (the “Revolving Facility” and, together with the Bridge Facility, the “Senior Credit Facilities”).

We intend to use the proceeds of borrowings under the Revolving Facility for general corporate purposes of Spinco and its subsidiaries. We intend to use the proceeds of the Bridge Facility either to finance a portion of the previously announced EPC Power Acquisition or to fund a cash dividend to Flex, the proceeds of which would be used to retire bridge loan indebtedness incurred by Flex to finance the EPC Power Acquisition, and to pay related fees and expenses incurred in connection with the financing.

Borrowings under the Senior Credit Facilities will bear interest, at Spinco’s option, at a base rate or at a rate based on Term SOFR, in each case plus an applicable margin. The applicable margin will vary based on Spinco’s long term issuer credit rating.

The obligations of Spinco under the Senior Credit Facilities will be unconditionally guaranteed by each of Spinco’s existing and subsequently acquired or organized wholly-owned subsidiaries organized in the United States and certain other agreed jurisdictions, subject to customary exceptions and thresholds. The Senior Credit Facilities will be secured by a perfected security interest in substantially all of the assets of Spinco and the guarantors, subject to permitted liens and customary exceptions.

We anticipate that the Senior Credit Facilities will contain representations and warranties, events of default and affirmative and negative covenants that are customary for similar financings, including, among other things and subject to certain significant exceptions, limitations on liens, indebtedness, mergers and asset sales, as well as customary reporting and compliance obligations. We also expect to be required to maintain compliance with a maximum net leverage ratio and a minimum interest coverage ratio, tested quarterly. Certain covenants and other provisions, including the security and guarantee requirements are expected to be subject to modification or release upon Spinco’s achievement of an investment grade ratings status.

The foregoing summarizes some of the currently expected terms of our Senior Credit Facilities. However, the foregoing summary does not purport to be complete, and the terms of the Senior Credit Facilities have not yet been finalized. There may be changes to the expected size and other terms of the Senior Credit Facilities, some of which may be material.


205


Table of Contents

DESCRIPTION OF CAPITAL STOCK

Our certificate of formation and bylaws will be amended and restated prior to the Spin-Off. The following is a summary of the material terms of our capital stock that will be contained in our amended and restated certificate of formation and amended and restated bylaws. These descriptions contain all information which we consider to be material but may not contain all of the information that is important to you. The summaries and descriptions below do not purport to be complete statements of the relevant provisions of our amended and restated certificate of formation, our amended and restated bylaws to be in effect at the time of the Distribution or the TBOC and is qualified by reference to Texas statutory and common law and the full texts of such documents. The summary is qualified in its entirety by reference to these documents, which you should read, along with the applicable provisions of the TBOC, for complete information on our capital stock at the time of the Distribution. Our amended and restated certificate of formation and our amended and restated bylaws that will be in effect at the time of the Distribution are included as exhibits to this information statement.

General

Immediately following the Spin-Off, our authorized capital stock will consist of    shares of common stock, par value $0.0001 per share, and   shares of preferred stock, par value $0.0001 per share.

Common Stock

Immediately following the Spin-Off, we expect that    shares of the Spinco common stock will be issued and outstanding, based on Flex ordinary shares outstanding as of     , 2026.

Dividends. Payment of dividends on Spinco common stock may be made at the discretion of the Spinco Board of Directors out of legally available funds, subject to any preferential dividend rights of any then outstanding shares of Spinco preferred stock.

Voting Rights. Holders of Spinco common stock will be entitled to one vote for each share held of record on all matters submitted to a vote of Spinco shareholders. With certain exceptions, at a duly called Spinco shareholder meeting at which a quorum is present the vote of the holders of a majority of the voting power of the shares of stock present in person or represented by proxy and entitled to vote on the subject matter shall decide any question brought before such meeting. Except with respect to vacancies and newly created directorships, our amended and restated bylaws will provide that the board’s directors are elected by the vote of a plurality of the votes cast with respect to that director in respect of the shares present in person or represented by proxy at the meeting and entitled to vote on the election of directors. Our amended and restated certificate of formation will not provide for cumulative voting.

Other Rights. In the event of Spinco’s liquidation, dissolution, or winding up, the holders of Spinco common stock will be entitled to share ratably in all assets remaining after satisfaction of liabilities and the liquidation preference of any then outstanding shares of Spinco preferred stock. Holders of Spinco common stock will have no preemptive rights and no right to convert their Spinco common stock into any other securities. There will be no redemption or sinking fund provisions applicable to the Spinco common stock. The rights, preferences, and privileges of holders of Spinco common stock will be subject to, and could be adversely affected by, the rights of holders of shares of any series of Spinco preferred stock which Spinco may designate and issue in the future without further Spinco shareholder approval.

Listing. We intend to apply to list Spinco common stock on Nasdaq under the symbol “AXM.”


206


Table of Contents

Preferred Stock

The Spinco Board of Directors will have the authority, within the limitations and restrictions that will be stated in the Spinco amended and restated certificate of formation, to authorize the issuance of shares of Spinco preferred stock in one or more classes or series, and to fix each such class or series such voting powers, fully or limited, or no voting powers, and such designations, preferences and relative, participating, optional, or other special rights and such qualifications, limitations, or restrictions of the shares of each class or series, including the dividend rights, dividend rates, conversion rights, voting rights, terms of redemption, redemption price or prices, liquidation preferences, and the number of shares constituting any series or designations of any series.

Anti-Takeover Effect of Our Certificate of Formation and Bylaws and Texas Law

Certain provisions of our amended and restated certificate of formation, our amended and restated bylaws and the TBOC could have the effect of delaying, deferring, or discouraging another party from acquiring Spinco. These provisions encourage persons considering unsolicited tender offers or other unilateral takeover proposals to negotiate with the Spinco Board of Directors rather than pursue non-negotiated takeover attempts. These provisions include the below summarized items.

Texas Business Combination Law. Spinco is subject to the provisions of Title 2, Chapter 21, Subchapter M of the TBOC, referred to herein as the “Texas Business Combination Law.” Under the TBOC, a Texas “issuing public corporation” is generally prohibited from, directly or indirectly, entering into specified transactions with an “affiliated shareholder,” or with any affiliate or associate of an affiliated shareholder, for a period of three years after the date the shareholder obtained affiliated shareholder status. The prohibited transactions include mergers, share exchanges or conversions; dispositions of assets having an aggregate market value of ten percent or more of the corporation’s consolidated assets, the aggregate market value of its outstanding voting stock, or its earning power or net income on a consolidated basis; issuances or transfers of shares to an affiliated shareholder or its affiliates or associates; liquidation or dissolution plans or proposals; transactions, including reclassifications, share distributions and recapitalizations, that have the effect of increasing the affiliated shareholder’s proportionate ownership percentage; and loans, advances, guarantees, pledges or other financial assistance, or tax credits or other tax advantages, the recipient of which is an affiliated shareholder or its affiliates or associates. The TBOC defines an “issuing public corporation” as a Texas corporation that has 100 or more shareholders of record as shown by its share transfer records, a class or series of voting shares registered under the Exchange Act, or a class or series of voting shares qualified for trading on a national securities exchange. The prohibition does not apply if:


the board of directors of the corporation approves the transaction or the acquisition of shares by the affiliated shareholder before the affiliated shareholder becomes an affiliated shareholder; or


the holders of at least two-thirds of the outstanding voting shares not beneficially owned by the affiliated shareholder or an affiliate or associate of the affiliated shareholder approve the transaction at a meeting of shareholders called for that purpose and held no earlier than six months after the shareholder acquires such ownership. The TBOC expressly provides that this shareholder approval may not be given by written consent.

The TBOC generally defines an “affiliated shareholder” as a person who beneficially owns, or has owned within the preceding three-year period, twenty percent or more of the outstanding voting stock of a Texas public corporation. A corporation may expressly elect in its certificate of formation or bylaws not to be governed by the Texas Business Combination Law. Neither the amended and restated certificate of formation nor the amended and restated bylaws contains such an election, and Spinco therefore expects to remain subject to the Texas Business Combination Law. As a result, the Texas Business Combination Law may have the effect of inhibiting a non-negotiated merger or other business combination involving Spinco, even if such a transaction would be beneficial to Spinco’s shareholders.


207


Table of Contents

Special Shareholder Approval for Certain Transactions. Under the TBOC, unless otherwise provided for in the TBOC or the certificate of formation, shareholders holding at least two-thirds of the outstanding shares of a class entitled to vote on the matter must typically approve fundamental business transactions such as a merger, an interest exchange, a conversion, or a sale of all or substantially all of the corporation’s assets that is not made in the usual and regular course of the corporation’s business, and the certificate of formation may provide for a different threshold, but not less than a majority of the shares entitled to vote. To the maximum extent permitted by the TBOC, but subject to the rights, if any, of the holders of Common Stock or Preferred Stock as specified in the amended and restated bylaws, in the amended and restated certificate of formation, or in any certificate of designation, the affirmative vote of shareholders holding at least two-thirds of the voting power of all of the then-issued and outstanding shares of stock entitled to vote on the matter is sufficient to approve, authorize, adopt, or to otherwise cause the Company to take, or affirm the Company’s taking of, any “fundamental action” or any “fundamental business transaction,” each as defined in the TBOC. When voting as a single class, no class of shares that does not have voting rights has any right to participate in such vote.

Board Composition and Powers. The Spinco Board of Directors will have the power to fix the number of directors by resolution. The directors, other than any directors elected by the holders of a series of preferred stock, will be divided into three classes, as nearly equal in number as is reasonably possible, with the initial term of office of the first class to expire at the first annual meeting of shareholders following the effective date of the amended and restated certificate of formation, the initial term of office of the second class to expire at the second annual meeting of shareholders following the effective date of the amended and restated certificate of formation, and the initial term of office of the third class to expire at the third annual meeting of shareholders following the effective date of this amended and restated certificate of formation, with each director to hold office until his or her successor shall have been duly elected and qualified, subject, however, to such director’s earlier death, resignation, disqualification or removal, and the Spinco Board of Directors shall be authorized to assign members of the Spinco Board of Directors, other than those directors who may be elected by the holders of any series of preferred stock, to such classes. At each annual meeting of shareholders, directors elected to succeed those directors whose terms then expire shall be elected for a term of office to expire at the third succeeding annual meeting of shareholders after their election, with each director to hold office until his or her successor shall have been duly elected and qualified, subject, however, to such director’s earlier death, resignation, disqualification or removal. Subject to the rights of any series of Preferred Stock to elect additional directors under specified circumstances, neither the Spinco Board of Directors nor any individual director may be removed without cause. Subject to any limitations imposed by applicable law, any individual director or directors may be removed with cause by the affirmative vote of the holders of a majority of the voting power of all of the then-issued and outstanding shares of stock entitled to vote generally at an election of directors, voting together as a single class. Vacancies and newly created directorships resulting from any increase in the authorized number of directors may be filled in any manner permitted by the TBOC, including by the affirmative vote of a majority of the Spinco Board of Directors then in office, provided that in the case of a newly created directorship resulting from an increase in the number of directors a quorum is present, and, in the case of any other vacancy, even if less than a quorum, or by a sole remaining director. Under the TBOC, the Spinco Board of Directors may not fill more than two vacancies caused by an increase in the size of the board between any two annual meetings of shareholders, and any director appointed by the board of directors to fill a newly created directorship resulting from an increase in the number of directors may serve only until the next annual election of directors by the shareholders.

Advance Notice Requirements for Shareholder Proposals and Director Nominations. The amended and restated bylaws will provide that in order for a Spinco shareholder to make a nomination or propose business at an annual meeting of Spinco shareholders, a Spinco shareholder’s notice must be delivered to Spinco not less than ninety (90) days nor more than one hundred and twenty (120) days prior to the first anniversary of the preceding year’s annual meeting; provided, however, that if the annual meeting date is advanced by more than thirty (30) days, or delayed by more than seventy (70) days, from the anniversary date of the previous year’s meeting, or if no annual meeting was held in the preceding year, notice by the shareholder in order to be timely must be so delivered not earlier than hundred and twenty (120) days prior to such annual meeting and not later than the close of business


208


Table of Contents

on the later of the ninetieth 90th day prior to such annual meeting or the tenth (10th) day following the day on which public announcement of the date of such meeting is first made by Spinco. Public announcement of an adjournment or postponement of an annual meeting will not commence a new time period, or extend any time period, for the giving of a shareholder’s notice.

Share Ownership Threshold for Shareholder Proposals. The amended and restated bylaws affirmatively elect for Spinco to be governed by Section 21.373 of the TBOC. Accordingly, for so long as the Spinco is a nationally listed corporation within the meaning of Section 21.373 of the TBOC, a shareholder or group of shareholders may submit a proposal for approval at a meeting of shareholders (other than a nomination of a person for election as a director or a procedural resolution ancillary to the conduct of the meeting) only if such shareholder or group of shareholders (i) holds shares entitled to vote at the meeting having a market value of at least $1,000,000, determined as of the date the proposal is submitted, or constituting at least three percent (3%) of Spinco’s voting shares, (ii) has held such shares continuously for at least six (6) months before the date of the meeting and holds such shares through the date of the meeting, and (iii) solicits the holders of shares representing at least sixty-seven percent (67%) of the voting power of shares entitled to vote on the proposal.

Ownership Threshold for Derivative Proceedings. No shareholder or group of shareholders may institute or maintain a derivative proceeding brought on behalf of Spinco against any director or officer in his or her official capacity unless the shareholder or group, at the time the derivative proceeding is instituted, beneficially owns a number of shares of common stock sufficient to meet an ownership threshold of at least three percent of the outstanding shares of Spinco. If the TBOC is amended to increase the maximum allowable minimum ownership threshold, the threshold in the amended and restated certificate of formation will automatically increase to match it, without any further action by Spinco or its shareholders.

Special Meetings of Shareholders. Under the TBOC, a corporation may not prohibit its shareholders from calling a special meeting of shareholders. Special meetings of the shareholders may be called at any time by (i) the chairperson of the Spinco Board of Directors, (ii) a majority of the authorized number of directors, (iii) to the extent required by the TBOC, the president, or (iv) the holders of not less than [20]% of the voting power of Spinco’s then issued and outstanding shares of stock entitled to vote at such special meeting.

Undesignated Preferred Stock. Pursuant to the amended and restated certificate of formation, Spinco will be able to issue preferred stock in one or more series, with such designations, powers, preferences and rights as the Spinco Board of Directors may determine, without further shareholder approval, subject to any shareholder votes or consents required by the amended and restated certificate of formation or any Preferred Stock Series Resolution. This authority may delay, defer or prevent a change of control of Spinco.

Shareholder Action by Written Consent

Under the TBOC, shareholders may act without a meeting, without prior notice and without a vote, with the written consent of (1) all shareholders or (2) if authorized by the certificate of formation, the shareholders having at least the minimum number of votes that would be necessary to take the action that is the subject of the consent at a meeting in which each owner or member entitled to vote on the action is present and votes. If less than unanimous written consent is given, the corporation must give prompt notice of the action taken to the non-consenting shareholders. Our amended and restated certificate of formation authorizes action by less than unanimous written consent, providing that any action required or permitted to be taken at a meeting of the shareholders may be taken without a meeting, without prior notice and without a vote, if a consent or consents in writing, setting forth the actions to be so taken, is signed by the holders of stock having not less than the minimum number of votes that would be necessary to authorize or take such action at a meeting at which all shares entitled to vote thereon were present and voted, in a manner that complies with the requirements of the TBOC. Such written consent must be delivered to Spinco in the manner set forth in the amended and restated bylaws or to an officer or agent of Spinco having custody of the book in which proceedings of meetings are


209


Table of Contents

recorded. The amended and restated bylaws permit shareholder action by written consent only to the extent permitted by and in the manner provided in the amended and restated certificate of formation and in accordance with the TBOC.

Authorized but Unissued Shares

Subject to the requirements of Nasdaq and other applicable law, authorized but unissued shares of Spinco common stock may be available for future issuance without shareholder approval. Spinco may use these additional shares for a variety of corporate purposes, including future public offerings to raise additional capital, corporate acquisitions, and employee benefit plans. The existence of authorized but unissued shares of Spinco common stock could render more difficult or discourage an attempt to obtain control of Spinco by means of a proxy contest, tender offer, merger or otherwise. Subject to the provisions of any Preferred Stock Series Resolution (as defined in the amended and restated certificate of formation, no holder of shares of stock of Spinco shall have any preemptive or other rights, except as such rights are expressly provided by contract, to purchase or subscribe for or receive any shares of any class, or series thereof, of stock of Spinco, whether now or hereafter authorized, or any warrants, options, bonds, debentures or other securities convertible into, exchangeable for or carrying any right to purchase any shares of any class, or series thereof, of stock of Spinco; but, subject to the provisions of any Preferred Stock Series Resolution, such additional shares of stock and such warrants, options, bonds, debentures or other securities convertible into, exchangeable for or carrying any right to purchase any shares of any class, or series thereof, of stock of the Corporation may be issued or disposed of by the Spinco Board of Directors to such Persons, and on such terms and for such lawful consideration, as in its discretion it shall deem advisable or as to which Spinco shall have by binding contract agreed.

Amendment of Provisions in Certificate of Formation and Bylaws

Under the TBOC, subject to limited exceptions, an amendment to the certificate of formation requires the approval of the board of directors and the holders of at least two-thirds of the outstanding shares of a Texas corporation, unless a different threshold, not less than a majority, is specified in the certificate of formation. In lieu of the vote required under Section 21.364 of the TBOC, and subject to any other vote required by the amended and restated certificate of formation, the affirmative vote of shareholders holding at least a majority of the voting power of all outstanding shares of capital stock entitled to vote, voting together as a single class, will be required to amend, alter, repeal or adopt any provision of our amended and restated certificate of formation. The amended and restated bylaws will provide that our amended and restated bylaws, or any of them, may be altered, amended, or repealed, and new bylaws may be adopted, (i) by the Spinco Board of Directors, unless the amended and restated certificate of formation or the laws of the State of Texas reserve the power exclusively to the shareholders in whole or in part, or the shareholders, in amending, repealing or adopting a particular bylaw, expressly provide that the Spinco Board of Directors may not amend or repeal such bylaw, or (ii) by the affirmative vote of the holders of a majority of the voting power of all of the then-issued and outstanding shares of stock entitled to vote thereon, even though the bylaws may also be amended, repealed or adopted by the Spinco Board of Directors.

Exclusive Forum and Waiver of Jury Trial

Our amended and restated certificate of formation will provide that, unless we consent in writing to the selection of an alternative forum, the Texas Business Court in the Third Business Court Division of the State of Texas (the “Austin Business Court”) will be the sole and exclusive forum for (i) any derivative action or proceeding brought on our behalf, (ii) any action asserting a claim of breach of a fiduciary duty owed by any director or officer or shareholder of Spinco to Spinco or the Spinco’s shareholders, (iii) any action asserting a claim against us or any of our current or former directors, officers, employees, or shareholders arising pursuant to any provision of the TBOC, or our amended and restated certificate of formation or our amended and restated bylaws, (iv) any action


210


Table of Contents

asserting a claim against us or any of our directors, officers, employees or shareholders governed by the internal affairs doctrine, (v) any action asserting an “internal entity claim” as that term is defined in Section 2.115 of the TBOC, or (vi) any other action or proceeding in which the Business Court of the State of Texas has jurisdiction. If the Austin Business Court lacks jurisdiction or otherwise may not, or may decline to, hear the applicable cause of action, the forum will be the Texas Business Court in the First Business Court Division of the State of Texas (the “Dallas Business Court”), and if the Dallas Business Court lacks jurisdiction or otherwise may not, or may decline to, hear the applicable cause of action, the United States District Court for the Western District of Texas, Austin Division, and if that court lacks jurisdiction or otherwise may not, or may decline to, hear the applicable cause of action, the state district court of Travis County, Texas. Our amended and restated certificate of formation will also provide that, unless we consent in writing to the selection of an alternative forum, the federal district courts of the United States of America will, to the fullest extent permitted by law, be the sole and exclusive forum for resolving any complaint asserting a cause of action arising under the Securities Act.

Our amended and restated certificate of formation also contains a waiver of jury trial providing that: TO THE FULLEST EXTENT PERMITTED BY THE TBOC, UNLESS THE CORPORATION CONSENTS IN WRITING TO A JURY TRIAL, THE CORPORATION AND EACH SHAREHOLDER, DIRECTOR, OFFICER AND EMPLOYEE OF THE CORPORATION HEREBY IRREVOCABLY AND UNCONDITIONALLY WAIVE ANY RIGHT THAT THE CORPORATION OR SUCH PERSON MAY HAVE TO A TRIAL BY JURY IN ANY LEGAL ACTION, PROCEEDING, CAUSE OF ACTION, COUNTERCLAIM, CROSS-CLAIM OR THIRD-PARTY CLAIM ARISING OUT OF OR RELATING TO ANY “INTERNAL ENTITY CLAIM” AS THAT TERM IS DEFINED IN SECTION 2.115 OF THE TBOC, AND EACH SHAREHOLDER AGREES THAT SUCH SHAREHOLDER’S HOLDING OR ACQUISITION OF SHARES OF STOCK OF THE CORPORATION OR, TO THE EXTENT PERMITTED BY LAW, OPTIONS OR RIGHTS TO ACQUIRE SHARES OF STOCK OF THE CORPORATION FOLLOWING THE ADOPTION OF THIS AMENDED AND RESTATED CERTIFICATE OF FORMATION CONSTITUTES SUCH SHAREHOLDER’S INTENTIONAL AND KNOWING WAIVER OF ANY RIGHT TO TRIAL BY JURY WITH RESPECT TO SUCH CLAIMS. Under Texas law, a party in a civil case generally has a right to a jury trial to determine questions of fact if the party timely demands a jury and pays the jury fee, but a corporation may include a waiver of jury trial in its governing documents.

Moreover, Section 27 of the Exchange Act creates exclusive federal jurisdiction over all claims brought to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder and our amended and restated certificate of formation will provide that the exclusive forum provision does not apply to suits brought to enforce any duty or liability created by the Exchange Act. Accordingly, actions by our shareholders to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder must be brought in federal court.

Our amended and restated certificate of formation will also provide that any person or entity purchasing or otherwise acquiring any interest in any security of Spinco will be deemed to have notice of and to have consented to the foregoing provisions; provided, however, that shareholders will not be deemed to have waived our compliance with the federal securities laws and the rules and regulations thereunder. We recognize that the forum selection clause in our amended and restated certificate of formation may impose additional litigation costs on shareholders in pursuing any such claims, particularly if the shareholders do not reside in or near the State of Texas. Additionally, the forum selection clause in our amended and restated certificate of formation may limit the ability of our shareholders to bring a claim in a forum that they find favorable for disputes with us or our directors, officers, employees, or agents, which may discourage such lawsuits against us and our directors, officers, employees, and agents even though an action, if successful, might benefit our shareholders. The Texas Business Court may also reach different judgments or results than would other courts, including courts where a shareholder considering an action may be located or would otherwise choose to bring the action, and such judgments may be more or less favorable to us than our shareholders. The Texas Business Court was recently established as a specialized trial court created to resolve certain complex business disputes, and a meaningful body of case law interpreting the recent amendments to the TBOC has not yet developed.


211


Table of Contents

For more information on the risks associated with our choice of forum provision, see “Risk Factors—Risks Related to Our Common Stock—Our amended and restated certificate of formation will contain an exclusive forum provision, and a waiver of the right to trial by jury for any “internal entity claim,” that could limit a shareholder’s ability to bring a claim in a judicial forum that the shareholder believes is favorable for such disputes and may discourage lawsuits against us and any of our directors, officers, or other employees.”

Comparison of Rights of Spinco Shareholders and Flex Shareholders

On the terms and subject to the conditions set forth in the Separation Agreement, Flex shareholders will receive shares of Spinco common stock pursuant to the Spin-Off. Flex is incorporated under the laws of Singapore, and Spinco is incorporated under the laws of the state of Texas. The rights of Flex shareholders with respect to such shares of Spinco common stock in the Spin-Off will be governed by Spinco’s certificate of formation and bylaws, rather than by the applicable laws of Singapore and Flex’s Constitution. As a result, Flex shareholders will have different rights with respect to their ownership of Spinco common stock once they become Spinco shareholders due to the differences in the organizational documents of Flex and Spinco and applicable law.


Axiom Solutions International, Inc. (Texas)    Flex Ltd. (Singapore)
Board of Directors

Under the TBOC, the number of directors will be set by, or in the manner provided by, the certificate of formation or bylaws, except that the number of directors on the initial board of directors must be set by the certificate of formation.


The number of directors may be increased or decreased by amendment to, or as provided by, the certificate of formation or bylaws.


If the certificate of formation or bylaws do not set the number constituting the board of directors or provide for the manner in which the number of directors must be determined, the number of directors is the same as the number constituting the initial board of directors as set by the certificate of formation.


Our amended and restated certificate of formation provides that the business affairs of the Company shall be managed by or under the direction of the Spinco Board of Directors. The number of directors shall be determined in accordance with the amended and restated bylaws. The directors are divided into three classes, as nearly equal in number as is reasonably possible, with staggered three-year terms.


Flex’s Constitution provides that the number of directors shall not be less than two nor, unless otherwise determined by Flex in a general meeting, more than 12.

Limitation on Personal Liability of Directors

Under the TBOC, a Texas corporation is permitted to provide in the certificate of formation that a director or officer is not liable, or is liable only to the extent provided by the certificate of formation, to the corporation or its shareholders for monetary damages


Pursuant to the Singapore Companies Act, any provision (whether in the constitution, contract or otherwise) purporting to exempt or indemnify a director (to any extent) from or against any liability attaching in connection with any negligence, default,


212


Table of Contents

for an act or omission by the person in the person’s capacity as a director or officer.


The TBOC, however, does not permit any limitation of the liability of a director or officer for: (1) a breach of the duty of loyalty to the corporation or its shareholders; (2) an act or omission not in good faith that constitutes a breach of duty of the person to the corporation or involves intentional misconduct or a knowing violation of law; (3) a transaction from which the director or officer obtains an improper benefit, regardless of whether the benefit resulted from an action taken within the scope of the person’s duties; or (4) an act or omission for which the liability of a director or officer is expressly provided by an applicable statute (such as wrongful distributions).


Our amended and restated certificate of formation provides that, to the fullest extent permitted by the TBOC, as it presently exists or may hereafter be amended, no director or officer of the Company shall be personally liable to the Company or its shareholders for monetary damages for breach of fiduciary duty as a director or officer, as applicable, except for such liability as is expressly not subject to limitation under the TBOC, as the same exists or may hereafter be amended to further eliminate such liability. Any repeal or amendment of the foregoing by the shareholders of the Company or by change in law, or the adoption of any provision inconsistent with the foregoing, will, unless otherwise required by law, be prospective only (except to the extent such amendment or change in law permits the Corporation to further limit or eliminate the liability of directors or officers) and shall not adversely affect any right or protection of a director or officer of the Corporation existing at the time of such repeal or amendment of such inconsistent provision with respect to acts or omissions occurring prior to such repeal or amendment or adoption of such inconsistent provision. If the TBOC is amended to authorize corporate action further eliminating or limiting the personal liability of directors or officers, then the liability of a director or officer of the Corporation shall be eliminated or limited to the fullest extent permitted by the TBOC, as so amended.


breach of duty or breach of trust in relation to Flex will be void except as permitted under the Singapore Companies Act.


Flex’s Constitution provides that, subject to the provisions of the Singapore Companies Act and every other act for the time being in force concerning companies and affecting Flex, every director, auditor, secretary or other officer of Flex is entitled to be indemnified by Flex against all costs, charges, losses, expenses and liabilities incurred or to be incurred by such person in the execution and discharge of such person’s duties (including, without limitation, where such person serves at the request of Flex as a director, officer, employee or agent of another corporation, partnership, joint venture or other enterprise) or in relation thereto.


In addition, Flex’s Constitution provides that no director, secretary or other officer of Flex will be liable for the acts, receipts, neglects or defaults of any other director or officer or for joining in any receipt or other act for conformity or for any loss or expense happening to Flex through the insufficiency or deficiency of title to any property acquired by order of the directors for or on behalf of Flex or for the insufficiency or deficiency of any security in or upon which any of the moneys of Flex shall be invested or for any loss or damage arising from the bankruptcy, insolvency or tortious act of any person with whom any moneys, securities or effects will be deposited or left or for any other loss, damage or misfortune whatever which shall happen in the execution of the duties of such person’s office or in relation thereto unless the same happens through such person’s own negligence, willful default, breach of duty or breach of trust.

Interested Shareholders Business Judgment Rule

Our amended and restated certificate of formation provides that the Company affirmatively elects to be governed by Section 21.419 of the TBOC and any successor provisions thereto, which codifies the business judgment rule and establishes a statutory presumption


There are no comparable provisions under Flex’s Constitution or under the Singapore Companies Act in respect of competing with, or referring corporate opportunities to, controlling shareholders that apply


213


Table of Contents

that directors and officers, in making business decisions, acted in good faith, on an informed basis, in furtherance of the interests of the corporation and in obedience to the law and the corporation’s governing documents.


to public companies which are not listed on the Singapore Exchange Securities Trading Limited.

Removal of Directors

Under the TBOC, subject to the exceptions discussed below or as otherwise provided by the certificate of formation or bylaws of a corporation, the holders of a majority of shares then entitled to vote at an election of directors may remove a director or the entire board of directors with or without cause.


Unless the certificate of formation provides otherwise, if a Texas corporation’s directors serve staggered terms, a director may be removed only for cause.


Where the certificate of formation provides that separate classes or series of shareholders are entitled, as such a class or series, to elect separate directors, in calculating the sufficiency of votes for removal of such a director, only the votes of the holders of such a class or series are considered.


Our amended and restated certificate of formation provides that, subject to the rights of any series of Preferred Stock to elect additional directors under specified circumstances, neither the Spinco Board of Directors nor any individual director may be removed without cause. Subject to any limitations imposed by applicable law, any individual director or directors may be removed with cause by the affirmative vote of the holders of a majority of the voting power of all of the then-issued and outstanding shares of stock entitled to vote generally at an election of directors, voting together as a single class.


According to the Singapore Companies Act, directors of a public company may be removed before expiration of their term of office with or without cause by ordinary resolution (i.e., a resolution which is passed by a simple majority of those shareholders present and voting in person or by proxy). Special notice of the intention to move such a resolution has to be given to Flex not less than 28 days before the meeting at which it is moved. Flex shall then give notice of such resolution to its shareholders not less than 14 days before the meeting. Where any director removed in this manner was appointed to represent the interests of any particular class of shareholders or debenture holders, the resolution to remove such director will not take effect until such director’s successor has been appointed.


Flex’s Constitution provides that Flex may by ordinary resolution of which special notice has been given remove any director before the expiration of such director’s period of office, notwithstanding anything in Flex’s Constitution or in any agreement between Flex and such director but without prejudice to any claim such director may have for damages for breach of any such agreement.

Filling Vacancies on the Board of Directors

Under Section 21.410 of the TBOC, a vacancy may be filled by election at an annual or special meeting of shareholders or by the affirmative vote of a majority of the remaining directors, even if less than a quorum, and a director elected to fill a vacancy serves for the unexpired term of his or her predecessor. A directorship created by an increase in the number of directors may be filled by the shareholders or by the board of directors, but a director appointed by the board to a newly-created directorship serves only until the next election of directors by the shareholders, and the board of directors may not fill more than two newly created directorships between successive annual meetings of shareholders.


Flex’s Constitution provides that the directors shall have power at any time and from time to time to appoint any person to be a director either to fill a casual vacancy or as an additional director but so that the total number of directors will not at any time exceed the maximum number fixed by or in accordance with Flex’s Constitution.


In addition, Flex’s Constitution provides that the shareholders in a general meeting may appoint another person in place of a director so removed from office in accordance with the Singapore Companies Act and Flex’s Constitution, provided that the procedural requirements and deadlines set forth in the


214


Table of Contents


Our amended and restated certificate of formation provides that any newly-created directorship resulting from an increase in the number of directors may be filled in any manner permitted by the TBOC, including by the affirmative vote of a majority of the directors then in office, provided that a quorum is present, and that any other vacancy on the Spinco Board of Directors may be filled in any manner permitted by TBOC, including by the affirmative vote of a majority directors then in office, even if less than a quorum, or by a sole remaining director.


Our amended and restated certificate of formation provides a director elected to fill a vacancy not resulting from an increase in the number of directors holds office for the remaining term of his or her predecessor unless otherwise determined by the Spinco Board of Directors.


Singapore Companies Act and Flex’s Constitution have been satisfied.

Amendment of Governing Documents

Under the TBOC, subject to limited exceptions, an amendment to the certificate of formation requires the approval of (1) the board of directors and (2) the holders of at least two-thirds of the outstanding shares of a Texas corporation, unless a different threshold, not less than a majority, is specified in the certificate of formation.


If a class or series of shares is entitled to vote as a class or series on an amendment to the certificate of formation, the affirmative vote of the holders of at least two-thirds, unless a different threshold, not less than a majority, is specified in the certificate of formation, of the outstanding shares in each such class or series of shares entitled to vote on the amendment as a class or series is also required to approve an amendment to the certificate of formation, although the TBOC allows corporations to provide that all shares vote as a single class for such an amendment.


In addition, the TBOC also allows corporations to provide in their certificate of formation that no separate class vote or votes will be required to increase or decrease the aggregate number of authorized shares of a class, in which case a share increase or decrease amendment would instead be approved by the holders of all outstanding shares, voting together as a single class.


Our amended and restated certificate of formation provides that the affirmative vote of shareholders holding at least a majority of the voting power of all outstanding shares of capital stock entitled to vote, voting together as a single class, shall be required to amend, alter, repeal or adopt any provision as part of the amended and restated certificate of formation.


Flex’s Constitution may be altered by special resolution (i.e., a resolution passed by at least a three-fourths majority of the shares entitled to vote, present in person or by proxy at a meeting for which not less than 21 days’ written notice is given). The Flex Board of Directors has no right to amend Flex’s Constitution.


215


Table of Contents


Under the TBOC, the board of directors generally may amend, repeal or adopt a Texas corporation’s bylaws. However, (1) the shareholders may amend, repeal or adopt bylaws even if the directors also have that power and (2) a Texas corporation’s certificate of formation may wholly or partly reserve the power to amend, repeal or adopt bylaws exclusively to the shareholders. Similarly, the shareholders, in amending, repealing or adopting a particular bylaw, may expressly provide that the board of directors may not amend, readopt or repeal that bylaw.


The Spinco Board of Directors is expressly authorized to amend, alter or repeal the amended and restated bylaws, in whole or in part, or adopt new bylaws, without any action on the part of the shareholders; provided, that bylaws adopted or amended by the Spinco Board of Directors may be amended, altered or repealed by the shareholders.

  
Meetings of Shareholders

Annual and Special Meetings


Under the TBOC, an annual meeting of shareholders must be held at a time stated in or fixed in accordance with the corporation’s bylaws. If an annual meeting is not held, or a written consent in lieu of an annual meeting is not executed, within any 13-month period, a shareholder who has previously requested the meeting in writing may apply to a court for an order that the meeting be held. Any such application may be subject to the exclusive forum provisions in our amended and restated certificate of formation.


Our amended and restated bylaws provides that annual meetings of shareholders may be held at such place, time and date as the Spinco Board of Directors shall determine.


Under the TBOC, special meetings of the shareholders of a corporation may be called by (1) the president, the board of directors, or any other person authorized to call special meetings by the certificate of formation or bylaws of the corporation or (2) the holders of the percentage of shares specified in the certificate of formation, not to exceed 50% of all of the shares of the corporation entitled to vote at the proposed special meeting or, if no percentage is specified, at least 10% of all of the shares of the corporation entitled to vote at the proposed special meeting. Under the TBOC, a corporation may not prohibit its shareholders from calling a special meeting of shareholders.


Annual General Meetings


All companies are required to hold an annual general meeting once every calendar year. Annual general meetings must be held within six months after Flex’s financial year end.


Flex’s Constitution provides that Flex will hold an annual general meeting in accordance with the provisions of The Singapore Companies Act.


Extraordinary General Meetings


Any general meeting other than the annual general meeting is called an “extraordinary general meeting.”


The Singapore Companies Act provides that two or more members (shareholders) holding not less than 10% of the total number of issued shares (excluding treasury shares) may call an extraordinary general meeting.


The Singapore Companies Act provides that the directors of a company, despite anything in its constitution, must convene a general meeting if required to do so by requisition (i.e., written notice to directors requiring that a meeting be called) by shareholder(s) holding not less than 10% of the total number of paid-up shares carrying voting rights.


Flex’s Constitution provides that the directors may, whenever they think fit, convene an extraordinary general meeting and extraordinary general meetings will also be convened on such requisition or, in


216


Table of Contents


Our amended and restated certificate of formation and amended and restated bylaws provide that special meetings of the shareholders may be called at any time by (i) the chairperson of the Spinco Board of Directors, (ii) a majority of the authorized number of directors, (iii) to the extent required by the TBOC, the president, or (iv) the holders of not less than [20]% of the voting power of Company’s then issued and outstanding shares of stock entitled to vote at such special meeting.


Quorum Requirements


Under the TBOC, subject to the following sentence, the holders of the majority of the shares entitled to vote at a meeting of the shareholders of a Texas corporation that are present or represented by proxy at the meeting are a quorum for the consideration of a matter to be presented at that meeting. The certificate of formation of a corporation may provide that a quorum is present only if (1) the holders of a specified portion of the shares that is greater than the majority of the shares entitled to vote are represented at the meeting in person or by proxy or (2) the holders of a specified portion of the shares that is less than the majority but not less than one-third of the shares entitled to vote are represented at the meeting in person or by proxy.


Subject to the following sentence, directors of a corporation will be elected by a plurality of the votes cast by the holders of shares entitled to vote in the election of directors at a meeting of shareholders at which a quorum is present. The certificate of formation or bylaws of a corporation may provide that a director of a corporation will be elected only if the director receives: (1) the vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote in the election of directors; (2) the vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote in the election of directors and represented in person or by proxy at a meeting of shareholders at which a quorum is present; or (3) the vote of the holders of a specified portion, but not less than the majority, of the votes cast by the holders of shares entitled to vote in the election of directors at a meeting of shareholders at which a quorum is present.


Subject to the following paragraph, with respect to a matter other than the election of directors or a matter for which the affirmative vote of the holders of a specified portion of the shares entitled to vote is required by the TBOC, the affirmative vote of the holders of the majority of the shares entitled to vote on, and who voted for, against, or expressly abstained with respect to, the matter at a shareholders’ meeting of a corporation at which a quorum is present is the act of the shareholders.


default, may be convened by such requisitionists, as provided under the Singapore Companies Act.


Quorum Requirements


Flex’s Constitution provides that a quorum at any general meeting consists of members holding in the aggregate not less than 33 1/3% of the total number of issued and fully paid shares in the capital of Flex for the time being, present in person or by proxy. In the event a quorum is not present, (a) the meeting (if not requisitioned by registered shareholders) may be adjourned for one week and (b) the meeting shall be dissolved if the meeting was requisitioned by registered shareholders.


217


Table of Contents


With respect to a matter other than the election of directors or a matter for which the affirmative vote of the holders of a specified portion of the shares entitled to vote is required by the TBOC, the certificate of formation or bylaws of a corporation may provide that the act of the shareholders of the corporation is: (1) the affirmative vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote on that matter; (2) the affirmative vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote on that matter and represented in person or by proxy at a shareholders’ meeting at which a quorum is present; (3) the affirmative vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote on, and who voted for or against, the matter at a shareholders’ meeting at which a quorum is present; or (4) the affirmative vote of the holders of a specified portion, but not less than the majority, of the shares entitled to vote on, and who voted for, against, or expressly abstained with respect to, the matter at a shareholders’ meeting at which a quorum is present.


Our amended and restated bylaws provide that, unless otherwise required by applicable law, the amended and restated certificate of formation or the rules or regulations of any stock exchange upon which our securities are listed, the holders of record of a majority of the voting power of the issued and outstanding shares of capital stock entitled to vote thereon, present in person or represented by proxy, will constitute a quorum for the transaction of business at all meetings of shareholders. Where a separate vote by a class or series or classes or series is required, a majority in voting power of the outstanding shares of such class or series or classes or series, present in person or represented by proxy, constitutes a quorum entitled to take action with respect to the vote on that matter. Once a quorum is present to organize a meeting, it will not be broken by the subsequent withdrawal of any shareholders or by the refusal of any shareholder present or represented by proxy at such meeting to vote.


Our amended and restated bylaws further provide that, when a quorum is present or represented at any meeting, the vote of the holders of a majority of the voting power of the shares of stock present in person or represented by proxy and entitled to vote on the subject matter will decide any question brought before such meeting, unless the question is one upon which a different vote is required by express provision of applicable law, the rules or regulations of any stock exchange applicable to the Company, any regulation applicable to the Company


218


Table of Contents

or its securities, the amended and restated certificate of formation or the amended and restated bylaws, in which case such express provision will govern and control the decision of such question. Because this standard is measured against shares present and entitled to vote rather than votes cast, an abstention will have the same effect as a vote against a matter other than the election of directors. Notwithstanding the foregoing and subject to the amended and restated certificate of formation, all elections of directors will be determined by a plurality of the votes cast at the meeting by the holders of shares entitled to vote on the election of directors. Because directors are elected by a plurality of votes cast, abstentions and broker non-votes will have no effect on the outcome of the election of directors.


[Our amended and restated certificate of formation provides that, at any meeting held for the purpose of electing directors, the presence in person or by proxy of the holders of a majority in voting power of the outstanding shares of capital stock entitled to vote in the election of directors will be required, and, subject to the rights of the holders of any series of preferred stock to elect directors, will be sufficient, to constitute a quorum for the election of directors. The amended and restated bylaws are adopted subject to the amended and restated certificate of formation, and any conflict between the two is resolved in favor of the amended and restated certificate of formation.


Indemnification of Officers, Directors and Employees


Under the TBOC, a Texas corporation may indemnify a director, former director, or delegate who was, is, or is threatened to be made a respondent in a proceeding against (1) judgments and (2) expenses (other than a judgment) reasonably and actually incurred by the person in connection with the proceeding. Indemnification is permitted only if the person (1) acted in good faith, (2) reasonably believed, in the case of conduct in the person’s official capacity, that the person’s conduct was in the corporation’s best interests, and otherwise, that the person’s conduct was not opposed to the corporation’s best interests, and (3) in the case of a criminal proceeding, did not have reasonable cause to believe the person’s conduct was unlawful.


If the director or officer is found liable to the corporation, or is found liable on the basis that the director or officer received an improper personal benefit, indemnification is limited to the reimbursement of reasonable expenses actually incurred in connection with the proceeding, and excludes a judgment, a penalty,


The Singapore Companies Act specifically provides that Flex is allowed to:


purchase and maintain for any officer, insurance against any liability attaching to such officer in respect of any negligence, default, breach of duty or breach of trust in relation to Flex;


indemnify any officer against liability incurred by such officer to a person other than Flex, except when the indemnity is against (i) any liability of such officer to pay a fine in criminal proceedings or a sum payable to a regulatory authority by way of a penalty in respect of non-compliance with any requirement of a regulatory nature (however arising); or (ii) any liability incurred by such officer (1) in defending criminal proceedings in which such officer is convicted, (2) in defending civil proceedings brought by Flex or a related company of Flex in which judgment is given against such officer or (3) in connection with an


219


Table of Contents

a fine, and an excise or similar tax, including an excise tax assessed against the person with respect to an employee benefit plan. In addition, no indemnification will be available if a director or officer is found liable for (1) willful or intentional misconduct in the performance of the person’s duty to the corporation, (2) breach of the person’s duty of loyalty owed to the corporation, or (3) an act or omission not committed in good faith that constitutes a breach of a duty owed by the person to the corporation.


The TBOC requires indemnification of a director for reasonable expenses actually incurred only if the director is wholly successful, on the merits or otherwise, in the defense of the proceeding.


A determination that indemnification is appropriate generally must be made: (1) by a majority vote of the directors who, at the time of the vote, are disinterested and independent, regardless of whether such directors constitute a quorum; (2) by a majority vote of a special committee of the board of directors if the committee is designated by a majority vote of the directors who at the time of the vote are disinterested and independent, regardless of whether such directors constitute a quorum, and is composed solely of one or more directors who are disinterested and independent; (3) by special legal counsel selected by majority vote referred to in clause (1) or (2) above; (4) by the shareholders in a vote that excludes those shares held by directors who, at the time of the vote, are not disinterested and independent; or (5) by a unanimous vote of the shareholders of the corporation.


A corporation may pay or reimburse reasonable expenses incurred by a present director or officer who was, is, or is threatened to be made a respondent in a proceeding in advance of the final disposition of the proceeding, without making the determinations required for permissive indemnification, after the corporation receives (1) a written affirmation by the person of the person’s good faith belief that the person has met the standard of conduct necessary for indemnification and (2) a written undertaking by or on behalf of the person to repay the amount paid or reimbursed if the final determination is that the person has not met that standard or that indemnification is prohibited by the TBOC.


The TBOC generally provides that a corporation may indemnify and advance expenses to a person who is not a director, including an officer, employee, or agent, as provided by (1) the corporation’s governing documents,


application for relief under specified sections of the Singapore Companies Act in which the Singapore court refuses to grant relief to such officer;


indemnify any auditor against any liability incurred or to be incurred by such auditor in defending any proceedings (whether civil or criminal) in which judgment is given in such auditor’s favor or in which such auditor is acquitted; or


indemnify any auditor against any liability incurred by such auditor in connection with any application under specified sections of the Singapore Companies Act in which relief is granted to such auditor by a court.


In cases where, inter alia, an officer is sued by Flex, the Singapore Companies Act gives the Singapore court the power to relieve the officer either wholly or partly from the consequences of their negligence, default, breach of duty or breach of trust. In order for relief to be obtained, it must be shown that (i) the director acted reasonably; (ii) the director acted honestly; and (iii) it is fair, having regard to all the circumstances of the case including those connected with such director’s appointment, to excuse the director.


Flex’s Constitution provides that, subject to the provisions of the Singapore Companies Act and every other act for the time being in force concerning companies and affecting Flex, every director, auditor, secretary or other officer of Flex is entitled to be indemnified by Flex against all costs, charges, losses, expenses and liabilities incurred or to be incurred by such person in the execution and discharge of such person’s duties (including, without imitation, where such person serves at the request of Flex as a director, officer, employee or agent of another corporation, partnership, joint venture or other enterprise) or in relation thereto.


220


Table of Contents

(2) general or specific action of the corporation’s board of directors, (3) resolution of the shareholders, (4) contract, or (5) common law. A corporation must indemnify an officer to the same extent that indemnification is required under the TBOC for a director. A determination of indemnification for a person who is not a director, including an officer, employee, or agent, is not required to be made in accordance with the procedures set out in the relevant sections of the TBOC.


A Texas enterprise is also allowed to purchase or procure, or establish and maintain, insurance or another arrangement to indemnify or hold harmless an existing or former governing person, delegate, officer, employee, or agent against any liability (1) asserted against and incurred by the person in that capacity or (2) arising out of the person’s status in that capacity. The insurance or other arrangement may insure or indemnify against that liability without regard to whether the enterprise otherwise would have had the power to indemnify the person against that liability under the TBOC.


For the benefit of persons to be indemnified by the enterprise, an enterprise may, in addition to purchasing or procuring, or establishing and maintaining, insurance or another arrangement, (1) create a trust fund, (2) establish any form of self-insurance, including a contract to indemnify, (3) secure the enterprise’s indemnity obligation by grant of a security interest or other lien on the assets of the enterprise, or (4) establish a letter of credit, guaranty, or surety arrangement.


Our amended and restated certificate of formation and the amended and restated bylaws require the Company to indemnify each present and former director and officer to the fullest extent authorized by the TBOC, as the same exists or may hereafter be amended (but, in the case of any such amendment, only to the extent that such amendment permits the Corporation to provide broader indemnification rights than such law permitted the Corporation to provide prior to such amendment) against all expense, liability and loss, including attorneys’ fees, judgments, fines, ERISA excise taxes or penalties, and amounts paid in settlement, reasonably incurred in connection with any threatened, pending or completed proceeding, whether civil, criminal, administrative or investigative, arising by reason of such service. Indemnification is not available for a proceeding initiated by the indemnified person unless the Spinco Board of Directors authorized it, other than a proceeding to enforce indemnification or advancement rights, and is not available for settlements made without


221


Table of Contents

Spinco’s consent or for disgorgement of profits under Section 16(b) of the Exchange Act.


The right to indemnification includes advancement of expenses before final disposition, conditioned on delivery of a written undertaking to repay if the person is ultimately determined not to be entitled to indemnification and a written affirmation of the person’s good faith belief that the applicable standard of conduct has been met. If a claim is not paid within the periods specified, the claimant may sue to recover it, and Spinco bears the burden of proving that the claimant is not entitled to indemnification.


Coverage continues after service ends and extends to heirs, executors, and administrators, and the rights conferred are contract rights that may not be impaired retroactively by amendment or repeal. These rights are not exclusive of any other rights available by law, agreement, or shareholder or director action.


We may purchase and maintain insurance, at our expense, covering directors, officers, employees, and agents against any expense, liability or loss, whether or not we would have the power to indemnify the person under the TBOC, and are subrogated to the indemnitee’s recovery rights under any such policy to the extent of our payment. The Spinco Board of Directors may extend indemnification and advancement to employees and agents on the same terms. To the extent required by the TBOC, we will report any indemnification or advancement to shareholders within one year, with or before the notice for the next shareholder meeting or written consent.

  
Shareholder Approval of Business Combinations

Under the TBOC, a Texas “Issuing Public Corporation” is generally prohibited from, directly or indirectly, entering into the following: (1) mergers, share exchanges or conversions with an “Affiliated Shareholder” or other entity that after such transaction would be an affiliate or associate of an Affiliated Shareholder, and certain other entities; (2) sales, leases, exchanges, mortgages, pledges, transfers or other dispositions of assets having an aggregate market value of 10% or more of (a) the aggregate market value of the consolidated assets of such Texas public corporation, (b) the aggregate market value of the outstanding voting stock of such Texas public corporation or (c) the earning power or net income of such Texas public corporation on a consolidated basis; (3) certain transactions that


The Singapore Companies Act mandates that specified corporate actions require approval by the shareholders in a general meeting, notably:


notwithstanding anything in Flex’s Constitution, directors are not permitted to carry into effect any proposals for disposing of the whole or substantially the whole of Flex’s undertaking or property unless those proposals have been approved by shareholders in a general meeting;


subject to the constitution of each amalgamating company, an amalgamation proposal must be approved by the shareholders of each amalgamating company via special resolution at a general meeting; and


222


Table of Contents

would result in the issuance or transfer of shares of such Texas public corporation to an Affiliated Shareholder or an affiliate or associate of an Affiliated Shareholder; (4) liquidation or dissolution plans or proposals with an Affiliated Shareholder or an associate or an affiliate of an associate of an Affiliated Shareholder; (5) certain transactions, including reclassifications of securities or other share distributions or recapitalizations, that have the effect, directly or indirectly, of increasing the proportionate ownership percentage of the outstanding shares of a class or series of voting shares or securities convertible into voting shares of the Issuing Public Corporation that is beneficially owned by the Affiliated Shareholder or an affiliate or associate of the Affiliated Shareholder, except as a result of immaterial changes due to fractional share adjustments; or (6) loans, advances, guarantees, pledges or other financial assistance or a tax credit or other tax advantages the recipient of which is an Affiliated Shareholder or an affiliate or associate of an Affiliated Shareholder, in each case, with an Affiliated Shareholder or any affiliate or associate of the Affiliated Shareholder for a period of three years after the date the shareholder obtained Affiliated Shareholder status.


The TBOC defines “Issuing Public Corporation” as a Texas corporation that has (1) 100 or more shareholders of record as shown by the share transfer records of the corporation, (2) a class or series of the corporation’s voting shares registered under the Exchange Act, or (3) a class or series of the corporation’s voting shares qualified for trading on a national securities exchange.


The TBOC generally defines “Affiliated Shareholder” as a person who beneficially owns (or has owned within the preceding three-year period) 20% or more of the outstanding voting stock of a Texas public corporation.


The TBOC provides an exception to this prohibition if (1) the board of directors of the corporation approves the transaction or the acquisition of shares by the Affiliated Shareholder prior to the Affiliated Shareholder becoming an Affiliated Shareholder or (2) the holders of at least two-thirds of the outstanding voting shares not beneficially owned by the Affiliated Shareholder or an affiliate or associate of the Affiliated Shareholder approve the transaction at a meeting held no earlier than six months after the shareholder acquires such ownership. The TBOC expressly provides that the foregoing shareholder approval may not be by written consent.


notwithstanding anything in Flex’s Constitution, the directors may not, without the prior approval of shareholders, issue shares, including shares being issued in connection with corporate actions.


223


Table of Contents


A corporation may expressly elect in its certificate of formation or bylaws to not be governed by this statute. Neither the amended and restated certificate of formation nor the amended and restated bylaws contains such an election, and we therefore expect to remain subject to the Texas Business Combination Law.


As a result, the Texas Business Combination Law may have the effect of inhibiting a non-negotiated merger or other business combination involving us, even if such a merger or combination would be beneficial to our shareholders.


Under the TBOC, unless otherwise provided in the TBOC or the certificate of formation, shareholders holding at least two-thirds of the outstanding shares of a class entitled to vote on the matter must typically approve fundamental business transactions such as a merger, an interest exchange, a conversion, or a sale of all or substantially all of the corporation’s assets not made in the usual and regular course of business; the certificate of formation may provide for a different threshold, but not less than a majority of the shares entitled to vote.


Our amended and restated certificate of formation exercises that election by providing that, to the maximum extent permitted by the TBOC, but subject to the rights, if any, of the holders of common stock or preferred stock as specified in the bylaws, in the certificate of formation (including Article XI (Amendment of Certificate of Formation)) or in any certificate of designation, the affirmative vote of shareholders holding at least two-thirds of the voting power of all of the then-issued and outstanding shares of stock entitled to vote on the matter shall be sufficient to approve, authorize, adopt or otherwise cause Spinco to take, or affirm Spinco’s taking of, any “fundamental action” or any “fundamental business transaction” (each as defined in the TBOC). When voting as a single class, no class of shares that does not have voting rights has any right to participate in such vote.

  
Shareholder Action Without a Meeting

Our amended and restated certificate of formation provides that any action required or permitted to be taken at a meeting of the shareholders may be taken without a meeting, without prior notice and without a vote, if a consent or consents in writing, setting forth the actions to be so taken, is signed by the holders of stock having not less than the minimum number of votes that would be necessary to authorize or take such action at a meeting at which all shares entitled to vote thereon were


There are no provisions under the Singapore Companies Act in respect of the passing of shareholders’ resolutions by written means that apply to public companies which are listed on a securities exchange. Flex’s Constitution allows, subject to the provisions of the Singapore Companies Act, a resolution in writing signed unanimously by every registered shareholder entitled to vote or, being a corporation, by its duly authorized representative


224


Table of Contents

present and voted, in a manner that complies with the requirements of the TBOC.


Under the TBOC, shareholders may act without a meeting, without prior notice and without a vote, with the written consent of (1) all shareholders or (2) if authorized by the certificate of formation, the shareholders having at least the minimum number of votes that would be necessary to take the action that is the subject of the consent at a meeting at which each shareholder entitled to vote on the action is present and votes; if less than unanimous written consent is given, the Corporation must give prompt notice of the action taken to the non-consenting shareholders. The consent must be delivered to the Corporation in the manner set forth in the Bylaws or to an officer or agent having custody of the book in which proceedings of meetings are recorded. The Bylaws permit action by written consent only to the extent permitted by and in the manner provided in the Certificate of Formation and in accordance with the TBOC.


shall have the same effect and validity as an ordinary resolution of Flex passed at a general meeting duly convened, held and constituted.

Shareholder Suits

Under the TBOC, a shareholder may not institute or maintain a derivative proceeding unless (1) the shareholder was a shareholder at the time of the transaction in question, or became a shareholder by operation of law originating from a person that was a shareholder at that time, and (2) the shareholder fairly and adequately represents the interests of the corporation in enforcing the right of the corporation; publicly traded corporations and corporations with over 500 shareholders may set a share ownership threshold in their governing documents not to exceed 3% of the corporation’s voting shares.


Our amended and restated certificate of formation provides that the Company affirmatively elects to be governed by Section 21.419 of the TBOC. No shareholder or group of shareholders may institute or maintain a derivative proceeding brought on behalf of the Company against any director and/or officer of the Company in his or her official capacity unless the shareholder or group of shareholders, at the time the derivative proceeding is instituted, beneficially owns a number of shares of common stock sufficient to meet an ownership threshold of at least three percent of the outstanding shares of the Company. The amended and restated certificate of formation further provides that if the TBOC is amended to increase the maximum allowable minimum ownership threshold, the ownership threshold shall automatically increase to match the


Derivative actions


The Singapore Companies Act has a provision which provides a mechanism enabling any registered shareholder to apply to the Singapore court for permission to bring a derivative action on behalf of Flex.


In addition to registered shareholders, the Singapore courts are given the discretion to allow such persons as they deem proper to apply (e.g., beneficial owners of shares or individual directors). It should be noted that this provision of the Singapore Companies Act is primarily used by minority shareholders to bring an action in the name and on behalf of the company or intervene in an action to which the company is a party for the purpose of prosecuting, defending or discontinuing the action on behalf of the company. Class actions


The concept of class action suits, which allows individual shareholders to bring an action seeking to represent the class or classes of shareholders, generally does not exist in Singapore. However, it is possible as a matter of procedure for a number of shareholders to lead an action and establish liability on behalf of themselves and other shareholders who join in or who are made parties to the action. Further, there are certain circumstances in which shareholders may file and prove their claims for compensation in


225


Table of Contents

maximum allowable minimum ownership threshold allowed under the TBOC, without any further action by us or our shareholders.


Under Texas law, a party generally has a right to a jury trial in civil cases, but a corporation may include a waiver of jury trial in its governing documents concerning any “internal entity claims” (as defined in Section 2.115 of the TBOC).


Our amended and restated certificate of formation includes a jury trial waiver consisting of the following language: TO THE FULLEST EXTENT PERMITTED BY THE TBOC, UNLESS THE CORPORATION CONSENTS IN WRITING TO A JURY TRIAL, THE CORPORATION AND EACH SHAREHOLDER, DIRECTOR, OFFICER AND EMPLOYEE OF THE CORPORATION HEREBY IRREVOCABLY AND UNCONDITIONALLY WAIVE ANY RIGHT THAT THE CORPORATION OR SUCH PERSON MAY HAVE TO A TRIAL BY JURY IN ANY LEGAL ACTION, PROCEEDING, CAUSE OF ACTION, COUNTERCLAIM, CROSS-CLAIM OR THIRD-PARTY CLAIM ARISING OUT OF OR RELATING TO ANY “INTERNAL ENTITY CLAIM” AS THAT TERM IS DEFINED IN SECTION 2.115 OF THE TBOC, AND EACH SHAREHOLDER AGREES THAT SUCH SHAREHOLDER’S HOLDING OR ACQUISITION OF SHARES OF STOCK OF THE CORPORATION OR, TO THE EXTENT PERMITTED BY LAW, OPTIONS OR RIGHTS TO ACQUIRE SHARES OF STOCK OF THE CORPORATION FOLLOWING THE ADOPTION OF THIS AMENDED AND RESTATED CERTIFICATE OF FORMATION CONSTITUTES SUCH SHAREHOLDER’S INTENTIONAL AND KNOWING WAIVER OF ANY RIGHT TO TRIAL BY JURY WITH RESPECT TO SUCH CLAIMS.


the event that Flex has been convicted of a criminal offense or has a court order for the payment of a civil penalty made against it.

Distributions and Dividends; Repurchases and Redemptions

Our amended and restated certificate of formation provides that dividends on the common stock may be declared and paid out of the assets of the Company legally available therefor. Subject to the provisions of any Preferred Stock Series Resolution (as defined in the amended and restated certificate of formation), the holders of common stock shall be entitled to share equally, on a per share basis, in such dividends and other distributions of cash, stock or other securities or property as may be declared by the Spinco Board of


The Singapore Companies Act provides that no dividends can be paid to shareholders except out of profits.


The Singapore Companies Act does not provide a definition on when profits are deemed to be available for the purpose of paying dividends and this is accordingly governed by case law. Flex’s Constitution provides that no dividend can be paid otherwise than out of profits of Flex.


226


Table of Contents

Directors from time to time with respect to the common stock out of the assets of the Company legally available therefor.


Subject to the provisions of any Preferred Stock Series Resolution, no holder of shares of stock of the Company shall have any preemptive or other rights, except as such rights are expressly provided by contract, to purchase or subscribe for or receive any shares of any class or series of stock of the Company, whether now or hereafter authorized, or any warrants, options, bonds, debentures or other securities convertible into, exchangeable for or carrying any right to purchase any shares of any class, or series thereof, of stock of the Company; but, subject to the provisions of any Preferred Stock Series Resolution, such additional shares of stock and such warrants, options, bonds, debentures or other securities convertible into, exchangeable for or carrying any right to purchase any shares of any class, or series thereof, of stock of the Company may be issued or disposed of by the Spinco Board of Directors to such Persons (as defined in the amended and restated certificate of formation), and on such terms and for such lawful consideration, as in its discretion it shall deem advisable or as to which the Company shall have by binding contract agreed.


Under the TBOC, a distribution is defined as a transfer of cash or other property (except a corporation’s own shares or rights to acquire its shares or a split-up or division of the issued shares of a class of a corporation into a larger number of shares within the same class that does not increase the stated capital of the corporation), or an issuance of debt, by a corporation to its shareholders in the form of (1) a dividend on any class or series of outstanding shares, (2) a purchase or redemption, directly or indirectly, of its shares, or (3) a payment in liquidation of all or a portion of its assets.


A Texas corporation may not make a distribution if the distribution violates its certificate of formation, if the corporation’s surplus is less than the amount of the corporation’s stated capital (as determined under the TBOC), or, unless the corporation is in receivership or the distribution is made in connection with winding up and termination of the corporation, if it either renders the corporation unable to pay its debts as they become due in the course of its business or affairs or exceeds, depending on the type of distribution, either the net assets or the surplus of the corporation, or, subject to certain exceptions, if the distribution will be made to shareholders of another class or series. Directors who consent to a distribution that violates the TBOC are


Acquisition of a company’s own shares


The Singapore Companies Act generally prohibits a company from acquiring its own shares subject to certain exceptions. Any contract or transaction by which a company acquires or purports to acquire its own shares in contravention of the Singapore Companies Act is void. However, provided that it is expressly permitted to do so by its constitution and subject to the special conditions of each permitted acquisition contained in the Singapore Companies Act, a company may:


redeem redeemable preference shares (the redemption of these shares will not reduce the capital of the company). Preference shares may be redeemed out of capital if all the directors make a solvency statement in relation to such redemption in accordance with the Singapore Companies Act;


whether listed (on an approved exchange in Singapore or any securities exchange outside Singapore) or not, make an off-market purchase of its own shares in accordance with an equal access scheme authorized in advance at a general meeting;


whether listed on a securities exchange (in Singapore or outside Singapore) or not, make a selective off-market purchase of its own shares in accordance with an agreement authorized in advance at a general meeting by a special resolution where persons whose shares are to be acquired and their associated persons have abstained from voting; and


whether listed (on an approved exchange in Singapore or any securities exchange outside Singapore) or not, make a purchase of its own shares under a contingent purchase contract which has been authorized in advance at a general meeting by a special resolution.


A company may also purchase its own shares by an order of a Singapore court.


The total number of ordinary shares that may be acquired by a company in a relevant period may not exceed 20% of the total number of ordinary shares in that class as of the date of passing of the resolution (excluding treasury shares and any ordinary shares which are held by subsidiary(ies) under Sections 21(4B) or 21(6C) of the Singapore Companies Act) pursuant to the relevant share repurchase provisions


227


Table of Contents

liable only for the amount of the distribution that exceeds the amount permitted to be distributed.


Under the TBOC, as noted above, the purchase or redemption by a Texas corporation of its shares constitutes a distribution. Accordingly, the discussion above relating to distributions is applicable to stock redemptions and repurchases.


under the Singapore Companies Act. Where, however, a company has reduced its share capital by a special resolution or a Singapore court made an order to such effect, the total number of ordinary shares in any class shall be taken to be the total number of ordinary shares in that class as altered by the special resolution or the order of the court. Payment must be made out of the company’s distributable profits or capital, provided that the company is solvent. Such payment may include any expenses (including brokerage or commission) incurred directly in the purchase or acquisition by the company of its ordinary shares.


Financial assistance for the acquisition of shares


A public company or a company whose holding company or ultimate holding company is a public company may not give financial assistance to any person whether directly or indirectly for the purpose of:


the acquisition or proposed acquisition of shares in the company or units of such shares; or


the acquisition or proposed acquisition of shares in its holding company or ultimate holding company, as the case may be, or units of such shares.


Financial assistance may take the form of a loan, the giving of a guarantee, the provision of security, the release of an obligation, the release of a debt or otherwise.


However, it should be noted that a company may provide financial assistance for the acquisition of its shares or shares in its holding company if it complies with the requirements (including, where applicable, approval by the board of directors or by the passing of a special resolution by its shareholders) set out in the Singapore Companies Act. Flex’s Constitution provides that subject to the provisions of the Singapore Companies Act, Flex may purchase or otherwise acquire its issued shares on such terms and in such manner as Flex may from time to time think fit. These shares may be held as treasury shares or cancelled as provided in the Singapore Companies Act or dealt with in such manner as may be permitted under the Singapore Companies Act. On cancellation of the shares, the rights and privileges attached to those shares will expire.


228


Table of Contents
Transactions with Officers or Directors

The TBOC provides that an otherwise valid and enforceable contract or transaction between a corporation and (1) one or more directors or officers, or one or more affiliates or associates of one or more directors or officers, of the corporation, or (2) an entity or other organization in which one or more directors or officers, or one or more affiliates or associates of one or more directors or officers, of the corporation (a) is a managerial official or (b) has a financial interest is valid and enforceable, and is not void or voidable, notwithstanding such relationship or interest if any one of the following conditions is satisfied: (i) the material facts as to the applicable relationship or interest and as to the contract or transaction are disclosed to or known by (A) the corporation’s board of directors or a committee of the board of directors, and the board of directors or committee in good faith authorizes the contract or transaction by the approval of the majority of the disinterested directors or committee members, regardless of whether the disinterested directors or committee members constitute a quorum; or (B) the shareholders are entitled to vote on the authorization of the contract or transaction, and the contract or transaction is specifically approved in good faith by a vote of the shareholders; or (ii) the contract or transaction is fair to the corporation when the contract or transaction is authorized, approved or ratified by the board of directors, a committee of the board of directors or the shareholders.


The TBOC expressly provides that if at least one of the above conditions is satisfied, neither the corporation nor any of the corporation’s shareholders will have a cause of action against any of the corporation’s directors or officers for breach of duty with respect to the making, authorization or performance of the contract or transaction because the person had an applicable relationship or interest.


We have affirmatively elected to be governed by Section 21.419 of the TBOC. The codified business judgment rule presumes that directors and officers acted in good faith, on an informed basis, in furtherance of the interests of the corporation and in obedience to the law and the corporation’s governing documents; a plaintiff bears the burden of rebutting the presumption and must plead with particularity that the alleged breach constitutes fraud, intentional misconduct, an ultra vires act or a knowing violation of law.


Under the Singapore Companies Act, directors and chief executive officers are not prohibited from dealing with Flex, but where they have an interest in a transaction with Flex, that interest must be disclosed to the board of directors. In particular, every director and chief executive officer who is in any way, whether directly or indirectly, interested in a transaction or proposed transaction with Flex must, as soon as practicable after the relevant facts have come to such director or officer’s knowledge, declare the nature of such director or officer’s interest at a board of directors’ meeting or send a written notice to Flex containing details on the nature, character and extent of his or her interest in the transaction or proposed transaction with Flex.


In addition, a director or chief executive officer who holds any office or possesses any property whereby, directly or indirectly, any duty or interest might be created in conflict with such director or officer’s duties or interests as director or, as the case may be, chief executive officer is required to declare the fact and the nature, character and extent of the conflict at a meeting of directors or send a written notice to Flex setting out the fact and the nature, character and extent of the conflict.


The Singapore Companies Act extends the scope of this statutory duty of a director or chief executive officer to disclose any interests by pronouncing that an interest of a member of the director’s or, as the case may be, the chief executive officer’s family (including spouse, son, adopted son, step-son, daughter, adopted daughter and step-daughter) will be treated as an interest of the director or, as the case may be, the chief executive officer. There is however no requirement for disclosure where the interest of the director or, as the case may be, the chief executive officer consists only of being a member or creditor of a corporation which is interested in the transaction or proposed transaction with Flex if the interest may properly be regarded as immaterial. Where the transaction or proposed transaction relates to any loan to Flex, no disclosure need be made where the director or chief executive officer has only guaranteed the repayment of such loan, unless the constitution provides otherwise.


Further, where the proposed transaction is to be made with or for the benefit of a related corporation (i.e. the holding company, subsidiary or subsidiary of a


229


Table of Contents
  

common holding company), no disclosure need be made of the fact that the director or chief executive officer is also a director or, as the case may be, chief executive officer of that corporation, unless the constitution provides otherwise.


Subject to specified exceptions, including a loan to a director for expenditure in defending criminal or civil proceedings, etc. or in connection with an investigation, or an action proposed to be taken by a regulatory authority in connection with any alleged negligence, default, breach of duty or breach of trust by such director in relation to the company, the Singapore Companies Act prohibits a company from: (i) making a loan or quasi-loan to its directors or to directors of a related corporation (each, a “relevant director”); (ii) giving a guarantee or security in connection with a loan or quasi-loan made to a relevant director by any other person; (iii) entering into a credit transaction as creditor for the benefit of a relevant director; (iv) giving a guarantee or security in connection with such credit transaction entered into by any person for the benefit of a relevant director; (v) taking part in an arrangement where another person enters into any of the transactions in (i) to (iv) above or (vi) below and such person obtains a benefit from the company or a related corporation; or (vi) arranging for the assignment to the company or assumption by the company of any rights, obligations or liabilities under a transaction in (i) to (v) above. Companies are also prohibited from entering into the transactions in (i) to (vi) above with or for the benefit of a relevant director’s spouse or children (whether adopted or naturally or step-children).

Dissenters’ Rights

Under the TBOC, except for the limited classes of mergers, consolidations, sales and asset dispositions for which no shareholder approval is required under Texas law, shareholders of Texas corporations with voting rights have dissenters’ rights in the event of a merger, consolidation, interest exchange, conversion, sale, lease, exchange or other disposition of all, or substantially all, of the property and assets of the corporation.


However, a shareholder of a Texas corporation has no dissenters’ rights with respect to any plan of merger or conversion in which there is a single surviving or new domestic or foreign corporation, or with respect to any plan of exchange if: (1) the ownership interest, or a depository receipt in respect of the ownership interest,


There are no equivalent provisions under the Singapore Companies Act.


230


Table of Contents

held by the owner is part of a class or series of ownership interests, or depository receipts in respect of ownership interests, that are, on the record date set for purposes of determining which owners are entitled to vote on the plan of merger, conversion or exchange, as appropriate, (a) listed on a national securities exchange or (b) held of record by at least 2,000 owners; (2) the owner is not required by the terms of the plan of merger, conversion or exchange, as appropriate, to accept for the owner’s ownership interest any consideration that is different from the consideration to be provided to any other holder of an ownership interest of the same class or series as the ownership interest held by the owner, other than cash instead of fractional shares or interests the owner would otherwise be entitled to receive; and (3) the owner is not required by the terms of the plan of merger, conversion or exchange, as appropriate, to accept for the owner’s ownership interest any consideration other than (a) ownership interests, or depository receipts in respect of ownership interests, of another entity of the same general organizational type that, immediately after the effective date of the merger, conversion or exchange, as appropriate, will be part of a class or series of ownership interests, or depository receipts in respect of ownership interests, that are (i) listed on a national securities exchange or authorized for listing on the exchange on official notice of issuance or (ii) held of record by at least 2,000 owners; (b) cash instead of fractional ownership interests the owner would otherwise be entitled to receive; or (c) any combination of the ownership interests and cash above.


Under the TBOC, an owner of an ownership interest in a Texas domestic entity subject to dissenters’ rights is entitled to dissent from an amendment to a Texas for-profit corporation’s certificate of formation to add required provisions to elect to be a public benefit corporation or delete required provisions, which in effect cancels the corporation’s election to be a public benefit corporation if the owner owns shares that were entitled to vote on the amendment, except if the shares held by the owner are part of a class or series of shares listed on a national securities exchange or are held of record by at least 2,000 owners.

  
Anti-Takeover Measures

Our amended and restated certificate of formation authorizes the Spinco Board of Directors to issue preferred stock in one or more series, with such designations, powers, preferences and rights as the Spinco Board of Directors may determine, without shareholder approval, subject to any shareholder votes


The constitution of a Singapore company typically provides that the company may allot and issue new shares of a different class with preferential, deferred, qualified or other special rights as its board of directors may determine with the prior approval of the company’s shareholders in a general meeting.


231


Table of Contents

or consents required by the amended and restated certificate of formation or any Preferred Stock Series Resolution. This authority could potentially be used to discourage attempts by others to acquire control of the Company.


In addition, the directors are divided into three classes, as nearly equal in number as is reasonably possible, with the initial term of office of the first class to expire at the first annual meeting of shareholders following the effective date of the amended and restated certificate of formation, the initial term of office of the second class to expire at the second annual meeting of shareholders following the effective date of the amended and restated certificate of formation, and the initial term of office of the third class to expire at the third annual meeting of shareholders following the effective date of this amended and restated certificate of formation, with each director to hold office until his or her successor shall have been duly elected and qualified, subject, however, to such director’s earlier death, resignation, disqualification or removal, and the Spinco Board of Directors shall be authorized to assign members of the Spinco Board of Directors, other than those directors who may be elected by the holders of any series of preferred stock, to such classes. At each annual meeting of shareholders, directors elected to succeed those directors whose terms then expire shall be elected for a term of office to expire at the third succeeding annual meeting of shareholders after their election, with each director to hold office until his or her successor shall have been duly elected and qualified, subject, however, to such director’s earlier death, resignation, disqualification or removal. Elections of the members of the Board of Directors need not be by written ballot unless the Bylaws shall so provide.


Advance notice of shareholder nominations for the election of directors and of any other business to be brought by shareholders before any meeting of the shareholders must be given in the manner provided in the Bylaws. No shareholder or group of shareholders may institute or maintain a derivative proceeding against any director or officer in his or her official capacity unless the shareholder or group beneficially owns at least three percent of the outstanding shares of Spinco at the time the proceeding is instituted. Special meetings of the shareholders may be called by the holders of not less than [20]% of the voting power of Spinco’s then issued and outstanding shares entitled to vote at such special meeting.


Flex’s Constitution provides that no shares may be issued by the directors without the prior approval of Flex shareholders in a general meeting except that the directors may allot and issue shares or grant options over or otherwise dispose of the same to such persons on such terms and conditions and for such consideration (if any) and at such time as Flex shareholders may approve at a general meeting.


Singapore law does not generally prohibit a corporation from adopting “poison pill” arrangements which could prevent a takeover attempt and also preclude shareholders from realizing a potential premium over the market value of their shares.


However, under the Singapore Code on Take-overs and Mergers, if, in the course of an offer, or even before the date of the offer announcement, the board of the offeree company has reason to believe that a bona fide offer is imminent, the board must not, except pursuant to a contract entered into earlier, take any action, without the approval of shareholders at a general meeting, on the affairs of the offeree company that could effectively result in any bona fide offer being frustrated or the shareholders being denied an opportunity to decide on its merits.


232


Table of Contents


The Bylaws affirmatively elect to be governed by Section 21.373 of the TBOC. Accordingly, for so long as the Company is a nationally listed corporation within the meaning of that section, a shareholder or group of shareholders may submit a proposal for approval at a meeting of shareholders, other than a nomination of a person for election as a director or a procedural resolution ancillary to the conduct of the meeting, only if the shareholder or group (i) holds shares entitled to vote at the meeting having a market value of at least $1,000,000, determined as of the date the proposal is submitted, or constituting at least three percent of Company’s voting shares, (ii) has held such shares continuously for at least six (6) months before the date of the meeting and holds such shares through the date of the meeting, and (iii) solicits the holders of shares representing at least 67% of the voting power of shares entitled to vote on the proposal.


Our amended and restated certificate of formation also designates the Texas Business Court as the sole and exclusive forum for derivative actions, fiduciary duty claims, claims arising under the TBOC or the Company’s governing documents, claims governed by the internal affairs doctrine, and any “internal entity claim” as that term is defined in Section 2.115 of the TBOC.


Under the TBOC, a Texas “Issuing Public Corporation” is generally prohibited from, directly or indirectly, entering into specified transactions with an “Affiliated Shareholder,” or with any affiliate or associate of an Affiliated Shareholder, for a period of three years after the date the shareholder obtained Affiliated Shareholder status. The prohibited transactions include mergers, share exchanges or conversions; dispositions of assets having an aggregate market value of ten percent or more of the corporation’s consolidated assets, the aggregate market value of its outstanding voting stock, or its earning power or net income on a consolidated basis; issuances or transfers of shares to an Affiliated Shareholder or its affiliates or associates; liquidation or dissolution plans or proposals; transactions, including reclassifications, share distributions and recapitalizations, that have the effect of increasing the Affiliated Shareholder’s proportionate ownership percentage; and loans, advances, guarantees, pledges or other financial assistance, or tax credits or other tax advantages, the recipient of which is an Affiliated Shareholder or its affiliates or associates. The TBOC defines “Issuing Public Corporation” as a Texas corporation that has 100 or more shareholders of record as shown by its share transfer records, a class or series


233


Table of Contents

of voting shares registered under the Exchange Act, or a class or series of voting shares qualified for trading on a national securities exchange, and generally defines “Affiliated Shareholder” as a person who beneficially owns, or has owned within the preceding three-year period, twenty percent or more of the outstanding voting stock of a Texas public corporation.


The prohibition does not apply if the board of directors approves the transaction or the acquisition of shares by the Affiliated Shareholder before the shareholder becomes an Affiliated Shareholder, or if the holders of at least two-thirds of the outstanding voting shares not beneficially owned by the Affiliated Shareholder or its affiliates or associates approve the transaction at a meeting held no earlier than six months after the shareholder acquires such ownership, which approval may not be given by written consent. A corporation may expressly elect in its certificate of formation or bylaws not to be governed by this statute. Neither the amended and restated certificate of formation nor the amended and restated bylaws contains such an election, and we therefore expect to remain subject to the Texas Business Combination Law.


Limitations on Director and Officer Liability

Under the TBOC, a corporation may indemnify and advance expenses to a person who is or was a director or officer, and must indemnify an officer to the same extent that indemnification is required under the TBOC for a director. If, however, the director or officer is found liable to the corporation or is found liable on the basis that such director or officer received an improper personal benefit, indemnification is limited to the reimbursement of reasonable expenses actually incurred in connection with the proceeding, and excludes a judgment, a penalty, a fine, and an excise or similar tax, including an excise tax assessed against the person with respect to an employee benefit plan. In addition, no indemnification will be available if a director or officer is found liable for (1) willful or intentional misconduct in the performance of the person’s duty to the corporation, (2) breach of the person’s duty of loyalty owed to the corporation, or (3) an act or omission not committed in good faith that constitutes a breach of a duty owed by the person to the corporation. Under the provisions of our amended and restated certificate of formation and bylaws, each of our directors and officers will, subject to certain limitations, be indemnified by us as of right to the fullest extent permitted by law, and advancement of expenses is available upon delivery of a written undertaking to repay all amounts advanced if it is ultimately determined that the indemnified person is not entitled to indemnification and a written affirmation of the person’s good faith belief that he or she has met the standard of conduct necessary for indemnification. To the extent required by the TBOC, no later than one year from the date Spinco indemnifies or advances expenses to a director or officer, Spinco must give a written report of such indemnification or advancement to its shareholders, which report must be made with or before the notice or waiver of notice of the next shareholders’ meeting or the next submission to shareholders of a written consent without a meeting.

In addition, the TBOC permits a Texas corporation to limit or eliminate the personal liability of directors and officers to the corporation and its shareholders for monetary damages for breach of fiduciary duty as a director or officer, as applicable. The TBOC does not permit any limitation of the liability of a director or officer for (1) a breach of the duty of loyalty to the corporation or its shareholders, (2) an act or omission not in good faith that


234


Table of Contents

constitutes a breach of duty of the person to the corporation or involves intentional misconduct or a knowing violation of law, (3) a transaction from which the director or officer obtains an improper benefit, regardless of whether the benefit resulted from an action taken within the scope of the person’s duties, or (4) an act or omission for which the liability of a director or officer is expressly provided by an applicable statute. Our amended and restated certificate of formation will contain such a director exculpation provision.

The limitation of liability and indemnification provisions that will be in our amended and restated certificate of formation and bylaws may discourage shareholders from bringing a lawsuit against directors for breach of their fiduciary duty. These provisions may also have the effect of reducing the likelihood of derivative litigation against our directors and officers, even though such an action, if successful, might otherwise benefit us and our shareholders. However, these provisions will not limit or eliminate our rights, or those of any shareholders, to seek non-monetary relief such as an injunction or rescission in the event of a breach of a director’s duty of care. The provisions will not alter the liability of directors under the federal securities laws.

Sale of Unregistered Securities

Not applicable.

Transfer Agent and Registrar

We expect that the transfer agent and registrar for the shares of Spinco common stock will be Computershare Trust Company, N.A. The transfer agent and registrar’s address is 1505 Energy Park Drive, St. Paul, MN 55108.


235


Table of Contents

WHERE YOU CAN FIND MORE INFORMATION

We have filed a registration statement on Form 10 with the SEC with respect to shares of our common stock being distributed in the separation as contemplated by this information statement. This information statement is a part of, and does not contain all of the information set forth in, the registration statement and the exhibits to the registration statement. For further information with respect to the Spinco, please refer to the registration statement, including its exhibits. Statements made in this information statement relating to any contract or other document are not necessarily complete, and you should refer to the exhibits attached to the registration statement for the full text of the actual contract or document. You may review a copy of the registration statement, including its exhibits, at the Internet website maintained by the SEC at www.sec.gov. Information contained on any website referenced in this information statement is not incorporated by reference into this information statement or the registration statement of which this information statement forms a part.

Information contained on, or connected to, any website we refer to in this information statement does not and will not constitute a part of this information statement or the registration statement of which this information statement is a part.

After the separation, we will become subject to the information and reporting requirements of the Exchange Act, and, in accordance with the Exchange Act, we will file periodic reports, proxy statements, and other information with the SEC. Our future filings will be available from the SEC as described above.


236


Table of Contents

COMBINED FINANCIAL STATEMENTS

Index To Combined Financial Statements


     Page No  

Combined Financial Statements


Report of Independent Registered Public Accounting Firm

     F-3  

Combined Balance Sheets as of March  31, 2026 and March 31, 2025

     F-5  

Combined Statements of Operations for the fiscal years ended March 31, 2026, March 31, 2025 and March 31, 2024

     F-6  

Combined Statements of Comprehensive Income for the fiscal years ended March 31, 2026, March 31, 2025 and March 31, 2024

     F-7  

Combined Statements of Equity for the fiscal years ended March 31, 2026, March 31, 2025 and March 31, 2024

     F-8  

Combined Statements of Cash Flows for the fiscal years ended March 31, 2026, March 31, 2025 and March 31, 2024

     F-9  

Notes to Combined Financial Statements

     F-10  


     Page No  

Condensed Combined Financial Statements - Unaudited


Condensed Combined Balance Sheets as of June 26, 2026 and March 31, 2026

     F-36  

Condensed Combined Statements of Operations for the three-month periods ended June 26, 2026 and June 27, 2025

     F-37  

Condensed Combined Statements of Comprehensive Income for the three-month periods ended June 26, 2026 and June 27, 2025

     F-38  

Condensed Combined Statements of Equity for the three-month periods ended June 26, 2026 and June 27, 2025

     F-39  

Condensed Combined Statements of Cash Flows for the three-month periods ended June 26, 2026 and June 27, 2025

     F-40  

Notes to the Condensed Combined Financial Statements

     F-41  


     Page No  

Charge Parent, LLC and Subsidiaries Consolidated Financial Statements


Report of Independent Auditors

     F-52  

Consolidated Balance Sheets as of December 31, 2025 and December 31, 2024

     F-54  

Consolidated Statements of Operations for the fiscal years ended December 31, 2025 and December 31, 2024

     F-55  

Consolidated Statements of Comprehensive Loss for the fiscal years ended December 31, 2025 and December 31, 2024

     F-56  

Consolidated Statements of Changes in Members’ Equity for the fiscal years ended December 31, 2025 and December 31, 2024

     F-57  

Consolidated Statements of Cash Flows for the fiscal years ended December 31, 2025 and December 31, 2024

     F-58  

Notes to the Consolidated Financial Statements

     F-60  


F-1


Table of Contents
     Page No  

Charge Parent, LLC and Subsidiaries Condensed Consolidated Financial Statements


Condensed Consolidated Balance Sheets as of June 30, 2026 and December 31, 2025

     F-87  

Condensed Consolidated Statements of Operations for the six-month periods ended June 30, 2026 and June 30, 2025

     F-88  

Condensed Consolidated Statements of Comprehensive Income (Loss) for the six-month periods ended June 30, 2026 and June 30, 2025

     F-89  

Condensed Consolidated Statements of Changes in Members’ Equity for the six-month periods ended June 30, 2026 and June 30, 2025

     F-90  

Condensed Consolidated Statements of Cash Flows for the six-month periods ended June 30, 2026 and June 30, 2025

     F-91  

Notes to the Condensed Consolidated Financial Statements

     F-92  


F-2


Table of Contents

[SpinCo]

(A Business of Flex Ltd.)

REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM

To the Shareholders and Board of Directors of Flex Ltd., Archer SpinCo, Inc.

Opinion on the Financial Statements

We have audited the accompanying combined balance sheets of Archer SpinCo, Inc. (the “Company”) as of March 31, 2026 and 2025, the related combined statements of operations, comprehensive income, equity, and cash flows, for each of the three years in the period ended March 31, 2026, and the related notes (collectively referred to as the “financial statements”). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of March 31, 2026 and 2025, and the results of its operations and its cash flows for each of the three years in the period ended March 31, 2026, in conformity with accounting principles generally accepted in the United States of America.

Basis for Opinion

These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.

We conducted our audits in accordance with the standards of the PCAOB and in accordance with auditing standards generally accepted in the United States of America. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. The Company is not required to have, nor were we engaged to perform, an audit of its internal control over financial reporting. As part of our audits, we are required to obtain an understanding of internal control over financial reporting but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control over financial reporting. Accordingly, we express no such opinion.

Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.

Emphasis of a Matter

As described in Note 1 to the financial statements, the accompanying combined financial statements have been derived from the historical accounting records maintained by Flex Ltd. as if the operations of the Company had been conducted independently from Flex Ltd. and were prepared on a stand-alone basis in accordance with accounting principles generally accepted in the United States of America. These financial statements may not be indicative of what they would have been had the Company operated as an independent, stand-alone entity.

Critical Audit Matter

The critical audit matter communicated below is a matter arising from the current-period audit of the financial statements that was communicated or required to be communicated to the audit committee and that (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging,


F-3


Table of Contents

subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.

Revenue – Variable Consideration and Associated Customer-Related Accruals for Pricing Adjustments — Refer to Notes 2 and 4 to the Combined Financial Statements

Critical Audit Matter Description

Certain of the Company’s customer agreements include potential price adjustments which may result in variable consideration. These price adjustments include, but are not limited to, sharing of cost savings, committed price reductions, purchase price variances earned over the period that are contractually required to be paid to the customers, rebates, refunds tied to performance metrics such as on-time delivery, and other periodic pricing resets that may be refundable to customers. The Company estimates the variable consideration related to these price adjustments as part of the total transaction price and recognizes revenue in accordance with the pattern applicable to the performance obligation, subject to a constraint. The Company constrains the amount of revenue recognized for these contractual provisions based on its best estimate of the amount which will not result in a significant reversal of revenue in a future period. The Company determines the amounts to be recognized based on the amount of potential refunds required by the contract, historical experience and other surrounding facts and circumstances. These potential price adjustments are included as part of other current liabilities on the combined balance sheet and disclosed as part of customer-related accruals.

We identified the estimation of variable consideration and the associated customer-related accruals for pricing adjustments as a critical audit matter due to the judgments necessary to determine variable consideration and reassess the variable consideration in subsequent periods for pricing adjustments. This required extensive audit effort and a higher degree of auditor judgment when performing audit procedures to evaluate the reasonableness of the variable consideration and associated customer-related accruals for pricing adjustments.

How the Critical Audit Matter Was Addressed in the Audit

Our audit procedures related to variable consideration and associated customer-related accruals for pricing adjustments included the following, among others:


We evaluated the Company’s accounting policy with respect to variable consideration, as well as its process for identifying contracts that include potential price adjustment clauses.


We selected a sample of contracts with customers that included potential price adjustment clauses and performed the following:


We read the customer contracts to develop an understanding of clauses that could give rise to variable consideration and evaluated whether the Company’s accounting conclusions with respect to those clauses were reasonable.


We obtained and tested the mathematical accuracy of the Company’s calculations of customer-related accruals and evaluated the Company’s judgments regarding the amount of variable consideration that should be deferred and the related adjustments recorded to customer-related accruals. In making this evaluation, we considered both the terms included in the customer contract and the Company’s historical experience in settling amounts with the customer.

/s/ DELOITTE & TOUCHE LLP

San Jose, California

July 8, 2026

We have served as the Company’s auditor since 2026.


F-4


Table of Contents

ARCHER SPINCO, INC.

(A BUSINESS OF FLEX LTD.)

COMBINED BALANCE SHEETS


     As of March 31,  
     2026      2025  
     (In millions)  
ASSETS


Current assets:


Cash and cash equivalents

   $ 7      $ 24  

Accounts receivable, net of allowance for credit losses

     1,336        635  

Contract assets

     257        87  

Inventories

     1,598        1,166  

Customer-controlled inventory

     1,000        207  

Other current assets

     290        93  


Total current assets

     4,488        2,212  

Property and equipment, net

     568        246  

Operating lease right-of-use assets, net

     186        80  

Goodwill

     498        490  

Intangible assets, net

     259        303  

Other non-current assets

     33        12  


Total assets

   $ 6,032      $ 3,343  


LIABILITIES AND EQUITY


Current liabilities:


Accounts payable

   $ 3,279      $ 1,297  

Accrued payroll and benefits

     130        83  

Deferred revenue and customer working capital advances

     212        217  

Other current liabilities

     223        118  


Total current liabilities

     3,844        1,715  

Operating lease liabilities, non-current

     166        70  

Other non-current liabilities

     59        39  


Total liabilities

   $ 4,069      $ 1,824  

Commitments and contingencies (Note 8)


Equity


Net Parent Investment

   $ 1,948      $ 1,513  

Accumulated other comprehensive income

     15        6  


Total equity

     1,963        1,519  


Total liabilities and equity

   $ 6,032      $ 3,343  


The accompanying notes are an integral part of these combined financial statements.


F-5


Table of Contents

ARCHER SPINCO, INC.

(A BUSINESS OF FLEX LTD.)

COMBINED STATEMENTS OF OPERATIONS


     Fiscal Year Ended March 31,  
     2026     2025      2024  
     (In millions)  

Net sales

   $ 6,614     $ 4,799      $ 3,244  

Cost of sales

     5,831       4,176        2,843  


Gross profit

     783       623        401  

Selling, general and administrative expenses

     253       184        123  

Intangible amortization

     50       36        32  


Operating income

     480       403        246  

Interest expense

     5       6        4  

Other charges (income), net

     (7     8        (1


Income from operations before income taxes

     482       389        243  

Provision for income taxes

     69       69        61  


Net income

   $ 413     $ 320      $ 182  


The accompanying notes are an integral part of these combined financial statements.


F-6


Table of Contents

ARCHER SPINCO, INC.

(A BUSINESS OF FLEX LTD.)

COMBINED STATEMENTS OF COMPREHENSIVE INCOME


     Fiscal Year Ended March 31,  
      2026        2025       2024   
     (In millions)  

Net income

   $ 413      $ 320     $ 182  

Other comprehensive income (loss), net of tax:


Foreign currency translation adjustments

     9        (4     (3


Comprehensive income

   $ 422      $ 316     $ 179  


The accompanying notes are an integral part of these combined financial statements.


F-7


Table of Contents

ARCHER SPINCO, INC.

(A BUSINESS OF FLEX LTD.)

COMBINED STATEMENTS OF EQUITY


     Net Parent
Investment
    Accumulated
Other
Comprehensive
Income (Loss)
    Total
Equity
 
     (In millions)  

BALANCE AT APRIL 1, 2023

   $ 838     $ (1   $ 837  

Net income

     182             182  

Other comprehensive income (loss), net of tax

           3       3  

Net transfers (to) Parent

     (145           (145


BALANCE AT MARCH 31, 2024

     875       2       877  

Net income

     320             320  

Other comprehensive income (loss), net of tax

           4       4  

Net transfers from Parent

     318             318  


BALANCE AT MARCH 31, 2025

     1,513       6       1,519  


Net income

     413             413  

Other comprehensive income (loss), net of tax

           9       9  

Net transfers from Parent

     22             22  


BALANCE AT MARCH 31, 2026

   $ 1,948     $ 15     $ 1,963  


The accompanying notes are an integral part of these combined financial statements.


F-8


Table of Contents

ARCHER SPINCO, INC.

(A BUSINESS OF FLEX LTD.)

COMBINED STATEMENTS OF CASH FLOWS


     Fiscal Year Ended March 31,  
      2026       2025       2024   
     (In millions)  

Cash flows from operating activities:


Net income

   $ 413     $ 320     $ 182  

Adjustments to reconcile net income to net cash provided (used in) by operating activities:


Depreciation

     62       40       26  

Amortization

     50       36       32  

Other non-cash (income) / expense

     1       —        —   

Non-cash lease expense

     42       16       13  

Stock-based compensation

     33       23       14  

Deferred income taxes

     (19     (23     12  

Changes in operating assets and liabilities, net of acquisitions:


Accounts receivable

     (692     (277     (6

Contract assets

     (159     (32     (25

Inventories

     (415     (353     (3

Customer-controlled inventory

     (793     (130     (22

Other current and noncurrent assets

     (199     (58     (6

Accounts payable

     1,947       570       103  

Other current and noncurrent liabilities

     140       43       (78


Net cash provided by operating activities

     411       175       242  


Cash flows from investing activities:


Purchases of property and equipment

     (238     (104     (78

Proceeds from the disposition of property and equipment

     1       6       7  

Acquisitions of businesses, net of cash acquired

     (40     (347     —   


Net cash (used in) investing activities

     (277     (445     (71


Cash flows from financing activities:


Net transfers from (to) Parent

     (151     281       (167


Net cash provided by (used in) financing activities

     (151     281       (167


Effect of exchange rates on cash

     —        —        —   

Net increase (decrease) in cash and cash equivalents

     (17     11       4  

Cash and cash equivalents, beginning of year

     24       13       9  


Cash and cash equivalents, end of year

   $ 7     $ 24     $ 13  


The accompanying notes are an integral part of these combined financial statements.


F-9


Table of Contents

[SpinCo]

(A Business of Flex Ltd.)

NOTES TO THE COMBINED FINANCIAL STATEMENTS

1. ORGANIZATION OF THE COMPANY

On May 5, 2026, Flex Ltd (‘‘Flex’’ or “Parent”) announced its plan to separate its businesses into two distinct, publicly traded companies (the “Separation”). Under the plan, Flex would execute a tax-free spinoff (the “Spin-Off”) to Flex shareholders of its Cloud & Power Infrastructure business (“Spinco,” the “Company,” “we,” or “our”). Flex expects the transaction to be completed in the first half of calendar year 2027. The separation will be effected through a pro rata distribution of between approximately 88.0% to 94.0% of the outstanding shares of common stock of Spinco to Flex’s shareowners, with each Flex shareowner receiving shares of Spinco in proportion to their ownership of Flex common stock, in a transaction intended to be tax-free for U.S. federal income tax purposes. The separation, Spin-Off and listing remain subject to final approval of Flex’s Board of Directors, our shareholders, and the High Court of the Republic of Singapore. There can be no assurances that a separation, spin-off or listing will occur.

Spinco is a global provider of end-to-end power and thermal management products and integrated infrastructure systems serving AI data centers and mission-critical applications. Through its critical power and electrical infrastructure portfolio, Spinco delivers electrification solutions that enable the efficient generation, distribution, and management of power. Deep expertise across critical power infrastructure, embedded and distributed power systems, power electronics, electrified architectures, advanced cooling, and compute integration allows Spinco to deliver coordinated system-level solutions designed to replace fragmented, multi-vendor approaches.

Spinco operates and reports its financial performance through two segments: (i) Power and (ii) Cloud & Cooling. The Power segment historically operated in Flex’s Industrial business unit and was presented within the results of the Reliability segment. Furthermore, the Cloud & Cooling segment historically operated in Flex’s Communications, Enterprise, & Cloud business unit and was presented within the results of the Agility segment. The Power and Cloud & Cooling segments are aligned with the end markets that the Company serves:

(i) Power is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment supports grid modernization and related power infrastructure applications.

(ii) Cloud & Cooling includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments.

2. SUMMARY OF ACCOUNTING POLICIES

Basis of Presentation

These combined financial statements have been derived from the consolidated financial statements and accounting records of Flex Ltd. These combined financial statements reflect the combined historical results of operations, financial position and cash flows of the Company for the periods presented as historically operated within Flex in conformity with generally accepted accounting principles in the United States (“U.S. GAAP”). The combined financial statements may not be indicative of the Company’s future performance and do not necessarily reflect what the financial position, results of operations, and cash flows would have been had it operated as an independent company during the periods presented. Actual costs would depend on a number of factors, including the chosen organization structure, what functions were outsourced or performed by employees, and strategic decisions made in areas such as information technology and infrastructure. Accordingly, the Company has determined that it is not practicable to estimate the actual costs that would have been incurred had it operated as a standalone company during those periods.


F-10


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


All intracompany transactions have been eliminated. Intercompany transactions between Spinco and Flex are deemed to have settled immediately through Net Parent Investment. The net effect of deemed settled transactions is reflected in the combined statements of cash flows as a financing activity and in the combined balance sheets as net parent investment. Historically, Flex provided certain corporate support functions to the Company. The cost of such services were allocated to the Company based on direct usage when identifiable, with the remainder allocated on the basis of revenue, expenses, headcount or other relevant metrics. These costs are deemed settled in cash by Spinco to Flex in the period in which the costs were recorded within cost of sales or selling, general and administrative expenses in the combined statement of operations. Refer to Note 12 for additional information. Flex believes the basis on which the expenses have been allocated are a reasonable reflection of the utilization of services provided to, or the benefit received by, Spinco during the periods presented; however, they may not be indicative of actual expense that would have been incurred had the Company been operating as a standalone company for the periods presented. Going forward, the Company may perform these functions using its own resources or outsourced services. For an interim period, however, some of these functions may continue to be provided between Flex and the Company under a Transition Services Agreement following the separation.

Use of Estimates

The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosures of contingent assets and liabilities at the date of the financial statements, as well as the reported amounts of revenues and expenses during the reporting period. Estimates are based on several factors, including the facts and circumstances available at the time the estimates are made, historical experience, risk of loss, general economic conditions and trends, and the assessment of the probable future outcome. Actual results could differ from those estimates. Estimates and assumptions are reviewed periodically, and the effects of changes, if any, are reflected in the Combined Statements of Operations in the period in which they are determined.

Translation of Foreign Currencies

The financial position and results of the operations for certain of the Company’s subsidiaries are measured using a currency other than the U.S. dollar as their functional currency. Accordingly, all assets and liabilities are translated into U.S. dollars at the current exchange rates as of the respective balance sheet dates. Revenue and expense items are translated at the average exchange rates prevailing during the period. Cumulative gains and losses from these translations are reported as other comprehensive income (loss), a component of equity. Foreign exchange gains and losses arising from transactions denominated in a currency other than the functional currency of the entity involved, and re-measurement adjustments for foreign operations where the U.S. dollar is the functional currency, are included in the Company’s combined results of operations. Non-functional currency transaction gains and losses, and re-measurement adjustments were not material to the Company’s combined results of operations for all periods presented, and have been classified as a component of other charges (income), net in the combined statements of operations.

Revenue Recognition

In determining the appropriate amount of revenue to recognize, the Company applies the following steps: (i) identifies the contracts with the customers; (ii) identifies performance obligations in the contracts; (iii) determines the transaction price; (iv) allocates the transaction price to the performance obligations per the contracts; and (v) recognizes revenue when (or as) the Company satisfies a performance obligation. Further, the Company assesses whether control of the products or services promised under the contract is transferred to the customer at a point in time (“PIT”) or over time (“OT”). The Company is first required to evaluate whether its contracts meet the criteria for OT recognition. For certain contracts the Company has determined that for a


F-11


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


portion of its contracts the Company is manufacturing products for which there is no alternative use (due to the unique nature of the customer-specific product and intellectual property restrictions) and the Company has an enforceable right to payment including a reasonable profit for work-in-progress inventory with respect to these contracts. For certain other contracts, the Company’s performance creates and enhances an asset that the customer controls as the Company performs under the contract. As a result, revenue is recognized under these contracts OT based on the cost-to-cost method as it best depicts the transfer of control to the customer measured based on the ratio of costs incurred to date as compared to the total estimated costs at completion of the performance obligation. For all other contracts that do not meet these criteria, the Company recognizes revenue when it has transferred control of the related manufactured products which generally occurs upon delivery and passage of title to the customer. Service contract revenue is recognized on an over time basis using the output method. Certain of the Company’s customer agreements include potential price adjustments which may result in variable consideration. These price adjustments include, but are not limited to, sharing of cost savings, committed price reductions, purchase price variances earned over the period that are contractually required to be paid to the customers, rebates, refunds tied to performance metrics such as on-time delivery, and other periodic pricing resets that may be refundable to customers. The Company recognizes estimates of this variable consideration that are not expected to result in a significant revenue reversal in the future, primarily based on the amount of potential refunds required by the contract, historical experience and other surrounding facts and circumstances. Certain of the Company’s customer contracts involve buy-sell arrangements in which the Company purchases raw materials from customers or their affiliates at the direction of the customer for use in manufacturing or service activities. Payments made to customers in these arrangements are accounted for as consideration payable to a customer and are recorded as a reduction of the transaction price, and therefore, recorded on a net sales basis. Finished goods billings related to these products are reported net of the associated material cost in net sales in the combined statements of operations. Refer to note 4 “Revenue” for further details.

Government Incentives and Grants

The Company receives incentives from federal, state and local governments in different regions of the world that primarily encourage the Company to establish, maintain, or increase investment, employment, or production in the regions. The Company accounts for government incentives as a reduction in the cost of the capital investment or a reduction of expense, based on the substance of the incentives received. Benefits are generally recorded when all conditions attached to the incentive have been met and there is reasonable assurance of receipt. The Company records capital-related incentives as a reduction to Property and equipment, net on the combined balance sheets and recognizes a reduction to depreciation and amortization expenses over the useful life of the corresponding acquired asset. The Company records operating grants as a reduction to expense in the same line item on the combined statements of operations as the expenditure for which the grant is intended to compensate. Government incentives and grant transactions are not material to the Company’s financial position, results of operations or cash flows.

Concentration of Credit Risk

Financial instruments which potentially subject the Company to concentrations of credit risk are primarily accounts receivable and cash and cash equivalents.

Customer Credit Risk

The Company has an established customer credit policy, through which it manages customer credit exposures through credit evaluations, credit limit setting, monitoring, and enforcement of credit limits for new and existing customers. The Company performs ongoing credit evaluations of its customers’ financial condition and makes provisions for credit losses based on the outcome of those credit evaluations. The Company evaluates the collectability of its accounts receivable based on specific customer circumstances, current economic trends,


F-12


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


historical experience with collections and the age of past due receivables. To the extent the Company identifies exposures as a result of credit or customer evaluations, the Company also reviews other customer related exposures, including but not limited to inventory and related contractual obligations.

The Company’s allowance for credit losses was zero as of March 31, 2026 and $1 million as of March 31, 2025.

A significant portion of our revenues are concentrated with a number of customers. The comparability of customer concentrations for the periods presented are impacted by the timing of customer initiatives, market trends, and other fluctuations in demand. Revenues from each customer that were greater than 10% of total revenues were as follows:


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Customer (a)

   $ 2,236        34   $ 1,889        39   $ 840        26

Customer (b)

     2,015        30     1,298        27     1,117        34

Revenues for customer (a) and customer (b) are reported in both the Cloud & Cooling and Power segments.

Total accounts receivables related to customers (a) and (b) amounted to 20% and 50% of total accounts receivables as of March 31, 2026 and 22% and 27% of total accounts receivables as of March 31, 2025, respectively.

Cash and Cash Equivalents

Cash and cash equivalents may include cash on hand, demand deposits and all highly liquid investments with original maturities at the time of purchase of three months or less. The Company maintains amounts on deposit at various financial institutions that may, at times, exceed federally insured limits. However, management periodically evaluates the creditworthiness of these institutions and has not experienced any losses on such deposits during the periods presented. The Company participates in Flex’s cash management and financing programs. The cash reflected on the combined balance sheet represents cash on hand at certain foreign and domestic locations which do not participate in Flex’s centralized cash management program and are specifically identifiable to the Business.

Inventories

Inventories are stated at the lower of cost (on a first-in, first-out basis) or net realizable value. The stated cost is comprised of direct materials, labor and overhead. The components of inventories, net of applicable lower of cost or net realizable value write-downs, were as follows:


     As of March 31,  
     2026      2025  
    

(In millions)


Raw materials

   $ 1,151      $ 772  

Work-in-progress

     225        198  

Finished goods

     222        196  


   $ 1,598      $ 1,166  


Customer-controlled inventories

Customer-controlled inventories consist of inventory subject to customer-specific contractual arrangements, including repurchase options and pass-through contracts, that is held at Spinco locations. Although the Company has purchased


F-13


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


and may physically possess or manage such inventory, the Company does not control the inventory as the counterparty retains the ability to direct use of or, obtain substantially all of the remaining benefits from, the inventory due to contractual restrictions. Accordingly, customer-controlled inventories are excluded from inventories on the combined balance sheets and are presented separately.

Property and Equipment, Net

Property and equipment are stated at cost, less accumulated depreciation and amortization. Depreciation and amortization are recognized on a straight-line basis over the estimated useful lives of the related assets, with the exception of building leasehold improvements, which are depreciated over the term of the lease, if shorter. Repairs and maintenance costs are expensed as incurred. Property and equipment is comprised of the following:


     Depreciable
Life
(In Years)
     As of March 31,  
     2026      2025  
            (In millions)  

Machinery and equipment

     2 – 10      $ 390      $ 284  

Buildings

     30        186        68  

Leasehold improvements

    
Shorter of lease term or useful
life of the improvement
 
 
     45        25  

Furniture, fixtures, computer equipment and software, and other

     3 – 7        23        16  

Land

     —         41        4  

Construction-in-progress

     —         181        44  


        866        441  

Accumulated depreciation and amortization

        (298      (195


Property and equipment, net

      $ 568      $ 246  


Total depreciation expense associated with property and equipment was $62 million, $40 million and $26 million in fiscal years 2026, 2025 and 2024, respectively.

The Company reviews property and equipment for impairment at least annually and whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. Recoverability of property and equipment is determined by comparing its carrying amount to the lowest level of identifiable projected undiscounted cash flows the property and equipment are expected to generate. An impairment loss is recognized when the carrying amount of property and equipment exceeds its fair value.

Income Taxes

Income taxes, as presented in the combined financial statements, attribute current and deferred income taxes of Flex to the Company’s standalone financial statements in a manner that is systematic, rational and consistent with the asset and liability method prescribed by Accounting Standard Codification (“ASC”) 740 Income Taxes. Accordingly, the Company’s income tax provision was prepared following the separate return method. The separate return method applies ASC 740 to the standalone financial statements of each member of the consolidated group as if the group members were separate taxpayers. As a result, actual transactions included in the consolidated financial statements of Flex may not be included in the separate combined financial statements of the Company. Similarly, the tax treatment of certain items reflected in the combined financial statements of the Company may not be reflected in the consolidated financial statements and tax returns of Flex. Therefore, items such as net operating losses, credit carryforwards and valuation allowances may exist in the standalone financial statements that may or may not exist in Flex’s consolidated financial statements. As such, the income


F-14


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


taxes of the Company as presented in the combined financial statements may not be indicative of the income taxes that the Company will generate in the future.

The Company provides for income taxes in accordance with the asset and liability method of accounting for income taxes. Under this method, deferred income taxes are recognized for the tax consequences of temporary differences between the carrying amount and the tax basis of existing assets and liabilities by applying the applicable statutory tax rate to such differences. Additionally, the Company assesses whether each income tax position is “more likely than not” of being sustained on audit, including resolution of related appeals or litigation, if any. For each income tax position that meets the “more likely than not” recognition threshold, the Company would then assess the largest amount of tax benefit that is greater than 50% likely of being realized upon effective settlement with the tax authority.

Since the Company’s results are included in the Parent’s consolidated tax returns, payments to certain tax authorities are made by the Parent and not by the Company. For tax jurisdictions where the Company is included with the Parent in a consolidated tax filing, the Company does not maintain taxes payable to or from the Parent. The payments are deemed to be settled immediately with the legal entities paying the tax in the respective tax jurisdictions and are reflected in the combined statements of cash flows as net transfers from (to) Parent within financing activities and in the combined balance sheet as net parent investment.

Accounting for Business and Asset Acquisitions

The Company has strategically pursued business acquisitions. For acquisitions that meet the definition of a business under ASC 805 Business Combinations, the fair value of the net assets acquired and the results of the acquired businesses are included in the Company’s combined financial statements from the acquisition dates forward. The Company is required to make estimates and assumptions that affect the reported amounts of assets and liabilities and results of operations during the reporting period. Estimates are used in accounting for, among other things, the fair value of acquired net operating assets, property and equipment, intangible assets and related deferred tax liabilities, useful lives of plant and equipment and amortizable lives for acquired intangible assets. Any excess of the purchase consideration over the fair value of the identified assets and liabilities acquired is recognized as goodwill and if the fair value of assets acquired and liabilities assumed exceeds the purchase consideration a gain on bargain purchase is recognized.

The Company estimates the preliminary fair value of acquired assets and liabilities as of the date of acquisition based on information available at that time. Contingent consideration is recorded at fair value as of the date of the acquisition with subsequent adjustments recorded in earnings. Changes to valuation allowances on acquired deferred tax assets are recognized in the provision for income taxes. The valuation of these tangible and identifiable intangible assets and liabilities is subject to further management review and may change materially between the preliminary allocation and end of the purchase price allocation period, which does not exceed a year from the acquisition date. Any changes in these estimates may have a material effect on the Company’s combined operating results or financial position.

Goodwill

The Company evaluates goodwill for impairment at the reporting unit level annually and in certain circumstances, such as a change in reporting units, or whenever there are indications that goodwill might be impaired. As of January 1, 2026, the Company performed a qualitative assessment of goodwill and determined that it was more likely than not that the fair value of each of its two reporting units exceeded its respective carrying amount; accordingly, no quantitative goodwill impairment test was required, and no goodwill impairment was recognized.


F-15


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Recoverability of goodwill is measured at the reporting unit level by comparing the reporting unit’s carrying amount, including goodwill, to the fair value of the reporting unit, which typically is measured based upon, among other factors, market valuations, market multiples for comparable companies as well as a discounted cash flow analysis. Certain of these approaches use significant unobservable inputs, or Level 3 inputs, as defined by the fair value hierarchy and require management to make various judgmental assumptions about sales, operating margins, growth rates and discount rates which consider the Company’s budgets, business plans and economic projections, and are believed to reflect market participant views. Some of the inherent estimates and assumptions used in determining fair value of the reporting units are outside the control of management, including interest rates, cost of capital, tax rates, market EBITDA comparable and credit ratings. While the Company believes it has made reasonable estimates and assumptions to calculate the fair value of the reporting units, it is possible a material change could occur. If the actual results are not consistent with management’s estimates and assumptions used to calculate fair value, it could result in material impairments of the Company’s goodwill.

If the recorded value of the assets, including goodwill, and liabilities (“net book value”) of any reporting unit exceeds its fair value, an impairment loss may be required to be recognized.

The following table summarizes the activity in the Company’s goodwill during fiscal years 2026 and 2025:


     Cloud &
Cooling
     Power      Total  
     (In millions)  

Balance at March 31, 2024

   $ 7      $ 282      $ 289  

Acquisitions (1)

     31        170        201  


Balance at March 31, 2025

     38        452        490  

Acquisitions (2)

     —         8        8  


Balance at March 31, 2026

   $ 38      $ 460      $ 498  


(1)

Represents goodwill of $170 million from the Crown acquisition and $31 million from the JetCool acquisition. Refer to Note 10 for further details.

(2)

Represents goodwill of $8 million from the Bielsko Biala acquisition. Refer to Note 10 for further details.

Intangible Assets

The Company’s acquired intangible assets are subject to amortization over their estimated useful lives and are reviewed for impairment whenever events or changes in circumstances indicate that the carrying amount of an intangible asset may not be recoverable. An impairment loss is recognized when the carrying amount of an intangible asset exceeds its fair value. The Company reviewed the carrying value of its intangible assets as of March 31, 2026, and concluded that such amounts continued to be recoverable.

Intangible assets are comprised of customer-related intangible assets that include contractual agreements and customer relationships, and licenses and other intangible assets that are primarily comprised of trademarks, and developed technologies. Generally, both customer-related intangible assets and licenses and other intangible assets are amortized on a straight-line basis, over a period of up to 15 years. No residual value is estimated for any intangible assets. The fair value of the Company’s intangible assets purchased through business combinations is determined based on management’s estimates of cash flow and recoverability. During fiscal years 2026 and 2025, the total value of intangible assets increased by $2 million and $148 million, respectively, as a result of the Company’s acquisitions during the periods. Refer to note 10 for additional information.


F-16


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


The components of acquired intangible assets are as follows:


    As of March 31, 2026     As of March 31, 2025  
    Weighted-
Average
Remaining
Useful life

(in Years)
    Gross
Carrying
Amount
    Accumulated
Amortization
    Net
Carrying
Amount
    Gross
Carrying
Amount
    Accumulated
Amortization
    Net
Carrying
Amount
 
    (In millions)  

Intangible assets:


Customer-related intangibles

    8.4     $ 224     $ (84   $ 140     $ 217     $ (55   $ 162  

Licenses and other intangibles

    6.0       193       (74     119       206       (65     141  


Total

    $ 417     $ (158   $ 259     $ 423     $ (120   $ 303  


Total intangible asset amortization expense recognized in operations during fiscal years 2026, 2025 and 2024 was $50 million, $36 million and $32 million, respectively. The gross carrying amounts of intangible assets are removed when fully amortized. The estimated future annual amortization expense for acquired intangible assets is as follows:


Fiscal Year Ending March 31,

   Amount  
     (In millions)  

2027

   $ 47  

2028

     41  

2029

     38  

2030

     33  

2031

     32  

Thereafter

     68  


Total amortization expense

   $ 259  


The Company owns or licenses various United States and foreign patents relating to a variety of technologies. For certain of the Company’s proprietary processes, inventions, and works of authorship, the Company relies on trade secret or copyright protection. The Company also maintains trademark rights (including registrations) for the Company’s corporate name and several other trademarks and service marks that the Company uses in the Company’s business in the United States and other countries throughout the world. The Company has policies and procedures (including both technological means and training programs for the Company’s employees) to identify and protect the Company’s intellectual property, as well as that of the Company’s customers and suppliers.

Customer Working Capital Advances

Customer working capital advances were $145 million and $140 million as of March 31, 2026 and 2025, respectively. The customer working capital advances are not interest-bearing, do not generally have fixed repayment dates and are generally reduced as the underlying working capital is consumed in production or the customer working capital advance agreement is terminated.

Other Current Liabilities

Other current liabilities include customer-related accruals of $102 million and $62 million as of March 31, 2026 and 2025, respectively.


F-17


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Leases

The Company is a lessee with several non-cancelable operating leases, primarily for warehouses, buildings, and other assets such as vehicles and equipment. The Company determines if an arrangement is a lease at contract inception. A contract is a lease or contains a lease when (1) there is an identified asset, and (2) the Company has the right to control the use of the identified asset. The Company recognizes a right-of-use (“ROU”) asset and a lease liability at the lease commencement date for the Company’s operating leases. For operating leases, the lease liability is initially measured at the present value of the unpaid lease payments at the lease commencement date. The Company has elected the short-term lease recognition and measurement exemption for all classes of assets, which allows the Company to not recognize ROU assets and lease liabilities for leases with a lease term of 12 months or less and with no purchase option the Company is reasonably certain of exercising. The Company has also elected the practical expedient to account for the lease and non-lease components as a single lease component, for all classes of underlying assets. Therefore, the lease payments used to measure the lease liability include all of the fixed considerations in the contract. Lease payments included in the measurement of the lease liability comprise the following: fixed payments (including in-substance fixed payments), and variable payments that depend on an index or rate (initially measured using the index or rate at the lease commencement date). As the Company cannot determine the interest rate implicit in the lease for the Company’s leases, the Company uses the Company’s estimate of the incremental borrowing rate as of the commencement date in determining the present value of lease payments. The Company’s estimated incremental borrowing rate is the rate of interest it would have to pay on a collateralized basis to borrow an amount equal to the lease payments under similar terms. The lease term for all of the Company’s leases includes the non-cancelable period of the lease plus any additional periods covered by either an option to extend (or not to terminate) the lease that the Company is reasonably certain to exercise, or an option to extend (or not to terminate) the lease controlled by the lessor.

As of March 31, 2026 and 2025, current operating lease liabilities were $25 million and $11 million, respectively, and are included in other current liabilities on the combined balance sheets.

Recently Issued Accounting Pronouncements

In December 2025, the FASB issued ASU 2025-10 “Government Grants (Topic 832),” which establishes comprehensive guidance on the recognition, measurement, presentation, and disclosure of government grants. The Company expects the new guidance will have an immaterial impact on its combined financial statements and intends to adopt the guidance prospectively when it becomes effective in the first quarter of fiscal year 2030.

In November 2024, the FASB issued ASU 2024-03 “Income Statement-Reporting Comprehensive Income-Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses,” which requires public entities to disclose specified information about certain costs and expenses. In January 2025, the FASB issued ASU 2025-01 on the same topic to clarify the amendments for ASU 2024-03 are effective for the Company in the fourth quarter of fiscal year 2028. The amendment will be applied retrospectively to all prior periods presented on its combined financial statements. We are currently evaluating the guidance to determine the impact on the Company’s financial statements and disclosures.

Recently Adopted Accounting Pronouncements

In November 2023, the FASB issued ASU 2023-07 “Segment Reporting—Improvements to Reportable Segment Disclosures,” which updates reportable segment disclosure requirements, primarily through enhanced disclosures about significant segment expenses and information used to assess segment performance. The guidance is effective for the Company beginning in the fourth quarter of fiscal year 2025. The Company adopted the guidance retrospectively during the fourth quarter of fiscal year 2025. See note 11 for reportable segment disclosures.


F-18


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


In December 2023, the FASB issued ASU 2023-09 “Income Taxes (Topic 740): Improvements to Income Tax Disclosures,” which expands disclosures in an entity’s income tax rate reconciliation table and income taxes paid both in the U.S. and foreign jurisdictions. This standard improves the transparency of income tax disclosures by requiring consistent categories and greater disaggregation of information in the effective tax rate reconciliation and income taxes paid disaggregated by jurisdiction. It also includes certain other amendments to improve the effectiveness of income tax disclosures. The adoption of this new standard did not have a material impact on the Company’s consolidated financial statements and was adopted on a prospective basis as it is effective for the Company, beginning in the fourth quarter of fiscal year 2026. For additional information, see note 9—“Income Taxes.”

In July 2025, the FASB issued ASU 2025-05 “Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets,” which provides for the use of a new practical expedient when estimating expected credit losses for accounts receivable and contract assets arising from transactions accounted for under Topic 606 that assumes that current conditions as of the balance sheet date do not change for the remaining life of the asset. The guidance is effective for the Company, and has been adopted, beginning in the second quarter of fiscal year 2026.

3. LEASES

The Company has several commitments under operating leases for warehouses, buildings, and equipment. The Company also has a number of finance leases with an immaterial impact on its combined financial statements. Leases have remaining lease terms ranging from 1 year to 20 years.

The components of lease cost recognized were as follow (in millions):


Lease cost

   Fiscal Year Ended  
     March 31,
2026
     March 31,
2025
     March 31,
2024
 

Operating lease cost

   $ 42      $ 16      $ 13  

Amounts reported in the combined balance sheet as of the fiscal years ended March 31, 2026 and 2025 were (in millions, except weighted average lease term and discount rate):


     As of
March 31,
2026
    As of
March 31,
2025
 

Operating Leases:


Operating lease right of use assets

   $ 186     $ 80  

Operating lease liabilities *

     191       81  

Weighted-average remaining lease term (In years)


Operating leases

     11.7       12.6  

Weighted-average discount rate


Operating leases

     4.6     4.5


*

Operating lease liabilities includes $25 million and $11 million current lease liabilities and $166 million and $70 million non-current lease liabilities as of March 31, 2026 and 2025, respectively.


F-19


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Other information related to leases was as follows (in millions):


     Fiscal Year Ended  
     March 31,
2026
     March 31,
2025
     March 31,
2024
 

Cash paid for amounts included in the measurement of lease liabilities:


Operating cash flows from operating leases

   $ 32      $ 11      $ 9  

Right-of-use assets obtained in exchange for lease liabilities


Operating Lease

   $ 46      $ 36      $ 11  

Future lease payments under non-cancelable leases as of March 31, 2026 were as follows (in millions):


Fiscal Year Ended March 31,

   Operating
Leases
 

2027

   $ 33  

2028

     35  

2029

     30  

2030

     27  

2031

     25  

Thereafter

     76  


Total undiscounted lease payments

     226  

Less: imputed interest

     35  


Total lease liabilities

   $ 191  


Total rent expense amounted to $44 million, $22 million and $17 million in fiscal years 2026, 2025 and 2024, respectively.

4. REVENUE

Revenue Recognition

The Company provides a comprehensive suite of products and services supporting the design, manufacture and servicing of end-to-end power and infrastructure solutions for its customers in the data center and utility industries. The first step in its process for revenue recognition is to identify a contract with a customer. A contract is defined as an agreement between two parties that creates enforceable rights and obligations and can be written, verbal, or implied. The Company generally enters into master supply agreements (“MSAs”) with its customers that provide the framework under which business will be conducted. This includes matters such as warranty, indemnification, transfer of title and risk of loss, liability for excess and obsolete inventory, pricing formulas, payment terms, etc., and the level of business under those agreements may not be guaranteed. In those instances, the Company bids on a program-by-program basis and typically receives customer purchase orders for specific quantities and timing of products. As a result, the Company considers its contract with a customer to be the combination of the MSA and the purchase order, or any other similar documents such as a statement of work, product addendum, forecast commitments, emails or other communications that embody the commitment by the customer. See Note 2 “Summary of Accounting Policies” for additional discussion surrounding revenue recognition considerations.


F-20


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Customer Contracts and Related Obligations

Certain of the Company’s customer agreements include potential price adjustments which may result in variable consideration. These price adjustments include, but are not limited to, sharing of cost savings, committed price reductions, purchase price variances earned over the period that are contractually required to be paid to the customers, rebates, refunds tied to performance metrics such as on-time delivery, and other periodic pricing resets that may be refundable to customers. The Company estimates the variable consideration related to these price adjustments as part of the total transaction price and recognizes revenue in accordance with the pattern applicable to the performance obligation, subject to a constraint. The Company constrains the amount of revenues recognized for these contractual provisions based on its best estimate of the amount which will not result in a significant reversal of revenue in a future period. The Company determines the amounts to be recognized based on the amount of potential refunds required by the contract, historical experience and other surrounding facts and circumstances. Often these obligations are settled with the customer in a period after shipment through various methods which include reduction of prices for future purchases, issuance of a payment to the customer, or issuance of a credit note applied against the customer’s accounts receivable balance. In many instances, the agreement is silent on the settlement mechanism. Any difference between the amount accrued for potential refunds and the actual amount agreed to with the customer is recorded as an increase or decrease in revenue. These potential price adjustments are included as part of other current liabilities on the combined balance sheet and disclosed as part of customer-related accruals in note 2.

Performance Obligations

The Company derives its revenues by delivering products and services to customers operating in the data center and utility industries.

A performance obligation is an implicitly or explicitly promised good or service that is material in the context of the contract and is both capable of being distinct (customer can benefit from the good or service on its own or together with other readily available resources) and distinct within the context of the contract (separately identifiable from other promises). The Company considers all activities typically included in its contracts, and identifies those activities representing a promise to transfer goods or services to a customer. These include, but are not limited to, design and engineering services, prototype products, tooling, services, etc. Each promised good or service with regards to these identified activities is accounted for as a separate performance obligation only if it is distinct—i.e., the customer can benefit from it on its own or together with other resources that are readily available to the customer. Certain activities on the other hand are determined not to constitute a promise to transfer goods or service, and therefore do not represent separate performance obligations for revenue recognition (e.g., procurement of materials and standard workmanship warranty).

A contract’s transaction price is allocated to each distinct performance obligation and recognized as revenue when, or as, the performance obligation is satisfied. The majority of the Company’s contracts have a single performance obligation as the promise to transfer the individual good or service is not separately identifiable from other promises in the contract and is, therefore, not distinct. Promised goods or services that are immaterial in the context of the contract are not separately assessed as performance obligations. In the event that more than one performance obligation is identified in a contract, the Company is required to allocate the transaction price between the performance obligations. The allocation would generally be performed on the basis of a relative standalone price for each distinct good or service. This standalone price most often represents the price that the Company would sell similar goods or services separately. As most of the Company’s contracts have an expected duration of one year or less, we have applied the practical expedient such that specified disclosures pertaining to remaining performance obligations are not required.


F-21


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Contract Balances

A contract asset is recognized when the Company has recognized revenue, but not issued an invoice for payment. Contract assets are classified separately on the combined balance sheets and transferred to receivables when rights to payment become unconditional and invoiced.

A contract liability is recognized when the Company receives payments in advance of the satisfaction of performance. Contract liabilities, identified as deferred revenue, were $100 million and $82 million as of March 31, 2026 and 2025, respectively, of which $67 million and $77 million, respectively, is included in deferred revenue and customer working capital advances under current liabilities.

Warrant

During the second quarter of fiscal year 2026, Flex issued a warrant (“the Warrant”) to a customer for the purchase of up to an aggregate of 3.9 million ordinary shares of Flex (“Warrant Shares”). The Warrant Shares vest based on qualifying payments (as defined in the Warrant) for the purchase of all products and services over the term of the Warrant and are recognized as a deduction to revenue as qualifying revenues are recognized. Refer to note 5 “Share-Based Compensation and Warrants” for additional information.

Disaggregation of Revenue

The following table presents the Company’s revenue disaggregated based on timing of transfer—PIT and OT for the fiscal years ended March 31, 2026, 2025 and 2024:


     Fiscal Year Ended March 31,  
     2026      2025      2024  
Timing of Transfer    (In millions)  

Cloud & Cooling


Point in time

   $ 4,350      $ 3,460      $ 2,218  

Over time

     179        48        4  


Total

     4,529        3,508        2,222  

Power


Point in time

     1,810        1,228        1,014  

Over time

     275        63        8  


Total

     2,085        1,291        1,022  

Spinco


Point in time

     6,160        4,688        3,232  

Over time

     454        111        12  


Total

   $ 6,614      $ 4,799      $ 3,244  


During the years ended March 31, 2026 and 2025, certain existing customer contractual relationships were changed to provide an enforceable right to payment for work completed to date that had the effect of transitioning revenue with those customers from being recognized on a point in time to an over time basis, with prospective effect. This change had the effect of increasing contract assets by $83 million and $8 million as of March 31, 2026 and 2025, respectively. Contract assets are generally transferred to receivables in the succeeding quarter due to the short-term nature of the Company’s manufacturing cycle.


F-22


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


5. SHARE-BASED COMPENSATION AND WARRANTS

Stock-Based Compensation Expense

The Company’s employees have historically participated in the Parents stock-based compensation plans. The combined statements of operations include all stock-based compensation expenses directly attributable to Spinco employees, as well as an allocation of any stock-based compensation expenses related to Flex corporate and other shared employees. Accordingly, the amounts presented are not necessarily indicative of future awards and do not necessarily reflect the results that the Business would have experienced as an independent company for the periods presented.

The compensation cost in the combined statements of operations of the stock-based compensation arrangements that have been attributed to the Company are as follows:


     Fiscal Year Ended
March 31,
 
     2026      2025      2024  
     (In millions)  

Cost of sales

   $ 7      $ 5      $ 3  

Selling, general and administrative expense

     26        18        11  


Total stock-based compensation expense

   $ 33      $ 23      $ 14  


Warrant

On August 15, 2025, Flex issued a Warrant to Amazon.com NV Investment Holdings LLC (“Warrantholder”), a wholly-owned subsidiary of Amazon.com, Inc. (“Parent”) to purchase up to an aggregate of 3,859,851 Warrant Shares at an exercise price of $51.29 per share, which was the preceding 30 trading days Volume-Weighted Average Price. The Warrant allows for cashless exercise and expires on August 15, 2030; however, if there are unexercised Warrant Shares as of the expiration date, and Flex and Warrantholder maintain a continued commercial relationship, the Company shall negotiate in good faith with Warrantholder to agree to issue to Warrantholder a new two-year warrant as of the expiration date that provides the same exercise price and other terms for vested and unexercised Warrant Shares, that also takes into account the commercial relationship in effect at such time. The Warrant Shares are subject to vesting based on qualifying payments (as defined in the Warrant) for the purchase of all products and services by or on behalf of Parent and its affiliates over the term of the Warrant. Upon the consummation of an acquisition transaction (as defined in the related transaction agreement), subject to a specified condition, the unvested portion of the Warrant will vest in full. So long as the Warrant is unexercised, the Warrant does not entitle Warrantholder to any voting rights or any other shareholder rights. The exercise price and the number of Warrant Shares are subject to customary anti-dilution adjustments. The expense associated with the Warrant Shares will be recorded as a deduction to revenue as the customer purchases products and services over the vesting period.

The estimated fair value of the Warrant was determined as of the issuance date, using the Black-Scholes option pricing model. The following assumptions were used in the model:


     As of August 15,
2025
 

Expected volatility

     45.8%  

Expected dividend yield

     — %  

Expected life

     7 years  

Risk-free interest rate

     4.0%  


F-23


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


The calculated fair value of each Warrant Share at the issuance date was $25.47. The Company recorded charges of $6 million during the fiscal year ended March 31, 2026. As of March 31, 2026, no Warrant Shares have vested or been exercised.

6. SUPPLEMENTAL CASH FLOW DISCLOSURES

The following table represents supplemental cash flow disclosures and non-cash investing and financing activities.


     Fiscal Year Ended
March 31,
 
     2026      2025      2024  
     (In millions)  

Net cash paid for:


Interest

   $ 5      $ 6      $ 4  

Income taxes

     31        27        16  

Non-cash investing and financing activity:


Unpaid purchases of property and equipment

     72        35        15  

Non-cash parent capital contributions

   $ 173      $ 37      $ 22  

7. TRADE RECEIVABLES SALES PROGRAMS

The Company sells accounts receivables to certain third-party banking institutions under factoring programs. The outstanding balance of receivables sold and not yet collected on accounts where the Company has continuing involvement was $0.3 billion and $0.3 billion as of March 31, 2026 and 2025, respectively. For the fiscal years ended March 31, 2026 and 2025, total accounts receivable sold to certain third party banking institutions was $2.1 billion and $1.9 billion, respectively. The receivables that were sold were removed from the combined balance sheets and the cash received was included as cash provided by operating activities in the combined statements of cash flows.

8. COMMITMENTS AND CONTINGENCIES

The Company is subject to routine legal proceedings, as well as demands, claims and threatened litigation that arise in the normal course of business. The ultimate outcome of any litigation is often uncertain and unfavorable outcomes could have a negative impact on the results of operations and financial condition. The Company regularly reviews the status of each significant matter and assesses its potential financial exposure. If the potential loss from any claim or legal proceeding is considered probable and the amount or the range of loss can be estimated, the Company accrues a liability for the estimated loss. Legal proceedings are subject to uncertainties, and the outcomes are difficult to predict. Because of such uncertainties, accruals are based on the Company’s judgments using the best information available at the time.

The Company determined that no disclosure of estimated loss is required for a claim against us because: (i) there is not a reasonable possibility that a loss exceeding amounts already recognized (if any) may be incurred with respect to such claim; (ii) a reasonably possible loss or range of loss cannot be estimated; or (iii) such estimate is immaterial.


F-24


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


9. INCOME TAXES

The domestic and foreign components of income before income taxes were comprised of the following:


     Fiscal Year Ended
March 31,
 
     2026      2025      2024  
     (In millions)  

Domestic

   $ 106      $ 111      $ 83  

Foreign

     376        278        160  


Total

   $ 482      $ 389      $ 243  


The provision for income taxes consisted of the following:


     Fiscal Year Ended
March 31,
 
     2026      2025      2024  
     (In millions)  

Current:


Domestic

   $ 35      $ 37      $ 5  

US State

     9        8        2  

Foreign

     44        47        42  


     88        92        49  

Deferred:


Domestic

     (13      (11      16  

US State

     (2      (2      2  

Foreign

     (4      (10      (6


     (19      (23      12  


Provision for income taxes

   $ 69      $ 69      $ 61  


F-25


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


The Parent of Spinco will be domiciled in the United States and therefore the statutory tax expense is based on the U.S. federal rate of 21%. Upon adoption of ASU 2023-09, Improvements to Income Tax Disclosures, as described in Note 2, Summary of Significant Accounting Policies, the reconciliation of the income tax expense expected based on domestic statutory income tax rates to the expense (benefit) for income taxes included in the combined statements of operations for the year ended March 31, 2026 is as follows (in millions, except for percentages):


     Fiscal Year Ended
March 31, 2026
 
     Amounts      Percent  

Income taxes based on domestic statutory rates

   $ 101        21

State and local income tax (1)

     5        1

Effect of jurisdictional tax rate differential:


Singapore:


Statutory tax rate difference between Singapore and the US

     (7      (2 )% 

Nontaxable income

     (32      (7 )% 

Mexico:


Statutory tax rate difference between Mexico and the US

     7        2

Other

     (3      (1 )% 

Malaysia:


Reinvestment allowance

     (7      (2 )% 

Other

     6        1

Changes in unrecognized tax benefits

     (2     

Effect of cross border tax laws

     3        1

Nondeductible or nontaxable items


Excess compensation (Section 162(m))

     5        1

Stock-based compensation

     (6      (1 )% 

Other

     (1     


Provision for income taxes

   $ 69        14


(1)

State taxes in Virginia and Oregon made up the majority (greater than 50 percent) of the tax effect in this category.

The reconciliation of taxes at the federal statutory rate to the Company’s provision for (benefit from) income taxes for the years ended March 31, 2025 and 2024 in accordance with the guidance prior to the adoption of ASU 2023-09 was as follows:


     Fiscal Year Ended
March 31,
 
     2025      2024  

Income taxes based on domestic statutory rates

   $ 82      $ 51  

Effect of jurisdictional tax rate differential

     (25      (1

Change in unrecognized tax benefit

            1  

Liability for undistributed earnings

     2        3  

Global intangible low-taxed income (GILTI)

     4        3  

U.S. state taxes

     5        4  

Other

     1        —   


Provision for income taxes

   $ 69      $ 61  


F-26


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Upon adoption of ASU 2023-09, Improvements to Income Tax Disclosures, as described in Note 2, Summary of Significant Accounting Policies, cash paid for income taxes, net of refunds, during the fiscal year ended March 31, 2026 was as follows:


     Fiscal Year Ended
March 31, 2026
 
     (in millions)  

Federal

   $ —   

State

     —   

Foreign:


Mexico

     19  

United Kingdom

     7  

Ireland

     3  

Other Countries

     2  


Total cash paid for income taxes, net of refunds

   $ 31  


A number of countries in which the Company is located allow for tax holidays or provide other tax incentives to attract and retain business. In general, these holidays were secured based on the nature, size and location of the Company’s operations. The aggregate dollar effect on the Company’s income resulting from tax holidays and tax incentives to attract and retain business for the fiscal years ended March 31, 2026, 2025 and 2024 were $3 million, $4 million and $3 million, respectively. The Company’s existing holidays do not expire.

The components of deferred income taxes are as follows:


     As of March 31,  
     2026      2025  
     (In millions)  

Deferred tax liabilities:


Fixed assets

   $ (4    $ (8

Operating lease right-of-use assets

     (41      (16

Intangible assets

     (35      (38

Others

     (1      (1


Total deferred tax liabilities

     (81      (63


Deferred tax assets:


Deferred compensation

     14        8  

Inventory valuation

     11        7  

Deferred revenue

     7        6  

Lease liabilities

     42        16  

Net operating loss and other carryforwards

     19        18  

Others

     10        5  


Total deferred tax assets

     103        60  

Valuation allowances

     (17      (15


Total deferred tax assets, net of valuation allowances

     86        45  


Net deferred tax asset (liability)

     5        (18


The net deferred tax (liability) is classified as follows:


Long-term asset

     26        7  

Long-term liability

     (21      (25


Total

   $ 5      $ (18


F-27


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Utilization of the Company’s deferred tax assets is limited by the future earnings of the Company in the tax jurisdictions in which such deferred assets arose. As a result, management is uncertain as to when or whether these operations will generate sufficient profit to realize any benefit from the deferred tax assets. The valuation allowance provides a reserve against deferred tax assets that are not more likely than not to be realized by the Company. However, management has determined that it is more likely than not that the Company will realize certain of these benefits and, accordingly, has recognized a deferred tax asset from these benefits. The change in valuation allowance is net of certain increases and decreases to prior year losses and other carryforwards that have no current impact on the tax provision.

Deferred tax assets as of March 31, 2026, 2025 and 2024 were reduced by a valuation allowance of $17 million, $15 million and $21 million, respectively, provided for certain non-U.S. tax attributes. The change in the valuation allowance resulted in an increase of $2 million, $5 million and $4 million to income tax expense in 2026, 2025 and 2024, respectively. If the Company determines that the likelihood of realization of existing deferred tax assets changes, a corresponding increase or decrease to the valuation allowance will be recognized as an increase or reduction to income tax expense in the period that determination is made.

The Company has recorded deferred tax assets of $19 million related to tax losses and other carryforwards. These tax losses and other carryforwards will expire at various dates as follows:


Expiration dates of deferred tax assets related to operation losses
and other carryforwards

 
Fiscal year    (In millions)  

2026–2031

   $ —   

2032–2037

     12  

Indefinite

     7  


   $ 19  


The amount of deferred tax assets considered realizable, however, could be reduced or increased in the near-term if facts, including the amount of taxable income or the mix of taxable income between subsidiaries, differ from management’s estimates.

A reconciliation of the beginning and ending amount of unrecognized tax benefits is as follows:


     Fiscal Year Ended
March, 31
 
     2026      2025      2024  
     (In millions)  

Change in unrecognized tax benefits


Balance, beginning of fiscal year

   $ 7      $ 6      $ 6  

Additions based on tax position related to the current year

     —         1        —   

Additions for tax positions of prior years

     —         —         1  

Reductions for tax positions of prior years

     (1      —         —   

Reductions related to lapse of applicable statute of limitations

     (2      —         —   

Impact from foreign exchange rates fluctuation

     —         —         —   

Settled with Parent through Net Parent investment

     —         —         (1


Balance, end of fiscal year

   $ 4      $ 7      $ 6  


The Company and its subsidiaries file federal, state, and local income tax returns in multiple jurisdictions around the world. With few exceptions, the Company is no longer subject to income tax examinations by tax authorities for years before 2008.


F-28


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Of the $4 million of unrecognized tax benefits at March 31, 2026, $4 million will affect the annual effective tax rate (“ETR”) if the benefits are eventually recognized. The amount that does not impact the ETR relates to positions that would be settled with a tax loss carryforward previously subject to a valuation allowance.

The Company recognizes interest and penalties accrued related to unrecognized tax benefits within the Company’s tax expense. The Company had approximately $1 million, $1 million and $1 million accrued for the payment of interest and penalties as of the fiscal years ended March 31, 2026, 2025 and 2024, respectively.

10. BUSINESS ACQUISITIONS

Fiscal 2026 Acquisitions

On April 30, 2025, the Company completed the acquisition of a manufacturing business in Bielsko Biala, Poland, for total purchase consideration of $35 million. The business is included in the Power segment. The results of the acquired business are included in the Company’s consolidated financial statements from the acquisition date. The allocation of the purchase price to the tangible and identifiable intangible assets acquired and liabilities assumed is based on their fair values as of the date of acquisition.

The following represents the Company’s allocation of the total purchase price to the acquired assets and liabilities of Bielsko Biala (in millions):


Current Assets:


Inventories

   $ 15  

Contract assets

     9  

Accounts receivable

     1  


Total current assets

     25  

Operating lease right-of-use assets, net

     28  

Property and equipment, net

     4  

Intangible assets (1)

     2  

Goodwill

     8  


Total assets

   $ 67  


Current liabilities:


Accrued payroll

   $ 4  

Operating lease liabilities

     2  


Total current liabilities

     6  

Operating lease liabilities, non-current

     26  


Total liabilities

     32  


Total aggregate purchase price

   $ 35  


(1)

Intangible assets of $2 million relate to customer relationships and will be amortized over a weighted-average estimated useful life of 5 years.

Fiscal 2025 Acquisitions

The Company completed two acquisitions during fiscal year 2025, accounted for as business combinations. The results of the acquired businesses are included in the Company’s combined financial statements from their respective acquisition dates. See Note 2 “Summary of Accounting Policies” for additional information related to the accounting for acquisitions. Pro forma results of operations have not been presented because the effects were not material to the Company’s combined financial results for all periods presented.


F-29


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Acquisition of Crown Technical Systems (“Crown”)

On November 19, 2024, the Company completed the business acquisition of 100% ownership of Crown, a U.S. leader in critical power solutions for a total purchase consideration of $319 million, including cash of $313 million and $6 million of customary closing adjustments. The acquisition adds complementary capabilities to our existing portfolio in the United States, primarily strengthening our critical power solutions.

Crown is included in the Power segment. The following represents the Company’s allocation of the total purchase price to the acquired assets and liabilities of Crown (in millions):


Current Assets:


Cash

   $ 5  

Accounts receivable

     23  

Inventory

     10  

Other current assets

     2  


Total current assets

     40  

Property and equipment

     1  

Operating lease right-of-use assets

     7  

Intangible assets

     128  

Goodwill

     170  


Total assets

   $ 346  


Current liabilities:


Accounts payable

   $ 4  

Accrued liabilities & other current liabilities

     17  


Total current liabilities

     21  

Operating lease liabilities, non-current

     6  


Total aggregate purchase price

   $ 319  


The intangible assets of $128 million are comprised of customer related intangible assets of $83 million and licenses and other intangible assets such as trade names and patented technology of $45 million. Customer related assets will be amortized over a weighted-average estimated useful life of 12.6 years while licenses and other intangibles will be amortized over a weighted-average estimated useful life of 10.0 years.

The excess of the purchase price over the estimated fair value of the net assets acquired was recognized as goodwill. The goodwill recognized in connection with the Crown acquisition is primarily attributable to expected synergies that will be generated with the rest of the Company.


F-30


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Acquisition of JetCool Technologies Inc. (“JetCool”)

On November 14, 2024, the Company acquired 100% ownership of JetCool, a provider of liquid cooling solutions tailored for the data center market, for approximately $43 million in cash, a deemed settled pre-existing loan from Flex of approximately $5 million, and $5 million of contingent consideration for a total estimated purchase price of $53 million. JetCool is included in the Cloud & Cooling segment. The following represents the Company’s allocation of the total purchase price to the acquired assets and liabilities of JetCool (in millions):


Current Assets:


Cash

   $ 4  

Inventory

     1  


Total current assets

     5  

Property and equipment

     1  

Operating lease right-of-use assets

     2  

Intangible assets

     21  

Goodwill

     31  


Total assets

   $ 60  


Operating lease liabilities

   $ 2  

Deferred tax liability

     5  


Total aggregate purchase price

   $ 53  


Intangible assets of $21 million relate to developed technology and will be amortized over a weighted-average estimated useful life of 6.5 years.

The excess of the purchase price over the estimated fair value of net assets was recognized as goodwill. The goodwill was primarily attributed to synergies that will be generated with the rest of the Company.

11. SEGMENT REPORTING

The Company’s Chief Commercial Officer is our Chief Operating Decision Maker (“CODM”) who evaluates how we allocate resources, assess performance and make strategic and operational decisions. Based on such evaluation, the Company determined as of and for the period ended March 31, 2026, that Spinco has two operating and reportable segments.

The Power segment is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment supports grid modernization and related power infrastructure applications.

The Cloud & Cooling segment includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments.

The determination of the separate operating and reporting segments is based on several factors, including the nature of products and services, the nature of production processes, customer base, delivery channels and similar economic characteristics.

An operating segment’s performance is evaluated based on its segment income. The CODM compares actual segment income to budgeted financial performance in allocating resources and assessing segment performance. Segment income is defined as net sales less cost of sales and segment selling, general and administrative expenses, and does not include corporate and other expense, amortization of intangibles, stock-based compensation, certain restructuring charges, legal and other, interest expense, and other charges (income).


F-31


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Selected financial information by segment is in the tables below:


Fiscal Year Ended March 31, 2026

   Cloud &
Cooling
     Power      Total  

Net Sales

   $ 4,529      $ 2,085      $ 6,614  

Segment cost of sales

     (4,096      (1,721   

Segment selling, general and administrative expenses

     (90      (106   


Segment income

   $ 343      $ 258      $ 601  


Corporate & other expense (1)

         $ 12  

Intangible amortization

           50  

Stock-based compensation

           33  

Restructuring charges (2)

           10  

Interest expense

           5  

Legal and other (3)

           16  

Other charges (income), net

           (7


Income before income taxes

         $ 482  


(1)

Corporate and other primarily includes corporate service costs that are not included in the CODM’s assessment of the performance of each of the identified reportable segments.

(2)

Restructuring charges primarily consist of charges related to employee severance, including an allocation of corporate severance charges.

(3)

Legal and other consists of one-time acquisition costs related to acquisitions made by the Company including Bielsko Biala, Electrical Power Products, Inc. and other contemplated acquisitions.


Fiscal Year Ended March 31, 2025

   Cloud &
Cooling
     Power      Total  

Net Sales

   $ 3,508      $ 1,291      $ 4,799  

Segment cost of sales

     (3,129      (1,036   

Segment selling, general and administrative expenses

     (68      (81   


Segment income

   $ 311      $ 174      $ 485  


Corporate & other expense (1)

         $ 13  

Intangible amortization

           36  

Stock-based compensation

           23  

Restructuring charges (2)

           5  

Interest expense

           6  

Legal and other (3)

           5  

Other charges (income), net

           8  


Income before income taxes

         $ 389  


(1)

Corporate and other primarily includes corporate service costs that are not included in the CODM’s assessment of the performance of each of the identified reportable segments.

(2)

Restructuring charges primarily consist of charges related to employee severance, including an allocation of corporate severance charges.

(3)

Legal and other consists of one-time acquisition costs related to the Crown and JetCool acquisitions that occurred during fiscal year 2025.


F-32


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Fiscal Year Ended March 31, 2024

   Cloud &
Cooling
     Power      Total  

Net Sales

   $ 2,222      $ 1,022      $ 3,244  

Segment cost of sales

     (1,997      (840   

Segment selling, general and administrative expenses

     (39      (65   


Segment income

   $ 186      $ 117      $ 303  


Corporate & other expense (1)

         $ 8  

Intangible amortization

           32  

Stock-based compensation

           14  

Restructuring charges (2)

           3  

Interest expense

           4  

Legal and other


Other charges (income), net

           (1


Income before income taxes

         $ 243  


(1)

Corporate and other primarily includes corporate service costs that are not included in the CODM’s assessment of the performance of each of the identified reportable segments.

(2)

Restructuring charges primarily consist of charges related to facility closures or consolidations and workforce alignment.

The Company does not disclose total assets by segment as this is not provided to the CODM.

Property and equipment on a segment basis is not separately identified and is not internally reported by segment to the Company’s CODM as described above. During fiscal years 2026, 2025 and 2024, total depreciation expense, including amounts allocated to the reportable segments, is as follows:


     Fiscal Year Ended
March 31,
 
     2026      2025      2024  
     (In millions)  

Depreciation expense:


Cloud & Cooling

   $ 29      $ 22      $ 14  

Power

     33        18        12  


Total depreciation expense

   $ 62      $ 40      $ 26  


Geographic information of net sales is as follows:


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Net sales by region:


Americas

   $ 4,320        65   $ 3,335        69   $ 2,055        63

Europe

     1,245        19     941        20     710        22

Asia

     1,049        16     523        11     479        15


   $ 6,614        $ 4,799        $ 3,244     


Revenues are attributable to the country in which the product is manufactured or service is provided.


F-33


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


The following table summarizes the countries that accounted for more than 10% of net sales in fiscal years 2026, 2025 and 2024:


     Fiscal Year Ended March 31,  
     2026     2025     2024  
     (In millions)  

Net sales by country:


U.S.

   $ 2,457        37   $ 1,537        32   $ 1,331        41

Mexico

     1,856        28     1,790        37     720        22

Malaysia

   $ 701        11   $ 298        6   $ 177        5

Geographic information of property and equipment, net is as follows:


     As of March 31,  
     2026     2025  
     (In millions)  

Property and equipment, net:


Americas

   $ 360        64   $ 118        48

Asia

     150        26     92        37

Europe

     58        10     36        15


   $ 568        $ 246     


The following table summarizes the countries that accounted for more than 10% of property and equipment, net in fiscal years 2026 and 2025:


     As of March 31,  
     2026     2025  
     (In millions)  

Property and equipment, net:


Mexico

   $ 334        59   $ 112        46

Malaysia

     97        17     67        27

12. RELATED PARTY TRANSACTIONS

The combined financial statements have been prepared on a standalone basis and are derived from the consolidated financial statements and accounting records of Flex. The following discussion summarizes activity between the Company and Flex.

Corporate allocations

The combined financial statements reflect allocations of certain expenses from the Parent including, but not limited to, legal, accounting, information technology, human resources and other infrastructure support. For the years ended March 31, 2026, 2025, and 2024, the cost of these services allocated to the Company included $20 million, $17 million, and $10 million, respectively, which were recorded in cost of sales, and $133 million, $101 million and $62 million, respectively, which were recorded in selling, general, and administrative expense. In addition to corporate allocated costs, stock-based compensation expense for corporate and shared employees amounted to $30 million, $22 million and $13 million for the years ended March 31, 2026, 2025 and 2024, respectively.


F-34


Table of Contents

NOTES TO THE COMBINED FINANCIAL STATEMENTS (Continued)


Cash management and net parent investment

Flex uses a centralized approach for the purpose of cash management and financing of its operations. The Company’s excess cash is transferred to Flex, and Flex funds the Company’s operating and investing activities as needed. The Parent operates a centralized non-interest-bearing cash pool in the U.S. and regional interest-bearing cash pools outside of the U.S. The total net effect of the settlement of these intercompany transactions is reflected in the combined statements of cash flows as a financing activity and in the combined balance sheets as net parent investment.

13. SUBSEQUENT EVENTS

On May 1, 2026, the Company completed the business acquisition of 100% of Electrical Power Products, Inc., a leading provider of engineered-to-order electrical power control and protection systems, for a purchase price of $1,187 million, including customary closing adjustments, in an all-cash transaction. The acquisition broadens the Company’s power portfolio and deepens its utility presence.

The acquisition will be accounted for using the acquisition method of accounting. Due to the timing of the closing date, the Company is still evaluating the fair values of the assets acquired and liabilities assumed as of the acquisition date. The initial accounting for the business combination is incomplete as of the issuance date of these financial statements, and the Company continues to assess, among other items, the valuation of acquired tangible and identifiable intangible assets, assumed liabilities and related tax effects. Based on preliminary analyses, identifiable intangible assets are expected to approximate $0.5 billion; however, these estimates are subject to change, which could be material, as the Company finalizes its valuation analyses.

Pro forma financial information has not been presented as the impact of the acquisition is not material to the Company’s consolidated revenues and results of operations.

The Company evaluated subsequent events for recognition or disclosure through July 8, 2026, the date the combined financial statements were available to be issued.


F-35


Table of Contents

CONDENSED COMBINED BALANCE SHEETS (Unaudited)


     As of June 26,
2026
     As of March 31,
2026
 
     (In millions)  
ASSETS  

Current assets:


Cash and cash equivalents

   $ 20      $ 7  

Accounts receivable, net of allowance for credit losses

     1,810        1,336  

Contract assets

     488        257  

Inventories

     1,813        1,598  

Customer-controlled inventory

     1,161        1,000  

Other current assets

     272        290  


Total current assets

     5,564        4,488  

Property and equipment, net

     766        568  

Operating lease right-of-use assets, net

     205        186  

Goodwill

     971        498  

Intangible assets, net

     716        259  

Other non-current assets

     47        33  


Total assets

   $ 8,269      $ 6,032  


LIABILITIES AND EQUITY  

Current liabilities:


Accounts payable

   $ 3,688      $ 3,279  

Accrued payroll and benefits

     104        130  

Deferred revenue and customer working capital advances

     361        212  

Other current liabilities

     323        223  


Total current liabilities

     4,476        3,844  

Operating lease liabilities, non-current

     182        166  

Other non-current liabilities

     85        59  


Total liabilities

   $ 4,743      $ 4,069  

Commitments and contingencies (Note 6)


Equity


Net Parent Investment

   $ 3,515      $ 1,948  

Accumulated other comprehensive income

     11        15  


Total equity

     3,526        1,963  


Total liabilities and equity

   $ 8,269      $ 6,032  


The accompanying notes are an integral part of these condensed combined financial statements.


F-36


Table of Contents

CONDENSED COMBINED STATEMENTS OF OPERATIONS (Unaudited)


     Three-Month Periods Ended  
     June 26, 2026      June 27, 2025  
     (In millions)  

Net sales

   $ 2,202      $ 1,626  

Cost of sales

     1,937        1,434  


Gross profit

     265        192  

Selling, general and administrative expenses

     82        57  

Intangible amortization

     18        13  


Operating income

     165        122  

Interest expense

     1        2  

Other charges (income), net

     —         2  


Income from operations before income taxes

     164        118  

Provision for income taxes

     11        14  


Net income

   $ 153      $ 104  


The accompanying notes are an integral part of these condensed combined financial statements.


F-37


Table of Contents

CONDENSED COMBINED STATEMENTS OF COMPREHENSIVE INCOME (Unaudited)


     Three-Month Periods Ended  
     June 26, 2026     June 27, 2025  
     (In millions)  

Net income

   $ 153     $ 104  

Other comprehensive income (loss), net of tax:


Foreign currency translation adjustments

     (4     16  


Comprehensive income

   $ 149     $ 120  


The accompanying notes are an integral part of these condensed combined financial statements.


F-38


Table of Contents

CONDENSED COMBINED STATEMENTS OF EQUITY (Unaudited)

Three Months Ended June 26, 2026


     Net Parent
Investment
     Accumulated
Other
Comprehensive
Income (Loss)
    Total
Equity
 
     (In millions)  

BALANCE AT MARCH 31, 2026

     1,948        15       1,963  

Net income

     153        —        153  

Other comprehensive income (loss), net of tax

     —         (4     (4

Net transfers from Parent

     1,414        —        1,414  


BALANCE AT JUNE 26, 2026

   $ 3,515      $ 11     $ 3,526  


Three Months Ended June 27, 2025


     Net Parent
Investment
    Accumulated
Other
Comprehensive
Income (Loss)
     Total
Equity
 
     (In millions)  

BALANCE AT MARCH 31, 2025

     1,513       6        1,519  

Net income

     104       —         104  

Other comprehensive income (loss), net of tax

     —        16        16  

Net transfers (to) Parent

     (85     —         (85


BALANCE AT JUNE 27, 2025

   $ 1,532     $ 22      $ 1,554  


The accompanying notes are an integral part of these condensed combined financial statements.


F-39


Table of Contents

CONDENSED COMBINED STATEMENTS OF CASH FLOWS (Unaudited)


     Three-Month Periods Ended  
     June 26, 2026     June 27, 2025  
     (In millions)  

Cash flows from operating activities:


Net income

   $ 153     $ 104  

Adjustments to reconcile net income to net cash provided (used in) by operating activities:


Depreciation

     21       16  

Amortization

     20       13  

Non-cash lease expense

     12       8  

Stock-based compensation

     13       9  

Deferred income taxes

     (3     (5

Changes in operating assets and liabilities, net of acquisitions:


Accounts receivable

     (406     (205

Contract assets

     (170     (25

Inventories

     (117     (84

Customer-controlled inventory

     (161     (42

Other current and noncurrent assets

     12       (27

Accounts payable

     397       387  

Other current and noncurrent liabilities

     160       51  


Net cash provided by (used in) operating activities

     (69     200  


Cash flows from investing activities:


Purchases of property and equipment

     (160     (42

Acquisitions of businesses, net of cash acquired

     (1,134     (41


Net cash (used in) investing activities

     (1,294     (83


Cash flows from financing activities:


Net transfers from (to) Parent

     1,378       (106


Net cash provided by (used in) financing activities

     1,378       (106


Effect of exchange rates on cash

     (2     3  

Net increase in cash and cash equivalents

     13       14  

Cash and cash equivalents, beginning of year

     7       24  


Cash and cash equivalents, end of year

   $ 20     $ 38  


Non-cash investing and financing activities:


Unpaid purchases of property and equipment

   $ 75     $ 32  

Right-of-use assets obtained in exchange for operating lease liabilities

     1       34  

Non-cash parent capital contributions

   $ 36     $ 21  

The accompanying notes are an integral part of these condensed combined financial statements.


F-40


Table of Contents

NOTES TO THE CONDENSED COMBINED FINANCIAL STATEMENTS (Unaudited)

1. ORGANIZATION OF THE COMPANY AND BASIS OF PRESENTATION

On May 5, 2026, Flex Ltd (‘‘Flex’’ or “Parent”) announced its plan to separate its businesses into two distinct, publicly traded companies (the “Separation”). Under the plan, Flex would execute a tax-free spinoff (the “Spin-off”) to Flex shareholders of its Cloud & Power Infrastructure business (“Spinco,” the “Company,” “we,” or “our”). Flex expects the transaction to be completed in the first half of calendar year 2027. The separation will be effected through a pro rata distribution of between approximately 88.0% to 94.0% of the outstanding shares of common stock of Spinco to Flex’s shareowners, with each Flex shareowner receiving shares of Spinco in proportion to their ownership of Flex common stock, in a transaction intended to be tax-free for U.S. federal income tax purposes. The separation, Spin-off and listing remain subject to final approval of Flex’s Board of Directors, our shareholders, and the High Court of the Republic of Singapore. There can be no assurances that a separation, spin-off or listing will occur.

Spinco is a global provider of end-to-end power and thermal management products and integrated infrastructure systems serving AI data centers and mission-critical applications. Through its critical power and electrical infrastructure portfolio, Spinco delivers electrification solutions that enable the efficient generation, distribution, and management of power. Deep expertise across critical power infrastructure, embedded and distributed power systems, power electronics, electrified architectures, advanced cooling, and compute integration allows Spinco to deliver coordinated system-level solutions designed to replace fragmented, multi-vendor approaches.

Spinco operates and reports its financial performance through two segments: (i) Power and (ii) Cloud & Cooling. The Power segment historically operated in Flex’s Industrial business unit and was presented within the results of the Reliability segment. Furthermore, the Cloud & Cooling segment historically operated in Flex’s Communications, Enterprise, & Cloud business unit and was presented within the results of the Agility segment. The Power and Cloud & Cooling segments are aligned with the end markets that the Company serves:

(i) Power is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment supports grid modernization and related power infrastructure applications.

(ii) Cloud & Cooling includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments.

Basis of Presentation

These condensed combined financial statements have been derived from the consolidated financial statements and accounting records of Flex Ltd. These condensed combined financial statements reflect the combined historical results of operations, financial position and cash flows of the Company for the periods presented as historically operated within Flex in conformity with generally accepted accounting principles in the United States (“U.S. GAAP”). The condensed combined financial statements may not be indicative of the Company’s future performance and do not necessarily reflect what the financial position, results of operations, and cash flows would have been had it operated as an independent company during the periods presented. Actual costs would depend on a number of factors, including the chosen organization structure, what functions were outsourced or performed by employees, and strategic decisions made in areas such as information technology and infrastructure. Accordingly, the Company has determined that it is not practicable to estimate the actual costs that would have been incurred had it operated as a standalone company during those periods.

The condensed combined results for the interim periods are not necessarily indicative of results to be expected for the full year. They do not include all of the information and footnotes required by U.S. GAAP for complete financial statements, and should be read in conjunction with the Company’s financial statements and notes for the year ended March 31, 2026. In the opinion of management, the accompanying unaudited condensed combined financial statements reflect all adjustments necessary for a fair presentation of our financial position.


F-41


Table of Contents

The first quarters for fiscal years 2027 and 2026 ended on June 26, 2026 and June 27, 2025, respectively, and are comprised of 87 days and 88 days, respectively.

All intracompany transactions have been eliminated. Intercompany transactions between Spinco and Flex are deemed to have settled immediately through Net Parent Investment. The net effect of deemed settled transactions is reflected in the combined statements of cash flows as a financing activity and in the combined balance sheets as net parent investment. Historically, Flex provided certain corporate support functions to the Company. The cost of such services were allocated to the Company based on direct usage when identifiable, with the remainder allocated on the basis of revenue, expenses, headcount or other relevant metrics. These costs are deemed settled in cash by Spinco to Flex in the period in which the costs were recorded within cost of sales or selling, general and administrative expenses in the combined statement of operations. Refer to Note 9 for additional information. Flex believes the basis on which the expenses have been allocated are a reasonable reflection of the utilization of services provided to, or the benefit received by, Spinco during the periods presented; however, they may not be indicative of actual expense that would have been incurred had the Company been operating as a standalone company for the periods presented. Going forward, the Company may perform these functions using its own resources or outsourced services. For an interim period, however, some of these functions may continue to be provided between Flex and the Company under a Transition Services Agreement following the separation.

Use of Estimates

The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosures of contingent assets and liabilities at the date of the financial statements, as well as the reported amounts of revenues and expenses during the reporting period. Estimates are based on several factors, including the facts and circumstances available at the time the estimates are made, historical experience, risk of loss, general economic conditions and trends, and the assessment of the probable future outcome. Actual results could differ from those estimates. Estimates and assumptions are reviewed periodically, and the effects of changes, if any, are reflected in the Combined Statements of Operations in the period in which they are determined.

Recently Issued Accounting Pronouncements

In November 2024, the FASB issued ASU 2024-03 “Income Statement-Reporting Comprehensive Income-Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses”, which requires public entities to disclose specified information about certain costs and expenses. The guidance is effective for the Company beginning in the fourth quarter of fiscal year 2028 and will be applied retrospectively to all prior periods presented on its consolidated financial statements. The Company is currently evaluating the guidance to determine the impact on the Company’s disclosures. In January 2025, the FASB issued ASU 2025-01 on the same topic to clarify the amendments for ASU 2024-03 are effective for the Company in the fourth quarter of fiscal year 2028.

In December 2025, the FASB issued ASU 2025-12 “Codification Improvements”, which includes numerous refinements and enhancements, including clarifications on the accounting for the retirement of treasury stock among others. The guidance is effective for the company beginning in the first quarter of fiscal year 2028. The Company is currently evaluating the guidance to determine the method of adoption and impact on the Company’s disclosures.


F-42


Table of Contents

2. BALANCE SHEET ITEMS

Inventories

The components of inventories, net of applicable lower of cost or net realizable value write-downs, were as follows:


     As of June 26,
2026
     As of March 31,
2026
 
     (In millions)  

Raw materials

   $ 1,390      $ 1,151  

Work-in-progress

     199        225  

Finished goods

     224        222  


   $ 1,813      $ 1,598  


Goodwill and Other Intangible Assets

During the three-month period ended June 26, 2026, goodwill increased by $473 million from an acquisition completed in the first quarter of fiscal year 2027. See note 7 for further details.

The components of acquired intangible assets are as follows:


     As of June 26, 2026      As of March 31, 2026  
     Weighted-
Average
Remaining
Useful life

(in Years)
     Gross
Carrying
Amount
     Accumulated
Amortization
    Net
Carrying
Amount
     Gross
Carrying
Amount
     Accumulated
Amortization
    Net Carrying
Amount
 
     (In millions)  

Intangible assets:


Customer-related intangibles

     14.7      $ 524      $ (96   $ 428      $ 224      $ (84   $ 140  

Licenses and other intangibles

     10.6        370        (82     288        193        (74     119  


Total

      $ 894      $ (178   $ 716      $ 417      $ (158   $ 259  


The gross carrying amounts of intangible assets are removed when fully amortized.

The estimated future annual amortization expense for acquired intangible assets is as follows:


Fiscal Year Ending March 31,

   Amount  
     (In millions)  

2027 (1)

   $ 70  

2028

     89  

2029

     66  

2030

     59  

2031

     58  

Thereafter

     374  


Total amortization expense

   $ 716  


(1)

Represents estimated amortization for the remaining nine-month period of the fiscal year ending March 31, 2027.


F-43


Table of Contents

For the three-month periods ended June 26, 2026 and June 27, 2025, amortization expense included $2 million and $0 million, respectively, which were recorded in cost of sales, and $18 million and $13 million, respectively, which were recorded in intangible amortization.

Customer Working Capital Advances

Customer working capital advances were $257 million and $145 million as of June 26, 2026 and March 31, 2026, respectively. The customer working capital advances are not interest-bearing, do not generally have fixed repayment dates and are generally reduced as the underlying working capital is consumed in production or the customer working capital advance agreement is terminated.

Other Current Liabilities

Other current liabilities include customer-related accruals of $112 million and $102 million as of June 26, 2026 and March 31, 2026, respectively.

3. REVENUE

Contract Balances

A contract asset is recognized when the Company has recognized revenue, but not issued an invoice for payment. Contract assets are classified separately on the combined balance sheets and transferred to receivables when rights to payment become unconditional and invoiced.

A contract liability is recognized when the Company receives payments in advance of the satisfaction of performance. Contract liabilities, identified as deferred revenue, were $163 million and $100 million as of June 26, 2026 and March 31, 2026, respectively, of which $104 million and $67 million, respectively, is included in deferred revenue and customer working capital advances under current liabilities.

Disaggregation of Revenue

The following table presents the Company’s revenue disaggregated based on timing of transfer - Point in time (“PIT”) and over time (“OT”):


      Three-Month Periods Ended   
     June 26, 2026      June 27, 2025  
Timing of Transfer      (In millions)  

Cloud & Cooling


Point in time

   $ 959      $ 1,229  

Over time

     477        27  


Total

     1,436        1,256  

Power


Point in time

     571        336  

Over time

     195        34  


Total

     766        370  

Spinco


Point in time

     1,530        1,565  

Over time

     672        61  


Total

   $ 2,202      $ 1,626  


F-44


Table of Contents

Concentration of Risk

A significant portion of our revenues are concentrated with a number of customers. The comparability of customer concentrations for the periods presented are impacted by the timing of customer initiatives, market trends, and other fluctuations in demand. Revenues from each customer that were greater than 10% of total revenues were as follows:


     Three-Month Periods Ended  
     June 26, 2026            June 27, 2025         
     (In millions)  
Customer (a)    $ 928        42   $ 610        38

Customer (b)

     482        22     545        34

Revenues for customer (a) and customer (b) are reported in both the Cloud & Cooling and Power segments.

Total accounts receivables related to customers (a) and (b) amounted to 22% and 47% of total accounts receivables as of June 26, 2026.

4. SHARE-BASED COMPENSATION AND WARRANTS

Stock-Based Compensation Expense

The Company’s employees have historically participated in the Parents stock-based compensation plans. The combined statements of operations include all stock-based compensation expenses directly attributable to Spinco employees, as well as an allocation of any stock-based compensation expenses related to Flex corporate and other shared employees. Accordingly, the amounts presented are not necessarily indicative of future awards and do not necessarily reflect the results that the Business would have experienced as an independent company for the periods presented.

The compensation cost in the combined statements of operations of the stock-based compensation arrangements that have been attributed to the Company are as follows:


     Three-Month Periods Ended  
     June 26, 2026      June 27, 2025  
     (In millions)  
Cost of sales    $ 2      $ 2  
Selling, general and administrative expense      11        7  


Total stock-based compensation expense

   $ 13      $ 9  


Warrant

On August 15, 2025, Flex issued a Warrant to the Warrantholder, a wholly-owned subsidiary of Amazon, to purchase up to the Warrant Shares, at an exercise price of $51.29 per share, which expires on August 15, 2030. The Warrant Shares are subject to vesting based on qualifying payments (as defined in the Warrant) for the purchase of all products and services by or on behalf of Amazon and its affiliates over the term of the Warrant. The Warrant also provides that, upon certain distributions (which would include the Distribution), the exercise price will be adjusted, concurrent with the Distribution Record Date, by reducing the exercise price by the per share fair market value (as defined in the Warrant) of the Distribution. The Warrant further provides that the exercise price may not be reduced below $0.01 per share and that if the exercise price becomes $0.01, then the Warrantholder will be entitled to participate in the Distribution as if the Warrantholder had previously exercised and would be the holder of all Warrant Shares, whether vested or not, subject to the Warrant before the Distribution Record Date. Flex, Spinco and the Warrantholder are negotiating and expect to execute an


F-45


Table of Contents

amendment to the Warrant which will provide that, instead of Spinco shares, the Warrantholder would receive the Spinco Warrant. As a result, we expect that the exercise price of the Flex Warrant will be reduced to $0.01 per share and that, upon the consummation of the Distribution, the Warrantholder will receive the Spinco Warrant.

The estimated fair value of the Warrant was determined as of the issuance date, using the Black-Scholes option pricing model. The following assumptions were used in the model:


     As of August 15,
2025
 

Expected volatility

     45.8

Expected dividend yield


Expected life

     7 years  

Risk-free interest rate

     4.0

The calculated fair value of each Warrant Share at the issuance date was $25.47. The Company recorded charges of $2 million during the three month period ended June 26, 2026. As of the quarter ended June 26, 2026, 0.1 million Warrant Shares have vested and are exercisable.

5. TRADE RECEIVABLES SALES PROGRAMS

The Company sells accounts receivables to certain third-party banking institutions under factoring programs. The outstanding balance of receivables sold and not yet collected on accounts where the Company has continuing involvement was $0.3 billion and $0.3 billion as of June 26, 2026 and March 31, 2026, respectively. For the three-month periods ended June 26, 2026 and June 27, 2025, total accounts receivable sold to certain third party banking institutions was $0.3 billion and $0.6 billion, respectively. The receivables that were sold were removed from the condensed consolidated balance sheets and the cash received was included as cash provided by operating activities in the condensed consolidated statements of cash flows.

6. COMMITMENTS AND CONTINGENCIES

The Company is subject to routine legal proceedings, as well as demands, claims and threatened litigation that arise in the normal course of business. The ultimate outcome of any litigation is often uncertain and unfavorable outcomes could have a negative impact on the results of operations and financial condition. The Company regularly reviews the status of each significant matter and assesses its potential financial exposure. If the potential loss from any claim or legal proceeding is considered probable and the amount or the range of loss can be estimated, the Company accrues a liability for the estimated loss. Legal proceedings are subject to uncertainties, and the outcomes are difficult to predict. Because of such uncertainties, accruals are based on the Company’s judgments using the best information available at the time.

The Company determined that no disclosure of estimated loss is required for a claim against us because: (i) there is not a reasonable possibility that a loss exceeding amounts already recognized (if any) may be incurred with respect to such claim; (ii) a reasonably possible loss or range of loss cannot be estimated; or (iii) such estimate is immaterial.

7. BUSINESS ACQUISITIONS

On May 1, 2026, the Company completed the acquisition of 100% ownership of Electrical Power Products, Inc. (“EPP”), a U.S. leader in critical power solutions for a total estimated purchase consideration of $1.2 billion in cash. The allocation of the purchase price to tangible and identifiable intangible assets acquired and liabilities assumed is based on their estimated fair values as of the date of the acquisition. The business is included in the Power segment. Additional information which existed as of the acquisition date, may become know to the Company during the remainder of the measurement period, a period which is not to exceed 12 months from the


F-46


Table of Contents

date of the acquisition. Changes to amounts recorded as assets and liabilities may result in a corresponding adjustment to goodwill during the measurement period.

The following represents the Company’s initial allocation of the total purchase price to the acquired assets and liabilities of the acquired business (in millions):


ASSETS    Amount ($M)  

Current Assets:

  
Cash    $ 23  

Accounts receivable

     69  

Inventory

     99  

Contract assets

     62  

Other current assets

     5  


Total current assets

     258  

Operating lease right-of-use assets, net

     1  

Property and equipment

     44  

Intangible assets

     478  

Goodwill

     473  


Total assets

   $ 1,254  


LIABILITIES AND PURCHASE CONSIDERATION  

Current Liabilities:


Accounts payable

   $ 10  

Deferred revenue

     36  

Accrued liabilities

     11  

Operating lease liabilities

     1  

Other current liabilities

     9  


Total liabilities

     67  


Total purchase consideration

   $ 1,187  


The following represents the Company’s initial allocation of intangible assets identified in the purchase price allocation of the acquired business (in millions):


     Amount ($M)      Estimated
Useful Life
 

Identifiable Intangible Assets


Trade Names

   $ 132        15 years  

Know-How

     46        10 years  

Backlog

     44        2 years  

Customer Relationships

     256        20 years  


Total

   $ 478     


8. SEGMENT REPORTING

The Company’s Chief Commercial Officer is our Chief Operating Decision Maker (“CODM”) who evaluates how we allocate resources, assess performance and make strategic and operational decisions. Based on such evaluation, the Company determined as of and for the period ended June 26, 2026, that Spinco has two operating and reportable segments.


F-47


Table of Contents

The Power segment is comprised of Critical Power and Embedded Power. These offerings address utility and facility-level power intake and distribution, as well as rack- and board-level power delivery. This segment supports grid modernization and related power infrastructure applications.

The Cloud & Cooling segment includes IT Hardware and Cooling. This segment provides rack-scale integration and advanced liquid cooling solutions designed to support high-density deployments.

The determination of the separate operating and reporting segments is based on several factors, including the nature of products and services, the nature of production processes, customer base, delivery channels and similar economic characteristics.

An operating segment’s performance is evaluated based on its segment income. The CODM compares actual segment income to budgeted financial performance in allocating resources and assessing segment performance. Segment income is defined as net sales less cost of sales and segment selling, general and administrative expenses, and does not include corporate and other expense, amortization of intangibles, stock-based compensation, certain restructuring charges, legal and other, interest expense, and other charges (income).

Selected financial information by segment is in the tables below:


Three Months Ended June 26, 2026

   Cloud & Cooling      Power      Total  

Net Sales

   $ 1,436      $ 766      $ 2,202  

Segment cost of sales

     (1,299      (629   

Segment selling, general and administrative expenses

     (25      (35   


Segment income

   $ 112      $ 102      $ 214  


Corporate & other expense(1)

         $ 4  

Intangible amortization

           20  

Stock-based compensation

           13  

Interest expense

           1  

Legal and other(2)

           12  


Income before income taxes

         $ 164  


(1)

Corporate and other primarily includes corporate service costs that are not included in the CODM’s assessment of the performance of each of the identified reportable segments.


F-48


Table of Contents
(2)

Legal and other primarily consists of one-time acquisition costs related to acquisitions made by the Company including Electrical Power Products, Inc.


Three Months Ended June 27, 2025

   Cloud & Cooling      Power      Total  

Net Sales

   $ 1,256      $ 370      $ 1,626  

Segment cost of sales

     (1,126      (306   

Segment selling, general and administrative expenses

     (23      (20   


Segment income

   $ 107      $ 44      $ 151  


Corporate & other expense(1)

         $ 3  

Intangible amortization

           13  

Stock-based compensation

           9  

Restructuring charges(2)

           1  

Interest expense

           2  

Legal and other (3)

           3  

Other charges (income), net

           2  


Income before income taxes

         $ 118  


(1)

Corporate and other primarily includes corporate service costs that are not included in the CODM’s assessment of the performance of each of the identified reportable segments.

(2)

Restructuring charges primarily consist of charges related to employee severance, including an allocation of corporate severance charges.

(3)

Legal and other consists of one-time acquisition costs related to acquisitions made by the Company including Bielsko Biala and other contemplated acquisitions.

The Company does not disclose total assets by segment as this is not provided to the CODM.

Property and equipment on a segment basis is not separately identified and is not internally reported by segment to the Company’s CODM as described above.

During the three-month periods ended June 26, 2026 and June 27, 2025, total depreciation expense, including amounts allocated to the reportable segments, is as follows:


     Three-Month Periods Ended  
     June 26, 2026      June 27, 2025  
     (In millions)  

Depreciation expense:


Cloud & Cooling

   $ 9      $ 10  

Power

     12        6  


Total depreciation expense

   $ 21      $ 16  


9. RELATED PARTY TRANSACTIONS

The combined financial statements have been prepared on a standalone basis and are derived from the consolidated financial statements and accounting records of Flex. The following discussion summarizes activity between the Company and Flex.

Corporate allocations

The combined financial statements reflect allocations of certain expenses from the Parent including, but not limited to, legal, accounting, information technology, human resources and other infrastructure support. For the


F-49


Table of Contents

three-month periods ended June 26, 2026 and June 27, 2025, the cost of these services allocated to the Company included $7 million and $2 million, respectively, which were recorded in cost of sales, and $45 million and $31 million, respectively, which were recorded in selling, general, and administrative expense. In addition to corporate allocated costs, stock-based compensation expense for corporate and shared employees amounted to $11 million and $8 million for the three-month periods ended June 26, 2026 and June 27, 2025, respectively.

Cash management and net parent investment

Flex uses a centralized approach for the purpose of cash management and financing of its operations. The Company’s excess cash is transferred to Flex, and Flex funds the Company’s operating and investing activities as needed. The Parent operates a centralized non-interest-bearing cash pool in the U.S. and regional interest-bearing cash pools outside of the U.S. The total net effect of the settlement of these intercompany transactions is reflected in the combined statements of cash flows as a financing activity and in the combined balance sheets as net parent investment.

10. SUBSEQUENT EVENTS

On September 3, 2026, the Company announced that it entered into a definitive agreement to purchase of Charge Parent, LLC and Subsidiaries, who designs, develops, and manufactures premier utility-scale inverters, for a purchase price of $4.4 billion, including customary closing adjustments, in an all-cash transaction. The acquisition broadens the Company’s power portfolio and deepens its utility presence.

The acquisition will be accounted for as a business combination using the acquisition method of accounting. Due to the timing of the closing date, the Company is still evaluating the fair values of the assets acquired and liabilities assumed as of the acquisition date. The initial accounting for the business combination is incomplete as of the issuance date of these financial statements, and the Company continues to assess, among other items, the valuation of acquired tangible and identifiable intangible assets, assumed liabilities and related tax effects. Based on preliminary analyses, identifiable intangible assets and goodwill are expected to represent substantially all of the acquisition value; however, these estimates are subject to change, which could be material, as the Company finalizes its valuation analyses.

The Company evaluated subsequent events for recognition or disclosure through September 15, 2026, the date the combined financial statements were available to be issued.


F-50


Table of Contents


LOGO


Charge Parent, LLC and Subsidiaries

Consolidated Financial Statements

December 31, 2025 and 2024


F-51


Table of Contents

Charge Parent, LLC and Subsidiaries

REPORT OF INDEPENDENT AUDITORS

To the Board of Directors of Charge Parent, LLC.

Opinion

We have audited the accompanying consolidated financial statements of Charge Parent, LLC. and its subsidiaries (the “Company”), which comprise the consolidated balance sheets as of December 31, 2025 and 2024, and the related consolidated statements of operations, of comprehensive loss, of changes in members’ equity and of cash flows for the years then ended, including the related notes (collectively referred to as the “consolidated financial statements”).

In our opinion, the accompanying consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2025 and 2024, and the results of its operations and its cash flows for the years then ended in accordance with accounting principles generally accepted in the United States of America.

Basis for Opinion

We conducted our audit in accordance with auditing standards generally accepted in the United States of America (US GAAS). Our responsibilities under those standards are further described in the Auditors’ Responsibilities for the Audit of the Consolidated Financial Statements section of our report. We are required to be independent of the Company and to meet our other ethical responsibilities, in accordance with the relevant ethical requirements relating to our audit. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our audit opinion.

Emphasis of Matter

As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for redeemable preferred units, leases and goodwill as of January 1, 2024. Our opinion is not modified with respect to this matter.

Responsibilities of Management for the Consolidated Financial Statements

Management is responsible for the preparation and fair presentation of the consolidated financial statements in accordance with accounting principles generally accepted in the United States of America, and for the design, implementation, and maintenance of internal control relevant to the preparation and fair presentation of consolidated financial statements that are free from material misstatement, whether due to fraud or error.

In preparing the consolidated financial statements, management is required to evaluate whether there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company’s ability to continue as a going concern for one year after the date the consolidated financial statements are available to be issued.

Auditors’ Responsibilities for the Audit of the Consolidated Financial Statements

Our objectives are to obtain reasonable assurance about whether the consolidated financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditors’ report that includes our opinion. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with US GAAS will always detect a material misstatement when


F-52


Table of Contents

Charge Parent, LLC and Subsidiaries


it exists. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. Misstatements are considered material if there is a substantial likelihood that, individually or in the aggregate, they would influence the judgment made by a reasonable user based on the consolidated financial statements.

In performing an audit in accordance with US GAAS, we:


Exercise professional judgment and maintain professional skepticism throughout the audit.


Identify and assess the risks of material misstatement of the consolidated financial statements, whether due to fraud or error, and design and perform audit procedures responsive to those risks. Such procedures include examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements.


Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control. Accordingly, no such opinion is expressed.


Evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management, as well as evaluate the overall presentation of the consolidated financial statements.


Conclude whether, in our judgment, there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company’s ability to continue as a going concern for a reasonable period of time.

We are required to communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit, significant audit findings, and certain internal control-related matters that we identified during the audit.


LOGO

San Diego, California

May 8, 2026, except for the change in the manner in which the Company accounts for redeemable preferred units, leases and goodwill discussed in Note 1 to the consolidated financial statements, as to which the date is August 31, 2026


F-53


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED BALANCE SHEETS


     As of December 31,  
     2025     2024  

ASSETS


Current assets:


Cash and cash equivalents

   $ 114,644,573     $ 26,859,891  

Restricted cash

     2,110,111       1,590,626  

Accounts receivable, net

     57,713,079       38,855,102  

Inventories

     45,586,398       26,180,545  

Prepaid expenses and other

     12,405,668       2,932,491  

Due from related parties

     8,284,607       5,321,125  

Inflation reduction act energy tax credit

     22,490,262       10,046,400  


Total current assets

     263,234,698       111,786,180  

Property and equipment, net

     12,057,439       5,838,714  

Goodwill

     110,180,146       110,180,146  

Intangible assets, net

     45,927,325       54,956,849  

Right-of-use asset, operating

     15,762,051       6,802,016  

Other assets

     2,735,649       1,002,253  


Total assets

   $ 449,897,308     $ 290,566,158  


LIABILITIES AND EQUITY


Current liabilities:


Accounts payable

   $ 32,882,190     $ 20,054,549  

Accrued expenses

     17,012,917       13,811,333  

Contingent consideration

     —        1,590,626  

Current portion of unearned warranty revenue

     2,458,103       659,753  

Current portion of operating lease liability

     1,311,508       658,074  

Customer deposits

     129,541,131       6,880,618  

Short-term debt

     48,924       7,522,793  


Total current liabilities

     183,254,773       51,177,746  

Operating lease liability, net

     15,800,932       7,209,075  

Unearned warranty revenue, net

     13,651,911       12,378,253  

Long-term debt

     33,370,562       40,467  


Total liabilities

     246,078,178       70,805,541  

Commitments and contingencies (Note 18)


Mezzanine equity:


Preferred units (176,225 issued and outstanding as of December 31, 2025 and 2024; redemption amount of $264,336,176)

     201,569,250       193,559,796  

Members’ equity:


Series A units (58,742 issued and outstanding as of December 31, 2025 and 2024)

     58,741,137       58,741,137  

Accumulated deficit

     (56,682,515     (32,482,532

Accumulated other comprehensive income (loss)

     191,258       (57,784


Total members’ equity

     2,249,880       26,200,821  


Total liabilities, mezzanine equity, and members’ equity

   $ 449,897,308     $ 290,566,158  


See notes to consolidated financial statements


F-54


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED STATEMENTS OF OPERATIONS


     For the years ended December 31,  
     2025     2024  

Net sales

   $ 180,343,270     $ 99,949,611  

Net sales - related parties

     15,447,602       27,707,974  


Total net sales

     195,790,872       127,657,585  

Operating expenses


Cost of goods sold (exclusive of depreciation and amortization expense)

     163,034,413       98,423,877  

Research and development

     14,978,460       11,839,001  

Selling, general and administrative expenses

     29,229,641       28,280,959  

Depreciation and amortization expense

     10,785,049       10,036,669  


Total operating expenses

     218,027,563       148,580,506  


Operating loss

     (22,236,691     (20,922,921

Other income (expense)


Interest expense

     (800,198     (18,710

Other income

     997,881       959,504  

Other taxes

     (459,183     (1,154,457

Loss on foreign currency transactions

     (90,947     (58,686


Other income (expense), net

     (352,447     (272,349


Loss before taxes

     (22,589,138     (21,195,270

Income tax expense

     186,522       162,711  


Net loss

   $ (22,775,660   $ (21,357,981


See notes to consolidated financial statements


F-55


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED STATEMENTS OF COMPREHENSIVE LOSS


     For the years ended December 31,  
     2025     2024  
Net loss    $ (22,775,660   $ (21,357,981

Other comprehensive loss:


Foreign currency translation gains (losses)

     249,042       (133,132


Total comprehensive loss

   $ (22,526,618   $ (21,491,113


See notes to consolidated financial statements


F-56


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED STATEMENTS OF CHANGES IN MEMBERS’ EQUITY


     Series A units     Additional
Paid-In Capital
    Accumulated
Deficit
    Accumulated
Other
Comprehensive
Income (Loss)
    Total Members’
Equity
 
     Unit     Amount     Amount     Amount     Amount     Amount  

Balance at December 31, 2023

     59,241     $ 59,103,408     $ (4,922,638   $ (5,448,630   $ 75,348     $ 48,807,488  

Repurchase and cancellation of shares

     (548     (411,250     1,645,000       —        —        1,233,750  

Member contributions

     49       48,979       (167,929     —        —        (118,950

Unit-based compensation

     —        —        5,466,146       —        —        5,466,146  

Accretion of redeemable preferred stock

     —        —        (2,020,579     (5,675,921     —        (7,696,500

Net loss

     —        —        —        (21,357,981     —        (21,357,981

Foreign currency translation adjustments

     —        —        —        —        (133,132     (133,132


Balance at December 31, 2024

     58,742     $ 58,741,137     $ —      $ (32,482,532   $ (57,784     26,200,821  

Unit-based compensation

     —        —        6,585,132       —        —        6,585,132  

Accretion of redeemable preferred stock

     —        —        (6,585,132     (1,424,323     —        (8,009,455

Net loss

     —        —        —        (22,775,660     —        (22,775,660

Foreign currency translation adjustments

     —        —        —        —        249,042       249,042  


Balance at December 31, 2025

     58,742     $ 58,741,137     $ —      $ (56,682,515   $ 191,258     $ 2,249,880  


See notes to consolidated financial statements


F-57


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED STATEMENTS OF CASH FLOW


     For the years ended December 31,  
     2025     2024  

Cash flows from operating activities:


Net loss

   $ (22,775,660   $ (21,357,981

Adjustments to reconcile net loss to net cash (used in) provided by operating activities:


Depreciation

     1,755,525       847,305  

Amortization of intangible assets

     9,029,524       9,189,364  

Amortization of debt issue costs

     158,915       —   

Unit-based compensation

     6,585,132       5,466,146  

Discount on inflation reduction act energy tax credit transfer

     2,552,862       1,561,200  

Noncash lease expense

     285,255       350,467  

Inventory write down

     4,484,658       670,062  

Noncash other items, net

     19,144       26,926  

Changes in operating assets and liabilities:


Accounts receivable

     (18,877,121     (11,553,600

Inventories

     (23,890,511     10,779,045  

Prepaid expenses and other

     (9,473,177     (393,603

Due from related parties

     (2,963,482     (4,969,438

Other assets

     (352,227     (579,074

Accounts payable

     12,644,674       (2,277,339

Accrued expenses

     2,393,144       3,352,525  

Inflation reduction act energy tax credit accrual

     (14,996,724     7,907,400  

Customer deposits

     122,660,513       (4,808,376

Unearned warranty revenue

     3,072,009       6,791,859  


Net cash provided by operating activities

     72,312,453       1,002,888  


Cash flows from investing activities:


Capital expenditures

     (8,766,480     (2,149,926

Proceeds from disposal of assets

     —        41,533  


Net cash used in investing activities

     (8,766,480     (2,108,393


Cash flows from financing activities:


Distribution from loan

     35,000,000       7,500,000  

Payments of loan closing costs

     (1,325,000     (145,000

Principal payments on debt

     (7,534,951     (51,042

Payments of contingent consideration

     (1,590,626     —   

Member contributions

     —        27,988  


Net cash provided by financing activities

     24,549,423       7,331,946  


Effect of exchange rate changes on cash and cash equivalents      208,771       (122,365


Net change in cash and cash equivalents and restricted cash      88,304,167       6,104,076  
Cash and cash equivalents and restricted cash at beginning of period      28,450,517       22,346,441  


Cash and cash equivalents and restricted cash at end of period

   $ 116,754,684     $ 28,450,517  


See notes to consolidated financial statements


F-58


Table of Contents

Charge Parent, LLC and Subsidiaries

CONSOLIDATED STATEMENTS OF CASH FLOW


     For the years ended
December
 
     2025      2024  

Supplemental disclosure of cash flow information:


Cash paid for interest

     399,096        6,518  

Cash paid for income taxes

     67,702        3,664  

Non-cash capital expenditures

     708,225        342,374  

See notes to consolidated financial statements


F-59


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements

NOTES TO CONSOLIDATED FINANCIAL STATEMENTS

Note 1. Nature of Operations and Summary of Significant Accounting Policies

Nature of Operations

Charge Parent, LLC and Subsidiaries (the Company) designs, develops, and manufactures premier utility-scale inverters. The Company is based in Poway, California, and has manufacturing facilities located in California and South Carolina. The Company also has an engineering and sales branch in Finland. Primarily serving the utility and C&I sectors, the Company focuses on energy storage and solar power conversion. The Company’s main product line includes the M Inverter, a 662 kW inverter for utility-scale and commercial applications, and the M-Rack, a liquid-cooled configuration of the M inverter. The M inverter is sold in M systems which range from 2-6 MW for utility grade applications to support solar, storage, and data center markets. Additionally, the Company sells the 1 MW – 6 MW CAB1000 for utility-grade applications, and the 250 kW – 500 kW Power Drawer for business and facility applications. The Company’s solutions are fully scalable and have been deployed at 100+ MW sites. Serving customers globally, the Company’s products are certified to North American Standards (UL1741 / IEEE1547 / CSA 22.2), as well as Australian and European standards and grid codes (IEC / VDE), and quality standards, including ISO 9001:2015.

Foreign operations in Finland, after intercompany eliminations, account for less than 1% of the Company’s net sales and net assets for the years ended December 31, 2025 and December 31, 2024.

Principles of Consolidation

The consolidated financial statements include the assets, liabilities and operating results of Charge Parent, LLC, a Delaware limited liability company, along with its wholly owned subsidiaries, EPC Power Corp. and EPC Power Oy. Intercompany balances and transactions have been eliminated in consolidation.

Financial Statement Preparation

The preparation of financial statements in conformity with accounting principles generally accepted in the United States of America (GAAP) requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities, the disclosure of contingent assets and liabilities at the date of the financial statements, and the reported amounts of revenues and expenses during the reporting period. Actual results could differ from those estimates. Significant estimates used in preparing the Company’s consolidated financial statements include, but are not limited to, the following: the valuation of inventories, valuation of goodwill, intangible assets and long-lived assets, valuation of lease assets and liabilities, valuation allowances for deferred tax assets, product warranty accrual, bonus accrual, and evaluation of contingencies associated with potential litigation.

Foreign Currency Translation

Assets and liabilities of EPC Finland are translated into U.S. dollars at the exchange rates in effect at the consolidated balance sheet dates. Income and expense items are translated at the average exchange rate during the year. Unrealized currency translation adjustments are included as a separate component of accumulated other comprehensive income (loss), within members’ equity.

Fair Value Measurements

US GAAP defines fair value as the exchange price that would be received for an asset or paid to transfer a liability (an exit price) in the principal or most advantageous market for the asset or liability in an orderly transaction between market participants.


F-60


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


US GAAP establishes a fair value hierarchy that prioritizes the inputs to valuation techniques used to measure fair value into three levels. The hierarchy gives the highest priority to unadjusted quoted prices in active markets for identical assets or liabilities (Level 1 measurements) and the lowest priority to unobservable inputs (Level 3 measurements).

The three levels of the fair value hierarchy are described below:


Level 1 - Valuation is based on quoted prices for identical assets or liabilities in active markets;


Level 2 - Valuation is based on quoted prices for similar assets or liabilities in active markets or other inputs that are observable for the asset or liability, either directly or indirectly, for the full term of the financial instrument; and


Level 3 - Unobservable inputs that are supported by little or no market activity, therefore requiring an entity to develop its own assumptions about the assumptions that market participants would use in pricing.

As of December 31, 2025 the Company’s financial instruments consist primarily of cash and cash equivalents, accounts receivable, accounts payable, accrued expenses, and debt. Given their short-term nature, the carrying amounts of cash and cash equivalents, receivables, accounts payable, and accrued expenses generally approximate their fair values. Additionally, the Company believes the carrying amounts of the variable-rate borrowings, if any, approximate fair value.

Certain nonfinancial assets, including property and equipment, operating lease right-of-use assets and finite-lived intangible assets, are not measured at fair value on a recurring basis. These assets are evaluated for impairment when events or changes in circumstances indicate that their carrying amounts may not be recoverable. If an asset group is determined to be not recoverable, the Company measures the asset group at fair value on a nonrecurring basis for purposes of determining the impairment loss. Such fair value measurements are generally determined using valuation techniques that incorporate significant unobservable inputs and are therefore classified within Level 3 of the fair value hierarchy.

Goodwill and indefinite-lived intangible assets are evaluated for impairment annually or more frequently if events or changes in circumstances indicate that potential impairment exists. Fair value measurements of reporting units and indefinite-lived intangible assets used in quantitative impairment assessments are generally classified within Level 3 of the fair value hierarchy.

Cash and Cash Equivalents and Restricted Cash

The Company considers cash and highly liquid investments with a maturity of three months or less at the time of purchase to be cash and cash equivalents. Cash and cash equivalents are stated at cost, which approximates or equals fair value due to their short-term nature. The Company is required to maintain restricted cash primarily pertaining to a debt service reserve account that may be used as collateral which is included in restricted cash in the accompanying consolidated balance sheets.

Accounts Receivable

Accounts receivable consists of trade accounts arising in the normal course of business. The Company recognizes an allowance for credit losses for trade and other receivables to present the net amount expected to be collected as of the consolidated balance sheet date. Such allowance is based on the expected credit losses which includes consideration of historical losses as well as past, current, and future events as of the balance sheet date.


F-61


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Receivables are written off when the Company determines that such receivables are deemed uncollectible. The Company pools its receivables based on similar risk characteristics in estimating its expected credit losses. In situations where a receivable does not share the same risk characteristics with other receivables, the Company measures those receivables individually. The Company also continuously evaluates such pooling decisions and adjusts as needed from period to period as risk characteristics change. The allowance for expected credit losses was not material as of December 31, 2025 and 2024.

Prepaid Expenses

Prepaid expenses consist primarily of prepaid purchases, prepaid insurance, prepaid subscriptions, and other fees paid in advance. Amortization is calculated using the straight-line method.

Property and Equipment

Property and equipment acquired as part of an acquisition are recorded at fair market value, and those purchased thereafter are recorded at cost. Major improvements and betterments are capitalized. Maintenance and repairs are expensed as incurred. When assets are retired or otherwise disposed, their costs and related accumulated depreciation are removed from the accounts and resulting gains or losses are included in income. Property and equipment are depreciated over estimated useful lives as outlined below. Depreciation is calculated using the straight-line method for financial purposes and accelerated methods for income tax purposes.


     Estimated
Useful Life (in
Years)

Machinery and equipment

   3 - 7

Vehicles

   5

Leasehold improvements

   3 - 10

Office equipment

   3 - 5

Goodwill and Intangible Assets

Goodwill is an asset representing the future economic benefits arising from other assets during an acquisition that are not individually identified and separately recognized. Goodwill is not amortized; but rather, the Company reviews goodwill for impairment annually in the fourth quarter or more frequently whenever events or changes in circumstances indicate that the related carrying amounts may not be recoverable. No impairment in the carrying value of Goodwill was observed during 2025 or 2024.

Intangible assets are amortized on a straight-line basis over their estimated useful lives. The amortization method reflects an approximate allocation of the costs of the intangible assets in proportion to the economic benefits obtained by the Company each year.

The estimated useful lives of the Company’s intangible asset classes are as follows:  


     Estimated
Useful Life (in
Years)
 

Tradename

     15  

Developed technology

     7  

Patents

     14  

Backlog

     2  

Customer relationships

     10  


F-62


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Impairment of Long-Lived Assets

The Company evaluates the recoverability of its long-lived assets, including definite lived intangible assets, for impairment whenever events or changes in circumstances indicate that the carrying amount may not be recoverable. No impairment losses were incurred for the years ended December 31, 2025 and 2024.

Advertising

The Company expenses the cost of advertising as incurred. Advertising expenses totaled $1,090,387 and $1,201,021 for the years ended December 31, 2025 and 2024, respectively. Advertising expenses are included in selling, general and administrative expenses in the accompanying consolidated statements of operations and comprehensive loss.

Shipping and Handling Costs

Shipping and handling costs charged to customers have been included in net sales in the accompanying consolidated statements of operations and comprehensive loss. Shipping and handling costs incurred by the Company are included in cost of goods sold in the accompanying consolidated statements of operations and comprehensive loss.

Research and Development

Research and development costs are expensed as incurred.

Sales Taxes

The Company’s policy is to present sales taxes from customers, which are then remitted to governmental authorities, on a net basis. The Company records the amounts collected as a current liability and relieves such liability upon remittance to the taxing authority without impacting revenue recognized. As of December 31, 2025 and 2024, the Company recorded a reserve of $1,496,525 and $1,074,628, respectively, primarily related to sales tax exposure for the periods prior to 2024.

Leases

At lease inception, leases are classified as either finance leases or operating leases with the associated right-of-use asset and lease liability measured at the net present value of future lease payments. Operating leases are expensed on a straight-line basis as lease expense over the noncancelable lease term.

Inflation Reduction Act Energy Tax Credit

In August 2022, the Inflation Reduction Act (IRA) was enacted, introducing clean energy tax incentives, notably the advanced manufacturing production credit (Section 45X). This credit pertains to each domestically produced and sold clean energy component, including utility inverters, which aligns with the Company’s primary product line of premium utility-scale inverters.

Manufacturers have the option to either receive a direct payment from the Internal Revenue Service or transfer the tax credit. The Company elected to transfer all tax credits earned in 2025 and 2024 to an unrelated eligible taxpayer.


F-63


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Effective January 1, 2025, the Company changed its accounting principle for the presentation of Section 45X credits from recognizing the credits within other income to presenting the credits as a reduction of cost of goods sold. The Company accounts for the Section 45X credits as government grants by analogy to International Accounting Standard 20, Accounting for Government Grants and Disclosure of Government Assistance (“IAS 20”). The Company believes the new accounting principle is preferable because the Section 45X credits are generated from the Company’s qualifying manufacturing activities and presenting the credits as a reduction of cost of goods sold more closely associates the benefit of the credits with the related manufacturing costs.

The Company applied this change in accounting principle retrospectively to all periods presented. Accordingly, for the year ended December 31, 2024, the Company reclassified $13.9 million of Section 45X tax credit income from other income to cost of goods sold.

As a result, cost of goods sold decreased by $13.9 million and loss from operations decreased by $13.9 million for the year ended December 31, 2024. The change had no effect on loss before income taxes, net loss, loss per share, or total shareholders’ equity, and therefore no cumulative-effect adjustment to beginning accumulated deficit was required. For the year ended December 31, 2025, $36.2 million of Section 45X tax credits was recognized as a reduction of cost of goods sold.

Section 45X tax credits earned by the Company and expected to be transferred are recognized as current receivables in the consolidated balance sheets. Cash proceeds from transfers of the credits are classified within operating activities in the consolidated statements of cash flows.

In December of 2023, the Company entered into an agreement to sell $39.6 million of Section 45X tax credits generated during 2024 and 2023 for aggregate cash proceeds of $36.3 million. The Company received initial cash proceeds of $26.3 million during the year ended December 31, 2024 and received the remaining cash proceeds of $10.0 million during the year ended December 31, 2025.

In August of 2025, the Company entered into a separate agreement to sell $42.5 million of Section 45X tax credits generated during 2025 for aggregate cash proceeds of $40.0 million. The Company received initial cash proceeds of $17.5 million during the year ended December 31, 2025, with the remaining cash proceeds of $22.5 million subsequently received in March of 2026.

Revenue Recognition

The Company recognizes revenue in accordance with Accounting Standards Codification (“ASC”) 606, Revenue from Contracts with Customers. Under this guidance, the Company recognizes revenue when control of promised goods or services transfers to the customer in an amount that reflects the consideration to which the Company expects to be entitled in exchange for those goods or services, applying the following five-step model: (i) identification of the contract with a customer; (ii) identification of the performance obligations in the contract; (iii) determination of the transaction price; (iv) allocation of the transaction price to the performance obligations; and (v) recognition of revenue as, or when, the performance obligations are satisfied.

The Company identifies contracts with customers that create enforceable rights and obligations and for which collection of consideration is probable. Performance obligations under these contracts generally consist of the sale of products, services, and extended warranty arrangements. Assurance-type warranties, which only guarantee that a product will perform as intended in accordance with published specifications, are not considered separate performance obligations and are accounted for as warranty obligations under other applicable guidance.

The transaction price is determined based on fixed contractual pricing, adjusted, where applicable, for variable consideration such as estimated product returns, warranty obligations, and other similar items. Variable


F-64


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


consideration is included in the transaction price only to the extent it is probable that a significant reversal of cumulative revenue recognized will not occur when the uncertainty is subsequently resolved. For contracts containing multiple performance obligations, the transaction price is allocated to each distinct performance obligation on a relative standalone selling price basis.

Revenue is recognized when, or as, the Company satisfies each performance obligation, either at a point in time or over time, depending on the nature of the goods or services promised and the pattern in which control transfers to the customer.

Share-Based Compensation

Share-based compensation expense for equity-classified awards, related to profits interest, is measured at the grant date based on the estimated fair value of the award and is recognized over the employee’s requisite service period.

The fair value of the profits interest is estimated on the date of grant using the option pricing model that uses assumptions noted in the following table for the years ended December 31:


     2025   2024

Expected annual dividend yield

   N/A   N/A

Expected volatility

   60.00%   60.00%

Discount for lack of marketability

   16.70%   16.70%

Risk-free rate of return (weighted)

   3.51% to 4.65%   3.51% to 4.65%

Expected option term (years)

   4   4

The expected term of the time-based units granted is determined based on the period the units granted are expected to be outstanding. The risk-free rate for periods within the contractual life of the unit is based on the U.S. Treasury yield curve in effect at the time of grant. The expected volatility is based on the Company’s structure and volatility of similar entities referred to as guideline companies. In determining similar entities, the Company considered industry, stage of life cycle, size, and financial leverage. The dividend yield on the Company’s stock is assumed to be zero since the Company has not historically paid dividends. The fair value of the underlying company stock is determined using valuation techniques, which includes an income approach and a market approach to determining fair value. Forfeitures are accounted for when they occur.

Income Taxes

The Company accounts for income taxes under the asset and liability method, which requires recognition of deferred tax assets and liabilities for the expected future tax consequences of events that have been included in the financial statements or tax returns. Under this method, deferred tax assets and liabilities are determined based on the difference between the financial statement and tax basis of assets and liabilities using enacted tax rates in effect for the year in which the differences are expected to reverse. The effect of a change in tax rates on deferred tax assets and liabilities is recognized in the period that includes the enacted date. A valuation allowance is recorded when it is more-likely-than-not some of the deferred tax assets may not be realized. Significant judgment is applied when assessing the need for a valuation allowance and the Company considers all available positive and negative evidence, including future taxable income, reversals of existing deferred tax assets and liabilities and ongoing prudent and feasible tax planning strategies in making such assessment. Should a change in circumstances lead to a change in judgment regarding the utilization of deferred tax assets in future years, the Company will adjust the related valuation allowance in the period such change in circumstances occurs.


F-65


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The Company records uncertain tax positions on the basis of the two-step process in which (i) it determines whether it is more-likely-than-not that the tax positions will be sustained on the basis of the technical merits of the position and (ii) for those tax positions that meet the more-likely-than-not recognition threshold, the Company would recognize the largest amount of tax benefit that is more than 50% likely to be realized upon ultimate settlement with the related tax authority. The Company classifies interest and penalties recognized on uncertain tax positions as a component of income tax expense.

Change in Accounting Policy

The accompanying consolidated financial statements have been prepared in accordance with U.S. GAAP and the applicable requirements of Regulation S-X for inclusion in a filing with the Securities and Exchange Commission pursuant to Rule 3-05 of Regulation S-X. Solely for purposes of these financial statements, the Company is considered a public business entity because its financial statements are included in an SEC filing. Accordingly, the financial statements reflect the accounting principles, adoption dates, and disclosure requirements applicable to public business entities.

The following items were changed to align with the public-company external reporting requirements:

The Company discontinued its amortization of goodwill using the straight-line method over ten years and testing for impairment upon a triggering event to assessing goodwill for impairment at least annually, or more frequently if a triggering event occurs. Goodwill is not subject to amortization in the accompanying consolidated financial statements and was tested for impairment at the reporting unit level.

The Company also adopted a change to distinguish temporary, or mezzanine, equity from permanent equity. Under this new method, the Preferred Units were classified as temporary equity and presented in the ‘Mezzanine equity’ section of the consolidated balance sheets. The carrying value is also accreted to the redemption value through the earliest contractual redemption date using the interest method.

Finally, the Company has applied an incremental borrowing rate to measure operating lease liabilities and right-of-use assets when the rate implicit in the lease is not readily determinable, rather than using a risk-free rate as the discount rate.

These accounting changes were applied retrospectively to the earliest period presented, resulting in a cumulative effect that was recorded as an adjustment of $14,415,235 to opening accumulated deficit and an adjustment of $(9,639,180) to opening additional paid-in capital as of January 1, 2024.


F-66


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The impacts of these changes on certain financial statement line items in the Company’s consolidated balance sheets and consolidated statements of operation were as follows:


Consolidated Balance Sheet as of
December 31, 2025
   As Reported      Effect of Change      As Adjusted  

Goodwill

   $ 73,728,881      $ 36,451,265      $ 110,180,146  

Right-of-use asset, operating

     19,555,900        (3,793,849      15,762,051  

Current portion of operating lease liability

     2,950,587        (1,639,079      1,311,508  

Operating lease liability, net

     17,955,702        (2,154,770      15,800,932  

Mezzanine equity


Preferred units

     176,224,117        25,345,133        201,569,250  

Members’ equity


Additional paid-in capital

     18,244,890        (18,244,890      —   

Accumulated deficit

     (86,033,536      29,351,021        (56,682,515

Consolidated Balance Sheet as of December 31, 2024


Goodwill

   $ 84,746,895      $ 25,433,251      $ 110,180,146  

Right-of-use asset, operating

     8,887,798        (2,085,782      6,802,016  

Current portion of operating lease liability

     1,399,586        (741,512      658,074  

Operating lease liability, net

     8,553,346        (1,344,271      7,209,075  

Mezzanine equity


Preferred units

     176,224,117        17,335,679        193,559,796  

Members’ equity

     —         

Additional paid-in capital

     11,659,758        (11,659,758      —   

Accumulated deficit

     (52,239,862      19,757,330        (32,482,532

Consolidated Statement of Operations for the year ended December 31, 2025


Depreciation and amortization expense

   $ 21,803,064      $ (11,018,015    $ 10,785,049  

Net loss1

     (33,793,674      11,018,015        (22,775,660

Consolidated Statement of Operations for the year ended December 31, 2024


Depreciation and amortization expense

   $ 21,054,684      $ (11,018,015    $ 10,036,669  

Net loss1

     (32,375,997      11,018,015        (21,357,981


(1)

Certain amounts in the accompanying table may not add due to rounding.  

Recent Accounting Pronouncements

Recently Adopted Accounting Pronouncements

In December 2023, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) No. 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures. ASU No. 2023-09 enhances the transparency and decision usefulness of income tax disclosures. The amendments in this ASU


F-67


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


require consistent categories and greater disaggregation of information in the rate of reconciliation and income taxes paid disaggregated by jurisdiction. ASU No. 2023-09 is effective for fiscal years beginning after December 15, 2024. Early adoption is permitted. The amendments in this ASU should be applied on a prospective basis. Retrospective application is permitted. The Company adopted the new requirements on January 1, 2025 on a prospective basis.

New Accounting Pronouncements Not Yet Adopted

In January 2024, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) No. 2024-01Compensation—Stock Compensation (Topic 718): Scope Application of Profits Interest and Similar Awards. This update provides clarification on the application of stock compensation guidance to profits of interest and similar awards. ASU No. 2024-01 is effective for the Company for fiscal years beginning after December 15, 2025. The Company will adopt the new requirements starting in 2026 on a prospective basis.

In July 2025, the FASB issued ASU 2025-05, Financial Instruments – Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets, which permits entities to elect a practical expedient to assume current conditions as of the balance sheet date will not change for the remaining life of accounts receivable and contract assets when developing forecasts as part of estimating expected credit losses. The amendments in ASU 2025-05 are effective for fiscal years beginning after December 15, 2025, and interim periods within those fiscal years, with early adoption permitted. The amendments should be applied prospectively. The Company is currently evaluating the impact of this standard on its consolidated financial statements.

In November 2024, the FASB issued ASU 2024-03, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses.” The update requires entities to tabularly disclose in the footnotes to the financial statements, the amounts of purchased inventory, employee compensation, intangible asset amortization, and depreciation included in each relevant expense caption. The standard also requires disclosure of the amount, and a qualitative description of, other items remaining in relevant expense captions that are not separately disaggregated. This update is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027. Early adoption and both prospective and retrospective application are permitted. The Company is currently assessing the effect of this update.

In September 2025, the FASB issued ASU 2025-06, Intangibles – Goodwill and Other – Internal-Use Software (Subtopic 35040): Targeted Improvements to the Accounting for Internal-Use Software, which removes all references to software development project stages and requires entities to start capitalizing software costs when both of the following occur: (i) management has authorized and committed to funding the software project and (ii) it is probable that the project will be completed and the software will be used to perform the function intended. The amendments in ASU 2025-06 are effective for fiscal years beginning after December 15, 2027, and interim periods within those fiscal years, with early adoption permitted as of the beginning of a fiscal year. The amendments can be applied prospectively, retrospectively, or via a modified prospective transition method. The Company is currently evaluating the impact of ASU 2025-6 on its consolidated financial statements.

In December 2025, the FASB issued ASU 2025-10, “Accounting for Government Grants Received by Business Entities” (“ASU 202510”), which establishes the accounting and presentation for government grants received by a business entity. ASU 2025-10 is effective for annual reporting periods beginning after December 15, 2028, and interim reporting periods within those annual reporting periods. Early adoption is permitted. ASU 2025-10 permits an entity to apply the new guidance using a modified prospective basis, a modified retrospective basis, or a full retrospective basis. The Company is currently evaluating the impact of ASU 2025-10 on its consolidated


F-68


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


financial statements and does not expect the adoption of this guidance to have a material impact on its consolidated financial statements.

Note 2. Business Combination

On September 9, 2022, EPC Power Corp. and its wholly owned subsidiary were acquired by Charge Parent, LLC. The purchase price of the acquisition was $178,054,777, net of cash acquired of $6,950,140. The acquisition was funded with operating cash, debt assumed of $10,000,000, rollover equity of $93,445,000 and contingent consideration of $5,203,000. The rollover equity and contingent consideration were valued by a valuation specialist. The business combination was completed to achieve certain financial objectives, including the goals of bolstering profitability, enhancing overall financial performance, maximizing shareholder value, and optimizing access to capital markets.

The acquisition was accounted for under the acquisition method of accounting under ASC Topic 805, Business Combinations. Goodwill recognized in the acquisition was attributable to the future operations of the Company. The goodwill related to this acquisition is not deductible for income tax purposes.

The contingent consideration was related to two revenue targets and an indemnification period to be completed on the third anniversary of the acquisition date. The first revenue target was based on the one-year period starting on the date of inception, September 9, 2022. The second revenue target was based on the period beginning January 1, 2022, and ending December 31, 2023. If a revenue target was not met, the Company would collect from the escrow an amount disclosed in the purchase agreement and exercise its call right of Series A units and Preferred units. On the third anniversary of the original acquisition date, the remaining cash balance in escrow would be disbursed to rollover shareholders.

During the year ended December 31, 2024, the Company resolved a portion of the contingent consideration linked to the second revenue target. This led to the Company receiving funds from escrow and exercising its call option for Series A and Preferred units.

As of December 31, 2024, the contingent consideration was $1,590,626, which was paid out in September 2025.

Note 3. Revenue Recognition

The Company recognizes revenue when a good or service promised in a contract (i.e., a performance obligation) is satisfied, which is upon the transfer of control of the contracted goods and services to the customer. Performance obligations related to product sales are satisfied at a point in time. Control is transferred when a customer can direct the use of and obtain all of the remaining benefits from that good. Control typically transfers to the customer upon shipment or pick-up or delivery, depending on contract terms.

For goods sold under bill-and-hold arrangements, revenue is recognized when title and risk of loss have passed to the customer and the Company does not have the ability to use the product or direct it to other customers. Under bill-and-hold arrangements, the Company bills a customer for product to be delivered at a later date; control typically transfers when the product is ready for physical transfer to the customer, and the Company has a present right to payment. Typically, a bill-and-hold arrangement is entered when a customer does not have sufficient storage capacity or is experiencing temporary project delays and requests that the Company keep the product in the Company’s custody. In such cases, the product is crated and palletized in the Company’s warehouses or designated third-party storages till it is ultimately shipped to the customer.

Revenue from service-based contracts is recognized at a point in time or over time depending on the nature of the performance obligation promised in the contract.


F-69


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


A contract with a customer may involve multiple products or services and/or multiple delivery dates. The Company assesses the promised goods and services within the contract to identify distinct performance obligations. For a contract with multiple performance obligations, the contract transaction price is allocated to each performance obligation based on relative standalone selling prices.

The revenue recorded is measured as the amount of consideration the Company expects to receive in exchange for transferring control of the products or performing services. Consideration is typically determined based on a fixed unit price, adjusted for variable consideration, including estimated product returns, as applicable, for the quantity of products or services transferred. The Company generally invoices up to 90% of the contract value upon delivery, with payment due within 120 days. The remaining 10% is billed approximately on commissioning or up to 180 days from shipment in accordance with contractual terms. Revenue is recognized upon delivery when control of the product transfers to the customer, as the deferred billing is not contingent upon the satisfaction of any additional performance obligations by the Company.

The Company provides general assurance warranties for a period up to five years that its products will perform as intended for periods beyond the date of sale. General assurance warranties are inherent within the Company’s products and services and do not provide customers with a service other than the assurance that the Company’s goods and services will perform as intended, therefore the Company does not account for its general assurance warranties as separate and/or distinct performance obligations.

The Company recognizes provisions for estimated warranty costs and product returns based on historical experience at the time revenue is recognized, or for specific items, at the time existence of the claims is known and the amounts are determinable.

The Company also offers extended warranties which go beyond the general assurance periods, and these warranties are accounted for as separate and distinct performance obligations in the revenue recognition process. Revenue associated with extended warranty contracts is recognized ratably over the contractual warranty coverage period as the Company satisfies its performance obligation to stand ready to provide warranty services.

Disaggregation of Revenue

The Company disaggregates revenue from contracts with customers into categories that depict how the nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factors. The Company has determined that disaggregation by revenue type and by geography provides the most meaningful depiction of how the nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factors.

The following tables present the disaggregation of the Company’s revenue by revenue type and by geography for the years ended December 31, 2025 and 2024:


     2025      2024  

Product

   $ 189,966,747      $ 122,870,623  

Service and other

     5,824,125        4,786,962  


Net sales

   $ 195,790,872      $ 127,657,585  


F-70


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The following table presents the Company’s revenue disaggregated by geographical region for the year ended December 31:


     2025      2024  

United States

   $ 165,778,082      $ 95,717,491  

International

     30,012,790        31,940,094  


Net sales

   $ 195,790,872      $ 127,657,585  


Contract Assets and Contract Liabilities

The Company’s contracts with customers may contain invoicing and/or payment terms which result in the recognition of contract assets and liabilities. Contract assets, or unbilled revenue, which is part of the accounts receivable, are recorded when the Company transfers a good or service before it is invoiced. Contract liabilities, including unearned warranty revenue and/or customer deposits, are recorded when the Company receives consideration in advance of transferring a good or performing a service.

Supplemental balance sheet information related to contracts from customers as of the years ended December 31, 2025 and 2024:


     2025      2024  

Unbilled revenue

   $ 8,065,020      $ 3,332,342  


Total contract assets

   $ 8,065,020      $ 3,332,342  


Unearned warranty revenues

   $ 16,110,014      $ 13,038,006  

Customer deposits

     129,541,131        6,880,618  


Total contract liabilities

   $ 145,651,145      $ 19,918,624  


Contract assets: Contract assets, or unbilled revenue, represent the Company’s right to consideration for products or services transferred to customers when such rights are conditioned on factors other than the passage of time. Unbilled revenue primarily arises when revenue is recognized prior to invoicing in accordance with the contractual terms of the underlying arrangement. Contract assets are included within accounts receivable in the accompanying consolidated balance sheets.The increase in contract assets as of December 31, 2025 as compared to December 31, 2024 was primarily attributable to the timing of contractual billing milestones, under which revenue was recognized in advance of the Company’s contractual right to invoice customers.

Customer deposits: Customer deposits relate to advance payments received from customers for products or services that have not yet been transferred. Revenue is recognized and the related contract liability is reduced when control of the promised goods or services is transferred to the customer. The increase in customer deposits as of December 31, 2025 as compared to December 31, 2024 was primarily attributable to contractual requirements for customers to remit a portion of consideration in advance of the Company satisfying the related performance obligations and recognizing revenue.

During the years ended December 31, 2025 and 2024, the Company recognized revenue of $16,685,189 and $13,076,819, respectively, related to contract liabilities outstanding at the beginning of each respective year.

Remaining Performance Obligations

Remaining performance obligations, which are primarily included in unearned revenues (as presented on the consolidated balance sheet), represent the aggregate amount of the transaction price of certain customer contracts yet to be recognized as revenues as of the end of the reporting period.


F-71


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


As of December 31, 2025 and 2024, the aggregate amount of the transaction price allocated to remaining (unsatisfied or partially unsatisfied) performance obligations was $16,110,014 and $13,038,006, respectively, which related to the Company’s extended warranty contracts. The Company expects to recognize approximately 15% of its remaining performance obligation over the next 12 months, approximately 49% will be recognized over the next 13 to 36 months and the remainder thereafter.

The Company has elected to adopt certain practical expedients and exemptions allowed under ASC 606:


Practical expedient to recognize the incremental costs of obtaining a contract as an expense when incurred if the amortization period of the asset that the entity otherwise would have recognized is one year or less.


Practical expedient from recognizing shipping and handling activities as activities to fulfill the promise to transfer the goods.


Practical expedient to present revenue net of sales taxes and other similar taxes.

Note 4. Inventories

Inventories consisted of the following as of December 31:  


     2025      2024  

Raw materials

   $ 33,569,112      $ 23,362,833  

Work in process

     2,896,655        1,502,621  

Finished goods

     9,120,631        1,315,091  


Inventories

   $ 45,586,398      $ 26,180,545  


The Company recognized an inventory write-down of $4,484,658 and $670,062 during the years ended December 31, 2025 and 2024 respectively. The increase during the year ended December 31, 2025, as compared to the year ended December 31, 2024 was primarily attributable to excess inventory resulting from reduced demand for legacy product lines, as well as supplier and manufacturing quality issues associated with the ramp-up of a newly introduced product line. The write-down was recorded within cost of goods sold in the accompanying consolidated statements of operations.

Note 5. Property and Equipment

Property and equipment consisted of the following as of December 31:  


     2025      2024  

Machinery and equipment

   $ 10,355,641      $ 3,026,478  

Vehicles

     85,000        85,000  

Leasehold improvements

     2,928,069        2,638,745  

Office equipment

     1,465,547        1,315,778  

Construction in progress

     750,929        531,658  


Total

     15,585,186        7,597,659  

Less accumulated depreciation

     (3,527,747      (1,758,945


Property and equipment, net

   $ 12,057,439      $ 5,838,714  


F-72


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Depreciation expense was $1,755,525 and $847,305 for the years ended December 31, 2025 and 2024, respectively and is included in depreciation and amortization in the accompanying consolidated statements of operations and comprehensive loss.

Note 6. Intangible Assets

Intangible assets consisted of the following as of December 31, 2025:


     Cost      Accumulated
Amortization
     Net Book
Value
 

Tradename

   $ 13,300,000      $ (2,933,389    $ 10,366,611  

Developed technology

     46,700,000        (22,071,310      24,628,690  

Patents

     3,800,000        (897,976      2,902,024  

Backlog

     500,000        (500,000      —   

Customer relationships

     12,000,000        (3,970,000      8,030,000  


Intangible assets, net

   $ 76,300,000      $ (30,372,675    $ 45,927,325  


Intangible assets consisted of the following as of December 31, 2024:


     Cost      Accumulated
Amortization
     Net Book
Value
 

Tradename

   $ 13,300,000      $ (2,046,722    $ 11,253,278  

Developed technology

     46,700,000        (15,399,881      31,300,119  

Patents

     3,800,000        (626,548      3,173,452  

Backlog

     500,000        (500,000      —   

Customer relationships

     12,000,000        (2,770,000      9,230,000  


Intangible assets, net

   $ 76,300,000      $ (21,343,151    $ 54,956,849  


Amortization expense was $9,029,524 and $9,189,364 for the years ended December 31, 2025 and 2024, respectively. The following presents the estimated amortization expense for intangible assets for each of the next five years and thereafter:


     Amortization
expense
 

Years ending December 31:


2026

   $ 9,029,524  

2027

     9,029,524  

2028

     9,029,524  

2029

     6,972,500  

2030

     2,358,095  

Thereafter

     9,508,158  


Total

   $ 45,927,325  


Note 7. Leases

The Company’s operating leases primarily consist of corporate office space and manufacturing and warehouse facilities, used in the ordinary course of business. The Company’s finance leases consist primarily of manufacturing equipment, which are not material to the Company’s consolidated financial statements.

Right-of-use assets represent the Company’s right to use an underlying asset for the lease term, while lease liabilities represent the Company’s obligation to make lease payments arising from the lease.


F-73


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Right-of-use assets and lease liabilities are recognized at the commencement date of a lease, based on the net present value of lease payments over the lease term.

Certain of the Company’s leases include variable lease payments such as rent payments that are recalculated annually based on changes in a local cost-of-living index. Variable lease payments are excluded from the measurement of the related lease liability and are recognized as lease expense in the period in which the obligation for those payments is incurred.

Certain of the Company’s leases include options to renew or terminate the lease. The exercise of lease renewal or early termination options is at the Company’s sole discretion. The Company regularly evaluates the renewal and early termination options and, as of December 31, 2025, has determined none of its renewal or termination options are reasonably certain of exercise; accordingly, no renewal or termination options have been included in the determination of the Company’s lease terms.

The Company’s lease agreements do not contain any material residual value guarantees or material restrictive covenants.

Right-of-use assets are assessed for impairment in accordance with the Company’s long-lived asset policy. The Company reassesses lease classification and remeasures right-of-use assets and lease liabilities when a lease is modified and that modification is not accounted for as a separate new lease or upon certain other events that require reassessment in accordance with Topic 842.

The Company has made the following accounting policy elections regarding its lease accounting:


The Company has elected not to separate lease and non-lease components for all asset classes.


When the rate implicit in the lease is not determinable, the Company uses an estimated incremental borrowing rate as of the commencement date in determining the present value of lease payments. The estimated incremental borrowing rate is the rate of interest the Company would have to pay on a collateralized basis to borrow an amount equal to the lease payments under similar terms.


The Company elected not to apply the recognition requirements to all leases with an original term of 12 months or less, for which the Company is not likely to exercise a renewal option or purchase the asset at the end of the lease; rather, short-term leases will continue to be recorded on a straight-line basis over the lease term.

The Company made significant assumptions and judgments in applying the requirements of Topic 842. In particular, the Company:


Evaluated whether a contract contains a lease, by considering factors such as whether the Company obtained all rights to control

an identifiable underlying asset and whether the lessor has substantive substitution rights;


Determined whether contracts contain embedded leases;


Determined for leases that contain a residual value guarantee, whether a payment at the end of the lease term was probable and, accordingly, whether to consider the amount of a residual value guarantee in future lease payments.


F-74


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The following table summarizes operating lease right-of-use assets and operating lease liabilities as of December 31:


     2025      2024  

Operating lease right-of-use assets

   $ 15,762,051      $ 6,802,016  

Operating lease liabilities:


Current

     1,311,508        658,074  

Long-term

     15,800,932        7,209,075  


Total operating lease liabilities

   $ 17,112,440      $ 7,867,149  


Expenses incurred pertaining to operating leases for the years ended December 31, 2025 and 2024, were $2,324,521 and $1,570,627, respectively.

The operating right-of-use asset and lease liability were calculated using a weighted average discount rate of 10% at December 31, 2025 and 2024. As of December 31, 2025 and 2024, the weighted average remaining lease term was 6.77 years and 7.63 years, respectively.

The table below summarizes the Company’s scheduled future minimum lease payments for each of the next five years and thereafter:


     Operating  

Years ending December 31:


2026

   $ 2,950,587  

2027

     3,398,924  

2028

     3,501,148  

2029

     3,503,180  

2030

     3,578,553  

Thereafter

     6,930,359  


Total

     23,862,751  

Less amount representing interest

     (6,750,311


Present value of net minimum lease payments

     17,112,440  

Less current portion

     (1,311,508


Long-term portion

   $ 15,800,932  


The following table includes supplemental cash flow and non-cash information related to the leases for the years ended December 31:


     2025      2024  

Cash paid for amounts included in the calculation of lease liabilities:


Operating cash flows from operating leases

   $ 2,063,035      $ 1,217,709  

Operating lease assets obtained in exchange for lease liabilities

   $ 10,158,208      $ 235,505  


F-75


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Note 8. Accrued Expenses

Accrued expenses consisted of the following at December 31:


     2025      2024  

Accrued wages

   $ 2,635,893      $ 2,338,088  

Accrued vacation

     2,087,330        1,592,005  

Accrued warranty

     4,607,162        3,545,677  

Accrued sales tax

     1,753,407        2,721,431  

Accrued purchases

     4,064,109        2,348,208  

Accrued inventory in transit

     —         940,327  

Accrued other

     1,865,016        325,597  


Total accrued expenses

   $ 17,012,917      $ 13,811,333  


Note 9. Accrued Warranty

The warranty liability consisted of the following at December 31:


     2025      2024  

Beginning balance

   $ 3,545,677      $ 2,893,554  

Provision for warranties

     7,627,435        2,511,551  

Change in warranty estimate

     (1,131,776      —   

Warranty claims paid

     (5,434,174      (1,859,428


Ending balance

   $ 4,607,162      $ 3,545,677  


Note 10. Debt

Asset-Based Loan Facility

In December 2024, the Company entered into a U.S. asset-based revolving credit facility (the “ABL Facility”) with Citibank, N.A., as administrative agent, which provides for borrowings of up to $25,000,000, including letters of credit. Subject to the satisfaction of customary conditions, the borrowing capacity may be increased to $35,000,000. The ABL Facility has a three-year term and matures in December 2027.

In August 2025, the Company entered into a First Amendment to the ABL Facility, which modified certain terms of the ABL Facility, including revisions to the borrowing base calculation, inventory eligibility provisions, limitations on the inclusion of eligible tax credits, and certain permitted indebtedness provisions. The Company accounted for the amendment as a debt modification.

On December 29, 2025, the Company entered into a Second Amendment to the ABL Facility, which, among other things, updated certain schedules, revised select definitions and covenant provisions, and made conforming changes in connection with a term loan facility and related inter creditor arrangements. The amendment also modified revolving credit availability, including establishing an aggregate revolving credit commitment of $15,000,000, subject to borrowing base limitations, and revised the borrowing base to (i) establish tiered advance rates for different categories of eligible receivables, (ii) permit the inclusion of eligible tax credits subject to a cap equal to the lesser of (a) 20% of the line cap and $5,000,000 through August 6, 2026, and (b) thereafter 10% of the line cap and $2,500,000, and (iii) revise inventory advance rate mechanics based on net orderly liquidation value. The administrative agent may establish additional reserves, which could reduce borrowing availability.


F-76


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The Company accounted for the amendment as a debt modification. All other material terms of the agreements remained unchanged. As of December 31, 2025, total borrowing availability under the ABL Facility was $15,000,000.

Borrowings bear interest, at the Company’s election, at either (i) Term SOFR plus an applicable margin or (ii) a base rate plus an applicable margin. The applicable margin ranges from 1.75% to 2.25% per annum for Term SOFR borrowings and from 0.75% to 1.25% for base rate borrowings, based on average excess availability. The Company is also required to pay a commitment fee on unused availability ranging from 0.25% to 0.375%.

As of December 31, 2025, the applicable margin was 2.25% for Term SOFR borrowings and 1.25% for base rate borrowings, and the commitment fee on unused availability was 0.375%.

As of December 31, 2024, the applicable margin was 2.00% for Term SOFR borrowings and 1.00% for base rate borrowings, and the commitment fee on unused availability was 0.375%.

The ABL Facility is secured by a first-priority lien on substantially all assets of the Company, subject to customary exclusions.

Term Loan Facility

On December 29, 2025, the Company entered into a term loan facility (the “Term Loan Agreement”) with certain lenders and EPIC Administration LLC, as administrative agent and collateral agent, which provides for a senior secured term loan facility with total commitments of up to $50,000,000. The Term Loan Agreement consists of an initial term loan of $35,000,000, which was funded on the closing date, and up to $15,000,000 of additional term loan commitments, which may be drawn in up to three borrowings through June 29, 2027, subject to customary conditions. Amounts borrowed and subsequently repaid may not be reborrowed. The loans mature on December 29, 2029.

Borrowings under the Term Loan Agreement bear interest, at the Company’s option, at either (i) an alternate base rate plus an applicable margin of 6.00% or (ii) a Term SOFR rate, subject to a 3.00% floor, plus an applicable margin of 7.00%. Interest is payable quarterly in arrears. Upon the occurrence and during the continuance of an event of default, the applicable interest rate is increased by 2.00% per annum. The Company is also required to pay a commitment fee equal to 1.50% per annum on the unused portion of the additional term loan commitments, payable quarterly in arrears through the earlier of the funding of such commitments or June 29, 2027.

The Term Loan Agreement provides for quarterly principal amortization equal to 1.875% of the highest aggregate principal amount of loans outstanding, commencing June 30, 2027, with the remaining outstanding principal balance due at maturity. The Company may voluntarily prepay the loans, subject to a minimum investment return (“MOIC”) requirement, which generally ranges from 1.15x to 1.30x of funded principal depending on the timing of repayment. Mandatory prepayments are required upon certain asset dispositions, casualty events, incurrences of additional indebtedness, and specified equity contributions, subject in certain cases to customary reinvestment rights.

The obligations under the Term Loan Agreement are guaranteed by the Company’s parent holding company and certain subsidiaries and are secured by substantially all assets of the Company and such guarantors, subject to customary permitted liens and an intercreditor agreement with respect to the Company’s ABL Facility. In addition, the Term Loan Agreement requires the Company to maintain a debt service reserve account (“DSRA”) subject to a control agreement in favor of the collateral agent. The required balance of the DSRA is equal to the debt service reserve amount, which is defined as (i) six months of scheduled debt service through June 30, 2027 and (ii) three months of scheduled debt service thereafter.


F-77


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Covenants and Other Terms

Both the ABL Facility and the Term Loan Agreement contain customary affirmative and negative covenants, including limitations on additional indebtedness, liens, investments, asset dispositions, restricted payments, and transactions with affiliates, as well as financial covenants, including minimum liquidity and maximum total leverage ratio requirements. As of December 31, 2025, the Company was in compliance with all covenants under both the ABL Facility and the Term Loan Agreement. As of December 31, 2024, the Company was in compliance with all covenants under the ABL Facility.

The following table provides a summary of the long-term debt as of December 31, 2025:  


Principal Payment    Amount  

2026

   $ —   

2027

     1,968,750  

2028

     2,625,000  

2029

     30,406,250  


Total term loan principal

     35,000,000  

Unamortized discount, including debt issuance costs

     (1,761,300

Debt related to finance leases

     131,862  


Long-term debt

   $ 33,370,562  


Note 11. Provision for Income Taxes

The following is a geographical breakdown of income before the provision for (loss) income taxes as of December 31:


     2025      2024  

Federal

   $ (22,723,836    $ (21,475,320

Foreign

     134,698        280,050  


Pre-tax income (loss)

   $ (22,589,138    $ (21,195,270


F-78


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Income tax expense for the years ended December 31 is comprised of the following:  


     2025      2024  

Current


Federal

   $ —       $ —   

State

     148,495        13,502  

Foreign

     38,027        149,209  


Total current tax expense

     186,522        162,711  


Deferred


Federal

     —         —   

State

     —         —   

Foreign

     —         —   


Total deferred tax expense

     —         —   


Income tax expense


Federal

     —         —   

State

     148,495        13,502  

Foreign

     38,027        149,209  


Total income tax expense

   $ 186,522      $ 162,711  


The Company’s deferred taxes reflect the net tax effects of temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes.

Significant components of the Company’s deferred tax assets and liabilities as of December 31, are as follows:


     2025      2024  

Net operating loss

   $ 17,125,523      $ 11,947,062  

Tax credits

     4,607,218        3,595,001  

Lease liability

     4,477,748        2,088,147  

Product warranty

     4,055,520        2,490,547  

Capitalized research & development

     2,698,641        3,986,770  

Inventory and inventory reserve

     1,833,622        637,250  

Unearned revenue

     1,800,426        165,697  

Accrued expenses

     1,113,571        870,660  

Allowance for bad debt

     14,642        10,087  


Total deferred tax asset

     37,726,911        25,791,221  

Intangible assets

     (12,017,631      (15,058,902

Right-of-use asset

     (4,124,397      (1,797,362

Fixed assets

     (621,481      (235,478

Other

     (269,044      (563,479


Total deferred tax liability

     (17,032,553      (17,655,221


Valuation allowance

     (20,694,358      (8,136,000


Net deferred tax asset

   $ —       $ —   


F-79


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


A reconciliation of the statutory U.S. federal tax rate to the Company’s effective tax rate for tax years after the adoption of ASU 2023-09 is as follows:


     December 31, 2025  
     Amount      Percent  

U.S. federal statutory tax rate

   $ (4,743,719      21.00

State taxes, net of federal benefit1

     (30,199      0.13

Enactment of new tax laws


Effect of cross-border tax laws


Global intangible low-taxed income

     534,965        (2.37 )% 

Tax credits


Federal and research development credit

     (597,581      2.65

Change in valuation allowance

     10,740,618        (47.55 )% 

Nondeductible items


45X tax credits

     (7,608,772      33.68

Share-based compensation

     1,382,878        (6.12 )% 

Other

     88,627        (0.39 )% 

Worldwide changes in unrecognized tax benefits

     409,774        (1.81 )% 

Other

     87,909        (0.39 )% 

Foreign tax effects


Other

     (77,978      0.35


Total

   $ 186,522        (0.82 )% 


1

States and local jurisdictions that contribute the majority (greater than 50%) of the tax effect in this category include Texas and California

A reconciliation of the statutory U.S. federal tax rate to the Company’s effective tax rate for tax years prior to the adoption of ASU 2023-09 is as follows:


     December 31,
2024
 

Statutory tax rate

     21.00

State tax

     7.84

45X tax credits

     13.57

Share-based compensation

     (5.35 )% 

Global intangible low-taxed income

     (2.39 )% 

Other permanent items

     (0.29 )% 

Valuation allowance

     (36.50 )% 

Federal and research development credit

     1.96

Unrecognized tax benefits

     (0.47 )% 

Foreign rate differential

     0.01

Other

     (0.15 )% 


Total

     (0.77 )% 


F-80


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The cash paid for income taxes (net of refunds) during the year was as follows:


     2025  

Federal

   $ —   

State and local


Texas

     45,053  

California

     800  


Total

     45,853  


Foreign


Finland

     21,849  


Total

   $ 67,702  


The Company elected to account for the global intangible low-taxed income inclusion as a period cost.

The Company recorded a valuation allowance against its US net deferred tax assets as realization of such assets is not more likely than not. The increase in the Company’s valuation allowance was $12,558,358 during the year ended December 31, 2025 and $7,737,083 during the year ended December 31, 2024.

As of December 31, 2025, US federal and state net operating loss carry forwards of $64,660,638 and $52,467,838 are available to offset future federal and state taxable income, respectively. As of December 31, 2024, US federal and state operating loss carry forwards of $39,033,178 and $35,027,456, respectively.

Federal net operating loss carryforwards of $61,522,739 carry forward indefinitely and $3,137,899 will begin expiring in 2035. The Company’s state net operating loss carryforwards will begin to expire during various years, dependent on the jurisdiction.

Additionally, as of December 31, 2025, the Company has federal and state research and development credit carryforwards of $4,134,957 and $2,541,772 respectively. The federal will begin to expire in 2038 and the state credits carry forward indefinitely.

The Company records uncertain tax positions in accordance with ASC 740, on the basis of a two-step process in which (i) the Company determines whether it is more likely than not a tax position will be sustained on the basis of the technical merits of such position and (ii) for those tax positions meeting the more-likely-than-not recognition threshold, the Company would recognize the largest amount of tax benefit that is more than 50.0% likely to be realized upon ultimate settlement with the related tax authority.

The following table summarizes the gross amount of the Company’s uncertain tax positions:


     2025      2024  

Balance at beginning of the year

   $ 1,480,063      $ 1,456,578  

Increases related to prior year tax positions

     185,937        94,930  

Decreases related to prior year tax positions

     —         (209,896

Increases related to current year tax positions

     258,414        138,451  

Decreases related to lapse of statute of limitations

     —      


Balance at end of the year

   $ 1,924,414      $ 1,480,063  


Included in the balance of uncertain tax positions as of December 31, 2025, is $1,924,414 that would affect the effective tax rate, if reversed, subject to changes in the Company’s valuation allowance.


F-81


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The Company’s policy is to recognize interest and penalties related to income tax matters as a component of income tax expense. As of December 31, 2025, $10,394 of interest and penalties have been recognized.

The Company is subject to audit by federal and state tax authorities in the ordinary course of business. The Company’s federal income tax returns remain subject to examination generally for the 2015 taxable year through the current taxable year due to net operating loss carry forwards that will remain subject to examination until the expiration of the statute of limitations for the taxable years of utilization of such net operating losses. The Company files tax returns in multiple US state jurisdictions which remain subject to examination for various years depending on such state jurisdiction. The Company is also subject to audit by tax authorities in Finland for which returns are subject to examination for the 2022 taxable year through the current taxable year.

The Organization for Economic Co-operation and Development (“OECD”) has introduced a framework to implement a global minimum corporate tax of 15%, referred to as Pillar Two. Many aspects of Pillar Two are effective beginning in calendar year 2024 and other aspects will be effective beginning in calendar year 2025. While the Company does not expect Pillar Two to have a material impact on its effective tax rate, the Company’s analysis is ongoing as the OECD releases additional guidance and countries implement additional legislation.

The One Big Beautiful Bill Act (“OBBB Act”) was enacted on July 4, 2025, in the United States. The OBBB Act includes several significant provisions, including re-establishing a 100% bonus depreciation deduction, re-establishing rules in calculating business interest expense limitations pursuant to Internal Revenue Code §163(j), changing the calculation of international tax inclusions, and removing the capitalization requirements for domestic research or experimental (R&E) expenditures paid or incurred in tax years beginning after December 31, 2024. Management has considered applicable tax impacts of the OBBB Act within the 2025 financial statements.

Note 12. Members’ Equity

Series A Stock

As of December 31, 2025 and 2024, there were 58,742 units of Series A stock, with a par value of $1,000 each that had been authorized, issued and were currently outstanding. Units issued in accordance with rollover contributions are subject to a call provision, as disclosed in Note 2. Business Combination. During the year ended December 31, 2024, 548 units of Series A stock were cancelled by the Company as part of the call provision. Rollover shareholders have the option to recover the units by purchasing them back at $1,000 a unit. During the year ended December 31, 2024, 49 units of Series A stock were repurchased by the rollover shareholders.

Note 13. Redeemable preferred units

On September 9, 2022, the Company issued Preferred Units in connection with the acquisition of EPC Power Corp. (Refer to Note 2. Business Combination for further detail). The rights and preferences of the Preferred Units are governed by the Amended and Restated Limited Liability Company Agreement dated September 9, 2022. The Company is authorized to issue unlimited shares of the Preferred Units.

As of December 31, 2025 and 2024, 176,225 units of preferred stock, with a par value of $1,000 each were issued and outstanding.

Distribution and Liquidation Rights

Upon liquidation, dissolution or winding up of the Company, and after satisfaction of the Company’s obligations to creditors, assets of the Company available for distribution are made in the following order: holders of


F-82


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Preferred Units will first receive a return of their unpaid capital contributions and then additional distributions until they have achieved a 1.5x multiple on invested capital (“MOIC”); holders of Series A Units will receive a return of their invested capital and then additional distributions until they have achieved a 1.5x MOIC; any remaining distributions are allocated 87% to holders of Series A Units and 13% to holders of Series B Units.

Redemption Rights

On or after September 9, 2032, holders representing a majority of the Preferred Units may require the Company to redeem their Preferred Units for an amount equal to the holders’ invested capital plus additional proceeds sufficient to provide a 1.5x MOIC, reduced by any prior distributions received with respect to such units.

The non-redeeming holders of a majority of the Preferred Units and Series A Units may elect to pursue a sale transaction in lieu of redemption within 30 days following the receipt of the redemption notice. If such an election is made, the redemption notice is revoked and the redemption right terminates.

The Preferred Units are classified as mezzanine, or temporary, equity because the units are redeemable at the holder’s option after the tenth anniversary of the original issuance and the ability of the non-redeeming holders to elect a sale transaction in lieu of redemption is also outside the Company’s control. The Company also concluded that the Preferred Units are probable of becoming redeemable.

Accordingly, the Company accretes the carrying amount of the Preferred Units to the redemption amount through the earliest contractual redemption date using the interest method.

Share Cancellations and Repurchases

Preferred units issued in accordance with rollover contributions are subject to a call provision, as disclosed in Note 2. Business Combination. During the year ended December 31, 2024, 1,645 preferred units were cancelled by the Company as part of the noncash call provision. Rollover shareholders have the option to recover the preferred units by purchasing them back at $1,000 a unit. During the year ended December 31, 2024, 147 units were repurchased by the rollover shareholders.

During the years ended December 31, 2025 and 2024, the Company recorded accretion of $8,009,455 and $7,696,500, respectively, related to the Preferred Units. Such accretion was recorded as a reduction of additional paid-in capital to the extent available, with any excess recorded as an increase to accumulated deficit.

Note 14. Unit-Based Compensation

On September 9, 2022, in conjunction with the formation of the Company, 1,000,000 Series B units were authorized. The Series B units, which are profits interest, vest over four years from the date of grant. Upon termination of a Series B unit holder’s employment with the Company for any reason, all unvested Series B units shall automatically be forfeited without any payment.


F-83


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


The following is a summary of employee Series B units transactions that contain only service requirements to vest:


     Number of Shares      Weighted-Average
Grant Date Fair
Value
 

Series B units outstanding at December 31, 2023

     645,480        30.32  

Series B units granted

     570,378        30.43  

Series B units cancelled/forfeited

     (290,952      30.32  


Series B units outstanding at December 31, 2024

     924,906        30.38  

Series B units granted

     87,087        30.50  

Series B units cancelled/forfeited

     (46,224      30.45  


Series B units outstanding at December 31, 2025

     965,769        30.39  


Compensation expense of $6,585,132 and $5,466,146 was recorded for the years ended December 31, 2025 and 2024, respectively, and is recorded in selling, general, and administrative expenses on the consolidated statements of operations and comprehensive loss. As of December 31, 2025 and 2024, unrecognized compensation expense was $13,782,977 and $19,123,999, respectively, which is expected to be recognized over a weighted-average period of 2.35 years and 3.04 years, respectively.

In June 2025, the board of directors approved an employee incentive plan, which provides incentive compensation opportunities to certain employees contingent upon specified liquidity events. As of December 31, 2025, no amounts were probable or reasonably estimable, and no liability or compensation expense has been recognized.

Note 15. Employee 401(k) Plan

The Company maintains a defined contribution retirement plan for substantially all employees, excluding EPC Finland employees. Under this plan, eligible employees can defer a portion of their compensation pursuant to Section 401(k) of the Internal Revenue Code. The Company contributes a safe harbor matching contribution equal to 100% of the first 3% of employees’ compensation plus 50% of the next 2% of employees’ compensation.

The Company’s contributions to the plan were $990,478 and $892,678 for the years ended December 31, 2025 and 2024, respectively.

Note 16. Concentrations

During the year ended December 31, 2025, two customers accounted for 44% of net sales and 40% of accounts receivable. During the year ended December 31, 2024, two customers accounted for 43% of net sales and 39% of accounts receivable. No other customer accounted for more than 10% of net sales or accounts receivable.

The Company maintains cash balances at 6 and 5 financial institutions as of December 31, 2025 and 2024, respectively. At December 31, 2025 and 2024, accounts held at institutions in the United States are insured by the Federal Deposit Insurance Corporation (FDIC) up to $250,000 for interest bearing and non-interest bearing accounts. Cash balances exceed this federally insured limit at times. The Company maintains its cash at reputable financial institutions and does not believe it is exposed to any significant credit risk.


F-84


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Consolidated Financial Statements


Financial instruments which potentially subject the Company to concentrations of credit risk consist principally of accounts receivable. The Company extends credit to its customers based upon evaluation of the customer’s financial condition and credit history and does not require collateral. Credit losses are provided for in the consolidated financial statements and consistently have been within management’s expectations.

Note 17. Related-Party Transactions

The Company has sales to related parties due to their common ownership and affiliation. The net sales and accounts receivable balances with related parties result from the sale of power conversion systems, spare parts, and related services provided under customer contracts in the ordinary course of business. During the years ended December 31, 2025 and 2024, the Company recorded net sales of $15,447,602 and $27,707,974 to related parties, respectively. As of December 31, 2025 and 2024, the amounts due from these related parties were $8,284,607 and $5,321,125, respectively. Amounts due from related parties are unsecured, non-interest bearing and generally subject to the same payment terms as the Company’s third-party customer receivables.

Note 18. Commitments and Contingencies

Purchase Commitments

As of December 31, 2025, the Company’s non-cancelable purchase commitments for inventory to be used in the ordinary course of business were $9,576,150, of which $7,763,468 is expected to be purchased during 2026 and $1,812,682 is expected to be purchased during 2027. These commitments are based on fixed or determinable prices and do not contain variable pricing components. As of December 31, 2024, the Company’s non-cancelable purchase commitments were not material. Amounts purchased under the Company’s non-cancelable purchase commitments during the years ended December 31, 2025 and 2024 were not material.

Inventory purchase orders issued in the ordinary course of business represent authorizations to purchase inventory from vendors rather than binding agreements and, therefore, are excluded from the amount disclosed above. Such purchase orders are based on the Company’s current inventory needs and are generally fulfilled by suppliers within a short period of time.

Litigation

In the normal course of business, the Company could be exposed to litigation involving its products, facilities, or personnel. The Company maintains insurance to cover such actions and believes that the resolution of any such litigation will not have a material adverse effect on the Company.

Note 19. Subsequent Events

Subsequent events have been evaluated through May 8, 2026, the date the financial statements were originally available to be issued. In connection with the reissuance of these financial statements, the Company also evaluated events occurring after the original issuance date and through August 31, 2026 for disclosure.


F-85


Table of Contents

LOGO

Charge Parent, LLC and Subsidiaries

Condensed Consolidated Financial Statements

As of June 30, 2026 and December 31, 2025 and for

the six months ended June 30, 2026 and 2025


F-86


Table of Contents

Charge Parent, LLC and Subsidiaries

CONDENSED CONSOLIDATED BALANCE SHEETS


     As of
June 30, 2026
    As of
December 31, 2025
 

ASSETS


Current assets:


Cash and cash equivalents

   $ 139,116,056     $ 114,644,573  

Restricted cash

     2,110,348       2,110,111  

Accounts receivable, net

     127,371,843       57,713,079  

Inventories

     170,128,869       45,586,398  

Prepaid expenses and other

     41,722,924       12,405,668  

Due from related parties

     145,480       8,284,607  

Inflation reduction act energy tax credit

     53,918,405       22,490,262  


Total current assets

     534,513,925       263,234,698  

Property and equipment, net

     19,192,878       12,057,439  

Goodwill

     110,180,146       110,180,146  

Intangible assets, net

     41,412,563       45,927,325  

Right-of-use asset, operating

     14,899,977       15,762,051  

Other assets

     4,710,936       2,735,649  


Total assets

   $ 724,910,425     $ 449,897,308  


LIABILITIES AND EQUITY


Current liabilities:


Accounts payable

   $ 98,405,318     $ 32,882,190  

Accrued expenses

     60,331,246       17,012,917  

Current portion of unearned warranty revenue

     3,240,570       2,458,103  

Current portion of operating lease liability

     1,779,607       1,311,508  

Customer deposits

     282,194,927       129,541,131  

Short-term debt

     48,925       48,924  


Total current liabilities

     446,000,593       183,254,773  

Operating lease liability, net

     14,868,318       15,800,932  

Unearned warranty revenue, net

     12,804,984       13,651,911  

Long-term debt

     33,539,375       33,370,562  


Total liabilities

     507,213,270       246,078,178  

Commitments and contingencies (Note 10)


Mezzanine equity:


Preferred units (176,225 issued and outstanding as of June 30, 2026 and December 31, 2025; redemption amount of $264,336,176)

     205,663,087       201,569,250  

Members’ equity:


Series A units

     58,741,137       58,741,137  

Accumulated deficit

     (46,880,212     (56,682,515

Accumulated other comprehensive income (loss)

     173,143       191,258  


Total members’ equity

     12,034,068       2,249,880  


Total liabilities, mezzanine equity, and members’ equity

   $ 724,910,425     $ 449,897,308  


See notes to condensed consolidated financial statements


F-87


Table of Contents

Charge Parent, LLC and Subsidiaries

CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS


     Six Months Ended  
     June 30, 2026     June 30, 2025  

Net sales

   $ 229,590,569     $ 39,881,411  

Net sales - related parties

     293,717       2,189,349  


Total net sales

     229,884,286       42,070,760  

Operating expenses


Cost of goods sold (exclusive of depreciation and amortization expense)

     181,329,939       33,261,705  

Research and development

     9,066,071       8,040,565  

Selling, general and administrative expenses

     22,801,622       14,374,778  

Depreciation and amortization expense

     5,918,406       5,134,263  


Total operating expenses

     219,116,038       60,811,311  


Operating gain (loss)

     10,768,248       (18,740,551

Other income (expense)


Interest expense

     (2,418,003     (462,088

Other income

     2,124,728       250,463  

Other taxes

     (184,670     —   

Loss on foreign currency transactions

     (30,070     (35,944


Other income (expense), net

     (508,015     (247,569


Gain (loss) before taxes

     10,260,233       (18,988,120

Income tax expense

     —        —   


Net gain (loss)

   $ 10,260,233     $ (18,988,120


See notes to condensed consolidated financial statements


F-88


Table of Contents

Charge Parent, LLC and Subsidiaries

CONDENSED CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME (LOSS)


     Six Months Ended  
     June 30, 2026     June 30, 2025  

Net income (loss)

   $ 10,260,233     $ (18,988,120

Other comprehensive income (loss):


Foreign currency translation gains (losses)

     (18,115     213,720  


Total comprehensive income (loss)

   $ 10,242,118     $ (18,774,400


See notes to condensed consolidated financial statements


F-89


Table of Contents

Charge Parent, LLC and Subsidiaries

CONDENSED CONSOLIDATED STATEMENTS OF CHANGES IN MEMBERS’ EQUITY


     Series A units      Additional
Paid-In
Capital
    Accumulated
Deficit
    Accumulated
Other
Comprehensive
Income (Loss)
    Total
Members’
Equity
 
     Unit      Amount      Amount     Amount     Amount     Amount  

Balance at December 31, 2025

     58,742      $ 58,741,137      $ —      $ (56,682,515   $ 191,258     $ 2,249,880  

Unit-based compensation

     —         —         3,635,907       —        —        3,635,907  

Accretion of redeemable preferred stock

     —         —         (3,635,907     (457,930     —        (4,093,837

Net gain (loss)

     —         —         —        10,260,233       —        10,260,233  

Foreign currency translation adjustments

     —         —         —        —        (18,115     (18,115


Balance at June 30, 2026

     58,742      $ 58,741,137      $ —      $ (46,880,212   $ 173,143     $ 12,034,068  


Balance at December 31, 2024

     58,742      $ 58,741,137      $ —      $ (32,482,532   $ (57,784   $ 26,200,821  

Unit-based compensation

     —         —         3,224,766       —        —        3,224,766  

Accretion of redeemable preferred stock

     —         —         (3,224,766     (706,400     —        (3,931,166

Net gain (loss)

     —         —         —        (18,988,120     —        (18,988,120

Foreign currency translation adjustments

     —         —         —        —        213,720       213,720  


Balance at June 30, 2025

     58,742      $ 58,741,137      $ —      $ (52,177,052   $ 155,936     $ 6,720,021  


See notes to condensed consolidated financial statements


F-90


Table of Contents

Charge Parent, LLC and Subsidiaries

CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS


     Six Months Ended  
     June 30, 2026     June 30, 2025  

Cash flows from operating activities:


Net income (loss)

   $ 10,260,233     $ (18,988,120

Adjustments to reconcile net loss to net cash (used in) provided by operating activities:


Depreciation

     1,403,644       619,501  

Amortization of intangible assets

     4,514,762       4,514,762  

Amortization of debt issue costs

     272,752       79,458  

Unit-based compensation

     3,635,907       3,224,766  

Discount on inflation reduction act energy tax credit transfer

     4,652,035       425,857  

Noncash lease expense

     397,560       96,170  

Inventory write down

     7,015,586       229,078  

Noncash other items

     47,275       —   

Changes in operating assets and liabilities:


Accounts receivable

     (69,706,039     18,962,717  

Inventories

     (131,558,057     (36,610,648

Prepaid expenses and other

     (29,317,256     (3,452,638

Due from related parties

     8,139,127       3,507,074  

Other assets

     (2,054,745     (68,313

Accounts payable

     64,767,742       3,859,235  

Accrued expenses

     42,812,851       1,010,597  

Inflation reduction act energy tax credit accrual

     (36,080,179     2,522,933  

Customer deposits

     152,653,796       29,704,205  

Unearned warranty revenue

     (64,460     760,188  


Net cash provided by operating activities

     31,792,534       10,396,822  


Cash flows from investing activities:


Capital expenditures

     (7,278,217     (2,570,569


Net cash used in investing activities

     (7,278,217     (2,570,569


Cash flows from financing activities:


Payments of loan closing costs

     —        (1,013,021

Principal payments on debt

     (24,482     —   


Net cash used in financing activities

     (24,482     (1,013,021


Effect of exchange rate changes on cash and cash equivalents

     (18,115     199,081  

Net change in cash and cash equivalents and restricted cash

     24,471,720       7,012,313  

Cash and cash equivalents and restricted cash at beginning of period

     116,754,684       28,450,517  


Cash and cash equivalents and restricted cash at end of period

   $ 141,226,404     $ 35,462,830  


Supplemental disclosure of cash flow information:


Cash paid for interest

   $ 2,099,795     $ 275,132  

Non-cash capital expenditures

     1,260,866       315,373  

See notes to condensed consolidated financial statements


F-91


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements

NOTES TO CONDENSED CONSOLIDATED FINANCIAL STATEMENTS

Note 1. Nature of Operations and Basis of Presentation

Nature of Operations

Charge Parent, LLC and Subsidiaries (“the Company”) designs, develops, and manufactures premier utility-scale inverters. The Company is based in Poway, California, and has manufacturing facilities located in California and South Carolina. The Company also has an engineering and sales branch in Finland. Primarily serving the utility and C&I sectors, the Company focuses on energy storage and solar power conversion. The Company’s main product line includes the M Inverter, a 662 kW inverter for utility-scale and commercial applications, and the M-Rack, a liquid-cooled configuration of the M inverter. The M inverter is sold in M systems which range from 2-6 MW for utility grade applications to support solar, storage, and data center markets. Additionally, the Company sells the 1 MW – 6 MW CAB1000 for utility-grade applications, and the 250 kW – 500 kW Power Drawer for business and facility applications. The Company’s solutions are fully scalable and have been deployed at 100+ MW sites. Serving customers globally, the Company’s products are certified to North American Standards (UL1741 / IEEE1547 / CSA 22.2), as well as Australian and European standards and grid codes (IEC / VDE), and quality standards, including ISO 9001:2015.

Foreign operations in Finland, after intercompany eliminations, account for less than 1% of the Company’s net sales and net assets for the six months ended June 30, 2026 and 2025.

Basis of Presentation

These condensed consolidated financial statements include the assets, liabilities and operating results of Charge Parent LLC, a Delaware limited liability company, along with its wholly owned subsidiaries in which the Company exercises control over operating and financial policies and are prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP” or “GAAP”) for interim financial information. Accordingly, they do not include all information and notes required by U.S. GAAP for annual financial statements.

The accompanying condensed consolidated financial statements reflect all adjustments, including normal recurring adjustments, necessary for a fair presentation of the Company’s condensed consolidated balance sheets as of June 30, 2026 and December 31, 2025, the condensed consolidated statements of operations for the six months ended June 30, 2026 and 2025, the condensed consolidated statements of comprehensive income (loss) for the six months ended June 30, 2026 and 2025, condensed consolidated statements of changes in members’ equity and condensed consolidated statements of cash flows for the six months ended June 30, 2026 and 2025.

The financial data and other information disclosed in the notes to condensed consolidated financial statements related to these periods are unaudited. These condensed consolidated financial statements should be read in conjunction with the audited consolidated financial statements and notes thereto included elsewhere in the Company’s annual financial statements for the years ended December 31, 2025 and 2024. The condensed consolidated balance sheets data as of December 31, 2025 was derived from the Company’s audited consolidated financial statements but does not include all disclosures required by U.S. GAAP for annual financial statements. Intercompany accounts and transactions have been eliminated in consolidation.

There have been no further material changes to the Company’s significant accounting policies or recent accounting pronouncements during the interim period from those described in Note 1 – Nature of Operations and Summary of Significant Accounting Policies to the audited consolidated financial statements included in the Company’s annual financial statements for the years ended December 31, 2025 and 2024.


F-92


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Recent Accounting Pronouncements

Recently Adopted Accounting Pronouncements

In December 2023, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) No. 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures. ASU No. 2023-09 enhances the transparency and decision usefulness of income tax disclosures. The amendments in this ASU require consistent categories and greater disaggregation of information in the rate of reconciliation and income taxes paid disaggregated by jurisdiction. ASU No. 2023-09 is effective for fiscal years beginning after December 15, 2024. Early adoption is permitted. The amendments in this ASU should be applied on a prospective basis. Retrospective application is permitted. The Company adopted the new requirements on January 1, 2025 on a prospective basis.

In January 2024, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) No. 2024-01Compensation—Stock Compensation (Topic 718): Scope Application of Profits Interest and Similar Awards. This update provides clarification on the application of stock compensation guidance to profits of interest and similar awards. ASU No. 2024-01 is effective for the Company for fiscal years beginning after December 15, 2025. The Company adopted the new requirements on January 1, 2026 on a prospective basis.

In July 2025, the FASB issued ASU 2025-05, Financial Instruments – Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets, which permits entities to elect a practical expedient to assume current conditions as of the balance sheet date will not change for the remaining life of accounts receivable and contract assets when developing forecasts as part of estimating expected credit losses. The amendments in ASU 2025-05 are effective for fiscal years beginning after December 15, 2025, and interim periods within those fiscal years, with early adoption permitted. The amendments should be applied prospectively. The Company adopted the new requirements on January 1, 2026 on a prospective basis. The adoption did not have a material impact on the Company’s condensed financial statements.

New Accounting Pronouncements Not Yet Adopted

In November 2024, the FASB issued ASU 2024-03, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses.” The update requires entities to tabularly disclose in the footnotes to the financial statements, the amounts of purchased inventory, employee compensation, intangible asset amortization, and depreciation included in each relevant expense caption. The standard also requires disclosure of the amount, and a qualitative description of, other items remaining in relevant expense captions that are not separately disaggregated. This update is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027. Early adoption and both prospective and retrospective application are permitted. The Company is currently assessing the effect of this update.

In September 2025, the FASB issued ASU 2025-06, Intangibles – Goodwill and Other – Internal-Use Software (Subtopic 350-40): Targeted Improvements to the Accounting for Internal-Use Software, which removes all references to software development project stages and requires entities to start capitalizing software costs when both of the following occur: (i) management has authorized and committed to funding the software project and (ii) it is probable that the project will be completed and the software will be used to perform the function intended. The amendments in ASU 2025-06 are effective for fiscal years beginning after December 15, 2027, and interim periods within those fiscal years, with early adoption permitted as of the beginning of a fiscal year. The amendments can be applied prospectively, retrospectively, or via a modified prospective transition method. The Company is currently evaluating the impact of ASU 2025-06 on its condensed consolidated financial statements.


F-93


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


In December 2025, the FASB issued ASU 2025-10, “Accounting for Government Grants Received by Business Entities” (“ASU 2025-10”), which establishes the accounting and presentation for government grants received by a business entity. ASU 2025-10 is effective for annual reporting periods beginning after December 15, 2028, and interim reporting periods within those annual reporting periods. Early adoption is permitted. ASU 2025-10 permits an entity to apply the new guidance using a modified prospective basis, a modified retrospective basis, or a full retrospective basis. The Company is currently evaluating the impact of ASU 2025-10 on its condensed consolidated financial statements and does not expect the adoption of this guidance to have a material impact on its condensed consolidated financial statements.

Note 2. Balance Sheet Items

Fair Value Measurements

US GAAP defines fair value as the exchange price that would be received for an asset or paid to transfer a liability (an exit price) in the principal or most advantageous market for the asset or liability in an orderly transaction between market participants.

US GAAP establishes a fair value hierarchy that prioritizes the inputs to valuation techniques used to measure fair value into three levels. The hierarchy gives the highest priority to unadjusted quoted prices in active markets for identical assets or liabilities (Level 1 measurements) and the lowest priority to unobservable inputs (Level 3 measurements).

The three levels of the fair value hierarchy are described below:


Level 1 - Valuation is based on quoted prices for identical assets or liabilities in active markets;


Level 2 - Valuation is based on quoted prices for similar assets or liabilities in active markets or other inputs that are observable for the asset or liability, either directly or indirectly, for the full term of the financial instrument; and


Level 3 - Unobservable inputs that are supported by little or no market activity, therefore requiring an entity to develop its own assumptions about the assumptions that market participants would use in pricing.

As of June 30, 2026 the Company’s financial instruments consist primarily of cash and cash equivalents, accounts receivable, accounts payable, accrued expenses, and debt. Given their short-term nature, the carrying amounts of cash and cash equivalents, receivables, accounts payable, and accrued expenses generally approximate their fair values. Additionally, the Company believes the carrying amounts of the variable-rate borrowings, if any, approximate fair value.

Certain nonfinancial assets, including property and equipment, operating lease right-of-use assets and finite-lived intangible assets, are not measured at fair value on a recurring basis. These assets are evaluated for impairment when events or changes in circumstances indicate that their carrying amounts may not be recoverable. If an asset group is determined to be not recoverable, the Company measures the asset group at fair value on a nonrecurring basis for purposes of determining the impairment loss. Such fair value measurements are generally determined using valuation techniques that incorporate significant unobservable inputs and are therefore classified within Level 3 of the fair value hierarchy.

Goodwill and indefinite-lived intangible assets are evaluated for impairment annually or more frequently if events or changes in circumstances indicate that potential impairment exists. Fair value measurements of reporting units and indefinite-lived intangible assets used in quantitative impairment assessments are generally classified within Level 3 of the fair value hierarchy.


F-94


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Accounts Receivable

Accounts receivable consists of trade accounts arising in the normal course of business. The Company recognizes an allowance for credit losses for trade and other receivables to present the net amount expected to be collected as of the consolidated balance sheet date. Such allowance is based on the expected credit losses which includes consideration of historical losses as well as past, current, and future events as of the balance sheet date. Receivables are written off when the Company determines that such receivables are deemed uncollectible. The Company pools its receivables based on similar risk characteristics in estimating its expected credit losses. In situations where a receivable does not share the same risk characteristics with other receivables, the Company measures those receivables individually. The Company also continuously evaluates such pooling decisions and adjusts as needed from period to period as risk characteristics change. The allowance for expected credit losses was not material as of June 30, 2026 and December 31, 2025.

Inventories

Inventories consisted of the following:


     As of June 30, 2026      As of December 31, 2025  

Raw materials

   $ 118,538,343      $ 33,569,112  

Work in process

     27,433,296        2,896,655  

Finished goods

     24,157,230        9,120,631  


Inventories

   $ 170,128,869      $ 45,586,398  


The increase in inventories reflects the Company’s expectations of future business growth and the associated inventory requirements necessary to support anticipated demand and operations. The Company recognized an inventory write-down of $7,015,586 and $229,078 for the six months ended June 30, 2026 and 2025, respectively, reflecting the excess of the carrying value of certain inventory over its estimated net realizable value. The increase during the six months ended June 30, 2026 was primarily attributable to excess inventory resulting from reduced demand for legacy product lines, as well as supplier and manufacturing quality issues associated with the ramp-up of a newly introduced product line. The write-down was recorded within cost of goods sold in the accompanying condensed consolidated statements of operations.

Prepaid Expenses and Other

Prepaid expenses consist primarily of short-term deposits and advances of $36,897,214 and $10,274,912 as of June 30, 2026 and December 31, 2025, respectively. Prepaid expenses also included other balances that were individually and in the aggregate immaterial to the consolidated financial statements. The increase in prepaid expense is primarily related to advance payments to certain vendors for procurement of inventory.

Inflation Reduction Act Energy Tax Credit

In August 2022, the Inflation Reduction Act (IRA) was enacted, introducing clean energy tax incentives, notably the advanced manufacturing production credit (Section 45X). This credit pertains to each domestically produced and sold clean energy component, including utility inverters, which aligns with the Company’s primary product line of premium utility-scale inverters.

Manufacturers have the option to either receive a direct payment from the Internal Revenue Service or transfer the tax credit. The Company elected to transfer all tax credits earned in 2025 and 2024 to an unrelated eligible taxpayer.


F-95


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Effective January 1, 2025, the Company changed its accounting principle for the presentation of Section 45X credits from recognizing the credits within other income to presenting the credits as a reduction of cost of goods sold. The Company accounts for the Section 45X credits as government grants by analogy to International Accounting Standard 20, Accounting for Government Grants and Disclosure of Government Assistance (“IAS 20”). The Company believes the new accounting principle is preferable because the Section 45X credits are generated from the Company’s qualifying manufacturing activities and presenting the credits as a reduction of cost of goods sold more closely associates the benefit of the credits with the related manufacturing costs.

For the six months ended June 30, 2026 and 2025, $50.3 million and $5.5 million, respectively, of Section 45X tax credits were recognized as a reduction of cost of goods sold.

Section 45X tax credits earned by the Company and expected to be transferred are recognized as current receivables in the consolidated balance sheets. Cash proceeds from transfers of the credits are classified within operating activities in the consolidated statements of cash flows.

In December of 2023, the Company entered into an agreement to sell $39.6 million of Section 45X tax credits generated during 2024 and 2023 for aggregate cash proceeds of $36.3 million. The Company received initial cash proceeds of $26.3 million during the year ended December 31, 2024 and received the remaining cash proceeds of $10.0 million during March of 2025.

In August of 2025, the Company entered into a separate agreement to sell $42.5 million of Section 45X tax credits generated during 2025 for aggregate cash proceeds of $40.0 million. The Company received initial cash proceeds of $17.5 million during the year ended December 31, 2025, with the remaining cash proceeds of $22.5 million received in March of 2026.

As of June 30, 2026, the Company had not entered into any agreements to sell or transfer Section 45X tax credits generated during 2026, and the increase in tax credits recognized during the current period was primarily driven by higher sales volumes of eligible products. The tax credits were recognized as current receivables on the condensed consolidated balance sheets, and included in cost of goods sold on the condensed consolidated statements of operations.

Property and Equipment

Property and equipment consisted of the following:


     As of June 30, 2026      As of December 31, 2025  

Machinery and equipment

   $ 10,407,779      $ 10,355,641  

Vehicles

     85,000        85,000  

Leasehold improvements

     2,928,069        2,928,069  

Office equipment

     1,496,339        1,465,547  

Construction in progress

     9,130,504        750,929  


Total

     24,047,691        15,585,186  

Less accumulated depreciation

     (4,854,813      (3,527,747


Property and equipment, net

   $ 19,192,878      $ 12,057,439  


Depreciation expense was $1,403,644 and $619,501 for the six months ended June 30, 2026 and 2025, respectively.


F-96


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Intangible assets consisted of the following as of June 30, 2026:


     Estimated Useful
Life (in Years)
     Cost      Accumulated
Amortization
     Net Book Value  

Tradename

     15      $ 13,300,000      $ (3,376,722    $ 9,923,278  

Developed technology

     7        46,700,000        (25,407,024      21,292,976  

Patents

     14        3,800,000        (1,033,691      2,766,309  

Backlog

     2        500,000        (500,000      —   

Customer relationships

     10        12,000,000        (4,570,000      7,430,000  


Intangible assets, net

      $ 76,300,000      $ (34,887,437    $ 41,412,563  


Intangible assets consisted of the following as of December 31, 2025:


     Estimated Useful
Life (in Years)
     Cost      Accumulated
Amortization
     Net Book Value  

Tradename

     15      $ 13,300,000      $ (2,933,389    $ 10,366,611  

Developed technology

     7        46,700,000        (22,071,310      24,628,690  

Patents

     14        3,800,000        (897,976      2,902,024  

Backlog

     2        500,000        (500,000      —   

Customer relationships

     10        12,000,000        (3,970,000      8,030,000  


Intangible assets, net

      $ 76,300,000      $ (30,372,675    $ 45,927,325  


Amortization expense was $4,514,762 during each of the six months ended June 30, 2026 and 2025. The following presents the estimated amortization expense for intangible assets for each of the next five years and thereafter:


     Amortization expense  

Years ending December 31:


2026

   $ 4,514,762  

2027

     9,029,524  

2028

     9,029,524  

2029

     6,972,500  

2030

     2,358,095  

Thereafter

     9,508,158  


Total

   $ 41,412,563  


Accounts Payable

Accounts payable increased from $32,882,190 as of December 31, 2025 to $98,405,318 as of June 30, 2026. The increase was primarily attributable to higher inventory purchases during the period and the related obligations outstanding to suppliers at period end.


F-97


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Accrued Warranty

The warranty liability consisted of the following:


     As of June 30, 2026      As of June 30, 2025  

Beginning balance

   $ 4,607,162      $ 3,545,677  

Provision for warranties

     4,474,997        776,312  

Change in warranty estimate

     —         —   

Warranty claims paid

     (5,436,905      (968,169


Ending balance

   $ 3,645,254      $ 3,353,820  


The warranty liability as of June 30, 2026 remained relatively consistent with the balance as of December 31, 2025. Warranty claims paid during the six months ended June 30, 2026 primarily related to retrofit projects for which the Company had recorded an incremental warranty reserve of approximately $3.5 million as of December 31, 2025 to cover the estimated costs associated with these projects. These retrofit projects were substantially completed during the six months ended June 30, 2026, resulting in a reduction of the related warranty reserves. The reduction in reserves associated with these projects was largely offset by warranty provisions recorded for current-period product shipments.

Note 3. Revenue

The Company recognizes revenue when a good or service promised in a contract (i.e., a performance obligation) is satisfied, which is upon the transfer of control of the contracted goods and services to the customer. Performance obligations related to product sales are satisfied at a point in time. Control is transferred when a customer can direct the use of and obtain all of the remaining benefits from that good. Control typically transfers to the customer upon shipment or pick-up or delivery, depending on contract terms.

For goods sold under bill-and-hold arrangements, revenue is recognized when title and risk of loss have passed to the customer and the Company does not have the ability to use the product or direct it to other customers. Under bill-and-hold arrangements, the Company bills a customer for product to be delivered at a later date; control typically transfers when the product is ready for physical transfer to the customer, and the Company has a present right to payment. Typically, a bill-and-hold arrangement is entered when a customer does not have sufficient storage capacity or is experiencing temporary project delays and requests that the Company keep the product in the Company’s custody. In such cases, the product is crated and palletized in the Company’s warehouses or designated third-party storages till it is ultimately shipped to the customer.

Revenue from service-based contracts is recognized at a point in time or over time depending on the nature of the performance obligation promised in the contract.

A contract with a customer may involve multiple products or services and/or multiple delivery dates. The Company assesses the promised goods and services within the contract to identify distinct performance obligations. For a contract with multiple performance obligations, the contract transaction price is allocated to each performance obligation based on relative standalone selling prices.

The revenue recorded is measured as the amount of consideration the Company expects to receive in exchange for transferring control of the products or performing services. Consideration is typically determined based on a fixed unit price, adjusted for variable consideration, including estimated product returns, as applicable, for the quantity of products or services transferred. The Company generally invoices up to 90% of the contract value upon delivery, with payment due within 120 days. The remaining 10% is billed approximately on commissioning


F-98


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


or up to 180 days from shipment in accordance with contractual terms. Revenue is recognized upon delivery when control of the product transfers to the customer, as the deferred billing is not contingent upon the satisfaction of any additional performance obligations by the Company.

The Company provides general assurance warranties for a period up to five years that its products will perform as intended for periods beyond the date of sale. General assurance warranties are inherent within the Company’s products and services and do not provide customers with a service other than the assurance that the Company’s goods and services will perform as intended, therefore the Company does not account for its general assurance warranties as separate and/or distinct performance obligations.

The Company recognizes provisions for estimated warranty costs and product returns based on historical experience at the time revenue is recognized, or for specific items, at the time existence of the claims is known and the amounts are determinable.

The Company also offers extended warranties which go beyond the general assurance periods, and these warranties are accounted for as separate and distinct performance obligations in the revenue recognition process. Revenue associated with extended warranty contracts is recognized ratably over the contractual warranty coverage period as the Company satisfies its performance obligation to stand ready to provide warranty services.

Disaggregation of Revenue

The Company disaggregates revenue from contracts with customers into categories that depict how the nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factors. The Company has determined that disaggregation by revenue type and by geography provides the most meaningful depiction of how the nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factors.

The following tables present the disaggregation of the Company’s revenue by revenue type and by geography for the six months ended June 30, 2026 and 2025:


     Six Months Ended  
     June 30, 2026      June 30, 2025  

Product

   $ 224,205,129      $ 39,872,699  

Service and other

     5,679,157        2,198,061  


Total revenues

   $ 229,884,286      $ 42,070,760  


The following table presents the Company’s revenue disaggregated by geographical region for the six months ended June 30, 2026 and 2025:


     Six Months Ended  
     June 30, 2026      June 30, 2025  

United States

   $ 222,604,716      $ 35,447,356  

International

     7,279,570        6,623,404  


Total revenues

   $ 229,884,286      $ 42,070,760  


Contract Assets and Contract Liabilities

The Company’s contracts with customers may contain invoicing and/or payment terms which result in the recognition of contract assets and liabilities. Contract assets, or unbilled revenue, which is part of the accounts


F-99


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


receivable, are recorded when the Company transfers a good or service before it is invoiced. Contract liabilities, including unearned warranty revenue and/or customer deposits, are recorded when the Company receives consideration in advance of transferring a good or performing a service.

Supplemental balance sheet information related to contracts from customers as of:


     As of June 30, 2026      As of December 31, 2025  

Contract Assets


Unbilled revenue

   $ 15,273,118      $ 8,065,020  


Total

   $ 15,273,118      $ 8,065,020  


Contract Liabilities


Unearned warranty revenues

   $ 16,045,554      $ 16,110,014  

Customer deposits

     282,194,927        129,541,131  


Total

   $ 298,240,481      $ 145,651,145  


Contract assets: Contract assets, or unbilled revenue, represent the Company’s right to consideration for products or services transferred to customers when such rights are conditioned on factors other than the passage of time. Unbilled revenue primarily arises when revenue is recognized prior to invoicing in accordance with the contractual terms of the underlying arrangement. Contract assets are included within accounts receivable in the accompanying consolidated balance sheets. The increase in contract assets as of June 30, 2026 as compared to December 31, 2025 was primarily attributable to the timing of contractual billing milestones, under which revenue was recognized in advance of the Company’s contractual right to invoice customers.

Customer deposits: Customer deposits relate to advance payments received from customers for products or services that have not yet been transferred. Revenue is recognized and the related contract liability is reduced when control of the promised goods or services is transferred to the customer. The increase in customer deposits as of June 30, 2026 as compared to December 31, 2025 was primarily attributable to contractual requirements for customers to remit a portion of consideration in advance of the Company satisfying the related performance obligations and recognizing revenue.

During the six months ended June 30, 2026 and 2025, the Company recognized revenue of $57,106,952 and $7,239,527, respectively, related to contract liabilities outstanding as of the end of each prior reporting period.

Remaining Performance Obligations

Remaining performance obligations, which are primarily included in unearned revenues (as presented on the condensed consolidated balance sheets), represent the aggregate amount of the transaction price of certain customer contracts yet to be recognized as revenues as of the end of the reporting period.

As of June 30, 2026, the aggregate amount of the transaction price allocated to remaining (unsatisfied or partially unsatisfied) performance obligations was $16,045,554, which related to the Company’s extended warranty contracts. The Company expects to recognize approximately 20% of its remaining performance obligation over the next 12 months, approximately 50% will be recognized over the next 13 to 36 months and the remainder thereafter.

The Company has elected to adopt certain practical expedients and exemptions allowed under ASC 606:


Practical expedient to recognize the incremental costs of obtaining a contract as an expense when incurred if the amortization period of the asset that the entity otherwise would have recognized is one year or less.


F-100


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Practical expedient from recognizing shipping and handling activities as activities to fulfill the promise to transfer the goods.


Practical expedient to present revenue net of sales taxes and other similar taxes.

Note 4. Provision for Income Taxes

The Company did not record an income tax provision for the six months ended June 30, 2026 and 2025, primarily due to operating losses and the maintenance of a full valuation allowance against its deferred tax assets.

Significant judgment is required in determining the Company’s provision for income taxes, including the recognition and measurement of deferred tax assets and liabilities and the assessment of the related valuation allowance. Deferred tax assets are recognized for deductible temporary differences and net operating loss carryforwards and are reduced by a valuation allowance if, based on available evidence, it is more likely than not that some or all deferred tax assets will not be realized.

In evaluating the realizability of its deferred tax assets, the Company considers both positive and negative evidence, including cumulative losses in recent periods and the lack of sufficient objectively verifiable future taxable income. Based on this evaluation, the Company concluded that it is more likely than not that its deferred tax assets will not be realized. Accordingly, a full valuation allowance has been recorded as of June 30, 2026, and December 31, 2025.

The Company reassesses the realizability of its deferred tax assets at each reporting period.

Note 5. Members’ Equity

Series A Stock

As of June 30, 2026 and December 31, 2025, there were 58,742 units of Series A stock, with a par value of $1,000 each that had been authorized, issued and were currently outstanding. There were no share cancellations or repurchases of Series A stock during the six months ended June 30, 2026 and 2025.

Note 6. Redeemable preferred units

On September 9, 2022, the Company issued Preferred Units in connection with the acquisition of EPC Power Corp. The rights and preferences of the Preferred Units are governed by the Amended and Restated Limited Liability Company Agreement dated September 9, 2022. The Company is authorized to issue unlimited shares of the Preferred Units.

As of June 30, 2026 and December 31, 2025, 176,225 units of preferred stock, with a par value of $1,000 each are issued and outstanding.

Distribution and Liquidation Rights

Upon liquidation, dissolution or winding up of the Company, and after satisfaction of the Company’s obligations to creditors, assets of the Company available for distribution are made in the following order: holders of Preferred Units will first receive a return of their unpaid capital contributions and then additional distributions until they have achieved a 1.5x multiple on invested capital (“MOIC”); holders of Series A Units will receive a return of their invested capital and then additional distributions until they have achieved a 1.5x MOIC; any remaining distributions are allocated 87% to holders of Series A Units and 13% to holders of Series B Units.


F-101


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Redemption Rights

On or after September 9, 2032, holders representing a majority of the Preferred Units may require the Company to redeem their Preferred Units for an amount equal to the holders’ invested capital plus additional proceeds sufficient to provide a 1.5x MOIC, reduced by any prior distributions received with respect to such units.

The non-redeeming holders of a majority of the Preferred Units and Series A Units may elect to pursue a sale transaction in lieu of redemption within 30 days following the receipt of the redemption notice. If such an election is made, the redemption notice is revoked and the redemption right terminates.

The Preferred Units are classified as mezzanine, or temporary, equity because the units are redeemable at the holder’s option after the tenth anniversary of the original issuance and the ability of the non-redeeming holders to elect a sale transaction in lieu of redemption is also outside the Company’s control. The Company also concluded that the Preferred Units are probable of becoming redeemable.

Accordingly, the Company accretes the carrying amount of the Preferred Units to the redemption amount through the earliest contractual redemption date using the interest method. Share Cancellations and Repurchases

There were no share cancellations or repurchases of the Preferred Units during the six months ended June 30, 2026 and 2025.

During the six months ended June 30, 2026 and 2025, the Company recorded accretion of $4,093,837 and $3,931,166, respectively, related to the Preferred Units. Such accretion was recorded as a reduction of additional paid-in capital to the extent available, with any excess recorded as an increase to accumulated deficit.

As of June 30, 2026 and December 31, 2025, the Preferred Units had carrying amounts of $205,663,087 and $201,569,250, respectively. Such accretion was recorded as a reduction of additional paid-in capital to the extent available, with any excess recorded as an increase to accumulated deficit.

Note 7. Unit-Based Compensation

On September 9, 2022, in conjunction with the formation of the Company, 1,000,000 Series B units were authorized. The Series B units, which are profits interest, vest over four years from the date of grant. Upon termination of a Series B unit holder’s employment with the Company for any reason, all unvested Series B units shall automatically be forfeited without any payment.

The following is a summary of employee Series B units transactions that contain only service requirements to vest:


     Number of Shares      Weighted-Average
Grant Date Fair
Value
 

Series B units outstanding at December 31, 2025

     965,769        30.39  

Series B units granted

     30,000        58.87  

Series B units cancelled/forfeited

     (61,384      30.44  


Series B units outstanding at June 30, 2026

     934,385        31.30  


F-102


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


     Number of Shares      Weighted-Average
Grant Date Fair
Value
 

Series B units outstanding at December 31, 2024

     924,906        30.38  

Series B units granted

     30,374        30.50  

Series B units cancelled/forfeited

     (3,040      30.45  


Series B units outstanding at June 30, 2025

     952,240        30.39  


Compensation expense of $3,635,907 and $3,224,766 was recorded for the six months ended June 30, 2026 and 2025, respectively, and is recorded in selling, general, and administrative expenses on the condensed consolidated statements of operations. As of June 30, 2026 and December 31, 2025, unrecognized compensation expense was $10,044,615 and $13,782,977, respectively, which is expected to be recognized over a weighted-average period of 1.68 years and 2.35 years, respectively.

In June 2025, the board of directors approved an employee incentive plan, which provides incentive compensation opportunities to certain employees contingent upon specified liquidity events. As of June 30, 2026 and December 31, 2025, no amounts were probable or reasonably estimable, and no liability or compensation expense has been recognized.

Note 8. Concentrations

During the six months ended and as of June 30, 2026, four customers accounted for 80% of net sales and 79% of accounts receivable, respectively. During the six months ended June 30, 2025 and as of December 31, 2025, two customers accounted for 55% of net sales and 40% of accounts receivable, respectively. No other customer accounted for more than 10% of net sales or accounts receivable.

As of June 30, 2026 and December 31, 2025, accounts held at institutions in the United States are insured by the Federal Deposit Insurance Corporation (FDIC) up to $250,000 for interest bearing and non-interest bearing accounts. Cash balances exceed this federally insured limit at times. The Company maintains its cash at reputable financial institutions and does not believe it is exposed to any significant credit risk.

Financial instruments which potentially subject the Company to concentrations of credit risk consist principally of accounts receivable. The Company extends credit to its customers based upon evaluation of the customer’s financial condition and credit history and does not require collateral. Credit losses are provided for in the condensed consolidated financial statements and consistently have been within management’s expectations.

Note 9. Related-Party Transactions

The Company has sales to related parties due to their common ownership and affiliation. The net sales and accounts receivable balances with related parties result from the sale of power conversion systems, spare parts, and related services provided under customer contracts in the ordinary course of business. During the six months ended June 30, 2026 and 2025, the Company recorded net sales of $293,717 and $2,189,349 to a related party, respectively. As of June 30, 2026 and December 31, 2025, the amounts due from this related party were $145,480 and $8,284,607, respectively. Amounts due from related parties are unsecured, non-interest bearing and generally subject to the same payment terms as the Company’s third-party customer receivables.


F-103


Table of Contents

Charge Parent, LLC and Subsidiaries

Notes to Condensed Consolidated Financial Statements


Note 10. Commitments and Contingencies

Purchase Commitments

As of June 30, 2026 and December 31, 2025, the Company’s non-cancelable purchase commitments for inventory to be used in the ordinary course of business were $26,480,132 and $9,576,150, respectively. Of the $26,480,132 outstanding as of June 30, 2026, $20,337,332, $4,792,800, and $1,350,000 are expected to be purchased during the remainder of 2026, 2027, and 2028, respectively. These commitments are based on fixed or determinable prices and do not contain variable pricing components. Amounts purchased under the Company’s non-cancelable purchase commitments were $7,763,468 for the six months ended June 30, 2026. Amounts purchased under the Company’s non-cancelable purchase commitments for the six months ended June 30, 2025 were not material.

Inventory purchase orders issued in the ordinary course of business represent authorizations to purchase inventory from vendors rather than binding agreements and, therefore, are excluded from the amount disclosed above. Such purchase orders are based on the Company’s current inventory needs and are generally fulfilled by suppliers within a short period of time.

Litigation

In the normal course of business, the Company could be exposed to litigation involving its products, facilities, or personnel. The Company maintains insurance to cover such actions and believes that the resolution of any such litigation will not have a material adverse effect on the Company.

Note 11. Subsequent Events

Subsequent events have been evaluated through August 31, 2026, the date the condensed consolidated financial statements were available to be issued.


F-104