© Fifth Third Bancorp | All Rights Reserved Barclays Global Financial Services Conference September 15, 2026
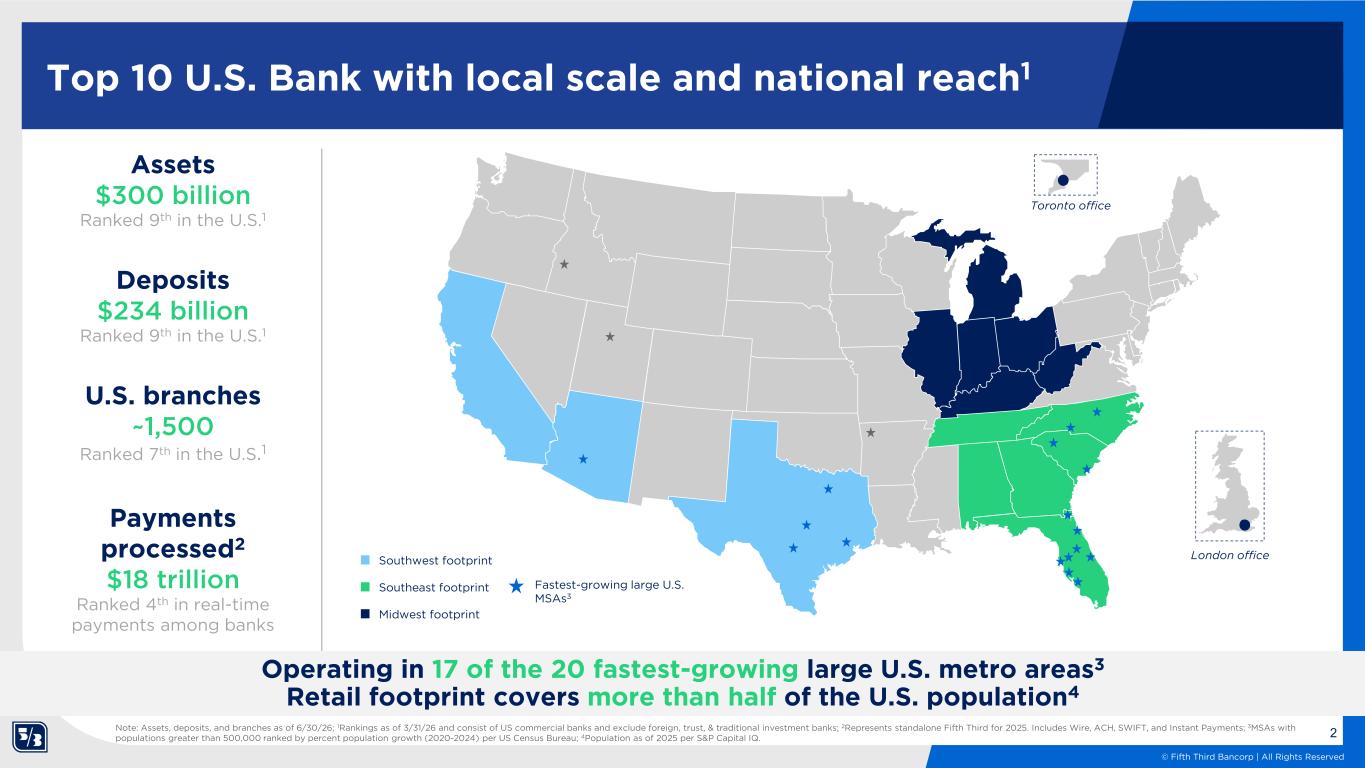
2 © Fifth Third Bancorp | All Rights Reserved Top 10 U.S. Bank with local scale and national reach1 Assets $300 billion Ranked 9th in the U.S.1 Deposits $234 billion Ranked 9th in the U.S.1 U.S. branches ~1,500 Ranked 7th in the U.S.1 Note: Assets, deposits, and branches as of 6/30/26; 1Rankings as of 3/31/26 and consist of US commercial banks and exclude foreign, trust, & traditional investment banks; 2Represents standalone Fifth Third for 2025. Includes Wire, ACH, SWIFT, and Instant Payments; 3MSAs with populations greater than 500,000 ranked by percent population growth (2020-2024) per US Census Bureau; 4Population as of 2025 per S&P Capital IQ. Payments processed2 $18 trillion Ranked 4th in real-time payments among banks Fastest-growing large U.S. MSAs3 Toronto office London office Operating in 17 of the 20 fastest-growing large U.S. metro areas3 Retail footprint covers more than half of the U.S. population4 Southwest footprint Midwest footprint Southeast footprint
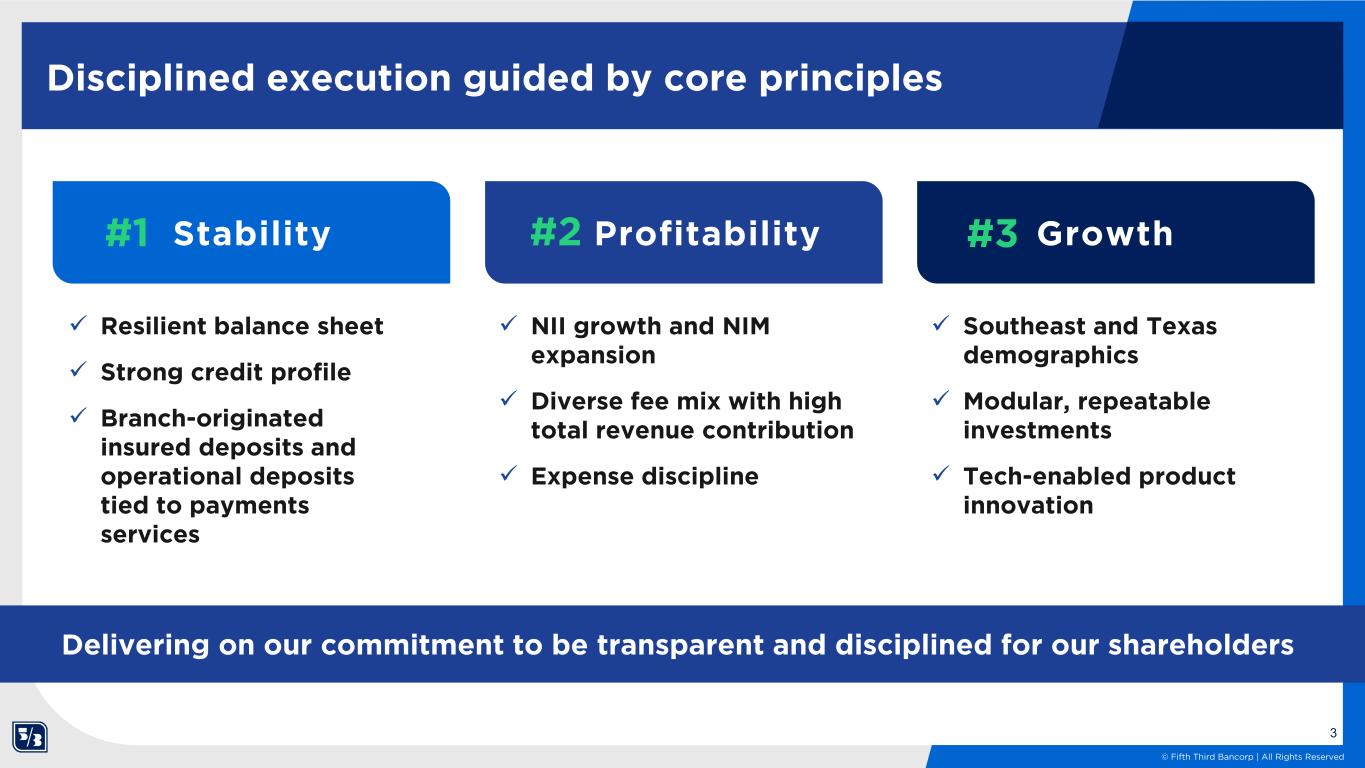
3 © Fifth Third Bancorp | All Rights Reserved Disciplined execution guided by core principles Stability Profitability Growth Resilient balance sheet Strong credit profile Branch-originated insured deposits and operational deposits tied to payments services NII growth and NIM expansion Diverse fee mix with high total revenue contribution Expense discipline Southeast and Texas demographics Modular, repeatable investments Tech-enabled product innovation #2 #3#1 Delivering on our commitment to be transparent and disciplined for our shareholders
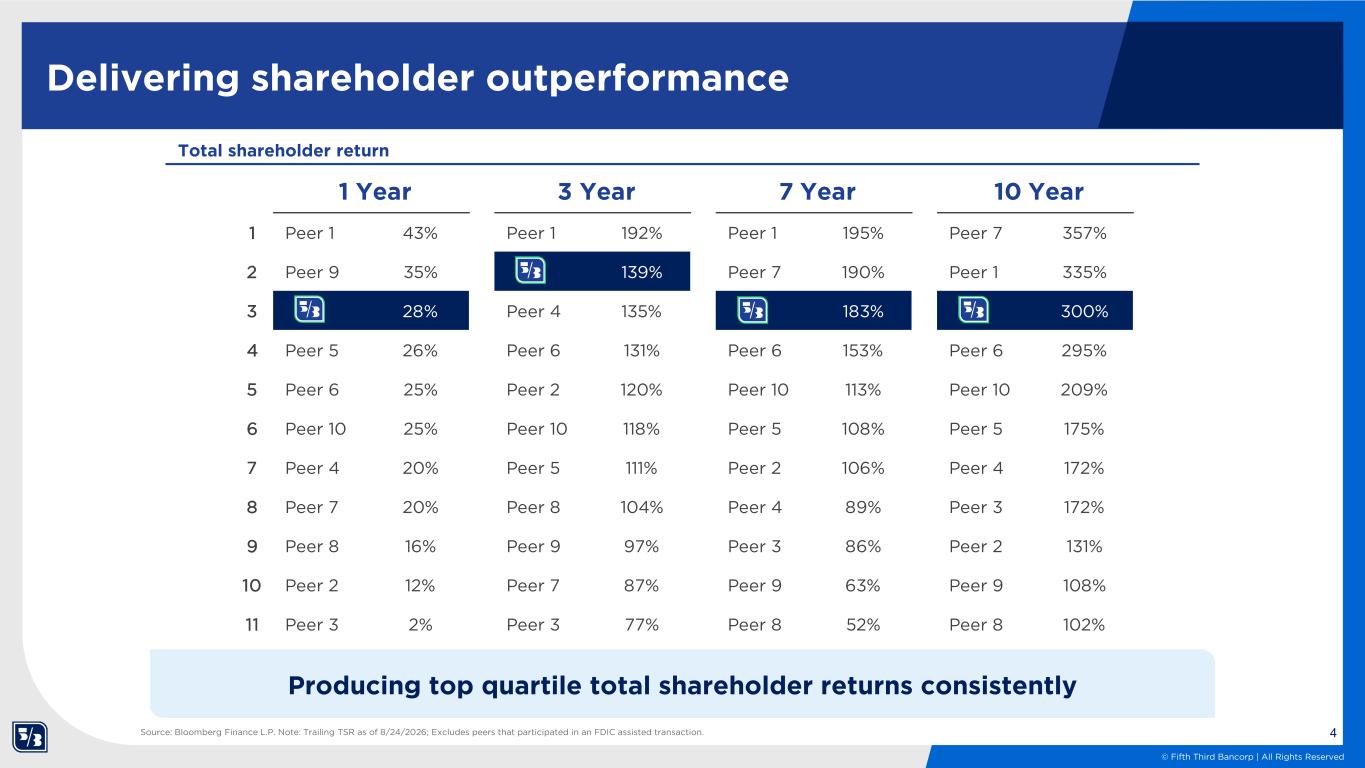
4 © Fifth Third Bancorp | All Rights Reserved 1 Peer 1 43% Peer 1 192% Peer 1 195% Peer 7 357% 2 Peer 9 35% FITB 139% Peer 7 190% Peer 1 335% 3 FITB 28% Peer 4 135% FITB 183% FITB 300% 4 Peer 5 26% Peer 6 131% Peer 6 153% Peer 6 295% 5 Peer 6 25% Peer 2 120% Peer 10 113% Peer 10 209% 6 Peer 10 25% Peer 10 118% Peer 5 108% Peer 5 175% 7 Peer 4 20% Peer 5 111% Peer 2 106% Peer 4 172% 8 Peer 7 20% Peer 8 104% Peer 4 89% Peer 3 172% 9 Peer 8 16% Peer 9 97% Peer 3 86% Peer 2 131% 10 Peer 2 12% Peer 7 87% Peer 9 63% Peer 9 108% 11 Peer 3 2% Peer 3 77% Peer 8 52% Peer 8 102% 7 Year 10 Year 1 Year 3 Year Delivering shareholder outperformance Total shareholder return Source: Bloomberg Finance L.P. Note: Trailing TSR as of 8/24/2026; Excludes peers that participated in an FDIC assisted transaction. Producing top quartile total shareholder returns consistently
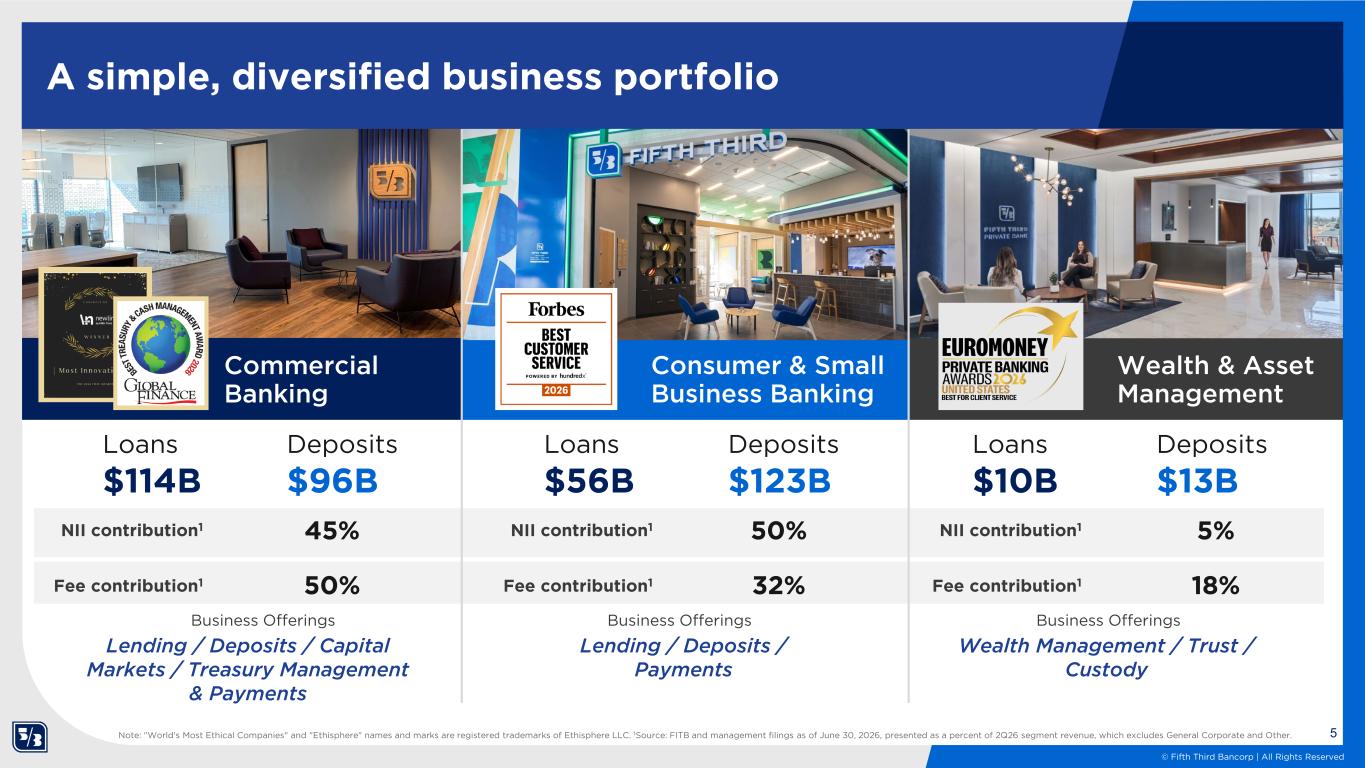
5 © Fifth Third Bancorp | All Rights Reserved NII contribution1 45% 50% 5% 50% 32% 18%Fee contribution1 A simple, diversified business portfolio • Texas Commercial Banking Loans $56B Deposits $123B Loans $10B Deposits $13B Loans $114B Deposits $96B Consumer & Small Business Banking Wealth & Asset Management Lending / Deposits / Capital Markets / Treasury Management & Payments Lending / Deposits / Payments Wealth Management / Trust / Custody NII contribution1 Fee contribution1 NII contribution1 Fee contribution1 Business Offerings Business Offerings Business Offerings Note: "World's Most Ethical Companies" and "Ethisphere" names and marks are registered trademarks of Ethisphere LLC. 1Source: FITB and management filings as of June 30, 2026, presented as a percent of 2Q26 segment revenue, which excludes General Corporate and Other.
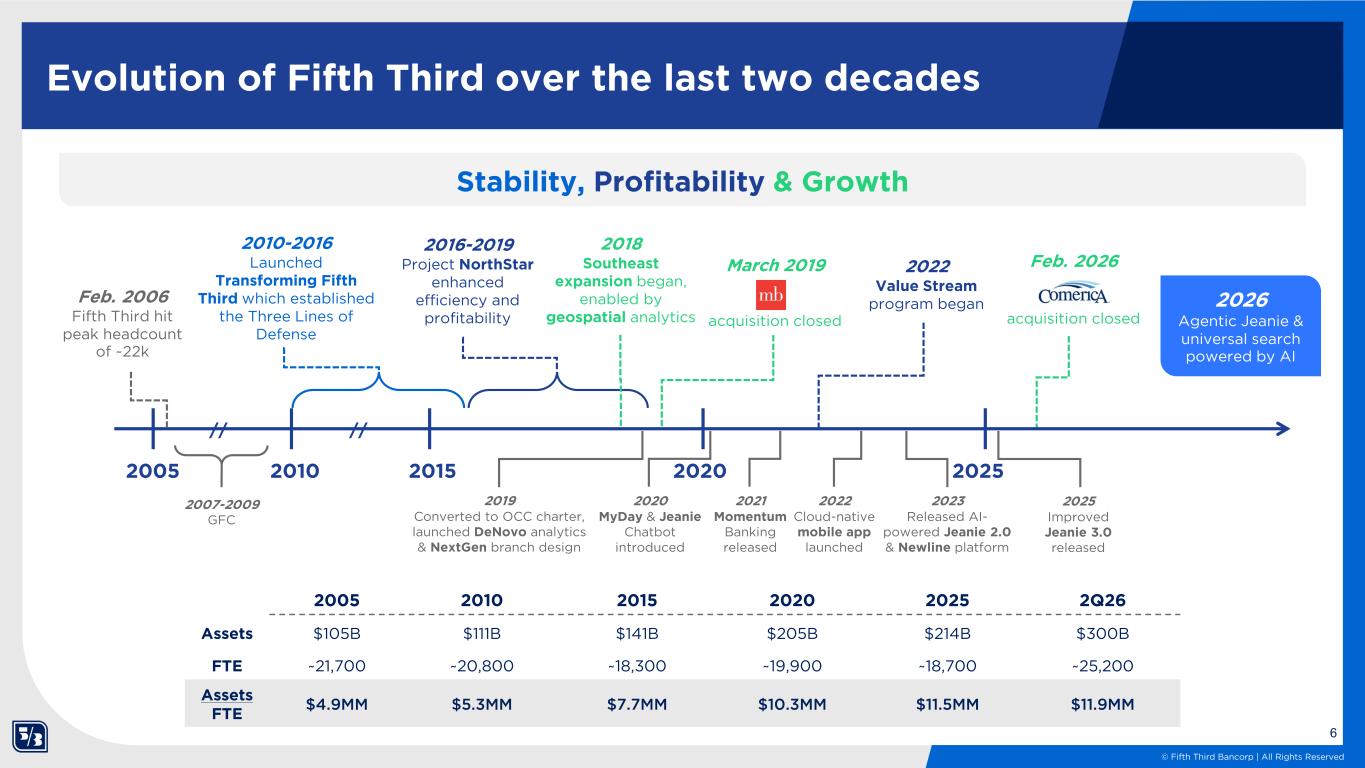
6 © Fifth Third Bancorp | All Rights Reserved Evolution of Fifth Third over the last two decades 2005 2010 2015 2020 2025 2005 2010 2015 2020 2025 2Q26 Assets $105B $111B $141B $205B $214B $300B FTE ~21,700 ~20,800 ~18,300 ~19,900 ~18,700 ~25,200 Assets FTE $4.9MM $5.3MM $7.7MM $10.3MM $11.5MM $11.9MM 2010-2016 Launched Transforming Fifth Third which established the Three Lines of Defense 2016-2019 Project NorthStar enhanced efficiency and profitability Feb. 2026 Comerica acquisition closed 2026 Agentic Jeanie & universal search powered by AI March 2019 acquisition closed Feb. 2006 Fifth Third hit peak headcount of ~22k Stability, Profitability & Growth 2022 Value Stream program began // // 2023 Released AI- powered Jeanie 2.0 & Newline platform 2018 Southeast expansion began, enabled by geospatial analytics 2019 Converted to OCC charter, launched DeNovo analytics & NextGen branch design 2007-2009 GFC 2020 MyDay & Jeanie Chatbot introduced 2025 Improved Jeanie 3.0 released 2021 Momentum Banking released 2022 Cloud-native mobile app launched
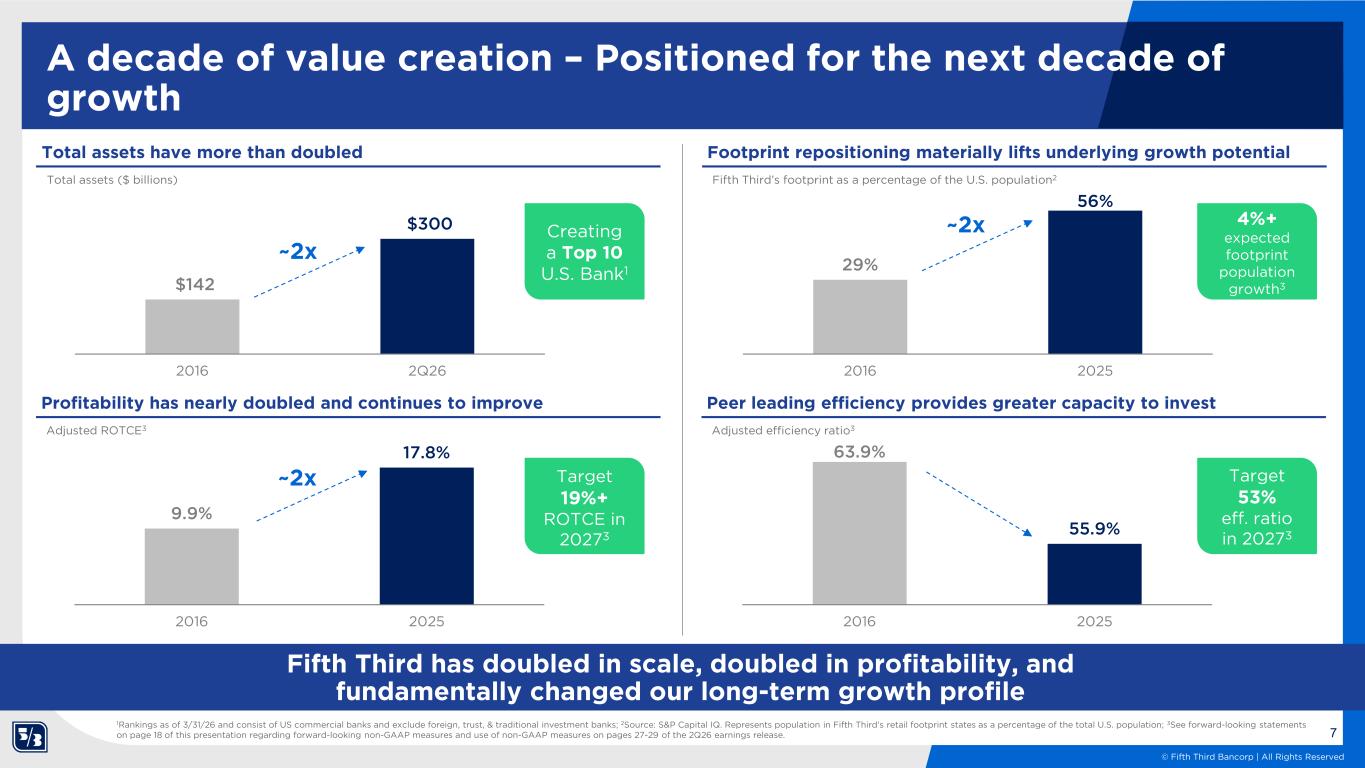
7 © Fifth Third Bancorp | All Rights Reserved Total assets have more than doubled A decade of value creation – Positioned for the next decade of growth Total assets ($ billions) 1Rankings as of 3/31/26 and consist of US commercial banks and exclude foreign, trust, & traditional investment banks; 2Source: S&P Capital IQ. Represents population in Fifth Third’s retail footprint states as a percentage of the total U.S. population; 3See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release. Fifth Third has doubled in scale, doubled in profitability, and fundamentally changed our long-term growth profile $142 $300 2016 2Q26 Profitability has nearly doubled and continues to improve Adjusted ROTCE3 9.9% 17.8% 2016 2025 ~2x Footprint repositioning materially lifts underlying growth potential Fifth Third’s footprint as a percentage of the U.S. population2 29% 56% 2016 2025 Peer leading efficiency provides greater capacity to invest Adjusted efficiency ratio3 63.9% 55.9% 2016 2025 ~2x ~2x Creating a Top 10 U.S. Bank1 Target 19%+ ROTCE in 20273 4%+ expected footprint population growth3 Target 53% eff. ratio in 20273
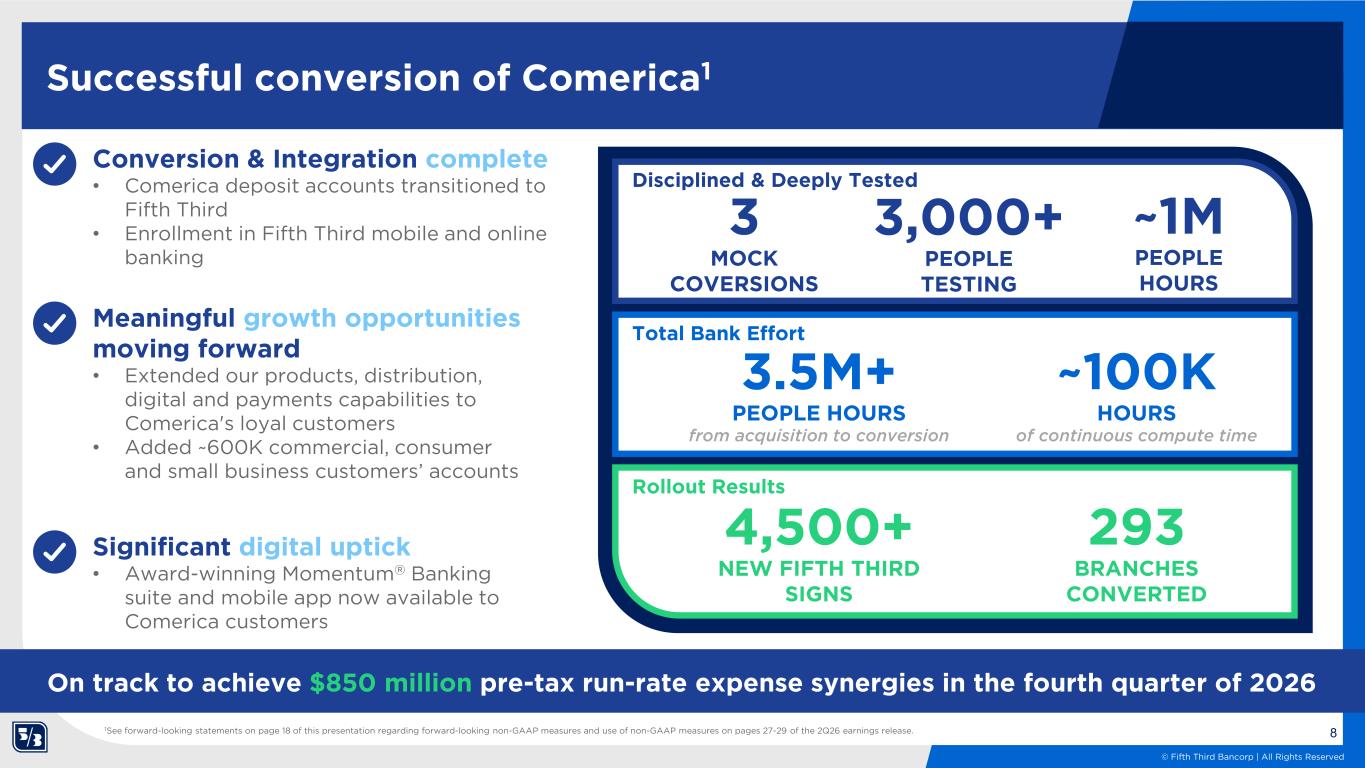
8 © Fifth Third Bancorp | All Rights Reserved Successful conversion of Comerica1 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release. Conversion & Integration complete • Comerica deposit accounts transitioned to Fifth Third • Enrollment in Fifth Third mobile and online banking Meaningful growth opportunities moving forward • Extended our products, distribution, digital and payments capabilities to Comerica's loyal customers • Added ~600K commercial, consumer and small business customers’ accounts Significant digital uptick • Award-winning Momentum® Banking suite and mobile app now available to Comerica customers Rollout Results 3 MOCK COVERSIONS ~1M PEOPLE HOURS 3,000+ PEOPLE TESTING 3.5M+ PEOPLE HOURS from acquisition to conversion ~100K HOURS of continuous compute time 4,500+ NEW FIFTH THIRD SIGNS 293 BRANCHES CONVERTED Total Bank Effort Disciplined & Deeply Tested On track to achieve $850 million pre-tax run-rate expense synergies in the fourth quarter of 2026
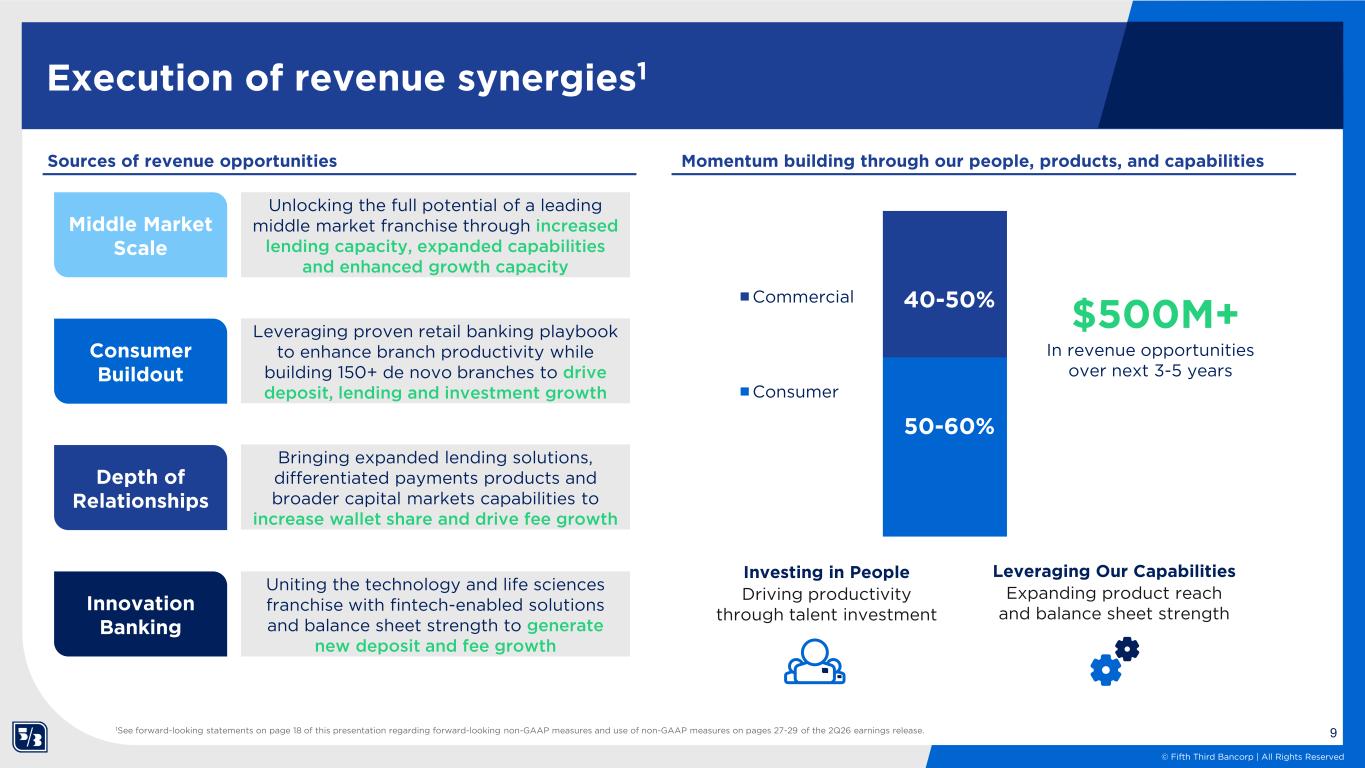
9 © Fifth Third Bancorp | All Rights Reserved Momentum building through our people, products, and capabilities Commercial Consumer Execution of revenue synergies1 Sources of revenue opportunities In revenue opportunities over next 3-5 years $500M+ 50-60% 40-50% 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release. Middle Market Scale Unlocking the full potential of a leading middle market franchise through increased lending capacity, expanded capabilities and enhanced growth capacity Depth of Relationships Bringing expanded lending solutions, differentiated payments products and broader capital markets capabilities to increase wallet share and drive fee growth Consumer Buildout Leveraging proven retail banking playbook to enhance branch productivity while building 150+ de novo branches to drive deposit, lending and investment growth Innovation Banking Uniting the technology and life sciences franchise with fintech-enabled solutions and balance sheet strength to generate new deposit and fee growth Leveraging Our Capabilities Expanding product reach and balance sheet strength Investing in People Driving productivity through talent investment
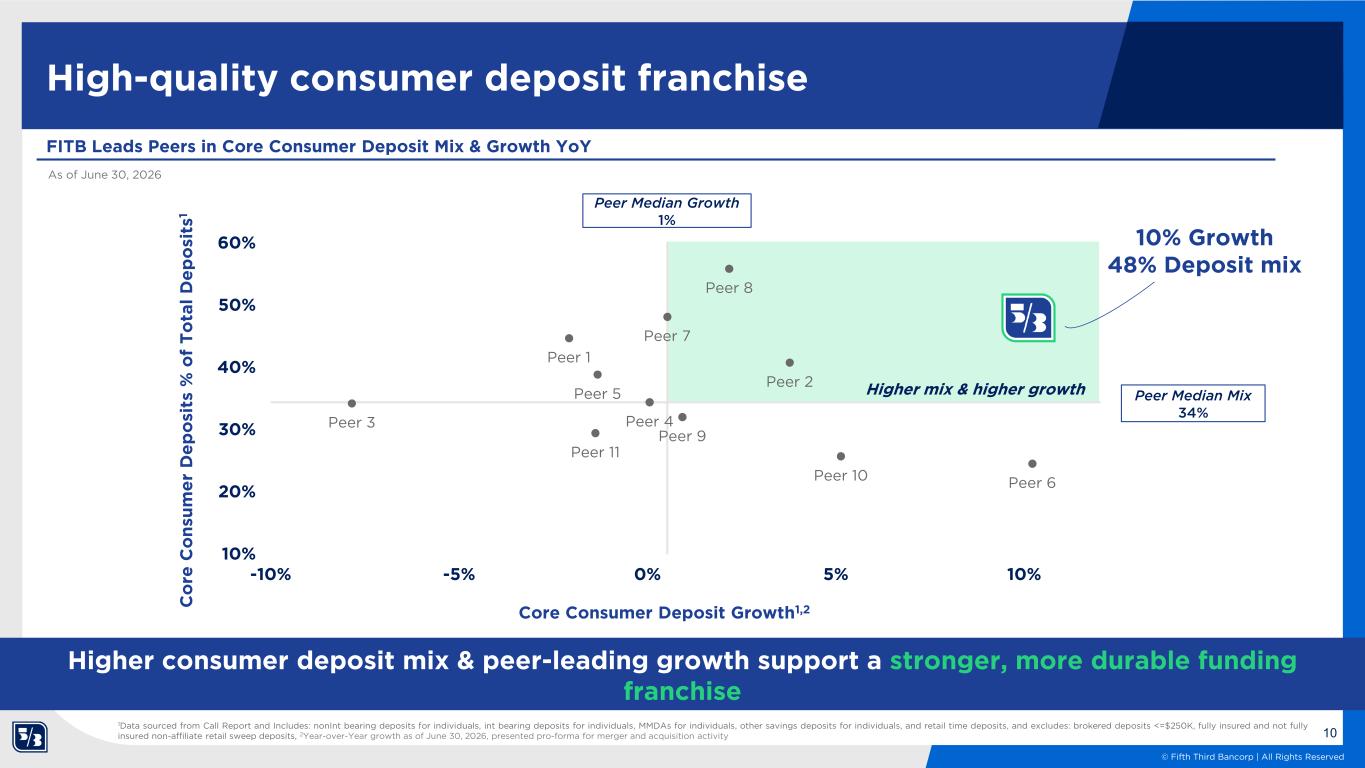
10 © Fifth Third Bancorp | All Rights Reserved x Peer 1 Peer 2 Peer 3 Peer 4 Peer 5 Peer 6 Peer 7 Peer 8 Peer 9 Peer 10 Peer 11 10% 20% 30% 40% 50% 60% -10% -5% 0% 5% 10% High-quality consumer deposit franchise 1Data sourced from Call Report and Includes: nonInt bearing deposits for individuals, int bearing deposits for individuals, MMDAs for individuals, other savings deposits for individuals, and retail time deposits, and excludes: brokered deposits <=$250K, fully insured and not fully insured non-affiliate retail sweep deposits, 2Year-over-Year growth as of June 30, 2026, presented pro-forma for merger and acquisition activity Core Consumer Deposit Growth1,2 As of June 30, 2026 Higher consumer deposit mix & peer-leading growth support a stronger, more durable funding franchise Higher mix & higher growth C o re C o n su m e r D e p o si ts % o f T o ta l D e p o si ts 1 Peer Median Growth 1% Peer Median Mix 34% 10% Growth 48% Deposit mix FITB Leads Peers in Core Consumer Deposit Mix & Growth YoY
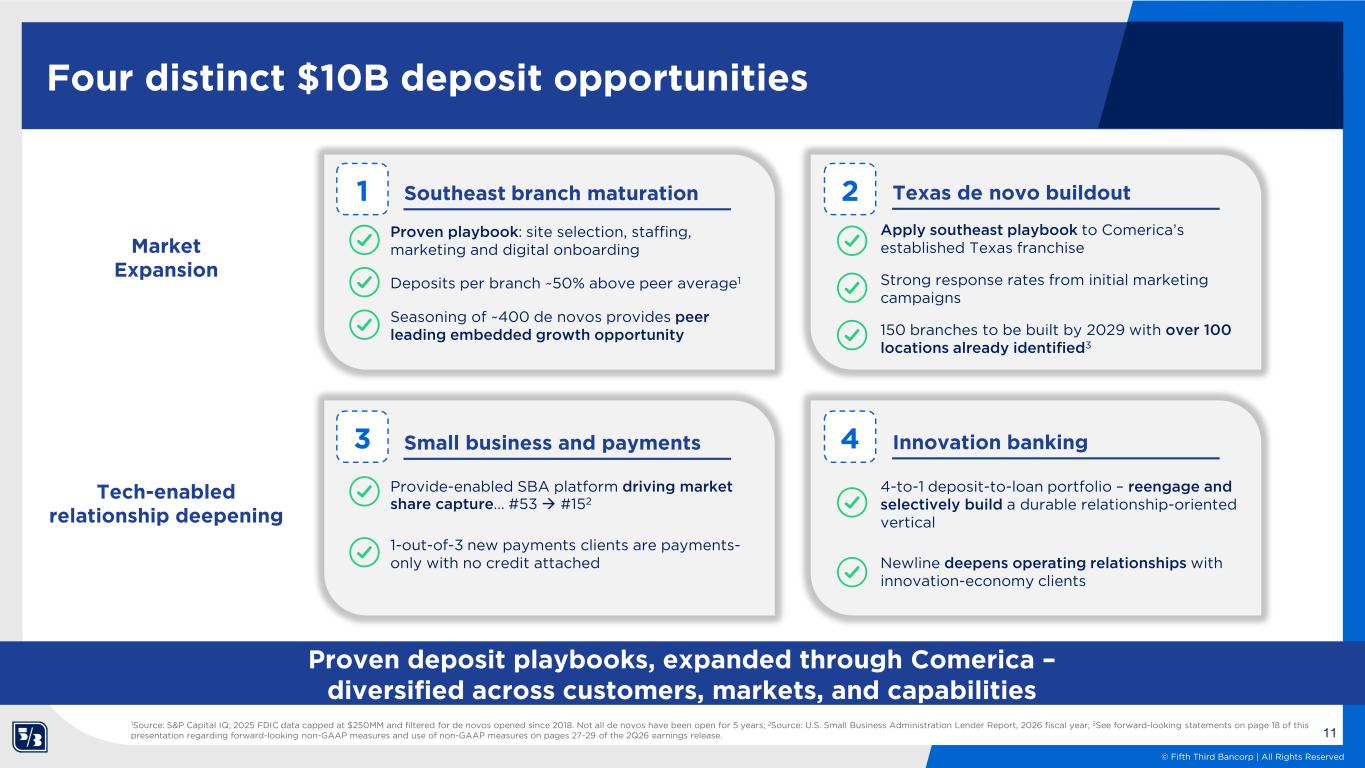
11 © Fifth Third Bancorp | All Rights Reserved Four distinct $10B deposit opportunities Market Expansion Tech-enabled relationship deepening Proven deposit playbooks, expanded through Comerica – diversified across customers, markets, and capabilities 1 2 3 4 Southeast branch maturation Texas de novo buildout Small business and payments Innovation banking Proven playbook: site selection, staffing, marketing and digital onboarding Deposits per branch ~50% above peer average1 Seasoning of ~400 de novos provides peer leading embedded growth opportunity Apply southeast playbook to Comerica’s established Texas franchise Strong response rates from initial marketing campaigns 150 branches to be built by 2029 with over 100 locations already identified3 Provide-enabled SBA platform driving market share capture… #53 #152 1-out-of-3 new payments clients are payments- only with no credit attached 4-to-1 deposit-to-loan portfolio – reengage and selectively build a durable relationship-oriented vertical Newline deepens operating relationships with innovation-economy clients 1Source: S&P Capital IQ; 2025 FDIC data capped at $250MM and filtered for de novos opened since 2018. Not all de novos have been open for 5 years; 2Source: U.S. Small Business Administration Lender Report, 2026 fiscal year; 3See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release.
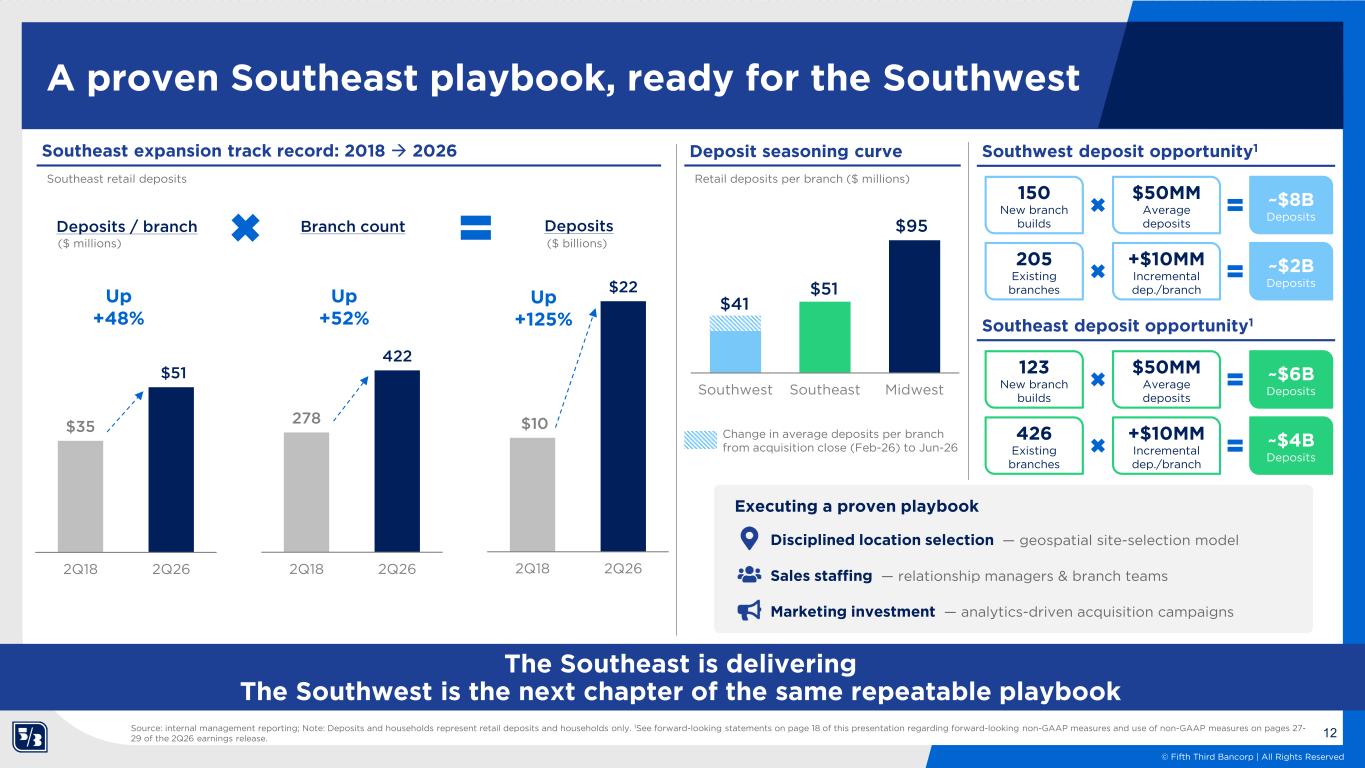
12 © Fifth Third Bancorp | All Rights Reserved Southeast expansion track record: 2018 2026 A proven Southeast playbook, ready for the Southwest Southeast retail deposits The Southeast is delivering The Southwest is the next chapter of the same repeatable playbook $35 $51 2Q18 2Q26 Deposits / branch Up +48% Deposit seasoning curve Retail deposits per branch ($ millions) $41 $51 $95 Southwest Southeast Midwest Executing a proven playbook Disciplined location selection — geospatial site-selection model Sales staffing — relationship managers & branch teams Marketing investment — analytics-driven acquisition campaigns Source: internal management reporting; Note: Deposits and households represent retail deposits and households only. 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27- 29 of the 2Q26 earnings release. Change in average deposits per branch from acquisition close (Feb-26) to Jun-26 278 422 2Q18 2Q26 Branch count $10 $22 2Q18 2Q26 Deposits ($ millions) ($ billions) Up +52% Up +125% 150 New branch builds Southwest deposit opportunity1 $50MM Average deposits ~$8B Deposits 205 Existing branches +$10MM Incremental dep./branch ~$2B Deposits 123 New branch builds Southeast deposit opportunity1 $50MM Average deposits ~$6B Deposits 426 Existing branches +$10MM Incremental dep./branch ~$4B Deposits
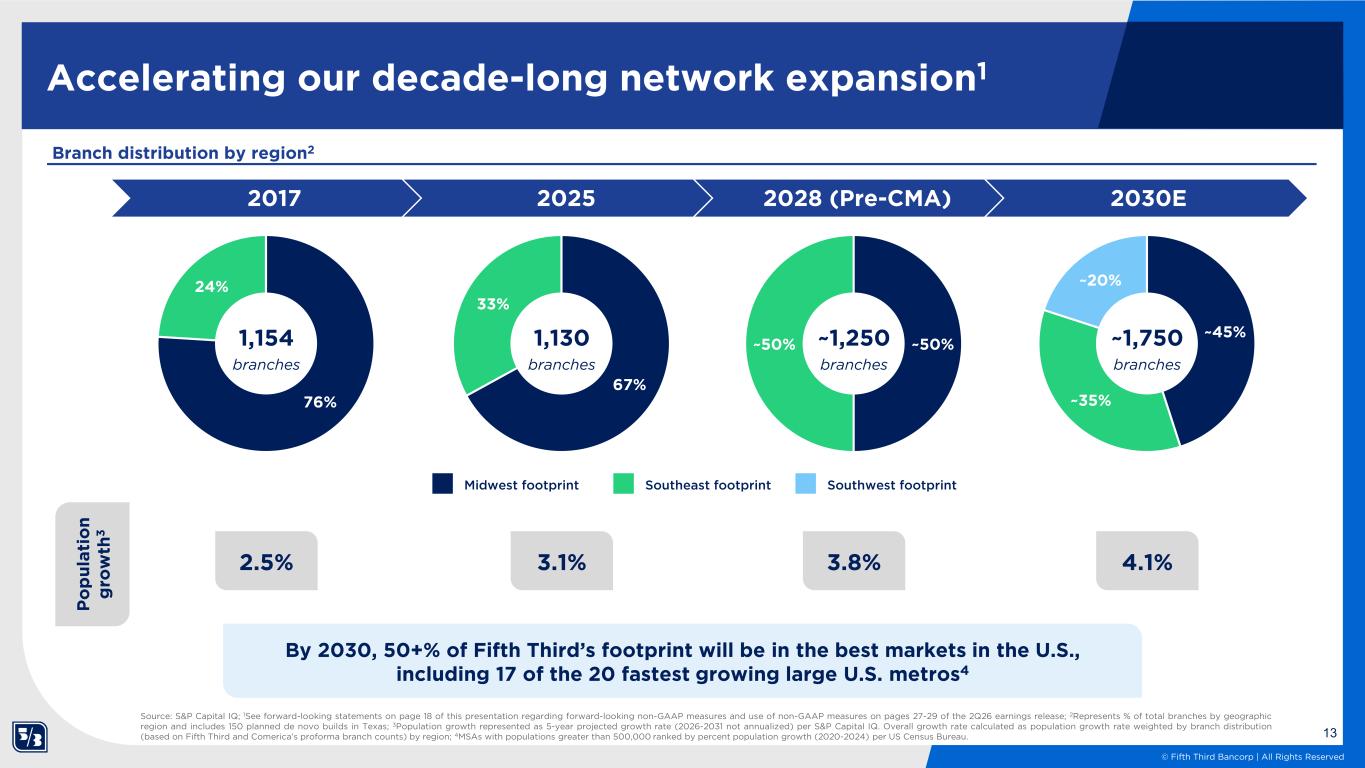
13 © Fifth Third Bancorp | All Rights Reserved Accelerating our decade-long network expansion1 Branch distribution by region2 Source: S&P Capital IQ; 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release; 2Represents % of total branches by geographic region and includes 150 planned de novo builds in Texas; 3Population growth represented as 5-year projected growth rate (2026-2031 not annualized) per S&P Capital IQ. Overall growth rate calculated as population growth rate weighted by branch distribution (based on Fifth Third and Comerica’s proforma branch counts) by region; 4MSAs with populations greater than 500,000 ranked by percent population growth (2020-2024) per US Census Bureau. By 2030, 50+% of Fifth Third’s footprint will be in the best markets in the U.S., including 17 of the 20 fastest growing large U.S. metros4 76% 24% 1,154 branches 2017 2025 2028 (Pre-CMA) 2030E 67% 33% 1,130 branches ~50%~50% ~1,250 branches ~45% ~35% ~20% ~1,750 branches Midwest footprint Southeast footprint Southwest footprint P o p u la ti o n g ro w th 3 2.5% 3.1% 3.8% 4.1%
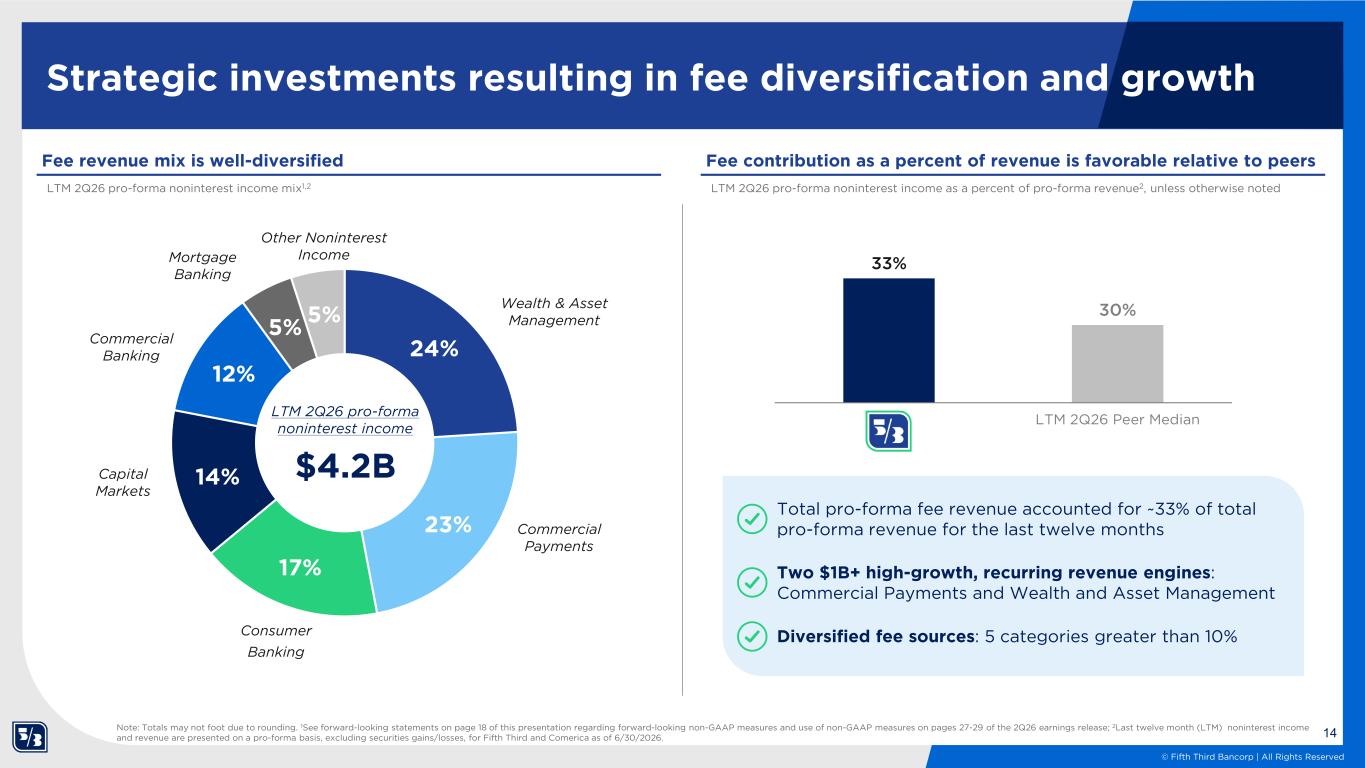
14 © Fifth Third Bancorp | All Rights Reserved 33% 30% x LTM 2Q26 Peer Median Fee revenue mix is well-diversified 24% 23% 17% 14% 12% 5% 5% Commercial Banking Mortgage Banking Other Noninterest Income Wealth & Asset Management Commercial Payments Consumer Banking Capital Markets Strategic investments resulting in fee diversification and growth LTM 2Q26 pro-forma noninterest income $4.2B LTM 2Q26 pro-forma noninterest income mix1,2 Fee contribution as a percent of revenue is favorable relative to peers LTM 2Q26 pro-forma noninterest income as a percent of pro-forma revenue2, unless otherwise noted Note: Totals may not foot due to rounding. 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release; 2Last twelve month (LTM) noninterest income and revenue are presented on a pro-forma basis, excluding securities gains/losses, for Fifth Third and Comerica as of 6/30/2026. Total pro-forma fee revenue accounted for ~33% of total pro-forma revenue for the last twelve months Two $1B+ high-growth, recurring revenue engines: Commercial Payments and Wealth and Asset Management Diversified fee sources: 5 categories greater than 10%
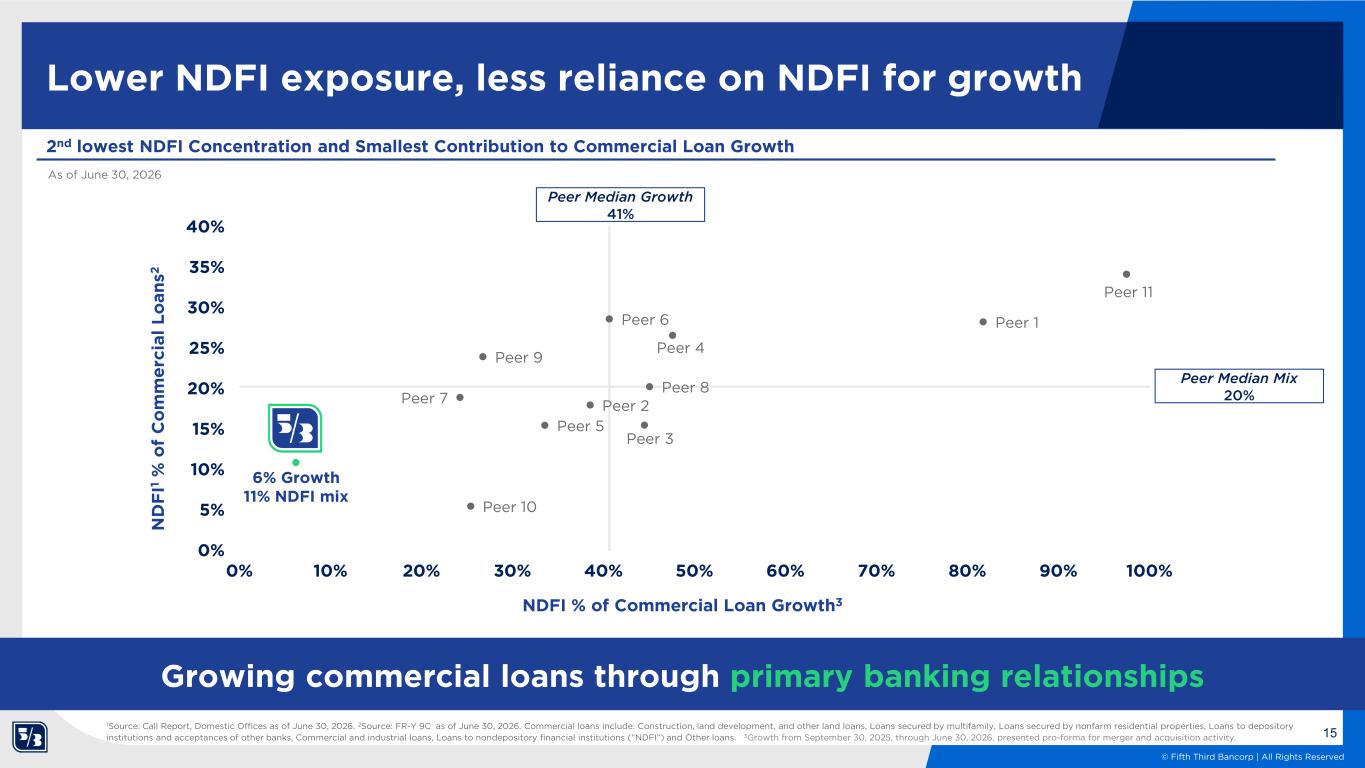
15 © Fifth Third Bancorp | All Rights Reserved Lower NDFI exposure, less reliance on NDFI for growth Peer 7 Peer 10 Peer 9 Peer 5 Peer 2 Peer 6 Peer 3 Peer 8 Peer 4 Peer 1 Peer 11 0% 5% 10% 15% 20% 25% 30% 35% 40% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% NDFI % of Commercial Loan Growth3 N D F I1 % o f C o m m e rc ia l L o a n s2 As of June 30, 2026 2nd lowest NDFI Concentration and Smallest Contribution to Commercial Loan Growth Growing commercial loans through primary banking relationships Peer Median Growth 41% Peer Median Mix 20% 6% Growth 11% NDFI mix 1Source: Call Report, Domestic Offices as of June 30, 2026. 2Source: FR-Y 9C as of June 30, 2026. Commercial loans include: Construction, land development, and other land loans, Loans secured by multifamily, Loans secured by nonfarm residential properties, Loans to depository institutions and acceptances of other banks, Commercial and industrial loans, Loans to nondepository financial institutions (“NDFI”) and Other loans. 3Growth from September 30, 2025, through June 30, 2026, presented pro-forma for merger and acquisition activity.
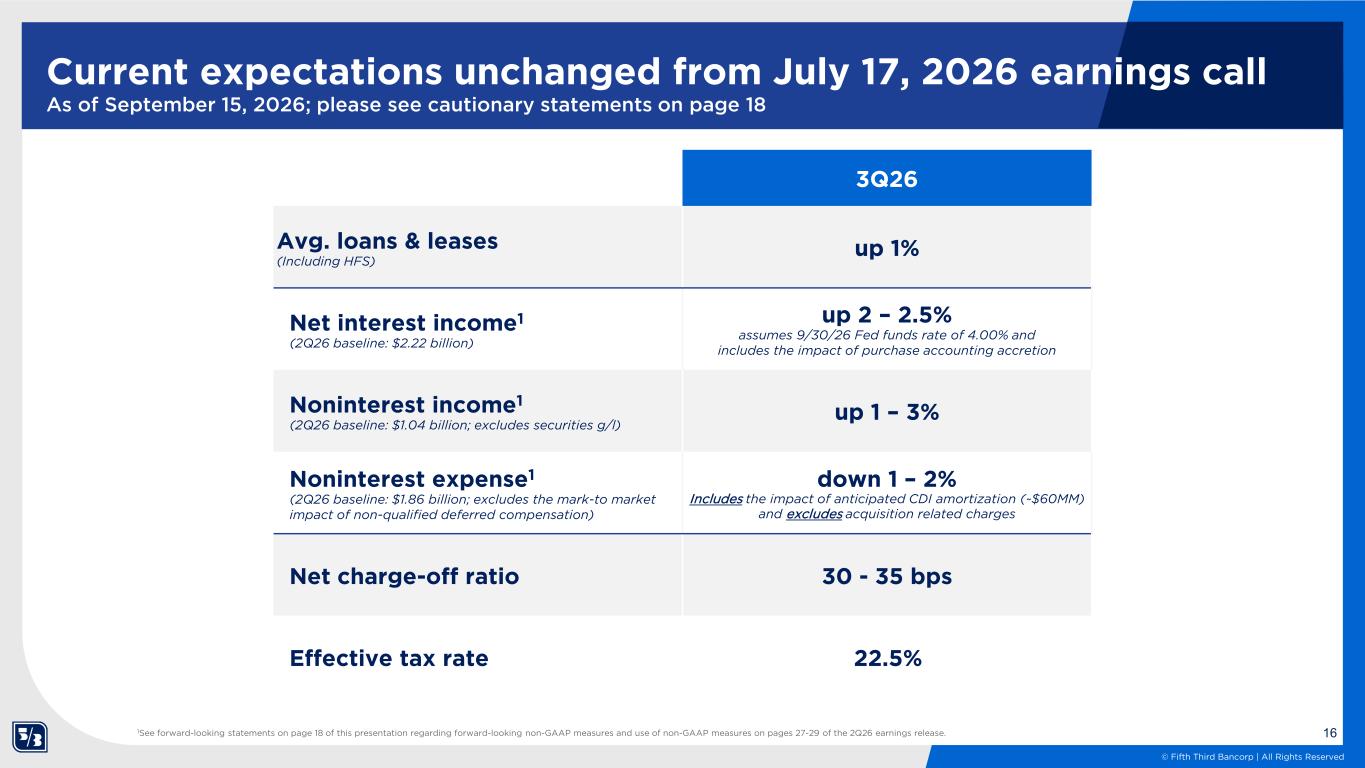
16 © Fifth Third Bancorp | All Rights Reserved 3Q26 Avg. loans & leases (Including HFS) up 1% Net interest income1 (2Q26 baseline: $2.22 billion) up 2 – 2.5% assumes 9/30/26 Fed funds rate of 4.00% and includes the impact of purchase accounting accretion Noninterest income1 (2Q26 baseline: $1.04 billion; excludes securities g/l) up 1 – 3% Noninterest expense1 (2Q26 baseline: $1.86 billion; excludes the mark-to market impact of non-qualified deferred compensation) down 1 – 2% Includes the impact of anticipated CDI amortization (~$60MM) and excludes acquisition related charges Net charge-off ratio 30 - 35 bps Effective tax rate 22.5% 1See forward-looking statements on page 18 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the 2Q26 earnings release. Current expectations unchanged from July 17, 2026 earnings call As of September 15, 2026; please see cautionary statements on page 18
17 © Fifth Third Bancorp | All Rights Reserved Why Fifth Third Positioned to generate long-term sustainable value to shareholders despite the environment Well-diversified and resilient balance sheet to provide stability and profitability Consistent investments to generate balanced and growing revenue streams while maintaining peer-leading expense discipline Multi-year track record of making appropriate and preemptive changes to the business Transparent management team
18 © Fifth Third Bancorp | All Rights Reserved Cautionary Statement This presentation contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. All statements other than statements of historical fact are forward-looking statements. These statements relate to our financial condition, results of operations, plans, objectives, future performance, capital actions or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”). There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) deteriorating credit quality; (2) loan concentration by location or industry of borrowers or collateral; (3) any instability or disruption in the financial system, including those caused by actual or perceived issues affecting the soundness of other financial institutions or market participants; (4) inadequate sources of funding or liquidity; (5) unfavorable actions of rating agencies; (6) inability to maintain or grow deposits; (7) limitations on the ability to receive dividends from subsidiaries; (8) cyber-security risks; (9) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (10) failures by third-party service providers; (11) inability to manage strategic initiatives and/or organizational changes; (12) inability to implement technology system enhancements, including the use of artificial intelligence; (13) failure of internal controls and other risk management programs; (14) losses related to fraud, theft, misappropriation or violence; (15) inability to attract and retain skilled personnel; (16) adverse impacts of government regulation; (17) governmental or regulatory changes or other actions; (18) failures to meet applicable capital requirements; (19) regulatory objections to Fifth Third’s capital plan; (20) regulation of Fifth Third’s derivatives activities; (21) deposit insurance premiums; (22) assessments for the orderly liquidation fund; (23) weakness in the national or local economies; (24) global political and economic uncertainty or negative actions; (25) changes in interest rates and the effects of inflation; (26) changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs; (27) changes and trends in capital markets; (28) fluctuation of Fifth Third’s stock price; (29) volatility in mortgage banking revenue; (30) litigation, investigations, and enforcement proceedings; (31) breaches of contractual covenants, representations and warranties; (32) competition and changes in the financial services industry; (33) potential impacts of the adoption of real-time payment networks; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; (45) Fifth Third’s ability to meet its environmental and/or social targets, goals and commitments; and (46) risks relating to the merger with Comerica Incorporated, including Fifth Third’s inability to realize the anticipated benefits of the merger and potential disruption to Fifth Third’s business resulting from post-merger integration. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its totality, and any stipulations, conditions or provisos that apply to a given piece of information in one part of this report should be read as applying mutatis mutandis to every other instance of such information appearing herein. You should refer to our periodic and current reports filed with the Securities and Exchange Commission, or “SEC,” for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its totality, and any stipulations, conditions or provisos that apply to a given piece of information in one part of this press release should be read as applying mutatis mutandis to every other instance of such information appearing herein. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. In this presentation, we may sometimes provide non-GAAP financial information. Please note that although non-GAAP financial measures provide useful insight to analysts, investors and regulators, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures. We provide a discussion of non-GAAP measures and reconciliations to the most directly comparable GAAP measures in slides 41-42 of our 2Q26 earnings presentation, as well as on pages 27 through 29 of our 2Q26 earnings release. Management does not provide a reconciliation for forward-looking non-GAAP financial measures where it is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the occurrence and the financial impact of various items that have not yet occurred, are out of the Bancorp's control or cannot be reasonably predicted. For the same reasons, Bancorp's management is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures provided without the most directly comparable GAAP financial measures may vary materially from the corresponding GAAP financial measures.