false
--09-30
2026-03-31
0001985139
0001985139
2025-10-01
2026-03-31
0001985139
2026-03-31
0001985139
2025-09-30
0001985139
us-gaap:NonrelatedPartyMember
2026-03-31
0001985139
us-gaap:NonrelatedPartyMember
2025-09-30
0001985139
us-gaap:RelatedPartyMember
2026-03-31
0001985139
us-gaap:RelatedPartyMember
2025-09-30
0001985139
us-gaap:CommonClassAMember
2026-03-31
0001985139
us-gaap:CommonClassAMember
2025-09-30
0001985139
us-gaap:CommonClassBMember
2026-03-31
0001985139
us-gaap:CommonClassBMember
2025-09-30
0001985139
2024-10-01
2025-03-31
0001985139
LSE:ThirdPartyMember
2025-10-01
2026-03-31
0001985139
LSE:ThirdPartyMember
2024-10-01
2025-03-31
0001985139
us-gaap:RelatedPartyMember
2025-10-01
2026-03-31
0001985139
us-gaap:RelatedPartyMember
2024-10-01
2025-03-31
0001985139
us-gaap:CommonStockMember
2024-09-30
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2024-09-30
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2024-09-30
0001985139
LSE:SubscriptionReceivableMember
2024-09-30
0001985139
us-gaap:AdditionalPaidInCapitalMember
2024-09-30
0001985139
LSE:StatutoryReserveMember
2024-09-30
0001985139
us-gaap:RetainedEarningsMember
2024-09-30
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2024-09-30
0001985139
us-gaap:ParentMember
2024-09-30
0001985139
us-gaap:NoncontrollingInterestMember
2024-09-30
0001985139
2024-09-30
0001985139
us-gaap:CommonStockMember
2025-09-30
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2025-09-30
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2025-09-30
0001985139
LSE:SubscriptionReceivableMember
2025-09-30
0001985139
us-gaap:AdditionalPaidInCapitalMember
2025-09-30
0001985139
LSE:StatutoryReserveMember
2025-09-30
0001985139
us-gaap:RetainedEarningsMember
2025-09-30
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2025-09-30
0001985139
us-gaap:ParentMember
2025-09-30
0001985139
us-gaap:NoncontrollingInterestMember
2025-09-30
0001985139
us-gaap:CommonStockMember
2024-10-01
2025-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2024-10-01
2025-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2024-10-01
2025-03-31
0001985139
LSE:SubscriptionReceivableMember
2024-10-01
2025-03-31
0001985139
us-gaap:AdditionalPaidInCapitalMember
2024-10-01
2025-03-31
0001985139
LSE:StatutoryReserveMember
2024-10-01
2025-03-31
0001985139
us-gaap:RetainedEarningsMember
2024-10-01
2025-03-31
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2024-10-01
2025-03-31
0001985139
us-gaap:ParentMember
2024-10-01
2025-03-31
0001985139
us-gaap:NoncontrollingInterestMember
2024-10-01
2025-03-31
0001985139
us-gaap:CommonStockMember
2025-10-01
2026-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2025-10-01
2026-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2025-10-01
2026-03-31
0001985139
LSE:SubscriptionReceivableMember
2025-10-01
2026-03-31
0001985139
us-gaap:AdditionalPaidInCapitalMember
2025-10-01
2026-03-31
0001985139
LSE:StatutoryReserveMember
2025-10-01
2026-03-31
0001985139
us-gaap:RetainedEarningsMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2025-10-01
2026-03-31
0001985139
us-gaap:ParentMember
2025-10-01
2026-03-31
0001985139
us-gaap:NoncontrollingInterestMember
2025-10-01
2026-03-31
0001985139
us-gaap:CommonStockMember
2025-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2025-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2025-03-31
0001985139
LSE:SubscriptionReceivableMember
2025-03-31
0001985139
us-gaap:AdditionalPaidInCapitalMember
2025-03-31
0001985139
LSE:StatutoryReserveMember
2025-03-31
0001985139
us-gaap:RetainedEarningsMember
2025-03-31
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2025-03-31
0001985139
us-gaap:ParentMember
2025-03-31
0001985139
us-gaap:NoncontrollingInterestMember
2025-03-31
0001985139
2025-03-31
0001985139
us-gaap:CommonStockMember
2026-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassAMember
2026-03-31
0001985139
us-gaap:CommonStockMember
us-gaap:CommonClassBMember
2026-03-31
0001985139
LSE:SubscriptionReceivableMember
2026-03-31
0001985139
us-gaap:AdditionalPaidInCapitalMember
2026-03-31
0001985139
LSE:StatutoryReserveMember
2026-03-31
0001985139
us-gaap:RetainedEarningsMember
2026-03-31
0001985139
us-gaap:AccumulatedOtherComprehensiveIncomeMember
2026-03-31
0001985139
us-gaap:ParentMember
2026-03-31
0001985139
us-gaap:NoncontrollingInterestMember
2026-03-31
0001985139
us-gaap:IPOMember
2024-12-20
2024-12-20
0001985139
us-gaap:IPOMember
2024-12-20
0001985139
us-gaap:OverAllotmentOptionMember
2025-01-08
0001985139
us-gaap:OverAllotmentOptionMember
2025-01-08
2025-01-08
0001985139
us-gaap:IPOMember
2025-01-08
2025-01-08
0001985139
us-gaap:CommonClassAMember
2025-11-27
2025-11-27
0001985139
us-gaap:CommonClassAMember
2025-11-27
0001985139
us-gaap:CommonClassBMember
2025-11-27
2025-11-27
0001985139
us-gaap:CommonClassBMember
2025-11-27
0001985139
LSE:PolarEnergyCompanyLimitedMember
2025-11-27
0001985139
LSE:WisepowerEnergyServicesCoLtdMember
2025-11-27
0001985139
us-gaap:CommonClassAMember
LSE:PolarEnergyCompanyLimitedMember
2025-11-27
0001985139
us-gaap:CommonClassAMember
LSE:WisepowerEnergyServicesCoLtdMember
2025-11-27
0001985139
us-gaap:CommonClassBMember
LSE:PolarEnergyCompanyLimitedMember
2025-11-27
0001985139
us-gaap:CommonClassBMember
LSE:WisepowerEnergyServicesCoLtdMember
2025-11-27
0001985139
LSE:LeishenEnergyHoldingCoLtdLeishenCaymanMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyHoldingCoLtdLeishenCaymanMember
2026-03-31
0001985139
LSE:LeishenEnergyGroupHoldingCoLtdLeishenHoldingHongKongMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyGroupHoldingCoLtdLeishenHoldingHongKongMember
2026-03-31
0001985139
LSE:LeishenEnergyGroupCoLtdLeishenHongKongMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyGroupCoLtdLeishenHongKongMember
2026-03-31
0001985139
LSE:ZJYTechnologiesCoLtdZJYTechnologiesMember
2025-10-01
2026-03-31
0001985139
LSE:ZJYTechnologiesCoLtdZJYTechnologiesMember
2026-03-31
0001985139
LSE:ChinaOilBlueOceanPetroleumTechnologyIncChinaOilBlueOceanMember
2025-10-01
2026-03-31
0001985139
LSE:ChinaOilBlueOceanPetroleumTechnologyIncChinaOilBlueOceanMember
2026-03-31
0001985139
LSE:LeishenEnergyTechnologyNanjingCoLtdLeishenNanjingMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyTechnologyNanjingCoLtdLeishenNanjingMember
2026-03-31
0001985139
LSE:LeishenGreenEnergyTechnologyDevelopmentCoLtdBeijingLeishenGreenEnergyMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenGreenEnergyTechnologyDevelopmentCoLtdBeijingLeishenGreenEnergyMember
2026-03-31
0001985139
LSE:LeishenEnergyTechnologyShandongCoLtdLeishenShandongMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyTechnologyShandongCoLtdLeishenShandongMember
2026-03-31
0001985139
LSE:LeishenEnergyServicesCoLtdLeishenServicesMember
2025-10-01
2026-03-31
0001985139
LSE:LeishenEnergyServicesCoLtdLeishenServicesMember
2026-03-31
0001985139
LSE:SichuanLeishenHongzhuoEnergyDevelopmentCoLtdSichuanLeishenHongzhuoMember
2025-10-01
2026-03-31
0001985139
LSE:SichuanLeishenHongzhuoEnergyDevelopmentCoLtdSichuanLeishenHongzhuoMember
2026-03-31
0001985139
LSE:SichuanHuayouHuitongNewMaterialCoLtdHuayouHuitongMember
2025-10-01
2026-03-31
0001985139
LSE:SichuanHuayouHuitongNewMaterialCoLtdHuayouHuitongMember
2026-03-31
0001985139
LSE:XinjiangBreslinOilAndGasServiceCoLtdXinjiangBreslinMember
2025-10-01
2026-03-31
0001985139
LSE:XinjiangBreslinOilAndGasServiceCoLtdXinjiangBreslinMember
2026-03-31
0001985139
LSE:LionizeEngineeringTechnologyLimitedMember
2025-10-01
2026-03-31
0001985139
LSE:LionizeEngineeringTechnologyLimitedMember
2026-03-31
0001985139
LSE:SuqianHanmoEnergyServiceCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:SuqianHanmoEnergyServiceCoLtdMember
2026-03-31
0001985139
LSE:LseEnergyInternationalCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:LseEnergyInternationalCoLtdMember
2026-03-31
0001985139
LSE:LseEnergyAmericaIncMember
2025-10-01
2026-03-31
0001985139
LSE:LseEnergyAmericaIncMember
2026-03-31
0001985139
LSE:ChinaOilBlueOceanHydrogenEnergyTechnologyCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:ChinaOilBlueOceanHydrogenEnergyTechnologyCoLtdMember
2026-03-31
0001985139
LSE:ChinaOilBlueOceanEquipmentSichuanCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:ChinaOilBlueOceanEquipmentSichuanCoLtdMember
2026-03-31
0001985139
LSE:CNYMember
2026-03-31
0001985139
LSE:CNYMember
2025-09-30
0001985139
LSE:CNYMember
2025-03-31
0001985139
LSE:EmployeeContributionPlansMember
2025-10-01
2026-03-31
0001985139
LSE:EmployeeContributionPlansMember
2024-10-01
2025-03-31
0001985139
us-gaap:OfficeEquipmentMember
srt:MinimumMember
2026-03-31
0001985139
us-gaap:OfficeEquipmentMember
srt:MaximumMember
2026-03-31
0001985139
us-gaap:VehiclesMember
2026-03-31
0001985139
us-gaap:MachineryAndEquipmentMember
srt:MinimumMember
2026-03-31
0001985139
us-gaap:MachineryAndEquipmentMember
srt:MaximumMember
2026-03-31
0001985139
us-gaap:SoftwareDevelopmentMember
srt:MaximumMember
2026-03-31
0001985139
us-gaap:FairValueInputsLevel1Member
2026-03-31
0001985139
us-gaap:FairValueInputsLevel2Member
2026-03-31
0001985139
us-gaap:FairValueInputsLevel3Member
2026-03-31
0001985139
us-gaap:FairValueInputsLevel1Member
2025-09-30
0001985139
us-gaap:FairValueInputsLevel2Member
2025-09-30
0001985139
us-gaap:FairValueInputsLevel3Member
2025-09-30
0001985139
LSE:SalesOfCleanEnergyEquipmentMember
2025-10-01
2026-03-31
0001985139
LSE:SalesOfCleanEnergyEquipmentMember
2024-10-01
2025-03-31
0001985139
LSE:SalesOfDigitalizationAndIntegrationEquipmentMember
2025-10-01
2026-03-31
0001985139
LSE:SalesOfDigitalizationAndIntegrationEquipmentMember
2024-10-01
2025-03-31
0001985139
LSE:SalesOfNewEnergyMember
2025-10-01
2026-03-31
0001985139
LSE:SalesOfNewEnergyMember
2024-10-01
2025-03-31
0001985139
LSE:DeliveryOfOilAndGasEngineeringTechnicalServicesMember
2025-10-01
2026-03-31
0001985139
LSE:DeliveryOfOilAndGasEngineeringTechnicalServicesMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerAMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerAMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerBMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerBMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerMember
2024-10-01
2025-03-31
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerBMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerBMember
2024-10-01
2025-09-30
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerCMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerCMember
2024-10-01
2025-09-30
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsReceivableMember
us-gaap:CustomerConcentrationRiskMember
LSE:CustomerMember
2024-10-01
2025-09-30
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorAMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorAMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorBMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorBMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorCMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorCMember
2024-10-01
2025-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorMember
2025-10-01
2026-03-31
0001985139
us-gaap:SalesRevenueNetMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorMember
2024-10-01
2025-03-31
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorBMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorBMember
2024-10-01
2025-09-30
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorDMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorDMember
2024-10-01
2025-09-30
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorMember
2025-10-01
2026-03-31
0001985139
us-gaap:AccountsPayableMember
us-gaap:CustomerConcentrationRiskMember
LSE:VendorMember
2024-10-01
2025-09-30
0001985139
us-gaap:TradingAssetsExcludingDebtAndEquitySecuritiesMember
2026-03-31
0001985139
us-gaap:TradingAssetsExcludingDebtAndEquitySecuritiesMember
2025-09-30
0001985139
us-gaap:EquitySecuritiesMember
2026-03-31
0001985139
us-gaap:EquitySecuritiesMember
2025-09-30
0001985139
us-gaap:MachineryAndEquipmentMember
2025-10-01
2026-03-31
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2025-09-30
0001985139
LSE:SichuanZhuoyueShuxinTechnologyCoLtdMember
2025-09-30
0001985139
LSE:SichuanJiahongyiInformationTechnologyConsultingCoLtdMember
2025-09-30
0001985139
LSE:SichuanTIBOMember
LSE:JiningEniEnergyTechnologyCoLtdMember
2025-09-30
0001985139
LSE:SuzhouKerunMember
2025-09-25
0001985139
2025-09-25
0001985139
us-gaap:MachineryAndEquipmentMember
2026-03-31
0001985139
us-gaap:MachineryAndEquipmentMember
2025-09-30
0001985139
us-gaap:OfficeEquipmentMember
2026-03-31
0001985139
us-gaap:OfficeEquipmentMember
2025-09-30
0001985139
us-gaap:VehiclesMember
2025-09-30
0001985139
2024-10-01
2025-09-30
0001985139
us-gaap:SoftwareDevelopmentMember
2026-03-31
0001985139
us-gaap:SoftwareDevelopmentMember
2025-09-30
0001985139
LSE:PolarPetroleumEquipmentShandongCoLtdMember
2026-03-31
0001985139
LSE:PolarPetroleumEquipmentShandongCoLtdMember
2025-09-30
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2026-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-09-30
0001985139
LSE:JiningEniEnergyTechnologyCoLtdMember
2026-03-31
0001985139
LSE:JiningEniEnergyTechnologyCoLtdMember
2025-09-30
0001985139
LSE:XianlongTechnologyBeijingCoLtdMember
2026-03-31
0001985139
LSE:XianlongTechnologyBeijingCoLtdMember
2025-09-30
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2026-03-31
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2025-09-30
0001985139
LSE:JosephPetroleumTechnologyBeijingCoLtdMember
2026-03-31
0001985139
LSE:JosephPetroleumTechnologyBeijingCoLtdMember
2025-09-30
0001985139
LSE:BeiiingChenghuiShengsiTechnologyCoLtdMember
2026-03-31
0001985139
LSE:BeiiingChenghuiShengsiTechnologyCoLtdMember
2025-09-30
0001985139
LSE:AccruedInterestReceivableMember
2026-03-31
0001985139
LSE:AccruedInterestReceivableMember
2025-09-30
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2024-03-25
2024-03-25
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-10-24
2025-10-24
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
us-gaap:SubsequentEventMember
2026-06-25
2026-06-25
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2026-03-31
2026-03-31
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2025-09-30
2025-09-30
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2026-03-31
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
2025-09-30
0001985139
LSE:ZJYTechnologiesMember
2024-01-01
0001985139
LSE:ZJYTechnologiesMember
2024-01-01
2024-01-01
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2025-10-31
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2025-09-01
2025-09-30
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2026-03-31
2026-03-31
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2025-09-30
2025-09-30
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2026-03-31
0001985139
LSE:BeijingChenghuiShengsiTechnologyCoLtdMember
2025-09-30
0001985139
2024-04-13
0001985139
2024-05-23
0001985139
2024-04-12
0001985139
2024-11-01
2024-11-30
0001985139
2024-12-01
2024-12-31
0001985139
2025-05-31
0001985139
LSE:PolarPetroleumEquipmentShandongCoLtdMember
2026-03-31
0001985139
LSE:PolarPetroleumEquipmentShandongCoLtdMember
2025-09-30
0001985139
LSE:ChinaOilBlueOceanMember
2024-03-25
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2024-06-25
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-04-30
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-01-22
2025-01-22
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
srt:ScenarioForecastMember
2026-10-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-04-20
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-04-20
2025-04-20
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2026-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-09-30
0001985139
LSE:EniEnergyMember
2025-05-01
0001985139
LSE:EniEnergyMember
2025-05-01
2025-05-01
0001985139
LSE:EniEnergyMember
2025-05-16
0001985139
LSE:EniEnergyMember
2026-03-31
0001985139
LSE:EniEnergyMember
2025-09-30
0001985139
LSE:XinjiangBreslinMember
2025-05-14
0001985139
LSE:XinjiangBreslinMember
2025-09-29
0001985139
LSE:XinjiangBreslinMember
2025-05-14
2025-05-14
0001985139
LSE:XinjiangBreslinMember
2025-09-29
2025-09-29
0001985139
LSE:XinjiangBreslinMember
srt:ScenarioForecastMember
2026-10-31
0001985139
LSE:XinjiangBreslinMember
2026-03-31
0001985139
LSE:XinjiangBreslinMember
2025-09-30
0001985139
LSE:ZJYTechnologiesMember
2025-05-29
0001985139
LSE:ZJYTechnologiesMember
2025-06-05
0001985139
LSE:ZJYTechnologiesMember
2025-10-10
0001985139
LSE:SichuanTIBOMember
2025-10-10
0001985139
LSE:PetroChinaInformationTechnologyCoLtdMember
2025-10-10
0001985139
LSE:BeijingYouyiNaturalTechnologyCoLtdMember
us-gaap:SubsequentEventMember
2026-06-09
2026-06-09
0001985139
LSE:XinjiangBreslinMember
LSE:JosephPetroleumMember
2025-09-29
0001985139
LSE:XinjiangBreslinMember
LSE:JosephPetroleumMember
2026-03-31
0001985139
LSE:XinjiangBreslinMember
LSE:JosephPetroleumMember
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankOneMember
2026-03-31
0001985139
LSE:IndustrialAndCommercialBankOneMember
2025-10-01
2026-03-31
0001985139
LSE:IndustrialAndCommercialBankTwoMember
2026-03-31
0001985139
LSE:IndustrialAndCommercialBankTwoMember
2025-10-01
2026-03-31
0001985139
LSE:BankOfChinaMember
2025-09-30
0001985139
LSE:BankOfChinaMember
2024-10-01
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankOneMember
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankOneMember
2024-10-01
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankTwoMember
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankTwoMember
2024-10-01
2025-09-30
0001985139
LSE:IndustrialAndCommercialBankOfChinaBeijingYayuncunSubbranchOneMember
2026-03-16
0001985139
LSE:IndustrialAndCommercialBankOfChinaBeijingYayuncunSubbranchOneMember
2026-03-25
0001985139
LSE:BankOfChinaChengduZijingWestRoadSubbranchTwoMember
2023-11-21
0001985139
LSE:BankOfChinaChengduZijingWestRoadSubbranchOneMember
2024-10-31
2024-10-31
0001985139
LSE:BankOfChinaChengduZijingWestRoadSubbranchTwoMember
2025-10-15
2025-10-15
0001985139
LSE:BankOfChinaChengduZijingWestRoadSubbranchOneMember
2025-09-16
2025-09-16
0001985139
LSE:BankOfChinaChengduZijingWestRoadSubbranchTwoMember
2025-10-16
2025-10-16
0001985139
LSE:IndustrialAndCommercialBankOfChinaBeijingYayuncunSubbranchOneMember
2025-03-18
0001985139
LSE:IndustrialAndCommercialBankOfChinaBeijingYayuncunSubbranchTwoMember
2025-03-25
0001985139
LSE:SichuanLeishenHongzhuoMember
2022-01-22
0001985139
LSE:SichuanLeishenHongzhuoMember
2022-01-22
2022-01-22
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2023-04-01
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2023-04-01
2023-04-01
0001985139
LSE:LiHongqiMember
2026-03-31
0001985139
LSE:LiHongqiMember
2025-09-30
0001985139
LSE:LiHongliangMember
2026-03-31
0001985139
LSE:LiHongliangMember
2025-09-30
0001985139
LSE:BeijingHappinessStarMember
2026-03-31
0001985139
LSE:BeijingHappinessStarMember
2025-09-30
0001985139
LSE:EquipmentSalesToSichuanTIBOFluidTechnologyCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:EquipmentSalesToSichuanTIBOFluidTechnologyCoLtdMember
2024-10-01
2025-03-31
0001985139
LSE:LNGCNGSalesToHongzhuoShuyaEnergyCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:LNGCNGSalesToHongzhuoShuyaEnergyCoLtdMember
2024-10-01
2025-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdLessorMember
2025-10-01
2026-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdLessorMember
2024-10-01
2025-03-31
0001985139
LSE:LiHongliangMember
2025-10-01
2026-03-31
0001985139
LSE:LiHongliangMember
2024-10-01
2025-03-31
0001985139
LSE:LiHongqiMember
2025-10-01
2026-03-31
0001985139
LSE:LiHongqiMember
2024-10-01
2025-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2025-10-01
2026-03-31
0001985139
LSE:SichuanTIBOFluidTechnologyCoLtdMember
2024-10-01
2025-03-31
0001985139
LSE:ZJYTechnologiesMember
2023-03-20
2023-03-20
0001985139
LSE:LiHongqiMember
2023-10-01
2024-09-30
0001985139
LSE:LiHongliangMember
2023-10-01
2024-09-30
0001985139
LSE:ChinaOilBlueOceanMember
2025-10-22
0001985139
2025-10-22
0001985139
LSE:ChinaOilBlueOceanMember
2020-05-29
0001985139
LSE:EquityTransactionAgreementsMember
LSE:ChinaOilBlueOceanMember
LSE:XianDeMember
2025-11-30
0001985139
2025-11-01
2025-11-30
0001985139
LSE:ChinaOilBlueOceanMember
2026-03-31
0001985139
LSE:PRCSubsidiariesMember
2026-03-31
0001985139
LSE:PRCSubsidiariesMember
2025-09-30
0001985139
LSE:HuayouHuitongMember
2026-03-31
0001985139
LSE:HuayouHuitongMember
2025-09-30
0001985139
country:CN
2025-10-01
2026-03-31
0001985139
country:CN
2024-10-01
2025-03-31
0001985139
LSE:ChinaOilBlueOceanAndZJYTechnologiesMember
srt:MaximumMember
2022-12-01
2022-12-31
0001985139
LSE:ChinaOilBlueOceanAndZJYTechnologiesMember
srt:MinimumMember
2022-12-01
2022-12-31
0001985139
LSE:CleanEnergyEquipmentMember
2025-10-01
2026-03-31
0001985139
LSE:DigitalizationAndIntegrationEquipmentMember
2025-10-01
2026-03-31
0001985139
LSE:NewEnergyProductionAndOperationMember
2025-10-01
2026-03-31
0001985139
LSE:OilAndGasEngineeringTechnicalServicesMember
2025-10-01
2026-03-31
0001985139
LSE:CleanEnergyEquipmentMember
2024-10-01
2025-03-31
0001985139
LSE:DigitalizationAndIntegrationEquipmentMember
2024-10-01
2025-03-31
0001985139
LSE:NewEnergyProductionAndOperationMember
2024-10-01
2025-03-31
0001985139
LSE:OilAndGasEngineeringTechnicalServicesMember
2024-10-01
2025-03-31
0001985139
LSE:CleaningEnergyEquipmentMember
2026-03-31
0001985139
LSE:CleaningEnergyEquipmentMember
2025-09-30
0001985139
LSE:DigitalizationAndIntegrationEquipmentMember
2026-03-31
0001985139
LSE:DigitalizationAndIntegrationEquipmentMember
2025-09-30
0001985139
LSE:NewEnergyProductionAndOperationMember
2026-03-31
0001985139
LSE:NewEnergyProductionAndOperationMember
2025-09-30
0001985139
LSE:OilAndGasFieldEngineeringTechnicalServicesMember
2026-03-31
0001985139
LSE:OilAndGasFieldEngineeringTechnicalServicesMember
2025-09-30
0001985139
LSE:OtherCorporateAssetsMember
2026-03-31
0001985139
LSE:OtherCorporateAssetsMember
2025-09-30
0001985139
us-gaap:SubsequentEventMember
2026-06-01
2026-06-30
0001985139
us-gaap:SubsequentEventMember
LSE:ClassAOrdinarySharesMember
2026-06-30
0001985139
LSE:SuqianAsgardEnergyServiceCoLtdMember
us-gaap:SubsequentEventMember
2026-08-31
0001985139
srt:ParentCompanyMember
2026-03-31
0001985139
srt:ParentCompanyMember
2025-09-30
0001985139
srt:ParentCompanyMember
us-gaap:CommonClassAMember
2026-03-31
0001985139
srt:ParentCompanyMember
us-gaap:CommonClassAMember
2025-09-30
0001985139
srt:ParentCompanyMember
us-gaap:CommonClassBMember
2026-03-31
0001985139
srt:ParentCompanyMember
us-gaap:CommonClassBMember
2025-09-30
0001985139
us-gaap:ParentMember
us-gaap:CommonClassAMember
2026-03-31
0001985139
us-gaap:ParentMember
us-gaap:CommonClassAMember
2025-09-30
0001985139
us-gaap:ParentMember
us-gaap:CommonClassBMember
2026-03-31
0001985139
us-gaap:ParentMember
us-gaap:CommonClassBMember
2025-09-30
0001985139
srt:ParentCompanyMember
2025-10-01
2026-03-31
0001985139
srt:ParentCompanyMember
2024-10-01
2025-03-31
0001985139
srt:ParentCompanyMember
2024-09-30
0001985139
srt:ParentCompanyMember
2025-03-31
iso4217:USD
xbrli:shares
iso4217:USD
xbrli:shares
xbrli:pure
iso4217:AUD
iso4217:EUR
LSE:Integer
iso4217:GBP
iso4217:CNY
LSE:Segment
Exhibit 99.1
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
INDEX
TO UNAUDITED CONDENSED CONSOLIDATED FINANCIAL STATEMENTS
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
CONDENSED
CONSOLIDATED BALANCE SHEETS
| | |
March 31,
2026 | | |
September 30,
2025 | |
| | |
(Unaudited) | | |
| |
| ASSETS | |
| | | |
| | |
| Current Assets: | |
| | | |
| | |
| Cash | |
$ | 10,249,822 | | |
$ | 10,159,656 | |
| Restricted cash | |
| 67,102 | | |
| 931 | |
| Short-term investments | |
| 16,898,215 | | |
| 18,680,071 | |
| Accounts receivable, net | |
| 18,011,916 | | |
| 15,327,945 | |
| Notes receivable | |
| 275,889 | | |
| 28,111 | |
| Advance to suppliers, net | |
| 4,110,057 | | |
| 4,532,267 | |
| Inventories | |
| 2,760,175 | | |
| 3,653,380 | |
| Loans receivable | |
| 3,767,896 | | |
| 3,777,909 | |
| Loan receivable - related party | |
| 631,035 | | |
| | |
| Loan receivable | |
| 631,035 | | |
| | |
| Prepaid expenses and other current assets, net | |
| 3,322,338 | | |
| 2,969,288 | |
| Total current assets | |
| 60,094,445 | | |
| 59,129,558 | |
| | |
| | | |
| | |
| Non-current assets: | |
| | | |
| | |
| Long-term investment | |
| 722,606 | | |
| - | |
| Accounts receivable, non-current | |
| 3,339,165 | | |
| 4,306,546 | |
| Property and equipment, net | |
| 3,519,543 | | |
| 3,464,953 | |
| Construction in process | |
| 85,050 | | |
| - | |
| Intangible assets | |
| 116,644 | | |
| 121,771 | |
| Operating lease right-of-use assets, net | |
| 686,373 | | |
| 708,944 | |
| Loans receivable, non-current | |
| 894,012 | | |
| 963,243 | |
| Deferred tax assets, net | |
| 768,909 | | |
| 602,258 | |
| Other non-current assets | |
| 31,808 | | |
| 35,359 | |
| Total non-current assets | |
| 10,164,110 | | |
| 10,203,074 | |
| | |
| | | |
| | |
| Total Assets | |
$ | 70,258,555 | | |
$ | 69,332,632 | |
| | |
| | | |
| | |
| LIABILITIES AND EQUITY | |
| | | |
| | |
| Current Liabilities: | |
| | | |
| | |
| Short-term loans | |
$ | 2,890,424 | | |
$ | 3,068,046 | |
| Accounts payable | |
| 8,597,561 | | |
| 7,532,959 | |
| Advance from customers | |
| 1,200,778 | | |
| 1,280,421 | |
| Taxes payable | |
| 4,628,938 | | |
| 3,781,738 | |
| Due to related parties | |
| 5,937,528 | | |
| 5,755,817 | |
| Operating lease liabilities | |
| 101,369 | | |
| 82,653 | |
| Other payables and other current liabilities | |
| 1,740,808 | | |
| 1,747,207 | |
| Total current liabilities | |
| 25,097,406 | | |
| 23,248,841 | |
| | |
| | | |
| | |
| Non-current Liabilities: | |
| | | |
| | |
| Operating lease liabilities, non-current | |
| 585,004 | | |
| 626,291 | |
| Total non-current liabilities | |
| 585,004 | | |
| 626,291 | |
| | |
| | | |
| | |
| Total Liabilities | |
| 25,682,410 | | |
| 23,875,132 | |
| | |
| | | |
| | |
| Commitments and Contingencies | |
| - | | |
| - | |
| | |
| | | |
| | |
| Equity: | |
| | | |
| | |
| Ordinary shares (par value $0.001 per share, 50,000,000 shares authorized; 17,025,000 and 17,025,000 shares issued and outstanding as of September 30, 2025) | |
| - | | |
| 17,025 | |
| Class A Ordinary Shares (par value $0.001 per share, 467,290,000 shares authorized, 4,315,000 shares issued and outstanding as of March 31, 2026) | |
| 4,315 | | |
| - | |
| Class B Ordinary Shares (par value $0.001 per share, 32,710,000 shares authorized, 12,710,000 shares issued and outstanding as of March 31, 2026) | |
| 12,710 | | |
| - | |
| Ordinary shares | |
| 12,710 | | |
| - | |
| Subscription receivable | |
| (15,500 | ) | |
| (15,500 | ) |
| Additional paid-in capital | |
| 6,526,821 | | |
| 6,544,298 | |
| Statutory reserves | |
| 2,592,642 | | |
| 2,076,469 | |
| Retained earnings | |
| 35,784,864 | | |
| 38,207,918 | |
| Accumulated other comprehensive loss | |
| (329,707 | ) | |
| (1,397,475 | ) |
| Total equity attributable to Leishen Energy Holding Co., Ltd | |
| 44,576,145 | | |
| 45,432,735 | |
| Non-controlling interests | |
| - | | |
| 24,765 | |
| Total Equity | |
| 44,576,145 | | |
| 45,457,500 | |
| | |
| | | |
| | |
| Total Liabilities and Equity | |
$ | 70,258,555 | | |
$ | 69,332,632 | |
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
UNAUDITED
CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS AND COMPREHENSIVE LOSS
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Revenues: | |
| | | |
| | |
| Revenues - third parties | |
$ | 20,978,428 | | |
$ | 25,199,614 | |
| Revenues - related parties | |
| - | | |
| 2,995,670 | |
| Total revenues | |
| 20,978,428 | | |
| 28,195,284 | |
| Cost of revenues | |
| (15,753,600 | ) | |
| (23,256,253 | ) |
| Gross profit | |
| 5,224,828 | | |
| 4,939,031 | |
| | |
| | | |
| | |
| Operating expenses: | |
| | | |
| | |
| Selling and marketing | |
| 1,535,890 | | |
| 635,306 | |
| General and administrative | |
| 2,133,900 | | |
| 3,045,282 | |
| Provision for expected credit losses | |
| 2,145,919 | | |
| 3,317,683 | |
| Research and development | |
| 97,448 | | |
| 163,008 | |
| Total operating expenses | |
| 5,913,157 | | |
| 7,161,279 | |
| | |
| | | |
| | |
| Loss from operations | |
| (688,329 | ) | |
| (2,222,248 | ) |
| | |
| | | |
| | |
| Other (expenses) income: | |
| | | |
| | |
| Interest expense | |
| (36,080 | ) | |
| (20,035 | ) |
| Exchange (loss) gains | |
| (167,571 | ) | |
| 45,795 | |
| Income from equity investment | |
| - | | |
| 171,368 | |
| Net investment (loss) gain from short-term investments | |
| (1,064,172 | ) | |
| 826,153 | |
| Interest income from loans receivable | |
| 93,183 | | |
| 50,805 | |
| (Loss) gain from disposal of property and equipment | |
| (288,176 | ) | |
| 116,311 | |
| Other income, net | |
| 197,232 | | |
| 77,831 | |
| Total other (expenses) income, net | |
| (1,265,584 | ) | |
| 1,268,228 | |
| | |
| | | |
| | |
| | |
| | | |
| | |
| Income tax (benefit) expense | |
| (117,174 | ) | |
| 14,635 | |
| | |
| | | |
| | |
| Net loss | |
| (1,836,739 | ) | |
| (968,655 | ) |
| Less: net loss attributable to non-controlling interests | |
| - | | |
| (344,240 | ) |
| Net loss attributable to Leishen Energy Holding Co., Ltd | |
$ | (1,836,739 | ) | |
$ | (624,415 | ) |
| | |
| | | |
| | |
| Comprehensive loss | |
| | | |
| | |
| Net loss | |
$ | (1,836,739 | ) | |
$ | (968,655 | ) |
| Foreign currency translation gain (loss) | |
| 1,078,411 | | |
| (943,577 | ) |
| Total comprehensive loss | |
| (758,328 | ) | |
| (1,912,232 | ) |
| Less: comprehensive loss attributable to non-controlling interests | |
| 10,643 | | |
| (359,623 | ) |
| Comprehensive loss attributable to Leishen Energy Holding Co., Ltd | |
$ | (768,971 | ) | |
$ | (1,552,609 | ) |
| | |
| | | |
| | |
| Loss per ordinary share | |
| | | |
| | |
| – Basic and diluted | |
$ | (0.11 | ) | |
$ | (0.04 | ) |
| | |
| | | |
| | |
| Weighted average number of ordinary shares outstanding | |
| | | |
| | |
| – Basic and diluted | |
| 16,793,967 | | |
| 16,330,631 | |
The
accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
UNAUDITED
CONDENSED CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY
SIX
MONTHS ENDED MARCH 31, 2026 AND 2025
| | |
Shares | | |
Amount | | |
receivable | | |
capital | | |
reserves | | |
earnings | | |
loss | | |
Co., Ltd | | |
interests | | |
equity | |
| | |
Ordinary shares | | |
Subscription | | |
Additional paid-in | | |
Statutory | | |
Retained | | |
Accumulated other comprehensive | | |
Total equity attributable to Leishen Energy Holding | | |
Non-controlling | | |
Total | |
| | |
Shares | | |
Amount | | |
receivable | | |
capital | | |
reserves | | |
earnings | | |
loss | | |
Co., Ltd | | |
interests | | |
equity | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| |
| Balance as of September 30, 2024 | |
| 15,500,000 | | |
$ | 15,500 | - | - |
$ | (15,500 | ) | |
$ | 1,617,966 | | |
$ | 1,690,994 | | |
$ | 37,339,006 | | |
$ | (861,374 | ) | |
$ | 39,786,592 | | |
$ | 668,921 | | |
$ | 40,455,513 | |
| Shares issued in initial public offering | |
| 1,525,000 | | |
| 1,525 | | |
| - | | |
| 4,814,013 | | |
| - | | |
| - | | |
| - | | |
| 4,815,538 | | |
| - | | |
| 4,815,538 | |
| Net loss | |
| - | | |
| - | - | - |
| - | | |
| - | | |
| - | | |
| (624,415 | ) | |
| - | | |
| (624,415 | ) | |
| (344,240 | ) | |
| (968,655 | |
| Appropriation to statutory reserve | |
| - | | |
| - | | |
| - | | |
| - | | |
| 46,030 | | |
| (46,030 | ) | |
| - | | |
| - | | |
| - | | |
| - | |
| Foreign currency translation adjustment | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| (928,194 | ) | |
| (928,194 | ) | |
| (15,383 | ) | |
| (943,577 | |
| Balance as of March 31, 2025 (Unaudited) | |
| 17,025,000 | | |
$ | 17,025 | - | - |
$ | (15,500 | ) | |
$ | 6,431,979 | | |
$ | 1,737,024 | | |
$ | 36,668,561 | | |
$ | (1,789,568 | ) | |
$ | 43,049,521 | | |
$ | 309,298 | | |
$ | 43,358,819 | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
Total equity | | |
| | |
| |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
attributable | | |
| | |
| |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
Accumulated | | |
to Leishen | | |
| | |
| |
| | |
Ordinary | | |
Class A Ordinary | | |
Class B Ordinary | | |
| | |
Additional | | |
| | |
| | |
other | | |
Energy | | |
Non- | | |
| |
| | |
Shares | | |
Shares* | | |
Shares* | | |
Subscription | | |
paid-in | | |
Statutory | | |
Retained | | |
comprehensive | | |
Holding | | |
controlling | | |
Total | |
| | |
shares | | |
Amount | | |
shares | | |
Amount | | |
shares | | |
Amount | | |
receivable | | |
capital | | |
reserves | | |
earnings | | |
loss | | |
Co., Ltd | | |
interests | | |
equity | |
| Balance as of September 30, 2025 | |
| 17,025,000 | | |
$ | 17,025 | | |
| - | | |
$ | — | | |
| - | | |
$ | — | | |
$ | (15,000 | ) | |
$ | 6,544,298 | | |
$ | 2,076,469 | | |
$ | 38,207,918 | | |
$ | (1,397,475 | ) | |
$ | 45,432,735 | | |
$ | 24,765 | | |
$ | 45,457,500 | |
| Balance | |
| 17,025,000 | | |
$ | 17,025 | | |
| - | | |
$ | — | | |
| - | | |
$ | — | | |
$ | (15,000 | ) | |
$ | 6,544,298 | | |
$ | 2,076,469 | | |
$ | 38,207,918 | | |
$ | (1,397,475 | ) | |
$ | 45,432,735 | | |
$ | 24,765 | | |
$ | 45,457,500 | |
| Shares re-designated and re-classified | |
| (17,025,000 | ) | |
| (17,025 | ) | |
| 4,315,000 | | |
| 4,315 | | |
| 12,710,000 | | |
| 12,710 | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | |
| Purchase of non-controlling interests | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| (17,477 | ) | |
| - | | |
| - | | |
| - | | |
| (17,477 | ) | |
| (35,408 | ) | |
| (52,885 | ) |
| Net loss | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| (1,836,739 | ) | |
| - | | |
| (1,836,739 | ) | |
| - | | |
| (1,836,739 | ) |
| Appropriation to statutory reserve | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| 516,173 | | |
| (516,173 | ) | |
| - | | |
| - | | |
| - | | |
| - | |
| Cash dividends paid | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| (70,142 | ) | |
| - | | |
| (70,142 | ) | |
| - | | |
| (70,142 | ) |
| Foreign currency translation adjustment | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| - | | |
| 1,067,768 | | |
| 1,067,768 | | |
| 10,643 | | |
| 1,078,411 | |
| Balance as of March 31, 2026 (Unaudited) | |
| - | | |
| - | | |
| 4,315,000 | | |
$ | 4,315 | | |
| 12,710,000 | | |
$ | 12,710 | | |
$ | (15,000 | ) | |
$ | 6,526,821 | | |
$ | 2,592,642 | | |
$ | 35,784,864 | | |
$ | (329,707 | ) | |
$ | 44,576,145 | | |
$ | - | | |
$ | 44,576,145 | |
| Balance | |
| - | | |
| - | | |
| 4,315,000 | | |
$ | 4,315 | | |
| 12,710,000 | | |
$ | 12,710 | | |
$ | (15,000 | ) | |
$ | 6,526,821 | | |
$ | 2,592,642 | | |
$ | 35,784,864 | | |
$ | (329,707 | ) | |
$ | 44,576,145 | | |
$ | - | | |
$ | 44,576,145 | |
The
accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
UNAUDITED
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Cash flows from operating activities: | |
| | | |
| | |
| Net loss | |
$ | (1,836,739 | ) | |
$ | (968,655 | ) |
| Adjustments to reconcile net loss to net cash provided by (used in) operating activities: | |
| | | |
| | |
| Depreciation and amortization | |
| 263,827 | | |
| 236,414 | |
| Loss (gain) from disposal of property and equipment | |
| 288,176 | | |
| (116,311 | ) |
| Unrealized net investment loss (gain) from short-term investments | |
| 1,121,746 | | |
| (826,153 | ) |
| Provision for credit losses of receivables and advances to suppliers | |
| 2,145,919 | | |
| 3,317,683 | |
| Income from equity investment | |
| - | | |
| (171,368 | ) |
| Non-cash lease expense | |
| 41,067 | | |
| 28,670 | |
| Deferred income tax | |
| (148,385 | ) | |
| 55,422 | |
| Changes in operating assets and liabilities: | |
| | | |
| | |
| Accounts receivable | |
| (2,272,915 | ) | |
| (1,688,477 | ) |
| Notes receivable | |
| (243,628 | ) | |
| 623,613 | |
| Advance to suppliers | |
| (660,631 | ) | |
| (2,176,850 | ) |
| Inventories | |
| 627,921 | | |
| 1,609,405 | |
| Due from related parties | |
| - | | |
| (27,636 | ) |
| Prepaid expenses and other current assets | |
| (523,355 | ) | |
| 93,910 | |
| Accounts payable | |
| 1,412,546 | | |
| (2,417,661 | ) |
| Advance from customers | |
| (112,513 | ) | |
| (937,625 | ) |
| Taxes payable | |
| 735,390 | | |
| (228,932 | ) |
| Due to related parties | |
| (14,626 | ) | |
| 1,620,234 | |
| Other payables and other current liabilities | |
| (52,658 | ) | |
| 23,817 | |
| Lease liabilities | |
| (41,067 | ) | |
| (31,027 | ) |
| Net cash provided by (used in) operating activities | |
| 730,075 | | |
| (1,981,527 | ) |
| | |
| | | |
| | |
| Cash flows from investing activities: | |
| | | |
| | |
| Purchase of property and equipment | |
| (157,843 | ) | |
| (160,561 | ) |
| Proceeds from disposal of property and equipment | |
| 6,414 | | |
| 701,336 | |
| Payments related to construction in progress | |
| (83,881 | ) | |
| - | |
| Loan repayment from a related party | |
| - | | |
| 91,904 | |
| Loan to a related party | |
| (622,364 | ) | |
| - | |
| Loans repayment from third parties | |
| 1,562,188 | | |
| - | |
| Loans to third parties | |
| (1,514,666 | ) | |
| (2,299,751 | ) |
| Purchase of short-term investments | |
| (16,921,805 | ) | |
| (17,231,516 | ) |
| Maturity of short-term investments | |
| 18,052,936 | | |
| 24,563,110 | |
| Purchase of long-term investment | |
| (712,677 | ) | |
| - | |
| Net cash (used in) provided by investing activities | |
| (391,698 | ) | |
| 5,664,522 | |
| | |
| | | |
| | |
| Cash flows from financing activities: | |
| | | |
| | |
| Proceeds from short-term loans | |
| 2,850,708 | | |
| 3,055,629 | |
| Repayments of short-term loans | |
| (3,107,272 | ) | |
| (42,655 | ) |
| Repayments of long-term loans | |
| - | | |
| (279,053 | ) |
| Net proceeds from initial public offering | |
| - | | |
| 5,380,488 | |
| Payment of offering expenses | |
| - | | |
| (127,297 | ) |
| Purchase of non-controlling interests | |
| (42,559 | ) | |
| - | |
| Dividend to shareholders | |
| (70,142 | ) | |
| - | |
| Net cash (used in) provided by financing activities | |
| (369,265 | ) | |
| 7,987,112 | |
| | |
| | | |
| | |
| Effect of foreign exchange rate on cash | |
| 187,225 | | |
| (176,524 | ) |
| | |
| | | |
| | |
| Net increase in cash and restricted cash | |
| 156,337 | | |
| 11,493,583 | |
| Cash and restricted cash at the beginning of the period | |
| 10,160,587 | | |
| 7,301,014 | |
| Cash and restricted cash at the end of the period | |
$ | 10,316,924 | | |
$ | 18,794,597 | |
| | |
| | | |
| | |
| Reconciliation of cash and restricted cash | |
| | | |
| | |
| Cash | |
$ | 10,249,822 | | |
$ | 10,159,656 | |
| Restricted cash | |
| 67,102 | | |
| 931 | |
| Total cash and restricted cash shown in the statements of cash flows | |
$ | 10,316,924 | | |
$ | 18,794,597 | |
| | |
| | | |
| | |
| Supplemental disclosures of cash flow information: | |
| | | |
| | |
| Income taxes paid | |
$ | 94,689 | | |
$ | 153,192 | |
| Interest paid | |
$ | 36,080 | | |
$ | 19,372 | |
| | |
| | | |
| | |
| Non-cash transactions: | |
| | | |
| | |
| Operating right-of-use assets recognized for related operating lease liabilities | |
$ | - | | |
$ | (4,315 | ) |
| Reclassification of deferred offering cost | |
$ | - | | |
$ | 437,653 | |
| Transfer of self-produced products from inventories to property and equipment | |
$ | 354,795 | | |
$ | - | |
The
accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
LEISHEN
ENERGY HOLDING CO., LTD. AND SUBSIDIARIES
NOTES
TO THE CONDENSED CONSOLIDATED FINANCIAL STATEMENTS
March
31, 2026 and September 30, 2025
NOTE
1 – ORGANIZATION AND BUSINESS DESCRIPTION
Leishen
Energy Holding Co., Ltd. (“Leishen Cayman”) was incorporated under the laws of Cayman Islands as an exempted company with
limited liability on October 19, 2022. As a holding company with no material operations, Leishen Cayman conducts substantially all of
its operations through its operating subsidiaries (collectively, the “Company”) in the People’s Republic of China (“PRC”
or “China”). The Company is a provider of clean-energy equipment and integrated solutions to the oil and gas industry, with
a commitment to providing customers high-performance, safe and cost-effective energy solutions. The Company’s major businesses
segments include (i) clean-energy equipment; (ii) oil and gas engineering technical services; (iii) new energy production and operation;
and (iv) digitalization and integration equipment.
Business
Reorganization
A
reorganization of legal structure (“Reorganization”) was completed on March 24, 2023. The reorganization involved the incorporation
of Leishen Energy Group Holding Co., Ltd. (“Leishen (Holding) Hong Kong”), and the transfer of the 100% equity interest of
Leishen Energy Group Co., Limited (“Leishen Hong Kong”). Consequently, Leishen Cayman, through its subsidiaries Leishen (Holding)
Hong Kong and Leishen Hong Kong, directly controls ZJY Technologies Co., Ltd. (“ZJY Technologies”), China Oil Blue Ocean
Petroleum Technology Inc. (“China Oil Blue Ocean”), Leishen Energy Technology (Nanjing) Co., Ltd. (“Leishen Nanjing”),
Leishen Green Energy Technology Development Co., Ltd. (“Beijing Leishen Green Energy”), Leishen Energy Technology (Shandong)
Co., Ltd. (“Leishen Shandong”) and Leishen Energy Services Co., Ltd. (“Leishen Services”), and became the ultimate
holding company of all other entities mentioned above.
The
Reorganization was accounted for as a reorganization among entities under common control since the same shareholders, controlled all
these entities before and after the Reorganization. The consolidation of the Company and its subsidiaries was accounted for at historical
cost and prepared on the basis as if the aforementioned transaction became effective as of the beginning of the first period presented
in the accompanying consolidated financial statements. Results of operations for the periods presented comprise those of the previously
separate entities combined from the beginning to the end of the period, eliminating the effects of intra-entity transactions.
The
Company’s corporate structure as of March 31, 2026 was as follows:
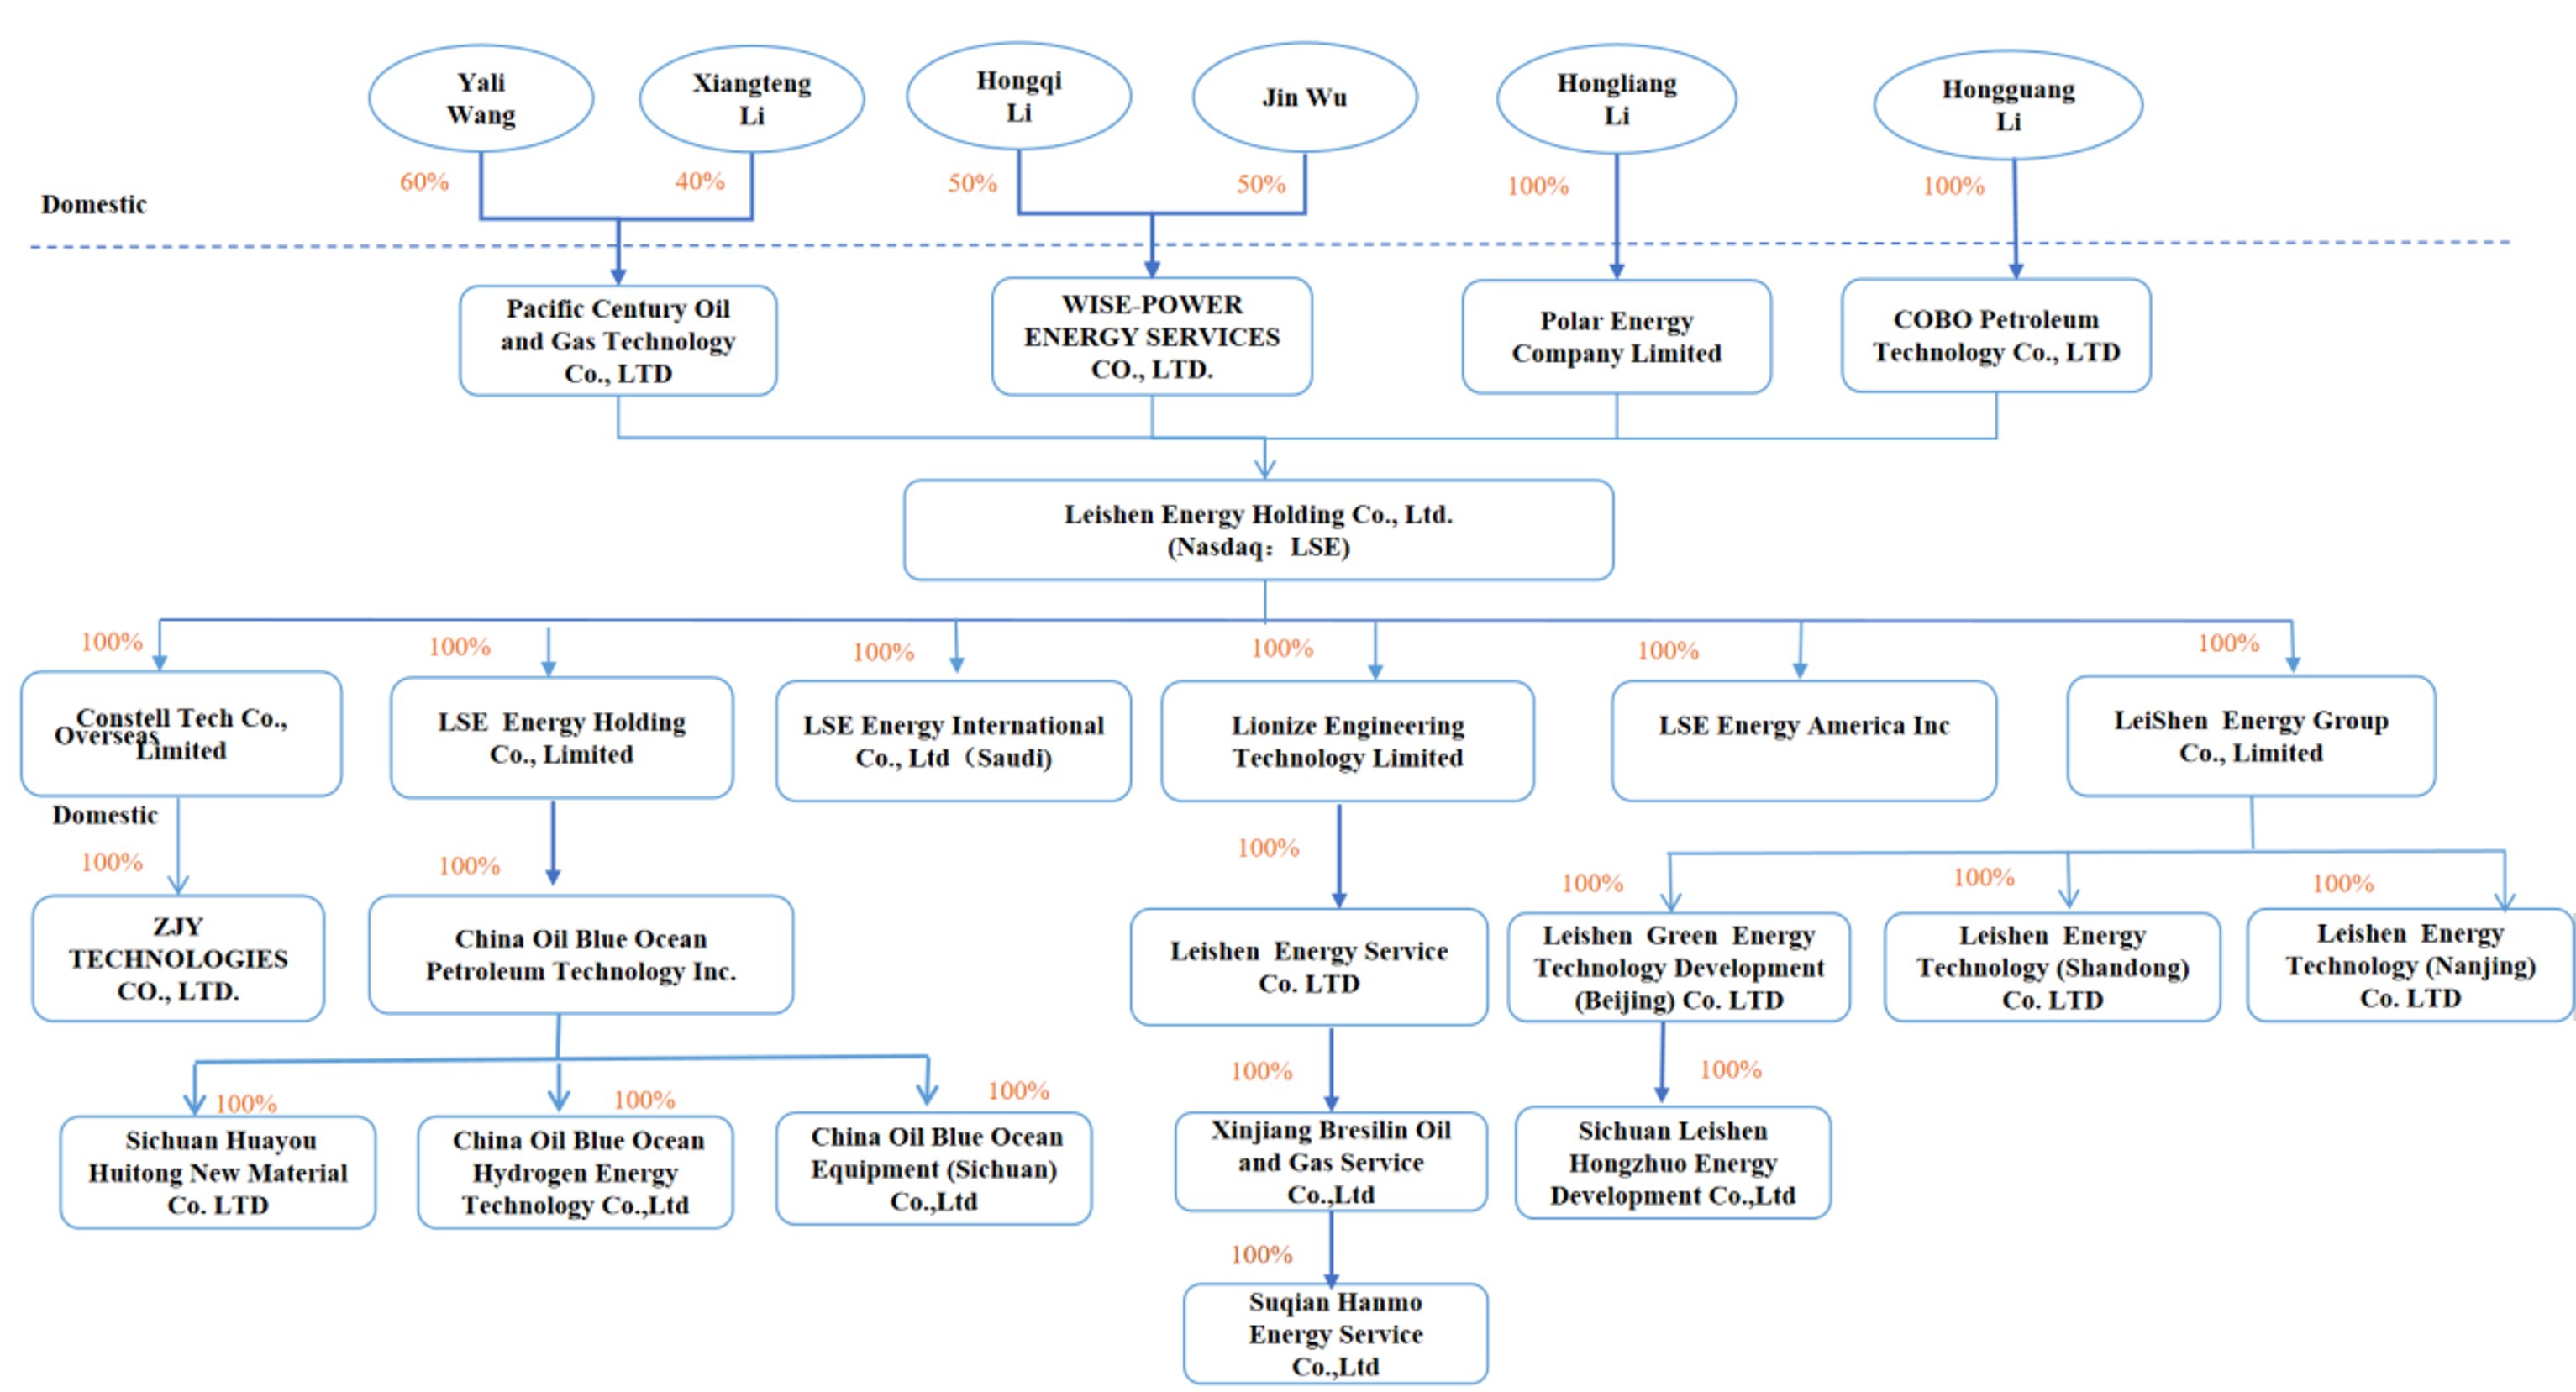
Below
is an overview of the Company’s principal subsidiaries as of March 31, 2026:
SCHEDULE OF COMPANY AND SUBSIDIARIES
| Legal
Entity |
|
Place
of
Incorporation |
|
Date
of
Incorporation |
|
Percentage
of
beneficial ownership |
|
Principal
activities |
| Leishen Energy Holding
Co., Ltd (“Leishen Cayman”) |
|
Cayman
Islands |
|
October
19, 2022 |
|
— |
|
Holding
company |
| |
|
|
|
|
|
|
|
|
| Leishen Energy Group Holding Co., Ltd. (“Leishen (Holding) Hong Kong”) |
|
Hongkong,
China |
|
November
25, 2022 |
|
100% |
|
Holding
company |
| |
|
|
|
|
|
|
|
|
| Leishen Energy Group
Co., Ltd. (“Leishen Hong Kong”) |
|
Hongkong,
China |
|
February
11, 2010 |
|
100% |
|
Purchase
and sale of oil and gas professional equipment and instruments |
| |
|
|
|
|
|
|
|
|
| ZJY Technologies Co.,
Ltd. (“ZJY Technologies”) |
|
Beijing,
China |
|
March
2, 2007 |
|
100% |
|
Design
and sale of oil and gas professional equipment and after-sales support, and oilfield digitalization and integration service |
| |
|
|
|
|
|
|
|
|
| China Oil Blue Ocean
Petroleum Technology Inc. (“China Oil Blue Ocean”) |
|
Beijing,
China |
|
October
19, 2007 |
|
100% |
|
Design
and sale of oil and gas equipment and instruments, and engineering technology services |
| |
|
|
|
|
|
|
|
|
| Leishen Energy Technology (Nanjing) Co., Ltd. (“Leishen Nanjing”) |
|
Nanjing,
China |
|
September
27, 2022 |
|
100% |
|
Purchase
and sale of oil and gas professional equipment and instruments |
| |
|
|
|
|
|
|
|
|
| Leishen Green Energy
Technology Development Co., Ltd. (“Beijing Leishen Green Energy”) |
|
Beijing,
China |
|
January
29, 2018 |
|
100% |
|
No
business operations as a holding company subsidiary |
| |
|
|
|
|
|
|
|
|
| Leishen Energy Technology
(Shandong) Co., Ltd. (“Leishen Shandong”) |
|
Shandong,
China |
|
September
14, 2010 |
|
100% |
|
Sales
of oil and gas professional equipment and instruments |
| |
|
|
|
|
|
|
|
|
| Leishen
Energy Services Co., Ltd. (“Leishen Services”) |
|
Shandong,
China |
|
January
23, 2019 |
|
100% |
|
No
business operations as a holding company subsidiary |
| |
|
|
|
|
|
|
|
|
| Sichuan Leishen Hongzhuo
Energy Development Co., Ltd. (“Sichuan Leishen Hongzhuo”) |
|
Chengdu,
China |
|
January
16, 2019 |
|
100% |
|
Production,
storage and transportation of natural gas (LNG/CNG) |
| |
|
|
|
|
|
|
|
|
| Sichuan Huayou Huitong
New Material Co. Ltd. (“Huayou Huitong”) |
|
Chengdu,
China |
|
May
29, 2020 |
|
100% |
|
Production
and sales of bonded composite pipes |
| |
|
|
|
|
|
|
|
|
| Xinjiang
Breslin Oil and Gas Service Co., Ltd. (“Xinjiang Breslin”) |
|
Xinjiang,
China |
|
August
22, 2024 |
|
100% |
|
Purchase
and sale of oil and gas professional equipment and instruments, and sales of oil and gas engineering technical service |
| Legal
Entity |
|
Place
of
Incorporation |
|
Date
of
Incorporation |
|
Percentage
of
beneficial ownership |
|
Principal
activities |
| Lionize Engineering
Technology Limited |
|
Hongkong,
China |
|
February
21, 2025 |
|
100% |
|
No
business operations as a holding company subsidiary |
| |
|
|
|
|
|
|
|
|
| Suqian Hanmo Energy Service Co., Ltd. (“Suqian Hanmo”) |
|
Jiangsu, China |
|
April 21, 2025 |
|
100% |
|
Purchase and sale of oil and gas professional equipment
and instruments, and sales of oil and gas engineering technical service |
| |
|
|
|
|
|
|
|
|
| LSE Energy International Co., Ltd (“LSE Energy
International”) |
|
Saudi Aribia |
|
June 29, 2025 |
|
100% |
|
No business operations |
| |
|
|
|
|
|
|
|
|
| LSE Energy America Inc (“LSE Energy America”) |
|
United States |
|
August 14, 2025 |
|
100% |
|
No business operations |
| |
|
|
|
|
|
|
|
|
| China Oil Blue Ocean Hydrogen Energy Technology Co., Ltd. (“China
Oil Hydrogen Energy”) |
|
Beijing, China |
|
August 5, 2025 |
|
100% |
|
No business operations |
| |
|
|
|
|
|
|
|
|
| China Oil Blue Ocean Equipment (Sichuan) Co., Ltd. |
|
Chengdu, China |
|
December 11, 2025 |
|
100% |
|
Purchase and sale of oil and gas professional equipment
and instruments, and sales of oil and gas engineering technical service |
Initial
Public Offering (the “IPO”)
On
December 20, 2024, Leishen Cayman (Nasdaq: LSE) consummated its initial public offering (the “IPO”) of 1,375,000 ordinary
shares, par value $0.001 at $4.00 per share (each, an “Ordinary Share”), with gross proceeds of $5.5 million. On January
8, 2025, Leishen Cayman issued and sold 150,000 additional Ordinary Shares at $4.00 per share, pursuant to the partial exercise of the
Over-Allotment Option, resulting in additional gross proceeds of $600,000. As a result, Leishen Cayman raised aggregate gross proceeds
of $6.1 million in the IPO. After deducting the underwriting discounts and commissions, the Company received total net proceeds of $5.4
million.
Adoption
of Dual-Class Share Structure
On
November 27, 2025, the Company’s shareholders approved an amendment to the memorandum and articles of association to adopt a dual-class
share structure. The authorized share capital of the Company is US$50,000 divided into 467,290,000 Class A Ordinary Shares of a nominal
or par value of US$0.001 each and 32,710,000 Class B Ordinary Shares of a nominal or par value of US$0.001 each. All of the issued and
outstanding ordinary shares (except the 6,355,000 and 6,355,000 held by Polar Energy Company Limited and WISE-POWER ENERGY SERVICES CO.,
LTD., respectively, were re-designated into Class A ordinary shares of par value US$0.001 each; the 6,355,000 and 6,355,000 Ordinary
Shares held by Polar Energy Company Limited and WISEPOWER ENERGY SERVICES CO., LTD., respectively, were re-designated into class B ordinary
shares of a par value of US$0.001 each; 20,000,000 of the authorized but unissued ordinary shares were re-designated into Class B ordinary
shares of par value US$0.001 each; and all of the remaining authorized but unissued ordinary shares were re-designated into Class A ordinary
shares of par value US$0.001 each. Under the new structure, the Company’s share capital consists of Class A Ordinary Shares and
Class B Ordinary Shares. Each Class A Ordinary Share carries one (1) vote per share, and each Class B Ordinary Share carries twenty-five
(25) votes per share and the other rights attached to it as set out in the Company’s amended and restated memorandum and articles.
NOTE
2 – SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
Basis
of presentation
The
accompanying unaudited condensed consolidated financial statements were prepared in accordance with accounting principles generally accepted
in the U.S. of America (“U.S. GAAP”) and the rules and regulations of the Securities Exchange Commission (“SEC”).
All adjustments necessary to present fairly in all material respects the financial position, results of operations and cash flows for
all periods presented were made. While these condensed consolidated financial statements are prepared in accordance with US GAAP, they
do not include all the information required for annual financial statements and should be read in conjunction with the audited condensed
consolidated financial statements and accompanying notes included in the Company’s Form 20-F for the year ended September 30, 2025, as amended.
Principles
of consolidation
The
condensed consolidated financial statements include the financial statements of the Company and its majority-owned subsidiaries. All
transactions and balances between the Company and its subsidiaries were eliminated upon consolidation.
Non-controlling
interests
Non-controlling
interests are recognized to reflect the portion of subsidiary’s equity that is not attributable, directly or indirectly, to the
Company as the controlling shareholder. Non-controlling interests are presented as a separate line item in the equity section of the
Company’s consolidated balance sheets and are separately disclosed in the Company’s consolidated statements of operations
and comprehensive (loss) income to distinguish the interests from that of the Company.
Use
of estimates
In
preparing the consolidated financial statements in conformity with U.S. GAAP, management makes estimates and assumptions that affect
the reported amounts of assets and liabilities and disclosures of contingent assets and liabilities at the dates of the consolidated
financial statements, as well as the reported amounts of revenue and expenses during the reporting periods. Significant items subject
to such estimates and assumptions include, but are not limited to, the assessment of the allowance for credit losses, the valuation of
inventories, useful lives of property and equipment and intangible assets, uncertain tax positions and realization of deferred tax assets.
Actual results could differ from those estimates.
Foreign
Currency Translation
The
results of operations and the consolidated statements of cash flows are translated at the average rate of exchange during the reporting
period. Assets and liabilities at the balance sheet date are translated at the applicable rates of exchange in effect at that date. The
equity is translated at the historical rate of exchange at the time of capital contribution. Because cash flows are translated based
on the average translation rate, amounts related to assets and liabilities reported on the consolidated statements of cash flows will
not necessarily agree with changes in the corresponding balances on the consolidated balance sheets. Translation adjustments arising
from the use of different exchange rates from period to period are included as a separate component of accumulated other comprehensive
income (loss) included in consolidated statements of changes in equity. Gains and losses from foreign currency transactions are included
in the Company’s consolidated statements of operations and comprehensive income.
The
value of RMB against USD and other currencies fluctuates and is affected by, among other things, changes in the PRC’s political
and economic conditions. Any significant revaluation of RMB may materially affect the Company’s financial condition in terms of
USD reporting. The following table outlines the currency exchange rates used in preparing the condensed consolidated financial statements:
SCHEDULE OF FOREIGN CURRENCY TRANSLATION
| | |
March 31, | | |
September 30, | | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | | |
2026 | | |
2025 | |
| Foreign currency | |
Balance Sheet | | |
Balance Sheet | | |
Profits/Loss | | |
Profits/Loss | |
| RMB:1USD | |
| 6.9194 | | |
| 7.1055 | | |
| 7.0158 | | |
| 7.1671 | |
Cash
Cash
includes cash on hand and demand deposits in accounts maintained with commercial banks. The Company maintains its bank accounts in mainland
China and Hong Kong. In accordance with China’s Deposit Insurance Regulation that became effective in May 2015, pursuant to which
banking financial institutions, such as commercial banks, established in the PRC are required to purchase deposit insurance for deposits
in RMB and in foreign currency placed with them. The insurance limit is RMB 500,000 (approximately US$70,000) for each bank in China.
Restricted
Cash
Cash
that is legally restricted as to withdrawal or for use or pledged as security is reported separately on the face of the Company’s
consolidated balance sheets. The Company’s restricted cash consisted of cash pledged as security for banker’s letter of guarantee.
The Company follows Financial Accounting Standards Board (“FASB”) Accounting Standards Update (“ASU”) No. 2016-18,
Statement of Cash Flows (Topic 230): Restricted Cash and presented restricted cash within the ending cash and restricted cash balances
on the Company’s consolidated statements of cash flows for the periods presented.
Short-term
investments
The
Company’s short-term investments mainly consist of investment in trading securities and held-to-maturity securities. Trading securities
include common stocks listed in public market and wealth management products issued by commercial banks that can be redeemed at any time.
Held-to-maturity securities primarily consist of wealth management products issued by commercial banks with maturities of less than one
year.
The
Company accounts for its short-term investments in accordance with FASB ASC Topic 320 “Investments — Debt and Equity Securities.”
Dividend and interest income, including amortization of the premium and discount arising at acquisition, for all categories of investments
in securities is included in consolidated statements of operations. Net realized and unrealized holding gains and losses for short-term
investments are included in net investment income in the consolidated statements of operations. The Company elected the fair value method
to measure its short-term investments.
Accounts
Receivable, net
Accounts
receivable are presented net of an allowance for credit losses. The Company follows ASC 326, Credit Losses (“ASC 326”) to
account for the related expected credit losses.
In
accordance with ASC 326, the Company maintains an allowance for credit losses and records the allowance for credit losses as an offset
to assets such as accounts receivable, and the estimated credit losses charged to the allowance are presented in the consolidated statements
of operations and comprehensive loss. The Company assesses collectability by reviewing receivables on a collective basis where similar
characteristics exist, primarily based on the size and nature of specific customer’s receivables (the “CECL model”).
In determining the amount of the allowance for credit losses, the Company considers not only the input from its CECL model but also historical
collectability based on past due status, the age of the receivable balances, credit quality of customers based on ongoing credit evaluations,
current economic conditions, reasonable and supportable forecasts of future economic conditions, and other factors that may affect the
Company’s ability to collect from customers. Actual credit losses and related allowance are written off as incurred.
Notes
Receivable
Notes
receivable are trade accounts receivable due from various customers where the customers’ banks guaranteed the payments, which are
non-interest bearing and generally range from three to six months from the date of issuance. The Company has the ability to submit request
for payment to the customer’s bank earlier than the scheduled payment date but will incur an interest charge and a processing fee.
Advance
to Suppliers, net
Advance
to suppliers are balances paid to suppliers for inventories or services not provided or received. The Company reviews its advance to
suppliers on a periodic basis and set up an allowance for credit losses in accordance with ASC 326.
Inventories
Inventories
consist of raw materials, self-produced products, purchased products and compressed natural gas, and are stated at the lower of cost
or net realizable value. Raw materials are primarily used to manufacture cleaning equipment which is the Company’s self-produced
products, primarily including high-end cleaning equipment accessories. Cost is determined using the weighted average method. The Company
periodically evaluates its inventories and will record an allowance for inventories that are either obsolete, slow-moving, may not be
saleable or whose cost exceeds its net realizable value.
From
time to time, the Company produces certain machinery and equipment (e.g., compressors) in anticipation of customer demand. Upon completion
of such equipment and receipt of customer orders, the corresponding inventories will be transferred to machinery and equipment in fixed
assets.
Loans
receivable
Loans
receivable primarily refers to loans provided by the Company to third parties and related parties. As of March 31, 2026, loans receivable
consists of ten loans provided to seven third parties and one loan to a related party. As of September 30, 2025, loans receivable consists
of ten loans provided to six third parties. The average annual interest rate on all loans provided by the Company was approximately 3.5%
as of March 31, 2026 and September 30, 2025. Loans receivables are stated at the historical carrying amount, net of allowance for credit
losses, if any.
Property
and Equipment, net
Property
and equipment are carried at cost and are depreciated on the straight-line basis over the estimated useful lives of the underlying assets.
The cost of repairs and maintenance is expensed as incurred; major replacements and improvements are capitalized. When assets are retired
or disposed of, the cost and accumulated depreciation and amortization are removed from the accounts, and any resulting gains or losses
are included in income in the year of disposition. The Company examines the possibility of decreases in the value of its property and
equipment, when events or changes in circumstances reflect the fact that their recorded value may not be recoverable.
Estimated
useful lives are as follows:
SCHEDULE OF ESTIMATED USEFUL LIFE
| Category |
|
Estimated
useful lives |
| Office equipment |
|
3-5 years |
| Vehicle |
|
4 years |
| Machine and equipment |
|
5-10 years |
Intangible
Assets, net
Intangible
assets consist primarily of accounting software that is carried at acquisition cost less accumulated amortization and impairment, if
any. It is tested for impairment if triggering events occurred that could affect their carrying value. There were no asset impairment
charges incurred during the six months ended March 31, 2026 and 2025. Amortization of intangible assets with finite lives is computed
using the straight-line method over the estimated useful lives as below:
SCHEDULE OF AMORTIZATION OF INTANGIBLE ASSETS
| Category |
|
Estimated
useful lives |
| Software |
|
10 years |
Fair
value of financial instruments
FASB
ASC 820, “Fair Value Measurement,” requires certain disclosures regarding the fair value of financial instruments. fair value
is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market
participants at the measurement date. A three-level fair value hierarchy prioritizes the inputs used to measure fair value. The hierarchy
requires entities to maximize the use of observable inputs and minimize the use of unobservable inputs. The three levels of inputs used
to measure fair value are as follows:
| |
● |
Level 1 - inputs to the
valuation methodology are quoted prices (unadjusted) for identical assets or liabilities in active markets. |
| |
|
|
| |
● |
Level 2 - inputs to the
valuation methodology include quoted prices for similar assets and liabilities in active markets, quoted market prices for identical
or similar assets in markets that are not active, inputs other than quoted prices that are observable and inputs derived from or
corroborated by observable market data. |
| |
|
|
| |
● |
Level 3 - inputs to the
valuation methodology that are unobservable. |
Unless
otherwise disclosed, the fair value of the Company’s financial instruments including cash, short-term investments, accounts receivable,
notes receivable, advance to suppliers, inventories, due from related parties, prepaid expenses and other current assets, short-term
loans, accounts payable, advance from customers, taxes payable, due to related parties, and other payables and other current liabilities
approximate their recorded values due to their short-term maturities. The fair value of longer-term leases approximates their recorded
values as their stated interest rates approximate the rates currently available.
The
Company’s non-financial assets, such as property and equipment would be measured at fair value only if they were determined to
be impaired.
The
Company measured its short-term investments at fair value. As of March 31, 2026 and September 30, 2025, the Company held investments
in common stocks that were publicly traded on the Hong Kong Stock Exchange and bank wealth management products. The common stocks investments
were classified as trading securities measured using Level 1 inputs. Among the wealth management products, those redeemable on demand
were classified as trading securities measured using Level 2 inputs, and those with a fixed maturity were classified as a held-to-maturity
security measured using Level 2 inputs.
The
following table presents information about short-term investments that are measured at fair value as of March 31, 2026 and September
30, 2025 and indicates the fair value hierarchy of the valuation techniques we utilized to determine such fair value. The valuation techniques
are based on the fair value measurement on a recurring basis of trading securities and held-to-maturity securities.
SCHEDULE OF FAIR VALUE MEASUREMENT ON RECURRING BASIS
| | |
| | |
Quoted | | |
Significant | | |
Significant | |
| | |
| | |
Prices in | | |
Other | | |
Other | |
| | |
As of | | |
Active | | |
Observable | | |
Unobservable | |
| | |
March 31 | | |
Markets | | |
Inputs | | |
Inputs | |
| | |
2026 | | |
(Level 1) | | |
(Level 2) | | |
(Level 3) | |
| | |
| (Unaudited) | | |
| | | |
| | | |
| | |
| Trading securities | |
$ | 13,064,956 | | |
$ | 1,978,219 | | |
$ | 11,086,737 | | |
$ | - | |
| Held-to-maturity securities | |
| 3,833,259 | | |
| - | | |
| 3,833,259 | | |
| - | |
| Total | |
$ | 16,898,215 | | |
$ | 1,978,219 | | |
$ | 14,919,996 | | |
$ | - | |
| | |
| | |
Quoted | | |
Significant | | |
Significant | |
| | |
| | |
Prices in | | |
Other | | |
Other | |
| | |
As of | | |
Active | | |
Observable | | |
Unobservable | |
| | |
September 30 | | |
Markets | | |
Inputs | | |
Inputs | |
| | |
2025 | | |
(Level 1) | | |
(Level 2) | | |
(Level 3) | |
| Trading securities | |
$ | 14,446,867 | | |
$ | 3,098,972 | | |
$ | 11,347,895 | | |
$ | - | |
| Held-to-maturity securities | |
| 4,233,204 | | |
| - | | |
| 4,233,204 | | |
| - | |
| Total | |
$ | 18,680,071 | | |
$ | 3,098,972 | | |
$ | 15,581,099 | | |
$ | - | |
Long-term
Investment
The Company measures its long-term equity investment using the equity method
or the measurement alternative, as applicable. Equity method investments are the Company’s investment in privately-held companies,
over which it has significant influence but does not own a majority equity interest or otherwise control. The Company applies the equity
method to account for an equity investment, in common stock or in-substance common stock, according to ASC 323 “Investment —
Equity Method and Joint Ventures”.
An
investment in in-substance common stock is an investment in an entity that has risk and reward characteristics that are substantially
similar to that entity’s common stock. The Company considers subordination, risks and rewards of ownership and obligation to transfer
value when determining whether an investment in an entity is substantially similar to an investment in that entity’s common stock.
Under
the equity method, the Company’s share of the post-acquisition profits or losses of the equity investee is recognized in the consolidated
income statements and its share of post-acquisition movements in accumulated other comprehensive income is recognized in shareholders’
equity. When the Company’s share of losses in the equity investee equals or exceeds its interest in the equity investee, the Company
does not recognize further losses, unless the Company has incurred obligations or made payments or guarantees on behalf of the equity
investee.
The
Company continually reviews its investment in equity investees under equity method to determine whether a decline in FV to below the
carrying value is other-than-temporary. The primary factors the Company considers in its determination are the duration and severity
of the decline in FV, the financial condition, operating performance and the prospects of the equity investee, and other company specific
information such as recent financing rounds. If the decline in FV is deemed to be other-than-temporary, the carrying value of the equity
investee is written down to FV.
Under the measurement alternative, investment is initially measured at
cost, less any impairment, and is adjusted for observable price changes from orderly transactions for identical or similar investments
of the same issuer. The Company assesses the need for impairment at each reporting period by considering factors such as the investee’s
financial condition, operating performance, and business outlook. Any impairment, if identified, is recognized in the consolidated statements
of operations.
There
was no impairment during the six months ended March 31, 2026 and 2025.
Leases
ASC
842 requires lessees to recognize a right-of-use (“ROU”) asset and corresponding lease liability on the Consolidated Balance
Sheets for all leases. The Company determines if an arrangement is a lease at inception of the arrangement and if such lease will be
classified as an operating lease or a finance lease. As of March 31, 2026 and September 30, 2025, all of the Company’s leases are
accounted for as operating leases.
ROU
assets are the Company’s right to use an underlying asset for the lease term and lease liabilities are the Company’s obligation
to make lease payments arising from the leases. ROU assets and lease liabilities are recognized at the lease commencement date based
on the present value of lease payments over the lease term. Most leases do not provide an implicit interest rate; therefore, the Company
used its incremental borrowing rate based on the information available at the inception date to determine the present value of the lease
payments. Lease terms include options to extend the lease when it is reasonably certain that the Company will exercise that option. Lease
cost for lease payments is recognized on a straight-line basis over the lease term. All ROU assets are reviewed for impairment annually.
There was no impairment of the Company’s ROU assets during the six months period ended March 31, 2026 and 2025.
Restricted
net assets
Foreign
exchange and other regulations in the PRC may further restrict the Company’s subsidiaries from transferring funds to the Company
in the form of dividends, loans and advances. Amounts restricted include paid-in capital and statutory reserves of the Company’s
PRC subsidiaries as determined pursuant to PRC generally accepted accounting principles.
Revenue
recognition
In
accordance with FASB ASC 606, Revenue from Contracts with Customers, the Company recognizes revenue for the transfer of products or services
to customers in an amount that reflects the consideration to which the Company expects to be entitled in such exchange. This requires
the Company identify contractual performance obligations and determine whether revenue should be recognized at a point in time or over
time, based on when control of the product or the benefit of the services transfers to the customer. Under the guidance of ASC 606, the
Company is required to (a) identify the contract with a customer, (b) identify the performance obligations in the contract, (c) determine
the transaction price, (d) allocate the transaction price to the performance obligations in the contract and (e) recognize revenue when
(or as) the Company satisfies its performance obligations.
In
accordance with ASC 606-10-55-89 through 55-91, the Company selected the type of good or service for presentation of disaggregated revenue.
The Company’s presentation of its disaggregated revenues is aligned with information that can be reviewed by the Company’s
chief operating decision maker for evaluating the financial performance of operating segments. The Company derives its revenues mainly
from: sales of clean-energy equipment, sales of digitalization and integration equipment, sales of new energy and delivery of oil and
gas engineering technical services. Revenues are the amount of consideration the Company is entitled to in exchange for the transfer
of promised goods or services in the ordinary course of the Company’s activities and is recorded net of value-added tax (“VAT”).
Consistent with the criteria of ASC 606, the Company recognizes revenue when the performance obligation in a contract is satisfied by
transferring the control of promised goods or services to the customer. The Company also evaluates whether it is appropriate to record
the gross amount of goods and services sold and the related costs.
The
following table sets forth the breakdown of the Company’s revenues for the six months ended March 31, 2026 and 2025:
SCHEDULE OF BREAKDOWN OF REVENUES
| | |
2026 | | |
2025 | |
| | |
Amount | | |
% | | |
Amount | | |
% | |
| | |
(Unaudited) | | |
| | |
(Unaudited) | | |
| |
| Sales of clean-energy equipment | |
$ | 10,412,332 | | |
| 49.6 | | |
$ | 13,196,043 | | |
| 46.8 | |
| Sales of digitalization and integration equipment | |
| 2,226,141 | | |
| 10.6 | | |
| 2,629,399 | | |
| 9.3 | |
| Sales of new energy | |
| 6,454,584 | | |
| 30.8 | | |
| 10,337,148 | | |
| 36.7 | |
| Delivery of oil and gas engineering technical services | |
| 1,885,371 | | |
| 9.0 | | |
| 2,032,694 | | |
| 7.2 | |
| Total | |
$ | 20,978,428 | | |
| 100.0 | | |
$ | 28,195,284 | | |
| 100.0 | |
Sale
of clean-energy equipment
The
Company signs contracts with customers and delivers clean-energy equipment according to the sales contract or sales list. The
customer issues an acceptance document after checking the quantity and quality of equipment received. Revenue is recognized when the
Company receives confirmation of equipment acceptance. Revenues are recorded net of value-added tax, discounts, and surcharges and
allowance for returns. And in accordance with ASC 606, the Company evaluates whether it is appropriate to record the gross amount of
goods sales and related costs or the net amount earned as commissions. The Company concludes it is the principal as the control of
the specified equipment remains with the Company before it is transferred to the customers. Revenue is
recognized as the gross amount of consideration to which the Company expects to be entitled in exchange for the specified equipment
transferred.
Sale
of digitalization and integration equipment
The
Company signs contracts with customers and provides digitalization and integration equipment according to the sales contract or
sales list. The customer issues an acceptance document after checking the quantity and quality of the equipment received and
installed. Revenue is recognized when the Company receives confirmation of equipment acceptance. Revenues are recorded net of
value-added tax, discounts, and surcharges and allowance for returns. In accordance with ASC 606, the Company evaluates whether it
is appropriate to record the gross amount of goods sales and related costs or the net amount earned as commissions. The Company
concludes it is the principal as the control of the specified equipment remains with the Company before it is transferred to the
customers. Revenue is recognized as the gross amount of consideration to which the Company expects to be
entitled in exchange for the specified equipment transferred.
Sales
of new energy
The
Company signs contracts with customers and sells new energy, such as liquefied natural gas (“LNG”) and compressed
natural gas (“CNG”), purchased from third parties to the customers. The customer issues an acceptance document after
acquiring the new energy. Revenue is recognized when the Company receives confirmation of natural gas acceptance. Revenues are
recorded net of value-added tax, discounts, and surcharges and allowance for returns. In accordance with ASC 606, the Company
evaluates whether it is appropriate to record the gross amount of new energy sales and related costs or the net amount earned as
commissions. The Company concludes it is the principal as the control of the new energy remains with the Company before it is
transferred to the customer. Revenue is recognized as the gross amount of consideration to which it expects
to be entitled in exchange for the new energy transferred.
Delivery
of oil and gas engineering technical services
The
Company signs contracts with customers and delivers compressor booster service to them during their shale gas production process. An
evaluation is performed to determine whether the Company is a principal or agent in these transactions. Under the terms of these compressor
booster service contracts, the Company concludes it is the agent as title to the shale gas production remains with a third-party producer.
Revenue is recognized on a net basis since the Company is providing a service. The Company concludes the services provided each month
are substantially similar and result in the transfer of substantially similar services to the third-party each month. That is, the benefit
consumed by the third-party is substantially similar for each month, even though the exact volume of services may vary. Therefore, the
Company concludes the monthly compressor booster service revenue satisfies the requirements of ASC 606-10-25-14(b) to be accounted for
as a single performance obligation. Accordingly, based on the output method, the Company recognizes revenues over time when it satisfies
its performance obligations throughout the contract terms.
Cost
of revenues
Cost
of revenues (“COR”) for sales of clean-energy equipment includes purchased cost of equipment and accessories from third parties,
labor cost and handling costs.
COR
for sales of digitalization and integration equipment includes labor costs, purchased cost of equipment and accessories from third parties,
and handling costs.
COR
for sales of new energy primarily includes gas cost purchased from third parties.
COR
for delivery of oil and gas engineering technical service includes labor costs, and depreciation expenses
General
and administrative expenses
General
and administrative expenses consist mainly of payroll and related costs for employees involved in general corporate functions, including
accounting, finance, tax, legal and human resources, professional fees and other general corporate expenses as well as costs associated
with the use by these functions of facilities and equipment, such as depreciation and rental expenses.
Selling
and Marketing expenses
Selling
expenses consist mainly of payroll and benefits for employees involved in the sales and distribution functions, and marketing expense.
Research
and development expenses
Research
and development expenses consist primarily of payroll and related costs for employees involved in research functions and other general
corporate expenses as well as costs associated with the use by these functions of facilities and equipment, such as depreciation and
rental expenses.
Interest
expenses
Interest
expense is for interest on short-term borrowings.
Other
(expenses) income, net
Other
(expenses) income, net primarily consist of rent revenue, bank charges and other miscellaneous expenses, net of interest income from
banks and other miscellaneous income.
Mainland
China employee contribution plans
As
stipulated by the regulations of the PRC, full-time employees of the Company are entitled to various government statutory employee benefit
plans, including medical insurance, maternity insurance, workplace injury insurance, unemployment insurance and pension benefits through
a PRC government-mandated multi-employer defined contribution plan. The Company is required to make contributions to the plan based on
certain percentages of employees’ salaries. These expenses are recorded in general and administrative and selling expenses. The
expenses the Company incurred for the plans were $362,711 and $334,168 for the six months ended March 31, 2026 and 2025, respectively.
Income
taxes
The
Company’s subsidiaries in the PRC and Hong Kong are subject to the income tax laws of the PRC and Hong Kong, respectively. No taxable
income was generated outside the PRC for the six months ended March 31, 2026 and 2025. The Company accounts for income taxes in accordance
with ASC 740, Income Taxes. ASC 740 requires an asset and liability approach for financial accounting and reporting for income taxes
and allows recognition and measurement of deferred tax assets based upon the likelihood of realization of tax benefits in future years.
Under the asset and liability approach, deferred taxes are provided for the net tax effects of temporary differences between the carrying
amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes. A valuation allowance
is provided for deferred tax assets if it is more likely than not these items will either expire before the Company is able to realize
their benefits, or future deductibility is uncertain.
ASC
740-10-25 prescribes a more-likely-than-not threshold for financial statement recognition and measurement of a tax position taken (or
expected to be taken) in a tax return. It also provides guidance on the recognition of income tax assets and liabilities, classification
accounting for interest and penalties associated with tax positions, years open for tax examination, accounting for income taxes in interim
periods and income tax disclosures. There were no uncertain tax positions as of March 31, 2026 and September 30, 2025.
Value
Added Tax (“VAT”)
The
VAT rate for revenue generated from providing products is 13%. VAT is reported as a reduction of revenue when incurred. Entities that
are VAT general taxpayers are allowed to offset qualified input VAT paid to suppliers against their output VAT liabilities. The net VAT
balance between input VAT and output VAT is recorded in taxes payable. The Company records a VAT payable or receivable net of payments
in the accompanying consolidated financial statements. All of the VAT returns filed by the Company’s subsidiaries in the PRC, have
been and remain subject to examination by the tax authorities for five years from the date of filing.
Earnings
(loss) per share
The
Company computes earnings (loss) per share (“EPS”) in accordance with ASC 260, “Earnings per Share” (“ASC
260”). ASC 260 requires companies with complex capital structures to present basic and diluted EPS. Basic EPS is computed by dividing
net income (loss) available to ordinary shareholders of the Company by the weighted average ordinary shares outstanding during the period.
Diluted EPS takes into account the potential dilution that could occur if securities or other contracts to issue ordinary shares were
exercised and converted into ordinary shares. When the Company has a net (loss), diluted securities are not included as they would be
anti-dilutive. For the six months ended March 31, 2026 and 2025, there were no dilutive securities.
Comprehensive
income (loss)
Comprehensive
income (loss) consists of two components, net income (loss) and other comprehensive income (loss). Net income (loss) refers to revenue,
expenses, gains, and losses that under U.S. GAAP are recorded as an element of equity. Other comprehensive income (loss) consists of
foreign currency translation adjustments from the Company not using the U.S. dollar as its functional currency.
Segment
reporting
ASC
Topic 280, “Segment Reporting,” requires use of the management approach model for segment reporting. The Company
identifies operating segments as components of the consolidated operations for which discrete financial information is available and
is regularly reviewed by the chief operating decision maker (“CODM”), in making decisions regarding resource allocation
and evaluating financial performance. The Company defines the term CODM to be its Chief Executive Officer. The Company has
determined it operates in one operating and reportable segment. The CODM reviews operating income (loss) presented only on a
consolidated basis and uses this information for purposes of allocating resources and evaluating financial performance. There are no
reconciling items between segment information and consolidated financial information.
The
significant segment expenses and other segment items that are provided to the CODM align with expense information that is included in
the Company’s consolidated statements of operations and notes thereto.
Based
on management’s assessment, the Company determined it has four operating segments: (i) clean-energy equipment; (ii) oil and gas
engineering technical services; (iii) new energy production and operation; and (iv) digitalization and integration equipment.
Significant
risks
Concentration
of credit risk
Currently,
all of the Company’s operations are in the PRC. Accordingly, the Company’s business, financial condition and results of operations
may be influenced by the political, economic and legal environment in the PRC, and by the general state of the PRC’s economy. The
Company’s results may be adversely affected by changes in governmental policies with respect to laws and regulations, anti-inflationary
measures, currency conversion and remittance abroad, and rates and methods of taxation, among other things.
Financial
instruments which potentially subject the Company to concentrations of credit risk consist principally of cash, restricted cash, accounts
receivable, notes receivable, advances to suppliers and due from related parties. A portion of the Company’s sales are credit sales
which are to the customers whose ability to pay is dependent upon industry economics prevailing in these areas; however, concentrations
of credit risk with respect to trade accounts receivable is limited due to most clients of the Company are state-owned enterprises. The
Company also performs ongoing credit evaluations of its customers to help further reduce credit risk.
Concentration
of customers and suppliers
Details
of the customers accounting for 10% or more of the Company’s total revenues are as follows:
SCHEDULE OF CONCENTRATIONS
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
| | |
(Unaudited) | | |
| |
| Customer A | |
$ | - | | |
| - | % | |
$ | 6,176,480 | | |
| 21.9 | % |
| Customer B | |
| 4,208,476 | | |
| 20.1 | % | |
| 3,893,576 | | |
| 13.8 | % |
| Total | |
$ | 4,208,476 | | |
| 20.1 | % | |
$ | 10,070,056 | | |
| 35.7 | % |
Details
of the customers which accounted for 10% or more of the Company’s accounts receivable are as follows:
| | |
As of March 31, | | |
As of September 30, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
| | |
| | |
| |
| Customer B | |
$ | 6,287,015 | | |
| 23.9 | % | |
$ | 4,650,537 | | |
| 19.9 | % |
| Customer C | |
| 3,339,165 | | |
| 12.7 | % | |
| 4,306,546 | | |
| 18.4 | % |
| Total | |
$ | 9,626,180 | | |
| 36.6 | % | |
$ | 8,957,083 | | |
| 38.3 | % |
Details
of the vendors which accounted for 10% or more of the Company’s purchases are as follows:
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
| | |
(Unaudited) | | |
| |
| Vendor A | |
$ | - | | |
| - | % | |
$ | 2,838,054 | | |
| 13.2 | % |
| Vendor B | |
| - | | |
| - | % | |
| 2,128,178 | | |
| 9.9 | % |
| Vendor C | |
| 2,103,730 | | |
| 12.7 | % | |
| - | | |
| - | % |
| Total | |
$ | 2,103,730 | | |
| 12.7 | % | |
$ | 4,966,232 | | |
| 23.1 | % |
Details
of the vendors which accounted for 10% or more of the Company’s accounts payable are as follows:
| | |
As of March 31, | | |
As of September 30, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
| | |
| | |
| |
| Vendor B | |
$ | 3,324,655 | | |
| 38.7 | % | |
$ | 3,600,703 | | |
| 47.8 | % |
| Vendor D | |
| 1,442,065 | | |
| 16.8 | % | |
| - | | |
| - | % |
| Total | |
$ | 4,766,720 | | |
| 55.5 | % | |
$ | 3,600,703 | | |
| 47.8 | % |
Related
parties
A
party is considered related to the Company if it directly or indirectly or through one or more intermediaries, controls, is controlled
by, or is under common control with the Company. Related parties also include principal owners of the Company, its management, members
of their immediate families and other parties with which the Company may deal if one party controls or can significantly influence the
management or operating policies of the other to an extent that one of the transacting parties might be prevented from fully pursuing
its own separate interests. A party which can significantly influence the management or operating policies of the transacting parties
or if it has an ownership interest in one of the transacting parties and can significantly influence the other to an extent that one
or more of the transacting parties might be prevented from fully pursuing its own separate interests is also a related party.
Recent
accounting pronouncements
In
December 2023, the FASB issued ASU 2023-09, Improvements to Income Tax Disclosures, which requires disaggregated information about an
entity’s effective tax rate reconciliation and additional discloses on income taxes paid. The new requirements are effective for
annual periods beginning after December 15, 2024. The guidance is to be applied prospectively, with an option for retrospective application.
The Company adopted this ASU on January 1, 2026. The adoption did not have a material impact on the consolidated financial statements.
In
November 2024, the FASB issued ASU 2024-03 on Disaggregation of Income Statement Expenses that enhances disclosure of certain costs and
expenses to provide enhanced transparency into the expenses presented in the income statement. The updates are effective for annual periods
beginning after December 15, 2026. The Company is still assessing the impact of the related disclosure requirements.
The
Company does not believe other recently issued but not yet effective accounting standards, if currently adopted, would have a material
effect on its unaudited condensed consolidated financial statements.
NOTE
3 – SHORT-TERM INVESTMENTS
Short-term
investments consisted of the following:
SCHEDULE OF SHORT TERM INVESTMENT
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Trading securities | |
$ | 13,064,956 | | |
$ | 14,446,867 | |
| Held-to-maturity securities | |
| 3,833,259 | | |
| 4,233,204 | |
| Total short-term investments | |
$ | 16,898,215 | | |
$ | 18,680,071 | |
As
of March 31, 2026, the Company held investments in three common stocks of $1,978,219 that were publicly traded on the Hong Kong Stock
Exchange and five bank wealth management products of $14,919,996. As of September 30, 2025, the Company held investments in three common
stocks of $3,098,972 that were publicly traded on the Hong Kong Stock Exchange and three bank wealth management products of $15,581,099.
Net
investment (loss) gain for the six months ended March 31, 2026 and 2025 consists of the following:
SCHEDULE OF NET INVESTMENT INCOME
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Gain from redemption of wealth management products investments | |
$ | 57,574 | | |
$ | 119,262 | |
| Unrealized gain from wealth management products investments | |
| 65,810 | | |
| | |
| Unrealized (loss) gain from common stocks | |
| (1,187,556 | ) | |
| 706,891 | |
| Net investment (loss) gain | |
$ | (1,064,172 | ) | |
$ | 826,153 | |
NOTE
4 – ACCOUNTS RECEIVABLE, NET
Accounts
receivable, net consisted of the following:
SCHEDULE
OF ACCOUNTS RECEIVABLE
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Trade accounts receivable | |
$ | 26,337,418 | | |
$ | 23,403,393 | |
| Less: allowance for expected credit losses | |
| (4,986,337 | ) | |
| (3,768,902 | ) |
| Accounts receivable, net | |
$ | 21,351,081 | | |
$ | 19,634,491 | |
| Current portion | |
$ | 18,011,916 | | |
$ | 15,327,945 | |
| Non-current portion | |
$ | 3,339,165 | | |
$ | 4,306,546 | |
The
non-current portion represents trade receivables to be collected beyond one year due to the payment terms negotiated between the Company
and its customers.
The
movement of allowance of for expected credit losses for the six months ended March 31, 2026 and 2025 was as follows:
SCHEDULE
OF ALLOWANCE FOR EXPECTED CREDIT LOSSES
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Balance at beginning of the period | |
$ | 3,768,902 | | |
$ | 2,393,968 | |
| Addition during the six-month period | |
| 1,100,734 | | |
| 1,626,922 | |
| Exchange differences | |
| 116,701 | | |
| (56,962 | ) |
| Balance at end of the period | |
$ | 4,986,337 | | |
$ | 3,963,928 | |
NOTE
5 –NOTES RECEIVABLE
Notes
receivable are trade accounts receivable due from customers where the customers’ banks guaranteed the payments, which are non-interest
bearing and generally range from three to six months from the date of issuance. As of March 31, 2026 and September 30, 2025, no notes
were guaranteed or collateralized. The balance of $275,889 as of March 31, 2026 was fully collected as of the date of this report.
NOTE
6 – ADVANCE TO SUPPLIERS, NET
Advance
to suppliers, net consisted of the following:
SCHEDULE OF ADVANCE TO SUPPLIERS, NET
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Advance for products and services from third parties | |
$ | 8,606,539 | | |
$ | 7,728,834 | |
| Less: allowance for expected credit losses | |
| (4,496,482 | ) | |
| (3,196,567 | ) |
| Advance to suppliers, net | |
$ | 4,110,057 | | |
$ | 4,532,267 | |
The
movement of allowance for credit losses for the six months ended March 31, 2026 and 2025 was as follows:
SCHEDULE
OF MOVEMENT OF ALLOWANCE FOR CREDIT LOSS ADVANCE TO SUPPLIER
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Balance at beginning of the period | |
$ | 3,196,567 | | |
$ | 1,669,088 | |
| Addition during the six-month period | |
| 1,197,262 | | |
| 1,907,921 | |
| Exchange differences | |
| 102,653 | | |
| (39,715 | ) |
| Balance at end of the period | |
$ | 4,496,482 | | |
$ | 3,537,294 | |
NOTE
7 – INVENTORIES
Inventories
consist of the following:
SCHEDULE OF INVENTORIES
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Raw materials | |
$ | 1,075,310 | | |
$ | 964,215 | |
| Work in progress | |
| 255,970 | | |
| 916,949 | |
| Self-produced products | |
| 55,979 | | |
| 562,577 | |
| Purchased products - clean-energy equipment | |
| 1,277,054 | | |
| 1,106,968 | |
| Purchased products - digitalization and integration equipment | |
| 95,862 | | |
| 102,671 | |
| Total inventories | |
$ | 2,760,175 | | |
$ | 3,653,380 | |
Self-produced
products include compressors, water injection pump skids and wellhead control panels.
The
Company entered into service contracts with separate customers during the period from October 2024 to September 2025. To fulfill these
contracts, five self-produced compressors with a total carrying value of $775,141 were transferred to machinery and equipment upon completion
as of March 31, 2026. These equipment are used to provide oil and gas engineering technical services to clients. Depreciation on such
equipment will commence when it is placed into service and is recorded as part of the cost of revenues.
The
Company reviews its inventories periodically to determine if any reserves are necessary for slow-moving inventory or if a write-down
is necessary when the carrying value exceeds net realizable value. There was no allowance for its inventories as of March 31, 2026 and
September 30, 2025.
NOTE
8 – PREPAID EXPENSES AND OTHER CURRENT ASSETS, NET
Prepaid
expenses and other current assets consisted of the following:
SCHEDULE
OF PREPAID EXPENSES AND OTHER CURRENT ASSETS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Deposits (1) | |
$ | 609,341 | | |
$ | 516,685 | |
| Staff advances (2) | |
| 294,063 | | |
| 104,950 | |
| VAT Credit to be deducted (3) | |
| 1,516,675 | | |
| 1,048,418 | |
| Advanced service fee (4) | |
| 22,895 | | |
| 420,185 | |
| Equity transaction (5) | |
| 1,010,492 | | |
| 984,026 | |
| Other (6) | |
| 101,376 | | |
| 271,595 | |
| Less: allowance for expected credit losses | |
| (232,504 | ) | |
| (376,571 | ) |
| Prepaid expenses and other current assets, net | |
$ | 3,322,338 | | |
$ | 2,969,288 | |
| (1) |
|
| |
|
| (2) |
|
| |
|
| (3) |
Since
fiscal year 2025, revenues generated by Leishen Nanjing, Leishen Shandong, ZJY Technologies and Sichuan Leishen Hongzhuo were lower
than their costs and expenses, resulting in a larger amount of input VAT invoices received compared to output VAT invoices issued.
The excess portion could not be deducted in the current period and thus classified as other current assets, to be carried forward
for deduction in future periods. |
| |
|
| (4) |
|
| |
|
| (5) |
|
| |
|
| (6) |
|
The
movement of allowance for credit losses for the six months ended March 31, 2026 and 2025 was as follows:
SCHEDULE
OF ALLOWANCE FOR CREDIT LOSSES
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Balance at beginning of the period | |
$ | 376,571 | | |
$ | 190,303 | |
| Reversal of allowance during the period | |
| (152,077 | ) | |
| (22,074 | ) |
| Exchange differences | |
| 8,010 | | |
| (4,528 | ) |
| Balance at end of the period | |
$ | 232,504 | | |
$ | 163,701 | |
NOTE
9 – LONG-TERM INVESTMENT
Long-term
investment consisted of the following:
SCHEDULE
OF LONG-TERM INVESTMENTS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Equity investment using the measurement alternative | |
$ | 722,606 | | |
$ | - | |
| Long-term investment | |
$ | 722,606 | | |
$ | - | |
As
of March 31, 2026, the Company’s long-term investment is consisted of an investment in Suzhou Kerun New Materials Co., Ltd. (“Suzhou
Kerun”), which is accounted for using the measurement alternative.
Suzhou
Kerun is a limited liability company incorporated on April 10, 2019, under the laws of PRC, engaged in new material technology services.
On September 25, 2025, China Oil Hydrogen Energy acquired 0.15% of the equity of Suzhou Kerun at a purchase price of RMB 5 million ($722,606).
Considering the Company does not participate in actual operation of Suzhou Kerun, its fair value cannot be determined. Based on this,
the Company uses alternative accounting for this investment without readily determinable fair value.
The
Company recognized net investment income of nil and $171,368 in its consolidated statements of operations and comprehensive income for
the six months ended March 31, 2026 and 2025, respectively.
During
the six months ended March 31, 2025, the investment income realized was attributable to long-term investments in Shuifu Yongcheng Technology
Co., Ltd. (“Shuifu Yongcheng”) and Sichuan Hongzhuo Shuya Energy Co., Ltd. (“Hongzhuo Shuya), which were accounted
for using the equity method. As of September 30, 2025, both investments were fully disposed and carried no balance on the books.
NOTE
10 – PROPERTY AND EQUIPMENT, NET
Property
and equipment, at cost less accumulated depreciation, consisted of the following:
SCHEDULE
OF PROPERTY, PLANT, AND EQUIPMENT
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Machinery and equipment | |
$ | 4,483,382 | | |
$ | 4,285,476 | |
| Office equipment | |
| 134,463 | | |
| 130,941 | |
| Vehicles | |
| 506,254 | | |
| 541,512 | |
| Subtotal | |
| 5,124,099 | | |
| 4,957,929 | |
| Property and equipment, gross | |
| 5,124,099 | | |
| 4,957,929 | |
| Less: accumulated depreciation | |
| (1,604,556 | ) | |
| (1,492,976 | ) |
| Property and equipment, net | |
$ | 3,519,543 | | |
$ | 3,464,953 | |
The
movement of machinery and equipment was presented in the following table:
SCHEDULE
MOVEMENT OF MACHINERY AND EQUIPMENT
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Balance at the beginning of the period | |
$ | 4,285,476 | | |
$ | 4,877,172 | |
| Purchases | |
| 142,700 | | |
| 83,704 | |
| Equipment transferred from inventories | |
| 354,795 | | |
| 448,686 | |
| Disposals | |
| (414,848 | ) | |
| (1,056,751 | ) |
| Exchange differences | |
| 115,259 | | |
| (67,335 | ) |
| Balance at the end of the period | |
$ | 4,483,382 | | |
$ | 4,285,476 | |
For
the six months ended March 31, 2026 and 2025, depreciation was $254,598 and $228,303, respectively.
NOTE
11 – INTANGIBLE ASSETS, NET
Intangible
assets, net consisted of the following:
SCHEDULE OF INTANGIBLE ASSETS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Software | |
$ | 168,043 | | |
$ | 163,642 | |
| Less: accumulated amortization | |
| (51,399 | ) | |
| (41,871 | ) |
| Intangible assets, net | |
$ | 116,644 | | |
$ | 121,771 | |
For
the six months ended March 31, 2026 and 2025, amortization was $8,287 and $8,112 respectively.
NOTE
12 – LOANS RECEIVABLE
Loans
receivable consisted of the following:
SCHEDULE OF LOAN RECEIVABLE
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Polar Petroleum Equipment (Shandong) Co., Ltd (“Polar”) (1) | |
$ | 867,127 | | |
$ | 844,416 | |
| Sichuan TIBO Fluid Technology Co., Ltd. (“Sichuan TIBO”) (2) | |
| 1,098,361 | | |
| 1,069,596 | |
| Jining Eni Energy Technology Co., Ltd (“Eni Energy”) (3) | |
| 289,042 | | |
| 281,472 | |
| Xianlong Technology (Beijing) Co., Ltd. (“Xianlong”) (4) | |
| 578,085 | | |
| 1,401,731 | |
| Beijing Youyi Natural Technology Co., Ltd. (“Beijing Youyi”) (5) | |
| 121,398 | | |
| 267,398 | |
| Joseph Petroleum Technology (Beijing) Co., Ltd. (“Joseph Petroleum”) (6) | |
| - | | |
| 703,680 | |
| Beijing Chenghui Shengsi Technology Co., Ltd. (“Beiiing Chenghui”) (7) | |
| 1,464,722 | | |
| 18,999 | |
| Accrued Interest Receivable | |
| 243,172 | | |
| 153,860 | |
| Total loans | |
$ | 4,661,908 | | |
$ | 4,741,152 | |
| Less: current portion | |
$ | 3,767,896 | | |
$ | 3,777,909 | |
| Loans receivable, non-current | |
$ | 894,012 | | |
$ | 963,243 | |
| (1) |
In
May 2025, China Oil Blue Ocean lent RMB 6 million ($867,127) to Polar with annual interest of 3.5% and a term of three years. Interest
accrued on this loan was RMB 186,027 ($26,885) and 81,315 ($11,444) as of March 31, 2026 and September 30, 2025. The loan will mature
in May 2028. |
| (2) |
On
April 20, 2025, China Oil Blue Ocean provided an additional loan of RMB 2.6 million ($375,755) to Sichuan TIBO with interest of 3.5%
and a term of six months. On October 24, 2025, China Oil Blue Ocean and Sichuan TIBO agreed to extend the maturity date of the loan
to June 30, 2026. On June 25, 2026, both parties agreed to extend the maturity date of the loan to October 31, 2026.
As
of March 31, 2026 and September 30, 2025, the outstanding loan receivable from TIBO amounted to $1,098,361 and $1,069,596 respectively.
Interest accrued on above two loans was RMB 368,816 ($53,302) and RMB 236,180 ($33,239) as of March 31, 2026 and September 30, 2025
respectively. |
| (4) |
Interest
accrued on these loans were RMB 260,645 ($ 37,669) and RMB 94,540 ($13,305) as of March 31, 2026 and September 30, 2025 respectively. |
| (5) |
Sichuan
TIBO and PetroChina Information Technology Co., Ltd. (“PetroChina Information”) are both procurement suppliers of ZJY Technologies.
Pursuant to a tripartite assignment of debt agreement executed on October 10, 2025, ZJY Technologies assigned its RMB 1,097,242 ($158,575)
loan principal and all accrued interest to its creditors: RMB 821,574($118,735) to Sichuan TIBO and RMB 275,668 ($39,840) to PetroChina
Information. Beijing Youyi shall repay the amount to Sichuan TIBO and PetroChina Information, respectively, in respect of the assigned
agreements.
As
of March 31, 2026 and September 30, 2025, the outstanding loan receivable from Beijing Youyi amounted to RMB 840,000 ($121,398) and
RMB 1,900,000 ($267,398) respectively. Interest accrued on this loan was nil and RMB 21,566 ($3,035) as of March 31, 2026 and September
30, 2025. On June 9, 2026, Beijing Youyi repaid the outstanding loan balance of RMB 840,000 ($121,398). |
| (7) |
As
of March 31, 2026 and September 30, 2025, the outstanding loan receivable from Beijing Chenghui amounted to RMB 10,135,000 ($1,464,722)
and RMB135,000($18,999) respectively. Interest accrued from Beijing Chenghui was RMB 796,254 ($115,075) and RMB 628,008 ($88,384)
as of March 31, 2026 and September 30, 2025.
On
May 29, 2026, Beijing Chenghui, ZJY Technologies, Leishen Shandong, and Sichuan TIBO executed a debt offset agreement, under which
Beijing Chenghui directly repays to Sichuan TIBO all principal and interest owed to ZJY Technologies, and all chain debts among the
four parties are simultaneously settled in full. |
Interest
accrued on all the above-mentioned loans receivable was RMB 1,682,606 ($243,172) and RMB1,093,253 ($153,860) as of March 31, 2026 and
September 30, 2025 respectively.
NOTE
13 –BANK LOANS
The
loans of the Company consisted of the following:
SCHEDULE OF BANK LOANS
| | |
March 31, 2026 | | |
|
| | |
Principal
Amount | | |
Annual
Interest Rate | | |
Contract term |
| | |
(Unaudited) | | |
| | |
|
| Industrial and Commercial Bank (1) | |
$ | 1,445,212 | | |
| 2.35 | % | |
2026-03-16- 2027-03-15 |
| Industrial and Commercial Bank (2) | |
| 1,445,212 | | |
| 2.35 | % | |
2026-03-25- 2027-03-19 |
| Total loans | |
$ | 2,890,424 | | |
| | | |
|
| Less: current portion | |
$ | 2,890,424 | | |
| | | |
|
| Long-term loans | |
$ | - | | |
| | | |
|
| | |
September 30, 2025 | | |
|
| | |
Principal
Amount | | |
Annual
Interest Rate | | |
Contract term |
| Bank of China (3) | |
$ | 253,326 | | |
| 3.35 | % | |
2024/10/16-2025/10/15 |
| Industrial and Commercial Bank (4) | |
| 1,407,360 | | |
| 2.45 | % | |
2025/3/18-2026/03/17 |
| Industrial and Commercial Bank (5) | |
| 1,407,360 | | |
| 2.45 | % | |
2025/3/25-2026/03/24 |
| Total loans | |
| 3,068,046 | | |
| | | |
|
| Less: current portion | |
| 3,068,046 | | |
| | | |
|
| Long-term loans | |
$ | - | | |
| | | |
|
NOTE
14 – OTHER PAYABLES AND OTHER CURRENT LIABILITIES
Other
payables and other current liabilities consisted of the following:
SCHEDULE OF OTHER PAYABLES AND OTHER CURRENT LIABILITIES
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Payroll payable | |
$ | 1,260,439 | | |
$ | 1,212,196 | |
| Deposits | |
| 8,262 | | |
| 981 | |
| Other | |
| 472,107 | | |
| 534,030 | |
| Other payables and other current liabilities | |
$ | 1,740,808 | | |
$ | 1,747,207 | |
Other
payable is for employee business expense reimbursement and freight.
NOTE
15– LEASES
The
Company leases office spaces and factories under non-cancellable operating leases, with terms from 24 to 120 months. The Company considers
those renewal or termination options that are reasonably certain to be exercised in the determination of the lease term and initial measurement
of right of use assets and lease liabilities. Lease expense for lease payment is recognized on a straight-line basis over the lease term.
Leases with initial term of 12 months or less are not recorded on the balance sheet.
The
Company’s lease agreements do not contain any material residual value guarantees or material restrictive covenants.
The
table below presents the operating lease related assets and liabilities recorded on the balance sheets:
SCHEDULE OF OPERATING LEASE RELATED ASSETS AND LIABILITIES
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Operating lease ROU assets | |
$ | 686,373 | | |
$ | 708,944 | |
| | |
| | | |
| | |
| Operating lease liabilities - current | |
$ | 101,369 | | |
$ | 82,653 | |
| Operating lease liabilities - non-current | |
| 585,004 | | |
| 626,291 | |
| Total operating lease liabilities | |
$ | 686,373 | | |
$ | 708,944 | |
On
January 22, 2022, Sichuan Leishen Hongzhuo leased a vacant land from Chengdu Longxing Natural Gas Co., Ltd. for the construction of a
natural gas recovery station, which complies with national land-use standards. The lease term is eleven years and the annual rent is
RMB 133,745($19,329).
On
April 1, 2023, Sichuan TIBO Fluid Technology Co., Ltd. leased the factory at Shiliba Industrial Park, Xinshi Town, Jianyang City, Sichuan
Province to China Oil Blue Ocean. The term is ten years and the rent is RMB6,440,367 ($930,770) in total.
SCHEDULE OF WEIGHTED AVERAGE OF OPERATING LEASE
| | |
March 31, 2026 | |
| Weighted-average remaining lease term (Unaudited) | |
| 7 years | |
| | |
| | |
| Weighted-average discount rate (Unaudited) | |
| 4.2 | % |
A
summary of lease cost recognized in Company’s unaudited condensed consolidated financial statements and supplemental cash flow
information for operating leases is as follows for the six months ended March 31, 2026 and 2025:
SCHEDULE OF OPERATING LEASE COST
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Operating lease cost | |
$ | 54,977 | | |
$ | 46,181 | |
| Cash paid for operating leases | |
$ | - | | |
$ | 1,393 | |
A
summary of maturity of operating lease liabilities under the Company’s non-cancelable operating leases as of March 31, 2026 is
as follows:
SCHEDULE OF MATURITY OF OPERATING LEASE LIABILITIES
| Six months ending March 31, | |
| |
| 2027 | |
$ | 111,486 | |
| 2028 | |
| 111,486 | |
| 2029 | |
| 111,486 | |
| 2030 | |
| 111,486 | |
| After 2031 | |
| 331,388 | |
| Total lease payments | |
| 777,332 | |
| Less: Imputed Interest | |
| (90,959 | ) |
| Present value of operating lease liabilities | |
$ | 686,373 | |
NOTE
16 – RELATED PARTY BALANCES AND TRANSACTIONS
The
table below sets forth the major related parties and their relationships with the Company as of March 31, 2026:
| Name
of related parties |
|
Relationship
with the Group |
| Li Hongqi |
|
Chairman of the Board |
| Li Hongliang |
|
Chief Executive Officer,
brother of Li Hongqi |
| Li Hongguang |
|
A shareholder of the Company,
brother of Li Hongqi |
| Sichuan Hongzhuo Shuya
Energy Co., Ltd. (“Sichuan Hongzhuo”) |
|
An equity investee of the
Company. On September 12, 2025, the Company sold its equity interest in Sichuan Hongzhuo to a third party. |
| Beijing Happiness Star
No.1 Enterprise Management Center (Limited Partnership) (“Beijing Happiness Star”) |
|
Li Hongqi and Li Hongliang
each holds 42.98% of the equity interest but Beijing Happiness Star is controlled by Li Hongliang. |
| Sichuan TIBO Fluid Technology
Co., Ltd. (“Sichuan TIBO”) |
|
An equity investee of the
Company. On February 8, 2025, the Company sold its equity interest in Sichuan TIBO to a third party. |
The
following related party balances are non-interest bearing as of March 31, 2026 and September 30, 2025:
SCHEDULE OF RELATED PARTY TRANSACTIONS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Amounts due to related parties: | |
| | | |
| | |
| Li Hongqi (1) | |
$ | 4,387,911 | | |
$ | 4,254,385 | |
| Li Hongliang (1) | |
| 1,549,617 | | |
| 1,501,432 | |
| Amount
due from related party | |
$ | 5,937,528 | | |
$ | 5,755,817 | |
| | |
| | | |
| | |
| Loan receivable - related party: | |
| | | |
| | |
| Beijing Happiness Star (2) | |
$ | 631,035 | | |
$ | - | |
| Loan
receivable from a related party | |
$ | 631,035 | | |
$ | - | |
The
following are related party transactions for the six months ended March 31, 2026 and 2025:
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Revenues: | |
| | | |
| | |
| Equipment sales to Sichuan TIBO Fluid Technology Co., Ltd. | |
$ | - | | |
$ | 843,144 | |
| LNG/CNG sales to Sichuan Hongzhuo Shuya Energy Co., Ltd. | |
| - | | |
| 2,152,526 | |
| Revenues | |
$ | - | | |
$ | 2,995,670 | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Leases | |
| | | |
| | |
| Sichuan TIBO Fluid Technology Co., Ltd. (Lessor) | |
$ | - | | |
$ | 44,930 | |
| Li Hongliang | |
| 7,697 | | |
| 8,232 | |
| Li Hongqi | |
| 22,745 | | |
| 28,940 | |
| Factory
lease | |
$ | 30,442 | | |
$ | 82,102 | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Purchase of equipment: | |
| | | |
| | |
| Sichuan TIBO Fluid Technology Co., Ltd. | |
$ | - | | |
$ | 2,243,086 | |
| Purchase
of equipment | |
$ | - | | |
$ | 2,243,086 | |
NOTE
17 – EQUITY
Cash
dividends declared and paid
On
September 30, 2025, the shareholders of Huayou Huitong approved a dividend distribution of RMB 984,209
($140,285) to its
shareholders, of which RMB 492,105
($70,143)
would be paid to China Oil Blue Ocean, the controlling shareholder, and RMB 492,104
($70,142)
to Xi’an De’an New Material Technology Co., Ltd. (“Xi’an De’an New Material”), the then
non-controlling shareholder. All dividends were paid in cash on December 8, 2025.
Non-controlling
interests
Non-controlling
interests consist of the following:
SCHEDULE OF NON - CONTROLLING INTERESTS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
Huayou Huitong | |
| Paid-in capital | |
$ | - | | |
$ | 53,405 | |
| Deficit | |
| - | | |
| (11,473 | ) |
| Accumulated other comprehensive loss | |
| - | | |
| (17,167 | ) |
| Total non-controlling interests | |
$ | - | | |
$ | 24,765 | |
Huayou
Huitong is a limited liability company incorporated on May 29, 2020, under the laws of China; China Oil Blue Ocean holds a 51% equity
interest. In November 2025, China Oil Blue Ocean signed equity transaction agreements with Xi’an De’an New Material to purchase
49% of the equity interest. The total purchase price for the equity interest was RMB 298,585 ($42,559). As a result of the equity transaction,
China Oil Blue Ocean owns 100% of the equity in Huayou Huitong. As of March 31, 2026, the Company had no non-controlling interests.
Restricted
net assets
The
Company’s ability to pay dividends is primarily dependent on the Company receiving distributions of funds from its PRC operating
subsidiaries. Relevant PRC statutory laws and regulations permit payments of dividends by the Company’s PRC subsidiaries only out
of their retained earnings, if any, as determined in accordance with PRC accounting standards and regulations. The results of operations
reflected in the consolidated financial statements prepared in accordance with GAAP differ from those reflected in the statutory financial
statements of the Company’s subsidiaries. As of March 31, 2026 and September 30, 2025, restricted net assets of the Company’s
PRC subsidiaries were $8,169,003 and $3,308,960, respectively.
NOTE
18 – TAXES
Enterprise
income taxes (“EIT”)
The
Company is subject to income taxes on an entity basis on income derived from the location in which each entity is domiciled.
Leishen
Energy Holding Co., Ltd. is incorporated in Cayman Islands as an offshore holding company and is not subject to tax on income or capital
gains under the laws of Cayman Islands.
Leishen
Energy Group Holding Co., Limited is incorporated in Hong Kong as a holding company with no activities. Under the Hong Kong tax laws,
an entity is not subject to income tax if no revenue is generated in Hong Kong.
Leishen
Energy Group Co., Limited is incorporated in Hong Kong, exempted from profit tax on its foreign-sourced income, and there are no withholding
taxes in Hong Kong on remittance of dividends.
Under
the Enterprise Income Tax (“EIT”) Law of the PRC, domestic enterprises and Foreign Investment Enterprises (the “FIE”)
are subject to a unified 25% EIT rate while preferential tax rates, tax holidays, and even tax exemptions may be granted on case-by-case
basis. The PRC tax authorities grant preferential tax treatment to High and New Technology Enterprises (“HNTEs”). Under this
preferential tax treatment, HNTEs are entitled to an income tax rate of 15%, subject to a requirement that they re-apply for HNTE status
every three years. Since China Oil Blue Ocean was approved as an HNTE in December 2022, China Oil Blue Ocean is entitled to a reduced
income tax rate of 15% beginning October 2022 and is able to enjoy the reduced income tax rate through October 2025. In October 2025,
China Oil Blue Ocean renewed its HNTE certification for another three years. Since ZJY Technologies was approved as an HNTE in December
2022, ZJY Technologies is entitled to a reduced income tax rate of 15% beginning October 2022 and is able to enjoy the reduced income
tax rate through October 2025. In December 2025, ZJY Technologies renewed its HNTE certification for another three years.
ASC
740-10-25 prescribes a more-likely-than-not threshold for financial statement recognition and measurement of a tax position taken (or
expected to be taken) in a tax return. It also provides guidance on the recognition of income tax assets and liabilities, classification
accounting for interest and penalties associated with tax positions, years open for tax examination, accounting for income taxes in interim
periods and income tax disclosures. Deferred tax assets and liabilities are determined based on the difference between the financial
reporting and tax bases of assets and liabilities using enacted tax rates that will be in effect in the period in which the differences
are expected to reverse. The Company records a valuation allowance to offset deferred tax assets if, based on the weight of available
evidence, it is more-likely-than-not that some portion, or all, of the deferred tax assets will not be realized. There were no material
uncertain tax positions as of March 31, 2026 and September 30, 2025. As of the date of which the condensed consolidated financial statements
is released, the tax years ended December 31, 2021 through December 31, 2025 for the Company’s PRC subsidiaries remain open for
statutory examination for PRC tax.
(Loss)
income before income taxes consisted of:
SCHEDULE OF INCOME BEFORE PROVISION FOR INCOME TAXES
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
The
income tax (benefit) expense is consisted of the following:
SCHEDULE OF PROVISION FOR INCOME TAX
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Current | |
| | | |
| | |
| China | |
$ | 31,211 | | |
$ | (40,787 | ) |
| Current | |
$ | 31,211 | | |
$ | (40,787 | ) |
| Deferred | |
| | | |
| | |
| China | |
| (148,385 | ) | |
| 55,422 | |
| Deferred | |
| (148,385 | ) | |
| 55,422 | |
| Income tax (benefit) expense | |
$ | (117,174 | ) | |
$ | 14,635 | |
The
following table reconciles the statutory rate to the Company’s effective tax rate:
SCHEDULE OF STATUTORY RATE OF EFFECTIVE TAX RATE
| | |
| | | |
| | | |
| | | |
| | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Income tax at expected tax rates | |
$ | (488,479 | ) | |
| 25.0 | % | |
$ | (238,505 | ) | |
| 25.0 | % |
| Additional deduction of research and development expenses | |
| (14,617 | ) | |
| 0.7 | % | |
| (12,980 | ) | |
| 1.4 | % |
| Non-deductible expenses | |
| 23,652 | | |
| (1.2 | )% | |
| 14,911 | | |
| (1.6 | )% |
| Effect of PRC preferential tax rates (1) | |
| (1,240,612 | ) | |
| 63.6 | % | |
| 202,166 | | |
| (21.1 | )% |
| Non-PRC entities not subject to PRC tax (2) | |
| 585,288 | | |
| (30.0 | )% | |
| 20,217 | | |
| (2.2 | )% |
| Change of valuation allowance (3) | |
| 1,017,594 | | |
| (52.1 | )% | |
| - | | |
| - | |
| Other | |
| - | | |
| - | | |
| 28,826 | | |
| (3.0 | )% |
| Effective tax rate | |
$ | (117,174 | ) | |
| 6.0 | % | |
$ | 14,635 | | |
| (1.5 | )% |
| (1) |
For
the six months ended March 31,2026, net income generated by Xinjiang Breslin was offset by the losses of other subsidiaries of the
Company, therefore the preferential tax rate of Xinjiang Breslin increased the overall effective tax rate of the Company. |
| |
|
| (2) |
|
| |
|
| (3) |
|
Deferred
tax assets and liabilities
Components
of deferred tax assets and liabilities were as follows:
SCHEDULE OF COMPONENTS OF DEFERRED TAX ASSETS AND LIABILITIES
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Deferred tax assets | |
| | | |
| | |
| Allowance for doubtful accounts | |
$ | 1,525,526 | | |
$ | 1,229,011 | |
| Impairment of a long-term investment | |
| | | |
| | |
| Unbilled cost | |
| 4,045,974 | | |
| 3,533,431 | |
| Net operating loss carryforwards | |
| 1,017,594 | | |
| 408,789 | |
| Total deferred tax assets | |
| 6,589,094 | | |
| 5,171,231 | |
| Less: valuation allowance | |
| (1,017,594 | ) | |
| - | |
| Deferred tax assets, net | |
| 5,571,500 | | |
| 5,171,231 | |
| Deferred tax liabilities | |
| | | |
| | |
| Unbilled revenue | |
| (4,692,113 | ) | |
| (4,350,674 | ) |
| Other | |
| (110,478 | ) | |
| (218,299 | ) |
| Total deferred tax liabilities | |
| (4,802,591 | ) | |
| (4,568,973 | ) |
| Net deferred tax assets | |
$ | 768,909 | | |
$ | 602,258 | |
Taxes
Payable
Taxes
payable consisted of the following:
SCHEDULE OF TAXES PAYABLE
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| VAT payable | |
$ | 1,629,024 | | |
$ | 857,680 | |
| Income taxes payable | |
| 2,990,430 | | |
| 2,915,661 | |
| Other | |
| 9,484 | | |
| 8,397 | |
| Total | |
$ | 4,628,938 | | |
$ | 3,781,738 | |
Uncertain
tax positions
There
were no uncertain tax positions as of March 31, 2026 and September 30, 2025 and management does not anticipate any potential future adjustments
which would result in a material change to its tax positions.
NOTE
19 – COMMITMENTS AND CONTINGENCIES
Contingencies
From
time to time, the Company may be subject to legal proceedings, claims and disputes that arise in the ordinary course of business. Amounts
accrued, as well as the total amount of possible losses with respect to such matters, individually and in the aggregate, are not deemed
to be material to the unaudited condensed consolidated financial statements.
NOTE
20 – SEGMENT INFORMATION
The
Company follows the guidance of ASC 280, “Segment Reporting,” which establishes standards for reporting information about
operating segments on a basis consistent with the Company’s internal organizational structure. The Company uses the management
approach to determine reportable operating segments. The Company has determined that it has four reportable operating segments: (i) clean-energy
equipment; (ii) digitalization and integration equipment; (iii) new energy; and (iv) oil and gas engineering technical services. These
segments are organized based on the nature of products and services offered and the way they are managed. The Company currently sells
its products primarily within China, consequently no segment information based on geography is disclosed.
Chief
Operating Decision Maker (“CODM”)
The
Company’s Chief Executive Officer (“CEO”) has been identified as the CODM. The CEO reviews segment operating results,
including segment revenues, total cost of revenues and gross profit on a quarterly and annual basis to evaluate the performance of each
operating segment and make decisions about the allocation of resources to individual segments. The CODM uses gross profit as the primary
measure of segment profit or loss for all four reportable segments.
Significant
Expense Categories Reviewed by the CODM
For
each reportable segment, on a quarterly basis, the CODM reviews the main reasons for period-to-period (and actual vs. prior) fluctuations
in total cost of revenues and evaluates their impact on gross margin.
The
CODM does not allocate any of the following corporate expenses: selling and marketing expenses, general and administrative expenses,
provision for expected credit losses, research and development expenses, interest expense, and income taxes in his evaluation of the
quarterly and annual segment operating results as such expenses are managed and reviewed at the consolidated level.
Segment
Information
The
tables below summarize the Company’s segment operating results for the six months ended March 31, 2026 and 2025:
SCHEDULE OF OPERATING SEGMENT INFORMATION
| | |
| | |
| | |
| | |
| | |
| |
| | |
Six Months Ended March 31, 2026 | |
| | |
Clean-energy
equipment | | |
Digitalization
and integration
equipment | | |
New energy
production
and operation | | |
Oil and gas
engineering
technical
services | | |
Total | |
| | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | |
| Revenues | |
$ | 10,412,332 | | |
$ | 2,226,141 | | |
$ | 6,454,584 | | |
$ | 1,885,371 | | |
$ | 20,978,428 | |
| Cost of revenues | |
| 6,842,781 | | |
| 2,064,862 | | |
| 6,276,614 | | |
| 569,343 | | |
| 15,753,600 | |
| Gross profit | |
$ | 3,569,551 | | |
$ | 161,279 | | |
$ | 177,970 | | |
$ | 1,316,028 | | |
$ | 5,224,828 | |
| | |
| | |
| | |
| | |
| | |
| |
| | |
Six Months Ended March 31, 2025 | |
| | |
Clean-energy
equipment | | |
Digitalization
and integration
equipment | | |
New energy
production
and operation | | |
Oil and gas
engineering
technical
services | | |
Total | |
| | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | | |
(Unaudited) | |
| Revenues | |
$ | 13,196,043 | | |
$ | 2,629,399 | | |
$ | 10,337,148 | | |
$ | 2,032,694 | | |
$ | 28,195,284 | |
| Cost of revenues | |
| 10,528,452 | | |
| 2,032,358 | | |
| 10,178,056 | | |
| 517,387 | | |
| 23,256,253 | |
| Gross profit | |
$ | 2,667,591 | | |
$ | 597,041 | | |
$ | 159,092 | | |
$ | 1,515,307 | | |
$ | 4,939,031 | |
Reconciliation
of Segment Profit (Gross Profit) to Consolidated Income Before Income Taxes
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Total segment profit (gross profit) | |
$ | 5,224,828 | | |
$ | 4,939,031 | |
| Corporate expenses: | |
| | | |
| | |
| Selling and marketing expenses | |
| (1,535,890 | ) | |
| (635,306 | ) |
| General and administrative expenses | |
| (2,133,900 | ) | |
| (3,045,282 | ) |
| Provision for expected credit losses | |
| (2,145,919 | ) | |
| (3,317,683 | ) |
| Research and development expenses | |
| (97,448 | ) | |
| (163,008 | ) |
| Total operating expenses | |
| (5,913,157 | ) | |
| (7,161,279 | ) |
| Loss from operations | |
| (688,329 | ) | |
| (2,222,248 | ) |
| Other (expense) income, net | |
| (1,265,584 | ) | |
| 1,268,228 | |
Reconciliation
of Segments’ assets to the Consolidated assets.
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Clean-energy equipment | |
$ | 54,895,295 | | |
$ | 44,096,905 | |
| Digitalization and integration equipment | |
| 9,201,480 | | |
| 7,904,522 | |
| New energy production and operation | |
| 2,142,356 | | |
| 1,658,836 | |
| Oil and gas engineering technical services | |
| 37,180,355 | | |
| 23,558,598 | |
| Other corporate assets | |
| 31,641,977 | | |
| 46,535,830 | |
| Total assets | |
$ | 135,061,463 | | |
$ | 123,754,691 | |
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| Total assets related to reportable segments | |
$ | 103,419,486 | | |
$ | 77,218,861 | |
| Other corporate assets | |
| 31,641,977 | | |
| 46,535,830 | |
| Elimination of intercompany balances | |
| (64,802,908 | ) | |
| (54,422,059 | ) |
| Total consolidated assets | |
$ | 70,258,555 | | |
$ | 69,332,632 | |
NOTE
21 – SUBSEQUENT EVENTS
On
May 29, 2026, Beijing Chenghui, ZJY Technologies, Leishen Shandong, and Sichuan TIBO (which is a supplier of the Company) executed a
debt offset agreement, under which Beijing Chenghui directly repays to Sichuan TIBO all principal and interest owed to ZJY Technologies,
and all chain debts among the four parties are simultaneously settled in full.
In
June 2026, the Company filed a registration statement on Form F-3 with the SEC that was declared effective on June 18, 2026. In
accordance with the F-3, the Company may offer issue and sell its registered securities from time to time up to $150,000,000,
or its equivalent in any other currency, currency units, or composite currency or currencies, of its Class A ordinary shares of par
value $0.001
each, warrants to purchase Class A Ordinary Shares, debt securities, rights and a combination of such securities, separately or as
units, in one or more offerings. The Company has not sold any securities under the Form F-3. Any such offering would be made pursuant to a prospectus
supplement filed with the SEC.
In
August 2026, Suqian Asgard Energy Service Co., Ltd (“Suqian Asgard”) was incorporated in Suqian Jiangsu Province, China.
Suqian Asgard is 100% controlled by Xinjiang Breslin and it currently has no business operations.
NOTE
22 – PARENT COMPANY INFORMATION
Pursuant
to the requirements of Rule 12-04(a), 5-04(c) and 4-08(e)(3) of Regulation S-X, the condensed financial information of the parent company
shall be filed when the restricted net assets of consolidated subsidiaries exceed 25% of consolidated net assets as of the end of the
most recently completed fiscal year. The Company performed a test on the restricted net assets of consolidated subsidiaries in accordance
with such requirement and concluded that it was applicable to the Company as the restricted net assets of the Company’s PRC subsidiary
exceeded 25% of the consolidated net assets of the Company. Therefore, the condensed financial statements for the parent company are
included herein.
For
purposes of the above test, restricted net assets of consolidated subsidiaries shall mean that amount of the Company’s proportionate
share of net assets of consolidated subsidiaries (after intercompany eliminations) which as of the end of the most recent fiscal year
may not be transferred to the parent company by subsidiaries in the form of loans, advances or cash dividends without the consent of
a third party.
The
condensed financial information of the parent company was prepared using the same accounting policies as set out in the Company’s
condensed consolidated financial statements except that the parent company used the equity method to account for investment in its subsidiaries.
Such investment is presented on the condensed balance sheets as “Investment in subsidiaries” and the respective profit or
loss as “Equity in earnings of subsidiaries” on the condensed statements of operations.
As
of March 31, 2026 and September 30, 2025, and six months ended March 31, 2026 and 2025, there were no material contingencies, significant
provisions for long-term obligations, or guarantees of the Company, except for those which have been separately disclosed in the condensed
consolidated financial statements, if any.
PARENT
COMPANY BALANCE SHEETS
SCHEDULE OF PARENT COMPANY BALANCE SHEETS
| | |
March 31, 2026 | | |
September 30, 2025 | |
| | |
(Unaudited) | | |
| |
| ASSETS | |
| | | |
| | |
| Current assets: | |
| | | |
| | |
| Cash and cash equivalents | |
$ | 2,890,744 | | |
$ | 3,497,762 | |
| Amounts due from a subsidiary | |
| 1,600,000 | | |
| 1,500,000 | |
| Total current assets | |
| 4,490,744 | | |
| 4,997,762 | |
| | |
| | | |
| | |
| Non-current assets: | |
| | | |
| | |
| Investment in subsidiaries | |
| 40,085,401 | | |
| 40,434,973 | |
| Total non-current assets | |
| 40,085,401 | | |
| 40,434,973 | |
| | |
| | | |
| | |
| Total Assets | |
$ | 44,576,145 | | |
$ | 45,432,735 | |
| | |
| | | |
| | |
| LIABILITIES AND EQUITY | |
| | | |
| | |
| | |
| | | |
| | |
| LIABILITIES | |
$ | - | | |
$ | - | |
| | |
| | | |
| | |
| COMMITMENTS AND CONTINGENCIES | |
| - | | |
| - | |
| | |
| | | |
| | |
| EQUITY | |
| | | |
| | |
| Ordinary shares Ordinary shares (par value $0.001 per share, 50,000,000 shares authorized; 17,025,000 and 17,025,000 shares issued and outstanding as of September 30, 2025.) | |
| - | | |
| 17,025 | |
| Class A Ordinary Shares (par value $0.001 per share, 467,290,000 shares authorized, 4,315,000 shares issued and outstanding as of March 31, 2026) | |
| 4,315 | | |
| - | |
| Class B Ordinary Shares (par value $0.001 per share, 32,710,000 shares authorized, 12,710,000 shares issued and outstanding as of March 31, 2026) | |
| 12,710 | | |
| - | |
| Ordinary Shares, value | |
| 12,710 | | |
| - | |
| Subscription receivable | |
| (15,500 | ) | |
| (15,500 | ) |
| Additional paid-in capital | |
| 6,526,821 | | |
| 6,544,298 | |
| Statutory reserves | |
| 2,592,642 | | |
| 2,076,469 | |
| Retained earnings | |
| 35,784,864 | | |
| 38,207,918 | |
| Accumulated other comprehensive loss | |
| (329,707 | ) | |
| (1,397,475 | ) |
| Total Equity | |
| 44,576,145 | | |
| 45,432,735 | |
| | |
| | | |
| | |
| Total Liabilities and Equity | |
$ | 44,576,145 | | |
$ | 45,432,735 | |
PARENT
COMPANY STATEMENTS OF OPERATIONS AND COMPREHENSIVE LOSS
SCHEDULE OF PARENT
COMPANY STATEMENTS OF OPERATIONS AND COMPREHENSIVE INCOME
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Equity in loss of subsidiaries | |
$ | (1,329,721 | ) | |
$ | (372,214 | ) |
| | |
| | | |
| | |
| Operating expenses: | |
| | | |
| | |
| Selling and marketing | |
| (35,000 | ) | |
| - | |
| General and administrative | |
| (403,835 | ) | |
| (288,023 | ) |
| Total Operating expenses | |
| (438,835 | ) | |
| (288,023 | ) |
| | |
| | | |
| | |
| Other (expenses) income: | |
| | | |
| | |
| Other (expenses) income, net | |
| (68,183 | ) | |
| 43,346 | |
| Total other (expenses) income, net | |
| (68,183 | ) | |
| 43,346 | |
| | |
| | | |
| | |
| Net loss | |
$ | (1,836,739 | ) | |
$ | (616,891 | ) |
| Foreign currency translation gain (loss) | |
| 1,067,768 | | |
| (928,194 | ) |
| Comprehensive loss | |
$ | (768,971 | ) | |
$ | (1,545,085 | ) |
PARENT
COMPANY STATEMENTS OF CASH FLOWS
SCHEDULE OF PARENT COMPANY STATEMENTS OF CASH FLOWS
| | |
2026 | | |
2025 | |
| | |
Six Months Ended March 31, | |
| | |
2026 | | |
2025 | |
| | |
(Unaudited) | | |
(Unaudited) | |
| Cash flows from operating activities | |
| | | |
| | |
| Net loss | |
$ | (1,836,739 | ) | |
$ | (616,891 | ) |
| Adjustments to reconcile net loss to net cash used in operating activities: | |
| | | |
| | |
| Equity in loss of subsidiaries | |
| 1,329,721 | | |
| 372,214 | |
| Changes in other current assets | |
| - | | |
| (100 | ) |
| Changes in due from a subsidiary | |
| (100,000 | ) | |
| | |
| Net cash used in operating activities | |
| (607,018 | ) | |
| (244,777 | ) |
| | |
| | | |
| | |
| Cash flows from financing activities: | |
| | | |
| | |
| Net proceeds from initial public offering | |
| - | | |
| 5,380,488 | |
| Net cash provided by financing activities | |
| - | | |
| 5,380,488 | |
| | |
| | | |
| | |
| Net change in cash | |
| (607,018 | ) | |
| 5,135,711 | |
| Cash at the beginning of the period | |
| 3,497,762 | | |
| - | |
| Cash at the end of the period | |
$ | 2,890,744 | | |
$ | 5,135,711 | |