NOTICE OF ANNUAL AND SPECIAL MEETING OF SHAREHOLDERS
NOTICE IS HEREBY GIVEN that an annual and special meeting (the "Meeting") of the holders (the "Stroud Shareholders") of common shares ("Stroud Shares") of Stroud Resources Ltd. ("Stroud" or the "Corporation") will be held at 10:30 a.m. (Toronto time) on September 28, 2026 virtually with the following link:
https://teams.microsoft.com/meet/259414103806908?p=sZhVoHoWH9djsCCG13
Meeting ID: 259 414 103 806 908
Passcode: 6Jo6xZ3J
The Meeting will be held for the following purposes:
1. to receive and consider the audited consolidated financial statements of the Corporation for the financial years ended December 31, 2025 and 2024, together with the report of the auditor thereon;
2. to elect the directors of the Corporation for the ensuing year;
3. to re-appoint McGovern Hurley LLP, Chartered Professional Accountants, as auditor of the Corporation for the ensuing year and to authorize the directors to fix the remuneration to be paid to the auditor;
4. to consider and, if thought advisable, to pass, with or without variation, a special resolution (the "Amalgamation Resolution"), the full text of which is set forth in Appendix "A" to the accompanying management information circular (the "Circular"), approving the amalgamation (the "Amalgamation") of the Corporation with 1001629888 Ontario Inc. ("Subco"), a wholly-owned subsidiary of Silver Hammer Mining Corp. ("Silver Hammer"), pursuant to section 174 of the Business Corporations Act (Ontario) (the "OBCA") and on the terms and conditions set out in the business combination agreement dated July 17, 2026 among the Corporation, Silver Hammer and Subco (the "Combination Agreement"); and
5. to transact such other business as may properly come before the Meeting or any adjournment or postponement thereof.
The full text of the Combination Agreement is attached as Appendix "C" to the Circular and is also available under Stroud's profile on SEDAR+ at www.sedarplus.ca.
In order to become effective, the Amalgamation Resolution will require the affirmative vote of at least two-thirds (662⁄3%) of the votes cast by the Stroud Shareholders who vote in person or by proxy at the Meeting. In accordance with MI 61-101, Stroud will also be required to obtain "minority approval" (as defined in MI 61-101) of the Amalgamation Resolution, meaning the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Full details of the Amalgamation are provided in the Circular, which forms part of this notice.
The board of directors of the Corporation has set the close of business on August 25, 2026 (the "Record Date") as the record date for determining Stroud Shareholders who are entitled to receive notice of and to vote at the Meeting. Only Stroud Shareholders of record at the close of business on the Record Date are entitled to vote at the Meeting. The failure of any Stroud Shareholder to receive notice of the Meeting does not deprive such Stroud Shareholder of the right to vote at the Meeting.
DISSENT RIGHTS. Registered Stroud Shareholders have the right to dissent in respect of the Amalgamation Resolution and, if the Amalgamation becomes effective, to be paid the fair value of their Stroud Shares in accordance with section 185 of the OBCA. A registered Stroud Shareholder who wishes to dissent must send a written objection to the Amalgamation Resolution to the Corporation at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, Attention: Mirsad Jakubovic, at or before the Meeting. Failure to strictly comply with the requirements set forth in section 185 of the OBCA may result in the loss of any right of dissent. Persons who are beneficial owners of Stroud Shares registered in the name of an intermediary who wish to dissent should be aware that only registered holders of Stroud Shares are entitled to dissent. See "Dissenting Shareholder Rights" in the Circular and Appendix "B" thereto.
Whether or not you intend to attend the Meeting, if you wish to vote your Stroud Shares you are required to complete, sign, date and return the enclosed form of proxy to TSX Trust Company (Attention: Proxy Department) at 301 - 100 Adelaide Street West, Toronto, Ontario M5H 4H1, or vote online at www.voteproxyonline.com using the 12-digit control number found on your form of proxy, in each case not later than 48 hours (excluding Saturdays, Sundays and statutory holidays) prior to the time of the Meeting.
If you are a registered Stroud Shareholder, please also complete and return the accompanying Letter of Transmittal in accordance with the instructions included therein.
DATED at Toronto, Ontario this 28th day of August, 2026.
BY ORDER OF THE BOARD OF DIRECTORS OF STROUD RESOURCES LTD.
(Signed) "Jeff Kennedy"
Director, Stroud Resources Ltd.
STROUD RESOURCES LTD.
NOTICE OF ANNUAL AND SPECIAL MEETING OF SHAREHOLDERS
- and -
MANAGEMENT INFORMATION CIRCULAR OF
STROUD RESOURCES LTD.
WITH RESPECT TO, AMONG OTHER THINGS, THE PROPOSED BUSINESS
COMBINATION AND AMALGAMATION INVOLVING
STROUD RESOURCES LTD.
SILVER HAMMER MINING CORP.
- and -
1001629888 ONTARIO INC.
TO BE HELD ON SEPTEMBER 28, 2026 AT 10:30 a.m. (TORONTO TIME)
These materials are important and require your immediate attention. They require shareholders
("Stroud Shareholders") of Stroud Resources Ltd. ("Stroud" or the "Corporation") to make
important decisions. If you are in doubt as to how to make such decisions, please contact your
financial, legal, tax or other professional advisors.
Dated as of August 28,2026
The deadline for the receipt of proxies for the Meeting is no later than 48 hours (excluding
Saturdays, Sundays and statutory holidays) prior to the time of the Meeting.
No securities regulatory authority has in any way passed upon the merits of the business
combination described in this management information circular.
LETTER TO SHAREHOLDERS
August 28, 2026
Dear Stroud Shareholders:
The board of directors (the "Stroud Board") of Stroud Resources Ltd. ("Stroud") invites you to attend the annual and special meeting (the "Meeting") of the holders (the "Stroud Shareholders") of common shares (the "Stroud Shares") of Stroud to be held on September 28, 2026.
The Amalgamation
At the Meeting, Stroud Shareholders will be asked to consider and, if thought advisable, to pass, with or without variation, a special resolution (the "Amalgamation Resolution") approving an amalgamation (the "Amalgamation") of Stroud with 1001629888 Ontario Inc. ("Subco"), a wholly-owned subsidiary of Silver Hammer Mining Corp. ("Silver Hammer"), under section 174 of the Business Corporations Act (Ontario) (the "OBCA"), pursuant to a business combination agreement dated July 17, 2026 among Stroud, Silver Hammer and Subco (the "Combination Agreement").
Prior to the effective time of the Amalgamation, Silver Hammer will complete a consolidation of its common shares on the basis of one (1) post-consolidation share for each four (4) pre-consolidation shares (the "Consolidation"). If the Amalgamation is completed, each Stroud Shareholder (other than Stroud Shareholders who validly exercise Dissent Rights) will receive 0.777963 of a post-Consolidation common share of Silver Hammer for each Stroud Share held (the "Exchange Ratio"), being the equivalent of approximately 3.111852 pre-Consolidation Silver Hammer Shares for each Stroud Share.
Upon completion of the Amalgamation, Stroud will continue as the amalgamated corporation under the name "Stroud Resources Ltd." as a wholly-owned subsidiary of Silver Hammer, and Stroud Shareholders will become shareholders of Silver Hammer, which is expected to be renamed "Silver Frontier Resources Corp." (as so continued, the "Resulting Issuer"). The Resulting Issuer Shares will continue to be listed and posted for trading on the Canadian Securities Exchange (the "CSE") and the Stroud Shares will be delisted from the TSX Venture Exchange (the "TSXV").
The Amalgamation is being completed concurrently with, and is conditional upon, the satisfaction or waiver of the conditions to Silver Hammer's acquisition of SilverMark Resources Inc. ("SilverMark") and the completion by SilverMark of a concurrent brokered private placement of subscription receipts for minimum gross proceeds of $7,000,000 (the "Private Placement").
Further details regarding the Amalgamation can be found in the management information circular accompanying this letter (the "Circular") under the headings "The Amalgamation" and "Summary of the Combination Agreement".
Reasons for the Amalgamation
• The Exchange Ratio implies a value of $0.1867 per Stroud Share based on the closing price of the Silver Hammer Shares on the CSE on July 17, 2026 (the last trading day prior to announcement of the Transaction), representing a premium of 86.72% to the closing price of the Stroud Shares on the TSXV on that date.
• The Amalgamation provides Stroud Shareholders with continued participation in the Santo Domingo silver-gold project, together with exposure to Silver Hammer's silver assets in Idaho and Nevada and, indirectly, to SilverMark's rights in respect of a portfolio of mineral assets in Morocco.
• The Resulting Issuer is expected to be capitalized by the Private Placement of a minimum of $7,000,000 and up to $10,000,000 (or such greater amount as may be determined by the parties), which Stroud has been unable to raise on a stand-alone basis.
• Stroud Shareholders will receive freely tradeable securities of a larger issuer listed on the CSE, which is expected to provide greater liquidity and a broader capital markets following than the Stroud Shares currently enjoy.
• The Combination Agreement was negotiated at arm's length and the Stroud Board retains the ability to consider and respond to a Superior Proposal prior to completion of the Amalgamation, subject to Silver Hammer's right to match and the payment of a $500,000 Compensation Fee in specified circumstances.
• Registered Stroud Shareholders who oppose the Amalgamation may, on strict compliance with section 185 of the OBCA, exercise Dissent Rights and be paid the fair value of their Stroud Shares.
Stroud Board Recommendation
The Stroud Board has unanimously determined that the Amalgamation is in the best interests of Stroud and is fair to Stroud Shareholders, and unanimously recommends that Stroud Shareholders vote FOR the Amalgamation Resolution.
Voting Support Agreements
In connection with the execution of the Combination Agreement, Silver Hammer entered into voting support agreements (the "Voting Support Agreements") with each member of the Stroud Board, each officer of Stroud, and each Stroud Shareholder holding, directly or indirectly, more than 10% of the Stroud Shares, including 2176423 Ontario Ltd., a corporation beneficially owned by Mr. Eric Sprott, which holds 37,277,777 Stroud Shares, representing approximately 58.59% of the outstanding Stroud Shares on a non-diluted basis. Together, those securityholders hold 39,053,643 Stroud Shares, representing approximately 61.38% of the outstanding Stroud Shares on a non-diluted basis. Under the Voting Support Agreements, those securityholders have agreed, among other things, to vote their Stroud Shares in favour of the Amalgamation Resolution and not to exercise Dissent Rights.
In the aggregate, holders of approximately 61.38% of the outstanding Stroud Shares have agreed to vote in favour of the Amalgamation Resolution.
Approval Requirements
The Amalgamation Resolution will require the affirmative vote of at least two-thirds (662⁄3%) of the votes cast by the Stroud Shareholders who vote in person or by proxy at the Meeting.
In accordance with MI 61-101, Stroud will also be required to obtain "minority approval" (as defined in MI 61-101) of the Amalgamation Resolution, meaning the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Subject to receiving Stroud Shareholder approval and the satisfaction or waiver of the other conditions to completion of the Amalgamation, the Amalgamation is currently anticipated to be completed on or about October 15, 2026. Under the Combination Agreement, either party may terminate if the Amalgamation has not been completed by November 30, 2026.
Annual Business
Because the Meeting is an annual and special meeting, Stroud Shareholders will also be asked to receive the audited consolidated financial statements of the Corporation for the financial years ended December 31, 2025 and 2024, to elect directors for the ensuing year and to re-appoint the auditor of the Corporation.
Delivery of Meeting Materials
Stroud has not elected to use the notice-and-access provisions of National Instrument 54-101 Communication with Beneficial Owners of Securities of a Reporting Issuer ("NI 54-101") in respect of the Meeting. Proxy-related materials are being sent to registered Stroud Shareholders and, through intermediaries, to non-objecting beneficial owners of Stroud Shares. Stroud is not sending proxy-related materials directly to non-objecting beneficial owners and is not paying for delivery of proxy-related materials to objecting beneficial owners.
How to Obtain Your Amalgamation Consideration
If you are a registered Stroud Shareholder, please complete and return the accompanying letter of transmittal (the "Letter of Transmittal") to Endeavor Trust Corporation, in its capacity as depositary, in accordance with the instructions contained therein.
Shareholder Questions
If you have any questions or require more information with regard to voting your shares, please contact TSX Trust Company at 1-866-600-5869.
On behalf of the Stroud Board, management and the employees of Stroud, I would like to express our gratitude for the support our shareholders have demonstrated.
Yours truly,
(Signed) "Jeff Kennedy"
Director, Stroud Resources Ltd.
YOUR VOTE IS IMPORTANT REGARDLESS OF THE NUMBER OF STROUD SHARES YOU OWN. PLEASE VOTE TODAY.
NOTICE OF ANNUAL AND SPECIAL MEETING OF SHAREHOLDERS
NOTICE IS HEREBY GIVEN that an annual and special meeting (the "Meeting") of the holders (the "Stroud Shareholders") of common shares ("Stroud Shares") of Stroud Resources Ltd. ("Stroud" or the "Corporation") will be held at 10:30 a.m. (Toronto time) on September 28, 2026 virtually with the following link:
https://teams.microsoft.com/meet/259414103806908?p=sZhVoHoWH9djsCCG13
Meeting ID: 259 414 103 806 908
Passcode: 6Jo6xZ3J
The Meeting will be held for the following purposes:
1. to receive and consider the audited consolidated financial statements of the Corporation for the financial years ended December 31, 2025 and 2024, together with the report of the auditor thereon;
2. to elect the directors of the Corporation for the ensuing year;
3. to re-appoint McGovern Hurley LLP, Chartered Professional Accountants, as auditor of the Corporation for the ensuing year and to authorize the directors to fix the remuneration to be paid to the auditor;
4. to consider and, if thought advisable, to pass, with or without variation, a special resolution (the "Amalgamation Resolution"), the full text of which is set forth in Appendix "A" to the accompanying management information circular (the "Circular"), approving the amalgamation (the "Amalgamation") of the Corporation with 1001629888 Ontario Inc. ("Subco"), a wholly-owned subsidiary of Silver Hammer Mining Corp. ("Silver Hammer"), pursuant to section 174 of the Business Corporations Act (Ontario) (the "OBCA") and on the terms and conditions set out in the business combination agreement dated July 17, 2026 among the Corporation, Silver Hammer and Subco (the "Combination Agreement"); and
5. to transact such other business as may properly come before the Meeting or any adjournment or postponement thereof.
The full text of the Combination Agreement is attached as Appendix "C" to the Circular and is also available under Stroud's profile on SEDAR+ at www.sedarplus.ca.
In order to become effective, the Amalgamation Resolution will require the affirmative vote of at least two-thirds (662⁄3%) of the votes cast by the Stroud Shareholders who vote in person or by proxy at the Meeting. In accordance with MI 61-101, Stroud will also be required to obtain "minority approval" (as defined in MI 61-101) of the Amalgamation Resolution, meaning the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Full details of the Amalgamation are provided in the Circular, which forms part of this notice.
The board of directors of the Corporation has set the close of business on August 25, 2026 (the "Record Date") as the record date for determining Stroud Shareholders who are entitled to receive notice of and to vote at the Meeting. Only Stroud Shareholders of record at the close of business on the Record Date are entitled to vote at the Meeting. The failure of any Stroud Shareholder to receive notice of the Meeting does not deprive such Stroud Shareholder of the right to vote at the Meeting.
DISSENT RIGHTS. Registered Stroud Shareholders have the right to dissent in respect of the Amalgamation Resolution and, if the Amalgamation becomes effective, to be paid the fair value of their Stroud Shares in accordance with section 185 of the OBCA. A registered Stroud Shareholder who wishes to dissent must send a written objection to the Amalgamation Resolution to the Corporation at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, Attention: Mirsad Jakubovic, at or before the Meeting. Failure to strictly comply with the requirements set forth in section 185 of the OBCA may result in the loss of any right of dissent. Persons who are beneficial owners of Stroud Shares registered in the name of an intermediary who wish to dissent should be aware that only registered holders of Stroud Shares are entitled to dissent. See "Dissenting Shareholder Rights" in the Circular and Appendix "B" thereto.
Whether or not you intend to attend the Meeting, if you wish to vote your Stroud Shares you are required to complete, sign, date and return the enclosed form of proxy to TSX Trust Company (Attention: Proxy Department) at 301 - 100 Adelaide Street West, Toronto, Ontario M5H 4H1, or vote online at www.voteproxyonline.com using the 12-digit control number found on your form of proxy, in each case not later than 48 hours (excluding Saturdays, Sundays and statutory holidays) prior to the time of the Meeting.
If you are a registered Stroud Shareholder, please also complete and return the accompanying Letter of Transmittal in accordance with the instructions included therein.
DATED at Toronto, Ontario this 28th day of August, 2026.
BY ORDER OF THE BOARD OF DIRECTORS OF STROUD RESOURCES LTD.
(Signed) "Jeff Kennedy"
Director, Stroud Resources Ltd.
TABLE OF CONTENTS
|
NOTICE TO U.S. STROUD SHAREHOLDERS THIS EXCHANGE OFFER OR BUSINESS COMBINATION IS MADE FOR THE SECURITIES OF A FOREIGN COMPANY. THE OFFER IS SUBJECT TO DISCLOSURE REQUIREMENTS OF A FOREIGN COUNTRY THAT ARE DIFFERENT FROM THOSE OF THE UNITED STATES. FINANCIAL STATEMENTS INCLUDED IN THE DOCUMENT, IF ANY, HAVE BEEN PREPARED IN ACCORDANCE WITH INTERNATIONAL FINANCIAL REPORTING STANDARDS, AS ISSUED BY THE INTERNATIONAL ACCOUNTING STANDARDS BOARD, WHICH MAY NOT BE COMPARABLE TO THE FINANCIAL STATEMENTS OF UNITED STATES COMPANIES. IT MAY BE DIFFICULT FOR YOU TO ENFORCE YOUR RIGHTS AND ANY CLAIM YOU MAY HAVE ARISING UNDER THE FEDERAL SECURITIES LAWS, SINCE THE ISSUER IS LOCATED IN A FOREIGN COUNTRY, AND SOME OR ALL OF ITS OFFICERS AND DIRECTORS MAY BE RESIDENTS OF A FOREIGN COUNTRY. YOU MAY NOT BE ABLE TO SUE A FOREIGN COMPANY OR ITS OFFICERS OR DIRECTORS IN A FOREIGN COURT FOR VIOLATIONS OF THE U.S. SECURITIES LAWS. IT MAY BE DIFFICULT TO COMPEL A FOREIGN COMPANY AND ITS AFFILIATES TO SUBJECT THEMSELVES TO A U.S. COURT'S JUDGMENT. |
MANAGEMENT INFORMATION CIRCULAR
Introduction
This management information circular (the "Circular") is furnished in connection with the solicitation of proxies by and on behalf of the management of Stroud Resources Ltd. ("Stroud" or the "Corporation") for use at the annual and special meeting (the "Meeting") of the holders of common shares of Stroud (the "Stroud Shareholders") to be held on September 28, 2026, and at any adjournments or postponements thereof. No person has been authorized to give any information or make any representation in connection with the Amalgamation or any other matters to be considered at the Meeting other than those contained in this Circular and, if given or made, any such information or representation must not be relied upon as having been authorized.
All summaries of, and references to, the Transaction, the Amalgamation, the Combination Agreement and the Amalgamation Agreement in this Circular are qualified in their entirety by reference to the complete text of those documents. Stroud Shareholders are urged to read carefully the full text of the Combination Agreement, a copy of which is attached as Appendix "C" to this Circular.
All capitalized terms used in this Circular but not otherwise defined herein have the meanings set forth under the heading "Glossary of Terms". Information contained in this Circular is given as of August 28th, 2026 unless otherwise stated.
The information concerning Silver Hammer, Subco and SilverMark contained in this Circular, including the appendices hereto, has been provided by or on behalf of Silver Hammer for inclusion in this Circular. Although Stroud has no knowledge that any statement contained herein taken from or based on such information is untrue or incomplete, Stroud assumes no responsibility for the accuracy or completeness of such information, or for any failure by Silver Hammer to disclose events which may have occurred or which may affect the completeness or accuracy of such information but which are unknown to Stroud.
This Circular does not constitute an offer to sell, or a solicitation of an offer to purchase, the securities to be issued under or in connection with the Transaction, or the solicitation of a proxy, in any jurisdiction in which, or from any person to whom, it is unlawful to make such an offer or solicitation.
THE SECURITIES ISSUABLE PURSUANT TO THE AMALGAMATION HAVE NOT BEEN APPROVED OR DISAPPROVED BY ANY CANADIAN SECURITIES REGULATORY AUTHORITY, THE UNITED STATES SECURITIES AND EXCHANGE COMMISSION OR ANY STATE SECURITIES REGULATORY AUTHORITY, NOR HAS ANY SUCH AUTHORITY PASSED UPON THE ACCURACY OR ADEQUACY OF THIS CIRCULAR.
FORWARD-LOOKING STATEMENTS
Certain statements in this Circular, including the documents incorporated by reference herein, are forward-looking statements that are not historical facts. Forward-looking statements are provided for the purpose of presenting information about management's current expectations and plans relating to the future and readers are cautioned that such statements may not be appropriate for other purposes. When used in this Circular, words such as "may", "will", "expect", "believe", "plan", "intend", "should", "anticipate" and similar expressions identify forward-looking statements.
In particular, this Circular contains forward-looking statements relating to the Transaction including, without limitation: the timing of the Meeting and the Silver Hammer Meeting; the satisfaction or waiver of the conditions to the completion of the Amalgamation, the SilverMark Amalgamation and the Private Placement; the anticipated Effective Date; the completion of the Consolidation; the Exchange Ratio and the number of Resulting Issuer Shares to be issued; the treatment of the Stroud Options; the expected name, board of directors, management, capital structure and business of the Resulting Issuer; the listing of the Resulting Issuer Shares on the CSE and the delisting of the Stroud Shares from the TSXV; the expected benefits of the Transaction; the exploration and development plans in respect of Santo Domingo and the other properties of the Resulting Issuer; and the Canadian federal income tax consequences of the Amalgamation.
Since forward-looking statements address future events and conditions, they involve known and unknown risks, uncertainties and other factors that may cause actual results or events to differ materially from those anticipated. These include, without limitation, the failure to obtain the required Stroud Shareholder, Silver Hammer Shareholder, SilverMark shareholder, TSXV, CSE or other regulatory approvals; the failure to complete the Private Placement for minimum gross proceeds; the failure to satisfy the other conditions to the Amalgamation; the exercise of Dissent Rights in respect of more than 5% of the Stroud Shares; the exercise of termination rights under the Combination Agreement; the risks inherent in mineral exploration; commodity price volatility; political, regulatory, permitting and title risks in Mexico and Morocco; currency fluctuations; and the other risks described under "Risk Factors Relating to the Amalgamation" and in the documents incorporated by reference in this Circular.
The reader is cautioned that the foregoing list of factors is not exhaustive. Forward-looking statements are made as of the date of this Circular and, except as required by applicable securities laws, Stroud assumes no obligation to update or revise them.
REPORTING CURRENCIES AND ACCOUNTING PRINCIPLES
The financial statements of, and summaries of financial information concerning, Stroud and Silver Hammer contained or incorporated by reference in this Circular are reported in Canadian dollars and have been prepared in accordance with International Financial Reporting Standards. All references to "$" in this Circular are to Canadian dollars unless otherwise indicated.
GLOSSARY OF TERMS
Unless the context otherwise requires, when used in this Circular the following terms have the meanings set forth below.
"Acquisition Proposal" has the meaning ascribed to it under "Summary of the Combination Agreement - No Solicitation";
"affiliate" has the meaning ascribed thereto in National Instrument 45-106 Prospectus Exemptions;
"Agents" means Red Cloud Securities Inc. as lead agent and sole bookrunner, together with any other agents forming part of the syndicate in connection with the Private Placement;
"Agents' Option" means the option granted to the Agents, exercisable in full or in part up to 48 hours prior to the closing of the Offering, to sell up to an additional 7,692,308 Subscription Receipts at the Offering Price for additional gross proceeds of up to C$2,000,000";
"Amalco" means Stroud Resources Ltd., being the corporation continuing from the amalgamation of Stroud and Subco, which will be a wholly-owned subsidiary of Silver Hammer;
"Amalco Shares" means the common shares in the capital of Amalco;
"Amalgamation" means the amalgamation of Stroud and Subco under section 174 of the OBCA on the terms and conditions set out in the Amalgamation Agreement, as contemplated by the Combination Agreement;
"Amalgamation Agreement" means the amalgamation agreement to be entered into among Silver Hammer, Stroud and Subco, substantially in the form attached as Schedule "A" to the Combination Agreement;
"Amalgamation Consideration" means 0.777963 of a post-Consolidation Silver Hammer Share for each Stroud Share;
"Amalgamation Resolution" means the special resolution of the Stroud Shareholders approving the Amalgamation, substantially in the form set out in Appendix "A" to this Circular, which must, in order to become effective, receive the vote of (i) at least two-thirds (662⁄3%) of the votes cast by the Stroud Shareholders who vote in person or by proxy at the Meeting; and (ii) the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101";
"Applicable Securities Laws" means all applicable securities laws of the provinces and territories of Canada and the respective rules, regulations, instruments, blanket orders and published policies made thereunder;
"Articles of Amalgamation" means the articles of amalgamation required under the OBCA to be filed with the Director in connection with the Amalgamation;
"Beneficial Stroud Shareholders" means persons who are beneficial holders of Stroud Shares that are not registered in their own names;
"Business Day" means any day, other than a Saturday, a Sunday or a statutory holiday in Toronto, Ontario;
"Certificate of Amalgamation" means the certificate of amalgamation issued by the Director under subsection 178(4) of the OBCA in connection with the Amalgamation;
"Circular" means this notice of annual and special meeting of shareholders and management information circular of Stroud;
"Combination Agreement" means the business combination agreement dated July 17, 2026 among Stroud, Silver Hammer and Subco, together with the schedules attached thereto, as amended, amended and restated or supplemented from time to time, a copy of which is attached as Appendix "C" to this Circular;
"Compensation Fee" means the fee of $500,000 payable in the circumstances described under "Summary of the Combination Agreement - Compensation Fee";
"Consolidation" means the consolidation of the Silver Hammer Shares on the basis of one (1) post-Consolidation Silver Hammer Share for each four (4) pre-Consolidation Silver Hammer Shares, to be completed before the effective time of the Amalgamation;
"Contingent Value Shares" means the contingent value shares of the Resulting Issuer proposed to be created and issued in connection with the SilverMark Amalgamation, as described under "Information Concerning Silver Hammer - The SilverMark Amalgamation";
"CSE" means the Canadian Securities Exchange;
"Depositary" means Endeavor Trust Corporation, or such other depositary as Stroud and Silver Hammer may agree in writing;
"Director" means the Director appointed under section 278 of the OBCA;
"Dissent Rights" means the rights of dissent in respect of the Amalgamation provided for in section 185 of the OBCA;
"Dissenting Shareholder" means a registered Stroud Shareholder who, in connection with the Amalgamation Resolution, has validly exercised Dissent Rights in strict compliance with section 185 of the OBCA and has not withdrawn such exercise;
"Effective Date" means the date shown on the Certificate of Amalgamation;
"Effective Time" means the time on the Effective Date at which the Amalgamation becomes effective;
"Exchange Ratio" means 0.777963 of a Silver Hammer Share, on a post-Consolidation basis, for each Stroud Share;
"Governmental Entity" has the meaning ascribed thereto in the Combination Agreement;
"IFRS" means International Financial Reporting Standards as issued by the International Accounting Standards Board;
"Intermediary" means a broker, custodian, nominee or other intermediary holding Stroud Shares on behalf of a Beneficial Stroud Shareholder;
"Lead Agent" means Red Cloud Securities Inc;
"Letter of Transmittal" means the letter of transmittal accompanying this Circular pursuant to which registered Stroud Shareholders are required to deliver certificates or other evidence of ownership representing Stroud Shares in exchange for the Amalgamation Consideration;
"Material Adverse Change" and "Material Adverse Effect" have the meanings ascribed thereto in the Combination Agreement;
"Meeting" means the annual and special meeting of Stroud Shareholders to be held on September 28, 2026, including any adjournments or postponements thereof;
"MI 61-101" means Multilateral Instrument 61-101 Protection of Minority Security Holders in Special Transactions;
"NI 43-101" means National Instrument 43-101 Standards of Disclosure for Mineral Projects; "NI 51-102" means National Instrument 51-102 Continuous Disclosure Obligations;
"NI 54-101" means National Instrument 54-101 Communication with Beneficial Owners of Securities of a Reporting Issuer;
"OBCA" means the Business Corporations Act (Ontario) and the regulations made thereunder; "Parties" means Stroud, Silver Hammer and Subco, and "Party" means any one of them;
"Private Placement" means the private placement of subscription receipts of SilverMark to be completed in connection with the Transaction for minimum gross proceeds of $7,000,000 and maximum gross proceeds of $10,000,000, or such greater amount as may be determined by the parties, at a price of $0.26 per subscription receipt;
"Privcos" means Amalco and SilverMark Amalco;
"Record Date" means the close of business on August 25, 2026, being the record date for determining Stroud Shareholders entitled to receive notice of and vote at the Meeting;
"Registered Stroud Shareholders" means the registered holders of Stroud Shares;
"Resulting Issuer" means Silver Hammer following completion of the Transaction, which is expected to be renamed "Silver Frontier Resources Corp.";
"Resulting Issuer Shares" means the common shares in the capital of the Resulting Issuer;
"Santo Domingo" means the Santo Domingo silver-gold property located in the Western Silver-Gold Belt, Jalisco, Mexico, in which Stroud holds an effective 100% interest through the Mexican Subsidiary;
"SEDAR+" means the System for Electronic Data Analysis and Retrieval + at www.sedarplus.ca;
"Silver Hammer" means Silver Hammer Mining Corp., a company existing under the laws of British Columbia;
"Silver Hammer Board" means the board of directors of Silver Hammer;
"Silver Hammer Meeting" means the annual general and special meeting of Silver Hammer Shareholders to be held to consider, among other things, the Transaction, the creation and authorization of the Contingent Value Shares and the approval of an omnibus equity incentive compensation plan;
"Silver Hammer Shareholders" means the holders of Silver Hammer Shares; "Silver Hammer Shares" means the common shares in the capital of Silver Hammer;
"SilverMark" means SilverMark Resources Inc., a company existing under the laws of Canada;
"SilverMark Amalco" means the CBCA company formed pursuant to the SilverMark Amalgamation, which company will be a wholly-owned subsidiary of Silver Hammer;
"SilverMark Amalgamation" means the three-cornered amalgamation under the Canada Business Corporations Act pursuant to which Silver Hammer will acquire all of the issued and outstanding shares of SilverMark;
"Stroud Board" means the board of directors of Stroud;
"Stroud Options" means the options to purchase Stroud Shares outstanding immediately prior to the Effective Time;
"Stroud Shareholders" means, at any time, the holders of Stroud Shares; "Stroud Shares" means the common shares in the capital of Stroud;
"Subco" means 1001629888 Ontario Inc., a wholly-owned subsidiary of Silver Hammer existing under the laws of Ontario;
"Superior Proposal" has the meaning ascribed thereto under "Summary of the Combination Agreement - Superior Proposals";
"Tax Act" means the Income Tax Act (Canada) and the regulations thereunder;
"Transaction" means, collectively, the Amalgamation, the Consolidation, the SilverMark Amalgamation and the Private Placement;
"Transfer Agent" means TSX Trust Company; "TSXV" means the TSX Venture Exchange;
"United States" or "U.S." means, as the context requires, the United States of America, its territories and possessions, any state of the United States, and/or the District of Columbia;
"U.S. holder" has the meaning ascribed thereto in Rule 800(h) under the U.S. Securities Act;
"U.S. person" has the meaning ascribed thereto in Rule 902(k) of Regulation S under the U.S. Securities Act;
"U.S. Securities Act" means the U.S. Securities Act of 1933, as amended; and
"Voting Support Agreements" means the voting support agreements entered into between Silver Hammer and each member of the Stroud Board, each officer of Stroud and each Stroud Shareholder holding, directly or indirectly, more than 10% of the Stroud Shares.
SUMMARY
The following is a summary of certain information contained in this Circular. This summary is not intended to be complete and is qualified in its entirety by the more detailed information appearing elsewhere in this Circular and in the appendices hereto.
The Meeting
The Meeting will be held at 10:30 a.m. (Toronto time) on September 28, 2026 virtually with the following link https://teams.microsoft.com/meet/259414103806908?p=sZhVoHoWH9djsCCG13
Meeting ID: 259 414 103 806 908
Passcode: 6Jo6xZ3J
Record Date
Only Stroud Shareholders of record at the close of business on August 25, 2026 are entitled to receive notice of and to vote at the Meeting.
Purpose of the Meeting
At the Meeting, Stroud Shareholders will be asked to: (i) receive the audited consolidated financial statements of the Corporation for the financial years ended December 31, 2025 and 2024; (ii) elect directors for the ensuing year; (iii) re-appoint the auditor and authorize the directors to fix its remuneration; and (iv) consider and, if thought appropriate, pass the Amalgamation Resolution, the full text of which is attached as Appendix "A" to this Circular.
The Parties
Stroud. Stroud is a mineral exploration company existing under the OBCA with its head office at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6. The Stroud Shares are listed and posted for trading on the TSXV under the symbol "SDR". Stroud holds an effective 100% interest in the Santo Domingo silver-gold property in Jalisco, Mexico through its subsidiary Compañia Minera San Diego y La Espanola S.A. de C.V. Stroud's only other subsidiary is Grande Pleiad Oil Ltd. See "Information Concerning Stroud".
Silver Hammer. Silver Hammer is a mineral exploration and development company existing under the Business Corporations Act (British Columbia) with its head office in Vancouver, British Columbia. The Silver Hammer Shares are listed and posted for trading on the CSE under the symbol "HAMR". Silver Hammer holds interests in three exploration-stage silver properties in Idaho and Nevada. See "Information Concerning Silver Hammer".
Subco. Subco is a corporation incorporated under the OBCA solely for the purpose of effecting the Amalgamation. Subco is a wholly-owned subsidiary of Silver Hammer, has one common share outstanding, paid-up capital of $1.00 and no liabilities.
The Resulting Issuer. Upon completion of the Transaction, Silver Hammer will continue as the Resulting Issuer, expected to be renamed "Silver Frontier Resources Corp.", carrying on the business of Silver Hammer as expanded to include the mineral assets of Stroud and, on completion of the SilverMark Amalgamation, SilverMark's rights in respect of a portfolio of mineral assets in Morocco. See "Information Concerning the Resulting Issuer".
The Amalgamation
Pursuant to the Amalgamation, each Stroud Shareholder (other than Dissenting Shareholders) will be entitled to receive, on the Effective Date, 0.777963 of a post-Consolidation Silver Hammer Share for each Stroud Share held. Stroud and Subco will amalgamate under section 174 of the OBCA and continue as Amalco under the name "Stroud Resources Ltd.", which will be a wholly-owned subsidiary of the Resulting Issuer.
Based on the 63,623,199 Stroud Shares outstanding as at the date of the Combination Agreement, an aggregate of approximately 49,496,496 Resulting Issuer Shares will be issued to Stroud Shareholders pursuant to the Amalgamation, assuming no Stroud Options are exercised and no Dissent Rights are exercised. No fractional Resulting Issuer Shares will be issued; fractional entitlements will be rounded down to the nearest whole number without compensation.
Each outstanding Stroud Option has been amended such that, effective on the Effective Date, the obligation to issue Stroud Shares on exercise will be replaced with an obligation to issue Resulting Issuer Shares, with the number of shares issuable and the exercise price adjusted in accordance with the Exchange Ratio. Based on the 1,155,000 Stroud Options outstanding, up to approximately 898,561 Resulting Issuer Shares will be issuable on exercise of the amended Stroud Options.
Effective Date
Subject to receipt of the required approvals and the satisfaction or waiver of the conditions to closing, it is currently anticipated that the Effective Date will occur on or about October 15, 2026. Either Stroud or Silver Hammer may terminate the Combination Agreement if the Transaction is not completed by November 30, 2026.
Shareholder Approval of the Amalgamation
At the Meeting, Stroud Shareholders will be asked to consider and, if thought appropriate, to pass, with or without variation, the Amalgamation Resolution approving the Amalgamation. The full text of the Amalgamation Resolution is set out in Appendix "A" to this Circular. The Amalgamation Resolution will require the affirmative vote of at least two-thirds (662⁄3%) of the votes cast by the Stroud Shareholders who vote in person or by proxy at the Meeting.
In accordance with MI 61-101, Stroud will also be required to obtain "minority approval" (as defined in MI 61-101) of the Amalgamation Resolution, meaning the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Recommendation of the Stroud Board
The Stroud Board UNANIMOUSLY recommends that Stroud Shareholders vote FOR the Amalgamation Resolution.
Voting Support Agreements
Holders of approximately 61.38% of the outstanding Stroud Shares, including 2176423 Ontario Ltd. (which holds approximately 58.59% of the outstanding Stroud Shares), have entered into Voting Support Agreements with Silver Hammer pursuant to which they have agreed to vote their Stroud Shares in favour of the Amalgamation Resolution. See "The Amalgamation - Voting Support Agreements".
Conditions to the Amalgamation
Completion of the Amalgamation is subject to a number of conditions, including: approval of the Amalgamation Resolution at the Meeting; approval of the Transaction by Silver Hammer Shareholders at the Silver Hammer Meeting; receipt of TSXV and CSE approval; completion of the Consolidation; satisfaction or waiver of all conditions to the SilverMark Amalgamation other than completion of the Amalgamation; completion of the Private Placement for minimum gross proceeds of $7,000,000 and satisfaction of the escrow release conditions; approval of the listing of the Resulting Issuer Shares on the CSE; Dissent Rights not having been exercised in respect of more than 5% of the outstanding Stroud Shares; and the absence of any Material Adverse Change. See "Summary of the Combination Agreement - Conditions Precedent to the Amalgamation".
Dissent Rights
Pursuant to section 185 of the OBCA, Registered Stroud Shareholders have Dissent Rights entitling them, if the Amalgamation becomes effective and they strictly comply with section 185, to be paid the fair value of their Stroud Shares. A registered Stroud Shareholder who wishes to exercise Dissent Rights must send a written objection to Stroud at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, Attention: Mirsad Jakubovic, at or before the Meeting. See "Dissenting Shareholder Rights" and Appendix "B".
Certain Canadian Federal Income Tax Considerations
This Circular contains a summary of the principal Canadian federal income tax considerations applicable to certain Stroud Shareholders in respect of the Amalgamation. Generally, a Resident Holder who exchanges Stroud Shares for Resulting Issuer Shares under the Amalgamation will not realize a capital gain or capital loss. See "Certain Canadian Federal Income Tax Considerations to Stroud Shareholders". This Circular does not address non-Canadian tax considerations.
Letter of Transmittal
A Letter of Transmittal has been mailed, together with this Circular, to each Registered Stroud Shareholder. Each Registered Stroud Shareholder must forward a properly completed and signed Letter of Transmittal, together with the certificate(s) (if any) representing their Stroud Shares, to the Depositary in order to receive the Amalgamation Consideration.
Stock Exchange Listing and Reporting Issuer Status
If the Amalgamation is completed, the Stroud Shares will be delisted from the TSXV and Amalco is expected to apply to cease to be a reporting issuer in each jurisdiction in which it is currently a reporting issuer. The Resulting Issuer Shares will continue to be listed and posted for trading on the CSE. See "Certain Securities Laws Matters".
Interests of Certain Persons in the Amalgamation
In considering the recommendation of the Stroud Board, Stroud Shareholders should be aware that certain directors and officers of Stroud have interests in the Amalgamation that are different from, or in addition to, those of Stroud Shareholders generally, including proposed positions with the Resulting Issuer. See "The Amalgamation - Interests of Certain Persons in the Amalgamation".
Financial Statements
The unaudited pro forma consolidated financial statements of the Resulting Issuer and the financial statements of Silver Hammer are attached to this Circular as Appendices D and E, respectively. See "Information Concerning the Resulting Issuer - Financial Information".
Risk Factors
Stroud Shareholders should carefully consider the risk factors relating to the Amalgamation described under "Risk Factors Relating to the Amalgamation" and the risks relating to the business of the Resulting Issuer described under "Information Concerning the Resulting Issuer - Risk Factors" and in the documents incorporated by reference in this Circular.
INFORMATION CONCERNING THE MEETING
Date, Time and Place of Meeting
The Meeting will be held at 10:30 a.m. (Toronto time) on September 28, 2026 virtually with the following link https://teams.microsoft.com/meet/259414103806908?p=sZhVoHoWH9djsCCG13
Meeting ID: 259 414 103 806 908
Passcode: 6Jo6xZ3J
Solicitation of Proxies
This Circular is furnished in connection with the solicitation of proxies by the management of Stroud for use at the Meeting. It is expected that the solicitation will be primarily by mail; however, proxies may also be solicited personally, by telephone or by electronic means by the regular officers, employees or agents of Stroud, at nominal cost. The cost of solicitation will be borne by Stroud. Stroud may also reimburse Intermediaries for their reasonable costs incurred in sending proxy-related materials to Beneficial Stroud Shareholders.
Appointment and Revocation of Proxies
The persons named in the accompanying form of proxy are directors and/or officers of Stroud. A Stroud Shareholder has the right to appoint a person (who need not be a Stroud Shareholder) other than the persons named in the enclosed form of proxy to attend and act on the Stroud Shareholder's behalf at the Meeting. To exercise this right, a Stroud Shareholder must strike out the names of the persons named in the form of proxy and insert the name of the desired nominee in the blank space provided, or complete another proper form of proxy.
To be valid, a proxy must be deposited with TSX Trust Company (Attention: Proxy Department) at 301 - 100 Adelaide Street West, Toronto, Ontario M5H 4H1, or voted online at www.voteproxyonline.com, in each case not less than 48 hours (excluding Saturdays, Sundays and statutory holidays) before the time of the Meeting or any adjournment thereof. The chair of the Meeting may waive the proxy cut-off in his or her discretion without notice.
The proxy must be signed by the Stroud Shareholder or by his or her attorney authorized in writing or, if the Stroud Shareholder is a corporation, by a duly authorized officer.
Revocation. In addition to revocation in any other manner permitted by law, a Registered Stroud Shareholder who has given a proxy may revoke it: (a) by completing and signing a proxy bearing a later date and depositing it as described above; (b) by depositing an instrument in writing executed by the Stroud Shareholder or by the Stroud Shareholder's attorney authorized in writing
(i) at the registered office of Stroud at any time up to and including the last Business Day preceding the day of the Meeting or any adjournment thereof, or (ii) with the chair of the Meeting prior to the commencement of the Meeting on the day of the Meeting or any adjournment thereof; or (c) in any other manner permitted by law.
A Beneficial Stroud Shareholder may revoke a voting instruction form given to an Intermediary at any time by written notice to the Intermediary, except that an Intermediary may not be required to act on a revocation received less than seven days before the Meeting.
Voting of Proxies
The persons named in the enclosed form of proxy will vote or withhold from voting the Stroud Shares in respect of which they are appointed in accordance with the instructions of the Stroud Shareholder as indicated on the proxy. In the absence of any instruction, the Stroud Shares represented by a proxy in favour of the management nominees will be voted FOR each of the matters identified in the Notice of Meeting, including FOR the Amalgamation Resolution.
The enclosed form of proxy confers discretionary authority upon the persons named therein with respect to amendments or variations to the matters identified in the Notice of Meeting and with respect to other matters which may properly come before the Meeting. As at the date of this Circular, management of Stroud knows of no such amendments, variations or other matters.
Voting Securities and Principal Holders Thereof
The authorized share capital of Stroud consists of an unlimited number of Stroud Shares. As at the Record Date there were 63,623,199 Stroud Shares issued and outstanding. Each Stroud Share entitles the holder to one vote on all matters to be acted upon at the Meeting.
To the knowledge of the directors and executive officers of Stroud, as at the date of this Circular, no person or company beneficially owns, or exercises control or direction over, directly or indirectly, voting securities of Stroud carrying 10% or more of the voting rights attached to all outstanding Stroud Shares, other than as set out below:
| Name | Number of Stroud Shares |
Percentage of Issued and Outstanding |
| 2176423 Ontario Ltd.(1) | 37,277,777 | 58.59% |
Notes:
(1) 2176423 Ontario Ltd. is a corporation beneficially owned by Mr. Eric Sprott. On July 21, 2026, 2176423 Ontario Ltd. filed an early warning report under National Instrument 62-103 The Early Warning System and Related Take-Over Bid and Insider Reporting Issues in connection with its entry into a Voting Support Agreement with Silver Hammer. A copy of that early warning report is available under Stroud's profile on SEDAR+.
Advice to Beneficial Holders of Stroud Shares
The information set forth in this section is of significant importance to Stroud Shareholders who do not hold Stroud Shares in their own name. Only Registered Stroud Shareholders, or the persons they appoint as their proxies, are entitled to attend and vote at the Meeting. In many cases, Stroud Shares beneficially owned by a Beneficial Stroud Shareholder are registered either (a) in the name of an Intermediary, or (b) in the name of a clearing agency such as CDS Clearing and Depository Services Inc. of which the Intermediary is a participant.
In accordance with NI 54-101, Stroud has distributed copies of the Meeting materials to clearing agencies and Intermediaries for onward distribution to non-objecting Beneficial Stroud Shareholders. Stroud is not sending proxy-related materials directly to non-objecting beneficial owners, and Stroud is not paying for the delivery of proxy-related materials to objecting beneficial owners. Objecting beneficial owners will therefore not receive this Circular or a voting instruction form unless their Intermediary elects to deliver those materials at its own expense.
Beneficial Stroud Shareholders who have not waived the right to receive Meeting materials will generally either (a) be given a voting instruction form which must be completed and returned in accordance with the directions on it, or (b) be given a form of proxy already signed by the Intermediary and restricted as to the number of Stroud Shares beneficially owned, but otherwise uncompleted. A Beneficial Stroud Shareholder who wishes to attend and vote at the Meeting (or have another person do so on its behalf) should strike out the names of the persons named in the proxy and insert its own name (or that of its nominee) in the blank space provided or, in the case of a voting instruction form, follow the corresponding instructions on the form.
Beneficial Stroud Shareholders should note that only Registered Stroud Shareholders are entitled to exercise Dissent Rights. A Beneficial Stroud Shareholder who wishes to dissent must arrange for the Stroud Shares beneficially owned by that person to be registered in that person's name prior to the time the written objection to the Amalgamation Resolution is required to be received by Stroud, or alternatively make arrangements for the Registered Stroud Shareholder holding those shares to dissent on that person's behalf. See "Dissenting Shareholder Rights".
Depositary
Endeavor Trust Corporation will act as Depositary for the receipt of certificates representing Stroud Shares and Letters of Transmittal deposited pursuant to the Amalgamation. No fee or commission is payable by a Stroud Shareholder who transmits Stroud Shares directly to the Depositary.
Interest of Certain Persons or Companies in Matters to be Acted Upon
Other than as disclosed in this Circular, and other than the election of directors, no (a) director or executive officer of Stroud who has held such position at any time since the beginning of Stroud's last completed financial year, (b) proposed nominee for election as a director of Stroud, or (c) associate or affiliate of any of the foregoing persons, has any material interest, direct or indirect, by way of beneficial ownership of securities or otherwise, in any matter to be acted upon at the Meeting. See "The Amalgamation - Interests of Certain Persons in the Amalgamation" and "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Other Business
As at the date of this Circular, management of Stroud does not intend to present, and does not have any reason to believe that others will present, any item of business other than those set out in this Circular.
PARTICULARS OF MATTERS TO BE ACTED UPON - ANNUAL BUSINESS
1. Financial Statements
The audited consolidated financial statements of the Corporation for the financial years ended December 31, 2025 and 2024, together with the report of the auditor thereon, will be placed before the Meeting. No vote by Stroud Shareholders is required in connection with the presentation of the financial statements.
2. Election of Directors
The Stroud Board currently consists of four directors, each of whose term expires at the Meeting. At the Meeting, the following four (4) persons will be proposed for election as directors of the Corporation to hold office until the close of the next annual meeting of Stroud Shareholders or until their successors are duly elected or appointed.
| Name and Municipality of Residence |
Office Held with the Corporation |
Principal Occupation for the Preceding Five Years |
Director Since |
Number of Stroud Shares Beneficially Owned, Controlled or Directed |
| Mirsad Jakubovic, Toronto, Ontario, Canada |
Chief Financial Officer, Secretary and Director | Chief Financial Officer, Stroud Resources Ltd. | December 2013 | 1,480,200 |
| Dr. Scott Jobin- Bevans, Santiago, Chile |
Chief Executive Officer and Director | Principal Geoscientist and Director, Caracle Creek International Consulting Inc.; Managing Director, Caracle Creek Chile SpA | July 2014 | 295,666 |
| William J. (Jeff) Kennedy, Toronto, Ontario, Canada |
Director | Managing Director, Equity Capital Markets and Operations, Cormark Securities Inc. until July 2019; Administrator, 2176423 Ontario Ltd. since June 2020 |
January 2021 | Nil |
| Conor O'Brien, Toronto, Ontario, Canada |
Director | Portfolio Manager Eric Sprott Family Office | September 24, 2025 | Nil |
Notes: The information as to Stroud Shares beneficially owned, controlled or directed has been furnished by the respective nominees individually.
As a group, the proposed directors beneficially own, control or direct, directly or indirectly, 1,775,866 Stroud Shares, representing approximately 2.79% of the issued and outstanding Stroud Shares as at the date of this Circular.
Biographical information regarding the proposed directors is set out below.
Mr. Jeff Kennedy. Mr. Kennedy was appointed to the Board in January 2021. In addition, Mr. Kennedy is also a director of Jaguar Mining Inc. Prior to joining the Board, Mr. Kennedy served as Managing Director Equity Capital Markets and Operations at Cormark Securities Inc. until July 2019. Mr. Kennedy has been an Administrator at 2176423 Ontario Ltd, the controlling shareholder of Stroud Resources Ltd. since June 2020. With over 30 years of experience, Mr. Kennedy also served as the CFO of Cormark Securities Inc. where he was responsible for financial oversight, controls and governance of operations. Mr. Kennedy is a Chartered Professional Accountant from the Institute of Chartered Professional Accountants of Ontario and obtained his Bachelor of Commerce from McMaster University.
Conor O'Brien: Mr. O'Brien was appointed to the Board in September 2025. Mr. O'Brien is a seasoned financial professional in global capital markets. With over 20 years of experience in equities, derivatives, fixed income and credit default swaps, he has consistently demonstrated an ability to navigate complicated financial instruments and environments. Prior to joining the Eric Sprott Family Office he worked for prominent Canadian brokerages GMP Securities and more recently, Paradigm Capital. Previously, he worked in New York for Cantor Fitzgerald in equity derivatives.
Dr. Scott Jobin-Bevans: Dr. Jobin-Bevans has over 30 years in mineral exploration with public and private company experience as an officer, director and technical advisor. Dr. Jobin-Bevans is President and CEO of Caracle Creek International Consulting Inc. (also a Co-Founder and Director) and is P.M.P. Certified in project management. His areas of expertise include project evaluation, generation and management and he has led multimillion dollar projects from generative stage to advanced exploration and development. Dr. Jobin-Bevans is a member of the Board of Directors for several public and private companies and is Past President (2010-2012) and a past Director (2001-2010) of the Prospectors and Developers Association of Canada (PDAC). In 2013, he was awarded the Queen Elizabeth Diamond Jubilee Medal in recognition of his significant contributions and achievements in the Canadian minerals industry.
Mr. Mirsad Jakubovic, MBA, CPA, CA. Mr. Jakubovic has over 30 years of financial and management experience and has grown and developed Canadian operations for several international businesses. He has been the Chief Financial Officer for two publicly traded companies and has worked for many years in industries that are regulated by Health Canada. He is a Chartered Professional Accountant and holds an MBA degree from the Richard Ivey School of Business, Western University.
Cease Trade Orders, Bankruptcies, Penalties and Sanctions
To the knowledge of the Corporation, no proposed director of the Corporation is, as at the date of this Circular, or has been, within the ten years preceding the date of this Circular, a director, chief executive officer or chief financial officer of any company that was subject to a cease trade order or similar order, or became bankrupt, made a proposal under bankruptcy or insolvency legislation, or was subject to any penalties or sanctions required to be disclosed pursuant to Item 7.2 of Form 51-102F5.
The Stroud Board recommends that Stroud Shareholders vote FOR the election of each of the proposed nominees set forth above as directors of the Corporation.
3. Appointment and Remuneration of Auditor
At the Meeting, Stroud Shareholders will be asked to re-appoint McGovern Hurley LLP, Chartered Professional Accountants, of 251 Consumers Road, Suite 800, Toronto, Ontario M2J 4R3, as auditor of the Corporation to hold office until the close of the next annual meeting of Stroud Shareholders, and to authorize the directors of the Corporation to fix the auditor's remuneration. McGovern Hurley LLP was first appointed auditor of the Corporation on April 19, 2016.
The Stroud Board recommends that Stroud Shareholders vote FOR the re-appointment of McGovern Hurley LLP as auditor of the Corporation and the authorization of the directors to fix its remuneration.
STATEMENT OF EXECUTIVE COMPENSATION
The Corporation is a "venture issuer" as defined in NI 51-102 and provides the disclosure required by Form 51-102F6V Statement of Executive Compensation - Venture Issuers in respect of the financial years ended December 31, 2025 and December 31, 2024.
Introduction
All direct and indirect compensation provided to certain executive officers and directors for, or in connection with, services they have provided to the Corporation or a subsidiary of the Corporation must be disclosed in this Circular pursuant to the requirements of Form 51-102F6V Statement of Executive Compensation - Venture Issuers ("Form 51-102F6V"). The Corporation is required to disclose annual and long-term compensation for services in all capacities to the Corporation and its subsidiaries for the two most recently completed financial years in respect of the individuals comprised of the Chief Executive Officer ("CEO"), the Chief Financial Officer ("CFO") and the most highly compensated executive officers of the Corporation whose individual total compensation for the most recently completed financial year exceeds $150,000, and any individual who would have satisfied these criteria but for the fact that the individual was not serving as an officer at the end of the most recently completed financial year (the "Named Executive Officers" or "NEOs").
Director and NEO compensation is disclosed below in accordance with Form 51-102F6V under the following tables: (1) table of compensation excluding compensation securities; (2) stock options and other compensation securities; and (3) exercise of compensation securities by directors and NEOs.
Named Executive Officers of the Corporation for the Years Ended December 31, 2025 and 2024
During the financial years ended December 31, 2025 and December 31, 2024, the Corporation had two NEOs: (i) Dr. Scott Jobin-Bevans, Chief Executive Officer and director; and (ii) Mirsad Jakubovic,Chief Financial Officer, Secretary and director.
Director and Named Executive Officer Compensation
The following table (and the notes thereto) states the name of each NEO and director and his annual compensation, consisting of salary, consulting fee, bonus and other annual compensation, excluding compensation securities, for each of the Corporation's two most recently completed financial years.
| Name and position | Year | Salary, consulting fee, retainer, commission ($) |
Bonus ($) |
Committee or meeting fees ($) |
Value of perquisites ($) |
Value of all other compensation ($) |
Total compensation ($) |
| Dr. Scott Jobin-Bevans, CEO and director(1) |
2025 | $15,000 | N/A | N/A | N/A | $32,837 | $47,837 |
| 2024 | $15,000 | N/A | N/A | N/A | N/A | $15,000 | |
| Mirsad Jakubovic, CFO, Secretary and director(2) | 2025 | $75,000 | N/A | N/A | N/A | $25,721 | $100,721 |
| 2024 | $75,000 | N/A | N/A | N/A | N/A | $75,000 | |
| Jeff Kennedy, director(3) | 2025 | $15,000 | N/A | N/A | N/A | $25,721 | $40,721 |
| 2024 | $15,000 | N/A | N/A | N/A | N/A | $15,000 | |
| Conor O'Brien, director(4) | 2025 | $3,750 | N/A | N/A | N/A | $25,721 | $29,471 |
| 2024 | nil | N/A | N/A | N/A | N/A | nil |
(1) Dr. Scott Jobin-Bevans has been CEO (initially on an interim basis) effective July 22, 2019 and a director effective July 2014.
(2) Mr. Mirsad Jakubovic was appointed CFO effective November 2011 and a director effective December 2013.
(3) Mr. Jeff Kennedy was appointed director effective January 12, 2021.
(4) Mr. Conor O'Brien was appointed director effective September 24, 2025.
Stock Options and Other Compensation Securities
The Stock Option Plan provides for the acquisition of Stroud Shares by directors, officers, employees or consultants of the Corporation, or any affiliated entity of the Corporation, for the purpose of advancing the interests of the Corporation through the motivation, attraction and retention of key employees and directors, and to secure for the Corporation and the Stroud Shareholders the benefits inherent in the ownership of Stroud Shares by key employees and directors.
The following table sets out, for each director and NEO, all compensation securities granted or issued during the year ended December 31, 2025, including the date of issue, exercise price, the closing price of the underlying security on the date of grant and at financial year end, and the expiry date.
| Name and position |
Type of compensation security |
Number of compensation securities, number of underlying securities, and percentage of class |
Date of issue or grant |
Issue, conversion or exercise price ($) |
Closing price of underlying security on date of grant ($) |
Closing price of underlying security at year end ($) |
Expiry date |
| Dr. Scott Jobin-Bevans, CEO and director |
Options to purchase Stroud Shares | 300,000 .0047% of class |
September 24, 2025 | $0.12 | $0.12 | $0.20 | September 24, 2030 |
| Mirsad Jakubovic, CFO, Secretary and director |
Options to purchase Stroud Shares | 235,000 .0037% of class |
September 24, 2025 | $0.12 | $0.12 | $0.20 | September 24, 2030 |
| Jeff Kennedy, Director | Options to purchase Stroud Shares | 150,000 235,000 .0061% of class |
September 24, 2025 | $0.55 $0.12 |
$0.55 $0.12 |
$0.20 $0.20 |
September 30, 2026 September 24, 2030 |
| Conor O'Brien, Director | Options to purchase Stroud Shares | 235,000 .0037% of class |
September 24, 2025 | $0.12 | $0.12 | $0.20 | September 24, 2030 |
Exercise of Compensation Securities by Directors and NEOs
During the financial years ended December 31, 2025 and December 31, 2024, no compensation securities were exercised by the NEOs or by non-NEO directors.
External Management Companies
Except as otherwise disclosed in this Circular, the management functions of the Corporation are performed by the directors and executive officers of the Corporation and not by any other person or company.
Employment, Consulting and Management Agreements
Management of the Corporation is performed by the directors and officers of the Corporation and not by any other person. There are no plans in place with respect to compensation of the NEOs in the event of a termination of employment without cause or upon the occurrence of a change of control, other than with respect to Mirsad Jakubovic, the Chief Financial Officer and a director of the Corporation.
Oversight and Description of Director and Named Executive Officer Compensation
The Compensation Committee determines the compensation of the Corporation's NEOs and the directors of the Corporation with a view to ensuring that the remuneration appropriately reflects the responsibilities and risks involved in being an effective executive officer and/or director of the Corporation. The Compensation Committee periodically reviews the Corporation's compensation philosophy and objectives, taking into consideration the factors discussed below.
Nature and Responsibilities of the Compensation Committee
The Compensation Committee is responsible for making recommendations to the Stroud Board with respect to, among other things: executive and director compensation, including reviewing and determining director compensation; overseeing the Corporation's base compensation structure and equity-based compensation program; recommending compensation of the Corporation's officers and employees; and evaluating the performance of officers generally and in light of annual goals and objectives, with a view to providing competitive compensation programs which attract, motivate and retain high-calibre individuals.
The Compensation Committee also assumes responsibility for reviewing and monitoring the long-term compensation strategy for the Corporation's senior management, and reviews the compensation of senior management on an annual basis taking into account compensation paid by other issuers of similar size and activity. Recommendations of the Compensation Committee are referred to the Stroud Board for approval, modification or amendment.
Composition of the Compensation Committee
The Compensation Committee was constituted by the Stroud Board on May 1, 2015 for the purposes of assisting the Stroud Board in discharging its oversight responsibilities relating to the compensation and retention of key senior management, and assumes responsibility for recommending to the Stroud Board compensation philosophy and policies, the evaluation of cash, equity-based and incentive compensation of the Corporation's directors and officers, goals and objectives relative to compensation for the Corporation's NEOs, the performance of the NEOs in light of those goals, and compensation disclosure before the Corporation publicly discloses that information. The Compensation Committee has adopted a written mandate.
The Compensation Committee currently comprises Dr. Scott Jobin-Bevans and Mr. Jeff Kennedy. Each member of the Compensation Committee has more than 10 years of experience in his respective field and, throughout that period, each has been closely involved with implementing and reviewing compensation policies at his respective organization. Each member has held senior roles with public and private companies directly related to the mining industry. All members of the Compensation Committee other than Dr. Jobin-Bevans qualify as independent directors within the meaning of NI 58-101. The Compensation Committee met one time during the year ended December 31, 2025 and one time during the year ended December 31, 2024.
Philosophy and Objectives of the Compensation Program
The Corporation is a junior resource company with limited resources. The intention of the compensation program is to ensure that the corporate objectives and strategy approved by the Stroud Board are supported by appropriate compensation awards on a results-oriented basis. The compensation program for the senior management and directors of the Corporation is designed within this context, with a view that the level and form of compensation should achieve certain objectives, including:
(a) to enable the Corporation to attract, retain and motivate qualified executive officers and directors of the highest caliber, in light of the strong competition in the mining sector for qualified personnel;
(b) to ensure that the interests of the Corporation's executive officers and directors are aligned with the interests of the Corporation and the Stroud Shareholders;
(c) to provide a strong incentive to the executive officers and directors of the Corporation to contribute to the achievement of the Corporation's short-term and long-term corporate goals;
(d) to recognize that the successful implementation of the Corporation's corporate strategy cannot necessarily be measured, for a junior resource company, only with reference to quantitative measurement criteria of corporate or individual performance; and
(e) to provide fair, transparent and defensible compensation.
The compensation paid to the Corporation's executive officers generally consists of a base amount of consulting fees or salary accrued on a monthly basis and equity incentives. The Corporation's compensation policy reflects a belief that an element of total compensation for the Corporation's executive officers should be "at risk" and aligned with the long-term interests of the Corporation and the Stroud Shareholders in the form of Stroud Shares or Stroud Options, so as to create a strong incentive to build shareholder value.
Elements of Compensation
Given the size of the Corporation's operations and the very small number of employees and executives, the Corporation's compensation practices must be flexible, entrepreneurial and geared to the objective of securing the best executives to manage the Corporation. During the financial years ended December 31, 2025 and December 31, 2024, there were two key elements used to compensate the NEOs, consisting of consulting fees and long-term incentives in the form of Stroud Options. The Compensation Committee reviewed the compensation of other publicly listed junior exploration companies with a view to analyzing NEO compensation.
The Corporation believes that providing competitive overall compensation enables it to attract and retain qualified executives. Grants of long-term incentives in the form of Stroud Options serve to further encourage the retention of the Corporation's NEOs while incentivizing them to create and protect shareholder value.
Determination of Compensation
The Compensation Committee is, among other things, responsible for determining all forms of compensation and for evaluating the performance of the Chief Executive Officer and the other NEOs. In setting compensation, the Compensation Committee considers various factors: first, the remuneration package for each executive, as a whole, must be reasonably competitive with similar companies; and second, the cash component must be such that the Corporation, in the junior resource sector, can reasonably support it, taking into account that cash is directed into exploration, expansion and acquisition programs.
The Corporation has no pre-set formula for determining amounts to be paid as a bonus. Instead, the approach is to consider the overall position of the Corporation compared to the objectives and strategy previously approved by the Stroud Board. In addition, the Compensation Committee has identified the significant elements of each senior management position and uses these criteria as one of the bases for determining compensation for each NEO. No cash bonuses were paid during the financial years ended December 31, 2025 and December 31, 2024.
Base Salaries
Base salaries, or equivalent consulting fees, for the NEOs are generally fixed by the Stroud Board following recommendations from the Compensation Committee. Increases or decreases on a year-over-year basis are dependent on the Compensation Committee's assessment of the performance of the Corporation overall, the Corporation's projects and the individual's overall performance and skills.
Share-Based and Option-Based Awards
Long-term equity incentive compensation in the form of Stroud Options comprises a significant portion of overall compensation for the NEOs and the Stroud Board. The Compensation Committee believes that this is appropriate because it creates a strong correlation between variations in the price of the Stroud Shares and the compensation of the Corporation's executives, thereby aligning the interests of the Corporation's executives and the Stroud Shareholders.
The Stock Option Plan provides that Stroud Options will be issued pursuant to option agreements to directors, officers, employees or consultants of the Corporation or a subsidiary of the Corporation. The grant of Stroud Options to executive officers is determined by the Stroud Board as recommended by the Compensation Committee. Previous grants of Stroud Options are taken into account when considering new grants.
Board Retainers or Cash Compensation
In the Stroud Board's view, board retainers or cash compensation should be determined based on the requirements of the members of the board of a junior resource company, as well as a subjective assessment of the compensation the individual could reasonably expect to receive from the Corporation's peers and the Corporation's capacity to pay. The Compensation Committee reviews board retainers or cash compensation annually to ensure they remain externally competitive.
Assessment of Risks Associated with the Corporation's Compensation Policies and Practices
The Compensation Committee has assessed the Corporation's compensation plans and programs for its executive officers to ensure alignment with the Corporation's business plan and to evaluate the potential risks associated with those plans and programs. The Compensation Committee has concluded that the Corporation's compensation policies and practices do not create any risks that are reasonably likely to have a material adverse effect on the Corporation.
No NEO or director of the Corporation is permitted to purchase financial instruments, including prepaid variable forward contracts, equity swaps, collars or units of exchange funds, that are designed to hedge or offset a decrease in the market value of equity securities granted as compensation or held, directly or indirectly, by the NEO or director.
Safeguards to Mitigate Compensation Risk
The Stroud Board is of the view that the executive compensation of the Corporation should not raise the Corporation's risk profile. Accordingly, the Corporation's compensation programs are founded on principles that support the management of risk, ensuring that management's plans and activities are prudent and focused on generating shareholder value within an effective risk control environment. The primary method of providing management with incentives is through the granting of Stroud Options, and the Stroud Board and the Compensation Committee consider equity-linked instruments to be an effective method of risk mitigation, as the potential for long-term gains minimizes any incentive for management to conduct activities with a view to short-term gains.
Pension Plan Benefits
During the financial years ended December 31, 2025 and December 31, 2024, the Corporation did not maintain any defined benefit plans, defined contribution plans or deferred compensation plans for the benefit of its NEOs or directors.
SECURITIES AUTHORIZED FOR ISSUANCE UNDER EQUITY COMPENSATION PLANS
Stock Option Plan
The Stock Option Plan is the Corporation's only equity compensation plan. As at December 31, 2025, there were 1,155,000 Stroud Options outstanding.
The Stock Option Plan provides for the acquisition of Stroud Shares by directors, officers, employees or consultants of the Corporation, or any affiliated entity of the Corporation, for the purpose of advancing the interests of the Corporation through the motivation, attraction and retention of key employees and directors, and to secure for the Corporation and the Stroud Shareholders the benefits inherent in the ownership of Stroud Shares by key employees and directors, it being generally recognized that stock option plans aid in attracting, retaining and encouraging employees and directors by reason of the opportunity offered to them to acquire a proprietary interest in the Corporation.
Equity Compensation Plan Information
The following table sets out details of the securities of the Corporation authorized for issuance under the Stock Option Plan as at December 31, 2025, being the end of the Corporation's most recently completed financial year.
| Plan Category | Number of securities to be issued upon exercise of outstanding options, warrants and rights (a) |
Weighted-average exercise price of outstanding options, warrants and rights (b) |
Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) (c) |
| Equity compensation plans approved by securityholders | 1,155,000 | $0.176 | Nil |
| Equity compensation plans not approved by securityholders | Nil | Nil | Nil |
| Total | 1,155,000 | $0.176 | Nil |
INDEBTEDNESS OF DIRECTORS AND EXECUTIVE OFFICERS
Since the beginning of the Corporation's last completed financial year, none of the executive officers, directors, employees or former executive officers, directors or employees of the Corporation, none of the proposed nominees for election as a director of the Corporation, and none of their respective associates, is or has been indebted to the Corporation, nor has any such person been indebted to any other entity where that indebtedness is or was the subject of a guarantee, support agreement, letter of credit or other similar arrangement or understanding provided by the Corporation.
AUDIT COMMITTEE AND CORPORATE GOVERNANCE
The disclosure required by National Instrument 52-110 Audit Committees is attached to this Circular as Appendix "G". The disclosure required by National Instrument 58-101 Disclosure of Corporate Governance Practices in Form 58-101F2 Corporate Governance Disclosure (Venture Issuers) is attached to this Circular as Appendix "H".
THE AMALGAMATION
Overview
The Transaction will be effected pursuant to the terms of the Combination Agreement, which provides for, among other things, Silver Hammer's acquisition of all of the issued and outstanding Stroud Shares by way of a "three-cornered" amalgamation of Stroud and Subco under section 174 of the OBCA. Upon completion of the Amalgamation, Amalco will be a wholly-owned subsidiary of Silver Hammer and former Stroud Shareholders (other than Dissenting Shareholders) will hold Resulting Issuer Shares.
Background to the Transaction
The following is a summary of the principal events leading up to the negotiation and execution of the Combination Agreement and the Amalgamation Agreement between the Company, Silver Hammer and Subco.
Stroud's principal asset is its 100% interest in the Santo Domingo silver-gold property located in the Western Silver-Gold Belt in Jalisco, Mexico. Historically, the Company had explored a range of strategic alternatives for advancing Santo Domingo, including the pursuit of a stand-alone drilling and metallurgical program and the possibility of a sale or joint venture of the property, as part of the Company's ongoing go-forward planning.
During the fall of 2025, representatives of Silver Hammer approached the Company to discuss a potential strategic transaction involving Stroud's Santo Domingo property. Following these preliminary discussions, the Company and Silver Hammer entered into a letter of intent dated July 16, 2026, setting out the proposed principal terms of a business combination between the parties.
Following the commencement of discussions, the Company undertook a due diligence review of Silver Hammer, including a review of publicly available information respecting Silver Hammer's principal mining projects. Silver Hammer and its advisors conducted a corresponding due diligence review of the Company and Santo Domingo, including a review of Stroud's data room. No matters were identified in the course of this due diligence review that the Board considered to be materially adverse to the Company or that would suggest that the Company should not proceed with the Transaction. Mirsad Jakubovic, Chief Financial Officer of the Company, prepared an internal valuation analysis of the Company's silver assets for the Board's consideration in connection with the Transaction.
Over the course of the second quarter of 2026, representatives of the Company and Silver Hammer, together with their respective legal counsel, negotiated the terms of the Combination Agreement, including the exchange ratio pursuant to which holders of Stroud Shares would receive Resulting Issuer Shares. These negotiations culminated in an implied enterprise valuation for the Company of approximately CAD$12,869,000, or approximately CAD$0.50 per ounce of silver reserves/resources.
On July 14, 2026, management of the Company circulated to the Board a memorandum summarizing the material terms of the proposed Transaction and the advantages and disadvantages thereof from the perspective of the Company and its shareholders.
On July 16, 2026, the Board held a duly convened meeting, at which a quorum was present throughout, to consider the Transaction. At the meeting, the Board reviewed and considered, among other things: (i) the memorandum prepared for the Board summarizing the material advantages and disadvantages of the Transaction; (ii) drafts of the Combination Agreement and related transaction documents, including the form of Amalgamation Agreement; and (iii) such other information, valuation materials and advice of the Company's legal, financial and other advisors as the Board considered necessary or advisable. Following such review, the Board unanimously determined that the Transaction was in the best interests of the Company and approved the Combination Agreement and the Transaction.
The Combination Agreement was executed on July 17, 2026. On July 20, 2026, Silver Hammer and Stroud jointly announced the execution of the Combination Agreement and the SilverMark Agreement.
Reasons for the Amalgamation
The Board consulted with management and with Stroud's legal and financial advisors in evaluating the Amalgamation and, in reaching their respective conclusions and formulating their recommendations, reviewed significant information and considered a number of factors, including the following, among others:
• The Exchange Ratio implies a value of $0.1867 per Stroud Share based on the closing price of the Silver Hammer Shares on the CSE on July 17, 2026 (the last trading day prior to announcement of the Transaction), representing a premium of 86.72% to the closing price of the Stroud Shares on the TSXV on that date.
• The Amalgamation provides Stroud Shareholders with continued participation in the Santo Domingo silver-gold project, together with exposure to Silver Hammer's silver assets in Idaho and Nevada and, indirectly, to SilverMark's rights in respect of a portfolio of mineral assets in Morocco.
• The Resulting Issuer is expected to be capitalized by the Private Placement of a minimum of $7,000,000 and up to $10,000,000 (or such greater amount as may be determined by the parties), not inclusive of the Agents' Option, which Stroud has been unable to raise on a stand-alone basis.
• Stroud Shareholders will receive freely tradeable securities of a larger issuer listed on the CSE, which is expected to provide greater liquidity and a broader capital markets following than the Stroud Shares currently enjoy.
• The Combination Agreement was negotiated at arm's length and the Stroud Board retains the ability to consider and respond to a Superior Proposal prior to completion of the Amalgamation, subject to Silver Hammer's right to match and the payment of a $500,000 Compensation Fee in specified circumstances.
• Registered Stroud Shareholders who oppose the Amalgamation may, on strict compliance with section 185 of the OBCA, exercise Dissent Rights and be paid the fair value of their Stroud Shares.
Recommendation of the Stroud Board
After careful consideration of, among other things, the terms of the Combination Agreement and such other matters as it considered relevant, the Stroud Board has unanimously determined that the Amalgamation is in the best interests of Stroud and is fair to Stroud Shareholders.
The Stroud Board UNANIMOUSLY recommends that Stroud Shareholders vote FOR the Amalgamation Resolution.
Voting Support Agreements
The following is a summary of the material terms of the Voting Support Agreements and is qualified in its entirety by the full text of the form of Voting Support Agreement attached as Schedule "C" to the Combination Agreement.
Concurrently with the execution of the Combination Agreement, Silver Hammer entered into Voting Support Agreements with each member of the Stroud Board, each officer of Stroud, and each Stroud Shareholder holding, directly or indirectly, more than 10% of the Stroud Shares (each, a "Consenting Securityholder"), including 2176423 Ontario Ltd., which holds 37,277,777 Stroud Shares representing approximately 58.59% of the outstanding Stroud Shares on a non-diluted basis.
Pursuant to the Voting Support Agreements, each Consenting Securityholder has agreed, among other things:
(a) to vote (or cause to be voted) all of its Stroud Shares and other securities of Stroud entitled to vote (i) in favour of the approval, consent, ratification and adoption of the Transaction at every meeting of securityholders of Stroud at which such matters are considered, and not to withdraw any proxies or change its vote in respect thereof; and (ii) against any resolution proposed by Stroud or any other person that would reasonably be expected to adversely affect or reduce the likelihood of the successful completion of the Transaction or delay or interfere with its completion;
(b) not to sell, transfer, gift, assign, pledge, hypothecate, encumber, convert or otherwise dispose of any of its Stroud Shares or other relevant securities, subject to limited exceptions permitting the exercise of options and transfers to controlled entities that agree to be bound;
(c) not to vote or grant to any person other than Silver Hammer a proxy to vote, or enter into any voting trust, vote pooling or other agreement with respect to the right to vote, its relevant securities in favour of any Acquisition Proposal;
(d) to deliver a duly executed proxy voting its relevant securities in favour of the Transaction no later than ten (10) days before the date of the Meeting;
(e) not to solicit, initiate, knowingly encourage or otherwise facilitate any Acquisition Proposal, and not to accept, approve, endorse or recommend any Acquisition Proposal;
(f) not to assert or exercise any Dissent Rights in respect of the Transaction; and
(g) not to commence or participate in any class action against Stroud or Silver Hammer relating to the negotiation, execution or consummation of the Transaction.
The Voting Support Agreements do not restrict a Consenting Securityholder from acting in his or her capacity as a director or officer of Stroud, including from exercising fiduciary duties in that capacity.
Each Voting Support Agreement terminates automatically on the earlier of the Effective Date and the mutual written consent of the parties. A Consenting Securityholder may also terminate its Voting Support Agreement if: (i) a representation or warranty of Silver Hammer is untrue or incorrect in a material respect and is not cured within ten Business Days of written notice; (ii) the form or amount of the consideration offered by Silver Hammer is reduced or changed in a manner materially adverse to the Consenting Securityholder; (iii) the Stroud Board publicly announces its recommendation in support of a Superior Proposal; or (iv) the Transaction is not completed by November 30, 2026, provided in each case that the Consenting Securityholder is not then in material default of its own obligations.
The Consenting Securityholders are 2176423 Ontario Ltd., Mirsad Jakubovic, Dr. Scott Jobin-Bevans, Jeff Kennedy and Conor O'Brien. Each of the Voting Support Agreements is dated July 17, 2026. As at the date of this Circular, the Consenting Securityholders collectively hold 39,053,643 Stroud Shares, representing approximately 61.38% of the issued and outstanding Stroud Shares on a non-diluted basis, and Stroud Options to acquire an aggregate of 1,155,000 Stroud Shares. The relevant securities held by each Consenting Securityholder are set out below.
| Consenting Securityholder | Number of Stroud Shares |
Percentage of Outstanding Stroud Shares |
Number of Stroud Options |
| 2176423 Ontario Ltd. | 37,277,777 | 58.59% | Nil |
| Mirsad Jakubovic | 1,480,200 | 2.33% | 235,000 |
| Dr. Scott Jobin-Bevans | 295,666 | 0.46% | 300,000 |
| Jeff Kennedy | Nil | 0.00% | 385,000 |
| Conor O'Brien | Nil | 0.00% | 235,000 |
| Total | 39,053,643 | 61.38% | 1,155,000 |
Stroud Shareholder Approval of the Amalgamation
At the Meeting, Stroud Shareholders will be asked to consider and, if thought appropriate, to pass the Amalgamation Resolution, the full text of which is attached as Appendix "A" to this Circular. The Amalgamation Resolution must be passed by at least two-thirds (66⅔%) of the votes cast by Stroud Shareholders present in person or represented by proxy at the Meeting and entitled to vote thereon. In accordance with MI 61-101, Stroud will also be required to obtain "minority approval" (as defined in MI 61-101) of the Amalgamation Resolution, meaning the approval of a simple majority of Stroud Shareholders, excluding Scott Jobin-Bevans and 2176423 Ontario Ltd. and any other persons required to be excluded from such vote in accordance with MI 61-101. See "Certain Securities Laws Matters - Canadian Securities Laws Matters - MI 61-101".
Amalgamation Mechanics
Subject to the rights-of-termination contained in the Combination Agreement, upon the Amalgamation Resolution being passed and the other conditions in the Combination Agreement being satisfied or waived, Stroud and Subco will jointly file the Articles of Amalgamation with the Director under the OBCA.
At Effective Time, Stroud and Subco will be amalgamated and will continue as one corporation, being Amalco, on the following terms:
(a) the name of Amalco will be "Stroud Resources Ltd." or such other name as Silver Hammer may determine;
(b) the registered office of Amalco will be located at Suite 4400, 181 Bay Street, Toronto, Ontario M5J 2T3;
(c) there will be no restriction on the business Amalco is authorized to carry on or on the powers it may exercise;
(d) the authorized capital of Amalco will consist of an unlimited number of common shares;
(e) the number of directors of Amalco will consist of a minimum of one (1) and a maximum of ten (10), initially fixed at 1, and the first director of Amalco will be Peter Ball;
(f) the by-laws of Amalco will be the by-laws of Subco in effect immediately prior to the Effective Time;
(g) the auditor of Amalco will be that of the Resulting Issuer and the financial year-end of Amalco will be that of the Resulting Issuer;
(h) the stated capital of the Amalco Shares will be equal to the aggregate stated capital of each of Stroud and Subco immediately prior to the Effective Date;
(i) Stroud and Subco will cease to exist as entities separate from Amalco; and
(j) Amalco will possess all the property, rights, privileges and franchises and will be subject to all liabilities, including civil, criminal and quasi-criminal, and all contracts, disabilities and debts of each of Stroud and Subco.
Principal Steps of the Amalgamation
At the Effective Time, the following will occur and will be deemed to occur in the following order:
(a) each issued and outstanding Stroud Share held by Silver Hammer, if any, will be cancelled without any repayment of capital in respect thereof;
(b) each issued and outstanding Stroud Share, other than Stroud Shares held by Silver Hammer and by Dissenting Shareholders, will be cancelled and exchanged for fully paid and non-assessable Resulting Issuer Shares on the basis of the Exchange Ratio, and the holder thereof will cease to be the holder of such Stroud Share, the name of the holder will be removed from the applicable register of Stroud, and the certificate (if any) representing such Stroud Share will be deemed to have been cancelled;
(c) each issued and outstanding common share of Subco will be cancelled and exchanged for one (1) fully paid and non-assessable Amalco Share;
(d) Amalco will issue one Amalco Share to Silver Hammer for each Subco share cancelled pursuant to paragraph (c) and for each Resulting Issuer Share issued to former Stroud Shareholders pursuant to paragraph (b); and
(e) each issued and outstanding Stroud Option will be amended such that the exercise of such Stroud Option will be for post-Consolidation Resulting Issuer Shares, with the number of shares issuable and the exercise price adjusted to reflect the Exchange Ratio, on the same economic terms and conditions and subject to approval of Silver Hammer's omnibus equity incentive plan by Silver Hammer Shareholders at the Silver Hammer Meeting.
Stroud Shares held by a Dissenting Shareholder who is ultimately entitled to be paid the fair value of those shares will be deemed to have been irrevocably transferred to Stroud and cancelled immediately prior to the Amalgamation, and will not be exchanged for Resulting Issuer Shares.
No fractional Resulting Issuer Shares will be issued pursuant to the Amalgamation. Any exchange that would otherwise result in a fractional Resulting Issuer Share will be rounded down to the next whole number, and no cash or other compensation will be paid in lieu of the fractional interest.
For a complete description of the mechanics of the Amalgamation, please see the Combination Agreement, a copy of which is attached as Appendix "C" to this Circular, and the form of Amalgamation Agreement attached as Schedule "A" thereto.
Letter of Transmittal and Procedure for Exchange of Certificates
Registered Stroud Shareholders are required to return a duly completed Letter of Transmittal, together with the certificate(s) (if any) representing their Stroud Shares, to the Depositary in order to receive the Amalgamation Consideration to which they are entitled.
On the Effective Date, Silver Hammer will deposit with the Depositary, for the benefit of the holders of Stroud Shares entitled to receive Resulting Issuer Shares, the Resulting Issuer Shares issuable in connection with the Amalgamation. Upon surrender to the Depositary of a certificate which immediately prior to the Effective Time represented Stroud Shares, together with a duly completed Letter of Transmittal and such additional documents as the Depositary may reasonably require, the holder will be entitled to receive the Resulting Issuer Shares to which such holder is entitled.
Until surrendered, each certificate which immediately prior to the Effective Time represented Stroud Shares will represent only the right to receive, upon such surrender, the Resulting Issuer Shares to which the holder is entitled.
Any certificate which immediately prior to the Effective Date represented outstanding Stroud Shares and which has not been surrendered, together with all other required instruments, on or prior to the sixth anniversary of the Effective Date will cease to represent a claim or interest of any kind or nature, and the Resulting Issuer Shares to which the former holder would otherwise have been entitled will be deemed to have been surrendered for no consideration and will be returned to the Resulting Issuer for cancellation.
If a Stroud Share certificate has been lost, stolen or destroyed, upon the making of an affidavit of that fact by the holder claiming the certificate to be lost, stolen or destroyed, the Depositary will issue the Resulting Issuer Shares deliverable in respect thereof, subject to such bond or indemnity as the Resulting Issuer may require.
Beneficial Stroud Shareholders whose Stroud Shares are registered in the name of an Intermediary should contact that Intermediary for instructions and assistance.
Silver Hammer, Stroud and the Depositary are entitled to deduct and withhold from any consideration otherwise payable to any holder such amounts as they are required to deduct and withhold under any provision of applicable tax law.
Interests of Certain Persons in the Amalgamation
In considering the recommendation of the Stroud Board, Stroud Shareholders should be aware that certain directors and officers of Stroud have interests in the Amalgamation that are, or may be, different from or in addition to the interests of Stroud Shareholders generally. These interests include the following:
Related parties. The Amalgamation is considered a "business combination", and is a "connected transaction" with each of the Private Placement and the SilverMark Amalgamation. Dr. Scott Jobin-Bevans is a related party of each of Stroud and SilverMark at the time the transactions were entered into. Specifically, he is the Chief Executive Officer and a director of Stroud, and currently holds 3,857,778 of the common shares (27.78%) and 1,260,000 Class B special shares (32%) of SilverMark. It is anticipated that after the completion of the Transactions, Dr. Jobin-Bevans will hold 1,565,401 Resulting Issuer Shares (comprising approximately 1.34% of the issued and outstanding Resulting Issuer Shares assuming completion of the Minimum Private Placement and approximately 1.22% of the issued and outstanding Resulting Issuer Shares assuming completion of the Maximum Private Placement). Dr. Jobin-Bevans' entitlement to receive Contingent Value Shares in exchange for his Class B special shares of SilverMark constitutes a "collateral benefit" for the purposes of MI 61-101. See "Certain Securities Laws Matters - MI 61-101". He is also expected to hold 1,938,462 Contingent Value Shares. See Information Concerning the Resulting Issuer - Directors, Officers and Promoters in Appendix "F" to this Circular.
Additionally, 2176423 Ontario Ltd. is a control person of Stroud, as it currently holds 37,277,777 Stroud Shares (being approximately 58.59% of the issued and outstanding Stroud Shares). It is anticipated that 2176423 Ontario Ltd. will participate in the Private Placement and will be a control person of the Resulting Issuer.
Positions with the Resulting Issuer. Silver Hammer has announced that, upon completion of the Transaction, three of the six directors of the Resulting Issuer will be nominees of Stroud, initially being Dr. Scott Jobin-Bevans, Mr. Jeff Kennedy (as Chairman) and Mr. Conor O'Brien. In addition, Dr. Scott Jobin-Bevans, the Chief Executive Officer and a director of Stroud, is expected to be appointed Vice President, Exploration of the Resulting Issuer and it is anticipated that he will receive a salary of C$170,000 in this role.
Stroud Options. Directors and officers of Stroud hold Stroud Options which, on the Effective Date, will become exercisable for Resulting Issuer Shares on the adjusted basis described above.
Resignations and Mutual Releases. Under section 3.5(k) of the Combination Agreement, it is a condition in favour of Silver Hammer that it receive a written mutual release and resignation from all positions with Stroud from each member of the Stroud Board and such officers of Stroud as Silver Hammer may request.
Continuing Indemnification and Insurance. Under section 3.6 of the Combination Agreement, provided the relevant directors and officers have executed a mutual release, Silver Hammer has agreed that all rights to indemnification or exculpation in favour of current and former directors and officers of Stroud, as provided in Stroud's articles and by-laws or in any agreement entered into on or prior to the Effective Date, will survive, and has agreed to maintain directors' and officers' liability insurance in respect thereof.
Effect of the Amalgamation
If the Amalgamation is Completed. If the Amalgamation Resolution is approved and the other conditions in the Combination Agreement are satisfied or waived, Articles of Amalgamation will be filed under the OBCA and, on the Effective Date, Stroud Shareholders (other than Dissenting Shareholders) will cease to hold Stroud Shares and will instead hold Resulting Issuer Shares. Amalco will be a wholly-owned subsidiary of the Resulting Issuer. The Stroud Shares will be delisted from the TSXV and Amalco is expected to apply to cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
If the Amalgamation is Not Completed. If the Amalgamation Resolution is not approved by Stroud Shareholders, or if the Amalgamation is not completed for any other reason, Stroud Shareholders will not receive the Amalgamation Consideration, the Stroud Shares will continue to be listed on the TSXV and Stroud will continue as a stand-alone reporting issuer. In those circumstances, Stroud will remain subject to the risks currently affecting its business, including its need to raise additional capital to fund the exploration and development of Santo Domingo and its ongoing corporate obligations, and there can be no assurance that financing will be available on acceptable terms or at all. In certain circumstances, Stroud may also be required to pay the Compensation Fee of $500,000. See "Summary of the Combination Agreement - Compensation Fee".
SUMMARY OF THE COMBINATION AGREEMENT
The following is a summary of the principal terms of the Combination Agreement. This summary does not purport to be complete and is qualified in its entirety by reference to the full text of the Combination Agreement, a copy of which is attached as Appendix "C" to this Circular and is available under Stroud's profile on SEDAR+ at www.sedarplus.ca.
The Combination Agreement and the summary of its material terms in this Circular have been included to provide Stroud Shareholders with information regarding the terms of the Combination Agreement. The representations, warranties and covenants contained in the Combination Agreement were made solely for the benefit of the Parties, may be subject to limitations agreed between the Parties, and may have been made for the purposes of allocating contractual risk between the Parties rather than establishing matters as facts. Accordingly, they should not be read alone or relied upon as characterizations of the actual state of facts of Stroud, Silver Hammer or Subco.
Overview
On July 17, 2026, the Parties entered into the Combination Agreement, pursuant to which the Parties agreed that, subject to the terms and conditions set out therein, Silver Hammer will acquire all of the issued and outstanding Stroud Shares by way of the Amalgamation, with Stroud Shareholders receiving Resulting Issuer Shares on the basis of the Exchange Ratio.
Representations and Warranties
The Combination Agreement contains customary representations and warranties of each of Stroud and Silver Hammer relating to, among other things: corporate existence, power and authority; capitalization; subsidiaries; the absence of cease trade orders; required consents and approvals; financial statements; the absence of a material adverse change; title to properties and assets; the absence of conflicts; enforceability; management and employment contracts; reporting issuer status and continuous disclosure compliance; exchange listings; brokerage and finder's fees; litigation; liabilities; tax matters; insurance; environmental matters; compliance with laws; material contracts; books and records; and solvency for the purposes of the Amalgamation.
Stroud has also represented that, to its knowledge, no "related party" of Stroud (as defined in MI 61-101), together with its "associated entities", beneficially owns or exercises control or direction over 1% or more of the outstanding Silver Hammer Shares, except for related parties who will not receive a "collateral benefit" as a consequence of the Transaction.
Covenants
Covenants of Stroud. Stroud has covenanted with Silver Hammer and Subco that, until the earlier of termination of the Combination Agreement and the day following the Effective Date, it will, and will cause its subsidiaries to, among other things:
(a) convene and hold the Meeting as soon as reasonably practicable and in any event no later than September 30, 2026, and cooperate with Silver Hammer to prepare this Circular in form and substance satisfactory to both Parties, acting reasonably;
(b) take all reasonable actions necessary to give effect to the Transaction, including soliciting proxies to be voted at the Meeting in favour of the Amalgamation and using its best efforts to obtain the approval of Stroud Shareholders and of all applicable regulatory authorities;
(c) not declare or pay any dividends or make any distribution of its properties or assets, or retire or redeem any of its outstanding securities;
(d) except pursuant to currently existing obligations, not issue, or agree to issue, or grant options, warrants or rights to purchase, any shares or other securities;
(e) not merge or consolidate with, or sell or transfer all or any part of its assets to, any other person, or perform any act or enter into any transaction or negotiation which might interfere or be inconsistent with the consummation of the Amalgamation;
(f) not make any loans, advances or other payments other than ordinary course compensation, routine employee expense advances and other payments made on commercially reasonable terms, provided that the aggregate of such amounts does not exceed $200,000;
(g) not amend its articles or by-laws in any manner which may adversely affect the success of the Transaction;
(h) use commercially reasonable efforts to obtain all necessary assignments, regulatory approvals (including TSXV approval), waivers, amendments or terminations;
(i) not enter into any transaction or Material Contract outside the ordinary course of business, or engage in any business different from that carried on as of the date of the Combination Agreement, without Silver Hammer's prior written approval;
(j) ensure that the information relating to Stroud contained in this Circular and in the Silver Hammer information circular complies as to form and substance with the requirements of the OBCA and applicable securities laws and contains no misrepresentation;
(k) promptly notify Silver Hammer of any material breach or threatened material breach of a Voting Support Agreement and, if requested, use commercially reasonable efforts to enforce it; and
(l) use commercially reasonable efforts to cause the conditions precedent in its favour and in favour of Silver Hammer to be satisfied on or before the Effective Date.
Covenants of Silver Hammer. Silver Hammer has given substantially reciprocal covenants to Stroud, including to convene and hold the Silver Hammer Meeting no later than September 30, 2026, to solicit proxies in favour of the Transaction, to obtain CSE approval, not to declare dividends or amend its constating documents in a manner adverse to the Transaction, and to ensure that the information relating to Silver Hammer and Subco contained in this Circular and in the Silver Hammer information circular complies with applicable requirements and contains no misrepresentation.
Conditions Precedent to the Amalgamation
Mutual Conditions. The obligations of each Party to consummate the Amalgamation are subject to the following conditions being satisfied on or before the Effective Date:
(a) the Amalgamation having been approved at the Meeting in accordance with the OBCA, the requirements of the TSXV and all applicable laws;
(b) the Transaction having been approved at the Silver Hammer Meeting in accordance with the Business Corporations Act (British Columbia), the requirements of the CSE and all applicable laws;
(c) the Transaction having received all requisite approvals under applicable laws, rules, regulations and policies, including those of the TSXV and the CSE, and all other governmental and regulatory orders and decrees;
(d) Silver Hammer having completed the Consolidation;
(e) all conditions precedent to the SilverMark Acquisition having been satisfied or waived to the satisfaction of each of Silver Hammer and Stroud, other than completion of the Amalgamation;
(f) SilverMark having completed the Private Placement for minimum gross proceeds of $7,000,000, and all conditions to the release of those proceeds from escrow having been satisfied;
(g) there being no order or decree in force restraining or enjoining the consummation of the Amalgamation;
(h) receipt of all necessary approvals in respect of the listing and posting for trading on the CSE of the Resulting Issuer Shares to be issued pursuant to the Amalgamation;
(i) the distribution of the Resulting Issuer Shares pursuant to the Amalgamation being exempt from, or otherwise not subject to, the prospectus requirements of applicable Canadian securities laws; and
(j) the distribution of the Resulting Issuer Shares in the United States in exchange for Stroud Shares pursuant to the Amalgamation being exempt from the registration requirements of United States securities laws.
Conditions in Favour of Stroud. The obligation of Stroud to consummate the Amalgamation is subject to conditions including: performance by Silver Hammer and Subco of their covenants and the accuracy in all material respects of their representations and warranties; delivery of a legal opinion of counsel to Silver Hammer and Subco addressing corporate existence and power, due authorization, the valid allotment and issuance of the Resulting Issuer Shares as fully paid and non-assessable, enforceability, the absence of conflict with constating documents, and the availability of the prospectus exemption in section 2.11 of NI 45-106; delivery of an executed Amalgamation Agreement by Subco; receipt of all required third party and regulatory approvals including CSE approval; the Resulting Issuer Shares being issued free and clear of encumbrances; no Material Adverse Change having occurred in respect of Silver Hammer; the absence of material legal or regulatory proceedings and of any prohibition at law; and the absence of any inquiry or investigation in relation to Silver Hammer or its directors or officers that could have a material adverse effect.
Conditions in Favour of Silver Hammer. The obligation of Silver Hammer to consummate the Amalgamation is subject to conditions including: performance by Stroud of its covenants and the accuracy in all material respects of its representations and warranties; delivery of a legal opinion of counsel to Stroud; delivery of an executed Amalgamation Agreement by Stroud; receipt on the date of the Combination Agreement of executed Voting Support Agreements from each member of the Stroud Board, each officer of Stroud and each Stroud Shareholder holding more than 10% of the Stroud Shares; receipt of all required third party and regulatory approvals including TSXV approval and Stroud Shareholder approval; Dissent Rights not having been validly exercised (and not withdrawn) in respect of more than 5% of the Stroud Shares outstanding immediately prior to the Effective Date; no Material Adverse Change having occurred in respect of Stroud; the absence of material legal or regulatory proceedings, of any prohibition at law and of any inquiry or investigation in relation to Stroud or its directors or officers; Stroud not having any indebtedness, liabilities or obligations other than those disclosed in its most recent financial statements filed on SEDAR+ or incurred in the ordinary course consistent with past practice; receipt of written mutual releases and resignations from each member of the Stroud Board and such officers as Silver Hammer may request; and receipt of duly executed written consents from each holder of Stroud Options consenting to the amendment of the Stroud Options.
The conditions set out in Article 3 of the Combination Agreement will be conclusively deemed to have been satisfied, waived or released on the filing of the Articles of Amalgamation under the OBCA.
No Solicitation
During the period from July 17, 2026 until the earlier of the Effective Date and the termination date under the Combination Agreement, each of Stroud and Silver Hammer has agreed that it will not, directly or indirectly, and will not authorize or permit any of its representatives to, directly or indirectly, solicit, initiate, encourage, engage in or respond to (other than to decline) any inquiries or proposals regarding an Acquisition Proposal, subject to the fiduciary out described below.
Under the Combination Agreement, a "de facto change of control" means, with respect to a Party, the purchase or sale of 20% or more of the assets of the Party, or any purchase or sale of, or tender or exchange offer for, voting securities of the Party that, if consummated, would result in any person beneficially owning securities representing 20% or more of the total voting power of that Party.
Superior Proposals
Stroud or Silver Hammer, or their respective directors, may, in respect of any Acquisition Proposal received prior to the approval of the Amalgamation by that Party's shareholders, change their recommendation to shareholders regarding the approval of the Amalgamation (a "Recommendation Change") if, prior to the Recommendation Change, they have determined that the Acquisition Proposal constitutes a Superior Proposal, advised the other Party of that fact and of their intention to make a Recommendation Change, and afforded the other Party the opportunity to match. The first public announcement or other communication to shareholders of a Recommendation Change is referred to as the "Change Date".
A "Superior Proposal" is a bona fide unsolicited written Acquisition Proposal received after the date of the Combination Agreement that: (A) is made for all of the outstanding Stroud Shares or Silver Hammer Shares, as applicable, or all of the assets of Stroud or Silver Hammer, as applicable; (B) is not conditional on obtaining financing or on the completion of any due diligence by the person making the Acquisition Proposal; (C) is reasonably capable of being completed in accordance with its terms; and (D) in respect of which the board of directors of the relevant Party has determined, acting in good faith, that the Acquisition Proposal would, if consummated, result in a transaction more favourable to that Party's shareholders than the Transaction.
At any time following the Change Date, the other Party may elect, by notice in writing, to terminate the Combination Agreement, in which case the terminating Party's counterparty will be obliged to pay the Compensation Fee. Alternatively, notwithstanding a Recommendation Change, a Party may require the other Party to hold its shareholders meeting.
Compensation Fee
If: (a) following a Recommendation Change by Stroud or Silver Hammer, that Party's shareholders do not approve the Amalgamation at the applicable meeting; or (b) (i) following the date of the Combination Agreement either Party receives a written Acquisition Proposal that has been publicly announced or otherwise disclosed to the public which is determined to be a Superior Proposal, (ii) that Party's shareholders do not approve the Amalgamation at the applicable meeting, and (iii) within twelve (12) months following the date of that meeting the Party accepts, approves or recommends, or enters into an agreement in respect of, the Superior Proposal, then the Party accepting the Superior Proposal must pay the other Party a cash amount equal to $500,000 (the "Compensation Fee").
The Parties have acknowledged that the Compensation Fee is a payment of liquidated damages representing a genuine pre-estimate of the damages the recipient would suffer, and is not a penalty.
Termination
The Combination Agreement may be terminated:
(a) by the mutual consent of the Parties;
(b) by Silver Hammer or Stroud in the circumstances permitted by section 4.2 (Superior Proposals);
(c) by either Party if the other provides notice of its inability to comply with any of the covenants, conditions or agreements to be complied with or satisfied by it;
(d) by Silver Hammer, if Stroud has breached any representation, warranty, covenant or agreement in any material respect and the breach is not cured within ten (10) Business Days following written notice, or is incapable of being cured;
(e) by Stroud, if Silver Hammer has breached any representation, warranty, covenant or agreement in any material respect and the breach is not cured within ten (10) Business Days following written notice, or is incapable of being cured;
(f) by either Party, if the Transaction has not been completed by November 30, 2026 as a result of the failure of one or more of the conditions in that Party's favour to be satisfied or waived, provided that the terminating Party is not then in material breach; or
(g) by either Party, if a material adverse effect on the other Party, or any event that could reasonably be expected to constitute a material adverse effect on the other Party, has occurred.
Alternative Transaction
The Parties have agreed to cooperate in good faith and to take all reasonable steps to complete the Transaction as promptly as practicable. If a Party concludes that it is necessary or desirable to proceed with another form of transaction (such as a plan of arrangement), or to change the order of steps in the Transaction for tax or other valid business reasons, the Parties have agreed to consider such an alternative transaction, subject to the conditions set out in section 3.7 of the Combination Agreement.
Amendment
The Combination Agreement may be amended by written agreement of the Parties before or after the Meeting, without further notice to or authorization on the part of Stroud Shareholders, provided that any such amendment does not materially adversely change the consideration to be received by Stroud Shareholders.
Expenses
Except as otherwise provided in the Combination Agreement, each of Stroud and Silver Hammer will pay its own expenses in connection with the preparation and execution of the Combination Agreement and the transactions contemplated thereby.
CERTAIN SECURITIES LAWS MATTERS
MI 61-101 - Protection of Minority Security Holders in Special Transactions
MI 61-101 regulates certain transactions to ensure equality of treatment among securityholders, generally through enhanced disclosure, approval by a majority of securityholders excluding "interested parties", and in some cases an independent valuation and approval by a special committee of independent directors.
The Amalgamation is considered a "business combination", and is a "connected transaction" with each of the Private Placement and the SilverMark Amalgamation. Dr. Scott Jobin-Bevans is a related party of each of Stroud and SilverMark at the time the transactions were entered into. Specifically, he is the Chief Executive Officer and a director of Stroud, and currently holds 3,857,778 of the common shares (27.78%) and 1,260,000 Class B special shares (32%) of SilverMark. It is anticipated that Dr. Jobin-Bevans' shares in SilverMark will be converted into 1,938,461 Contingent Value Shares, and that in addition to this Contingent Value Shares, he will ultimately hold 1,565,401 of Resulting Issuer Shares (comprising approximately 1.34% of the issued and outstanding Resulting Issuer Shares assuming completion of the Minimum Private Placement and approximately 1.22% of the issued and outstanding Resulting Issuer Shares assuming completion of the Maximum Private Placement). See Information Concerning the Resulting Issuer - Directors, Officers and Promoters in Appendix "F" to this Circular.
Additionally, 2176423 Ontario Ltd. is a control person of Stroud, as it currently holds 37,277,777 Stroud Shares (being approximately 58.59% of the issued and outstanding Stroud Shares). It is anticipated that 2176423 Ontario Ltd. will participate in the Private Placement, which is a "connected transaction" with the Amalgamation. 2176423 Ontario Ltd. will be a control person of the Resulting Issuer. By virtue of its anticipated participation in the Private Placement, which is a "connected transaction" to the Amalgamation, 2176423 Ontario Ltd. is an "interested party" within paragraph (c)(ii) of the definition thereof in MI 61-101, and the votes attaching to the Stroud Shares beneficially owned or controlled by it will be excluded from the minority approval vote pursuant to section 8.1(2)(b) of MI 61-101. Dr. Jobin-Bevans' entitlement to receive Contingent Value Shares in exchange for his Class B special shares of SilverMark constitutes a "collateral benefit" for the purposes of MI 61-101, and he is accordingly an "interested party" within paragraph (c)(iii)(B) of the definition thereof; the votes attaching to his Stroud Shares will likewise be excluded pursuant to section 8.1(2)(b) of MI 61-101.
Formal Valuation
The Amalgamation is exempt from the formal valuation requirements of MI 61-101 under section 4.4(1)(a) of MI 61-101 as no securities of Stroud are listed or quoted on the Toronto Stock Exchange, Aequitas NEO Exchange Inc., the New York Stock Exchange, the American Stock Exchange, the NASDAQ Stock Market, or a stock exchange outside of Canada and the U.S. other than the Alternative Investment Market of the London Stock Exchange or the PLUS markets operated by PLUS Markets Group plc.
Minority Approval
In determining minority approval for a "business combination", Stroud is required to exclude the votes attached to Stroud Shares that, to the knowledge of Stroud and its directors and senior officers after reasonable inquiry, are beneficially owned or over which control or direction is exercised by all "interested parties" and their "related parties" and "joint actors", all as defined in MI 61-101 (collectively, the "Stroud Interested Parties"). The Stroud Shares held by the Stroud Interested Parties will be excluded in determining whether minority approval of the Amalgamation Resolution for the purposes of MI 61-101 is obtained. To date, to the knowledge of Stroud and its directors and senior officers after reasonable inquiry and for the purposes of MI 61-101, it is expected that the votes in respect of an aggregate of 37,573,443 Stroud Shares which represent approximately 59.05% of the issued and outstanding Stroud Shares held by the Stroud Interested Parties will be excluded in determining whether approval of the Amalgamation by the disinterested Stroud Shareholders has been obtained. Details of the shareholdings of the Stroud Interested Parties as at the date of this Circular are as follows:
| Name of Stroud Shareholder |
Stroud Shares Beneficially Owned or Controlled or Directed |
| Dr. Scott Jobin-Bevans | 295,666 Stroud Shares (approximately 0.46% of the issued and outstanding Stroud Shares) |
| 2176423 Ontario Ltd. | 37,277,777 Stroud Shares (approximately 58.59% of the issued and outstanding Stroud Shares) |
Prior Valuations and Prior Offers
MI 61-101 also requires Stroud to disclose any "prior valuations" (as defined in MI 61-101) of Stroud or its material assets or securities made within the 24-month period preceding the date of this Circular. After reasonable inquiry, neither Stroud nor any director or senior officer of Stroud has knowledge of any such "prior valuation". Disclosure is also required for any bona fide prior offer for the Stroud Shares or that is otherwise relevant to the Amalgamation during the 24 months before the Combination Agreement was agreed to. There has not been any such offer during the 24 months before the Combination Agreement was agreed to.
Background to the Amalgamation
The Amalgamation was reviewed and approved by the Board at a meeting held on July 16, 2026, at which all four directors of Stroud were present. At the meeting, Dr. Scott Jobin-Bevans disclosed his interest in the Transactions, being his ownership of shares of SilverMark, and recused himself from voting on the Transactions.
In advance of and at the meeting, Mr. Jakubovic circulated to the Board an internal assessment of the proposed business combination and a memorandum summarizing the material advantages and disadvantages of the Transactions to Stroud and the Stroud Shareholders. Mr. Jakubovic also reported to the Board on his due diligence review of publicly available information concerning Silver Hammer and of Silver Hammer's four principal mineral projects, conducted through the data room made available by Silver Hammer, which review was satisfactory. The Board reviewed the memorandum, the results of the due diligence review and drafts of the Combination Agreement.
Following discussion, the Board determined that the Transactions are in the best interests of Stroud and approved the Transactions and the entering into of the Combination Agreement, subject to the finalization, to the satisfaction of Stroud's legal counsel, of the Exchange Ratio, confirmation that the Compensation Fee was reasonable and reciprocal, and confirmation of the conditions relating to the substantially concurrent completion of the SilverMark Amalgamation, each of which was subsequently resolved in the Combination Agreement executed on July 17, 2026. The resolutions were passed by the affirmative vote of Messrs. Kennedy, O'Brien and Jakubovic; Dr. Jobin-Bevans did not vote. No director expressed a materially contrary view with respect to the Transactions, and there were no abstentions other than Dr. Jobin-Bevans' recusal.
The Board did not constitute a special committee of independent directors in connection with the Transactions. The Board was of the view that a special committee was not necessary in the circumstances because the Amalgamation was negotiated at arm's length between Stroud and Silver Hammer, the only director with an interest in a connected transaction disclosed that interest and recused himself from voting, and completion of the Amalgamation is conditional on minority approval in accordance with MI 61-101, which excludes the votes of all Stroud Interested Parties. Except as set forth above, no "related party" is expected to directly or indirectly receive a "collateral benefit" in connection with the Amalgamation.
Reporting Issuer Status and Stock Exchange Listing
Stroud is a reporting issuer in the Provinces of Ontario, British Columbia and Alberta. The Stroud Shares are listed and posted for trading on the TSXV under the symbol "SDR". If the Amalgamation is completed, the Stroud Shares will be delisted from the TSXV and Amalco intends to apply to the applicable securities regulatory authorities to cease to be a reporting issuer.
Silver Hammer is a reporting issuer in the Provinces of British Columbia, Alberta and Ontario and will continue to be a reporting issuer in those jurisdictions following completion of the Transaction. The Silver Hammer Shares are listed and posted for trading on the CSE under the symbol "HAMR". The Resulting Issuer Shares will continue to be listed and posted for trading on the CSE on a post-Consolidation basis, expected to be under the symbol "SLVF".
Distribution and Resale of Resulting Issuer Shares under Canadian Securities Laws
The distribution of the Resulting Issuer Shares pursuant to the Amalgamation will constitute a distribution of securities that is exempt from the prospectus requirements of Canadian securities legislation pursuant to section 2.11 of NI 45-106. The Resulting Issuer Shares issued pursuant to the Amalgamation may be resold in each province and territory of Canada without hold period restrictions, provided that (a) the Resulting Issuer is and has been a reporting issuer in a jurisdiction of Canada for the four months immediately preceding the trade, (b) the trade is not a "control distribution", (c) no unusual effort is made to prepare the market or create a demand for the securities, (d) no extraordinary commission or consideration is paid in respect of the trade, and (e) if the seller is an insider or officer of the Resulting Issuer, the seller has no reasonable grounds to believe that the Resulting Issuer is in default of securities legislation.
Stroud Shareholders who will hold more than 20% of the outstanding Resulting Issuer Shares following completion of the Transaction, or who otherwise become "control persons" of the Resulting Issuer, will be subject to the "control distribution" restrictions and should consult their own legal advisors.
United States Securities Law Matters
The Resulting Issuer Shares to be issued to Stroud Shareholders pursuant to the Amalgamation have not been and will not be registered under the U.S. Securities Act or any U.S. state securities laws. Silver Hammer has advised that the Resulting Issuer Shares to be issued to Stroud Shareholders who are, or who are acting or for the account or benefit of, U.S. persons or persons in the United States, in connection with the Amalgamation will be issued in reliance upon the exemption from registration provided by Rule 802 under the U.S. Securities Act, together with available exemptions under applicable U.S. state securities laws.
Overview of Rule 802 under the U.S. Securities Act
Rule 802 provides an exemption from the registration requirements of Section 5 of the U.S. Securities Act for securities issued in exchange offers and business combinations involving a "foreign private issuer" (as defined in Rule 405 under the U.S. Securities Act) where U.S. holders hold no more than 10% of the subject securities. Silver Hammer is, and the Resulting Issuer will be, a "foreign private issuer" as defined under U.S. securities laws.
The exemption under Rule 802 is available where the following principal conditions are satisfied:
(a) U.S. Holder Threshold. U.S. holders must hold, in aggregate, no more than 10% of the class of securities that is the subject of the business combination - in this case, the Stroud Shares. For the purposes of Rule 802, a "U.S. holder" is any holder whose last address of record is in the United States. Silver Hammer has determined, based on a review of the shareholder register of Stroud and other reasonably available information, that U.S. holders hold no more than 10% of the outstanding Stroud Shares.
(b) Equal Treatment of U.S. Holders. Subject to applicable laws, U.S. holders of Stroud Shares must be offered the same consideration as all other Stroud Shareholders. Pursuant to the Amalgamation, each Stroud Shareholder (other than Dissenting Shareholders) will receive 0.777963 of a post-Consolidation Resulting Issuer Share for each Stroud Share held. All Stroud Shareholders will receive the same consideration on the same terms.
(c) Disclosure Documents. The exemption requires that any disclosure document distributed to U.S. holders in connection with the business combination: (i) include a legend on the cover page or other prominent place substantially in the form prescribed by Rule 802(b) (see the Notice to U.S. Stroud Shareholders included on the cover page of this Circular); and (ii) be furnished to the SEC on Form CB no later than the business day on which such disclosure document is first published or sent or given to U.S. holders. A written irrevocable consent to service of process on Form F-X must also be filed concurrently with the SEC. Silver Hammer intends to comply with these requirements in connection with the Amalgamation.
U.S. Resale Restrictions
The Resulting Issuer Shares to be issued pursuant to the Amalgamation will be unregistered "restricted securities" within the meaning of Rule 144 under the U.S. Securities Act ("Rule 144") to the same extent and proportion that the securities exchanged by Stroud Shareholders pursuant to the Amalgamation were restricted securities.
Stroud Shareholders who hold Stroud Shares that are restricted securities under Rule 144 will receive Resulting Issuer Shares that are restricted securities under Rule 144. Restricted securities will be represented by physical share certificates or Direct Registration System (DRS) statements imprinted with a U.S. restrictive legend substantially in the following form, and may not be sold or transferred unless registered under the U.S. Securities Act and applicable U.S. state securities laws, or unless an exemption or exclusion from registration is available:
THE SECURITIES REPRESENTED HEREBY HAVE NOT BEEN REGISTERED UNDER THE UNITED STATES SECURITIES ACT OF 1933, AS AMENDED (THE "U.S. SECURITIES ACT"), OR THE SECURITIES LAWS OF ANY STATE OF THE UNITED STATES. THE HOLDER HEREOF, BY PURCHASING SUCH SECURITIES, AGREES FOR THE BENEFIT OF THE COMPANY THAT SUCH SECURITIES MAY BE OFFERED, SOLD OR OTHERWISE TRANSFERRED ONLY: (A) TO THE COMPANY; (B) OUTSIDE THE UNITED STATES IN ACCORDANCE WITH RULE 904 OF REGULATION S UNDER THE U.S. SECURITIES ACT AND IN ACCORDANCE WITH ALL LOCAL LAWS AND REGULATIONS; (C) IN ACCORDANCE WITH THE EXEMPTION FROM REGISTRATION UNDER THE U.S. SECURITIES ACT PROVIDED BY RULE 144 THEREUNDER, IF AVAILABLE, AND IN COMPLIANCE WITH ANY APPLICABLE STATE SECURITIES LAWS; OR (D) IN A TRANSACTION THAT DOES NOT REQUIRE REGISTRATION UNDER THE U.S. SECURITIES ACT AND ANY APPLICABLE STATE SECURITIES LAWS; AND, IN THE CASE OF CLAUSE (C) OR (D), THE SELLER FURNISHES TO THE COMPANY AN OPINION OF COUNSEL OF RECOGNIZED STANDING IN FORM AND SUBSTANCE SATISFACTORY TO THE COMPANY TO SUCH EFFECT. THE PRESENCE OF THIS LEGEND MAY IMPAIR THE ABILITY OF THE HOLDER HEREOF TO EFFECT "GOOD DELIVERY" OF THE SECURITIES REPRESENTED HEREBY ON A CANADIAN STOCK EXCHANGE.
Stroud Shareholders who hold Stroud Shares that are not restricted securities under Rule 144 will receive Resulting Issuer Shares pursuant to the Amalgamation that are not restricted securities. Stroud Shareholders who receive such Resulting Issuer Shares and who are not "affiliates" (as defined under Rule 144 under the U.S. Securities Act) of the Resulting Issuer, and were not affiliates of Stroud within the 90 days prior to the Amalgamation, will be able to resell such Resulting Issuer Shares without restriction under U.S. federal securities laws, subject to the requirements of applicable U.S. state securities laws. Stroud Shareholders who are or were "affiliates" of Stroud or the Resulting Issuer - generally, persons who directly or indirectly control, are controlled by, or are under common control with, the Resulting Issuer - will be subject to the resale restrictions applicable to "control securities" under Rule 144 under the U.S. Securities Act in respect of any Resulting Issuer Shares received as non-restricted securities. Such persons should consult their own legal advisors regarding the restrictions applicable to any resale of Resulting Issuer Shares.
General
This Circular does not constitute an offer to sell, or a solicitation of an offer to buy, any securities in the United States. The foregoing summary of certain aspects of U.S. securities laws is provided for general informational purposes only, is not intended to be a complete description, and does not constitute legal advice. Stroud Shareholders who are located in or are residents of the United States are urged to consult their own legal advisors regarding the U.S. securities law considerations applicable to their particular circumstances.
RISK FACTORS RELATING TO THE AMALGAMATION
If the Amalgamation Resolution is approved and the Amalgamation is completed, Stroud Shareholders will become shareholders of the Resulting Issuer and will be subject to all of the risks associated with the operations of the Resulting Issuer. Stroud Shareholders should carefully consider the following risk factors, together with the risk factors described in the documents incorporated by reference in this Circular, in evaluating whether to approve the Amalgamation Resolution.
Completion of the Transaction is Subject to a Number of Conditions. Completion of the Amalgamation is subject to a number of conditions, several of which are outside the control of Stroud, including approval of the Transaction by Silver Hammer Shareholders, approval of the SilverMark Amalgamation by SilverMark's shareholders, receipt of TSXV and CSE approvals, completion of the Consolidation, and completion of the Private Placement for minimum gross proceeds of $7,000,000 together with satisfaction of the escrow release conditions. There can be no assurance that these conditions will be satisfied or waived.
The Amalgamation is Conditional on Unrelated Transactions. Completion of the Amalgamation is conditional upon matters relating to third parties over which Stroud has no control, namely the SilverMark Amalgamation and the Private Placement. If the SilverMark Amalgamation does not proceed, or if the Private Placement cannot be completed on acceptable terms or at all, the Amalgamation will not be completed even if the Amalgamation Resolution is approved and all conditions relating to Stroud and Silver Hammer are satisfied.
Failure to Complete the Transaction Could Negatively Impact the Market Price of the Stroud Shares. If the Transaction is not completed, the market price of the Stroud Shares may decline to the extent that the current market price reflects a market assumption that the Transaction will be completed. Stroud will also have incurred significant costs and will have diverted substantial management resources to the Transaction.
Termination in Certain Circumstances; Compensation Fee. Each of Stroud and Silver Hammer has the right to terminate the Combination Agreement in certain circumstances, including if the Transaction has not been completed by November 30, 2026. In certain circumstances Stroud may be required to pay a Compensation Fee of $500,000, which may reduce the funds available to Stroud to pursue alternatives.
The Exchange Ratio is Fixed and Will Not be Adjusted. The Exchange Ratio is fixed and will not be adjusted to reflect changes in the market price of the Stroud Shares or the Silver Hammer Shares between the date of the Combination Agreement and the Effective Date. The market price of the Resulting Issuer Shares on the Effective Date may be materially lower than the market price of the Silver Hammer Shares on the date of the Combination Agreement or the date of this Circular.
The Consolidation May Adversely Affect the Trading Price of the Silver Hammer Shares. There can be no assurance that the market price of the Silver Hammer Shares following the Consolidation will be four times the market price prior to the Consolidation, or that the Consolidation will not adversely affect the liquidity of the Silver Hammer Shares.
Dilution. Following completion of the Transaction, former Stroud Shareholders will hold approximately 49,496,496 (approximately 55%) of the outstanding Resulting Issuer Shares before giving effect to the Private Placement, and a smaller percentage after giving effect to the Private Placement, the Contingent Value Shares and the securities issuable on exercise of the Resulting Issuer's outstanding options and warrants. The interests of former Stroud Shareholders will be further diluted by any additional equity financings undertaken by the Resulting Issuer.
No Fractional Shares. No fractional Resulting Issuer Shares will be issued and no cash will be paid in lieu of fractional entitlements. Stroud Shareholders holding a small number of Stroud Shares may therefore receive a materially lower value than the Exchange Ratio would otherwise imply.
Restrictions on Soliciting Alternative Transactions. The Combination Agreement restricts Stroud's ability to solicit alternative transactions and requires Stroud to afford Silver Hammer an opportunity to match any Superior Proposal. These provisions, together with the Voting Support Agreements covering approximately 61.38% of the Stroud Shares in the aggregate (including approximately 58.59% held by 2176423 Ontario Ltd. alone), may discourage a third party from proposing a competing transaction that might be more advantageous to Stroud Shareholders.
Concentration of Ownership of the Resulting Issuer. Following completion of the Transaction, 2176423 Ontario Ltd. is expected to be the largest shareholder of the Resulting Issuer, holding approximately 27.02% of the Resulting Issuer Shares. That shareholder will be in a position to exercise significant influence over matters requiring shareholder approval and its future sales of Resulting Issuer Shares could adversely affect the market price of the Resulting Issuer Shares.
Dissent Rights. It is a condition in favour of Silver Hammer that Dissent Rights not be exercised in respect of more than 5% of the outstanding Stroud Shares. Silver Hammer may, in its sole discretion, waive this condition, but is not obliged to do so. If Dissent Rights are exercised in respect of more than 5% of the Stroud Shares and the condition is not waived, the Amalgamation will not be completed.
Change of Listing and Regulatory Regime. Following the Transaction, former Stroud Shareholders will hold securities listed on the CSE rather than the TSXV. The CSE and the TSXV apply different listing standards and continued listing requirements.
Foreign Operations. The Resulting Issuer's assets will be located in Mexico, the United States and, indirectly, Morocco. Operations in those jurisdictions are subject to risks including political and regulatory instability, changes in mining and tax laws, expropriation, title and permitting risk, community relations risk, currency fluctuations and difficulty in enforcing judgments.
Integration. The Resulting Issuer may not realize the anticipated benefits of the Transaction. The integration of three businesses across three jurisdictions may divert management attention and result in unanticipated costs.
Additional Risks. Additional risks and uncertainties, including those currently unknown to or considered immaterial by Stroud, may also adversely affect the Resulting Issuer Shares and the business of the Resulting Issuer following the Amalgamation.
CERTAIN CANADIAN FEDERAL INCOME TAX CONSIDERATIONS TO STROUD SHAREHOLDERS
The following summary describes the principal Canadian federal income tax considerations generally applicable in respect of the Amalgamation to a beneficial owner of Stroud Shares who, for the purposes of the Income Tax Act (Canada) (the "Tax Act") and at all relevant times, holds Stroud Shares, and will hold Resulting Issuer Shares acquired pursuant to the Amalgamation, as capital property, deals at arm's length with each of Stroud and Silver Hammer, and is not affiliated with either of them (a "Holder").
Stroud Shares and Resulting Issuer Shares will generally be considered capital property to a Holder unless the Holder holds such securities in the course of carrying on a business of buying and selling securities or has acquired them in a transaction considered to be an adventure or concern in the nature of trade.
This summary is not applicable to a Holder: (i) that is a "financial institution" for the purposes of the mark-to-market rules in the Tax Act; (ii) that is a "specified financial institution"; (iii) an interest in which is a "tax shelter investment"; (iv) that has made a functional currency reporting election; (v) that has entered into a "derivative forward agreement" or a "synthetic disposition arrangement" in respect of Stroud Shares or Resulting Issuer Shares; or (vi) that is a corporation resident in Canada that is or becomes controlled by a non-resident person or group for the purposes of the "foreign affiliate dumping" rules in section 212.3 of the Tax Act. Such Holders should consult their own tax advisors.
This summary does not address the tax consequences of exercising Dissent Rights. Stroud Shareholders wishing to exercise Dissent Rights should consult their own tax advisors.
This summary is of a general nature only and is not exhaustive of all possible Canadian federal income tax considerations. It is not intended to be, nor should it be construed to be, legal or tax advice to any particular Stroud Shareholder. Stroud Shareholders should consult their own tax advisors having regard to their own particular circumstances.
Holders Resident in Canada
The following portion of this summary applies to a Holder who, at all relevant times, is or is deemed to be resident in Canada for the purposes of the Tax Act (a "Resident Holder").
Exchange of Stroud Shares for Resulting Issuer Shares. A Resident Holder who receives Resulting Issuer Shares on the Amalgamation in exchange for Stroud Shares will generally be deemed to have disposed of those Stroud Shares for proceeds of disposition equal to the aggregate adjusted cost base of the Stroud Shares to the Resident Holder immediately before the Amalgamation, and to have acquired the Resulting Issuer Shares at a cost equal to that amount. Accordingly, a Resident Holder will generally not realize a capital gain or capital loss on the exchange. This treatment applies automatically; no election is required.
Taxation of Dividends. Dividends received or deemed to be received on Resulting Issuer Shares by a Resident Holder who is an individual will be included in computing the individual's income and will be subject to the gross-up and dividend tax credit rules applicable to taxable dividends received from taxable Canadian corporations, including the enhanced gross-up and dividend tax credit in respect of "eligible dividends". Dividends received or deemed to be received by a Resident Holder that is a corporation will be included in computing income and will generally be deductible in computing taxable income, subject to the limitations in the Tax Act. A Resident Holder that is a "private corporation" or a "subject corporation" may be liable for the refundable tax under Part IV of the Tax Act on dividends received to the extent they are deductible in computing taxable income.
Dispositions of Resulting Issuer Shares. A Resident Holder that disposes or is deemed to dispose of Resulting Issuer Shares will generally realize a capital gain (or capital loss) to the extent that the proceeds of disposition, net of reasonable costs of disposition, exceed (or are less than) the adjusted cost base of those shares.
Taxation of Capital Gains and Losses. Generally, a Resident Holder is required to include in computing income for a taxation year the taxable portion of any capital gain realized in the year, and may deduct the allowable portion of any capital loss realized in the year against taxable capital gains realized in the year, with any excess carried back three years or forward indefinitely, in each case in accordance with the Tax Act. The amount of any capital loss realized by a Resident Holder that is a corporation on the disposition of a share may be reduced by the amount of dividends received or deemed to have been received on that share, subject to and in accordance with the Tax Act. Analogous rules apply where a corporation is a member of a partnership or a beneficiary of a trust that owns shares.
Minimum Tax. Capital gains realized and dividends received or deemed to be received by individuals and certain trusts may give rise to minimum tax under the Tax Act.
Eligibility for Investment. Provided the Resulting Issuer Shares are listed on a "designated stock exchange" for the purposes of the Tax Act (which currently includes the CSE) or the Resulting Issuer qualifies as a "public corporation", the Resulting Issuer Shares will be qualified investments under the Tax Act for a trust governed by a registered retirement savings plan, registered retirement income fund, registered education savings plan, registered disability savings plan, tax-free savings account, first home savings account or deferred profit sharing plan (each, a "Registered Plan"). Notwithstanding the foregoing, the holder, subscriber or annuitant under a Registered Plan will be subject to a penalty tax if the Resulting Issuer Shares are a "prohibited investment" for the Registered Plan. Holders should consult their own tax advisors.
Holders Not Resident in Canada
The following portion of this summary applies to a Holder who, for the purposes of the Tax Act and at all relevant times, is not and is not deemed to be resident in Canada and does not use or hold, and is not deemed to use or hold, Stroud Shares or Resulting Issuer Shares in carrying on a business in Canada (a "Non-Resident Holder").
Exchange of Stroud Shares for Resulting Issuer Shares. The discussion above under "Holders Resident in Canada - Exchange of Stroud Shares for Resulting Issuer Shares" generally also applies to a Non-Resident Holder. If a Non-Resident Holder's Stroud Shares are "taxable Canadian property", the Resulting Issuer Shares received in exchange therefor will generally also be deemed to be taxable Canadian property to the Non-Resident Holder for a period of 60 months following the exchange.
Dividends on Resulting Issuer Shares. Dividends paid, deemed to be paid or credited on Resulting Issuer Shares to a Non-Resident Holder will be subject to Canadian non-resident withholding tax at a rate of 25% of the gross amount of the dividend, subject to reduction under the provisions of an applicable income tax treaty or convention.
Dispositions of Resulting Issuer Shares. A Non-Resident Holder will not be subject to tax under the Tax Act on a capital gain realized on the disposition of Resulting Issuer Shares unless those shares are "taxable Canadian property" and are not "treaty-protected property". Generally, Resulting Issuer Shares will not be taxable Canadian property to a Non-Resident Holder at a particular time provided the shares are listed on a designated stock exchange at that time, unless at any time during the 60-month period immediately preceding that time (a) 25% or more of the issued shares of any class of the capital stock of the Resulting Issuer were owned by, or belonged to, any combination of the Non-Resident Holder, persons not dealing at arm's length with the Non-Resident Holder and partnerships in which the Non-Resident Holder or such persons hold a membership interest directly or indirectly through one or more partnerships, and (b) more than 50% of the fair market value of the shares was derived directly or indirectly from any combination of real or immovable property situated in Canada, Canadian resource properties, timber resource properties, and options or interests in respect of any of the foregoing.
Non-Resident Holders should consult their own tax advisors having regard to their own particular circumstances, including with respect to the requirement to obtain a clearance certificate under section 116 of the Tax Act where taxable Canadian property is disposed of.
OTHER TAX CONSIDERATIONS
This Circular does not address any tax considerations of the Amalgamation other than certain Canadian federal income tax considerations. Stroud Shareholders who are resident in, or subject to tax in, a jurisdiction other than Canada should consult their own tax advisors with respect to the tax implications of the Amalgamation, including any associated filing requirements, in that jurisdiction.
INFORMATION CONCERNING STROUD
Documents Incorporated by Reference
The following documents filed by Stroud with the securities regulatory authorities in the Provinces of Ontario, British Columbia and Alberta are specifically incorporated by reference into, and form an integral part of, this Circular:
Any document of the type referred to in section 11.1 of Form 44-101F1 filed by Stroud with a securities commission or similar authority in Canada after the date of this Circular and prior to the Meeting is deemed to be incorporated by reference in this Circular.
Any statement contained in this Circular or in a document incorporated or deemed to be incorporated by reference herein is deemed to be modified or superseded, for the purposes of this Circular, to the extent that a statement contained herein or in any subsequently filed document that is also incorporated or deemed to be incorporated by reference herein modifies or supersedes that statement.
Copies of the documents incorporated or deemed to be incorporated by reference may be obtained on request without charge from Stroud at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, telephone 416.888.8731, and are also available under Stroud's profile on SEDAR+ at www.sedarplus.ca.
Corporate Structure
Stroud is a corporation existing under the OBCA, which was incorporated on March 18, 1983. Its head and registered office is located at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6.
Stroud has two subsidiaries, as follows: (i) Compañia Minera San Diego y La Espanola S.A. de C.V. (the "Mexican Subsidiary"), of which Stroud holds, directly or indirectly, 99.999985% of the issued and outstanding equity securities, with the remaining 0.000015% held by a nominee solely to satisfy the minimum shareholder requirements under applicable Mexican corporate law, and that nominee holds such equity securities for the benefit of Stroud; and (ii) Grande Pleiad Oil Ltd., a corporation existing under the laws of the Province of Alberta of which Stroud holds all of the issued and outstanding equity securities.
General Description of the Business
The following is a description of the general development of the business of Stroud over its three most recently completed financial years and up to the date of this Circular. The discussion includes the major events or conditions that have influenced that development through the aforementioned period. Stroud's financial year end is December 31. Additional information regarding the matters described below may be found under Stroud's profile on SEDAR+ at www.sedarplus.ca.
History
Year Ended December 31, 2023
On May 9, 2023, Stroud provided a summary of its 2021-2022 drilling program on the Santo Domingo property. The 2021-2022 exploration drilling program consisted of approximately 9,936 m in 32 diamond drill holes. The drilling program was designed to explore the extent of known epithermal vein-hosted silver mineralization on the Santo Domingo property and to begin to define additional silver mineralized zones and vein systems which were anticipated to run parallel to the existing La Raya and Guadalupe silver vein systems.
On May 29, 2023, Stroud announced that it had closed a private placement, which consisted of the issuance of a convertible debentures in the amount of $600,000, bearing interest of 14% and maturing 90 days from the date of issuance. In accordance with their terms, the convertible debentures would convert into units at a price of at $0.10 per unit. Each unit was comprised of one common share and one common share purchase warrant, with each warrant being exercisable into one common share at a price of $0.10 for a period of three from closing. Eric Sprott, through 2176423 Ontario Ltd., a corporation which is beneficially owned by him which at the time held approximately 49% of the issued and outstanding Stroud Shares, acquired the convertible debenture. The convertible debentures were converted and the units were issued on September 12, 2023.
Year Ended December 31, 2024
During the year ended December 31, 2024, Stroud continued to advance its Santo Domingo Silver-Gold Project in Jalisco, Mexico, and maintained its mineral concessions in good standing through the incurrence of minimum annual exploration expenditures and payment of semi-annual concession fees to the Secretaría de Economía. Stroud continued to hold its 3.75% working interest in six natural gas wells in central Alberta, operated by Gran Tierra Canada Ltd. (formerly I3 Energy Inc.), which generated ongoing revenue net of royalties and operating expenses.
Year Ended December 31, 2025
On September 24, 2025, Stroud announced the appointment of Conor O'Brien as an independent director, as well as the grant of Stock Options exercisable for an aggregate of 1,005,000 Stroud Shares at an exercise price of $0.12 for a period of five years.
In November 2025, Eric Sprott, through 2176423 Ontario Ltd., exercised 3,000,000 common share purchase warrants (originally issued in connection with the September 2023 conversion of the convertible debenture referenced above) at $0.10 per warrant, for gross proceeds to the Company of $300,000.
On September 24, 2025, Stroud granted stock options to certain officers and directors of the Company, exercisable at $0.12 per Stroud Share and having a five-year term, with an aggregate grant date fair value of $110,000.
During the year, the Company received an unsecured loan of $75,000 from 2176423 Ontario Ltd., bearing interest at 12% per annum, which was repaid in full prior to year end.
The Company continued to maintain its Santo Domingo mineral concessions in good standing and its 3.75% working interest in six natural gas wells in central Alberta.
Subsequent Events
Subsequent to year end, on March 27, 2026, 2176423 Ontario Ltd. exercised its remaining 3,000,000 common share purchase warrants at an exercise price of $0.10 per Stroud Share, for gross proceeds to the Company of $300,000.
On July 17, 2026, Stroud entered into the Combination Agreement. Significant Acquisitions
Stroud has not completed any significant acquisitions during its most recently completed financial year for which disclosure is required under Part 8 of NI 51-102.
Summary Description of the Business
Overview
Stroud is a Canadian mineral exploration company whose principal asset is an effective 100% interest in the Santo Domingo silver-gold property located in the Western Silver-Gold Belt in Jalisco, Mexico, held through the Mexican Subsidiary. Stroud's principal activities are focused on the exploration of the Santo Domingo property. Stroud's strategy is to enhance shareholder value through the acquisition and advancement of exploration stage properties with the potential to host significant economic mineralization in established and prospective mining districts in Mexico.
Principal Products or Services
Stroud is an exploration-stage company and does not currently mine, produce, or sell any mineral products. The Santo Domingo property hosts a current NI 43-101 Mineral Resource Estimate (as disclosed in the Company's August 21, 2026 Technical Report), but does not contain any known mineral reserves as defined under applicable securities legislation. Stroud's exploration activities are focused primarily on silver.
Production and Sales
Stroud has no producing properties and therefore has no production or sales activities at this time.
Specialized Skills and Knowledge
Mineral exploration and development requires a broad range of specialized skills and expertise, including geology, engineering, environmental compliance, drilling, logistical planning, project management, finance, accounting, and legal. Stroud relies on both internal personnel and external consultants who possess these skills, including in Mexico, being the jurisdiction in which Stroud's primary mineral property is located.
Competitive Conditions
The precious metals exploration and mining industry is extremely competitive, and Stroud competes with other mining companies for precious metals properties, for joint venture partners and opportunities and for the acquisition of investments in other mining companies.
Specifically, as a mineral exploration and development company, Stroud may compete with other entities in the mineral exploration and development business in various aspects, including: (a) seeking out and acquiring mineral exploration and development properties; (b) obtaining the resources necessary to identify and evaluate mineral properties and to conduct exploration and development activities on such properties; and (c) raising the capital necessary to fund its operations. The mining industry is intensely competitive in all its phases, and Stroud may compete with other companies that have greater financial resources and technical facilities. Competition could adversely affect Stroud's ability to acquire suitable properties or prospects in the future or to raise the capital necessary to continue with operations. See "Risk Factors."
Cycles
The mineral exploration industry is cyclical. Stroud's ability to raise capital and advance exploration programs is heavily influenced by global economic conditions and by fluctuations in the prices of commodities, particularly silver and gold. These prices have experienced substantial volatility in recent years and are difficult to forecast. Periods of declining commodity prices can reduce investor interest in exploration companies, restrict access to capital, and negatively impact the economic potential of Stroud's mineral projects.
External events, including global economic disruptions, financial market instability, geopolitical developments, and public health emergencies, may further exacerbate commodity price volatility and financing challenges. Such conditions may affect Stroud's ability to implement its business plans. See "Risk Factors."
Economic Dependence
As an exploration-stage company with no producing assets or significant operating revenue, Stroud is economically dependent on its ability to obtain external financing to fund its operations and exploration programs. Stroud's future business prospects are dependent on the successful advancement of the Santo Domingo property. These additional properties will expand the Resulting Issuer's geographic and jurisdictional exposure significantly, including to jurisdictions that carry materially different political, regulatory, and operational risks. See "Risk Factors".
Stroud may additionally depend on a limited number of consultants, contractors, and service providers to carry out key exploration and technical activities. Any disruption in access to financing, Stroud's mineral projects, or essential third-party services could have a material adverse effect on Stroud's business and planned exploration activities.
Environmental Protection
Stroud's exploration and evaluation activities are subject to environmental laws and regulations, which are continually evolving and may become more stringent over time. Stroud has incurred, and expects to continue to incur, expenditures to maintain such compliance. In particular, Stroud is subject to the laws and regulations relating to environmental matters in all jurisdictions in which it operates (including in particular, in Mexico), including provisions relating to property reclamation, discharge of hazardous materials and other matters. Stroud may also be held liable should environmental problems be discovered that were caused by former owners and operators of its properties. Stroud conducts its mineral exploration activities in compliance with applicable environmental protection legislation, and management of Stroud believes that it is, in all material respects, in compliance with applicable environmental legislation. Stroud is not aware of any existing environmental problems related to any of its properties that may result in material liability to Stroud.
Future changes to environmental laws or regulations, or more stringent enforcement, could result in increased costs, operating restrictions, or delays in planned exploration activities. Additional information on environmental risks is provided under "Risk Factors".
Employees
As of the date hereof, Stroud has no permanent full-time and no part-time employees. Stroud's operations are managed by its directors and officers, and Stroud anticipates engaging consultants in geology, exploration, and related technical and administrative fields as required.
Foreign Operations and Emerging Markets Considerations
Stroud's operations are carried out in Mexico, which is considered to be an emerging market, and as such, Stroud's operations may be affected by possible political or economic instability and government regulations relating to the mining industry and foreign investors therein. Mineral exploration and mining activities may be affected in varying degrees by government regulations with respect to restrictions on production, price controls, export controls, income taxes, expropriation of property, maintenance of property, environmental legislation, land use, land claims of local people, water use and property safety. The effect of these factors on Stroud cannot be accurately predicted. See also "Risk Factors - Risks Related to the Company's Business" for more information about the risk and uncertainties concerning Stroud's foreign operations.
Corporate Structure Controls
The risks of the corporate structure of Stroud and its subsidiaries are risks that are typical and inherent for issuers who have material assets and property interests held indirectly through foreign subsidiaries and located in foreign jurisdictions. As a result, Stroud's business and operations are exposed to various levels of political, economic and other risks and uncertainties associated with operating in a foreign jurisdiction such as difference in laws, business cultures and practices, banking systems and internal control over financial reporting.
Such risks are mitigated by the use of local experts (legal, accounting, tax and directors), by maintaining local bank accounts with "as needed cash balances" with accredited banking institutions and exercising controls over the use of cash, performing regular reviews of the consolidated books and records at Stroud's head office and frequent personal inspection and visits to the offices and project location of the foreign subsidiaries by Stroud's key management on a regular basis.
Board Oversight
Stroud has implemented a system of corporate governance, internal controls over financial matters, and disclosure controls and procedures that apply to Stroud and its subsidiaries, which are overseen by the Board and implemented by senior management.
While the exploration operations of each of Stroud's Mexican subsidiaries are managed locally, the Board is responsible for the overall stewardship of Stroud and, as such, supervises the management of the business and affairs of Stroud and each of its subsidiaries. More specifically, the Board is responsible for reviewing the strategic business plans and corporate objectives, and approving acquisitions, dispositions, investments, capital expenditures, and other transactions and matters that are material to Stroud including those of its subsidiaries.
The Board has effective oversight of Stroud's, including Stroud's bank accounts. Stroud has put in place senior management in Mexico, and members of Stroud's executive management are directors of the subsidiaries.
Executive management of Stroud meets with the Board at least on a quarterly basis and generally more frequently on an informal basis to discuss any relevant or key topics in Mexico as they relate to operations, and with respect to potential merger and acquisition transactions and corporate opportunities. Key topics include social and environmental licenses, and government influence at the federal, state, and municipal levels. Stroud holds minimal cash in Mexican bank accounts and funds the Mexican operations from Canada on a monthly basis.
Board and Management Experience
Key members of Stroud's management team and Board have extensive experience running public and private business operations in North and South America.
Dr. Scott Jobin-Bevans, the Chief Executive Officer and a director of Stroud since 2014, is also the Managing Director and Principal Geoscientist of Caracle Creek Chile SpA and Principal Geoscientist and a Director of Caracle Creek International Consulting Inc. (Canada), both international private geological and geophysical consulting companies. Dr. Jobin-Bevans has spent nearly 30 years building and operating exploration platforms across emerging jurisdictions, including Chile, the Dominican Republic, South Africa, and Zambia, and has served as an officer, director, or technical advisor to numerous public and private issuers with assets across Latin America and Africa, including involvement in taking several private companies public. He is also a Director of International Prospect Ventures Ltd. (also VP Exploration), Northern Shield Resources Inc., Vision Lithium Inc., Thunder Gold Corp., Sienna Resources Inc., EV Minerals Corporation, and Makenita Resources Inc.
Mirsad Jakubovic, has served as Chief Financial Officer, Corporate Secretary and a director of Stroud since 2011, during which time Stroud has focused on the discovery and exploration of silver deposits in Mexico. His broader career reflects sustained financial and operational experience across emerging markets, including his roles as CFO of mPath Therapeutics Corp. and Seven-10
Pharmaceuticals Ltd., both GMP-certified pharmaceutical operations based in Jamaica producing for export to the EU, Brazil, Mexico, and CARICOM markets. He has also held CFO roles with Medifocus Inc. (TSX-V/NASDAQ) and 48 North Cannabis Corp., and holds an MBA from the Richard Ivey School of Business, University of Western Ontario, and a Chartered Accountant designation from ICAO.
William "Jeff" Kennedy, a director of Stroud, also currently serves as Chair and Director of Jaguar Mining Inc., a TSX-listed gold producer with all of its mining operations based in Brazil, giving him board-level oversight of emerging-market operating risk. Previously, Mr. Kennedy served as a director of Uranium Participation Corp, eventually serving as Chair, from the inception in 2005 until the corporation was reconfigured as a commodity trust in 2021. From 1998 onwards, Mr. Kennedy held senior executive roles at Sprott Securities and its successor Cormark Securities Inc. until retiring in 2019.
Conor O'Brien, a director of Stroud, has held senior executive roles in various entities managed by Eric Sprott Family Office. His more than 20 years in global capital markets have centered on financing and advising junior mining issuers whose projects are frequently located in emerging and frontier jurisdictions across Latin America, Africa, and elsewhere, giving him direct exposure to the financing and risk dynamics of emerging-market resource development.
Internal Control Over Financial Reporting
Stroud maintains internal control over financial reporting with respect to its Mexican operations by taking various measures. Differences in banking systems and controls between Mexico and Canada are addressed by having controls over cash in both locations; particularly over access to cash, cash disbursements, appropriate authorization levels, and performing and reviewing bank reconciliations on a monthly and quarterly basis. The Chief Financial Officer of Stroud reviews and approves the financial statements of Stroud on a monthly basis.
Stroud maintains various cash and investment accounts with Mexican and Canadian banks under the direction of the Chief Financial Officer of Stroud. Payments to Mexican and Canadian creditors are reviewed and approved by the Chief Financial Officer, who has the appropriate level of approval authority. All expenditures that are unbudgeted or outside the normal course of business are referred to Stroud's management in Canada for approval and/or payment where appropriate.
The difference in cultures and practices between the two countries is addressed by employing competent staff and consultants in both countries who are familiar with the local laws, business culture and standard practices, have local language proficiency, are experienced in working in the respective jurisdictions and dealing with the local government authorities, and have experience and knowledge of the local banking systems and treasury requirements. Stroud documents and assesses the design of internal controls over financial reporting on an annual basis. Furthermore, key controls for the accounts in scope are tested across Stroud on an annual basis. This process is undertaken by the Chief Financial Officer of Stroud.
Stroud has adopted formal policies and procedures for the evaluation of related party transactions, including, but not limited to, ensuring that in camera sessions are held at Board meeting with only independent directors present on an ad hoc basis; and establishing a process for independent vetting by the Audit Committee of any related party arrangements or transactions.
Legal Framework
The Mexican legal framework is based in a civil law system, and therefore the majority of legal principles are set out in written codes and laws. Written codes and laws are the main source for law, leaving case law and customs as a limited and secondary source of interpretation. This, as opposed to common law systems, provides a fairly stable legal environment, allowing citizens and corporations to have a clear understanding of their rights and obligations.
Notwithstanding the foregoing, certain matters may be subject to case law interpretations, which usually relate to a mining title owner's ability to perform activities under the rights granted under its properties and assets, than to the good standing of its properties and assets. The following matters are the most common issues subject to judicial and administrative interpretation: (i) the presence of ethnic minorities in the territory covering a mining right, and the need for public hearings prior to the commencement of certain mining activities; and (ii) the presence of environmental areas of special interest, or those restricted from mining and the possibility to perform mining activities in overlapping areas. These matters have been widely considered under Mexican constitutional case law, setting a clear understanding of its scope and framework.
Permits and Approvals
Stroud has experienced senior management, who have extensively dealt with permitting, licensing, and other regulatory approvals on a consistent basis in Mexico and are in continuous contact with government authorities to ensure all are in place in order to operate under Mexican laws. There are currently no restrictions or conditions imposed by the government on Stroud, nor does Stroud anticipate and restrictions or conditions to be imposed.
Lending Operations, Investment Policies and Restrictions
Stroud has not adopted any specific investment or lending policies but will ensure that any investment or debt-related activities undertaken are consistent with the interests of Stroud and its shareholders.
Bankruptcy and Similar Procedures
There is no bankruptcy, receivership or similar proceedings against Stroud, nor is management of Stroud aware of any such pending or threatened proceedings. There have not been any voluntary bankruptcy, receivership or similar proceedings by Stroud since incorporation or currently proposed for the current financial year.
Reorganizations
There have been no material reorganizations of or involving Stroud within the three most recently completed financial years or during the current financial year. Stroud has proposed the Amalgamation, which, if completed, may constitute a material reorganization of Stroud. The Amalgamation has not yet been completed as at the date of the Information Circular. See "The Amalgamation" for further details.
Social or Environmental Policies
At its current stage of development and activities, Stroud has limited financial obligations in meeting applicable environmental standards. This may change as Stroud advances its projects.
Environmental regulations applicable to Stroud cover a wide variety of matters, including, without limitation, prevention of waste, pollution and protection of the environment, labour regulations and worker safety. While Stroud does not currently expect the impact of costs and other effects related to compliance with environmental, health and safety regulations to have a material adverse effect on its financial condition or results of operations, such regulations are evolving in a manner which is likely to result in stricter standards and enforcement, increased fines and penalties for non-compliance, more stringent environmental assessments of proposed projects, and a heightened degree of responsibility for companies and their directors and employees. Such stricter standards could impact Stroud's costs and have an adverse effect on results of operations. Furthermore, an environmental, safety or security incident could impact Stroud's reputation in such a way that the result could have a material adverse effect on its business and on the value of its securities.
Trends, Commitments, Events or Uncertainties
There are significant uncertainties related to the price of silver, gold, and other minerals, as well as the availability of equity financing required to support current and future mineral exploration and development activities. Mineral prices have experienced substantial volatility in recent years, and similar fluctuations are expected to continue. There is no guarantee that Stroud will be able to secure the financing necessary to advance its exploration programs or pursue new opportunities. Any inability to raise funds on a timely basis may constrain Stroud's ability to grow and execute its business strategy. Apart from these risks and those identified under "Risk Factors", Stroud is not aware of any additional trends, commitments, events, or uncertainties that are reasonably likely to have a material adverse effect on its business, financial condition, or results of operations.
Santo Domingo
As at the date of the Circular, the Santo Domingo property is Stroud's only material mineral property. On August 28, 2026 Stroud filed on SEDAR+ a NI 43-101 compliant technical report titled "National Instrument 43-101 Mineral Resource Estimate on the Santo Domingo Silver-Gold Deposit and Technical Report for the Santo Domingo Project" and dated effective August 21, 2026 for the Santo Domingo Project A description of the Santo Domingo property is set out below.
The information contained below is substantially reproduced from the summary section of the Technical Report. Such information is subject to certain assumptions, qualifications and procedures described in the Technical Report and is qualified in its entirety by the full text of the Technical Report, which is incorporated by reference herein and is available on SEDAR+ (www.sedarplus.ca) under Silver Hammer and Stroud's issuer profiles. Capitalized terms and abbreviations used in this section have the meanings ascribed to such terms and abbreviations as set forth in the Technical Report.
Property Description, Location and Access
Stroud. owns 100% of the Santo Domingo II and Nombre de Dios mining concessions, together the Santo Domingo Project, located in the mining district of Hostotipaquillo, Jalisco State, Mexico. Hostotipaquillo is located approximately 100 km by road, west of Guadalajara. These mining concessions are located along the south side of the Grand Rio de Santiago river valley, centred at approximately 21°6'21"N Latitude, 103°58'45"W Longitude or 606023 mE, 2334200 mN (WGS84 Zone 13N).
The Property consists of two mining concessions (together the "Mining Concessions") registered 100% to Compañía Minera San Diego y La Española, S.A. de C.V. ("SDLE"), a wholly-owned subsidiary of Stroud (Table 1-1).
Table 1-1. Summary of information for the Santo Domingo Mining Concessions (Atticus, 2026).
| Name | Title No. | Area (ha) | Holder | Type | Date Granted | Expiry (dd/mm/yyyy) | |
| Santo Domingo II | 186469 | 40 | SDLE | Exploitation | 2 April 1990 | 02/04/2040 | |
| Nombre de Dios | 187901 | 95 | SDLE | Exploitation | 22 November 1990 | 22/11/2040 | |
| Total: | 135 |
The Property comprises two exploitation concessions held by SDLE. Both were granted in 1990 under the mining law then in force, which provided for a term of fifty years. As of the Effective Date of this report, both concessions are paid up to the current period. Declarations for the second half of 2026 were filed with the Servicio de Administración Tributaria on 24 July 2026.
The surface rights over the Santo Domingo II and Nombre de Dios concessions, and the surrounding area, is held by the Ejido of Santo Domingo de Guzmán. The ejido settlement of the same name lies approximately 1.9 km from the centre of the concessions.
Stroud holds a surface access agreement with the Ejido of Santo Domingo de Guzmán through November 2033.
The Property is accessed by paved road from Magdalena to Hostotipaquillo and then on to La Labor de Guadalupe. Magdalena is approximately 70 km via the Guadalajara-Tepic toll-highway west of Guadalajara. From La Labor, a single lane, dirt road joins to Santo Domingo De Guzman. The Property is approximately 5 km by road from Santo Domingo de Guzman, along a road that leaves from the local school and winds down into the Valley of the Grand Rio de Santiago.
The Ejido of Santo Domingo de Guzman owns the surface rights covering the Mining Concessions and surrounding area. Stroud has not had any issues with entering the Project and conducting exploration work on the Property.
The Project district climate is made up of a dry season (November to May) and a wet season (June to October). The rainy/wet season brings overcast skies, high humidity, and frequent afternoon thunderstorms. While mornings can be sunny, precipitation is highly likely during the latter half of the day.
In general, all types of exploration work can be conducted year-round with the best times of year from late April to mid-June and from mid-October to early November. Although climatic conditions do not impose significant operational constraints, exploration programs in the rainy/wet season may be somewhat compromised.
The Property lies within the Municipality of Hostotipaquillo, which has a population of approximately 8,700. The municipal seat, Hostotipaquillo, lies 9.5 km from the Property and had a population of 8,732. Hostotipaquillo, Magdalena (22 km from the Property with a population of just over 33,049), and the largest nearby population centre, Tequila (29 km away with a population of around 44,353) have varied hospitality, communications, education, and health services Santo Domingo de Guzmán, the nearest community to the Property, is a village with a population of around 250 with basic services (Instituto Nacional de Estadística y Geografía, 2020).
The State Capital of Guadalajara lies approximately 82 km east-southeast of the Property in direct distance. The city had a population of approximately 1.39 million at the most recent census, and its metropolitan area a population of approximately 5.3 million (Instituto Nacional de Estadística y Geografía, 2020). Guadalajara is served by an international airport.
The La Yesca hydroelectric project, officially the Proyecto Hidroeléctrico Ing. Alfredo Elías Ayub, lies approximately 16 km downstream of the Property on the Río Grande de Santiago. Grid power is available in the district. The nearest mapped high-voltage transmission line lies approximately
6.0 km from the concessions, and the nearest mapped substation approximately 14.2 km. A 22,860 V distribution line crosses the Property and a 112.5 kVA substation stepping down to 480 V is installed on SDLE's concessions at the river side (Dolbear, 2010).
An old cyanide mill from past underground mining programs can be found on the Property, but it is not operational (Dolbear, 2010). Water is available year-round from the Río Grande de Santiago, down slope to the northeast from the main adit and showing area at a distance of approximately 500 vertical metres.
History
The Mining Concessions occur in an area of established silver-gold epithermal mineral occurrences and a prolific Spanish mining production history (McBride, 2017). Mineral exploration and mining in the Hostotipaquillo region goes back to the beginning of seventeenth century, when the Spanish targeted high-grade ore shoots easily accessible for mining by hand. The town of Hostotipaquillo was settled and became the centre for mining activity.
Mineral rights are held 100% by Compañía Minera San Diego y La Española, S.A. de C.V. ("SDLE"), a wholly-owned subsidiary of Stroud. Stroud optioned the Property in 1999 from the original founders of SDLE. On 18 April 2002 (amended 27 September 2002), Stroud and its 50% joint-venture partner New Bullet Group Inc. ("NBG") purchased a 91.3% stake in SDLE, with NBG able to earn 50% of Stroud's interest by matching Stroud's US$1,000,000 investment. NBG became Amerix Precious Metals Corporation ("Amerix") on 31 May 2004. Stroud acquired the remaining 8.7% minority interest by private settlement in 2005 and bought out Amerix's entire interest on 8 August 2006 for C$1,800,000, subject to a 5% NSR capped at C$1,000,000, at which point SDLE became wholly-owned by Stroud. On 20 July 2026, Silver Hammer announced a definitive arm's length business combination agreement of 17 July 2026 to acquire Stroud.
Mining took place in two principal phases. Prior to the 1850s, high-grade quartz-calcite veins carrying galena, sphalerite and chalcopyrite were mined by hand from surface exposures and followed underground by adits. The La Raya vein system was traced 500 m from the Nombre de Dios Mine to Bella Vista, and the Socavon III-Guadalupe system was traced over more than 800 m horizontally. Workings seldom extend more than 150 m into the hillside, and mineralization was followed to roughly 100 m depth. McBride (2017) estimates 150,000 to 250,000 tonnes were mined during this period at an estimated 30 troy ounces of silver per tonne (about 933 g/t Ag). A second phase, identified by metal tools and drill holes, drove the El Cobre and La Esperanza cross-cuts and carried out limited mining. A small processing plant dated to the late nineteenth or early twentieth century shows that refining was attempted, but no evidence of significant production was recorded.
Noranda Mines completed 11 diamond drill holes in 1954 and 1973-1974, three of them underground from the La Esperanza tunnel, returning intervals of interest including 2 m at 1,835 g/t Ag and 3 g/t Au in hole E-8. No follow-up was done. The Comisión de Fomento Minero completed technical studies and chip sampling in the latter 1970s and 1988. In 1994, the Consejo de Recursos Minerales sampled the mine dumps from 64 pits and 77 samples and estimated 21,595 tonnes grading 308 g/t Ag and 1.53 g/t Au. A US$93,000 FIFOMI loan from 1990 became a lien against the concessions and was removed on 8 March 2004 following a US$200,000 settlement by SDLE.
Behre Dolbear de México, S.A. de C.V. reported the first estimate on 25 January 2010, based on 30 core holes totalling 5,335.60 m: Measured 1,846,352 t at 0.46 g/t Au and 90 g/t Ag, Indicated 2,501,382 t at 0.39 g/t Au and 88 g/t Ag, and Inferred 3,424,622 t at 0.33 g/t Au and 83 g/t Ag. Derek McBride Geological and Management Services Ltd. updated the estimate on 17 November 2017 to include the 2011 and 2012 drilling, using a 45 g/t AgEq cut-off, a 72:1 gold to silver ratio and assumed 100% metallurgical recovery: Measured and Indicated 6,081,799 t at 134.91 g/t AgEq containing 25,738,178 oz AgEq, and Inferred 3,482,160 t at 119.56 g/t AgEq containing 13,387,222 oz AgEq. Neither estimate considered Reasonable Prospects for Eventual Economic Extraction. A Qualified Person has not independently confirmed these estimates and is not treating them as current. They are presented for historical context only and should not be relied upon.
Geological Setting and Mineralization
The Project lies in the southern Sierra Madre Occidental ("SMO"), a Cenozoic silicic volcanic province extending more than 1,200 km from near the United States border to its intersection with the Trans-Mexican Volcanic Belt ("TMVB") near Guadalajara (Ferrari et al., 2007). The volcanic pile averages more than 1,000 m thick, and the Project lies approximately 25 km north of the SMO-TMVB boundary. The SMO comprises an Eocene to Oligocene Lower Volcanic Group of intermediate to mafic lavas and an Upper Volcanic Group dominated by felsic ash-flow tuffs, the latter erupted principally during ignimbrite flare-ups at approximately 32 to 28 Ma and 24 to 20 Ma (Ferrari et al., 2002; Ferrari et al., 2007). The southern termination of the province is occupied by the Tepic-Zacoalco Rift, and the Project lies near the northwestern part of the Plan de Barrancas-Santa Rosa graben, in the vicinity of the regional Cinco Minas normal fault. The SMO hosts one of the largest epithermal precious-metal provinces in the world, and the Cinco Minas, Bolaños, and San Martín de Bolaños districts lie closest to the Project.
The Río Grande de Santiago has incised the volcanic section, exposing the oldest rocks at approximately 500 mASL. These are commonly termed andesites, though they may be more basaltic, and Behre Dolbear (2010) considered them likely to belong to the Lower Volcanic Group near its contact with the Upper Volcanic Group. Above the andesites, an essentially conformable rhyolitic sequence extends to approximately 1,200 m asl and includes porphyritic tuff, a similar non-porphyritic cherty unit, and a rhyolite agglomerate. The agglomerate is the most important unit on the Property, as most of the better mineralization identified to date occurs within it. The La Raya, Jazmine, Guadalupe, and La Zopilote vein systems appear capped by a thick rhyolitic ash unit, while the Santa Fe and Santa Clara systems occur in the agglomerate where it dips off to the northwest. The sequence is generally flat lying, with local dips of up to 30 degrees. Major faulting has been postulated along the Río Grande de Santiago but is difficult to document; the capping ash-fall tuffs show no obvious displacement across the river, and the mud seams observed in core and workings represent minor, post-mineralization normal faults (McBride, 2017). At the district scale, a northwest-trending zone of fracturing and pervasive silicification striking N30°W to N45°W and dipping 70 to 75 degrees northeast hosts the quartz-calcite veins over a strike length of approximately 900 m and a width of 20 m to 30 m (Behre Dolbear, 2003; Behre Dolbear, 2010).
Mineralization is concentrated in northwest-southeast striking, steeply east-dipping quartz-carbonate vein systems and their halos, hosted principally by the rhyolite agglomerate. Six vein systems have been identified: La Raya, Jazmine, Guadalupe, La Zopilote, Santa Fe, and Santa Clara. High-grade shoots lie within broad zones of quartz veining up to 30 m wide dipping about 60 degrees east. Vein-hosted and disseminated mineralization includes argentite (acanthite), sphalerite, galena, and minor native gold in silicified rock and quartz veins, with total sulphide content below 1 to 2 percent by volume and secondary oxides including malachite common near surface. Veins are commonly laminated and vuggy, with brecciation of quartz in a calcite matrix characteristic. Drilling prior to 2017 returned widths in excess of 40 m grading 30 g/t to 60 g/t Ag in fresh-appearing agglomerate, and mineralized widths of up to 97 m combining vein and disseminated material. The veins narrow or stop downward in the underlying andesites, and at La Zopilote the upper vein margin carries iron and manganese oxides without sulphides, interpreted to record venting at a paleosurface later buried by ash-fall tuff (McBride, 2017). Drilling by Stroud in 2021 and 2022, approximately 9,936 m in 32 diamond drill holes, confirmed continuity of the La Raya and Guadalupe systems and identified the parallel Zopilote Zone west of La Raya (Stroud Resources Ltd., 2023).
Deposit Types
Santo Domingo is a volcanic-hosted, low to intermediate sulphidation epithermal silver-gold vein system, consistent with the district-scale characterization of the Hostotipaquillo district, where the nearby Cinco Minas and Gran Cabrera deposits are classified as low-sulphidation adularia-sericite systems (Munroe, 2006; Behre Dolbear, 2010; Camprubí et al., 2016). Epithermal gold-silver deposits form at depths generally less than about 1.5 km and temperatures generally below about 300°C in subaerial hydrothermal systems associated with arc magmatism (Simmons et al., 2005; John et al., 2018). Low-sulphidation systems form from reduced, near-neutral pH, meteoric-dominated fluids, with precious metals deposited principally in response to boiling, producing crustiform and colloform banding, bladed calcite, hydrothermal breccias, and adularia-bearing gangue (Hedenquist et al., 2000; Simmons et al., 2005). Because boiling is depth-controlled, ore is commonly restricted to a vertical interval of a few hundred metres. Camprubí and Albinson (2007) showed that low- and intermediate-sulphidation styles are not mutually exclusive in Mexico, and the association of silver with galena and sphalerite at Santo Domingo suggests intermediate-sulphidation stages may be present within a dominantly low-sulphidation system. District mapping reports fluid inclusion homogenization temperatures of approximately 236°C and salinity of approximately 0.4 wt% NaCl equivalent (Servicio Geológico Mexicano, 2006).
The most important recorded production in the area is from Cinco Minas, approximately 9.5 km southeast along a parallel regional structure, where Munroe (2006) reports approximately 1.083 Mt averaging 3.17 g/t Au and 476 g/t Ag was produced between 1922 and 1928, with mining reaching approximately 700 m depth. Adularia from banded veins at Cinco Minas yielded 40Ar/39Ar ages of 24.50 ± 0.07 Ma and 23.46 ± 0.26 Ma (Camprubí et al., 2016). The Santo Domingo veins have not been dated; a latest Oligocene to early Miocene age is considered likely by analogy, but this remains an inference. The model has direct implications for exploration: the productive boiling interval and associated high-grade shoots may extend below the historically mined levels, and the occurrence of the Santa Fe and Santa Clara systems beneath or at the margin of the capping tuffs indicates that additional blind vein systems may be concealed beneath the ash cover (McBride, 2017).
Exploration
Stroud first worked on the Property in 1997 and secured its option over the Mining Concessions in 1999. Exploration has since been carried out intermittently. Work other than drilling has comprised reconnaissance chip sampling of the accessible adits and surface exposures, surface and underground geological mapping, channel and chip sampling of the mapped workings, investigation of the historical mine workings for target definition, and supporting petrographic and mineralogical studies.
Drilling
Diamond drilling is the principal subsurface exploration method completed at the Santo Domingo Silver-Gold Project and all drilling was completed by Stroud. The drilling has tested epithermal vein-hosted silver-gold mineralization associated with the La Raya, Guadalupe, Jazmine and Zopilote vein systems, together with broader mineralized intervals developed within the favourable rhyolitic agglomerate host rock.
The drilling database currently comprises 85 diamond drill holes for 18,184.05 metres. Historical drilling from 1999 to 2011 defined the La Raya and Guadalupe vein systems and established the basis for the geological interpretation. The 2021 and 2022 drilling campaigns extended testing across the established mineralized corridor and identified the Zopilote vein system west of, and broadly parallel to, the La Raya and Guadalupe systems. (Stroud Resources, 2023).
Downhole deviation measurements were taken approximately every 50 m to 100 metres. Measurements were taken by running the tool down the drill barrel. Readings with magnetic intensity values between 39,000 nT and 43,000 nT were considered acceptable and not significantly affected by local magnetism. Survey data were exported from the Champ Discoverer and Reflex EZ-Trac tools as Excel files, reviewed, cleaned and imported into the drilling database. For the 2021-2022 drilling database, 26 holes were measured using downhole survey tools. The remaining six unmeasured holes, including three abandoned holes, were assigned the planned azimuth and dip.
The 2021 and 2022 drilling confirmed the extension and geological interpretation of the La Raya and Guadalupe vein systems and identified the Zopilote vein system to the west. The Zopilote system was the principal focus of the 2022 drilling campaign. (Stroud Resources, 2023)
Selected intersections from the 2021 and 2022 drilling include high-grade narrow intervals in the Guadalupe East Zone, broader mineralized intersections in the La Raya Zone, and significant silver-equivalent intervals in the newly identified Zopilote Zone.
Important intersections include 625 g/t AgEq over 1.55 m in SD-21-49 and 680 g/t AgEq over 1.65 m in SD-21-74 in the Guadalupe East Zone; 230 g/t AgEq over 10.35 m in SD-21-50, 159 g/t AgEq over 36.80 m in SD-21-71, 152 g/t AgEq over 34.70 m in SD-21-75, and 196 g/t AgEq over 15.10 m plus 233 g/t AgEq over 6.45 m in SD-21-52 in the La Raya Zone; and 173 g/t AgEq over 1.05 m in SD-21-58 and 147 g/t AgEq over 32.15 m in SD-21-81 in the Zopilote Zone (Stroud Resources, 2023). Silver Equivalent (AgEq) was calculated using a silver to gold price ratio of 75:1, metal prices of US$1,500/oz Au and US$20/oz Ag, and presumed recoveries of 100%.
Sampling, Analysis and Data Verification
Sample Preparation, Analysis and Security
The sampling and analytical procedures used for the Project include geological logging, geotechnical recording, selection of sample intervals, core splitting, sample dispatch, laboratory preparation, laboratory analysis, insertion of QA/QC control samples and validation of assay data.
The 2021 and 2022 drilling campaigns provide the principal recent drill core sample dataset for the Project. Historical drilling and sampling data from the 1999 to 2011 campaigns remain part of the Project database and have been reviewed to support geological interpretation and assessment of data reliability. Historical sample preparation, analytical, security and verification procedures are summarised in this section where relevant to the use of the historical drill hole data. (McBride, 2017)
The procedures described are considered appropriate for the style of mineralization and the current stage of exploration and resource evaluation at the Project. Overall, the sample preparation, analytical and security procedures are considered adequate for use in geological interpretation and mineral resource evaluation. The main issue identified is the need for continued monitoring of silver precision, particularly in high-grade intervals where the distribution of silver minerals may be irregular.
Data Verification
The Authors reviewed historical and current data relating to past and recent exploration work completed on the Property. The data reviewed included drill hole collar records, downhole survey data, lithological logs, assay records, assay certificates, alteration and mineralization logs, RQD information, historical databases and supporting technical documentation.
The 2021 and 2022 drilling campaigns were supported by complete digital datasets and laboratory certificates. These data included drill hole logs, assay certificates and database validation records, allowing detailed review of the recent drilling information.
Historical drill hole data from the 1999 to 2011 campaigns were checked against available information supplied by Stroud, including historical Access database files, Excel drill logs and published project technical reports. The historical dataset is less complete than the recent drilling dataset, but the available records provide sufficient support for the historical drilling information retained in the database.
Overall, the data verification completed for the Santo Domingo Project supports the use of the drilling, sampling and assay database for geological modelling, mineralized domain interpretation and mineral resource estimation.
Mineral Processing and Metallurgical Testing
The Author (QP) is not aware of any mineral processing and metallurgical testwork done on material from the Property by Stroud, Silver Hammer or of any historical testwork having been completed.
Mineral Resources
Atticus Geoscience Consulting Ltd. (Atticus) was retained by Silver Hammer and Stroud to prepare a NI 43-101 compliant Mineral Resource Estimate ("MRE") for the Santo Domingo Silver-Gold Project, located in the Hostotipaquillo area of Jalisco State, Mexico. The MRE incorporates the available drill hole, geological, analytical, density and topographic information that could be confidently verified, including the 2021 and 2022 diamond drilling completed by Stroud Resources.
The MRE was prepared under the direction of Simon Mortimer, Qualified Person and Author, with assistance from Luis Huapaya, geologist/geostatistician, Sheyla Pinto, geologist and Ronaldo Cabezas Cortez, data management scientist. Mr. Mortimer was responsible for the geological interpretation and construction of the lithological, structural and mineralized-domain models, with geological modelling support from Ms. Pinto. Mr. Huapaya completed the statistical analysis, geostatistical studies, grade interpolation and density modelling. Mr. Cabezas Cortez supported database management and data integration throughout the estimation process.
The Resource Database supporting the Santo Domingo Mineral Resource Estimate was compiled from historical and recent diamond drilling completed by Stroud Resources between 1999 and 2022. The database includes collar, downhole survey, lithology, assay, alteration, mineralization, vein system and RQD information, where available. The drill hole database currently comprises 85 diamond drill holes for a total of 18,184.05 m.
The Mineral Resource is reported for the Guadalupe, La Raya and Zopilote vein systems. The estimate is constrained within the interpreted mineralized domains and is based on the regularised underground reporting model developed to consider a minimum underground working width. The Mineral Resource Statement is presented in Table 1-2, effective 21 August 2026.
Table 1-2. Santo Domingo Mineral Resource Statement, reported above a break-even underground US$90/t NSR cut-off.
| Category |
NSR Cut-Off (US$/t) |
Tonnes |
SG |
Grades | Contained Metal | |||||
| Ag (ppm) |
Au (ppm) |
*AgE q (ppm) |
NSR (US$/t) |
Ag (koz) |
Au (koz) |
*AgE q (koz) |
||||
| Guadalupe Vein | ||||||||||
| Indicated | 90.00 | 740,000 | 2.65 | 63 | 0.20 | 77 | 139 | 1,500 | 5 | 1,800 |
| Inferred | 90.00 | 1,500,000 | 2.65 | 61 | 0.24 | 78 | 141 | 2,900 | 11 | 3,700 |
| Category |
NSR Cut-Off (US$/t) |
Tonnes |
SG |
Grades | Contained Metal | |||||
| Ag (ppm) |
Au (ppm) |
*AgE q (ppm) |
NSR (US$/t) |
Ag (koz) |
Au (koz) |
*AgE q (koz) |
||||
| La Raya Vein | ||||||||||
| Measured | 90.00 | 1,200,000 | 2.65 | 97 | 0.51 | 132 | 240 | 3,730 | 19 | 5,040 |
| Indicated | 90.00 | 3,700,000 | 2.65 | 76 | 0.43 | 106 | 192 | 9,100 | 51 | 13,00 0 |
| Measured + Indicated: | 90.00 | 4,920,000 | 2.65 | 81 | 0.45 | 112 | 203 | 12,800 | 71 | 18,000 |
| Inferred | 90.00 | 2,000,000 | 2.65 | 69 | 0.35 | 93 | 169 | 4,400 | 23 | 6,000 |
| Zopilote Vein | ||||||||||
| Inferred | 90.00 | 460,000 | 2.65 | 68 | 0.36 | 92 | 168 | 1,000 | 2 | 1,100 |
| Total Resources | ||||||||||
| Measured + Indicated: | 90.00 | 5,660,000 | 2.65 | 79 | 0.42 | 108 | 195 | 14,300 | 76 | 20,000 |
| Inferred: | 90.00 | 3,900,000 | 2.65 | 66 | 0.31 | 87 | 159 | 8,300 | 36 | 11,000 |
Notes to Table 1-2:
1. The independent Qualified Person for the Mineral Resource Estimate (MRE), as defined by National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101"), is Mr. Simon Mortimer (FAIG #7795) of Atticus Geoscience Consulting Ltd. The effective date of the Mineral Resource Estimate is August 21, 2026.
2. The MRE was prepared following the CIM Estimation of Mineral Resources & Mineral Reserves Best Practice Guidelines (2019) and the CIM Definition Standards for Mineral Resources & Mineral Reserves (2014). Mineral Resources are not Mineral Reserves and do not have demonstrated economic viability.
3. The quantity and grade of the mineral resources reported in this exploration study are sufficient to define them as Inferred, Indicated, or Measured mineral resources. It is reasonably expected that the majority of the Inferred and Indicated mineral resources may be reclassified as Indicated or Measured mineral resources with continued exploration and drilling.
4. Estimation domains were built from geological data of drill holes, surface mapping and using Ag grade thresholds of 15 ppm Ag based on statistical analysis of the core assay.
5. The Mineral Resource Statement is reported at a break-even cut-off of US$90.00/t NSR, based on commodity prices, metallurgical recoveries, selling costs, operating costs, and appropriate underground mine modifying factors.
6. Geological and block models for the MRE used data from a total of 61 surface drill holes, completed by Stroud Resources Ltd. The drill hole database was validated prior to resource estimation and QA/QC checks were made using industry-standard control charts for blanks, core duplicates and commercial certified reference material inserted into assay batches by Stroud.
7. Tonnes, grades and contained metal values have been rounded; totals may not sum exactly due to rounding. Estimates have been rounded to 3 SF for Measured Resources and 2 SF for Indicated and Inferred resources.
8. A 2 m x 2 m x 2 m block model was created, and samples were composited at 1.5 m intervals. Grade estimation from drill hole data was carried out for Ag and Au using the Inverse Distance Weight interpolation method in Micromine software. The final resource was reported using a regularized block model with a block size of 2 m x 2 m x 2 m, which was deemed appropriate for the mineralization style and potential mining selectivity.
9. The MRE is reported above a base economic cut-off grade of US$90.00/t NSR, based on the continuity of mineralized blocks within the model. The following parameters were applied to define this economic threshold:
10. The Mineral Resource Statement reports resources using both calculated AgEq and NSR. Block value was calculated as:
11. The NSR values for each metal was determined using the metal prices and recoveries stated in point 9.
12. Grade estimation was validated by comparison of input and output statistics (Nearest Neighbour and Inverse Distance Squared methods), swath plot analysis, cross-plots of declustered samples, and by visual inspection of the assay data, block model, and grade shells in cross-sections.
13. The density estimate is based on historical reference density information obtained from similar deposits. An average density of 2.65 g/cm³ (t/m³) was applied.
Interpretation and Conclusions
The Santo Domingo Silver-Gold Project database was verified and no material errors were identified. The sample preparation, analytical, security and verification procedures are considered appropriate for the style of mineralization and the current stage of the Project. The principal QA/QC issue identified is reduced precision in Ag pulp duplicate results, particularly relevant to high-grade silver intervals where silver-bearing minerals may be irregularly distributed. Continued monitoring of silver precision and laboratory duplicate performance is recommended during future drilling programs.
The Mineral Resource Estimate was prepared in accordance with the CIM Definition Standards (CIM, 2014), with consideration of the CIM Estimation of Mineral Resources and Mineral Reserves Best Practice Guidelines (CIM, 2019), and is reported above an underground NSR cut-off of US$90/t. The Mineral Resource comprises 5.7 Mt of Measured and Indicated material and 3.9 Mt of Inferred material (see Table 1-2), with an effective date of 21 August 2026. The Author (QP) considers the Mineral Resource classification appropriate for the current stage of the Project.
No Mineral Reserves have been declared for the Project, and no mining method, recovery method, market study, capital or operating cost estimate, or economic analysis has been prepared at the current stage of study. The principal gaps in the supporting information are the absence of Project-specific metallurgical testwork and the limited density database. The metallurgical recovery assumptions used for NSR and AgEq reporting are benchmarked from adjacent or similar deposit types and should be confirmed through metallurgical testwork on representative Santo Domingo mineralized material during future work programs.
The vein systems remain open along strike and down dip. The Jazmine, Santa Fe and Santa Clara systems are not included in the current Mineral Resource Estimate, and the historical workings reach only approximately 80 m to 100 m below surface compared with the approximately 700 m depth extent of the analogous Cinco Minas ore shoot. The current Mineral Resource Estimate provides a reasonable basis for further technical work, including resource conversion drilling, extension drilling, metallurgical testwork, density data collection, environmental and permitting review, and future updates to the geological and Mineral Resource models.
The Property currently holds no active environmental authorizations, and any future exploration or drilling program will require the necessary authorizations before work is undertaken. The Project's location within C.A.D.N.R. 043 Estado de Nayarit should be reviewed in relation to the current environmental and protected-area regulatory framework before future field programs are advanced. It is the opinion of the Author (QP) that the geological setting, the character of the silver and gold mineralization delineated to date, and the potential of the vein systems that remain open along strike and down dip are of sufficient merit to justify further exploration expenditure.
Recommendations
It is the opinion of the Author (QP), that the geological setting, current Mineral Resource Estimate, mineralization style and exploration potential of the Santo Domingo Silver-Gold Project are of sufficient merit to justify further technical work, subject to confirmation of the environmental, permitting and surface-access pathway. The recommended work program is intended to improve confidence in the current Mineral Resource, test strike and depth extensions of known mineralization, advance selected untested or partly tested vein systems, refine the geological and structural model, and provide the technical information required to assess whether the Project should advance toward a future Preliminary Economic Assessment ("PEA") or similar conceptual study.
The first priority should be to confirm the permitting, environmental and surface-access requirements for renewed field programs. This is particularly important because the Project lies within C.A.D.N.R. 043 Estado de Nayarit, a federally administered protected natural area. A new Manifestación de Impacto Ambiental (MIA) or Environmental Impact Statement is expected to be required in connection with future drill pad permitting, and the permitting review should confirm the applicable SEMARNAT, CONAGUA, protected-area, water-use, access-road, drill-pad and field-program requirements before drilling is undertaken.
The recommended initial work should include targeted geological mapping and rock sampling, together with a property-wide surface geophysical program. The geophysical work should include 2D induced polarization ("IP") surveying, with selected 3D IP coverage in areas where the geology and mineralization are better understood, particularly around known vein systems. This work should be used to refine the structural interpretation, identify possible extensions of known vein systems, develop new targets, and improve the ranking of drill targets before the next drilling phase is finalized.
Subject to receipt of the necessary permits and confirmation of access requirements, the next stage of work should include diamond drilling at La Raya, Guadalupe and Zopilote. The drilling should be designed to test continuity of mineralization along strike and down dip, support possible Mineral Resource conversion, and test extensions of known mineralized zones. Additional drill testing should also be considered for new targets generated from geological mapping, surface sampling and geophysical interpretation. Future drilling should include systematic density sampling, QA/QC monitoring, structural and geotechnical logging, and collection of representative material for metallurgical and mineralogical testwork.
The geological model should be updated after completion of the recommended drilling, geophysical review and supporting technical work. Particular attention should be given to improving the structural model, volcanic stratigraphic model, mineralized-domain geometry, alteration interpretation and integration of field mapping data. Faults, lineaments, possible offsets and apparent structural movements should be reviewed in 3D and, where possible, confirmed using drilling or field evidence. The updated interpretation should be used to review the mineralized domains, estimation parameters, density assignment, NSR and AgEq assumptions, Mineral Resource classification and the potential for future conversion of Inferred Mineral Resources to Indicated Mineral Resources.
Project-specific metallurgical and mineralogical testwork is recommended as a priority technical item because the current NSR and AgEq assumptions are based on benchmarked recovery assumptions and have not yet been confirmed using representative Santo Domingo mineralized material. The testwork should include representative samples from La Raya, Guadalupe and Zopilote and should assess mineralogy, silver and gold deportment, oxidation state, sulphide content, vein style, host-rock influence and preliminary recovery response. The results should be used to review the current recovery, cut-off grade, NSR and AgEq assumptions used for Mineral Resource reporting.
Environmental baseline work and community engagement should be advanced in parallel with the permitting review. The Company should continue communication with the Ejido of Santo Domingo de Guzmán and local stakeholders before field activities restart. The scope of engagement should include planned work programs, access requirements, water use, environmental controls, local employment opportunities, site rehabilitation and any compensation arrangements that may be required.
Proposed Work Program and Budget
The recommended work program is divided into two phases. Phase 1 should include permitting and legal review, environmental baseline scoping, surface access and community engagement, access and site preparation, exploration camp maintenance, geological mapping and sampling, property-wide geophysical surveys, data compilation, reporting and target generation. Phase 2 should include diamond drilling, metallurgical and mineralogical testwork, density sampling, geotechnical logging, QA/QC monitoring, database validation, geological model updates, a Mineral Resource update, conceptual mining review and study-readiness assessment. Phase 2 should only proceed once the required permitting pathway, environmental requirements, surface-access arrangements and practical field constraints have been confirmed.
The recommended 2-Phase work program, with Phase 2 contingent on permitting and results of Phase 1, is estimated at approximately US$3.95 million (~C$5.5M), including a 10% contingency. The Phase 1 budget is estimated at approximately US$1.05M and the Phase 2 budget is estimated at approximately US$2.6M, both before contingency (Table 1-3).
Table 1-3. Summary of recommended 2-Phase work program budget for the Santo Domingo Silver-Gold Project, Mexico.
| Work Program Component | Estimated Cost (US$) |
| Phase 1: Permitting, environmental and access review, low-impact exploration, geological mapping, geophysical surveys, data compilation and targeting | $1,045,000 |
| Phase 2: Diamond drilling, metallurgical and mineralogical testwork, density sampling, geotechnical logging, database validation, geological modelling, Mineral Resource update and study-readiness review | $2,550,000 |
| Sub-total: | $3,595,000 |
| Contingency: | $359,500 |
| Total Estimated (US$): | $3,954,500 |
The budget is preliminary and should be considered an order-of-magnitude planning allowance only. It should be refined after receipt of specialist legal and environmental advice, confirmation of the permitting pathway, drill contractor quotations, assay and metallurgical laboratory quotations, geophysical contractor quotations, geological modelling quotations, access requirements, field logistics requirements and final drill collar locations.
Consolidated Capitalization
The following table summarizes Stroud's capitalization as at March 31, 2026 and as at the date of the Information Circular. The table should be read in conjunction with the financial statements of Stroud which can be found on Stroud's SEDAR+ profile at www.sedarplus.ca.
| Security | Amount Authorized |
Outstanding as at March 31, 2026 (unaudited) |
Outstanding as at the date of the Information Circular (unaudited) |
Outstanding after giving effect to the Amalgamation (unaudited) |
| Common Shares | Unlimited | 63,623,199 Stroud Shares |
63,623,199 Stroud Shares |
49,496,496 Stroud Shares(1) |
| Stroud Options | Unlimited | Nil | 1,155,000 | 1,155,000 (1) |
| Stroud Warrants | Nil | Nil | Nil | Nil |
Notes:
(1) Includes Stroud Shares held by existing Stroud Shareholders (63,623,199) and Stroud Shares issuable in exchange for securities of Silver Hammer pursuant to the Amalgamation and the SilverMark Amalgamation.
Ownership of Securities by Directors and Officers
The following table sets out the number of Stroud Shares and Stroud Options beneficially owned, or over which control or direction is exercised, by each director and officer of Stroud as at the date of this Circular:
| Name | Number of Stroud Shares |
Percentage of Issued and Outstanding |
Number of Stroud Options |
| Mirsad Jakubovic | 1,480,200 | 2.33% | 235,000 |
| Dr. Scott Jobin-Bevans | 295,666 | 0.46% | 300,000 |
| William J. (Jeff) Kennedy | Nil | 0.00% | 385,000 |
| Conor O'Brien | Nil | 0.00% | 235,000 |
| Total | 1,775,866 | 2.79% | 1,155,000 |
Management's Discussion and Analysis
Selected Financial Information and Management's Discussion and Analysis of Stroud
Stroud presents its financial statements in accordance with IFRS. The following table sets forth summary financial information of Stroud for the three months ended March 31, 2026, the financial year ended December 31, 2025, and the financial year ended December 31, 2024, and should be read in conjunction with Stroud's financial statements, including the notes thereto.
| Three months ended March 31, 2026 (unaudited) |
Financial Year Ended December 31, 2025 (audited) |
Financial Year Ended December 31, 2024 (audited) |
|
| Revenues | $6,807 | $24,620 | $26,070 |
| Net loss for the period | $60,689 | $381,666 | $315,737 |
| Cash and cash equivalent | $313,073 | $119,035 | $37,319 |
| Total assets | $341,576 | $134,033 | $75,607 |
| Total liabilities | $136,781 | $168,549 | $138,457 |
| Total shareholders' equity (deficit) | $204,795 | ($34,516) | ($62,850) |
Stroud's financial statements for the three months ended March 31, 2026, the financial year ended December 31, 2025, and the financial year ended December 31, 2024, together with the related MD&A for each such period, can be found on Stroud's SEDAR+ profile at www.sedarplus.ca and should be read in conjunction with the summary financial information set out above.
The MD&A for Stroud should be read in conjunction with Stroud's financial statements and the accompanying notes thereto. Certain information contained in Stroud's MD&A constitutes forward-looking statements. These statements relate to future events or to Stroud's future financial performance and involve known and unknown risks, uncertainties and other factors that may cause Stroud's actual results, levels of activity, performance or achievements to be materially different from any future results, levels of activity, performance or achievements expressed or implied by such forward-looking statements. See "Note Regarding Forward-Looking Information" and "Risk Factors".
Additional Disclosure for Venture Issuers Without Significant Revenue
As of March 31, 2026, Stroud has generated $nil revenue from operations since incorporation on March 18, 1983. See "Risk Factors".
Additional Disclosure for Venture Issuers
As at July 31, 2026, Stroud had an estimated working capital of approximately $70,328. There is no guarantee that Stroud will be able to raise any additional funds when and if needed and if such funds would be available on terms favourable to Stroud. See "Risk Factors".
Description of Capital Structure
Common Shares
Stroud's authorized capital consists of an unlimited number of common shares without par value. As of the date hereof, a total of 63,623,199 Stroud Shares are issued and outstanding.
Each Stroud Share ranks equally with all other Stroud Shares with respect to dissolution, liquidation or winding-up of Stroud and payment of dividends. The holders of Stroud Shares are entitled to one vote for each share of record on all matters to be voted on by such holders and are entitled to receive pro rata such dividends as may be declared by the Board of Stroud out of funds legally available therefor and to receive, pro rata, the remaining property of Stroud on dissolution. The holders of Stroud Shares have no redemption, retraction, purchase, pre-emptive or conversion rights. The rights attaching to the Stroud Shares can only be modified by the affirmative vote of at least two-thirds of the votes cast at a meeting of shareholders called for that purpose.
Warrants
During the three months ended March 31, 2026, Stroud issued 3,000,000 Stroud Shares pursuant to the exercise of common share purchase warrants. Subsequent to the exercise of the warrants, no remaining common share purchase warrants were outstanding after exercise and as at the date of this Circular.
Options
As of March 31, 2026, there were 1,155,000 Stroud stock options outstanding and exercisable, with exercise prices ranging from $0.12 to $0.55 per Stroud Share and expiry dates ranging from September 30, 2026 to September 24, 2030. The weighted average exercise price of the outstanding options is $0.176 per Stroud Share and the weighted average remaining contractual life is approximately 4.0 years.
As of the date of the Circular, there are 1,155,000 Stroud stock options outstanding.
Trading Price and Volume
The following table showing the monthly high and low intra-day prices and volumes of the Stroud Shares on the TSXV for the 12 months preceding the date of this Circular, together with the closing price on the last trading day before announcement of the Transaction (July 17, 2026):
| Month | High ($) | Low ($) | Volume |
| August 2025 | 0.095 | 0.080 | 163,975 |
| September 2025 | 0.185 | 0.075 | 774,759 |
| October 2025 | 0.185 | 0.110 | 859,876 |
| November 2025 | 0.160 | 0.095 | 1,048,684 |
| December 2025 | 0.260 | 0.125 | 1,041,676 |
| January 2026 | 0.270 | 0.180 | 964,200 |
| February 2026 | 0.225 | 0.135 | 704,742 |
| March 2026 | 0.180 | 0.100 | 1,507,983 |
| April 2026 | 0.135 | 0.100 | 748,039 |
| May 2026 | 0.230 | 0.090 | 358,551 |
| June 2026 | 0.140 | 0.090 | 322,361 |
| July 2026 | 0.160 | 0.095 | 1,013,030 |
| August 2026 (partial) |
0.180 | 0.140 | 542,353 |
Prior Sales
The following table sets forth information in respect of issuances or purchases of Stroud Shares and securities that are convertible or exchangeable into Stroud Shares within the 12 months prior to the date of the Circular, including the price at which such securities have been issued, the number of securities issued, and the date on which such securities were issued:
| Date of Issuance | Reason for Issuance | Number and Type of Security | Issuance / Exercise Price |
| March 27, 2026 | Exercise of warrants | 3,000,000 Common Shares | $0.10 |
| November 13, 2025 | Exercise of warrants | 3,000,000 Common Shares | $0.10 |
Escrowed Securities and Resale Restrictions
Escrowed Securities
To the knowledge of the directors and officers of Stroud, as of the date of this Circular, there are no Stroud Shares or other securities of Stroud held in escrow or subject to any escrow agreement.
Contractual Resale Restrictions
To the knowledge of the directors and officers of Stroud, as of the date of this Circular, there are no Stroud Shares or other securities of Stroud subject to any contractual resale restrictions.
Dividend Policy
Stroud has not paid any dividends on the Stroud Shares. There are no restrictions in Stroud's articles on its ability to pay dividends, and Stroud has no present intention of declaring or paying dividends.
Promoters
Stroud does not have, and has not had within the two years immediately preceding the date of the Circular, any promoters within the meaning of applicable securities legislation.
Expenses of the Transaction
The aggregate expenses of Stroud in connection with the Transaction are estimated to be approximately $60,000, including legal fees, accounting fees, transfer agent and depositary fees, printing and mailing costs and filing fees.
Legal Proceedings
There are no legal proceedings outstanding, threatened or pending, as of the date hereof, by or against Stroud or to which Stroud is a party or to which its properties are subject, nor to Stroud's knowledge are any such legal proceedings contemplated which could become material to a purchaser of Stroud Shares.
Stroud is not currently aware of any:
penalties or sanctions imposed against Stroud by a court relating to provincial and territorial securities legislation or by a securities regulatory authority since its incorporation;
other penalties or sanctions imposed by a court or regulatory body against Stroud, the disclosure of which are necessary for this Circular to contain full, true and plain disclosure of all material facts relating to the securities being distributed; or
settlement agreements Stroud entered into before a court relating to provincial and territorial securities legislation or with a securities regulatory authority within the three years immediately preceding the date of the Circular.
Risk Factors
Whether or not the Amalgamation is completed, Stroud will continue to face many of the risks it currently faces with respect to its business and affairs. Certain of these risks are described below and in the documents incorporated by reference in this Circular. See also "Risk Factors Relating to the Amalgamation".
Risks Related to the Company's Business
There are significant uncertainties and risks related to the exploration and development of Stroud's projects
Stroud is subject to inherent uncertainties and risks related to the development and potential construction of its projects, the principal of which include:
Calculations of mineral resources are estimates and are subject to uncertainty
Stroud's calculations of mineral resources are estimates and depend upon geological interpretation and statistical inferences drawn from drilling and sampling analysis, which may prove to be inaccurate. Actual recoveries of gold and silver from mineralized material may be lower than those indicated by test work. Any material changes in the quantity of mineralization, grade or stripping ratio, may affect the economic viability of the Santo Domingo property.
In addition, there can be no assurance that metal recoveries in small-scale laboratory tests will be duplicated in larger scale tests under on-site conditions or during production. Notwithstanding pilot plant tests for metallurgy and other factors, there remains the possibility that the ore may not react in commercial production in the same manner as it did in testing. Mining and metallurgy are inexact sciences and, accordingly, there always remains an element of risk that a mine may not prove to be commercially viable.
Until a deposit is actually mined and processed, the quantity of mineral resources and grades must be considered as estimates only. In addition, the quantity of mineral resources may vary depending on, among other things, metal prices, cut-off grades and operating costs. Any material change in quantity of mineral resources or grade may affect the economic viability of the Santo Domingo property.
Resource Exploration and Development is a Speculative Business
Resource exploration and development is a speculative business and involves a high degree of risk, including, among other things, unprofitable efforts resulting not only from the failure to discover mineral deposits but from finding mineral deposits which, though present, are insufficient in size to return a profit from production. The marketability of natural resources that may be acquired or discovered by Stroud will be affected by numerous factors beyond its control. These factors include market fluctuations, the proximity and capacity of natural resource markets, government regulations, including regulations relating to prices, taxes, royalties, land use, importing and exporting of minerals and environmental protection. The exact effect of these factors cannot be accurately predicted, but the combination of these factors may result in Stroud not receiving an adequate return on invested capital.
Substantial expenditures are required to establish ore reserves through drilling and metallurgical and other testing techniques, determine metal content and metallurgical recovery processes to extract metal from the ore, and construct, renovate or expand mining and processing facilities. No assurance can be given that any level of recovery of ore reserves will be realized or that any identified mineral deposit, even it is established to contain an estimated resource, will ever qualify as a commercial mineable ore body which can be legally and economically exploited. The great majority of exploration projects do not result in the discovery of commercially mineable deposits of ore.
General economic conditions may adversely affect our growth and profitability
Recent events in global financial markets have had a profound impact on the global economy. Many industries, including the precious and base metals mining industry, are impacted by these market conditions. Some of the key impacts of the current financial market turmoil include contraction in credit markets resulting in a widening of credit risk, devaluations and high volatility in global equity, commodity, foreign exchange and precious metal markets, and a lack of market liquidity. A continued or worsened slowdown in the financial markets or other economic conditions, including but not limited to, consumer spending, employment rates, business conditions, inflation, fuel and energy costs, consumer debt levels, lack of available credit, the state of the financial markets, interest rates, and tax rates may adversely affect Stroud's growth and profitability.
Stroud will require additional capital to finance other acquisitions and current projects. If Stroud obtains equity financing, existing shareholders may suffer dilution. There can be no assurance that Stroud would be successful in overcoming these risks or any other problems encountered in connection with such financings. Stroud anticipates that further financing will be required for its projects to be successful.
Changes in the market price of gold, silver and other metals, which in the past have fluctuated widely, could negatively affect the profitability of Stroud's operations and financial condition
The commercial viability of Stroud's properties is dependent on, among other things, the market price of gold, silver and other base and precious metals. A reduction in the market price of gold, silver and other base and precious metals may prevent Stroud's properties from being economically mined or result in the write-off of assets whose value is impaired as a result of low metals prices.
The market price of gold, silver and other base and precious metals is volatile and is impacted by numerous factors beyond Stroud's control, including, among others:
The effect of these factors on the price of precious and base metals cannot be accurately predicted and there can be no assurance that the market price of these metals will remain at current levels or that such prices will improve. A decrease in the market price of gold, silver and other precious metals could affect Stroud's ability to finance the exploration and development of its properties, which would have a material adverse effect on its business, financial condition, results of operations and prospects.
Stroud will need to raise additional capital
Stroud will need to raise additional capital to fund future property option payments, acquisitions or joint ventures. Additional capital may not be available, at such times or in amounts, as needed. Even if capital is available, it might be on adverse terms. There can be no assurance that unforeseen developments or circumstances will not alter Stroud's requirements for capital. Any additional equity financing will be dilutive to Stroud's shareholders. If access to sufficient capital is not available as and when needed, Stroud's business may be impaired.
There can be no guarantee that Stroud's title to its properties will not be challenged
Although Stroud has received or will receive title opinions for any properties in which it has a material interest, there is no guarantee that title to such properties will not be challenged or impugned. Stroud's properties may be subject to prior unregistered agreements or transfers or native land claims and title may be affected by unidentified or unknown defects. Stroud has conducted as thorough an investigation as possible on the title of properties that it has acquired or will be acquiring to be certain that there are no other claims or agreements that could affect its title to the properties.
Stroud's operations are subject to political and country risk
Stroud conducts mineral exploration activity in Mexico. These operations are potentially subject to a number of political, social, economic and other risks. Stroud is not able to quantify the impact of political, social, economic or other risks on its future financial position, including:
Furthermore, in the event of a dispute arising from such activities, Stroud may be subject to the exclusive jurisdiction of courts outside Canada or may not be successful in subjecting persons to the jurisdiction of the courts in Canada, which could adversely affect the outcome of a dispute.
Stroud is subject to government regulation
Exploration on Stroud's properties is affected to varying degrees by political stability and government regulations relating to such matters as environmental protection, health, safety and labour, mining law reform, tax increases, maintenance of claims, tenure, and expropriation of property. There is no assurance that future changes in such regulations, if any, will not adversely affect Stroud's operations. The activities of Stroud require licenses and permits from various governmental authorities. While Stroud currently has been granted the requisite licenses and permits to enable it to carry on its existing business and operations, there can be no assurance that Stroud will be able to obtain all the necessary licenses and permits which may be required to carry out exploration, development and mining operations for its projects.
Stroud may not have adequate land and/or surface rights
Stroud may require additional surface rights to exploit the resources on its properties. Stroud will require access to additional land beyond that currently owned, which will require negotiations with private landowners for the additional ownership and/or surface rights in order for Stroud to fully operate. Surface rights may also be regulated and restricted by applicable law. There is no assurance that Stroud will be able to obtain the required surface rights or negotiate successfully with private landowners to allow it to develop its properties and establish commercial mining operations on a timely basis.
Environmental risks and other hazards
All phases of a company's mining operations are typically subject to environmental regulation in the various jurisdictions in which operates take place. Environmental legislation in many countries is evolving and the trend has been toward stricter standards and enforcement, increased fines and penalties for non compliance, more stringent environmental assessments of proposed projects and increasing responsibility for companies and their officers, directors and employees.
Compliance with environmental laws and regulations may require significant capital outlays on behalf of the Company and may cause material changes or delays in its intended activities. There can be no assurance that future changes in environmental regulations will not adversely affect Stroud's business, and it is possible that future changes in these laws or regulations could have a significant adverse impact on some portion of Stroud's business, causing Stroud to re-evaluate those activities at that time.
Mining involves various other types of risks and hazards, including industrial accidents; metallurgical and other processing problems; unusual or unexpected rock formations; structural cave-ins or slides; flooding; fires; metals losses; and periodic interruptions due to inclement or hazardous weather conditions.
These risks could result in damage to, or destruction of, mineral properties, production facilities or other properties, personal injury, death to contractors or employees, delays in mining, increased production costs, monetary losses and possible legal liability. Stroud may be subject to liability for clean-up work. Stroud currently carries insurance to protect against certain risks in such amounts as it considers adequate. Risks not insured include environmental pollution and mine flooding. Therefore, Stroud may suffer a material adverse impact on its business if it incurs losses related to any significant events that are not covered by its insurance policies.
Stroud depends on key management personnel and may not be able to attract and retain qualified personnel
Stroud is dependent on a number of key management personnel, including the services of certain key employees. Stroud's ability to manage its operations, exploration and development activities, and hence its success, will depend in large part on the ability to retain current personnel and attract and retain new personnel, including management, technical and unskilled workforce. The loss of the services of one or more key management personnel could have a material adverse effect on Stroud's ability to manage and expand its business.
Stroud may experience growth in its number of employees or contractors as a result of its growth strategy. This growth will place substantial demands on Stroud and its management. Stroud's ability to recruit and assimilate new personnel will be critical to its performance. Stroud will be required to recruit additional personnel and to train, motivate and manage its employees and contractors. The international mining industry is very active and Stroud is facing increased competition for personnel in all disciplines and areas of operation, and there can be no assurance that it will be able to retain current personnel and attract and retain new personnel.
Stroud operates in Mexico and is subject to risks relating to foreign operations
Stroud's operations are currently conducted through subsidiaries principally in Mexico. As such, its operations are exposed to various levels of political, economic and other risks and uncertainties which could result in work stoppages, blockades of Stroud's mining operations and appropriation of assets. Some of Stroud's operations are located in areas where suspected Mexican drug cartels operate. Criminal activity and violence are well documented in Mexico and have increased over time in certain areas. These risks and uncertainties vary from region to region and include, but are not limited to: terrorism; hostage taking; local drug gang activities; military repression; expropriation and nationalization; extreme fluctuations in currency exchange rates; changes in royalty regimes, including the elimination of tax exemptions; underdeveloped industrial and economic infrastructure; unenforceability of judgements; prohibitions on restrictions for carrying out mining activities due to legal actions by Indigenous communities; high rates of inflation; labour unrest; the risks of war or civil unrest; renegotiation or nullification of existing concessions, licenses, permits and contracts; illegal mining; changes in taxation policies; restrictions on foreign exchange and repatriation; and changing political conditions arising from changes in government and otherwise, currency controls, import and export regulations and governmental regulations that favour or require the awarding of contracts to local contractors or require foreign contractors to employ citizens of, or purchase supplies from, a particular jurisdiction. Criminal activity such as kidnapping and extortion is a possible concern and may lead to a delay or suspension in operations at the Santo Domingo property, increased security and operational costs, and result in harm to our employees, contractors, visitors or community members, all of which could materially and adversely affect Stroud's operations and financial results. Local opposition to mine development projects could arise in Mexico and such opposition could be violent. If Stroud were to experience resistance or unrest in connection with its Mexican operations, it could have a material adverse effect on its operations and profitability. To the extent that Stroud acquires mineral properties in jurisdictions other than Mexico, it may be subject to similar and additional risks with respect to its operations in those jurisdictions. Mexico is currently subject to political instability, changes and uncertainties, which may cause changes to existing governmental regulations affecting mineral exploration and mining activities. Any changes in governmental laws, regulations, economic conditions or shifts in political attitudes or stability in Mexico are beyond the control of Stroud and may adversely affect Stroud's business.
Stroud is dependent on Mexican legal counsel, consultants and contractors
Stroud's material mineral property is located in Mexico. The banking system and controls, legal and regulatory requirements applicable to companies conducting mineral exploration activities, local business culture and practices in Mexico are different from those in Canada. Although some members of management and the Board have previous experience working and conducting business in Mexico, the officers and directors of Stroud must rely, to a great extent, on Stroud's Mexican legal counsel and local consultants and contractors retained by Stroud in order to keep abreast of material legal, regulatory and governmental developments as they pertain to and affect its business operations, and to assist Stroud with its governmental relations. Stroud also relies on the advice of local experts and professionals in connection with current and new regulations that develop in respect of banking, financing and tax matters in Mexico. Any developments or changes in such legal, regulatory or governmental requirements or in local business practices in Mexico are beyond the control of Stroud and may adversely affect its business.
Uninsured or Uninsurable Risks
Exploration, development and mining operations involve various hazards, including environmental hazards, industrial accidents, metallurgical and other processing problems, unusual or unexpected rock formations, structural cave-ins or slides, flooding, fires, metal losses and periodic interruptions due to inclement or hazardous weather conditions. These risks could result in damage to or destruction of mineral properties, facilities or other property, personal injury, environmental damage, delays in operations, increased cost of operations, monetary losses and possible legal liability. Stroud may not be able to obtain insurance to cover these risks at economically feasible premiums or at all. Stroud may elect not to insure where premium costs are disproportionate to Stroud's perception of the relevant risks. The payment of such insurance premiums and of such liabilities would reduce the funds available for exploration and production activities.
Risks Related to Ownership of Stroud Shares
Global financial conditions are volatile
Global financial conditions continue to be characterized as volatile. In recent years, global markets have been adversely impacted by various credit crises and significant fluctuations in fuel and energy costs and metals prices, including as a result of inflation rates, interest rates and significant fluctuations in commodity prices as a result of the ongoing military conflicts in the Middle East, the Russian invasion of Ukraine and the economic sanctions imposed on Russia in connection therewith. Many industries, including the mining industry, have been impacted by these market conditions. Global financial conditions remain subject to sudden and rapid destabilizations in response to international events, as government authorities may have limited resources to respond to future crises. A continued or worsened slowdown in the financial markets or other economic conditions, including but not limited to consumer spending, employment rates, business conditions, inflation, tariffs, supply chain disruptions, sovereign debt crises, fuel and energy costs, economic recession, consumer debt levels, lack of available credit, the state of the financial markets, interest rates and tax rates, may adversely affect Stroud's growth and profitability. Future crises may be precipitated by any number of causes, including natural disasters, geopolitical instability (such as the Russian invasion of Ukraine and the ongoing conflicts in the Middle East), changes to energy prices or sovereign defaults. If increased levels of volatility continue or in the event of a rapid destabilization of global economic conditions, it may result in a material adverse effect on commodity prices, demand for metals, the strength and confidence in the U.S. dollar, availability of credit, investor confidence, and general financial market liquidity, all of which may adversely affect Stroud's business and the market price of Stroud's securities.
Stroud has not paid dividends
Stroud has not paid dividends in the past and given the nature and stage of its development and does not anticipate paying dividends in the foreseeable future.
An investment in Stroud is highly speculative
An investment in Stroud carries a high degree of risk and should be considered as a speculative investment. Stroud has a very limited history of earnings, limited cash reserves, has not paid dividends, and is unlikely to pay dividends in the foreseeable future.
General Business Risks
Stroud's directors and officers may be subject to conflicts of interest
Certain of Stroud's directors and officers are, and may continue to be, involved in the mineral exploration industry through their direct and indirect participation in corporations, partnerships or joint ventures which are potential competitors of Stroud. Situations may arise in connection with potential acquisitions or opportunities where the other interests of these directors and officers may conflict with Stroud's interests. Directors and officers of Stroud with conflicts of interest will be subject to and must follow the procedures set out in applicable corporate and securities legislation, regulations, rules and policies. Notwithstanding this, there may be corporate opportunities which Stroud is not able to procure due to a conflict of interest of one or more of Stroud's directors or officers.
Changes in tax regulations may negatively impact Stroud
Stroud strives to run its business in as tax efficient a manner as possible. It is incorporated in Canada, has material subsidiaries incorporated under the laws of Mexico and holds assets in Mexico, and therefore may be subject to taxation in multiple jurisdictions. The tax systems in certain of the jurisdictions where Stroud and its subsidiaries are incorporated and where Stroud does business are complicated and subject to change. For this reason, the possibility of future negative effects on the results of Stroud due to changes in tax regulations cannot be excluded. Repatriation of any future earnings to Canada from other jurisdictions may be subject to withholding taxes. Stroud has no control over withholding tax rates.
Internal controls cannot provide absolute assurance with respect to the reliability of financial reporting and financial statement preparation
Internal controls over financial reporting are procedures designed to provide reasonable assurance that transactions are properly authorized, assets are safeguarded against unauthorized or improper use, and transactions are properly recorded and reported. A control system, no matter how well designed and operated, can provide only reasonable, not absolute, assurance with respect to the reliability of financial reporting and financial statement preparation.
There are uncertainties relating to enforcements of legal rights
Stroud has material subsidiaries organized under the laws of Mexico. Given that the majority of its material assets are located outside of Canada, investors may have difficulty in effecting service of process within Canada and collecting from or enforcing against Stroud, any judgments issued by the Canadian courts or Canadian securities regulatory authorities and predicated on the civil liability provisions of Canadian securities legislation or other laws of Canada. Similarly, in the event a dispute arises in connection with Stroud's foreign operations, Stroud may be subject to the exclusive jurisdiction of foreign courts or may not be successful in subjecting foreign persons to the jurisdiction of courts in Canada.
Stroud's operations depend on information technology ("IT") systems
Information systems and other technologies, including those related to Stroud's financial and operational management, and its technical and environmental data, are an integral part of Stroud's business activities. These IT systems could be subject to network disruptions caused by a variety of sources, including computer viruses, security breaches and cyberattacks, as well as disruptions resulting from incidents such as cable cuts, damage to physical plants, natural disasters, terrorism, fire, power loss, vandalism and theft. Stroud's operations also depend on the timely maintenance, upgrade and replacement of networks, equipment, IT systems and software, as well as pre-emptive expenses to mitigate the risks of failures. Any of these and other events could result in IT system failures, delays or increase in capital expenses. The failure of IT systems or a component of IT systems could, depending on the nature of any such failure, adversely impact Stroud's reputation and results of operations. Although to date Stroud has not experienced any material losses relating to cyber-attacks or other information security breaches, there can be no assurance that Stroud will not incur such losses in the future. Stroud's risk and exposure to these matters cannot be fully mitigated because of, among other things, the evolving nature of these threats. As a result, cyber security and the continued development and enhancement of controls, processes and practices designed to protect systems, computers, software, data and networks from attack, damage or unauthorized access remain a priority. As cyber threats continue to evolve, Stroud may be required to expend additional resources to continue to modify or enhance protective measures or to investigate and remediate any security vulnerabilities.
Risks Related to General Economic Factors
The global economy is subject to volatility that may negatively impact Stroud's business
Economic uncertainty in many parts of the world has adversely affected businesses and industries in almost every sector in more significant and unpredictable ways than in more stable economic times. Prolonged depressed economic conditions and volatility in the worldwide economy may continue to adversely affect individuals and institutions investing in junior mineral exploration and development companies, which could negatively affect Stroud's business and prospects.
Stroud maintains cash and cash equivalents in accounts with major banks, and Stroud's deposits at these institutions, may at times, exceed insured limits. Market conditions can impact the viability of these institutions. In the event of failure of any of the financial institutions where Stroud maintains its cash and cash equivalents, there can be no assurance that Stroud would be able to access uninsured funds in a timely manner or at all. Any inability to access or delay in accessing these funds could adversely affect Stroud's business and financial position.
Stroud's business and operations may be negatively impacted by global tariffs
On February 1, 2025, the United States' Trump Administration issued executive orders imposing broad based tariffs at the rate of 25% on all goods exported from Canada and Mexico into the United States, which were to come into effect on March 4, 2025, and were subsequently amended to allow for an exemption on U.S. tariffs for any products of Canada and Mexico that are CUSMA-compliant. The situation has continued to evolve rapidly since such time, including pursuant to a variety of administrative and judicial proceedings.
Amendments and modifications to tariffs have already been, and may continue to be, implemented on an irregular and ad-hoc basis, which makes the determination of the impact on Stroud's business difficult to predict. More broadly, these tariffs, and any changes to these tariffs or imposition of any new tariffs, taxes or import or export restrictions or prohibitions, could have a material adverse effect on the Canadian and Mexican economies, the Mexican mining industry and Stroud's business and operations. Furthermore, there is a risk that the tariffs imposed by the United States on other countries will trigger a broader global trade war, which could have a material adverse effect on the Canadian, Mexican and global economies, and by extension the Canadian mining industry and Stroud.
Auditor, Transfer Agent and Registrar
The auditor of Stroud is McGovern Hurley LLP, Chartered Professional Accountants, of 251 Consumers Road, Suite 800, Toronto, Ontario M2J 4R3, first appointed on April 19, 2016. They have advised Silver Hammer that they are independent of Stroud within the meaning of the ethical requirements that are relevant to their audit of the consolidated financial statements in Canada.
The transfer agent and registrar for the Stroud Shares is TSX Trust Company at its office in Toronto, Ontario.
Interest of Management and Others in Material Transactions
Except as disclosed herein, no director, executive officer or persons or companies who beneficially own, control or direct, directly or indirectly, more than ten percent of any class of outstanding voting securities of Stroud, nor any associate or affiliate of the foregoing persons, has or has had any material interest, direct or indirect, in any transactions with Stroud within the three most recently completed financial years or during the current financial year that has materially affected or is reasonably expected to have a material effect on Stroud, other than ordinary course participation in private placement financings.
Material Contracts
There are no contracts of Stroud, other than contracts entered into in the ordinary course of business, that are material to Stroud, other the Combination Agreement dated July 17, 2026 between Stroud, 1001629888 Ontario Inc. and Silver Hammer and the Voting Support Agreements.
Electronic Copies of the Combination Agreement and the Voting Support Agreements are available on the SEDAR+ website under Stroud's profile.
Other Material Facts
To management's knowledge, there are no other material facts relating to Stroud that are not otherwise disclosed in this Circular or are necessary for the Circular to contain full, true and plain disclosure of all material facts relating to Stroud.
INFORMATION CONCERNING SILVER HAMMER
The information concerning Silver Hammer contained in this Circular has been provided by Silver Hammer for inclusion herein. Although Stroud has no knowledge that any statement contained herein taken from or based upon such information is untrue or incomplete, Stroud assumes no responsibility for the accuracy or completeness of such information or for any failure by Silver Hammer to disclose events which may have occurred or may affect the completeness or accuracy of such information but which are unknown to Stroud.
Detailed disclosure regarding Silver Hammer can be found at Appendix "E" attached hereto; the following summary is qualified in its entirety by the information detailed in Appendix "E".
The Consolidation
Prior to the effective time of the Amalgamation, Silver Hammer will complete a consolidation of all issued and outstanding Silver Hammer Shares on the basis of one (1) post-Consolidation Silver Hammer Share for each four (4) pre-Consolidation Silver Hammer Shares. Completion of the Consolidation is a condition to the completion of the Amalgamation.
The SilverMark Amalgamation
Concurrently with the execution of the Combination Agreement, Silver Hammer entered into a business combination agreement dated July 17, 2026 with 18076421 Canada Inc. and SilverMark Resources Inc. (the "SilverMark Agreement"), pursuant to which Silver Hammer will acquire all of the issued and outstanding shares of SilverMark by way of a three-cornered amalgamation under the Canada Business Corporations Act. SilverMark is party to a series of option and joint venture agreements with SABI-AIM Minerals, a corporation organized under the laws of Morocco, pursuant to which SilverMark has the right to earn up to a 75% interest in a portfolio of mineral assets in Morocco, including the past-producing Akka Mine and related mineral properties, additional mining concessions and permits, and certain stockpile areas.
Upon completion of the SilverMark Amalgamation, each of the 13,888,889 issued and outstanding SilverMark Class A common shares (other than shares held by shareholders who validly exercise dissent rights) will be cancelled and exchanged for Resulting Issuer Shares at a ratio of 0.346154 of one Resulting Issuer Share per SilverMark Class A common share. The outstanding SilverMark Class B special shares will be cancelled and exchanged for such number of Contingent Value Shares as is equal to $1,575,000 divided by the price per subscription receipt under the Private Placement. Each Contingent Value Share will be convertible into one Resulting Issuer Share upon the achievement of specified project milestones relating to the Moroccan Assets. The Contingent Value Shares will not be transferable, will carry no voting rights, will not entitle holders to dividends and will carry no right of voluntary conversion; any that remain unconverted following the applicable milestone deadline may be redeemed and cancelled by the Resulting Issuer without compensation. The creation and authorization of the Contingent Value Shares is subject to approval by Silver Hammer Shareholders at the Silver Hammer Meeting.
The Private Placement
In connection with the Transaction, a private placement of subscription receipts is anticipated to be completed and is a condition to completion of the Amalgamation. The Private Placement will consist of the issuance of a minimum of 26,923,077 Subscription Receipts and a maximum of 38,461,538 Subscription Receipts (or such greater amount as may be determined by the parties), with each Subscription Receipt representing the right to receive one post-Consolidation Resulting Issuer Share and one warrant of the Resulting Issuer a "Resulting Issuer Warrant"). The Subscription Receipts will be sold at the Offering Price for minimum gross proceeds of $7,000,000 and maximum gross proceeds of $10,000,000 (or such greater amount as may be determined by the parties), subject to the Agents' Option (described below). Upon the satisfaction of certain escrow release conditions (the "Escrow Release Conditions"), including the satisfaction or waiver of all conditions to the completion of the Amalgamation and the SilverMark Amalgamation, the Subscription Receipts will be converted, for no additional consideration, into units of SilverMark (each, a "Unit"), with each Unit comprising one Class A common share of SilverMark (a "Class A Common Share") and one Class A Common Share purchase warrant of SilverMark a "Warrant"). Upon completion of the SilverMark Amalgamation, the Class A Common Shares and Warrants underlying the Units will be exchanged for post-Consolidation Resulting Issuer Shares and warrants of the Resulting Issuer ("Resulting Issuer Warrants") pursuant to the SilverMark Amalgamation. On conversion of the Subscription Receipts the holders of Subscription Receipts will receive such number of Units that will result in them receiving one Resulting Issuer Share and one Resulting Issuer Warrant in the SilverMark Amalgamation for each Subscription Receipt. Each Resulting Issuer Warrant will entitle the holder thereof to purchase one Resulting Issuer Share at a price of $0.38 for a period of 36 months from the Closing Date (as defined herein), subject to adjustment in certain circumstances.
The Offering will be led by Red Cloud Securities Inc. (the "Lead Agent"), acting as lead agent and sole bookrunner on behalf of a syndicate of agents (collectively, the "Agents").
SilverMark has granted the Agents an option (the "Agents' Option"), exercisable in full or in part up to 48 hours prior to the closing of the Offering, to sell up to an additional 7,692,308 Subscription Receipts at the Offering Price for additional gross proceeds of up to C$2,000,000.
The gross proceeds of the Offering, net of reasonable out-of-pocket expenses incurred by the Agents (the "Escrowed Funds"), will be delivered to and held by a Canadian trust company or other escrow agent acceptable to SilverMark, Silver Hammer and the Lead Agent (the "Subscription Receipt Agent"), in an interest-bearing account, pending the satisfaction or waiver, as applicable, of the Escrow Release Conditions. Upon satisfaction of the Escrow Release Conditions (the "Release Date"), the Escrowed Funds (including interest thereon) will be released to SilverMark, net of any amounts payable to the Agents in accordance with the terms described below. If the Escrow Release Conditions are not satisfied or waived prior to October 31, 2026 (or such other date as may be agreed upon by SilverMark, Silver Hammer and the Agents), or if SilverMark advises the Lead Agent or announces to the public that it does not intend to satisfy the Escrow Release Conditions, the Subscription Receipt Agent will return to holders of Subscription Receipts an amount equal to the aggregate Offering Price of the Subscription Receipts held by them and their pro rata portion of any interest earned thereon, and the Subscription Receipts will be cancelled.
SilverMark has agreed to pay the Agents: (a) a cash commission equal to 7.0% of the gross proceeds raised from the sale of Subscription Receipts (including any Subscription Receipts issued upon exercise of the Agents' Option), of which 50% will be payable on the Closing Date and the remaining 50% will be payable on the Release Date; and (b) such number of broker warrants of SilverMark (the "Broker Warrants") as is equal to 7.0% of the aggregate number of Subscription Receipts sold under the Offering (including any Subscription Receipts issued upon exercise of the Agents' Option), to be issued on the Release Date. Each Broker Warrant will be exercisable to acquire one Class A Common Share at an exercise price equal to the Offering Price for a period of 24 months from the Release Date. Upon completion of the SilverMark Amalgamation, the Broker Warrants will be exchanged for warrants of the Resulting Issuer on the same terms and conditions, pursuant to the Transaction.
INFORMATION CONCERNING THE RESULTING ISSUER
The information concerning Resulting Issuer contained in this Circular has been provided by Silver Hammer for inclusion herein. Although Stroud has no knowledge that any statement contained herein taken from or based upon such information is untrue or incomplete, Stroud assumes no responsibility for the accuracy or completeness of such information or for any failure by Silver Hammer to disclose events which may have occurred or may affect the completeness or accuracy of such information but which are unknown to Stroud.
Upon completion of the Transaction, the Resulting Issuer will be a reporting issuer in British Columbia, Alberta and Ontario and will carry on the business of Silver Hammer and the Privcos, including the development of Santo Domingo. The Resulting Issuer Shares will continue to be listed on the CSE. Information relating to the Resulting Issuer after the Transaction is contained in Appendix "F" to this Circular.
DISSENTING SHAREHOLDER RIGHTS
The following is a summary of the provisions of section 185 of the OBCA relating to Dissent Rights. This summary is qualified in its entirety by the full text of section 185 of the OBCA, which is set out in Appendix "B" to this Circular.
A Registered Stroud Shareholder who intends to exercise Dissent Rights should carefully consider and strictly comply with the provisions of section 185 of the OBCA. Failure to strictly comply with the requirements set forth in section 185 may result in the loss of Dissent Rights. Registered Stroud Shareholders who wish to exercise Dissent Rights should seek their own legal advice.
A Registered Stroud Shareholder who fully complies with section 185 of the OBCA is entitled, if the Amalgamation becomes effective, to be paid the fair value of the Stroud Shares in respect of which the holder dissents, determined as of the close of business on the day before the Amalgamation Resolution is adopted.
Only Registered Stroud Shareholders may exercise Dissent Rights. A Beneficial Stroud Shareholder whose Stroud Shares are registered in the name of an Intermediary and who wishes to dissent should be aware that only the registered holder is entitled to dissent. A Beneficial Stroud Shareholder who wishes to exercise Dissent Rights must make arrangements for the Stroud Shares beneficially owned by that person to be registered in that person's name prior to the time the written objection is required to be received by Stroud, or alternatively make arrangements for the registered holder to dissent on that person's behalf.
A Dissenting Shareholder must:
(a) send to Stroud a written objection to the Amalgamation Resolution (a "Dissent Notice"), which must be received by Stroud at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, Attention: CFO, at or before the Meeting;
(b) not vote in favour of the Amalgamation Resolution;
(c) within twenty (20) days after receiving notice from Stroud that the Amalgamation Resolution has been adopted (or, if the Dissenting Shareholder does not receive such notice, within twenty (20) days after learning that the Amalgamation Resolution has been adopted), send to Stroud a written notice containing the Dissenting Shareholder's name and address, the number and class of shares in respect of which the shareholder dissents, and a demand for payment of the fair value of those shares; and
(d) within thirty (30) days after sending the notice referred to in paragraph (c), send the certificates (if any) representing the Stroud Shares in respect of which the shareholder dissents to Stroud or its transfer agent.
A Dissenting Shareholder who fails to comply with subsections 185(6), (10) and (11) of the OBCA has no right to make a claim under section 185. The execution or exercise of a proxy does not constitute a written objection for the purposes of subsection 185(6). A Dissenting Shareholder may only claim under section 185 with respect to all of the shares of a class held on behalf of any one beneficial owner and registered in the name of the Dissenting Shareholder.
On sending the notice referred to in paragraph (c) above, a Dissenting Shareholder ceases to have any rights as a Stroud Shareholder other than the right to be paid the fair value of the shares, except in the limited circumstances set out in subsection 185(14) of the OBCA.
Stroud is required, not later than seven (7) days after the later of the Effective Date and the date on which Stroud received the notice referred to in paragraph (c) above, to send to each Dissenting Shareholder a written offer to pay for the shares in an amount considered by the directors of Stroud to be the fair value thereof, accompanied by a statement showing how the fair value was determined. Every such offer for shares of the same class must be on the same terms. If Stroud fails to make an offer, or if a Dissenting Shareholder fails to accept an offer, Stroud may, within fifty (50) days after the Effective Date, apply to the court to fix the fair value of the shares. If Stroud fails to apply, a Dissenting Shareholder may apply to the court for the same purpose within a further period of twenty (20) days.
It is a condition in favour of Silver Hammer that Dissent Rights not be validly exercised (and not withdrawn) in respect of more than 5% of the Stroud Shares outstanding immediately prior to the Effective Date. That condition may be waived by Silver Hammer in its sole discretion.
Stroud Shares held by a Dissenting Shareholder who is ultimately entitled to be paid the fair value of those shares will be deemed to have been irrevocably transferred to Stroud and cancelled immediately prior to the Amalgamation.
LEGAL MATTERS
Certain legal matters in connection with the Amalgamation will be passed upon by Corporate Counsel USA PLLC on behalf of Stroud, and by McMillan LLP on behalf of Silver Hammer. As at the date of this Circular, the partners and associates of Corporate Counsel USA PLLC, as a group, beneficially own, directly or indirectly, less than 1% of the outstanding securities of Stroud and of Silver Hammer.
INTEREST OF INFORMED PERSONS IN MATERIAL TRANSACTIONS
Except as disclosed in this Circular, including under "The Amalgamation - Interests of Certain Persons in the Amalgamation", no informed person of Stroud, no proposed nominee for election as a director of Stroud, and no associate or affiliate of any of the foregoing, has any material interest, direct or indirect, in any transaction since the commencement of Stroud's most recently completed financial year or in any proposed transaction that has materially affected or would materially affect Stroud or any of its subsidiaries.
Scott Jobin-Bevans is the Chief Executive Officer and a director of Stroud and a proposed director and officer of the Resulting Issuer. Dr. Jobin-Bevans holds 3,857,778 SilverMark Class A Common Shares and 1,260,000 SilverMark Class B Special Shares. Pursuant to the SilverMark Amalgamation, Dr. Jobin-Bevans' SilverMark Class A Common Shares will be exchanged for Resulting Issuer Shares in accordance with the SilverMark Exchange Ratio, and Dr. Jobin-Bevans' SilverMark Class B Special Shares will be exchanged for Contingent Value Shares in accordance with the Class B Exchange Ratio. As a result, Dr. Jobin-Bevans has a material interest in the Amalgamation that is in addition to, and distinct from, his interest as a Stroud Shareholder.
MANAGEMENT CONTRACTS
Except as otherwise disclosed in this Circular, management functions of Stroud are not, to any substantial degree, performed by a person other than the directors and executive officers of Stroud.
EXPERTS
Opinions
Except as disclosed in this Circular, no Person or company whose profession or business gives authority to a statement made by the Person and who is named as having prepared or certified a part of this Circular or as having prepared or certified a report or valuation described or included in this Circular holds any beneficial interest, direct or indirect, in any securities or property of Stroud or the Resulting Issuer, or of an Associate or Affiliate thereof and no such person is expected to be elected, appointed or employed as a director, senior officer or employee of Stroud or the Resulting Issuer, or of an Associate or Affiliate thereof and no such Person is a Promoter of Stroud or the Resulting Issuer, or an Associate or Affiliate thereof.
Interests of Experts
The following opinions or reports have been described or included in this Circular:
the audit report of Stroud is provided by McGovern Hurley LLP. for the fiscal years ended December 31, 2025 and 2024;
the audit report of Silver Hammer is provided by Manning Elliott LLP, Chartered Professional Accountants for the fiscal years ended September 30, 2025 and 2024; and
Simon Mortimer (FAIG Australia), Principal Consultant at Atticus Geoscience Consulting Ltd. (UK, Peru), prepared the Technical Report and Mineral Resource Estimate which is referred to in this Circular. Simon Mortimer is a Qualified Person as defined by NI 43-101 and is independent of Stroud, Silver Hammer Mining Corp., and SilverMark.
McGovern Hurley LLP has confirmed that they are independent of Stroud within the meaning of the Rules of Professional Conduct of the Chartered Professional Accountants of Ontario.
Manning Elliott LLP, Chartered Professional Accountants has confirmed that they are independent of Silver Hammer within the meaning of the Rules of Professional Conduct of the Chartered Accountants of British Columbia.
Neither McGovern Hurley LLP nor Manning Elliott LLP beneficially owns, directly or indirectly, any securities or property of Stroud or the Resulting Issuer, or of any Associate or Affiliate thereof.
Moreover, none of the foregoing Persons or any of their respective directors, officers or employees is, or expects to be, elected, appointed or employed as a director, officer or employee of the Resulting Issuer or its Associates or Affiliates.
ADDITIONAL INFORMATION
Additional information relating to Stroud is available under Stroud's profile on SEDAR+ at www.sedarplus.ca. Stroud Shareholders may contact Stroud at 1090 Don Mills Road, Suite 404, Toronto, Ontario M3C 5R6, telephone 416.888.8731, to request copies of Stroud's financial statements and management's discussion and analysis. Financial information relating to Stroud is provided in Stroud's comparative annual financial statements and management's discussion and analysis for the financial year ended December 31, 2025.
Additional information relating to Silver Hammer is available under Silver Hammer's profile on SEDAR+ at www.sedarplus.ca.
DIRECTORS' APPROVAL
The contents of this Circular and the sending thereof to the Stroud Shareholders have been approved by the Stroud Board.
DATED at Toronto, Ontario this 28th day of August, 2026.
BY ORDER OF THE BOARD OF DIRECTORS
(Signed) "Jeff Kennedy"
Jeff Kennedy, Director
APPENDIX A - AMALGAMATION RESOLUTION
BE IT RESOLVED BY SPECIAL RESOLUTION THAT:
1. The amalgamation (the "Amalgamation") pursuant to the provisions of the Business Corporations Act (Ontario) (the "OBCA") of Stroud Resources Ltd. ("Stroud") and 1001629888 Ontario Inc. ("Subco"), a wholly-owned subsidiary of Silver Hammer Mining Corp. ("Silver Hammer"), all as more particularly described and set forth in the management information circular of Stroud dated August 28, 2026 (the "Circular") accompanying the notice of this meeting, and all transactions contemplated thereby, are hereby authorized, approved and adopted.
2. Stroud is hereby authorized to enter into an amalgamation agreement (the "Amalgamation Agreement") substantially upon the terms set forth in the form thereof attached as Schedule "A" to the business combination agreement dated July 17, 2026 among Stroud, Silver Hammer and Subco (the "Combination Agreement"), a copy of which Combination Agreement is attached as Appendix "C" to the Circular, with such amendments or variations thereto as may be approved by any director or officer of Stroud, such approval to be conclusively evidenced by the execution and delivery of the Amalgamation Agreement.
3. The (i) Combination Agreement, the Amalgamation Agreement and the transactions contemplated thereby, (ii) actions of the directors of Stroud in approving the Combination Agreement and the Amalgamation Agreement, and (iii) actions of the directors and officers of Stroud in executing and delivering the Combination Agreement and the Amalgamation Agreement, and any amendments thereto, are hereby confirmed, ratified, authorized and approved.
4. Notwithstanding that this resolution has been passed (and the Amalgamation authorized, approved and adopted) by the shareholders of Stroud, the board of directors of Stroud is hereby authorized and empowered, without further notice to or approval of the shareholders of Stroud, (i) to amend the Combination Agreement or the Amalgamation Agreement to the extent permitted thereby, and (ii) subject to the terms of the Combination Agreement, not to proceed with the Amalgamation and to revoke this resolution at any time prior to the endorsement by the Director appointed under section 278 of the OBCA of a certificate of amalgamation giving effect to the Amalgamation.
5. Any officer or director of Stroud is hereby authorized and directed, for and on behalf of Stroud, to execute, under the corporate seal of Stroud or otherwise, and to deliver or cause to be delivered, articles of amalgamation and all such other documents as are necessary or desirable to give effect to the Amalgamation in accordance with the Combination Agreement and the Amalgamation Agreement, such determination to be conclusively evidenced by the execution and delivery of such articles of amalgamation and such other documents.
6. Any officer or director of Stroud is hereby authorized and directed, for and on behalf of Stroud, to execute or cause to be executed and to deliver or cause to be delivered all such other documents and instruments and to perform or cause to be performed all such other acts and things as in such person's opinion may be necessary or desirable to give full effect to the foregoing resolutions and the matters authorized thereby, such determination to be conclusively evidenced by the execution and delivery of such document or instrument or the doing of any such act or thing.
APPENDIX B - SECTION 185 OF THE OBCA
185(1) Rights of dissenting shareholders
Subject to subsection (3) and to sections 186 and 248, if a corporation resolves to,
(a) amend its articles under section 168 to add, remove or change restrictions on the issue, transfer or ownership of shares of a class or series of the shares of the corporation;
(b) amend its articles under section 168 to add, remove or change any restriction upon the business or businesses that the corporation may carry on or upon the powers that the corporation may exercise;
(c) amalgamate with another corporation under sections 175 and 176;
(d) be continued under the laws of another jurisdiction under section 181; or
(e) sell, lease or exchange all or substantially all its property under subsection 184(3),
a holder of shares of any class or series entitled to vote on the resolution may dissent.
185(2) Idem
If a corporation resolves to amend its articles in a manner referred to in subsection 170(1), a holder of shares of any class or series entitled to vote on the amendment under section 168 or 170 may dissent, except in respect of an amendment referred to in,
(a) clause 170(1)(a), (b) or (e) where the articles provide that the holders of shares of such class or series are not entitled to dissent; or
(b) subsection 170(5) or (6).
185(2.1) One class of shares
The right to dissent described in subsection (2) applies even if there is only one class of shares.
185(3) Exception
A shareholder of a corporation incorporated before the 29th day of July, 1983 is not entitled to dissent under this section in respect of an amendment of the articles of the corporation to the extent that the amendment,
(a) amends the express terms of any provision of the articles of the corporation to conform to the terms of the provision as deemed to be amended by section 277; or
(b) deletes from the articles of the corporation all of the objects of the corporation set out in its articles, provided that the deletion is made by the 29th day of July, 1986.
185(4) Shareholder's right to be paid fair value
In addition to any other right the shareholder may have, but subject to subsection (30), a shareholder who complies with this section is entitled, when the action approved by the resolution from which the shareholder dissents becomes effective, to be paid by the corporation the fair value of the shares held by the shareholder in respect of which the shareholder dissents, determined as of the close of business on the day before the resolution was adopted.
185(5) No partial dissent
A dissenting shareholder may only claim under this section with respect to all the shares of a class held by the dissenting shareholder on behalf of any one beneficial owner and registered in the name of the dissenting shareholder.
185(6) Objection
A dissenting shareholder shall send to the corporation, at or before any meeting of shareholders at which a resolution referred to in subsection (1) or (2) is to be voted on, a written objection to the resolution, unless the corporation did not give notice to the shareholder of the purpose of the meeting or of the shareholder's right to dissent.
185(7) Idem
The execution or exercise of a proxy does not constitute a written objection for purposes of subsection (6).
185(8) Notice of adoption of resolution
The corporation shall, within ten days after the shareholders adopt the resolution, send to each shareholder who has filed the objection referred to in subsection (6) notice that the resolution has been adopted, but such notice is not required to be sent to any shareholder who voted for the resolution or who has withdrawn the objection.
185(9) Idem
A notice sent under subsection (8) shall set out the rights of the dissenting shareholder and the procedures to be followed to exercise those rights.
185(10) Demand for payment of fair value
A dissenting shareholder entitled to receive notice under subsection (8) shall, within twenty days after receiving such notice, or, if the shareholder does not receive such notice, within twenty days after learning that the resolution has been adopted, send to the corporation a written notice containing,
(a) the shareholder's name and address;
(b) the number and class of shares in respect of which the shareholder dissents; and
(c) a demand for payment of the fair value of such shares.
185(11) Certificates to be sent in
Not later than the thirtieth day after the sending of a notice under subsection (10), a dissenting shareholder shall send the certificates, if any, representing the shares in respect of which the shareholder dissents to the corporation or its transfer agent.
185(12) Idem
A dissenting shareholder who fails to comply with subsections (6), (10) and (11) has no right to make a claim under this section.
185(13) Endorsement on certificate
A corporation or its transfer agent shall endorse on any share certificate received under subsection
(11) a notice that the holder is a dissenting shareholder under this section and shall return forthwith the share certificates to the dissenting shareholder.
185(14) Rights of dissenting shareholder
On sending a notice under subsection (10), a dissenting shareholder ceases to have any rights as a shareholder other than the right to be paid the fair value of the shares as determined under this section except where,
(a) the dissenting shareholder withdraws notice before the corporation makes an offer under subsection (15);
(b) the corporation fails to make an offer in accordance with subsection (15) and the dissenting shareholder withdraws notice; or
(c) the directors revoke a resolution to amend the articles under subsection 168(3), terminate an amalgamation agreement under subsection 176(5) or an application for continuance under subsection 181(5), or abandon a sale, lease or exchange under subsection 184(8), in which case the dissenting shareholders rights are reinstated as of the date the dissenting shareholder sent the notice referred to in subsection (10).
185(14.1) Same
A dissenting shareholder whose rights are reinstated under subsection (14) is entitled, upon presentation and surrender to the corporation or its transfer agent of any share certificate that has been endorsed in accordance with subsection (13),
(a) to be issued, without payment of any fee, a new certificate representing the same number, class and series of shares as the certificate so surrendered; or
(b) if a resolution is passed by the directors under subsection 54(2) with respect to that class and series of shares,
(i) to be issued the same number, class and series of uncertificated shares as represented by the certificate so surrendered, and
(ii) to be sent the notice referred to in subsection 54(3).
185(14.2) Same
A dissenting shareholder whose rights are reinstated under subsection (14) and who held uncertificated shares at the time of sending a notice to the corporation under subsection (10) is entitled,
(a) to be issued the same number, class and series of uncertificated shares as those held by the dissenting shareholder at the time of sending the notice under subsection (10); and
(b) to be sent the notice referred to in subsection 54(3).
185(15) Offer to pay
A corporation shall, not later than seven days after the later of the day on which the action approved by the resolution is effective or the day the corporation received the notice referred to in subsection (10), send to each dissenting shareholder who has sent such notice,
(a) a written offer to pay for the dissenting shareholder's shares in an amount considered by the directors of the corporation to be the fair value thereof, accompanied by a statement showing how the fair value was determined; or
(b) if subsection (30) applies, a notification that it is unable lawfully to pay dissenting shareholders for their shares.
185(16) Idem
Every offer made under subsection (15) for shares of the same class or series shall be on the same terms.
185(17) Idem
Subject to subsection (30), a corporation shall pay for the shares of a dissenting shareholder within ten days after an offer made under subsection (15) has been accepted, but any such offer lapses if the corporation does not receive an acceptance thereof within thirty days after the offer has been made.
185(18) Application to court to fix fair value
Where a corporation fails to make an offer under subsection (15) or if a dissenting shareholder fails to accept an offer, the corporation may, within fifty days after the action approved by the resolution is effective or within such further period as the court may allow, apply to the court to fix a fair value for the shares of any dissenting shareholder.
185(19) Idem
If a corporation fails to apply to the court under subsection (18), a dissenting shareholder may apply to the court for the same purpose within a further period of twenty days or within such further period as the court may allow.
185(20) Idem
A dissenting shareholder is not required to give security for costs in an application made under subsection (18) or (19).
185(21) Costs
If a corporation fails to comply with subsection (15), then the costs of a shareholder application under subsection (19) are to be borne by the corporation unless the court otherwise orders.
185(22) Notice to shareholders
Before making application to the court under subsection (18) or not later than seven days after receiving notice of an application to the court under subsection (19), as the case may be, a corporation shall give notice to each dissenting shareholder who, at the date upon which the notice is given,
(a) has sent to the corporation the notice referred to in subsection (10); and
(b) has not accepted an offer made by the corporation under subsection (15), if such an offer was made, of the date, place and consequences of the application and of the dissenting shareholder's right to appear and be heard in person or by counsel, and a similar notice shall be given to each dissenting shareholder who, after the date of such first mentioned notice and before termination of the proceedings commenced by the application, satisfies the conditions set out in clauses (a) and (b) within three days after the dissenting shareholder satisfies such conditions.
185(23) Parties joined
All dissenting shareholders who satisfy the conditions set out in clauses (22)(a) and (b) shall be deemed to be joined as parties to an application under subsection (18) or (19) on the later of the date upon which the application is brought and the date upon which they satisfy the conditions, and shall be bound by the decision rendered by the court in the proceedings commenced by the application.
185(24) Idem
Upon an application to the court under subsection (18) or (19), the court may determine whether any other person is a dissenting shareholder who should be joined as a party, and the court shall fix a fair value for the shares of all dissenting shareholders.
185(25) Appraisers
The court may in its discretion appoint one or more appraisers to assist the court to fix a fair value for the shares of the dissenting shareholders.
185(26) Final order
The final order of the court in the proceedings commenced by an application under subsection (18) or (19) shall be rendered against the corporation and in favour of each dissenting shareholder who, whether before or after the date of the order, complies with the conditions set out in clauses (22)(a) and (b).
185(27) Interest
The court may in its discretion allow a reasonable rate of interest on the amount payable to each dissenting shareholder from the date the action approved by the resolution is effective until the date of payment.
185(28) Where corporation unable to pay
Where subsection (30) applies, the corporation shall, within ten days after the pronouncement of an order under subsection (26), notify each dissenting shareholder that is unable lawfully to pay dissenting shareholders for their shares.
185(29) Idem
Where subsection (30) applies, a dissenting shareholder, by written notice sent to the corporation within thirty days after receiving a notice under subsection (28), may,
(a) withdraw a notice of dissent, in which case the corporation is deemed to consent to the withdrawal and the shareholder's full rights are reinstated; or
(b) retain a status as a claimant against the corporation, to be paid as soon as the corporation is lawfully able to do so or, in a liquidation, to be ranked subordinate to the rights of creditors of the corporation but in priority to its shareholders.
185(30) Idem
A corporation shall not make a payment to a dissenting shareholder under this section if there are reasonable grounds for believing that,
(a) the corporation is or, after the payment, would be unable to pay its liabilities as they become due; or
(b) the realizable value of the corporation's assets would thereby be less than the aggregate of its liabilities.
185(31) Court order
Upon application by a corporation that proposes to take any of the actions referred to in subsection (1) or (2), the court may, if satisfied that the proposed action is not in all the circumstances one that should give rise to rights arising under subsection (4), by order declare that those rights will not arise upon the taking of the proposed action, and the order may be subject to compliance upon such terms and conditions as the court thinks fit and, if the corporation is an offering corporation, notice of any such application and a copy of any order made by the court upon such application shall be served upon the Commission.
185(32) Commission may appear
The Commission may appoint counsel to assist the court upon the hearing of an application under subsection (31), if the corporation is an offering corporation.
APPENDIX C - BUSINESS COMBINATION AGREEMENT
[See attached]
Execution Copy
BUSINESS COMBINATION AGREEMENT
THIS AGREEMENT is made as the 17th day of July, 2026,
BETWEEN:
STROUD RESOURCES LTD., a company existing under the laws of the Province of Ontario,
(hereinafter referred to as "SDR")
- and -
SILVER HAMMER MINING CORP., a company existing under the laws of British Columbia,
(hereinafter referred to as "Silver Hammer")
- and -
1001629888 ONTARIO INC., a company existing under the laws of the Province of Ontario,
(hereinafter referred to as "Subco")
WHEREAS Silver Hammer is a publicly traded company, the common shares of which are listed and posted for trading on the CSE;
WHEREAS SDR is a publicly traded company, the common shares of which are listed and posted for trading on the TSXV;
WHEREAS Subco is a wholly-owned subsidiary of Silver Hammer;
WHEREAS the Companies intend to effect a business combination pursuant to which Silver Hammer will acquire all of the issued and outstanding SDR Shares not already owned by Silver Hammer (the "Transaction");
WHEREAS the Companies desire to effect the Transaction by way of a "three-cornered" amalgamation pursuant to which SDR and Subco shall amalgamate pursuant to Section 174 of the OBCA and continue under the name of "Stroud Resources Ltd." and the former shareholders of SDR (other than Silver Hammer and SDR Shareholders who exercise Dissent Rights) will receive Silver Hammer Shares (the "Amalgamation"), subject to the terms and conditions of this Agreement and the Amalgamation Agreement; and
WHEREAS the Companies have entered into this Agreement to provide for the matters referred to in the foregoing recitals and for other matters relating to the Amalgamation;
NOW THEREFORE THIS AGREEMENT WITNESSES that in consideration of the premises and the mutual covenants hereinafter contained, the Companies agree as follows:
ARTICLE 1
INTERPRETATION AND GENERAL
1.1 Definitions
In this Agreement, unless the context otherwise requires, the following words and phrases shall have the meanings hereinafter set forth:
"Acquisition Proposal" has the meaning ascribed thereto in Section 4.1;
"Agreement", "this Agreement", "hereof", "herein" and "hereunder" and similar expressions refer to this agreement and not to any particular article, section or other portion hereof and include any agreement or instrument supplementary or ancillary hereto;
"Alternative Transaction" has the meaning ascribed thereto in Section 3.7;
"Amalgamated Corporation" means the continuing corporation constituted upon the Amalgamation becoming effective, to be named "Stroud Resources Ltd.";
"Amalgamating Corporations" means SDR and Subco;
"Amalgamation" has the meaning ascribed thereto in the preamble to this Agreement;
"Amalgamation Agreement" means the amalgamation agreement to be entered into among Silver Hammer and the Amalgamating Corporations, substantially in the form attached hereto as Schedule "A";
"Articles of Amalgamation" means the Articles of Amalgamation with respect to the Amalgamation required under the OBCA to be filed with the Director;
"BCBCA" means the Business Corporations Act (British Columbia);
"business day" means any day other than a Saturday, Sunday or federal holiday in Canada or a day on which commercial banks in Vancouver or Toronto are required to or permitted to close;
"Change Date" has the meaning ascribed thereto in Section 4.2;
"Common Shares" means the common shares in the capital of the Amalgamated Corporation; "Companies" means, collectively, Silver Hammer and the Amalgamating Corporations; "Compensation Fee" has the meaning ascribed thereto in Section 4.3;
"Consolidation" means the consolidation of the Silver Hammer Shares on the basis of one (1) post-Consolidation Silver Hammer Share for each four (4) pre-Consolidation Silver Hammer Shares, to be completed before the effective time of the Amalgamation;
"Concurrent Financing" means a private placement of subscription receipts of SilverMark to be completed in connection with the Transaction for gross proceeds of a minimum of $7,000,000 and a maximum of $10,000,000 at a price per subscription receipt to be determined by Silver Hammer having regard to prevailing market conditions at the time of pricing of the Concurrent Financing;
"CSE" means the Canadian Securities Exchange;
"Director" means the Director appointed under Section 278 of the OBCA;
"Dissent Rights" means the rights of dissent in respect of the Amalgamation described in the Amalgamation Agreement;
"Effective Date" means the date shown on the Certificate of Amalgamation endorsed by the Director under the OBCA giving effect to the Amalgamation;
"Environmental Consents" includes all material consents issued by or issuable by any regulatory authority under Environmental Laws;
"Environmental Laws" means all laws applicable to the environment, occupational health and safety, product safety, product liability and public safety;
"Exchange Ratio" means 0.777963 Silver Hammer Shares for each SDR Share, on a post-Consolidation basis of the Silver Hammer Shares;
"first party" has the meaning ascribed thereto in Section 4.4(c);
"Governmental Entity" means any: (i) supranational, multinational, federal, territorial, provincial, state, regional, municipal, local or other governmental or public ministry, department, authority, body, central bank, court, commission, tribunal, board, bureau or agency, domestic or foreign; (ii) subdivision, agent or authority of any of the above; (iii) quasi-governmental or private body, including any tribunal, commission, regulatory agency or self-regulatory organization, exercising any regulatory, expropriation or Taxation Authority under or for the account of any of the above; or (iv) stock exchange (including the TSXV or the CSE);
"Hazardous Substance" means any material or substance that may impair the quality of the environment or which under Environmental Laws is deemed to be "hazardous", a "pollutant", "toxic", "deleterious", "caustic", "dangerous", a "waste", a "hazardous material", a "source of contamination" or analogous substance including, without limitation, petroleum and petroleum products, asbestos, polychlorinated biphenyls, and flammable and radioactive materials;
"IFRS" means International Financial Reporting Standards formulated by the International Accounting Standards Board, required for publicly accountable enterprises by the Canadian Accounting Standards Board, as updated and amended from time to time;
"material adverse change" or "material adverse effect" means, in respect of any Party, any change (including a decision to implement a change made by the directors or senior management of SDR or Silver Hammer), effect, event, occurrence or change in a state of facts that is, or would reasonably be expected to be, material and adverse to the business, operations, financial condition, results, assets, properties, rights, liabilities or prospects of such corporation, but excluding any change, effect, event, occurrence or change in a state of facts relating or attributable to: (a) general economic conditions in Canada, the global economy, or securities markets in general; (b) the mining industry in general and not specifically relating to Silver Hammer or SDR; (c) gold prices in general; (d) changes or proposed changes in IFRS as issued by the International Accounting Standards Board applicable to Silver Hammer or SDR or the enforcement or interpretation thereof; (e) the announcement or pendency of this Agreement or the Transaction, or otherwise contemplated by or resulting from the terms of this Agreement; or (f) a change in the market trading price of publicly traded securities of that Party, either related to this Agreement and the Transaction or the announcement thereof;
"Material Contract" in respect of a Party means: (a) any contract involving aggregate payments to or by such Party or any of such Party's subsidiaries in excess of $150,000; (b) any contract with annual payments to or by such Party or any of such Party's subsidiaries in excess of $150,000, with a term or commitment that may reasonably extend beyond one year and which cannot be terminated without penalty on less than 30 days notice or which is outside the ordinary course of business; and any other contract which is material to such Party, excluding contracts entered into for the purposes of the Transaction contemplated herein;
"material fact" has the meaning given thereto in the Securities Acts;
"MI 61-101" means Multilateral Instrument 61-101 Protection of Minority Security Holders in Special Transactions;
"NI 45-106" means National Instrument 45-106 Prospectus Exemptions;
"NI 51-102" means National Instrument 51-102 Continuous Disclosure Obligations;
"OBCA" means the Business Corporations Act (Ontario), together with the regulations thereunder, as the same may be amended from time to time;
"person" means any individual, body corporate, partnership, firm, joint venture, syndicate, trust, association, any other form of entity or organization and any Governmental Entity or other agency;
"Recommendation Change" has the meaning ascribed thereto in Section 4.2;
"Release" means any material release, spill, leak, emission, discharge, leach, dumping, migration, pumping, pouring, emitting, emptying, injecting, spraying, burying, abandoning, incinerating, seeping, escape, disposal or similar or analogous act as defined in any Environmental Laws;
"SDR Board" means the board of directors of SDR;
"SDR Disclosure Documents" means, collectively, all of the documentation which has been filed by or on behalf of SDR since January 1, 2025 with the relevant securities regulatory authorities pursuant to the requirements of applicable Canadian securities laws and which is publicly available for review on SEDAR+, including all press releases and financial statements filed on SEDAR+;
"SDR Information Circular" means the information circular to be prepared in connection with the solicitation of proxies by the management of SDR for the SDR Meeting and includes any and all documents specifically incorporated by reference therein;
"SDR Material Contracts" means the Material Contracts entered into by SDR;
"SDR Meeting" means the special meeting of the shareholders of SDR to be held to consider, and, if deemed advisable, approve the Amalgamation;
"SDR Options" means the options to purchase SDR Shares which remain unexercised and unexpired as disclosed in Schedule "B" hereto;
"SDR Shareholders" means holders of SDR Shares;
"SDR Shares" means common shares in the capital of SDR;
"Securities Acts" means all Canadian securities legislation applicable to the Companies together with all regulations, instruments, companion policies, blanket orders and policy statements adopted in connection therewith;
"SEDAR+" means the System for Electronic Document Analysis and Retrieval accessible on www.sedarplus.ca;
"Silver Hammer Board" means the board of directors of Silver Hammer;
"Silver Hammer Disclosure Documents" means, collectively, all of the documentation which has been filed by or on behalf of Silver Hammer since October 1, 2024 with the relevant securities regulatory authorities pursuant to the requirements of applicable Canadian securities laws and which is publicly available for review on SEDAR+, including all press releases and financial statements filed on SEDAR+;
"Silver Hammer Information Circular" means the information circular to be prepared in connection with the solicitation of proxies by the management of Silver Hammer for the Silver Hammer Meeting and includes any and all documents specifically incorporated by reference therein;
"Silver Hammer Material Contracts" means the Material Contracts entered into by Silver Hammer;
"Silver Hammer Meeting" means the annual general and special meeting of the shareholders of Silver Hammer to be held to consider, and, if deemed advisable, approve the Transaction;
"Silver Hammer Options" means the options to purchase Silver Hammer Shares; "Silver Hammer Shares" means the common shares in the capital of Silver Hammer;
"Silver Hammer Subsidiaries" means Silverstrand Exploration Corp., 1304562 B.C. Ltd., 123456 US Inc., Subco and 18076421 Canada Inc.;
"SilverMark" means SilverMark Resources Inc., a company existing under the laws of Canada;
"SilverMark Acquisition" means the acquisition of all of the outstanding shares of SilverMark by Silver Hammer to be completed pursuant to the terms of a Business Combination Agreement dated July 17, 2026 among Silver Hammer, SilverMark and 18076421 Canada Inc.;
"Stroud Subsidiaries" means Compañia Minera San Diego y La Espanola S.A. de C.V. and Grande Pleiad Oil Ltd;
"Superior Proposal" has the meaning ascribed thereto in Section 4.2;
"Tax Returns" means any return, declaration, report, claim for refund, election, or information return or statement relating to Taxes, including any schedule or attachment thereto and any amendment thereof;
"Taxation Authority" means the Canada Revenue Agency, the Ontario Ministry of Finance and any other national, federal, state, provincial, regional, territorial, municipal or local governmental authority in Canada or in any other jurisdiction which has authority to collect Tax from SDR or Silver Hammer, as applicable, or impose obligations upon SDR or Silver Hammer, as applicable, with respect to Taxes;
"Taxes" means any Canadian, multinational, foreign, federal, state, provincial, regional, territorial, municipal and local capital, capital stock, disability, customs duties, employment, environmental, estimated, excise, franchise, capital gains, employer health, income, license, alternative or add-on minimum, occupation, payroll, premium, profits, windfall profits, personal property, real property, gross receipts, registration, gross revenue, sales, goods and services, severance, social security (or similar), stamp, transfer, turnover, unemployment, use, value added, withholding, net worth, or other tax of any kind whatsoever, including employment insurance and Canada/Quebec Pension Plan premiums, as well as any interest or penalty in respect thereof and any addition thereto, whether disputed or not;
"Termination Date" has the meaning ascribed thereto in Section 4.4;
"Transaction" has the meaning ascribed thereto in the preamble to this Agreement;
"Triggering Event" has the meaning ascribed thereto in Section 4.3;
"TSXV" means the TSX Venture Exchange;
"U.S. Securities Laws" means the "blue sky" or securities law of any state or territory of the United States or the District of Columbia, together with the United States Securities Exchange Act of 1934, as amended and the United States Securities Act of 1933, as amended, and the rules and regulations of the United States Securities and Exchange Commission thereunder; and
"Voting Support Agreements" means, collectively: (A) the voting support agreements entered into between Silver Hammer and: (i) each member of the SDR Board; (ii) each officer of SDR; (iii) each SDR shareholder (other than Silver Hammer) holding directly or indirectly more than 10% of the SDR Shares; and (B) the voting support agreements entered into between SDR and: (iv) each member of the Silver Hammer Board; (v) each officer of Silver Hammer; (vi) each Silver Hammer shareholder holding directly or indirectly more than 10% of the Silver Hammer Shares; and (vii) such other parties as may be agreed upon by SDR and Silver Hammer acting reasonably, in each case in the form as set forth in Schedule "C" hereto.
Words and phrases used herein that are defined in the OBCA shall have the same meaning herein as in the OBCA unless the context otherwise requires.
1.2 Interpretation not affected by Headings, etc.
The division of this Agreement into articles and sections and the insertion of headings are for convenience of reference only and shall not affect the construction or interpretation of this Agreement.
1.3 Number, Etc.
Unless the context requires the contrary, words importing the singular only shall include the plural and vice versa; words importing the use of any gender shall include all genders.
1.4 Date for any Action
In the event that any date on which any action is required to be taken hereunder by any of the Companies is not a business day in the place where the action is required to be taken, such action shall be required to be taken on the next succeeding day which is a business day in such place.
1.5 Entire Agreement
This Agreement, together with the agreements and documents herein and therein referred to, constitute the entire agreement among the Companies pertaining to the subject matter hereof and supersedes all prior agreements, understandings, negotiations and discussions, whether oral or written, among the Companies with respect to the subject matter hereof.
1.6 Transaction
The Companies agree to effect the Transaction by effecting the Amalgamation subject to the terms and conditions of this Agreement and the Amalgamation Agreement. The SDR Shares (other than SDR Shares held by Silver Hammer and SDR Shareholders who exercise Dissent Rights) will be exchanged for Silver Hammer Shares based on the Exchange Ratio and SDR will amalgamate with Subco to form the Amalgamated Corporation, which will become a wholly-owned subsidiary of Silver Hammer. No fractional Silver Hammer Shares will be issued in connection with the Amalgamation and, where the aggregate number of Silver Hammer Shares otherwise issuable to a holder of SDR Shares would result in a fraction of a Silver Hammer Share, the number of Silver Hammer Shares issued to such holder will be rounded down to the nearest whole number. In addition, the SDR Options will be amended prior to the Effective Date such that, effective as of the Effective Date, the obligation to issue SDR Shares on exercise will be replaced with an obligation to issue Silver Hammer Shares, and the number of Silver Hammer Shares issued and the exercise price therefor will be adjusted in accordance with the Exchange Ratio. All other terms of such SDR Options shall remain the same.
ARTICLE 2
REPRESENTATIONS AND WARRANTIES
2.1 Representations and Warranties of SDR
SDR represents and warrants to and in favour of Silver Hammer and Subco as follows and acknowledges that Silver Hammer and Subco are relying upon such representations and warranties in connection with the transactions contemplated herein:
(a) SDR and each of the SDR Subsidiaries is a company duly organized, validly existing and in good standing with respect to all filings required under applicable laws and has the corporate power to own or lease its property and assets and to carry on its business as now conducted by it, is duly licensed or qualified as an extra-provincial or foreign corporation in each jurisdiction in which the character of the property and assets now owned by it or the nature of its business as now conducted by it requires it to be so licensed or qualified (save where failure to have such licence or qualification is not in the aggregate material) and each of SDR and the SDR Subsidiaries has the corporate power to enter into, execute and deliver this Agreement and perform its obligations hereunder;
(b) the authorized capital of SDR consists of an unlimited number of SDR Shares of which 63,623,199 SDR Shares are, as at the date hereof, validly issued and outstanding as fully paid and non-assessable. No Stroud Subsidiary has any shares or other equity securities issued and outstanding other than those held, directly or indirectly, by SDR, except that Compañia Minera San Diego y La Espanola S.A. de C.V. (the "Mexican Subsidiary") has a nominal number of shares outstanding that are not held by SDR, as more particularly described in Section 2.1(d);
(c) SDR has no subsidiaries other than the Stroud Subsidiaries. SDR holds, directly or indirectly, 99.999985% of the issued and outstanding equity securities of the Mexican Subsidiary. The remaining 0.000015% of the equity securities of the Mexican Subsidiary is held by a nominee solely to satisfy the minimum shareholder requirements under applicable Mexican corporate law. Such nominee holds such equity securities for the benefit of, or at the direction of, SDR, has no independent economic or voting interest in the Mexican Subsidiary other than as required by applicable Mexican law, and has no rights, entitlements or claims in respect of the Mexican Subsidiary or its assets, properties or business other than as may be required to comply with such minimum shareholder requirements. SDR has the exclusive right to direct the affairs and operations of the Mexican Subsidiary and exercises effective control over the Mexican Subsidiary. The interest held by such nominee does not constitute a material third-party interest in the Mexican Subsidiary and does not adversely affect SDR's ability to control, manage or dispose of the assets of the Mexican Subsidiary;
(d) the SDR Shares are not subject to any cease trade order issued by any securities regulatory authority;
(e) no filing or registration with, or authorization, notification, consent or approval of, any person is required in connection with the entering into of this Agreement by SDR and the consummation of the transactions contemplated under this Agreement by SDR except for the: (i) approval of the holders of SDR Shares; (ii) approval of the TSXV; and (iii) filing of the Articles of Amalgamation;
(f) except as disclosed in Schedule "B" hereto, no person has any agreement, option, understanding or commitment (including convertible securities, warrants or convertible obligations of any nature), for the purchase or issue of or conversion into any of the unissued SDR Shares or any unissued securities of SDR or any of the Stroud Subsidiaries;
(g) the financial statements of SDR contained in or comprising the SDR Disclosure Documents present fairly the financial position of SDR at the relevant dates and the results of its operations and the changes in its financial position for the periods indicated in the said statements and have been prepared in accordance with IFRS applied on a consistent basis;
(h) except as disclosed in the SDR Disclosure Documents, there has been no material adverse change in the business or condition, financial or otherwise of SDR or any of the Stroud Subsidiaries since December 31, 2025;
(i) SDR and each of the Stroud Subsidiaries is the beneficial owner of the properties and assets described as being owned by it in the SDR Disclosure Documents with good and marketable title thereto free and clear of material liens, charges, encumbrances or adverse interests, and no person has any agreement, option, understanding or commitment for the purchase of any of the properties or assets of SDR or any of the Stroud Subsidiaries, except as disclosed in the SDR Disclosure Documents;
(j) the execution and delivery of this Agreement and the consummation of the Amalgamation do not and will not:
(i) result in the breach of or violate any term or provision of the constating documents or by-laws of SDR;
(ii) conflict with, result in a breach of, constitute a default under, or accelerate or permit the acceleration of the performance required by, any agreement, instrument, licence, permit or authority to which SDR or any of the Stroud Subsidiaries is a party or by which any of them is bound or to which any property of SDR or any of the Stroud Subsidiaries is subject or result in the creation of any lien, charge or encumbrance upon any of the assets of SDR or any of the Stroud Subsidiaries under any such agreement or instrument, or give to others any material interest or rights, including rights of purchase, termination, cancellation or acceleration, under any such agreement, instrument, licence, permit or authority; or
(iii) violate any provision of law or administrative regulation or any judicial or administrative order, award, judgment or decree applicable to SDR or any of the Stroud Subsidiaries;
(k) the execution and delivery of this Agreement has been duly approved by the members of the SDR Board entitled to vote thereon and this Agreement constitutes a legal, valid and binding obligation, enforceable against SDR in accordance with its terms, except as may be limited by bankruptcy, reorganization, insolvency or similar laws of general application relating to the enforcement of creditor's rights or the relief of debtors or by equitable relief including the remedies of specific performance and injunctive relief, being available only in the discretion of the applicable court;
(l) neither SDR nor any of the Stroud Subsidiaries is a party to any oral or written management contract or contract for the employment of any officer except as disclosed in the SDR Disclosure Documents;
(m) there are no agreements, covenants, undertakings or other commitments of SDR, any of the Stroud Subsidiaries or any partnership or joint venture in which any of them is a partner or participant or any instruments binding on any of them or any of their respective properties:
(i) under which the consummation of the Amalgamation would have the effect of imposing restrictions or obligations on SDR or any of the Stroud Subsidiaries materially greater than those imposed upon SDR, any of the Stroud Subsidiaries or any such partnership or joint venture at the date hereof;
(ii) which would give a third party, as a result of the consummation of the Amalgamation, a right to terminate any material agreement to which SDR, any of the Stroud Subsidiaries or any such partnership or joint venture is a party or to purchase any of their respective assets;
(iii) under which the consummation of the Amalgamation would impose material restrictions on the ability of SDR or any of the Stroud Subsidiaries to carry on any business which it might choose to carry on within any geographical area, to acquire property or dispose of its property and assets in their entirety or to change its corporate status, other than area of mutual interest clauses and similar clauses in existing agreements; or
(iv) under which the consummation of the Amalgamation would impose material restrictions on the ability of SDR or any of the Stroud Subsidiaries to pay any dividends or make other distributions to its shareholders or to borrow money and to mortgage and pledge its property as security therefor;
(n) SDR is a reporting issuer not in default under the Securities Act (Ontario) and has similar status and is not in default under the Securities Acts of British Columbia and Alberta and is not a reporting issuer (or the equivalent) under any other Securities Act;
(o) SDR has filed all required reports, statements, forms and other documents required to be filed by it in accordance with the Securities Acts and, as of their respective dates, the documents and materials comprising the SDR Disclosure Documents (including all exhibits and schedules thereto and documents incorporated by reference therein) did not contain any misrepresentation, and complied in all material respects with the Securities Acts. SDR has not filed any confidential material change or other similar report or document with any Governmental Entity which at the date hereof remains confidential;
(p) the SDR Shares are listed or posted for trading on the TSXV;
(q) neither SDR nor any of the Stroud Subsidiaries has incurred any liability for brokerage fees, finder's fees, agent's commissions or other similar forms of compensation in connection with this Agreement or the Amalgamation;
(r) there are no actions, suits, proceedings or investigations commenced, or to the knowledge of SDR contemplated or threatened, against or affecting SDR or any of the Stroud Subsidiaries or before or by any person or before any arbitrator of any kind which would prevent or hinder the consummation of the Amalgamation or which involve the possibility of any judgment or liability which can reasonably be expected to have a material adverse effect on the business operations, properties, assets or condition, financial or otherwise, of SDR or any of the Stroud Subsidiaries;
(s) there are no known or anticipated material liabilities of SDR or any of the Stroud Subsidiaries of any kind whatsoever (including absolute, accrued or contingent liabilities) nor any commitments whether or not determined or determinable, in respect of which SDR or any of the Stroud Subsidiaries is or may become liable other than the liabilities disclosed on, reflected in or provided for in the financial statements contained in or comprising the SDR Disclosure Documents or incurred in the ordinary course of business, which may have a material adverse effect on SDR or any of the Stroud Subsidiaries;
(t) each of SDR and the Stroud Subsidiaries has duly and on a timely basis filed all Tax Returns, elections and designations required to be filed by it with any Taxation Authority, or if not filed on a timely basis, all fees, penalties, interest and other amounts payable as a result thereof have been paid. No such returns, elections or designations contain any material misstatement or omit any material statements that should have been included and each return, election and designation, including accompanying schedules and statements is true, correct and complete in all material respects. Each of SDR and the Stroud Subsidiaries has paid in full all amounts owing to each Taxation Authority due and payable by it and has withheld and remitted all amounts required by law to be withheld by it by any federal, provincial or municipal Taxation Authority. There are no proposed reassessments, audits, actions, suits, proceedings, investigations or claims which have arisen or are pending or threatened against SDR or any of the Stroud Subsidiaries in respect of Taxes, nor matters under discussion with any Taxation Authority with respect to Taxes;
(u) all insurance policies maintained by SDR and the Stroud Subsidiaries are in full force and effect, all premiums due and payable thereon have been paid, and each of SDR and the Stroud Subsidiaries is in compliance with the material terms and conditions of such policies. Neither SDR nor any of the Stroud Subsidiaries has received any notice of cancellation, termination or nonrenewal of any such policy or arrangement or any notice of material adjustment in the amount of the premiums payable with respect to any such policy, and there is no material claim pending under any of such policies or arrangements as to which coverage has been questioned, denied or disputed by the underwriters of such policies or arrangements;
(v) with respect to environmental matters:
(i) each of SDR and the Stroud Subsidiaries, the operation of their respective businesses and the assets owned or used by any of them have been and are in compliance in all material respects with all Environmental Laws, including all Environmental Consents;
(ii) neither SDR nor any of the Stroud Subsidiaries has been charged with or convicted of any offence for noncompliance with Environmental Laws in any material respect, or been fined or otherwise sentenced or settled any prosecution short of conviction in any material respect and there are no notices of judgment or commencement of proceedings of any material nature and neither SDR nor any of the Stroud Subsidiaries has ever been investigated relating to any breach or alleged breach of Environmental Laws in any material respect;
(iii) each of SDR and the Stroud Subsidiaries has obtained all Environmental Consents necessary to conduct its business and to own, use and operate its properties and assets;
(iv) there are no Hazardous Substances that could, individually or in the aggregate, have a material adverse effect on SDR or any of the Stroud Subsidiaries, located on or in or under the surface of any real properties, and no Release of any Hazardous Substances has occurred on, in or from any real properties or has resulted from the operation of the business of SDR or any of the Stroud Subsidiaries and the conduct of activities thereon;
(v) neither SDR nor any of the Stroud Subsidiaries has used its properties to produce, generate, manufacture, treat, store, handle, transport or dispose of any Hazardous Substances except in material compliance with Environmental Laws;
(vi) there are no underground or aboveground storage tanks or associated piping or appurtenances (active or abandoned), or urea formaldehyde foam insulation, asbestos, polychlorinated biphenyls or radioactive substances located on or in or under the surface of any of the real properties of SDR or any of the Stroud Subsidiaries or other assets used thereon that could, individually or in the aggregate, have a material adverse effect on SDR or any of the Stroud Subsidiaries; and
(vii) neither SDR nor any of the Stroud Subsidiaries is, nor is there any basis upon which SDR or any of the Stroud Subsidiaries could become, responsible for any clean-up or corrective action under any Environmental Laws in any material respect. There are no material environmental audits, site assessments or studies (or drafts thereof) concerning any of the real properties, or that are in any way related to the business of SDR or any of the Stroud Subsidiaries, that any of them has ever conducted or that are in its possession or control;
(w) each of SDR and the Stroud Subsidiaries has complied with and is in compliance with all laws applicable to the operation of its business, except where such non-compliance would not, considered individually or in the aggregate, have a material adverse effect on SDR or any of the Stroud Subsidiaries or on the ability of SDR to consummate the Transaction, and each of SDR and the Stroud Subsidiaries holds all material certificates, authorities, permits or licences issued by the appropriate Governmental Entity necessary to carry on the business currently carried on by it;
(x) each of SDR and the Stroud Subsidiaries has performed in all material respects all respective obligations required to be performed by it to date under the SDR Material Contracts. Neither SDR nor any of the Stroud Subsidiaries is in material breach or default under any SDR Material Contract and none of them is aware of any condition that with the passage of time or the giving of notice or both would result in such a breach or default. SDR does not know of, nor has it received written notice of, any material breach or default under (nor, to the knowledge of SDR, does there exist any condition which with the passage of time or the giving of notice or both would result in such a breach or default under) any SDR Material Contract by any other party thereto. No change of control provisions exist under any SDR Material Contracts. All SDR Material Contracts are legal, valid, binding and, to the knowledge of SDR, in full force and effect and are enforceable against SDR or the applicable Stroud Subsidiary in accordance with their respective terms (subject to bankruptcy, insolvency and other applicable laws affecting creditors' rights generally, and to general principles of equity) and are the product of arms' length negotiations between the parties thereto;
(y) the books and records of each of SDR and the Stroud Subsidiaries have been maintained in accordance with all applicable laws in all material respects, and the minute books of each of SDR and the Stroud Subsidiaries are complete and accurate in all material respects and have been maintained in accordance with the requirements of applicable law. The financial books and records and accounts of each of SDR and the Stroud Subsidiaries in all material respects: (i) have been maintained in accordance with IFRS and requirements of applicable laws on a basis consistent with prior years; (ii) are stated in reasonable detail and fairly reflect the transactions and dispositions of assets of SDR and the Stroud Subsidiaries; and (iii) fairly reflect the basis for SDR's financial statements;
(z) to the knowledge of SDR, no "related party" of SDR (as such term is defined in MI 61-101), together with its "associated entities" (as such term is defined in MI 61-101), beneficially owns or exercises control or direction over 1% or more of the outstanding Silver Hammer Shares, except for related parties who will not receive a "collateral benefit" (as such term is defined in MI 61-101) as a consequence of the Transaction;
(aa) none of the representations, warranties or statements of fact made in this Section contain any untrue statement of a material fact or omit to state any material fact necessary to make any such warranty or representation not misleading;
(bb) there are reasonable grounds for believing that, with such belief in respect of matters relating to Subco being in reliance on the representation and warranty of Silver Hammer in Section 2.2(aa):
(i) each Amalgamating Corporation is, and the Amalgamated Corporation will be able to pay its liabilities as they become due;
(ii) the realizable value of the Amalgamated Corporation's assets will not be less than the aggregate of its liabilities and stated capital of all classes; and
(iii) no creditor will be prejudiced by the Amalgamation; and
(cc) each holder of SDR Options has provided its written consent to the amendment of the SDR Options as contemplated in Section 1.6 of this Agreement, pursuant to which, effective as of the Effective Date, the obligation to issue SDR Shares on exercise will be replaced with an obligation to issue Silver Hammer Shares, and the number of Silver Hammer Shares issued and the exercise price therefor will be adjusted in accordance with the Exchange Ratio, and such consents have been delivered to Silver Hammer prior to the date of execution of this Agreement, in form and substance satisfactory to Silver Hammer, acting reasonably, and remain in full force and effect as of the date hereof.
2.2 Representations and Warranties of Silver Hammer
Silver Hammer represents and warrants to and in favour of SDR as follows with respect to Silver Hammer and each of the Silver Hammer Subsidiaries and acknowledges that SDR is relying upon such representations and warranties in connection with the transactions contemplated herein:
(a) Silver Hammer and each of the Silver Hammer Subsidiaries is a company duly organized, validly existing and in good standing with respect to all filings required under applicable laws and has the corporate power to own or lease its property and assets and to carry on its business as now conducted by it, is duly licensed or qualified as an extra-provincial or foreign corporation in each jurisdiction in which the character of the property and assets now owned by it or the nature of its business as now conducted by it requires it to be so licensed or qualified (save where failure to have such licence or qualification is not in the aggregate material) and each of Silver Hammer and the Silver Hammer Subsidiaries has the corporate power to enter into, execute and deliver this Agreement and perform its obligations hereunder;
(b) the authorized capital of Silver Hammer consists of an unlimited number of Silver Hammer Shares, and 139,922,966 Silver Hammer Shares are, as at the date hereof, validly issued and outstanding as fully paid and non-assessable. No Silver Hammer Subsidiary has any shares or other equity securities issued and outstanding other than those held, directly or indirectly, by Silver Hammer;
(c) Silver Hammer has no subsidiaries other than the Silver Hammer Subsidiaries;
(d) the Silver Hammer Shares are not subject to any cease trade order issued by any securities regulatory authority;
(e) no filing or registration with, or authorization, notification, consent or approval of, any person is required in connection with the entering into of this Agreement by Silver Hammer and the consummation of the transactions contemplated under this Agreement by Silver Hammer except for the: (i) approval of the CSE; (ii) approval of the holders of Silver Hammer Shares; and (iii) filing of the Articles of Amalgamation;
(f) except as disclosed in the Silver Hammer Disclosure Documents and pursuant to this Agreement, no person has any agreement, option, understanding or commitment (including convertible securities, warrants or convertible obligations of any nature), for the purchase or issue of or conversion into any of the unissued Silver Hammer Shares or any unissued securities of Silver Hammer or any of the Silver Hammer Subsidiaries;
(g) the financial statements of Silver Hammer contained in or comprising the Silver Hammer Disclosure Documents present fairly the financial position of Silver Hammer at the relevant dates and the results of its operations and the changes in its financial position for the periods indicated in the said statements and have been prepared in accordance with IFRS applied on a consistent basis;
(h) except as disclosed in the Silver Hammer Disclosure Documents, there has been no material adverse change in the business or condition, financial or otherwise of Silver Hammer or any of the Silver Hammer Subsidiaries since September 30, 2025;
(i) Silver Hammer and each of the Silver Hammer Subsidiaries is the beneficial owner of the properties and assets described as being owned by it in the Silver Hammer Disclosure Documents with good and marketable title thereto free and clear of material liens, charges, encumbrances or adverse interests, and no person has any agreement, option, understanding or commitment for the purchase of any of the properties or assets of Silver Hammer or any of the Silver Hammer Subsidiaries, except as disclosed in the Silver Hammer Disclosure Documents;
(j) the execution and delivery of this Agreement and the consummation of the Amalgamation do not and will not:
(i) result in the breach of or violate any term or provision of the constating documents or by-laws of Silver Hammer or any of the Silver Hammer Subsidiaries;
(ii) conflict with, result in a breach of, constitute a default under, or accelerate or permit the acceleration of the performance required by, any agreement, instrument, licence, permit or authority to which Silver Hammer or any of the Silver Hammer Subsidiaries is a party or by which any of them is bound or to which any property of Silver Hammer or any of the Silver Hammer Subsidiaries is subject or result in the creation of any lien, charge or encumbrance upon any of the assets of Silver Hammer or any of the Silver Hammer Subsidiaries under any such agreement or instrument, or give to others any material interest or rights, including rights of purchase, termination, cancellation or acceleration, under any such agreement, instrument, licence, permit or authority; or
(iii) violate any provision of law or administrative regulation or any judicial or administrative order, award, judgment or decree applicable to Silver Hammer or any of the Silver Hammer Subsidiaries;
(k) the execution and delivery of this Agreement has been duly approved by the members of the Silver Hammer Board entitled to vote thereon and this Agreement constitutes a legal, valid and binding obligation, enforceable against Silver Hammer in accordance with its terms, except as may be limited by bankruptcy, reorganization, insolvency or similar laws of general application relating to the enforcement of creditor's rights or the relief of debtors or by equitable relief including the remedies of specific performance and injunctive relief, being available only in the discretion of the applicable court;
(l) neither Silver Hammer nor any of the Silver Hammer Subsidiaries is a party to any management contract or any oral or written contract for the employment of any officer except as disclosed in the Silver Hammer Disclosure Documents;
(m) there are no agreements, covenants, undertakings or other commitments of Silver Hammer, any of the Silver Hammer Subsidiaries or any partnership or joint venture in which any of them is a partner or participant or any instruments binding on any of them or any of their respective properties:
(i) under which the consummation of the Amalgamation would have the effect of imposing restrictions or obligations on Silver Hammer or any of the Silver Hammer Subsidiaries materially greater than those imposed upon Silver Hammer, any of the Silver Hammer Subsidiaries or any such partnership or joint venture at the date hereof;
(ii) which would give a third party, as a result of the Amalgamation, a right to terminate any material agreement to which Silver Hammer, any of the Silver Hammer Subsidiaries or any such partnership or joint venture is a party or to purchase any of their respective assets;
(iii) under which the consummation of the Amalgamation would impose material restrictions on the ability of Silver Hammer or any of the Silver Hammer Subsidiaries to carry on any business which it might choose to carry on within any geographical area, to acquire property or dispose of its property and assets in their entirety or to change its corporate status, other than area of mutual interest clauses and similar clauses in existing agreements; or
(iv) under which the consummation of the Amalgamation would impose material restrictions on the ability of Silver Hammer or any of the Silver Hammer Subsidiaries to pay any dividends or make other distributions to its shareholders or to borrow money and to mortgage and pledge its property as security therefor;
(n) Silver Hammer is a reporting issuer not in default under the Securities Act (Ontario) and has similar status and is not in default under the Securities Acts of British Columbia and Alberta, and is not a reporting issuer (or the equivalent) under any other Securities Act;
(o) Silver Hammer has filed all required reports, statements, forms and other documents required to be filed by it in accordance with the Securities Acts and, as of their respective dates, the documents and materials comprising the Silver Hammer Disclosure Documents (including all exhibits and schedules thereto and documents incorporated by reference therein) did not contain any misrepresentation, and complied in all material respects with the Securities Acts. Silver Hammer has not filed any confidential material change or other similar report or document with any Governmental Entity which at the date hereof remains confidential;
(p) the Silver Hammer Shares are listed and posted for trading on the CSE;
(q) neither Silver Hammer nor any of the Silver Hammer Subsidiaries has incurred any liability for brokerage fees, finder's fees, agent's commissions or other similar forms of compensation in connection with this Agreement or the Amalgamation;
(r) there are no actions, suits, proceedings or investigations commenced, or to the knowledge of Silver Hammer contemplated or threatened, against or affecting Silver Hammer or any of the Silver Hammer Subsidiaries or before or by any person or before any arbitrator of any kind which would prevent or hinder the Amalgamation or which involve the possibility of any judgment or liability which can reasonably be expected to have a material adverse effect on the business operations, properties, assets or condition, financial or otherwise, of Silver Hammer or any of the Silver Hammer Subsidiaries;
(s) there are no known or anticipated material liabilities of Silver Hammer or any of the Silver Hammer Subsidiaries of any kind whatsoever (including absolute, accrued or contingent liabilities) nor any commitments whether or not determined or determinable, in respect of which Silver Hammer or any of the Silver Hammer Subsidiaries is or may become liable other than the liabilities disclosed on, reflected in or provided for in the financial statements contained in or comprising the Silver Hammer Disclosure Documents or incurred in the ordinary course of business, which may have a material adverse effect on Silver Hammer or any of the Silver Hammer Subsidiaries;
(t) each of Silver Hammer and the Silver Hammer Subsidiaries has duly and on a timely basis filed all Tax Returns, elections and designations required to be filed by it with any Taxation Authority, or if not filed on a timely basis, all fees, penalties, interest and other amounts payable as a result thereof have been paid. No such returns, elections or designations contain any material misstatement or omit any material statements that should have been included and each return, election and designation, including accompanying schedules and statements is true, correct and complete in all material respects. Each of Silver Hammer and the Silver Hammer Subsidiaries has paid in full all amounts owing to each Taxation Authority due and payable by it and has withheld and remitted all amounts required by law to be withheld by it by any federal, provincial or municipal Taxation Authority. There are no proposed reassessments, audits, actions, suits, proceedings, investigations or claims which have arisen or are pending or threatened against Silver Hammer or any of the Silver Hammer Subsidiaries in respect of Taxes, nor matters under discussion with any Taxation Authority with respect to Taxes;
(u) all insurance policies maintained by Silver Hammer and the Silver Hammer Subsidiaries are in full force and effect, all premiums due and payable thereon have been paid, and each of Silver Hammer and the Silver Hammer Subsidiaries is in compliance with the material terms and conditions of such policies. Neither Silver Hammer nor any of the Silver Hammer Subsidiaries has received any notice of cancellation, termination or nonrenewal of any such policy or arrangement or any notice of material adjustment in the amount of the premiums payable with respect to any such policy, and there is no material claim pending under any of such policies or arrangements as to which coverage has been questioned, denied or disputed by the underwriters of such policies or arrangements;
(v) with respect to environmental matters:
(i) each of Silver Hammer and the Silver Hammer Subsidiaries, the operation of their respective businesses and the assets owned or used by any of them have been and are in compliance in all material respects with all Environmental Laws, including all Environmental Consents;
(ii) neither Silver Hammer nor any of the Silver Hammer Subsidiaries has been charged with or convicted of any offence for noncompliance with Environmental Laws in any material respect, or been fined or otherwise sentenced or settled any prosecution short of conviction in any material respect and there are no notices of judgment or commencement of proceedings of any material nature and neither Silver Hammer nor any of the Silver Hammer Subsidiaries has ever been investigated relating to any breach or alleged breach of Environmental Laws in any material respect;
(iii) each of Silver Hammer and the Silver Hammer Subsidiaries has obtained all Environmental Consents necessary to conduct its business and to own, use and operate its properties and assets;
(iv) there are no Hazardous Substances that could, individually or in the aggregate, have a material adverse effect on Silver Hammer or any of the Silver Hammer Subsidiaries, located on or in or under the surface of any real properties, and no Release of any Hazardous Substances has occurred on, in or from any real properties or has resulted from the operation of the business of Silver Hammer or any of the Silver Hammer Subsidiaries and the conduct of activities thereon;
(v) neither Silver Hammer nor any of the Silver Hammer Subsidiaries has used its properties to produce, generate, manufacture, treat, store, handle, transport or dispose of any Hazardous Substances except in material compliance with Environmental Laws;
(vi) there are no underground or aboveground storage tanks or associated piping or appurtenances (active or abandoned), or urea formaldehyde foam insulation, asbestos, polychlorinated biphenyls or radioactive substances located on or in or under the surface of any of the real properties of Silver Hammer or any of the Silver Hammer Subsidiaries or other assets used thereon that could, individually or in the aggregate, have a material adverse effect on Silver Hammer or any of the Silver Hammer Subsidiaries; and
(vii) neither Silver Hammer nor any of the Silver Hammer Subsidiaries is, nor is there any basis upon which Silver Hammer or any of the Silver Hammer Subsidiaries could become, responsible for any clean-up or corrective action under any Environmental Laws in any material respect. There are no material environmental audits, site assessments or studies (or drafts thereof) concerning any of the real properties, or that are in any way related to the business of Silver Hammer or any of the Silver Hammer Subsidiaries, that any of them has ever conducted or that are in its possession or control;
(w) each of Silver Hammer and the Silver Hammer Subsidiaries has complied with and is in compliance with all laws applicable to the operation of its business, except where such non-compliance would not, considered individually or in the aggregate, have a material adverse effect on Silver Hammer or any of the Silver Hammer Subsidiaries or on the ability of Silver Hammer to consummate the Transaction, and each of Silver Hammer and the Silver Hammer Subsidiaries holds all material certificates, authorities, permits or licences issued by the appropriate Governmental Entity necessary to carry on the business currently carried on by it;
(x) each of Silver Hammer and the Silver Hammer Subsidiaries has performed in all material respects all respective obligations required to be performed by it to date under the Silver Hammer Material Contracts. Neither Silver Hammer nor any of the Silver Hammer Subsidiaries is in material breach or default under any Silver Hammer Material Contract and none of them is aware of any condition that with the passage of time or the giving of notice or both would result in such a breach or default. Silver Hammer does not know of, nor has it received written notice of, any material breach default under (nor, to the knowledge of Silver Hammer, does there exist any condition which with the passage of time or the giving of notice or both would result in such a breach or default under) any Silver Hammer Material Contract by any other party thereto. All Silver Hammer Material Contracts are legal, valid, binding and, to the knowledge of Silver Hammer, in full force and effect and are enforceable against Silver Hammer or the applicable Silver Hammer Subsidiary in accordance with their respective terms (subject to bankruptcy, insolvency and other applicable laws affecting creditors' rights generally, and to general principles of equity) and are the product of arms' length negotiations between the parties thereto;
(y) the books and records of each of Silver Hammer and the Silver Hammer Subsidiaries have been maintained in accordance with all applicable laws in all material respects, and the minute books of each of Silver Hammer and the Silver Hammer Subsidiaries are complete and accurate in all material respects and have been maintained in accordance with the requirements of applicable law. The financial books and records and accounts of each of Silver Hammer and the Silver Hammer Subsidiaries in all material respects: (i) have been maintained in accordance with IFRS and requirements of applicable laws on a basis consistent with prior years; (ii) are stated in reasonable detail and fairly reflect the transactions and dispositions of assets of Silver Hammer and the Silver Hammer Subsidiaries; and (iii) fairly reflect the basis for Silver Hammer's financial statements;
(z) none of the representations, warranties or statements of fact made in this Section contain any untrue statement of a material fact or omit to state any material fact necessary to make any such warranty or representation not misleading;
(aa) there are reasonable grounds for believing that, with such belief in respect of matters relating to SDR being in reliance on the representation and warranty of SDR in Section 2.1(bb):
(i) each Amalgamating Corporation is, and the Amalgamated Corporation will be able to pay its liabilities as they become due;
(ii) the realizable value of the Amalgamated Corporation's assets will not be less than the aggregate of its liabilities and stated capital of all classes; and
(iii) no creditor will be prejudiced by the Amalgamation;
(bb) Silver Hammer is the registered and beneficial owner of one common share of Subco, representing all of the issued and outstanding common shares of Subco; and
(cc) Subco is a company duly organized, validly existing and in good standing with respect to all filings required under applicable laws, has one common share outstanding, a paid-up capital of $1.00 and no liabilities.
ARTICLE 3
COVENANTS
3.1 Covenants of SDR
SDR covenants and agrees with Silver Hammer and Subco that it will, and will cause the Stroud Subsidiaries, until the earlier of the termination of this Agreement and the day following the Effective Date (unless otherwise consented to by Silver Hammer in writing) to:
(a) convene and hold the SDR Meeting for the purpose of considering the Amalgamation as soon as reasonably practicable and in any event no later than September 30, 2026 or such later date as may be mutually agreed upon. In connection with the SDR Meeting, as promptly as reasonably practicable, SDR shall cooperate with Silver Hammer to prepare the SDR Information Circular in form and substance satisfactory to both parties, acting reasonably, together with any other documents required by applicable law, in connection with the consideration of the Amalgamation by the shareholders of SDR. The SDR Information Circular will contain, among other things, the unanimous recommendation of the SDR Board that the shareholders of SDR vote in favour of the Amalgamation on the basis that the SDR Board has unanimously determined the Amalgamation to be in the best interests of SDR and the consideration to be paid to shareholders of SDR to be fair to the shareholders of SDR;
(b) take all reasonable actions necessary to give effect to the transactions contemplated by this Agreement, including, without limitation, soliciting proxies to be voted at the SDR Meeting in favour of the Amalgamation, and using its best efforts to obtain such approvals of the holders of SDR Shares as may be required by the OBCA and all applicable regulatory authorities, and all necessary assignments, regulatory approvals, waivers, amendments or terminations to any instruments and take all such similar or other actions or proceedings as may be necessary or advisable with a view to consummating the Transaction, including the joint filing with Subco of the Articles of Amalgamation under the OBCA in connection with the Amalgamation;
(c) not declare or pay any dividends or make any distribution of its properties or assets to its shareholders or to others or retire or redeem any of its outstanding shares or other of its securities;
(d) except pursuant to currently existing obligations, not issue, or enter into any agreement or agreements to issue, or grant options, warrants or rights to purchase, any shares of its capital stock or other of its securities;
(e) not merge or consolidate with, or sell or transfer all or any part of its assets to, any other person or perform any act or enter into any transaction or negotiation which might interfere or be inconsistent with the consummation of the Amalgamation or which would render materially inaccurate any of the representations and warranties set forth in Section 2.1 hereof (as if such representations and warranties were made at a time subsequent to such act or transaction and all references to the date of this Agreement were deemed to be as at such later date);
(f) not make any loans, advances or other payments, other than (i) ordinary course compensation; (ii) routine advances to employees of SDR for expenses incurred in the ordinary course of business; and (iii) other loans, advances or payments made on commercially reasonable terms; provided that the aggregate amount of all loans, advances and other payments under clauses (i), (ii) and (iii) shall not exceed
$200,000 in the aggregate, or as otherwise agreed to by Silver Hammer in advance in writing;
(g) not amend SDR's articles or by-laws (or equivalent thereof) in any manner which may adversely affect the success of the Transaction, except as required to give effect to the matters contemplated herein;
(h) subject to the provisions hereof, cooperate fully with Silver Hammer and to use all reasonable commercial efforts to assist Silver Hammer in its efforts to complete the Transaction;
(i) use its commercially reasonable efforts to obtain all necessary assignments, regulatory approvals (including, without limitation, the approval of the TSXV), waivers, amendments or terminations to any instruments and take such other measures as may be appropriate to fulfill its obligations thereunder and to consummate the Amalgamation;
(j) except as permitted or contemplated herein, not to enter into any transaction or Material Contract not in the ordinary course of business and not to engage in any business enterprise or activity different from that carried on as of the date hereof, unless prior written approval of Silver Hammer is obtained;
(k) furnish to Silver Hammer and Subco such information, in addition to the information contained in this Agreement, relating to the financial condition, business, properties and affairs of SDR as may reasonably be requested by Silver Hammer or Subco, which information shall be true and complete in all material respects and shall not contain an untrue statement of any material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements therein, in the light of the circumstances in which they are made, not misleading;
(l) ensure that the information and financial statements, if any, related to SDR to be contained in the SDR Information Circular and the Silver Hammer Information Circular and any related documentation to be distributed in connection with the solicitation of proxies by the management of SDR for the SDR Meeting or Silver Hammer for the Silver Hammer Meeting comply as to form and substance with the requirements of the OBCA and the Securities Acts and such information and data contained therein shall be true, correct and complete in all material respects and shall not contain any untrue statement of any material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements therein not misleading in light of the circumstances in which they are made;
(m) promptly notify Silver Hammer in the event that it becomes aware of any material breach or threatened material breach of a Voting Support Agreement by a counterparty thereto and shall, if requested by Silver Hammer, use commercially reasonable efforts to enforce the provisions of such Voting Support Agreement, including by seeking injunctions to prevent any such breaches and to enforce specifically the terms and provisions thereof; and
(n) use its commercially reasonable efforts to cause each of the conditions precedent set forth in Sections 3.3 and 3.5 hereof to be complied with on or before the Effective Date.
3.2 Covenants of Silver Hammer
Silver Hammer covenants and agrees with SDR that it will, and will cause the Silver Hammer Subsidiaries, until the earlier of the termination of this Agreement and the day following the Effective Date (unless otherwise consented to by SDR in writing) to:
(a) convene and hold the Silver Hammer Meeting for the purpose of considering the Transaction as soon as reasonably practicable and in any event no later than September 30, 2026 or such later date as may be mutually agreed upon. In connection with the Silver Hammer Meeting, as promptly as reasonably practicable, Silver Hammer shall cooperate with SDR to prepare the Silver Hammer Information Circular in form and substance satisfactory to both parties, acting reasonably, together with any other documents required by applicable law, in connection with the consideration of the Transaction by the shareholders of Silver Hammer. The Silver Hammer Information Circular will contain, among other things, the unanimous recommendation of the Silver Hammer Board that the shareholders of Silver Hammer vote in favour of the Transaction on the basis that the Silver Hammer Board has unanimously determined the Transaction to be in the best interests of Silver Hammer and the consideration to be paid to shareholders of Silver Hammer to be fair to the shareholders of Silver Hammer. The Silver Hammer Information Circular will also specify that the Silver Hammer Board will be comprised of six (6) members, three (3) of whom shall be nominees of SDR, initially being Dr. Scott Jobin-Bevans, Jeff Kennedy and Conor O'Brien, or such other nominee(s) as the Parties may mutually agree;
(b) take all reasonable actions necessary to give effect to the transactions contemplated by this Agreement, including, without limitation, soliciting proxies to be voted at the Silver Hammer Meeting in favour of the Transaction, and using its best efforts to obtain such approvals of the holders of Silver Hammer Shares as may be required by the BCBCA and the CSE and all applicable regulatory authorities, and all necessary assignments, regulatory approvals, waivers, amendments or terminations to any instruments and take all such similar or other actions or proceedings as may be necessary or advisable with a view to consummating the Transaction, including the joint filing by Subco with SDR of the Articles of Amalgamation under the OBCA in connection with the Amalgamation;
(c) not declare or pay any dividends or make any distribution of its properties or assets to its shareholders or to others or retire or redeem any of its outstanding shares or others of its securities;
(d) not merge or consolidate with, or sell or transfer all or any part of its assets to, any other person or perform any act or enter into any transaction or negotiation which might interfere or be inconsistent with the consummation of the Amalgamation or which would render materially inaccurate any of the representations and warranties set forth in Section 2.2 hereof (as if such representations and warranties were made at a time subsequent to such act or transaction and all references to the date of this Agreement were deemed to be as at such later date);
(e) not amend Silver Hammer's articles or by-laws (or equivalent thereof) in any manner which may adversely affect the success of the Transaction, except as required to give effect to the matters contemplated herein;
(f) subject to the provisions hereof, cooperate fully with SDR and to use all reasonable commercial efforts to assist SDR in its efforts to complete the Transaction;
(g) use its commercially reasonable efforts to obtain all necessary regulatory approvals (including, without limitation, the approval of the CSE) and take such other measures as may be appropriate to fulfill its obligations thereunder and to consummate the Amalgamation;
(h) furnish to SDR such information, in addition to the information contained in this Agreement, relating to the financial condition, business, properties and affairs of Silver Hammer and Subco as may reasonably be requested by SDR which information shall be true and complete in all material respects and shall not contain an untrue statement of any material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements therein, in the light of the circumstances in which they are made, not misleading;
(i) promptly notify SDR in the event that it becomes aware of any material breach or threatened material breach of a Voting Support Agreement by a counterparty thereto and shall, if requested by SDR, acting reasonably, use commercially reasonable efforts to enforce the provisions of such Voting Support Agreements, including by seeking injunctions to prevent any such breaches and to enforce specifically the terms and provisions thereof;
(j) ensure that the information and financial statements related to Silver Hammer and Subco to be contained in the SDR Information Circular and the Silver Hammer Information Circular and any related documentation to be distributed in connection with the solicitation of proxies by the management of SDR for the SDR Meeting or Silver Hammer for the Silver Hammer Meeting shall comply as to form and substance with the requirements of the BCBCA and the Securities Acts and such information and data contained therein shall be true, correct and complete in all material respects and shall not contain any untrue statement of any material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements therein not misleading in light of the circumstances in which they are made; and
(k) use its commercially reasonable efforts to cause each of the conditions precedent set forth in Sections 3.3 and 3.4 hereof to be complied with on or before the Effective Date.
3.3 Mutual Conditions
The respective obligations of each of the Companies to consummate the Amalgamation shall be subject to fulfillment, on or before the Effective Date, of the following conditions:
(a) the Amalgamation shall have been approved at the SDR Meeting in accordance with the provisions and requirements of the OBCA, the TSXV and all applicable laws;
(b) the Transaction shall have been approved at the Silver Hammer Meeting in accordance with the provisions and requirements of the BCBCA, the CSE and all applicable laws;
(c) the Transaction shall have received all requisite approvals under applicable laws, rules, regulations and policies, including the rules and/or policies of the TSXV or the CSE, as applicable, and all other governmental and regulatory orders and decrees;
(d) Silver Hammer shall have completed the Consolidation;
(e) all conditions precedent to the SilverMark Acquisition shall have been satisfied or waived to the satisfaction of each of Silver Hammer and SDR, other than the completion of the Amalgamation;
(f) SilverMark shall have completed the Concurrent Financing for minimum gross proceeds of $7,000,000 and all of the conditions to the release of the gross proceeds from escrow shall have been satisfied;
(g) there shall not be in force any order or decree restraining or enjoining the consummation of the Amalgamation; and
(h) receipt of all necessary approvals required in respect of the listing and posting for trading on the CSE of the Silver Hammer Shares to be issued pursuant to the Amalgamation;
(i) the distribution of the Silver Hammer Shares pursuant to the Amalgamation shall be exempt from, or otherwise not subject to, prospectus requirements of the Securities Acts; and
(j) the distribution of the Silver Hammer Shares in the United States in exchange for the SDR Shares pursuant to the Amalgamation shall be exempt from registration requirements under U.S. Securities Laws.
3.4 Conditions to Obligations of SDR
The obligation of SDR to consummate the Amalgamation is subject to the satisfaction, on or before the Effective Date, of the following conditions, any of which may be waived by SDR without prejudice to its right to rely on any other or others of them:
(a) each of the acts and undertakings of Silver Hammer and Subco to be performed on or before the Effective Date pursuant to the terms of this Agreement shall have been duly performed by it;
(b) Silver Hammer and Subco shall have furnished SDR with a legal opinion, dated the day of the Effective Date, satisfactory in form and substance in all material respects to SDR, to the effect that:
(i) Silver Hammer and Subco are each validly existing under their jurisdiction of incorporation and each has the corporate power to own or lease its property and assets and to carry on its business as now conducted by it;
(ii) each of Silver Hammer and Subco have taken all necessary corporate action to authorize the execution and delivery of this Agreement and the consummation of the Amalgamation;
(iii) the Silver Hammer Shares issuable in connection with the Transaction have been duly authorized and validly allotted for issuance by Silver Hammer and such shares, when issued, will be outstanding as fully paid and non-assessable shares;
(iv) each of this Agreement and the Amalgamation Agreement has been duly executed by Silver Hammer and Subco and is a legal, valid and binding obligation of Silver Hammer and Subco, as applicable, enforceable against each company in accordance with its terms;
(v) the execution, delivery and performance by each of Silver Hammer and Subco of its obligations under this Agreement and the Amalgamation Agreement do not and will not conflict with or result in the breach of any provisions of the constating documents of either Silver Hammer and Subco; and
(vi) the issuance of the Silver Hammer Shares in connection with the Transaction are exempt from the "prospectus requirement" (as such term is defined in National Instrument 14-101 Definitions) of applicable Canadian securities laws under Section 2.11 of NI 45-106 and will generally not be subject to any resale restrictions under applicable Canadian securities laws;
(c) Subco shall have furnished SDR with an executed copy of the Amalgamation Agreement;
(d) Silver Hammer shall have complied with its covenants contained in Article 3 hereof and, except as affected by the transactions contemplated by this Agreement or referred to or contemplated in the SDR Information Circular and/or the Silver Hammer Information Circular, the representations and warranties of Silver Hammer contained in Section 2.2 shall be true in all material respects as of the Effective Date with the same effect as though made at and as of such time and SDR shall have received a certificate of a senior officer of Silver Hammer to that effect, dated as of the Effective Date;
(e) receipt of all required third party and regulatory approvals by Silver Hammer required to complete the Transaction, including, without limitation, the approval of the CSE;
(f) the Silver Hammer Shares that are issued as consideration for the SDR Shares pursuant to the Amalgamation shall be issued as fully paid and non-assessable common shares in the capital of Silver Hammer, free and clear of any and all encumbrances, liens, charges and demands of whatsoever nature;
(g) no material adverse change shall have occurred in the business, results of operations, assets, liabilities, financial condition or affairs of Silver Hammer, financial or otherwise, between the date hereof and the Effective Date, except for a decrease in Silver Hammer's working capital position reasonably necessary to facilitate the Transaction and to meet its customary obligations as a publicly traded company;
(h) there being no legal proceeding or regulatory actions or proceedings against Silver Hammer, on a consolidated basis, at the Effective Date, other than any legal proceeding or regulatory action disclosed in writing between the Parties prior to the date hereof, which may, if determined against the interest of Silver Hammer, have a material adverse effect on Silver Hammer or its business, assets or financial condition;
(i) there being no prohibition at law against the completion of the Transaction; and
(j) there being no inquiry or investigation (whether formal or informal) in relation to Silver Hammer or its directors or officers, commenced or threatened by any Governmental Entity or official of the CSE or any securities regulatory body having jurisdiction such that the outcome of such inquiry or investigation could have a material adverse effect on Silver Hammer or its business, assets or financial condition.
3.5 Conditions to Obligations of Silver Hammer
The obligation of Silver Hammer to consummate, and to cause Subco to consummate, the Amalgamation is subject to the satisfaction, on or before the Effective Date, of the following conditions, any of which may be waived by Silver Hammer without prejudice to its right to rely on any other or others of them:
(a) each of the acts and undertakings of SDR to be performed on or before the Effective Date pursuant to the terms of this Agreement shall have been duly performed by it;
(b) SDR shall have furnished Silver Hammer with a legal opinion dated the day of the Effective Date, satisfactory in form and substance in all material respects to Silver Hammer, to the effect that:
(i) SDR is validly existing under the laws of its jurisdiction of incorporation and has the corporate power to own or lease its property and assets and to carry on its business as now conducted by it;
(ii) SDR has taken all necessary corporate action to authorize the execution and delivery of this Agreement and the consummation of the Amalgamation;
(iii) each of this Agreement and the Amalgamation Agreement has been duly executed by SDR and is a legal, valid and binding obligation of SDR, enforceable against SDR in accordance with its terms; and
(iv) the execution, delivery and performance by SDR of its obligations under this Agreement and the Amalgamation Agreement do not and will not conflict with or result in the breach of any provisions of the constating documents of SDR;
(c) SDR shall have furnished Silver Hammer and Subco with an executed copy of the Amalgamation Agreement;
(d) SDR shall have complied with its covenants contained in Article 3 hereof and, except as affected by the transactions contemplated by this Agreement or referred to or contemplated in the SDR Information Circular and/or the Silver Hammer Information Circular, the representations and warranties of SDR contained in Section 2.1 shall be true in all material respects as of the Effective Date with the same effect as though made at and as of such time and Silver Hammer shall have received a certificate of a senior officer of SDR to that effect, dated as of the Effective Date;
(e) Silver Hammer shall have received on the date of this Agreement executed copies of the Voting Support Agreements between it and each: (i) member of the SDR Board; (ii) officer of SDR; and (iii) each SDR shareholder (other than Silver Hammer) holding directly or indirectly more than 10% of the SDR Shares;
(f) receipt of all required third party and regulatory approvals by SDR, including, without limitation, the approval of the TSXV and the approval of SDR's shareholders for the Amalgamation and any related matters;
(g) the aggregate number of SDR Shares held, directly or indirectly, by those holders of such shares who have validly exercised Dissent Rights and not withdrawn such exercise in connection with the Transaction (or instituted proceedings to exercise Dissent Rights) shall not exceed 5% of the aggregate number of SDR Shares issued and outstanding immediately prior to the Effective Date;
(h) no material adverse change shall have occurred in the business, results of operations, assets, liabilities, financial condition or affairs of SDR, financial or otherwise, between the date hereof and the Effective Date, except for a decrease in SDR's working capital position reasonably necessary to facilitate the Transaction and to meet its customary obligations as a publicly traded company;
(i) there being no legal proceeding or regulatory actions or proceedings against SDR, on a consolidated basis, at the Effective Date, other than any legal proceeding or regulatory action disclosed in writing between the Parties prior to the date hereof, which may, if determined against the interest of SDR, have a material adverse effect on SDR or its business, assets or financial condition;
(j) there being no prohibition at law against the completion of the Transaction;
(k) there being no inquiry or investigation (whether formal or informal) in relation to SDR or its directors or officers commenced or threatened by any Governmental Entity or regulatory body having jurisdiction such that the outcome of such inquiry or investigation could have a material adverse effect on SDR or its business, assets or financial condition;
(l) SDR shall not have any indebtedness, liabilities or obligations of any nature, except for: (i) liabilities and obligations that are specifically disclosed in SDR's most recent financial statements as filed on SEDAR+; or (ii) liabilities and obligations in the ordinary course of business that are consistent with past practice; and
(m) receipt by Silver Hammer of the written mutual release and resignation from all positions with SDR from each member of the SDR Board and such officers of SDR as Silver Hammer may request.
(n) Silver Hammer shall have received, on or prior to the date hereof, duly executed written consents from each holder of SDR Options consenting to the amendment of the SDR Options as contemplated in Section 1.6 of this Agreement, in form and substance satisfactory to Silver Hammer, acting reasonably, and such consents shall remain in full force and effect as of the Effective Date.
3.6 Insurance
Provided that those directors and officers of SDR asked to resign by Silver Hammer have executed a mutual release with Silver Hammer and SDR, in form and substance satisfactory to Silver Hammer, acting reasonably, Silver Hammer covenants and agrees that all rights to indemnification or exculpation in favour of current and former directors or officers of SDR, as provided in the articles and by-laws thereof, or in any agreement to be entered into on or prior to the Effective Date, and any directors' and officers' insurance now existing in favour of the directors and officers of SDR, shall survive the completion of the Transaction and shall continue in full force and effect for a period of not less than six (6) years from the Effective Date. Further, Silver Hammer acknowledges that, on or prior to the Effective Date, SDR may enter into standard indemnification agreements with its current directors and officers, which indemnification agreements shall be satisfactory to SDR and Silver Hammer, acting reasonably.
3.7 Alternative Transaction
The Parties agree to cooperate in good faith with each other and to take all reasonable steps and actions to assist all Parties to complete the Transaction as promptly as practicable. In addition, in the event that a Party concludes that it is necessary or desirable to: (i) proceed with another form of transaction (such as a plan of arrangement); or (ii) change the order of steps in the Transaction for tax or other valid business reasons, in each case whereby a Party or either of their affiliates would effectively acquire all of the securities of such Party within the same time periods and on economic terms (including, without limitation, tax treatment) having consequences to the shareholders of one of the Parties hereto which are equivalent to or better than those contemplated by this Agreement (an "Alternative Transaction"), such Party agrees to support the completion of such Alternative Transaction in the same manner as the Transaction and shall otherwise fulfill its covenants contained in this Agreement in respect of such Alternative Transaction.
3.8 Satisfaction of Conditions
The conditions set out in this Article 3 shall be conclusively deemed to have been satisfied, waived or released on the filing of the Articles of Amalgamation under the OBCA.
ARTICLE 4
NO SOLICITATION
4.1 No Solicitation
During the period commencing on the date hereof and continuing until the first to occur of: (i) the Effective Date; and (ii) the Termination Date, each of SDR and Silver Hammer agrees that it will not, directly or indirectly, and will not authorize or permit any of its directors, officers, employees, representatives, agents or advisors (collectively, "Representatives") to, directly or indirectly, (a) solicit, initiate, encourage, engage in or respond to (other than to decline) any inquiries or proposals regarding any merger, amalgamation, share exchange, business combination, take-over bid, sale or other disposition of its assets, any recapitalization, reorganization, liquidation, material sale or issue of treasury securities or rights or interests therein or thereto or rights or options to acquire any material number of treasury securities or any type of similar transaction which would or could, in any case, constitute a de facto change of control (each an "Acquisition Proposal"), other than the Amalgamation; (b) encourage or participate in any discussions or negotiations regarding any Acquisition Proposal; (c) agree to, approve or recommend an Acquisition Proposal; (d) withdraw, modify or qualify, or propose publicly to withdraw, modify or qualify, in any manner adverse to Silver Hammer or SDR, as applicable, the approval or recommendation of the SDR Board or Silver Hammer Board, as applicable, with respect to the Amalgamation; or (e) enter into any agreement related to an Acquisition Proposal provided, however, that subject as hereinafter provided, nothing shall prevent SDR or Silver Hammer, as applicable, from furnishing non-public information to, or entering into a confidentiality agreement and/or discussions and/or negotiations with, any person in response to a bona fide unsolicited Acquisition Proposal that is submitted by such person in writing after the date hereof which is not withdrawn if: (i) the independent members of the SDR Board or Silver Hammer Board, as applicable, unanimously conclude in good faith, after consultation with legal counsel and financial advisors, that such action is required in order for the directors to comply with their fiduciary obligations under applicable law; (ii) prior to furnishing such non-public information to, entering into a confidentiality agreement with, or entering into discussions with, such person, SDR or Silver Hammer gives the other Party written notice of its intention to furnish non-public information to, enter into a confidentiality agreement with, or enter into discussions with, such person not less than five (5) business days prior to entering into such confidentiality agreement or furnishing such information; (iii) any confidentiality agreement entered into with such person shall contain terms that are no less restrictive than those contained in any confidentiality agreement between SDR and Silver Hammer and shall not contain any provision that would restrict SDR or Silver Hammer from complying with its obligations under this Agreement, including its obligations to provide information to Silver Hammer or SDR hereunder; and (iv) SDR or Silver Hammer shall promptly (and in any event within twenty-four (24) hours) provide to Silver Hammer or SDR, as applicable, copies of all non-public information furnished to such person that was not previously provided to Silver Hammer or SDR. SDR or Silver Hammer, as applicable, shall immediately after the execution hereof terminate all existing discussions or negotiations with any person (other than those ongoing between them) with respect to any potential Acquisition Proposal and shall immediately request the return or destruction of all confidential information previously provided to any such person. Concurrent with the execution hereof each of SDR and Silver Hammer shall advise the other Party of any current Acquisition Proposal and such Party shall promptly (and in any event within twenty-four (24) hours) notify the other Party of any future Acquisition Proposal which any of its directors, senior officers, Representatives or agents is or becomes aware of, any amendment to any of the foregoing or any request for non-public information relating to SDR or Silver Hammer, as applicable. Such notice shall include a description of the material terms and conditions of any such proposal and the identity of the person making such proposal, inquiry, request or contact.
As used in this Agreement, "de facto change of control" means, with respect to a Party, the purchase or sale of 20% or more of the assets of the Party or any purchase or sale of, or tender or exchange offer for, voting securities of the Party that, if consummated, would result in any person (or the shareholders of such person), other than Silver Hammer or SDR, as applicable, beneficially owning securities representing 20% or more of the total voting power of Silver Hammer or SDR, as applicable.
4.2 Superior Proposals
Silver Hammer or SDR, as applicable, or its directors may, in respect of any Acquisition Proposal received by them prior to the approval by such Party's shareholders of the Amalgamation, change their recommendation to the shareholders regarding the approval of the Amalgamation (a "Recommendation Change") if prior to the Recommendation Change: (i) they have determined that such Acquisition Proposal constitutes a Superior Proposal and advised the other Party of that fact and their intention to make a Recommendation Change; (ii) Silver Hammer or SDR, as applicable, has been provided with a copy of the document containing such Superior Proposal (with such deletions as are necessary to protect any confidential portions of such document, provided that material terms and conditions of, and the identity of the person making, such Superior Proposal may not be deleted); and (iii) five (5) business days have elapsed from the later of the date on which Silver Hammer or SDR, as applicable, received the material required to be provided to it pursuant to (i) and (ii). SDR and Silver Hammer agree that if the other Party so elects, during the five (5) business day period referred to in (iii), they and their financial and legal advisors shall negotiate in good faith to make such adjustments to the terms and conditions of this Agreement as would enable Silver Hammer or SDR, as applicable, to not make its Recommendation Change, while allowing their respective boards of directors to comply with their fiduciary duties under applicable law. If Silver Hammer or SDR, as applicable, proposes any adjustments to the terms and conditions of this Agreement during such period, the SDR Board or Silver Hammer Board, as applicable, shall review such proposal in good faith in consultation with its legal counsel and financial advisors and shall not make a Recommendation Change unless the SDR Board or Silver Hammer Board, as applicable, has unanimously determined in good faith, after such consultation, that the Acquisition Proposal continues to constitute a Superior Proposal when assessed against the terms and conditions of this Agreement as proposed to be amended by Silver Hammer or SDR, as applicable. During such five (5) business day period, Silver Hammer or SDR, as applicable, shall not enter into any agreement in respect of the Superior Proposal with the party making the Superior Proposal; provided, however, that Silver Hammer or SDR, as applicable, may, during that time, enter into or continue discussions with such party, but such discussions shall in no way affect the rights of the other Party under this Agreement to require that Silver Hammer or SDR, as applicable, hold the SDR Meeting or Silver Hammer Meeting and, if the Silver Hammer or SDR, as applicable, shareholders approve the Amalgamation and the other conditions for such Party's benefit are satisfied or waived, proceed to complete the Amalgamation. For greater certainty, in the event that any Acquisition Proposal that has been determined to constitute a Superior Proposal is modified or amended in any respect, such modified or amended Acquisition Proposal shall constitute a new Acquisition Proposal for the purposes of this Section 4.2 and Silver Hammer or SDR, as applicable, shall be required to again comply with the requirements of this Section 4.2 with respect to such new Acquisition Proposal, including providing a new five (5) business day matching period to Silver Hammer or SDR, as applicable.
The SDR Board or Silver Hammer Board may communicate to their shareholders a Recommendation Change in such manner as it may elect, including the issuance of a press release and such other communication it determines necessary. The first public announcement or other communication to the shareholders of the Recommendation Change is referred to as the "Change Date".
At any time following the Change Date, Silver Hammer or SDR, as applicable, may elect, by notice in writing to the other Party, to terminate this Agreement pursuant to Section 4.4 hereof, and upon such Party so doing, that party will be obliged to make payment of the Compensation Fee contemplated by, and in accordance with, Section 4.3 hereof; alternatively, notwithstanding any Recommendation Change, Silver Hammer or SDR, as applicable, may require the other Party to hold their shareholders meeting, and if the affected Party takes no action, it shall be deemed to have not terminated this Agreement and Silver Hammer or SDR, as applicable, will proceed to hold the SDR Meeting or the Silver Hammer Meeting.
As used in this Agreement, "Superior Proposal" means a bona fide unsolicited written Acquisition Proposal received after the date hereof that: (A) is made for all of the outstanding SDR Shares or Silver Hammer Shares, as applicable or all of the assets of SDR or Silver Hammer, as applicable; (B) is not conditional on obtaining financing or on the completion of any due diligence by the person making such Acquisition Proposal; (C) is reasonably capable of being completed in accordance with its terms, having regard to all legal, financial, regulatory and other aspects of such Acquisition Proposal and the person making such Acquisition Proposal; and (D) in respect of which the independent directors of SDR or Silver Hammer, as applicable, have unanimously determined in good faith, after consultation with, and receiving advice (which may include a written opinion) from, as appropriate, their financial, legal and other advisors that such Acquisition Proposal would, if consummated in accordance with its terms, result in a transaction which is more favourable from a financial point of view to the holders of SDR Shares or Silver Hammer Shares, as applicable, than the Transaction (taking into consideration any adjustment to the terms and conditions of the Transaction proposed by a Party pursuant to this Section 4.2).
4.3 Compensation Fee
If:
(a) following a Recommendation Change to shareholders by SDR or Silver Hammer in accordance with Section 4.2 hereof, the SDR or Silver Hammer shareholders do not approve the Amalgamation at the SDR Meeting or Silver Hammer Meeting; or
(b) (i) following the date of this Agreement, either of Silver Hammer or SDR receives a written Acquisition Proposal that has been publicly announced or otherwise disclosed to the public which is determined to be a Superior Proposal; (ii) such Party's shareholders do not approve the Amalgamation at the SDR Meeting or Silver Hammer Meeting, as applicable; and (iii) within twelve (12) months following the date of such meeting, Silver Hammer or SDR, as applicable, accepts, approves or recommends, or enters into an agreement (whichever occurs first) with respect to any merger, amalgamation, share exchange, business combination, take-over bid, sale or other disposition of its assets, any recapitalization, reorganization, liquidation, material sale or issue of treasury securities or rights or interests therein or thereto or rights or options to acquire any material number of treasury securities or any type of similar transaction which would or could, in any case, constitute a de facto change of control, whether or not such transaction is the Acquisition Proposal received following the date of this Agreement,
(any such event being a "Triggering Event"), then the Party accepting the Superior Proposal shall pay the other Party an amount in cash equal to $500,000 (the "Compensation Fee"). Such payment will be made in immediately available funds to an account designated by the Party receiving the Compensation Fee. Such payment shall be made, in the circumstances set forth in Section 4.3(a) or 4.3(b) hereof, within three (3) business days of the termination of this Agreement by Silver Hammer or the vote by the shareholders at the SDR Meeting or Silver Hammer Meeting, and, in the circumstances set forth above, at the time that is the first to occur of such Acquisition Proposal being accepted, approved or recommended or an agreement with respect to such Acquisition Proposal being executed. The obligation to make any payment required by this paragraph shall survive any termination of this Agreement.
SDR and Silver Hammer hereby each acknowledge that the payment amount set out in this subparagraph is a payment of liquidated damages which is a pre estimate of the damages which a Party will suffer or incur as a result of the event giving rise to such damages and the resultant non completion of the Amalgamation and is not a penalty. The Party accepting the Superior Proposal hereby irrevocably waives any right it may have to raise as a defence that any such liquidated damages are excessive or punitive. Upon receipt of payment of such Compensation Fee, the receiving Party shall have no further claim against the other Party in respect of the failure to complete the Amalgamation, provided that nothing herein shall preclude a Party from seeking injunctive relief to restrain any breach or threatened breach by the other Party of any of its obligations hereunder or otherwise to obtain specific performance without the necessity of posting bond or security in connection herewith. In addition, neither party is precluded from seeking damages in respect of any breach of this Agreement by the other party which breach occurred prior to the termination hereof.
4.4 Termination
This Agreement may be terminated by:
(a) the mutual consent of the Companies;
(b) Silver Hammer or SDR in the circumstances permitted by Section 4.2 hereof;
(c) Silver Hammer or SDR (as used in this subparagraph, the "first party"), if the other party provides notice of its inability to comply with any of the covenants, conditions or agreements to be complied with or satisfied by it hereunder and provides to the first party such details and supporting materials relating to such inability as the first party shall reasonably request in order to assess the impact thereof;
(d) Silver Hammer, if SDR shall have breached any representation, warranty, covenant or agreement contained in this Agreement in any material respect and such breach shall not have been cured within ten (10) business days following receipt by SDR of written notice of such breach from Silver Hammer, or such breach is incapable of being cured;
(e) SDR, if Silver Hammer shall have breached any representation, warranty, covenant or agreement contained in this Agreement in any material respect and such breach shall not have been cured within ten (10) business days following receipt by Silver Hammer of written notice of such breach from SDR, or such breach is incapable of being cured;
(f) Silver Hammer, in the event that the Transaction has not been completed by November 30, 2026, as a result of the failure of one or more of the conditions in a party's favour to be satisfied (or waived by that party) provided that Silver Hammer shall not be entitled to terminate this Agreement pursuant to this Section 4.4(f) if Silver Hammer is then in material breach of any of its representations, warranties, covenants or agreements contained in this Agreement;
(g) SDR, in the event that the Transaction has not been completed by November 30, 2026, as a result of the failure of one or more of the conditions in a party's favour to be satisfied (or waived by that party), provided that SDR shall not be entitled to terminate this Agreement pursuant to this Section 4.4(g) if SDR is then in material breach of any of its representations, warranties, covenants or agreements contained in this Agreement;
(h) Silver Hammer, if a material adverse effect on SDR or any event, occurrence, circumstance or development that could reasonably be expected to constitute a material adverse effect on SDR has occurred; or
(i) SDR, if a material adverse effect on Silver Hammer or any event, occurrence, circumstance or development that could reasonably be expected to constitute a material adverse effect on Silver Hammer has occurred.
The date upon which this agreement is terminated pursuant to this Section 4.4 is referred to herein as the "Termination Date". Termination of this Agreement shall not relieve either party of the obligations it may then have pursuant to Section 4.3 and Sections 6.2 and 6.4 hereof.
ARTICLE 5
AMENDMENT
5.1 Amendment
This Agreement may, at any time and from time to time before or after the holding of the SDR Meeting, be amended by written agreement of the Companies without further notice to or authorization on the part of the holders of SDR Shares (provided that such amendment does not materially adversely change the consideration to be received by the holders of SDR Shares) without the prior approval of such holders in the same manner as required for the Amalgamation and any such amendment may, without limitation:
(a) change the time for performance of any of the obligations or acts of the Companies;
(b) waive any inaccuracies in, or modify, any representation contained herein or in any document delivered pursuant hereto;
(c) cure any ambiguity in or correct or supplement any provision hereof;
(d) to the extent permitted by law and the applicable regulatory authorities, waive compliance with or modify any of the covenants herein contained and waive or modify performance of any of the obligations of the Companies; and/or
(e) amend this Agreement in accordance with or to comply with the directions or requirements of any regulatory authority.
ARTICLE 6
GENERAL
6.1 Binding Effect
This Agreement shall be binding upon and enure to the benefit of the Companies and their respective successors and permitted assigns.
6.2 Expenses
Whether or not the Transaction becomes effective and, except as hereinafter provided, each of SDR and Silver Hammer shall pay its own expenses in connection with the preparation and execution of this Agreement and the transactions contemplated hereby or incidental hereto.
6.3 Assignment
No Company may assign its rights or obligations under this Agreement without the prior written consent of each of the other Companies.
6.4 Announcements
Each of the Companies shall cooperate with the others in releasing information concerning this Agreement and the Transaction and shall furnish to the others drafts of all news releases prior to publication; provided, however, that nothing contained herein shall prevent any Company at any time from furnishing any information to any Governmental Entity or as otherwise required by law.
6.5 Notices
Any notice, consent, waiver, direction or other communication required or permitted to be given under this Agreement by a Company shall be in writing and shall be personally delivered to the addressee or sent by electronic mail to the addressee and: (i) a notice which is personally delivered shall, if delivered on a business day, be deemed to be given and received on that day and, in any other case, be deemed to be given and received on the first business day following the day on which it is delivered; and (ii) a notice which is sent by electronic mail shall be deemed to be given and received on the first business day following the day on which it is confirmed to have been sent.
(a) if to SDR:
Stroud Resources Ltd.
1090 Don Mills Rd., Suite 404, Toronto,
Ontario, M3C 5R6, Canada
Attention: Mirsad Jakubovic
Email: 
with a copy (which shall not itself constitute notice) to:
Corporate Counsel USA PLLC
1110 Brickell Ave, Suite 505, Miami, FL, 33131
Attention: Michael Bluestein
Email: mbluestein@corpcounselusa.com
(b) if to Silver Hammer or Subco:
Silver Hammer Mining Corp.
Suite 300 - 1055 West Hastings Street,
Vancouver, British Columbia, V6E 2E9, Canada
Attention: Peter Ball, Chief Executive Officer
Email: 
with a copy (which shall not itself constitute notice) to:
McMillan LLP
Royal Centre, Suite 1500
1055 West Georgia Street, PO Box 11117
Vancouver, British Columbia
Canada V6E 4N7
Attention: Mark Neighbor
Email: mark.neighbor@mcmillan.ca
6.6 Governing Law
This Agreement shall be governed by and construed in accordance with the laws of the Province of Ontario and the laws of Canada applicable therein.
[REMAINDER OF PAGE INTENTIONALLY LEFT BLANK]
IN WITNESS WHEREOF the Companies have executed this Agreement as of the date first written above.
STROUD RESOURCES LTD.
"Mirsad Jakubovic·
______________________________________________
Name: Mirsad Jakubovic
Title: CEO
SILVER HAMMER MINING CORP.
"Peter A. Ball"
______________________________________________
Name: Peter A. Ball
Title: President & CEO
1001629888 ONTARIO INC.
•peter A. Baff"
______________________________________________
Name: Peter A. Ball
Title:President & CEO
Execution Copy
SCHEDULE "A"
FORM OF AMALGAMATION AGREEMENT
THIS AMALGAMATION AGREEMENT made as of the ____ day of _________________, 2026.
BETWEEN:
SILVER HAMMER MINING CORP., a company existing under the laws of the Province of British Columbia,
(hereinafter referred to as "Silver Hammer")
- and -
STROUD RESOURCES LTD., a company existing under the laws of the Province of Ontario,
(hereinafter referred to as "SDR")
- and -
1001629888 ONTARIO INC., a company existing under the laws of the Province of Ontario,
(hereinafter referred to as "Subco")
WHEREAS Subco is a wholly owned subsidiary of Silver Hammer;
AND WHEREAS SDR and Subco have agreed to amalgamate pursuant to Section 174 of the Act upon the terms and conditions hereinafter described and for such purpose Silver Hammer has agreed to issue Silver Hammer Shares as hereinafter provided;
NOW THEREFORE THIS AGREEMENT WITNESSES that in consideration of the premises and the mutual covenants hereinafter contained, the parties hereto agree as follows:
ARTICLE 1
INTERPRETATION
1.1 Definitions
In this Agreement, unless the context otherwise requires, the following words and phrases shall have the meanings hereinafter set forth:
"Act" means the Business Corporations Act (Ontario), together with the regulations thereunder, as the same may be amended from time to time.
"Agreement", "this Agreement", "hereof", "herein" and "hereunder" and similar expressions refer to this Agreement and not to any particular article, section or other portion hereof and include any agreement or instrument supplementary or ancillary hereto.
"Amalgamated Corporation" means the continuing corporation constituted upon the Amalgamation becoming effective, to be named "Stroud Resources Ltd.".
"Amalgamating Corporations" means SDR and Subco.
"Amalgamation" means the amalgamation of the Amalgamating Corporations under the provisions of the Act as contemplated in this Agreement.
"Articles of Amalgamation" means the Articles of Amalgamation with respect to the Amalgamation.
"Common Shares" means the common shares in the capital of the Amalgamated Corporation.
"Depositary" means Endeavor Trust Company, or any other depositary or trust company, bank or financial institution agreed to in writing between SDR and Silver Hammer for the purpose of, among other things, exchanging certificates representing SDR Shares for Silver Hammer Shares in connection with the Amalgamation.
"Dissent Rights" means the rights of dissent exercisable by SDR shareholders in respect of the Amalgamation pursuant to Section 185 of the Act.
"Dissenting Shareholder" means a registered SDR shareholder who, in connection with the special resolution of the SDR shareholders which approves and adopts this Agreement, has exercised the right to dissent pursuant to Section 185 of the Act in strict compliance with the provisions thereof and thereby becomes entitled to receive, if the Amalgamation is completed, the fair value of his or her SDR Shares as determined by a court.
"Effective Date" means the date shown on the Certificate of Amalgamation endorsed by the Director under the Act giving effect to the Amalgamation.
"Exchange Ratio" means 0.777963 Silver Hammer Shares for each SDR Share, on a post-Consolidation basis of the Silver Hammer Shares.
"SDR Shares" means the common shares in the capital of SDR as constituted on the Effective Date.
"Subco Share" means the common share in the capital of Subco.
"Silver Hammer Shares" means the common shares in the capital of Silver Hammer as constituted on the Effective Date.
"Transmittal Letter" means the letter of transmittal to be sent by SDR to SDR Shareholders for use in connection with the Amalgamation.
1.2 Interpretation Not Affected by Headings, etc.
The division of this Agreement into articles and sections and the insertion of headings are for convenience of reference only and shall not affect the construction or interpretation of this Agreement.
1.3 Number, etc.
Unless the context requires the contrary, words importing the singular only shall include the plural and vice versa and words importing the use of any gender shall include all genders.
1.4 Date for any Action
In the event that any date on which any action is required to be taken hereunder by any of the parties is not a business day in the place where the action is required to be taken, such action shall be required to be taken on the next succeeding day which is a business day in such place.
ARTICLE 2
THE AMALGAMATION
2.1 The Amalgamation
The parties agree to effect the combination of their respective businesses and assets by way of a "three-cornered" amalgamation among Silver Hammer and the Amalgamating Corporations pursuant to which the Amalgamating Corporations will amalgamate and the former holders of SDR Shares, other than Silver Hammer and Dissenting Shareholders, will receive Silver Hammer Shares, on the terms and conditions set out in this Agreement.
2.2 Terms and Effect of Amalgamation
The Amalgamating Corporations hereby agree to amalgamate pursuant to the provisions of Section 174 of the Act and to continue as one corporation on the terms and conditions herein set forth. In this regard, each of Silver Hammer, SDR and Subco shall take all steps as are necessary or desirable for the implementation of the Amalgamation and the filing of the Articles of Amalgamation under the Act. Upon the Articles of Amalgamation becoming effective:
(a) the Amalgamating Corporations shall be amalgamated and shall continue as one corporation under the terms and conditions prescribed in this Agreement;
(b) the Amalgamating Corporations shall cease to exist as entities separate from the Amalgamated Corporation;
(c) the Amalgamated Corporation shall possess all the property, rights, privileges and franchises and will be subject to all liabilities, including civil, criminal and quasi-criminal, and all contracts, disabilities and debts of each of the Amalgamating Corporations;
(d) a conviction against, or a ruling, order or judgment in favour of or against an Amalgamating Corporation may be enforced by or against the Amalgamated Corporation;
(e) the Articles of Amalgamation shall be deemed to be the Articles of Incorporation of the Amalgamated Corporation, and, except for purposes of Subsection 117(1) of the Act, the Certificate of Amalgamation shall be deemed to be the Certificate of Incorporation of the Amalgamated Corporation; and
(f) the Amalgamated Corporation shall be deemed to be the party plaintiff or the party defendant, as the case may be, in any civil action commenced by or against an Amalgamating Corporation before the Amalgamation has become effective.
2.3 Condition for the Benefit of Silver Hammer
The obligations of Silver Hammer to consummate the transactions contemplated hereby, in particular the Amalgamation, are subject to the satisfaction, on or before the Effective Date, of the condition that Dissent Rights shall not have been exercised with respect to more than 5% of the outstanding SDR Shares. The foregoing condition is for the exclusive benefit of Silver Hammer and may be waived by Silver Hammer in its sole discretion. Silver Hammer will not exercise Dissent Rights in respect of any of the SDR Shares held by Silver Hammer.
ARTICLE 3
AMALGAMATED CORPORATION
3.1 Name
The name of the Amalgamated Corporation shall be "Stroud Resources Ltd.", or such other name as Silver Hammer may determine.
3.2 Business of the Amalgamated Corporation
There shall be no restriction or limit on the business which the Amalgamated Corporation is authorized to carry on or the powers it may exercise.
3.3 Registered Office
The registered office of the Amalgamated Corporation shall be located at Suite 4400, 181 Bay St, Toronto ON M5J 2T3.
3.4 Authorized Capital
The authorized capital of the Amalgamated Corporation shall consist of an unlimited number of shares designated as "Common Shares".
3.5 Rights, Privileges, Restrictions and Conditions Attaching to the Common Shares
The rights, privileges, restrictions and conditions attaching to the Common Shares shall be as follows:
(a) Each holder of the Common Shares shall be entitled to receive notice of and to attend all meetings of the shareholders of the Amalgamated Corporation, except meetings at which only holders of other classes or series of shares are entitled to attend, and at all such meetings shall be entitled to one vote in respect of each Common Share held by such holder.
(b) The holders of Common Shares shall be entitled, subject to the rights of holders of shares of any class ranking prior to the Common Shares, to receive dividends if and when declared by the board of directors of the Amalgamated Corporation.
(c) In the event of any liquidation, dissolution or winding-up of the Amalgamated Corporation or other distribution of the assets of the Amalgamated Corporation among its shareholders for the purpose of winding-up its affairs, the holders of Common Shares shall be entitled, subject to the rights of holders of shares of any class ranking prior to the Common Shares, to receive the remaining property or assets of the Amalgamated Corporation.
3.6 Directors
(a) Number of Directors. The number of directors of the Amalgamated Corporation shall, until otherwise changed in accordance with the Act, consist of a minimum of one (1) and a maximum of ten (10) directors. The number of directors shall initially be fixed at [●]. The board of directors of the Amalgamated Corporation shall be empowered to determine, from time to time, by resolution the number of directors within the minimum and maximum provided in the Articles of Amalgamation.
(b) First Directors. The first directors of the Amalgamated Corporation, who shall hold office until the first annual meeting of the shareholders of the Amalgamated Corporation or until his successor is duly elected or appointed, shall be the persons whose names appear below:
| Name | Resident Canadian |
3.7 Officers
The officers of the Amalgamated Corporation shall, until changed by the directors of the Amalgamated Corporation, be as follows:
| Name | Office |
3.8 Articles
The Articles of Amalgamation shall be in the form annexed hereto as Exhibit "A".
3.9 By-laws
The by-laws of the Amalgamated Corporation, to the extent not inconsistent with this Agreement, shall be the by-laws of Subco, until repealed, amended or altered, and a copy of such by-laws may be examined at the registered office of the Amalgamated Corporation and Subco located at Suite 4400, 181 Bay St, Toronto ON M5J 2T3.
3.10 Auditors
The auditors of the Amalgamated Corporation, until the first annual meeting of shareholders, shall be [●], unless they resign or are removed in accordance with the Act.
3.11 Financial Year-End
The financial year-end of the Amalgamated Corporation shall be [●], until changed by the directors of the Amalgamated Corporation.
3.12 Stated Capital
The stated capital of the Common Shares shall be equal to the aggregate stated capital of each of SDR and Subco immediately prior to the Effective Date.
ARTICLE 4
ISSUANCE OF SILVER HAMMER SHARES AND COMMON SHARES UPON THE AMALGAMATION
4.1 SDR Options
Upon the consummation of the Amalgamation, each issued and outstanding SDR Option shall be amended whereby the exercise of such SDR Option shall be for post-Consolidation Silver Hammer Shares subject to the number of shares and exercise price being adjusted to reflect the Exchange Ratio.
4.2 Treatment and Exchange of Shares
Upon the consummation of the Amalgamation:
(a) each issued and outstanding SDR Share held by Silver Hammer shall be cancelled without any repayment therefor;
(b) each issued and outstanding SDR Share, other than those held by Silver Hammer and Dissenting Shareholders, shall be cancelled and exchanged for fully-paid and non-assessable Silver Hammer Shares on the basis of the Exchange Ratio;
(c) each issued and outstanding Subco Share shall be cancelled and exchanged for one (1) fully paid and non-assessable Common Share; and
(d) the Amalgamated Corporation shall issue one Common Share to Silver Hammer for each Subco Share cancelled pursuant to Section 4.2(c) and for each Silver Hammer Share issued to former SDR Shareholders pursuant to Section 4.2(b).
No fractional Silver Hammer Shares shall be issued upon the exchange of SDR Shares. Any exchange or conversion that results in less than a whole number of securities shall be rounded down to the next whole number.
4.3 Issuance of Silver Hammer Shares
On the Effective Date, Silver Hammer shall deposit with the Depositary, for the benefit of the holders of SDR Shares who are entitled to receive Silver Hammer Shares in connection with the Amalgamation, the Silver Hammer Shares that are issuable in connection with the Amalgamation. Upon surrender to the Depositary of a certificate (if any) which immediately prior to or upon the Effective Date represented SDR Shares in respect of which the holder is entitled to receive Silver Hammer Shares in connection with the Amalgamation, together with a duly completed letter of transmittal and such additional documents and instruments as the Depositary may reasonably require, the holder of such surrendered certificate (if any) shall be entitled to receive in exchange therefor, and after the Effective Date the Depositary shall deliver to such holder, a certificate representing that number (rounded down to the nearest whole number) of Silver Hammer Shares which such holder has the right to receive. In the event of a transfer of ownership of SDR Shares that was not registered in the securities register of SDR, a certificate representing the proper number of Silver Hammer Shares may be issued to the transferee if the certificate representing such SDR Shares is presented to the Depositary as provided above, accompanied by all documents required to evidence and effect such transfer. Until surrendered as contemplated by this Section 4.3, each certificate which immediately prior to or upon the Effective Date represented one or more SDR Shares shall be deemed at all time after the Effective Date to represent only the right to receive upon such surrender a certificate representing that number (rounded down to the nearest whole number) of Silver Hammer Shares which such holder has the right to receive.
4.4 Lost Certificates
In the event any certificate which immediately prior to the Effective Date represented one or more outstanding SDR Shares shall have been lost, stolen or destroyed, upon the making of an affidavit of that fact by the holder of SDR Shares claiming such certificate to be lost, stolen or destroyed, the Depositary will issue in exchange for such lost, stolen or destroyed certificate, one or more certificates representing one or more Silver Hammer Shares pursuant to Section 4.3 hereof in each case deliverable in accordance with the Amalgamation. The holder to whom certificates representing Silver Hammer Shares are to be issued shall, as a condition precedent to the issuance thereof, give a bond satisfactory to Silver Hammer, SDR and the Depositary in such sum as Silver Hammer or SDR may direct or otherwise indemnify Silver Hammer or SDR in a manner satisfactory to Silver Hammer or SDR against any claim that may be made against Silver Hammer or SDR with respect to the certificate alleged to have been lost, stolen or destroyed.
4.5 Extinguishment of Rights
Any certificate which immediately prior to the Effective Date represented outstanding SDR Shares that has not been deposited with all other instruments required by Section 4.3 hereof on or prior to the sixth anniversary of the Effective Date shall cease to represent a claim or interest of any kind or nature as a holder of Silver Hammer Shares. On such date, the Silver Hammer Shares (and any dividends or distributions with respect thereto) to which the former holder of the certificate referred to in the preceding sentence was ultimately entitled shall be deemed to have been surrendered for no consideration to Silver Hammer, together with all entitlements to dividends, distributions and interest in respect thereof held for such former holder. None of Silver Hammer, SDR or the Depositary shall be liable to any person in respect of Silver Hammer Shares (or dividends and/or distributions thereon) delivered to a public official pursuant to and in compliance with any applicable abandoned property, escheat or similar law.
4.6 Withholding Rights
Silver Hammer, SDR and the Depositary shall be entitled to deduct and withhold from any dividend or consideration otherwise payable to any holder of Silver Hammer Shares or SDR Shares such amounts as Silver Hammer, SDR or the Depositary are required to deduct and withhold with respect to such payment under any provision of federal, provincial, territorial, state, local or foreign Tax law. To the extent that amounts are so withheld, such withheld amounts shall be treated for all purposes hereof as having been paid to the holder of the SDR Shares in respect of which such deduction and withholding was made, provided that such withheld amounts are actually remitted to the appropriate Taxation Authority. To the extent that the amount so required to be deducted or withheld from any payment to a holder exceeds the consideration otherwise payable to the holder, Silver Hammer, SDR and the Depositary are hereby authorized to sell or otherwise dispose of such portion of the consideration as is necessary to provide sufficient funds to Silver Hammer, SDR or the Depositary, as the case may be, to enable it to comply with such deduction or withholding requirement and Silver Hammer, SDR or the Depositary shall notify the holder thereof and remit any unapplied balance of the net proceeds of such sale.
ARTICLE 5
DISSENT RIGHTS
5.1 Right of Dissent
Holders of SDR Shares may exercise rights of dissent (the "Dissent Rights") in connection with the Amalgamation with respect to their SDR Shares pursuant to and in the manner set forth in Section 185 of the Act. Holders of SDR Shares who duly exercise Dissent Rights and who are ultimately entitled to be paid fair value for their SDR Shares by the Amalgamated Corporation (as successor corporation to SDR following the Amalgamation) shall be deemed to have irrevocably transferred their SDR Shares to SDR and cancelled immediately prior to the Amalgamation. Silver Hammer will not exercise Dissent Rights in respect of any SDR Shares held by Silver Hammer.
5.2 Recognition of Dissenting Shareholders
Neither Silver Hammer, SDR, Subco nor any other person shall be required to recognize a Dissenting Shareholder as a registered or beneficial owner of SDR Shares at or after the Effective Date, and at the Effective Date the names of such Dissenting Shareholders shall be deleted from the register of holders of SDR Shares maintained by or on behalf of SDR.
ARTICLE 6
ARTICLES OF AMALGAMATION
6.1 Articles of Amalgamation
The Amalgamating Corporations shall jointly file under the Act, Articles of Amalgamation and such other documents as may be required by the Act to give effect to the Amalgamation.
6.2 Modification or Amendment
The Amalgamating Corporations and Silver Hammer and each of them may, by resolution of their respective boards of directors, assent to any modification of this Agreement which their respective shareholders, directors or any regulatory authority may require, and this Agreement shall be deemed to include such modifications.
ARTICLE 7
GENERAL
7.1 Governing Law
This Agreement shall be governed by and construed in accordance with the laws of the Province of Ontario.
[REMAINDER OF PAGE INTENTIONALLY LEFT BLANK]
IN WITNESS WHEREOF this Agreement has been executed by the parties hereto.
STROUD RESOURCES LTD.
Per:_______________________________________
Name:
Title:
SILVER HAMMER MINING CORP.
Per:______________________________________
Name:
Title:
1001629888 ONTARIO INC.
Per:______________________________________
Name:
Title:
EXHIBIT "A"
ARTICLES OF AMALGAMATION
[See attached.]
Execution Copy
SCHEDULE "B"
SDR - CONVERTIBLE SECURITIES OUTSTANDING
Outstanding Stock Options
| Date of Issue | Exercise Price |
Expiry Date | Stock Options Outstanding |
Option Holder |
| 12-Jan-21 | $0.55 | 12-Sep-26 | 150,000 |  |
| 24-Sep-25 | $0.12 | 24-Sep-30 | 235,000 | |
| 24-Sep-25 | $0.12 | 24-Sep-30 | 300,000 |  |
| 24-Sep-25 | $0.12 | 24-Sep-30 | 235,000 |  |
| 24-Sep-25 | $0.12 | 24-Sep-30 | 235,000 |  |
Outstanding Warrants
Nil
Execution Copy
SCHEDULE "C"
FORM OF VOTING SUPPORT AGREEMENT
VOTING SUPPORT AGREEMENT
In consideration of Silver Hammer Mining Corp. (the "Purchaser"") entering into an agreement dated July 17, 2026 (the "Business Combination Agreement") with Stroud Resources Ltd. (the "Company") and 1001629888 Ontario Inc. ("Subco"), a wholly-owned subsidiary of the Purchaser, providing for a business combination involving the Company, the Purchaser and Subco (the "Transaction"), this voting support agreement (the "Agreement") dated as of , 2026 sets out the terms on which the undersigned (the "Consenting Securityholder") undertakes to take certain actions and do certain things to support the Transaction.
WHEREAS:
A. The Company is proposing to hold an annual general and special meeting (the "Company Meeting") of the shareholders of the Company to approve, inter alia, (i) the direct or indirect acquisition of the common shares of the Company by the Purchaser by way of the Transaction; and (ii) such other ancillary matters as the board of directors of the Company (the "Board") may deem necessary or advisable in order to give effect to the Transaction;
B. The Transaction requires the approval of at least a two-thirds majority of the votes cast by shareholders of the Company present in person or by proxy at the Company Meeting"";
C. The Consenting Securityholder wishes to support the Transaction subject to the terms and conditions contained herein; and
D. The parties hereto have agreed to enter into this Agreement to provide for the support by the Consenting Securityholder of the Transaction;
NOW THEREFORE this Agreement witnesses that, in consideration of the premises and the covenants and agreements herein contained and other good and valuable consideration, the receipt and sufficiency of which is acknowledged, the parties hereto agree as follows:
ARTICLE 1
INTERPRETATION
1.1 Defined Terms.
(a) Capitalized terms used herein and not otherwise defined shall have the respective meanings ascribed thereto in the Business Combination Agreement.
(b) The Consenting Securityholder and the Purchaser are collectively referred to as the "parties" and each a "party".
(c) "Common Shares" means the common shares in the capital of the Company.
(d) "Relevant Securities" means the Common Shares, options to acquire Common Shares, and other convertible securities of the Company listed on Schedule "A" and any Common Shares acquired by the Consenting Securityholder or any affiliate of the Consenting Securityholder subsequent to the date hereof, and shall include all securities which such Relevant Securities may be converted into, exchanged for or otherwise changed into.
1.2 Certain Rules of Interpretation.
In this Agreement, unless otherwise specified:
(a) Headings, etc. The division of this Agreement into Articles and Sections and the insertion of headings are for convenient reference only and do not affect the construction or interpretation of this Agreement.
(b) Gender and Number. Any reference to gender includes all genders. Words importing the singular number only include the plural and vice versa.
(c) Certain Phrases, etc. The words: (i) "including", "includes" and "include" mean "including (or includes or include) without limitation"; and (ii) unless stated otherwise, "Article", "Section", and "Schedule" followed by a number or letter mean and refer to the specified Article or Section of or Schedule to this Agreement.
(d) References to persons and Agreements. Any reference to a person includes its heirs, administrators, executors, legal personal representatives, successors and permitted assigns. The term "Agreement" and any reference in this Agreement to this Agreement or any other agreement or document includes, and is a reference to, this Agreement or such other agreement or document as it may have been, or may from time to time be amended, restated, replaced, supplemented or novated and includes all Schedules to it.
(e) Computation of Time. A period of time is to be computed as beginning on the day following the event that began the period and ending at 4:30 p.m. on the last day of the period, if the last day of the period is a business day, or at 4:30 p.m. on the next business day if the last day of the period is not a business day.
(f) Time References. References to time are to local time, Toronto, Ontario.
1.3 Schedule.
The Schedule attached to this Agreement forms an integral part of this Agreement for all purposes of it.
ARTICLE 2
REPRESENTATIONS AND WARRANTIES
2.1 Representations and Warranties of Consenting Securityholder.
(a) The Consenting Securityholder hereby represents and warrants to the Purchaser as of the date hereof and as of the Effective Date (and acknowledges that the Purchaser is relying upon such representations and warranties in entering into the Business Combination Agreement) that:
(i) The Consenting Securityholder is the registered and/or beneficial owner of, has good and valid title to, or exercises control or direction over, all of the Relevant Securities listed in Schedule "A", in each case with full power to vote, agree, transfer and deliver such Relevant Securities, free and clear of all liens, charges, pledges, security interests, claims, restrictions, options, proxies, voting trusts, voting agreements or other encumbrances of any nature whatsoever.
(ii) Other than the Relevant Securities, the Consenting Securityholder does not own (as registered owner or beneficial owner), or exercise control or direction over, any Common Shares or any options, warrants or other rights to acquire any additional Common Shares or any security exercisable for or convertible into Common Shares.
(iii) Except pursuant hereto, no person has any agreement or option, or any right or privilege (whether by law, pre-emptive or contractual) capable of becoming an agreement or option, for the purchase, acquisition or transfer of any of the Relevant Securities, or any interest therein or right thereto, and none of the Relevant Securities are subject to any proxy, voting trust, vote pooling or other agreement or arrangement with respect to the right to vote, sell, transfer or otherwise dispose of the Relevant Securities, call meetings of holders of the Common Shares or give consents or approvals of any kind, and the Consenting Securityholder has not granted any person any right of first refusal, right of first offer or similar right with respect to any of the Relevant Securities.
(iv) The Consenting Securityholder has the full authority and capacity to vote or direct the voting of the Relevant Securities, to give or cause to be given a proxy for the Relevant Securities in connection with the Company Meeting, and has the power and authority to dispose of the entire legal and beneficial interest in the Relevant Securities.
(v) This Agreement has been duly executed and delivered by the Consenting Securityholder and constitutes a legal, valid and binding obligation of the Consenting Securityholder, enforceable in accordance with its terms, subject to laws of general application and bankruptcy, insolvency and other similar laws affecting creditors' rights generally and general principles of equity.
(vi) The execution and delivery of this Agreement by the Consenting Securityholder and the performance by the Consenting Securityholder of its obligations contemplated herein do not and will not: (i) violate or conflict with any judgment, order, notice, decree, statute, law, ordinance, rule or regulation applicable to the Consenting Securityholder or any of its assets,
(ii) require any consent, approval or authorization of, or declaration or filing with, any Governmental Entity or other person on the part of the Consenting Securityholder, or (iii) constitute a default, violation or breach under any contract, commitment, agreement, arrangement, understanding or restriction to which the Consenting Securityholder is a party or by which it is bound.
(vii) To the best of its knowledge, there is no proceeding, claim or investigation pending before any Governmental Entity, or threatened against the Consenting Securityholder or any of its properties that, individually or in the aggregate, could reasonably be expected to have an adverse effect on the Consenting Securityholder's ability to execute and deliver this Agreement and to perform its obligations contemplated by this Agreement.
(viii) The information set out in Schedule "A" is complete, true and accurate as of the date hereof and accurately sets forth all Relevant Securities owned (of record or beneficially) or controlled or directed, directly or indirectly, by the Consenting Securityholder as of the date hereof.
(ix) No voluntary or involuntary proceeding in bankruptcy, receivership, insolvency, winding-up, liquidation, dissolution or other similar proceeding has been commenced or is pending or threatened against the Consenting Securityholder, and the Consenting Securityholder has not made any assignment for the benefit of creditors or taken any action with a view to or in contemplation of any of the foregoing.
(x) The Consenting Securityholder has had the opportunity to seek and was not prevented or discouraged from seeking independent legal advice prior to the execution and delivery of this Agreement and the Consenting Securityholder has read this Agreement and understands the nature and consequences of this Agreement and of each provision hereof.
2.2 Representations and Warranties the Purchaser.
(a) The Purchaser hereby represents and warrants to the Consenting Securityholder (and acknowledges that the Consenting Securityholder is relying upon such representations and warranties) that:
(i) The Purchaser is a corporation existing under the laws of the Province of British Columbia.
(ii) The Purchaser has all necessary corporate power and authority to execute and deliver this Agreement.
(iii) This Agreement has been duly executed and delivered by the Purchaser, and constitutes a legal, valid and binding obligation of the Purchaser, enforceable in accordance with its terms, subject to laws of general application and bankruptcy, insolvency and other similar laws affecting creditors' rights generally and general principles of equity.
(iv) The execution and delivery of and performance by the Purchaser of this Agreement: (i) do not and will not (or would not with the giving of notice, the lapse of time or the happening of any other event or condition) constitute or result in a violation or breach of, or conflict with, or allow any other person to exercise any rights under, any of the terms or provisions of its constating documents or by-laws; and (ii) to the knowledge of the Purchaser, do not and will not (or would not with the giving of notice, the lapse of time or the happening or any other event or condition) constitute or result in a breach or violation of, or conflict with or allow any other person to exercise any rights under, any of the terms or provisions of any material contracts or instruments to which it is a party, except, in each case, as would not reasonably be expected to have a material adverse effect on the Purchaser's ability to execute and deliver this Agreement and to perform its obligations contemplated by this Agreement.
(v) To the best of the knowledge of the Purchaser, there is no proceeding, claim or investigation pending before any Governmental Entity, or threatened against the Purchaser that, individually or in the aggregate, could reasonably be expected to have a material adverse effect on the Purchaser's ability to execute and deliver this Agreement and to perform its obligations contemplated by this Agreement.
ARTICLE 3
CONSENTING SECURITYHOLDER COVENANTS
3.1 Transfer of Relevant Securities.
(a) The Consenting Securityholder agrees that during the term of this Agreement, it will not, except as expressly contemplated by this Agreement, directly or indirectly, in any manner:
(i) sell, transfer, gift, assign, pledge, hypothecate, encumber, convert or otherwise dispose of any of the Relevant Securities or any right or interest therein or enter into any agreement, arrangement, understanding, option or commitment (whether or not in writing) in connection therewith, provided that, the Consenting Securityholder may: (i) exercise options to acquire additional Common Shares; and (ii) transfer Relevant Securities to a corporation, family trust, registered retirement savings plan or other entity directly or indirectly owned or controlled by the Consenting Securityholder or under common control with or controlling the Consenting Securityholder, provided that (w) such transfer shall not relieve or release the Consenting Securityholder of or from any of its obligations under this Agreement, including, without limitation, the obligation of the Consenting Securityholder to vote or cause to be voted all Relevant Securities in favour of the Transaction, (x) prompt written notice of such transfer is provided to the Purchaser, (y) the transferee agrees to be bound by the terms hereof pursuant to documentation approved in writing by the Purchaser in advance of such transfer, and (z) the transferee continues to be a corporation or other entity directly or indirectly controlling the Consenting Securityholder, or owned or controlled by the Consenting Securityholder, at all times prior to the Effective Date; or
(ii) deposit any of the Relevant Securities into a voting trust, or grant (or permit to be granted) any proxies or powers of attorney or attorney in fact, or enter into a voting agreement, understanding or arrangement, with respect to the voting of its Relevant Securities, in each case, without having first obtained the prior written consent of the Purchaser, which consent is within the sole discretion of the Purchaser and may be unreasonably withheld.
3.2 Non-Solicitation.
(a) The Consenting Securityholder agrees that it shall:
(i) not, directly or indirectly:
(A) solicit, initiate, knowingly encourage or otherwise facilitate (including by way of furnishing or providing copies of, access to, or disclosure of, any confidential or non-public information, properties, facilities, books or records of the Company or any of its subsidiaries, or entering into any form of agreement, arrangement or understanding) any inquiry, proposal or offer regarding an Acquisition Proposal or potential Acquisition Proposal, or otherwise knowingly facilitate any effort or attempt by any person to make an Acquisition Proposal;
(B) enter into or otherwise engage or participate in any discussions or negotiations with any person (other than the Purchaser) regarding any inquiry, proposal or offer regarding an Acquisition Proposal or potential Acquisition Proposal;
(C) accept, approve, endorse or recommend, or publicly propose to accept, approve, endorse or recommend, any Acquisition Proposal; and
(D) accept or enter into, or publicly propose to accept or enter into, any agreement, arrangement, understanding or contract with any person relating to an Acquisition Proposal; and
(ii) immediately cease and terminate, and cause to be terminated, any solicitation, encouragement, discussions or negotiations commenced prior to the date of this Agreement with any person (other than the Purchaser) by or on behalf of the Consenting Securityholder with respect to any Acquisition Proposal or potential Acquisition Proposal, whether or not initiated by the Consenting Securityholder, provided that if at any time, prior to obtaining the approval by the holders of Common Shares eligible to vote in respect of the resolution authorizing the Transaction, the Company receives a written Acquisition Proposal that did not result from a breach of any provision of any agreement then in effect between the Company and the Purchaser or a breach by the Consenting Securityholder of the provisions of this Agreement, the Consenting Securityholder may engage in or participate in discussions or negotiations with such person regarding such Acquisition Proposal provided that: (i) the Board first determines in good faith, after consultation with its outside legal and financial advisors, that such Acquisition Proposal constitutes or could reasonably be expected to lead to a Superior Proposal; (ii) the Company is otherwise permitted to take such actions under any provision of any agreement then in effect between the Company and the Purchaser (including that such person making such Acquisition Proposal has entered into a confidentiality agreement with the Company on terms no less favourable to the Company than those contained in any confidentiality agreement between the Company and the Purchaser); (iii) the Consenting Securityholder has promptly (and in any event within twenty-four (24) hours) notified the Purchaser in writing of such Acquisition Proposal, including the material terms and conditions thereof and the identity of the person making such Acquisition Proposal; and (iv) such Acquisition Proposal did not result from a breach by the Consenting Securityholder of the provisions of this Agreement.
3.3 Voting.
(a) The Consenting Securityholder hereby irrevocably covenants, undertakes and agrees that it shall:
(i) vote (or cause to be voted) all of the Relevant Securities (to the extent that such Relevant Securities are entitled to a vote in respect of such matters):
(A) in favour of the approval, consent, ratification and adoption of the Transaction (and any actions required in furtherance thereof) at every meeting of the securityholders of the Company at which such matters are considered and at every adjournment or postponement thereof, and not withdraw any proxies or change its vote in respect thereof; and
(B) against any resolution proposed by the Company or any other person that would reasonably be expected to adversely affect or reduce the likelihood of the successful completion of the Transaction or delay or interfere with, the completion of the Transaction;
(ii) except as contemplated by this Agreement, not vote or grant to any person other than the Purchaser a proxy to vote or enter into any voting trust, vote pooling or other agreement with respect to the right to vote the Relevant Securities (and will cause such Relevant Securities not to be voted) in favour of any Acquisition Proposal;
(iii) deliver, or cause to be delivered, to the Company's transfer agent, or as otherwise directed by the Company, after receipt of proxy materials for, and no later than ten (10) days before the date of, the Company Meeting or any other meeting of the securityholders (or any of them) of the Company called for the purpose of approving the Transaction, a duly executed proxy directing that the Relevant Securities be voted at such meeting in favour of the Transaction and all related matters;
(iv) not, directly or indirectly, support, assist, participate in or encourage any action that is intended or would reasonably be expected to impede, interfere with, delay, postpone or discourage the completion of the Transaction; and
(v) not, directly or indirectly, do anything that would reasonably be expected to frustrate, hinder or reduce the likelihood of the successful consummation of the Transaction.
(b) The Consenting Securityholder shall not, and hereby agrees not to:
(i) assert or exercise any Dissent Rights in respect of the Transaction or the transactions associated therewith that the Consenting Securityholder may have; and
(ii) commence or participate in, and shall, and hereby agrees to, take all actions necessary to opt out of any class in any class action with respect to, any claim, derivative or otherwise, against the Company or Purchaser or any of their respective subsidiaries or affiliates (or any of their respective successors, directors, officers, employees or agents) relating to the negotiation, execution and delivery of any agreement relating to the Transaction or the consummation of the Transaction.
(c) The Consenting Securityholder hereby revokes any and all previous proxies granted that may conflict or be inconsistent with the matters set forth in this Agreement and the Consenting Securityholder agrees not to, directly or indirectly, grant any other proxy or power of attorney with respect to the matters set forth in this Agreement except as expressly required or permitted by this Agreement.
3.4 Change in Nature of Transaction.
(a) In the event that: (a) the Purchaser, in consultation with the Company, determines in its good faith judgment that it is necessary or desirable to proceed with an alternative transaction structure, including a plan of arrangement, take-over bid or asset purchase, in conjunction with or instead of the Transaction; (b) such alternative transaction provides for consideration to the holders of Common Shares that is not less than the consideration contemplated by the Transaction; and (c) such alternative transaction is capable of being completed on or before November 30, 2026, (as described in each of the foregoing clauses (a), (b) and (c), a "Revised Transaction"), the Consenting Securityholder shall support the completion of the Revised Transaction in the same manner and to the same extent that it has agreed to support the Transaction under this Agreement and, in the event of a take-over bid, tender the Relevant Securities to such bid.
(b) In the event of any proposed Revised Transaction, the references in this Agreement to the Transaction shall be deemed to be changed to "Revised Transaction" and all terms, covenants, representations and warranties of this Agreement shall be and shall be deemed to have been made in the context of the Revised Transaction.
3.5 No Agreement as Director or Officer.
The Consenting Securityholder makes no agreement or understanding in this Agreement in its capacity as a director or officer of the Company, and nothing in this Agreement: (a) will limit or affect any actions or omissions taken by the Consenting Securityholder in its capacity as such a director or officer, including in exercising rights under the Agreement, and no such actions or omissions shall be deemed a breach of this Agreement; or (b) will be construed to prohibit, limit or restrict the Consenting Securityholder from exercising its fiduciary duties as a director or officer of the Company.
ARTICLE 4
TERMINATION
4.1 Termination.
(a) This Agreement shall automatically terminate upon the earlier of:
(i) the Effective Date; and
(ii) the mutual consent in writing of the parties.
(b) This Agreement may be terminated by the Consenting Securityholder if:
(i) any representation or warranty of the Purchaser under this Agreement is untrue or incorrect in any material respect and such misrepresentation or breach of warranty is not cured within ten (10) business days following written notice thereof from the Consenting Securityholder to the Purchaser (provided that the Consenting Securityholder is not then in material breach of any of its representations, warranties or covenants under this Agreement);
(ii) the form or amount of the consideration offered by the Purchaser to the holders of Common Shares pursuant to the Transaction is reduced or changed and publicly announced by the Purchaser in any respect that is, in each case, materially adverse to the Consenting Securityholder;
(iii) the Board publicly announces its recommendation in support of a Superior Proposal; or
(iv) the Transaction is not completed by November 30, 2026, provided that at the time of such termination, the Consenting Securityholder is not in material default in the performance of its obligations under this Agreement and the failure to complete the Transaction by such date was not caused by, or the result of, any breach by the Consenting Securityholder of any of its representations, warranties, covenants or obligations under this Agreement.
4.2 Effect of Termination.
If this Agreement is terminated in accordance with the provisions of this Article 4, no party shall have any further liability to perform its obligations under this Agreement except as expressly contemplated by this Agreement, and provided that neither the termination of this Agreement nor anything contained in this Article 4 shall relieve any party from any liability for any breach by it of this Agreement, including from any inaccuracy in its representations and warranties and any non-performance by it of its covenants made herein.
4.3 Remedies.
The parties agree that irreparable harm would occur for which money damages would not be an adequate remedy at law in the event that any of the provisions of this Agreement were not performed by the Consenting Securityholder or the Purchaser in accordance with their specific terms or were otherwise breached by the Consenting Securityholder or the Purchaser. It is accordingly agreed that the parties shall be entitled to injunctive and other equitable relief to prevent breaches of this Agreement, and to enforce compliance with the terms of this Agreement against the Consenting Securityholder or the Purchaser, as applicable, without any requirement for the securing or posting of any bond in connection with the obtaining of any such injunctive or other equitable relief, this being in addition to any other remedy to which the parties may be entitled at law or in equity.
ARTICLE 5
GENERAL PROVISIONS
5.1 Disclosure.
(a) The Consenting Securityholder agrees:
(i) to the existence and factual details of this Agreement (other than registration particulars set out in Schedule "A") being set out in any public disclosure, including, without limitation, press releases and information circulars, produced by the Company or the Purchaser, at the discretion of the Company or the Purchaser, in connection with the Transaction; and
(ii) to this Agreement (other than registration particulars set out in Schedule "A") being filed and/or available for inspection by the public to the extent required by applicable securities laws or stock exchange rules.
5.2 Notices.
Any notice, or other communication given regarding the matters contemplated by this Agreement must be in writing, sent by personal delivery, courier, facsimile or electronic mail and addressed:
(a) to the Purchaser at:
Silver Hammer Mining Corp.
Suite 300 - 1055 West Hastings Street,
Vancouver, British Columbia, V6E 2E9, Canada
Attention: Peter Ball, Chief Executive Officer
Email: 
with a copy (which shall not itself constitute notice) to:
McMillan LLP
Royal Centre, Suite 1500
1055 West Georgia Street, PO Box 11117
Vancouver, British Columbia
Canada V6E 4N7
Attention: Mark Neighbor
Email: mark.neighbor@mcmillan.ca
(b) to the Consenting Securityholder at:
______________________________________
______________________________________
______________________________________
_______________________________________
Attention: ______________________________
Email:__________________________________
5.3 Time of the Essence.
Time is of the essence in this Agreement.
5.4 Waiver.
No waiver of any of the provisions of this Agreement will constitute a waiver of any other provision (whether or not similar). No waiver will be binding unless executed in writing by the party to be bound by the waiver. A party's failure or delay in exercising any right under this Agreement will not operate as a waiver of that right. A single or partial exercise of any right will not preclude a party from any other or further exercise of that right or the exercise of any other right.
5.5 Entire Agreement.
This Agreement constitutes the entire agreement between the parties with respect to the transactions contemplated by this Agreement and supersedes all prior agreements, understandings, negotiations and discussions, whether oral or written, of the parties. There are no representations, warranties, covenants, conditions or other agreements, express or implied, collateral, statutory or otherwise, between the parties in connection with the subject matter of this Agreement, except as specifically set forth in this Agreement. The parties have not relied and are not relying on any other information, discussion or understanding in entering into and completing the transactions contemplated by this Agreement.
5.6 Successors and Assigns.
(a) This Agreement becomes effective only when executed by the Consenting Securityholder and the Purchaser. After that time, it will be binding upon and enure to the benefit of the Consenting Securityholder and the Purchaser.
(b) Neither this Agreement nor any of the rights or obligations under this Agreement are assignable or transferable by any party without the prior written consent of the other party.
5.7 Severability.
If any provision of this Agreement is determined to be illegal, invalid or unenforceable by an arbitrator or any court of competent jurisdiction, that provision will be severed from this Agreement and the remaining provisions shall remain in full force and effect. Upon such determination that any term or other provision is invalid, illegal or incapable of being enforced, the parties shall negotiate in good faith to modify this Agreement so as to effect the original intent of the parties as closely as possible in an acceptable manner to the end that the transactions contemplated hereby are fulfilled to the fullest extent possible.
5.8 Governing Law.
(a) This Agreement will be governed by and interpreted and enforced in accordance with the laws of the Province of Ontario and the federal laws of Canada applicable therein.
(b) Each party irrevocably attorns and submits to the exclusive jurisdiction of the Ontario courts situated in the City of Toronto and waives objection to the venue of any proceeding in such court or that such court provides an inconvenient forum.
5.9 Rules of Construction.
The parties to this Agreement waive the application of any law or rule of construction providing that ambiguities in any agreement or other document shall be construed against the party drafting such agreement or other document.
5.10 Language.
The parties expressly acknowledge that they have requested that this Agreement and all ancillary and related documents thereto be drafted in the English language only. Les parties aux présentes reconnaissent avoir exigé que la présente entente et tous les documents qui y sont accessoires soient rédigés en anglais seulement.
5.11 Counterparts.
This Agreement may be executed in any number of counterparts and all such counterparts taken together shall be deemed to constitute one and the same instrument. The parties shall be entitled to rely upon delivery of an executed facsimile or similar executed electronic copy of this Agreement, and such facsimile or similar executed electronic copy shall be legally effective to create a valid and binding agreement between the parties.
[REMAINDER OF PAGE INTENTIONALLY LEFT BLANK]
This Agreement has been agreed and accepted on the date first written above.
| SILVER HAMMER MINING CORP. | ||
| By: | ||
| Name: | ||
| Title: | ||
| If a corporation: | If an individual: | |
| By: __________________________________ | ||
| Consenting Securityholder | ||
| Witness | ||
Execution Copy
SCHEDULE "A"
RELEVANT SECURITIES
| Class of Securities | Number of Securities Held | |
| Common Shares | ||
| Options |
APPENDIX D - PRO FORMA CONSOLIDATED FINANCIAL STATEMENTS OF THE RESULTING ISSUER
[See attached]
SILVER HAMMER MINING CORP.
(TO BE RENAMED SILVER FRONTIER RESOURCES CORP.)
Pro Forma Consolidated Financial Statements
(Unaudited - Prepared by Management of Silver Hammer Mining Corp.)
March 31, 2026
(Expressed in Canadian Dollars)
| SILVER HAMMER MINING CORP. Pro Forma Consolidated Statements of Financial Position (unaudited) As of March 31, 2026 (Expressed in Canadian Dollars) |
||||||||||||||||||
| Stroud Resources Ltd. March 31, 2026 $ |
Silver Hammer Mining Corp. March 31, 2026 $ |
SilverMark Resources Inc. March 31, 2026 $ |
Pro forma adjustments $ |
Note | Pro forma Silver Frontier Resources Corp. (Consolidated) March 31, 2026 $ |
|||||||||||||
| ASSETS | ||||||||||||||||||
| Current assets | ||||||||||||||||||
| Cash and cash equivalents | 313,073 | 3,776,631 | - | (300,000 | ) | c | 10,299,704 | |||||||||||
| 7,000,000 | e | |||||||||||||||||
| (490,000 | ) | e | ||||||||||||||||
| Accounts receivable | 18,520 | 27,376 | - | 45,896 | ||||||||||||||
| Prepaid expenses | 9,983 | 376,363 | - | 386,346 | ||||||||||||||
| 341,576 | 4,180,370 | - | 6,210,000 | 10,731,946 | ||||||||||||||
| Non-current assets | ||||||||||||||||||
| Reclamation deposits | - | 31,483 | - | 31,483 | ||||||||||||||
| Exploration and evaluation assets | - | 8,733,967 | - | (3,455,057 | ) | a | 1,336,805 | |||||||||||
| 300,000 | c | |||||||||||||||||
| (4,313,940 | ) | c | ||||||||||||||||
| 71,835 | d | |||||||||||||||||
| - | 8,765,450 | - | (7,397,162 | ) | 1,368,288 | |||||||||||||
| TOTAL ASSETS | 341,576 | 12,945,820 | - | (1,187,162 | ) | 12,100,234 | ||||||||||||
| LIABILITIES | ||||||||||||||||||
| Current liabilities | ||||||||||||||||||
| Accounts payable and accrued liabilities |
136,781 | 248,436 | - | 385,217 | ||||||||||||||
| 136,781 | 248,436 | - | - | 385,217 | ||||||||||||||
| Non-current liabilities | ||||||||||||||||||
| - | - | - | - | - | ||||||||||||||
| TOTAL LIABILITIES | 136,781 | 248,436 | - | - | 385,217 | |||||||||||||
| SHAREHOLDERS' EQUITY | ||||||||||||||||||
| Common shares | 26,894,854 | 18,517,535 | - | (18,517,535 | ) | b | 37,177,013 | |||||||||||
| 3,700,324 | c | |||||||||||||||||
| 71,835 | d | |||||||||||||||||
| 7,000,000 | e | |||||||||||||||||
| (490,000 | ) | e | ||||||||||||||||
| Reserves | 4,113,462 | 2,972,344 | - | (2,972,344 | ) | b | 5,341,525 | |||||||||||
| 1,228,063 | c | |||||||||||||||||
| Accumulated deficit | (30,805,252 | ) | (8,792,495 | ) | - | (3,455,057 | ) | a | (30,805,252 | ) | ||||||||
| 12,247,552 | b | |||||||||||||||||
| Accumulated other comprehensive income (loss) |
1,731 | - | - | 1,731 | ||||||||||||||
| TOTAL SHAREHOLDERS' EQUITY | 204,795 | 12,697,384 | - | (1,187,162 | ) | 11,715,017 | ||||||||||||
| TOTAL LIABILITIES AND SHAREHOLDERS' EQUITY |
341,576 | 12,945,820 | - | (1,187,162 | ) | 12,100,234 | ||||||||||||
| SILVER HAMMER MINING CORP. Pro Forma Consolidated Interim Statements of Loss and Comprehensive Loss (unaudited) For the three months ended March 31, 2026 (Expressed in Canadian Dollars) |
||||||||||||||||||
| For the three months ended March 31, 2026 | ||||||||||||||||||
| Stroud Resources Ltd. $ |
Silver Hammer Mining Corp. $ |
SilverMark Resources Inc. $ |
Pro forma adjustments $ |
Note | Pro forma Silver Frontier Resources Corp. (Consolidated) $ |
|||||||||||||
| Revenue, net of royalties | 6,807 | - | - | 6,807 | ||||||||||||||
| Operating expenses | (4,949 | ) | - | - | (4,949 | ) | ||||||||||||
| Income from oil and gas operations | 1,858 | - | - | - | - | 1,858 | ||||||||||||
| Expenses | ||||||||||||||||||
| Consulting fees | - | 89,917 | - | 89,917 | ||||||||||||||
| Exploration and evaluation costs | 3,400 | - | - | 96,280 | a | 99,680 | ||||||||||||
| Foreign exchange gain (loss) | - | 8,121 | - | 61,466 | a | 69,587 | ||||||||||||
| General and administrative expenses | 19,122 | 8,651 | - | 27,773 | ||||||||||||||
| Licences and fees | 8,933 | - | - | 8,933 | ||||||||||||||
| Director fees | 15,000 | - | - | 15,000 | ||||||||||||||
| Professional fees | 15,018 | 72,629 | - | 87,647 | ||||||||||||||
| Project evaluation costs | - | 677 | - | 677 | ||||||||||||||
| Rent | 1,211 | - | - | 1,211 | ||||||||||||||
| Shareholder information and investor relations | - | 90,614 | - | 90,614 | ||||||||||||||
| Transfer agent, regulatory and filing fees | - | 13,142 | - | 13,142 | ||||||||||||||
| Travel | - | 14,042 | - | 14,042 | ||||||||||||||
| Total expenses | (62,684 | ) | (297,793 | ) | - | (157,746 | ) | - | (518,223 | ) | ||||||||
| Other income (expenses) | ||||||||||||||||||
| Finance income | 137 | - | - | 137 | ||||||||||||||
| Net income (loss) | (60,689 | ) | (297,793 | ) | - | (157,746 | ) | - | (516,228 | ) | ||||||||
| Other comprehensive income (loss) | ||||||||||||||||||
| Items that may be reclassified subsequently to profit or loss: | ||||||||||||||||||
| Foreign currency translation differences for foreign operations | - | 61,835 | - | 61,835 | ||||||||||||||
| Income (loss) and comprehensive income (loss) | (60,689 | ) | (235,958 | ) | - | (157,746 | ) | - | (454,393 | ) | ||||||||
| Basic and diluted loss per share for the period attributable to common shareholders ($ per common share) | (0.00 | ) | ||||||||||||||||
| Weighted average number of common shares outstanding - basic and diluted | 116,980,430 | |||||||||||||||||
| SILVER HAMMER MINING CORP. Pro Forma Consolidated Interim Statements of Loss and Comprehensive Loss (unaudited) For the year ended December 31, 2025 (Expressed in Canadian Dollars) |
||||||||||||||||||
| For the three months ended December 31, 2025 | ||||||||||||||||||
| Stroud Resources Ltd. $ |
Silver Hammer Mining Corp. $ |
SilverMark Resources Inc. $ |
Pro forma adjustments $ |
Note | Pro forma Silver Frontier Resources Corp. (Consolidated) $ |
|||||||||||||
| Revenue, net of royalties | 24,620 | - | - | 24,620 | ||||||||||||||
| Operating expenses | (21,699 | ) | - | - | (21,699 | ) | ||||||||||||
| Income from oil and gas operations | 2,921 | - | - | - | 2,921 | |||||||||||||
| Expenses | ||||||||||||||||||
| Consulting fees | - | 206,250 | - | 206,250 | ||||||||||||||
| Depreciation | - | 809 | - | 809 | ||||||||||||||
| Exploration and evaluation costs | 18,084 | - | - | 328,655 | a | 346,739 | ||||||||||||
| Foreign exchange gain (loss) | 2,449 | 82,916 | - | (150,743 | ) | a | (65,378 | ) | ||||||||||
| General and administrative expenses | 78,699 | 26,284 | - | 104,983 | ||||||||||||||
| Licences and fees | 14,048 | - | - | 14,048 | ||||||||||||||
| Director fees | 48,750 | - | - | 48,750 | ||||||||||||||
| Professional fees | 100,098 | 253,055 | - | 353,153 | ||||||||||||||
| Project evaluation costs | - | 10,006 | - | 10,006 | ||||||||||||||
| Rent | 4,724 | - | - | 4,724 | ||||||||||||||
| Share-based payments | 110,000 | 218,285 | - | 328,285 | ||||||||||||||
| Shareholder information and investor relations |
- | 42,034 | - | 42,034 | ||||||||||||||
| Transfer agent, regulatory and filing fees | - | 20,989 | - | 20,989 | ||||||||||||||
| Travel | - | 32,021 | - | 32,021 | ||||||||||||||
| Total expenses | (376,852 | ) | (892,649 | ) | - | (177,912 | ) | - | (1,447,413 | ) | ||||||||
| Other income (expenses) | ||||||||||||||||||
| Finance income | 256 | - | - | 256 | ||||||||||||||
| Finance costs | (7,991 | ) | - | - | (7,991 | ) | ||||||||||||
| Loss on debt settlement | - | (105,904 | ) | - | (105,904 | ) | ||||||||||||
| Total other income (expenses) | (7,735 | ) | (105,904 | ) | - | - | - | (113,639 | ) | |||||||||
| Net income (loss) | (381,666 | ) | (998,553 | ) | - | (177,912 | ) | - | (1,558,131 | ) | ||||||||
| Other comprehensive income (loss) | ||||||||||||||||||
| Items that may be reclassified subsequently to profit or loss: |
||||||||||||||||||
| Foreign currency translation differences for foreign operations |
- | (67,578 | ) | - | (67,578 | ) | ||||||||||||
| Income (loss) and comprehensive income (loss) | (381,666 | ) | (1,066,131 | ) | - | (177,912 | ) | - | (1,625,709 | ) | ||||||||
| Basic and diluted loss per share for the period attributable to common shareholders ($ per common share) | (0.01 | ) | ||||||||||||||||
| Weighted average number of common shares outstanding - basic and diluted | 116,980,430 | |||||||||||||||||
| SILVER HAMMER MINING CORP. Notes to the Pro Forma Consolidated Interim Financial Statements (Expressed in Canadian Dollars) |
1. DESCRIPTION OF OPERATIONS
Silver Hammer Mining Corp. ("Silver Hammer" or the "Company"), which will be renamed Silver Frontier Resources Corp. ("Silver Frontier" or the "Resulting Issuer"), is a publicly traded Canadian mineral exploration and development company listed on the Canadian Securities Exchange (CSE). The Company focuses on acquiring, exploring, and advancing precious-metal assets, with an emphasis on silver and gold projects. Silver Hammer operates in Canada and the United States and pursues growth through strategic transactions, including the acquisitions of SilverMark Resources Inc. and Stroud Resources Ltd. The Company's strategy centers on consolidating high-potential mining assets, advancing exploration programs, and leveraging public-market access to capital to fund development.
Stroud Resources Ltd. ("Stroud") is a publicly traded Canadian mineral exploration company listed on the TSX Venture Exchange (TSXV). Stroud's primary assets are held through its subsidiaries, including Compañia Minera San Diego y La Española S.A. de C.V., which operates in Mexico. Stroud focuses on the exploration and development of silver and gold projects, with its Mexican subsidiary holding substantially all operational mineral interests. Stroud maintains effective control over its subsidiaries and has historically advanced exploration programs through technical studies, drilling, and resource delineation. Following the business combination with Silver Hammer, Stroud becomes a wholly owned subsidiary, contributing its Mexican mineral portfolio to Silver Hammer's consolidated asset base.
SilverMark Resources Inc. ("SilverMark") is a private Canadian mineral exploration company holding a portfolio of significant mining option agreements known as the SABI-AIM Option Agreements ("SABI-AIM Agreements"). The SABI-AIM Agreements provide SilverMark with earn-in rights to multiple mineral properties in Morocco, these concessions include land, mineral rights, technical data, and stockpiled ore. SilverMark's business model is centered on advancing these earn-in projects toward defined milestones such as resource estimates and ownership thresholds. Through the business combination with Silver Hammer, SilverMark becomes a wholly owned subsidiary, enabling public-market funding for the advancement of its Moroccan portfolio.
2. SIGNIFICANT ACCOUNTING POLICIES
These unaudited pro forma consolidated financial statements have been compiled using the significant accounting policies as set out in the audited consolidated financial statements of Stroud as of December 31, 2025. Management has determined that no material pro forma adjustments are necessary to conform the Company's accounting policies to the accounting policies used by Stroud in the preparation of its audited financial statements.
3. BASIS OF PRESENTATION
The unaudited pro forma consolidated financial statements of the Resulting Issuer have been prepared by management of Silver Hammer for inclusion in the information circular in connection with the proposed transaction described in Note 4, as of March 31, 2026.
The pro forma consolidated financial statements of the Resulting Issuer have been compiled from the following financial statements:
• The unaudited financial statements of Silver Hammer as at and for the six months ended March 31, 2026;
• The audited financial statements of Silver Hammer as at and for the year ended September 30, 2025;
• The unaudited financial statements of Stroud as at and for the three months ended March 31, 2026; and
• The audited financial statements of Stroud as at and for the year ended December 31, 2025.
| SILVER HAMMER MINING CORP. Notes to the Pro Forma Consolidated Interim Financial Statements (Expressed in Canadian Dollars) |
3. BASIS OF PRESENTATION (CONTINUED)
These unaudited pro forma consolidated financial statements are not necessarily indicative of the Resulting Issuer's financial position on closing of the proposed transaction. In preparing these unaudited pro forma consolidated financial statements, no adjustments have been made to reflect additional costs or savings that could result from the transaction described in Note 4. Actual amounts recorded upon approval of the transaction will likely differ from those recorded in the unaudited pro forma consolidated financial statements.
The accompanying unaudited pro forma consolidated financial statements of the Resulting Issuer have been prepared by management from information derived from the financial statements, which were prepared in accordance with International Financial Reporting Standards ("IFRS"), of Silver Hammer, Stroud and SilverMark to show effect of the proposed transaction as discussed in Note 4.
The unaudited pro forma consolidated financial statements should be read in conjunction with the following:
• The unaudited financial statements of Silver Hammer as at and for the six months ended March 31, 2026;
• The audited financial statements of Silver Hammer as at and for the year ended September 30, 2025;
• The unaudited financial statements of Stroud as at and for the three months ended March 31, 2026; and
• The audited financial statements of Stroud as at and for the year ended December 31, 2025.
4. PROPOSED TRANSACTIONS
On July 17, 2026, Silver Hammer entered into two definitive business combination agreements: (i) a Business Combination Agreement with SilverMark and 18076421 Canada Inc. ("SM Subco"), a wholly owned subsidiary of Silver Hammer; and (ii) a Business Combination Agreement with Stroud and 1001629888 Ontario Inc. ("SDR Subco"), also a wholly owned subsidiary of Silver Hammer (collectively, the "Agreements"). Pursuant to the Agreements, Silver Hammer will acquire all of the issued and outstanding shares of SilverMark and all issued and outstanding shares of Stroud not already owned by Silver Hammer (together, the "Transactions").
• Stroud Transaction
On or immediately prior to the completion of the Stroud Transaction, it is anticipated that:
a) SDR Subco will amalgamate with Stroud under the OBCA to form an amalgamated corporation ("Stroud Amalco").
b) All issued and outstanding Stroud common shares (other than those already held by Silver Hammer and those held by dissenting shareholders) will be exchanged for post-Consolidation Silver Hammer Shares at an exchange ratio of 0.777963 Silver Hammer Shares per Stroud Share.
c) All outstanding Stroud options will be amended such that, upon completion of the Transaction, they become exercisable for Silver Hammer Shares, adjusted in accordance with the exchange ratio.
d) Stroud Amalco will become a wholly owned subsidiary of Silver Hammer and will continue under the name "Stroud Resources Ltd."
| SILVER HAMMER MINING CORP. Notes to the Pro Forma Consolidated Interim Financial Statements (Expressed in Canadian Dollars) |
4. PROPOSED TRANSACTIONS (CONTINUED)
• SilverMark Transaction
On or immediately prior to the completion of the SilverMark Transaction, it is anticipated that:
a) SM Subco will amalgamate with SilverMark under the CBCA to form an amalgamated corporation ("SilverMark Amalco").
b) All issued and outstanding Class A common shares of SilverMark will be exchanged for post-Consolidation Silver Hammer common shares based on an exchange ratio of 0.346154 Silver Hammer Shares per SilverMark Class A Share.
c) All issued and outstanding Class B special shares of SilverMark will be exchanged for Silver Hammer contingent value shares ("CV Shares"), with the number of CV Shares determined in accordance with the Exchange Ratio formula set out in the Agreement.
d) All outstanding SilverMark warrants will become exercisable for Silver Hammer Shares, adjusted in accordance with their terms.
e) SilverMark Amalco will become a wholly owned subsidiary of Silver Hammer and will continue under the name "SilverMark Resources Inc." or such other name Silver Hammer may determine.
In connection with the SilverMark Transaction, SilverMark is expected to complete a concurrent financing of subscription receipts for gross proceeds of $7,000,000 to $10,000,000 (the "Concurrent Financing"). Each subscription receipt will convert into one SilverMark Class A common share immediately prior to closing of the Transaction.
In addition, immediately prior to the completion of the Stroud Transaction and SilverMark Transaction, Silver Hammer will complete a consolidation of its common shares on a 1 post-consolidation share for 4 pre-consolidation shares basis.
Following completion of both Transactions, Silver Frontier will continue as the parent company of SilverMark Amalco and Stroud Amalco and will carry on the combined business of Silver Hammer, SilverMark, and Stroud (the "Resulting Issuer"). The Resulting Issuer will hold mineral exploration and development assets in Canada, Morocco, Mexico, and the United States through its subsidiaries.
5. ACCOUNTING FOR RTO
Silver Hammer does not meet the definition of a business nor does this transaction meet the definition of a business combination under IFRS 3. The acquisition of Stroud by Silver Hammer constitutes a reverse asset acquisition where purchase of Silver Hammer's net assets is considered an equity-settled share-based payment under IFRS 2 (Share-based Payment) by Stroud. Accordingly, as a result of the transaction, the pro forma financial statements have been adjusted for the elimination of Silver Hammer's equity balances.
The pro forma adjustments and allocations of the estimated consideration transferred are based in part on estimates of the fair value of assets to be acquired and liabilities to be assumed. The final determination of the consideration transferred and the related allocation of the fair value of the Company's net assets to be acquired pursuant to the Agreements will ultimately be determined after the closing of the transactions.
| SILVER HAMMER MINING CORP. Notes to the Pro Forma Consolidated Interim Financial Statements (Expressed in Canadian Dollars) |
6. PRO FORMA ASSUMPTIONS AND ADJUSTMENTS
a) To expense Silver Hammer's historical exploration and evaluation expenditures in order to align its accounting policy with that of Stroud.
b) To eliminate Silver Hammer's historical shareholders' equity balances with the following adjustments:
- A reduction in share capital of $18,517,535;
- A reduction of $2,972,344 in reserves; and
- An adjustment of $ 8,792,495 of accumulated deficit.
c) Based on Silver Hammer's consolidated statements of financial position as of March 31, 2026, Stroud will be acquiring net assets with the estimated fair market value as follows:
| $ | |||
| Consideration transferred | |||
| 34,980,742 shares a fair value of $0.093 per share issued to the shareholders of Silver Hammer Mining Corp. | 3,253,209 | ||
| 4,807,692 shares a fair value of $0.093 per share issued to the shareholders of SilverMark Resources Inc. | 447,115 | ||
| 14,555,191 warrants issued to the shareholders of Silver Hammer Mining Corp.(1) | 1,095,799 | ||
| 1,526,250 options issued to the shareholders of Silver Hammer Mining Corp.(2) | 113,923 | ||
| 288,461 options issued to the shareholders of SilverMark Resources Inc.(3) | 18,341 | ||
| Transaction costs | 300,000 | ||
| 5,228,387 | |||
| Cash and cash equivalents | 3,776,631 | ||
| Accounts receivable | 27,376 | ||
| Prepaid expenses | 376,363 | ||
| Reclamation deposits | 31,483 | ||
| Exploration and evaluation assets | 1,264,970 | ||
| Accounts payable and accrued liabilities | (248,436 | ) | |
| 5,228,387 |
(1) Valued using the Black-Scholes Option Pricing Model using volatility of 172%, strike price of $0.40, risk free rate of 2.93%, expected life of 3.72 years and dividend yield of 0%.
(2) Valued using the Black-Scholes Option Pricing Model using volatility of 170%, strike price of $0.39, risk free rate of 2.98%, expected life of 3.82 years and dividend yield of 0%.
(3) Valued using the Black-Scholes Option Pricing Model using volatility of 185%, strike price of $0.35, risk free rate of 2.79%, expected life of 2.10 years and dividend yield of 0%.
d) To record the common shares issued per the SABI-AIM Agreements.
e) To record the Concurrent Financing requires recognizing $7,000,000 of gross proceeds and a 7% cash commission of $490,000, resulting in net proceeds of $6,510,000.
| SILVER HAMMER MINING CORP. Notes to the Pro Forma Consolidated Interim Financial Statements (Expressed in Canadian Dollars) |
7. PRO FORMA SHARE CAPITAL
Shares in the unaudited pro forma consolidated financial statements are comprised of the following:
| Number of | Share capital | ||||||
| Note | shares | ($) | |||||
| Silver Hammer Mining Corp.'s common shares outstanding - January 31, 2025 post 1 for 4 consolidation of Silver Hammer Mining Corp.'s shares | 34,980,742 | 18,517,535 | |||||
| Reverse takeover adjustment - Silver Hammer Mining Corp.'s common shares | - | (18,517,535 | ) | ||||
| Common shares issued to Stroud Resources Ltd.'s shareholders | 49,496,496 | 26,894,854 | |||||
| Common shares issued to SilverMark Resources Inc. 's shareholders | 6(b) | 4,807,692 | 447,115 | ||||
| Consideration transferred to shareholders of Stroud Resources Ltd. | - | 3,253,209 | |||||
| Common shares issued per option agreement | 6(c) | 772,423 | 71,835 | ||||
| Common shares issued in private placement | 6(d) | 26,923,077 | 7,000,000 | ||||
| Share issuance costs | 6(d) | - | (490,000 | ) | |||
| Pro forma consolidated share capital | 116,980,430 | 37,177,013 |
The business combination agreement with SilverMark includes a contingent consideration arrangement whereby additional Resulting Issuer common shares ("Contingent Value Shares") may be issued to former SilverMark shareholders upon the achievement of specified milestone events. Management has evaluated the likelihood of these milestone events occurring based on information available as of the pro forma reporting date and determined that the probability of achievement is remote. Accordingly, no amount related to the Contingent Value Shares has been included in the pro forma purchase consideration or reflected in the pro forma financial information.
APPENDIX E - INFORMATION CONCERNING SILVER HAMMER
[To be inserted.]
APPENDIX "E"
INFORMATION CONCERNING SILVER HAMMER
The following information reflects the business, financial and share capital position of Silver Hammer and is provided as at the date of the Circular, except as otherwise indicated. See "Forward Looking Statements" in the Circular and "Note Regarding Forward-Looking Information" herein in respect of forward-looking statements that are included in this Appendix "E".
All capitalized terms used in this Appendix "E" and not defined herein have the meaning ascribed to such terms in the "Glossary of Terms" or elsewhere in the Circular. The information contained in this Appendix "E", unless otherwise indicated, is given as of the date of the Circular. Unless otherwise indicated herein, references to "$" are to Canadian dollars and references to "US$" are to United States dollars.
The scientific and technical information in this Appendix "E" has been reviewed and approved by Donald J. Birak, Registered Member of SME, Fellow of AusIMM, an independent director of Silver Hammer and a "Qualified Person" as defined by National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101").
Note Regarding Forward-Looking Information
Except for statements of historical fact relating to Silver Hammer, certain statements in this Appendix "E" constitute forward-looking information within the meaning of applicable Canadian securities laws. Forward-looking information relates to future events or future performance and often includes terminology such as "may", "will", "could", "should", "expect", "plan", "anticipate", "believe", "estimate", "intend", "seek", "forecast", "project", "potential", "target", "continue", or similar expressions (including negative variations thereof). These statements reflect management's current expectations and assumptions regarding Silver Hammer's future operations, strategy, exploration activities, financial position, the proposed Amalgamation and the SilverMark Amalgamation, and the broader economic and regulatory environment in the jurisdictions in which Silver Hammer operates or intends to operate.
Forward-looking information in this Appendix "E" includes, without limitation:
Forward-looking information is based on a number of assumptions that, while considered reasonable by management at the time made, may prove to be incorrect. These assumptions include, without limitation:
Forward-looking information is subject to a variety of known and unknown risks, uncertainties, and other factors that may cause actual results, performance, or achievements to differ materially from those expressed or implied. These risks include, but are not limited to:
Readers are cautioned not to place undue reliance on forward-looking information. All forward-looking statements in this Appendix "E" are qualified by these cautionary statements and by the detailed risk factors set out under "Risk Factors" herein, which readers are encouraged to review in their entirety. Forward-looking information is made as of the date of the Circular, and Silver Hammer does not undertake any obligation to update or revise such information to reflect new events or circumstances after the date of the Circular, except as required by applicable securities laws.
Selected Financial Information of Silver Hammer
Silver Hammer presents its financial statements in accordance with International Financial Reporting Standards ("IFRS").
Silver Hammer's audited consolidated financial statements for the financial years ended September 30, 2025 and September 30, 2024, together with the related management's discussion and analysis for each such period, and Silver Hammer's unaudited condensed consolidated interim financial statements for the six months ended March 31, 2026, together with the related management's discussion and analysis for such period (collectively, the "Silver Hammer Financial Statements") are available on Silver Hammer's SEDAR+ profile at www.sedarplus.ca.
The MD&A for Silver Hammer should be read in conjunction with Silver Hammer's financial statements and the accompanying notes thereto. Certain information contained in Silver Hammer's MD&A constitutes forward-looking statements. These statements relate to future events or to Silver Hammer's future financial performance and involve known and unknown risks, uncertainties and other factors that may cause Silver Hammer's actual results, levels of activity, performance or achievements to be materially different from any future results, levels of activity, performance or achievements expressed or implied by such forward-looking statements. See "Note Regarding Forward-Looking Information" and "Risk Factors" in this Appendix "E".
Corporate Structure
Name, Address and Incorporation
Silver Hammer was incorporated under the laws of the Province of British Columbia and under the Business Corporations Act (British Columbia) ("BCBCA") on May 2, 2017 under the name "Lakewood Exploration Inc.". On October 1, 2021, Silver Hammer changed its name to "Silver Hammer Mining Corp.".
Silver Hammer's head office is located at Suite 300-1055 West Hastings Street, Vancouver, British Columbia, V6E 2E9. Silver Hammer's registered office is located at Suite 1500 - 1055 West Georgia Street, Vancouver, British Columbia, V6E 4N7.
The Silver Hammer Shares trade on the CSE under the symbol "HAMR". Silver Hammer is a reporting issuer in the provinces of British Columbia, Alberta and Ontario.
Intercorporate Relationships
Silver Hammer has four wholly-owned direct subsidiaries: (i) Silverstrand Exploration Corp. (formerly Silver Hammer Mining Corp.), a company incorporated under the laws of Canada; (ii) 1304562 B.C. Ltd., a company incorporated under the laws of British Columbia; (iii) 1001629888 Ontario Inc., a company incorporated under the laws of Ontario for the purposes of the Amalgamation; and (iv) 18076421 Canada Inc., a company incorporated under the laws of Canada for the purposes of the SilverMark Amalgamation. Silverstrand Exploration Corp. holds one wholly-owned subsidiary: 123456 US Inc., a company incorporated under the Delaware General Corporate Law. 1304562 B.C. Ltd. holds one wholly-owned subsidiary: 1304562 Nevada Ltd., a corporation incorporated under the laws of Nevada.
Silver Hammer's corporate structure is set out in the diagram below.
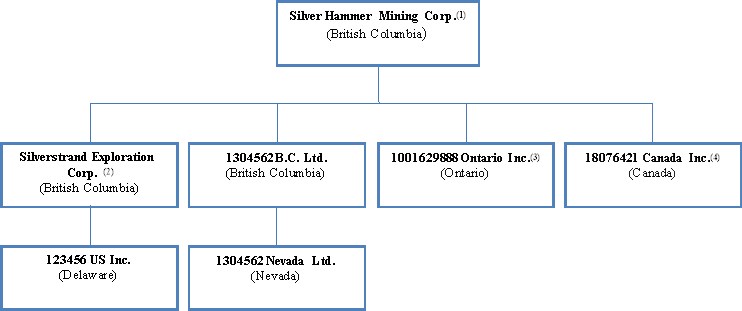
Notes:
(1) Formerly Lakewood Exploration Inc.
(2) Formerly Silver Hammer Mining Corp.
(3) Incorporated for the purposes of the Amalgamation.
(4) Incorporated for the purposes of the SilverMark Amalgamation.
General Development of the Business
The following is a description of the general development of the business of Silver Hammer over its three most recently completed financial years and up to the date of the Circular. The discussion includes the major events or conditions that have influenced that development through the aforementioned period. Silver Hammer's financial year end is September 30. Additional information regarding the matters described below may be found under Silver Hammer's profile on SEDAR+ at www.sedarplus.ca.
History
Year Ended September 30, 2023
In October 2022, Silver Hammer reported soil sampling results at its Eliza Silver Project in White Pine County, Nevada, with a total of 518 soil samples collected from the northern area of the property. The program outlined four distinct target areas - the Passynak, Belmont, California, and a newly identified Western Anomaly - all of which were identified for further evaluation as drill targets.
On November 23, 2022, Morgan Lekstrom resigned as President and Chief Executive Officer of Silver Hammer, and Warwick Smith was appointed as Interim President and Interim Chief Executive Officer, effective immediately.
In January 2023, Silver Hammer reported results from its Phase II drilling program at the Silver Strand Project in the Silver Valley Mining District near Coeur d'Alene, Idaho, comprising nine drill holes from an underground drilling station focused on testing historically mined gold-silver mineralization at greater depth and along strike.
On February 15, 2023, Silver Hammer appointed Peter A. Ball as President, Chief Executive Officer and Director, replacing Warwick Smith as Interim President and CEO. In connection with his appointment, Mr. Ball was granted options to purchase up to 750,000 common shares at an exercise price of $0.24 per share, and Silver Hammer granted an aggregate of 1,000,000 additional options to certain directors, officers, employees and consultants at $0.24 per share.
On March 15, 2023, Silver Hammer appointed Donald Birak as Board Advisor and granted Mr. Birak 185,000 stock options at an exercise price of $0.24 per common share for a period of five years.
In April 2023, Silver Hammer completed a property-wide geophysical compilation at the Silver Strand Project, identifying 15 moderate to priority exploration target zones, with the highest-ranked targets associated with chargeability anomalies within the Revett Formation, which hosts the Silver Strand Mine.
On April 5, 2023, Silver Hammer filed a NI 43-101 compliant technical report titled "Independent NI 43-101 Technical Report for the Silver Strand Gold-Silver Project, Kootenai County, Idaho, USA" on SEDAR+. An updated version of the technical report was subsequently filed on May 18, 2023 to make minor corrections and update certain information.
On April 11, 2023, Silver Hammer submitted a Plan of Operations to the United States Forest Service ("USFS") for the Silver Strand Project, proposing surface disturbance of 0.15 acres, up to 1,200 metres of drilling, and a comprehensive property-wide exploration program including geophysics, geologic mapping and structural analysis.
On May 2, 2023, Silver Hammer submitted a Plan of Operations to the Humboldt-Toiyabe National Forest Ranger District of the USFS for the Eliza Silver Project in White Pine County, Nevada, proposing 17 drill sites, 1.3 kilometres of road construction and rehabilitation, and up to 2,100 metres of drilling.
In May 2023, Silver Hammer commenced a property-wide airborne magnetic and radiometric survey at its 100%-owned Silverton Silver Mine Project in Nye County, Nevada. The airborne survey at the Eliza Project followed shortly thereafter.
On May 24, 2023, Silver Hammer closed a brokered private placement pursuant to the listed issuer financing exemption under Part 5A of National Instrument 45-106 - Prospectus Exemptions ("NI 45-106"), issuing 7,296,500 units at $0.25 per unit for gross proceeds of $1,824,125. Each unit consisted of one common share and one-half of one transferable common share purchase warrant, with each whole warrant entitling the holder to purchase one additional common share at $0.33 for a period of 24 months from the closing date. The agents received a cash commission of
$118,050, 472,200 broker warrants and a corporate finance fee of 120,000 units.
On September 27, 2023, Silver Hammer entered into a definitive share purchase agreement to acquire a 100% interest in the Shafter silver deposit located in Presidio County, Texas from Aurcana Silver Corporation ("Aurcana"), together with a proposed corporate reorganization to be implemented by way of a court-approved plan of arrangement under
the BCBCA. The consideration included US$800,000 in cash, 23,000,000 shares of a newly incorporated company ("Newco"), certain contingent payments, and, for the settlement of existing debt, $4,000,000 in secured convertible debentures and 8,000,000 units of Newco. In connection with the proposed transaction, Silver Hammer appointed Donald J. Birak as a director, replacing Joness Lang, who stepped down from the Director role but remained as a strategic advisor to Silver Hammer. Trading of Silver Hammer's common shares was halted upon announcement of the proposed transaction in accordance with the policies of the CSE.
Year Ended September 30, 2024
In January 2024, Silver Hammer reported that its Plan of Operations for the Silver Strand Project had been approved by the USFS, subject to payment of a reclamation bond, and that the Silverton Silver Mine Project had been permitted since March 2022 for up to 13 drill sites and 8,530 feet of drilling covering 2.35 acres. Silver Hammer continued to advance permitting at the Eliza Project.
On May 3, 2024, Silver Hammer determined that sufficient capital and investor interest was not available to proceed with the acquisition of the Shafter silver deposit and terminated the definitive share purchase agreement with Aurcana. Following termination, trading of Silver Hammer's common shares resumed on the CSE.
On September 23, 2024, Silver Hammer announced its intention to settle an aggregate of $186,400.02 in outstanding amounts owing for past consulting and accounting services by issuing 3,389,092 common shares at a deemed price of
$0.055 per share.
On October 1, 2024, Silver Hammer settled $186,400 in outstanding amounts owing to the President and CEO and CFO by issuing an aggregate of 3,389,092 common shares at a deemed price of $0.055 per share.
On December 16, 2024, Silver Hammer closed a private placement, issuing 3,072,700 units at $0.055 per unit for gross proceeds of $168,998.50. Each unit consisted of one common share and one transferable common share purchase warrant, with each warrant entitling the holder to purchase one additional common share at $0.07 for a period of three years from the closing date. Silver Hammer paid cash finders' fees of $5,285 and issued 96,089 non-transferable finders' warrants exercisable at $0.07 for three years.
Year Ended September 30, 2025
On April 7, 2025, Silver Hammer issued an aggregate of 4,569,956 common shares at a deemed price of $0.055 per share to settle outstanding payables totalling $251,347.56 owing pursuant to past consulting, accounting, legal and other services.
On April 21, 2025, Silver Hammer closed a non-brokered private placement, issuing 572,727 units at $0.055 per unit for gross proceeds of $31,500. Each unit consisted of one common share and one transferable common share purchase warrant, with each warrant entitling the holder to purchase one additional common share at $0.07 for a period of three years from the closing date. No finder's fees were paid in connection with the offering.
On May 1, 2025, Lawrence Roulston resigned as a director of Silver Hammer.
On August 1, 2025, Silver Hammer closed the first tranche of a non-brokered private placement, issuing 6,026,418 units at $0.055 per unit for gross proceeds of $331,453. Each unit consisted of one common share and one transferable common share purchase warrant, with each warrant entitling the holder to purchase one additional common share at
$0.07 for a period of five years from the date of issuance. In connection with the first tranche, Silver Hammer paid cash finders' fees of $7,315 and issued 133,000 finders' warrants exercisable at $0.07 for a period of five years from the date of issuance.
On August 5, 2025, Silver Hammer granted 4,300,000 stock options to directors, officers and consultants at an exercise price of $0.055 per share, exercisable for a period of five years, all of which vested immediately.
On September 15, 2025, Silver Hammer appointed Mr. Michael Willett, P.Eng., as a director of Silver Hammer, replacing Ron Burk, who resigned as a director but remained with Silver Hammer as Senior Technical Board Advisor. Silver Hammer also appointed Mr. Damir Cukor, P.Geo., as Technical Advisor - Projects and Qualified Person. In connection with these appointments, Silver Hammer granted 750,000 stock options at an exercise price of $0.08 per share, exercisable for a period of five years, all of which vested immediately. Also on September 15, 2025, Silver Hammer entered into an agreement to settle debt of US$90,684, including applicable interest, owing to a former service provider through the issuance of 1,500,000 common shares.
On September 18, 2025, Silver Hammer closed the second and final tranche of a non-brokered private placement, issuing 26,864,491 units at $0.055 per unit for gross proceeds of $1,477,547. Each unit consisted of one common share and one transferable common share purchase warrant, with each warrant entitling the holder to purchase one additional common share at $0.07 for a period of five years from the date of issuance. In connection with the second tranche, Silver Hammer paid cash finders' fees of $44,679 and issued 1,012,353 finders' warrants exercisable at $0.07 for a period of five years from the date of issuance.
During the year ended September 30, 2025, Silver Hammer changed its corporate office and principal place of business from Suite 400-1681 Chestnut Street, Vancouver, British Columbia, V6J 4M6 to Suite 300-1055 West Hastings Street, Vancouver, British Columbia, V6E 2E9.
Subsequent Events
On October 1, 2025, Silver Hammer issued 1,500,000 common shares at a deemed value of $0.0837 per share to settle debt of US$90,684 owing to a former service provider, as previously announced on September 15, 2025.
On October 10, 2025, Silver Hammer received an updated exploration drill permit for its Silverton Project in Nye County, Nevada, and subsequently posted its reclamation bond with the United States Bureau of Land Management.
On October 20, 2025, Silver Hammer entered into a mining option agreement (the "Fahey Option Agreement") with Fahey Group Mines, Inc. ("Fahey"), pursuant to which Silver Hammer was granted the right to acquire a 100% legal and beneficial interest in the Fahey Group Property (the "Fahey Property"), consisting of 360 acres covered by 18 unpatented US lode claims situated in the Silver Belt portion of the Coeur d'Alene Mining District in Shoshone County, Idaho. Under the terms of the Fahey Option Agreement, Silver Hammer may earn a 100% interest in the Fahey Property by: (i) paying Fahey an aggregate of US$50,000 in cash, payable in two installments of US$25,000 each; (ii) issuing an aggregate of $450,000 worth of common shares of Silver Hammer in installments through December 31, 2030, with each issuance priced at the volume-weighted average trading price of Silver Hammer's common shares on the CSE for the twenty (20) trading days prior to issuance, subject to CSE minimum pricing requirements, and with any shortfall resulting from a deemed price below $0.05 per share payable in cash; and (iii) incurring a minimum of $1,500,000 in eligible exploration expenditures on the Fahey Property, including a minimum of $200,000 on or before December 31, 2027 and a further $1,300,000 on or before December 31, 2030. Silver Hammer may extend the final share payment and exploration expenditure deadlines by one year through the issuance of an additional $50,000 worth of its common shares. Upon exercise of the Fahey Option, Fahey will retain a 2.0% net smelter returns royalty, which may be reduced by 0.5% upon payment of US$1,000,000, and a milestone payment of US$1,500,000 is payable upon commencement of commercial production. The Fahey Option Agreement is an arm's length transaction and no finder's fees are payable in connection therewith.
On October 29, 2025, Silver Hammer engaged Alford Drilling, LLC of Elko, Nevada to complete the Phase 1 drill program at the Silverton Project, comprising up to 5,000 feet in up to eight reverse circulation holes. Drilling commenced on December 3, 2025 and the Phase 1 program was completed in December 2025, comprising 2,420 feet within six reverse circulation holes, with samples submitted to ALS Laboratories in Reno, Nevada for analysis.
On February 17, 2026, Silver Hammer commenced an advanced data compilation of completed property-wide geophysical and geological datasets at both the Eliza and Silverton projects in advance of its 2026 exploration program.
On February 20, 2026, Silver Hammer closed a non-brokered private placement pursuant to the listed issuer financing exemption under Part 5A of NI 45-106, issuing 39,136,170 units at $0.10 per unit for gross proceeds of $3,913,617. Each unit consisted of one common share and one-half of one common share purchase warrant, with each whole warrant entitling the holder to purchase one additional common share at $0.15 for a period of 36 months from the closing date. In connection with the offering, Silver Hammer paid cash finders' fees of $147,490 and issued 1,474,900 finders' warrants exercisable at $0.15 for 36 months.
On March 11, 2026, Silver Hammer announced plans for a Phase 1 drill program of up to 15 holes comprising approximately 1,500 metres on its 100%-owned California Patented Claim within the Eliza Silver Project in White Pine County, Nevada, targeting five mineralized structures identified from historical geological data.
On April 7, 2026, Silver Hammer reported positive assay results from its Phase 1 drill program at the Silverton Silver Mine Project in Nye County, Nevada, comprising six drill holes totalling 738 metres.
On May 11, 2026, Silver Hammer announced the commencement of a summer surface reconnaissance program at the Fahey Property, focused on confirming the surface location of the Upper Revett Formation across fault blocks and reviewing mineralization at known adit portals and vein exposures, with a view to filing a Plan of Operations by end of summer to receive a permit for an anticipated deep drill hole program.
On July 15, 2026, Andrew Gillin was appointed Vice President, Corporate Development & Investor Relations of Silver Hammer.
On July 27, 2026, Silver Hammer announced the commencement of a surface exploration program at its Eliza Silver Project located in Elko County, Nevada. The program consists of geological mapping, rock and soil sampling, and prospecting over approximately 2,400 hectares, with results intended to prioritize targets for future drill programs.
See "Amalgamation" and "SilverMark Amalgamation" in this Appendix "E" for a description of the pending Amalgamation and the SilverMark Amalgamation.
Significant Acquisitions
Silver Hammer has not completed any significant acquisitions during its most recently completed financial year for which disclosure is required under Part 8 of National Instrument 51-102 - Continuous Disclosure Obligations ("NI 51-102").
Amalgamation
On July 17, 2026, Silver Hammer entered into the Combination Agreement with 1001629888 Ontario Inc. ("Subco"), a wholly-owned Ontario subsidiary of Silver Hammer incorporated for the purposes of the Amalgamation, and Stroud. Pursuant to the Combination Agreement, Silver Hammer will acquire all of the issued and outstanding Stroud Shares by way of a three-cornered amalgamation under the OBCA, pursuant to which Subco and Stroud will complete the Amalgamation, with the resulting amalgamated corporation continuing as a wholly-owned subsidiary of Silver Hammer.
For a description of the material terms of the Amalgamation and the Combination Agreement, see "The Amalgamation" and "Summary of the Combination Agreement" in the Circular.
Consolidation
Prior to the effective time of the Amalgamation, Silver Hammer will complete the Consolidation of all issued and outstanding Silver Hammer Shares on a 4:1 basis (one post-Consolidation Silver Hammer Share for each four pre-Consolidation Silver Hammer Shares). No fractional Silver Hammer Shares will be issued in connection with the Consolidation; any fractional entitlements will be rounded down to the nearest whole number.
SilverMark Amalgamation
Parties and Structure
Concurrently with the execution of the Combination Agreement, on July 17, 2026, Silver Hammer entered into a business combination agreement (the "SilverMark Agreement") with 18076421 Canada Inc. ("CAN Subco"), a wholly-owned subsidiary of Silver Hammer incorporated under the laws of Canada for the purposes of the SilverMark Amalgamation, and SilverMark Resources Inc. ("SilverMark"), a private corporation existing under the laws of Canada. SilverMark does not have any subsidiaries. SilverMark has entered into a series of option agreements with SABI-AIM Minerals, a corporation organized under the laws of Morocco, pursuant to which SilverMark has the right to acquire up to a 75% interest (or the maximum earn-in interest available) in a portfolio of Moroccan mineral assets (collectively, the "Moroccan Assets"), including: (i) the past-producing Akka Mine and related mineral properties (the "Akka Mine"); (ii) a portfolio of additional mining concessions and permits designated as "Group A Properties" and "Group B Properties" respectively under the applicable SABI-AIM Option Agreements (as defined below); and (iii) certain stockpile areas and associated ore, tailings and rock (the "Stockpile Properties"). Upon completion of the SilverMark Amalgamation, Silver Hammer will assume all of SilverMark's obligations under the SABI-AIM Option Agreements and will succeed to SilverMark's rights to earn into the Moroccan Assets.
Pursuant to the SilverMark Agreement, Silver Hammer will acquire all of the issued and outstanding Class A common shares of SilverMark (the "SilverMark Class A Common Shares") and Class B special shares of SilverMark (the "Class B Special Shares") by way of a three-cornered amalgamation under the Business Corporations Act (Canada) ("CBCA"), pursuant to which CAN Subco and SilverMark will amalgamate (the "SilverMark Amalgamation"), with the resulting amalgamated corporation continuing under the name "SilverMark Resources Inc." as a wholly-owned subsidiary of Silver Hammer. The SilverMark Amalgamation is expected to occur prior to or concurrently with the Amalgamation. The SilverMark Amalgamation does not itself require shareholder approval from Silver Hammer shareholders; however, Silver Hammer shareholders are required to approve the creation and authorization of the Contingent Value Shares (as defined herein) as part of the items to be considered at the Silver Hammer Meeting.
Share Capital
As at the date of the SilverMark Agreement, the authorized capital of SilverMark consisted of an unlimited number of SilverMark Class A Common Shares and an unlimited number of Class B Special Shares, of which 13,888,889 SilverMark Class A Common Shares and 3,937,500 Class B Special Shares were validly issued and outstanding as fully paid and non-assessable. As at the date of the SilverMark Agreement, SilverMark had 833,333 outstanding warrants to acquire SilverMark Class A Common Shares, with each SilverMark warrant entitling the holder to acquire one SilverMark Class A Common Share at a price of $0.12 per share until May 4, 2028. As at the date of the SilverMark Agreement, SilverMark had no outstanding stock options or other convertible securities, other than the SilverMark warrants.
SilverMark is not a reporting issuer in any jurisdiction and its shares are not listed or posted for trading on any stock exchange.
Consideration
As consideration for the SilverMark Amalgamation: (i) each of the 13,888,889 issued and outstanding SilverMark Class A Common Shares (other than shares held by SilverMark shareholders who validly exercise dissent rights) will be cancelled and exchanged for 0.346154 of one (1) Silver Hammer Share on a post-Consolidation basis (the "SilverMark Exchange Ratio"), resulting in the issuance of approximately 4,807,692 Silver Hammer Shares to SilverMark Class A Common Shareholders (on a post-Consolidation basis); and (ii) each of the 3,937,500 issued and outstanding Class B Special Shares (other than shares held by SilverMark shareholders who validly exercise dissent rights) will be cancelled and exchanged for such number of Contingent Value Shares as is equal to the quotient obtained by dividing (x) $1,575,000 by (y) the product of the Offering Price (as defined herein) multiplied by the number of Class B Special Shares outstanding immediately prior to the effective time of the SilverMark Amalgamation (the "Class B Exchange Ratio"). The Class B Exchange Ratio is approximately 1.5384. No fractional Silver Hammer Shares or Contingent Value Shares will be issued. The Contingent Value Shares will be created and authorized pursuant to an amendment to Silver Hammer's articles, subject to approval by Silver Hammer shareholders at the Silver Hammer Meeting. Each Contingent Value Share will be convertible into one (1) Silver Hammer Share upon the occurrence of the applicable Milestone Conversion Event in accordance with the Milestone Conversion Table (as described below), pursuant to the Conversion Notice process described under "Description of Capital Structure - Contingent Value Shares". Up to an aggregate of 6,057,692 Contingent Value Shares are issuable and convertible into Silver Hammer Shares upon the occurrence of all Milestone Conversion Events (based on the Offering Price of $0.26 per Subscription Receipt and 3,937,500 Class B Special Shares outstanding). Each of the 833,333 outstanding SilverMark warrants will, in accordance with its terms, following the effective time of the SilverMark Amalgamation, be adjusted to reflect the SilverMark Exchange Ratio and be exercisable for up to an aggregate of 288,461 Silver Hammer Shares (on a post-Consolidation basis) at an adjusted exercise price reflecting the SilverMark Exchange Ratio.
Milestone Conversion Events
The Milestone Conversion Events and the corresponding number of Contingent Value Shares convertible upon the occurrence of each are set out below:
Conditions Precedent
Completion of the SilverMark Amalgamation is subject to a number of conditions precedent, including the following:
Mutual Conditions
(i) the SilverMark shareholder approval being obtained by written consent resolution in accordance with the CBCA; (ii) the approval of the Silver Hammer shareholders at the Silver Hammer Meeting, including approval of the creation and authorization of the Contingent Value Shares and any required amendments to Silver Hammer's articles; (iii) receipt of all requisite regulatory approvals, including the approval of the CSE; (iv) completion of the Consolidation; (v) satisfaction or waiver of all conditions precedent to the Amalgamation, other than completion of the SilverMark Amalgamation itself; (vi) completion of the Private Placement for minimum gross proceeds of $7,000,000; (vii) receipt of all required approvals for the listing on the CSE of the Silver Hammer Shares issuable pursuant to the SilverMark Amalgamation; (viii) no order or decree being in force restraining or enjoining the completion of the SilverMark Amalgamation; (ix) the distribution of Silver Hammer Shares and Contingent Value Shares pursuant to the SilverMark Amalgamation being exempt from, or not subject to, prospectus requirements under applicable Canadian securities laws; and (x) the distribution of Silver Hammer Shares and Contingent Value Shares in the United States in exchange for SilverMark Shares being exempt from registration requirements under applicable U.S. securities laws.
Additional Conditions in Favour of Silver Hammer
(i) all representations and warranties of SilverMark being true in all material respects as of the effective date; (ii) SilverMark having complied with its covenants under the SilverMark Agreement; (iii) no material adverse effect on SilverMark having occurred; (iv) holders of no more than 5% of the SilverMark Shares having validly exercised dissent rights; (v) the SABI-AIM Option Agreements being in good standing and enforceable and no notice of default having been delivered by any party thereunder; (vi) SilverMark having no undisclosed indebtedness, liabilities or obligations; and (vii) receipt by Silver Hammer of executed releases and resignations from all members of the SilverMark board and such officers of SilverMark as Silver Hammer may request.
Additional Conditions in Favour of SilverMark
Under the SilverMark Agreement, the following conditions in favour of SilverMark are required to be satisfied prior to closing the SilverMark Amalgamation: (i) all representations and warranties of Silver Hammer being true in all material respects as of the effective date; (ii) Silver Hammer having complied with its covenants under the SilverMark Agreement; (iii) receipt of all required third-party and regulatory approvals by Silver Hammer, including approval of the CSE; (iv) no material adverse effect on Silver Hammer having occurred; and (v) the Silver Hammer Shares and Contingent Value Shares issued as consideration being fully paid and non-assessable, free and clear of all encumbrances.
There can be no certainty, nor can Silver Hammer provide any assurance, as to if and when all conditions will be satisfied or waived.
Termination
The SilverMark Agreement may be terminated in certain circumstances, including: (i) by mutual consent of the parties;
(ii) by either party, if the other party provides notice of its inability to comply with any covenant, condition or agreement to be complied with or satisfied by it under the SilverMark Agreement; (iii) by either party, if the other party is in material breach of any representation, warranty, covenant or agreement that is not cured within ten (10) business days of written notice; (iv) by either party, if the SilverMark Amalgamation has not been completed by November 30, 2026, provided the terminating party is not itself in material breach; (v) by Silver Hammer, if a material adverse effect on SilverMark has occurred; (vi) by SilverMark, if a material adverse effect on Silver Hammer has occurred; or (vii) by Silver Hammer, following a Recommendation Change by the SilverMark board. Termination of the SilverMark Agreement will not relieve any party of obligations that have accrued prior to termination, including SilverMark's payment obligations in respect of the SilverMark Compensation Fee (defined below).
Compensation Fee and D&O Protection
A compensation fee equal to $500,000 (the "SilverMark Compensation Fee") is payable by SilverMark to Silver Hammer (and is a genuine pre-estimate of Silver Hammer's damages, and not a penalty) upon the occurrence of any of the following events: (a) following a Recommendation Change by the SilverMark board, the SilverMark shareholder approval is not obtained; (b) the SilverMark shareholder approval is not obtained following a Superior Proposal and, within 12 months of the date on which shareholder approval was sought, SilverMark enters into or consummates an alternative change of control transaction; or (c) SilverMark fails to obtain the SilverMark shareholder approval within 21 days of signing the SilverMark Agreement (or such later date as may be mutually agreed). Directors and officers of SilverMark who are asked to resign upon completion of the SilverMark Amalgamation will receive indemnification rights and directors' and officers' liability insurance coverage maintained by Silver Hammer for a period of not less than six (6) years from the effective date of the SilverMark Amalgamation.
SABI-AIM Option Agreements
Upon completion of the SilverMark Amalgamation, Silver Hammer will assume all of SilverMark's rights and obligations under the SABI-AIM Option Agreements, pursuant to which SilverMark has the right to earn up to a 75% interest (or the maximum earn-in interest available) in each of the Moroccan Assets. The SABI-AIM Option Agreements consist of four separate option agreements, each dated July 16, 2026, between SilverMark (as optionee) and the applicable Moroccan optionor(s) (collectively, "SABI-AIM"), in respect of: (i) the Akka Mine exploitation licence and related mineral properties (the "Akka Mine Agreement"); (ii) a portfolio of 18 mining exploration permits and one exploitation licence designated as the Group A Properties (the "Group A Agreement"); (iii) a portfolio of 14 mining exploration permits designated as the Group B Properties, together with an additional permit and up to 30 further permits comprising the "Subgroup B2 Permits" (the "Group B Agreement"); and (iv) the Stockpile Properties, together with an associated processing mill (the "Stockpile Agreement", and together with the Akka Mine Agreement, the Group A Agreement and the Group B Agreement, the "SABI-AIM Option Agreements").
The share consideration payable under the SABI-AIM Option Agreements is denominated in common shares of the publicly listed entity resulting from the going public transaction contemplated thereunder - being, following completion of the Amalgamation and the SilverMark Amalgamation, Resulting Issuer Shares. Under each agreement, Silver Hammer (as successor to SilverMark) is solely responsible for all costs and expenses of every kind in respect of the applicable properties, including upkeep, maintenance, technical work, property holding costs, renewals, governmental charges and operational expenditures, until the final option under each respective agreement is exercised. Silver Hammer is also obligated to carry out all operations on the properties in a careful and professional manner, in accordance with recognized industry practices and in full conformity with all applicable mining and environmental laws and regulations of Morocco, and to undertake sufficient work to keep each property in good standing under applicable law.
The earn-in payments under each of the four SABI-AIM Option Agreements are structured as a series of options, each of which Silver Hammer may elect to exercise in sequence to earn up to a maximum 75% interest in the applicable property. The share consideration payable at the closing of the Amalgamation and the SilverMark Amalgamation (i.e., at the First Option Deadline) is valued at the implied price per Resulting Issuer Share of the Private Placement; share consideration payable in respect of any subsequent option payments is valued at the greater of: (i) the volume weighted average price of the Resulting Issuer Shares for the twenty (20) trading days prior to the date of exercise of the applicable option; and (ii) the minimum price at which the applicable stock exchange will permit. No fractional Resulting Issuer Shares will be issued in connection with any share issuance under the SABI-AIM Option Agreements.
The aggregate initial earn-in consideration payable at the closing of the Amalgamation and the SilverMark Amalgamation across all four agreements is US$667,647 in cash and US$145,529 in post-Consolidation Silver Hammer Shares, which will result in SilverMark exercising the first earn-ins under each of the SABI-AIM Option Agreement and acquiring a 51% interest in each of the Moroccan Assets except the permits comprising the "Subgroup B2 Permits" governed by the Group B Agreement, in which SilverMark will acquire a 60% interest. If all options under all four agreements are exercised to earn the maximum 75% interest, the combined aggregate earn-in consideration payable by Silver Hammer (inclusive of all closing and subsequent payments) would be approximately US$1,350,000 in cash and US$248,000 in Silver Hammer Shares (subject to applicable pricing mechanics).
The earn-in payment schedule under each agreement, inclusive of the closing payment, is as follows:
Akka Mine Agreement (four options in total; maximum 75% interest):
The total aggregate earn-in consideration under the Akka Mine Agreement (inclusive of the closing payment) is approximately US$360,000 in cash and US$60,000 in Resulting Issuer Shares.
Group A Agreement (four options in total; maximum 75% interest):
The total aggregate earn-in consideration under the Group A Agreement (inclusive of the closing payment) is approximately US$240,000 in cash and US$48,000 in Resulting Issuer Shares.
Group B Agreement (five options in total; maximum 75% interest across Subgroup B1 and Subgroup B2 Permits):
The total aggregate earn-in consideration under the Group B Agreement (inclusive of the closing payment) is approximately US$450,000 in cash and US$90,000 in Resulting Issuer Shares.
Stockpile Agreement (two options in total; maximum 75% interest in the Polymetallic Stock):
The total aggregate earn-in consideration under the Stockpile Agreement (inclusive of the closing payment) is approximately US$300,000 in cash and US$50,000 in Resulting Issuer Shares.
Under each of the Akka Mine Agreement, Group A Agreement and Group B Agreement, Silver Hammer may purchase one six-month extension to exercise any subsequent option for US$5,000 in cash payable to the applicable optionor.
Additional Payment Obligations and Arrangements
In addition to the earn-in payments described above, the SABI-AIM Option Agreements provide for the following additional payment obligations and arrangements:
Private Placement
In connection with the Amalgamation and the SilverMark Amalgamation, SilverMark intends to complete the Private Placement of a minimum of 26,923,077 and a maximum of 38,461,538 Subscription Receipts at a price of $0.26 per Subscription Receipt (the "Offering Price") for aggregate gross proceeds of up to $10,000,000 (or such greater amount as may be determined by the parties), with a minimum gross proceeds threshold of $7,000,000 required for the release of escrowed funds. The Private Placement is being conducted on a "best efforts" basis by Red Cloud Securities Inc. as Lead Agent and sole bookrunner, together with Research Capital Corp. as co-lead agent and any additional Agents appointed by the Lead Agent. The Lead Agent has also been granted the Agents' Option, exercisable up to 48 hours prior to the closing of the Private Placement, to sell up to an additional 7,692,308 Subscription Receipts at the Offering Price for additional gross proceeds of up to $2,000,000. If the Agents' Option is exercised in full, the aggregate maximum gross proceeds of the Private Placement would be $12,000,000 (or such greater amount as may be determined by the parties). The net proceeds of the Private Placement are intended to be used to fund advancement of the Resulting Issuer's silver project portfolio and for working capital and general corporate purposes.
All subscription funds received in connection with the Private Placement, net of the Agents' reasonable out-of-pocket expenses, will be held in escrow by the Subscription Receipt Agent, being a Canadian trust company or other escrow agent acceptable to SilverMark and the Agents, in an interest-bearing account, pending satisfaction of the escrow release conditions. The escrow release conditions include, among other things: (i) satisfaction or waiver of all conditions precedent to the Amalgamation and the SilverMark Amalgamation; (ii) receipt of all required regulatory approvals, including the approval of the CSE; and (iii) such other conditions as may be agreed between SilverMark and the Agents. Upon satisfaction or waiver of the escrow release conditions, each Subscription Receipt will be automatically converted, without payment of additional consideration or further action by the holder, into such number of units of SilverMark as is equal to the reciprocal of the SilverMark Exchange Ratio (being the number obtained by dividing one (1) by the SilverMark Exchange Ratio of 0.346154, being approximately 2.888889 SilverMark units for each Subscription Receipt), with each unit consisting of: (i) one (1) SilverMark Class A Common Share; and (ii) one (1) SilverMark warrant. The SilverMark Class A Common Shares and SilverMark warrants issuable on conversion of the Subscription Receipts will, pursuant to the SilverMark Amalgamation, be exchanged for Resulting Issuer Shares and warrants exercisable for Resulting Issuer Shares (the "Resulting Issuer Warrants"), respectively, such that each Subscription Receipt will ultimately result in the issuance of one (1) Resulting Issuer Share and one (1) Resulting Issuer Warrant (calculated as the product of approximately 2.888889 SilverMark Class A Common Shares or SilverMark warrants, as applicable, multiplied by the SilverMark Exchange Ratio of 0.346154, which in each case equals one (1)). Each such Resulting Issuer Warrant will be exercisable to acquire one Resulting Issuer Share at a price of $0.38 per share (on a post-Consolidation basis) for a period of 36 months following the closing date of the Private Placement. No fractional Resulting Issuer Shares or Resulting Issuer Warrants will be issued.
In the event that the escrow release conditions are not satisfied or waived prior to October 31, 2026 (or such other date as may be agreed upon by SilverMark, Silver Hammer and the Agents), or if SilverMark advises the Lead Agent or announces to the public that it does not intend to satisfy the escrow release conditions, the Subscription Receipt Agent will return to each holder of Subscription Receipts an amount equal to the aggregate Offering Price of the Subscription Receipts held by such holder, together with such holder's pro rata portion of any interest earned on the escrowed funds (less any applicable withholding taxes). In such circumstances, the Subscription Receipts will be cancelled and of no further force or effect.
In connection with the Private Placement, SilverMark will pay the Agents a cash commission equal to 7.0% of the gross proceeds from the sale of Subscription Receipts, and will issue to the Agents broker warrants equal to 7.0% of the number of Subscription Receipts sold, with each broker warrant exercisable to acquire one SilverMark Class A Common Share (exchangeable for one Resulting Issuer Share pursuant to the Amalgamation and the SilverMark Amalgamation) at the Offering Price for a period of 24 months following the closing date. The broker warrants will only be exercisable upon satisfaction or waiver of the escrow release conditions.
Description of Business
Overview
Silver Hammer is a mineral exploration and development company focused on acquiring, exploring, and advancing precious metals projects. Silver Hammer's current strategy is centered on advancing its portfolio of silver projects in Idaho and Nevada (USA). Upon completion of the Amalgamation and the SilverMark Amalgamation, Silver Hammer's portfolio will expand to include the Santo Domingo silver-gold property in Jalisco, Mexico and an indirect interest in the Akka Mine silver and polymetallic project in Morocco. Silver Hammer's strategy is centered on:
Silver Hammer currently holds three exploration-stage mineral properties: the Silver Strand Project, located in the Silver Valley Mining District of Kootenai County, Idaho; the Eliza Silver Project, located in White Pine County, Nevada; and the Silverton Silver Mine Project, located in Nye County, Nevada. In October 2025, Silver Hammer entered into the Fahey Option Agreement to acquire a 100% interest in the Fahey Property, comprising 18 unpatented US lode mining claims in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho. Silver Hammer fundamentally believes in the long-term value of precious metals exploration, especially silver and gold.
Silver Hammer's common shares are listed on the CSE under the symbol "HAMR". Silver Hammer is led by a technical and management team with extensive experience in exploration, permitting, capital markets, and development of mining projects in the Western United States, including Idaho and Nevada.
Principal Products or Services
Silver Hammer is an exploration-stage company and does not currently mine, produce, or sell any mineral products. None of Silver Hammer's properties contain any known or identified mineral resources or mineral reserves as defined under applicable securities legislation. Silver Hammer's exploration activities are focused primarily on silver, with secondary exposure to gold and copper.
As an exploration-stage issuer with no producing properties, Silver Hammer does not generate operating income, cash flow, or revenue. Silver Hammer has not completed any mineral resource estimates on its properties. There is no assurance that a commercially viable mineral deposit exists on any of Silver Hammer's projects. Silver Hammer does not expect to receive income from its properties in the foreseeable future.
Silver Hammer intends to continue evaluating, exploring, and advancing its projects through additional financings. Silver Hammer's primary objective is to explore and assess its portfolio of silver projects, and it intends to undertake exploration work programs consistent with recommendations from its geological and technical advisors.
Production and Sales
Silver Hammer has no producing properties and therefore has no production or sales activities at this time. Specialized Skill and Knowledge
Mineral exploration and development requires a broad range of specialized skills and expertise, including geology, engineering, environmental compliance, drilling, logistical planning, project management, finance, accounting, and legal. Silver Hammer relies on both internal personnel and external consultants who possess these skills. To attract and retain qualified individuals, Silver Hammer seeks to maintain competitive compensation structures and consultant arrangements.
Competitive Conditions
As a mineral exploration and development company, Silver Hammer may compete with other entities in the mineral exploration and development business in various aspects, including: (a) seeking out and acquiring mineral exploration and development properties; (b) obtaining the resources necessary to identify and evaluate mineral properties and to conduct exploration and development activities on such properties; and (c) raising the capital necessary to fund its operations. The mining industry is intensely competitive in all its phases, and Silver Hammer may compete with other companies that have greater financial resources and technical facilities. Competition could adversely affect Silver Hammer's ability to acquire suitable properties or prospects in the future or to raise the capital necessary to continue with operations. See "Risk Factors" in this Appendix "E".
Cycles
The mineral exploration industry is cyclical. Silver Hammer's ability to raise capital and advance exploration programs is heavily influenced by global economic conditions and by fluctuations in the prices of silver and gold. These prices have experienced substantial volatility in recent years and are difficult to forecast. Periods of declining commodity prices can reduce investor interest in exploration companies, restrict access to capital, and negatively impact the economic potential of Silver Hammer's projects.
External events, including global economic disruptions, financial market instability, geopolitical developments, and public health emergencies, may further exacerbate commodity price volatility and financing challenges. Such conditions may affect Silver Hammer's ability to implement its business plans. See "Risk Factors" in this Appendix "E".
Economic Dependence
As an exploration-stage company with no producing assets or operating revenue, Silver Hammer is economically dependent on its ability to obtain external financing to fund its operations and exploration programs. Silver Hammer also relies heavily on its portfolio of mineral projects in Idaho and Nevada, and its future business prospects are dependent on the successful advancement of these projects. Upon completion of the Amalgamation and the SilverMark Amalgamation, Silver Hammer will also have exposure to the Santo Domingo silver-gold property in Jalisco, Mexico and the Akka Mine silver and polymetallic project in Morocco. These additional properties will expand Silver Hammer's geographic and jurisdictional exposure significantly, including to jurisdictions that carry materially different political, regulatory, and operational risks. See "Risk Factors" in this Appendix "E".
Silver Hammer may additionally depend on a limited number of consultants, contractors, and service providers to carry out key exploration and technical activities. Any disruption in access to financing, Silver Hammer's mineral projects, or essential third-party services could have a material adverse effect on Silver Hammer's business and planned exploration activities.
Environmental Protection
Silver Hammer is subject to the laws and regulations relating to environmental matters in all jurisdictions in which it operates, including provisions relating to property reclamation, discharge of hazardous materials and other matters. Silver Hammer may also be held liable should environmental problems be discovered that were caused by former owners and operators of its properties. Silver Hammer conducts its mineral exploration activities in compliance with applicable environmental protection legislation. Silver Hammer is not aware of any existing environmental problems related to any of its properties that may result in material liability to Silver Hammer.
Future changes to environmental laws or regulations, or more stringent enforcement, could result in increased costs, operating restrictions, or delays in planned exploration activities. Additional information on environmental risks is provided under "Risk Factors" in this Appendix "E".
Employees
As of the date hereof, Silver Hammer has no permanent full-time or part-time employees. Silver Hammer's operations are managed by its directors and officers, and Silver Hammer anticipates engaging consultants in geology, exploration, and related technical and administrative fields as required.
Foreign Operations and Governmental Regulation
Silver Hammer's mineral projects are located in the United States and are subject to the political, economic, regulatory, and social conditions of that jurisdiction. Silver Hammer's exploration activities across its Idaho and Nevada projects are governed by extensive federal, state, and local laws and regulations relating to environmental protection; the use and management of hazardous substances and explosives; natural resource management; mineral exploration; mine development, operation, and closure; reclamation and remediation; exports; taxation; business dealings with Indigenous peoples; labour and occupational health and safety (including mine safety); and the preservation of historic and cultural resources.
Regulatory approvals, permits, and licences are required for various aspects of Silver Hammer's exploration activities, and such approvals may not be granted on a timely basis or at all. Changes to permitting processes, amendments to taxation or mining policies, shifts in enforcement practices, or broader regulatory changes at the federal or state level could impose additional costs, new restrictions, or delays on Silver Hammer's planned exploration programs. Failure to comply with applicable laws may result in fines, penalties, permit revocation, loss of mineral rights, or requirements to undertake corrective or remedial measures, which could involve significant expenditures. Silver Hammer may also be required to compensate third parties for loss or damage arising from regulatory non-compliance.
These regulatory and governmental risks, together with broader U.S. political and economic uncertainties - such as currency fluctuations, inflation, labour issues, or increased environmental advocacy - could have a material impact on Silver Hammer's operations, financial condition, or future profitability. See "Risk Factors" in this Appendix "E".
Upon completion of the Amalgamation and the SilverMark Amalgamation, Silver Hammer's operations will expand to include mineral projects in Mexico and Morocco, each of which carries its own distinct regulatory, political, and operational risk profile. The Santo Domingo property in Jalisco, Mexico, held through Stroud, will subject Silver Hammer to Mexican federal and state laws and regulations governing mineral exploration and development, environmental protection, land use, Indigenous community consultation, and export controls, as well as the general political and economic conditions of Mexico, including risks relating to changes in government policy, currency controls, taxation, and social instability. The Akka Mine project in Morocco, held indirectly through SilverMark's interest in the Moroccan Assets, will subject Silver Hammer to Moroccan laws and regulations governing mining rights, foreign investment, environmental standards, labour, and export of mineral products. Silver Hammer's ability to maintain and advance its interest in the Akka Mine is also subject to the terms and conditions of the SABI-AIM Option Agreements, including the satisfaction of earn-in obligations. Operating in these jurisdictions exposes Silver Hammer to risks that are in addition to, and in some respects materially greater than, those associated with its existing U.S. operations, including less developed legal and regulatory frameworks, the potential for adverse changes in foreign investment laws, and heightened currency and repatriation risk. See "Risk Factors" in this Appendix "E".
Lending Operations, Investment Policies and Restrictions
Silver Hammer has not adopted any specific investment or lending policies but will ensure that any investment or debt-related activities undertaken are consistent with the interests of Silver Hammer and its shareholders.
Bankruptcy and Similar Procedures
There is no bankruptcy, receivership or similar proceedings against Silver Hammer, nor is Silver Hammer aware of any such pending or threatened proceedings. There have not been any voluntary bankruptcy, receivership or similar proceedings by Silver Hammer since incorporation or currently proposed for the current financial year.
Reorganizations
There have been no material reorganizations of or involving Silver Hammer within the three most recently completed financial years or during the current financial year. Silver Hammer has proposed the Amalgamation, which, if completed, may constitute a material reorganization of Silver Hammer. The Amalgamation and the SilverMark Amalgamation have not yet been completed as at the date of the Circular. See "Amalgamation" and "SilverMark Amalgamation" in this Appendix "E" for further details.
Social or Environmental Policies
At its current stage of development and activities, Silver Hammer has limited financial obligations in meeting applicable environmental standards. This may change as Silver Hammer advances its projects. Environmental regulations applicable to Silver Hammer cover a wide variety of matters, including, without limitation, prevention of waste, pollution and protection of the environment, labour regulations and worker safety. While Silver Hammer does not currently expect the impact of costs and other effects related to compliance with environmental, health and safety regulations to have a material adverse effect on its financial condition or results of operations, such regulations are evolving in a manner which is likely to result in stricter standards and enforcement, increased fines and penalties for non-compliance, more stringent environmental assessments of proposed projects, and a heightened degree of responsibility for companies and their directors and employees. Such stricter standards could impact Silver Hammer's costs and have an adverse effect on results of operations. Furthermore, an environmental, safety or security incident could impact Silver Hammer's reputation in such a way that the result could have a material adverse effect on its business and on the value of its securities.
Trends, Commitments, Events or Uncertainties
There are significant uncertainties related to the price of silver, gold, and other minerals, as well as the availability of equity financing required to support current and future mineral exploration and development activities. Mineral prices have experienced substantial volatility in recent years, and similar fluctuations are expected to continue. There is no guarantee that Silver Hammer will be able to secure the financing necessary to advance its exploration programs or pursue new opportunities. Any inability to raise funds on a timely basis may constrain Silver Hammer's ability to grow and execute its business strategy. Apart from these risks and those identified under "Risk Factors" in this Appendix "E", Silver Hammer is not aware of any additional trends, commitments, events, or uncertainties that are reasonably likely to have a material adverse effect on its business, financial condition, or results of operations.
Mineral Projects
Silver Hammer holds a 100% interest in three mineral exploration properties: the Silver Strand Project, located in the Silver Valley Mining District of Kootenai County, Idaho; the Eliza Silver Project, located in White Pine County, Nevada; and the Silverton Silver Mine Project, located in Nye County, Nevada. Silver Hammer also holds an option to acquire a 100% interest in the Fahey Property, comprising 18 unpatented lode mining claims in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho.
As at the date of the Circular, the Silver Strand Project is Silver Hammer's only material property. On April 5, 2023, Silver Hammer filed an NI 43-101 compliant technical report titled "Independent NI 43-101 Technical Report for the Silver Strand Gold-Silver Project, Kootenai County, Idaho, USA" on SEDAR+, an updated version of which was subsequently filed on May 18, 2023 to make minor corrections and update certain information. A description of the Silver Strand Project is set out under "Mineral Projects - Silver Strand Project" below in this Appendix "E".
Silver Strand Project
As at the date of the Circular, the Silver Strand Project is Silver Hammer's only material property.
The following disclosure regarding the Silver Strand Project is primarily extracted and derived from the technical report entitled "Independent NI 43-101 Technical Report for the Silver Strand Gold-Silver Project, Kootenai County, Idaho, USA" (the "Technical Report") prepared by Dr. Wayne Barnett, Ph.D., P.Geo. of SRK Consulting (Canada) Inc. ("SRK"), with an effective date of November 3, 2022 and a report date of May 13, 2023. The Technical Report was prepared in accordance with NI 43-101 and is available under Silver Hammer's profile on SEDAR+ at www.sedarplus.ca. The following disclosure is subject to all of the assumptions, qualifications and procedures set out in the Technical Report, and readers are encouraged to review the Technical Report in its entirety.
Property Description and Location
The Silver Strand Mine is located in Kootenai County, Idaho, approximately 19 km (12 miles) east-northeast of Coeur d'Alene in northern Idaho. The property lies on Lone Cabin Creek, a tributary of Burnt Cabin Creek and of the Little North Fork Coeur d'Alene River, within the Coeur d'Alene mining district. The land subdivision location is Section 19, T51N, R1W and the adjacent Section 24, T51N, R2W. The property is situated within the Idaho Panhandle National Forest, administered by the Fernan Ranger District of the U.S. Forest Service. Access to the property is via the Fernan Lake Road east of Coeur d'Alene, with forest service roads providing access that is limited in winter by heavy snowfall. A secondary access route is available via the Coeur d'Alene River Road from Enaville, Idaho. The property lies within the Coeur d'Alene ranges of the Northern Rocky Mountains, with the access road situated at approximately 975 m (3,200 ft) above mean sea level and the hilltop at approximately 1,290 m (4,229 ft) above mean sea level. The climate in Kootenai County is characterized by warm summers and cool winters, with average annual precipitation of approximately 82.3 cm (32.4 inches). Snow accumulation during winter months may inhibit access to drilling sites. For further details regarding the property's location, access, physiography, and climate, see Sections 4 and 5 of the Technical Report.
Ownership and Agreements
The Silver Strand Mine is 100% owned by Silver Hammer through its subsidiary 123456 US Inc. The property consists of 78 unpatented lode mining claims located on Federal land. Silver Hammer holds 25 claims (Strand 1-25) originally staked by Silver Strand Development LLC and transferred to Lakewood US, a subsidiary of Silver Strand Development LLC; 8 claims (Lone Cabin 1-4 and Burnt Cabin 1-4) purchased from Gold Rush Expeditions of Salt Lake City, Utah in 2020; and 44 additional claims (Strand 26-70) staked in 2021. All claims were transferred to Silver Hammer Mining Corp. following the name change from Lakewood Exploration Inc. in September 2021. The mineral claims were in good standing as of February 2023, with annual maintenance fees of US$165 per claim payable at the beginning of September each year. For further details regarding mineral tenure, see Section 4.1 of the Technical Report.
No additional surface rights exist beyond the unpatented mining claims. The QP is not aware of any significant factors or risks that may affect access, title, or the right or ability to perform work on the property. In connection with the purchase agreement entered into by New Jersey Mining Company in 2000, Trend Mining Company retained a net smelter returns royalty of 1.5% (capped at US$50,000) and 0.5% thereafter on the property. For further details, see Sections 4.2 through 4.5 of the Technical Report.
Permits and Environmental Assessment
The predecessor entity, Lakewood Exploration Inc., initiated applications for a permit to explore the property. An Environmental Assessment ("EA") is required for small preliminary mining operations conducted by underground mining and hauling ore out of the forest on Federal land. A mining and mill operation would require an Environmental Impact Statement ("EIS"). All surface drilling sites would require a Categorical Exclusion option for small programs. In January 2024, Silver Hammer reported that its Plan of Operations for the Silver Strand Project had been approved by the U.S. Forest Service, subject to payment of a reclamation bond.
Previous owners and operators of the Silver Strand claims raised several environmental issues, including noxious weeds on roadbeds and mine portals, water quality, and collapse of stopes or raises to surface. No additional environmental considerations have been raised, and Silver Hammer has stated that it will address such issues when directed by government agencies after permits have been provided. The timeline for permitting is subject to uncertainty and could be delayed. For further details, see Sections 4.3 and 4.4 of the Technical Report.
History
The Silver Strand deposit was discovered in the 1960s during nearby logging activity. The Silver Strand Mine was owned and developed by Silver Strand Mining Company from 1969 to 1988. Initial exploration included soil and trench sampling as well as percussion drilling in 1969, and from 1970 to 1982 mine development on two levels (No. 2 and No. 3) and one stope (No. 225) progressed. A total of 12,476 tonnes (13,752 tons) of material grading at 2.91 g/t gold and 300 g/t silver (87.1% silica) was produced. The mine shut down in 1983 when the ASARCO Tacoma smelter, the only facility that would accept the high-arsenic material, closed.
Subsequent exploration and ownership history includes: geochemical soil sampling in 1987-1988; a merger between Silver Trend Mining Co. and Silver Strand Mining Co. in 1989-1991; a gob stope leaching field study by the U.S. Bureau of Mines in 1992; a four-hole surface diamond drill program (793 m) by Silver Trend Mining Company in 1997; a purchase agreement by New Jersey Mining Company ("NJMC") in 2000; underground drilling (five NX core holes, 324 m) by NJMC in 2002; a geophysical and geochemical survey in 2004; milling of 200 tonnes of stockpiled ore by NJMC in 2006 with 70% recovery at 139.94 g/t gold and 12,261 g/t silver; a joint venture between NJMC and Silverstar Mining Corp. in 2008; a historical resource estimate in 2009; development work and a Plan of Operations filing in 2010; acquisition by Shoshone Silver and Gold Mining Co. in 2012; and acquisition by Lakewood Exploration Inc. (subsequently renamed Silver Hammer Mining Corp.) in 2021.
No significant historical mineral resource or reserve estimates have been completed for the Silver Strand Mine that are considered current. For further details regarding the property's history, see Section 6 of the Technical Report.
Geological Setting, Mineralization and Deposit Types
Regional and Local Geology
The prevailing country rocks of the Coeur d'Alene Mountains are strata of the pre-Cambrian Belt Series, which hosts most of the metalliferous deposits of the Coeur d'Alene mining district. The Belt Series includes all members of the Coeur d'Alene district - the Prichard, Burke, Revett, St. Regis, Wallace, and Striped Peak formations. The primary structural feature of the region is a broad, heavily faulted, west-northwest trending anticlinal uplift, broken along its crest and flanks by large magnitude longitudinal faults, including the well-known Osburn, Placer Creek, and Burnt Cabin faults.
The Silver Strand property lies north of the Osburn Fault and is underlain by Proterozoic sediments, primarily of the Revett and St. Regis Formations, and in certain instances by the middle and lower member of the Wallace Formation. The Burnt Cabin Fault runs parallel to the southern base of the property and is considered an important structural control on mineralization in the area. For further details regarding regional and local geology, see Section 7 of the Technical Report.
Mineralization
The mineralization at the Silver Strand Mine consists of a nearly vertical, white quartz body or zone that cuts flat to moderately dipping Revett Formation beds. The quartz body lacks regularity and shape, has no prominent through-going fault structure, and is not considered to be vein-like. Occasional euhedral crystals of pyrite and a fahlore mineral (likely tetrahedrite) have been observed. Microscopic work and metallurgical testing have confirmed the presence of pyrite, tetrahedrite, tennanite, galena, sphalerite, arsenopyrite, and stibnite. Elevated gold and silver values are common throughout the quartz zone, with higher gold content tending to correlate with elevated silver values.
The QP's review of 2002 drill core during the August 2022 site visit indicated localized increased Au and Ag grades associated with silicification alteration and within faults adjacent to or within dolerite dykes. Spatial comparison of the location of the dolerite dykes relative to increased Au and Ag grades shows that higher grades are proximal and subparallel to the trend of the dykes. The QP notes that an anomalous Au and Ag grade zone is located immediately below the previous mine workings, with intersection widths up to 3.4 m wide and grades greater than 3 g/t Au (243 g/t Ag equivalent). For further details regarding mineralization, see Sections 7.3 and 8 of the Technical Report.
Deposit Types
The main deposit types at the Silver Strand property are classified as either replacement deposits or fissure fillings, containing silver, lead, zinc, copper, arsenic, bismuth, and barium. The fissure fillings are primarily quartz with minimal to variable amounts of metallic minerals and carbonates. The replacement deposits include high-temperature lead-zinc, pyrrhotite and arsenopyrite, as well as moderate-temperature lead-zinc-siderite, siderite, silver, and barite deposits. The exploration model considers the steeply dipping vein system as the primary target for extending known mineralization at depth. For further details, see Section 8 of the Technical Report.
Exploration
In 2021, following Silver Hammer's acquisition of the property, a brief sampling program was conducted, including soil and grab samples managed by Phillip Mulholland, P.Geo. and Eric Saderholm, P.Geo. In August 2021, John Childs, P.Geo. and Bibek Giri conducted geological mapping, prospecting, and sampling across the property. Surface grab samples collected near the No. 1 portal included highlights of up to 255.43 g/t Ag and 1.27 g/t Au. Underground samples from the No. 3 level included a grab sample grading 9.77 g/t Au and 1,669.03 g/t Ag from the stope area.
In August 2021, a UAV magnetic survey was conducted by MWH Geo-Surveys over an area of 13.2 km², capturing 521 line-km with 25 m spacing. In July 2022, Big Sky Geophysics conducted three lines of dipole-dipole resistivity/induced polarization ("IP") surveys designed to map gold-bearing quartz veins near the Silver Strand Mine. The QP considers the exploration activities undertaken by Silver Hammer to be appropriate for the deposit type. For further details regarding exploration activities, see Section 9 of the Technical Report.
Drilling
After acquiring the Silver Strand Mine in May 2021, Silver Hammer commenced core drilling on the property. In 2021, two surface holes (BC21-001 and SS21-002) and six underground holes (SS21-003 to SS21-008) totalling 358.7 m were drilled from an underground drill station constructed to confirm historical drilling results and test down-dip and along-strike mineralization extensions. In 2022, the underground drilling program continued with nine additional underground holes drilled from the same location, for a combined total of 1,025.36 m across 17 holes.
Of the 17 completed underground drill holes, 15 encountered gold and silver mineralization. Significant intercepts from the 2021-2022 drill programs include, among others: 4.57 m grading 106.20 g/t Ag and 3.93 g/t Au (SS21-003);
0.91 m grading 85.10 g/t Ag and 4.96 g/t Au (SS21-004); 0.61 m grading 392.00 g/t Ag and 0.64 g/t Au (SS21-006);
1.82 m grading 185.63 g/t Ag and 0.99 g/t Au (SS22-009); 0.91 m grading 101.00 g/t Ag and 2.38 g/t Au (SS22-014); and 0.50 m grading 613 g/t Ag (SS22-015). The drill intercepts are not true thickness. For further details regarding drilling, see Section 10 of the Technical Report.
Sampling, Analyses and Data Verification
Soil and rock chip samples collected by Silver Hammer in 2021 and 2022 were personally transported to laboratories by authorized personnel to ensure chain of custody. Soil samples were analyzed by American Analytical Services Inc. ("AAS") in Osburn, Idaho using ICP-35 element scan analysis. Rock chip samples were analyzed by CCI Laboratory in Smelterville, Idaho using fire assay methods with a gravimetric finish for gold and silver.
Drill core samples were collected by Silver Hammer geologists following core photography and logging, with sample selection controlled by lithology, alteration, and mineralization breaks. Primary sampling was by split core using an on-site core saw. Samples were hand-delivered to AAS in batches of approximately 20 samples. The analytical method included fire assay silver/gold ratio with an ICP finish (FA/ICP Ag/Au), followed by a four-acid digest ICP-MS for 35 elements. Values exceeding ICP limits of 100 g/t were completed with a gravimetric finish.
Each batch of approximately 20 samples contained a standard and a blank. Certified Reference Materials (CRMs) were ordered from OREAS (OREAS 611, lot PR2105-6088). The QP reviewed the QAQC results, including 23 CRM samples, 20 blanks, and 22 duplicates for the 2021-2022 drilling campaign. The QP noted that the blank material used (pea gravel from a local Home Depot store) showed sporadic mineralization and recommended that a new source of non-mineralized blank material be considered. The QP also recommended that routine duplicate sampling be implemented for core, coarse, and pulp reject samples, and that a percentage of duplicates be sent to an umpire laboratory as an independent check on AAS analytical results.
The QP conducted data verification, including re-logging of 2002 drill core, a site visit to the AAS laboratory, and comparison of paper logs to the electronic Vulcan drillhole database. The QP found no material discrepancies and concluded that Silver Hammer's drilling, logging, and QAQC procedures were in accordance with industry standard practices. For further details regarding sampling, analyses, and data verification, see Sections 11 and 12 of the Technical Report.
Mineral Processing and Metallurgical Testing
No mineral processing or metallurgical testing has been carried out for the Silver Strand Project. For further details, see Section 13 of the Technical Report.
Mineral Resources and Mineral Reserves
No mineral resource estimate has been conducted for the Silver Strand Project. No mineral reserve estimates have been completed for the Silver Strand Project. Neither a mineral resource estimate nor a mineral reserve estimate is a requirement of a mineral project exploration information technical report at this stage of the project. For further details, see Sections 14 and 15 of the Technical Report.
Mining Operations
There is no active mining on the Silver Strand Project. No assessments of mining methods have been completed. For further details, see Section 16 of the Technical Report.
Processing and Recovery Operations
No assessments of processing and recovery methods have been completed for the Silver Strand Project. For further details, see Section 17 of the Technical Report.
Infrastructure, Permitting and Compliance Activities
There is currently no mining taking place on the Silver Strand Project. The historical underground mining infrastructure on the property includes three developed underground levels (No. 2, No. 225, and No. 3), of which only the No. 3 level is currently accessible and safe for exploration. The infrastructure and facilities used to support exploration activities include forest service road access, a core logging shed, and covered core storage facilities. No on-site facilities for fresh water, general supplies, or power currently exist. Supplies and services can be obtained from Coeur d'Alene to the west, or from the mining towns of Wallace and Osborne to the east. For further details regarding infrastructure, see Sections 5 and 18 of the Technical Report.
Capital and Operating Costs
Capital and operating costs have not been estimated for the Silver Strand Project and are not requirements of a mineral project exploration information technical report at this stage. For further details, see Section 21 of the Technical Report.
No market studies have been undertaken for the Silver Strand Project and no contracts are in place or under negotiation for mining, concentrating, smelting, refining, transportation, handling, sales, hedging, or forward sales arrangements. For further details, see Section 19 of the Technical Report.
Exploration, Development, and Production
Silver Hammer's current and contemplated exploration activities at the Silver Strand Project are focused on advancing the property through additional geological mapping, geophysical surveys, and drilling. The QP recommends further detailed structural mapping of outcrop on surface and in the underground workings to understand structural controls on Au and Ag mineralization and to develop a targeting strategy. A targeted drilling campaign focused down-dip of the quartz silicification and dolerite dykes is recommended to test for possible new brecciation zones. Additional underground drillhole survey tests using a Reflex Gyro are recommended to measure possible deviations due to magnetism from observed mafic dykes. The QP also recommends implementing a recognized database system for logging and a process for bulk density data collection. For further details regarding recommendations, see Section 26 of the Technical Report.
Adjacent Properties
The author of the Technical Report has not completed any assessment on properties directly adjacent to the Silver Strand Mine or claims beyond those owned by Silver Hammer. The closest operating mine is the Bunker Hill Mine, located in the Coeur d'Alene Silver Valley approximately 38.4 km (17.6 mi) southeast of the Silver Strand Mine. The QP recognizes that information relating to adjacent properties is not necessarily indicative of the mineralization on the Silver Strand Project exploration area, and information on adjacent properties has been sourced from external parties and is not considered verified by the QP. For further details, see Section 23 of the Technical Report.
Eliza Silver Project
The Eliza Silver Project is an exploration-stage property located in White Pine County, Nevada, comprising unpatented lode mining claims prospective for silver mineralization. Silver Hammer holds a 100% interest in the Eliza Silver Project.
The Eliza Silver Project is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Eliza Silver Project. Silver Hammer's exploration activities on the property have been limited to preliminary geological assessment, surface sampling, and target identification. Silver Hammer intends to continue evaluating the Eliza Silver Project through additional exploration work as warranted by results and available funding.
Silverton Silver Mine Project
The Silverton Silver Mine Project is an exploration-stage property located in Nye County, Nevada, encompassing historical silver workings and surrounding mineral claims. Silver Hammer holds a 100% interest in the Silverton Silver Mine Project.
The Silverton Silver Mine Project is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Silverton Silver Mine Project. Silver Hammer's exploration activities on the property have been limited to preliminary geological assessment, compilation of historical data, and surface sampling. Silver Hammer intends to continue evaluating the Silverton Silver Mine Project through additional exploration work as warranted by results and available funding.
Fahey Property
The Fahey Property comprises 18 unpatented US lode mining claims located in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho, an area historically prospective for silver, lead, and zinc mineralization. Silver Hammer does not currently hold a direct interest in the Fahey Property but has an option to acquire a 100% interest therein pursuant to the Fahey Option Agreement entered into in October 2025. For a description of the material terms of the Fahey Option Agreement, see "General Development of the Business".
The Fahey Property is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Fahey Property. Silver Hammer's exploration activities on the property remain at a preliminary stage, consisting principally of initial geological review and assessment of historical data.
Dividends and Distributions
Silver Hammer has not paid any dividends since incorporation, and it has no plans to pay dividends for the foreseeable future. The directors of Silver Hammer will determine if and when dividends should be declared and paid in the future based on Silver Hammer's financial position at the relevant time. All of Silver Hammer's common shares are entitled to an equal share of any dividends declared and paid.
Management's Discussion and Analysis
Selected Financial Information and Management's Discussion and Analysis of Silver Hammer
Silver Hammer presents its financial statements in accordance with IFRS. The following table sets forth summary financial information of Silver Hammer for the six months ended March 31, 2026, the financial year ended September 30, 2025, and the financial year ended September 30, 2024, and should be read in conjunction with Silver Hammer's financial statements, including the notes thereto.
| Six months ended March 31, 2026 (unaudited) |
Financial Year Ended September 30, 2025 (audited) |
Financial Year Ended September 30, 2024 (audited) |
|
| Revenues | Nil | Nil | Nil |
| Net loss for the period | $(556,449) | $(893,896) | $(1,575,755) |
| Cash and cash equivalent | $3,776,631 | $1,248,302 | $35,767 |
| Total assets | $12,945,820 | $9,595,165 | $8,232,803 |
| Total liabilities | $248,436 | $430,207 | $885,280 |
| Total shareholders' equity | $12,697,384 | $9,164,958 | $7,347,523 |
Silver Hammer's financial statements for the six months ended March 31, 2026, the financial year ended September 30, 2025, and the financial year ended September 30, 2024, together with the related MD&A for each such period, are available on Silver Hammer's SEDAR+ profile at www.sedarplus.ca and should be read in conjunction with the summary financial information set out above.
The MD&A for Silver Hammer should be read in conjunction with Silver Hammer's financial statements and the accompanying notes thereto. Certain information contained in Silver Hammer's MD&A constitutes forward-looking statements. These statements relate to future events or to Silver Hammer's future financial performance and involve known and unknown risks, uncertainties and other factors that may cause Silver Hammer's actual results, levels of activity, performance or achievements to be materially different from any future results, levels of activity, performance or achievements expressed or implied by such forward-looking statements. See "Note Regarding Forward-Looking Information" and "Risk Factors" in this Appendix "E".
Additional Disclosure for Venture Issuers Without Significant Revenue
As of March 31, 2026, Silver Hammer has generated $nil revenue from operations since incorporation on May 2, 2017. See "Risk Factors" in this Appendix "E".
Additional Disclosure for Venture Issuers
As at March 31, 2026, Silver Hammer had working capital of approximately $3,931,934. There is no guarantee that Silver Hammer will be able to raise any additional funds when and if needed and if such funds would be available on terms favourable to Silver Hammer. See "Risk Factors" in this Appendix "E".
Description of Capital Structure
Common Shares
Silver Hammer's authorized capital consists of an unlimited number of common shares without par value. As of March 31, 2026, a total of 139,922,966 Silver Hammer Shares were issued and outstanding. As of the date hereof, a total of 139,922,966 Silver Hammer Shares are issued and outstanding.
Each common share ranks equally with all other common shares with respect to dissolution, liquidation or winding-up of Silver Hammer and payment of dividends. The holders of Silver Hammer Shares are entitled to one vote for each share of record on all matters to be voted on by such holders and are entitled to receive pro rata such dividends as may be declared by the board of directors of Silver Hammer (the "Board") out of funds legally available therefor and to receive, pro rata, the remaining property of Silver Hammer on dissolution. The holders of Silver Hammer Shares have no redemption, retraction, purchase, pre-emptive or conversion rights. The rights attaching to the Silver Hammer Shares can only be modified by the affirmative vote of at least two-thirds of the votes cast at a meeting of shareholders called for that purpose.
Contingent Value Shares
In connection with the Amalgamation and the SilverMark Amalgamation, Silver Hammer's Articles will be amended to create an unlimited number of contingent value shares (the "Contingent Value Shares"), which will be issued in exchange for Class B Special Shares of SilverMark in accordance with the Class B Exchange Ratio pursuant to the SilverMark Amalgamation Agreement. The number of Contingent Value Shares issuable for each Class B Special Share is equal to the quotient obtained by dividing (x) $1,575,000 by (y) the product of the Offering Price multiplied by the number of Class B Special Shares outstanding immediately prior to the effective time of the SilverMark Amalgamation. The Class B Exchange Ratio is approximately 1.5384. Based on the Offering Price of $0.26 per Subscription Receipt and 3,937,500 Class B Special Shares outstanding, up to 6,057,692 Contingent Value Shares will be issued and outstanding upon completion of the SilverMark Amalgamation. Upon the occurrence of a Milestone Conversion Event, Silver Hammer will, within ten (10) business days of the occurrence of such Milestone Conversion Event, provide written notice of conversion to each holder of Contingent Value Shares specifying: (i) the number of Contingent Value Shares to be converted in accordance with the Milestone Conversion Table; and (ii) the date on which such conversion shall be effected (the "Conversion Date"), which date shall not be later than twenty (20) business days following the occurrence of the applicable Milestone Conversion Event. On the Conversion Date, without any further act or formality on the part of the holder, each such Contingent Value Share shall be converted into one (1) fully paid and non-assessable Silver Hammer Share. There is no right of voluntary conversion. Holders of Contingent Value Shares are not entitled to receive notice of, attend, or vote at any general meeting of shareholders, except as otherwise required under the BCBCA. Holders of Contingent Value Shares are not entitled as of right to receive any dividends. On a liquidation, dissolution or winding-up of Silver Hammer, holders of Contingent Value Shares are not entitled to receive any assets or other distribution whatsoever. The Contingent Value Shares are not transferable by any holder, whether by sale, assignment, pledge, hypothecation or otherwise, except for a transfer that occurs solely by operation of applicable laws governing estates or succession upon the death of a holder. No fractional Silver Hammer Shares will be issued upon the conversion of Contingent Value Shares; any conversion that results in less than a whole number of Silver Hammer Shares will be rounded down to the next whole number, with no cash payment in lieu of fractional shares. Each Contingent Value Share converted will be cancelled and returned to the authorized and unissued capital of Silver Hammer. Any Contingent Value Shares that have not been converted by the Milestone Deadline, being the date that is 60 months after the Effective Date of the SilverMark Amalgamation, will be redeemable by Silver Hammer and Silver Hammer will be entitled to redeem and cancel all such unconverted Contingent Value Shares without notice to the holders thereof and without payment of any consideration. The special rights and restrictions attaching to the Contingent Value Shares may not be altered or amended without the approval of a majority of the holders of the Contingent Value Shares and the prior written consent of Silver Hammer. For a description of the Milestone Conversion Events and the Milestone Conversion Table, see "SilverMark Amalgamation - Milestone Conversion Events" above in this Appendix "E".
Warrants
As of March 31, 2026, there were 58,220,763 Silver Hammer common share purchase warrants outstanding, each exercisable to acquire one Silver Hammer Share at prices ranging from $0.07 to $0.15, with expiry dates ranging from December 16, 2027 to September 18, 2030.
As of the date of the Circular, there are 58,220,763 Silver Hammer common share purchase warrants outstanding, comprised of: (i) 37,177,778 warrants exercisable at $0.07, with expiry dates ranging from December 16, 2027 to September 18, 2030; (ii) 19,568,085 warrants exercisable at $0.15, expiring February 20, 2029; and (iii) 1,474,900 finder's warrants exercisable at $0.15, expiring February 20, 2029.
Options
As of March 31, 2026, there were 6,755,000 Silver Hammer stock options outstanding and exercisable, with exercise prices ranging from $0.055 to $0.62 per share and expiry dates ranging from June 16, 2026 to September 15, 2030. The weighted average exercise price of the outstanding options is $0.13 per share and the weighted average remaining contractual life is approximately 3.64 years.
As of the date of the Circular, there are 6,105,000 Silver Hammer stock options outstanding.
Consolidated Capitalization
Consolidated Capitalization
The following table summarizes Silver Hammer's capitalization as at March 31, 2026 and as at the date of the Circular, in each case presented on a post-Consolidation basis (reflecting the 4:1 Consolidation). The table should be read in conjunction with the financial statements of Silver Hammer that are available on Silver Hammer's SEDAR+ profile at www.sedarplus.ca.
Security |
Amount Authorized |
Outstanding as at March 31, 2026 (unaudited) |
Outstanding as at the date of the Circular (unaudited) |
Outstanding after giving effect to the Amalgamation and the SilverMark Amalgamation (unaudited) |
| Common Shares | Unlimited | 34,980,742 Silver Hammer Shares(1) |
34,980,742 Silver Hammer Shares(1) |
89,284,930 Silver Hammer Shares(2) |
| Contingent Value Shares | Unlimited | Nil | Nil | 6,057,692(3) |
| Long Term Debt | Nil | Nil | Nil | Nil |
Notes:
(1) The "Outstanding as at March 31, 2026" and "Outstanding as at the date of the Circular" columns are presented on a post-Consolidation basis (reflecting the 4:1 Consolidation). Silver Hammer had 139,922,966 Silver Hammer Shares issued and outstanding on a pre-Consolidation basis as at each of March 31, 2026 and the date of the Circular.
(2) Includes Silver Hammer Shares held by existing Silver Hammer shareholders (34,980,742 on a post-Consolidation basis) and Silver Hammer Shares issuable in exchange for securities of Stroud and SilverMark pursuant to the Amalgamation and the SilverMark Amalgamation. Does not include Silver Hammer Shares issuable in connection with the Private Placement. The "Outstanding after giving effect to the Amalgamation and the SilverMark Amalgamation" column is presented on a post-Consolidation basis. See "Fully Diluted Capitalization" in this Appendix "E".
(3) In connection with the SilverMark Amalgamation, each Class B Special Share of SilverMark will be cancelled and exchanged for such number of Contingent Value Shares as is determined by the Class B Exchange Ratio (see "Description of Capital Structure - Contingent Value Shares" in this Appendix "E"), which, based on the Offering Price of $0.26 per Subscription Receipt and 3,937,500 Class B Special Shares outstanding, results in approximately 1.5384 Contingent Value Shares per Class B Special Share. Each Contingent Value Share will be convertible into one (1) Silver Hammer Share upon the occurrence of each applicable Milestone Conversion Event in accordance with the Milestone Conversion Table, pursuant to the Conversion Notice process described under "Description of Capital Structure - Contingent Value Shares" in this Appendix "E". See "SilverMark Amalgamation" in this Appendix "E".
Fully Diluted Capitalization
The following table summarizes the anticipated fully diluted share capital of Silver Hammer before and after giving effect to the Amalgamation and the SilverMark Amalgamation, presented on a post-Consolidation basis (reflecting the 4:1 Consolidation of Silver Hammer Shares).
| Number of Silver Hammer Shares issued or reserved for issuance |
Percentage of issued and outstanding Silver Hammer Shares (non-diluted) |
Percentage of issued and outstanding Silver Hammer Shares (fully-diluted) |
|
| Silver Hammer Shares outstanding as at the date of the Circular(1) | 34,980,742 | 29.90% | 20.68% |
| Silver Hammer Shares issuable upon exercise of existing Silver Hammer warrants(2) | 14,555,191 | 0% | 8.61% |
| Number of Silver Hammer Shares issued or reserved for issuance |
Percentage of issued and outstanding Silver Hammer Shares (non-diluted) |
Percentage of issued and outstanding Silver Hammer Shares (fully-diluted) |
|
|
Silver Hammer Shares issuable upon exercise of existing Silver Hammer options(3) |
1,526,250 |
0% |
0.90% |
|
Silver Hammer Shares to be exchanged pursuant to the Amalgamation(4) |
49,496,496 |
42.31% |
29.27% |
|
Silver Hammer Shares issuable upon exercise of the outstanding Stroud Options(5) |
898,561 |
0% |
0.53% |
|
Silver Hammer Shares to be exchanged pursuant to the SilverMark Amalgamation(6) |
4,807,692 |
4.11% |
2.84% |
|
Contingent Value Shares to be exchanged pursuant to the SilverMark Amalgamation(6) |
6,057,692 |
0% |
3.58% |
|
Silver Hammer Shares issuable upon exercise of the outstanding SilverMark warrants(7) |
288,461 |
0% |
0.17% |
|
Silver Hammer Shares issuable to SABI-AIM pursuant to the SABI-AIM Option Agreements upon closing of the SilverMark Amalgamation(8) |
772,423 |
0.66% |
0.46% |
|
Silver Hammer Shares issuable in exchange for SilverMark Class A Common Shares to be issued pursuant to the Private Placement(9) |
26,923,077 |
23.02% |
15.92% |
|
Silver Hammer Shares issuable upon exercise of warrants to be issued by SilverMark in connection with the Private Placement(10) |
26,923,077 |
0% |
15.92% |
|
Silver Hammer Shares issuable upon exercise of the broker warrants issued by SilverMark in connection with the Private Placement(11) |
1,884,615 |
0% |
1.11% |
|
TOTAL: |
169,114,277 |
100% |
100% |
Notes:
(1) As of the date of the Circular, Silver Hammer has 139,922,966 Silver Hammer Shares issued and outstanding on a pre-Consolidation basis, representing 34,980,742 Silver Hammer Shares on a post-Consolidation basis (reflecting the 4:1 Consolidation).
(2) As of the date of the Circular, Silver Hammer has 58,220,763 common share purchase warrants outstanding on a pre-Consolidation basis, representing 14,555,191 warrants on a post-Consolidation basis (reflecting the 4:1 Consolidation). See "Description of Capital Structure - Warrants" in this Appendix "E".
(3) As of the date of the Circular, Silver Hammer has 6,105,000 stock options outstanding on a pre-Consolidation basis, representing 1,526,250 stock options on a post-Consolidation basis (reflecting the 4:1 Consolidation). See "Description of Capital Structure - Options".
(4) As at the date of the Combination Agreement, there were 63,623,199 Stroud Shares issued and outstanding. The number of Silver Hammer Shares issuable will be determined by reference to the Stroud Exchange Ratio and the number of Stroud Shares outstanding immediately prior to the effective time of the Amalgamation. See "Amalgamation" in this Appendix "E".
(5) As at the date of the Combination Agreement, there were 1,155,000 Stroud Options outstanding. The number of Silver Hammer options to be issued will be determined by reference to the Stroud Exchange Ratio and the number of Stroud Options outstanding immediately prior to the effective time of the Amalgamation. See "Amalgamation" in this Appendix "E".
(6) As at the date of the SilverMark Agreement, there were 13,888,889 SilverMark Class A Common Shares and 3,937,500 Class B Special Shares issued and outstanding. Each SilverMark Class A Common Share will be exchanged for 0.346154 of one (1) post-Consolidation Silver Hammer Share pursuant to the Exchange Ratio. Each Class B Special Share will be exchanged for such number of Contingent Value Shares as is determined by the Class B Exchange Ratio ("Description of Capital Structure - Contingent Value Shares" in this Appendix "E"), which, based on the Private Placement Offering Price of $0.26 per Subscription Receipt and 3,937,500 Class B Special Shares outstanding, results in 6,057,692 Contingent Value Share(s) per Class B Special Share, with each Contingent Value Share convertible into one (1) Silver Hammer Share upon the occurrence of each applicable Milestone Conversion Event. See "SilverMark Amalgamation" in this Appendix "E".
(7) As of the date of the SilverMark Agreement, there were 833,333 SilverMark warrants outstanding, each exercisable to acquire one SilverMark Class A Common Share at $0.12 per share until May 4, 2028. Following the effective time of the SilverMark Amalgamation, the SilverMark warrants will, in accordance with their terms, be adjusted to give effect to the SilverMark Exchange Ratio, such that the SilverMark warrants will thereafter be exercisable to acquire an aggregate of 288,461 Silver Hammer Shares at an adjusted exercise price. See "SilverMark Amalgamation" in this Appendix "E".
(8) Pursuant to the SABI-AIM Option Agreements, Silver Hammer is required to pay aggregate initial earn-in consideration at the closing of the Amalgamation and the SilverMark Amalgamation of US$667,647 in cash and US$145,529 in Resulting Issuer Shares. The number of Silver Hammer Shares issuable in respect of the share component of such consideration is determined by: (i) converting the applicable US dollar amount to Canadian dollars at an assumed exchange rate of 1.39 (being approximately C$200,830); (ii) dividing the resulting Canadian dollar amount by the deemed price per pre-Consolidation Silver Hammer Share of $0.065 ($0.26 on a post-Consolidation basis), resulting in 3,089,693 pre-Consolidation Silver Hammer Shares; and (iii) adjusting for the 4:1 Consolidation, resulting in 772,423 Resulting Issuer Shares issuable to SABI-AIM. See "SilverMark Amalgamation - SABI-AIM Option Agreements" in this Appendix "E".
(9) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 26,923,077 SilverMark Class A Common Shares to be exchanged for Silver Hammer Shares pursuant to the Amalgamation and the SilverMark Amalgamation. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount. See "Private Placement" in this Appendix "E".
(10) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 26,923,077 SilverMark warrants to be exchanged for warrants exercisable for Silver Hammer Shares pursuant to the Amalgamation and the SilverMark Amalgamation. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount. See "Description of Capital Structure - Warrants" in this Appendix "E".
(11) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 1,884,615 broker warrants (equal to 7.0% of Subscription Receipts sold), each exercisable to acquire one SilverMark Class A Common Share (exchangeable for one Resulting Issuer Share pursuant to the Amalgamation and the SilverMark Amalgamation) at $0.26 per share for 24 months following closing. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount or if the Agents' Option is exercised. See "Private Placement" in this Appendix "E".
Options to Purchase Securities
Outstanding Awards
As at the date of the Circular, Silver Hammer has 6,105,000 Silver Hammer Options outstanding. See "Description of Capital Structure - Options" in this Appendix "E".
10% Rolling Stock Option Plan
Silver Hammer currently has in place a 10% rolling stock option plan (the "Option Plan") dated September 17, 2021. The following is a brief summary of the material terms of the Option Plan and does not purport to be complete. A complete copy of the Option Plan is available from Silver Hammer upon request.
The Option Plan is administered by the Board, which has full authority and sole discretion to grant Silver Hammer Options under the Option Plan to any eligible party, including directors, officers, employees and consultants of Silver Hammer or its subsidiaries. The purpose of the Option Plan is to provide Silver Hammer with a share-related mechanism to attract, retain and motivate qualified executives, employees and consultants, to incent such individuals to contribute toward the long-term goals of Silver Hammer, and to encourage such individuals to acquire Silver Hammer Shares as long-term investments.
The maximum number of Silver Hammer Shares that may be reserved for issuance pursuant to the exercise of Silver Hammer Options granted under the Option Plan shall not exceed 10% of the issued and outstanding Silver Hammer Shares at any given time on a rolling basis. If any Silver Hammer Option granted under the Option Plan expires or terminates for any reason without being exercised, the Silver Hammer Shares subject thereto shall again be available for the purposes of the Option Plan.
The exercise price of each Silver Hammer Option shall be determined by the Board at the time of grant and shall not be less than the minimum prevailing price permitted by the policies of the CSE. Silver Hammer Options may have a maximum term of ten (10) years from the date of grant. Subject to any vesting restrictions imposed by the CSE, Silver Hammer Options shall vest when granted unless otherwise determined by the Board on a case-by-case basis.
If a holder of Silver Hammer Options ceases to be a director, officer, employee or consultant of Silver Hammer (other than by reason of death, disability or termination for cause), any vested Silver Hammer Options held by such holder shall expire on the earlier of the applicable expiry date and the date that is 90 days following the date the holder ceases to be a director, officer, employee or consultant of Silver Hammer. If a holder of Silver Hammer Options ceases to be a director, officer, employee or consultant as a result of death or disability, any Silver Hammer Options held by such holder shall be exercisable by the holder or the holder's personal representative until the earlier of one year following the date of death or disability and the applicable expiry date. If a holder of Silver Hammer Options is terminated for cause, all Silver Hammer Options held by such holder, whether vested or unvested, shall terminate immediately upon such termination.
Should the expiry date of a Silver Hammer Option fall within a Black Out Period (as defined in the Option Plan, being the period during which the relevant holder is prohibited from exercising a Silver Hammer Option due to trading restrictions imposed by Silver Hammer pursuant to any policy of Silver Hammer respecting restrictions on trading that is in effect at that time) or within nine (9) business days following the expiration of a Black Out Period, such expiry date shall be automatically extended to the tenth business day after the end of the Black Out Period. Silver Hammer Options granted under the Option Plan are non-assignable and non-transferable.
The Board may from time to time, subject to regulatory or shareholder approval if required under the policies of the CSE, amend or revise the terms of the Option Plan. In connection with the Amalgamation and the SilverMark Amalgamation, Silver Hammer expects to adopt the new 2026 Omnibus Equity Incentive Compensation Plan in substitution for the Option Plan.
Prior Sales
Trading Price and Volume
The principal market on which the Silver Hammer Shares trade on is the CSE. The following table shows the high and low trading prices and monthly trading volume of the Silver Hammer Shares on the CSE for the 12-month period preceding the date of the Circular:
| Month | High ($) | Low ($) | Volume |
| August 1-27, 2026 | 0.095 | 0.07 | 8,423,936 |
| July 2026 | 0.085 | 0.06 | 2,566,036 |
| June 2026 | 0.09 | 0.055 | 4,888,051 |
| May 2026 | 0.095 | 0.06 | 6,532,697 |
| April 2026 | 0.1 | 0.065 | 6,196,660 |
| March 2026 | 0.1 | 0.065 | 10,493,848. |
| February 2026 | 0.125 | 0.09 | 15,784,960 |
| January 2026 | 0.15 | 0.095 | 18,138,991 |
| December 2025 | 0.145 | 0.08 | 5,983,429 |
| November 2025 | 0.11 | 0.07 | 3,934,118 |
| October 2025 | 0.18 | 0.08 | 12,085,610 |
| September 2025 | 0.13 | 0.045 | 22,272,046 |
| August 2025 | 0.065 | 0.03 | 2,299,008 |
Prior Sales
The following table sets forth information in respect of issuances or purchases of Silver Hammer Shares and securities that are convertible or exchangeable into Silver Hammer Shares within the 12 months prior to the date of the Circular, including the price at which such securities have been issued, the number of securities issued, and the date on which such securities were issued:
Date of Issuance |
Reason for Issuance |
Number and Type of Security |
Issuance / Exercise Price |
| September 15, 2025 | Stock option grant(1) | 750,000 options | $0.08 |
| September 18, 2025 | Private placement(2) | 26,864,491 common shares | $0.055 |
| September 18, 2025 | Private placement(2)(3) | 26,864,491 warrants | $0.07 |
| September 18, 2025 | Private placement(4) | 1,012,353 finder's warrants | $0.07 |
| October 1, 2025 | Debt settlement(5) | 1,500,000 common shares | $0.0837 |
| February 20, 2026 | Private placement(6) | 39,136,170 common shares | $0.10 |
| February 20, 2026 | Private placement(6)(7) | 19,568,085 warrants | $0.15 |
| February 20, 2026 | Private placement(8) | 1,474,900 finder's warrants | $0.15 |
Notes:
(1) Granted pursuant to the Stock Option Plan. All Silver Hammer Options vested immediately upon grant and are exercisable for five (5) years from the date of grant.
(2) Comprised the second tranche of a non-brokered private placement. Each unit consisted of one Silver Hammer Share and one warrant. Securities issued pursuant to this tranche were subject to a four-month statutory hold period expiring January 19, 2026. See "General Development of the Business" in this Appendix "E".
(3) Each warrant is exercisable to acquire one Silver Hammer Share at $0.07 per share until September 18, 2030.
(4) Each finder's warrant is exercisable to acquire one Silver Hammer Share at $0.07 for a period of five (5) years from issuance.
(5) Issued at a deemed price of $0.0837 per share (aggregate fair value of $217,500) to settle a debt of US$90,684 owed to a former service provider. Subject to a four-month statutory hold period.
(6) Each unit consisted of one Silver Hammer Share and one-half of one warrant. Completed pursuant to the Listed Issuer Financing Exemption under Part 5A of NI 45-106. No hold period applies to the Silver Hammer Shares issued thereunder. See "General Development of the Business" in this Appendix "E".
(7) Each whole warrant is exercisable to acquire one Silver Hammer Share at $0.15 for a period of 36 months from the date of issuance.
(8) Issued to finders in connection with the February 20, 2026 private placement. Each finder's warrant is exercisable to acquire one Silver Hammer Share at $0.15 for 36 months from issuance.
Escrowed Securities and Resale Restrictions
Escrowed Securities
To the knowledge of the directors and officers of Silver Hammer, as of the date of the Circular, there are no Silver Hammer Shares or other securities of Silver Hammer held in escrow or subject to any escrow agreement.
Contractual Resale Restrictions
To the knowledge of the directors and officers of Silver Hammer, as of the date of the Circular, there are no Silver Hammer Shares or other securities of Silver Hammer subject to any contractual resale restrictions.
Principal Securityholders
To the knowledge of the directors and officers of Silver Hammer, no person beneficially owns, or controls or directs, directly or indirectly, voting securities of Silver Hammer carrying 10% or more of the voting rights attached to any class of voting securities of Silver Hammer as at the date of the Circular.
Directors and Executive Officers
Name, Occupation and Security Holding
The following table sets out the names, provinces or states of residence, positions, principal occupations, and the number and percentage of Silver Hammer Shares that are beneficially owned or controlled by each of the current directors and executive officers of Silver Hammer. The current directors of Silver Hammer are Peter A. Ball, Alnesh Mohan, Donald J. Birak and Michael Willett, and the current officers of Silver Hammer are Peter A. Ball (President and CEO), Alnesh Mohan (CFO and Corporate Secretary) and Andrew Gillin (Vice President, Corporate Development & Investor Relations). Silver Hammer's directors are expected to hold office until the next annual general meeting of Silver Hammer's shareholders and are elected annually and, unless re-elected, retire from office at the end of the next annual general meeting of Silver Hammer's shareholders.
The Board has three standing committees: the Audit Committee, the Corporate Governance Committee and the Compensation Committee. The Audit Committee consists of Michael Willett (Chair), Donald J. Birak and Alnesh Mohan. See "Audit Committee" below for further details. The Corporate Governance Committee consists of Donald Birak (Chair), Michael Willett and Peter A. Ball. See "Corporate Governance Committee" below for further details. The Compensation Committee consists of Donald Birak (Chair) and Michael Willett. See "Compensation Committee" below for further details.
| Name, age and city of residence |
Position(s) | Principal occupations held during the last five years |
Number and Percentage of Common Shares as at the date of the Circular(1) |
Date Appointed |
| Peter A. Ball(3) Age 58 Vancouver, British Columbia, Canada |
President, Chief Executive Officer and Director |
President, Chief Executive Officer and Director of Silver Hammer Mining Corp. (February 2023 - present); and prior thereto, executive roles in the resource sector, most recently with Noram Lithium |
3,784,128(5) (2.70%) | February 15, 2023 |
| Alnesh Mohan(2) Age 55 Vancouver, British Columbia, Canada |
Chief Financial Officer, Corporate Secretary and Director |
Partner, Quantum Advisory Partners LLP (a professional services firm providing outsourced CFO, financial advisory, and accounting services), since 2005 |
1,989,183(6) (1.42%) | May 14, 2021 |
| Andrew Gillin Age 44 Toronto, Ontario, Canada |
Vice President, Corporate Development & Investor Relations |
Vice President, Corporate Development & Investor Relations |
Nil (0.00%) | July 15, 2026 |
| Donald J. Birak(2)(3)(4) Age 73 Coeur d'Alene, Idaho, USA |
Independent Director | Independent Consulting Geologist, Registered Member of SME and Fellow of AusIMM |
Nil(7) (0.00%) | September 27, 2023 |
| Michael Willett(2)(3)(4) Age 67 Saskatoon, Saskatchewan, Canada |
Independent Director | Director of Silver Hammer Mining Corp. (September 2025 - present); prior thereto, mining executive and independent advisor providing senior-level project evaluation and advisory services to mining companies across North America |
Nil(8) (0.00%) | September 15, 2025 |
Notes:
(1) Based on 139,922,966 Silver Hammer Shares issued and outstanding as at the date of the Circular.
(2) Denotes a member of the Audit Committee of Silver Hammer.
(3) Denotes a member of the Corporate Governance Committee of Silver Hammer.
(4) Denotes a member of the Compensation Committee of Silver Hammer.
(5) Such Silver Hammer Shares are held by Ariston Capital Corp., a private company of which Mr. Ball is the principal. Mr. Ball also holds 2,750,000 Silver Hammer Options and 3,584,128 common share purchase warrants through Ariston Capital Corp. and Lolgorian Holdings Inc., each a private company of which Mr. Ball is the principal. See "Executive Compensation - Stock Options and Other Compensation Securities" and "Description of Capital Structure - Warrants" in this Appendix "E".
(6) 1,814,183 of such Silver Hammer Shares are held by Quantum Advisory Partners LLP, a professional services firm of which Mr. Mohan is a partner. Mr. Mohan also holds 1,385,000 Silver Hammer Options and 1,800,000 common share purchase warrants, the latter held through Quantum Advisory Partners LLP. See "Executive Compensation - Stock Options and Other Compensation Securities" and "Description of Capital Structure - Warrants" in this Appendix "E".
(7) In addition to the Silver Hammer Shares set out above, Mr. Birak holds 835,000 Silver Hammer Options. Mr. Birak does not hold any common share purchase warrants. See "Executive Compensation - Stock Options and Other Compensation Securities" in this Appendix "E".
(8) In addition to the Silver Hammer Shares set out above, Mr. Willett holds 500,000 Silver Hammer Options. Mr. Willett does not hold any common share purchase warrants. See "Executive Compensation - Stock Options and Other Compensation Securities" in this Appendix "E".
Biographies
The following are brief biographies of the above individuals:
Peter A. Ball, President, Chief Executive Officer and Director
Mr. Ball brings a progressive track record of proven leadership experience covering more than thirty years in the mining and finance sectors. He has demonstrated competencies in the resource industry on an international level, and held various senior management roles with precious and base metals mining companies in mine engineering, corporate finance, securities trading, business development, corporate communications, public relations and marketing functions. Mr. Ball began his career in the late 1980s working as a mining engineer at Sherritt Gordon Mines, Hudson Bay Mining & Smelting Ltd. and Echo Bay Mines Ltd. Commencing in the 1990s, he held various management and senior executive and corporate roles for numerous companies, including Eldorado Gold Corporation, RBC Dominion Securities Inc., Adriana Resources, Century Mining, Argentex Mining, Columbus Gold Corp., Redstar Gold Corp., NV Gold, and most recently Noram Lithium Corp. Mr. Ball has led and assisted in raising over $250 million in capital in the resource sector, is a graduate of the Haileybury School of Mines, Georgian Business College, UBC's Canadian Securities Course and is a member of CIMM. Mr. Ball is also an independent director of Big Gold Inc. (BG:CSE).
Mr. Ball devotes approximately 90% of his time to Silver Hammer's activities but will at all times devote sufficient time as is reasonably necessary to discharge his responsibilities as President, CEO and a director.
Mr. Ball is not an employee of Silver Hammer but is an independent contractor to Silver Hammer. Mr. Ball has not entered into a non-competition or non-disclosure agreement with Silver Hammer.
Alnesh Mohan, Chief Financial Officer, Corporate Secretary and Director
Alnesh Mohan is a finance executive with over 20 years of experience providing advisory services to a wide array of clients. He has been a partner at Quantum Advisory Partners LLP, a professional services firm focused on providing Chief Financial Officer and full-cycle accounting services to private and public companies, since 2005. Acting on behalf of several public companies, Alnesh has acquired considerable experience in financial reporting, corporate governance and regulatory compliance. He holds a Bachelor of Business Administration from Simon Fraser University, a Master's of Science in Taxation from Golden Gate University and is a Chartered Professional Accountant (CPA, CA).
Mr. Mohan devotes approximately 25% of his time to Silver Hammer's activities, but will at all times devote sufficient time as is reasonably necessary to discharge his responsibilities as CFO, Corporate Secretary and Director.
Mr. Mohan is not an employee of Silver Hammer but is an independent contractor to Silver Hammer. Mr. Mohan has not entered into a non-competition or non-disclosure agreement with Silver Hammer.
Andrew Gillin, Vice President, Corporate Development & Investor Relations
Andrew Gillin is the Vice President, Corporate Development & Investor Relations of Silver Hammer. Mr. Gillin is a seasoned investment banking and corporate development professional with over 15 years of experience in the metals and mining sector. Throughout his career, he has advised on more than 25 M&A transactions and over 50 lead financing mandates. Most recently, he served as Director, Investment Banking at Echelon Wealth Partners (now Ventum Financial), where he completed transactions with an aggregate value exceeding C$1.2 billion. Prior to Echelon, Mr. Gillin held senior investment banking roles at Eight Capital, where he was a member of the firm's founding partnership group, and Dundee Capital Markets. Earlier in his career, he worked at Paradigm Capital and also gained international private equity experience at an Abu Dhabi-based asset manager. Mr. Gillin holds a Bachelor of Commerce degree from McGill University and an MBA from the University of Cambridge.
Mr. Gillin devotes such time to Silver Hammer's activities as is reasonably necessary to discharge his responsibilities as Vice President, Corporate Development & Investor Relations.
Mr. Gillin is not an employee of Silver Hammer but is an independent contractor to Silver Hammer. Mr. Gillin has not entered into a non-competition or non-disclosure agreement with Silver Hammer.
Donald J. Birak, Independent Director
Mr. Birak has over 40 years of experience in mineral exploration and operations, including the roles of Senior Vice-President of Exploration with Coeur Mining, Inc. (2004 to 2013) responsible for global Greenfields and Brownfields exploration, Vice President of Exploration for AngloGold North America Inc. (1998 to 2004), Independence Mining Company (1995 to 1998), and Hudson Bay Mining & Smelting Ltd. (1992 to 1995) and Chief Geologist & Exploration Geologist for Freeport-McMoRan Gold Company (1978 to 1991).
In 2000, he received the Bill Dennis Prospector of the Year award presented by the Prospectors and Developers Association of Canada, for several copper and zinc deposit discoveries in the Flin Flon-Snow Lake region of Manitoba, Canada. Mr. Birak has a Master of Science degree in Geology from Bowling Green State University and has authored and co-authored several professional publications on the geology and metallurgy of sediment-hosted and epithermal precious metal deposits and on the use of geostatistics in resource modeling and grade control. More recently, Don has co-authored publications and presentations on the new US SEC S-K1300 regulation and on Best Practice in mineral exploration.
Mr. Birak devotes such time to Silver Hammer's activities as is required to fulfill his responsibilities as an Independent Director. Mr. Birak has not entered into a non-competition or non-disclosure agreement with Silver Hammer.
Michael Willett, Independent Director
Mr. Willett, P. Eng. is a seasoned mining executive with 40+ years in mine engineering, development, and operations including senior level project evaluation and advisory roles for project re-starts with various mining companies across North America including Battle North Gold Corporation and Hudbay Minerals Inc. for 20+ years. Mike has operated at many senior roles including Chief Executive Officer and Vice President, more recently, Mr. Willett held the position of Vice President of Operations and Projects for Battle North Gold Corporation and was part of that team which successfully sold the company to Evolution Mining Limited for $343 Million in 2021. Mr. Willett is a graduate of Queen's University, with a BSc. in Mining Engineering and a Masters Certificate in Project Management from the Schulich School of Business.
Mr. Willett devotes such time to Silver Hammer's activities as is required to fulfill his responsibilities as an Independent Director. Mr. Willett has not entered into a non-competition or non-disclosure agreement with Silver Hammer.
Security Holding
As of the date hereof, the directors and officers of Silver Hammer, as a group, own or control or exercise direction over 5,773,311 Silver Hammer Shares, representing 4.13% of the issued and outstanding Silver Hammer Shares.
Corporate Cease Trade Orders or Bankruptcies
To the knowledge of Silver Hammer, other than as disclosed below, no current director or executive officer of Silver Hammer has, within the last ten years prior to the date of the Circular, been a director, chief executive officer or chief financial officer of any issuer (including Silver Hammer) that, (i) while the person was acting in the capacity as director, chief executive officer or chief financial officer, was the subject of a cease trade or similar order or an order that denied the relevant issuer access to any exemption under securities legislation, that was in effect for a period of more than 30 consecutive days; or (ii) was subject to an order that resulted, after the director, executive officer or securityholder holding a sufficient number of securities of Silver Hammer to affect materially the control of Silver Hammer ceased to be a director, chief executive officer or chief financial officer of an issuer, in the issuer being the subject of a cease trade or similar order or an order that denied the relevant issuer access to any exemption under securities legislation, for a period of more than 30 consecutive days, which resulted from an event that occurred while that person was acting as a director, chief executive officer or chief financial officer of the issuer.
Alnesh Mohan was a director of Premier Diversified Holdings Inc. (now Aja Health and Wellness Inc.) ("PDH") when, on February 2, 2024, the British Columbia Securities Commission and the Ontario Securities Commission issued a cease trade order ("CTO"). The CTO resulted from PDH's late filing of the annual audited financial statements and the annual management's discussion and analysis certification of the annual filings. On March 1, 2024, the British Columbia Securities Commission issued a second CTO resulting from PDH's late filing of the first quarter interim financial statements and the interim management's discussion and analysis certification of the interim filings. On July 26, 2024, both CTOs were revoked and are no longer in effect. Mr. Mohan resigned as director on April 17, 2025.
Alnesh Mohan was a director of VSBLTY Groupe Technologies Corp. ("VSBLTY") when the following CTOs and management cease trade orders ("MCTOs" and each an "MCTO") were issued: (a) on May 3, 2023, an MCTO was issued against VSBLTY for failure to file its audited annual financial statements, management discussion and analysis and related certificates for the year ended December 31, 2022. On July 11, 2023, the MCTO was revoked and is no longer in effect; (b) on April 30, 2024, an MCTO was issued against VSBLTY for failure to file its audited annual financial statements, management discussion and analysis and related certificates for the year ended December 31, 2023. On July 23, 2024, the MCTO was revoked and is no longer in effect; (c) on May 1, 2025, an MCTO was issued against VSBLTY, which was replaced on July 16, 2025 by a CTO, in each case for failure to file its audited annual financial statements, management discussion and analysis and related certificates for the year ended December 31, 2024. On March 10, 2026, the CTO was revoked and is no longer in effect; and (d) on May 5, 2026, a CTO was issued against VSBLTY for failure to file its audited annual financial statements, management discussion and analysis and related certificates for the year ended December 31, 2025, which remains in effect as of the date hereof.
To the knowledge of Silver Hammer, no current director or executive officer of Silver Hammer has, within the last ten years prior to the date of the Circular, been a director or executive officer of any company (including Silver Hammer) that, while that person was acting in that capacity, or within a year of that person ceasing to act in that capacity, became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency or was subject to or instituted any proceedings, arrangement or compromise with creditors or had a receiver, receiver manager or trustee appointed to hold its assets.
Penalties or Sanctions
To the knowledge of Silver Hammer, no current director or officer or securityholder holding a sufficient number of securities of Silver Hammer to affect materially the control of Silver Hammer has been subject to: (i) any penalties or sanctions imposed by a court relating to securities legislation or by a securities regulatory authority or has entered into a settlement agreement with a securities regulatory authority; or (ii) any other penalties or sanctions imposed by a court or regulatory body that would likely be considered important to a reasonable investor in making an investment decision.
Personal Bankruptcies
To the knowledge of Silver Hammer, no current director or officer or securityholder holding a sufficient number of securities of Silver Hammer to affect materially the control of Silver Hammer has, within the last ten years prior to the date of the Circular, been a director or executive officer of any company (including Silver Hammer) that, while such person was acting in that capacity, or within a year of that person ceasing to act in that capacity, became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency or was subject to or instituted any proceedings, arrangement or compromise with creditors or had a receiver, receiver manager or trustee appointed to hold its assets.
In addition, to the knowledge of Silver Hammer, no current director or officer or securityholder holding a sufficient number of securities of Silver Hammer to affect materially the control of Silver Hammer has, within the last ten years prior to the date of the Circular, become bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency, or become subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold the assets of the director, officer or securityholder.
Conflicts of Interest
There are no existing material conflicts of interest between Silver Hammer and any director or officer of Silver Hammer. Directors and officers of Silver Hammer may serve as directors and/or officers of other companies or have significant shareholdings in other resource companies and, to the extent that such other companies may participate in ventures in which Silver Hammer may participate, certain directors may have a conflict of interest in negotiating and conducting terms in respect of any transaction involving such companies. In the event that such conflict of interest arises at a meeting of the Silver Hammer board, a director who has such a conflict is required to disclose such conflict and abstain from voting for or against the approval of such transaction.
The directors and officers of Silver Hammer will not be devoting all of their time to Silver Hammer. The directors and officers of Silver Hammer are directors and officers of other companies, some of which are in the same business as Silver Hammer. The directors and officers are required by law to act in the best interests of Silver Hammer. They have the same obligations to the other companies in respect of which they act as directors and officers. Discharge by the directors and officers of their obligations to Silver Hammer may result in a breach of their obligations to the other companies, and in certain circumstances this could expose Silver Hammer to liability to those companies. Similarly, discharge by the directors and officers of their obligations to the other companies could result in a breach of their obligations to act in the best interests of Silver Hammer. Such conflicting legal obligations may expose Silver Hammer to liability to others and impair its ability to achieve its business objectives.
Executive Compensation
The following information is provided as required under Form 51-102F6V for Venture Issuers, as such term is defined in NI 51-102.
For the purposes of this section:
During the financial year ended September 30, 2025, based on the definition above, the NEOs of Silver Hammer were: Peter A. Ball, President, CEO and Director, and Alnesh Mohan, CFO, Corporate Secretary and Director. The directors of Silver Hammer who were not NEOs during the financial year ended September 30, 2025 were: Donald J. Birak, Michael Willett, and Ron Burk.
Corporate Actions during the Financial Year Ended September 30, 2025
Effective September 15, 2025, Ron Burk resigned as a director of Silver Hammer and was appointed as Senior Technical Board Advisor. Effective September 15, 2025, Michael Willett was appointed a Director of Silver Hammer. Effective May 1, 2025, Lawrence Roulston resigned as a director of Silver Hammer.
Director and NEO Compensation, Excluding Options and Compensation Securities
The following table of compensation, excluding options and compensation securities, provides a summary of the compensation paid by Silver Hammer to NEOs and directors of Silver Hammer for the two completed financial years ended September 30, 2025 and September 30, 2024. Options and compensation securities are disclosed under the heading "Stock Options and Other Compensation Securities" in this Appendix "E".
| Table of Compensation Excluding Compensation Securities | |||||||
| Name and Position | Year(1) | Salary, consulting fee, retainer or commission ($) |
Bonus ($) |
Committee or meeting fees ($) |
Value of perquisites ($) |
Value of all other compensation ($) |
Total compensation ($) |
| Peter A. Ball(2), President & CEO, Director | 2025 | $200,000 (3) | Nil | Nil | Nil | $7,922(4) | $207,922 |
| 2024 | $200,000 (3) | Nil | Nil | Nil | Nil | $200,000 | |
| Alnesh Mohan(5) CFO & Corporate Secretary, Director | 2025 | $125,260 (6) | Nil | Nil | Nil | $24,500(7) | $149,760 |
| 2024 | $132,580 (6) | Nil | Nil | Nil | $12,500(8) | $145,080 | |
| Donald J. Birak Director |
2025 | Nil | Nil | Nil | Nil | Nil | Nil |
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | |
| Michael Willett(9) Director |
2025 | Nil | Nil | Nil | Nil | Nil | Nil |
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | |
| Ron Burk(10) Senior Technical Board Advisor, Former Director | 2025 | Nil | Nil | Nil | Nil | Nil | Nil |
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | |
| Lawrence Roulston(11) Director | 2025 | Nil | Nil | Nil | Nil | Nil | Nil |
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | |
Notes:
(1) For the financial years ended September 30.
(2) Mr. Ball has served as CEO, President and a director of Silver Hammer since February 15, 2023.
(3) Paid to Ariston Capital Corp., a private company of which Mr. Ball is the principal.
(4) Paid to Ariston Capital Corp. for share-issuance costs.
(5) Mr. Mohan has served as CFO and a director of Silver Hammer since May 14, 2021 and as Corporate Secretary of Silver Hammer since October 14, 2021.
(6) Paid to Quantum Advisory Partners LLP, a private company of which Mr. Mohan is a principal.
(7) Paid to Quantum Advisory Partners LLP for share-issuance costs.
(8) Paid to Quantum Advisory Partners LLP for project evaluation costs.
(9) Mr. Willett was appointed as a director of Silver Hammer on September 15, 2025.
(10) Mr. Burk resigned as a director of S i l v e r H a m m e r effective September 15, 2025 and was appointed as Senior Technical Board Advisor September 15, 2025.
(11) Mr. Roulston resigned as a director of Silver Hammer on May 1, 2025.
External Management Companies
Silver Hammer has not engaged the services of an external management company to provide executive management services to Silver Hammer, directly or indirectly, at the September 30, 2025 financial year end.
Stock Options and Other Compensation Securities
The following table discloses all compensation securities outstanding to each NEO of Silver Hammer and to a director who was not an NEO of Silver Hammer, or a subsidiary of Silver Hammer, in the most recently completed financial year ended September 30, 2025 for services provided or to be provided, directly or indirectly, to Silver Hammer, or a subsidiary of Silver Hammer.
| Compensation Securities | |||||||
Name and Position |
Type of Compensation Security(1) |
Number of Compensation Securities, underlying securities and percentage of class (#) |
Date of Grant or Issue (mm/dd/yy)(7) |
Issue, conversion or exercise price ($) |
Closing price of security or underlying security on date of grant ($) |
Closing price of security or underlying security at year end ($) |
Expiry Date (mm/dd/yy) |
| Peter A. Ball(2) President & CEO, Director | Stock option | 750,000 | 02-15-23 | 0.240 | 0.240 | 0.125 | 02-15-28 |
| Stock option | 2,000,000 | 08-05-25 | 0.055 | 0.055 | 0.125 | 08-05-30 | |
| Alnesh Mohan(3) CFO & Corporate Secretary, Director | Stock option | 200,000 | 06-16-21 | 0.620 | 0.620 | 0.125 | 06-16-26 |
| Stock option | 185,000 | 02-15-23 | 0.240 | 0.240 | 0.125 | 02-15-28 | |
| Stock option | 1,200,000 | 08-05-25 | 0.055 | 0.055 | 0.125 | 08-05-30 | |
| Donald J. Birak(4) Director |
Stock option | 185,000 | 03-15-23 | 0.240 | 0.230 | 0.125 | 03-15-28 |
| Stock option | 650,000 | 08-05-25 | 0.055 | 0.055 | 0.125 | 08-05-30 | |
| Michael Willett(5) Director |
Stock option | 500,000 | 09-15-25 | 0.080 | 0.080 | 0.125 | 09-15-30 |
| Ron Burk(6) Senior Technical Board Advisor, Former Director | Stock option | 185,000 | 02-15-23 | 0.240 | 0.240 | 0.125 | 02-15-28 |
| Stock option | 350,000 | 08-05-25 | 0.055 | 0.055 | 0.125 | 08-05-30 | |
Notes:
(1) Each stock option is exercisable or redeemable into one Silver Hammer Share.
(2) Lolgorian Holdings Inc., a private company of which Mr. Ball is the principal, held 2,750,000 stock options at the end of the financial year September 30, 2025.
(3) Mr. Mohan held 1,585,000 stock options at the end of the financial year September 30, 2025.
(4) Mr. Birak held 835,000 stock options at the end of the financial year September 30, 2025.
(5) Mr. Willett held 500,000 stock options at the end of the financial year September 30, 2025.
(6) Mr. Burk held 535,000 stock options at the end of the financial year September 30, 2025.
(7) All stock options vested immediately upon grant.
Exercise of Compensation Securities by NEOs and Directors
There were no compensation securities exercised by any of the NEOs or directors of Silver Hammer who were not NEOs in the financial year ended September 30, 2025.
Stock Option Plans and Other Incentive Plans
Silver Hammer currently has in place a "rolling" stock option plan whereby the maximum number of shares that may be reserved for issuance pursuant to the exercise of options is 10% of the issued shares of Silver Hammer. For a description of the material terms of the Option Plan, see "Options to Purchase Securities" above in this Appendix "E".
Employment, Consulting and Management Agreements
On February 15, 2023, Silver Hammer entered into an agreement (the "Ball Agreement") with Peter A. Ball, the CEO and a director of Silver Hammer. Pursuant to the Ball Agreement, Mr. Ball is entitled to an amount equal to 12 months' of his base fee, plus three additional months of his base fee for each full year of service (pro-rated for any partial year of service and rounded up) after the effective date, up to a maximum of 24 months' of his base fee (the "Termination Fee") and any outstanding options will expire and will cease to be exercisable 90 days following the date of termination. Additionally, if a Change of Control Event occurs, and the Ball Agreement is terminated for any reason during the Change of Control Period (excluding termination for Just Cause), or Mr. Ball terminates the Ball Agreement for Good Reason during the Change of Control Period, Silver Hammer is required to pay Mr. Ball one and one half (1.5) times the Termination Fee that is payable to Mr. Ball pursuant to section 5.3(c) of the Ball Agreement.
On June 22, 2021, Silver Hammer entered into an agreement (the "Mohan Agreement") with Alnesh Mohan, the CFO and Corporate Secretary of Silver Hammer. Pursuant to the Mohan Agreement, if Silver Hammer terminates the Mohan Agreement without cause, and such termination occurs either prior to 6 months before or after 12 months following a Change of Control or a Fundamental Transaction effective no later than 30 days following the termination, then Mr. Mohan is entitled to receive a lump sum termination fee equal to 12 months of the service fees, as in effect immediately prior to the termination date of the Mohan Agreement.
Oversight and Description of Director and Named Executive Officer Compensation
Director compensation and NEO compensation is determined by the Compensation Committee of Silver Hammer in consultation with management. Compensation is reviewed annually around the calendar year end.
The Compensation Committee is established by the board of directors to assist the Board in fulfilling its responsibilities relating to matters of human resources and compensation, including equity compensation, and to establish a plan of continuity and development of senior management. The Committee has responsibility for evaluating and making recommendations to the Board regarding the compensation of Silver Hammer's CEO, the range of compensation for other executives, and the equity-based and incentive compensation plans, policies and programs of Silver Hammer. The Committee will also review and recommend to the Board the compensation payable to directors. The Committee shall review management's annual report on executive compensation for recommendation to the Board for approval and inclusion in Silver Hammer's disclosure documents. The Compensation Committee consists of Donald Birak (Chair) and Michael Willett.
Silver Hammer's compensation objectives include the following: to assist Silver Hammer in attracting and retaining highly-qualified individuals; to create among directors, officers, consultants and employees a sense of ownership in Silver Hammer and to align their interests with those of the shareholders; and to ensure competitive compensation that is also financially affordable for Silver Hammer. The compensation program is designed to provide competitive levels of compensation. Silver Hammer recognizes the need to provide a total compensation package that will attract and retain qualified and experienced executives as well as align the compensation level of each executive to that executive's level of responsibility. In general, Silver Hammer's NEOs may receive compensation that is comprised of three components: salary, wages or contractor payments; stock option grants; and/or bonuses. The objective and reason for this system of compensation is to allow Silver Hammer to remain competitive compared to its peers in attracting experienced personnel. The base salary of a NEO is intended to attract and retain executives by providing a reasonable amount of non-contingent remuneration. The base salary review of each NEO takes into consideration the current competitive market conditions, experience, proven or expected performance, and the particular skills of the NEO. Base salary is not evaluated against a formal "peer group". The Board relies on the general experience of its members in setting base salary amounts. Stock option grants are designed to reward the NEOs and directors for success on a similar basis as the shareholders of Silver Hammer, although the level of reward provided by a particular stock option grant is dependent upon the volatile stock market. Any bonuses paid to the NEOs are allocated on an individual basis related to the review by the Board of the work planned during the year and the work achieved during the year, including work related to mineral exploration, administration, financing, shareholder relations and overall performance. The bonuses are paid to reward work done above the base level of expectations set by the base salary, wages or contractor payments.
Pension Disclosure
Silver Hammer has no pension plans that provide for payments or benefits to any NEO at, following or in connection with retirement. Silver Hammer also does not have any deferred compensation plans relating to any NEO.
Indebtedness of Directors and Executive Officers
No person who is, or who has been, a director, executive officer or employee of Silver Hammer or any associate of any of the aforementioned, is or has been indebted to Silver Hammer or any of its subsidiaries or to any entity which has been provided a guarantee, support agreement, letter of credit or similar arrangement by Silver Hammer at any time before the date of the Circular.
Audit Committee
The audit committee of Silver Hammer (the "Silver Hammer Audit Committee") assists the Silver Hammer Board in fulfilling its financial oversight responsibilities. The Silver Hammer Audit Committee reviews and considers in consultation with the auditors the financial reporting process, the system of internal control and the audit process. In performing its duties, the Silver Hammer Audit Committee maintains effective working relationships with the Silver Hammer Board, management, and the external auditors. To effectively perform his or her role, each Silver Hammer Audit Committee member must obtain an understanding of the principal responsibilities of audit committee membership as well as Silver Hammer's business, operations and risks.
Audit Committee Charter
The Silver Hammer Board has adopted a Charter of the Silver Hammer Audit Committee, which sets out the Silver Hammer Audit Committee's mandate, organization, powers and responsibilities. The Charter is attached as Exhibit "A" to this Appendix "E".
Composition of the Audit Committee
As at the date of the Circular, the following are the members of the Silver Hammer Audit Committee:
| Name | Independent/Not Independent(1) | Financially Literate(2) |
| Michael Willett (Chair) | Independent | Yes |
| Donald J. Birak | Independent | Yes |
| Alnesh Mohan | Not Independent | Yes |
Notes:
(1) A member is independent if the member has no direct or indirect material relationship with Silver Hammer, which could, in the view of the Silver Hammer Board, reasonably interfere with the exercise of that member's independent judgment.
(2) A member is financially literate if such member has the ability to read and understand a set of financial statements that present a breadth of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can reasonably be expected to be raised by Silver Hammer's financial statements.
In accordance with section 6.1.1(3) of National Instrument 52-110 - Audit Committees ("NI 52-110") relating to the composition of the audit committee for venture issuers, a majority of the members of the Silver Hammer Audit Committee are not executive officers, employees or control persons of Silver Hammer. All the members of the Silver Hammer Audit Committee are considered to be financially literate as required by section 1.6 of NI 52-110. Also see "Corporate Governance" in this Appendix "E".
Relevant Education and Experience
Each member of the Silver Hammer Audit Committee has had extensive experience reviewing financial statements. Each member of the Silver Hammer Audit Committee has an understanding of Silver Hammer's business and an appreciation for the relevant accounting principles for that business. In particular, Silver Hammer believes that each of the members of the Silver Hammer Audit Committee possesses: (a) an understanding of the accounting principles used by Silver Hammer to prepare its financial statements; (b) the ability to assess the general application of such accounting principles in connection with the accounting for estimates, accruals and reserves; (c) experience preparing, auditing, analyzing or evaluating financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of issues that can reasonably be expected to be raised by Silver Hammer's financial statements, or experience actively supervising one or more individuals engaged in such activities; and (d) an understanding of internal controls and procedures for financial reporting.
For a summary of the experience and education of the Silver Hammer Audit Committee members see "Directors and Executive Officers" in this Appendix "E".
Audit Committee Oversight
At no time has a recommendation of the Silver Hammer Audit Committee to nominate or compensate an external auditor not been adopted by the Silver Hammer Board.
Reliance on Certain Exemptions
Silver Hammer has not relied on certain exemptions set out in NI 52-110, namely section 2.4 (De Minimis Non-audit Services), subsection 6.1.1(4) (Circumstance Affecting the Business or Operations of the Venture Issuer), subsection 6.1.1(5) (Events Outside Control of Member), subsection 6.1.1(6) (Death, Incapacity or Resignation), and any exemption, in whole or in part, in Part 8 (Exemptions).
Silver Hammer expects to rely on the exemption in Section 6.1 of NI 52-110 from the requirement of Parts 3 (Composition of the Audit Committee) and 5 (Reporting Obligations).
Pre-Approval Policies and Procedures
The Silver Hammer Audit Committee has not adopted formal policies and procedures for the engagement of non-audit services. Subject to the requirements of NI 52-110, the engagement of non-audit services is considered by, as applicable, the Silver Hammer Board and the Silver Hammer Audit Committee, on a case-by-case basis.
External Auditors Service Fees
The following table discloses the fees billed to Silver Hammer by its external auditors for the financial years ended September 30, 2025 and September 30, 2024:
| Year Ended | Audit Fees (1) | Audit-Related Fees(2) | Tax Fees(3) | All Other Fees(4) |
| September 30, 2025 | $54,624 | $Nil | $12,000 | $66,624 |
| September 30, 2024 | $52,624 | $Nil | $10,000 | $62,624 |
Notes:
(1) "Audit Fees" include fees necessary to perform the annual audit and quarterly reviews of Silver Hammer's financial statements. Audit Fees include fees for review of tax provisions and for accounting consultations on matters reflected in the financial statements. Audit Fees also include audit or other attest services required by legislation or regulation, such as comfort letters, consents, reviews of securities filings and statutory audits.
(2) "Audit-Related Fees" include services that are traditionally performed by the auditor. These audit-related services include employee benefit audits, due diligence assistance, accounting consultations on proposed transactions, internal control reviews and audit or attest services not required by legislation or regulation.
(3) "Tax Fees" include fees for all tax services other than those included in "Audit Fees" and "Audit-Related Fees". This category includes fees for tax compliance, tax planning and tax advice. Tax planning and tax advice includes assistance with tax audits and appeals, tax advice related to mergers and acquisitions and requests for rulings or technical advice from tax authorities.
(4) "All Other Fees" include all other non-audit services.
Corporate Governance Disclosure
Corporate governance refers to the policies and structure of the Board of a corporation, whose members are elected by and are accountable to the shareholders of the company. Corporate governance encourages establishing a reasonable degree of independence of the Board from executive management and the adoption of policies to ensure the Board recognizes the principles of good management. The Board is committed to sound corporate governance practices, as such practices are both in the interests of shareholders and help to contribute to effective and efficient decision-making.
Silver Hammer's corporate governance practices are summarized below.
Independence of Members of Board
Directors are considered to be independent if they have no direct or indirect material relationship with Silver Hammer. A "material relationship" is a relationship which could, in the opinion of the Board, be reasonably expected to interfere with the exercise of a director's independent judgment.
The Board facilitates its exercise of independent judgment in carrying out its responsibilities by carefully examining issues and consulting with outside counsel and other advisors in appropriate circumstances. The Board requires management to provide complete and accurate information with respect to Silver Hammer's activities and to provide relevant information concerning the mineral exploration industry in order to identify and manage risks. The Board is responsible for monitoring Silver Hammer's senior officers, who in turn are responsible for the maintenance of internal controls and management information systems.
The independent members of the Board are Donald J. Birak and Michael Willett. The non-independent members of the Board are Peter A. Ball (President and Chief Executive Officer) and Alnesh Mohan (Chief Financial Officer and Corporate Secretary).
Participation of Directors in Other Reporting Issuers
The following table sets out, as at the date of the Circular, the current directors and nominees for director of Silver Hammer that are currently directors of other reporting issuers:
| Name | Name of Reporting Issuer | Name of Exchange or Market |
| Peter A. Ball | Big Gold Inc. | CSE |
| Alnesh Mohan | DGL Investments No. 1 Inc. VSBLTY Groupe Technologies Corp. Trail Blazer Capital Corp. |
CSE, OTCQB CSE TSXV |
| Donald J. Birak | Stria Lithium Inc. | TSXV |
| Michael Willett | None | N/A |
Orientation and Continuing Education
New directors participate in an orientation discussion with Silver Hammer's management and incumbent directors regarding the role of the Board, its committees, and the nature and operations of Silver Hammer's business. Members of the Board are encouraged to communicate with management of Silver Hammer, external legal counsel and auditors, and other external consultants to educate themselves about Silver Hammer's business, the mining industry and applicable legal and regulatory developments.
Ethical Business Conduct
The Board views good corporate governance as an integral component to the success of Silver Hammer and to meet responsibilities to shareholders. However, the Board has not adopted a Code of Conduct.
The Board, through its meetings with management and other informal discussions with management, encourages a culture of ethical business conduct and believes Silver Hammer's high caliber management team promotes a culture of ethical business conduct throughout Silver Hammer's operations and is expected to monitor the activities of Silver Hammer's employees, consultants and agents in that regard.
It is a requirement of applicable corporate law that directors and senior officers who have an interest in a transaction or agreement with Silver Hammer promptly disclose that interest at any meeting of the Board at which the transaction or agreement will be discussed and, in the case of directors, abstain from discussions and voting in respect to same if the interest is material. These requirements are also contained in Silver Hammer's Articles, which are made available to directors and senior officers of Silver Hammer.
Nomination of Directors
The Board considers its size each year when it considers the number of directors to recommend to shareholders for election at the annual meeting of shareholders, taking into account the number required to carry out the Board's duties effectively and to maintain a diversity of views and experience.
The Board does not have a nominating committee, and these functions are currently performed by the Board as a whole. However, if there is a change in the number of directors required by Silver Hammer, this practice may be reviewed.
Compensation
The Board has established a Corporate Governance Committee to assist the Board in its oversight of corporate governance practices. The compensation of directors and officers is determined by the Board, after consideration of various relevant factors, including the expected nature and quantity of duties and responsibilities, past performance, comparison with compensation paid by other issuers of comparable size and nature, and the availability of financial resources.
Board Committees
The Board has the following standing committees: the Audit Committee; the Compensation Committee; and the Corporate Governance Committee.
Corporate Governance Committee
The Corporate Governance Committee assists the Board in its oversight of Silver Hammer's corporate governance practices and in assessing the effectiveness of the Board and its committees. The Corporate Governance Committee consists of Donald Birak (Chair), Michael Willett and Peter A. Ball. The Charter of the Corporate Governance Committee is available on the SEDAR+ website under Silver Hammer's profile at www.sedarplus.ca.
Audit Committee
The primary function of the Audit Committee is to assist the Board in fulfilling its financial oversight responsibilities with respect to the financial reporting process and the quality, transparency and integrity of the financial statements and other related public disclosures; Silver Hammer's systems of internal controls regarding finance and accounting and Silver Hammer's auditing, accounting and financial reporting processes. Consistent with this function, the Audit Committee will encourage continuous improvement of, and should foster adherence to, Silver Hammer's policies, procedures and practices at all levels. The Audit Committee consists of Michael Willett (Chair), Donald Birak, and Alnesh Mohan. The Audit Committee meets at least four times annually.
See "Audit Committee" for details about its composition and function. The Charter of the Audit Committee is attached as Exhibit "A" to this Appendix "E".
Compensation Committee
The Compensation Committee is established by the board of directors to assist the Board in fulfilling its responsibilities relating to matters of human resources and compensation, including equity compensation, and to establish a plan of continuity and development of senior management. The Committee has responsibility for evaluating and making recommendations to the Board regarding the compensation of Silver Hammer's CEO, the range of compensation for other executives, and the equity-based and incentive compensation plans, policies and programs of Silver Hammer. The Committee will also review and recommend to the Board the compensation payable to directors. The Committee shall review management's annual report on executive compensation for recommendation to the Board for approval and inclusion in Silver Hammer's disclosure documents. The Compensation Committee consists of Donald Birak (Chair) and Michael Willett.
See "Compensation Committee" for details about its composition and function. The Charter of the Compensation Committee is available on the SEDAR+ website under Silver Hammer's profile at www.sedarplus.ca.
Assessments
The Board monitors the adequacy of information given to directors, communication between the Board and management, and the strategic direction and processes of the Board and its committees.
No formal policy has been established to monitor the effectiveness of the directors, the Board and its committees. However, Silver Hammer believes that its corporate governance practices are appropriate and effective given Silver Hammer's stage of development.
Risk Factors
An investment in Silver Hammer Shares involves a significant degree of risk and should be considered speculative due to the nature of Silver Hammer's business and the present stage of its development. In evaluating the proposed transactions, shareholders should carefully consider all of the information in this section, and, in particular, should evaluate the risk factors set out below. However, such risks may not be the only risks faced by Silver Hammer. Risks and uncertainties not presently known by Silver Hammer or which are presently considered immaterial may also adversely affect Silver Hammer's business, properties, results of operations and/or condition (financial or otherwise).
Risks Related to the Business of Silver Hammer
Resource Exploration and Development is a Speculative Business
Resource exploration and development is a speculative business and involves a high degree of risk, including, among other things, unprofitable efforts resulting not only from the failure to discover mineral deposits but from finding mineral deposits which, though present, are insufficient in size to return a profit from production. The marketability of natural resources that may be acquired or discovered by Silver Hammer will be affected by numerous factors beyond its control. These factors include market fluctuations, the proximity and capacity of natural resource markets, government regulations, including regulations relating to prices, taxes, royalties, land use, importing and exporting of minerals and environmental protection. The exact effect of these factors cannot be accurately predicted, but the combination of these factors may result in Silver Hammer not receiving an adequate return on invested capital.
Substantial expenditures are required to establish ore reserves through drilling and metallurgical and other testing techniques, determine metal content and metallurgical recovery processes to extract metal from the ore, and construct, renovate or expand mining and processing facilities. No assurance can be given that any level of recovery of ore reserves will be realized or that any identified mineral deposit, even it is established to contain an estimated resource, will ever qualify as a commercial mineable ore body which can be legally and economically exploited. The great majority of exploration projects do not result in the discovery of commercially mineable deposits of ore.
Ability to Raise Funding to Continue Exploration and other Activities
Silver Hammer has no revenues from operations and has recorded losses since inception. Silver Hammer expects to incur operating losses in future periods due to continuing expenses associated with general and administrative costs, costs of seeking new business opportunities, and advancing its projects.
Silver Hammer has finite financial resources and its ability to achieve and maintain profitability and positive cash flow is dependent upon its ability to:
Silver Hammer may rely on a combination of equity and debt financing to meet its capital requirements. Additional funds raised by Silver Hammer through the issuance of equity or convertible debt securities will cause current Silver Hammer shareholders to experience dilution. Such securities may grant rights, preferences or privileges senior to those of the Silver Hammer shareholders.
Silver Hammer does not have any contractual restrictions on its ability to incur debt and accordingly, Silver Hammer could incur significant amounts of indebtedness to finance its operations. Any such indebtedness could contain covenants, which would restrict Silver Hammer's operations.
Silver Hammer may need to pursue alternative ways to finance its future operations and seeks new business opportunities. There are no assurances or guarantees that any financing alternative will be successful. There is no certainty that additional financing either through traditional equity and debt financing arrangements or an alternative transaction, or any combination thereof, will be available at all or on acceptable terms.
Development of Properties
Silver Hammer is an exploration and development company and all of its properties and property interests are in the exploration stage. Silver Hammer has not defined or delineated any mineral resources or mineral reserves on any of its properties, which include the Silver Strand Project and Fahey Group Silver Project in Idaho, and the Eliza Silver Project and Silverton Silver Mine in Nevada.
Fluctuation of Metal Prices
Even if commercial quantities of mineral deposits are discovered by Silver Hammer, there is no guarantee that a profitable market will exist for the sale of the metals produced. Factors beyond the control of Silver Hammer may affect the marketability of any substances discovered. The prices of various metals have experienced significant movement over short periods of time and are affected by numerous factors beyond the control of Silver Hammer, including international economic and political trends, expectations of inflation, currency exchange fluctuations, interest rates and global or regional consumption patterns, speculative activities and increased production due to improved mining and production methods. The supply of and demand for metals are affected by various factors, including political events, economic conditions and production costs in major producing regions. There can be no assurance that the price of any commodities will be such that any of the properties in which Silver Hammer has, or has the right to acquire, an interest may be mined at a profit.
Increased Costs
Management anticipates that costs at Silver Hammer's projects will frequently be subject to variation from one year to the next due to a number of factors, such as the results of ongoing exploration activities (positive or negative), changes in the nature of mineralization encountered, and revisions to exploration programs, if any, in response to the foregoing. Increases in the prices of such commodities or a scarcity of consultants or drilling contractors could render the costs of exploration programs to increase significantly over those budgeted. A material increase in costs for any significant exploration programs could have a significant effect on Silver Hammer's operating funds and ability to continue its planned exploration programs.
Reclamation
There is a risk that monies allotted for land reclamation may not be sufficient to cover all risks, due to changes in the nature of the waste rock or tailings and/or revisions to government regulations. Therefore, additional funds, or reclamation bonds or other forms of financial assurance may be required over the tenure of any mineral project of Silver Hammer to cover potential risks. These additional costs may have a material adverse effect on Silver Hammer's business, financial condition and results of operations.
Mining Industry is Intensely Competitive
Silver Hammer's business of the acquisition, exploration and development of mineral properties is intensely competitive. Increased competition could adversely affect Silver Hammer's ability to attract necessary capital funding or acquire suitable producing properties or prospects for mineral exploration in the future.
Permits and Licenses
The operations of Silver Hammer will require licenses and permits from various governmental authorities. There can be no assurance that Silver Hammer will be able to obtain all necessary licenses and permits that may be required to carry out exploration, development and mining operations at its projects, on reasonable terms or at all. Delays or a failure to obtain such licenses and permits or a failure to comply with the terms of any such licenses and permits that Silver Hammer does obtain, could have a material adverse effect on Silver Hammer.
Government Regulation
Any exploration, development or mining operations carried on by Silver Hammer, will be subject to government legislation, policies and controls relating to prospecting, development, production, environmental protection, mining taxes and labour standards. In addition, the profitability of any mining prospect is affected by the market for precious and/or base metals which is influenced by many factors including changing production costs, the supply and demand for metals, the rate of inflation, the inventory of metal producing corporations, the political environment and changes in international investment patterns.
Environmental Restrictions
The activities of Silver Hammer are subject to environmental regulations promulgated by government agencies in different countries from time to time. Environmental legislation generally provides for restrictions and prohibitions on spills, releases or emissions into the air, discharges into water, management of waste, management of hazardous substances, protection of natural resources, antiquities and endangered species and reclamation of lands disturbed by mining operations. Certain types of operations require the submission and approval of environmental impact assessments. Environmental legislation is evolving in a manner which means stricter standards, and enforcement, fines and penalties for non-compliance are more stringent. Environmental assessments of proposed projects carry a heightened degree of responsibility for companies and directors, officers and employees. The cost of compliance with changes in governmental regulations has a potential to reduce the profitability of operations.
Public Health Crises
Silver Hammer's business, operations and financial condition could be materially and adversely affected by the outbreak of epidemics or pandemics or other health crises. The occurrence of such events could result in temporary business closures, quarantines and a general reduction in consumer and economic activity across multiple jurisdictions, including Canada, the United States, Europe and Asia. Governments and international jurisdictions may impose travel, gathering and other public health restrictions in response to such events.
Such public health crises can result in volatility and disruptions in the supply and demand for metals and minerals, global supply chains and financial markets, as well as declining trade and market sentiment and reduced mobility of people, all of which could affect commodity prices, interest rates, credit ratings, credit risk and inflation. The risks to Silver Hammer of such public health crises also include risks to employee health and safety, a slowdown or temporary suspension of operations in geographic locations impacted by an outbreak, increased labour and fuel costs, regulatory changes, political or economic instabilities or civil unrest. Any of these could affect Silver Hammer's ability to advance exploration and development with such risks to include challenges in recruiting and retaining staff and personnel, restricted access for employees and contractors to the Projects, equipment and materials not being delivered to site on schedule or at all, and further inefficiencies required to be put in place to health and safety resulting in less productivity.
Geopolitical and International Conflict Risks
Geopolitical instability, armed conflicts, and international tensions in various regions of the world could lead to heightened volatility in the global financial markets, increased inflation, and turbulence in mining and commodity markets. In response to armed conflicts or other geopolitical events, governments and international bodies may impose economic sanctions, export control measures, trade restrictions, or other measures that could disrupt global supply chains, commodity markets, and capital flows. Such measures have and could in the future result in, among other things, severe or complete restrictions on exports and other commerce and business dealings involving affected regions and particular entities and individuals. While Silver Hammer does not currently have direct exposure to active conflict zones, geopolitical events are rapidly developing situations and it is uncertain as to how such events and any related economic sanctions or trade restrictions could impact the global economy, commodity prices, or Silver Hammer's ability to raise capital or conduct operations. Any negative developments in respect thereof could have an adverse effect on Silver Hammer's business, operations, financial condition, and the value of Silver Hammer's securities.
Title Matters
Although Silver Hammer has taken steps to verify the title to the mineral properties in which it has or has a right to acquire an interest in accordance with industry standards for the current stage of exploration of such properties, these procedures do not guarantee title (whether of Silver Hammer or of any underlying vendor(s) from whom Silver Hammer may be acquiring its interest). Title to mineral properties may be subject to unregistered prior agreements or transfers and may also be affected by undetected defects or the rights of indigenous peoples. Silver Hammer has investigated title to all of its mineral properties and, to the best of its knowledge, title to all of its properties for which titles have been issued are in good standing.
Indigenous and First Nations Rights
Silver Hammer's mineral exploration and development activities may be affected by the rights of Indigenous Peoples in the jurisdictions where it operates. Silver Hammer currently holds mineral properties in the United States, including in Idaho and Nevada, where certain federal and state permitting processes require consultation with Indigenous or Tribal Nations whose traditional territories may overlap with mineral projects. In Canada, governments may be required to consult and, where appropriate, accommodate Indigenous Peoples in connection with the granting of mineral rights or the issuance or amendment of project authorizations. These consultation obligations and related legal frameworks continue to evolve.
Legislative developments may result in enhanced consultation requirements or additional accommodations, including financial commitments, employment and training opportunities, or other terms under impact and benefit agreements. Such requirements may affect the timing and cost of obtaining mineral titles, permits, or approvals, and could delay or increase the cost of exploration and development activities.
Unforeseen claims, grievances, or opposition by Indigenous Peoples could impact Silver Hammer's existing or planned operations, project timelines, or future acquisitions. The need to address Indigenous rights considerations may increase operating costs and could affect Silver Hammer's ability to advance, expand, or dispose of its mineral projects.
Exploration and Mining Risks
Fires, power outages, labour disruptions, flooding, explosions, cave-ins, landslides and the inability to obtain suitable or adequate machinery, equipment or labour are other risks involved in the operation of mines and the conduct of exploration programs. Substantial expenditures are required to establish reserves through drilling, to develop metallurgical processes, to develop the mining and processing facilities and infrastructure at any site chosen for mining. Although substantial benefits may be derived from the discovery of a major mineralized deposit, no assurance can be given that minerals will be discovered in sufficient quantities to justify commercial operations or that funds required for development can be obtained on a timely basis. The economics of developing mineral properties is affected by many factors including the cost of operations, variations of the grade of ore mined, fluctuations in the price of minerals produced, costs of processing equipment and such other factors as government regulations, including regulations relating to royalties, allowable production, importing and exporting of minerals and environmental protection. In addition, the grade of mineralization ultimately mined may differ from that indicated by drilling results and such differences could be material. Short term factors, such as the need for orderly development of ore bodies or the processing of new or different grades, may have an adverse effect on mining operations and on the results of operations. There can be no assurance that minerals recovered in small scale laboratory tests will be duplicated in large scale tests under on-site conditions or in production scale operations. Material changes in geological resources, grades, stripping ratios or recovery rates may affect the economic viability of projects.
Regulatory Requirements
The activities of Silver Hammer are subject to extensive regulations governing various matters, including environmental protection, management and use of toxic substances and explosives, management of natural resources, exploration, development of mines, production and post-closure reclamation, exports, price controls, taxation, regulations concerning business dealings with indigenous peoples, labour standards on occupational health and safety, including mine safety, and historic and cultural preservation. Failure to comply with applicable laws and regulations may result in civil or criminal fines or penalties, enforcement actions thereunder, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed, and may include corrective measures requiring capital expenditures, installation of additional equipment, or remedial actions, any of which could result in Silver Hammer incurring significant expenditures. Silver Hammer may also be required to compensate those suffering loss or damage by reason of a breach of such laws, regulations or permitting requirements. It is also possible that future laws and regulations, or more stringent enforcement of current laws and regulations by governmental authorities, could cause additional expense, capital expenditures, restrictions on or suspension of Silver Hammer's operations and delays in the exploration and development of Silver Hammer's properties.
Influence of Third Parties
The mineral properties in which Silver Hammer holds an interest, or the exploration equipment and road or other means of access which Silver Hammer intends to utilize in carrying out its work programs or general business mandates, may be subject to interests or claims by third party individuals, groups or companies. In the event that such third parties assert any claims, Silver Hammer's work programs may be delayed even if such claims are not meritorious. Such claims may result in significant financial loss and loss of opportunity for Silver Hammer.
No Assurance of Profitability
Silver Hammer has no history of earnings and, due to the nature of its business there can be no assurance that Silver Hammer will ever be profitable. Silver Hammer has not paid dividends on its shares since incorporation and does not anticipate doing so in the foreseeable future. The only present source of funds available to Silver Hammer is from the sale of its shares or, possibly, from the sale or optioning of a portion of its interest in its mineral properties. Even if the results of exploration are encouraging, Silver Hammer may not have sufficient funds to conduct the further exploration that may be necessary to determine whether or not a commercially mineable deposit exists. While Silver Hammer may generate additional working capital through further equity offerings or through the sale or possible syndication of its properties, there can be no assurance that any such funds will be available on favorable terms, or at all. At present, it is impossible to determine what amounts of additional funds, if any, may be required. Failure to raise such additional capital could put the continued viability of Silver Hammer at risk.
Uninsured or Uninsurable Risks
Exploration, development and mining operations involve various hazards, including environmental hazards, industrial accidents, metallurgical and other processing problems, unusual or unexpected rock formations, structural cave-ins or slides, flooding, fires, metal losses and periodic interruptions due to inclement or hazardous weather conditions. These risks could result in damage to or destruction of mineral properties, facilities or other property, personal injury, environmental damage, delays in operations, increased cost of operations, monetary losses and possible legal liability. Silver Hammer may not be able to obtain insurance to cover these risks at economically feasible premiums or at all. Silver Hammer may elect not to insure where premium costs are disproportionate to Silver Hammer's perception of the relevant risks. The payment of such insurance premiums and of such liabilities would reduce the funds available for exploration and production activities.
Potential Conflicts of Interest
The directors and officers of Silver Hammer may serve as directors and/or officers for other public and private companies, including companies in which Silver Hammer has invested in, and may devote a portion of their time to manage other business interests. This may result in certain conflicts of interest. To the extent that such other companies may participate in ventures in which Silver Hammer is also participating, and to the extent that such companies may receive funds from Silver Hammer, such directors and officers of Silver Hammer may have a conflict of interest in negotiating and reaching an agreement with respect to the extent of each company's participation. The BCBCA, which governs Silver Hammer, requires the directors and officers to act honestly, in good faith, and in the best interests of Silver Hammer and its shareholders. However, in conflict-of-interest situations, directors and officers of Silver Hammer may owe the same duty to another company and will need to balance the competing obligations and liabilities of their actions. There is no assurance that the needs of Silver Hammer will receive priority in all cases. From time to time, several companies may participate together in the acquisition, exploration and development of natural resource properties, thereby allowing these companies to: (i) participate in larger programs; (ii) acquire an interest in a greater number of programs; and (iii) reduce their financial exposure to any one program. A particular company may assign, at its cost, all or a portion of its interests in a particular program to another affiliated company due to the financial position of Silver Hammer making the assignment. In determining whether or not Silver Hammer will participate in a particular program and the interest therein to be acquired by it, it is expected that the directors and officers of Silver Hammer will primarily consider the degree of risk to which Silver Hammer may be exposed and its financial position at that time.
Key Executives and Outside Consultants
Silver Hammer is dependent upon the services of key executives, including the directors of Silver Hammer, and will be dependent on a small number of highly skilled and experienced executives and personnel. Due to the relatively small size of Silver Hammer, the loss of these persons or the inability of Silver Hammer to attract and retain additional highly skilled employees may adversely affect its business and future operations.
Silver Hammer has also relied upon outside consultants, geologists, engineers and others and intends to rely on these parties for their exploration and development expertise. Substantial expenditures are required to construct mines, to establish mineral resources and reserves estimates through drilling, to carry out environmental and social impact assessments, to develop metallurgical processes and to develop the development, exploration and plant infrastructure at any particular site. If such parties' work is deficient or negligent or is not completed in a timely manner, it could have a material adverse effect on Silver Hammer's business, financial condition and results of operations.
Joint ventures
Silver Hammer may enter into joint venture arrangements with regard to future exploration, development and production properties. There is a risk any future joint venture partner does not meet its obligations and Silver Hammer may therefore suffer additional costs or other losses. It is also possible that the interests of Silver Hammer or future joint venture partners are not aligned resulting in project delays or additional costs and losses. Silver Hammer may have minority interests in the companies, partnerships and ventures in which it invests and may be unable to exercise control over the operations of such companies.
Infrastructure
Mining, processing, development and exploration activities depend, to one degree or another, on adequate infrastructure. Reliable roads, bridges, power sources and water supply are important determinants which affect capital and operating costs. Unusual or infrequent weather phenomena, terrorism, sabotage, government or other interference in the maintenance or provision of such infrastructure could adversely affect Silver Hammer's operations, financial condition and results of operations.
Accounting Policies and Internal Controls
Silver Hammer prepares its financial reports in accordance with IFRS. In preparation of its financial reports, management may need to rely upon assumptions, make estimates or use their best judgment in determining the financial condition of Silver Hammer. Significant accounting policies are described in more detail in Silver Hammer's audited financial statements. In order to have a reasonable level of assurance that financial transactions are properly authorized, assets are safeguarded against unauthorized or improper use, and transactions are properly recorded and reported, Silver Hammer has implemented and continues to analyze its internal control systems for financial reporting, as further explained in its audited financial statements. Although Silver Hammer believes its financial reporting and financial statements are prepared with reasonable safeguards to ensure reliability, Silver Hammer cannot provide absolute assurance in this regard.
Negative Operating Cash Flow
Silver Hammer has incurred losses since inception and currently experiences negative operating cash flow, a trend that is expected to continue for the foreseeable future. Although Silver Hammer aims to advance its mineral projects and ultimately generate revenues, there is no assurance that it will ever achieve profitability. As an exploration-stage company with no material revenues to date, Silver Hammer must rely on its cash reserves and will likely require additional financing - through equity, debt or other means - to fund ongoing operations and planned exploration activities. Many of Silver Hammer's expenditures are fixed or committed in nature, including costs associated with exploration programs, property maintenance, technical consultants, and corporate overhead.
Silver Hammer's ability to generate future revenues and move toward profitability depends on the successful exploration and development of its mineral properties, the availability of capital, favourable commodity prices, and the receipt of required regulatory approvals. There can be no assurance that Silver Hammer will ever achieve or sustain profitability, that additional financing will be available when needed, or that such financing will be available on acceptable terms. If Silver Hammer continues to incur losses for an extended period or is unable to secure adequate financing, it may be unable to continue its business or advance its projects.
Limited Operating History
Silver Hammer is subject to many of the risks common to early-stage enterprises, including under-capitalization, cash shortages, limitations with respect to personnel, financial, and other resources and lack of revenues. There is no assurance that Silver Hammer will be successful in achieving a return on shareholders' investment and the likelihood of success must be considered in light of the early stage of operations.
Reputation Risk
Damage to Silver Hammer's reputation can be the result of the actual or perceived occurrence of any number of events, and could include any negative publicity, whether true or not. The increased usage of social media and other web-based tools used to generate, publish and discuss user-generated content and to connect with other users has made it increasingly easier for individuals and groups to communicate and share opinions and views regarding Silver Hammer and its activities, whether true or not. Although Silver Hammer believes that it operates in a manner that is respectful to all stakeholders and that it takes care in protecting its image and reputation, Silver Hammer does not ultimately have direct control over how it is perceived by others. Reputation loss may result in decreased investor confidence, increased challenges in developing and maintaining community relations and an impediment to Silver Hammer's overall ability to advance its projects, thereby having a material adverse impact on financial performance, financial condition, cash flows and growth prospects.
Liability for Actions of Employees, Contractors and Consultants
Silver Hammer could be liable for fraudulent or illegal activity by its employees, contractors and consultants resulting in significant financial losses to claims against Silver Hammer.
Silver Hammer is exposed to the risk that its employees, independent contractors and consultants may engage in fraudulent or other illegal activity. Misconduct by these parties could include intentional, reckless and/or negligent conduct or disclosure of unauthorized activities to Silver Hammer that violates: (i) government regulations; (ii) manufacturing standards; (iii) fraud and abuse laws and regulations; or (iv) laws that require the true, complete and accurate reporting of financial information or data. It is not always possible for Silver Hammer to identify and deter misconduct by its employees and other third parties, and the precautions taken by Silver Hammer to detect and prevent this activity may not be effective in controlling unknown or unmanaged risks or losses or in protecting Silver Hammer from governmental investigations or other actions or lawsuits stemming from a failure to be in compliance with such laws or regulations. If any such actions are instituted against Silver Hammer, and it is not successful in defending itself or asserting its rights, those actions could have a significant impact on its business, including the imposition of civil, criminal and administrative penalties, damages, monetary fines, contractual damages, reputational harm, diminished profits and future earnings, the curtailment of Silver Hammer's operations or asset seizures, any of which could have a material adverse effect on Silver Hammer's business, financial condition and results of operations.
Litigation
Defense and settlement costs of legal claims can be substantial, even with respect to claims that have no merit. Like most companies, Silver Hammer is subject to the threat of litigation and may be involved in disputes with other parties in the future which may result in litigation or other proceedings. The results of litigation or any other proceedings cannot be predicted with certainty. If Silver Hammer is unable to resolve these disputes favourably, it could have a material adverse effect on Silver Hammer's business, financial condition and results of operations.
Information Systems
Targeted attacks on Silver Hammer's systems (or on systems of third parties that Silver Hammer relies on), failure or non-availability of a key information technology ("IT") systems or a breach of security measures designed to protect Silver Hammer's IT systems could result in disruptions to Silver Hammer's operations, extensive personal injury, property damage or financial or reputational risks. Silver Hammer has engaged IT consultants to implement and test system controls and disaster recovery infrastructure for certain IT systems. As the threat landscape is ever-changing, Silver Hammer must make continuous mitigation efforts, including: risk prioritized controls to protect against known and emerging threats; tools to provide automate monitoring and alerting and backup and recovery systems to restore systems and return to normal operations.
Risks Related to the Common Shares
Market for Securities and Volatility of Share Price
The Silver Hammer Shares are listed and posted for trading on the CSE under the symbol "HAMR". Securities of small-cap companies have experienced substantial volatility in the past, often based on factors unrelated to the companies' financial performance or prospects. These factors include macroeconomic developments in North America and globally and market perceptions of the attractiveness of particular industries. Factors unrelated to Silver Hammer's performance that may affect the price of the Silver Hammer Shares include the following: other developments that affect the breadth of the public market for the Silver Hammer Shares; the release or expiration of lock-up or other transfer restrictions on the Silver Hammer Shares; the attractiveness of alternative investments; the extent of analytical coverage available to investors concerning Silver Hammer's business may be limited if investment banks with research capabilities do not follow Silver Hammer; lessening in trading volume and general market interest in the Silver Hammer Shares may affect an investor's ability to trade significant numbers of Silver Hammer Shares; the size of Silver Hammer's public float may limit the ability of some institutions to invest in Silver Hammer Shares; and a substantial decline in the price of the Silver Hammer Shares that persists for a significant period of time could cause the Silver Hammer Shares to be delisted from the CSE, further reducing market liquidity. As a result of any of these factors, the market price of the Silver Hammer Shares at any given point in time may not accurately reflect Silver Hammer's long-term value and may be volatile in the future, which may result in losses to investors. Securities class action litigation often has been brought against companies following periods of volatility in the market price of their securities. Silver Hammer may in the future be the target of similar litigation. Securities litigation could result in substantial costs and damages and divert management's attention and resources.
External factors outside of Silver Hammer's control, such as announcements of quarterly variations in operating results, revenues and costs, and sentiments toward stocks, may have a significant impact on the market price of the Silver Hammer Shares. Global stock markets, including the CSE, have experienced extreme price and volume fluctuations from time to time. There can be no assurance that an active or liquid market will be sustained for the Silver Hammer Shares.
Future Sales of Common Shares by Existing Shareholders
Sales of a large number of Silver Hammer Shares in the public markets, or the potential for such sales, could decrease the trading price of the Silver Hammer Shares and could impair Silver Hammer's ability to raise capital through future sales of Silver Hammer Shares. Silver Hammer has previously completed private placements at prices per share which may be, from time to time, lower than the market price of the Silver Hammer Shares. Accordingly, a significant number of Silver Hammer's shareholders at any given time may have an investment profit in the Silver Hammer Shares that they may seek to liquidate.
Dividends
Silver Hammer has not paid dividends in the past and does not anticipate paying dividends in the near future. Silver Hammer intends to retain earnings, if any, to finance the growth and development of Silver Hammer's business and, where appropriate, retire debt. The payment of future cash dividends, if any, will be reviewed periodically by the Board and will depend upon, among other things, conditions then existing including earnings, financial condition and capital requirements, restrictions in financing agreements, business opportunities and conditions and other factors.
Dilution
Future sales or issuances of equity securities could decrease the value of the Silver Hammer Shares, dilute shareholders' voting power and reduce future potential earnings per Silver Hammer Share. Silver Hammer intends to sell additional equity securities in subsequent offerings (including through the sale of securities convertible into Silver Hammer Shares) and may issue additional equity securities to finance its operations, development, exploration, acquisitions or other projects. Silver Hammer cannot predict the size of future sales and issuances of equity securities or the effect, if any, that future sales and issuances of equity securities will have on the market price of the Silver Hammer Shares. Sales or issuances of a substantial number of equity securities, or the perception that such sales could occur, may adversely affect prevailing market prices for the Silver Hammer Shares. With any additional sale or issuance of equity securities, investors will suffer dilution of their voting power and may experience dilution in earnings per Silver Hammer Share.
As a result of any of these factors, the market price of the Silver Hammer Shares at any given point in time may not accurately reflect the long-term value of Silver Hammer. Securities class-action litigation often has been brought against companies following periods of volatility in the market price of their securities. Silver Hammer may in the future be the target of similar litigation. Securities litigation could result in substantial costs and damages and divert management's attention and resources.
Additional Financing
Silver Hammer will require equity and/or debt financing to support ongoing operations, to undertake capital expenditures or to undertake acquisitions or other business combination transactions. There can be no assurance that additional financing will be available to Silver Hammer when needed or on terms which are acceptable. Silver Hammer's inability to raise financing to fund ongoing operations, capital expenditures or acquisitions could limit its growth and may have a material adverse effect upon Silver Hammer's business, results of operations, financial condition or prospects.
If additional funds are raised through further issuances of equity or convertible debt securities, existing shareholders could suffer significant dilution, and any new equity securities issued could have rights, preferences and privileges superior to those of holders of Silver Hammer Shares. Any debt financing secured in the future could involve restrictive covenants relating to capital raising activities and other financial and operational matters, which may make it more difficult for Silver Hammer to obtain additional capital and to pursue business opportunities, including potential acquisitions.
Risks Related to the Amalgamation and the SilverMark Amalgamation
There can be no certainty that all conditions precedent to the Amalgamation and the SilverMark Amalgamation will be satisfied
The completion of each of the Amalgamation and the SilverMark Amalgamation is subject to a number of conditions precedent, certain of which are outside the control of Silver Hammer, including receipt of all required regulatory approvals (including the approvals of the CSE and the TSXV), completion of the Consolidation, completion of the minimum amount of the Private Placement, and the listing and posting for trading on the CSE of the Silver Hammer
Shares to be issued pursuant to the Amalgamation and the SilverMark Amalgamation. There can be no certainty, nor can Silver Hammer provide any assurance, if and when these conditions will be satisfied or waived. These conditions also include approval of the Amalgamation and the SilverMark Amalgamation by the shareholders of Silver Hammer at the Silver Hammer Meeting and approval of the Amalgamation by Stroud shareholders at the Stroud meeting. If, for any reason, the conditions to the Amalgamation and/or the SilverMark Amalgamation are not satisfied or waived and the Amalgamation and the SilverMark Amalgamation are not completed, the market price of the Silver Hammer Shares may be adversely affected and the announcement of the Amalgamation and the SilverMark Amalgamation and the dedication of substantial resources of Silver Hammer to the completion thereof could have a negative impact on Silver Hammer's business relationships and could have a material adverse effect on the current and future operations, financial condition and prospects of Silver Hammer. If the Amalgamation and the SilverMark Amalgamation are not completed and the Board decides to seek another merger or arrangement, there can be no assurance that it will be able to find a party willing to pay an equivalent or more attractive price than the consideration payable pursuant to the Amalgamation and the SilverMark Amalgamation.
The Combination Agreement or SilverMark Agreement may be terminated in certain circumstances, including in the event of a material adverse change with respect to Silver Hammer
Each of the parties to the Combination Agreement and the SilverMark Agreement has the right to terminate the applicable agreement and the corresponding Amalgamation in certain circumstances. Accordingly, there is no certainty, nor can Silver Hammer provide any assurance, that the Combination Agreement or the SilverMark Agreement will not be terminated before the completion of the respective amalgamation. For example, Stroud has the right, in certain circumstances, to terminate the Combination Agreement if changes occur that, in the aggregate, result in a material adverse effect with respect to Silver Hammer. Although a material adverse effect excludes certain events that are beyond the control of Silver Hammer, there is no assurance that a material adverse effect with respect to Silver Hammer will not occur before the completion of the Amalgamation and the SilverMark Amalgamation, in which case the applicable counterparty could elect to terminate the relevant agreement and the applicable amalgamation would not proceed.
While the Amalgamation and the SilverMark Amalgamation are pending, Silver Hammer is restricted from taking certain actions
The Combination Agreement and the SilverMark Agreement restrict Silver Hammer from taking specified actions until the respective amalgamation is completed without the consent of the applicable counterparty. These restrictions may prevent Silver Hammer from pursuing attractive business opportunities that may arise prior to the completion of the Amalgamation and the SilverMark Amalgamation.
The issuance of a significant number of Silver Hammer Shares could adversely affect the market price of Silver Hammer Shares
If the Amalgamation and the SilverMark Amalgamation are completed, a significant number of additional Silver Hammer Shares will be issued and will become available for trading in the public market. The increase in the number of Silver Hammer Shares may lead to sales of such shares or the perception that such sales may occur, either of which may adversely affect the market for, and the market price of, Silver Hammer Shares.
Market for Silver Hammer Shares
There can be no assurance that an active public market for the Silver Hammer Shares will be sustained following the completion of the Amalgamation and the SilverMark Amalgamation. Even if an active market is maintained, there is no assurance that the prevailing market price of the Silver Hammer Shares will reflect the value of Silver Hammer's business and assets following the Amalgamation and the SilverMark Amalgamation. If an active public market for the Silver Hammer Shares is not sustained, the liquidity of a shareholder's investment may be limited, and the Silver Hammer Share price may decline. In addition, any significant increase in demand to buy or sell the Silver Hammer Shares can create volatility in price and volume.
Private Placement Risk
The completion of each of the Amalgamation and the SilverMark Amalgamation is conditional upon, among other things, the completion of the Private Placement for minimum gross proceeds. The Private Placement involves the sale of subscription receipts of SilverMark on a best efforts basis, and there can be no assurance that the minimum amount of the Private Placement will be raised or that the Private Placement will be completed on the terms described herein or at all. If the minimum amount of the Private Placement is not raised, the Amalgamation and the SilverMark Amalgamation will not be completed unless this condition is waived by the applicable parties. Failure to complete the Private Placement could result in the Amalgamation and the SilverMark Amalgamation not proceeding, which could have a material adverse effect on the market price of the Silver Hammer Shares and on Silver Hammer's business relationships and prospects.
Foreign Operations and Moroccan Asset Risks
Following completion of the Amalgamation and the SilverMark Amalgamation, Silver Hammer's portfolio will include the Santo Domingo silver-gold property in Jalisco, Mexico (acquired through the Amalgamation) and an indirect interest in the Akka Mine silver/polymetallic project in Morocco, held through SilverMark's rights under the SABI-AIM Option Agreements. Operations in foreign jurisdictions, including Morocco, are subject to risks not typically associated with operations in Canada or the United States, including: political instability or changes in government; changes in laws or regulations governing foreign investment, mining, taxation, royalties, or repatriation of capital; currency exchange controls or fluctuations; expropriation or nationalization of assets; civil unrest or social instability; difficulties in enforcing legal rights or obtaining regulatory approvals; and the complexity of operating through joint venture structures with local partners. The SABI-AIM Option Agreements governing SilverMark's rights to earn into the Moroccan Assets may give rise to disputes or disagreements between the parties, and there can be no assurance that Silver Hammer will be able to exercise effective control over the Moroccan Assets or that SABI-AIM will fulfill its obligations under such agreements. There can be no assurance that any of these properties will be successfully advanced to the development or production stage. Any of these factors could have a material adverse effect on Silver Hammer's business, financial condition and results of operations.
Promoters
Silver Hammer does not have, and has not had within the two years immediately preceding the date of the Circular, any promoters within the meaning of applicable securities legislation.
Legal Proceedings and Regulatory Actions
There are no legal proceedings outstanding, threatened or pending, as of the date hereof, by or against Silver Hammer or to which Silver Hammer is a party or to which its properties are subject, nor to Silver Hammer's knowledge are any such legal proceedings contemplated which could become material to a purchaser of Silver Hammer Shares.
Silver Hammer is not currently aware of any:
(a) penalties or sanctions imposed against Silver Hammer by a court relating to provincial and territorial securities legislation or by a securities regulatory authority since its incorporation;
(b) other penalties or sanctions imposed by a court or regulatory body against Silver Hammer, the disclosure of which are necessary for this Appendix "E" to contain full, true and plain disclosure of all material facts relating to the securities being distributed; or
(c) settlement agreements Silver Hammer entered into before a court relating to provincial and territorial securities legislation or with a securities regulatory authority within the three years immediately preceding the date of the Circular.
Interest of Management and Others in Material Transactions
Except as disclosed herein, no director, executive officer or persons or companies who beneficially own, control or direct, directly or indirectly, more than ten percent of any class of outstanding voting securities of Silver Hammer, nor any associate or affiliate of the foregoing persons, has or has had any material interest, direct or indirect, in any transactions with Silver Hammer within the three most recently completed financial years or during the current financial year that has materially affected or is reasonably expected to have a material effect on Silver Hammer, other than ordinary course participation in private placement financings.
Auditors, Transfer Agents and Registrars
Auditors
Manning Elliott LLP, located at 17th Floor, 1030 West Georgia Street, Vancouver, British Columbia, V6E 2Y3, serves as the auditor of Silver Hammer. They have advised Silver Hammer that they are independent of Silver Hammer within the meaning of the ethical requirements that are relevant to their audit of the consolidated financial statements in Canada.
Registrar and Transfer Agent
The transfer agent and registrar for the Silver Hammer Shares is Endeavor Trust Corporation, located at 702 - 777 Hornby Street, Vancouver, British Columbia, V6Z 1S4.
Material Contracts
There are no contracts of Silver Hammer, other than contracts entered into in the ordinary course of business, that are material to Silver Hammer, other than as set forth below:
Electronic copies of the above-noted material contracts are available on the SEDAR+ website under Silver Hammer's profile at www.sedarplus.ca.
Interests of Experts
Wayne Barnett, Ph.D., P.Geo., Principal Consultant and SRK Practice Leader at SRK Consulting (Canada) Inc., prepared the Technical Report which is referred to in this Appendix "E". Wayne Barnett, Ph.D., P.Geo. is a qualified person as defined by NI 43-101 and is independent of Silver Hammer.
The scientific and technical content relating to Silver Hammer in this Appendix "E" has been reviewed and approved by Donald J. Birak, Registered Member of SME, Fellow of AusIMM, an independent director of Silver Hammer Mining Corp. and a qualified person as defined NI 43-101. Mr. Birak is not independent of Silver Hammer.
Manning Elliott LLP, Silver Hammer's auditors, are independent within the meaning of the ethical requirements applicable to their audit of Silver Hammer's consolidated financial statements in Canada.
The aforementioned firms and persons held either less than one percent or no securities of Silver Hammer or of any associate or affiliate of Silver Hammer when they prepared the technical reports or information referred to, or following the preparation of such reports or information.
Other Material Facts
To management's knowledge, there are no other material facts relating to Silver Hammer that are not otherwise disclosed in this Appendix "E" or are necessary for the Circular to contain full, true and plain disclosure of all material facts relating to Silver Hammer.
EXHIBIT A
AUDIT COMMITTEE CHARTER
SILVER HAMMER
Purpose of the Committee
The purpose of the audit committee (the "Audit Committee") of the directors of the Company (the "Board") is to provide an open avenue of communication between management, the Company's independent auditor and the Board and to assist the Board in its oversight of:
The Audit Committee shall also perform any other activities consistent with this Charter, the Company's articles and governing laws as the Audit Committee or Board deems necessary or appropriate.
The Audit Committee shall consist of at least three directors. Members of the Audit Committee shall be appointed by the Board and may be removed by the Board in its discretion. The members of the Audit Committee shall elect a Chairman from among their number. A majority of the members of the Audit Committee must not be officers or employees of the Company or of an affiliate of the Company. The quorum for a meeting of the Audit Committee is a majority of the members who are not officers or employees of the Company or of an affiliate of the Company. With the exception of the foregoing quorum requirement, the Audit Committee may determine its own procedures.
The Audit Committee's role is one of oversight. Management is responsible for preparing the Company's financial statements and other financial information and for the fair presentation of the information set forth in the financial statements in accordance with International Financial Reporting Standards ("IFRS") as issued by the International Accounting Standards Board. Management is also responsible for establishing internal controls and procedures and for maintaining the appropriate accounting and financial reporting principles and policies designed to assure compliance with accounting standards and all applicable laws and regulations.
The independent auditor's responsibility is to audit the Company's financial statements and provide its opinion, based on its audit conducted in accordance with IFRS, that the financial statements present fairly, in all material respects, the financial position, results of operations and cash flows of the Company in accordance with IFRS.
The Audit Committee is responsible for recommending to the Board the independent auditor to be nominated for the purpose of auditing the Company's financial statements, preparing or issuing an auditor's report or performing other audit, review or attest services for the Company, and for reviewing and recommending the compensation of the independent auditor. The Audit Committee is also directly responsible for the evaluation of and oversight of the work of the independent auditor. The independent auditor shall report directly to the Audit Committee.
Authority and Responsibilities
In addition to the foregoing, in performing its oversight responsibilities the Audit Committee shall:
1. Monitor the adequacy of this Charter and recommend any proposed changes to the Board.
2. Review the appointments of the Company's CFO and CEO and any other key financial executives involved in the financial reporting process.
3. Review with management and the independent auditor the adequacy and effectiveness of the Company's accounting and financial controls and the adequacy and timeliness of its financial reporting processes.
4. Review with management and the independent auditor the annual financial statements and related documents and review with management the unaudited quarterly financial statements and related documents, prior to filing or distribution, including matters required to be reviewed under applicable legal or regulatory requirements.
5. Where appropriate and prior to release, review with management any news releases that disclose annual or interim financial results or contain other significant financial information that has not previously been released to the public.
6. Review the Company's financial reporting and accounting standards and principles and significant changes in such standards or principles or in their application, including key accounting decisions affecting the financial statements, alternatives thereto and the rationale for decisions made.
7. Review the quality and appropriateness of the accounting policies and the clarity of financial information and disclosure practices adopted by the Company, including consideration of the independent auditor's judgment about the quality and appropriateness of the Company's accounting policies. This review may include discussions with the independent auditor without the presence of management.
8. Review with management and the independent auditor significant related party transactions and potential conflicts of interest.
9. Pre-approve all non-audit services to be provided to the Company by the independent auditor.
10. Monitor the independence of the independent auditor by reviewing all relationships between the independent auditor and the Company and all non-audit work performed for the Company by the independent auditor.
11. Establish and review the Company's procedures for the:
12. Conduct or authorize investigations into any matters that the Audit Committee believes is within the scope of its responsibilities. The Audit Committee has the authority to retain independent counsel, accountants or other advisors to assist it, as it considers necessary, to carry out its duties, and to set and pay the compensation of such advisors at the expense of the Company.
13. Perform such other functions and exercise such other powers as are prescribed from time to time for the audit committee of a reporting company in Parts 2 and 4 of National Instrument 52-110 of the Canadian Securities Administrators, the Business Corporations Act (British Columbia) and the articles of the Company.
APPENDIX F - INFORMATION CONCERNING THE RESULTING ISSUER
The following information is presented on a post-Transaction basis and is reflective of the projected business, financial and share capital position of the Resulting Issuer. This section only includes information respecting the Resulting Issuer that is materially different from information provided earlier in the Circular. Following the completion of the Transactions, the Resulting Issuer will carry on the businesses currently carried on by Silver Hammer and the Privcos. See the various headings under "Information Concerning Silver Hammer", "Information Concerning Stroud", and "Information Concerning the Resulting Issuer" for additional information regarding the business of Silver Hammer, Privcos and the Resulting Issuer. See also the Pro Forma Financial Statements of the Resulting Issuer attached hereto as Appendix "D".
All capitalized terms used in this Appendix "F" and not defined herein have the meaning ascribed to such terms in the "Glossary of Terms" or elsewhere in the Circular. The information contained in this Appendix "F", unless otherwise indicated, is given as of the date of the Circular. Unless otherwise indicated herein, references to "$" are to Canadian dollars and references to "US$" are to United States dollars.
NOTE REGARDING FORWARD-LOOKING INFORMATION
Except for statements of historical fact relating to the Resulting Issuer, certain statements in this Appendix "F" constitute forward-looking information within the meaning of applicable Canadian securities laws. Forward-looking information relates to future events or future performance and often includes terminology such as "may", "will", "could", "should", "expect", "plan", "anticipate", "believe", "estimate", "intend", "seek", "forecast", "project", "potential", "target", "continue", or similar expressions (including negative variations thereof). These statements reflect management's current expectations and assumptions regarding the Resulting Issuer's future operations, strategy, exploration activities, financial position, the proposed Amalgamation and SilverMark Amalgamation, and the broader economic and regulatory environment in the jurisdictions in which the Resulting Issuer operates or intends to operate.
Forward-looking information in this Appendix "F" includes, without limitation:
Forward-looking information is based on a number of assumptions that, while considered reasonable by management at the time made, may prove to be incorrect. These assumptions include, without limitation:
Forward-looking information is subject to a variety of known and unknown risks, uncertainties, and other factors that may cause actual results, performance, or achievements to differ materially from those expressed or implied. These risks include, but are not limited to:
Readers are cautioned not to place undue reliance on forward-looking information. All forward-looking statements in this Appendix "F" are qualified by these cautionary statements and by the detailed risk factors set out under "Risk Factors", which readers are encouraged to review in their entirety. Forward-looking information is made as of the date of the Circular, and the Resulting Issuer does not undertake any obligation to update or revise such information to reflect new events or circumstances after the date of the Circular, except as required by applicable securities laws.
SELECTED FINANCIAL INFORMATION OF THE RESULTING ISSUER
The pro forma consolidated financial statements of the Resulting Issuer, giving effect to the Transactions (the "Pro Forma Financial Statements"), are attached hereto as Appendix "D" to this Circular and form an integral part of the Circular.
CORPORATE STRUCTURE
Name, Address and Incorporation
Silver Hammer was incorporated under the laws of the Province of British Columbia and under the BCBCA on May 2, 2017 under the name "Lakewood Exploration Inc.". On October 1, 2021, Silver Hammer changed its name to "Silver Hammer Mining Corp.".
Following the completion of the Amalgamation and the SilverMark Amalgamation, it is anticipated that the Resulting Issuer will continue as a British Columbia corporation and will be governed by the BCBCA and will change its name to "Silver Frontier Resources Corp." or such other name as may be determined by the Resulting Issuer Board.
The Resulting Issuer's head office will be located at Suite 300 - 1055 West Hastings Street, Vancouver, British Columbia, V6E 2E9 and the registered office will be located at Suite 1500 - 1055 West Georgia Street, Vancouver, British Columbia, V6E 4N7.
The Resulting Issuer Shares are expected to trade on the CSE under the symbol "SLVF". The Resulting Issuer will be a reporting issuer in the provinces of British Columbia, Alberta and Ontario.
INTERCORPORATE RELATIONSHIPS
Subsidiaries
The Resulting Issuer will have four (4) wholly-owned direct subsidiaries: (i) Amalco 1 will be created pursuant to the Stroud Amalgamation and exist pursuant to the OBCA; (ii) Amalco 2 will be created pursuant to the SilverMark Amalgamation and exist pursuant to the CBCA; (iii) Silverstrand Exploration Corp. (formerly Silver Hammer Mining Corp.), a company incorporated under the laws of Canada; and (iv) 1304562 B.C. Ltd., a company incorporated under the laws of British Columbia. Silverstrand Exploration Corp. holds one wholly-owned subsidiary: 123456 US Inc., a company incorporated under the Delaware General Corporate Law. 1304562 B.C. Ltd. holds one wholly-owned subsidiary: 1304562 Nevada Ltd., a corporation incorporated under the laws of Nevada.
The Resulting Issuer's corporate structure is set out in the diagram below.
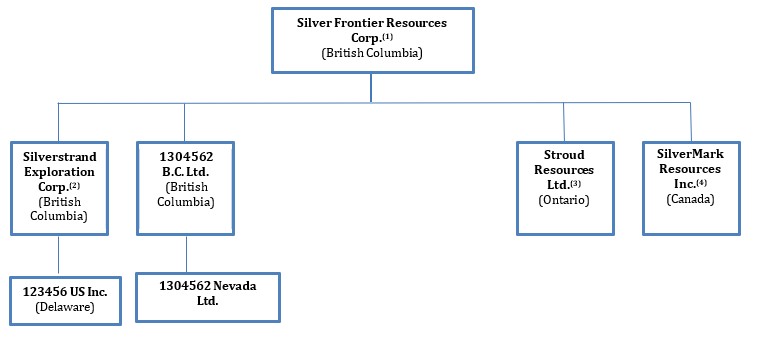
Notes:
(1) Silver Frontier Resources Corp., being the name of Silver Hammer Mining Corp. upon completion of the Amalgamation and the SilverMark Amalgamation (formerly Lakewood Exploration Inc.).
(2) Formerly Silver Hammer Mining Corp.
(3) Amalco, created pursuant to the Amalgamation.
(4) SilverMark Amalco, created pursuant to the SilverMark Amalgamation.
Related Parties
Scott Jobin-Bevans is the Chief Executive Officer and a director of Stroud and a proposed director and officer of the Resulting Issuer. Dr. Jobin-Bevans holds 3,857,778 SilverMark Class A Common Shares and 1,260,000 SilverMark Class B Special Shares. Pursuant to the SilverMark Amalgamation, Mr. Jobin-Bevans' SilverMark Class A Common Shares will be exchanged for Resulting Issuer Shares in accordance with the SilverMark Exchange Ratio, and Mr. Jobin-Bevans' SilverMark Class B Special Shares will be exchanged for Contingent Value Shares in accordance with the Class B Exchange Ratio. As a result, Mr. Jobin-Bevans has a material interest in the Amalgamation that is in addition to, and distinct from, his interest as a Stroud Shareholder.
Peter A. Ball is the President, Chief Executive Officer and a director of Silver Hammer and a proposed director and officer of the Resulting Issuer. Mr. Ball holds 2,577,778 SilverMark Class A Common Shares and 787,500 SilverMark Class B Special Shares. Pursuant to the SilverMark Amalgamation, Mr. Ball's SilverMark Class A Common Shares will be exchanged for Resulting Issuer Shares in accordance with the SilverMark Exchange Ratio, and Mr. Ball's SilverMark Class B Special Shares will be exchanged for Contingent Value Shares in accordance with the Class B Exchange Ratio. As a result, Mr. Ball has a material interest in the SilverMark Amalgamation that is in addition to, and distinct from, his interest as a Silver Hammer Shareholder.
NARRATIVE DESCRIPTION OF THE BUSINESS
The business of the Resulting Issuer will primarily be the business of Silver Hammer and the Privcos. See "Information Concerning Silver Hammer" "Information Concerning Stroud Resources Ltd." for additional information regarding the business of Silver Hammer and the Privcos.
Stated Business Objectives
The Resulting Issuer's main business objectives for the 12 months following completion of the Amalgamation and the SilverMark Amalgamation will be as follows: (i) advancement of the Resulting Issuer's silver project portfolio, including Santo Domingo, the Moroccan Assets and existing Silver Hammer exploration properties; (ii) satisfying earn-in obligations under the SABI-AIM Option Agreements; and (iii) general working capital and corporate purposes.
The Resulting Issuer Board may, in its discretion, for sound business reasons, make decisions that do not conform to the above business objectives.
Overview
The Resulting Issuer will be a mineral exploration and development company focused on acquiring, exploring, and advancing precious metals projects. The Resulting Issuer's strategy will be focused on advancing the Santo Domingo Project, the Moroccan Assets, and its portfolio of silver projects in Idaho and Nevada (USA). Upon completion of the Amalgamation and the SilverMark Amalgamation, Silver Hammer's portfolio will expand to include the Santo Domingo silver-gold property in Jalisco, Mexico and an indirect interest in the Akka Mine silver and polymetallic project in Morocco. The Resulting Issuer's strategy will be centered on:
Aside from the Santo Domingo project and its projects in Morocco, the Resulting Issuer will hold three exploration-stage mineral properties: the Silver Strand Project, located in the Silver Valley Mining District of Kootenai County, Idaho; the Eliza Silver Project, located in White Pine County, Nevada; and the Silverton Silver Mine Project, located in Nye County, Nevada. In October 2025, Silver Hammer entered into the Fahey Option Agreement to acquire a 100% interest in the Fahey Property, comprising 18 unpatented US lode mining claims in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho.
Principal Products or Services
The Resulting Issuer is an exploration-stage company and does not currently mine, produce, or sell any mineral products. None of the Resulting Issuer's properties contain any known or identified mineral resources or mineral reserves as defined under applicable securities legislation. The Resulting Issuer's exploration activities are focused primarily on silver, with secondary exposure to gold and copper.
As an exploration-stage issuer with no producing properties, the Resulting Issuer does not generate operating income, cash flow, or revenue. The Resulting Issuer has not completed any mineral resource estimates on its properties. There is no assurance that a commercially viable mineral deposit exists on any of the Resulting Issuer's projects. The Resulting Issuer does not expect to receive income from its properties in the foreseeable future.
The Resulting Issuer intends to continue evaluating, exploring, and advancing its projects through additional financings. The Resulting Issuer's primary objective is to explore and assess its portfolio of silver projects, and it intends to undertake exploration work programs consistent with recommendations from its geological and technical advisors.
Production and Sales
The Resulting Issuer has no producing properties and therefore has no production or sales activities at this time.
Specialized Skill and Knowledge
Mineral exploration and development requires a broad range of specialized skills and expertise, including geology, engineering, environmental compliance, drilling, logistical planning, project management, finance, accounting, and legal. The Resulting Issuer relies on both internal personnel and external consultants who possess these skills. To attract and retain qualified individuals, the Resulting Issuer seeks to maintain competitive compensation structures and consultant arrangements.
Competitive Conditions
As a mineral exploration and development company, the Resulting Issuer may compete with other entities in the mineral exploration and development business in various aspects, including: (a) seeking out and acquiring mineral exploration and development properties; (b) obtaining the resources necessary to identify and evaluate mineral properties and to conduct exploration and development activities on such properties; and (c) raising the capital necessary to fund its operations. The mining industry is intensely competitive in all its phases, and the Resulting Issuer may compete with other companies that have greater financial resources and technical facilities. Competition could adversely affect the Resulting Issuer's ability to acquire suitable properties or prospects in the future or to raise the capital necessary to continue with operations. See "Risk Factors."
Cycles
The mineral exploration industry is cyclical. The Resulting Issuer's ability to raise capital and advance exploration programs is heavily influenced by global economic conditions and by fluctuations in the prices of silver and gold. These prices have experienced substantial volatility in recent years and are difficult to forecast. Periods of declining commodity prices can reduce investor interest in exploration companies, restrict access to capital, and negatively impact the economic potential of the Resulting Issuer's projects.
External events, including global economic disruptions, financial market instability, geopolitical developments, and public health emergencies, may further exacerbate commodity price volatility and financing challenges. Such conditions may affect the Resulting Issuer's ability to implement its business plans. See "Risk Factors."
Economic Dependence
As an exploration-stage company with no producing assets or operating revenue, the Resulting Issuer is economically dependent on its ability to obtain external financing to fund its operations and exploration programs. The Resulting Issuer also relies heavily on its portfolio of mineral projects in Idaho and Nevada, and its future business prospects are dependent on the successful advancement of these projects. Upon completion of the Amalgamation and the SilverMark Amalgamation, the Resulting Issuer will also have exposure to the Santo Domingo silver-gold property in Jalisco, Mexico and the Akka Mine silver and polymetallic project in Morocco. These additional properties will expand the Resulting Issuer's geographic and jurisdictional exposure significantly, including to jurisdictions that carry materially different political, regulatory, and operational risks. See "Risk Factors".
The Resulting Issuer may additionally depend on a limited number of consultants, contractors, and service providers to carry out key exploration and technical activities. Any disruption in access to financing, the Resulting Issuer's mineral projects, or essential third-party services could have a material adverse effect on the Resulting Issuer's business and planned exploration activities.
Environmental Protection
The Resulting Issuer is subject to the laws and regulations relating to environmental matters in all jurisdictions in which it operates, including provisions relating to property reclamation, discharge of hazardous materials and other matters. The Resulting Issuer may also be held liable should environmental problems be discovered that were caused by former owners and operators of its properties. The Resulting Issuer conducts its mineral exploration activities in compliance with applicable environmental protection legislation. The Resulting Issuer is not aware of any existing environmental problems related to any of its properties that may result in material liability to the Resulting Issuer.
Future changes to environmental laws or regulations, or more stringent enforcement, could result in increased costs, operating restrictions, or delays in planned exploration activities. Additional information on environmental risks is provided under "Risk Factors".
Employees
As of the date hereof, the Resulting Issuer has no permanent full-time or part-time employees. The Resulting Issuer's operations are managed by its directors and officers, and the Resulting Issuer anticipates engaging consultants in geology, exploration, and related technical and administrative fields as required.
Foreign Operations and Governmental Regulation
The Resulting Issuer's mineral projects will be located in the United States, Mexico and Morocco. Each of these jurisdictions carries its own distinct regulatory, political, and operational risk profile and is subject to the political, economic, regulatory, and social conditions of that jurisdiction.
The Resulting Issuer's exploration activities across its Idaho and Nevada projects are governed by extensive federal, state, and local laws and regulations relating to environmental protection; the use and management of hazardous substances and explosives; natural resource management; mineral exploration; mine development, operation, and closure; reclamation and remediation; exports; taxation; business dealings with Indigenous peoples; labour and occupational health and safety (including mine safety); and the preservation of historic and cultural resources.
Regulatory approvals, permits, and licences are required for various aspects of the Resulting Issuer's exploration activities, and such approvals may not be granted on a timely basis or at all. Changes to permitting processes, amendments to taxation or mining policies, shifts in enforcement practices, or broader regulatory changes at the federal or state level could impose additional costs, new restrictions, or delays on the Resulting Issuer's planned exploration programs. Failure to comply with applicable laws may result in fines, penalties, permit revocation, loss of mineral rights, or requirements to undertake corrective or remedial measures, which could involve significant expenditures. The Resulting Issuer may also be required to compensate third parties for loss or damage arising from regulatory non-compliance.
The Santo Domingo property in Jalisco, Mexico, held through Amalco, will subject the Resulting Issuer to Mexican federal and state laws and regulations governing mineral exploration and development, environmental protection, land use, Indigenous community consultation, and export controls, as well as the general political and economic conditions of Mexico, including risks relating to changes in government policy, currency controls, taxation, and social instability. The Akka Mine project in Morocco, held indirectly through SilverMark Amalco's interest in the Moroccan Assets, will subject the Resulting Issuer to Moroccan laws and regulations governing mining rights, foreign investment, environmental standards, labour, and export of mineral products. The Resulting Issuer's ability to maintain and advance its interest in the Akka Mine is also subject to the terms and conditions of the SABI-AIM Option Agreements, including the satisfaction of earn-in obligations. Operating in these jurisdictions exposes the Resulting Issuer to risks that are in addition to, and in some respects materially greater than, those associated with its existing U.S. operations, including less developed legal and regulatory frameworks, the potential for adverse changes in foreign investment laws, and heightened currency and repatriation risk.
These regulatory and governmental risks, together with broader global political and economic uncertainties - such as currency fluctuations, inflation, labour issues, or increased environmental advocacy - could have a material impact on the Resulting Issuer's operations, financial condition, or future profitability. See "Risk Factors".
Lending Operations, Investment Policies and Restrictions
The Resulting Issuer has not adopted any specific investment or lending policies but will ensure that any investment or debt-related activities undertaken are consistent with the interests of the Resulting Issuer and its shareholders.
Bankruptcy and Similar Procedures
There is no bankruptcy, receivership or similar proceedings against the Resulting Issuer, nor is the Resulting Issuer aware of any such pending or threatened proceedings. There have not been any voluntary bankruptcy, receivership or similar proceedings by the Resulting Issuer since incorporation or currently proposed for the current financial year.
Reorganizations
The completion of the Amalgamation will be the only material reorganization of or involving the Resulting Issuer within the three most recently completed financial years or during the current financial year.
Social or Environmental Policies
At its current stage of development and activities, the Resulting Issuer has limited financial obligations in meeting applicable environmental standards. This may change as the Resulting Issuer advances its projects. Environmental regulations applicable to the Resulting Issuer cover a wide variety of matters, including, without limitation, prevention of waste, pollution and protection of the environment, labour regulations and worker safety. While the Resulting Issuer does not currently expect the impact of costs and other effects related to compliance with environmental, health and safety regulations to have a material adverse effect on its financial condition or results of operations, such regulations are evolving in a manner which is likely to result in stricter standards and enforcement, increased fines and penalties for non-compliance, more stringent environmental assessments of proposed projects, and a heightened degree of responsibility for companies and their directors and employees. Such stricter standards could impact the Resulting Issuer's costs and have an adverse effect on results of operations. Furthermore, an environmental, safety or security incident could impact the Resulting Issuer's reputation in such a way that the result could have a material adverse effect on its business and on the value of its securities.
Trends, Commitments, Events or Uncertainties
There are significant uncertainties related to the price of silver, gold, and other minerals, as well as the availability of equity financing required to support current and future mineral exploration and development activities. Mineral prices have experienced substantial volatility in recent years, and similar fluctuations are expected to continue. There is no guarantee that the Resulting Issuer will be able to secure the financing necessary to advance its exploration programs or pursue new opportunities. Any inability to raise funds on a timely basis may constrain the Resulting Issuer's ability to grow and execute its business strategy. Apart from these risks and those identified under "Risk Factors", the Resulting Issuer is not aware of any additional trends, commitments, events, or uncertainties that are reasonably likely to have a material adverse effect on its business, financial condition, or results of operations.
Post-Closing Board Composition
Following completion of the Transactions, the Resulting Issuer Board will be comprised of six (6) members, three (3) of whom will be nominees of Stroud, initially being Dr. Scott Jobin-Bevans, Jeff Kennedy and Conor O'Brien, or such other nominees as may be mutually agreed by the parties. The remaining three directors will be nominees of Silver Hammer, being Peter A. Ball, Donald Birak and Michael Willett.
MINERAL PROJECTS
Upon completion of the Amalgamation and the SilverMark Amalgamation, the Resulting Issuer will hold a 100% interest in the Santo Domingo project and three mineral exploration properties in the United States: the Silver Strand Project, located in the Silver Valley Mining District of Kootenai County, Idaho; the Eliza Silver Project, located in White Pine County, Nevada; and the
Silverton Silver Mine Project, located in Nye County, Nevada. The Resulting Issuer will also hold an option to acquire a 100% interest in the Fahey Property, comprising 18 unpatented lode mining claims in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho, pursuant to the Fahey Option Agreement. In addition, the Resulting Issuer will hold an indirect interest in the Akka Mine silver and polymetallic project in Morocco, subject to the terms and conditions of the SABI-AIM Option Agreements.
On August 28, 2026 Stroud filed on SEDAR+ a NI 43-101 compliant technical report titled "National Instrument 43-101 Mineral Resource Estimate on the Santo Domingo Silver-Gold Deposit and Technical Report for the Santo Domingo Project" and dated effective August 21, 2026 for the Santo Domingo Project.
The Santo Domingo Project
The Resulting Issuer will acquire the Santo Domingo project through the Amalgamation. The Santo Domingo project is expected to be the only material property of the Resulting Issuer. For a detailed description of the Santo Domingo project, please see "Santo Domingo" under "Information Concerning Stroud Resources Ltd." in this Circular.
Moroccan Assets
The Resulting Issuer will hold an indirect interest in the Moroccan Assets through SilverMark Amalco, which will be created pursuant to the SilverMark Amalgamation. The Moroccan Assets comprise a portfolio of Moroccan mineral assets held by SABI-AIM Minerals, a corporation organized under the laws of Morocco, in respect of which SilverMark has the right to acquire up to a 75% interest (or the maximum earn-in interest available) pursuant to the SABI-AIM Option Agreements. The Moroccan Assets include: (i) the past-producing Akka Mine and related mineral properties; (ii) a portfolio of additional mining concessions and permits designated as "Group A Properties" and "Group B Properties" under the applicable SABI-AIM Option Agreements; and
(iii) certain stockpile areas and associated ore, tailings and rock. Upon completion of the SilverMark Amalgamation, the Resulting Issuer will assume all of SilverMark's obligations under the SABI-AIM Option Agreements and will succeed to SilverMark's rights to earn into the Moroccan Assets. The Resulting Issuer's interest in the Moroccan Assets is subject to the terms and conditions of the SABI-AIM Option Agreements, including the satisfaction of earn-in obligations. The Moroccan Assets are not expected to be a material property of the Resulting Issuer.
The Akka Mine is a past-producing polymetallic (Ag-Pb-Zn-Cu-Au) mine located in one of Morocco's four historical medieval silver districts. The mineralized system at the Akka Mine is characterized by a ridge approximately 7 km by 2.5 km in extent, hosting multiple parallel vein structures with individual vein widths of up to approximately 20 metres and spaced approximately 200 to 250 metres apart.
The Moroccan Assets also include an option to earn into an existing permitted flotation-gravity processing facility with a capacity of approximately 200 tonnes per day, capable of producing lead-zinc-silver concentrates and processing copper, barite, and antimony ores. Pursuant to the SABI-AIM Option Agreements, the Resulting Issuer will have the right to earn a 75% interest in such processing facility within 12 months of signing the applicable agreement.
The broader Moroccan Assets portfolio consists of up to approximately 70 mineral properties, with a focus on silver.
The Moroccan Assets are subject to Moroccan laws and regulations governing mining rights, foreign investment, environmental standards, labour, and the export of mineral products. No mineral resource estimate or mineral reserve estimate has been completed in respect of the Moroccan Assets. The Resulting Issuer intends to continue evaluating the Moroccan Assets and satisfying its earn-in obligations as warranted by results and available funding.
Silver Strand Project
The Silver Strand Project is an exploration-stage gold-silver property located in the Silver Valley Mining District of Kootenai County, Idaho, USA, within the Coeur d'Alene Mining District, one of the world's most prolific silver-producing regions. The property encompasses the historic Silver Strand Mine and surrounding mineral claims. Silver Hammer acquired a 100% interest in the Silver Strand Project in 2021. The Silver Strand Project is not expected to be a material property of the Resulting Issuer.
Mineralization at the Silver Strand Mine consists of a steeply dipping quartz body cutting Revett Formation beds, with elevated gold and silver values associated with silicification alteration and mafic dykes. No mineral resource estimate or mineral reserve estimate has been completed for the Silver Strand Project. Since acquiring the property in 2021, Silver Hammer's exploration activities have included geological mapping, UAV magnetic and induced polarization geophysical surveys, and underground core drilling. The Resulting Issuer intends to continue evaluating the Silver Strand Project through additional exploration work as warranted by results and available funding.
A technical report entitled "Independent NI 43-101 Technical Report for the Silver Strand Gold-Silver Project, Kootenai County, Idaho, USA", prepared by Dr. Wayne Barnett, Ph.D., P.Geo. of SRK Consulting (Canada) Inc., with an effective date of November 3, 2022 and a report date of May 13, 2023, is available under the Resulting Issuer's profile on SEDAR+ at www.sedarplus.ca. Readers are encouraged to review the technical report in its entirety.
Eliza Silver Project
The Eliza Silver Project is an exploration-stage property located in White Pine County, Nevada, comprising unpatented lode mining claims prospective for silver mineralization. Silver Hammer holds a 100% interest in the Eliza Silver Project.
The Eliza Silver Project is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Eliza Silver Project. Silver Hammer's exploration activities on the property have been limited to preliminary geological assessment, surface sampling, and target identification. Silver Hammer intends to continue evaluating the Eliza Silver Project through additional exploration work as warranted by results and available funding.
Silverton Silver Mine Project
The Silverton Silver Mine Project is an exploration-stage property located in Nye County, Nevada, encompassing historical silver workings and surrounding mineral claims. Silver Hammer holds a 100% interest in the Silverton Silver Mine Project.
The Silverton Silver Mine Project is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Silverton Silver Mine Project. Silver Hammer's exploration activities on the property have been limited to preliminary geological assessment, compilation of historical data, and surface sampling. Silver Hammer intends to continue evaluating the Silverton Silver Mine Project through additional exploration work as warranted by results and available funding.
Fahey Property
The Fahey Property comprises 18 unpatented US lode mining claims located in the Silver Belt portion of the Coeur d'Alene Mining District, Shoshone County, Idaho, an area historically prospective for silver, lead, and zinc mineralization. Silver Hammer does not currently hold a direct interest in the Fahey Property but has an option to acquire a 100% interest therein pursuant to the Fahey Option Agreement entered into in October 2025.
The Fahey Property is not a material property of Silver Hammer and, accordingly, no technical report has been prepared in respect thereof pursuant to NI 43-101. No mineral resource or mineral reserve estimates have been completed for the Fahey Property. Silver Hammer's exploration activities on the property remain at a preliminary stage, consisting principally of initial geological review and assessment of historical data.
DESCRIPTION OF SECURITIES
Upon completion of the Transactions, the Resulting Issuer will have issued and outstanding the Resulting Issuer Shares held by existing Silver Hammer Shareholders, the Resulting Issuer Shares issued to Stroud Shareholders and SilverMark Shareholders pursuant to the Amalgamation and the SilverMark Amalgamation, and the Resulting Issuer Shares issued upon conversion of the Subscription Receipts pursuant to the Private Placement.
In addition, Contingent Value Shares will be issued to holders of SilverMark Class B Special Shares in accordance with the Class B Exchange Ratio. There will be no preferred shares issued or outstanding. See "Fully Diluted Share Capital".
Common Shares
The Resulting Issuer's authorized capital consists of an unlimited number of common shares without par value. Following the Transactions, and assuming completion of the Minimum Private Placement, it is expected that 116,980,430 Resulting Issuer Shares will be issued and outstanding.
Each common share ranks equally with all other common shares with respect to dissolution, liquidation or winding-up of the Resulting Issuer and payment of dividends. The holders of Resulting Issuer Shares are entitled to one vote for each share of record on all matters to be voted on by such holders and are entitled to receive pro rata such dividends as may be declared by the Resulting Issuer Board out of funds legally available therefor and to receive, pro rata, the remaining property of the Resulting Issuer on dissolution. The holders of Resulting Issuer Shares have no redemption, retraction, purchase, pre-emptive or conversion rights. The rights attaching to the Resulting Issuer Shares can only be modified by the affirmative vote of at least two-thirds of the votes cast at a meeting of shareholders called for that purpose.
Contingent Value Shares
Following the Transactions, it is expected that 6,057,692 Contingent Value Shares will be issued and outstanding.
Warrants
Upon completion of the Transactions, assuming completion of the Minimum Private Placement, the Resulting Issuer expects to have 43,651,344 Resulting Issuer Warrants outstanding, comprised of: (i) the Silver Hammer Warrants outstanding as of the date of the Circular, which will remain outstanding as warrants of the Resulting Issuer, adjusted for the Consolidation, resulting in 14,555,190 Resulting Issuer Warrants; (ii) the Resulting Issuer Warrants to be issued in exchange for SilverMark Warrants outstanding immediately prior to the completion of the Amalgamation and the SilverMark Amalgamation, in accordance with the applicable exchange ratio; and (iii) the Resulting Issuer Warrants issuable upon conversion of the Subscription Receipts pursuant to the Minimum Private Placement, and the broker warrants to be issued to the Agents in connection therewith.
As of the date of the Circular, there are 58,220,763 Silver Hammer Warrants outstanding on a pre-Consolidation basis, comprised of: (i) 37,177,778 warrants exercisable at $0.07, with expiry dates ranging from December 16, 2027 to September 18, 2030; (ii) 19,568,085 warrants exercisable at $0.15, expiring February 20, 2029; and (iii) 1,474,900 finder's warrants exercisable at $0.15, expiring February 20, 2029. Following the Consolidation, such Silver Hammer Warrants will be adjusted to result in 14,555,190 Resulting Issuer Warrants, comprised of: (i) 9,294,444 Resulting Issuer Warrants exercisable at $0.28, with expiry dates ranging from December 16, 2027 to September 18, 2030; (ii) 4,892,021 Resulting Issuer Warrants exercisable at $0.60, expiring February 20, 2029; and (iii) 368,725 finder's warrants exercisable at $0.60, expiring February 20, 2029, all on a post-Consolidation basis.
In addition, upon completion of the Amalgamation and the SilverMark Amalgamation, 288,461 Resulting Issuer Warrants will be issued in exchange for 833,333 SilverMark Warrants outstanding immediately prior to the completion of the Amalgamation and the SilverMark Amalgamation, each such Resulting Issuer Warrant entitling the holder to acquire one Resulting Issuer Share at an exercise price reflecting the SilverMark Exchange Ratio (being an adjusted exercise price based on an original exercise price of $0.12 per SilverMark Class A Common Share), expiring on May 4, 2028, all on a post-Consolidation basis.
Upon completion of the Amalgamation and the SilverMark Amalgamation, assuming the Minimum Private Placement, each Subscription Receipt will be automatically converted into one unit of SilverMark consisting of one SilverMark Class A Common Share and one SilverMark Warrant, which SilverMark Warrants will, pursuant to the SilverMark Amalgamation, be exchanged for Resulting Issuer Warrants, resulting in the issuance of an aggregate of 26,923,077 Resulting Issuer Warrants (assuming completion of the Minimum Private Placement), each such Resulting Issuer Warrant will be exercisable to acquire one Resulting Issuer Share at a price of
$0.38 per share (on a post-Consolidation basis) for a period of 36 months following the closing date of the Private Placement. In addition, assuming completion of the Minimum Private Placement, 1,884,615 broker warrants will be issued to the Agents in connection therewith, equal to 7.0% of the number of Subscription Receipts sold, with each broker warrant exercisable to acquire one Resulting Issuer Share at the Offering Price for a period of 24 months following the closing date of the Private Placement.
Options
Upon completion of the Transactions, the Resulting Issuer expects to have 2,424,811 Resulting Issuer Options outstanding, comprised of: (i) 1,526,250 Resulting Issuer Options (being 6,105,000 Silver Hammer Options outstanding as of the date of the Circular, adjusted for the Consolidation), which will remain outstanding as options of the Resulting Issuer; and (ii) up to 898,561 Resulting Issuer Shares issuable upon exercise of the amended Stroud Options, as described below, subject to the Omnibus Plan being approved by Silver Hammer Shareholders at the Silver Hammer Meeting.
As of the date of the Circular, there are 6,105,000 Silver Hammer Options outstanding, which will, following the Consolidation, result in 1,526,250 Resulting Issuer Options. In addition, each of the 1,155,000 outstanding Stroud Options will be amended prior to the effective date of the Stroud Amalgamation such that the obligation to issue Stroud Shares on exercise will be replaced with an obligation to issue Resulting Issuer Shares, and the number of Resulting Issuer Shares issuable on exercise and the exercise price therefor will be adjusted in accordance with the Stroud Exchange Ratio, on the same economic terms and conditions, resulting in up to 898,561 Resulting Issuer Shares being issuable upon exercise of such amended Stroud Options, subject to the Omnibus Plan being approved by Silver Hammer Shareholders at the Silver Hammer Meeting. All other terms of the Stroud Options shall remain unchanged.
PRO FORMA CONSOLIDATED CAPITALIZATION
The following table outlines the expected pro forma share capitalization of the Resulting Issuer on completion of the Transactions. This table should be read in conjunction with the pro forma financial statements of the Resulting Issuer, attached as Appendix "D" to this Circular.
| Designation of Security | Amount Authorized | Amount Outstanding after Completion of the Amalgamation, the SilverMark Amalgamation and the Minimum Private Placement (Subscription Receipts at the Offering Price) |
Amount Outstanding after Completion of the Amalgamation, the SilverMark Amalgamation and the Maximum Private Placement (Subscription Receipts at the Offering Price) |
| Resulting Issuer Shares |
Unlimited | 116,980,430 | 128,518,891 |
| Contingent Value Shares | Unlimited | 6,057,692 | 6,057,692 |
| Resulting Issuer Warrants | 43,651,344 | 55,997,498 | |
| Resulting Issuer Options | Up to 10% of the aggregate number of issued and outstanding Resulting Issuer Shares (combined with Resulting Issuer RSUs) | 2,424,811 |
2,424,811 |
| Resulting Issuer RSUs | Up to 10% of the aggregate number of issued and outstanding Resulting Issuer Shares (combined with Resulting Issuer Options) |
Nil | Nil |
Fully Diluted Share Capital
The following table outlines the expected number and percentage of securities of the Resulting Issuer to be outstanding on a fully diluted basis after giving effect to the Transactions:
| Number of Resulting Shares issued or reserved for issuance |
Percentage of issued and outstanding Resulting Issuer Shares, assuming the Minimum Private Placement (non-diluted) |
Percentage of issued and outstanding Resulting Issuer Shares, assuming the Minimum Private Placement (fully-diluted) |
|
| Resulting Issuer Shares held by existing Silver Hammer shareholders(1) | 34,980,742 | 29.90% | 20.68% |
| Resulting Issuer Shares issuable upon exercise of existing Silver Hammer warrants(2) | 14,555,191 | 0% | 8.61% |
| Resulting Issuer Shares issuable upon exercise of existing Silver Hammer options(3) | 1,526,250 | 0% | 0.90% |
| Resulting Issuer Shares to be issued pursuant to the Stroud Amalgamation(4) | 49,496,496 | 42.31% | 29.27% |
| Resulting Issuer Shares issuable upon exercise of the outstanding Stroud Options(5) | 898,561 | 0% | 0.53% |
| Resulting Issuer Shares to be issued pursuant to the SilverMark Amalgamation(6) | 4,807,692 | 4.11% | 2.84% |
| Contingent Value Shares to be issued pursuant to the SilverMark Amalgamation(6) | 6,057,692 | 0% | 3.58% |
| Resulting Issuer Shares issuable upon exercise of the outstanding SilverMark warrants(7) | 288,461 | 0% | 0.17% |
| Resulting Issuer Shares issuable to SABI-AIM pursuant to the SABI-AIM Option Agreements upon closing of the SilverMark Amalgamation(8) | 772,423 | 0.66% | 0.46% |
| Number of Resulting Shares issued or reserved for issuance |
Percentage of issued and outstanding Resulting Issuer Shares, assuming the Minimum Private Placement (non-diluted) |
Percentage of issued and outstanding Resulting Issuer Shares, assuming the Minimum Private Placement (fully-diluted) |
|
| Resulting Issuer Shares issuable in exchange for SilverMark Class A Common Shares to be issued pursuant to the Private Placement(9) | 26,923,077 | 23.01% | 15.92% |
| Resulting Issuer Shares issuable upon exercise of warrants to be issued by SilverMark in connection with the Private Placement(10) | 26,923,077 | 0% | 15.92% |
| Resulting Issuer Shares issuable upon exercise of the broker warrants issued by SilverMark in connection with the Private Placement(11) | 1,884,615 | 0% | 1.11% |
| TOTAL: | 169,114,277 | 100% | 100% |
Notes:
(1) As of the date of the Circular, Silver Hammer has 139,922,966 Silver Hammer Shares issued and outstanding on a pre-Consolidation basis, representing 34,980,742 Silver Hammer Shares on a post-Consolidation basis (reflecting the 4:1 Consolidation).
(2) As of the date of the Circular, Silver Hammer has 58,220,763 common share purchase warrants outstanding on a pre-Consolidation basis, representing 14,555,191 warrants on a post-Consolidation basis (reflecting the 4:1 Consolidation).
(3) As of the date of the Circular, Silver Hammer has 6,105,000 stock options outstanding on a pre-Consolidation basis, representing 1,526,250 stock options on a post-Consolidation basis (reflecting the 4:1 Consolidation).
(4) As at the date of the Combination Agreement, there were 63,623,199 Stroud Shares issued and outstanding. The number of Resulting Issuer Shares issuable will be determined by reference to the Stroud Exchange Ratio and the number of Stroud Shares outstanding immediately prior to the effective time of the Stroud Amalgamation. See "The Stroud Amalgamation".
(5) As at the date of the Combination Agreement, there were 1,155,000 Stroud Options outstanding. Each Stroud Option will be amended prior to the effective date of the Stroud Amalgamation such that the number of Resulting Issuer Shares issuable on exercise and the exercise price therefor will be adjusted in accordance with the Stroud Exchange Ratio, on the same economic terms and conditions, resulting in up to 898,561 Resulting Issuer Shares being issuable upon exercise of such amended Stroud Options. See "The Stroud Amalgamation".
(6) As at the date of the SilverMark Agreement, there were 13,888,889 SilverMark Class A Common Shares and 3,937,500 Class B Special Shares issued and outstanding. Each SilverMark Class A Common Share will be exchanged for 0.346154 of one (1) post-Consolidation Silver Hammer Share pursuant to the Exchange Ratio. Each Class B Special Share will be exchanged for such number of Contingent Value Shares as is determined by the Class B Exchange Ratio, which, based on an assumed Private Placement Price of $0.26 per Subscription Receipt and 3,937,500 Class B Special Shares outstanding, results in approximately 1.5384 Contingent Value Share(s) per Class B Special Share, with each Contingent Value Share convertible into one (1) Silver Hammer Share upon the occurrence of each applicable Milestone Conversion Event. See "The SilverMark Amalgamation.
(7) As of the date of the SilverMark Agreement, there were 833,333 SilverMark warrants outstanding, each exercisable to acquire one SilverMark Class A Common Share at $0.12 per share until May 4, 2028. Following the effective time of the SilverMark Amalgamation, the SilverMark warrants will, in accordance with their terms, be adjusted to give effect to the SilverMark Exchange Ratio, such that the SilverMark warrants will thereafter be exercisable to acquire an aggregate of 288,461 Resulting Issuer Shares at an adjusted exercise price. See "The SilverMark Amalgamation".
(8) Pursuant to the SABI-AIM Option Agreements, Silver Hammer is required to pay aggregate initial earn-in consideration at the closing of the Amalgamation and the SilverMark Amalgamation of US$667,647 in cash and US$145,529 in post-Consolidation Silver Hammer Shares. The number of Silver Hammer Shares issuable in respect of the share component of such consideration is determined by: (i) converting the applicable US dollar amount to Canadian dollars at an assumed exchange rate of 1.38 (being approximately C$200,830); (ii) dividing the resulting Canadian dollar amount by the deemed price per pre-Consolidation Silver Hammer Share of $0.065 ($0.26 on a post-Consolidation basis), resulting in 3,089,693 pre-Consolidation Silver Hammer Shares; and (iii) adjusting for the 4:1 Consolidation, resulting in 772,423 post-Consolidation Silver Hammer Shares issuable to SABI-AIM. See "SilverMark Amalgamation - SABI-AIM Option Agreements".
(9) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 26,923,077 SilverMark Class A Common Shares to be exchanged for Resulting Issuer Shares pursuant to the Amalgamation and the SilverMark Amalgamation. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount. See "Private Placement".
(10) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 26,923,077 SilverMark warrants to be exchanged for warrants exercisable for Resulting Issuer Shares pursuant to the Amalgamation and the SilverMark Amalgamation. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount. See "Description of Capital Structure - Warrants".
(11) Assumes minimum gross proceeds of $7,000,000 (being 26,923,077 Subscription Receipts at $0.26 per Subscription Receipt), resulting in 1,884,615 broker warrants (equal to 7.0% of Subscription Receipts sold), each exercisable to acquire one SilverMark Class A Common Share (exchangeable for one Resulting Issuer Share pursuant to the Amalgamation and the SilverMark Amalgamation) at $0.26 per share for 24 months following closing. The actual number may be greater if the Private Placement is completed for gross proceeds in excess of the minimum amount or if the Over-Allotment Option is exercised. See "Private Placement".
Other than as disclosed above, no other securities will be outstanding which are convertible into, or exchangeable for, Resulting Issuer Shares following the completion of the Transactions.
AVAILABLE FUNDS AND PRINCIPAL PURPOSES
Available Funds
As at July 31, 2026, Silver Hammer had gross working capital of $3,047,899, and the estimated working capital of Stroud was $70,328.
The closing of the Private Placement will allow for additional net proceeds of at least $7,000,000 and up to $10,000,000, or such greater amount as may be determined by the parties (plus up to an additional $2,000,000 pursuant to the Over-Allotment Option), representing net proceeds (after deducting the Agents' cash commission of 7.0%) of at least $6,510,000 and up to $9,300,000 (plus up to an additional $1,860,000 pursuant to the Over-Allotment Option).
It is anticipated that the available funds, together with anticipated revenues to be earned by Silver Hammer and Stroud over the next 12 months, will be sufficient to meet the Resulting Issuer's operating expenses for the following 12 months and to achieve the Resulting Issuer's principal purposes as described in this Circular. The following table sets forth the estimated working capital of Silver Hammer and Stroud, as at July 31, 2026, before and after giving effect to the Transactions.
Based on Minimum funds raised through Offering - $7,000,000
| Silver Hammer |
Stroud | Consolidated Estimate |
|
| Estimated working capital (deficit) | $3,047,899 | $70,328 | $3,118,227 |
| Net proceeds from closing of the Minimum ($7M) Private Placement (after deducting Agents' cash commission of 7.0%) | $6,510,000 |
$Nil |
$6,510,000 |
| Revenues - next 12 months | Nil | Nil | Nil |
| Total | $9,557,899 | $70,328 | $9,628,227.00 |
Based on Maximum funds raised through Offering - $10,000,000
| Silver Hammer |
Stroud | Consolidated Estimate |
|
| Estimated working capital deficit | $3,047,899 | $70,328 | $3,118,227 |
| Net proceeds from closing of the Anticipated ($10M) Private Placement (after deducting Agents' cash commission of 7.0%) | $9,300,000 |
$Nil |
$9,300,000 |
| Revenues - next 12 months | Nil | Nil | Nil |
| Total | $12,347,899 | $70,328 | $12,418,227.00 |
Principal Purpose of Funds
The Resulting Issuer expects to use the funds available to it upon the completion of the Transactions for the following purposes:
| Use of Available Funds | Minimum Amount |
Maximum Amount |
| Mexico Exploration (Santo Domingo Project) | $3,349,500 | $4,785,000 |
| Idaho Exploration (Silver Strand Project) | $625,000 | $850,000 |
| Idaho Exploration (Fahey Project) | $245,000 | $350,000 |
| Nevada Exploration (Eliza Silver Project) | $670,000 | $850,000 |
| Morocco Exploration (Akka Mine Project) | $700,000 | $1,000,000 |
| Morocco Exploration (Portfolio A Projects) | $200,000 | $500,000 |
| Morocco Exploration (Portfolio B Projects) | $100,000 | $250,000 |
| Morocco Mill / Processing Plant Due Diligence | $280,000 | $400,000 |
| First Earn-In Cash Payment Akka Mine / Stockpiles / Group A/B Projects | $915,000 | $915,000 |
| General and administrative expenses for the first 12 months including support and service fees, payroll and other operational expenses | $1,925,000 | $1,925,000 |
| Unallocated working capital to fund ongoing operations | $618,727 | $593,227 |
| TOTAL USES | $9,628,227 | $12,418,227 |
Notwithstanding the proposed uses of available funds discussed above, there may be circumstances where, for sound business reasons, a reallocation of funds may be necessary. It is difficult, at this time, to definitively project the total funds necessary to effect the planned activities of the Resulting Issuer. For these reasons, management of Silver Hammer and the Privcos consider it to be in the best interests of the Resulting Issuer and its shareholders to afford management a reasonable degree of flexibility as to how the funds are employed among the uses identified above, or for other purposes, as the need arises. Further, the above uses of available funds should be considered estimates. See "Forward-Looking Information" above in this Appendix "F".
Dividends and Distributions
There will be no restrictions in the Resulting Issuer's articles or elsewhere which would prevent the Resulting Issuer from paying dividends subsequent to the completion of the Amalgamation and the SilverMark Amalgamation. It is not contemplated that any dividends will be paid on the Resulting Issuer Shares in the immediate future following the completion of the Amalgamation and the SilverMark Amalgamation, as it is anticipated that all available funds will be invested to finance the growth of the Resulting Issuer's business. The Resulting Issuer Board will determine if, and when, dividends will be declared and paid in the future from funds properly applicable to the payment of dividends based on the Resulting Issuer's financial position at the relevant time. All of the Resulting Issuer Shares are entitled to an equal share in any dividends declared and paid. See "Forward-Looking Information" above in this Appendix "F".
Additional Disclosure for Venture Issuers Without Significant Revenue
As of March 31, 2026, the Resulting Issuer has generated no revenue from operations since incorporation on May 2, 2017. See "Risk Factors" in this Appendix "F".
Additional Disclosure for Venture Issuers
As at March 31, 2026, Silver Hammer had working capital of approximately $3,931,934. There is no guarantee that Silver Hammer will be able to raise any additional funds when and if needed and if such funds would be available on terms favourable to Silver Hammer. See "Risk Factors" in this Appendix "F".
RISK FACTORS
An investment in Resulting Issuer Shares involves a significant degree of risk and should be considered speculative due to the nature of the Resulting Issuer's business and the present stage of its development. In evaluating the proposed transactions, shareholders should carefully consider all of the information in this section, and, in particular, should evaluate the risk factors set out below. However, such risks may not be the only risks faced by the Resulting Issuer. Risks and uncertainties not presently known by the Resulting Issuer or which are presently considered immaterial may also adversely affect the Resulting Issuer's business, properties, results of operations and/or condition (financial or otherwise).
Risks Related to the Business of the Resulting Issuer
Resource Exploration and Development is a Speculative Business
Resource exploration and development is a speculative business and involves a high degree of risk, including, among other things, unprofitable efforts resulting not only from the failure to discover mineral deposits but from finding mineral deposits which, though present, are insufficient in size to return a profit from production. The marketability of natural resources that may be acquired or discovered by the Resulting Issuer will be affected by numerous factors beyond its control. These factors include market fluctuations, the proximity and capacity of natural resource markets, government regulations, including regulations relating to prices, taxes, royalties, land use, importing and exporting of minerals and environmental protection. The exact effect of these factors cannot be accurately predicted, but the combination of these factors may result in the Resulting Issuer not receiving an adequate return on invested capital.
Substantial expenditures are required to establish ore reserves through drilling and metallurgical and other testing techniques, determine metal content and metallurgical recovery processes to extract metal from the ore, and construct, renovate or expand mining and processing facilities. No assurance can be given that any level of recovery of ore reserves will be realized or that any identified mineral deposit, even it is established to contain an estimated resource, will ever qualify as a commercial mineable ore body which can be legally and economically exploited. The great majority of exploration projects do not result in the discovery of commercially mineable deposits of ore.
Ability to Raise Funding to Continue Exploration and other Activities
The Resulting Issuer has no revenues from operations and has recorded losses since inception. The Resulting Issuer expects to incur operating losses in future periods due to continuing expenses associated with general and administrative costs, costs of seeking new business opportunities, and advancing its projects.
The Resulting Issuer has finite financial resources and its ability to achieve and maintain profitability and positive cash flow is dependent upon its ability to:
The Resulting Issuer may rely on a combination of equity and debt financing to meet its capital requirements. Additional funds raised by the Resulting Issuer through the issuance of equity or convertible debt securities will cause current Resulting Issuer Shareholders to experience dilution. Such securities may grant rights, preferences or privileges senior to those of the Resulting Issuer Shareholders.
The Resulting Issuer does not have any contractual restrictions on its ability to incur debt and accordingly, the Resulting Issuer could incur significant amounts of indebtedness to finance its operations. Any such indebtedness could contain covenants, which would restrict the Resulting Issuer's operations.
The Resulting Issuer may need to pursue alternative ways to finance its future operations and seeks new business opportunities. There are no assurances or guarantees that any financing alternative will be successful. There is no certainty that additional financing either through traditional equity and debt financing arrangements or an alternative transaction, or any combination thereof, will be available at all or on acceptable terms.
Development of Properties
The Resulting Issuer is an exploration and development company and all of its properties and property interests are in the exploration stage. The Resulting Issuer has not defined or delineated any mineral resources or mineral reserves on any of its properties, which include the Silver Strand Project and Fahey Group Silver Project in Idaho, and the Eliza Silver Project and Silverton Silver Mine in Nevada. Following completion of the Amalgamation and the SilverMark Amalgamation, the Resulting Issuer's portfolio will also include the Santo Domingo silver-gold property in Jalisco, Mexico (acquired through the Amalgamation) and an indirect interest in the Moroccan Assets, including the Akka Mine silver/polymetallic project in Morocco, held through SilverMark's rights under the SABI-AIM Option Agreements. There can be no assurance that any of these properties will be successfully advanced to the development or production stage.
Fluctuation of Metal Prices
Even if commercial quantities of mineral deposits are discovered by the Resulting Issuer, there is no guarantee that a profitable market will exist for the sale of the metals produced. Factors beyond the control of the Resulting Issuer may affect the marketability of any substances discovered. The prices of various metals have experienced significant movement over short periods of time and are affected by numerous factors beyond the control of the Resulting Issuer, including international economic and political trends, expectations of inflation, currency exchange fluctuations, interest rates and global or regional consumption patterns, speculative activities and increased production due to improved mining and production methods. The supply of and demand for metals are affected by various factors, including political events, economic conditions and production costs in major producing regions. There can be no assurance that the price of any commodities will be such that any of the properties in which the Resulting Issuer has, or has the right to acquire, an interest may be mined at a profit.
Increased Costs
Management anticipates that costs at the Resulting Issuer's projects will frequently be subject to variation from one year to the next due to a number of factors, such as the results of ongoing exploration activities (positive or negative), changes in the nature of mineralization encountered, and revisions to exploration programs, if any, in response to the foregoing. Increases in the prices of such commodities or a scarcity of consultants or drilling contractors could render the costs of exploration programs to increase significantly over those budgeted. A material increase in costs for any significant exploration programs could have a significant effect on the Resulting Issuer's operating funds and ability to continue its planned exploration programs.
Reclamation
There is a risk that monies allotted for land reclamation may not be sufficient to cover all risks, due to changes in the nature of the waste rock or tailings and/or revisions to government regulations. Therefore, additional funds, or reclamation bonds or other forms of financial assurance may be required over the tenure of any mineral project of the Resulting Issuer to cover potential risks. These additional costs may have a material adverse effect on the Resulting Issuer's business, financial condition and results of operations.
Mining Industry is Intensely Competitive
The Resulting Issuer's business of the acquisition, exploration and development of mineral properties is intensely competitive. Increased competition could adversely affect the Resulting Issuer's ability to attract necessary capital funding or acquire suitable producing properties or prospects for mineral exploration in the future.
Permits and Licenses
The operations of the Resulting Issuer will require licenses and permits from various governmental authorities. There can be no assurance that the Resulting Issuer will be able to obtain all necessary licenses and permits that may be required to carry out exploration, development and mining operations at its projects, on reasonable terms or at all. Delays or a failure to obtain such licenses and permits or a failure to comply with the terms of any such licenses and permits that the Resulting Issuer does obtain, could have a material adverse effect on the Resulting Issuer.
Government Regulation
Any exploration, development or mining operations carried on by the Resulting Issuer, will be subject to government legislation, policies and controls relating to prospecting, development, production, environmental protection, mining taxes and labour standards. In addition, the profitability of any mining prospect is affected by the market for precious and/or base metals which is influenced by many factors including changing production costs, the supply and demand for metals, the rate of inflation, the inventory of metal producing corporations, the political environment and changes in international investment patterns.
Environmental Restrictions
The activities of the Resulting Issuer are subject to environmental regulations promulgated by government agencies in different countries from time to time. Environmental legislation generally provides for restrictions and prohibitions on spills, releases or emissions into the air, discharges into water, management of waste, management of hazardous substances, protection of natural resources, antiquities and endangered species and reclamation of lands disturbed by mining operations. Certain types of operations require the submission and approval of environmental impact assessments. Environmental legislation is evolving in a manner which means stricter standards, and enforcement, fines and penalties for non-compliance are more stringent. Environmental assessments of proposed projects carry a heightened degree of responsibility for companies and directors, officers and employees. The cost of compliance with changes in governmental regulations has the potential to reduce the profitability of operations.
Public Health Crises
The Resulting Issuer's business, operations and financial condition could be materially and adversely affected by the outbreak of epidemics or pandemics or other health crises. The occurrence of such events could result in temporary business closures, quarantines and a general reduction in consumer and economic activity across multiple jurisdictions, including Canada, the United States, Europe and Asia. Governments and international jurisdictions may impose travel, gathering and other public health restrictions in response to such events.
Such public health crises can result in volatility and disruptions in the supply and demand for metals and minerals, global supply chains and financial markets, as well as declining trade and market sentiment and reduced mobility of people, all of which could affect commodity prices, interest rates, credit ratings, credit risk and inflation. The risks to the Resulting Issuer of such public health crises also include risks to employee health and safety, a slowdown or temporary suspension of operations in geographic locations impacted by an outbreak, increased labour and fuel costs, regulatory changes, political or economic instabilities or civil unrest. Any of these could affect the Resulting Issuer's ability to advance exploration and development with such risks to include challenges in recruiting and retaining staff and personnel, restricted access for employees and contractors to the Projects, equipment and materials not being delivered to site on schedule or at all, and further inefficiencies required to be put in place to health and safety resulting in less productivity.
Geopolitical and International Conflict Risks
Geopolitical instability, armed conflicts, and international tensions in various regions of the world could lead to heightened volatility in the global financial markets, increased inflation, and turbulence in mining and commodity markets. In response to armed conflicts or other geopolitical events, governments and international bodies may impose economic sanctions, export control measures, trade restrictions, or other measures that could disrupt global supply chains, commodity markets, and capital flows. Such measures have and could in the future result in, among other things, severe or complete restrictions on exports and other commerce and business dealings involving affected regions and particular entities and individuals. While the Resulting Issuer does not currently have direct exposure to active conflict zones, geopolitical events are rapidly developing situations and it is uncertain as to how such events and any related economic sanctions or trade restrictions could impact the global economy, commodity prices, or the Resulting Issuer's ability to raise capital or conduct operations. Any negative developments in respect thereof could have an adverse effect on the Resulting Issuer's business, operations, financial condition, and the value of the Resulting Issuer's securities.
Title Matters
Although the Resulting Issuer has taken steps to verify the title to the mineral properties in which it has or has a right to acquire an interest in accordance with industry standards for the current stage of exploration of such properties, these procedures do not guarantee title (whether of the Resulting Issuer or of any underlying vendor(s) from whom the Resulting Issuer may be acquiring its interest). Title to mineral properties may be subject to unregistered prior agreements or transfers and may also be affected by undetected defects or the rights of indigenous peoples. The Resulting Issuer has investigated title to all of its mineral properties and, to the best of its knowledge, title to all of its properties for which titles have been issued are in good standing.
Indigenous and First Nations Rights
The Resulting Issuer's mineral exploration and development activities may be affected by the rights of Indigenous Peoples in the jurisdictions where it operates. The Resulting Issuer currently holds mineral properties in the United States, including in Idaho and Nevada, where certain federal and state permitting processes require consultation with Indigenous or Tribal Nations whose traditional territories may overlap with mineral projects. In Canada, governments may be required to consult and, where appropriate, accommodate Indigenous Peoples in connection with the granting of mineral rights or the issuance or amendment of project authorizations. These consultation obligations and related legal frameworks continue to evolve.
Legislative developments may result in enhanced consultation requirements or additional accommodations, including financial commitments, employment and training opportunities, or other terms under impact and benefit agreements. Such requirements may affect the timing and cost of obtaining mineral titles, permits, or approvals, and could delay or increase the cost of exploration and development activities.
Unforeseen claims, grievances, or opposition by Indigenous Peoples could impact the Resulting Issuer's existing or planned operations, project timelines, or future acquisitions. The need to address Indigenous rights considerations may increase operating costs and could affect the Resulting Issuer's ability to advance, expand, or dispose of its mineral projects.
Exploration and Mining Risks
Fires, power outages, labour disruptions, flooding, explosions, cave-ins, landslides and the inability to obtain suitable or adequate machinery, equipment or labour are other risks involved in the operation of mines and the conduct of exploration programs. Substantial expenditures are required to establish reserves through drilling, to develop metallurgical processes, to develop the mining and processing facilities and infrastructure at any site chosen for mining. Although substantial benefits may be derived from the discovery of a major mineralized deposit, no assurance can be given that minerals will be discovered in sufficient quantities to justify commercial operations or that funds required for development can be obtained on a timely basis. The economics of developing mineral properties is affected by many factors including the cost of operations, variations of the grade of ore mined, fluctuations in the price of minerals produced, costs of processing equipment and such other factors as government regulations, including regulations relating to royalties, allowable production, importing and exporting of minerals and environmental protection. In addition, the grade of mineralization ultimately mined may differ from that indicated by drilling results and such differences could be material. Short term factors, such as the need for orderly development of ore bodies or the processing of new or different grades, may have an adverse effect on mining operations and on the results of operations. There can be no assurance that minerals recovered in small scale laboratory tests will be duplicated in large scale tests under on-site conditions or in production scale operations. Material changes in geological resources, grades, stripping ratios or recovery rates may affect the economic viability of projects.
Regulatory Requirements
The activities of the Resulting Issuer are subject to extensive regulations governing various matters, including environmental protection, management and use of toxic substances and explosives, management of natural resources, exploration, development of mines, production and post-closure reclamation, exports, price controls, taxation, regulations concerning business dealings with indigenous peoples, labour standards on occupational health and safety, including mine safety, and historic and cultural preservation. Failure to comply with applicable laws and regulations may result in civil or criminal fines or penalties, enforcement actions thereunder, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed, and may include corrective measures requiring capital expenditures, installation of additional equipment, or remedial actions, any of which could result in the Resulting Issuer incurring significant expenditures. The Resulting Issuer may also be required to compensate those suffering loss or damage by reason of a breach of such laws, regulations or permitting requirements. It is also possible that future laws and regulations, or more stringent enforcement of current laws and regulations by governmental authorities, could cause additional expense, capital expenditures, restrictions on or suspension of the Resulting Issuer's operations and delays in the exploration and development of the Resulting Issuer's properties.
Influence of Third Parties
The mineral properties in which the Resulting Issuer holds an interest, or the exploration equipment and road or other means of access which the Resulting Issuer intends to utilize in carrying out its work programs or general business mandates, may be subject to interests or claims by third party individuals, groups or companies. In the event that such third parties assert any claims, the Resulting Issuer's work programs may be delayed even if such claims are not meritorious. Such claims may result in significant financial loss and loss of opportunity for the Resulting Issuer.
No Assurance of Profitability
The Resulting Issuer has no history of earnings and, due to the nature of its business there can be no assurance that the Resulting Issuer will ever be profitable. The Resulting Issuer has not paid dividends on its shares since incorporation and does not anticipate doing so in the foreseeable future. The only present source of funds available to the Resulting Issuer is from the sale of its shares or, possibly, from the sale or optioning of a portion of its interest in its mineral properties. Even if the results of exploration are encouraging, the Resulting Issuer may not have sufficient funds to conduct the further exploration that may be necessary to determine whether or not a commercially mineable deposit exists. While the Resulting Issuer may generate additional working capital through further equity offerings or through the sale or possible syndication of its properties, there can be no assurance that any such funds will be available on favorable terms, or at all. At present, it is impossible to determine what amounts of additional funds, if any, may be required. Failure to raise such additional capital could put the continued viability of the Resulting Issuer at risk.
Uninsured or Uninsurable Risks
Exploration, development and mining operations involve various hazards, including environmental hazards, industrial accidents, metallurgical and other processing problems, unusual or unexpected rock formations, structural cave-ins or slides, flooding, fires, metal losses and periodic interruptions due to inclement or hazardous weather conditions. These risks could result in damage to or destruction of mineral properties, facilities or other property, personal injury, environmental damage, delays in operations, increased cost of operations, monetary losses and possible legal liability. The Resulting Issuer may not be able to obtain insurance to cover these risks at economically feasible premiums or at all. The Resulting Issuer may elect not to insure where premium costs are disproportionate to the Resulting Issuer's perception of the relevant risks. The payment of such insurance premiums and of such liabilities would reduce the funds available for exploration and production activities.
Potential Conflicts of Interest
The directors and officers of the Resulting Issuer may serve as directors and/or officers for other public and private companies, including companies in which the Resulting Issuer has invested in, and may devote a portion of their time to manage other business interests. This may result in certain conflicts of interest. To the extent that such other companies may participate in ventures in which the Resulting Issuer is also participating, and to the extent that such companies may receive funds from the Resulting Issuer, such directors and officers of the Resulting Issuer may have a conflict of interest in negotiating and reaching an agreement with respect to the extent of each company's participation. The BCBCA, which governs the Resulting Issuer, requires the directors and officers to act honestly, in good faith, and in the best interests of the Resulting Issuer and its shareholders. However, in conflict-of-interest situations, directors and officers of the Resulting Issuer may owe the same duty to another company and will need to balance the competing obligations and liabilities of their actions. There is no assurance that the needs of the Resulting Issuer will receive priority in all cases. From time to time, several companies may participate together in the acquisition, exploration and development of natural resource properties, thereby allowing these companies to: (i) participate in larger programs; (ii) acquire an interest in a greater number of programs; and (iii) reduce their financial exposure to any one program. A particular company may assign, at its cost, all or a portion of its interests in a particular program to another affiliated company due to the financial position of the Resulting Issuer making the assignment. In determining whether or not the Resulting Issuer will participate in a particular program and the interest therein to be acquired by it, it is expected that the directors and officers of the Resulting Issuer will primarily consider the degree of risk to which the Resulting Issuer may be exposed and its financial position at that time.
Key Executives and Outside Consultants
The Resulting Issuer is dependent upon the services of key executives, including the directors of the Resulting Issuer, and will be dependent on a small number of highly skilled and experienced executives and personnel. Due to the relatively small size of the Resulting Issuer, the loss of these persons or the inability of the Resulting Issuer to attract and retain additional highly skilled employees may adversely affect its business and future operations.
The Resulting Issuer has also relied upon outside consultants, geologists, engineers and others and intends to rely on these parties for their exploration and development expertise. Substantial expenditures are required to construct mines, to establish mineral resources and reserves estimates through drilling, to carry out environmental and social impact assessments, to develop metallurgical processes and to develop the development, exploration and plant infrastructure at any particular site. If such parties' work is deficient or negligent or is not completed in a timely manner, it could have a material adverse effect on the Resulting Issuer's business, financial condition and results of operations.
Joint Ventures
The Resulting Issuer may enter into joint venture arrangements with regard to future exploration, development and production properties. There is a risk any future joint venture partner does not meet its obligations and the Resulting Issuer may therefore suffer additional costs or other losses. It is also possible that the interests of the Resulting Issuer or future joint venture partners are not aligned resulting in project delays or additional costs and losses. The Resulting Issuer may have minority interests in the companies, partnerships and ventures in which it invests and may be unable to exercise control over the operations of such companies.
Infrastructure
Mining, processing, development and exploration activities depend, to one degree or another, on adequate infrastructure. Reliable roads, bridges, power sources and water supply are important determinants which affect capital and operating costs. Unusual or infrequent weather phenomena, terrorism, sabotage, government or other interference in the maintenance or provision of such infrastructure could adversely affect the Resulting Issuer's operations, financial condition and results of operations.
Accounting Policies and Internal Controls
The Resulting Issuer prepares its financial reports in accordance with IFRS. In preparation of its financial reports, management may need to rely upon assumptions, make estimates or use their best judgment in determining the financial condition of the Resulting Issuer. Significant accounting policies are described in more detail in the Resulting Issuer's audited financial statements. In order to have a reasonable level of assurance that financial transactions are properly authorized, assets are safeguarded against unauthorized or improper use, and transactions are properly recorded and reported, the Resulting Issuer has implemented and continues to analyze its internal control systems for financial reporting, as further explained in its audited financial statements. Although the Resulting Issuer believes its financial reporting and financial statements are prepared with reasonable safeguards to ensure reliability, the Resulting Issuer cannot provide absolute assurance in this regard.
Negative Operating Cash Flow
The Resulting Issuer has incurred losses since inception and currently experiences negative operating cash flow, a trend that is expected to continue for the foreseeable future. Although the Resulting Issuer aims to advance its mineral projects and ultimately generate revenues, there is no assurance that it will ever achieve profitability. As an exploration-stage company with no material revenues to date, the Resulting Issuer must rely on its cash reserves and will likely require additional financing - through equity, debt or other means - to fund ongoing operations and planned exploration activities. Many of the Resulting Issuer's expenditures are fixed or committed in nature, including costs associated with exploration programs, property maintenance, technical consultants, and corporate overhead.
The Resulting Issuer's ability to generate future revenues and move toward profitability depends on the successful exploration and development of its mineral properties, the availability of capital, favourable commodity prices, and the receipt of required regulatory approvals. There can be no assurance that the Resulting Issuer will ever achieve or sustain profitability, that additional financing will be available when needed, or that such financing will be available on acceptable terms. If the Resulting Issuer continues to incur losses for an extended period or is unable to secure adequate financing, it may be unable to continue its business or advance its projects.
Limited Operating History
The Resulting Issuer is subject to many of the risks common to early-stage enterprises, including under-capitalization, cash shortages, limitations with respect to personnel, financial, and other resources and lack of revenues. There is no assurance that the Resulting Issuer will be successful in achieving a return on shareholders' investment and the likelihood of success must be considered in light of the early stage of operations.
Reputation Risk
Damage to the Resulting Issuer's reputation can be the result of the actual or perceived occurrence of any number of events, and could include any negative publicity, whether true or not. The increased usage of social media and other web-based tools used to generate, publish and discuss user-generated content and to connect with other users has made it increasingly easier for individuals and groups to communicate and share opinions and views regarding the Resulting Issuer and its activities, whether true or not. Although the Resulting Issuer believes that it operates in a manner that is respectful to all stakeholders and that it takes care in protecting its image and reputation, the Resulting Issuer does not ultimately have direct control over how it is perceived by others. Reputation loss may result in decreased investor confidence, increased challenges in developing and maintaining community relations and an impediment to the Resulting Issuer's overall ability to advance its projects, thereby having a material adverse impact on financial performance, financial condition, cash flows and growth prospects.
Liability for Actions of Employees, Contractors and Consultants
The Resulting Issuer could be liable for fraudulent or illegal activity by its employees, contractors and consultants resulting in significant financial losses to claims against the Resulting Issuer.
The Resulting Issuer is exposed to the risk that its employees, independent contractors and consultants may engage in fraudulent or other illegal activity. Misconduct by these parties could include intentional, reckless and/or negligent conduct or disclosure of unauthorized activities to the Resulting Issuer that violates: (i) government regulations; (ii) manufacturing standards; (iii) fraud and abuse laws and regulations; or (iv) laws that require the true, complete and accurate reporting of financial information or data. It is not always possible for the Resulting Issuer to identify and deter misconduct by its employees and other third parties, and the precautions taken by the Resulting Issuer to detect and prevent this activity may not be effective in controlling unknown or unmanaged risks or losses or in protecting the Resulting Issuer from governmental investigations or other actions or lawsuits stemming from a failure to be in compliance with such laws or regulations. If any such actions are instituted against the Resulting Issuer, and it is not successful in defending itself or asserting its rights, those actions could have a significant impact on its business, including the imposition of civil, criminal and administrative penalties, damages, monetary fines, contractual damages, reputational harm, diminished profits and future earnings, the curtailment of the Resulting Issuer's operations or asset seizures, any of which could have a material adverse effect on the Resulting Issuer's business, financial condition and results of operations.
Litigation
Defense and settlement costs of legal claims can be substantial, even with respect to claims that have no merit. Like most companies, the Resulting Issuer is subject to the threat of litigation and may be involved in disputes with other parties in the future which may result in litigation or other proceedings. The results of litigation or any other proceedings cannot be predicted with certainty. If the Resulting Issuer is unable to resolve these disputes favourably, it could have a material adverse effect on the Resulting Issuer's business, financial condition and results of operations.
Information Systems
Targeted attacks on the Resulting Issuer's systems (or on systems of third parties that the Resulting Issuer relies on), failure or non-availability of a key information technology ("IT") systems or a breach of security measures designed to protect the Resulting Issuer's IT systems could result in disruptions to the Resulting Issuer's operations, extensive personal injury, property damage or financial or reputational risks. The Resulting Issuer has engaged IT consultants to implement and test system controls and disaster recovery infrastructure for certain IT systems. As the threat landscape is ever-changing, the Resulting Issuer must make continuous mitigation efforts, including: risk prioritized controls to protect against known and emerging threats; tools to provide automate monitoring and alerting and backup and recovery systems to restore systems and return to normal operations.
Risks Related to the Resulting Issuer Shares
Market for Securities and Volatility of Share Price
Following completion of the Transactions, the Resulting Issuer Shares are expected to be listed and posted for trading on the CSE under the symbol "SLVF". Securities of small-cap companies have experienced substantial volatility in the past, often based on factors unrelated to the companies' financial performance or prospects. These factors include macroeconomic developments in North America and globally and market perceptions of the attractiveness of particular industries. Factors unrelated to the Resulting Issuer's performance that may affect the price of the Resulting Issuer Shares include the following: other developments that affect the breadth of the public market for the Resulting Issuer Shares; the release or expiration of lock-up or other transfer restrictions on the Resulting Issuer Shares; the attractiveness of alternative investments; the extent of analytical coverage available to investors concerning the Resulting Issuer's business may be limited if investment banks with research capabilities do not follow the Resulting Issuer; lessening in trading volume and general market interest in the Resulting Issuer Shares may affect an investor's ability to trade significant numbers of Resulting Issuer Shares; the size of the Resulting Issuer's public float may limit the ability of some institutions to invest in Resulting Issuer Shares; and a substantial decline in the price of the Resulting Issuer Shares that persists for a significant period of time could cause the Resulting Issuer Shares to be delisted from the CSE, further reducing market liquidity. As a result of any of these factors, the market price of the Resulting Issuer Shares at any given point in time may not accurately reflect the Resulting Issuer's long-term value and may be volatile in the future, which may result in losses to investors. Securities class action litigation often has been brought against companies following periods of volatility in the market price of their securities. The Resulting Issuer may in the future be the target of similar litigation. Securities litigation could result in substantial costs and damages and divert management's attention and resources.
External factors outside of the Resulting Issuer's control, such as announcements of quarterly variations in operating results, revenues and costs, and sentiments toward stocks, may have a significant impact on the market price of the Resulting Issuer Shares. Global stock markets, including the CSE, have experienced extreme price and volume fluctuations from time to time. There can be no assurance that an active or liquid market will be sustained for the Resulting Issuer Shares.
Future Sales of Resulting Issuer Shares by Existing Shareholders
Sales of a large number of Resulting Issuer Shares in the public markets, or the potential for such sales, could decrease the trading price of the Resulting Issuer Shares and could impair the Resulting Issuer's ability to raise capital through future sales of Resulting Issuer Shares. The Resulting Issuer has previously completed private placements at prices per share which may be, from time to time, lower than the market price of the Resulting Issuer Shares. Accordingly, a significant number of the Resulting Issuer's shareholders at any given time may have an investment profit in the Resulting Issuer Shares that they may seek to liquidate.
Dividends
The Resulting Issuer has not paid dividends in the past and does not anticipate paying dividends in the near future. The Resulting Issuer intends to retain earnings, if any, to finance the growth and development of the Resulting Issuer's business and, where appropriate, retire debt. The payment of future cash dividends, if any, will be reviewed periodically by the Resulting Issuer Board and will depend upon, among other things, conditions then existing including earnings, financial condition and capital requirements, restrictions in financing agreements, business opportunities and conditions and other factors.
Dilution
Future sales or issuances of equity securities could decrease the value of the Resulting Issuer Shares, dilute shareholders' voting power and reduce future potential earnings per Resulting Issuer Share. The Resulting Issuer intends to sell additional equity securities in subsequent offerings (including through the sale of securities convertible into Resulting Issuer Shares) and may issue additional equity securities to finance its operations, development, exploration, acquisitions or other projects. The Resulting Issuer cannot predict the size of future sales and issuances of equity securities or the effect, if any, that future sales and issuances of equity securities will have on the market price of the Resulting Issuer Shares. Sales or issuances of a substantial number of equity securities, or the perception that such sales could occur, may adversely affect prevailing market prices for the Resulting Issuer Shares. With any additional sale or issuance of equity securities, investors will suffer dilution of their voting power and may experience dilution in earnings per Resulting Issuer Share.
As a result of any of these factors, the market price of the Resulting Issuer Shares at any given point in time may not accurately reflect the long-term value of the Resulting Issuer. Securities class-action litigation often has been brought against companies following periods of volatility in the market price of their securities. The Resulting Issuer may in the future be the target of similar litigation. Securities litigation could result in substantial costs and damages and divert management's attention and resources.
Additional Financing
The Resulting Issuer will require equity and/or debt financing to support ongoing operations, to undertake capital expenditures or to undertake acquisitions or other business combination transactions. There can be no assurance that additional financing will be available to the Resulting Issuer when needed or on terms which are acceptable. The Resulting Issuer's inability to raise financing to fund ongoing operations, capital expenditures or acquisitions could limit its growth and may have a material adverse effect upon the Resulting Issuer's business, results of operations, financial condition or prospects.
If additional funds are raised through further issuances of equity or convertible debt securities, existing shareholders could suffer significant dilution, and any new equity securities issued could have rights, preferences and privileges superior to those of holders of Resulting Issuer Shares. Any debt financing secured in the future could involve restrictive covenants relating to capital raising activities and other financial and operational matters, which may make it more difficult for the Resulting Issuer to obtain additional capital and to pursue business opportunities, including potential acquisitions.
Risks Related to the Amalgamation and the SilverMark Amalgamation
There can be no certainty that all conditions precedent to the Amalgamation and the SilverMark Amalgamation will be satisfied
The completion of the Amalgamation and the SilverMark Amalgamation is subject to a number of conditions precedent, certain of which are outside the control of the Resulting Issuer, including receipt of all required regulatory approvals (including the approvals of the CSE and the TSXV), completion of the Consolidation, completion of the minimum amount of the Private Placement, and the listing and posting for trading on the CSE of the Resulting Issuer Shares to be issued pursuant to the Amalgamation and the SilverMark Amalgamation. There can be no certainty, nor can the Resulting Issuer provide any assurance, if and when these conditions will be satisfied or waived. These conditions also include approval of the Amalgamation and the SilverMark Amalgamation by the shareholders of Silver Hammer at the Silver Hammer Meeting and approval of the Stroud Amalgamation by Stroud shareholders at the Stroud meeting. If, for any reason, the conditions to the Amalgamation and the SilverMark Amalgamation are not satisfied or waived and the Amalgamation and the SilverMark Amalgamation are not completed, the market price of the Silver Hammer Shares may be adversely affected and the announcement of the Amalgamation and the SilverMark Amalgamation and the dedication of substantial resources of Silver Hammer to the completion thereof could have a negative impact on Silver Hammer's business relationships and could have a material adverse effect on the current and future operations, financial condition and prospects of the Resulting Issuer. If the Amalgamation and the SilverMark Amalgamation are not completed and the Board decides to seek another merger or arrangement, there can be no assurance that it will be able to find a party willing to pay an equivalent or more attractive price than the consideration payable pursuant to the Amalgamation and the SilverMark Amalgamation.
The Combination Agreement or SilverMark Agreement may be terminated in certain circumstances, including in the event of a material adverse change with respect to Silver Hammer
Each of the parties to the Combination Agreement and the SilverMark Agreement has the right to terminate the applicable agreement and the corresponding Amalgamation in certain circumstances. Accordingly, there is no certainty, nor can Silver Hammer provide any assurance, that the Combination Agreement or the SilverMark Agreement will not be terminated before the completion of the respective Amalgamation. For example, Stroud has the right, in certain circumstances, to terminate the Combination Agreement if changes occur that, in the aggregate, result in a material adverse effect with respect to Silver Hammer. Although a material adverse effect excludes certain events that are beyond the control of Silver Hammer, there is no assurance that a material adverse effect with respect to Silver Hammer will not occur before the completion of the Amalgamation and the SilverMark Amalgamation, in which case the applicable counterparty could elect to terminate the relevant agreement and the applicable Amalgamation would not proceed.
While the Amalgamation and the SilverMark Amalgamation are pending, Silver Hammer is restricted from taking certain actions
The Combination Agreement and the SilverMark Agreement restrict Silver Hammer from taking specified actions until the respective transaction is completed without the consent of the applicable counterparty. These restrictions may prevent Silver Hammer from pursuing attractive business opportunities that may arise prior to the completion of the Amalgamation and the SilverMark Amalgamation.
The issuance of a significant number of Silver Hammer Shares could adversely affect the market price of Silver Hammer Shares
If the Amalgamation and the SilverMark Amalgamation are completed, a significant number of additional Resulting Issuer Shares will be issued and will become available for trading in the public market. The increase in the number of Resulting Issuer Shares may lead to sales of such shares or the perception that such sales may occur, either of which may adversely affect the market for, and the market price of, Resulting Issuer Shares.
Market for Silver Hammer Shares
There can be no assurance that an active public market for the Resulting Issuer Shares will be sustained following the completion of the Amalgamation and the SilverMark Amalgamation. Even if an active market is maintained, there is no assurance that the prevailing market price of the Resulting Issuer Shares will reflect the value of the Resulting Issuer's business and assets following the Amalgamation and the SilverMark Amalgamation. If an active public market for the Resulting Issuer Shares is not sustained, the liquidity of a shareholder's investment may be limited, and the Resulting Issuer Share price may decline. In addition, any significant increase in demand to buy or sell the Resulting Issuer Shares can create volatility in price and volume.
Private Placement Risk
The completion of the Amalgamation and the SilverMark Amalgamation is conditional upon, among other things, the completion of the Minimum Private Placement. The Private Placement involves the sale of Subscription Receipts on a best efforts basis, and there can be no assurance that the Minimum Private Placement will be raised or that the Private Placement will be completed on the terms described herein or at all. If the Minimum Private Placement is not raised, the Amalgamation and the SilverMark Amalgamation will not be completed unless this condition is waived by the applicable parties. Failure to complete the Private Placement could result in the Amalgamation and the SilverMark Amalgamation not proceeding, which could have a material adverse effect on the market price of the Silver Hammer Shares and on Silver Hammer's business relationships and prospects.
Foreign Operations and Moroccan Asset Risks
Following completion of the Amalgamation and the SilverMark Amalgamation, the Resulting Issuer's portfolio will include the Santo Domingo silver-gold property in Jalisco, Mexico (acquired through the Amalgamation) and an indirect interest in the Akka Mine silver/polymetallic project in Morocco, held through SilverMark's rights under the SABI-AIM Option Agreements. Operations in foreign jurisdictions, including Morocco, are subject to risks not typically associated with operations in Canada or the United States, including: political instability or changes in government; changes in laws or regulations governing foreign investment, mining, taxation, royalties, or repatriation of capital; currency exchange controls or fluctuations; expropriation or nationalization of assets; civil unrest or social instability; difficulties in enforcing legal rights or obtaining regulatory approvals; and the complexity of operating through joint venture structures with local partners. The SABI-AIM Option Agreements governing SilverMark's rights to earn into the Moroccan Assets may give rise to disputes or disagreements between the parties, and there can be no assurance that the Resulting Issuer will be able to exercise effective control over the Moroccan Assets or that SABI-AIM will fulfill its obligations under such agreements. There can be no assurance that any of these properties will be successfully advanced to the development or production stage. Any of these factors could have a material adverse effect on the Resulting Issuer's business, financial condition and results of operations.
PRINCIPAL SECURITYHOLDERS
To the knowledge of Silver Hammer and the Privcos, no Person will, as at the completion of the Transactions, own of record or beneficially, directly or indirectly, or exercise control or direction over, more than 10% of the Resulting Issuer Shares other than as follows:
| Name and Location of Residence |
Resulting Issuer Shares Beneficially Owned, Directly or Indirectly, or Over Which Control or Direction is Exercised |
|
| Number and Percentage after Completion of the Amalgamation, the SilverMark Amalgamation and the Minimum Private Placement(1) |
Number and Percentage after Completion of the Amalgamation, the SilverMark Amalgamation and the Maximum Private Placement(2) |
|
| 2176423 Ontario Ltd. (Eric Sprott) | 29,000,731 (24.79%) | 29,000,731 (22.57%) |
| TOTAL | 29,000,731 (24.79%) | 29,000,731 (22.57%) |
Notes:
(1) Based on 116,980,430 Resulting Issuer Shares issued and outstanding following the completion of the Transactions, assuming the Minimum Private Placement.
(2) Based on 128,518,891 Resulting Issuer Shares issued and outstanding following the completion of the Transactions, assuming the Maximum Private Placement.
DIRECTORS, OFFICERS AND PROMOTERS
The names, municipalities of residence, the number of voting securities beneficially owned, directly or indirectly, or over which each exercises control or direction, following the Closing of the Transactions, and the offices to be held by each in the Resulting Issuer and the principal occupation of the proposed directors and senior officers of the Resulting Issuer during the past five years are as follows:
| Name, Location of Residence and Age |
Position or Office |
Principal Occupation |
Director or Officer of Silver Hammer or Privcos Since |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Minimum Private Placement (1) |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Maximum Private Placement (2) |
| Peter A. Ball Vancouver, British Columbia, Canada 58 years old |
President, Chief Executive Officer and Director | President, Chief Executive Officer and Director of Silver Hammer Mining Corp. (February 2023 - present); and prior thereto, executive roles in the resource sector, most recently with Noram Lithium. |
Officer and Director of Silver Hammer since February 15, 2023 |
1,838,339(3) 1.57% |
1,838,339(3) 1.43% |
| Name, Location of Residence and Age |
Position or Office |
Principal Occupation |
Director or Officer of Silver Hammer or Privcos Since |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Minimum Private Placement (1) |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Maximum Private Placement (2) |
| Alnesh Mohan Vancouver, British Columbia, Canada 55 years old |
Chief Financial Officer, Corporate Secretary | Partner, Quantum Advisory Partners LLP (a professional services firm providing outsourced CFO, financial advisory, and accounting services), since 2005 |
Chief Financial Officer, Corporate Secretary, and Director of Silver Hammer since May 14, 2021 | 497,296(4) (0.43%) |
497,296(4) (0.39%) |
| Dr. Scott Jobin-Bevans Santiago, Chile 59 years old |
Vice President, Exploration, Director | Registered Geoscientist (PGO), Founder Caracole Creek Group - International Geo-Consulting, Santiago, Chile | Director of Stroud since June 9, 2014 and CEO since July 22, 2019 |
1,565,401(5) (1.34%) |
1,565,401(5) (1.22%) |
| Andrew Gillin Toronto, Ontario Canada 44 years old |
Vice President, Corporate Development & Investor Relations | Vice President, Corporate Development & Investor Relations | Vice President, Corporate Development & Investor Relations of Silver Hammer since 07/15/2026 |
Nil (0%) | Nil (0%) |
| Name, Location of Residence and Age |
Position or Office |
Principal Occupation |
Director or Officer of Silver Hammer or Privcos Since |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Minimum Private Placement (1) |
Number and Percentage of Resulting Issuer Shares Beneficially Owned, or Controlled or Directed, Directly or Indirectly after Completion of the Amalgamation, the SilverMark Amalgamation and the Maximum Private Placement (2) |
| Donald J. Birak Coeur d'Alene, Idaho, USA 73 years old | Independent Director | Independent Consulting Geologist, Registered Member of SME and Fellow of AusIMM. |
Director of Silver Hammer since 09/27/2023 | Nil(6) (0)% |
Nil(6) (0)% |
| Michael Willett Saskatoon, Saskatchewan, Canada 67 years old | Independent Director | Director of Silver Hammer Mining Corp. (September 2025 - present); prior thereto, mining executive and independent advisor providing senior-level project evaluation and advisory services to mining companies across North America. |
Director of Silver Hammer since 09/15/2025 | Nil(7) (0)% |
Nil(7) (0)% |
| William J. Kennedy Toronto, Ontario, Canada 67 years old |
Chairman & Independent Director | Chairman of the Board and Director, Jaguar Mining Inc. | Director of Stroud since January 12, 2021 |
Nil(8) (0)% |
Nil(8) (0)% |
| Conor O'Brien | Independent Director | Portfolio Manager, | Director of Stroud since | Nil(9) (0)% |
Nil(9) (0)% |
| Toronto, Ontario, Canada 49 years old |
Eric Sprott Family Office | September 24, 2025 |
Notes:
(1) Based on 116,980,430 Resulting Issuer Shares issued and outstanding following the completion of the Transactions, assuming the Minimum Private Placement.
(2) Based on 128,518,891 Resulting Issuer Shares issued and outstanding following the completion of the Transactions, assuming the Maximum Private Placement.
(3) Such Resulting Issuer Shares will be held by Ariston Capital Corp., a private company of which Mr. Ball is the principal. The figure above reflects post-Consolidation share counts (pre-Consolidation: 7,353,359 Resulting Issuer Shares). Mr. Ball will also hold (i) 1,211,538 Contingent Value Shares, (ii) 687,500 Resulting Issuer Options (pre-Consolidation: 2,750,000), and (iii) 896,032 Resulting Issuer Warrants (pre-Consolidation: 3,584,128) through Ariston Capital Corp. and Lolgorian Holdings Inc., each a private company of which Mr. Ball is the principal.
(4) 453,546 of such Resulting Issuer Shares will be held by Quantum Advisory Partners LLP, a professional services firm of which Mr. Mohan is a partner (pre-Consolidation: 1,814,183 Resulting Issuer Shares held by Quantum Advisory Partners LLP; 1,989,183 Resulting Issuer Shares in aggregate). Mr. Mohan will also hold 396,250 Resulting Issuer Options (pre-Consolidation: 1,585,000) and 450,000 Resulting Issuer Warrants (pre-Consolidation: 1,800,000), the latter held through Quantum Advisory Partners LLP.
(5) Dr. Jobin-Bevans will also hold 1,938,462 Contingent Value Shares.
(6) Mr. Birak will also hold 208,750 Resulting Issuer Options (pre-Consolidation: 835,000). Mr. Birak is not expected to hold any Resulting Issuer Warrants.
(7) Mr. Willett will also hold 125,000 Resulting Issuer Options. Mr. Willett is not expected to hold any Resulting Issuer Warrants.
(8) Mr. Kennedy will also hold 299,517 Resulting Issuer Options. Mr. Kennedy is not expected to hold any Resulting Issuer Warrants.
(9) Mr. O'Brien will also hold 182,822 Resulting Issuer Options. Mr. O'Brien is not expected to hold any Resulting Issuer Warrants.
As of the closing of the Transactions, the directors, officers, Insiders and Promoters of the Resulting Issuer will own, as a group, directly or indirectly, 32,901,767 Resulting Issuer Shares, representing 25.60% of the then issued and outstanding Resulting Issuer Shares on an undiluted basis if the Maximum Private Placement is completed and 28.13% of the then issued and outstanding Resulting Issuer Shares on an undiluted basis if the Minimum Private Placement is completed.
Management
Upon closing of the Transactions, the management team of the Resulting Issuer will consist of Peter A. Ball as President and Chief Executive Officer, Alnesh Mohan as Chief Financial Officer and Corporate Secretary, Dr. Scott Jobin-Bevans as Vice President, Explorations, and Andrew Gillin as Vice President, Corporate Development & Investor Relations. It is anticipated that the Resulting Issuer Board will consist of six (6) directors.
In addition to the information set out in the table above, the following are summaries of the proposed directors and principal management of the Resulting Issuer, including their respective proposed positions with the Resulting Issuer and relevant work and educational background.
Peter A. Ball
Peter A. Ball is a proposed director and the President and Chief Executive Officer of the Resulting Issuer. Mr. Ball brings a progressive track record of proven leadership experience covering more than thirty years in the mining and finance sectors. He has demonstrated competencies in the resource industry on an international level, and held various senior management roles with precious and base metals mining companies in mine engineering, corporate finance, securities trading, business development, corporate communications, public relations and marketing functions. Mr. Ball began his career in the late 1980s working as a mining engineer at Sherritt Gordon Mines, Hudson Bay Mining and Smelting and Echo Bay Mines. Commencing in the 1990s, he held various management and senior executive and corporate roles for numerous companies, including Eldorado Gold, RBC Dominion Securities, Adriana Resources, Century Mining, Argentex Mining, Columbus Gold, Redstar Gold, NV Gold, and Noram Lithium. Mr. Ball has led and assisted in raising over $250 million in capital in the resource sector, and is a member of CIMM. Mr. Ball is also an independent director of Big Gold Inc.
Jeff Kennedy
Jeff Kennedy is the proposed chairman of the Resulting Issuer. Mr. Kennedy served as the Managing Director Equity Capital Markets and Operations at Cormark Securities Inc. With over 30 years of experience, Mr. Kennedy also served as the CFO of Cormark Securities Inc. where he was responsible for financial oversight, controls and governance of operations. He is a Chartered Professional Accountant from the Institute of Chartered Professional Accountants of Ontario and completed his Bachelor of Commerce from McMaster University.
Alnesh Mohan
Alnesh Mohan is the Chief Financial Officer and Corporate Secretary of the Resulting Issuer. Mr. Mohan brings over 20 years of experience and is a partner at Quantum Advisory Partners LLP, a professional services firm focused on providing Chief Financial Officer and full-cycle accounting services to private and public companies, since 2005. Alnesh has acquired considerable experience in financial reporting, corporate governance and regulatory compliance. He holds a Bachelor of Business Administration from Simon Fraser University, a Master of Science in Taxation from Golden Gate University and is a Chartered Professional Accountant (CPA, CA).
Dr. Scott Jobin-Bevans
Dr. Scott Jobin-Bevans is a proposed director of the Resulting Issuer and the Vice President, Exploration (Stroud nominee). Dr. Jobin-Bevans brings over 30 years in the mineral exploration industry and more than 25 years of direct experience with public and private companies as an officer, director and technical advisor and has been involved with taking numerous private companies public. He is a registered geoscientist with PGO (Ontario), APEGS (Saskatchewan), EGM (Manitoba), and PEGNL (Newfoundland), adjunct Professor in the Department of Geology, Lakehead University, and a certified Project Management Professional (PMP). Dr. Jobin-Bevans has a wide range of exploration experience in most commodities including expertise in magmatic sulphides (Ni-Cu-Co) and PGE (Pt-Pd) mineralization, gold, silver, copper (porphyry) and base metals (VMS). Dr. Jobin-Bevans has an extensive industry and government network and served as President (2010-2012) and a Director (2002-2010) of the Prospectors and Developers Association of Canada (PDAC).
Andrew Gillin
Andrew Gillin is the proposed Vice President, Corporate Development & Investor Relations, with the Resulting Issuer. Mr. Gillin is a seasoned investment banking and corporate development professional with over 15 years of experience in the metals and mining sector. Throughout his career, he has advised on more than 25 M&A transactions and over 50 lead financing mandates.
Most recently, he served as Director, Investment Banking at Echelon Wealth Partners (now Ventum Financial), where he completed transactions with an aggregate value exceeding C$1.2 billion. Prior to Echelon, Mr. Gillin held senior investment banking roles at Eight Capital, where he was a member of the firm's founding partnership group, and Dundee Capital Markets. Earlier in his career, he worked at Paradigm Capital and also gained international private equity experience at an Abu Dhabi-based asset manager. Mr. Gillin holds a Bachelor of Commerce degree from McGill University and an MBA from the University of Cambridge.
Conor O'Brien
Conor O'Brien is a proposed director of the Resulting Issuer. Mr. O'Brien is a seasoned financial professional in global capital markets. With over 20 years of experience in equities, derivatives, fixed income and credit default swaps, he has consistently demonstrated an ability to navigate complicated financial instruments and environments. Prior to joining the Eric Sprott Family Office he worked for prominent Canadian brokerages GMP Securities and more recently, Paradigm Capital. Previously, he worked in New York for Cantor Fitzgerald in equity derivatives.
Donald Birak
Donald Birak is a proposed director of the Resulting Issuer. Mr. Birak has over 40 years of experience in mineral exploration and operations, including the roles of Senior Vice-President of Exploration with Coeur Mining (2004 to 2013) responsible for global Greenfields and Brownfields exploration, Vice President of Exploration for AngloGold North America (1998 to 2004), Independence Mining Company (1995 to 1998), and Hudson Bay Mining & Smelting Ltd. (1992 to 1995) and Chief Geologist & Exploration Geologist for Freeport-McMoRan Gold Company (1978 to 1991). In 2000, he received the Bill Dennis Prospector of the Year award presented by the PDAC. Mr. Birak has a M. Sc. Geology and has authored and co-authored several professional publications on the geology and metallurgy of sediment-hosted and epithermal precious metal deposits and on the use of geostatistics in resource modeling and grade control.
Michael Willett
Michael Willett is a proposed director of the Resulting Issuer. Mr. Willett, P. Eng. (Director) is a seasoned mining executive with 40+ years in mine engineering, development, and operations including senior level project evaluation and advisory roles for project re-starts with various mining companies across North America including Battle North Gold and Hudbay Minerals for 20+ years. Mike has operated at many senior roles including Chief Executive Officer and Vice President, more recently, Mr. Willett held the position of Vice President of Operations and Projects for Battle North Gold and was part of that team which successfully sold the company to Evolution Mining for $343 Million in 2021. Mr. Willett is a graduate of Queens University, with a BSc. in Mining Engineering and a Masters Certificate in Project Management from the Schulich School of Business.
Promoter Consideration
No person or company is or has been within the two years immediately preceding the date of the Circular, a promoter of Silver Hammer or the Privcos.
Corporate Cease Trade Orders or Bankruptcies
Except as disclosed below and under "Securityholder Approval" - "Particulars of Matters to be Acted on at the Silver Hammer Meeting" - "Appointment of Directors" in this Circular, no proposed director, officer or Promoter of the Resulting Issuer or shareholder anticipated to hold a sufficient number of securities of the Resulting Issuer to affect materially the control of the Resulting Issuer is or has, within the past 10 years, been a director, officer or Promoter of any Person or issuer that, while such Person was acting in that capacity, was the subject of a cease trade or similar order or an order that denied that Person or issuer access to any exemptions under applicable securities legislation for a period of more than 30 consecutive days or became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency or was subject to or instituted any proceedings, arrangement or compromise with creditors or had a receiver, receiver-manager or trustee appointed to hold the assets of that Person.
Penalties or Sanctions
No proposed director, officer or Promoter of the Resulting Issuer or shareholder anticipated to hold a sufficient number of securities of the Resulting Issuer to affect materially the control of the Resulting Issuer or a personal holding corporation of such Persons is or has been subject to any penalties or sanctions imposed by a court relating to securities legislation or by any securities regulatory authority or has entered into a settlement agreement with a securities regulatory authority or been subject to any other penalties or sanctions proposed by a court or regulatory body, including a self-regulatory body, that would be likely to be considered important to a reasonable securityholder making a decision about the Amalgamation and the SilverMark Amalgamation.
Personal Bankruptcies
No proposed director, officer or Promoter of the Resulting Issuer or shareholder anticipated to hold a sufficient number of securities of the Resulting Issuer to affect materially the control of the Resulting Issuer, or a personal holding corporation of such Persons is or has, within the past 10 years, become bankrupt, made a proposal under bankruptcy or insolvency legislation or been subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold their assets.
Conflicts of Interest
Some of the individuals proposed for appointment as directors or officers of the Resulting Issuer upon the completion of the Amalgamation and the SilverMark Amalgamation are also directors, officers and/or Promoters of other reporting and non-reporting issuers. There may be potential conflicts of interest to which the directors, officers, and Insiders of the Resulting Issuer may be subject in connection with the operations of the Resulting Issuer, and situations may arise where a director, officer or Insider will be in direct competition with the Resulting Issuer. As of the date of this Circular and to the knowledge of the directors and officers of Silver Hammer and the Privcos, there are no existing conflicts of interest between the Resulting Issuer and any of the individuals proposed for appointment as directors or officers following the completion of the Amalgamation and the SilverMark Amalgamation. Conflicts of interest will be subject to, and will be resolved in accordance with, the procedures and remedies under the BCBCA.
CORPORATE GOVERNANCE
Corporate governance refers to the policies and structure of the Board of a corporation, whose members are elected by and are accountable to the shareholders of the company. Corporate governance encourages establishing a reasonable degree of independence of the Board from executive management and the adoption of policies to ensure the Board recognizes the principles of good management. The Board will be committed to sound corporate governance practices, as such practices are both in the interests of shareholders and help to contribute to effective and efficient decision-making.
The Resulting Issuer's proposed corporate governance practices are summarized below.
Independence of Members of Board
Directors are considered to be independent if they have no direct or indirect material relationship with the Resulting Issuer. A "material relationship" is a relationship which could, in the opinion of the Board, be reasonably expected to interfere with the exercise of a director's independent judgment.
The Board will facilitate its exercise of independent judgment in carrying out its responsibilities by carefully examining issues and consulting with outside counsel and other advisors in appropriate circumstances. The Board will require management to provide complete and accurate information with respect to the Resulting Issuer's activities and to provide relevant information concerning the mineral exploration industry in order to identify and manage risks. The Board will be responsible for monitoring the Resulting Issuer's senior officers, who in turn will be responsible for the maintenance of internal controls and management information systems.
Participation of Directors in Other Reporting Issuers
The following table sets out, as at the date of the Circular, the proposed directors of the Resulting Issuer that are currently directors of other reporting issuers:
| Name | Name of Reporting Issuer | Name of Exchange or Market |
| Peter A. Ball | Big Gold Inc. | CSE |
| Donald J. Birak | Stria Lithium Inc. | TSXV |
| Michael Willett | None | N/A |
| Dr. Scott Jobin-Bevans | International Prospect Ventures Ltd. Northern Shield Resources Inc. Vision Lithium Inc. Thunder Gold Corp., Sienna Resources Inc., EV Minerals Corporation, and Makenita Resources Inc. |
TSXV TSXV TSXV TSXV CSE CSE |
| Jeff Kennedy | Jaguar Mining Inc. | TSX |
Orientation and Continuing Education
Upon the completion of the Amalgamation and the SilverMark Amalgamation, new directors of the Resulting Issuer will participate in an orientation discussion with the Resulting Issuer's management and incumbent directors regarding the role of the Board, its committees, and the nature and operations of the Resulting Issuer's business. Members of the Board will be encouraged to communicate with management of the Resulting Issuer, external legal counsel and auditors, and other external consultants to educate themselves about the Resulting Issuer's business, the mining industry and applicable legal and regulatory developments.
Ethical Business Conduct
The Board views good corporate governance as an integral component to the success of the Resulting Issuer and to meeting its responsibilities to shareholders. The Resulting Issuer intends to adopt a Code of Conduct following the completion of the Amalgamation and the SilverMark Amalgamation.
The Board, through its meetings with management and other informal discussions with management, will encourage a culture of ethical business conduct and believes the Resulting Issuer's high calibre management team will promote a culture of ethical business conduct throughout the Resulting Issuer's operations and will be expected to monitor the activities of the Resulting Issuer's employees, consultants and agents in that regard.
It will be a requirement of applicable corporate law that directors and senior officers who have an interest in a transaction or agreement with the Resulting Issuer promptly disclose that interest at any meeting of the Board at which the transaction or agreement will be discussed and, in the case of directors, abstain from discussions and voting in respect of same if the interest is material. These requirements will also be contained in the Resulting Issuer's Articles, which will be made available to directors and senior officers of the Resulting Issuer.
Nomination of Directors
The Board will consider its size each year when it considers the number of directors to recommend to shareholders for election at the annual meeting of shareholders, taking into account the number required to carry out the Board's duties effectively and to maintain a diversity of views and experience.
The Board will not initially have a nominating committee, and these functions will be performed by the Board as a whole. However, if there is a change in the number of directors required by the Resulting Issuer, this practice may be reviewed.
Compensation
The Board has established a Corporate Governance Committee, which will continue to assist the Board in its oversight of corporate governance practices following the completion of the Amalgamation and the SilverMark Amalgamation. The compensation of directors and officers will be determined by the Board, after consideration of various relevant factors, including the expected nature and quantity of duties and responsibilities, past performance, comparison with compensation paid by other issuers of comparable size and nature, and the availability of financial resources.
Board Committees
Upon completion of the Amalgamation and the SilverMark Amalgamation, the Board will have the following standing committees: the Audit Committee; the Compensation Committee; and the Corporate Governance Committee.
Corporate Governance Committee
The Corporate Governance Committee will continue to assist the Board in its oversight of the Resulting Issuer's corporate governance practices and in assessing the effectiveness of the Board and its committees. The Corporate Governance Committee will consist of Donald Birak (Chair), Michael Willett and Peter A. Ball. The Charter of the Corporate Governance Committee will be available on the SEDAR+ website under the Resulting Issuer's profile.
Audit Committee
The primary function of the Audit Committee will be to assist the Board in fulfilling its financial oversight responsibilities with respect to the financial reporting process and the quality, transparency and integrity of the financial statements and other related public disclosures; the Resulting Issuer's systems of internal controls regarding finance and accounting; and the Resulting Issuer's auditing, accounting and financial reporting processes. Consistent with this function, the Audit Committee will encourage continuous improvement of, and will foster adherence to, the Resulting Issuer's policies, procedures and practices at all levels. The Audit Committee will consist of Michael Willett (Chair), Donald Birak, and Peter A. Ball. The Audit Committee will meet at least four times annually.
See "Audit Committee" for details about its composition and function. The Charter of the Audit Committee is attached as Appendix "G" to the Circular.
Compensation Committee
The Compensation Committee will continue to assist the Board in fulfilling its responsibilities relating to matters of human resources and compensation, including equity compensation, and to establish a plan of continuity and development of senior management. The Compensation Committee will have responsibility for evaluating and making recommendations to the Board regarding the compensation of the Resulting Issuer's Chief Executive Officer, the range of compensation for other executives, and the equity-based and incentive compensation plans, policies and programs of the Resulting Issuer. The Compensation Committee will also review and recommend to the Board the compensation payable to directors. The Compensation Committee will review management's annual report on executive compensation for recommendation to the Board for approval and inclusion in the Resulting Issuer's disclosure documents. The Compensation Committee will consist of Jeff Kennedy (Chair), Donald Birak and Michael Willett.
See "Compensation Committee" for details about its composition and function. The Charter of the Compensation Committee will be available on the SEDAR+ website under the Resulting Issuer's profile.
Assessments
The Board will monitor the adequacy of information given to directors, communication between the Board and management, and the strategic direction and processes of the Board and its committees.
No formal policy has been established to monitor the effectiveness of the directors, the Board and its committees. However, the Resulting Issuer believes that its corporate governance practices will be appropriate and effective given the Resulting Issuer's stage of development.
EXECUTIVE COMPENSATION
The Resulting Issuer anticipates negotiating compensation agreements with its directors and officers following completion of the Amalgamation and the SilverMark Amalgamation. Under this heading, the Resulting Issuer is including the disclosure required by Form 51-102F6V - Statement of Executive Compensation - Venture Issuers under National Instrument 51-102 Continuous Disclosure Obligations.
Compensation Discussion and Analysis
Executive Compensation is required to be disclosed for (i) each CEO (or individual who served in a similar capacity during the most recently completed financial year), (ii) each CFO (or individual who served in a similar capacity during the most recently completed financial year), (i) the most highly compensated executive officers (other than the CEO and the CFO) who were serving as executive officers at the end of the most recently completed fiscal year and whose total compensation was, individually, more than $150,000; and (iv) each individual who would meet the definition set forth in (iii) but for the fact that the individual was neither an executive officer of the company, nor acting in a similar capacity, at the end of that financial year (the "NEOs").
Based on the above criteria, the NEOs for the Resulting Issuer are expected to be Peter A. Ball, President and Chief Executive Officer, Alnesh Mohan, Chief Financial Officer and Corporate Secretary, Dr. Scott Jobin-Bevans, Vice President, Explorations, and Andrew Gillin, Vice-President, Corporate Development & Investor Relations.
Philosophy and Objectives
The Resulting Issuer will implement a compensation committee (the "Compensation Committee") to oversee, among other things, the consulting agreements, compensation of all directors and executive officers, and development of corporate governance policies.
The objective of the Compensation Committee in setting compensation levels will be to attract and retain individuals of high calibre to serve as officers of the Resulting Issuer, to motivate their performance in order to achieve the Resulting Issuer's strategic objectives and to align the interests of executive officers with the long-term interests of the Resulting Issuer's shareholders. These objectives are designed to ensure that the Resulting Issuer continues to grow on an absolute basis as well as to grow cash flow and earnings for shareholders. The Compensation Committee will set the compensation received by NEOs so as to be generally competitive with the compensation received by persons with similar qualifications and responsibilities who are engaged by other companies of corresponding size, stage of development, having similar assets, number of employees, market capitalization and profit margin, companies.
Compensation
The Resulting Issuer will compensate its executive officers based on their skill and experience levels and the existing stage of development of the Resulting Issuer. Executive officers will be rewarded on the basis of the skill and level of responsibility involved in their position, the individual's experience and qualifications, the Resulting Issuer's resources, industry practice, and regulatory guidelines regarding executive compensation levels.
The Resulting Issuer intends to implement three levels of compensation to align the interests of the executive officers with those of the shareholders. First, executive officers will be paid a monthly consulting fee or salary determined by the Compensation Committee, if appropriate. Second, the Compensation Committee and Board of Directors may award executive officers long term incentives in the form of stock options. Finally, and only in special circumstances, the Compensation Committee may award cash or share bonuses for exceptional performance that results in a significant increase in shareholder value. The Resulting Issuer is not expected to provide pension or other benefits to the executive officers.
The base compensation of the executive officers will be reviewed and set annually by the Compensation Committee. The CEO has substantial input in setting annual compensation levels. The CEO will be directly responsible for the financial resources and operations of the Resulting Issuer. In addition, the CEO and Compensation Committee from time to time will determine the stock option grants to be made pursuant to the Omnibus Plan. Previous grants of stock options are taken into account when considering new grants. The Compensation Committee may award bonuses at its sole discretion, there is currently no preexisting performance criteria or objectives.
Compensation for the most recently completed financial year should not be considered an indicator of expected compensation levels in future periods. All compensation is subject to and dependent on the Resulting Issuer's financial resources and prospects. The Resulting Issuer intends to maintain the management contracts of Silver Hammer and the Privcos. See "Information Concerning Silver Hammer - Executive Compensation - Employment, Consulting and Management Agreements" for information concerning the management contracts. Compensation of the NEOs will be reviewed by the Compensation Committee on an annual basis.
Director and NEO Compensation Table (Excluding Compensation Securities)
The following Summary Compensation Table provides a summary of the proposed compensation to be paid by the Resulting Issuer to the NEOs and directors for the 12 month period following the Closing.
| Name and Principal Position |
Salary, consulting fee, retainer or commission ($) |
Bonus ($) |
Committee or meeting fees ($) |
Value of perquisites ($) |
Value of all other Compensation ($) |
Total Compensation ($) |
| Peter A. Ball, President, CEO and director |
$325,000(1) | Nil(3) | Nil | Nil | Nil | $325,000 (1) |
| Alnesh Mohan, CFO and Corporate Secretary | $180,000(1) | Nil(3) | Nil | Nil | Nil | $180,000(1) |
| Dr. Scott Jobin-Bevans, Vice President, Exploration and director | $170,000(1) | Nil(3) | Nil | Nil | Nil | $170,000(1) |
| Andrew Gillin, Vice President, Corporate Developmen t & Investor Relations | $260,000(1) | Nil(3) | Nil | Nil | Nil | $260,000(1) |
| Donald J. Birak, director | $18,000(2) | Nil |
Nil |
Nil |
Nil |
$18,000(2) |
| Michael Willett, director | $18,000(2) | Nil |
Nil |
Nil |
Nil |
$18,000(2) |
| Jeff Kennedy, Chairman | $18,000(2) | Nil | Nil | Nil | Nil | $18,000(2) |
| Conor O'Brien, director | $18,000(2) | Nil | Nil | Nil | Nil | $18,000(2) |
Notes:
(1) See "Employment, Consulting and Management Agreements" below for further details.
(2) Related to independent board fees payable of $1500 per month and paid quarterly after closing.
(3) A bonus may be payable upon successful completion of established performance targets.
Employment, Consulting and Management Agreements
Silver Hammer and Peter A. Ball intend to enter into an addendum to the Ball Agreement (the "Amended Ball Agreement"). Pursuant to the Amended Ball Agreement, Mr. Ball will provide management services as the Chief Executive Officer of Silver Hammer and the Resulting Issuer, as applicable, for yearly compensation of $325,000, effective as of September 28, 2026. All other terms and conditions of the Ball Agreement as set out under "Information Concerning Silver Hammer" - "Executive Compensation" - "Employment, Consulting and Management Agreements" in this Circular will continue in force with no amendments thereto.
On July 15, 2026, Silver Hammer entered into a consulting agreement (the "Gillin Agreement") with Southwood Strategic Corp. ("Southwood"), pursuant to which Andrew Gillin will perform the services of Vice President, Corporate Development and Investor Relations for the Resulting Issuer. Pursuant to the Gillin Agreement, Southwood is entitled to a base fee of $260,000 per annum following completion of the Transactions (and $14,000 per month during the period between the date of the Gillin Agreement and the Closing Date). If the Gillin Agreement is terminated the Resulting Issuer without cause or by Southwood for Good Reason, Southwood is entitled to a termination fee equal to six (6) months' base fee, plus three (3) additional months of base fee for each full year of service (pro-rated for any partial year and rounded up) after the effective date, up to a maximum of 18 months' base fee (the "Termination Fee"), and any outstanding stock options will expire and cease to be exercisable 90 days following the date of termination. Additionally, if a Change of Control Event occurs and the Gillin Agreement is terminated for any reason during the Change of Control Period (excluding termination for failure, default or other breach), or Southwood terminates the Gillin Agreement for Good Reason during the Change of Control Period, the Resulting Issuer is required to pay Southwood one and one quarter (1.25) times the Termination Fee that is payable pursuant to the Gillin Agreement.
Following the Closing Date, the Resulting Issuer intends to enter into a consulting agreement (the "Jobin-Bevans Agreement") with Caracle Creek International Consulting Inc. (Canada) ("Caracle Creek"), pursuant to which Dr. Scott Jobin-Bevans will perform the services of Vice President, Exploration for the Resulting Issuer. Pursuant to the Jobin-Bevans Agreement, Caracle Creek is entitled to a base fee of $170,000 per annum following completion of the Transactions. If the Jobin-Bevans Agreement is terminated by the Resulting Issuer without cause or by Caracle Creek for Good Reason, Caracle Creek is entitled to a termination fee equal to six (6) months' base fee, plus three (3) additional months of base fee for each full year of service (pro-rated for any partial year and rounded up) after the effective date, up to a maximum of 18 months' base fee (the "Termination Fee"), and any outstanding stock options will expire and cease to be exercisable 90 days following the date of termination. Additionally, if a Change of Control Event occurs and the Jobin-Bevans Agreement is terminated for any reason during the Change of Control Period (excluding termination for failure, default or other breach), or Caracle Creek terminates the Jobin-Bevans Agreement for Good Reason during the Change of Control Period, the Resulting Issuer is required to pay Caracle Creek one and one quarter (1.25) times the Termination Fee that is payable pursuant to the Jobin-Bevans Agreement.
On September 1, 2026, Silver Hammer entered into a consulting services agreement and accounting services agreement (together, the "Ascend Agreements") with Ascend Advisory Partners LLP, pursuant to which Alnesh Mohan will continue to serve as Chief Financial Officer of the Resulting Issuer. Pursuant to the Ascend Agreements, Ascend is entitled to (i) a monthly fee of $10,000 plus applicable taxes (being $120,000 per annum) in respect of the services of Alnesh Mohan as Chief Financial Officer, and (ii) a monthly base fee of $5,000 plus applicable taxes (being $60,000 per annum) for up to 30 hours per month of accounting services (collectively, the "Ascend Fees"). The Resulting Issuer may terminate the Ascend Agreements without cause by providing 120 days' prior written notice or by paying the equivalent service fees in lieu of such notice. If the Resulting Issuer terminates the Ascend Agreements without cause and such termination occurs either prior to six (6) months before or after twelve (12) months following a Change of Control or a Fundamental Transaction, effective no later than 30 days following the termination, then Mr. Mohan is entitled to receive a lump sum termination fee equal to 18 months of the Ascend Fees ($180,000), as in effect immediately prior to the termination date of the Ascend Agreements, with up to fifty percent (50%) of such lump sum payable in shares at the Resulting Issuer's election.
Incentive Plan Awards
Share-based awards
During the 12 month period following the completion of the Amalgamation and the SilverMark Amalgamation, it is not expected that the Resulting Issuer will grant any share-based awards, being awards granted under an equity incentive plan of equity-based instruments that do not have option-like features, including, for greater certainty, common shares, restricted shares, restricted share units, deferred share units, phantom shares, phantom share units, common share equivalent units, and stock. See "Forward-Looking Information".
Option-based awards
The Resulting Issuer will likely grant future option-based awards, being awards under an equity incentive plan of options, including, for greater certainty, by granting stock options to its directors, officers and employees. The timing, amounts, and exercise price of these future option-based awards are not yet determined. Such stock options are expected to be granted under Omnibus Plan. See "Securityholder Approval" - "Particulars of Matters to be Acted on at the Silver Hammer Meeting" - "2026 Omnibus Equity Incentive Compensation Plan".
INDEBTEDNESS OF DIRECTORS AND OFFICERS
No individual who: (a) is a director or officer of Silver Hammer or any of the Privcos or is proposed to be a director or officer of the Resulting Issuer; (b) at any time during the most recently completed financial year of Silver Hammer or any of the Privcos, was a director or officer of Silver Hammer or any of the Privcos or (c) is an Associate of any of the foregoing, is either: (i) indebted to Silver Hammer or any of the Privcos or any of their subsidiaries; or (ii) indebted to another entity with such indebtedness being the subject of a guarantee, support agreement, letter of credit or other similar arrangement or understanding provided by Silver Hammer, the Privcos or any of their subsidiaries.
INVESTOR RELATIONS ARRANGEMENTS
The Resulting Issuer has not arranged any investor relations agreements nor does it have any understanding regarding investor relations arrangements; however, the Resulting Issuer may enter into investor relations arrangements in the future.
OPTIONS TO PURCHASE SECURITIES
As at the date hereof, there are no stock options to purchase securities of any of the Privcos and none will be issued and outstanding upon Closing of the Amalgamation and the SilverMark Amalgamation.
As at the date of the Circular, there are 6,105,000 Silver Hammer Options outstanding, which will, following the Consolidation, result in 1,526,250 Resulting Issuer Options. In addition, each of the 1,155,000 outstanding Stroud Options will be amended prior to the effective date of the Stroud Amalgamation such that the obligation to issue Stroud Shares on exercise will be replaced with an obligation to issue Resulting Issuer Shares, and the number of Resulting Issuer Shares issuable on exercise and the exercise price therefor will be adjusted in accordance with the Stroud Exchange Ratio, on the same economic terms and conditions, resulting in up to 898,561 Resulting Issuer Shares being issuable upon exercise of such amended Stroud Options, subject to the Omnibus Plan being approved by Silver Hammer Shareholders at the Silver Hammer Meeting. All other terms of the Stroud Options shall remain unchanged.
Upon Closing, the following Resulting Issuer Options will be outstanding to the following groups:
| Held By | Number of Resulting Issuer Options |
Number of Resulting Issuer Shares to be issued on exercise of the Resulting Issuer Options |
| Officers and directors of the Resulting Issuer | 2,083,237(1) | 2,083,237(1) |
| Officers and directors of subsidiaries of the Resulting Issuer who are not also officers and directors of the Resulting Issuer | Nil | Nil |
| All other employees of the Resulting Issuer | Nil | Nil |
| All other consultants of the Resulting Issuer | 329,074(2) | 329,074(2) |
| Any other person or company | Nil | Nil |
Notes:
(1) Includes Resulting Issuer Options held by: (i) Lolgorian Holdings Inc., a private company controlled by the CEO, Peter
A. Ball, who holds 687,500 Resulting Issuer Options, (ii) CFO Alnesh Mohan holds 346,250 Resulting Issuer Options, (iii) VP Exploration Dr. Scott Jobin-Bevans holds 233,291 Resulting Issuer Options, (iv) Director Don Birak holds 208,750 Resulting Issuer Options, (v) Director Michael Willett holds 125,000 Resulting Issuer Options, (vi) Director Jeff Kennedy holds 299,517 Resulting Issuer Options, and (vii) Director Conor O'Brien holds 182,822 Resulting Issuer Options.
(2) Includes Resulting Issuer Options held by: (i) Board advisor Ron Burke holds 133,750 Resulting Issuer Options, (ii) Corporate Administrator Angie Ball holds 12,500 Resulting Issuer Options, and (iii) Mirsad Jakubovic holds 182,822 Resulting Issuer Options.
There are no assurances that the stock options described above will be exercised in whole or in part.
2026 Omnibus Equity Incentive Compensation Plan
The Resulting Issuer will approve and adopt the Omnibus Plan. For additional information on the terms of the Omnibus Plan, please see "Securityholder Approval" - "Particulars of Matters to be Acted on at the Silver Hammer Meeting" - "2026 Omnibus Equity Incentive Compensation Plan".
Escrowed Securities
As at the date of this Circular, there are no Silver Hammer Shares held in escrow.
AUDIT COMMITTEE
A summary of the responsibilities and activities and the membership of the Audit Committee of the Resulting Issuer is set out below, as required by Form 52-110 F2 - Disclosure by Venture Issuers. The Charter of the Audit Committee is attached hereto as Appendix "G".
Composition of the Audit Committee
The following directors will be the members of the Audit Committee:
| Name | Independent/Not Independent(1) | Financially Literate(2) |
| Michael Willett (Independent Director) | Chair and Independent | Yes |
| Don Birak (Independent Director) | Independent | Yes |
| Peter A. Ball (President & CEO) | Not Independent | Yes |
Notes:
(1) A member is independent if the member has no direct or indirect material relationship with the Resulting Issuer, which could, in the view of the board of directors of the Resulting Issuer, reasonably interfere with the exercise of that member's independent judgment.
(2) A member is financially literate if such member has the ability to read and understand a set of financial statements that present a breadth of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can reasonably be expected to be raised by the Resulting Issuer's financial statements.
In accordance with section 6.1.1(3) of National Instrument 52-110 - Audit Committees ("NI 52-110") relating to the composition of the audit committee for venture issuers, a majority of the members of the Audit Committee will not be executive officers, employees or control persons of the Resulting Issuer. All the members of the Audit Committee will be considered to be financially literate as required by section 1.6 of NI 52-110.
Relevant Education and Experience
As a result of their education and experience, each member of the Audit Committee has familiarity with, an understanding of, or experience with:
The relevant education and experience of each member of the Audit Committee is set out in the biographical information of the directors of the Resulting Issuer under "Resulting Issuer - Directors and Officers" in this Appendix "F".
AUDITOR, TRANSFER AGENT AND REGISTRAR
Auditor
The auditor of the Resulting Issuer will be Manning Elliott LLP.
Transfer Agent and Registrar
It is expected that Endeavor Trust Corporation will serve as the Resulting Issuer's registrar and transfer agent. It is expected that transfers of the securities of the Resulting Issuer may be recorded at registers maintained by Endeavor Trust Corporation in Vancouver, British Columbia.
APPENDIX G - AUDIT COMMITTEE DISCLOSURE (FORM 52-110F2)
COMPOSITION OF THE AUDIT COMMITTEE
The Corporation's Audit Committee is comprised of four directors consisting of Mirsad Jakubovic, Scott Jobin-Bevans, Jeff Kennedy and Conor O'Brien. The Chair of the Audit Committee is Jeff Kennedy. The following table sets out the names of the members of the Audit Committee and whether they are "independent" and "financially literate" for the purposes of National Instrument 52-110 Audit Committee ("NI 52-110").
| Name of Member | Independent(1) | Financially Literate(2) |
| William J. Kennedy | Yes | Yes |
| Scott Jobin-Bevans | No | Yes |
| Mirsad Jakubovic | No | Yes |
| Conor O'Brien | Yes | Yes |
Notes:
(1) To be independent, a member of the Audit Committee must not have any direct or indirect "material relationship" with the Corporation. A material relationship is a relationship, which could, in the view of the Board, reasonably interfere with the exercise of a member's independent judgment. Accordingly, an executive officer of the Corporation is not independent, nor is a director that is paid consulting fees for non-director services provided to the Corporation.
(2) To be considered financially literate, a member of the audit committee must have the ability to read and understand a set of financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can reasonably be expected to be raised by the Corporation's financial statements.
RELEVANT EDUCATION AND EXPERIENCE
NI 52-110 provides that an individual is "financially literate" if he or she has the ability to read and understand a set of financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can reasonably be expected to be raised by the Corporation's financial statements.
Further information about the relevant education and experience of the Audit Committee members is set out below. All of the members of the Corporation's current audit committee are "financially literate" as that term is defined in NI 52-110.
Mr. Jeff Kennedy. Mr. Kennedy was appointed to the Board in January 2021. In addition, Mr. Kennedy is also a director of Jaguar Mining Inc. Prior to joining the Board, Mr. Kennedy served as Managing Director Equity Capital Markets and Operations at Cormark Securities Inc. until July 2019. Mr. Kennedy has been an Administrator at 2176423 Ontario Ltd, the controlling shareholder of Stroud Resources Ltd. since June 2020. With over 30 years of experience, Mr. Kennedy also served as the CFO of Cormark Securities Inc. where he was responsible for financial oversight, controls and governance of operations. Mr. Kennedy is a Chartered Professional Accountant from the Institute of Chartered Professional Accountants of Ontario and obtained his Bachelor of Commerce from McMaster University.
Conor O'Brien: Mr. O'Brien was appointed to the Board in September 2025. Mr. O'Brien is a seasoned financial professional in global capital markets. With over 20 years of experience in equities, derivatives, fixed income and credit default swaps, he has consistently demonstrated an ability to navigate complicated financial instruments and environments. Prior to joining the Eric Sprott Family Office he worked for prominent Canadian brokerages GMP Securities and more recently, Paradigm Capital. Previously, he worked in New York for Cantor Fitzgerald in equity derivatives.
Dr. Scott Jobin-Bevans: Dr. Jobin-Bevans has over 30 years in mineral exploration with public and private company experience as an officer, director and technical advisor. Dr. Jobin-Bevans is President and CEO of Caracle Creek International Consulting Inc. (also a Co-Founder and Director) and is P.M.P. Certified in project management. His areas of expertise include project evaluation, generation and management and he has led multimillion dollar projects from generative stage to advanced exploration and development. Dr. Jobin-Bevans is a member of the Board of Directors for several public and private companies and is Past President (2010-2012) and a past Director (2001-2010) of the Prospectors and Developers Association of Canada (PDAC). In 2013, he was awarded the Queen Elizabeth Diamond Jubilee Medal in recognition of his significant contributions and achievements in the Canadian minerals industry.
Mr. Mirsad Jakubovic, MBA, CPA, CA. Mr. Jakubovic has over 30 years of financial and management experience and has grown and developed Canadian operations for several international businesses. He has been the Chief Financial Officer for two publicly traded companies and has worked for many years in industries that are regulated by Health Canada. He is a Chartered Professional Accountant and holds an MBA degree from the Richard Ivey School of Business, Western University.
All members have an understanding of the accounting principles used by the Corporation to prepare its financial statements and have an understanding of its internal controls and procedures for financial reporting.
AUDIT COMMITTEE OVERSIGHT
At no time since the commencement of the Corporation's most recently completed financial year was a recommendation of the Audit Committee to nominate or compensate an external auditor adopted by the Board. At the Meeting, it is proposed to re-appoint McGovern Hurley LLP as auditor of the Corporation and to authorize remuneration to be fixed by the Board. The auditor of the Corporation will hold office until the next annual general meeting of the Shareholders or until its successor is appointed.
PRE-APPROVAL POLICIES AND PROCEDURES
Formal policies and procedures for the engagement of non-audit services are set out in the Audit Committee Charter.
EXEMPTION
In respect of the most recently completed financial year, the Corporation relied upon the exemptions set out in Section 6.1 of NI 52-110 with respect to compliance with the requirements of Part 3 (Composition of the Committee) and Part 5 (Reporting Obligations) of NI 52-110.
EXTERNAL AUDITOR SERVICE FEES (BY CATEGORY)
In the following table, "audit fees" are fees billed by the Corporation's external auditors for services provided in auditing the Corporation's annual financial statements for the subject year. "Audit-related fees" are fees not included in audit fees that are billed by the auditors for assurance and related services that are reasonably related to the performance of the audit or review of the Corporation's financial statements. "Tax fees" are fees billed by the auditors for professional services rendered for tax compliance, tax advice and tax planning. "All other fees" are fees billed by the auditors for products and services not included in the foregoing categories.
The aggregate fees billed by the Corporation's external auditors in each of the last two fiscal years for audit fees are as follows:
| Financial Year Ending December 31 |
Audit Fees | Audit Related Fees |
Tax Fees | All Other Fees |
| 2025 | $40,000 | Nil | Nil | Nil |
| 2024 | $40,000 | Nil | Nil | Nil |
THE AUDIT COMMITTEE'S CHARTER
PURPOSE OF THE AUDIT COMMITTEE
The purpose of the Audit Committee is to fulfill the applicable public company audit committee legal and regulatory obligations and to provide assistance to the board of directors of the Corporation (the "Board") to enable it to fulfill its oversight responsibilities in relation to the financial reporting process, the system of internal controls and the audit process and management of significant risks to the Corporation, as they relate to financial reporting.
Audit Committee Mandate
The Audit Committee (the "Committee") is appointed by the Board to assist the Board in fulfilling its oversight responsibilities of the Corporation. In so doing, the Committee provides an avenue of communication among the external auditors, management and the Board.
The Committee's purpose is to ensure the integrity of financial reporting and the audit process, and that sound risk management and internal control systems are developed and maintained. In pursuing these objectives, the Audit Committee oversees relations with the external auditors, and reviews the effectiveness of the internal audit function.
STRUCTURE OF THE COMMITTEE
Composition
The Committee is a standing committee of the Board and will be composed of not less than three directors, with not more than one director being an executive officer, related party or employee of the Corporation.
Quorum
A quorum of the Committee will be a majority of members present in person, by telephone or any combination thereof.
Appointment of Members and Chairman
Members of the Committee shall be appointed by the Board annually on the recommendation of the Corporate Governance and Nominating Committee to hold office at the pleasure of the Board. No more than two members of the Committee will resign from the Committee in any given year.
Chairman
The Board shall appoint one of the members as the Committee Chair. In the absence of the Chair from any meeting, the Committee shall appoint a member to be the Chair for the purposes of the conduct of that meeting.
Qualification of Members
Members of the Committee shall meet applicable requirements and guidelines for audit committee service, including requirements and guidelines with respect to being independent and unrelated to the Corporation and to having accounting or related financial management expertise and financial literacy.
The determination as to whether a particular Director satisfies the requirements for membership on the Audit Committee shall be made by the full Board.
Vacancy
A vacancy occurring in the membership of the Committee may be filled by the Board at its discretion, but in any event, the Board shall fill any vacancy to ensure a minimum of three members on the Committee at all times.
Number and Timing of Meetings
The Audit Committee meets at least four times a year, with meetings being scheduled to permit timely review of quarterly and annual financial statements. Additional meetings may be held at the discretion of the Chair or at the request of a member, external auditors or management.
Secretary
A secretary shall be designated, and that person shall act as recording secretary for the Committee and produce minutes of the meetings.
Meetings with Management and External Auditors
The Committee shall meet separately with management and external auditors at least once per quarter and shall meet at such other times, as the Committee deems appropriate.
Notice and Place of Meetings
Notice of time and place of meetings shall be communicated to members of the Committee no less than 48 hours prior to the time set for the meeting, provided that any member may waive such notice.
A member of the Committee who attends a meeting for the purpose of objecting to whether the meeting was lawfully called shall not be considered to have waived required notice.
Invitees
By invitation of the Chair, individuals who are not members of the Committee may attend meetings from time to time and may participate in discussions related to issues before the Committee.
Minutes and Procedures of Meetings
Subject to statutory requirements and by-laws of the Corporation, the Committee may set its own procedures at meetings, keep records of its proceedings and report to the Board when the Committee considers it appropriate, but in any event not later than the next Board meeting. Minutes of the Committee meeting shall be tabled at the next Board meeting.
Delegation of Responsibilities
The Committee may delegate to any person or committee of persons any of the Committee's responsibilities that may be lawfully delegated.
External Auditors
External auditors are ultimately accountable to the Board and shall report directly to the Committee. The external auditors are accountable to the Board and the Audit Committee as representatives of the shareholders of the Corporation.
Mandate
The Committee will review and reassess the adequacy of the Audit Committee Mandate on an annual basis to ensure that it accurately specifies the scope of the Committee's responsibilities and adequately sets out how it carries out those responsibilities.
PRIMARY RESPONSIBILITIES OF THE COMMITTEE
The Committee's primary duties and responsibilities are as follows:
Review and recommend to the Board the external auditor to be nominated for the purpose of preparing or issuing an auditor's report or performing other audit, review or attest services for the Corporation; and the compensation to be paid to the external auditor.
Assume direct responsibility for overseeing the work of the external auditors engaged to prepare or issue an audit report or perform other audit, review or attest services for the Corporation, including the resolution of disagreements between management and the external auditors regarding financial reporting.
Pre-approve all non-audit services to be provided to the Corporation or its subsidiary entities by its external auditors.
Review the Corporation's financial statements, management's discussion and analysis and annual and interim earnings press releases before such documents are publicly disclosed by the Corporation.
To satisfy itself that adequate procedures are in place for the review of the Corporation's public disclosure of financial information extracted or derived from the Corporation's financial statements and periodically assess the adequacy of those procedures.
Establish procedures for: (a) the receipt, retention and treatment of complaints received by the Corporation regarding accounting, internal accounting controls, or auditing matters; and (b) the confidential, anonymous submission by employees of the Corporation of concerns regarding questionable accounting or auditing matters.
Review and approve the Corporation's hiring policies regarding partners, employees and former partners and employees of the present and any former external auditor of the Corporation.
Authority of the Committee
The Committee shall have the authority to engage independent counsel and other advisors as it determines necessary to carry out its duties and to set and pay the compensation for any advisors engaged by it. The Committee shall also have the authority to communicate directly with the external auditors.
DUTIES OF THE COMMITTEE
Compliance
The Committee is ultimately responsible for ensuring the Corporation's compliance with legal and regulatory requirements in respect to financial reporting and disclosure.
The Committee, on behalf of the Board, is responsible for monitoring management's actions in this regard to ensure that the Corporation has implemented appropriate systems to identify and monitor the response by management and the board of directors to such issues as:
Significant business risks.
Legal, ethical and regulatory compliance.
Internal systems of control and the effectiveness of such internal controls to ensure compliance with policies and procedures.
Meetings
The Committee is responsible for preparing minutes of all of its meetings and submitting the minutes to the Board for approval and having the Chairman of the Committee report to the Board on all significant issues addressed at the Committee meeting.
The Committee is also responsible for reviewing the interim and annual financial statements as well as the Corporation's financial disclosures and related party transactions.
Internal Controls
The Committee is responsible for maintaining the integrity and quality of the Corporation's financial reporting and systems of internal control by overseeing management's system of internal control and reporting process in respect to those controls.
External Auditors
The Committee has the following responsibilities with respect to the Corporation's external auditors:
Reviewing and ensuring the qualifications and independence of the Corporation's external auditors.
Making recommendations to the Board in respect of the appointment of external auditors for the purpose of preparing or issuing an auditor's report or performing other audit, review or attest services for the Corporation and making recommendations to the Board on the compensation for the external auditor.
Overseeing and evaluating the performance of the external auditors.
Reviewing the annual audit plan prepared by the external auditors and management (Chief Financial Officer and Chief Executive Officer) in addition to proposed audit fees.
Reviewing the external audit process and determining whether it has been effectively carried out and whether any matters that the external auditors wish to bring to the attention of the Board have been afforded adequate attention.
Assessing the external audit function with a view to whether external auditors should be appointed. Such responsibility of the Committee shall include the appointment, retention, termination, compensation and oversight of the external audit function.Pre-approving all audit services and non-audit services to be
performed for the Corporation by the external auditors.
Meeting separately with internal audit, external auditors and management at least quarterly to assess issues and make determinations on whether issues need to be taken to the Board for review and assessment.
Evaluating independence of the external auditor in accordance with Canadian professional requirements and determining whether disclosed relationships or services may impact the objectivity and independence of the auditors and whether such independence has been documented in written correspondence to the Committee.
Overseeing any work of the external auditor that includes the resolution of disagreements regarding financial reporting between management and the external auditors.
Evaluating the external audit process and determining whether the external audit has been completed in accordance with applicable law.
Financial Reporting
Reviewing annual and interim financial statements of the Corporation.
Reviewing changes in significant accounting policies and evaluates impact on the current and future financial statements of the Corporation.
Preparing, if required, a committee report for inclusion in the Corporation's annual management proxy circular in accordance with applicable rules and regulations.
Ensuring the effectiveness of disclosure controls and procedures to ensure material information potentially requiring public disclosure is made known in a timely fashion to senior officers of the Corporation.
Being satisfied that adequate procedures are in place for the review of the Corporation's public disclosure of financial information extracted or derived from the Corporation's financial statements and periodically assessing the adequacy of those procedures.
Reviewing and recommending to the Board for approval the public release and filing of any annual audited consolidated financial statements and quarterly unaudited consolidated financial statements of the Corporation, including news releases and management's discussion and analysis (MD&A).
Reviewing the information contained in the Corporation's quarterly reports, annual report to shareholders, MD&A, annual information forms (AIF), prospectuses and other disclosures to determine if such information is complete and fairly presented.
Reviewing material litigation and tax assessments in order to determine if any such matters may have a material impact on the financial position of the Corporation.
Considering the Corporation's annual financial statements and ascertaining after a review with external auditors and management whether they are presented fairly in all material respects in accordance with generally accepted accounting principles, whether the selection of accounting policies is appropriate and whether the annual financial statements are recommended to the Board.
Reviewing Terms of Reference and Committee's Performance
The Committee should routinely assess its effectiveness against the mandate and shall report regularly to the Corporate Governance and Nominating Committee and Board on that assessment.
Reviewing Reports to Shareholders
When required by applicable statute or regulation, the Committee shall prepare reports to shareholders regarding the activities undertaken in the discharge of its responsibilities. A report will be prepared by the Committee for inclusion in the annual report as required.
MEETINGS AND OPERATING PROCEDURES
In the absence of the Chairman of the Committee, the members shall appoint an acting Chairman.
A copy of the minutes of each meeting of the Committee shall be provided to each member of the Committee and to each director of the Corporation in a timely fashion.
The Chairman of the Committee shall prepare and/or approve an agenda in advance of each meeting.
The Committee, in consultation with management and the external auditors, shall develop and participate in a process for review of important financial topics that have the potential to impact the Corporation's financial policies and disclosures.
The Committee shall communicate its expectations to management and the external auditors with respect to the nature, timing and extent of its information needs. The Committee expects that written materials will be received from management and the external auditors in advance of meeting dates.
The Committee should meet privately in an executive session at least quarterly with management, the external auditors and as a committee to discuss any matters that the Committee or each of these groups believes should be discussed.
In addition, the Committee or at least its Chair should communicate with management and the external auditors quarterly to review the Corporation's financial statements and significant findings based upon the auditor's limited review procedures.
The Committee shall annually review, discuss and assess its own performance. In addition, the Committee shall periodically review its role and responsibilities.
The Committee expects that, in discharging their responsibilities to the shareholders, the external auditors shall be accountable to the Board through the Committee. The external auditors shall report all material issues or potentially material issues to the Committee.
The Committee shall review and reassess the adequacy of this Charter at least annually, submit it to the Board for approval and ensure that it is in compliance with the TSX Venture Exchange and OSC regulations.
GENERAL
In addition to the responsibilities and duties of the Committee stated above, the Committee shall attend to the following items:
Review the Corporation's hiring policies regarding employees and former employees of the present and former external auditors of the Corporation. Review business practices undertaken by senior management to assess appropriateness with corporate policies.
Review complaints procedures and whether they adequately track and record complaints to the Corporation regarding accounting, internal accounting or auditing matters.
Engage and pay independent counsel and other special advisors as it deems necessary from time to time in order to carry out Committee duties.
Investigate any activity of the Corporation as it deems appropriate. All employees of the Corporation are required to cooperate with the efforts or enquiries of the Committee.
Retain persons having special expertise to assist it in the performance of its duties.
Communicate with the Board to ensure sufficient funding for the Audit Committee to permit it to fulfill its responsibilities.
Make provisions for confidential, anonymous submissions by employees of the Corporation of concerns regarding accounting, internal accounting controls or auditing matters, ensuring that the existing processes adequately provide for such submission and establishing a process whereby the external auditor will receive timely notice of any such submission.
Review at least annually the risk management and insurance programs.
Review any issues referred to the Committee by the Board.
The procedures set forth herein have been set out as guidelines only as opposed to inflexible rules and the Committee may alter these procedures as it deems necessary in order to perform its responsibilities.
APPENDIX H - CORPORATE GOVERNANCE DISCLOSURE (FORM 58-101F2)
General
CORPORATE GOVERNANCE
STATEMENT OF CORPORATE GOVERNANCE PRACTICES
The board of directors (the "Board") of the Corporation believes that effective corporate governance contributes to improved corporate performance and enhanced Shareholder value. The Corporation's governance practices are subject to at least an annual review and evaluation through the Board's Nominating and Corporate Governance Committee to ensure that, as the Corporation's business develops and grows, changes in structure and process necessary to ensure continued good governance are identified and implemented. The Nominating and Corporate Governance Committee is currently comprised of Scott Jobin-Bevans, Mirsad Jakubovic and Conor O'Brien.
The Canadian Securities Administrators ("CSA") have adopted National Policy 58-201 Corporate Governance Guidelines, which provides non-prescriptive guidelines on corporate governance practices for reporting issuers such as the Corporation. In addition, the CSA has implemented National Instrument 58-101 Disclosure of Corporate Governance Practices ("NI 58-101") which prescribes certain disclosure by the Corporation of its corporate governance practices.
This section sets out the Corporation's approach to corporate governance and provides the disclosure required by Form 58-101F2 Corporate Governance Disclosure (Venture Issuers). The following statement has been prepared and approved by the Board.
BOARD OF DIRECTORS
As of the date hereof, the Board is comprised of four members. All four of the directors are standing for re-election. The Board is responsible for determining whether or not each director is "independent". To do this, the Board analyzes all of the relationships of the directors with the Corporation and its subsidiaries. Pursuant to NI 58-101 and National Instrument 52-110 Audit Committees ("NI 52-110"), a director is independent if such director has no direct or indirect material relationship with the Corporation, which could, in the view of the Board, be reasonably expected to interfere with the exercise of a member's independent judgment. None of the independent directors are engaged in the day-to-day operations of the Corporation or are a party to any material on-going contracts with the Corporation. More information about each director can be found in the Circular under the heading "Election of Directors".
The role of the Chairman for each Board meeting is determined on a revolving basis among the various members of the Board. The primary roles for the meeting's Chairman are setting the meeting agenda and chairing meetings of the Board, working to ensure that the Board works together as a cohesive team with open communication.
The Role of the Chief Executive Officer
The Chief Executive Officer of the Corporation is a member of the Board. In additional to being the primary liaison with the Board itself, the Chief Executive Officer's role is to directly oversee the day-to-day operations of the Corporation, lead and manage the senior management of the Corporation, and to implement the strategic plans, risk management and policies of the Corporation. The Board and the Chief Executive Officer work together to ensure that critical information flows to the Board, that discussions and debate of key business issues are fostered and afforded adequate time and consideration, that consensus on important matters is reached, and decisions, delegation of authority and actions are taken in such a manner as to enhance the Corporation's business and functions. The Board currently believes that it is in the best interests of the Corporation and its shareholders that the Chief Executive Officer of the Corporation is a member of the Board.
DIRECTORSHIPS
The following table provides details regarding directors of the Corporation who served as a director on the board of another reporting issuer as of the date of the Circular:
| Director | Other Company |
| Dr. Scott Jobin-Bevans | International Prospect Ventures (IZZ) Northern Shield Resources (NRN) Nubian Resources (NBR) Sienna Resources Inc. Vision Lithium (VLI) White Metal Resources Corp. (WHM) |
| Jeff Kennedy | Jaguar Mining Inc. (JAG) |
ORIENTATION AND CONTINUING EDUCATION
The Corporation does not provide a formal orientation or education program for new directors. However, when new directors are appointed, they receive an informal orientation, commensurate with their previous experience, relating to the Corporation's industry, business and operations and the responsibilities of directors of public companies, as well as training with respect to the Corporation's corporate strategy and the role of the Board, its committees and its directors by the current directors and senior officers. The members of the Board have experience in mineral exploration projects, mining, legal, financial and audit matters and capital markets and they continue to work in these areas. New directors meet with the management of the Corporation in addition to the other directors of the Corporation to discuss the Corporation's business. The Board receives a monthly report from management with respect to the Corporation's business. The Board encourages directors to participate in continuing education opportunities in order to ensure that directors maintain or enhance their skills and abilities as directors and maintain a current and thorough understanding of the Corporation's business.
The Corporation, at the direction of the Nominating and Corporate Governance Committee, is in the process of preparing a Board Policy Manual which is intended to provide a comprehensive introduction to the Board, the committees of the Board and their mandates. The orientation and continuing education process is reviewed on an annual basis by the Nominating and Corporate Governance Committee.
ETHICAL BUSINESS CONDUCT
The Board has determined that the fiduciary duties placed on individual directors by the Corporation's governing corporate legislation, the common law and the restrictions placed by applicable corporate legislation on an individual director's participation in decisions of the Board in which the director has an interest, have been sufficient to ensure that the Board operates independently of management and in the best interests of the Corporation.
The Board has established a Whistle Blower Policy (the "Whistle Blower Policy") which, among other things, establishes procedures for the receipt, recording and treatment of complaints and concerns regarding accounting activities, internal controls or auditing matters and the confidential submission of concerns in these areas. In addition, the Board has established a Code of Business Conduct and Ethics (the "Code") which, among other things, is intended to establish the Corporation's commitment to a culture of honesty, integrity and accountability. The Code together with the Whistle Blower Policy provide the guidelines for employee behavior and establishes the basis for open communication with a view to ensuring that employees are acting in good faith and have the means to report actual or potential violations.
The Board has also established a Disclosure Policy, the objective of which is to ensure that communications with the public about the Corporation are timely, factual, accurate, balanced and disseminated in accordance with applicable legal and regulatory requirements.
Each of the policies is reviewed annually. The policies allow employees throughout the organization to report any unethical or illegal activity without fear of reprisal from their fellow employees, supervisor or other officials of the Corporation. Illegal activities include but are not limited to fraud, theft, accounting irregularities and bribery.
NOMINATION OF DIRECTORS
The Board works with the Nominating and Corporate Governance Committee to periodically review the size of the Board and any possible requirement for an increase or decrease in members of the Board. It also recruits and reviews candidates for the position of director and selects the most appropriate for submission to the Board as a whole for consideration as a potential director nominee.
The Nominating and Corporate Governance Committee's considerations include:
(a) competencies and skills that the Board, as a whole, should possess and the competencies and skills of each current director. The Board reviews, on an annual basis, the requisite skills and criteria for Board members as well as the composition and size of the Board as a whole in order to ensure that the Board has the requisite expertise, that its membership consists of persons with sufficiently diverse and independent backgrounds, and that its membership consists of an appropriate number of independent directors;
(b) identification of individuals qualified to become Board members, consistent with criteria set out by the Board; and
(c) questions of independence and possible conflicts of interest of members of the Board and of senior managers.
COMPENSATION
The Compensation Committee of the Board determines compensation and incentive awards for the directors and senior officers of the Corporation based on the individual's skill level and the comparative industry compensation level.
OTHER BOARD COMMITTEES
Technical Committee - The primary purpose of the Technical Committee is to stay abreast with progress of engineering studies, exploration programs, acquisitions, joint ventures or similar opportunities and report progress to the Board. The Technical Committee also works to assist the Board with its duties and responsibilities in evaluating, overseeing the exploration and development of, and reporting on, the Corporation's mining projects.
In addition, the Technical Committee assists the senior officers of the Corporation in fulfilling their responsibility for oversight of the development of exploration and development projects, subject to the supervision and oversight of the senior officers by reviewing and approving technical (geological, drilling, mine engineering and process engineering) plans, schedules, and budgets and the release of material containing technical (engineering or geological) information for compliance with National Instrument 43-101 Standards of Disclosure for Mineral Projects and industry standards, and designing, establishing and monitoring the Corporation's controls and other procedures (which may include procedures currently used by the Corporation) that are designed to ensure that development of corporate exploration and development projects are on schedule and within budget.
The Technical Committee currently consists of Mirsad Jakubovic and Scott Jobin-Bevans. Mirsad Jakubovic and Scott Jobin-Bevans are not independent directors within the meaning of NI 58-101. The Technical Committee met frequently during the years ended December 31, 2024, and December 31, 2025.
ASSESSMENTS
The Board monitors the adequacy of information given to directors, communication between the Board and management and the strategic direction and processes of the Board and Board committees.
The Board assesses, on an informal basis, the effectiveness of the Board as a whole, the Chairman of the Board, Board committees and the contribution of individual directors. The Board monitors the adequacy of information given to directors, communication between the Board and management, and the strategic direction and processes of the Board and its committees. As a result of the Corporation's size, its stage of development, and the number of directors of the Corporation, the Board has considered this assessment process to be appropriate at this time. The Nominating and Corporate Governance Committee will review this process periodically and make recommendations with respect to the assessment process as necessary.