Exhibit 99.2
HERE BE DRAGONS Bitcoin Mining Enters Unknown Territory Raphael Zagury Chief Executive Officer, Twenty One Capital · Founder of Elektron Energy
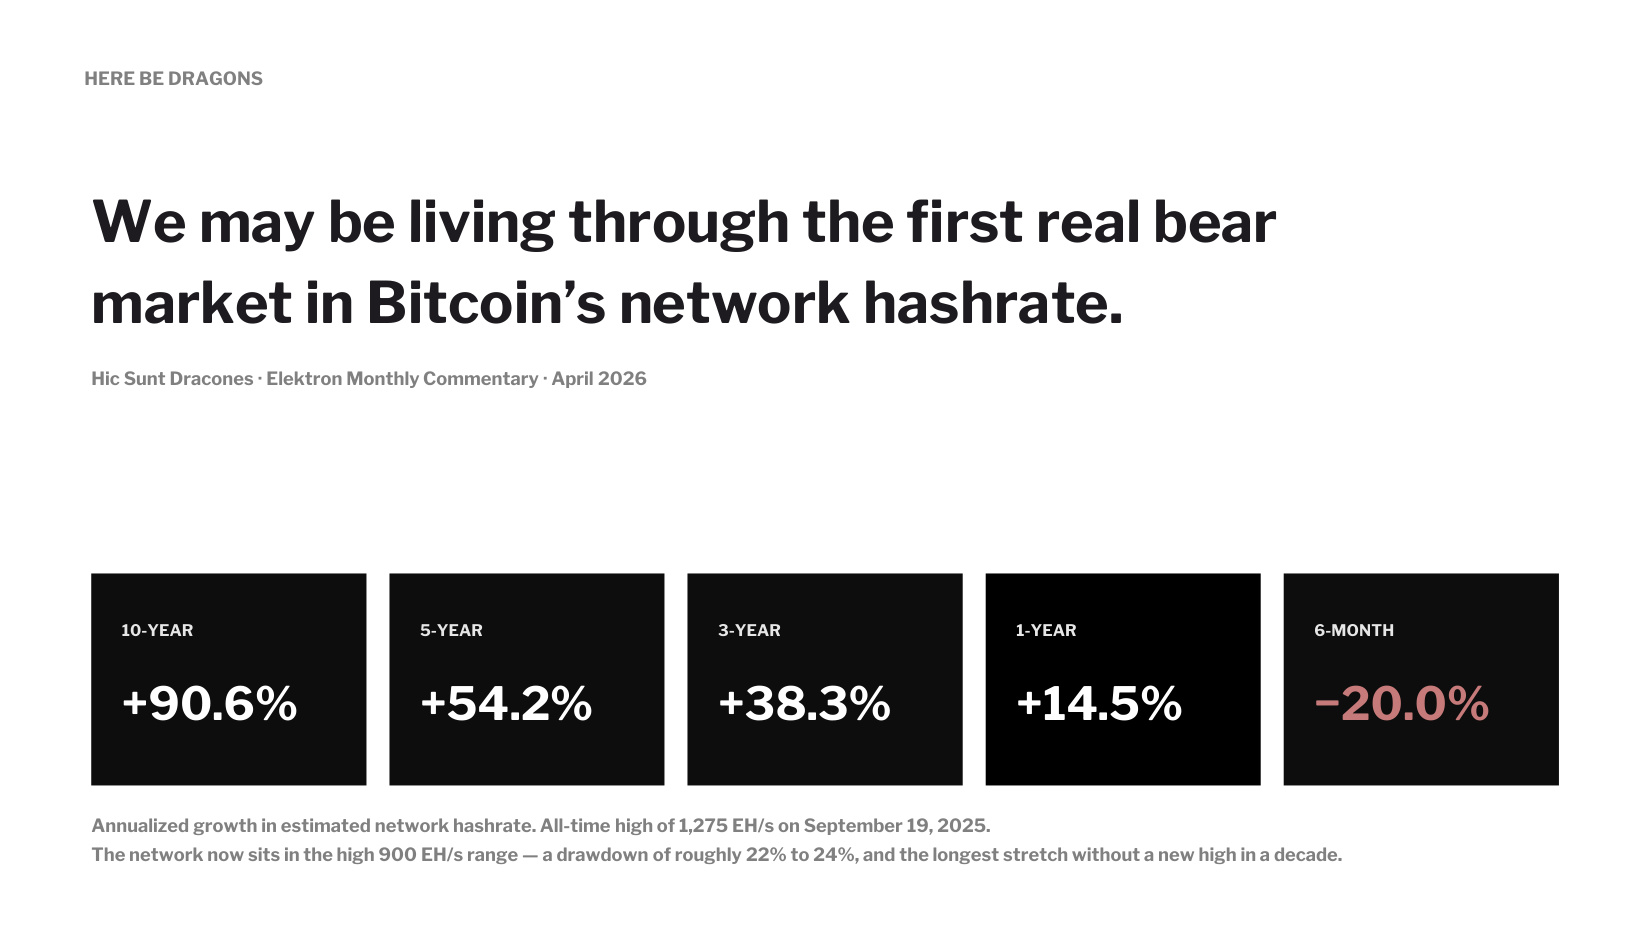
HERE BE DRAGONS We may be living through the first real bear market in Bitcoin's network hashrate. Hic Sunt Dracones · Elektron Monthly Commentary · April 2026 10-YEAR +90.6% 5-YEAR +54.2% 3-YEAR +38.3% 1-YEAR +14.5% 6-MONTH −20.0% Annualized growth in estimated network hashrate. All-time high of 1,275 EH/s on September 19, 2025. The network now sits in the high 900 EH/s range — a drawdown of roughly 22% to 24%, and the longest stretch without a new high in a decade.
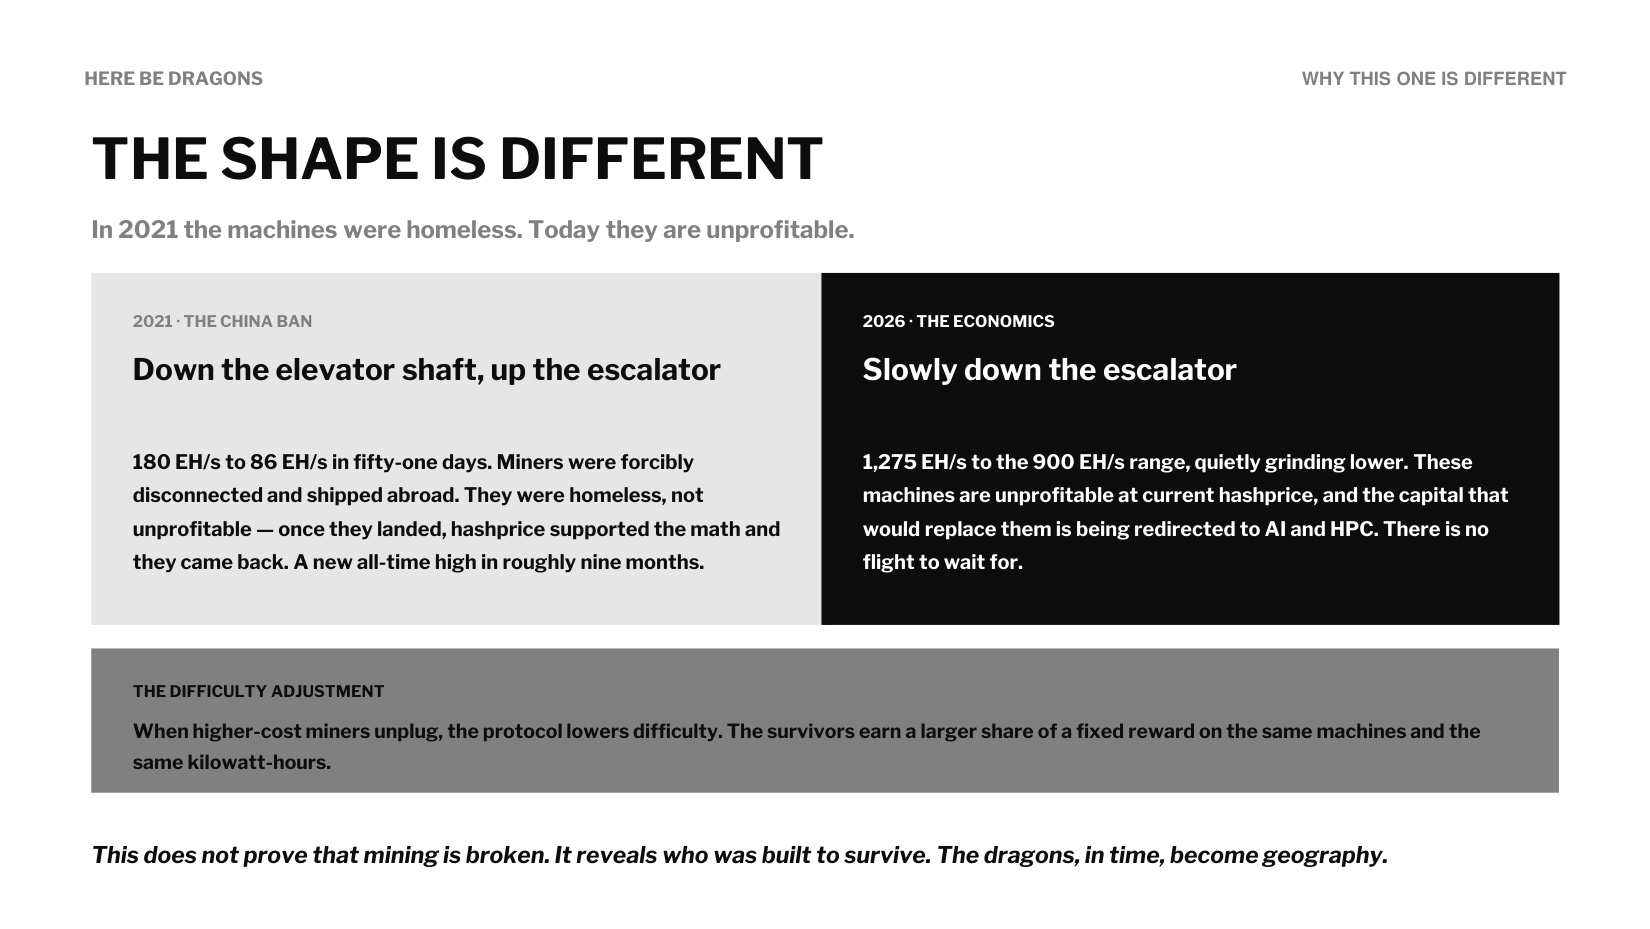
HERE BE DRAGONS WHY THIS ONE IS DIFFERENT THE SHAPE IS DIFFERENT In 2021 the machines were homeless. Today they are unprofitable. 2021 · THE CHINA BAN Down the elevator shaft, up the escalator 180 EH/s to 86 EH/s in fifty-one days. Miners were forcibly disconnected and shipped abroad. They were homeless, not unprofitable — once they landed, hashprice supported the math and they came back. A new all-time high in roughly nine months. 2026 · THE ECONOMICS Slowly down the escalator 1,275 EH/s to the 900 EH/s range, quietly grinding lower. These machines are unprofitable at current hashprice, and the capital that would replace them is being redirected to AI and HPC. There is no flight to wait for. THE DIFFICULTY ADJUSTMENT When higher-cost miners unplug, the protocol lowers difficulty. The survivors earn a larger share of a fixed reward on the same machines and the same kilowatt-hours. This does not prove that mining is broken. It reveals who was built to survive. The dragons, in time, become geography.
Bitcoin mining is stuck between two accusations: it's bad business, and it's wasted energy.
"Bitcoin mining is a bad business." CLAIM 01
Commodity businesses don't come in good and bad THE FRAME They come in positions on a cost curve.
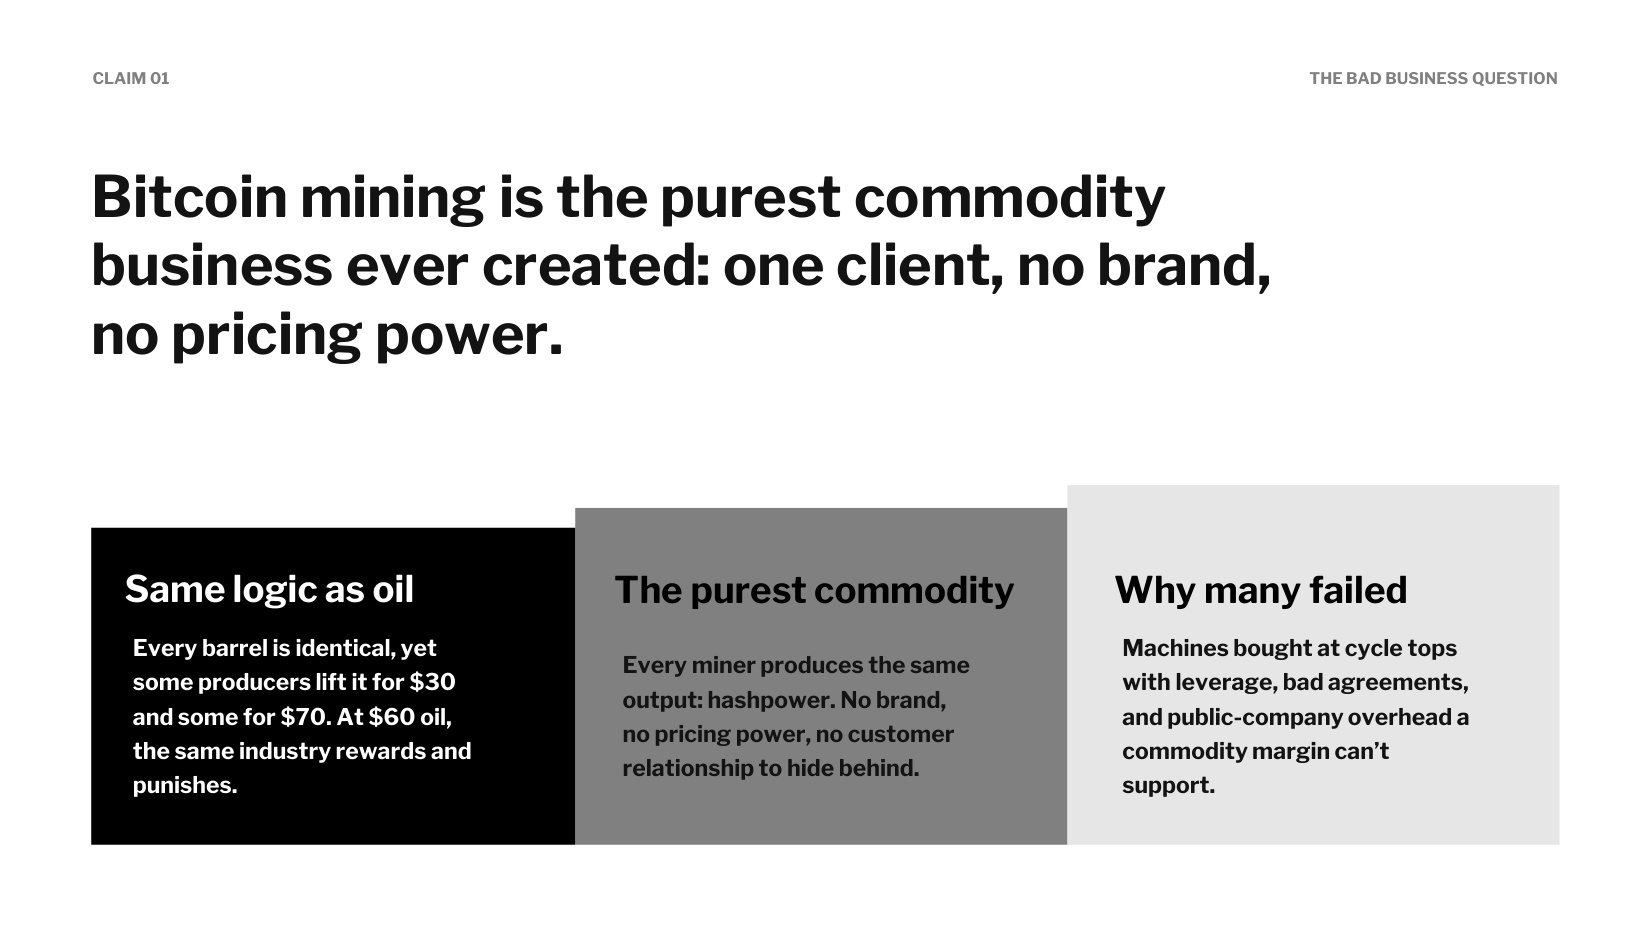
CLAIM 01 THE BAD BUSINESS QUESTION Bitcoin mining is the purest commodity business ever created: one client, no brand, no pricing power. Same logic as oil Every barrel is identical, yet some producers lift it for $30 and some for $70. At $60 oil, the same industry rewards and punishes. The purest commodity Every miner produces the same output: hashpower. No brand, no pricing power, no customer relationship to hide behind. Why many failed Machines bought at cycle tops with leverage, bad agreements, and public-company overhead a commodity margin can't support.
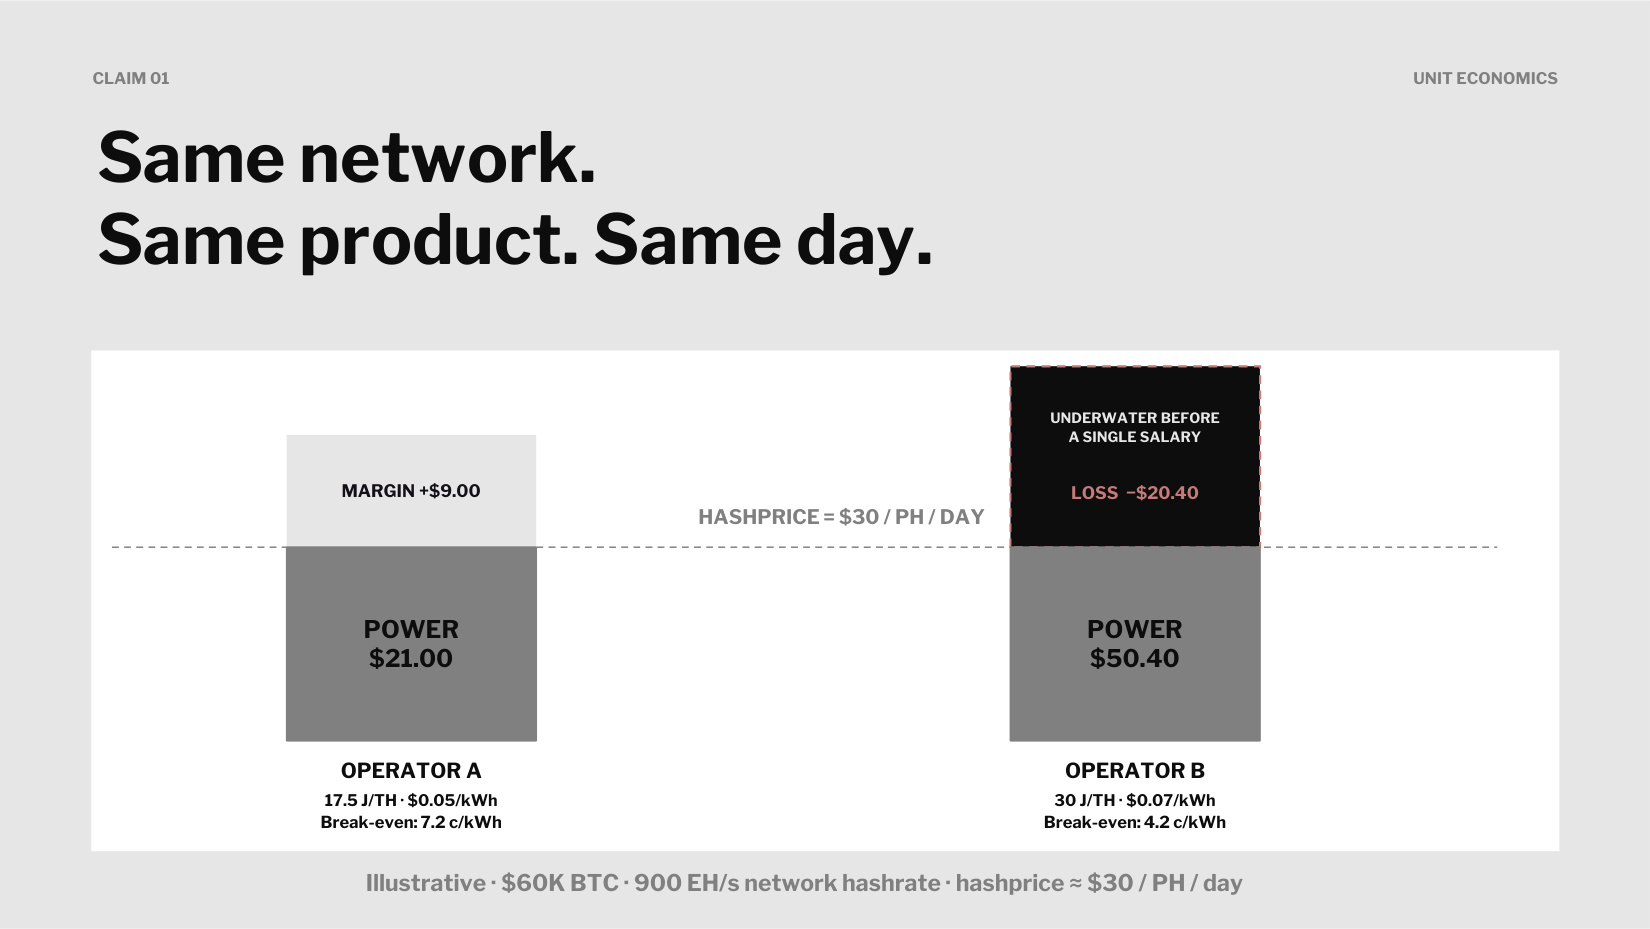
Same network. Same product. Same day. HASHPRICE = $30 / PH / DAY MARGIN +$9.00 POWER $21.00 OPERATOR A 17.5 J/TH · $0.05/kWh Break-even: 7.2 c/kWh UNDERWATER BEFORE A SINGLE SALARY LOSS −$20.40 POWER $50.40 OPERATOR B 30 J/TH · $0.07/kWh Break-even: 4.2 c/kWh Illustrative · $60K BTC · 900 EH/s network hashrate · hashprice ≈ $30 / PH / day UNIT ECONOMICS CLAIM 01
Does the mining investment outperform buying Bitcoin?
Most of the time: buy Bitcoin Across most of mining's history, holders beat operators. Hashrate growth and ASIC cycles ran against miners for years. If someone has one dollar and one decision, my advice hasn't changed: buy Bitcoin. But we may be living through the first real economic hashrate bear market of Bitcoin's industrial era. When mining wins Mining outperforms holding when price grows faster than network hashrate. The miner earns that spread while the holder earns only the price. Now, in a hashrate bear market, that spread can run in reverse for the first time at scale. CLAIM 01
THE ALLOCATOR ANSWER For a company, mining vs. Bitcoin was never the right question Portfolios aren't built by ranking assets in isolation. Diversification exists to improve the odds of a good outcome across many possible futures, not to hold whatever wins in hindsight. CLAIM 01
"Bitcoin mining wastes energy." CLAIM 02 The goal was never low energy consumption. The goal is high energy productivity: more human progress per joule.
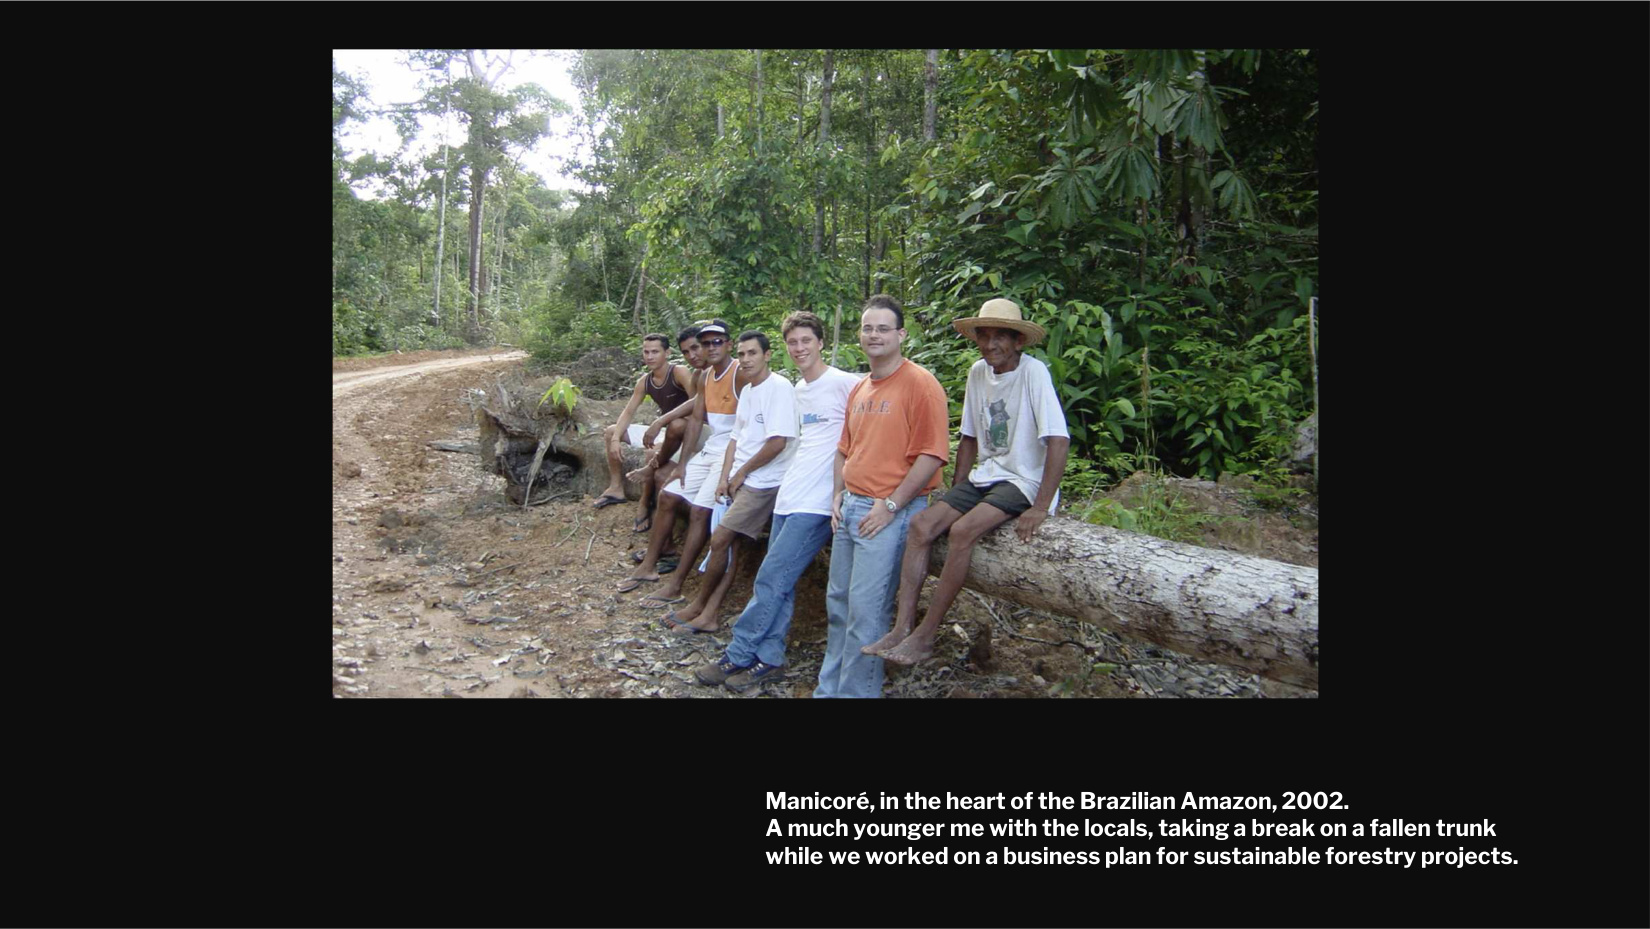
Manicoré, in the heart of the Brazilian Amazon, 2002. A much younger me with the locals, taking a break on a fallen trunk while we worked on a business plan for sustainable forestry projects.
Energy is the substrate of everything we call development. Every debate about Bitcoin mining is really a debate about energy: who gets to use it, and what counts as legitimate. "Progress comes from producing more useful energy, not from asking humanity to do less." THE FRAME
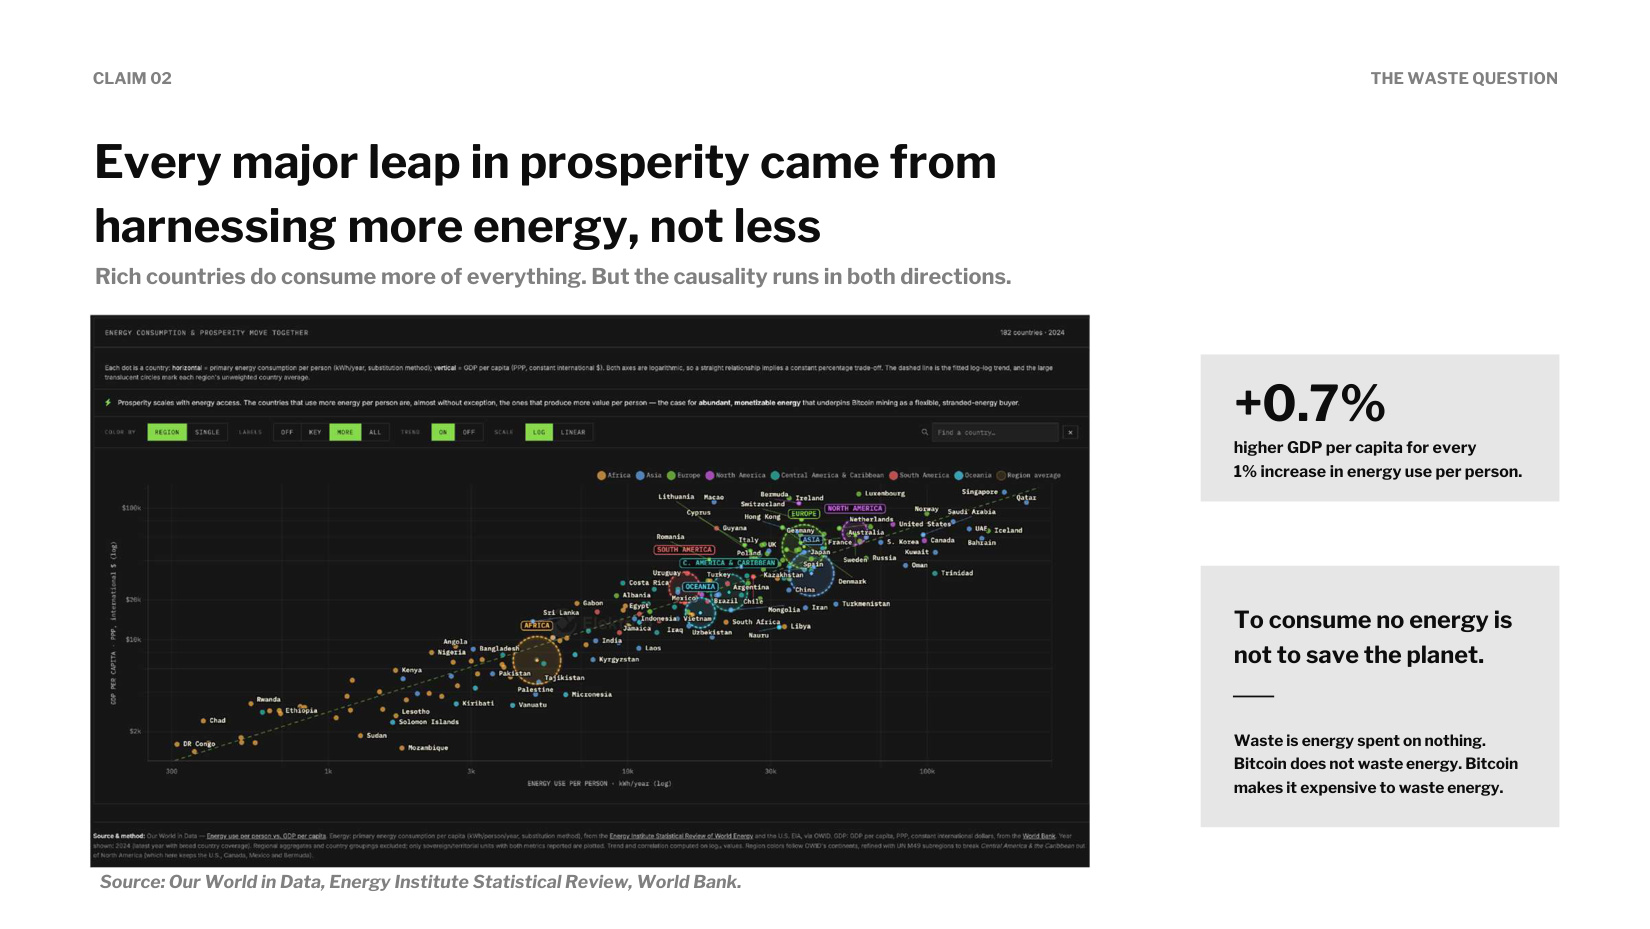
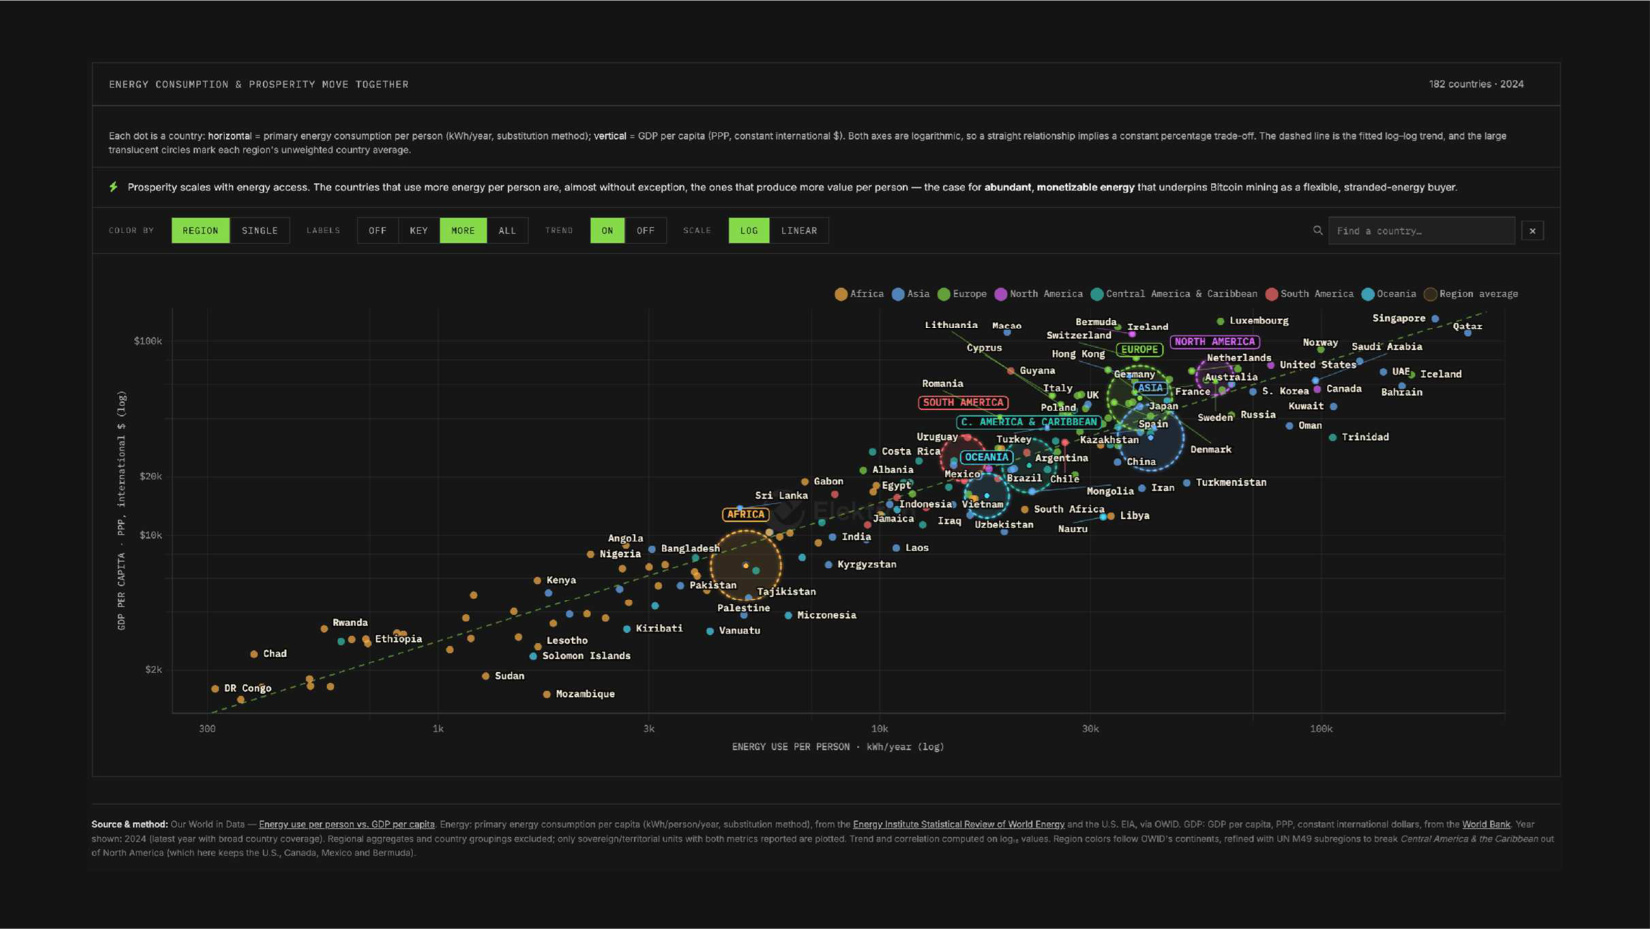
Rich countries do consume more of everything. But the causality runs in both directions. Source: Our World in Data, Energy Institute Statistical Review, World Bank. +0.7% higher GDP per capita for every 1% increase in energy use per person. To consume no energy is not to save the planet. Waste is energy spent on nothing. Bitcoin does not waste energy. Bitcoin makes it expensive to waste energy. THE WASTE QUESTION Every major leap in prosperity came from harnessing more energy, not less CLAIM 02
Mining is the most flexible large industrial load ever built Buyer of last resort For elektrons that would otherwise be wasted: curtailed wind, stranded hydro, flared gas. Seller of first resort Powers down in seconds when the grid is stressed, freeing capacity for homes, hospitals, and critical loads. GRID FLEXIBILITY CLAIM 02
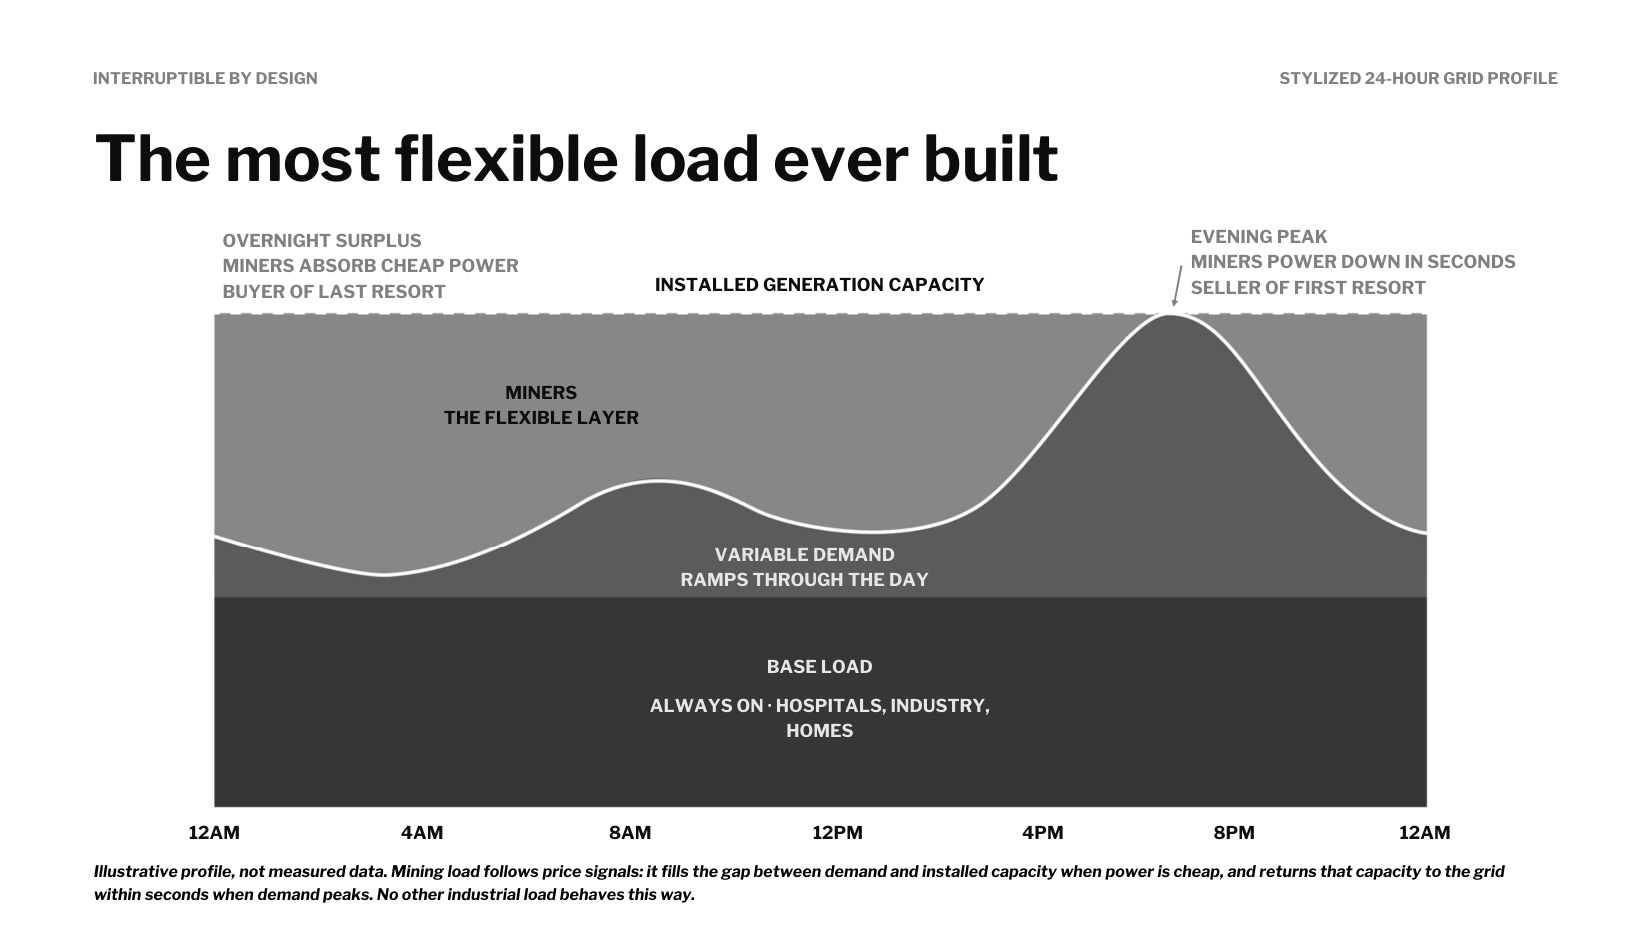
The most flexible load ever built INTERRUPTIBLE BY DESIGN STYLIZED 24-HOUR GRID PROFILE Illustrative profile, not measured data. Mining load follows price signals: it fills the gap between demand and installed capacity when power is cheap, and returns that capacity to the grid within seconds when demand peaks. No other industrial load behaves this way. OVERNIGHT SURPLUS MINERS ABSORB CHEAP POWER BUYER OF LAST RESORT INSTALLED GENERATION CAPACITY EVENING PEAK MINERS POWER DOWN IN SECONDS SELLER OF FIRST RESORT MINERS THE FLEXIBLE LAYER VARIABLE DEMAND RAMPS THROUGH THE DAY BASE LOAD ALWAYS ON · HOSPITALS, INDUSTRY, HOMES 12AM 4AM 8AM 12PM 4PM 8PM 12AM
The fish are not wasting energy swimming upstream. CLAIM 02 · THE VERDICT They are converting it into the next generation. Mining doesn't compete with civilization for energy. It monetizes energy civilization can't use, and steps aside when civilization wants it back.
This is not the 2021 drawdown. WHY NOW That was a relocation shock: machines waiting for a flight. This time, the machines coming offline are simply unprofitable, and the capital that would replace them is being redirected to AI and HPC.
Your competitors' capitulation shows up in your revenue automatically WHY NOW THE DIFFICULTY ADJUSTMENT ~2,016 blocks every ~2 weeks Every day, the market asks every machine on Earth the same question: can you still pay for your power? The ones that answer "no" unplug. The protocol automatically adjusts difficulty and rewards the survivors. It becomes easier to find a block. Very few businesses turn a competitor's exit directly into your own revenue. A second transfer: assets Alongside the hashrate, a washout moves good machines, good sites, and good energy contracts to market, at prices that exist only when the seller has no choice. Dismissing mining in public has become socially safe. That usually happens after the pain, not before it.
THE OPPORTUNITY A mining operation isn't a single bet. It's a stack of options. Energy option Control over low-cost elektrons: power contracts, interconnections, sites, generator relationships. Infrastructure option Powered land, transformers, and energy contracts keep the door open to AI/HPC, on our terms. Share option Staying still while others leave is itself a position. Network share grows without deploying a dollar. Proximity option Operating inside the network: Bitcoin below spot, a compounding treasury, real-time market visibility.
BACK TO FIRST PRINCIPLES A stretch where mining Bitcoin is decisively better than buying it, for the first time at scale Bitcoin is in a price bear market. Mining is in the first hashrate bear market in its history. If price recovers before hashrate rebuilds, the same spread that punished miners for fifteen years runs in reverse. For informational purposes only; not investment advice. See Important Disclosures at the end of this presentation.
Mining is a bad business for high-cost operators, over- levered balance sheets, and teams chasing narratives. It is not a bad business by definition. It is a brutally difficult one. Difficult businesses reward discipline, cost control, and operational obsession.
Legal Disclaimer Industry Information This Presentation includes estimates regarding market and industry data. Unless otherwise indicated, information concerning the Bitcoin mining industry, including our general expectations, Bitcoin's hashrate, market opportunity, are based on our management's knowledge and experience, together with currently available information obtained from various sources, including publicly available information, industry reports and publications, surveys and other contacts in the markets. We have not independently verified data obtained from third-party sources and cannot guarantee its accuracy or completeness. In presenting this information, we have made certain assumptions that we believe to be reasonable based on such data and other similar sources and on our knowledge of, and our experience to date in, the Bitcoin mining market. While we believe the estimated market and industry data included in this presentation is reliable, such information is inherently uncertain and imprecise. Market and industry data is subject to change and may be limited by the availability of raw data, the nature of the data gathering process and other limitations inherent in any statistical survey of such data. In addition, projections, assumptions and estimates of the future performance are necessarily subject to uncertainty and risk due to a variety of factors. These and other factors could cause results to differ materially from those expressed in the estimates made by third parties and by us. Accordingly, you are cautioned not to place undue reliance on such market and industry data or any other such estimates. Forward-Looking Statements This Presentation contains forward-looking statements that reflect our current views with respect to, among other things, future events and our future business, financial condition, results of operations, and prospects. These statements are often, but not always, made through the use of words or phrases such as "may," "should," "could," "predict," "potential," "believe," "will likely result," "expect," "continue," "will," "anticipate," "seek," "estimate," "intend," "plan," "projection," "would," and "outlook," or the negative version of those words or phrases or other comparable words or phrases of a future or forward-looking nature. These forward-looking statements are not statements of historical fact, and are based on current expectations, estimates, and projections about our industry as well as certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond our control. We cannot guarantee that future results reflected in the forward-looking statements will occur. Except to the extent required by law, we do not undertake to update any of the information contained in this presentation. Forward-looking statements in this Presentation include, among others, statements regarding: the Bitcoin's network hashrate and mining machines' profitability; the return on investment from holding Bitcoin versus Bitcoin mining; the energy consumption of Bitcoin mining; and the allocation of capital towards Bitcoin mining.